JBizNews | U.S. Market Opening Recap — Tuesday, October 13, 2026 | 10:00 a.m. ET
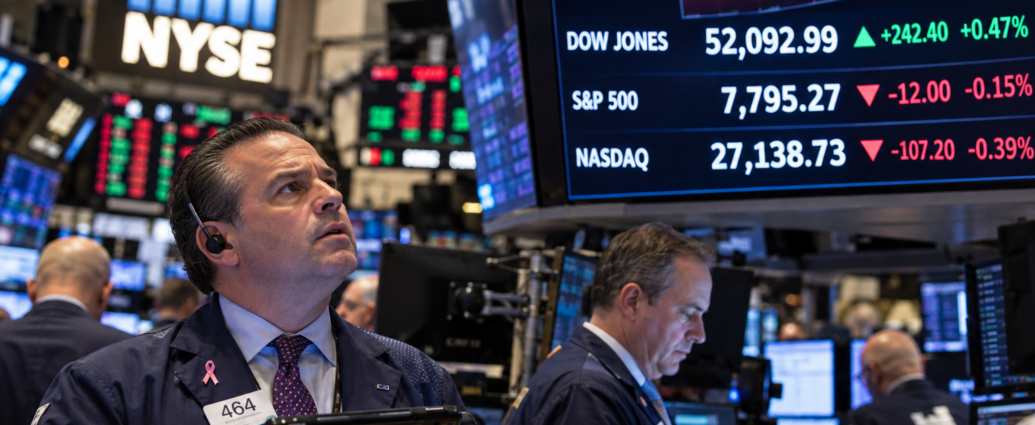
NEW YORK — Wall Street opened mixed Tuesday as disappointing earnings from some of America’s largest banks and renewed selling in semiconductor stocks raised concerns about the strength of the economy. The Dow Jones Industrial Average advanced, but the S&P 500 and Nasdaq declined as investors assessed corporate profits, borrowing costs and growing competition in the artificial intelligence industry.
The Dow opened at 52,092.99, up 242.40 points, or 0.47%. The S&P 500 fell 12 points, or 0.15%, to 7,795.27, while the Nasdaq Composite dropped 107.20 points, or 0.39%, to 27,138.73.
The figures represent the confirmed 9:30 a.m. opening levels reported by Reuters. Exact 10:00 a.m. quotations were not independently verified and should not be mistaken for live readings.
The uneven start followed Monday’s trading session, when the Dow advanced but technology stocks weakened amid concerns about rising energy prices and the profitability of enormous AI investments.
Tuesday’s biggest developments came from the banking and semiconductor industries, where investors received two different warnings about the outlook for corporate earnings.
JPMorgan Misses Earnings Expectations as Trading Slows
JPMorgan Chase, the nation’s largest bank, reported a rare quarterly earnings disappointment despite continued growth in consumer lending and business activity.
The bank earned $5.57 per share in the third quarter, below Wall Street’s expectation of $5.85. It was JPMorgan’s first earnings miss since the fourth quarter of 2023.
Investment banking fees declined 8% from the previous quarter, although they remained 14% higher than a year earlier.
Fixed-income trading revenue fell 4%, reflecting weaker activity in bond markets, while equity trading revenue surged 49% as investors adjusted their portfolios amid volatile interest rates and energy prices.
The bank’s overall markets revenue increased 15% from a year earlier, but the results fell toward the lower end of management’s previous expectations.
The results are important because JPMorgan’s performance offers a broad view of American economic activity.
Its customers include households, small businesses, major corporations and institutional investors. Changes in lending, spending and borrowing can provide early indications of financial pressure throughout the economy.
There were encouraging signs.
JPMorgan reported that average loans increased 10% from a year earlier, while net interest income excluding markets rose 6% to $24.7 billion.
That suggests consumers and businesses continued borrowing despite elevated interest rates.
However, higher borrowing costs could eventually discourage new loans, slow investment and increase the financial burden on households carrying debt.
Goldman Sachs Gains as Other Banks Face Pressure
The opening of third-quarter earnings season produced sharply different reactions across major financial institutions.
Goldman Sachs attracted buying interest following stronger results, while JPMorgan and Wells Fargo faced pressure after their reports fell short of certain Wall Street expectations.
The mixed performance suggests investors are looking beyond headline profits and examining how banks are generating revenue.
Trading activity, investment banking fees, loan growth and deposit costs are becoming increasingly important as interest rates remain elevated.
Higher rates can benefit banks by increasing income from loans, but they also raise funding costs and make borrowing more expensive for customers.
For businesses seeking financing, the earnings reports offer a reminder that access to credit depends not only on the Federal Reserve’s interest-rate decisions but also on banks’ willingness to lend.
Chinese Chip Breakthrough Raises New Concerns for U.S. Technology Companies
Semiconductor stocks were among Tuesday’s biggest losers after reports that Chinese memory-chip manufacturer ChangXin Memory Technologies, known as CXMT, had made progress on a new memory-chip design.
The development raised concerns that Chinese manufacturers could eventually challenge the dominance of established suppliers, including Micron Technology, Samsung Electronics and SK Hynix.
Micron fell approximately 3.9% in early trading, while Advanced Micro Devices declined about 2.3%. Broadcom and Nvidia also came under pressure.
South Korea’s benchmark Kospi index plunged 5.5%, demonstrating how quickly concerns about semiconductor competition spread across international markets.
Memory chips are essential components in smartphones, computers and artificial intelligence data centers.
Demand has surged as technology companies invest billions of dollars in more powerful AI systems. However, investors are increasingly questioning whether today’s high chip prices and profit margins can be sustained if new competitors expand production.
For American businesses purchasing computers, servers and AI equipment, greater competition could eventually reduce technology costs. For established chipmakers, it could mean lower prices and tighter profit margins.
The reported Chinese advances do not establish that CXMT has matched its leading competitors in commercial production.
UnitedHealth Rises as Healthcare Earnings Beat Expectations
Healthcare provided a source of strength Tuesday.
UnitedHealth Group shares gained after the company reported earnings above Wall Street expectations and raised its full-year profit forecast.
The insurer’s improved outlook reflected efforts to control medical expenses and strengthen profitability across parts of its business.
The company rose approximately 4.4% in premarket trading, helping support the Dow.
For consumers, the results highlight the financial pressures affecting health insurers as they balance medical expenses, insurance premiums and government reimbursement rates.
Johnson & Johnson moved in the opposite direction, declining after its quarterly results narrowly missed some analyst expectations despite an improved annual outlook.
Small Business Confidence Falls as Owners Worry About Costs
Tuesday’s major confirmed morning economic report showed that small-business owners are becoming more cautious.
The National Federation of Independent Business reported that its Small Business Optimism Index fell 0.8 points to 97.9 in September, slightly below its 52-year average of 98.
Its Uncertainty Index increased to 90, substantially above the historical average of 68.
Hiring also remains difficult. Among small-business owners who were hiring or attempting to hire, 87% reported receiving few or no qualified applicants for available positions.
The report illustrates the challenges facing Main Street businesses.
Higher borrowing costs make expansion more expensive, while fuel and material costs pressure operating budgets. At the same time, difficulty finding qualified employees can prevent companies from taking on additional customers or increasing production.
The survey provides evidence of growing caution among business owners, even as large corporations continue reporting substantial profits.
September existing-home-sales data was also scheduled for 10 a.m. ET. Its actual result was not independently verified for this recap and is not presented as released data.
Oil Retreats While Treasury Yields Ease
Oil prices declined Tuesday after rising sharply the previous session.
Brent crude traded near $105.20 a barrel, down approximately 1.4% during Asian trading, as investors weighed potential additional diesel supplies from Russia against continuing Middle East supply risks.
The benchmark 10-year Treasury yield declined approximately five basis points to 5.192% as regular bond trading resumed following Monday’s federal holiday.
These were verified earlier-session quotations, not exact 10 a.m. prices.
For businesses and consumers, the direction of both markets remains important.
Lower oil prices could eventually ease transportation and fuel costs. Lower Treasury yields can help reduce pressure on mortgages, business loans and corporate financing.
However, both remain elevated enough to create significant financial challenges.
What to Watch
Wednesday’s September Consumer Price Index report will be one of the week’s most important economic releases.
Investors will be watching whether inflation is becoming more persistent and whether the Federal Reserve may need to keep interest rates elevated.
Thursday’s Producer Price Index and retail sales figures will provide additional insight into business costs and consumer spending.
Corporate earnings will also remain central to the market’s direction, particularly reports from major banks, technology companies and businesses sensitive to energy prices.
The biggest question is whether strong corporate profits can continue supporting stocks while expensive financing, rising competition and geopolitical uncertainty threaten growth.
Tuesday’s opening offered two competing signals.
Major banks and healthcare companies demonstrated continued earnings strength, but semiconductor losses and weakening small-business confidence revealed growing concerns beneath the market’s surface.
The Dow began the day higher, but weakness in the S&P 500 and Nasdaq showed that investors remain increasingly selective about where they put their money.
JBizNews Desk | Trenton, N.J.
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.