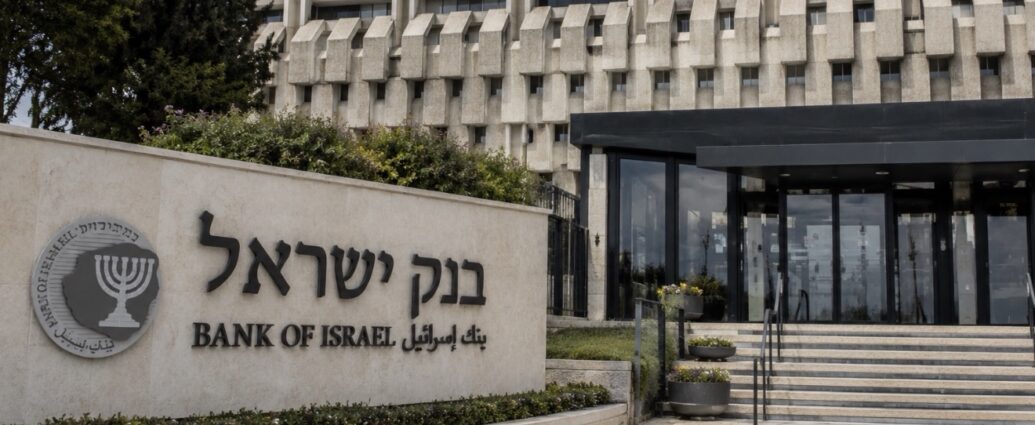
The Bank of Israel cut its benchmark interest rate by another quarter percentage point Tuesday, bringing it down to 3.25% as inflation cools and the Israeli economy continues recovering from the war with Iran.
It is the central bank’s fourth rate cut of 2026, following reductions in January, May and July.
The move is important because it signals that policymakers believe the economy is strong enough — and inflation contained enough — to continue lowering borrowing costs despite ongoing geopolitical uncertainty.
For Israeli businesses and households, that means money is gradually becoming cheaper again.
Why the Bank Cut Rates
The Bank of Israel said inflation has moderated in recent months and is now running below the midpoint of its target range.
At the same time, the economy has been rebounding.
Second-quarter data show Israel’s GDP was 6.2% higher than in the fourth quarter of 2025 on an annualized basis.
That number partly reflects the sharp recovery from the disruption caused earlier this year by the military operation against Iran.
Even excluding production abroad by Israeli companies, GDP was still 3.8% higher than in the fourth quarter of 2025 on an annualized basis.
In simple terms:
The economy took a hit during the war, but activity has bounced back quickly enough that the Bank of Israel now has more room to lower rates.
What Lower Rates Actually Mean
Interest rates influence the cost of borrowing throughout the economy.
When the Bank of Israel cuts rates, commercial banks can eventually offer cheaper financing.
That can lower borrowing costs for:
- Businesses financing expansion or equipment
- Homebuyers taking mortgages
- Consumers using credit
- Real estate developers
- Companies refinancing existing debt
It does not mean every loan becomes cheaper immediately.
But over time, lower central-bank rates usually work their way through the financial system.
Real Estate Could Feel It Quickly
Israel’s real estate market is especially sensitive to interest rates.
Higher borrowing costs made mortgages more expensive and put pressure on buyers and developers.
A lower benchmark rate could gradually make monthly mortgage payments more manageable and encourage buyers who have been sitting on the sidelines to return.
Developers may also find it easier to finance projects.
That does not automatically mean housing prices will surge.
But lower borrowing costs remove one of the major pressures that has been holding activity back.
Businesses Get Some Breathing Room
For companies, especially smaller businesses, interest expense has become a major cost.
A business borrowing money for inventory, equipment, real estate or expansion has been paying significantly more than it did several years ago.
Every quarter-point reduction helps.
If the Bank of Israel continues lowering rates, businesses could eventually see meaningful savings on financing.
That can also encourage companies to invest rather than keep projects on hold.
The Shekel Matters Too
The Bank of Israel also noted that the shekel has remained broadly stable.
That is important because cutting interest rates can sometimes weaken a currency.
A sharply weaker shekel could make imported goods, fuel and raw materials more expensive and push inflation higher again.
So far, the central bank appears comfortable that currency conditions remain stable enough to continue easing.
Israel’s risk premium has also declined substantially from the levels reached during the war.
That means investors currently view the country as less financially risky than they did during the height of the conflict.
But The Bank Is Still Cautious
The central bank made clear that uncertainty remains high.
Geopolitical tensions have not disappeared.
Another major escalation could affect energy prices, government spending, investment, the shekel and inflation.
That means policymakers are unlikely to promise a long series of cuts in advance.
They will continue watching inflation, economic growth, financial markets and security developments before each decision.
What It Means for Businesses
The message from the Bank of Israel is becoming increasingly clear.
The emergency economic conditions created by the war are easing.
Inflation is under better control.
Economic activity is recovering.
And the central bank is gradually shifting from protecting against inflation toward supporting growth.
For businesses, homeowners and borrowers, that is an important change.
Israel entered 2026 with borrowing costs still relatively high.
The benchmark rate is now down to 3.25% after four cuts this year.
If inflation remains contained and the recovery continues, businesses could enter 2027 with meaningfully cheaper financing than they had at the beginning of this year.
That is good news for investment, construction, hiring and consumer spending.
But the Bank of Israel is still walking a narrow line:
Support the recovery without allowing inflation or geopolitical risk to return.
For now, it believes another quarter-point cut is a risk worth taking.
JBizNews Desk | Jerusalem
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.