German Investment in U.S. Plunges Nearly Two-Thirds as Companies Hold Back New Capital

German companies sharply reduced new investment in the United States during the first half of 2026, offering one of the clearest indications yet that trade-policy uncertainty is beginning to influence where multinational companies put their money.

German direct investment into the U.S. fell nearly two-thirds from a year earlier to €4.3 billion, or about $5 billion, according to calculations by the German Economic Institute using Bundesbank data. That was the lowest first-half level since 2023 and almost 80% below the comparable 2024 figure. Before the pandemic, German companies averaged €15.8 billion of first-half U.S. investment. 

There is an important distinction: German companies already operating in America are still reinvesting profits. What has weakened is the willingness to commit fresh equity capital to new projects. That makes the data less a verdict on the U.S. market itself and more a warning about what policy uncertainty can do to future factories, expansions and jobs.

India Orders Major Cooking-Gas Production Push as Hormuz Disruption Hits Supplies

India has ordered its refiners and energy companies to build the country’s domestic production of liquefied petroleum gas to as much as 63,810 metric tons per day, an extraordinary intervention aimed at protecting household fuel supplies after Middle East disruptions exposed India’s dependence on imports.

Before the war, India sourced roughly 90% of its imported cooking gas from the Middle East. The government’s August 13 order requires companies to maintain enough storage and transportation infrastructure to handle the new targets, with production requirements updated every January and July. Reliance Industries alone was assigned a target of 18,000 tons per day from its domestic-market refinery. 

The significance goes beyond India. One of the world’s largest energy consumers is effectively redesigning part of its fuel supply chain because of the Strait of Hormuz crisis — another example of geopolitical risk turning into permanent infrastructure spending.

Nvidia Discusses Another $3 Billion Bet on OpenAI Infrastructure

Nvidia is in talks to invest as much as $3 billion in SB Energy, the SoftBank-backed company developing a massive Ohio data-center project for OpenAI, according to a report by The Information cited by Reuters.

The proposed investment would sit alongside discussions involving roughly $100 billion of credit support for the Ohio campus. Nvidia has reportedly considered investing half when the project is signed and the remainder around a possible SB Energy IPO. Reuters said it could not independently verify the report, and Nvidia and SB Energy had not commented. 

The bigger story is how deeply chipmakers are becoming intertwined with the financing of their own customers. Nvidia is no longer benefiting only from companies buying GPUs; increasingly, the AI ecosystem is exploring structures in which capital, chips, power infrastructure and data-center financing all support one another.

Europe Discovers a $50 Billion Heat Problem That Insurance Barely Covers

Europe’s extreme heat is emerging as a major business-interruption risk — but one that traditional insurance policies often do not cover.

Moody’s estimated that last summer’s European heatwaves caused about €43 billion, or $50 billion, in lost economic output, while insured payouts totaled only about €500 million. In and around Padua, Italy, more than 80% of roughly 600 hospitality businesses surveyed reported sales declines of around 20% during the latest heatwave. 

Unlike a hurricane that destroys a building, heat can empty restaurants, reduce worker productivity, disrupt rail networks and raise factory cooling costs without producing obvious physical damage. Insurers are increasingly exploring temperature-triggered “parametric” policies that automatically pay when heat crosses specified thresholds.

For businesses, the lesson is changing quickly: extreme heat is becoming a balance-sheet risk even when nothing visibly breaks.

Kalshi and Nevada Escalate Fight Over $120,000-a-Day Penalties

The legal fight over prediction markets intensified over the weekend as Kalshi accused Nevada regulators of violating federal law while the state seeks penalties of $120,000 per day over alleged failures to block Nevada users.

Nevada’s Gaming Control Board previously required Kalshi to implement a multi-source geofencing system by August 12 after investigators were able to enter sports, election and entertainment contracts from inside the state. The state’s agreement specified the $120,000 daily penalty if Kalshi missed that deadline. 

Nevada investigators later said they were still able to place nine trades using cellular networks. Kalshi says it hired GeoComply at Nevada’s request and argues investigators misrepresented their residences and, in at least one instance, circumvented blocking measures. 

The case is becoming an important test of whether federally regulated prediction markets can operate nationwide over the objections of individual state gambling regulators.

Peter Thiel Makes $76 Million Bet on Argentina’s Oil Boom

Peter Thiel’s Thiel Macro fund has purchased approximately 1.2 million American Depositary Shares of Vista Energy worth about $76 million, giving the investor roughly 1% of one of the leading producers in Argentina’s Vaca Muerta shale region.

The position was disclosed in a U.S. Securities and Exchange Commission filing. Vista currently produces around 160,000 barrels of oil equivalent per day and has invested more than $6.5 billion in Argentina. 

Thiel Macro’s disclosed portfolio totals about $418.7 million and also contains significant exposure to U.S. electricity and power companies, making the Vista purchase consistent with a broader bet on energy demand and infrastructure.

Vaca Muerta contains the world’s second-largest shale-gas resources and fourth-largest shale-oil resources, turning Argentina into an increasingly important destination for global energy capital.

India Opens One-Time Offshore Asset Amnesty

India opened a new tax-amnesty program Sunday allowing smaller taxpayers to voluntarily disclose previously unreported foreign income and assets.

Taxpayers with up to 10 million rupees, roughly $105,000, of undisclosed foreign income can participate by paying a 30% tax plus an equal penalty. Separately, taxpayers who already paid tax on overseas assets but failed to report assets worth as much as 50 million rupees, about $524,000, can regularize them through a 100,000-rupee payment. 

The program runs through December 31, 2026 and particularly targets smaller cases involving students, non-resident Indians and taxpayers who accumulated overseas assets without properly reporting them.

No U.S. Markets Today — Consumer Weakness Is What Wall Street Carries Into Monday

U.S. markets are closed Sunday, leaving Friday’s close as the starting point for the coming week.

The S&P 500 finished Friday at 7,785.76, down 0.17%, while the Nasdaq fell 0.28% and the Dow slipped 0.20%. The S&P still gained 0.4% for the week, its third consecutive weekly advance. 

The bigger economic signal came from consumers. July retail sales unexpectedly fell 0.6%, the first monthly decline in nine months, while the University of Michigan’s preliminary consumer-sentiment index dropped to 51.0 from 55.2 in July. 

Those numbers have weakened the case for an immediate Federal Reserve rate increase. The Fed’s current target remains 3.50% to 3.75%, with three policymakers having voted for a quarter-point hike at the July meeting. 

The question heading into Monday is therefore no longer simply whether inflation is cooling. It is whether the consumer is cooling faster.

JBizNews Desk | New York / Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
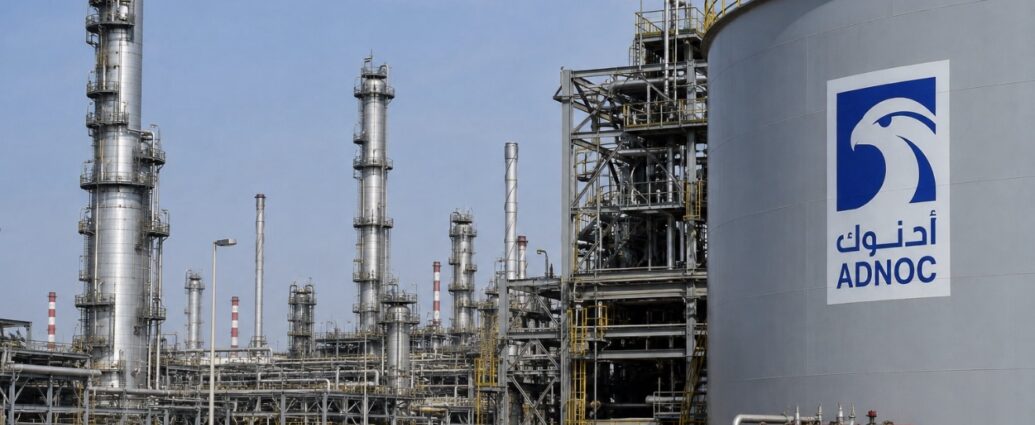
Abu Dhabi National Oil Company is changing how it prices every barrel of crude it sells, replacing the Murban futures benchmark it spent years building with a regional physical pricing benchmark as volatility from the Iran conflict continues reshaping Middle Eastern energy markets.

Beginning November 1, ADNOC will calculate monthly official selling prices for all of its Abu Dhabi crude grades—including Murban, Das, Umm Lulu and Upper Zakum—using prompt-month Platts Dubai pricing instead of Murban crude futures. Price differentials to Dubai will be announced during the month before cargoes load, bringing pricing closer to actual market conditions at the time of shipment.

The move ends a pricing framework that has been in place since the launch of the ICE Futures Abu Dhabi Murban contract in 2021. Under that system, buyers typically committed to prices roughly two months before cargoes loaded. The new approach shortens that timeline to approximately one month, reducing the disconnect between contracted prices and actual shipping conditions.

That timing matters. During the Iran conflict, freight rates, insurance premiums and security risks surrounding the Strait of Hormuz have changed rapidly, leaving refiners and traders exposed when oil was priced weeks before those costs became known. By narrowing the pricing window, ADNOC reduces the risk that customers pay based on market conditions that no longer exist when shipments actually depart.

The change also follows the United Arab Emirates’ departure from OPEC and OPEC+, which became effective May 1 and gave ADNOC greater flexibility over production and commercial strategy. Earlier this year, Platts removed the pricing floor linking Murban to Dubai after expanding Murban production increased its influence within regional crude markets. ADNOC’s decision now extends that evolution to its official sales program.

The reversal is notable because ADNOC spent years promoting Murban futures as the Middle East’s first internationally traded regional crude benchmark capable of competing with Brent. ICE Futures Abu Dhabi said it will continue listing Murban futures contracts that already have open interest while suspending future contract months without active positions.

In practice, the transition has already begun. Since June, ADNOC has been selling cargoes through spot tenders priced against Dubai differentials, making the formal announcement more of a confirmation than an unexpected policy shift. Market participants had largely expected any change to apply only to offshore marine grades, but ADNOC instead expanded it across its full production portfolio.

The company said the revised pricing mechanism reinforces its commitment to transparent pricing while continuing to meet all contractual delivery obligations. ADNOC also stated the change is not expected to materially affect outstanding debt securities, including bonds and sukuk issued under its financing programs.

Energy market specialists believe the implications could extend well beyond Abu Dhabi. Joel Hanley, Executive Director for Strategy and Development at S&P Global Energy, said aligning benchmark timing more closely with physical trading reduces basis risk and could encourage broader changes across global oil pricing systems. As Gulf crude increasingly trades on similar timelines, benchmark consistency becomes more valuable for both producers and buyers.

That possibility carries significance for American energy companies. Saudi Aramco, Kuwait Petroleum and Iraq’s state oil marketer all rely on similar official selling price systems. If other Gulf producers shorten their pricing windows as well, refiners, commodity traders, airlines and industrial fuel consumers could face meaningful changes in how they hedge Middle Eastern crude purchases and manage future fuel costs.

For businesses across the United States already navigating elevated diesel, jet fuel and freight expenses after two years of geopolitical disruptions, the new pricing mechanism will not necessarily reduce energy costs. It should, however, make pricing more closely reflect actual market conditions at the time oil is delivered, reducing one source of uncertainty in an energy market that has experienced little stability.

JBizNews Desk | Abu Dhabi

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Long-awaited banking regulation—also known as the Basel III Endgame framework—will be released next month, said the Federal Reserve’s top banking regulator.
Fed Vice Chair for Supervision Michelle Bowman, appearing at a Senate Banking Committee hearing on Feb. 26, confirmed that regulators are expected to release an updated Basel III proposal at the end of March.
But while this is the chief goal, Bowman hinted that the deadline might need to be extended.
She told lawmakers that officials at the Fed, Office of the Comptroller of the Currency, and the Federal Deposit Insurance Corporation have reached a consensus on the reproposal….

This post was originally published here

Out-of-market buyers dominated residential home purchases—especially in areas where data-center campuses and artificial intelligence (AI) jobs are flourishing—in the nation’s largest metropolitan markets in the final quarter of 2025, according to a new report from online real estate listing service Realtor.com.
According to the cross-market demand report released on Feb. 26, out-of-market buyers accounted for the majority of home purchases in 87 percent of the country’s 100 biggest metropolitan markets. Just less than two-thirds of all online traffic viewing home listings came from out-of-market shoppers, up sharply from 48 percent in the same quarter in 2019, an indicator that the residential housing market is experiencing a fundamental shift in buyer demand, Realtor.com economist Jiayi Xu noted….

This post was originally published here

With wealthy buyers relocating from states such as New York and California and large financial institutions drawn by local economic policies, pending sales and demand for luxury real estate in West Palm Beach, Florida, are bucking national sales trends.
Pending sales in January for luxury homes in the area spiked 30 percent from a year ago, real estate brokerage Redfin reported on March 2. That jump—the sharpest among the 50 most populated metropolitan regions in the United States—follows a 31.5 percent year-over-year gain in pending sales in December, Redfin said.
Nationally, however, pending sales of luxury homes dipped 3.6 percent year over year in January, while non-luxury pending sales declined 1.8 percent, according to Redfin….

This post was originally published here

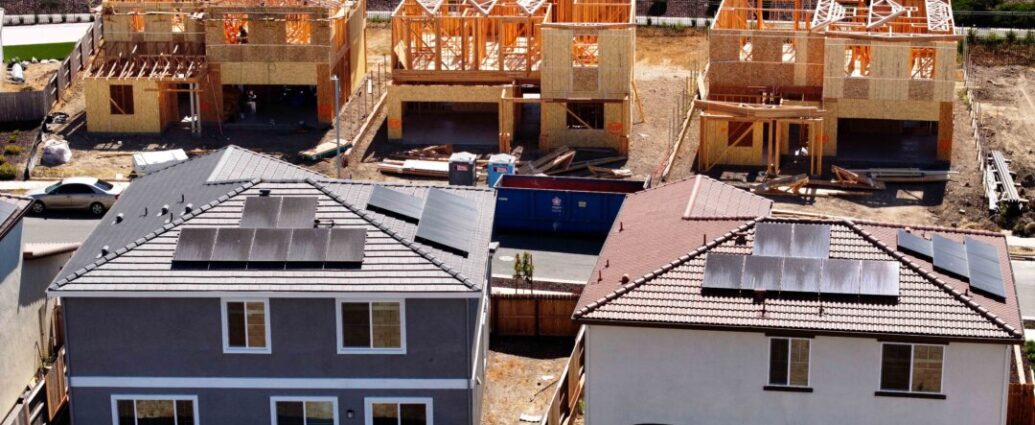
The U.S. construction industry missed its mark again as the country’s housing-supply gap grew to an estimated 4.03 million homes in 2025 from 3.8 million in 2024.
Realtor.com’s 2026 Housing Supply Gap Report, issued on March 3, indicates that construction once again fell short in meeting housing demands, particularly from younger households. The data shows nearly 1.41 million new households were formed last year, compared with just 1.36 million housing starts.
“Even when annual construction and household formation are roughly balanced, the market is still digging out from more than a decade of underbuilding,” Realtor.com chief economist Danielle Hale said in the report.
“A supply gap exceeding 4 million homes underscores how deeply rooted the shortage has become. Without a sustained and targeted increase in housing supply, particularly in areas with strong job growth and persistent demand, affordability challenges will continue to sideline many would-be buyers.”…

This post was originally published here

U.S. homeowners stayed in their houses for about 12 years as of 2025—the longest median time since 2022.
In a March 4 report, Redfin noted that the “stay put” trend peaked at 13.4 years in 2020, then gradually declined every year until 2024, when it hit 11.8 years. Last year’s rising home costs and interest rates led to an uptick to 12 years.
“High mortgage rates and home prices perpetuate a cycle that locks up housing inventory,” Redfin’s head of economics research, Chen Zhao, said in the report.
“It can keep existing homeowners in place and financially discourage them from moving to a different home or a different neighborhood, which drives prices up even higher for first-timers trying to break into the market.”…

This post was originally published here

Nearly 45,000 homes that were delisted in 2025 were back on the market in January, according to a Redfin report on March 5. This marks the highest relisting numbers since 2016, when Redfin began tracking this metric.
Home delistings soared in 2025 as sellers began to outnumber buyers, giving them more negotiating power and forcing some sellers to offer concessions. Those sellers unwilling or unable to negotiate retreated from the market, with delistings reaching a record high of 112,788 in December.
These start-of-year relistings represented 3.6 percent of all homes on the market.
“Many sellers who pulled their homes off the market last year are relisting now in hopes of capitalizing on spring homebuying season,” Redfin Austin, Texas, agent Andrew Vallejo said in the report….

This post was originally published here

U.S. existing home sales saw a 1.7 percent month-over-month increase in February to a seasonally adjusted annual rate of 4.09 million units. While sales of year-over-year existing homes fell by 1.4 percent, the National Association of Realtors (NAR) remains cautiously optimistic about the upcoming spring market.
The month-over-month increase exceeded the market estimate, which had projected a decline to 3.89 million.
“Housing affordability is improving, and consumers are responding,” NAR Chief Economist Lawrence Yun said in the firm’s March 10 report.
“Still, there is a long way to go to return to pre-pandemic levels of transaction activity. There are more than 6 million more jobs than in 2019, yet home sales per year are down by one million.”…

This post was originally published here

Australians now own $12.3 trillion (US$8.8 trillion) worth of residential real estate after the value of homes rose by $384.8 billion or 3.2 percent in the December quarter of 2025, according to figures released today by the Australian Bureau of Statistics (ABS).
The mean price of residential dwellings rose in all states and territories, led by Western Australia (7.5 percent or $70,500), Queensland (4.8 percent or $48,800) and South Australia (4.5 percent or $40,800).
Western Australia became the third state—after New South Wales and Queensland—to reach a mean house price of over $1 million. It was also an outlier in new construction, being the only state besides Tasmania not to record a decline in new home approvals in January compared with the previous month….

This post was originally published here

In the fourth quarter of 2025, 18.8 percent of house hunters across the United States were looking to relocate to a different part of the country.
This was up from 17.9 percent a year back and 15.9 percent five years ago during the COVID pandemic period, real estate brokerage Redfin said in a March 10 statement.
During the pandemic in 2020 and 2021, the average weekly mortgage rate on a 30-year fixed-rate mortgage mostly hovered around 2.5–3.5 percent, according to Freddie Mac. Pandemic-fueled remote work was also common. These factors drove many people to relocate, the brokerage said.
Mortgage rates began to climb in the following years, hitting a peak of 7.79 percent in October 2023. In January 2025, rates hit 7.04 percent and have been declining since. For the week ending March 4, the rate was 6 percent….

This post was originally published here

While the national luxury housing threshold increased to $1,205,081 in February, some top U.S. metropolitan areas were offering lower entry-level luxury prices, making these homes more accessible to more buyers.
In its February Luxury Housing Report, released on March 10, Realtor.com noted that entry-level luxury home prices experienced a 1 percent month-over-month growth, but fell by 3.1 percent year over year.
When analyzing the top 10 percent of the country’s most expensive homes, Realtor.com uses the 90th percentile price point to serve as a baseline for the luxury market in a particular region. Typically, luxury homes start at 2.9 times the median price, while high-end luxury homes start at 4.6 times the median….

This post was originally published here

The number of “accidental landlords”—homeowners who initially listed their properties for sale but pulled their listings after a few weeks and instead offered their homes for rent—has risen to near-record highs, online real estate company Zillow said.
Unsold listings that are now offered as rental properties accounted for 2.3 percent of all housing inventory currently listed on Zillow, the company reported on March 11. It’s the highest number of homeowners turning their properties into rentals since November 2022, when accidental landlords reached 2.4 percent, Zillow noted.
Kara Ng, senior economist at Zillow, said sellers face a different reality than just a few years ago as the housing market continues to rebalance….

This post was originally published here

The Senate overwhelmingly passed a bipartisan bill on March 12 that aims to lower home prices and make housing more affordable for Americans.
The upper chamber voted 89–10 to advance the 21st Century ROAD to Housing Act. The bill must now be reviewed and voted upon by the House of Representatives.
Lawmakers opposed to the bill included Sens. Ted Cruz (R-Texas), Mike Lee (R-Utah), Rand Paul (R-Ky.), Brian Schatz (D-Hawaii), and Rick Scott (R-Fla.).
The bill package was led by Sens. Tim Scott (R-S.C.) and Elizabeth Warren (D-Mass.), and combines the Senate’s ROAD to Housing Act of 2025 with provisions from the House of Representatives’ Housing for the 21st Century Act, according to a March 10 statement from the Senate Committee on Banking, Housing, and Urban Affairs….

This post was originally published here


President Donald Trump signed two executive orders on March 13 related to improving home-ownership opportunities for Americans by reducing regulatory burdens and increasing access to mortgage loans.
“Every American seeking to buy a home should have access to a mortgage from a reliable lender, at a rate commensurate with his or her creditworthiness,” Trump wrote in an order titled “Promoting Access to Mortgage Credit.”
“Layers of unnecessary regulatory barriers, slow permitting processes, and onerous mandates at all levels of government have delayed construction, restricted development, and driven up the costs of new housing.”
The directive seeks to mitigate the impact of compliance costs originating from legislative actions over the past 20 years….

This post was originally published here


Renters across the United States may be able to save a bit more on apartment leases this month, as rents nationwide hit a four-year low last month, marking the 30th consecutive month of declines.
In its February Rental Report issued on March 17, Realtor.com recorded that the national median rent was $1,667, with 15 major markets posting rents more than 10 percent below their pandemic-era peaks.
The median rent for studio, one-bedroom, and two-bedroom apartments fell last month to its lowest level since March 2022. Nationally, the median rent fell by $29, or 1.7 percent, from a year earlier. While rents remained 14.2 percent higher than pre-pandemic levels in February 2020, they were $90, or 5.1 percent, lower than their peak in the summer of 2022….

This post was originally published here


Interest rates are at their highest levels since late December, leading to slower mortgage market activity, according to new industry data released on Wednesday.
For the week ending March 18, the average contract rate on 30-year fixed-rate mortgages rose to 6.3 percent, according to the Mortgage Bankers Association. This is up from 6.19 percent the previous week.
Despite the increase, the 30-year rate is still down from last year’s 6.72 percent.
Mortgage rates typically track the U.S. Treasury market, particularly the yield on the benchmark 10-year government bond.
Even as Wall Street experiences jitters while traders seek shelter in safe‑haven assets amid the war in Iran, yields have shown little sign of retreating this month….

This post was originally published here


Fannie Mae and Freddie Mac unveiled new rules for mortgages that will help in reducing homeowners insurance bills for millions in American families, especially in condos and rural areas, the Federal Housing Finance Agency (FHFA) said in a March 18 statement.
According to the agency, which is responsible for the overall management of Fannie Mae and Freddie Mac, a key change relates to Actual Cash Value (ACV) and Replacement Cost Value (RCV) coverage for homes.
An ACV policy pays for the cost of repair or replacement of part or whole of a homeowner’s property, accounting for depreciation of the asset. In contrast, an RCV policy pays the full repair amount using materials of similar quality and kind, without considering depreciation….

This post was originally published here


Sales of newly built homes fell by more than expected in January, hitting their lowest level since 2022, the latest federal government figures suggest.
New single-family home sales came in at a seasonally adjusted annual rate of 587,000 in January, the U.S. Census Bureau said on Thursday. That was down 17.6 percent from the downwardly revised December 2025 reading of 712,000 and 11.3 percent below the level recorded in January 2025.
The slowdown in sales pushed inventory higher. The supply of new homes on the market rose to 9.7 months in January, meaning it would take that long to clear the existing inventory at the current sales pace. That was up from 8.0 months in December and 7.8 percent higher than the 9.0-month supply estimated a year earlier….

This post was originally published here


The United States has nearly 50 percent more home sellers than home buyers, a new analysis suggests, a shift that could put downward pressure on prices even as high mortgage rates continue to strain affordability.
New estimates published by Redfin on March 23 found that, as of February 2026, there were 630,000 more people selling homes than buying them. That is the largest gap the online real estate brokerage has recorded since it began tracking the data in 2013.
Redfin said the seller-to-buyer ratio climbed to 46.3 percent in February, marking a record high. The ratio rose to about 30 percent at the start of the COVID-19 pandemic, then swung to roughly minus 30 percent in 2021 as buyers vastly outnumbered sellers. It has since reversed course, returning to early COVID-19 pandemic levels in spring 2025 before surging to a new peak this year….

This post was originally published here


David Simon, who built the Simon Property Group into one of the world’s largest retail real estate firms, has died at 64 after battling cancer.
“Our family is deeply grateful for the tremendous outpouring of love and support we have received from across the globe,” a family spokesperson said in a statement.
“Our beloved husband, father, grandfather, and brother poured his heart and soul into building Simon Property Group.”
Simon leaves behind his wife of more than 40 years, Jackie, and their five children—Eli, Rebecca, Hannah, Sam, and Noah—as well as seven grandchildren.
The Indianapolis-based firm’s board of directors has appointed his son, Eli Simon, as CEO. Meanwhile, Eli Simon will continue to serve as chief operating officer and a member of the board….

This post was originally published here


Mortgage demand tanked for the second straight week as higher interest rates slowed homebuying and refinancing activity, new industry data show.
For the week ended March 20, total mortgage application volumes declined by 10.5 percent, according to figures from the Mortgage Bankers Association released on March 25.
Applications also fell, by 10.9 percent, during the previous week.
The index for refinancing tumbled by 15 percent while applications to purchase a home decreased by 5 percent.
Weaker mortgage market activity was driven by rising interest rates and affordability constraints, says Joel Kan, deputy chief economist and vice president of the Mortgage Bankers Association.
“The threat of higher for longer oil prices continued to keep Treasury yields elevated, and mortgage rates finished last week higher,” Kan said in a news release….

This post was originally published here


Home-loan giant Fannie Mae will soon accept so-called crypto-backed mortgages for the first time, marking another step in cryptocurrencies’ push into mainstream consumer finance.
On Thursday, mortgage lender Better Home & Finance and crypto exchange Coinbase Global announced a new product that ties digital assets to down payments on Fannie Mae-eligible home loans.
Under the structure, homebuyers can pledge Bitcoin or USDC stablecoin as collateral for a separate loan that funds the cash down payment—rather than converting those assets into U.S. dollars, which not only incur tax liabilities but also cost them any potential future gains.
Crypto-backed mortgages are not new, but the Better–Coinbase product is the first to be accepted by Fannie Mae, a government-sponsored enterprise overseen by the Federal Housing Finance Agency (FHFA) and a central force in the U.S. housing market….

This post was originally published here


The average rate on the 30-year fixed mortgage climbed to 6.38 percent, according to a survey by Freddie Mac published on March 26.
The rate jumped from 6.22 percent the previous week and now stands at its highest level in more than six months. The 15-year fixed-rate mortgage rose to 5.75 percent from 5.54 percent.
Freddie Mac chief economist Sam Khater said: “The housing market continues to show gradual improvements compared to a year ago amid recent rate volatility. Purchase and refinance applications are up year-over-year, and rates remain lower than last year when they averaged 6.65 percent.”
The survey covers conventional, conforming loans with 20 percent down and excellent credit. Freddie Mac did not cite specific reasons for the increase….

This post was originally published here


The interest rate on the nation’s most popular home loan climbed again last week, adding pressure on prospective homebuyers and driving down the number of applications.
The Mortgage Bankers Association on Wednesday reported that the average contract interest rate on a 30-year fixed mortgage rose to 6.57 percent in the week ended March 27, up 14 basis points from one week earlier.
Over the past four weeks, the rate has jumped by nearly half a percentage point, the sharpest increase since 2024, the MBA said. The figure comes from the national group’s weekly applications survey, which tracks rates tied to submitted mortgage applications reported by lenders….

This post was originally published here


The median monthly mortgage payment in the United States hit $2,742 for the four weeks ending March 29, marginally up from last year and registering the first year-over-year increase in almost six months, real estate brokerage Redfin said in an April 2 statement.
“Housing payments are climbing because the Iran war and rising oil prices have pushed the weekly average mortgage rate up to a six-month high of 6.38 percent,” the brokerage said.
In 2025, the average weekly mortgage rate on a 30-year fixed-rate mortgage had hit its annual high of 7.04 percent in mid-January, according to data from Freddie Mac. Rates then entered a downward trend, falling to a low of 5.98 percent for the week ending Feb. 25 this year, the first time since September 2022 that rates had fallen below the 6 percent level….

This post was originally published here


In some corners of the United States, a seven-figure home price tag does not signal exceptional wealth so much as simply the mere cost of entry.
A Realtor.com report published on Wednesday identified 13 U.S. housing markets that fit this profile. In each of them, at least half of active home listings were priced at $1 million or more, while the total number of such listings remained below 500.
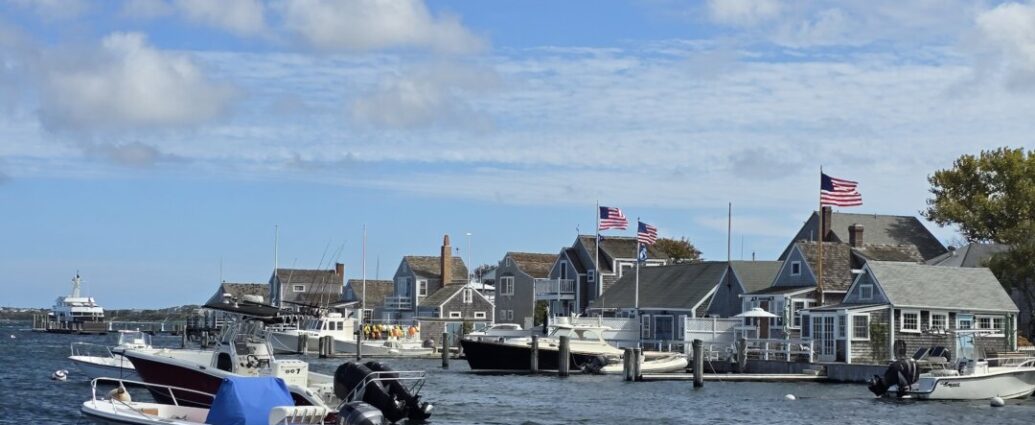
A prime example is Nantucket, Massachusetts. The small island, home to about 14,000 year-round residents, topped the list, with nearly all of its active home listings priced at $1 million or above. Its median listing price stood at $4.08 million….

This post was originally published here


The United States has a shortage of 10 million homes, a gap that the White House’s newly released 2026 Economic Report of the President attributes in part to government regulations that have increased construction costs.
The estimated shortage was calculated by tracking how many single-family homes would have been built if the historical pace up to 2008 had continued, according to the report, issued on April 13 by the Council of Economic Advisers.
Housing costs surged as demand outpaced supply, with regulatory hurdles such as fees, mandates, and permitting delays adding what it described as a six-figure “bureaucrat tax” to the cost of building a new home. The report highlights “California-style” regulations as a key example….

This post was originally published here


Golden handcuffs in the U.S. housing market remain firmly locked, with COVID-19 pandemic‑era mortgage rates still accounting for about half of all outstanding loans.
At the onset of the COVID-19 pandemic in 2020, the Federal Reserve slashed interest rates to zero percent to cushion the economic blows of the public health crisis.
The decision fueled historically low borrowing costs across the economy. Homebuyers and homeowners who refinanced were some of the chief beneficiaries, as millions of households locked in 30-year mortgage rates as low as 2.65 percent.
Several years later, these loans continue to account for a large share of the U.S. mortgage market….

This post was originally published here


San Francisco’s housing market continued to heat up in March as the artificial intelligence boom generated new wealth and high-paying jobs, according to a report from Redfin.
The real estate brokerage said on April 16 that the median home sale price in the San Francisco metropolitan area jumped by 14.4 percent year over year in March to a record $1.7 million, the biggest increase since March 2018.
Redfin said the gain was also the largest among the nation’s 50 most populous metro areas. It now identifies San Francisco as the major U.S. metro with the highest home prices, overtaking neighboring San Jose, California, which held that title for much of 2024 and 2025….

This post was originally published here


The aftermath of Austin’s tech boom in the COVID-19 pandemic era, and the layoffs that followed, are still reshaping the Texas city’s housing market, according to a new report.
During the COVID-19 pandemic, an influx of tech workers created an unprecedented spike in housing demand that sent sales and property values soaring, according to a report released on April 20 by Homes.com.
The Austin real estate market hit its all-time peak in 2022, with a median sold price of $555,400. The surge was driven in part by some of the country’s highest-profile tech employers—including Tesla, Apple, and Amazon—which either relocated headquarters or expanded their presence in the area to take advantage of Texas’s favorable tax environment….

This post was originally published here


Mortgage market activity surged last week as interest rates declined for the third consecutive week, new industry data released on April 22 show.
Total mortgage applications climbed nearly 8 percent for the week ending April 17, according to the Mortgage Bankers Association.
Application for new-home purchases advanced 10 percent, while refinancing jumped 6 percent.
“Mortgage rates declined last week as financial markets responded positively to the Middle East ceasefire and the lower trend in oil prices,” Mike Fratantoni, the group’s chief economist and senior vice president, said in a news release.
“Despite the geopolitical uncertainty, housing demand is being supported by a still resilient job market, and homebuyers are experiencing a buyer’s market in most of the country given the higher levels of inventory relative to last year.”…

This post was originally published here


America’s housing market is increasingly splitting into two different realities: one where desirable homes are snapped up almost immediately, and another where listings linger for weeks.
A Zillow analysis released on Thursday found that 18.5 percent of homes nationwide went under contract within seven days in February 2026. This March, the typical home that sold went pending in 19 days, while the median active listing had already been sitting on the market for 56 days.
That 37-day gap marks the widest divide for any March since 2020, just before the pandemic-era housing boom began, according to Zillow.
In parts of the Midwest and Northeast, where limited new construction has kept supply in check, homes continue to move quickly. Zillow found that at least three in 10 homes sold within a week in Midwest metro areas such as St. Louis, Cincinnati, and Kansas City….

This post was originally published here