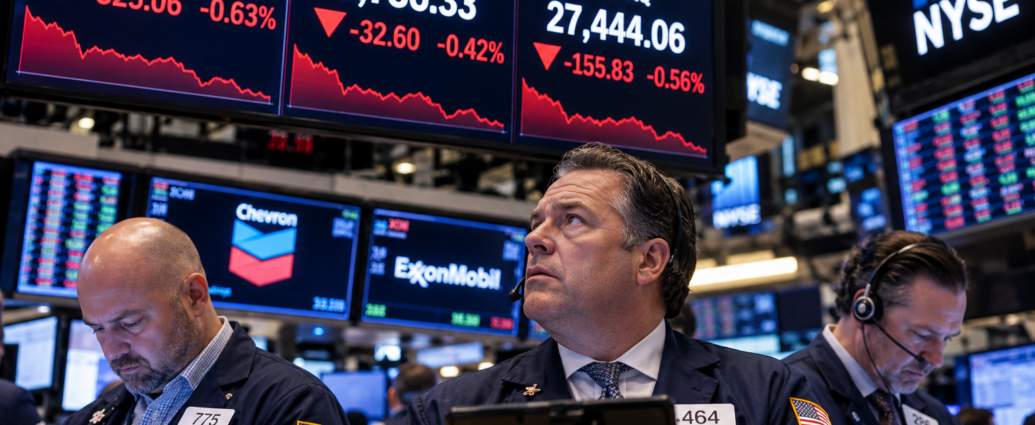
U.S. stocks opened sharply lower Wednesday as oil climbed back above $100 a barrel and long-term Treasury yields returned to 24-year highs, forcing investors to confront higher energy and borrowing costs just one day after the S&P 500 and Nasdaq closed at records.
At the opening bell, the Dow Jones Industrial Average fell 325.06 points, or 0.63%, to 51,196.22. The S&P 500 dropped 32.60 points, or 0.42%, to 7,786.33, while the Nasdaq Composite lost 155.83 points, or 0.56%, to 27,444.06. These are Reuters’ confirmed opening readings rather than premarket futures.
The reversal followed Tuesday’s record closes for the S&P 500 and Nasdaq, when falling yields and oil prices allowed enthusiasm surrounding artificial intelligence and the coming earnings season to dominate trading. Wednesday brought the opposite combination: oil rebounded, bonds sold off and investors took some profits while waiting for minutes from the Federal Reserve’s September meeting.
Treasury Yields Return to 24-Year Highs
The bond market is again the biggest immediate pressure point for Wall Street.
The 30-year Treasury yield briefly reached 5.7041% Wednesday, a fresh 24-year high, as the global government-bond selloff resumed. Long-term yields are being driven by persistent inflation concerns, elevated government borrowing and investor demands for greater compensation to own long-dated debt.
For consumers and businesses, this is not simply a Wall Street story. Treasury yields influence mortgage rates, corporate loans and other borrowing costs across the economy.
The consequences are already showing up in housing. The Mortgage Bankers Association reported Wednesday that the average rate on a 30-year fixed mortgage jumped 19 basis points to 7.49% in the week ended Oct. 2, its highest level since November 2023. Total mortgage applications declined 4.2% from the previous week.
That means a household trying to buy a home is confronting substantially more expensive financing even as affordability is already stretched by high property prices.
Bond investors face another major test later Wednesday with a 10-year Treasury auction, followed Thursday by a 30-year sale. Weak demand at either auction could push yields still higher.
Oil Climbs Back Above $100
Energy markets added another layer of inflation pressure.
Brent crude rose more than 1% to around $101.50 a barrel Wednesday morning as Middle East supply concerns and other potential disruptions brought buyers back into the market.
The rebound follows Tuesday’s decline, when improving Middle East exports and emergency reserve releases had given investors hope that energy pressures were beginning to ease.
Oil above $100 matters because its effects reach far beyond gasoline. Higher crude can raise diesel, aviation, freight, manufacturing and shipping costs, creating the possibility that businesses eventually pass those increases to consumers.
The energy shock is already producing extraordinary profits in parts of the oil industry. Shell said Wednesday that it expects third-quarter refining margins of about $42 a barrel, up from $24 in the second quarter, as disruptions tied to the Middle East conflict tightened global fuel supplies.
The G7 has agreed to release diesel and crude from emergency reserves, but geopolitical and supply risks remain unresolved.
Economic Data: Mortgage Rates Hit 7.49%; No Major BLS Release
Wednesday morning did not bring a major scheduled Bureau of Labor Statistics report. The BLS calendar shows no national release for Oct. 7; September CPI and real-earnings data are scheduled for Oct. 14.
The important domestic reading Wednesday morning instead came from housing finance.
The Mortgage Bankers Association said the average 30-year fixed mortgage rate rose to 7.49% from 7.30%, while mortgage applications fell 4.2%. Rates are now roughly 1.4 percentage points higher than before the Middle East conflict sharply intensified earlier this year, closely tracking the rise in Treasury yields.
The report reinforces the growing split inside the U.S. economy. AI investment and parts of corporate America remain exceptionally strong, while interest-rate-sensitive sectors such as housing face increasingly difficult financing conditions.
Chip Stocks Retreat After Record Rally
Technology shares were among Wednesday’s early pressure points after helping push the broader market to records Tuesday.
Micron Technology, AMD, Broadcom and Marvell Technology all entered the session under pressure as investors took profits in semiconductor shares following their recent surge. Before the bell, Reuters reported Micron down 2.8%, with AMD, Broadcom and Marvell off between 1.3% and 2.1%. Those figures are premarket indications and are included only to explain the direction of the opening trade, not as current post-open prices.
The pullback comes after Marvell raised its fiscal 2028 revenue forecast to approximately $20 billion, above the $18.2 billion Wall Street consensus cited by Reuters, because of booming demand for custom AI data-center chips.
The contrast captures the market’s central tension: AI-related corporate growth remains enormous, but the price investors are willing to pay for those future profits becomes harder to justify as government bonds offer yields above 5%.
SpaceX Falls on Report of $40 Billion Financing Push
SpaceX also came under pressure after the Financial Times reported that Elon Musk’s rockets-to-AI company is seeking approximately $40 billion in financing to fund purchases of Nvidia chips.
Reuters reported SpaceX shares down 1.6% before the bell. The financing details originate from the FT report and therefore remain a developing report rather than a company-confirmed transaction.
If completed, the financing would be another indication of the extraordinary amounts of capital being committed to AI infrastructure.
Constellation Brands Slides After Margin Warning
Constellation Brands, the company behind Corona and Modelo beer in the United States, also entered Wednesday under pressure after lowering its annual operating-margin forecast.
Shares were down 3.8% in premarket trading, according to Reuters.
The warning adds a consumer-facing company to Wednesday’s list of concerns at a time when investors are trying to determine how higher energy prices, borrowing costs and other expenses are affecting corporate profitability.
Fed Minutes Take Center Stage
The day’s biggest scheduled event comes later Wednesday with publication of the Federal Reserve’s September meeting minutes.
At that meeting, policymakers unanimously raised the federal-funds target range by a quarter percentage point to 3.75% to 4%, the first increase in three years. The minutes could reveal more about how strongly officials support additional tightening.
There are already visible differences inside the Fed.
Some officials have argued that persistent inflation warrants additional increases, while others have urged patience following softer inflation and employment readings.
Markets currently see only about a 21.6% probability of another rate increase in October, while the implied probability of a December increase stands around 68.6%, according to market pricing cited by Reuters.
That makes the minutes important not because another October hike is expected, but because investors want to know how close policymakers may be to moving again in December.
What to Watch
The 30-year Treasury yield near 5.7% is the day’s most immediate warning signal. If Wednesday’s 10-year Treasury auction attracts weak demand, yields could rise further and put additional pressure on technology, housing and other rate-sensitive stocks.
Next is oil above $100. Tuesday’s relief proved temporary. A sustained rise in Brent could revive fears that higher gasoline, transportation and manufacturing costs will slow progress on inflation and force the Fed to remain restrictive for longer.
The Federal Reserve minutes will then become the main event. Investors will be looking for evidence of how many policymakers favor another increase this year and how concerned officials are about the trade-off between persistent inflation and softer job growth.
Investors should also watch the AI and semiconductor complex. Tuesday’s record-setting rally demonstrated that enthusiasm surrounding artificial intelligence remains powerful, but Wednesday’s pullback shows that even the market’s strongest stocks remain vulnerable when Treasury yields rise rapidly.
Finally, the coming third-quarter earnings season will test whether record stock valuations are supported by profits. LSEG estimates cited by Reuters currently call for S&P 500 earnings to rise 30.6% from a year earlier, led by an expected 114.7% increase in energy-sector earnings and a 66.5% rise in technology profits.
For businesses and consumers, Wednesday’s opening carries a straightforward message: Wall Street’s AI boom remains intact, but the cost of money and energy is moving higher again. If Treasury yields and oil continue climbing together, those two pressures could become increasingly difficult for stocks — and the broader economy — to ignore.
JBizNews Desk | Trenton, N.J.
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.