The bond-market shock that hit Wall Street Tuesday is carrying directly into Wednesday morning, with long-term U.S. borrowing costs remaining near levels not seen since before the financial crisis even as expectations for another Federal Reserve rate increase continue to fade.
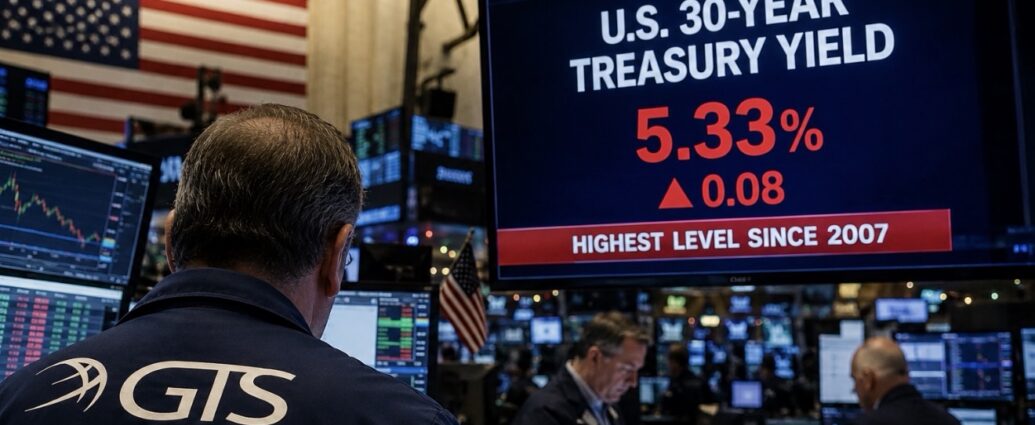
The yield on the 30-year U.S. Treasury surged to roughly 5.33% Tuesday, its highest level since 2007, before easing modestly Wednesday morning to around 5.28%.
That small retreat does not change the larger story.
Long-term borrowing costs have moved sharply higher even though investors increasingly believe the Federal Reserve may leave short-term interest rates unchanged in September.
Normally, expectations for fewer Fed hikes would push borrowing costs lower across the Treasury market.
This time, the opposite is happening at the long end.
Investors are demanding more compensation to lend the U.S. government money for 20 or 30 years because of a combination of persistent inflation risk, enormous federal borrowing requirements, rising government debt and uncertainty over how long energy prices will remain elevated.
Oil is adding another complication.
Brent crude pushed above $90 a barrel Tuesday as tensions surrounding Iran and the Strait of Hormuz intensified. Prices remained elevated Wednesday, keeping pressure on fuel costs even as some other inflation indicators have softened.
That matters because energy works its way through almost every corner of the economy.
Higher crude eventually raises diesel, trucking, aviation, shipping, manufacturing and distribution expenses. Businesses that never purchase a barrel of oil directly still pay for it through transportation and supply chains.
The bond market is effectively saying that the Federal Reserve’s next meeting is only part of the interest-rate story.
The Fed controls very short-term rates.
Markets determine what companies, homeowners and the government must pay to borrow for decades.
And right now those markets are demanding considerably more.
The difference can be enormous.
A business financing a property, factory or infrastructure project for 20 or 30 years does not receive much benefit from expectations that the Fed may skip a quarter-point increase next month if the underlying long-term rate used to price that financing is simultaneously climbing toward two-decade highs.
Homebuyers face the same arithmetic.
Long-term Treasury yields feed directly into mortgage pricing, meaning elevated bond yields can keep mortgage rates high even without another Fed increase.
Corporations are feeling it as well.
Companies are issuing enormous quantities of debt to finance artificial-intelligence data centers, power infrastructure and other capital projects at the same time the Treasury is borrowing heavily to finance federal deficits.
All of those borrowers are competing for the same pool of investment capital.
The more debt markets are asked to absorb, the greater the yield investors can demand.
Tuesday showed how quickly that pressure can reach stocks.
Technology shares fell sharply as long-term yields climbed because higher interest rates reduce the present value investors place on profits expected years into the future. Expensively valued AI and growth companies are particularly sensitive to that calculation.
Wednesday brings another test.
The Federal Reserve will release the minutes from its July 28–29 meeting at 2 p.m. ET, giving investors a closer look at how policymakers are balancing persistent inflation against growing evidence that consumers, housing and parts of the economy are slowing.
But the most important message from markets may already be visible.
Wall Street is becoming less worried that the Fed will raise rates next month.
It is becoming more worried about what borrowing money for the next 30 years will cost.
Those are two very different problems — and for businesses financing long-term investments, the second may ultimately matter much more.
JBizNews Desk | Wall Street
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.