
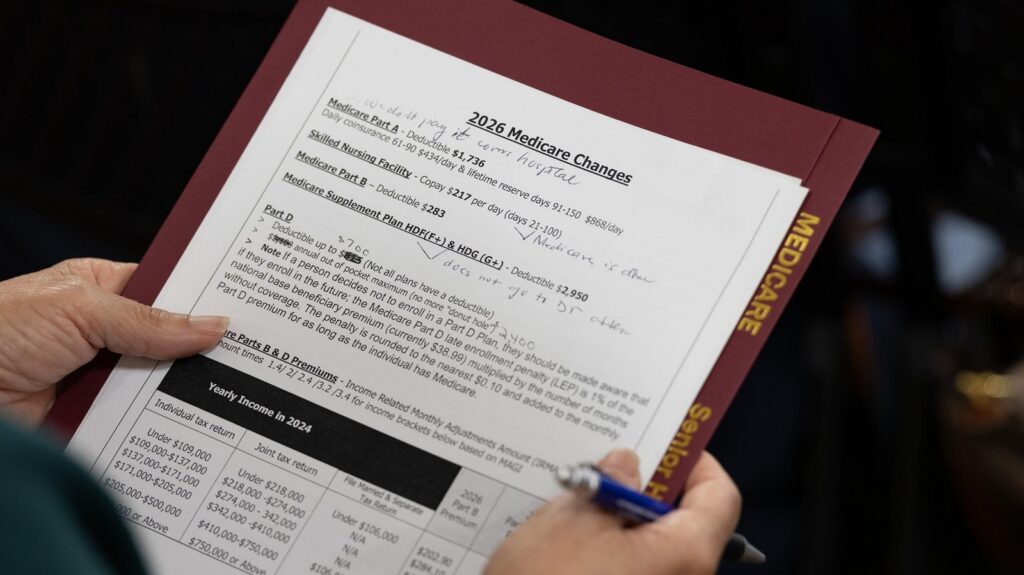
Photo: Barry Sloan / Newsday (Oct. 27 seminar)
About 33,000 Long Island Medicare beneficiaries will need to review their coverage because their current plans are being discontinued for 2027, according to Centers for Medicare & Medicaid Services figures reported by Newsday. The change ends those particular plans, not the beneficiaries’ eligibility for Medicare itself.
The annual enrollment period ends Dec. 7, with changes taking effect Jan. 1. People whose plans will not be renewed may also qualify for a special enrollment period, but waiting can change when replacement coverage begins.
Brian Krantz, founder of Melville-based insurance brokerage Plan Medicare, told Newsday that more than 10 Medicare Advantage plans are leaving Nassau and Suffolk counties. He said his brokerage is receiving a steady flow of calls from people trying to find a replacement.
What happens when a plan ends
For beneficiaries in a Medicare Advantage plan that is not renewed, Medicare says they will return to Original Medicare if they do not join another Advantage plan before their existing coverage ends. That does not automatically resolve every coverage need: separate prescription drug coverage and supplemental insurance may need attention.
Medicare’s special enrollment rules provide a window from Dec. 8 through the last day of February for people whose Medicare Advantage, drug or Cost Plan contract is not renewed. For plans ending this year, that window runs through Feb. 28, 2027. Eligibility depends on the circumstances in the plan’s notice.
Beneficiaries should not confuse that extra time with a promise that a late choice will provide uninterrupted coverage from Jan. 1. Medicare says special-enrollment coverage generally starts on the first of the month after a plan receives the request. Its annual enrollment guidance says a plan must receive a request by Dec. 7 for coverage beginning Jan. 1.
Compare more than the monthly premium
A plan that continues into 2027 can still change its costs, covered drugs or provider network. Newsday’s report advises beneficiaries to check the exact plan accepted by their doctors and hospitals, rather than relying on the name of the insurance company. A practice may accept some of an insurer’s plans but not others.
Prescription coverage also deserves a close look. Medicare recommends adding regularly used drugs when comparing plans, checking pharmacy networks and reviewing both monthly premiums and estimated yearly drug costs. A plan with a $0 premium can still carry deductibles, copayments and other expenses.
People expecting treatment or medical equipment should ask about prior authorization. Extra dental, vision or hearing benefits can have limits that are not obvious from a summary. Newsday quoted KFF policy expert Jeannie Fuglesten Biniek warning that a dental-benefit check mark does not mean every plan provides the same coverage.
Protect personal information while shopping
Consumer advocates interviewed by Newsday also warned that confusing coverage changes create opportunities for misleading sales pitches and fraud. Beneficiaries should protect their Medicare numbers, be cautious with unsolicited callers and review claims for services or equipment they did not receive.
For help comparing options, Medicare directs beneficiaries to its plan comparison services or 1-800-MEDICARE (1-800-633-4227). Newsday also lists New York’s Health Insurance Information, Counseling and Assistance Program at 800-701-0501 for free, unbiased counseling. Anyone facing a discontinued plan should review the notice and confirm their enrollment rights before choosing replacement coverage.
JBizNews Desk | Long Island
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.




