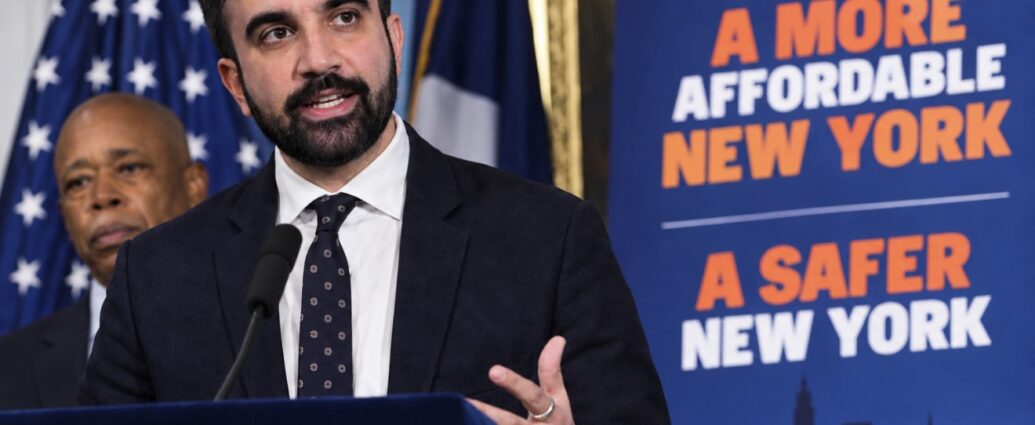
NEW YORK, Sunday, October 11, 2026 — New York City has approved more than half of the exemption applications filed against Mayor Zohran Mamdani’s new luxury second-home tax, raising serious questions about whether the controversial measure can generate the $500 million in annual revenue promised by City Hall.
The city’s Department of Finance confirmed that approximately 5,700 of 10,000 exemption applications had been approved as of Friday, a 57% approval rate, according to figures reported Sunday by the New York Post.
The approvals mean thousands of property owners initially identified as potentially subject to the surcharge have successfully demonstrated that they qualify for exemptions.
For the Mamdani administration, the numbers represent a significant challenge to a tax promoted as a major source of revenue for public services. The situation is further complicated by a court ruling against the city’s implementation of the tax and separate lawsuits challenging its legality.
The exemptions were approved administratively by New York City’s Department of Finance, not by the courts. The judicial challenges are separate proceedings that could have broader consequences for the tax.
The measure, introduced by Mamdani in partnership with New York Gov. Kathy Hochul, imposes an additional annual property tax on certain expensive residences that are not used as primary homes.
It generally applies to condominium and cooperative apartments valued at $1 million or more and one-, two- and three-family homes valued above $5 million.
The surcharge is based on property value, meaning owners of qualifying luxury residences could face substantial additional annual tax bills.
However, properties used as primary residences by owners, qualifying family members or tenants generally are exempt.
That distinction is central to the latest controversy.
When the Department of Finance began implementing the tax in July, it sent notices to approximately 17,000 property owners who might be subject to the surcharge. That number was subsequently reduced, with city officials identifying approximately 10,000 to 13,000 potentially affected properties.
The high exemption approval rate raises questions about how accurately the city identified properties subject to the new tax before notifying homeowners.
On September 29, Staten Island Supreme Court Justice Wayne Ozzi ruled that the Department of Finance had improperly implemented the surcharge by shifting the burden of establishing exemption eligibility onto property owners.
The judge found that the city had relied on an overly broad property list rather than making sufficient individualized determinations before sending notices.
The ruling directed the city to restart portions of its implementation process.
Mamdani’s administration appealed, temporarily suspending the effect of the ruling and allowing the tax program to proceed while the case is reviewed.
The dispute is particularly significant for property owners who received notices despite using their residences as primary homes.
Those homeowners have been required to gather records and submit applications to establish that they should not be subject to the additional tax.
Attorney Ben Williams, who represents a homeowner challenging the measure, questioned whether the administration’s projected revenue was realistic.
Williams warned that removing primary residences from the taxable population and addressing disputed property valuations could leave the city collecting considerably less than anticipated.
The financial implications extend beyond individual homeowners.
City Hall has promoted the surcharge as a means of generating more than $500 million annually to help fund municipal services.
A substantial revenue shortfall could complicate future budget planning, particularly if projected collections have already been incorporated into spending assumptions.
However, the 57% exemption approval rate does not mean the city will automatically lose 57% of its anticipated revenue. The approved applications concern properties that may carry different taxable values, and some applicants may never have been legally subject to the surcharge.
The actual financial impact will depend on the value of the remaining taxable properties, additional exemption decisions and the outcome of pending litigation.
The administration now faces the challenge of demonstrating that its original revenue assumptions remain achievable.
Beyond the administrative dispute, high-profile property owners including casino executive Steve Wynn and former U.S. Commerce Secretary Wilbur Ross have brought separate legal challenges.
Those lawsuits question whether the tax unlawfully discriminates against people who own property in New York City while maintaining their primary residences elsewhere.
The legal claims remain unresolved.
Supporters of the tax argue that wealthy owners of expensive secondary residences should contribute more toward maintaining the public services and infrastructure that support New York City’s economy.
Opponents contend that the surcharge places an additional burden on property owners already paying substantial taxes and could discourage investment in the city’s luxury real estate market.
The controversy also creates uncertainty for property investors evaluating the long-term costs of owning New York City real estate.
Unlike a one-time transaction tax, the surcharge could become a recurring expense that affects ownership costs, property valuations and investment decisions.
For homeowners who have received notices, the immediate deadline is approaching.
The Department of Finance has extended the exemption application deadline to Tuesday, October 13, giving affected property owners additional time to demonstrate that their residences qualify for exclusion.
The city says the surcharge will appear on property tax bills due January 1, 2027, for properties ultimately determined to be subject to the tax.
For now, the administration must continue processing applications while defending its implementation in court.
The next test will come as additional exemption decisions establish how many properties remain taxable and whether the city can substantiate its projected collections.
With 57% of exemption applications already approved and multiple lawsuits pending, New York City’s $500 million tax plan faces a growing gap between its original expectations and the revenue it may ultimately collect.
JBizNews Desk | New York
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.