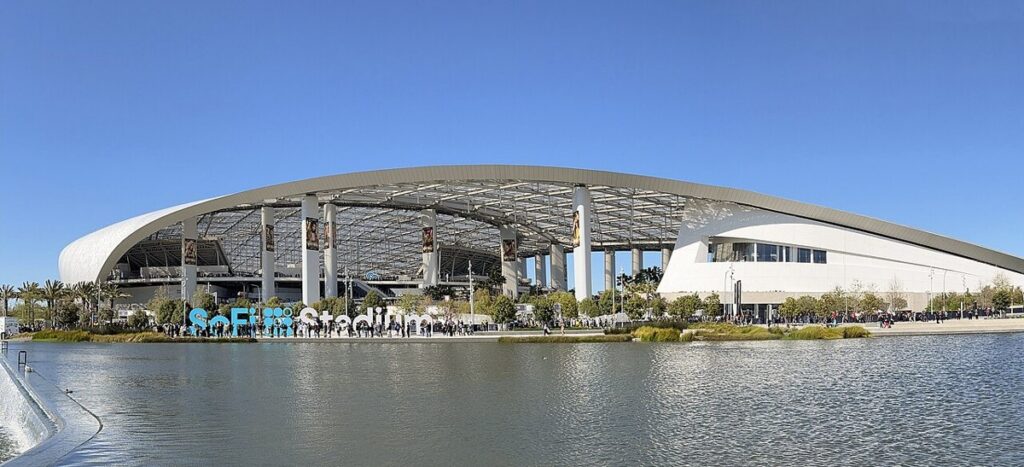
SoFi Stadium, which carries the company’s name. Photo: Troutfarm27, Wikimedia Commons, CC BY-SA 4.0. Image resized.
SoFi reported record loan originations and a surge in deposits Tuesday, raising its full-year revenue outlook as more customers used the digital financial company’s borrowing, saving and investing products.
The company originated $16.9 billion in loans during the third quarter, up 71% from a year earlier. Personal loans accounted for $12.6 billion, student loans for $2.9 billion and home loans for $1.4 billion, SoFi said.
The results offer a view of household borrowing and competition for savings, though they describe one growing lender rather than all U.S. consumers. SoFi’s growth also includes loans originated for outside investors, not only borrowing that stays on its own balance sheet.
Borrowing expands across products
Personal loan originations rose 69%, including $3.6 billion originated on behalf of third parties through SoFi’s Loan Platform Business. Student loan volume increased 96% to the highest quarterly level in the company’s history.
Home loan originations increased 44%. Home equity loans accounted for about 40% of that volume, showing that lending against existing housing equity was an important part of the total, rather than all the growth coming from loans to purchase homes.
SoFi said personal-loan credit performance remained in line with expectations. Its reported annualized personal-loan charge-off rate was 2.26%, but that figure includes the effects of asset sales, new originations and delinquent-loan sales.
Excluding late-stage delinquent-loan sales and including recoveries, the company estimated an annualized net charge-off rate of about 3.4%, down from both the previous quarter and a year earlier. Charge-offs measure loans written off as uncollectible; the different calculations should not be treated as interchangeable readings of credit risk.
Deposits lower funding costs
Total deposits grew by $5.8 billion during the quarter to $51.3 billion. Average deposits accounted for 90% of average total liabilities, SoFi said.
For a lender, those balances provide money to fund loans. SoFi said its average rate paid on deposits was 1.45 percentage points below the cost of its warehouse funding facilities, translating to roughly $745 million in annualized interest-expense savings. That is the company’s funding-cost comparison, not a savings rate offered to customers.
Net interest income rose 59% to $929.5 million, driven by growth in interest-earning assets and a lower cost of funds. Financial Services revenue increased 25% to $525.1 million as consumer deposits and other products expanded.
More members, higher outlook
SoFi added a record 1.2 million members in the quarter, reaching 17.1 million, up 35% from a year earlier. Its product count rose 44% to 26.7 million. Products are not unique customers: existing members opened 51% of new products, and the company averaged about 1.56 products per member.
Third-quarter net revenue under generally accepted accounting principles rose 44% to about $1.4 billion. Net income was $241 million, or 18 cents a diluted share. Adjusted net income was $243 million, and adjusted EBITDA reached $469.8 million.
The company now expects about $5.04 billion in full-year adjusted net revenue and $1.66 billion in adjusted EBITDA, with adjusted net income of about $840 million and adjusted earnings of 61 cents a share.
It also introduced a 2027 outlook calling for approximately $6.4 billion in adjusted net revenue, $2.24 billion in adjusted EBITDA and 90 cents in adjusted earnings per share. Those are management forecasts, with the revenue target representing about 27% growth over its updated 2026 outlook.
JBizNews Desk | San Francisco
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.