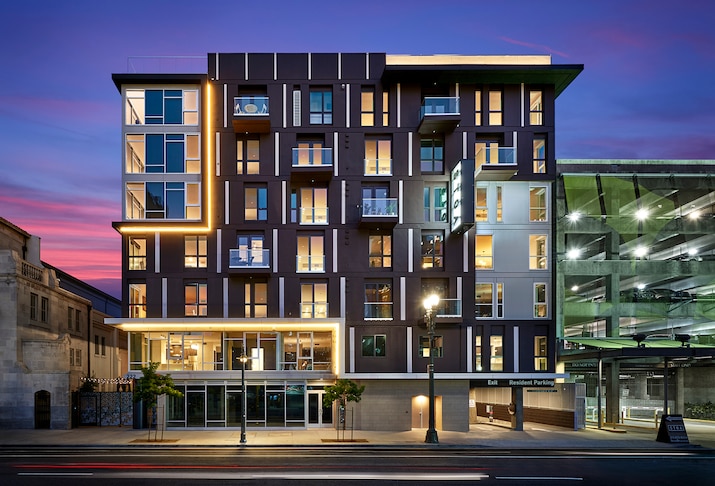
Photo: Vivmark / company portfolio archive
Renters who stayed put at Vivmark Residential’s apartments paid much bigger increases than new arrivals in the third quarter. The newly merged landlord reported a 5.3% increase on renewals, compared with a 0.4% increase on new leases, as it began combining the former Equity Residential and AvalonBay businesses.
The gap is a reminder that an apartment owner’s average rent growth does not tell every tenant’s story. Vivmark’s blended lease rate rose 3.1%, but the increase depended heavily on whether a household renewed or moved in.
In its first earnings release since the August 17 merger, the company also raised its expected annual operating benefits from the combination by $10 million to $135 million. It expects to reach that annual pace by March 2028. Those are projected benefits, not savings already fully delivered.
Rent growth meets a bigger expense bill
Across a merged same-store portfolio of 157,377 apartment homes, revenue rose 2.4% from a year earlier while operating expenses climbed 3.6%. That left net operating income, the property-level measure before items such as depreciation and corporate overhead, up 1.7%.
Physical occupancy was 95.8%, compared with 95.9% a year earlier. The renewal and new-lease increases are portfolio averages, not promises about the rent on any individual apartment.
The merged same-store figures put qualifying properties from both predecessor companies on a common operating basis. That matters because the reported financial statements follow different rules: they include AvalonBay alone before August 17 and the combined company afterward. A simple comparison of headline totals would not measure growth across the same business.
Merger costs weigh on reported earnings
Vivmark reported a third-quarter net loss of $1.27 a share and funds from operations of 8 cents a share. Core funds from operations, an adjusted measure widely used by property investors, was $1.03 a share. The quarter included 92 cents a share of merger costs that were excluded from core FFO. Core FFO is not a substitute for net income.
The company now expects total merger-related costs of about $725 million, below its earlier $750 million estimate. The updated figure includes transaction and integration costs; the original estimate covered transaction costs only.
For the fourth quarter, it forecast core FFO of $1.01 to $1.05 a share. For the full year, it expects merged same-store operating expenses to rise 4.1% to 4.7%, faster than revenue growth of 2.0% to 2.4%. That would leave property-level net operating income growth of 0.8% to 1.4%.
One pressure point is California property taxes. Vivmark expects merger-related reassessments on former AvalonBay properties to add about $16 million to expenses this year, with an estimated annual impact of $50 million beginning in 2027.
The business is collecting higher rents and targeting savings from its larger scale. The test is whether those gains can outrun rising costs without losing residents.
JBizNews Desk | Arlington / Chicago
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.