Traders in Toronto spent Tuesday bracing for a punch that never landed.
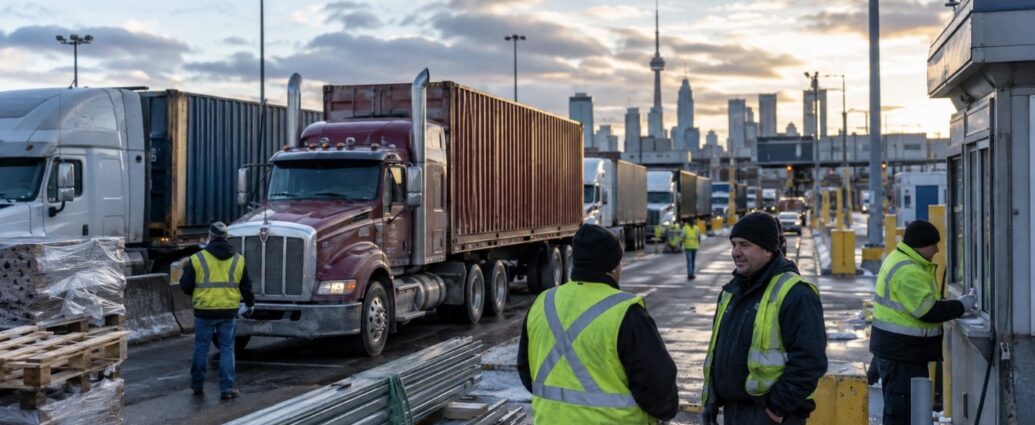
The market had been sliding for three straight sessions, and Tuesday was the worst day of the month — everyone watching the clock tick toward midnight, when a 50% tariff on a long list of Canadian goods was supposed to take effect. Wine, hockey equipment, cement, furniture, building materials. Around $28 billion worth of merchandise that suddenly wouldn’t make sense to ship.
Then, a couple of hours before the deadline, Trump posted that he was pausing the tariffs for three days because the two countries have a deal, subject to finalizing the documents.
Wednesday morning, the mood flipped. The Toronto index climbed nearly 200 points and the Canadian dollar firmed up. Miners led the way, with gold up almost 3%. The companies that actually live off cross-border trade moved too — auto parts maker Magna and fertilizer producer Nutrien both gained, along with the railways and pipeline operators that haul the freight. New York went along for the ride, with all three major U.S. indexes higher.
Relief, in other words. But look at what it’s built on.
Three days. No signed agreement. Prime Minister Mark Carney was noticeably more careful than Trump, saying real progress had been made but important work is still left. Alcohol and autos remain the fights that haven’t been settled, and Trump says he expects the whole thing done within 48 to 72 hours.
Until Friday, nothing changes at the border. A load of Ontario wine or Quebec cement clears the same way it did last week, at the same price. Canada’s retaliation is frozen on the same clock. That’s the whole reprieve — three days for lawyers to turn a Truth Social post into a signed document. If they don’t get there, the 50% is sitting exactly where it was, and Wednesday’s good mood goes away faster than it arrived.
JBizNews Desk | Wall Street
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.