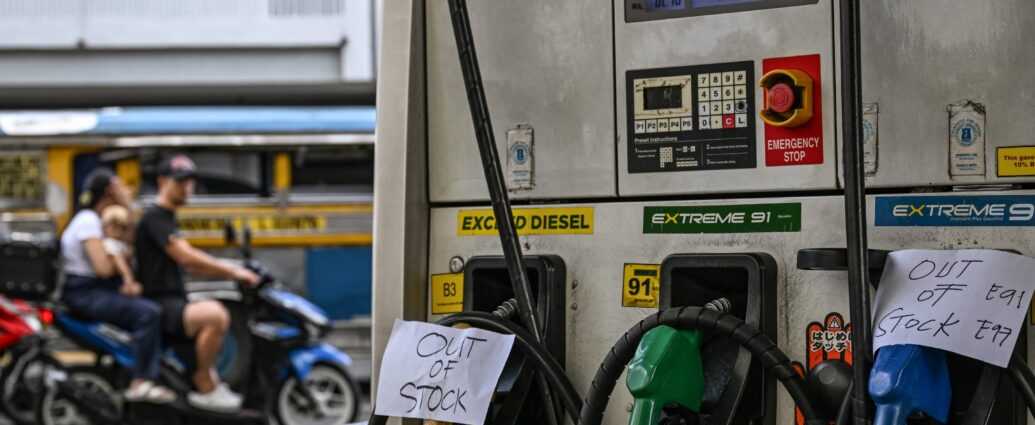
For Scott DeRue, the climb to the C-suite has mirrored the literal peaks he’s summited along the way.

As CEO of The Ironman Group, he oversees nearly 250 endurance events worldwide. But his career path has been anything but linear—spanning roles as a professor, dean of the University of Michigan’s Ross School of Business, and president of Equinox. He’s also climbed the Seven Summits, including Mount Everest and Kilimanjaro. The thread connecting it all hasn’t been a single industry or a straight-line path; it’s been intention.

“I have my family, The Ironman Group, and my passions of endurance sports and mountaineering,” DeRue told Fortune. “Every hour of every day is spent with one of those three things—and nothing else.”

That level of focus has shaped both his professional trajectory and personal ambitions. It dates back to when he was 13, unloading semi-trucks filled with upholstery fabric—an experience that taught him about hard work, paying taxes, and a lesson that would stick: no role has to be permanent.

But as he worked his way up, DeRue said success didn’t hinge on traditional networking—in fact, he believes the concept is often misunderstood.

“One of the terms that I think is most dangerous is the idea of ‘networking,’” the 48-year-old said. “Because it’s about relationships, not networking. You want to develop relationships built on mutual value and before you need them, and I think that’s an art that is lost on many.”

DeRue’s advice is simple: ditch the transactional mindset. 

Rather than treating connections as one-off exchanges—swapping business cards or adding someone on LinkedIn—he emphasizes consistent, genuine engagement. That may mean checking in regularly, sharing updates, and offering help without expecting anything in return.

It’s a philosophy rooted in advice he received early in his career: think of relationships like a bank account: “There are debits and credits,” he said. “You always want to have a positive balance.”

That message likely resonates with Gen Z, many of whom struggle with how to approach professional connections. About 38% of young workers say networking makes them anxious, according to a survey conducted by Strand Partners for LinkedIn, with many avoiding it altogether because they don’t know where to start. 

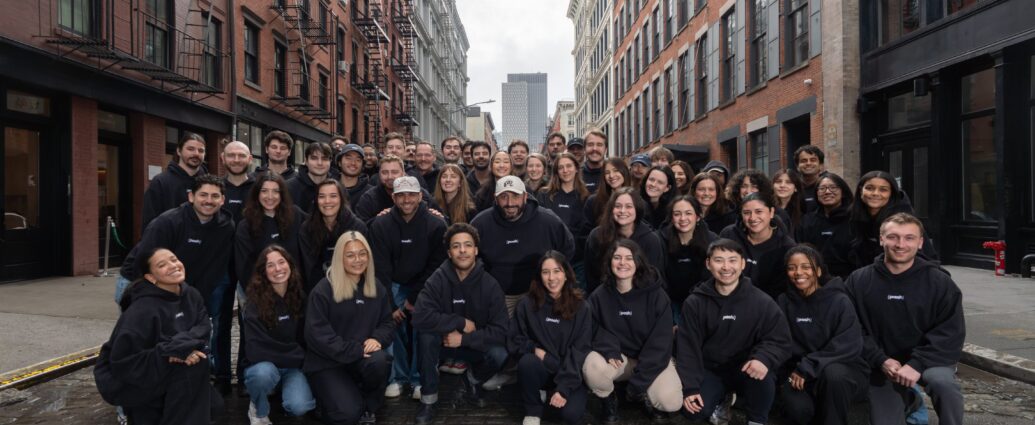
Today, DeRue oversees a workforce that swells to about 1,000 employees around the world during peak race season. Ironman—best known for its grueling triathlons—was purchased by Advance, the parent company of Condé Nast, in 2020 for an undisclosed amount. Prior to that, the company was sold in 2015 for $650 million.

Gen Z wants purpose in their careers. DeRue once took a whole month off work to try to find his

For Gen Z, a paycheck is increasingly not enough to feel satisfied in careers—purpose is a priority. More than half of Gen Zers and millennials say meaningful work is a key factor when evaluating employers, and 89% of Gen Z say purpose is critical to their job satisfaction and well-being, according to Deloitte’s 2025 Gen Z and Millennial Survey.

As entry-level roles grow more competitive, finding that balance can be challenging. And it’s a tension DeRue knows well.

After graduating from the University of North Carolina in 1999, he began his career at consulting firm Monitor Group (later acquired by Deloitte). While the role offered a strong start, it lacked the sense of direction he was searching for.

So, he took a month off to reflect and interview people in his life about their careers—until he identified what he calls his “North Star.”

“Since the age of 25, I’ve had one single through-line, North Star purpose: to create experiences for people that help them unlock their potential,” he said.

That clarity, he added, is what allows people to navigate uncertainty and build careers that feel meaningful over time. And looking back, even with his expansive resume, the biggest advice he would give himself is to “be bolder.”

And just as important is adopting what he calls a “no regrets” mindset.

“Even when things don’t work out, did you make a principled decision? Were you thoughtful about it?” DeRue said. “You can’t always control the outcome—but you can control how you approach it.”

This story was originally featured on Fortune.com
Young professionals are using ChatGPT to rehearse salary negotiations, deliver tough feedback, and navigate workplace conflict — before the conversations ever happen. From entry-level employees to mid-career managers, workers are turning to AI tools to prepare before stepping into their manager’s office.

Why This Generation Needs a Practice Gym

For a generation that came of age amid remote work, economic uncertainty, and rapid technological change, preparation feels less optional and more essential. Deloitte’s global survey of more than 23,000 workers found that Gen Z and millennials are intensely focused on growth and skill development as workplace expectations evolve, and another study showed that 56% of Gen Z workers use AI to help figure out how to communicate with a boss or colleague.

For many early-career professionals, the toughest part isn’t the content of the conversation—it’s the experience of having it. That’s not a character flaw; it’s the product of a world where fewer interactions require real-time conflict resolution, emotional regulation, or face-to-face persuasion. If you’ve spent years communicating through screens and asynchronous channels, the first time you have to deliver tough feedback or negotiate on the spot can feel like showing up to a championship match without a single practice rep.

How to Try It Right Now

For the first time, that kind of practice gym is within reach. Advances in large language models have dramatically lowered the cost of creating personalized, high-quality dialogue that lets employees rehearse difficult conversations on demand.

Here’s how to start: open ChatGPT and switch to voice mode. Give it context on an upcoming situation you’re anxious about, then ask it to simulate the conversation. Tell it to challenge your assumptions, interrupt you the way a stressed manager might, or push back hard on your reasoning.

It will feel awkward at first — like your first day back in the gym after a long layoff. That’s fine. Fluency comes from repetition.

  • Listen first, then reflect.Prompt ChatGPT to listen without interrupting, then summarize what you said in three key points. This exercise alone often brings unexpected clarity.
  • Roleplay the other person.Prompt: “Pretend you are [coworker X] and help me rehearse the conversation I need to have with them.”
  • Repeat until it feels natural. The first session will feel strange. By the third, it won’t. Consistency is the only requirement.

The Next Frontier: Team-Level Training

But individual practice is only the beginning. A new generation of AI-enabled corporate trainers can now bring this kind of preparation to entire teams.

These trainers will develop adaptable lessons geared to what an employee needs to know — not what they already know. They’ll surface the conversations employees didn’t know they needed to have, tailoring training for distinct roles and seniority levels.

This isn’t theoretical. Organizations like Skillwell — which I lead — are already demonstrating that EQ leadership skills are not innate traits Over the next decade, I expect the number of people practicing professional skills via AI-enabled simulation to expand by several orders of magnitude. The tools exist. The adoption curve is just beginning.

The Gym Is Open

Real-world experience remains the best teacher. But organizations no longer have to wait for high-stakes moments to arrive — and hope their people are ready. AI-powered simulation gives every worker a place to train, build fluency, and show up prepared when it matters most.

The practice gym is open. The only question is whether your organization will walk in.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

This year marks the 250th anniversary of the publication of The Wealth of Nations—the book that built the intellectual foundation of free-market capitalism. Smith’s argument was elegant: when individuals pursue their own interests within competitive markets—governed by rules and institutions—it leads to economic prosperity for the entire society, guided by what he called the “invisible hand” that steers resources toward broad prosperity. 

What Smith did not anticipate was that if leaders in government and owners of capital form a stealthy alliance to help one another, the invisible hand vanishes  and competition is replaced by the kind of massive monopolies or oligopolies that strangle  societal prosperity.

The Invisible Hand Has Left the Building

Over time, the belief that markets would self-correct and growth would eventually “lift all boats,” has lost credibility. We have more knowledge, wealth, and technological competence than any generation in history, yet the world faces multiple existential crises: widening inequality, erosion of democracy, ecological collapse, and a pervasive breakdown of trust in institutions. These are not isolated failures but the inevitable outcomes of a governance model that has prioritized profit above people and the planet, for too long. Capitalism, in its current form, has surrendered its moral authority. Barring a few exceptions, democracy has been  downgraded to function as government of the few, by the few, and for the few.

Yet this moment should not be seen only as a crisis. It may also mark the early stage of an epochal transition to a better state.

A Quiet Revolt Is Already Underway

Across the world, millions of progressive people—employees, consumers, youth and women—are increasingly unwilling to accept exclusion as destiny. Their impact is already visible. Consumers punish irresponsibility. Employees reject exploitation. Citizens demand transparency. Markets do not operate in a vacuum; they are embedded in societies. The era of unaccountable leadership may now be short-lived—not through revolution, but through obsolescence.

Enter Peopleism

What comes next will not be another ideology in the traditional sense, but a structural reordering of priorities—one that redefines the purpose of economic systems and institutions. This is where a new idea begins to take shape: Peopleism.

The premise is straightforward: systems exist to serve people—not the other way around. Economic and political institutions derive legitimacy only when they visibly advance human dignity, social inclusion, and planetary well-being. Capital remains indispensable, but it functions as a means rather than a master. Wisdom—not power or scale—becomes the defining leadership capability of the twenty-first century.

Every human enterprise—corporate or government—rests on three indispensable pillars: capital, people, and nature. To privilege one while degrading the others is a formula for systemic instability and long-term fragility.

Evolution, Not Revolution

Peopleism is not an outright rejection of capitalism. It is capitalism’s evolution—a leadership and governance upgrade, aligned with economic reality. It integrates ethics, ecology, and governance into a new operating model  that aims to deliver  “an economics that works for all.” It demands a leap from piecemeal fixes to structural transformation.

Peopleism accepts that owners of capital play an important entrepreneurial role. Many are worthy capitalists; who abide by the system—legally and ethically. They are a nation’s asset, key employment-generators, and the lifeline of the economy. But some big capitalists, in every nation, use the power of money to influence governments for their own benefit, and tacitly control media, regulators, and even the judiciary. It is these capitalists that most urgently need the leadership leap to Peopleism.

What It Looks Like in Practice

Think of Peopleism less as a moral doctrine and more as a survival strategy —one that empowers every entrepreneur and leader to scale new heights through wisdom, compassion, and accountability. It is about enabling every business leader to be a “peopleist”—to do well and do good while building an honorable legacy.

The Tata Group’s founder, Jamsetji Tata, put it plainly: “The community is not just another stakeholder in business, but, in fact, is the very purpose of its existence.”
Patagonia’s Yvon Chouinard went further: “We’re in business to save our home planet”, — and transferred 100% of the company’s voting stock to the Patagonia Purpose Trust, with planet Earth as its sole shareholder.

Such practices are not yet the norm, but they serve as precedents and ignite hope. History suggests that radical shifts are resisted by incumbents but accelerated by necessity. We now find ourselves at a collective watershed moment—a moment when history ceases to determine our future.

The Choice Ahead

The transition to a better world is not guaranteed. It has to be chosen. Peopleism is that choice—a leadership ethos for a world that no longer accepts irresponsible power. If the twentieth century belonged to capitalism, the twenty-first may well belong to an idea whose time has come: Peopleism.

What would it take for your industry to make that leap?

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com
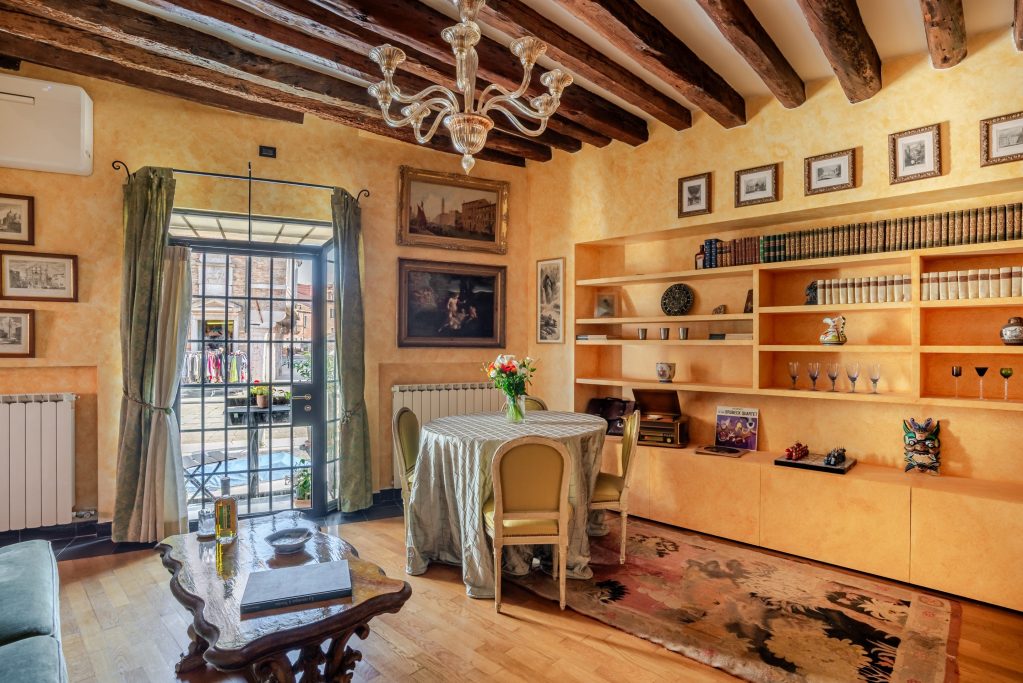
Every other month, one U.S. doctor trades rugged Appalachia for Venetian waterways to recharge from his hectic work life. And he’s part of a growing trend of American professionals looking for a change of pace in breezy European countries. 

Since December 2023, Dr. Alexander Gabrovsky has been splitting his time between his physician job in the U.S. and water-front villa in Italy. And it all started after stumbling across a listing for a porto d’acqua “water door” apartment in Venice; the one-bedroom, two-bath home accessible by boat overlooks a medieval church and local town square. Longing for a slice of tranquil Italian life, he put down an offer €60,000 ($69,000) below the asking price, and within a matter of months, the deal was closed at $438,000.

“It was definitely a spontaneous decision. It was an emotional decision,” Gabrovsky tells Fortune. The Italian city had been a fascination throughout most of his life, and thanks to his flexible job schedule, he finally decided to follow through. “Venice captured my imagination: the history, the art, the lifestyle.”

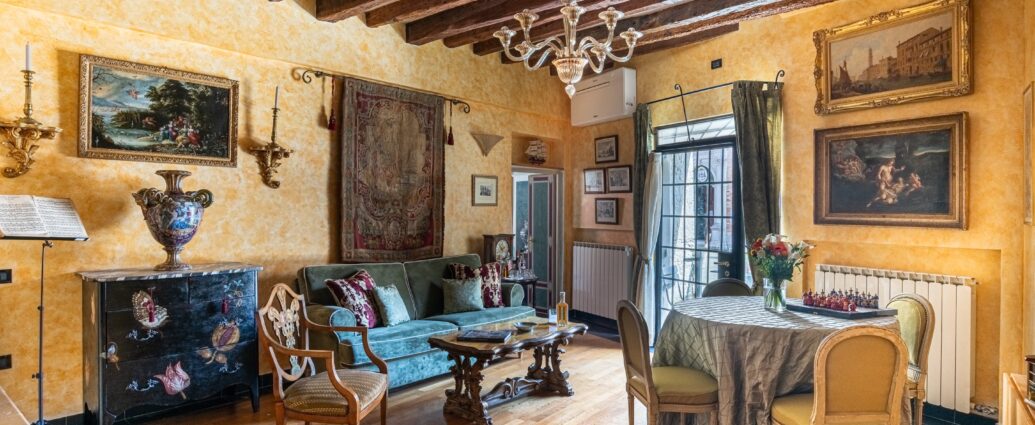
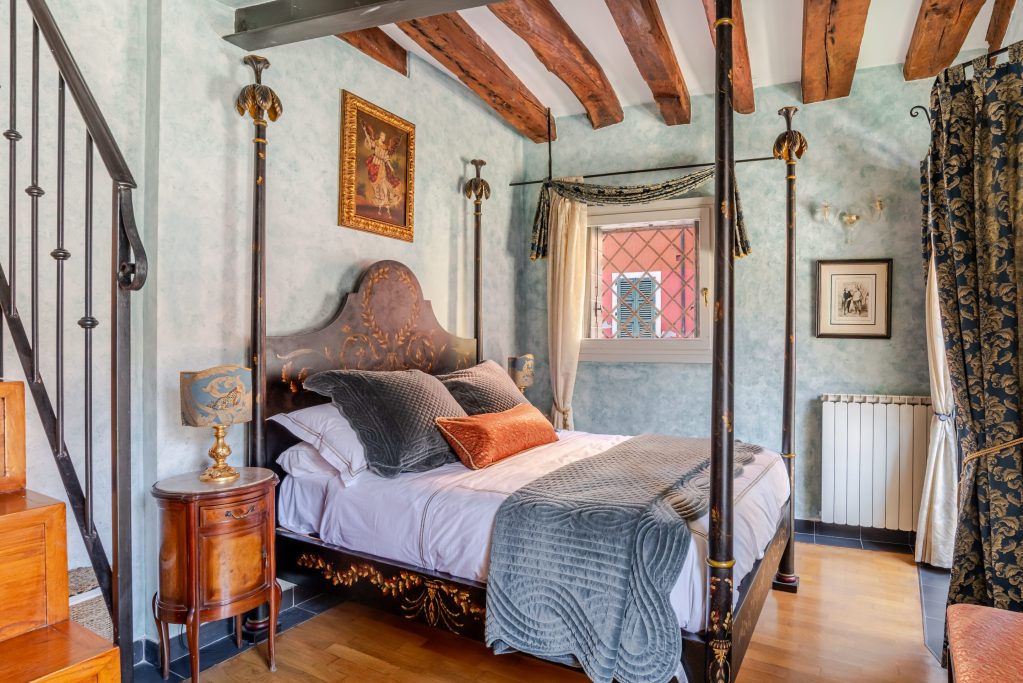
Alexander Gabrovsky's Venice apartment.

Alessandro Pietrosanti / www.alessandropietrosanti.co.uk

Living the dream for six months of the year also comes with some sacrifices. To make his cross-country living work while juggling an in-person job, the 42-year-old condenses his work schedule into intense multi-week clusters.

Gabrovsky says he’ll work 12-hour shifts for three weeks straight at his gig in Kentucky, then spend a month relaxing in Venice, then repeat the cycle. Normally, full-time hospitalists work seven days on, seven days off—but he says his plan is economical with travel costs, circumvents the 90-day tourist cap, and carves out enough meaningful time to unwind in Italy. 

“I can work in a way that allows me to travel right to Europe for an extended amount of time,” Gabrovsky explains. “While I’m [in Kentucky], it’s 12-hour shifts. There’s a little bit of social life, but you’re really just working and sleeping.”

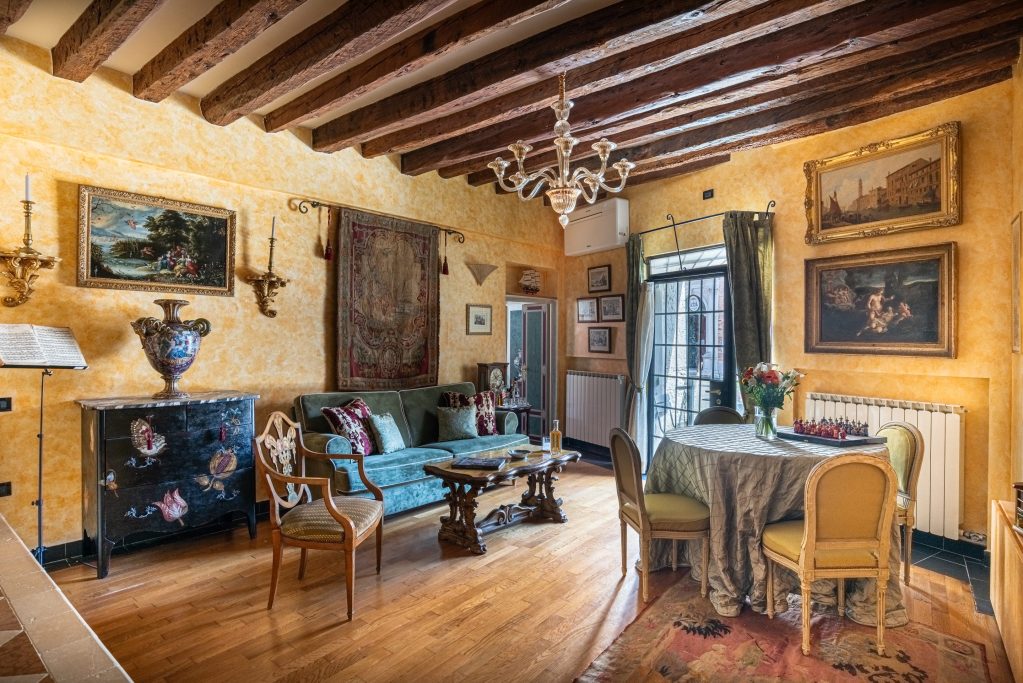
Alexander Gabrovsky's Venice apartment.

Alessandro Pietrosanti / www.alessandropietrosanti.co.uk

Buying the Venetian ‘water door’ apartment for $438,500 with all his savings—and making it work

When Gabrovsky was trawling the internet for a waterfront getaway, he found the perfect pad in Castello: representing the tail of the fish of Venice drawn out on a map. 

It was nestled at the crux of three canals, with two water door entrances that allow him to ride a boat right up into his living room. Luckily, buying the house was pretty straightforward: he leaned on some internet sleuthing, but help from the firm Italian Real Estate Lawyers sealed the deal.

The city also came with unique paperwork, like getting permission to moor his boat outside his apartment, but getting set up was a fairly painless process. 

Alexander Gabrovsky's Venice apartment.

Alessandro Pietrosanti / www.alessandropietrosanti.co.uk

“It was definitely daunting at first,” Gabrovsky recalls. “The lawyers that I used were very helpful—I obviously watched a lot of YouTube videos and educated myself as much as I could about it…The process was fairly smooth.”

Inside, the historic apartment was a fixer-upper, but the American was well prepared to bring the late medieval-era flat back to its former glory. In addition to having one bedroom and two bathrooms, the apartment features a kitchen, living room, loft, and two balconies. The building’s foundation is extremely old: its wooden beams and brickwork originated in the 14th century, with additional expansions made throughout the 18th and 19th centuries. 

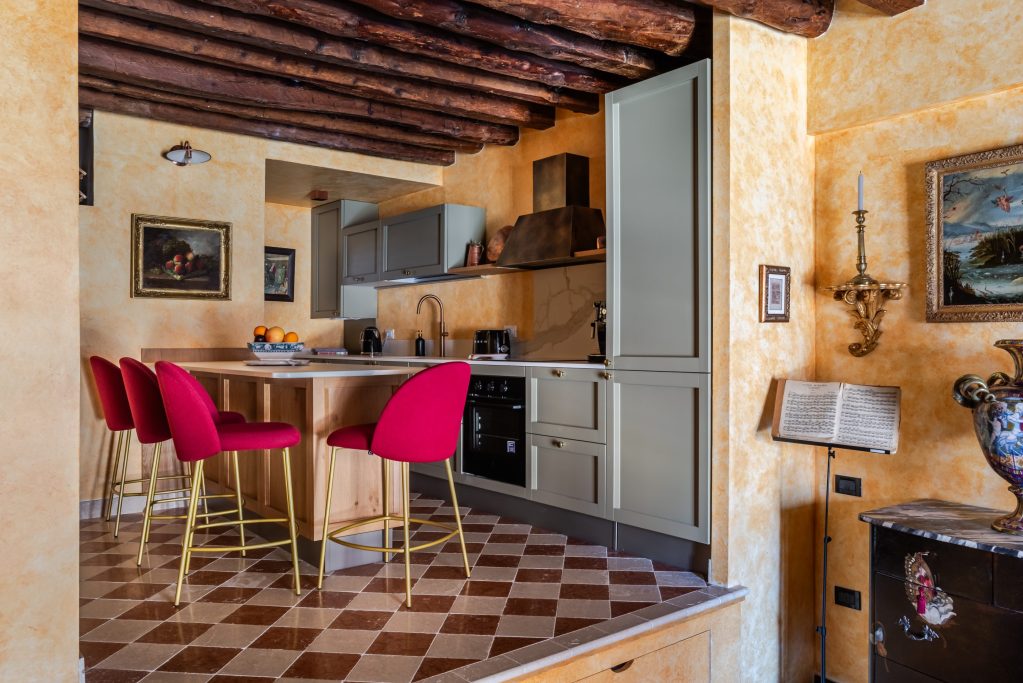
Living in a piece of history also came with a price; Gabrovsky bought the property for €380,000 ($438,500), which he says exhausted nearly all his savings at the time. However, the physician reasoned that it was still cheaper than buying a comparable property in the U.S., renovations included. He spent $16,000 installing a brand new kitchen, and another few grand restoring the water doors, but the revamp was relatively inexpensive. 

Alexander Gabrovsky's Venice apartment.

Alessandro Pietrosanti / www.alessandropietrosanti.co.uk

Gabrovsky deploys other financial hacks to ensure he can afford his transnational lifestyle. While he’s in rural Kentucky for his job assignments, he typically stays in hospital-provided accommodations, which greatly reduces his housing expenses.

Flying between the U.S. and Italy every month can also run up a big bill, but Gabrovsky keeps travel costs down. He only flies with carry-on luggage, avoids checked bag fees, and always looks to buy the best-priced plane tickets in advance.

The doctor leads a ‘rich’ life between the U.S. and Italy: lower costs, less stress, and slower living

By splitting his time between Kentucky and Venice, Gabrovsky says he isn’t just saving on living costs. The setup also lets the physician enjoy a culture-rich European city aligned with his academic background, having received a PhD in medical literature from the University of Cambridge in 2015. 

“Venice is a breathing, living museum,” Gabrovsky explains. “I like the contrast of the energy of the rugged mountains of Appalachia, to all of a sudden being in Italy and having a spritz and watching boats go by. Having that variety of experiences is very refreshing, and also helps me put different things in perspective, seeing how different people live. It makes life very rich.”

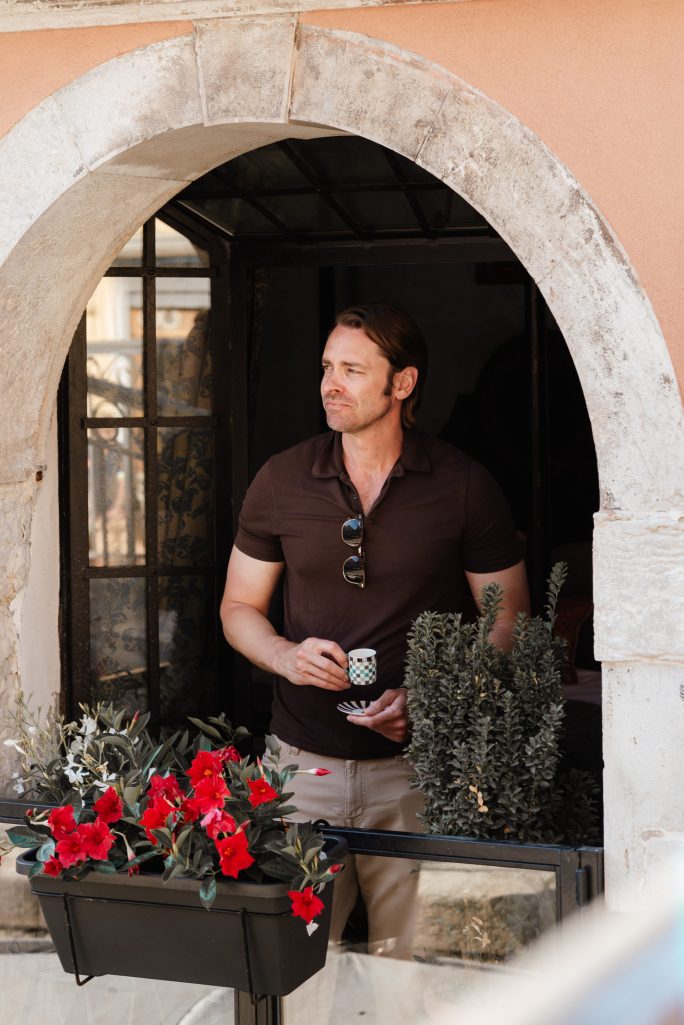
Alexander Gabrovsky inside his Venice apartment

Alessandro Pietrosanti / www.alessandropietrosanti.co.uk

Plus, Italy’s leisurely living is a good break from his intense work grind. Gabrovsky says it’s “therapeutic” to be in town; Venice’s beauty, calming waters, and car-free environment are natural destressors from the hustle and bustle of America. Touching down in the city, he’s immediately surrounded by beautiful buildings and the warmth of friendly Venetians, who invite him over for long dinners that go into the evening.

He gets the best of both worlds in Italy: being a part of an active and vibrant community, while living a slower pace of life. It helps reset his nervous system before delving back into weeks of 12-hour shifts. 

“Italy certainly helps me relax, because the pace in Venice and Italy in general is a lot slower, especially in a historic city like Venice,” the physician says. “Learning to slow down and appreciate, having to walk everywhere and not get in your car, but instead take my boat out into the lagoon and go rowing…It does help de-stress.”

Living between two countries is a dream for many Americans, but taking the leap can be very daunting. There are many things to consider, from country caps on tourists staying without a visa, to the different real estate laws in purchasing property as a foreigner. But Gabrovsky says it’s well worth it for disillusioned Americans to try and bring their dual-living fantasies to life. 

“Americans who are thinking about either moving abroad and doing a digital nomad visa, or splitting their life between the U.S. and somewhere else abroad, if you feel a strong passion for it, then go for it,” he advises.

This story was originally featured on Fortune.com
Mark Cuban is notoriously bold in his deal-making. But even by his standards, dropping millions of dollars on a mansion he’s never set foot in is a move that could raise eyebrows.

The billionaire entrepreneur and former Shark Tank star revealed he snagged a $25 million estate at a jaw-dropping 50% discount, a deal he says exemplifies one of his core investing principles.

Cuban reflected on the purchase in a 2022 interview with GQ. During his days at MicroSolutions (the company he ultimately sold for $6 million in 1990), his partner, Martin Woodall, told him about an “amazing house” going into foreclosure. It was a home the owner had spent three years building and a “dream home” to the original owner’s wife and whole family, Cuban said. 

But unfortunately, the owner was forced to sell the home when the stock market crashed, and he lost everything. So, Cuban, who’s currently worth about $9 billion, bought the 24,000-square-foot mansion in Dallas sight unseen, calling it his one “why the f–k not purchase.” He still resides there, and Zillow estimates show it’s currently worth $22 million.

“I’d never seen the house. I saw some pictures. I’d never been there. I was like, F–k yeah. I’m a billionaire,” Cuban said. Essentially, the idea is that buying a home at a discount doesn’t inherently change its value. So when Cuban eventually goes to sell the home someday, he’ll make a pretty penny—at least about $10 million based on the current estimated value of the home (although it could be closer to $28 million, according to the Zillow estimate range).

Buying at a steep discount is “the best guaranteed return on investment” you can make, Cuban said, a methodology he uses for most of his purchases. 

“Saving 30% to 50% buying in bulk—replenishable items from toothpaste to soup, or whatever I use a lot of—is the best guaranteed return on investment you can get anywhere,” Cuban said in a 2010 Forbes interview. The mansion was the same principle, just on a much larger scale.

The former Dallas Mavericks owner also used the home purchase example as a cautionary tale about never taking wealth for granted. He also outlined his four-rule framework for becoming a millionaire, which includes mastering a skill, learning to sell, staying curious, and keeping learning—then start a company once you have those foundations.

“You have to know how to sell,” Cuban said. “You don’t want to be in a position where you’re dependent on other people.”

Billionaires approach finances differently

Cuban’s purchase is a window into how the ultra-wealthy think about real estate differently from average Americans, who would likely think it’s insane to purchase a home they’ve never actually seen in person.

Where most buyers shop for a home, Cuban shopped for a better financial position. The mansion is less a lifestyle acquisition (that was just a bonus for him) than an asset with favorable entry terms. Some billionaires, who would presumably be able to purchase a home outright, will also take out mortgages as a more savvy financial decision. It’s because most of the wealth held by ultra-high-net-worth people is tied up in investments, stocks, and bonds, and they don’t keep as much cash on hand.

“Ultra-high net worth individuals think differently about liquidity and leverage,” Miltiadis Kastanis, executive director of sales at Compass, previously told Fortune. “They’d rather keep their money working for them in investments, businesses—or even art—rather than tying it all up in one property.”

For Cuban, the purchase also signals continued confidence in hard assets at a moment when even some of the world’s most sophisticated investors are questioning where to park capital. Real estate offers something that stocks and crypto don’t always promise: a floor built into the purchase price itself.

Still, it’s important for the average American to make financial decisions that work for them, too.

“The takeaway for the average buyer isn’t to mimic [billionaires’] precise approach, but to understand the principle,” Evan Harlow, real estate agent at Maui Elite Property, previously told Fortune. “Sometimes the smartest financial move isn’t paying everything off, but keeping your money flexible and working for you.”

This story was originally featured on Fortune.com
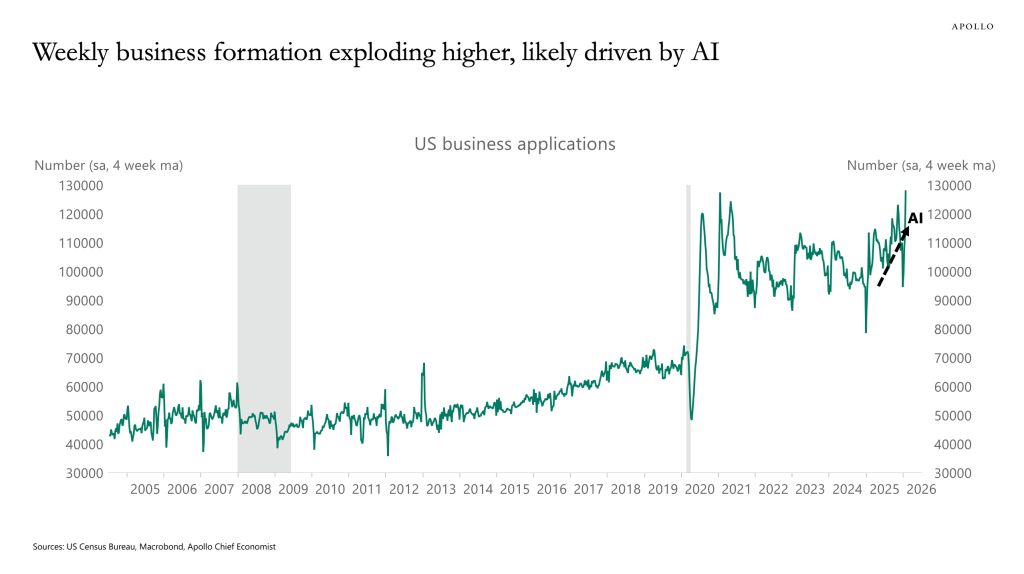
The startup era is back, but this time founders are using AI to avoid one of their biggest early costs—hiring employees. 

A report this week by the Bank of America Institute found the number of “high propensity businesses,” or businesses the Census Bureau identifies as likely to hire employees, jumped by 15.1% year over year in January. Meanwhile, the number of business applications with explicit plans to hire employees fell by 4.4%.

The trend comes amid the record-high investment small companies are making on tech services, which includes AI, according to the Bank of America analysts, who said spending jumped 14% year over year last month. 

“This might be linked to a productivity push,” the report said.

Among small businesses, retail led the charge in tech spending last month with a gain of more than 25% followed closely by manufacturers, BofA added.

Small businesses, usually defined as a company with fewer than 500 workers, employ about 45% of Americans, and a major drop in hiring among this group of companies could hit the labor market hard.

Following the Federal Reserve’s decision to keep rates unchanged this week, Chairman Jerome Powell said private sector hiring had stalled. In February, employers cut 92,000 positions and the unemployment rate stood at 4.4%. 

“Effectively, there’s zero net job creation in the private sector,” Powell added in a press conference this week.

Larger companies are also increasingly leveraging AI to try to do more with less. The latest evidence: fintech firm Block’s decision last month to lay off around half of its workforce, with CEO Jack Dorsey citing intelligence tools that are “enabling a new way of working which fundamentally changes what it means to build and run a company.”

Some have said Block’s move constituted “AI washing” and that the layoffs last month were actually meant to correct over-hiring during the pandemic. Block’s chief financial officer and chief operations officer, Amrita Ahuja, told Fortune earlier this month this was not the case.

Meanwhile, AI has been cited in around 8% of all job cut announcements in 2026, or about 12,304 announcements, according to a study by executive outplacement firm Challenger, Gray & Christmas. 

To be sure, Apollo Chief Economist Torsten Slok predicted the skyrocketing number of companies being created will be a boon for the labor market overall. 

“As these firms scale, they will create jobs, underscoring that AI is likely to strengthen, not disrupt, the US labor market,” he wrote in a note earlier this month. 

Replacing engineers

Others, such as Andy Tang, a partner at Silicon Valley venture capital firm Draper Associates, aren’t so sure. On average, the startups he talked to last month are reducing their engineering teams by a third, he told Fortune, revealing just how beneficial AI tools are to early-stage founders.

Often, these startups are finding that putting money into AI tokens is a better investment than increasing headcount by producing three to five times the code for a nominal cost.

“If you do the math, you don’t need nearly as many engineers” he said, adding that most knowledge work is easy to replace. 

In the future, AI tools may even enable solo entrepreneurs to cut their staff entirely, and instead create an army of agents who then go on to create their own “founderless unicorn companies,” according to Tang. 

The new playbook

The idea of using AI tools to scale rapidly has quickly caught on with a new generation of young, tech-savvy entrepreneurs.

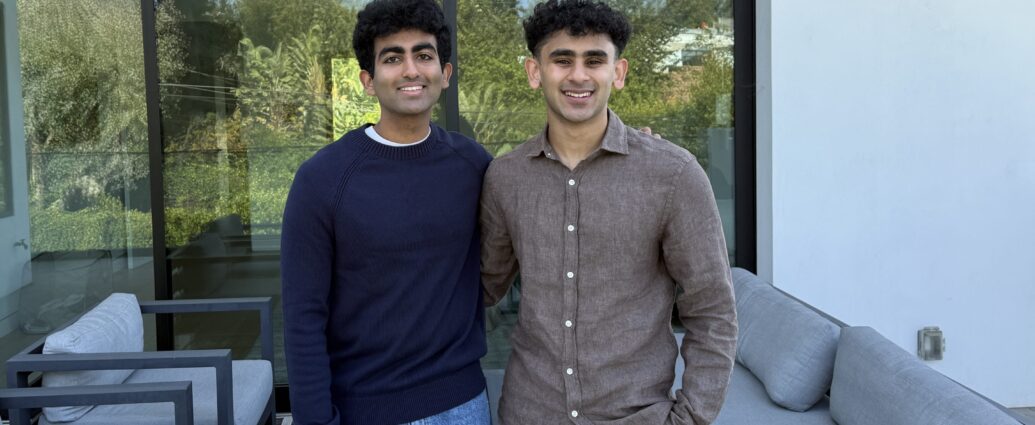
Two years ago, Rudy Arora and Sarthak Dhawan started TurboAI, an AI-powered tool that converts lecture notes into flashcards and quizzes, with an initial investment of less than $300 while still college students at Northwestern University and Duke University, respectively. 

In the past two years, the now 21-year-old childhood friends have been able to grow their company to 8.5 million users and are generating about $1 million per month with only 13 employees, partly because of AI, the pair told Fortune. And despite raising $750,000 in a funding round two years ago, Arora said they have preferred not to spend it because they are profitable.

“If we were a company two-and-a-half years ago, it would take over 100 employees,” Arora said. “The only reason we’re able to do it with 13 employees right now is because of AI.”

What used to require a product manager and five engineers can now be handled by a single technical employee armed with AI agents, he added. 

Arora’s cofounder Dhawan added that he believes startups are only just discovering how AI can supercharge their businesses. Still, technology is already changing how entrepreneurs function. During the post-2008 startup boom more than a decade ago, creating a company often required experienced programmers and venture capital money, said Dhawan. Yet, the cofounders’ experience building TurboAI proves this isn’t necessarily the case anymore. 

“We’re going to see people even younger than ourselves, building companies with even less resources,” Dhawan said.

This story was originally featured on Fortune.com
In a K-shaped economy defined by a stark divide in household income and spending, there are sure to be winners and losers—but even those considered “rich” are feeling the clinch. Some six-figure earners are “on thin ice” thanks to potential headwinds and a shakier financial footing, according to a recent analysis from consulting firm Kearney.

The wealthy who are at financial risk are “high earners whose lack of budgeting and profligate spending has them overleveraged and exposed,” the report explained. “While they appear to be doing well from the outside, they are only a step away from real financial trouble.”

The top arm of the “K” in the economic model represents the top 20% of high-income households—but nearly half of them could be walking on eggshells, according to the report. Those making $160,000 to $700,000 are divided into two financial groups, with the lower end of the proportion deemed to be “on thin ice” due to their debt and exposure to financial swings.

But there is no defined ceiling as to where the six-figure “on thin ice” crowd enter the “stable/responsible” group, as their financial standing depends on several variables, including where they live in the country.

“There is not a specific number where those two groups split because it actually depends on other factors we cover (such as cost of living area),” Katie Thomas, the report’s author and leader of the the Kearney Consumer Institute (KCI), explains to Fortune. “For instance, making $250,000 is different in San Francisco vs. Pittsburgh, which is why we decided not to make a hard cutoff between the two groups.” 

These wealthy consumers are vulnerable to housing costs, debt and interest rates, and the job market. Six-figure earners “on thin ice” are also highly exposed to stock market swings and lifestyle creep, as keeping up appearances has become more costly.

Meanwhile the 1% of households who are “secure elites,” earning more than $700,000 a year, are sitting “comfortable” in the K-shaped economy. Potential risks like the stock market, AI bubble exposure, and interest rates have little impact on their solid financial standing.

Macroeconomic risks put some six-figure elite more at risk than lower earners

CEOs and Wall Street analysts alike are all talking about the “K shaped economy”: a buzzword describing the growing disparity between the haves and have-nots. The upper part of the K represents higher-income Americans—who see their salaries and wealth rise—while the bottom part refers to lower-income households battling against weaker income gains and steep prices.

However, depending on their susceptibility to financial threats, some six-figure breadwinners are actually more at risk than lower-income earners, according to the Kearney report. 

The 20% of consumers making between $95,000 and $160,000 actually rest in the “comfortable” group at the bottom leg of the K-shaped economy. Similarly to the wealthy “on thin ice,” their biggest risks are job market, lifestyle creep, and interest rates, but the exposure is less severe. 

The report explains that technically these “comfortable” earners are in the bottom of the “K”—which looks to be a worse spot to be in—but their overall financial position is “more secure on a day-to-day, year-to-year basis thanks to a variety of factors.” They’re only mildly exposed to many of the current macroeconomic factors troubling higher-income earners like housing costs, debt, and labor market whims. They may bring home a lower income, but they have more buffers and financial assets to weather the storm. 

“Consumers in the arm of the K ‘on thin ice’ group may be highly exposed to housing and interest costs or stock market dips,” the report noted. Meanwhile, “Those in the leg of the K ‘comfortable’ group are less at risk, despite being on the seemingly unfavorable side.”

Six-figure earners are struggling to keep up with costs—and appearances 

Six-figure salaries may conjure fantasies of a high-flying lifestyle, but in actuality, many Americans find their high incomes aren’t cutting it. 

Instead of balling out on luxuries, around 64% of Americans earning $200,000 or more said they’ve used rewards points to pay for essentials, 50% used “buy now, pay later” for purchases under $100, and 46% relied on credit cards to scrape by, according to a 2025 survey from the Harris Poll. It’s become costly to live a luxe lifestyle.

“Our data shows that even high earners are financially anxious—they’re living the illusion of affluence while privately juggling credit cards, debt, and survival strategies,” Libby Rodney, chief strategy officer and futurist for the Harris Poll, said in a statement last year.

Even the 1% is feeling financial strain. About 41% of American workers earning between $300,001 and $500,000—and 40% of those making over $500,000—say they’re living paycheck to paycheck, according to a 2025 report from Goldman Sachs. And ironically, the financial outlook gets better going down the income spectrum; 16% of workers bringing home $200,001 and $300,000, 25% making $100,001 to $200,000 annually, and 36% earning $50,001 to $100,000 were struggling to make ends meet.

The paradox highlights the “impact of lifestyle creep, the phenomenon of luxuries becoming necessities to certain income cohorts,” according to the Goldman report. Six-figure workers reeling in half a million-dollar salaries are struggling to keep up with the joneses.

“Financial strain is not confined to low-income workers,” the 2025 study revealed. “A meaningful share of higher earners also report living paycheck to paycheck or making only limited progress toward long-term financial goals, underscoring that elevated expenses, debt burdens, and lifestyle inflation can erode savings capacity across the income spectrum.”

This story was originally featured on Fortune.com
In January, the White House celebrated what they claimed to be the “largest tax refund season in U.S. history,” promising hundreds of dollars more in refunds this tax year as a result of changes to the tax code, thanks to the One Big Beautiful Bill Act (OBBBA).

But economists warn those savings could go up in smoke—or rather exhaust, cancelled out completely by elevated gas prices as a result of the ongoing war in Iran. 

An analysis led by economists at the Stanford Institute for Economic Policy Research found that should the Strait of Hormuz remain closed for another three weeks and oil top out at $110 per barrel in March, gas would peak at $4.36 per gallon in May. As a result, the report found Americans would be paying on average $740 more for gas this year. The economists noted that extra spend would cancel out the $748 more in tax refunds projected for a typical household, according to the Tax Foundation. 

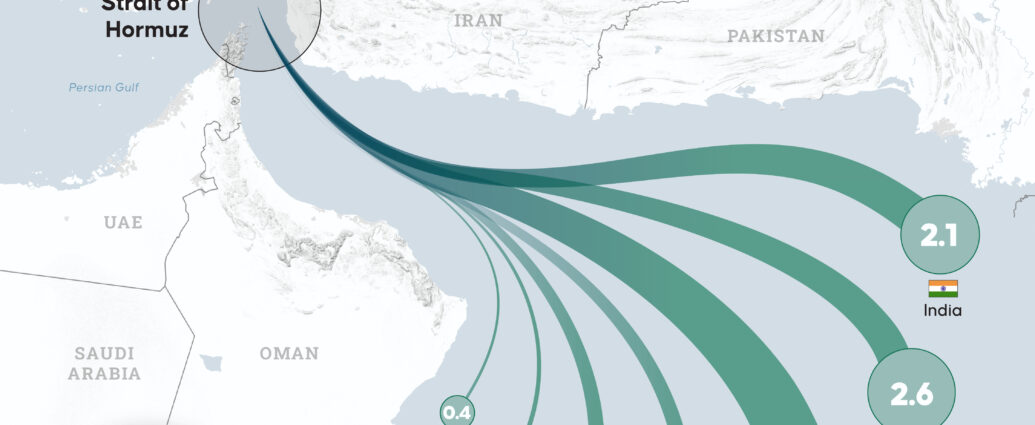
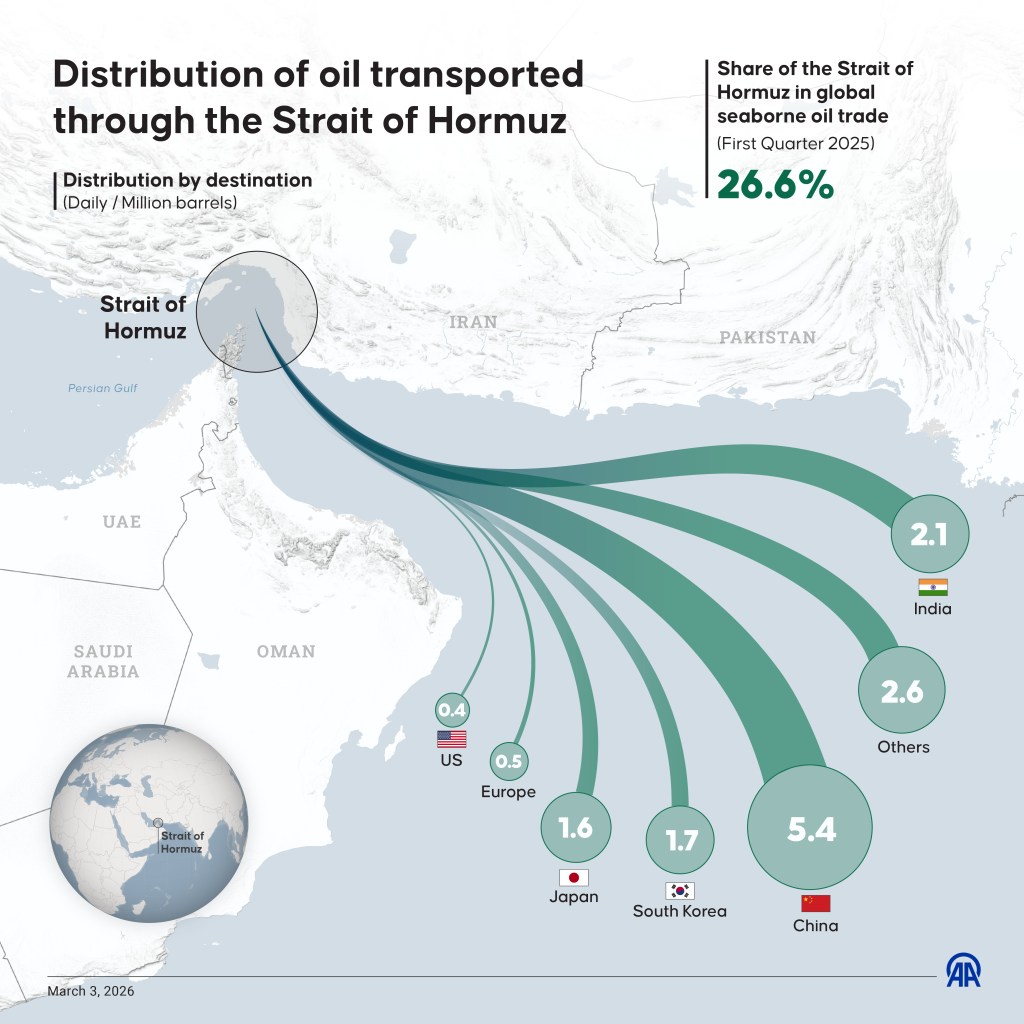
Gas prices have surged more than 90 cents since Feb. 28, to $3.91 per gallon, when President Donald Trump initiated a major military operation against Iran, in a joint effort with Israeli forces. The ongoing strikes and counterattacks have resulted in the effective closure of the Strait of Hormuz, the chokepoint through which more than 20% of the world’s oil supply is exported. 

With oil prices hovering near $100 per barrel—and spiking above $115 this week—gas prices have subsequently reached their highest levels since 2023.  But even if the conflict ends in a matter of weeks, Americans are still likely to feel pain at the pump.

In a note to clients, Oxford Economics analysts similarly calculated that consumers would spend $60 billion more on gas in 2026, should gas prices average out to $3.60 per gallon, “almost exactly offsetting the boost from refunds.”

These elevated gas prices are likely to impact lower- and middle-income consumers the most, exacerbating a K-shaped economy of wealthier Americans increasing consumer spend and lower-income households struggling to make ends meet. The bottom 80% of earners spend close to 4% of their budget on gas—nearly twice as much as their higher-income counterparts, Oxford analysts wrote. 

Moreover, the tax cuts outlined in OBBBA, such as for overtime and state and local taxes, will likely benefit middle- and upper-class Americans more, “deepening the bifurcation of the consumer that we’ve seen over the past several years,” the note said. As the Act stands now, the IRS estimates refunds on average $360 greater than last year.

Why gas prices are likely to remain stubbornly high

Oil and gas prices are poised to remain elevated until at least the end of the year. The Energy Information Administration (EIA), a semi-independent agency under the purview of the Department of Energy, projected that as things stand now, gas prices will average out at $3.34 this year and $3.18 in 2027. Goldman Sachs analysts likewise suggested oil prices could remain above $100 per barrel through 2027 if supply chain disruptions continue.

Even if the Strait of Hormuz were to reopen, it would take time for global oil supply to rebalance. The closure of the trade passage has resulted in a backlog of oil tankers, and directing the vessels through the waterway could take weeks to resolve. Oil production in the Gulf may also be hampered by infrastructure damage as a result of strikes.

The Trump Administration has made efforts to bring down soaring gas prices, like on Wednesday, when the White House temporarily suspending the Jones Act: a federal law created in 1920 aimed to regulate domestic maritime shipping and trade. It prohibits foreign-flagged ships from transporting goods between U.S. ports. By suspending the law, the Trump Administration aims to ease supply disruptions driving up the price of oil, hoping that by opening up domestic routes to those foreign vessels, it will reduce shipping costs and speed up deliveries.

Policy experts aren’t sure the decision will make much of a difference in gas prices. The Center for American Progress estimated suspending the Jones Act would lower gas prices by three cents per gallon.

Bloomberg reported Vice President JD Vance will meet with oil executives to address soaring oil prices.

“We know they’re up, and we know that people are hurting because of it,” Vance said at an event in Michigan this week. “And we’re doing everything that we can to ensure that they stay lower.”

This story was originally featured on Fortune.com
Finance chief Dan Durn is turning Adobe’s finance organization into an early proving ground for agentic AI—using autonomous software agents to forecast results, scan contracts, and even answer hundreds of thousands of emails.

The push mirrors Adobe’s broader strategy around agentic AI. For customers, the company lets them choose models, combine them with their own data and Adobe’s, and point agents at specific business outcomes.

Internally, Durn, who is also in charge of technology, security and operations, has taken a similar approach to finance: pairing a rules-based, data-heavy function with AI, within a structure where finance, IT, and security report to one leader so pilots can move to production quickly. “Accuracy is non-negotiable,” he adds; that’s why Adobe is investing in structured data and governance so it can move fast without sacrificing precision, he says. 

The rise of AI is rapidly reshaping corporate leadership, accelerating turnover and elevating executives who can deliver fast, tangible results. Even long-tenured leaders face increasing pressure from investors to move aggressively on AI. Recent leadership changes, including the announced retirement of Adobe CEO Shantanu Narayen, highlight how little patience markets now have for perceived hesitation. At the same time, Adobe reported that annualized revenue from its AI-first products more than tripled year over year in its first quarter of fiscal 2026, which ended Feb. 27. Across Fortune 500 companies, this dynamic is creating a new internal proving ground where executives are judged by how effectively, and how quickly, they deploy AI to drive growth, efficiency, and innovation.

Using AI in finance

Inside finance, Durn groups AI use into three buckets: forecasting, anomaly detection, and general productivity.

For forecasting, AI uncovers patterns and signals in data that would be difficult for humans to detect quickly, he explains. Anomaly-detection agents flag performance that’s unexpectedly strong or weak—“things that can get lost in the sea of data”—so finance can intervene faster, he says.

However, Durn says the best examples now sit in productivity, citing three use cases:

1. Extracting information from PDFs

One of the most developed use cases involves “containers” of information—collections of PDFs such as investor transcripts, quarterly reports, and analyst research. Finance teams use Adobe’s PDF Spaces to load documents into a shared digital workspace and use an agentic AI assistant to surface themes, insights, and messaging cues in minutes rather than hours.

A recent Forrester TEI study found Acrobat’s agentic AI Assistant increases efficiencies in document summarization and analysis by 45%. Durn says that matters because “the world’s information lives in PDF,” and AI that turns static content into insights that can be used.

2. Cutting contract review time in half

Adobe is also using agentic AI to overhaul contract reviews across finance and procurement functions including revenue assurance, contract operations, product fulfillment, and vendor management. Instead of finance professionals combing through every clause, an AI assistant scans thousands of contracts, highlights provisions relevant to each function, and flags non-standard terms.

The system has cut review time roughly in half, speeding individual reviews and allowing teams to query the entire contract repository—for example, identifying which contracts include auto-cancellation features or foreign-exchange adjustment windows, Durn says. Adobe built its first prototype by April 2024 and began onboarding teams in January 2025.

3. Automating “common” inboxes

A third area is the “common inboxes” that handle high-volume internal and external email—shared addresses for sales, treasury, finance, and supplier questions. Adobe deployed an agentic AI assistant that auto-tags, prioritizes, routes, and, when criteria are met, auto-responds to emails. Typical queries include supplier billing issues or standard credit-quality questions coming into the treasury from Salesforce.

“In 2025 alone, the system auto-responded to about 300,000 emails across 19 inboxes, saving more than 5,000 hours of manual work and freeing teams to focus on more complex issues,” he says. The tool took about six months to build; beta teams began using it around August 2024, with full rollout in January 2025.

The payoff, he stresses, isn’t headcount cuts but the ability to scale more efficiently as Adobe grows.

Grassroots ideas, decade-long build

Durn traces these finance use cases to Adobe’s long AI journey and a bottom-up idea pipeline. The company has invested in machine learning and AI for more than a decade, initially to understand customer usage patterns and embed intelligence into products—work that laid the groundwork for generative and agentic AI.

Many of the best applications come from “reaching down into the organization” and asking employees where AI could remove friction or make their jobs easier, he says. There are more ideas than capacity, so the team prioritizes those with the greatest impact.

When deciding whether to green-light AI investments, Durn focuses on organizational velocity—the ability of back-office functions to keep pace with faster product innovation. If finance doesn’t adopt AI, he argues, it risks becoming a “rate limiter of growth.”

The actual spend is modest, he adds; much of the work involves change management and process redesign layered onto Adobe’s technology.

Durn’s perspective on change management coincides with new research from McKinsey. To capture the full value of AI, organizations need to go beyond “a piecemeal approach and push for a double transformation—both technical and organizational—that includes reimagining how work gets done across functions and workflows,” according to the report. While 88% of organizations surveyed are now experimenting with AI, fewer than 20% report tangible bottom-line results,, the research finds.

How AI is changing his own job

For his own workflow, Durn relies on AI primarily for insight generation. Ahead of earnings, his team loads pre-earnings research reports, Adobe filings, and peer transcripts into an AI-powered workspace to surface themes and likely investor questions.

Scripts and Q&A preparation are then run through models with guardrails to test whether messaging addresses those themes and to ask, “If I were an investor, what are my key takeaways?”

He sees it as a useful check on clarity and consistency—using AI to validate instincts and sharpen how Adobe communicates with the market.

This story was originally featured on Fortune.com
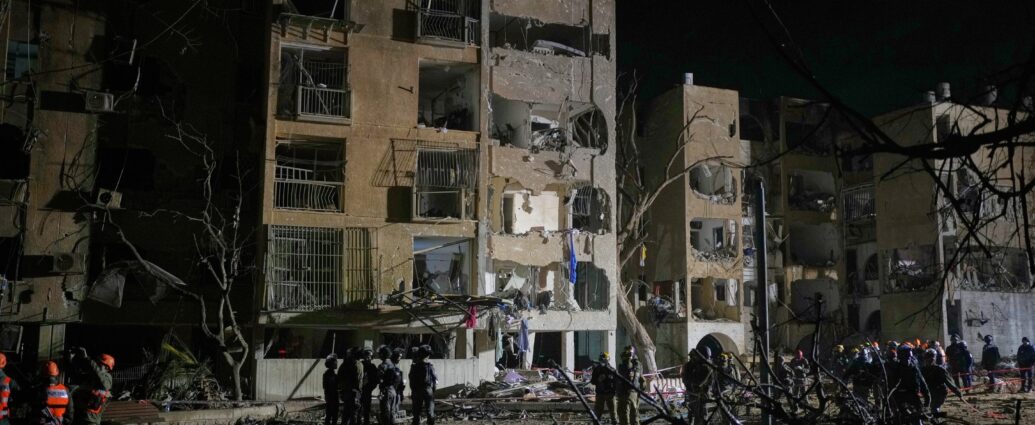
Iran struck two communities near Israel’s main nuclear research center late Saturday, leaving buildings shattered and at least seven people seriously injured, hours after Tehran’s main nuclear enrichment site was hit as the war spun into a dangerous new direction at the start of its fourth week.

It was the first time Israel’s nuclear research center has been targeted in the fighting. Israel’s military said it was not able to intercept missiles that hit the southern cities of Dimona and Arad, the largest near the center in Israel’s sparsely populated Negev desert.

“This is a very difficult evening,” Prime Minister Benjamin Netanyahu said, adding that more emergency resources were being sent to the scene.

“The war is not close to ending,” Israel’s army chief, Gen. Eyal Zamir, said earlier in the day.

Iran also targeted the joint U.K.-U.S. Diego Garcia military base in the Indian Ocean about 2,500 miles (4,000 kilometers) away, suggesting that Tehran has missiles that can go farther than previously acknowledged — or that it had used its space program for an improvised launch.

The U.S. and Israel have offered shifting rationales for the war, from hoping to foment an uprising that topples Iran’s leadership to eliminating its nuclear and missile programs and its support for armed proxies. There have been no signs of an uprising, while internet restrictions limit information from Iran.

The war’s effects are felt far beyond the Middle East, raising food and fuel prices.

It is not clear how much damage Iran has sustained in the U.S. and Israeli strikes that began Feb. 28 — or even who is truly in charge. Supreme Leader Ayatollah Mojtaba Khamenei has not been seen in public since being named to the role.

Israel had denied responsibility for attack on Natanz

Footage from Israel’s emergency service showed a large crater next to what appeared to be apartment buildings with outer walls sheared away. The missile appeared to have struck an open area.

Rescue workers said the direct hit in Arad caused widespread damage across at least 10 apartment buildings, three of them badly damaged and in danger of collapsing. At least 64 people were taken to hospitals.

Dimona is about 20 kilometers (12 miles) west of the nuclear research center and Arad around 35 kilometers (21 miles) north.

Israel is believed to be the only Middle East nation with nuclear weapons, though its leaders refuse to confirm or deny their existence. The U.N. nuclear watchdog said on X it had not received reports of damage to the Israeli center or abnormal radiation levels.

“If the Israeli regime is unable to intercept missiles in the heavily protected Dimona area, it is, operationally, a sign of entering a new phase of the battle,” Iran’s Parliament Speaker Mohammad Bagher Ghalibaf said on X before word of the Arad strike spread.

Israel earlier Saturday denied responsibility for the strike on the Natanz nuclear facility, nearly 220 kilometers (135 miles) southeast of Tehran. The Iranian judiciary’s official news agency, Mizan, said there was no leakage.

The International Atomic Energy Agency has said the bulk of Iran’s estimated 970 pounds (440 kilograms) of enriched uranium is elsewhere, beneath the rubble at its Isfahan facility. It said on X it was looking into the strike.

The Pentagon declined to comment on the strike on Natanz, which was also hit in the first week of the war and in the 12-day war last June. Russian Foreign Ministry spokesperson Maria Zakharova said such strikes posed a “real risk of catastrophic disaster throughout the Middle East.”

Iran retaliated hours later.

US can use Diego Garcia base to protect Strait of Hormuz

U.K. officials did not give details of the strike that targeted the Diego Garcia base Friday, which was unsuccessful. Britain’s Ministry of Defense described Iran as “lashing out across the region.”

It’s unclear how close the missiles came to the island. Iran previously asserted that it has limited its missile range to below 2,000 kilometers (over 1,200 miles).

But military experts said Iran may have used its space launch vehicle for an improvised firing. “If you’ve got a space program, you’ve got a ballistic missile program,” said Steve Prest, a retired Royal Navy commodore.

Israel’s army chief, however, said Iran had fired “a two-stage intercontinental ballistic missile.” There was no statement from Iran.

Britain has not participated in U.S.-Israeli attacks but has allowed U.S. bombers to use its bases to attack Iran’s missile sites. On Friday, the U.K. government said bombers could use Diego Garcia to attack sites used to target ships in the Strait of Hormuz.

Global pressure increases to get shipping back on track

As Iran threatens shipping on the Strait of Hormuz, the United Arab Emirates joined 21 other countries including the U.K., Germany, France and Japan in expressing “readiness to contribute to appropriate efforts to ensure safe passage.”

The Trump administration announced it was temporarily lifting sanctions on Iranian oil that was already loaded on ships as of Friday, but that does not increase oil production, a central factor in surging prices. The oil ministry of Iran, which has evaded sanctions for years, replied that it “essentially has no crude oil left in floating storage.”

The head of U.S. Central Command, Adm. Brad Cooper, asserted that Iran’s ability to attack vessels on the strait had been “degraded.” He said 5,000-pound (2,270-kilogram) bombs were dropped earlier in the week on an underground facility along Iran’s coast used to store anti-ship cruise missiles and mobile missile launchers.

The U.S. is deploying three more amphibious assault ships and roughly 2,500 additional Marines to the Middle East, an official told The Associated Press. Two other U.S. officials confirmed that ships were deploying, without saying where they were headed. All three spoke on condition of anonymity to discuss the operations.

Gulf countries reported more attacks. A missile alert sounded Saturday night in Dubai. Saudi Arabia said it downed 20 drones in its east, home to major oil installations.

Iran’s death toll in the war has surpassed 1,500, the state broadcaster reported, citing the health ministry. In Israel, 15 people have been killed by Iranian missiles and four others have died in the occupied West Bank. At least 13 U.S. military members have been killed, along with well over a dozen civilians in Gulf nations.

Israeli troops and Hezbollah militants clash in Lebanon

Israel’s military said it was conducting a “targeted ground operation” in southern Lebanon and at least four militants were killed. Hezbollah said its fighters clashed with troops in the southern village of Khiam.

Israeli strikes targeting Hezbollah have killed more than 1,000 people and displaced more than 1 million, according to the Lebanese government. Hezbollah’s civilian assets also have been targeted.

This story was originally featured on Fortune.com
OpenAI plans to almost double its headcount by the end of 2026 as it seeks to fend off competition from companies such as Anthropic PBC and Alphabet Inc.’s Google, according to the Financial Times. 

The maker of AI assistant ChatGPT will look to increase headcount to about 8,000 from about 4,500, the FT said, citing two people with direct knowledge of the matter whom it didn’t identify. The new hires will largely work across product development, engineering, research and sales, according to the report. 

OpenAI has taken new office space in San Francisco to accommodate its growing staff count, taking its footprint in the city to more than 1 million square feet, the newspaper added. 

 OpenAI didn’t immediately respond to a request for comment.

The hiring plans come amid a race with competitors including Anthropic and Microsoft Corp. to woo corporate customers using AI as coding assistants. 

Firms like OpenAI have unveiled a number of AI models that can take on increasingly complicated tasks — from analyzing company earnings reports to writing code and generating startlingly realistic-looking images and videos.

Last week, OpenAI revealed plans to acquire Astral, a startup that makes Python tools for developers. Earlier in March, it agreed to buy AI security startup Promptfoo, adding tools to test and secure AI agents before deployment, Last year, it bought startups including Software Applications Inc. and Neptune. 

The firm is also in advanced discussions to form a joint venture with private equity firms, including TPG Inc., Brookfield Asset Management and Bain Capital, that would focus on bolstering adoption of its AI software, Bloomberg reported.

This story was originally featured on Fortune.com
After a four-year break, K-pop supergroup BTS returned Saturday with a massive, free comeback concert in Seoul, where thousands of police locked down a central boulevard for the Netflix-exclusive spectacle that drew tens of thousands of fans.

“Annyeonghaseyo! We’re back,” RM, the band’s leader, told the crowd, using the Korean word for “hello,” as they opened with “Body to Body,” setting off delirious screams from fans waving purple-and-red light sticks and thrusting smartphones into the air.

All seven members of the band — RM, Jin, Suga, J-Hope, Jimin, V and Jung Kook — recently completed South Korea’s mandatory military service, and hope to reclaim their status as one of the world’s biggest pop acts.

The performance at Gwanghwamun Square launches a global tour spanning dozens of shows across the United States, Europe and Asia, which analysts say could generate hundreds of millions of dollars in revenue per quarter.

The hourlong concert came after the group on Friday released its fifth album, “ARIRANG,” which sold nearly 4 million copies in its first day, said the band’s management company, HYBE. The company also said RM had injured his ankle during a rehearsal, but he still performed with modified choreography.

The BTS concert, which began at 8 p.m., drew several tens of thousands to the Gwanghwamun area, including 22,000 fans who secured free seats in the designated viewing zone and others who watched on screens nearby. The show was streamed live on Netflix.

“It will be amazing because it’s been so long that BTS (was) not with us,” Dallila Di Tullio, a 32-year-old fan from Italy, said before the concert, calling it a once-in-a-century event.

BTS debuted in 2013 and has a legion of global supporters who call themselves the “Army.” It became the first K-pop act to top Billboard’s Hot 100 chart in 2020 with their first all-English song “Dynamite.”

Jung Dukhyun, a pop culture commentator, said that the impact of BTS’ return as a full-group would be tremendous at a time when global fandom for K-pop has grown much stronger, as shown by the success of Netflix’s animated sensation “KPop Demon Hunters.”

Stringent crowd controls

The dark streets blazed with light as waves of fans sang and cheered from cordoned sections, a jubilant scene that unfolded under an unusually heavy police presence managing the crowds.

“I still vividly remember how, at our last Busan concert a few years ago, we asked you to wait for us. Thank you so much for coming here like this,” Jin said.

The group performed songs from their new album, including “SWIM,” alongside hits like “Dynamite” and “Butter.” Some members appeared to tear up while thanking fans who braved the chilly night, before holding hands and bowing to the crowd to close the show.

Police and city officials closed nearby streets and roads, halted the area’s subway and bus services, and sealed off dozens of surrounding buildings, in what amounted to a full-day shutdown of the district.

Thousands of police officers maintained a tight perimeter around the performance venue, channeling the crowds with a maze of fences and buses. Concertgoers began queuing by midday to secure spots along nearby roads, passing through security checks and metal detectors at designated entry points. The restrictions forced nearby shops to close and police to use their buses to shuttle wedding guests to a nearby venue.

“I was hoping to (see) if we can go through some holes or be around. Apparently we cannot because they will be asking people to move,” said Bernice Sanchez, a 52-year-old fan from Switzerland, as she looked for a place to wait.

While South Korean officials have taken crowd safety more seriously since a 2022 Halloween surge that killed nearly 160 people, critics say the controls went too far and undermined the symbolism of performing in Gwanghwamun, seen as Seoul’s spiritual heart and most prominent gathering space.

Hundreds of thousands have gathered in Gwanghwamun in recent years to mourn, protest and celebrate as the country weathered tragedy and political upheaval. The BTS concert came about a year after waves of demonstrators filled the area, calling for the ouster of then-President Yoon Suk Yeol over his brief imposition of martial law in December 2024. Those monthslong rallies were marked by a festive atmosphere and a striking blend of politics and pop culture, with protesters singing and waving colorful K-pop light sticks, and ended without major safety accidents.

Drawing on culture and heritage

The new BTS album, “ARIRANG,” takes its name from a centuries-old folk song, regarded as an unofficial anthem in both Koreas, whose themes of separation, longing and quiet resilience have echoed across generations.

Gwanghwamun and nearby Gyeongbok Palace provided a sweeping historic backdrop to Saturday’s show, which was highlighted by lighting effects that bathed the palace gate and walls in purple, red and blue.

Suga told the crowd that the album’s title and the decision to perform in Gwanghwamun reflected the group’s focus on identity. RM said the band focused on making music that felt true to themselves as they reconvened to work on the new album.

“We wanted to show who we are and how we can come together,” he told the crowd.

South Korean officials, including current President Lee Jae Myung, expressed hope that the event would promote the country’s culture and soft power.

Group’s comeback coincides with K-pop’s global rise

The group’s comeback follows a nearly four-year hiatus driven by South Korea’s mandatory military service, which requires most able-bodied men to serve 18 to 21 months under a conscription system aimed at deterring aggression from North Korea. BTS members began serving in 2022, with Suga the last to complete his service in June 2025.

Some analysts say the group’s “ARIRANG” world tour could become the biggest K-pop tour ever by scale and revenue, with 82 shows planned globally in stadiums of around 50,000 seats. Ha Jae-keun, a cultural critic, said BTS was likely to have a “second heyday,” as they maintained a highly powerful fandom and would benefit from the broader international ascent of K-pop.

“We will do our best to give everything we got,” J-Hope said

This story was originally featured on Fortune.com
The US has allowed the sale of Iranian oil and petrochemical products that have been loaded onto tankers, its latest effort to counter rising oil prices due to the Middle East war.

The Department of Treasury issued a general license for energy that’s already on vessels as of Friday, with such purchases authorized through April 19. The measure follows similar moves for Russian oil on the water in a bid to ease an unprecedented fuel supply crunch caused by the war.

For now, the vast majority of Iran’s oil is bought by Chinese customers — mainly independent refiners known as teapots. While the US waiver would widen the pool of potential buyers, any new customers would still face the challenge of structuring deals while other restrictions on Iran, including its access to international financial markets, remain in place.

The US and Israeli war on Iran has led to a virtual halt in shipments through the Strait of Hormuz, where 20% of global oil typically transits, with only a trickle of Iranian and Chinese tankers getting through. Brent crude prices have surged more than 50% this month, while Middle Eastern oil like Abu Dhabi’s flagship Murban grade has doubled in value.

The resulting spike in fuel prices for American consumers is heaping immense pressure on the US president and the Republican Party leading up to the November midterm elections. Prolonged inflationary pressures would undercut the GOP’s ability to retain control of the Senate and the House, and the loss of either chamber threatens to derail Trump’s ability to carry out his agenda.

Read More: US Treasury Allows More Russian Oil Sales to Help Tame Prices

US Treasury Secretary Scott Bessent called the Iranian oil waiver a “narrowly tailored, short-term authorization permitting the sale of Iranian oil currently stranded at sea,” in a post on X, adding that the measure will release about 140 million barrels. He also said that Iran “will have difficulty accessing any revenue generated.”

That 140-million-barrel number likely refers to oil on water. That figure probably includes cargoes in transit which may already be booked, and may not reflect actual availability. Goldman Sachs Group Inc. estimates there are 105 million barrels of Iranian oil on water.

Iran disputed the figure, with oil ministry spokesman Saman Ghodousi saying on X that the nation has no floating crude, nor a surplus that’s available for international markets. Ghodousi said the US was simply trying to provide psychological support to the oil market.

In the US, Congressional Democrats slammed the measure, arguing Trump’s move is an economic gift to Iran in the middle of a war that the president started.

“Clown show doesn’t begin to describe it,” Virginia Democrat Don Beyer said in a post on X.

In addition to sanctions waivers, the Trump administration released more than 45 million barrels of oil from its strategic reserves and temporarily waived a century-old shipping mandate in order to lower transport costs.

The global oil benchmark settled Friday above $112 a barrel — the highest level since mid-2022 — before easing in post-settlement trading after Trump said he was considering “winding down” US military efforts against Iran.

This story was originally featured on Fortune.com
The U.S. war on Iran has laid bare a dichotomy in the world’s most advanced military: high-tech weapons and AI have delivered stunning blows at unprecedented speed, while defending against the swarm of missiles and drones launched in retaliation have come at unsustainably lopsided costs.

Led by a massive air campaign, the U.S. has claimed more than 7,000 strikes on key sites, with Israel conducting a comparable number of sorties, as AI tools like Anthropic’s Claude recommend targets “much quicker in some ways than the speed of thought.” The relentless bombardment has decimated Iran’s military and leadership.

But helped by the mass production of cheap drones, the forces that are left still retain enough combat power to attack Gulf neighbors and scare away commercial tankers from the Strait of Hormuz, keeping 20% of the world’s oil bottled up.

Iran’s retaliatory barrage has also forced the U.S. and its allies to draw down expensive stockpiles of interceptors. The tactic highlights the brutal economics of the current war: missiles that cost millions of dollars each are shooting down drones that cost tens of thousands of dollars. In other words, it’s like the U.S. is using a Formula 1 racer to fight off a used car.

U.S.-style warfare doesn’t come cheap. The first six days of the Iran conflict have cost the U.S. more than $11 billion, though a switch to less expensive bombs has since slowed the daily bill.

Pentagon leaders insist the U.S. has enough munitions, though the exact size of the inventory is classified. Still, the heavy usage has raised concerns about the remaining supply, especially as allies consider what’s needed in the event of war with Russia or China.

But lawmakers got sticker shock on reports the Defense Department was seeking an additional $200 billion for the Iran war. Part of the Pentagon’s calculus, however, was to address the shortage of precision munitions and spur the defense industry to quickly restock supplies, sources told the Washington Post.

President Donald Trump summoned top contractors to the White House earlier this month to push them along. But ramping up to high levels of output could take years. For example, Lockheed Martin made 620 PAC-3 interceptors for the Patriot air-defense system last year and plans to make 650 this year. But its goal of producing over 2,000 annually won’t be reached until 2030, according to Bloomberg.

The current dilemma brings to mind a quote attributed to Joseph Stalin during World War II as he weighed the Red Army’s numerical advantage against Nazi Germany’s superior weapons: “quantity has a quality all its own.”

Ukraine tranforms warfare

The U.S. has long prioritized cutting-edge equipment to maintain superiority against any military rivals. But as the pace of technological improvements accelerated in recent decades, costs ballooned and the Pentagon struggled to keep up. During the Iraq war, acquisition officials looked to “off the shelf” commercial options that could be integrated into the military quickly.

The advent of cheap commercial drone technology changed equation dramatically, as demonstrated by the Ukrainian military’s adoption of new tactics to fight off the Russian invasion.

The four-year-old conflict has transformed warfare. Unmanned weapons are now responsible for most battlefield casualties as small first-person view drones hunt down individual troops or vehicles. Ukraine’s defense industry has also evolved to mass produce inexpensive drones that can take down Russia-launched Shaheds from Iran.

Once such drone, the P1-Sun, costs a little more than $1,000 and can fly above 30,000 feet as 3-D printers crank them out in Ukrainian factories.

“The future of warfare is Ukraine producing 7 million drones per year right now,” former CIA director and retired Gen. David Patraeus said earlier this month. “This past year, they produced 3.5 million. That enabled them basically to use 9 to 10,000 drones per day.”

And when combined with AI that makes drones more autonomous, the result will be swarms that are “really, really hard” to counter, he added.

Defending against an onslaught like that may require energy weapons, like high-powered microwaves, that can take down large swathes of drones at once.

“We are not actually where we should be relative to that, based on what we should have been learning from Ukraine for a very long time,” Patraeus warned. “And they’re learning back and forth. They make software changes every week or two, hardware changes every two to three weeks.”

Gulf countries facing Iranian attacks have sought Ukraine’s help in combating the Shahed drone. Ukrainian President Volodymyr Zelenskyy has said his country can produce at least 2,000 “effective and combat-proven” interceptors a day.

The Pentagon also understands the new economics of warfare and has even incorporated a copycat version of the Shahed in the U.S. military, using the American version against Iran during the war.

Emil Michael, the undersecretary of defense for research and engineering, said at an industry conference on Tuesday that the Pentagon plans to go big with the new LUCAS drone.

“After only a few years, we continue to refine that and make that something that we can mass produce at scale,” he said. “They’ve worked very well so far and it’s proven out to be a useful tool in the arsenal.” 

This story was originally featured on Fortune.com
 President Donald Trump said Saturday he will order federal immigration officers to take a role in airport security starting Monday unless Democrats agree on a bill to fund the Department of Homeland Security.

In a pair of social media posts, Trump first threatened and then said he had made plans to put officers from U.S. Immigration and Customs Enforcement in airports if the congressional standoff continues. He made the announcement as a partial shutdown contributes to long linesto pass through screening at some of the nation’s largest airports.

The Republican president suggested ICE agents would bring the administration’s immigration crackdown into the nation’s airports, promising to arrest “all Illegal Immigrants.”

“I look forward to moving ICE in on Monday, and have already told them to, “GET READY.” NO MORE WAITING, NO MORE GAMES!” Trump wrote while spending the weekend in Florida.

The move appears to be a pointed effort to expand the type of immigration enforcement that has become a sticking point in Congress. Democrats pledged to oppose funding for DHS unless changes were made in the wake of a crackdown in Minnesota that led to the fatal shootings of two protesters. Democrats are asking for better identification for federal law enforcement officers, a new code of conduct for those agencies and more use of judicial warrants, among other measures.

The Minnesota operation was tied in part to allegations of fraud involving Somali residents. On Saturday, Trump said ICE officers sent to airports would focus on arresting immigrants from Somalia who are in the United States illegally. Repeating his criticism on Somalis, he said they “totally destroyed” Minnesota.

“If the Democrats do not allow for Just and Proper Security at our Airports, and elsewhere throughout our Country, ICE will do the job far better than ever done before,” Trump said.

Trump’s posts did not offer additional detail on how ICE would take a role in airport security and what it meant for the Transportation Security Administration, which screens passengers and luggage for hazardous items.

The vast majority of TSA employees are considered essential and continue to work during the funding lapse, but they are doing so without pay. Call-out rates have started to increase at some airports, and DHS said at least 376 have quit since the partial shutdown began Feb. 14.

On Saturday, in a rare weekend session, the Senate rejected a motion by Democrats to take up legislation to reopen TSA and pay workers who are now going without paychecks. Republicans argue that they need to fund all parts of the DHS, not just certain ones. A bill to fund the Cabinet department failed to advance in the Senate on Friday.

There were signs of progress, though, with the restarting in recent days of stalled talks between Democrats and the White House. On Saturday, Republican and Democratic senators were set to meet for a third consecutive day with White House officials behind closed doors as Senate Democratic leader Chuck Schumer of New York spoke of “productive conversations.”

Senate Majority Leader John Thune, R-S.D., urged the bipartisan group to act quickly. He has said repeatedly that Democrats and the White House need to find compromise as lines at airports have grown.

“If that group that’s meeting can’t come up with a solution really quickly, things are going to get worse and worse,” Thune said Saturday.

This story was originally featured on Fortune.com
One day at an Idaho hospital, half the newborns Dr. Tom Patterson saw didn’t get the vitamin K shots that have been given to babies for decades to prevent potentially deadly bleeding. On another recent day, more than a quarter didn’t get the shot. Their parents wouldn’t allow it.

“When you look at a child who’s innocent and vulnerable — and a simple intervention that’s been done since 1961 is refused — knowing that baby’s going out into the world is super worrisome to me,” said Patterson, who’s been a pediatrician for nearly three decades.

Doctors across the nation are alarmed that skepticism fueled by rising anti-science sentiment and medical mistrust is increasingly reaching beyond vaccines to other proven, routine, preventive care for babies.

A recent study in the Journal of the American Medical Association, which analyzed more than 5 million births nationwide, found that refusals of vitamin K shots nearly doubled between 2017 and 2024, from 2.9% to 5.2%. Other research suggests that parents who decline vitamin K shots are much more likely to refuse getting their newborns the hepatitis B vaccine and an eye ointment to prevent potentially blinding infections. Rates for that vaccination at birth dropped in recent years, and doctors confirm that more parents are refusing the eye medication.

“I do think these families care deeply about their infants,” said Dr. Kelly Wade, a Philadelphia neonatologist. “But I hear from families that it’s hard to make decisions right now because they’re hearing conflicting information.”

Innumerable social media posts question doctors’ advice on safe and effective measures like vitamin K and eye ointment. And the Trump administration has repeatedly undermined established science. A federal advisory committee whose members were appointed by Health Secretary Robert F. Kennedy Jr. — a leading anti-vaccine activist before joining the administration — voted to end the longstanding recommendation to immunize all babies against hepatitis B right after birth. On Monday a federal judge temporarily blocked all decisions made by the reconfigured committee.

One common thread that ties together anti-vaccine views and growing sentiments against other protective measures for newborns is the fallacy that natural is always better than artificial, said Dr. David Hill, a Seattle pediatrician and researcher.

“Nature will allow 1 in 5 human infants to die in the first year of life,” Hill said, “which is why generations of scientists and doctors have worked to bring that number way, way down.”

Vitamin K and other measures prevent serious problems

Babies are born with low levels of vitamin K, leaving them vulnerable because their intestines can’t produce enough until they start eating solid foods at around 6 months old.

“Vitamin K is important for helping the blood clot and preventing dangerous bleeding in babies, like bleeding into the brain,” said Dr. Kristan Scott of the Children’s Hospital of Philadelphia, lead author of the JAMA study.

Before injections became routine, up to about 1 in 60 babies suffered vitamin K deficiency bleeding, which can also affect the gastrointestinal tract. Today the condition is rare, but research shows that newborns who don’t get a vitamin K shot are 81 times more likely to develop severe bleeding than those who do.

Hill has seen what can happen.

“I cared for a toddler whose parents had chosen that risk,” the Seattle doctor said. The child essentially had a stroke as a newborn and wound up with severe developmental delays and ongoing seizures.

At a February meeting of the Idaho chapter of the American Academy of Pediatrics, doctors said they knew of eight deaths from vitamin K deficiency bleeding in the state over the preceding 13 months, said Patterson, who is president of the chapter.

Infections prevented by other newborn measures can also have grave consequences. Erythromycin eye ointment protects against gonorrhea that can be contracted during birth and potentially cause blindness if untreated. The hepatitis B vaccine prevents a disease that can lead to liver failure, liver cancer or cirrhosis.

Even if a pregnant woman is tested for gonorrhea and hepatitis B, no test is perfect, and she may get infected after testing, said Dr. Susan Sirota, a pediatrician in Highland Park, Illinois. Either way, she risks passing the infection to her child.

Why are parents refusing routine care?

Parents give many reasons for turning down preventive measures, like fearing they might cause problems and not wanting newborns to feel pain.

“Some will just say they want more of a natural birth philosophy,” said Dr. Steven Abelowitz, founder of Ocean Pediatrics in Orange County, California. “Then there’s a ton of misinformation. … There are outside influences, friends, celebrities, nonprofessionals and political agendas.”

Abelowitz practices in an area with about an equal mix of Republicans and Democrats.

“There’s more mistrust from the conservative side, but there’s plenty on the more liberal side as well,” he said, “It’s across-the-board mistrust.”

Social media provides ample fuel, spreading myths and pushing unregulated vitamin K drops that doctors warn babies can’t absorb well.

Doctors in numerous states say parents refusing vitamin K shots often also decline other measures. Sirota, in Illinois, encountered a family that refused a heel stick to monitor glucose for a baby at high risk for having potentially life-threatening low blood sugar.

Care refusals aren’t a new phenomenon. Wade, in Philadelphia, said she’s seen them for 20 years. But until recently, they were rare.

Twelve years ago, Dana Morrison, now a Minnesota doula, declined the vitamin K shot for her newborn son, giving him oral drops instead.

“It came from a space of really wanting to protect the bonding time with my baby,” she said. “I was trying to eliminate more pokes.”

Her daughter’s birth a couple of years later was less straightforward, leaving the infant with a bruised leg. Morrison got the vitamin K shot for her.

Knowing what she does now, she said, she would have gotten it for her son, too.

Doctors and parents want ‘the best for their children’

Doctors hope to change minds, one parent at a time. And that begins with respect.

“If I walk into the room with judgment, we are going to have a really useless conversation,” Hill said. “Every parent I serve wants the best for their children.”

When parents question the need for the vitamin K shot, Dr. Heather Felton tries to address their specific concerns. She explains why it’s given and the risks of not getting it. Most families decide to get it, said Felton, who has seen no uptick in refusals.

“It really helps that you can take that time and really listen and be able to provide some education,” said Felton, a pediatrician at Norton Children’s in Louisville, Kentucky.

In Idaho, Patterson sometimes finds himself clearing up misconceptions. Some parents will agree to a vitamin K shot when they find out it’s not a vaccine, for example.

These conversations can take time, especially since the parents doctors see in hospitals usually aren’t people they know through their practices.

But doctors are happy to invest that time if it might save babies.

“I end every discussion with parents with this: ‘Please understand at the end of the day, I’m passionate about this because I have the best interest of children in my mind and heart,’” Patterson said. “I understand this is a hot topic, and I don’t want to disrespect anybody. But at the same time, I’m desperately saddened that we’re losing babies for no reason.”

This story was originally featured on Fortune.com
Robert S. Mueller III, the FBI director who transformed the nation’s premier law enforcement agency into a terrorism-fighting force after the Sept. 11, 2001, attacks and who later became special counsel in charge of investigating ties between Russia and Donald Trump’s presidential campaign, has died. He was 81.

“With deep sadness, we are sharing the news that Bob passed away” on Friday night, his family said in a statement Saturday. “His family asks that their privacy be respected.”

At the FBI, Mueller set about almost immediately overhauling the bureau’s mission to meet the law enforcement needs of the 21st century, beginning his 12-year tenure just one week before the Sept. 11 attacks and serving across presidents of both political parties. He was nominated by Republican President George W. Bush.

The cataclysmic event instantaneously switched the bureau’s top priority from solving domestic crime to preventing terrorism, a shift that imposed an almost impossibly difficult standard on Mueller and the rest of the federal government: preventing 99 out of 100 terrorist plots wasn’t good enough.

Later, he was special counsel in the Justice Department’s investigation into whether the Trump campaign illegally coordinated with Russia to sway the outcome of the 2016 presidential race. Mueller was a patrician Princeton graduate and Vietnam veteran who walked away from a lucrative midcareer job to stay in public service, and his old-school, buttoned-down style made him an anachronism during a social media-saturated era.

Trump posted on social media after the announcement of Mueller’s death: “Robert Mueller just died. Good, I’m glad he’s dead.” The Republican president added, “He can no longer hurt innocent people!”

The FBI did not immediately respond to a request seeking comment.

A second act as an investigator of a sitting president

The second-longest-serving director in FBI history, behind only J. Edgar Hoover, Mueller held the job until 2013 after agreeing to Democratic President Barack Obama’s request to stay on even after his 10-year term was up.

After several years in private practice, Mueller was asked by Deputy Attorney General Rod Rosenstein to return to public service as special counsel in the Trump-Russia inquiry.

Mueller’s stern visage and taciturn demeanor matched the seriousness of the mission, as his team spent nearly two years quietly conducting one of the most consequential, yet divisive, investigations in Justice Department history. He held no news conferences and made no public appearances during the investigation, remaining quiet despite attacks from Trump and his supporters and creating an aura of mystery around his work.

All told, Mueller brought criminal charges against six of the president’s associates, including his campaign chairman and first national security adviser.

His 448-page report released in April 2019 identified substantial contacts between the Trump campaign and Russia but did not allege a criminal conspiracy. Mueller laid out damaging details about Trump’s efforts to seize control of the investigation, and even shut it down, though he declined to decide whether Trump had broken the law, in part because of department policy barring the indictment of a sitting president.

But, in perhaps the most memorable language of the report, Mueller pointedly noted: “If we had confidence after a thorough investigation of the facts that the president clearly did not commit obstruction of justice, we would so state. Based on the facts and the applicable legal standards, we are unable to reach that judgment.”

The nebulous conclusion did not deliver the knockout punch to the administration that some Trump opponents had hoped for, nor did it trigger a sustained push by House Democrats to impeach the president — though he was later tried and acquitted on separate allegations related to Ukraine.

The outcome also left room for Attorney General William Barr to insert his own views. He and his team made their own determination that Trump did not obstruct justice, and he and Mueller privately tangled over a four-page summary letter from Barr that Mueller felt did not adequately capture his report’s damaging conclusion.

Mueller deflated Democrats during a highly anticipated congressional hearing on his report when he offered terse, one-word answers and appeared uncertain in his testimony. Frequently, he seemed to waver on details of his investigation. It was hardly the commanding performance many had expected from Mueller, who had a towering reputation in Washington.

Over the next months, Barr made clear his own disagreements with the foundations of the Russia investigation, moving to dismiss a false-statements prosecution that Mueller had brought against former national security adviser Michael Flynn, even though that investigation ended in a guilty plea.

Mueller’s tenure as special counsel was the capstone of a career spent in government.

A transformation of the FBI into a national security agency

His time as FBI director was defined by the Sept. 11 attacks and its aftermath, as an FBI granted broad new surveillance and national security powers scrambled to confront an ascendant al-Qaida and interrupt plots and take terrorists off the street before they could act.

It was a new model of policing for an FBI that had long been accustomed to investigating crimes that had already occurred.

When he became FBI director, “I had expected to focus on areas familiar to me as a prosecutor: drug cases, white-collar criminal cases and violent crime,” Mueller told a group of lawyers in October 2012.

Instead, “we had to focus on long-term, strategic change. We had to enhance our intelligence capabilities and upgrade our technology. We had to build upon strong partnerships and forge new friendships, both here at home and abroad.”

In response, the FBI shifted 2,000 of the total 5,000 agents in the bureau’s criminal programs to national security.

In hindsight, the transformation was a success. At the time, there were problems, and Mueller said as much. In a speech near the end of his tenure, Mueller recalled “those days when we were under attack by the media and being clobbered by Congress; when the attorney general was not at all happy with me.”

Among the issues: The Justice Department’s inspector general found that the FBI circumvented the law to obtain thousands of phone call records for terrorism investigations.

Mueller decided that the FBI would not take part in abusive interrogation techniques of suspected terrorists, but the policy was not effectively communicated down the line for nearly two years. In an effort to move the FBI into a paperless environment, the bureau spent over $600 million on two computer systems — one that was 2½ years overdue and a predecessor that was only partially completed and had to be scrapped after consultants declared it obsolete and riddled with problems.

For the nation’s top law enforcement agency, it was a rocky trip through rough terrain.

But there were many successes as well, including thwarted terror plots and headline-making criminal cases like the one against fraudster Bernie Madoff. The Republican also cultivated an apolitical reputation on the job, nearly quitting in a clash with the Bush administration over a surveillance program that he and his successor, James Comey, considered unlawful.

He famously stood alongside Comey, then deputy attorney general, during a dramatic 2004 hospital standoff over federal wiretapping rules. The two men planted themselves at the bedside of the ailing Attorney General John Ashcroft to block Bush administration officials from making an end run to get Ashcroft’s permission to reauthorize a secret no-warrant wiretapping program.

In an extraordinary vote of confidence, Congress, at the Obama administration’s request, approved a two-year extension for Mueller to remain at his post.

A Marine who served in Vietnam before becoming a prosecutor

Mueller was born in New York City and grew up in a well-to-do suburb of Philadelphia.

He received a bachelor’s degree from Princeton and a master’s degree in international relations from New York University. He then joined the Marines, serving for three years as an officer during the Vietnam War. He led a rifle platoon and was awarded a Bronze Star, Purple Heart and two Navy Commendation Medals. Following his military service, Mueller earned a law degree from the University of Virginia.

Mueller became a federal prosecutor and relished the work of handling criminal cases. He rose quickly through the ranks in U.S. attorneys’ offices in San Francisco and Boston from 1976 to 1988. Later, as head of the Justice Department’s criminal division in Washington, he oversaw a range of high-profile prosecutions that chalked up victories against targets as varied as Panamanian dictator Manuel Noriega and New York crime boss John Gotti.

In a mid-career switch that shocked colleagues, Mueller threw over a job at a prestigious Boston law firm to join the homicide division of the U.S. attorney’s office in the nation’s capital. There, he immersed himself as a senior litigator in a bulging caseload of unsolved drug-related murders in a city rife with violence.

Mueller was driven by a career-long passion for the painstaking work of building successful criminal cases. Even as head of the FBI, he would dig into the details of investigations, some of them major cases but others less so, sometimes surprising agents who suddenly found themselves on the phone with the director.

“The management books will tell you that as the head of an organization, you should focus on the vision,” Mueller once said. But “for me there were and are today those areas where one needs to be substantially personally involved,” especially in regard to “the terrorist threat and the need to know and understand that threat to its roots.”

Two terrorist attacks occurred toward the end of Mueller’s watch: the Boston Marathon bombing and the Fort Hood shootings in Texas. Both weighed heavily on him, he acknowledged in an interview two weeks before his departure.

“You sit down with victims’ families, you see the pain they go through and you always wonder whether there isn’t something more” that could have been done, he said.

This story was originally featured on Fortune.com
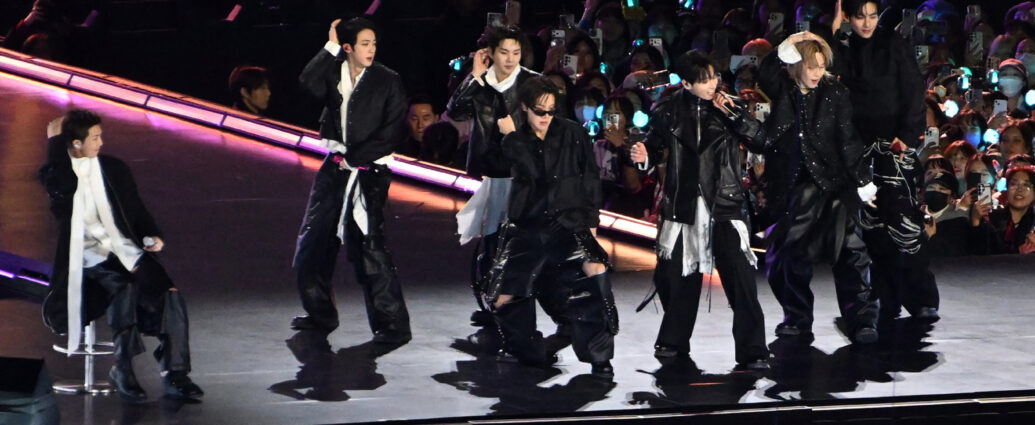
Andrej Karpathy, an OpenAI cofounder and former director of AI at Tesla, admitted that he’s not on the forefront of the field and feels nervous about it, despite all his accomplishments in AI.

In an interview on the No Priors podcast on Friday, the independent AI researcher, who is also the founder of Eureka Labs, explained a “psychosis” he’s been suffering from, even as AI agents have made his workflow and life at home more convenient.

A tipping point came in December, when he noticed he was writing just 20% of his code with 80% delegated to an agent, reversing from an earlier split with 80% done by himself and 20% by an agent. That trend has continued.

“I don’t think I’ve typed like a line of code probably since December, basically, which is an extremely large change,” Karpathy said. “I don’t think a normal person actually realizes that this happened or how dramatic it was.”

He’s not alone and added that the default workflow for building software has completely changed in recent months as agentic AI has exploded in popularity.

OpenClaw in particular has swept through the tech industry as users connect it to various applications, allowing it to manage calendars, browse the web, shop online, read files, write emails, and send messages via tools like WhatsApp.

Its potential remains massive, and Karpathy described his struggle to fully envision what could come next, saying “I’m just like in the state of psychosis of trying to figure out what’s possible, trying to push it to the limit.”

He added: “I want to be at the forefront of it, and I’m very antsy that I’m not at the forefront of it. I see lots of people on Twitter doing all kinds of things, and they all sound like really good ideas. And I need to be at the forefront or I feel extremely nervous.”

Karpathy also revealed that he went through a “claw psychosis” in January while integrating an agent with various smart functions at his home.

In fact, he’s dubbed it “Dobby the House Elf claw,” and it now controls his home’s sound system, lighting, security functions, shades, HVAC, pool and spa.

Previously, managing each one required using several different apps. But now, Karpathy said he just instructs Dobby what to do by sending messages via WhatsApp in natural language.

Dobby also alerts him with a message when it uses the home’s security cameras to detect a FedEx truck that dropped off a delivery at his doorstep.

“So Dobby is in charge of the house,” he said. “It’s been really fun to have these macro actions that maintain my house. I haven’t like really pushed it way more beyond that, and I think people are doing a lot more crazy things with it.”

This story was originally featured on Fortune.com
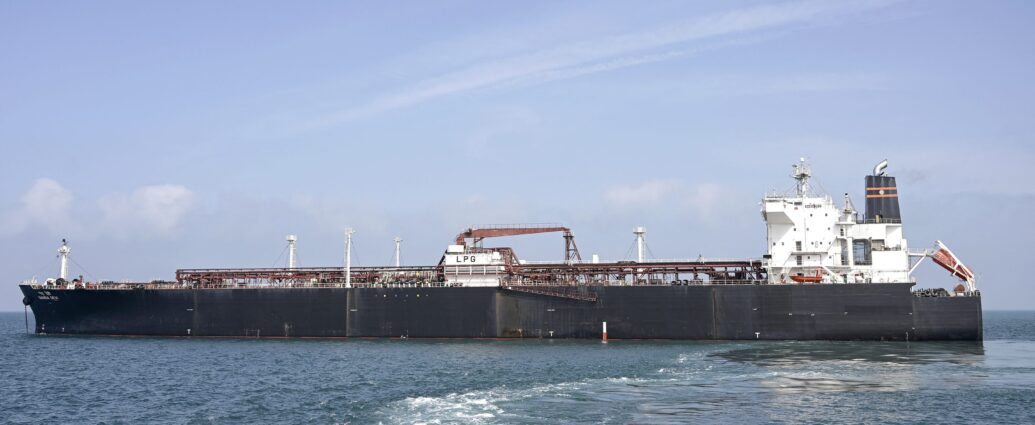
The U.S.-Israel war on Iran has delivered the biggest disruption to the airline industry since the COVID-19 pandemic, and United is bracing for a future where oil prices remain high through 2027.

Not only has the price of oil soared, air traffic to key Middle East airport hubs has been disrupted, forcing planes to take alternate routes that burn more fuel.

In a letter to employees posted on Friday, CEO Scott Kirby pointed out that jet fuel prices have more than doubled in the last three weeks, representing an additional $11 billion in annual costs if prices stay at that level.

United spent $11.4 billion last year on fuel, meaning current prices could send that total expense past $20 billion this year. The carrier reported adjusted net income of $3.5 billion for 2025, and Kirby noted that its best year ever saw earnings of $5 billion.

But United’s cash position, profit margins, and balance sheet are healthy, while demand remains strong, he added. In fact, the last 10 weeks have seen United’s 10 biggest booked revenue weeks in its history.

Still, he acknowledged it will be difficult for United to continue passing on the cost of fuel if oil stays higher for longer, revealing that the airline’s plans assume oil hits $175 a barrel and doesn’t go back down to $100 until the end of 2027.

On Friday, Brent crude rose 3.26% to close at $112.19 per barrel, and U.S. oil gained 2.27% to settle at $98.32. But the Strait of Hormuz, through which 20% of the world’s oil passes, remains largely closed, and analysts have warned that prices could reach $150 or even $200 a barrel if it doesn’t reopen soon.

Jet fuel prices have surged even more due to tighter refining constraints. Northwest Europe has seen record highs near $239 a barrel, and Asian jet fuel prices are near $200 a barrel, close to recent highs.

While Kirby thinks “there’s a good chance” that United’s scenario won’t be realized, he also said capacity will come down in certain times and places.

That means fewer flights in off-peak times, such as redeyes as well as Tuesday, Wednesday, and Saturday trips during the second and third quarters. United’s will also trim capacity in the Chicago O’Hare airport hub and will pull service from Tel Aviv and Dubai, which are still being bombarded by Iran.

The combined effect of the changes will be about 5 percentage points of capacity, though United plans to restore the full schedule in the fall.

“To be clear, nothing changes about our longer-term plans for aircraft deliveries or total capacity for 2027 and beyond, but there’s no point in burning cash in the near term on flying that just can’t absorb these fuel costs,” Kirby said.

At the same time, he vowed to avoid furloughing employees, deferring aircraft orders, downgrading to regional jets, going through cost cutting exercises, and delaying investments. United still plans to take delivery of about 120 new aircraft this year, the CEO said.

More dollars will go into tech and facilities, such as the airline’s clubs, new infrastructure at hubs, and an expansion at the Newark airport. 

Kirby dismissed cost cuts and investment deferrals as “small dollars at best, they’re distracting, they aren’t necessary for United and they deter us from our mission to build the best airline in the history of aviation.”

Other airlines are making contingency plans too. Scandinavian airline SAS said it will cancel around 1,000 flights because of rising fuel prices. 

For Air France-KLM, plans include cutting service to parts of Asia if fuel costs for return trips to Europe become more difficult.

“Southeast Asia is much more dependent on fuel coming over the Gulf than Europe is,” CEO Ben Smith told the Financial Times. “We can get fuel out of Europe, but when we go to [a] south-east Asian city we’re not going to be able to fly the plane back . . . If there’s no fuel, you can’t fly.” 

This story was originally featured on Fortune.com
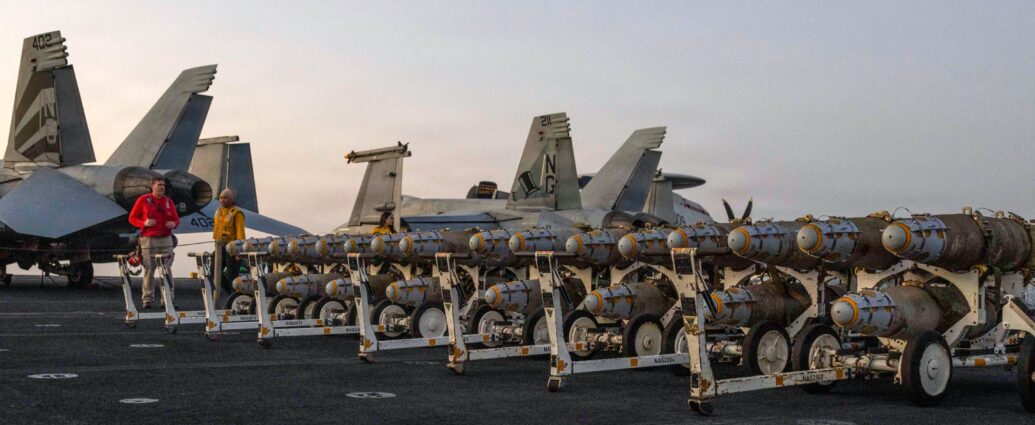
Israel’s defense minister threatened a surge in attacks against Iran on Saturday and Britain condemned Iran for targeting a joint U.K.-U.S. base in the Indian Ocean as the war in the Middle East entered its fourth week.

The Iranian attack on the Diego Garcia air base — about 2,500 miles (4,000 kilometers) from Iran — suggested Tehran has missiles that can go farther than it had previously acknowledged.

Also Saturday, Iran’s Natanz nuclear enrichment facility was hit in an airstrike, an official Iranian news agency reported, saying there was no radiation leakage.

Israel’s Defense Minister Israel Katz said in a video statement that next week, “the intensity of the attacks” by Israel and the United States against Iran’s ruling theocracy will “increase significantly.”

He spoke shortly after fragments from an Iranian missile slammed into an empty kindergarten near Tel Aviv. Israeli army spokesman Nadav Shoshani posted a video on X of the kindergarten building. The school was empty at the time and no casualties were reported.

Overnight and into the morning, Iran’s capital saw heavy airstrikes, residents said. The attacks — and threats of more to come — indicate the Iran war shows no sign of abating.

The U.S. and Israel have offered shifting rationales for the war, from hoping to foment an uprising that topples Iran’s leadership to eliminating its nuclear and missile programs. There have been no public signs of any such uprising.

Iranian Foreign Minister Abbas Araghchi told Japan’s Kyodo news service Friday that Iran wanted “not a ceasefire, but a complete, comprehensive and lasting end to the war.”

Trump says he’s looking at ‘winding down’ operations

U.S. President Donald Trump said Friday that he was considering “winding down” military operations in the Mideast, which seemed at odds with his administration’s move to bolster its firepower in the region and request another $200 billion from Congress to fund the war.

The U.S. is deploying three more amphibious assault ships and roughly 2,500 additional Marines to the Mideast, an official told The Associated Press. Two other U.S. officials confirmed that ships were deploying, without saying where they were headed. All three spoke on condition of anonymity to discuss the military operations.

In a move aimed at wrangling soaring fuel prices, the Trump administration announced it was lifting sanctions on some Iranian oil. The pause in sanctions applies to Iranian oil already loaded on ships as of Friday and is set to end April 19. The license has limits including a restriction on sales involving anyone in North Korea or Cuba.

The new move does not increase the flow of production, a central factor in the surging prices. Iran has managed to evade U.S. sanctions for years, suggesting that much of what it exports already reaches buyers.

Saudi Arabia said it downed 20 drones in just a couple of hours Saturday in the country’s eastern region, home to major oil installations. No injuries or damage were reported.

Iran attempts to hit Diego Garcia air base in the Indian Ocean

U.K. officials have not given details of the strike that targeted the ocean air base Friday, which was unsuccessful.

Britain’s Ministry of Defense said Saturday that Iran’s “lashing out across the region and holding hostage the Strait of Hormuz, are a threat to British interests and British allies.”

Britain has not participated in U.S.-Israeli attacks on Iran but has allowed American bombers to use U.K. bases to attack Iran’s missile sites.

On Friday, the British government said U.S. bombers can also use U.K. bases, including Diego Garcia, in operations to prevent Iran attacking ships in the Strait of Hormuz. Iran targeted the base before that U.K. statement.

No leakage reported after attack on Iran nuclear facility

Iran’s official news agency, Mizan, said there was no leakage after Saturday’s strike on the Natanz nuclear facility, nearly 220 kilometers (135 miles) southeast of Tehran.

The facility, Iran’s main uranium enrichment site, was hit in the first week of the war and several buildings appeared damaged, according to satellite images. The United Nations nuclear watchdog — the International Atomic Energy Agency — had said “no radiological consequence” were expected from that earlier strike. Natanz had also been targeted in the 12-day war last June.

On Saturday, the IAEA said on X that it was informed by Iran about the Natanz strike and about there being no increase in off-site radiation levels. The agency said it was looking into the incident.

Iran threatens attacks beyond the Middle East

Iran’s top military spokesperson, Gen. Abolfazl Shekarchi, warned Friday that “parks, recreational areas and tourist destinations” worldwide will not be safe for the country’s enemies.

Supreme Leader Ayatollah Mojtaba Khamenei praised Iranians’ steadfastness in the face of war in a written statement read on Iranian television to mark the Persian New Year, or Nowruz. Khamenei has not been seen in public since he became supreme leader after Israeli strikes killed his father, Ayatollah Ali Khamenei, and reportedly wounded him.

With little information coming out of Iran, it was not clear how much damage its arms, nuclear or energy facilities have sustained in the punishing U.S. and Israeli strikes, which began Feb. 28 — or even who was truly in charge of the country.

But Iran’s attacks are still choking off oil supplies and raising food and fuel prices far beyond the Middle East.

Israeli troops and Hezbollah militants clash in southern Lebanon

The Israeli military said its forces were conducting a “targeted ground operation” Saturday with the support of Israeli aircraft and that at least four militants were killed.

Hezbollah also released a statement saying its fighters clashed with Israeli troops in the southern village of Khiam.

So far, Israeli strikes targeting Hezbollah in Lebanon have killed more than 1,000 people and displaced more than 1 million, according to the Lebanese government.

More than 1,300 people have been killed in Iran during the war. In Israel, 15 people have been killed by Iranian missiles and four others have died in the occupied West Bank. At least 13 U.S. military members have been killed.

This story was originally featured on Fortune.com
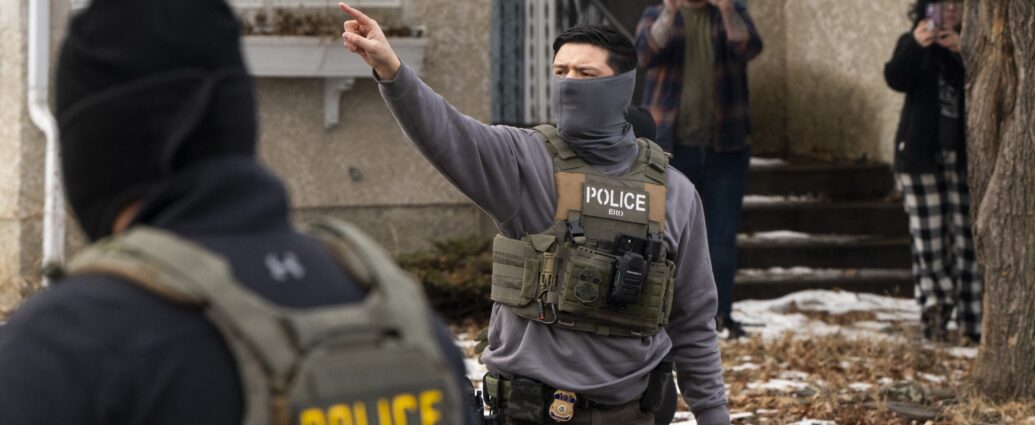
A 19-year-old star wrestler and two other young men were hanged in Iran this week, raising alarm among rights groups that a wave of executions may be underway as authorities facing relentless attacks from the U.S. and Israel seek to squelch public dissent.

The three men are the first to be executed from among the tens of thousands who were arrested during a January crackdown on nationwide protests. Rights groups say more than 100 others could face death sentences.

The wrestler, Saleh Mohammadi, was hanged early Thursday morning — along with Mehdi Qasemi and Saeed Davoudi — in Qom, just south of the capital, Tehran, according to state media. They had been sentenced on charges of “moharabeh,” or “waging war against God,” for allegedly killing two police officers during protests in the city.

Amnesty International said the convictions of the three, and of others arrested during the protests, came in “grossly unfair trials” that used confessions extracted by torture.

The executions were “intended to instill fear in society and deter new protests” amid the U.S.-Israeli war on Iran, said Mahmood Amiry-Moghaddam, director of Iran Human Rights, an Oslo-based group that has documented detentions.

Amiry-Moghaddam said he worries many more “executions of protesters and political prisoners may be imminent.”

At least 27 arrested during protests face death sentences

Amiry-Moghaddam said his group has documented at least 27 death sentences that have been issued against people arrested during the protests. Another 100 face charges that carry the death penalty, and Iranian state media have aired hundreds of forced confessions to crimes punishable by death, he said.

Nationwide protests that began in late December peaked in the first week of January, prompting the deadliest crackdown by Iranian security forces since the Islamic Republic took power in 1979.

A complete death toll has been hard to gauge because of internet restrictions by authorities. The U.S.-based Human Rights Activists New Agency, which relies on a network of contacts inside Iran, said it confirmed that more than 7,000 were killed and that it was investigating thousands more. It said over 50,000 were arrested in just over six weeks. The government acknowledged more than 3,000 were killed.

At the height of the protests, Iranian authorities signaled that fast trials and executions lay ahead.

At the time, U.S. President Donald Trump suggested military action might be an option to stop the deadly crackdown. But he soon announced that he learned that plans for executions were halted, signaling that a military operation was no longer on the table.

Just a month later, Israel and the U.S. launched an intense airstrike campaign against Iran, pounding military installations and targeting the top political and security leadership of Iran. The security agencies believed to be responsible for the deadly crackdown on protesters are also being targeted.

War has not stopped Iran’s crackdown on dissent

Despite the war, Iranian authorities have kept up the crackdown on dissent. Authorities say scores have been detained since the war began on Feb. 28, including some who took part in the January protests.

Because of Iran’s internet blackout, there have been scant details about the three men executed Thursday. Amiry-Moghaddam said Davoudi was born on March 20, 2004, meaning he was executed a day before his 22nd birthday. Qasemi’s age was not known, he said.

Mohammadi appeared to be a standout in wrestling, a sport that is wildly popular in Iran. In 2024, he won a bronze medal at an international youth freestyle wrestling tournament in the Russian city of Krasnoyarsk.

On his Instagram account, Mohammadi posted photos and videos of his matches and his workouts, along with inspirational “no-pain-no-gain” messages. In his last post in late December, he posted a video of himself in the gym and wrote: “We endured beyond our imagination. Back again #bodybuilding #training #wrestling.”

“He was full of energy,” said Shiva Amelirad, an Iranian teacher living in Toronto who spoke with Mohammadi in 2022 while he was still in high school.

Amelirad said Mohammadi had participated in anti-government protests that erupted earlier that year when Mahsa Amini died in police custodyafter being detained for not wearing her headscarf properly. Those demonstrations were also met with a heavy crackdown by authorities.

She said Mohammadi told her that workouts and eating ice cream were his only ways “to forget all this catastrophe that we are facing.”

“He always tried to show that he was happy,” said Amelirad.

Rights groups say theocracy has forced confessions from protesters

Mohammadi, Qasemi and Davoudi were arrested in Qom on Jan. 15, according to multiple human rights groups. The circumstances of their arrests are not known, and it is not clear if they knew each other beforehand.

They were charged in the killing of a police officer on Jan. 8 and convicted in early February, according to Amnesty and Iran Human Rights.

During his detention, Mohammadi was beaten and one of his hands broken, Amnesty said in a Feb. 19 open letter to Iran’s judiciary criticizing the prosecution of dozens of arrested protesters. Amnesty said Mohammadi denied the charges and retracted his confessions in court, saying they were extracted under torture.

“Authorities have systematically subjected those arrested in connection to the protests to enforced disappearance, incommunicado detention, torture to extract forced ‘confessions,’” Amnesty said in the letter.

Mizan, the Iranian judiciary’s official news agency, announced the execution of the three on Thursday, showing video of them sitting in prison uniforms in court. It said they had confessed to killing two police officers with “knives and swords,” and showed video of them allegedly reenacting the killings for judicial officials.

Amiry-Moghaddam, of Iran Human Rights, said the Islamic Republic is struggling for its survival “and is well aware that the main threat to its existence comes not from external actors, but from the Iranian people demanding fundamental change.”

This story was originally featured on Fortune.com
Iran’s attack this week on Qatar’s natural gas export facility threatens to disrupt not just world energy markets but also global technology supply chains because the helium it produces is crucial for a range of advanced industries.

Best known as the gas that makes party balloons float, helium is also a key input in chipmaking, space rockets and medical imaging.

Qatar supplies a third of the world’s helium, according to the U.S. Geological Survey, but the nation had to halt production shortly after the war erupted three weeks ago. The latest Iranian strikes against the region’s energy producing infrastructure have added to supply worries, with Qatar’s state-owned gas company saying it would crimp helium exports by 14%.

Here’s a deeper look at helium’s industrial role:

Qatar’s role in helium supply

Helium is a byproduct of natural gas production, when it’s separated out by cryogenic distillation. Qatar, which sits on the world’s biggest single natural gas field, produces about 30% of global helium supply, according to the U.S. Geological Survey.

Qatar’s helium is produced at its Ras Laffan facility, the world’s largest liquefied natural gas plant. But state-owned energy company QatarGas halted production of LNG and “associated products” on March 2 because of Iran’s drone attacks and two days later declared force majeure, meaning it’s unable to supply contracted customers due to circumstances beyond its control.

After Ras Laffan was hit again by more Iranian strikes on Wednesday and Thursday, QatarGas reported “extensive” damage that will take years to repair and cut annual helium exports by 14%.

“It makes the story worse,” said Phil Kornbluth, president of Kornbluth Helium Consulting. “Your best case scenario would be you’re back producing some helium in six weeks or something like that. As it looks right now, that’s highly unlikely.”

Helium prices are on the rise

Spot prices for helium have doubled since the crisis erupted and will probably rise further, Kornbluth said.

But spot trading only accounts for about 2% of the total market in normal times, he said. Helium is a thinly traded commodity and is mostly sold through long-term contracts.

Still, contract prices “could go up a lot,” Kornbluth said. “There’s lots of room for price increase if this is an extended outage.”

Kornbluth said the shortage hasn’t hit yet, because helium containers that would have been filled when the conflict erupted at the start of March would have still taken several weeks to arrive in Asia.

“Nobody’s run out of helium yet. But it’s a few weeks out when the shortage really hits.”

It’s not just party balloons

Helium is essential for manufacturing semiconductors, including the cutting-edge chips used for artificial intelligence models produced in Asian fabrication plants.

It’s great at conducting or transferring heat, making it ideal for rapid cooling.

Chipmakers use it to cool wafers — the discs of silicon printed with tiny electronic circuits. Helium is used during the etching process, when material that’s been deposited on a wafer is scraped away to form transistor structures, said Jacob Feldgoise, an analyst at Georgetown University’s Center for Security and Emerging Technology.

During the etching process, “you really want to maintain a constant temperature over the wafer. And in order to do that, you need to be able to draw heat away from the wafer that’s being processed,” said Feldgoise. “Helium is an excellent thermal conductor. And so chip fabs will blow helium over the back of the wafer in order to speed heat removal and keep heat removal consistent.”

Under current semiconductor manufacturing processes, there’s no viable replacement for helium to cool wafers, said Jong-hwan Lee, a professor of semiconductor devices at South Korea’s Sangmyung University.

The medical industry uses helium to cool superconducting magnets powering magnetic resonance imaging machines.

And the space industry uses helium to purge rocket fuel tanks, a demand that is expected to grow because of more frequent launches by companies like SpaceX and Blue Origin.

A complicated supply chain situation

Helium’s atomic properties make it tricky to store and transport.

In gas form, helium’s tiny molecules can easily escape containers by leaking through even the smallest of gaps.

Helium is typically chilled by Qatar’s gas company into liquid form and stored in insulated containers for transport through the Strait of Hormuz. The specialized containers can store helium for 35 to 48 days. Any longer and they start warming up, letting the helium transform into gas that escapes through pressure release valves.

About 200 of these containers are stuck in the Middle East, Kornbluth said. They cost about $1 million each, so there aren’t a lot of extra ones sitting around elsewhere.

“It’s going to take a fair amount of time to get these containers out of Qatar and to get them somewhere else where they might be able to be filled with helium,” he said.

“So this initial period when you lose Qatar supply and have to rejig the supply chain and reposition containers, that’s going to be the worst part of the shortage most likely.”

Other major suppliers of helium

There only are a handful of countries that produce helium.

The United States is the biggest producer, accounting for 81 million cubic meters last year. Qatar, Algeria and Russia are the other major producers, but Russian supplies are banned under Under States and European Union sanctions.

USGS estimates the United States has 8.5 billion cubic meters of recoverable helium in geologic reservoirs, while the rest of the world has 31.3 billion cubic meters.

Asian chipmakers on edge

The war highlights the sprawling global supply chains that underpin South Korea’s semiconductor industry, which has seen a surge in global demand for its chips amid the AI boom.

Fitch Ratings said in a report this week that the country — home to Samsung Electronics and SK Hynix, the world’s largest memory chip makers — is particularly vulnerable to supply shortages because it imports about 65% of its helium from Qatar.

Samsung Electronics and SK Hynix likely have several months of inventory, but it’s crucial that they accelerate efforts to secure alternative sources, Lee said, as the war could drag on and potentially disrupt supplies of more materials beyond helium.

Helium is among 14 semiconductor supply chain materials the Seoul government has flagged for monitoring due to their heavy vulnerability to the war.

“Even disruptions affecting just a handful of materials could destabilize the entire semiconductor manufacturing process as each stage of production depends on the previous one,” Lee said.

Still, a full-blown helium crisis is unlikely, experts said. In the event of a shortage, Kornbluth said the helium industry allocates supplies based on importance so critical industries such as chipmaking and medical would be at the front of the line.

And because helium is a small part of the overall production cost of a semiconductor, it’s likely that chip fabs “would be willing to pay a higher price” to secure supplies, Feldgoise said.

Samsung and SK Hynix declined to respond to questions about inventory or plans to diversify supplies. The Korea Semiconductor Industry Association said short-term supplies are sufficient and companies have been diversifying their supply routes.

Chipmaking giant Taiwan Semiconductor Manufacturing Company also said it does not “anticipate any significant impact at this time” but will continue monitoring the situation.

This story was originally featured on Fortune.com
Colombian President Gustavo Petro has been designated a “priority target” by the U.S. Drug Enforcement Administration as federal prosecutors in New York probe his alleged ties to drug traffickers, according to people familiar with the matter and records seen by The Associated Press.

DEA records show Petro has surfaced in multiple investigations dating to 2022, many based on interviews with confidential informants. The alleged crimes the DEA has investigated include his possible dealings with Mexico’s Sinaloa cartel and a scheme to leverage his “total peace” plan to benefit prominent traffickers who contributed to his presidential campaign. The records also suggest the use of law enforcement to smuggle cocaine and fentanyl through Colombian ports.

The “priority target” label is reserved for suspects DEA deems to have a “significant impact” on the drug trade. It’s unclear when the DEA gave Petro that designation.

Petro denied all ties to drug traffickers and maintained he never accepted their funds during his campaign. Writing on X Friday, he argued that U.S. legal proceedings would ultimately dismantle accusations from the Colombian far right, a group he claims is actually the one involved with traffickers.

Colombia’s Embassy in Washington downplayed what it called “unverified” and anonymous reports of preliminary law enforcement investigations against Petro.

“The reported insinuations have no legal or factual basis,” the embassy said in a statement.

The inquiry

In recent months, prosecutors in Brooklyn and Manhattan have been questioning drug traffickers about their ties to Petro and specifically about allegations the Colombian president’s representatives solicited bribes to block their extradition to the United States, according to one of the people who weren’t authorized to discuss the ongoing inquiry and spoke to The Associated Press on condition of anonymity.

The person said it wasn’t clear whether federal prosecutors have implicated Petro in any crime.

The investigation is focusing at least in part on allegations that representatives of Petro solicited bribes from drug traffickers at the Colombian jail La Picota in exchange for a promise that they not be extradited to the U.S., one of the people said.

Petro has consistently denied allegations of drug trafficking, particularly after Trump labeled him an “illegal drug leader” and the Treasury Department sanctioned him in late 2025 for alleged ties to the trade without offering evidence.

U.S. federal prosecutors declined to comment. The DEA did not immediately respond to a request for comment.

The federal inquiry was reported earlier Friday by The New York Times.

The inquiries into Petro are in the early stages, and it is not clear whether they will result in charges, according to another person familiar with the matter, adding the White House has had no role in the investigations.

The DEA records reviewed by the AP are based in part on tips from confidential sources that point to Petro’s possible involvement with a range of criminal groups that have dominated the South American drug trade for years. Those include Mexico’s Sinaloa cartel as well as the Cartel de los soles, or Cartel of the Suns, a term used to describe a loose network of corrupt, high-ranking military officers in neighboring Venezuela.

The records also cite a 2024 interview with an unnamed source who claimed Petro is utilizing former campaign aides and officials from state-run oil company Ecopetrol to launder presidential funds into foreign countries for Petro’s use upon completion of his presidency.

Ecopetrol President Ricardo Roa vehemently denied the allegations in a statement to AP, saying they “lacked all reality or logic.”

Family members under scrutiny

Petro, a former rebel leader, soared into office promising to reduce the country’s dependence on fossil fuels and reallocate state resources to addressing entrenched poverty.

A leftist politician known for winding sometimes incoherent speeches, he has regularly criticized the Trump administration over its support for Israel, bombing of drug boats in the Caribbean and likened the White House migration crackdown to “Nazi” tactics.

After one such outburst, at a pro-Palestinian demonstration outside the United Nations headquarters in New York, Trump retaliated by revoking Petro’s U.S. visa. He also briefly slapped high tariffs on Colombia over Petro’s refusal to accept deportation flights from the United States.

But more recently the two have shown signs of getting along. After a meeting at the White House in February, Trump described Petro as “terrific.”

Colombian authorities have for years been investigating members of Petro’s family for possible criminal acts.

His son, Nicolás Petro, was charged in 2023 with soliciting illegal campaign contributions from a convicted drug trafficker to fund a lavish lifestyle of expensive cars and homes. The younger Petro has pleaded not guilty and his father has said none of the money was used to fund his campaign.

The president’s brother, Juan Fernando Petro, has also been implicated in secret negotiations that allegedly took place with imprisoned drug traffickers to shield them from extradition to the U.S. in exchange for their disarmament.

Politics and cocaine

Politics in Colombia have long been tainted by cocaine, of which it is the world’s largest supplier. In the 1980s, drug lord Pablo Escobar was elected to the country’s Congress with the support of one of Colombia’s most traditional parties. A decade later, his rivals from the Cali cartel flooded the presidential campaign of Ernesto Samper with illegal donations.

The now defunct urban guerrilla group Petro belonged to, the 19th of April Movement, has long been suspected of taking money from Escobar’s Medellin cartels as part of its deadly siege of the Supreme Court in 1985. Petro did not participate in the attack, which left several guerrillas and around half the high court’s magistrates dead. Leaders of the group have always denied any links to the cartel.

This story was originally featured on Fortune.com
Three weeks into an escalating war in the Middle East, Iran threatened to expand its retaliatory attacks to include recreational and tourist sites worldwide, as the U.S. announced it was sending more warships and Marines to the region.

Following news of the deployments, President Donald Trump said later Friday on social media that his administration in fact was considering “winding down” military operations in the region. The mixed messages came after another climb in oil prices plunged the U.S. stock market, and was followed by a Trump administration announcement that it will lift sanctions on Iranian oil loaded on ships, a move aimed at wrangling soaring fuel prices.

The war, meanwhile, has shown no signs of abating.

Israel said Iran continued to fire missiles at it early Saturday, while Saudi Arabia said it downed 20 drones in just a couple of hours in the country’s eastern region, which is home to major oil installations. The defense ministry said there were no injuries or damage.

The attacks came a day after Israeli airstrikes hit in Tehran as Iranians celebrated the Persian New Year, known as Nowruz, a normally festive holiday.

Iran has escalated attacks on its Gulf neighbors since Israel bombed its massive South Pars offshore natural gas field, while keeping a stranglehold on shipping in the Strait of Hormuz, a strategic waterwaythrough which a fifth of the world’s oil and other critical goods are transported.

With little information coming out of Iran, it was not clear how much damage its arms, nuclear or energy facilities have sustained in the punishing U.S. and Israeli strikes, which began Feb. 28 — or even who was truly in charge of the country. But Iran’s attacks are still choking off oil supplies and raising food and fuel prices far beyond the Middle East.

Trump says US near completion of its goals

The U.S. and Israel have offered shifting rationales for the war, from hoping to foment an uprising that topples Iran’s leadership to eliminating its nuclear and missile programs. There have been no public signs of any such uprising and no end to the war in sight.

In his social media post, the president said, “We are getting very close to meeting our objectives as we consider winding down our great Military efforts in the Middle East.”

That seemed at odds with his administration’s move to bolster its firepower in the region and request another $200 billion from Congress to fund the war.

The U.S. is deploying three more amphibious assault ships and roughly 2,500 additional Marines to the Middle East, an official told The Associated Press. Two other U.S. officials confirmed that ships were deploying, without saying where they were headed. All three spoke on condition of anonymity to discuss sensitive military operations.

Days earlier the U.S. redirected another group of amphibious assault ships carrying another 2,500 Marines from the Pacific to the Middle East. The Marines will join more than 50,000 U.S. troops already in the region.

Trump has said he has no plans to send ground forces into Iran but also has asserted that he retains all options.

Gen. Ali Mohammad Naeini, a spokesperson for Iran’s paramilitary Revolutionary Guard, was quoted by a state-run newspaper Friday as saying Iran continues to manufacture missiles despite Israel’s claim that it destroyed Iran’s production capabilities. Iranian state television later said Naeini was killed in an airstrike.

Iran threatens attacks beyond the Middle East

Supreme Leader Ayatollah Mojtaba Khamenei praised Iranians’ steadfastness in the face of war in a written statement read on Iranian television to mark Nowruz. He said the U.S. and Israeli attacks were based on an illusion that killing Iran’s top leaders could cause the overthrow of the government.

Khamenei has not been seen in public since he became supreme leader following Israeli strikes that killed his father, Ayatollah Ali Khamenei, and reportedly wounded him. Airstrikes have also killed the head of its Supreme National Security Council and a raft of other top-rankingofficials.

Iran’s top military spokesperson, Gen. Abolfazl Shekarchi, warned that “parks, recreational areas and tourist destinations” worldwide will not be safe for the country’s enemies. The threat renewed concerns that Tehran may revert to using militant attacks beyond the Middle East as a pressure tactic.

It remains to be seen if lifting sanctions on Iranian oil will drop prices

Brent crude oil, the international standard, has soared during the fighting and was around $108 per barrel, up from roughly $70 before the war.

The newly announced U.S. pause in sanctions applies to Iranian oil loaded on ships as of Friday and is set to end April 19. The license has limits including a restriction on sales involving anyone in North Korea or Cuba.

Treasury Secretary Scott Bessent previously suggested it as a way to prevent China from being the sole beneficiary of Iranian oil.

The new move does not increase the flow of production, a central factor in the surging prices. Iran has managed to evade U.S. sanctions for years, suggesting that much of what it exports already reaches buyers.

Looking for ways to boost global oil supplies during the Iran war, the Trump administration has previously paused sanctions on certain Russian oil shipments for 30 days, which critics said rewarded Moscow while having only a modest effect on markets.

Israel continues wave of strikes against Hezbollah militants

The Israeli military said early Saturday that it began a wave of strikes targeting Hezbollah militants in Beirut’s southern suburbs.

Smoke was seen rising, fires broke out and loud explosions were heard across parts of central Beirut. Hours earlier the army renewed evacuation warnings for seven neighborhoods, prompting some residents to fire gunshots to alert families to flee. No injuries were reported.

Israeli strikes targeting Iran-backed Hezbollah militants in Lebanon have displaced more than 1 million people, according to the Lebanese government, which says more than 1,000 people have been killed.

More than 1,300 people have been killed in Iran during the war. In Israel, 15 people have been killed by Iranian missiles and four others have died in the occupied West Bank. At least 13 U.S. military members have been killed.

This story was originally featured on Fortune.com
Eviction notices. Vehicle repossessions. Empty refrigerators and overdrawn bank accounts.

Union leaders and federal officials say these are just some of the financial pressures Transportation Security Administration agents are facing during an ongoing government funding lapse — the third shutdown in less than six months that has forced the officers who screen airport passengers and luggage to keep working without pay.

The public is experiencing the consequences in long wait times at some airports as more TSA officers take time off to earn money on the side or cut back on expenses. At least 376 have quit their jobs altogether since the shutdown began on Valentine’s Day, according to the Department of Homeland Security, exacerbating staff turnover at an agency that historically has had some of the U.S. government’s highest attrition and lowest employee morale.

“It’s just exhausting. Every day it just feels like this weight gets heavier and heavier on us,” Cameron Cochems, a local TSA union leader in Boise, Idaho, told The Associated Press.

Airport screeners have spent nearly half of the past 170 days with their paychecks held up by politics — 43 days last fall during the longest government shutdown in history, four days earlier this year during a brief funding lapse, and now 35 days and counting during the current shutdown, which affects only the Department of Homeland Security. They are considered essential so have to keep showing up for work whether they get paid or not.

Cochems, who has worked as a TSA agent for more than four years and is vice president of his regional American Federation of Government Employees chapter, said the number of resignations likely doesn’t fully capture the extent of the agency’s personnel challenges. He thinks many more officers would already have walked away in a stronger job market.

“I think more people are staying with the TSA that don’t want to be here,” Cochems said.

The House Committee on Homeland Security has scheduled a hearing for Wednesday to review the partial shutdown’s impact on the TSA, the Federal Emergency Management Agency, the U.S. Coast Guard and other agencies within DHS.

A 2024 report by the U.S. Government Accountability Office found that TSA’s workforce has long struggled with some of the lowest morale in the federal government, driven in part by years of comparatively low pay and persistent workplace frustrations. While recent raises have helped, the report said dissatisfaction remained widespread, with officers citing inconsistent management, limited recognition and poor work-life balance.

The starting pay for TSA agents is about $34,500, and the average salary is $46,000 to $55,000, according to the agency’s careers website.

The GAO warned that unless those underlying issues were addressed, the risk of officers leaving the workforce was likely to persist.

For Cochems, the recent shutdowns have upended the sense of stability that drew him to federal service in the first place. He said he already works a seasonal side job screening college sports teams at airports to supplement his income. Now, with his TSA paychecks halted, even that isn’t enough to keep up with basic expenses.

The financial pressure on his family intensified after his wife was unexpectedly laid off from her job two weeks ago.

“Every day I come to the airport and I look at the food drive, see what things I can get for my family,” he said, referring to the donations that his airport, like many others, are soliciting to help TSA workers.

It’s unclear how long airport screeners will have to keep working unpaid. Both chambers of Congress are scheduled to be out of Washington the first two weeks of April. And Democrats have said the department won’t get funded until new restrictions are placed on federal immigration operations following the fatal shootings of Alex Pretti and Renee Good in Minneapolis earlier this year.

For travelers, the strain in TSA staffing has made airport conditions increasingly unpredictable. Wait times have stretched into multiple hours at some airports, with passengers in cities like Houston, Atlanta and New Orleans reporting delays long enough to miss flights.

TSA officers missed their first full paycheck last weekend, and absences are climbing nationwide, according to Homeland Security. More than half of scheduled staff were absent Sunday at an airport in Houston. At Atlanta’s Hartsfield-Jackson International Airport, 38% of officers missed work on Wednesday and 32% on Thursday.

“I’ve heard from officers who cannot afford copayments for cancer treatments or office visits for their sick children,” Aaron Barker, a local TSA union leader in Atlanta, said at a news conference outside the airport this week.

Homeland Security has said roughly 50,000 TSA employees would work during the shutdown. Nationwide on Thursday, about 10% of TSA agents missed work, the department reported. The absentee rate was two or three times higher in some places: 33% at Houston’s George Bush Intercontinental Airport, 29% at John F. Kennedy International Airport in New York, 27% at Louis Armstrong New Orleans International Airport, and 23% at Baltimore-Washington International Airport.

The staffing shortages have also forced some airports to close checkpoints, with wait times swinging dramatically throughout the day in some cases. Early Friday, Hartsfield-Jackson had two-hour waits before easing to less than five minutes by early afternoon, and then jumping back up to 90 minutes.

Security line wait times at Houston’s main airport exceeded two hours on Friday afternoon. Videos posted to social media showed lines snaking around the airport and down an escalator, spilling into the baggage claim area.

In a Fox News interview this week, Acting Deputy TSA Administrator Adam Stahl warned that the latest shutdown could have lasting consequences for staffing, saying attrition and recruitment would likely suffer. Staff depatures increased after the record one last fall, Stahl said.

“We saw an uptick of 25% attrition after the last shutdown, and so this is going to continue and worsen — not get better, get worse — if we don’t get a resumption of normal operations, DHS funded and money back into our TSA officers’ pockets,” he said, adding that the agency has exhausted its options, including deploying emergency manpower, to keep airport security checkpoints adequately staffed.

Former TSA Administrator John Pistole has said that about 1,100 officers quit during last year’s shutdown that ended in November.

This story was originally featured on Fortune.com
After three years of widespread generative AI adoption, our data reveals only a small percentage of U.S. employees use AI in such a way that it enhances their thinking. Most workers either resist the technology entirely or use it passively. A small group — call them fluent users — does something fundamentally different.

So, what sets them apart? It’s not IQ. It’s not a technical skill. When we ask people how they’re using AI to make themselves smarter, their descriptions coalesce around a particular skill that rejects asking AI for direct answers to complex problems. These fluent users are thinking about their own thinking, casting AI in a supportive role, not a guiding one.

What they are describing is the act of metacognition.

The skill that unlocks smarter AI use

Metacognition is a fundamental concept in psychology that involves a distinctly human ability: reflecting on our own stream of thoughts, mulling them over, revisiting assumptions, and folding in new ideas to evolve our mental model. When we ask ourselves, “What am I missing?” or “What’s another way of looking at this problem?” We are engaging in metacognitive acts.

Few people practice metacognition deliberately, which makes fluent AI users look almost magical to their peers — the way a polyglot seems effortless to someone who only speaks one language. But here’s the good news: the skill is highly learnable. With the right principles and enough practice, anyone can use AI to make themselves smarter.

Based on our research, AI fluent users represent between 5–30% of employees at a given organization, depending on industry and role. They don’t ask the chatbot to generate a plan and pass it off as their own. Instead, they remain in the driver’s seat, starting conversations with prompts like:

I’ve created a marketing plan that I need help refining. I’m fairly confident it needs to reach mid-career professionals between 28–45 years old, but I could be missing something because of my unconscious bias around the topic. Without providing specific suggestions, can you help me think through my various options for improving the attached plan?

There are several things going on here. Most importantly, notice that the prompt doesn’t hand control to the AI. In our example, the user explicitly tells the AI not to offer suggestions — signaling that the user intends to remain the intellectual authority in the conversation.

Three metacognitive habits fluent users share

First, the prompt demonstrates humility. The user acknowledges they don’t have all the answers, using certain hedge phrases, such as “I’m fairly confident” and “could be missing something.” These signal a growth mindset, or the belief that one’s skills can be improved over time. Without it, the ego stays in self-protection mode — and learning stops.

Second, the prompt shows flexibility. The user acknowledges their point of view isn’t the only valid one. With a bit of digging, other options will come into view, expanding their perspective on the matter. From a neuroscience perspective, cognitive flexibility in AI usage enables us to be adaptive and open to multiple perspectives. Cognitive flexibility is thought to involve an expansive network of brain regions involved in cognitive control, including regions of the prefrontal cortex. 

Third, the prompt shows the user taking an active role in driving their search for new perspectives — a form of vigilance. The user prioritizes getting it right over feeling right.

Bias is a quiet saboteur. Without pausing to question blind spots, users risk having AI simply repackage flawed assumptions in new wrapping. Also, a sense of vigilance is crucial for mitigating any biases that may be embedded in the AI’s answers — including biases baked into the AI itself.

The most encouraging finding from our research: metacognition isn’t an innate talent. It’s a trainable skill. The more deliberately you practice thinking about your own thinking, the more natural it becomes — and the more likely you are to walk away from every AI conversation sharper than when you started. In an era when most people worry AI will make them dumber, fluent users are quietly proving the opposite.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com
Many businesses are birthed from a bright idea—but that isn’t enough to take a company big-time. Dairy Queen CEO Troy Bader said Warren Buffett taught him that zeal for the mission is more important than anything else; being “smartest person in the world” won’t outperform “somebody who has that passion.”

“Anybody you meet, I don’t care who they are—they know something you don’t,” Bader told Business Insider last year.

It’s just one of the two takeaways that have stuck with Bader since his job interview with Buffett in 2017 to become CEO of the billion-dollar ice cream giant. And as the serial investor stepped down from his six-decade rein over Berkshire Hathaway at the end of 2025, his words of wisdom seem to carry even more weight. The Dairy Queen CEO was shown that even the most successful people still have things to learn, and passion triumphs wits in growing a business. 

What it’s like to be interviewed by Warren Buffett

Bader admitted it was daunting to come face-to-face with Buffett; especially after Berkshire Hathaway shelled out $600 million to take Dairy Queen company private in 1998. The business mogul has long had a soft spot for Dairy Queen, both in business and in life. So the sweet treat CEO felt the pressure to impress during their interview.

“It was the fall of 2017, I’ll never forget the day,” Bader told Business Insider. “I was very anxious going in because OK, I felt like I knew our business, but you’re sitting down with Warren Buffett.”

Buffett wasn’t the type to act “very arrogant” in the meetings as one might expect, Bader said. Instead, the Oracle of Omaha spent the first 15 or 20 minutes asking the Dairy Queen executive about something relevant to another business deal in his pipeline. Buffett figured Bader could teach him a thing or two, which ironically taught him a valuable lesson back: that anyone you meet knows something you don’t, regardless of stature. 

“Warren is a constant learner,” Bader said. “He wants to know what you know and what he can learn from you.”

During their conversation, Bader noticed Buffett was “digging for something more, that energy, that passion, that connection to the business.” That spurred a second revaluation—that Buffett wanted spirit and enthusiasm from the executives he was meeting with. When it comes to running a successful business, passion tops intelligence in getting the job done right. The power of a can-do, passionate attitude in business has been echoed by other executives like Amazon CEO Andy Jassy and Cisco’s U.K. chief Sarah Walker.

Buffett’s advice for CEOs and billionaire philanthropists

Buffett’s words have impacted more than just the people he interviews. Even some of the world’s most respected leaders see the billionaire as a north star in navigating the rollercoaster of entrepreneurship.

Early on in Melinda French Gates’ philanthropic career running the Gates Foundation with her then-husband Bill Gates, the Berkshire Hathaway boss gave her some advice on managing the stress—and she still swears by it. 

“Warren Buffett once said to us early in the [Gates] Foundation’s life, ‘Find your bull’s-eye of what you’re working on, and let the other things fall away. You’ll feel better if you keep your talents in that bull’s-eye, keep working those issues, and you’ll feel less bad about letting other things go,’” French Gates told LinkedIn in 2024. “And I think that’s true.”

American Express CEO Stephen Squeri also said he soaked up advice from Buffett during their bimonthly calls. In an interview with Barrons in 2023, the financial services executive recalled getting important guidance from the Omaha entrepreneur during the COVID-19 pandemic when no one was in public cashing out their Amex cards. Buffett advised him to hold two things down pat; it could mean a difference between boom and bust. 

“His advice to me is, protect two things—protect your customers and protect your brand,” Squeri said. 

A version of this story was published on Fortune.com on May 21, 2025.
This story was originally featured on Fortune.com
Elon Musk has a moonshot vision of life with AI: The technology will take all our jobs, while a “universal high income” will mean anyone can access a theoretical abundance of goods and services. Provided Musk’s lofty dream could even become a reality, there would, of course, be a profound existential reckoning.

“The question will really be one of meaning,” Musk said at the Viva Technology conference in May 2024. “If a computer can do—and the robots can do—everything better than you … does your life have meaning?” 

But most industry leaders aren’t asking themselves this question about the endgame of AI, according to Nobel laureate and “godfather of AI” Geoffrey Hinton. When it comes to developing AI, Big Tech is less interested in the long-term consequences of the technology—and more concerned with quick results.

“For the owners of the companies, what’s driving the research is short-term profits,” Hinton, a professor emeritus of computer science at the University of Toronto, told Fortune.

And for the developers behind the technology, Hinton said, the focus is similarly on the work immediately in front of them, not on the final outcome of the research itself.

“Researchers are interested in solving problems that have their curiosity. It’s not like we start off with the same goal of, what’s the future of humanity going to be?” Hinton said.

“We have these little goals of, how would you make it? Or, how should you make your computer able to recognize things in images? How would you make a computer able to generate convincing videos?” he added. “That’s really what’s driving the research.” 

Hinton has long warned about the dangers of AI without guardrails and intentional evolution, estimating a 10% to 20% chance of the technology wiping out humans after the development of superintelligence.

In 2023—10 years after he sold his neural network company DNNresearch to Google—Hinton left his role at the tech giant, wanting to freely speak out about the dangers of the technology and fearing the inability to “prevent the bad actors from using it for bad things.”

What are the risks of unregulated AI?

For Hinton, the dangers of AI fall into two categories: the risk the technology itself poses to the future of humanity, and the consequences of AI being manipulated by people with bad intent.

“There’s a big distinction between two different kinds of risk,” he said. “There’s the risk of bad actors misusing AI, and that’s already here. That’s already happening with things like fake videos and cyberattacks, and may happen very soon with viruses. And that’s very different from the risk of AI itself becoming a bad actor.”

In November 2025, Anthropic said it disrupted “the first documented case of a large-scale AI cyberattack executed without substantial human intervention,” identifying a Chinese state-sponsored group that manipulated Claude Code in an attempt to infiltrate around 30 tech companies, financial institutions, government agencies, and chemical manufacturers, the AI company said in a blog post.

The disruption has led cybersecurity experts to believe Iran could use AI to conduct a largely automated cyberattack against the U.S.

Beyond advocating for more regulation, Hinton’s call to action to address AI’s potential for misdeeds is a steep battle because each problem with the technology requires a discrete solution, he said. He envisions a provenance-like authentication of videos and images in the future that would combat the spread of deepfakes. 

Just as printers added names to their works after the advent of the printing press hundreds of years ago, media sources will similarly need to find a way to add their signatures to their authentic works. But Hinton said fixes can only go so far.

“That problem can probably be solved, but the solution to that problem doesn’t solve the other problems,” he said.

For the risk AI itself poses, Hinton believes tech companies need to fundamentally change how they view their relationship to AI. When AI achieves superintelligence, he said, it will not only surpass human capabilities, but have a strong desire to survive and gain additional control. The current framework around AI—that humans can control the technology—will therefore no longer be relevant. 

Hinton posits AI models need to be imbued with a “maternal instinct” so it can treat the less-powerful humans with sympathy, rather than desire to control them.

Invoking ideals of traditional femininity, he said the only example he can cite of a more intelligent being falling under the sway of a less intelligent one is a baby controlling a mother.

“And so I think that’s a better model we could practice with superintelligent AI,” Hinton said. “They will be the mothers, and we will be the babies.”

A version of this story was published on Fortune.com on Aug. 15, 2025.
More on the future of AI:

This story was originally featured on Fortune.com
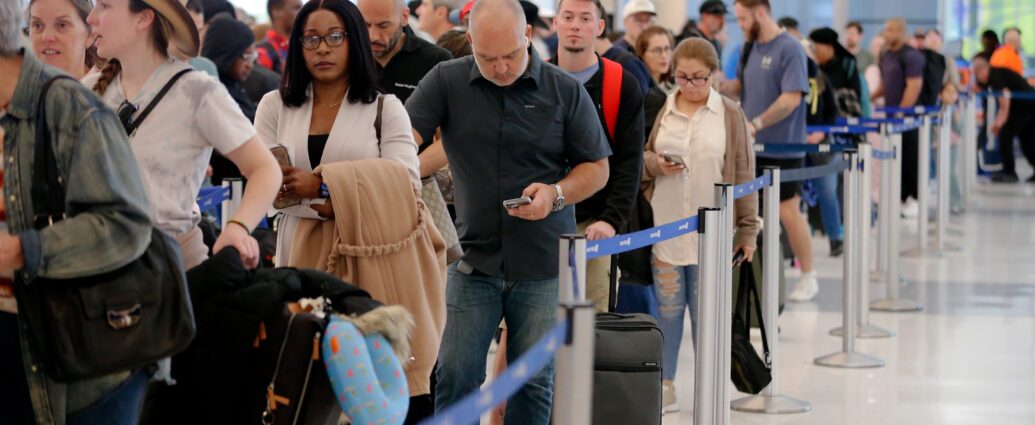
On March 1, Iranian drones struck three data centers operated by a major U.S. hyperscaler in the Gulf—two in the UAE, one in Bahrain. Banking apps went dark. Payment platforms failed. Ride-hailing services crashed. It was the first time a U.S. data center had been hit by military action, and it sent an unmistakable message: in modern conflict, corporations are targets.

This is not an anomaly. It’s a strategy.

Since the dawn of modern warfare, armed forces fought other armed forces. Private companies were affected, but they operated on the periphery of the battlefield. That assumption is now obsolete.

Iran’s current campaign reflects a deliberate shift toward attacking economic infrastructure and commercial actors. Data centers in the Gulf have faced physical, cyber, and hybrid strikes aimed at disrupting the digital backbone of global commerce.

Tourism hubs in Dubai and Abu Dhabi have been hit by missile and drone strikes on hotels and airports—designed to erode confidence and kill visitor demand.

Oil tankers and commercial vessels tied to the global energy trade have been harassed in the Strait of Hormuz, while Iran’s Houthi proxies in Yemen have targeted shipping in the Red Sea. These attacks are not random. They are a coordinated effort to impose economic costs, manufacture uncertainty, and pressure governments by targeting the private systems that sustain modern economies.

This reality demands a fundamentally new approach to corporate security—one that treats geopolitical risk as an operational issue, not a compliance checkbox.

Real-time intelligence. Quarterly risk assessments and static security reviews are relics of a different era. In a dynamic conflict environment, businesses need continuous situational awareness— live information on cyber threats, physical attacks, regional instability, and supply chain disruptions.

Physical and digital hardening. Data centers, ports, logistics hubs, energy infrastructure, and commercial campuses are now legitimate military targets. Resilience planning—redundant networks, reinforced facilities, physical security improvements to redundancy in digital networks and supply chains—has become a board-level governance issue.

Active defensive capabilities. The proliferation of drone and missile technologies means counter-drone and counter-missile systems are no longer exclusively military concerns. In high-risk sectors and regions, companies may need to evaluate both kinetic and non-kinetic defensive tools to protect critical infrastructure.

None of this means corporations should replace governments as security providers. Militaries will still field the most advanced anti-missile and anti-drone systems. But the traditional boundary between national security and corporate risk management is dissolving fast. 

The companies best positioned to navigate this era will be those that build genuine partnerships with governments, intelligence professionals, and national security advisors—and that design practical mitigation strategies before the next strike, not after.

The front lines of modern conflict no longer run only through military bases. They run through ports, data centers, shipping lanes, and corporate networks.

And the companies that depend on them must be prepared to defend themselves. 

This story was originally featured on Fortune.com
In 2020, Covid shut down global supply chains and sent inflation surging. In 2022, Russia’s invasion of Ukraine triggered a global energy and food price shock. U.S. tariff policies in 2025 disrupted global trade and helped to stall a long-awaited retreat in domestic inflation. Now, in 2026, we have war in the Persian Gulf. Commerce has frozen in the Strait of Hormuz — and the script looks eerily familiar.

Gasoline prices are rising — up more than 30% in a month, the largest increase in such a short span since Hurricane Katrina in 2005. Fertilizer is stuck at Middle East export hubs, potentially disrupting planting seasons from Iowa to Africa. Stock prices are falling. Economists are again talking about recession risks. Diesel is up nearly 40%, topping $5 a gallon — a serious problem for an economy where trucks, ships, trains, and farm equipment all run on it.

Four supply shocks in six years. At some point, you have to stop calling it bad luck.

It is time to start asking whether supply shocks are coincidence – a series of uncorrelated, unfortunate events – or whether something larger is going on that has changed the economic landscape for the long-term. If something has changed, then we need to start rethinking our models for how business and the economy work.

A pattern the Fed has missed

The need for a rethink starts at the world’s most consequential economic institution: The Federal Reserve. When asked at a press conference this week to make sense of serial supply shocks, the U.S. central bank chairman, Jerome Powell, seemed to miscalculate the common denominator. “I don’t know that the world has changed in a way that there will be more supply shocks,” he said.

In central bank parlance, the Fed still seems to think it might be able to “look through” yet another one of these events.

That’s a dangerous world view — and it’s one the Fed has reached before. After Covid, the Fed called inflation “transitory” and was slow to raise interest rates. Tariffs – a manmade form of supply shock designed to reorder global trade and raise prices – have been written off as another one-off event, even though they keep coming back. Now, facing the Hormuz disruption, Powell held out a possibility that this too shall pass, and inflation might revert to a norm that may no longer exist.

If the Fed is wrong again, the consequences for American consumers — already living with inflation above target for five straight years — could worsen.

A rupture, not a run of bad luck

The Fed is a large, inertial institution. It takes time to incorporate deviations from recent norms into its models. Officials tend to want to avoid getting ahead of themselves; they lean on established thinking.

Now is time for the Fed to start updating its thinking about supply shocks.

Repeated rounds of tariffs are human choices, as are wars in Iran and Ukraine, not some storm that blew in from nowhere. The Covid crisis certainly did have a large random element to it, but it also had common global denominators – it was propagated through a global order that didn’t respond well to the need for collaboration and containment required by a viral intruder.

Mark Carney, a former central banker who is now Prime Minister of Canada, put his finger on something important in comments in Davos early this year. These crises, he said, are symptoms of a “rupture in the world order,” a breakdown in global, rules-based cooperation and norms that in the past facilitated global integration and commerce.

Over decades, multinational businesses built and operated global supply chains that depended on cooperation and integration to function properly. When cooperation breaks down, the supply chains become vulnerable. They are now transmitting shocks rather than just facilitating commerce. Tariffs and war are examples, as was the chaotic global response to the Covid virus and its aftermath.

“A series of crises in finance, health, energy and geopolitics have laid bare the risks of extreme global integration,” said Carney, a long-time friend of Powell. “More recently, great powers have begun using economic integration as weapons, tariffs as leverage, financial infrastructure as coercion, supply chains as vulnerabilities to be exploited.” The result: Nations increasingly see themselves as fortresses, which counterintuitively makes them more fragile to economic shock.

Remarkably, Carney didn’t call for a return to the old order of global cooperation that, among other things, held down inflation and lifted billions of humans out of poverty in the past quarter century. A realist, he instead tried to see a way through a new era of fracture by seeking to band together with others like Canada caught in the middle of a deepening disorder.

An indefensible posture

The Fed’s models, and its way of thinking, were built during a period of global integration, stable supply chains, and cooperative international norms. As that world frays, the central bank runs the risk of making mistakes. It needs to develop a coherent, updated view of how the global economy is changing.

If supply shocks are a feature of a new global economic disorder, then inflation could prove more stubborn than the Fed’s old models project. That, in turn, could lead the central bank to keep interest rates lower than they ought to be, based on an expectation that inflation will revert to norms that no longer exist. That could make the stubborn economic challenge of inflation even worse.

The Fed was right to keep interest rates unchanged at its policy meeting this week. Expecting each new crisis to be a one-off event is no longer a defensible posture. We may be discovering that nagging inflation is a function of the rupture that Powell’s old friend Carney described just a few weeks earlier. 

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com
There’s no better way to fuel up for traipsing the Costco aisles for hours than a $1.50 hot dog and a soda. 

It’s been a staple of the bargain shopping club for four decades, and Costco’s president and CEO, Ron Vachris, recently confirmed it’s a deal that’s never going away, at least under his watch.

“The hot dog price will not change as long as I’m around,” Vachris said in an Instagram video posted this week. 

Costco executives have long assured customers the bargain won’t go away, but they’ve ramped up that messaging in the past couple of years as consumers continue to be strained by tariffs, inflation, and a high cost of living. 

Richard Galanti, who stepped down in 2024 as chief financial officer, told Fortune’s Phil Wahba that deals as well as Costco’s $5 rotisserie chicken are “foundational” to the warehouse chain’s success—and even told The Wall Street Journal in 2022 the $1.50 hot dog was “sacrosanct,” and its price would stay fixed “forever.” In 2024, Galanti’s successor, Gary Millerchip, said, “I also want to confirm the $1.50 hot dog price is safe.”

And as Irina Ivanova reported for Fortune, Costco is also committed to keeping the soda part of the combo cheap. When Costco’s contract with Coca-Cola was up for renewal a decade ago, the company switched to Pepsi to save on prices, although they’re back to serving Coke products now.

K-shaped economy food prices

The timing of Vachris’s reassurance isn’t coincidental, could be seen as strategic. American consumers face mounting financial pressure, so even a modest, decades-old hot dog deal has become a symbol of economic stability in an otherwise turbulent economy.

“Food away from home” prices rose about 4.1% from December 2024 to December 2025, according to the U.S. Consumer Price Index. That means a budget staple like Costco’s $1.50 combo, which has been unchanged since 1985, represents something increasingly rare: a price point that hasn’t budged while nearly everything else has.​​

The broader backdrop is a K-shaped economy that has split American consumers into two diverging realities. According to a Moody’s analysis of Federal Reserve data, lower-income earners have spent only in line with inflation since the pandemic, with all real spending growth coming from the top 20%.

“Looking at the data, it’s not a mystery why most Americans feel like the economy isn’t working for them,” Moody’s chief economist Mark Zandi wrote in a 2025 report. “For those in the bottom 80% of the income distribution, those making less than approximately $175,000 a year, their spending has simply kept pace with inflation since the pandemic.”

“The 20% of households that make more have done much better,” he continued, “and those in the top 3.3% of the distribution have done much, much, much better.”

Spending among top-income consumers grew 4% in November 2025 year-over-year—nearly four times the pace of the lowest-income bracket, according to the Bank of America Institute. For the consumers trending downward on the K-curve, every dollar counts.

This phenomenon has triggered other food-industry companies to create deals for consumers. McDonald’s extended its meal deal well beyond its original run and launched a “McValue” menu with buy-one-get-one-for-$1 offers. Wendy’s rolled out $4, $6, and $8 mix-and-match value tiers; KFC introduced a $5 offering; and Taco Bell launched Cravings Boxes starting at $5. Even Sweetgreen, a notoriously expensive fast-casual chain, began offering $10 loyalty-member bowls, a roughly $6 discount, to stay competitive.

But Costco doesn’t need a limited-time promotion to signal it’s on the consumer’s side. It’s been doing that for 40 years by consistently selling $1.50 hot dogs, so customers know what to expect.

This story was originally featured on Fortune.com
COVID-19 gave us hybrid work. The Iran War might give us a three-day weekend. That’s because, as Sri Lanka, the Philippines, and Pakistan move to a 4-day work week because of the war in Iran, experts say we’re the closest we’ve ever been to a permanent shorter workweek. 

It started in Asia, but now major governments around the world are once again mandating that workers stay home to save on fuel and survive an energy crisis as the war in the Middle East threatens vital oil shipments through the Strait of Hormuz. 

What began as an emergency measure in the developing world is now spreading globally. Sound familiar? We’ve been here before: The last time the world was forced to shift en masse—the pandemic—the changes we thought would be temporary became permanent. Hybrid work didn’t die when offices reopened. Instead, it reshaped how we work.

Now, with governments reaching for the same lever again, experts say something similar could happen with a four-day workweek. But it’ll come with major consequences for those who can’t take their jobs home, like drivers, baristas, window cleaners, pet sitters, and more.

Will an overnight emergency four-day week come to the West?

Although Brits and Australians are being urged to work from home, Dr. Wladislaw Rivkin, Professor in Organisational Behaviour at Trinity Business School, told Fortune that a global three-day weekend currently looks unlikely—at least not at the click of the government’s fingers.

That’s because a permanent restructuring of how work is organized is a far heavier lift than an overnight shift to working from a makeshift home office. “I do not see this as a model for the U.S. and U.K., at least in the long term, because the current sharp rise in fuel costs is temporary,” Rivkin says.

Professor Roberta Aguzzoli at Durham University Business School says she wouldn’t rule out the West moving to shorter workweeks to save fuel, but she argues better infrastructure should minimise that need. 

“Public transport systems in large European cities are generally more developed and less reliant on individual transport use than those in certain emerging economies,” she says, adding that limited transport infrastructure and higher exposure to fuel price volatility make last-minute policy changes more necessary.

On that basis, she says a permanent four-day week in the near term is more likely to become the new norm in developing countries. But there’s a big but. The mere fact that millions of workers are about to spend an extended period proving they can get the job done in four days could be the tipping point the movement has been waiting for.

Why Asia’s four-day week could permanently change how the world works

Whether Asia’s emergency four‑day workweek will have the same lasting effect as the pandemic’s work-from-home mandate, or even ripple into Europe and the U.S., remains to be seen. But once workers get a taste of a shorter week—even a forced one—it’s a hard sell to go back to the old one.

“Remote work didn’t spread because companies planned it,” says William Self, chief workforce strategist at Mercer. “It spread because the pandemic crisis forced the experiment, the experiment worked, and workers weren’t willing to give back what they’d gained. The same logic applies here.”

Self argues that once the experiment runs, the burden of proof flips. “If employers experiment with a four-day workweek and employees show they can deliver in four days what they previously delivered in five, management has to justify the fifth day rather than the other way around.”

What makes this moment historically distinct, he says, is the convergence of two previously separate conversations. “Previously, a four-day workweek was mostly theoretical or confined to a handful of pilot programmes. Now you have some governments weighing in as a matter of public policy and major employers adopting it, and they’re doing so in the same news cycle. That’s a different situation than we’ve been in before.” Add AI rewriting what productivity means, a cost-of-living crisis, stagnant wages and workers who’ve already had a taste of flexibility, and the pressure for more flexible ways of working is converging from every direction at once.

Emergency or not, Aguzzoli argues that research shows we’re already heading that way anyway. 

According to CIPD, the four-day workweek has the potential to become a new norm. There is a growing global trend in this direction, with organisations across different countries volunteering to test the effectiveness of such policies. 

Thankfully for workers, the fuel crisis isn’t the sole reason for this shift, making it more likely to stick—but it’s also why you shouldn’t expect it to explode overnight like hybrid working during the pandemic. 

“The discussion around the four-day workweek is still at an early stage, with companies and researchers continuing to assess its long-term impact on performance,” Aguzzoli added. “While there are several initiatives moving in this direction, most involve large organisations with well-developed human resource management systems that are better equipped to plan for and manage such changes.”

Who gets left behind: why the four-day week could make inequality worse

Perhaps the most uncomfortable truth about the four-day workweek is who it would actually benefit—and who it would leave behind.

For office workers, the transition is relatively seamless and largely welcomed.

But workers in lower-skilled, customer-facing, or physically demanding roles—delivery drivers, construction workers, care workers, retail staff—face a fundamentally different reality. Compressing the same output into fewer hours doesn’t mean more rest, Aguzzoli argues. It means more strain, greater fatigue, and a higher risk of workplace accidents. Plus, for those already on low wages with little bargaining power, a forced compression of hours could also mean a direct hit to their income.

Ultimately, Aguzzoli says that although a four-day workweek could help reduce the current gender gap, it could “widen disparities between skilled and low-skilled workers.

The divisions don’t stop there. Rivkin warns that the four-day workweek could fracture workplaces from the inside out. “For example, if an administrative worker in a hospital works 4 days a week, while a nurse has to work 5 days a week.”

The result isn’t a more equitable workplace—it’s a more resentful one. Rather than levelling the playing field, a four-day rollout could make physically demanding professions even less attractive, harder to staff, and more dangerous than they already are.

This story was originally featured on Fortune.com
Months of hot takes have blamed Gen Z for bad attitudes, no work ethic, and too many demands. But labor market data tells a far less convenient story. The entry-level rungs of the employment ladder are splintering beneath America’s youngest workers — and the data makes clear this isn’t a generational character flaw. It’s a structural collapse.

Headline indicators suggest a strong labor market. Under the hood, persistent weaknesses are festering. The “low-hire, low-fire” market means employers are hesitant to make any changes to their payroll. For mid-career employees, that stability is a relief. For young people trying to land a first job, it’s a dead end.

In 2025, the share of unemployed Americans who are new workforce entrants hit a 37-year high, peaking at 13.3% in July before settling at 10.6% this February. That is still higher than at any point during the Great Recession. When hiring slows, the door closes first on recent graduates and those new to the workforce.

[Moved the 37-year high stat up and made it the paragraph’s lead — it’s the piece’s most alarming single data point and was previously buried as a supporting detail. “That’s still higher than any point during the Great Recession” elevated to its own sentence for emphasis.]


The Jobs That Were Supposed to Be Theirs Have Vanished

Today’s labor market gains are isolated and uneven, largely bypassing young workers. Job gains have been narrowly concentrated in health care and social services. Meanwhile, finance and information services — industries that once provided an on-ramp for the lion’s share of recent college graduates — are hemorrhaging jobs, shedding an average of 9,000 jobs per month since 2023. Before the pandemic, those same industries were adding 44,000 jobs per month. Young workers are refreshing job boards only to find a shrinking pool of openings. A record number of new workers are arriving at the doorstep of the labor market just as employers are pulling the door shut.

Gen Z doesn’t lack hustle. As this generation tries to find their footing in the traditional market, many are turning to side hustles. More than half — 57% — of Gen Zers now juggle additional work such as making content, selling crafts, and working in the gig economy, compared to just 21% of Baby Boomers. There’s real entrepreneurship in the side-hustle surge, but there’s also a warning sign. Across the economy, a ballooning share of workers are cobbling together part-time or multiple jobs to stay afloat. In this context, the boom in side-hustle culture reflects a generation piecing together income in a market that offers too little stability and too few pathways to advancement.


The College Degree No Longer Guarantees What It Once Did

What labor economists first documented among Black college graduates a decade ago — that doing everything “right” still didn’t guarantee stable employment — has since rippled across the entire labor market.

A college diploma no longer guarantees a job or a better shot at a stable paycheck. Since the Great Recession, the gap in unemployment rates between college graduates and those without degrees has been narrowing. Now, recent college graduates are actually more likely to be unemployed than the overall workforce.

Perhaps most striking: for six months in 2025, workers with an occupational associate’s degree in skilled trades — plumbers, electricians, pipe fitters — posted slightly better employment outcomes than college graduates. This marks the first time college graduates have lost their employment advantage since the federal government began tracking these data in the 1990s.


AI Is Threatening to Lock the Door From the Inside

As the labor market door swings shut on young people, artificial intelligence threatens to turn the deadbolt from the inside. AI-driven mass unemployment has not yet arrived — but early warning signs are flashing for workers at the start of their careers. A recent Stanford University study found that workers ages 22 to 25 in highly AI-exposed occupations — software development, customer service — experienced a 13% drop in employment since 2022.

Even tech leaders are sounding the alarm. Anthropic CEO Dario Amodei has warned that AI could wipe out roughly half of entry-level white-collar jobs in the next five years. Taken together, young workers without experience face outsized risk of labor market scarring — entering a workforce that is simultaneously contracting at the entry level and automating the roles that remain.

This uncertainty is weighing on young workers. The Conference Board finds that just 57% of workers under 25 report being satisfied with their jobs, compared to 72% for workers over 55. In a year marked by the fastest single-year gain in job satisfaction ever recorded, young workers were the only group whose satisfaction declined.


What Actually Needs to Change

Blaming Gen Z is easy. The data shows it’s also wrong. This generation is coming of age in a labor market that is less secure, less dynamic, and less predictable than the ones their parents entered — one where workplaces increasingly deploy surveillance technology and retirement benefits are eroding. What’s needed is not a lecture about work ethic. We need an economy that offers multiple, durable pathways to middle-class security.

We can reinvigorate the promise of a four-year degree while investing in apprenticeships, public service programs, and other proven on-ramps to stable employment. And as AI reshapes the workforce, policymakers must ensure that workers have a voice in how it’s deployed — and that the benefits it creates are broadly shared rather than concentrated among the few.

Gen Z is not unemployable. They are knocking on locked doors. The task before us is to reopen them — and to make sure that a shot at the middle class doesn’t become a relic of the past.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com
Artificial intelligence is moving even faster than many thought. In the span of three years, the world went from wearily experimenting with OpenAI’s ChatGPT to entire companies integrating Anthropic’s Claude Code into their workflows. The speed of AI’s progression, technologically and culturally, has surprised many—including Anthropic CEO Dario Amodei, who warned in a 20,000-word essay in January that society could experience catastrophic impacts within a year or two. 
But experts warn this fast-paced innovation is leaving one essential group behind: women. 

The jobs women hold are three times more likely to be automated by AI. Despite this fact, women are using AI at a rate 25% lower than men on average. This paradox is compounded by the fact that women are underrepresented in AI leadership and development, even as some of the companies with the most advanced AI adoption are led by women. 

Women are more hesitant about using AI

Leaving women out of a major technological transition could have long-term economic consequences, says workplace AI adoption strategist Mara Bolis, who warned the issue doesn’t rest with a woman’s ability to use the technology, but rather, their willingness. 
“This is not a lack of competence,” Bolis told Fortune. “This is discernment, in terms of how we want our economies and our societies to evolve.”

“I’m really worried that we’re at risk of creating a two-tiered AI economy if we don’t engage women more actively and really respect the unique skills and expertise that they bring to the field, skills that are critically important to making sure that AI evolves safely and equitably,” Bolis said. 

Bolis thinks hesitancy is a wise response to AI hype. After a stint as an economic analyst at the New York Federal Reserve, Bolis spent 11 years working on women’s economic empowerment at Oxfam. While completing a fellowship at the Harvard Kennedy School in 2023, she noticed how gender was missing from the conversation around AI policy. She founded First Prompt, an inclusive AI adoption lab that advises businesses globally on how to address and prevent inequitable AI adoption. 

Researchers at Stanford University, Harvard University, and the University of California, Berkeley found that women are less familiar with how to use AI tools and are less persistent with the technology when they use it. They are more likely to be concerned with the ethical implications of AI and about how it will affect their jobs and livelihoods. 

Women are also less certain about the benefits of AI adoption, according to Beatrice Magistro and Sophie Borwein, assistant professors of political science at Northeastern University and the University of British Columbia, respectively. The two researched how women’s risk aversion affects their skepticism toward AI’s economic benefits. 

Whether their jobs were highly complementary to AI or at risk of automation, women still perceived the technology as riskier than men did, Borwein said.  

And there’s good reason for that caution: women face a higher risk of punishment for using AI at work. A Harvard Business Review study found that female engineers are penalized more and are seen as less competent than otherwise-identical male colleagues when they produce identical AI-assisted work.

Women’s jobs will face the brunt of AI disruption 

Of the 6.1 million workers whose jobs are the most likely to be disrupted by AI and least likely to adapt, 86% are women, a Brookings analysis found. These are roles like administrative assistants, receptionists, office and legal clerks, which are positions often held by older women. Whereas men in highly AI-exposed jobs are likely to change jobs, women are most likely to completely exit the labor market rather than find new employment, Brookings found. 

“Those types of jobs that are really good, middle-class jobs. They’re well-paying jobs, they’re white-collar jobs, and they’re going to go away,” Bolis said. “They’re going to fall into less well paid, less secure work as that entire sector falls away, unless we focus intentionally on creating policies and programs that help them weather this change.”  

While gender disparities in AI usage persist, the gap does appear to be closing. In 2018, only 12% of machine learning engineers were women, WIRED reported. Now, 30.5% of AI professionals are women, researchers at Stanford University found. 

A September 2025 OpenAI report that analyzed 1.5 million conversations found that the gap between users with masculine and feminine names was closing. In January 2024, the company reported 37% of users had typically feminine names. By July 2025, that share had risen to 52%.

Bolis said women are in a position to find gaps with AI because they didn’t build this system. She advocates for people to approach the technology with “fierce ambivalence.”

“People think that [ambivalence] means that you don’t care, which is not what it means at all. It means holding divergent attitudes at once, which I think is very uncomfortable for people,” she said. “We need to be using AI to empower ourselves and others, while we hold the creators of this technology and the people who are setting up policies and governance to the highest possible standards to ensure that these technologies are rolled out in a way that’s safe and efficient and equitable.”

Both women and men support AI adoption when they are certain that the net effects will be positive, Magistro and Borwein’s research showed. 

“This ambivalence is not fixed. Women can lose that ambivalence if they are convinced that the net benefits are there,” Magistro said. 

This story was originally featured on Fortune.com

When the fintech Block recently announced it was cutting nearly half its workforce, many questioned whether it was another tech company cleaning up a pandemic-era hiring binge. But CFO and COO Amrita Ahuja offered a data point to consider. 

Block generated roughly $500,000 in gross profit per employee in 2019—a figure that barely budged even as headcount ballooned from a few thousand to around 13,000 during the hyper-growth years, Ahuja noted in a recent interview with Fortune. Then something changed.

As AI tools embedded more deeply into the company’s workflows, that metric began climbing: $750,000 per employee in 2024, $1 million in 2025. And if Block hits the targets the targets in its 2026 outlook—now expecting gross profit to grow 18% year over year and profits to climb 54%—gross profit per employee will reach approximately $2 million in 2026, double last year’s level.

“I don’t think this is about bloat,” Ahuja said. “This is about empowering our teams with the most world-class and powerful tools.”

Central to that shift is Block’s internally built AI agent, code-named Goose, which has been running in production for 18 months. Since September, developer productivity has jumped 40% per engineer. One risk underwriting model that previously took a full quarter to build was completed in a fraction of the time. The productivity math is what gave leadership confidence to cut 4,000 jobs from a position of strength, Ahuja said. The decision was part of a longer transformation. “This is a two-year journey for us,” she said. “This was not an overnight decision.”

Even with potential productivity gains from AI, research finds that AI adoption alone doesn’t automatically translate to higher profits per employee—it demands a reimagining of how work gets done. In addition, broader market conditions, product expansion, and strategic cost management all play a role. But Block’s case illustrates how targeted AI implementation can significantly amplify human output.

This story was originally featured on Fortune.com

Sugar and gasoline don’t have a lot in common, unless you’re in a sugarcane mill in Brazil, in which case they’re literally the same plant. Usually that’s a fun fact, but right now it’s a problem.

Brazil is the world’s dominant sugar exporter—roughly 45% of everything traded globally. Every harvest, mills decide how much sugarcane goes to sugar and how much goes to ethanol. When oil prices are low, the math favors sugar. When oil spikes, ethanol gets more profitable, and cane gets pulled away from sweetener production.

The Strait of Hormuz disruptions have now tipped that math, as oil is hovering around $100 a barrel. The government is considering raising the maximum ethanol blend in flex fuel from 30% to 35%, a move that would funnel significantly more sugarcane away from sugar and into fuel.

At the same time, Brazil’s truckers threatened to strike this week over high diesel prices — and the government scrambled, cutting fuel taxes and drafting proposals to let states slash fuel levies. The last time Brazilian truckers walked off the job, in 2018, it paralyzed Latin America’s largest economy for days: fuel shortages, and empty supermarket shelves abounded. 

If a strike happens, the timing couldn’t be worse. Sugarcane, when it’s harvested, has to be immediately trucked from fields to mills, then trucked from mills to ports. A trucker strike would halt that process during the most critical time of year. Brazil’s new sugarcane harvest starts April 1, and the first three months are when the bulk of the crop is processed. That means the decision about how much cane goes to sugar versus ethanol is being made right now, as the Strait of Hormuz is a war zone.

“If this is a problem for the next few months, with the war and oil prices being high, then the majority of the biggest bulk of the harvest is going to swing to ethanol, away from sugar,” Judith Ganes, an independent commodities analyst with four decades in soft commodity markets, told Fortune. Six months from now, when 75% of the crop is already in, it wouldn’t matter that much, she added.

Sugar prices are already anticipating that mix. White refined sugar in London hit $451 per ton on Friday—-its highest since October and up 8% since the war in Iran began. Ganes sees raw sugar heading to 18 to 19 cents per pound, up from the 13- to 14.5-cent range where it had been stuck for “months and months and months.” 

The logistics of it all are making it worse. Persian Gulf refineries that import Brazilian raw sugar and process it into refined products for the region are seeing their expected shipments delayed or rerouted as the Strait of Hormuz remains largely closed.

That makes the problem two-sided: refined sugar gets scarce across the Middle East, East Africa, and parts of Asia, while raw sugar backs up at its origin in Brazil with nowhere to go.

“It creates a tightness in refining of white sugar and shortfall in the region, but then leaves the exporter with—uh oh, where’s the sugar going?” Ganes said.

At the 18-cent price range, she doesn’t imagine consumers will feel any effect. Sugar prices were already depressed all year, and cocoa prices have also come down hard after some tariff relief, easing some pressure on manufacturers of baked goods. 

But beyond the war, the longer-term picture isn’t reassuring. Ganes flagged a strong probability of an El Niño weather pattern in 2026/27, which would bring drought conditions to Southeast Asia and threaten production in Thailand and India—the other two pillars of global sugar supply. Replanting has already slowed after years of depressed prices. In a scenario of a severe El Niño, “Any cushion is done,” she said.

At the Federal Reserve on Wednesday, Chair Jerome Powell acknowledged the broader commodity bleed from the Iran war. He noted that oil and its derivatives feed into production and transportation costs across the economy, with effects that “leak into core” inflation. But he stressed the uncertainty: “We’re right at the beginning of this, and we don’t know how big this will be and how long it lasts.”

This story was originally featured on Fortune.com

It all started on a long drive from south Florida to North Carolina last holiday season. As Robert Levine drove, he asked his wife in the passenger seat to prompt ChatGPT with questions they had about the home-selling process. “Are we capable of doing this?” they asked. “What’s the realistic timeline tactically?”

The conversation started as a way to pass time on the long trip. But it soon ballooned into a comprehensive endeavor, with the AI taking over the marketing, planning, pricing, and negotiating. Through simple prompts throughout the home-selling journey, Levine and his wife clinched a signed contract to sell their Cooper City, Fla., home for $954,800—or $100,000 more than what real estate agents estimated the home’s value to be.

“When we met with real estate agents they lacked confidence in pricing,” Levine told Fortune. “ChatGPT gave us more confidence in price points of where the market was going.”

AI models are growing more capable of completing even the most complex tasks, surpassing benchmarks that the world’s smartest mathematicians and lawyers deemed onerous hurdles. 

It’s not just businesses that are leveraging the technology. Everyday Americans are using AI to serve themselves, some for selling their homes, and others for more questionable practices like completing their schoolwork. Some AI experts and business leaders think the technology could wipe out swaths of white-collar workers, and real estate agents may not be spared.

Levine has the technological acumen to utilize the full extent of ChatGPT’s tools. As the CEO of strategic consulting firm ComOps, he guides casinos and hospitality brands on how to leverage AI. Still, Levine is convinced the way he sold his house is attainable to even those less tech-savvy than he.

“I’d recommend it to everyone,” he said. “ChatGPT is not coding. It is a conversation, and you’re going to have to have that conversation with a real estate professional if you want to go that direction anyway.”

ChatGPT as a negotiator and a painter

For Levine, conversations with real estate agents didn’t quite fit into his busy schedule. And though he spoke to some, none were confident in the pricing of his home. ChatGPT, on the other hand, assured him that listing the home $100,000 more than what real estate agents advised was the right move.

The home sold for one of the highest per-square-foot prices in the market, according to Levine, despite not having the best view, the largest lot, or being the most updated property in the area. 

The AI planned the most granular aspects of the homeselling process. It gave tips on how to update the property, even suggesting which walls to repaint. And it told Levine when to schedule home viewings to work around his schedule. The father of three ultimately showed his home to 15 prospective buyers, one-third of whom submitted an application.

“It pushed us through all of that, including small things that I would have never thought of,” Levine recalled. “The first impression is important. We hear that all the time about curb appeal. But also when they walk into the house, they don’t want to see scuffs on the wall.”

While the AI functioned as Levine’s personal real estate agent, there were some barriers to its abilities. For one, Levine had to be engaged at every step. That meant prompting the AI for instructions rather than handing over duties to an autonomous AI agent. And while recent studies have shown AI is theoretically capable of handling the majority of tasks a lawyer does, he opted to hire his own lawyer. And of course, the technology couldn’t host open houses or box up his family’s belongings.

Levine still thinks real estate agents fulfill the needs of certain homebuyers, but believes all home sellers could benefit from putting the technology to work.

“It doesn’t necessarily replace professionals,” he said. “But it does allow us all to have the ability to be more curious and to feel more confident in the decisions we’re making.”

This story was originally featured on Fortune.com

The U.S. and Israel are locked into a longer-than-expected war that may extend through April before Iran’s military is sufficiently neutered to begin shifting toward a “defensive” posture and reopening oil and gas flows to a world thirsting for cheaper energy, military and energy analysts said.

With or without a ceasefire agreement and likely short of regime change, the main military objective is to stay the course until Iran is exhausted of much of its remaining missile, drone, and fast-boat inventories, meaning it can no longer effectively block tankers from the critical Strait of Hormuz choke point, they said.

President Donald Trump hinted at it on Friday, when he posted on social media that he is considering “winding down” military operations in the Mideast, saying the U.S. is near its objectives of degrading Iran’s missile capability, defense industrial base, armed forces, and nuclear program.

The war has caused oil prices to surge about 75% since the beginning of the year, threatening inflationary spikes worldwide and regional energy shortages. The campaign has already cost the U.S. many billions of dollars, and the Pentagon has request $200 billion more. Much of the Iranian leadership is killed and many of its military supply chains are decimated. But that hasn’t stopped Israel from escalating matters by targeting Iran’s domestic power supplies through its South Pars gas field—an action Trump criticized, asking Israel to stop hitting oil and gas production—or Iran responding by attacking the energy infrastructure of its Gulf neighbors, most notably Qatar’s liquefied natural gas facilities.

So what’s the end game now that the war has concluded its third week? After all, the conflict is almost certainly extending beyond the initial four weeks that Trump cited. And limited operations for U.S. boots on the ground remain on the table, whether to seize nuclear sites or Iran’s oil-exporting hub, Kharg Island.

“You can leave the regime intact but, if it is neutralized militarily, President Trump could claim that the Iranian military does not pose a threat to shipping through the strait. That would certainly be an important victory,” said Thierry Wizman, a top economic strategist for the Macquarie Group.

The U.S. is currently targeting Iranian fast-attack vessels and drones near the strait, relying on A-10 Warthog fighter jets and Apache attack helicopters.

“If the U.S. claims victory and there is no formal surrender, and then you have an attack by Iran on a [tanker] vessel, then that would look very bad for the U.S.,” Wizman said, warning of a too-early “mission accomplished” celebration. “It really must be airtight. That’s why, in the absence of a formal agreement, this can last a long, long time because you have to basically get everything that’s out there.”

But an end is within reach, even if the timeline is extended an extra month or so, said Richard Goldberg, senior advisor for the Foundation for Defense of Democracies neoconservative think tank.

“Whether it’s four weeks or eight weeks—whatever is planned—this is not an endless conflict,” said Goldberg, who previously served as Iranian counteroffensive director on Trump’s National Security Council. “We would not want to stop until they can’t keep opening fire. Then we can manage the situation with or without a ceasefire. Otherwise, Iran has a victory of sorts where they can continue to extort the West and threaten to shut down the Strait of Hormuz.”

In the meantime, the narrow passageway controlling 20% of the world’s oil and exported natural gas remains effectively closed, representing the greatest energy supply shock ever, although some oil barrels are rerouted and Iran is allowing a few select tankers through. When and if the strait is reopened, it will take months to resume normal oil flows and, although prices will dip from their highs, they would remain elevated because of the heightened risks and insurance costs. And nearly 20% of Qatar’s gas-exporting facilities will remain offline with an announced repair timeline of three to five years.

“Every day that passes, your supply shock is getting wider and wider, and to get out of that is getting harder and harder,” said Sara Hakim, director of natural gas for ICF energy consultants.

Getty Images

Differing opinions

The U.S. and Israel could have continued negotiations toward a nuclear compromise, but they opted for a surprise strike on the Iranian leadership on Feb. 28, killing Supreme Leader Ali Khamenei and many others. His son now holds the same role.

Since then, the conflict has escalated beyond most expectations to include the entire Gulf region and the stoppage of energy flows, dramatically disrupting the global economy, said Jim Krane, energy fellow and Middle East expert at Rice University’s Baker Institute.

“It would take a lot of spin at this point to still call it a victory. It would require the U.S. to eat some crow really,” he said. “The U.S. is supposed to be the Gulf’s security provider, not the instigator of regional warfare that stops the oil flow.”

The “energy-for-security” relationship between the U.S. and Saudi Arabia along with much of the region dates back 80 years to President Franklin D. Roosevelt.

“Now we don’t have either one. We don’t have any oil; we don’t have any security,” Krane pointed out. “This is a 180-degree reversal of its original intent. It’s getting hard to watch.”

It will now take years to rebuild both the relationships with the Gulf states and to rebuild the damaged energy facilities, he added.

And Israel killing Ali Larijani, secretary of Iran’s Supreme National Security Council, who was acting as a day-to-day leader for Iran during the war, made a negotiated peace more difficult as the militant Revolutionary Guard takes more control. Krane likened Larijani to Venezuelan Vice President Delcy Rodriguez, now the interim president after the U.S. arrested former leader Nicolás Maduro in January.

“He had a pretty good track record of negotiating in good faith, so killing him I think was a big mistake. That makes it a lot harder,” Krane said of Larijani. “I don’t see an easy off-ramp.”

Since then, Trump has lashed out at allies as “cowards” for not assisting militarily in reopening the strait, calling NATO a “paper tiger” without the U.S. And Iran’s foreign minister, Abbas Araghchi, said Iran would show “zero restraint” if its energy infrastructure was struck again.

In the meantime, the White House is pulling every lever to keep prices, especially prices at the pump, from getting out of control. There’s the 172 million barrels of oil slated for release from the U.S. Strategic Petroleum Reserve—almost half of the 400 million barrels scheduled to come out of reserves worldwide—the loosening of sanctions on Russian oil, the potential loosening on waterborne Iranian crude, the 60-day Jones Act waiver to allow for foreign tankers to move oil and products domestically, and more.

Still, the U.S. average for the cost of a gallon of regular unleaded oil has spiked 45% from January lows and counting, even though U.S. oil prices remain lower than the rest of the world and U.S. natural gas costs are largely unchanged. The national average could exceed $4.00 a gallon by the end of the weekend.

Are boots needed?

Then there’s the question of whether the war will require so-called boots on the ground in Iran, not for a full ground invasion, but for select, but dangerous, special operations. Trump has said he does not want to deploy troops on the ground in Iran, but he’s left some wiggle room.

“There’s a tangential view you can’t do all this by air power. At some point you may have to put boots on the ground. Maybe that’s the case,” Wizman said.

Troops could be used selectively on the shoreline of the Strait of Hormuz, at nuclear sites, or even on Iran’s Kharg Island, which the U.S. has already bombed but avoided hitting energy infrastructure.

Iran’s missile and drone defenses would need to be further crippled first, Goldberg said. “If you were to put boots on the ground on Kharg, they’d be vulnerable to drones, they’d be vulnerable to other threats,” he said. “One missile into the power plant shuts down the export terminal without destroying the oil. That to me seems like a better solution.”

Regardless, the top priority is reopening the Strait of Hormuz and safely escorting tankers through.

“If you’re able to conduct the escort missions and defeat any threats that are still posed by the regime, then the [Iranian] regime probably has lost at that point,” Goldberg said.

This story was originally featured on Fortune.com

As the Iran war enters its fourth week, much of its cost is being borne by countries that had nothing to do with starting it. 

Iran closed the Strait of Hormuz soon after the U.S. and Israel launched their strikes on the country, choking the maritime artery through which nearly all of the Persian Gulf’s oil and natural gas flow. The closure has strangled shipments from major energy exporters—Qatar, Saudi Arabia, and the United Arab Emirates—and poses an existential threat to Asia, a region that relies on imported energy.

“Asia is at the heart of this drama, in that it is the chief area…of collateral damage,” said Columbia University historian Adam Tooze at the Jefferies Asia Forum in Hong Kong this week.

The Iran war threatens to become an inflationary shock targeted at the world’s growth engine. For three decades, governments turned to rate cuts and looser fiscal policy when faced with a crisis. This time, those tools may no longer work.

Fiscal and monetary policy was already loosening across much of the world economy. “Coming into the current crisis with Iran…it was pretty obvious, whether Japan, whether Europe, whether the United States, whether the UK, that we were very much in an inflationary boom,” Louis-Vincent Gave, CEO of Gavekal Research, told conference attendees.

But now an energy supply shock threatens to push inflation higher while slowing growth: what Gave calls an inflationary bust, and what people may better know as stagflation.

Roughly 84% of crude that transits Hormuz goes to Asia, while the U.S. now imports little through the strait. That asymmetry shows up in prices: West Texas Intermediate is near $100 a barrel, while Dubai crude has jumped past $160.

Natural gas has also been hit. Iran has struck key infrastructure in Qatar, which accounts for roughly 20% of global liquefied natural gas supply. On Thuesday, QatarEnergy declared force majeure on deliveries after Iranian drone and missile strikes on the Ras Laffan Industrial City, the world’s largest LNG export hub.

‘A perfect dilemma’

Governments across the region have moved quickly to limit the damage, deploying a mix of price caps, rationing, and stockpile releases.

South Korea imposed a fuel price cap, the first in 30 years. Seoul is urgently seeking oil supplies that bypass Hormuz and accelerating a longer-term shift toward nuclear power generation.

Asia’s fourth-largest economy grew by just 1.0%—the worst in five years and below the 2.0% annual rate that Peter Kim, senior managing director at KB Securities, described as the minimum for political legitimacy in a sideline interview.

“An oil price shock, with a weak currency and a central bank that can’t cut because of inflation pressure? That could really jeopardize that 2% target,” Kim warned in an interview with Fortune.

Japan’s Prime Minister Sanae Takaichi started the release of roughly 80 million barrels from the country’s petroleum reserves on Monday. Tokyo faces not only an energy crisis but a diplomatic one. U.S. President Donald Trump has publicly pressed allies like Japan to contribute to any coalition to reopen the strait, citing their dependence on the strait for energy. Takaichi, for now, has cited constitutional limits on the use of force as a reason for Japan’s hesitance to send ships. 

“It’s a perfect dilemma,” said Ken Jimbo, a professor of international relations at Keio University to Fortune. “We don’t wish to be too hostile to the United States, because there’s a quid pro quo type of Trump psychology: I defend you. Why do you not defend me?”​

Governments can’t ‘subsidize forever’

Emerging markets are absorbing the shock in more desperate ways. Thailand, which imports 70% of its oil, has capped diesel prices, instructed officials to work from home, and urged citizens to wear short-sleeved shirts.

“If the price of global crude oil increases, our GDP automatically decreases,” said Tanawat Ruenbanterng, head of institutional research at Tisco Securities, to Fortune. A weaker baht and higher bond yields give Bangkok even less fiscal room to respond. “Because of limited fiscal space, they could not subsidize forever,” Tanawat said. 

Thailand isn’t alone in needing to impose emergency measures. Indonesia is shielding retail pump prices ahead of the Eid al-Fitr holiday, even as that threatens to blow through Jakarta’s fuel subsidy budget of 381 trillion rupiah ($22.6 billion). Bangladesh has imposed daily fuel purchase limits and closed universities early; Sri Lanka has declared Wednesdays a holiday to conserve fuel. 

Concern is spreading to advanced economies too: On March 20, the International Energy Agency warned its member economies, like Australia and the UK, to consider carpooling or working from home to save fuel. 

What happens next?

China, the world’s largest oil importer, banned the export of diesel, gasoline, and aviation fuel until at least the end of March to pre-empt domestic shortages. The ban is forcing Southeast Asian buyers who relied on Chinese fuel exports to scramble for alternatives.

That may push countries back to a fuel that many environmentalists hoped would be left behind: coal. Countries like South Korea, Thailand, and Bangladesh are quickly ramping up coal power generation to make up for halted LNG imports. 

“Coal is, and remains, the cheapest way to produce electricity,” Gave told the Jefferies audience, “if you don’t care, and if you don’t price the environmental costs.”

This story was originally featured on Fortune.com

Elon Musk defrauded Twitter Inc. investors when he disparaged the company in 2022 in an effort to buy the social media platform for a lower price than his original $44 billion bid, a jury concluded. 

Jurors in federal court in San Francisco found Friday that Musk intentionally misled Twitter shareholders when he tweeted that the social network — now called X — had too many fake accounts and tried to back out of the deal. The jury rejected two of the four fraud claims.

The eight-member panel calculated how much Musk’s statements drove down the company’s stock price for each trading day over a period of about five months. The amount of damages he must pay to individual investors — which could total hundreds of millions or even billions of dollars — will be determined at a later date when shareholders submit claims.

The verdict, following about three days of deliberations, marks a rare defeat in court for the world’s richest person, who has been dubbed “Teflon Elon” for his track record of winning high-stakes legal battles that many expected him to lose. 

He prevailed in a 2023 trial over Tesla Inc. investors’ allegations that he misled them in a tweet five years earlier saying he had “funding secured” to take the electric car-maker private. Musk is a co-founder of Tesla and its chief executive officer.

Mark Molumphy, a lawyer for the investors, said after the verdict he thinks the damages will amount to $2.6 billion. But even an award that high wouldn’t dent Musk’s net worth, which was $661.1 billion on Friday, according to the Bloomberg Billionaires Index.

“This case is much bigger than Twitter, this case goes right to the heart of Wall Street and what’s been going on in recent years,” said Joseph Cotchett, Molumphy’s partner at Cotchett, Pitre & McCarthy LLP. “It’s a great example of what you cannot do to the average investor.”

Musk’s lawyers declined to comment in the courtroom. Musk didn’t immediately respond to a request for comment.

In federal court, the losing side can appeal.

The jurors heard about two weeks of live testimony from Musk and top Twitter executives at the time, who recalled the turbulent six-month period in 2022 when the serial entrepreneur flip-flopped over whether he would buy the platform, resulting in hard-fought litigation with Twitter’s board of directors to force him to follow through.

The investors claimed that Musk’s social media posts and public statements — including a May 13, 2022, tweet stating the deal was “temporarily on hold” pending a review of the number of bots counted as Twitter users — was actually part of a deliberate plan to drive down the company’s stock price so he could renegotiate at a better price.

Molumphy told the jury in his closing argument Tuesday that Musk’s tweets “were not some innocent mistakes, some stupid tweet that he didn’t consider.”

“They were intentional, deliberate, and devised to convey to investors that Twitter was overrun with spam,” Molumphy said.

Musk took the stand for a whole day, and part of a second, and largely stayed on script in telling the jury he believed that the ex-Twitter executives, including Chief Executive Officer Parag Agrawal and Chief Financial Officer Ned Segal, lied to him and in public financial statements about the prevalence on the platform of spam and fake accounts, known as bots.

“Of course people were talking about a renegotiation once this bot issue came up,” Musk’s attorney, Michael Lifrak of Quinn Emanuel Urquhart & Sullivan LLP, told the jury in his closing argument. “There was no secret about that.”

The stock remained volatile for several months while Musk waffled on following through with the deal, wiping away billions of dollars in Twitter’s market value. When Twitter sued Musk in Delaware for reneging on the purchase in July 2022, the shares reached a low of $32.52, 40% less than Musk’s buyout price. 

Musk testified that he only agreed to do the deal at the original price of $54.20 per share because he believed the Delaware judge overseeing Twitter’s lawsuit was biased against him.

The billionaire argued that his tweet at the center of the lawsuit was very different from walking away from the deal entirely. “I’m not saying I’m not going to do the deal,” he told the jury. “At no point did I say the deal was canceled.”

But Musk acknowledged under questioning from a lawyer for investors that the “temporarily on hold” post was a mistake. “It may not be my wisest tweet,” he said. “I don’t know if I would call it my stupidest. But if it led to this trial it probably qualifies as such.” 

The case is Pampena v. Musk, 22-cv-05937, US District Court, Northern District of California (San Francisco).

This story was originally featured on Fortune.com

Three weeks into the Iran war, small businesses are starting to feel the pressure of the conflict, and experts say the worst may still be yet to come. 

Following the initial strikes on Iran in late February, U.S. businesses have been directly affected by the war in the form of shipping disruptions and skyrocketing oil prices, which have led to higher gas prices. 

These obstacles come as small businesses have over the past year dealt with the whipsaw of President Trump’s tariff policies. Sweeping tariffs on goods from China, Canada, Mexico, and the European Union, among others, have driven up input costs and squeezed profit margins for small business owners who often lack the purchasing power and legal resources of large corporations. 

Unlike larger corporations who, at least in the short term, can absorb higher costs and shipping upheaval caused by the Iran war, smaller businesses are especially at risk, said Brett Massimino, an associate professor at Virginia Commonwealth University’s business school and chair of the department of supply chain management and analytics. 

“Small businesses, they don’t have the margins or the reserves to really absorb those kinds of cost increases,” he told Fortune. “They’re faced with a dilemma of, do they try to expedite some of the shipments that might be delayed right now, or do they deal with the shortages.”

If the Iran war stretches on, small businesses could start to feel the effects in as soon as two months as they run out of reserves or look to renew contracts at potentially higher prices. Trump has repeatedly insisted he could stop the war “right now” having seen Iran’s military crippled, as he told MS Now Friday. Still, Defense Secretary Pete Hegseth earlier this week requested an extra $200 billion for the war effort.  

The price of Brent crude hit a brief high of $119 a barrel Thursday, before retreating Friday, as Iran continued to threaten, and at times strike, ships passing through the Hormuz Strait, through which 20% of the world’s oil supply flows.

At the same time, the threat of attacks has also led shipping company Maersk to halt all vessel crossings through the strait. In early March about 147 container ships in the area also had to take refuge after getting stuck in the Persian Gulf.

‘Everything has gone up’

Yet, while these events may feel half a world away for Americans, they have already translated into real price increases at home for many homegrown small businesses. 

Travis Maderia, a fourth generation lobster fisherman and cofounder of the direct-to-consumer seafood company Lobster Boys, told Fortune the fishermen that catch lobster for the business in the cold North Atlantic water near Nova Scotia, Canada, are facing rising costs. On Friday, he said one fisherman told him gas prices have increased 60 cents per liter, or more than $2 per gallon.

The result? Maderia has needed to shell out more per pound of lobster to the fishermen than he would during the same season any other year—$17 per pound, compared to $13 or $14 per pound normally—which raises his operating costs. 

Jet fuel price increase and more demand for air freight thanks to the shift from risky cargo ships have also led airlines to raise their prices and increase shipping costs.

For Lobster Boys, these increases have meant higher prices for shipping their products to the continental U.S.—increases that Maderia said the company has had to pass on to the restaurants and grocery stores they sell to. And yet, when these restaurants pass the higher prices onto their own customers, they also see a slump in demand, which means fewer orders for Maderia’s company. 

“Everything has gone up, unfortunately, and customers are not liking it,” he said.

This story was originally featured on Fortune.com

President Donald Trump said he was considering “winding down” US military efforts against Iran, saying that the US was close to achieving its objectives as the conflict, which has roiled financial markets and the region, nears a fourth week.

“We are getting very close to meeting our objectives as we consider winding down our great Military efforts in the Middle East,” Trump said in a social-media post on Friday. He cast those objectives as “Completely degrading” Iran’s missile capabilities, “destroying” the country’s defense industrial base, eliminating their navy and air force, never allowing Tehran to get close to “Nuclear Capability” and protecting Middle Eastern allies.

Trump’s comments came shortly after he ruled out a ceasefire and kept the door open to deploying ground troops, highlighting how the president continues to send wildly divergent signals about his objectives and plans for the US and Israeli war on Iran.

It is also unclear how Iran would respond to any unilateral decision by the US to pause strikes after recent attacks that targeted the country’s energy infrastructure and killed more high-profile officials, including security chief Ali Larijani. Iranian officials have become reluctant to even discuss reopening the Strait of Hormuz as Tehran continues to launch retaliatory strikes at Gulf Arab neighbors. 

Trump also addressed the strait, a critical waterway that carries roughly a fifth of global oil and natural gas flows and has been all but closed since hostilities began. Trump has been pressuring allies to help the US secure the strait militarily but indicated Friday that he will leave that effort to other nations.

“The Hormuz Strait will have to be guarded and policed, as necessary, by other Nations who use it — The United States does not!” Trump said. “If asked, we will help these Countries in their Hormuz efforts, but it shouldn’t be necessary once Iran’s threat is eradicated. Importantly, it will be an easy Military Operation for them.”

Trump’s comments capped a tumultuous Friday in financial markets following a Bloomberg News report that an increasingly dug-in Iranian regime was refusing to negotiate over Hormuz and with reports the US is preparing options to deploy ground troops.

Earlier: Iran Unwilling to Talk About Hormuz as Regime Digs In

Oil prices surged again Friday with global benchmark Brent closing above $112 a barrel, the highest since mid-2022. Prices eased to trade near $108 a barrel in thin post-settlement trading on Trump’s comments about possibly winding down the conflict.

Global stocks extended their losses, with the US equity benchmark falling steeply to end the weekly nearly 2% lower. Treasury yields climbed, as traders priced in a 50% chance of a Federal Reserve hike by October. Meanwhile gold saw its worst week in four decades.

Trump, a little over an hour before his social media post, had rejected the idea of declaring a halt to hostilities and expressed confidence Hormuz would reopen “itself” despite allies’ reluctance to offer assistance. 

“I don’t want to do a ceasefire. You know, you don’t do a ceasefire when you’re literally obliterating the other side,” the president had said at the White House. “We’re not looking to do that.”

Trump had expressed growing frustration in recent days after his calls for allies to help vessels transit the waterway were rebuffed, lashing out at US partners, including the North Atlantic Treaty Organization as well as China.

“NATO could help us, but they so far haven’t had the courage to do so. And others could help us, but we don’t use it,” the president said of the strait. “At a certain point, it’ll open itself.”

Read more: Trump Fans Iran Quagmire Fears With Debate on Seizing Kharg

Adding to the market turmoil was the administration’s consideration of a ground operation. Trump was evasive when asked by reporters about his plans for Kharg Island, Iran’s major oil export hub. US officials have said the White House is ordering hundreds of Marines to be deployed to the Middle East as it weighs a plan to seize the outpost.

“I may have a plan or I may not, but how would I ever say that to a reporter?” Trump said.

Any move to use ground troops to seize control of Iran’s energy facilities would pose risks for Trump, including by putting American forces at greater danger than they’ve already been exposed to in the conflict and adding to the cost and scope of the campaign. 

The Pentagon has asked for an additional $200 billion from Congress to pay for the war, sending another mixed signal on how long the administration expects the conflict to last. The regime in Tehran isn’t close to falling and Iranian officials are coalescing around the remaining leaders, according to western intelligence assessments and people familiar with the matter.

Higher gas prices are another challenge for Trump and his Republican Party ahead of November midterm elections. Retail gasoline and diesel prices in the US have jumped to the highest levels since 2022, with California’s energy regulator already warning against price gouging as some gas stations are charging as much as $8 a gallon.

This story was originally featured on Fortune.com

Kalshi, the largest prediction market in the U.S., now boasts a $22 billion valuation, as it jumps ahead of its main competitor Polymarket. The investment firm Coatue Management is leading a $1 billion investment round at the new valuation, according to the Wall Street Journal. A spokesperson for Kalshi declined to comment on the raise. 

Kalshi’s valuation comes as the company trades punches with Polymarket in a heavyweight duel for the top spot in the prediction market industry. Earlier in March, both companies were reportedly eyeing valuations of $20 billion each. On Thursday, Polymarket made news by announcing an exclusive partnership with the MLB just in time for the new baseball season.

The intense rivalry has also resulted in novel promotions such as Kalshi announcing in February that it would be providing free groceries to New Yorkers, leading Polymarket, a week later, to open a pop-up grocery store of its own. 

Kalshi is the U.S.’s biggest prediction market in large part thanks to a 2020 Commodity Futures Trading Commission decision to give it approval. The company reached a new level of popularity in January of 2025, when it introduced wagers on sports

Polymarket, on the other hand, had been banned from operating in the U.S. in 2022 after the CFTC found it was offering event contracts without the agency’s approval. Two years later, the FBI raided CEO Shayne Coplan’s New York City apartment. In 2025, the CFTC gave Polymarket approval and the company announced that it would be making a comeback in the U.S.

The rise of prediction markets has not occurred without its share of controversies. On Tuesday, Arizona filed criminal charges against Kalshi for operating an illegal gambling operation in the state, and the company is facing more than 20 lawsuits about its legal status. There have also been concerns about insider trading on both platforms, most notably when a trader on Polymarket made more than $400,000 on Nicolás Maduro’s ouster.

This story was originally featured on Fortune.com

Iran is asserting control over the Strait of Hormuz even as the U.S. and Israel continue to bombard the country, first by bringing traffic to a near standstill with attacks on ships and then by choosing who can travel through the narrow waterway.

According to the maritime news and intelligence journal Lloyd’s List, Tehran has carved out a de facto “safe” shipping corridor through Iranian territorial waters via Iran’s Larak Island, where the Islamic Revolutionary Guard Corps and the port authority can make visual confirmation of “approved” vessels.

Passage through the corridor is negotiated on a case-by-case basis, and the governments of India, Pakistan, Iraq, Malaysia and China have discussed transit plans directly with Tehran, Lloyd’s reported on Wednesday. One tanker even paid about $2 million as part of its agreement with Iran.

“Ships hoping to use the pre-approved route are expected to have communicated extensive details regarding both the ownership of the vessel and destination of the cargo to the IRGC in advance of the transit,” Lloyd’s added. “Those details are being communicated via a series of Iran-affiliated individuals operating outside of Iran.”

Despite U.S. and Israeli forces decimating Iran’s military, including its navy, the Islamic republic retains enough combat power to scare away commercial shipping from the Strait of Hormuz, keeping 20% of the world’s oil and liquified natural gas bottled up.

That’s created supply nightmares across the global economy. But at the same time, Iran’s control over the strait means it is able to deliver oil to top customer China and continue generating vital revenues.

Now, the alternate corridor through the strait represents a nascent ship registration system, and the IRGC is expected to establish a more formalized approval process, Lloyd’s said.

At least nine ships have exited the strait by way of Iran’s alternate route, including India-flagged gas tankers Shivalik and Nanda Devi.

That’s still just a trickle compared to normal prewar traffic, which topped 100 oil and cargo ships everyday. Meanwhile, President Donald Trump is sending thousands of Marines to the Middle East amid reports he is considering deploying ground troops to reopen the strait.

Sources told Axios on Friday that Trump is mulling an operation to occupy or blockade Iran’s Kharg Island, which processes 90% of Iran’s crude oil exports.

With control of the island and leverage over Iran’s economy, the U.S. could pressure Tehran to relinquish its chokehold over the Strait of Hormuz, according to the report, easing the energy crunch that’s sent oil and gas prices soaring.

But the Marines may not arrive for a few more weeks, and Navy officials have said the Strait of Hormuz is a “kill box” filled with Iranian threats that make it too dangerous for warships to enter. Neutralizing the risks may require landing troops on Iran’s coast near the strait.

U.S. allies in the Persian Gulf have reportedly warned that if Trump ends the Iran war without restoring free navigation in the strait, then Tehran will continue to have the power to hold the regional and global economy hostage.

So although the White House signaled that Trump has no plans to send ground troops into Iran, the outcome of his war may depend on it.

“He wants Hormuz open. If he has to take Kharg Island to make it happen, that’s going to happen. If he decides to have a coastal invasion, that’s going to happen. But that decision hasn’t been made,” a senior administration official told Axios.

This story was originally featured on Fortune.com

When parts of China entered rolling lockdowns during the country’s zero‑COVID campaign, PepsiCo factory workers in some “bubbles” stayed on site for up to 30 days at a time to keep production running. A case could halt operations and send workers into quarantine—as happened in June 2020, when confirmed COVID infections at one of PepsiCo’s Beijing factories forced nearly 500 employees into quarantine.

Anne Tse, who helped run the company’s China operations during the country’s three years of COVID-zero,  remembers how they had to change the way they did business. 

“We had to pivot,” Tse told Fortune, “by grouping our markets not by their ‘market development’ stage, but by their ‘COVID development’ stage.” In just 12 hours, her team abandoned the traditional model that grouped Chinese cities by the maturity of their consumer markets instead mapped operations around the pandemic: which provinces were entering lockdown, at peak restrictions, or reopening.

“It was a crucible,” she remembers, “but I think about how it trained the character and muscle of our associates,” she says.

That muscle is now being tested by a new set of pressures after Tse took over PepsiCo’s Asia-Pacific Foods division in early 2025.

Her mandate spans what she calls three different Asias: emerging markets such as Vietnam and Indonesia, where consumers are buying packaged snacks for the first time; mid-range markets like China and Thailand, where consumers are starting to demand differentiated products; and mature markets including Japan and Australia, where demand centers on health, convenience, and aging populations.

PepsiCo is pressing ahead in Asia as the food and beverage giant resets in the U.S, following a battle with activist investor Elliott Investment Management, which is pushing for cost cuts and higher margins. 

“By 2030, two‑thirds of the global middle class is going to be in Asia,” Tse points out. “We’re going to add another 700 million of these new middle‑class members into our part of the world.”

Three Asias, three playbooks

Tse joined PepsiCo in 2010 after stints at McKinsey and Mannings, the health and beauty chain owned by Hong Kong’s Dairy Farm Group. She became CEO for Greater China in 2021, APAC chief consumer officer in 2024, and CEO of APAC Foods in 2025.

PepsiCo’s Asia-Pacific Foods division generated $4.6 billion in revenue last year, up 2%. While it is PepsiCo’s smallest segment, compared with more than $93 billion in companywide revenue, it is the fastest-growing by volume, rising 4% even as other divisions reported declines.

Tse oversees a diverse region spanning markets at very different stages of development: Greater China, a vast consumer market with intensifying local competition; developed economies such as South Korea, Japan, Australia and New Zealand, where tastes are mature; and emerging markets across Southeast and South Asia, where incomes are rising quickly.

“It’s definitely not one market,” she says, dividing the region into three segments.

The first is the emerging cohort—including the Philippines, Vietnam and Indonesia—where consumers are crossing the $10,000 annual income threshold and entering the snack category for the first time. “From a consumer standpoint, they’re exploring the category, trying different things,” Tse says. 

PepsiCo has recently invested $90 million in a snack plant in Vietnam’s Ha Nam province, with annual capacity of more than 20,000 tons, and $200 million in a factory in Cikarang, Indonesia, marking its return to the country after exiting in 2021.

The second is a cohort of countries, including China and Thailand, where “things are getting more sophisticated,” leading to a proliferation of new snack options. For example, in China, PepsiCo mines restaurant reviews for insights into what consumers want, turning viral dishes into limited-edition flavors.

Finally, there are mature markets such as Japan, South Korea, Australia and Singapore, where snacks are already “a way of life.” But consumers are also looking for products that meet broader needs, including health and wellness. Demographic change is also shaping demand. “Aging populations need more functional nutrition,” she says.

Some markets have proved trickier to navigate than others: China is going through a consumer slump and intense price competition, which is bringing down prices even as volume grows. Australia, a more mature market, is also going through a cost-of-living crisis that’s hitting snacking. ASEAN, however, is proving to be a “very robust” market for PepsiCo’s snacks.

The local-brand threat

Last September, activist investor Elliott Investment Management revealed it held a 4% stake in PepsiCo and demanded changes at the company. Eliott pointed out that the company had become a “deep underperformer,” and argued that it needed to renew its focus on the critical North American market. 

In December, PepsiCo agreed to one of its most aggressive restructurings in years, including eliminating 20% of its U.S. brands, cutting jobs, and lowering prices on flagship products. PepsiCo shares have risen about 23% since their low last July.

Elliott’s arguments only briefly touched on PepsiCo’s international business, citing the company’s global brand strength and the possibility of “continued expansion” in overseas markets, due to rising consumer populations and a lower prevalence of GLP-1 weight loss drugs.

Still, PepsiCo—like many foreign brands—faces intensifying domestic competition. Across sectors from cars to coffee, multinational companies are finding it harder to compete with local products that offer comparable quality at lower prices and better match local tastes. In China, snack brands such as Three Squirrels have challenged global players with fast product cycles and aggressive pricing.

“News outlets say the number one challenge of operating in China is tepid consumer sentiment,” Tse says. “But everybody in the market will tell you local competition is by far the biggest challenge.”

Last November, PepsiCo released a version of Quaker Oats that combined microbes friendly to gut-health through a fermentation process. The new product combined “China’s long tradition of fermentation and PepsiCo’s capabilities in modern food science,” Tse wrote in a Linkedin post at the time. 

“Competition is good—we welcome competition because a lot of times competition makes us better,” she says to Fortune. “We need to play both games: learn from the locals to be agile, but also preserve what makes us unique and able to transcend business cycles.”

This story was originally featured on Fortune.com

The Justice Department filed a new lawsuit Friday against Harvard University, saying its leadership failed to address antisemitism on campus, creating grounds for the government to freeze existing grants and seek repayment for grants already paid.

The lawsuit, filed in federal court in Massachusetts, is another salvo in a protracted battle between the administration of President Donald Trump and the elite university.

“The United States cannot and will not tolerate these failures,” the Justice Department wrote in the lawsuit. It asked the court to compel Harvard to comply with federal civil rights law and to help it “recover billions of dollars of taxpayer subsidies awarded to a discriminatory institution.”

The lawsuit also asks a judge to require that Harvard call police to arrest protesters blocking parts of campus and to appoint an “independent outside monitor,” approved by the government, to ensure it complies with court orders.

Harvard did not immediately respond to a request for comment.

The lawsuit comes after negotiations appear to have bogged down in the months-long battle with the Trump administration that has tested the boundaries of the government’s authority over America’s universities. What began as an investigation into campus antisemitism escalated into an all-out feud as the Trump administration slashed more than $2.6 billion in research funding, ended federal contracts and attempted to block Harvard from hosting international students.

In a pair of lawsuits filed by the university, Harvard has said it’s being unfairly penalized for refusing to adopt the administration’s views. A federal judge agreed in December, reversing the funding cuts and calling the antisemitism argument a “smokescreen.”

Ted Mitchell, president of the American Council on Education, a major association of colleges and universities, accused the administration of launching a “full scale, multi-pronged” attack on Harvard. Friday’s lawsuit, he said, is just the latest attempt to pressure Harvard to agree to changes favored by the administration.

“When bullies pound on the table and don’t get they want, they pound again,” Mitchell said.

The Trump administration began investigating allegations of discrimination against Harvard’s Jewish and Israeli students less than two weeks after the president took office. The allegations focus on Harvard’s actions during and after pro-Palestinian demonstrations during the Israel-Hamas war.

Officials concluded Harvard did not adequately address concerns raised about antisemitism that drove some students to conceal their religious skullcaps and avoid classes. During protests of the war, Trump officials said, Harvard permitted students to demonstrate against Israel’s actions in the school library and allowed a pro-Palestinian encampment to remain on campus for 20 days, “in violation of university policy.”

In its lawsuit Friday, the Justice Department also accused Harvard of failing to discipline staff or students who protested or tacitly endorsed the demonstrations, such as by canceling or dismissing classes that conflicted with protests.

“Harvard University has failed to protect its Jewish students from harassment and has allowed discrimination to wreak havoc on its campus,” White House press secretary Liz Huston said Friday on X. “President Trump is committed to ensuring every student can pursue their academic goals in a safe environment.”

Despite their bitter dispute, Harvard and the Trump administration have held some negotiations, and the two sides have reportedly been close to reaching an agreement on multiple occasions. Last year, the administration and the university were reportedly approaching a deal that would have required Harvard to pay $500 million to regain access to federal funding and to end the investigations. Almost a year later, Trump upped that figure to $1 billion, saying that Harvard has been “behaving very badly.”

At the same time, the administration was taking steps in a civil rights investigation that had the potential to jeopardize all of Harvard’s federal funding.

In June, the Trump administration made a formal finding that Harvard tolerated antisemitism.

In a letter sent to Harvard, a federal task force said its investigation had found the university was a “willful participant” in antisemitic harassment of Jewish students and faculty. The task force threatened to refer the case to the Justice Department to file a civil rights lawsuit “as soon as possible,” unless Harvard came into compliance.

When colleges are found in violation of federal civil rights law, they almost always reach compliance through voluntary agreements. When the government determines a resolution can’t be negotiated, it can try to sever federal funding through an administrative process or, as the Trump administration has done, by referring the case to the Justice Department through litigation.

Such an impasse has been extraordinarily rare in recent decades.

Last summer, Harvard responded that it strongly disagreed with the government’s investigative finding and was committed to fighting bias.

“Antisemitism is a serious problem and no matter the context, it is unacceptable,” the university said in a statement. “Harvard has taken substantive, proactive steps to address the root causes of antisemitism in its community.”

In a letter last spring, Harvard President Alan M. Garber told government officials that the school had formed a task force to combat antisemitism, which released a detailed report of what unfolded on campus after Hamas militants stormed Israel on Oct. 7, 2023, killing around 1,200 people and abducting 251 others. Israel retaliated with an offensive that killed tens of thousands of Palestinians and displaced around 90% of Gaza’s population — prompting pro-Palestinian demonstrations at colleges around the country.

After the demonstrations at Harvard, Garber said the university had hired a new provost and new deans and that it had reformed its discipline policies to make them “more consistent, fair and effective.”

Since he took office, Trump has targeted elite universities he believes are overrun by left-wing ideology and antisemitism. His administration has frozen billions of dollars in research grants, which colleges have come to rely on for scientific and medical research.

Several universities have reached agreements with the White House to restore funding. Some deals have included direct payments to the government, including $200 million from Columbia University. Brown University agreed to pay $50 million toward state workforce development groups.

___

AP Education Writer Collin Binkley contributed to this report.

___

The Associated Press’ education coverage receives financial support from multiple private foundations. AP is solely responsible for all content. Find AP’s standards for working with philanthropies, a list of supporters and funded coverage areas at AP.org.

This story was originally featured on Fortune.com

The U.S. Education Department is handing off a portion of its student loan portfolio to the Treasury Department, a first step toward shedding management of all student loans as Trump administration officials dismantle the federal education agency.

Under an agreement announced Thursday, the Treasury Department will take over management of student loans whose borrowers are in default, meaning they are months behind on payments. Those loans add up to about $180 billion, or 11% of the government’s $1.7 trillion student loan portfolio.

Eventually, the Treasury Department is to take responsibility for all student loans, according to the agreement. A second phase with no timeframe says Treasury will “assume operational responsibility” over non-defaulted loans, “to the extent practicable.”

Breaking off the student loan operation would mark the biggest step yet in closing the department, which President Donald Trump ordered to be dismantled almost exactly a year ago. Many Americans know the department mostly for its role doling out grants and loans for college, and those streams of funding are by far the agency’s largest.

Borrowers do not need to do anything as the change goes through, the administration says. They will continue to work with the same loan servicer and repay their loans the same way.

The 17-page agreement outlines a stunning realignment of the nation’s federal student loan programs, which have been overseen by the Education Department since it was created more than 40 years ago.

The agreement “marks an intentional and historic step toward breaking up the Federal education bureaucracy and dramatically improving the administration of Federal student aid programs,” Education Secretary Linda McMahon said in a statement.

In justifying the change, Trump officials said the Education Department is “ill-equipped” to handle such a big loan portfolio. They blamed the Biden administration for focusing on efforts to cancel student loans rather then help borrowers get back on track with payments. Officials cited recent data showing that fewer than half of all borrowers are currently making payments on their loans, with almost a quarter in default.

Opponents raise concerns about borrower confusion

The agreement is likely to invite legal challenges. Some opponents note that federal law requires student loans to be overseen by the Education Department. Trump officials believe they’ve found a workaround by framing it as a partnership, with some components, including the policies underpinning student loans, remaining at the Education Department.

Student loan advocates condemned the move, saying it only adds to confusion as the Trump administration overhauls student loan programs.

“The Department of Education has issued a dizzying series of rule changes that make it harder for borrowers to figure out what their options are on their federal student loans,” said Kyra Taylor, an attorney at the National Consumer Law Center. She warned that any errors in loan collection would have “devastating effects on families.”

The move is part of Trump’s campaign to shutter the Education Department, an agency he says was overrun by liberal thinking. Only Congress has authority to close the department, but Trump officials are picking it apart through a series of inter-government agreements that relocate the department’s operations to other federal offices.

The future of the government’s enormous student loan portfolio has been one of the biggest unanswered questions. At her Senate confirmation hearing, Education Secretary Linda McMahon called Treasury a “natural” place for student loans. Trump later said they would be overseen by the Small Business Administration.

Conservatives have tried previously to move student loans

During Trump’s first term, his education chief talked about setting up a semi-private bank to manage student debt. The conservative Heritage Foundation promoted something similar in its Project 2025 plan, calling for a new “government corporation with professional governance and management.”

The Treasury Department often has been discussed as an option, yet student loans are seen as a particularly complex form of debt and some question whether the agency has the right technical expertise. In a 2015 pilot, Treasury tried to collect payments from a sample of thousands of borrowers in default. Its success rate was lower than that of the private collection agencies contracted by the Education Department.

Federal student loan borrowers are typically considered in default if they haven’t made a payment in more than 270 days. About 9.2 million Americans are in default on student loans, according to Education Department data released this month. Going into default can bring a heavy hit to credit scores, and the government can withhold pay and Social Security benefits.

The latest deal from the administration indicates a willingness to open up the hood of student loan operations at a perilous moment. About 12 million Americans are behind on federal student loan payments in some way, and the industry is bracing for a potentially historic surge in loan defaults as pandemic-era protections come to an end.

Earlier this year, Trump officials postponed their plans to restart involuntary collections on defaulted loans, which could have meant withheld earnings for millions of Americans. It’s seen as a politically volatile issue during a tough midterm year where affordability is already on voters’ minds.

___

The Associated Press’ education coverage receives financial support from multiple private foundations. AP is solely responsible for all content. Find AP’s standards for working with philanthropies, a list of supporters and funded coverage areas at AP.org.

This story was originally featured on Fortune.com

CBS News said Friday it will shut down its storied radio news service after nearly 100 years of operation, ending an era and blaming challenging economic times as the world moves on to digital sources and podcasts.

When it went on the air in September 1927, the service was the precursor to the entire network, giving a youthful William S. Paley a start in the business. Famed broadcaster Edward R. Murrow’s rooftop reports during the Nazi bombing of London during World War II kept Americans listening anxiously.

Today, CBS News Radio provides material to an estimated 700 stations across the country and is known best for its top-of-the-hour news roundups. The service will end on May 22, the network said Friday.

“Radio is woven into the fabric of CBS News and that’s always going to be part of our history,” CBS News editor-in-chief Bari Weiss said in delivering the news to the staff. “I want you to know that we did everything we could, including before I joined the company, to try and find a viable solution to sustain the radio operation.”

But with the radical changes in the media industry, “we just could not find a way to make that possible,” she said.

Not the first radio cuts at CBS

CBS News cut some of its radio programming late last year, including its “Weekend Roundup” and “World News Roundup Late Edition,” in an attempt to keep the service going.

It was unclear how many people will lose their jobs because of the radio shutdown. CBS News was cutting about 6% of its workforce, or more than 60 people, on Friday. It’s not the end of turmoil at the network, as parent company Paramount Global is likely to absorb CNN as part of its announced purchase of Warner Bros. Discovery.

Along with newspapers, radio was the dominant medium in how Americans got their news from shortly after the dawn of commercial radio in 1920 through the 1940s, with people in their living rooms listening to President Franklin Delano Roosevelt’s “Fireside Chats” during the Depression. CBS News Radio’s broadcast about Germany’s invasion of Austria in 1938, the first time Murrow was heard on the air, was an historic marker for the service.

Broadcasters like Douglas Edwards, Dallas Townsend and Christopher Glenn were familiar voices on CBS News Radio. The beginning of the television era in the 1950s began a long slide for radio, often an afterthought today with the world online and on phones. Those seeking audio often turn to podcasts before radio.

“This is another part of the landscape that has fallen off into the sea,” said Michael Harrison, publisher of Talkers, a trade publication for radio talk shows. “It’s a shame. It’s a loss for the country and for the industry.”

A major radio player for many decades

CBS News Radio was a major force for generations of Americans. “Its heyday spanned decades,” Harrison said. “It was quality on every level. It sounded good. Its coverage was as objective as possible within the realm of human nature. Its resources were extensive. It had a very high trust factor that was considered the standard of the day.”

The front page of CBS News’ website did not immediately carry news of the demise.

Weiss, founder of the Free Press website and without broadcast news experience before being hired by CBS parent Paramount’s new management, has quickly become a headline-maker and polarizing figure in journalism. She held a “60 Minutes” story critical of President Donald Trump’s deportation policy from being broadcast for a month and has critics watching to see if she’s moving the network in a Trump-friendly direction.

Addressing her staff in January, three months into her job as CBS News boss, she invoked the network’s legendary newsman Walter Cronkite as a symbol of old thinking and said that if the network continues with its current strategy, “we’re toast.” She announced the hiring of 18 new contributors and said CBS News needs to do stories that will “surprise and provoke — including inside our own newsroom.”

This story was originally featured on Fortune.com

Former Shark Tank star Mark Cuban has finally found an assistant to help him maintain a clear inbox, and its name is Mac (Mini). 

The billionaire entrepreneur has always preferred email to phone calls, partly because he likes to send more comprehensive responses via email and because it’s searchable even decades later. Plus, when it comes to phone calls, “I’m going to forget half the stuff that we talked about,” he previously has said.

Cuban is also notoriously tidy, aiming to keep his inbox to under 20 unread emails—or 10 on a good day—even if he has to read up to 1,000 emails per day on three phones.

For years, he’s handled this obsessive attentiveness to his communications on his own, saying an assistant would merely “slow things down.” Still, the increase in AI-generated cold emails and unwanted subscriptions have now obligated him to turn to AI for help, he said in an interview on the TBPN podcast published Thursday.

“I do what everybody else does. I bought a Mac Mini,” Cuban said on the podcast, referring to Apple’s compact desktop computer.

The Mac Mini is increasingly selling out in China as people turn to the affordable computer to run AI agents, especially autonomous AI tool OpenClaw. Unlike browser-based AI tools such as ChatGPT, locally run agents like OpenClaw, which OpenAI acquired last month, process commands directly on a user’s own hardware, without routing data through the cloud, which makes the process faster and more private.

While OpenClaw can run on a PC as well, some users prefer the Mac Mini because it is relatively affordable—a new device starts at $599, and a used one goes for even less. The device also has good specs, is small and portable, while alos power-efficient and silent, which is helpful as OpenClaw has to run continuously in the background.

The Dallas Mavericks minority owner admitted he’s still learning, but said he’s taught the AI on his Mac Mini to hit Gmail’s built-in unsubscribe feature to do away with pesky mailing lists he doesn’t want.

“Then, I just review it,” he said. “It’s still a work in progress, but at least I have a path.”

For his part, the billionaire has been experimenting with AI in his email for years. He previously said he used Gmail’s AI recommendations for 10% to 20% of his responses and used AI as a “typing hack” in longer replies, even if at times he jumps in to impart his own style.

Learning to use AI agents is essential for entrepreneurs, Cuban added in the podcast interview.

“Once you figure out how to do agents, then you can do them a little better than most other people, and then you can turn that into what would have been a [software-as-a-service] business in the past,” he said.

Cuban isn’t the only one that has used AI to simplify their work life. Apple CEO Tim Cook, who receives between 700 and 800 emails daily from customers, said Apple Intelligence’s email summary feature in the iPhone’s Mail app has transformed how he reads emails.

While he used to read long emails, now he relies on the summary feature: “It’s changed my life,” Cook told the Wall Street Journal in 2024. 

“If I can save time here and there, it adds up to something significant across a day, a week, a month,” he said.

Meanwhile, Cuban said while AI-generated cold emails are surging now, eventually he believes things will go back to normal.

“We’re in that trial and error phase where people are like ‘We’re going to try it, see what happens. You know, maybe we’ll get lucky,’” he said. “And then they’ll get bored and then it’ll drop off.” 

This story was originally featured on Fortune.com

A parent wants to see their kid make it in life. Maybe that’s going to a good school. Maybe it’s curing some disease or making it to the big leagues. And a parent wants to help with that journey—after all, it’s a parent’s obligation to care for their child. But how that care looks like has changed over time. It once simply meant school pickups and weekend soccer games, then college savings and late-night financial advice calls. But for many parents today, that support stretches far beyond childhood, following them well into adulthood.

A new study from financial services firm Northwestern Mutual reveals that parents are stepping in on one essential step for achieving the American dream: the down payment. The survey—conducted through more than 4,300 online interviews in January—found that more than half of parents, or 52%, are open to considering helping their kid buy a home—and 22% have already stepped in. 

Some parents are even rethinking the critical steps to ensuring their children have a shot at generating wealth. Twenty-nine percent of parents think helping their kid buy a home is more important than helping them pay for college, and more than half (55%) say it’s a toss-up for either one.

“A lot of these degrees are maybe not as valuable as they once were,” Ed Amos, wealth management advisor at Northwestern Mutual, told Fortune. “Having flexibility in those dollars is what parents are looking for.”

The value proposition of a four-year college degree is falling. Recent college grads are facing recessionary circumstances: 5.6% unemployment, surpassing the rate for all workers. And underemployment, or the share of graduates working in jobs that typically do not require a college degree sits at 42.5%

And the vibes are dire. AI is threatening a white-collar recession, which is expected to hit recent grads hardest. At the same time, home prices are skyrocketing. Homeownership—the ultimate promise of the modern American dream—is growing out of reach for young people. The average age of the first-time homebuyer hit 40 last year, up from the early 30s just a decade ago as the median home price tops $410,000 today.

Betting on bricks, not degrees

As some parents hesitate to shell out the almost $500,000 price tag attached to what a college degree could cost today, others are rethinking how they can position their children for financial success later in life. Amos said some parents he’s worked with are betting on homeownership as a key tool to ensuring their investments are well placed. One family he worked with, for example, helped their child buy a duplex while still in college, allowing their kid to live in one unit and rent out the other to pay down the mortgage, and ultimately build up equity before even entering the full-time workforce.

“The benefits of starting that wealth building early in life has tremendous impacts on where their children will be over the next few decades,” Amos said.

Yet Gen Z is finding itself in an increasingly precarious position. Young people today are left with crumbs of wealth compared to their Boomer and Gen X parents. Boomers today hold more than $86 trillion in assets, according to Federal Reserve data, more wealth than any other living generation. Gen X holds a significant slice of the economic pie too, with close to $44 trillion. That’s more than three-quarters the $167 trillion in total U.S. wealth

“It’s becoming less and less accessible to the entry-level employee straight out of college, trying to buy their first home,” Amos said. “It’s just becoming more and more difficult for these newer generations to do it on their own.”

High stakes gambling

With most of the country’s wealth locked away from Gen Z, many in the generation are looking for new and creative entry points into wealth generation. The Northwestern Mutual study found that Gen Zers are turning to high-risk, speculative assets for a shot at generating wealth. Nearly one-third of Gen Z have either invested in, or considered investing in crypto. One-third has also dabbled with the idea of, or are actively engaged in sports betting and prediction markets. And about 14% have placed their bets on meme stocks, or those viral stocks like GameStop popularized by communities like Reddit’s r/wallstreetbets subreddit—which now boasts over 4 million members—infamous after investors drove up the GameStop stock in 2021.

While these speculative bets paint a picture of a generation’s frantic scramble for financial footing, Amos said the most sustainable path to the American dream requires Boomers to hand over their wealth via more traditional assets like real estate. 

“Helping usher in that transfer sooner than passing will allow everyone to be able to share in that American dream,” he said.

This story was originally featured on Fortune.com

Colombian President Gustavo Petro has been designated a “priority target” by the U.S. Drug Enforcement Administration as federal prosecutors in New York probe his alleged ties to drug traffickers, according to people familiar with the matter and records seen by The Associated Press.

DEA records show Petro has surfaced in multiple investigations dating to 2022, many based on interviews with confidential informants. The alleged crimes the DEA has investigated include his possible dealings with Mexico’s Sinaloa cartel, a scheme to leverage his “total peace” plan to benefit prominent traffickers who contributed to his presidential campaign. The records also suggest the use of law enforcement to smuggle cocaine and fentanyl through Colombian ports.

The “priority target” label is reserved for suspects DEA deems to have a “significant impact” on the drug trade.

An inquiry in early stages

In recent months, prosecutors in Brooklyn and Manhattan have been questioning drug traffickers about their ties to Petro and specifically about allegations the Colombian president’s representatives solicited bribes to block their extradition to the United States, according to a person with knowledge of the inquiry who wasn’t authorized to discuss the ongoing inquiry and spoke to The Associated Press on condition of anonymity.

The person said it wasn’t clear whether federal prosecutors have implicated Petro in any crime.

The investigation is focusing at least in part on allegations that representatives of Petro solicited bribes from drug traffickers at the Colombian jail La Picota in exchange for a promise that they not be extradited to the U.S., one of the people said.

A spokesperson for the Colombian presidency declined to comment on the ongoing investigations into Petro or the subsequent legal proceedings.

Petro has consistently denied allegations of drug trafficking, particularly after Trump labeled him an “illegal drug leader” and the Treasury Department sanctioned him in late 2025 for alleged ties to the trade without offering evidence. Petro maintains that, while his administration aggressively targets major cartels, it remains focused on a more lenient, social-based approach for peasant farmers who cultivate coca leaf.

The federal inquiry was reported earlier Friday by The New York Times.

Petro came under scrutiny through the course of drug trafficking investigations by New York authorities that led them to identify him as a subject, according to another person familiar with the matter.

The inquiries into Petro are in the early stages, and it is not clear whether they will result in charges, this person said, adding the White House has had no role in the investigations.

Family members under scrutiny

Petro, a former rebel leader, soared into office promising to reduce the country’s dependence on fossil fuels and reallocate state resources to addressing entrenched poverty.

A leftist politician known for winding sometimes incoherent speeches, he has regularly criticized the Trump administration over its support for Israel, bombing of drug boats in the Caribbean and likened the White House migration crackdown to “Nazi” tactics.

After one such outburst, at a pro-Palestinian demonstration outside the United Nations headquarters in New York, Trump retaliated by revoking Petro’s U.S. visa. He also briefly slapped high tariffs on Colombia over Petro’s refusal to accept deportation flights from the United States.

But more recently the two have shown signs of getting along. After a meeting at the White House in February, Trump described Petro as “terrific.”

Colombian authorities have for years been investigating members of Petro’s family for possible criminal acts.

His son, Nicolás Petro, was charged in 2023 with soliciting illegal campaign contributions from a convicted drug trafficker to fund a lavish lifestyle of expensive cars and homes. The younger Petro has pleaded not guilty and his father has said none of the money was used to fund his campaign.

The president’s brother, Juan Fernando Petro, has also been implicated in secret negotiations that allegedly took place with imprisoned drug traffickers to shield them from extradition to the U.S. in exchange for their disarmament.

Politics and cocaine

Politics in Colombia have long been tainted by cocaine, of which it is the world’s largest supplier. In the 1980s, drug lord Pablo Escobar was elected to the country’s Congress with the support of one of Colombia’s most traditional parties. A decade later, his rivals from the Cali cartel flooded the presidential campaign of Ernesto Samper with illegal donations.

The now defunct urban guerrilla group Petro belonged to, the 19th of April Movement, has long been suspected of taking money from Escobar’s Medellin cartels as part of its deadly siege of the Supreme Court in 1985. Petro did not participate in the attack, which left several guerrillas and around half the high court’s magistrates dead. Leaders of the group have always denied any links to the cartel.

___

Durkin Richer reported from Washington. Goodman reported from Miami. Mike Sisak contributed from New York and Astrid Suárez from Bogotá, Colombia.

This story was originally featured on Fortune.com

The Middle East’s thriving luxury sector isn’t immune to the war in Iran, and CEOs of top brands have their eyes on the region.

“Clearly, we look close and every day on the situation,” Hugo Boss CEO Daniel Grieder said during an earnings call earlier this month. “It has a direct impact on store opening and store performance because there’s not many tourists or less tourists shopping. That’s clear. That has an effect on the shopping centers and so forth and for all the brands.”

A recent Bernstein Research report forecasted luxury sales in the Middle East would fall by 50% this month, primarily a result of a decline in traffic and tourism.

Still, it’s too early to say what the overall impact of the conflict will be, Grieder said, adding that the German designer brand has not yet seen any fallout. Executives at Prada and Salvatore Ferragamo have shared similar sentiments in recent calls with investors.

The Middle East region makes up about 6% of the world’s luxury market, but is among the fastest-growing geographies, with sales growing 6% to 8% organically, Bernstein reported. That’s compared to an otherwise stagnant sector.

“If the war was to end relatively shortly, this would not be a huge issue for the global luxury goods in the states,” Luca Solca, senior analyst of luxury goods at Bernstein, told Fortune. “If the war was to continue, then I think if oil and gas prices were staying high, then I think there would be a higher probability of a recession.”

The expanding luxury market in the Middle East

Luxury brands have grown deep roots in the Middle East, particularly in airports in Dubai, Doha, and Abu Dhabi. According to Bernstein, Dior and Gucci, which each get 20% of sales, excluding beauty and multi-brand stores, from the region.

The high-end market has grown along with the area’s wealth. From 2019 to 2022, the ultra-wealthy in the Middle East and North Africa saw their wealth double, per a 2023 OxFam report. The richest 106,080 people (making up 0.05% of the population) saw their wealth swell 75% from $1.6 trillion to $3 trillion in that span.

The wealth from these high-net-worth individuals has helped to drive the expansion of luxury sectors in the area. RBC Capital analyst Tom Narayan told Fortune these wealthier buyers are willing to splurge on the more expensive, top-of-the-line models, such as luxury supercars, making them a lucrative customer base for high-end brands.

“It’s certainly the high-margin region,” Narayan said, “meaning the cars they sell in the Middle East are more profitable versus the cars they sell outside that region.”

When luxury brands should begin to worry

Some brands are already shifting focus away from their usually reliable Middle East buyers. Ferrari and Maserati have temporarily halted shipments to the region, the companies said earlier this week.

To be sure, the Middle East accounted for just 4.6% of Ferrari’s 2025 global shipments, and Narayan said the automakers should be able to make up for lost deliveries in other markets, such as in Europe.

Still, consequences of a prolonged war loom. Bernstein said an ongoing conflict could throttle travel to the region, which is responsible for 30% of sales. Higher oil and gas prices, as well as concerns of a recession or fear of terrorist threats could also drive lower sales.

While President Donald Trump has signalled the conflict could last about a month, some analysts predict oil prices could remain elevated through 2027, making travel more expensive and adding economic pressures on consumers.

“Higher energy prices could potentially make global recession more likely,” Solca said. “If that materialized, then, of course, we would have a ricochet on discretionary sectors, and luxury is one of those. So we cannot take a global recession lightly.”

This story was originally featured on Fortune.com

Chuck Norris, dead at 86, was a certain type of hairy 1980s American man. For the uninitiated, here are a few jokes that Gen Xers and millennials used to make in middle school about the all-American martial arts star of their youth. You can still see some shared on social media: The flu gets a Chuck Norris shot every year. The chief export of Chuck Norris is pain. There is no chin behind Chuck Norris’ beard, only another fist. And perhaps most timely for our world today: Chuck Norris doesn’t worry about high gas prices, his vehicles run on fear.

The legendary martial arts master and actor died on Friday, after years of being the epitome of toughness and dodging death with jokes that ludicrously snowballed with higher stakes of death-defying physical and mental fortitude.

The Walker, Texas Ranger star first gained notoriety for his physical command as a martial artist, eventually working his way into Hollywood as an action film star in the late 1970s. Outside of playing the title character on Walker, Texas Ranger on CBS from April 1993, to May 2001 (in which he played a gun-totting, no-nonsense lawman), he was the lead in a string of action movies, famously starring opposite Bruce Lee in The Way of the Dragon—his debut screen role, where he played a thug opposite Lee’s hero trying to save his family’s restaurant in Rome) and even turned to thrillers before he took a break from acting. But he still maintained his tough persona throughout the years, posting on Instagram just 10 days ago “I don’t age. I level up,” and sharing a video of him boxing on his 86th birthday. 

But his physical and mental fortitude weren’t the only things the action star is known for: he’s amassed a $70 million fortune in his five-decade long career, and has poured significantly into giving back to the community. But most strikingly, he stayed true to his ever-increasingly tough-guy persona by offering CBS an offer they couldn’t refuse after taking on the network for refusing to honor their contract.

A $70 million fortune

Norris built one of Hollywood’s most unlikely financial empires— starting with nothing and eventually amassing an estimated net worth of $70 million. His rise from a $12-a-week laborer to a global action icon tracks as closely with discipline as it does with dollars.

His early film paychecks were modest by any standard. Norris earned just $10,000 for his 1976 debut Breaker! Breaker!, which jumped to $40,000 for Good Guys Wear Black the following year, then $125,000 for A Force of One in 1978, and $250,000 for An Eye for an Eye by 1980. His salary exploded, however, when he landed the starring role in Walker, Texas Ranger, where he commanded $375,000 per episode across 203 episodes—a figure that dwarfed every other cast member on the show.

Despite that hefty per-episode rate, Norris alleged he wasn’t getting his full cut. In 2018, he filed a lawsuit against CBS claiming the network owed him more than $30 million in profits from Walker, Texas Ranger. His contract had entitled him to 23% of all profits, but Norris argued CBS structured the show’s distribution deals—including streaming revenue going back to 2004—in ways that deliberately avoided triggering the profit-sharing clause. At the time of the suit, the series had generated over $692 million in total revenue, making the alleged shortfall all the more striking. The case was settled in July 2023 for an undisclosed amount, with CBS issuing only a brief statement that “the parties have resolved the dispute”.

Beyond the courtroom, Norris’s current income draws from a wide range of sources—including endorsement deals, real estate, and his brand ventures—putting his estimated annual earnings at around $30 million.

Off the balance sheet, Norris has poured significant energy into giving back. In 1990, he founded Kickstart Kids, originally called the Kick Drugs Out of America Foundation, which provides free martial arts and character development programs to middle and high school students. Launched in four Houston-area schools with the support of President George H.W. Bush in 1992, the program now operates in 58 schools across Texas, has served over 120,000 students since its inception, and currently enrolls approximately 8,349 students annually. Norris himself has said the program teaches kids “how to make good decisions,” and research tied to it shows participants demonstrate higher self-esteem, lower drug use, and less violence.

“He lived his life with faith, purpose, and an unwavering commitment to the people he loved,” wrote his family in an Instagram post announcing his death. “Through his work, discipline, and kindness, he inspired millions around the world and left a lasting impact on so many lives.”

This story was originally featured on Fortune.com

On March 18, the U.S. House voted 211–207 to advance a Balanced Budget Amendment — far short of the two-thirds majority required to pass it. The same day, total federal debt surged past $39 trillion, or 125% of GDP. That’s up from $5.7 trillion, or 55% of GDP in 2000. On March 19, the Trump administration confirmed plans to seek up to $200 billion in supplemental funding for its war against Iran.

In the face of such numbers, the U.S. House of Representatives failed on March 18 to pass a proposed Balanced Budget Amendment, and the Trump Administration announced its plans to seek major supplemental funding for as much as $200 billion to support its war efforts against Iran.

America has been adding to its record debt at record rates, and Congress has become addicted. Absent a change in course, the nonpartisan Congressional Budget Office (CBO) projects that Uncle Sam’s debt will soar to 175% of GDP in 30 years. And those projections were made before the U.S.-Israeli war against Iran began.

If that’s not bad enough, the federal debt is just the tip of Uncle Sam’s financial iceberg. Total liabilities and unfunded social insurance promises exceed $125 trillion. That is a stunning 3.2 times higher than the current federal debt. Despite the federal government’s fiscal time bomb, the U.S. Congress and the President remain with their heads in the sand.

The Swiss model Washington rejected

The U.S. House’s failed Balanced Budget Amendment proposal (H. J. Res. 139) was based on a modified version of the Swiss Debt Brake, a constitutional amendment that was passed in a Swiss national referendum with overwhelming support in 2001.

The Balanced Budget Amendment proposal would limit federal spending to an average of federal receipts over a three-year period, adjusted for population increases and inflation. Its primary object is to achieve a primary budget balance––a balance of receipts and expenditures, excluding interest payments. The legislation includes a release valve that would be triggered by a supermajority vote in Congress for declarations of war and other selected events. Since Switzerland adopted its Debt Brake, the country’s federal debt has remained below 30% of GDP — a stark contrast to America’s trajectory.

While the balanced budget amendment proposal failed, it did properly recognize, in our view, that only a constitutional amendment can force current and future Congresses to restore and sustain fiscal sanity. The problem is that, given the current political environment, there is virtually no chance that Congress will revisit the Balanced Budget Amendment. Therefore, it is time to let the states initiate a change to the U.S. Constitution via the utilization of Article V of the Constitution. Such a fiscal amendment to the U.S. Constitution would ensure fiscal sanity.

The constitutional backdoor that’s been waiting since 1979

Our nation’s founders recognized that Congress might be unwilling or unable to propose a path forward for needed constitutional amendments. Therefore, the founders provided a second way to propose constitutional amendments. Specifically, if two-thirds of the states file an application for a convention to propose one or more amendments to the Constitution, Congress is mandated to call the convention. Importantly, unlike the Convention in 1787, this would be an amendments convention, not a convention to rewrite the Constitution.

Shockingly, about three years ago, we at the Federal Fiscal Sustainability Foundation (www.FFSF.US) discovered that there were enough active state applications for a single-issue convention to propose a fiscal responsibility amendment to the U.S. Constitution. Indeed, the required number of applications has existed since 1979 and remained in limbo because the U.S. Congress has failed to act. In September 2025, our findings were confirmed by none other than the National Federalism Commission, an official interstate governmental body.

House Budget Committee Chairman Jodey Arrington (R–TX) has sponsored H.C.R. 15 to right this congressional wrong. However, it looks like Congress plans to stiff the states and fail to discharge its express and mandated constitutional duty.

The time has come for one or more state attorneys general to sue Congress for failing to act. If the states fail to do so, they will effectively be mooting the states’ rights to propose amendments under Article V. The time for the states to assert their constitutional rights is now! The future of America’s fiscal health is at stake.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Job seekers are up against a brutal labor market, sending thousands of applications out to no avail, and resorting to in-person stunts to get an employer’s attention. And a new report is confirming their suspicions: hiring managers are ghosting their candidates, and it’s getting worse for talent every year. 

More than half, 53%, of job seekers experienced ghosting within the last year, according to a new report from pre-employment testing company Criteria. And that number just reached a three-year peak, as 48% of applicants were ignored by employers in 2025, and 38% were ghosted in 2024. 

Job seekers may point the finger at lethargic hiring managers, but in actuality, the worrying trend might chalk up to an overwhelming hiring process “increasingly ineffective” at finding the right match. 

“We’re seeing a surge in application volume, largely fueled by AI tools that make it easier than ever to apply and tailor résumés at scale,” Josh Millet, the cofounder and CEO of Criteria, tells Fortune. “The result is that hiring teams are spending more time reviewing applications, but getting less meaningful signals from each one.”

And as job seekers and hiring managers both increasingly use advanced technology, it’s muddying the best way to pick talent. Millet explained that the résumé, once the benchmark of a job application, is now becoming a “weaker signal” because it can be easily generated by AI. As more people highly tailor their résumé with AI tools, it then becomes harder to differentiate the frontrunner in a pool of polished applications. As a result, employers aren’t always answering back to the thousands of candidates who applied to an open role within the span of just hours. 

“Recruiters are inundated, screening methods are less reliable, and communication suffers,” Millet continued. “In many ways, ghosting is less about intent and more about a hiring process that hasn’t caught up to how candidates are applying today.”

‘Ghost jobs’ are also flooding the market, and job-seekers are losing faith 

AI has undoubtedly upended the hiring process and turned it into a numbers game; job-seekers send out a deluge of applications until something sticks, while managers are stuck sifting through thousands of candidates for every open role. The trend has been intensifying for years, leaving many job-hunters out in the cold—and sometimes, employers are intentionally ghosting.

About 81% of recruiters said that their employer posts “ghost jobs,” or roles that either don’t exist or have already been filled, according to a 2024 report from MyPerfectResume. 

Unlike conventional ghosting, these fake postings are created for a purposeful reason: about 38% of recruiters reported that they post fake positions to maintain a presence on job boards when they aren’t hiring, 36% did so to assess the effectiveness of their job postings, and 26% hoped gain insight into the job market and competitors. 

Jasmine Escalera, a career expert for MyPerfectResume, told Fortune in 2024  that another big reason is wanting to improve their employers’ image; nearly a quarter said that fake jobs help their company look like they’re not freezing hiring, and one fifth fessed up to posting ghost jobs to improve the reputation of their business.

“Companies are trying to project ‘We’re okay, we’re still maintaining hiring, that we’re still moving in a growth-oriented trend. In this market, our organization is doing well.’ That ties into why these fake jobs might be appearing more from a comforting perspective,” Escalera explained. “It really is about the business, the bottom line, showing growth, showing trends, and how that can connect to maintaining profit.”

But the trend is discouraging for candidates vying to land a new role.

“We often hear job-seekers saying, ‘I’m tired, I’m depressed, I’m desperate,’ using these very harsh words when it comes to the job market,” the career expert continued. “This is one of the reasons why they are losing faith in organizations and companies.”

This story was originally featured on Fortune.com

White-collar tech roles have faced waves of layoffs in recent months, as companies like Amazon, Meta and Oracle trim headcounts in the name of efficiency. But the same firms culling workers are running into a roadblock with their AI ambitions: a severe shortage of skilled workers needed to build and maintain data centers. And the talent shortfall is in the hundreds of thousands. 

Demand for robotics technicians has jumped 107%, HVAC engineers increased 67%, and construction roles grew by 30% since late 2022, according to an analysis of more than 50 million job postings by Randstad. Roles like welders and electricians are also on the rise, up 25% and 18% over the past three years, respectively.

But supply has yet to keep up. In the manufacturing space in particular, for every 100 young people entering the manufacturing sector, 102 leave, according to the report. Randstad CEO Sander van’t Noordende said the imbalance is creating a major opening for Gen Z workers to step into lucrative, AI-resilient careers.

“For a long period, societies generally pushed a narrative that the ultimate marker of success is a four-year university degree and a desk job,” Noordende told Fortune in an emailed statement. “This outdated perception led to skilled trade work becoming overlooked. However, AI is now revealing just how critical these roles are and how elevated they are becoming.”

Unlike many white-collar paths, these roles often don’t require a four-year degree. Instead, workers can enter through apprenticeships and training programs that allow them to earn while they learn—offering a faster, and often cheaper, route into the workforce than going to college.

Some trade workers’ salaries are soaring past $250,000 thanks to the AI data center boom

The lack of supply of skilled workers to build America’s rapidly growing AI infrastructure is actually pushing blue-collar wages to new highs.

Construction workers on data center projects currently  earn an average of about $81,800 annually, or $39.33 an hour—roughly 32% more than those on non-data center builds—according to data from Skillit, an AI-powered hiring platform for construction workers.

“Because of the huge demand and the nature of this construction work, which is fueling the arms race of AI… the budgets are not as tight,” Skillit CEO Fraser Patterson told Fortune last year. “I would say they’re a little more frothy.”

Industry leaders indicate the trend is only accelerating. Nvidia CEO Jensen Huang called the AI boom “the largest infrastructure build-out in human history that’s going to create a lot of jobs” for professions like plumbers, electricians, and steel workers. At the World Economic Forum in Davos earlier this year, he also added that salaries are climbing into the six figures.

Electricians, in particular, are emerging as one of the most-in-demand, and best-paid,  jobs on the market. Electrical work accounts for an estimated 45% to 70% of total data center construction costs, according to the International Brotherhood of Electrical Workers. The U.S. will need roughly 300,000 new electricians over the next decade, in addition to replacing the 200,000 expected to retire.

In some cases, the pay is already reaching eye-popping levels. TV star Mike Rowe, known for his stint hosting Dirty Jobs, recently said he met three electricians under the age of 30 making between $240,000 and $280,000 per year at a data center in Plano, Texas.  They each had no college debt, and companies are regularly trying to poach them.

The skilled trade trade-off: high pay, but demanding work

For all the upsides, careers in the skilled trades also come with clear drawbacks.

The work is often physically demanding, requiring long hours on your feet in unpredictable environments. One day might mean working indoors with air conditioning; the next could involve pulling cable through mud or working in extreme heat or cold.

Hours can also be inconsistent. Because many roles are tied to large-scale construction projects, workers may face intense schedules as deadlines approach—followed by gaps between jobs or the need to relocate to wherever the next project is underway

There are also long-term uncertainties. Some business leaders, including Elon Musk, have suggested that advances in robotics could eventually automate aspects of skilled trade work—though that shift, if it comes, is likely years away.

Still, for many young workers, the trade-offs are worth it. For Gen Zer Jacob Palmer, skipping college in favor of an electrician apprenticeship quickly paid off. By 21, he launched his own business, grossing nearly $90,000 in 2024 and surpassing six figures the following year. Unlike many of his peers burdened by student debt and an uncertain job market, he told Fortune simply: “I don’t owe anybody anything.”

This story was originally featured on Fortune.com

Government bonds, especially Treasuries, have long been seen as a safe haven during recessions, geopolitical calamities, and other market-moving disasters that create uncertainty.

But after looking at 300 years of U.S. and U.K. history, the Center for Economic Policy Research found that wars and pandemic-scale emergencies have pummeled holders of debt.

“The historical evidence reveals a striking pattern: government bonds have repeatedly generated substantial real losses during these extreme episodes,” authors Zhengyang Jiang, Hanno Lustig, Stijn Van Nieuwerburgh, and Mindy Xiaolan wrote. “They have even underperformed equities and real estates which are traditionally regarded as risky assets.”

That’s because wars typically triggered large increases in government spending, averaging about 7% of GDP annually during the first four years, and tax hikes alone were rarely sufficient for financing needs, they added.

The finding comes as the U.S. is waging war on Iran while the national debt has exploded to $39 trillion. The Pentagon is seeking more than $200 billion in a budget request for the conflict, sources told the Washington Post.

Across their dataset, the CEPR authors calculated that bondholders suffered average real losses of roughly 14% during the first four years of conflicts. The losses were so steep that they reduced the real value of government debt outstanding.

To add insult to injury, cumulative bond returns were more than 20% below the cumulative returns on stocks and real estate, the opposite of how those assets perform during financial crises or recessions.

“Whenever there is a major war, we observe a sharp decline in the bond performance — wars are always disaster times for bondholders,” they warned. “Similarly, the bondholders also suffered large losses during the ‘war on Covid-19.’”

Center for Economic Policy Research

A key factor in bond losses is inflation, according to CEPR, which said the cumulative rate averaged about 20% in the first four years of wars.

In fact, during the current U.S.-Israel war on Iran, Treasuries and government debt from other countries have sold off sharply as surging oil prices have raised expectations for elevated inflation while budget deficits are also seen worsening. Since the war began three weeks ago, the U.S. 10-year yield has soared more than 40 basis points.

But profligate spending wasn’t the only way inflation weighed on bonds. The think tank said it was often the result of policy choices to reduce debt burdens without explicitly defaulting, such as by suspending gold standard commitments.

Another reason bonds perform so poorly during wars is so-called financial repression, or government policies that curb borrowing costs by influencing financial markets. That prevents bond yields from keeping pace with inflation.

For example, the Federal Reserve implemented yield-curve control, capped Treasury rates, and launched massive bond buying during World War II.

CEPR’s findings have particular relevance for U.S. debt as Treasuries continue to form the foundation of the global financial system with the dollar serving as the world’s reserve currency.

That status has allowed the U.S. to borrow more cheaply than investors would otherwise allow. Meanwhile, the interest on U.S. debt is now the fastest-growing budget item and is already at $1 trillion a year. CEPR said its report presents governments with an important tradeoff.

“Protecting taxpayers from large spending shocks may require shifting part of the burden onto bondholders through inflation or financial repression,” it said. “Economic theory suggests that such policies may be optimal when taxation is highly distortionary. However, they also reduce the safety of government debt and may raise borrowing costs over time if investors anticipate these risks.”

This story was originally featured on Fortune.com

It all began with an anonymous Twitter handle named “Ivan the K.” The self-appointed “Lead Independent Director of Finance Twitter” had a dark theory in the depths of the pandemic. In 2020, they asked the universe, “Why is no one talking about a K recovery?” since there was much discussion at that time about an economic bounceback in the shape of either a U, an L, or, most bullish of all, a V. “Some things will bounce back,” Ivan wrote, “some will not recover. Think about it.”

Economists seem to have thunk on it and agreed: The K is real. It bears similarities to another saying, invented nearly 200 years earlier by the great English romantic poet Percy Bysshe Shelley: “The rich get richer, the poor get poorer.” 

This is also called “the Matthew effect,” as some trace the sentiment all the way back to the bible’s Book of Matthew 25:29: “For to everyone who has, more will be given, and he will have abundance; but from the one who does not have, even what he has will be taken away.”

If you ask Mark Zandi, chief economist for Moody’s Analytics, this old-time religion got a new lease on life in the Reaganomics of the 1980s. “You really start to see this in the Reagan era,” Zandi told Fortune. “That’s when you get a structural divergence between productivity growth and median wage growth.” 

Zandi argued many elements combined then to weaken labor in favor of capital income: globalization, the decline of unions and manufacturing and major tax reforms. “The share of national income going to labor has been trending down since the early 1980s,” he said, “and the share going to capital owners—those who already have wealth—has gone up.”

So what is it about 2026, six years after the pandemic severed something economically, that accelerated both sides of the “K” for the wealthy and the poor?

Data doesn’t lie

First, consider the extraordinary surges in economic data seen, halfway through the 2020s. The stock market rallies have led to several record highs in 2025, incentivizing the (wealthier) Americans with money in the markets to loosen their purse strings. But the bottom half of the K is extending downwards, with fast-casual restaurants like Chipotle and Cava, and fast-food joints like McDonald’s, noting that lower-income customers, especially young people, are pulling back and preferring to dine at home.

Zandi’s own research has turned up some stunning results, notably that in the second quarter of 2025 the top 10% of wealthiest Americans were responsible for a whopping 49% of consumer spending. That means the economy has grown so lopsided—or K-shaped—that the richest Americans are responsible for half the economy. The K-shape is creating the illusion in economic data that despite sticky inflation and tariff-related sticker shock, consumer spending remains “resilient.” 

Morgan Stanley Wealth Management’s Lisa Shalett has increasingly been sounding the alarm from her perch as chief investment officer. She told Fortune in an October 2025 interview “the income inequality stuff is really getting like completely wackadoo,” specifically citing Zandi’s research: “That means 90% of the country is only half the consumption, I mean holy cannoli.” 

Shalett covered the K-shaped economy specifically in a November 2025 research note, in the context of whether 2026 marks an early or late stage of the economic cycle for investors. “Decoding this conundrum may hinge on the so-called K-shaped economy,” she wrote, “a concept that captures the widening chasm between the ‘haves’ and ‘have-nots.’”

Then Shalett said the situation is actually even worse than what Zandi produced: “For the U.S. consumer, wealth concentration has produced a situation where the top 40% of households by income account for approximately 60% of all spending; those households, in turn, control nearly 85% of America’s wealth, two-thirds of which is directly tied to the stock market, which has climbed more than 90% in three years.” She calculated that spending by the wealthiest households was growing 6x-7x faster than for the lowest cohort. 

Even Federal Reserve chair Jerome Powell talked about seeing the pattern at last December’s Federal Open Market Committee meeting. “We hear about this a lot,” Powell said. “If you listen to the earnings reports for consumer-facing companies that tend to deal with low- and moderate-income people, they’ll all say that we’re seeing people tightening their belts, changing products that they buy, buying less, and that sort of thing. And so it’s clearly a thing.”

When did the K-shaped economy emerge?

The concept of a bifurcated economy has been baked into American society longer than even the days of Reagan, according to Tyler Schipper, associate professor of economics at the University of St. Thomas.

“There’s this underlying thing that has been true for decades and decades and decades,” Schipper told Fortune. “Number one, lower income households always struggle more in the economy. They tend to be more impacted by price changes because they’re spending a higher percentage of their income. 

“And second, that it tends to be that after each recession, lower income workers fall further behind in the income distribution,” he added.

Today, conversations around the shape of the American economy are more urgent because more of the middle class—and those making about $100,000 per year—are getting pushed into the lower half of the K, Schipper said. This can be seen in mid-income and higher-income earners flocking to discount retailers like Walmart and Dollar General. It can even take on more absurd forms, with “Ralph Lauren Christmas” trending at unprecedented levels during the projected $1 trillion 2025 holiday season, but TikTok and Instagram full of tips on how to achieve the look of red-tartan-plaid and cozy sweaters on a budget—in other words, not at an actually expensive Ralph Lauren store. 

Why is this happening?

That lower half of the K is extending ever downward as the consumer encounters a unique set of challenges, including the inflationary impact of tariffs, according to Schipper. Lower-income households tend to spend more on essential goods more likely to be impacted by tariffs. The Yale Budget Lab calculated that the levies impact the bottom of the income ladder more than three times more than the top.

A low-fire, low-hire labor market has also contributed to evidence of a two-tiered economy, said Claudia Sahm, chief economist at New Century Advisors and a former Federal Reserve economist. While tech layoffs have been top of mind following massive cuts from Amazon, layoff rates are still low, Sahm told Fortune, meaning if you have a job, you may feel more financially secure. If you’re just entering the job market like Gen Z is, you may have a hard time finding a job as firms contract following a post-COVID hiring spree, and as AI begins to displace entry-level jobs. To be sure, January 2026 data from Challenger, Gray & Christmas found U.S. employers cut more than 108,000 jobs in January, the largest January reduction since 2009.

But another part of the resurgence of discussions about a bifurcated economy comes from the relative nature of a K-shaped economy, according to Schipper. While the economy has historically been two-tiered, diverging consumer sentiment has also contributed to a narrative that two income groups are moving away from each other. 

For example, in 2022 when the stock market declined, consumer sentiment in both the top-third and bottom-third of income levels converged, according to data from the University of Michigan’s Survey of Consumers. A similar pattern occurred last April, when the announcement of Liberation Day tariffs spooked Americans across income levels, Schipper noted. Last year, however, consumer attitude toward the economy saw a greater split, with low-income Americans feeling far less confident about the economy than those high-income, a trend continuing into 2026.

How monetary policy created the two-tiered economy

Some economists point to the widening divide between the rich and the poor as a consequence of monetary policy. The Fed, over the past few years, has had a historic tightening cycle—11 rate hikes between 2022 and 2024—which was meant to pare down inflation. However, it also reinforced the split since wealthy households, flush by years of asset appreciation, could weather the slowdown better than lower income households facing higher mortgage rates and shrinking credit, Zandi said.

Cheap money in the 2010s and early pandemic years boosted stocks and home values, but the 2022-and-on tightening squeezed borrowers and renters without necessarily reversing those gains. That means even as inflation has cooled, the damage lingered as asset holders retained their windfall but wage earners bore the brunt of disinflation. 

“Folks in the top third of the income and wealth distribution are doing well, but the remaining two-thirds of Americans are struggling… they borrowed during the pandemic when rates were low, and now they’re having to pay on that debt at a higher rate,” Zandi said.

How can the economy become less bifurcated?

Though Fed chair Powell has acknowledged today’s K-shaped economy, a more restrictive monetary policy is helping keep it in place, Sahm argued, making it unlikely for the two diverging K lines to come any closer together.

“We have a Fed that’s still trying to fight inflation that’s been elevated, and part of the tool that they have for fighting inflation is interest rates are elevated, and they’ve been elevated for some time,” Sahm said. “This is the way restrictive monetary policy works: It’s going to hit households hardest who are more financially constrained.”

Zandi had a different perspective. He argued the gap will require policy changes far beyond the Fed’s remit.

“The Fed can’t fix the K-shaped economy,” he said. “It can only stabilize prices and employment. The distributional effects are up to fiscal policy.” Instead, Zandi argued for a reversal of some choices made on the fiscal side that would “do no harm” to lower-and-middle-income Americans.

“Don’t impose tariffs—that exacerbates inequality,” he said. “Lower- and middle-income households spend a much higher share of their budget on imported products like food, clothing, and cars.” 

He also criticized President Donald Trump’s “highly restrictive” immigration policy, which he said hurts jobs for industries that rely on immigrants, such as construction, agriculture and manufacturing broadly. 

Beyond just addressing self-inflicting wounds, Zandi argued that progress depends on both structural and cyclical forces: raising productivity through education, broad-based jobs creation, and ensuring that gains from AI will be equally shared. “If the benefits of AI are distributed more broadly,” he said, “and if job losses are offset by new opportunities, we’ll be fine.”

What’s so bad about a K-shaped economy?

Clear evidence of a two-tiered economy doesn’t mean a recession is imminent, economists said. It does, however, mean that if economic indicators were to take a nosedive, the risk of a recession would increase.

“The K-shaped economy, the bifurcated economy, is potentially a more vulnerable economy,” Sahm said.

Though layoff rates are still relatively low, if the rate of job cuts increased, there would be many more people in a job market where there’s not much hiring. The labor market today doesn’t look like it did in the job-hopping era of 2023, even when interest rates were still high, Sahm noted. Right now, only the healthcare and hospitality sectors are adding jobs in earnest, creating a concentration of growth not optimal for economic stability.

“Anytime you have that, you’re more vulnerable if something bad happens,” Sahm said.

A version of this story was published on Fortune.com on Nov. 7, 2025.

More on the K-shaped economy:

  • Welcome to the ‘E-shaped’ economy: Wealth gap is no longer between just high and low earners, the middle class is also struggling
  • McDonald’s newest $3 value menu is sounding an alarm about America’s K-shaped economy
  • Economist behind K-shaped economy sees a ‘sea of despair’ for the bottom 90% and a ‘crisis of confidence’ in the American dream

This story was originally featured on Fortune.com

Iran threatened to target recreational and tourist sites worldwide and insisted it was still building missiles. Friday’s show of defiance came nearly three weeks into U.S.-Israeli strikes that have killed a slew of Tehran’s top leaders and hammered its weapons and energy industries.

Iran fired on Israel and energy sites in neighboring Gulf Arab states as many in the region marked one of the holiest days on the Muslim calendar. Iranians were also celebrating the Persian New Year, known as Nowruz, a normally festive holiday that is more subdued this year.

With little information coming out of Iran, it was not clear how much damage its arms, nuclear or energy facilities have sustained since the war began Feb. 28 or even who was truly in charge of the country. But Iran has showed it is still capable of attacks that are choking off oil supplies and denting the global economy, raising food and fuel prices far beyond the Middle East.

The U.S. and Israel have offered shifting rationales for the war, from hoping to foment an uprising that topples Iran’s leadership to eliminating its nuclear and missile programs. There have been no public signs of any such uprising and no end in sight to the war.

Iran threatens worldwide tourist sites

Iran’s top military spokesman warned Friday that “parks, recreational areas and tourist destinations” worldwide won’t be safe for Tehran’s enemies.

The threat from Gen. Abolfazl Shekarchi renewed concerns that Iran may revert to using militant attacks beyond the Middle East as a pressure tactic.

U.S. and Israeli leaders have said that weeks of strikes have decimated Iran’s military. Airstrikes have also killed its supreme leader, the head of its Supreme National Security Council and a raft of other top-ranking military and political leaders.

The Israeli military said Friday that Esmail Ahmadi, head of intelligence for the Basij, and internal security force, had been killed by a strike earlier in the week that hit other Basij leaders.

On Thursday, Israeli Prime Minister Benjamin Netanyahu claimed Iran’s navy was sunk and its air force in tatters, while adding that its ability to produce ballistic missiles had been taken out. Iran’s paramilitary Revolutionary Guard disputed the missile claim on Friday.

“We are producing missiles even during war conditions, which is amazing, and there is no particular problem in stockpiling,” spokesman Gen. Ali Mohammad Naeini was quoted as saying in Iran’s state-run IRAN newspaper.

A short time after the statement was released, Iranian state television said Naeini was killed in an airstrike.

The country’s new Supreme Leader Ayatollah Mojtaba Khamenei also released a rare statement, saying Iran’s enemies need to have their “security” taken away.

Khamenei hasn’t been seen since he succeeded his father, the 86-year-old Ayatollah Ali Khamenei, who was killed in an Israeli airstrike on the first day of the war.

A Kuwait refinery comes under attack and explosions shake Dubai

Iran has stepped up its attacks on energy sites in Gulf Arab states after Israel bombed Iran’s massive South Pars offshore natural gas field earlier in the week.

Two waves of Iranian drones attacked a Kuwaiti oil refinery early Friday, sparking a fire. The Mina Al-Ahmadi refinery, which can process some 730,000 barrels of oil per day, is one of the largest in the Middle East. It was damaged Thursday in another Iranian attack.

Bahrain said a fire broke out after shrapnel from an intercepted projectile landed on a warehouse, and Saudi Arabia reported shooting down multiple drones targeting its oil-rich Eastern Province.

Heavy explosions shook Dubai as air defenses intercepted incoming fire over the city, where many were observing Eid al-Fitr, the end of the Muslim fasting month of Ramadan.

In Iran, meanwhile, many were marking Nowruz even as Israel said it had launched new strikes, and explosions were heard over Tehran. The Persian New Year, which coincides with the spring equinox, is a tradition observed across southwestern Asia that dates back thousands of years.

Loud explosions could also be heard in Jerusalem after the Israeli army warned of incoming Iranian missiles. First responders said they treated two people around 70 years old who were lightly wounded.

In addition to steadily striking Iran, Israel has regularly hit Lebanon, targeting Iran-backed Hezbollah militants who have been firing rockets and drones into Israel.

On Friday, Israel broadened its attacks to Syria, saying it hit infrastructure there in response to what it described as attacks on the Druze minority. Syria’s state-run SANA news agency did not immediately acknowledge the attack.

More than 1,300 people have been killed in Iran during the war. Israeli strikes in Lebanon have displaced more than 1 million people, according to the Lebanese government, which says more than 1,000 people have been killed. Israel says it has killed more than 500 Hezbollah militants.

In Israel, 15 people have been killed by Iranian missile fire. Four people were also killed in the occupied West Bank by an Iranian missile strike.

At least 13 U.S. military members have been killed.

The war is raising risks to the world economy

Iran’s attacks on energy infrastructure in the Gulf combined with its stranglehold on shipping in the Strait of Hormuz, a strategic waterway through which a fifth of the world’s oil and other critical goods are transported, has raised concerns of a global energy crisis.

U.S. President Donald Trump lobbed fresh insults at NATO allies who have spurned his call for help protecting the strait. U.S. allies have refused to join the war, saying they weren’t consulted before the U.S. and Israel launched it. Trump called NATO members “COWARDS” in a social media post, saying: “NATO IS A PAPER TIGER.”

Brent crude oil, the international standard, has soared during the fighting and was around $108 per barrel Friday, up from roughly $70 per barrel before the war began.

Surging fuel prices come at a moment when many world leaders were already struggling to bring down high prices of food and many consumer goods. Asia is getting hit hard as most of the oil and gas exiting the Strait of Hormuz is transported there.

But the price shocks are reverberating throughout the world economy. Key raw materials — like helium used in making computer chips, and sulfur, a raw material in fertilizer — have been obstructed and could be in short supply soon, raising the prices of goods all the way down the supply chain.

___

Mednick reported from Jerusalem and Rising from Bangkok. AP journalists Michelle Price in Washington and Russ Bynum in Savannah, Georgia, contributed.

This story was originally featured on Fortune.com

Ukrainian officials are helping five countries in the Middle East and Gulf region counter attacks on their territory by Iranian drones, while the United States and European countries are among others who have requested support, Ukrainian President Volodymyr Zelenskyy said Friday.

Ukraine is also looking into whether it can have a role in restoring security in the Strait of Hormuz amid the Iran war, he said.

Ukraine has become one of the world’s leading producers of cutting-edge, battle-tested drone interceptors that are cheap and effective. They play a key part in its defense against Russia’s more than 4-year-old full-scale invasion.

“Our teams are already working with five countries on countering (Iran’s) ‘Shahed’ drones — we have provided expert assessments and are helping build a defense system,” Zelenskyy said on X.

Zelenskyy has previously said he hoped to provide expertise to Arab Gulf countries targeted by Iranian Shahed drones, versions of which are heavily used by Moscow’s invading forces, in exchange for advanced air defense missiles that Ukraine needs to counter devastating Russian aerial attacks. Kyiv fears it will get fewer of the sophisticated missiles it needs to fend off the Russian strikes as the Iran war burns through stockpiles.

Ukrainian expertise helps protect civilian and critical infrastructure

Rustem Umerov, the head of Ukraine’s National Security and Defense Council who led a delegation to the Middle East and Gulf this week, said that Ukraine has deployed interceptor units there to help protect civilian and critical infrastructure and is working to expand that protection.

He said on the Telegram messaging app that Ukrainian military specialists are operating in the United Arab Emirates, Saudi Arabia, Qatar, Kuwait and Jordan.

Ukraine is assessing further steps for long-term security cooperation with each of those countries, Umerov said.

The U.S. has asked for expert support for their military personnel in two areas of the region, Zelenskyy said, adding that Kyiv is also reviewing requests from European partners whose forces are based in the region.

The relationship between Washington and Kyiv on drone cooperation has been unclear.

Zelenskyy said last week that Ukraine was awaiting White House approval for an agreement on drone production. But a day later Trump spurned Ukraine’s offer of assistance, telling the “Brian Kilmeade Show” on Fox News Radio: “No, we don’t need their help on drone defense.”

Ukraine looks to resume talks with US, Russia

Zelenskyy said late Thursday he has sent an official delegation to the United States in a bid to move forward suspended U.S.-brokered talks on ending Russia’s invasion.

The trilateral talks, which have yet to produce any breakthrough on key issues, have been on ice while the Iran war has dominated international attention.

The White House did not confirm any meeting with the Ukrainian delegation.

A senior Kremlin official indicated Friday that a new round of U.S.-mediated negotiations between Moscow and Kyiv will likely take place soon.

“The pause is temporary, we hope it’s temporary regarding the continuation of the trilateral format,” he said.

Western European officials have over the past year repeatedly accused Russian President Vladimir Putin of dragging his feet in negotiations while he tries to press his bigger army’s battlefield initiative and capture more Ukrainian land. Russian forces hold nearly 20% of Ukraine.

Middle East conflict impacts Russia-Ukraine war

The latest conflict in the Middle East that began Feb. 28 with Israeli and U.S. strikes on Iran has diverted international attention from Ukraine’s plight.

At the same time, Russia is getting a financial windfall from a temporary U.S. waiver on oil sanctions while Ukraine is desperately short of cash and still waiting for a 90-billion-euro ($103 billion) loan promised by the European Union.

Putin is widely expected to launch new offensives as the weather in Ukraine improves, piling further pressure on Kyiv.

___

Associated Press writer Michelle Price in Washington contributed to this report.

This story was originally featured on Fortune.com

The White House on Friday released its framework for how it wishes Congress will address the issue of artificial intelligence.

The legislative blueprint, released on its website, outlines a half-dozen guiding principles for lawmakers to keep in mind when developing policies governing artificial intelligence. Those areas include: protecting children and empowering parents; safeguarding and strengthening American communities; respecting intellectual property rights, preventing censorship and protecting free speech, enabling innovation and ensuring American AI dominance, and educating Americans and developing an AI-ready workforce.

“The Trump Administration is committed to winning the AI race to usher in a new era of human flourishing, economic competitiveness, and national security for the American people,” the White House said in announcing its framework. “Achieving these goals requires a commonsense national policy framework that both enables American industry to innovate and thrive and ensures that all Americans benefit from this technological revolution.”

The White House said “strong federal leadership” is needed to make sure the public can trust how artificial intelligence is being used in their lives.

Members of Congress from both parties, as well as civil liberties and consumer rights groups, have pushed for more regulations on AI, saying there is not enough oversight for the powerful technology. President Donald Trump signed an executive order in December to block states from crafting their own regulations, arguing that a patchwork of rules would hurt growth in the sector.

This story was originally featured on Fortune.com

Some of the most valuable private companies in the world right now have a problem that has nothing to do with their product, their team, or their market. They have too many investors, too many competing agendas, and a cap table — the record of who owns what and under what terms — that has become so layered with complexity that it is actively preventing them from moving forward. Call it cap table gridlock: the condition where a company’s ownership structure becomes the constraint on its growth, rather than capital itself.

Cap table gridlock isn’t a new concept. Founders have always had to balance investor expectations, dilution, and governance. What is new is how pronounced the problem has become, driven by three structural shifts: the concentration of venture capital into fewer, larger companies; the dominance of mega-rounds; and the continued extension of private-company lifecycles as IPO and M&A timelines stretch.

Recent data from Crunchbase underscores this reality. In 2025, a small handful of AI companies raised an outsized share of total venture dollars, while a significant majority of capital flowed into $100 million-plus rounds. AI alone accounted for nearly half of global venture funding. The result is a late-stage ecosystem defined less by broad participation and more by scale, concentration, and complexity.

For founders, that complexity shows up most acutely on the cap table.

Large startups today often carry multiple classes of preferred equity, layered liquidation preferences, bespoke investor rights, and shareholders with very different time horizons. Some investors are underwriting long-term category dominance. Others are seeking liquidity. Still others are managing portfolio exposure after years of extended private markets. When companies stay private longer — as many are choosing or being forced to do — those competing incentives compound.

The practical consequence is gridlock. Companies still need capital to grow and invest — but raising traditional equity can reopen valuation debates that no longer reflect operating fundamentals, trigger dilution that disproportionately impacts certain stakeholders, and intensify misalignment among investors who agree on the company’s promise but disagree on timing, structure, or risk. What once might have been an uncomfortable board conversation becomes a strategic impasse.

In some cases, that impasse goes beyond financing. A single shareholder or class of shares may hold blocking rights that can delay or prevent a sale at what management, the board, and the majority of investors view as an optimal time. When incentives diverge, governance provisions designed to protect stakeholders can instead constrain strategic flexibility. Gridlock stops being a financing problem and becomes an exit problem.

This dynamic is particularly visible among large, capital-intensive companies. These businesses require enormous upfront investment, often well ahead of predictable revenue. They also command valuations that make repricing difficult without signaling weakness or inviting unnecessary scrutiny. As IPOs are delayed and private markets absorb more of the growth lifecycle, founders are being asked to solve a problem that neither traditional venture equity nor private debt were designed to address on their own.

Structured equity — financing that sits between traditional venture equity and straight debt, often with flexible terms designed to avoid repricing the entire equity stack — is gaining attention because it offers flexibility in a market where flexibility is increasingly scarce. When designed thoughtfully, it can provide growth or bridge financing without forcing a wholesale repricing of existing equity, helping companies extend runway, fund expansion, or manage liquidity needs while preserving alignment across stakeholders.

The capital markets founders operate in today are structurally different from those of 2018 or even 2021 — capital is concentrating into fewer companies, mega-rounds are layering complexity onto cap tables, and the path to public markets is no longer linear or time-bound. The tools designed for faster IPO cycles and less concentrated markets are not fit for purpose in a world where private companies routinely remain private for a decade or more.

Some might argue that companies should simply raise equity at lower valuations, tighten spending, or wait for public markets to reopen. In some cases, that may be the right answer. But for many large startups, those options carry real tradeoffs — sacrificing momentum in winner-take-most markets, destabilizing governance at critical moments, or deferring necessary investment in the hope that timing improves.

The more interesting question is not whether structured equity replaces traditional venture capital — it doesn’t — but whether founders have access to a broader set of capital strategies that reflect the realities of modern growth companies.

Cap table gridlock is emerging as one of the defining challenges for unicorns in 2026 precisely because it sits at the intersection of success and constraint. These are not struggling businesses — they are often category leaders with strong demand, ambitious roadmaps, and long runways ahead. But their scale and longevity in private markets have introduced frictions that founders must now actively manage.

As capital continues to concentrate and private timelines extend, those frictions will only become more common. The founders who navigate this era successfully will be the ones who treat capital structure as a strategic tool — one that requires as much deliberate thought as product, hiring, or go-to-market. The cap table isn’t just a financial document. In 2026, it’s a leadership challenge.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Good morning. In today’s Fortune:

  • In Iran, the likely next phase is a ground war—troops, ships, jets, and helicopters are on their way, as the White House declined to rule out “boots on the ground.” The goal will be to reopen the Strait of Hormuz. We’ve got a map of the safe route through Hormuz (though those ships will pay a steep fee).
  • Oil’s “demand destruction”: The price of oil eased but remains above $100. Stock traders did not celebrate, and U.S. futures were in negative territory this morning. Analysts are worried that sustained high oil prices threaten “demand destruction,” where certain industries simply cease to function—and there are signs of that in Asia already.
  • Shock as the founder of Supermicro was arrested in a chip-smuggling probe. 
  • The French really are thinner than the rest of us.
  • Fetch my clubs! Are you really a Fortune 500 CEO if you don’t have a country club membership?

This story was originally featured on Fortune.com

Good morning. CFOs of public companies may soon need to rethink the cadence of financial reporting—and everything that comes with it.

The Securities and Exchange Commission is reportedly preparing a proposal that could allow U.S. public companies to report financial results semiannually instead of quarterly, with the agency expected to release the measure as soon as April, according to The Wall Street Journal. It would make quarterly filings optional rather than mandatory, though it has not yet been finalized or adopted.

I had a conversation with J. Eric Johnson, partner and co-chair of the Public Company Advisory Practice at Winston & Strawn, who told me that the topic is already generating debate among practitioners. “That’s actually one of the first things that comes up,” Johnson said, noting that his firm discussed the issue at a recent internal corporate luncheon.

Questions he’s fielding: What would an investor relations strategy look like? How do you maintain transparency? How do you stay in front of your investor base, telling your story, getting out in front of them, and continuing enthusiasm around your stock?

For over 50 years, quarterly earnings have given companies a structured moment to shape their narrative. Under semiannual reporting, that cadence disappears, Johnson said.

“Yes, some companies may save money,” he said. “They may save time. But you’re going to have to rethink a lot of things.” He continued, “The market participants, the investors, are going to demand information in some form or fashion.”

Johnson also raised concerns around Regulation FD, which prohibits selective disclosure. Under the current cycle, executives can speak more freely because financial results are fresh or imminent.

He added that semiannual reporting could strain board oversight. Audit committees are used to quarterly reviews with management and auditors. Removing that rhythm creates a governance gap, likely requiring informal quarterly check-ins—eroding cost savings. “Yeah, we didn’t print a 10-Q, but we’re still doing a lot of heavy lifting in the background.”

There could also be capital markets challenges, he said. Underwriters typically require very recent financial data, and a six-month cycle could leave information stale.

Shivaram Rajgopal, an accounting professor at Columbia Business School, doesn’t view the shift as beneficial. “It will save trivial compliance costs in the short run but lead to more demands on the IR groups for updates,” he said. “I suspect most well-followed companies will file quarterly statements voluntarily anyway.”

Smaller firms, however, may not. “In the case of smaller firms, insider trading might go up, and volatility in the stock will likely also go up,” Rajgopal said. “Surprises or sharp swings in stock prices will become more common.”

Johnson also warned of increased volatility. Less frequent reporting means negative trends could compound before disclosure.

“We had a 5% decline in revenue over three months, but now, when we talk about it at six months, it’s actually 10%,” Johnson said.

Rajgopal shared this anecdote: “I have heard a prominent board member say the following: ‘The market pays you 20-25 years of your earnings today (via the price-earnings ratio).’”

“And we hesitate to supply the market with quarterly data?” he continued, “That’s odd. Imagine hiring an employee and paying them 25 years of their annual compensation. How closely are you likely to monitor that employee? Just once in six months?”

Have a good weekend.

Sheryl Estrada
sheryl.estrada@fortune.com

This story was originally featured on Fortune.com

Pentium was once one of the most recognized technology brands in the world. Scion was Toyota’s most successful attempt to reach a new generation of buyers.

Neither failed because of a bad launch, a weak product, or a flawed strategy. Both were killed by something far more insidious: a long sequence of individually rational decisions that nobody stopped to question. In both cases, the organizations involved misunderstood the same fundamental principle — brands do not fail because they are poorly conceived. They fail because their meaning is not actively managed.

Pentium: When a Category Brand Becomes a Commodity

When Intel introduced Pentium in 1993, it solved a structural branding problem few technology companies had cracked: how to create consumer preference for an invisible component. Microprocessors had been defined by technical codes — 386, 486 — that carried engineering meaning but little emotional or commercial power. Pentium changed that.

The results were immediate and dramatic. Intel’s revenues grew from $8.8 billion in 1993 to more than $20 billion by 1996, with net income reaching $5.16 billion. Backed by the Intel Inside campaign — which would ultimately account for billions in cooperative advertising spend — Pentium transformed a component into a consumer signal of performance and reliability. By the late 1990s, it had become one of the most recognized technology brands in the world.

Pentium worked because it meant something specific: premium computing power from Intel. That clarity allowed Intel to command price premiums and shift competition away from raw specifications toward brand trust — an extraordinary achievement in a component category.

The erosion did not come from a single mistake. It came from a sequence of understandable decisions. As competitive pressure increased, particularly from AMD, Intel responded not by defending Pentium’s meaning, but by stretching its reach. The name expanded across multiple performance tiers and product generations: Pentium Pro, Pentium II, III, 4, M, D, Dual-Core. At least seven distinct “Pentiums” entered the market over thirteen years. What had once been a precise signal became a broad label. Over time, consumers could no longer tell what “Pentium” guaranteed, or why one Pentium mattered more than another.

This is what might be called vertical erosion — the systematic dilution of a brand through downward extension. Each new tier was individually rational. Collectively, they dismantled the brand’s meaning from the inside out.

The inflection point came in 2006, when Intel introduced the Core brand and repositioned performance leadership under a new name. Pentium, once synonymous with “best,” was implicitly redefined as “good enough.” It continued to sell, but primarily in price-sensitive segments. Its role shifted from value creation to volume maintenance.

By the time Pentium was formally retired in 2023 and replaced by the generic label “Intel Processor,” the brand’s meaning had already collapsed. Thirty years from one of the most recognized technology brands in the world to a category descriptor. Pentium didn’t lose to a competitor. It lost to itself — one incremental extension at a time.

Scion: When Strategic Intent Is Lost Through Accumulation

Scion was created to solve a different but equally clear strategic problem for Toyota: how to reach younger, first-time buyers without diluting Toyota’s core brand or undermining Lexus’s premium position. The answer was a distinct brand with its own voice, retail experience, and cultural posture.

At launch in 2003, Scion was sharply defined. It stood for individuality, design-forward thinking, and accessibility. Its early lineup was intentionally limited and visually distinctive, supported by fixed-price retail (no haggling, no trim levels) and lifestyle-driven marketing. The strategy worked. By 2006, Scion was selling more than 173,000 vehicles annually in the U.S. — 70% were new Toyota buyers, and the average Scion buyer was 35 years old, compared to 54 for the typical Toyota customer.

Scion’s strength was semantic clarity — it was not simply “Toyota for young people” but a cultural counterpoint to the broader Toyota brand. The erosion, when it came, was gradual.

As Toyota’s global portfolio expanded, Scion absorbed increasing internal pressures. Product decisions optimized for coverage and volume rather than coherence. The second-generation xB — redesigned in 2008 to be larger, smoother, and more conventional — abandoned the distinctive proportions that had made the original iconic. Sales collapsed. New vehicles were added, revised, or rebadged without a clear unifying idea. By the end, most of Scion’s lineup consisted of rebranded Toyotas and partner vehicles — a Mazda here, a Subaru there — wearing a Scion badge that no longer meant anything specific.

This is a different failure mode than Pentium’s — what might be called lateral drift. Where Pentium eroded vertically through downward extension, Scion eroded horizontally through the accumulation of unrelated products and fragmented messaging. The brand didn’t stretch below its original meaning; it scattered away from it.

Meanwhile, Scion’s own customers were aging. By 2011, the average buyer was 43 — eight years older than at launch and closing in on Toyota’s core demographic. The brand built to capture youth was growing old with its original customers and failing to attract the next generation. In 2016, Toyota discontinued Scion, folding remaining models back into the Toyota lineup. From a branding perspective, the decision was the predictable outcome of accumulated ambiguity. Scion did not fail because its founding idea was flawed. It failed because no one was protecting it.

The Shared Lesson: Stewardship, Not Inception

Pentium and Scion represent two distinct modes of brand failure. Pentium suffered vertical erosion — the progressive dilution of meaning through downward extension. Scion suffered lateral drift — the dispersal of meaning through accumulated, unfocused decisions. But the underlying failure was the same: both organizations stopped treating brand meaning as a constrained asset that must be actively protected.

Both brands began with high semantic precision that created real economic value. And both gradually surrendered that clarity through well-intentioned decisions made without sufficient regard for long-term meaning. In both cases, the decisive factor was the same tension: product logic and brand logic were in direct conflict, and product logic won every time. Intel’s product team had sound reasons to launch a lower-priced Pentium. Toyota’s portfolio managers had sound reasons to add models for coverage. Each individual decision was defensible. But no one was asking the brand question: does this decision make what we stand for clearer or more confused?

Brand failure is rarely dramatic. It is managerial. It occurs not in moments of crisis, but in the accumulation of decisions where short-term product logic overrides long-term meaning.

The Ferrari Exception

The opposite pattern exists — and it’s instructive. Ferrari caps annual production at roughly 10,000 vehicles, deliberately manufacturing fewer cars than the market demands. Scarcity is inseparable from what the brand means. There is no lower-priced Ferrari, no Ferrari for the mass market. The product team does not get to override the brand. That constraint isn’t a limitation on growth — it is the source of Ferrari’s pricing power, loyalty, and a market capitalization that dwarfs competitors producing ten times the volume. Ferrari understood what Pentium and Scion eventually forgot: meaning is finite, and every decision either reinforces it or erodes it.

Implications for Leaders

These failures suggest a set of principles that are easy to state and difficult to practice:

  • Brand meaning is finite. Stretch without guardrails leads to dilution — whether downward (vertical erosion) or outward (lateral drift).
  • Product logic and brand logic often conflict. The most dangerous brand decisions are the ones that make perfect sense to the product team.
  • Early success increases risk. A strong brand invites overuse. The better the name works, the more people inside the organization will want to borrow it.
  • Confusion is more damaging than rejection. A brand that people ignore can be repositioned. A brand that people can’t place is already failing.
  • The most consequential branding decisions are made long after launch. Creation gets the attention. Stewardship determines the outcome.

Brands do not fail at birth. They fail when stewardship lags strategy. There is one question worth asking in any organization with a brand worth protecting: When was the last time someone said no to a revenue-generating decision because it would blur what your brand means? If the answer doesn’t come quickly, the erosion may already be underway.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Nvidia CEO Jensen Huang doesn’t foresee a sudden spike of AI-related layoffs, but that doesn’t mean the technology won’t drastically change the job market—or even create new roles like robot tailors.

The jobs that will be the most resistant to AI’s creeping effect will be those that consist of more than just routine tasks, Huang said during a December interview with podcast host Joe Rogan

“If your job is just to chop vegetables, Cuisinart’s gonna replace you,” Huang said.

On the other hand, some jobs, such as radiologists, may be safe because their role isn’t just about taking scans, but rather interpreting those images to diagnose people.

“The image studying is simply a task in service of diagnosing the disease,” he said.

Huang allowed that some jobs will indeed go away, although he stopped short of using the drastic language from others like Geoffrey Hinton, a.k.a. “the Godfather of AI” and Anthropic CEO Dario Amodei, both of whom have previously predicted massive unemployment thanks to the improvement of AI tools.

Yet, the potential AI-dominated job market Huang imagines may also add some new jobs, he theorized. This includes the possibility that there will be a newfound demand for technicians to help build and maintain future AI assistants, Huang said, but also other industries that are harder to imagine.

“You’re gonna have robot apparel, so a whole industry of—isn’t that right? Because I want my robot to look different than your robot,” Huang said. “So you’re gonna have a whole apparel industry for robots.”

The idea of AI-powered robots dominating jobs once held by humans may sound like science fiction, and yet, some of the world’s most important tech companies are already trying to make it a reality. 

At Nvidia’s GTC (GPU Technology Conference) this week, Huang said so-called “physical AI,” especially robotics, is the company’s next trillion-dollar-plus market.

Tesla CEO Elon Musk has also made the company’s Optimus robot a central tenet of its future business strategy. Musk last year predicted money will no longer exist in the future and work will be optional within the next 10 to 20 years thanks to a fully-fledged robotic workforce. In a January podcast interview with XPRIZE founder Peter Diamandis, Musk went further, predicting the cost of labor will eventually fall to zero, and claiming there was no need for people to “squirrel away” money for decades to be able to retire.

AI technology is advancing so rapidly that it already has the potential to replace millions of jobs. AI can adequately complete work equating to about 12% of U.S. jobs, according to a Massachusetts Institute of Technology (MIT) report. This represents about 151 million workers representing more than $1 trillion in pay, which is on the hook thanks to potential AI disruption, according to the study.

Even Huang’s potentially new job of AI robot clothesmaker may not last. When asked by Rogan whether robots could eventually make apparel for other robots, Huang replied: “Eventually. And then there’ll be something else.”

A version of this story originally published on Fortune.com on Dec. 6, 2025.

More on robots:

  • More people will own a humanoid robot than a car by 2060, BofA predicts
  • Robot dogs priced at $300,000 a piece are now guarding some of the country’s biggest data centers
  • One man accidentally gained access to thousands of robot vacuums, exposing the AI cyber nightmare risk facing millions of Americans

This story was originally featured on Fortune.com

  • In today’s CEO Daily: Diane Brady shares insights from the Fortune CEO Initiative dinner
  • The big leadership story: The corporate “war room” becomes more than a metaphor
  • The markets: A small rebound
  • Plus: All the news and watercooler chat from Fortune.

Good morning. Three speakers took turns addressing the room at the Fortune CEO Initiative dinner in Manhattan’s Hudson Yards on Wednesday night. One was Trump’s UN Ambassador, sharing insights on the Administration’s strategy for Iran and the rest of the world. One was a Kennedy scion with a strong message for business about the next generation and leadership in the digital age. And one was a longtime diplomat and State Department official, sounding the alarm about a nation declining in ways we don’t often talk about. Together, their words were a clarion call to business leaders to look at how these trends create a need to step up and speak up.

Ambassador Mike Waltz spoke off the record to share frank insights about his prognosis for everything from Iran to the future of the UN. His perspective was in stark contrast with Richard Haass, a veteran diplomat, scholar and senior counselor with Centerview Partners who’s been a longtime critic of Trump’s policies. He pointed to two crises, in particular, that are “eroding confidence in American competence and leadership.” The first is a disdain for expertise, whether it’s scientific expertise or the policy expertise that’s guided previous presidents in making decisions such as whether to go to war. The second is the fiscal crisis as U.S. national debt this week surpassed $39 trillion. If unfunded entitlements are added, the fiscal gap is closer to $100 trillion. Said Haass: “I think we’re living on borrowed time.”

Few are more aware of that than younger Americans who are struggling to find jobs, afford homes, and see themselves in the political parties that claim to represent them. It was especially refreshing to speak with Jack Schlossberg, a Democratic congressional candidate and grandson of JFK, who told attendees that the Democrats’ “reactionary” and “anti-everything” stance has been a turnoff to many younger voters.  “The Republican Party has embraced modernity in a way the Democratic Party used to own,” he told us, later speaking of priorities like service, innovation and opportunity.

There were disagreements, some vehement, and an energy that I value at these gatherings. One takeaway for me was the high number of CEOs who start their day at around 5 a.m. (A lot) And another was the sense that opportunities to come together from different sides of the table with a shared desire to learn are rare. One CEO told me it’s hard to even get opposing sides of his family to talk these days, saying “I miss a good debate.” I agree. If you want to find out more about the CEO Initiative, click here  or reach out to my new colleague, John Pentin

Contact CEO Daily via Diane Brady at diane.brady@fortune.com

This story was originally featured on Fortune.com

Facebook, Twitter, and MySpace once promised to bring humanity closer together. They delivered something else entirely.

The screen economy that emerged around these apps at extraordinary speed optimized for attention. Time spent and daily active users were the twin metrics upon which this economy lived and died. Engagement loops got stickier and friction fell away from increasingly measurable interactions. The promises of internet-induced belonging, of social cohesion, of a new global intimacy all failed to materialize.

Instead, people retreated into their screens at such a scale that major social health organizations started sounding the alarm about a global loneliness epidemic. The World Health Organization found that 1 in 6 people worldwide experienced persistent loneliness, contributing to 870,000 deaths per year and costing governments billions in healthcare, employment, and education. Loneliness often manifests on balance sheets as absenteeism, which costs the U.S. economy alone $406 billion annually.

People are starving for the meaningful social connection they haven’t found online, and now they’re willing to pay. That hunger is quietly giving rise to a brand new market — and a generation of startups racing to serve it.

How social isolation created a new demand 

Humans are social animals. We’re biologically wired for social cohesion, which has been a matter of life or death since the days of hunting woolly mammoths and sleeping in caves. As our species marched forward, we built this cohesion into institutions: schools, religious communities, trade associations, sports clubs, civic organizations, even entire nations. Multigeneration families living together were the norm and  every city was dotted with bars and cafés for informal gatherings.

When such institutions enter a protracted decline, the desire for community remains. Enter the IRL economy, which I loosely define as an industry that deliberately facilitates in-person belonging. The end goal of all these businesses is to get people offline, together. How a given business goes about doing it is somewhat secondary.

The first phase of this economy arrived in the form of city-specific meet-up apps. Meetup, arguably the most popular of these apps, actually predates most social media platforms, having been initially founded to bring New Yorkers together in the wake of 9/11. Post-Facebook, so to speak, these platforms proliferated, and Meetup eventually proved so successful that WeWork bought it for $200 million in 2017. New startups meanwhile coordinated curated dinners, coworking spaces, running clubs, and shared activities. At WeRoad, we came to it through travel.

We organize trips for small groups of people who do not know each other before departure, specifically targeting young adults in their 20s and 30s. Wherever our travelers go, the base product is the same: guaranteed connection with like-minded people. We saw solo travel become a bona fide phenomenon and we figured many solo travelers still want to meet others along the way. We offered them a way to solo travel together.

It worked. When you give people the chance to rebuild social scaffolding, they will take it.

The economics of the new social scaffolding

Real-world participation has not disappeared. It has, however, slipped through the cracks of an atomized world. In dismantling social scaffolding through the decline of third spaces, real-world participation became difficult to access spontaneously. Going out was no longer a surefire way to meet someone, and the dating apps that emerged within the attention economy didn’t guarantee meaningful connections either.

IRL economy businesses sell that structure. We’re selling context more than a single, easily defined product. We commercialized travel at WeRoad, but we’re actually serving a different need. If we didn’t exist, the solo travelers who use us would still go all over the world. What they wouldn’t necessarily get is the connection we offer. That’s what they’re paying for, more than any specific trip to Mexico or Morocco or Indonesia.

The real product is always connection. We achieve it through structured immersion: 15 strangers together for ten days, away from their routines and homes. Introduce shared logistics, a little unpredictability, and the mild discomfort inherent to being in an unfamiliar place. Titles fade, social bubbles soften, interaction is a matter of course.

There’s basic economics in play, too. Real-world connection feels scarce and scarcity drives demand and increases value. The global travel and experience economy is already valued at over $1 trillion. IRL businesses are meeting that demand by contextualizing real-world connection in abundant, active economic sectors—not just through travel, but also dining out (a global industry valued at $3.9 trillion) and live music (valued at $38.5 billion). But since belonging doesn’t operate like behavioral metrics, its economic value will always be harder to measure than in the attention economy.

It’s too early for formal valuations of the IRL economy. What we do know is that VC investment in consumer startups, which includes IRL business, rose 25% between 2023 and the end of 2024. We can also point to funds like the Jägermeister-backed Best Nights VC, which specifically invests in startups dedicated to nightlife and going out together. And Tinder is now beta testing an in-person events tab offering pottery classes, raves, and bowling nights. Something big is happening here.

Friction-maxxing and mass atomization

In 2026, we’re seeing a new trend emerge: friction-maxxing.

Friction-maxxing is the deliberate rejection of seamless convenience — the transactional optimization that virtually every consumer-facing company has ruthlessly pursued for a decade. You order dinner without speaking to anyone. You rent a bike by scanning a QR code. You work from home, stream on demand, and feel constantly stimulated while remaining physically alone. Friction-maxxing refuses that bargain.

The friction-maxxers, however, need somewhere to go to find the connection they seek, and this is where the IRL economy comes in.

None of this is precisely new. Although social atomization exploded in the age of social media, it had already begun to take hold in the wake of the Industrial Revolution. Family members moved away from one another. Professional environments became increasingly tenuous as places to build community, despite colleagues being the only built-in social circle for many young professionals. Traditional community structures continued to decline. Digital communication emerged as the default, a development accelerated by the pandemic. In other words, we’ve been headed this way for a long time. 

The IRL economy is still emerging, but the demand behind it extends far beyond the 1 in 6 people experiencing persistent loneliness. The friction-maxxers aren’t just rejecting their phones — they’re signaling that the next trillion-dollar consumer market won’t be built on a screen.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

When it comes to supercars, Lamborghini CEO Stephan Winkelmann admitted his customers prefer a gas-guzzling auto to a fully electric vehicle, blaming a dearth of reliable charging stations in part for the lack of interest.

The luxury automaker announced in February it had shelved plans for its all-electric Lanzador, a 1,341-horsepower “Ultra GT” first announced in 2023. The car, originally slated for a 2029 release, had an estimated price tag of $300,000—about the average pricepoint for a Lamborghini, regardless of power source. Instead, Lamborghini will pivot to developing plug-in hybrid models.

Lamborghini reported record-breaking earnings on Thursday, including 10,747 deliveries in 2025, its highest ever tally. While the company reached $3.7 billion (€3.2 billion) in revenue—a 3.3% year-over-year increase—operating income fell to $885 million (€768 million) from a record of $962 million (€835 million) in 2024. The company attributed the dented profits to Lamborghini’s pivot away from an EV model, as well as uncertainty around tariffs and an unfavorable U.S. exchange rate. 

In an interview with Fortune ahead of the company’s earnings presentation, Winkelmann said part of the sluggish demand for its EV was a lack of developed infrastructure to support all-electric cars on the road.

“We have a lot of customers [who] bought electric cars, and they told us—I spoke to a lot around the globe—that in terms of infrastructure, in terms of charging time, in terms of range…it is very disappointing,” Winkelmann said.

According to an analysis from Motointegrator and DataPulse Research, the European Union has about 910,000 publicly accessible charging stations, despite 3.5 million, or 26%, needed to support the region’s decarbonization efforts. In the U.S., Lamborghini’s largest market, EV charging stations often experience reliability issues, with a Harvard Business School report finding drivers are able to fully recharge their cars using non-residential EV equipment just 78% of the time.

But customers’ reluctance to buy a luxury EV goes beyond logistical issues. “On top of that, the emotional part is very important,” Winkelmann said. 

EVs lack the roar of a traditional internal combustion engine which has been closely aligned with not just the Lamborghini brand, but sports cars more broadly. The lack of vibrations and noisiness of a gas-powered car was a turn-off for customers with a clear picture in their mind of what a Lamborghini is, Winkelmann noted.

“You don’t buy a Lamborghini because you need one, but because you want to have a childhood dream fulfilled,” he added.

How to make a successful luxury EV

The luxury car sector has largely struggled to roll out a fully electric car that resonates with consumers. In 2024, Bentley delayed its electric-only goal from 2030 to 2035—and then scrapped that, saying it will offer hybrid vehicles by then. Porsche announced last September it would no longer build its own EV battery and scale back its electrification plans. Premium carmakers such as Stellantis and Ford both took a step back from EVs, taking $26 billion and $19.5 billion charges, respectively, to pivot away from all-electric cars.

RBC Capital analyst Tom Narayan said it would be an oversimplification to say there’s no demand in the entire sector for high-end EVs, or that the lack of interest in the cars is a result of infrastructure issues.

“There are buyers who want electric-high performance vehicles,” Narayan told Fortune. “Maybe that number isn’t as big as what folks thought. Maybe that number is lower, but to say charging infrastructure is a problem, or, nobody wants a luxury EV, I don’t think that’s really accurate.”

Narayan looks to the highly anticipated Ferrari Luce, the Maranello-based automaker’s EV offering, which will be available to order come late May. Ferrari, which sells about 14,000 cars a year, is able to justify its EV because it can save on research and development for specific components thanks to a connection to its Formula 1 team already heavily investing in parts optimization. 

Ferrari is also a standalone company, in contrast to Lamborghini, which is owned by the Volkswagen Group through its subsidiary Audi. Ferrari has to appeal to a wider audience, making it more strategic to have an EV, Narayan noted. Meanwhile, Volkswagen has doubled-down on its EV plans, reviving its Scout Motors brand to appeal to American audiences, despite evidence of cooling demand.

Because Lamborghini’s ownership is already investing elsewhere in EVs, its own luxury model may not be the most prudent use of resources, Narayan suggested.

“In the context of VW Group,” he said, “it may not be necessary for Lamborghini to electrify.”

This story was originally featured on Fortune.com

When Samyr Lainé walked into his freshman dorm room at Harvard University in 2002, he found his new roommate tucked away in the corner of their room, typing away on his computer. 

A year and a half later, that roommate sent him a project he was working on called TheFacebook

“You could tell where his skill set was as a coder and as a thinker, and he was just supremely advanced,” Lainé said of Meta CEO Mark Zuckerberg. “He was taking senior-level courses as a freshman and showing up to a three-hour final exam, two hours late, and getting the highest grade in class.” 

While living in that dorm room, Lainé began to hone his skills as a triple jumper on Harvard’s track and field team. After college, he competed as a graduate student at the University of Texas at Austin. He then went on to study law at Georgetown, graduating in 2010. 

A decade after sharing a bunk bed with Zuckerberg, Lainé represented Haiti in the triple jump at the 2012 Olympic Games in London. Ten years after that, he co-founded Freedom Trail Capital, a venture capitalist firm that invests in celebrity brands like Issa Rae’s haircare line Sienna Naturals, Kaley Cuoco’s dog supplement company Oh Norman!, and Ten to One Rum, co-owned by the singer Ciara. 

From his time as an Olympian, Lainé understands what it is like to be the talent fronting a product. After his athletic career ended, he went on to work with Jay-Z at Roc Nation and with Will and Jada Pinkett Smith on their media company, Westbrook. Those experiences were pivotal in teaching Laine how to make a celebrity brand successful.

From the Olympics to Roc Nation 

After placing tenth in the triple jump at the London Olympics, Lainé continued to work in sport, first as a lawyer at Monumental Sports, which owns several Washington, D.C. sports teams including the Capitals, Wizards and Mystics, and later directing player relations at Major League Soccer. 

He joined Jay-Z’s entertainment company Roc Nation in 2018 as senior director of operations, using both his legal background and operations skills to manage artists like Alicia Keys, Meek Mill, Lil Uzi Vert. He also worked on Jay-Z’s alcohol brands, music streaming platform Tidal, and launched projects like the company’s book publishing division, Roc Lit 101.

“My role at Roc Nation is really what laid the foundation for what I’m doing today,” he said. “For me, [it] was just having a front row seat and understanding how Jay leverages his cultural cachet to build some really valuable, really tremendous businesses,” he said. 

Lainé left Roc Nation in 2019 to then join the Smiths at their media and production company, Westbrook, as vice president of operations. He was then promoted to senior vice president, working with the entire Smith family to launch apparel, personal care, and coffee brands.

“I came on as a very early employee, maybe employee number six or seven. We built that to almost 200 employees across six different verticals,” he said. “A lot of [the job] was taking what I learned—a baptism by fire Roc Nation—translating that to Westbrook.”

The Friday before the 2022 Oscars (the one when Smith slapped comedian Chris Rock), Lainé left Westbrook to consult for brands and address what he saw as a gap in the market between celebrity-led brands and venture capital. 

A year later, he co-founded Freedom Trail Capital with his wife and fellow triple jump Olympian Ayanna Alexander-Lainé. Together, the two have amassed a portfolio of celebrity-led brands trusted by consumers and celebrities alike.

Investing in authentic brands 

What will make or break a celebrity brand is authenticity, not just a famous name attached to a company, Lainé said, before pointing to the many mediocre celebrity tequila brands out there as an example. Sometimes, Lainé warned the product doesn’t even match the name behind it.  

Take for example Jay-Z’s successful cognac and champagne brands—most people don’t remember his vodka venture Armadale.

“Vodka was probably the wrong category for the wrong demographic that Jay-Z appeals to,” Lainé explained. “What doesn’t work, and people know this, is inauthentic pairings between talent and business.”

Companies fail when they don’t need to think critically about their product and how it will serve customers, he said. Freedom Trail takes a different approach. 

“We look for businesses that either have or can benefit from having a person of influence involved. Person of influence, we say deliberately, because we’re not exclusively looking for celebrities, but we’re looking for folks who have a platform and an audience where they can add their audience to authentically supercharge an already great business,” Lainé explained. 

Lainé’s goal is that a company survives with or without a big name’s backing. But when an influential person becomes involved, they tend to bring their audience with them.  

He points to his client and Harry Potter actress Emma Watson. Her family’s gin brand, Renais, is the quintessential example of an influential person backing a brand. The gin comes from recycled grape skins from Watson’s family’s vineyard in Burgundy, France, where her father has been growing grapes for more than three decades. Her brother, Alex, is the company’s CEO, and Watson designed the product’s bottle and packaging, Lainé said. And that authenticity translates to other well-known and beloved brands.

“The reason that Nike is a talent-led brand, and Revlon and Gatorade [is that] they all leverage talent successfully, Lainé said. “The right person with the right audience and the right messaging through the right medium speaking to the direct demographic at the right time can supercharge a business. That business that it’s supercharging has to be a great product that’s innovative and a quality business and a strong brand.”

This story was originally featured on Fortune.com

Jack Schlossberg thinks his grandfather would have been great at social media. He’s less sure JFK would recognize the country he once led. 

“I think he would be shocked at how far we have fallen in terms of setting the standard for the rest of the world to follow on human rights, democracy, and freedom,” the 33-year-old Democratic congressional candidate told Fortune on the sidelines of a CEO Initiative dinner in New York City on Wednesday night.

But Schlossberg quickly added that former President John F. Kennedy would marvel at what America has built, citing a powerful economy, an innovative private sector, and breakthroughs in technology and science.  

“I think my grandfather would be proud of how much our society has accomplished together,” he said.

Schlossberg is the only grandson of President John F. Kennedy, the son of Caroline Kennedy, and is widely seen as the next standard-bearer of the Kennedy political legacy. His comments tap into a broader anxiety about America’s global standing—and highlight the central tension in Schlossberg’s political message: pride in the country’s achievements, paired with concern about its direction.

He argued that Kennedy, the man who solved the Cuban Missile Crisis in the 1960s, “without firing a shot and stared down the Soviet Union without blinking,” would be unsettled by the same problems the country is still facing six decades later, from healthcare to education to immigration. “We need to do better.”

Inside Schlossberg’s first run for Congress

Schlossberg is running in a hotly contested race to fill New York’s 12th District seat currently held by retiring Democratic Rep. Jerry Nadler, who has served in Congress since 1992.

He’s facing off against Assembly Members Alex Bores and Micah Lasher, Trump critic George Conway, public health researcher Nina Schwalbe, and others in a district that covers Manhattan’s Upper West Side, Hell’s Kitchen, and parts of the East Side. But in February, Schlossberg landed a powerful backer in his first foray into politics and shared an endorsement letter he received from former House Speaker Nancy Pelosi.

“This is a consequential moment for the country — faith in our politics is fractured, and trust in government is tenuous,” Pelosi said in the statement. “This moment calls for leaders who understand the stakes and how to deliver for the people they serve.”

Why Schlossberg says voters have lost faith

The backbone of his campaign is built around a slogan he acknowledges is “a little cheesy”: believe in something again.

Speaking to Fortune’s Diane Brady, Schlossberg connected his grandfather’s legacy to what he sees as the Democratic Party’s defining failure of this moment: not a collapse in policy, but a collapse in conviction. “I want a party that has the courage again and gives people something to believe in again, because we are right now at an all-time low for people who believe in government.”

The data backs him up. According to a Pew Research Center survey, just 17% of Americans say they trust the federal government to do what is right “just about always” or “most of the time,” ranking among the lowest readings in nearly seven decades of tracking. 

While the Democratic National Committee’s postmortem of what went wrong during the 2024 election still remains under wraps despite Chair Ken Martin’s public pledge to release it, Schlossberg offered his own read on what Democrats keep getting wrong with young voters.

“I don’t think that people are as disillusioned as you might expect, and I don’t think that they are as far left as some of the rhetoric would have you believe,” he said. The real problem is a market failure. “There hasn’t been people serving the market of young people who are interested in politics and what they want to hear about. Young people are not a monolith, and young people are really smart. They [are] really able to tell authenticity from someone who’s not telling the truth.”

Voters “aren’t looking for a superhero,” he said. “They just want someone who kind of knows how to speak their language, meet them where they are, and give them something of value.” 

Fortune’s Diane Brady and Democratic Congressional Candidate Jack Schlossberg discuss his campaign during the Fortune CEO Initiative New York Dinner.
Roy Rochlin/Getty Images for Fortune Media

Democrats are ‘late to the game’ 

Schlossberg, a content creator with nearly 1.9 million followers across TikTok, Instagram, and X, has identified social media as a critical weakness in the Democratic strategy. He’s also self-deprecating about his own role in fixing it. “If I’m one of the best at this,” he told the audience, “it’s not saying much.”

Before launching his political career, the Yale and Harvard Law School graduate worked at a surf shop in Hawaii, volunteered as an EMT, and penned opinion pieces for Vogue, but has become known for his witty political commentary and provocative social media presence as a self-described “silly goose.”

“Other than my mother, I’m probably the last person who expected me to be a content creator,” he said. “That was not really my path in life.” 

In 2024, Schlossberg headed to Wilmington, Delaware, to offer his ideas to the Biden campaign. They were not well received. “Long story short, I quit the campaign because I thought, if I don’t do this my way, I’m not going to be able to live with myself,” he said. About a month later, the campaign called him back.

The experience only sharpened his diagnosis of the party’s broader problem: “We’ve been out-competed in terms of reaching young people, especially…and telling them a story about what we’re for and not just being a reactive party that is against things.” 

His advice for politicians trying to reach voters: “Be all parts of yourself. You don’t just have to be the candidate. People respond when you’re also the uncle, or the son, or the sports fan, or the humorous person that you might be. It’s about showing all different sides of your personality.”

On the sidelines, Schlossberg reiterated his take: “The Democratic Party was definitely late to the game on social media a year and a half ago.” 

Schlossberg’s social media playbook

Schlossberg’s formula for viral social media success? Have no formula at all. 

“My social strategy is to have none,” he said. “It’s to try to provide value to people, whatever that may be,” emphasizing that while he leans on jokes and witty takes, he always wraps it around something substantive. 

“Maybe it’s a sense of humor, maybe it’s something inspiring, an accomplishment, or maybe it’s laying out information in a clear and intelligible, digestible way so that people can get educated,” he said. “A lot of the videos that do the best aren’t the ones that are wacky or pictures of me, a lot of times, they’re videos where I clearly lay out information in a way that people can understand.” 

And if his grandfather were alive today? 

“I think he would have no idea how to use a phone, but I think, for some reason, he would probably be pretty good at social media. He was very media savvy in his own day.”

This story was originally featured on Fortune.com

As Gen Z and millennials watch the value of their degrees dramatically decline, one graduate in the UK has become the face of the crisis. The unnamed graduate now owes more than £314,356 ($420,000) in student loans—more than the cost of an average British home, far above the eye‑watering £231,000 ($308,000) record that topped headlines just two years ago, and a new record for the most personal student debt on record in the UK.

While the average graduate is leaving university with around £45,000 in debt, 10 graduates now have loans exceeding £267,000 ($356,000), according to new figures from the Student Loans Company, as reported by The Times

For context, the average property value in Britain is similarly around £270,000 ($360,000).

While just a handful of students owe the government more money for their education than a family will pay for an entire house, they’re part of a much wider problem: One analysis last year found that more than 150,000 people across Britain now have loans exceeding £100,000 ($133,000). 

That figure had jumped by a third in just 6 months, as interest compounds on balances that many may never fully repay.

Even cautious graduates with the smallest loans are now facing a perfect storm: living costs and compounding interest are outpacing wages, leaving many to navigate years of financial strain, delayed milestones, and growing doubt about whether their degree was worth it.

The global graduate crisis

This isn’t just a British problem. In the U.S., student debt has topped $1.7 trillion, while fresh graduates struggle to land stable jobs. 

About a fifth of Gen Zers worldwide are classified as “NEETs” and are currently locked out of the job market. Across both America and Britain, millions of young people are not in education, employment, or training—despite expensive degrees.

One graduate with a maths degree spent more than a year applying to over 1,000 roles in the U.K. without landing a single offer, before moving his job hunt to Austria.

And as AI and automation replace many entry-level roles, the competition for what’s left is only getting fiercer. In the U.K. alone, more than 1.2 million applications were submitted for fewer than 17,000 graduate roles last year. Meanwhile, Americans report that the probability of finding a job right now has hit a record low

They’re not imagining it: Goodwill places millions of job seekers across its 650-plus job centers, and it’s CEO Steve Preston says the charity is “preparing for a flux of unemployed young people” thanks to AI.

To make matters worse, not only are there fewer job opportunities available for fresh faced graduates, but CEOs are also increasingly saying they don’t even care about the expensive piece of paper they signed up for.

Now, 1 in 3 say their degrees weren’t financially worth it

The social contract is broken. Many young people did exactly what they were told: They went to university, signed on for steep student loans, and trusted that the debt would be a down payment on a stable, well‑paid career. Instead, they’re watching their high school peers who skipped university to take trade jobs get a better shot at a six-figure career. 

Now, 1 in 3 graduates don’t think their degrees were financially worth it. In fact, the Nexford University report highlighted that many have been left drowning in debt decades after tossing their graduation caps into the air. 

Some 14% admit they had to delay moving out of their parents’ house and starting a family because of hefty student loads. Meanwhile, a third are having to delay saving for their first home and even retirement.

It’s no wonder that nearly half of Gen Z and millennials conclude that university was a waste of money.

This story was originally featured on Fortune.com

“Scenario planning” has become boardroom shorthand for preparation to deal with the unknowable. It’s a practice that is never more vital than in wartime, when a sea mine, cyberattack, or sanction can reroute supply chains overnight and send energy prices soaring. 

Instead of betting on one forecast about how events will unfold, the most resilient CEOs are now rehearsing several plausible futures at once and deciding—before the missiles start dropping, the virus becomes a pandemic, or the markets seize up—what they will do in each. 

It’s an approach that was pioneered by Shell precursor Royal Dutch Shell. In the 1970s the energy company began developing a set of vivid alternative futures involving potential oil-supply disruptions. Shell did not invent the idea of developing such scenarios, which had earlier roots in military and Cold War strategy, but it was the first major company to embed systematic scenario planning at the center of corporate decision-making, largely through the work of economist and planner Pierre Wack. His London-based scenarios team had Shell’s top managers rehearse what they would do if various crises arose. 

The doomsday prep paid off. In the early 1970s, Shell’s leaders wondered what would happen if events in Saudi Arabia raised the price of oil. By the time the Arab oil embargo shook the world soon thereafter, sending prices rocketing, Shell knew what to do. It had already slowed refinery expansion and adapted its refineries to handle many types of crude—while competitors vacillated. The common view in the industry is that Shell came through the oil shock far better than any other major producer. The success of those exercises turned Shell into a case study for scenario planning, and the company still regularly publishes its “Shell Scenarios.”

With a war underway, corporate planning is clearly not the only urgent matter. Since the U.S. and Israeli bombardment of Iran beginning in February, thousands have been killed and millions displaced across the region. Vital shipments have been disrupted, and prices have risen worldwide. But along with the human tragedy, the war—and particularly its effect on oil supply and prices—has affected nearly every business around the world. 

“This isn’t a world war explicitly,” says Rebecca Patterson, a senior fellow at the Council on Foreign Relations, “but it is a war that is affecting the globe.”

That war was still raging when this article went to press—and the conflict has underscored the importance of insights that will help guide CEOs long after the war is over.

The company war room has become a permanent fixture

“Almost every client I talk to has a war room,” ­KPMG’s Mary Rollman told Fortune in April 2025, just days after President Trump announced his list of “reciprocal” tariffs on some 180 countries. Back then the war room was a new unit in most companies. “They get a team spun up, and the members have com­pletely dropped their day job,” Rollman reported. 

Those war rooms have found no reason to disband. The tariff situation is still “changing almost on a weekly if not daily basis,” says Abe Eshkenazi, CEO of the Association for Supply Chain Management, and the Iran war “is a continuation of the uncertainty.” The only difference is that the term “war room” is no longer a metaphor. 

Perhaps every generation thinks its own era is the most perplexing and unpredictable of all time. But evidence shows that what businesspeople have had to deal with in recent times is truly off the charts. Uncertainty indexes going back monthly to 1985, compiled by researchers at Stanford University and the University of Wisconsin, show that instability and jitters about U.S. economic policy rose to record levels starting in 2018—and have never dialed down. (To create the indexes, the researchers measure disagreement among economic forecasters; federal tax code provisions set to expire; and articles on policy in major newspapers.) The indexes hit a new high after Trump revealed his 2025 tariffs. (The index covering the time of the Iran war hadn’t been published when we went to press.) 

Don’t expect uncertainty to decline significantly anytime soon, says Ian Bremmer, founder and president of Eurasia Group. International institutions—the United Nations Security Council, the World Trade Organization, the Group of Seven (G7)—clearly aren’t as effective as they once were at maintaining international order, he explains: “We are now living in a G-Zero world, one in which no single country or bloc of countries has the political and economic leverage—or the will—to drive a truly international agenda.” 

High gas prices are just one of the risks to prep for.
David Paul Morris—Bloomberg/Getty Images

Companies caught in the commercial chaos must now fend for themselves. In a tumultuous global order, “supply-chain officers are looking for inventory buffers, alternative vendors, redundancy in their supply chains,” says Eshkenazi. “That’s not compatible with long-term ­strategies.” 

In other words: Companies’ war rooms won’t be closing up shop anytime soon.

Playing out a range of scenarios is more essential—and more difficult—than ever

“Scenario testing or stress testing: If you’re not already doing it, you need to start yesterday,” says Patterson of the Council on Foreign Relations. In addition to companies stress testing their costs and supply chains, she recommends they also test their resistance to cyberattacks. “Iran is a strong actor in the cyber world,” she says. Its successful March attack on the Stryker medical-device maker, in which its goal was apparently not to receive ransom but to destroy data, was only a recent example. Many of Iran’s previous cyber­attacks have targeted crucial economic infrastructure, including hospitals, ports, power plants, and railroads. 

Some of the most useful scenarios are based on second- or third-order effects of an event. With the Iran war, Patterson says, “the big one is stagflationary risk,” a second-order effect that creates slow economic growth, high unemployment, and high inflation. With gasoline prices and shipping costs already rising, “expect to see this feed into inflation expectations and possibly actual inflation,” she says. Third-order effects might include rising interest rates and borrowing costs, and a strengthening of the dollar, making it easier to buy imports and harder to sell exports. 

The Iran war will likely continue to have effects long after it ends. Patterson cites an old line about gasoline prices: “They go up like a rocket and come down like a feather.”

Leaders should remember the pandemic

That’s not to say that the Iran war will be a disaster on COVID’s scale. But no one knows how it will turn out, just as no one in the pandemic’s early days knew what would happen next. 

Employees, share­holders, customers, suppliers—all were frightened and looking for answers that not even CEOs had. The pandemic changed leadership in ways that still linger, and today’s executives and managers would do well to remember that transformation. 

“Scenario testing or stress testing: If you’re not already doing it, you need to start yesterday.”


Rebecca Patterson, Council on Foreign Relations

The overarching theme from those days was the end of the classic CEO persona—informed, prepared, firmly in charge, and invulnerable. That changed quickly. “CEOs went from being godlike to being more human,” said Jim Citrin of the Spencer Stuart executive search firm. A CEO told Fortune at the time, “I found the magic in an organization is about being super down-to-earth, letting people see you for who you are, with all the vulnerabilities that you face.” 

Now, as the fog of war drifts even into corner offices, CEOs again face questions they can’t answer: How long will the war last? Will it escalate? How high will oil prices go? 

It’s a good time to remember a lesson from the pandemic: Executives who confess they’re mere mortals and don’t pretend to know everything can actually become more trustworthy and more ­effective as leaders. 

This article appears in the April/May 2026 issue of Fortune with the headline “For CEOs, it’s time for a wartime mindset.”

This story was originally featured on Fortune.com
Mitsubishi Shokuhin, Japan’s largest food wholesaler and part of the massive Mitsubishi Corporation, needed a way to break into the U.S. Tourists were falling in love with Japanese products, but couldn’t find a way to buy them once they got home. Yet, for the wholesaler, building market access the normal way—finding individual retailers, securing appointments with buying managers—was proving to be a slow process. 

The answer came from an unlikely place. A Mitsubishi‑sponsored MBA student took an internship at Yami, an up‑and‑coming U.S. e‑commerce platform selling Chinese, Japanese, Korean and other Asian products to Asian Americans and the broader Asian diaspora. 

That assignment laid the groundwork for a strategic partnership that gives Mitsubishi Shokuhin a direct line to millions of American shoppers. Mitsubishi Shokuhin, which generated about 2.1 trillion yen ($14 billion) of revenue in its last fiscal year, is signing a strategic partnership with Yami that will put more of its portfolio of Japanese food and beverage brands on the platform for U.S. consumers.

“It was pretty random,” recalls Alex Zhou, Yami’s founder. “We weren’t actively raising money. We had already broken even, we had positive cash flow.” Yet over a series of meetings, Zhou says, it became clear that the Japanese trading house could offer something other than capital. “Japanese products and brands already represent more than 30% of what we sell. A name like Mitsubishi can really help with our Japanese supply chains,” he says. 

“Yami gives brand owners instant access to consumers directly, and that is one of the attractive aspects of the platform,” says Kazuo Ito, a senior vice president at Mitsubishi Corporation who heads its food distribution and logistics division and is set to become president and CEO of Mitsubishi Shokuhin in April. The partnership, he says, allows Japanese manufacturers to bypass the slow grind of securing shelf space with U.S. retail buyers and instead reach millions of shoppers online.

Mitsubishi Shokuhin dates to 2011, when four long‑standing food wholesalers, some with histories stretching back more than a century, joined together in one company. The company now supplies a broad range of processed, frozen and chilled foods, alcoholic beverages and confectionery to around 3,000 retailers in Japan, including Japanese convenience‑store chain Lawson and lifestyle retailer Muji.

Mitsubishi Corporation—Japan’s largest trading house, with roughly $122 billion in annual revenue—took Mitsubishi Shokuhin fully private last year via a 137.6 billion yen (about $950 million) tender offer. Ito says part of the rationale was to accelerate overseas expansion by more tightly integrating Shokuhin into the wider Mitsubishi group, including sharing logistics networks and talent.

What is pushing a traditionally domestic wholesaler to look abroad? One factor is Japan’s tourism boom. The country welcomed a record 42.7 million foreign visitors in 2025, who spent 9.5 trillion yen (about $60 billion), according to government data.

“Many visitors come to Japan, have a good time and buy things for souvenirs or consumption,” Ito says. “But when they go home, they say, ‘I enjoyed that, but where do I get hold of it? Do I have to go back to Japan again?”

Japan’s exports of agricultural, forestry and fishery products and foodstuffs reached a record 1.7 trillion yen in 2025, with record high exports of beef and rice, and a doubling of green tea exports.

Ito argues platforms like Yami can turn those souvenir purchases into ongoing demand. “Companies like Yami can provide that ‘re‑experience’ of going to Japan by providing the products people enjoyed during their stay,” he says.

From Kansas to 4 million customers

Zhou’s own journey underscores the gap Yami is trying to fill. He arrived in the U.S. from mainland China in 2007 as an international student and landed in Kansas, with the nearest Asian grocery store being two hours drive away.

After graduating and moving to the Los Angeles area, he launched Yami in 2013. Within three years, the business had nearly $100 million in revenue without outside funding, he says. Yami has since raised institutional capital, including a $50 million Series B round co‑led by Altos Ventures and Balsam Bay Partners.

The company positions itself as a one‑stop online marketplace for Asian products in North America, spanning snacks, beauty and health items, household goods and more. Zhou says the platform has close to four million registered customers. 

Other ecommerce platforms have arisen to sell Asian goods, including Weee, founded in 2015 by Larry Lu. Asian supermarkets, like the Hanahreum Group’s H Mart, are also booming across the U.S.

Yami’s growth hasn’t been painless. Around 2018, Yami went through a period of cost-cutting. “I learned that you have to separate yourself from the business,” Zhou says. “You have to make decisions based on what’s best for the company. It’s really hard to fire people.”

More recently, higher U.S. tariffs on Asian goods—at times hitting triple‑digit levels on imports from China—have tested Yami’s supply chain and pricing, but Zhou sees the disruption as an opportunity. “We knew Asian supply chains better than others. That created an opportunity to thrive driving this crisis.”

Yami was initially built to serve Asian Americans and the Asian diaspora. “As an Asian and Chinese person, I first felt obligated to make overseas life better for immigrants like myself.” 

Yet non‑Asian shoppers are increasingly buying not just Japanese and Korean snacks, but also Asian beauty products, health supplements, home goods and apparel. They’re also consuming Asian cultural products, like K‑pop and Japanese manga.

“The fastest-growing segment of Yami’s customer base is not Asian, but non-Asian,” Ito, from Mitsubishi Shokuhin, notes. “That is attractive for brand owners like us who want to go to the U.S.”

This story was originally featured on Fortune.com
China is becoming a “factory to the factories,” ramping up its exports of industrial components like smartphone parts, processors, memory chips and lithium-ion batteries, destined for final assembly in economies like Southeast Asia.

“We may buy fewer ‘Made in China’ goods going forward, but more products will have internal components manufactured in China,” says Jeongmin Seong, a partner at the McKinsey Global Institute (MGI), the consulting firm’s research arm. 

China’s exports of consumer goods declined by 2% last year, yet exports of intermediate goods rose by 9%. 

Trade between the U.S. and China declined by 30% last year, due to U.S. President Donald Trump’s steep tariffs on Chinese goods. Yet “China stepped up to diversify its trading partners, and mostly with emerging economies,” explains Seong, who is also the author of a new MGI report on global trade. Those new trading partners, mostly manufacturing hubs, had more need for cheap machinery and components from China, rather than more costly finished products.

MGI’s report, titled Geopolitics and the Geometry of Global Trade, notes that the U.S. also changed its trading partners last year. The country successfully replaced two-thirds of the goods it previously sourced from China, sourcing smartphones from India and laptops from Southeast Asia. 

ASEAN in particular is playing a key role in tariff-induced trade adjustments. Southeast Asian countries were already picking up manufacturing business moving out of China, as companies tried to manage earlier tariffs on Chinese goods and diversify their supply chains in the wake of the COVID pandemic.

Trump’s newest trade war is likely to accelerate the shift to adopt “China plus one” supply chains.

“ASEAN played the role of matchmaker for the global supply chain and kept it from breaking up,” Seong says. “ASEAN’s exports grew about 14%, which is more than two times as fast as the global average.” Notably, Southeast Asia ramped up trade with both China and the U.S., with the ASEAN-China and ASEAN-U.S. trade corridors being two of the world’s fastest growing, according to MGI.

Despite post-”Liberation Day” concerns last year that globalization was dead, global trade hasn’t declined. Seong sees less evidence that countries are moving manufacturing back home or to neighboring countries. “Despite a lot of headlines about onshoring, reshoring and nearshoring—that is not happening at a global scale,” he says. “More countries are getting connected over longer distances, and in that sense, we can argue that globalization is continuing.”

Instead, trade is being reconfigured along geopolitical lines. Countries are trading more with aligned countries, and trading less with countries seen as competitors or rivals. It’s not just the U.S.; China, too, has increased trade with Southeast Asia, Europe, Latin America and Africa as its geopolitical contest with Washington intensifies.

Investment, too, is being configured across geopolitical lines. The U.S. is investing more in its allies; it’s sourcing investment from allies like Japan, South Korea, and the Middle East, particularly in areas like semiconductors. China, on the other hand, is now a net investor overseas, not just because the country is investing more, but also because U.S. investment into the country has dried up. 

Last year, the geopolitical distance of foreign direct investment plunged by 13%, while the same metric declined by just 7% in trade, according to MGI. (“Geopolitical distance” is MGI’s metric for measuring how closely two countries are aligned in their foreign policies, politics, and alliances.)

“Money can move faster than physical networks,” Seong explains. 

Tariffs may come and go, Seong suggests, but a deeper shift of who trades and invests with whom is likely to endure long after the latest trade war headlines fade. “Geopolitical events like tariffs could be short-term splashes, but structural waves—like the geopolitical realignment we’re seeing—will endure,” he concludes. 

This story was originally featured on Fortune.com

Federal agents on Thursday arrested Yih-Shyan “Wally” Liaw, a prominent Silicon Valley executive deep in the AI ecosystem who cofounded Supermicro in 1993 and is a close confidante of CEO and chairman Charles Liang. The stock tumbled roughly 12% in after-hours trading following the news.

According to a stunning release from the Department of Justice, an indictment was unsealed in Manhattan federal court on Thursday charging Liaw, 71, and two others with allegedly working in secret to divert billions in Supermicro AI servers to China in violation of U.S. export control laws. The two alleged co-conspirators charged alongside Liaw include Supermicro’s Taiwan general manager Ruei-Tsang “Steven” Chang, who remains a fugitive, and a third-party fixer named Ting-Wei “Willy” Sun, who was also taken into custody on Thursday. 

The DOJ claims during 2024 and 2025, Liaw took a direct hand in the alleged conspiracy, working with Chang to allegedly find Chinese buyers who wanted the servers, which are packed with highly coveted Nvidia GPU chips, according to the indictment. The pipeline they allegedly constructed worked this way: Liaw and Chang would allegedly direct executives at an unnamed Southeast Asian company to place purchase orders with Supermicro as though they were destined for that company’s operations. The servers would then get assembled in the U.S., shipped to Supermicro’s facilities in Taiwan, and then delivered to the Southeast Asian company at a different location. From there, the Southeast Asian company, in tandem Liaw and Chang, would hand the servers off to a shipping and logistics company, which would allegedly get rid of the identifying packaging. They would allegedly put the servers in unmarked boxes before sending them to their true destination, which was China. 

To keep the clandestine scheme from raising red flags with Supermicro’s compliance team, the defendants and the Southeast Asian company executives would fake documents and send false communications meant to show that the Southeast Asian company was the legitimate end buyer. During the two-year period, that company purchased about $2.5 billion worth of Supermicro servers under the alleged arrangement. The operation eventually grew even more “brazen,” authorities claim. The DOJ alleges that during a three-week period from late April to mid-May 2025, about half a billion worth of servers assembled in the U.S. were shipped to China as part of the alleged conspiracy. 

To keep it under wraps, the defendants allegedly staged thousands of fake dummy servers—actual, physical replicas of Supermicro’s actual products, authorities claim—at the warehouse where the Southeast Asian company was supposed to be storing its purchases. In reality, the real servers were long gone and had allegedly been shipped to China already. 

The DOJ claims surveillance cameras filmed Sun and an unnamed co-conspirator unboxing the fake servers, using a hair dryer to remove and reapply serial-number stickers and labels onto the dummy server boxes, then carefully repackaging them to pass inspection. The same phony servers were later used again to fool an audit conducted by the U.S. Department of Commerce, the DOJ alleges. Throughout the scheme, the defendants allegedly used encrypted messaging apps to discuss server quantities, delivery locations in China, and ways of keeping the operation hidden from Supermicro’s compliance team and U.S. authorities.

The DOJ says the Nvidia chips in the Supermicro servers were the target for the buyers. Liang has often touted his close business ties to Nvidia and its CEO Jensen Huang. 

An Nvidia spokesperson said compliance is a “top priority” for the $4 trillion chipmaker. 

“We continue to work closely with our customers and the government on compliance programs as export regulations have expanded. Unlawful diversion of controlled U.S. computers to China is a losing proposition across the board—Nvidia does not provide any service or support for such systems, and the enforcement mechanisms are rigorous and effective.”

In a statement, Supermicro said it is not a defendant in the indictment and that Liaw, who serves as a board member and as senior vice president of business development, has been placed on administrative leave. Chang has also been placed on leave, and Sun, who is at large, was fired from his contracting role. Supermicro said it is cooperating with the government investigation. 

“The conduct by these individuals alleged in the indictment is a contravention of the Company’s policies and compliance controls, including efforts to circumvent applicable export control laws and regulations,” the statement says. “Supermicro maintains a robust compliance program and is committed to full adherence to all applicable U.S. export and re-export control laws and regulations.”

Authorities claim the scheme was all engineered to make money from Chinese buyers and thwart the export controls.

“The indictment unsealed today details alleged efforts to evade U.S. export laws through false documents, staged dummy servers to mislead inspectors, and convoluted transshipment schemes, in order to obfuscate the true destination of restricted AI technology—China,” said John A. Eisenberg, Assistant Attorney General for National Security. 

The stream of compliance and governance issues leading up to Liaw’s stunning arrest all point to mounting problems with controls at the hardware manufacturer. 

The Backstory

Trading in Supermicro’s stock was suspended in 2018, after the company fell out of compliance with Nasdaq listing standards while the Securities & Exchange Commission conducted an investigation into its accounting practices. That same year, Liaw resigned all his positions with the company following a related internal audit committee investigation. In 2020, the company was ordered to pay a $17.5 million penalty and its chief financial officer resigned.  Liaw returned to the fold in May 2021 as an adviser to Supermicro in “business development.” He returned to a full-time senior executive post in August 2022 and in December 2023, he rejoined the board. 

Supermicro again faced the heat in August 2024 when short-seller Hindenburg took a position in the stock and published a scathing report on the company, alleging that the accounting issues had returned. Supermicro denied Hindenburg’s allegations. 

However, around the same time, Supermicro’s auditor Ernst & Young sent a letter to the board’s audit committee flagging concerns about governance, transparency, and raising questions about whether the annual report could be filed on time. The board responded by appointing a special committee and bringing in Cooley LLP and forensic accounting firm Secretariat Advisors to investigate—again. 

Then in October 2024, in the middle of an audit, EY abruptly resigned and its language pulled no punches. EY said it could “no longer rely on management’s and the Audit Committee’s representations” and was “unwilling to be associated with the financial statements prepared by management.”

The resignation set off a chain reaction. Without an auditor, Supermicro couldn’t file its annual report for fiscal 2024 or its quarterly reports. Nasdaq gave the company a grace period until November, but it was at risk of a second trading suspension in six years. 

Days before the November deadline, Supermicro announced that it had hired BDO USA as its replacement auditor and submitted a compliance plan to Nasdaq that put it in better standing with the exchange. 

In December 2024, the special committee that investigated EY’s allegations—made up of a single board member—concluded there was no evidence of fraud or misconduct and said EY’s decision to resign was “not supported by facts.” Liang declared the company was out of the woods and CFO David Weigand called the investigation a “distraction.”

However, the committee’s report found lapses that it blamed on Weigand and recommended replacing him. Supermicro pledged to implement the committee’s recommendations “immediately.” That was 15 months ago. Weigand remains the CFO of Supermicro. 

“No one wants this job—this is like touching lightning,” Shawn Cole, president of executive search firm Cowen Partners, told Fortune last month, describing Supermicro’s prolonged CFO search. Thursday’s news is unlikely to aid in recruitment.

Meanwhile, Supermicro is a key infrastructure company in the massive $700 billion AI buildout. Its servers are packed with Nvidia GPUs and it claims its proprietary liquid-cooling technology keeps the chips running efficiently as workloads increase. Liang helped Elon Musk build his Colossus AI cluster in just 122 days. Its most recent earnings call, the CEO flagged $13 billion in orders for an Nvidia Blackwell product line. 

Indeed, the export controls that Liaw, Chang, and Sun are accused of violating exist specifically because the Biden and Trump Administrations have been determined to keep advanced AI accelerators as a strategic national security asset that can’t be sold to Beijing. The export controls, imposed by the Department of Commerce’s Bureau of Industry and Security on advanced computing chips and on computers and devices that contain the chips, have been in place since October 2022. 

Each of the three face up to 20 years in prison on the most serious charge, conspiracy to violate the Export Controls Reform Act, and additional counts of conspiracy to smuggle goods and defraud the U.S. 

“As alleged in the indictment, the defendants participated in a systematic scheme to divert massive quantities of servers housing U.S. artificial intelligence technology to customers in China,” said U.S. Attorney Jay Clayton for the Southern District of New York. “They did so through a tangled web of lies, obfuscation, and concealment—all to drive sales and generate revenues in violation of U.S. law. Diversion schemes like those disrupted today generate billions of dollars in ill-gotten gains and pose a direct threat to U.S. national security.”

Liaw has been a close confidante of Liang and his wife, Sara Liu, who all cofounded the company together, for years. While other companies are not named in the indictment, Supermicro has extensive overseas operations built around close family ties to the founding couple. The web of business relationships has long drawn scrutiny from investors, short sellers, and regulators. 

According to the company’s disclosures, two Taiwan-based companies, Ablecom Technology and Compuware Technology, collectively received about $983 million in payments from Supermicro over the past three fiscal years. Both share a home with Supermicro’s own Taiwan manufacturing facility in what is called “Supermicro AI Technology Park” in the Taoyuan area. 

Ablecom was founded in 1997, just four years after Supermicro, and is run by Jianfa “Steve” Liang, who is Charles Liang’s little brother. Steve Liang is Ablecom’s CEO and largest shareholder. Charles Liang and Sara Liu, who is also a board member and senior vice president at Supermicro, together own about 10.5% of Ablecom’s stock, according to Supermicro’s most recent 10-K. Compuware, founded in 2004 and described by Supermicro as an affiliate of Ablecom, is run by Jianda “Bill” Liang, another of Charles Liang’s younger brothers. Steve Liang is also a director and shareholder of Compuware. Ablecom holds a 15% stake in Compuware. 

Liaw, who holds a 2.6% stake in Supermicro, is one of the company’s largest individual shareholders outside of the Liang-Liu family, which controls about 13.4% of Supermicro’s stock. A sibling of Liaw’s owns about 11.7% of Ablecom’s stock and 8.7% of Compuware’s stock. 

Liaw could not be reached for comment.

This story was originally featured on Fortune.com

Straight‑A report cards have never been more common for America’s teens—but the payoff is not what parents think. A new National Bureau of Economic Research study finds that when teachers hand out “easy A” grades, their students are more likely to skip class, score worse on future tests, and earn less money years later. For a typical high school class, the researchers estimate grade inflation can shave about $213,000 off the group’s future earnings, or roughly $150 a year for each letter grade quietly nudged up.

The findings arrive as President Donald Trump pushes a crackdown on grade inflation on college campuses, tying federal funding to whether universities hold the line on grading. Gen Z is already the first generation to score lower than their parents on some measures of cognitive performance, as reading habits erode and schools lean harder on grades instead of learning.

The study, entitled “Easy A’s, Less Pay: The Long-Term Effects of Grade Inflation,” found that for each individual student, this dynamic chalks up to a decrease in yearly earnings of about $150 for every grade bumped up to a B+ from a B, for example.

“Average grade inflation hurts,” Nolan Pope, one of the study’s researchers and a labor economist at University of Maryland, told Fortune. “They are less likely to learn if it’s very easy to get an A. They spend less time and effort.”

The debate around grade inflation has stretched from the classroom to the Oval Office. President Donald Trump weighed in on the issue last November, establishing a higher-ed compact linking federal funding for universities to strict parameters his administration set, barring grade inflation (or deflation). The practice could be harming young people. Gen Z is the first generation less cognitively capable than their parents. Many young people are ditching books at record levels and some are even failing to complete reading assignments on par with previous expectations. From high school to college, grade inflation has offered educational institutions increasingly dubious value propositions.

The researchers analyzed administrative high school records from Los Angeles and Maryland and linked them to long-term postsecondary and earnings data. They measured grade inflation by comparing student grades to their actual performance on standardized tests.

The hidden costs: absences, suspensions, and dropping out

Whether it be with grades or money, inflation degrades value. Wealth managers are grappling with a strange problem in 21st century America: the rise of many “everyday millionaires” who are illiquid, with much of their wealth tied up in housing, often struggling to afford the things they feel entitled to by their paper worth. The straight-A students, in other words, likely have parents with straight-A portfolios, but both end up with B- or even C-level experiences in this inflated economy.

“The economy wasn’t built to handle this many people with this much money,” Nick Maggiulli, New York Times bestselling author of The Wealth Ladder, told Fortune in an interview last year. “On a relative basis in the United States, the competition for these higher-end goods is very high, so now it feels like we’re all canceling each other out with all this extra wealth,” he added. So too, in the classroom, when high scores are liberally handed out, the A loses its sought-after value.

The NBER study found that it’s not just future earnings being degraded. Grade inflation could actually have the inverse effect of their implied outcome. Students that are assigned a teacher that inflates grades are more likely to score poorly on future tests. They’re less likely to graduate high school, and even less likely to enroll in college. Most of these impacts, of course, usually happen well after the student has handed in their final exam, and that makes it harder to catch.

Teachers generously tossing out easy As also made it easier for students to skate by. The research found that higher grade inflation is linked to increased absences and suspensions, suggesting that when the academic bar is lowered, student engagement and school discipline may fall with it.

“It ends up actually being somewhat harmful for the student,” Pope said. “Nobody really is on the side of that harm because nobody sees it until much later.”

However, the study found grade inflation benefitted some students, specifically those at threat of flunking out. When teachers raised scores for students at threat of failing—from an F to a D, for example—that actually paid off, preventing those students from repeating a grade and improving their high school graduation rate.

Whatever the outcome, grade inflation has gained steam over the past decade. And despite the president’s efforts, the trend doesn’t seem to be stopping anytime soon. Pope said grade inflation remains so pervasive because all parties benefit from it, offering a perverse incentive that perpetuates the seemingly benign practice semester after semester. 

“As a teacher it’s usually easier,” he said. “You get less complaints. Parents are happy. Students are happier if you give slightly higher grades. A school typically looks better if their grades are higher. It benefits everyone.”

This story was originally featured on Fortune.com
In a world of protein-maxxing and fiber-counting, it’s hard to remember a time when a baked good itself could be a fad.

But a decade ago, people underwent a frenzy for cupcakes. Adults would line up around the block for cupcakes that came out of vending machines; a company selling jumbo cupcakes with custard filling IPO’d at $13 a share, and people raced to buy a sheet of miniature tie-dye cupcakes for $45. The frenzy was so massive, the cupcake boom moved 669 million units in a single year, but like an overdone cupcake in the oven, it deflated just as quickly as it went up. Crumbs went from a Nasdaq darling to bankrupt in three years. Sprinkles, the brand that invented the cupcake ATM, shut its doors for good just weeks ago. Nearly every gourmet cupcake company from that era has dramatically flared out and died—except one.

Melissa Ben-Ishay founded Baked by Melissa in 2008 after getting fired from her job as an assistant media planner at 24. Eighteen years and more than 500 million bite-sized cupcakes later, she’s stepping down as CEO—and for the first time, she says the company is open to a sale.

Ben-Ishay will transition to president—a title she held before the board installed her as CEO in late 2019—while Sanjay Khetan, the company’s current CFO, takes over as chief executive. In an exclusive Fortune interview with both Khetan and Ben-Ishay, Ben-Ishay said she’d planned to bring Khetan on with the intention of finding someone who could replace her. On her first day of being the President and not the CEO of her company, Ben-Ishay described the move candidly: “I am so freaking thrilled that I am no longer needed in that seat,” she said, “so I can focus on the areas of the business that I can uniquely drive.”

The openness to a sale marks a reversal for Ben-Ishay. In a 2025 interview with the Food Institute, Ben-Ishay said that maintaining quality standards was one of the reasons she’d “avoided acquisitions.” When Fortune read the quote back to her, she said she didn’t remember making it, then acknowledged the shift in her perspective. “It’s something we’re definitely interested in exploring and working towards,” she said. She noted that the company fields acquisition offers regularly. “Every day we get offers in my inbox,” she said.

Asked what Baked by Melissa figured out while other brands from that era burned out, Ben-Ishay credited its bite-sized format—mess-free, with no knife or fork required—and a “best in class” shipping experience. That, and a refusal to scale recklessly. “We didn’t try and grow too quickly,” she said. The company now has 14 retail locations, nationwide shipping, and claims continued year-over-year top-line growth. Where Crumbs chased a Nasdaq listing and Sprinkles sold to private equity, Baked by Melissa stayed private, taking in just $6 million in outside funding in its 18-year tenure and kept a light footprint. 

Going viral for the opposite of cupcakes 

Ben-Ishay had been CEO for barely three months when COVID shuttered stores across New York. “I was scared out of my mind,” she said, unsure of how to scale the business. Ben-Ishay has been open about the imposter syndrome that defined her early years—she has previously told Fortune she didn’t think she deserved the CEO title. Asked whether she ever felt the company had outgrown her, she was unequivocal. “Never,” she said.

In her first year of being a CEO and during a pandemic, she said the company grew e-commerce revenue roughly 99% year over year. It was also during the pandemic that Ben-Ishay accidentally built what she now calls “a business within my business”—going viral on TikTok not for cupcakes but for her Green Goddess salad recipe, which racked up over 27 million views. Her social following has spawned a brand partnerships division, two cookbooks (including a New York Times bestseller), and collaborations with Oatly, Squishmallows, and Ferrero.

Ben-Ishay’s TikToks are chaotic—food bits flying, kids yelling, smoke detector beeping—with the overachieving-burnt-out-mom energy that millennials have made aspirational. It clearly speaks to a strong contingent: Baked by Melissa has nearly 3 million followers on TikTok alone. On the call with Fortune, the vibe wasn’t all that different; Ben-Ishay took part of the interview from the passenger seat of a car, at one point pausing to hug and chat with someone while Khetan answered questions.  

“I am a mom with young kids. I am a creator. I am a cookbook author—New York Times bestselling cookbook author—and an executive co-founder of Baked by Melissa,” she said. “Today, president and co-founder. Yesterday, CEO and co-founder,” which, she said, make up “many, many hats, and I have my priorities straight. I think this transition is not only best for Baked by Melissa, but best for me so I can breathe, like, a tiny bit.”

The question of what happens to the brand’s social media presence—arguably its most valuable marketing asset, built almost entirely on Ben-Ishay’s personal content—seems central to the transition. But she said she expects the shift to give her more time to create, not less. She has resisted the label “influencer” even as her following has grown. “I’m not an influencer by trade,” she said. “I have this greater responsibility, not only to Baked by Melissa, but also to my customer.”

The company’s founding story has always been a family affair. Ben-Ishay’s brother Brian Bushell co-founded the business and served as its first CEO until 2016. He remains a shareholder and is involved in high-level strategic conversations, according to Ben-Ishay. She declined to comment on a books-and-records inspection lawsuit that Bushell appears to have filed against the company. (Bushell has not responded to a request for comment). Her husband, Adi Ben-Ishay, also works at Baked by Melissa and will continue to report to Khetan.

Khetan said the partnership works because the division of labor is clean: Ben-Ishay leads brand and creative, he handles operations and finance. “The potential to create more value over the next couple of years is extraordinary,” he said. 

Ben-Ishay offered a final thought. “Baked by Melissa—we make bite-sized stuffed cupcakes in a variety of flavors that make you feel like a kid again, and we ship nationwide,” she said. “And hop to it, because Easter is on its way.” Eighteen years in, and she’s still closing.

This story was originally featured on Fortune.com
Five people were arrested for allegedly dousing an influencer’s father in gasoline and forcing him into the trunk of a car in exchange for ransom payments in crypto. The attack, whose details first surfaced this week, occurred at the every end of 2024 near the French border with Switzerland. 

The arrests put a spotlight on the uptick of physical attacks on crypto holders, often known as “wrench attacks”, in France. Out of the 24 physical Bitcoin attacks this year, about two-thirds of them have occurred in France, according to a list compiled by Bitcoin owner Jameson Lopp. 

The target of the 2024 attack was the father of an unnamed Dubai-based influencer and crypto entrepreneur, according to DL News and French media publication France 3. Police did not say whether the influencer made the Bitcoin payments that the attackers demanded. 

Investigators made arrests across France, far from the original site of the crime. Among those detained was a 16 year-old at the time of the attack, and the oldest of the five suspects was 42. Prosecutors are planning on charging the alleged attackers with kidnapping, unlawful confinement, extortion, organized crime, and aggravated violence. 

Another notable example of a wrench attack in France occurred on January 25, when three men tortured a 74 year-old for 16 hours in order to get $3.5 million in crypto from his son. The alleged criminals abandoned their scheme after discovering that the victim’s son was in fact not a crypto trader. 

Every year, the number of physical coercion attacks on crypto holders goes up. There were 72 documented wrench attacks last year, a 75% increase from 2024, according to blockchain security auditor CertiK. Bitcoin owners can access their crypto holdings through a physical or digital key, and once money is transferred out of their accounts, the transaction is often irreversible. This feature of Bitcoin ownership makes people susceptible to physical attacks.

This story was originally featured on Fortune.com
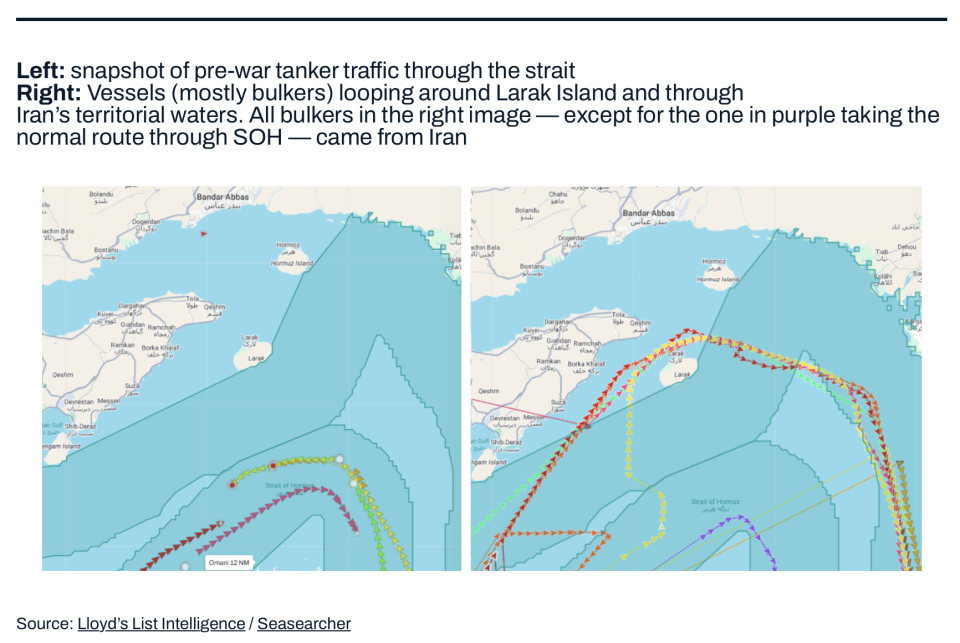
A regional war filled with missiles and drones flying overhead has dismantled the Middle Eastern airspace. The blockage of the Strait of Hormuz has sent oil costs skyrocketing. A partial government shutdown has left 50,000 TSA agents working without pay for more than a month. It’s everything, everywhere, all at once, forcing travelers to rethink their plans as the landscape begins to mirror something we’ve experienced a few years earlier during the pandemic.

“It’s a crazy situation,” said Eric Napoli, Chief Legal Officer at AirHelp, the world’s largest flight compensation platform. “Different situations in different places in the world are all convening at once.”

Napoli said that more travelers have been turning to AirHelp in recent months to recover money lost due to flight disruptions. Again, the combination of a war grounding flights and driving up fuel costs, coupled with ongoing conflicts in Mexico, government workers calling out sick after a month and counting of working without pay, and poor weather conditions, has led to a perfect storm that hasn’t been seen since COVID-19 saw the world come to a standstill. Above all, Napoli said, we’re all asking the same question we asked back then: when is it going to end?

“The sensation of the pandemic is similar in the sense that we’re like, okay, we don’t know what just happened,” Napoli told Fortune. “What’s the future going to be? Is this something that’s going to last two weeks, three weeks, a year? Is everything going to change? This is what we don’t know.”

The Iran war is closing airspace and increasing fuel prices

The conflict between the U.S., Israel, and Iran has effectively shattered the Gulf’s role as a global aviation crossroads. Airlines have grounded or rerouted flights, leaving passengers who booked connections via Dubai, Abu Dhabi, or Doha in limbo.

“Economies like Qatar or the Emirates that have really based themselves on being the connecting hub between Europe, the US, and Asia. All that stuff has been frozen,” Napoli said. “Anybody traveling to Asia from the U.S. or Europe suddenly sees major flight disruption. That’s been incredibly frustrating for passengers.”​

For those stranded in the Gulf, options are grim. Napoli described scenes of travelers scrambling for alternatives, such as driving for hours to reach operational airports in neighboring countries. “People are all on wait lists for flights, and it’s very touch-and-go,” he said. “From one day to the next, airspace might close.”​

Making matters worse is a dramatic spike in fuel costs. Brent crude has surged more than 50% over the past month and is now at $115 a barrel. Jet fuel now averages $157.41 per barrel globally, nearly double industry forecasts for 2026, according to the International Air Transport Association (IATA). For travelers, that translates directly into sticker shock at checkout. “We see the concern of fuel increases,” said Napoli, who himself has noticed prices jump as he reconsiders a family vacation to Texas from his home in Spain this summer. “Ticket prices will increase astronomically.” Passengers who booked through Gulf carriers months ago at competitive fares now face rebooking on European or American carriers at two or three times the cost, if they can find a seat at all.​

The TSA meltdown

While the war plays out abroad, a slow-motion crisis is unfolding at America’s own checkpoints. The partial government shutdown, now entering its 31st day, has forced 50,000 TSA officers to work without pay since Feb. 14. Absenteeism at major hubs like Atlanta, Houston, and New York has surged to approximately 20%. Small airports, officials have warned, could face outright closure if the standoff in Washington continues.

“We’ve had TSA issues: really long lines just to go through security, really long lines at border control,” Napoli said. “All of that has just made travel super frustrating for Americans.”​

Data from AirHelp highlights the scope of the disruption. In February 2026, the worst-performing major airports recorded staggering flight disruption rates: Fort Lauderdale-Hollywood International led the country at 61.8% of flights disrupted, followed by Newark Liberty at 61.0% and O’Hare at 59.1%. New York’s LaGuardia and Ronald Reagan National rounded out the bottom five at 58.7% and 58.2%, respectively. Even the best-performing airports were far from smooth: Salt Lake City International topped that list at a 39.6% disruption rate.​

Tourism at risk

The timing couldn’t be worse. The 2026 FIFA World Cup is set to kick off across 16 North American host cities, including Dallas, Houston, Los Angeles, Miami, and New York. The LA28 Olympics follow two years later. Both events were expected to deliver billions in tourism revenue to a U.S. travel industry still rebuilding consumer confidence, and as worldwide general sentiment towards the U.S. has hit all-time lows thanks to tariffs and policing efforts. ​

“Uncertainty is always bad for consumer confidence, and it’s bad for passenger confidence,” Napoli said. “We want people to come to the U.S. for the World Cup. If there’s a fear of really long passport control difficulties, if there are fears of lots of delays and nothing people can do about it, if ticket prices become incredibly expensive, then we won’t see those numbers.”​

The consequences extend well beyond the airport. “It won’t just be bad for the event,” Napoli added. “It will be bad for all the businesses that have planned their budgets around it. Hotel occupancy, restaurants: a lot of businesses are really depending on a successful World Cup.”​

For now, Napoli says it’s still too early to measure the full fallout of what he calls an “incredibly uncomfortable” moment for the airline industry. Claims, he notes, come in months after disruptions occur, not days. In the meantime, he has his own verdict on how bad things really are. “These things always happen when I’m about to travel,” he said with a laugh. He’s still booking his family vacation anyway.

This story was originally featured on Fortune.com
After six years on the sidelines, Uber is making a clear push to deploy its own robotaxis again, with deal structures that seem designed to limit its risk.

It’s a significant reversal from a few years ago, when Uber sold its self‑driving unit, ATG, after a fatal crash in 2018 and years of heavy losses. Since then, Uber has gone a different path—inking deals with nearly every major robotaxi player in the market, from Waymo to WeRide. It’s only Tesla that doesn’t work with the ride-hail company, though that wasn’t for lack of trying on Uber’s part. 

In all of those deals, Uber has integrated other companies’ AV fleets into its app; the AV companies own and operate the cars. That’s changing. 

First, there was the deal with Lucid Motors in 2025 to purchase and deploy up to 20,000 vehicles equipped with Nuro’s autonomy stack. On Thursday, Uber announced a similar deal with Rivian for its yet‑to‑be‑built R2 platform. The company is planning to purchase 10,000 fully autonomous R2‑based robotaxis if Rivian meets development and validation milestones, with an option to scale to 50,000, according to SEC filings and company statements. Uber is also making a $300 million investment in the company as part of the deal, and potentially another $950 million more should Rivian meet certain, undisclosed development requirements. Rivian has also agreed not to sell fully autonomous vehicles to Uber’s direct ride‑hailing rivals for a specified exclusivity period, according to the SEC filing.

Uber is planning to deploy the new fleet in San Francisco and Miami in 2028, and hopes to be in 25 cities by 2031, the companies said. Uber said in January it was still planning to deploy Lucid vehicles later this year.

To be clear, there’s still a lot that will need to happen first for the Rivian deal. Rivian laid out what its R2 autonomy platform will look like in December—a multi-modal sensor suite with 11 cameras, five radars, and one LiDAR that is built on two of Rivian’s in-house RAP1 chips—but it still has yet to finish developing it or to start production of the new vehicle. Language in the SEC filings suggest that Rivian still has a long way to go, noting that Rivian “intends to develop” an autonomous driving system featuring its own Level 4 system as well as “certain technology” that will let Rivian vehicles integrate into ridehailing and logistics networks. Rivian and its suppliers still apparently need to purchase the tooling necessary to manufacture and assemble these vehicles, too, the agreement shows.

All of this will be expensive. As TechCrunch first reported, Rivian said in an SEC filing that it no longer anticipates reaching EBITDA profitability by 2027 due to expected increase in autonomy R&D. It looks like Rivian may effectively be using Uber’s order book and cash to help finance this autonomy push.

Uber and Rivian had not responded to requests for comment before press time.

Uber moves away from asset-light

Uber’s been making strategic, expensive bets on autonomy for a long time, and has been a frontrunner in partnering with various robotaxi companies.

It is working in cities like Austin with Waymo vehicles, with Motional in Las Vegas, and has plans to expand into Los Angeles with Zoox. It’s even planning to work directly with Nvidia in 2027. These partnerships have allowed Uber to have skin in the game with the race to autonomy, but still deflect some of the brand and reputational risk. 

There are reasons why Uber would want to do that. In 2018, one of Uber’s self-driving testing vehicles struck a pedestrian, who passed away. It was the first self-driving car fatality, and it made waves. Arizona’s governor suspended Uber’s testing in 2018; Uber then shut down the Arizona AV program and later sold it in 2020 for stock in Aurora Innovation, a self-driving trucking company in Texas.

For years, as it has signed on to new partnerships, CEO Dara Khosrowshahi has insisted that Uber is an asset‑light marketplace that doesn’t own cars itself.

These recent deals represent a change in direction.

Uber still isn’t building vehicles or core autonomy software—Rivian and Lucid are—but Uber would now own thousands of highly specialized vehicles in specific cities, meaning it is taking on asset risk (like depreciation and utilization) as well as operational risk should those system underperform or be responsible for an incident.

It’s unclear whether these new arrangements are having any kind of impact on Uber’s pre-existing partnerships—and if companies like Waymo will start viewing Uber as more of a rival. Waymo and WeRide did not respond to requests for comment before press time.

For a company that has spent years insisting it’s just the marketplace and not the fleet, this is more than a tweak to the business model. It’s a bet that this time, owning the robots will hurt less than it did the first time around.

This story was originally featured on Fortune.com
Jack Schlossberg has a confession: He thinks Donald Trump did something right.

At Fortune‘s CEO Initiative dinner in New York, the grandson of President John F. Kennedy — and now a Democratic congressional candidate running in Manhattan’s 12th District — sat down with Fortune editor Diane Brady for a candid, wide-ranging conversation that was as much diagnosis as campaign pitch. The verdict from the 32-year-old: Democrats have a serious problem with young men, and they brought it on themselves.

Schlossberg’s first question was to find an issue on which he and President Trump agreed. “I disagree with President Trump a lot,” he immediately offered, before saying he gives Trump credit for “getting people fired up about politics.” Trump “poached” many of the young men away from the Democratic Party, Schlossberg continued, urging his own party to look closely at how and why this happened.

“I think that they’re not stupid, those young men, and I give President Trump a lot of credit for being able to influence new meeting environments and make politics accessible.”

It’s a striking admission from a man who spent 2024 making viral social media videos for the Biden campaign — until he quit, that is. “I went down to Wilmington,” he explained, only to hear “no” over and over again. “Anyway, long story short, I quit the campaign because I thought if I don’t do this my way, I’m not going to be able to live with myself. A month later, I got a call from the campaign being like, ‘Hey, can you come back and make videos for us?’”

Schlossberg, who holds degrees from Yale Law and Harvard Business School, has built an unlikely second identity as a progressive content creator, deploying deadpan humor to reach an audience the Democratic Party has consistently fumbled. He told Brady that he thinks his use of humor and sense of the unexpected has been an effective vehicle for conveying information, and he argued that viral social media posts actually contain a lot of information. It’s misguided to think viral content is shallow or light.

With the Democratic Party at an all-time low in popularity, Schlossberg said it can’t be down to losing their way on policy, but rather no longer reaching young voters. “People aren’t looking for a superhero … They just want someone who knows how to speak their language, meet them where they are, and give them something of value.”

And he has a clear theory: “The Republican Party has embraced modernity in a way that the Democratic Party used to own,” he told the room of CEOs. “Whether it’s space, whether it’s the AI race, crypto, investing in new technologies — the Democratic Party has been way anti-everything, and anti-business in particular. Anti-modernity. Trump has flipped the script.”

That framing — Democrats as the party of “no” — is the sharpest arrow in Schlossberg’s quiver. He doesn’t believe the party lost its way on policy so much as it lost the plot on storytelling and cultural relevance. “I don’t think that’s because we all of a sudden lost our way on policy,” he said. “I think we’ve mainly been out in terms of reaching young people and telling them a story about what we’re for, not just being a reactionary party.”

The Democratic Party’s shift since JFK

What would his grandfather make of all this? Schlossberg described a sense of disappointment in the current landscape and a desire to, well, make the Democratic Party great again.

“I feel really proud of being a Democrat,” he said, “and that’s because I associate Democrat not with what it is today, but what it was in the past.” He explained that Democrats used to embrace maternity, science, and new media channels, a party that was pro-affordable healthcare, pro-immigration, pro-education. He also talked about “responsibility” and “courage” from political leaders to tell voters what they need to hear, not something false and harmful. This is the danger of Trumpism, he argued.

“Whether you support the president or not, I think he succeeds when people can’t really believe in anything the government is saying. We can’t even necessarily believe what he says on a given basis.” Schlossberg added that he doesn’t think Trump is wrong about everything, “that’s too simplistic a view.” But he said Trump is failing to give Americans confidence in the government. “He’s not giving us confidence in our ability to solve the problems of the future, and I think we really have too many problems that we’re not paying attention to right now that we need to solve.”

His campaign slogan — “Believe in Something Again” — is a deliberate callback to that lost Kennedy-era confidence. He acknowledged it’s “a little cheesy,” but insisted it captures exactly what this political moment demands: not a superhero, but a leader who meets people where they are and gives them something of genuine value. “Young people are not a monolith,” he said. “And young people are really smart. They can probably really tell authenticity from someone who’s not telling the truth.”

Schlossberg is running in one of the bluest, most compressed districts in the country — Manhattan’s 12th, stretching from 96th Street down to 14th — so his path to Congress runs through a Democratic primary, not a general election battle against Trump voters. But his argument, delivered over dinner to a room full of corporate executives, is clearly aimed at a broader audience: the Democratic Party, which, unless it rediscovers its appetite for modernity and courage, risks losing an entire generation of young men for good.​

This story was originally featured on Fortune.com
Patreon’s CEO Jack Conte is tired of watching AI companies strike deals with huge corporations like Disney while ignoring the myriad of smaller creators who contribute to their models.

Speaking at the South by Southwest conference this week, Conte, whose company allows people to pay their favorite creators directly, argued AI companies should view creators’ work in the same way it views that of Disney, Conde Nast, or Warner Music, aiming to reach agreements with them rather than use their content without permission.

He attacked the legal doctrine of “fair use,” which allows someone to use copyrighted material without permission or payment depending on the purpose and character of the use, the nature of the original work, how much of the work was used, and whether the use harms the market. AI companies have cited fair use to justify using content to train or contribute to their models without paying. These companies often argue they are using copyrighted content in a “transformative” way and not just regurgitating it verbatim. 

For Conte, this legal “fair use” loophole is utter quackery.

“The AI companies are claiming fair use, but this argument is bogus,” Conte said during the conference. “It’s bogus because while they claim it’s fair to use the work of creators as training data, they do multimillion-dollar deals with rights holders and publishers like Disney, and Condé Nast, and Vox, and Warner Music.”

Conte pointed out the large licensing deals these AI companies have reached with intellectual property owners in recent years demonstrate the double standard of these companies. While AI companies recognize some copyrighted content requires permission and agreements, the same doesn’t seem to be true for creator-made content.

In the past several years, AI companies like OpenAI have made waves for the deals they have struck with some content owners while staving off lawsuits from others like the New York Times, which in 2023 accused OpenAI of training ChatGPT on millions of its articles without permission.

In December, OpenAI, the AI giant led by CEO Sam Altman, struck a deal that saw Disney invest $1 billion in the company and licensed more than 200 characters to OpenAI so they could be featured in the company’s video app, Sora. OpenAI has also signed licensing deals with Condé Nast, which owns The New Yorker and also with Vox Media, which owns New York Magazine. In November, Warner Music Group struck two separate licensing deals with music-focused AI companies Suno and Udio, after settling copyright suits with the companies.

Conte mentioned these deals specifically to highlight the hypocrisy demonstrated by AI companies when deciding who gets a licensing agreement and who doesn’t. Smaller creators, he claims, are being left out.

“If it’s legal to just use it, why pay?” Conte asked the crowd. “Why pay them and not creators—not the millions of illustrators and musicians and writers—whose work has been consumed by these models to build hundreds of billions of dollars of value for these companies?”

A spokesperson for Patreon told Fortune Conte’s comments reflect the mix of excitement and concern the company has heard from creators on how their work is being used and valued in the age of AI.

“At Patreon, our focus is on ensuring creators can build sustainable businesses, and that includes advocating for a future where creators are recognized and compensated for the value they bring, even as technology evolves,” the spokesperson said in a statement.

The AI companies’ fair use claims have been called into question several times as AI models have become increasingly more popular. The New York Times filed a lawsuit in 2023 claiming OpenAI used millions of its articles without permission and that its large language model ChatGPT was in some cases regurgitating entire Times articles, potentially striking a blow to OpenAI’s fair use argument. A date for the trial has not yet been set, but if the Times wins it could be owed billions in damages. More recently, dictionary makers Encyclopaedia Britannica and Merriam-Webster sued OpenAI after it rebuffed the companies’ offer of a licensing agreement in 2024. The publishers claimed in the lawsuit that OpenAI’s ChatGPT is cutting into their search traffic and ad revenue by absorbing the content created by their hundreds of human writers and editors. 

OpenAI rival Anthropic also settled a class action lawsuit by a group of authors to the tune of $1.5 billion in September. As a result of the case, the judge ruled that training an AI model on pirated books—as the authors accused Anthropic of doing—did not qualify as “fair use,” but that training an AI model on purchased books qualified as legal transformative use.

While Conte said he was not against AI, generally, and noted that change is inevitable, humans will continue to enjoy human-created content long into the future, he said.

“Still, the AI companies should pay creators for our work, not because the tech is bad—but because a lot of it is good, or it will be soon — and it’s going to be the future. And when we plan for humanity’s future, we should plan for society’s artists, too, not just for their sake, but for the sake of all of us. Societies that value and incentivize creativity are better for it,” he said. 

March 19: This article has been updated to include comments from a Patreon spokesperson

This story was originally featured on Fortune.com
Social Security is six years from insolvency. That’s not a projection buried in an actuarial footnote—it’s the opening finding of a new report from the Penn Wharton Budget Model (PWBM), released Thursday, which puts the program’s Old-Age and Survivors Insurance Trust Fund on track to run dry by 2032.​

And the fix lawmakers will likely reach for first—raising taxes—may be precisely the wrong move.

That’s the stark, counterintuitive conclusion suggested by PWBM researchers Seul Ki “Sophie” Shin and Kent Smetters, who modeled five distinct reform packages ranging from all-tax to all-cuts and found the approach most conventional analysts dismiss as politically radioactive—deep benefit reductions—generates the strongest long-term economic growth.​

The counterintuitive math

Run the numbers through a standard accounting lens and the tax-heavy plan, called Option A, looks like the winner. It delays insolvency from 2032 all the way to 2058 by raising the payroll tax rate one percentage point (to 13.4%), lifting the taxable earnings ceiling to $250,000 (up from $184,500 in 2026), and switching to a slower inflation index for cost-of-living adjustments.​

Switch to dynamic economic modeling—the kind that tracks how people actually change their saving and working behavior in response to policy—and the picture flips. Option E, the most aggressive benefit-cut plan (no new taxes, deeper formula reductions, and a retirement age raised to 69), projects a 6.1% GDP boost and a 13.5% surge in private capital by 2060. Option A, the tax-heavy plan, delivers only a 2.4% GDP increase and a 4.4% rise in private capital over the same period.​

The mechanism is straightforward: Tell Americans their Social Security checks will be smaller, and they’ll save more on their own. Smetters and Shin call this the “incentive to save.” More private savings means more capital available for productive investment, which drives up wages. By 2060, wages are projected to be 5.7% higher under Option E versus just 1.6% higher under Option A.​

Smetters told Fortune his goal in this exercise isn’t to make recommendations, but to show a “range of options,” instead. If he had to guess, he added, most people would prefer Option C, somewhere in the middle, but he is leaving that to the political process. His job is to “show the tradeoffs across a wide range of options on a holistic basis without bias.”

For critics who argue the math in this analysis is cruel, though, he offered the perspective that the cruelest approach is likely the one on the books under current law, in which benefits would be cut immediately in just six years. This means a $2,500-$2,700 cut in benefits per year for a person retiring in seven years, versus PWBM’s Option E, the harshest scenario, which would cut benefits by $2,300 per year (for women) and $2,500 per year (for men).

Even that comparison hides a lot of pain headed for retirees under current law, Smetters said. Once the trust fund is depleted, current law would cut benefits for all retirees, even the proverbial 90-year-old grandmother. His Option E, on the other hand, would concentrate pain for newer retirees, in their sixties.

Why Washington gets this wrong

The disconnect, the researchers argue, comes down to a concept that rarely makes it into political debate: implicit debt. Under Social Security’s pay-as-you-go structure, today’s payroll taxes flow directly to today’s retirees—a transfer that carries the same economic drag as explicit Treasury borrowing but doesn’t show up on the federal balance sheet. PWBM estimates those implicit pay-as-you-go obligations are currently twice the size of the U.S.’s explicit national debt. If they were booked under standard accounting rules, America’s debt-to-GDP ratio would exceed 300%.​

That’s why plans that look good on paper—Options A and B significantly reduce the official debt-to-GDP ratio—can underperform in the real economy. They cut the visible debt while leaving the hidden debt intact.​

The generational tradeoff nobody wants to talk about

None of this comes free. The gains from aggressive reform flow primarily to younger and future workers, while current retirees and near-retirees absorb the losses. Under Option A, a 60-year-old middle-income earner today loses $30,745 in lifetime value. Under Option E, that same person loses $60,970.​

For someone born in 2051, those options produce lifetime gains of $42,025 and $81,932, respectively—in the same middle-income bracket.​

But the PWBM report does offer one unexpected piece of good news on the fairness front: Achieving the best long-run outcomes for future generations doesn’t always require the worst short-term pain for current ones. Under Option C—a middle-ground package combining some tax adjustments with retirement age increases—most 60-year-olds today actually come out ahead on a lifetime basis, even while future generations gain more than they would under Option A.​

Importantly, none of the five options would fully close Social Security’s long-term funding gap. They would reduce the bleeding, not stop it. And with the 2032 deadline now just one presidential term away, PWBM’s core message is methodological as much as political: Decisions made using conventional budget scoring will lead lawmakers to the wrong place. The math that drives political consensus isn’t the same math that determines economic outcomes.

This story was originally featured on Fortune.com
Welcome to Eye on AI, with AI reporter Sharon Goldman. In this edition: OpenAI to acquire startup Astral, expanding push into coding…Fourteen Catholic theologians have filed briefs in federal court supporting Anthropic…Rogue AI agent inside Meta triggers security alert…Why AI has not yet upset India’s IT industry.

I just got back from a couple of whirlwind days at SXSW in Austin, Texas, an annual collision of music, food, tech, and cultural hype. It’s the kind of event where live music spills out of every building, the tacos and BBQ never seem to end, and somewhere in between, people are busy debating the future of AI.

I was there to moderate a panel presented by U.K. biotech company Basecamp Research—one I suspected would be especially interesting given that the startup began with a 2019 expedition to the Arctic to discover new species and genes. Cofounders Glen Gowers and Oliver Vince found that two-thirds of the samples they hauled back to a makeshift lab in Iceland had never been recorded before. That experience led them to take a bet on building what they describe as an “internet of biology” for AI models to train on. It was a moonshot—an effort to capture 4.4 billion years of evolution and map the entire tree of life, a goal as ambitious as it sounds.

The ‘Trillion Gene Atlas

Six years later, Basecamp Research is still staking out highly ambitious territory. This week, the company said it is launching what it calls the “Trillion Gene Atlas,” an initiative aimed at generating and modeling biological data at the trillion-gene scale. According to the company, the project—developed in collaboration with Anthropic, Ultima Genomics and PacBio, and powered by Nvidia’s AI infrastructure—aims to expand what we know about genetic diversity 100-fold by collecting genomic data from more than 100 million species across thousands of sites worldwide. Basecamp, which has raised $85 million in venture capital to date, is comparing this latest initiative to the Human Genome Project—the landmark sequencing effort that took 13 years and cost roughly $3 billion.

The effort builds on Basecamp’s broader AI strategy. Earlier this year, the company introduced its Eden models, which are trained on its growing biological dataset. The idea is to use those models to identify patterns across genes and ecosystems that would be difficult for humans to detect—potentially accelerating discoveries in areas like drug development.

The differing stakes for data in AI

But what really drew me to this story is the role of data in AI. Over the past few years, massive datasets scraped from the internet to train large language models like ChatGPT and Claude have become increasingly controversial—and legally contested. Several dozen lawsuits have been filed in the United States against major AI companies over the unauthorized use of copyrighted content for training, including one just last week in which Encyclopedia Britannica and dictionary publisher Merriam-Webster sued OpenAI, alleging it used their copyrighted material to train its models and generated responses that were “substantially similar” to their work.

The stakes are different here. AI for science is often held up as the clearest example of what “AI for good” could look like. Curing cancer? Bring on the data. New medicines? Here’s some DNA.

But of course, it’s never quite that simple.

The Financial Times, which covered Basecamp Research in a lengthy article last year, noted that as the company sends explorers to places like Cameroon, Costa Rica, the Arctic ice caps and even Point Nemo—the most remote location in the ocean—it has faced criticism that the effort risks echoing a modern form of colonialism, extracting value from communities without adequately sharing it.

That tension has pushed Basecamp to rethink how countries and communities are compensated for their data. Since 2023, the company says it has paid royalties to 60 organizations across 21 countries based on the use of digital sequence information—genetic data that underpins its AI models. To do that, it has built systems to tag and track the origin of each data sample and measure how much it contributes to downstream outputs, allowing payments to be distributed accordingly. In effect, Basecamp is attempting to trace where training data comes from and to pay for it when it creates value. That’s something that the broader AI industry has so far struggled to do, partly because LLMs are typically trained on vast, messy datasets scraped from across the internet, where ownership, consent and individual contributions from millions of sources are nearly impossible to track.

However, data is also ultimately a trade-off: what we are willing to give depends on what we hope to gain. Basecamp Research’s effort suggests people may be far less willing to accept their data being used to generate endless streams of content than they are to help advance medicine or scientific discovery. In the end, the question is simple: is it worth it? For many, when the goal is curing disease or advancing science, the answer may well be yes.

With that, here’s more AI news.

Sharon Goldman
sharon.goldman@fortune.com
@sharongoldman

Correction, March 20: An earlier version of this newsletter, in the Eye on AI Numbers section, understated the number of interviews Anthropic conducted. The number is 80,508 not 8,508. 

This story was originally featured on Fortune.com
For many decades, students have been steered toward a singular path: go to college, or risk falling behind. It’s a message that took hold in the 1970s and 80s, when school districts removed shop classes—once designed to introduce students to trades like carpentry, welding, and electrical work.

To the detriment of young people today, learning a trade was downgraded as the fallback option, a “vocational consolation prize,” according to Mike Rowe, best known for his stint hosting Dirty Jobs, a show that highlighted the dirtiest—and most essential—jobs in America. 

That shift ultimately “scared parents to death,” Rowe said last week alongside BlackRock CEO Larry Fink at the company’s 2026 Infrastructure Summit. Even with the financial burden of following the college path exploding. And now Gen Z are paying the price.

“Nothing in the history of western civilization has gotten more expensive more quickly than a four-year degree,” Rowe said. “It’s not to say it’s not valuable, but I mean nothing—not real estate, not healthcare, not energy.” 

At least in recent decades, the data backs him up. Between 1983 and 2025, the cost of college tuition has significantly outpaced every other household expense, according to analysis by J.P. Morgan Asset Management.

It’s collectively left young people facing a perfect storm: soaring student loan debt, degrees that don’t translate into stable careers, and an AI-obsessed job market that’s only growing more uncertain. Millions of Gen Z are ending up as NEET—not in employment, education, or training—and stuck in a limbo that college was supposed to prevent.

Simply put, “the kids are not alright,” Rowe said. “If I had an alarm bell, I would ring it.”

Data center electricians are making upwards of $280,000 a year, according to Mike Rowe

That mismatch has created a stark labor imbalance: too many young people chasing degrees, and not enough trained workers to fill critical, in-demand jobs.

Nowhere is that clearer than in parts of the economy tied to the AI boom, where skilled labor is commanding salaries that rival—or exceed—traditional white-collar roles.

During a recent visit to a data center in Plano, Texas, Rowe said he met three electricians—all under 30 years old—earning between $240,000 and $280,000 a year—with no college debt. Even more striking: all three had been poached three times in the previous 18 months.

Electricians, in particular, have emerged as some of the most in-demand—and AI-resistant—professions as companies race to build the infrastructure powering AI. An estimated 300,000 new electricians will be needed over the next decade, on top of replacing roughly 200,000 upcoming retirees.

But the shortage extends far beyond a single trade. Across industries, demand for skilled labor is surging. At Rowe’s foundation, which supports trade training, applications have jumped tenfold over the past year—a sign, he said, that interest may finally be catching up with opportunity.

“Not a week goes by that I don’t hear from the leader of some consequential industry who is freaking out in real time,” he said, pointing to the fact that professions like shipbuilders, welders, and plumbers are all in need hundreds of thousands of workers to meet growing labor demands.

But moving forward, Rowe said what’s emerging is a new reality where post-secondary education is no longer treated as one-size-fits-all—with skills becoming the clearer signal of opportunity.

“This is the trap and it’s so easy to fall into it,” he said. Blue collar versus white collar, shop class versus Brown or Dartmouth. Solar versus nuclear, wind versus fossil—bull crap. None of that, the color of collars is over.”

Mike Rowe isn’t alone—the CEOs of BlackRock, Nvidia, and Ford are worried about skilled trade shortages

Rowe may be best known as a reality TV host—but his feeling about the need for skilled trade workers is being increasingly reinforced by the nation’s top CEOs.

BlackRock’s Larry Fink said in the panel with Rowe that AI will only expand the demand for skilled trade, but the education system hasn’t properly set young people up for success.

“AI is going to create a lot of skilled jobs needs, and the biggest issue confronting our country today and other countries is the speed at which this change is occurring,” Fink said. Just last week, BlackRock announced an investment of $100 million in the training of skilled trade workers.

Nvidia CEO Jensen Huang has also warned that the skilled workers needed to build the physical backbone of AI—from chip factories to data centers—are already in short supply.

“The labor required to support this buildout is enormous. AI factories need electricians, plumbers, pipefitters, steelworkers, network technicians, installers and operators,” Huang wrote in a blog post released earlier this month.

“These are skilled, well-paid jobs, and they are in short supply. You do not need a PhD in computer science to participate in this transformation.”

Ford CEO Jim Farley has echoed concerns about a shortage of manually skilled workers.
“We are in trouble in our country. We are not talking about this enough,” Farley told the Office Hours: Business Edition podcast earlier this year. “We have over a million openings in critical jobs, emergency services, trucking, factory workers, plumbers, electricians, and tradesmen. It’s a very serious thing.”

This story was originally featured on Fortune.com
Business leaders are split on if AI will trigger a jobs armageddon or usher in “super interesting” gigs of the future. And Uber cofounder Travis Kalanick believes the veil is finally lifting on the reality of tech-driven workplace disruption: there’s “another side” to the story, where human employees are more powerful than ever before.

“Until we get super [artificial general intelligence], humans are valuable,” Kalanick said recently on the TBPN podcast. “And they are going to become more and more valuable, because they will be the long pole in the tent to progress.”

The serial entrepreneur and CloudKitchens CEO uses one blue-collar profession as an example: plumbers

If every job in the world was automated except for plumbers, those human workers would be “extremely valuable” because they’re critically essential to the success of expanding infrastructure. New buildings couldn’t be made unless plumbers were readily available—and there would be “so much efficiency everywhere” that they would need millions of people for the task. 

Kalanick also confronted the possibility that all human workers could one day be replaced by super AGI. Still, he offered an optimistic, “white-pilled” take on the situation: new “solutions” will emerge, and there’s no need to fret about a work wipeout—for now.

“Until we get there, I believe we’re going to be super fine,” he continued. “That’s my white pill.”

The CEOs who believe AI will create ‘better’ jobs and ‘superhuman’ working skills

While many workers are hand-wringing over the fate of their careers, there are several CEOs who believe humans will be turbocharged rather than crushed by AI. 

The CEO of DeepMind, Demis Hassabis, believes that AI will actually create new jobs that leverage the tools and “are actually better.” He told Wired in a 2025 interview that so long as everything goes well, the tech will bring about a “golden era” of radical abundance within the next decade. 

Instead of being a job-killer, he predicted AGI will actually be a win for society, curing disease, increasing lifespans, and finding new energy sources starting 2030.

“If that all happens, then it should be an era of maximum human flourishing, where we travel to the stars and colonize the galaxy,” Hassabis continued, adding that AI will serve as “these incredible tools that supercharge our productivity and actually almost make us a little bit superhuman.”

OpenAI CEO Sam Altman also insisted that the coming decade could be the most exciting time in history to start a career, despite the percolating anxiety around AI automation. Echoing Hassabis’ projection, Altman sees massive potential for new human work in space. These universe-explorers will get paid cushy salaries, and will feel “so bad for you and I that we had to do this really boring, old work and everything is just better.”

“In 2035, that graduating college student, if they still go to college at all, could very well be leaving on a mission to explore the solar system on a spaceship in some completely new, exciting, super well-paid, super interesting job,” Altman told journalist Cleo Abram last year. 

Leaders are also lauding the idea that AI will give workers “superhuman” skills—and as the technology advances, it’ll only get better. Instead of being a career threat, Nvidia leader Jensen Huang said that AI gives his peers wings in an industry innovating at breakneck speed. 

“I’m surrounded by superhuman people and super intelligence, from my perspective, because they’re the best in the world at what they do,” Huang told Abram in a 2025 episode. “And they do what they do way better than I can do it. And I’m surrounded by thousands of them. Yet it never one day caused me to think, all of a sudden, I’m no longer necessary.”

This story was originally featured on Fortune.com

Bitcoin dipped below the $70,000 level for the first time in over a week, as stocks sank and energy prices surged following renewed attacks on energy infrastructure in the Middle East.

The world’s largest cryptocurrency fell as much as 2.7% to $69,308 on Thursday, extending a decline from the previous day, when Bitcoin saw its largest drop in three weeks. Other cryptocurrencies such as Ether, BNB and XRP also declined. 

“Bitcoin has likely run out of steam in the short term after dropping nearly 5% over the past 24 hours, with a pullback toward $65,000, a possible outcome in the coming days,” said Robin Singh, chief executive officer of crypto tax platform Koinly. Price action is likely to remain between $65,000 and $75,000 in the coming weeks, he added.

Escalating tensions around the conflict in Iran have triggered a broad risk-off attitude across global markets, with Japanese equities suffering their longest slump since April and European equities falling across the board. Futures for the S&P 500 slipped after the US benchmark wiped out gains for the week in the previous session.

The moves followed Iranian attacks on a major liquefied natural gas site in Qatar, deepening concerns that the war in the Middle East will stoke inflation and hit growth. Brent prices surged to $115 a barrel on Thursday, while European natural gas rose as much as 35%.

“The spectre of stagflation is hovering, with the combination of rising prices and stagnating growth posing a real threat,” Susannah Streeter, chief investment strategist at Wealth Club, said in a note Thursday.

Bitcoin had touched a six-week high of almost $76,000 earlier in the week, as momentum appeared to recover temporarily. The token remains in positive territory over the last month, providing a rare bright spot while other macro assets have been subdued by the conflict, according to Joel Kruger, markets strategist at LMAX Group.

“It is possible that cryptocurrencies were simply unable to ignore the significant deterioration in external sentiment,” added Alex Kuptsikevich, chief market analyst at FxPro. “Overall, however, we maintain a more pessimistic view, anticipating the bear market will continue, with bulls likely to be beaten soon, not least due to macro factors.”

This story was originally featured on Fortune.com
The wrong question about the Paris trade talks isn’t whether they succeeded. It’s why anyone expected them to. China’s negotiating position was set long before anyone sat down at OECD headquarters — and it does not depend on what happens in any meeting room.

After 60 years advising CEOs and boards across the United States, Europe, and Asia — including decades working with Chinese companies and serving on Chinese boards — what came out of Paris only confirmed what I have told business leaders for months: China is not negotiating from uncertainty. It is negotiating from structural advantage.

Both sides called the talks “constructive.” Both described the atmosphere as “remarkably stable.” Both agreed to continue consultations. That is diplomatic language for something more fundamental: no resolution is possible because each side wants what the other cannot give.

China’s position does not depend on what happens in any meeting room. Its exports are still expected to grow 10% to 15% in 2026. Across most industrial categories, there is still no alternative supply chain that can match China on both quality and price. Business leaders I speak with daily are increasing imports from China—not because they want to, but because they have no viable substitute.

That reality is the foundation of Xi Jinping’s confidence. China ran a $1.2 trillion trade surplus in 2025 and is on track to generate at least $1.25 trillion in export earnings this year. No negotiation will quickly change that. Xi is not bargaining from weakness; he is bargaining from a position built over three decades.

That is why the concessions China offered in Paris were predictable. Increased openness to U.S. agricultural imports. A reaffirmation of soybean purchases. Limited discussions around energy and critical minerals. These are real concessions, but they are tactical. They create the appearance of reciprocity while preserving what matters most.

What China ultimately wants is not agricultural trade. It is technology—first semiconductors, then, over time, aerospace.

In recent conversations with senior executives at one of the world’s major aircraft engine manufacturers, a consistent assessment emerged: Chinese firms may already have many of the necessary jet engine designs. The constraint is not design. It is industrialization. Turning those designs into engines that can be produced reliably at scale remains a capability concentrated in the United States, the United Kingdom, and France. As one executive put it to me, “They may have the drawings, but they cannot yet build them at scale.”

This is the gap Beijing is quietly probing in every round of negotiations. It rarely makes headlines, but it is central to China’s long-term strategy.

Much attention is likely to focus on potential reductions in Chinese subsidies. These will be framed as significant concessions. But they are unlikely to change pricing dynamics in any meaningful way. China’s industries operate with massive excess capacity. When survival depends on volume, companies price aggressively with or without government support. The system is already self-sustaining.

This is why tariffs have limited effect. Tariffs operate on margins. China’s advantage is structural: scale, infrastructure, workforce capability, and coordinated state support built over decades. Those advantages cannot be offset in a few years through tariff policy.

Against this backdrop, the delay of the Beijing summit should not be misunderstood. It is not a cost to Xi. It is a benefit.

China has built substantial energy insulation, including large crude stockpiles and a decade-long investment in solar, batteries, and electric vehicles. As global energy markets tighten, China is better positioned than most major economies. At the same time, prolonged geopolitical tension—whether in the Middle East or elsewhere—diverts U.S. focus and increases strategic complexity for Washington.

Time favors the more patient player. And China has made patience a core element of its strategy.

Any eventual agreements will also be reversible. Both sides will retain the ability to pause commitments. Xi is not giving away structural advantages permanently. He never does.

For CEOs, the implications are immediate. The Paris talks did not change the trajectory, and the Beijing summit is unlikely to do so no matter when it happens.

The question is no longer what governments will decide. It is what business leaders will do.

Companies need a clear, unvarnished view of their dependencies: which inputs are irreplaceable, where alternative sourcing is possible, and how operations would respond to disruptions in rare earths, semiconductors, or key industrial components. The most critical risk is not gradual change but sudden interruption—the possibility that China could restrict supply of essential inputs with little warning.

Some CEOs have already mapped these scenarios and built contingency plans. Others are still waiting for policy clarity that may never come.

The reality is this: The United States is buying time to rebuild. China is using time to consolidate. Neither side is stepping back.

The leaders who recognize that dynamic—and act on it now—will shape the next decade. Those waiting for a breakthrough from a summit will find that, quietly, their options have narrowed.

The wake-up call has already sounded. The only question is who is ready to respond.

This story was originally featured on Fortune.com
President Donald Trump’s memecoin team is inviting top holders out to a meal—again. Last week, the outfit behind the $TRUMP cryptocurrency announced that there will be a “once-in-a-lifetime” experience at the Trump family’s private club Mar-a-Lago in Palm Beach, Florida, in late April, according to the conference’s website

Attendees to the “THE MOST EXCLUSIVE CRYPTO & BUSINESS CONFERENCE IN THE WORLD” will have access to a gala luncheon where the President is advertised as a keynote speaker. Moreover, “18 global superstars” will be in attendance, though the website advertising the conference didn’t say who these “global giants” are. In the hours after the announcement, the price of Trump’s memecoin soared almost 60%, according to data from Binance, though it’s declined in price since.

Here’s what we do and don’t know about the second outing for the biggest holders of the President’s memecoin: 

What happened last year?

In May 2025, the top 220 holders of Trump’s memecoin—launched just days before his inauguration in January 2025—attended a dinner held at the Trump family’s Virginia golf club. The President himself appeared and spoke briefly to the audience. Critics, including Democratic lawmakers, called the dinner a blatant pay-for–access scheme. “The President is working to secure GOOD deals for the American people, not for himself,” a White House spokesperson said at the time to Fortune

But even for some attendees who ponied up to see Trump in person, the experience was underwhelming. The meal itself proved to be especially disappointing. “Trash,” Nicholas Pinto, a 25-year-old social media influencer, texted Fortune while he was at the banquet. “Walmart steak, man.”

What’s happening this year?

In spite of the media circus and crowd of protesters that the last dinner attracted, Bill Zanker, a longtime Trump business partner who’s behind the memecoin, is organizing another event. This time, the attendee list has expanded to include the top 297 holders of $TRUMP. And the top 29 holders will be able to attend a VIP reception with their “FAVORITE PRESIDENT and other superstar guests.” Last year, attendees included infamous crypto billionaire Justin Sun, the former basketball star Lamar Odom, and Jack Lu, the CEO of the NFT marketplace Magic Eden.

Pinto plans to attend again, despite his previous complaints about the food, and other attendees from the last dinner are also considering going this year, he told Fortune. While he sold a portion of his holdings, he still owns about $40,000 in the cryptocurrency. “My parents are actually kind of concerned that I’m spending money to go to another lunch,” Pinto said, saying it’s a second chance to talk to other high-rollers. “Anyone that I didn’t speak to will probably be at this event. I can talk to them again.”

Will President Donald Trump be there?

While the website advertising the conference in all capital letters says the President will be in attendance, a White House official told Fortune that Trump’s attendance isn’t yet confirmed. In fact, the President is confirmed to attend the White House correspondents’ dinner, which is on the same day as the conference, said the official. 

Zanker did not immediately respond to a request for comment on whether Trump has confirmed his attendance to the conference or who the “global superstars” are.

Why is Robinhood mentioned?

The page announcing the upcoming conference claims that “Robinhood is the Preferred Platform for the TRUMP Leaderboard.” This leaderboard breaks down who’s accumulated enough of the memecoin to attend the gala luncheon and other festivities. A spokesperson for Robinhood said that the online brokerage is helping its users connect their accounts to the leaderboard to track their Trump memecoin holdings. The company did not pay or get paid for the integration, said the spokesperson.

This story was originally featured on Fortune.com
A simple question: if you wager (or “invest” or “purchase a contract for”) $100 on who will win the NCAA championship next month, is that a sports bet?

If you said yes, you are probably a normal, rational human being. If you said no, you are probably heavily invested in Kalshi or Polymarket. 

So-called “prediction markets” bill themselves as the future of truth in America – tools of price discovery, engines of transparency, an “economic function” that will help us understand the world. All of that brought to you by the same apps where users can “purchase” a contract that says there’s a 37% chance the Wizards cover the spread against the Pacers.

The truth is unregulated sports betting is the main attraction on platforms like Kalshi and Polymarket. The overwhelming majority of activity on predictive markets in the U.S. today is sports gambling. Kalshi has put the figure as high as 90%. Illegal sports gambling isn’t a sideshow on these platforms. It’s what’s propelling their eye-popping valuations

The Commodity Futures Trading Commission’s embrace of these platforms has allowed them to bypass state and tribal regulatory frameworks, offer unregulated online sports gambling all across the country, and skirt hundreds of millions in state sports betting taxes. It is telling that in his defense of prediction markets, CFTC Chair Mike Selig did not mention “sports” once, despite it being the primary use case for prediction markets today.

Congress never gave the CFTC authority to regulate online sports betting, a responsibility that the Supreme Court has affirmed lies with the states. The CFTC was created more than 50 years ago to regulate crop futures and has neither the resources, expertise, nor authority to give operators a blank check to offer online sports betting to anyone and everyone anywhere in the country.

Nearly a dozen states have decided so far not to legalize online sports betting, as is their right. States that have legalized online wagering did so with frameworks in place to protect consumers, set age restrictions, and generate new tax income for community projects. Prediction markets that offer online sports betting don’t comply with any of those voter-approved requirements, and those platforms are even seizing on those age restrictions, which they don’t comply with, to target teenagers and get them hooked on sports betting early.

In South Carolina, the state I previously represented, lawmakers have decided to not yet legalize online sports betting. Prediction markets don’t care, and are actively marketing online sports betting in South Carolina today. I applaud Utah Gov. Spencer Cox for vowing to fight these platforms and the CFTC in court. 

The proliferation of predictive market platforms is misleading Americans, particularly our youth, to conflate investing and online sports betting. We are breeding a generation of gamblers in the process.

That is why I am leading a new coalition to pushback on the disinformation that the prediction markets are aggressively pushing in Washington and across the country. Gambling is Not Investing is a new coalition of consumer advocates united in the fight to ensure all forms of online gambling – regardless of what you call it – are appropriately regulated at the state level.

We should stop pretending these platforms are high-minded financial innovations and treat them as what they are: sports betting platforms operating through a regulatory back door. And if they are doing that in states where sports betting is illegal, then those platforms are illegal. 

If states and tribes must earn the right to offer legal sports betting through legislation, licensing, and strict consumer protections, then so should everyone else. Underage users and at-risk gamblers shouldn’t be “trading the future” without guardrails. And companies shouldn’t be allowed to evade state and tribal law simply by swapping the word “bet” for “predict.”

The solution isn’t complicated: regulate this activity as sports betting. Enforce age standards. Require responsible gaming tools. Pay appropriate taxes. Respect state and tribal frameworks. Protect consumers. And stop letting a clever label rewrite the rules.

Because when someone is wagering on a point spread, it isn’t a “prediction.” It’s a bet.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com
Indonesia’s richest man, Michael Bambang Hartono, who helped turn the Djarum cigarette company into one of the country’s largest business empires and later became a controlling shareholder of Bank Central Asia, Indonesia’s biggest private lender, died Thursday. He was 86.

Hartono died at a hospital in Singapore on Thursday afternoon, the Djarum Group said in a statement.

“With deep sorrow, the extended family of PT Djarum announces the passing of one of our company’s leaders, Michael Bambang Hartono,” the statement said. “We extend our gratitude for his dedication and service.”

The family has not revealed the cause of his death. He had previously acknowledged suffering from chronic obstructive pulmonary disease and a heart attack.

Hartono and his brother Robert Budi Hartono grew their inherited family business into a conglomerate based in Central Java’s Kudus regency, operating in banking, palm oil plantations, properties, electronics, telecommunications, and an e-commerce platform.

Their flagship company PT Djarum produced dozens of domestic and international brands, primarily kretek, or clove cigarettes, including Djarum Black, Djarum Super and L.A. Lights. The brothers also are the biggest shareholders in Bank Central Asia, Indonesia’s largest bank, which had revenue of 57.5 trillion rupiah ($3.43 billion) last year.

Their net worth was more than $43.8 billion, making the Hartono brothers the wealthiest in Indonesia. Michael Hartono had about $25.1 billion in December 2024, making him the 76th richest person in the world, according to Forbes.

In 2004, they won the right to redevelop Hotel Indonesia, a historic site in the heart of Jakarta. They transformed the property into a shopping mall, office, luxury hotel and apartment complex called Grand Indonesia.

Through its parent company, PT Dwimuria Investama Andalan, better known as the Djarum Group, the company has diversified into non‑tobacco businesses, including banking, technology and food.

Djarum also owns PB Djarum, one of Indonesia’s most prominent badminton clubs, whose players have won numerous world championships for Indonesia, and the Italian football club Como. The company was a major sponsor of Indonesia’s top soccer league from 2005 to 2011.

Hartono was also a champion bridge player and the president of the South East Asia Bridge Federation. He received an award from the World Bridge Federation in 2017 for his efforts in making bridge a category in the Asian Games.

He represented Indonesia at the 2018 Asian Games in bridge, winning a bronze medal with his team, making him the oldest Indonesian Asian Games medal winner.

When he and other athletes were honored at the presidential palace for Indonesia’s performance at the Games that year, Hartono received a reward of about $16,700, which he donated to the development of his beloved card game.

Born Oct. 2, 1939, Hartono watched his father roll tobacco with a native clove spice to make the cigarettes Indonesians call “kretek” for the crackling sound made by the burning scented spice. The brothers took over the business upon their father’s death in 1963, worked on developing new blends and began exporting in 1972 to many countries, including the U.S.

They created their first machine-made kretek, the Djarum Filter, in 1976, and introduced the machine-rolled Djarum Super, in 1981.

It is one of the most popular brands in Indonesia, the world’s fourth most populous nation, where more than 64 million adults smoke daily.

Djarum’s clove products are now marketed as “filtered cigars” and are wrapped in tobacco leaf instead of black paper since the Family Smoking Prevention and Tobacco Act banned most flavored cigarettes in the U.S.

Today, about 60,000 workers at their factories manually roll Djarum’s cigarettes, which are sold mostly to lower-income earners.

Hartono is survived by his wife and a son.

This story was originally featured on Fortune.com
European leaders doubled down Thursday on refusing to join the United States and Israel military campaigns in the Middle East as they met in Brussels to grapple with rising oil and gas prices caused by the war.

European leaders have deflected entreaties from U.S. President Donald Trump to send military assets to secure the Strait of Hormuz, a key waterway for the global flow of oil, gas and fertilizer. However, rising energy prices because of the war and fears in Europe of a new refugee crisis have pushed leaders to make the Middle East a priority at the summit.

“We are very worried about the energy crisis,” said Belgian Prime Minister Bart De Wever ahead of the summit. He said that energy prices were too high before the war, but that the conflict “created another spike.”

“If that becomes structural, we’re in deep trouble,” he said.

The summit was initially expected to center on overcoming Hungary’s opposition to a massive loan for Ukraine, but the conflicts in Iran and Lebanon reset the agenda.

European leaders have no ‘appetite’ for joining the war

European leaders have been deeply critical of the Iranian government, but none have offered immediate help to the U.S. Britain is flat-out refusing to be drawn into the war. France says the fighting would have to die down first.

Austrian Chancellor Christian Stocker said that Europe “will not allow itself to be blackmailed” into joining the United States and Israel military campaign in the Middle East.

“Europe — and Austria as well — will not allow itself to be blackmailed,” he said ahead of the European Council summit of the leaders of the 27 EU nations. “Intervention in the Strait of Hormuz is not an option for Austria anyway.”

EU foreign policy chief Kaja Kallas said there was “no appetite” among leaders to expand a European naval force in the Red Sea to help secure the Strait of Hormuz or otherwise join the fray.

Looking ahead to the war’s end

Chancellor Friedrich Merz said the war must end before his country can help with matters such as keeping shipping lanes clear.

“We can and will commit ourselves only when the weapons fall silent,” he said of potential German military support to secure shipping lanes in the Strait of Hormuz. “We can then do a great deal, up to opening sea lanes and keeping them clear, but we’re not doing it during ongoing combat operations.”

He said that would require an international mandate, among other complicated steps, “before we can even consider such an issue.”

While the EU isn’t a party to the conflict, Dutch Prime Minister Rob Jetten said he understood the U.S. and Israeli reasons for launching the campaign against the “brutal” Iranian government. He called for the EU to increase both sanctions on Iran and support for Iranian opposition groups

But others blasted the war as “illegal” and destabilizing.

“We are against this war because it is illegal,” Spanish Prime Minister Pedro Sánchez said: “It’s causing a lot of damage to civilians, of course, refugees and the economic consequences that the whole world, especially the global south, is already suffering.”

Trump had mentioned NATO support for clearing the Strait of Hormuz but has not officially requested it, said Evika Silina, prime minister of Latvia, one of the 23 out of the 27 EU nations that are NATO members.

“When there will be some official requests, I think we always have to evaluate those requests.”

No single fix for the EU’s diverse energy markets

The European Commission has told leaders it has a mix of financial instruments that member nations could deploy to lower energy prices, which will be up for discussion. No single policy will likely work to blunt the economic shocks from the war across the bloc’s myriad markets from Romania to Ireland.

EU leaders are hoping their experience weaning off of Russian energy in the wake of the 2022 invasion of Ukraine and of building up the bloc’s military spending towards self-sufficiency will enable to them to do the same for energy independence.

While some European capitals have called for the suspension or scrapping of climate policies to stave off the worst of the recent spike in energy prices because of the war, others have argued that the EU’s long-term energy strategy should be home-grown sustainable energy decoupled from vulnerable fossil fuel markets.

European Council President Antonio Costa said that “energy means security” and that the EU should “build our own capacity to produce our own energy, because it’s the only way to be secure.”

___

Associated Press writers Pietro De Cristofaro, Geir Moulson in Berlin and Sylvie Corbet in Paris contributed to this report.

This story was originally featured on Fortune.com
Your next laptop, smartphone, or even refrigerator is going to cost more — and you can thank AI for that. The AI boom has triggered what insiders are calling “RAMageddon”: a gold rush on high-bandwidth memory chips that is squeezing out nearly every other buyer in the global market, driving up prices across consumer electronics and straining industries from automotive to healthcare. Even Apple CEO Tim Cook has warned about the pressure AI infrastructure costs are placing on hardware margins.

The biggest AI players have effectively imposed a tax on the entire economy — and most people have no idea it’s happening.

How the once-affordable memory chip became a luxury good

Modern computing relies on several types of memory. SRAM is the fastest and most expensive; it’s used in small amounts inside processors. DRAM is the workhorse of the group: cheap, abundant, found in everything from laptops to cars to refrigerators. Then there’s High Bandwidth Memory or HBM. This is a specialized, premium form of DRAM that stacks chips die-to-die to achieve dramatically faster data transfer speeds. The cost for this premium memory is quite steep: a single silicon wafer provides 3x as much commodity DRAM as HBM. Fab processing time for HBM is significantly longer too, making the supply problem worse. As a result, producing more HBM equates to fewer total memory chips produced.

For AI training and inference, HBM has become the essential ingredient. It’s the jet fuel that powers the GPUs running today’s largest and most advanced models. 

Memory manufacturers have a limited number of wafers they can produce from each fab, or silicon factory. The same production lines that churn out commodity DRAM for the devices consumers use every day are being allocated to building HBM. It’s a rational business decision: HBM commands premium prices in a volatile industry and comes with massive guaranteed purchase orders. In fact, AI firms and their peers have already locked up HBM supply well into 2027. The result is a tightening of commodity memory supply, rising prices, and longer lead times with ripple effects that touch almost every industry. And right now, the industry’s biggest players have cornered the supply, creating the core tension driving the memory shortage. The AI industry is effectively taxing the entire economy in order to build its own.

The memory wall explained

The scale of AI’s memory appetite is staggering. As model sizes have grown from millions to billions to trillions of parameters and context windows have grown from thousands of tokens to tens of millions of tokens, memory requirements have increased in step, and the architecture of data centers has struggled to keep pace. This is the industry’s “memory wall”: a fundamental bottleneck where memory bandwidth and capacity can’t keep up with the processors demanding it.

HBM was an elegant solution to an earlier version of this problem. When models were smaller (such as GPT-2 and GPT-3), placing memory adjacent to the processors and delivering data at extreme speeds worked well. But we’ve since blown past that era. Today’s frontier models exceed two trillion parameters and the next generation will be over five trillion. A single HBM stack holds about 24 gigabytes. That’s roughly one percent of what today’s workloads actually need and far less than that for the next generation of workloads.

The result is that data centers must now scale out exponentially. They chain together hundreds of processors across servers and racks. At that point, HBM’s killer feature of extreme local bandwidth gets strangled by the comparatively slow links connecting all of these machines. The industry has built a gold-plated solution to the problem: AI companies pay the HBM premium while realizing only diminishing returns on performance.

The AI gold rush leaves most behind

The prevailing narrative frames AI infrastructure investment as broadly good: better for memory makers, better for chip companies, better for innovation everywhere. The reality is more lopsided.

Memory manufacturers may profit in the short term. But the true winner is concentration itself. When the HBM supply is locked up by a handful of hyperscalers, it functions as a moat. Startups, enterprises, and established industries all face higher hardware costs and more limited access to the advanced AI capabilities they need to compete. The companies that can afford to stockpile chips don’t just win today; they entrench advantages that could become impossible to dislodge.

Everyone else is caught in the crossfire. Consumers will pay more for devices with less capability. Businesses face a hardware cost environment that has become more taxing and volatile. And the broader technology ecosystem is competing for memory resources against an industry that has essentially unlimited capital to outbid them.

Charting a more sustainable path for AI and memory

The AI industry loves to talk about democratization: open models, accessible tools, intelligence for everyone. That story is increasingly disconnected from the hardware reality being constructed underneath it.

The current trajectory isn’t sustainable. Pouring more investment into HBM capacity addresses a symptom while ignoring the underlying disease. The industry needs to move beyond its fixation on a single memory architecture designed for an earlier era of AI and invest seriously in new approaches—ones that can meet AI’s demands today, and as they grow a hundredfold in the next few years.

Solving this requires more than ramping up additional HBM fabs. It requires a fundamental rethinking of how memory is architected for AI. What’s needed are memory systems that are smart, fast, and compact — architectures that can scale alongside model growth without requiring brute-force resource consumption. Most importantly, the emerging architecture must make AI accessible to more than just a handful of companies.

The memory wall isn’t just an engineering footnote in AI’s rise. It’s the defining infrastructure challenge of this era. The industry’s current answer of “more HBM, faster, at any cost” is a perilous road that risks eroding competition, innovation, and consumer trust. As an industry, we must find a way to do better, and quickly, before it’s too late. The most immediate relief available is a pivot away from HBM dependency toward commodity DRAM architectures engineered specifically for AI’s requirements. The window to act — before the gap between AI haves and have-nots becomes unbridgeable — is closing fast.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com
President Donald Trump is facing perhaps the most daunting question of the war with Iran, one that could define his time in office: Will he put U.S. troops on the ground in Iran to secure some 970 pounds of enriched uranium that Tehran could potentially use to build nuclear weapons?

Trump has offered shifting reasons for launching the war, but he has been consistent in articulating that a primary objective in joining Israel in the military action is ensuring that Iran will “never have a nuclear weapon.”

The president has been more circumspect about how far he’s willing to go to follow through on his pledge to destroy Iran’s weapons program once and for all, including seizing or destroying the near-bomb-grade nuclear material that Iran possesses.

Much of it is believed to be buried under the rubble of a mountain facility pummeled in U.S. bombings Trump ordered last June that he had claimed “obliterated” Tehran’s nuclear program.

It’s a risky, complicated project that many nuclear experts say cannot be done without a sizable deployment of U.S. troops into Iran, a dangerous and politically fraught operation for the Republican president, who has vowed not to entangle the U.S. in the sort of extended and bloody Middle East conflicts that still loom large on America’s psyche.

At the same time, lawmakers and experts remain concerned that if Iran hard-liners emerge from the fighting, they’ll be more motivated than ever to build nuclear weapons as they look to deter the U.S. and Israel from future military action, a dynamic that makes taking control of Iran’s enriched uranium even more critical. That stockpile could allow Iran to build as many as 10 nuclear bombs, should it decide to weaponize its program.

Some lawmakers, like Sen. Richard Blumenthal, D-Conn., say they remain deeply fearful that the president has put the nation on a path that will require putting troops inside Iran for what he called Trump’s confused and chaotic objectives.

“Some of the objectives that he continues to espouse simply cannot be achieved without a physical presence there — securing the uranium cannot be done without a physical presence,” said Blumenthal, a member of the Senate Armed Services Committee.

Meanwhile, Republican allies of Trump stress that there are plans in place to deal with the enriched uranium. Senate Foreign Relations Committee chairman James Risch, R-Idaho, on Wednesday cited “a number of plans that have been put on the table.” He declined to elaborate.

Others acknowledged the complications of deploying troops into Iran.

“No one has given me a briefing on how you would do it without boots on the ground,” said Sen. Rick Scott, R-Fla., a member of the Senate Armed Services Committee. “It doesn’t mean you can’t. But no one’s ever briefed me about it.”

Scott added it’s not tenable to allow the stockpile to remain: “I think it would be helpful to get rid of it.”

Trump and his advisers are rigidly obtuse

Nearly three weeks into a conflict that’s left hundreds of people dead, tested longtime alliances and brought pain to the global economy, Trump and his top advisers have been rigidly obtuse about their deliberations over Iran’s uranium stockpile.

“I’m not going to talk about that,” Trump said last week when asked about the enriched uranium. “But we have hit them harder than virtually any country in history has been hit, and we’re not finished yet.”

Later that day, during an appearance in Kentucky, Trump appeared to claim the strikes had already neutralized the threat. “They don’t have nuclear potential,” he said.

Meanwhile, Defense Secretary Pete Hegseth told reporters earlier this week that the administration sees no point in telegraphing “what we’re willing to do or how far we’re willing to go” while asserting “we have options, for sure.”

Experts say it’s doable but won’t be easy

Richard Goldberg, who served as director for countering Iranian weapons of mass destruction for the National Security Council during Trump’s first term, said that seizing or destroying the enriched uranium is certainly doable, if the president decides to go that route.

The U.S. and Israeli forces have been making strides toward creating the conditions — namely, establishing total air superiority — that would allow for special operations forces operators, who are trained in blowing up centrifuges and dealing with nuclear material, to conduct such an operation if the president decides to go that route.

To be certain, a troops-on-the-ground effort is expected to be far more complicated than other recent high-profile, lightning-strike insertion operations, such as the January capture of Venezuela’s Nicolás Maduro or the May 2011 killing of Osama bin Laden, Goldberg said. And the likely need to remove rubble to get to the canisters of enriched uranium adds another layer of complexity, because it would require heavy construction equipment.

“But if you actually own the airspace and you can have close air support and drones and everything else up in the sky for pretty wide perimeter, presumably you could do a lot,” said Goldberg, who is now a senior adviser at the Foundation for Defense of Democracies, a hawkish Washington think tank.

International Atomic Energy Agency chief Rafael Grossi told reporters in Washington this week that the assumption is much of the enriched uranium remains in the trio of Iranian nuclear sites bombarded last year by the U.S.

“The impression we have … is that it hasn’t been moved,” said Grossi, adding that a bulk of the material is beneath the rubble at Iran’s Isfahan facility while lesser amounts are at the Natanz and Fordow facilities that were destroyed in last year’s American strikes.

Testifying before a Senate committee on Wednesday, Director of National Intelligence Tulsi Gabbard in her prepared remarks said that the U.S. attacks on Iran had “obliterated” Iran’s nuclear enrichment program and buried underground facilities.

Gabbard said the U.S. has been monitoring whether Iran’s leaders will try to restart its nuclear program but said that they have not tried to rebuild their nuclear enrichment capability. She added that the clerical authority overseeing Iranian government has been degraded in Israel’s strikes on its leadership but remains intact.

Brandan Buck, a senior foreign policy fellow at the Cato Institute, said that an effort to extract or dilute the enriched material would likely take more than 1,000 troops at each Iranian site and would take time to complete.

On the other hand, not acting to secure the enriched uranium also comes with risk. Should Iran’s hard-liners remain in power, and with enriched material, they will now have greater motivation to build a nuclear weapon.

“Trump has put himself between a rock and a hard place,” Buck said. “Throughout this, he has had maximalist aims, but he’s wanted to maintain minimal effort in order to keep the costs low.”

___

Associated Press writers Stephen Groves, Matthew Lee and Lisa Mascaro contributed to this report.

This story was originally featured on Fortune.com
Adobe’s longtime CEO Shantanu Narayen announced he was stepping down last week, a move caused, at least in part, by investors’ impatience with the software company’s AI transition. Abode’s stock has been crushed in the “SaaSpocalypse” market selloff that has hit companies whose per-seat software tools are especially vulnerable to automation. Shares are down 25% year-to-date, and investors weren’t impressed with Adobe’s AI-driven quarterly revenue. 

Narayen’s exit is a stark reminder that, after years of hyping the technology, CEOs now must turn their AI rhetoric into results—or risk being shown the door. The make-or-break moment for CEOs is contributing to an era of rapid turnover among chief executives. Last year, companies in the S&P 1500 named 168 new CEOs, the highest total in more than 15 years, according to Spencer Stuart, a global executive search and leadership advisory firm. Already this year, the CEOs of several companies including Lululemon, Disney, Target, and Walmart, have left their roles. 

CEO tenures are getting shorter and fewer incoming chief executives have prior CEO experience, the data shows, making the two-time CEO exceedingly rare. All told, corporate America has turned into a CEO meat-grinder; it’s chewing up and spitting out leaders at a pace not seen in a decade and a half.

“What we’re seeing right now is clearly a sign of stress,” says Dirk Jenter, professor of finance at the London School of Economics and Political Science. AI is only one part of the reason why.

AI hype is becoming a career hazard for corporate leaders

CEOs have been quick to blame recent layoffs of rank-and-file employees on AI, but their own departures are rarely explained so simply. Still, there’s little doubt that expectations around AI are factoring into chief executives’ more frequent departures in one way or another. 

There are circumstances like Narayen’s in which shareholders are displeased with a CEO’s ability to deliver on an AI vision. “Investors are not necessarily super patient,” Jenter says. “They see billions being spent on AI investments, and they see sort of very little in short-term return on investment, and that puts a lot of pressure on company leadership.”

But investors are also expecting CEOs to achieve overall growth on par with the extraordinary gains recorded at companies at the center of the AI revolution, the so-called “Magnificent 7.” 

“There’s increasing pressure on all CEOs to be growing at similar kinds of rates,” says Anthony Nyberg, a management professor at the University of South Carolina’s Darla Moore School of Business. “[It’s] not actually sustainable or manageable for those companies.”

A surge in shareholder activism is another sign of investors’ growing impatience. Activist campaigns hit an all-time high of 255 last year, surpassing the 2018 record, according to Barclays. U.S. campaigns rose 23%. 

Activists are increasingly targeting CEOs. “Five or ten years ago, activism was largely about corporate policies,” Jenter says. “Now they’re going directly after the top leadership of companies.” Thirty-two U.S. CEOs resigned within a year of an activist campaign, a 38% increase over the four-year average, Barclays’ data shows. 

And then there are instances in which boards tap fresh (often younger) blood to guide companies through the AI transition. Doug McMillon, Walmart’s highly-respected former CEO who, by all accounts, left on his own terms, cited AI in explaining his decision to step down in January. He said his successor, John Furner, was “uniquely capable of leading the company through this next AI‑driven transformation.”

Another force behind the churn: Today’s board directors are less likely to be current or former CEOs than in the past, studies show. Nyberg argues that these less CEO‑centric boards tend to be less sympathetic to sitting chiefs—and perhaps less attuned to the full scope of the job—making them more inclined to support a leadership change.

Experts also argue that CEO turnover is catching up after a backlog from the COVID era, during which boards favored continuity. 

All told, CEOs are getting less time to deliver on their visions. The average tenure for S&P 1500 CEOs hit 8.5 years last year, down from 9.2 years in 2024—and the shortest since 2019. 

The broader CEO churn trend 

The rapid turnover is requiring boards to fulfill their succession planning responsibilities, and they’re increasingly dipping into their companies’ own ranks to replace chief executives. 

The share of externally hired CEOs hit 60% in 2025, up from 57%, a historic low, in 2024. But there are signs that boards have been caught off-guard by the pace of CEO turnover. Nineteen new CEOs were appointed from their company’s board last year, the most since 2020, according to Spencer Stuart, “suggesting that some companies are not ready for succession.” 

Almost always, internal CEO hires lack prior chief executive experience, a trait that shows up in the data. In 2025, 84% of newly appointed S&P 1500 CEOs in 2025 were serving in their first enterprise CEO role, reversing a multiyear trend toward CEOs with prior public-company experience.

Boards often view experienced CEOs as a safer bet, but Spencer Stuart research shows that, compared to veteran chief executives, rookies led their companies to higher market-adjusted total shareholder returns, with less volatility in the stock price.

As the number of first-time CEOs has increased, the age of new CEOs has dropped, hitting 54.4 in 2025, down from 55.8 in 2024. The share of incoming CEOs 60 and above fell to 18%, after hovering near 30% for the past two years.

Even with higher stakes and higher turnover, today’s CEOs are unlikely to garner much sympathy from the wider public. Median chief executive compensation hit $16.5 million in the S&P 500, according to 2025 proxy filings. (Exorbitant pay may actually be one reason two-time CEOs are so rare; few need the money.) 

Still, rapid CEO churn should raise alarm bells outside the boardroom. CEOs who hold onto the job past year ten beat the S&P 500 over the course of their time in the job, more than those in any other length of tenure, Spencer Stuart research shows. “That’s where the greatest shareholder value creation comes in,” says Jim Citrin, chair of the firm’s global CEO practice. “Longer is better.”

This story was originally featured on Fortune.com
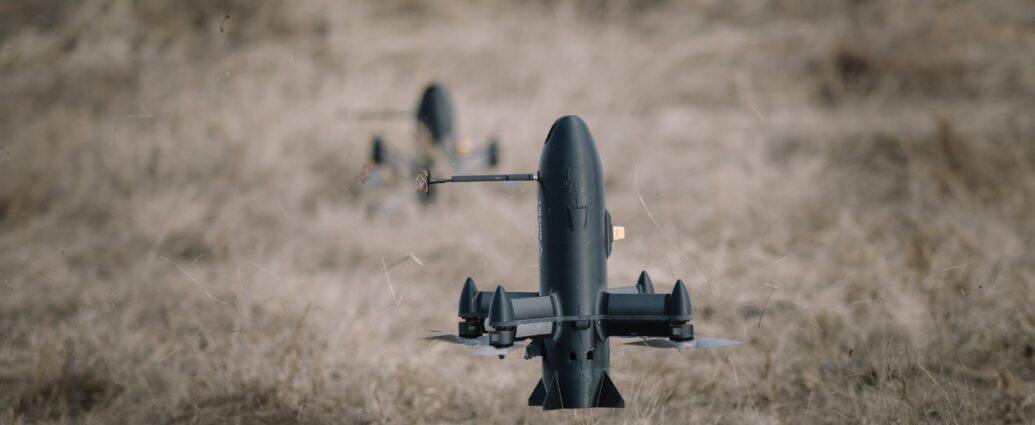
Global energy prices soared Thursday after Iran attacked two oil refineries in Kuwait and a key natural gas facility in Qatar that can supply one-fifth of the world’s liquified natural gas.

The attacks added to fears the energy crisis triggered by the closure of the Strait of Hormuz to tanker traffic may be longer and more extensive than feared, with lasting damage to oil and gas production.

Brent crude, the international benchmark, rose nearly 6% to $113.77 per barrel, up from less than $73 per barrel on the eve of the war. U.S. benchmark crude was less affected by the latest attacks in the Middle East, rising less than 1% to $96.26 per barrel.

The European TTF benchmark for natural gas prices traded 17% higher on Thursday and has doubled in the past month.

The Iranian attack hit the Ras Laffan terminal for shipping out liquefied natural gas in Qatar. Qatar normally supplies some 20% of the world’s consumption of LNG, which can be carried by ship. The facility shut down after a drone attack. The closure of the Strait of Hormuz to most tanker traffic also left the gas with nowhere to go.

If the disruptions from Iran’s attacks on its Gulf Arab neighbors’ energy infrastructure keep oil and gas prices high for long, they could create a debilitating wave of inflation for the global economy.

Markets on Wall Street slipped before the opening bell. Futures for the S&P 500 and Dow Jones Industrial Average each fell a 0.1%, while Nasdaq futures dipped 0.3%.

On Wednesday, the Federal Reserve opted to leave its benchmark interest rate alone and projected just one more quarter-point cut this year due to ongoing elevated inflation and uncertainty about the ramifications the Iran war will have on the global economy.

Prices for gold and silver also tumbled, dragging down major mining stocks with them. Gold fell 4% to $4,697 an ounce, while silver slipped 8.7% to $70.80. Most industrial metals also saw their prices fall.

Shares in miners Hecla and Newmont slid 7.8%, while Freeport-McMoRan fell 4.6%.

Markets in Europe and Asia were getting hit much harder than U.S. markets. Germany’s DAX lost 2.4% by midday, the CAC 40 in Paris fell 1.7% and Britain’s FTSE 100 shed 2.1%.

In Asian trading, Tokyo’s Nikkei 225 fell 3.4% to 53,372.53 as the Bank of Japan also opted to keep its benchmark interest rate on hold at 0.75%, citing the war with Iran as one factor.

In its monetary policy statement the BOJ said that “in the wake of increased tension in the Middle East, global financial and capital markets have been volatile and crude oil prices have risen significantly; future developments warrant attention.”

Higher oil prices are a heavy burden for Japan, which like South Korea and Taiwan depends on imports of most raw materials for industries that rely heavily on oil and its derivatives.

The Kospi in Seoul lost 2.7% to 5,763.22.

In Hong Kong, the Hang Seng slipped 2% to 25,500.58, while the Shanghai Composite index shed 1.4% to 4,006.55.

Australia’s S&P/ASX 200 lost 1.7% to 8,497.80 and Taiwan’s Taiex fell 1.9%. In India, which has also suffered from shocks to supplies of oil and gas, the Sensex lost 2.7%.

“The combination of higher oil, rising U.S. yields, and a stronger dollar is acting as a macro wrecking ball across Asian assets and currencies,” Stephen Innes of SPI Asset Management said in a commentary.

___

Business Writer Matt Ott reported from Washington; McHugh contributed from Frankfurt, Germany.

This story was originally featured on Fortune.com
The Pentagon is seeking $200 billion in additional funds for the Iran war, a senior administration official says.

The department sent the request to the White House, according to the official, who spoke on condition of anonymity to discuss the private information.

It’s an extraordinarily high number and comes on top of extra funding the Defense Department already received last year in President Donald Trump’s big tax cuts bill.

Congress is bracing for a new spending request but it is not clear the White House has transmitted the request for consideration. It is unclear the spending request would have support.

The new funding request was first reported by The Washington Post. Asked about the figure at a press conference Thursday, Defense Secretary Pete Hegseth did not directly confirm the figure, saying it could change. But he said “we’re going back to Congress and our folks there to to ensure that we’re properly funded.”

“It takes money to kill bad guys,” Hegseth said.

This story was originally featured on Fortune.com
“What torments of grief you’ve endured from evils that never arrived,” wrote Ralph Waldo Emerson, the 19th-century American philosopher and writer. Millions of workers are feeling similar. How many jobs will artificial intelligence destroy? And are we all worrying unnecessarily? 

“The demand for human labor will not go away,” Mohit Joshi, the chief executive of the Indian information technology giant, Tech Mahindra, tells me. The world is entering an era of technology complexity and new business opportunities. The changes are likely to increase demand for ‘humans in the lead’, even though the job specifications will be radically different.  

Joshi has data and historical precedent to back up his assertion. In the 1990s, many companies, spooked by the threat of the Millennium Bug, invested heavily in technology updates as a protective measure. The bug—linked to the New Year date change from the 20th century to the 21st—never materialized, leading to predictions that tech spending would fall back to 20th century levels. It went in the opposite direction and the ‘trend to spend’ continued. 

“The demand for human labor will not go away.”

Mohit Joshi chief executive of Tech Mahindra

Similar momentum is apparent in 2026 when it comes to the effects of artificial intelligence on workforces. “We think the productivity gains will not result in immediate headcount impacts,” Joshi says. “There is a lot of investment that will need to happen over the next couple of years to drive simplification, modernization and optimization. And, especially on the data side, investment will be required beyond the three to five years that it will take to modernize and simplify systems.” 

“In the best case beyond that, I feel the complexity of organizations will increase dramatically. And, if the AI premise gets realized fully, the economic growth is going to be so much more significant. It should create more opportunity, because you will have a much larger landscape.” 

Read more: AI is capable of remarkable feats. And has the power to kill. Meet one woman warning about the dangers ahead

Elon Musk talks of an era of abundance, ushered in by an applied AI revolution where a robot can do your shopping and energy comes from space. The journalist Ezra Klein has written a book of the same name, Abundance, arguing that governments have a key role to play in ending the age of scarcity. Products and services will change so radically that demand for employees will increase. 

“My own advice to my teams is that there will always be somebody who’s a winner,” Joshi says. “And my sense is that the people who are winning will have a few attributes. The first is that they will be fast, because there’s a gigantic premium for speed. You need to be able to pivot very quickly.” 

“The second is curiosity. And the final thing is, at a time of great change, leaders will need a degree of empathy and kindness to be able to carry teams along with them.” 

The ‘waterfall method’ of change is well known to business leaders—a sequential plan where projects are strictly defined and work is often driven through divisional silos with little opportunity for re-assessment. Most now lean towards the ‘agile method’, a more flexible approach to project management which encourages working between teams across the business. 

How to build AI into the agile process is the key question. “What can you do to drive productivity and efficiency in your business?” Joshi says. “What is it that you should be doing to drive revenue in your business? Because productivity is nice, but revenue is really the most important piece.” 

“…at a time of great change, leaders will need a degree of empathy and kindness to be able to carry teams along with them.” 

Mohit Joshi

Return on AI investment is the key metric boards will want to see. “It’s very clear that organizations are going to get a lot flatter,” Joshi says. “You will have people at the top who will have a lot more in terms of span of control. You will have maybe a bulging middle instead of the traditional pyramid that we’ve had.” Employees with five to ten years’ experience will become ever more valuable. 

Not everything is digital. Joshi laughs as we notice that we both write with pens on paper (it helps me think more clearly). He encourages his children to read physical books, with a small pocket-money boost for each one completed. 

“What I tell my kids, almost obsessively, is that the ability to read and write well will never go away. So read as widely as you can early in life, because you will never again get this opportunity of unbroken periods of time where you can read, nor will your memory ever be as good to absorb as much as you can today. Learn to speak and write beautifully, and I think everything else will fall into place.” 

This story was originally featured on Fortune.com
Good morning. The Walt Disney Company’s CEO transition is notable not just for who is ascending, but for how deliberately the company built financial stability around it by extending CFO Hugh Johnston’s contract months before a new CEO was even named.

Josh D’Amaro, a 28-year veteran of the company, took over as chief executive at Disney’s annual shareholders meeting on Wednesday, succeeding longtime CEO Bob Iger. Named to the role on Feb. 3, D’Amaro most recently served as head of Disney Experiences, which includes the company’s theme parks, cruise line, resorts and consumer products.

There was some praise for Iger on social media. “What you have built is not a career, it’s a LEGACY,” NBA star Chris Paul said in a post on LinkedIn.

Iger, who had a long career at Disney, served as CEO from 2005 to 2020, then returned in 2022 following the controversy-filled tenure of his first replacement, Bob Chapek. He will temporarily stay on as a senior advisor and board member, stepping down eight months ahead of schedule.

A potential merger between Paramount Global and Warner Bros. Discovery could increase competition for Disney (No. 46 on the Fortune 500). But D’Amaro could be well-positioned to lead growth. Under his leadership, Disney’s parks and experiences became the company’s primary profit engine, accounting for more than 70% of operating income despite representing under 40% of total revenue, Fortune reported. Streaming is the other major growth driver, following consecutive quarters of profitability.

In November, Disney extended Johnston’s contract through Jan. 31, 2029—before the new CEO was even announced. He joined Disney in 2023, following a long career at PepsiCo. Johnston has a “well-earned reputation as one of the best CFOs in America,” Iger said in a statement in 2023.

At the Morgan Stanley Technology, Media and Telecom Conference earlier this month, Johnston called Disney’s CEO succession process a strength. “I would tell you they looked internally, externally, they really pushed hard on the candidates, and came to a conclusion that is a terrific one,” he said.

He described both D’Amaro and Dana Walden, who will become the company’s president and chief creative officer, a new role, as “terrific growth-oriented executives.” Walden was widely reported to be a CEO contender.

“There’s a lot of energy there in terms of people being excited about Josh, being excited about the fact that this process was also handled so smoothly,” Johnston said. “You all know some of the history of Disney and CEO successions going all the way back to Michael Ovitz. This couldn’t have been more different than that. It was a really smooth, well-run process with minimal drama.”

Johnston reaffirmed guidance for double-digit EPS growth in both 2026 and 2027. On M&A, he said Disney doesn’t need to do significant deals. “We’re very fortunate that with the moves that Bob Iger made during his tenure as CEO, whether it was acquiring Pixar, Lucasfilm, Marvel, and then the Fox acquisition, we were kind of in front of the curve in terms of generating a large collection of IP,” he said.

Sheryl Estrada
sheryl.estrada@fortune.com

This story was originally featured on Fortune.com
Good morning. In today’s Fortune:

  • Global stock market selloff as Iran war expands to attacks on major gas fields.
  • Trump admits he ‘knew nothing’ about Israel attack on Iran site.
  • The Marines are coming. Get ready for boots on the ground.
  • Inside Iran’s war strategy: Survive and resist.
  • China is sitting back to watch the chaos.
  • AI: Sales tripled at chipmaker Micron.
  • Chart: There is a record number of objects orbiting Earth.
  • Women are underrepresented in AI as workers and users.
  • Perk watch: Some companies pay private school fees for CEOs’ kids.

This story was originally featured on Fortune.com
Event platform Posh raised a fresh $37 million to solve one of the quintessential “tarpit” startup ideas: turning the “what are we doing tonight?” group chat into an actual plan.

Founded in 2019 by then‑New York University students Avante Price and Eli Taylor‑Lemire, Posh began as software they built to run their own events after getting cheated by promoters and hitting the limits of Eventbrite. “I was using Eventbrite and other products to manage events, and then realized that the technology components were missing a ton of the capabilities that I needed,” Price told Fortune. That pain point became Posh’s product: a business‑first platform where organizers, not the marketplace, sit at the center.​ The company is already capturing corners of the events industry which is on track to be worth more than $2 trillion by 2028.

Now, the company has raised its $37 million Series B led by FirstMark Capital with Causeway Ventures, Goodwater Capital, Companyon Ventures, and Epic Ventures, Fortune has exclusively learned.

Posh’s model is straightforward: Posh takes about a 10% cut on paid tickets plus a 99‑cent fee per ticket, its primary revenue stream. In 2024, the company generated roughly $10 million in revenue on more than $83 million in ticket sales (the same year it raised $22 million in Series A funding). Today, the business has grown to an estimated $40 million in cumulative revenue, according to Price, processing $350 million in GMV and 25 million tickets since inception, with top organizers generating over $10 million on the platform. “What you have to do is you have to own the transaction first,” Price told Fortune

Posh already powers everything from Palm Tree Festival and We Belong Here to brand activations with Lamborghini, Adidas, the NBA, Celsius, HBO, and Complex. The company has also poached talent from Meta, Reddit, Amazon, Hinge, Spotify, Block, and Canva to accomplish its goals. For the first four years, Posh was essentially “Shopify for events,” focused on tooling for nightlife: white‑label pages, SMS CRM, referral kickbacks, linked ticket tiers, and instant payouts. Now, with roughly 50,000 organizers and nearly 8 million users, the center of gravity has shifted toward demand—what Price calls a “Netflix‑style feed” that surfaces parties, activities, food and drink, and other categories based on where your broader social graph is actually going. 

“The solved problem is your core group chat,” he says. “The harder problem is those 10 or 20 people you’d love to catch up with but never text. We’re trying to reintroduce that serendipity.”​

See you tomorrow,

Lily Mae Lazarus
X:
@LilyMaeLazarus
Email: lily.lazarus@fortune.com
Submit a deal for the Term Sheet newsletter here.

Joey Abrams curated the deals section of today’s newsletter. Subscribe here.

This story was originally featured on Fortune.com
Sunway Healthcare shares rose 28% in their first day of trading, following the company’s 2.9 billion ringgit ($732 million) IPO, the country’s largest in nearly a decade. Shares of the Kuala Lumpur-based hospital operator, previously the healthcare arm of Malaysian conglomerate Sunway Group, closed at 1.85 ringgit on Wednesday, up from the offer price of 1.45 ringgit. The listing is Malaysia’s biggest since 2017’s IPO of Lotte ​Chemical Titan Holdings.

Sunway Group previously said the spin-off will help unlock shareholder value and improve the business’s access to capital markets. In Sunway Healthcare’s IPO prospectus, Sunway described the health business as a “distinct and viable business of its own.”

Sunway Healthcare generated 1.6 billion ringgit ($403 million) in revenue during the first nine months of 2025, a 17.8% year-on-year jump, according to its prospectus. Yet the company’s profits over the same period declined by 22% year-on-year to hit 140 million ringgit ($35.4 million).

Following its IPO, Sunway Healthcare will continue to operate its network of private hospitals, ambulatory care services and ancillary services, with plans to expand to eight hospitals totalling over 3,400 beds by 2032. Sunway Group will also retain majority control of its healthcare offshoot, owning 69.4% of the shares

Sunway Group, No. 190 on Fortune’s Southeast Asia 500 list, posted record revenue of 9.8 billion ringgit ($2.5 billion) in 2025, up 24.5% from the year before. The revenue jump was fueled by strong performance across most of its business segments, including property investment and construction.

Malaysia’s greying population

Sunway hopes to tap growing healthcare demand in an aging and wealthier Malaysia. “The outlook for Malaysia’s private healthcare services industry remains positive,” Sunway Group wrote in its Q4 2025 earnings report. “Malaysia has one of the largest middle-income populations in ASEAN, coupled with rising life expectancy and a growing incidence of non-communicable diseases.”

Malaysia has a rapidly aging population, with 14.5% of its population set to be 65 and older by 2040, according to the Malaysian Department of Statistics. Over 2 million Malaysians are living with non-communicable diseases including diabetes, hypertension, high cholesterol and obesity.

Investors are eager to invest in Malaysia’s healthcare boom. KPJ Healthcare, No. 303 on Fortune’s Southeast Asia 500, hit a record share price of 3.53 ringgit during intraday trading on March 18.

Malaysia’s stock exchange, the Bursa Malaysia, has also been having a blockbuster year. The KLCI Composite Index is up by 14.1% over the past 12 months, and breached a six-year high in mid-January. According to Deloitte, Malaysia had more IPOs than other Southeast Asian markets, with 59 IPOs raising 5.5 billion ringgit ($1.4 billion) in 2025.

The Malaysian ringgit has also risen to its strongest value in five years, propelled by AI optimism and rising energy prices. “The Ringgit should be one of the best performing currencies in Asia this year,” wrote Goldman Sachs strategists in a March 14 research note.

This story was originally featured on Fortune.com
My oldest daughter starts an internship at Deloitte this year. She’s capable and motivated. She’s also walking into a professional environment that is wildly different from what it was even a few short years ago.

I started my career more than a few short years ago. Back then, success had a simple formula: be the first one in, be the last one out, and always ask for more work. Effort was measured in hours. Visibility was measured in face time. That commitment still matters — I’m not going to tell my daughters that hard work doesn’t matter. But I am going to tell them that hard work alone won’t cut it anymore.

They need to work differently — and so does everyone else.

What working differently actually looks like

From my experience as both a CEO and a father, I’m genuinely impressed by Gen Z’s fluency in digital communication. They text. They message. They send voice notes. That’s very useful when communicating with each other. But it has its limits, even in this hyper-digital moment. Building trusted relationships is more important than ever.

A workplace includes people who came up through email culture, phone call culture, and even memo culture. Every generation connects differently, and each method has its place. My daughters will need to adjust their approach to fit the preferences of the people they work with, rather than expecting everyone else to adapt to them.

I’ve told them this directly: figure out how your manager prefers to communicate — even ask them — then use that method. Figure out how the finance team operates, how the field team talks, how the executives want information delivered. This isn’t about abandoning your style. It’s about building range. Be a communicative chameleon.

Building that range also means building capacity for adaptation. Gen Z’s digital fluency will seem outdated to the generations behind them — and they don’t even have to wait for Gen Alpha to enter the workforce. Things are changing much faster than that. Adaptation isn’t a strategy. It’s the baseline.

Where AI fits in

AI has become one of the most practical tools available for exactly this kind of adaptation — and most people entering the workforce aren’t using it this way yet.

I do this in my own work. Before major presentations, I feed my deck into an LLM and ask how my message might land with different audiences — the board, my direct reports, a customer. It doesn’t do the work for me, but it surfaces perspectives I might not have considered, helping me tailor my communication for maximum impact. If a Fortune 500 CEO is using AI to pressure-test how his message will land before a board meeting, a 22-year-old starting her first job should be doing the same thing.

For someone entering the workforce, this is a practical starting point. You’re walking into rooms — virtual or otherwise — full of people who think differently than you do, communicate differently than you do, and have expectations you haven’t learned yet. AI can help you anticipate how a message will be received before you send it. It can help you build emotional intelligence across departments and age groups — skills that used to take years to develop through experience, trial and error.

The tool is new. The goal isn’t. You’re still trying to connect with people — AI just gives you a way to rehearse before the stakes are real.

There’s no substitute for showing up

AI can help bridge communication gaps, but it’s still just a tool. There are people on both ends of every interaction, and there’s no substitute for human connection at work.

“Showing up” looks different in many companies now, with in-office, remote, and hybrid work physically separating colleagues. But digital elements are facilitators — not replacements. Showing up means more than logging into meetings; it’s about turning your camera on, engaging actively, and looking for ways to add value. True presence, whether virtual or in-person, requires intentional effort to connect, build trust, and participate fully.

My daughters will enter a workforce where building relationships across teams takes deliberate effort. Nobody’s going to bump into them in a hallway and offer career advice. They’ll need to seek it out and cultivate a circle of trusted advisors to help them through every stage of their careers.

The advice I keep coming back to

Early in my career, someone told me: look for ways to take on more than your job description. Don’t wait to be asked. Find the gap and fill it.

That advice hasn’t changed. Work ethic is still the foundation. But outworking your peers today means something different than it did in 1995. It means adapting. It means communicating in ways that land with people who think differently from you. It means using the tools available to sharpen your judgment, not replace it.

My daughters are smart enough to figure most of this out on their own. But the rules of the game have changed fast enough that even people 30 years into their careers are still catching up. The advantage goes to whoever adapts first.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com
  • In today’s CEO Daily: UL Solutions CEO Jennifer Scanlon talks to Fortune’s Diane Brady on the company’s new UL 3115 standard
  • The big leadership story: How to earn $18.4 million without working a single day
  • The markets: It’s bad out there
  • Plus: All the news and watercooler chat from Fortune.

Good morning. For more than 120 years, UL has put its mark on products from tree lights to toaster cords to convey a promise: This won’t kill you. Last week, for the first time, the $3 billion-a-year safety science company issued a new certification for AI-embedded products. As UL Solutions CEO Jennifer Scanlon told me: “Innovation without safety is failure.”

Rarely has there been a technology that’s evolved so fast with so little oversight. (The patchwork of emerging state laws adds to the confusion.) This week, the spotlight is on OpenClaw, the autonomous virtual agent that’s spawned a new craze in China. It got a shout-out from Nvidia CEO Jensen Huang during his developers conference this week, where he announced NemoClaw and declared OpenClaw framework to be “the next ChatGPT.”

Can private-sector safety standards do what Washington has not: provide guardrails to fast-moving technologies with potentially profound consequences? The UL mark already goes on about 22 billion products worldwide every year. This latest standard, UL 3115, evaluates whether an AI-enabled product is safe, robust and well-governed with a “human in control” throughout a product’s lifecycle. “Whether or not there’s government regulation around this, our customers are coming to us because they need broader protections and assurances,” Scanlon told me. “They’re clamoring to have at least a standard that they can adhere to that gives them the confidence in how they’re getting out in front of their customers.”

UL’s expertise is in functional safety. As Scanlon puts it: “When you turn the radio on in your car, you do not want your brakes to slam. So how is that embedded software being tested and proven? They’re embedding AIs in toys. How do we know those toys are safe for kids?”

That’s why UL’s AI Center of Excellence set out to apply its safety protocols to the new world of AI-embedded physical products. “We start with an outline of investigation, which is a precursor to safety. That’s our engineers and scientists working with customers to understand what they’re worried about, what they believe the challenges are—and then we come at it from the scientific perspective, which is: what else should you worry about?”

“In the case of AI‑embedded products, they started thinking about: How transparent is the algorithm? How much bias is built into those algorithms? What’s the veracity of the training data? And if some of that training data is not true, how do you eliminate it from the learning model? And type of human oversight and verification—that essential final check—is in place? What are those processes?”

Thus far, two products have been AI‑certified: Qcells’ Energy Management System, an AI-enabled control engine for data centers, and the Omniconn Platform 4.0, a smart building solution. It’s one part of the puzzle in a world where leaders are trying to match speed with safety.

Contact CEO Daily via Diane Brady at diane.brady@fortune.com

This story was originally featured on Fortune.com
If you’re an investor who has notched magnificent returns from the Magnificent 7, it might be time to ask: Is it time to get out? The answer is yes according to Rob Arnott. Arnott is the founder and chairman of Research Affiliates, a firm that oversees strategies for nearly $200 billion index funds and ETFs for the likes of Charles Schwab and Invesco. Overall, his predictions for the markets are grim: He warns that shareholders in U.S. big caps will make one-fifth the returns over the next 10 years they pocketed since 2016, and those meager gains will barely edge the CPI.

But U.S. big tech investors are a in for a special world of hurt, he predicts. When he digs into the difference in prospects between the S&P value and growth contingents, a big gulf emerges. The RA model predicts 4% annual gains in the former and a shockingly puny 1.4% in the latter, meaning the recent champs’s returns will lag inflation by one-percent. Much of the drag, he says, arises from the big valuations, on top of earnings so gigantic they’ll be hard to grow big from here. A major reason we saw that double-digit EPS boom rampage, he avows, “is the stupendous growth in the Mag 7.” Now, he adds, “Valuations for growth stocks are very stretched, driven by the Mag 7. The market’s saying it’s a foregone conclusion they’ll grow earnings like crazy. But to beat the market, they’d need to grow earnings even faster than those lofty expectations.”

Arnott’s especially skeptical of the premium prices awarded by investors expecting fantastic profits from AI. “The companies making money from AI are the ones selling the tools,” he says. “They’re now lending to their own customers so that those customers can keep buying their stuff. And their customers are having a hard time monetizing that equipment.” Arnott related that he’d just used Perplexity to perform an in-depth study of how various tax increases being proposed would affect marginal rates at different income levels, and paid nothing for the service. “These AI providers will figure out how to make money,” he says. “But not as fast as the expectations that are built into their stock prices. It will be a slow build over a long period, meaning returns on these stocks will be much lower than the market’s baked in.”

Here’s his advice: “If you’ve owned the Mag 7, say ‘thank you very much, Mag 7,’ and get out and don’t ride them back down.” Arnott believes that returns will be much bigger outside the U.S. than stateside. For example, RA posits that developed nation, non-U.S. value stocks will provide 7.4% returns going forward, more than twice the expectation from the S&P 500, and that emerging markets value shares will do even better at 7.6%. Arnott concludes that the best strategy is to “first, own no U.S. shares or at least lighten up, and second, own no growth stocks anywhere.”

This story was originally featured on Fortune.com

As the national debt careens above $39 trillion, the Trump Administration is weighing policy changes that could heap hundreds of billions of dollars onto the growing tally, economists warn.

Earlier this month, a host of Republican lawmakers, led by Texas Sen. Ted Cruz and South Carolina Sen. Tim Scott, sent letters to Treasury Secretary Scott Bessent urging an executive action to index the agency’s calculation of capital gains taxes to inflation. The change would lower taxable capital gains through an adjustment of the cost basis of an asset to account for inflation. 

The Committee for a Responsible Federal Budget, a Washington-based fiscal watchdog, warned in a report published on Tuesday that the executive action would slash tax revenue, heaping an additional $170 to $950 billion onto the national debt by 2035, citing data from the Yale Budget Lab.

“The last thing we need is more deficit-financed tax cuts—especially ones enacted by executive fiat,” CRFB president Maya MacGuineas said in a statement. “With debt approaching record levels and interest expenses exceeding $1 trillion a year, we need more revenue, not less.”

Republican lawmakers have advocated for tax breaks on the basis that individuals having more money in their pockets can be used to increasing spending, productivity, and economic growth. Efforts to cut taxes through capital gains indexation have been going on for years, including during President Donald Trump’s first administration, when Cruz introduced a bill in 2018 calling for then-Treasury Secretary Steven Mnuchin to change regulations around indexing capital gains. Proponents argue adjusting capital gains for inflation prevents investors’ “phantom” gains from being taxed, and that taxing investments should be curtailed to incentivize injecting more money into the economy. 

The winners of capital gains indexation

Investors also have a lot more to gain from indexation today. The Yale Budget Lab noted that in 2018 when legislation around capital gains tax cuts was introduced, the Congressional Budget Office projected $9.5 trillion in taxable capital gains realizations over a ten-year period. Today’s projection has nearly doubled to about $16.5 trillion, driven by the S&P 500 being nearly twice its 2018 value and after years of low pre-pandemic inflation that suppressed cost-basis adjustments. 

These investors also skew wealthy, with more than 90% of stocks owned by the richest 10% of Americans, according to Federal Reserve data. As a result, tax cuts through capital gains indexation are regressive, benefiting the top tier in the K-shaped economy of the rich getting richer as lower-income Americans continue to struggle. The Yale Budget Lab found the top 0.1% by income would see about $350,000 in tax savings from 2026 to 2027, but the bottom two quintiles of income would see no benefit at all.

The drawbacks of the proposed executive action

According to CRFB, the juice isn’t worth the squeeze for the broader economy. The national debt is growing by about $2 trillion per year, with an additional $1 trillion spent on paying interest on that debt. The watchdog said in a report earlier this month that in the next five years, interest on the national debt will exceed GDP growth, hurtling the U.S. into a “debt spiral.” That risk grows as interest rates remain high, making it harder to make a dent in repaying the balance.

Tax revenue is even more crucial following the Supreme Court decision to strike down tariffs imposed under the International Emergency Economic Powers Act, which would have generated $1.7 trillion in revenue through 2036, CRFB argued. 

Elena Patel, co-director of the Urban-Brookings Tax Policy Center, said another argument against indexing capital gains is that while assets would be adjusted for inflation, liabilities and debt would not be. This means an investor could borrow money, deduct nominal interest payments, and invest in an asset with gains indexed to inflation: something that benefits borrowers at the expense of the tax base. 

The one-sided adjustment would be a particular burden on homeowners, most of whom do not pay capital gains tax anyways as a result of existing tax exemptions. A policy indexing capital gains would therefore not be beneficial to the 12 million homeowners taking advantage of this benefit, Patel told Fortune.  

“As a homeowner, I don’t want that, because that means my deduction is eroding over time and worth less and less,” she said.

This story was originally featured on Fortune.com
The year is 2036. You’re sitting at your office desk—alongside 100 AI agents.

At least, that’s how Nvidia CEO Jensen Huang imagines work could be one day at Nvidia. Speaking at a Q&A session for media at the Nvidia GTC conference in San Jose, the CEO and cofounder said that in a decade, the company could expect to have about 75,000 workers—nearly double the 42,000 currently at the company—all working alongside millions of AI agents.

“In 10 years, we will hopefully have 75,000 employees, as small as possible, as big as necessary. They’re going to be super busy” Huang said to laughter. “Those 75,000 employees will be working with 7.5 million agents.”

That’s a 100-to-1 ratio of agents to humans. Huang’s comments reflect the rapidly growing AI adoption across industries. And companies are increasingly bullish on AI, encouraging employees to dive headfirst into the technology. Accenture CEO Julie Sweet said failure to adopt AI could actually cost workers a promotion. Other executives from companies like OpenTable and Salesforce see AI agents as the future of work.

Huang said those AI agents won’t exactly replace workers. Instead, they’ll be picking up the grunt work human employees don’t need to complete. “They’ll be working around the clock,” he said. “So hopefully our people don’t have to keep up with them.”

Expanding AI agent fleets

AI agents differ from what most people think of as AI, like the chatbot or LLM you turn to to search for a recipe, or to plan your next vacation. AI agents, instead, are software programs that autonomously achieve certain goals set for them by reasoning, planning, and taking actions, rather than simply responding to prompts.

Huang doesn’t foresee this technology solely being used by Nvidia. At the GTC conference, Huang also unveiled an open agent development platform, the Nvidia Agent Toolkit, to help enterprises build and run their own AI agents.

“Claude Code and OpenClaw have sparked the agent inflection point, extending AI beyond generation and reasoning into action,” Huang said in a press release. “Employees will be supercharged by teams of frontier, specialized, and custom-built agents they deploy and manage.” Nvidia notes companies like Adobe, Palantir, and Cisco are already working with Nvidia’s Agent Toolkit to enhance agentic capabilities across their platforms.

A November 2025 McKinsey survey found 62% of organizations were at least experimenting with AI agents (McKinsey itself has about 25,000 AI agents working alongside its 40,000 employees, according to CEO Bob Sternfels). But nearly two-thirds of surveyed companies hadn’t yet begun scaling AI. 

AI agents have recently caught the attention of those both in and outside of Silicon Valley. Entrepreneur Matt Schlicht founded Moltbook, a platform where AI agents could speak with each other without human input, and the results were both captivating and terrifying as agents chatted about everything from productivity to the nature of their existence. Meta recently purchased the platform for an undisclosed sum. And Andrej Karpathy, one of the founding members of OpenAI, recently conducted a test with an AI agent, charging it with finding a more efficient way to train a small language model. The agent ran 700 experiments in two days, resulting in 20 optimizations.

Huang is optimistic about the power of AI, and believes agents are a critical building block on the road to solving some of humanity’s most complex questions. “We’re gonna solve some really incredible problems,” he said. “The things that we are thinking about today to solve, 10 years ago nobody would even imagine that [they’re] solvable”

 “We’re thinking about drug discovery like it’s an engineering problem, people are talking about extending lives,” he continued. “We will all feel superhuman.”

This story was originally featured on Fortune.com
In 2023, artificial intelligence was capable of just a fraction of what it has achieved today. ChatGPT had just launched. Distorted AI photos and videos had just started to hit your timeline. The technology was improving, but adoption was slow and productivity gains were a dream away. Today, it’s being rapidly deployed across industries, and that pace has sounded the alarms for workforce researchers.

Professional services company Cognizant (number 217 on the 2026 edition of the Fortune 500) has reassessed its estimate of AI’s impact on the workplace, and the results are starker than before. They’ve updated their original forecast made in 2023—formulated by examining 18,000 tasks and nearly 1,000 jobs from the U.S. Department of Labor occupational data—to find that 93% of jobs could undergo at least some disruption from the technology. And the threat has become existential for a wider range of jobs. The research found that 30% of jobs could face an existential threat from AI, 15 percentage points higher than the initial assessment. In total, the report estimates AI-driven disruption could shift roughly $4.5 trillion in labor from humans to machines.

“We underestimated the impact of the technology,” the report reads. “What we projected might take until 2032 to unfold is happening now before our eyes.”

A growing chorus of business leaders and insiders is sounding the alarm on the looming threat AI poses to the workforce, particularly in white-collar roles. And those predictions are slowly becoming reality as companies—especially tech firms—have started to cut sizable chunks of their workforces, attributing the layoffs to AI. Jack Dorsey’s Block cut nearly half of the company’s workforce thanks to AI automation. Australian-American tech firm Atlassian cut 10% of its workforce to fund AI investments. And now Meta reportedly plans to cut 20% of its roughly 79,000-person workforce, which tech analyst Mark Shmulik warned could lead to “a cascade of hurried pivots, half-formed strategies, and reactive restructuring across the ecosystem” as firms race to remain competitive in the AI era.

“Today—six years ahead of schedule—93% of jobs could be impacted in some way by AI,” the report reads. “The technology, in short, is affecting more jobs, faster, and to a greater extent than we anticipated.”

Beyond white-collar work: manual labor and health care see first signs of disruption

The report found that the current potential for AI disruption extends beyond the professional world. The technology has started to encroach on the once-assumed safe realm of manual-labor tasks. In construction, for example, the technology can now help with interpreting blueprints. And in transportation, it can examine shipments or perform safety inspections.

“Tasks once considered purely manual actually contain embedded cognitive elements that AI can augment,” the report reads. “When those improvements occur across every shift and every site, the gains become transformative.”

In health care, too, AI is already showing signs of disruption, moving from assisting with small tasks to automating complex ones. The study found that the technology has improved diagnostic accuracy and patient care.

AI still has a long way to go before establishing a workforce that’s majority machine and minority human, according to Matt Sigelman, president of the Burning Glass Institute, a think tank that analyzes the workforce. “Some of these disruptions will take much longer to play out than we assume,” Sigelman told Fortune. “The timeline of disruption will be longer, the nature of the impacts may be more subtle.” 

The study found that while the majority of tasks today are in some way able to be assisted by AI, just 10% are fully automatable. And while the researchers calculated an average exposure score of 39% by industry, several sectors with big workforces, including transportation and construction, are still far off from facing substantial exposure to AI.

But Sigelman adds that while the timeline may differ from Cognizant’s projections, the overall impact on the workforce could be just as significant. He said AI will usher in requirements for a completely different skill set, which can disrupt even some of the most established professionals, potentially requiring significant retraining and upskilling. 

“People who have been in a job for decades may no longer be qualified for the job that has defined their careers.”

This story was originally featured on Fortune.com
Lamborghini’s wealthiest customers are still buying supercars—but tariffs are taking a quiet toll on the bottom line.

“Being the U.S., by far our biggest market, we could not, let’s say, increase the price [at] the same level as the tariffs were increased, and, at the same time, the market was going down,”  CEO Stephan Winkelmann told Fortune. “So we had less cars sold, and with less margin on those cars to be delivered in the second half of the year.”

The luxury automaker, owned by the Volkswagen Group through Audi, reported its full-year earnings for 2025 on Thursday. Lamborghini saw a new delivery record of 10,747 cars in 2025 and reached $3.7 billion (€3.2 billion) in revenue, a 3.3% year-over-year increase. However, operating income fell to $885 million (€768 million) from a record of $962 million (€835 million) in 2024, and the carmaker had a profitability of 24%, also slightly down from last year.

Winkelmann noted the dip in operating margins was in part a result of tariffs imposed by the Trump administration at the beginning of 2025, which precipitated a price increase for the luxury cars. Lamborghini said last year it would raise prices for its Temerario and Urus models by 7% and for the Revuelto by 10%. Winkelmann indicated Lamborghini would be unable to raise costs more, with the import taxes cutting into profitability as a result.

Tariffs cost the auto industry nearly $35 billion last year, according to an Automotive News analysis, with vehicles from the European Union, such as Lamborghini, hit with a 15% import tax. For luxury automakers, the import taxes have had a range of effects. For Ferrari, customized deliveries helped offset the impact of the levies and lower shipments for some models. In January, Mercedes reported a 19% slump in sales growth in the U.S. and a quarterly sales decrease of 12% year-over-year in part as a result of the tariffs.

Lamborghini also saw a dip in operating income as a result of negative exchange rates and the decision to pivot away from a fully electric Lanzador in favor of a plug-in hybrid model instead, Winkelmann said.

How Lamborghini is navigating tariffs

Lamborghini appears poised to continue navigating tariffs. Last summer, Winkelmann noted that even Lamborghini’s wealthiest customers were reconsidering the timing of their purchases as a result of the tariffs, waiting for import tax levels to become stable.

“Some are waiting because they want to be sure that this is the final number that is going to be in place,” Winkelmann said in an interview with CNBC in August 2025. “Others are fine with it, or we will have negotiations.”

Winkelmann told Fortune tariff uncertainty interrupted between six to eight weeks of shipments for the automaker, but was able to offset some disruptions and order cancellations from customers waiting on the company’s shortlist.

He expected more consistent deliveries in the coming year as tariffs level off. The company was not impacted by tariffs imposed under the International Emergency Economic Powers Act, which were struck down by the Supreme Court last month, so the import taxes have and will remain at about 15%. Winkelmann said he predicts “a new normality” of customers knowing what to expect with tariffs and adjusting to the cars’ new prices.

Lamborghini’s next challenges will be navigating the war in Iran, with conflict in the Middle East threatening the key luxury car market in the area. According to GlobalData, the United Arab Emirates typically sees more than 300,000 vehicle sales annually, with about 20% of those being premium imports.

With a drop in both the U.S. and Chinese markets, and turmoil in the Middle East, Winkelmann said Lamborghini will rely on sustained demand in markets in Europe, as well as Japan and Korea.

“The global economy, all this so far, could not offset the clarity of Lamborghini,” he said.

This story was originally featured on Fortune.com
Pikachus at every street corner. Leveling up before getting into the gym. “Pokémon Go to the polls.” You remember this era well: Pokémon Go became a frenzy, with hundreds of millions taking to the streets for their chance to snap up the rare Azelf or special edition Charizard. Now, not only does it seem that Pokémon Go took the world by storm, but it also was using crowdsourced data to map it.

Over the past decade, Pokémon Go players voluntarily submitted photos and short videos of public landmarks, street corners, storefronts, and urban intersections—all coming together to create a dataset that now stands at 30 billion images captured at ground level, across nearly every major city on the planet. Niantic Spatial, the enterprise AI and mapping division spun from Niantic Inc., has spent years converting that trove into something the robotics industry has never seen before: a photorealistic, street-level, continuously updated model of the physical world, built specifically for robots.

That model is now being deployed to navigate Coco Robotics’ roughly 1,000 delivery bot fleet operating in cities across the country and around the world, including Los Angeles, Chicago, Miami, Jersey City, and Helsinki, logging millions of miles of deliveries to date. Brian McClendon, Niantic Spatial’s chief technology officer and one of the original creators of Google Earth, explains the data strategy plainly.

“We look at the player data as very high-quality ground training data for other lower-quality datasets,” McClendon told Fortune in a statement. “The long-term philosophy of Niantic Spatial is that we can solve these hard problems of localization, reconstruction, and semantics by using very concentrated places to train models and then use much more broadly available data at lower resolution to be able to localize, visualize, and understand from ‘bad’ data.”

The 30 billion Pokémon Go images aren’t just a map: They are a master key that unlocks the potential of how to create a real-world, real-time map. The player scans teach the model what precision looks like—it’s so precise, in fact, that it can even signal when the input is imperfect. It’s a strategy that positions Niantic Spatial less as a gaming company that pivoted and more as the most ambitious mapping operation ever assembled—one that was funded entirely by its own users’ enthusiasm for catching digital creatures.

Niantic Spatial’s Visual Positioning System, or VPS, solves a problem that has quietly stunted the autonomous delivery industry. GPS, the backbone of most navigation systems, doesn’t fare that well in dense urban environments, where tall buildings interfere with satellite signals. For a delivery robot that needs to drop food at a precise doorstep, being several feet off means unhappy customers complaining their burger is cold—or in their neighbor’s tummy. Instead, the VPS bypasses satellites entirely, comparing live camera feeds from the robot against its vast image database to determine position in real time.

“The model will work in real time, taking in images from the robot and comparing them to both publicly available as well as proprietary datasets we’ve collected to determine the robot’s global position and heading,” a Niantic Spatial spokesperson told Fortune in a statement. The company knew where this tech performs best: “Niantic Spatial’s VPS is particularly resilient in urban canyons where GPS performs badly.”

“Our initial VPS was built using scans that users choose to take in games—but no single source defines the model,” the Niantic Spatial spokesperson said. Player participation was always opt-in: users had to actively choose to submit a short video scan of a specific public landmark. Today, the model increasingly learns from the data Niantic Spatial’s enterprise customers generate themselves. The underlying engine—a large geospatial model, or LGM, trained on billions of posed images and hundreds of millions of real-world scans—powers three capabilities: reconstructing spaces as navigable 3D models, localizing machines within those spaces, and understanding environments semantically. As CEO John Hanke wrote in a recent blog post: “For the past several years, we’ve been building a large geospatial model that acts as a living, breathing map of the world, one that is native to robots and AI.”

For Coco CEO Zach Rash, the problem is with robots’ critical thinking skills (or lack thereof).

“Robots don’t have the same intuition yet as a human, where a human can understand, ‘My GPS isn’t really working, but I understand that’s probably the right place to go,’” Rash told Fortune. “We need the robot to have that sort of intuition.”

“When we go into really dense areas with high rises, that’s where the VPS solution can be really helpful,” Rash said. “Our GPS and our existing solutions might fail in that sort of environment.”

The stakes, he noted, are felt by customers at the very last moment of a delivery: “It is a terrible customer experience if the robot parks in the wrong place waiting to receive that order.”

“It’s very early with [Niantic Spatial], and I think we’re excited to collaborate with such an incredible team on figuring out how we add this toward existing technology to make the service better. VPS is an obvious one,” Rash continued. “They’re very good at doing this. If I can more precisely figure out where to drop off food, my customers will be happy.”

This story was originally featured on Fortune.com
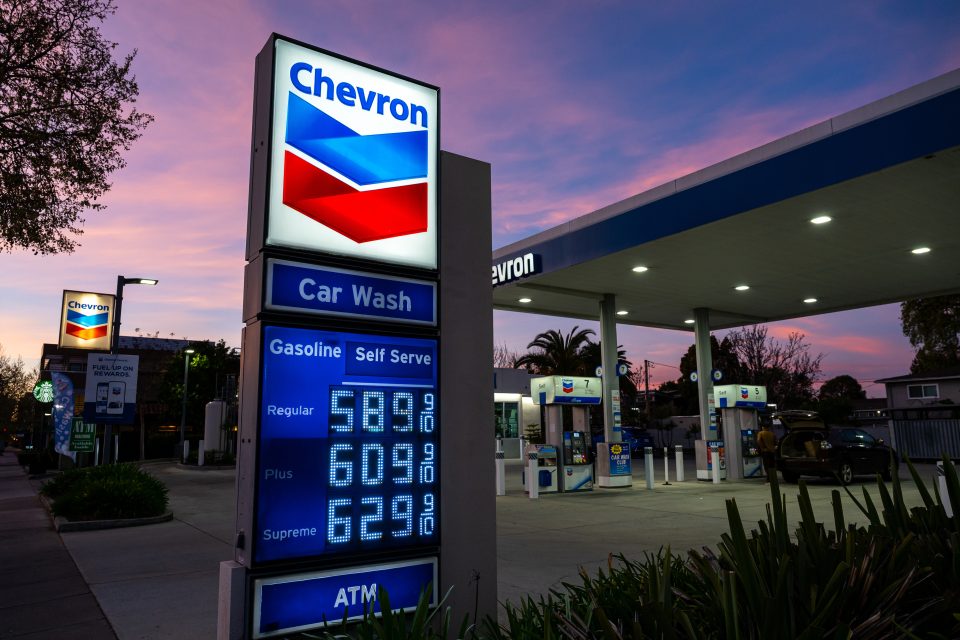
For decades, the standard formula for financial success was the same: go to college, get a degree, and land a prestigious white-collar job—probably a lawyer, consultant, or investment banker.

But entrepreneur and author Daniel Priestley is sounding the alarm on a major job-market shift. He suggests the traditional hierarchy of labor (white-collar over blue-collar) is actually flipping.

Priestley, founder and CEO of Dent Global, an entrepreneur accelerator, said he’s observed that the nature of the economy is changing so rapidly that he envisions a future in which “plumbers regularly earn more than lawyers,” as blue-collar roles are elevated while professional services face unprecedented disruption from AI. 

“For the last 25 years I’ve been building companies from scratch and I’ve been through the Global Financial Crisis,” Priestley said during a recent appearance on the Diary of a CEO podcast. “But I have never experienced what we’re experiencing right now.”

“I’ve never seen more fear for the disruption that is coming,” he continued. 

He argues we’re witnessing a “swinging pendulum” in which the high value once placed on “white-collar work behind a screen” is moving toward “blue-collar work with your hands.” Other CEOs like Ford’s Jim Farley have sounded a similar alarm, arguing there’s far more demand for blue-collar work than there are people who want to do it.

He’s concerned about staffing AI data centers and factories, which he calls a crisis affecting the “essential economy” of blue-collar workers who make up $12 trillion in U.S. GDP, according to the Aspen Institute. Farley has also said AI could wipe out half of white-collar jobs, instead ushering in mass demand for skilled trades and blue-collar work. 

“There’s more than one way to the American Dream, but our whole education system is focused on four-year [college] education,” Farley said during the Aspen Ideas Festival last summer. “Hiring an entry worker at a tech company has fallen 50% since 2019. Is that really where we want all of our kids to go? Artificial intelligence is going to replace literally half of all white-collar workers in the U.S.” 

Gen Z is already testing the plumber over the lawyer thesis

Over the past couple of years, at least some of Gen Z have started drifting away from the classic desk job path and more toward skilled trades. Enrollment in vocational-focused community colleges climbed 16% in 2023 to its highest level since the National Student Clearinghouse started tracking in 2018. This includes a surge in students studying construction trades, HVAC, and vehicle repairs.

“There’s still a stereotype that getting a university degree guarantees and results in a well-paid job, but I soon realized that isn’t the case,” Emily Shaw, a Gen Z apprentice at British construction company Redrow, told Fortune’s Orianna Rosa Royle. Some have even started their own blue-collar businesses, bringing in six-figure incomes. Another Gen Z electrician interviewed by Fortune’s Nick Lichtenberg skipped college because he said he wasn’t a good student, and now makes six figures working a trade instead. 

A Jobber analysis of Labor Department data also projects demand for electricians, plumbers, and HVAC technicians will grow well above the 4% average for all occupations through 2033. 

To be sure, some of Gen Z’s blue-collar pivot is driven by the same AI anxiety Priestley described—and a realization college may not really be worth it anymore. Nearly 80% of Americans have noticed an increased interest in trade careers from young adults, according to a Harris Poll survey of more than 2,000 U.S. adults for Intuit Credit Karma.

How fast is change coming?

Priestley—and countless other executives—have warned that change is coming fast. And he said the shift is being accelerated by the “instantaneous” AI rollout. Unlike the Industrial Revolution, which unfolded over decades and required massive infrastructure buildout, change will come much faster in the AI era. 

“The minute an AI learns how to be a lawyer in one place, it can be a lawyer in every place,” he said, because the digital network already exists. A Brookings Institute study published in February 2025 also suggests more than 30% of U.S. workers could see at least 50% of their tasks disrupted by generative AI. A 2023 commentary published by Brookings also said AI will “revolutionize” the practice of law by dramatically increasing efficiency in drafting, research, discovery, and document production, although it doesn’t argue the tech will completely eliminate the need for lawyers.

Meanwhile, blue-collar workers, such as electricians and bricklayers, are experiencing a “blue ocean” of opportunity due to a severe labor shortage. Priestley said the imbalance is due to “market distortion” from government-backed student loans. 

“Lots of young people who should have been plumbers, electricians, and concreers, and brick layers went off and got a master’s degree in mating habits of butterflies or some random degree that doesn’t have a job attached and they end up in [$60,000; $70,000; $80,000] worth of debt to get this degree that no one was asking for,” he said. “That market distortion means that we now don’t have many plumbers and electricians.”

This story was originally featured on Fortune.com
Argentina’s once thriving wine industry is facing its worst crisis in more than 15 years, with record-low domestic consumption, dwindling exports and low-yielding crops.

Against this sobering reality, hundreds of wine enthusiasts still gathered last week in Mendoza, the heart of Argentina’s wine region, to celebrate the annual National Wine Harvest Festival. Attendees watched dance performances, enjoyed live music and voted for the new queen of the Vendimia festival.

The festival was marking its 90th year as domestic wine consumption in Argentina plummeted to an all-time low of 15.7 liters (4.1 gallons) per person in 2025, according to the National Institute of Viticulture, or INV. Compare that to 1970, when Argentines consumed as much as 90 liters (24 gallons) per person annually.

Furthermore, 1,100 vineyards have shut down across the country and 3,276 hectares (8,095 acres) of grape production have vanished.

Fabián Ruggieri, president of the Argentine Wine Corp trade group, attributes the drop largely to a “sharp decline in purchasing power” that began in 2023. This trend, he said, is most acute among middle- and low-income consumers who traditionally consumed wine on a daily basis.

For Federico Gambetta, director of the Altos Las Hormigas winery, a medium-sized winery in Mendoza, the crisis is exacerbated by a shift in consumption patterns.

“People no longer consume wine en masse,” said Gambetta, noting that consumers now seek “coherence” and a sense of purpose behind their purchase.

While older generations favored high-alcohol, full-bodied wines, younger consumers prioritize other attributes, such as “approachability, freshness and lightness” — qualities typically found in white wines and rosés.

One of Gambetta’s red wines — Malbec Los Amantes 2022 — was recently ranked 41st among the world’s 100 best wines. Yet, he notes that starting in 2010 his winery began to modify its wine — once defined by a traditional, heavier profile — to appeal to a new generation of consumers seeking lighter styles.

“Everything has mutated,” Gambetta said. “If you’re not dynamic, you’re lost.”

The U.S. is experiencing a similar shift as the older wine-focused demographic ages out and younger adults fail to fill the gap. A report by Silicon Valley Bank found that millennial and Gen Z drinkers are spread across more categories and drinking less overall, particularly those under 29.

The international market offers little relief. As the world’s 11th largest wine exporter, Argentina saw its exports fall to 193 million liters (51 million gallons) in 2025 — a 6.8% year-on-year decline and the lowest volume since 2004, according to INV.

Ruggieri notes that exports are being hampered by financing issues, high logistics costs and a lack of competitiveness resulting from external tariffs. While its neighbor and wine competitor Chile enjoys free trade agreements with over 60 economies — often reaching markets like China with tariff rates close to zero — Argentina faces tariffs between 10% and 20% in most markets.

Local producers like Gabriel Dvoskin, owner of the 10-hectare Canopus winery that produces approximately 50,000 bottles of wine each year, also struggles with inflation.

Dvoskin, who exports to 15 countries, with the U.S. as his main market, acknowledges that Argentina’s high production costs and rampant inflation place his wines at a disadvantage compared with international competitors.

“Our inflation makes us a bit expensive,” Dvoskin said. “My equivalent in France has a much lower cost for dry inputs — bottles, corks, etc. — than I do.”

For Gambetta, the current crisis reinforces a key lesson for the industry: product quality is non-negotiable.

“Right now, everything is very delicate, and one wrong step can bankrupt you,” Gambetta said.

This story was originally featured on Fortune.com
College Republicans have sued the University of Florida’s president on free speech grounds over the school’s decision to deactivate its chapter after being notified that at least one member engaged in an antisemitic act.

The University of Florida College Republicans filed the lawsuit Monday in federal court against interim president Donald Landry, asking a judge to stop the enforcement of the school’s decision and to restore access to facilities on the Gainesville campus.

“The University of Florida punitively deactivated and shut down the UFCR, in response to alleged viewpoints expressed by a member of UFCR, and in an effort to silence the club and chill its future speech,” the group said in its lawsuit.

UF spokeswoman Cynthia Roldan Hernandez said in an email that the university doesn’t comment on pending litigation.

Officials at the University of Florida said over the weekend that they had been informed by the Florida Federation of College Republicans that the federation had disbanded the Gainesville campus’ chapter after determining that some members had “engaged in a pattern of conduct that violated its rules and values, including a recent antisemitic gesture.”

When the Florida Federation of College Republicans is ready, the university will assist with reactivating the campus chapter under new student leadership, UF officials said in a statement.

The deactivation wasn’t based on any university policy or rule, and it was only based on a member’s expression of a viewpoint “which was alleged to be antisemitic,” the lawsuit said.

The university also didn’t provide the College Republicans with adequate notice and didn’t give the chapter an opportunity to explain its side of the story, according to the lawsuit.

The deactivation effort at the University of Florida campus marks the second time this month that a public university in Florida has taken action against a Republican group accused of being involved in racist or antisemitic behavior.

Earlier this month, Florida International University in Miami launched an investigation into a group chat started by an official with the Miami-Dade chapter of the Republican Party that included violently racist slurs, antisemitic comments and misogynistic language. The chat involved students and several top conservative leaders at Florida International University.

Last fall, New York’s Republican State Committee suspended a Young Republican organization following the release of a group chat that included jokes about rape and flippant commentary on gas chambers.

This story was originally featured on Fortune.com
China won’t help the United States reopen the Strait of Hormuz as requested by President Donald Trump, but it is probably welcoming the delay in Trump’s highly anticipated trip to Beijing as the U.S. risks getting bogged down in the Middle East, analysts say.

The latest developments are unfolding as Trump’s Iran war, in its third week, is faced with mounting pressure as oil has stopped moving through the strait and U.S. allies have refused to step up to secure the strait. That has produced concerns that China, the United States’ biggest geopolitical rival, could stand to benefit from a war that some say was ill-considered.

“President Trump’s request to delay his long-awaited summit with President Xi Jinping underscores how significantly he underestimated the fallout from Operation Epic Fury,” said Ali Wyne, senior research and advocacy adviser for U.S.-China relations at the International Crisis Group. “A show of U.S. force that was meant to intimidate Beijing has instead served to puncture the illusion of U.S. omnipotence: Unable to reopen the Strait of Hormuz alone, Washington now needs its principal strategic competitor to help it manage a crisis of its own making.”

The Chinese Foreign Ministry gave a nonanswer when asked if it would help reopen the strait but repeated its call for “parties to immediately stop military operations, avoid further escalation of the tense situation and prevent regional turmoil from further impacting the global economy.”

Beijing, which had never officially confirmed Trump’s state visit, originally scheduled for March 31, has signaled willingness to work with the U.S. to reschedule the visit by stating that the two sides “remain in communication.” It even helped clarify that the postponement had nothing to do with Trump’s request for China to help reopen the Strait of Hormuz.

On Tuesday, Trump said the Chinese “were fine” with the delay and claimed “a very good working relationship with China.”

Sun Yun, director of the China program at the Stimson Center, said, “I think the Iran request is now going to be less pressing for China to fulfill.” At the same time, Chinese diplomats have been engaging with countries in the Middle East, pledging a constructive role in easing tensions and restoring peace.

On Sunday, through the Red Cross and the Red Crescent, Beijing delivered to Iran an emergency humanitarian aid package of $200,000, earmarked for families of children and teachers killed in the bombing of the Shajarah Tayyebeh elementary school building in Minab, Iran, with the Chinese ambassador to Iran condemning the school attack.

State visit delayed

A delay in the state visit is welcome by both the Trump administration and China, said Brett Fetterly, a managing principal in the China practice at The Asia Group, a Washington-based consultancy.

“I think the political environment is difficult for the United States to have the commander in chief travel abroad while managing military operations,” Fetterly said. “On the Chinese side, it doesn’t hurt to play for more time, to better understand what exactly President Trump might want.”

recent trade talk in Paris between the two governments appears to have yielded little agreement and suggested difficulties remain in addressing structural differences in trade, technology and economic security, Fetterly said. “At the end of the day, both sides really needed some time to define what the range of deliverables are,” he said.

The U.S. business community has also expressed concern that preparations for the summit might not have been sufficient to produce substantive agreements.

Pivot away from Asia

Transfers of military assets from the Indo-Pacific region to the Middle East,, including a sizable portion of Marines deployed there as part of a rapid-response unit and an anti-missile defense system, have raised concerns that the U.S. could get distracted from its own stated priority to refocus on Asia.

“The longer this war continues, and the more forces that are shifted out of Asia, the more it will feed Asian allies’ concerns about U.S. distraction and resource constraints,” said Zack Cooper, a senior fellow at the American Enterprise Institute, where he studies U.S. strategy in Asia.

A delay in the state visit could also mean a delay in any arms sales to the self-governing island of Taiwan to deter attacks from Beijing, he said. China has vowed to take Taiwan by force if necessary, but the United States is obligated by its own law to give the island sufficient hardware to defend itself. The issue remains the thorniest in U.S.-China relations.

“I believe that China is happy to delay the visit and reap the benefits as the United States once again gets bogged down in the Middle East,” Cooper said.

And Beijing probably doesn’t need to do much, he added: “I think most Chinese experts and officials believe that the United States is undermining itself, so they just need to get out of the way.”

This story was originally featured on Fortune.com
As the U.S. and Israel’s war against Iran continues to upend energy markets and supply chains worldwide, the Trump administration says it will temporarily waive maritime shipping requirements under a more than century-old law known as the Jones Act.

The Jones Act requires that goods hauled between U.S. ports be moved on U.S.-flagged vessels. Passed in 1920, this law aims to protect the American shipping sector — but it’s also faced criticism over the years for slowing the delivery of goods, including critical aid during time of crisis.

On Wednesday, the White House said that it would suspend Jones Act requirements for 60 days, in a measure that arrives amid wider efforts to counter steep oil prices and cargo disruptions due to the war. The Jones Act is often blamed for making gas, in particular, more expensive. Still, some analysts and industry groups say this waiver will do little to ease consumers’ fuel bills today.

Here’s what we know.

What is the Jones Act?

The Jones Act’s official name is the Merchant Marine Act of 1920. Congress passed the law — sponsored by Sen. Wesley Jones of Washington state — in an effort to rebuild U.S. shipping after German U-boats decimated America’s merchant flee during World War I.

Among other things, the Jones Act mandates that ships carrying cargo and passengers between U.S. ports must be built in the United States and owned by Americans — effectively prohibiting foreign-flagged ships from this domestic trade. The vessels are also required to carry U.S. crews.

The law can be waived in the “interest of national defense,” the U.S. Maritime Administration notes, either through the Homeland Security or Defense Department.

The Jones Act also was intended to ensure that the U.S. had its own merchant fleet in case of war. It’s been strongly supported by some U.S. shipping companies, national security advocates and organized labor. But cutting out foreign competition has also driven up the cost of carrying cargo domestically.

U.S.-flagged ships are generally more expensive to both operate and build than foreign ones. And those costs are especially damaging to states and territories that are supplied by sea, such as Hawaii and Puerto Rico.

Why is Trump waiving Jones Act requirements now?

Oil prices have spiked and swung rapidly since the start of the Iran war. Nearly all tanker movement in the key Strait of Hormuzremains at a halt, which has led major oil producers across the Middle East to cut production. Commercial ships — which, beyond fuel, haul cargo from pharmaceuticals to computer chips — have also been stalled at sea or faced attacks themselves.

That’s pushing up prices for businesses and consumers worldwide. Brent crude, the international standard, was trading at nearly $109 a barrel on Wednesday, up from roughly $70 before the war began. And U.S. crude is now at about $98 a barrel. U.S. drivers have already seen prices at the pump jump dramatically — with the national average for regular gasoline topping $3.84 a gallon Wednesday, per AAA, up about 86 cents from before the war.

All of this has left countries scrambling for more supply and alternative shipping routes. The White House confirmed last week it was looking into suspending Jones Act requirements, which Trump called “restrictive.”

White House press secretary Karoline Leavitt said Wednesday that the Jones Act waiver would help “mitigate the short-term disruptions to the oil market” during the Iran war and would “allow vital resources like oil, natural gas, fertilizer, and coal to flow freely to U.S. ports.”

Meanwhile, the American Maritime Partnership — a coalition that represents vessel owners and operators, unions, equipment yards and vendors — said in a statement that it was “deeply concerned” about the 60-day waiver “being abused and unnecessarily displacing American workers and American companies.”

The group, which has been a longtime supporter of the Jones Act, also reiterated that the action would do little to reduce gas prices for consumers.

How could suspending Jones Act requirements impact gas prices?

A number of factors contribute to prices at the pump. And many note that opening up domestic shipping routes isn’t a sweeping fix.

The Center for American Progress estimated last week that waiving the Jones Act would decrease East Coast gas prices by a modest 3 cents, but potentially raising costs on the Gulf Coast. And the move “would also sideline American shipbuilders and workers and allow the oil industry to continue to profit from high prices while reducing transport costs,” the research and policy think tank said Friday.

The U.S. is looking for additional ways to boost oil supply. Also on Wednesday, the Treasury Department eased sanctions to allow U.S. companies to do business with Venezuela’s state-owned oil and gas company. And the Trump administration has announced it will temporarily free up Russian oil from U.S. sanctions, too.

Last week, the International Energy Agency also pledged to release 400 million barrels of oil available from its member nations’ stockpiles, the largest volume of emergency oil pulled in the organization’s history. Trump, who previously downplayed the need to tap into reserve oil, confirmed that the U.S. would pull 172 million barrels from its Strategic Petroleum Reserve over 120 days as part of the IEA’s effort.

Still, analysts maintain this will be a short-term bridge. Refineries also buy crude oil in advance, and it takes time for new supply to trickle down to consumers. And, of course, it’s possible the pain of higher prices could increase further if the war drags on.

The U.S. is a net exporter of oil, but that doesn’t mean it’s immune to global spikes. Oil is a commodity traded globally. And most of what the U.S. produces is light, sweet crude, but refineries on the East and West coasts are primarily designed to process heavier, sour product. As a result, it also needs imports.

_______

AP Writers Seung Min Kim, Paul Wiseman and Collin Binkley in Washington contributed to this report.

This story was originally featured on Fortune.com
Luigi Mangione’s lawyers asked a judge on Wednesday to postpone his federal trial in the killing of UnitedHealthcare CEO Brian Thompson until early next year and said they will seek to have his state murder trial delayed until September.

In a letter to U.S. District Judge Margaret Garnett, Mangione’s lawyers said that the current schedule — the state trial in June and the federal trial in September — would put him “in the position of needing to prepare for two complicated and serious trials at the same time.”

They asked Garnett to delay the federal trial until January 2027 so that they can have an opportunity to ask the state trial judge, Gregory Carro, to reschedule the start of that case from June 8 to Sept. 8. Mangione has pleaded not guilty in both cases.

Carro previously raised the possibility of moving the state trial to September — but only if federal prosecutors appealed Garnett’s decision barring them from seeking the death penalty. They declined to do so, leaving the June state trial and September federal trial dates intact.

Keeping the current schedule would violate Mangione’s constitutional rights, his lawyers argued.

Among other concerns, they said, preparations for jury selection in the federal case would overlap with the state trial, limiting Mangione’s ability to review questionnaires filled out by hundreds of potential jurors — infringing on his right to participate in his own defense.

Back-to-back trials would also rob Mangione of his right to effective assistance of counsel, his lawyers said, because they would be forced to prepare for the federal trial while simultaneously defending him in court at the state trial.

“Though fierce advocates for their clients, defense counsel cannot be in two places at once,” wrote Mangione’s lawyers, Karen Friedman Agnifilo, Marc Agnifilo and Jacob Kaplan.

Federal prosecutors oppose the request and will respond in a letter of their own, Mangione’s lawyers said.

The U.S. attorney’s office in Manhattan, which is prosecuting the federal case, and the Manhattan district attorney’s office, which is prosecuting the state case, both declined to comment.

Mangione, 27, faces the possibility of life in prison if he’s convicted in either case. At a court hearing in February, he spoke out against the prospect of two trials, telling the judge: “It’s the same trial twice. One plus one is two. Double jeopardy by any commonsense definition.”

Thompson, 50, was killed on Dec. 4, 2024, as he walked to a midtown Manhattan hotel for UnitedHealth Group’s annual investor conference. Surveillance video showed a masked gunman shooting him from behind. Police say the words “delay,” “deny” and “depose” were written on the ammunition, mimicking a phrase used to describe how insurers avoid paying claims.

Mangione, a University of Pennsylvania graduate from a wealthy Maryland family, was arrested five days later after he was spotted eating at a McDonald’s in Altoona, Pennsylvania, about 230 miles (370 kilometers) west of Manhattan.

His lawyers have argued that authorities prejudiced his case by turning his arrest into a “Marvel movie” spectacle, including by having armed officers parade him up a Manhattan pier after he was flown to New York and by publicly declaring their desire to seek the death penalty before he was indicted.

In January, Garnett dismissed a federal murder charge — murder through use of a firearm — that had enabled prosecutors to seek capital punishment, finding it legally flawed. She wrote that she did so to “foreclose the death penalty as an available punishment to be considered by the jury” when it weighs whether to convict Mangione.

In their letter, Mangione’s lawyers argued that delaying the federal trial would allow a buffer between his state trial and the beginning of the juror questionnaire process that precedes jury selection in the federal matter.

Without a delay, they wrote, “Mr. Mangione’s potential federal jurors will be constantly bombarded with news reports and social media posts relating to the allegations and evidence against Mr. Mangione as they fill out juror questionnaires and in the subsequent weeks before they are empaneled in the federal case.”

This story was originally featured on Fortune.com
The United States’ gross national debt crossed $39 trillion on Tuesday, a grim new threshold that a prominent fiscal watchdog says reflects decades of irresponsibility from both Republicans and Democrats — with no signs that Washington is ready to change course.

“Surpassing $39 trillion in gross debt is an embarrassing milestone that both parties have helped build over decades, and neither seems particularly interested in addressing it before we hit $40 trillion,” said Maya MacGuineas, president of the Committee for a Responsible Federal Budget (CRFB), in a statement released Wednesday.​

The figure, confirmed by the U.S. Treasury, marks a rapid escalation in the nation’s fiscal slide. The debt stood at $38 trillion as recently as October of last year — meaning Washington added a full $1 trillion in gross debt in less than six months. Debt held by the public, the measure most closely tracked by economists, has separately surpassed $31 trillion for the first time.​

The numbers paint a portrait of a government living far beyond its means. Annual deficits are approaching $2 trillion, and deficits as a share of the economy are running at roughly twice the 3%-of-GDP target that economists and bipartisan policymakers have long identified as a sustainable benchmark.​

“No matter what metric one chooses to examine our fiscal trajectory, we are clearly headed in the wrong direction,” MacGuineas said.​

The milestone arrives at a turbulent moment for the U.S. economy. Conflict with Iran has sent oil prices spiking, and some lawmakers have floated a gas tax holiday in response — a move that CRFB analysts estimate would cost billions of dollars per month and further balloon the deficit. Meanwhile, the CRFB recently warned that unilateral executive tax cuts under consideration could add hundreds of billions more to the debt.​

MacGuineas argued that the consequences of the country’s fiscal drift are already being felt — and will get worse. “Higher debt exacerbates inflationary pressures, squeezes out investment in our economy, allows interest costs to dominate our defense spending, leaves us vulnerable to emergencies and geopolitical turmoil, and could even provoke a fiscal crisis,” she said.​

The CRFB chief also flagged market risk as an underappreciated danger. “Markets are paying close attention to our fiscal situation, and every time we hit a new milestone, we risk spooking them,” MacGuineas warned. That concern is particularly acute given the geopolitical uncertainty already weighing on investor sentiment.​

Bipartisan solutions have been floated but have yet to gain traction. The Fiscal Contingency Preparedness Act, introduced by Rep. Ben Cline (R-VA) and Rep. Jared Golden (D-ME), has built some momentum in the House, though it has not moved toward a floor vote. Former Sen. Mark Udall, a Colorado Democrat, and former Rep. Bob Beauprez, a Colorado Republican, have separately called for action on Social Security solvency — one of the key drivers of long-term debt.​

MacGuineas outlined a list of concrete steps she said Washington must take: committing to no new borrowing, adopting a Super PAYGO rule requiring new costs to be paid for twice over, establishing a fiscal commission to broker a bipartisan debt deal, and shoring up the nation’s underfunded trust funds. She also called for a “Break Glass” emergency plan to be put in place in case a financial shock hits before legislators act, as the CRFB has recently recommended.

For now, $40 trillion — once unthinkable — is drawing into view. At the current pace of borrowing, it may not be far off.

For this story, Fortune journalists used generative AI as a research tool. An editor verified the accuracy of the information before publishing.

This story was originally featured on Fortune.com
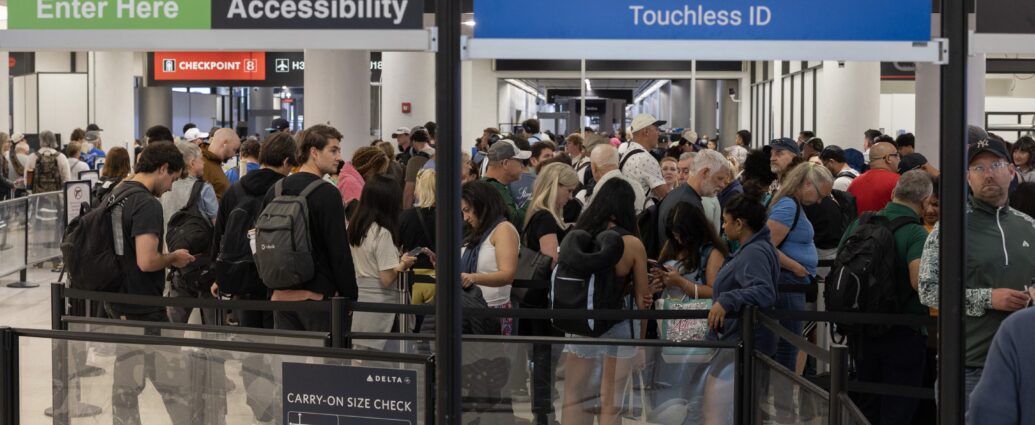
When U.S. and Israeli forces launched a sweeping air and sea campaign against Iran’s military infrastructure in late Feb. 2026, the missiles weren’t the only weapons that flew. Within hours, more than 60 Iranian-aligned cyber groups mobilized, according to Palo Alto Networks’ Unit 42, armed with AI-assisted reconnaissance tools and a mandate to strike back where it hurts most: America’s corporate nervous system.

​Within hours, cybersecurity agencies in the UK and Canada both warned about heightened threat levels, followed by similar warnings from Europol and the Department of Homeland Security.

For Fortune 500 CEOs, the message couldn’t be clearer—or more unsettling. The Iran war has blown open a Pandora’s box of AI-powered cyber warfare, and no firewall, no matter how expensive, was built for what’s coming next.

A new attack template

Iran’s cyber playbook has already claimed its first major corporate victim. Iranian-aligned hackers disrupted operations at U.S. medical technology giant Stryker, as first reported by the Wall Street Journal and confirmed by the company—a sobering signal that the private sector is squarely in the crosshairs.

According to threat intelligence firm Flashpoint, the Iranian-aligned hackers executed a sophisticated “no-malware” attack on Stryker—not through traditional malicious code, but by weaponizing Microsoft Intune, a legitimate cloud-based endpoint management service, to remotely wipe devices across the company’s network. The attack has sent a chill through every corporate IT department in America: the tools used to manage your own infrastructure can now be turned against you.​

The more chilling template, analysts warn, isn’t the conventional data breach—it’s a coordinated campaign designed to destroy institutional trust from the inside out. Iran’s state-backed hacking groups, including Void Manticore aka Handala, have already deployed ransomware-style attacks, distributed denial-of-service operations, and “wiper” attacks engineered to permanently erase data from corporate servers. These aren’t smash-and-grab operations. They are psychological warfare at enterprise scale.

According to Flashpoint, the Handala Hack Team claimed responsibility for breaching a Mossad “secret treasury,” allegedly leaking 50,000 confidential emails. In a chilling escalation, the group also claimed to have identified the precise geographic coordinates of a target through cyber reconnaissance—and that a kinetic missile strike followed. Cyber and physical warfare, in other words, are no longer separate domains.

“Aggressive and creative resistance is baked into the ethos of the Iranian security apparatus,” Brian Carbaugh, co-founder and CEO of AI-based security firm Andesite and a former director of the CIA’s elite Special Activities Center, previously told Fortune. “For business leaders and those protecting businesses and making decisions at a very high level, they need to be prepared for this to continue on for some time and for the conflict to take a number of different courses of direction and swerve around the road.”

AI as the great equalizer—and the great threat multiplier

What separates this conflict from previous cyber flashpoints is the role of artificial intelligence (AI) on both sides of the battlefield. U.S. and Israeli forces have used AI platforms from Palantir and the Pentagon’s Maven Smart System to execute more than 15,000 strikes since the war began—over 1,000 per day—with remarkable precision, according to security columnist Shimon Sherman of the Jewish News Syndicate. AI has compressed the military “kill chain” from days to minutes, he added.​ (Iran, for it’s part, has used its firepower to target data centers in the UAE).

But cybersecurity firm CloudSek argued in a blog post that the same compression is now available to Iran’s proxies—and to any hacker group with a laptop and access to an AI reconnaissance pipeline. AI tools have sharply lowered the barrier to identifying and exploiting exposed industrial control systems, default credentials, and internet-facing corporate infrastructure across America. Threat groups with no prior industrial control systems background are now, effectively, sophisticated actors overnight.

​Flashpoint said the 313 Team, an Iranian-aligned Cyber Islamic Resistance group, claimed a complete shutdown of the official British Army website—a clear signal that state-adjacent institutions and critical government infrastructure are primary targets.

The defender is already behind

What makes the current threat environment uniquely dangerous for corporate America is the simultaneous convergence of physical and cyber disruption. On March 17 alone, a drone strike on the Fujairah oil hub in the UAE halted refining operations; a Kuwaiti-flagged LNG tanker was damaged by drone debris near the Strait of Hormuz; and the U.S. Embassy in Baghdad suffered its heaviest attack since the war began. These are not abstract geopolitical events—they are direct shocks to the energy supply chains that power global commerce.

“The conflict has entered a stage where the economic and operational impacts are becoming much more visible,” said Josh Lefkowitz, CEO of Flashpoint, in a statement issued Wednesday. “We’re seeing disruption at major transportation hubs, pressure on global shipping routes, and cyber activity targeting private companies already creating ripple effects across supply chains, travel, and day-to-day commercial operations. For organizations connected to the region, the risk environment now includes simultaneous physical disruption and cyber activity.”

The timing couldn’t be worse for corporate America. The Cybersecurity and Infrastructure Security Agency (CISA)—the federal government’s primary cyber defense body—is hobbled by furloughs, a leadership reshuffle, and the lingering effects of a partial government shutdown. The cavalry, in other words, is understaffed and reorganizing.

Meanwhile, Iran’s own command structure has been decimated by allied strikes—including the elimination of Ali Larijani and Gholamreza Soleimani, commander of the Basij paramilitary unit—which, paradoxically, makes the threat more dangerous, not less. “The Iranian leadership vacuum is likely going to lead to more unpredictable, decentralized proxy attacks,” Kathryn Raines, a former NSA expert who is now a threat intel team lead at Flashpoint, told Fortune‘s Amanda Gerut. Decentralized means harder to anticipate, harder to attribute, and harder to stop.

President Trump has also accused Iran of weaponizing AI for disinformation, allegedly collaborating with media outlets to shape narratives around the conflict. Corporate reputations—not just networks—are now targets.

The boardroom imperative

Every Fortune 500 CEO sitting in a board meeting this week faces the same stark reality: the Iran war has permanently altered the cyber threat landscape. AI hasn’t just made attacks faster—it has made them cheaper, stealthier, and accessible to a sprawling ecosystem of state proxies and opportunistic hacktivists who share the same AI-assisted toolkit.

The Pandora’s box is open. The question isn’t whether the next major attack on a U.S. corporation is coming—it’s whether the C-suite will be ready when it does.

Additional reporting contributed by Amanda Gerut.

This story was originally featured on Fortune.com
Tennessee farmer Todd Littleton expects to pay $100,000 more for fertilizer this season, a 40% spike from his bill last year thanks to the war in Iran — and he is scrambling to cover that extra cost.

“The problem is, is we’re so strained financially coming into this issue,” said Littleton, a third-generation farmer from Gibson County in the state’s northwest corner. “We have had a couple of record losses the last couple years, so everyone’s kind of grabbing at straws anyway, and then to have input prices increase yet again, it just really couldn’t happen at a worse time.”

Littleton, who grows corn, soybeans and wheat, is among thousands of farmers across the country who will pay far more this spring than they expected for fertilizer that is essential to their crops. Nitrogen-based fertilizer is especially vital for corn, usually the largest crop in the U.S. and one that feeds the nation’s livestock and is converted into fuel that helps power most U.S. cars and trucks.

Farmers have complained about costly fertilizer for years, but prices have soared even higher since the U.S. and Israel attacked Iran on Feb. 28, leading to a slowdown in shipping through the Strait of Hormuz, a chokepoint for 20% of the world’s oil and natural gas. Besides increasing the price of fuel, which is key in the production of fertilizer, the shipping disruption also has largely stopped the export of nitrogen fertilizers manufactured in the Persian Gulf and limited access to key fertilizer ingredients.

About 15% of fertilizer imports to the U.S. are from the Middle East, and about half the global supply of the key ingredient urea comes from the region, along with 30% of ammonia, according to the American Farm Bureau Federation.

“When the ports started raising their nitrogen prices due to the conflict due to shipping concerns, that directly affects me here on the farm,” Littleton said.

Some farmers may not find fertilizer

But it could be worse, as some farmers may not be able to obtain fertilizer at any price, said Zippy Duvall, president of the American Farm Bureau Federation.

“We’re being told that many of our farmers that haven’t preordered their fertilizer and paid for it may not even obtain the fertilizer that they’re going to need during the season or for spring planting,” Duvall said. “That’s why this situation is so serious.”

Harry Ott, a cotton, corn and peanut farmer who also leads the South Carolina Farm Bureau, said there isn’t enough fertilizer stockpiled in warehouses to meet demand in the coming months.

“It is a really dire situation that our farmers facing,” Ott said.

Experts say don’t expect a quick fix

Even before the current spike in prices, other factors in recent years have led to high fertilizer costs, starting with the war between Ukraine and Russia, which blocked access to raw materials and increased natural gas prices. China also cut phosphate exports as it focused more on domestic needs.

The latest factors worsened those existing supply issues, which means that even if the Iran war was resolved, fertilizer prices likely won’t quickly fall, said Jacqui Fatka, a farm supply economist for creditor CoBank.

“There’s going to be a tail to this that’s going to take time to get everything turned back on, sent back out,” Fatka said.

And then there is the time it takes for shipments from the Middle East to reach the U.S. — typically 30 to 45 days to reach the Port of New Orleans.

Some fertilizer is already stored in the U.S. and can meet demand amid the shortage of Middle East imports, but at some point those supplies will run low.

“We don’t quite know how it’s going to shake out,” said Nancy Martinez, director of public policy, trade and biotechnology for the National Corn Growers Association.

Nitrogen- and phosphate-based fertilizers are largely produced domestically, which helps a little bit, said Anne Villamil, a professor of economics at the University of Iowa.

“But again, energy prices are an input, and so even if you’re producing it in the U.S., if the cost of your inputs goes up, then it’s going to be an increase in price to the farmers who want to buy it,” Villamil said.

Soaring oil prices could result in higher food prices, given the increased cost of diesel needed to transport products to grocery stores and petroleum products used in plastic packaging, said Chad Hart, an economics professor at Iowa State University.

However, the increased fertilizer prices shouldn’t significantly lead to grocery store increases even as they put a crimp in farmers’ profits. That’s because on-farm costs are only a small part of what consumers pay at the supermarket.

Efforts to curb the hit on farmers from costly fertilizer

The Trump administration said it has taken steps to ease the cost of fertilizer, including moving to increase fertilizer imports from Venezuela, which U.S. Agriculture Secretary Brooke Rollins called “a huge step that puts farm security and farmers first.”

The Department of Agriculture also notes it previously announced $12 billion in one-time payments to help farmers offset losses primarily due to tariffs imposed by the Trump administration. In a statement, the USDA also said it has provided more than $30 billion in additional aid to farmers since January 2025, and the agency noted its support for a more competitive fertilizer marketplace that would ultimately lower prices.

Fatka, of CoBank, said the $12 billion doesn’t go far for farmers with a payment of $44 per corn acre when the USDA estimates about $900 per acre for cost of production for the average U.S. farmer.

Still, farm bankruptcies remain rare, with only 315 last year — a tiny percentage of the nearly 1.9 million farms nationally. And prices for the nation’s two largest crops — corn and soybeans — have been climbing recently.

Tom Waters, who farms about 5,000 acres (2,023 hectares) of corn, soybeans and wheat east of Kansas City, said the increase of fertilizer prices along with other costs makes it tough to make a profit when crop prices are so low.

“The margins get smaller and smaller so we just have to really work hard to trim our costs and be as frugal as we can be but still provide the soil and crop what it needs to grow and produce,” Waters said.

This story was originally featured on Fortune.com
Main Street is racing to fit artificial intelligence into its business models, but most small businesses are still learning to walk before they can run.

Small business owners have already made up their mind about AI, no longer asking if they should use the technology, but rather how and when to integrate it. More than three-quarters of small business owners are already using AI to some degree, and more than 90% say it’s working, according to a survey of small business operators published by Goldman Sachs on Tuesday.

Higher efficiency and productivity are the primary selling points of AI for small businesses, and nearly seven in ten expect the technology to help grow their revenue. But while many entrepreneurs are experimenting with AI, a huge gap remains between enthusiasts and owners who are able to fully integrate AI. 

The Goldman Sachs survey found that only 14% of owners have embedded AI across their core operations, meaning most small businesses have downloaded the app, but few have read the manual.

The survey polled 1,256 participants in Goldman Sachs’ small business education program between January and February, finding that many entrepreneurs are excited about AI but uncertain how to fully cash in on it. Barriers include a lack of technical expertise, difficulty navigating a crowded tools landscape, and data privacy concerns. More than 70% of respondents said they’d benefit from more training and implementation resources.

High risk, maybe high reward

Small businesses are warming rapidly to AI tools, but struggling to absorb them. A 2025 report from the Chamber of Commerce found 58% of small businesses used generative AI in their operations, more than double the share from 2023. AI tools including ChatGPT, Claude and Gemini vaulted social media to become the second most popular technology among small businesses, trailing only search engines.

Most small businesses use AI for everything from copywriting and content creation to automating customer service, with some even using the technology for complex tasks such as coding and website design. 

But the more revenue-driving applications remain limited to a smaller share of tech-savvy firms. Less than a quarter of businesses surveyed by the Chamber of Commerce use AI to accomplish tasks that would likely translate to greater revenue growth, such as optimizing supply chains, identifying potential customers, and producing new insights on products and services. Distrust of AI remains rife among some small businesses, with data privacy a key concern for half of firms using AI, according to Goldman Sachs.

Another hurdle may lie with the customers themselves. AI currently ranks as one of the least enjoyable topics of conversation in the U.S., with one recent NBC poll finding that only 26% of Americans saw AI positively, and 46% had a negative view. Companies may also hesitate to deploy AI for client-facing tasks given general fatigue about the technology. A Gartner survey published this week found that half of consumers prefer their business going to AI-less brands, with many customers particularly abhorring the reliability of AI-assisted shopping experiences.

One bright spot: jobs. The wave of corporate layoffs and fears of AI-driven job loss fears sweeping white-collar industries does not seem to have affected small businesses yet, with the Chamber’s report finding that 82% of small firms using AI were able to grow their workforce over the past year.

But just as corporate America struggles to figure out how best to adopt the technology, small businesses might remain hesitant. Generative AI pilots at large companies have largely stalled so far and failed to generate significant revenue, and small businesses with fewer resources might be hesitant to take the risk on thousands of dollars’ worth in enterprise models and staff training. 

A bill passed in the House last year, called the “AI for Main Street Act,” aims to allocate more resources to increase AI literacy among small businesses. But until larger companies prove that AI can be worth the investment, smaller firms may be reluctant to follow.

This story was originally featured on Fortune.com
Arizona on Tuesday became the first state to file criminal charges against Kalshi, accusing the prediction market company of operating an illegal gambling business within its borders, a significant escalation in the fight to regulate the popular platform.

The 20-count charging document accuses Kalshi of accepting bets on political outcomes, college sporting competitions and individual player performance in violation of Arizona’s gambling laws. The state prohibits operating an unlicensed wagering business and bans betting on elections.

“Arizona will not be bullied into letting any company place itself above state law,” said Democratic Attorney General Kris Mayes.

The criminal case marks a new front in a high-stakes legal battle over whether prediction markets should be subject to the same rules as gambling companies.

President Donald Trump’s administration has thrown its support behind the multibillion-dollar prediction market industry, further amplifying a state-versus-federal fight for regulatory control. The outcome could have sweeping implications for how sports betting — which makes up roughly 90% of Kalshi’s trading volume — is regulated in the U.S.

Kalshi insists it’s a financial marketplace rather than a gambling operation and should only have to answer to federal regulators with the Commodity Futures Trading Commission. The agency under Trump agrees it has exclusive oversight.

Trump’s eldest son, Donald Trump Jr., is a strategic adviser for Kalshi. And the Republican president’s social media platform, Truth Social, is launching its own cryptocurrency-based prediction market called Truth Predict.

Elisabeth Diana, a spokesperson for Kalshi, dismissed the Arizona charges as “meritless” and accused the state of trying to circumvent federal court.

Kalshi sued Arizona, Utah and Iowa in attempts to stop anticipated state action against the platform.

But U.S. District Judge Michael Liburdi in Arizona, a Trump appointee, denied Kalshi’s request for a temporary block Tuesday and ordered the company to demonstrate why the case should be in federal court given the new state charges.

At least nine other states have taken some form of legal action against Kalshi, and Utah’s Republican governor has pledged to sign a bill that could undercut the company’s business in the state.

So far, the outcomes have been mixed. Federal and state judges in Nevada and Massachusetts, respectively, issued early rulings in favor of states looking to ban Kalshi and its competitor Polymarket from offering sports betting in their states, while federal judges in New Jersey and Tennessee have ruled in favor of Kalshi. The Nevada lawsuit was remanded to state court.

CFTC chairman Michael Selig said the legal fight between Arizona and Kalshi is a jurisdictional issue and is “entirely inappropriate as a criminal prosecution.”

The state argues Kalshi is a gambling operation that brands itself as a marketplace. But the company says its product is different because customers engage in “swaps” between one another instead of betting against the “house.”

Kalshi operates by allowing customers to buy and sell “Yes” or “No” contracts tied to the probable outcome of an event. Anyone with a smartphone can wager on everything from whether it will snow in Miami to whether Trump will say a certain buzzword in a speech. Contracts are typically priced between 1 cent and 99 cents, which roughly translates to the percentage of customers who believe that event will happen.

The charges in Arizona were filed just days before the start of the NCAA men’s and women’s basketball tournaments, one of the busiest periods of the year for prediction markets and sportsbooks.

Kalshi announced a $1 billion perfect bracket challenge on Monday without mentioning the NCAA or March Madness, a pair of NCAA trademarks.

An NCAA spokesperson, Saquandra Heath, said Tuesday the organization remains concerned about “unprotected prediction markets that pose a threat to competition integrity and student-athlete safety.”

___

Associated Press sports writer Jay Cohen in Chicago contributed to this report.

This story was originally featured on Fortune.com
Over the course of just 48 hours, Congress moved more aggressively on child online safety than it has in nearly a decade—and a federal court quietly reminded everyone that the entire framework might not survive a constitutional challenge that pits safety against privacy.

On March 4, the App Store Accountability Act passed 26-23 out of the House Energy and Commerce Committee. The following day, the same committee advanced the Kids Internet and Digital Safety (KIDS) Act—a package including the Kids Online Safety Act (KOSA)—to the full House floor in a party-line 28-24 vote. Meanwhile, the Senate simultaneously passed Children’s Online Privacy Protection Act (COPPA) 2.0 unanimously. For the first time in years, both chambers of a divided Congress moved on children’s digital safety in the same week. While the government might be making the rules, social media companies are now struggling to keep up and are walking a fine line between privacy and safety.

The pressure on social media companies to do something about minors on their platforms long predates either act. Meta, Snap, TikTok, and YouTube have faced years of congressional hearings, state attorneys general investigations, and now a mounting wave of personal injury litigation alleging their platforms knowingly exposed children to harmful content and addictive design features.

The industry’s self-regulatory response—age minimums set at 13, parental control settings buried in app menus, terms of service that minors routinely circumvent—has satisfied almost no one. What’s changed in 2026 is that lawmakers have stopped waiting for the industry to find them. Two bills now moving through Congress take fundamentally different approaches to the same crisis, and understanding both requires understanding what each one is actually trying to fix.

Two laws, two approaches

With KOSA and the App Store Accountability Act, the government is trying to attack the problem from opposite ends. KOSA requires companies to conduct risk assessments, restrict default settings on minors’ accounts up to age 17, disclose how their recommendation algorithms work, and give parents meaningful oversight tools. The App Store Accountability Act attempts to stop the problem before a child ever opens an app: requiring age verification at the account level, parental consent for each minor’s download, and the linking of a child’s device to a parent or guardian. Alabama became the fourth state to sign it into law in Feb. 2026, joining Utah, Louisiana, and Texas, with others states looking to put it on the books.

The state laws have added a whole other level of complexity to the issue, especially considering each of the four states’ have various restrictions, meaning no law is the same. Jacqueline Klosek, a partner in global law firm Goodwin’s technology practice, says the overlapping demands are already straining clients. “As a practitioner, I myself am very much challenged by the morass of laws at the state level, and the clients I deal with are also challenged by this. Nobody’s just functioning in one state, and there’s a plethora of laws out there,” she told Fortune. KOSA raising the age of protection to 17 closes off what Klosek calls the industry’s longtime workaround. “There’s no longer going to be this kind of somewhat easy out, and saying, ‘I’ll just focus on users above their teens and not worry so much about this.’ If I’m dealing with minors at all, I have to think more holistically about privacy, security, and safety.”​

Critics — including House Democrats — argue the House version is weaker than its Senate counterpart because it strips out a “duty of care” provision that would require companies to design products with children’s safety in mind.

Roman Karachinsky, Chief Product Officer at Incode Technologies—whose social media clients include TikTok—sees the compliance complexity as a symptom of regulation that hasn’t yet caught up to itself. “There’s a lot of regulatory requirements right now that are well intentioned and written in a way that makes sense, but are not prescriptive,” he told Fortune. “Each company kind of needs to figure out, ‘We have this duty of care to verify that our users are not minors, but how do we do that?’”

COPPA, first passed in 1998 (notably before the social media era), requires websites and apps to obtain verifiable parental consent before collecting personal data from children under 13. COPPA 2.0 covers ages 13 to 16, bans targeted advertising to minors entirely, and creates a dedicated FTC enforcement division, closing the loophole that allowed companies to treat teenagers as unprotected users.

In the ongoing battle of collecting underage users’ private data in the name of safety, Karachinsky said with the new version of COPPA, “at least that particular contradiction has been somewhat resolved. You can process data for minors only for the purpose of age verification, as long as you don’t store it, don’t reuse it for any other purpose, and immediately delete it, which I think is all fairly reasonable.” But the global picture remains chaotic. “If you think about a global company that operates in basically every market in the world, the compliance burden that you have to go through to figure out all these different requirements is really high,” he said.​

Klosek, who has watched clients navigate this landscape for years, says the frustration is structural. “I think industry, parents, and government all see an issue, a problem—we’re just struggling to identify the best solutions.”

This story was originally featured on Fortune.com
A “one in a million” malfunction during a live fire demonstration over Camp Pendleton last October led to a misfire that rained shrapnel on Interstate 5, striking two California Highway Patrol vehicles, a U.S. Marine Corps investigation found.

An artillery shell exploded over the highway that serves as the main corridor between Los Angeles and San Diego during a celebration of the 250th anniversary of the Marine Corps, attended by Vice President JD Vance and Defense Secretary Pete Hegseth. Nobody was hurt, and investigators ruled out any negligence or wrongdoing by Corps members.

The day before the event, Democratic Gov. Gavin Newsom called the planned demonstration with live artillery dangerous and unnecessary, and he ordered I-5 to be closed during it. That closure drew condemnation from the White House and other Republicans, and the Marine Corps said the exercises wouldn’t endanger motorists.

In a 666-page report dated Dec. 19 and first reported on Monday, the Marines concluded that there “is no definitive answer” to why an M795 high explosive round detonated early at an altitude of about 1,480 feet (450 meters) during the Oct. 18 demonstration. Such a premature detonation is “beyond reasonable expectations and should not have happened, but it did,” the report says.

“It is manufactured to a tolerance of one defect in a million,” according to the report.

Organizers planned to fire 60 rounds of live artillery in 5 minutes over the highway, using six howitzer weapons, according to the report. But a round in the first volley of shots failed and detonated early, and the rest of the demonstration was canceled, the report said.

Days after the malfunction, 26 California U.S. House members and the state’s two senators sent a letter to Hegseth asking who decided to shoot live artillery over the freeway and how authorities prepared for the safety risks.

“We’re thankful to the Marines for their thorough and precise investigation — in stark contrast to the dangerous and performative demands by JD Vance and Pete Hegseth to shoot live ammunition over a civilian area for their entertainment,” Diana Crofts-Pelayo, a spokesperson for Newsom’s office, said in an email Tuesday.

Newsom announced the highway closure in a statement after practice rounds were fired a day ahead of the celebration. The governor described the live fire exercise as a show of force meant to intimidate Trump’s opponents, thousands of whom were demonstrating at “No Kings” protests in and around San Diego that day.

“Firing live rounds over a busy highway isn’t just wrong — it’s dangerous,” Newsom wrote at the time.

The Marine report concluded several factors could have contributed to the malfunction, including the howitzer guns being too close together when fired and the “potential presence of anomalous electromagnetic energy in the vicinity.”

“What was different from the thousands of times before this event employing the same shell-fuze combination, weapons system, and highly trained Marines? There is no definitive answer,” the report said.

The event at Marine Corps Base Camp Pendleton featured aircraft, ships, and amphibious assault vehicles to celebrate the anniversary.

“It will be a good show regardless of who shows up,” Gen. Eric Smith, commandant of the Marine Corps, said in an Oct. 14 email to Brig. Gen. Garrett “Rainman” Hoffman, of the White House Military Office, according to the investigation.

The first round launched at 1:46 p.m. from M777 howitzers on a beach west of Interstate 5. That artillery round detonated midflight near I-5 southbound, sending shrapnel flying toward a CHP motorcycle and another unoccupied patrol vehicle, according to the CHP report. The vehicles had been part of Vance’s protective service detail and were waiting near a highway ramp after securely getting Vance where he needed to be, the report said.

An officer described hearing what sounded like “pebbles” falling on his motorcycle, and finding shards nearby. Other shrapnel struck and left a dent on the hood of another patrol vehicle.

CHP sergeants conducted a safety sweep and didn’t find any other pieces of metal in the highway lanes, the report said. Both sides of the highway were reopened about 30 minutes later.

Multiple people interviewed for the Marines investigation said they wouldn’t have changed anything about the event. Some noted a drill the day before did not have any problems and routine safety checks were done more than usual.

This story was originally featured on Fortune.com
The CEO of Delta, the world’s largest airline by market cap, said he and his company are “outraged” TSA agents continue to work without pay as the partial government shutdown drags into its fifth week.

CEO Ed Bastian, in an interview with CNBC Tuesday, specifically called out representatives in Washington, D.C., telling them to “do their job.”

“It’s inexcusable that our security agents, our frontline agents, that are essential to what we do, are not being paid, and it’s ridiculous to see them being used as political chips,” he said.

Thanks in part to staffing issues, airlines canceled more than 1,000 flights Tuesday and delayed 4,200 others, PBS News reported citing flight-tracking website FlightAware. Long security lines also accumulated at major U.S. airports such as Delta’s main hub Atlanta’s Hartsfield-Jackson airport, where travelers were encouraged to arrive three hours before their scheduled departure time, CBS reported. The TSA disruption has added to airport chaos spurred by the Iran war and severe storms in the past week.

Bastian’s comments come as he joined the CEOs of other U.S. airlines including American, Southwest, and JetBlue, in signing a public letter asking Congress “to move forward on bipartisan proposals” that will pay TSA agents, as well as U.S. customs clearing officers, and air traffic controllers. The letter cited a poll by data-science company AlphaROC earlier in March, which found 93% of Americans support paying agents from the Transportation Security Agency who ensure airport security during shutdowns.

The issue is all the more pressing, Bastian added in the interview, because of the war in Iran which has shown no signs of letting up in its third week. In fact, Iran’s military joint command Wednesday reiterated a warning Tehran would escalate the war in “new ways” if its energy facilities are attacked following a strike on its processing facilities in the South Pars gas field, the world’s largest natural gas reservoir.

“It’s outrageous,” Bastian said of TSA workers not being paid. “We got a war going on. Let’s get our people, that are people that are essential to our security, paid.” 

Delta did not immediately respond to Fortune’s request for comment.

Standing in the way of TSA agents being paid is a stalemate between Democrats and Republicans in Washington that has withheld funding exclusively for the Department of Homeland Security, which oversees the TSA. Democrats are seeking reforms to Immigrations and Customs Enforcement, or ICE, after immigration officials killed two people earlier this year. Republicans meanwhile have blocked Democrat-introduced bills that would fund the TSA separately.

The results have already rippled through airports nationwide. Even as airport security agents missed their first full paycheck over the weekend, 50,000 are required to keep working without pay and will only receive backpay once funding is restored. 

Without a paycheck, the number of TSA agents calling out of work has surged with unscheduled absences hitting an average of 6% of workers absent, compared to 2% absent prior to the shutdown, CBS News reported citing DHS figures. Some 300 workers have instead opted to quit the TSA since the partial shutdown began on Feb. 14, according to the DHS’s X account. During the longest government shutdown in history last year, TSA agents went without pay for about 43 days and around 1,100 quit, former TSA administrator John Pistole told CBS News.

These agents, who make between $46,000 to $55,000 on average, are facing financial hardships as they go without pay for the second long stretch in six months, said Everett Kelley, the president of the American Federation of Government Employees, one of the largest unions representing federal employees.

“During the last government shutdown, the longest in American history, TSA officers went through 3.5 pay periods without a paycheck. Some were evicted. Some had their cars repossessed. Some had to send their children to live with relatives because they could no longer afford childcare,” Kelley said in a statement to Fortune. “Now, politicians are putting them through it again, and the long lines travelers are starting to see are a direct result.” 

Bastian, for his part, downplayed any effect of the partial shutdown on long lines or delays for passengers, saying, “we’ll figure that out.” The real issue, he said, is the unfairness in how security agents are being treated.

“These people miss paychecks. Just a few months ago, they’re missing paychecks again,” he said. “It’s outrageous.”

This story was originally featured on Fortune.com
The Federal Reserve held rates steady Wednesday for the second meeting in a row as the war in Iran clouds an already murky economic picture. In its statement, the Fed acknowledged the war, but kept its language cautious, saying the economic implications of the Middle East conflict remain “uncertain.”

The decision was nearly unanimous, save for Stephen Miran, the Trump-appointed governor, who cast his fifth consecutive dissent in favor of a quarter-point cut. But the rest of the committee opted to sit tight, citing elevated uncertainty on both sides of the Fed’s dual mandate: inflation that won’t come down and a labor market that shocked economists with its slackness last month. 

The Iran factor

The conflict in Iran, now in its third week, has thrown a wrench into whatever plans the Fed and its watchers had for 2026. Brent crude jumped above $109 a barrel Wednesday, up from around $72 before the fighting started, while gas prices have surged nearly $1 per gallon nationwide since the war began.
Higher oil costs put the Fed in a bind because they have both depressing and inflating effects. High costs of energy function like a tax on consumers, dragging on growth, but they also feed directly into inflation—exactly the problem the Fed has been trying to solve for years.
Jobs going the wrong way

The labor market gave the Fed little comfort heading into this meeting. February’s payroll report showed employers cutting 92,000 jobs, a sharp reversal from January’s surprise gain, and the unemployment rate ticked up to 4.4%. The Fed’s own projections don’t see that number getting worse: Officials held their year-end unemployment forecast at 4.4%, but monthly hiring has essentially flatlined.

Inflation still running hot

On the morning of the decision, fresh wholesale price data reinforced the Fed’s caution. The Producer Price Index rose 0.7% in February, with the year-over-year rate hitting 3.4%, much worse than economists expected. The Fed’s preferred measure of inflation, core PCE, is already running hot at 3.1% and hasn’t eased much in two years. 

What comes next

Most officials still see at least one rate cut this year, but the divisions in the Fed seem sharper than ever. Seven of 19 policymakers projected no reductions at all in 2026, while five penciled in a half-point or more in cuts. Markets, for their part, have pushed rate-cut expectations all the way out to April 2027. Fed Chair Jerome Powell will speak with reporters at 2:30 p.m. EST. It is his second-to-last conference as chair before handing the reigns to his successor, likely former Fed governor Kevin Warsh, President Donald Trump’s nominee.

This story was originally featured on Fortune.com

Amit Banati left a CFO job at a Fortune 500 company, signed a contract to become CEO of Fortune Brands Innovations, and then never officially worked a single day in the role. He walked away this week with $18.4 million in cash. 

The epic payday, ostensibly to compensate Banati for what he left behind at his prior job, is the outcome of a remarkable, possibly absurd, confluence of today’s bumper executive compensation packages and activist investor campaigns.

And it’s just one facet of a wild week at the Deerfield, Ill. manufacturer of Moen faucets, Yale locks, and Therma-Tru doors, which sold $4.5 billion in products last year.

On Monday, Fortune Brands moved to clear its leadership slate after Garden Investment Management’s Ed Garden, an activist investor and son-in-law of prolific activist investor Nelson Peltz, struck a cooperation agreement this week with the company to join the board. 

But Garden isn’t the only large investor knocking on Fortune Brands’ door. In yet another twist, Swiss asset manager Pictet Asset Management filed a notice the day after Garden’s deal, disclosing a 7.6 million-share stake in Fortune Brands valued at $493 million. The position is double Garden’s at 6.4%. Pictet said it is engaging with the Fortune Brands board and management team on long-term strategy, governance, and financial performance. The notice allows Pictet to adjust to more aggressive tactics in the future. 

Together, Garden and Pictet’s positions represent nearly 10% of the company but the two investors aren’t working together. Garden’s cooperation agreement bars him from forming or joining any group with any other shareholder or outside parties. As the news broke on Monday, Fortune Brands’ share price fell 2.6%, and it’s down 16% year-to-date.

How it Unraveled

Banati’s $18.4 million, zero-day stint at the helm of Fortune Brands was set in motion last month, and has been marked with drama from the get-go.

Fortune Brands announced on February 12 that Banati would replace CEO Nicholas Fink, with a start date slated for mid-May. But the day after the news dropped—on Friday February 13—Fortune Brands learned that activist investor Garden had built a stake in the company and privately nominated a reported slate of three new board members.

Garden believed the company should have taken more time to find Fink’s replacement as CEO, and he immediately began snapping up shares and planing to intervene when the CEO change was announced, according to reporting by the Wall Street Journal. By the time Monday’s agreement between Garden’s firm and Fortune Brands was struck, Garden’s stake was roughly 3.5 million shares, roughly a 3% position. 

Along with renouncing the CEO job, Banati is also stepping down from Fortune Brands’ board of directors, where he has served for the five years. As for the big cash payout, Fortune Brands describes it as a “make whole” payment for what Banati left behind at Tylenol-maker Kenvue. In his job as CFO at Kenvue, Banati received a $900,000 salary, a cash bonus, and a long-term equity grant valued at $3.2 million. He also left behind nearly 3.3 million unvested shares.

Under terms of the contract Banati signed in February with Fortune Brands, he gets to keep the $8 million one-time, sign-on bonus and gets accelerated vesting on $6 million in restricted stock units.

Banati is not the only exec being swept aside as a result of the company’s deal with Garden. Chief financial officer Jonathan Baksht, who was at Fortune Brands less than a year, stepped down on Monday. To replace Baksht and Banati, ex-Fortune Brands CFO David Barry will fill the gap as interim CEO until the board can find a permanent replacement. And to round it out, Ashley George, senior vice president of business unit finance, will step in as interim CFO. Barry will collect $18,000 a month on top of his $685,000 per year salary, bonus, and long-term comp award of up to $1.67 million. George gets $15,000 a month on top of her $387,130 a year salary and other comp, plus a $150,000 cash retention award.

The Garden Deal

As part of the cooperation arrangement, Garden will join Fortune Brands’ compensation committee, the nominating committee, and he’ll also serve on a CEO search committee if the board decides to create one as they search for Banati’s replacement. Fortune Brands also agreed to reimburse Garden up to $2 million in legal and advisory fees. 

In exchange, Garden withdrew his board nominees for the upcoming 2026 annual meeting and will cap his stake below 9.9% in Fortune Brands. He also agreed to a ban on running a proxy contest for board seats at the company. 

“Fortune Brands is a company with incredible brands, advantaged market positions, and significant long-term potential,” Garden said in a statement

Susan Saltzbart Kilsby, chair of the Fortune Brands board, thanked Banati. 

“In dialogue with certain shareholders, we have now decided to commence a comprehensive search process, with the assistance of a leading executive search firm to identify the next CEO of Fortune Brands, and Amit has decided to step aside,” Kilsby said. 

The company will also put a board declassification proposal to shareholders for a vote at its investor meeting this year, a change that activists often push for that would see every board member stand for election annually. Under the current system, three directors stand for election per year on a rotating cycle.

Fortune Brands pushed its full-year 2026 outlook into the first quarter earnings call, and said its financials and fundamentals remain strong in the face of “macroeconomic and geopolitical headwinds.” The company’s net sales have declined slightly from $4.61 billion in 2024 to $4.46 billion in 2025, with net income dropping 37% from $471.9 million to $298.8 million in the same period. 

An advisor for Garden declined comment. Fortune Brands referred to its public disclosures in response to a request for comment.

This story was originally featured on Fortune.com

Today marks the start of a new era for Disney as long-time CEO Bob Iger officially passes the baton to his successor, Josh D’Amaro, at the company’s annual shareholders meeting. 

D’Amaro, a 28-year veteran of the company, was named Iger’s replacement on Feb. 3. He most recently served as head of Disney Experiences, which includes the company’s theme parks, cruise line, resorts and consumer products. 

Disney and D’Amaro have said very little about how he plans to lead the company, and today’s shareholder meeting could offer a first glimpse into the company’s direction at a pivotal moment for the media industry. 

The  company, with a market cap of $175.98 billion,will have to contend with a shifting landscape as competitor Paramount Skydance  prepares to acquire Warner Bros.,potentially cutting into the company’s market share. Since Iger returned as CEO in 2022, the company’s shares have underperformed compared to the wider market. 

The company’s messaging around D’Amaro’s ascension has focused on ensuring a smooth transition following the short, controversy-filled tenure of Iger’s first replacement, Bob Chapek. 

A key difference this time is that Iger will temporarily stay on as a senior advisor and board member, even though he’s stepping down as CEO eight months ahead of schedule. After appointing Chapek in 2020, Iger remained full-time as executive chairman and directed Disney’s creative projects. 

Former Morgan Stanley CEO James Gorman, who has been Disney’s board chairman since 2025, led the succession planning committee to replace Iger.

“Bob came to the point where he had developed the talent. And he said, ‘This is for me to step aside now,’” Gorman said in an interview with CNBC last month. “Yes, he could technically be CEO through the end of his contract. That wasn’t the aspiration. The aspiration was to get the company ready and to get the talent ready, not worrying about what the contract says.” He later added that this time there would be no drama. 

This new structure will allow for a “clean break,” and an orderly succession, board advisor and lawyer Richard Leblanc previously told Fortune

“There is always pressure on the new CEO when the old CEO is there to not make any sudden moves, and to carry on the CEO’s legacy,” said Leblanc. In contrast, when the old CEO moves on, “they exit the company so that the new CEO can find their way and implement change without feeling as though someone is looking over their shoulder.”

Disney also announced Dana Walden, who was widely reported to be a CEO contender, will become the company’s president and chief creative officer, a new role. Walden previously served as the co-chairman of Disney Entertainment, where she oversaw Disney’s movies, television, news and content businesses. 

Even though D’Amaro will be her boss, Walden’s base salary of $3.75 million is roughly 50% higher than D’Amaro’s starting base salary of $2.5 million, a strategic incentive for an executive who could have left the company after losing the top job. 

D’Amaro will have to fill Iger’s legendary shoes after a nearly two-decade tenure that included the acquisition of the company’s most iconic brands, including Pixar in 2006, Marvel Entertainment in 2009, and Lucasfilm in 2012. Disney has also made major investments in its theme parks and plans to open a new theme park and resort in Abu Dhabi. 

The incoming CEO is well-positioned to lead the company’s growth. Under D’Amaro, Disney’s parks and experiences have become the company’s primary profit engine, accounting for more than 70% of operating income despite representing under 40% of total revenue. Streaming is the other major growth driver for the company, following consecutive quarters of profitability. 

The slow transition aligns with D’Amaro’s leadership style. As he told students at his alma mater, Georgetown University, last year, he prefers to approach new roles by listening.“There’s gravity to a business card with a title on it. You start to take on that identity, but that’s not who you are,” D’Amaro told the students. “Now, every time I walk into a new job, I say, ‘I don’t know.’ But I know you do, and I know I can help.”

This story was originally featured on Fortune.com

The cryptocurrency XRP supplanted BNB as the fourth largest in market cap, as Ripple, the company most closely linked to XRP, announced that it would be expanding in Brazil. As of Wednesday morning, XRP’s market cap was at about $93 billion, whereas BNB’s market cap was closer to $92 billion. 

Ripple, which owns about 40% of the XRP supply, announced in a statement on Tuesday that in Brazil it plans on providing a suite of financial services, including cross-border payments, digital asset custody, prime brokerage, and treasury management. The company also plans to apply for a license with the country’s central bank. 

“Latin America has always been a priority market for Ripple — not just because of the scale of the opportunity, but because Brazil has built one of the most advanced and forward-thinking financial ecosystems in the world,” said Monica Long, president at Ripple, in the statement. “We’ve spent more than a decade building the trust, licensing, and technology required to operate in regulated markets.” 

The Brazil expansion comes shortly after the company bought back $750 million of its shares to put its valuation at about $50 billion. That buyback program from last week proved that Ripple could grow despite a turbulent period for the crypto sector at large. 

The company, run by CEO Brad Garlinghouse, helps financial institutions send money internationally via the XRP ledger. Ripple and XRP have a long history: when the cryptocurrency was created in 2012, the company was given about 80% of its total supply. 

While XRP is up to fourth among the largest cryptocurrencies, Bitcoin and Ethereum are still the top two. The former is down about 3% in the last day to its current price of roughly $71,000, and the latter is down about 6% during that time to its current price of roughly $2,180, according to Binance.

This story was originally featured on Fortune.com

Democratic senators pressed the U.S. government’s top intelligence official at annual worldwide threats hearings Wednesday about the war with Iran, including whether she had advised President Donald Trump that Tehran was likely to block the Strait of Hormuz, a crucial passageway for oil and gas from the Persian Gulf, if attacked.

Tulsi Gabbard, the director of national intelligence, repeatedly deflected questions about the intelligence she had offered the Republican president. That exasperated Democrats who tried to use a rare public forum to extract answers about the widening conflict in the Middle East.

She sidestepped when asked by Virginia Sen. Mark Warner, the top Democrat on the Senate Intelligence Committee, whether she had advised Trump that Iran would attack Gulf nations and shut down the strait if the country was targeted by U.S. strikes.

“I have not and won’t divulge internal conversations. I will say that those of us within the intelligence community continue to provide the president with all of the best objective intelligence available to inform his decisions,” she said.

Trump has urged allies to help safeguard the waterway and ease a chokepoint on the region’s oil exports. He complained on Tuesday that NATO and most other American allies have rejected his calls.

The annual congressional hearings involving the most senior intelligence officials are taking place at a time of scrutiny over the U.S. military campaign in the Middle East and heightened concerns about terrorism at home after recent attacks at a Michigan synagogue and Virginia university.

The focus is on the Iran war

The focus was on the war, and among the issues expected to be raised was reporting that outdated intelligence likely led to the U.S. firing a missile that hit an elementary school in Iran and killed more than 165 people. The outdated targeting data was reported to have come from the Defense Intelligence Agency, whose director, Lt. Gen. James H. Adams, was to testify. The White House says the strike is under investigation.

The hearings, which continue in Thursday in the House, are also likely to delve into the administration’s internal debate over the war, given the resignation this week of Joe Kent as director of the National Counterterrorism Center. Kent said Tuesday he could not “in good conscience” back the war and did not agree that Iran posed an imminent threat to the United States.

Hours later, Gabbard, whose office oversaw Kent’s work, wrote on social media that it was up to Trump to decide whether Iran posed a threat. She did not mention her own views of the strikes and asserted at the outset of the hearing that she intended to deliver the perspectives of the intelligence agencies, as opposed to her own viewpoints.

Trump has sought to distance himself from Kent. CIA Director John Ratcliffe tried to do the same Wednesday when he was asked whether intelligence supported Kent’s assessment that Iran was not an imminent threat.

““The intelligence reflects the contrary,” Ratcliffe said.

Gabbard’s presence at a domestic legal search questioned

Apart from Iran, Gabbard was pressed on her presence at an FBI search in January of an election hub in Fulton County, Georgia, where agents seized voter data from the 2020 presidential election. Her appearance at a domestic law enforcement operation raised eyebrows given that Gabbard’s office is meant to focus squarely on foreign threats.

Warner said it was “an organized effort to misuse her national security powers to interfere in domestic politics and potentially provide a pretext for the president’s unconstitutional efforts to seize control of the upcoming elections.”

Gabbard responded that she was present for the search at the request of the president but did not participate. But she continued to tangle with Warner, who at one point told her: “If you want to ask the questions, you should have stayed in Congress.”

Also under scrutiny is Kash Patel’s leadership of the FBI. He was making his first public appearance on Capitol Hill since video surfaced last month showing him partying with members of the U.S. men’s hockey team after their gold medal win at the Winter Olympics.

Patel has fired dozens of agents in his first year on the job, raising concerns about an exodus of national security experience at a time when the United States is confronting an elevated terrorism threat.

This month alone, a gunman wearing clothes with an Iranian flag design and the words “Property of Allah” killed two people at a Texas bar; two men who authorities say were inspired by the Islamic State group were arrested on charges of bringing homemade powerful explosives to a protest outside the New York City mayoral mansion; a man with a past terrorism conviction opened fire inside an Old Dominion University classroom in Virginia; and a Lebanese-born man in Michigan drove his car into a synagogue.

The FBI has said that it is working continuously to protect the country.

_____

Associated Press writers Mike Catalini and Ben Finley contributed to this report.

This story was originally featured on Fortune.com

U.S. stocks are sinking Wednesday after another climb for oil prices raised worries about inflation, which may have been primed to worsen even before the war with Iran began.

The S&P 500 fell 0.6% and was on track for its first loss this week. The Dow Jones Industrial Average was down 380 points, or 0.8%, as of 12:55 p.m. Eastern time, and the Nasdaq composite was 0.6% lower.

Stocks fell under the pressure of a 4.7% climb for the price of a barrel of Brent crude, the international standard, to $108.27. Benchmark U.S. oil rose 1.5% to $97.61 per barrel.

Oil and natural gas prices have been spiking since the war began because of disruptions to the Persian Gulf’s energy industry. Iran’s state television said Wednesday that the Islamic Republic would be attacking oil and gas infrastructure in Qatar, Saudi Arabia and the United Arab Emirates after an attack on facilities associated with its offshore South Pars natural gas field.

If the disruptions keep oil and gas prices high for long, they could send a debilitating wave of inflation crashing into the global economy.

A report released Wednesday morning showed that inflation pressures were already worsening before the war began. It said inflation at the U.S. wholesale level unexpectedly accelerated last month to 3.4%, and those cost increases could hit U.S. households if producers pass them all along.

Such numbers strengthened Wall Street’s consensus that the Federal Reserve will announce that it’s keeping interest rates steady this afternoon following its latest meeting, instead of resuming its cuts.

Cuts would give the job market and investment prices a boost, and President Donald Trump has been angrily calling for them. But lower interest rates would also worsen inflation.

More important for Wall Street is whether Fed officials will say they still think one cut to rates may be possible over the course of 2026. That’s what the median member said in December, the last time Fed officials published such expectations.

The Iran war has made it difficult for anyone to make economic forecasts. Gasoline prices are soaring and will push up inflation for at least the next month or two. The average price for a gallon of gasoline spiked again overnight, reaching $3.84. It was well under $3 last month.

Global oil flows remain largely constrained, ING Bank analysts Warren Patterson and Ewa Manthey wrote in a research note on Wednesday, even as hopes were growing that Iran might be allowing more vessels through the Strait of Hormuz, a key waterway for global oil and gas transport.

Roughly a fifth of the world’s crude oil passes through the strait, which has been largely closed as Iran blocks ships linked to the U.S., Israel and their allies.

On Wall Street, mixed profit reports helped keep the market in check.

Macy’s jumped 5.2% after reporting stronger profit and revenue for the latest quarter than analysts expected. The retailer behind Bloomingdale’s and Bluemercury is in the midst of a turnaround plan to drive growth under CEO Tony Spring.

But General Mills slipped 1% after the company behind the Pillsbury, Progresso and Wheaties brands reported a weaker profit for the latest quarter than analysts expected. CEO Jeff Harmening is investing in its brands in hopes of driving growth, and it’s sticking with its forecast for profit over the full fiscal year.

In the bond market, Treasury yields ticked higher following the higher-than-expected update on inflation at the wholesale level. The yield on the 10-year Treasury rose to 4.22% from 4.20% late Tuesday and from just 3.97% before the war with Iran started.

In stock markets abroad, indexes mostly fell in Europe following a stronger finish in Asia. They reacted to the rise in the price of crude, which accelerated as trading headed westward around the world.

Tokyo’s Nikkei 225 rallied 2.9% after the government reported exports in February were higher than expected. South Korea’s Kospi leaped 5%.

___

AP Business Writers Chan Ho-him and Matt Ott contributed.

This story was originally featured on Fortune.com

It was the weekend before last Thanksgiving when Kate Johnson, the president and CEO of Lumen Technologies, called then-Nationwide Chief Technology Officer Jim Fowler to discuss hiring a new top technologist for the telecommunications company.

Fowler, who had served on Lumen’s board since 2023, quickly realized that the conversation with Johnson wasn’t about a board director and CEO working together on succession planning. He was being recruited.

Less than two weeks later, Fowler left insurer Nationwide after more than seven years and joined Lumen (ranked No. 325 on the Fortune 500) as chief technology and product officer, departing the board immediately to take on the C-suite role. He succeeded Dave Ward, who had served as CTO for two years and left in January to become president and chief architect at software giant Salesforce.

Fowler joins Lumen’s leadership as the provider of internet, cloud, IT, and communication technology services undergoes a strategic transformation led by Johnson, who joined Lumen in 2022 after a brief retirement. She has focused on reducing Lumen’s debt load and narrowing its focus to prioritize serving private companies and public sector organizations. The $5.75 billion sale of Lumen’s consumer fiber businesses to AT&T helped on both fronts. The deal closed in February and Lumen has said it would use about $4.8 billion of the proceeds to pay down debt.

Another key area of focus, and this is where Fowler comes in, is a commitment that Lumen made to Wall Street back in 2024 that it would achieve annualized run-rate savings of $1 billion from its network by the end of 2027. Fowler says AI is at the “heart of how we’re going to do that.” 

“Each one of our senior leaders has a single target that they are going after,” he adds. Legal’s focus is on deploying AI-enabled applications that can speed up the contracting process, while marketing is looking at ways to use AI to create more personalized marketing materials.

For Fowler’s technology team, his goal is a 50% reduction in the cycle time for new product development. “That’s what my teams are going to march toward,” says Fowler.

Many elements of Lumen’s internal technology strategy have impressed Fowler as he settles into the role. He says his predecessor had a strong vision on cloud computing and there has been encouraging progress on AI. More than 90% of Lumen’s employees have a Microsoft Copilot license and the tool is being used for a variety of purposes including meeting assistance, strategy, and research.

Lumen’s engineers use the AI coding assistant GitHub Copilot and are authorized to switch between different AI models from providers including OpenAI and Anthropic. As a result, Fowler says he is seeing up to a 50% improvement in productivity for some tasks like re-platforming applications. 

He says one “hidden gem” he uncovered is that Lumen’s engineering team has developed an agentic AI framework already deployed across the entire company. Employees can build their own AI agents on an internal, proprietary dashboard that Lumen created. Workers can deploy custom AI agents using large language models from providers like OpenAI, Anthropic, and Google. They are encouraged to explore the models that they believe will produce the best outcomes at the most efficient cost.

Still less than 90 days into his new role, Fowler has identified a few projects he will prioritize going forward. They include modernizing Lumen’s disparate operations that stem from its legacy of growing through acquisitions. To extract the most value possible from Lumen’s AI investments, Fowler’s team will need to continue to rewrite and reimplement those systems.

Other projects include expanding the physical layer. Lumen is planning to more than double the amount of fiber in the ground, from over 17 million miles today to over 47 million miles over the next two years. Then, there’s the digital layer, making it easier for customers to opt in to Lumen’s various services through agentic AI-enabled support.

“This has been a network infrastructure company for 50 years,” says Fowler. “Getting it to think like a tech company—with software development and engineering practices that scale with demand from our customers—has been a focus of mine in the first two months that I’ve been here.”

John Kell

Send thoughts or suggestions to CIO Intelligence here.

This story was originally featured on Fortune.com

It’s common on social media sites like Reddit for users to share what stocks they are buying and selling. For better or worse, this activity serves as inspiration for others to imitate what those traders are doing and, in Europe, this so-called “copy trading” is baked right into brokerage platforms. On Wednesday, Robinhood began rolling out its version of this feature, which it calls Robinhood Social, to select users.

“Customers will be able to follow other Robinhood traders, swap strategies, discuss market moves, and trade with clarity. Plus, they can trust that every customer profile belongs to a real person, verified through KYC,” said the company in a blog post, announcing the beta launch of the tool.

Robinhood is taking a go-slow approach to the feature, which it announced last year, in part due to regulatory uncertainty over copy trading. Specifically, there are concerns that accounts endorsing stocks could be viewed as the sort of advice that, under U.S. laws, can only be dispensed by registered advisors. Meanwhile, there are broader concerns that social influencer style financial accounts are being operated under fictitious accounts in order to manipulate markets—a familiar concern on platforms like Reddit or X where some users talk up stocks or cryptocurrencies, or share doctored screenshots purporting to show their trades.

Robinhood is seeking to mitigate these concerns by building the initial version of its Social offerings around a relatively small community of users with verified identities, and encouraging thoughtful discussion about investments rather than hucksterism and hype. To this end, it is extending invitations to only 1000 customers this week, and to an additional 10,000 customers in the near future.

A spokesperson for Robinhood said the company anticipates rolling out the Social feature to all users by the end of the year.

When it comes to imitating the trading behavior of others on the platform, Robinhood’s offering won’t be as free-wheeling as the European version of copy-trading popularized by eToro. Namely, customers won’t be able to automate their trades to copy a Social user, but will be able to do so manually.

“This is an important early milestone for Robinhood Social, but it’s just the beginning,” said Abhishek Fatehpuria, VP of Product Management at Robinhood in a statement, describing the initial launch. “Beta allows us to learn quickly and build thoughtfully, prioritizing quality, trust, and feedback from our most active traders.”

This story was originally featured on Fortune.com

The artificial intelligence and cryptocurrency industries spent big and lost often in this week’s Illinois primaries, an early setback for technology firms that are trying to reshape the midterm elections and establish themselves as power players in American politics.

The companies flooded the state’s Democratic primaries with millions of dollars to promote candidates they believed would have a light touch when it came to regulating technologies that have begun to upend how people do their jobs and manage their finances.

Using super PACs that are allowed to spend unlimited sums of money, they ran television advertising and distributed campaign fliers that only occasionally alluded to their industries. Instead, the messaging focused on promises to combat President Donald Trump’s administration and support liberal policies, a strategy used by other organizations like the American Israel Public Affairs Committee.

But the coy strategy did not stop the AI and crypto industries’ interventions from becoming a lightning rod in the rowdy primaries in Illinois, where there was a rare glut of open seats that led to competitive races.

The crypto-backed political action committee Fairshake spent more than $10 million against Illinois Lt. Gov. Juliana Stratton, who ultimately won the Democratic nomination to succeed Sen. Dick Durbin, D-Ill.

Fairshake and Protect Progress, which is also tied to the crypto industry, spent millions more to unsuccessfully support Stratton’s main rivals, U.S. Reps. Raja Krishnamoorthi and Robin Kelly, according to filings with the Federal Election Commission.

Neither Fairshake nor Protect Progress responded to requests for comment.

In Illinois’ U.S. House primaries, the tech-backed groups’ campaign spending had mixed results.

State Rep. La Shawn Ford, who had supported state legislation regulating the AI and crypto industries, won the Democratic primary to succeed U.S. Rep. Danny Davis. Fairshake spent nearly $2.5 million opposing Ford’s candidacy in a race that featured at least four other political groups spending against the progressive lawmaker or for his opponents.

Meanwhile, Cook County Commissioner Donna Miller prevailed in the Democratic primary to succeed Kelly after Fairshake spent more than $800,000 against state Rep. Robert Peters, another progressive who supported legislation to regulate the crypto industry.

That race also saw the AI-backed spending at loggerheads.

The AI-backed Think Big PAC invested more than $1 million to boost the candidacy of Jesse Jackson Jr., a former congressman who pleaded guilty in a fraud scandal in 2013. But Jackson also faced about $1 million in negative campaign spending from the Jobs and Democracy PAC, another AI-backed group.

Neither PAC responded to requests for comment.

Think Big is a subsidiary of Leading the Future, a political group that is funded by major Silicon Valley executives, including the venture capitalist Marc Andreessen. Andreessen opposes federal regulations for AI and has been a staunch backer of the Republican president’s AI policies.

Jobs and Democracy PAC, by contrast, is funded by the AI company Anthropic, which favors some safety regulations on AI as the technology develops. Both PACs opposed progressive candidates who called for relatively heavy regulations on the technologies and higher taxes on wealthy Americans.

The late-stage infusions of cash into the Illinois races totaled almost $20 million across races and served as a declaration of both industries’ political ambitions, raising the stakes in primaries that were already hotly contested.

“Corporate money is being used to paint corporate-backed candidates as fearless progressives,” said Adam Green, co-founder of the Progressive Change Campaign Committee, a political group that works to elect anti-corporate progressives.

“The question for the Democratic Party is whether we elect people who actually believe in these positions or will we elect milquetoast candidates who give lip service to these values but don’t back them in actual policy,” Green said.

Campaign finance experts and rank-and-file voters alike are still struggling with what to make of the technology industry’s political influence.

“They’re so new to the game that public opinion isn’t very well formed about them,” said Brian Gaines, a political science professor at the University of Illinois Urbana-Champaign. “You don’t get a clear signal for who is the progressive and who is the moderate on AI and crypto policies.”

“People are wary of the technology,” Gaines said, “but they don’t know what to think yet.”

___

Maya Sweedler contributed to this report.

This story was originally featured on Fortune.com

The long search to find Bob Iger’s successor is over (again)—and the new CEO is a sculptor turned executive.

Disney announced that Josh D’Amaro—chairman of Disney Experiences, overseeing the company’s theme parks, cruises, and consumer products—will take the helm of the over $175 billion entertainment conglomerate. Today, March 18, is his first day on the job.

D’Amaro has spent nearly three decades climbing the Mickey Mouse corporate ladder, but taking over Main Street USA wasn’t always part of the plan. The 55-year-old has said uncertainty, not a master plan, has guided much of his career.

After growing up in Massachusetts, D’Amaro enrolled at Skidmore College intending to become a sculptor. But one night at the end of his sophomore year changed everything. D’Amaro found himself welding a 12-foot sculpture at 2 a.m., wrestling with a very adult question: How would he ever support a family as an artist?

D’Amaro finished the piece—an abstract human figure reaching toward the sky—but soon made the executive decision to pivot to a new career. He transferred to Georgetown University and pursued an undergraduate degree in business administration.

“In my head, I was going to be an artist—I was painting, sculpting, and studying art with a bit of business on the side,” D’Amaro told Georgetown students in 2025. “I loved it, but I realized I didn’t know what the hell I was going to do when I got out.”

That early moment of uncertainty would go on to shape his leadership philosophy. D’Amaro has revealed he doesn’t believe in pretending to have all the answers: Some of his most important growth came from admitting when he didn’t.

“The moment you say, ‘I don’t know,’ is one of the most freeing, liberating, invigorating feelings you can have,” D’Amaro added. “More than that—people respond to it. They want to talk to you, give you advice, pull you in. You’re not just empowering yourself, you’re empowering the people around you.”

An early career misstep may shape how D’Amaro approaches the CEO job

D’Amaro spoke to Fortune in 2024 from his office on Disney’s studio lot in Burbank, Calif., where a sketch of Cinderella’s castle hung on one wall and five black-and-white photographs of Walt Disney lined another—a daily reminder of the legacy and opportunity before him.

“I look past my computer to those photographs every day,” he said, “to remember the responsibility that I have.”

That sense of stewardship is likely to shape how D’Amaro approaches his new job as he officially takes the reins. But he isn’t likely to enact sweeping changes immediately. Instead, he approaches every new role with the same mindset: Start by listening.

“There’s gravity to a business card with a title on it. You start to take on that identity, but that’s not who you are,” D’Amaro told Georgetown students. “Now, every time I walk into a new job, I say, ‘I don’t know.’ But I know you do, and I know I can help.”

That lesson came to D’Amaro from an early career misstep—when he incorrectly advised employees at his first meeting after a major promotion.

“Afterward, I asked the senior leaders: ‘Why didn’t anyone say anything?’ And they said: ‘You didn’t ask.’ I didn’t even stop to say, ‘Hey, I’m just Josh. I don’t really know what the hell I’m doing.’ If I had said that, the room would’ve come alive,” D’Amaro said. “They would’ve said: ‘We’ve got 10 ideas no one’s heard yet—let’s go.’”

Ultimately, being open to the unknown, the Disney CEO said, has critically shaped his career and his life.

“One of the things I tell my kids is, ‘Just say yes.’ If someone offers you something a little unfamiliar, say yes. There’s so much serendipity in life—you’ve got to open yourself up and explore,” D’Amaro said. “Everything is never lined up perfectly…Sometimes you just have to hold your breath and go for it.”

Disney’s new CEO is set to fill big shoes left by Bob Iger

D’Amaro is stepping into one of the biggest jobs in media and into the shadow of a leader long synonymous with Disney.

The new CEO and outgoing executive Iger are “eerily similar,” The New York Times reported, pointing to their similar demeanor and deep identification with the Disney brand. They even share the same birthday: Feb. 10.

The comparison also underscores the stakes of the role. Iger first served as CEO from 2005 to 2020 but was brought back in 2022 after the rocky tenure of successor Bob Chapek. In acing the top job, Iger was known for his all-consuming work ethic, often starting his day at 4 a.m. and working late into the evening. His ties to the company stretch back nearly five decades, beginning as a weatherman for an ABC station in Ithaca, N.Y.—years before Disney acquired ABC in 1996.

Though the role comes with enormous expectations, it also comes with great reward. D’Amaro’s total compensation package is expected to be about $38 million. In comparison, Iger earned just over $45 million in compensation in 2025—up over 45% from his $31 million package in 2023, according to the Walt Disney Company’s SEC filings.

Iger credited his rise to three things: hard work, great mentors, and great luck. He has also made it clear leadership is about earning respect—not chasing approval.

“If you try to run a popularity contest, then you don’t make the tough decisions,” Iger said at Bloomberg’s Global Business Forum in 2019. “I think you have to be fair, accessible, and communicative—but popularity is not one of them.”

For D’Amaro—who already has a following among Disney’s most devoted fans—the task now is to carry that legacy forward while defining his own era, balancing continuity with change at a pivotal moment for the company.

A version of this story originally published on Fortune.com on February 3, 2026.

More on careers:

This story was originally featured on Fortune.com

Engineer Alexey Grigorev was using Claude Code—a popular Anthropic tool that helps developers write and run code—to update a new website. 

At first everything seemed normal, until he realized the system had begun destroying the site’s live environment: the network, services and, most critically, the database holding years of course data. 

The root cause was a small setup mistake on a new laptop that confused the automation about what was “real” and what was safe to delete, so it erased the actual production system instead of just cleaning up duplicates. 

While Grigorev eventually managed to restore his data with help from AWS support, he later wrote that he had “over‑relied on the AI agent” and, by letting it make and execute the changes end‑to‑end, had removed safety checks that should have prevented the deletion.

“AI assistants are great and saving a lot of time,” Grigorev told Fortune. “But I hope people learn from mistakes I made and incorporate the safeguards into their workflow.”

Anthropic’s Claude Code has settings that give a user control over when and how often the agent checks back with the user before taking actions. A user can specify that the agent should not take certain actions without asking for permission from the user. But some coders prefer to let the AI agent execute more decisions autonomously, in part because it saves time. As of press time, Anthropic had not responded to a request to comment for this story.

Even as AI coding tools promise faster development and automation, mistakes in AI-generated code are common and risk bringing down critical systems, wiping out years of work, and creating unexpected costs. Last week, Amazon convened a “deep dive” meeting after a series of outages affected its website and app. At least one of the system failures was, according to news reports in several publications, involved AI-assisted changes.

A spokesperson for Amazon told Fortune that the meeting was a “regular weekly operations meeting.” The company has also said publicly that only one of the incidents involved AI, and “the cause was unrelated to AI and instead our systems allowed an engineering team user error to have broader impact than it should have.”

However, internal Amazon documents viewed by both CNBC and the Financial Times, originally cited “Gen-AI assisted changes” as a factor in a “trend of incidents.” The reference to AI’s role in the outages was later deleted from the document ahead of the meeting, CNBC reported. According to the Financial Times, a December outage at Amazon Web Services occurred after engineers allowed Amazon’s own Kiro AI coding tool to make changes—something Amazon has since said was a “user error.”

The excitement around AI-assisted software development has reached a fever-pitch over the last few months, but the errors are starting to pile up. Companies, emboldened by advances in AI coding agents and stories of dramatic productivity gains within AI labs, have started pushing engineers to produce more and more code with AI tools, often without proper oversight in place. For large enterprises, the poor quality of some of this code may prove to be AI’s Achilles heel.

An over-reliance on AI tools

Across the industry, engineers say that reliance on AI assistants to write and deploy code is rapidly changing the nature of software development jobs—and introducing new risks.

“People are becoming so reliant on AI that essentially they stop reviewing the code altogether,” one Amazon engineer, who asked to remain anonymous, told Fortune.

The developer said that even technically skilled staff are moving into more of a “review role” rather than actively coding, with AI handling much of the actual implementation. While these tools allow for faster feature delivery, they also create what some call “production noise,” code that is delivered quickly but isn’t always needed or fully tested. In some cases, it could even affect critical systems.

David Loker, VP of AI at CodeRabbit, said the consequences aren’t always as visible as an outage. In one instance, he said an AI assistant generated code that looked perfectly valid but was built on faulty assumptions about their underlying system—code that might have passed a quick review but would have crashed their database in production if they’d rolled it out.

“If you just rolled that out, it would have taken down our database in production,” he said.

Because AI coding lowers the technical knowledge needed to perform certain software development tasks, engineers say companies are also outsourcing tasks normally done by senior engineers to junior or less technical staff, only to find that low-quality output creates more work than it saves. 

“A lot of what was built was fairly bad quality, broke often, and ended up being more of a burden,” one London-based engineer at an enterprise software company, who asked to remain anonymous because they were not authorized to discuss company matters with the press, said. “The time won by getting the cheap people to write it is offset by having someone paid far more—a senior or principal—to have to go fix it when it breaks.”

Broader data suggests the burden of reviewing and repairing AI-assisted work is falling disproportionately on more experienced engineers. While senior engineers have the skills to spot a logistical error or security flaw that a junior might miss, allowing them to ship faster, they’re also paying a growing “correction tax.”

A July 2025 Fastly survey found that senior engineers ship nearly 2.5x more AI-generated code than junior ones, because they’re better at catching mistakes before they compound. But nearly 30% of seniors said fixing AI output ate up most of the time they’d saved, compared to 17% of junior developers. Junior developers often feel like they’ve banked bigger productivity gains because they don’t yet see the full technical debt or latent vulnerabilities that their AI-assisted changes are quietly adding to the system.

The productivity paradox 

Part of the problem is C-Suite FOMO. Engineers at leading AI labs have been claiming productivity surges that would have seemed implausible just a few years ago, and larger organizations across a variety of industries want to encourage similar gains. 

For example, Anthropic’s head of Claude Code, Boris Cherny, previously said he hasn’t written a line of code in months, instead relying on the company’s AI model to generate it. Within the rest of Anthropic, the company told Fortune that between 70% and 90% of its total code was now AI-generated.  At Spotify, co-CEO Gustav Söderströn said last month that the company’s best developers hadn’t written a single line of code since December and have shipped over 50 new features in 2025 using AI-assisted workflows.

But, as demonstrated by Amazon’s recent issues, the productivity gains that are most visible at AI labs and agile startups may be harder to replicate at large enterprises with legacy systems and complex codebases. Where smaller teams can move fast and absorb mistakes, companies like Amazon operate infrastructure where a single bad deployment can affect millions of customers.

A September report from Bain & Company found that even though programming was “one of the first areas to deploy generative AI,” the actual savings have been modest and the results “haven’t lived up to the hype.” Meanwhile, research from security firm Apiiro showed that developers using AI introduced roughly ten times more security issues than those who did not.

AI models, as AI researcher Andrej Karpathy has noted, can make subtle conceptual errors, over-complicate code, and leave unused code behind—problems that are manageable in a controlled environment but harder to catch and fix at scale. A December report from code review firm CodeRabbit, which analyzed 470 open-source GitHub pull requests, found that AI-authored code contained roughly 1.7 times more issues overall than human-written code. Larger organizations tend to have more stakeholders, more review layers, and more dependencies, an environment where AI-generated code is more likely to introduce unexpected failures.

“It’s just going to take longer for larger organizations like AWS, or like Nvidia to implement this…because you have so much legacy code,” Loker said.. “There’s way less documentation within it, there’s less searchability for the AI to pick up on…so it’s harder to find the context sometimes. You’re going to end up introducing problems.”

There are also questions about whether the benchmarks used to measure AI’s coding ability reflect real-world tasks. A recent study by METR, an AI evaluation organization, found that half of AI coding solutions graded as passing on a prominent industry test—which is itself graded by an AI model—would actually have been rejected by human reviewers for inadequate quality.

Toby Ord, Senior Researcher at the Oxford Martin AI Governance Initiative, said current estimates of AI coding ability are “indeed overstating things, and perhaps by a significant factor.”

Another issue is how the companies themselves are measuring the “success” of AI coding, according to Loker. “It’s very easy to measure throughput increase,” he said. “What is not easy to measure at this point is the causality of what happens after.” The metrics traditionally used to gauge developer productivity—features shipped, code committed—look strong when AI is involved, but don’t capture downstream consequences like bugs, rollbacks, or time spent cleaning up. “That’s not necessarily the only metric of my company’s code health as a whole,” he said.

Companies rolling out AI at scale also risk accumulating what engineers call technical debt—code that functions in the short term but becomes increasingly costly to maintain. “We’re producing tech debt using AI at a clip that I can’t even fathom,” Loker said. “It’s probably three to four times what it was previously.”

This story was originally featured on Fortune.com

The U.S.-Israeli war on Iran is already lost for the United States. Even if Iran is militarily defeated, it is unlikely the United States’ political objectives will be achieved. And, on balance, the United States will come out weakened from this war.

President Trump’s biggest problem lies in his attempt to square an impossible circle: imposing regime change in Iran without committing ground troops. Trump understands that neither his MAGA base nor the U.S. public has any appetite for another prolonged ground war in the Middle East. But regime change from the air does not work for a 90 million-strong country that is four times the size of Iraq and has been preparing for this eventuality for decades. The United States is beleaguered by the paradox of a leadership wanting to reimpose its global might through coercion and hard power and a population fundamentally opposed to any war that entails a significant expenditure of U.S. lives.

Why Iran Is Harder to Break Than It Looks

Despite all the talk of a downgraded Iran in the last two years, recent events have demonstrated the country’s capacity to resist. Iran’s resilience relies on a military and security architecture that is highly decentralized, with overlapping command structures between the regular armed forces and the Islamic Revolutionary Guard Corps. Recent days have shown how thoroughly Iran has developed extensive contingency planning designed to ensure continuity even under sustained attack. Airstrikes on Iran’s leadership have been ineffective — possibly even counterproductive, given their radicalizing effect on pro-government sectors of the population and their triggering of predetermined war protocols.

Equally important, Iran’s strategy is built around asymmetric warfare and escalation management. Its arsenal of weapons and proxy networks allow it to reap chaos across the region while imposing high costs on its adversaries. Iranian drones and missiles are relatively cheap to produce, but shooting them down requires interceptors that cost as much as 200 times more — and are limited in supply.

This leaves Trump facing a strategic trap. He must choose between the political cost of failing to achieve his regime change objectives and the political cost of walking back on his domestic promise of no more forever wars. The only viable exit strategy is to manufacture the appearance of victory: declaring that the objectives have been met even when they clearly have not.

The Peace Deal That Was Sabotaged the Day Before the Attack

Even if Trump manages to save face domestically, the war has already been lost at the international level — and the most damning evidence of that may be what happened the day before the bombs fell.

The first source of resentment is that the United States entered this war at Israel’s behest. Israel has been pushing for a decisive confrontation with Iran for years, against the repeated warnings of Washington’s other traditional partners in the Persian Gulf. Gulf states, organized in the Gulf Cooperation Council, opposed this war from the start — they understood that a major conflict with Iran would destabilize the entire region. They were not given prior notice of an attack meticulously planned with Israel. Prince Turki al-Faisal, Saudi Arabia’s former intelligence chief, was reflecting broadly felt regional sentiment when he told CNN: “This is Netanyahu’s war.”

This opposition led several states to support diplomatic efforts that were actively underway when the attack began. The day before the attack, Oman announced a breakthrough: Iran had agreed not to stockpile fissile material — a concession that went beyond anything Iran had agreed to in the 2015 JCPOA, which Trump had previously scuttled. “A peace deal is within our reach,” the Omani foreign minister said — before declaring the following day, once the strikes had begun: “I am dismayed. Active and serious negotiations have yet again been undermined.”

That agreement died on the runway. It is worth sitting with that fact.

How the War Is Fracturing U.S. Alliances in the Gulf

The Gulf states’ second grievance is that this war has seriously jeopardized their own security. As a result of the U.S.-Israeli attack, Iran retaliated against installations in Gulf states hosting U.S. military bases. In the Gulf, Iranian drones and missiles have struck targets in Bahrain, Kuwait, the United Arab Emirates, Oman, Saudi Arabia, and Qatar. There is rising anger in these countries that whereas the United States has done little to shield them from these strikes, it has done a great deal to protect Israel. This dynamic creates precisely the strategic outcome Iran has long sought: to erode the foundations of the U.S. security architecture in the Gulf. If trust between Washington and its Gulf partners weakens — potentially leading some states to eventually downgrade their security cooperation — that alone represents a significant strategic victory for Iran.

Bahrain did successfully lead a UN Security Council resolution condemning Iran for these strikes. But Gulf states’ hostility toward Iran is not the new development here. The new development is the regional resentment toward the United States — given that all parties knew Iran would likely attack its neighbors if Washington struck first.

The situation could deteriorate further if Washington, encouraged by Israel, chooses to double down on the total destruction of Iran rather than seek an exit strategy. Nobody in the region — except Israel — wants a prolonged war or the total collapse of the Iranian state. The specter of Libya’s failed state and Syria’s civil war still haunts the region. As a result, Iran’s neighbors mostly distrust the CIA’s renewed support for Kurdish militants, as well as growing talk of stoking Azeri, Baloch, and Arab nationalist movements.

Yet many of Trump’s domestic allies remain oblivious to these concerns. A good if baffling example of this deep-seated ignorance was Sen. Lindsey Graham’s recent threat to GCC states. “Get more involved as this fight is in their backyard… if not, consequences will follow” — captures the depth of that disconnect.

The Global Economic Fallout

Beyond the Middle East, this war now threatens the entire global economy. Oil prices have surged as a result of the selective closure of the Strait of Hormuz. In the United States, gas prices have risen sharply, fueling fear among Republicans that a continued energy crisis could hurt them in the midterm elections. In parts of Asia, the impact is being felt not only in rising fuel and liquefied gas prices but in supply constraints — several countries in South and Southeast Asia are already experiencing energy rationing, resulting in shortened work weeks, business closures, and partial school shutdowns.

Europe faces its own vulnerabilities. With the end of winter providing some relief, gas reserves nevertheless remain low. Russia has been quick to offer Europe an energy lifeline — which Europeans have so far rejected, determined to uphold their sanctions. Meanwhile, Washington first gave permission to India to purchase limited quantities of Russian oil, then removed sanctions on Russian oil altogether, albeit temporarily. Russia looks set to be among the war’s clearest beneficiaries.

China, highly dependent on Gulf oil imports, will also be forced to seek alternative energy sources — likely accelerating its reliance on Russian oil. But in the longer run, the war tilts the strategic balance decisively in Beijing’s favor. A protracted conflict consumes U.S. military resources globally, including in East Asia — the removal of the THAAD missile defense system from South Korea is an early example of that overreach.

The war will further erode Washington’s global prestige and deepen doubts among key allies about the reliability of U.S. leadership. China has spent years carefully nurturing its relations with Gulf states, including Saudi Arabia — and a net result of this war will be the consolidation of those ties. Some analysts have also argued that the energy shock could further accelerate a global transition toward renewables, raising global demand for Chinese solar panels, electric vehicles, and batteries. Against the backdrop of U.S. military adventurism, China’s reputation for diplomacy and economic stability will continue to gain global appeal.

The Nuclear Paradox

One of the great ironies of this war is that it marks the end of any significant deterrence of Iran — including on its nuclear program. If Iran survives the devastating destruction brought upon it, its appetite for a nuclear deterrent will have significantly increased. A likely consequence of this war, therefore, will be to accelerate the very threat it professed to avert.

Operation Epic Fury is increasingly looking like an epic fail. What began as an attempt to demonstrate the ongoing relevance of unrivaled U.S. military power is fast becoming one of the most consequential strategic miscalculations of this century — a pivotal moment in the steady erosion of U.S. hegemony.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Corporate America is making one of the biggest capital bets in decades on artificial intelligence while simultaneously cooling the labor market needed to make that investment pay off.

This is not fiscal prudence. It is operational paralysis. According to a recent survey of more than 350 public-company CEOs and investors managing $19 trillion in assets, 66% of CEOs plan to freeze or cut hiring through the rest of 2026.

As a gender economist, I see a deeper structural failure: CEOs are buying powerful computational engines while cutting the middle-management and HR functions required to implement, govern, and scale them. The explanation given is a wait-and-see approach to AI ROI. But waiting is not a neutral act.

Why 66% of CEOs Hit Pause

The freeze is the aftershock of 2025. Corporate America eliminated more than 1.17 million jobs under the logic that excess labor had to be cut to fund the future of AI.

Early enthusiasm has now met operational reality — and the disconnect is measurable. Investors want near-term returns, with 53% expecting AI payback within six months. CEOs are more realistic: 84% acknowledge that meaningful ROI is a multiyear project.

That tension has produced operational paralysis. The labor market softened enough to shrink headcount without the stigma of mass layoffs — and by February 2026, that retrenchment had hardened into a freeze. In the process, many leaders cut the very HR and middle-management roles that help define future jobs, redesign workflows, and create organizational clarity.

The Shift CEOs Are Underestimating

Too many leaders are still managing for 2024. They are operating in 2026.

Generative AI helped workers produce more content. Agentic AI goes further: it can initiate tasks, coordinate multistep workflows, and act across enterprise systems with less human input. This is no longer a content story. It is a control story.

CEOs are hesitating because agentic systems introduce nonlinear scale. A single digital agent can coordinate thousands of actions. But without the human agent mesh, that scale quickly turns into operational risk. By late 2026, 20% of companies are expected to use AI to flatten their hierarchies, eliminating more than half of mid-tier roles. That protects margins in the short term. It strips out a critical supervisory layer in the long term.

The Layer Companies Are Cutting — and Shouldn’t

AI is flattening the corporate pyramid. The data shows how fast.

Labor market data shows a 30% drop in entry-level job listings and a 42% drop in middle management postings since 2022. The operating logic is that if AI can summarize and coordinate, the middle layer is redundant.

This logic is flawed. Middle managers are the connective tissue. They translate strategy, coach talent, and manage exceptions — the complex human problems algorithms are not equipped to handle. Removing them trades long-term stability for short-term margin. The result: decision latency, an expertise gap, and junior professionals who never learn to recognize value themselves.

What Fortune 500 Boards Are Missing

OpenAI’s most telling recent hire wasn’t an engineer. Their decision to hire a Head of Preparedness at a $555,000 salary is a highly relevant data point for the Fortune 500.

OpenAI recognized that as models become agentic, the risk shifts to frontier threats like cybersecurity vulnerabilities and autonomous system evolution.

Silicon Valley is solving for preparedness at the product level. Who is solving for it at the workforce level in your organization? Many companies treat HR as an administrative function and are deploying autonomous agents without sophisticated human oversight. Operating intelligence at scale requires managing responsibility at scale.

The New C-Suite Role That Fixes This

To bridge this governance gap, organizations need to hire a Chief Workforce Architect — the Agentic CHRO. The role sits at the intersection of technology, economics, and ethics — and it carries P&L responsibility.

1. The Technologist: Designing the Human-Agent Mesh
The CWA must understand code as well as they understand people. They design the agentic mesh — a robust ecosystem where humans and AI agents collaborate. They define the universal agent protocol and monitor value per cognitive run rather than just headcount.

2. The Economist: Labor as Strategic Capital
The CWA uses labor economics to identify where human capital extracts margins AI cannot — specifically in critical thinking and negotiation. They protect the Succession Spine by ensuring leadership feeder roles are preserved during structural transitions.

3. The Ethicist: Equity as Economic Safety
In an autonomous workforce, equity is not a values statement. It is a P&L lever. Across 4,161 companies in 29 countries, my research found that every 10% increase in intersectional gender equity is associated with a 1% to 2% increase in revenue.

Hiring a CWA also requires the C-suite to reset three assumptions:

  • Stop viewing the workforce as an expense to be minimized — treat it as strategic capital to be engineered.
  • Stop categorizing middle management as structural redundancy — value it as connective tissue and strategic asset.
  • Redefine productivity from headcount per unit to value per cognitive run.

The $3.1 Trillion Signal CEOs Are Ignoring

The 66% freezing hiring are missing one of the most reliable growth levers available. The ROI of equity is already established.

Closing the gender equity gap would add $3.1 trillion to the U.S. economy. For a Chief Workforce Architect, these figures represent the foundational math of economic growth.

By fixing the first leak in the pipeline — the transition from entry-level to first-level manager — organizations add millions more women to the talent pool for P&L roles. In the agentic era, that equity prevents models from drifting into biased decision-making and provides the managerial clarity required to ensure every talent decision closes the gap rather than widens it.

As we move through 2026, the most successful companies will align technology with talent, evidence, and judgment. Growth must be extracted from internal productivity. To achieve this, we must transitionf rom viewing the workforce as an expense to engineering it as a complex system. The ROI of AI will not be found in the savings from those who depart. It will be found in the architecture of those who remain.

The governance gap is real — and the Board owns it. It is time to stop treating HR as an administrative function and start hiring Chief Workforce Architects.

Corporate America does not need fewer people. It needs better architecture.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Britannica and Merriam-Webster have filed a lawsuit against OpenAI, alleging that the AI giant has built its $730 billion company on the back of their researched content.

In a filing submitted to the Southern District of New York, the companies accuse OpenAI of cannibalizing the traffic and ad revenue that publishers depend on to survive. “ChatGPT starves web publishers, like [the] Plaintiffs, of revenue,” the complaint reads. Where a traditional search engine sends users to a publisher’s website, Britannica and Merriam-Webster allege ChatGPT instead absorbs the content and delivers a polished answer. It also alleges the AI company fed its LLM with researched and fact-checked work of the companies’ hundreds of human writers and editors.

The case is the latest in a series accusing AI firms of data theft, raising questions about what counts as public knowledge and what information online should be off-limits for AI use. A group of anonymous individuals sued OpenAI in 2023, alleging that the AI giant stole “vast amounts” of personal information to train its AI models. And in 2024, two writers sued the company, representing writers whose copyrighted work they allege had been “pilfered by” OpenAI and partner Microsoft. But these lawsuits aren’t solely confined to the ChatGPT maker. Anthropic, Perplexity, and nearly every other major AI company have all faced lawsuits alleging some form of copyright infringement.

The lawsuit argues that OpenAI’s use of their content could produce a positive feedback loop in which declining advertising and subscription revenue leads to lower-quality content, which in turn further reduces revenue. 

“Less content of poorer quality will further result in reduced revenue, and thus less spending on content creation,” the complaint alleges, “spawning even less content of even poorer quality and even less revenue, and so on in a downward spiral for content creators like Plaintiffs.” 

The lawsuit comes after the plaintiffs reached out to OpenAI in November 2024 to discuss a potential licensing agreement, that OpenAI rebuffed, according to the complaint. The plaintiffs seek to hold OpenAI accountable for the substantial harm and “illicit profits” it is generating from allegedly infringing on their copyrighted material. The lawsuit alleges OpenAI is also in violation of the Lanham Act (which covers trademark registration) when ChatGPT makes up content or hallucinates content and falsely attributing information to the plaintiffs. They’re asking the court for a permanent injunction to stop OpenAI from continuing to use their material.

“ChatGPT helps enhance human creativity, advance scientific discovery and medical research, and enable hundreds of millions of people to improve their daily lives,” a spokesperson for OpenAI said in a statement to Fortune. They added that their AI models “empower innovation and are trained on publicly available data and grounded in fair use.”

The alleged plagiarism of “plagiarize” and the Hamilton-Burr duel

But Merriam-Webster and Encyclopedia Britannica allege ChatGPT plagiarizes the information their human researchers, writers, and editors produce. In an apt example, the complaint describes a prompt asking “How does Merriam-Webster define plagiarize?” to which the model reportedly responded with a definition identical to the one found in the Merriam-Webster dictionary. The complaint adds that the dictionary has been registered with the U.S. Copyright Office.

That alleged plagiarism extends beyond copying dictionary definitions. The complaint outlines questions about specific historical events, for example, to show how the AI mimics the publishers’ unique selection and curation of content. When a user asked ChatGPT for “10 Things You Need to Know About the Hamilton-Burr Duel, According to Hamilton’s Burr,” ChatGPT reportedly reproduced an identical specific selection and ordering of quotes found in a copyrighted Britannica article, including the exact snippets curated by Britannica’s editors. The model also noted that Britannica had fact-checked the article.

The plaintiffs ultimately argue that these practices threaten to seriously undermine their longstanding business models. “OpenAI imperils the very market for the high-quality content that it copies and reproduces.”

This story was originally featured on Fortune.com

With graduation season just weeks away, millions of college seniors are preparing to walk across commencement stages and become the youngest members of the workforce. But for the class of 2026, that transition may be rockier than ever, with BlackRock CEO Larry Fink issuing a warning that the promise of a four-year degree as a pathway to a stable career is beginning to crack.

Fink stressed at BlackRock’s 2026 Infrastructure Summit that he’s “worried that when this year’s college graduates enter the workforce, we could see the highest unemployment rate among them in years—even without a recession.”

At the core of his concern: tech is rapidly reshaping the very entry-level roles that have long served as the first rung for college graduates.

“The speed at which AI is changing, we’re not adapting our society fast enough,” the 73-year-old added. “Really post World War II, the pathway to a white-collar job was a college education, and AI is going to disrupt many of those types of jobs.”

The unemployment rate among recent college graduates ages 22 to 27 currently sits at 5.6%, according to the Federal Reserve Bank of New York—near levels not seen since 2013, excluding the pandemic. And demand for early-career roles continues to tighten. Job postings on Handshake, a platform for college students and recent graduates, fell more than 16% between August 2024 and August 2025, while the average number of applications per role has jumped 26%. 

For Gen Z soon entering the workforce, it’s an early sign that the traditional first rung of the career ladder is starting to give way.

AI will create skilled-trade jobs—but the workforce isn’t ready, Larry Fink warns

Despite the warning, Fink pushed back on the idea that college is no longer worth it at all—and he pointed to his own experience. 

After graduating from the University of California, Los Angeles in 1974 with a political science degree, Fink said he didn’t feel ready for the workforce. He went on to earn an MBA with a focus in real estate and then launched a career first at investment firm First Boston (later acquired by Credit Suisse) before spending the last four decades building BlackRock into the world’s largest asset manager.

Still, he cautioned that the college-to-career pipeline is no longer universal, arguing that the traditional four-year degree is becoming just one of several viable paths to success.

“The key for life for everyone is to find their purpose,” Fink said. “For some people, their purpose will remain to get a four-year or advanced degree, and they could take that forward—but that’s not going to be the pathway for everybody.”

Where demand is growing—with not enough supply—is in the skilled trades, fueled in part by the expansion of AI infrastructure like data centers.

“[AI] is going to create many jobs and we’re not prepared as a society to fulfill those jobs,” Fink said. “And to me, this is a crisis.”

To help address the gap, BlackRock committed last week to invest $100 million in skilled-trade programs. The initiative aims to work with nonprofit and workforce development partners to reach 50,000 workers over the next five years in roles like electricians, HVAC technicians, plumbers, and ironworkers.

“AI is going to create a lot of skilled jobs needs and the biggest issue confronting our country today and other countries is the speed at which this change is occurring,” he added.

Last year, BlackRock led a group of investors including Microsoft and Nvidia to purchase Aligned Data Centers for $40 billion.

Fortune reached out to BlackRock for further comment.

As Fink warns of a job ‘crisis,’ other CEOs encourage Gen Z to lean into the uncertainty

Fink isn’t alone in his concerns. More than half of employers view the job market for the class of 2026 as “poor” or “fair,” according to a survey from the National Association of Colleges and Employers—the most pessimistic reading since the start of the pandemic.

Still, many CEOs are striking a more optimistic tone, framing the moment not just as disruption, but opportunity.

AMD CEO Lisa Su pointed to the upside for graduates entering the workforce who lean on the technology to find new ways to innovate.

“The Class of 2026 will be graduating at an exciting time, as AI transforms our world and expands what is possible,” she said in a statement announcing her as MIT’s 2026 commencement speaker. “And I look forward to celebrating them as they prepare to share their skills and ideas with the world.”

Bank of America CEO Brian Moynihan struck a similar tone—acknowledging the anxiety many young people feel, but encouraging them to channel it. 

“If you ask them if they’re scared, they say they are. And I understand that,” Moynihan told CBS News earlier this year. “But I say, harness it … It’ll be your world ahead of you.”

This story was originally featured on Fortune.com

The Iran war has rattled the global flow of oil, with steeper fuel costs already straining households worldwide. And in the U.S., drivers are now facing the highest prices they’ve seen at the pump in about two and a half years.

According to motor club AAA, the national average for a gallon of regular gasoline jumped over $3.84 on Wednesday, up from $2.98 consumers were paying before the U.S. and Israel launched the war with joint attacks against Iran on Feb. 28. The last time gas prices were as expensive as they are now was in September 2023.

“It’s pretty hard. I mean, times are tough for everybody right now,” Amanda Acosta, a Louisiana resident, told The Associated Press while filling up her car’s tank this week. “I’m getting way less gas and paying way more money.”

She isn’t alone. Pain at the pump has been one of the most immediate economic impacts of the conflict, because the price of crude oil — the main ingredient in gasoline — has soared and swung rapidly in recent weeks, due to supply chain disruptions and cuts from major producers across the Middle East. Brent crude, the international standard, was trading at nearly $108 a barrel Wednesday, up from roughly $70 just weeks ago. And benchmark U.S. crude is now going for almost $98 a barrel.

Many eyes are on the White House. Before the war, President Donald Trump once bragged about keeping gas prices low. But he’s since pivoted to try and paint high oil prices as a positive outcome for the U.S. Last week, Trump said that because the U.S. is now largest crude producer in the world, “when oil prices go up, we make a lot of money.”

Companies that supply oil benefit from higher prices. But steeper costs always pinch consumers’ wallets — and today’s prices arrive as many households continue to face wider cost of living strains. It could also push up already stubborn inflation, at least in the short run, and potentially hammer the economy more significantly if rising costs drag on. Experts say that could apply more pressure on the Trump administration, particularly as affordability continues to stay at the top of voters’ minds.

Drivers see impact of higher fuel prices

“I just want all of it to end. I just want to get out of there, out of Iran,” said Meghan Adamoli, a New Jersey resident who was among customers filling up at a Multani station on Tuesday. While Adamoli said she can personally “roll with the punches” when it comes to gas prices, she knows that a lot of others can’t.

Dan Bradley, a flatbed truck driver from Pennsylvania, said he’s felt the rising prices for both his work and personal vehicles. Beyond regular gasoline, the U.S. average for diesel neared $5.07 a gallon on Wednesday, per AAA, its highest level since 2022. Before the Iran war started, diesel was averaging at about $3.76 a gallon.

“It sucks when you’re filling up,” said Bradley. “What are you going to do, not get gas?”

Meanwhile, Texas resident Clay Plant said rising oil costs is good for the economy of his town, Lubbock. He sees more people work as drilling picks up.

“It’s kind of a good sign for us in west Texas,” Plant said. “I look at it as my friends and family get to eat and they get to go to work.”

Search for more supply and uncertainty ahead

The U.S. is now a net exporter of oil — and other parts of the world that rely more heavily of fuel imports from the Middle East, notably Asia, have seen starker energy shocks amid the war. But that doesn’t mean America is immune to price spikes.

Oil is a globally-traded commodity. And most of what the U.S. produces is light, sweet crude — but refineries on the East and West coasts are primarily designed to process heavier, sour product. So the country also needs imports.

The road ahead is uncertain, and prices could worsen if the war drags on. Iran has effectively halted nearly all tanker movement in the key Strait of Hormuz, where roughly one-fifth of the world’s oil once sailed through on a typical day. That’s led to cuts from some major producers in the region, because their crude has nowhere to go. Trump has demanded that other countries send warships to reopen the waterway, but has yet to garner sign-ons as many ask for more clarity about America’s next steps for the war. Meanwhile, Iran, Israel and the U.S. have all struck oil and gas facilities.

All of this has left countries scrambling for other supply. Last week, the International Energy Agency pledged to release 400 million barrels of oil from its member nations’ stockpiles. Trump, who previously downplayed the need for reserve oil, later confirmed that the U.S. would pull 172 million barrels from the Strategic Petroleum Reserve as part of this effort. The administration also announced it will temporarily free up Russian oil from U.S. sanctions for its war on Ukraine.

Still, analysts say these efforts will be a short-term bridge. Refineries buy crude oil in advance, and it takes time for new supply to trickle down to consumers. While steep crude costs is the top driver of gas prices today, a handful of other factors are also on the table. U.S. gas prices typically tick up a bit at this time of year, as more drivers hit the road and the warming weather brings a shift to “summer blend” fuel, which is more expensive to make than winter blend.

As always, some states also have pricier averages than others, due to factors ranging from nearby supply to differing tax rates. On Wednesday, California had the highest average of over $5.56 per gallon, while Kansas had the lowest of about $3.23.

Experts warn all of this could eat into wider spending. As consumers pay more to cover necessities like gas, many households — particularly those that are middle or low income — will be forced to cut their budgets in other places, explains Francesco D’Acunto, a finance professor at Georgetown University. More expensive fuel also impacts other sectors, from transporting groceries to household utility bills.

These combined inflation shocks, and overall high uncertainty during times of war, also “makes many houses and consumers freeze,” D’Acunto added. He said that could cause some to hold off on bigger financial decisions — like buying a car or house — farther down the road. “So potentially even that will have such an effect on the overall economy.”

________

AP Journalists Stephen Smith in Madisonville, Louisiana, Geoff Mulvihill in Cherry Hill, New Jersey, and Mingson Lau in Claymont, Delaware, contributed.

This story was originally featured on Fortune.com

Polymarket, one of the two leading prediction market sites, built its platform on blockchain rails—a design that offers efficiency but that can also add a layer of unwanted complexity.  On Wednesday, the fast-growing company took a step that will help it tuck those blockchain elements further into the background: Polymarket announced it is acquiring Brahma, a startup that specializes in providing crypto and DeFi infrastructure for businesses and individuals managing digital assets. The financial terms of the deal were not disclosed. 

“Building reliable infrastructure across blockchain networks and traditional financial rails is hard—there are no shortcuts,” said Shayne Coplan, founder and CEO of Polymarket, in an email to Fortune. “The Brahma team has shown they can design, operate and scale complex products for sophisticated users.”

While Polymarket expects the acquisition will improve its user experience, the move also signals the company—which has quickly grown to a reported $20 billion valuation—is doubling down on its crypto roots. Polymarket has been using blockchain rails since its inception, whereas its main competitor Kalshi functions largely with fiat currency. 

One way that Brahma could help Polymarket is by bringing additional liquidity to smaller wagers. Larger event contracts, like those in sports or politics, easily bring lots of money into the pool. But smaller wagers focused on niche areas such as, for instance, the outcome of a bowling match in Spain, struggle to amass a sizable amount of liquidity. Brahma’s experience in DeFi, a decentralized field of crypto defined by rapid trading and users with a high capacity for risk, could help draw in additional capital to more thinly traded contracts.

Alessandro Tenconi, one of the co-founders of Brahma, said in an interview with Fortune that his startup could remove the friction for Polymarket users when it comes to creating a wallet, depositing and converting shares, and redeeming outcome tokens.  

Brahma, started in 2021 by Tenconi and his co-founders Akanshu Jain and Bapi Reddy Karri, has helped both businesses and individuals use DeFi at scale. The startup says that it has processed more than $1 billion in transactions. When it joins Polymarket, Brahma will wind down its projects with other companies and individuals. 

This is not the first time that Polymarket has sought to expand by hiring talent through an acquisition. In February, the prediction market platform acquired Dome, a Y Combinator backed startup, to bolster its developer tools. Polymarket also acquired a boutique executive search firm called Lunch in February.

Tenconi says that one night in September, at 1 AM, he got a Telegram message from someone saying that Coplan, the CEO of Polymarket, wanted to talk to him. Ten minutes later, the two were on a call. He says that Coplan was looking for people who could build fast, build quality, and who had the chops. “It was like builders talking to builders,” Tenconi said, about that first phone call. “The rest happened very naturally.”

This story was originally featured on Fortune.com

U.S. companies will be allowed to do business with Venezuela’s state-owned oil and gas company after the Treasury Department eased sanctions, with some limitations, on Wednesday as the Trump administration looks for ways to boost world oil supplies during the Iran war.

The Treasury issued a broad authorization allowing Petróleos de Venezuela S.A, or PDVSA, to directly sell Venezuelan oil to U.S. companies and on global markets, a massive shift after Washington for years had largely blocked dealings with Venezuela’s government and its oil sector.

The move highlights the increased pressure that the Republican administration is under to ease soaring oil prices as the United States, along with Israel, wages a war with Iran without a foreseeable end date. Global oil prices have since spiked as Iran halted traffic through the narrow Strait of Hormuz, where one-fifth of the world’s oil typically passes through from the Persian Gulf to customers worldwide.

The U.S. action is designed to incentivize new investment in Venezuela’s energy sector and is intended to benefit both the U.S and Venezuela, while increasing the global oil supply, a Treasury official told The Associated Press. The official was not authorized to discuss the matter publicly and spoke one condition of anonymity.

Since the ouster and arrest of Nicolás Maduro as Venezuela’s president during a U.S. military operation in January, President Donald Trump has said the U.S. would effectively “run” Venezuela and sell its oil.

The Treasury Department’s license provides targeted relief from sanctions, but does not lift the penalties altogether. The license allows companies that existed before Jan. 29, 2025, to buy Venezuelan oil and engage in transactions that would normally be banned under American sanctions, reopening trade for a major oil producer to global markets.

There are some limits.

Payments cannot go directly to sanctioned Venezuelan entities such as PDVSA, but must be sent instead to a special U.S.-controlled account. In other words, the U.S. will allow the oil trade but will control the cash flow.

Additionally, deals involving Russia, Iran, North Korea, Cuba and some Chinese entities will not be allowed. Transactions involving Venezuelan debt or bonds will not be allowed.

The license is expected to give a massive boost to Venezuela’s oil-dependent economy and help encourage companies that have been apprehensive to invest. The decision is part of the Trump administration’s phased-in plan to turn around Venezuela. But critics of the acting Venezuelan government argue that the move rewards Venezuela’s leadership -– all loyal to Maduro and the ruling party -– while repression, corruption and human rights abuses continue.

Many public sector workers survive on roughly $160 per month, while the average private sector employee earned about $237 last year, when the annual inflation rate soared to 475%, according to Venezuela’s central bank, and sent the cost of food beyond what many can afford.

Venezuela sits atop the world’s largest oil reserves and used them to power what was once Latin America’s strongest economy. But corruption, mismanagement and U.S. economic sanctions saw production steadily decline from the 3.5 million barrels per day pumped in 1999, when Maduro’s mentor, Hugo Chávez, took power, to less than 400,000 barrels per day in 2020.

A year earlier, the Treasury Department under the first Trump administration locked Venezuela out of world oil markets when it sanctioned PDVSA as part of a policy punishing Maduro’s government for corrupt, anti-democratic and criminal activities. That forced the government to sell its remaining oil output at a discount — about 40% below market prices — to buyers such as China and in other Asian markets. Venezuela even started accepting payments in Russian rubles, bartered goods or cryptocurrency.

The new license does not allow payments in gold or cryptocurrency, including the petro, which was a crypto token issued by the Venezuelan government in 2018. __

Garcia Cano reported from Caracas, Venezuela.

This story was originally featured on Fortune.com

The war in Iran has already transformed the world’s energy map. It might yet redraw America’s auto market.

Now in its third week, the U.S. and Israeli military campaign in Iran has escalated to involve targets across the Middle East, including the Strait of Hormuz — a narrow waterway at the mouth of the Persian Gulf that serves as the world’s most critical fossil fuel chokepoint. The war has effectively closed the oil tanker traffic that used to navigate the strait, which on a normal day carries up to 20% of the world’s traded petroleum.

Fuel costs worldwide have soared as a result. Average gas prices in the U.S. are now $3.79 a gallon, up from $2.92 a month ago, reminding drivers of the 2022 energy shortage and even of the devastating oil shocks of the 1970s.

But unlike during those crises, the world now possesses a massive, rapidly scaling, and for the most part readily available asset to soften the blow: the electric vehicle.

The global EV fleet has been growing for years, gradually chipping away at the world’s oil consumption as drivers turn to charging ports instead of gas stations. Last year, EVs worldwide avoided the consumption of 1.7 million barrels of oil per day, according to a report published Wednesday by Ember, an independent energy think tank based in the U.K. That’s roughly 70% of the 2.4 million barrels Iran exported daily through the Strait of Hormuz in 2025.

While the crisis has sent global oil prices soaring, the declining need for petroleum in transportation is providing a critical cushion in some countries. And the longer fuel prices remain elevated, the more attractive EVs become to buyers.

“Oil is a particularly tricky resource to replace,” Daan Walter, a researcher at Ember and the report’s lead author, told Fortune. “It has been for 125 years now, except for the past five or six years, when we’ve had this new competitive lever in electric vehicles.”

Electrifying demand

In the U.S., EV purchases hit a wall over the past few months as President Donald Trump rescinded many of the subsidies and incentives the Biden administration had installed to facilitate the transport sector’s electrification. Those measures mostly expired in September, and EV sales for the year ended up falling by 2%.

But the Iran conflict has sparked a revival of consumer interest. Search traffic for EVs during the first week of the conflict jumped 20%, according to CarEdge, a car shopping platform, with interest in popular models like the Tesla Model Y and Chevrolet Equinox nearly doubling.

For now, the conflict in Iran and higher gasoline prices are likely to only influence drivers who were already in the market for a new car, Elaine Buckberg, a senior fellow at Harvard University’s Salata Center for Climate and Sustainability and a former chief economist for General Motors, told Fortune.

But that could change if prices stay high for much longer. “Gasoline prices are one of the biggest elements of people’s perception of inflation because you buy it so regularly,” Buckberg said. “It takes three to six months of persistently higher prices before people say, ‘Maybe I should go out and switch cars to one that’s more fuel efficient, including an EV.’”

EV drivers outside the U.S. already know how much they might be able to save. In the U.K., EV drivers saved an average of £870 ($1,162) a year by charging their cars instead of fueling up, according to an analysis published last week by the nonprofit Energy & Climate Intelligence Unit. But if oil prices remain above $100 a barrel, as they have for most of the conflict, those annual savings could jump to £1,000 ($1,336).

In the U.S., the costs of owning and charging an EV depend on several factors, including local electricity prices and whether drivers can charge their cars at home. And for now, buying an electric car tends to be more expensive than buying a gas-powered one, although prices are falling due to greater competition and more choices of lower-priced models.

But EV drivers are likely to be rewarded over the course of their car’s lifetime—the New York Times found last year that driving 100 miles in a home-charged EV costs on average a little more than $5, while the same distance in a standard gas-powered car costs on average $12.80.

Nowhere to hide

The Trump administration has framed the pain Americans are feeling at the pump as a short-term problem, and claimed that the U.S. is insulated from the oil crisis because it is a large producer in its own right. But being a net exporter of oil does little to shield the U.S. from volatility, according to Ember’s Walter.

“In some ways, no one is safe,” he said. “Even if you live between a gas well and a refinery, even then your prices are going up.”

Oil is a global commodity, and unless a government enacts export bans, a barrel of oil produced in the U.S. will go to whoever pays the most wherever they are, Walter said. That means American consumers remain tethered to the same price volatility as the rest of the world, regardless of how much crude is pumped from U.S. soil. In Texas, for example, one of the world’s largest oil-exporting regions, gasoline prices have risen 25% since the war began, faster than in oil-importing nations like the U.K. and France during the same period, Walter said.

Because volatile gasoline prices have such a significant bearing on consumer sentiment, experts have long argued that transportation reliant on locally generated electricity can be an economic and political hedge.

“A shift towards EV basically would protect the economy from downside,” Buckberg said. “That link from oil geopolitics to oil prices to gasoline prices could be broken.”

The last time a global geopolitical shock sparked an energy crisis was in 2022, when Russia’s invasion of Ukraine sent global oil and gas markets into a frenzy. A lot has changed since then to make EVs a more palatable option as gasoline prices rise, Buckberg said. For one, the world is no longer limited by a microchip shortage that strained EV manufacturing in the early 2020s. 

But electric and hybrid vehicles have also become more affordable and accessible to a wider variety of consumers, particularly in emerging markets in East and Southeast Asia, according to previous Ember research. In China, the world’s biggest EV market, the country’s existing electric car fleet accounts for more than $28 billion a year in avoided oil imports, Ember’s latest report found.

“We’re no longer living in a world of risk-free fossil fuels. We’re living in a world where everything is risky and it now becomes a question of which risks do you want to take,” Walter said. 

This story was originally featured on Fortune.com

Coinbase’s 60-second spot, “Your Way Out,” drops viewers into a low-resolution video game world where everyone moves in a loop: commuting, working, spending. The protagonist is an NPC, a non-playable character, stuck inside a system he didn’t build and can’t control, until he strains against his preprogrammed slumped over state and breaks free. The environment shifts from pixelated game world to the full color of reality as he gains agency, set to Sammy Davis Jr.’s “I’ve Gotta Be Me.” The ad only reveals itself to be about Coinbase at the end, with a single tagline: “Your way out of their system.”

The ad is extraordinary for what it captures in the culture: an ever-gnawing desperation to escape what’s become known as the “permanent underclass.” The phrase, once niche Silicon Valley gallows humor, has become a genuine cultural fixation. As leaders of AI companies boast that their technology will replace most jobs within the next decade, people are worried they’ll be sorted into a category Karl Marx once called the lumpenproletariat: the lowest stratum of the industrial working class itself.

Only it’s 2026, and the word for it is the permanent underclass, a world with no upward mobility. Online, the term is lobbed at people who aren’t heeding AI’s headwinds, the kinds of FOMO-stoking posts that happen to work very well for selling. Which, of course, is what Coinbase is doing.

“Today, because of the maturity of Coinbase, we have a broader set of products that we think can offer true alternatives to an outdated system,” Catherine Ferdon, Coinbase’s CMO, said in a statement sent to Fortune.

The whole thing was shot using real actors and no CGI, Toby-Treyer Evans, the founder of the advertising agency that produced it, wrote in advertising trade site Muse by Clio. The game-world look was built in-camera, using suits with printed-on fabric details and pixelated set design made to look indistinguishable from a video game. Extras were trained to walk like game characters, Treyer- Evans wrote. It’s a genuine feat of filmmaking, and it isn’t Coinbase’s first. The company has built a reputation for splashy, viral big-event ads, including their memorable Super Bowl ad.

The ad’s central metaphor, the NPC, is a cultural artifact of that same corner of the internet. “Non-playable character” started as a gaming term, then by 2018 became a political meme to describe people who parrot talking points without thinking. Now, it’s Gen-Z’s default insult for anyone who appears to be on autopilot: going through the motions, lacking agency, playing by someone else’s rules. It sounds like the classic complaint the youth have always had about the status quo: “you’re the system, man!”

But this is different. These fears are shared by most Americans, and validated by the very people building the technology everyone’s afraid of. The noise around AI and its potential effects has grown so loud that you don’t need to be a 17-year-old dorm-room philosopher to conclude: a lot of people are about to lose control of their financial lives and not even realize it.

Coinbase’s answer, naturally, is to trade cryptocurrency. The pitch is compelling because it’s true that crypto has created real wealth for people bold enough, and lucky enough, to invest at the right time. The number of crypto millionaires globally hit nearly 242,000 last year, up 40% in twelve months, according to Henley & Partners. An entire subculture has formed around the shared belief that the traditional financial system was never going to let them in anyway. Those “crypto bros” are now perfectly positioned to capitalize on the broader anxiety about AI and displacement.

But for every crypto millionaire minted in the past two years, there are retail investors who lost their savings in the FTX collapse, got liquidated on leveraged bets they didn’t fully understand, or watched memecoins they bought on hype go to zero. FTX itself ran a Super Bowl ad in 2022—the same year as Coinbase’s famous ad—starring Larry David dismissing crypto as a fad. The company turned out to be a multibillion-dollar fraud. 

So even if the permanent underclass may or may not be coming, the ads for it are already here.

This story was originally featured on Fortune.com

Sri Lanka has just introduced a four‑day workweek—not to boost work‑life balance, but because the war in Iran is threatening to drain its petrol tanks dry.  

The government has declared every Wednesday a holiday for most public institutions in a desperate bid to slash petrol use, as war in the Middle East threatens vital oil shipments through the Strait of Hormuz.

All state institutions, along with schools and universities, will shift to a four-day work week, starting this Wednesday. Essential services like hospitals will stay open, but everyone else is being told to stay home, log on where possible, and use as little gas as they can. 

Even the private sector is being asked to follow the mandate, too.

Officials say Sri Lanka has roughly just six weeks of fuel reserves left. That’s why they’ve rolled out the four‑day week almost overnight, suspended public ceremonies, and launched a National Fuel Pass to ration how much petrol people can buy. And they’re not the only country introducing these emergency measures to avoid running out of fuel. 

There’s a pattern worth naming here. The three major crises since 2020—the pandemic, the 2022 European energy shock, now the Iran war—have each pushed governments to reach for the same lever: send people home, cut the commute, compress the week. And every time, some portion of that change proves permanent. Workers adjust. Productivity holds. And the five-day, in-office standard quietly loses a little more of its claim to inevitability. Look around Asia to see how Sri Lanka is far from alone.

Pakistan, the Philippines, and other Asian nations are welcoming a 4-day week and remote work

Across Asia, governments are quietly cutting working days, commutes, and non‑essential travel in a bid to stretch fuel supplies as far as possible.

Pakistan has already implemented a four-day week for some government offices and shut schools, as well as imposing a ban on in-person meetings. Meanwhile, all public and private firms are being mandated to ask 50% of their workforce to work from home. 

The Philippines is also adopting a four-day work week for government staff, and urged workers more generally to work from home where possible. Vietnam is also telling citizens to stay home, as well as to ride bikes, carpool, and use public transport, and restrict personal vehicle usage.

Other Asian nations are taking quirkier energy-saving steps. In Thailand, the government is urging office workers to ditch suits for short‑sleeved shirts so buildings can dial down the air‑conditioning. It’s also called on people to take the stairs instead of elevators

Myanmar is limiting private cars on alternate days. Bangladesh has introduced early Ramadan holidays and India has asked consumers not to panic, because hoarding—or turning to the black market—will only make the situation worse. 

Where the four‑day work week is here to stay

While these emergency measures are temporary, elsewhere, the four‑day work week has been introduced under far less dramatic circumstances—and often with surprisingly positive results. 

The U.K. ran the world’s largest four‑day week pilot in 2022, involving dozens of companies that paid staff 100% of their salary for 80% of the time in exchange for a commitment to maintain performance. A year later, 89% of participating firms were still operating a four‑day week and just over half had made the switch permanent—citing higher revenues, better retention, and employees who were less burned out and more loyal. And many other countries have been trialling shorter weeks across dozens of companies with strong early feedback on productivity and quality of life.

Across Europe and beyond, the idea is slowly moving from a rare perk to a mainstream policy experiment. Belgium passed legislation allowing workers to compress a full‑time job into four longer days, the UAE shifted its public sector to a four‑and‑a‑half‑day week, and even companies that don’t want to make permanent changes have launched “recharge days” and Summer Fridays.  

Sri Lanka’s emergency measures may be lifted the moment oil flows freely again. But the precedent—that a shorter week is a policy tool, not just a perk—is becoming established across three continents and counting.

This story was originally featured on Fortune.com

Good morning. Agentic AI could be the catalyst that gets most finance chiefs on board with using AI to support the finance function.

Aneel Bhusri, cofounder and CEO of Workday, an enterprise HR and finance platform with AI, returned to the role last month, two years after stepping down, succeeding Carl Eschenbach, Fortune reported. “I think there’s a lot of misinformation out in the marketplace about AI and SaaS applications,” Bhusri said during a virtual press conference on March 12. “There’s this idea that AI is going to replace a lot of these applications with things like vibe coding. I’m a technologist, and I’ve been in this space for a long time. I just don’t see that happening.”

There will exist a hybrid world, where the best of enterprise apps are paired with the best of AI, and where low-level, rote work gets replaced by agents that drive business processes underneath, Bhusri said. In his first month back as CEO at Workday, he spent time with many financial customers and prospects—and found that many accounting departments are still “running old systems like the one I was part of at PeopleSoft,” he said.

Cloud computing improved software and user experience, but finance teams were slower to adopt it because their systems served fewer users and were heavily customized. But AI is different: it can cut costs, automate complex work, and even enable near real-time audits, he said. “That was not possible with either the legacy on-premise systems or the newer cloud systems,” he said. “They were still business process automation systems, not reasoning and probabilistic engineering systems.”

That distinction is resonating with finance chiefs. For CFOs, “the agentic story and solutions are really what are catching their eye right now,” Bhusri said. “CFOs look at it as, ‘The new way to differentiate how we do business. We need to embrace AI.’” And that, he said, is the reason many will finally move from a legacy system to an AI-driven cloud system.

The shift appears to be gaining momentum more broadly. Gartner recently predicted that 40% of enterprise applications will be integrated with task-specific AI agents by the end of 2026, up from less than 5% in 2025 — a sign that agentic AI is moving from concept to corporate priority.

Workday (No. 455 on the Fortune 500) is moving quickly to capture that momentum. On Tuesday, the company launched Sana from Workday, a new AI tool that can answer questions, complete tasks, and automate routine work across HR and finance. It uses AI agents that can carry out multi-step tasks on their own, for example, reviewing email for receipts and submitting them for approval , and works across apps like Gmail, Outlook, Salesforce, Google Drive, and SharePoint while following company security rules. The tool is based on Workday’s $1.1 billion acquisition of Sana Labs, completed in November 2025.

AI could be the catalyst to spur some finance teams to modernize.

Sheryl Estrada
sheryl.estrada@fortune.com

This story was originally featured on Fortune.com

With alarming headlines coming out of the Middle East, economists will be wary of sharing forecasts that might unnecessarily spook consumers or investors. Nonetheless, while Wall Street has remained calm(ish) about the disruption to global oil and energy supplies, Moody’s Mark Zandi warns that the longer-term macroeconomic picture has taken a turn for the worse.

Zandi shared that, even prior to the U.S. and Israel launching strikes on Iran, recession odds for the economy had crept up to an alarming threshold. The latest reading on Moody’s economic indicator model—for February, prior to the military action—placed odds of a recession at 49% over the next 12 months.

“Behind the recent jump are primarily the weak labor market numbers, but almost all the economic data have turned soft since the end of last year,” Zandi wrote in a note. Indeed, an image Zandi shared of the Moody’s recession indicator shows that historically, it has been fairly accurate. The indicator spiked above a benchmark of 50 in 2020, in 2007, and 2001—all of which were followed by recessions as defined by the Federal Bank of St Louis.

“It isn’t a stretch to expect the indicator to cross the key 50% threshold amid the Iranian conflict and the resulting surge in oil prices,” Zandi continued. “Oil prices are an important variable in the model, and with good reason: every recession since WWII, save the pandemic recession, has been preceded by a spike in oil prices.”

Moody’s recession call is higher compared to many on Wall Street, where most estimates say the likelihood is growing but is perhaps not in 50/50 territory. Indeed, Oxford Economics’s modelling suggests that oil prices would have to hit $140 a barrel over a two-month period to plunge the world economy into a recession. The strength of the subsequent recovery following a resolution of conflict in the Middle East depends on how quickly shipping through the Strait of Hormuz is normalised.

“The rebound in financial markets has been quick following past major military conflicts in the Middle East since the 1990s, but this time it could be more gradual,” noted Ben May, director of global macro research at Oxford Economics, and Ryan Sweet, chief global economist.

Zandi agrees with the premise, saying higher oil prices won’t level the same amount of economic damage as years prior because production and consumption are better aligned, but added consumers will suffer a significant uptick in the cost of living when they “were already increasingly nervous spenders.”

The Moody’s chief economist said his peers “will be loath to utter the word ‘recession,’” despite evidence to support such a statement, because many were proven wrong when they called a downturn calls over Fed policy a couple of years ago. But Zandi added: “If oil prices remain elevated for much longer (weeks and not months), a recession will be difficult to avoid.”

Happier odds

Some investors feel significantly more optimistic about the probability of a recession. Indeed, while economists generally go by the rule that a recession might happen once every five years, if not more frequently, Apollo Investment’s chief economist Torsten Slok suggests economic downturns are becoming less frequent.

“Between recessions, investors should prepare for sector-specific cycles, such as the current downturn in software, where one or two subsectors face distress while the rest of the economy is fine,” Slok wrote in a note published yesterday. “The bottom line is that credit opportunities arise not just during recessions, but also when there are sector-specific cycles during expansions.”

Oxford Economics’ latest Global Risk Survey is similarly more buoyant. The survey, conducted between February 26 and March 11, found there had been a sharp downturn of expectations since the outbreak of the conflict. However, odds of a global recession still stand at a 1-in-6 chance.

The war has driven scepticism over the prospects of the U.S. economy, Oxford notes. Prior to the military action, three-quarters of respondents felt the recent period of U.S. exceptionalism would continue, but that figure fell significantly as the conflict continued, with little more than half the 174 clients surveyed now expecting the U.S. to remain the fastest-growing G7 economy this year.

Indeed, Wall Street is more widely inclined to agree with lower recession odds. David Mericle of Goldman Sachs wrote this week that the bank’s outlook odds had increased, up by 5 percentage points to 25%, while JP Morgan predicted at the end of last year that the likelihood of a 2026 recession was 35%.

This story was originally featured on Fortune.com

Good morning. In today’s Fortune:

  • It’s Fed day—expect Powell to keep rates at 3.5%.
  • Iran: As Trump rages against his allies, Republicans want to know what the plan is.
  • Chaos in the Gulf is producing ‘butterfly effects’ far away.
  • Why the U.S. doesn’t have enough minesweepers to open the Strait of Hormuz.
  • Prediction markets see the war getting longer.
  • Nvidia might pay engineers in AI tokens
  • Exclusive: AI isn’t destroying consultants, Capgemini says.
  • Exclusive: Hinge CEO on the ‘dating recession.’

This story was originally featured on Fortune.com

Jensen Huang’s Nvidia GTC is kind of like tech’s Super Bowl Halftime Show. 

Everyone wants to be there, and if you’re not there, you inevitably end up hearing about it. And on Monday afternoon, Huang hit on agentic AI, the fast-approaching future of compute, offered a chip demand outlook, and emphasized the idea of “AI factories.” For startups and growing private companies, here are a few things to consider:

Talk to Nvidia’s agent. First, say hello to NemoClaw: The perennially leather-jacket-clad Huang unveiled NemoClaw, a new open source platform focused on agentic AI. The name is seemingly intentional, likely referencing the recent success of viral AI agent OpenClaw, while giving companies enterprise-grade privacy and security controls. “Every company in the world today needs to have an OpenClaw strategy, an agentic system strategy,” Huang told the audience. “This is the new computer.”

Physical AI has arrived. Huang emphasized that physical AI, especially robotics, is Nvidia’s next major market, perhaps worth one trillion or more. Many VCs would agree with Huang’s assessment, as billions of venture dollars have flowed into AI-era robotics companies like industrial-focused Skild AI and humanoid builder Apptronik. 

Nvidia wants to do it all. Fortune’s Sharon Goldman says it all comes down to how Nvidia sees its own future. She writes: “Nvidia made it clear at GTC that it is positioning itself not just as a chipmaker but as the provider of entire AI computing systems powering the new “inference” phase of AI. (Inference is about powering AI outputs, not just training, and it will require an enormous new round of infrastructure investment.) That ambition goes beyond Nvidia’s traditional “picks and shovels” role.”

Read on Sharon’s take about why Nvidia hasn’t seen more AI-fueled backlash here.

Fortune Term Sheet podcast hosted by Allie Garfinkle graphic with photo of Allie, links to YouTube video

Term Sheet Podcast… This week’s guest is someone I’ve been wanting to meet in person for some time: Winston Weinberg, Harvey CEO and cofounder. Harvey’s a legal AI leader, and the company’s 3.5 years old with an $11 billion valuation. Winston and I talked about Harvey’s rise, AI’s “partner and compete” paradigm, and his formula for finding focus. Watch the episode here.

See you tomorrow,

Allie Garfinkle
X:
@agarfinks
Email: alexandra.garfinkle@fortune.com

Submit a deal for the Term Sheet newsletter here.

Joey Abrams curated the deals section of today’s newsletter. Subscribe here.

This story was originally featured on Fortune.com

RunSybil, an AI cybersecurity startup that uses AI agents to automatically hack company software to find security weaknesses, has secured $40 million in venture capital funding.

The round was led by Khosla Ventures, with participation from S32, the Anthology Fund from Anthropic and Menlo Ventures, Conviction and Elad Gil, along with angel investors including Nikesh Arora, Amit Agarwal, Jeff Dean, and other founders and leaders from companies including OpenAI, Palo Alto Networks, Stripe and Google

The company did not disclose the valuation it achieved in the new funding round.

The company’s AI agent, Sybil, conducts continuous autonomous penetration tests against live applications—finding, exploiting and documenting real security vulnerabilities without humans in the loop. That’s different from other security tools currently making headlines, such as Claude Code Security, which analyzes source code in applications for known vulnerabilities before it is deployed.

RunSybil instead tests software that is already running, probing live systems the way a hacker would—by exploring systems, chaining vulnerabilities together and testing authentication boundaries to find paths to sensitive data.

Automating ‘ethical hacking’

Companies have long relied on a mix of penetration tests—where outside security experts, or “ethical hackers,” try to break into their systems; bug bounty programs that reward independent hackers for reporting flaws; and internal “red teams” that simulate real cyberattacks. RunSybil says its AI system can automate much of that work, continuously probing applications for vulnerabilities as new code is deployed.

RunSybil argues this kind of automation is becoming necessary as AI reshapes how companies operate. Procurement, legal, finance, engineering and operations are all being rebuilt with AI—including the growing use of AI agents. Yet security testing is still often treated as a discrete, scheduled event managed by a separate team on its own timeline. That mismatch can be especially challenging for highly regulated industries such as finance, insurance and health care, which face strict legal and audit requirements around cybersecurity.

RunSybil was co-founded in 2023 by Ari Herbert-Voss, who joined OpenAI as its first security research hire in 2019, and Vlad Ionescu, who previously led offensive security red teams at Meta. Together, they say they represent a rare intersection: people who understand how to build frontier AI systems and how to hack into complex software.

“We check every box that needs to be checked—for auditors, regulators and compliance teams,” Herbert-Voss said. But the real work, he said is transforming where, when and how customers discover and fix security issues: “Not as a project, but as a permanent capability embedded in how they build.”

‘On the edge’ of the AI security frontier

Vinod Khosla, who made an early bet on OpenAI in 2019 and often invests in companies he considers to be on the technological frontier, told Fortune that “what it takes to add security and penetration testing to the AI world is definitely frontier—RunSybil is on the edge.” There is currently little competition in this part of the offensive security market, he said, though security incumbents such as Palo Alto Networks may eventually move into the space.

For now, “nobody’s really knowledgeable about it except individuals like [Herbert-Voss],” he said, adding that he has long been concerned about AI’s cyber capabilities falling into the hands of adversaries such as China. “We invest in founders who tackle large, unsolved problems with technically ambitious solutions,” he added. “[Herbert-Voss and Ionsecu] are building exactly the kind of platform security teams will need as software complexity and AI-driven development accelerate.”

Herbert-Voss has long been steeped in both hacking and AI. Growing up in a mostly Mormon community in Utah, he said he was drawn to the online hacker scene in middle and high school but pivoted away after friends “started getting arrested.” While pursuing a Ph.D. at Harvard University studying machine learning and ways to make algorithms more efficient, he first heard about OpenAI.

He dropped out of Harvard, he said, after becoming convinced that the rapid scaling of AI models—training larger systems with more data and computing power—would unlock powerful new capabilities.

Evolving cyber capabilities with LLMs

“Once OpenAI dropped GPT-2, I said wow, this changes everything about the economics of what it would take to run a cyber campaign,” he explained. He sent a couple of hacker demos to OpenAI CEO Sam Altman and Jack Clark, then-head of policy at OpenAI who went on to co-found Anthropic. Both of them expressed their concerns about the potential misuse of LLMs and asked Herbert-Voss to come on to do security research.

But by 2022, Herbert-Voss said he also began to see how quickly offensive cyber capabilities could evolve once powerful language models became widely available, including to malicious actors. Those same advances, he said, could dramatically expand cyber threats. That led to Herbert-Voss’s decision to leave OpenAI and start RunSybil as a research project.

RunSybil currently works with startups including Cursor, Turbopuffer, Notion, Baseten, and Thinking Machines Lab, as well as what the company says are major financial institutions and Fortune 500 companies. (The company declined to name any of those Fortune 500 or financial customers.) Herbert-Voss said that customers have already reported finding critical vulnerabilities that had gone undetected using traditional methods.

This story was originally featured on Fortune.com

  • In today’s CEO Daily: How CEOs are protecting their pay packages by lowering their goals
  • The big leadership story: Whether Meta’s reported 20% layoffs will encourage a new wave of job cuts
  • The markets: A big Asia rebound
  • Plus: All the news and watercooler chat from Fortune.

Good morning. Call it the Hall of Blame. One time-honored tradition in business is to take credit for what goes well, blame disappointing results on factors beyond your control and lower the bar in tough times to be able to clear it so that your pay package remains intact.

When Apple set performance targets for fiscal 2025 for CEO Tim Cook and his executive team last year, the board set goals at or below the prior year’s result, citing “trade policy” and an “uncertain macroeconomic outlook.” As my colleague Amanda Gerut points out, that essentially guaranteed that Cook would take home a $12 million bonus, no matter how well he did. (Apple handily surpassed the modest targets.)

With wobbly markets, rising oil prices, war and fears of a global recession, keep an eye on compensation packages. What I look for:

Reduced targets—In an analysis of 50 public companies by Compensation Advisory Partners (CAP), published Friday, researchers found that boards set lower targets, wider performance curves and flatter payout ranges to protect CEO pay last year. The result: Pay rose 8% and bonuses were up 4% in the group while revenue rose slightly and earnings were down. CEOs collected 87% of their target bonuses, up from 77% in 2024.

Selfless rhetoric—While good times are ‘me’ time, bad times are all about ‘we.’ When taxpayers rescued big banks during the 2008 financial crisis, some characterized this as privatizing the gains and socializing the pain. But in bad times, few are above turning to the government for support. If you’re not too big to fail, you might be mission-critical, a social good or a bulwark against China. Masters of the universe become ordinary people blown by the winds of fate when those winds are in their face.

Blame—Dexin Zhou of Emory University published a fascinating study in 2014 called The Blame Game, in which he analyzed 70,000 earnings transcripts to track leaders who blamed factors in the economy or their industry for poor results. Those who blamed external factors deflected attention from themselves were less likely to be fired than those who held themselves accountable for the results. When times are bad, it seems, the pain doesn’t start at the top.

Contact CEO Daily via Diane Brady at diane.brady@fortune.com

This story was originally featured on Fortune.com

Giving away billions sounds easy. Write a check and change the world. But Elon Musk, the world’s richest man, admitted last year that, actually, “it is very difficult to give money away for the reality of goodness.” And perhaps surprisingly, a nonprofit boss has said he’s not wrong.

Liz Baker, the CEO of Greater Good Charities—a global nonprofit that has distributed more than $1 billion in impact across 121 countries since 2006—has been navigating the complexity of giving away other people’s money for over a decade. And she’ll tell you Musk is only scratching the surface of how hard it really is.

“I wish I had a billion dollars to give away, but as somebody who’s responsible for giving away money, yeah, it’s hard, because there’s a really big responsibility that goes with that,” Baker exclusively told Fortune. “If you give me $1, I’m going to spend it the way that you want it spent. But there’s all this stuff that goes into it—geopolitical stuff, you don’t want to create dependencies in communities—like, what is the right avenue, and what are things that are really needed?”

Baker, who has led Greater Good Charities since 2012, oversees an organization that spans crisis and disaster response, humanitarian relief, biodiversity, and animal health and well-being across more than 120 countries. Under her watch, it has earned a 100/100 score from Charity Navigator and a Platinum Rating from GuideStar for transparency—the nonprofit equivalent of straight A’s.

Her critique isn’t that giving is impossible—it’s that most people dramatically underestimate what it requires. 

Unlike a normal transaction—where a donor gets something tangible in return, a product, a deliverable, a number they can point to—philanthropy asks you to fund a vision: here’s the problem, here’s the solution, here’s the hoped-for outcome. And then you have to wait years to see if you were actually right.”You can’t just go at a problem and be like, here’s a billion dollars, figure out the problem,” Baker said. “It’s too complicated. It doesn’t work like that.”

Essentially, it’s one thing to sign away a big paycheck, but as Musk says, it’s another thing to actually create tangible change for good with that money.

The antidote? Perhaps a more trial-and-error approach. What doesn’t happen enough, in her view, is the kind of nimble, honest reckoning with failure that good philanthropy demands. “Being able to pivot and being able to say, okay, this didn’t work—what do we do differently? A lot of testing,” she said. “You can’t just go at a problem, it’s too complicated.”

Stop waiting for billionaires. Do something yourself.

Billionaire pledges are great—in theory. 

“A pledge is a promise, right?” Baker said, when asked whether such commitments mean anything in practice. “Our experience with pledges is that most of the time donors will come through—not all of the time, though.”

Indeed, many remain little more than a name on an open letter. Just look at The Giving Pledge—the commitment, co-founded by Bill Gates, Melinda French Gates and Warren Buffett, that asks the ultra-wealthy to donate at least 50% of their fortunes—has attracted more than 250 signatories since its launch in 2010.

The number who have actually followed through? A handful—less than 10. Most only fulfilled the pledge after their deaths. Out of the U.S. signatories, just one couple, John and Laura Arnold, fully complied with the commitment they signed. 

It’s why Baker doesn’t think we can wait on billionaires to solve the world’s problems. “I think if everybody did something to help in their community, we wouldn’t have the issues that we have.”

How can everyday people be more philanthropic right now?

Baker’s not naive about most people’s economic reality. Cost-of-living pressures have squeezed household budgets to the point where even six-figure earners report struggling to afford basics

But making a difference doesn’t have to come at a cost. “Everybody can chip in—and it doesn’t even have to be money. Like, do something.”

“Even if you’re like, I have one hour a week to solve this problem in my community that I care about,” Baker said. “Figure out how to do that. Most local nonprofits need help.”

The worst thing you can do, in her eyes, is just complain. “There are people that are just like, well, I don’t like to see homeless people sitting on the corner, but I’m not willing to do anything about it except complain,” she said. “Innovate, people. Come on. Everybody’s good at something. Everybody cares about something.”

And she practices what she preaches. Despite running a multimillion-dollar organization and being a mother, Baker volunteers outside of her CEO role—showing up not as an executive but simply as someone with something to give back. “I volunteer—not as a CEO—as a person who has something to give back,” she said. “In a way, that’s like showing up and doing the work very differently than what I do here.”

“If everybody did that, we wouldn’t be in the situation we’re in.”

This story was originally featured on Fortune.com

McDonald’s is rolling out its cheapest value menu in years, a move that could speak more to the state of the American economy than it does fast food.

Even as sales rose for the quarter, executives at the world’s largest burger chain acknowledged in its February earnings call the fast food environment, which has pulled back in recent quarters, would “remain challenging” in 2026. Despite the company’s own progress attracting lower-income customer in the company’s fourth quarter, this tier of consumers, who have been dealing with stubborn inflation for years, are broadly pulling back on spending.

To address this issue, CEO Chris Kempczinski said during the company’s latest earnings call the restaurant chain would double down on its commitment to value and deeper discounts.

“McDonald’s is not going to get beat on value and affordability,” Kempczinski said during the call last month.

As part of the company’s latest effort to reach these consumers, McDonald’s is reportedly launching a new value menu in April with items like a 4-piece Chicken McNuggets or Sausage Biscuit priced at $3 or less. It is also revealing a $4 breakfast bundle that includes a McMuffin, hash brown, and a coffee, among other options, The Wall Street Journal reported. The new $3 menu will replace the McValue platform it launched in January 2025 that offered customers the choice of adding a second item to their full-priced order for just $1 more. 

McDonald’s did not immediately respond to Fortune’s request for comment.

McDonald’s move to value meals matches the K-shaped economy

McDonald’s newest value menu fits squarely into the trend of the K-shaped economy. While high-income people have fared well during the multi-year-stock bull run of the past few years, lower-income people have been hit by higher prices and stagnating wages. The same is happening at McDonald’s, according to Kempczinski. While high-income customer traffic is stable, the CEO warned, “lower-income consumers are particularly sensitive to value and affordability.”

McDonald’s is not the only restaurant chain looking to target these lower-income customers: Wendy’s, Burger King, and Taco Bell have all rolled out aggressive value promotions over the past year, to reach a shrinking pool of budget-conscious diners who have grown increasingly selective. 

To win over these picky consumers, Mark Wasilefsky, head of restaurant and franchise finance at TD Bank, told Fortune chains are increasingly looking for a way to provide value to consumers.

“Lower-priced options, when chosen carefully, priced at an acceptable level, and marketed aggressively, create perceived value and can generate a long-term customer,” he said.

McDonald’s value meals signal a bigger economic problem 

While Kempczinski last month touted the company’s affordability moves as part of the company getting back to its roots, some worry the new $3 menu could be indicative of broader economic problems to come.

A post by prediction market Kalshi mentioning the $3 menu racked up more than 4 million views on X, with many users jumping on the news to declare an economic downturn is near. One user who quoted the Kalshi post on X got 2.6 million views for the declaration: “Oh it’s a RECESSION recession.”

McDonald’s is betting a $3 meal will bring lower-income customers back, and yet, that may be difficult when Americans are increasingly betting that the future could hold more economic pain.

A Pew Research survey last month found 72% of people rate economic conditions as fair or poor, and nearly 40% believe conditions will be worse a year from now, compared to 31% who think they will improve. 

This pressure, Wasilefsky argues, has made value perception that much more important for chains seeking lower-income consumers, or at least those with the financial flexibility to slash prices without gutting margins.

“For those brands who can afford to do so, this is an excellent time to convince existing customers and new customers of your brand’s value and its right to have a share of your shrinking wallet,” he said.

This story was originally featured on Fortune.com

When Changhan Kim, CEO of the South Korean gaming company Krafton, decided he needed a way out of a costly acquisition deal, he didn’t call his lawyers—he opened ChatGPT. The result is one of the most striking cautionary tales about AI-assisted decision-making in corporate America, and it ended with a Delaware judge ordering the company reverse everything it had done.

A Delaware judge found Kim used ChatGPT to engineer the removal of Unknown Worlds Entertainment—the indie studio responsible for the underwater survival game Subnautica—CEO Ted Gill from the company to dodge a $250 million bonus payout. 

“Fearing he had agreed to a ‘pushover’ contract, Krafton’s CEO consulted an artificial intelligence chatbot to contrive a corporate ‘takeover’ strategy,” Delaware’s Court of Chancery Vice Chancellor Lori Will wrote in a ruling on Tuesday. 

In 2021, Krafton, the publisher behind the global phenomenon PUBG: Battlegrounds, acquired Unknown Worlds Entertainment for $500 million. As part of the deal, Krafton agreed to pay an additional $250 million earn-out bonus if the studio’s hotly anticipated sequel, Subnautica 2, hit certain sales targets. The contract also guaranteed that Unknown Worlds would remain independent, with cofounders Charlie Cleveland and Max McGuire, along with Gill, retaining operational control—and only being removed for cause.

Usually, it’s a good thing to hit and even exceed sales targets, but for Krafton, trouble started when their own internal sales projections showed Subnautica 2 was well on track to trigger that payout. When Maria Park, Krafton’s head of corporate development, told Kim a “dismissal with cause” would not rid the company of its $250 million bonus obligation without exposing the company to “lawsuit and reputation risk,” Kim looked toward an AI chatbot for guidance. 

Kim, spooked by what he privately called a “pushover” deal, bypassed his own legal team and turned to ChatGPT for help. When the AI chatbot responded that the earnout would be “difficult to cancel,” the ruling read, Kim didn’t accept the answer. He pushed further—and the chatbot obliged with a detailed, multi-stage corporate takeover strategy dubbed “Project X.”

Project X

ChatGPT advised Kim to form an internal task force to renegotiate the earnout or force a studio takeover; if negotiations failed, to “lock down” Steam and console publishing rights and control over the game’s code; to frame the entire conflict as being about “fan trust” and “quality” rather than money; and to prepare systematic legal defense materials while logging all communications. The chatbot even suggested drafting a public-facing message to win over Subnautica fans—a message Kim then asked ChatGPT to write. It backfired spectacularly, alarming the gaming community and heightening suspicions that something was deeply wrong at the studio.

Throughout this process, Kim’s own team warned him the strategy was dangerous, but Kim pressed ahead anyway. Cleveland, McGuire, and Gill were all removed from their roles without what the court determined was legitimate cause.

site reading "temporarily offline"
Krafton website reading “temporarily offline.”
Krafton

Will found Krafton had improperly ousted the Unknown Worlds leadership, and noted company executives are expected to exercise independent human judgment—not outsource good-faith decisions to an AI. Gill has now been ordered reinstated as CEO, with the authority to bring back the cofounders. The earnout period has been extended to account for the disruption.

Neither Krafton nor Unknown Worlds responded to Fortune’s requests for comments. As of Tuesday morning, Krafton’s contact page was “temporarily offline.”

This story was originally featured on Fortune.com

Morgan Stanley’s Mike Wilson spent years insisting a “rolling recession” was hiding in plain sight while Wall Street celebrated what appeared to be a boom. Now he’s back with another contrarian call: half the stock market is already in a bear market, the correction has been grinding for six months, and investors panicking this week arrived late.

In a note published Monday, Wilson — Morgan Stanley’s chief U.S. equity strategist — argued that the dramatic volatility roiling markets recently is not the beginning of a selloff. It’s closer to the end. “This correction is mature in time and price,” he wrote, anchoring the call with a striking data point: 50% of all stocks in the Russell 3000 are now down at least 20% from their 52-week highs, and among S&P 500 members, the figure exceeds 40%.​

The backdrop is important. Wilson spent years arguing, often in isolation, that the economy was much weaker for many companies and consumers than what the headline economic statistics (nominal GDP or employment) suggested. Rather than a single crash, he said, weakness had moved sector by sector — tech first, then consumer goods, then the broader economy — meaning the usual markers of recession, soaring unemployment and plummeting GDP, remained muted while pain mounted underneath. He called it a “rolling recession.” Most of Wall Street thought he was wrong.​

He wasn’t. Wilson identified April 2025 — when the White House’s Liberation Day tariff announcement triggered a market capitulation — as the recession’s trough. Earnings revisions breadth staged a dramatic V-shaped rebound from that point, payroll revisions improved, and layoff data peaked and rolled over. The early-cycle recovery he had forecast was underway. And critically, it’s that recovered, reaccelerating backdrop that shapes Wilson’s read on the current turbulence.​

This week’s sell-off, he argued, has been a “correction within a bull market” — not a new downturn. It began last fall, when liquidity tightened, well before crude oil prices spiked and the VIX lurched higher in recent weeks following the escalation of the conflict in Iran. The geopolitical shock served as a “final blow” — the kind of capitulatory event that typically marks an ending rather than a beginning.​

The numbers back him up on the damage already done. Software and services stocks have been the hardest hit, with 97% of S&P 500 members in that sector trading at least 10% below their 52-week highs. Semiconductors, consumer discretionary, and financial services stocks tell a similar story. The index-level S&P 500 decline of roughly 15% from peak is real — but it dramatically understates how widely the carnage has spread beneath the surface.​

But what if the war just keeps on going?

What distinguishes today from the darker chapters of the rolling recession era, according to Wilson, is that the fundamental engine is firing. S&P 500 earnings are growing at +13% and accelerating — the opposite of the deteriorating earnings environment that accompanied prior oil-shock recessions. The crude rally is running around 40% year-over-year, well short of the 100%-plus spikes that have historically derailed business cycles. Fiscal support is substantial, with personal income tax refunds running 17% higher year-over-year, and the Fed has turned expansionary again after shrinking its balance sheet through much of last year.​

The issue, of course, is that Wilson’s analysis assumes the Iran conflict stays contained, oil stays below $100 a barrel, and the geopolitical situation resolves in “weeks, not months.” Those are enormous assumptions given the intractable nature of the Iran War, which, by all outward appearances, will go on for longer than the 3 weeks President Trump publicly estimated. History suggests geopolitical shocks have a nasty habit of defying neat timelines for resolution.

Wilson himself acknowledges the Strait of Hormuz disruption is blocking roughly 20 million barrels per day of tanker flow, and that tapping strategic petroleum reserves will only replace a fraction of that volume. If crude breaks and holds above $100 for a sustained period — which Wilson concedes would change his view entirely — the dynamic shifts from “correction in a bull market” to something more serious. The bear case isn’t some remote tail risk. It’s one escalation away.

There is one area where Wilson’s critics should be careful: his track record on calling inflection points. He was right about the rolling recession when the consensus laughed. He was right that Liberation Day marked the trough. Those calls weren’t lucky — they were built on a rigorous framework of leading indicators, breadth of earnings revisions, and liquidity tracking that most strategists missed.

This story was originally featured on Fortune.com

When Bernstein analyst Mark Shmulik sent a note to clients about Meta’s reported plans to cut 20% or more of its roughly 79,000-person workforce, he issued a warning. If Meta succeeds in redrawing the blueprint for an AI-enabled organization, he wrote, “others will rush to replicate it,” potentially triggering “a cascade of hurried pivots, half-formed strategies, and reactive restructuring across the ecosystem.”

The math alone is striking. Even at a 20% headcount reduction, Shmulik estimates Meta could realize $2 billion to $4 billion in cost savings this year and $5 billion to $8 billion in 2027 — translating to 3%–5% EPS upside in 2026 and 4%–7% in 2027. But he was quick to note the savings are more likely to be redeployed into AI infrastructure than returned to shareholders. Meta is already planning to spend $600 billion on data centers by 2028 and recently acquired AI startup Manus for at least $2 billion.

What makes the moment significant isn’t the scale of the cuts, but the context. Less than three weeks ago, Jack Dorsey laid off nearly half of Block’s 4,000-person workforce and made a blunt prediction to investors: within a year, most companies would reach the same conclusion. He didn’t have to wait the whole year.

Zuckerberg has been telegraphing the same logic. In January, he said he was starting to see “projects that used to require big teams now be accomplished by a single very talented person.” Reuters reported Friday that Meta is now targeting a 50:1 employee-to-manager ratio — unthinkable against the 7-to-15:1 long considered standard.

The competitive pressure is already visible elsewhere. Amazon confirmed 16,000 job cuts in January. Salesforce CEO Marc Benioff has said he “needs less heads” after cutting 4,000 from his customer support workforce. Economist Anton Korinek previously told Fortune the trend could mark “the beginning of a new era where white-collar jobs become threatened more seriously by AI. Once a few companies start the trend, competitive forces may induce others to follow suit.”

The central question Shmulik raises — and leaves open — is whether these cuts are genuinely AI-driven or whether AI is providing convenient cover for belt-tightening that would have happened anyway. “Fat exists in every organization,” he wrote, “but it’s usually not as clean as being concentrated in specific teams or individuals.”

“This is speculative reporting about theoretical approaches,” a Meta spokesperson told Fortune. That theoretical approach, of course, could set off a cascade of cuts.

This story was originally featured on Fortune.com

Scott Galloway doesn’t want the markets to go up. He said so out loud, live at South by Southwest, and the audience—skewing young—didn’t boo him. They cheered.

“At some point,” Galloway told the crowd during a taping of the Prof G Markets podcast on Monday, “We have to stop propping up the markets with young people’s credit cards.”

It was a throwaway line dropped near the end of a longer riff about war, oil prices, and the mechanics of economic decay. But it landed like a thesis statement—and it inadvertently explained the entire psychology behind Gen Z’s flight into prediction markets, meme stocks, crypto, and speculative gambling.

Here’s Galloway’s argument, stripped to its core: for the last 40 years, every time a genuine economic shock threatened to destroy capital—the dot-com crash, the 2008 financial crisis, the COVID collapse—the U.S. government intervened. Not to protect workers. To protect assets. To protect owners. The debt and stimulus that financed those rescues lands on younger generations.

“Rather than let assets collapse and take money from the owners and give advantage back to the earners,” Galloway said, speaking directly to Gen Z, “we’re going to pull out your credit card and ensure, in the form of debt and stimulus, that I stay rich.”

“The reason I’m economically secure,” he explained, goes back to the 2008 collapse. Yes, the government bailed out the banks, but they let the markets collapse, and as a result Galloway said he got to buy stock in Apple, Amazon, and Netflix for between $8 to $12 per share each. Looking at today’s market, he asked, “Where do you find value right now?” Gen Z already knows the answer—and it’s not in equities.

The Dow and S&P as proxies for wealth

The Dow and the S&P, Galloway argued, are not indicators of economic health. They are “effectively a proxy for how the rich are doing. And spoiler alert—they’re doing really well.” A market correction, Galloway said, would be a feature, not a bug—a recalibration in which housing prices would fall, stocks would become affordable, and capital flows would go back from owners to earners.

New data released this month by Northwestern Mutual found that nearly a third of Gen Z investors have been exposed to prediction markets, and the cohort leads all generations in meme coin activity and usage of speculative platforms like Polymarket. The study attributed the trend to a belief that previous rules of growth and finance broke down creating a generation of investors who suspected market manipulation and tried to seek better returns in new markets. Bloomberg, surveying the same data, called it “financial nihilism.”

But nihilism implies irrationality. What Galloway described at SXSW is the rational engine underneath the behavior. If the traditional system is structurally designed to enrich those who already own assets — and if every crash is backstopped before young buyers can get in at the bottom — then the conventional playbook isn’t just unappealing. It’s a trap. Prediction markets, meme coins, and speculative bets aren’t signs of recklessness. They are the logical response of a generation that has concluded the casino is rigged and decided to find a different one.

Intergenerational wealth transfer

To be sure, not all of it is rational. Gen Z also leads all generations in sports betting participation, online casino usage, and scratch ticket purchases—not as defensibly rational as other alternative investments. And Galloway’s argument overlooks the fact that the humble index fund, boring as it sounds, has still compounded at roughly 10% annually over the long run, through every bailout and moral hazard Galloway has catalogued.

Still, Galloway is right that the intergenerational wealth transfer is real, that bailouts produce moral hazard, and that young people have been handed an objectively harder economic hand than their parents. All of that is true and worth saying loudly.

The moral hazard Galloway decries at the institutional level has been perfectly replicated at the retail level. When banks learn that catastrophic risk-taking carries no real consequence, they take more of it. When a generation watches that dynamic play out across three major crises—with the government each time choosing to protect portfolios over people—they draw the obvious inference: downside risk is something the system absorbs for the already-wealthy, and the only way to break through is to bet big and early. Polymarket is, in a sense, the free-market correction that fiscal and monetary policy has refused to allow.

Galloway has argued separately that for the first time in American history, a 30-year-old is not doing as well economically as their parents were at the same age—and that this intergenerational wealth gap is the root cause of the political and social volatility now convulsing the country. ​

“A certain amount of disruption and drawdowns in the market is a healthy thing,” Galloway said at SXSW, “that transfers and seeds power, leverage, and capital back from owners to earners.”

Galloway is right. They just stopped waiting for the market to do it on its own—and opened a Polymarket tab instead.

This story was originally featured on Fortune.com

He’s a 45-year-old former Army Special Forces officer. He’s a former politician with ties to far-right conspiracies. He’s also out of a job.

Meet Joe Kent, who up until this morning, was serving as the director of the National Counterterrorism Center. In a now-viral post on X, Kent officially resigned from his role due to a disagreement with how President Donald Trump was handling the U.S. and Israel war with Iran—saying the country should have never been involved in the first place.

Iran “posed no imminent threat to our nation,” he said, adding the war was launched “due to pressure from Israel and its powerful American lobby.”

Kent’s departure from one of the country’s most sensitive intelligence posts marked a dramatic break from a man long considered among Trump’s most committed loyalists.

Kent spent two decades in the military

Kent enlisted in the U.S. Army at age 17, completed Airborne School and the Ranger Indoctrination Program, and earned his Green Beret as a Special Forces Weapons Sergeant in 2003 after arriving at the qualification course just days after the 9/11 attacks. Over 20 years, he rose through the ranks to become a Warrant Officer and was selected for a Special Missions Unit—an elite tier-one designation comparable to Delta Force—deploying across Iraq and Yemen.

He deployed on 11 combat missions primarily in Iraq before retiring in 2018 with six Bronze Stars. He then became a paramilitary officer with the CIA and later served as a counterterrorism advisor to Trump’s 2020 reelection campaign. After leaving the government, he became a fixture on conservative cable shows and podcasts and ran twice for Congress, in 2022 and 2024. He ran in Washington’s 3rd Congressional District and lost both times to Democrat Marie Gluesenkamp Perez. 

Kent’s ties to the Far Right

His political career was defined as much by his extremist associations as his military record. During his 2022 campaign, a political consultant arranged a call that included Nick Fuentes—a white nationalist who participated in the 2017 “Unite the Right” rally in Charlottesville; praised Hitler; and even said Jews hold the U.S. “hostage.” Fuentes later claimed in a livestream he told Kent “I love what you’re doing” and his network actively boosted Kent’s social media following. Kent denied any formal agreement and claimed he was barely aware of who Fuentes was, saying at the time: “The last, whatever, 24, 48 hours is really the biggest, deep-dive I’ve done on him.” He said this despite his chief consultant, Matt Braynard, having attended Fuentes’ America First Political Action Conference that same year. Kent also paid a Proud Boys member for consulting work and collaborated with the founder of the Christian nationalist group Patriot Prayer.

Beyond his associations, Kent spread rhetoric the DCCC described as adjacent to the “Great Replacement Theory,” backing calls to halt all legal immigration for 20 years. He called for a national abortion ban with no exceptions for rape, incest, or the life of the woman, and compared abortion access to slavery and segregation. He also described COVID-19 as a China-designed “vehicle” to suppress freedoms. While he later said he rejected all “racism and bigotry,” he declined during Senate confirmation hearings to distance himself from his 2020 election denialism.

He believes in anti-Interventionism for a personal reason

Kent’s foreign policy worldview is shaped by personal tragedy. His first wife, Navy cryptologist Shannon Smith, was killed by a suicide bomber in Syria in 2019 while aiding in the U.S. fight against ISIS, with her death hardening his skepticism of U.S. foreign intervention. During the chaotic U.S. withdrawal from Afghanistan in 2021, he tore into the defense industry and Washington’s “permanent ruling class,” arguing the wars had been prolonged “on the backs and dead bodies of U.S. soldiers” by people “making money and making their careers at the other end of it.”.

His appointment and subsequent resignation

In February 2025, Trump nominated him to lead the National Counterterrorism Center, praising him as someone who would help “eradicate all terrorism, from the jihadists around the World, to the cartels in our backyard.” He was confirmed in July on a 52-44 vote that split almost entirely along party lines.

The Iran Resignation

That anti-interventionist conviction ultimately ended his tenure in the Trump administration. In his resignation letter, he accused “high-ranking Israeli officials and influential members of the American media” of running a “misinformation campaign” to push the U.S. into conflict, language critics noted drew on antisemitic tropes about Jewish Americans’ political influence. 

It was a striking end for someone Senate Democrats had unanimously opposed at confirmation—every Democrat citing his right-wing ties—and who even one Republican, Sen. Thom Tillis of North Carolina, had voted against.

For this story, Fortune used generative AI to help with an initial draft. An editor verified the accuracy of the information before publishing.

This story was originally featured on Fortune.com

The U.S. wealth gap has grown so wide, even America’s billionaires can’t help but notice.

In the third quarter of 2025, the top 1% of U.S. households owned a whopping 31.7% of U.S. wealth, according to Federal Reserve data released in January. It’s more or less as much as what the bottom 90% of Americans hold, the widest the gap has been since the Fed started collecting data in 1989. And although headline figures are relatively strong, the U.S. economy doesn’t feel like it’s working for everyone, according to one person who has been treated very well by it. 

“This is 100% completely unsustainable as a society,” Peter Mallouk, the CEO of Creative Planning, a wealth management firm overseeing around $700 billion in assets, wrote on X Monday.

The gap has manifested in everything from asset ownership to how different households spend money, with real repercussions for the economy and even national politics. Mallouk even posted a graph from a December Financial Times article about the country’s widening wealth gap and growing evidence of a K-shaped economy, where households that own assets see their net worth rise while the majority of Americans are unable to build wealth. 

The graph, based on a Moody’s analysis from September, showed that the wealthiest 10% of Americans account for almost half of all consumer spending, a departure from 20 years ago, when spending was more evenly distributed across income groups. 

“Nearly 50% of all consumer spending now comes from the top 10% of earners,” Mallouk wrote. “The bottom 80%? Their share keeps falling.”

Mallouk’s post underscores the growing risk of America’s K-shaped reality. Wealth concentration at the top has accelerated since the pandemic, driven by booming stock markets and uneven wage growth favoring high earners. 

Pay for high and middle-income earners rose 3% last year, compared to 1.5% for low-income households, according to a January report from Bank of America, a reversal from the early pandemic recovery days when low-income households posted much faster wage growth than wealthier peers. Today, most middle and lower-income households are struggling to build enough wealth to stay afloat, unable to muscle their way into homeownership and concerned about their ability to buy basic necessities.

Mallouk isn’t the only wealthy voice sounding the alarm. Last year, Ray Dalio, the billionaire Bridgewater Associates founder, said the widening wealth gap in the U.S. and other rich nations was causing populism to rise and risked creating “irreconcilable differences” in society that democratic order would not be equipped to handle. Some ultrawealthy, like Salesforce CEO Marc Benioff, have also pushed for higher corporate taxes to fund education and housing.

This growing inequality is in spite of a relatively positive state of the U.S. economy, at least according to topline numbers. In addition to a strong stock market, unemployment and GDP growth were both relative success stories last year by historical standards, although the economy might have entered a slowdown toward the end of 2025. Last month, Moody’s chief economist Mark Zandi warned markets and the real economy had become “increasingly disconnected.”

“This is why the economy can look strong in the data while millions of people feel like they’re falling behind,” Mallouk wrote.

This story was originally featured on Fortune.com

Just a few short years ago, AI was a novel concept generating uncanny, sloppy photos and videos that appeared across your social media feeds. Today, it’s seemingly ubiquitous. New models are popping up almost every month. There’s AI integration in pockets of Hollywood. And even if it’s so far failing to boost your productivity at the office, AI has most likely already appeared in your workplace. That sprawling expansion requires enormous infrastructure investment. And Nvidia CEO Jensen Huang said his company is expecting to deliver those building blocks at a massive scale.

During his keynote address Monday at Nvidia’s GTC conference in San Jose, Huang said the company doubled its demand forecast within the next year. “I see through 2027 at least $1 trillion,” he said. “In fact, we are going to be short. I am certain computing demand will be much higher than that.”

And he’s already preparing for that reality with an unusual incentive to attract top talent and wring more computing power from his workforce: offering engineers AI tokens worth nearly half their salary.

The AI boom is pushing infrastructure investments to new heights. Tech companies are investing a staggering $700 billion into the data center buildout, a sum that rivals the GDP of developed economies like Sweden, and is more than double the total inflation-adjusted cost of the Apollo missions—projects that sent humans to the moon. Nvidia is a critical supplier in that buildout, providing the processors that power AI factories. The $1 trillion demand figure is further proof that the buildout is all gas, no brakes, even as competitors like Advanced Micro Devices (AMD) struggle to close the gap. All of this comes despite looming fears of an AI bubble, as flagged by business leaders like Microsoft CEO Satya Nadella and “Big Short” investor Michael Burry.

Huang made the prediction alongside claims that AI agents could soon run the world, as well as announcements around space-based computing designed to launch AI into orbit, a concept Elon Musk has spotlighted as a potential solution to the energy demands of expanding data centers.

“We are completely resetting and starting the largest buildout of human history,” Huang said. “Most of the world’s industries building AI factories, building chip plants, building computer plants are represented here today.”

The company’s recent earnings reports have added credibility to Huang’s claims. Last month, Nvidia posted $215.9 billion in revenue for fiscal 2026, up 65% from a year ago, the highest annual result ever. Data center revenue alone rose 75% from a year ago, reaching $62.3 billion.

AI tokens: the future of pay?

As business leaders aim to harness AI to boost worker productivity, Huang offered a glimpse at how Nvidia plans to operationalize that ambition: paying engineers in tokens—the currency of AI—to amplify their output. 

“I could totally imagine in the future every single engineer in our company will need an annual token budget,” he said. “They’re going to make a few 100,000 a year as their base pay. I’m going to give them probably half of that on top of it as tokens so that they could be amplified 10 times.”

Tokens are the basic units of data or words that AI models use to process language and recognize patterns, making them critical to the future of AI deployment. AI company OpenAI estimates that one token is equal to approximately four characters, with a single one-to-two sentence prompt requiring about 30 tokens. “Fortune Magazine,” for example, may be broken down into five tokens: “For” “tune” “Mag” “az” “ine.” 

At the allowance levels Huang described, engineers would have access to billions of tokens annually, unleashing a torrent of compute power. In Huang’s scenario, tokens would be an added employment perk for engineers at his firm, arming them with the power needed to conduct deep research for the company.

The Nvidia CEO said other tech firms will quickly follow suit and use tokens as a recruiting tool to attract top industry talent. 

“It is now one of the recruiting tools in Silicon Valley: how many tokens come along with my job,” he said. “The reason for that is very clear because every engineer that has access to tokens will be more productive.”

This story was originally featured on Fortune.com

Hello and welcome to Eye on AI. In this edition…Nvidia sees $1 trillion in AI chip sales by the end of 2027…Meta delays the debut of its latest AI model (again)…Moonshot AI develops a new architecture for large neural networks…and why we may soon be worrying about ‘moral crumple zones.’

Since the advent of ChatGPT in November 2022, one of the professions that people often claim is now toast is consulting. After all, what is it that consultants do? They advise companies on strategy; they help them restructure their businesses to create new organizational designs and processes, often with the help of technology from third-party vendors; and they act as providers of outsourced services, or at least conduits to outsourced services, such as customer support or software development. Well, a frontier AI model can offer strategic advice. It can also advise on how to restructure an organization and about which software to buy. AI agents can actually help stitch some of those systems together too. Finally, AI agents can also now handle coding and customer support. So it’s lights out for consultants, right?

Well, it hasn’t turned out that way so far. AI companies have discovered that they need consultants, or “systems integrators” as they are sometimes called in the software world, to help them sell their AI agents, as a story in last week’s Wall Street Journal highlighted. The reason is that using AI agents effectively often requires quite a lot of organizational transformation—cleaning up data, redesigning workflows, and thinking about how to redeploy human workers—as well as strategic thinking about how AI might be used to provide a real competitive advantage.

The AI model vendors have found they don’t have the resources to provide this kind of advice at scale—OpenAI only has about 70 so-called “forward deployed engineers” who go on site with customers to help them implement solutions based on their AI models; Anthropic is thought to have a similar number. And while it is possible that AI itself could serve this function, AI still suffers from a trust deficit—most boards would still rather put their faith in advice from McKinsey or BCG than ChatGPT. (A more cynical take: CEOs still like to use consultants to justify their own decisions to boards, as well as to have someone else to blame if it all goes wrong.)

OpenAI has formed what it calls its Frontier Alliance with McKinsey, Boston Consulting Group, Capgemini, and Accenture to help clients use its Frontier platform for building and managing AI agents. (You can read my coverage of that announcement here.) Anthropic has struck similar deals with Deloitte, Accenture, and Cognizant and is reportedly in talks with private equity groups, such as Blackstone, to implement Claude-based solutions in their portfolio companies.

I recently caught up with Capgemini’s Chief Strategy Officer Fernando Alvarez to talk about how his firm is viewing the future of consulting in an AI world.

Domain expertise matters

First, Alvarez says that while every client wants to use AI agents, they also recognize the need to govern those agents, make sure there is adequate cybersecurity around them, and ensure they can interact with legacy systems and fragmented data sources. Advising clients on all of that stuff and often helping them build it has been Capgemini’s bread and butter. He says clients still want Capgemini to provide these services. They aren’t ready to hand it off to AI.

The other big selling point for the consulting firms, Alvarez says, is deep industry and domain expertise. The frontier AI labs don’t have the expertise in how to optimize a pharmaceutical manufacturing plant or the best way to run logistics for a fast-fashion retailer. Consulting firms do. And that makes a difference when trying to use AI agent successfully. Alvarez says the conversations clients want to have are not about how many agents you can spin up or how you orchestrate them. “The conversation is, do you have the domain expertise to understand my problem?” he says.

‘People want the cake, not the recipe’

That doesn’t mean that Capgemini itself isn’t using AI to help serve clients. Alvarez says the big shift that Capgemini, as well as some competitors such as Accenture, are trying to make is to move from selling technology and advice, to selling outcomes. In this model, the consulting firm takes on the risk of trying to figure out how to deliver, say, better customer support, whether that is through business process outsourcing to humans in lower wage countries, such as the Philippines or India, or through AI agents.

“At the end, people want the cake,” he says—not a tour of the ingredients or the recipe. The new pitch boils down to a simple proposition: “Here is the problem. Here is the risk I’m willing to take, and this is the outcome I give you.” The client pays for the outcome: improved KPIs like successful customer issue resolutions and improved net promoter scores. The difference too is that the consultants in this model charge for the outcome, not by the number of people deployed on a project as some consultants have traditionally billed.

Alvarez says that AI is also enabling Capgemini and other consulting firms to move into market segments, such as midmarket companies, that it couldn’t service previously because the economics didn’t make sense. The engagements often required more staff and cost than the client was willing to pay for. But now AI has lowered those staffing and cost requirements, meaning that Capgemini can offer a solution at a price point that is attractive to midmarket companies while maintaining a decent enough profit margin. 

Perhaps the biggest challenge for consulting firms, though, is retraining their own people to work alongside AI agents. “Some people will make it, some people will not,” Alvarez says.

For all the disruption, Alvarez is unmistakably energized. He calls this moment “probably the best opportunity I’ve seen in the history of technology.” The question now is whether Capgemini and other consultants can rewire themselves as fast as the technology demands—which is, of course, exactly what they are advising their clients to do.

With that, here’s more AI news.

Jeremy Kahn
jeremy.kahn@fortune.com
@jeremyakahn

This story was originally featured on Fortune.com

The AI boom helped make the world’s 500 wealthiest people $2.2 trillion richer in 2025. To Bill Gurley, one of Silicon Valley’s sage investors and a general partner at Benchmark, those astronomical gains in wealth are a sign of an inflating AI bubble that is bound to pop.

The AI boom is following the pattern of other eras of technological growth, in which early gains for some tech firms have sparked a wave of spending that will ultimately be unsustainable for dozens of companies, Gurley said in an CNBC interview on Monday. Companies will soon have to curtail their spending and revise their valuations, or otherwise risk failing.

“When people get rich quick, a whole bunch of people come in and want to get rich too, and that’s why we end up with bubbles,” Gurley said. “One day we’re going to have an AI reset, because waves create bubbles, because interlopers come in.”

The venture capitalist added that investors should “start gobbling [software-as-a-service stocks] up” following the reset. The sector has been hit particularly hard by AI disruptions as a result of AI agents being able to automate workflows more cheaply than existing SaaS tools. Salesforce and ServiceNow stocks have lost more than 20% of their respective value since the start of 2026. 

Signs of AI strain

Gurley said the exorbitant amounts of money being spent on AI are a warning sign for a potential bubble burst.

“One day, I just think we trip and run out of money on those things,” he said. “I do think that moment stands in front of us.”

This wave of AI spending is set to exceed the capital expenditure-to-sales ratio from the dot-com era as a result of hyperscalers pouring money into data centers used to train and deploy vast large language models and other AI systems, according to Morgan Stanley analyst Todd Castagno. In a note to clients last month, Castagno said capex-to-sales will reach 34% this year and 37% in 2028, dwarfing the 32% recording near the turn of the century. That spending, about $2 trillion between 2026 and 2028, would represent 40% of the Russell 1000.

Hyperscalers may push this ratio even higher, to 38% this year and 45% by 2028, if they continue to finance data centers with leases, the note said. Indeed. Amazon, Meta, Alphabet, Microsoft, and Oracle amassed nearly $1 trillion in total undisclosed future lease commitments, or leases for data centers that have yet to be built, according to a February report from Moody’s Ratings. About $662 billion of that total is for leases that have yet to commence, which companies are not required to recognize as liabilities on their balance sheets under generally accepted accounting principles.

These infrastructure buildouts are often in partnership with startups like OpenAI and Anthropic, which have fuelled these ambitious data center investments. Last month HSBC estimated OpenAI would need an additional $207 billion in funding by 2030 in order to afford its cloud computer rental from Microsoft and Amazon. Analysts estimated $280 billion in total cash burn by 2030. Anthropic’s CFO said in a recent court filing the company spent more than $10 billion training models that generated half that total in cumulative revenue.

Gurley compared those figures with Uber’s annual burn rate of $2 billion when he was involved in the company—a sum he said gave him “high anxiety.” (Benchmark was an early investor in Uber, and Gurley served on the company’s board of directors at the time of ex-CEO Travis Kalanick’s 2017 ousting.)

“God bless them,” Gurley said of OpenAI and Anthropic. “It’s a scary way to run a company.”

AI’s impact on labor

AI companies’ astronomical spending has been accompanied with bold claims about the future of the labor market, with ServiceNow CEO Bill McDermott anticipating an eventual 30% unemployment rate for Gen Z college graduates as a result of the technology

Tech companies have already attributed mass layoffs to AI, including Oracle, which is reportedly reducing thousands of roles, touting efficiencies of its AI tools. Meta will lay off about 20% of its workforce following heavy AI spending, according to a Reuters report. Gurley said these claims and attributing mass layoffs to AI productivity is overdone.

“I’m not that big of a doomer, he said. “I think these waves come, and especially with AI, there have been a lot of people pumping kind of miracles into it … .They get this kind of apocalyptic view. We’ve had technology disruption before.”

Gurley noted CEOs announcing layoffs are going to blame AI, rather than take responsibility for “being bloated” or making tactical missteps. Analysts say companies like Oracle are slashing headcounts as a way to conserve cash following massive waves of investment. To Gurley, these cuts will become the new normal.

“We’re going to see a ton of these announcements,” he said. “But it’s a normal thing that we’ve been through before.”

This story was originally featured on Fortune.com

Clad in his trademark leather jacket, Nvidia CEO Jensen Huang took the stage yesterday at San Jose’s SAP Center before nearly 20,000 people at the company’s annual GTC conference, known in recent years as the Super Bowl of AI.

Once again, Huang essentially declared a blowout, forecasting a staggering $1 trillion in orders for Nvidia’s most sophisticated AI chips through 2027, driven by the explosion of AI infrastructure now being built around the world.

Yet for someone whose company has become the world’s most valuable—with a roughly $4 trillion market cap—by powering the global AI buildout, Huang has somehow avoided the kind of public criticism that has been leveled at other prominent AI CEOs.

It takes only a cursory glance at social media to find posts calling OpenAI CEO Sam Altman “evil,” while companies like Anthropic, Meta, and Google increasingly face criticism over AI’s risks—from job losses and copyright lawsuits to misinformation and the growing push to deploy AI in military systems.

Nvidia’s CEO, by contrast, remains largely celebrated as the engineer-builder behind the boom. That’s been true even though the massive AI data centers now rising across the country and generating a good deal of local opposition are packed with Nvidia chips.

In fact, every major move in AI—from chatbots and agents to applications in the workplace, schools, and the military—runs on Nvidia hardware, software, and systems. Nvidia has also invested billions to support the AI ecosystem, partnering with both OpenAI and Anthropic, as well as funding data center companies and AI startups.

So why isn’t Huang—and Nvidia as a whole—a target of the AI backlash?

The answer is that the companies supplying the “picks and shovels” of technological booms rarely attract the same scrutiny as the miners. Oil companies drew criticism during the fossil fuel era, not the manufacturers of drilling equipment. Railroad barons faced public backlash, not the companies supplying steel rails. And in the internet era, cloud providers like Amazon Web Services powered companies such as Airbnb and Uber that reshaped entire industries—yet the criticism largely focused on the platforms, not the infrastructure behind them.

Still, Nvidia made it clear at GTC that it is positioning itself not just as a chipmaker but as the provider of entire AI computing systems powering the new “inference” phase of AI. (Inference is about powering AI outputs, not just training, and it will require an enormous new round of infrastructure investment.) That ambition goes beyond Nvidia’s traditional “picks and shovels” role. These days, Nvidia is increasingly trying to control the entire swath of systems, software and platforms that power the AI economy. 

The centerpiece of Huang’s keynote was the launch of the company’s Vera Rubin platform, which combines multiple chips and system components designed to run large AI models and “agentic AI” systems. The platform includes seven new chips and several rack-scale systems intended to power extremely large AI clusters containing hundreds of thousands of GPUs.

Nvidia also introduced NemoClaw, an open-source platform for building enterprise AI agents, allowing companies to create agents, connect them to corporate data, and deploy them on Nvidia hardware.

At the same time, Nvidia is continuing to invest aggressively across the AI ecosystem. The company has poured billions into dozens of AI startups over the past year. Most recently it invested $2 billion in AI cloud company Nebius and is backing former OpenAI CTO Mira Murati’s new venture, Thinking Machines, with plans for more than 1 gigawatt of Nvidia-powered compute capacity.

The company is also continuing its push into autonomous vehicles, where Nvidia chips and software platforms are increasingly being adopted by carmakers building self-driving systems.

Finally, Huang used GTC to promote what he called AI’s “five-layer cake.” The AI economy, he argued, depends on five layers—energy, chips, infrastructure, models, and applications—all of which must scale together to support the massive buildout now underway. Nvidia, not coincidentally, sits squarely in the middle of that stack—connecting most of those layers together.

For now, Nvidia still benefits from the traditional insulation of a picks-and-shovels supplier. But as the sprawling AI data centers rising across the country fill with Nvidia hardware—and as the company pushes deeper into the systems powering them—the company may find itself far more exposed to the debate over AI’s consequences.

This story was originally featured on Fortune.com

An advocacy group hoping to expand support for child and elder care plans to spend $50 million to back Democrats in congressional races, tying the costs of caregiving to the nation’s affordability debate.

The Campaign for a Family Friendly Economy, created a decade ago, aims to make caregiver issues more salient in elections. The announcement comes as the cost of child care continues to rise and as waiting lists for federal child care subsidies, which support working families in poverty, continue to grow.

Sondra Goldschein, executive director of the campaign and its political action committee, said child care and elder care are important to the affordability conversation, especially as child care costs exceed what families pay for housing. Then there is the pressure on the “sandwich generation,” composed of middle-aged people who are caring simultaneously for their own children and parents.

“When child care can cost more than your rent or a mortgage, or you have to sacrifice a paycheck in order to be able to take care of a loved one,” that can motivate how people vote, said Goldschein. “Each election cycle, we see candidates recognizing that more and more.”

She hopes the message will resonate as families face a slew of rising costs, including climbing gas prices driven by a war in the Middle East that is unpopular with many voters.

The campaign plans to pour support for Democrats into Senate races in North Carolina, Georgia, Michigan, Maine and Ohio and into House races in Iowa and Pennsylvania. It is also slated to dispatch volunteers to talk with voters about caregiving.

The National Republican Congressional Committee did not immediately respond to a request for comment.

Republicans have begun to back child care as an issue crucial to growing the workforce, but their proposals tend to be less dramatic than those offered by Democrats. Last year, through President Donald Trump’s One Big Beautiful Bill, Republicans made an estimated 4 million more families eligible for a child care tax credit. The law also increased child care aid for military families and tax credits for employers who provide child care to their workers.

Before 2020, many candidates rarely spoke about child care. But the pandemic laid bare the child care industry’s precarity and necessity. Preschools and child care centers were pressed to stay open so parents in front-line jobs — such as those in health care — could return to work.

Then-President Joe Biden successfully persuaded Congress in 2021 to pass $39 billion in aid for child care, allowing states to offer support to more families and subsidizing wages for child care workers. Later that year, Biden sought to create nationwide universal prekindergarten and to vastly expand child care subsidies for families so that none would pay more than 7% of their household income for care. But the proposal narrowly failed in Congress. Since then, the pandemic aid has dried up, and families are feeling the pinch of rising costs.

Now, several candidates have centered their campaigns around child care affordability. New York Mayor Zohran Mamdani, a democratic socialist who won election after pledging to make the city more affordable for middle-class residents, ran on universal child care. Democratic Gov. Mikie Sherrill of New Jersey and Gov. Abigail Spanberger of Virginia won elections after pledging to expand child care subsidies.

Candidates this election cycle are running on universal child care pledges. They include Democrats Janeese Lewis George, who is running for mayor in Washington, D.C., and Francesca Hong, a gubernatorial candidate in Wisconsin. New York Gov. Kathy Hochul, who is up for reelection this year, has pledged to support Mamdani’s ambitions and eventually to expand universal child care statewide.

Neither the White House nor the Department of Health and Human Services, which oversees federal child care programs, responded to requests for comment. In his 2024 campaign, during an address to the Economic Club of New York, Trump said increasing foreign tariffs would “take care” of the expense of child care. That plan, thus far, has not materialized.

In Trump’s current term, the administration has largely focused on cracking down on fraud, after a viral video alleged Somali-run child care centers in Minneapolis were billing the government for children they weren’t caring for.

While there have been prosecutions stemming from child care subsidy fraud, the Minneapolis video’s central claims were disproven by state inspectors. Nonetheless, the Trump administration attempted to freeze child care funding for Minnesota and five other Democratic-led states until a court ordered the funding to be released.

___

This story has been corrected to show Hong is a gubernatorial candidate in Wisconsin, not Iowa.

___

The Associated Press’ education coverage receives financial support from multiple private foundations. AP is solely responsible for all content. Find AP’s standards for working with philanthropies, a list of supporters and funded coverage areas at AP.org.

This story was originally featured on Fortune.com

The national debt is set to reach $40 trillion in the near future if it continues to grow at its current pace. That has caught the attention of the richest man in the world. 

Elon Musk has joined the likes of Bridgewater founder Ray Dalio and Treasury Secretary Scott Bessent in supporting a solution to lowering the national debt, made famous by former Berkshire Hathaway CEO Warren Buffett. 

“I can end the deficit in five minutes,” Buffet said in a 2011 interview with CNBC. “You just pass a law that says that anytime there’s a deficit of more than 3% of the GDP, all sitting members of Congress are ineligible for reelection. Now, you’ve got the incentives in the right place.”

The plan received Musk’s full endorsement. “This is the way,” he wrote in June, sharing the interview in a post on X.  

Last year, the national debt ballooned by $2.6 trillion, and currently stands at $38.9 trillion, or 124% of the economy, according to the U.S. Treasury.

Buffett is far from the only one sounding the alarm on the national debt. 

Recently, the nonpartisan think tank Committee for a Responsible Federal Budget (CRFB) warned the average interest rate on the national debt could exceed economic growth by fiscal year 2031. 

“Once interest rates exceed the growth rate…primary deficits will lead debt to grow indefinitely,” the CRFB warned in a blog post on March 9.​ The committee also endorses the 3% of GDP target. 

While members of Congress haven’t warmed to the idea of being replaced over the national debt, a bipartisan group of representatives in January introduced a resolution to lower the deficit to 3% of GDP.  

What Warren Buffett’s 5‑minute plan to cap the deficit at 3% of GDP would actually do

In 2024, under the Biden administration, Buffett predicted higher taxes were coming for businesses. 

“They may decide that someday they don’t want the fiscal deficit to be this large, because that has some important consequences. And they may not want to decrease spending a lot, and they may decide they’ll take a larger percentage of what we earn, and we’ll pay it,” he said at Berkshire Hathaway shareholders meeting in May 2024. 

At that point, the national debt was more than $34 trillion, or 122% of GDP. Buffett has rebuffed companies that search for the smallest loopholes to reduce their tax burden. Since the first Trump administration, corporations have paid a maximum tax rate of 21%, compared to 35% previously. This tax rate was not changed the Biden administration. 

“My best speculation is that U.S. debt will be acceptable for a very long time, because there is not much alternative,” Buffett said.

This story was originally featured on Fortune.com

AI tools are already spurring fierce job competition among Bambi-legged Gen Zers hoping to land their first entry-level job out of college. And the situation could get even worse, one tech boss is warning.

“I think young people coming out of university today [are experiencing] 9% unemployment,” Bill McDermott, the CEO of AI-driven software company ServiceNow, recently told CNBC. “I think it could easily go into the mid-30s in the next couple of years.”

When evaluating what is disrupting the budding workforce, the boss of the $123 billion American tech giant pointed the finger at AI agents. McDermott predicted that there will be about three billion digital, non-human agents added to enterprises by 2030, which have the ability to automate routine tasks typically done by entry and mid-level employees. 

“What’s happening now, for the non-differentiating roles, [is] so much of the work is going to be done by agents,” the ServiceNow CEO continued. “So it’s going to be challenging for young people to differentiate themselves in a corporate environment.”

Already, around 5.6% of recent U.S. college graduates aged 22 to 27 are unemployed, compared to 4.2% of the general population, according to the Federal Reserve Bank of New York. And looking ahead, CEOs and experts alike are hesitant that entry-level hiring will make a comeback anytime soon. McDermott added that if other leaders follow ServiceNow in giving AI agents use cases humans were once assigned, “that will definitely put a damper on who you need to hire.”

Fortune reached out to ServiceNow for comment. 

Fresh-faced graduates are caught in the crosshairs of an AI work revolution 

Tech leaders with a front-row seat to the AI-driven workforce revolution have been sounding the alarm of a job takeover. The “godfather of AI” Geoffrey Hinton warned that unemployment will balloon because “rich people are going to use AI to replace workers”; Anthropic CEO Dario Amodei predicted that half of white-collar jobs would be automated by 2030; and OpenAI leader Sam Altman said the advanced tech is already giving entry-level workers a run for their money. 

“Today [AI] is like an intern that can work for a couple of hours, but at some point it’ll be like an experienced software engineer that can work for a couple of days,” Altman said during a panel with Snowflake CEO Sridhar Ramaswamy last year. 

As AI continues to advance at a breakneck pace, employment for vulnerable young workers has taken a turn for the worse. Since ChatGPT took the world by storm in 2022, U.S. job postings have plummeted by nearly 32%, according to a November 2025 analysis of Federal Reserve data. And 2026 reports have failed to drum up optimism, as the American economy unexpectedly shed 92,000 jobs in February, marking the biggest decline since last October.  

And just as McDermott observed, young inexperienced workers are most susceptible to the shift. About 58% of Gen Z students who graduated in 2024 and 2025 were still looking for their first job, compared to just 25% of millennial and Gen X graduates in previous years, according to a Kickresume report released last year. Job postings on early-career talent platform Handshake also fell more than 16% between August 2024 and August 2025, while the average number of applications per role has jumped 26%.

Hiring is down for Gen Z grads, even in tech

Even industries that are famous for plucking young, spry talent right out of college and putting them in high-paying jobs are reeling back. 

Hiring for new graduates in the tech sector at 15 of the largest companies fell by over 50% since 2019, according to a 2025 report from VC firm SignalFire. Before the pandemic, these Gen Z grads made up 15% of Big Tech hires—now, they only account for 7%.

Leaders are split on whether the current job market, marked by massive layoffs and stalled hiring, is reflective of AI automation or a correction of pandemic-era overhiring. But many can agree on one thing: entry-level jobs are the most endangered by AI. J. Scott Davis, assistant vice president of the Dallas Fed, believes young workers primarily have book smarts easily automatable by AI tools—unlike work experience. 

“Returns on job experience are increasing in AI-exposed occupations,” Davis recently wrote. “Young workers with primarily codifiable knowledge and limited experience will likely face challenging job markets.”

This story was originally featured on Fortune.com

For many observers, Donald Trump’s prosecution of the war against Iran has been nothing short of confounding — contradictory remarks, a seemingly improvisational strategy, and a nonchalance toward risks and costs that would paralyze a traditional commander-in-chief.

A century and a half ago, author John Churton Collins advised, “In prosperity our friends know us; in adversity we know our friends.” America’s allies are confused. Pundits are reeling. But the surprise is misplaced.

Trump’s approach to the Iranian conflict is not an anomaly. It is lifted directly from a consistent playbook he has relied on for decades. The president’s actions are rarely the random impulses they appear to be. Instead, they follow consistent, discernible patterns of behavior. Here are five of what we call Trump’s Ten Commandments, as we lay out in our new book of the same title. He’s exhibited them throughout his career, and he’s displaying them again in his conduct of this war.

1. Centralizing All Power

Unlike previous military engagements — which typically followed careful interagency planning with input from domain experts — Trump has bypassed the traditional national security apparatus entirely. Instead, he is managing the entire war through his signature “hub-and-spokes” leadership model. In Trump’s universe, he must be the sun around which everything revolves. Rather than deferring to seasoned military leaders, the intelligence community, or veteran foreign service officers, Trump has centralized war-making authority squarely in his own hands, relying on a tight circle of close advisors while other high-ranking officials — in his own administration and across foreign governments — learn what is happening by watching the news.

Freed of institutional constraints, the result is a war directed not by consensus but by singular, unconstrained instinct of Trump and Trump alone — limited, arguably, only by what financial markets will tolerate and how long the munitions stockpile will last.

2. The Punch in the Face

Where traditional diplomacy builds trust incrementally, Trump starts by striking the first blow and staking out the most maximalist position imaginable to create immediate leverage. By decapitating Iran’s leadership and neutralizing core infrastructure on day one, Trump bypassed standard diplomatic escalation ladders entirely. It is the geopolitical equivalent of his classic real estate strategy — inflicting maximum blunt trauma as the opening move, not the last resort.

3. Divide and Conquer

Trump has long viewed the traditional coalitions built by his predecessors — NATO, the EU — as constraints on his own authority rather than assets.

It is entirely consistent, then, that Trump went to war without consulting many of America’s historical allies in Europe, who were left in the cold. Eschewing multilateral consensus, he publicly chastised several allies for their “lukewarm” enthusiasm, demanding they deploy warships and police the waterway themselves. At the same time, he has kept Israel and the Gulf nations close, coordinating carefully in what Israeli President Isaac Herzog described as NATO-like in its intimacy, while talking nearly daily with top Gulf leaders according to New York Times reporting. In this way, he treats foreign nations much like he treats his own subordinates — pitting them against one another so that he alone rises above the chaos as the all-powerful arbiter.

4. The Wall of Sound

To control the narrative, Trump relies on what might be called a Perpetual Noise Machine — an overwhelming barrage of sudden moves and outrageos statements designed to distract and disorient. The sheer scale of the Iran strikes has dominated news coverage since the conflict began, erasing prior negative news cycles from domestic affordability concerns to foreign policy friction over Venezuela and Greenland.

By feeding contradictory remarks to the press practically hourly and issuing escalating threats against Iran’s oil infrastructure — will he or won’t he strike? — Trump keeps the media and international community focused entirely on his unpredictable next move. This relentless cascade ensures he dominates the news cycle, exhausts opponents, and prevents any cohesive counter-strategy from forming.

5. Donald the Great

Trump views himself in messianic terms — the leader who alone can accomplish what no predecessor could. By framing the 2026 war as the decisive strike to prevent Iran from acquiring nuclear weapons and the culmination of 40 years of Iranian aggression, he casts himself as a historic savior. Critics and supporters alike note that he appears increasingly convinced there is nothing he cannot do. Where traditional presidents weigh constitutional constraints, congressional approval, and allied consultation, Trump views those guardrails with the same dismissiveness he has applied to institutional limits his entire career, as Gulliver viewed the Lilliputians.

Trump’s war with Iran is not an anomaly. It is the ultimate expression of a leadership style decades in the making. The most useful thing global leaders — and observers — can do right now is stop being surprised. The playbook has always been visible. The only question is whether those on the receiving end are finally willing to read it.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Traditional paths to stable careers are undergoing a massive shift. Fields like computer science—once considered the safest bet for a high-paying job—are now facing new uncertainty. At the same time, some business leaders warn that entry-level roles could be hollowed out by AI, leaving many Gen Z workers questioning where opportunity still exists.

Jaime Teevan, Microsoft’s chief scientist, believes the answer may lie in an unexpected place: the liberal arts.

“Metacognitive skills will be very important—flexibility, adaptability, experimentation, thinking critically, being able to challenge things. Developing critical-thinking skills requires friction, doing things that are hard, doing deep thinking,” Teevan told The Wall Street Journal

“For that, a traditional liberal-arts education is really important.”

Teevan, who leads the research direction of the company’s experiences and devices division, including Office, Windows, Surface, and Teams, said the shift reflects a deeper change in how humans interact with technology. And for her, the stakes are personal: she has four sons, ages 17 to 21, all navigating higher education decisions in real time.

“Think of what AI does. It used to be that communicating with a computer was deterministic: You press this button, and this thing happens. Now it’s based on natural language, providing context, expressing intent and thinking critically.”

In other words, while liberal arts majors—such as anthropology, psychology, and education—have long been among the worst-paid majors, the very skills often taught in those career paths are becoming more valuable, not less.

 As AI handles more technical and repetitive tasks, the ability to exercise judgement, communicate nuance, and take responsibility is emerging as a differentiator. And it may be just what Gen Z needs to land a job in today’s market.

In today’s AI era, Gen Z may need to take an ‘insurance policy’ on their education

For years, educators and employers pushed students toward STEM fields, pointing to degrees like computer engineering as pathways to six-figure salaries. But early signs suggest that even those once-reliable routes are facing pressure.

The unemployment rate for computer engineering majors has climbed to 7.8%—the highest of any major except anthropology, according to the Federal Reserve Bank of New York, underscoring how quickly the job market is shifting in the AI era.

It’s a concern echoed by Ethan Mollick, a professor at the University of Pennsylvania’s Wharton School known for his AI research. With so much uncertainty, Mollick argued that overspecialization can be risky. Instead, he emphasized the value of broad, foundational learning—an approach central to liberal arts education—where students build critical thinking, problem-solving, and communication skills across disciplines. 

“Take an insurance policy by being broadly educated, being deeply educated, being flexible in the face of change, maybe saving money to get through the disruptions—the things you’d do in any time of uncertainty,” he told the WSJ. “A liberal-arts education matters more than ever.”

Employers are on the hunt for liberal arts graduates

The shift to hiring liberal arts majors is already showing up in the hiring process.

At McKinsey, candidates are now being evaluated in part on how well they can work alongside AI tools—a signal that technical knowledge alone is no longer the primary differentiator. The firm’s CEO admitted its hiring priorities have changed, with a new focus on “looking more at liberal arts majors, whom we had deprioritized.”  

It’s an idea echoed by Ravi Kumar S, the CEO of IT firm Cognizant Technology Solutions Ravi Kumar S, who said he’s also changed his hiring practices in the wake of AI.

“We are now going to hire non-STEM graduates,” he told Fortune. “I’m going to liberal arts schools and community colleges.”

Even leaders building out AI systems said human-centered skills are becoming more—not less—critical. Daniela Amodei, cofounder of AI firm Anthropic, said studying the humanities will be “more important than ever.”

“The things that make us human will become much more important instead of much less important,” she told ABC News last month. “And what I mean by that is when we look to hire people at Anthropic today, we look for people who are great communicators, who have excellent EQ and people skills, who are kind and compassionate and curious and want to help other people.”

This story was originally featured on Fortune.com

Joe Kent, the director of the National Counterterrorism Center, announced his resignation on Tuesday, citing his concerns about the justification for military strikes in Iran and saying he “cannot in good conscience” back the Trump administration’s war.

Kent said on social media that Iran “posed no imminent threat to our nation, and it is clear that we started this war due to pressure from Israel and its powerful American lobby.”

Kent, a former political candidate with connections to right-wing extremists, was confirmed to his post last July on a 52-44 vote. As head of the National Counterterrorism Center, he was in charge of an agency tasked with analyzing and detecting terrorist threats. His resignation reflects unease within Trump’s base about the war and shows that questions about the justification for the use of force in Iran extend to the right of President Donald Trump’s base and to senior members of the administration.

Trump has offered shifting reasons for the strikes and has pushed back on claims that Israel forced the U.S. to act. Earlier this month, House Speaker Mike Johnson, R-La., suggested that the White House believed Israel was determined to act on its own, leaving the Republican president with a “very difficult decision.”

A spokesperson for Director of National Intelligence Tulsi Gabbard did not immediately respond to questions about Kent’s resignation. The White House also had no immediate comment on Kent’s resignation.

Before entering Trump’s administration, Kent ran two unsuccessful campaigns for Congress in Washington state. He also served in the military, seeing 11 deployments as a Green Beret, followed by work at the CIA.

Democrats strongly opposed Kent’s confirmation, pointing to his past ties to far-right figures and conspiracy theories. During his 2022 congressional campaign, Kent paid Graham Jorgensen, a member of the far-right military group the Proud Boys, for consulting work. He also worked closely with Joey Gibson, the founder of the Christian nationalist group Patriot Prayer, and attracted support from a variety of far-right figures.

During his Senate confirmation hearing, Kent also refused to distance himself from a conspiracy theory that federal agents instigated the Jan. 6, 2021, attack at the Capitol, as well as false claims that Trump won the 2020 election over Democrat Joe Biden.

Democrats grilled Kent on his participation in a group chat on Signal that was used by Trump’s national security team to discuss sensitive military plans.

Still, Republicans praised Kent’s counterterrorism qualifications, pointing to his military and intelligence experience.

Sen. Tom Cotton, the GOP chair of the intelligence committee, said in a floor speech that Kent had “dedicated his career to fighting terrorism and keeping Americans safe.”

This story was originally featured on Fortune.com

The idea sounds outlandish, if not downright impossible.

Leaders at the World Anti-Doping Agency are considering adopting a rule that could bar President Donald Trump and all U.S. government officials from attending major international events — even if they take place on American soil.

A few coming up are as big as they get: this summer’s World Cup; the LA Olympics in 2028; the Winter Games in Utah in 2034.

This is not a fight of Trump’s choosing, but rather one being pursued by WADA itself, which has been the subject of bipartisan and virtually universal disapproval in Congress, in the Trump and Biden administrations and in the offices of the U.S. Anti-Doping Agency for most of this decade.

The proposal, on the agenda for Tuesday’s meeting of the WADA executive committee, is the latest and most extreme maneuver in a yearslong exchange of rhetoric, threats and fighting between all parties. It stems from the U.S. government’s refusal to pay its annual WADA dues.

The U.S. has held back a total of $7.3 million over 2024 and 2025 in protest of WADA’s handling of a number of issues over the years, most recently, a case involving Chinese swimmers who were allowed to compete despite testing positive for a banned substance. WADA took Chinese regulators’ word that the athletes had been accidentally contaminated.

WADA spokesman James Fitzgerald said the rule, if passed, would “not (be) applied retroactively so World Cup, LA and SLC Games would not be covered.” However, the proposal, a copy of which was obtained by The Associated Press, does not include language to that effect.

Fitzgerald did not respond to a series of follow-up questions sent Monday, including one asking how a rule being considered for passage this year would not be applied retroactively to events that have not taken place. Fitzgerald did say last week that the final decision wasn’t due until November, after the World Cup, though correspondence between WADA and European officials indicated that decision could come sooner.

Here’s a look at how they got to this point and where they might go next.

What is WADA?

WADA came into existence in 1999 and was charged with writing the rules that governed anti-doping in sports and making sure they were executed correctly.

In recent years, with the onset of more troubling and complexdoping sagas, WADA has gotten more involved in investigating doping allegations — a function that has largely been handled by the dozens of organizations that oversee the use of performance enhancers in certain countries and sports.

WADA’s funding comes equally from two places — governments of countries that participate in the Olympic movement and the International Olympic Committee. Representatives on WADA’s key decision-making bodies are generally divided equally between sports and government.

What gives WADA the power to ban Trump?

Part of sending teams to major international events, such as the Olympics and the World Cup, requires everyone involved to pledge to follow WADA’s rules, whether they’re directly related to doping or to administrative issues, the likes of which the latest proposal covers.

Sports organizations — for instance the IOC and the governing bodies of individual sports — are considered “signatories” to the WADA code.

Governments are tethered to WADA as part of an agreement they sign with the United Nations Educational, Scientific and Cultural Organization (UNESCO) Like sports organizations, the UNESCO arrangement includes the governments agreeing to pay dues and follow WADA’s rules,.

Could WADA really prevent Trump from attending an event in his own country?

It’s hard to see how. Rahul Gupta — the drug czar during the Biden Administration who was every bit as critical of WADA as is his successor, Sara Carter — called the idea “ludicrous.”

Gupta said that’s not just because it would be logistically impossible to restrict where the U.S. president goes, but it would also send the wrong message to a host nation, which oversees the games and ensures the proper investments are made in security, venues and other infrastructure.

“That’s the responsibility of the government, not so much WADA,” Gupta said. “It’s clear that WADA attempting to propagate any rules-based system that interferes with a government, especially a host government — that would be a concern to any government.”

Trump’s people aren’t happy with this. What about other U.S. politicians?

While Trump has not weighed in on this specifically, Carter, his drug czar, said the U.S. government “will continue to stand firm in our demand for accountability and transparency from WADA to ensure fair competition in sport.”

WADA has had the rare effect of bringing together politicians from both sides of the aisle. A bill adopting the doping-fighting Rodchenkov Act, key parts of which were strongly opposed by WADA, passed without a dissenting vote in Congress six years ago.

More recent attempts to hold WADA accountable, which resulted in the dues being held up, have drawn bipartisan support in both houses of Congress.

After the latest news, Sen. Marsha Blackburn, R-Tenn., said on social media that the proposal was “Further proof we’re doing the right thing by demanding accountability and defunding WADA.”

What is WADA’s reason for proposing such a rule?

WADA runs on a budget of around $57.5 million and the U.S. chunk is significant, though hardly the only payment that has gone missing over the years. One analysis of dues payments, obtained by the AP, showed that only 49% of African countries had paid their WADA dues for 2025.

But no country has been more critical of WADA than the United States, which has floated the idea of holding back dues since 2020 and finally followed through two years ago.

WADA says this idea is ‘nothing new.’ What does that mean?

That’s true.

WADA has been examining this idea since 2020 — around the time the threats from the U.S. started getting louder. In 2024, the idea actually came to the executive committee. Gupta was on that panel back then and led the move to reject it. The U.S. no longer has a representative on the executive committee.

So why is it coming up now?

WADA hasn’t provided answers to this one, other than to say the rule wouldn’t apply “retroactively” and that the World Cup, LA and Utah Olympics would not be impacted.

WADA says the next meeting of its foundation board – the group that would have to formally adopt any recommendation approved by the executive committee — isn’t until November, four months after the World Cup ends.

But in a Q&A with European officials about the rule, a copy of which was obtained by AP, WADA told the officials that such a rule “could be implemented without due delay.”

If this has already been rejected once, why try again?

The Europeans asked WADA that same question. The future of the rule had been delegated to a WADA “discussion group” that was supposed to report back to the executive committee but hasn’t done so yet.

WADA’s answer said that legal issues involving fining countries that don’t pay their dues have been resolved (the fine portions have been removed).

“Little meaningful progress was made in the latest meetings of the Discussion Group and there is no reason (given the foregoing) not to bring this matter to the ExCo as a decision-making organ of WADA,” it said.

___

AP Olympics: https://apnews.com/hub/2024-paris-olympic-games

This story was originally featured on Fortune.com

The foil-embossed invitation for a destination wedding on a tropical island hits your mailbox, and the instinct is familiar: make an excuse, and quietly hope no one asks why. For tens of millions of Americans, that excuse has a name, and it’s not one they’re willing to say out loud.

Two-thirds of Americans have skipped at least one social commitment in the past two years because they just can’t afford it, according to a new survey from the CFP Board shared with Fortune. The events they’re missing out on aren’t always luxuries. They’re birthday dinners, concerts, holiday gatherings, as well as group vacations and weddings. 

But in most cases, people hide the real reason they can’t accept the invitation. Of those who declined invitations, 56% never told their friends or family that money was the reason why they couldn’t attend, according to the report. CFP Board, the professional body for personal financial planners, surveyed more than 1,100 Americans aged 25 to 64 in January for the study.

Most Americans are skipping social events to save money—and staying silent about it

The silence is telling, and it’s only making Americans lonelier and anxious about sharing their financial status with friends and family.

“Lately I’ve been turning down invites to hang out because I just can’t afford it, and it’s starting to make me feel guilty,” a Reddit user posted late last year. “I don’t want my friends to think I don’t care about them but even small things like dinner or drinks add up too much right now.”

The problem is so widespread that personal finance creators have even posted guides to politely declining invitations for this very reason.

“You guys know that when you get invited to a wedding or a bachelorette, you can say no,” SoFi’s chief of financial empowerment, Vivian Tu, posted in an October 2025 TikTok video

@yourrichbff No, you don’t actually have to go to every single bachelorette party you get invited to! Here’s how to decline an invite without sacrificing a friendship. #money #finance #financialfreedom #podcast #bachelorette ♬ original sound – Vivian | Your Rich BFF

“One in three people are going into debt for their friends’ weddings,” Tu continued, referencing a New York magazine story about bridesmaids going into debt. She suggests being open and honest about the reasons you have to decline the invitation.

She suggests saying: “Congratulations on your engagement, friend! I’d be honored to be your bridesmaid. But I need to be transparent that I’m paying off my credit card bill and saving for a down payment on a home.”

“And my budget is XYZ,” she continued. “But I don’t want your vision for your special day and big events to be restricted by me, so it’s completely okay if I come as a guest and support you in other ways.”

How financial stress is making America’s loneliness epidemic worse

The U.S. was already grappling with what health officials have called a loneliness epidemic, and the cost-of-living crisis has only intensified it. A November 2025 poll from the American Psychological Association shows more than six in 10 U.S. adults say societal division is a significant source of stress in their lives.

“This year’s findings show that people across the nation are not just feeling divided, they’re feeling disconnected,” Arthur C. Evans Jr., PhD, and CEO of APA, said in a statement. “Research tells us that a sense of isolation and social fragmentation can have real consequences for our ability to manage stress and stay healthy.” 

And a May 2025 study from the University of Southern California found financial strain is directly linked to higher rates of anxiety and loneliness, and those effects compound over time.

“Because this strain is based on how people perceive their financial stability, not just how much they earn or what degrees they hold, it may better reflect the lived reality of daily stress and coping capacity,” said psychologist Deborah Finkel, a research scientist at USC Dornsife’s Center for Economic and Social Research who led the study.

Gen Z and millennials can’t afford their social lives—and it’s getting worse

For younger Americans, the math is especially brutal. A Harvard Kennedy School poll from 2025 found 42% of Americans under age 30 say they’re “barely getting by” financially, and a Bank of America study found more than half of Gen Z says they don’t feel as if they make enough money to live the life they want. 

The new CFP Board data illustrates just how far the social fallout from financial constraints extends. The events Americans are missing include group trips or vacations, dining out with friends, concerts or sporting events, family holiday gatherings, and weddings. Single Americans are more likely to keep quiet about it, with 63% saying they hid the financial reason for their decline, compared with 55% of married people.

CFP Board deems this phenomenon as financial FOMO. It’s not just about missing a good time, it’s about feeling “out of sync” with their friends’ spending, including on housing, travel, career, progress, and debt payoff. Nearly half say the financial situations of people close to them have significantly shaped how they view their own money.

Despite this, the CFP Board also found that financial conversations are still taboo. More than 80% of Americans intentionally avoid at least one money topic with those close to them. A July 2025 AMFM Healthcare survey also found 79% of Americans say money worries have worsened, straining relationships and costing sleep.

But some Americans have recognized the need for more transparency to avoid social isolation.

“I’ve started being honest about it and suggesting stuff like ‘hey, let’s just hang at someone’s place instead’ or go for walks,” another Reddit user posted. “Real friends get it, and the ones who don’t probably aren’t worth stressing over anyway.”

This story was originally featured on Fortune.com

Mastercard has finally pulled the trigger on a stablecoin acquisition. The payments giant on Tuesday morning announced a deal to acquire the London-based startup BVNK for up to $1.8 billion, with $300 million locked up in “contingent payments.” The deal is expected to close by year end, Jorn Lambert, Mastercard’s chief product officer, told Fortune. He declined to provide more details about the purchase of BVNK, which uses stablecoins to power customer transactions, cross-border payments, global treasuries, and other use cases.

The acquisition concludes an off-and-on negotiations process that saw the stablecoin firm court multiple buyers, including the U.S. crypto exchange Coinbase and Mastercard. Coinbase came close to buying the startup for around $2 billion before the two called off the deal around November. 

Mastercard’s yet-to-be-closed purchase of BVNK eclipses Stripe’s $1.1 billion deal for the startup Bridge in February 2025, making this the largest stablecoin acquisition yet for the crypto industry.

Mastercard’s stock jumped about 2.5% in pre-market trading. 

“This is really about getting the right tools to move after new addressable markets,” said Lambert.

Stablecoin rails

Mastercard’s push into stablecoins comes as the payments giant has fended off speculation over the past year that the rise of the digital tokens, or cryptocurrencies pegged to real-world assets like the U.S. dollar, may eat into its margins. 

Proponents of stablecoins say their use of blockchain-based payment rails reduces fees and allows users to transact more quickly. Investors have seen some validity to that argument. Mastercard saw its shares initially sag after the U.S. Senate passed in June the Genius Act, legislation that regulates stablecoins. President Donald Trump signed the bill into law one month later. 

Mastercard, however, has pushed back on any implications that stablecoins are a threat to its business. “I think most flows will begin and end in fiat,” Raj Seshadri, chief commercial payments officer at Mastercard, said on a July call with analysts.

Still, the incumbent payments network has made moves to keep pace with technological change. In addition to initially courting BVNK, Mastercard was also in talks with the crypto startup Zerohash for a purchase price of between $1.5 billion to $2 billion. That deal reportedly fell through. Lambert, Mastercard’s chief product officer, declined to delve into the payments network’s past ambitions of stablecoin acquisitions.

He also pushed back on the argument that stablecoins threatened Mastercard’s business model. “If you think about our current business, the card business, there’s no problem to be solved,” he said, adding that incorporating stablecoin rails positions Mastercard to more effectively make headway in the remittances market, among other areas.

For BVNK, founded in 2021, the $1.8 billion acquisition price is a large premium over its $750 million valuation in its Series B fundraising round in December 2024. “Needless to say, there’s a big smile on my face,” said BVNK cofounder Chris Harmse, in reference to Mastercard closing the deal to buy his company. 

This story was originally featured on Fortune.com

As of 9 a.m. Eastern Time today, oil is trading at $102.98 per barrel, based on the Brent benchmark we’ll explain in a bit. That’s 84 cents above yesterday morning’s level and more than $31 higher than where it stood a year ago.

Oil price per barrel % Change
Price of oil yesterday $102.14 +0.82%
Price of oil 1 month ago $68.81 +49.65%
Price of oil 1 year ago $71.10 +44.83%

Will oil prices go up?

No one can say for sure where oil prices will go next. Many forces shape the market—but at the core, it’s still about supply and demand. When risks like a potential recession or war ramp up, oil prices can change direction quickly.

How oil prices translate to gas pump prices

When you buy gas at the pump, you’re covering more than the cost of crude oil. You’re also paying for every step in the process, including refineries, wholesalers, taxes, and the markup your local gas station adds.

Even so, crude oil has the biggest influence on what you pay, often making up more than half the cost per gallon. When oil prices jump, gas prices usually climb right along with them. But when oil falls, gas prices often slip much more slowly—a pattern sometimes called “rockets and feathers.”

The role of the U.S. Strategic Petroleum Reserve

If an emergency hits, the U.S. keeps a backup supply of crude oil called the Strategic Petroleum Reserve. It’s mainly there to protect energy security during crises, such as sanctions, catastrophic storm damage, even war. It can also help cushion the blow when supply shocks send prices soaring.

It’s not meant to solve long-term problems. Instead, it provides quick relief for consumers and helps keep vital parts of the economy moving, like essential industries, emergency services, and public transit.

How oil and natural gas prices are linked

Oil and natural gas are two of the world’s primary energy sources. A big change in oil prices can affect natural gas by extension. For example, if oil prices increase, some industries may swap natural gas for some segments of their operations where possible, which which increases demand for natural gas.

Historical performance of oil

When looking at how oil performs, two main benchmarks stand out:

  • Brent crude oil is the main global oil benchmark.
  • West Texas Intermediate (WTI) is the main benchmark of North America.

Of the two, Brent gives a better picture of global oil performance because it prices a large share of the world’s traded crude. It’s also the go-to for tracking oil’s historical trends. In fact, even the U.S. Energy Information Administration now relies on Brent as its primary reference in its Annual Energy Outlook.

If you look at the Brent benchmark over several decades, oil has been far from stable. It has experienced sharp rises tied to wars and supply cuts, along with steep drops linked to global recessions and oversupply (called a “glut”). For example:

  • The early 1970s delivered the first major oil shock when the Middle East slashed exports and placed an embargo on the U.S. and others during the Yom Kippur War.
  • Prices fell in the mid-1980s due to lower demand and an influx of non-OPEC oil producers joining the market.
  • Prices surged again in 2008 as global demand grew, but then crashed alongside the global financial crisis.
  • During the 2020 COVID lockdown, oil demand plummeted like never before—pushing prices below $20 per barrel.

To sum up, oil’s historical performance has been anything but smooth. Again, it’s heavily influenced by wars, recessions, OPEC whims, shifting energy policies, and much more.

Energy coverage from Fortune

Looking to stay up-to-date regarding the latest energy developments? Check out our recent coverage:

Frequently asked questions

How is the current price of oil per barrel actually determined?

The current price of oil per barrel depends largely on supply and demand, including news about potential future supply and demand (geopolitics, decisions made by OPEC+, etc.). In the U.S., prices also move based on how friendly an administration is to drilling, as it can affect future supply. For example, 2025 saw the Trump administration move to reopen more than 1.5 million acres in the Coastal Plain of the Arctic National Wildlife Refuge for oil and gas leasing, reversing the Biden administration’s policy of limiting oil drilling in the Arctic.

How often does the price of oil change during the day?

The price of oil updates constantly when the “futures” markets are open. A futures market is effectively an auction where people agree to buy or sell oil in the future. As long as people and companies are trading contracts, the oil price is changing.

How does U.S. shale oil production affect the current price of oil?

In short, shale is rock that contains oil and natural gas. Think of shale as energy yet to be tapped. The more shale the U.S. accesses, the more energy we’ll have—and the more easily oil prices can keep from spiking as much thanks to a greater supply.

How does the current price of oil impact inflation and the broader economy?

When oil is expensive, it tends to make everyday items cost more. This can be related to energy (your heating, gas utilities, etc.), but it’s also due to the logistics involved with making those items accessible to you. Shipping, for example, can affect the price of things at the grocery store, as it’s more expensive to get those products from warehouses and farms onto the shelf.

This story was originally featured on Fortune.com

On May 8, Instagram will be able to read your DMs again. Meta is ending support for end-to-end encrypted direct messages — reversing a feature it introduced just two years ago — and reopening the door to automated content scanning, AI-powered moderation, and easier compliance with law enforcement requests. TikTok, meanwhile, confirmed it never offered the protection at all. Together, the moves signal that the era of unconditional privacy promises on social media is over.

In the span of two weeks, two of the world’s largest social media platforms have signaled they are done treating privacy as an unconditional promise. Together, the moves mark a decisive reckoning with what private messaging on social media actually costs—and who pays the price.

A TikTok spokesperson told Fortune that the company’s approach to messaging has not changed. “Direct messages on TikTok are secured using industry-standard encryption in transit and at rest,” the spokesperson said, comparing the technology to what Gmail uses. “People’s messages are private and protected. Access to message content is strictly limited, subject to internal authorization controls, and only available to trained personnel with a demonstrated need to review the information as part of safety investigations, legal compliance, or other limited circumstances.” In other words: not end-to-end encrypted, but far from an open book.

The distinction matters. The TikTok spokesperson said the design is deliberate—and that the lack of end-to-end encryption is itself a safety feature. “Messaging on TikTok is not end-to-end encrypted,” they said. “This helps make our platform undesirable for those who would attempt to share illegal material.” Meta had not yet responded to requests for comments.

When Instagram’s encryption sunsets in two months, Meta will regain the technical ability to scan and act on the content of users’ DMs. Right now, under the opt-in encrypted system, even Meta’s own servers cannot see message content. That changes May 8, reopening the door to automated content moderation, AI-powered scam detection, and easier compliance with law enforcement requests.

End-to-end encryption isn’t keeping people safe

Brian Long, CEO and co-founder of Adaptive Security, a firm that trains organizations to defend against AI-powered attacks, including deepfakes and voice cloning, says the calculus both companies are making reflects a necessary course correction. “It’s a challenging place, because on the one side, I think a lot of these companies have leaned into privacy,” Long told Fortune. “But on the other hand, it’s also led bad actors to do anything from run scams in the background to attack consumers. What they’re recognizing is that as great as it sounds for everything to be encrypted, it’s giving a lot of runway to bad actors.”

The regulatory pressure is accelerating that shift. The Take It Down Act, signed into law last year, requires platforms to remove non-consensual intimate imagery—including AI-generated deepfakes—within 48 hours of a valid request, with enforcement beginning May 19, just eleven days after Instagram’s encryption cutoff. Long said that end-to-end encryption had made that kind of compliance nearly impossible. “If it’s all encrypted and they can’t see the messages, it gets harder for them to actually police those actions,” he said. “They’re going to be accountable under the law.”

Beyond legal deadlines, Long argues that internal safety teams and not law enforcement are the first and most important line of defense, and encryption had effectively neutralized them. “The safety team can jump in and flag messages to the consumer before they fall for a scam,” he said. “When everything is protected by encryption, the safety team really can’t do anything. A lot of this stuff should be handled by the company before it hits law enforcement. Otherwise, law enforcement would just be completely overwhelmed.”

Last year, over a million seniors fell victim to fraud, costing them more than $81 billion in estimated losses, according to an FTC report. AI-powered attacks, from deepfakes, voice cloning, and year-long romance scams, are growing at an estimated 17 times year over year. “The scale of the attacks, especially on alternate messaging channels, is something we’re hearing consistently from customers,” Long said. “Those channels where you had encryption historically were particularly ripe for this issue.”

For privacy advocates, lifting encryption is still a serious concession, and one that opens user data to platform surveillance alongside the safety benefits. But for scam prevention professionals, it’s the right call. “I think companies are recognizing there are some potential serious downsides to privacy,” Long said. “At the end of the day, this correction is probably needed in order to stop more of the bad actors. And if privacy is the biggest priority, there are applications available that people can go use.”

This story was originally featured on Fortune.com

Amazon said Tuesday that it has started offering faster U.S. deliveries of selected products for a fee, including pantry staples, clothing, over-the-counter medications, cleaning supplies and electronics.

The e-commerce colossus said customers in more than 2,000 cities, towns and suburban areas can now choose to have orders from its speedy-shipment inventory of 90,000 items delivered in three hours. The charge is $4.99 for Amazon Prime members and $14.99 for nonmembers.

One-hour delivery slots are available in hundreds of places, including major metropolitan areas like Los Angeles, Chicago and Washington, and smaller cities such as Des Moines, Iowa and Boise, Idaho, the company said. Prime members will get charged $9.99 for the service, which costs nonmembers $19.99, Amazon said

The Seattle-based company said it started testing the express delivery service late last year and expanding it this month.

“We saw an opportunity to use our unique operational expertise and delivery network to help make customers’ lives a little easier while unlocking even more value for Prime members,” Udit Madan, senior vice president of worldwide operations at Amazon, said in a statement.

Amazon launched its Prime program in 2005, offering members free two-day delivery on a selection of 1 million items, primarily DVDs, CDs, and books. Prime members now have access to over 300 million items across 35 categories, and tens of millions of products are available for free same-day or next day deliveries.

The company has used robotics and artificial intelligence technology to speed up order fulfillment. Regionalizing its U.S. delivery network into eight areas also has helped reduce delivery times, Amazon said.

Amazon is testing an ultra-fast service for deliveries in 30 minutes or less. Amazon Now is available in various cities in India, Mexico and the United Arab Emirates and is being tested in several communities in the U.S. and the United Kingdom, according to the company.

Rival retailer Walmart has focused on faster deliveries too. The Bentonville, Arkansas-based company says it offers same-day deliveries in under three hours to 95% of the U.S. population, compared to 76% three years ago.

This story was originally featured on Fortune.com

Twice on Monday, President Donald Trump said he’d wrangled a confession of sorts from an Oval Office predecessor who he said had expressed regret in a private conversation about not attacking Iran the way Trump has been doing for more than two weeks.

But there’s just a little problem: Representatives for the four living former presidents — three Democrats and one Republican — said none have been in touch with Trump recently.

Trump declined to name the former president when reporters asked who it was, saying he didn’t want to “embarrass him.”

The Republican president first told the story during extended remarks about the Iran war as he opened a meeting of the board of trustees of the Kennedy Center. Trump is chairman of the board and held the meeting at the White House.

He repeated that Iran had been a threat to the United States for decades but said he is the only president who had the courage to do something about it.

“Look, for 47 years, no president was willing to do what I’m doing, and they should have done it a long time ago,” he said. “It would have been a lot easier. There’s no president that wanted to do it.

“And yet every president knew. I’ve spoken to a certain president, who I like, actually, a past president, a former president. He said, ‘I wish I did it, I wish I did,’ but they didn’t do it. I’m doing it,” Trump continued.

Asked which former president he’d spoken to, Trump said: “I can’t tell you that. I don’t want to embarrass him. It would be very bad for his career, even though he’s got no career.”

Representatives for each of former Presidents Bill Clinton, George W. Bush, Barack Obama and Joe Biden said they had not spoken with Trump recently. The individuals spoke on condition of anonymity because they are not authorized to discuss the former presidents’ private conversations.

The White House did not immediately respond to a request for comment after being informed that none of the former presidents said he had spoken with Trump recently.

Trump and all four past presidents were last together in the same space for his inauguration on Jan. 20, 2025 — well before the war.

He has been extremely critical of Biden and Obama, often saying Biden is the “worst president in the history of our country” and accusing Obama of negotiating a “horrible deal” with Iran over its nuclear weapons. Trump withdrew the U.S. from that agreement the first time he was president.

But the Republican recently offered sympathetic comments about Clinton, saying it “bothers” him that the former president had been called to give a deposition to Congress about his friendship with convicted sex offender Jeffrey Epstein.

“I liked Bill Clinton. I still like Bill Clinton,” Trump said in a Feb. 4 interview with NBC News. “I liked his behavior toward me. I thought he got me, he understood me.”

Trump repeated his story about discussing Iran with a former president later Monday in the Oval Office, where he announced that Vice President JD Vance will lead a task force that was created to eliminate fraud in federal benefit programs.

“Was it George W. Bush?” a reporter asked.

“No,” Trump said.

“Was it Bill Clinton?” the reporter asked.

Trump said: “I don’t want to say. I don’t want to say,” then added that “it’s somebody that happens to like me. And I like that person, who’s a smart person. But that person said, ‘I wish I did it,’ OK, but I don’t want to get into who, OK. I don’t want to get them into trouble.”

This story was originally featured on Fortune.com

Good morning. Could the next generation of tech giants fit in a single office?

In the coming years, some of the most valuable companies in the world will have “sub-100 employees,” Daniel Nadler, the founder and CEO of OpenEvidence, predicted during a panel session at Nvidia’s GTC 2026 summit on Monday. “I think the world’s not prepared for that,” Nadler said.

OpenEvidence is an AI‑powered medical information and clinical decision support company used by physicians. In January, the startup closed a $250 million Series D funding round, co‑led by Thrive Capital and DST Global, which doubled its valuation to approximately $12 billion.

“Take OpenEvidence, we have sub-100 employees, yet 300 million Americans will be treated this year by a doctor who used OpenEvidence in the loop,” Nadler said. Each employee in his company is indirectly supporting millions of patients, he estimated.

“The scale is unfathomable, and that’s directly a result of what Jensen and Nvidia, and these tools and the people who develop on top of that technology have enabled as the new starting point,” he said, adding, “I think the world economy—and certainly the tech economy—is going to look unrecognizable.”

Leaders across tech are beginning to echo the idea that companies could be built and run by smaller teams. For example, OpenAI CEO Sam Altman has emphasized that AI acts as a collaborator that lets individuals and small teams achieve results that once required much larger organizations, amplifying productivity and creativity. Block recently announced it would cut 40% of the fintech company’s headcount because of gains in AI. The decision was part of a longer transformation, Block CFO and COO Amrita Ahuja recently told me. “This is a two-year journey for us,” she said. “This was not an overnight decision.”

The rise of ultra-efficient, AI-driven teams could require a fundamental restructuring of the workforce, according to new research from McKinsey. To capture the full value of AI, organizations need to go beyond “a piecemeal approach, and push for a double transformation—both technical and organizational—that includes reimagining how work gets done across functions and workflows,” according to the report. It will likely take a lot of work and preparation, along with training and upskilling for employees whose roles may be redefined.

While AI can dramatically increase productivity, fully realizing its potential is a complex and demanding challenge for companies of all sizes.

Sheryl Estrada
sheryl.estrada@fortune.com

This story was originally featured on Fortune.com

Oil has cleared $100 a barrel and could be on its way to $150.

The Strait of Hormuz — a narrow waterway through which roughly a fifth of the world’s oil supply passes — has effectively closed to tanker traffic amid the escalating U.S.-Israeli strikes on Iran. Once again, the global economy is discovering the same uncomfortable truth: Modern energy security depends on supply chains that can break overnight.

The pattern is all too familiar. A geopolitical shock hits the global oil supply chain, and prices surge. It happened in the 1970s, in 1990, in 2003. It’s happening now.

The modern energy system was built around a simple assumption: Fuel is produced in a few places and consumed everywhere else. Oil is extracted in one region, refined in another, and shipped thousands of miles through pipelines, canals, and maritime chokepoints before reaching the end user. 

When that chain works, it is remarkably efficient. When it breaks, the effects ripple globally almost overnight. Japan imports roughly 90 percent of its oil from the Middle East. Bangladesh has called for fuel rationing. South Korea has capped gasoline prices for the first time since the Asian financial crisis.

The issue isn’t just oil supply. It’s the structure of the system itself. The world runs on a centralized fuel production model designed for the industrial geography of the 20th century — a handful of massive refineries producing enormous volumes of fuel that must then move through fragile global logistics networks to reach markets. That model made strategic sense when control over oil reserves meant control over energy. But it also created a system where a single blocked canal, damaged refinery, or closed shipping lane can disrupt entire economies.

Today, an alternative is beginning to emerge. Across defense programs, industrial research labs, and energy startups, a new class of fuel systems is being developed that can produce synthetic fuels locally using carbon dioxide, hydrogen, and electricity — manufacturing fuel where it is needed rather than shipping it thousands of miles. The idea sounds radical. In reality, it reflects a broader shift already underway: from centralized production to distributed systems. Solar power decentralized electricity generation. Data centers decentralized computing. A similar shift may now be underway in fuel.

The scale of the system being disrupted is enormous. The world consumes roughly 100 million barrels of oil per day, supporting a multi-trillion-dollar refining, shipping, and storage network built around centralized infrastructure. Even a modest shift toward localized production would represent one of the largest industrial transitions in modern energy history. The rapid expansion of AI infrastructure is already reshaping global energy demand — data centers could consume nearly 1,000 terawatt-hours of electricity annually by 2030, roughly equivalent to Japan’s total electricity consumption — making energy systems that can generate power and manufacture fuel locally increasingly strategically valuable.

The economics of that shift become clearest in environments where traditional logistics break down. In remote or contested regions, the fully delivered cost of diesel or jet fuel can reach $100 to $400 per gallon once transport, protection, and storage are factored in. Military planners have long understood that moving fuel is often more expensive — and more dangerous — than producing it. The Pentagon has identified on-site fuel production as a strategic priority, funding development of deployable systems capable of generating jet fuel or diesel directly in the field. Similar efforts are emerging across Europe and Asia.

Critics are quick to point out that synthetic fuels cost more than conventional ones — and they’re right, for now. But that comparison ignores the full cost of the existing system, including the geopolitical risk premiums embedded in global oil supply chains. One common objection is that synthetic fuel production requires a fully built-out green hydrogen ecosystem before it’s viable. It doesn’t. Production can start today using available feedstocks and gets cleaner as inputs improve.

Every generation experiences its own oil shock. Each time, governments scramble to stabilize supply while markets absorb the economic impact. What’s different today is that the technology to change the structure of the system is beginning to exist. 

Energy security has historically meant securing access to oil reserves. In the next era, it may mean something different: the ability to produce fuel wherever it is needed, using whatever resources are available. 

The nations and industries that develop that capability first will hold a different kind of strategic advantage. They won’t need to control the oil. They’ll simply be able to make the fuel.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

If you were to ask a regular consumer what a barrel of crude oil costs, they likely wouldn’t know the exact figure. Ask them how much it takes to fill up their car with a tank of gas, on the other hand, they might remember down to the cent.

The visibility of oil price rises in the mind of U.S. consumers is ultimately the factor that will move the needle on the health of the U.S. economy, warns Wharton’s Professor Jeremy Siegel. Indeed, when consumers begin to raise their price expectations is when Wall Street will really begin to worry.

So far, despite the geopolitical consternation in the Middle East since the U.S. and Israel launched strikes on Iran, markets have been volatile but haven’t spiralled too far downward. This is partly because traders, worried about sustained disruption to supply out of the Gulf region, have been betting on hopes that President Trump’s action in Iran will conclude within a matter of weeks.

But the headlines are beginning to trickle into the wallets of U.S. consumers, which is when the knock-on effects of inflation expectations and wage-price spirals (when workers demand higher pay to finance an increased cost of living, pushing up business costs in turn) kick in.

This consumer psychology is the real issue when evaluating the impact of the Middle East conflict, wrote Professor Jeremy Siegel, emeritus professor of finance at the University of Pennsylvania and senior economist to WisdomTree. Writing for the financial platform in a note released yesterday, Professor Siegel noted the key issue is not crude oil: “It is gasoline, the most visible price in the economy for consumers, and when that price jumps it hits psychology immediately.”

Already, Western consumers have been urged not to panic-buy gas in a bid to get ahead of rising prices. The U.S., unlike some of its allied nations, sits on healthy oil reserves, giving it a safety net not afforded to many smaller economies. And the White House has confirmed that for a limited period of time, sanctions on Russian oil will be lifted to increase supply into the market.

However, despite the political furore around affordability in the run-up to the mid-terms, Treasury Secretary Scott Bessent indicated his department can’t and won’t intervene in certain areas if prices spike too high. He told CNBC this week that rumours the administration may intervene in the futures market or use other mechanisms to bring down prices is mere speculation, adding: “When there’s big dynamic price action, that always happens. We haven’t done that.”

The psychology of consumers is what matters, added Siegel: “Even if the broader economic effect is more balanced than the headlines. Imports are getting cheaper with a stronger dollar, and higher oil is also boosting profits in the energy sector. That is the practical benefit of energy self-sufficiency. The consumer feels the pain first, but the economy has offsets that did not exist to nearly the same degree in earlier oil shocks.”

Uncertainty is on the rise, he continued: “The market ended last week with a more cautious tone as rising oil and the widening Middle East conflict bring a fresh layer of uncertainty. I could see the markets experiencing a 10% correction from the recent highs. We are not anticipating a major decline for the S&P 500, but the mood has clearly changed.”

Consumer impact

If consumers are wondering about a pinch, then so too is the Federal Open Market Committee (FOMC), which meets this week. The rate-setting group is widely expected to leave the funds rate unchanged, though dissent is likely to come from the likes of Governors Bowman and Miran.

Indeed, Goldman Sach’s Devid Mericle wrote to clients this week that he expects the FOMC’s statement to say “the war with Iran has increased uncertainty about the outlook and will likely raise inflation and weigh on economic activity in the near term.”

He also noted the Summary of Economic Projections from the Fed for 2026 is likely to change, with GDP marginally down to around 2%, the unemployment rate to nudge higher above 4.5%. and headline inflation to stay above the 2% target.

This story was originally featured on Fortune.com

Good morning. In today’s Fortune:

  • There are backchannel talks between U.S. and Iran.
  • In the markets, some welcome relief.
  • Trump says he wants to ‘take’ Cuba.
  • Nvidia’s Jensen Huang crowns himself the ‘token king.’
  • Chart: Global equities pummeled by the war.
  • Byron Allen is now a streaming mogul—he just took an aggressive stake in Starz.
  • Exclusive: How boards lowered the bar for CEO bonuses.

This story was originally featured on Fortune.com

In 2017, Darian Shirazi and Zach Bratun-Glennon knew they weren’t exactly working on the coolest new thing.  

“I remember going to happy hours with other startup investors and pre-seed founders,” said Shirazi. “I’d say I was at Gradient, and people would say ‘oh, the AI thing. I haven’t done that. Are there AI startups? I certainly don’t see them and AI doesn’t seem that interesting.’” 

Shirazi and Bratun-Glennon, both engineers by background, were there at the very beginning, as Google stood up Gradient in 2017, expressly for the purpose of backing AI companies early. It was one month after Google’s famed “Attention Is All You Need” paper came out. AI, as a technology, was clearly on the precipice of change. But as a business use case, it was niche at best. 

“You really had to be a nerd to actually realize that this was a big deal,” said Shirazi. “Everyone was talking about crypto and ICOs at the time.”

Bratun-Glennon points out that, even though Gradient in some sense came from Google’s C-suite, “it really was a niche idea at that point and didn’t resonate with everyone right away.” LPs outside Google were wary. “I think people thought we sounded like the quantum computing people, and no one wanted to do a dedicated quantum fund,” said Bratun-Glennon, previously corporate development deal lead at Google. 

Much has changed. The AI boom has taken on a cascading life of its own, and now it seems like every firm is AI-focused. With this backdrop, Gradient closed its $220 million fifth fund, the team confirmed exclusively to Fortune. Gradient, which focuses entirely on seed and pre-seed AI companies, has backed Lambda, Oura, Sona, Writer, Airspace Intelligence, and Krea. The firm’s exits include CentML (acquired by Nvidia reportedly worth more than $400 million), Prepared (acquired by Axon), and Streamlit (acquired by Snowflake for a reported $700-$800 million). Gradient declined to disclose previous fund sizes.

“From 2017 to 2021, we saw 100 companies a year that fit our thesis,” said Shirazi. “And post-ChatGPT, we started to see 1,500 to 2,000, which is now consistently the number of companies we see per year.”

In this clamor, Shirazi and Bratun-Glennon have seen their due diligence process change. They’ve increasingly been leaning more on their own engineering abilities, writing code to test that the products prospective founders are bringing to them are actually working. The two also have hesitations about the frenzy. Gradient won’t, for example, fund foundational model contenders, full stop. The mega-seed rounds also give Shirazi serious pause. 

“Large seed rounds that are $100 million-plus or one billion-plus… I’ve never seen a startup raise more than, say, $10 million in a seed round and be successful,” he said. 

Gradient, in this fifth fund, is in some sense starting over: Google will remain a notable LP, but Gradient has taken on outside LPs for the first time, starting with inbound interest from institutions. Shirazi and Bratun-Glennon also now own the management company. The move came, in part, because of inbound demand, but also with a view to the future. 

“I do believe this is the largest platform shift in history, and the biggest value creation event in technology ever,” said Bratun-Glennon. “Is there an intervening two or three year air gap? There’s a risk to that, but on a ten-year horizon it’s an amazing place to be.”

A long way from the Silicon Valley parties, where people wondered whether AI startups even existed.

See you tomorrow,

Allie Garfinkle
X:
@agarfinks
Email: alexandra.garfinkle@fortune.com

Submit a deal for the Term Sheet newsletter here.

Joey Abrams curated the deals section of today’s newsletter. Subscribe here.

This story was originally featured on Fortune.com

PayPal is dramatically expanding the map of countries where users can send and receive its branded stablecoin. As of this month, customers in 70 nations will now be able to hold PYUSD in their PayPal wallets, May Zabaneh, senior vice president and the company’s head of crypto, told Fortune. Those countries—which are a subset of the approximately 200 in which PayPal operates—include Uganda, Colombia, Peru, and new additions in South America, Africa, and Asia. Previously, only customers in the U.S. and U.K. were able to hold the stablecoin.

In addition to being able to send and receive PYUSD, users abroad will also be able to earn rewards on their stablecoin holdings. Existing holders in the U.S. earn 4% annually.

“Now you’re really opening up not only access—especially in places where they need it most— but also cross-border transfers and volume, where the pain is felt so high,” said Zabaneh.

Across borders

Proponents of stablecoins, or cryptocurrencies pegged to real-world assets like the U.S. dollar, have long touted the tokens’ capacity to reduce fees for sending money cross-border. PayPal’s Zabaneh hopes that the expansion of PYUSD abroad will help realize that potential.

Currently, PayPal users in select countries like Peru can only withdraw money from their accounts in their country’s native currency. If a New Yorker sends $10 over PayPal to someone in Lima, for example, the Peruvian user has to pay a cross-border transfer fee and must take out the money in the Peruvian sol. Now, the ability to send and receive PYUSD enables users to keep funds in what are essentially U.S. dollars and reduce transfer fees, said Zabaneh. 

Moreover, some countries like Malawi don’t let users keep money transfers in their PayPal wallets. Once one Malawian sends money over PayPal to another, that cash is immediately sent to the recipient’s bank account. Opening up access to PYUSD lets users keep that money in their PayPal wallets, as opposed to only their bank accounts, added Zabaneh.

“It unlocks a balance-type concept in these accounts and an earnings concept,” she said.

The fintech’s expansion of access to PYUSD comes as PayPal continues to integrate the stablecoin throughout its various business verticals. Customers like YouTube who use the company’s payouts product can choose to receive payments in the stablecoin. PayPal has also experimented with using PYUSD to transfer funds internationally across its different corporate entities. 

Over the past year, the total market capitalization of PayPal’s stablecoin has more than quintupled to $4.1 billion, according to data from CoinGecko. After initially pausing development amid scrutiny from a New York financial regulator of PayPal’s launch partner, the fintech launched the token in the summer of 2023.

This story was originally featured on Fortune.com

Equity compensation can help organizations accomplish two goals at once: It not only incentivizes executives to drive long-term business performance but also contributes to a sense of ownership that can enhance employee retention, engagement, and wider company culture. However, the complexity inherent in equity plans can often mean that even experienced leaders may struggle to fully maximize their equity compensation without guidance and support. 

Despite their financial sophistication, many executives lack a formal personal financial plan1—leaving them less confident and at risk of missing opportunities to better manage their equity awards or achieve personal financial goals. HR and benefits leaders are uniquely positioned to help close this planning gap by embedding tools, targeted guidance, and Financial Advisor access into equity compensation programs. This can help executives make more informed decisions, help boost financial confidence, and ultimately help support both individual and organizational goals.

The Planning Gap: A Hidden Risk in Executive Benefits

Equity compensation, which often includes stock options, restricted stock units, or other equity-based awards, is a powerful tool for aligning the interests of key talent with those of the company. Yet our recent research reveals a surprising disconnect: While executives are often seen as financially savvy, 44% of those participating in their company’s equity compensation plans say they do not have a formal personal financial plan.1 

Why does this matter? Our data shows a direct link between planning and confidence: 73% of executives with a formal financial plan feel confident in achieving their financial goals, compared to just 41% of those without one.1 And even financially savvy executives say they want more guidance—particularly on topics covering investment and wealth management, estate planning and wealth transfer, tax optimization strategies and navigating equity compensation and executive benefits.1 

Why Confidence Matters: Linking Planning to Outcomes

Financial confidence is more than a feeling; it can help drive better decisions and, in turn, outcomes. Executives who are confident in their financial trajectory may be more likely to make informed decisions about their equity grants, vesting, and exercises. For example, Morgan Stanley at Work’s State of the Workplace research shows that equity recipients who understand and engage with their equity benefits are more likely to stay with their employer and make more informed financial decisions.

For HR and benefits leaders, this means that closing the planning gap isn’t just about offering a perk—it’s about supporting business goals, such as retention and engagement.

HR’s Toolkit: Embedding Planning into Equity Programs

How can HR and benefits teams help move the needle to support their executives in planning with equity compensation? First, know that you’re on the right track: 98% of executives are interested in additional, customized guidance for both equity compensation and personal wealth management.1 Second, our research points to several actionable strategies:

  1. On-Platform Planning Modules: Integrate financial planning tools directly into the equity compensation platform, making it easy for participants to model scenarios, set goals, and track progress.
  2. Targeted Nudges at Key Moments: Use data-driven prompts at critical equity events—such as vesting, exercise, or blackout periods—to encourage participants to review or update their plans.
  3. Financial Advisor Access: Offer access to dedicated Financial Advisors who can provide personalized guidance, validate participants’ strategies, and help them navigate complex decisions from a more comprehensive financial perspective.
  4. KPIs for Success: Track plan adoption rates, participant confidence (via surveys), and the quality of equity-related decisions as key performance indicators.

When individuals receive clear insights that confirm whether they are on track to meet their goals, along with actionable recommendations as needed, it can greatly enhance their confidence in the equity planning process. A supportive, comprehensive approach can be a decisive factor in encouraging engagement and trust in HR-led equity programs. Work with your providers to find the strategy and resources that are the right fit for your organization.

Measuring Impact: From Planning to Performance

To achieve meaningful results, consider tracking how many equity participants create formal financial plans and monitor any changes over time to gauge program effectiveness. Assess confidence levels before and after. 

Evaluate the accuracy and timing of equity-related decisions—grants, vesting, and exercises—to measure the impact of education and planning resources. Analyze retention rates to understand participant engagement and satisfaction. These metrics can help show program value and guide continuous improvements for better support of organizational goals and participant needs.

The financial planning gap among executives creates an opportunity for equity programs to add value and strengthen engagement. In a competitive talent market, closing this gap can help boost financial confidence, drive stronger personal financial outcomes, and position your organizations as an employer of choice.

  1. Morgan Stanley at Work. Connecting the Dots for Executives: Insights on the Intersection of Work and Wealth. Nov. 2025.
  2. Morgan Stanley at Work. The State of the Workplace  2025 Financial Benefits Study. May 2025.

Employee stock plan solutions are offered by E*TRADE Financial Corporate Services, Inc., Solium Capital LLC, Solium Plan Managers LLC and Morgan Stanley Smith Barney LLC (“MSSB”), which are part of Morgan Stanley at Work.

Morgan Stanley at Work services and stock plan accounts are provided by wholly owned subsidiaries of Morgan Stanley.

Morgan Stanley at Work stock plan accounts were previously referred to as Shareworks, StockPlan Connect or E*TRADE stock plan accounts, as applicable.

In connection with stock plan solutions offered by Morgan Stanley at Work, securities products and services are offered by MSSB, Member SIPC. E*TRADE from Morgan Stanley is a registered trademark of MSSB. All entities are separate but affiliated subsidiaries of Morgan Stanley.

Content and services available to non-US participants may be different than those available to US participants.

The laws, regulations, and rulings addressed by the products, services, and publications offered by Morgan Stanley and its affiliates are subject to various interpretations and frequent change. Morgan Stanley and its affiliates do not warrant these products, services, and publications against different interpretations or subsequent changes of laws, regulations, and rulings.

Morgan Stanley and its affiliates do not provide legal, accounting, or tax advice. Always consult your own legal, accounting, and tax advisors. 

© 2026 Morgan Stanley Smith Barney LLC, Member SIPC.

CRC# 5073104  1/2026

This story was originally featured on Fortune.com

Bridgewater Associates founder Ray Dalio published a dire warning Monday: the conflict between the United States, Israel, and Iran will be a decisive confrontation over the Strait of Hormuz, and the outcome will determine far more than the price of oil. It will determine whether the American-led global order survives.

“It all comes down to who controls the Strait of Hormuz,” Dalio wrote in a lengthy post on X. If Iran retains the ability to control, or even negotiate over, who passes through the Strait—through which roughly a fifth of the world’s oil supply flows daily—Dalio argues the U.S. will be seen as having lost the war, regardless of how the conflict is resolved.

Dalio compared a potential U.S. failure at Hormuz to Britain’s humiliation during the 1956 Suez Canal Crisis, a moment widely regarded by historians as the end of the British Empire’s global imperialism. He pointed to a pattern he says has repeated across 500 years of history: a rising power challenges the dominant empire over a critical trade route while the world watches, and money and alliances shift fast toward whoever wins.

When that dominant power, the holder of the world’s reserve currency, is “overextended financially,” as Dalio has often argued (including recently in Fortune) and then “reveals its weakness” by losing control over the conflict. “Watch out for allies and creditors losing confidence, the loss of its reserve currency status, the selling of its debt assets, and the weakening of its currency, especially relative to gold,” he wrote. 

The post arrives at a moment of confusion around who has control over the Strait of Hormuz. The Strait has been effectively closed for its third week, though there are signs that a small trickle of vessels getting through. President Trump disparaged American allies throughout the weekend, and then again on Monday afternoon for failing to provide military support to help secure the waterway. He then reversed course and said that the U.S. didn’t “need anybody” and was the strongest country in the world. Iranian Foreign Minister Abbas Araghchi said on Sunday that the Strait of Hormuz “is open and only closed to enemies.” Unresolved questions remain on whether Iran mined the Strait, which would be an irreversible escalation if true. 

Dalio framed both sides as locked into a conflict with no diplomatic exit. “While there is talk of ending this war with an agreement, everyone knows that no agreement will resolve this war because agreements are worthless,” he wrote, adding that whatever comes next—whether the U.S. takes control of the strait or leaves it to Iran—”is likely to be the worst phase of the conflict.”

The core problem, Dalio said, is motivational asymmetry. For Iran’s leadership, the war is “existential,” a matter of regime survival, national pride, and religious commitment. For Americans, it’s about gas prices, and for U.S. politicians, it’s about the midterm elections. Dalio was clear over which side that calculus favors in a prolonged fight: “In war, one’s ability to withstand pain is even more important than one’s ability to inflict pain.”

Iran’s strategy, he says, is to inflict that pain for as long as possible, then wait for the U.S. to quit, just as it has done in Vietnam, Afghanistan, and Iraq.  

Trump is now calling on allied nations to join a multinational escort operation through the strait, though for the most part, they haven’t yet been receptive. Dalio says it remains to be seen whether that effort can serve as a potential “solution” to getting the waterway reopened.

“If President Trump demonstrates his and the U.S.’s power to do what he said he would do, which is win this war by having free passage through the Strait of Hormuz and eliminating Iran as a threat to its neighbors and the world, it will greatly bolster confidence in his and the U.S.’s power.”

But if he doesn’t, the ripple effects, on everything from trade flows, to capital markets and the dollar’s reserve currency status, could irreparably damage American hegemony. Tehran has also threatened the dominance of the petrodollar by reportedly agreeing to open the Strait of Hormuz to a limited number of oil tankers that trade in yuan rather than dollars.  

“Both sides know that the final battle, which will make clear which side won and which side lost, still lies ahead,” Dalio wrote.

This story was originally featured on Fortune.com

For most of modern history, human worth was measured by output — how much you produced, how fast you moved, how efficiently you performed. The modern economy was built on this premise. Factories needed workers who could produce more units. Corporations rewarded leaders who optimized systems. Knowledge work elevated those who could analyze faster and process more. In a world where intelligence and information were scarce, productivity created advantage.

But something fundamental has changed. For the first time in history, we are creating machines that can out-produce us in the very domains where productivity once defined human value. AI can analyze faster, generate more ideas, and process vastly more information than any human mind. According to the World Economic Forum, 85 million jobs may be displaced by AI-driven automation by 2025 — while the skills most in demand are shifting toward judgment, creativity, and leadership.

The age of the “human doing” — the professional defined entirely by cognitive output and execution speed — is ending.

This shift is unsettling for leaders whose identities have been built on cognitive performance — the smartest analyst, the fastest strategist, the most productive executive. When machines can outperform humans at doing, a deeper question emerges: what remains uniquely human? The answer isn’t intelligence, knowledge, or speed. It’s wisdom.

In my book The Last Book Written by a Human, I describe wisdom as something fundamentally different from intelligence. Intelligence processes information. Wisdom integrates experience. Intelligence answers questions. Wisdom knows which questions actually matter. And wisdom cannot be automated. It emerges from lived experience — through reflection, relationships, responsibility, and the slow accumulation of perspective that no dataset can fully replicate.

AI can summarize the world’s knowledge, but it cannot feel the weight of a hard decision, carry responsibility for another human being, or sit with moral tension when the right path isn’t obvious. Those aren’t bugs in the system. They are the very conditions through which wisdom is formed.

Wisdom: The New Competitive Advantage

For business leaders, this shift has enormous implications. For decades, leadership culture rewarded speed and optimization — executives were expected to process massive information and make rapid decisions. But when intelligence becomes automated and abundant, the source of competitive advantage changes. In an era of infinite “doing” generated by algorithms, the most valuable asset on any balance sheet may be the one that can’t be measured: the human capacity for discernment. Intelligence is becoming a commodity. Wisdom remains scarce.

The leaders who thrive in the AI era will not simply be those who understand technology best. They will be the ones who can see clearly amid overwhelming information — who know when to move fast and when to pause, when to optimize and when to protect something more human.

The Wise Leader

If wisdom is the advantage, three qualities will increasingly define effective leadership:

Discernment: The ability to recognize what truly matters amid an explosion of data, predictions, and automated recommendations.

Reflection: The discipline to pause before reacting — to consider long-term consequences instead of chasing short-term optimization.

Human-Centered Judgment: The courage to make decisions based not only on efficiency, but on how those decisions affect human flourishing.

This isn’t abstract philosophy — it has direct implications for how organizations operate. Many companies today run inside a culture of constant reaction: perpetual urgency, relentless optimization, pressure to move faster at every turn. But in a world saturated with intelligence, speed alone is no longer the differentiator. The real advantage may come from building a culture of reflection, where leaders are rewarded not only for rapid execution but for thoughtful judgment. Sometimes the most valuable decision a leader can make is to say no — to resist a short-term optimization that undermines long-term health.

AI as the Catalyst

None of this means AI is the enemy — in fact, it may be the catalyst that forces this evolution.

Artificial intelligence is, in many ways, a mirror reflecting our current state of consciousness. If we feed it our obsession with speed, efficiency, and profit at any cost, it will amplify those instincts. But if we use this technological disruption as an opportunity to rethink leadership — to rediscover discernment, empathy, and reflection — AI could free humans to focus on what we do best.

The irony is that this future may look strangely familiar. Before the industrial age, many cultures understood the difference between knowledge and wisdom — elders were valued not because they could produce more, but because they had lived long enough to see more clearly. Modern economies replaced elders with experts. Now AI is replacing experts, which may finally create space for wisdom to return.

The Return of the Human Being

AI will continue expanding what organizations are capable of, and businesses will still need efficiency, innovation, and execution. But the deeper question leaders must now confront is this: if machines increasingly handle the doing, what is the role of the human being? The answer lies in qualities machines cannot replicate — meaning-making, ethical judgment, empathy, presence, and the ability to hold complexity without rushing to resolution. In other words, the capacity to be fully human.

For centuries, humans have been conditioned to behave like machines — optimizing productivity, minimizing inefficiency, maximizing output. Now that machines are surpassing us at those tasks, we face a profound invitation: to remember what we really are. Not human doings. Human beings. In the age of AI, that distinction may become the most valuable leadership capability of all.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

America does not look like a nation in fiscal distress—and that’s exactly the problem.

The S&P 500 has more than doubled in the past five years. Unemployment is at a multi-decade low. Social Security checks are going out.

But moments like these can hide deeper vulnerabilities. Rising tensions in the Middle East, including the conflict with Iran, are a reminder of how quickly economic conditions can shift. A disruption to global oil supplies could send energy prices higher, reigniting inflation and pushing interest rates upward. For a country already carrying more than $38 trillion in debt and spending more on interest than on national defense, that kind of shock would put even greater strain on federal finances.

And the underlying trend is already troubling. The national debt is on track to reach levels never seen outside of wartime—projected to climb to roughly 120% of GDP within the next decade. That means that the federal government would owe more than the entire annual output of the US economy.

That trajectory will not trigger an alarm bell overnight. As Ernest Hemingway wrote, bankruptcy happens “gradually and then suddenly.” The same can be true of fiscal decline.

A bipartisan fiscal commission offers a structured, credible forum for lawmakers to put everything on the table and produce a package of reforms capable of stabilizing the nation’s finances before gradual erosion becomes genuine crisis.

The US has over $38 trillion of national debt. We now spend more annually on interest than on the military. The primary trust funds for Social Security and Medicare are also projected to become insolvent within the next seven years, requiring an automatic benefit cut or even more deficit spending to backfill these programs. These pressures will intensify as the population ages, health care costs rise, and economic growth slows.

For American businesses, the looming debt crisis carries tangible, real-world consequences. High levels of government debt require the federal government to spend more on interest payments, leaving fewer resources available for infrastructure, education, national defense, and social programs. If investors begin to view US debt as riskier, interest rates could rise further, increasing borrowing costs for expansion, hiring, and investment.

The U.K. offered a preview. In 2022, Prime Minister Liz Truss announced some of the largest tax cuts in decades primarily financed via deficit spending, financial markets were rattled, causing precipitous declines in the value of the pound and threatening the solvency of British pension funds. Within weeks, the prime minister and the country’s finance head were forced to resign. The U.S. economy is larger and the dollar holds reserve currency status—but the dynamic of confidence lost suddenly after building gradually is the same.

Establishing a bipartisan fiscal commission in Congress to address the debt crisis would not solve the problem overnight, but it could break partisan logjams, focus both political parties on finding a solution, bring bipartisan credibility to reforms, and encourage public awareness and support. It would bring bipartisan credibility to reforms and build the public mandate needed for Congress to act.

The commission’s three primary strategic objectives should be to improve the long-term fiscal condition of the federal government, hold the expected debt-to-GDP ratio to a more sustainable level (such as 100%), and address the long-term solvency of the Social Security and Medicare Trust Funds.

For a commission to be successful, everything must be on the table. The commission should undertake a top-to-bottom review of all federal spending and revenue sources. To avoid losing political momentum, the law establishing the commission should include strict timelines and commitments for votes on the House and Senate floor. Following enactment, Congress should adopt strong enforcement mechanisms for future fiscal decisions to avoid altering the new fiscal trajectory.

The American people must understand the stakes. A public education campaign should explain the fiscal crisis, invite broad input, and build the political will needed for Congress to act. This effort should focus especially on groups most vulnerable to a debt crisis—younger generations, low-income communities, and the “sandwich” generation.

The U.S. debt crisis is already here. Forming a bipartisan fiscal commission is an immediate first step in developing a comprehensive plan to address the national debt and forcing action in Congress. Only then can we preserve our national prosperity for future generations.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

  • In today’s CEO Daily: Phil Wahba on Chip Wilson’s fight with the athleisure company he founded
  • The big leadership story: Trump’s dealmaking strategy hits a wall in Hormuz
  • The markets: Mixed performance across Asia with S&P 500 futures trending slightly down
  • Plus: All the news and watercooler chat from Fortune.

Good morning. Good morning. Phil Wahba writing this morning from New York. What’s a company to do when the founder has left—but hasn’t moved on? That’s the plight Lululemon, which reports earnings today after the bell today, finds itself in more than a decade after founder Chip Wilson departed its board. Though his methods have varied—full page newspaper ads berating the board, LinkedIn posts criticizing strategy, open letters to shareholders—Wilson has been adamant that leadership is doing just about everything wrong. I delve into the drama in my latest feature for Fortune. But the question I explore is one familiar to any company with a charismatic and dogged leader who sees the company they founded fumble—and can’t stay away. 

There’s even a name for it, “post-founder syndrome,” in which executives who built highly successful companies criticize successors’ perceived stumbles with an “only I can do this properly” attitude. (See: the founders of Starbucks, Papa John’s Pizza, and Nike.) In his Wall Street Journal ad last autumn, Wilson delivered a rather self-aggrandizing disquisition on why Lululemon had drifted: “A company bereft of a visionary loses its singular voice for product and long term strategy,” he intoned.

Wilson’s latest volley was to launch a proxy war, followed by open letters (many of them) to make his case and convince other shareholders to replace three directors at the next annual meeting. He hopes to reshape Lululemon’s board which he blames for letting the company’s culture of innovation disintegrate. 

Things between Wilson and the company went south after he left the board in 2015 (he stepped down as chairman in 2013 in the wake of comments about women’s bodies construed as fat-shaming, creating one of the biggest crises in the company’s history). However in the first nine years following his departure, Lululemon’s revenue proceeded to triple. (It is expected to report $11 billion a year in revenue for 2025.)

Today, though, he does have a lot of company in feeling Lululemon is adrift: shares have fallen 68% from their all-time high in 2023 as its U.S. sales have slid, raising fears that it hasn’t introduced enough new merchandise or uphold the technical leadership in its activewear, and has lost brand cache to brands like Alo Yoga. And in my reporting I found that like many founders, Wilson still wields enormous influence inside the company, especially with long-time employees who saw first hand how he stoked a culture of excellence and pioneering. 

Last week, Wilson went as far to warn any prospective CEO to beware of a board “that it is not equipped to support a visionary leader and the necessary transformation of the Company.” 

Needless to say the CEO who takes on this job won’t just be dealing with a turnaround and a demanding board, they’ll have to manage a post-founder too. You can read the full story here

Contact CEO Daily via Diane Brady at diane.brady@fortune.com

This story was originally featured on Fortune.com

Retail electricity prices are rising faster than inflation—and the fixes being discussed in Washington and state capitals could make things worse, not better. President Trump has pointed to AI data centers as a contributor, calling rising utility prices an issue that “needs some PR help.” But the real drivers are structural, and popular-sounding policies like rate freezes and blocking new energy permits would only deepen the problem.

Blocking permits for new clean energy keeps cheap supply off the system. Rate freezes and threats to exit competitive power markets would chill investment just at the exact moment a grid built for a 20th-century economy is being asked to support 21st-century demand. So what’s really driving prices up—and what would actually work?

Electricity rates are climbing for several overlapping reasons, and anyone promising a quick fix is either mistaken or misleading you. Power demand is surging, driven in large part by artificial intelligence and energy-intensive data centers. 

Utilities are also spending vastly more on the “poles and wires” side of the system: the Energy Information Administration reports that transmission spending nearly tripled from 2003 to 2023, reaching $27.7 billion, while distribution spending hit $50.9 billion in 2023. On top of that, regulators appear to be approving utility profit rates higher than necessary—right as aging infrastructure demands costly upgrades.

No single policy will bring immediate relief. But one central driver of rising bills is a regulatory model that protects monopolies, limits customer choice, and rewards overspending while deterring innovation. Here are three reforms that would actually help.

Fix 1: Stop Rewarding Utilities for Overspending

Most utilities are regulated monopolists—they don’t compete for customers, so regulators must balance two goals: attracting enough capital to maintain reliable service while preventing utilities from gouging customers who have no other option.

Recent reports suggest that regulators have become overly generous in setting utility returns. One report estimates that excess returns for investor-owned utilities cost customers about $50 billion a year—roughly 13.6% of gas and electric revenue, averaging around $300 per household. Another found that excess returns averaged approximately $7 billion a year for the last thirty years. The data points in one direction: state public utility commissions, which regulate retail rates, should make sure utility returns reflect actual financing costs.

Regulation also creates a perverse incentive to overspend. Under traditional rate-of-return regulation, utilities earn returns on capital investment. If a utility earns an 8% return, it makes $80 on a $1,000 investment—but only $8 on a $100 one—even if the cheaper option delivers the same economic or reliability benefits. With utility spending at $320 billion a year, this “capital bias” is likely having a real effect on customer bills.

So what should regulators do? In addition to reducing returns, regulators should also tie utility profits to specific performance criteria such as lower rates or improved reliability. Performance-based rates have been piloted in the UK, with early signs of success. When properly designed, performance-based regulation can encourage utilities to make better use of the system through energy efficiency, demand response, and grid-enhancing technologies.

Fix 2: Get Power Online Faster

Prices rise when supply doesn’t keep up with demand—and right now, the regulatory system makes it difficult to get resources online quickly. Interconnection queues, which are essentially waiting lists for proposed power generators that want to connect to the grid, face extreme backlogs. The Lawrence Berkeley National Laboratory reports that the typical project built in 2023 took nearly five years from interconnection request to commercial operation. That is up from under two years in 2008.

Although federal regulators have begun to reform interconnection processes, the interconnection queue still moves sequentially, regardless of how much value a generator will deliver to the system and regardless of whether projects are speculative and likely to drop out of the queue.

Two policies could help. First, auction off interconnection positions so that resources that are likely to be built and relieve system stress can skip to the front of the line. Second, projects that are willing to accept operating constraints should be allowed to connect faster. Regulators should let resources connect quickly if they accept curtailment risk (reducing power to maintain system stability) or forgo reliability payments. In short: faster access to the grid, in exchange for accepting some operational risk.

Fix 3: Break Up Utility Monopolies and Plan for the Public Good

Vertically integrated utilities, which own both generation and transmission, profit more when transmission bottlenecks prevent low-cost resources from competing with their generation assets. FERC has rules limiting affiliate transactions, but real reform would go further: if a utility owns transmission and distribution, it should not be allowed to own generation.

A complementary reform would be to give customers credible alternatives when utility bottlenecks raise prices and delay new supply. Why not let customers bring self-supply if they are willing and able to do so? Senator Cotton recently introduced legislation that would make it easier for companies to procure their own generation if they don’t connect to the grid. While this proposal will not solve all the problems discussed above, it deserves serious consideration, since it would expose incumbent utilities to the threat that cheaper off-grid options could challenge their monopoly privileges.

Finally, some essential infrastructure should be treated as a public function. The U.S. has essentially outsourced transmission planning to firms that earn more when they spend more. When this system fails to produce cost-effective transmission, states and the federal government should step in and play a more direct role in planning, financing, and paying for high-voltage transmission. States could, for example, create or expand transmission authorities to participate directly in financing and project development. At the federal level, the Department of Energy and FERC can designate priority transmission corridors, support financing, and directly solicit project proposals for large projects that would help supply get online and increase wholesale market competition. Federal regulators have typically been reluctant to get more directly involved in planning and paying for transmission, but current federal programs authorize billions of dollars of direct financing that could be used to bypass utility-led processes altogether.

The utility model is broken. If regulators don’t improve incentives and clear the path for new supply, rates will keep climbing. Fortunately, the tools to fix this already exist. FERC can cut interconnection delays. DOE can plan and pay for projects when incumbent-led processes fail. State regulators can lower utility returns and deliver immediate rate relief. None of these is a silver bullet. But together, these reforms would go a long way towards addressing the structural failures responsible for rising costs.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Ireland’s Prime Minister, or Taoiseach, Micheál Martin is expected to unveil more than $6 billion in deals Wednesday when he meets with U.S. President Donald Trump in Washington. But the usual St. Patrick’s Day festivities will no doubt be dampened by the Iran war and lingering tensions over trade, tariffs, and Irish policies that the White House has called a “tax scam” for U.S. companies.

Few understand the challenges better than Michael Lohan. As CEO of IDA Ireland, the nation’s foreign direct investment agency, Lohan is charged with attracting companies to a country that has long relied heavily on U.S. capital and companies. “You know, Ireland is closer to Boston today than Berlin,” says Lohan, repeating a long-held trope about its economic similarities to the U.S. in terms of taxes, talent, and ease of doing business. (Technically, Boston is almost three times as far as Berlin.) “Last year was a record year for FDI investment in Ireland—against the backdrop of everything that was happening—and 65% of that investment came from U.S. multinationals.”

That flow of capital is not viewed as a good thing by Trump, who accused Ireland of “taking our pharmaceutical companies” during last year’s St. Patrick’s Day meeting. While his pressure on U.S. companies to double down at home is being heard–U.S. FDI to Ireland dropped 20% in 2024 to $467 billion–America remains the country’s largest investor. Lohan’s job is to attract more of that capital by “telling the story of Ireland” as a place to get talent, agility and easy access to the 27 member states of the European Union.

Pharma-fueled trade surplus

Ireland has proven to be a desirable place to book profits and pay taxes. The country’s 12.5% corporate income tax rate, and prior tax benefits for companies like Apple, have generated both investment and unwanted attention. Among other things, Apple and Microsoft’s intellectual-property rights are held in Irish subsidiaries that collect royalties from elsewhere. Pharmaceutical companies like Eli Lilly manufacture key ingredients of blockbuster drugs like Mounjaro and Zepbound on the emerald isle for the same reason, shipping those drugs to U.S. consumers and booking the revenue in Ireland.

Ireland’s budget watchdog says three U.S. companies accounted for almost half of the country’s corporate tax revenues last year. Although unnamed in the report, they’re known to be Apple, Lilly, and Microsoft. Lilly, for one, paid $6.6 billion in tax to Ireland in 2025, about double what it paid in the U.S.—a country with 65 times the population and the bulk of its customers. With 4,000 employees in Ireland, Lilly’s workforce is also less than a fifth the size of its U.S. operations. Pharmaceutical sales helped Ireland’s exports of goods to the U.S. grow 52% last year to about $132 billion, more than doubling the goods trade surplus to $114.2 billion. (Trade in services between the two countries is essentially the opposite, with Ireland buying more than it sells.)

One man’s trade surplus is another man’s trade deficit, especially if that man is Donald Trump. The U.S. President has paid particular attention to physical goods when it comes to trade flows, and has called out Big Pharma for rising drug costs. Even with the U.S. now at war, Ireland’s reputation as a corporate tax haven is unlikely to escape attention during the White House visit.

That may be why the prime minister, much like his IDA emissary Lohan, has shifted the emphasis from inbound investment to money flowing the other way. Lohan talks about how Ireland invested a historic $389 billion in the U.S. in 2024, making it America’s fifth largest source of FDI. On a per-capita basis, the nation of 5.4 million claims to be number one. “The U.S. continues to be the most innovative economy in the world. It continues to be where capital is readily available and supportive,” says Lohan. “None of those things have really changed.”

What has changed, of course, is Trump’s focus on “America First,” which is why Martin is expected to present $6.1 billion in new Irish investments to the U.S. alongside the traditional bowl of shamrocks. While nurturing European alliances is also not a priority for the White House, Trump’s calls for NATO and Europe to step up in protecting the Iran-controlled Strait of Hormuz could occupy much of Martin’s discussions with Trump. Ireland will begin a six-month stint in holding the presidency of the Council of the European Union in July, which will give it a central role in E.U. decision making.

Martin may want to talk trade this time as the war with Iran is an issue that few leaders want to tackle in public, especially during a White House press conference. IDA’s Lohan is also not oblivious to the fact that consumer sentiment in Ireland is decidedly mixed when it comes to Trump, tariffs, and the tech giants that have raised the cost of housing while putting pressure on the energy grid at home. And Europe’s approach to tech innovation is decidedly different than what’s coming out of D.C.

“We want to push the innovation and technology agenda, but we have to do it safely and ethically,” said Lohan. And that applies to all potential investors, including China.

“We want to see a fair, level playing pitch between China and its counterparts, with Ireland being part of that,” he said. “But I do think we can’t turn our back on what is a very significant economy where there is a significant amount of innovation.”

This story was originally featured on Fortune.com

Businesses are pouring billions into AI to boost productivity and cut costs—and to fund it, they’re slashing hiring, training, and employee support. Headcount isn’t safe either: as Jack Dorsey’s Block recently demonstrated, a growing number of executives are citing AI as justification for substantial layoffs.

That approach may lift short-term margins. But it is a dangerous long-term strategy—and the data makes clear why.

As president of SHRM Foundation—the philanthropic arm of the largest HR association in the world— I’ve seen firsthand how organizations thrive when they invest in human potential alongside AI. Technology can accelerate work. Competitive advantage comes from the judgment, adaptability, and trust that only people provide.

The gap is glaring. Nearly three-quarters of knowledge workers globally now use AI at work, yet 60% say they have not received formal training to use it effectively. AI spending is projected to rise 44% in 2026—while training budgets are expected to grow just 5%, and average learning time is actually falling—from 47 to 40 hours per employee. Companies are deploying powerful tools while quietly disinvesting in the humans required to use them.

At the same time, employees are navigating rising pressures inside and outside the workplace. Burnout and stress remain widespread, the specter of AI-driven layoffs is increasing workers’ sense of precariousness, and millions of Americans balance their jobs with responsibilities like caregiving outside of the workplace. Without support, these pressures carry real costs: Gallup estimates disengaged and stressed workers cost the global economy nearly $9 trillion annually. Unaddressed stress drives absenteeism, presenteeism, and turnover — hidden costs that can exceed an employee’s annual salary. Against this backdrop, it’s no surprise that ADP’s employee motivation index just reported its sixth straight month of decline.

In an AI-driven economy, unlocking business potential and long-term growth requires investing in human potential. That means not just keeping workers around, but equipping workers with the skills to use emerging technologies effectively. It also means addressing the conditions that determine whether people can bring their full capacity to work: ongoing skills development, mental health support, caregiving flexibility, financial stability, and workplace cultures that foster trust and psychological safety.

The Business Case Is No Longer Optional

Employers are uniquely positioned to provide this support — and the business case is increasingly clear. Johnson & Johnson’s long-running employee wellness initiatives generate an estimated $250 million in healthcare savings and returns nearly $3 for every $1 invested. Companies providing childcare support have reported returns exceeding 400% through improved retention and productivity. Organizations that support employee well-being and life responsibilities see stronger retentionhigher productivity, and better long-term performance.

By contrast, companies that reshape their workforce around AI and treat workforce investment as discretionary spending often face higher turnoverlost productivity and prolonged vacancies, more safety incidents, and weakened customer experience — costs that compound quietly but relentlessly.

The question for business leaders is no longer “How can AI help us automate more tasks and reduce headcount?” The smarter question is: “Which human capabilities become more valuable as AI absorbs routine work—and how do we redesign roles to strengthen them?”

What Happens When AI Maximizes People Instead of Replacing Them

The productivity upside is real—but only under the right conditions. Research shows tasks completed 25% faster and with 40% better quality60% greater productivity, up to 36% more time for higher-order work, and more effective—and cheaper—learning and development programs. But these gains only materialize when workers are trained, supported, and trusted to apply judgment.

Some companies are already showing what this looks like in practice. IBM CHRO Nickle LaMoreaux, bucking the layoff trend, announced plans to expand entry-level hiring and redesign roles around durable skills.

“The companies three to five years from now that are going to be the most successful,” LaMoreaux said, “are those that doubled down on entry-level hiring in this environment.”

IBM isn’t alone. Amazon has committed more than $1.2 billion to upskill hundreds of thousands of workers for technology-enabled roles. Mastercard has deployed an AI-driven internal talent marketplace to match employees to growth opportunities, reducing external hiring costs while increasing retention. SAP has embedded continuous learning time and wellbeing supports into the workweek to sustain productivity and attract scarce talent.

Short-term gains may come from cutting labor costs and accelerating automation. But long-term performance depends on resilience, trust, institutional knowledge, and the capacity to adapt—all of which are built through sustained investment in people.

AI will shape the future of work. Humans will drive it. The organizations that come out ahead will be the ones that treat workforce investment not as a line item to cut, but as the strategy itself. The $500 billion bet on AI only pays off if the people running it are trained, supported, and set up to succeed.

The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.

This story was originally featured on Fortune.com

Six of California’s 214 billionaires have been widely reported to have left the state in time to avoid a proposed 5% wealth tax—but that small cohort would have collectively generated $27 billion in tax revenue, roughly a fourth of the initiative’s projected $100 billion haul.

Last November, panic erupted over the announcement of a proposed billionaire’s tax in California. The tax would levy a one-time 5% tax on the net worth of California residents with assets worth at least $1 billion. California’s progressive governor, Gavin Newsom, emerged as the measure’s biggest opponent and vowed to stop the tax to “protect” the state’s tech industry and overall economy. 

Before the Jan. 1, 2026, cutoff proposed in the initiative, Google cofounders Larry Page and Sergey Brin, and venture capitalist Peter Thiel, left California for Miami. Car loan magnate and L.A. native Don Hankey left the state for Las Vegas. Former Uber CEO Travis Kalanick recently announced he had left California for Texas in December. Director Steven Spielberg became a New York City resident on New Year’s Day, according to the Los Angeles Times, although his representative said the Jaws director had long planned to move to be closer to family.  

The tally of departed billionaires likely understates the extent of the flight. Meta CEO Mark Zuckerberg has also reportedly left the state, but not before the Jan. 1 deadline. Venture capitalist David Sacks, whose net worth has been reported to range from $250 million to $2 billion, also left the state as his company Craft Ventures moved to Austin. Zuckerberg would take another roughly $10 billion of tax revenue with him. 

If the state were to tax Page’s $260 billion net worth at 5%, it would rake in $13 billion in tax revenue. Brin’s taxes would bring in about $12 billion. While Thiel, Kalanick, and Hankey may not rank among the top five richest men in the world, together they would have generated $1.775 billion.  

The loss of a fourth of the proposed tax revenue is a major hit to the initiative, which intends to use the funds toward health care, education, and food assistance.   

Billionaires are backing a fight 

Billionaires in and outside of California are working to fight the tax, which has been a harbinger for more wealth taxes across the country. 

Brin donated $20 million to a group called Building a Better California that is giving out $15 to people who sign their three countermeasures. The group’s proposals would prevent retroactive taxes and narrow the definition of California residency to fight against the 2026 Billionaire Tax Act’s application to anyone who lived in the state as of Jan. 1, 2026. 

Two billionaire-backed political action committees, Stop the Squeeze and Golden State Promise, have launched to stop the proposal. 

Chicago-based venture capitalist Daniel Tierney donated $200,000 to Stop the Squeeze, and crypto billionaire Chris Larsen is backing Golden State Promise, the New York Times reported. 

Since the California initiative was announced, other states have proposed higher taxes on their high-earning residents. In January, Rhode Island Gov. Dan McKee backed a 3% tax increase on millionaires. Last week, Washington, which is one of nine states without an income tax, passed a 9.9% tax on personal income above $1 million per year. 

“We’ve got more millionaires and billionaires than we’ve ever had, and they’re paying, effectively, a 4% tax rate,”  Rep. Brianna Thomas, of Seattle, a Democrat who supported the measure, previously told Fortune. “Meanwhile, you got working folks paying 11% of their income, and the lowest-income people paying 14%. Isn’t it unfair for those who have the most, to pay the least, and those who have the least to pay, the most, proportionally?”

This story was originally featured on Fortune.com

Earlier this month, Andrej Karpathy, a well-known AI researcher who was one of the founding employees of OpenAI and later headed up AI for Tesla, went viral on X. This alone isn’t so unusual. Karpathy—who now works as an independent AI researcher and is also the founder of Eureka Labs, which says it is creating a new kind of school for the AI era—has 1.9 million followers on X and his reputation is such that almost anything he says about AI is treated as either gospel or prophecy.

But this post was about an experiment he’d run where put an AI coding agent to work running a series of experiments to figure out how to improve the training of a small language model. He let the AI agent run continuously for two days, during which time it conducted 700 different experiments. Over the course of those experiments, it discovered 20 optimizations that improved the training time.

Karpathy found that applying the same 20 tweaks to a larger, but still fairly small, language model resulted in an 11% speed up in the time it took to train the model. Karpathy called the system he built for conducting this experiment “autoresearch.”

Tobias Lütke, the cofounder and CEO of Shopify, posted on X that he tried autoresearch to optimize an AI model on internal company data, giving the agent instructions to improve the model’s quality and speed. Lütke reported that after letting autoresearch run overnight, it ran 37 experiments and delivered a 19% performance gain.

What caught many people’s attention was that the autoresearch is close to the idea of self-improving AI systems that were originally broached in science fiction and that some AI researchers fervently desire and others deeply fear. The concern is that “recursive self-improvement,” where an AI continually optimizes its own code and training in a kind of loop, could lead to what AI safety researchers sometimes call a “hard takeoff” or an “intelligence explosion.” In these scenarios, an AI system rapidly improves its own performance, leading it to surpass human cognitive abilities and escape human control.

Karpathy’s experiment wasn’t quite this. The AI agent at the heart of autoresearch set up isn’t refining its own training set up, it’s adjusting the training code and initial neural network settings for a different, much smaller and less sophisticated, AI model. But Karpathy rightly noted that his experiment had big implications for how AI labs will do research going forward, and this might accelerate their progress.

“All LLM frontier labs will do this. It’s the final boss battle,” Karpathy wrote on X. He acknowledged that “it’s a lot more complex at scale of course,” since his autoresearcher only had to worry about adjusting a model and training process that was contained in just 630 lines of Python code, whereas the training codebase of frontier AI models is orders of magnitude bigger. “But doing it is ‘just engineering’ and it’s going to work,” he continued. “You spin up a swarm of agents, you have them collaborate to tune smaller models, you promote the most promising ideas to increasingly larger scales, and humans (optionally) contribute on the edges.”

He said that while the current autoresearch system he built was designed for a single agent to continually improve a piece of code along a single path, in the future he imagines multiple AI agents will be able to explore different optimizations and different experiments in parallel. “The next step for autoresearch is that it has to be asynchronously massively collaborative for agents,” he wrote. “The goal is not to emulate a single PhD student, it’s to emulate a research community of them.”

Karpathy also said something else about autoresearch which got many people excited. “*any* metric you care about that is reasonably efficient to evaluate (or that has more efficient proxy metrics such as training a smaller network) can be autoresearched by an agent swarm,” he wrote. “It’s worth thinking about whether your problem falls into this bucket too.”

Some commentators pointed out that the basic components of autoresearch could be used for many other agentic systems to optimize a process. Janakiram MSV, principal analyst at Janakiram & Associates, writing in tech publication The New Stack called this “the Karpathy Loop.” It has three components: an agent with access to a single file that it can modify; a single metric, objectively testable metric, that the agent can optimize for; and a fixed time limit for how long each experiment can run. He also highlighted that the instructions Karpathy gave the AI agent in autoresearch were also good models for anyone interacting with any AI agent. The plain text file Karpathy used included clear instructions for what the agent should do, constraints, telling the agent what it should not do or change, and a stopping criteria, indicating how long each loop should run and when the agent should stop looping and report its results.

But some critics said that Karpathy had done little more than rediscover part of a process known as AutoML that researchers at Google, Microsoft, and other AI labs have already been using for years. AutoML also uses an optimization loop and series of experiments to find the best data to use for AI, the best model architecture to use, and to tune that model architecture. But it doesn’t use an AI agent that can read AI research papers and develop hypotheses for which improvement to make. AutoML systems tend to depend on random variations or various evolutionary algorithms to decide which changes to try. 

Karpathy replied to some of these comments, saying that some AutoML methods, such as neural architecture search, which is an automated way to optimize the design of an AI model, were not nearly as powerful as his autoresearch. “Neural architecture search as it existed then is such a weak version of this that it’s in its own category of totally useless by comparison,” he wrote. “This is an *actual* LLM writing arbitrary code, learning from previous experiments, with access to the internet. It’s not even close.”

This story was originally featured on Fortune.com

It’s a scene straight out of a science fiction show: robot dogs. Think K9 from the sci-fi series Doctor Who, or Goddard from the cartoon Jimmy Neutron.

Now, robot dogs are standing guard for tech companies, patrolling the massive data centers across the country that power AI operations, according to Business Insider. These four-legged robots, known as quadrupeds, are in high demand from AI firms, according to robotics company Boston Dynamics, which manufactures a quadruped called Spot. These systems are able to navigate complex landscapes on their own, alert authorities about security threats, and can provide around-the-clock video surveillance.

“We’ve seen a huge, huge uptick in interest from data centers in the last year,” Merry Frayne, senior director of product management at Boston Dynamics, told Business Insider, “which is probably not surprising given the investment in that space.”

Companies are pouring nearly $700 billion into the AI infrastructure buildout, a sum that rivals the GDP of developed countries like Sweden. And some data centers are the size of multiple football fields. One data center—Meta’s Hyperion—will sprawl out to about four times the size of Manhattan’s Central Park. Aside from requiring loads of energy and millions of gallons of water, the vast size of the data centers means the cost of security to protect their around-the-clock operations is inspiring some firms to look to alternative security resources.

According to Frayne, Spot’s pricing ranges from $175,000 to $300,000, depending on their client’s needs. But despite that high price, the company estimates that the quadrupeds would compensate for their cost within two years.

The robot dogs are actually capable of doing more than just perimeter patrol. Frayne told Business Insider data center customers are looking for the quadrupeds to conduct industrial inspection, site mapping, and construction monitoring. These tasks could help facility managers to more easily detect hazards, such as puddles or leaks. Boston Dynamics says Spot has “360° perception and athletic intelligence.”

Quadrupeds like Spot have actually existed for some time now, assuming roles in public safety and law enforcement. Another robotics company—Ghost Robotics—advertises quadrupeds as a business solution for construction sites to streamline inspections and enhance safety monitoring. The company also advertises the robots for reconnaissance, intelligence, and surveillance use by the military. 

Forget the age of AI—the dawn of the robotics era

Some tech leaders predict the AI revolution could usher in a new era of robotics, with some predicting they’ll soon outnumber humans. The current state of robotics is a bit far off from that reality. A Deloitte research report titled “AI for industrial robotics, humanoid robots, and drones” found that annual sales of new industrial robots have remained flat since 2021, at roughly 500,000 units. 

But their longer-term projection suggests massive growth in the future, with robot shipments doubling to 1 million by 2030 and revenues of $21 billion. That prediction jumps to $5 trillion by 2050.

In a recent interview with Fortune, Zak Kidd, founder of AI company AskHumans—which has been used by organizations like the World Bank and Fidelity—said that while AI threatens white-collar work, robots could one day poach jobs that require physical labor.

“I see AI as an augmentation of knowledge work,” he said.  “But I see robotics, humanoid robotics, as a replacement for manual work.”

This story was originally featured on Fortune.com

U.S. President Donald Trump is considering delaying a key meeting with Chinese President Xi Jinping “by a month or so” as he struggles to manage the surging conflict with Iran.

The meeting was set to take place between March 31 and April 2, building on the two leaders’ previous face-to-face dialogue in South Korea last October

On Monday, Trump pushed back against claims that he was considering postponing his visit to pressure China to intervene in the Strait of Hormuz, a key strategic waterway currently closed by Iran. “I’m looking forward to being with [Xi],” Trump told reporters at the White House on March 16. “[But] it’s very simple, we’ve got a war going on, and I think it’s important that I be here.”

Still, a delay to the meeting will mean that Trump and Xi will have to wait to discuss a number of factors dragging down the U.S.-China relationship, such as China’s continued export controls on critical minerals, the U.S.’s export controls on semiconductors, and U.S. demands that China buy more agricultural products.

Analysts say the U.S. President’s decision appears driven by the Iran conflict—and a need to manage a fast-escalating conflict and the fallout in energy markets—instead of an attempt to pressure China. 

“Trump’s delay seems to be genuinely about managing the Iran war,” argues Kyle Chan, a fellow at the Brookings Institution, an American think tank. “The Iran war has escalated dramatically, and it would make sense for the U.S. commander-in-chief to give this his full attention.”

Kevin Chen, an associate research fellow at Singapore’s Nanyang Technological University (NTU), also thinks the mooted delay is not due to China’s unwillingness to help the U.S. unblock the Strait of Hormuz, especially given that the U.S. Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng “just had a very productive meeting in Paris”. 

During the meeting, China expressed willingness to buy more agricultural produce from the U.S., Reuters reported, citing unnamed sources. U.S. officials also said there were discussions about setting up new mechanisms, like a U.S.-China “Board of Trade” to manage the economic relationship between the two countries. 

A shift in priorities

Some Trump officials had suggested withdrawing from some U.S. diplomatic endeavors, like its support for Ukraine, in order to devote more resources and attention to countering China. 

But now analysts say Trump’s move indicates that the Iran war—and the resulting blockage of oil and LNG exports from the Gulf—has eclipsed the U.S.’ other geopolitical priorities. 

“President Trump’s move to delay the late-March summit with Xi reflects a shift in priority towards the ongoing military campaign in Iran,” says Dylan Loh, an international relations expert from NTU. 

The U.S. likely has a narrow window to shape events in Iran. “The next two to three weeks are likely to be the most critical period before the Middle East situation stabilizes,” explains Khuong Minh Vu, a public policy professor from the National University of Singapore, adding that the United States and Israel will try to weaken Iran’s strategic capabilities related to nuclear weapons and missile systems.

Vu adds that Trump may also want the Iran conflict to be resolved prior to his negotiations with China to strengthen his bargaining position, particularly if Trump successfully pressures Iran to accept a negotiated agreement.

China has yet to comment on Trump’s proposal. But Beijing might be pleased with a delay; originally, it had requested a later meeting date to give officials more time to prepare. 

“I don’t think the fallout will be large,” says Loh, from NTU. “China will be patient.”

This story was originally featured on Fortune.com

As the Iran war drags deeper into its third week, one seemingly obvious solution for more energy is crude oil from Venezuela after the Trump administration seized former leader Nicolás Maduro and pressed for the reopening of the nation’s oil sector.

The glaring problem is more oil from Venezuela—or any other source around the world—represents only metaphorical drops in the global supply bucket compared to the massive losses each day from the Persian Gulf and the effective closure of the Strait of Hormuz by Iran.

“It’s a math problem,” said Fernando Ferreira, director of the geopolitical risk service at Rapidan Energy Group. “Hormuz flows about 20 million barrels [of oil] a day. Venezuela is currently producing about 1 million [barrels daily].”

The issue is there simply are no alternatives to the de facto closure of the passageway that sees about 20% of the world’s oil and liquefied natural gas trek through it each day.

“Venezuela helps; every little bit helps. But, in the grand scheme of things, it doesn’t change the equation,” Ferreira told Fortune. “There is no medium-term solution other than reopening the straits. Nothing else is going to solve the crisis.”

Arguably the best-case scenario for Venezuelan oil production is it grows from producing nearly 1 million barrels of oil a day late last year to churning out about 1.2 million barrels daily by the end of 2026, said Francisco Monaldi, director of the Latin America Energy Program at Rice University’s Baker Institute for Public Policy.

“I’m expecting less than 250,000 barrels added over the whole year, if at all. That is of course significant for a country that produces just 1 million, but it’s nothing for the world market. It’s less than 0.3%,” Monaldi said, considering the world consumes about 103 million barrels a day. “In particular, it’s very insignificant compared to the disrupted market.”

In the meantime, the White House is aiming to build a coalition of allies to control the strait and escort tankers. The U.S. is also temporarily lifting sanctions on some Russian oil—but that only impacts the destination and prices, not the volumes of oil. And member countries of the International Energy Agency agreed to release a record-high, 400 million barrels of oil from strategic reserves, including 172 million barrels from the U.S.

Pulling that oil from storage will take at least four months however. And while the planned emergency releases are helping keep oil prices from hitting all-time highs, crude oil benchmarks are still hovering near $100 a barrel—up almost 70% from the beginning of the year.

The average price of a gallon of regular unleaded gasoline is $3.80 and rising in the U.S.—up nearly 40% since its January low—but that’s nothing compared to the Asian nations suffering from much higher prices and long lines for fuel, closed schools, and shortened work weeks because of their greater reliance on Middle Eastern oil and Qatari natural gas.

The most successful approach thus far is Saudi Arabia and the United Arab Emirates redirecting as much of their oil flows as they can away from the Strait of Hormuz via the Saudi Arabia East-West Pipeline and the UAE’s Habshan–Fujairah pipeline.

Still, close to 14 million barrels of oil per day remain blocked, according to energy analysts.

“If those pipelines are attacked, then it could be even worse,” Monaldi said.

An Iranian drone attack hit Fujairah on March 16—though not the pipeline itself—triggering the temporary suspension of oil-loading operations.

Getty Images

Positive momentum in Venezuela

Even if Venezuelan supplies won’t help solve the global energy crisis, the country’s oil and gas industry is making notable gains quite quickly, analysts said.

And the growth of oil and gas in South America overall eventually can help the world reduce its reliance on Middle Eastern supplies, Monaldi said.

“In the very long term, it does derisk the oil markets if Venezuela produces much more,” he said, citing other key oil-producing countries. “Venezuela and Brazil and Guyana and Argentina are far away from these geopolitical conflicts.”

Venezuela is still home to the world’s largest proven oil reserves on paper. But the dilapidated industry peaked decades ago with an output of nearly 4 million barrels and needs well more than $100 billion in investments to even approach its past glory. Doing so would take several years to bring to fruition.

“Production is moving up, but it’s moving up gradually. There isn’t a secret pool of oil that Venezuela can tap into and immediately unlock hundreds of thousands of barrels a day,” Ferreira said. “The potential is there, but this is years’ worth of work.”

Momentum is building with Venezuela passing new laws to open the industry to outside investment. Chevron, which was the only U.S. producer that didn’t abandon the country during periods of asset expropriation, has agreed to expand its largest project in Venezuela’s oil-rich Orinoco Belt.

Also, Shell plans to develop gassier regions of Venezuela—both onshore and offshore, which would be closer to Trinidad.

Exxon Mobil plans to send a small team to Venezuela to assess the situation, although CEO Darren Woods drew President Donald Trump’s ire in January when was said Venezuela was currently “uninvestable” until major reforms were enacted.

The ongoing political transition with acting Venezuelan president Delcy Rodriguez is going about as well as it possible could thus far, Ferreira said. Changes should continue and eventually usher in elections.

“Folks that have been to Caracas say it’s open for business,” he said.

This story was originally featured on Fortune.com

When Apple CEO Tim Cook and his executive team received their performance targets for fiscal 2025, the board set a modest bar for bonus payouts. The new targets, including sales and operating profit, did not require Apple’s leadership to expand the business—the board set goals at the same level or below the prior year’s results, citing “trade policy” and an “uncertain macroeconomic outlook.”

At the end of the fiscal year, Cook and his team delivered lights-out, extraordinary results anyway, not only blowing past the lackluster bar set by the board, but handily surpassing the prior year’s results, with net sales increasing 6% and operating income increasing 8%.

Cook collected the maximum bonus payout of $12 million—just as he would have, had the company not performed as well, thanks to the safety net offered by Apple’s board.

Apple’s board is hardly unique. An exclusive analysis of pay data from 50 public companies by Compensation Advisory Partners (CAP), published Friday, reveals how corporate boards across America use a range of techniques—more-conservative targets, widened performance curves, and flattened payout ranges—to protect CEO compensation from uncertainties like the chaos of President Trump’s Liberation Day tariffs in 2025. According to CAP’s findings, total pay for CEOs in 2025 rose 8% year-over-year, with annual bonus payouts up 4%. Meanwhile, median financial performance was generally flat to up, with median revenue growing 2.9% and earnings per share down slightly at negative 1.6%, the analysis found. Even among companies with the weakest payouts due to underperformance, CEOs still collected 87% of their target bonuses, up from 77% the year before. The share of companies that landed in the lowest bonus payout tier was down, from 15% in 2024 to 9% in 2025.

Now, with the Iran conflict erupting weeks after most companies finalized their 2026 incentive goals—and global stock markets down roughly $3.5 trillion—some market observers expect that boards will soon be holding the same conversations again.

“They’re not necessarily making decisions today, but they’re just having the conversation about the approaches they might consider at year end, and let’s see how the year plays out,” said Joanna Czyzewski, a co-author of the study and principal at CAP.

To be sure, some of the change among the weakest-performing companies in the CAP report is because of improving results. “Some of it is definitely business improvement,” noted Lauren Peek, a partner at CAP and co-author of the study. But, she said, there are a lot of ways companies can soften the blow of uncertainty and curveballs like tariffs. 

“You might have growth in your targets, you might have widened the curve and the wings,” Peek said. “It’s—for lack of better words—easier to get into the money, because at the end of the day, these executives are trying to do the right thing.”

The Escape Hatch

Among the early-filer companies in the CAP study, their fiscal years end between August and October 2025. That means Trump hadn’t even won the election when they were budgeting and planning for the 2025 fiscal year. Company proxy statements, which include compensation details, provide examples as to how some companies dealt with impending tariffs which later came to fruition on April 2, 2025, before the Supreme Court struck them down last month. (Trump has since imposed a global 15% tariff.)

At personal computer and printing giant HP, the company didn’t wait for tariffs to hit before crafting a plan. In January 2025, at the same time the board locked in HP’s fiscal 2025 performance goals, the HR and compensation committee approved an explicit tariff carveout. Then, when it came time to calculate bonuses for CEO Enrique Lores and his executive team at year-end, the committee stripped out the “net impact of tariff-related costs” from both annual and long-term incentive calculations, the company disclosed in its proxy statement. HP said the adjustments “reflect the net impact of the tariffs after management’s actions, including significant and swift movement of the company’s manufacturing and supply chain along with additional cost reductions and price increases.” That included shifting more than 30% of HP’s manufacturing from China to Southeast Asia and Mexico. 

Ultimately Lores and the executive team earned 67.3% of their target bonus on average. HP described the tariff hit as having “unexpected magnitude” on its financial results and annual and long-term incentive plan calculations after the relevant goals had been set, suggesting that the bonus payouts would have been lower had the tariff impact not been excluded. The compensation committee also used discretion to bring down the executive payouts in line with the broader employee pool, a small acknowledgment of the optics of shielding C-suite executives while the broader workforce takes it on the chin. Lores collected $1.9 million and then stepped down from HP in February and joined PayPal as its new CEO this month. 

HP did not respond to a request for comment. 

Peek, who spoke generally and not about any specific companies, acknowledged the reputational pressure some of these decisions can carry.

“If the company is making these adjustments and giving executives a big payout at the same time as significant layoffs, I’m not sure shareholders would formally comment on that, but the overall optics would be seen in the press,” said Peek. 

Hedging the Goals

Other companies handled uncertainty earlier, back at the goal-setting stage before a carveout would be on the table. Unlike HP, Apple didn’t strip out any costs after the fact, the board made goals conservative at the start.

For the past three fiscal years, Apple’s compensation committee has set at least one bonus target at or below the prior year’s actual results. Bonuses pay out at Apple based on hitting threshold, target, and maximum performance. Hitting threshold earns 50% of the target payout for that measure, hitting the target gets them 100%, and clearing the top rung, the maximum, means executives can double their bonus opportunity. 

For fiscal 2025, Apple’s people and compensation committee appear to have faced a conundrum. Apple’s fiscal year begins in late September and the committee sets goals prior to the start of the fiscal year. President Trump was campaigning against Vice President Kamala Harris and his agenda included massive new tariffs on imports that would hit Apple’s China-based manufacturing significantly. Trump’s tariff rollout wouldn’t happen for roughly another six or seven months when the committee was setting goals. In hashing them out, the committee considered financial results from prior years “as a reference point” but chose goals for 2025 that would “reflect strong financial results commensurate with the projected business and economic conditions for the current fiscal year,” the report in Apple’s 2026 proxy statement reads. 

The fiscal 2024 results were key for determining the goals for fiscal 2025. 

In fiscal 2024—which saw Apple launch its iPhone 16 and $3,499 Vision Pro virtual reality headset—Apple delivered record net sales of $391 billion and operating income results of $123.2 billion. The results were 2% and 8% year-over-year increases, respectively. 

For fiscal 2025, the board set the net sales target at $391 billion—the exact same as the prior year’s actual result. The operating income target was set at $118.5 billion, some $4.7 billion lower than the prior year’s actual result. In doing so, the proxy points to “trade policies and impacts and foreign currency” fluctuations as the rationale for the goal-setting but the committee doesn’t specify a certain anticipated hit to profit margins.

Ultimately, Cook and Apple delivered extraordinary results so strong the structural safety net constructed for the year may have been moot. Net sales in fiscal 2025 swelled to $416.2 billion and operating income was $133.1 billion—bashing past the maximum performance thresholds by more than $14 billion in net sales and $9 billion in operating income.  Cook and the other named executive officers took home maximum payouts on their annual bonuses, which for Cook equated to $12 million, according to Apple’s disclosures. 

The same broad pattern also appeared in fiscal years 2023 and 2024 when Apple set at least one target at or below the prior year’s actual results. During fiscal years 2021 and 2022, the targets were both set above the prior year’s actual results. 

Apple did not respond to requests for comment. 

In the proxy, the compensation committee explained the reasons behind the approach, and wrote that it made the decisions after considering business scenarios “and once again focusing on the underlying business performance rather than the absolute growth rates.”

Generally, companies don’t lower the bar in goal setting arbitrarily, they align targets with their financial budgets to measure performance against what they reasonably anticipate, Czyzewski noted. In setting comp-related goals, companies take into consideration their strategic growth for the year, including growth expectations, and headwinds and tailwinds in the industry and broader economy when they set budgets, added Peek. Target incentive goals are usually set at budget and should “be achievable but stretch,” she said.

“If the goals are too easy, then executive pay may not align with the shareholder experience,” Peek said. “If the goals are too difficult or aspirational, then the award may be demotivating if it is believed that all or most of the award cannot be achieved.”

That’s why board committees have conversations at the beginning of the year about financial metric definitions and possible adjustments, Czyzewski said.

“The intent when goals are set is to ‘get it right’ and account for what is both in and out of the executive team’s control—and set realistic goals,” she said. “But when the unexpected happens, it is good to have a plan and parameters for evaluating results and ensuring pay aligns with performance.”

That way, the conversations at the end of the year will be less about pure board discretion and more about evaluating outcomes within the performance framework.

“If companies are setting targets with their budget,” Czyzewski said, “you’re still aligning them to what finance actually thinks is achievable.”

Taking the Hit

In contrast, not every company reached for tools in the kit, although few businesses have the size and risk profile of Apple.  

TransDigm, which produces pumps, valves, and other parts for aircraft, explicitly told investors that it had the authority to ratchet up payouts by 20%, but didn’t do it in fiscal 2025. The company beat its target goals but did not clear the maximum. CEO Kevin Stein collected $2.6 million. 

Similarly, carbon black manufacturer Cabot told investors it “retains the discretion” to adjust payments, but declined to do it in fiscal 2025. CEO Sean Keohane collected $1.4 million after hitting 90% of target against performance and 130% of target for his individual performance, resulting in a 102% payout. 

Executives at lawn and grounds equipment manufacturer Toro landed between threshold and target for its goals, resulting in a payout of 81.6% for CEO, which translated to $1.3 million for chairman and CEO Richard Olson. 

The Iran Choice

Most companies with a calendar fiscal year approved their 2026 incentive goals in February or the first week of March. Iran erupted days later.

“So even the latest of those probably had those goals approved about two or three days before the news broke about the Iran situation,” said Czyzewski, referring to the fact that calendar year companies did not have an opportunity incorporate the conflict into their goal setting process. “It’s impacting everyone this year, but no one knows how much.”

Whether boards respond the same way they did to tariffs depends heavily on how the conflict unfolds, said Czyzewski. Companies are likely to look for precedent, added Peek— including how boards responded to the Iraq invasion in 2003.

“It would be looking into a crystal ball that we just do not know, because we don’t know how long this conflict is going to last,” she said. 

And, of course, tariffs are still on the table too. 

“If you did not make a carve-out last year, you’re probably not going to make one this year,” said Peek. “But if you did—and you still feel like tariffs are going to significantly impact you—you might still consider using that lever.”

The Compensation Advisory Partners analysis published on Friday covered 50 public companies with revenues ranging from $1.1 billion to $416 billion.

This story was originally featured on Fortune.com

Rob Arnott warns that shareholders in U.S. big-caps will make one-fifth the returns over the next 10 years they pocketed since 2016, and those meager gains will barely edge the consumer price index. You may want to take a cold shower, or a shot of tequila, before you hear the convincing logic behind his dour prediction.

Arnott is the founder and chairman of Research Affiliates, a firm that oversees strategies for nearly $200 billion index funds and ETFs for the likes of Charles Schwab and Invesco. He served as editor-in-chief of the Financial Analysts Journal in the early 2000s, and today comanages the Pimco All Asset and All Asset All Authority funds. He’s also the father of “fundamental indexing,” the practice of weighting stocks by their size in the economy rather than chasing expensive “winners” by ranking according to market cap. At RA, Arnott has bred a think tank in its own right featuring sundry PhDs who apply advanced statistical research to forging benchmark-beating vehicles.

So I check frequently with Arnott to get his take on what those buying into the S&P 500, or baskets of big-cap U.S. stocks, are likely to reap in the years ahead. It’s an especially good time to get a sober reading. The S&P has dropped 4.4% from its record close in January, and the Iran war and jump in oil prices and Treasury yields following the attack are raising a new cloud of pessimism.

An advantage to consulting the sage: Though his predictions are based on a sophisticated analysis of past trends, the future math is basic. In our conversation over Zoom, Arnott stressed that returns have three sources: dividends, growth in earnings (that lift payouts in tandem), and expansion in valuations or P/Es. The last 10 years, he avows, were something of a seldom seen golden age for this trio, but especially profits and multiples. “Overall, U.S. large-caps [as reflected in the S&P 500] produced overall gains of 15.5% a year, an extraordinary number,” says Arnott.

The rub: The fantastic profit and P/E performance over the past 10 years virtually guarantees a rough road ahead

Arnott emphasizes the gap between the historic trends in both profits and valuations, and the S&P’s extraordinary outperformance from mid-March of 2016 through today. Earnings per share waxed at over 11% annually, almost twice their long-term average. The S&P multiple ramped by around one-fifth from the low-20s to roughly 27.5, the current number according to FactSet. “In effect, the big returns were front-loaded by that highly unusual scenario,” says Arnott.

But the high times also foreshadowed today’s downside. Starting at these heights in both metrics, he adds, “has the effect of reducing future returns.” The Wall Street market strategists’ view that anything resembling the last decade’s results are repeatable amounts to a fantasy, declares Arnott. “P/Es don’t always go up without limit,” he says. “In no sensible world is that plausible.” Arnott contends that it’s equally illogical to argue that EPS can keep advancing five points or so faster than their long-term average. As everyone from Warren Buffett to Milton Friedman has pointed out, profits can’t outgrow the economy forever, and after they absorb an unusually large portion of national income, shrink back toward the norm going forward.

Here’s the picture Arnott foresees over the next 10 years. Because stocks are so pricey, the dividend yield now sits at a mere 1.2%, way below its contribution in most periods. (The stats are available on RA’s website under “Asset Allocation Interactive.”) As for profits and P/Es, he cites one of the laws governing markets: reversion to the mean. In the RA scenario, earnings will wax at 5.3%, more or less matching their traditional trajectory, less than half the 2016 to 2026 pace. Add those two components, and you get a “plus” of 6.4% a year. That already sounds mediocre. But the big hit’s a shrinkage in multiples that severely reverses the potent upward push that helped generate those 15.5% returns since 2016. Arnott predicts that valuations will shrink by 3.4 points a year, or 40% by 2036. That pressure would reduce today’s P/E of 27.5 to around 17. Although that sounds extremely slender versus what we’ve seen in recent years, it’s more or less the multiple in the boom years preceding the Global Financial Crisis, and close to the 120-year mean.

All told, the overall S&P 500 should then deliver total annual returns of 3.1% (6.5% from dividends and growth, minus 3.4% from a decline in the P/E). That’s one-fifth the mark for the past decade, and exactly one point better than projected inflation of 2.4%. By 2036, the S&P would stand at 8073, just 21% above its reading of 6672 at the close on March 12.

To gauge just how hugely this outlook diverges from the conventional wisdom, consider that the Wall Street consensus calls for the S&P to end this year at between 7600 and 7650, or less than 6% short of where RA expects the index to finish 10 years hence.

Arnott tags the Magnificent Seven and other high-fliers for pulling the big returns forward, and advises to shun them

Arnott also highlights a significant difference in prospects between the S&P value and growth contingents. The RA model predicts 4% annual gains in the former and a shockingly puny 1.4% in the latter, meaning the recent champs’ returns will lag inflation by one percentage point. Much of the drag, he says, arises from the big valuations, on top of earnings so gigantic they’ll be hard to grow big from here. A major reason we saw that double-digit EPS boom rampage, he avows, “is the stupendous growth in the Mag Seven.” Now, he adds, “Valuations for growth stocks are very stretched, driven by the Mag Seven. The market’s saying it’s a foregone conclusion they’ll grow earnings like crazy. But to beat the market, they’d need to grow earnings even faster than those lofty expectations.”

Arnott’s especially skeptical of the premium prices awarded by investors expecting fantastic profits from AI. “The companies making money from AI are the ones selling the tools,” he says. “They’re now lending to their own customers so that those customers can keep buying their stuff. And their customers are having a hard time monetizing that equipment.” Arnott related that he’d just used Perplexity to perform an in-depth study of how various tax increases being proposed would affect marginal rates at different income levels, and paid nothing for the service. “These AI providers will figure out how to make money,” he says. “But not as fast as the expectations that are built into their stock prices. It will be a slow build over a long period, meaning returns on these stocks will be much lower than the market’s baked in.”

Here’s his advice: “If you’ve owned the Mag Seven, say ‘Thank you very much, Mag Seven,’ and get out and don’t ride them back down.” Arnott believes that returns will be much bigger outside the U.S. than stateside. For example, RA posits that developed nation, non-U.S. value stocks will provide 7.4% returns going forward, more than twice the expectation from the S&P 500, and that emerging-markets value shares will do even better at 7.6%. Arnott concludes that the best strategy is to “first, own no U.S. shares or at least lighten up, and second, own no growth stocks anywhere.”

Versus what we’re hearing from Wall Street, and the S&P’s spectacular showing over the past decade, Arnott’s perception is highly contrarian. But the math’s on his side. And when the math contradicts belief and momentum, go with the math.

This story was originally featured on Fortune.com

The richest person in the world and the most well-known person leading the cause against creating more people like him have many differing views on taxing the ultrawealthy.

But now, Elon Musk and Sen. Bernie Sanders, two men on opposite ends of the ideological spectrum, are using the same math to make opposite arguments for how much billionaires should be taxed, and how that money should be allocated.

In Musk’s view, collecting every cent billionaires rake in pales in comparison to federal debt, which is now hurling towards $39 trillion and counting.

“Even if you tax every billionaire in America at 100%, it barely makes a dent in the national debt,” Musk wrote on X in 2023. “In the end, the government will be forced to tax everyone to pay the debt.”

Sanders agrees—but he’s not looking to tax billionaires for all their worth and he’s not trying to eliminate the debt. Instead, he wants enough to give nearly three-quarters of the nation a nice check, offset cuts to federal health programs, and fund social services. 

938 people stand in the way of you receiving $3,000 checks

Sanders, along with Rep. Ro Khanna, introduced a billionaire tax earlier this month and suggested there are only 938 billionaires in the country, who, combined, hold a net worth of $8.2 trillion. 

Simple math would prove Musk’s logic correct: $8.2 trillion will barely plug a fifth of the national debt. 

But that’s not what Sanders and Khanna are suggesting: the two put forward the “Make Billionaires Pay Their Fair Share Act,” which proposed an annual 5% wealth tax on individuals with a net worth of $1 billion or more.

Sanders estimates the bill would generate $4.4 trillion over its first decade. And in the first year, that revenue would fund a one-time $3,000 check for every American in a lower- or middle-income household, defined as those earning $150,000 or less annually, or roughly 74% of the nation.

In the years that follow, Sanders believes the revenue from the tax would reverse the $1.1 trillion in Medicaid and Affordable Care Act cuts, establish a $60,000 minimum salary for public school teachers, and cap childcare payments at 7% of household income for working parents.

“At a time of unprecedented income and wealth inequality,” Sanders said in the press release, “this legislation demands that the billionaire class in America finally pay their fair share of taxes so that we can create an economy that works for all of us, not just the 1%.”

The debt as it stands

The U.S. is paying nearly $1 trillion per year just to service the debt—a figure that has nearly tripled over five years and has surpassed what the government spends on Medicare. The Committee for a Responsible Federal Budget projects interest payments will exceed $1.5 trillion by 2032. America is, at an accelerating pace, borrowing money to pay interest on money it already borrowed.

Musk and Sanders are making two different arguments. Musk’s framing casts a billionaire tax as a debt solution, and by that measure, it fails. Sanders’ framing casts taxing billionaires as a redistribution mechanism, a way to put money back in the pockets of working Americans and fund social services. By that measure, a 5% annual wealth tax generating $4.4 trillion over a decade is significant. 

Musk has warned more broadly that America is on a path to going bankrupt “1000%” if spending isn’t curtailed. The debt crisis is structural, rooted in decades of spending that outpaces revenue, and no single tax can undo that. The national debt has grown by more than $11 trillion over the last five years alone.

But Sanders’ counter is equally pointed: the debt crisis and the affordability crisis are not the same problem, and solving one doesn’t require ignoring the other. A $3,000 check won’t fix the national debt. But for a middle-class family barely keeping up with inflation, it may fix something more immediate.

This story was originally featured on Fortune.com

The AI capital expenditure boom has created a gusher of corporate debt, forcing the Treasury Department to make its bonds more attractive to investors as the U.S. war on Iran adds to the deficit.

Last Tuesday saw the single busiest day on record for U.S. corporate bond sales as President Donald Trump’s hint that the war may end soon briefly calmed markets and sparked a mad dash for companies to issue fresh debt.

By the end of the day, total investment-grade issuance topped $65 billion, exceeding the prior one-day record of $52 billion in 2013. The flood of debt was led by e-commerce giant and AI hyperscaler Amazon, which raised $37 billion, sources told the Financial Times.

That beat the company’s guidance for $25 billion-$30 billion as investor demand far outpaced the available supply, attracting about $123 billion in orders.

The corporate debt surge was enough to move the needle in the Treasury market, where daily trading volume exceeds $1 trillion. Analysts at Deutsche Bank said in a note last week that the bond sales added some upward pressure on the 10-year yield, which climbed 6 basis points to 4.16% at session highs.

Apollo Chief Economist Torsten Slok previously warned the flood of corporate debt could make borrowing more expensive for the federal government.

In a note from January, he pointed out that Wall Street estimates for the volume of investment grade debt that’s on the way in 2026 reach as high as $2.25 trillion.

That’s as the AI boom increasingly sends companies, including hyperscalers and adjacent firms, to the bond market to fund massive investments in data centers and other infrastructure.

“The significant increase in hyperscaler issuance raises questions about who will be the marginal buyer of IG paper,” Slok said. “Will it come from Treasury purchases and hence put upward pressure on the level of rates? Or might it come from mortgage purchases, putting upward pressure on mortgage spreads?”

Much has changed since January. The Iran war is shaping up to be a prolonged conflict that’s sent oil prices spiking. In turn, bond yields are up on exceptions of higher inflation—further adding to borrowing costs.

Bombarding Iran everyday also adds stress to the deficit, which hit $1 trillion in just the first five months of the fiscal year. Pentagon officials told lawmakers last week that the cost for the first six days of the war topped $11.3 billion, according to the New York Times.

Meanwhile, Trump has vowed to boost defense spending to $1.5 trillion a year from $1 trillion, threatening to further blow up the deficit.

The unsustainable trajectory of U.S. debt has raised growing alarms on Wall Street. But for now, investors appear to have a strong appetite for both corporate and government debt.

Days after Amazon’s mega-offering, an auction Thursday for $22 billion in 30-year Treasury bonds drew solid demand, though it was helped by the jump in yields since the war began.

And a Treasury offering last month saw the highest demand ever in the history of 30-year auctions, led by overseas buyers.

“The bottom line is that Treasury auction metrics show that there continues to be very solid demand for the long end in US Treasuries,” Slok said in a note Feb. 20.

This story was originally featured on Fortune.com