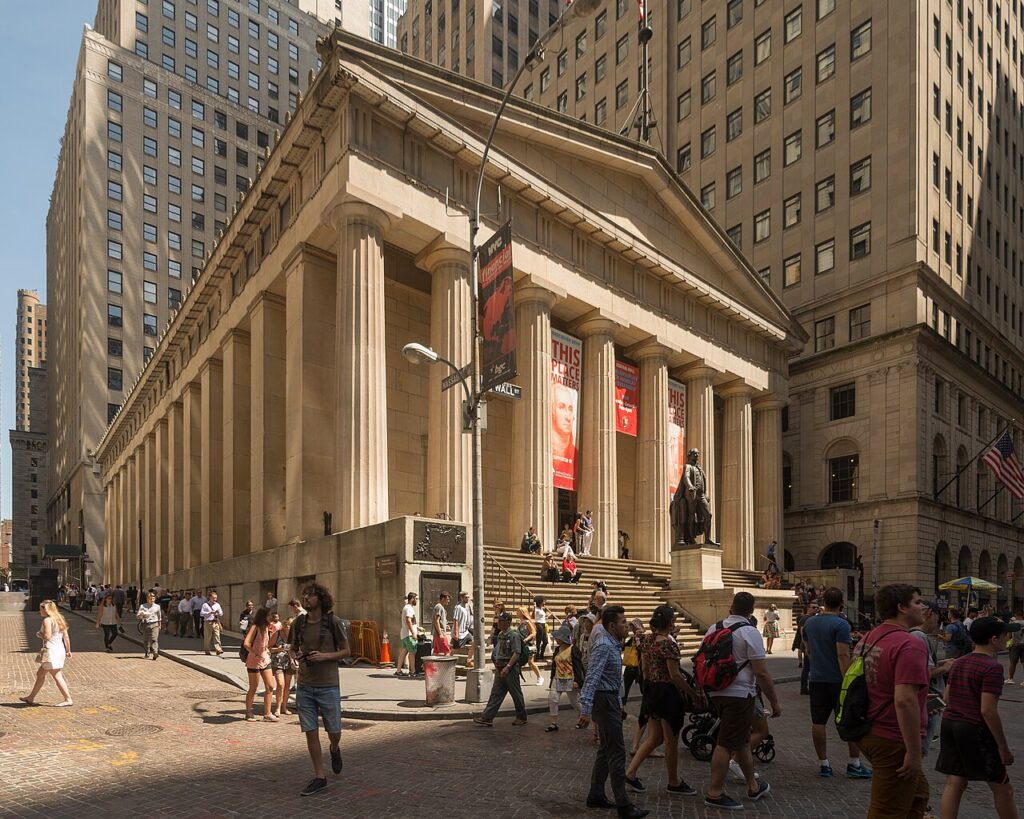
Photo: Arild Vagen / Wikimedia Commons (archive photo)
Oil crashed 7% Monday on renewed hopes for U.S.-Iran diplomacy, splitting the tape in two: the Dow rose and financials rallied while the Nasdaq fell for a third straight session, with Intel sinking below $60 and the chip rout deepening hours before Apple reports its results.
The Dow Jones Industrial Average gained 214 points, or 0.4%, to 51,984, snapping a two-day losing streak. The S&P 500 slipped 0.5% to 7,542 and the Nasdaq Composite fell 1.1% to 25,164, each down a third straight day. The Russell 2000 ended roughly flat.
Oil’s collapse. U.S. crude settled at $96.46 a barrel, down 7.3% from Friday’s $104.12 settlement, after trading as much as 8% lower, as traders priced the possibility that diplomacy between Washington and Tehran could defuse the conflict premium that drove oil above $100 last week. The drop hit energy shares – Exxon Mobil fell 4.1% – and handed airlines, transports and consumers the reverse trade. Gasoline futures sank with crude, and pump prices, which had climbed with the war premium, are poised to follow.
Intel’s slide deepens. Intel tumbled another 8.8% to $59.97, closing below $60, stretching its two-session loss to about 35% over the two-session selloff, as sellers returned after Friday’s 28.6% crash on a weak holiday-quarter outlook. The chip sector fell 3.4%, its third straight daily drop, with Microsoft down 2.8% and Nvidia off 1.3%.
The rotation. The Dow’s gain against the Nasdaq’s decline told the day’s story: money kept leaving the most crowded AI trades and looking for value. Financial stocks rose 1.8%, and Amazon rebounded 2.2% as buyers returned to a name that had been punished Thursday night for its $220 billion spending plan.
Rates, gold, volatility. The 10-year Treasury yield eased about 2 basis points to roughly 4.91%. Gold rebounded, settling up 1.4% at $3,969.60 an ounce after Friday’s 3.5% dump. The VIX jumped about 10% to roughly 21.
What to watch. Apple reports after the bell, with Palantir also due tonight – the week’s first big test of whether the market will pay for AI growth or keep punishing its cost. Then the midterm elections Tuesday and the October jobs report Friday.
JBizNews Desk | Wall Street
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.