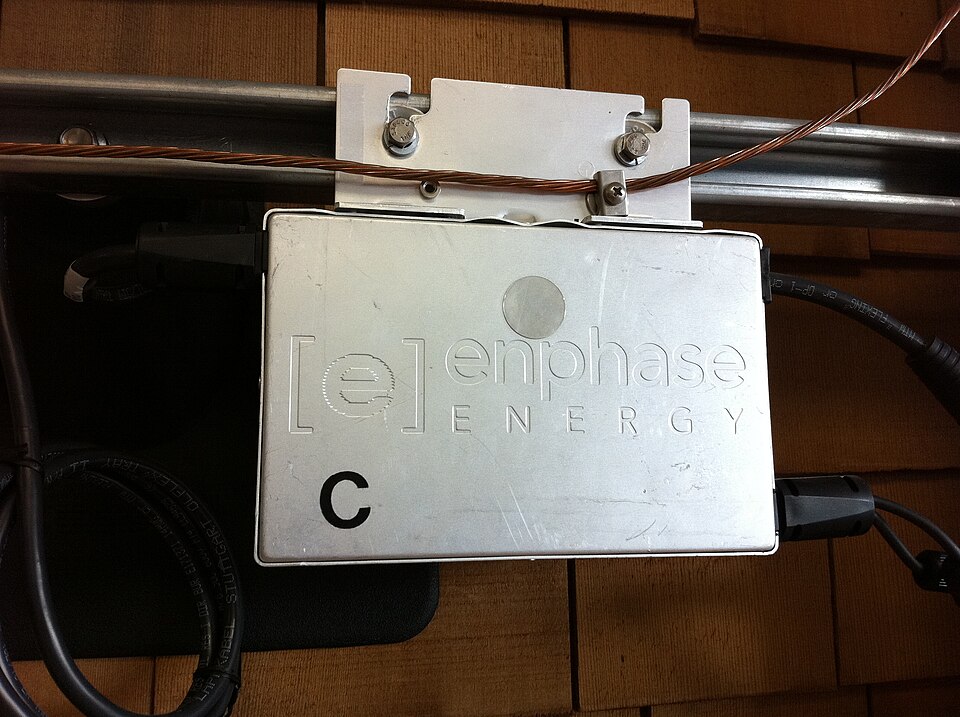
Enphase Energy reported a sharp year-over-year revenue decline Tuesday and forecast a weaker fourth quarter, saying soft demand for home solar systems continues to weigh on its core market even as it develops power equipment for artificial-intelligence data centers.
The company reported third-quarter revenue of $293.3 million, down 28.5% from $410.4 million a year earlier. Revenue was slightly higher than the second quarter’s $291.9 million, but end-customer demand grew less than Enphase had expected.
Global sell-through, the company’s measure of product moving through its sales channel to customers, rose about 1% from the previous quarter rather than the 10% increase it had anticipated. In the United States, sell-through rose 5% from the second quarter but fell 35% from a year earlier. European sell-through declined 12% sequentially.
A smaller fourth quarter ahead
Enphase forecast fourth-quarter revenue of $225 million to $255 million, below the third-quarter total across the entire range. Its outlook assumes sell-through will decline 10% from the third quarter and includes about $51.2 million of safe-harbor revenue. The third quarter included $85 million of safe-harbor revenue.
The company cited higher interest rates and the expiration of the Section 25D federal tax credit as headwinds for its U.S. residential solar business. Those pressures matter beyond a single equipment supplier: financing and tax incentives help determine whether a household can make the cost of a rooftop solar installation work.
Enphase’s own sales figures do not measure every solar installer or every household purchase. They do show how a major supplier of solar electronics and batteries is experiencing the slowdown, including weaker-than-expected demand in the latest quarter.
Third-quarter net income under generally accepted accounting principles was $23.4 million, or 17 cents a diluted share, compared with $66.6 million, or 50 cents a share, a year earlier. Adjusted earnings, which exclude certain costs, were 41 cents a share. The company said an investment impairment reduced GAAP earnings by 15 cents a share and adjusted earnings by 14 cents.
Enphase reported a 43.3% GAAP gross margin. Its adjusted gross margin was 45%, and the company said reciprocal tariffs reduced that measure by about 1.3 percentage points during the quarter. It expects roughly a two-percentage-point tariff impact in the fourth quarter.
AI power equipment remains a longer-term project
Alongside the solar results, Enphase said it demonstrated a solid-state transformer converting 13.8-kilovolt alternating current into 800-volt direct current at its Austin research lab. The system is intended to reduce the number of power-conversion stages serving AI computing equipment.
The company said it is working with a leading hyperscaler and a global AI computing company, without naming them. These are development engagements, not disclosed commercial shipments. Enphase expects customer pilots in 2027 and commercial shipments beginning in 2028, with further technical tests planned before the end of this year.
Its existing battery business shipped 129.9 megawatt-hours in the third quarter, up from 113.8 in the second. The company ended September with $931.8 million in cash, cash equivalents and marketable securities, while operating cash flow was about $100,000 for the quarter.
JBizNews Desk | Fremont, California
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.