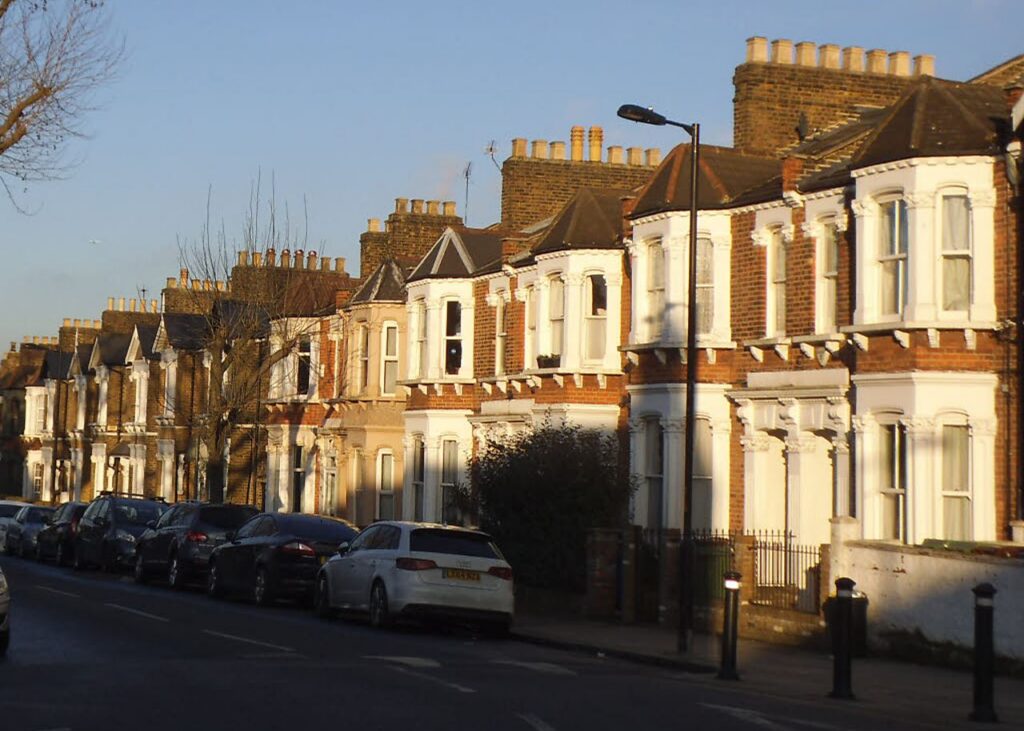
Photo: Stephen Craven/Geograph / CC BY-SA 2.0 (cropped)
British mortgage lenders gain more flexibility Wednesday to offer loans at least 4.5 times borrowers’ income, as a new framework removes an individual-lender cap while keeping a market-wide safeguard.
The Prudential Regulation Authority and Financial Conduct Authority announced the final policy on October 14, with an effective date of October 28. The change concerns the share of new mortgages lenders can make at high loan-to-income multiples, not the deposit a buyer needs or the interest rate charged.
Under the previous firm-specific limit, loans at or above 4.5 times income were capped at 15% of a lender’s new residential mortgages. The new framework removes that individual cap, allowing a lender to exceed 15% while the aggregate market flow remains consistent with the Financial Policy Committee’s 15% limit.
More flexibility, not automatic approval
The definition of a high loan-to-income mortgage remains unchanged: the amount borrowed is at least 4.5 times the individual borrower’s income, or joint income for joint borrowers, when assessed by the lender.
That threshold does not give every applicant a right to borrow 4.5 times income, let alone six times income. Lenders still determine their own lending strategies and risk appetite, and borrowers remain subject to affordability and risk checks.
Some firms had already used interim regulatory waivers or individual guidance. Wednesday’s change therefore does not mean every British lender is gaining this flexibility for the first time. The regulators say those interim directions automatically fall away as the new framework takes effect.
The market-wide safeguard remains
The PRA’s supervisory statement says that if the aggregate becomes persistently inconsistent with the 15% limit, regulators can expect firms lending above that level to reduce their future high-multiple lending gradually toward 15%. Firms below that level would be expected to remain below it during an adjustment.
Individual lenders measure their high loan-to-income flow over a rolling four-quarter period. Regulators monitor the aggregate using single calendar quarters. That distinction is intended to allow gradual adjustments rather than abrupt changes to lending.
The adjustment applies to future lending decisions. Firms are not expected to withdraw mortgage offers they have already approved. The FCA’s corresponding guidance covers mortgage lenders outside the PRA framework.
JBizNews Desk | Real Estate
© JBizNews.com. All rights reserved.
Unauthorized reproduction or redistribution is strictly prohibited.