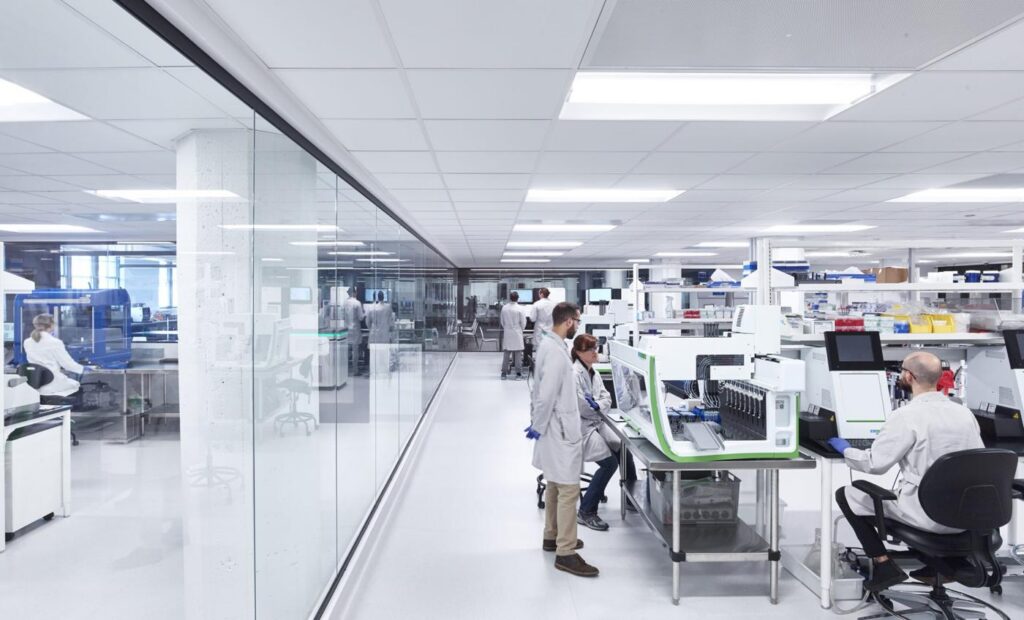
Photo: Tempus
Tempus AI raised its full-year revenue outlook after reporting 23% quarterly sales growth, while Cipher Digital recorded its first high-performance computing lease revenue as it continued a transition away from bitcoin mining. IDEXX Laboratories also raised its annual outlook, while Krystal Biotech outlined later clinical milestones and a new share-buyback authorisation. Choice Hotels raised its room-revenue outlook but cut its GAAP profit guidance.
Tempus raises revenue guidance
Tempus reported revenue of $411.5 million for the three months ended September 30, up from $334.2 million a year earlier, according to its Monday results release. Diagnostics revenue rose 20% to $303.5 million, while Data and Applications revenue increased 33% to $108.1 million.
Oncology testing volume increased 32%. Minimal residual disease testing volume reached approximately 12,000, up 300%, the company said. Gross profit rose 27% to $266.7 million.
The company narrowed its net loss to $14.9 million, or 8 cents a share, from $80.0 million, or 46 cents a share, a year earlier. The latest quarter included $50.8 million in stock-based compensation and related payroll taxes as well as $42.8 million in unrealized gains on marketable securities.
Adjusted EBITDA increased to $25.6 million from $1.5 million. That adjusted measure excludes items included in the company’s GAAP results and is not a substitute for net income or loss.
Tempus increased its 2026 revenue guidance to $1.600 billion to $1.605 billion, representing approximately 25% annual growth. It continued to expect roughly $65 million in full-year adjusted EBITDA. The company ended the quarter with $854.4 million in cash and marketable securities.
Its pending acquisition of Personalis had cleared regulatory review, but the company said the shareholder meeting to approve it was planned for November 30. The acquisition had not been completed in the results announcement.
Cipher begins recognizing HPC lease revenue
Cipher Digital reported $26.7 million in total third-quarter revenue, down from $71.7 million a year earlier, in its business update and financial statements. Bitcoin mining revenue declined to $20.8 million from $71.7 million, while HPC leasing contributed $5.9 million for the first time.
The first HPC revenue followed the start of rent at Black Pearl. Cipher said additional data halls at Black Pearl and Barber Lake were scheduled to come online through year-end.
Its operating loss widened to $71.9 million from $37.6 million a year earlier. Adjusted EBITDA was negative $10.0 million, compared with positive $40.8 million in the prior-year period.
Cipher reported net income of $31.6 million, helped by a $127.2 million gain from a change in the fair value of warrant liabilities. Its financial statements nevertheless showed a diluted loss of 22 cents a share. The operating loss, warrant-related gain and adjusted EBITDA should be considered separately rather than treating one measure as a complete account of performance.
The company highlighted a previously announced extension of its Barber Lake lease to 20 years, increasing total contracted revenue to approximately $9.1 billion. That figure is contracted revenue over the lease’s life, not revenue earned in the quarter.
Cipher also said it received a conditional base-load classification for 1 gigawatt at Colchis and conditional studied-load classifications for another 1.6 gigawatts. These are conditional development milestones, not evidence that all that capacity is operating. Its pipeline totals approximately 5.9 gigawatts, the company said.
Both companies’ outlooks depend on future execution. Tempus’ guidance remains a forecast, while Cipher’s planned data-center capacity, lease deliveries and potential generation projects remain subject to construction, financing and other risks.
IDEXX lifts annual revenue and earnings outlook
IDEXX Laboratories reported third-quarter revenue of $1.214 billion, up 10% on both a reported and organic basis, and diluted earnings of $4.01 a share, up 18%, in its Monday results release. Companion Animal Group diagnostics recurring revenue increased 11% on both measures.
The veterinary diagnostics company placed more than 1,900 inVue Dx analyzers during the quarter, bringing the installed base to nearly 11,000. Operating margin reached 33.1%, up one percentage point from the prior-year period.
IDEXX raised its full-year revenue guidance to $4.741 billion to $4.767 billion, up $32 million at the midpoint, including $5 million related to its CoVet acquisition. It increased its diluted earnings outlook to $14.96 to $15.16 a share, up 25 cents at the midpoint.
The stronger sales and earnings forecast did not mean every outlook metric improved. IDEXX lowered its reported operating-margin forecast to 32.1% to 32.3%, including acquisition-related effects, from 32.3% to 32.5% previously.
Krystal’s product growth accompanies later clinical readouts
Krystal Biotech reported $127.3 million of third-quarter Vyjuvek net product revenue, up 30% from $97.8 million a year earlier, according to its financial and operating update. Net income was $63.1 million, or $2.05 a diluted share, compared with $79.4 million, or $2.66 a share, in the prior-year quarter. Cash, equivalents and investments totalled $1.2 billion.
Alongside the commercial results, Krystal said several trial milestones now fall in 2027. The last patient visit in the IOLITE study of KB803 is expected in February 2027, with top-line results shortly afterward. The company added patients to replace two who withdrew for reasons unrelated to safety and to provide additional supporting evidence.
Enrollment in the EMERALD-1 study of KB801 has been slower than initially anticipated, reflecting eligibility criteria and the difficulty of enrolling a placebo-controlled study where approved therapy exists. Krystal now expects to complete enrollment of approximately 60 patients and report top-line results in 2027. Interim results from its repeat-dose KB407 cystic-fibrosis study are now expected in the first half of 2027.
Krystal’s board also authorised repurchases of up to $400 million of common stock. Management expects opportunistic buying over two years, but the authorisation has no expiration date and does not oblige the company to purchase any amount. It is permission for future repurchases, not $400 million already spent.
Choice Hotels raises RevPAR outlook but cuts GAAP profit guidance
Choice Hotels reported Monday morning that third-quarter U.S. revenue per available room increased 3.8%, reflecting stronger occupancy and rates. Revenue was $458 million, compared with $447 million a year earlier, and adjusted diluted earnings were $2.33 a share.
Net income fell to $58 million from $180 million. The year-earlier quarter included a $100 million joint-venture acquisition gain, while the current quarter included a $24 million contract-termination charge and $6 million of hotel impairment charges. Those items were excluded from adjusted results.
Choice raised its 2026 U.S. RevPAR growth outlook to 1.5%-2.5%, from 0%-1.25%, but lowered its GAAP net-income outlook to $178 million-$185 million from $230 million-$241 million. The lower profit forecast reflects higher expected reimbursable marketing and reservation-system expenses, current charges, lower affiliate earnings and higher interest expense. The mixed revisions are not a blanket guidance increase.
JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.