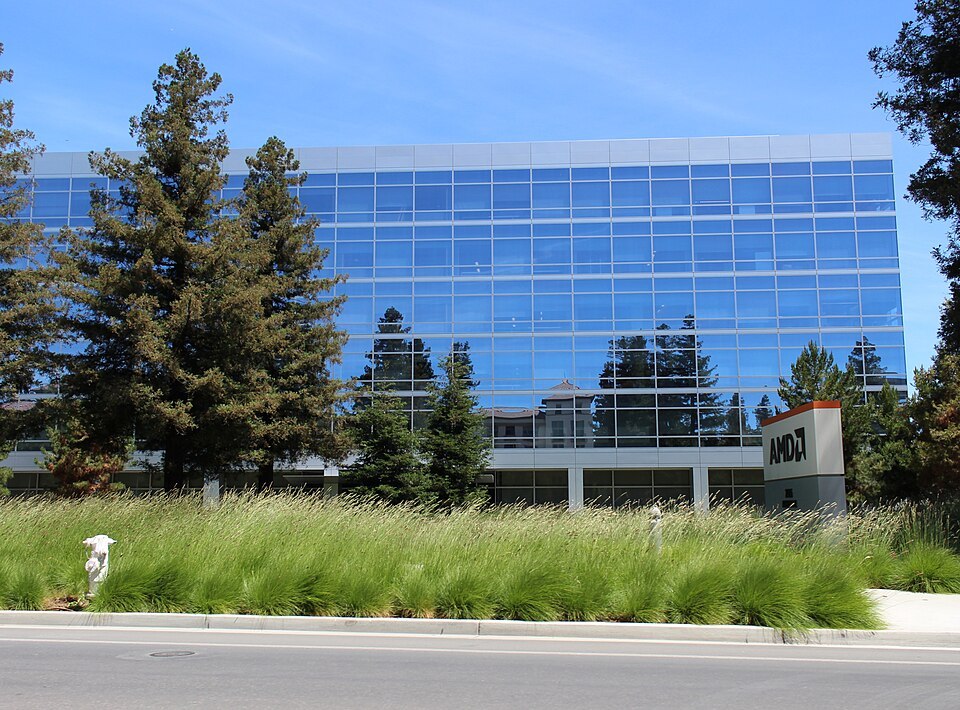
Photo: Coolcaesar / CC BY-SA 4.0 (archive)
AMD reported a sharp jump in sales Tuesday after the close and forecast another acceleration in the holiday quarter, as demand for data-center processors and artificial intelligence chips outweighed a slump in gaming. Shares rose nearly 7% in extended trading.
Third-quarter revenue reached $13.377 billion, up 45% from a year earlier, while adjusted earnings rose to $2.09 a share. Both topped the $13.09 billion in revenue and $1.95 in adjusted earnings analysts expected, according to estimates reported by CNBC.
AMD traded at $517.51 at 4:29pm Eastern, up $33.61, or 6.95%, from its $483.90 regular-session close, according to CNBC’s extended-hours quote. The move followed a 3.65% gain during Tuesday’s regular session. After-hours prices can change quickly.
Data centers drive the growth
AMD’s earnings release put Data Center revenue at a record $8.5 billion, up 97% from a year earlier. The company credited strong demand for EPYC server processors and the launch of its Instinct MI450 series graphics processors.
“We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year,” chair and CEO Lisa Su said in the release.
The results show why the spending needed to run AI systems matters beyond the companies building the models. Chipmakers supply the computing hardware, while cloud providers and businesses must decide how much capacity to buy and how quickly they can put it to work.
Under standard accounting rules, AMD earned $2.428 billion, or $1.46 a diluted share, compared with $1.243 billion, or 75 cents, a year earlier. Adjusted earnings exclude items such as stock compensation and acquisition-related expenses and should not be confused with the standard-accounting result.
A $17 billion outlook, with weaker gaming sales
AMD forecast fourth-quarter revenue of about $17 billion, plus or minus 3%. The midpoint would represent roughly 66% growth from a year earlier and 27% growth from the third quarter. CNBC reported that analysts had expected $16.2 billion.
The company expects an adjusted gross margin of about 55%, slightly below the 55.3% analyst estimate cited by CNBC. That makes profitability, along with the pace of sales, a point for investors to watch as AMD scales its data-center products.
Not every part of the business shared the AI momentum. Combined Client and Gaming revenue fell 8% to $3.7 billion. Client revenue rose 7% to $2.9 billion, but gaming revenue dropped 40% to $773 million as semi-custom and graphics revenue declined.
Embedded revenue rose 29% to $1.1 billion, with growth across aerospace and defense, automotive, communications and industrial markets, AMD said.
Su said AMD expects growth to accelerate as it scales Helios systems and Venice production. The next test is whether the company can turn that demand into shipments and profits consistent with its forecast. The outlook is a company projection, not a guaranteed result.
JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.