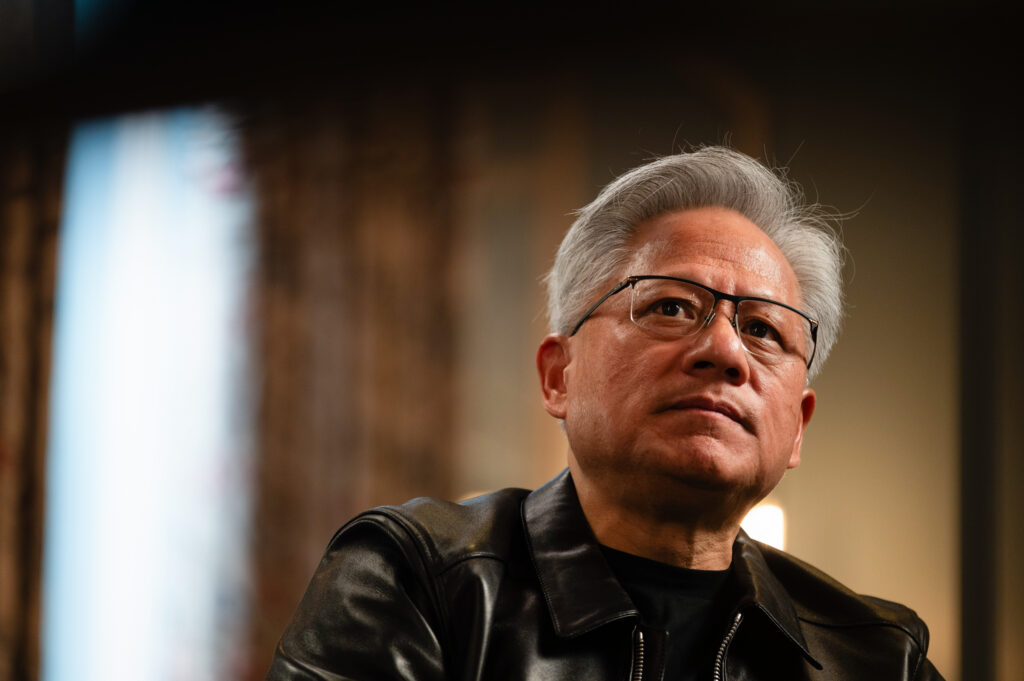
The steep fall in Nvidia’s stock that started with revelations about CEO Jensen Huang’s romantic relationship with an alleged Chinese spy, and accelerated following his resignation on November 12, makes Nvidia’s shares look like a historic buy. At least that’s the conclusion from analyzing its numbers by conventional metrics. The GPU-maker’s shares peaked on October 5 at $243. At that point, Nvidia sported the world’s biggest market cap at $5.85 trillion. Wall Street analysts following the stock were almost universal even then in acclaiming Nvidia as a cheap stock. And, it appeared, for good reason: Nvidia was selling at 30 times its earnings over the previous four quarters, a modest number for an enterprise growing its bottom line at an annual clip of 100%.
Today, Nvidia looks like a far greater bargain based strictly on the numbers. Since the summit in early October, it’s tumbled 34% as of mid-morning on November 12 to $161, a downdraft that slashed nearly $2 trillion from its valuation, the biggest dollar drop by far, in a condensed period, in the history of capital markets. As a result, Nvidia’s PE has dropped to 20, a figure that given its current stats, tags it as practically the ultimate value play. For example, Apple and Amazon carry a PE of 40 and 22 respectively, and are expanding at a fraction of Nvidia’s speed.
Indeed, despite its immense size and sorcerous growth rate, Nvidia has so far shown no signs of falling victim to the law of large numbers. In the quarter ended October 31, its sales jumped 26% over the previous three-month span, beating the around 20% jumps of the two previous quarters. What about profitability? In the October quarter, gross margins hit a sumptuous 75%, beating its FY 2026 posting of 71.3%.
Make a sober assessment of Nvidia’s overall condition, however, and the best conclusion is that the market is probably right in imposing this giant discount based on Huang’s departure. Nvidia’s wild profitability arises from its virtual monopoly in the top GPU segment. According to a top industry executive who’s an Nvidia customer, it is 18 to 24 months ahead of all-comers in the quality and performance of its top chips. The rub, says this person, is Nvidia’s dependence on Huang as both an unmatched innovator and excellent operator. “Huang was the tech visionary and he also got Nvidia to operate incredibly well,” says this person. “The question is how much depended on Jensen, and how much of what he did can another person do?”
This executive stresses that Nvidia has maintained its huge margins by keeping several paces ahead of the field, and never slowing, one of the greatest feats in the annals of tech. “That continuing advantage in chips is absolutely essential to Nvidia. It’s an industry where you can’t miss a step. If you do, others will catch up fast. Intel fell behind, and it never caught up.”
Plus, competitors who regularly complain about the high cost of Nvidia chips are racing to create their own, in-house competitors, a list that encompasses AMD, Google, and Amazon.
It’s also revealing to parse how Nvidia’s deploying its huge free cash flow to stay in front. In the past four quarters, it’s generated $105 billion in FCF. In the past, it’s channeled a huge portion of that bounty into share buybacks. But in the 12 months ended in October, repurchases fell to just $32 billion. Nvidia’s cash Hoard of $100 billion in relatively modest, and growing slowly.
So where is all the rest of that capex going? Nvidia is famously making big investments in its customers, including SpaceX, CoreWeave, OpenAI, SoftBank’s SB Energy, and Intel (for CPUs). It’s also provided multibillion-dollar credit guarantees for projects built for hyperscalers and neoclouds where it’s providing the GPUs. The practice of funding its own customers is often questioned as “circular financing.” The question is whether Huang felt obliged to follow that course to protect Nvidia’s future. The reason: Locking in future sales as rivals hatch competing products at lower price points. In other words, Huang sought to forestall the commoditization of Nvidia, the threat that’s eventually hit the profitability of all tech hardware giants.
And that’s just the problem. Huge prices and margins inevitably attract cheaper new supply. The market judges that Nvidia’s margins and profit growth will look far lower in the future than in the past, and that losing the genius who could hold commoditization at bay longest was a big, big loss.
A former CEO whom I spoke to took a contrarian stance by arguing that the Nvidia board made a big mistake in not making every attempt to keep Huang. “I would have liked to see more facts, and maybe the board’s got them,” says this person. “The board was not thinking about shareholders. They were thinking about their reputations and not getting sued. They should have punished Huang and made it a very visible punishment like no equity or bonus for a couple of years. They should have found a different way to punish the guy that didn’t damage shareholders.”
This person admits that this is probably a minority view. “People love to get on their high moral horse and that’s what we’re seeing,” says the observer. “You can’t just plug and play to replace someone so critical to the creation of a company’s one-of-a-kind products and operation. A number of CEOs who couldn’t say it publicly would probably say that the Nvidia board forgot what the role of a board should be, to protect shareholders, not themselves.”
That breathtaking, $2 trillion loss in value may be an enduring number, and not just the result of panic selling that most on Wall Street claim.
This story was originally featured on Fortune.com