SpaceX is expected to raise $75 billion during its IPO as soon as June, making it two and a half times larger than Saudi Aramco’s $30 billion raise—the previous record holder.

BlackRock Wants 13% Of The Deal

BlackRock Inc. (NYSE:BLK) wants over 13% of the entire offering. The IPO is already oversubscribed before going live, with the world’s largest asset manager leading demand.

Pre-IPO markets on Hyperliquid have SpaceX trading at $2.5 trillion. The company generated $6 billion in revenue last year, putting the valuation at 417 times sales.

Ron Baron projects SpaceX could hit $10 trillion to $30 trillion long-term, with Starlink alone worth $14 …

Full story available on Benzinga.com

This post was originally published here
VF Corporation (NYSE:VFC) stock slipped Wednesday even after the apparel company reported better-than-expected quarterly results and projected another year of growth.

Investors appeared focused on management’s warning that tariffs and higher oil prices could pressure margins in the second half of fiscal 2027.

Quarter In Detail

VF reported fourth-quarter adjusted earnings of break-even per share, topping analyst estimates for a loss of 1 cent per share. Quarterly revenue rose 1% year over year to $2.17 billion, exceeding Wall Street expectations of $2.13 billion.

Revenue excluding the Dickies business increased 4%, or 1% in constant currency. The company sold Dickies during the third quarter of fiscal 2026.

Fiscal 2026 gross margin expanded 130 basis points year over year to 54.8%. Operating income increased …

Full story available on Benzinga.com

This post was originally published here
Blue Owl Capital (NYSE:OWL) co-founder Doug Ostover is selling his remaining stake in the NFL’s Washington Commanders back to the Josh-Harris-led ownership group.

Ostover, who sold part of his stake last year, is offloading the rest now, according to Bloomberg News

In 2023, Ostrover and Blue Owl co-founder Marc Lipschultz joined an investor group led by Harris, which purchased the Commanders for over $6 billion. That was the largest amount ever paid for a professional sports team in the U.S. at the time. 

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Private Equity’s Big Four Are Starting To Crack As Exits Slow, Credit Stress Mounts

This post was originally published here
SpaceX’s expected initial public offering has drawn a new warning after former OpenAI staffers and several artificial intelligence (AI) safety nonprofits urged potential backers to weigh risks tied to Elon Musk’s AI venture, xAI.

The letter, addressed to investors, said the market may not be fully accounting for xAI’s downsides and asked for additional detail ahead of SpaceX’s prospectus. The authors also pointed to SpaceX’s reported goal of raising as much as $75 billion and said the combined structure raises questions that investors should press on.

“Investors evaluating SpaceX’s AI exposure need more information to reasonably price it, accounting for both the upside and the downside. The path forward remains unclear: will SpaceX continue competing at the frontier of AI development, and if so, will it adopt the safety and security practices upon which its peers are converging?” the letter questioned.

Benzinga reached out to SpaceX for comment but did not receive a response by publication time.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Elon Musk’s xAI Doubles Down On Unpermitted Turbines During Pollution Fight

This post was originally published here
Software development company Discord has completed the rollout of end-to-end encryption (E2EE) for voice and video calls across its platform. 

The company said the feature now protects all voice and video communications except Stage Channels, and users do not need to enable any settings for the encryption to work.

With the update, Discord users can communicate privately without third parties — including Discord itself — being able to access or listen to their calls.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Federal Judge Calls US Crackdown On Anthropic ‘Spectacular Overreach’

This post was originally published here
Carnival Corp (NYSE:CCL) stock is surging during Wednesday’s trading session, handed a major tailwind by a sharp decline in global oil prices.

The Nasdaq is up 1.16% while the S&P 500 has gained 0.74%.

• Carnival stock is surging to new heights today. Why is CCL stock up today?

Oil Prices Plunge Below $100

Midday trading on Wednesday saw a significant sell-off in energy markets, with WTI crude oil futures dropping more than 5% to break below the $100 per barrel threshold, according to Trading Economics. This slide offers immediate relief to fuel-sensitive cruise lines such as Carnival, as lower crude costs directly translate to reduced operational expenses and fatter margins.

Trump Signals Final Stages Of Iran Talks

The catalyst behind the crude collapse stems from fresh geopolitical developments. According to a Reuters report …

Full story available on Benzinga.com

This post was originally published here
The Cleveland Browns sold 10% of the club at a valuation of more than $9 billion to private equity firm Arctos Partners.

The deal will be completed in three separate tranches, sources familiar with the matter told Bloomberg. NFL owners approved the first tranche, representing a 3% stake in the team, while approvals for the remaining two portions are expected at a later date.

“The Cleveland Browns are one of the NFL’s most iconic and historic franchises, with a deeply loyal fan base and a leadership team committed to both the future of the organization and the surrounding community,” Chad Hutchinson, partner at Arctos said in a statement. “We are excited to join the Browns as a limited partner and support the organization’s long-term priorities.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Federal Judge Calls US Crackdown On Anthropic ‘Spectacular Overreach’

This post was originally published here
Meiwu Technology Co Ltd (NASDAQ:WNW) stock climbed on Wednesday, extending its positive momentum into midweek. Traders are heavily buying the micro-cap stock following earlier disclosures regarding a private financing deal structured to fund an artificial intelligence skincare expansion.

The Nasdaq is up 1.24% while the S&P 500 has gained 0.83%.

•  What should traders watch with WNW?

Private Placement Fuels Capital

On Tuesday, Meiwu secured approximately $15.65 million in fresh capital through a private share sale involving 25 million ordinary shares. The firm executed the transaction under a securities purchase agreement signed on May 5, which officially closed on May 8. Meiwu sold the shares at $0.626 each, leaving the company with roughly 26.33 million ordinary shares outstanding.

AI Skincare Expansion Plans

The company intends …

Full story available on Benzinga.com

This post was originally published here
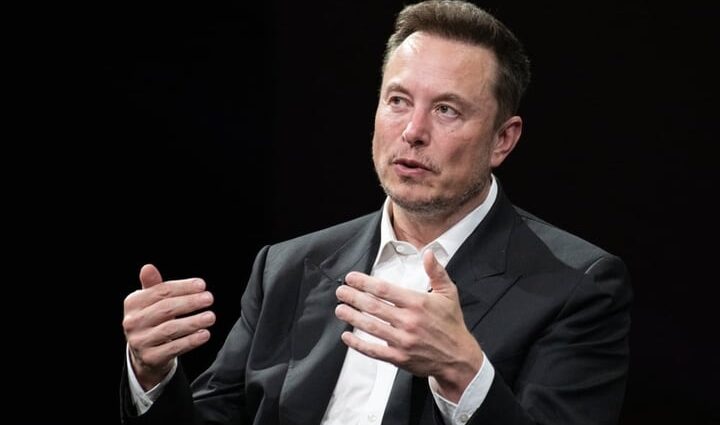
Elon Musk is raiding his own companies to rescue xAI, pulling trusted lieutenants from SpaceX, Tesla (NASDAQ:TSLA) and Starlink into the struggling AI firm just weeks before what may become the largest public offering ever, according to a Bloomberg report.

A copy of xAI’s org chart reviewed by Bloomberg shows more than a dozen Musk allies now running engineering, product and finance.

SpaceX President Gwynne Shotwell helps oversee operations, longtime Starlink executive Michael Nicolls took over as xAI president in April, and SpaceX finance chief Bret Johnsen now runs xAI’s books.

The shuffle matters because Musk folded xAI into SpaceX in February. xAI posted a roughly $6.4 billion operating loss last year and burned an estimated $14 billion in cash, even as Starlink doubled …

Full story available on Benzinga.com

This post was originally published here
TJX Companies, Inc. (NYSE:TJX) stock rose Wednesday after the off-price retailer reported first-quarter results that topped Wall Street expectations and raised its full-year earnings outlook.

Investor sentiment also improved after the company posted broad-based comparable sales growth and margin expansion across several key divisions.

Quarterly Results Beat Expectations

The company reported first-quarter earnings of $1.19 per share, exceeding the analyst consensus estimate of $1.01. Revenue rose 9% year over year to $14.32 billion, above Wall Street expectations of $14.00 billion.

TJX said consolidated comparable sales increased 6% in the quarter, ahead of its internal forecast.

Comparable sales increased 6% at Marmaxx, 9% at HomeGoods and 7% at TJX Canada during the first quarter of fiscal 2027. TJX International posted a 4% increase in comparable sales from a year earlier.

Gross profit margin expanded to 31.3% …

Full story available on Benzinga.com

This post was originally published here
OpenAI could file confidentially for an initial public offering as soon as Friday, a dramatically faster timeline than the artificial intelligence giant had signaled, the Wall Street Journal reported today.

The ChatGPT-maker has been working with bankers at Goldman Sachs Group (NYSE:GS) and Morgan Stanley (NYSE:MS) on a draft prospectus, with the goal of being ready to go public as early as September, people familiar with the matter told the Journal.

That is far more aggressive than what OpenAI had signaled before.

CFO Sarah Friar had reportedly been targeting a filing in the second half of 2026, with the actual listing slipping into 2027.

For public investors, the most direct read-through is Microsoft (NASDAQ:MSFT), which holds roughly 27% of OpenAI from its October recapitalization, a stake valued at about $135 billion.

An early listing would hand Microsoft a liquidity valve …

Full story available on Benzinga.com

This post was originally published here
The iShares 20+ Year Treasury Bond ETF (NASDAQ:TLT) attracted $652.41 million in inflows on May 19, per Etf.com, signaling some investors are piling into long-duration Treasuries even with fears of higher inflation and interest rates driving yields up. In the past 30 days, the fund has seen net inflows of around $1.7 billion.

The inflows came as the 30-year Treasury yield climbed to 5.18% on Tuesday, its highest level since 2007, intensifying the sell-off across long-duration bond ETFs. The demand for higher yields has hammered Treasury prices, given bond prices move inversely to yields, leaving funds like TLT under pressure. The ETF recently fell to around $83.66, its lowest level since November 2023.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Bond Yields Can Become A Bigger Threat To AI ETFs, Not Iran— Can Nvidia Earnings Help The Trade?

This post was originally published here
Nvidia Corp. (NASDAQ:NVDA) reports first-quarter 2027 earnings after the close Wednesday, and the bar has never been higher.

According to Benzinga Pro estimates, Wall Street is expecting the world’s most valued company to report $78.8 billion in revenue and $1.77 in adjusted earnings per share for the January-March period — implying roughly 78% revenue growth and a 119% surge in EPS from the same quarter of 2025.

If achieved, it would mark the largest quarterly revenue print ever generated by a semiconductor company.

On paper, the setup looks straightforward.

Nvidia has beaten revenue estimates in each of the last 17 quarters. The company also topped EPS expectations in 15 of those 17 reports.

But the historical trading data show something important has changed.

The market is no longer rewarding Nvidia simply for beating estimates.

Nvidia Historical Earnings Scorecard: Perfect On Revenue, Punished Anyway

Across the last 17 quarterly reports, Nvidia produced a perfect 100% revenue beat rate and an 88% EPS beat rate.

The only two EPS misses came during the 2022 semiconductor downturn, when collapsing gaming demand and the implosion of crypto-mining pressured results.

On average, Nvidia exceeded revenue expectations by 5.3% and EPS estimates by 7.8%.

Those are extraordinary numbers for a mega-cap company already operating at massive scale.

But the stock reaction has become less automatic.

Quarter Report Date Reported EPS Reported Rev. EPS Surp. Rev Surp. NVDA Stock Reaction: 1-Day 7-Day 30-Day
4Q FY26 02-25-2026 $1.62 $68.13B +5.3% +2.9% -5.46% -9.07% -5.96%
3Q FY26 11-19-2025 $1.30 $57.01B +3.5% +3.7% -3.15% -3.54% +0.86%
2Q FY26 08-27-2025 $1.05 $46.74B +4.1% +1.5% -0.79% -7.32% +6.04%
1Q FY26 05-28-2025 $0.81 $44.06B +8.0% +1.9% +3.25% +5.13% +22.34%
4Q FY25 02-26-2025 $0.89 $39.33B +5.3% +3.1% -8.48% -14.16% -12.91%
3Q FY25 11-20-2024 $0.81 $35.08B +8.5% +5.8% +0.53% -4.98% +2.43%
2Q FY25 08-28-2024 $0.68 $30.04B +5.7% +4.5% -6.38% -15.24% +7.32%
1Q FY25 05-22-2024 $0.61 $26.04B +9.7% +6.0% +9.32% +21.12% +35.02%
4Q FY24 02-21-2024 $0.52 $22.10B +11.4% +7.6% +16.40% +21.95% +27.32%
3Q FY24 11-21-2023 $0.40 $18.12B +18.7% +12.5% -2.46% -6.37% -1.70%
2Q FY24 08-23-2023 $0.27 $13.51B +29.4% +21.9% +0.10% +2.96% -5.15%
1Q FY24 05-24-2023 $0.11 $7.19B +18.9% +10.3% +24.37% +28.27% +38.12%
4Q FY23 02-22-2023 $0.09 $6.05B +9.5% +0.5% +14.02% +15.11% +29.52%
3Q FY23 11-16-2022 $0.06 $5.93B -17.4% +1.9% -1.46% -0.52% -8.15%
2Q FY23 08-24-2022 $0.05 $6.70B -1.6% +0.1% +4.01% -20.76% -23.76%
1Q FY23 05-25-2022 $0.14 $8.29B +4.9% +2.4% +5.16% +10.67% -10.74%
4Q FY22 02-16-2022 $0.13 $7.64B +7.9% +2.9% -7.56% -8.02% +2.92%
Source: Koyfin, Tradingview

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Forget About Micron: The Hottest US Semiconductor Stock Is Already Up 100% This Month

This post was originally published here
NASA says it has successfully tested a high-powered plasma thruster that could eventually reduce Mars travel times from months to far shorter missions.

NASA Administrator Jared Isaacman said in a statement late last month that the test marked progress toward future crewed Mars missions and demonstrated the agency’s ability to operate electric propulsion systems at unprecedented power levels in the U.S

“The successful performance of our thruster in this test demonstrates real progress toward sending an American astronaut to set foot on the Red Planet,” Isaacman said.

Don’t Miss:

A New Generation Of Electric Propulsion

The lithium-fed magnetoplasmadynamic, or MPD, thruster was tested in February at NASA Jet Propulsion Laboratory in Southern California. During testing, the propulsion system reached power levels of up to 120 kilowatts, according to the agency.

NASA said the prototype exceeded the power levels of current electric thrusters used on agency spacecraft, including the propulsion system aboard NASA’s Psyche asteroid mission. Psyche uses continuous low-thrust propulsion to gradually accelerate the spacecraft to speeds of roughly 124,000 miles per hour.

Unlike traditional chemical rockets, the MPD engine uses electromagnetic forces to accelerate lithium plasma. NASA said electric propulsion systems can use up to 90% less propellant than conventional rockets while operating continuously over long periods.

Trending: 1.5M+ Users. $29M Raised. Pre-IPO Shares Still at $0.72 — Learn How to Invest Before the Deadline

Why NASA Is Pursuing Plasma Thrusters

NASA researchers believe scaling the technology to megawatt-class power levels could help support human Mars missions by reducing launch mass while carrying larger payloads. The agency said future crewed missions may require between 2 megawatts and 4 megawatts of total propulsion power.

As NASA advances toward longer-duration crewed missions to Mars, supporting technologies like advanced remote diagnostics and healthcare monitoring are also expected to play a growing role in ensuring astronaut health far from Earth. Companies such as rHealth are focused on modernizing diagnostics and healthcare delivery through data-driven platforms that aim to make advanced testing more accessible and efficient.

“Designing and building these thrusters over the last couple of years has been a long lead-up to this first test,” JPL senior research scientist James Polk said in the statement. “It’s a huge moment for us because we not only showed the thruster works, but we also hit the power levels we were targeting.”

NASA’s latest test comes as governments and aerospace organizations continue exploring advanced electric propulsion systems for future deep-space missions. Russian state nuclear agency Rosatom recently announced its own plasma propulsion concept, claiming the technology could theoretically shorten Mars transit times compared with conventional rocket systems.

See Also: This Lithium Breakthrough Is Turning Heads on Wall Street — See Why Investors Are Watching

The …

Full story available on Benzinga.com

This post was originally published here
SpaceX may still be private, but an increasingly crowded ecosystem is emerging around one simple investor obsession: getting a piece of Elon Musk‘s rocket giant before any IPO arrives.

A series of recent SEC Form D filings shows that private investment vehicles tied to SpaceX exposure have quietly raised millions of dollars from dozens — and sometimes hundreds — of investors.

The catch? Entry into this unofficial SpaceX marketplace often starts around $25,000.

The filings paint a picture of what increasingly looks like a parallel stock market forming around one of the world’s most sought-after private companies.

The $25K Backdoor Into SpaceX

One filing for “HII SpaceX Series II” disclosed nearly $15.9 million raised from 150 investors, with a minimum investment amount of $25,000. Another filing tied to Hiive — a secondary marketplace for private-company shares — showed a separate SpaceX-focused opportunity fund raising $6 million with the same $25,000 minimum buy-in.

The structures vary. Some are SPVs, or special purpose vehicles, designed solely to hold SpaceX shares. Others resemble feeder funds or syndicates pooling investor …

Full story available on Benzinga.com

This post was originally published here
GeoVax Labs, Inc. (NASDAQ:GOVX), a clinical-stage biotech company, is trading higher on Wednesday as investors assess the company’s recent financing deal alongside growing attention on its vaccine platform developments.

• Geovax Labs stock is charging ahead with explosive momentum. Why are GOVX shares rallying?

Ebola Outbreak Highlights Vaccine Demand

GeoVax highlighted the World Health Organization’s emergency declaration tied to the Bundibugyo Ebola outbreak, noting that no broadly approved vaccine currently exists for the strain.

It also emphasized the potential of MVA-based vaccine technologies to address emerging hemorrhagic fever threats, including Ebola and Marburg viruses.

GeoVax cited prior preclinical data from its MVA-based hemorrhagic fever vaccine programs. The data included single-dose protection against Zaire Ebola and survival benefits in Sudan Ebola and Marburg studies.

MVA Platform Supports Pipeline Expansion

The company said the outbreak reinforces the strategic relevance of its MVA platform for developing rapid-response vaccines against emerging infectious diseases.

CEO David A. Dodd said the outbreaks demonstrate that “preparedness …

Full story available on Benzinga.com

This post was originally published here
Amesite Inc. (NASDAQ:AMST) shares climbed on Wednesday, extending a sharp rally that has pushed the stock up as much as 147% since Monday. The surge comes after a combination of a major commercial win and modest improvements in financial results.

The primary catalyst was Amesite’s announcement that it secured its largest enterprise customer to date for its AI-native NurseMagic documentation platform. The contract covers an approximately 2,700-patient census, with the unnamed client deploying the system across its workforce to streamline clinical workflows and integrate electronic medical record (EMR) and electronic visit verification (EVV) systems.

The company said the rollout is designed to reduce administrative workloads that can consume up …

Full story available on Benzinga.com

This post was originally published here
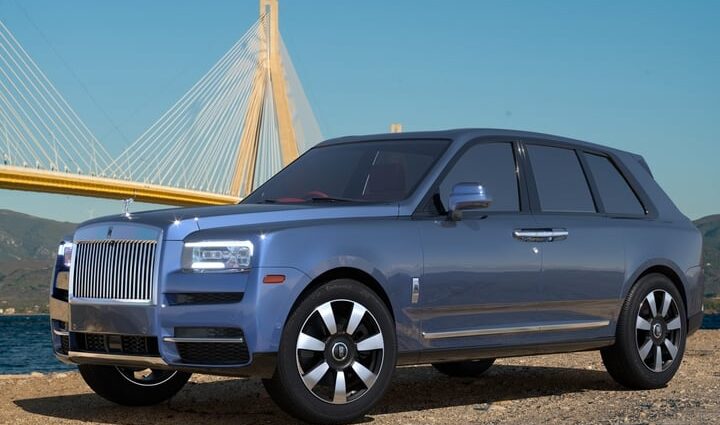
A $400,000 Rolls-Royce became a short-lived lesson in luxury for one NBA star.

Letting go of the SUV after about a month made more sense than keeping up with the lease payments, Indiana Pacers guard Tyrese Haliburton said recently on the “It Is What It Is” podcast.

“I’m not even a car guy,” he said.

The conversation also touched on Haliburton’s playoff heartbreak, Achilles injury recovery, money habits and expectations for the Pacers’ future.

Don’t Miss:

The Lease Payment Changed Everything 

Haliburton has tried to be responsible with money since signing his five-year contract extension worth up to $260 million with the Pacers in 2023, but the Cullinan became the purchase that stood out most.

The monthly cost became harder to ignore. “Man, I got tired of seeing that lease payment come across my bank statement,” Haliburton said on the podcast. “I got rid of it like a month ago. I said, ‘Man, I’m tired of this.'”

Even with that purchase, Haliburton did not frame his spending as reckless overall. For the most part, he said, he has tried to “live correctly.”

Trending: 1.5M+ Users. $29M Raised. Pre-IPO Shares Still at $0.72 — Learn How to Invest Before the Deadline

How Fast Everything Changed For Haliburton 

The conversation later shifted from finances to the difficult recovery process that followed Haliburton’s torn right Achilles tendon during Indiana’s playoff run last June. 

“It was just more so about the heartbreak of being in that situation somewhere you dream of being at your whole life and it just kind of get ripped out of your hand so fast,” Haliburton said on the podcast.

He said the injury changed daily life almost immediately. After being one game away from an NBA championship, he needed help showering, getting dressed and moving around normally. 

Watching basketball also became difficult during his recovery. Haliburton said he avoided old playoff games and struggled at times to watch the NBA because it reminded him he could not play. 

See Also: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

Haliburton’s Confidence Never Really Changed

Haliburton pointed to a longer offseason, more recovery time for players and his own return for the 2026-27 season while discussing what comes next for Indiana.

“I think we’re going to be one of the best teams in the East competing for a championship to be honest,” Haliburton said on the podcast. “I know who I am, and people know who I am, so we’ll be ready.”

As athletes and young high-income earners navigate …

Full story available on Benzinga.com

This post was originally published here
TJX Companies (NYSE:TJX) held its first-quarter earnings conference call on Wednesday. Below is the complete transcript from the call.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://edge.media-server.com/mmc/p/wg9zjttx/

Watch the full earnings call below:

Summary

TJX Companies reported first-quarter fiscal 2027 results with sales, profitability, and earnings per share exceeding expectations; comp sales rose 6%.

The company increased its full-year sales and profitability outlook, driven by strong performance across all divisions, including notable growth in apparel and home categories.

Strategic initiatives include expanding the global footprint, enhancing marketing strategies targeting younger demographics, and leveraging a diverse merchandise mix.

Operational highlights include a 9% comp sales increase at HomeGoods and a successful store opening in Spain, indicating international growth potential.

Management emphasized strong execution and the potential to capture additional market share, with plans to open more stores and invest in marketing and talent development.

Full Transcript

OPERATOR

Ladies and gentlemen, thank you for standing by. Welcome to The TJX company’s first quarter fiscal 2027 financial results conference call. At this time, all participants are in listen only mode. Later, we will conduct a question and answer session at that time. If you have a question, you will need to press star one. As a reminder, this conference is being recorded May 20, 2026. I would like to turn the conference call over to Mr. Ernie Herman, Chief Executive Officer and President of the TJX Companies. Please go ahead sir.

Ernie Herman (Chief Executive Officer and President)

Thanks Ted. Before we begin, Deb has some opening comments.

Deb

Thank you Ernie and good morning. Today’s call is being recorded and includes forward looking statements about our results and plans. These statements are subject to risks and uncertainties that could cause the actual results to vary materially from these statements, including, among others, the factors identified in our filings with the sec. Please review our press release for a cautionary statement regarding forward looking statements as well as the full safe harbor statements included in the Investor section of our website tjx.com we have also detailed the impact of foreign exchange on our consolidated results and our international divisions in today’s press release and in the investor section of tjx.com along with reconciliations to non GAAP measures we discuss. Thank you and now I’ll turn it back over to Ernie.

Ernie Herman (Chief Executive Officer and President)

Good morning. Joining me and Deb on the call is John. I want to begin by thanking our global associates for their hard work. I truly appreciate their ongoing commitment to both TJX and to our customers. Now to an overview of our first quarter results. I am extremely pleased with our excellent first quarter results. First quarter sales, profitability and earnings per share were all well above our expectations. Overall comp sales were up an outstanding 6%. I am particularly pleased that each of our divisions delivered strong comp sales growth and drove increases in customer transactions. With our above planned first quarter sales, we are raising our full year sales and profitability outlook. John will give some more detail about our first quarter results and full year guidance in a moment. Our terrific first quarter performance is a testament to the strong execution across the company. Our global teams work together as one TJX to offer customers across a wide demographic excellent values in an exciting treasure hunt shopping experience every day. I am confident that our values and merchandise assortment resonated with consumers across all of our retail banners and that each of our divisions grew their customer base. Looking ahead, the second quarter is off to a good start and we have many initiatives underway that we believe can continue to drive sales and customer traffic. Availability of quality branded merchandise continues to be outstanding and we are in a great position to take advantage of the plentiful opportunities we’re seeing in the marketplace. Longer term, we are energized by the opportunities we see to continue driving sales and profitability and expanding our global footprint and gaining market share in the US and internationally. Now I’ll turn the call over to John to cover our first quarter results in more detail.

John

Thanks Ernie. I also want to add my gratitude to all of our global associates for their continued hard work and commitment to TJX. Now I’ll share some additional details on the first quarter versus last year as Ernie mentioned, our first quarter consolidated comp sales increased 6% which is well above our plan. Our first quarter comp was driven equally by a higher average basket and an increase in customer transactions. Further, we saw very strong comp sales increases in both our apparel and home categories. Pretax Profit margin was 12%, up 170 basis points and well above our plan. Gross margin was 31.3% up 180 basis points. This increase was primarily driven by an increase in merchandise margin, a benefit from favorable inventory and fuel hedges and expense leverage on sales. SGA was 19.5%, unfavorable by 10 basis points. Net interest income was neutral to pretax profit margin versus last year. All this led to diluted earnings per share of $1.19 up 29% and well above our plan. First quarter pretax profit margin and diluted earnings per share were both well above our plan. This was primarily due to expense leverage on our above planned sales, favorable fuel hedges and stronger than expected merchandise margin. Now to our first quarter divisional performance. Once again, we are extremely pleased that every division delivered strong comp sales growth and saw increases in customer transactions. At Marmax, comp sales grew an outstanding 6% and segment profit margin increased 100 basis points to 14.7%. Comp sales in both Marmax’s apparel and home categories were strong. Also, we were very pleased with the broad strength of comp sales across each of Marmax’s region and income demographics at our Sierra stores and U.S. e commerce sites which we report as part of this division comp we saw a very strong comp increase. We continue to see excellent opportunities to keep growing Marmax, our largest division across the U.S. at HomeGoods, comp sales increased a remarkable 9%. Similar to Marmax, HomeGoods saw strong comp sales increases across each of their region and income demographics. Segment Profit margin increased 270 basis points to 12.9% HomeGoods offers consumers an exciting, eclectic assortment of merchandise sourced from around the world, all at great value. We believe our HomeGoods and HomeSense banners are highly differentiated from other home fashion retailers and would be very hard for others to replicate. We see a tremendous opportunity to grow this division further and believe we are very well positioned to capture additional share with of the US home market. TGX Canada comp sales were up an outstanding 7% segment profit margin on a constant currency basis grew 100 basis points to 11. Across all three of our Canadian banners. We are Canada’s only major off price retailer and we believe we are well positioned to keep growing our customer base across across the country. At TJX International Comp sales increased a strong 4%. We were pleased with our sales growth in Europe and the strong sales increase in Australia. TJX International segment profit margin on a constant currency basis improved by 40 basis points to 4.7% during the quarter. We opened our first store in Spain and the customer response was terrific. We are very excited about our growth plans in Spain and remain confident in the opportunities we see to capture additional market share in both Europe and Australia. Moving to inventory first quarter balance sheet inventory was up 8% and inventory on a per store basis was up 7%. We feel great about our inventory levels and the excellent availability we’re seeing in the marketplace. As to our capital allocation, we continue to reinvest in the growth of our business while returning $1.1 billion to shareholders through our buyback and dividend programs in the first quarter. As we mentioned in our press release this morning, we have increased our fiscal 2027 share buyback guidance to a range of 2.75 billion to $3 billion, which will allow us to buy more opportunistically at favorable stock price levels. Now I’ll turn it back to Ernie.

Ernie Herman (Chief Executive Officer and President)

Thanks John. I would now like to delve into the ways we are playing offense to drive our top line and gain larger share of both the apparel and home fashions markets. First is how we’re approaching our marketing this year. Many of our retail banners are launching fresh new campaigns and exciting partnerships that continue to reinforce our value leadership. Our marketing targets a broad demographic, including younger shoppers through a wide variety of channels with a strong emphasis on digital media. We are continuously testing new ways to engage today’s consumers to demonstrate our value proposition, highlight the joy of shopping our stores and build loyalty among our customers. I am very pleased with the results we have seen so far and I’m confident our marketing Strategy will continue to attract new shoppers and encourage existing shoppers to visit more often. Next is our exciting mix of merchandise at great value every day. This all starts with our team of more than 1,400 buyers who are in the marketplace. Throughout the year. They work with our vast vendor network to find the best assortments at the best values across good, better and best brands. Our planning and allocation team does the terrific work of allocating the goods based on the demographic characteristics of each individual store. This allows us to offer a curated mix of exciting categories and brands that we believe will resonate with shoppers every time they visit. Whether it’s their first time shopping with us or they are a long time customer availability of merchandise is off the charts. In addition to our long term mutually beneficial relationships, we typically add thousands of new vendors each year. We work hard to be the first call for vendors when they have excess goods. As TJX continues to open stores, grow its top line and attract broad range of shoppers, we believe we are becoming even more appealing to vendors who are looking to clear inventory and and grow their business further. With our global footprint, we can introduce brands to new geographies around the world. As we pursue our future growth plans, we are extremely confident there will be more than enough merchandise to support our growth. In fact, the bigger we have become, the more availability we see. Next is the in store shopping experience and investing in our stores through our remodeling program and new prototypes. We believe keeping our stores refreshed helps drive consistent comp sales growth across different store ages. Further, we continue to invest in our store payroll to maintain a high level of customer satisfaction and are always looking at ways to improve the store environment and the speed of checkout. All of this has led to very strong customer satisfaction scores at each of our divisions, moving to our global store growth and increasing our exposure to our price around the world. We now operate stores in 10 countries and we see the potential to add another 1700 plus stores in these countries alone. With our existing banners again, we recently opened our first store in Spain and customer reaction has been outstanding. We are on track to open additional stores in Spain this year and are excited about our growth potential in that country. In Mexico, we are very pleased with our joint venture with AXO and the Promota stores. The teams are working together very effectively combining our merchandising expertise with their local operating knowledge. While still early, we are very optimistic about the long term potential in Mexico regarding our investment in brands for less in the Middle East. Beyond the current geopolitical environment we remain confident in the long term opportunity for that business. Lastly, and most importantly, we continue to play offense by investing in the teaching and training of our associates. I strongly believe the tenure and depth of our off price knowledge and expertise within TJX is unmatched. We have a very deep bench and are laser focused on developing the next generation of TJX leaders in order to maintain continuity in the business for many years to come. I am so proud of our culture which I believe will continue to be a major contributor to our success going forward. Summing up we are extremely pleased with our performance in the first quarter and with the opportunities we see for our business going forward. Our teams across our entire organization are driving excellent execution of our off price fundamentals. We feel great about our plans for the remainder of the year and as always, we will strive to beat them throughout our 50 year history. We believe that the flexibility and resiliency of our business model and our wide customer demographic have been tremendous advantages that have allowed us to successfully navigate through many types of macroeconomic and retail environments. We are convinced that our strategies to play offense and the characteristics of our business set us up very well to capitalize on the market share and growth opportunities that we see for many years to come. Now I’ll turn the call back to John to cover our second quarter and full year guidance and then we’ll open it up for questions.

John

Thanks again Ernie. I’ll start with our second quarter guidance. We are planning overall comp sales to increase 2 to 3%. Consolidated sales to be in the range of 15 to $15.1 billion, up 4 to 5%. Pretax profit margin to be in the range of 11.4 to 11.5% flat to up 10 basis points versus last year’s 11.4%. Gross margin to be in the range of 30.9 to 31% which would be up 20 to 30 basis points versus last year’s 30.7%. We are expecting an increase in merchandise margin in the second quarter SG&A to be 19.6% 10 basis points unfavorable versus last year. This would be due to incremental store wage and payroll costs. We’re assuming net interest income of 28 million which we expect to be neutral to the second quarter. Pre tax. Also assumes a tax rate of 24.9% and a weighted average share count of approximately 1.12 billion shares. As a result of these assumptions, we expect second quarter diluted earnings per share to be in the range of $1.15 to $1.17, up 5 to 6% versus last year’s $1.10. Moving to the full year, we now expect overall comp sales growth of 3 to 4%. We are increasing our full year consolidated sales guidance to be in the range of 63.2 to $63.7 billion, up 5% to 6% versus last year. We are increasing our full year pretax profit margin guidance to be in the range of 11.9 to 12% up 20 to 30 basis points versus last year’s adjusted 11.7%. Moving to gross margin, we now expect it to be in the range of 31.2% to 31.3%, up 20 to 30 basis points versus last year’s adjusted 31%. We continue to expect full year SGA to be 19.5% flat versus last year’s adjusted 19.5%. We’re now assuming net interest income of about $122 million, which we expect to be neutral to our full year pretax profit margin versus last year. Our full year guidance assumes a tax rate of 24.7% and a weighted average share count of approximately 1.12 billion shares. As a result of these assumptions, we are increasing our full year diluted earnings per share to be in the range of $5.08 to $5.15. This will represent a 7 to 9% increase versus last year’s adjusted $4.73. I want to mention that we did not flow the entire first quarter pre tax profit and earnings per share beat to the full year as we are now planning current fuel prices to remain in place for the rest of the year. Of course, if fuel prices come down from their current levels, we would expect to see favorability to our full year profitability plan. In closing, I want to reiterate that we are excited about the growth and market share opportunities we see in the near and long term. We are in an excellent position to …

Full story available on Benzinga.com

This post was originally published here
Oklo Inc. (NYSE:OKLO) stock is surging on Wednesday. Traders are aggressively buying the dip following a steep multi-session decline tied to the company’s first-quarter earnings report.

Investors Buy The Post-Earnings Dip

The nuclear energy player’s stock tumbled 30.64% from $78.13 on May 11 to $54.19 on Tuesday.

The slide accelerated after Oklo reported a first-quarter net loss of $33.07 million and an operational loss of $51.25 million on Tuesday after the closing bell.

Despite a net loss of 19 cents per share—which beat analyst estimates of a 20-cent loss—shares initially dipped. However, day traders are capitalizing on the Wednesday discount, driven by Oklo’s robust liquidity. The company exited the first quarter with $1.6 billion in cash and cash equivalents …

Full story available on Benzinga.com

This post was originally published here
Driven Brands Holdings Inc (NASDAQ:DRVN) reported upbeat earnings for the fourth quarter on Tuesday.

The company posted quarterly earnings of 34 cents per share which beat the analyst consensus estimate of 25 cents per share. The company reported quarterly sales of $460.102 million which beat the analyst consensus estimate of $455.500 million.

Driven Brands said it sees FY2026 adjusted EPS of $1.15-$1.25, versus market estimates of $1.27. The company sees sales of $1.950 billion-$2.050 billion, versus expectations of $2.030 billion.

“Driven Brands delivered a solid fourth quarter and full year, anchored by Take 5’s 3.7% same store sales growth, our 22nd consecutive quarter of growth,” said Danny Rivera, President and Chief Executive Officer. “In 2025, we took important steps to strengthen our foundation, including …

Full story available on Benzinga.com

This post was originally published here
Divorcing a basketball superstar usually comes with tabloid fireworks, courtroom drama, and enough attorney billable hours to buy another mansion. Shaquille O’Neal and Shaunie Henderson went another direction entirely.

There were no public screaming matches over luxury estates or endless headlines about who got what. According to Henderson, the goal was far simpler: leave the marriage with peace of mind intact and make sure the kids stayed protected.

“Despite my lawyers’ advice, I didn’t want anything from Shaquille. I just wanted out,” Henderson wrote in her memoir, “UNDEFEATED: Changing the Rules and Winning on My Own Terms,” published in 2024. “I kept telling him, ‘You don’t have to give me anything, just take care of the kids.'”

Don’t Miss:

  • Explore whether your retirement strategy is optimized for income, taxes, and long-term withdrawals — take the AdviserMatch quiz today.
  • This Under-$1 Pre-IPO AI Company Is Still Open to Retail Investors — Learn More

That perspective gave their split a very different tone from the celebrity divorces that usually turn into financial cage matches played out in public.

Shaunie Henderson Walked Away From The Lifestyle

Henderson said she made the decision early in the divorce process not to pursue a drawn-out battle over wealth or assets, even as attorneys encouraged her to think differently.

“I told my divorce attorneys I didn’t want to fight with Shaquille. I just wanted him to take care of his kids. I didn’t care about anything else,” she wrote. “I had also told them I didn’t want a cent of Shaquille’s money, and I meant it.”

That meant turning away from a lifestyle most people would spend a lifetime chasing.

“I wanted to be free to have the life I wanted, on my terms,” Henderson wrote. “I’d turned my back on mansions, luxury cars, private jets, and a lifetime of wealth and privilege.”

The couple filed for divorce in 2009, and it was finalized in 2011. Henderson made clear that child support and stability for the children mattered most, while the larger focus centered on honesty, peace, and moving forward without resentment.

“The only other thing I wanted was peace of mind,” she wrote. “I was hungry for it.”

Trending: Explore Jeff Bezos-backed Arrived Homes and see how investors are earning passive rental income — now with a limited-time 1% bonus match for new investors.

Major life transitions like divorce, remarriage, estate planning, or restructuring finances can also bring complicated financial decisions. Consulting a financial advisor can help families navigate those changes with clearer long-term planning and fewer emotionally driven mistakes.

Shaq Publicly Took The Blame

O’Neal has never tried to publicly rewrite the story of why the marriage ended. The NBA Hall of Fame center took responsibility for the collapse of the relationship, saying, “I was bad. She was awesome, he said on the “The Pivot Podcast” in 2022. “It was all me.”

He later described living a “double life” and admitted he failed to protect his vows despite having what he viewed as an ideal family situation at home. O’Neal also spoke openly about the emotional fallout after the divorce, describing the loneliness of returning to an empty house after years of constant family noise and activity.

In later …

Full story available on Benzinga.com

This post was originally published here
Snowflake Inc. (NYSE:SNOW) stock is trading lower on Wednesday. The decline reflects a natural cooling-off period for the cloud data analytics provider following a rapid short-term rally, rather than a single catastrophic catalyst.

• Snowflake stock is among today’s weakest performers. What’s weighing on SNOW shares?

Pre-Earnings Volatility Hits

Traders are bracing for heightened volatility ahead of Snowflake’s first quarter of fiscal 2027 earnings report, scheduled for release on May 27.

The stock surged 12.46% from $150.76 last Thursday to $169.55 on Tuesday, prompting some near-term profit-taking.

Wall Street Estimates

Analysts estimate Snowflake will post earnings per share of 14 cents on quarterly revenue of $1.32 billion. Notably, the company carries strong fundamental momentum into …

Full story available on Benzinga.com

This post was originally published here
A retiree created a wide-ranging discussion after sharing how managing money in retirement has become far more complicated than expected.

The poster explained that after decades with a money manager, they eventually discovered they were paying a 1% management fee while also being charged commissions and high-load mutual fund fees. After taking control of their investments about 15 years ago, they said they had “done quite well” on their own. But retirement planning itself has become increasingly difficult.

“I have to admit, it’s getting real complex in retirement, with Medicare, [Income-Related Monthly Adjustment Amount], Roth conversions, Social Security and annuity income, and deciding where to pull money from when we need it,” the retiree wrote on Reddit.

Don’t Miss:

Many Retirees Prefer To Manage Their Own Money

The post quickly turned into a larger debate about whether retirees should manage their own finances or hire professionals.

Many commenters said they handle everything themselves, often after disappointing experiences with financial advisors.

One retiree said they had “a very bad experience” with an advisor who made excessive trades and charged fees on each transaction. Another commenter said they were “fired” by their money manager after questioning poor returns and high fees.

“I have killed the market investing in growth stocks,” the commenter wrote, adding that taking over their family’s portfolio was “the best thing we ever did.”

Trending: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

Others Say Advisors Provide Peace Of Mind

Not everyone agreed that self-management is the best path.

A large group of retirees said they gladly pay advisory fees because they don’t want retirement to feel like a second job.

“The last thing I want to spend time on is managing them now,” one retiree wrote after turning their accounts over to Fidelity.

Another commenter said using a financial advisor allows them to “sleep soundly every night.”

Several people said financial advisors help with more than investment performance. They pointed to estate planning, taxes, trusts, required minimum distributions and helping spouses who may not feel comfortable managing money alone.

See Also: See if you can cut your monthly debt payments by 40% — check your eligibility in minutes.

A recurring concern throughout the discussion was cognitive decline.

“Cognitive decline is the elephant in the room that no one wants to talk about,” one retiree wrote. “Financial management seems to be one of the first skills to deteriorate.”

Many retirees said they are simplifying accounts, consolidating investments and involving spouses or …

Full story available on Benzinga.com

This post was originally published here
Ellington Credit (NYSE:EARN) reported fourth-quarter financial results on Wednesday. The transcript from the company’s fourth-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/8wm3cryv/

Summary

Ellington Credit experienced a decline in NAV during the first quarter due to volatility in the CLO market, particularly impacting CLO equity assets.

The company issued $54 million of 8.5% five-year senior unsecured notes in March to capitalize on market dislocations and has substantially deployed these funds into new opportunities.

Management remains optimistic about future performance, citing improved market conditions in the second quarter and a strong monthly economic return of nearly 7% in April.

Ellington Credit’s portfolio repositioning focuses on CLO mezzanine debt for stability and CLO equity for upside potential, supported by active trading and strategic hedging.

The company aims to enhance its net investment income and dividend coverage by rotating investments and maintaining a disciplined approach to risk management.

Full Transcript

Aladdin Chalet (Associate General Counsel)

Thank you. Before we begin, I’d like to remind everyone that this conference call may include forward-looking statements within the meaning of the safe harbor provisions of the Private Security Litigation Reform act of 1995. These statements are not historical in nature and involve risks and uncertainties detailed in our registration statement on Form N-2. Actual results may differ materially from these statements so they should not be considered to be predictions of future events. The Fund undertakes no obligation to update these forward-looking statements. Joining me today are Larry Penn, Chief Executive Officer of Ellington Credit Co. Greg Borenstein, Portfolio Manager and Chris Mernoff, Chief Financial Officer. Our earnings conference call presentation is available on our website ellingtoncredit.com today’s call will track that presentation and all statements and references are qualified by the important notice and endnotes at the back of the presentation. With that, I’ll turn it over to Larry.

Larry Penn (Chief Executive Officer)

Thanks, Aladdin and good morning everyone. We appreciate your time and interest in Ellington Credit Co. Which we often refer to by its New York stock exchange ticker Ellington Credit for short. Please turn to slide 3. The first calendar quarter of 2026 was marked by continued volatility in the CLO market. As we previously communicated in our monthly portfolio updates. The broader market environment exerted significant pressure on asset valuations and led to a decline in our nav. But our active trading and up in the capital stack bias once again drove our outperformance versus Peers we believe that the first quarter largely represented a technical dislocation that reset valuations and expanded the opportunity set rather than a fundamental deterioration in underlying credit quality. Much of the asset valuation declines in the sector stemmed from yield spread widening and heavy selling pressure in clo, mezzanine and equity tranches as well amid thin liquidity and concerns around software sector exposure as opposed to any broad based weakening in borrower fundamentals. Importantly, we were able to issue debt capital at the end of March which enabled us to move quickly to capitalize in this opportunity rich environment by deploying those proceeds promptly and opportunistically. Market conditions have subsequently improved so far in the second quarter and this has been a tailwind for what is shaping up to be a strong quarter. I will cover the details of that debt capital raise and deployment as well as our performance in April shortly. Let’s start by reviewing our results for the first quarter. The quarter began on a constructive note with credit spreads tightening and leveraged loan prices rising early in the new year. But that initial momentum faded in late February as concerned over AI driven disruption in the software sector, which is a small but meaningful component of most CLO collateral pools, triggered a sharp decline in those credits. By quarter end, U.S. and European leveraged loan prices had fallen by more than 2% from their January peaks. This weakness, amplified by geopolitical tensions, fueled a broader risk off sentiment that widened spreads on CLO debt tranches as shown on slide three. While the senior AAA through single A rated CLO tranches held up relatively well, CLO mezzanine debt came under significant selling pressure in February and March with lower rated tranches, particularly double B rated tranches experiencing sharp yield spread. Widening CLO equity faced multiple headwinds including compressed excess spread from a loan repricing wave in January, wider market clearing yields and concerns surrounding those lower quality loan borrowers. As estimated by Nomura Research,, the median CLO equity return for the quarter was negative 13%. That said, many valuation declines, particularly in CLO equity, occurred on light trading volume and in our view reflected technical market dislocations and liquidity driven price weakness rather than deterioration in underlying fundamentals or broad based credit impairment for Ellington Credit. Unrealized losses on CLO equity assets were the primary driver of the NAV decline in the first quarter, more than offsetting net investment income, trading gains and gains from mezzanine tranche redemptions. Turning to our capital structure in late March the fund issued $54 million of 8.5% five year senior unsecured notes. This transaction strengthened our balance sheet by extending our liability profile, adding non mark to market financing and providing dry powder to capitalize on a dislocated market. At March 31, our CLO portfolio totaled $308 million and we held a sizable $58 million in cash. Consistent with our positioning throughout the volatility, we prioritized CLO mezzanine debt over equity during the quarter, favoring the subordination levels and structural protections afforded by debt tranches while staying disciplined in our hedging strategy. As illustrated on slide 10, we increased our credit hedge portfolio to approximately $187 million of high yield CDX notional equivalents at March 31, up from $175 million at year end. With overall corporate credit spreads remaining tight relative to CLO spreads, we were able to add this protection at compelling levels on both a relative value basis and an absolute value basis. Following the significant spread widening in the latter part of the first quarter, market conditions improved materially in April and into May. Real money buyers have come back into the market, improving liquidity and driving CLO yield spreads tighter. From our standpoint, the sell off has reinvigorated the opportunity set. Prepayments and repricings have slowed, partially relieving the excess spread compression experienced in 2025. Investment yields have moved higher and CLO managers can again build par and preserve excess spread by acquiring performing loans at discounted prices, a dynamic that enhances the long term return potential for CLO equity investors. In addition, as a meaningful portion of our CLO equity portfolio exits, its non call period refinancing and reset opportunities should enhance underlying cash flows, further improving our asset yields and supporting future growth in in our net investment income. These factors created an attractive market environment for deployment. We responded to this favorable environment by rapidly investing the majority of our dry powder into new opportunities with deployment substantially complete by the end of April. Improved secondary market liquidity has also allowed …

Full story available on Benzinga.com

This post was originally published here
T1 Energy Inc (NYSE:TE) stock is trading higher on Wednesday as shares experience a recovery. The price action follows a highly volatile week marked by alternating institutional optimism and aggressive short-seller allegations.

• T1 Energy shares are powering higher. Why are TE shares rallying?

High Short Interest Fuels Squeeze Potential

Short interest in T1 Energy increased during the last reporting period, rising from 42.29 million to 44.16 million shares. This means short sellers have borrowed and sold 27.26% of the company’s publicly available shares. Based on the recent average volume of 15.49 million shares traded per day, it would take 2.85 days for these short sellers to close out their positions.

Shaking Off Fuzzy Panda Allegations

The Wednesday rally serves as a sharp reversal from Tuesday. TE shares plunged 9.14% to $6.36 after Fuzzy Panda Research released a short report.

The …

Full story available on Benzinga.com

This post was originally published here
CorVel (NASDAQ:CRVL) released fourth-quarter financial results and hosted an earnings call on Wednesday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://event.choruscall.com/mediaframe/webcast.html?webcastid=7c1X0Jk8

Summary

CorVel achieved a 7% revenue increase for the March quarter, reaching $249 million, and a 17% rise in earnings per share year-over-year to $0.61.

The company is experiencing strong growth in Network Solutions, with double-digit revenue and profit growth, bolstered by large payer engagements and post-payment recoveries.

CorVel is investing in technology and AI to enhance operational efficiency, focusing on automation and AI-enabled workflow enhancements to reduce manual processes.

New bookings increased by 56% year-over-year, with significant multi-year contracts expected to drive revenue and profit growth in the latter half of the year.

Strategically, the company is expanding its prepay solutions within the SARIS platform, aligning with market trends towards proactive payment accuracy and cost management.

CorVel’s fiscal year 2026 net income rose by 14% to $110 million, with operating margins improving to 15%, supported by reduced general administrative costs.

The company repurchased 872,744 shares during the fiscal year, reflecting strong operating cash flow and a robust, debt-free balance sheet.

Full Transcript

OPERATOR

Greetings and welcome to the CorVel Quarterly Earnings Report. At this time all participants are in listen only mode. A question and answer session will follow a formal presentation and you may be placed into question queue at any time by pressing star 1 on your telephone keypad. As a reminder, this conference is being recorded and if anyone should require operator assistance, please press Star zero. It’s now my pleasure to turn the call over to President and CEO Michael Combs. Please go ahead sir. Thank you.

Michael Combs (President and CEO)

Good morning. Thank you for joining us to review CorVel’s March quarter and fiscal year results. Brian Nichols,, CorVel’s Chief Financial Officer, is on the call with me today. Today I will review business performance, the current environment and market trends, and progress on product and service offerings. But let’s start with Brian providing an overview of the March quarter and fiscal year results.

Brian Nichols (Chief Financial Officer)

Thank you, Michael and good morning everyone. The March quarter revenues were $249 million, an increase of 7% compared to 232 million in the March 2025 quarter. Earnings per share for the quarter ended March 31, 2026, or $0.61, up from $0.51 in the same period of the previous year. For the fiscal year 2026, revenues were $959 million, up 7% from 896 million in the prior fiscal year, and earnings per share was $2.14, an increase of 17% compared to $1.83 for the fiscal year ended March 31, 2025. The effective tax rate increased compared to the prior year, which included a discrete benefit from stock option exercises that did not recur at similar levels for the fiscal year. Network Solutions delivered strong results with double digit revenue and profit growth driven by continued momentum across its offerings and solid execution in both property and casualty and commercial health. Results within Network Solutions included the impact of certain one time events primarily within Cirrus, which contributed in part to elevated revenue and profit during the period and added $0.02 of earnings per share. This performance was driven by accelerated post payment recoveries associated with large payer engagement reflecting a timing related benefit. Importantly, this engagement along with these additional large payer wins is expected to contribute to ongoing revenue and profit tailwinds as these programs scale and mature. Patient management generated low single digit revenue and profit growth reflecting a stable demand environment and consistent focus on operational efficiency. The company is making targeted investments to enhance service quality and consistency as a key differentiator while advancing systems and technology to support more scalable delivery. Personnel levels increased during the period to support service delivery and implementation activity reflecting near term execution priorities. These levels are expected to normalize as deployments mature and as automation and AI enabled workflow enhancements are deployed. Through the remainder of the year and into 2027, the company expects to realize sustained productivity gains, reduce reliance on manual processes and further improve operating leverage. Overall, the Company’s balanced portfolio positions it to deliver scalable growth through Network Solutions while driving increased differentiation and future growth in patient management through ongoing …

Full story available on Benzinga.com

This post was originally published here
POET Technologies Plc (NASDAQ:POET) witnessed a sharp decline followed by a recovery in its stock price on Wednesday. Traders actively sold off the equity in the market following the closing of a massive $400 million registered direct offering on Monday.

The capital raise involved issuing 19.05 million new common units and an equal number of warrants to a single institutional investor at $21 per unit.

Short Seller Alleges Dead Partnerships

Compounding the volatility, short-seller firm Night Market Research disclosed a bearish position against the semiconductor company on Friday. In its published note, the firm alleged that POET has systematically overstated its partnerships and misled investors about its commercialization timeline.

Night Market Research explicitly claimed that key corporate relationships are defunct, stating, “Celestial AI / Marvell Technology Inc (NASDAQ:MRVL) …

Full story available on Benzinga.com

This post was originally published here
Nvidia Corp. (NASDAQ:NVDA) is set to report earnings after the close Wednesday, and options traders are positioning for a sizable move in the AI chip leader’s stock.

Expectations remain high heading into the print. Consensus estimates call for adjusted earnings of $1.76 per share on revenue of $78.8 billion, according to Benzinga Pro data.

But for Nvidia, the question is rarely whether the company can beat Wall Street estimates. It is whether the beat, and more importantly the guidance, will be strong enough to satisfy investors.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Did Jim Cramer Call The Top On ServiceNow Stock?

This post was originally published here
President Donald Trump said the U.S. is in the “final stages” of talks to end the war with Iran, and that he would give the diplomatic effort “one shot.”

Vice President JD Vance echoed the optimism, saying the administration has made “a lot of progress” and that Iran wants a deal, framing renewed military action as “option B.”

It is not the first time the end has looked close. Trump has set and reset at least four “final” deadlines for Iran since March 21, each time threatening strikes before backing down.

Iran’s Revolutionary Guard, meanwhile, warned Wednesday it would retaliate “beyond the region” with “crushing blows in places you do not expect” if attacks resume, according to the semi-official Tasnim news agency.

The stakes are visible at the pump.

The average US gas price is $4.55, up more than 43% from a year ago, as the Hormuz disruption keeps fuel costs near multi-year highs.

A South Korean supertanker carrying 2 million barrels of crude passed through the Strait of Hormuz …

Full story available on Benzinga.com

This post was originally published here
Target Corporation (NYSE:TGT) stock fell Wednesday despite the retailer reporting first-quarter results that topped Wall Street estimates and raising its full-year sales outlook, as investors focused on management’s warning of tougher year-over-year comparisons in the quarters ahead.

Quarterly Earnings Beat Expectations

The retailer reported first-quarter adjusted earnings of $1.71 per share, beating analyst estimates of $1.46. Sales rose 6.7% year over year to $25.44 billion, ahead of the Street consensus of $24.64 billion.

Comparable sales increased 5.6% in the quarter, supported by broad-based growth across merchandise categories and sales channels. Comparable traffic rose 4.4% from the prior-year period.

Target said net sales increased across all six core merchandising categories. Digital comparable sales climbed 8.9%, driven by more than 27% growth in same-day delivery through Target Circle 360.

Non-merchandise revenue increased nearly 25%, aided by higher Roundel advertising revenue, Target Circle 360 membership revenue and growth in the Target+ marketplace.

CEO Commentary And Margin Expansion

“As we look ahead, we’re focused on staying disciplined and …

Full story available on Benzinga.com

This post was originally published here
U.S. stocks traded higher midway through trading, with the Dow Jones index gaining around 1% on Wednesday.

The Dow traded up 1% to 49,856.91 while the NASDAQ gained 1.27% to 26,199.40. The S&P 500 also rose, gaining, 0.87% to 7,417.31.

Leading and Lagging Sectors

Information technology shares jumped by 0.8% on Wednesday.

In trading on Wednesday, consumer staples stocks fell by 1.4%.

Top Headline

Lowe’s Companies, Inc. (NYSE:LOW) posted upbeat first-quarter earnings and revenue.

The home improvement retailer reported first-quarter fiscal 2026 adjusted EPS of $3.03, beating analyst estimates of $2.97, while revenue of $23.1 billion topped estimates of $22.98 billion.

Equities Trading UP
           

  • Immunovant Inc (NASDAQ:IMVT) shares shot up 28% to $33.55 following fourth-quarter results.
  • Shares of Roivant Sciences Ltd (NASDAQ:ROIV) got a boost, surging 12% to $31.72 after the company …

Full story available on Benzinga.com

This post was originally published here
On Wednesday, Analog Devices (NASDAQ:ADI) discussed second-quarter financial results during its earnings call. The full transcript is provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/85zqim66/

Watch the full earnings call below:

Summary

Analog Devices reported record revenue of $3.62 billion in the second quarter, with a 15% sequential and 37% year-over-year increase, driven by strong performance in industrial and data center sectors.

The company highlighted its strategic focus on AI-driven computing, connectivity, autonomy, proactive healthcare, sustainable energy transition, and immersive consumer experiences.

Analog Devices announced the planned acquisition of Empower Semiconductor to enhance its power technology portfolio, targeting increased market share in the AI accelerator space.

The company expects third-quarter revenue to be $3.9 billion, with an operating margin of 49% and adjusted EPS of $3.30.

Analog Devices maintains a robust supply chain and capacity to handle growing demand, supported by internal and external manufacturing expansions.

Full Transcript

OPERATOR

Good morning and welcome to The Analog Devices Second Quarter Fiscal Year 2026 Earnings Conference Call which is being audio, webcast via telephone and over the web. I’d now like to introduce your host for today’s call, Mr. Jeff Ambrose, head of Investor Relations. Sir, the floor is yours.

Jeff Ambrose (Head of Investor Relations)

Thank you Jonathan and good morning everybody. Thank you for joining our SECond quarter fiscal 2026 conference call. Joining me today is ADI CEO and Chair Vincent Roesch and ADI CFO Richard Puccio. For anyone who missed the release, you can find it at investor.analog.com along with related financial schedules. The information we’re about to discuss includes forward looking statements which are subject to certain risks and uncertainties as further described in our earnings release, periodic reports and other materials filed with the SEC. Actual results could differ materially from the forward looking information as these statements reflect our expectations only as the date of this call, we undertake no obligation to update these statements except as required by law. References to gross margin, operating and non operating expenses, operating margin, tax rate, earnings per share and free cash flow and our comments today will be on a non GAAP basis which excludes special items when comparing our results to our historical performance. Special items are also excluded from prior periods. Reconciliations of these non GAAP measures to their most directly comparable GAAP measures and additional information about our non GAAP measures are included in today’s earnings release. References to earnings per share are on a fully diluted basis and with that I will turn the call over to ADI CEO and Chair Vincent Roesch.

Vincent Roesch (Chief Executive Officer and Chair)

Thanks very much Jeff and a very good morning to you all. Well, as you’ve seen by now, second quarter revenue, profitability and earnings per share finished above the high end of our guidance establishing new high-water marks for both revenue and for earnings. Despite the quarter’s heightened geopolitical tensions and ongoing macroeconomic challenges, we’re currently seeing record demand for our products and solutions. It’s at times like these when our dynamic hybrid manufacturing model performs. Our robust investments over recent years have enhanced the scale and the optionality of our supply chain, enabling ADI to address demand surges and capture upside. The combination of this supply agility and resilience and our robust R&D investments across core analog segments as well as digital software and AI form the foundation for our growing criticality to our customers. They also enable us to pursue areas that we believe offer the greatest future growth potential for ADI, namely AI driven computing and connectivity, autonomy, proactive healthcare, sustainable energy transition and immersive consumer experience. As I mentioned last quarter, our data center and ATE businesses are taking advantage of strong AI driven infrastructure investments to achieve new highs. These two businesses are on steep growth trajectories and as we move through 2026 our confidence in their continued growth into 27 is increasing. Another robust growth market for ADI is our aerospace and defence business which reached a new revenue high this quarter and where increased focus on national sovereignty concerns is accelerating. An already strong multi year growth path. In general, industrial, which includes ATE as well as aerospace and defense, is our most profitable business with 15 to 20 year average product life cycles. We continue to outperform in this space, so today I’d like to unpack more of that story for you by focusing on our industrial business beyond AT E and aerospace and defence, namely automation, electronic test and measurement, sustainable energy, health care and the broad market. Collectively, these markets have grown more than 40% in the first half of fiscal 26. Customers across these sectors are consuming more semiconductors with each new product generation and from a cyclical perspective, these businesses are still well below their prior cycle highs with lean channel inventories. This combination of secular and cyclical positioning along with strong demand signals gives us confidence that all of our industrial sectors are poised for continued strong growth in the coming quarters and indeed over the longer term. So now, going a little deeper into these markets, I’ll begin with our automation business. Numerous megatrends including the on shoring of advanced manufacturing and evolving labor dynamics are increasing demand for digital factories and next generation robots. The digital factory vision is unlocking new opportunities for ADI and our portfolio of high performance sensing, signal chain, power management and connectivity solutions. We’re enabling the edge intelligence and real time communication necessary in automated semiconductor fabs, biopharma data centers and other discrete and process manufacturing environments, for example. Additionally, as robots make up ever larger percentages of investments in factories and elsewhere, our higher value products and subsystems for content rich robotics are aiding automation’s fast recovery. Longer term humanoids and other advanced robotics modalities are steadily increasing our opportunity pipeline value. Overall, we believe we’re well positioned to continue capitalizing on automation’s tailwinds today and in the future as automation transitions to autonomy. Turning now to our electronic test and measurement or ETM business. While ATE systems are geared to enable efficient high volume manufacturing of chips and electronic systems, ETM supports end to end product development and delivery from R and D prototyping, debugging and validation all the way through mass production in areas such as AI, EVs and secure communications for example. ETM is a highly diversified performance driven market and ADI’s innovative RF mixed signal and PAR solutions have built our strong position in high value applications and are propelling our growth in our design pipeline as customers grapple with increasing levels of complexity and shrinking innovation cycles. Switching now to our energy business the continued evolution of consumption patterns due to deeper electrification and high performance computing, for example, is putting immense pressure on legacy electrical grids and creating profound challenges from energy generation to transmission, distribution, storage and of course consumption. Customers trust ADI to accurately monitor, meter and manage all levels of the grid. We reliably convert real world environmental and system data into digital information, delivering the essential edge intelligence, connectivity and power management solutions today’s systems require. Notably, we’re also leveraging our high performance battery management platform to support the energy storage systems that are increasingly crucial to a stable grid. Demand for our BMS portfolio from our ESS customers continues to be strong in 26, having grown more than 50% in fiscal 25. In short, our technology helps customers upgrade electrical infrastructure, ingest and manage the intermittency of renewable resources, and smooth the energy demand spikes from applications like EVs, AI and so on and so forth. As the trend of electrification accelerates and demand patterns continue to evolve, we believe energy will continue its growth trajectory for many, many years to come. Turning next to healthcare where technologies and solutions protect and save lives across both clinical and non clinical care settings each and every day we’re enabling the ongoing digitalization of clinical environments through the combination of our deep domain expertise and breadth of technological capabilities. Across hardware, software and advanced packaging, we’re seeing sector growth in for example advanced imaging, patient monitoring and surgical robotic applications where high performance driven solutions are further extending our leadership position. And as healthcare increasingly migrates beyond clinical to nonclinical environments, demand is accelerating for our wearable solutions for outpatient management of e.g. cardiopulmonary and metabolic conditions, essentially extending the digital network edge all the way to the surface of the human body. We’re driving double digit revenue growth in our healthcare market and we expect continued growth over the coming years due to increasing design ends with larger OEMs this year. Turning finally to our broad market industrial business which has returned to robust growth, this market encompasses a long tail of tens of thousands of established and emerging companies who are addressing a vast array of applications. The tremendous breadth of these customers needs aligns perfectly with the extensive scope of our diversified performance leading technologies and application ready solutions spanning center to cloud, nanowatts to kilowatts and antenna to bits. Now, before I conclude my remarks today, let me speak briefly about our planned acquisition of Empower Semiconductor, which will further augment our power technology portfolio and provide the final piece of our comprehensive grid to core power platform. With Empower we gain cutting edge proprietary integrated voltage regulator or IVR technology and silicon capacitors that enable us to offer true vertical power delivery to our customers. The extreme power density of Empower’s platforms eliminates customers needs for bulky external components, shrinks their power footprint by up to four times, slashes their data center compute power consumption by an estimated 10 to 15% and delivers the ultra fast transient response required by volatile AI workloads. This transaction will expand ADI’s total addressable market within the hypergrowth AI accelerator space and further solidify our position as an indispensable hardware partner in the drive for maximum compute density per server rack. And we look forward to sharing more of our vision in this exciting space when the transaction closes a little later following regulatory approval. So in closing, we believe our industrial end market is currently in a cycle of broad based high growth that is being further compounded by our strong investments in the most attractive secular opportunities. As ADI works to bring physical intelligence to the electrophysical interface. Our competitive advantage lies in our extensive and evolving tech stack and six decades of experience as well as our deep application domain expertise. These differentiators continue to grow in importance as our customers tackle bigger, more complex challenges at the intelligent edge and as such our confidence in our future has never been greater. And with that I’ll pass you over

Richard Puccio (Chief Financial Officer)

to Rich thank you Vince and let me add my welcome to our second quarter earnings call. Revenue in the second quarter was a record 3.62 billion, finishing above the high end of our outlook while growing 15% sequentially and 37% year over year growth was led by our industrial and data center businesses. Industrial, which represented 50% of our second quarter revenue, finished up 20% sequentially and 56% year over year. All of our industrial businesses increased sequentially and year over year led by aerospace and defense, ATE ETM and the broad market. Automotive represented 24% of revenue finishing up 8% sequentially and 2% year over year. We continue to capitalize globally on content and share gains in next generation ADAs and infotainment systems with increased demand for our GMSL,, functionally safe power and A2B technologies. In addition, our BMS solutions for EVs …

Full story available on Benzinga.com

This post was originally published here
A debt-free husband in a $210,000 household still hesitated over a $7,000 vacation. 

George said on “The Ramsey Show” that he and his wife were weighing whether a yearly vacation fit their financial plans. 

The Hartford, Connecticut, couple had no debt except their mortgage, but George said the yearly trip his wife wanted still made him hesitate. He said he could go “10, 15 years” without taking a vacation.

Don’t Miss:

The Vacation Wasn’t The Real Problem

George walked hosts Ken Coleman and Rachel Cruze through their finances. Between their 401(k)s and Roth IRAs, he and his wife had about $315,000 saved for retirement, plus $60,000 in CDs, $20,000 to $25,000 in cash and a $10,000 education account for their children. They owed about $110,000 on their home and had no other debt.

George said they were trying to save $40,000 to $50,000 a year so they could eventually move to another state and buy a larger house.

The vacation did not appear to block that goal. George said he could save enough for another trip in about three months while still working toward the larger home goal.

The concern was what could happen financially after spending the money. The couple already took one trip to Cancun, Mexico, and George admitted he wanted to go back.

“You can save the [$40,000 to $50,000] a year and cash-flow the vacation,” Coleman told him.

Trending: 1.5M+ People Work in Headsets Every Week— Here’s the Under-$1 Pre-IPO Company Behind It

‘Enjoy Your Life’

Cruze said George already had room in the budget to enjoy life while continuing to save for the future.

“You guys are doing everything right,” she said. “There is margin there for you to enjoy your life.”

Cruze also told him he was worrying about situations that had not happened and said the couple could adjust later if their finances changed.

The Fear Started Long Before The Budget

George said he grew up poor and barely left the state as a child. Even now, he told the hosts, he still buys clothes from Goodwill. 

Cruze said those experiences can stay with people long after their finances improve, but reminded George he built a stable life for his family. “You’re not that little boy anymore,” she said.

George’s hesitation reflects a common pattern in which past financial experiences continue to shape decisions even after income and savings have improved. For households navigating similar dynamics, AdviserMatch helps connect individuals with fiduciary advisers who can provide guidance on balancing present lifestyle decisions with long-term …

Full story available on Benzinga.com

This post was originally published here
Dorian LPG (NYSE:LPG) reported fourth-quarter financial results on Wednesday. The transcript from the company’s fourth-quarter earnings call has been provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://viavid.webcasts.com/starthere.jsp?ei=1763349&tp_key=a37e2a0ce5

Summary

Dorian LPG reported a strong financial performance for Q4 2026, with $82 million cash flow from operations and a dividend increase to $1 per share, reflecting robust market conditions.

The company completed strategic fleet transactions including the sale of the Cobra, generating a gain of approximately $30 million, and the repurchase of the Corsair, enhancing liquidity and flexibility.

Future outlook remains positive, with expectations for continued strong LPG trade despite geopolitical tensions; the company is focused on fleet expansion and maintaining a solid balance sheet.

Operational highlights include high fleet utilization at 97.8% and significant TCE earnings per day, driven by favorable VLGC market conditions.

Management emphasized a balanced capital allocation strategy, prioritizing shareholder returns through dividends while being open to fleet reinvestment opportunities.

Full Transcript

OPERATOR

Thank you for your continued patience. please press Star zero and a member of our team will be happy to help you. Please stand by. Your meeting is about to begin. Good morning and welcome to the Dorian LPG fourth quarter and fiscal year 2026 earnings conference call. At this time, all participants are in a listen only mode. A brief question and answer session will follow the formal presentation. As a reminder, this conference is being recorded. Additionally, a live audio webcast of today’s conference call is available on Dorian LPG’s website, which is www.dorianlpg.com. i would now like to turn the conference over to Ted Young, Chief Financial Officer. Thank you Mr. Young. Please go ahead.

Ted Young (Chief Financial Officer)

Thanks Madison, Good morning everyone and thank you all for joining us for our fourth quarter 2026 results conference call. With me today are John Hajibateras, Chairman, President and CEO of Dorian LPG Ltd.; John Lacouris, Head of Energy Transition; and Tim Hansen, Chief Commercial Officer. As a reminder, this conference call, webcast and a replay of this call will be available through May 27, 2026, Many of our remarks today contain forward looking statements based on current expectations. These statements may often be identified with words such as expect, anticipate, believe or similar indications of future expectations. Although we believe that such forward looking statements are reasonable, we cannot assure you that any forward looking statements will prove to be correct. These forward looking statements are subject to known and unknown risks and uncertainties and other factors as well as general economic conditions. Should one or more of these risks or uncertainties materialize or should underlying assumptions or estimates prove to be incorrect, actual results may vary materially from those we express today. Additionally, let me refer you to our unaudited results for the quarterly and annual periods ended March 31, 2026 that were filed this morning on Form 8K. In addition, please refer to our previous filings on Forms 10K and 10-Q where you’ll find risk factors that could cause actual results to differ materially from those forward looking statements. Please note that we expect to file our full 10-K no later than May 29, 2026. Finally, I would encourage you to review the investor highlight slides posted this morning on our website. With that, I’ll turn over the call to John Hajibateras.

John Hajibateras (Chairman, President and CEO)

Thank you Ted and thanks for joining us. Today. My colleagues will share some useful and interesting information about the past quarters and our views of the market. First, I’d like to say a few words on capital allocation and provide some historical context on fleet development which relates to risk management in a volatile market with a view to capturing upside. Today’s price of a new building VLGC at approximately 115 million reflects an increase of approximately 2.5% per annum over the cost of our first VLGC which was delivered to our predecessor company 20 years ago. It was ordered for a price of approximately 65 million in 2004. When she was delivered in 2006, the new building replacement cost was over 90 million. From 2009 to 2012 the new building price hovered in the low 70 million range and the next order we placed was in 2012 for advanced echo type series at just under 70 million each. The new building prices stayed in the $70 million range until 2021. The total VLGC fleet in 2005 comprised 102 ships. Today the total fleet is 427 VLGCs and there are about 124 ships on order representing nearly 30% of the existing fleet compared to the all time high of more than 50% in 2007. Our owned fleet comprises 18 echo type with efficiency enhancing features and two new fuel ships. The average age of Our fleet is 10.3 years. In the next few years we hope to expand our fleet by adding new ships and expect that the catalyst for our investment in replacement tonnage will be innovation in the design and efficiency of new buildings. The advent of ultra long stroke electronic engines informed our investment decision in 2012 and the development of dual fuel engines supported our decisions for our investments in the Captain Marcos delivered in 2023 and via our VLGC Rion delivered a couple of months ago. We have witnessed the volatility I’ve described and we’ve been the beneficiaries of a tremendous increase in the volume of seaborne trade of LPG in both absolute terms and in ton mile terms. We have confidence in the further expansion of this trade and our intention is, as always with our capital allocation to proceed judiciously. Mindful of our steadfast commitment to maintaining a solid balance sheet. We believe that this is the route by which we can earn the best return for our investors and continue to provide top quality services to our customers and a safe and fair working environment for our people at sea and onshore. And now I’ll pass you on to Ted.

Ted Young (Chief Financial Officer)

Thanks John. My comments today will focus on capital allocation, our financial position and liquidity and our unaudited Fourth Quarter Results We’ve been active since the beginning of calendar 2026 in growing our business and rewarding shareholders. First, we took delivery of the Arianee in late March, our fully ammonia capable 93,000 cbm VLGC. As you would expect, she immediately started contributing to earnings and though we won’t see the P and L impact until the first quarter of our fiscal 2027, the most recent irregular dividend of a dollar per share, a significant increase from the prior quarters reflected the strong underlying market and our board’s commitment to creating shareholder value. Second, we completed the sale of the 2015 built Cobra in May, paying off $16.5 million of debt in the process. We expect to generate a gain on sale of approximately $30 million from her sale and I would note that her sale price was actually greater than her contract price in 2015. Finally, we will complete the repurchase of the Corsair for her sale leaseback before month end, which will require a payment of about $24.2 million in total and positions us to be flexible with any potential opportunities. At March 31, 2026 we reported $327.4 million of free cash which was sequentially up from the previous quarter. Cash flow from operations was $82 million or nearly $2 per share, and as we noted in our press Release, we borrowed $62.9 million upon closing of the delivery of the Ariane, covering the final payment to the yard. As we disclosed then, the ariane loan has two tranches, one 7 years and one 12 years and a weighted average margin between the two tranches of 125 basis points over SOFR. We closed the fiscal year therefore with a debt balance of 565.8 million, but given the payoff of the debt in connection with the sale of the COBRA and the Corsair repurchase, the pro forma balance would be 524.7 million. Based on our stated book, however, quarter end of 565 point million of debt, our debt to total book cap stood at 33.2% and net debt to total cap of 14%. We continue to have well structured and attractively priced debt capital with a current all in cost of about 5 million, an undrawn revolver of 42.9 million and one debt free vessel. Coupled with our strong free cash balance we have a comfortable measure of financial flexibility. We expect our cash cost per day for the coming year to be approximately 26,000 per day excluding capital expenditures for the dry docking of the Captain John which is currently planned for our fourth fiscal quarter. For the discussion of our fourth quarter results, you may find it useful to refer to the investor highlight slides posted this morning on our website. I remind you that my remarks will include a number of terms such as tce, available Days and adjusted ebitda. Please refer to our filings for the definitions of these terms. Looking at Our fourth Quarter Chartering Results since our entire spot trading program is conducted through the Helios Pool, its reported spot results are the best measure of our spot chartering performance. For the March 31st quarter, the Helios Pool earned a Time Charter Equivalent (TCE) per day for its spot and COA voyages of 65,600 per day, reflecting more favorable VLGC market conditions. Our utilization improved sequentially to 97.8% this quarter from 94.6% in the prior quarter as the last of our dry dockings for the 2014-2016 class was completed. The overall Time Charter Equivalent (TCE) result for the pool of nearly 63,300 per day reflects that very strong rate environment as well as our time Charter out portfolio. On page four of our Investor Highlights material, you can see that we have six Dorian vessels on time charter within the pool, indicating spot exposure of just over 80% for the 31 vessels in the Helios pool. Dorian’s reported Time Charter Equivalent (TCE) revenue per available day for the quarter was about $63,615, which is the second highest Time Charter Equivalent (TCE) rate we have earned in our corporate existence. For the year, we earned 52,238 per day with the fourth quarter completely offsetting our sector’s relatively slow start to the fiscal year. The current rate environment remains healthy, though Panama Canal transit fees are having an impact on realized rates. We’d note that most posted Time Charter Equivalent (TCE) rates do not include auction fees for VLGCs transiting the canal, which have ranged from 200,000 to as high as 4 million in the last and also they do not include the effect of ballasting around the Cape of Good Hope, which can also have a significant impact on realized Time Charter Equivalent (TCE)s. We plan to issue our forward booking information in the near future. Daily OPEX for The quarter was $9,548, excluding dry docking related expenses, which was virtually flat with the prior quarter’s 9,558. Our gross time charter in expense for the six TCN vessels came in at 18.4 …

Full story available on Benzinga.com

This post was originally published here
Nvidia Corp. (NASDAQ:NVDA) reports fiscal Q1 2027 earnings after the bell today.

The company has topped earnings estimates for 13 straight quarters, which may be why Polymarket gives it roughly a 95% chance of beating the $1.77 non-GAAP EPS consensus tonight.

The more interesting action is on Kalshi, where traders are betting on which specific words Huang and his team will say on the 5 p.m. ET call.
What Kalshi Predicts Jensen Will Say

“Self Driving” is at 82%, reflecting a segment that is finally pulling its weight.

Nvidia’s automotive revenue hit a record $2.3 billion last fiscal year, up 39%, and it landed an autonomous-driving partnership with Uber (NYSE:UBER) at its March conference, alongside deals with Lyft and several automakers.

“TSMC” is at 80%. Nvidia depends on Taiwan Semiconductor Manufacturing Co. (NYSE:TSM) for …

Full story available on Benzinga.com

This post was originally published here
e.l.f. Beauty, Inc. (NYSE:ELF) stock fell Wednesday as investors continued selling into the stock’s broader downtrend despite a firmer market backdrop ahead of the company’s earnings report due later today. The Nasdaq gained 0.53%, while the S&P 500 rose 0.16%.

According to Benzinga Pro, ELF stock has lost over 36% in the past year. Investors can gain exposure to the stock via Corgi Beauty, Skincare & Aesthetics ETF (BATS:GLAM).
On Tuesday, Piper Sandler analyst Anna Andreeva maintained a Neutral rating on the stock and lowered the price forecast from $85 to $60.

Investors are now focused on e.l.f. Beauty’s fourth-quarter earnings report scheduled for release later Wednesday. Wall Street expects earnings of 23 cents per share on revenue of $423.59 million. The company has topped EPS estimates in each of the past four quarters.

Bets Big On ‘SURVIVOR’ Fandom

Separately, e.l.f. Beauty’s e.l.f. Beauty cosmetics brand partnered with CBS reality series SURVIVOR for a marketing campaign tied to the “SURVIVOR 50” finale airing …

Full story available on Benzinga.com

This post was originally published here

CAVA Group Inc (NYSE:CAVA) reported upbeat financial results for the first quarter after the market close on Tuesday.

Cava posted first-quarter revenue of $438.27 million, beating the consensus estimate of $411.25 million, according to Benzinga Pro. The company reported adjusted earnings of 20 cents per share, beating analyst estimates of 17 cents per share.

“These results, which include the lap of strong prior year comparisons, speak to the structural strength of our business, the resonance of our compelling value proposition, and our position as the dominant leader in Mediterranean – all of which fuel our confidence to sustain this momentum going forward,” said Brett Schulman, co-founder and CEO …

Full story available on Benzinga.com

This post was originally published here

Keysight Technologies, Inc. (NYSE:KEYS) posted upbeat second-quarter results on Tuesday.

Keysight reported quarterly earnings of $2.87 per share, which beat the analyst consensus estimate of $2.32 by 23.71%, according to Benzinga Pro data. Quarterly revenue clocked in at $1.72 billion, which beat the analyst consensus estimate of $1.71 billion and was up from $1.31 billion in the same period last year.

“Keysight delivered the strongest quarter in the company’s history, capping a record first half with all-time highs in orders, revenue, EPS and free cash flow,” said Satish Dhanasekaran, CEO of Keysight.

Keysight expects third-quarter EPS in a range of $2.43 to $2.49, versus …

Full story available on Benzinga.com

This post was originally published here

Shares of Plug Power Inc. (NASDAQ:PLUG) rose in Wednesday premarket trading after the company said a final investment decision had been reached for the 30-megawatt Barrow Green Hydrogen project in the U.K., where it will supply electrolyzers.

The project, part of the U.K. Government’s Hydrogen Business Model, is expected to help cut carbon emissions at Kimberly-Clark’s manufacturing facility in Barrow-in-Furness by supplying green hydrogen.

The Barrow project will use six 5 MW Plug GenEco PEM electrolyzers and is expected to produce about 100 GWh of green hydrogen annually, supporting the U.K.’s low-carbon hydrogen goals.

CEO Jose Luis Crespo expects Barrow to be the first of several Plug-supplied projects in Europe to transition into execution this year, with Plug Power technology ready to support delivery at scale.

Broader market strength also supported sentiment on Wednesday, with S&P 500 futures trading modestly higher.

Technical Analysis

Plug Power’s current price of $3.33 is positioned at 2% above its 20-day simple moving average (SMA) and 20.4% above its 50-day SMA, indicating a bullish trend. The stock has experienced a remarkable 301.21% increase over the past 12 …

Full story available on Benzinga.com

This post was originally published here

Roivant Sciences (NASDAQ:ROIV) reported fourth-quarter financial results on Wednesday. The transcript from the company’s fourth-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://edge.media-server.com/mmc/p/6w4qcx9w

Summary

Roivant Sciences reported strong execution momentum with multiple strategic updates, including a $2.25 billion settlement with Moderna and advancements in their drug development pipeline.

Financially, the company maintains a robust position with $4.3 billion in cash and no debt, and they continue active share repurchase programs.

Key clinical developments include promising data from the 1402 study in a difficult-to-treat rheumatoid arthritis population, and ongoing progress in launching Brepocitinib for dermatomyositis by September, pending FDA approval.

The company highlighted its strategic focus on Moseli, an inhaled SGC activator, with upcoming Phase 2 data expected in the second half of 2026, targeting PH-ILD with a potentially first-in-class treatment.

Roivant Sciences remains optimistic about future data releases and indicated a strong pipeline with significant upcoming milestones in multiple therapeutic areas.

Full Transcript

OPERATOR

Ladies and gentlemen, thank you for standing by. Welcome to the Roivant fourth quarter 2025 earnings call. At this time, all participants are in a listen only mode. After the speaker’s presentation there will be a question and answer session and to ask a question during the session you will need to press Star one one on your telephone. You will then hear an automated message advising your hand is raised. We ask that you Please limit to one question and to withdraw your question please press Star one one again. Please be advised that today’s conference is being recorded. I would like now to turn the conference over to Stephanie Lee from Roivant Sciences. Please go ahead.

Stephanie Lee

Good morning and thanks for joining today’s call to review business updates from Roivant’s fourth quarter and fiscal year ended March 31, 2026. I’m Stephanie Lee with Roivant Presenting today we have Matt Glein, CEO of Roivant and Drew Frumpkin, CEO of Pulmovant. For those dialing in via conference call, you can find the slides being presented today as well as a press release announcing these Updates on our IR website at www.investor.roivant.com. We will also be providing the current slide numbers as we present to help you follow along. I’d like to remind you that We will be making certain forward looking statements during today’s presentation. We strongly encourage you to review the information that we have filed with the U.S. Securities and Exchange Commission for more information regarding these forward looking statements and related risks and uncertainties. And with that I’ll turn it over to Matt.

Matt Glein (CEO)

Thanks Stephanie. Thank you everyone for dialing in this morning. I’m glad to be talking. We have an unexpectedly busy agenda with a bunch of topics. I’m looking forward to going through all of it, including obviously what we announced this morning, which is the preliminary open label period Data from the 1402 study in D3TRA as well as a plan spotlight we’ve been planning to do for a while on Mosely, getting into that data, which Drew will take us through and some smaller updates on the PrEP Sentinel program. Although exciting, so a lot to cover. I want to, before I get into all that, use one small bit of executive privilege and wish my father Jerry a happy 75th birthday. Today is his 75th birthday, so happy birthday dad. He sometimes listens in on these calls. I don’t know if he’s listening in now. If not, I’ll catch it on the replay. Okay, into the important topics. Now starting on important business topics. Now starting on Slide 5. Look, this has been a pretty wild 12 months for Roivant and We continue to see just tremendous execution momentum across our development portfolio. An update that will get drowned in some of the other things for today, but is actually pretty great is that PrEP Citinib was awarded Breakthrough designation Breakthrough Therapy designation Sarcoidosis, which just underscores indication selection and development there in terms of what that could mean for those patients. Obviously also in this quarter we announced LPP as an indication for Brevacitinib and that study is already enrolling. We’re exciTED (thyroid eye disease) about how that’s going. And then a ton of work ongoing in commercial prep for the launch for DM which assuming FDA goes as we expect it to, will launch by the end of September. Obviously the bIgGest data update for today in the FcRn franchise is what I mentioned earlier, which is that 1402 showed we think clinically meaningful, pretty exciting ACR response rates across ACR20, 50 and 70 in the D3TRA (dual therapy for refractory arthritis) study in the open label portion. We’ll talk more about that, but that’s obviously encouraging data that we’re looking forward to spending some time on. We’re also fully enrolled on CLE (cutaneous lupus erythematosus) with top line data expecTED (thyroid eye disease) in that study in the second half. And earlier in this quarter we announced the failure of the bapineuzumab studies in TED (thyroid eye disease), but also that the hyperthyroid patients showed normalization which was supportive of our Graves’ studies which are ongoing. Continue to enroll. Well also and then finally hard to believe it was this quarter. But earlier this quarter we also announced our two and a quarter billion dollar settlement with Moderna and we expect to receive the first portion of that payment, the $950 million upfront, in July. So just an incredibly busy quarter of execution for us and an incredibly busy fiscal year for us. It’s really hard to believe how much has changed in a year for Roivantt. None of that though is to say on slide 6 that we’re done. And the next 12 months are also incredibly exciting. Obviously one of the most important things going on, we will hopefully be launching brevacitinib for primary, hopefully launching brevacitinib in Dermatomyositis by the end of September. The phase three study in cannium sarcoidosis we expect to begin this year as well and we expect The NIU (non-infectious uveitis) Phase 3 top line data in the back half of this year. So a transformative year for brepo as all of that comes around. We’ll spend time on this today, but the Moseli PHLD (pulmonary hypertension with interstitial lung disease) Phase 2B top line data is expecTED (thyroid eye disease) in the second half. That also will potentially underscore that as a really important program and hopefully look forward to that data and to talk more about it, obviously D3TRA (dual therapy for refractory arthritis), some of the data is around today, but we’re looking forward to providing a pretty significant update later this year with a little bit more data as well as detailed analysis we’re doing at a patient level and hopefully with some feedback from FDA on a go forward plan given what we’ve now seen. And then obviously we’ll get to see all the PoC (proof of concept) topline data as well. And then next year is a huge year with 1402 data enGraves’s and MG coming in a ton to look forward to and frankly as much in the windshield in the rearview mirror. I think I’ve got the car analogy right there. Great. Okay, I’m going to go in now without spending any more time on the preamble and talk a little bit about this D3TRA data, which I would call surprisingly good. We were pretty exciTED (thyroid eye disease) to see what we saw here. It has slowly been a little bit hard to process just how exciting this data is and so we’re still doing a lot of work on it. As a reminder on slide 8 of what we’re talking about today, this was a unique study design in a few ways. First of all, as I think everyone’s aware, this was a study in heavily refractory patients. Every patient in this study, in addition to failing steroids and DMARDs, also had to fail at least two advanced lines of therapy. So most commonly that’s two of for example TNs, JAK inhibitors and IL-6 inhibitors and we’ll talk a little bit about that. There’s obviously some other things that could be in that bucket as well. The study also had a pretty strict entry criteria on autoantibody-positive. We had a criteria on aqua-positive above a certain level and that was also specific to the study of design. And then the other way in which the study was unique is it was a randomized withdrawal study with two periods. First, an open label active treatment period of 16 weeks at high dose 1402 600mg followed by a period two 12 week re randomization where ACR20 responders at week 14 and 16 both are re randomized into a 12 week randomized withdrawal period where some of them stay on 600, some go down to 300 and some go down to placebo. What we have to share today is preliminary data. We’re still actually cleaning and finalizing it all, but it shouldn’t move very much from here on the top line treatment Vect from Period One, Period Two is still ongoing with more than half of patients still being dosed in the study. So we don’t have any data or information about period two to share today. And then even for Period One, there’s a whole bunch of data like IgG, for example, that we haven’t analyzed fully and are not ready to share. So nothing to say about it other than that we’re going to be sharing a pretty limiTED (thyroid eye disease) subset of this data today. On slide 9 you can see baseline characteristics for the patients in the study with 165 valuable patients. I’m not going to go through all of this in detail other than say this is quite a sick patient population. Obviously by design it’s refractory and we’ll talk more about that in a second. But for example, if you look at the DAS28-CRP score 6.1, that’s quite high for a study like this. There’s a bunch of measures on here that suggest a quite sick population, which was the goal. Right. This is the population that we set out to enroll. And so we feel good about who’s in the study on prior lines of therapy, specifically on 10. So you can see on the right hand side, we succeeded with our entry criteria. That is basically all of these patients have failed more than two advanced therapy mechanisms. And that’s very different than either the Nippon study or really any of the later line RA studies that have been run. And actually one thing that we’re highlighting today, because I think it’s particularly interesting, 65% of these patients roughly have failed specifically JAK inhibitors. And notably, and we’ll highlight this elsewhere as well, basically every single one of the patients who failed a JAK inhibitor also failed the tnf. So this is a TNF and JAK refractory patient population that we’re focused on. So look, Slide 11 is the headline here. And the headline is, with all of the appropriate caveats for an open label study, these numbers are high. We saw 73% of patients roughly with ACR20 responses. And not just that, but we saw quite deep responses. We saw over half of patients with an ACR 50 and over a third of patients with an ACR 70. And notably, once you get onto the deeper end of that with ACR 50s and ACR70s, you just don’t see a lot of placebo response in that level of responder analysis. And so it feels to us like looking at this data there’s something going on that’s meaningful and interesting with this drug and something that merits enthusiasm and a lot of further investigation. And we’re certainly doing all that work now as we get ready to take the program forward. I’ll Highlight on slide 12 the one other bit of interesting data from the study that we’re able to present today, which is we pulled out the subset of patients who are JAK-experienced. Remember those patients, 107 of them are both JAK and TNF experienced. All of them, Some of them have also failed something else as well. And one thing that I think is maybe most exciting about this data is it’s basically fully preserved in that subset. And so as you think about that opportunity where these patients have really failed, all of the most advanced options available to them were able to deliver in an open label setting. Pretty exciting response rates for those patients, which I think bodes well for the exact biological thesis with which we ran the study to begin with, that autoantibody-positive is an orthogonal mechanism, some of the other anti inflammatory options, and that for aqua-positive patients this could be an effective treatment option. So look, I think on slide 13, just to reiterate what we’re showing here, look, these are sick patients, a difficult to treat patient population who have failed a lot or all of the available options and come in with highly active disease. We showed really great response rates in the data that we’re exciTED (thyroid eye disease) to see how they evolve through the rest of this study and on deeper patient level analysis. And also notably, this is the largest patient population dosed with IMVT-1402 to date. It was safe and well toleraTED (thyroid eye disease) in the study. Nothing new drug relaTED (thyroid eye disease) from a safety signal perspective identified. So a clean data set overall and further underscoring what we think We’ve got with 14.02 path forward from here. Obviously you look at this data and you feel pretty good about what this could be. Significant potential benefit, a differentiaTED (thyroid eye disease) mechanism, a difficult to treat population with not a lot of options. So we’re actively working right now to get ready to talk to FDA about this data and plan a path forward. The data is encouraging, I’ll make one comment about it, which is the depth of responses is exactly what’s exciting about the data set. It’s exactly what makes us believe there is something beyond placebo happening in the data set. But as you’ll recall, the randomized withdrawal period, the primary endpoint of period two is do patients taken off drug lose their ACR20 response in 12 weeks, which was a relatively short period to begin with and almost certainly would have been fine. If we had seen more marginal benefit on ACR20. But the truth is, once you’re looking at ACR 50 and 70 responders, I think the bar has actually gotten a fair amount higher for period two. And so paradoxically, I think we still have a good shot of success there. But in some ways, period two was less meaningful than it might otherwise have been. And I think there are plenty of scenarios where we don’t see a P value in period two and continue forward with the drug, given the overall quality of this data. And Conversely, depending on FDA’s feedback, potentially situations where we do see a P value period too, and just need to make sure we’re comfortable with the plan forward. So I think much more interesting than the period 2 data at this point is more patient level analysis as well as the results of those FDA discussions. And we expect to share all of that in the second half of this year. We’re working on it right now. And my hope, given the quality of this data, is that we’ll be coming back to you with an enthusiastic update about next steps here that lay the groundwork for just a really big opportunity. Remember, we presenTED (thyroid eye disease) some data at our Investor day suggesting this is at least a 70,000 patient population and some more specific revised commercial analysis, but Immunovant has now done that. Looks like that number could be 85,000 or higher. It’s a big patient population in need. And I think underscoring that the speed with which this trial enrolled, the enthusiasm that physicians have for putting patients on study, is just further evidence that there’s really something interesting here. And with that, actually, I just want to also just give a shout out to the Immunovant team who have continued to execute really well. Obviously the data itself is strong, but also the speed of enrollment, the speed with which we’re moving through these studies, the full enrollment on cle, and I think that spans all of our programs. I think we’re exciTED (thyroid eye disease) about what obviously what Private’s been able to do with Brev sitting in from a clinical enrollment perspective. We’re exciTED (thyroid eye disease) about the speed of enrollment for Moseley. Obviously the quality of that data. We’ll find out soon, but look really exciTED (thyroid eye disease) about what we’ve been able to do across the portfolio in clinical execution. So much appreciation for the enormous number of people who are working toward those goals. Cool. I’m going to pivot now to Moseley Cigarette and do a little bit of a data preview there because the next time we get together, that data could potentially be very close in front of us. And so we wanTED (thyroid eye disease) to get out ahead of that and give people a chance to just ground themselves in what’s coming, as we did last year around this time or a little later for Brevacitinib in drivenomystitis. Look, I’ll do a little bit of an introduction here. And then you all heard from Drew back at Investor Day in December. He’s in the room with me and is going to talk through a little bit more about the program, look intense on that medical need. These patients, in the extreme, a significant proportion of them die. They’re very sick. There is currently only one approved mechanism with two therapies. And we think there’s probably 200,000 patients across the US and Europe. And that one mechanism for prosthenol is underscoring multiple really great launches at this point. So we’re exciTED (thyroid eye disease) to see the commercial enthusiasm and exciTED (thyroid eye disease) to see these patients have access to something that provides real benefit already. And we’re hoping to add to that. Mosely has a completely differentiaTED (thyroid eye disease) mechanism of action for the disease. It’s an SDC activator, it’s an inhaled SCC activator. It is potentially the first non verprostenol that could be available for these patients. We expect this to be a polypharmacy combination therapy market, as PAH has been. And we think Mosely has a chance to be first line, has a chance to be a major part of the treatment paradigm. And we’re just looking forward to getting this data moving forward there in our phase one data across healthy volunteers and pulmonary hypertension patients. And Drew will remind us of this data. Specifically, we saw among the best PVR reductions to date. And one thing we’re going to remind people of today is that although we saw a 38% PVR reduction in some of those patients, that basically anything that has ever showed 20 plus percent PVR reductions has been able to deliver clinically meaningful benefit. I think it’s true that there has not been any class of drugs showing a 20 plus percent PVR reduction that has not gone on to be a commercially successful class of drugs. And then finally, as a reminder, unsurprisingly, the top line data from that study is on track and we expect to get it in the second half of 2026. It’s 135 patients studied. So with that, I’m going to hand it over to Drew, who’s going to take you through the next handful of slides here on the program and then I’ll come back for a little summary at the End and the rest of the presentation.

Drew Frumpkin (CEO)

Drew, that’s great. Thank you. Thanks. Amelia, Matt and I can tell you there’s a lot of excitement about Moseli ciguat. So Moseli is an inhaled SGC activator that’s delivered directly to the lungs to activate SGC and restore impaired SGC function. SGC is a key enzyme in the NO-SGC-cGMP pathway. And in oxidative stress environments like pH, I, L D, nitric oxide may be reduced and the SGC binding site can become impaired leading to SGC dysfunction.

Drew Frumpkin (CEO)

Now, typically, SGC is activated when nitric oxide engages SGC in the presence of hemet and CGMP is then produced. Unlike cgmp SGC stimulators that requires nitric oxide and heme to activate the sgc. Inhaled Mosasigua binds to the heme pocket independent of the need for NO and heme producing cgmp, which results in vasodilation of the pulmonary arteries and potential reduction of fibrosis and inflammation of the lung tissue. Next slide. So we know many pulmonary diseases are heterogeneous in nature and that fact can make patient treatment complex.

Drew Frumpkin (CEO)

To start, there’s disease of the pulmonary vasculature and disease of the lung parenchyla. The combination of these two disorders is embodied in pulmonary hypertension with interstitial lung disease, which is the first indication we’re exploring in our phase two focus study. We believe Moseley has the potential to address both the pulmonary vascular and the lung parenchymal diseases experienced with patients with ph I L, D. Moseley, next slide. I want to make sure that all I’m going to do is call out the slide numbers. If everyone’s got. Okay, okay, let me pull out the slide numbers. Okay, thank you very much. I appreciate that. I want to make sure we’re advancing. Okay. Most of these preclinical properties led Bayer to take mosase into phase one trials and and a total of 170 patients including healthy volunteers and patients with group one pulmonary arterial hypertension (PAH) and group four CFAP. In the phase one study, Fire studied Moseley, CGWAT and 132 healthy volunteers and 38 pH patients. The healthy volunteers underwent studies with single and multiple dose formats and Moseley proved to be well tolerated, …

Full story available on Benzinga.com

This post was originally published here

Perion Network (NASDAQ:PERI) reported first-quarter financial results on Wednesday. The transcript from the company’s first-quarter earnings call has been provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://perion-q1-2026-earnings-call.open-exchange.net/registration

Summary

Perion Network Ltd reported a 6% year-over-year increase in Perion 1 spend, with total revenue for Q1 2026 at $90.4 million, despite macroeconomic headwinds.

Advertising Solutions revenue decreased due to a decline in web activity, but Perion 1’s contribution x stack increased by 7%, signaling a strategic shift towards this platform.

The company expects a meaningful EBITDA inflection in the second half of the year, driven by strategic agreements and a strong pipeline, reiterating their full-year guidance for 2026.

Perion Network Ltd’s net loss on a GAAP basis was $10 million, but the non-GAAP net income was $4.8 million, maintaining a strong liquidity position with $293 million in cash and equivalents.

Management highlighted the significant growth of Outmax, emphasizing its unique capability to operate across CTV, web, and social platforms, and discussed ongoing investments in AI and strategic agreements to bolster future growth.

Full Transcript

OPERATOR

Retail media have been consistently outpacing the broader market. These impressive growth rates drove a 6% year over year increase in total perion1 spend compensating for the decrease in Web the aggregate impact of the customer spend shows a growing momentum through this important KPI. In the first quarter of 2026 we achieved a solid 6% increase in Perion One spend while navigating the near term macro headwinds and cautious advertisers planning cycles. This is a testament of the increasing demand for our solutions and our expected scale as we look towards the second half of the year. Revenue for the first quarter came in at $90.4 million with advertising solutions revenue at $66.7 million and search at $23.7 million. Contribution ex stock remained flat year over year at $39.7 million. The 44% margin was stable and consistent with last year while Advertising Solutions revenue decreased in the first quarter due to the anticipated decline in the web activity, it is important to emphasize that Perion One contribution X Stack increased by 7% year over year aligned with the spend trajectory. This demonstrates that as we are gradually shifting our business to the Perion One platform, Contribution x Stack and Spend are becoming the true indicators of our underlining growth. Perron One Contribution XSTAC continue to be the main profit driver representing 81% of the total Contribution X stack, up from 75% in the first quarter of 2025. We expect this structural shift to continue with Perion One growing to 85 to 90% of the full year 2026. With respect to our search revenue, as we transition away from the Microsoft agreement, the margin profile of our search activity is naturally shrinking. As a result, even though search revenue increased year over year by 21%, the related contribution ex stuck decreased by 70%. As expected, adjusted EBITDA for the first quarter was half a million dollars compared to $1.8 million in the first quarter of 2025. While we are laser focused on operational efficiency and disciplined execution, the year over year delta was expected. This reflects the incremental expense base from the Greenbits acquisition in the second quarter of 2025 and additional go to market investments to support our three year growth plan. In addition, during the first quarter of 2026 the headwinds from the US dollar weakness represented $1.4 million impact related to foreign exchange. Excluding this foreign exchange impact, adjusted EBITDA would have been $1.9 million largely flat year over year despite the additional costs planned for. As we onboard several large strategic agreements currently in advanced stages, we we expect adjusted EBITDA to inflect meaningfully in the second half of the year. This is consistent with the second half weighted profile of our business. Similar to last year. On a GAAP basis, net loss was $10 million or $0.26 per diluted share. This compares with a net loss of $8.3 million or $0.19 per diluted share in the first quarter last year. On a non GAAP basis, net income was $4.8 million or $0.11 per diluted share. This compares with $5.4 million or $0.11 per diluted share in the first quarter last year. Net cash provided by operating activities was $6.7 million and adjusted free cash flow was $7 million. The cash generative quality of our business model and our disciplined capex investments practices ensure that our internal operations are streamlined to support our growth. We ended the first quarter with $293 million in cash, cash equivalents, short term bank deposits and marketable securities on our balance sheet. While we continue to generate positive cash flow from operations, the $20 million reduction from year end is driven by $24.1 million returning cash to our investors and in a form of share repurchases. This strong liquidity profile gives us the financial flexibility to pursue organic investments, MA opportunities and continued shareholders return. Our capital allocation priorities remain highly disciplined, focused on creating long term value. During the first quarter we repurchased 2.5 million shares for a total of $24.1 million. Under our current authorized program, we have now repurchased a cumulative total of 15.3 million shares for $142.2 million. Since the program’s initiation, we have acquired these shares at an average price of 9.$27 per share. This is notably lower than our average stock price at the last 30 days. By doing so, we have already generated immediate tangible value for our shareholders. Buying back our own stock at current valuation levels alongside disciplined organic and inorganic investments is the most effective use of our excess cash. It reflects our confidence in Perion’s long term intrinsic value despite the expected macro headwinds for the second quarter. Given the momentum we see building in our pipeline for the back half of the year, particularly the several large strategic agreements that are in advanced stages, we are reiterating our full year 2026 guidance. To conclude, Perion entered 2026 with a strong financial foundation, a proven platform strategy, highly disciplined operations and a set of growth engines that are constantly outpacing their markets. The infrastructure is in place. The pipeline is building continuously and we are prioritizing sustainable, profitable growth and, and long term value creation for our shareholders. With that I will turn the call back to the operator to open the line for questions. Thank you. We will now begin the Q and A. If you would like to ask a question, we ask that you please use the raised hand function at the bottom of your zoom screen. Or if you have dialled in, please press Star nine. Our first question today comes from Andrew Marrock at Raymond James. Andrew, you may now unmute your line and ask your question. Thank you.

Andrew Marrock (Equity Analyst)

Hi, thanks for taking my questions. Wanted to start off with one on outmax. Some really good numbers there and we’re seeing the agency space getting increasingly crowded I guess. How are you differentiating outmax in the marketplace in your go to market process that is allowing it to more than triple spend year over year. And then I have a follow up.

OPERATOR

Yeah, thank you, Andrew. Yes. So you saw Outmax, the AI agent technology that we have grew by over 300%. The main thing in our main advantage is we’re the only technology out there that can perform this across both CTV, web and social with the walled gardens, which is a major advantage. To have only one AI agent technology and infrastructure that can run across all those channels, all those platforms is a major, major advantage. Great, thank you.

Andrew Marrock (Equity Analyst)

And then maybe one for Elad. Can you expand a little bit on the commentary that you gave in your prepared remarks on the uneven macro conditions and some of the caution you’re seeing from advertisers? You know, from your peer set. We’re kind of hearing feedback that’s, that’s quite variable. So I’d just like to get a little bit more granularity of what you’re seeing from your position. Thank you.

Elad

Sure. Thanks Indra. So in terms of the headwinds that we are seeing, we see that the inflation in the, in the oil prices and all of the tension in the Middle east caused some uncertainty in terms of the budget spends especially I would say around CPG we see and slightly around auto in. In addition to that we are continuing to see the slow, I would say short, short planning cycles of the, of the advertisers in terms of their, their budget spend. So this is what we see currently in, towards, in towards Q2. But it is important to say that we already started to see some more momentum growing in our pipeline towards the second half of the year. Now of course we do not know yet the timing of when one of those headwinds will really be over. We don’t know to anticipate but we do see more and more strength into our pipeline moving forward especially around Outmax, the adoption of more and more customers to this solution. And of course we’re taking all of those consideration when we are building the guidance towards the rest of the year. Thank you. Appreciate the detail.

OPERATOR

Thank you. Our next question comes from Jason Healthsteam at Offenheimer. Jason, please unmute your line by pressing Star six and ask your question.

Jason Healthsteam

Hey Dan, can you hear me? Yes, thank you. Yeah, good morning. So first your comment just about …

Full story available on Benzinga.com

This post was originally published here

Elon Musk’s SpaceX is looking to raise $80 billion or more in its IPO, a haul that would make it the largest public offering in history, with The Goldman Sachs Group (NYSE:GS) set to lead the deal.

The Wall Street Journal reported on Monday that the $80 billion raise would be roughly three times Saudi Aramco’s $26 billion offering in 2019, the current record.

At a valuation of around $1.7 trillion, SpaceX would also rank among the most valuable companies ever to go public.

After SpaceX absorbed Musk’s xAI earlier this year, its implied worth jumped from around $1.25 trillion to the $1.75 trillion-to-$2 trillion range now circulating.

Starlink, SpaceX’s profit engine, doubled its operating income to $4.42 billion last year, according to Reuters. The newly absorbed xAI does the opposite, posting a roughly $6.4 billion …

Full story available on Benzinga.com

This post was originally published here

Rubico Inc. (NASDAQ:RUBI) plunged on Wednesday, extending heavy selling pressure after a brief volatility-driven rally in the previous session.

The move followed a Tuesday filing showing Rubico sold 1,744,902 shares of common stock to B. Riley Principal Capital II, LLC under an existing Equity Line Purchase Agreement, generating nearly $4 million in gross proceeds.

The issuance is set to significantly dilute existing shareholders. Rubico said the transaction, expected to settle on or before Wednesday, will increase its outstanding share count to about 2.51 million from roughly 768,000 shares.

History of Capital Adjustments

This dilution follows aggressive corporate restructuring earlier this year. Rubico executed a 1-for-7 reverse stock split …

Full story available on Benzinga.com

This post was originally published here

International Business Machines Corporation (NYSE:IBM) shares are slighlty lower on Wednesday’, as the company is expanding its AI-powered security offerings.

This movement comes as IBM announced the latest expansion of its enterprise security program, which includes partnerships aimed at enhancing defenses against AI-driven cyber threats.

IBM’s recent announcement highlights its commitment to bolstering security measures in response to the growing threat of AI-powered attacks.

The company is collaborating with Anthropic as part of Project Glasswing, focusing on protecting critical software infrastructure and sharing findings with the broader community.

Technical Analysis

The stock’s 12-month performance shows a decline of 16.71%, and it currently trades at $222.40, which is 2.4% below its 20-day simple moving average (SMA) of $227.59. The moving average convergence divergence (MACD) is below its signal line, indicating that momentum is fading, which suggests that the upside pressure may be cooling unless it can reclaim that baseline.

Key Resistance: $258.50 — a nearby level where rebounds can stall, reflecting a significant round-number area. Key Support: $221.50 — a nearby level where buyers previously stepped …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks traded mixed this morning, with the Nasdaq Composite gaining around 100 points on Wednesday.

Following the market opening Wednesday, the Dow traded down 0.03% to 49,349.19 while the NASDAQ gained 0.39% to 25,971.51. The S&P 500 also rose, gaining, 0.17% to 7,366.18.

Leading and Lagging Sectors

Information technology shares jumped by 0.7% on Wednesday.

In trading on Wednesday, consumer staples stocks fell by 0.9%.

Top Headline

Target Corp (NYSE:TGT) reported upbeat earnings for the first quarter and raised its FY2026 sales forecast.

The company posted quarterly earnings of $1.71 per share which beat the analyst consensus estimate of $1.46 per share. The company reported quarterly sales of $25.443 billion which beat the analyst consensus estimate of $24.639 billion ar.

Equities Trading UP
           

  • Silexion Therapeutics Corp (NASDAQ:

Full story available on Benzinga.com

This post was originally published here

On Wednesday, Toll Brothers (NYSE:TOL) discussed second-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://edge.media-server.com/mmc/p/hcwotfn4/

Summary

Toll Brothers exceeded guidance on both the top and bottom lines for Q2 FY2026, delivering strong margins and raising full-year guidance across key homebuilding metrics.

The company delivered 2,491 homes at an average price of $1,009,000, generating $2.5 billion in revenue, and achieved an adjusted gross margin of 26.2%.

Toll Brothers plans to grow community count by 8-10% annually and recently acquired Buffington Homes, entering Northwest Arkansas, a market poised for growth.

The company repurchased $175 million in common stock during the quarter, with a total target of $650 million for fiscal 2026, and raised its quarterly dividend.

Management highlighted the strength of the luxury segment, noting affluent buyers are less sensitive to affordability pressures, and emphasized a focus on reducing finished spec homes and improving margins.

Full Transcript

OPERATOR

Good morning and welcome to The Toll Brothers second quarter fiscal year 2026 conference call. All participants will be in listen only mode. Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today’s presentation, there will be an opportunity to ask questions. To ask a question, you may press star then one on your telephone keypad. To withdraw your question, please press star then two. The company is planning to end the call at 9:30 when the market opens. During the Q and A, please limit yourself to one question and one follow up. Please note this event is being recorded. I would now like to turn the conference over to Doug Yearle, Executive Chairman. Please go ahead.

Doug Yearle (Executive Chairman)

Thank you Bailey Good morning, welcome and thank you all for joining us. With me today are Karl Mistry, Chief Executive Officer Greg Zigler, Chief Financial Officer Rob Parajaczyk, President and Chief Operating Officer and Wendy Marlette, Chief Marketing Officer. We are also joined today by Seth Ring who will succeed Rob as President and Chief Operating Officer when Rob retires on June 30 and transitions to his new role as a senior advisor to the company. Rob has been an invaluable leader and contributor to the company’s growth and transformation over the past 40 years and I wish him well in his retirement. He has also done a great job of helping to mentor the next generation of leadership, working closely with Seth to prepare him for his new role. Seth is a proven leader and industry veteran who in his own right with over 20 years of experience with the company is just terrific. He is the perfect successor to Rob and I’m excited to watch as he partners with Carl and Greg to help lead this company into the future. During today’s call, I will provide a brief overview of our results in the quarter, discuss the market at a macro level and touch on our strategic initiatives. Carl will focus on our operational results and provide a deeper dive on conditions across our markets. And as usual, Greg will provide a detailed review of our financial results in the quarter and discuss guidance for the balance of the year. Before we start, however, I will provide the usual cautionary notice that many statements on this call are forward looking based on assumptions about the economy, world events, housing and financial markets, interest rates, the availability of labor and materials, inflation and many other factors beyond our control that could significantly affect future results. Please read our statement on forward looking information in our earnings release of last night and on our website to better understand the risks associated with our forward looking statements. We are very pleased with our second quarter results. We beat guidance on both the top and bottom lines and posted another quarter of strong margins. Based on our first half performance, we are raising our full year guidance across all key homebuilding metrics. Our results in the second quarter reflect our unique position as America’s luxury homebuilder as well as the success of our strategies of expanding our geographies, product lines and price points. Our results also reflect the skills and experience of our teams who continue to respond to a challenging demand environment with discipline, effectively balancing pace, price and incentives to drive sales while maximizing returns. We are quite simply a more efficient and less cyclical homebuilder. Even in a difficult market, our business continues to perform well. In the second quarter, our orders were up 7% gross and flat on a per community basis. This trend has continued into the first three weeks of our third quarter where overall deposits are up modestly year over year and flat per community. In this environment, we are pleased to be serving a more affluent customer base, a segment of the housing market that has proven more resilient despite the challenges facing the broader market. Overall, our buyers are less sensitive to affordability pressures as they have benefited from years of income growth, stock market gains, home equity appreciation. Serving this market is in our DNA. We have spent nearly 60 years building and perfecting the business model required to meet the high standards of the luxury segment of the new home market. Through the desirable locations of our communities, the distinctive architecture of our homes, the the unrivaled choice we provide in our design studios, and the extraordinary customer experience we deliver, we have set our business apart. Our performance in the second quarter and over the past few years highlights the strengths of our differentiated business. Finally, I note that in our second quarter we repurchased $175 million, our common stock, bringing our year to date total to approximately $226 million and we raised our quarterly dividend. We continue to target $650 million of share repurchases in fiscal 2026. Our balance sheet remains very healthy. We have ample liquidity, significant operating cash flows, low net debt and a strong investment grade credit rating. Our solid financial position and healthy cash flows will enable us to continue investing in the future growth of our business while also returning capital to our stockholders. With that, I will turn the call over to Carl.

Carl Mistry (Chief Executive Officer)

Thank you Doug and good morning everyone. I would also like to extend my congratulations to Rob and Seth. Rob has been an incredible mentor to both me and Seth. We’ve learned so much at his side and we look forward to building on the strong foundation that Rob, along with Doug, Bob and many others, have built at Toll Brothers. As Doug mentioned, our second quarter results were quite strong. In the quarter we delivered 2,491 homes at an average price of $1,009,000, generating $2.5 billion of home building revenue, or approximately $110 million above the midpoint of our guidance. Our adjusted gross margin was 26.2% in the quarter or 70 basis points better than guidance, and our SGA expense as a percentage of home building revenues was 10.3%, or 40 basis points better than guidance. We earned $260.6 million in the quarter, or $2.72 per diluted share, an 18 cent beat relative to the midpoint of our guidance. In addition, we signed 2,834 net agreements in the quarter for $2.8 billion, up 7% in units and 8% in dollars. This increase was driven by the successful execution of our growth strategy over the past several years. At quarter end, we were selling from 459 communities versus 421 one year earlier and 386 just two years ago. We remain focused on opening new communities across the country and expect to end the year with 480 to 490 selling communities, including the communities we acquired in the Buffington Homes transaction which closed earlier this month. We plan to grow community count at a similar 8 to 10% rate in fiscal 2027 and beyond, and we currently own or control sufficient land to do so. We are very excited to enter Northwest Arkansas with the acquisition of Buffington Homes, the home of Walmart and a host of terrific other companies. The Fayetteville Bentonville market is vibrant and growing. Buffington Homes is the leading builder of luxury homes in the area and it is a great fit for toll rovers. We look forward to leveraging their local expertise and strong land position to scale their business well into the future. Turning to Market Trends As Doug mentioned, the demand environment remained challenging in the second quarter and through the first three weeks of our third quarter. Against this backdrop, we are pleased that we were able to increase sales by 7% year over year, keep our per community sales pace flat, maintain our margins in the quarter. Geographically, Florida was a bright spot in the quarter with improved demand in all our markets in the state. Boston all the way down to South Carolina continued to perform well as did Boise and Las Vegas in our mountain region and Austin, Texas in the South. Weaker markets included Atlanta, San Antonio, Seattle, Portland and San Francisco among our buyer segments. Our luxury move up business continued to perform the best in the second quarter. Our move up business accounted for 62% of home sales revenues, up from 59% in the first quarter. Luxury first time was 22% and move down was 16%. Our luxury move up business has the highest margin among our buyer segments, so we are very pleased that it remains the largest part of our business. As Doug mentioned in the quarter, we continue to operate with discipline, effectively balancing sales pace, price and incentives to drive sales while maximizing returns. We are pleased that our average incentive for new contracts in the second quarter remained flat at 8% of the gross sales price the fourth consecutive quarter it has remained in this range. This is a testament to the immense appeal of our brand and the desirability of our homes and communities. It also speaks to the financial strength of our customers who continue to demonstrate their desire to invest in new homes. Consistent with the past several quarters, approximately 23% of our buyers paid all cash in the second quarter and the loan to value for buyers who took a mortgage was approximately 69%. Also consistent with recent quarters, we are also benefiting from the breadth of our offerings, which is the widest in the industry and includes a balanced mix of built to order and spec homes. In the quarter, spec homes represented approximately 51% of deliveries and 41% of home sales revenues, which is broadly consistent with the range we have targeted and maintained over the past few years. We are very comfortable with our delivery mix in this 5050 range. It is important to remember that we sell our specs at various stages of construction. Although the mix can change from quarter to quarter, on average, approximately one third of our specs sell before framing is completed. The margin profile for these homes is very similar to the 30% adjusted gross margin we routinely achieve on our build to order homes. Our goal is to sell our specs as early in the construction cycle as possible. Incentives are generally lower on specs that are sold earlier, and there is greater opportunity for our customers to visit our design studios and personalize their homes with finishes that match their tastes. The ability to customize remains an important competitive advantage for Toll Brothers, as design studio upgrades tend to be highly accretive to our margins in the second quarter. Design studio upgrades, structural options, and lot premiums averaged $219,000, or 25% of our average base sales price. Given our focus on selling spec homes earlier in the construction process, I’m pleased to report that in the first half of fiscal 2026, we reduced the number of finished specs in our inventory by 28%. We held 2 finished specs per community at second quarter end versus 2.8 at the end of fiscal 2025. In the second quarter, we also continued to benefit from improved production efficiencies. For our build to order homes, our cycle time improved to approximately nine months. The cycle time for our spec homes is generally about one month shorter than built to order homes. Overall, our building costs remained flat in the quarter even with the cost of lumber rising in the period. Turning to land at second quarter end, we owned or controlled approximately 76,800 lots, 58% of which were optioned. This existing lot position allows us to maintain our highly disciplined approach to acquiring and developing land, including our rigorous underwriting standards. When buying land, we actively seek out acquisition and development opportunities that improve our capital efficiency while achieving prudent and balanced financing structures. Where possible, we favor seller financing, joint ventures and traditional option arrangements, but we also utilize land banking when it makes sense to do so. I would also point out that because we are a luxury builder buying land at the corner of Maine and Main where not as many of the big public and private builders play, we often find there are fewer bidders at the table when we are pursuing deals. This is one of our competitive advantages. In many markets, we often compete for land against smaller custom builders who do not have the same financial strength or access to capital that we enjoy. In addition, for larger master plan communities, our recognized luxury brand serves to elevate the community which can present us with more opportunities. Combined, all of these factors put us in a favorable position when buying land, helping us improve returns. With that, I’ll turn it over to Greg.

Greg Zigler (Chief Financial Officer)

Thanks Carl. As mentioned, in the second quarter we delivered 2,491 homes at an average price of $1,009,000, generating home sales revenue of $2.5 billion. We earned $350.4 million before taxes and $260.6 million after, or $2.72 per diluted share. We exceeded the midpoint of our guidance for both home deliveries and average delivered price, which was primarily due to favorable mix out of our Pacific region, better than expected performance in Florida, and a greater contribution from our luxury move up business. We signed 2,834 net agreements for $2.8 billion in the quarter, up 7% in units and 8% in dollars. Compared to the second quarter of fiscal year 2025, the average price of contracts signed in the quarter was approximately $990,600, up 1%. Compared to the second quarter of fiscal 2025, our second quarter adjusted gross margin was 26.2%, 70 basis points better than our guidance of 25 point. Our gross margin benefited from the favorable mix from our Pacific region, Florida and our luxury move up business that I mentioned earlier as well as continued improvement in operating efficiencies across our business write offs. In our home sales Gross margin totaled $32.5 million in the quarter. Approximately 20 million of these $20 million of these related to pre development costs and option write offs on deals we dropped that no longer met our underwriting standards. The remainder was associated with a handful of operating communities in different markets around the …

Full story available on Benzinga.com

This post was originally published here

NEW YORK, NY, May 20, 2026 (GLOBE NEWSWIRE) — Speed is the invisible tax on retail investing. While institutional algorithms execute in milliseconds, individual investors click buttons, refresh charts, and watch prices move against them. New research commissioned by AriseAlpha quantifies the damage: 81% of retail investors believe their lack of execution speed has cost them real money over the past 12 months.

Today, AriseAlpha launches a platform built to erase that disadvantage. The company’s new AI trading bot ecosystem operates across four major asset classes — cryptocurrencies, stocks, funds, and forex — with execution speeds averaging under 200 milliseconds from signal to order. The platform includes a dedicated AI stock trading bot, an AI crypto trading bot, and automated strategies for exchange-traded funds and currency pairs.

“We asked retail investors what holds them back,” said an AriseAlpha spokesperson. “They didn’t say lack of knowledge. They didn’t say bad strategies. They said speed. By the time they see an opportunity and click a button, the moment has passed. Our AI trading bot removes that delay entirely. It sees. It decides. It executes. All before a human can blink.”

Market Data: The Retail Speed Gap

AriseAlpha analyzed execution timing across 15,000 manually placed trades by retail investors in Q1 2026. The findings reveal a consistent pattern:

From the moment a clear trading signal appears (e.g., a breakout above resistance or a bullish divergence on RSI), the average retail investor takes 47 seconds to act. In that time, markets move. Slippage accumulates. Profits shrink or turn to losses.

Institutional algorithms, by contrast, act in under 10 milliseconds. The AriseAlpha AI trading bot bridges this gap by operating at 200 milliseconds — not institutional grade, but faster than any human and fast enough to capture the majority of available alpha.

The data also showed that speed disadvantages compound. Investors who missed entries by even five seconds saw average profit reductions of 12% per trade. Over a year of active trading, the drag from slow execution alone erased an estimated 18% of potential returns.

Source: AriseAlpha Execution Analysis Lab, March 2026 (anonymized trade data)

Platform Introduction: Built for Speed, Designed for Humans

AriseAlpha’s platform is not a collection of disconnected tools. It is a unified operating system for automated investing across every major asset class a retail investor might touch.

Asset Coverage

The AI trading bot monitors and trades four distinct markets simultaneously:

Cryptocurrencies
The AI crypto trading bot covers Bitcoin, Ethereum, and the …

Full story available on Benzinga.com

This post was originally published here

You make about $83,000 a year and still feel tight on money? Personal finance expert Dave Ramsey says the issue is not your paycheck — it’s your spending habits. 

In a March 31 Facebook post, Ramsey called it a “lie” that it’s not possible to live in the U.S. on an average income. He said many Americans burn through their paychecks without noticing where the money goes and blamed spending habits for most financial problems. 

“You’ve probably heard it a hundred times: ‘You can’t make it on an average income anymore.'” Ramsey said. “I don’t buy it. After doing this for 30+ years, I can tell you that the issue probably isn’t your income. It’s what you’re doing with it.”

Don’t Miss:

Ramsey cited U.S. government data in his post that shows the median household income in the country is $83,730, while average annual household spending is $78,535. 

Rising inflation and slowing wage growth are squeezing American households harder than ever. US consumer sentiment fell to a new low in May amid rising gas prices due to the Middle East conflict, according to the University of Michigan Surveys of Consumers.

About 65% of middle-income Americans say their income is falling behind the cost of living, according to a survey by financial services company Primerica. The survey points to rising grocery prices, higher gas costs, and increasing utility bills as the main pressures squeezing household budgets.

Trending: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

‘You Don’t Have To Live That Way’

Ramsey said not knowing where your money goes and constantly feeling tight has become “normal,” which he calls “broke.”  Households earning an average salary can often turn things around just by tracking spending and making more intentional choices, he said.

“You don’t have to live that way,” Ramsey said on Facebook. “When you get intentional, when you get on a proven plan, when you say no to things that don’t matter so you can say yes to things that do, everything changes.”

Reality Check in Comments

Ramsey’s post sparked a split in the comments, with many agreeing with his take on budgeting, while others argued rising costs make it harder to get by on a middle-income income.

One commenter, 23, said he and his wife earn a total household income of about $80,000 with a $1,500 mortgage, adding they live comfortably.

See Also: Turn your trading skills into real income — without risking your own capital: Get funded by Apex Trader Funding and keep up to 90% of the profits.

Another said a two-bedroom apartment in South Florida is easily over $2,600 a month, and that by typical affordability standards, you’d need about $93,000 a year to comfortably afford it.

Others said it all comes down to where you live and the local cost of …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks were higher, with the Nasdaq Composite gaining over 100 points on Wednesday.

Shares of TAT Technologies Ltd (NASDAQ:TATT) rose sharply after the company reported better-than-expected first-quarter financial results.

TAT Techs posted quarterly earnings of 26 cents per share, beating market estimates of 19 cents per share. The company’s sales came in at $41.147 million topping estimates of $40.400 million.

TAT Technologies shares jumped 11.7% to $36.52 on Wednesday.

Here are some other big stocks recording gains in today’s session.

  • Immunovant Inc (NASDAQ:IMVT) shares jumped 22.2% to $32.12 following fourth-quarter results.
  • Sellas Life Sciences Group Inc (NASDAQ:SLS) gained 17.6% to $8.92 as traders react to the company’s latest update on its acute myeloid leukemia pipeline and the timeline for a pivotal Phase 3 readout.
  • T1 Energy Inc (NYSE:TE) gained 17% to $8.05.
  • Vuzix Corp (NASDAQ:VUZI) …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Baird analyst David George initiated coverage on Pinnacle Financial Partners Inc (NYSE:PNFP) with an Outperform rating and announced a price target of $115. Pinnacle Finl shares closed at $94.33 on Tuesday. See how other analysts view this stock.
  • Needham analyst Neil Young initiated coverage on QuickLogic Corp (NASDAQ:QUIK) with a …

Full story available on Benzinga.com

This post was originally published here

GCT Semiconductor Holding Inc. (NYSE:GCTS) stock is flashing bright green on Wednesday. Traders are fueling continued upward momentum following the company’s recent blockbuster first-quarter earnings report for 2026 and a pivotal technology partnership.

Blockbuster Revenue Growth In Q1

The fabless chipmaker achieved a massive 287% year-over-year increase in total first-quarter revenue, reaching $1.92 million.

This top-line figure beat analyst consensus expectations of $1.76 million, offsetting an earnings per share (EPS) loss of 15 cents, which was slightly wider than the estimated 12-cent loss.

Shipments And Margins

A 58% sequential increase in 5G chipset shipments to 3,000 units heavily drove the revenue spike. This commercialization ramp also transformed the company’s profitability profile during the quarter.

Gross margin leaped to 49.3%, up …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Morgan Stanley analyst Dara Mohsenian downgraded Newell Brands Inc (NASDAQ:NWL) from Equal-Weight to Underweight and cut the price target from $4 to $3.5. Newell Brands shares closed at $3.55 on Tuesday. See how other analysts view this stock.
  • Wolfe Research analyst Andrew Rosivach downgraded Crown Castle Inc

Full story available on Benzinga.com

This post was originally published here

On Wednesday, Super Hi International (NASDAQ:HDL) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/owz49p9j/

Summary

Super Hi International reported a 14.2% year-over-year increase in total revenue for Q1 2026, reaching $226 million, with Haidilao restaurant operations contributing 90.4% of the revenue.

The company saw a significant improvement in profitability, with operating profit increasing by 17.7% year-over-year to $13.993 million and operating margin rising to 6.2%.

Strategic initiatives included strengthening employee and customer focus, menu innovation, and expanding the Red Pomegranate project with multiple new brands and stores.

The company’s operational highlights included a net increase of four restaurants year-over-year, with a focus on flexibility in operations and store manager discretion to enhance customer satisfaction.

Management emphasized a long-term strategy prioritizing customer experience and employee engagement, and noted that despite external challenges, the company’s market resilience and adaptability are expected to drive future growth.

Full Transcript

Sa (Operator)

Hello respected investors and analysts, thank you for joining today’s Super Hi earnings call. Participating in Today’s meeting are Mr. Li Yu, Executive Director and CEO, and Ms. Chu Zong, Financial Controller and Board Secretary. Today’s meeting may contain forward looking statements including but not limited to, the Company’s statements on strategies and business plans as well as outlook on performance. The content public published by the Company during the earnings presentation as well as comments in response to all your questions represent only management views as of today. Please refer to the latest Safe harbor statement in the earnings press release which applies to the conference call. The meeting is conducted in Chinese with simultaneous English interpretation provided by external agency. In case of any discrepancies, the Chinese version shall prevail. The presentation materials have been uploaded to the Company’s investor relations page for your review. Hello investors and analysts, I’m Li Yu, Executive Director and CEO of Superhigh International. Welcome to Superhigh International Q1 2026 earnings call and I’m going to be talking to you about. On behalf of the Company, I thank you for your interest and support. It is my honor to share with you the Super Hi international operating performance for this quarter. In the first quarter of 2026, the company’s operations maintained a positive improvement trend with all core operating metrics achieving Simultaneous as of 31st 2026, the company operated a total 127 Haidilao restaurants in Overseas Market. Added one new store in Southeast Asia during the period recorded a net increase of four stores compared to the same period last year. At the same time, the operating quality of the existing store is continuously being strengthened. In the first quarter, Haidilao restaurant revenue was 204 million, an increase of 8.4% year over year. Same store sales increased by 4% year over year. Total custom traffic exceeded 8.1 million visits and the overall table turnover rate was 4 turns per day, an increase of 0.1 turn per day compared to the same period last year. Meanwhile, the delivery business, the Red Pomegranate project and other businesses continue to contribute to incremental growth with a combined year over year increase of 130.9%. The multiple initiatives drove the company’s total revenue to 226 million a year over year, increase of 14.2%. On this basis, thanks to increase the customer traffic and refined operations, we have seen a significant release of operating leverage. In the first quarter, the company’s operating profit reached 13.993 million a year over year, increase of 17.7%. The operating profit margin rose from 4.1% last year to 6.2%, representing a substantial improvement in profitability. In terms of specific business initiatives, we continue to focus on strengthening the three fundamentals focus on employees, focus on customers and focus products during the daily store visits. We realized that past reliance on standards had to some extent limited the warmth of service provided by frontline employees. Therefore, the quarter we continuously emphasized flexible operations, helping employees understand the logic behind services actions by strengthening post event reviews and store manager mentoring and granting them more on site discretion while maintaining high standard operations. We provide more personalized and flexible service, thereby continuous improving customer satisfaction at individual stores. We’re gradually seeing that these actions focused on enhancing employee awareness and capabilities are translating into better customer experiences. In terms of the product and menu innovation this quarter, headquarters focused on scenario segmentation, differentiation and product empowerment, providing targeted support to various regional markets globally. First, we deeply explored dining scenarios. We offered various kids meal sets for families with young children for late night hours. We focused on launching spicy braised dishes paired with refreshing drinks to precisely drive the consumption during that period. Second, following the summer season, we collaboratively launched a combination product such as vegetable and mushroom platter and beef and lamb combo in multiple regions. For core categories, we focused on upgrading the beef series offering premium Australian Wagyu and freshly cut beef to meet the quality experience needs of different customer segments. Looking at the the results, the menu innovation in the first quarter were more customer centric and each market produced excellent localized products. This not only effectively drove a single store sale, but also validated the effectiveness of our strategy of localized products selection and refining manual planning in terms of the business expansion, we added one new restaurant in Southeast Asia during this period. Since last year, the company has imposed stricter requirements on new store location, accuracy, profit expectation and execution quality. Currently, our pipeline of reserved stores remains in the double digits and the overall expansion pace going forward will continue to adhere to the principle of balancing stability and quality. Regarding the Red Pomegranate project, we are actively building a multiple brand matrix, continuously incubating prototype stores and second brand projects in different countries. To date we have operated a total of 10 brands with a total of 18 stores including formats such as Canadian Malatang, Indonesian Halal, Japanese Isa Kawa, Korean Schools and Spark Cora bbq. This quarter, other business revenues achieved a strong growth of 166.7%, marking substantial growth in the diversifying of our revenue structure and expanding our customer base. Looking ahead, the company remains committed to its long term development goal of becoming a leading global integrated catering group, continuously improving in Five areas, customer experience, restaurants, network operational and enhancement, new businesses and headquarter capabilities. That concludes my introduction of the business situation. Next, Let me invite Mr. Chu Zong to present the financials. Thank you, President Li Yu. Next, I will report on the financial situation. In the first quarter of 2026, the company achieved a total revenue of 226 million, an increase of 14.2% year over year. Haidilao Restaurant operating revenue accounted for 90.4% of total revenue, reaching 204 million. This an increase of 8.4% year over year. This was mainly attributable to first, the continued improvement in operating performance of existing Haidilaoo stores, with increases in both table turnover rate and customer traffic. Second, a net increase of four stores in the company’s restaurant network compared to the same period last year, with adjustment in the store network layout contributing incremental revenue delivery businesses revenue accounted for 3.2% of total revenue, reaching 7.3 million this quarter and increase of 82.5% year over year. Primarily because we continue to optimize delivery products and services based on market demand and strengthened cooperation and joint marketing with local delivery platforms. Other businesses revenue accounted for 6.4% of total revenue, reaching 14.4 million this quarter, an increase of 166.7% year over year. The revenue growth came primarily from the sales of food products and seasoning under the Haidian brand and from the company’s own central kitchen, as well as from the active development of some new brand restaurant business under the Red Pomegranate project. In other business this quarter, external sales from the central kitchen contributed significantly. We have commercially converted some of the central kitchen’s excess capacity for external use. Although the growth margin of this type of B end supply chain business is lower than that of the C end restaurant business and there is also order volatility, it dilutes our supply chain fixed cost. Of course, from the perspective of our core model, the Haidilao restaurant main business remains our most core business. Next, regarding cost and expenses benefiting from the company’s proactive investment in employee management and customer experiences throughout 2025, the operating leverage brought by revenue growth in this quarter has led to …

Full story available on Benzinga.com

This post was originally published here

Photo: Proposed layout of Homerun’s planned solar glass manufacturing complex in Bahia, Brazil showing a rooftop-solar-equipped plant and surrounding farmland.

Disseminated on Behalf of: Homerun Resources Inc.

  • Homerun’s Bankable Feasibility Study assigns a base-case net present value of USD$670 million and an internal rate of return of 20.2 per cent to what is positioned as the first dedicated solar pattern glass plant in the Americas.
  • The 1,000 tonne-per-day Belmonte, Bahia facility targets a Brazilian solar market that imported 17.9 gigawatts of photovoltaic modules in 2025 with no domestic solar glass producer to supply it.
  • With letters of intent (LOIs) for roughly 380,000 tonnes per year against plant capacity of 288,300 tonnes, Homerun enters its financing phase with demand visibility above run-rate output.

Brazil is Latin America’s largest solar market, and yet it produces none of its own solar glass. That mismatch defines one of the cleanest first-mover openings in the Americas’ energy transition.

The country imported 17.9 gigawatts of photovoltaic modules in 2025. Roughly 79 per cent went to rooftop and distributed generation. Every panel relies on imported glass moving through 60–90-day Chinese supply chains exposed to tariffs, freight inflation and the long rationalization underway in China’s own solar sector.

That is where Homerun Resources Inc. (TSXV:HMR) (OTCQB:HMRFF) (FSE: 5ZE) (BDR: HMRN31) now finds itself. The Vancouver-based materials company controls the Santa Maria Eterna silica sand district in Belmonte, Bahia, a low-iron, high-purity deposit that feeds a four-vertical strategy spanning industrial silica, solar glass manufacturing, long-duration thermal energy storage and AI-enabled energy management. The solar glass plant sits at the center of that platform, and on May 12th, 2026, the company released a Bankable Feasibility Study confirming the economics of the build.

“Completion of this Bankable Feasibility Study marks a transformational milestone for Homerun and provides a clear technical and financial blueprint for the development of what is intended to be Brazil’s first solar glass manufacturing operation,” —Brian Leeners, CEO of Homerun Resources.

From Validation To A Bankable Number

Before the BFS landed, the Homerun story rested on a thesis that had yet to be quantified: a world-class silica resource paired with the Americas’ missing manufacturing link. The BFS, prepared by Germany-based engineering firm, DTEC PMP GmbH, replaces that thesis with hard numbers.

The base case shows a net present value of USD$670 million, an internal rate of return of 20.2 per cent against a weighted average cost of capital of 4.6 per cent, and an estimated payback of 7.6 years inside a 13-year operating life. Total initial capital expenditure comes in at USD$396.5 million, net of VAT and local taxes.

Indicative gross margins reach approximately 50 per cent at projected 2030 domestic pricing of USD$1,033 per tonne, against unit costs of USD$520 per tonne. By 2033, when the plant reaches full …

Full story available on Benzinga.com

This post was originally published here

Home Depot Inc (NYSE:HD) on Tuesday reported upbeat earnings for the first quarter.

The company posted first-quarter sales of $41.77 billion, up 4.8% year over year and above analyst estimates of $41.53 billion. Adjusted diluted EPS fell to $3.43 from $3.56 but beat analyst estimates of $3.41.

“Our first quarter results were in line with our expectations. The underlying demand in our business was relatively similar to what we saw throughout fiscal 2025, despite greater consumer uncertainty and housing affordability pressure,” said Ted Decker, chair, president, and CEO.

Home Depot reaffirmed fiscal 2026 guidance, including total sales growth of 2.5% to 4.5%, implying sales of $168.80 billion to …

Full story available on Benzinga.com

This post was originally published here

Auna (NYSE:AUNA) held its first-quarter earnings conference call on Wednesday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://events.q4inc.com/attendee/288424677

Summary

Auna reported a 10% revenue growth in the first quarter of 2026, though adjusted EBITDA decreased by 5% due to revenue adjustments and payroll increases.

The company stabilized its hospital platforms in Mexico and Colombia, and expanded higher complexity services in Peru, contributing to strong cash flow and growth momentum.

Auna reaffirmed its annual revenue and EBITDA guidance, expecting stronger growth in the second half of the year driven by improved service utilization and strategic initiatives.

Operational highlights include a 19% quarter-over-quarter increase in adjusted EBITDA in Mexico and a 13% revenue growth in Colombia, with a focus on risk-sharing agreements for predictable cash flow.

Management emphasized efforts to streamline operations and improve billing cycles, particularly in Peru, to mitigate penalties and enhance revenue predictability.

Full Transcript

OPERATOR

Good morning and welcome to Auna first quarter 2026 earnings conference call. My name is Rob and I will be your operator for today’s call. At this time all participants are in listen only mode and please note that this call is being recorded. There will be an opportunity for you to ask questions at the end of today’s presentation. Now I would like to turn the call over to Anna Maria Mora, Head of Investor Relations. Ma’am. Please go ahead.

Anna Maria Mora (Head of Investor Relations)

Thank you operator hello everyone and welcome to Auna’s conference call to review our first quarter results. Please note that there is a webcast presentation to accompany the discussion during this call. If you need a copy of the presentation, please go to our Investor Relations website or contact Auna’s Investor Relations team. Please note that when we discuss variances we will be doing so on a year over year basis and in FX neutral or local currency terms with regard to Mexico and Colombia. Unless we note otherwise, let’s move to slide 2. In addition to reporting on audited financial results in accordance with International Financial Reporting Standards, we will discuss certain non IFRS financial measures and operating metrics, including foreign exchange neutral calculations. Investors should carefully read the definitions of these measures, the metrics and reconciliations included in our earnings press release published yesterday after market close to ensure that they understand them. Non-IFRS financial measures and operating metrics should not be considered in isolation as a substitute for or superior to IFRS financial measures and are provided as supplemental information only before we begin our remarks. Please also note that certain statements made during the course of today’s discussion may constitute forward looking statements which are based on management’s current expectations and beliefs and which are subject to a number of risks and uncertainties that could cause actual results to materially differ, including factors that may be beyond the company’s control. This includes, but are not limited to our target leverage ratio. Suppliers and Information Systems in Mexico the results of the key initiatives we are implementing in Mexico, Colombia and Peru the expected capacity and market of Torres Treca once built the execution of our strategic plan including the recovery of our growth level and the rollout of the Auna Way in Mexico our planned investments, our expected revenue growth and adjusted EBITDA growth, our revenue and adjusted EBITDA guidance and the creation of further growth and sustainable value for all stakeholders. For a description of risks that may impact our forward looking statements, please refer to our Form 20F filing with the U.S. securities and Exchange Commission and our earnings press release. Slide 3 please on today’s call we have Suzo Zamora, our Executive Chairman and President Giselle Remi, our Chief Financial Officer and Executive Vice President, and Lorenzo Massart, our Executive Vice President of Strategy and Equity Capital Markets. They will discuss AWNA’s consolidated and segment financial and operating results for the first quarter as well as provide an update on our various strategic growth initiatives. After that, we will open the call for your questions. Tulsa, please. Go ahead.

Suzo Zamora (Executive Chairman and President)

Thanks Annie. Let’s move to slide 4 please. We got off to a good start in 2026 building commercial momentum across our regional healthcare platform, accelerating growth and generating strong cash flows. We have stabilized and restored growth in Auna’s Mexico hospital platform. We have strengthened Auna’s Colombia hospital platform by expanding our unique risk sharing businesses and deepening our relationships with the country’s largest and best capitalized payers. We continue to grow revenues from Auna Peru’s hospital platform by further expanding our higher complexity services and by growing plan memberships. Our path forward is clear, simplify our model, do more of what we do best and extend the reach of the Auna Way. Now turning to our financial results, Our top line grew 10% FXM in the first quarter with revenues increasing across all segments. However, due to two extraordinary items which we will detail later in the presentation, adjusted EBITDA decreased 5% FXN and margin contracted by 2.9 percentage points. Nonetheless, we are tracking well against our 2026 guidance. In Mexico, we delivered higher service volumes and utilization levels increased. More importantly, utilization grew in high complexity services, particularly in surgeries and oncology. Our operations in Mexico have delivered as planned 19% quarter over quarter increase in adjusted EBITDA. The Peru segment of our integrated platform performed well maintaining its growth momentum during the quarter despite adjustments related to payer reconciliations that impacted revenue and therefore profitability. Revenues increased 9% supported by strong volume growth in healthcare services including high complexity services, while Onco Salud continued to add new plan members through growing B2B sales. In Colombia, we have largely put the intervened payers behind us thanks to risk sharing businesses with establishing new payer relationships. These unique agreements have consistently produced more predictable top line and cash flow growth. Turning briefly to our balance sheet, our leverage ratio was 3.7 times. Our cash position increased 22% to 409 million soles with free cash flow increasing 2.6 times versus a comparable period last year, an important indicator of our ability to optimize our operations for effective cash management across our regional platform. Let’s turn to slide 5. Growing volumes and higher levels of capacity utilization in healthcare combined with increased plan memberships helped drive the quarter’s strong top line growth and cash flow. As you can see in the bottom left of this slide, total utilization increased 1.4 percentage points to 66%. However, our focus is on increasing utilization and higher margin high complexity services rather than on bed occupancy alone. In Peru where our business is vertically integrated, healthcare plan memberships grew 6% while oncology plans grew 3%. Furthermore, the oncology MLR was below 50% within its expected range. The run rate profitability of our regional platform also improved significantly during the quarter. Again, adjusted EBITDA was down 5% FXN, primarily due to revenue adjustments and certain payroll increases. Let’s now move to slide seven for a closer look at the performance of each segment of our platform starting with Mexico. Our Mexico operations recovered strongly during the quarter with revenue increasing 8%. This resulted from our new status in preferred provider tiers with two major payers and doctors hospital, the substantially improved economics of our new east leon contract, expanded B2B service packages and additional growth in the out of pocket segment. This also produced a 19% quarter over quarter increase in adjusted EBITDA and a 3.5 percentage point increase in margin. On a year over year basis, EBITDA increased 23% year over year. Please turn to slide 8. Revenue growth in Peru was 9% and was impacted by revenue adjustments related to higher revenue reconciliation penalties implemented by payers in the market. Revenues from healthcare services grew 7% reflecting the advantages of our growing scale. Commercial initiatives drove most of the volume and utilization increases. On the insurance side, Onco Salud revenues grew 12% driven both by annual price increases and growth in B2B plan memberships, including the 20,000 employees of a new group policy for the nation’s judiciary that we were awarded. We see a growing opportunity for commercial initiatives to increase our share of the B2B segment of Peru’s insurance market. First quarter adjusted EBITDA decreased 3% with margin contracting by 2.3 percentage points impacted by the aforementioned revenue adjustments as well as a delay in rebate recognitions and an increase in doctor compensation. Excluding the revenue adjustments, Peru’s adjusted ebitda would have increased 7%. Let’s move to Colombia on Slide 9. Our revenue growth in Colombia accelerated, growing 13% in the first quarter as we further reduced our reliance on intervene payers and increased the proportion of risk sharing agreements with payers which rose 6 percentage points to 21% of Columbia’s total revenue. It is important to note that revenues From Intervene payers fell 5 percentage points year over year from 19% to 14% at the same time, revenues from new payers increased 1.5 times versus the prior year quarter and currently represent 12% of total revenue. Clearly our franchise is strong in Colombia. We have effectively navigated the fallout from last year’s payer intervention and have emerged growing at a faster pace. Adjusted EBITDA increased 7% with a margin decreasing by 1.7 percentage points. The lower margin mainly reflects the higher proportion of risk sharing contracts and increased variable costs related to higher volumes serviced in high complexity care. Now I’ll turn the call over to Gcelle who will review our results in more detail.

Giselle Remi (Chief Financial Officer and Executive Vice President)

Thanks Susan Beginning with Slide 11, the revenue growth was strong across our regional platform with consolidated revenue reaching 1.2 billion soles at quarter end and year over year growth of 10% in FX neutral terms. As Suso noted, the growth followed the strategic measures that we implemented in Mexico and Colombia last year, helping us to build a healthier revenue mix while Peru continued leveraging its scale to capitalize on the many growth opportunities that remain in its market. Taking a closer look at Mexico’s recovery, this was primarily driven by surgery and oncology volumes which grew 15 and 32% sequentially. In Peru, growing B2B sales were a major growth driver, particularly the 20,000 additional plan memberships through the group policy that we secured with the nation’s judiciary and in our healthcare network. Higher conversion rates drove surgery volumes up significantly while emergency treatments increased 20%. From commercial initiatives applied to corporate policyholders, Colombia grew the strongest during the quarter. In addition to the growth drivers that Suso has already highlighted, it is important to note that our capacity utilization returned to 2024 levels before the revenue rebalancing we conducted reducing exposure to government intervene payers. Let’s now move on to adjusted EBITDA on slide number 12, consolidated adjusted EBITDA decreased 5% FXN and includes the impact of revenue adjustments in Peru and payroll increases in Mexico due to higher compensation costs related to the newly appointed leadership team and to investments in attracting and incentivizing physicians. In Colombia, a 23% increase in the minimum wage drove compensation costs higher versus last year. Adjust EBITDA recovered in Mexico growing 19% quarter on quarter versus fourth quarter of 2025. Let’s now turn to adjusted net income on slide number 13 reflecting the underlying strength of Auna’s regional platform. Our operating profit increased 11% to 155 million soles in the first quarter, which was more than offset by non cash FX losses due to the depreciation of the Peruvian solution below the levels of the protective range of the new hedging structure that we put in place at the end of 2025. This reset will help reduce FX losses in the future which otherwise would have been higher this quarter. Slide 14 Please Our free cash flow increased 2.6 times versus the first quarter of 2025 to 152 million soles primarily on a 45% increase in pre tax operating cash flow shown at the left of the bridge. This reflects our strong growth coupled with higher cash conversion resulting from solid working capital management as well as supplier financing initiatives that we’ve undertaken. Moving to the middle of the bridge, CapEx, which represented 3% of revenue, primarily consisted of infrastructure upgrades, purchases of medical equipment and costs related to the implementation of the new Hospital Information System and erp, mainly in Mexico. This cash use was reduced by an inflow resulting from the continued rebalancing of Auna to WUDOS investment portfolio towards liquid securities. The 88 million soles in financing activities at the right of the Bridge is comprised of 54 million soles of interest and hedge premium payments and interest on working capital facilities as well as a 34 million soles decrease in working capital borrowings. Lastly on this slide, the increase in free cash flow and the reduction in interest payments mean that we expect positive cash flow generation after interest payments to grow in 2026. This will work towards achieving our leverage target of three times in the medium term while also continuing to invest in our growth initiatives. Let’s now move on to slide 15. We began 2026 with a stronger capital structure benefiting from lower interest expenses, an improved maturity profile and reduced FX exposure. It’s important …

Full story available on Benzinga.com

This post was originally published here

Target (NYSE:TGT) reported first-quarter financial results on Wednesday. The transcript from the company’s first-quarter earnings call has been provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://app.webinar.net/j8pvmxBoG2Z

Summary

Target Corp reported a strong first quarter with a 5.6% comp growth driven by increased traffic and strategic changes in offerings.

The company is focused on extensive product and category resets, with significant changes planned for 2026, marking the largest shift in over a decade.

Target Corp is enhancing inventory reliability, utilizing AI for demand forecasting, and opening new facilities to improve product availability.

Partnerships and limited-time offerings, such as collaborations with Roller Rabbit and Pokemon, have been successful in boosting traffic and brand engagement.

The company maintains an optimistic outlook, raising its EPS guidance to the high end of the range, emphasizing sustainable growth and margin expansion.

Full Transcript

Kara

Yeah. And I might just layer on as we think about the areas that we’ve touched so far. We’ve continued to see momentum in our Fund 101 business, which we’ve talked about, which really started last year. As we think about a business like toys, the resets that we’ve done so far this year, adding in newness to Food and beverage, adding space and new items to our wellness and health categories, adding newness to beauty as well as the changes that I talked about, baby. We, we’re really pleased with what we’re seeing as we think about the quarter ahead. We are focusing on continuing to execute well and driving some of the bigger changes. So right now as we speak, we are resetting our dry grocery area. It’s our largest reset that we’ve had in this area in over a decade. We’re pleased with what we’re seeing but we’re really right in the middle of it. And then we are in the beginning of our transformation in home. And so later this quarter we’re going to add in really our threshold shop in shops in about 200 stores and start to really the beginning of that transformation when we think about our decorative accessories category. And then I would just have to also highlight really excited for the launch of the Target Beauty Studio. So the team is a multi month process to get ready for that reset. But we are heads down and really excited about what’s to come. Great, thank you.

OPERATOR

Thank you. Our next question comes from Kate McShane with Goldman Sachs. Your line is open.

Kate McShane (Equity Analyst)

Hi, good morning. Thanks for taking our question. We wanted to ask a few questions around inventory. Thanks for the commentary so far. But we were wondering if you could speak specifically about in stocks and product availability on the shelf, how this is being addressed, what improvements have been made and how, how it’s being measured.

Lisa

Yes. So as you mentioned in stocks are absolutely critical to our guest experience. …

Full story available on Benzinga.com

This post was originally published here

VF (NYSE:VFC) held its fourth-quarter earnings conference call on Wednesday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://events.q4inc.com/attendee/546809840

Summary

VF Corp reported normalized growth trends with Q1 seeing specific impacts due to timing shifts, but overall positive demand for brands like North Face.

Mitigating strategies are in place to handle potential product cost increases due to oil prices, with minimal impact expected for fiscal 27.

The company is aiming for a 10% operating margin run rate by the end of fiscal 28, with ongoing efforts to improve efficiency and reduce leverage.

Vans is showing signs of recovery in the Americas, with strategic product launches and marketing shifts contributing to growth.

Timberland wholesale declined due to reduced distressed sales, but overall inventory health is improving, with continued marketing investments planned.

Full Transcript

Laurent

Super helpful. Thank you very much. Very clear. Best of luck.

OPERATOR

Thanks, Laurent. Your next question comes from the line of Brooke Roach with Goldman Sachs. Your line is open. Please go ahead.

Brooke Roach (Equity Analyst)

Good morning and thank you for taking our question. In the prepared remarks you talked a little bit about some of the drivers of product costs as a result of some of these higher oil prices that will be flowing through the P&L. You mentioned several mitigating factors including pricing. Can you unpack for us a little bit more what the annualized headwind will be when it gets fully into your inventory cost and how much pricing actions you are contemplating both this year and into next year as a result of these inflationary factors, whether it is oil costs or tariffs or other factors in the environment. Thank you. Great. And then just a follow up. Can you unpack the trends that you are seeing in EMEA? What assumptions are you embedding for Western Europe beyond the 100basis points related to the Middle East? Are you seeing any change in demand in that region for any of your brands? Great. Thanks so much. Best of luck.

OPERATOR

Your next question comes from the line of Ike Burechow with Wells Fargo. Your line is open. Please go ahead.

Ike Burechow (Equity Analyst)

Hey guys, can you, can you hear me? Perfectly. Excellent.

Bracken

Hey, Bracken.

Paul

Clarification and a question I think for Paul. The, the refund benefit you saw in the first quarter, should we basically be modeling that as a negative impact? 50 million in the fourth quarter of next year. I’m assuming we should. I just want to kind of make sure that that’s the case. It’s not really a bad guy. So if you really, if you think about it, so the, the, so the full, if you think about the full year at the full year basically assumes that we didn’t have to pay the tariffs. We, we took a receivable to account for that which all hit in Q4. So we tried to normalize for Q4. So just as a level set like this, the, the operating margin, the 7% operating margin in fiscal 26 is a good clean margin. I wouldn’t think about the benefit. Is it a benefit in Q4? I think more a function of if the tariffs are put back in place at the end of July and if we’re back in an environment where, where we’re having to overcome the tariffs, it will impact the back half of the year. That was the 70 to 80 million or so that I mentioned earlier in terms of the, the incremental impact we would see in the back half of the year. So it’s not really, oh, we had a benefit. We didn’t because it’s not really a ‘benefit’. It’s just we had been assuming we’re going to have to pay something. We didn’t. So there’s no impact really at all. We have a clean 7% margin in 26. But next year we will potentially have to face increasing tariffs. If the, if the July announcement goes through and then we have higher top tariffs, it will make Q4 tougher. Compare. But it’s not really like for, like, it’s more that we will potentially have, you know, tariffs back in the mix for Q4 of next year. I’m sorry.

Ike Burechow (Equity Analyst)

Got it. Okay, that’s helpful. And then as a follow up on. On the fiscal 28 margins, I know what the analysts say. I believe you’re. I believe you guys said you were committed to achieving a margin of at least 10% in fiscal 28. I think now you’re saying it’s a run rate. I know there’s noise, tariffs, and other factors, so that’s understandable. But can you just elaborate what ‘run rate’ means? You know, that could mean a lot of things. Is there any more clarity you could kind of give us into what your expectation is for the annual margin in 28?

Bracken

Yeah, let me be crystal clear. So when we gave that, we said in fiscal 28, we would deliver 10%, what we meant was a run rate. And we then got a lot of feedback. Very understandable. Like, so you mean for the full year? And we said, no, we didn’t mean for the full year. We never intended that to be the full year. The idea was that during the year of fiscal 28, we’d reached that. That point where we’d be a 10% margin business. So we described that a couple of quarters ago. We tried to reiterate that to everybody, that it’s. So we use the term exit rate so you can count on as an exit rate fiscal year. As we exit fiscal year 28, we’ve got a 10% operating margin run rate. So the other way we could have said it, maybe we should have said it is full fiscal 29, you can count on 10% or better. So during fiscal 28, we’ll hit 10% sometime during that year, and we have now committed to a 10% exit rate. Is that clear enough?

Ike Burechow (Equity Analyst)

Yeah. I appreciate it. Thanks, Bragan.

Bracken

Great. Thank you. Thank you.

OPERATOR

Thanks for asking that. We were hoping we’d get that. If you hadn’t, Abhishek was gonna ask Paul.

Abhishek

My pleasure.

OPERATOR

Okay. And a kind reminder. If you would like to ask a question, please raise your hand using the raise hand function at the bottom of your screen. And if you have dialed into today’s call. Please press Star 9 to raise your hand. Your next question comes from the line of JSOL with ubs. Your line is open. Please go ahead. A kind reminder to mute yourself, unmute yourself locally.

Jay

Got it. Can everybody hear me now?

OPERATOR

We can hear you perfectly.

Jay

Super braggin. Thank you so much. I just want to ask about the free cash flow guidance for the year. You know, maybe can you elaborate on what ‘flat to up’ means and then what are you comparing it to? Because it looks like in the slide deck you’re comparing it to 405 million for this year. How do we think about the pension expense and the pension termination cash benefits from this year? Are you excluding those from that number? If you could maybe just define the fiscal 26 number, what’s in there and then tell us how you think about free cash flow in 27 in a little bit more detail, that’d be great. Thank you.

Bob

Yeah, sure. So yes, so the pension benefit was when we terminate the pension there was a cash benefit of about $100 million. So our free cash flow including that is 505 on a normalized basis we obviously don’t expect that that was a one time thing. We won’t get that every year. It’s real cash in the door. But so on a normalized basis it’s, you know, 405 million is our free cash flow now that’s up 90 million versus last year. And so again we had said all along that that we would have free cash flow in fiscal 26 that would be flat to up versus you know, last year and we obviously delivered 90 million more than …

Full story available on Benzinga.com

This post was originally published here

A trip to the hospital for an ovarian cyst takes a dark, satirical turn in the second season of Netfilx’s hit comedy-drama “Beef,” 

Confronted with a bleak waiting room, the main characters learn they face a $5,000 health insurance deductible. 

“Oh wow. We can deduct $5,000?” asks Ashley. “What if it costs less? Do they give us the difference?”

“It’s kind of the opposite,” her partner, Austin, replies.

While the exchange is written for laughs, the financial reality behind it is anything but funny. For millions of Americans, the struggle to decode health insurance jargon while staring down thousands of dollars in upfront medical bills is an annual drama. 

Don’t Miss:

According to a 2024 survey by the National Association of Insurance Commissioners, only about 25% of Gen Z adults can correctly define what a “deductible” actually is: the out-of-pocket amount a policyholder must pay before their insurance coverage kicks in.

The Rise of the Multithousand-Dollar Deductible

The era of the $5,000 deductible isn’t a Hollywood exaggeration. In the 1990s and early 2000s, deductibles were rare. Today, they are the industry standard as employers and insurers use them to curb healthcare use and lower premiums. 

Nearly 88% of workers with employer-sponsored coverage have a deductible, up from just 55% in 2006, Matthew Rae, associate director at healthcare research nonprofit KFF, told CNBC.

“A $5,000 deductible doesn’t surprise me at all,” he said. 

While some Affordable Care Act Marketplace plans carry upfront deductibles exceeding $7,000, those with employer-provided plans have seen deductibles jump 17% over the last five years and 43% over the last decade, according to KFF.

Trending: Find out if you qualify to reduce your monthly debt payments — see how much you could save with a quick, free consultation.

Today, about 1 in 5 workers has a single coverage deductible of $3,000 or more, according to KFF.

“Even if it’s not $5,000, that puts a huge financial strain on people,” Rae told CNBC. “It’s a shock to your budget.”  

The Real-World Health Toll

While experts say that high deductibles turn patients into “careful consumers,” health policy advocates warn they frequently backfire by forcing patients to skip essential care. 

“Many consumers may not realize that, with a high-deductible plan, they can face thousands of dollars in healthcare costs,” Georgetown Law O’Neill Institute Associate Director Miriam Straus told CNBC. 

Unaffordable upfront costs lead to worse medical outcomes, Straus said, adding that “among cancer patients, high-deductible health-plan coverage is associated with worse overall survival.” 

See Also: More Than Half of Americans Aren’t Prepared for Retirement — Including 62% of Gen Y

Navigating the Out-of-Pocket Drama

For consumers trapped in high-deductible plans, experts recommend a few tactical moves to manage the financial strain: 

  • Leverage free preventative care: Under the ACA, services like annual physicians, immunizations and select screenings must be 100% covered by in-network providers — even …

Full story available on Benzinga.com

This post was originally published here

Hasbro (NASDAQ:HAS) released first-quarter financial results and hosted an earnings call on Wednesday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/8s7abngq/

Summary

Hasbro reported a 13% revenue growth in Q1 2026, driven largely by Wizards of the Coast, with Magic: The Gathering setting new sales records.

The company maintained its full-year guidance, expecting 3-5% revenue growth, with strategic focus on high-growth categories such as gamified, entertainment-driven products.

Q1 net revenue was $1 billion, with adjusted operating profit up 29% and adjusted EPS up 41% year-over-year.

The cybersecurity incident in March is expected to delay $40-$60 million in consumer products revenue to later in the year, but overall guidance remains unchanged.

Management highlighted the success of new releases, strong partnerships, and upcoming entertainment slates as key growth drivers, while acknowledging challenges such as rising oil costs.

Full Transcript

OPERATOR

Good morning and welcome to the Hasbro’s first quarter 2026 earnings call. At this time, all parties will be in a listen only mode. A question and answer session will follow the formal presentation. If anyone should require operator assistance during the call, please press 0 on your telephone keypad. Today’s conference is being recorded. If you have any objections, you may disconnect at this time. Finally, I’d like to turn the call over to Fred Whiteman, Vice President, Hasbro Investor Relations. Please go ahead, sir.

Fred Whiteman (Vice President, Investor Relations)

Thank you and good morning everyone. Joining me today are Chris Cox, Hasbro’s Chief Executive Officer, and Gina Guider, Hasbro’s Chief Financial Officer and Chief Operating Officer. We’ll begin today’s call with Chris and Gina providing commentary on the company’s performance before taking your questions. Our earnings release and presentation slides for today’s call are posted on our investor website. The press release and presentation include information regarding non GAAP adjustments and non GAAP financial measures. Our call today will discuss certain adjusted measures which exclude these non GAAP adjustments. A reconciliation of GAAP to non GAAP measures is included in the press release and presentation. Please note that whenever we discuss Earnings Per share or EPS, we are referring to earnings per diluted share. Before we begin, I would like to remind you that during this call and the question and answer session follows, members of Hasbro Management may make forward looking statements concerning management’s expectations, goals, objectives and similar matters. There are many factors that could cause actual results or events to differ materially from the anticipated results or other expectations expressed in these forward looking statements. These factors include those set forth in our annual report on Form 10-K, our most recent 10-Q in today’s press release and in our other public disclosures. We undertake no obligation to update any forward looking statements made today to reflect events or circumstances occurring after the date of this call. I would now like to introduce Chris Cox.

Chris Cox (Chief Executive Officer)

Thanks, Fred and good morning everyone. Hasbro started 2026 with Momentum. Revenue grew 13% powered by Wizards of the coast while consumer products posted point of sale growth and share gains across our key gem squared categories. These results reinforce our confidence in the playing to win strategy as Hasbro’s defi portfolio, industry leading licensing capabilities and world class partners position us for success today and into the future. Let’s dig into results starting with Wizards of the coast. Q1 showed that Magic’s record 2025 was no fluke. Lorwyn Eclipsed, which debuted in January, became the best selling Magic premier set of all time and delivered the highest engagement and organized play statistics we’ve seen since the pandemic. We follow that with the Teenage Mutant Ninja Universes beyond collaboration that outpaced internal expectations. More proof that our multi franchise strategy is expanding. The Magic audience backlist was once again a standout, setting a quarterly record thanks to demand for the Last Airbender and Final fantasy. We’re only one quarter into the year, but 2026 already represents the third largest backlist year in Magic’s history. We’re seeing record demand extend beyond tabletop and digital into live experiences too. MagicCon Las Vegas sold more than 23,000 badges, making it the largest magic event ever. That demand is global. MagicCon Amsterdam is on track to sell out as well. From our tentpole MagicCons to weekly organized play events across More than 11,000 Wizards play network stores, the flywheel of new player acquisition, distribution growth and durable retention are showing up in the numbers. Magic’s momentum has carried into Q2, where secrets of Strixhaven already have surpassed Lorwyn Eclipsed as the largest Magic premier set ever. The rest of the year features a blockbuster Universes beyond slate with Marvel superheroes the Hobbit and Star Trek. And yesterday, in partnership with the Walt Disney Company, we announced Magic arena will feature full digital rights for the upcoming Marvel Superheroes launch. This is a meaningful step forward in our strategy to extend the magic ecosystem across platforms and reach new fans wherever they play. Outside of Magic, Wizards of the coast teams are polishing our AAA video game launches, Exodus from Archetype and Warlock from Invoke. Both titles remain on schedule to launch next year and we’re excited to share Exodus extended showcase with fans later this summer. D and D is on a great trajectory. We launched Dungeon Masters, our first official D and D actual play series on YouTube featuring talent from Baldur’s Gate 3 alongside top creators in the tabletop space. Turning to consumer products, we’re continuing to see POS momentum with positive trends in first quarter that have continued through the end of April with lean retailer inventories. We remain on plan to grow the segment for the year. Our focus on gem squared categories, those parts of the toy industry that are gamified, entertainment driven, multi purchase and multi generational, continues to pay dividends. These are structurally advantaged categories with above industry growth and we gained share in many of our key categories in the first quarter. Looking ahead, we’re two days away from Star Wars return to theaters for the first time since 2019 with the Mandalorian and Grogu, we have a strong lineup of product on shelves and if early demand for our ultimate grogu is any indication fans are as excited as we are. We have three additional tentpole releases ahead, including Disney and Pixar’s Toy Story 5, Brand New Day and Marvel Studios Doomsday. That is a stacked content lineup that creates real opportunity across consumer products with positive early reads from FIFA Monopoly, including Blaster boxes that are resonating with collectors and live sellers alike. Category first innovation from the Play DOH brand this summer and K Pop Demon Hunters product hitting shelves in July. There’s a lot to look forward to at Hasbro. Before I hand off to Gina to walk through the financials, I want to offer a sincere thank you to our team and partners for delivering a great start to 2026. I want to give a special call out to our IT sales, finance and operations teams who have kept Hasbro open for business despite the cybersecurity incident and enhanced precautions we have taken. With that, I’ll turn it over to Gina.

Gina Guider

Thanks Chris and good morning everyone. We delivered a strong start to 2026 with Q1 results, on track across revenue, profit and margin. Net revenue in the first quarter was $1 billion, up 13% year over year, driven by performance in Wizards. Adjusted operating profit of $287 million increased 29% with an adjusted operating margin of 28.7%, up 360 basis points versus last year from favorable business mix and cost savings. Adjusted earnings per diluted share were $1.47, up 41% year over year, reflecting strong operating leverage and disciplined execution. Looking more closely at the segments Wizards’ momentum continued. Segment revenue grew 26% to $582 million behind the Strength in Magic. Operating profit increased 29% to $298 million with a 51.2% operating margin up 140 basis points versus last year. Product mix and scale were more than able to offset the headwind of higher royalty and operating expense. The Magic’s ecosystem remained healthy through the quarter, with both Backlist and Secret Lair posting double digit growth and we achieved meaningful distribution gains within the Wizards Play network, underscoring the durability of the franchise. Digital and licensing revenue was up 3% and monopoly Go delivered $41 million of revenue in line with our expectations. Consumer products revenue was $398 million essentially flat year over year, with growth in toy and game volume offset by a decline in licensing as we lap challenging prior year compares. Adjusted operating loss was $41 million, a decline of roughly 10 million versus last year on an adjusted basis. The loss reflects higher royalty expense. Incremental tariffs and the impact of prior year licensing strength. As we move through the quarter, P.O.S. performance was in line with expectations and both owned and retail inventory levels remain healthy, providing a good setup in advance of key theatrical windows as well as the upcoming seasonal builds. The Entertainment segment delivered $20 million in revenue and $20 million in adjusted operating profit which was also in line with expectations. Q1 profitability was favorably impacted by the timing of entertainment backed revenues in the consumer products segment, namely for Peppa Pig. Our cost transformation efforts delivered $37 million in gross savings which has us on track for our full year commitment of $150 million. Total Hasbro adjusted EBITDA was 339 million and up 24% versus last year behind planned efficiencies across supply chain product development and SGA supporting margin expansion even as we absorbed elevated royalties and incremental investments for our upcoming 2027 digital game launches. From a balance sheet and cash flow perspective, we generated $338 million in operating cash flow, funded $50 million in strategic investments and returned $99 million to shareholders via our dividend and we started share repurchases under our recently authorized share repurchase program. Finally, we issued $400 million of new notes with the proceeds going towards fully repaying the November 2026 maturities and the balance applied to the repurchase of higher rate longer dated debt. We are encouraged by our strong start to the year and believe we are well positioned to continue the momentum and deliver on our full year financial commitments. The macro environment continues to require agility including absorbing and offsetting the impact of rising oil costs across the business which impacts our freight, resin and packaging costs. While the impact of higher inputs won’t be realized until the back half of 2026, we have several actions underway across a variety of operating levers including freight optimization, mix management and operating spend reductions to mitigate the impact. As we look to our full year outlook, …

Full story available on Benzinga.com

This post was originally published here

On CNBC’s “Halftime Report Final Trades,” Brian Belski, founder, CEO and chief investment officer at Humilis Investment Strategies, named NextEra Energy, Inc. (NYSE:NEE) as his final trade.

As per the recent news, NextEra Energy, on May 18, entered into a definitive agreement to combine with Dominion Energy. As per the terms, Dominion shareholders will receive 0.8138 NextEra shares per Dominion share. This implies an ownership split of approximately 74.5% for NextEra and 25.5% for Dominion shareholders in the combined entity.

Jim Lebenthal, partner at Cerity Partners, picked Transocean Ltd. (NYSE:RIG).

Supporting his view, Barclays analyst Eddie Kim, on May …

Full story available on Benzinga.com

This post was originally published here

NVIDIA Corporation (NASDAQ:NVDA) will release earnings for its first quarter after the closing bell on Wednesday, May 20.

Analysts expect the Santa Clara, California-based company to report quarterly earnings of $1.76 per share, up from 96 cents per share in the year-ago period. The consensus estimate for NVDA’s quarterly revenue is $79.04 billion (it reported $44.06 billion last year), according to Benzinga Pro.

The company has beaten analyst estimates for revenue in 14 straight quarters.

Nvidia shares fell 0.8% to close at $220.61 on Tuesday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate analysts have rated the company

Full story available on Benzinga.com

This post was originally published here

Rockwell Medical, Inc. (NASDAQ:RMTI) stock is up during Wednesday’s premarket session, trading higher by 6.40% as the company has renewed a product purchase agreement with aQua Dialysis.

This agreement, which spans two years with options for two additional one-year extensions, underscores the company’s commitment to providing essential hemodialysis products.

The renewed agreement with aQua Dialysis allows Rockwell Medical to continue supplying liquid and dry hemodialysis concentrates, reinforcing its long-standing relationship with the provider.

“We are pleased to continue supporting aQua Dialysis through our renewed agreement that reflects the strength of our long-standing relationship,” said Chief Commercial Officer Tim Chole at Rockwell Medical.

This partnership is seen as a testament to Rockwell’s product quality and service reliability.

Technical Analysis

RMTI is sitting …

Full story available on Benzinga.com

This post was originally published here

RLX Technology (NYSE:RLX) released first-quarter financial results and hosted an earnings call on Wednesday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://event.choruscall.com/mediaframe/webcast.html?webcastid=gs9Po49m

Summary

RLX Technology reported a strong revenue growth of 96.2% year-over-year and 38.9% quarter-over-quarter, driven by international expansion and stability in the Chinese market.

The company emphasized its strategic focus on international expansion, particularly in Europe, and its integrated smart manufacturing facility, Nexus, which enhances operational efficiency.

RLX Technology sees regulatory changes, such as the UK’s Tobacco and Vapes Act, as beneficial, positioning the company well in a market increasingly focused on harm reduction alternatives.

Gross margin improved to 31.8%, with non-GAAP operating margin reaching 19.6%, demonstrating effective cost management and operational efficiency.

The company maintains a robust financial position, with financial assets totaling RMB 14.53 billion, supporting future growth and expansion plans.

Full Transcript

OPERATOR

Hello, ladies and gentlemen. Thank you for standing by for RLX Technology Inc.’s first quarter 2026 earnings conference call. At this time, all participants are in listen only mode. After management’s remarks, there will be a question and answer session. Today’s conference call is being recorded and is expected to last for about 40 minutes. I will now turn the call over to your host, Mr. Sam Tsang, head of Capital Markets for the company. Please go ahead, Sam.

Sam Tsang (Head of Capital Markets)

Thank you very much. Hello everyone and welcome to RLX Technology first quarter 2026 earnings conference call. The Company’s financial and operational results were released through PL News via Services earlier today and have been made available online. You can also view the earnings press release by visiting our IR website at ir.relaxtech.com Participants on today’s call will include our Chief Executive Officer, Ms. Kei Zhuang, our Chief Financial Officer, Mr. Chao Lu, and me, Sam Tsang, Head of Capital Markets. Before we continue, please note that today’s discussion will contain forward looking information made under the safe harbor provisions of the U.S. private Securities Litigation Reform act of 1995. These statements usually contain words such as may, will, expect, anticipate, aim and estimates, intent, plan, belief, potential, continue, or other similar expressions. Forward looking statements involve inherent risks and uncertainties. The accuracy of these statements may be impacted by a number of missed risks and uncertainties that could cause actual results to differ materially from those projected or anticipated, many of which are factors beyond our control. The Company’s affiliates, advisors and representatives do not undertake any obligation to update this forward looking information except as required under the applicable law. Please note that RLX Technology earnings press release and this conference call include discussions of unaudited GAAP financial measures as well as unaudited non GAAP financial measures. Our press release contains a reconciliation of the unaudited non GAAP measures to the unaudited GAAP measures. For today’s call, management will use English as the main language. We will also provide simultaneous interpretation on the Chinese line. Please note that the Chinese line is in listen only mode and Chinese interpretation is for convenience only. In case of any discrepancy, management statements in the original language will prevail. I will now turn the call over to Ms. K. Swan. Please go ahead.

Kei Zwang (Chief Executive Officer)

Thank you, Sam, and thank you all for joining today’s call. We are off to a robust start in 2026, supported by a highly scalable global ecosystem and our ability to capture rising market opportunities. We achieved strong revenue growth, increasing by 96.2% year over year and 38.9% quarter over quarter. As we continue to accelerate our international expansion and deepen our global presence. Our international business sustains its rapid organic growth while our mainland China business demonstrated resilience and stability. We further refined our user first approach through highly localized strategies and engagement with trusted regional business partners across the value chain to ensure superior product market. We also integrated our R and D, manufacturing and commercial operation into our cutting edge hub which we called nexus, further enhancing our core capabilities and competitive edge. These initiatives, along with our growing operational agility, enable us to quickly align with evolving market dynamics and seamlessly meet global demand, further strengthening our presence across key international markets. Let me now walk you through our recent business update in more detail. The global regulatory landscape around tobacco and smokeless alternatives continues to evolve. The United Kingdom’s landmark Tobacco and VAPES act, which officially became law in April 2026, is a notable example, reflecting a growing global trend toward phasing out combustibles while maintaining regulated pathways for harm reduction alternatives. Under this rule, Anyone born after 2009 will never be legally permitted to purchase combustible cigarettes. Importantly, the ban applies only to cigarettes and exempts regulated harm reduction alternatives such as vapes. In effect, the UK is gradually eliminating the future consumer base for cigarettes while preserving the existing regulatory framework for our category. We believe that this will now be an isolated development. Public health improvements are increasing being pursued worldwide by restricting tobacco well regulating harm reduction products. For companies like RLX Technology with strong compliance capabilities, best in class product quality and a proactive regulatory approach, this represents a welcome structural tailwind rather than a headwind. A well regulated market rewards scale, compliance and innovation areas where we already lead. As regulatory uncertainty diminish, the competitive landscape is expected to become more defined and our differentiated position may become even more valuable. Moving on to our international expansion, Europe maintains a cornerstone of our global strategy given its increasingly mature regulatory environment and strong demand for high quality alternatives. Our May 2025 strategic investment in a European company has delivered value that extends well beyond the financial scope, strengthening our capability in navigating local market dynamics. Our successful integration and operational appearance have given us the confidence to evaluate further expansion across the continent. Our expansion in Europe is driven by a dual engine strategy that plays the equal importance on strategic M and A and organic growth. While we are optimistic about European’s potential, we maintain a highly selective approach to strategic investments, prioritizing long term synergy rather than …

Full story available on Benzinga.com

This post was originally published here

OpenAI and Alphabet Inc. (NASDAQ:GOOGL) are both deepening their Singapore AI investment commitments. Together, the two deals signal something far bigger than bilateral agreements. They tell investors where the next frontier of AI monetization is being built.

OpenAI Plants Its First Flag Outside the U.S.

OpenAI has signed a memorandum of understanding with Singapore’s Ministry of Digital Development and Information. The deal commits more than S$300 million, roughly USD 234 million, to strengthen the city-state’s AI ecosystem. Furthermore, it establishes the OpenAI Singapore Applied AI Lab, the company’s first outside the United States. According to Bloomberg and CNBC, the lab will expand OpenAI’s Singapore-based technical team to more than 200 roles over the next few years.

That distinction matters enormously for investors. OpenAI has not opened an applied AI lab in London, Tokyo, or Dubai. Singapore gets the first one. That is not a routine expansion. It is a strategic anchor.

The lab’s mandate also reveals a clear commercial logic. According to a joint statement from OpenAI and Singapore’s Ministry of Digital Development and Information, the work covers national priorities including public services, finance, healthcare, and digital infrastructure. Additionally, the initiative includes a mid-career engineer training program and co-developed AI startup accelerators. Those are long-term, government-backed revenue pipelines.

Moreover, OpenAI’s Chief Revenue Officer, Denise Dresser, confirmed the commercial framing. She noted that Singapore brings strong technical talent, trusted institutions, and a clear ambition to use AI for long-term growth. That language signals enterprise contract ambitions, not just research goodwill.

Google’s Strategy Is Different, and Equally Deliberate

Alphabet’s approach to Singapore follows a different but complementary logic. Google announced a new National AI Partnership with Singapore at the ATxSummit on May 20. Unlike OpenAI’s deal, Google’s announcement did not include a fixed cash commitment. However, the strategic depth is notable.

According to Google’s official blog and reporting by CNBC, the partnership covers education, healthcare, scientific research, workforce readiness, enterprise innovation, and building a secure AI ecosystem. Google is also working with Singapore’s Ministry of Education to train educators and with the National …

Full story available on Benzinga.com

This post was originally published here

On Wednesday, Cadeler (NYSE:CDLR) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://cadeler-q1-2026-earnings-presentation.open-exchange.net/registration

Summary

Cadeler A/S reported a solid financial performance in Q1 2026, with revenue of €124.7 million, up from €65.5 million last year, and EBITDA of €47 million.

The company maintains a strong backlog of €2.7 billion, providing robust earnings visibility, with significant projects underway and successful mobilization of key vessels.

Strategic initiatives include continued vessel expansion, with new builds on schedule, and the execution of a private placement to support future growth, including two new T-class vessels and a rock dumping installation vessel.

Management expressed confidence in future prospects, maintaining full-year guidance and highlighting strong market demand for offshore wind projects, particularly in Europe.

Operational highlights include successful project execution milestones, such as the installation of monopiles in the Hornsea 3 project, and high vessel utilization rates.

Full Transcript

OPERATOR

Good morning and welcome to Cadala’s Q1 2026 Earnings Good morning and welcome to Cadeler A/S’s Q1 2026 earnings presentation. Presenting today are Mikael Glierup, Chief Executive Officer and Peter Brogard, Chief Financial Office Officer. Please be reminded that the presenter’s remarks today will include forward looking statements. Actual results may differ materially from those contemplated. The risks and uncertainties that could cause cadla’s results to differ materially from today’s forward looking statements include Those detailed in Cadeler A/S’s Annual Report on Form 20F on file with the United States securities and Exchange Commission. Any forward looking statements made this morning are based on assumptions as of today and Cadeler A/S undertakes no objectives obligation to update these statements as a result of new information or future events. This morning’s presentation includes both IFRS and certain non IFRS financial measures. A reconciliation of non IFRS financial measures to the nearest IFRS equivalent is provided in Cadeler A/S’s annual report. The Annual report and today’s earnings presentation are available on Cadeler A/S’s website at Cadeler A/S. We ask that you please hold all questions until the completion of the formal remarks, at which time you will be given instructions for the question and answer session. As a reminder, this call is being recorded today. If you have any objections, please disconnect at this time. Mikhail Glierup, you may begin.

Mikael Glierup (Chief Executive Officer)

Thank you very much and hello to everyone and thank you for joining this Q1 2026 presentation from Cadeler A/S. Just to start off the presentation really a quarter that has has been running exactly as expected. Financial performance in line with our expectations, continuing a robust backlog of work standing currently at 2.7 billion euro which we believe provides a very solid earnings visibility for the company. New build program on track. We named the second A class vessel in April and she is about to deliver in the next couple of months as per the schedule. The second or the third rather A class vessel is delivering next year and is also on the schedule. We have continued with solid execution across the globe and I’m also very pleased to say that wind Ally and Windorca are fully mobilized and first complete monopile foundation has been installed on ONC3 which is very very important and a very important milestone for 2026 and we have a little bit extra on that presentation. Very strong utilization vessels operating across the world and NEXO has secured utilization on multiple projects in APEC and on the utilization. I would like just to quickly say that obviously we have many vessels that have been shifting between projects. So a lot of mobilization in the first quarter of the year, which has also been exactly as expected. Terms of growth, commercial highlights, vessels continuing to execute on projects across the fleet. Really a busy, busy, busy quarter in terms of managing vessels coming off projects, starting new projects and having other vessels coming in to take over on projects due to many different factors. But really overall I would also say a quarter where we have been able to support our clients and to do what has been necessary necessary to help them on their projects where they are currently engaged. Also very pleased to see that when Kiba has started its operation with Vestas and is performing on the project with Vestas as we speak. Next slide please on horn C3. As I said, really from concept to delivery, we have had many, many questions over the course of the last four years where we have been in process towards the horn C3 execution. A lot of planning is now finally coming to fruition and it’s very pleasing to be able to say that we now have proof of concept on the project with the first full monopile installed and also all the secondary components being installed on that and being commissioned and handed over to the client. And actually we have eight monopiles in the water as per today’s date. We have seven full secondary steel sets installed and five fully commissioned monopiles out there. So really the project is going as per the plan. The equipment that we have invested in that we are using on the project is working as we expected it and we are now slowly ramping up the speed on the project to get up to the speed where we want to be and to really make sure that there will be a smooth installation on this very, very important project, both for us and Cadeler A/S, but certainly also for our clients. So very, very pleased to say that we have proof of concept and that we are now delivering the full T Foundation project. Still sitting on a very significant backlog across key markets. 2.7 billion backlog, as I said, already provides a very solid earnings visibility. We continue to operate in the us, in Europe and in APEC and are really working on a lot of different opportunities for the future years as we have said in this quarter. Also we have executed a private placement for the investment in additional jack ups for the future and also for a rock dumping installation vessel that we believe all will strengthen our portfolio and our ability to support the clients going forward. We have also projects that are not in the backlog but where we are currently working and projects that will be added to the backlog as and when they come to fruition. But all in all, I would say that we have been reaffirmed in our opinion since the beginning, beginning of the year that we are looking at a very, very busy 26, 27. As we have also said, 28 is a different year, but we remain in the same position as we were when we did the annual report. And for 2029 we are working on some very, very interesting prospects at the moment. When we look into the new decade, we are also seeing very interesting projects and also a lot of projects currently in what we call category high. So this is really the category where we are working already now intensively with the client and where we believe that our vessels will be busy in the beginning of the next decade on the backlog, 82% of the backlog have reached FID. We believe that that is a very, very solid number and also gives us the earnings visibility that we really need as a company. We also see the start of nextra and the foundation of nextra starting to live the deliver contracts in Taiwan, which is of course very pleasing. And our ambitions on nextra continues to be strong and we continue to see that our main market for Nextra is the +1112 megawatt segment where we believe that we have a very good foundation to play for the main components replacements for the bigger turbine sets in the industry. We also have preferred supply agreement that is not included in the backlog and where we currently are negotiating with a client for installation in 28. In terms of the progress on the new builds, the windeis we expect the delivery in the beginning of the third quarter this year. We have basically done most of the of the material work there, but we are still having some tests planned for the vessel between now and the delivery and we believe that we are in a very, very good position to deliver this vessel on schedule and on budget. We had the naming ceremony this year and we were proud to have Ms. Lisa Western naming the vessel for us, the Wind Apex. As we also talked about on the annual report, we expect the Wind Apex to deliver in Q2 27 and we have been negotiating with the yacht to manage early delivery of this vessel because we are working with a client for the Wind Apex …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Raymond James analyst John Freeman upgraded SM Energy (NYSE:SM) from Underperform to Outperform and announced a $55 price target. SM Energy shares closed at $34.32 on Tuesday. See how other analysts view this stock.
  • Oppenheimer analyst Param Singh upgraded Rubrik Inc (NYSE:RBRK) from Perform to Outperform and announced a price target of $85. Rubrik shares closed at $64.33 on Tuesday.

Full story available on Benzinga.com

This post was originally published here

As of May 20, 2026, two stocks in the health care sector could be flashing a real warning to investors who value momentum as a key criteria in their trading decisions.

The RSI is a momentum indicator, which compares a stock’s strength on days when prices go up to its strength on days when prices go down. When compared to a stock’s price action, it can give traders a better sense of how a stock may perform in the short term. An asset is typically considered overbought when the RSI is above 70, according to Benzinga Pro.

Here’s the latest list of major overbought players in this sector.

Avanos Medical Inc (NYSE:AVNS)

  • On May 5, Avanos Medical posted better-than-expected quarterly earnings. “Building off our strong 2025 results, we delivered solid first quarter performance …

Full story available on Benzinga.com

This post was originally published here

World Gold Council CEO David Tait says Bitcoin (CRYPTO: BTC) is going to zero, calling it “pure instinct” with no reasoning behind the view.

Gold Council CEO: Bitcoin Doesn’t Offset Risk Assets

Tait explained on Tuesday that Bitcoin correlates with risk assets during crises instead of offsetting them as intended. 

He believes Bitcoin was meant to disassociate itself from risky assets but hasn’t delivered on that promise.

“I thought it was meant to be an offset, something that you could compensate for having exposure to risky assets,” Tait stated. “It didn’t really do that to that extent,” he added.

He also argued that investors should hold both gold and Bitcoin if they have either, since the assets offset each other. However, his personal view is that Bitcoin won’t sustain in the very long term.

When Asked What Would Change His Mind: Nothing

When pressed on what …

Full story available on Benzinga.com

This post was originally published here

On Wednesday, GDS Holdings (NASDAQ:GDS) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/srdchp4c/

Summary

GDS Holdings reported a resurgence in data center demand driven by AI, with bookings reaching 1.8 gigawatts and a target of adding 500 to 800 megawatts annually over the next three years.

The company plans to invest RMB 30 billion to RMB 50 billion in new data center development, supported by a strong balance sheet and customer commitments.

Financial performance showed a 7.9% growth in revenue and 8% growth in adjusted EBITDA for Q1 2026, with stable pricing and improved unit development costs.

GDS Holdings maintains a full-year sales target of at least 500 megawatts and has already achieved over 340 megawatts in new bookings year-to-date.

Management expressed confidence in meeting growth targets due to a solid pipeline, strategic land acquisitions, and a disciplined approach to new orders.

Full Transcript

Laura Chen (Moderator)

Laura hello everyone. Welcome to the first quarter 2026 earnings conference call of GDS Holdings Ltd. The company’s results were issued via PR Newswire Services earlier today and are posted online. A summary presentation which we will refer to during this conference call can be viewed and downloaded from our IR website at investors.gdsservices.com Leading today’s call is Mr. William Huang, GDS founder, chairman and CEO, who will provide an overview of our business strategy and performance. Mr. Dan Newman, GDS CFO, will then review the financial and operating results. Before we continue, please note that today’s discussion will contain forward looking statements made under the safe harbor provisions of the U.S. private Securities Litigation Reform act of 1995. Forward looking statements involve inherent risks and uncertainties. As such, the Company’s results may be materially different from the views expressed. Further information regarding these and other risks uncertainties is included in the Company’s prospectus as filed with the U.S. SEC. The Company does not assume any obligation to update any forward looking statements except as required under applicable law. Please also note that GDS earnings press release and its conference call can include discussions of unaudited GAAP financial information as well as unaudited non GAAP financial measures. GDS press release contains a reconciliation of the unaudited non GAAP measures to the unaudited, most directly comparable GAAP measures. I’ll now turn the call over to GDS founder, chairman and CEO Mr. William Huang.

William Huang (Founder, Chairman, and CEO)

Please go ahead William hello everyone, this is William. Thank you for joining us on today’s call. Over the past few quarters we have seen a resurgence in data center demand driven by AI. We believe this is the beginning of a multi year growth story supported by increasing availability of domestic chips. Customers are planning their future deployments at unprecedented scale with a high degree of conviction. As market leaders, GDS is well prepared to address these opportunities to the fullest extent. We have the trust of all the key customers, a multi gigawatt development pipeline in strategic locations and a very strong balance sheet. Up to the end of 1Q26 our total bookings stood at 1.8 gigawatts. In our three years business plan we target adding 500 megawatts to 800 megawatts of new bookings every year with the potential to do more to deliver this capacity. We are prepared to commit RMB 30 billion to RMB 50 billion of new investment over the next three years. The economics of the data center business in China is solid and this new investment will create significant value for our shareholders. On the last earnings call, we announced a sales target for 2026 of at least 500 megawatts in the year today we have already done over 340 megawatts of new bookings and we are still being selective. We are well on track to reach or exceed our full year target. We have won significant new orders from all of our largest customers for deployments across the whole of our platform including the new markets. For the hyperscale business, customers are planning gigawatt scale deployments in single clusters. When they sign new sales agreements with us, they commit to a certain amount of capacity which we disclose as bookings and ask us to reserve the rest of the site for their subsequent phases in a year or so. Today, total new bookings plus reservations comes to over 1 gigawatt. The reservation give us near certainty of winning follow on orders within the next one or two years. In order to fulfill our customer requirements, we expanded our platform to new locations which can accommodate the largest AI deployments. These new locations integrated well with our platform in established market enabling us to serve diversified customer requirement. Anticipating this demand trend, we increased our secured land bank to nearly 4 gigawatts. Typically, we are purchasing land from the government exclusively for our data center development. As we obtain customer commitment, we will be granted a power quota for this site. We synchronized the timing of construction with new bookings and fixed moving schedules. Over the past 15 months we initiated over 100,000 square meters or 400 megawatts of new construction which is almost entirely pre committed. Our backlog has increased to over 200,000 square meters or almost 600 megawatts, most of which will become billable within the next six to eight quarters. As this occurs, our growth will start to accelerate. AI in China is a transformational opportunity. We are super motivated to support this development and will commit all the resource requirements to the expansion of our AI infrastructure platform. I will now pass on to Dan for the financial and operating review.

Dan Newman (Chief Financial Officer)

Thank you William. Around new business, the unit development cost averages around 20,000 RMB per kilowatt or US$3 million per megawatt depending on specification, cooling technology and location. Pricing for new business is stable and at current levels we’re able to generate an adjusted gross profit yield of 10 to 11% for stabilized assets as shown on slide 13 across the whole of our in service portfolio. The adjusted gross profit yield is currently around 11%. We calculate this ratio based on adjusted gross profit which includes the cash cost of operating assets divided by gross PP and E which includes replacement capex already incurred. And for conservatism we added back historic impairment charges. The portfolio yield has been stable at around 11% for the past few years based on a portfolio with utilization rate of around 75%. As our new bookings are delivered, we expect the portfolio yield to remain in the 10% to 11% range, which in our view is a reasonable return. Assuming a six year investment cycle of development, ramp up stabilized operations and then asset monetization, we expect to generate a return on equity of around 20% from the incremental investment. This underpins our confidence in growing the business. As shown on slide 13 during the first quarter net additional area utilized was around …

Full story available on Benzinga.com

This post was originally published here

Bitcoin (CRYPTO: BTC) trades around $77,000, following $1 billion in outflows last week after a six-week inflow streak.

Bitcoin Failed At 200-Day MA On First Real Macro Shock

Bitcoin popped above $82,000 on the CLARITY Act vote, then reversed hard and now sits below the 200-day moving average at $82,200 after getting rejected five times this month.

Support holds at $76,000-$78,000. Breaking below $75,000 opens up $70,000-$72,000.

The weekend slide toward $77,000 triggered $657 million in liquidations, $584 million from longs.

Meanwhile, Ethereum (CRYPTO: ETH) dropped 10%, continuing to underperform across spot and derivatives. ETH/BTC pressed 0.0275 with funding softer and relative implied volatility elevated.

Institutions Sold …

Full story available on Benzinga.com

This post was originally published here

A San Antonio investor with $125,000 wanted to know whether flipping homes or buying rentals made more sense.

Jason raised the question on “The Ramsey Show” after he and his family completed three successful real estate transactions. 

“Flips are a pain in the butt,” personal finance expert Dave Ramsey said.

Don’t Miss:

The Legal Wall Ramsey Builds Around His Properties 

Jason asked Ramsey and co-host John Delony whether investment properties should be bought through an LLC or under his own name.

Ramsey said he places properties inside LLCs, forming new entities as his holdings grow.  

The setup, Ramsey said, is meant to protect other assets if a tenant sues after an accident at a rental house. In that case, the tenant would have to sue the LLC that owned the property. “If they were to win, they can take what that LLC owns but nothing else,” he said.

Ramsey advised Jason to form an LLC even if he only planned to buy one or two houses.

What 2,500 Flips Taught Ramsey 

Jason also wanted Ramsey’s take on flipping homes versus holding rentals.

Flipping meant renovating and reselling properties, according to Ramsey. Investors also end up managing subcontractors, choosing materials, handling roofs and pulling permits with local municipalities. “It’s like building a dadgum house,” he said.

Trending: See how accredited investors are tapping into Midwest multifamily deals most people never get access to—click here for details.

Ramsey said investors can make money flipping homes if they buy the property at the right price, but the work quickly becomes a job.

“I’ve probably done 2,500 flips in my life,” he said. Ramsey said he now usually buys properties and holds them long term instead of reselling them.

He said cable television had made flipping famous, but many people entering real estate “understand about 10% of how hard it’s going to be.”

Ramsey Pushes Back On ‘Passive’ Real Estate

Jason later told the hosts he parked the remaining $125,000 from a recent property sale in an S&P fund while deciding what to do next.

Lower-cost rentals can produce stronger returns, Ramsey said, but they also bring more hassle. Higher-end rentals usually attract more stable tenants, though the percentage returns may be lower.

See Also: What If Your Investment Income Didn’t Rely Entirely on Market Swings? Some Investors Are Taking a Different Approach

Still, Ramsey urged him to consider how a property would age over the next 10 years before buying it, especially if the house was already decades old.

Delony said the decision should start with the kind of life an investor wants, from handling property problems to working with contractors on renovation projects. “If you want to set it and forget it, that’s …

Full story available on Benzinga.com

This post was originally published here

U.S. stock futures were higher this morning, with the Nasdaq futures gaining around 150 points on Wednesday.

Shares of Lowe’s Companies Inc (NYSE:LOW) fell in pre-market trading after the company reported first-quarter financial results.

Lowe’s reported quarterly earnings of $3.03 per share which beat the analyst consensus estimate of $2.97 per share. The company reported quarterly sales of $23.078 billion which beat the analyst consensus estimate of $22.977 billion.

Lowe’s Companies said it sees FY2026 GAAP EPS of $11.75-$12.25, versus market estimates of $12.44.

Lowe’s shares dipped 2.5% to $213.02 in pre-market trading.

Here are some other stocks moving lower in pre-market trading.

  • OIO Group (NASDAQ:OIO) dipped 17.9% to $1.51 …

Full story available on Benzinga.com

This post was originally published here

Shares of Cisco Systems Inc. (NASDAQ:CSCO) have surged into the top tier of Benzinga Edge momentum rankings following a pivot toward artificial intelligence (AI) infrastructure and a bullish forecast from Wall Street.

Momentum Ranking Surges

Cisco’s relative strength is accelerating, as evidenced by Benzinga Edge’s Stock Rankings. Over the past week, its momentum score surged from 84.91 to 92.61. This momentum metric evaluates a stock’s relative strength based on price movement patterns and volatility across multiple timeframes.

This technical breakout aligns with Cisco‘s broader market performance. The stock has rallied 80.51% over the past year. The stock’s short, medium, and long-term price trends remain positive, and it also boasts a robust quality score of 84.99, reflecting strong operational efficiency and financial health.

Benzinga Edge's Stock Rankings for CSCO.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Texas Instruments Stock Rally Amid AI Boom Sparks Overvaluation Concerns— Value Rank …

This post was originally published here
Walmart Inc. (NYSE:WMT) will release earnings for its first quarter before the opening bell on Thursday, May 21.

Analysts expect the company to report quarterly earnings of 66 cents per share, up from 61 cents per share in the year-ago period. The consensus estimate for Walmart’s quarterly revenue is $174.8 billion. It reported $163.98 billion last year, according to Benzinga Pro.

Ahead of quarterly earnings, on May 15, Piper Sandler analyst Peter Keith maintained Walmart at Overweight and raised the price target from $130 to $137.

With the recent buzz around Walmart, some investors may be eyeing potential gains from the company’s dividends too. As of now, Walmart has an annual dividend yield of 0.74%, which is a quarterly dividend amount of 24.75 cents per share (99 cents a year).

To figure out how to earn $500 monthly from Walmart, we start with the yearly …

Full story available on Benzinga.com

This post was originally published here

The average U.S. 30-year fixed mortgage rate climbed to 6.75% on Tuesday, the highest level since July 2025, according to data from Mortgage News Daily, prompting warnings from analysts.

Market commentator The Kobeissi Letter warned the move could mark the beginning of another leg higher for borrowing costs.

“We believe the average rate on these mortgages will cross above 7.00% soon,” The Kobeissi Letter said in a thread on X, adding that “inflation is simply too hot.”

The account also referenced Mortgage News Daily’s daily rate survey while highlighting that average mortgage rates had surged from below 6% before the Iran war to nearly 6.75% this week.

Rates have jumped 33 basis points in just 10 days. The increase has already started affecting affordability. Monthly payments on a median-priced $420,000 home have risen by roughly $167 compared with …

Full story available on Benzinga.com

This post was originally published here

Gold has surrendered most of its 2026 gains, yet it remains one of the most debated asset classes.

For veteran strategist Jeffrey Currie, a former head of commodity research at Goldman Sachs, things will get worse before they ultimately get far, far better.  He sees the metal initially tumble to $4,000 an ounce before rising to $10,000.

In a thread on X, Currie has admitted he has been “short gold” since March despite describing himself as a “gold perma bull.” As volatility in the precious metals market picked up, gold slid below $4,500 amid war-related inflation fears, triggering heavy selling pressure.

Forced Selling Pressure

Currie argues that the near-term weakness in gold is directly tied to the structural fallout from the Middle East conflict and the disruption of the Strait of Hormuz. Surging energy prices are forcing some central banks to liquidate gold reserves to defend local currencies and finance energy imports.

“When the marginal central bank flips from structural buyer to forced seller to pay for energy, gold’s biggest bid disappears,” Currie wrote.

Turkey is one example of that dynamic. According to Currie, the …

Full story available on Benzinga.com

This post was originally published here

New products include Fidelity All-Canadian Equity ETF Fund

TORONTO, May 20, 2026 /CNW/ – With growing demand for investing opportunities in emerging markets, alternatives, and Canada, Fidelity Investments Canada ULC (“Fidelity”) is launching four new mutual funds and corresponding ETF series, as well as a new ETF Fund (the Funds). The ETFs will begin trading on the TSX as of this morning.

As of May 7, 2026, Fidelity’s ETF assets under management have reached $34.87 billion.

New Products

  • Fidelity Emerging Markets Opportunities Fund & ETF Series (FEMO)
  • Fidelity Global Concentrated Value Fund & ETF Series (FGCV)
  • Fidelity Alternative Bond Fund & ETF Series (FFAB)
  • Fidelity Multi-Alt Balanced Fund & ETF Series (FMAB)
  • Fidelity All-Canadian Equity ETF Fund

Why now: Emerging Markets Opportunities Fund & ETF Series (FEMO)

  • Emerging markets are among some of the fastest-growing regions in the world despite geopolitical uncertainties
  • FEMO is a convenient way to capture these growth opportunities

Why now: Fidelity Global Concentrated Value Fund & ETF Series (FGCV) 

  • Access a concentrated portfolio of high-conviction, value-oriented investments, selected by veteran portfolio manager Dan Dupont
  • Global equities matter: they expand the investable universe and provide access to differentiated sources of return across economies, industries, and business cycles

Why now: Fidelity Alternative Bond Fund & ETF Series (FFAB)

  • Go beyond traditional fixed income. As the interest rate environment evolves and inflation remains a key topic, long/short strategies may offer additional ways to generate return or reduce volatility

Why now: Fidelity Multi-Alt Balanced Fund & ETF Series (FMAB)

  • Simplify alternatives: access the breadth of Fidelity’s liquid alternative capabilities in a single solution
  • A multi-asset alternative fund which can act as a complement to traditional equity and fixed income

Why now:

Full story available on Benzinga.com

This post was originally published here

Despite growing fears that the AI stock boom led by giants like Nvidia Corp. (NASDAQ:NVDA) is mirroring the late-1990s dot-com bubble, Charles Schwab‘s Kevin Gordon argues that today’s market fundamentals tell a much healthier, diversified story.

Stop ‘Cherry-Picking’ Data

While it feels like a top-heavy market driven by a handful of AI titans, Gordon warned investors against “cherry-picking” narrow time horizons to prove a massive concentration risk.

Gordon, in conversation with Phil Rosnen, notes that while Nvidia is currently the top contributor to the S&P 500’s return purely due to its massive market cap, sheer contribution does not equal pure performance.

“If you look at its performance, there are almost 90 names in the S&P 500 that are seeing stronger gains this year, you know, in front of Nvidia,” Gordon explained.

He emphasized that there are still meaningful, often ignored pockets of outperformance in the market—such as small-cap tech significantly beating large-cap tech over the past year—if investors are willing to look under the surface.

Full story available on Benzinga.com

This post was originally published here

Zeta Global Holdings Corp. (NYSE:ZETA) stock saw a sharp surge in its momentum score, jumping from 27.38 to 80.5 on a week-over-week basis.

A momentum score is a measure that tracks how strongly a stock is trending by analyzing recent price movements and trading volume, helping indicate the strength of its current upward or downward trend.

Zeta Global Joins OSI To Standardize AI Data

Zeta Global announced it is joining the Open Semantic Interchange (OSI), an open-source initiative led by Snowflake Inc. (NYSE:SNOW) to standardize data definitions across enterprise systems.

The initiative aimed to build a vendor-neutral semantic model that ensured consistent metrics across dashboards, notebooks, and machine learning tools.

It also focused on creating a unified, open format for semantic metadata to improve interoperability between systems.

Zeta said the effort was expected to simplify data exchange, reduce operational complexity and support broader adoption of AI and business intelligence tools across industries.

Zeta Global CTO Says AI Needs Trusted Data

CTO and Head of Product at Zeta Global, Christian Monberg, said, “AI is only as effective as the data it can trust.”

He added that fragmented data definitions reduce confidence in …

Full story available on Benzinga.com

This post was originally published here

China, on Wednesday, confirmed a 200-aircraft order from Boeing Co (NYSE:BA) following President Donald Trump‘s meeting with Chinese President Xi Jinping last week.

China Confirms Boeing Deal

The country will purchase the aircraft, China’s Ministry of Commerce said in a statement, confirmed by Chinese state-run news agency Xinhua. The order is the first major order Boeing has secured from the world’s second-largest aviation market in over a decade.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Jim Cramer Says Beijing Can’t Afford More Planes On Trump-Xi Jinping 200 Boeing Aircraft Deal: ‘The Chinese Economy Is So Weak…’

This post was originally published here

Nearly 48,000 employees of Samsung Electronics (OTC:SSNLF) are preparing to strike following unsuccessful payment discussions.

The workers are ready to walk off the job after bonus payment negotiations ended without an agreement, reported Yonhap News on Wednesday. The strike could significantly disrupt the global chip supply and impact South Korea’s economy.

Despite the impending strike, hopes for a resolution were revived when talks resumed late Wednesday under the mediation of Labour Minister Kim Young-hoon. Union leader Choi Seung-ho had earlier stated that while the union had accepted a final proposal from the National Labor Relations Commission, the strike would go ahead due to unresolved issues with management.

The two sides agreed to remove bonus caps tied to 50% of annual salary, but remained split on bonus distribution for loss-making units and formalizing the agreement, as per the report.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

This post was originally published here

The firm also announced a risk rating change for Capital Group Monthly Income PortfolioTM (Canada) and commencement of securities lending for its ETFs

TORONTO, May 20, 2026 /CNW/ – Capital International Asset Management (Canada), Inc. (“Capital Group Canada”) announced that it will lower management fees for the majority of its mutual fund and ETFs as of July 1, 2026. The new management fee rates will be applied to seven mutual funds and two ETFs, with fee reductions ranging between 10 bps and 24 bps.

“Capital Group has a long history of leveraging its distinct active management and global economies of scale to help investors reach their long-term financial goals. Small differences in investment outcomes – just a few basis points – can compound over a lifetime and drive vastly different experiences for people,” said Rick Headrick, president of Capital Group Canada. “By lowering our management fees on more than 90 percent of our mutual fund and ETF assets under management we’re able to share with our clients the benefits of our global scale.”

Headrick added, “Over the past several years, our business has continued to grow as more and more Canadian investors appreciate the long-term value of Capital Group’s active management. With global markets broadening, investors are seeing first-hand the potential opportunities which our global team of investment professionals brings to our strategies, backed by deep, research-driven active management and global investment capabilities.”

The new annual management fees for the funds are detailed below:

The annual management fee rates for Series F, Series FH and Series F4 of a mutual fund, as applicable, are as follows: 

Series F, FH and F4

Annual management fee rate based on the
mutual fund’s net assets

Mutual fund name

On first

$5 B

$5 B –

$10 B

Over $10 B

Capital Group International Equity Fund™ (Canada)

Until June 30, 2026

0.70 %

0.67 %

0.65 %

Effective July 1, 2026

0.58 %

Capital Group U.S. Equity Fund™ (Canada)

Until June 30, 2026

0.60 %

0.57 %

0.55 %

Effective July 1, 2026

0.36 %

Capital Group Canadian Focused Equity Fund™ (Canada)

Until June 30, 2026

0.65 %

0.62 %

0.60 %

Effective July 1, 2026

0.46 %

Capital Group Capital Income Builder™ (Canada)

Until June 30, 2026

0.65 %

0.62 %

0.60 %

Effective July 1, 2026

0.54 %

Capital Group Global Balanced Fund™ (Canada)

Until June 30, 2026

0.65 %

0.62 %

0.60 %

Effective
July 1, 2026

Full story available on Benzinga.com

This post was originally published here

Renowned investor and media personality Kevin O’Leary said ultra-rare sports cards are emerging as a serious investment asset class after a Kobe Bryant-Michael Jordan card he bought for $12.93 million last year drew a $20 million bid.

“I found myself last August at 3:00 in the morning bidding on a dual Logoman Kobe Jordan auto,” O’Leary said in a video shared on X.

“It was at $8 million when my wife went to bed, and she said, “If you buy that card tonight, don’t come to bed.”

“Today, it got bid $20 million for it. So tell me an asset class that does better than that that’s liquid.”

Full story available on Benzinga.com

This post was originally published here

Tuttle Capital is seeking to widen the most crowded corner of the U. S. equity ETF market, filing to launch a Tuttle Capital Magnificent 10 ETF that would bundle the mega-cap tech winners with three additional high-profile names in semiconductors and AI-adjacent software.

While the ticker has not yet been disclosed, the fund will come with an expense ratio of 0.50%, according to the filing.

What’s Inside Magnificent 10 ETF  

According to Tuesday’s post by ETF Tracker on X, the proposed ETF will track a basket of 10 companies. This would include the so-called “Magnificent Seven” — Alphabet Inc. (NASDAQ:GOOGL) (NASDAQ:GOOG), Microsoft Corp. (NASDAQ:MSFT), Amazon.com Inc. (NASDAQ:AMZN), Meta Platforms Inc. (NASDAQ:META), Apple Inc. (NASDAQ:AAPL), Nvidia Corp. (NASDAQ:NVDA), and Tesla Inc. (NASDAQ:TSLA).

In addition to the mega-cap names, the ETF would provide exposure to Advanced Micro Devices Inc. (NASDAQ:AMD), …

Full story available on Benzinga.com

This post was originally published here

The most oversold stocks in the consumer staples sector presents an opportunity to buy into undervalued companies.

The RSI is a momentum indicator, which compares a stock’s strength on days when prices go up to its strength on days when prices go down. When compared to a stock’s price action, it can give traders a better sense of how a stock may perform in the short term. An asset is typically considered oversold when the RSI is below 30, according to Benzinga Pro.

Here’s the latest list of major oversold players in this sector, having an RSI near or below 30.

US Foods Holding Corp (NYSE:USFD)

  • On May 14, US Foods appointed CEO Dave Flitman to additional role of board chair. The company’s stock fell around 13% over the past month and has a 52-week low of $69.88.
  • RSI Value: 28.4
  • USFD Price Action: Shares of US Foods fell 1% …

Full story available on Benzinga.com

This post was originally published here

Gov. Jay Robert ‘JB’ Pritzker (D-IL) has hailed Rivian Technologies Inc.‘s (NASDAQ:RIVN) production ramp of the R2 crossover SUV at the automaker’s manufacturing facility in Normal, Illinois.

‘Made In Illinois’

“Made in Illinois,” Pritzker said in a post on X on Tuesday, sharing that the Normal, Illinois, plant, which earlier belonged to Japanese automaker Mitsubishi, had been closed for a decade.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Ross Gerber Is ‘Pretty Excited’ For Rivian’s Upcoming R2 Ahead Of Q4 Earnings: ‘Leading The Way…’

This post was originally published here

TKO Group Holdings Inc. (NYSE:TKO) is absorbing a $30 million loss to host an ultra-exclusive UFC match on the White House South Lawn curated by President Donald Trump, but Wall Street experts tell Benzinga the political spectacle is a calculated gamble that will pay off for the company’s bottom line.

Ultimate Status Symbol For Washington?

A hand-curated ticket from Trump to the custom-built UFC octagon on the White House South Lawn is currently the ultimate status symbol in Washington. But for TKO Group, the parent company of the UFC and WWE, the spectacle comes with a hefty price tag: an expected $30 million net loss for the upcoming second-quarter UFC Freedom 250 event.

While retail investors might balk at the eight-figure expense, Wall Street analysts are looking past the political flash to the underlying fundamentals.

‘Discretionary, Unique’ Global Stage

For Ian Moore, VP and Research Analyst for U.S. Entertainment at Bernstein, the high-stakes gamble is exactly what TKO needs to execute its long-term strategy. Moore maintains an “Outperform” rating on the stock with a $240 price target, noting that the underlying monetization engine is working so well that TKO can afford to take a hit for the sake of mainstream visibility.

“I think the Freedom 250 event is well understood by the street at this point – $60M loss with $30M recouped primarily via sponsorship,” Moore exclusively told Benzinga.

“Engagement metrics I follow, including US ratings for fights YTD, appear to be soaring already, so my view is that this is more of a discretionary, unique & very high-profile opportunity to promote the UFC on a global stage.”

Moore emphasized that the bulk of TKO’s earnings before interest, taxes, depreciation, and amortization (EBITDA) is locked …

Full story available on Benzinga.com

This post was originally published here

Intuit Inc. (NASDAQ:INTU) will release earnings for its third quarter after the closing bell on Wednesday, May 20.

Analysts expect the Mountain View, California-based company to report quarterly earnings of $12.57 per share, up from $11.65 per share in the year-ago period. The consensus estimate for Intuit’s quarterly revenue is $8.54 billion (it reported $7.75 billion last year), according to Benzinga Pro.

On March 16, Intuit said it will significantly speed up its share‑repurchase program and revealed that its senior leadership team is canceling all pre‑scheduled stock‑sale plans.

Intuit shares fell 0.9% to close at $399.71 on Tuesday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s …

Full story available on Benzinga.com

This post was originally published here

The S&P 500 posted its third straight losing session on Tuesday as surging Treasury yields pressured equities, but Polymarket traders are betting the benchmark index will rebound at Wednesday’s open ahead of Nvidia‘s (NASDAQ:NVDA) closely watched earnings report.

The S&P 500 fell 0.67% to close at 7,353.61 on Tuesday. However, the May 20 Polymarket contract implied a 71% probability that the index would open higher on Wednesday.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Nvidia Earnings No Longer About Beating Estimates, But About Whether Jensen Huang Can Prove AI Supercycle Still Has Years Left: Top Analyst

This post was originally published here

On Tuesday, WeWork and Upwork Inc. (NASDAQ:UPWK) CEO said artificial intelligence (AI) is putting pressure on entry-level hiring for Gen Z workers, while companies increasingly shift toward freelance and AI-skilled labor.

AI Disrupts Entry-Level Hiring For Gen Z

Speaking at Fortune’s Workplace Innovation Summit, WeWork CEO John Santora said entry-level workers are facing growing challenges as AI reshapes hiring needs across industries.

“There’s no question that the entry-level hire is under pressure,” Santora said.

He added that business leaders have a responsibility to train younger talent for future leadership roles.

Santora continued, “AI is not going to provide empathy and leadership and mentoring and all those skills that you need to lead a company for a company to be successful.”

Upwork CEO Hayden Brown also acknowledged growing anxiety among workers but argued that some companies are overstating AI’s impact on jobs.

“The hype is real,” Brown said.

He added, “The fear-mongering is a real challenge because it does create a lot of …

Full story available on Benzinga.com

This post was originally published here

Despite a notable pullback in gold prices, analysts at Goldman Sachs remain optimistic about the bullion market’s trajectory. The bank sees the forces driving the broad rally becoming increasingly entrenched, yet it is worth noting they’re getting as equally political.

The bank recently reaffirmed its forecast for gold to hit $5,400 per ounce by the end of 2026, even as investors and traders navigate temporary volatility driven by liquidation and profit-taking.

Yet, Goldman believes those moments are technical and liquidity-driven, rather than signs of weakening structural demand.

“Strong underlying interest in gold remains evident,” Goldman said in a recent note, pointing to both central bank surveys and intensifying geopolitical uncertainty. The bank acknowledged that its earlier estimates had underestimated sovereign buying activity after gaps emerged in official U.K. trade data from 2025 onward.

Goldman now sees the central bank purchase projections at around 50 tons per month on a rolling basis, nearly double its previous estimate of 29 tons. The pace is expected to accelerate further, averaging about 60 tons per month through 2026 as governments continue to diversify their reserves away from the U.S. dollar.

It is a part of a broader trend, one that has arguably started with sanctions and asset freezes following the Russian invasion of Ukraine in 2022. When the …

Full story available on Benzinga.com

This post was originally published here

In today’s rapidly evolving and fiercely competitive business landscape, it is crucial for investors and industry analysts to conduct comprehensive company evaluations. In this article, we will undertake an in-depth industry comparison, assessing Micron Technology (NASDAQ:MU) alongside its primary competitors in the Semiconductors & Semiconductor Equipment industry. By meticulously examining crucial financial indicators, market positioning, and growth potential, we aim to provide valuable insights to investors and shed light on company’s performance within the industry.

Micron Technology Background

Micron is one of the largest semiconductor companies in the world, specializing in memory and storage chips. Its primary revenue stream comes from dynamic random access memory, or DRAM, and it also has minority exposure to not-and or NAND, flash chips. Micron serves a global customer base, selling chips into data centers, mobile phones, consumer electronics, and industrial and automotive applications. The firm is vertically integrated.

Company P/E P/B P/S ROE EBITDA (in billions) Gross Profit (in billions) Revenue Growth
Micron Technology Inc 32.97 10.88 13.63 21.0% $18.48 $17.75 196.29%
NVIDIA Corp 45.02 33.97 25.04 31.11% $51.28 $51.09 73.21%
Broadcom Inc 80.13 24.37 29.29 9.12% $11.15 $13.16 29.47%
Advanced Micro Devices Inc 138.02 10.47 18.15 2.17% $2.4 $5.42 37.85%
Texas Instruments Inc 51.68 16.40 14.96 9.35% $2.42 $2.8 18.58%
Qualcomm Inc 21.03 7.56 4.76 29.27% $2.82 $5.7 -3.46%
Analog Devices Inc 75.74 5.99 17.44 2.46% $1.52 $2.04 30.42%
Marvell Technology Inc 57.42 10.79 18.71 2.79% $0.75 $1.15 22.08%
NXP Semiconductors NV 28.13 6.80 5.92 10.69% $1.7 $1.79 12.2%
Monolithic Power Systems Inc 105.09 19.61 24.14 5.36% $0.26 $0.45 26.14%
Microchip Technology Inc 417.32 7.72 10.62 1.79% $0.32 $0.71 10.56%
ON Semiconductor Corp 77.96 5.65 7.08 -0.45% $0.25 $0.58 4.68%
Credo Technology Group Holding Ltd 92.85 16.86 29.39 10.03% $0.16 $0.28 201.49%
Tower Semiconductor Ltd 116.47 9.50 17.67 2.2% $0.15 $0.11 15.48%
MACOM Technology Solutions Holdings Inc 152.76 19.32 25.33 3.34% $0.07 $0.16 22.5%
First Solar Inc 14.32 2.41 4.40 3.57% $0.51 $0.49 23.64%
Average 98.26 13.16 16.86 8.19% $5.05 $5.73 34.99%

Full story available on Benzinga.com

This post was originally published here

In the fast-paced and cutthroat world of business, conducting thorough company analysis is essential for investors and industry experts. In this article, we will undertake a comprehensive industry comparison, evaluating Microsoft (NASDAQ:MSFT) in comparison to its major competitors within the Software industry. By analyzing crucial financial metrics, market position, and growth potential, our objective is to provide valuable insights for investors and offer a deeper understanding of company’s performance in the industry.

Microsoft Background

Microsoft develops and licenses consumer and enterprise software. It is known for its Windows operating systems and Office productivity suite. The company is organized into three equally sized broad segments: productivity and business processes (legacy Microsoft Office, cloud-based Office 365, Exchange, SharePoint, Skype, LinkedIn, Dynamics), intelligence cloud (infrastructure- and platform-as-a-service offerings Azure, Windows Server OS, SQL Server), and more personal computing (Windows Client, Xbox, Bing search, display advertising, and Surface laptops, tablets, and desktops).

Company P/E P/B P/S ROE EBITDA (in billions) Gross Profit (in billions) Revenue Growth
Microsoft Corp 24.86 7.48 9.78 7.89% $50.28 $56.06 18.3%
Oracle Corp 32.58 15.56 8.22 11.65% $8.16 $11.1 21.66%
Palo Alto Networks Inc 133.41 20.73 17.26 4.78% $0.64 $1.91 14.93%
ServiceNow Inc 60.61 8.95 7.62 3.8% $0.94 $2.83 22.09%
Fortinet Inc 49.47 94.49 13.57 48.0% $0.7 $1.49 20.13%
Nebius Group NV 76.34 6.93 59.79 10.5% $0.92 $0.3 683.89%
Gen Digital Inc 15.50 5.64 3.01 20.72% $0.57 $0.97 3.47%
Check Point Software Technologies Ltd 12.96 4.66 4.96 6.73% $0.2 $0.57 4.8%
UiPath Inc 20.29 2.64 3.57 5.21% $0.09 $0.41 13.56%
Dolby Laboratories Inc 21.18 1.93 3.79 3.64% $0.14 $0.35 7.05%
CommVault Systems Inc 64.47 560.69 3.84 13.07% $0.03 $0.25 13.33%
Monday.Com Ltd 34.06 5.26 3.12 2.8% $0.02 $0.31 24.45%
BlackBerry Ltd 69 4.88 6.76 3.27% $0.04 $0.12 10.09%
Qualys Inc 17.97 6.19 5.29 8.96% $0.06 $0.15 9.84%
Teradata Corp 7.47 5.52 1.86 85.13% $0.47 $0.28 6.22%
A10 Networks Inc 46.36 9.22 6.90 5.57% $0.02 $0.06 13.4%
Average 44.11 50.22 9.97 15.59% $0.87 $1.41 57.93%

Full story available on Benzinga.com

This post was originally published here

In today’s rapidly changing and highly competitive business world, it is imperative for investors and industry observers to carefully assess companies before making investment choices. In this article, we will undertake a comprehensive industry comparison, evaluating Ondas (NASDAQ:ONDS) vis-à-vis its key competitors in the Communications Equipment industry. Through a detailed analysis of important financial indicators, market standing, and growth potential, our goal is to provide valuable insights and highlight company’s performance in the industry.

Ondas Background

Ondas Inc designs, develops, manufactures, sells, and supports FullMAX Software Defined Radio (SDR) technology in the United States, Israel, and India. The company operates in two business segments namely Ondas Networks and Ondas Autonomous Systems. The company generates maximum revenue from Ondas Autonomous Systems through the sales of the Optimus system and separately priced support, maintenance, and ancillary services related to the sale of the Optimus system. Geographically, the company operates in Israel, Germany, United Arab Emirates, United States, and Other Countries. It derives maximum revenue from Israel.

Company P/E P/B P/S ROE EBITDA (in billions) Gross Profit (in billions) Revenue Growth
Ondas Inc 101.44 4.21 29.38 47.84% $0.37 $0.02 1079.9%
Cisco Systems Inc 38.46 9.33 7.57 6.98% $4.67 $9.97 3.21%
Ciena Corp 345.17 27.44 15.36 5.44% $0.25 $0.63 33.09%
Lumentum Holdings Inc 156.71 23.29 29.89 7.46% $0.26 $0.36 90.12%
Motorola Solutions Inc 32.16 26.02 5.66 14.78% $0.69 $1.36 7.36%
Ubiquiti Inc 37.55 29.40 11.42 21.09% $0.3 $0.37 18.67%
F5 Inc 31.49 5.93 6.91 4.11% $0.2 $0.66 11.02%
Extreme Networks Inc 196.25 39 2.51 12.11% $0.02 $0.2 11.38%
NetScout Systems Inc 30 1.69 3.33 1.11% $0.03 $0.16 -0.95%
Calix Inc 81.35 3.45 2.63 1.4% $0.02 $0.16 27.13%
Vistance Networks Inc 16.43 0.55 1.23 306.72% $0.07 $0.23 21.57%
Digi International Inc 54.42 3.48 4.94 1.72% $0.03 $0.08 25.11%
Harmonic Inc 153.69 3.76 3.48 1.98% $0.02 $0.06 43.38%
Gilat Satellite Networks Ltd 28.83 2.11 2.09 1.01% $0.01 $0.04 20.03%
Ituran Location and Control Ltd 19.52 5.19 3.15 7.11% $0.03 $0.05 12.81%
Clearfield Inc 181.09 2.33 3.87 -0.21% $-0.0 $0.01 -15.34%
Ribbon Communications Inc 15.65 1.12 0.58 -7.95% $-0.02 $0.07 -10.3%
Average 88.67 11.51 6.54 24.05% $0.41 $0.9 18.64%

Full story available on Benzinga.com

This post was originally published here

The CNN Money Fear and Greed index showed a decline in the overall market sentiment, while the index remained in the “Greed” zone on Tuesday.

U.S. stocks settled lower on Tuesday, with the Dow Jones index falling more than 300 points during the session.

Investors are getting impatient over the unresolved U.S.–Iran standoff that has kept oil prices elevated and inflation expectations sticky.

In earnings, Amer Sports Inc. (NYSE:AS) reported better-than-expected first-quarter financial results and raised its FY26 guidance above estimates. The Home Depot Inc. (NYSE:HD) on Tuesday reported upbeat earnings for the first quarter on Tuesday.

On the economic data front, the ADP said US private employers added an average of 42,250 …

Full story available on Benzinga.com

This post was originally published here

President Donald Trump disclosed a multimillion-dollar investment in a sushi chain operator in the first quarter of 2026, despite being known for avoiding sushi and raw fish

According to the latest Office of Government Ethics (OGE) filing, Trump purchased shares of Kura Sushi USA Inc. (NASDAQ:KRUS), the American arm of Japan’s Kura Sushi Inc, valued between $1 million and $5 million on Feb 2.

KRUS shares rose 11.2% over the past week following the disclosure of Trump’s stake.

Sushi Chain Operator

The Japanese restaurant chain beat Benzinga earnings estimates by 75% in the second quarter of fiscal 2026 and revenue estimates by 2.92%. The company has posted revenue surprises for the seventh quarter in a row.

While the company is struggling with weak dining services and a surprise CFO transition, it has a strong growth potential, with adjusted EBITDA projected to …

Full story available on Benzinga.com

This post was originally published here

On Tuesday, Alphabet Inc.’s (NASDAQ:GOOG) (NASDAQ:GOOGL) Google and Samsung Electronics Co. (OTC:SSNLF) have unveiled new AI-powered smart glasses featuring Gemini integration, real-time translation and deep Android XR support, marking a major push into next-generation wearable computing.

AI Glasses Debut At Google I/O 2026

Google and Samsung introduced their first AI smart glasses at Google I/O 2026, developed in partnership with eyewear brands Gentle Monster and Warby Parker.

The device is designed to bring AI assistance into everyday eyewear rather than relying on phones or screens.

Powered By Android XR Platform

The glasses run on Google’s Android XR system and are designed to connect with both Android and iOS smartphones.

The platform enables the device to act as a companion for notifications, navigation and other daily tasks.

This post was originally published here

Alibaba Group Holding Ltd. (NYSE:BABA) announced the release of a new, more powerful artificial intelligence chip on Wednesday, as competitor Nvidia Corp (NASDAQ:NVDA) faces difficulties in the Chinese market.

The Zhenwu M890, Alibaba’s latest AI chip, delivers triple the performance of its predecessor, the Zhenwu 810E. The new processor, designed to handle memory-intensive agentic AI workloads, boasts 144 GB of GPU memory and an interchip bandwidth of 800 GB per second, reported CNBC.

At a conference in Hangzhou, Alibaba stated it has already shipped 560,000 Zhenwu units to over 400 customers across 20 industries. This new chip could potentially enhance Alibaba and its chip subsidiary T-Head’s competitiveness in China’s burgeoning domestic AI processor market, which includes rivals such as Huawei and Cambricon.

Alibaba also announced on Wednesday that it will soon launch its next-generation AI model, Qwen3.7-Max.

data-variant=”card”
data-news-mode=”manual”

This post was originally published here

Shares of 8×8 Inc (NASDAQ:EGHT) rose sharply in pre-market trading after the company reported better-than-expected fourth-quarter financial results.

8×8 reported quarterly adjusted earnings of 11 cents, which beat the eight-cent estimate, according to Benzinga Pro data. Quarterly revenue came in at $185.25 million, which beat the $181.12 million analyst estimate.

8×8 shares jumped 13.3% to $2.73 in pre-market trading.

Here are some other stocks moving in pre-market trading.

Gainers

  • GCL Global Holdings Ltd (NASDAQ:GCL) gained 136.3% to $1.02 in pre-market trading. The move followed GCL’s announcement Tuesday that its publishing subsidiary, 4Divinity Pte. Ltd., secured an additional $10 million strategic investment from ADATA Technology, a maker of memory, storage and gaming hardware products.
  • TDH Holdings Inc (NASDAQ:PETZ) gained 84% to $1.49 in pre-market trading after reporting full year 2025 audited financial results.
  • Work Medical Technology Group Ltd (NASDAQ:WOK) gained 52.6% to $0.36 in pre-market trading after dipping 38% on Tuesday.
  • Functional Brands Inc (NASDAQ:MEHA) rose 48.4% to $0.10 in pre-market trading after falling 6% on Tuesday.
  • Haoxi Health Technology Ltd (NASDAQ:HAO) gained 30% to $0.018 in pre-market trading. Haoxi Health Technology shares dipped 21% on Tuesday after …

Full story available on Benzinga.com

This post was originally published here

Jim Cramer is calling on local municipalities across the country to leverage their negotiating power against tech giants building data centers, urging towns to demand both environmental protections and significant community investments before allowing construction to begin.

Enforcing Environmental Accountability

As the artificial intelligence (AI) boom and digital transformation drive a massive expansion in technical infrastructure, Cramer took to X to warn communities about the historical ecological toll of these massive facilities.

He pointed out that “many data center builders initially got away with damaging the environment,” signaling an urgent need for a fundamental shift in how local governments handle tech zoning and corporate approvals.

“Each town must be sure to demand strict adherence to pollution rules,” Cramer stated. He empowered locales to hold their ground and walk away from inadequate deals, adding, “Ask for what your town needs. If they won’t give it, then let them go elsewhere.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Amazon, Meta And …

This post was originally published here
President Donald Trump, on Tuesday, warned that deterring Iran’s nuclear capabilities would take precedence over rising gas prices, signalling they would be coming down once the war was over, leading to widespread criticism.

Trump Signals Oil Prices Could Stay High

In a press briefing at the White House, Trump said that rising gas prices were “peanuts” compared to Iran’s nuclear capabilities. He also said that he appreciated Americans putting up with high fuel costs “for a little while.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Thomas Massie Loses To Trump-Backed Ed Gallrein In The Most Expensive House Primary To Date

This post was originally published here
Lowe’s Companies, Inc. (NYSE:LOW) will release earnings for its first quarter before the opening bell on Wednesday, May 20.

Analysts expect the Mooresville, North Carolina-based company to report quarterly earnings of $2.97 per share, up from $2.92 per share in the year-ago period. The consensus estimate for Lowe’s quarterly revenue is $22.88 billion. It reported $20.93 billion last year, according to Benzinga Pro.

On Feb. 25, Lowe’s reported upbeat earnings for the fourth quarter but issued weak earnings guidance.

Shares of Lowe’s gained 0.2% to close at $218.37 on Tuesday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate analysts have rated the …

Full story available on Benzinga.com

This post was originally published here
With U.S. stock futures trading mixed this morning on Wednesday, some of the stocks that may grab investor focus today are as follows:

  • Wall Street expects Nvidia Corp. (NASDAQ:NVDA) to report quarterly earnings at $1.76 per share on revenue of $79.04 billion after the closing bell, according to data from Benzinga Pro. Nvidia shares gained 0.4% to $221.54 in after-hours trading.
  • Toll Brothers Inc. (NYSE:TOL) reported upbeat earnings for the first quarter. The company posted quarterly earnings of $2.72 per share, which beat …

Full story available on Benzinga.com

This post was originally published here
Tesla Inc. (NASDAQ:TSLA) shares face increased pressure as higher long-term interest rates and elevated oil prices make the electric vehicle maker especially vulnerable, institutional investor Gary Black said on Tuesday, warning that broader market forces are working against the stock even without a change in the company’s fundamentals.

Higher Rates Weigh On Tesla Valuation

The managing partner of The Future Fund LLC, wrote on X that “there’s been no change in $TSLA fundamentals,” but said that was precisely the problem. Tesla shares have fallen this year, though Black’s stated 12% year-to-date decline differs from Benzinga Pro data, which shows the stock down 7.75%.

“When long-term int rates go higher, long-duration (high P/E names) get whacked the most mathematically,” Black wrote. He said Tesla stock is likely to continue moving lower if Brent crude oil holds at $110 a barrel and the 10-year Treasury yield stays at 4.6%.

Black’s argument centers on Tesla’s valuation. He suggests that high-growth companies such as Tesla often trade as “long-duration” assets because investors expect much of their future cash flow years ahead. When bond …

Full story available on Benzinga.com

This post was originally published here
The TJX Companies, Inc. (NYSE:TJX) will release earnings for its first quarter before the opening bell on Wednesday, May 20.

Analysts expect the Framingham, Massachusetts-based company to report quarterly earnings of $1.00 per share, up from 92 cents per share in the year-ago period. The consensus estimate for TJX’s quarterly revenue is $14.01 billion. It reported $13.11 billion last year, according to Benzinga Pro.

On March 30, TJX announced a 13% increase in common stock dividend.

Shares of TJX gained 0.3% to close at $150.68 on Tuesday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate analysts have rated the company in …

Full story available on Benzinga.com

This post was originally published here
The European Union (EU) confirmed a trade agreement with the U.S. early Wednesday, potentially sidestepping the tariffs President Donald Trump had threatened to impose.

Representatives from the European Parliament, the Council of the EU, and the European Commission reached a consensus after over five hours of deliberations. The agreement is rooted in a deal made last summer at Trump’s golf resort in Turnberry, Scotland.

“The EU walks the talk, while defending our interests. Once approved, it’ll boost transatlantic stability and cooperation, stated EU trade chief Maroš Šefčovič.

Meanwhile, EU Chief Ursula von der Leyen welcomed the European Parliament and Council’s agreement to lower tariffs on U.S. industrial exports to the EU, saying it fulfills part of the EU-U.S. Joint Statement and urging lawmakers to quickly finalize the process to support stable and mutually beneficial transatlantic trade.

“A deal is a deal, and the EU honours its commitments,” she wrote.

Full story available on Benzinga.com

This post was originally published here
Economist Peter Schiff warned of potential global economic consequences as a rapid jump in Japanese government bond yields could trigger shockwaves beyond Japan.

JGB Yields Rising

In Tuesday’s post on X, Schiff said, “A real crash” is in the making, and “the shockwaves will extend well beyond Japan. All fiscal chickens are coming home to roost.” The economist is referring to the government’s years-long policy to suppress Japan’s bond market and interest rates, sparking concerns of potential fallout.

The comments come as the 10-year JGB yield spiked to above 2.8%, the highest level in 29 years and higher than the 1.6% yields seen 10 months ago. The 30-year yield climbed above 4% for the first time.

Schiff previously said, “They are getting yippy in Japan,” describing …

Full story available on Benzinga.com

This post was originally published here
Radcom (NASDAQ:RDCM) released first-quarter financial results and hosted an earnings call on Tuesday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://www.veidan-conferencing.com/radcom

Summary

Radcom Ltd reported significant growth in gross bookings, reaching $10.4 billion in fiscal year 2026, with a compound annual growth rate of 34% over four years due to post-pandemic recovery and rising demand from the Indian middle class.

The company is leveraging AI technology, including the Myra conversational interface, to enhance customer interaction and booking processes, resulting in higher conversion rates and engagement, especially in tier 2 and smaller cities.

Radcom Ltd remains optimistic about future growth, aiming for revenue growth in the 20s during stable periods and focusing on AI-led transformations to drive efficiency and customer satisfaction across its platforms.

Full Transcript

OPERATOR

Fiscal 2026 fourth quarter and full Year Earnings Webinar Today’s event will be hosted by Companies Leadership team comprising Rajesh Mago, our Co Founder and Group Chief Executive Officer, Mohit Kabra, our Group Chief Operating Officer and Deep Kalra, our Group Chief Financial Officer. As a reminder, this live event is being recorded by the Company and will be made available for replay on our IR website shortly after the conclusion of today’s event. At the end of these prepared remarks, we will also be hosting a Q and A session. Furthermore, certain statements made during today’s event may be considered forward looking statements within the meaning of the Safe harbor provision of the U.S. private Securities Litigation Reform act of 1995. These statements are not guarantees of future performance, are subject to inherent uncertainties and actual results may differ materially. Any forward looking information relayed during this event speaks only as of this date and the Company undertakes no obligation to update the information to reflect changed circumstances. Additional information concerning these statements is contained in the Risk Factors and Forward Looking Statements section of the Company’s Annual report on Form 20F filed with the SEC on June 16, 2025. Copies of these filings are available from the SEC or from the Company’s Investor Relations Department. I would like to now turn over the call to Rajesh. Over to you Rajesh.

Rajesh Mago (Co Founder and Group Chief Executive Officer)

Thank you Vipul. Welcome everyone to our fourth quarter and full year call for fiscal 2026. Before we take you all through the quarter details, I would like to step back a bit and remind everyone about some fundamental structural changes that have emerged post Covid that has been shaping the travel market in India. When the world opened in 2022, the rebound that initially looked to be pent up demand coming out of the quiet phase due to pandemic soon formed a new baseline. This robust shift in demand is reflected in our reported numbers where gross bookings went from approximately 3.2 billion in fiscal year 22 to 6.6 billion in fiscal year 23 and a record 10.4 billion in fiscal year 26, compounding at roughly 34% over four years. This was a good combination of post pandemic recovery and behavior shift among Indian travelers, well supported by some key structural macro changes in the Indian economy. Major reasons for this robust demand shift are first is rising and aspirational middle class. As per a Bain study, the middle income household with annual income between $4,500 to $35,000 has been growing at a robust high single digit annual growth rate and is likely to further grow at an accelerated pace from 200 million in 2022 to 300 million in 2032, a growth of 50% in 10 years. India also added over 70 million passport holders in the last five years. Tier 2 and Tier 3 cities are now major growth drivers. A traveler from Indore or Coimbatore today has the same aspiration and increasingly the same purchasing power as one from Mumbai or Delhi five years ago. This is a massive multi year addressable market expansion and we are only in its early innings. Second, travel has shifted from occasion to habit. Our data shows booking frequency per user is rising year on year. Indians are no longer saving up for one big annual holiday. They are taking multiple trips a year. Three to six trips a year across leisure, religious and extended weekend categories is becoming the new normal for India’s connected earning class. The experiential economy is real and is a big opportunity. The cohort driving this is also the one with the longest consumption Runway ahead. As per Collingwood International’s 2024 research, Indian millennials annual travel spend was at about $6,000, making travel their single largest discretionary expense at 34% of annual spending. These millennials are not yet in their peak earning years. These millennials are not yet in their even peak earning years. The per trip wallet will only expand with time. Third, the growth of world class physical infrastructure. The demand story compounds if supply keeps pace. As we all know, new airports or routes, expressways, premium rail, train corridors, the government’s infrastructure investment is creating supply that meets this demand. Every new airport is a new market for us. Every new direct international route is a new booking opportunity. India’s expanding highway network and airport capacity are making travel faster, easier and more reliable across the country. Better road and air connectivity is opening up smaller cities and tourist destinations, reducing travel time and helping unlock tourism, local spending and regional economic growth on aviation. Operational airports have doubled from 74 in 2014 to 157 in 2024, improving access beyond major metros and making travel more affordable and widespread especially for tier 2 and tier 3 cities. This is expected to further expand to 400 airports by 2047, providing a multi decade opportunity. India’s highway network has expanded sharply with national highways rising from 91,287 km in 2014 to about 1 46,145 km in 2024, while construction speed increased to 33.8 km per day in 2324. Similarly listed hotel companies are projected to add over 70,000 keys to India’s hotel sector by fiscal year 2030, according to CBRE. Majority of new additions are being built into under supplied tier 2 markets and spiritual tourism corridors, both of which are future growth opportunities. Homestays have emerged as a flexible scalable supply addition as well. Now actively supported by governments, vacation rentals and boutique home stays are capturing outsized growth because they align with experiential itineraries that favor local immersion over standardized services. The physical infrastructure story only is half the job done in today’s digital age unless the digital infrastructure has kept pace with it. India has come a long way on digital infrastructure development as well, with Internet penetration touching about a billion people with high quality bandwidth becoming affordable, with data costs falling from rupees 269 per GB in 2014 to about nine rupees per GB in 2024. On top of this is the payments infrastructure. UPI processed 640 million transactions daily in 2025, clearing over 16 billion transactions in a single month by late 2025. The combined effect is that checkout friction, historically one of the largest causes of bookings abandonment, has largely been addressed. A traveler in a tier three city with a mid range Android device can now search, compare, book and pay in under five minutes without a credit card. We have also witnessed Indian market showing resilience to bounce back fairly quickly as the disruption starts to go away. Last year was another such year as it was impacted by many disruptions pretty much every quarter. But interesting part was that the travel demand remained resilient and robust during the unimpacted months of the year, reflecting the continued strength of underlying consumer sentiment and the structural growth trajectory of India’s travel market. We at MMIT continue to outpace industry growth despite disruptions with healthy momentum across segments. Sure, sure. Sorry. Is it fine now? Is it fine now? Yes, yes, much better. All right. While our international business started to get impacted in March due to Middle east conflict, the domestic business remains strong for the reported quarter. March was impacted due to West Asia conflict. January and February witnessed strong year …

Full story available on Benzinga.com

This post was originally published here
GCL Global Holdings (NASDAQ:GCL, NASDAQ:GCL) shares surged in after-hours trading on Wednesday.

GCL shares jumped 136.28% to $1.02 in after-hours trading after closing Tuesday’s regular session down 1.86% at $0.43. The stock is trading near its 52-week low of $0.41.

Strategic Investment Fuels Rally

The move followed GCL’s announcement Tuesday that its publishing subsidiary, 4Divinity Pte. Ltd., secured an additional $10 million strategic investment from ADATA Technology, a maker of memory, storage and gaming hardware products.

According to the company, the latest investment follows ADATA’s earlier $3 million investment announced in December 2025 and another $10 million investment announced in January 2026.

GCL said the funding will help 4Divinity secure high-profile global game titles, expand digital distribution infrastructure and strengthen its international publishing business.

The company also said the partnership could create operational synergies between ADATA’s …

Full story available on Benzinga.com

This post was originally published here
Elon Musk-led SpaceX has reportedly selected investment bank Goldman Sachs Group Inc. (NYSE:GS) as the lead underwriter for the commercial space flight company’s upcoming IPO.

Goldman Sachs Secures Key Position

On Tuesday, Reuters reported that Goldman was selected as the bank to lead the IPO, citing anonymous sources familiar with the matter. The report also said that both Goldman and investment bank Morgan Stanley (NYSE:MS) would be leading the IPO.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

The ‘Elon Musk Effect’ Could Send SpaceX Stock Into Wild Swings After IPO Even If Starlink Makes ‘Billions’ In Profit, Warns Expert

This post was originally published here
On Tuesday, Movano (NASDAQ:MOVE) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://events.q4inc.com/attendee/168163399

Summary

Corvex Inc reported Q1 2026 revenue of $510,000 with an operating loss of $4.8 million. On a pro forma basis, revenue was $3.65 million, primarily from the AI platform.

The company completed a merger with Corvex Legacy Holdings Inc, leading to a significant restructuring and issuance of new preferred stock.

Corvex Inc is focusing on building a vertically integrated AI infrastructure platform, targeting AI model labs, government initiatives, and enterprises with scalable infrastructure and secure computing technology.

Strategic initiatives include developing an AI factory, a scalable Token Factory, and confidential computing to enhance security and performance for AI workloads.

Management expressed optimism about capturing growth in the AI infrastructure market, highlighting their differentiated strategy and investment in high-value layers of the AI stack.

Full Transcript

OPERATOR

Hello everyone. Thank you for joining us and welcome to Corvex’s first quarter 2026 earnings call. I will now hand the call over to Jay Kogan, CFO. Please go ahead sir.

Jay Kogan (Chief Financial Officer)

Thanks, Kara. Good afternoon everyone and welcome to Corvex’s first quarter 2026 earnings conference call. Joining me today are Corvex’s CEO Jay Crystal and Co-Founder and Director Seth Dempsey. A press release detailing our results was issued this afternoon and is available in the Investor Relations section of our website. A replay and transcript will be posted following the call. During today’s call we will make forward looking statements based on current expectations. Our actual results may differ materially from such statements. Descriptions of the risks and uncertainties associated with Corvex are included in our SEC filings which can be accessed through our website. Today’s discussion also includes references to non GAAP financial measures. Reconciliation to the most directly comparable GAAP measure is included in our press release and on our IR website. On March 19, 2026, Corvex Inc. Formerly known as Movano Inc. acquired Corvex Legacy Holdings Inc. Also known as Corvex OpCo.. The Company was renamed Corvex Inc., effective March 23, 2026 pursuant to the merger agreement. At closing, we issued to the prior security holders of Corvex Opco 240,562 shares of Series B convertible Preferred Stock, representing no more than 19.9% of our outstanding common stock immediately prior to closing, as well as 23,551,519.5 shares of Series C Preferred Stock and 30,227,052.4 shares of Series D Preferred Stock on March 31, 2026, each share of Series B Preferred Stock automatically converted into 1,000 shares of common stock in the coming weeks. Subject to stockholder approval of the conversion proposal at our upcoming annual meeting, each share of Series C preferred stock will automatically convert into 1,000 shares of common stock and each share of Series D preferred stock will be convertible into 1,000 shares of common stock as part of the merger agreement. We also declared a stock dividend of 0.358 shares of common stock for every share outstanding at the close of …

Full story available on Benzinga.com

This post was originally published here
Skillz (NYSE:SKLZ) reported first-quarter financial results on Tuesday. The transcript from the company’s first-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://events.q4inc.com/attendee/800226182

Summary

Skillz Inc reported Q1 2026 GAAP revenue of $29 million, a 3% decrease quarter-over-quarter but a 33% increase year-over-year.

The company experienced a $13 million adjusted EBITDA loss due to increased litigation expenses, but underlying profitability improved with a normalized EBITDA loss of $7 million.

Skillz Inc won a significant legal victory against Papaya Gaming, with a jury awarding $420 million in damages, potentially increasing to over $1.2 billion upon court determination.

The company is focusing on three strategic initiatives: strengthening demand and engagement, executing an efficient go-to-market strategy, and improving platform performance.

Skillz Inc has acquired Blackout Bingo and Domino’s Gold, enhancing its content portfolio and demonstrating a shift towards owning and operating more of its top titles.

Full Transcript

OPERATOR

Good afternoon everyone. I’d like to welcome you to the Skillz Inc. first quarter 2026 results call. this time I would like to turn the conference over to your host Joe Giffone from JCIR to begin.

Joe Giffone

Good afternoon everyone. Skillz issued its 2026 first quarter earnings release on May 15, which is available on the Company’s investor relations website. Let me read the safe harbor language and then we’ll get right into the call. All statements and comments made by management during this conference call other than statements of historical fact may be deemed forward looking statements for purposes of the Private Securities Litigation Reform act of 1995. Skillz cautions that these forward looking statements are subject to risks and uncertainties that may cause actual results to differ materially from those reflected by the forward looking statements made during the call. For additional details on these risks and uncertainties, please see Skillz Annual report on Form 10K for the year ended December 31, 2025 as filed with the SECurities and Exchange Commission and Skillz subsequent public filings with the SEC. Skillz undertakes no obligation to update or revise any forward looking statements, whether as a result of new information, future events or otherwise. Additionally, we will reference various non Generally Accepted Accounting Principles (GAAP) financial measures and KPIs during this call. Please refer to our earnings release for an explanation of these measures and how we use them and in the case of the non Generally Accepted Accounting Principles (GAAP) financial measures, reconciliations to the nearest Generally Accepted Accounting Principles (GAAP) equivalents. It’s now my pleasure to turn the call over to Skillz CEO Andrew Paradise. Andrew, please go ahead.

Andrew Paradise (Chief Executive Officer)

Thank you Joe and good afternoon everyone. I’ll begin today’s call with a review of our first quarter results. For the first quarter, GAAP revenue was 29 million, down 3% quarter over quarter and up 33% year over year. Adjusted EBITDA loss was 13 million compared to a loss of 10 million in the fourth quarter. The increase in adjusted EBITDA loss is driven by higher litigation related expenses during the quarter. Importantly, excluding litigation related expenses, adjusted EBITDA in Q1 2026 improved to a loss of 7 million, representing a 15% improvement quarter over quarter on a normalized basis at Razor adjusted EBITDA as 2 million, marking a third consecutive quarter of profitability. We expect this improvement in underlying profitability across our portfolio as we continue to move into the second quarter. Paying Monthly Active Users (PMAU) for the skills platform was 128,000, down 9% quarter and up 3% year over year. This quarterly sequential decline in PMAU was partly driven by our decrease in User Acquisition (UA) spend, resulting in fewer new user cohort additions while top line PMAU has decreased, we’re encouraged that retention across our more mature cohorts improved from the previous quarter. This reflects a healthier platform demonstrated by our 7% quarter over quarter increase in average revenue per paying user. Moving to our Fair Play initiative and an update on our Litigation against Papaya Gaming In April, unanimous jury in the U.S. district Court for the Southern District of New York found Papaya liable for false advertising under the Lanham act and deceptive practices under New York law, awarding skills 420 million in actual damages, the largest false advertising award in U.S. history under the Lanham Act. The jury also made advisory findings supporting disgorgement of either 719 million based on Papaya’s profits or 652 million based on Papaya’s cost savings. These are alternative theories and will not be added together. The court will determine whether to award disgorgement and if so, the final amount it may accept, modify or decline the advisory finance entirely, ensuring there is no duplicative recovery where actual damages and discouragement overlap. Under the Lanham act, the court has the ability to enhance the actual damages award by up to three times the 420 million for any disgorgement the court chooses to award. There is no cap on enhancement. In simple terms, the total potential award ranges from 420 million to over 1.2 billion, depending on the court’s determination on disgorgement enhancement. To understand what this verdict means for the category we pioneered, it helps to understand some of the why Skillz founded the skill based competitive gaming category on a single premise. The players compete fairly against real human opponents for real prizes. As the category grew, we saw competitors gaining market share in ways that defied explanation. This turned out to be what we believe to be fraud. We had to use the legal system to fight back on behalf of our players and our shareholders. What we alleged against one of these competitors was confirmed by Papaya Gaming’s own internal documents. Bots were being deployed at scale. Bot scores selected by Papaya determined the outcomes and none of it was disclosed to the players. I remind you, we’ve taken this path before. In 2024, a federal jury found ABA Games liable for patent infringement and awarded 42.9 million in damages. We subsequently pursued a separate false advertising case against ABA Games, and the two cases ultimately sold together for 80 million. We applied those learnings and brought Papaya to trial on false advertising grounds directly. The evidence to trial is clear. Papaya Gaming’s bots outnumbered human players across tournaments, advertising approximately 6.7 billion in prize pools. Only about 2 billion was actually paid to real users, leaving roughly 4.7 billion in quote imaginary money, a term used by Papaya Gaming’s own defense counsel that was never paid to human players. The jury’s verdict confirms that these practices violated the LAND and MAX false advertising standards. We founded this industry and we remain committed to ensuring that fair competition is the standard every participant is held to on collectibility based on publicly available data. APAI operates at substantial scale with leading titles ranking among the most downloaded in the US Generating significant revenue based on independent analyst coverage …

Full story available on Benzinga.com

This post was originally published here
On Tuesday, Cava Group (NYSE:CAVA) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://events.q4inc.com/attendee/922188545

Summary

CAVA Group Inc reported a 32.2% increase in revenue for Q1 2026, with same restaurant sales up 9.7% and traffic growth of 6.8%.

The company opened 20 new restaurants, bringing the total to 459, and reported adjusted EBITDA of $61.7 million, a 37.6% increase year-over-year.

Strategic initiatives include the launch of CAVA Core, a modern data platform, and CAVA Current, a real-time commerce platform, aimed at improving operational efficiency and customer engagement.

CAVA Group Inc introduced its first seafood offering, Pomegranate Glazed Salmon, as part of its culinary innovation, which has received positive feedback.

The company is investing in its Flavor Your Future platform to develop talent, including the new Assistant General Manager role to support growth.

Future guidance was raised to expect 75 to 77 net new restaurant openings and same restaurant sales growth of 4.5% to 6.5% for the full year 2026.

Management remains committed to its long-term strategy, focusing on consistent menu innovation, operational execution, and avoiding significant price increases to maintain customer trust and value.

Full Transcript

OPERATOR

Hello everyone. Thank you for joining us and welcome to CAVA Group Inc Q1 2026 earnings call. After today’s prepared remarks, we will host a question and answer session. If you would like to ask a question, please press Star one to raise your hand. To withdraw your question, please press Star one again. I will now hand the conference over to Matt Milanovich, SVP of Finance. Please go ahead.

Matt Milanovich

Good afternoon and welcome to CAVA Group Inc’s First Quarter 2026 Financial Results Conference call. Before we begin, if you do not already have a copy, the earnings release and related 8-K furnished to the SEC are available on our websiteat investor.cava.com the purpose of this conference call is to give investors further details regarding the Company’s financial results as well as a general update on the Company’s progress. You will find reconciliations of any non GAAP financial measure discussed on today’s call to the most directly comparable financial measure calculated in accordance with GAAP to the extent available without unreasonable efforts in today’s earnings release and Supplemental deck, each of which is posted on the Company’s website. Before we begin, let me remind everyone that this call will contain forward looking statements for this purpose, any statements made during this call that are not statements of historical fact may be deemed to be forward looking statements. Investors should be aware that any forward looking statements are subject to various risks and uncertainties that could cause actual results to differ materially from those discussed here today. These risk factors are explained in detail in CAVA Group Inc’s most recent Annual Report on Form 10-K as may be updated by its reports on Form 10-Q and other filings with the SEC. Please refer to these filings for a more detailed discussion of forward looking statements in the risks and uncertainties of such statements. All forward looking statements are made as of today and except as required by law, CAVA undertakes no obligation to publicly update or revise any forward looking statements whether as a result of new information, future developments or otherwise. And now I’ll turn the call over to the Company’s co Founder and CEO Brett Shulman. Thanks Matt and welcome to the call everyone. In the first quarter of 2026 we further solidified our position as the clear leader in the Mediterranean Cuisine category while executing against our long term strategy with discipline and conviction. Despite today’s broader macroeconomic environment and geopolitical uncertainty, we sustained strong momentum and delivered exceptional results including positive traffic of 6.8%. Guided by the same steady focus that has shaped our business for the past 15 years, we will continue building for the long term as we gain market share with significant white space ahead while deepening our relationships with guests through a value proposition that clearly resonates our first quarter. Highlights include a 32.2% increase in CAVA Group Inc revenue, same restaurant sales of 9.7% driven by 6.8% traffic 20 net new restaurants ending the quarter with 459 restaurants, a 20.2% increase year over year adjusted EBITDA of 61.7 million, a 37.6% increase over the first quarter of 2025 net income of 23.6 million and 15.5 million in free cash flow. These results are a direct byproduct of the structural strength of our business and the dominant position we hold as the industry leader in Mediterranean, a cuisine category we have pioneered, defined and continue to shape. Central to that leadership is the value proposition rooted first and foremost in doing what is right by our team members and our guests. While many peers have responded to short term cyclical pressures with discounting and promotional activity, we have remained unwavering on our long term strategy. This past January we took an approximate 1.4% price increase while holding baseball and PITA pricing flat. Over the longer term, we have priced well below inflation with price adjustments representing only slightly more than half of cumulative CPI since the end of 2019. These decisions, deliberate and consistent, have compounded over time reinforcing the trust we have built with our guests and strengthening the foundation of our brand. And importantly, that value is not one dimensional. Whether a guest is looking for an accessible everyday meal or choosing to lean into one of our more premium offerings, we have created the flexibility for them to engage with CAVA on their terms in a way that fits their needs and moments. Ultimately, this all ties back to our concept essence making Mediterranean cuisine accessible to communities across the country while delivering it with warm hospitality. Hospitality that is delivered by our outstanding team members who we support with investments like our Flavor Your Future platform, which I will speak to in more detail later. The strength of our category, the competitive positioning of our brand and the power of our concept have enabled the success we saw this past quarter and that we continue to build on for the future. It is that foundation and focus on execution that guides our work across our four strategic pillars. Beginning with our first, expand our Mediterranean way in communities across the country. During the first quarter we opened 20 net new restaurants, ending the quarter with 459 locations across 29 states and the District of Columbia. Our expansion continues with both intention and incredible momentum reflected by recent new market openings at Cincinnati, St. Louis and Columbus and our upcoming entry into Minneapolis, Minnesota later this year, further deepening our presence across the Midwest. We are encouraged by the early performance of our 2026 cohort, which is tracking in line with or ahead of the strength of our 2025 class. With first quarter new restaurant productivity trending above 100% as we expand our reach across the country, our culinary innovation remains at the heart of what draws guests to our brand. This past January, we brought back our fan favorite Roasted White Sweet Potato to a warm reception, with guests embracing it as a complimentary meat and using it as a canvas to craft their own cotton experience. The launch resonated beyond our existing customer base as well, driving increased visit frequency among returning guests while introducing the brand’s new ones. We are pleased with the performance of the seasonal favorite and we look forward to welcoming it back to our menu again in the future. And from beloved returning favorites to new culinary firsts, our pipeline of innovation continues to move forward with discipline and purpose. I’m excited to share that we’ve officially launched our first ever seafood offering, Pomegranate Glazed Salmon across all restaurants nationwide. Our roasted flaky fillet is marinated in a subtly sweet blend of pomegranate, date molasses, harissa, red wine vinegar and bold spices. A protein rich option with omega 3s and essential vitamins like B12 and vitamin D, delivering both bold flavor and genuine nourishment in every bite. Salmon is a natural extension of our menu, fitting seamlessly within the Mediterranean diet while increasing the variety of choices we can offer our guests. This is an important culinary milestone for us and one we approached with care, ensuring it stayed true to our concept. Essence. We have seen promising early results as guests experience salmon for the first time at their local cabo. Shifting to our second pillar Deepen personal relationships with guests Even as we scale, we are encouraged by the strength of our loyalty program and the increasingly creative and engaging ways we are bringing it to life for our guests. This past quarter through our digital experience, we leaned into the cultural touch points that bring our guests together, finding intersections of joy, connection and food that feel organic to who we are. Our flavor bracket in app game and recent partnerships with WNBA number one pick AZ Thudd and NCAA men’s basketball champion Yaxel Lindenberg, each with their own digital exclusive bowl, brought the energy of March Madness to life in a way that felt both timely and uniquely cava. Together, these became one of our most highly engaged digital experiences to date and we will continue to broaden our array of engagement tools and tactics like these to further leverage the loyalty program and first party audience. We are growing. From the beginning it has always been about showing up authentically and becoming a genuine part of what our guests already love. It is through this kind of presence that we continue to deepen the relationships that keep our guests delighted and coming back. Bringing these relationships to life starts at a fundamental level with our people and our restaurants, which is reflected in the progress across our third and fourth pillars. Run great restaurants every location, every shift and operate as a high performing team Operating as a high performing team requires making foundational investments today that position us for the next decade and beyond. We’ve spoken before about being on the precipice of a decade of data transformation, a multi year transformation where data technology and AI will reshape how we run our business. I want to take a moment to share the recent progress we have made. Earlier this year we reached a meaningful milestone with the launch of Kava Core, our modern data platform. It establishes a unified scalable foundation for how we manage and use data across the business, enabling fast execution today while positioning us to leverage emerging AI capabilities. Building on that, we are in the early stages of delivering our new edge enabled operating platform Kava Current. A modular real time commerce platform, Kava Current is live today, actively processing orders across our restaurants and as it scales, it will drive more consistent execution with improved visibility and faster, more localized actions. Together, Kava Core and Kava Current create a connected real time system bringing data, applications and intelligence together to power our business. This enables us to deliver more meaningful personalized experiences for our guests, tailored to their preferences and behaviors, while also advancing more predictive operations that help our teams anticipate demand and better align staffing and preparation in real time. By building this platform internally, we gain greater control, flexibility and the ability to scale more efficiently over time. And while this is an important advancement, it is not a discrete initiative. It is a deliberate structural evolution creating the conditions for us to operate as a real time AI enabled business and move faster and more intelligently across every part of our organization. The work we are doing today will allow us to continue delivering value for our guests, our team members and our business for years to come. And finally, even the most sophisticated infrastructure only creates value when it is in service of the team members running great restaurants, every location, every shift. A core tenet of this strategic pillar is investing in our team members and talent and we remain deeply committed to building the next generation of leaders across our system. Our Flavor your Future initiative continues to show promise, focusing on attracting, developing and retaining talent across the organization. A recent key action under this platform was the launch of our new Assistant General Manager position with the critical goal of developing a deeper bench of role ready leaders to support our growth as we scale. Early indicators from the AGM rollout are promising. Restaurants with AGM coverage are outperforming Those without as AGMs provide additional leadership support during peak dinner and weekend shifts, strengthening operations, deepening the development of future team members, and building more sustainable restaurant teams over time. We look forward to sharing more on the broader Flavor your Future platform in the quarters ahead. And while the early results of the AGM rollout are encouraging, stories like Adriana Cervantes reflect the broader opportunity we are building toward through Flavor your Future Adriana joined CAVA as a Guest Experience Manager in Sherman Oaks and through her leadership, operational impact and commitment to our values, quickly progressed into the Assistant General Manager role before being promoted to General Manager earlier this year. Today she’s already working toward becoming an Academy Manager, helping develop future leaders across the organization. Her journey is a powerful reminder that when we invest in our team members and create opportunities for growth, we are able to build not just stronger restaurants but but meaningful and lasting careers for our people. Before I turn the call over, I want to thank our teams across the country for delivering a strong quarter and for staying true to our mission. It’s the consistency, intentionality and discipline with which we operate that have allowed us to establish ourselves as a clear leader in Mediterranean, the next large scale cultural cuisine category. As we look ahead, we remain committed to bringing heart, health and humanity to food and with that I will hand it over to Tricia to walk you through the financials.

Tricia

Thanks Brett and hello everyone. CAVA Group Inc revenue in the first quarter of 2026 grew 32.2% year over year to 434.4 million. Same restaurant sales increased 9.7% driven by traffic growth of 6%. During the quarter we opened 20 net new restaurants, bringing our total CAVA restaurant count to 459. As Brett noted, we are very pleased with our new restaurant openings which are tracking ahead of or in line with the strength of our 2025 class. New restaurant openings continue to exceed expectations in both top line and margin performance. With new restaurant productivity above 100%, our overall system wide average unit volumes are now $3,000,000. Cabo restaurant level profit in the first quarter was 108.9 million or 25.1% of revenue, compared to 82.3 million or 25.1 percent of revenue in the prior year period, representing a 32.3% increase. Kava’s food, beverage and packaging costs were 29.1% of revenue lower than the first quarter of 2025 by 20 basis points, largely driven by favorable mix. As a reminder, we anticipate Kava’s food, beverage and packaging costs to increase as a percent of revenue for the rest of the year as a result of the recent salmon launch. Kava labor and related costs were 25.7% of revenue approximately flat to the first quarter of 2025. This was driven by sales leverage offset by a 2% investment in team member wages which includes the expansion of our AGM role. CAVA occupancy and related expenses were 6.9% of revenue, an improvement of 50 basis points from the first quarter of 2025 due to sales leverage. CAVA Group Inc other operating expenses were 13.3% of revenue reflecting an increase of 80 basis points in the first quarter of 2025. This increase was primarily driven by a higher mix of third party delivery and other individually significant items shifting to overall performance. Our general and administrative expenses for the quarter including equity based compensation and executive Transition costs were 9.9% of revenue compared with 10.5% of revenue in Q1 of 2025. This 60 basis point improvement was driven by leverage from higher sales partially offset by investments to drive future growth and higher performance based incentive compensation. Preopening expenses were 6.2 million in the current quarter compared with 4.5 million in the prior year quarter. The $1.7 million increase includes a higher number of units under construction. Adjusted EBITDA for the first quarter was 61.7 million, a 37.6% increase versus Q1 of 2025. The increase in adjusted EBITDA was driven by 9.7% same restaurant sales growth. The number and continued strength of new restaurant openings partially offset by investments to support growth including higher reopening costs. For the first quarter of 2026, equity based compensation was $7.7 million. We continue to expect equity based compensation which includes our new programs to provide equity grants, GM and performance based LTI to be between 22 million and 24 million in aggregate for the full year. In the first quarter our effective tax rate was 21.5%. For the full year fiscal 2026. We expect our effective tax rate to be between 23% and 28% with the rate in Q2 being consistent with Q1 based on the timing of equity based vesting. As a reminder, the increase in our tax rate in 2026 versus the prior year is due to the lower permanent benefit from equity based compensation, our cash taxes will continue to be immaterial until we fully utilize our net operating losses. During the first quarter we reported 23.6 million of net income compared to 25.7 million of net income in Q1 of 2025. Diluted EPS was $0.20 in the first quarter compared with $0.22 in the first quarter of 2025. The decrease in net income and diluted EPS is due to the previously mentioned higher permanent benefit from equity based compensation within income tax in the prior year, partially offset by nearly 50% higher earnings before taxes. Turning …

Full story available on Benzinga.com

This post was originally published here
James Hardie Industries (NYSE:JHX) released fourth-quarter financial results and hosted an earnings call on Tuesday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://events.q4inc.com/attendee/602490831

Summary

James Hardie Industries PLC reported Q4 fiscal 2026 net sales of $1.4 billion and an adjusted EBITDA of $381 million, with an EBITDA margin of 27.1%. For the full fiscal year, net sales were $4.8 billion with an adjusted EBITDA of $1.3 billion and a 26.2% margin.

Strategic initiatives focused on the integration of Azek, achieving $125 million in run-rate commercial revenue synergies by fiscal 2027, and leveraging the Hardi operating system to drive productivity and cost savings.

The company aims for a return to growth in the fiber cement business in fiscal 2027, driven by market expansion efforts in underpenetrated regions and leveraging a combined sales force to enhance market presence.

Management highlighted successful commercial synergy momentum, including expanded relationships with partners like Lansing Building Products and CB USA to strengthen their product offering and market position.

Guidance for fiscal 2027 includes net sales between $5.25 billion and $5.41 billion, with an adjusted EBITDA range of $1.45 billion to $1.5 billion, and free cash flow exceeding $500 million.

Management expressed optimism in outperforming the market despite economic uncertainties, focusing on execution, cost management, and capturing growth opportunities through strategic initiatives.

Full Transcript

OPERATOR

Welcome to the James Hardy Fiscal fourth quarter 2026 earnings conference call. After prepared remarks by management, there will be an opportunity to ask questions. If you would like to ask a question, please press Star one to raise your hand. To withdraw your question, press Star one again. I would now like to hand the call over to Chris Russell, Senior Vice President of Global Strategy and Corporate Development. Please go ahead.

Chris Russell (Senior Vice President of Global Strategy and Corporate Development)

Thank you Operator and thank you to everyone for joining today’s call. I am joined today by Aaron Erter, Chief Executive Officer of James Hardy, Ryan Latta, Chief Financial Officer of James Hardy and John Skelly, President and General Manager of James Hardy North America Building Products. Before we begin the call, please note that during prepared remarks and Q and A we may refer to non-GAAP financial measures and make forward looking statements. You can refer to several related cautionary and other notes on slide 2 of our earnings presentation for more information. Forward looking statements made during today’s conference call and in the earnings materials speak only as of the date of this presentation. Forward looking statements are subject to risks and uncertainties that could cause actual results to differ materially from from those in the forward looking statements. Accordingly, investors are cautioned not to place undue reliance on forward looking statements. In addition, non-GAAP measures should not be considered in isolation or as a substitute for results prepared in accordance with GAAP. Reconciliations of non-GAAP measures discussed today can be found in our earnings presentation which is posted on our website. Also, unless otherwise indicated, our materials and comments refer to figures in US Dollars and any comparisons made are to the corresponding period in the prior fiscal year. Organic net sales comparisons exclude the impact of the Azek acquisition as well as the impact of exiting our Philippines business in Q2 fiscal year 25. With that opening, I’m pleased to hand the call to Aaron.

Aaron Erter (Chief Executive Officer)

Thanks Chris. I’d like to take a moment to thank Chris for his contributions during this transition period in investor Relations and to welcome Bill Seymour, our new Vice President of Investor Relations. Bill brings extensive IR experience to the role and a strong track record in the field. In my remarks today, I will briefly review the highlights for Q4 and fiscal 2026, discuss our strategy and end with our outlook. We delivered a solid fiscal fourth quarter and full year despite a challenging construction market. The result of staying focused on what we can control, execution, cost and serving our customers. For the fourth quarter we delivered net sales of $1.4 billion, an adjusted EBITDA of $381 million at ahead of expectations with adjusted EBITDA margin of 27.1% demand held up across our core categories despite weather related softness early in the quarter in the United States and our teams executed well protecting price, managing costs and supporting demand as conditions improved. For the full fiscal year we delivered net sales of $4.8 billion, an adjusted EBITDA of $1.3 billion with adjusted EBITDA margin of 26.2% reflecting the resilience of our portfolio and the actions we took across the business. Free cash flow for the year was $314 million reflecting tightly managed operations in the year and despite significant one time integration and acquisition related costs. While organic net sales declined in our fiber cement business during the year, we are confident in the underlying demand drivers and expect this business to grow in fiscal 2027. This confidence is reinforced by our great products, leading brands and best in class sales force which together position us to outperform the market and capture long term growth opportunities. As I look back on fiscal 2026, we delivered against a number of objectives. A key differentiator for us is the Hardie operating system. Through Hardiee Operating System (HOS), we’ve taken out and offset significant inflationary costs by improving procurement, driving productivity in our plants and applying operational discipline. Even with lower volumes, we were able to maintain best in class margins and keep the business performing at a high level. As we continue to bring the companies together, we are applying the Hardie operating system to the Azek manufacturing network. We are encouraged by the early progress in the Azek plants and believe that Hardiee Operating System (HOS) will drive productivity and savings over the long term. We utilized a Hardiee Operating System (HOS) framework to make the difficult decision to close two of our legacy fiber cement plants in January 2026. As we move forward, we will continue to leverage Hardiee Operating System (HOS) as a critical tool to drive productivity, manage costs and support both margin expansion and and reinvestment and growth. Another milestone in the integration we recently completed was combining our sales forces. We believe we have the largest most downstream focused sales team in our space, one salesforce, one company and a portfolio of leading pro brands, James Hardiee, TimberTech, Azek and more. We are seeing commercial synergy momentum build as a result of the combination with early wins validating the strength of our integrated go to market approach. These wins are both numerous and broad based. You can see two examples in our earnings presentation. One example is our expanded relationship with Lansing building products. Lansing has been a long time and valued partner of James Hardiee and through this expansion we are consolidating multiple PVC Trim brands to AZK across their footprint. This simplifies the offering for the channel increases attachment of Azek Trim on our fiber cement siding jobs and strengthens our ability to deliver a more complete exterior solution. Another example is our recently announced expansion with CB USA. This exclusive agreement adds timber tech to an existing relationship between James Hardiee and CB USA, expanding our share of wallet while positioning us as a single source provider of exterior products for custom builders. These are just two examples. The breadth of opportunities and early traction reinforces our confidence in hitting $125 million and run rate commercial revenue synergies exiting fiscal 2027 on cost synergies we’re ahead of schedule without sacrificing service or execution. Integration continues and our conviction in this combination grows. Next, I’d like to discuss our go to market strategy in our largest market, North America. Starting with the size of the prize. Our $23 billion exterior total addressable market remains heavily under penetrated by more resilient materials. Wood and vinyl still dominate siding, decking, railing and outdoor structures despite real limits on durability and maintenance. A $17 billion plus conversion opportunity the James Hardiee ASA combination positions us to capture it, build a leading exterior platform with the best brands and win in both R R and new construction. To capture it, we’re executing against five pillars that drive our growth and margin expansion. First, Material conversion. We’re replacing wood and vinyl with materials that are more resilient, need less maintenance and resist fire. We’re seeing this play out in real time. Contractors who trust our brands are switching competitive decking to timber tech and longtime Hardiee siding contractors are adding composite decking to their service offerings. There are approximately 60 million decks in the United States and the vast majority are wood representing a long Runway as the installed base weathers in the elements. These two way wins are exactly what we expected from the combination. With our brands, products and contractor relationships, we are positioned to continue to deliver above market growth. Second Channel expansion in scaling what each business does best across the combined footprint. In the south, approximately 2,500 locations stock Hardiee but not TimberTech. Yet a clear Runway for our outdoor portfolio into accounts where we have established relationships in the north. The inverse approximately 700 strong timber tech and AZK locations where Hardiee isn’t yet stocked. Disciplined approach Real growth opportunities the third pillar is innovation. The product and R D teams from both companies are now combined focused on solutions that accelerate exterior conversion. Innovation has been a key element of Azax 500 to 700 basis points above market growth per year. We’re applying that same playbook to fiber cement to expand our market and drive new product growth over time. Fourth Brand Preference James Hardiee Azek and timbertac are among the most recognized brands in our categories and we’re extending that lead through targeted marketing, contractor education and innovation, most of it in house. The impact is clear in our Deck, Rail and Accessories business. Brand search volume has increased at a 40% CAGR over the past three years while customer sample orders, a leading indicator of future demand, have grown at nearly 15% annually over the same period. This marketing strength also carries through to our loyal TimberTech pros where our data suggests that the consumer demand we are generating has established TimberTech as the leader in brand awareness among contractors. This positions us for sustained share gains over time. As we move forward, we have combined the marketing teams and are applying the AZK in house marketing approach to the fiber cement side of the business. As we scale this competency, we expect to drive increased awareness consideration and brand preference. Fifth, simplifying the consumer journey, we’re making it easier for homeowners to choose and purchase our products. A key part of this has been a full replatforming of our website designed to improve how homeowners research, compare and ultimately select products for their homes. Just as important, it better connects homeowners to our contractor network, helping turn interest into action. Underpinning it all is the hardy operating system, continuous improvement in safety, quality, service and cost. Together this is a clear path to sustainable growth, margin resilience and long term value. Now let me talk a little bit about our fiber cement growth plan. Beyond these five pillars, our fiber cement growth plan is central to the strategy. We have clear plans to reaccelerate siding and trim and as noted, we expect fiber cement to return to organic volume growth in fiscal 2027. Step one a deliberate focus on the Northeast and Midwest where we’re under penetrated and where R and R wood and wood look siding alone is an approximately $1 billion conversion opportunity. AZAC gives us immediate relevance, established channels, strong relationships and complementary products in these markets. We are actively pursuing the opportunity across multiple fronts including expanded dealer engagement, targeted training programs and scaled contractor conversion initiatives. Central to this effort is the continued rollout of expanded statement and Statement Essentials which ensure James Hardiee has the right offering for each contractor in our value chain. We launched this program with a Midwest pilot in April 2025 and the results to date provide clear evidence that the strategy is working. We are seeing consistent acceleration in ship to revenue across each quarter with growth culminating in double digit percentage gains. This reflects improved execution in the market and early success in converting demand into realized revenue and we are scaling this approach to other regions throughout our footprint we’re hitting these markets on multiple fronts. Hardiee Pro Lab, a series of mobile training units, supports contractor adoption with hands on training on ease, speed and economics of fiber cement install. Based on Midwest Pilot success, we’ve expanded the program across approximately 50 dealer locations in the broader Midwest and Northeast with strong early traction. Our approach focuses on three opportunities 11 converting vinyl siding, 2 winning against all wood siding types and 3 expanding our presence in premium products. First, vinyl we’re accelerating penetration in the Northeast, Midwest, Carolinas and Canada backed by new products, expanded color plus rollout and more contractor engagement and training. Second, Virginia winning against wood we are rolling out easier and faster to install products targeted downstream sales and marketing and expanded channel access including the Legacy AZK dealer network. Fire resilience is becoming an increasingly critical factor in this dynamic as building codes evolve, insurance requirements tighten and homeowners place greater emphasis on durability and risk mitigation. Fiber cements non combustible properties are emerging as a more meaningful differentiator versus wood and other combustible materials. While this is most pronounced in higher risk regions, we are also seeing broader awareness and adoption across markets, reinforcing the structural advantage of our portfolio and supporting continued material conversion. Third, premium products, timber hue and enhancements to artisan and other premium lines target custom builders and high end remodelers, leveraging our independent channel strength where design and durability drive the decision. Together these priorities position us to accelerate conversion, take share and drive durable volume growth and fiber cement siding. Let me talk to you a little bit about our external environment and outlook. Ryan will cover our outlook in more detail, but let me quickly frame how we see the external environment and touch on our approach to fiscal 2027. The market has shifted substantially in the last few months. At the start of the year, we plan for broadly flat market Demand in fiscal 2027. Since then, key variables have changed. 30 year mortgage rates below 6% late February move meaningfully higher after the Middle east escalation. Builder confidence and consumer sentiment have softened across our dealers and contractors. Nearly half cite economic uncertainty as their biggest challenge, while the broader market remains somewhat challenging. I want to be clear we are optimistic about our path forward. We are seeing solid momentum in the business and are intensely focused on execution. We expect to deliver market outperformance, a return to growth in fiber cement adjusted EBITDA expansion, and we expect to significantly grow our free cash flow which will drive meaningful deleveraging. Now over to Ryan who will take us through the financials.

Ryan Latta (Chief Financial Officer)

Thanks Aaron. I will walk through our results and then get into our planning assumptions. fourth quarter total net sales grew 45% to 1.4 billion, including 445 million of acquired AZEC revenue. Organic net sales declined 1% in the quarter. For the full year, Total net sales grew 25% to 4.8 billion with organic net sales down 2%. The organic decline in fiber cement reflects the market environment Aaron described. fourth quarter adjusted EBITDA was 381 million, margin was 27.1% for the full year, adjusted EBITDA was 1.27 billion, margin was 26.2%. A few items to highlight Adjusted corporate and unallocated R&D was 45.5 million in fourth quarter for modeling purposes, keep in mind that approximately 40% of our full year 2026 cost energy benefits are in that line. Our adjusted effective tax rate was 23.4% for the quarter and 20.2% for the full year, slightly above our prior 20% guide. Adjusted net interest was 65 million. Weighted average diluted shares were approximately 585 million. We expect both to remain consistent. In fiscal 2027, fourth quarter adjusted net income was 173 million and adjusted diluted EPS was $0.30. Free cash flow for fiscal 26 was 314 million, including the benefit of a completed Australia land sale in Q3 integration costs continue to weigh on cash, but those stepped down meaningfully in fiscal 2027. Combined with higher EBITDA from synergy realization and disciplined CAPEX, free cash flow will improve significantly and deleveraging remains a clear priority. In siting in trim, we delivered against our objectives to despite unfavorable weather. In fourth quarter net sales were 767 million, up 7% with adjusted EBITDA of 253 million at a 33% margin. Cold storms and above average precipitation, most pronounced in February and early March. Limited job site activity and delayed project starts in both new construction and R and R. We estimate the weather impact to our fiber cement sales was approximately 20 million in the quarter. Activity rebounded later in the quarter as conditions improved. Our manufacturing footprint optimization and expense management is already delivering with initial P&L benefits in fourth quarter, an example of actively managing the business for stronger profitability for the full year. Siding and TRIM delivered net sales of 2.96 billion, up 3% and adjusted EBITDA of 951 million at a 32.1% margin. In deck rail and accessories, fourth quarter net sales were 345 million, up 5%. Adjusted EBITDA was 97.5 million margin was 28.2%. Sell through grew low single digits. January was solid. February and early March were disrupted by weather, then activity recovered through the end of the month. We grew Deck, Rail and Accessories again this quarter, lapping strong fourth quarter growth in the prior year delivering against the down market over the past few years. We’ve meaningfully expanded our shelf position with continued gains this year across both pro and retail channels. During fourth quarter we shipped to support those new shelf wins and and saw pockets of sell through delayed by weather. Working with our channel partners, we are taking a slightly more conservative inventory position in Q1 to set up a strong back half of the year. Q1 sales and margins will be softer as a result. Underlying demand is intact. We expect positive sell through in both Q1 and for the full year. Full year on 3/4 of contribution. Net sales were 795.2 million. Adjusted EBITDA was 224.8 million, margin was 28.3%. We outperformed a market that declined low to mid single digits by more than 700 basis points in Australia and New Zealand. …

Full story available on Benzinga.com

This post was originally published here
Economist Justin Wolfers on Tuesday warned of rising food prices if the disruption in the Strait of Hormuz continues, which is not only driving oil prices higher but also fertilizer costs.

In a post on X, Wolfers wrote, “The big story right now is oil. The next story is food.” He added, “That’s the transmission channel people miss: if fertilizer is caught on the wrong side of the Strait of Hormuz, food prices can be next.”

Higher Fertilizer Prices Could Result In Food Crisis

Higher fertliizer prices are putting pressure on farmers and the agriculture sector. …

Full story available on Benzinga.com

This post was originally published here
Astera Labs, Inc. (NASDAQ:ALAB) shares are trending on Wednesday.

ALAB shares jumped 13.30% to close at $244.26 on Tuesday, nearing the stock’s 52-week high of $262.90.

Insider Sale Filings Surface

The move comes after multiple Form 144 filings disclosed proposed sales totaling 280,000 Astera Labs shares worth roughly $60.4 million.

The filings, submitted Tuesday, included a proposed sale of 200,000 shares tied to the Navad Trust dated Nov. 1, 2012, valued at about $43.1 million. Two additional filings tied to the RN2021 and SN2021 Irrevocable Trusts each disclosed proposed sales of 40,000 shares each worth about $8.6 million. The filings showed the sellers’ relationship to Astera Labs as “director” and “officer.”

The filings also referenced Rule 10b5-1 trading plans adopted in December 2025.

Astera …

Full story available on Benzinga.com

This post was originally published here
Jim Cramer said on Tuesday that President Donald Trump‘s comments no longer positively impact oil prices as uncertainty looms over the Strait of Hormuz amid tensions between Washington and Tehran.

The Big Problem With Oil

In a post on X, Cramer outlined the “big problem” with oil prices in recent times, saying that the prices go “down less when Trump says there is a hint of peace,” but rally when “there is a rumor of war.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Gavin Newsom Urges Trump To Lower Gas Prices As They Top $6— Traders Sees Over 70% Chance Fuel Costs Touch $7.40 In California

This post was originally published here
Major U.S. indices closed lower on Tuesday, with the Dow Jones Industrial Average declining 0.65% to 49,363.88, the S&P 500 slipping 0.67% to 7,353.61 and the Nasdaq falling 0.84% to 25,870.71.

These are the top stocks that gained the attention of retail traders and investors through the day:

Meiwu Technology Company Limited (NASDAQ:WNW)

Meiwu Technology shares soared by 97.10%, closing at $4.75. The stock hit an intraday high of $6.39 and a low of $3.70, with a 52-week range of $1,352 to $2.25. In the after-hours trading, the stock rose 13.26% to $5.38.

This surge follows the company’s announcement of a new private financing deal aimed at expanding its artificial intelligence capabilities. Meiwu Technology secured approximately $15.65 million through a private share sale of 25 million ordinary shares, with plans to develop an AI-powered skincare management platform.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Ross Gerber Says ‘Pay Attention’ To Nvidia And Micron As Jensen Huang Predicts AI Explosion

This post was originally published here
Workers are more likely to be replaced by people who know how to use artificial intelligence than by the technology itself, according to Nvidia (NASDAQ:NVDA) CEO Jensen Huang.

“It is unlikely most people will lose a job to AI,” Huang said last month during a Stanford Graduate School of Business panel discussion alongside Rep. Ro Khanna (D-CA). “It is most likely that most people will lose their job to somebody who uses AI.”

His remarks focused on AI adoption, changing workplace demands and how companies are using the technology inside existing jobs.

Don’t Miss:

Why Huang Says AI Has Made Him ‘Busier Than Ever’ 

Huang said during the discussion that AI can automate specific tasks while allowing companies to do more work. Using himself as an example, he pointed to typing and talking, two functions AI can already perform. Even so, he said he remains “busier than ever.”

“The purpose of your job and the tasks that you do in your job are related but not the same,” Huang said. In his view, automating tasks does not necessarily eliminate the job itself.

The Engineers Huang Says Are Winning In The AI Era 

Huang said at the panel that AI agents are already becoming part of Nvidia’s software engineering workflow.

“The software engineers who know how to use AI, know how to use agentic systems, are the most popular and the most successful,” he said.

Trending: Demand for Faster Diagnostics Is Surging — NASA- and NIH-Supported Space-Tested System Targets At-Home Lab-Quality Blood Testing

Before AI, engineers would come up with an idea and then spend time coding it, according to Huang. He said AI now helps shorten that process, allowing teams to move more quickly to the next idea.

Huang said the agents continuously prompt engineers for instructions and next steps during development work.

The Career AI Was Supposed To Kill 

Radiology was one example of how AI changed a profession without eliminating it, Huang told the Stanford panel.

“At the beginning of the AI revolution, one of the smartest and most influential computer scientists, and one of the fathers of AI, modern AI, said that in 10 years’ time, the one job you don’t want is radiology,” Huang said.

He said AI later became widely used in radiology departments and helped automate scan analysis. Huang said hospitals also hired more radiologists as departments handled higher scan volumes, treated more patients and generated more revenue. 

See Also: Small differences in withdrawal and tax strategy can significantly impact long-term retirement income — see where you stand today.

Khanna, whose district includes much of Silicon Valley, said even if AI creates more jobs over time, …

Full story available on Benzinga.com

This post was originally published here
CHARLOTTE, N.C., May 19, 2026 /PRNewswire/ — The Allspring Income Opportunities Fund (NYSE:EAD), the Allspring Multi-Sector Income Fund (NYSE:ERC), the Allspring Utilities and High Income Fund (NYSE:ERH), and the Allspring Global Dividend Opportunity Fund (NYSE:EOD) have each announced a distribution.

TICKER 

FUND NAME

DISTRIBUTION PER SHARE

FREQUENCY

CHANGE FROM PRIOR DISTRIBUTION

EAD

Allspring Income Opportunities Fund

$0.05337

Monthly

+$0.00007

ERC

Allspring Multi-Sector Income Fund

$0.07277

Monthly

+$0.00015

ERH

Allspring Utilities and High Income Fund

$0.08725

Monthly

+$0.00090

EOD

Allspring Global Dividend Opportunity Fund

$0.14211

Quarterly

+$0.00567

The following dates apply to today’s distribution declaration for each fund:

Declaration date               May 19, 2026
Ex-dividend date              June 11, 2026
Record date                     June 11, 2026

Full story available on Benzinga.com

This post was originally published here
A new federal tax rule is already shrinking poker schedules.  

Poker Hall of Famer Erik Seidel told CNBC recently that he is skipping bigger buy-in tournaments because the incoming rule will make high-volume poker harder to justify.

“This just creates a situation where it’s really untenable,” Seidel said.

Under the new rule, gamblers will be able to deduct only 90% of losses against winnings, down from 100%, meaning players could owe taxes on money they never actually kept. 

Don’t Miss:

A Tax Change Is Reshaping Poker Schedules

The 66-year-old poker professional has earned more than $48 million in live tournament winnings over a career that stretches back to the late 1980s, according to the Hendon Mob Poker Database.

Seidel played his first major tournament in 1988, finishing as runner-up in the World Series of Poker main event. He became a full-time professional poker player in 1995.

In recent years, he estimated playing roughly 130 to 150 tournament entries annually. Last year, his total tournament winnings topped $2.8 million.

That pace is changing as the new tax rules take effect this year.

Under President Donald Trump‘s One Big Beautiful Bill Act, gamblers can no longer fully deduct wagering losses against winnings. Instead, they can deduct only up to 90% of losses, while all winnings remain taxable income.

Trending: What If Your Investment Income Didn’t Rely Entirely on Market Swings? Some Investors Are Taking a Different Approach

For Seidel, the shift changes the math behind high-volume tournament poker, especially in events with large buy-ins.

“I’m going smaller because I don’t want the numbers to get too high if I’m only able to deduct 90%,” Seidel told CNBC. “I’ve just been really taking it easy and avoiding $10K [buy-in tournaments] and above, which are the tournaments that I normally play, and not traveling as much this year.”

The Math Gets Harder For Professional Players

Tax professionals say the rule matters most for players who put large sums at risk across many events, even when their final profit is small.

Clayton Financial and Tax principal and enrolled agent Russ Fox told CNBC that several professional poker players he works with have already reconsidered playing full time. 

See Also: Think the biggest tech gains happen after an IPO? Click here to see why some investors are looking at opportunities before companies go public.

Fox gave the example of a player who records $100,000 in winnings but also racks up $110,000 in losses over the year. Under the new rules, only 90% of losses can be deducted, meaning the player could owe taxes despite losing money overall.

He said he has encouraged clients to rerun previous years under the new rules to …

Full story available on Benzinga.com

This post was originally published here
Keysight Techs (NYSE:KEYS) released second-quarter financial results and hosted an earnings call on Tuesday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://events.q4inc.com/attendee/369175175

Watch the full earnings call below:

Summary

Keysight Techs reported record financial performance with a 56% growth in orders, 31% increase in revenue, and a 69% rise in earnings per share for Q2 2026.

The company is raising its growth expectations for fiscal 2026 with anticipated revenue growth in the high 20s percentage due to a strong start to the year and a robust pipeline.

Strong demand in AI-related solutions, wireline business, and aerospace and defense sectors drove significant growth, with notable engagements in AI infrastructure and 6G capabilities.

Record cash flow was reported with $472 million in free cash flow, alongside a strong balance sheet with over $2 billion in cash and cash equivalents.

Keysight Techs maintained its FY26 revenue guidance from acquisitions at $375 million, with ongoing integration and synergy realization on track.

Management highlighted continued investments in AI, defense technology, and space as key strategic initiatives for future growth.

Full Transcript

OPERATOR

Ladies and gentlemen and welcome to Keysight Technologies Fiscal Second Quarter 2026 Earnings Conference Call. My name is Abby and I will be your operator today. If at any time during the conference you need to reach an operator, please press star zero. This call is being recorded today, Tuesday, May 19, 2026 at 1:30pm Pacific Time. I would now like to hand the call over to Liz Morale, Vice President of Investor Relations. Please go ahead Ms. Morale..

Liz Morale (Vice President of Investor Relations)

Good afternoon and thank you for joining us for Keysight’s second quarter earnings conference call for fiscal year 2026. Joining me on today’s call are Satish Dhanasekaran, President and CEO, Neal Doherty, Executive Vice President and CFO Kailash Narayanan, President of the Communication Solutions Group Jason Carey, President of the Electronic Industrial Solutions Group and Steve Yoon, Senior Vice President of Global Sales. Following the prepared remarks from Satish and Neal, we will take your questions. The press release and information to supplement today’s discussion can be found on our investor relations website, investor.keysight.com. During today’s discussion we will make forward looking statements about the financial performance of the company. Actual results may differ materially from those mentioned in these forward looking statements as a result of risks and uncertainties. Information about these risks and uncertainties can be found in our most recent Forms 10K and 10Q filings with the SEC. We do not intend to update any forward looking statements. In addition, we will refer to non GAAP financial measures and reference core growth which excludes the impact of acquisitions or divestitures completed within the last 12 months and currency movements. The most directly comparable GAAP financial metrics and reconciliations can be found on our investor relations website and all comparisons are on a year over year basis unless otherwise noted. I will now turn the call over to Satish.

Satish Dhanasekaran (President and CEO)

Thank you Liz, Good afternoon and thank you for joining us today. Keysight delivered the best quarter in company history, capping off a record first half quarter. Two orders grew 56% year over year, surpassing $2 billion. Revenue grew 31%, earnings per share grew 69% and we generated a record $472 million in free cash flow. These results demonstrate the strength of keysight’s portfolio which has been built strategically to deliver first to market solutions that enable innovations across our end markets, including data centers, networking, defense, semiconductors and general electronics. We are raising our growth expectations for fiscal 2026 driven by the solid start to the year and the pipeline of opportunities we see in the second half. We now expect revenue growth in the high 20s percent for the fiscal year as the underlying trends driving our business are expected to continue. These investments we’re making in our comprehensive set of solutions and deep engagements with market defining customers positions us well for sustained value creation. Moving to our results by Business Communications solutions order growth significantly outpaced revenue growth of 35% year over year with broad strength across both commercial communications and aerospace, defense and government. This performance builds on the growth we saw in quarter two last year where CSG delivered 9% revenue growth in commercial communications. We continue to see accelerating momentum in our wireline business driven by the ongoing AI data center expansions. Wireline delivered record orders again this quarter with robust demand for both R and D and manufacturing solutions in the first half of fiscal 2026. Our AI related business has already surpassed the levels achieved in all of 2025. As I mentioned in our Q1 earnings call, this momentum continues to be driven by four key pillars of opportunity that we expect to AI infrastructure scaling, speed transitions, optical and photonics technologies, and system level emulations. First, the scaling challenge is intensifying as AI clusters integrate GPUs, CPUs, GPU, DPUs switches, NICs, memory fabrics and storage across multiple vendors and the networking technologies including EtherNet, UA Link, PCIe, NVMe and CXL. Customers are adopting Keysight solutions for end to end interoperability and system validation to ensure that these components function reliably together at scale. This quarter, keysight announced new scale up validation solutions for performance characterization. As systems become more complex and expensive, additional investments in deeper manufacturing validation and production test coverage are needed to improve yields and reduce post deployment failures. We saw a strong adoption for newly introduced ultra high density interconnect solutions that enable rapid characterization of rack backplanes for next generation scale up networks. Second, the industry continues to navigate multiple overlapping speed transitions with continued 800 gig deployments, accelerating adoption of 1.6 terabit architectures and increased R&D activity around 3.2 terabit technologies. The Optical Fiber Conference and Nvidia’s GTC this quarter reinforced the accelerating importance of networking as a critical enabler of AI data center scaling. At OFC, Keysight demonstrated our 1.6-terabit physical layer solutions with over 20 industry leaders. We also showcased 1.6-terabit traffic emulation, link reliability validation and SERDES signal integrity solutions for switch and system vendors. And we collaborated with Broadcom on the industry’s first public interoperability demonstration of Ultra Ethernet Consortium specifications, marking a major step towards production ready AI optimized Ethernet fabrics. Third, activity in Silicon Photonics and Co packaged optics continues to expand our early engagements in co packaged optics position Keysight well to capture value as the industry transitions to these architectures. We’re also seeing strong demand from next generation optical component and transceiver development and deployment driven by expansion in scale out networks. We recently expanded our optical portfolio with the industry’s first 220 GHz lightwave component analyzer to support advanced transceiver and photonics designs. Building on our existing chiplet and photonic design Solutions, our new 3D interconnect designer is also helping customers address the growing complexity of designing next generation 3D stack chip architectures. Finally, customers need system level emulation and benchmarking capabilities for data centers at scale. We saw strong adoption of our AI workload emulation solutions among hyperscalers at as they work to improve utilization of GPU power resources while addressing growing system and security complexity. This quarter we expanded keysight’s AI portfolio with the release of keysight AI Inference Builder designed to support emerging inference applications. Together these trends are driving increased demand for our solutions across multiple domains. The breadth of keysight solutions portfolio and ongoing R and D investments enable us to maintain a differentiated portfolio and an industry leading position. Turning to wireless orders saw robust growth in the quarter with activity in non terrestrial networks, 6G research and increased demand to support the supply chain associated with AI expansion. NTN is becoming an important layer of of future wireless architectures with new LEO constellation scaling and the industry targeting direct to cell deployments in the next few quarters. The increasing complexity of LEO environments including speed, dynamic link conditions and stringent positioning requirements is driving demand for keysight’s orbit emulation and Spiren’s PNT solutions which together provide customers with a differentiated ability to validate next generation NTN systems. As the industry explores new use cases for 6G such as integrated sensing and communication, energy efficient networks and expanded coverage capabilities, we are well positioned to intercept these opportunities through our portfolio of high fidelity tools for design and emulation. This quarter we expanded our collaboration with Qualcomm on RF Digital Twins and at Mobile World Congress conducted a joint demonstration with Samsung on AI RAN workflows. Next month Keysight will host the 3GPP meeting in Singapore where the timeline for 6G standardization is being solidified further reflecting Keysight’s leadership position as the ecosystem evolves towards commercialization. Turning to aerospace, defense and government, we saw broad based global momentum led by Europe supported by continued strength in Americas. As the global defense modernization priorities increasingly translate into new programs and investments in next generation systems, demand was strongest across radar and electromagnetic spectrum operations as governments and prime contractors expanded capacity to support evolving operational requirements. While activity in space, satellite and autonomous systems remained healthy, this drove ongoing customer engagement and new wins for our recently introduced radar target generation solutions. Keysight’s ability to accurately simulate radar signals and emulate threat environments is a key differentiator creating higher value system level opportunities with defense contractors and government agencies around the world. As contested spectrum environments drive a greater focus on radar survivability and autonomous operations, customers are increasingly adopting keysight solutions that include high fidelity emulation, signal analysis, PNT and RF validation to accelerate their development and deployment. This quarter we secured a key win with U.S. air Force to enable next generation operational flight line testing with more stringent requirements. Given the mission critical nature of this defense market, we also continue to see increased attach rate for our value added services to enable mission readiness and operations. Moving to Electronic Industrial Solutions group, we delivered a record quarter with all time highs for both orders and revenue with strong growth across all three EISG markets, General Electronics, semiconductors and automotive and energy. In general electronics, double digit order and revenue growth was driven by ongoing momentum in AI related innovation and infrastructure investments. Customer capacity investment for high performance PCBs was again strong this quarter. Greater complexity, increasing density, interconnects, multilayer architectures and higher speeds are driving customer engagement across multiple standards and and applications resulting in a higher test intensity for PCBs. In education, we saw healthy demand from governments and universities around the globe in the development of next generation of semiconductor workforce talent through our tailored training modules. Our solutions are also facilitating leading edge university research in advanced technologies. With key wins this quarter in quantum photonics, semiconductor and 6G in our semiconductor markets. We saw continued momentum in the pace of innovation and customer investments as the industry races to scale capacity through 2030. AI ecosystem demand further accelerated this quarter across advanced node memory and silicon photonics. Our collaborations with leading foundries from R and D to production are enabling faster development and commercial ramp timelines for increasingly complex chip architectures and packaging. This quarter we had key wafer test solution wins in support of silicon photonics and advanced node programs across Asia, the US and Europe, while our solutions for key lithography customers grew strongly as well. We expect this to be a sustainable contributor of growth for us over the next several years. Finally, in automotive and energy orders grew for the third consecutive quarter as the business has largely stabilized. Growth was across both software defined vehicles and EV charging solutions with key wins for in vehicle network, cybersecurity and over the air design and validation at OEMs and test labs globally. We’re leveraging our expertise and and leadership in networking applications to develop solutions for the new mobility market. In closing, the strong results we’re delivering in fiscal 2026 reflect the execution of our strategy we outlined at Investor Day in 2023 centered around consistently identifying and investing in long term growth opportunities across technology trends, transforming industries and global market dynamics. This framework has guided our disciplined organic and inorganic investments, enabling us to build a differentiated portfolio aligned with some of the world’s most important and fastest growing end markets. As we are focused on capitalizing on our early leadership in the AI data center infrastructure ecosystem, we’re equally excited by the broader set of secular growth opportunities we’re progressing, including defense technology, space 6G and quantum computing. We believe our portfolio’s technology leadership, product pipeline and deep customer relationships position us well to capitalize on these opportunities and continue creating long term value for our customers and shareholders. All of this value creation is enabled by the commitment of our team and the collaborative and innovative culture in the company. I want to acknowledge the entire keysight team for their hard work and dedication to our success. I’ll pass the call over to Neil to provide additional details on our financial performance and guidance.

Neal Doherty (Executive Vice President and CFO)

Neil, thank you Satish and hello everyone. We delivered outstanding results in fiscal Q2 setting new company records for orders, revenue and earnings per share. Our teams capitalized on the robust and dynamic demand environment resulting in strong double digit growth across all our business groups. Q2 orders of $2,051,000,000 were up 56% on a reported basis with acquisitions adding 700 basis points and currency adding 100 basis points on a core basis. Excluding those items, orders grew 48%. Revenue of $1.717 billion was up 31% on a reported basis and and up 24% on a core basis. Gross margin was 72.3% and operating expenses were $669 million. We delivered net income of $497,000,000 and earnings per share of $2.87. As noted in our earnings press release following the US Supreme Court decision invalidating the IEEPA tariffs in Q2, we recognized the impact of tariff refunds and the refund of associated surcharges collected from our customers. This resulted in a $40 million reduction in Q2 revenue and a $97 million reduction in costs and expenses. Excluding these one time impacts, Q2 revenue was $1,758,000,000, …

Full story available on Benzinga.com

This post was originally published here
Xcel Brands (NASDAQ:XELB) held its first-quarter earnings conference call on Tuesday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://edge.media-server.com/mmc/p/dk3zkyjv/

Summary

Xcel Brands reported revenue of $1.1 million for Q1 2026, down from $1.3 million in Q1 2025, primarily due to a temporary supply chain disruption for its Sea Wonder and Christie Brinkley brands.

The company launched two influencer-led brands in Q1 and plans to launch more throughout 2026, with strong social media growth from 5 million to over 46 million followers.

Xcel Brands sold its Judith Ripka brand in Q2 2026, aligning with its strategy to divest legacy brands and focus on influencer-led opportunities, which are trading at higher revenue multiples.

The company reported an adjusted EBITDA loss of $700,000, consistent with the previous year, and noted cost reductions that lowered operating expenses.

Management is optimistic about future growth, expecting significant brand expansion and new product launches, with strategic partnerships potentially announced by Q2’s end.

Full Transcript

OPERATOR

Hello and welcome. My name is Ayesha and I will be your conference operator today. I would like to welcome everyone to the Xcel Brands’ quarter one 2026 earnings conference call. Please note that this call is being recorded. After the prepared remarks there will be a question and answer session. If you’d like to ask a question during that time, please press the star key followed by one on your telephone keypad. Thank you.

Seth

Good afternoon everyone and thank you for joining us. Welcome to the Xcel Brands’ first quarter of 2026 earnings call. We greatly appreciate your participation and interest. With us on the call today are Chairman and Chief executive officer Robert DeLorean and chief financial Officer Jim Herron. By now everyone should have had access to the earnings release for the quarter ended March 31, 2026. In addition, we filed our quarterly report on Form 10Q with the Securities and Exchange Commission last Thursday. The release and quarterly report will be available on the company’s website at www.excelbrands.com. this call is being webcast and a replay will be available on the Company’s investor relations website. Before we begin, please keep in mind that this call will contain forward looking statements. All forward looking statements are subject to risks and uncertainties that could cause actual results to differ materially from certain expectations discussed here. These risk factors are explained in detail in the Company’s most recent annual report filed with the SEC. XCEL does not undertake any obligation to publicly update or revise any forward looking statements, whether as a result of new information, future events or otherwise. The dynamic nature of the current macroeconomic environment means that what is said on this call could change materially at any time. Finally, please note that on today’s call, management will refer to certain non GAAP financial measures, including non GAAP net income, non GAAP, diluted EPS and adjusted ebitda. Our management uses these non GAAP metrics as measures of operating performance, to assist in comparing performance from period to period on a consistent basis, and to identify business trends related to the Company’s results of operations. Our management believes these financial performance measurements are also useful because these measures adjust for certain costs and other events that management believes are not representative of our core business operating results, and thus they provide supplemental information to assist investors in evaluating the Company’s financial results. These non GAAP measures should not be considered in isolation or as alternatives to net income, earnings per share, or any other measure of financial performance calculated and presented in accordance with GAAP. You may refer to the attachment to the Company’s earnings Release or the Form 10Q for a reconciliation of non GAAP measures. And now I’m pleased to introduce Robert DeLorean, Chief Executive Officer. Bob, please go ahead.

Robert DeLorean (Chairman and Chief Executive Officer)

Thank you, Seth. Good afternoon everyone and thank you for joining us today. I would like to start today’s call with a brief update on recent developments since the recent filing of our annual form 10K and our outlook moving forward. After that, our CFO Jim Haron will discuss our financial results for the quarter in more detail. We continue to work hard with all our our licensee production partners, powerful influencers and strategic retail partners to drive our business. We launched two of our influencer or creator led brands toward the end of the first quarter and we expect to launch two more in the fall and another in spring 27th. As we previously mentioned, we announced our Influencer led brands with Cesar Milan, Gemma Stadtford, Jenny Martinez, Coco Rocha and Shannon Daugherty. These influencer led brands grew their social media following in our brand portfolio from 5 million to over 46 million. Based upon our pipeline of new influencer led brands, we are on Track to reach 100 million followers across our brand portfolio. We began wholesale shipments with our licensees for 2 of our influencer led brands during the first quarter and on air programming commenced for them on QVC and HSN in the second quarter. As I mentioned, the other influencer led brands will be shipping and launching throughout the rest of 2026 on interactive TV and at bricks and e commerce retailers. We are very pleased and optimistic given early results and demand for these brands. I should add that our TV and streaming content reaches well over 100 million households and generates tens of millions of media impressions per month. Many of our investors and licensing partners have asked why we are so excited by the Influencer led brand opportunity. Please allow me to illuminate this a little. According to a recent report issued by Goldman Sachs, the influencer or Creator economy generated $254 billion of sales in 2025 and is expected …

Full story available on Benzinga.com

This post was originally published here
Iridex (NASDAQ:IRIX) released first-quarter financial results and hosted an earnings call on Tuesday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/txnkof82/

Summary

Iridex reported flat revenue of $11.8 million for Q1 2026, aligning with guidance despite international supply chain and regulatory challenges.

The Glaucoma segment, particularly the G6 platform, showed strong performance with a 14% year-over-year increase in probe sales, despite flat system sales.

Operational improvements included cost reductions and strategic relocations, with expectations to complete manufacturing transitions by 2027 to enhance margins.

The company reaffirmed its 2026 revenue guidance of $51 million to $53 million, excluding Middle East contributions, indicating a 1-5% pro forma growth.

Management highlighted strategic partnerships, such as with IPRO GPO, to expand market reach and enhance sales of retina laser systems.

Full Transcript

OPERATOR

Thank you for standing by and welcome to IRIDEX First Quarter 2026 Earnings Conference Call. I’d like to remind everyone that this call is being recorded and all lines have been placed in mute to prevent any background noise. After the speaker’s remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press Star followed by the number one on your telephone keypad. If you would like to withdraw your question, press Star one again. Thank you. I would now like to turn the call over to Trip Taylor, Investor Relations. Please go ahead.

Trip Taylor (Investor Relations)

Thank you and thank you all for participating in today’s call. Joining me from the company are Patrick Mercer, Iridex Chief Executive Officer, and Romeo Dezon, the Company’s Chief Financial Officer. Earlier today, Iridex released financial results for the quarter ended April 4, 2026. A copy of the press release is available on the Company’s website. Before we begin, I’d like to remind you that management will make statements during this call that include forward looking statements within the meaning of federal securities laws which are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Any statements made during this call that are not statements of historical fact, including but not limited to statements concerning our strategic goals and priorities, products and development matters, sales trends and the markets in which we operate. All forward looking statements are based upon our current estimates and various assumptions. These statements involve material risks and uncertainties that could cause actual results or events to materially differ from those anticipated or implied by these forward looking statements. Accordingly, you should not place reliance on these statements for a discussion of the risks and uncertainties associated with our business, please see our most recent Form 10-K and Form 10-Q filings with the SEC. IRIDEX disclaims any intention or obligation, except as required by law, to update or revise any financial projections or forward looking statements, whether because of new information, future events or otherwise. This conference call contains time sensitive information and is accurate only as of the live broadcast today, May 19, 2026.. And with that, I’ll turn the call over to Patrick.

Patrick Mercer (Chief Executive Officer)

Good afternoon everyone and thank you for joining us. I am pleased to share our first quarter results and the continued progress we’re making as we build on the positive momentum we delivered throughout last year. For context, before diving into the first quarter, I want to highlight some of the significant milestones we achieved last year. In 2025, we delivered positive adjusted EBITDA for the first time in the Company’s recent history and we also achieved positive cash flow from operations in Q4. These achievements represent a fundamental shift in Iridex’s financial profile and reflect the hard work completed to reposition the business for sustainable profitability going forward. As a result of this work and our solid start to the year, we remain on track to be cash flow positive in 2026. We executed according to plan in the first quarter despite several anticipated headwinds including the Iran conflict, temporary supply chain constraints and extended timelines associated with certain regulatory approvals. Against this backdrop, we delivered revenue of 11.8 million essentially flat year over year and above the guidance communicated on our last earnings call. Our Highest margin business, G6 Probes was a clear bright spot during the quarter. Continued growth and adoption of our glaucoma solution underscore the strength of our clinical value proposition and the loyalty physicians have to the G6 platform. Internationally, we operated in a challenging environment with supply disruptions, regulatory delays and geopolitical volatility, particularly impacting revenue in Asia and the Middle East. Importantly, underlying demand remains solid and we believe revenue and earnings would have been higher had we been able to fulfill certain orders that were backlogged at the end of the quarter. Looking ahead, supply chain conditions and regulatory processes are improving and we continue to actively manage through these dynamics. As a result, we believe some of the timing relating impacts that affected our first quarter performance represent incremental revenue opportunities for the balance of the year. On the operations front, we again reduced our operating expense compared to the prior year period as we continue to drive efficiencies across the organization. We are pleased to report that the relocation of certain general and administrative functions out of California again delivering quarterly savings starting in the first quarter 2026. We also remain on schedule to relocate our headquarters later this year which is expected to reduce our fixed cost base by approximately 600,000 on an annualized basis. Additionally, our multi year initiative to transition production to lower cost third party contract manufacturers is underway with meaningful transfers initiated in the first quarter. Full implementation is expected to be completed in 2027 and this transition will drive gross margin improvement as we progress through the year and into next year. Turning now to our commercial performance in the first quarter, starting with our glaucoma business. In total in the first quarter we sold 15,500 pros versus 13,900 in the prior year period. This represented growth in the competitive glaucoma market which is a testament to the strength of our value proposition and physician loyalty to the G6 platform. Utilizing MedScout to target G6 adopters with average utilization continues to be our most effective strategy. Our MedScout platform continues to be a valuable tool for targeted outreach. Here we are focused on two groups. The first are those who already have G6 systems and are average users and the second are high volume facilities that do not currently perform micropulse procedures. With the mid-utilization accounts, we focus on education, working with physicians to expand their patient selection criteria to treat patients earlier in the glaucoma severity continuum. With the second group, the focus is also on education with particular focus on the efficacy of those patients who have already had a mixed procedure. Speaking of mix, the Medicare LCDs introduced last year are creating tailwinds for us including expanding our target segments and supporting earlier adoption of G6 therapy for both the mild to moderate and post migs glaucoma patients. Combined with our updated sweep speed procedural techniques and clinical data demonstrating the IOP lowering efficacy of the procedure, we believe we are well positioned to drive sustainable growth in this business throughout 2026. Pricing discipline also supported our the first quarter performance as RASP increases on both probes and systems in the US …

Full story available on Benzinga.com

This post was originally published here
The private equity industry’s biggest names are showing signs of strain as slowing deal exits, mounting pressure in private credit, and investor unease begin to chip away at one of Wall Street’s most lucrative runs.

Executives at Blackstone (NYSE:BX), Apollo Global Management (NYSE:APO), The Carlyle Group (NYSE:CG), and KKR & Co. (NYSE:KKR) delivered some of their weakest collective sentiment in years during first-quarter earnings calls, according to new data from S&P Global Market Intelligence. The firms, often referred to as private equity’s “Big Four,” are grappling with delayed portfolio company sales, choppy markets, and rising redemption requests from retail investors in private credit funds.

The average net positivity score across the four firms “fell to its lowest level since the fourth quarter of 2023, marking the third consecutive quarter that sentiment lagged behind the broader S&P 500,” the data reported.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Jim Cramer Says Private Equity Is ‘Under Attack Again’

This post was originally published here
Red Robin Gourmet Burgers (NASDAQ:RRGB) reported first-quarter financial results on Tuesday. The transcript from the company’s first-quarter earnings call has been provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://viavid.webcasts.com/starthere.jsp?ei=1755598&tp_key=ae5f2178ca

Summary

Red Robin Gourmet Burgers reported strong Q1 2026 results with improved traffic performance and the highest Q1 restaurant operating profit margin since 2021.

Same-store sales were down 0.6% due to a 1.6% decrease in traffic, but the average check increased by 1.0%, driven by the Big Yum Value platform.

The company’s First Choice Plan is delivering operational improvements, with labor efficiency initiatives saving 130 basis points year-over-year.

Restaurant-level operating margin improved by 50 basis points to 14.8%, the highest in five years, and adjusted EBITDA was in line with expectations.

The company is progressing with refranchising initiatives and plans to use proceeds to reduce debt and strengthen the balance sheet.

Red Robin maintains its full-year guidance for 2026, expecting comparable restaurant revenue growth of 0.5% to 1.5% and adjusted EBITDA between $70 million and $73 million.

Management highlights the success of targeted marketing and new product innovations, such as the Big Yum Value platform and Towering Sliders.

The company is continuing its Light Touch refresh program and technology upgrades to enhance the dining experience.

Full Transcript

OPERATOR

Good afternoon everyone and welcome to the Red Robin Gourmet Burgers first quarter 2026 earnings call. This conference is being recorded during Management’s presentation and in response to your questions they will be making forward looking statements among the Company’s business outlook and expectations. These forward looking statements and all other statements that are not historical facts reflect management’s beliefs and predictions as of today and therefore are subject to risks and uncertainties as described in the Company’s SEC filings. Management will also discuss non-GAAP financial measures as part of today’s conference call. These non-GAAP measures are not prepared in accordance with generally accepted Accounting principles, but are intended to illustrate alternative measures of the Company’s operating performance that may be useful. Reconciliations of the non-GAAP financial measures to the most directly comparable GAAP measures can be found in the Earnings release. The Company has posted its first quarter 2026 earnings release on its website at ir.redrobin.com on today’s call are Dave Pace, President and Chief Executive Officer Mark Graf, Chief Financial Officer and Chris Meyer, Interim Chief Financial Officer. Now I would like to turn the call over to Dave Pace.

Dave Pace (President and Chief Executive Officer)

Good afternoon everyone and thank you for your interest in Red Robin. I’m pleased to report that our first quarter results demonstrate continued improvement in the business, highlighted by our strongest traffic performance since the first quarter of 2023 and our highest Q1 restaurant operating profit margin since 2021. These results reinforce that the actions we’re taking to strengthen guest engagement are gaining traction. Our Big Yum Value platform continues to resonate with guests with high satisfaction scores and we’re seeing strong results across the system. In addition, our targeted first choice marketing efforts are improving both reach and brand awareness, helping us to engage guests more effectively to drive frequency. Importantly, the operational discipline embedded in our First Choice plan is delivering steady improvement across the P&L as well. Our teams remain focused on executing the fundamentals, enhancing the guest experience and positioning the business for sustainable growth. As it relates to our Q1 performance, same store sales were down 0.6% including a 1.0% increase in average check and a 1.6% decrease in traffic. This traffic result improved sequentially from Q4 and continued to narrow the traffic gap to the industry as compared to black box intelligence, reinforcing that our strategies are gaining traction despite a challenging macro environment. The current economic environment requires that we remain deliberate in highlighting value and disciplined in our approach to average check. Q1 was our third consecutive quarter where our check average increases were below the industry. Our PRUDENT approach to menu pricing, complemented by the expansion of our Big Yum platform, has positioned us for success and is reflected in our traffic momentum. Turning to profitability, we’re pleased with the continued incremental gains in 4 wall efficiency, including a 50 basis points improvement in restaurant level operating margin to 14.8%. This was our highest first quarter margin in five years. Our adjusted EBITDA was in line with our expectations and we remain on track for our full year objectives. With that, let me update you on our first choice plan and how we’re thinking about our strategic priorities for the remainder of the year. First, let’s start with Holdserve. Our team continues to do a great job sustaining the progress we’ve made in the past several quarters and this quarter is no different. During the first quarter, our labor efficiency initiatives drove approximately 130 basis points of year over year savings. Our labor percentage of 35.7% was our lowest first-quarter labor in three years. These improvements reflect the sustained accountability and ownership embedded in our managing partner model. What’s particularly encouraging is that we are achieving these efficiency gains without compromising the guest experience. Our satisfaction scores remain strong, reinforcing that operational excellence and genuine hospitality are not competing priorities, they’re complementary. Moving to our drive traffic pillar, we believe our value and innovation platforms are gaining traction with guests. The expanded Big Yum platform we launched in late January continues to address the need for value with the new offerings while serving as an incremental traffic driver. All in all, the six meal options across our $9.99 to $16.99 price range are strengthening our relevance with value seeking guests and supporting incremental traffic and trial. In total, our Big Yum offerings are mixing at over 13%, well within the expectations for this program. The platform’s appeal extends beyond burgers, including our hand breaded Classic Chicken sandwiches, Donato’s Pizza and Whiskey River Barbecue Chicken Wraps. Importantly, each meal includes our signature bottomless sides and beverages, reinforcing value while preserving the full Red Robin experience. Overall, the underlying traffic trends in the business are improving and our momentum is increasingly being driven by compelling platforms rather than relying on traditional discounting. Our deliberate barbell approach with the menu balances compelling value with higher priced indulgent options to expand guest reach across day parts and occasions. We believe this approach is building a more sustainable foundation for traffic generation. In addition, we continue to enhance our new product pipeline which provides additional opportunities to drive frequency. An example of this is our towering Sliders that we launched last month, which has generated record setting menu satisfaction scores and is driving incremental check growth. On the marketing front, our data driven First Choice strategy continues to gain traction. Our ability to deliver locally relevant messaging based on competitive dynamics in each trade area has improved both engagement and marketing efficiency. We’re seeing the benefits of this more precise, disciplined approach in our traffic performance and expect to build on this momentum as we refine our capabilities throughout the year. Now let me update you on our third pillar of the First Choice strategy, Find Money. I’m pleased to report that our momentum on corporate efficiency initiatives continues to deliver meaningful results. As we previously outlined, the G and A reductions we implemented in mid-2025 are providing sustained benefits and we remain on track to realize the full year step down we anticipated for 2026. Turning to our balance sheet optimization efforts, our tactical refranchising initiatives continues to move forward. We’re currently in the final stages of discussions with multiple parties and I’m pleased with both the pace of these conversations and the depth of engagement from prospective franchisees. These are sophisticated operators who recognize the operational progress we’ve made and see the opportunity to that our first choice strategy creates. The sustained level of interest we’re seeing reflects growing confidence in our system improvements and the strength of the Red Robin brand. I want to emphasize that we remain committed to being disciplined and selective in this process. Our objective is to partner with franchisees who share our commitment to operational excellence and guest experience while achieving terms that support our balance sheet objectives. We plan to use proceeds from any completed transactions to reduce debt and further strengthen our balance sheet. We look forward to providing further updates on this in the near future. Turning to our Fixed Restaurants pillar, we’re continuing our Light Touch refresh program in 2026. This initiative touches customer facing elements within our restaurants that can enhance the overall experience and support the quality of our food and service. We expect to have our first markets completed by the end of June. In addition to our facility refreshes, we’ve begun to roll out replacement devices for our server handheld technology and will shortly introduce …

Full story available on Benzinga.com

This post was originally published here
Anthropic faced a fresh round of legal scrutiny Tuesday as the Trump administration defended a Pentagon move that labels the AI company a supply chain risk.

The government detailed its position in response to Anthropic’s challenge to a designation that restricts its ability to pursue new Defense Department work.

In court, judges questioned the Pentagon’s rationale. “For the life of me, I do not see any evidence of maliciousness despite the best efforts of [Pentagon Under Secretary Emil Michael], who in his memo refers to you as having mal-intent, a bad motive, cannot be trusted,” Judge Karen Henderson said.

“To me, this is just a spectacular overreach by the department,” she added.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Anthropic Just Landed One Of AI’s Biggest Names

This post was originally published here
A frustrated Reddit user said they discovered their father had secretly opened 15 credit cards under their name, leaving them buried under roughly $94,000 in debt and facing a badly damaged credit score.

‘I Honestly Have No Idea What That Means’

“Last week, I checked my credit report because I noticed something weird with one of my bank accounts,” the poster wrote on Reddit. “It showed that I apparently had 15 active credit cards I never applied for.”

According to the post, about $28,000 of the debt came from legitimate student loans, but the remaining balance was tied to personal credit accounts they said they never opened.

Don’t Miss:

The emotional fallout appeared just as overwhelming as the financial damage.

“I feel betrayed, furious, and completely lost,” the poster said. “Do I confront him directly, talk to a lawyer, or go straight to the banks?”

The person also said they  felt conflicted about involving law enforcement.

“I really don’t want to press charges against my dad because my younger sister still depends on him, but I can’t ignore what he did to me either,” the post said.

The story quickly drew hundreds of comments, with many warning that failing to report the fraud could result in years of financial hardship.

“You report him for credit fraud and get your name cleared because it will ruin your entire life,” one commenter wrote. “He chose to destroy your future, so…”

Trending: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

Long-Term Damage

Commenters urged the poster to immediately freeze their credit, contact banks and file a police report. Others warned that the younger sister could also become a victim.

“He has almost certainly done this to your sister,” one commenter wrote.

The original poster later responded that their sister was still a minor.

However, many commenters pushed back, explaining that identity theft involving children is more common than many people realize.

“Your sister is not too young for a credit card,” one commenter replied. “The day a child is born and a social security number is made, your parents can use that social security number and open a credit card.”

See Also: This Under-$1 Pre-IPO AI Company Is Still Open to Retail Investors — Learn More

As the discussion continued, the poster appeared to accept that legal action may be unavoidable.

“I think you’re right, I’ll tell my lawyer and report it to the bank,” the person wrote.

Several people shared similar personal stories involving parents or relatives secretly opening …

Full story available on Benzinga.com

This post was originally published here
Elon Musk said Monday that he expects fully self-driving Tesla cars without human safety monitors to spread across the United States later this year, doubling down on a robotaxi timeline he has missed repeatedly over the past decade.

Tesla Inc. (NASDAQ:TSLA) currently operates monitor-free robotaxis in Austin, Dallas and Houston, and received a permit for a ride-hailing service in Arizona last November.

Speaking by video link to the Smart Mobility Summit in Tel Aviv, Musk told the audience that nationwide expansion is coming this year.

The California Problem

The most liquid market on Musk’s near-term promises sits on Polymarket, where traders price just a 10% chance that Tesla launches unsupervised robotaxis in California by June 30.

More than $105,000 has traded on the contract.

The skepticism is driven by hard regulatory math.

Tesla has not filed for a California …

Full story available on Benzinga.com

This post was originally published here
New York-based fintech startup Ramp CEO Eric Glyman said on CNBC’s “Squawk on the Street” on Tuesday that, for a long time, the fastest-growing companies were in the private markets. But now with the upcoming IPOs from SpaceX, Anthropic, OpenAI, it’s reshaping how investors are thinking about public markets and corporate growth. 

“I think that for a long time the fastest growing companies were in the private markets and with the rumors the company like SpaceX, even one day Anthropic and OpenAI potentially going out there you’re gonna start to see companies that are growing 50%, 100%, 800%… you’re starting to be out in the public market and so it’s interesting for something like ours, which is doubling each year to see these other companies in the public market. We’ll be watching it with interest,” Glyman said.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Anthropic Just Landed One Of AI’s Biggest Names

This post was originally published here
Jim Cramer has taken to X to say that private equity is “under attack again,” as some of the largest firms in the space, KKR & Co. (NYSE:KKR), Blackstone (NYSE:BX), Apollo Global (NYSE:APO), and Carlyle Group (NYSE:CG) stocks are all experiencing declines on Tuesday.

Private market stocks fell alongside the broader financial sector as surging Treasury yields weighed heavily on asset managers and alternative investment firms. 

KKR & Co. stock is trading at $93.22, down 2.88% today, and 26% on the year. The company also announced that it is selling its entire stake in Kokusai Electric. 

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Blue Owl Raises Stakes With Second $400 Million Bond Offering

This post was originally published here
SEI has launched the SEI High Yield Bond & Alternative Credit ETF (NASDAQ:LEND), its first fixed income ETF, after reorganizing the SIMT High Yield Bond Fund into an ETF structure. The actively managed ETF keeps the mutual fund’s long-standing investment objective, strategy, and portfolio management approach intact while shifting investors into a more liquid and potentially lower-cost ETF wrapper.

The ETF seeks total return through exposure to sub-investment-grade and high-yield fixed income securities, blending traditional junk bond allocations with alternative credit exposure through collateralized loan obligations, or CLOs. SEI said the strategy leverages more than 20 years of CLO management experience alongside its manager-research platform to source differentiated credit strategies across multiple …

Full story available on Benzinga.com

This post was originally published here
Anthropic has hired Andrej Karpathy, a co-founder of OpenAI and former director of artificial intelligence and Autopilot Vision at Tesla.

“I’ve joined Anthropic. I think the next few years at the frontier of LLMs will be especially formative. I am very excited to join the team here and get back to R&D (research and development). I remain deeply passionate about education and plan to resume my work on it in time,” Kathpathy wrote on X.

Karpathy began work this week inside Anthropic’s pre-training group and will operate under team lead Nick Joseph, TechChrunch reported. Anthropic describes pre-training as the stage that runs massive training jobs that underpin Claude’s baseline knowledge and abilities, and it is also among the most compute-heavy and costly parts of developing top-tier models.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Elon Musk’s xAI Doubles Down On Unpermitted Turbines During Pollution Fight

This post was originally published here
TORONTO, May 19, 2026 /CNW/ – Franklin Templeton Canada today announced the final net asset values for the ETF Series of Franklin ClearBridge International Growth Fund (TSX:FCSI) and Franklin Global Growth Fund (TSX:FGGE) (each, a “Fund” and collectively, the “Funds”).

On February 19, 2026, Franklin Templeton Canada pre-announced the termination of the ETF Series of the Funds. Effective at the close of business May 15, 2026, the ETF Series were terminated. The units of the ETF Series of each Fund were voluntarily de-listed, at the request …

Full story available on Benzinga.com

This post was originally published here
Investors have waited for SpaceX to go public for the longest time. Now, it finally looks like it’s happening.

Reports say Elon Musk’s space company could launch its IPO on June 12 with a valuation between $1.75 trillion and $2 trillion. If that happens, SpaceX could become the biggest IPO in history.

That is why so many people are excited.

But while many investors see this as a huge opportunity, others believe it could also become one of the riskiest stock launches Wall Street has ever seen.

What’s Causing the Hype Around SpaceX?

There are not many companies like SpaceX.

The company already leads the space industry with its reusable rockets and satellite business. It has worked closely with NASA and completed several astronaut missions into space.

SpaceX is also the company behind Starlink, the satellite internet service that is growing very quickly around the world.

Reports say Starlink already has close to 10,300 satellites in orbit and about 9 million users globally. The business reportedly made around $11.4 billion in revenue last year and has very high profit margins.

That alone is enough to get investors excited. But there’s more.

Earlier this year, Musk merged his AI company xAI into the SpaceX business. Reports also suggest SpaceX wants to build data centers in space to support artificial intelligence companies in the future.

Because of this, many investors no longer see SpaceX as just a rocket company. They now see it as a space, AI, the internet, and a technology giant all at once.

That’s a major reason why Wall Street believes the company could be worth nearly $2 trillion.

Wall Street Is So Bullish on SpaceX

Big investors are already lining up ahead of the IPO.

Reports say BlackRock could invest between $5 billion and $10 billion into the IPO. Several hedge funds that invested in SpaceX years ago are also expected to make billions if the company goes public at its expected valuation.

One hedge fund, D1 Capital Partners, reportedly invested in SpaceX back in 2020 when the company was worth around $36 billion. Today, that investment could be worth …

Full story available on Benzinga.com

This post was originally published here
Kerrisdale Capital released a new report on Tuesday, saying that it is short Everspin Technologies Inc. (NASDAQ:MRAM) because it believes the recent rally in MRAM shares is driven more by AI-related speculation than by any meaningful change in the company’s business.

Kerrisdale argued Everspin has been wrongly swept into the broader enthusiasm around memory stocks tied to AI infrastructure. 

Benzinga reached out to Everspin Technologies for comment, but did not receive an immediate response. 

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Palantir, Trump And Ukraine: Zelenskyy Signals Deeper Defense Tech Ties

This post was originally published here
Senator Elizabeth Warren (D-Mass.) on Tuesday questioned the Office of the Comptroller of the Currency letting nine crypto firms operate as banks without proper safeguards.

Warren Questions OCC Approval Of Nine Crypto Trust Charters

Warren, the ranking Democrat on the Senate Banking Committee, sent a letter to OCC chief Jonathan Gould questioning approvals for trusts belonging to Coinbase Global Inc. (NASDAQ:COIN), Paxos, Ripple (CRYPTO: XRP), BitGo, and Fidelity Digital Asset Services.

“These companies are effectively crypto banks that want to evade the fundamental safeguards and obligations that come with being a bank,” Warren wrote. 

She argued the OCC’s decision to facilitate this regulatory arbitrage conflicts with federal law and poses serious risks to consumers and the banking system.

The OCC has granted trust charters to crypto firms as the agency embraced President Donald …

Full story available on Benzinga.com

This post was originally published here
A newly developed biosensor designed to detect harmful bacteria in minutes could streamline food safety testing across the supply chain, the Worcester Polytechnic Institute in Massachusetts announced last week.

The device uses harmless viruses known as bacteriophages to capture and identify salmonella enterica in small fluid samples, according to a paper by WPI researchers published in ACS Applied Bio Materials.

 “We have a solid surface that can be used anywhere in the food supply chain, from farm to fridge, to detect foodborne bacteria with minimum human intervention,” WPI Department of Mechanical and Materials Engineering Associate Professor Yuxiang “Shawn” Liu, who led the research team, said in the announcement. 
Don’t Miss:

The technology could eventually support portable food safety devices and next-generation packaging systems capable of detecting contamination in real time, the institute said .

Why Faster Food Testing Matters

Salmonella enterica, one of the leading causes of foodborne illness, has been linked to contaminated eggs, meat, milk and produce, the research announcement said. Foodborne diseases cause millions of illnesses and an estimated 420,000 deaths globally each year, the study said.  

Traditional food safety testing often requires laboratory equipment, trained personnel and incubation periods lasting 24 to 48 hours, the researchers said. Some existing genetic and antibody-based tests also struggle to distinguish live pathogens from dead ones, limiting their effectiveness in field applications.

The biosensor was designed to simplify and accelerate that process while reducing dependence on centralized testing infrastructure. “We have a solid surface that can be used anywhere in the food supply chain, from farm to fridge, to detect foodborne bacteria with minimum human intervention,” Liu said..
Trending: Traditional banks aren’t the only place to park cash — see how eligible SoFi users are earning a competitive APY and potentially qualifying for up to $300 with direct deposit.

How The Biosensor Works

WPI researchers built the device using a textured polymer surface coated with bacteriophages, which are naturally occurring viruses that selectively attach to bacteria, according to the research announcement.

Small fluid samples containing salmonella are pumped through a palm-sized microfluidic channel, where the phages trap and concentrate the bacteria for detection. Researchers then use fluorescence imaging to identify bright spots where bacteria have accumulated.

The system successfully detected dangerous concentrations of salmonella that are difficult to identify using many existing portable testing approaches, the research announcement said.

Unlike some conventional testing systems, the biosensor does not require bacteria to be grown in a lab before detection, according to the researchers.

See Also: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

From Food Packaging To Smartphone Scanners

Liu said that the technology still requires additional development but could eventually expand beyond …

Full story available on Benzinga.com

This post was originally published here

Super League Enterprise Inc (NASDAQ:SLE) shares are charging higher on Tuesday, building on upward momentum triggered by the company’s first-quarter earnings beat reported before the market opened on Friday.

• Super League Enterprise stock is showing exceptional strength. What’s behind SLE gains?

Q1 Earnings Exceed Consensus Estimates

For the first quarter, Super League reported an adjusted loss of 98 cents per share, significantly beating the consensus analyst estimate of a $2.08 loss. The company posted revenue of $3 million, which topped the Wall Street consensus estimate of $2.81 million.

Execution Replaces Stabilization Strategy

The earnings report signals a structural turning point for the company. CEO Matt Edelman stated the quarter reflected the early stages of executing the company’s 2026 strategy, following a year spent bolstering the balance …

Full story available on Benzinga.com

This post was originally published here

Chewy Inc (NYSE:CHWY) stock dropped during Tuesday’s trading session, hitting a new 52-week low of roughly $19.74. The sharp intraday decline occurred on no significant new corporate news, given the pet e-commerce retailer’s recent stable financial reports.

The Nasdaq is down 0.04% while the S&P 500 has shed 0.21%.

Citigroup Slashed Price Forecast

The downward movement follows recent cautious adjustments from Wall Street. On May 12, Citigroup maintained its buy rating on Chewy but lowered its price forecast to $37.

Analysts Highlight Long-Term AI Efficiencies

Despite the negative price action, prior analyst notes focused heavily on Chewy’s operational improvements, following Chewy’s upbeat fourth-quarter report.

Guggenheim Securities analyst Steven Forbes reiterated a buy rating and a $45 price target. Forbes pointed to automated cost savings, noting,

“We see the potential for 30-40 basis points of …

Full story available on Benzinga.com

This post was originally published here

Carvana Co. (NYSE:CVNA) shares are trading lower on Tuesday. The drop comes amid a broader market pullback, with retail traders closely watching the stock’s post-split dynamics.

The Nasdaq is down 0.02% while the S&P 500 has shed 0.20%.

Recent 5-for-1 Stock Split

The Tuesday pullback follows a mechanical adjustment observed on May 8. Carvana executed a 5-for-1 stock split effective at that session’s market open.

Robust Q1 Earnings

The recent stock split followed a robust first-quarter earnings report from the online used car retailer. Carvana reported revenue of $6.43 billion, beating the analyst consensus estimate of $6.08 billion. Additionally, the company posted earnings of $1.69 per share.

Critical Price Levels To Watch For CVNA

From a trend perspective, the stock …

Full story available on Benzinga.com

This post was originally published here

Nauticus Robotics (NASDAQ:KITT) released first-quarter financial results and hosted an earnings call on Tuesday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://events.q4inc.com/attendee/228928122

Summary

Nauticus Robotics Inc reported Q1 2026 revenue of $0.2 million, a decline from the previous quarter, attributed to seasonal softness in the offshore market.

Operating expenses decreased to $5.8 million, with a net loss of $9.3 million, influenced by changes in debt instrument fair values.

Strategic initiatives include advancing Nautica’s Toolkit for autonomy in subsea systems, focusing on international expansion, particularly in the UAE, and integrating new sensors and high-definition cameras.

The company emphasizes growth in software licensing and international markets to offset seasonal revenue fluctuations.

Brian Allen joins as Chief Revenue Officer, focusing on expanding revenue streams and leveraging his experience in subsea robotics and AI.

Operational highlights include completing significant maintenance of ROV systems, advancing autonomous manipulation capabilities, and engaging in defense sector opportunities.

Full Transcript

OPERATOR

Hello everyone. Thank you for joining us and welcome to Nauticus Robotics Inc first quarter 2026 earnings call. After today’s prepared remarks, we will host a question and answer session. If you would like to ask a question, please press Star one to raise your hand. To withdraw your question, press Star one again. I will now hand the conference over to Kristin Moorman, Corporate Development Lead. Kristin, please go ahead.

Kristin Moorman

Thank you and good morning everyone. Joining me today and participating in the call are John Gibson, CEO and President, Ximene Begares, Interim CFO, and other members of our leadership team. On today’s call, we will first provide prepared remarks concerning our financial and operations results. Following that, we will answer questions. We have now released our results for the quarter ending March 31, 2026 which are available on our website. In addition, today’s call is being webcast and a replay will be available on our website shortly following the conclusion of the call. Please note that comments we make on today’s call regarding projections or expectations for future events are forward looking statements. Forward looking statements are subject to a number of risks and uncertainties, many of which are beyond our control. These risks and uncertainties can cause actual results to differ materially from our current expectations. We advise listeners to review our earnings release and the risk factors discussed in our filings with the SEC. Also, please refer to the reconciliations provided in our earnings press release. As we may discuss non-GAAP metrics on this call, I will now turn it over to John.

John Gibson (CEO and President)

Well, good morning. Thank you, Kristen. And thank you to everyone for joining us on the call today. The first quarter of 2026 was a seasonally softer quarter for offshore activity, and that’s consistent with what the broader subsea and offshore services market experienced during the winter operating season. We saw similar commentary from larger industry participants, including Helix and Oceaneering, both of which pointed to winter seasonality, lower first quarter utilization, and expectations for stronger activity in the second and third quarters of 2026. For Nauticus, the important point is this we use the quarter productively. While revenue was not where we wanted it to be, our team focused on the work that positions us for improved execution in the second half of the year. As the operating system strength season strengthens, we advanced fleet readiness, completed significant annual maintenance and refurbishment activities across several of the ROV systems, and continued preparing our systems for higher utilization opportunities during the remainder of the year. We also continued advancing Nauticus Toolkit, our proprietary autonomy software platform. Nauticus Toolkit is central to our strategy because it allows us to create value not only through services but also through software licensing, technology enabled services and deployment on customer owned vehicles. During the quarter we continued integrating Nauticus Toolkit across our subsea systems along with new high definition camera systems and other advanced sensors designed to improve navigation efficiency, data quality and customer value. We also made progress with Aquanaut and our autonomous manipulation capabilities. Aquanaut Vehicle 1 has now completed more than 500 hours of in water testing on client driven workflows and more than 200 successful vertical inspection behaviors on mooring lines. These are important steps towards offshore deployment and the data from that testing continues to guide our software and engineering improvements. International expansion also remains another important part of our growth strategy. During the quarter we continued advancing our UAE and broader GCC initiative including work toward a long term operational and commercial presence in Ras Al Khaimah. That region represents a meaningful opportunity for Nauticus across offshore energy technology, licensing, manufacturing support and strategic partnerships. Finally, we’re pleased to welcome Brian Allen as Chief Revenue Officer. Brian brings nearly two decades of subsea robotics autonomy and commercial leadership experience. His focus is clear convert customer interest into revenue opportunities across offshore services, software licensing, hardware sales, fence and international markets. So while Q1 reflected normal offshore seasonality, we believe Nauticus exited the quarter better prepared, more focused on commerciality and positioned to pursue a strong opportunity set through the balance of the year. With that, I’m going to turn it over to Amanda to walk you through the financials.

Amanda

Amanda, thank you, John and good morning everyone. I will now discuss our financial results for the quarter of first quarter of 2026 during our first quarter we remained focused on preserving liquidity, maintaining stockholder equity and securing financial resources necessary to support the company. Revenue for the first quarter was $0.2 million, which is down 0.9 million sequentially and essentially flat from the same quarter last year. This performance is consistent with the seasonal trends we typically experience in the first quarter and reflects the overall market John just discussed. Operating expenses for the quarter were $5.8 million, which is down 0.2 million from Q1 2024 and down 0.8 million sequentially. G&A costs for the quarter were $3.2 million, which is an improvement of 1.2 million compared to Q1 2025. Sequentially G&A has increased $0.6 million due to the non recurring legal fee credit received in Q4 2025. Net loss for the quarter was $9.3 million. This is a 9.9 million decrease in net loss sequentially and a 1.7 million increase in net loss from Q1 2025. These variations, both positive and negative, are largely related to the changes in fair value of our debt instruments. Adjusted net loss for the quarter was $6.4 million compared to 10.4 million for the fourth quarter of 2025 and 6.6 million in Q1 2025. Cash at the end of Q1 2026 was $5.9 million compared to the $7.6 million at the end of 2025. This decrease is related to cash used in operating activities. As we move into the SECond quarter, we remain disciplined in our approach to managing the business and preserving financial flexibility. I will now pass the call back to John

John Gibson (CEO and President)

thank you, Amanda. Now I’m going to turn it over to our leads that are working on international expansion revenue opportunities. Jason Close will be first with updates on our UAE expansion. Jason

Jason Close

thank you John. Since our last call, we’ve been focused on moving from strategy into execution around our UAE and broader GCC expansion efforts. While the current regional security environment has limited our ability to travel in person, it has not slowed our progress. In fact, we’ve continued to advance the foundational work needed to establish a presence in Ras Al Khaimah and support long term growth in the region. Over the past several weeks we’ve been actively engaged in identifying a location in Ras Al Khaimah that can support our long term operations and commercial goals. We’ve also engaged a UAE based marketing agency to support the next phase of our market activation efforts. That work includes improvements to our website, branding and go to market materials both for the regional market and more broadly as we continue refining how we position the Nauticus portfolio globally. At the same time, we are seeing that business opportunities in the regions continue to move forward and mature even with the broader uncertainty. The current environment has also reinforced the relevance of our solution for government and defense related applications, particularly where unmanned systems, remote operations and increased operational safety are a priority. We are being careful and disciplined in how we approach those opportunities, but we believe our portfolio is well aligned with with several of the region’s long term needs in parallel, we’re seeing increased interest outside the GCC region as we continue expanding our international commercial engagement efforts. Addition, we continue to make progress in our collaboration with Forum Energy Technologies around the Olympic Arm platform. During the first quarter the team completed a review of the existing design documents and in the second quarter we expect to begin collaborative testing activities around the current prototype. This remains an important opportunity to further validate our technology and expand its application through established industry channels. Overall, we continue to see long term potential in these international markets, remain focused on executing our growth strategy in a disciplined and structured way through 2026. With that, I will now hand the call over to Steve Walsh, our sales lead, for an update.

Steve Walsh (Sales Lead)

Thank you Jason and good morning. As expected, Q1 sales reflected the seasonal softness that has traditionally impacted operations across the Gulf of Mexico during the winter months. Weather conditions limited offshore activity throughout much of the quarter and lower oil prices contributed to a more cautious operating environment early in the year. More recently, however, we’ve seen energy markets begin to strengthen, driven in part by geopolitical instability and the ongoing conflict involving Iran. Despite the slower start to the year, we remain very encouraged by the outlook of the remainder of 2026. We are seeing strong momentum in upcoming offshore activity with several new contracts recently commencing across both offshore oil and gas sector and the offshore wind industry. This diversification continues to position us well as demand for subsea services expands across multiple energy markets. In addition, we are continuing to actively pursue project opportunities along both US Coasts, throughout the Gulf of Mexico and in select international markets. We are also expanding our focus within the defense sector where we believe our subsea capabilities, operational experience and technology platforms position us well for future opportunities. To that end, we’re excited to be deploying resources in early June in support of a large defense contractor, the first work of this variety in over a year. Importantly, our team used the slower offshore period productively during the quarter. We completed major annual maintenance and refurbishment activities across several of our ROV systems. These efforts ensure that our fleet is operating at peak efficiency and reliability as we move into what we expect will be a significantly more active 2026 operating season. We also continue to make meaningful progress on the technology front. Nauticus Toolkit, our proprietary software platform, along with new perception capabilities and other advanced sensor technologies are being successfully integrated across our subsea systems. These enhancements improve operational capability, data quality and overall client value while further differentiating us in an increasingly competitive subsea vehicle market as the year progresses. We believe these operational improvements, combined with strengthening offshore demand, geographic expansion, continued technology integration, and growing exposure to the defense related opportunities position the company well for growth and long term success. Thank you again for your continued support and confidence in our team. With that, I’ll turn it over to Brian Allen, our Revenue lead, for his thoughts on 2026.

Brian Allen (Chief Revenue Officer)

Thank you Steve and good morning everyone. I’m Brian Allen, the new Chief Revenue Officer at Nauticus and this is my first earnings call with the company. So I want to be straightforward with you about how I see things and what I intend to do. You’ve heard about the weather conditions that brought about our Q1 results and it’s going to be my job to broaden our revenue streams across technology, robotic hardware and services in other global locations that help smooth this and move us to more of a rapid growth. Briefly on my background, I spent the last decade building a subsea robotics and AI company called Beam Robotics from scratch to around 230 people, growing revenue at 60 to 100% year on year and creating an 840 million sales pipeline that brought in 90 million of sales and order book in my final 12 months. We sold autonomous inspection tech and tech enabled services into the exact same markets Nauticus operates in. Before that I spent 10 years at sea, starting off piloting RVs, then supervising and managing them to build oil fields and wind farms. So I know these customers, I know this market, and I know what it takes to sell advanced autonomy into exactly this industry. People have asked me why I chose Nauticus and the honest answer is two things I found during my technical diligence that I have not seen elsewhere in any other marine business. First, Nauticus Toolkit is the most advanced autonomy software available to purchase today for subsea vehicles. It is the leader in the category that matters commercially, a deployable supported product that customers can run on their existing vehicles today and I see several near term opportunities in the market for this software. Software sales are our clearest route to smoothing seasonality as they are not tied to weather. Second, this is what really changed my mind the company’s work on autonomous manipulator control. The IP here is potentially five years ahead of the closest competition when you consider how much of the offshore inspection, intervention and repair market is constrained by pilot ability and vessel costs. Reliable autonomous manipulation represents a very significant commercial opportunity. Bringing that to market alongside the core Nauticus Toolkit platform and offering it with Aquanaut is where I see the real step change for this business on what I intend to do. My first priority is generating early commercial wins that rebuild market confidence and I’ve already identified a small number of near term Nautica toolkit opportunities and potential high 7 low 8 figure Aquanaut services tender from my own network that I intend to move on quickly. Beyond that, I’m building the marketing function and sales infrastructure to drive tech sales, technology driven services and Aquanaut hardware sales globally. A key part of my role is generating clear commercial signals from the market that Ximene Begares and the engineering team can use to direct development efforts. The closer we tie what we build to what our customers are telling us they need, the faster the technology converts into revenue. I operate capital efficiently. That is a necessity in this market, and it’s how I’ve always built businesses. I’m already designing systems that use AI to automate parts of our sales marketing function, which allows us to strengthen commercial capability rapidly at a fraction of what a traditional approach would cost with fewer headcount in a company at our stage, every dollar of commercial spend needs to work hard. I want to close with this. I did have other opportunities on the table and I chose Nauticus because the technology here is genuinely differentiated, which is very rare in this industry. The team here is strong and I see an asymmetric opportunity that is worth committing to. I’ve taken a shareholding as part of my compensation because I want my interests aligned with all of yours. And this isn’t spin. I would not have joined if I did not see a bright future for this business. I’m looking forward to updating you all on our commercial progress over the coming quarters. And I’ll hand back to you, John.

John Gibson (CEO and President)

Thank you, Brian. We’re excited to have you here. We recognize that Q1 revenue reflects a slower seasonal period, but we’re encouraged by. the direction of the business. Our fleet readiness is improved. Our technology continues to advance. Nauticus Toolkit is becoming a clearer commercial opportunity and gives the ability to offset some of the seasonality. And our UAE and GCC expansion efforts are moving from strategy into execution. Most importantly, we’re sharpening our focus on revenue with Brian Allen joining the team. A stronger commercial structure and continued opportunities across software, offshore energy, defense, international markets, software licensing and the hardware sales that we believe Nauticus is positioned to build momentum through the remainder of 2026. We appreciate the continued support of our shareholders, our customers, our partners, and particularly our employees. We look forward to updating you on our progress in the quarters ahead with that operator, I’d like …

Full story available on Benzinga.com

This post was originally published here

On Tuesday, Antalpha Platform Holding (NASDAQ:ANTA) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://edge.media-server.com/mmc/p/4jef7vmv/

Summary

Antalpha Platform Holding Co reported a 52% year-over-year revenue growth for Q1 2026, highlighting strong business execution amid challenging market conditions.

The company emphasized its risk management approach, maintaining zero principal loss and managing substantial loan repayments, notably from Cango Inc.

Antalpha launched strategic growth initiatives including a Web3AI agent (Nina) and transitioning tokenized gold holdings into yield-generating deployments.

Total loan value decreased slightly due to repayments, but the company expects demand for crypto-collateralized financing to support loan book growth.

Financial performance included a 32% GAAP operating margin; however, operating expenses rose by 102% year-over-year due to restructuring and compensation costs.

The company provided a revenue guidance of $11 million to $13 million for Q2 2026, reflecting a reduction in the loan base from one-time repayments.

Management remains optimistic about strategic opportunities in the Web3 and AI sectors, particularly targeting the Asia-Pacific region.

Full Transcript

OPERATOR

Good day and thank you for standing by. Welcome to Antalpha Platform Holding Co’s first quarter 2026 earnings conference call. Today’s call is being recorded. All participants are now in a listen-only mode. After management’s prepared remarks, there will be a question and answer session. I would now like to turn the call over to Chris Mamoni, Managing Director of the Blue Shirt Group and Representative for Antalpha Platform Holding Co’s Investor Relations team. Mr. Mamoni, please go ahead.

Chris Mamoni (Managing Director of the Blue Shirt Group and Representative for Antalfa’s Investor Relations team)

Thank you Operator. Welcome to everyone participating in this call. Joining me today is Paul Yang, Antalpha Platform Holding Co’s Chief Financial Officer. Please note the following first, all year over year comparisons in today’s call are for Q1 2026 versus Q1 2025 unless otherwise stated. Second, consolidated financial statements including Aurelian began from Q4 2025. As such, Q1 2025 comparative figures reflect Antalpha Platform Holding Co’s standalone results. Third, our remarks today will include forward looking statements based on current expectations. These statements involve risks and uncertainties that could cause actual results to differ materially. For discussion of these risks, please refer to Antalpha Platform Holding Co’s filings with the SEC. We do not undertake any obligation to update forward looking statements except as required by law. This call also contains references to unaudited non-GAAP financial measures. Reconciliations to the most comparable GAAP measures can be found in our press release and SEC filings. Now I’ll turn the call over to Paul Yang who will provide the Q1 operating and strategic overview as well as the financial highlights and outlook. Paul, please go ahead.

Paul Yang (Chief Financial Officer)

Thanks Chris Good day everyone. Thank you again for joining us. I’m Paul Yang, CFO of Antalpha. Let me start with a brief framing of the quarter. Q1 2026 was a period of solid execution and business development for N Alpha amid a dynamic and challenging market backdrop for the crypto ecosystem. We delivered 52% year over year revenue growth and maintained our record of zero principle loss. At the same time, our loan book saw a one time reduction driven by substantial repayments from certain large borrowers which notably Cango Inc. I will address this in detail, but the key point is all borrowers repay with no loss of principle and we view it as a strong reflection of our borrowers overall financial health and the soundness of our credit model. Finally, we also want two important strategic growth initiatives, the beta launch of our Web3AI agent and the transition of our tokenization gold holdings into yield generating deployment. I want to provide some extra context on the Kengo repayment before moving to the loan book. On the large borrower can go repayment. I want to provide some extra context here before the financial results section. During the first quarter and into early quarter two, Cango Inc. A NASDAQ listed Bitcoin miner, has repaid approximately 530 million US dollar of its outstanding loan balance. This represents over 95% of Cango’s outstanding balance as of December 31st of 2025. Cango funded the repayment through a combination of publicly disclosed Bitcoin, asset sales and equity transactions. This is the type of positive outcome that our credit model is designed to produce, so we were pleased with how it all played out in practice. I will now cover our loan book update and risk management activities followed by our strategic initiatives, then walk through the rest of the financials and close with our Q2 outlook. Antalpha’s operating philosophy is a risk management first philosophy. We have been consistent in this approach since our inception and it’s central to how we manage the platform in Q1. Bitcoin prices were under considerable pressure in Q1, declining approximately 40% from their October 2025 peak. In this familiar environment, our approach was deliberate. We maintain active dialogue with every client to review market conditions, stress test positions and discuss their options as we do in our daily operation, especially every period of price volatility. We did not simply wait for the market to move, we engaged proactively. Our over collateralization model continue to underpin the long ball we require over collapse. Collateralization at origination and Bitcoin mined by client is deposited directly into our wallet, allowing the collateral pool to build continuously. The result of this approach is a proven track record. We are proud to stand behind. As of March 31, 2026, N Alpha has recorded no loss of principle since the inception of the company and it is the direct outcome of the prioritization of risk management above all else amidst every market bad job. Before reviewing our loan book matrix, let me provide some broader market context. We just discussed the devaluation of Bitcoin versus the October 2025 which created a more cautious environment for new loan deployment and broader activity. While the near term sentiment for digital assets has been softer and the long term demand backdrop remains constructive. Spot Bitcoin ETF assets under management stood at approximately 102 billion US dollar as of mid May 2026, reflecting continued institutional participation in the asset class. Historically, periods of price softness have been also coincide with increased interest in machine upgrade financing as miners began positioning for the next cycle. We expect this dynamic to once again support the long demand as market conditions stabilize. With that context, let me walk through the loan book metrics and in detail starting with TVL per-client, which I think it gives a clear picture of the underlying business TVL per-client increased 36% year-over-year reflecting growth in average loan size across the client base and the continual deepening of our client relationships. This growth stems from our proactive strategy to prioritize lower risk consumers ensuring a higher quality portfolio. Total value of loans were 1.6 billion as of March 36, 2026 and was down 3% year-over-year. This change reflects three factors. First, more measured new loan deployment in a weaker bitcoin price environment. Second, substantial one time loan repayment from two large borrowers, mostly from Cango, which we mentioned earlier, which repay approximately 526 million during the first quarter of 2026 for a modest reduction of approximately 3% in the remaining portion on a sequential basis. It is worth re emphasizing that we have never had a credit loss, we have never had a loss on principal across the entire loan book and we enter the recovery phase of the cycle with a well protected portfolio. As market conditions stabilize, we are positioned to redeploy capital and grow the loan book. Hash rate loans finance approximately 34.2 exahash of hashrate capacity as of March 31, 2026 representing approximately 3.3% of global hash rate. This compares to 81.3 EH as of December 31, 2025. The decrease was mainly attributable to Cango’s repayment as Cancoast facilities were predominantly hash rate backed loans. In summary, the overall health of our loan …

Full story available on Benzinga.com

This post was originally published here

Apple Inc. (NASDAQ:AAPL) unveiled a broad set of accessibility updates powered by Apple Intelligence on Tuesday, expanding capabilities across iPhone, iPad, Mac and Apple Vision Pro.

The company said the new features will arrive later this year and focus on navigation, visual assistance and communication tools.

Apple also introduced AI-driven subtitle generation, enhanced Voice Control functions and new wheelchair controls for Vision Pro users.

Apple also confirmed its Worldwide Developers Conference will run from June 8 through June 12, 2026, where investors may expect major software and Apple Intelligence updates.

In fact, Apple is reportedly preparing new AI-powered writing tools, wallpaper generation features and smarter Shortcuts capabilities for iOS 27 ahead of WWDC 2026, according to a Bloomberg report.

The update could also introduce natural language shortcut creation and Grammarly-style writing assistance across Apple devices.

AI Expands Accessibility Tools

Apple said VoiceOver will soon deliver …

Full story available on Benzinga.com

This post was originally published here

Polymarket announced the launch of the first prediction markets tied to private company performance on Tuesday, with Nasdaq Private Market serving as the exclusive resolution data provider.

The markets resolve on valuation milestones, IPO timing and secondary market activity for names like SpaceX and OpenAI.

Nasdaq Private Market, or NPM, is the institutional venue backed by Nasdaq Inc. (NASDAQ:NDAQ), Goldman Sachs, Morgan Stanley and Citi that has cleared nearly $80 billion in secondary liquidity for private company shareholders.

The Data Moat Is The Story

Private company valuations are notoriously opaque, usually anchored to sporadic funding rounds or stale 409A marks that may be months old.

NPM runs actual corporate-sponsored tender offers and structured secondary auctions, meaning Polymarket contracts will settle on …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks traded lower midway through trading, with the Nasdaq Composite falling more than 200 points on Tuesday.

The Dow traded down 0.35% to 49,512.48 while the NASDAQ dipped 0.93% to 25,849.08. The S&P 500 also fell, dropping, 0.56% to 7,361.93.

Leading and Lagging Sectors

Health care shares jumped by 1.2% on Tuesday.

In trading on Tuesday, materials stocks fell by 2.1%.

Top Headline

Amer Sports Inc (NYSE:AS) reported better-than-expected first-quarter financial results and raised its FY26 guidance above estimates.

Amer Sports posted adjusted EPS of 38 cents, beating market estimates of 30 cents. The company’s quarterly sales came in at $1.946 billion versus expectations of $1.835 billion.

Equities Trading UP
           

  • Amesite Inc (NASDAQ:AMST) shares shot up 198% to $2.35 after the company reported a year-over-year increase in third-quarter financial results.
  • Shares of …

Full story available on Benzinga.com

This post was originally published here

Money can buy a lot of things. Oceanfront homes. Private jets. A $200 million dorm project with thousands of beds and almost no windows. What it apparently cannot buy is universal applause, and Charlie Munger seemed perfectly fine with that trade.

When backlash erupted over the longtime Berkshire Hathaway vice chair’s controversial student housing design for the University of California, Santa Barbara in 2021, Munger did not launch a polished apology tour or suddenly pivot into people-pleasing mode. Instead, he delivered the kind of quote that sounded perfectly on-brand for a billionaire famous for blunt opinions and zero interest in sugarcoating them.

“You’ve got to get used to the fact that billionaires aren’t the most popular people in our society,” Munger told MarketWatch in 2021. “I’d rather be a billionaire and not be loved by everybody than not have any money.”

Don’t Miss:

The comment quickly became tied to one of the strangest campus controversies — a proposed mega dorm critics compared to everything from a cruise ship to a futuristic prison block.

Dormzilla Turned Into A Billionaire PR Nightmare

The uproar centered on Munger Hall, an enormous 11-story dormitory designed to house more than 4,500 UCSB students. The problem was not the size alone. Roughly 94% of the single-occupancy bedrooms were designed without windows, relying instead on artificial lighting and ventilation systems.

To Munger, the project was a practical solution to California’s brutal student housing shortage. The billionaire investor believed dense housing with large communal spaces could maximize efficiency and lower costs. Critics saw something far darker.

Dennis McFadden, a consulting architect who had served on UCSB’s Design Review Committee for 15 years, resigned in protest over the project. In his resignation letter, published by The New York Times, he described the dorm concept as “a social and psychological experiment” and called it “unsupportable” from his perspective “as an architect, a parent, and a human being.”

Trending: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

The criticism only intensified from there.

Architecture critic Paul Goldberger amplified the backlash writing, “This design is a grotesque, sick joke — a jail masquerading as a dormitory,” in a post on X in 2021. The line spread rapidly across coverage of the project and helped turn the proposed building into a national debate over billionaire influence on college campuses.

Despite the outrage, Munger never appeared especially rattled by the criticism.

Munger dismissed the criticism in comments to Architectural Record, saying McFadden “reacted with his gut like an idiot” and failed to study the building intelligently. Munger argued the architect never properly reviewed the project’s models, which he believed demonstrated the dorm’s strengths. “Everybody who sees the models goes ape-sh*t for them,” Munger said.

Munger Never Wanted A Popularity Contest

Long before the dorm controversy, Munger had built a reputation as one of Wall Street’s sharpest and most unapologetic thinkers. Born in Omaha, Nebraska in 1924, he started as a real estate lawyer before partnering …

Full story available on Benzinga.com

This post was originally published here

While Wall Street remains fixated on upcoming NVIDIA Corp (NASDAQ:NVDA) earnings, the bond market may be flashing the more important signal.

• NVIDIA stock is showing upward bias. Where are NVDA shares going?

Bond Market Sends Warning Signal

The yield on the 30-year Treasury bond climbed to 5.18% on Tuesday, its highest level since 2007, intensifying the sell-off in long-duration Treasury ETFs and reigniting fears that “higher for longer” interest rates are becoming a structural market problem rather than a temporary one.

That matters because rising Treasury yields do not just hit bonds — they also pressure the valuations of long-duration growth assets, particularly technology and AI stocks whose future cash flows become less attractive as rates climb.

AI Trade Faces Valuation Pressure

The timing is especially notable as investors prepare for Nvidia earnings, widely viewed as one of the market’s most important AI catalysts.

For much of the past …

Full story available on Benzinga.com

This post was originally published here

Rubico Inc. (NASDAQ:RUBI) stock was trading higher on Tuesday, fueled by intense market volatility following a prolonged period of steep downward pressure.

Volatility Sparks Massive Volume

Market data showed a notable increase in investor interest during the session. Rubico’s trading volume reached 45.96 million shares on Tuesday.

This figure contrasts with the company’s recorded average daily volume of 357 thousand shares.

Context Of Recent Capital Adjustments

The volume increase follows a series of changes to the company’s equity structure earlier this year. Rubico has undergone two consecutive reverse stock splits in 2026.

The company implemented a 1-for-7 reverse split on February 10. Subsequently, it enacted a 1-for-10 reverse split on April 7, according to Benzinga …

Full story available on Benzinga.com

This post was originally published here

C3is Inc. (NASDAQ:CISS) stock is retreating on Tuesday. This decline follows a surge of over 25% on Monday, suggesting a likely sell-the-news reaction or profit-taking from retail traders after the maritime transport company reported its first-quarter financial results for 2026.

Revenue Gains Versus EPS Declines

The Athens-Greece-based ship owner generated revenue of $11.6 million for the three months ended March 31. This represents an increase over the $8.671 million in sales recorded during the same period last year.

However, adjusted earnings per share dropped to $5.24 from $101.88 per share in the first quarter of 2025, according to Benzinga Pro.

C3is Short Interest Report

Traders should note a sharp shift in short interest, which recently climbed from 10,630 shares to 84,980 shares during the last reporting period.

This increase positions 15.72% of the company’s publicly available float short. Based on an average …

Full story available on Benzinga.com

This post was originally published here

Billionaire investor Carl Icahn quietly outperformed Berkshire Hathaway Inc. during the first quarter.

Icahn Outpaces Buffett In Q1

Performance data tracking billionaire hedge fund portfolios, aggregated by WhaleWisdom, showed Icahn’s manager-weighted returns climbed 11.64% during the first quarter, compared with a 4.99% gain for Berkshire Hathaway Inc. Common Stock (NYSE:BRK) (NYSE:BRK).

The rebound placed Icahn among the best-performing billionaire investors of the quarter, ahead of several major hedge fund names.

But the longer-term picture looks dramatically different.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Buffett Steps Aside: Abel’s First Berkshire 13F …

This post was originally published here

Andrej Karpathy, one of OpenAI’s founding members and the former director of AI at Tesla Inc (NASDAQ:TSLA), announced Tuesday morning that he is joining Anthropic.

“I think the next few years at the frontier of LLMs will be especially formative,” Karpathy wrote, adding that he plans to return to hands-on research.

Karpathy left OpenAI in February 2024 to launch education startup Eureka Labs, but the destination tells the real story. Sam Altman’s lab keeps losing senior alumni to Dario Amodei’s.

A Pattern, Not An Anecdote

Karpathy is the third high-profile OpenAI figure to land at Anthropic in under two years. Jan Leike, OpenAI’s former head of alignment, defected in May 2024. Co-founder John …

Full story available on Benzinga.com

This post was originally published here

Meiwu Technology Company Limited (NASDAQ:WNW) shares traded higher on Tuesday.

Earlier this month, the company disclosed a new private financing deal tied to its artificial intelligence expansion strategy. The firm raised fresh capital while outlining plans for an AI-powered skincare management platform.

Meiwu Technology said it secured approximately $15.65 million through a private share sale involving 25 million ordinary shares.

• Meiwu Technology Co shares are climbing with conviction. Why are WNW shares rallying?

Private Placement Fuels AI Plans

Meiwu sold shares at $0.626 each through a securities purchase agreement signed on May 5. The transaction closed three days later on May 8.

Following the offering, …

Full story available on Benzinga.com

This post was originally published here

Amer Sports, Inc. (NYSE:AS) shares rose Tuesday after the company reported first-quarter earnings and revenue that topped Wall Street estimates, fueled by strong demand across its technical apparel and outdoor categories.

The company also raised its full-year sales and earnings outlook, citing continued momentum in its Arc’teryx and Salomon businesses and expanding margins.

Amer Sports First-Quarter Results Beat Estimates

Amer Sports reported first-quarter adjusted earnings of 38 cents per share, above the analyst consensus estimate of 30 cents. Revenue climbed 32% year over year to $1.946 billion, exceeding Wall Street expectations of $1.835 billion.

Technical apparel revenue increased 33% during the quarter, supported by growth across regions, product categories and sales channels. Omni-channel comparable sales rose 19%.

Outdoor Performance revenue jumped 42% to $714 million, while Ball & Racquet Sports revenue increased …

Full story available on Benzinga.com

This post was originally published here

ChargePoint Holdings, Inc. (NYSE:CHPT) on Tuesday announced it is partnering with OBE Power to install about 2,500 EV charging ports at multifamily residences.

The initiative targets rising demand for home charging in apartments and condos, a segment that has lagged single-family housing in EV infrastructure. ChargePoint will provide its charging technology, while OBE Power will handle infrastructure and operations.

Broader market weakness may also be weighing on the stock, with the Russell 2000 down 1.16% and the S&P 500 off 0.52%.

Technical Analysis

ChargePoint’s shares are currently trading at $6.27, which is 4.8% below the 20-day simple moving average (SMA) of $6.53. The stock has declined 55.25% over the past 12 months, indicating a bearish long-term trend. The 50-day SMA is at $5.83, and the stock is trading 6.6% above this level, suggesting some short-term support.

The Relative Strength Index (RSI) is currently at 52.21, indicating a neutral momentum state, meaning the stock is neither overbought nor oversold at this time. This suggests there could be potential for upward or downward movement, depending on market conditions.

ChargePoint Holdings, Inc. designs, develops, and markets networked …

Full story available on Benzinga.com

This post was originally published here

A wife wanted to aggressively pay off their debt, but her husband wanted to continue enjoying hobbies and purchases that helped him “enjoy life” even after the couple refinanced credit card debt and maxed the cards out again.

The couple shared their issues on Ramit Sethi‘s “I Will Teach You To Be Rich” podcast to discuss how they accumulated more than $261,000 in debt while struggling to get on the same page financially.

Don’t Miss:

Different Views On Money

Ashley explained that Brandon wasn’t interested in managing finances together, leaving most of the responsibility on her shoulders.

“I’m the one figuring out how we’re going to pay off our debt,” she said. “And he kind of just wants to be able to spend the money.”

“Right now our goal is getting out of debt,” Ashley said. “I brought up the idea of selling a vehicle that is not a necessity.”

But Brandon pushed back because the Ford F-350 truck supported the lifestyle he had built around recreational hobbies. The couple previously bought the truck to pull a camper they admitted they only used a couple of times before selling it. In addition to the truck, Brandon also owned a snowmobile, four-wheeler, boat and pit bike.

Brandon admitted he rarely thought about finances unless he wanted to buy something. One example was a $2,500 snowmobile financed through a loan that took several years to pay off.

Looking back, Brandon acknowledged the purchase wasn’t a smart financial move.

“I probably should have waited,” he said.

Trending: This Under-$1 Pre-IPO AI Company Is Still Open to Retail Investors — Learn More

The couple’s financial struggles became even more complicated after taking out a large loan to pursue surrogacy and in vitro fertilization treatments in hopes of starting a family. The process was emotionally devastating after the pregnancy was lost, leaving them with significant debt but no child.

Ashley said the failed surrogacy process became a major motivator for her to finally eliminate debt and build financial stability.

Meanwhile, Brandon revealed that much of his spending habits were shaped by growing up poor and losing his brother in 2018.

“I just thought that enjoying life was more important than paying off all the debt right away,” he said.

Sethi pointed out that Ashley had spent years shielding Brandon emotionally while also handling nearly all of the financial responsibility.

“You’re actually not doing him any favors by taking all this burden on yourself,” Sethi told her.

See Also: More Than Half of Americans Aren’t Prepared for Retirement — Including 62% of Gen Y

The Turning Point

The conversation shifted after Sethi walked the couple through their financial numbers and showed them what life could look like without debt.

At the time, their fixed costs consumed 91% of their income. Sethi explained that if they aggressively paid off debt, they …

Full story available on Benzinga.com

This post was originally published here

A retirement party usually comes with sheet cake, forced applause, and at least one speech about finally sleeping past 6 a.m. This one came with a 47-year-old stepmother learning the house she had spent the last decade building a life in was never actually part of her future.

In a post on Reddit, the woman said a conversation about wills after her 65-year-old husband’s retirement celebration turned into a painful realization. While she expected to outlive her husband by many years due to their age gap, she said she was “completely blindsided and shocked” to learn their home would eventually go to his 30-year-old daughter instead of her.

According to the post, the house originally belonged to the husband’s late wife, who inherited it from her own parents. The husband told his current wife he planned to keep the property within that side of the family by leaving it to his daughter.

For the wife, the issue was not just real estate. It was the life she thought she had built inside it.

“I was really upset but also angry to learn I will most likely be kicked out of our house after my husband’s death and left homeless,” she wrote.

Don’t Miss:

The Retirement Conversation That Changed Everything

The woman said she struggled with the idea that she could spend “the last decades” of her life alone while also potentially losing the home she considered her own after 10 years of marriage.

She argued that the property had become their marital home and said she had invested years of time and emotional energy into it, writing that “it’s not fair that I will be kicked out of our home after I spend so much time and effort redecorating it and making it my own.”

She also pointed to the fact that she left the workforce during the marriage. In her update, she later explained she previously worked stressful customer-service jobs, including as an emergency call handler, and said her husband encouraged her to pursue a calmer life after seeing how badly the work affected her mental health.

Over time, she admitted she became financially dependent on him and comfortable living at home while focusing on hobbies, decorating, and managing life at her own pace.

Her husband saw things differently.

According to the post, he reminded her that the property came from his late wife’s family and argued it made sense for the house to eventually pass to their daughter. He also said his current wife would still receive his life insurance payout while remaining savings would be split between her and his daughter.

The disagreement escalated into a screaming match that ended with the woman crying in the guest room.

Trending: More Than Half of Americans Aren’t Prepared for Retirement — Including 62% of Gen Y

The Inheritance Debate Quickly Turned Personal

The argument stopped being just about property once both sides started tallying contributions inside the marriage.

The wife argued she had sacrificed her career and spent years supporting the household, while her husband responded that he never asked her to stop working in the first place. He also pointed out they hired cleaners and housekeepers for much of the domestic labor.

That detail became a major sticking point in the discussion that followed online.

Many people felt the daughter’s inheritance claim carried emotional …

Full story available on Benzinga.com

This post was originally published here

Firm Hits Fundraising Target with Approximately $1.5 Billion of Investable Capital1

HOUSTON, May 19, 2026 /PRNewswire/ — Stellus Capital Management, LLC (“Stellus” or the “Firm”), a leader in lower middle market direct lending, today announced the final close of Stellus Credit Fund IV (“SCF IV” or the “Fund”). The Firm met its fundraising target with approximately $1.5 billion of investable capital. SCF IV, the successor to Stellus Credit Fund III, closed on April 1, 2026, and has already invested in 44 portfolio companies.

Full story available on Benzinga.com

This post was originally published here

ServiceNow, Inc. (NYSE:NOW) stock is rallying in early Tuesday trading, continuing a sharp recovery from its year-to-date lows. Traders are watching the enterprise software provider as a wave of positive catalysts shifts momentum back into the sector.

Tuesday’s rally appears to be largely driven by renewed Wall Street optimism. On Monday, Bank of America Securities analyst Tal Liani reinstated coverage on ServiceNow with a buy rating and announced a $130 price forecast.

Growth Capital Rotates Back Into Enterprise Software

Market dynamics are also working in favor of the cloud platform. Investors are currently rotating out of high-flying semiconductor stocks and channeling capital into beaten-down enterprise software names.

Peers like Salesforce, Inc. (NYSE:CRM) and Workday, Inc. (NASDAQ:WDAY) are finding renewed interest alongside ServiceNow after …

Full story available on Benzinga.com

This post was originally published here

The recent announcement from Meta regarding the layoff of 8,000 employees is more than just another headline in the tech sector’s ongoing volatility; it is a signal of a structural shift that should alarm anyone who understands the foundational mechanics of a consumer economy. When Mark Zuckerberg admitted that the massive capital expenditures on artificial intelligence have directly contributed to the need to scale back the company, he laid bare a cold, mathematical reality that is beginning to play out across the globe.

Automator’s Paradox

We are witnessing the first major tremors of what economists are now calling the Automator’s Paradox. While it is entirely rational for an individual firm to replace a hundred-person team with ten people aided by advanced AI, the collective result of this behavior across the entire market is nothing short of economic cannibalism. If we continue on this path of wholesale human replacement, we are not building a more efficient future. Instead, we are dismantling the very engine of consumption that keeps the global economy alive.

The logic presented by Big Tech leadership is deceptively simple. Meta, Amazon, and Google are on track to spend a staggering $750 billion on AI this year alone. To justify these astronomical investments to shareholders, these companies must find efficiencies. In the corporate lexicon, efficiency is almost always a euphemism for reducing headcount. Zuckerberg’s observation that a team once requiring a hundred people might now only need ten is a testament to the sheer power of modern generative AI. This microeconomic victory masks a macroeconomic catastrophe. A company that automates its workforce saves on wages, but it also removes those wages from the pool of disposable income that fuels the rest of the economy. When this happens in isolation, the impact is negligible. When it happens simultaneously across the Fortune 500, we face a systemic collapse of demand.

The AI Layoff Trap

This brings us to the most chilling realization of our current era, which was highlighted in a landmark economic research paper titled “The AI Layoff Trap” released in March 2026. The study models a scenario in which companies automate faster than the broader economy can absorb displaced labor. It identifies a Prisoner’s Dilemma at the scale of the entire global economy. Each individual CEO is incentivized to automate to stay competitive and protect margins. As every company follows this rational path, they collectively destroy the consumer base that buys its products. We are approaching a tipping point where the supply side of the economy, powered by tireless AI, becomes hyper-productive, while the demand side, comprised of unemployed humans, withers away. Zuckerberg himself noted that Meta’s ad revenue fluctuated based on consumer discretionary spending linked to oil prices. He should perhaps be more concerned that his own internal efficiencies are removing the very consumers who would click on those ads in the first place.

This is particularly haunting because it tested every conventional safety net we have spent the last decade debating. We have long been told that universal basic income, worker equity participation, or massive upskilling …

Full story available on Benzinga.com

This post was originally published here

Home Depot (NYSE:HD) held its first-quarter earnings conference call on Tuesday. Below is the complete transcript from the call.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://event.choruscall.com/mediaframe/webcast.html?webcastid=prbb0CKb

Watch the full earnings call below:

Summary

Home Depot reported Q1 2026 sales of $41.8 billion, a 4.8% increase year-over-year, with comp sales rising 0.6% overall and 0.4% in the US.

Adjusted diluted EPS for the quarter was $3.43, down from $3.56 the previous year, with operating margins impacted by the acquisition of GMS.

Strategic initiatives include the acquisition of Mingledorf to expand HVAC distribution, and the ongoing rollout of merchandising execution teams to improve in-store customer service.

The company reaffirms its fiscal 2026 guidance, expecting comp sales growth between flat to 2% and total sales growth of 2.5% to 4.5%.

Management highlighted strong engagement in spring-related projects and noted a focus on expanding their Pro customer base and services.

Full Transcript

OPERATOR

Greetings and welcome to the Home Depot first quarter 2026 earnings call. this time all participants are in a listen only mode. A brief question and answer session will follow the formal presentation. If anyone should require operator assistance during the conference, please press Star0 on your telephone keypad. As a reminder, this conference is being recorded. It is now my pleasure to introduce your host, Isabel Janci.. Please go ahead.

Isabel Janci (Moderator)

Thank you, Christine, and good morning, everyone. Welcome to Home Depot’s first quarter 2026 earnings call. Joining us on our call today are Ted Decker, Chair, President and CEO Ann Marie Campbell, Senior Executive Vice President, Billy Bastick, Executive Vice President of merchandising, and Richard McVail, executive vice president and Chief Financial Officer. Following our prepared remarks, the call will be open for questions. Questions will be limited to analysts and investors, and as a reminder, please limit yourself to one question with one follow up. If we were unable to get to your question during the call, please call Investor Relations at 770. Before I turn the call over to Ted, let me remind you that today’s press release and the presentations made by our executives include forward looking statements under the federal securities laws, including as defined in the Private Securities Litigation Reform Act of 1995. These statements are subject to risks and uncertainties that could cause actual results to differ materially from our expectations and projections. These risks and uncertainties include, but are not limited to, the factors identified in the release in our most recent annual report on Form 10K and in our other filings with the securities and Exchange Commission. Today’s presentation will also include certain non GAAP measures, including, but not limited to, adjusted operating margin, adjusted diluted earnings per share, and return on invested capital. For a reconciliation of these and other non GAAP measures to the corresponding GAAP measures, please refer to our earnings press release and our website. Now let me turn the call over to Tess.

Ted Decker (Chair, President and CEO)

Thank you, Isabelle, and good morning, everyone. Sales for the first quarter were $41.8 billion, an increase of 4.4.8% from the same period last year. Comp sales increased 0.6% from the same period last year and comps in the US increased 0.4%. Adjusted diluted earnings per share were $3.43 in the first quarter compared to $3.56 in the first quarter of last year. Our results were in line with our expectations. In the US Our northern and western divisions had positive comps as customers engaged in outdoor projects when weather was favorable in local currency. Mexico had positive comps while Canada was negative. The underlying demand in our business was relatively similar to what we saw throughout fiscal 2025. Despite greater consumer uncertainty in housing affordability pressure, our teams are operating at a high level and we remain focused on executing our strategy of driving our core and culture, delivering a frictionless interconnected experience and winning. The Pro Spring is our biggest season and we feel great about our store readiness, product assortment and value proposition. As Anne will detail in a moment, our associates are providing excellent customer service. We’re also moving more store tasking to our merchandising execution team so our Orange Apron Associates can spend even more time engaged with customers. As Billy will share, our merchants are providing exceptional value in product innovation through strategic supplier partnerships which delivered strong event performance. Last week we completed the acquisition of Ingledores, a leading wholesale distributor of heating, ventilation and air conditioning equipment serving residential and commercial customers through 42 locations in five states across the southeastern United States. Mingledorf brings an extensive product portfolio, a robust distribution network and established customer relationships that are highly complementary to SRS’s existing business. In addition, Mangeldorf gives us an incredible opportunity to penetrate the national market for H Vac parts and services supplies, leveraging the power of our enterprise to create a superior value proposition for the Pro customer. H vac distribution represents an addressable market of approximately $100 billion and increases our total addressable market to $1.2 trillion. Srs can now serve more pros and one greater share of wallet in this highly fragmented market. As a reminder, Pro represents a $700 billion market opportunity. We know we have the right to win in this space as we continue developing differentiated capabilities to better serve residential pro customers. In addition to our 2,360 plus store network and 325 customer facing warehouses, SRS is a best in class specialty distribution platform with over 1300 branches combined. We now command a fleet of approximately 16,000 delivery assets in a professional sales force of over 5000 associates. What we are building is unique and not easy to replicate. We are confident our comprehensive product offering capabilities and services will deliver an exceptional experience for Pros leading to sustained growth and outsized market share gains. As always, I’d like to thank our associates and supplier partners for doing an incredible job serving our customers this quarter. With that, let me turn the call over to Ann.

Ann Marie Campbell (Senior Executive Vice President)

Thanks Ted and good morning everyone. We continue to focus on elevating the shopping experience across all stores and online by optimizing fulfillment options. To do this, we are simplifying processes in our stores, removing friction from the customer experience, increasing associate engagement and taking actions to drive more loyalty with the Pro. Late last year we began to transition more store tasking to a merchandising execution team. Today we have transitioned over 1000 stores. By creating distinct selling and tasking teams in our stores, we’ve been able to redistribute tasking in our stores to met. While our Orange Apron Associates focus on driving deeper engagement and better customer service. We expect to complete this transition in all stores by the end of fiscal 2026. As you know, we’ve been on a journey to remove friction from the shopping experience and we are continuously evolving the way we operate to deliver a more seamless experience. When customers place an order online to complete their project, they expect the right products delivered on time and complete. Over the last several quarters, we’ve leaned into faster delivery for customers using our proprietary model which leverages all of our assets to drive speed what we call ship from best location. This has resulted in tremendous growth in deliveries out of our stores. In order to enhance our ability to serve this interconnected purchase more effectively, we’re focused specifically on ensuring we have the right leadership and technology capabilities in place to simplify the operational demand on our stores and improve the speed and experience for customers. Last quarter we told you about our Operations Experience Manager whose responsibilities include driving uniform operational processes and enhancing the interconnected fulfillment experience. We’re evolving or sourcing logic and have begun to route orders to the optimal storage fulfillment based on distance, inventory availability and speed of delivery, real time and view purchase history. They can also share access with their teams which results in better visibility and collaborative expectations.

Billy Bastick (Executive Vice President of Merchandising)

And where we experienced favorable weather we had great engagement in spring related projects. In the first quarter, 9 of our 16 merchandising departments posted positive comps including storage, power, hardware, plumbing, electrical bath, indoor garden, paint and kitchens. During the first quarter, our comp average ticket increased 2.2% and comp transactions decreased 1.3%. Big ticket comp transactions for those over $1,000 were positive 0.8% compared to the first quarter of last year. We were pleased with the performance we saw in portable power and patio. However, larger discretionary projects remain under pressure. During the first quarter, PRO posted positive comps and outperformed diy. We saw strength in DIY across many spring related categories including live goods, outdoor power equipment, patio, grills and storage. And for Pro, we saw strength across many Pro heavy categories like power pipe and fittings, water heaters, fasteners and paint. The investments we are making are resonating with our pros as we see increased engagement. For example, we have made significant progress with the Pro who paints and continue to see share gains with this customer. Our expanded assortment of products and partnerships with Bayer and PPC as well as enhanced digital capabilities through OnePaint combined with improved job site delivery capabilities are helping to remove friction from their experience. Turning to Total Company Online Comp Sales Sales leveraging our digital platforms increased over 10% compared to the first quarter of last year. This is the fourth quarter in a row with double digit year over year growth driven by our ongoing investments across our interconnected platforms. Delivering the best interconnected experience is a key component of our strategy. We are continuously improving our site and leveraging technology to do that, whether it is better search functionality, more relevant recommendations, and easier and faster fulfillment options, to name a few. As Ann mentioned, our faster delivery speeds are resonating with customers and driving greater engagement and while we are pleased with the progress we are making, we remain relentlessly focused on getting better each and every day because we know that as we remove friction from the experience, we see incremental customer engagement leading to greater sales across all points of interaction. During the first quarter, we hosted our annual Spring Black Friday and Spring Gift center events and saw strong performance across both events. Our merchants did a fantastic job curating the best products and we saw strong engagement with our customers throughout the events. We are pleased with the results we saw, particularly in categories like Power Tools, Outdoor Power Equipment, Live Goods and patio. In fact, our power categories posted a first quarter record for sales led by portable power and outdoor power equipment. We know that demand for demand for cordless outdoor power equipment has never been stronger and our lineup of battery powered tools across Ryobi, Milwaukee, DeWalt and Makita is unmatched this quarter. I’m excited to announce that Ramboard will be exclusive to the Home Depot and the Big Box retail channel. This product is engineered to withstand the toughest conditions at the job site and that’s why Ramboard has been the go to for pros for heavy duty floor protection for over 25 years. As we look forward to the second quarter, we are ready to continue delivering the best spring assortment across all of our patio product categories. Our live goods look incredible with everything from shrubs to a variety of flowers, herbs and vegetables for every type of gardener. And we have all the outdoor essentials for your patio, whether it’s a new patio set or grill to enhance your outdoor living space. We’re excited about spring breaking across the country and we remain ready to help our customers with all of their outdoor projects and outdoor living needs. With that, let me turn the call over to Richard.

Richard McVail (Executive Vice President and Chief Financial Officer)

Thank you Billy and good morning everyone. In the first quarter, total sales were $41.8 billion, an increase of $1.9 billion, or 4.8% from last year. During the first quarter, our total company comps were positive 0.6%, with comps of positive 0.7% in February, positive 2% in March, and negative 0.5% in April. Comps in the US were positive 0.4% for the quarter, with comps of positive 0.4% in February, positive 2% In March, and negative 0.8% in April. Additionally, foreign exchange rates positively impacted total company comps by approximately 55 basis points for the quarter. In the first quarter, our gross margin was 33%, a decrease of approximately 75 basis points from the first quarter of last year, which was in line with our expectations and reflects a change in mix as a result of the GMS acquisition.. During the first quarter, operating expense as a percent of sales increased approximately 20 basis points to 21.1% compared to the first quarter of 2025. Our operating expense performance was in line with our expectations. Our operating margin for the first quarter was 11.9% compared to 12.9% in the first quarter of 2025. In the quarter, pre tax intangible asset amortization was $171 million. Excluding the intangible asset amortization in the quarter, our adjusted operating margin for the first quarter was 12.3% compared to 13.2% in the first quarter of 2025. Interest and other expense for the first quarter increased by $13 million to $604 million. In the first quarter, our effective tax rate was 24.9% compared to 24.4% in the first quarter of fiscal 2025. Our diluted earnings per share for the first quarter were $3.30 compared to $3.45 in the first quarter of 2025. Excluding intangible asset amortization, our adjusted diluted earnings per share for the first quarter were $3.43, a decrease of approximately 3.7% compared to the first quarter of 2025. During the first quarter, we opened 12 new stores, bringing our total store count to 2,361. At the end of the quarter, merchandise inventories were $27.3 billion, up approximately $1.5 billion compared to the first quarter of 2025, and inventory turns were 4.2x down from 4.3 times last year. Turning to capital allocation, during the first quarter we invested approximately $845 million back into our business in the form of capital expenditures, and during the quarter we paid approximately $2.3 billion in dividends to our shareholders. Computed on the average of beginning and ending long term debt and equity for the trailing 12 months, return on invested capital is 25.4% down from 31.3% in the first quarter of fiscal 2025. Now I will comment on our outlook for fiscal 2026. As you heard from Ted, our performance during the first quarter was in line with our expectations. The underlying demand during the quarter was relatively similar to what we experienced throughout fiscal 2025. As a result, we are reaffirming our fiscal 2026 guidance. We expect to continue to grow our market share and for our comp sales to range between flat to 2% growth with total sales growth of between approximately 2.5% and 4.5%. Reflecting the contribution of the GMS acquisition., new stores, branches and tuck in acquisitions. For the year, we expect SRS to deliver mid single digit percent organic sales growth. We plan to open approximately 15 new stores and 40 to 50 new SRS locations. Our gross margin is expected to be approximately 33.1%. Further, we expect operating margin of approximately 12.4 to 12.6% and adjusted operating margin of approximately 12.8 to 13%. Our effective tax rate is targeted at approximately 24.3%. We expect net interest expense of approximately $2.3 billion. We expect our diluted earnings per share and adjusted diluted earnings per share to both increase Approximately flat to 4% compared to fiscal 2025. We plan to continue investing in our business with capital expenditures of approximately 2.5% of sales for fiscal 2026. We believe that we will continue to grow market share as a result of our competitive advantages and ongoing investments by delivering the best customer experience and home improvement. Thank you for your participation in today’s call. And Christine, we are now ready for questions.

Christine

Thank you. We will now be conducting a question and answer session. If you would like to ask a question, please press Star one on your telephone keypad. A confirmation tone will indicate your line …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks were lower, with the Nasdaq Composite falling over 1% on Tuesday.

Shares of Waystar Holding Corp (NASDAQ:WAY) rose sharply after the company announced a $200 million stock repurchase plan.

Waystar Holding shares jumped 7.8% to $20.04 on Tuesday.

Here are some other big stocks recording gains in today’s session.

  • Agilysys Inc (NASDAQ:AGYS) shares jumped 29.9% to $91.16 after the company reported better-than-expected fourth-quarter financial results and issued FY27 sales guidance above estimates.
  • Bakkt Inc (NYSE:BKKT) gained 18.5% to $10.34 after Securities and Exchange …

Full story available on Benzinga.com

This post was originally published here

The U.S. has a lot to lose if it fails to pass cryptocurrency market structure legislation and even more to gain if it does, Galaxy Digital (NASDAQ:GLXY) CEO Mike Novogratz says.

“Pass the Clarity Act,” Novogratz said in an X post on May 12. “This is how America wins.” 

Failure to pass the Clarity Act could push the cryptocurrency industry offshore to the detriment of U.S. users, he said. 

Don’t Miss:

Novogratz pointed to the spot volume dominance of Binance, an offshore exchange. He said Binance controlled 40% of volumes, while the U.S.’s largest exchange Coinbase Global Inc. (NASDAQ:COIN) only controlled 6% despite the U.S. driving the demand.

However, Novogratz said there was more at stake than the offshoring of the cryptocurrency industry. The Clarity Act will encourage tokenization, allowing billions of people to invest in U.S. equities and treasuries, he said, framing it as a means of power projection.

Novogratz particularly called on Senate Democrats to throw their weight behind the Clarity Act, warning that they risked losing votes from key demographics such as young men, blacks and Latinos. Democratic lawmakers have been reluctant to support the bill amid ethical concerns over President Donald Trump‘s ties to the cryptocurrency industry.

Trending: Real estate, crypto, private deals, and more—see why investors are turning to self-directed IRAs through IRA Financial

Novogratz’s remarks came before the Senate Banking Committee on May 14  voted 15-9 largely along party lines to advance the bill to the full Senate. 

“A real moment for American competitiveness,” Novogratz said in an X post following the vote, lauding Sens. Ruben Gallego (D-AZ) and Angela Alsobrooks (D-MD) for crossing party lines to vote to advance the bill.

Read Next: 

Building Wealth Across More Than Just the Market

Building a resilient portfolio means thinking beyond a single asset or market trend. Economic cycles shift, sectors rise and fall, and no one investment performs well in every …

Full story available on Benzinga.com

This post was originally published here

Strategy Inc. (NASDAQ:MSTR) is down to $165 even as TD Cowen raised its price target to $400 from $395, citing faster Bitcoin (CRYPTO: BTC) accumulation and a $1.5 billion accretive repurchase of convertible notes.

Strategy Already Exceeded Q2 Bitcoin Purchase Forecast

Strategy has already acquired more Bitcoin partway through Q2 than TD Cowen had modeled for the entire quarter. 

The firm now forecasts roughly 100,000 BTC purchased in Q2 alone, lifting full-year BTC Yield projections to 19.8% from 18.2%.

Preferred equity issuance has dominated capital raises in Q2 with roughly $1.95 billion raised versus minimal common equity issuance. 

Nearly all proceeds have been deployed directly into Bitcoin purchases.

Bitcoin per 1,000 fully diluted shares reached 2.21x as of May 17, up from 1.95x at the end of 2025. TD Cowen called the trajectory a …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Guggenheim analyst Curry Baker upgraded Stubhub Holdings, Inc (NYSE:STUB) from Neutral to Buy and raised the price target from $8.5 to $12.5. Stubhub shares closed at $9.33 on Monday. See how other analysts view this stock.
  • Canaccord Genuity analyst Richard Close upgraded Progyny, Inc (NASDAQ:PGNY) from …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades and downgrades, please see our analyst ratings page.

  • Guggenheim cut the price target for Elastic N.V. (NYSE:ESTC) from $116 to $106. Guggenheim analyst Howard Ma maintained a Buy rating. Elastic shares closed at $53.92 on Monday. See how other analysts view this stock.
  • Morgan Stanley raised Harley-Davidson, Inc. (NYSE:HOG) price target from $12 to $15. Morgan Stanley analyst Adam Jonas maintained an Underweight rating. Harley-Davidson shares closed at $24.34 on Monday. See how other analysts view this stock.
  • Cantor Fitzgerald cut price target for Home BancShares, Inc. (NYSE:HOMB) from $31 to $30. Cantor Fitzgerald analyst Dave Rochester maintained a Neutral rating. Home BancShares shares closed at $26.12 on Monday. See how other analysts view this stock.
  • Scotiabank raised the …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • BMO Capital analyst Michael Zaremski downgraded Hanover Insurance Group Inc (NYSE:THG) from Outperform to Market Perform and raised the price target from $194 to $203. Hanover Insurance shares closed at $197.54 on Monday. See how other analysts view this …

Full story available on Benzinga.com

This post was originally published here

Eagle Point Credit Co (NYSE:ECC) reported first-quarter financial results on Tuesday. The transcript from the company’s first-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://viavid.webcasts.com/starthere.jsp?ei=1728964&tp_key=1d134257ee&_gl=1aq481u_gaMTMxNDgyNDUzLjE3Nzg2NzY1MDc._ga_EB1RC3REG8*czE3Nzg2NzY1MDckbzEkZzEkdDE3Nzg2NzY1MjUkajQyJGwwJGgw

Summary

Eagle Point Credit Co reported a challenging first quarter in 2026, with a decline in NAV by 26.8% due to volatile loan prices and market conditions impacted by geopolitical issues.

The company deployed $100 million into new investments, achieving a weighted average effective yield of 18.9%, and emphasized opportunities from discounted loans despite short-term market pressures.

Eagle Point Credit Co announced a NAV rebound in April, increasing by nearly 9%, and maintained its quarterly distribution at $0.06 per share, reflecting confidence in its long-term earnings potential and strategic positioning.

Management highlighted the strategic focus on diversifying beyond CLO equity into infrastructure credit and other structured investments, aiming to enhance income and improve portfolio diversification.

The company’s effective yield on CLO equity based on fair value is significantly higher at 26.3% compared to amortized cost, indicating potential for higher future returns.

Full Transcript

OPERATOR

Greetings and welcome to the Eagle Point Credit Company first quarter 2026 financial results call. At this time, all participants are in a listen only mode. A question and answer session will follow the formal presentation. If anyone should require operator assistance during the conference, please press Star0 on your telephone keypad. As a reminder, this conference is being recorded. I would now like to turn the conference over to your host, Darren Daugherty with Prospect Partners today. Thank you. Please begin.

Darren Daugherty (Moderator)

Thank you Operator and good morning. Welcome to Eagle Point Credit Company’s earnings conference call for the first quarter of 2026. Speaking on the call today are Thomas Majewski, Chief Executive Officer and Ken Inorio, Chief Financial Officer and Chief Operating Officer. Before we begin, I would like to remind everyone that the matters discussed on this call include forward looking statements or projected financial information that involve risks and uncertainties that may cause the Company’s actual results to differ materially from such projections. For further information on factors that could impact the company and the statements and projections contained herein, please refer to the Company’s filings with the Securities and Exchange Commission. Each forward looking statement or projection of financial information made during this call is based on the information available to us as of the date of this call. We disclaim any obligation to update our forward looking statements unless required by law. Earlier today we filed our first quarter 2026 financial statements and investor presentation with the Securities and Exchange Commission. These are also available in the Investor Relations section of the company’s website, eaglepointcreditcompany.com. A replay of this call will be made available later today. I will now turn the call over to Thomas Majewski, Chief Executive Officer of Eagle Point Credit Company.

Thomas Majewski (Chief Executive Officer)

Tom Thanks, Darren. Good morning everyone. We’re glad you’re joining us today on Eagle Point Credit Company’s quarterly call. I’ll start by providing some perspectives on the recent quarter. CLO Equity faced challenging market conditions in the first quarter of 2026 and the company was not immune to those broader dynamics. While CLO fundamentals remain relatively stable, a decline in loan prices, especially in the software sector, and a cautious tone in the credit markets broadly due to the ongoing war in Iran, weighed on our financial performance during the quarter. The software sector was particularly an area of focus during the quarter as investors continued to assess the potential impact of AI on certain business models and revenue streams. Importantly, however, our exposure is principally through broadly syndicated loans, not middle market lending that’s commonly found in BDCs. The loans in our CLOs are typically larger, more liquid institutionally syndicated credits that have observable market pricing which can result in more immediate mark to market volatility during sector specific pressure. ECC software exposure at quarter end stood at roughly 10.8%. While there’s not one definitive number, many market sources would say BDCs typically have software exposure in the mid 20% range. While the volatility in loan prices impacted our quarterly valuations, we believe it also created opportunities for many of our CLO collateral managers to reinvest pay downs and sale proceeds into discounted loans with attractive forward return potential. While these factors led to a decline in CLO equity valuations during the quarter, we believe the market typically undervalues the reinvestment option embedded in CLOs during times of dislocation. The ability to buy loans at material discounts to PAR has allowed CLOs equity to deliver attractive intermediate and long term returns following short term periods of volatility. During the quarter, we deployed $100 million into new investments at a weighted average effective yield of 18.9% as we took advantage of compelling relative value opportunities created by a particularly uncertain macro environment. Throughout the quarter, we continue to actively manage our CLO portfolio by completing four resets and three refinancings of our CLO equity positions, resulting in weighted average CLO debt cost savings of 43 basis points for those CLOs. In addition to lowering our debt costs, the reset positions extended their reinvestment periods to five years. Our portfolio’s weighted average remaining reinvestment period or WARP ended the quarter at 3.4 years. This is higher than the market average of 2.8 years and also higher than our year end level of 3.3 years. This reflects our continued focus on extending the reinvestment optionality in our CLO portfolio. We also continue to broaden ECC’s opportunity set across credit while CLO equity remains central to the company’s strategy. As we’ve mentioned on the prior call, we have selectively increased our exposure to complementary asset classes including infrastructure credit, regulatory capital, relief portfolio, debt securities, and certain other structured and specialty credit investments. These investments are sourced through dedicated teams across the EaglePoint platform and are designed to enhance income, improve diversification and capture attractive relative value beyond just traditional CLO equity. One recent example of this strategy in action is a directly originated infrastructure investment that we made in the fourth quarter of 2020. We were able to successfully realize this investment just four months later, crystallizing an attractive return. This outcome demonstrates our ability to originate and monetize differentiated credit opportunities outside of CLO Equity while still maintaining ECC’s income oriented investment focus. As of March 31, CLO Equity represented 67% of our portfolio while Other Credit Asset Classes represented 31%. The balance was held in cash. As of March 31, our NAV stood at $4.17, per share and this represents a decrease of 26.8% from $5.70 per share at year end. For the first quarter the company generated a GAAP return on equity of negative 20.2% and during the quarter we paid 42 cents per share in cash distributions to our common shareholders. That said, ECC’s portfolio rebounded sharply. In April, our NAV increased to between $4.49 and $4.59 per share, a nearly 9% increase at the midpoint. Last week we declared three monthly distributions of $0.06 per share for the third quarter of 2026. This is in line with our distributions for the second quarter. Our current distribution level is aligned with the Company’s near term earnings profile and reflects our focus on maintaining a sustainable distribution over time. Separately, as disclosed in our recent public filings, members of our adviser senior investment team purchased more than 167,000 shares of the company’s common stock during the first quarter, reflecting their confidence in the Company’s long term value and our view that the current trading levels do not fully reflect the intrinsic value of our stock. Subsequent to quarter end, we completed the full redemption of our ECCW and ECCX notes. With that, I’ll turn the call over to Ken to discuss the financial results in more detail.

Ken Inorio (Chief Financial Officer and Chief Operating Officer)

Thank you Tom and thanks everyone for joining us today. For the first quarter of 2026, the company recorded NII less realized losses from investments of 19 million or 14 cents per share. This compares to NII less realized losses from investments of negative $0.26 per share in the fourth …

Full story available on Benzinga.com

This post was originally published here

GeoVax Labs, Inc. (NASDAQ:GOVX) stock is pulling back in premarket trading on Tuesday after surging 79.67% to close sharply higher on Monday.

The stock is falling after the company announced a $3 million private placement of stock and warrants, fueling investor concerns about shareholder dilution. The sell-off also reflects profit-taking following the stock’s massive 80% rally in the previous session.

Private Placement Details

GeoVax Labs said Monday it priced a $3 million private placement financing with existing institutional investors. The deal includes about 2.03 million shares, or equivalents, along with Series A and Series B warrants tied to an additional 4.05 million shares, all with an …

Full story available on Benzinga.com

This post was originally published here

As SpaceX gears up for its IPO in June, an expert has voiced concerns about potential trading volatility amid the influence of founder and top boss Elon Musk.

University of Florida finance professor Jay Ritter told Forbes that an “Elon Musk effect” could significantly impact SpaceX’s valuation, driving heightened long-term volatility as stocks tied to Musk tend to swing more sharply than the broader market.

Tesla, Inc. (NASDAQ:TSLA) and SpaceX are expected to see divergent and volatile performance, according to Ritter. He noted Tesla faces competitive pressure from Chinese rivals, while SpaceX benefits from investor optimism around its cost-efficient satellite and cargo launch capabilities.

He also warned of “substantial downside potential” if SpaceX goes public at a valuation of $1.5 trillion or more, as Musk would receive shares that bestow more voting power on him than other shareholders.

Ritter warned that …

Full story available on Benzinga.com

This post was originally published here

Canaan (NASDAQ:CAN) reported first-quarter financial results on Tuesday. The transcript from the company’s first-quarter earnings call has been provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://edge.media-server.com/mmc/p/wyn2x8te/

Summary

Canaan reported Q1 2026 revenues of $62.7 million, aligning with guidance, despite a challenging market environment influenced by Bitcoin price declines and geopolitical uncertainties.

The company completed delivery and revenue recognition of a large North American order and expanded its mining business, maintaining positive cash flow even amidst low hash prices.

Canaan acquired a 49% stake in three mining sites in West Texas, leveraging low power costs, and is advancing R&D for its A16 series and next-gen products, focusing on energy plus computing infrastructure.

Operational highlights include a total installed hash rate increase to 11 exahash per second and maintaining a strong digital asset treasury with 1,808 Bitcoins and 3,952 Ethereum.

Management remains cautious for Q2, projecting revenues between $35 million and $45 million, emphasizing disciplined cost control, inventory management, and strategic focus on long-term energy and computing infrastructure growth.

Full Transcript

OPERATOR

Ladies and gentlemen, thank you for standing by and welcome to Canaan S first quarter 2026 earnings conference call. At this time, all participants are in a listen only mode. After the management prepared remarks, we will have a question and answer session. Please note that this event is being recorded now. I’d like to hand the conference over to your speaker today, Gwyn Lauber, Investor Relations for the company. Please go ahead, Gwyn.

Gwyn Lauber (Investor Relations)

Thank you. Operator. Hello everyone and welcome to our earnings conference call. Joining us today are Chairman and CEO Nangong Zhang and our Chief Financial Officer, Jin James Chang. Leo Wang, Vice President of Capital Markets and Corporate Development and Xi Zheng, Senior IR Manager will also be available during the question and answer session. Our CEO will start the call by providing an overview of the Company and performance highlights for the quarter. Our Chief Financial Officer will then provide details on the Company’s operating and financial results for the period before we open up the call for your questions. Before we begin, I would like to refer you to our Safe Harbor statement in our earnings press release. Today’s call will include forward looking statements. These statements include, but are not limited to, our outlook for the Company and statements that estimate or project future operating results and the performance of the Company. These statements speak only as of today and the Company assumes no obligation to revise any forward looking statements that may be made in today’s press release, call or webcast. Except as required by law, these statements do not guarantee future performance and are subject to risks, uncertainties and assumptions. Please refer to the press release and the risk factors and documents we file with the securities and Exchange Commission, including our most recent Annual report on Form 20F, for information on risks, uncertainties and assumptions that may cause actual results to differ materially from those set forth in such statements. In addition, during today’s call, we will discuss both Generally Accepted Accounting Principles (GAAP) financial measures and certain non Generally Accepted Accounting Principles (GAAP) financial measures which we believe are useful as supplemental measures of the Company’s performance. These non Generally Accepted Accounting Principles (GAAP) measures should be considered in addition to, and not as a substitute for or in isolation from Generally Accepted Accounting Principles (GAAP) results. You can find additional disclosures regarding these non Generally Accepted Accounting Principles (GAAP) measures, including reconciliations with comparable Generally Accepted Accounting Principles (GAAP) results in our earnings press release which is posted on the Company’s website. With that, I will now turn the call over to our Chairman and CEO, Nangong Jiang. Angie, please go ahead.

Nangong Jiang

Thank you, Guy. Hello everyone, this is Nangong, CEO of Canaan. Thank you for joining our earnings conference call today. James, our CFO and I are here at our Singapore headquarters to share our financial results and recent business Updates for the first quarter of 2026 Q1 of 2026 was a very challenging quarter. Bitcoin prices dropped sharply from the height at the beginning of the year and the hash price fell to very low levels. As a result, miners around the world became much more cautious with their investment after entering the second quarter. The market saw some recovery, but the recovery has still been limited. At the same time, uncertainties related to the Middle east situation, energy prices, global liquidity and the policies continue to keep the industry in a cautious environment. For us, a company going through a transition period, this kind of environment created a lot of pressure. But today I want to focus less on the difficulties we faced and more on what we did during the difficult times. I believe investors want to see whether we have strong execution discipline, operations and ability to navigate through market cycles. In the first quarter we completed several concrete tasks. First, we completed the final stage of production delivery and revenue recognition for our large order from a leading North American customer while entering the market downturn with a relatively light inventory position. Second, we continued expanding our mining business which still generated positive cash contribution even under extremely low hash price conditions while further increasing our digital assets. Treasury. Third, we completed the acquisition of ABC projects through a share exchange transaction, obtaining a 49% equity interest in three energized and operating mining sites with low power costs in West Texas. Fourth, we continue to advancing the R&D of a 16 series and our next generation products to prepare for the next mining equipment update cycle. Fifth, we continue shifting the company’s strategic focus from a pure mining machine business towards energy plus computing infrastructure. Taking together, these actions show that during a difficult market environment, we did not simply wait for the market to recover. Instead, we actively strengthened our survivability, improved our asset quality and expanded our long term strategic options. In the quarter we generated total revenues of 6.2.7 million US dollars in line with our previous guidance range. As of the end of the quarter we held 1808 bitcoins and 3952 Ethereum and our digital asset treasury reached another record high in mining machine sales. Industry demand was clearly under pressure. In the first quarter we sold 4.1 xhash per second of computing power with an average selling price of about 10.5 per terahash US dollar generating US$42.9 million in revenue. Many customers delayed purchase due to low hash price and high market uncertainty, and the market pricing also came under pressure. In this environment, we did not pursue short term growth through aggressive inventory buildup or lower quality orders. Instead, we placed higher priority on inventory control, cash flow management and order quality. This also reflects the operating discipline we have emphasized over the past several quarters. In Q4 of 2025 we captured the market window and secured a large North American order. With most of the deliveries completed in the first quarter of this year, we completed the final stage of execution. Through this the successful completion of this project, we further strengthened our brand reputation and customer base in the North American market. Mining machine business may not be the hottest story in the capital market today, but it remains the foundation of Kenya. As long as the Bitcoin network continues to operate and low cost power resources continue to exist around the world, miners will continue to need machines that are more efficient, more reliable and easy to deploy. Our job is is to run the mining machine business with stronger discipline and stay closer to the real needs of our customers. In the fourth quarter we continued advancing customized products and the system level solutions. Recently we expanded our collaboration with Kaiser by providing customized high density dashboard modules for its next generation emergent mining and computing systems. This type of partnership shows that leading customers are shifting from purchasing single standard manners to seeking integrated systems that are modular, maintainable, upgradable and adaptable to different operating scenarios. For Canaan, this is exactly where our long term strengths in ASIC design, system engineering, supply chain management and the global delivery can create value. In addition, as we announced earlier today, we stored approximately 8 megawatts of hydro cooled equipment to Nordic heating service provider to produce high grade hot water for district heating systems. Projects like this show that mining machines are gradually expanding beyond pure mining use cases into broader energy utilization scenarios. The combination of computing power, heat recovery and the local energy infrastructure is also an area we will continue to explore going forward in the consumer and SMB market. The main focus of Avenue Home series in the first half year has been channel expansion, customer reach and service system. Since the beginning of this year our home products have entered platforms including Best Buy, Canada’s online channel and Amazon. The consumer market is very different from the industrial mining machine market. Customers are not only about heart rate but also about noise level, stability, product design, easy for installation and after the sales service. We are currently working on the product upgrades for several Avalon home models and hope to launch them in the second half this year. We hope that better products, stronger sales channels and the year and shopping season together can help this business line contribute to higher quality revenue. Now let me move to our mining business. The mining environment in the first quarter was also very challenging. In January during the weak winter storm across North America, we voluntarily powered down and hotel operations in the certain regions to prioritize electricity supply to local residents and the power grid. We want to be trusted and responsible partner with a flexible computing load for the grid rather than adding additional pressure to inferiority of greatest strength. More importantly, even under a low hash price environment, our mining business continue to show strong competitiveness. During the quarter we generated 257 bitcoins in total and recognized US$19.12 million in mining revenue. From a cash operating perspective, this business continued to contribute positive liquidity inflow to the company. By the end of the quarter our global installed hash rate reached 11x hash per second up 66% year over year and 11 quarter over quarter. Our operating base continue to expand while our power and hosting cost remained relatively competitive. In April, our non GV installed hash rate remained around 11xhash per second with an average OEM power cost of about 4.4 US cents per kilowatt hour. At the same time, the ABCGV program also add 4.82 extra hash per second of installed hash rate and 120 megawatts of installed power capacity. I believe these numbers show one important thing, the mining business still has value even during the low point of cycle. It helps us to accumulate BTC and help us better understand the real operational needs and the pain points of miners. More importantly, it helps us to build real power consumption and operational capabilities as we continue to advancing in energy and computing infrastructure in the future. The most important development this quarter was the ABC projects. In late February, we acquired 49% equity interest in Elbows Bear and the Chief Mountain projects in West Texas from Cypher through a share exchange transaction together with 6840 Avalon A15 Pro mining machines. The biggest advantage of the ABC projects is the highly competitive power cost which is below $0.03 US dollar per kilowatt hour. Because of this cost advantage, the products maintained strong profitability and high uptime even during period of bitcoin price volatility. Among the ABC projects, the Elbows site has successfully completed grid interconnection and now operates under a hybrid model combining behind the meter wind power and wind power, which significantly improved over uptime. We have also been working closely with our partner WINDHQ to steadily upgrade the mining fleets at the site. At the end of April, the project’s installed hash rate increased from about 4.4 exit head per second to 4.82 exit head per second. In addition, the GV project also has potential for future power load expansion and we are currently evaluating related opportunities. Overall, the ABC projects operate under hybrid mining power model combining wind power and grid electricity with a total installed capacity of 120megawatts and the power cost below US$0.03 US dollar for kilowatt hour. The projects currently have an installed hash rate of approximately 4.82 exhaust per second. We have maintained a strong long term relationship with Cypher over the past years. The completion of the ABC project transaction also reflects our ability to take take over high quality assets released during the during Cyprus business transaction. Based on our long standing cooperation, we believe high quality power resources and the infrastructure capabilities will become increasingly important competitive advanced advantages in the industry over the long term. The completion of ABC projects not only future strengthened our footprint in North American energy and infrastructure, but also represented an important step in advancing our long term energy plus computing infrastructure strategy. Following the transaction, Cypher also became that became an important shareholder of cana, laying the foundation for deeper cooperation between the two parties in the future. This project has three important meaning for us. First, these are low cost power assets that are already energized, already operating and already generating computing power. In today’s North American market, assets with real operations are much more valuable than pipeline opportunities on paper. Second project is concrete result for our energy strategy in future strengthens our access to low cost power resources, mining operation experience and the local partnership networks in the United States. Third, it also provides us with stronger infrastructure capabilities and greater strategic flexibilities as we continue to explore future AI and HPC opportunities regarding our energy pipeline. We have indeed made some meaningful and encouraging progress. However, at Responsible Public Company, we do not believe these developments have yet reached the disclosure milestones required for us to provide more specific detail publicly. So at this stage I cannot share too much additional information, but I can reform our strategic view. High quality power resources will become one of the most important barriers in future computing infrastructure. Our goal is to secure power infrastructure that is controllable, developable and operable in regions that …

Full story available on Benzinga.com

This post was originally published here

Driven Brands Hldgs (NASDAQ:DRVN) reported fourth-quarter financial results on Wednesday. The transcript from the company’s fourth-quarter earnings call has been provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://events.q4inc.com/attendee/173006571

Summary

Driven Brands Hldgs reported a comprehensive restatement of financials due to identified errors, impacting revenues and EBITDA across 2023-2025.

The company divested non-core businesses and reduced debt, achieving a net leverage ratio of 3.7 times by the end of 2025.

Revenue grew by 6.3% to $1.9 billion in 2025, with adjusted EBITDA of $449 million, despite restatement-related reductions.

Take 5 oil change continued its growth trajectory with same store sales growth and new store openings, maintaining strong operational performance.

For 2026, the company expects revenue between $1.95 to $2.05 billion and adjusted EBITDA of $430 to $460 million, with a focus on reducing net leverage to 3 times by year-end.

Management emphasized strengthening finance leadership, systems, and controls to prevent future errors, while maintaining a focus on core automotive services.

Full Transcript

OPERATOR

Hello everyone. Good day everyone and welcome to Driven Brands Hldgs fourth quarter 2025 earnings call. Please note that this call is being recorded. After the speaker’s prepared remarks, there will be a question and answer session. If you would like to ask a question during that time, please press STAR followed by one on your telephone keypad. Thank you. I’d now like to hand the call over to Steve Alexander. Please go ahead, sir.

Steve Alexander (Moderator)

Good morning. Welcome to Driven Brands Hldgs fourth quarter 2025 earnings conference call. The earnings release and net leverage ratio reconciliation are available for download on our websiteat investors.drivenbrands.com on the call with me today are Danny Rivera, President and Chief Executive Officer and Mike Diamond, Executive Vice President and Chief Financial Officer. In a moment, Danny and Mike will walk you through our financial and operating performance for the quarter and full year. Before we begin our remarks, I would like to remind you that management will refer to certain non Generally Accepted Accounting Principles (GAAP) financial measures. You can find the reconciliations to the most directly comparable Generally Accepted Accounting Principles (GAAP) financial measures on the company’s investors relations website and in its filings with the Securities and Exchange Commission. During this call we may also make forward looking statements regarding our current plans, beliefs and expectations. These statements are not guarantees of future performance and are subject to a number of risks and uncertainties and other factors that could cause actual results and events to differ materially from results and events contemplated by these forward looking statements. Please see our earnings release and our filings with the Securities and Exchange Commission’s for more information. Today’s prepared remarks will be followed by a question and answer session. We ask that you limit yourself to one question and one follow up if you have additional questions. You may re enter the queue after your initial questions are answered. Now with that, I’ll hand the call over to Danny.

Danny Rivera (President and Chief Executive Officer)

Good morning and thank you for joining us to discuss Driven Brands Hldgs fourth quarter and full year 2025 results. Before discussing our results, I want to directly address our recent restatement. I’d also like to thank our shareholders for their patience as we completed this work with the rigor and accuracy it required. There are four questions I’d like to address directly. What happens? What were the root causes, why these issues were identified now and what are we doing to help ensure this does not happen again? Beginning with what Happens? During our 2025 year end closing process, we identified three issues requiring further review related to lease accounting, Auto Glass Now cash accounting and expense mischaracterization with Driven Advantage Marketplace. Each related to prior periods. As we reviewed these matters further, we determined that there were material errors requiring the restatement of prior periods’ financial statements. We engaged our audit committee, external auditors and outside advisors to conduct a comprehensive review of our previously issued financial statements. From the outset, we established two guiding principles. We would prioritize accuracy and completeness over speed, and we would take a broad and disciplined approach, reviewing all relevant areas to reduce the risk of identifying additional issues in future periods. Consistent with that approach, our review identified additional items requiring adjustment. The result is a comprehensive restatement across multiple prior periods and financial statements designed to help establish a reliable financial foundation going forward. In a moment, Mike will walk through some of the specific adjustments in detail. At a high level, the impacts include revenue reductions of $12 million in 2023, $4 million in 2024 and $5 million in 2025, and a reduction in adjusted EBITDA of $57 million in 2023, $12 million in 2024 and $8 million in 2025. Turning to root causes, the majority of the issues trace back to 2023, 2022 and prior a period of significant acquisition and integration activity for the company. During that time, we expanded into two new verticals, car wash and glass, and launched a new digital solution for our Driven Advantage Marketplace. While the underlying issues are varied, they can be grouped into two primary drivers. First, the pace and complexity of growth outstripped the scale and maturity of of certain back office people, processes and controls. Second, as the business grew in scale and complexity, we recognized the need for a more integrated and scalable ERP (ERP) environment, which led to the decision in 2023 to consolidate multiple ERP (ERP)s to Oracle, with the system going live in mid 2024. Turning to why this was identified now, the answer is straightforward. We have strengthened both our team and our systems. Mike joined as the CFO in the third quarter of 2024 and strengthened the finance leadership team, including the appointment of a new Chief Accounting Officer and other key roles. He also assumed direct oversight of the then in progress Oracle implementation, helping operationalize the system and enhance the control environment. These improvements in both personnel and systems enabled us to identify issues that had previously not been accounted for properly. Lastly, what are we doing to help prevent this from happening again? First, as I’ve outlined, we have strengthened and will continue to invest in our finance leadership systems and processes. Second, once a restatement became necessary, we deliberately broadened the scope of our review beyond the initially identified issues. Our objective was to address all relevant matters now rather than risk identifying additional issues in future periods. Third, Driven Brands is a simpler, more focused company today since 2023 we have streamlined our portfolio including the divestitures of US Car Wash, International Car Wash and PH Vitra and we have completed the integration of Auto Glass. Now, during that time we have also not entered into any new verticals. As a result, Driven today is focused on core businesses that we know well and have operated for many years. This has been a challenging but important process and it has increased our confidence in the team and systems we now have in place. We identified the issues, restated the financial statements and are strengthening our controls. That foundation positions us well as we move forward with an improved and still improving financial and control foundation in place. Our focus now is on executing our strategy, delivering consistent performance and maximizing long term shareholder value. Now Turning to our 2025 results, 2025 was a foundational year for Driven Brands as we executed our growth and cash strategy. We simplified our portfolio by exiting non core businesses and sharpening our focus on non discretionary automotive services in North America. We also materially strengthened the balance sheet, paying down $545 million of debt and reducing net leverage to 3.7 times by year end. We continued to execute on this strategy in the first quarter of 2026, completing the sale of our international car wash business in January and using the proceeds to pay down more than $470 million of additional debt, bringing our pro forma net leverage to 3.3 times. Alongside these portfolio and balance sheet actions, we also executed with discipline across the business, delivering against our 2025 outlook. Collectively, these actions have positioned Driven Brands as a simpler, more predictable and higher cash flow business. For the full year. Revenue grew 6.3% to approximately $1.9 billion and we generated adjusted EBITDA of $449 million. System wide sales increased 2.7% supported by 175 net new stores while same store sales increased 1%. Driven Brands Hldgs today is a simpler, more focused company centered on non discretionary automotive services in North America that generates scalable growth and sustainable cash flow. A historical view reinforces the strength of our model. Since 2021, Take Five has grown revenue by $627 million, added 634 locations and grown EBITDA by 171% while expanding margins from 27% to 34% by the end of 2025. Over the same period, our franchise segment delivered a sales Compound Annual Growth Rate (CAGR) of 5.3% and expanded margins by over 1200 basis points, finishing 2025 with margins of 62.7%. Auto Glass Now provides another lever for future growth. Since entering the automotive glass market in 2022, we have scaled the business to become the second largest operator in the industry. Over time we see additional opportunities to expand through additional locations and increase market share across retail, commercial and insurance. Together, these businesses create a model designed to deliver sustained growth, strong cash generation and long term value creation. Turning to Take Five oil change home of the Stay in youn Car 10 minute oil change in 2025, Take Five achieved its 22nd consecutive quarter of same store sales growth while opening 161 net new stores. System wide sales grew 17%, same store sales grew 6% and adjusted EBITDA increased 10% with margins of 34%. Operational execution remains strong with Bay Times consistently under 12 minutes, net promoter scores in the high 70s premium mix up 300 basis points and ancillary attachment rates up 380 basis points. Looking ahead, we remain highly confident in Take Five’s long term Runway to more than 2,500 total locations supported by a strong development pipeline of approximately 900 sites. We continue to see outstanding engagement from our franchise partners with over 65% signing second or third area development agreements. This strong partnership gives us excellent visibility into unit growth in 2026 and beyond. Our franchise segment did exactly what it is designed to do generate robust, reliable cash flow with ebitda margins of 63% for the year. Auto Glass now also made solid progress in 2025. Revenue and EBITDA improved 9% and 105% year over year respectively with EBITDA margins improving 470 basis points while still in incubation. We are encouraged by the foundation that has been built and continue to see meaningful long term potential at Auto Glass. Now turning to 2026. Our priorities remain consistent disciplined execution, continued growth from take five, strong cash generation from the franchise segment and achieving our target of reducing net leverage to three times by year end. Mike will walk through the details but at a high level. We expect revenue of approximately 1.95 to $2.05 billion, approximately 430 to $460 million in adjusted EBITDA. Importantly, that includes approximately $35 to $45 million of restatement related non recurring costs and excludes international car wash. Same store sales growth in the range of flat to 2% and approximately 160 to 190 net new units. I’d like to close with a few key takeaways. 2025 was a foundational year for driven brands. We delivered on our business commitments, growth from Take five, strong cash generation from our franchise businesses portfolio simplification and meaningful deleveraging. We also addressed prior period accounting issues through a comprehensive restatement and we are implementing stronger financial controls, improved systems and a more disciplined financial foundation. Looking ahead, our focus remains firmly on executing our growth and cash strategy. We expect another year of strong growth led by Take Five and we’ll deploy the cash we generate to achieve our targeted three times net leverage by year end 2026. I want to thank our 7100 driven brands, team members and our franchise partners for their commitment and execution throughout 2025. Their focus on delighting our customers every day is what drives our results. With that, I’ll turn it over to my partner and Driven CFO Mike thank

Mike Diamond (Executive Vice President and Chief Financial Officer)

you Danny and good morning everyone. Today we are Reporting our fiscal Q4 and full year 202425 results and filing our restated financial statements for fiscal years 202423 and 2024. I’d like to start by echoing Danny and thanking our investors for their patience throughout this process. As Danny noted, once we identified a restatement was necessary, we initiated a comprehensive review of our historical accounts across our financial statements to identify and incorporate all necessary adjustments. Given the scope of that review and the fact that findings evolved as the work progressed, we we believed it would have been premature to provide interim updates that could later prove incomplete or inaccurate. The priority for the company and for our investors was to deliver financial information that is accurate, complete, and provides a solid foundation for the company to move forward. In April, once we had sufficient visibility, we provided preliminary unaudited results. Today we are filing our complete restated financials. With that, let me walk you through the primary Restatement topics and the actions we’ve taken to date. A common theme across many of these items was the need for additional accounting resources, particularly with an appropriate level of technical accounting knowledge and experience, including knowledge in establishing effective internal controls. We have already begun strengthening the organization through a combination of targeted hires and external support. As mentioned in our initial Form 8-K in late February, the restatement primarily impacts 202423 and prior periods and relates to the following areas Cash Cash and cash equivalents, as stated on our balance sheet were overstated dating back to 202422. A majority of this overstatement occurred at AGN in 202422 and 202423 and was the result of 12 acquisitions with different ERP systems during a time when our back office processes did not keep pace with our rapid expansion. It is important to note that there was no impact on actual cash leaving the company, but rather the reporting of cash balances on the balance sheet following our acquisitions with the correction of the historical balances, cash reported on the balance sheet now appropriately reflects cash in the business leases. Lease related right of use assets and right of use liabilities were understated dating back to at least 202423, primarily driven by incorrect lease details in our lease datab. As part of our year end close process, we undertook a thorough review of our existing leases and have been implementing process improvements to better monitor new and modified leases. Operating Expense Classification within operating expenses, certain costs were misclassified between company operated store expenses and supply and other expenses in 202423 and 202424. This correction did not impact total operating expenses, operating income, or segment level profitability period. Starting in 202425, we removed the intercompany upcharge that drove this initial misapplication. In addition to those three topics addressed in the February 8th K, our comprehensive management review identified two additional significant areas. Accounts Payable when we launched our new digital platform for Driven Advantage, our internal marketplace, in 202423, technology integrations between the new ordering platform and our prior ERP were not correctly established. This issue was largely addressed with the rollout of Oracle in mid 202424, but during this Restatement we identified incorrect manual journal entries that were made in 202423. The impact of these incorrect entries resulted in an understatement of accounts payable. Correcting this understatement increased COGS for take 5 in 202423. Accounts receivable as part of the Restatement process, we conducted a thorough retesting of our accounts receivable balances. As part of this retesting, we identified historical balances that should have been reserved for in 2023, duplicated AR amounts as part of our Oracle transition, and a misapplication of certain credit balances. Our quarter end processes now include a robust evaluation of reserve amounts and the operational steps necessary to collect outstanding balances. In addition to these items, we identified other adjustments that were quantitatively insignificant individually …

Full story available on Benzinga.com

This post was originally published here

HIVE Digital Technologies Ltd (NASDAQ:HIVE) shares traded lower during Tuesday’s premarket session after the company unveiled a major Canadian AI infrastructure expansion plan.

The crypto mining and high-performance computing company plans to build a large-scale AI data center hub near Toronto through its subsidiary, BUZZ High Performance Computing Inc.

The project includes a planned AI gigafactory capable of supporting more than 100,000 GPUs at full capacity.

The development marks one of Canada’s largest proposed AI infrastructure projects.

Ontario Expansion

BUZZ acquired roughly 25 acres across two adjacent parcels in the Greater Toronto Area. The company paid approximately CAD$58 million combined for the properties.

The site carries access to nearly 320 megawatts of utility power. Management expects the project to enter service during the second half of 2027.

The company estimated that the total investment could approach CAD$3.5 billion. …

Full story available on Benzinga.com

This post was originally published here

Elon Musk lost his lawsuit against Sam Altman and OpenAI on Monday in under two hours, removing the last major legal overhang before one of the most anticipated tech IPOs in years.

A federal jury in Oakland, California ruled that Musk’s claims were filed too late under the three-year statute of limitations.

The jury determined Musk knew about OpenAI’s pivot to a commercial structure years before he filed in 2024. Judge Yvonne Gonzalez Rogers adopted the verdict on the spot.

The Tesla Inc. (NASDAQ:TSLA) CEO took to X to call the ruling a “calendar technicality” and accused Altman and OpenAI President Greg Brockman of “stealing a charity.”

“The only question is WHEN they did it,” Musk wrote, vowing to file an appeal with the Ninth Circuit.

A Three-Week Trial That Got Personal

OpenAI’s lawyers framed the suit as a bitter competitor using the courts …

Full story available on Benzinga.com

This post was originally published here

HCW Biologics Inc. (NASDAQ:HCWB) stock traded lower on Tuesday. Investors are locking in profits following a massive 262% surge in the stock price during the previous week.

Despite the recent pullback, the biotechnology stock remains higher overall.

Retail Investors Take Profits

The primary driver behind Tuesday’s decline is profit-taking. Traders are capitalizing on recent exponential gains.

HCW Biologics shares previously fell in Monday’s session. This downward pressure continued into Tuesday.

Broader market sentiment also weighed on equities, as Nasdaq futures are down 0.75% while S&P 500 futures have shed 0.41%.

Strong Q1 Financial Results

The initial rally started after strong first-quarter financial results.

For the first quarter, HCW Biologics reported earnings per share of 37 cents. Quarterly sales reached $6.54 million, an increase from the $5,06 millions a …

Full story available on Benzinga.com

This post was originally published here

One financially overwhelmed borrower sparked a heated discussion online after revealing they were drowning in nearly $89,000 in credit card debt despite cutting what they described as every non-essential expense from their life.

Posting in the r/debtfree subreddit recently, the person said they currently have eight credit cards across multiple banks and are now reaching a point where they may no longer be able to make minimum payments.

Debt Spiral Leaves Them Feeling Overwhelmed

“I lost my job two years ago, and after I got back to work, my income dropped significantly to the point where I could only afford making minimum payments,” they wrote.

Don’t Miss:

The poster said their debt was originally around $40,000, but said another roughly $40,000 had been added over the past two years because of interest charges while they struggled to stay current.

“At this point, I’m really no longer able to keep up,” they said. “Starting this month, I may not even be able to make the minimum payments anymore.”

The poster also said they were worried about the possibility of lawsuits and wage garnishment in California.

As the conversation continued, they described a life stripped down to essentials.

“Most of my expenses are basic living costs at this point: mortgage, utilities, gas, insurance, groceries, and work-related expenses,” they wrote. “I’ve already cut almost everything nonessential. No vacations, no luxury spending, no expensive hobbies, and I canceled pretty much every subscription I had.”

Trending: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

They added that work travel makes transportation and food costs difficult to control and said they can no longer afford daycare for their child.

The poster also said their situation could improve in about a year once their cars are paid off and an expected raise kicks in.

“For now, my disposable income is 0, but it’ll be better in one year from now,” they wrote.

Commenters Question The Numbers

What surprised many commenters, however, was the poster’s income.

After several people asked for a clearer breakdown of finances, they revealed they bring in around $10,000 per month while expenses run about the same amount.

“Income $10,000 Expenses $10,100 sometimes $10,000,” the person said.

That revelation immediately shifted the tone of the discussion. While many commenters sympathized with the stress of carrying such large balances, others questioned how someone earning roughly $120,000 annually could still be unable to gain traction.

See Also: Turn your trading skills into real income — without risking your own capital: Get funded by Apex Trader Funding and keep up to 90% of the profits.

Some argued that the math around the debt growth didn’t fully add up. Others pointed out that minimum payments …

Full story available on Benzinga.com

This post was originally published here

Amer Sports (NYSE:AS) held its first-quarter earnings conference call on Tuesday. Below is the complete transcript from the call.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://events.q4inc.com/attendee/111352163

Summary

Amer Sports Inc reported a strong Q1 2026 with 32% sales growth and a 160 basis point expansion in adjusted operating margin.

The company saw double-digit revenue growth across all regions, driven by strong performances from brands like Salomon, Arc’teryx, and Wilson.

Future outlook is positive with raised guidance for 2026 revenue growth to 20-22% and increased EPS guidance, reflecting confidence in ongoing momentum.

Significant investments are being made in expanding retail presence, especially in Asia, and enhancing brand awareness and distribution for Salomon and Arc’teryx.

Management highlighted the strength of the women’s segment for Arc’teryx and the growing demand for Salomon’s outdoor sneakers, particularly in North America and Asia.

Full Transcript

OPERATOR

Hello everyone. Thank you for joining us and welcome to Amer Sports first quarter 2026 earnings call. After today’s prepared remarks, we will host a question and answer session. If you would like to ask a question, please press Star one to raise your hand. To withdraw your question, please press Star one again. I will now hand the conference over to Omar Saad, SVP of Investor Relations and Capital Markets. Omar, please go ahead.

Omar Saad (Senior Vice President of Investor Relations and Capital Markets)

Welcome everyone. Thanks for joining Amer Sports Earnings call for the first quarter of fiscal year 2026. Earlier this morning we announced our financial results for the quarter ended March 31, 2026 and the release can be found on our IR website, investors.amersports.com A quick reminder to everyone that today’s call will contain forward looking statements within the meaning of the federal securities laws. These forward looking statements reflect our current expectations and beliefs only. They are subject to certain risks and uncertainties that could cause actual results to differ materially. Please see the Safe harbor statement in our earnings release and SEC filings. We will also discuss certain non IFRS financial measures. Please refer to our earnings release for important information regarding such non IFRS financial measures, including reconciliations to the most comparable IFRS financial measures. We will begin with prepared remarks from our CEO James Zhang and CFO Andrew Page followed by a Q&A session until 9am Eastern. James will cover key operational and brand highlights. Then Andrew will provide a financial review at both the group and segment level and will also walk through our updated guidance. Arc’ Teryx CEO Stuart Hazelden and Salomon CEO Guillaume Mazank will join for the Q and A session. With that, I’ll turn the call over to James.

James Zhang (Chief Executive Officer)

Thanks Omar. Our excellent Momentum continued in Q1 as our unique portfolio of technical sports and outdoor brands are creating white space and taking share globally. All segments, geographies and channels performed extremely well in the quarter led by exceptional Solomon Softgate Growth, a strong Arc’teryx omnicon and solid Wilson 10360 growth and we delivered strong results across the PNL including 32% sales growth and 160 basis points of adjusted operating margin expansion. All four regions achieved solid double digit revenue growth and that strong momentum has continued in Q2. Looking forward. Given the continued broad based momentum across our portfolio and the talented and ambitious teams we have in place around the world, we are very confident in the future outlook for Amer Sports Group. Several factors give me that confidence. First, we own and operate a unique portfolio of premium innovation driven sports and outdoor brands. These brands are still only small to medium size with significant room to grow globally. Second, Arc’teryx is a breakout outdoor brand with leading growth and profitability for the industry driven by its disruptive direct to consumer model. Third, demand for Salomon’s unique outdoor sneak offering is infracting globally, but the brand still only has a small share of the very large global sneak market. Fourth, our Wilson and Winter Sport Equipment franchises have leading market positions which we believe will deliver slower long term growth except for Wilson Soft Goods which we believe is unique in the marketplace and has significant potential. And fifth, we believe we have a strong and differentiated platform in Great China and APAC where we continue to deliver best in class performance across across our portfolio. Before I turn over to Andrew, I will briefly recap key highlights from our three segments starting with technical apparel. Acteryx delivered another great quarter with broad based strength across regions, channels and categories including another exceptional performance from women’s strong momentum in the direct to consumer channel continued driven by a 19% omnichannel. We continue to envision Arc’teryx as a truly global brand with significant Runway in all major markets and we are encouraged that the brand is generating strong double digit growth across all four regions including notable acceleration in North America. Women’s momentum continued in Q1, growing faster than any other category for acalics. Our confidence in the women’s opportunity is rising as we are both 1 attracting new female consumers to the brand and 2 driving higher engagement and spend with existing female consumers. We really see brand affinity with women rising as we improve fit, style and function while building expanded assortments, leveraging our unique design advantage. Our decision to redesign core ABCG models for her while also expanding feminine club politics is working well. We also believe that success in bottoms with franchises like the Clarke, Lutea and the Nio Pant is also helping us unlock the female consumers. On the men’s side, we are excited to welcome a new Arcteric Men’s designer. Paxton Medicine joined us most recently from Mountain Hardware and North Face. Prior to that his leadership will be instrumental as we continue to push the boundaries of our men’s offering when it comes to solving problems for the mountain athletes with technical performance and the beautiful design. Footwear had another great quarter with strong growth across region led by both existing styles and the new launch. Popular existing styles included Norvan LD 4 Trail Shoe which has strong consumer affinity and is our biggest volume driver followed by the Cocoon hiking shoe and we launched the Silens 2 in Q1 which is a technical trail run racing shoe. Looking forward, we are confident Actaris has an exciting pipeline of shoe release for the upcoming years we are investing in our design capabilities and the commercial teams on the ground in the US and building a strong infrastructure for both direct to consumer and wholesale channels. Our Veilance sub brand also had a strong double digit growth in Q1. We expect 2026 to be a year of impact for the brand as we invest in units, further develop our collections and expand distribution, all of which is creating excitement and engagement in the marketplace. Security and rebirth continue to be at the heart of Acterys. In Q4 we increased the credit guests receive when they trade in use and terrace products and this continue to drive strong triple digit growth in trade in activities in North America. All bit off a small base. Our on mountain Academies remained a critical role in community engagement and the Mammoth Mountain Academy we hosted in February was again a great Success With With 22,000 attendees over the weekend and the 42 clinics hosted by Acteryx athletes, academies are becoming a key platform for ReBird, generating consumer awareness, interest and the ReBird sales peak performance. Our other technical apparel brand delivered solid growth in Q1. After the brand returned to growth in 2025, the turnaround remains on track so far in 2026 with sales increase across key channels and regions. The brand also continued to improve profitability driven by our concentrated efforts to reduce promotionals and increase food price setting, especially in the Nordic market. Moving to the outdoor performance segment which was led by another outstanding quarter from Solomon Sophkus, the investment we are making to grow Salomon brand awareness and the distribution footprint are paying off as Salomon footwear momentum is expanding across regions, channels and in both sports style and performance. We are also excited to share that we are seeing a clear acceleration in North America as we leverage rising brand awareness to expand distribution with both new and existing wholesale partners. We also saw solid performance from our winter sports equipment franchise which continue taking share despite challenging market conditions. As you know, Salomon footwear has become a very important growth engine not just for Salomon but for Amer Sports Group. We are excited to see a demand infraction for Salomon unique outdoor sneak offering, especially since the brand still only has a small share of the global sneaker market. I’d like to highlight a few factors that give us the confidence that Salomon is well positioned to achieve its growth potential and do it in the right way. Number one, global sports dive momentum continues. We believe Salomon is connecting with younger consumers and the female consumers in a way traditional outdoor brands haven’t. Sports style is critical to developing Salomon’s position as the modern outdoor snake brand including franchises such as XT-6 and XT-Whisper. Second, our performance and running lines are also working well. We continue to believe our new Grind Rolls franchise is helping to unlock the run category for Salomon like never before. Salomon is gaining traction in the Run Specialty Channel in North America and EMEA. Recent running launches include the slab Phantom 3, which is an ultra lightweight racing shoe engineered for elite performance as well as the Aero Glide 4 with Optivibe foam 2. Third is Salomon amazing Brank Kit in Great China, Asia where we believe we operate the most productive and profitable snake shops in this industry. Great China was Salomon’s fastest growing region in Q1 driven by both sports style and performance as well as strong growth in apparel. Saruman is also experiencing surging demand in Korea and Japan, both large sneak markets. Fourth, our epicenter strategy is working. Our strategy to open a handful of brand stores alongside strategically elevated wholesale distribution and in key metro markets around the world is critical to elevating Solomon’s presence and awareness. Our tier one global epicenter cities include Paris, London, Shanghai, Beijing, Tokyo, New York, LA. We have seen both rising brand awareness and accelerating revenue in our epicenter cities. Fifth is the strong pull demand we are seeing from consumers in Europe. Salomon’s home market driving strong reorder pre orders and sell through sports style continue to be the growth driver but we have also seen a real inflection in gravel in Europe supported by marketing campaigns in store events and running event activations. Also we are seeing high E com demand growth in Europe even as we expand our retail and wholesale footprint. Sixth is North America which is the largest sneak market in the world but is still a small business for us. In the US we are seeing a clear growth inflection driven by sports style and performance. Not only are we expanding our shelf space and sell through in existing wholesale partner doors but we are also now starting to move Salomon Footwear into key wholesale partner in the us. As you know there’s a strong demand for Salomon sneakers in the US but still very limited distribution for consumers to find our products moving to BO and the rackets highlights boy and the rackets closed 13% in Q1 driven by continued strength in soccers and racket sports. Our 10,360 products continue to resonate very well with consumers from performance rackets to tennis pearl and footwear. And the Wilson Soft Goods continued its exceptional trajectory with very strong growth across all three major regions. The Wilson brand is unique in its ability to outfit tennis athletes from head to toe including rackets and accessories. We are pleased to see an increasing number of the world’s top planet players wearing head to toe wears and kits at key events including Marta Kostier winning the Major Open and The Men’s Top 10 Player Alex de Mina at India awares in Q1 we launched version 10 of our iconic Braid racket. The launch of Braid has been well received in the markets across all channels with reorders from key customers coming in already. We are also seeing strong validation of the Braid B10 on tour with world number one Arena Sabrina who won India Wheels and the Miami Open playing with a bracket hour version of the new Braid before it was launched publicly. With that I will turn over to

Andrew Page (Chief Financial Officer)

Andrew Thanks James Q1 was a great start to the year with strong sales margin expansion and EPS growth. The investments we’ve been making behind our biggest opportunities are paying off in terms of both sales growth and margin expansion. Today we’re experiencing exceptional trends across each of our three biggest growth engines, Arc’teryx, Solomon Soft Goods and and Wilson Tennis 360, which are all still relatively small franchises with significant room to expand. Turning to our Q1 results, Amherst Sports grew sales 32% in Q1 on a reported basis or 26% ex currency. The strong group sales performance was led by Outdoor Performance and technical apparel. Ball and Racket also had impressive double digit sales growth by channel. The group continues to be driven by D2C which grew 45%, led by Salomon and Arc’. Teryx. At the group level, D2C represented approximately 50% of revenue in Q1. Wholesale grew 21%, led by Salomon. Growth was also very strong across all geographies. Regional growth was led by Asia Pacific which increased 53% and China which grew 45%. EMEA accelerated to 27% and the Americas grew 18% in Q1. As it relates to our EMEA region, I wanted to touch on the Middle east conflict which thus far has had relatively low impact on our business. The region represents less than 1% of our global sales and the impact on both consumer demand as well as our supply chain and logistics operation has been immaterial thus far. We recently renegotiated our annual shipping contracts and this has also been incorporated in our latest guidance. That said, we continue to closely monitor this rapidly evolving situation which could create some logistical and cost headwinds should the price of oil remain elevated longer term. Turning to profitability, adjusted Gross margin increased 200 basis points to 60% in Q1, primarily driven by favorable channel, geographic product and brand mix. Adjusted SG and A expenses as a Percentage of revenue increased 60 basis points and represented 43.2% of revenue in Q1. This is a better SGA rate than what was implied in our previous guidance as we were able to leverage the higher sales growth against fixed costs. SGA leverage in both technical apparel and outdoor performance was offset by deleverage in ball and racket due to ongoing investments in Wilson Tennis360 and higher corporate expenses led by strong gross margin expansion. We generated a 160 basis point increase in our adjusted operating margin from 15.8% last year to 17.4 in Q1. Corporate expenses was $52 million, up from $27 million in Q1 of last year, mostly related to higher IT personnel and deferred compensation expenses. D&A was $103 million, which includes $50 million of rou depreciation. Adjusted net finance cost in the quarter was $30 million, which comprised primarily of $25 million from interest expense, with the remaining $5 million driven mostly by FX losses associated with the revaluation and settlement of monetary balances in the quarter. Our adjusted income tax expense was $86 million, which equates to an adjusted effective tax rate of 28%. Adjusted net income in Q1 was $218 million compared to $148 million in the prior year. Adjusted diluted earnings per share was 38 cents compared to adjusted diluted earnings per share of 27 cents last year. Now turning to segment results, technical Apparel revenues increased 33% to $885 million led by Arc’ Teryx. Growth was fueled by 41% DTC expansion, including a 19% omnichannel. Technical apparel wholesale revenues grew 16% regionally. The technical apparel growth rate was led by Asia Pacific and Greater China, followed by accelerating growth in the Americas and emea. It gives us high confidence in the arc’ Teryx global growth trajectory that all regions continue to grow strong double digits stores continue to be …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks traded lower this morning, with the Dow Jones index falling more than 100 points on Tuesday.

Following the market opening Tuesday, the Dow traded down 0.34% to 49,516.86 while the NASDAQ dipped 0.41% to 25,982.67. The S&P 500 also fell, dropping, 0.30% to 7,380.67.

Leading and Lagging Sectors

Health care shares jumped by 0.6% on Tuesday.

In trading on Tuesday, materials stocks fell by 1.8%.

Top Headline

The Home Depot Inc. (NYSE:HD) on Tuesday reported upbeat earnings for the first quarter on Tuesday.

The company posted first-quarter sales of $41.77 billion, up 4.8% year over year and above analyst estimates of $41.53 billion. Adjusted diluted EPS fell to $3.43 from $3.56 but beat analyst estimates of $3.41.

Equities Trading UP
           

  • Amesite Inc (NASDAQ:AMST) shares shot up …

Full story available on Benzinga.com

This post was originally published here

TORONTO, May 19, 2026 /CNW/ – Dynamic today announced the May 2026 cash distributions for the Dynamic Active ETFs and ETF series units of certain Dynamic Funds (ETF Series) listed on the TSX, which pay on a monthly basis. Unitholders of record on May 26, 2026, will receive cash distributions for the respective Dynamic Active ETFs and ETF Series payable on May 29, 2026. The details of the cash distribution amounts per unit are as follows:

Dynamic Active ETF and ETF Series

Ticker symbol

Cash distribution per unit ($)

Distribution frequency

Dynamic Active Bond ETF

DXBB

0.070

Monthly

Dynamic Active Canadian Bond ETF

DXBC

0.056

Monthly

Dynamic Active Canadian Dividend ETF

Full story available on Benzinga.com

This post was originally published here

On Tuesday, ATRenew (NYSE:RERE) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://event.choruscall.com/mediaframe/webcast.html?webcastid=1ALqoqas

Summary

ATRenew reported strong financial performance in Q1 2026, with total net revenues reaching RMB 6.16 billion, a 32.4% year-over-year increase, driven by 1P broad tech revenue growth of 34.4%.

The company improved its profitability, with non-GAAP operating profit growing 70.2% year-over-year to RMB 190 million, and the non-GAAP operating profit margin expanding to 3.16%.

Strategic initiatives included strengthening the 1P-centric strategy, expanding face-to-face fulfillment services to 80%, and increasing compliant refurbishment revenue by 76.1% year-over-year.

ATRenew continued its partnership with JD.com to enhance trade-in solutions, achieving a 70% share in trade-in orders through the JD sourcing channel.

The company expanded its multi-category recycling services across 966 stores and plans further expansion to self-operated AHS stores and franchisees.

For Q2 2026, ATRenew anticipates total revenues between RMB 6.24 billion and RMB 6.34 billion, representing a 25% to 27% year-over-year increase.

Management highlighted ongoing efforts to optimize store locations, increase fulfillment capabilities, and leverage AI technologies for long-term efficiency gains.

Full Transcript

OPERATOR

Good morning and good evening ladies and gentlemen. Thank you for standing by and welcome to ATRenew Inc.’s first quarter 2026 earnings conference call. At this time, all participants are in a listen only mode. We will be hosting a question and answer session after management’s prepared remarks. Please note today’s event is being recorded. I will now turn the call over to the first speaker today, Ms. Jessie Jin, head of Investor Relations. Please go ahead, ma’am.

Jessie Jin (Head of Investor Relations)

Thank you. Hello everyone and welcome to ATRenew first quarter 2026 earnings conference call. Speaking first today is Terry Chen, our Founder, Chairman and CEO and he will be followed by Rex Chen, our CFO. After that, we will open the call to questions from the analysts. The first quarter 2026 financial results were released earlier today. The earnings press release and investor slides accompanying this call are now available at our IR website, ir.atrenew.com. There will also be a transcript following this call for your convenience. For today’s agenda, Kerry will share his thoughts on our quarterly performance and business strategy followed by Rex who will address the financial highlights. Both Kerry and Rex will participate during the Q and A session. Please note our safe harbor statements. Some of the information you will hear during our discussion today will consist of forward looking statements and I refer to you our safe harbor statements in the earnings press release. Any forward looking statements that management makes on this call are based on assumptions as of today and that ATRenew does not take any obligations to upgrade our assumptions on these statements. Also, this call includes discussions of certain non GAAP financial measures. Please refer to our earnings press release which contains a reconciliation of non GAAP measures to GAAP measures. Finally, please note that unless otherwise stated, all figures mentioned during this conference call are in RMB and all comparisons are on a year over year basis. Now I’d like to turn the call over to Kerry for business and strategy updates. Hello everyone and thank you for joining ATRenew’s first quarter 2026 earnings conference call. We are pleased to review our operating results and share our latest perspective regarding capability building in the second hand industry this year. At the beginning of the year we maintained and interrupted services during the Chinese New Year holiday, achieving a strong start and delivering accelerated overall growth. In the first quarter, total net revenues reached RMB 6.16 billion, representing an accelerated growth rate of 32.4%. This momentum was primarily driven by 1P product revenue which surged 34.4% year over year while 3P service revenue maintained a healthy 10.4% year over year growth rate. Profitability also improved. Non-GAAP operating profit grew 70.2% year over year to 190 million RMB while the non-GAAP operating profit margin expanded by 69 basis points to 3.16%. Amid overall revenue and scale expansion, we continue to advance our one PE centric strategy, strengthening our core foundation in the recycling and trading of secondhand consumer electronics to drive greater value for retail users. We optimized our 1P 2C ratio by securing firsthand supply sources and enhancing compliant refurbishment output. On the supply side, we capitalize on industry trends by prioritizing trade in scenarios that deliver superior user experiences while shifting more fulfillment to offline via two door services. In 2026 the government maintained strong support for trade ins and further advanced fiscal and financial coordination. Against this backdrop, AHS Recycle continues to work closely with JD.com to create industry leading trade in solutions providing a seamless one stop trading experience at highly competitive prices to meet diverse consumer needs. As a result, within the JD sourcing channel, trading orders outpaced overall growth with volume share further expanding year over year to about 70%. Throughout the recycling fulfillment process, we actively guide users towards face to face transactions in offline settings. In the first quarter we expanded beyond our network of 2,156 stores across major cities and scaled up our door to door service team to 2,248 professionals bringing our services directly to users doorsteps. This strategy has lifted our face to face fulfillment ratio to 80% fostering deeper connection and trust through AHS Recycle’s fulfillment capabilities and brand presence. Looking ahead to peak seasons like major promotional campaigns and flagship device launches, we will further implement flexible workflow solutions to enhance face to face fulfillment timeliness and user experience even during the busiest times. During the first quarter we leveraged our proprietary compliant refurbishment business to add depth to our supply chain. With compliant refurbished Product revenue increasing 76.1% year over year, our on demand refurbishment model was a standout performer growing by roughly 180% in revenue. Our compliant refurbishment capabilities allowed us to provide more quality secondhand devices directly to consumers. In terms of retail channels, we expanded across pipeline selection, our official website and new media channels which drove nearly 150% year over year growth in 1P 2C retail revenue from refurbished devices. March marked a significant breakthrough with monthly retail sales of compliant refurbished products topping 200 million RMB. As a result, 1P 2C accounted for 45.1% of our product revenue in the first quarter of 2026, rising 12.1 percentage points from 33% year on year and 3.4 percentage points from 41.7% quarter over quarter. This strategic pivot toward direct to consumer sales allows us to align our recycling prices with real time retail trends, ensuring we offer better recycling prices, maintain a strong price advantage and create greater value for end users. Regarding high quality products from older generations, specifically M3 and N4 models, we targeted differentiated demand for device generations in the international markets to drive compliant exports. This strategy allows us to steadily expand our global scale and unlock an additional over 4% gross profit margin. Turning to our 3G business, PJT Marketplace also delivered healthy and rapid growth in both scale and revenue, further reinforcing its position as industry infrastructure. As we onboarded more new users, we offered free shipping on the first three orders to those new users on PJT Marketplace. We are also replicating the operational capabilities PJT Marketplace has used in serving large clients and extending them to small and medium sized merchants. By streamlining platform processes, we have lowered the barrier to using the platform and improved both transaction efficiency and convenience, enabling small and medium sized merchants to sell their products at better prices. Leveraging TJT Marketplace robust supply chain capabilities. As the industry’s leading B2B platform, we deliver high quality supplies to those merchants while reaching fragmented markets through Douyin’s user base. By …

Full story available on Benzinga.com

This post was originally published here

Hesai Gr (NASDAQ:HSAI) reported first-quarter financial results on Tuesday. The transcript from the company’s first-quarter earnings call has been provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://edge.media-server.com/mmc/p/v322eo5z/

Summary

Hesai Gr announced a strategic partnership with Mercedes Benz for Level 3 autonomy, marking a significant milestone in their LiDAR technology leadership.

The company unveiled its new AI algorithm integrated spatial intelligence device, Cosmo, which aims to expand beyond LiDAR into physical AI, with early customer traction and potential for high margins.

Financially, Hesai Gr reported a 30% year-over-year revenue increase to RMB681 million in Q1 2026, with a strong outlook for the rest of the year, projecting further revenue growth and sustained profitability.

Full Transcript

Operator

Hello ladies and gentlemen. Thank you for standing by. Welcome to Hesai Group first quarter 2026 earnings conference call. At this time all participants are in listen only mode. Please note that today’s conference call is being recorded. I will now turn the call over to our first speaker today, Guanting Shi, the company’s Head of Capital Markets. Please go ahead.

Guanting Shi (Head of Capital Markets)

Thank you Operator hello everyone. Thank you for joining Hesai Group’s first quarter 2026 earnings conference call. Our earnings release is now available on our IR website at investor.hesaitech.com as well as via Newswire services. Today you will hear from our CEO Dr. David Lee who will provide an overview of our recent Updates. Next, our CFO, Mr. Andrew Pham will address our financial results before we open the call for questions. Before we continue, I refer you to the Safe harbor statement in our earnings press release which applies to this call as we will make forward looking statements. Please also note that the company will discuss non GAAP measures today which are more thoroughly explained and reconciled to the most comparable measures reported under GAAP in our earnings release and SEC filings. With that, I’m pleased to turn over the call to our CEO, Dr. David Lee. David, please go ahead.

David Lee

Thank you Yuenting and thank you everyone. Today we are incredibly honored and excited to announce that Hesai serves as strategic LIDAR partner and confirmed supplier for Mercedes Benz models enabling level three autonomy. We see this as a major milestone, not only a strong validation of our technology leadership, but also a clear signal that LiDAR is moving to core infrastructure in the global evolution of intelligent driving. More importantly, I am thrilled to announce that HESAI has officially entered a new era of growth and possibility. 2026 marks a transformative chapter for us as we initiate a strategic paradigm shift evolving from spatial perception to spatial intelligence. Beyond our LiDAR business, we are actively forging the eyes and muscles of physical AI. This evolution underscores what has always been at the core of Hesai’s DNA a deep tech enterprise that leverages hardcore technological innovation and and sustained R and D intensity to deliver the world’s most cutting edge products, ultimately unlocking profound long term industry value. At our recent 2026 Tech Open Day, we unveiled several breakthrough innovations that we believe will redefine the industry landscape. I will come back to these in more details later in my remarks. Before turning to the broader opportunities in physical AI, let me first walk through our LiDAR business highlights for the quarter. Last year we delivered a record 1.6 million LiDAR units. This year we expect our total shipments to approximately double, reaching between 3 to 3.5 million units. We are confident that this level of scale firmly reinforces our leadership position in the global LiDAR industry. The trend we highlighted before is only accelerating. LiDAR is fast becoming the invisible airbag deployed across vehicles at scale. This was clearly demonstrated at a recent Beijing auto show where Hesai LIDAR was featured in 56 vehicle models across 24 leading automotive brands, ranking number one in LiDAR presence across exhibited models at the show. Our LiDARs were deployed across the automotive ecosystem from leading brands such as Audi, Cadillac, Lotus, Li Auto, Xiaomi, byd, Leap Motor, Geely, Greatwell Motor, Chang’an An, Chery to autonomous driving leaders like Pony AI and We Ride. This broad adoption reflects our deep ecosystem penetration and the growing strength of the HESAI Insight effect. According to Yole Group, we ranked number one globally in long range ADAS LiDAR shipments with a 43% market share in 2025. Our leadership only strengthened in March 2026 when our China market share surged to 55% according to Ganji, roughly triple that of the second ranked player, marking our 14th consecutive month in the number one position. This momentum was fueled by our industry leading product portfolio with our flagship ATX continuing to scale across major platforms. In April 2026 we began SOP for the revamped version of ATX OEM. Demand remained exceptionally strong with backlog now exceeding 6 million units as level 2 scales. Level 3 is emerging as the next major growth driver for the LiDAR industry. As responsibility shifts from the driver to the automaker, vehicle safety requirements are rising rapidly, thriving architectures from typically one LiDAR per vehicle last year representing roughly US$200 of LiDAR content per car to three to six LiDARs in level three platform platforms, increasing content to about US$350 in entry level multi LiDAR setups and 500 to US$1,000 in more advanced configurations. We are well positioned for this transition with multi LiDAR design wins secured across leading OEMs such as Li Auto, Xiaomi and Chang’an. An. Notably, Li Auto officially commenced deliveries of its multi LiDAR model on May 15, 2026 marking the deployment of our FTX blind spot. LiDAR Level 3 is not just about more sensors. It fundamentally elevates the role of LIDAR from a passive backup to an active decision enabler in safety critical driving scenarios. To lead this shift we introduced Picasso, the world’s first 6D full color ultra sensitive SPAD SoC. It fuses RGB color and precise 3D geometry at the true chip level generating real time colorized point clouds. In plain terms, it enables systems to see and understand the world more like humans do and directly addresses the long standing LiDAR versus camera debate. For the first time, we are delivering a unified perception stack in a single chip, bringing both worlds together and taking a real leap in how machines perceive and understand the physical world. For example, through native pixel level fusion of color and depth. Picasso equipped lidars help address challenging real world edge cases across intelligent systems, not only in autonomous driving but also in robotics and industrial applications such as distinguishing overlapping traffic lights at adjacent intersections or differentiating a yellow signal from sunlight. Scenarios where vision based systems can struggle. Powered by the Picaso platform, our flagship ETX LiDAR now supports up to 4320 channels and delivers a maximum 600 meter range enabling ultra high resolution full color 3D imaging with enhanced small object detection, ETX pushes safety margins to unprecedented heights. Commercial momentum is already building for this industry. First technology, we secured an exclusive design win with Cargobot for its phase two transport robots, deploying our 4320 channel ETX together with FTX blind spot lidars. This marks the first commercial vehicle contract for our 6D full color lidar. ETX is expected to enter mass production in the second half of 2026 across multiple flagship programs, with additional engagements actively progressing among both ADAS and robotics clients. Looking ahead, we see LiDAR expanding far beyond today’s boundaries, with many camera dominated applications naturally shifting toward lidar over time, positioning us for the next wave of physical AI. On the global side, we are incredibly honored and excited to announce that huisai serves as strategic LIDAR partner and confirmed supplier for Mercedes Benz models, enabling Level 3 autonomy. The new supply agreement supports Mercedes Benz programs in Europe and China with LiDAR production supported by HESIDE’s new Galileo manufacturing center in Thailand. In parallel, we continue to deepen our footprint with Chinese joint ventures as well as fast growing Chinese automakers expanding overseas. We have been selected for GAC Toyota’s 2026 BZ3X model, marking our first entry into the Japanese automotive E ecosystem. We have also secured new overseas design wins with Xiaomi, one of our largest customers with SOP expected to begin in 2027. Looking ahead, we see strong and sustained momentum driven by both global OEM partnerships and the continued international expansion of Chinese automakers. Together, these two forces are becoming the key structural growth drivers for HESAI in the years ahead. Beyond ADAS, robotics is emerging as an addressable market roughly 10 times larger. We are already a leader across key segments including humanoid and quadruped robots, robotaxis, robovans and robotic LawnMowers ranking number one according to GGII, Yole Group and Frost and Sullivan to share a few recent highlights in Humanoid Robotics, our JT128 LIDAR powered honors lightning robot to deliver a championship winning performance and break the human world record at the world’s first humanoid robot half marathon in Robovance. We secured an exclusive design win with Zelos for 200,000 LiDAR units and deepened our partnership with Neolix as its largest LiDAR supplier. We are also expanding into smart mobility with an FTX design win from New Technologies for Next Generation Electric two wheelers, a market with more than 60 million units sold annually in China. Having established ourselves as a global leader in 3D perception solutions, one thing is clear. Bringing AI into the physical world takes more than just LiDAR. That’s why we are taking our most exciting step yet, expanding from spatial perception to spatial intelligence. To build the uncompromised digital foundation for the physical AI era, we introduced Cosmo, an AI algorithm integrated spatial intelligence device. As physical AI accelerates, we believe richer, higher fidelity spatial data is becoming an increasingly scarce strategic resource, arguably even more critical than computing power itself. Cosmo is purpose built to break this bottleneck. Unlike traditional 3D reconstruction solutions that rely on bulky hardware and costly workflows, Cosmo combines Hesai’s ultra high precision LiDAR with proprietary 3DGs and AIGC algorithms to rapidly generate photorealistic production grade 3D environments at scale for a 200 square meter space. Cosmo requires only 1/5 the time of existing 3DGs solutions and roughly 1/50 the time of traditional methods with dramatically lower labor costs. More importantly, Cosmo is far beyond a hardware AI integrated product. It is the starting point of a scalable new business model combining hardware, AI software, spatial data and future platform services, creating recurring revenue streams, strong ecosystem effects and a durable long term moat. We believe Cosmo unlocks trillion RMB downstream opportunities across robotics, simulation and training, immersive media, 4D entertainment and beyond. Commercial traction is already building rapidly. We are actively engaging with a powerhouse roster of industry leaders spanning global pioneering embodied AI companies and top tier entertainment studios to market leading tech giants, AI driven industrial titans and global luxury brands. With some customers already having placed orders, we are incredibly excited about the long term growth potential ahead. Beyond Perception Bringing AI into the physical world also means enabling it to act, giving it the muscles to truly come to life. This leads to our next strategic pillar, Robotic actuation modules this is a natural extension of our systemic expertise in materials simulation, physical design and the manufacturing of delicate components. We also bring proven know how gained from millions of in house developed automotive grade motors and encoders deployed in our LiDAR products. Consider this a first glimpse an Easter egg. More exciting updates will follow in the nearest to wrap up Let me bring us back to the core theme today, our evolution from spatial perception to spatial intelligence. We are executing this across three clear dimensions. First, perceiving the world powered by our chip based LIDAR solutions, giving robots the eyes to see the physical world in high fidelity. Second, understanding the world with Cosmo and its ecosystem, transforming rich spatial data into actionable intelligence for real reasoning and decision making. Third, changing the world through our robotic actuation modules, the muscles that allow machines …

Full story available on Benzinga.com

This post was originally published here

Rep. Ritchie Torres (D-N.Y.) is preparing to introduce yet another prediction market bill, this one criminalizing the use of campaign funds to bet on platforms like Kalshi and Polymarket.

Axios reported on Tuesday that it is the latest in a string of more than a dozen prediction market bills introduced in Congress this year.

None has made meaningful progress, and the cumulative regulatory overhang now looms over Robinhood Markets (NASDAQ:HOOD), whose event contract revenue has become one of Wall Street’s fastest-growing line items.

The $147 Million Question

Robinhood reported $147 million in event contract revenue in the first quarter, up 320% year-over-year, with customers trading a record 8.8 billion contracts through its Kalshi-powered hub.

The brokerage and Kalshi split a two-cent fee per contract, and Robinhood has historically driven half of Kalshi’s total volume.

Its most recent 10-Q flags the …

Full story available on Benzinga.com

This post was originally published here

Many people dream about success, but far fewer are willing to accept the sacrifices that often come with it, according to “Shark Tank” investor Robert Herjavec.

In a recent video clip he shared on his YouTube channel, Herjavec reflected on the extreme work habits he adopted in his 20s while trying to build a better life for himself. Herjavec said the “price” of success changes throughout life, but when he was younger, that price was almost no sleep.

The Price Of Success Changes Over Time

“I think everybody wants to be successful, but very few people are willing to pay the price,” Herjavec said. “When I was 20, you know what that price was? Two to three hours of sleep.”

Don’t Miss:

He pushed back on the idea that successful people are somehow naturally wired to handle exhaustion better than everyone else.

“People would say to me, ‘Oh my god, you’re so lucky. You can function on two to three hours of sleep and you never get tired,’” Herjavec said. “And I’d be like, ‘Are you freaking kidding me? I’m tired all the time, but I would much rather be tired than poor.’”

During a 2025 appearance at Grant Cardone‘s 10X Growth Conference, Herjavec said people often misunderstand success because they only see the finished result.

“People come to me and they say, ‘Oh my gosh, it must be great to be you, it must be great to be successful,’ as though there’s this magic door you walk through,” he said.

Instead, he argued that success is built slowly through years of small improvements.

“People always overestimate what they can do in one year and underestimate what they can achieve in 10,” Herjavec said. “You can change your life forever in 10 years.”

Trending: What If Your Investment Income Didn’t Rely Entirely on Market Swings? Some Investors Are Taking a Different Approach

From Immigrant Struggles To Billion-Dollar Businesses

Herjavec also reflected on his upbringing after his family fled communist Yugoslavia. He said his father was jailed 22 times for criticizing communism before eventually escaping with the family and immigrating to Canada with just one suitcase.

That experience, Herjavec said, shaped how he views work, ambition and personal responsibility.

“My parents came to this country, gave up everything to give me a better life,” he said. “So what am I going to do? I’m going to party? I’m going to freaking hang out?”

Over the years, Herjavec built multiple technology and cybersecurity companies, including businesses later sold to Nokia (NYSE:NOK) and AT&T Canada. 

Even after decades of success, Herjavec said discipline still matters most during difficult periods.

“Success is doing it on the days where you …

Full story available on Benzinga.com

This post was originally published here

Dye & Durham (TSX:DND) reported third-quarter financial results on Tuesday. The transcript from the company’s third-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://app.webinar.net/mEdXo9eoV9j

Summary

DND reported a revenue decline of 12.3% for Q3 fiscal 2026, attributed to market downturns and divestiture impacts, but noted growth in banking technology.

Adjusted EBITDA decreased by 19%, primarily due to revenue impacts and increased professional fees, although cost-saving measures helped stabilize margins.

The company is executing a transformation program focused on Product Innovation, Commercial Excellence, Operations, and Financial Discipline, with significant progress noted.

DND launched new legal technology platforms and secured significant contracts, demonstrating strong momentum in product innovation and customer engagement.

Management emphasized ongoing cost optimization efforts, including global operational streamlining and office footprint reduction, expected to realize $17-19 million in savings over two years.

Future guidance includes continued focus on product development, customer acquisition, and strategic cost management to drive long-term EBITDA growth.

Full Transcript

OPERATOR

Good morning. Welcome to The DND third quarter fiscal 2026 results conference call. All lines have been placed on mute to prevent background noise. With me on the call today are George Sivin, DND’s Chief Executive Officer, and Sandra Bell, DND’s Interim Chief Financial officer. DND’s Q3 fiscal 2026 earnings press release, Financial statements and MDA are available on SEDAR Plus. Please note that statements made during this call may include forward looking statements and information and future oriented financial information regarding DND and its business. Any disclosure regarding possible future events, conditions or results are based on information currently available to management and indicate management’s current expectation of future growth, results of operations, business performance, and business prospects and opportunities. Such statements are made as of the date hereof and DND assumes no obligation to update or revise them to reflect events, disclosures or circumstances except as required by applicable securities laws. Such statements involve significant risks and uncertainties and are not a guarantee of future performance or results. A number of these risks or uncertainties could cause results to differ materially from the results discussed today. Given these risks and uncertainties, one should not place undue reliance on these statements information. Please refer to the Forward Looking Statements section of our Public filings, including without limitation, our recently filed MDA and Earnings press Release for additional information. In particular, for additional details regarding DND’s Run Rate Cost savings expectations, please refer to the section titled update on Q3 2025 forward looking information and Run Rate Cost Savings in DND’s Q3 fiscal 2026 MD&A and DND’s press releases dated November 12, 2025, November 26, 2025 and May 19, 2026. In addition, certain financial results discussed on this call are non IFRS financial measures, namely Adjusted EBITDA and Segment Adjusted ebitda. These measures are not recognized measures under ifrs, do not have a standardized meaning prescribed by ifrs and are therefore unlikely to be comparable to similar measures presented by other companies. Please refer to the Non IFRS Measures section of our public filings. Included without limitation are recently filed MDA and Earnings Press release for additional information on the Company’s use of non IFRS measures, including the Company’s definitions of Adjusted EBITDA and Segment Adjusted EBITDA and the applicable reconciliation of Adjusted EBITDA and Segment Adjusted EBITDA to their most directly comparable IFRS measure. Please note that today’s call is dedicated strictly to reviewing DND’s financial results and operational milestones for the quarter. Because DNDs is currently engaged in an active, ongoing review of strategic alternatives. The company has determined it is prudent not to host a live Q and A session during today’s call. They appreciate the continued support and patience of investors, partners and customers as they focus on maximizing value for all.

OPERATOR

DND Stakeholders I’ll now turn the call over to George Sivin.

George Sivin (Chief Executive Officer)

Good morning everyone and thank you for joining us in Q3. We made meaningful progress in stabilizing the business. While our results continued to reflect market headwinds and normal seasonality adjusted EBITDA remained resilient, supported by the underlying durability of our revenue base and the operating expense savings we have begun to realize. Sandra Bell, our interim cfo, will review the quarter’s financial performance in more detail. Shortly before that, I want to update you on our continued execution of the transformation program we announced in February, which is built on four pillars Product Innovation, Commercial Excellence, World class

George Sivin (Chief Executive Officer)

Operations and Talent and Financial Discipline. We are seeing strong momentum across each pillar. Within the Product Innovation pillar, we officially launched Unity in British Columbia and customer uptake is validating our belief in the differentiated value it provides. Notably, we secured a half million dollar deal with a firm that selected Unity specifically for its national coverage, allowing us to support their offices across Canada. We continue to streamline and enhance our customer workflows through ecosystem integrations.

George Sivin (Chief Executive Officer)

We integrated TreeFort and FCT identity verification programs into Unity in Canada, reinforcing our commitment to security and integrity in the home buying process. We connected Stewart Title’s Indemnity Insurance with Unity in the UK and both volume and revenue through this integration continue to grow. We introduced anti money laundering and counterterrorism financing checks in Unity Search in Australia, helping customers manage compliance within their existing workflows. And we integrated our own ECOR and Unity Entity management solutions, providing clients with an end to end entity management and corporate filing workflow nationally backed by our long standing record as a government provider. Speaking of eCorp, we secured a four year contract extension with the Ontario Business Registry, a vote of confidence for our market leading search and filing solution in Canada. And last week we launched new global platforms for legal workflows and due diligence which I’ll speak about shortly within the Commercial Excellence pillar. Despite real estate market weakness impacting activity volume across our major markets, we saw momentum with new customer acquisition, customer win backs and and key client renewals. We have shifted from a retention only posture to a proactive acquisition motion in Canada. Additionally, we are seeing bundled packages leading to successful cross sell opportunities including a recent six figure PMS contract with an existing search client in the uk, long standing customer relationships are driving deal velocity …

Full story available on Benzinga.com

This post was originally published here

Bilibili (NASDAQ:BILI) held its first-quarter earnings conference call on Tuesday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://edge.media-server.com/mmc/p/zprk2zfn/

Summary

Bilibili reported a 7% year-over-year growth in total revenues to RMB 7.5 billion, with a gross profit up 9% and a gross margin of 37.1%.

The company achieved a 30% year-over-year increase in advertising revenue, driven by high user engagement and AI-integration efforts.

User engagement metrics were strong, with average daily time spent increasing by 11 minutes year over year and total user time spent rising 19%.

AI investments focused on enhancing video understanding, distribution, and creation, contributing to user growth and improved advertising efficiency.

Game revenues faced a 12% decline year-over-year, but new titles are in development, with positive feedback received from soft launches.

Bilibili maintained its strategy of long-term game operations, focusing on creating games that resonate with the younger generation.

The company completed a US dollar 200 million share repurchase program and is considering renewing it to enhance shareholder returns.

Management expressed confidence in continued growth, with a focus on leveraging AI to drive efficiencies and innovation across its businesses.

Full Transcript

Chen

15 million and MAUs increased to 376 million. Average daily time spent reached a new high of 119 minutes, up 11 minutes year over year, which led to a 19% surge in total user time spent. We see this level of engagement as a powerful engine for our commercial business. In the first quarter, we delivered robust advertising revenue growth of 30% year over year, further accelerating from 2025. Meanwhile, MPUs increased by 7% year over year to 34.4 million. As more users directly pay for content and services they truly care about. On our platform, this commercial momentum led to a strong financial performance. Total revenues grew 7% year over year to RMB 7.5 billion. Gross profit was up 9% year over year and gross margin reached 37.1%, marking our 15th consecutive quarter of margin expansion. Thanks to our top line growth and increased operating leverage, our operating profit was over 10 times what it was a year ago. On a non GAAP basis, net profit grew by 62% year over year, with our adjusted net profit margin expanding to 7.8%. To us, this set of results confirms a fundamental shift in user behavior. In a world full of quick hits, more users are choosing to spend more time on quality content. That is exactly what Bilibili stands for and it will continue to drive our growth. With our average user now around 26.5 years old, our cohort is starting to spend more and spend better. As their needs evolve, we are staying close to them, offering the products and experiences they care about most. The content ecosystem we have built remains our most durable asset. Today, we are using AI to make this ecosystem even more powerful. We are focusing our investments on three key how we understand videos, how we recommend them, and how we help creators build them. Ultimately, we are not just evolving with AI, we are using it to reinforce the very thing that makes Bilibili unique. Having said that, we remain very disciplined with our capital. Although AI requires an upfront investment, the returns in engagement and monetization are already tangible. At the same time, AI is driving meaningful efficiencies across our operations, which is directly supporting our margin expansion. By combining the heart of our community with the power of our technology, we are creating lasting value for our users and shareholders. With that, let me walk you through our core pillars of content community and commercialization. Starting with Content and Community as content options multiply, users are becoming even more selective. They are coming to Bilibili for high quality PUGV content and a unique community experience that they cannot find anywhere else. Across our content categories, ACG remains our Cultural anchor in the first quarter, watch time for games in Chinese anime grew 27% and 20% year over year respectively, proving our enduring appeal to the younger generation. Beyond our ACG legacy, knowledge based content, including AI related information grew 20% year over year as users turned to us for deeper insights. Music categories also saw robust growth with a 25% year over year increase in time spent largely driven by AIGC. Music consumption related categories kept rising with watch time for parenting and early education and outdoor related categories surging by more than 50% year over year. The breadth of our content library is only one part of the story. Our deeper competitive moat lies in the humanity of the community. Every month our users generate over 17 billion real human interactions. In an AI driven world, they are the most authentic human signals available. While high quality data is becoming a global scarcity, our hundreds of billions of organic interactions provide us with the gold standard for understanding true human preferences. This profound insight is what fuels our engagement and loyalty. In the first quarter, total user time spent rose 19% year over year and 291 million official members maintained an 80% 12 month retention rate. Meanwhile, we continue to see AI as an amplifier for our ecosystem’s flight. On the supply side, the unique creative spirit of our community has found new momentum through the AI powered tools that scale creativity across the platform. By lowering the barriers to entry and boosting productivity, we have seen a significant influx of creators in content. In Q1, the number of daily active creators and daily submissions grew by 6% and 19% year over year respectively. But this isn’t just a game of volume. With AI assisting the creative process, more talent is producing high quality breakout content right out of the gate. Our recent AI creation contest is a perfect example. We attracted the most talented creators to join our platform, creating nearly 150 breakout works with over a million views each. By deepening our comprehension of both content and user behavior, we’ve made content discovery more efficient, directly accelerating growth for our creators. In the first quarter, the number of creators with over 1,000 followers grew by more than 30% year over year and those with 10,000, 100,000 and 1 million or more followers each grew over 20%. Naturally, as their audiences grow, earnings follow. Average income per creator rose 24% this quarter, creating a powerful, virtuous cycle. Now let us take a closer look at our commercial businesses and their progress. First, our advertising business once again delivered standout results. In Q1, revenues grew 30% year over year, reaching RMB 2.6 billion. This ongoing acceleration reflects the value of our community that we continue to unlock and how we are turning user engagement into real results for advertisers. In Q1, our top five ad verticals were gains Internet Services, Digital products and home appliances, E commerce and automotive game ads delivered strong incremental revenue growth this quarter. In the Internet services sector, AI advertisers kept scaling with ad budgets surging over 170% year over year. At the same time, our maturing user base is also capturing more advertisers budgets. Ad revenues from digital products and home appliances and automotive both grew over 30% year over year. In Q1, home decoration was a particular standout with ad spending jumping more than 130% year over year. Using AI to improve efficiency and drive ad business is a core priority this year. By integrating AI more deeply into our algorithms, we’ve gained much sharper insights into user interests and long term patterns. This clarity has meaningfully optimized how we match users with ads, resulting in a 25% year over year increase in CTCVR of performance based ads this quarter. Furthermore, our AIGC tools are streamlining creative production and crafting ads that resonate with users, helping advertisers connect with our community more effectively and drive higher click through rates. We are also unlocking growth across diverse platforms and touchpoints. In the first quarter, ad revenues from PC and OTT platforms grew by over 50% year over year while new scenarios like search and mini programs more than doubled. We’re exploring new integrated formats within video player, finding new ways to turn user time into commercial value. With expanding traffic, diverse new scenarios and continuous efficiency gains, we remain confident in the sustained momentum of our ad business. Now turning to our games business. Game revenues were RMB 1.5 billion, down 12% year over year and flat quarter over quarter. The year over year decline was mainly due to the high base set by Sun Mo Din Tianxia in the same period last year, while the latest seasons of Sun Mo performed steadily quarter over quarter, we’re focused on the game’s long term life cycle, keeping the experience balanced and the IP strong. Meanwhile, our evergreen titles FGO and Azure Land remain stable and continue to provide a solid revenue base in 2026. We’re building on Sun Mo’s success and expanding our presence in the Three Kingdoms IP. In April we soft launched NCard, a lighter casual card game that has received positive feedback on its core gameplay. We’re iterating the product and optimizing user acquisition as we prepare for its official launch this July. Meanwhile, our new SLG title San Wanguozhi Wang Dao Tianxia began initial testing in late March. Built on the original IP with enhanced 3D visuals, Sanwang targets a differentiated group of SLG fans and complements Sun Mo. Early user feedback was encouraging and we plan to roll the game out late this year. Beyond End Card and Sanhwang, our self developed simulation game Lumi Master Shyoba Lumi Master entered its paid testing in May. It has been well received for its …

Full story available on Benzinga.com

This post was originally published here

Florida Governor Ron DeSantis (R-Fla.) has criticized Big Tech for its contradictory stance on AI automation and the continued use of H-1B visas for cheaper foreign labor.

On Monday, DeSantis took to X to express his disapproval of tech companies forecasting the demise of white-collar jobs due to AI automation, while simultaneously advocating for H-1B visas that bring in lower-cost foreign labor.

He stated, “Not hard to see why people view Big Tech unfavorably.”

The Trump ally made the remarks in response to a user questioning an article about Microsoft Corp. (NASDAQ:MSFT) automating white-collar jobs.

The CEO of Microsoft AI, Mustafa Suleyman, in an interview with the Financial Times in February, warned that AI could automate most white-collar computer-based jobs within 18 months, predicting human-level AI performance across …

Full story available on Benzinga.com

This post was originally published here

Eagle Materials (NYSE:EXP) reported fourth-quarter financial results on Tuesday. The transcript from the company’s fourth-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/gcxp6aar

Summary

Eagle Materials reported record revenue of $2.3 billion for fiscal 2026, with earnings per share of $13.16. The company returned over $400 million to shareholders.

Significant strategic investments include modernizing the Mountain Cement and Duke Oklahoma Wallboard plants, aimed at reducing costs, improving reliability, and expanding capacity.

The company is bullish on long-term structural tailwinds supporting their industries despite current demand being below peak levels. They expect to benefit from future demand increases due to their low-cost production advantages.

Cement volumes increased by 8% due to strong infrastructure spending and data center projects, while aggregate volumes reached a record 6.6 million tons.

The company has locked in energy costs for fiscal 2027, insulating it from near-term disruptions. Wallboard sales volumes are steady, with price increases expected in response to rising freight costs.

Eagle Materials strengthened its balance sheet by issuing $750 million in senior notes, improving liquidity and capital structure alignment with strategic investments.

Management remains focused on disciplined capital allocation, emphasizing strategic growth initiatives, asset maintenance, and shareholder returns.

Full Transcript

OPERATOR

Good day everyone and welcome to Eagle Materials fourth quarter and fiscal 2026 earnings conference call. This call is being recorded at this time. I would like to turn the call over to Eagle Materials’ President and Chief Executive Officer, Michael Hack. Mr. Hack, please go ahead.

Michael Hack (President and Chief Executive Officer)

Thank you Bailey and welcome everyone. Joining me today are Craig Kessler, our Chief Financial Officer, and Alex Haddock, Senior Vice President of Investor Relations, Strategy and Corporate Development. There will be a slide presentation made in connection with this call. To access it, Please go to eaglematerials.com and click on the link to the webcast. While you’re accessing the slides, please note that the first slide covers our cautionary disclosure regarding forward looking statements made during this call. These statements are subject to risks and uncertainties that could cause results to differ from those discussed during the call. For further information, please refer to this disclosure, which is also included at the end of our press release. Thanks for joining us today to discuss another year of solid execution at Eagle Materials. In fiscal 2026, during unusually high uncertainty in the economic environment, the Eagle team delivered strong financial and operational Results. For the fifth straight year we generated record revenue, delivering 2.3 billion of annual revenue and strong earnings per share of $13.16. We also returned over 400 million of cash to our shareholders. Eagle Materials has a long track record of consistently investing where it matters. Let me start with the safety of our people. For the past five years, our combined businesses have on average maintained a total recordable incident rate below the industry average. In fiscal 2026, we also increased our near miss hazard observations, the best leading indicator to prevent safety incidents, by 24%. With regards to ensuring the long term sustainability of our operations, we have completed or started several very strategic investments. The most notable are over the next 18 months, Eagle Materials will complete the modernization of one of our oldest cement plants, Mountain Cement and one of our oldest wallboard plants in Oklahoma. These projects show our continued focus on investing in our assets to keep them in like new condition. The Mountain Cement plant modernization is approximately 60% complete and we expect commissioning of the new Kiln Line to begin in late calendar 2026. Construction on the Duke Oklahoma wallboard plant is approximately 30% complete and we expect to commission the new wallboard line in the second half of calendar 2027. These investments will lower our cost structure, improve reliability and expand the capacity of each plant which will further increase production flexibility across our plant network and strengthen our already low cost competitive position. Another area of strategic investment has been in our quarries. The limestone gypsum and rock that we have at each quarry and their proximity to their plants is crucial for Egle’s success across all of our business lines. Controlling decades of our primary raw materials gives us a critical competitive advantage in terms of cost and consistent high quality supply. This is particularly important in periods of cost spikes and supply chain disruptions. It also enables us to maintain a consistent, high quality product that is reliable for our customers through decades. We have over 50 years on average of quarried reserves at each plant and we have maintained the 50 year average on a rolling basis through land investments. Turning to the macro level view of our businesses, we could easily get distracted by headline noise and the near term volatility and become overly focused on the potential knock on effects for short term product demand. However, we are disciplined in maintaining a through the cycle view. From that perspective, we are still fundamentally bullish on the structural tailwinds that will continue to support our industries for many cycles to come. Our products are essential for building and renewal of America’s infrastructure, schools, hospitals and homes to name some applications. Though demand for our core products is trending well below prior peak levels, the US population has grown significantly and the US infrastructure of existing homes are reaching record age levels. At the same time, there are no scalable or viable substitutes for our products and supply constraints across cement, wallboard and aggregates will constrain capacity additions in each industry over the medium to long run. We believe that when demand does strengthen, we are well positioned given our low cost production advantages and our ongoing investments to reinforce those advantages. In fact, we are seeing this play out for Eagle Materials even in the current choppy business environment. In the cement sector, infrastructure and cement intensive non residential construction applications are tightening several of our regional markets. Given the federal infrastructure spending still ahead for iija, the strength of state level infrastructure budgets and the data center projects positively affecting our entire footprint, the volume outlook for our heavy materials businesses remain favorable across our entire footprint. On the cost side of our cement businesses, we are relatively well insulated from energy cost disruptions in the near term as we already locked in our fiscal 2027 primary fuel costs last winter. On the wallboard side, as we’ve discussed, the near term housing outlook is still facing several affordability headwinds. Most notably, we need mortgage rate relief to encourage home inventory turnover which should translate into normalized view normalized new home construction activity. We have seen wallboard sales volumes hold steady from a historical perspective and most importantly, we have seen relative price stability that is not surprising to us given supply constraints and raw material challenges for the rest of the industry in both our cement and aggregates businesses where volumes are inflecting positively currently and in our wallboard business where in the midterm we believe the volume is poised to rebound as the home building market normalizes, there is significant Runway for earnings across our core business lines. We are well positioned to capitalize on that Runway. We have continuously invested in our businesses throughout the cycle to capture upside opportunities as they materialize. As Craig will discuss, we have strengthened our already healthy balance sheet which in combination with our excess free cash flow generation enables prudent, disciplined investments that further strengthen our competitive position. Our rigorous strategic and financial criteria mean we will be patient and ensure our inorganic and organic investments will reinforce consistent through the cycle growth. With that, I’ll turn it over to Craig.

Craig Kessler (Chief Financial Officer)

All right, thank you, Michael. Fiscal year 2026 revenue was a record $2.3 billion, up 2% from the prior year. Fourth quarter revenue was also up 2% to a record $479 million. Both increases were driven by higher cement sales volume and contribution from the two acquired aggregates businesses, which were partially offset by lower wallboard sales volume and prices. Annual earnings per share was $13.16, down 4%. The decrease reflects lower net earnings, which were mostly the result of lower wallboard sales volume and prices, offset by a 5% reduction in fully diluted shares due to our share buyback program. Turning now to segment performance highlighted on the next slide, in our heavy materials sector, which includes our cement and concrete and aggregate Segments, revenue increased 10%, driven primarily by an 8% increase in cement sales volume and a 19% increase in concrete and aggregates revenue. Aggregate sales volume reached a record 6.6 million tons, up 70% year over year, reflecting contributions from our acquired aggregates operations. Importantly, organic aggregate sales volume increased 24%, underscoring healthy underlying demand. Sales volume growth in both business lines was supported by continued strength in public infrastructure spending as well as key areas of private non residential construction activity such as data center development. Operating earnings also increased 10%, driven primarily by higher cement sales volume, partially offset by a 1% decline in net cement sales prices. Moving to the light materials sector on the next slide, annual revenue in the sector decreased 9% to $881 million, reflecting lower wallboard and recycled paperboard sales volume and a 4% decline in wallboard sales prices resulting from continued softness in residential construction. Operating earnings in the sector were down 15% to $331 million, primarily because of lower wallboard sales volume and prices. Looking now at our cash flow. We continue to generate strong cash flow and allocate capital in a disciplined manner consistent with our long term strategic priorities. During fiscal 2026, operating cash flow increased 12% to $614 million, reflecting the strength of our business and the resiliency of our operating model. Capital expenditures totaled $417 …

Full story available on Benzinga.com

This post was originally published here

On Tuesday, KE Holdings (NYSE:BEKE) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://edge.media-server.com/mmc/p/ryatk9km/

Summary

KE Holdings reported a significant increase in non-GAAP operating profit to 1.67 billion RMB for Q1 2026, marking a 45.1% year-over-year increase and 416.2% quarter-over-quarter rise.

The company is focusing on strategic initiatives to balance scale and efficiency, including technology-driven empowerment and refining debt operations.

Despite a year-over-year decline in revenue, operational efficiency improved, with non-GAAP net profit margin reaching a record high over the past seven quarters.

The company spent approximately $195 million on share repurchases, reflecting confidence in its sustainable development and commitment to shareholder returns.

KE Holdings experienced a decline in GDV and revenue due to a high base effect from the previous year but achieved improvements in contribution margins across key business lines.

The company emphasized strategic restructuring and AI-driven improvements to enhance decision-making capabilities in its service offerings.

Management highlighted significant progress in their home renovation and leasing businesses, focusing on improving underlying capabilities and profitability.

The company anticipates continued year-over-year margin improvements and emphasized the importance of long-term strategic planning over short-term gains.

Full Transcript

Xu Tao (Chief Financial Officer)

Translation is for convenience purposes only. In the case of any discrepancy, management statement in their original language will prevail. With that, I will now turn the call over to our CFO, Mr. Xu Tao. Please go ahead. Thank you. Hello everyone. Thank you for joining our Q1 2026 earnings call. First, let me summarize the financial highlights of the quarter. In Q1, our non-GAAP operating profit reached 1.67 billion RMB up 45.1% year over year and 416.2% quarter over quarter. Non GA operating margin stood at 8.8% of reaching the highest level in the past seven quarters. The optimization of our cost and expense structure in 2025 has been reflected in our operating profit in Q1 this year and we expect it to provide a long term positive support to our operating performance going forward. Guided about a strategic focus on balancing scale and efficiency, we have rolled out initiatives including Refining Debt Operation and Technology driven empowerment. In Q1, the contribution margin of all of our core business lines improved year on year, reflecting the translation of our cost structure optimization efforts in 2025 into our income statement. We believe this is structural improvement rather than a cyclical one. Even with a year on year decline in the revenue in Q1, our contribution margin continued to expand, validating the release of property. Meanwhile, our operational efficiency continued to improve. The absolute amount of R and D selling and administrative expenses all decreased both year on year and quarter of quarter, marking the effectiveness of our refined management and cost control measures. Driven by the simultaneous improvement in both gross margin and operating expense ratios on a year over year and quarter over quarter basis, we saw further release of operating leverage with the non-GAAP net profit margin hitting a record high for the past seven quarters. In addition, we continue to deliver on our commitments to shareholders. During the quarter we spent around US$195 million on share repurchases and increasing of about 40% year on year. This move not only represents ongoing returns to shareholders, but also underscores our firm confidence in the company’s sustainable and steady development over the medium to long term. Turning to our key financial metrics for Q1 due to the high base from the real estate market in the same period last year, the group’s GDV and revenue decline year over year GTV reached 711.2 billion RMB down 15.6 rent year over year. The revenue was 18.9 billion down 19% year over year. That said, we achieved a meaningful improvement in operating efficiency. The group’s Gross margin reached 24.1% up 3.5 percentage points Year over year driven by gross margin expansion and improved operating efficiency. Our net margin also increased year over year. In the first quarter GAAP net income was 1.26 billion RMB up 46.7% year over year while the non-GAAP net income was 1.61 billion RMB up 15.7% year over year. Now let me provide you some more details for our existing home transaction services Business scale declined year over year due to the high base in the same period last year while profitability continued to improve in Q1 GTV reached 534.4 billion RMB down 7.9% year over year and up 10.9% quarter over quarter. Revenue from existing home transaction services reached 6.1 billion RMB down 7.7% year over year and up 12.7% quarter over quarter. The GDV declined less than revenue year over year mainly because of the higher proportion of existing home transaction GTV facilitated by connected agents where revenue is recognized on a net basis at platform services fee. On a quarter over quarter basis. Revenue growth also from GDV mainly due to an improvement in land job commission ratess. In particular, platform Service revenue increased by 3.8 percentage over year and 12.5% quarter over quarter, outperforming the overall GDV and demonstrating resilience of our platform model. Despite the year over year decline in revenue scale, contribution margin for the existing home transaction services reached 41.3% at the highest level in the past seven quarters. It was up 3.2 percentage point year over year, mainly attributable to the decline in fixed labor costs driven by the optimization of lean agent and store scale as well as improved organizational efficiency. The contribution margin also increased by 0.9% points quarter over quarter mainly driven by the operating leverage from the revenue recovery in Q1 with fixed labor costs remain relatively stable for new home businesses. Business scale declined year over year due to high market base in the same period last year while profitability improved year over year. Q1 GDV reached 1 45.9 billion RMB downs 37.2% year over year and 29.5% quarter on quarter. New home business revenue was 5.1 billion, down 37% every year and 30% quarter over quarter. The year on year and quarter over quarter. GDV performance was largely consistent with revenue reflecting our stable monetization capability for the business segment even amid a significant fluctuation in scale Q1 contribution margin of a new home business was 25.7% up 2.3 percentage points year over year benefiting from cost structure optimization brought by refined operations. It fell 2.6 percentage points quarter over quarter mainly due to the high base cost by the one off factors in the previous quarter for home renovation and furnishing services, Q1 revenue reached 2.3 billion RMB down 20.6% year over year and 35.3% over quarter. The year on year and quarter over quarter revenue decline was due to our proactive exit from low quality and efficient customer acquisition channels as well as cities with poor UE models. The contribution margin of home renovation and furnishing business was 36.2% in Q1 up 3.6 percentage points year on year, mainly driven by material cost savings from our continued efforts in centralized purchasing and tenor based local procurement as well as labor cost savings from improved order assignment efficiency. On a quarter over quarter basis, contribution margin increased by 7.4 percentage points mainly due to material cost savings and low base effect from certain one off factors in previous quarter. For our home rental services, revenue in Q1 reached 5, representing a slight year over year decline of 1.5% and a quarter over quarter decline of 7.4%. The decline was mainly due to the continuing iteration of Tier 3 ran toward our lighter and lower risk product model with a higher proportion of the home units recognized on a net revenue basis which had a temporary impact on reported revenue scale. However, this doesn’t change the growth strategy. A Trajectory of our managed rental units and service capabilities. As of the end of Q1, the number of rental units under our management exceeded 740,000 units, representing an increase of around 47% year over year. Meanwhile, contributory margin for our home rental services business reached 14.8% in Q1, up 8.1 percentage point year over year and 4 percentage points quarter over quarter, marking the sixth consecutive quarter of sequential improvement. This was mainly attributable to two factors. First, proportion of products recognized on the net revenue basis which have higher contribution margins continue to increase. Second, labor cost per unit declined driven by productivity improvements enabled by AI and a more specialized vision of labor for emerging and other businesses. Net revenue in Q1 was $321 million down 8.1% year over year and 30% quarter over quarter. Now let me walk you through the specific key financial metrics for the quarter Q1 store costs were $571 million down 20.3% year over year and 19.6% quarter quarter, mainly benefiting from the rental cost optimization and store network adjustments for Lianjia Q1 gross profit decreased by 5.4% year over year to 4.6 billion RMB and decreased by 4.1% quarter over quarter. Gross margin was 24.1% up 3.5 percentage points year over year and 2.7 percentage points quarter over quarter. Gross margin expanded year over year driven by three factors. First, improvement in rental services contribution margin. Second, favorable mix toward the existing home transactions which carry a higher contribution margin. Third, improvement in existing home contribution margin sequentially. The expansion was mainly due to higher mix of existing home revenue and improvement in existing home contribution margin. Q1 Total GAAP operating expenses were 3.3 billion RMB, reaching the lowest level in nearly three years down 22.3% of year over year. This was mainly attributable to the operating leverage released from improved organizational efficiency, strength in the financial discipline and optimized marketing spending efficiency. Operating expenses decreased by 33% quarter over quarter partly due to the high base from one time expenses related to the organization efficiency improvement and resource allocation in the prior quarter. Specifically, general and Administrative expenses were 1.7 billion down 8.6% year over year mainly due to a decrease in share based compensation expenses on a quarter over quarter basis. GNA expenses decreased by 24% mainly due to the high base of one time expenses in the prior quarter and low expenses driven by the improvement organizational efficiency. Sales and marketing expenses were $1.1 billion down 39% over year mainly driven by the improvement organizational efficiency and more refined management of marketing and promotion expenses on a quarter over quarter basis. Sales and marketing expenses decreased by 43.9% mainly due to the seasonal factors and high base of one time expenses in the prior quarter. R and D expenses were 493 million down 15.6% mainly due to improved organizational efficiency and lower technical services fees on a quarter on quarter basis. R and D expenses decreased by 31.1% primarily due to the high base one time expenses in the prior quarter. Moving to our bottom line performance, our GAAP operating profit was 1.27 billion RMB in Q1 compared with a profit of 591 million RMB in Q1 2025 and a loss of 147 million RMB in Q4 2025. The operating margin was 6.7%, a year over year increase of 4.2 percentage points and a sequential uptick of 7.4 percentage points. Q1 non-GAAP income from operations totaled 1.86 billion increasing 45.1% year over year and 416% quarter over quarter. The non-GAAP operating margin was 8.8% a year over year increase of 3.9 percentage points mainly due to the increase in gross margin and a sequential increase of 7.4 percentage point mainly due to the decrease in the operating expense ratio and the increase in the gross margin. Finally, GAAP net income total at 1.26 billion in Q1 up 46 billion 1425% quarter to quarter. Non GAAP net income was $1.61 billion up 15.7% year over year and 211.5% quarter. In terms of cash flow and balance sheet, we recorded a net operating cash outflow of $1.5 billion in Q1. Our operating cash flow was lower than our profitable performance mainly due to the timing factors related to the payment of accrued employee composition from the previous year. Excluding the impact of this timing factor and our operating cash flow performance was broadly in line with our profitability. In Q1. The turnover date of accounts receivables for our new home business was 64 days, largely stable year over year and remaining at a healthy level. In addition, even after spending approximately US$195 million on share repurchases during this quarter, our broader cash balances excluding customer deposits remain at a promising 65.6 billion RMB. Supported by our solid cash reserves. We place great importance on …

Full story available on Benzinga.com

This post was originally published here

Jim Cramer is pouring cold water on AT&T Inc.‘s (NYSE:T) massive 5G network expansion, warning investors that emerging satellite networks from tech billionaires will easily outpace traditional telecom companies in rural markets.

The Threat From the Sky

During a recent episode of CNBC’s “Mad Money,” a caller pitched AT&T as a potential long-term play, citing the telecom giant‘s move to purchase roughly $23 billion worth of EchoStar’s nationwide spectrum.

The primary goal of the acquisition is to bridge coverage gaps, bolster the 5G network, and lock in rural customers. However, Cramer was quick to reject the stock entirely.

“I don’t want to be in AT&T,” Cramer stated. He pointed directly to the rapidly expanding satellite internet market, which is currently being pioneered by Elon Musk‘s SpaceX and Jeff Bezos‘s Amazon.com Inc. (NASDAQ:AMZN).

“I also am very concerned about rural. I’m very worried about Starlink,” Cramer explained. He emphasized that both Starlink and Amazon’s Low Earth Orbit (LEO) satellite internet initiatives are going to be “considerable competitors to the rural part of …

Full story available on Benzinga.com

This post was originally published here

Shares of Texas Instruments Inc. (NASDAQ:TXN) have surged over 70% in 2026, fueled by the artificial intelligence (AI) infrastructure boom. However, this rapid price appreciation has pushed the semiconductor giant into overvalued territory.

Valuation Stretches As Shares Cross $300

According to the latest Benzinga Edge Stock Rankings, TXN’s week-on-week value score tumbled from 10.67 to a bottom-tier 9.27, landing the stock in the bottom 10% among its peers.

This specific metric evaluates a stock’s relative worth by comparing its current market price against underlying fundamental measures like assets, earnings, sales, and operating performance.

Momentum Vs. Value

Despite the valuation warning signs, TXN continues to exhibit exceptional operational strength and price momentum.

The company boasts a good momentum score of 92.63 and a quality score of 92.51, reflecting sturdy technical health, operational efficiency, and a clear upward price trend across short, medium, and long-term horizons.

Benzinga Edge Stock Rankings for TXN.

data-variant=”card”
data-news-mode=”manual”

This post was originally published here

On CNBC’s “Halftime Report Final Trades,” Jason Snipe, founder and chief investment officer of Odyssey Capital Advisors, picked ServiceNow, Inc. (NYSE:NOW) as his final trade.

Supporting his view, Bank of America Securities analyst Tal Liani, on Monday, reinstated ServiceNow with a Buy and announced a $130 price target.

Don’t forget to check out our premarket coverage here.

Stephen Weiss, chief investment officer and managing partner of Short Hills Capital Partners, named Alibaba Group Holding Limited (NYSE:BABA).

On the earnings front, Alibaba reported mixed fiscal fourth-quarter 2026 results on May 13. The company reported quarterly …

Full story available on Benzinga.com

This post was originally published here

U.S. stock futures were lower this morning, with the Nasdaq futures falling around 200 points on Tuesday.

Shares of XP Inc (NASDAQ:XP) fell in pre-market trading after the company reported worse-than-expected first-quarter financial results. The company also named Gustavo Alejo Viviani as CFO starting Aug. 3.

XP reported quarterly earnings of 47 cents per share which missed the analyst consensus estimate of 48 cents per share. The company reported quarterly sales of $898.872 million which missed the analyst consensus estimate of $952.600 million.

XP shares dipped 3.1% to $16.80 in …

Full story available on Benzinga.com

This post was originally published here

(Editor’s note: The future prices of benchmark tracking ETFs and the headline were updated in the story.)

U.S. stock futures were lower as the Nasdaq 100 index fell on Tuesday following Monday’s mixed close.

Inflation fears gripped Wall Street as Ed Yardeni anticipated an imminent policy shift, noting that recent CPI and PPI data suggest the Fed is currently “behind the curve” on inflation. He expects the central bank to completely drop its easing stance and adopt a “tightening bias” at its upcoming June meeting, followed by a 25-basis-point rate hike in July.

Meanwhile, the 10-year Treasury bond yielded 4.60%, and the two-year bond was at 4.06%. The CME Group’s FedWatch tool‘s projections show markets pricing a 98.8% likelihood of the Federal Reserve leaving the current interest rates unchanged during June’s meeting.

Index Performance (+/-)
Dow Jones -0.02%
S&P 500 -0.13%
Nasdaq 100 -0.24%
Russell 2000 -0.09%

The SPDR S&P 500 ETF Trust (NYSE:SPY) and Invesco QQQ Trust ETF (NASDAQ:QQQ), which track the S&P 500 and Nasdaq 100, respectively, were lower in premarket on Tuesday. The SPY was down 0.45% at $735.36, while the QQQ was lower by 0.84% to $699.96.

data-variant=”banner”
data-news-mode=”manual”

>


Read Also:

Nvidia Is Still ‘Cheapest Name’ In Tech, Says Market Strategist: Q1 Earnings Will Make Your ‘Jaw Drop’

This post was originally published here

As of May 19, 2026, two stocks in the financial sector could be flashing a real warning to investors who value momentum as a key criteria in their trading decisions.

The RSI is a momentum indicator, which compares a stock’s strength on days when prices go up to its strength on days when prices go down. When compared to a stock’s price action, it can give traders a better sense of how a stock may perform in the short term. An asset is typically considered overbought when the RSI is above 70, according to Benzinga Pro.

Here’s the latest list of major overbought players in this sector.

CNO Financial Group Inc (NYSE:CNO)

  • On April 30, the company …

Full story available on Benzinga.com

This post was originally published here

ECARX Holdings (NASDAQ:ECX) released first-quarter financial results and hosted an earnings call on Tuesday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://edge.media-server.com/mmc/p/st42j89f/

Summary

ECARX Holdings reported a 6% year-over-year decrease in sales of goods revenue to $140 million, with gross profit reaching $28 million and a gross margin expansion to 21.4%.

The company is accelerating its globalization strategy, investing in R&D, and maintaining robust cost discipline to sustain profitability, achieving positive adjusted EBITDA of $4 million for the third consecutive quarter.

Notable strategic initiatives include a major milestone in autonomous driving with Main Mobility and continued global expansion efforts supported by significant equity and board appointments.

ECARX Holdings reiterated their full-year 2026 revenue guidance of $1 to $1.1 billion, reflecting confidence in their strategic trajectory despite challenges such as memory cost dynamics.

The company announced the debut of its Zenith computing platform, showcasing its commitment to innovation and leadership in the automotive intelligence sector.

Full Transcript

OPERATOR

Good day and thank you for standing by. Welcome to the ECARX Q1 2026 earnings conference call. At this time, all participants are in a listen only mode. After the speaker’s presentation, there will be a question and answer session. To ask a question during the session, you will need to press Star one and one on your telephone. You will then hear an automated message advising your hand is raised. To withdraw your question. Please press Star one and one again. Alternatively, you may submit your questions via the webcast. Please be advised that today’s conference is being recorded. I’d now like to hand the conference over to your first speaker today, Mark Hankinson, Head of Investor Relations. Please go ahead. Thank you.

Mark Hankinson (Head of Investor Relations)

Good morning and welcome to Ecarx’s first quarter 2026 earnings conference call. With me today from Ecarx are our founder and Chief Executive Officer Ziyu Shen, Chief Operating Officer Peter Serino and Chief Financial Officer Dylan Zheng. Following their prepared remarks, they will all be available to answer your questions. Before we start, I would like to refer you to our forward looking statements at the bottom of our earnings press release, which also applies to this call. Further information on specific risk factors that could cause actual results to differ materially can be found in our filings with the SEC. In addition, this call will include discussions of certain non-GAAP financial measures. A reconciliation of the non-GAAP financial measures to the GAAP financial measures can also be found at the bottom of our earnings release. With that, I’d like to hand over the call to our founder and Chief Executive Officer Ziyu Shen. Ziyu, please go ahead.

Ziyu Shen (Founder and Chief Executive Officer)

Thank you Mark Hello, everyone, and thank you for joining us today. The first quarter was defined by continued disciplined execution and continuing momentum in our global strategy. Our vision for ECARX remains clear. push the boundaries of automotive intelligence globally and lead the industry’s transition from feature centric to intelligence centric experiences. We are building the high performance computing platforms or intelligent brands, that power software defined vehicles. We are uniquely positioned to to capitalize on the growing global demand for higher value software and physical AI across automotive industry. We have made strong progress on our strategic objectives since the start of 2026, building upon the momentum we gained last year. Throughout the first quarter we executed relentlessly on our core priorities for the year. Accelerating our globalization strategy, investing in our R and D roadmap and optimizing our lean operating strategy to sustain profitability. First, on our global expansion, we continue to build out of our global footprint and governance structure underscored by significant equity and board appointments. Crucially the nearly 200 million US dollar in capital we raised later last year and early this year is now being actively deployed. This is fueling the build out of our R and D hub in Germany and our operational infrastructure across South America and in our office in Singapore. Second, the global expansion is being fueled by our commercial execution and continuous investment in our R and D roadmap. We continue to make solid progress driving further technical innovation and winning new business. A critical component of accelerating this innovation is our broader ecosystem of strategic partnerships. Third, we announced a major milestone in autonomous driving. ECRX expects to develop and deliver thousands of autonomous enabled vehicles for Main Mobility’s next generation Autonomy system. This marks ecarx first entry into the Robotaxi market, a market with significant global potential. Finally, we are maintaining robust cost discipline, reducing our operating costs to sustain profitability. Our results for the quarter demonstrate the disciplined execution driving this next phase of growth and how we are actively accelerating that transformation to build a truly global business. Our results for the quarter demonstrated this disciplined execution driving this next phase of growth. They demonstrate how we are actively accelerating that transformation to build a truly global business and sustain this momentum. While the first quarter is traditionally impacted by seasonality, the broad market also navigated micro headwinds including shifting government policies and memory component inflation. However, our strong project pipeline and the robust backlog allowed us to largely mitigate the impact of these dynamics. As a result, we delivered sales of goods revenue of 140 million US dollar noted a 6% decrease year over year. This demonstrates the underlying resilience of our core business. Crucially, our disciplined execution translated into meaningful profitability improvements. Overall gross profit was 28 million US dollar driving and expansion increased margin to 21.4%. We also significantly narrowed our operating loss to 13 million US dollar, nearly halving the 25 million US dollar loss reported in the same period last year. Perhaps most notably, we achieved positive adjust ebitda for the third straight quarter, delivering US$4 million compared to negative US$15 million in the same quarter last year. This robust performance allows us to confidently repeat our four year 2026 revenue guidance of 1 to 1.1 billion US dollar. This financial resilience is no accident. It is the direct result of the strategic framework we established later last year. Let me dive a bit deeper into how we are executing against these priorities. Starting with our global expansion, we remain focused on our target of 50% of total revenue from international markets by 2030. To drive the execution of this, we spent the first quarter actively fortifying our corporate governance and global Leadership team As ECARX rapidly scales, it is crucial that we adopt top tier global governance standards to match our expanding commercial footprint. Last month we appointed Loner Shark as our new Chairperson. This separates the roles of Chairperson and CEO to strengthen governance and align the global Best Practices Loner has extensive experience across automotive technology and finance sectors. This will be invaluable as we scale and accelerate the expansion of our Central Computing Cockpit and ADA solution across Europe, the Americas and Asia. I’m also pleased to officially welcome our new Chief Financial Officer, Dylan Zheng. Dylan joined us in March to drive global financial discipline from our newly operationalized Singapore office. Mark Hexen, who spoke at the start of this call, joined us as Head of Investor Relationships and Corporate Development and it’s based alongside myself and Peter in London. Commercially, our global partnerships continue to deepen. Each vehicle rolling of partner production lines demonstrates the repeatability and scalability of our solutions. This unique ability to scale across diverse brands and markets is perfectly demonstrated by our strategic relationship with Volkswagen Group in Latin America. Peter will speak more about this later. Today we are excited to announce a major milestone in autonomous driving through our Strategic Framework agreement with Main Mobility, a leading US based autonomous vehicle company. Under agreement, ECARTX is expected to develop and deliver thousands of autonomous enabled vehicles to Main Mobility. This will include customized central computing tables, a full stack autonomous driving system kit and a complete sensor suit for Main Mobility’s next generation autonomy system. This collaboration brings together ECAI’s deep expertise in Full Stack Intelligent Driving solution and Main Mobility industry leading autonomous driving system. It will allow us to leverage the best of …

Full story available on Benzinga.com

This post was originally published here

A 65-year-old investor nearing retirement sparked a thoughtful discussion after sharing concerns about balancing growth and safety with a $1.35 million portfolio.

The investor, who still earns about $75,000 annually and plans to retire at 67, said they were struggling with a question many near-retirees face: “How much risk is reasonable at this point?”

“My bigger concern is protecting my investments in case of a downturn while still earning enough growth to keep pace with inflation and prepare for future income,” the poster wrote on Reddit.

Don’t Miss:

Balancing Growth And Safety

The investor explained that the portfolio was spread across taxable brokerage accounts, Roth and traditional IRAs, a simplified employee pension plan and an inherited IRA. The allocation currently sits around 65% equities and 35% fixed income and cash.

The poster asked whether it made sense to become more conservative before retirement, keep extra money in money market funds or stay invested and ride out future market swings.

Many commenters said the investor was already in a solid position and cautioned against making dramatic portfolio changes.

“You only have two more years; whatever you do in the next two years won’t change the course of what you built in the last 40 years,” one commenter replied.

Trending: Grow your IRA or 401(k) with Crypto – unlock the power of alternative investments including a Crypto IRA within your retirement account.

Some pushed back on the idea of focusing too heavily on dividend investing for retirement income. One person said retirees should focus on “total return” instead of building portfolios entirely around dividend-paying stocks.

“Dividends aren’t bad, per se,” another person wrote. “They simply shouldn’t form the basis for how you invest.” 

Still, some retirees defended dividend-focused strategies because they provide emotional comfort during retirement.

“My working theory is that it will be hard for me to go broke if I only spend dividends and interest and never have to sell principal,” one retiree commented.

The thread eventually turned into a broader conversation about risk tolerance and what retirement investing is really meant to accomplish.

“As a retiree, your job is not to become as wealthy as possible,” one commenter wrote. “Your job is to not die broke.”

See Also: Turn your trading skills into real income — without risking your own capital: Get funded by Apex Trader Funding and keep up to 90% of the profits.

Cash Buffers

Many commenters focused on the importance of keeping enough safe assets available to avoid selling stocks during a market downturn.

The investor later revealed they already had roughly $496,000 in cash and short-term fixed income investments, enough to cover an estimated eight to …

Full story available on Benzinga.com

This post was originally published here

Lowe’s Companies, Inc. (NYSE:LOW) is scheduled to report first-quarter earnings before the opening bell on Wednesday, May 20.

Analysts expect the home improvement retailer to post earnings of $2.97 per share, up from $2.92 a year earlier, on revenue of $22.88 billion compared with $20.93 billion last year, according to Benzinga Pro.

With growing attention on Lowe’s stock, some investors remain focused on its dividend appeal. Lowe’s currently offers an annual dividend yield of 2.20%, paying $1.20 per share quarterly, or $4.80 annually. Here’s how much investors would need to invest in Lowe’s to generate $500 in monthly dividend income.

To earn $500 per month or $6,000 annually from dividends alone, you would need an investment of approximately $272,525 or around 1,250 shares. For a more modest $100 per month or $1,200 …

Full story available on Benzinga.com

This post was originally published here

As borrowing costs continue to rise, experts are warning of a potential stock market correction, underscoring the widening disconnect between equities and the bond market.

Amundi‘s Chief Investment Officer, Vincent Mortier, warned that a market correction is inevitable. Mortier pointed out a shift in narratives within the equity market over the past six weeks, contrasting with bond investors’ focus on the surge in prices for commodities like diesel, petrol, and jet fuel due to Iran’s closure of the Strait of Hormuz, the Financial Times reported on Tuesday.

“We will see a correction — the question is more when than if, in my opinion,” said Mortier.

Raphaël Thuin, Head of Capital Markets Strategies at Tikehau Capital, expressed concern over the incompatibility of equities at all-time highs and high interest rates and energy markets pricing in a lasting impact on the economy. Thuin suggested that the market is due for a pause.

“Short-term, there are good reasons to be nervous,” he warned.

data-variant=”card”

This post was originally published here