Lisa Cook at the Federal Reserve in May2022.

Photo: Federal Reserve

The White House’s fight to remove Lisa Cook from the Federal Reserve is getting a later hearing date, not a resolution.

A committee appointed by President Donald Trump has moved its planned hearing from Thursday, November 5, to Monday, December 14, CNBC reported Wednesday evening, citing a White House official. Cook’s attendance has not been confirmed.

The panel is investigating allegations that Cook made false statements connected to mortgage applications. She denies wrongdoing. The new date does not remove her from the Fed or settle those allegations.

For borrowers, savers and investors, the issue is who gets to make decisions at the central bank that sets U.S. interest-rate policy. This delay extends the fight over the Fed’s independence; it does not change interest rates or announce a change in anyone’s mortgage payment.

A date is not an agreement to appear

The White House official told CNBC that the postponement came at Cook’s request. Her lawyer, Abbe Lowell, had said questions about the panel’s fairness and objectivity needed answers before a hearing could go ahead.

Reuters, citing the New York Times, also reported the December 14 date. It said Lowell had told the White House that Cook was unavailable for the original November 5 hearing and could not attend until after the Fed’s December 8-9 policy meeting.

Trump adviser Kevin Hassett, a member of the three-person committee, said last week that Cook’s lawyers had agreed to a December date, according to Reuters. That does not establish that she has agreed to attend this particular hearing. Both reports said her lawyer had not provided a fresh response to their requests for comment.

The firing fight remains open

Trump first tried to dismiss Cook in August 2025. She challenged that effort in court and argued that the mortgage allegations were a pretext to remove her because she would not support his demands for lower interest rates, CNBC reported.

In June, the Supreme Court left in place a lower-court order protecting her from removal while the case proceeds. CNBC reported that the justices found she had not been given due process in the first attempt to fire her; they did not decide whether a president ultimately has the power to remove a Fed governor in these circumstances.

Trump established the inquiry committee in October. Its job is to hold a hearing and recommend whether Cook should be fired, Reuters reported. That process, Cook’s objections to it and the separate court fight remain distinct from the Fed’s decisions on interest rates.

Cook remains listed as a governor on the Federal Reserve’s official website. For now, the confirmed change is the hearing calendar, not the composition of the Fed’s board.

JBizNews Desk | Washington

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Scott Olson/Getty Images (file)

Home Depot shares rose 6.5% Wednesday, extending a monthlong rebound as investors looked for lower borrowing costs to revive home sales and renovation spending.

The home-improvement retailer closed at $355.44, up $21.78, or 6.53%, in the regular trading session, according to Yahoo Finance’s closing quote. Those figures refer to the 4 p.m. Eastern market close, not after-hours trading.

The gain extended a rally of more than 25% since October 5, according to CNBC. Wednesday’s advance also brought the stock back into positive territory for the year.

Why rates matter to a home-improvement retailer

Home Depot’s business is tied to what happens inside the housing market. When people buy and sell homes, they often repair, repaint or remodel them. High mortgage costs can keep would-be buyers on the sidelines and leave homeowners reluctant to move.

That makes the prospect of lower rates important to investors in the retailer. A recovery in housing transactions or do-it-yourself projects could support demand, but a stock rally is not proof that customers are already spending more.

CNBC linked Wednesday’s housing-stock gains to hopes that the post-election shift in Congress could bring relief on affordability. Its analysis also pointed to falling oil prices and bond yields. Those are market expectations, not a guarantee that mortgage rates or renovation costs will fall.

The rally still needs a business follow-through

Jim Cramer argued that lower rates or a stronger do-it-yourself market would help sustain Home Depot’s momentum. His view appeared in a CNBC Investing Club analysis, which disclosed that his charitable trust owns the stock.

The distinction matters: Wednesday’s move reflects investors paying more for Home Depot shares in anticipation of better conditions. Whether that optimism becomes stronger sales depends on housing activity and customers’ willingness to take on projects.

CNBC also noted that previous periods of optimism about mortgage rates had produced rebounds that did not hold. The latest rally therefore leaves investors watching for sustained relief in borrowing costs and a pickup in home-improvement demand, rather than treating one strong trading day as a completed turnaround.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
The Tokyo Stock Exchange trading floor, with the electronic ticker board above the central trading cylinder

Photo: Wpcpey / Wikimedia Commons / CC BY 4.0

Updated at 9:38 a.m. Thursday in Seoul and Tokyo (7:38 p.m. ET Wednesday) with the first cash-market moves of the session.

Asia-Pacific markets opened mixed Thursday after Wall Street’s post-election rally, with South Korean stocks tumbling at the open while Tokyo edged higher.

South Korea’s KOSPI fell 3.14% to 5,505.50 at 9:38 a.m. Seoul time, down from Wednesday’s close of 5,683.80, per Naver data. Japan’s Nikkei 225 rose 0.31% to 62,384.50 at 9:38 a.m. Tokyo time, according to the Nikkei’s official index page. Australia’s S&P/ASX 200 had risen 1.81% in early Thursday trading as of about 6:27 p.m. ET Wednesday, CNBC reported earlier.

Investors read the Democrats’ sweep of both chambers of Congress as easing political uncertainty, with expectations of legislative gridlock that could constrain President Trump’s agenda; his acceptance of the results also helped calm markets, CNBC reported. Sentiment got a further lift from an 8% plunge in oil prices, as investors anticipated growing pressure on the administration to end the war in Iran.

On Wednesday the Dow Jones Industrial Average posted its best day since April 2025, gaining more than 1,500 points, or 3%, as oil settled down more than 8% at $88.12 a barrel. Weekly jobless claims land Thursday morning and the October jobs report arrives Friday.

For people with retirement money in international stock funds, Seoul’s fall is a reminder that a strong day on Wall Street does not mean every market is rising.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
1211 Avenue of the Americas in Manhattan, headquarters of News Corp

1211 Avenue of the Americas in Manhattan, headquarters of News Corp

Photo: Coolcaesar / Wikimedia Commons (CC BY-SA 3.0)

News Corp’s profit jumped 43% in its fiscal first quarter as growth at Dow Jones, Realtor.com and its book publishing arm lifted revenue 6% to $2.28 billion.

Net income reached $215 million, up from $150 million a year earlier, and Total Segment EBITDA rose 19% to $403 million, the company reported Wednesday. Earnings were 29 cents a share, up from 20 cents, marking a fourteenth consecutive quarter of year-over-year profit growth.

All three engines fired. Dow Jones revenue rose 8%, helped by 11% growth in its Risk & Compliance business. REA Group, the Australian real estate listings arm, grew 13%. Move, the operator of Realtor.com, grew 5% with improving profitability. Book publishing revenue climbed 9% on strong sales and digital growth.

CEO Robert Thomson framed the results around the fight over AI and content. “High quality content is the very essence of AI,” he said, praising licensing partners OpenAI and Meta and warning other platforms to “choose compensation over confiscation, principle over plunder. To that end, we will woo and we will sue.”

For readers of The Wall Street Journal and shoppers of HarperCollins books, the quarter shows the company behind them leaning into paid content and professional data services rather than chasing clicks.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Elise Amendola/AP (file)

AstraZeneca has made a non-binding offer of about $10 billion for Rhythm Pharmaceuticals, including up to $134 per share with milestone payments, Reuters reported Wednesday, citing three people familiar with the matter.

The proposal is not an agreed acquisition. The maximum reported per-share value includes payments tied to milestones and should not be read as an all-cash payment upfront.

The Wall Street Journal earlier reported that AstraZeneca had offered about $124 per share for Rhythm last month. Reuters subsequently reported the non-binding proposal and its milestone-linked terms based on its own sources.

Rhythm shares jump

Rhythm shares closed 28% higher at $110.68, giving the drugmaker a market value of about $7.64 billion, Reuters reported. The rally followed news of the approach, but neither company has announced a signed transaction.

AstraZeneca declined to comment. Rhythm representatives did not respond to a request for comment, according to Reuters.

Alexion would lead the acquisition

Two of Reuters’ sources said the acquisition would be led by Alexion, AstraZeneca’s rare-disease division. AstraZeneca acquired Alexion for $39 billion in 2021.

Rhythm develops treatments for rare neuroendocrine and metabolic disorders, including severe obesity. Its focus is distinct from the broader market for weight-loss treatments: the reported approach would expand AstraZeneca’s rare-disease portfolio as well as its presence in obesity.

The Journal reported that AstraZeneca had previously expressed interest in Rhythm and renewed its pursuit in recent months. Details of the latest proposal remain based on people familiar with the discussions, rather than a public agreement or company confirmation.

The terms and company responses are set out in the updated Reuters report. Whether the non-binding proposal leads to a negotiated deal, and on what final terms, remains unresolved.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
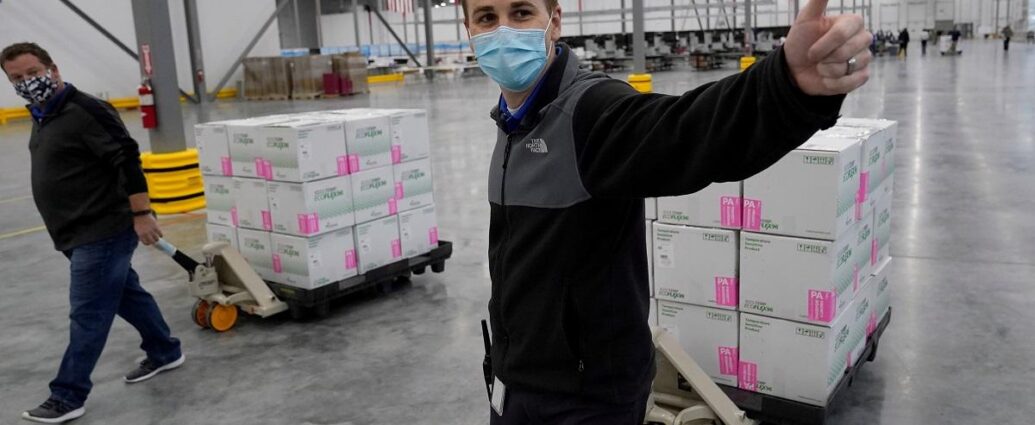
Workers with vaccine shipments at a McKesson distribution center in Mississippi in December 2020.

Paul Sancya/Pool via Reuters (file)

McKesson raised its fiscal 2027 adjusted earnings outlook Wednesday after quarterly revenue reached $111 billion, up 8%, as prescription volumes and specialty-drug distribution expanded.

The healthcare services company now expects adjusted earnings of $45.60 to $46.40 a share for the year, compared with its previous range of $44.20 to $45.00. The new forecast implies growth of 17% to 19% from the prior fiscal year.

For the second quarter ended September 30, reported diluted earnings were $10.44 a share, up from $8.92 a year earlier. Adjusted earnings, which exclude specified costs and other items, rose 18% to $11.68 a share from $9.86. The adjusted figure is not the same as profit calculated under generally accepted accounting principles.

Specialty distribution drives growth

North American Pharmaceutical, the largest business, generated $91.4 billion in revenue, a 6% increase. Its adjusted operating profit rose 22% to about $1 billion. Higher prescription transaction volumes, including specialty products supplied to health systems and strategic accounts, outweighed lower contributions from branded pharmaceuticals.

Oncology & Multispecialty revenue increased 24% to $15 billion, while adjusted operating profit rose 8% to $427 million. Prescription Technology Solutions revenue grew 10% to $1.5 billion, and adjusted operating profit increased 18% to $307 million.

The gains were not uniform. Medical-Surgical Solutions revenue rose 5% to $3.1 billion, but adjusted operating profit fell 10% to $225 million. McKesson attributed that decline to product mix in ambulatory care, partly offset by growth in extended care.

Cash generation and portfolio changes

McKesson generated $3.1 billion in operating cash flow during the quarter and reported $2.9 billion in free cash flow after capital spending. Across the first six months, it returned $3.6 billion to shareholders, including $3.4 billion in stock repurchases.

The company also extended its pharmaceutical distribution partnership with CVS Health through June 2032 and completed its acquisition of Precision Medicine Group on November 2. Its planned roughly $1.4 billion investment for a 49% stake in Option Care Health remains subject to shareholder and regulatory approvals.

The higher outlook is for adjusted earnings only. McKesson did not provide a GAAP earnings forecast, citing uncertainty around inventory adjustments, litigation, transaction costs and other items. The quarterly results and guidance are detailed in its earnings release.

JBizNews Desk | Irving, Texas

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
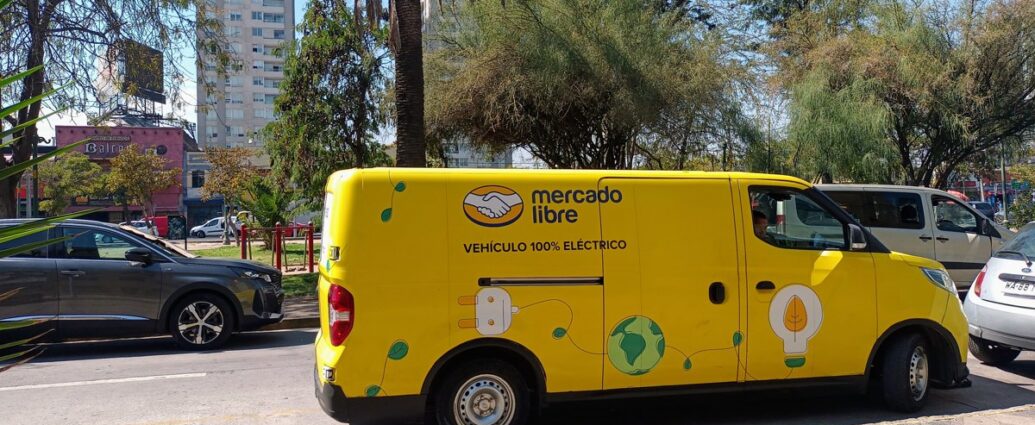
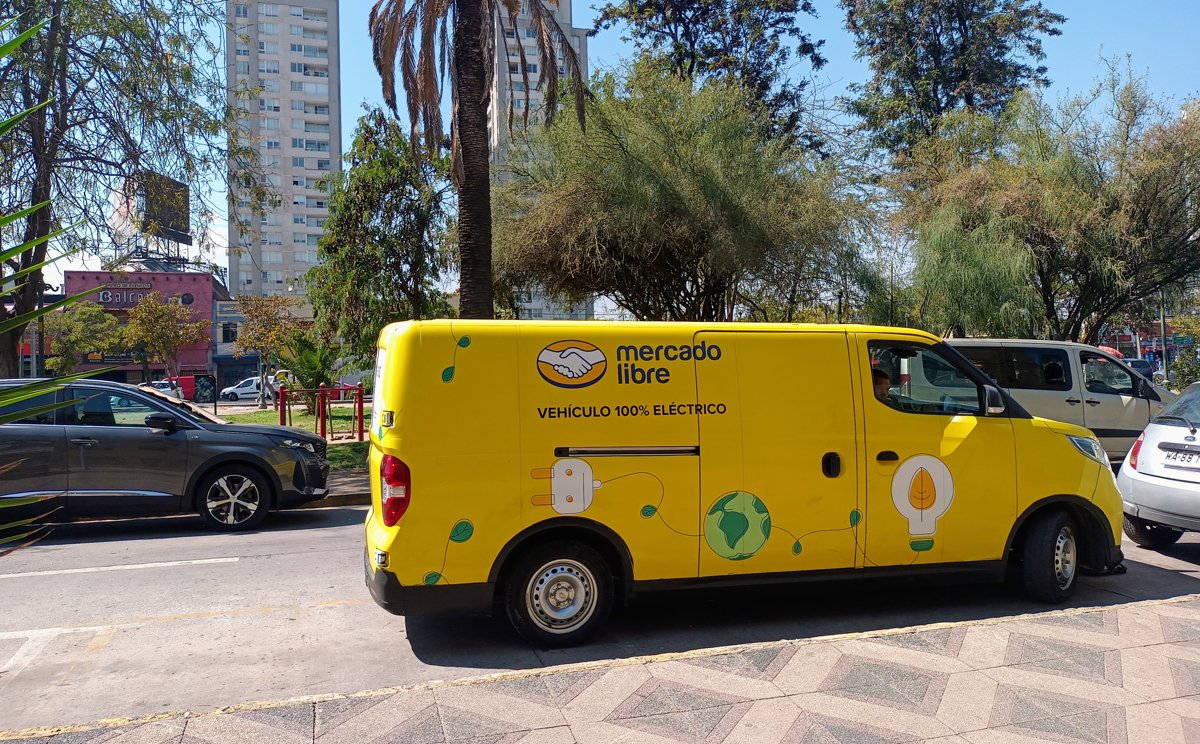
A MercadoLibre electric delivery van on a street in Chile

A MercadoLibre electric delivery van on a street in Chile

Photo: Igallards7 / Wikimedia Commons (CC BY-SA 4.0)

MercadoLibre grew revenue 45% to $10.75 billion in the third quarter, but profit fell short of expectations as the Latin American e-commerce giant spent heavily on free shipping and new warehouses, and the shares dropped after hours.

Adjusted earnings came in at $8.83 a share, missing the $9.34 analysts had projected, while revenue edged past the $10.69 billion expected. Operating income was $676 million, a 6.3% margin, down from 7.0% in the prior quarter, and net income was $448 million, the company reported Wednesday.

Shares fell 7.8% in after-hours trading, Investing.com reported at 4:14 p.m. ET.

Growth is not the problem. Gross merchandise value rose 38% to $23 billion, payment volume on Mercado Pago jumped 53% to $109 billion, fintech users grew 29% to 93 million and advertising revenue climbed 58%. The credit portfolio swelled 62% to nearly $18 billion. The squeeze came from the cost of that growth: expanded free shipping, fulfillment capacity up almost 20% from the prior quarter, and heavier marketing in Brazil.

The company said it gained market share in its three biggest markets, Brazil, Mexico and Argentina. For the millions of sellers and shoppers who treat MercadoLibre as the Amazon of Latin America, the strategy is familiar: sacrifice profit now to lock in customers for the long run. Investors on Wednesday were not in the mood to wait.

JBizNews Desk | Buenos Aires

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Close-up of an Arm-based processor chip package

Close-up of an Arm-based processor chip package

Photo: Caspertheghost / Wikimedia Commons (public domain)

Arm Holdings beat quarterly profit and revenue expectations but its forecast for the current quarter merely matched them, and the shares slipped after hours.

The British chip designer earned an adjusted 52 cents a share on revenue of $1.44 billion in its fiscal second quarter, up 27% from a year earlier and ahead of the 47 cents and $1.38 billion analysts had projected. On a GAAP basis, earnings fell to 12 cents a share from 22 cents.

Shares fell nearly 4% after hours, Investing.com reported in a 4:38 p.m. ET update.

The guide was the letdown. For the current quarter Arm forecast adjusted earnings of 52 to 60 cents a share on revenue of $1.49 billion to $1.59 billion, essentially in line with the 55 cents and $1.53 billion analysts expected. Investors who had priced in a blowout sold the news.

The engine is licensing. License and other revenue jumped 50% to $773 million while royalties rose 8% to $670 million, the company said in its shareholder letter. Royalties from data-center chips doubled, while smartphone royalties grew more slowly as high memory prices squeeze phone makers. Arm says hyperscalers, the giant cloud operators, now account for more than half its royalty base, a company claim that underscores its push beyond phones.

“AI is driving unprecedented demand for compute across the cloud, devices and autonomous systems, with Arm being the compute platform of choice,” CEO Rene Haas and finance chief Jason Child wrote, calling demand for its new Arm AGI data-center chip “extremely strong.”

The report lands in a rough patch for chip stocks. The Philadelphia Semiconductor Index slumped 15.4% in October and Arm’s U.S.-listed shares tumbled nearly 29% last month as investors question whether the AI spending boom will pay off. Arm’s designs sit inside nearly every smartphone on earth, and it collects a small royalty on each chip sold, so its results are a window into both the phone market and the AI buildout.

JBizNews Desk | Cambridge, England

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Photo: Frederic J. Brown/AFP (archive)

Zillow Group posted a $158 million third-quarter net loss Wednesday as revenue and adjusted earnings fell short of Wall Street expectations, despite growth in its rentals and mortgage businesses.

The online real estate marketplace generated $724 million in revenue, up 7% from a year earlier. Adjusted earnings were 55 cents a share. Both figures missed the Zacks analyst survey benchmarks of $754.3 million in revenue and 60 cents a share in adjusted earnings.

Shares fell about 15% in after-hours trading, Investing.com reported. That is an after-hours reaction, not the stock’s regular-session closing move.

Reported loss and adjusted profit tell different stories

The net loss equaled 70 cents per diluted share, compared with net income of $10 million, or 4 cents a share, in the third quarter of 2025. Adjusted net income was $124 million, up from $113 million, while adjusted earnings per share rose from 44 cents.

Zillow’s financial release separates those non-GAAP measures from its reported results. The adjusted measures exclude a $165 million charge related to the Zillow Offers securities class-action settlement, net of expected insurance recoveries, as well as other specified expenses.

The $165 million figure is the charge reflected in this earnings adjustment. It should not be confused with a statement that the entire settlement’s gross value is $165 million.

Adjusted EBITDA was $182 million, or 25% of revenue, within the company’s outlook range. Net cash provided by operating activities increased to $162 million from $105 million.

Rentals grow while residential revenue declines

Rentals revenue rose 26% to $220 million, with multifamily revenue growing 35%. Mortgage revenue increased 32% to $70 million as purchase-loan origination volume rose 55% to $2 billion.

Residential revenue fell 4% to $419 million. Combined with mortgages, total For Sale revenue was essentially flat at $489 million. Zillow attributed the residential decline to higher-than-expected mortgage rates that pressured housing transaction volume.

Chief Executive Jeremy Wacksman described the period as “one of the toughest housing markets in a generation,” while pointing to revenue growth and the company’s broader business mix.

Higher sales did not clear the earnings bar

The quarter shows the difference between growing a business and meeting investor expectations. Rentals and mortgages expanded, but total revenue still came in below the forecasts in the Zacks survey. Adjusted profit improved from a year earlier while reported earnings swung to a loss.

The company also reported weaker audience activity: average monthly unique users declined 3% to 215 million, and visits fell 5% to 2.3 billion. Those company operating metrics add another measure of performance beyond revenue and adjusted earnings.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
The Snapchat app open on a smartphone

The Snapchat app open on a smartphone

Photo: Santeri Viinamäki / Wikimedia Commons (CC BY-SA 4.0)

Snap swung to a third-quarter profit as revenue grew 14% to $1.722 billion, though the top line came in about $10 million shy of what analysts expected, and the shares slid after the report.

Net income reached $56 million, against a $104 million loss a year earlier, with earnings of 3 cents a share. Adjusted EBITDA more than doubled to $383 million from $182 million, operating cash flow was $210 million and free cash flow was $164 million, the company reported Wednesday.

Shares fell about 11% after hours in Seeking Alpha’s 4:14 p.m. ET report.

The audience keeps growing, slowly. Snapchat averaged 495 million daily users in the quarter, up 4% from a year earlier, though its most lucrative market, North America, held flat at 92 million. Snap also said it will switch to monthly users as its headline audience measure starting in early 2027, arguing that better reflects the size of its community.

CEO Evan Spiegel cast the quarter as proof the business model is maturing. “AI is becoming a significant advantage for our teams and advertising platform,” he said, adding that Snap is investing in its “long-term vision for augmented reality with the launch of SPECS,” its coming smart-glasses line. Those are his claims; the AI investments have yet to show up as faster revenue growth.

For the half a billion people who open Snapchat every day, mostly to message friends, the quarter means the company behind the app is finally making more money than it spends while it bets on glasses as the next big thing.

JBizNews Desk | Santa Monica

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Qualcomm headquarters campus in San Diego, California

Qualcomm headquarters campus in San Diego, California

Photo: Coolcaesar / Wikimedia Commons (CC BY-SA 4.0)

Qualcomm beat Wall Street’s quarterly expectations after the bell Wednesday as surging sales of chips for cars helped make up for a steep drop in its smartphone business.

The chipmaker reported adjusted earnings of $2.17 a share on revenue of $10.32 billion for its fiscal fourth quarter, ahead of the $2.16 a share and $10.12 billion analysts had projected, Yahoo Finance reported. A year earlier the company earned $3.00 a share on $11.27 billion in revenue.

Shares reversed lower and fell about 6% in extended trading, CNBC reported in an update shortly before 5 p.m. ET, as investors looked past the beat to the profit outlook.

The forecast was the real surprise. Qualcomm guided first-quarter revenue of $10.4 billion to $11.2 billion, with the midpoint above the roughly $10.6 billion analysts had expected.

The concern is on the profit line. Qualcomm projected first-quarter earnings of $2.15 to $2.35 a share, straddling the $2.27 analysts had expected, and warned that the industrywide memory shortage is forcing handset makers to raise prices and hurting demand for phones.

Cars carried the quarter. Automotive chip sales jumped 89% to $2 billion, the kind of growth that matters to drivers as Qualcomm silicon powers more dashboard screens and driver-assistance systems in new models. Handset revenue, still the company’s biggest business, plunged 26% to $5.1 billion, missing the $5.3 billion analysts expected. The broader QCT chip segment fell 8% to $9 billion but topped forecasts, and the licensing arm brought in $1.3 billion.

Qualcomm is pushing to rely less on phones. On Wednesday it announced a deal to supply technology for SpaceX’s Starlink mobile network, JBizNews reported earlier. In October it teamed up with defense tech firm Anduril on a laptop built around its Snapdragon X chips, and in September it signed an agreement to design custom chips for Amazon’s AWS AI infrastructure.

The handset slump reflects a wider memory and storage shortage that has forced electronics makers to raise prices on phones and laptops, dampening demand. Apple flagged the same margin pressure in its earnings this week, and Intel and AMD both warned of weaker PC sales ahead.

JBizNews Desk | San Diego

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
The Charging Bull statue on Broadway in New York's Financial District

Photo: Tdorante10 / Wikimedia Commons (CC BY-SA 4.0)

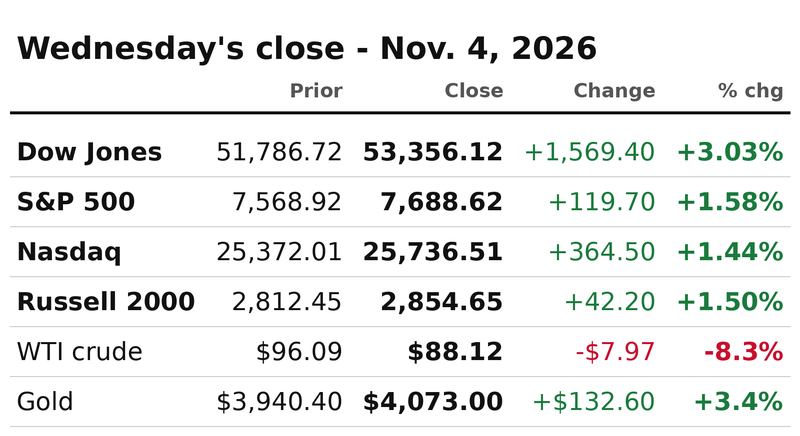
The Dow Jones Industrial Average jumped 1,569.40 points, or 3.0%, to 53,356.12 on Wednesday as Democrats won majorities in both chambers of Congress, AP reported, and oil prices plunged more than 8%. The S&P 500 rose 1.6% to 7,688.62, and the Nasdaq Composite gained 1.4% to 25,736.51, a second straight advance for both.

The Russell 2000 of smaller companies added 1.5% to 2,854.65. The VIX fear gauge dropped almost 20% to about 16.7.

Closing levels for the Dow, S&P 500, Nasdaq, Russell 2000, WTI crude and gold on Nov. 4, 2026

Oil falls as the Iran risk fades. WTI crude settled at $88.12 a barrel, down $7.97, or 8.3%, as investors bet that the election result lowers the odds of a wider Iran conflict, CNBC reported. Energy was the day’s worst sector, down 4.7%, and Exxon Mobil fell 4.5%. Gold settled up 3.4% at $4,073.00 an ounce.

Broad rally, three sectors lag. Eight of the S&P 500’s 11 sectors rose. Consumer discretionary led with a 4.3% gain, followed by financials (+3.5%), communication services (+3.5%), consumer staples (+3.4%), real estate (+3.3%), health care (+3.1%), materials (+2.5%) and utilities (+0.4%). Technology was flat, industrials slipped 1.1% and energy lost 4.7%.

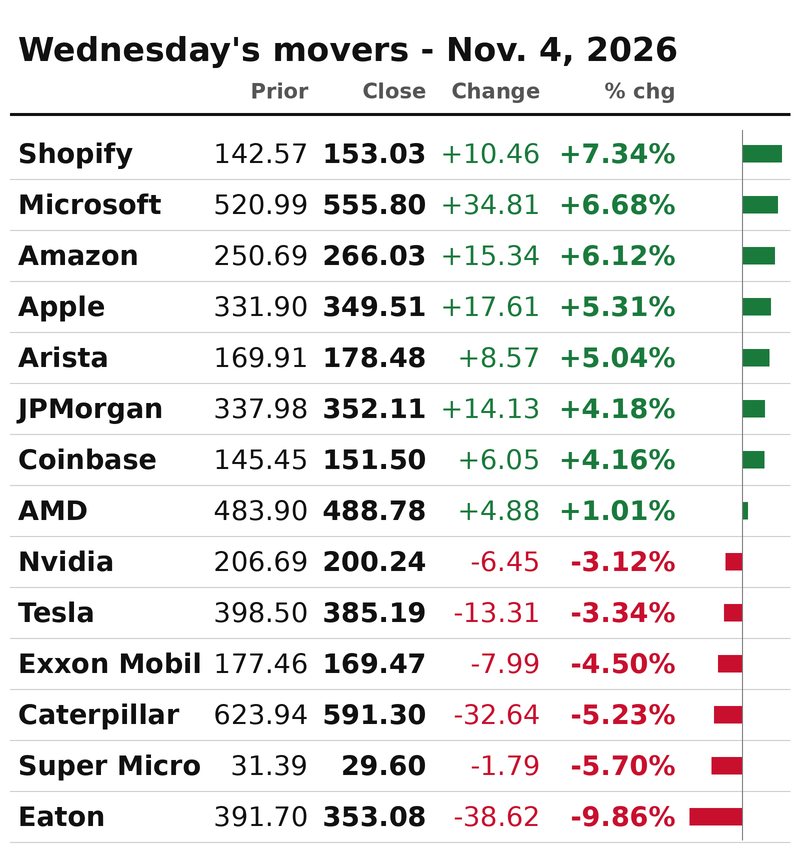
Megacaps lead. Microsoft rose 6.7%, Amazon 6.1% and Apple 5.3%, which more than recovered Tuesday’s 1.9% slide. JPMorgan gained 4.2% as bank shares climbed with the broad market, and Shopify jumped 7.3% to recover most of Tuesday’s 8.7% drop.

AI data-center names slip. Nvidia fell 3.1%, Tesla 3.3% and Caterpillar 5.2%. The Democratic wins, including the Texas governor’s race, raised questions about how fast AI data centers get built, CNBC reported. Eaton, a power-equipment maker tied to that buildout, sank 9.9% and gave back all of Tuesday’s 7% post-earnings gain. Super Micro fell 5.7% a day after its results despite a beat, while Arista rose 5.0% and AMD added 1.0%.

Rates, dollar, crypto. The 10-year Treasury yield eased about 6 basis points to roughly 4.89%. The dollar index slipped 0.3% to 101.52. Bitcoin rose about 3.6% to roughly $80,100 and Coinbase gained 4.2%.

Biggest stock movers on Nov. 4, 2026

What it means. Cheaper oil should ease pressure on gasoline prices over the coming weeks, and a lower Treasury yield can nudge mortgage rates down. Both depend on oil and bond markets holding these moves, which swung sharply after Tuesday’s limited U.S. strike on Iran.

What to watch. Berkshire Hathaway reports later this week and the October jobs report arrives Friday. For traders, the key question is whether the oil drop holds and whether AI infrastructure stocks stabilize after the election.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
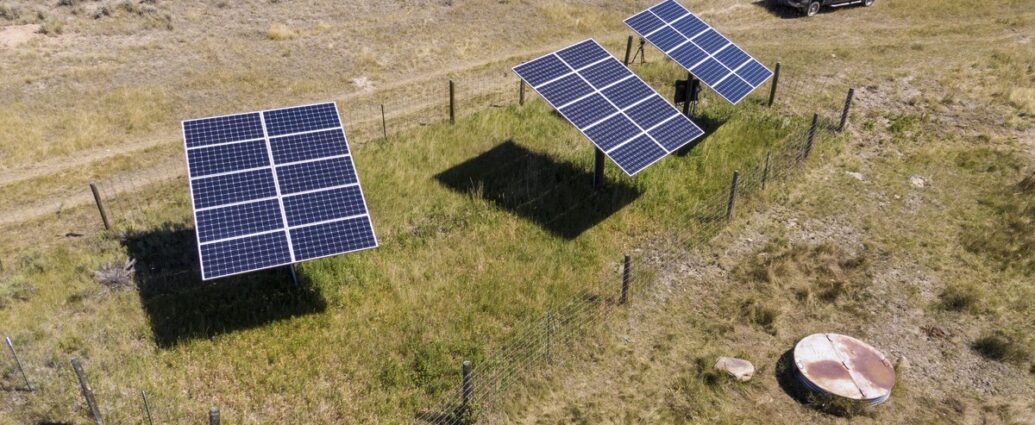
Solar panels at a rural installation

Photo: Lance Cheung / USDA (public domain).

Two companies that supply America’s solar farms agreed to merge on Wednesday in an all-stock deal valuing Shoals Technologies Group at about $1.32 billion, Reuters reported. The tie-up pairs ARRAY Technologies, which builds the steel trackers and mounts that hold solar panels and tilt them toward the sun, with Shoals, which makes the wiring and cable systems that carry the power away.

Shoals shareholders will receive 1.6931 ARRAY shares for each share they own – a price of $7.86 a share at announcement, about 7% below Shoals’ last closing price. Investors still cheered: Shoals stock rose about 5% and ARRAY jumped nearly 14% in premarket trading, a sign the market thinks the combined company will be worth more than the two apart.

The logic is simplicity. Today, a company building a solar farm buys the panel frames from one supplier and the electrical guts from another and pays contractors to make them work together. The merged company plans to sell both as one package, which it says will make installations faster and cheaper and the finished farms perform better. It expects $2.2 billion to $2.4 billion in combined revenue next year, including about $35 million in first-year cost savings.

In a twist, the smaller partner walks away in charge. Shoals shareholders will own about 65% of the combined company, Shoals CEO Brandon Moss will run it, and ARRAY CEO Kevin Hostetler becomes a special adviser, even though ARRAY is the legal buyer.

For households, the connection is electric bills. Solar is one of the cheapest sources of new electricity in the country, and when the companies building it can put up farms faster and for less money, that flows through to what power costs over time.

The deal is not done. It still needs shareholder and regulatory approvals and is expected to close in the first quarter of 2027.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
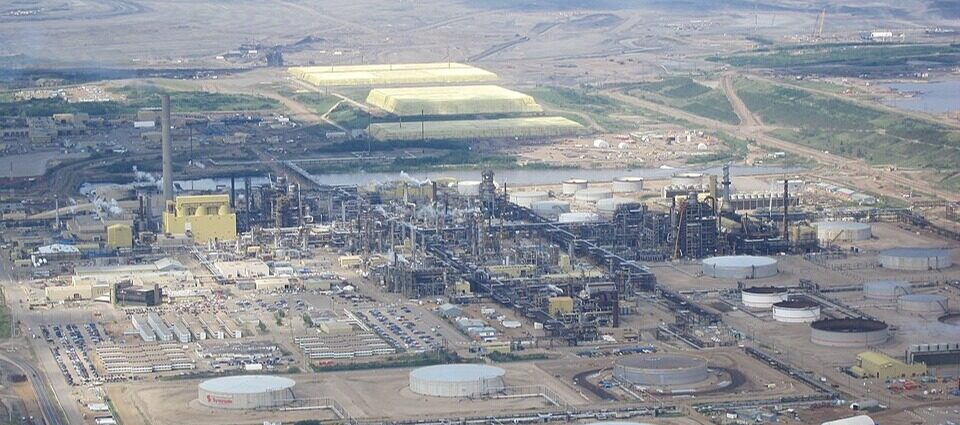
Syncrude oil sands facility in Alberta.

Photo: The Interior / CC BY-SA 3.0

Cenovus Energy crossed the one-million-barrel mark in average daily oil-and-gas production for the first time in the third quarter, as record output and stronger refining results lifted its profit.

The Canadian producer reported average upstream production of 1.024 million barrels of oil equivalent per day, according to its Wednesday results release. Net earnings rose to C$3.36 billion from C$1.29 billion a year earlier.

For businesses buying fuel and investors watching North American energy supply, the report shows more output reaching the market. A production increase at one company does not by itself determine gasoline or diesel prices.

Oil sands set records

Oil sands production reached a quarterly record of 833,000 barrels of oil equivalent per day. Cenovus reported records at Foster Creek, Christina Lake and Sunrise, while average oil sands operating costs fell to C$10.23 per barrel from the preceding quarter.

Its downstream operations processed 437,000 barrels of crude a day, with crude-unit utilization of 92%. Downstream operating margin reached C$1.8 billion, up from C$1.0 billion in the second quarter, reflecting better operations and refining spreads, the company said.

Cenovus returned C$1.9 billion to shareholders during the quarter through dividends and share repurchases. The results are for the three months ended September 30, not today’s oil-market trading.

JBizNews Desk | Calgary

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Frankfurt skyline at dusk, archive city photograph, not a photograph of the weekend unrest.

Frankfurt, Germany’s financial hub. Photo: Nir Himi / Unsplash (archive photo)

European stocks closed at a two-month high Wednesday, joining the global rally that followed Democrats’ sweep of the U.S. Congress, Reuters reported.

The pan-European STOXX 600 ended up 1.82% at 657.40, its strongest close in two months. Bank stocks led with a 4.6% jump, while the oil and gas sector fell 2.4% as crude prices tumbled.

Novo Nordisk surged 5.6% after the drugmaker raised its forecast, one of the day’s standout movers.

For U.S. investors with international funds, Europe’s close adds to a day of broad post-election gains; for European exporters and banks, the sweep resets expectations for U.S. trade, tariff and regulatory policy in the months ahead.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
A gold bullion bar

Photo: Szaaman (public domain).

Gold prices surged more than 3% Wednesday as the dollar slipped following Democrats’ sweep of Congress, with December gold futures at $4,072.80 an ounce, up $132.40, as of 3:06 p.m. Eastern, according to CNBC market data.

Spot prices for gold, silver and other precious metals jumped as projections pointed to major Democratic victories in the midterm elections, CNBC reported. Gold and silver both posted record-breaking rallies last year, surging 66% and 135% respectively.

A weaker dollar makes dollar-priced metals cheaper for overseas buyers, and political transitions typically feed demand for assets investors treat as stores of value.

For consumers, the move flows through to jewelry and bullion prices within days; for investors, Wednesday’s jump extends one of the strongest multi-year runs in the metal’s history.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
A person holding a physical bitcoin token over a laptop

Photo: Marco Verch (CC BY 2.0).

Traders who bet against bitcoin got run over Wednesday. As the biggest cryptocurrency climbed back from its election-night slide to top $81,000, about $950 million in leveraged crypto bets were wiped out in 24 hours – and 59% of the losses hit people wagering prices would fall, according to CoinGlass data reported by Unchained via Yahoo Finance.

Bitcoin traded near $80,500 late Wednesday morning, up 3.8% over 24 hours, a sharp U-turn from Tuesday night, when it dropped to about $75,600 as results showed Democrats winning both chambers of Congress. From that low to Wednesday morning’s high of $81,130, the climb was 7.3%. Ether rose even more, up 6.3% to about $2,437.

The pain was concentrated among short sellers – traders who borrow and sell, profiting only if prices drop. Of the bitcoin positions liquidated over the past day, 76% were shorts. One trader lost a $38 million bet on ether in a single order, the largest liquidation CoinGlass recorded.

The recovery had a clear leader: decentralized-finance tokens, the cryptocurrencies tied to apps that let people trade and lend without banks. CoinDesk’s DeFi index rose about 5%, the strongest of any sector it tracks, CoinDesk reported, while coins linked to President Trump fell. Even so, a widely watched fear-and-greed gauge sat at 37 – solidly in “fear” territory – a sign that everyday buyers have not rushed back in.

For regular investors, the lesson of the past 24 hours is an old one: borrowed money cuts both ways. People who used leverage to bet against bitcoin lost their stakes in hours, while those who simply held saw the dip erased by lunchtime.

The bigger question for crypto prices now sits in Washington. The Senate committees that write the industry’s rules pass to Democrats in January, and Democratic senators blocked the CLARITY Act – the bill that would have set national ground rules for crypto trading – earlier this session. Traders’ next test comes sooner: Friday’s U.S. jobs report, which shapes whether the Federal Reserve keeps cutting interest rates, a key driver of this year’s rally.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Archive photo: the U.S. Department of Education building in Washington, May 31, 2017. Not the current investigation.

Photo: Farragutful / CC BY-SA 4.0 (archive photo, cropped)

Duolingo shares jumped 32% to $169.40 in late-morning trading Wednesday, according to a Proactive Investors snapshot at 11:58 a.m. Eastern, after the language-learning company reported another quarter of rapid user growth.

Daily active users reached 64.9 million in the third quarter, up 29% from a year earlier, while paid subscribers rose 14% to 13.1 million, the company said in its quarterly results. Revenue grew 14% to $309.0 million and bookings rose 12% to $316.1 million.

Adjusted EBITDA came in at $78.7 million, down from $80.0 million a year earlier, with margin at 25.5% versus 29.5%. Gross margin was 72.9%. Net income totaled $27.2 million, compared with $292.2 million a year ago, a figure that included a one-time $222.7 million tax benefit.

The stock was among the biggest gainers in CNBC’s midday trading snapshot.

For the app’s tens of millions of learners, the growth figures signal continued investment in new courses and features; for investors, the question is whether user growth can keep outpacing pressure on profitability.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
An offshore oil and gas platform moored in a Norwegian fjord.

Photo: W. Bulach / CC BY-SA 4.0

U.S. crude oil prices tumbled below $90 a barrel Wednesday after Vice President JD Vance blamed the war against Iran for Republican losses in Tuesday’s midterm elections, CNBC reported.

West Texas Intermediate was nearly 9% lower at $87.59 a barrel as of 12:36 p.m. Eastern, while Brent crude, the international benchmark, fell more than 9% to $93.91.

“The reason we lost is the war,” Vance said in a social media post Wednesday. “The president himself said so last night.”

Democrats swept the House and Senate on Tuesday, giving the party leverage to press President Donald Trump to end the unpopular war, which has driven up gasoline and diesel prices. Analysts told CNBC the results lead the oil market to believe Trump now has a bigger incentive to cut a deal with Iran.

For drivers, a sustained drop in crude would start showing up at the pump within weeks, offering relief after months of war-driven fuel costs.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
AMD CEO Lisa Su speaking at Oak Ridge National Laboratory in 2019

Photo: Genevieve Martin / Oak Ridge National Laboratory (CC BY 2.0). AMD CEO Lisa Su in 2019.

Advanced Micro Devices shares jumped about 8% on Wednesday after the chipmaker posted the biggest quarter in its history and told investors the current one will be even bigger, Yahoo Finance reported. It was the clearest sign yet that the artificial-intelligence building boom that became a flashpoint in Tuesday’s midterm elections is still pulling in enormous money.

AMD’s third-quarter revenue reached a record $13.4 billion, up 45% from a year earlier, and adjusted profit of $2.09 a share beat the $1.94 Wall Street expected, the company announced. The engine is AMD’s data-center business – the chips that fill the giant computing halls powering AI – where sales nearly doubled to a record $8.5 billion.

“Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production,” CEO Lisa Su said, naming AMD’s AI chips and server processors. The company forecast roughly $17 billion in revenue this quarter, well above the $16.23 billion analysts had penciled in, which would be growth of about 66% from a year ago.

In plain terms: when Meta, Microsoft, OpenAI, Oracle or Anthropic builds a new AI data center, more of the bill is going to AMD. The company said all five are already running work on its newest Helios systems, and Meta signed an agreement earlier this year worth about $60 billion for AMD chips to power its AI expansion, a market long dominated by rival Nvidia.

For anyone with a 401(k), this is the other side of the data-center story. The same construction wave that drove up power bills and turned data centers into a campaign issue in Texas, Ohio and beyond is producing record sales for the companies supplying it. AMD’s stock has more than doubled this year – even after a 17.5% slide in October, when investors worried the AI spending spree had gotten ahead of itself – while Nvidia is up about 11% and the S&P 500 about 10%.

Wednesday’s results answered some of those worries. Analysts at Baird told clients that AMD’s forecast implies its server-processor revenue more than doubles again by 2027, a sign the company is steadily taking business in a market where, only a few years ago, it was an afterthought.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
ArchiveWallStreet sign andNYSE facade,notFridaytrading.

Photo: Carlos Delgado / CC BY-SA 3.0

FIS shares tumbled 24% in midday trading Wednesday after the financial technology company cut its full-year profit outlook, one of the steepest drops on the S&P 500 in CNBC’s midday trading snapshot.

The Jacksonville, Florida-based payments and banking-technology company now expects adjusted full-year earnings of $5.82 to $5.89 per share, down from its previous outlook of $6.15 to $6.24, according to CNBC.

In its third-quarter results, FIS reported GAAP revenue of about $3.5 billion, up 27% from a year earlier, lifted by an acquisition; on a pro forma basis, revenue grew 3.7%. Adjusted earnings came in at $1.61 per share.

The company also said a strategic review of its portfolio is ongoing. It has not announced any breakup or divestiture.

FIS’s software moves money for banks, merchants and capital-markets firms worldwide, so its outlook is read as an early signal on consumer and business payment volumes heading into the holiday quarter.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Photo: Mike Blake / Reuters (file)

Hospital operators and solar companies rallied while defense contractors and data-center businesses fell Wednesday, as investors adjusted their bets on federal spending and regulation after Democrats won control of Congress.

HCA Healthcare and Universal Health Services each gained about 10%, while Lockheed Martin fell nearly 7%, according to CNBC’s sector report published at 1:45 p.m. Eastern. The figures below are intraday snapshots from that report, not closing prices.

The divide matters beyond the headline market rally: businesses exposed to healthcare funding and clean-energy policy attracted buyers, while companies dependent on military spending or rapid AI-infrastructure expansion came under pressure. The moves reflected expectations about the next Congress, not newly enacted spending or regulatory changes.

Hospitals and insurers rise on healthcare hopes

Alongside the roughly 10% gains in HCA and Universal Health Services, Tenet Healthcare rose 9%. Among insurers, Centene gained 9%, Molina Healthcare added 8% and Elevance Health rose 4%, CNBC reported.

Investors were betting on a slowdown or reversal in healthcare spending cuts and the possibility of extending enhanced Affordable Care Act subsidies. Those outcomes still require political agreement.

In an earlier Reuters report, BNP Paribas economist Anis Bensaidani cautioned that Democrats might lack the numbers to restore major parts of the ACA, while still gaining bargaining power in negotiations over defense spending and government funding.

Solar shares gain as defense contractors retreat

Nextpower and Canadian Solar each jumped more than 11%, First Solar gained 8%, Plug Power rose 7.5% and Sunrun added 5% in CNBC’s snapshot. NextEra Energy rose 4%.

The clean-energy trade reflected hopes that a Democratic Congress would resist the Trump administration’s retreat from policies supporting the industry. Reuters also reported a premarket rally in renewable-energy shares, although its earlier percentage changes differed from CNBC’s later snapshot.

Defense stocks moved in the opposite direction. Lockheed Martin fell nearly 7%, Northrop Grumman dropped about 5%, Howmet Aerospace lost 4% and RTX slipped 3%, CNBC reported. Investors were weighing whether President Donald Trump’s $1.5 trillion fiscal 2027 defense request would face a tougher path through Congress.

The selling extended to drone manufacturers: Kratos Defense & Security Solutions fell 10.5%, while AeroVironment and Red Cat each lost 9%. Those price moves do not establish that contracts have been canceled or that Congress has cut the requested budget.

Data-center exposure becomes a dividing line

CoreWeave fell 9%, Iren dropped 10% and Nebius lost 6% in CNBC’s report. Infrastructure names also weakened, with Comfort Systems down 16% and Vistra falling 14%.

Investors were assessing the prospect of tighter scrutiny of AI infrastructure and local restrictions on construction. That did not translate into a uniform technology selloff: Apple and Microsoft each rose more than 6%, while Alphabet gained 4%, CNBC reported.

For companies planning investment, the distinction is between a change in political expectations and a change in law. Wednesday’s sector moves priced in possible shifts in spending, subsidies and oversight; the actual business effects will depend on what lawmakers and state officials do next.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
New York Stock Exchange facade and American flags, landscape archive photograph.

Photo: David Vives / Unsplash (archive photo)

Wall Street roared Wednesday as the midterm elections settled the balance of power in Washington, with the Dow Jones Industrial Average up more than 1,500 points, over 3%, in afternoon trading, according to CNBC’s live market data.

As of 3:16 p.m. Eastern, the Dow was up 1,588 points, or 3.1%, at 53,375. The S&P 500 climbed 130 points, or 1.7%, to 7,699, and the Nasdaq Composite gained 436 points, or 1.7%, to 25,808.

Big Tech led the surge. Apple, Amazon, Google, Meta and Microsoft all jumped after the Democratic sweep removed months of investor uncertainty, CNBC reported, while stocks tied to Trump adviser Elon Musk and data-center operators fell. In an earlier midday snapshot, Reuters calculated that five Big Tech stocks were on course to add more than $750 billion in market value if the gains hold, with Amazon up 7.4% and Apple up nearly 7%.

For anyone with a 401(k) or an index fund, Wednesday’s rally recovers a meaningful share of October’s slide in a single session. Even with the jump, the S&P 500 remains below its October 6 record close of 7,844.

Not everything joined the rally: oil prices plunged nearly 8% and data-center-linked stocks slipped after voters rebuffed data-center ballot measures in Tuesday’s voting.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Empty office desks and chairs, illustrative archive photograph, not a Nice office.

Photo: Craig Lovelidge / Unsplash

NiCE CEO Scott Russell linked the company’s planned reduction of about 500 jobs to AI-driven productivity gains in research and development, cuts in slower-growing businesses and the removal of management layers, CTech reported Wednesday, citing his comments on the third-quarter earnings call. The restructuring also reaches customer-facing roles; it is not a claim that AI is replacing all 500 employees.

Russell said developers are using AI tools to increase productivity while NiCE simplifies its organization. CFO Beth Gaspich said the reductions would be concentrated primarily in product development, as well as go-to-market operations, customer support and services, according to CTech. NiCE has not disclosed how many employees in Israel, if any, will be affected.

Earnings beat comes with a lower cloud-growth forecast

NiCE cut its full-year cloud-revenue growth forecast to about 12% from 13% to 15%, even as it raised its adjusted earnings outlook after third-quarter revenue rose 8% to $790.7 million, slightly above its forecast. The Israeli-founded customer-service software company also detailed a restructuring that will cut about 5% of its global workforce and produce a $15 million to $20 million pre-tax charge, mainly in the fourth quarter.

Adjusted diluted earnings were $2.84 a share, above the top of the company’s prior $2.73 to $2.83 range, according to its November 4 earnings release. Revenue had been expected to range from $780 million to $790 million.

For investors, the report combines a small forecast beat and a higher annual profit target with lower profit than a year earlier. For employees, it adds the expected cost and timing of a job-cut plan already reported Tuesday, not a separate new round of 500 cuts.

NiCE shares traded at $92.11 at 7:12 a.m. Eastern Wednesday, down $14.16, or 13.32%, from Tuesday’s $106.27 close, according to CNBC’s extended-hours Nasdaq quote. The move came before the U.S. regular session and after the results were released.

Revenue grows, but profit falls

Cloud revenue increased 10.6% to $622.7 million, compared with 12.6% growth in the second quarter. AI annual recurring revenue reached $392 million, up 46% from a year earlier. That recurring-revenue measure describes the annualized scale of the AI business; it is not an additional $392 million of revenue earned during the quarter.

The revenue figures included an unusual $10 million customer credit. NiCE said total revenue would have grown 9.4% without it, compared with the reported 8% increase. About $9 million of the credit reduced non-CXone cloud revenue; cloud growth would have been 12.2% without the credit, close to the prior quarter’s 12.6%. The credit therefore explains much of the reported quarterly slowdown.

Higher sales did not translate into higher earnings. GAAP net income fell to $95.1 million from $144.9 million, while GAAP diluted earnings declined to $1.60 a share from $2.29. Adjusted diluted earnings of $2.84 were also below the $3.18 reported a year earlier.

Adjusted operating margin narrowed to 27% from 31.5%. The adjusted figures exclude items specified by the company and should be read alongside its GAAP results, not as a replacement for them.

Cloud-growth outlook cut, earnings target raised

NiCE now expects full-year adjusted diluted earnings of $11.12 to $11.32 a share. It reiterated adjusted revenue guidance of $3.17 billion to $3.19 billion, with approximately 12% growth in cloud revenue expected for the year. That is below the 13% to 15% cloud-growth range in its August 5 company outlook.

CEO Scott Russell said international revenue grew 33% in the quarter. He described a market in which personal AI agents could increase customer interactions and demand for software that coordinates service across people and AI. Those are the company’s growth expectations, not a guarantee of future sales.

Job-cut plan was already reported Tuesday

CTech reported November 3 that the company planned about 500 global job cuts, citing a workforce of roughly 10,000, including around 1,000 employees in Israel. The Israeli figure describes the local workforce, not the number of jobs to be eliminated there.

Wednesday’s release confirms an approximately 5% global reduction as NiCE cuts management layers and simplifies decision-making. It also specifies the expected $15 million to $20 million restructuring charge, which will be excluded from adjusted results. NiCE says it will continue investing in AI, customer delivery and sales capabilities.

NiCE has not disclosed a country-by-country breakdown of the cuts. CTech’s earlier report cited estimates of limited impact in Israel, but the company has not announced an Israeli allocation.

The results were released before the U.S. regular trading session. Russell discussed the restructuring on Wednesday’s earnings call.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
A 100 gram fine gold bar in a sealed assay package.

Photo: B7khSy / CC BY 3.0 (archive photo)

Gold futures extended their post-election gain Wednesday, with the December contract at $4,078.80 an ounce, up $138.40, or 3.51%, from the previous settlement of $3,940.40, in CME Group’s quote stamped 12:41:59 p.m. Eastern. The reading was viewed around 12:51 p.m.; data are delayed at least 10 minutes. This is an intraday futures price, not spot gold or a new settlement.

The contract reached $4,080.70 in the same table. For investors, the gain can lift gold-linked holdings, but physical bullion prices include dealer spreads and other costs, and futures involve leverage. The move does not guarantee further gains.

Earlier overnight reaction

Gold futures rose above $4,000 an ounce overnight, trading at $4,043.70 as of about 3:39 a.m. Eastern on Wednesday, November 4, up 2.6 percent from Tuesday’s official settlement of $3,940.40, according to CME Group prices. The December contract rose as high as $4,048.80.

The jump came as Democrats won control of the House of Representatives in Tuesday’s midterm elections. Bitcoin traded up 2.4 percent at about $78,360 and ether up 3.2 percent at about $2,325, according to Coinbase market data.

Gold had settled down 0.7 percent on Tuesday after rising 1.8 percent on Monday.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Oil pumpjacks in a storage yard in Shackelford County, Texas

Photo: Larry D. Moore / CC BY 4.0 (archive photo)

U.S. crude futures fell below $88 a barrel Wednesday afternoon, extending a sharp selloff as energy markets weighed the election result, uncertainty over the war with Iran and U.S. supply data. The decline lowers a benchmark for fuel costs, but it is not an immediate matching cut in what drivers or businesses pay.

December West Texas Intermediate crude traded at $87.95 a barrel, down $8.14, or 8.47%, from the previous settlement of $96.09, in CME Group’s quote stamped 12:41:59 p.m. Eastern on November 4. The data are delayed at least 10 minutes; the reading was viewed around 12:51 p.m. These are intraday futures prices, not a new settlement or a retail fuel price.

The contract traded between $87.13 and $97.15 in the same CME table, showing the size of the session’s swing.

Election results do not settle the supply question

Democrats won control of the House and Senate in the midterm elections, but the result does not itself end the war or restore oil flows. Investors are watching what the change in Congress means for Washington’s next steps, alongside diplomatic efforts to end the conflict.

Qatar has stepped up mediation, but Iran and the United States remained far from an agreement on Tuesday, Reuters reported in a CNBC report. The report also described limited U.S. strikes on Iranian missile positions on Qeshm Island. Continuing military activity and talk of diplomacy leave traders facing competing signals rather than a completed peace deal.

For energy buyers, that means a lower morning quote should not be mistaken for certainty about supply. A company’s fuel budget depends on the prices it actually locks in, its contracts and delivery costs, not only the direction of a futures screen during the trading session.

Government inventories differ from the industry estimate

Commercial U.S. crude stocks fell about 900,000 barrels to 409.8 million barrels in the week ended October 30, OilPrice.com reported, citing the government’s weekly EIA release. It reported gasoline stocks down about 200,000 barrels and distillates down 3.6 million barrels, leaving distillates about 13% below their five-year average.

Those figures differ from the earlier American Petroleum Institute estimate of a 5.27 million-barrel crude draw reported by Reuters. The private industry survey and government series are separate measures. Neither a crude draw nor a single futures quote settles the wider supply outlook.

What it means for households and businesses

Crude oil is the largest component of the retail gasoline price, according to the EIA’s explanation. Taxes, refining, distribution and marketing also contribute. A drop in crude therefore does not translate dollar-for-dollar, or immediately, into cheaper gasoline at a nearby station.

Delivery companies, retailers and other fuel-intensive businesses have the same reason to watch the next steps rather than one quote: sustained lower energy costs can ease expenses, but the benefit depends on refined-fuel prices and purchasing arrangements. The key test is whether lower crude prices persist and reach the refined-fuel market.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
The facade of the New York Stock Exchange on Broad Street in Manhattan.

Photo: Jakub Hałun / CC BY 4.0 (archive photo)

The Dow Jones Industrial Average gained more than 1,500 points around midday Wednesday as U.S. stocks extended their post-election rally and crude oil fell below $90 a barrel. The move followed Democrats’ sweep of Congress, with investors weighing divided government alongside lower energy prices.

The Dow stood at 53,298.01, up 1,511.29 points, or 2.92%, in CNBC’s quote stamped 12:00 p.m. Eastern. The S&P 500 rose 138.70 points, or 1.83%, to 7,707.62 at 12:01 p.m., while the Nasdaq Composite gained 526.515 points, or 2.08%, to 25,898.524 in a quote with the same timestamp. These are regular-session index readings, not futures or closing results.

The gains followed President Donald Trump’s reported willingness to accept the election results and work with Democrats, easing one source of political uncertainty, CNBC reported. Divided government can limit major legislation, but it does not remove uncertainty around tariffs, energy costs or the war in Iran. The market’s response also does not mean every industry benefits equally.

Trump claims a record; the major-index data need a distinction

A Trump.fm archive entry attributes a 12:27 p.m. Eastern Truth Social post to President Donald Trump saying the stock market had hit another record high and that Americans’ 401(k)s were “through the roof.” JBizNews has not independently verified the original post on Truth Social.

The broad record claim is not established by the major-index data checked for this update. CNBC’s Dow quote stamped 12:06 p.m. showed a session high of 53,337.27, below its listed 52-week high of 54,744.33. Its S&P 500 quote at 12:29 p.m. showed a session high of 7,713.95 versus a 52-week high of 7,844.52. The Nasdaq Composite quote at 11:53 a.m. showed a session high of 26,048.829 versus 27,722.75. These snapshots do not demonstrate a new record in those three indexes, and the post did not specify an index.

A rising market can increase the value of stock holdings in retirement accounts, but individual 401(k) results depend on investments, contributions, withdrawals and fees. An intraday rally is not a guaranteed return or evidence that every account is at a record.

ADP hiring holds steady at 86,000

Private employers added 86,000 jobs in October, ADP reported, matching September’s revised gain. September was reduced from 90,000. The October reading was above the 75,000 Dow Jones estimate cited by CNBC, but it was not an acceleration from the revised prior month.

All-worker base pay rose 3.2% from a year earlier and gross pay rose 4.7%. Base pay rose 3.0% for job stayers and 4.8% for job changers. ADP measures private-sector employment; this is not the government’s jobs report and supplies no unemployment rate. Our ADP report explains the sector and pay split.

The turn higher follows a sharp overnight selloff as election results pointed toward Democratic control of both chambers. The political result sets up divided government and a harder path for legislation. Investors still have to weigh tariffs, energy prices and developments in the Iran conflict rather than assume gridlock settles every policy risk.

Oil drops below $90

December WTI crude futures fell $7.41, or 7.71%, to $88.68 a barrel in CME Group’s delayed quote stamped 11:51:59 a.m. Eastern, viewed around 12:01 p.m. Data are delayed at least 10 minutes. The prior settlement was $96.09; $88.68 is an intraday futures price, not a new settlement or the price at the pump.

A sustained oil decline can ease costs for transport, delivery and other fuel-heavy businesses. It does not guarantee an immediate matching drop in gasoline prices or customer surcharges, which also reflect refining, distribution, taxes and company pricing decisions.

Earlier morning snapshot: yields and gold

The 10-year Treasury yield stood at 4.921% at 7:23 a.m. Eastern, down 0.029 percentage points, or 2.9 basis points, from its previous close, according to CNBC’s quote. The dollar index was down 0.55% to 101.31 at 7:24 a.m.

In an earlier snapshot, December gold futures rose $106, or 2.69%, to $4,046.40 an ounce. That CME row was stamped 7:14 a.m. Eastern and viewed around 7:24 a.m., with at least a 10-minute delay. It is a futures price, not a spot-metal quote or new settlement.

Bitcoin traded near $78,135 at about 7:24 a.m. Eastern on Coinbase’s snapshot. That is a point-in-time price, not a claim about its return since midnight.

Earlier Europe trading and Asian closes

The Stoxx Europe 600 gained 1.37% to 654.49 in CNBC’s delayed quote stamped 12:09 p.m. GMT, or 7:09 a.m. Eastern. In completed Asian trading, Japan’s Nikkei 225 fell 1.42% to 62,188.63, while Hong Kong’s Hang Seng rose 1.67% to 23,919.50. Those are closing Asian readings, not markets still moving alongside U.S. futures.

AMD and McDonald’s put earnings in focus

AMD reported record third-quarter revenue of $13.4 billion, up 45%, in its earnings release after Tuesday’s close. Data-center revenue rose 97% to $8.5 billion. Chief Executive Lisa Su said the company expects growth to accelerate further in the fourth quarter. AMD shares rose 5.69% to $511.45 in regular trading at 9:47 a.m. Eastern, according to Nasdaq.

McDonald’s earnings beat comes with a warning about the consumer: fewer customers visited its U.S. restaurants, even as bigger checks largely offset that decline. Its adjusted profit beat expectations, but revenue missed. That distinction matters for businesses trying to judge whether customers are buying more or simply paying more per order.

Musk’s political spending faces a Texas setback

Not every part of the post-election market story is a broad rally. Musk spent at least $474 million on the midterms, including $224 million in Texas, according to CNBC’s analysis of campaign-finance records. Republican Senate nominee Ken Paxton and Governor Greg Abbott, whom he backed, lost to Democrats.

The business issue is what changes next in permitting, electricity supply, incentives and federal oversight, not an automatic dollar-for-dollar link between campaign spending and share prices. Texas Governor-elect Gina Hinojosa has called for a moratorium on new data centers, while Republicans’ continued control of the state Legislature limits her ability to rewrite policy. Our Tesla and SpaceX report explains those risks and the earlier share-price reaction.

What to watch next

The morning data calendar included ADP employment, ISM services and weekly oil inventories. Their scheduled release times have passed; the index and crude readings above are time-stamped market snapshots, not a claim that any one report caused the moves.

Uber’s quarterly results showed freight strength offsetting softer-than-expected ride-hailing and delivery sales. Qualcomm reports after the close, with its earnings call at 4:45 p.m.

What it means for your money and business

For retirement savers, the broad rally lifts the value of index-linked holdings during the session, but an intraday gain is not a final return and individual portfolios will move differently. A sharp intraday move is not by itself a reason to abandon a long-term plan. A lower Treasury yield can ease pressure on mortgage and business-loan pricing, but this small move does not promise cheaper loan offers today. Savers should compare the rates their bank actually pays rather than treat the Treasury move as an immediate change in deposit income.

Cheaper crude can help fuel costs if the decline lasts, but pump prices and delivery surcharges do not reset with every futures tick. A weaker dollar makes the same euro-priced hotel room or supplier invoice more expensive in dollars. For a business setting prices or ordering inventory, those currency and energy costs can matter as much as the stock-market headline.

Europe’s inflation reaches 4% as energy costs climb

Across the Atlantic, euro-area annual inflation rose to an estimated 4% in October from 3.8% in September, Eurostat’s flash estimate showed Wednesday. Energy prices were 20.8% higher than a year earlier, compared with an 18.9% annual increase in September. Overall consumer prices rose an estimated 0.4% from September.

For European households and businesses, that means another squeeze on the cost of heating, transport and everyday purchases. The pressure was not uniform: services inflation edged up to 3.3% from 3.2%, while inflation excluding energy, food, alcohol and tobacco held at 2.5%, according to Eurostat. The figures are preliminary; full October data are scheduled for November 18.

The reading keeps borrowing costs in focus. Markets were pricing in a little more than a 72% chance of a European Central Bank rate increase in December after the release, CNBC reported at 5:47 a.m. Eastern. That is a market expectation, not an ECB decision. A further increase would raise policy rates rather than guarantee the same change in every household or business loan.

The euro was up about 0.6% against the dollar Wednesday morning, CNBC reported, while the dollar also faced pressure from the US election results. The inflation report alone does not establish why the currency moved. For Americans paying euro-denominated travel or supplier bills, a stronger euro makes the same bill more expensive in dollars; for US investors in unhedged European assets, currency moves can change dollar returns alongside the assets’ own price moves.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Bernstein slashed its price targets on seven bitcoin miners by 35% to 54% Wednesday, citing tighter financing markets and uncertainty over Texas data center approvals after Democrats’ surprise win in the state’s governor’s race, CoinDesk reported. The cuts are to analysts’ price targets, not to the companies’ share prices.

The largest cut hit CleanSpark, whose target fell to $11 from $24, a drop of about 54%. Riot Platforms was cut to $18 from $35, IREN to $55 from $100, TeraWulf to $20 from $36, Core Scientific to $19 from $32, MARA Holdings to $10 from $17 and Cipher Mining to $15 from $23, according to the report.

Racks of machines inside a bitcoin mining facility

A bitcoin mining facility (Marko Ahtisaari / CC BY 2.0).

The trigger was political. Democrat Gina Hinojosa defeated heavily favored Republican incumbent Greg Abbott in Texas, and she wants to pause new data center approvals until the state adopts rules protecting residents from higher electricity and water costs. No statewide ban has been enacted, and PIMCO’s Libby Cantrill said she expects “a lot more sand in the gears” rather than a stop to construction, according to a roundup of analyst reactions cited by CoinDesk.

The stakes are large because of how much is planned, not yet built: Goldman Sachs estimates Texas accounts for roughly a quarter of planned U.S. data center capacity, and that states likely to tighten rules make up about 45% of planned capacity. Bernstein senior analyst Gautam Chhugani wrote that more than half the power capacity held or planned by the miners-turned-AI-developers his firm covers is in Texas. “We would expect the data center pause to continue and any data center potential legislation to remain in gridlock,” he wrote, saying the firm now values miners’ AI colocation businesses at 12 times expected 2030 earnings, down from earlier assumptions.

The pain may not be evenly shared. Chhugani said miners that already hold approved power connections – IREN, Riot and Cipher have the most Texas exposure but also gigawatts of approved capacity – could benefit if new hookups become “scarce and valuable.” Morgan Stanley analysts led by Stephen Byrd flagged Cipher, MARA and Galaxy Digital as facing the most uncertainty, while calling TeraWulf, Hut 8 and Applied Digital better positioned, CoinDesk reported.

What it means for you: if you own these stocks, Wall Street is not saying the AI boom is over – Microsoft, Meta, Amazon and Google are still expected to spend about $740 billion on capital projects this year – it is saying the easy-money phase of converting bitcoin mines into AI data centers just got slower, pricier and more political, and the winners will be the miners that already locked in their power.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Tel Aviv stocks closed sharply lower Wednesday, with the benchmark TA-35 index finishing below 4,000 points for the first time since the end of January, Globes reported. The TA-90 fell 1.6%, with the two leading indexes shedding nearly 2% between them.

The drop cut across sectors. Bank and insurance indexes fell 1.5% and 2.5% respectively, defense stocks fell 2.3% – Elbit Systems lost more than 3% – and dual-listed shares fell about 1%, with NICE tumbling after its third-quarter report despite revenue and profit that beat analyst forecasts; the company also officially announced a workforce reduction.

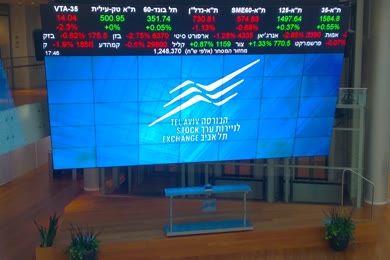
The lobby of the Tel Aviv Stock Exchange

The Tel Aviv Stock Exchange (Yaniv Morozovsky / CC BY-SA 4.0).

Analysts quoted by Globes pointed to an accumulation of uncertainty: the Democratic sweep in the U.S. midterm elections, President Trump’s announcement yesterday on halting U.S. military aid to Israel, and the foreign-interference investigation surrounding Israel’s own elections. Dual-listed stocks were also weighed down by earnings reports.

Eldad Tamir, CEO and owner of Tamir Fishman, told Globes that midterm results historically have no effect on U.S. market behavior, “but full Democratic control of both houses, together with the strengthening of the anti-Israel left within the Democratic Party, could certainly affect markets here for the worse and strengthen the dollar against the shekel.”

Oron Blutman, CEO of Analyst Mutual Funds, said the U.S. results reflect public opposition to Trump’s policies and negative sentiment toward American involvement in the region and support for Israel generally, raising investor concern about further erosion of U.S. backing – especially after the military-aid announcement. A constrained Trump could also focus the rest of his term on foreign policy, he said, raising the risk of further escalation with Iran. Blutman said October and the period since Israel’s elections already brought fund redemptions and a shift into safer assets: “Today is not exceptional, but mainly a continuation of the trend from the recent period.”

What it means for you: most Israelis own these indexes through their pension and savings funds, so a close below the watched 4,000 mark shows up in household statements – and if the analyst read is right, the pressure is about politics and the shekel, not one bad earnings day, which means it may not reverse quickly.

JBizNews Desk | Tel Aviv

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
CVS Pharmacy storefront in Sterling Heights, Michigan, in a December 2020 archive photograph.

Photo: ajay_suresh / Wikimedia Commons

CVS Health shares fell nearly 10% in early regular trading Wednesday after the company announced plans to split into two independent public companies in the first half of 2028, separating its roughly 9,000 retail pharmacies from Aetna, Caremark and its other health-services businesses.

CVS traded at $82.47, down $8.94, or 9.78%, in Nasdaq’s quote stamped 9:54 a.m. Eastern. That is a regular-session snapshot, not a premarket move or closing result. The decline shows investors reassessing the business on the day of the announcement; the quote alone does not establish a single cause for the selling.

The plan changes how those businesses will be owned and managed, not prescriptions or insurance coverage immediately. CVS said patients, customers and clients will continue receiving medicine, care, benefits and services without interruption while it prepares the separation.

The decision follows a strategic review by the board, CVS said in its November 4 company announcement. It moves the story beyond Tuesday’s reports that a breakup was under consideration.

What goes into each company

The healthcare-solutions company will include insurer Aetna, pharmacy-benefit manager CVS Caremark, CVS Specialty, primary-care business Oak Street Health and home-care provider Signify Health. It will be referred to as CVS Health in the interim.

The other company, to be named CVS Pharmacy, will include approximately 9,000 retail pharmacies, mail pharmacy, MinuteClinic and its virtual-care services, plus the Health100 technology-services business.

Caremark helps insurers and employers manage prescription-drug benefits. Keeping it with Aetna means the plan does not separate the insurer from its pharmacy-benefit manager; it separates the retail pharmacy business from that wider healthcare group.

Two management teams, two sets of shares

David Joyner, CVS Health’s current chairman and chief executive, will lead the healthcare-solutions company as chairman and CEO. Prem Shah, currently CVS Health’s group president, will become CEO of CVS Pharmacy. Other leadership and board appointments will be announced later.

Existing CVS Health shareholders will own shares in both companies after the separation. CVS intends the transaction to be tax-free to the company and its shareholders for U.S. federal income-tax purposes.

The first-half 2028 target depends on final board approval, an effective Form 10 registration statement with the Securities and Exchange Commission and customary confirmation of the intended tax treatment. CVS will continue operating as it does today until the separation is completed.

Why CVS is making the change

Joyner said separate companies would give management more focus on consumer engagement, affordability and care coordination. CVS says each business will have its own strategy and capital structure, letting it make investment and partnership decisions around its particular customers.

For the pharmacy business, that includes pursuing partnerships with insurers, pharmacy-benefit managers and drug manufacturers. For the healthcare-solutions company, the strategy keeps insurance, specialty pharmacy and care-delivery businesses together.

Those are the company’s reasons for the split, not an immediate promise of lower drug prices or premiums. The practical near-term message for a person filling a prescription or using Aetna coverage is continuity: CVS says existing medicines, benefits and services will carry on during the process.

CVS scheduled its investor call for 8 a.m. Eastern Wednesday to discuss the separation and its third-quarter results. The company said in the separation announcement that it also raised its full-year financial outlook in a separate earnings release.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Source photograph for How does the US Democrat's 'blue wave' shockwave effect global diplomacy, markets? - analysis

Photo: Kevin Dietsch / Getty Images

The US Democrats’ “blue wave” of midterm election victories is already causing ripples across the rest of the world, where trade partners, strategic allies and enemies all see implications in the result.

Iran and Israel

It is not immediately clear how US President Donald Trump’s loss of control over Congress will shape the course of his country’s eight-month-old conflict with Iran. Voters have shown they are weary of the conflict, which many blame for painfully higher fuel prices. Some Gulf governments now believe Trump has more reason than ever to seek a peace deal and that another full-scale assault on Iran is less likely after the midterms, two sources familiar with Gulf government thinking told Reuters.

But Trump’s electoral drubbing may also embolden Iran.

“If Tehran recognizes that Trump needs a deal, but not just any deal, a genuine opportunity could emerge to end the war,” said Ebtesam al-Ketbi of the Emirates Policy Center. However, reading the vote as weakness could instead invite “a new military escalation,” she added.

US Defense Secretary Pete Hegseth speaks during a round table with US President Donald Trump about foreign fraudulent cryptocurrency investment schemes and the Trump administration's efforts to prevent them, at the White House in Washington, DC, US, October 21, 2026.  (credit: REUTERS/KEVIN LAMARQUE)

For Israel, a Democrat-controlled House and Senate may intensify congressional scrutiny of Israel’s military operations in Iran as well as in Gaza and Lebanon, while threatening long-standing US support for Israel through military aid and weapons sales.

Rivals seeking to unseat Prime Minister Benjamin Netanyahu seized on the Democrats’ wins to lambaste him for a loss of bipartisan American support under his watch, as they seek to forge a coalition following an inconclusive Israeli election last week.

Fuel pump prices

The Iran war has choked supplies of crude oil and liquefied natural gas from the Gulf, driving up the cost of crude oil and prices at fuel pumps around the world.

The energy market wagered on Wednesday that the elections could breathe more life into US-Iran peace talks. Oil dropped for a third day, but tight stock levels prevented a larger selloff, analysts said.

“The market increasingly appears to be betting that President Trump wants to put the Middle East war behind him,” said Saxo Bank analyst Ole Hansen.

Ukraine

Trump has largely halted direct US financial and military aid to Ukraine as it fights a Russian invasion, despite broad support from Democratic and Republican lawmakers. He has angered members of Congress, including many Republicans, by lifting sanctions on Russian diesel and waiving sanctions on Russian energy only weeks after signing them into law.

Control of both chambers of Congress will allow Democrats to propose new aid to Ukraine. If they get enough backing from Republicans and secure a two-thirds majority, a new aid package would survive a Trump veto. However, any boost to US aid is unlikely to come quickly, and it will not address Ukraine’s most pressing need — a deficit of US-made Patriot air defense interceptors to protect its energy infrastructure and cities this winter.

Democrats could also target other Trump policies.

Democratic Representative Gregory Meeks of New York, a candidate to head the House Foreign Affairs Committee, has introduced bipartisan legislation to block Trump’s plan to bring Russian diesel back into the global market. But the midterms are unlikely to change the Trump administration’s position in trilateral peace talks with Russia, where it has pressured Ukraine to make concessions to reach a deal while it simultaneously discusses business deals with Moscow that would favor US investors.

The Kremlin said it hoped the midterm results would not impact what it called Trump’s “peacemaking efforts.”

Trade

The elections could give some countries in Asia more reason to slow-walk investment pledges they made to stave off tariffs, and hand economic rival China a perceived upper hand in ongoing trade talks, analysts said.

However, broad US-China economic relations will likely maintain a state of “fragile stability,” said Chim Lee, industrial policy analyst at the Economist Intelligence Unit in Beijing.

Trump’s midterm losses could spell relief for India’s negotiations for a trade deal with the United States, which has faced delays as New Delhi strives to protect its farmers.

“After the US midterm losses, President Donald Trump’s capacity to impose arbitrary tariffs will certainly face a challenge. At some point he needs the Congress’s approval for trade actions and, to that extent, he’s weakened,” said Anup Wadhawan, a former trade secretary to India’s federal government.

Congress has the right to regulate commerce and set import duties, but Trump has taken advantage of laws to impose tariffs on grounds of national security or unfair trade practices. Democratic Party efforts to limit that power would be likely to face a presidential veto.

Another question is whether Trump will follow through on more immediate threats, such as a 100% tariff on European countries that impose a digital services tax on American tech giants, or whether a €3 billion ($3.37 billion) loan to Airbus AIR.PA from the European Investment Bank will undermine what has been largely a transatlantic trade truce since 2025.

AI and tech

Exit polling revealed that many US voters were concerned about the aggressive buildout of AI data centers. That sent shivers through the shares of major Asian chip manufacturers.

“A Democratic sweep of Congress would put pressure on tech and potentially bring regulatory pressure on everything AI and possibly slow down the wild, wild west growth figures that we see daily and often take for granted,” said Jake Dollarhide, chief executive of Longbow Asset Management in Oklahoma.

Asian chip and AI stocks such as TSMC, Samsung Electronics, SK Hynix and Kioxia all fell on Wednesday.

Asian investors’ concerns were also reflected in pre-market trading in US markets, where shares in US data center operators fell, including Applied Digital APLD.O, TeraWulf, Core Scientific, and Iren.

This post was originally published on here. 

The French National Assembly has adopted an amendment that would require taxpayers to report self-custodied cryptocurrency holdings totaling at least 100,000 euros (about $112,000) to tax authorities, Cointelegraph reported – though the measure is far from becoming law.

The amendment, known as I-2701, was adopted Tuesday as part of the 2027 Finance Bill. The 100,000-euro threshold would be assessed on Dec. 31 of the relevant tax year, and would cover crypto held outside of regulated platforms, in wallets controlled directly by their owners.

The ministers' bench inside the French National Assembly

The ministers’ bench inside the French National Assembly (Sunala / CC BY-SA 3.0).

But the amendment only survives if the budget does. The Assembly has twice postponed its vote on the budget’s revenue section, and a likely rejection there could bring down the entire bill – including every amendment already adopted, Faustine Fleuret, global head of public affairs at crypto lending protocol Morpho, told Cointelegraph. The Assembly faces a Nov. 17 deadline to complete its first reading, and Senate debate is scheduled to begin Nov. 20.

The vote is one of a flurry of crypto tax measures moving through Paris this fall. On Friday, lawmakers rejected two proposals that would have applied exit taxes to unrealized crypto gains when taxpayers move their tax residence abroad. An earlier amendment, approved Oct. 16, would tax gains from converting crypto into certain stablecoins. A separate proposal to exempt small crypto payments for goods and services from tax was defeated.

What it means: nothing changes for French crypto holders today. But if the reporting rule survives the budget fight, holding six figures of bitcoin or ether in a private wallet would become something the tax office expects to hear about – a sign of where European crypto regulation is heading even when the laws themselves keep stalling.

JBizNews Desk | Paris

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
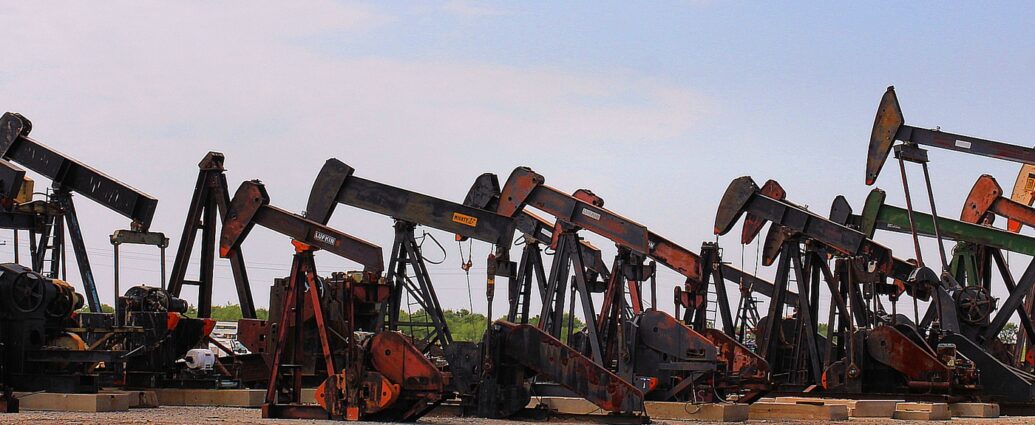
Uber offices in Mission Bay, San Francisco

Photo: HaeB / CC BY-SA 4.0 (archive photo)

Uber shares edged higher before the opening bell Wednesday after the company reported a 10% rise in quarterly revenue, with freight strength offsetting weaker-than-expected sales in ride-hailing and delivery. The results point to growing demand across the platform, but also to the cost of keeping enough drivers on the road.

Uber traded at $67.00, up 0.60%, at 8:55 a.m. ET, according to Nasdaq’s quote. That premarket snapshot is not a closing price and can change before regular trading begins.

Third-quarter revenue rose to $14.77 billion from $13.47 billion a year earlier, the company reported. That exceeded the $14.69 billion LSEG consensus cited by CNBC. Gross bookings, the value of transactions through the platform rather than Uber’s own revenue, rose 20% to $59.82 billion, roughly matching expectations.

Ride-hailing sales fall even as bookings grow

Mobility revenue fell 2% to $7.52 billion, below the $7.71 billion StreetAccount forecast cited by CNBC. But mobility bookings rose 18% to $29.51 billion. Those different trends matter: a decline in reported revenue does not mean customers spent less on rides.

Uber said business-model changes reduced total company revenue growth by eight percentage points. Chief Executive Dara Khosrowshahi also said elevated fuel prices and tighter driver availability weighed on supply growth in several international markets. The company is making targeted investments to strengthen driver supply.

Delivery revenue increased 23% to $5.49 billion, just below the $5.51 billion consensus. Freight revenue jumped 34% to $1.76 billion, beating the $1.49 billion estimate and helping lift the company-wide total above forecasts.

The profit comparison needs context

Net income fell 92% to $512 million from $6.63 billion a year earlier. The earlier quarter included a $4.9 billion tax benefit and a $1.5 billion pretax benefit from investment revaluations. This quarter instead included a $476 million pretax investment-revaluation loss. The headline profit drop therefore does not measure the change in the underlying ride and delivery businesses alone.

GAAP earnings were 25 cents per share. On Uber’s separate non-GAAP basis, earnings rose 35% to 88 cents per share. Operating income under GAAP rose 30% to $1.45 billion, and adjusted EBITDA increased 31% to $2.96 billion. Those accounting measures are not interchangeable.

The platform completed 4.06 billion trips, up 16%, and monthly active platform consumers increased 14% to 215 million. Free cash flow rose 14% to $2.54 billion.

Fourth-quarter outlook and driverless plans

Uber forecast fourth-quarter gross bookings of $63.25 billion to $65.25 billion, representing 18% to 22% growth at constant exchange rates. The midpoint is $64.25 billion, roughly in line with the $64.26 billion StreetAccount estimate cited by CNBC. The company forecast non-GAAP earnings of 95 to 99 cents per share and adjusted EBITDA of $3.13 billion to $3.23 billion.

Uber expects about 700 fully driverless vehicles on its platform by the end of 2026 and more than 2,000 in 2027. Those are expansion targets, not the number operating today, and they should not be confused with Uber owning that many vehicles.

What it means for riders, drivers and businesses

For riders and businesses booking employee travel, the near-term issue is driver supply, not just robotaxi plans. Uber’s comments about fuel costs and availability help explain why growing demand does not automatically translate into easier access to rides in every market. The earnings release does not establish a uniform change in fares.

For drivers, Uber’s planned supply investments are worth watching, but the company has not promised a specific pay increase for every driver. Restaurants and merchants face a delivery business that is still expanding quickly; freight customers are also using a growing operation. Investors, meanwhile, have to separate real transaction growth from accounting changes and last year’s unusually large tax benefit.

JBizNews Desk | San Francisco

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
United States Treasury building in Washington, D.C.

Photo: Wisneyykarin / CC BY-SA 4.0 (archive photo)

The U.S. Treasury will offer $125 billion in notes and bonds in its quarterly refunding, replacing about $97 billion of maturing debt and raising roughly $28 billion in new cash from private investors, the department said Wednesday.

The offering consists of $58 billion in three-year notes, $42 billion in ten-year notes and $25 billion in thirty-year bonds. The $125 billion headline is the total amount being sold, not $125 billion of new deficit financing. Most of it replaces debt coming due.

Auction sizes are expected to hold steady

Treasury said it expects to keep nominal coupon and floating-rate note auction sizes unchanged for the next several quarters, based on current borrowing projections. That is an expectation, not a permanent limit: the department said it continues to assess supply, demand, costs and risks.

Seasonal or unexpected financing needs can be met through changes in regular Treasury-bill auctions or cash-management bills. Treasury expects shorter-dated bill auction sizes to fall in December around tax receipts and rise across the bill curve in January as seasonal outflows increase.

Seven-year notes change format, not monthly frequency

Starting in March 2027, the seven-year note will move from a new issue every month to one new issue each quarter followed by two reopenings. New issues will come in March, June, September and December, with reopenings in the next two months of each cycle.

A reopening sells more of an existing security rather than creating a separate new issue. Seven-year auctions will still take place toward the end of every month. The change therefore does not mean Treasury will stop selling seven-year notes in the intervening months.

Buybacks are debt management, not Fed stimulus

Treasury also anticipates buying back up to $70 billion of older securities for liquidity support and up to $25 billion of securities in the one-month-to-two-year maturity range for cash management during the coming quarter. These are maximum planned amounts, not completed purchases.

The operations are Treasury debt-management buybacks, not a Federal Reserve quantitative-easing program. They should not be described as the Fed injecting an equivalent amount of stimulus or canceling the government’s debt.

What it means for savers and borrowers

For investors buying Treasuries, the announcement sets the supply schedule and the mix of maturities. The final yields will be determined by the auctions and market conditions, not by Wednesday’s offering totals.

For households and businesses, Treasury yields are an important reference for wider borrowing costs, but this announcement does not guarantee a change in mortgage, credit-card or business-loan offers. Stable auction sizes are different from stable interest rates.

The financing plan is also distinct from Treasury’s earlier quarterly borrowing estimate. Wednesday’s statement explains how part of that financing will be carried out, how much replaces maturing debt and which debt-management operations are planned.

JBizNews Desk | Washington

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Port Newark-Elizabeth Marine Terminal, New Jersey

Photo: Ken Lund / CC BY-SA 2.0 (archive photo)

The U.S. trade deficit narrowed slightly to $105.0 billion in September as exports grew faster than imports, the Bureau of Economic Analysis and Census Bureau reported Wednesday. The monthly improvement came alongside a widening three-month average gap, leaving a mixed picture rather than evidence of a trade boom.

The goods-and-services deficit fell $0.7 billion, or 0.7%, from a revised $105.7 billion in August. Exports rose 1.9% to $321.5 billion, while imports increased 1.2% to $426.6 billion. These figures are seasonally adjusted but not adjusted for price changes.

One month’s improvement, a wider recent trend

The year-to-date deficit was $92.4 billion, or 12.2%, smaller than in the same period of 2025. Exports were up 11.6% over that span and imports rose 6.2%.

But the average deficit for the three months ending in September increased $11.3 billion to $101.2 billion. Average imports rose $12.7 billion, far more than the $1.4 billion increase in average exports. The different time windows matter: the September improvement does not mean the recent trend narrowed every month.

Computers and aircraft lift exports

Goods exports increased $5.1 billion to $211.0 billion. On the Census basis used for the product breakdown, capital-goods exports rose $3.8 billion, including increases in computers, computer accessories and civilian aircraft. Soybean exports rose $1.3 billion.

Imports also showed strong technology demand. Capital-goods imports rose $11.6 billion on the Census basis, including gains of $7.6 billion in computers and $5.7 billion in computer accessories, partly offset by a $1.2 billion drop in semiconductors. Those detailed Census figures are adjusted separately to produce the report’s overall balance-of-payments totals.

The goods deficit narrowed to $135.9 billion, while the services surplus slipped by less than $0.1 billion to $30.9 billion. Services exports and imports both increased.

What businesses should take from the numbers

For exporters, rising overseas sales are a sign of demand, but the national total does not promise the same growth for every product or destination. For importers, higher dollar values do not by themselves establish that physical shipments increased by the same percentage: these figures are not adjusted for price changes.

The trade deficit is the difference between what the country imports and exports. It is not the federal budget deficit, a company’s profit measure or a direct reading of household finances.

For businesses planning inventory or overseas sales, the useful detail is the product mix and the broader trend. September’s slightly smaller gap is real, but the wider three-month average is a reason not to treat one month as a lasting reversal.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
ADP headquarters building in Roseland, New Jersey

Photo: ADPDigital / CC BY-SA 4.0 (archive photo)

U.S. private employers added 86,000 jobs in October, ADP reported Wednesday, keeping hiring at the same pace as September while gains in trade, health care and hospitality outweighed losses in professional services.

The payroll processor revised September’s increase down to 86,000 from 90,000. October’s result was slightly above the 75,000 Dow Jones estimate cited by CNBC, but it was not an acceleration from the revised previous month.

For job seekers, the report points to a market that is still adding positions, with opportunity unevenly spread across industries. For employers, it shows continuing competition for workers alongside pockets of weakness, rather than a uniform hiring boom.

Services lead, but business services lose jobs

Trade, transportation and utilities added 39,000 positions, education and health services gained 28,000, and leisure and hospitality added 19,000, according to ADP. Financial activities added 15,000 and construction gained 13,000.

Professional and business services lost 27,000 jobs, its third straight monthly decline. Natural resources and mining lost 8,000, information lost 2,000 and manufacturing shed 1,000. Overall, service providers added 82,000 positions and goods-producing employers added 4,000.

Employers in all size groups increased hiring. Those gains do not mean every company in a growing industry is expanding, or that an applicant will find the same conditions in every local market.

Base pay and total pay tell different stories

Across private-sector workers, median base pay rose 3.2% from a year earlier, while gross pay rose 4.7%. Those are different measures: gross pay can include bonuses, overtime and additional hours as well as base wages.

Workers staying in their jobs saw base pay rise 3.0%, compared with 4.8% for job changers. Gross pay increased 4.4% for stayers and 7.6% for changers. The 3.2% and 4.7% all-worker figures should not be confused with the stayer and changer figures.

ADP Chief Economist Nela Richardson said job changers were being drawn by a combination of bonuses, overtime, more hours and higher base pay. For someone comparing job offers, that makes the mix of guaranteed pay and variable compensation important, not only the advertised total.

This is not the government’s jobs report

ADP’s report is an independent measure based on anonymized weekly payroll data covering more than 26 million private-sector employees. Its pay analysis compares individual workers’ earnings over 12-month intervals.

The report does not measure government hiring and does not supply the U.S. unemployment rate. It should not be treated as the government’s monthly payroll report or as a guaranteed preview of that separate release.

For a business setting a staffing budget, the useful signal is the split between continued hiring and uneven industry demand. For households, annual pay growth alone does not show whether purchasing power has improved: that also depends on the prices they pay and the hours they work.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Photo: Getty Images

At 7 a.m. Eastern Time today, the price of oil sits at $105.84 per barrel, using Brent as the benchmark (we’ll explain what that means shortly). That’s a decrease of $4.61 since yesterday morning and $41 more than at this time last year.

Oil price per barrel % Change
Price of oil yesterday $110.45 -4.17%
Price of oil 1 month ago $106.48 -0.60%
Price of oil 1 year ago $64.84 +63.23%

Will oil prices go up?

Nobody can predict the future path of oil prices with certainty. A range of factors influence how oil trades, yet supply and demand remain the main drivers. When fears of economic slowdown, conflict, or similar shocks rise, oil prices can move sharply.

How oil prices translate to gas pump prices

The price you see at the gas pump reflects more than just crude oil. Also built in are the costs of refining, distribution through wholesalers, various taxes, and the margin your neighborhood station charges.

Crude oil is still the largest single driver of the final pump price, typically representing over half of each gallon’s cost. Spikes in oil prices tend to push gas prices higher in short order. But when oil prices decline, gas prices often ease down gradually, a behavior known as “rockets and feathers.”

The role of the U.S. Strategic Petroleum Reserve

In the event of an emergency, the U.S. maintains a stockpile of crude oil known as the Strategic Petroleum Reserve. Its main goal is to safeguard energy security when disasters strike—think sanctions, severe storm damage, or war. It can also do a lot to ease the pain of sudden price jumps when supply gets disrupted.

It’s not a permanent fix, as it’s more meant to provide immediate support for consumers and ensure critical parts of the economy like key industries, emergency services, public transportation, and so on can keep operating.

How oil and natural gas prices are linked

Both oil and natural gas play key roles as major sources of energy. A big change in oil prices can affect natural gas by proxy. If oil prices increase, some industries may swap natural gas for some segments of their operations where possible, increasing the demand for natural gas.

Historical performance of oil

Oil prices are often measured by two key benchmarks:

  • Brent crude oil is the main global oil benchmark.
  • West Texas Intermediate (WTI) is the main benchmark of North America.

Between the two, Brent is a better representation of global oil performance because it prices much of the world’s traded crude. It’s also often the best way to review historical oil trends. In fact, the U.S. Energy Information Administration now leans on Brent as its primary reference in its Annual Energy Outlook.

When you look at the Brent benchmark across multiple decades, you’ll see that oil has been anything but consistent. It has experienced spikes driven by wars and supply cuts, as well as crashes linked to global recessions and an oversupply (called a “glut”). For example:

  • The early 1970s brought the first big oil shock when the Middle East cut exports and imposed an embargo on the U.S. and others during the Yom Kippur War.
  • Prices dropped in the mid-1980s for reasons such as weaker demand and more non-OPEC oil producers entering the industry.
  • Prices spiked again in 2008 with rising global demand, but soon crashed alongside the global financial crisis.
  • During the 2020 COVID lockdown, oil demand collapsed like never before, bringing prices to under $20 per barrel.

In short, oil’s historical performance has been far from steady. It’s massively affected by wars, recessions, OPEC whims, evolving energy initiatives and policies, and much more.

Energy coverage from Fortune

Looking to stay up-to-date regarding the latest energy developments? Check out our recent coverage:

Frequently asked questions

How is the current price of oil per barrel actually determined?

The current price of oil per barrel depends largely on supply and demand, including news about potential future supply and demand (geopolitics, decisions made by OPEC+, etc.). In the U.S., prices also move based on how friendly an administration is to drilling, as it can affect future supply. For example, 2025 saw the Trump administration move to reopen more than 1.5 million acres in the Coastal Plain of the Arctic National Wildlife Refuge for oil and gas leasing, reversing the Biden administration’s policy of limiting oil drilling in the Arctic.

How often does the price of oil change during the day?

The price of oil updates constantly when the “futures” markets are open. A futures market is effectively an auction where people agree to buy or sell oil in the future. As long as people and companies are trading contracts, the oil price is changing.

How does U.S. shale oil production affect the current price of oil?

In short, shale is rock that contains oil and natural gas. Think of shale as energy yet to be tapped. The more shale the U.S. accesses, the more energy we’ll have—and the more easily oil prices can keep from spiking as much thanks to a greater supply.

How does the current price of oil impact inflation and the broader economy?

When oil is expensive, it tends to make everyday items cost more. This can be related to energy (your heating, gas utilities, etc.), but it’s also due to the logistics involved with making those items accessible to you. Shipping, for example, can affect the price of things at the grocery store, as it’s more expensive to get those products from warehouses and farms onto the shelf.

This story was originally featured on Fortune.com

This post was originally published here. 

Photo: Andrew Harnik / Getty Images

With only a couple of seats left to be called in the midterm elections, a “blue wave” is preparing to wash through Congress.

Voters made it clear they were unhappy with Republicans in the first two years of President Trump’s administration, with 54 Democrats elected to the Senate and 44 Republicans, as of this writing, per CNBC.

Consumers will want to see action on issues close to home from their newly elected officials, namely affordability and inflation. Military conflict with Iran has pushed up oil prices and, as a result, gas prices. That action came after Trump’s tariff scheme, which targeted exports from foreign countries, but economists say it resulted in increased costs being passed back to consumers.

While Main Street has a checklist of action it wants to see, Wall Street is hedging on how the new power dynamics on Capitol Hill will play out.

In the early hours of this morning, yields on longer-dated bonds trended downward as demand inversely rose. 30-Year Treasuries pushed below 5.3%, while the 10-year pushed down toward 4.9%.

Demand for the securities shows bonds remain the destination of choice in a market flight to safety—a question which seemed to hang over the market this summer as yields rose over 5%.

A more divided government increases the likelihood of government standoffs, particularly over spending. “Fiscal gridlock seems the likely default,” UBS’s Paul Donovan told clients this morning. “President Trump has seemingly retreated from an earlier pledge to veto everything the Democrats suggest, Treasuries have initially strengthened on the results.”

Beyond a shield against volatility, investors have additional motivations to look to bonds in the current political climate. President Trump and his team may now find it harder to push through policy packages that might require more spending and, as a result, more government borrowing. Likewise, Democrat spending packages could face roadblocks from a still sizeable Republican presence in Congress and Trump’s veto power.

Markets are also bracing for near-term volatility in equities, as UBS’s chief investment officer, Mark Haefele, noted to clients, “particularly in tech and other areas sensitive to greater regulatory scrutiny.” With AI driving stock gains this year, investors may seek to balance any hiccups with the dependable asset of Treasuries.

While spending gridlock may frustrate policymakers, it might calm the nerves of debt hawks. Concern over the fiscal trajectory of the U.S. is mounting, owing to federal deficits of between 6% and 7% of GDP, and interest payments on the national debt now demand more than $1 trillion a year.

A gridlock could slow the path of any spending bills, allaying some concerns about the U.S. budget picture. As Deutsche Bank’s Jim Reid noted this morning: “There’s been a rally for U.S. Treasuries … given that divided government has generally made it harder for fiscal stimulus to be passed. So that’s eased concerns on the fiscal trajectory a bit.”

Timeline for answers

Policymakers’ appetite for a conversation on fiscal responsibility may be gauged sooner rather than later. The current federal government funding package runs out on December 11 and will require bipartisan support to prevent a government shutdown.

While the officials elected in the midterms won’t be in office until the New Year, a shift in the tide may give Democrats more motivation to hold the line or make bolder demands in return for support.

The odds of a government shutdown jumped to 45% overnight on the prediction market platform Kalshi, up from around 30%.

This story was originally featured on Fortune.com

This post was originally published here. 

SolarEdge inverters on a school rooftop in Lauterach, Austria

Photo: Asurnipal / CC BY-SA 4.0 (archive photo)

SolarEdge shares fell more than 8% before Wednesday’s opening bell after the solar-equipment maker forecast fourth-quarter revenue well below Wall Street expectations, overshadowing a smaller third-quarter loss.

The shares traded at $30.1709, down 8.24%, in Nasdaq’s quote stamped 8:12 a.m. Eastern on November 4. That is a premarket snapshot, not a regular-session closing price.

SolarEdge expects revenue of $245 million to $275 million in the quarter ending December 31, according to its earnings release. Analysts had expected about $318 million, Globes reported. Even the top of the company’s range is below that estimate.

The margin comparison needs a tariff qualifier

The company forecast an adjusted gross margin of 17% to 21% for the fourth quarter, compared with 34.7% in the third quarter. But those numbers are not a clean measure of the change in underlying operations: third-quarter results included a $36 million benefit related to IEEPA tariff matters, while the fourth-quarter outlook excludes potential IEEPA refunds.

That distinction matters to investors weighing whether the last quarter’s profitability can be repeated. A benefit tied to tariffs is different from revenue earned by selling more equipment, and SolarEdge is warning of softer near-term demand.

A smaller loss, but weaker sales

Third-quarter revenue was $326.1 million, down 4.1% from a year earlier and 5.8% from the previous quarter. The company reported a net loss under standard accounting rules of $8.4 million, or 14 cents a diluted share, compared with a $50.1 million loss a year earlier.

On its adjusted basis, SolarEdge earned $21.1 million, or 29 cents a diluted share, compared with an $18.3 million adjusted loss a year earlier. Adjusted earnings exclude certain items and should be read alongside the standard-accounting loss, not treated as a replacement for it.

Cash from operations was $20.4 million, and free cash flow was $7.8 million, marking the fifth consecutive quarter of positive free cash flow. That gives a different view of the business from the share-price decline, but it does not remove the weaker sales outlook.

Cost cuts and an AI push

Chief Executive Shuki Nir said the company is taking steps to reduce costs and narrow its focus as near-term market uncertainty persists. Globes had previously reported about 200 job cuts. Those cuts are earlier reporting, not a newly announced layoff round in Wednesday’s earnings release.

Nir also said SolarEdge is accelerating work on power infrastructure for AI data centers. Demonstrations of its solid-state transformer technology are drawing interest from potential partners and customers, according to the company. Interest and demonstrations are not the same as signed contracts or booked revenue; the release did not announce a new customer contract for that effort.

For solar installers and distributors, the practical signal is the weaker sales outlook and the company’s response on costs. For investors, the next test is whether demand and margins stabilize without relying on tariff-related benefits. The AI work offers a possible additional market, but it does not yet replace the near-term outlook for the solar business.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Maxwell House coffee factory in Jacksonville, Florida

Photo: DXR / CC BY-SA 4.0 (archive photo)

Kraft Heinz agreed to sell control of its North America coffee business, including Maxwell House and Gevalia, to One Rock Capital Partners in a deal valuing the business at $650 million. Kraft Heinz will keep a 30% noncontrolling stake and expects about $500 million in after-tax cash proceeds, which it plans to use to pay down debt.

The deal is not completed. It is expected to close in mid-2027, subject to regulatory approval and other customary conditions, the companies said in their joint announcement Wednesday.

For coffee shoppers, the agreement changes who would control familiar brands, not what is on store shelves today. For employees and suppliers, the practical issue is the planned transfer of the operating business: about 250 full-time employees and two coffee factories are expected to move with it. The announcement describes employee transfers, not 250 layoffs.

What is included in the sale

The portfolio includes Maxwell House, Gevalia, Nabob, Yuban, Tassimo, Ethical Bean and Sanka. The transaction is expected to include the assets, customer support and functional resources needed to operate the North America coffee business.

The factories are in Jacksonville, Florida, and Vancouver, British Columbia. Employees expected to transition work across supply chain, sales, marketing, finance, people and performance, and research and development.

Kraft Heinz Chief Executive Steve Cahillane said the agreement would help the company focus investment on priority areas. The company said retaining a minority stake reflects confidence in the coffee brands’ longer-term prospects under One Rock’s ownership.

$650 million is not the cash Kraft Heinz will receive

The $650 million figure is the enterprise value assigned to the business in the agreement. It is not a promise that Kraft Heinz will collect $650 million in cash. The company’s estimate for net cash proceeds after taxes is approximately $500 million, with a 30% equity interest retained.

The distinction matters to shareholders evaluating debt reduction: the planned debt paydown is tied to the expected cash proceeds, not the larger headline valuation. Neither the cash proceeds nor the proposed transaction’s benefits are assured until the required conditions are met.

Quarterly sales still slipped

Kraft Heinz also reported quarterly net sales of $6.12 billion, down nearly 2% but above the $6.09 billion LSEG analyst estimate, CNBC reported.

Shares rose 3.71% to $25.43 in premarket trading at 8:04 a.m. Eastern, according to Nasdaq. That is an early trading snapshot, not a closing price.

The divestiture comes after Cahillane paused a broader plan to split Kraft Heinz into two companies, according to CNBC. Selling control of coffee gives the company a narrower portfolio decision to act on while it works to improve the remaining business.

One Rock Managing Partner Tony W. Lee said the firm intends to increase investment in the brands, innovation and retail relationships. Those are plans for the business, not announced changes to coffee prices or a guarantee of savings at the grocery checkout.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
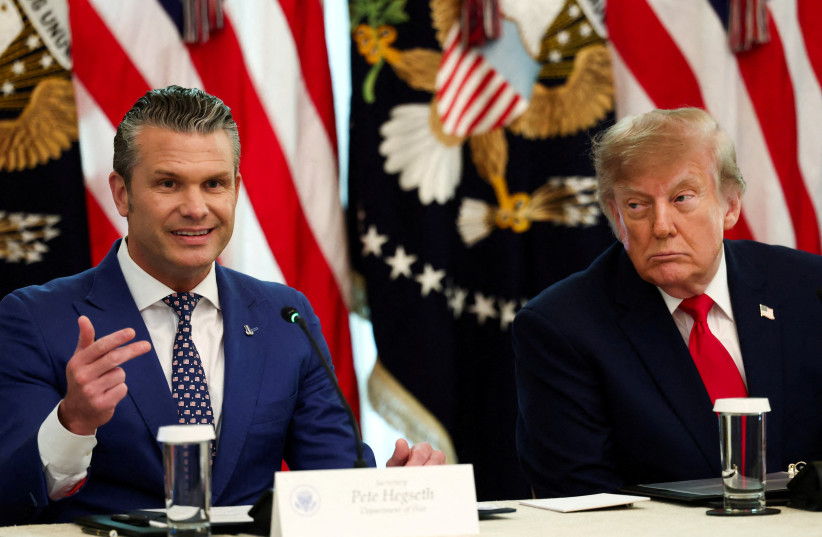
Circle co-founder and CEO Jeremy Allaire speaking at MoneyConf in Dublin

Photo: MoneyConf / CC BY 2.0 (archive photo)

Circle reported a 17% rise in third-quarter revenue and reserve income as transfers of its USDC stablecoin expanded sharply, but a token presale helped lift the headline result while income from reserves fell. The company also cut 5% of its workforce.

Circle shares traded down 2.59% at $73.27 in premarket trading at 7:53 a.m. Eastern Wednesday, according to Nasdaq. That is a later snapshot than early reports of a post-results share gain, and it can change before the 9:30 a.m. opening.

Total revenue and reserve income reached $865 million, while net income from continuing operations rose 5% to $226 million, Circle said in its earnings release. Adjusted earnings were 84 cents a share, CoinDesk reported. Adjusted figures exclude some costs included in standard accounting profit.

More USDC transfers do not mean the same growth in reserves

USDC onchain transaction volume rose 49% to $13.9 trillion during the quarter. Average USDC in circulation increased a more modest 8% to $73.3 billion. Transaction volume counts transfers over time; it is not the amount of money backing the stablecoin or new customer money deposited with Circle.

For businesses considering stablecoins for supplier payments or cross-border transfers, the growth shows more activity on the network. It does not by itself establish that a particular payment route is cheaper or faster than a bank transfer. Fees, conversion costs, local payout access and the recipient’s needs still determine the practical benefit.

Reserve income fell 8% to $658 million. Circle attributed the decline mainly to a 61-basis-point drop in the return earned on reserves, partly offset by the larger average amount of USDC outstanding. That distinction matters for shareholders: more tokens in use do not automatically produce faster income growth when the reserve return is lower.

ARC presale lifts revenue as Circle cuts jobs

Other revenue rose to $207 million, including $182 million from the private presale of ARC, the native token of Circle’s Arc blockchain. The token-sale contribution helped lift the overall revenue result, so the 17% increase should not be read as growth solely from recurring reserve income.

Adjusted EBITDA rose 85% to $317 million. Circle said the increase reflected ARC token presale revenue and lower distribution costs, partly offset by spending on new products.

CoinDesk reported that Circle reduced its workforce by 5%, recording a $9.1 million restructuring charge. The company described the change as a way to align its organization with its operating model. Stronger revenue and a workforce reduction can occur together; the results do not mean every part of the business is expanding at the same pace.

Tazapay deal is agreed, not completed

Circle said it signed a definitive agreement to acquire Singapore-based business-payments platform Tazapay. The transaction is expected to close in 2027, subject to regulatory approvals. Tazapay is not yet a completed acquisition that can simply be folded into Circle’s existing operating figures.

The company also highlighted Arc’s September 16 public mainnet launch and Binance’s announced $100 million equity investment. Those initiatives broaden Circle’s ambitions beyond issuing USDC, but investors still have to separate new-product and token-sale income from the reserve earnings at the center of the stablecoin business.

For USDC users, Circle’s quarterly profit is not an interest payment to token holders. For shareholders, the next question is whether payment activity and new services can build lasting income as reserve returns change. The company is scheduled to discuss its results in an 8 a.m. Eastern webcast Wednesday.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Caesarstone, the Israeli company whose quartz countertops sit in kitchens around the world, has delayed its third-quarter earnings report by a week, to November 11, saying it needs more time for talks on legal settlements, Globes reported.

The report had been scheduled for Wednesday. The company said the delay would “allow additional time for discussions related to legal settlements” and gave no further detail. No settlement has been announced, and the results themselves remain under wraps: investors will now wait a week to see the numbers while the company’s biggest legal fight stays open.

That fight is over silicosis, an incurable lung disease. Lawsuits in the United States claim that workers who cut and installed Caesarstone’s engineered-stone slabs fell ill from breathing silica dust on the job. Last week, a California jury found the company liable in one of those cases and awarded $67.3 million in damages, of which $46.5 million falls on Caesarstone. The company said then that it was reviewing its options.

A quartz kitchen countertop

A quartz kitchen countertop (ShiroMTUN / CC BY-SA 4.0).

The delay lands in a difficult stretch. Caesarstone, led by chief executive Yossi Shiran and traded on Nasdaq, is worth about $59 million today, down from a peak of $2.5 billion in 2012, squeezed by intensifying competition and the mounting legal cases, Globes reported. Kibbutz Sdot Yam, where the company was born, holds 30.2% of its shares, and the Tene private equity fund holds 10.4%.

Overnight the company also updated the summons to its next shareholder meeting. A long-standing voting agreement between the kibbutz and Tene had expired, but at a shareholder’s request a vote on re-electing chairman Ariel Halperin of Tene was added to the agenda, while another candidate, kibbutz business manager Aviv Ben Horin, withdrew.

What it means: nothing is settled yet – not the California case, not the remaining lawsuits, and not the quarter’s results. For investors, employees and the kibbutz that remains the company’s anchor shareholder, November 11 is now the date that matters, the day they find out what the legal fight is costing one of Israel’s best-known home brands.

JBizNews Desk | Tel Aviv

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Wayfair store exterior in Wilmette, Illinois

Photo: BanjoZebra / CC BY 4.0 (archive photo)

Wayfair’s sales rose 9.7% in the third quarter as the home-goods retailer delivered more orders and returned to a profit, even while management described the wider U.S. category as roughly flat. Shares were down 1.19% at $110 in premarket trading at 7:31 a.m. Eastern, according to Nasdaq.

The company reported revenue of $3.42 billion and adjusted earnings of 93 cents a share in its earnings release Wednesday. Both beat the LSEG analyst survey cited by CNBC, which called for revenue of $3.38 billion and adjusted earnings of 79 cents a share.

For households shopping for a sofa or dining table, the useful signal is that Wayfair is selling more orders without a higher average bill. For furniture suppliers and competing stores, it is evidence of growth at one retailer, not proof that the whole furniture market has recovered.

More orders, smaller average baskets

Wayfair delivered 11 million orders, up 12.2% from a year earlier. Average order value fell to $311 from $317. That measure reflects the mix of products, promotions and buying behavior; it does not by itself establish that prices fell on the same furniture items.

Active customers rose 4.7% to 22.2 million. Wayfair defines an active customer as someone who bought directly from its sites at least once during the preceding 12 months. Repeat customers accounted for 80% of quarterly orders, compared with 80.1% a year earlier.

U.S. revenue increased 11.4% to about $3 billion, while international revenue fell 2.3% to $380 million. Chief Executive Niraj Shah said U.S. growth came against a “roughly flat category” and described the result as market-share gains. That is management’s assessment of its position, not an independent finding that demand across the industry has improved.

A return to profit, with a comparison worth noting

Wayfair earned $62 million, or 45 cents a diluted share, compared with a loss of $99 million, or 76 cents a share, a year earlier. The earlier quarter included a $99 million loss on debt extinguishment, so the year-over-year swing is not solely a measure of better furniture sales.

Operating income rose to $106 million from $38 million. Adjusted EBITDA, a profit measure that excludes interest, taxes, depreciation and certain other costs, increased to $236 million from $208 million. Operating cash flow rose to $198 million, and free cash flow increased to $136 million from $93 million.

The company ended September with $1.1 billion in cash, cash equivalents and short-term investments, and $1.5 billion in total liquidity including available revolving credit. Long-term debt stood at $2.57 billion, down from $3.23 billion at the end of December.

The holiday test comes next

Finance chief Kate Gulliver told CNBC that promotional activity remains similar to last year’s as the company heads into the holiday season. She pointed to customer loyalty, new stores, the luxury business and value offers as contributors to Wayfair’s momentum.

Investors will be watching whether higher order volume keeps translating into profit when customers are spending less per order. Wayfair’s conference call is scheduled for 8 a.m. Eastern Wednesday. Its early share decline had narrowed from roughly 3% in a 7:13 a.m. Investing.com report; premarket prices can move quickly before the 9:30 a.m. opening.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Houses in Rochester, New York, April 2024 archive photograph

Photo: Warren LeMay / CC BY-SA 2.0 (archive)

Mortgage rates fell for a third consecutive week, but fewer Americans applied for loans to buy homes, a sign that modest borrowing-cost relief has yet to bring buyers back.

The average contract rate on a 30-year fixed mortgage with a conforming balance dropped to 7.30% from 7.37% in the Mortgage Bankers Association’s survey for last week, CNBC reported Wednesday. The figure is a survey average for last week, not a guaranteed rate available to a borrower today.

For homebuyers, the lower average offers some relief, but financing remains expensive. For sellers and housing businesses, the application figures suggest that a small rate decline alone has not restored demand.

Purchase applications fall again

Applications for mortgages to purchase homes declined 2% from the previous week and were 19% below the same week a year earlier. The weekly comparison comes from MBA’s seasonally adjusted survey.

The 7.30% average applied to conforming loan balances of $832,750 or less. Points fell to 0.75 from 0.76, including the origination fee, for loans with a 20% down payment. Those loan terms matter when comparing the headline rate with another lender’s offer.

MBA chief economist Mike Fratantoni said rates had moved to their lowest level since September following the Federal Reserve’s October decision to hold off on additional rate increases, according to CNBC.

Refinancing remains far below last year

Refinance applications edged up just 0.1% for the week and were 60% lower than a year earlier. CNBC reported that mortgage rates remained about a percentage point above their level at the same time last year, limiting the incentive for borrowers to replace existing loans.

That leaves the housing market with two separate weak spots: fewer applications from buyers and very little weekly improvement in refinancing activity.

Borrowers look at adjustable rates

The average rate on a 5/1 adjustable-rate mortgage fell to 6.29% from 6.41%. Fratantoni said more borrowers were choosing adjustable-rate mortgages to reduce their initial payments, with their share of applications at its highest since September 2025.

The lower initial rate comes with a trade-off: payments can change when the loan resets. It should not be treated as the same long-term borrowing commitment as a fixed-rate mortgage.

The report’s message is straightforward. Last week’s rates were lower, but purchase applications still fell. The decline in borrowing costs has not yet been enough to turn the demand figures around.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Israel’s largest food company is getting ready to try the stock market again. Tnuva is preparing an initial public offering on the Tel Aviv Stock Exchange at a valuation that could exceed NIS 10 billion, Globes reported – and if it happens, it would rank among the largest offerings the exchange has ever seen.

The effort is at an early stage: company executives have sought legal advice and begun a series of meetings with capital market players, with the move slated for next year. No formal offering has been launched, and Tnuva has not commented publicly on the new preparations.

Tnuva has been here before. A 2021 attempt, at an estimated valuation of NIS 9 to 10 billion, collapsed in a sharp dispute between its two ownership groups: China’s Bright Food, which holds 75% of the company, and the kibbutz organizations that hold the remaining 25%. Late last year, Tnuva was preparing for a 2026 listing that also did not materialize. Its chief executive, Gadi Cunia, said at the time that the decision rested with the shareholders: the company was profitable and growing and did not need to raise capital, though going public could offer other advantages.

The Tel Aviv Stock Exchange ticker board

The Tel Aviv Stock Exchange ticker board (David Shay / CC BY-SA 4.0).

Bright Food acquired control of Tnuva in 2015 from the Apax Partners fund and Mivtach Shamir, in a deal that valued the company at NIS 8.6 billion.

The renewed attempt follows a wave of food-sector listings in Tel Aviv. Meat producer Baladi, dairy maker Gad and food company Sugat all went public over the past year at valuations above NIS 1 billion each. But investor appetite has since cooled: a Tel Aviv food-stock index launched in May had shed more than 18% of its value by August, according to a Globes analysis at the time.

What it means: Tnuva’s products sit in nearly every Israeli refrigerator, and a public listing would put a company that touches almost every household’s grocery bill under market scrutiny for the first time, its prices, profits and ownership debated in the open. That day has not arrived. The preparations are real, but so is the track record of attempts that never happened.

JBizNews Desk | Tel Aviv

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Nasdaq MarketSite in Times Square, archive photograph from June 2019

Photo: Ajay Suresh / Wikimedia Commons

Taboola shares fell about 19% in Nasdaq premarket trading Wednesday after the Israeli advertising-technology company lowered its full-year revenue and adjusted-profit forecasts, even as third-quarter net income rose.

The stock traded at $2.74 at 7:16 a.m. Eastern, down 66 cents, or 19.41%, from Tuesday’s $3.40 close, according to Nasdaq’s quote. The move followed the company’s third-quarter earnings release.

For publishers and advertisers, the report shows a business still growing the money it retains after traffic-related costs, but at a lower annual pace than it had planned. For investors, the key change is the reduced outlook, rather than the increase in quarterly net income alone.

Revenue falls while profit rises

Taboola reported revenue of $462.3 million for the quarter ended September 30, down 6.9% from a year earlier, in its November 4 company release. GAAP gross profit rose 9.6% to $152.3 million.

Ex-TAC gross profit, the company’s measure that removes traffic-acquisition costs and makes other specified adjustments, increased 6.8% to $188.8 million. It is different from both total revenue and GAAP gross profit.

Net income reached $18.4 million, compared with $5.2 million a year earlier. Adjusted net income was about $39.9 million, while adjusted EBITDA, a profit measure before interest, taxes, depreciation, amortization and other adjustments, increased 16.1% to $56 million.

Operating cash flow fell to $35.6 million from $53.2 million. Free cash flow declined to $20.4 million from $46.3 million.

The annual targets move lower

Taboola now expects full-year revenue of $1.8825 billion to $1.8985 billion, down from the $1.930 billion to $1.956 billion range in its August company outlook.

Its annual Ex-TAC gross-profit range is now $754 million to $763 million, versus $772 million to $783 million previously. Separately, GAAP gross-profit guidance is $595 million to $604 million, down from $605 million to $615 million. The two measures should not be confused.

Adjusted EBITDA guidance fell to $212 million to $221 million from $228 million to $240 million. Adjusted net-income guidance declined to $151 million to $160 million from $168 million to $176 million.

For the fourth quarter, the company expects revenue of $477 million to $493 million, Ex-TAC gross profit of $204.5 million to $213.5 million and adjusted EBITDA of $73.5 million to $82.5 million.

Management focuses on publisher growth

Founder and CEO Adam Singolda said the company is focusing on adding premium publishers, increasing the revenue generated with existing publisher partners and investing in Taboola News and social commerce. Taboola’s software helps advertisers reach audiences through publisher websites and other digital placements.

The company’s annual guidance now sets a lower financial target for that strategy. Its adjusted measures offer another view of operating performance, but do not replace the GAAP revenue, gross-profit and net-income figures.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
McDonald's restaurant exterior in Lone Pine, California

Photo: m01229 / CC BY-SA 2.0 (archive photo)

McDonald’s beat Wall Street’s quarterly profit forecast Wednesday, but fewer customers visited its U.S. restaurants, a sign that the fight to win price-conscious diners is not over. Shares rose 2.27% to $269 in premarket trading at 7:13 a.m. Eastern, according to Nasdaq.

The company reported adjusted earnings of $3.57 a share for the third quarter, above the $3.38 analysts expected in the LSEG survey cited by CNBC ahead of the results. Revenue increased 1% to $7.157 billion, below the $7.29 billion forecast. Reported earnings were $3.51 a share, up 10% from a year earlier.

Fewer U.S. visits, bigger checks

U.S. comparable sales, which measure sales at established restaurants, fell 0.2%. That was a smaller decline than the 0.5% drop analysts had expected, according to CNBC’s StreetAccount estimate.

In its earnings release, McDonald’s said falling comparable guest counts were largely offset by growth in the average check. It did not give a percentage decline in U.S. traffic. Bigger checks can reflect menu prices, the mix of items customers buy or the size of orders; they do not mean more people walked through the door.

For families, the result keeps attention on meal deals and whether eating out feels worth the price. For restaurant owners and suppliers, the harder number is traffic: keeping sales nearly flat by collecting more per order is different from serving more customers.

Chief Executive Chris Kempczinski said the company was encouraged by improvement in the U.S. as the quarter progressed following its action on value. That is a description of progress, not a declaration that customer visits have recovered.

International business supports growth

Global comparable sales rose 1.5%. Sales at established restaurants in international operated markets increased 1.4%, led by Germany and Australia, with France partly offsetting those gains. International developmental licensed markets rose 4.2%, with Japan contributing growth and China recording negative comparable sales.

Systemwide sales, which include sales at company-operated and franchised restaurants, increased 4% to more than $38 billion. That measure is much larger than McDonald’s own revenue because franchisees keep most of the sales they collect.

Consolidated operating income rose 7% to $3.595 billion. Excluding restructuring-related charges, adjusted operating income increased 8%. McDonald’s also declared a 4% increase in its quarterly cash dividend to $1.93 a share.

The early stock gain suggests investors welcomed the earnings beat and a less severe U.S. sales decline than expected. The next test is whether value offers bring back repeat visits without putting too much pressure on restaurant profits. Premarket trading can be thin, and the price may change before the 9:30 a.m. opening.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Anthropic CEO Dario Amodei has written about creating AI powerful enough that it will be like “having a country of geniuses in a data center.” But the company’s recently-unveiled IPO prospectus sheds new light on the kind of precarious financing Anthropic will require to turn that vision into reality.

This week the company updated its prospectus to include its third quarter financial results, which showed a squeeze on the company’s margins as computing costs have risen. The company also revealed additional data center spending commitments. The company has now pledged to spend a whopping $895.4 billion stretching out to 2045.

Some of the companies selling Anthropic the chips and cloud services it needs are also helping it finance those very same purchases. Broadcom has agreed to absorb losses under a $63 billion equipment-financing arrangement if Anthropic defaults, with its maximum potential liability reaching about $43 billion once the equipment is deployed.

Such backing helps Anthropic obtain computing capacity without paying the full equipment cost upfront. Google and AMD also tie some funding to Anthropic leasing or deploying their hardware. Suppliers providing guarantees could face payouts to lenders and developers they backstop just as weaker AI demand reduces their own sales and market valuations.

Who bears the risk?

In the $63 billion transaction announced on Oct. 26, Bank of America, Citi, Morgan Stanley and Blackstone will finance a newly formed company that buys Broadcom chips and networking equipment and leases them to Anthropic. Deliveries are expected to begin in 2027. Anthropic will pay rent for those chips over time, providing the income financiers rely on to recover their investment. 

If Anthropic defaults on its lease, however, Broadcom has agreed to cover the difference between 72.5% of the amount still owed under the lease and what the equipment sells for. For example, if $100 remains owed and the equipment sells for $60, Broadcom would pay $12.50. 

Gil Luria, the head of technology research at D.A. Davidson tells Fortune that Broadcom basically has to cut a deal like this in order to make sure it doesn’t lose sales to rival Nvidia, which has also offered to backstop some of its biggest chip buyers. “In order to stay competitive with Nvidia’s support of its customers, other large semis companies like Broadcom and AMD have had to step in to support their customers as well,” Luria said. Luria upgraded Broadcom to buy on Oct. 27. 

Financiers’ ability to recover money after a default also depends on whether other customers can use the chips. Comparing Nvidia GPUs with Google’s specialized AI chips, known as TPUs, which are built by Broadcom, Andrew Giudici of credit-rating agency KBRA told Fortune, “Custom TPUs generally have greater re-leasing risk than Nvidia GPUs because they are designed for a more specialized ecosystem and have a narrower pool of potential users”.

Residual-value support, such as Broadcom’s agreement,  can help financiers recover money when equipment cannot be sold or re-leased for as much as expected, Giudici said. “However, it effectively transfers a portion of that risk to the support provider.” That makes the supplier’s creditworthiness, the enforceability of its commitment and the extent of its coverage important to assessing the financing, he said.

Broadcom CEO Hock Tan.
Broadcom CEO Hock Tan. Broadcom has agreed to backstop Anthropic in a financing deal that will allow the AI company to purchase TPUs, a kind of AI chip, produced by Broadcom.
David Paul Morris—Bloomberg via Getty Images

Cash-rich suppliers with substantial businesses outside AI have capacity to absorb losses, Stijn Van Nieuwerburgh, a professor of real estate and finance at Columbia Business School, said. But weaker AI demand could hit those partners’ hardware sales, cloud revenue and investment values at the same time as calls on their guarantees. “Separate contracts can transmit the same underlying demand shock across multiple balance sheets,” he said. “Individual loans can become safer while the broader system becomes more concentrated but also harder to assess.”

Anthropic’s IPO filing says its ability to expand computing capacity may depend on a small number of cloud providers, partners and financiers remaining willing and able to support them. Two of the most important, Amazon and Google, are also spending more cash on their own AI buildouts than their operations bring in. Amazon reported negative free cash flow of $42.4 billion over the preceding 12 months, primarily because of increased AI-related equipment investment. And Google’s parent Alphabet free cash flow was negative $9.1 billion in the third quarter. Both still generate substantial cash and can borrow readily, but their spending means that continued support for Anthropic increasingly competes with their own buildouts for capital.

CEO Dario Amodei has described how an AI company could grow extraordinarily quickly and still buy more computing capacity than it could afford. In a February interview with podcaster Dwarkesh Patel, he illustrated the financial danger with a hypothetical company buying computing capacity on the assumption that revenue would grow tenfold annually. Even fivefold growth could leave it unable to afford what it had ordered. The market could become enormous and still develop too slowly for the purchases made in anticipation of it. “If you’re off by a couple years, that can be ruinous,” he said.

Complex funding conditions

Under a March 2026 agreement, Anthropic can issue up to $42 billion in convertible notes to Broadcom to cover eligible quarterly rent, preserving cash it would otherwise need to pay out. Interest increases the debt, and the holder can choose to convert it into Anthropic shares at a discount.

Notes issued under the facility normally carry 9% interest, with the interest added to the debt, and with the notes deemable for stock at 90% of the market price. But notes issued when specified revenue conditions are unmet carry a 13% interest rate and convert at 85% of market price, giving noteholders more shares for each dollar and further diluting existing shareholders. Sustained failure to meet the agreement’s conditions can end access to further funding. Anthropic says the revenue-growth thresholds are significantly below its recent actual growth rates. The company reported 45% quarterly revenue growth in its third quarter financial results, and a year-over-year growth rate in excess of 1,000%. 

Google and AMD also tie funding to hardware commitments: certain Google funds become available as Anthropic takes on TPU lease obligations, while AMD’s investment becomes available as its GPUs reach delivery and deployment milestones. 

“Hardware-linked equity investments expose Amazon and AMD without making them blanket guarantors,” Van Nieuwerburgh told Fortune. If Anthropic cannot pay, Broadcom and Google bear losses within their backstops’ contractual limits, while lenders retain the uncovered risk, he said.

Anthropic says it has spent years enabling Claude to run across Amazon, Google, Nvidia and AMD chips, allowing it to allocate work according to price and performance. But funding attached to one supplier’s equipment does not automatically follow it to another. That could make it difficult for Anthropic to continue to be as flexible as it has been in which kind of chip it chooses for which workload. 

IPO cash could buy Anthropic more flexibility

Anthropic reported $146.6 billion in liquidity at September 30, including cash, short-term investments and available bank credit. That gives it substantial resources to meet payments and fund expansion, although the bank credit would add borrowing if drawn.

Trzcinka sees that liquidity as a positive for bondholders, but said whether Anthropic achieves an investment-grade rating for its debt “will depend on how the rating agencies assess its substantial future commitments, short operating history, and deeply interconnected relationships.” 

“The company has now disclosed its commitments, which are larger than we initially estimated at $895 billion, compared to our prior estimate of roughly $600 billion,” he said. His view is that those commitments and relationships would limit its ability to obtain financing at investment-grade spreads – the relatively low premiums over benchmark interest rates typically paid by investment-grade borrowers.

“The key question is whether revenue can compound fast enough to absorb the future commitments and outpace compute cost,” he said. He is watching whether Anthropic takes on additional commitments and how its liquidity holds up. “Draws on the revolver [credit facility] would also be a potential warning sign,” he said.

Through Anthropic Direct, a program under which Anthropic plans to build out its own cloud computing infrastructure, the company separates its commitments to data-center space from the larger investment in the chips that will run inside those data centers, giving it more time to assess demand before ordering equipment. It can reserve dedicated facilities operated by third parties on its behalf, then make the chip investment later. Data centers take longer to prepare than the equipment they house, the filing says. As the dedicated infrastructure comes online, Anthropic says it can replace the more expensive short-term compute with lower-cost, long-term capacity.

In the representative AI data-center project modeled in Van Nieuwerburgh’s paper, computing equipment and related systems account for roughly two-thirds of the initial cost, with the facility and power infrastructure making up the rest. 

The data-center commitments Anthropic makes before buying chips can still leave it paying for space that demand may not fill. A facility with secured power “could certainly become a stranded asset if data center demand ultimately disappoints,” Van Nieuwerburgh said, meaning it could be left without enough business to justify its cost and no obvious buyer to which the data center can be sold.

Anthropic says reducing its reliance on partners to pay for future facilities and equipment depends in part on obtaining financing from independent sources on its own credit. An IPO would add cash from shareholders that it could use for those purchases without waiting for a particular supplier’s hardware to reach a delivery or deployment milestone. Combined with Direct’s later equipment decisions, independently raised cash could let Anthropic compare hardware and funding options with less need for the company selling the machines to help pay for them.

IPO proceeds could give Anthropic more freedom to choose its hardware and financing. But as Van Nieuwerburgh put it, “Supplier financing supports construction; ultimately, paying for it requires revenue from end customers.

This story was originally featured on Fortune.com

This post was originally published here. 

Archive photo: aerial view of the Port Newark-Elizabeth Marine Terminal with container cranes and the Manhattan skyline

Photo: Chattus / CC BY-SA 4.0 (archive photo)

New Jersey Governor Mikie Sherrill on Monday, November 2, put the state’s port and terminal operators on notice that importing Russian diesel violates federal law, warning in a letter that doing so could carry serious civil and criminal consequences.

The letter follows the Treasury Department’s October 9 authorization of transactions related to the sale, delivery, offloading and importation of Russian diesel fuel. Russia has since dispatched multiple diesel tankers to the United States, including at least one that may be headed for the New Jersey coast, according to the letter.

Sherrill’s letter argues that the 2022 Ending Importation of Russian Oil Act banned Russian diesel and that its sanctions can be lifted only if the president certifies that Russia has agreed to withdraw its forces from Ukraine, a certification that has not been made.

“Every port and terminal operator, intermediary, and buyer is on notice: do not help bring illegal Russian diesel into New Jersey,” Sherrill said in a statement. She pledged to use all legal and regulatory tools available to keep the state’s ports from being used to advance interests contrary to those of the United States and New Jersey.

For port workers, terminal operators and fuel buyers in New Jersey, the message is direct: anyone who helps bring the Russian shipments ashore could face civil or criminal penalties, and the state says it is watching.

JBizNews Desk | Trenton

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.
Fletcher Williams saw six movies at AMC theaters last month. At full price, that would have run about $150. He paid $29.99.

Williams, 25, is one of more than 1.1 million members of AMC Stubs A-List, the subscription tier that lets moviegoers reserve up to four films a week, including IMAX and Dolby Cinema, for a monthly fee of roughly $24 to $30 depending on the state. As audiences return to theaters in 2026, AMC Entertainment is counting on the program to turn occasional ticket buyers into regulars.

The open question is whether that loyalty can do what a run of hit movies has not yet done: make AMC consistently profitable while it carries roughly $4 billion in debt.

A record quarter after a long way back

The rebound is real. AMC reported $1.60 billion in revenue for the second quarter of 2026, up 14.2% from a year earlier and the highest quarterly total in its 106-year history. Worldwide attendance rose 13.5% to 71.3 million.

Admissions brought in $863.1 million, up 13.2%. Food and beverage sales rose 15.3% to $576.1 million. The industry helped: the $2.99 billion domestic box office was the strongest second quarter in seven years, with six films opening above $75 million.

The hole was deep. AMC’s revenue fell 77% in 2020, from $5.47 billion to $1.24 billion, as the pandemic shut theaters. As recently as early 2025, chairman and CEO Adam Aron said the industry’s January-to-March domestic box office was its weakest since 1996, setting aside quarters hit by COVID.

Records have not yet meant profits. AMC posted an $11.4 million net loss in the second quarter as interest and other charges absorbed much of the gain. For 2025, it lost $632 million on $4.85 billion in revenue, according to Fortune’s company data.

Why a flat fee changes the math

For frequent moviegoers, the arithmetic is simple. A standard adult ticket at AMC typically runs $13 to $15 before premium formats like IMAX or 3D [source needed], so a movie a week can top $65 a month in tickets alone.

Williams first signed up in college, when he lived 15 minutes from an AMC. For the number of films he sees, he said, “The membership basically pays for itself.”

“$25 to $30 is roughly the equivalent of a single ticket for a new movie where I live. Paying that once a month for the ability to see up to 4 movies a week is incredibly worth it,” said Williams, who now lives in Los Angeles.

Members could see as many as 17 films a month, but the typical member sees two or three, according to AMC. Even at that pace, most come out roughly even or ahead.

“I used to watch them casually, but after getting into film in 2024, I decided to enroll. I usually see at least 2 movies a month, and since the membership pays for itself if you do that, I’ve stayed subscribed,” said Autumn Miller, 28, of New York City. She saw five movies last month.

AMC launched A-List in 2018, when Fortune tracked it as AMC’s answer to MoviePass. Membership has more than doubled over the past five years, and A-List members now account for about 20% of AMC’s U.S. attendance, Aron told analysts in July.

“We’ve seen significant membership growth in recent years, as movies have returned in much greater numbers to theatres, and at the end of the second quarter of 2026, A-List had grown to more than 1.1 million members,” AMC spokesperson Ryan Noonan wrote in an email. “A-Listers remain among our most engaged moviegoers, regularly seeing a broad range of films at AMC. We think the continued growth of A-List speaks volumes about how much our members enjoy the program and the value they see in it.”

Loyalty that shows up beyond the ticket

For some members, the subscription has changed how they spend on entertainment, not just how often they go out.

“I think it’s changed how I approach entertainment more than anything. Instead of treating a movie as an occasional expense, I can make it a regular activity, and I’m more inclined to spend my entertainment budget on experiences I genuinely enjoy. I still have streaming services at home, but going to the theater offers something different that I can’t fully replicate on my couch,” said Noah Osborne, 28, of Phoenix.

“I’d say I probably spend a bit less on streaming services since I’m able to watch the movie in the theater. A-Listers also have great deals on concessions, so I’m able to save some money there too,” said Sophie Guaman, 28, of [New York City / New York state].

That concession spending matters to AMC, which earns heavily on food and drinks. Food and beverage revenue per patron hit records in both its U.S. and international businesses in the second quarter.

Members also do some of AMC’s marketing. On TikTok, subscribers post under #amctheatres, showing off their trips through the A-List priority line near the concession counter.

“The enthusiasm our members continue to show for the program has exceeded our expectations, especially in the way they talk about A-List, both online and with their family and friends,” Noonan wrote.

The debt test for A-List

In October, AMC completed a $3.97 billion refinancing that pushed almost all of its debt maturities to 2031 and 2033 and, the company said, lowered its cost of capital. The deal buys time. It does not shrink the roughly $4 billion AMC owes.

That is the real test for A-List. A program that brings in a fifth of U.S. attendance can keep seats filled between blockbusters. Whether it can generate enough steady cash to help pay down debt is a different question.

The next read comes with AMC’s third-quarter report, covering July through September: whether attendance held after a record spring, and whether a bigger, more loyal audience starts to show up on the bottom line.

This story was originally featured on Fortune.com

This post was originally published here.