Democrats will take full control of Congress in January after winning both the House and the Senate on Tuesday night, NBC News projected. Republicans had entered Election Day with a 53-47 Senate majority and a 219-214 House majority.

It will be the first time in Trump’s second term that he hasn’t had full control of Congress. Since returning to the White House, he has dismantled federal agencies through the Department of Government Efficiency, imposed sweeping tariffs on his own authority and rescinded funding Congress had approved, while the Republican-controlled House and Senate mostly looked the other way, NBC reported.

Trump responded on Truth Social: “I wasn’t on the Ballot and if I was, we would have won IN A LANDSLIDE!”

The $5,000 promise

In his closing speech at the Lincoln Memorial Reflecting Pool on Monday, Trump said he had kept every promise he made, then added: “I’ve actually kept far more promises than I made,” the Mirror reported.

One of those promises was cash. At the GOP’s midterm convention in Dallas in September, he told the crowd, “If the Republicans win, you win with us and you get $5,000.” In an October Truth Social video, he said he would give $5,000 to “all Adult Citizens” if Republicans won both chambers. He renewed the promise in his last speech before Election Day.

Voters were skeptical. An Economist/YouGov survey found 57% of registered voters doubted Trump would deliver the payments even if Republicans kept Congress. The checks would have cost about $1.22 trillion and would have needed legislation to authorize them either way. Earlier promises of a $5,000 DOGE dividend and $2,000 tariff checks never produced the payments. As results came in Tuesday night, Fox News host Jesse Watters told viewers, “I don’t think we’re going to get our $5,000 checks.”

How Democrats won the House and Senate

Democrats flipped Republican-held seats in states Trump carried. James Talarico beat Ken Paxton in Texas, despite more than $200 million Elon Musk spent to help elect Paxton. Former Gov. Roy Cooper won North Carolina’s open seat. Annie Andrews defeated Sen. Darline Graham in South Carolina. Sherrod Brown defeated Sen. Jon Husted in Ohio. Josh Turek flipped Iowa’s seat, and Adam Hamilton won in Kansas, NBC projected.

Democrats needed a net gain of just three seats. In New Jersey’s 7th District, Rebecca Bennett defeated Rep. Tom Kean Jr., and in Virginia’s 2nd, Elaine Luria flipped the seat held by Rep. Jen Kiggans. Manny Rutinel won Colorado’s 8th, and Jamie Ager won North Carolina’s newly redrawn 11th. NBC’s Decision Desk estimates Democrats will finish with about 248 House seats.

The House gives Democrats subpoenas and control over spending bills. The Senate adds control over who serves in Trump’s government. A Democratic Senate can block Trump’s Cabinet nominees and freeze federal judicial appointments, including any Supreme Court pick if a seat opens. Chuck Schumer returns as majority leader, and Senate committees will run their own investigations. Schumer set up a working group in February to look into Epstein-related information the Justice Department has held back.

With both chambers, Democrats can also pass their own bills, including Speaker-in-waiting Hakeem Jeffries’s priorities on Medicaid, Affordable Care Act subsidies, tariff authority and the Iran war. But every bill still needs Trump’s signature, and he has promised to veto them. Overriding a veto takes two-thirds of both chambers, a margin Democrats won’t have.

The subpoenas

Rep. Robert Garcia, the incoming House Oversight chair, marked the win with a two-word statement: “Lawyer up.” He has said his panel will focus on “Trump family corruption,” including the president’s crypto ventures, and administration officials could face subpoenas on “day one”. Corporate ballroom donors and companies that did deals with Trump family members are expected to be among the first targets, Reuters reported.

Those subpoenas have limits. Administration officials could defy them, because a Justice Department led by Trump appointees is unlikely to enforce them, Reuters reported. The House can impeach with a simple majority, but conviction in the Senate takes two-thirds of senators. Jeffries has said Democrats “haven’t ruled anything in and we haven’t ruled anything out” on impeachment.

How Trump plans to govern

The White House is preparing to rely even more on executive power. Asked how comfortable Trump would be governing that way under a Democratic Congress, one person familiar with the planning told Reuters: “very comfortable.” Nathan Gonzales, editor of the nonpartisan Inside Elections, said Trump has largely ignored Congress and governed by executive order. “I think he will only continue if there are Democratic majorities,” Gonzales said.

The size of the Senate majority matters too. If Democrats end up with 51 seats, all eyes will turn to Sen. John Fetterman, MS NOW noted. The White House has blamed the candidates for the losses, The Hill reported.

This story was originally featured on Fortune.com

This post was originally published here. 

As housing prices increase nationwide and Americans increasingly voice their frustration with affordability, voters in North Carolina have approved a constitutional amendment that lowers the state’s income tax cap from 7% to 3.5%.

The Associated Press called the race at 9:21 p.m. Tuesday, with 61% of votes in favor and 89% of votes counted, according to WBTV. The amendment bars the General Assembly from raising the income tax rate above 3.5% unless voters approve another constitutional change. North Carolina currently has a 3.99% flat income tax rate for all earners, and that rate is scheduled to fall in the coming years. The new ceiling replaces the 7% cap voters approved in 2018. The Republican-led General Assembly put the amendment on the ballot over objections from Democratic lawmakers.

Republican state Sen. Michael V. Lee, who sponsored the legislation, argued earlier this year that the cap protects taxpayers from future increases and locks in more than a decade of tax cuts. Democratic Gov. Josh Stein opposed the amendment, calling it “a con, a cynical shell game and a millionaire protection cap.” He argued it would shield the wealthy from future income tax increases while regular people bear the cost.

A separate constitutional amendment on property taxes, which was still being counted late Tuesday, also had the support of the North Carolina General Assembly’s Republican majority. It would not immediately reduce property taxes, but would require the legislature to pass a law that would limit the amount of property tax a local government can raise from one year to the next, with details like the specific limit and exceptions to be decided by the state legislature at a later date.

In the run-up to the midterm election Tuesday, proponents said the property tax amendment would help people stay in their homes and would ease the burden on homeowners. Opponents of the constitutional measure, meanwhile, said it would restrict local governments’ revenue growth, potentially forcing them to cut services and would have a bigger effect on large corporations than on individual homeowners. 

State Rep. Brian Echevarria, a primary sponsor of the legislation that put the constitutional amendment on the ballot, wrote in an opinion piece last year that property tax increases based on property reevaluations amount to a “tax on unrealized gains” which he argued is unfair for homeowners, especially in fast-growing areas that have seen property tax rates increase significantly in recent years.

Meanwhile, opponents, including the North Carolina Housing Coalition claim that a limit on property taxes would translate to limited savings for homeowners while corporate property owners see millions in tax savings. According to an analysis by the coalition, if a 2% levy cap had been in place during their latest property revaluation cycle, the average homeowner would have saved $84 a year, while local government revenue would have plummeted by $950 million.

The income tax cap comes amid widespread concern among voters about the cost of living. Some 48% of registered voters said the cost of living was the top issue for deciding how they would vote, according to a Reuters/Ipsos poll.

The price of housing makes up a big part of that concern. The median existing single-family home price reached $422,700 in September, up 1.2% compared to a year earlier, according to the National Association of Realtors. Meanwhile, the average 30-year mortgage rate reached 7.24% in late October, up from 6.17% at the same time last year, increasing borrowing costs for homebuyers.

As Americans increasingly struggle to afford a home, those who already own one are also dealing with higher property taxes, which increased 3% compared to last year and now stand at about $4,427 annually, according to U.S. real estate and property data provider ATTOM.

National debate

The same affordability concerns that helped fuel Tuesday’s North Carolina vote also gave rise to other property tax-related measures in other states.

Voters on Tuesday weighed in on 15 measures across nine states dealing with property taxes, according to the National Conference of State Legislatures.

In Florida, voters approved an amendment that expands homestead exemptions for non-school property taxes to $250,000 by 2028. In Oklahoma, voters also considered tightening limits on how quickly property values can rise for tax purposes, including reducing the cap for qualifying homes from 3% to 1.75%.

The debate over property taxes has been contentious across several states for decades. 

In 1980 Massachusetts passed Proposition 2½, which has generally limited annual increases in municipal property-tax levies to 2.5%, plus revenue from new development since it went into effect in 1982. The law allows municipalities to seek voter-approved overrides.

Critics have said the proposition prevents local governments from raising the revenue they need to fund services as costs increase. Still, a 2025 poll by the Fiscal Alliance Foundation, which advocates for lowering taxes, found that 66% of 800 likely voters in Massachusetts viewed the measure favorably. 

Uncertain savings

At the same time, the push for tax relief in several states also raises questions about how cities and counties will finance the government services that citizens rely on.

Property taxes in North Carolina account for more than half of county general fund revenue, according to the North Carolina Association of County Commissioners. This fund helps pay for government services like healthcare, education, and transportation services.

Individual homeowners could still see their tax bills increase following property reassessments, even with limits put in place by the General Assembly at a later date.

Yet, because the constitutional amendment leaves undecided it’s hard to estimate the financial impact a property tax limit would have on local governments.

Still, local officials in some smaller counties have said they will be disproportionately affected by a uniform limit on property tax growth.

That includes David Clegg, the county manager of rural Tyrrell County in Eastern North Carolina, who told NC Newsline in May that the measure could deprive the 3,000-person county of needed revenue.

“Tyrrell County is providing the baseline human services and quality of life services that just keep us going,” Clegg told the outlet. “If you start cutting at that all of a sudden, you’re cutting social services, law enforcement, health, emergency medicine because there’s nothing else to cut.”

This story was originally featured on Fortune.com

This post was originally published here. 

Hong Kong's Victoria Harbour and skyline viewed from Victoria Peak on a rainy June night in 2019.

Photo: Benh Lieu Song / Wikimedia Commons, CC BY-SA 4.0

Asian markets turned mixed Wednesday as Seoul bounced back from its steepest drop in two weeks and Tokyo reopened lower after a holiday, while Beijing’s latest attempt to steady its sinking stock market drew a lukewarm response from investors.

South Korea’s Kospi rose 1.2 percent to 5,715.81 by 9:37 a.m. in Seoul, Korea Exchange data showed, after opening 2.4 percent higher. The index had closed down 3.6 percent at 5,648.79 on Tuesday, its sharpest one-day fall since Oct. 20, as Samsung Electronics lost 4.2 percent and SK Hynix shed 5 percent. Samsung recovered 0.9 percent and SK Hynix climbed 2.1 percent in early trade Wednesday.

In Tokyo, the Nikkei 225 fell 1.6 percent to 62,104 by 9:37 a.m. in Tokyo as the market reopened after Tuesday’s Culture Day holiday, catching up with a regional selloff that hit while it was closed, according to index data. The yen traded near 158.3 to the dollar.

In China, regulators on Monday rolled out fresh steps to support the sinking mainland market, including People’s Bank of China swap operations to help brokers, funds and companies finance share purchases, alongside calls for more buybacks. The response was tepid. The Shanghai Composite fell 0.8 percent Tuesday to 3,608.10, near one-year lows, and the tech-heavy ChiNext index dropped 2.7 percent. Hong Kong’s Hang Seng Index went the other way, rising 0.6 percent to 23,525.97 as technology shares gained.

The region traded against a mixed Wall Street finish on Election Day in the United States. The Nasdaq Composite rose 0.8 percent to 25,372.01 and the S&P 500 added 0.4 percent to 7,568.92, while the Dow Jones Industrial Average slipped 0.4 percent to 51,786.72. Polls in the midterm elections were closing across the eastern United States as Asian markets opened, with control of Congress at stake.

Oil steadied after two days of heavy losses. U.S. crude settled at $96.09 a barrel Tuesday on the New York Mercantile Exchange, down 37 cents, after dipping below $95 earlier in the session, and traded near $96.40 early Wednesday. Brent, the international benchmark, settled at $103.60. Diplomacy between Washington and Tehran continued to drain the conflict premium that pushed prices above $100 last week.

For households, the threads to watch are simple. Beijing’s rescue attempt signals official discomfort with a market slide that sits inside many U.S. retirement and college-savings funds through China and Hong Kong holdings. Oil holding near $96 keeps pointing toward relief at the gasoline pump in the coming weeks. And the midterm vote count unfolding overnight will shape the tax and spending debates that reach family budgets.

Hong Kong and Shanghai reopen for Wednesday’s session about half an hour after this report is published. Attention then turns to the U.S. midterm vote count and, on Friday, the October jobs report.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

A building at Amgen headquarters in Thousand Oaks, California, photographed in July 2016.

Photo: Coolcaesar / Wikimedia (archive)

Amgen raised its full-year sales and adjusted profit outlook Tuesday after third-quarter revenue climbed 8% to $10.4 billion, with cholesterol treatment Repatha and newer medicines offsetting a sharp fall in osteoporosis drug Prolia. Adjusted earnings rose 14% to $6.45 a share.

Both headline figures exceeded analyst expectations: revenue was above the $10.1 billion estimate and adjusted earnings topped the $5.79 forecast, according to LSEG data cited by Reuters. The earnings comparison is on an adjusted basis, not GAAP earnings.

Amgen shares nevertheless fell more than 2% to about $450 in after-hours trading, Reuters reported in its Tuesday account, updated at 5 p.m. That is the price reaction reported by the news agency, not a current live quote.

Repatha and newer treatments offset Prolia’s decline

Prolia sales dropped 45% to $632 million as patent expirations brought increased competition, Reuters reported. That missed the $697 million analyst forecast and showed how quickly an established drug’s revenue can erode as rivals enter the market.

Repatha sales rose 37% to $1.09 billion, according to Amgen’s quarterly release. Reuters said that was slightly above the $1.04 billion analysts expected. The cholesterol medicine remained a major source of growth as some older products weakened.

Uplizna sales increased 191% to $451 million, while lung-cancer treatment Imdelltra rose 128% to $406 million. Those newer growth drivers helped support the overall sales increase despite Prolia’s decline.

Amgen now expects 2026 adjusted earnings of $22.90 to $23.70 a share, up from $22.30 to $23.50. It raised its revenue outlook to $38.9 billion to $39.7 billion from $38.2 billion to $39.4 billion. These are management forecasts, not guaranteed results.

MariTide data and Tavneos review remain ahead

The company is also advancing MariTide, its experimental weight-loss medicine. Initial results from its broad Phase 3 trial program are not expected until next year, Reuters reported. Trial progress and expected data are not regulatory approval, and MariTide remains investigational.

Amgen’s release describes ongoing studies in obesity and related conditions, including cardiovascular disease, heart failure and obstructive sleep apnea. The program also includes studies of less-frequent dosing, but the clinical work still has to establish how the medicine performs.

Another unresolved issue is Tavneos, whose quarterly sales fell 2% to $105 million. Reuters reported that the Food and Drug Administration proposed withdrawing the medicine in April, citing concerns about effectiveness and the integrity of trial data. A proposed withdrawal is not a completed withdrawal.

Amgen said it continues to engage with the FDA and believes Tavneos demonstrates clinical effectiveness and a favorable benefit-risk profile. That is the company’s position in an ongoing regulatory dispute, rather than a resolution of the agency’s concerns.

The quarter shows growth from Repatha and newer medicines translating into a higher annual forecast. Investors are also weighing the decline in older products and the clinical and regulatory decisions still ahead, including next year’s MariTide results.

JBizNews Desk | Thousand Oaks
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Homes in Maple Grove,Minnesota in February2018, archive photograph

Photo: Tony Webster / Wikimedia Commons

Finance of America reported a $110 million third-quarter net loss on November 3, largely driven by noncash changes in portfolio values, even as the home equity lender increased funded loan volume by 24% from a year earlier.

Finance of America shares traded at $10.50 after hours Tuesday, down 0.28% from the $10.53 regular-session close, as of 5:15 p.m. ET, according to Yahoo Finance.

The company funded $748 million of loans in the quarter ended September 30, up from $603 million a year earlier. But growth in lending did not offset pressure from higher benchmark interest rates on origination margins and the value of assets retained in its financing business.

In its earnings release, the Plano, Texas-based company said $125 million in noncash fair-value adjustments was the main driver of the reported loss. The basic loss was $5.24 per share.

Adjusted profit tells a different, but weaker, story

Finance of America reported adjusted net income of $6 million, or 28 cents per share, and adjusted EBITDA of $17 million for the quarter. Those are company-defined non-GAAP measures, which exclude certain items and do not replace the reported net loss.

The adjusted results also weakened from a year earlier. HousingWire reported that adjusted net income was $33 million and adjusted EBITDA was $55 million in the third quarter of 2025.

The difference between the reported loss and adjusted profit reflects the importance of portfolio valuation changes to the company’s results. A noncash mark is not the same as cash leaving the company during the quarter, but it still affects reported earnings and the value assigned to its assets and liabilities.

More lending, tighter margins

The retirement solutions business, which includes reverse mortgages and other home equity-based financing, generated $67 million of revenue in the quarter. Funded volume grew, but higher benchmark rates put pressure on the revenue earned from that production, the company said.

The segment’s pretax income fell to $3 million from $10 million in the second quarter. Adjusted net income declined to $9 million from $15 million over the same period, according to the release.

For the first nine months of 2026, funded volume reached $2.074 billion, up 17% from a year earlier. Retirement solutions revenue for that period rose 14% to $208 million.

CEO Graham Fleming said the company believes the rate-driven earnings pressure is temporary and has already changed product pricing to improve margins. The company expects margins to return to historical levels. That is management’s outlook, not an assured recovery.

Portfolio marks weigh on results

The portfolio management business reported a pretax loss of $138 million. Finance of America attributed that result to negative noncash fair-value adjustments on retained interests in securitizations.

Assets under management reached $37.4 billion, up 23% year over year, HousingWire reported. The increase included new originations and the July 1 acquisition of Onity Mortgage’s HECM servicing portfolio.

Finance of America ended September with $118 million in cash and cash equivalents, an increase of $33 million during the quarter. It said cash generation from originations and capital markets activity supported that rise.

The company expects to pay down $60 million of senior secured notes in November. Its results leave investors with two distinct measures to weigh: growing demand for its home equity products, and lower profitability in a more difficult interest-rate environment.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

This post was originally published on here. 

Archive photo: Federal Trade Commission headquarters in Washington, November 6, 2005. Not today's lawsuit.

Photo: Carol M. Highsmith / LOC (archive)

Booking Holdings recorded a $900 million reduction in third-quarter revenue and a separate $100 million accrued loss tied to a Federal Trade Commission matter involving Priceline’s relationship with hotel-booking website Guest Reservations, the company disclosed Tuesday. The combined $1 billion accounting impact is not a fine ordered by a court or an agreed settlement.

No settlement has been reached, and litigation remains possible, the company said in a filing cited by Reuters. Booking warned that the dispute and similar claims in other jurisdictions could further affect its business, results and reputation.

The charge overshadowed continued growth in travel reservations. Gross bookings rose 10% to $54.5 billion and room nights increased 7% to 345 million, according to the company’s earnings release. Reported revenue fell 1% to $8.893 billion from $9.008 billion a year earlier.

Booking shares were down 1.5% in extended trading, Reuters reported in its Tuesday account, updated at 5:55 p.m. Eastern. That is the reaction reported at that point, not a live quote or a claim that the legal matter alone caused the move.

Scrutiny of hotel ads, identity and fees

The FTC has been investigating Priceline’s relationship with Guest Reservations, including whether the arrangement violates a rule against impersonating other businesses and other potential fee-related violations, Reuters reported. An FTC spokesperson declined to comment to the news agency.

Priceline supplies hotel-room inventory to Guest Reservations through Priceline Partner Solutions, according to an ongoing San Francisco lawsuit described by Reuters. The allegations concern how hotel bookings are marketed and sold, rather than whether demand for travel itself has disappeared.

Reuters said Guest Reservations has drawn more than 1,000 consumer complaints to the Better Business Bureau. Many consumers said they thought they were booking directly with hotels and complained about unexpected fees and difficulty getting help. Those complaints are consumers’ accounts, not findings that every transaction was unlawful.

Booking said a possible settlement would likely involve a direct payment by Priceline to the FTC and monetary restitution to certain U.S. consumers, Reuters reported. The company has not agreed to such a settlement, and the accounting entries do not establish what any final payment would be.

Travel growth and reported revenue move in different directions

The company excluded the $900 million revenue reduction and the $100 million loss accrual from its adjusted measures, as applicable. Adjusted revenue was $9.793 billion, up 9%, compared with the 1% decline in reported revenue. The adjusted figure helps separate operating trends from the FTC matter but does not erase its financial impact.

Gross bookings measure the total value of travel services booked, generally including taxes and fees and net of cancellations. They are not the revenue Booking keeps. The company said gross bookings did not reflect the FTC matter, which helps explain why that measure rose even as reported revenue declined.

Booking said travel demand moderated toward the end of the third quarter as international travel softened, while domestic demand remained resilient, according to Reuters. It also pointed to Middle East travel disruptions, elevated airfares linked to the conflict and localized unrest in some European cities as pressures on October demand.

The results leave investors weighing two separate issues: a travel business still expanding reservations and an unresolved regulatory exposure whose ultimate cost is not yet fixed. The company has recognized a substantial accounting impact, but the legal process and any settlement terms remain unsettled.

JBizNews Desk | Norwalk
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Residential subdivision near Union Kentucky. June2005 illustrative archive, not identified Chimera collateral.

Photo: Derek Jensen / Wikimedia Commons

Mortgage lenders and investment funds are competing for the right to service home loans, pushing pricing for some of the strongest portfolios toward levels industry executives say have not been seen in more than two decades.

High-quality conventional mortgage servicing rights, known as MSRs, are trading near 7 times in the market’s pricing shorthand, according to executives quoted in a November 3 HousingWire report. Those prices apply to a particular segment of the market, not every servicing portfolio.

The competition is producing two different responses. Some lenders are keeping servicing to maintain contact with borrowers and win their next mortgage. Others are selling portfolios while prices are strong to raise cash or reduce debt.

Keeping the customer relationship

Chicago-based Rate has retained all of its MSRs over the past 12 months, CEO Victor Ciardelli told HousingWire. He put that retention at more than $50 billion and said staying close to the customer is central to the strategy.

At the Mortgage Servicing Rights Conference in New York on Monday, Milliman’s John Sullivan said more clients are discussing holding their portfolios unless they need liquidity. The attraction is borrower recapture: when a homeowner wants another loan, the company already servicing that mortgage has an existing relationship to build on.

Different buyers approach that relationship differently. Banks may see servicing as a way to acquire customers and sell other financial products. Mortgage companies emphasize winning repeat mortgage business, while real estate investment trusts may focus on the investment return, executives told HousingWire.

Freedom Mortgage executive Simon Aldrich said a recapture operation is increasingly important at current prices. In his company’s model, slower repayments can help when rates rise, while its call center seeks new business when rates fall. That is one company’s strategy, not a guarantee that servicing values are insulated from changes in rates.

Strong prices also encourage sales

The same demand that makes servicing attractive to retain gives sellers an opportunity to turn portfolios into cash.

Rocket Companies sold servicing rights tied to $23 billion in unpaid loan principal during the third quarter for $379 million in proceeds, HousingWire reported. It retained subservicing and recapture services on nearly 70% of the rights sold.

Pennymac Financial Services agreed to sell rights associated with $29 billion in unpaid principal. Expected proceeds of $490 million would be used to pay down debt, with the transaction expected to close in the fourth quarter.

HousingWire also reported, citing sources, that United Wholesale Mortgage sold rights tied to about $60 billion in unpaid principal to JPMorgan Chase at roughly a 6-times multiple. Both companies declined to comment to the publication. The report described that sale as part of UWM’s plan to bring up to $80 billion of MSRs to market in the fourth quarter to reduce leverage.

The unpaid principal figures describe the balances of the underlying mortgages. They are not the cash prices paid for the servicing rights.

Returns depend on price and strategy

Investor interest does not remove the need for discipline. Newrez President Baron Silverstein told HousingWire that competition and the capital needed for hedging make it important to be selective about new investments.

Executives at the conference said elevated mortgage rates can support servicing cash flows by reducing early repayments. But large portfolios offered for sale could pressure pricing if buyers’ available cash does not keep pace.

BSI Financial Services executive Larry Goldstone said greater bank participation could support still higher multiples if changes to bank capital rules encourage banks back into the market. That is a conditional outlook, not an adopted rule or an assured price increase.

For lenders, the choice is therefore more than whether today’s bid looks attractive. It also depends on their need for cash, the cost of managing the portfolio and their ability to turn an existing servicing relationship into future mortgage business.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

This post was originally published on here. 

Toast official illustration of IQ Team scheduling, payroll and employee tools, introduced October 2026.

Image: Toast (product illustration)

Toast raised its full-year adjusted profit outlook Tuesday after the close as third-quarter revenue grew 21% and its restaurant and retail technology platform reached about 189,000 locations. The company also announced that President and Chief Financial Officer Elena Gomez will step away from her role at year-end.

Revenue was $1.981 billion for the quarter ended September 30, and net income increased to $169 million from $105 million a year earlier, according to the company’s earnings release. Diluted earnings were 29 cents a share under generally accepted accounting principles, compared with 16 cents a year earlier. That is GAAP earnings, not an adjusted earnings figure.

Toast shares traded at $32.22 at 5:34pm Eastern, down $1.31, or 3.91%, from the $33.53 regular-session close, according to CNBC’s extended-hours quote. The timestamped move describes the market reaction; it does not establish which part of the report drove the decline.

More locations and payments, with higher profits

Toast added about 8,500 net locations during the quarter, taking the total to roughly 189,000, up 21% from a year earlier. Gross payment volume rose 20% to $61.8 billion. Payment volume measures transactions processed through the platform, not revenue Toast keeps.

Annualized recurring run-rate, or ARR, increased 24% to $2.5 billion. ARR is a measure of the business’s recurring revenue pace, rather than the revenue recognized in the quarter.

Operating income rose to $165 million from $84 million a year earlier. Adjusted earnings before interest, taxes, depreciation and amortization reached $240 million, compared with $176 million. That adjusted measure differs from the company’s $169 million GAAP net income.

Cash provided by operating activities was $198 million, up from $165 million. Free cash flow, a non-GAAP measure, increased to $181 million from $153 million. The figures give investors another way to assess how growth is translating into cash.

Higher outlook and a finance leadership handoff

Toast raised its 2026 adjusted EBITDA forecast to $840 million to $850 million from $805 million to $825 million. For the fourth quarter, it expects adjusted EBITDA of $200 million to $210 million and non-GAAP subscription-services and financial-technology gross profit of $610 million to $620 million. These are management forecasts, not guaranteed results.

Gomez will leave her president and CFO role at the end of the calendar year. Senior Vice President of Finance Michael Senno will become CFO on January 1, 2027. Gomez will remain a non-executive employee in an advisory role through July 2, 2027, to support the transition, Toast said.

The company said Gomez had decided to take a break after five and a half years at Toast, including its 2021 stock-market debut. The release did not describe the change as a dismissal.

Toast also pointed to its fall product updates, including expanded IQ Grow marketing tools and the new IQ Team labor-management product, which combines forecasting, scheduling, payroll and tip tools. It has also launched Toast Fuel for independent fuel and convenience operators and expanded into Quebec.

For restaurant operators, these products address the daily costs of staffing, payments and attracting customers. For investors, the next tests are whether location additions and transaction growth continue to support cash generation and the higher profit target as the finance leadership changes.

JBizNews Desk | Boston
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

U.S. dollar and Israeli shekel banknotes and coins; currency archive image.

Photo: Shutterstock via Globes (currency archive)

The shekel fell to its weakest level against the U.S. dollar since late March on Tuesday, as political uncertainty in Israel and concerns about the next phase of the Iran conflict weighed on the currency, Globes reported.

The Bank of Israel published November 3 representative rates of NIS 3.1570 per U.S. dollar, up 0.67% on the day, and NIS 3.5306 per euro, up 0.392%. These official representative rates are distinct from the earlier interbank quotes below; they are reference rates, not mandatory transaction prices.

In its November 3 report published at 2:40pm Israel time, Globes put the dollar at NIS 3.154 in afternoon interbank trading, up 0.51%, and the euro at NIS 3.515, up 0.14%. A higher shekel-per-dollar exchange rate means the shekel is weaker. These are the report’s timestamped market figures, not a current live quote.

Globes said the shekel had weakened 3.42% against the dollar over the preceding month and 1.58% over the previous five days. Analysts interviewed by the publication pointed to a combination of interest-rate expectations, declines in U.S. technology shares and uncertainty over Israel’s next government.

Globes also described the dollar as roughly 4.5% stronger against the shekel since October 27. That comparison is attributed to the publication, rather than calculated from the Bank of Israel’s November 3 representative rate.

Political and security risks add pressure

Yossi Menashe, founder and co-CEO of Altshuler Shaham Financial Services, told Globes that differing interest-rate paths in Israel and the United States were one factor. He also cited uncertainty surrounding the U.S. elections and policy toward Iran as adding a risk premium.

Some local investors had taken short-term positions favoring the dollar to hedge U.S. election risk, Menashe said. Bank Hapoalim chief financial markets strategist Modi Shafrir separately pointed to the previous day’s Nasdaq decline, uncertainty over coalition formation versus another Israeli election, and the possibility of renewed action against Iran.

Those explanations are analysts’ assessments of the currency’s move, rather than proof that any single event drove the entire change. The report describes a market reacting to several overlapping domestic and international risks.

Exporters and consumers face different effects

A weaker shekel can help businesses that receive revenue in dollars but pay a substantial share of wages and operating expenses in shekels. Eytan Kleinman, a managing partner at Long Road, told Globes that such companies could benefit as dollar income converts into more local currency.

For households and import-dependent businesses, the same move can increase the shekel cost of overseas travel, imported products and online purchases priced in dollars. The benefits are therefore uneven across the economy.

Menashe cautioned that further significant depreciation could feed imported inflation and complicate the Bank of Israel’s policy choices. That was a warning about a possible consequence, not an announcement that the central bank has changed interest rates.

JBizNews Desk | Tel Aviv
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Archive data-center server racks, November 2015. Not an Amazon or Intel facility.

Photo: Carl Lender / CC BY 2.0 (archive)

Super Micro Computer and Arista Networks reported strong sales Tuesday after the close, offering two more readings on the AI infrastructure buildout: the servers that run computing workloads and the networks that connect them. Both stocks rose in extended trading.

Supermicro posted $19.9 billion in revenue for its fiscal first quarter ended September 30, while Arista’s third-quarter revenue rose 58.5% to $3.66 billion. Their reporting periods cover the same September quarter but sit in different fiscal calendars.

Supermicro shares traded at $33.11 at 4:30pm Eastern, up $1.72, or 5.47%, from the $31.39 regular-session close, according to CNBC’s extended-hours quote. Arista traded at $181.83 at 4:29pm, up $11.92, or 7.02%, from its $169.91 close, according to CNBC’s Arista quote. These are timestamped early reactions, not final after-hours prices.

Supermicro’s sales surge, with cash flow a watch point

Supermicro’s results release showed fiscal first-quarter sales of $19.9 billion, compared with $5.0 billion a year earlier and $11.1 billion in the preceding quarter. Standard-accounting earnings were $1.75 a diluted share, versus 26 cents a year earlier; adjusted earnings were $1.81, versus 35 cents.

CEO Charles Liang attributed the record sales to the company’s expansion as a provider of complete AI and information-technology data-center systems. The company sells infrastructure intended to help customers deploy computing capacity rather than simply buying individual components.

The gross margin was 12.7%, up from 9.3% a year earlier but down from 17.5% in the June quarter. That mixed comparison matters because higher revenue does not necessarily mean each dollar of sales produces more profit.

Supermicro used $434 million of cash in operations during the quarter. It ended September with $6.9 billion in cash and cash equivalents and $8.6 billion in bank debt and convertible notes, according to the release.

For its fiscal second quarter ending December 31, the company forecast revenue of $19.5 billion to $21.5 billion, with adjusted earnings of $1.66 to $1.90 a share. Its fiscal 2027 revenue outlook is $72 billion to $82 billion. Those figures are management forecasts, not completed sales.

Arista beats its own outlook as network demand rises

Arista’s results release put revenue at $3.66 billion, up 20.5% from the preceding quarter and above its own $3.3 billion guidance. CEO Jayshree Ullal described the 58.5% annual increase as the company’s fastest year-over-year revenue growth since its initial public offering.

Adjusted earnings were $1.20 a diluted share, above the $1.08 analyst estimate reported by Investing.com. Standard-accounting earnings were $1.22 a share, compared with 67 cents a year earlier. The adjusted and standard-accounting measures use different treatments of expenses and tax items.

Arista forecast fourth-quarter revenue of $3.9 billion to $4.0 billion, adjusted earnings of $1.26 to $1.30 a share and an adjusted operating margin of 48% to 49%.

The company builds networking equipment for AI, data-center, campus and routing environments. Its quarterly update included open Ethernet rack-scale architectures developed with partners including AMD, Arm, Broadcom, Meta, Microsoft and Qualcomm.

For investors, the two reports show demand across different layers of AI infrastructure rather than only at the chip level. The next question is how much of that demand converts into cash and lasting profits as customers expand capacity. Supermicro’s operating cash outflow and changing margins, alongside Arista’s next-quarter outlook, offer specific measures to track.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

AMD headquarters in Santa Clara, California, photographed in June 2020.

Photo: Coolcaesar / CC BY-SA 4.0 (archive)

AMD reported a sharp jump in sales Tuesday after the close and forecast another acceleration in the holiday quarter, as demand for data-center processors and artificial intelligence chips outweighed a slump in gaming. Shares rose nearly 7% in extended trading.

Third-quarter revenue reached $13.377 billion, up 45% from a year earlier, while adjusted earnings rose to $2.09 a share. Both topped the $13.09 billion in revenue and $1.95 in adjusted earnings analysts expected, according to estimates reported by CNBC.

AMD traded at $517.51 at 4:29pm Eastern, up $33.61, or 6.95%, from its $483.90 regular-session close, according to CNBC’s extended-hours quote. The move followed a 3.65% gain during Tuesday’s regular session. After-hours prices can change quickly.

Data centers drive the growth

AMD’s earnings release put Data Center revenue at a record $8.5 billion, up 97% from a year earlier. The company credited strong demand for EPYC server processors and the launch of its Instinct MI450 series graphics processors.

“We delivered a record quarter with revenue exceeding the high end of our guidance as Data Center segment sales nearly doubled year-over-year,” chair and CEO Lisa Su said in the release.

The results show why the spending needed to run AI systems matters beyond the companies building the models. Chipmakers supply the computing hardware, while cloud providers and businesses must decide how much capacity to buy and how quickly they can put it to work.

Under standard accounting rules, AMD earned $2.428 billion, or $1.46 a diluted share, compared with $1.243 billion, or 75 cents, a year earlier. Adjusted earnings exclude items such as stock compensation and acquisition-related expenses and should not be confused with the standard-accounting result.

A $17 billion outlook, with weaker gaming sales

AMD forecast fourth-quarter revenue of about $17 billion, plus or minus 3%. The midpoint would represent roughly 66% growth from a year earlier and 27% growth from the third quarter. CNBC reported that analysts had expected $16.2 billion.

The company expects an adjusted gross margin of about 55%, slightly below the 55.3% analyst estimate cited by CNBC. That makes profitability, along with the pace of sales, a point for investors to watch as AMD scales its data-center products.

Not every part of the business shared the AI momentum. Combined Client and Gaming revenue fell 8% to $3.7 billion. Client revenue rose 7% to $2.9 billion, but gaming revenue dropped 40% to $773 million as semi-custom and graphics revenue declined.

Embedded revenue rose 29% to $1.1 billion, with growth across aerospace and defense, automotive, communications and industrial markets, AMD said.

Su said AMD expects growth to accelerate as it scales Helios systems and Venice production. The next test is whether the company can turn that demand into shipments and profits consistent with its forecast. The outlook is a company projection, not a guaranteed result.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

New York Stock Exchange facade in a2012 archive photograph

Photo: Ken Lund / Wikimedia Commons

The Nasdaq snapped its three-day losing streak Tuesday, rising 0.8% as megacap technology stocks rebounded and Wall Street shrugged off a limited U.S. strike on Iran in the Strait of Hormuz, with Americans voting in midterm elections that will decide control of Congress.

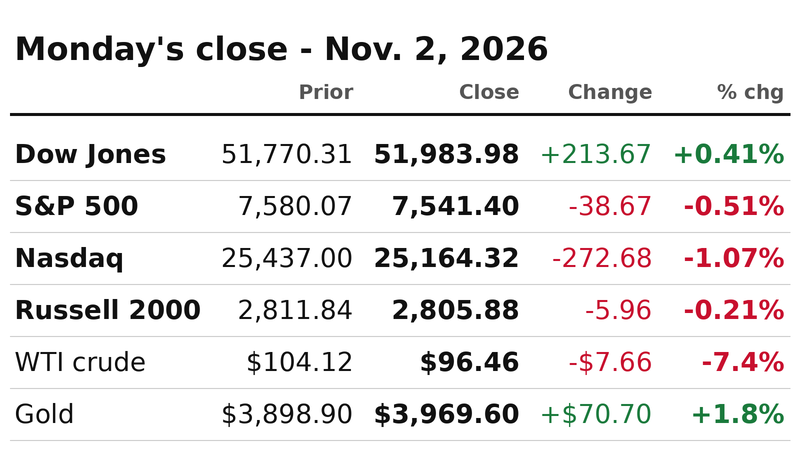
The Nasdaq Composite climbed 207.70 points to 25,372.01, its first gain in four sessions. The S&P 500 added 27.52 points, or 0.4%, to 7,568.92, also ending a three-day slide. The Dow Jones Industrial Average fell 197.26 points, or 0.4%, to 51,786.72. The Russell 2000 rose 0.3% to 2,813.42.

Tuesday November 3 2026 market close table: Dow 51786.72 -0.38%; S&P500 7568.92 +0.36%; Nasdaq25372.01 +0.83%; Russell2000 2813.42 +0.27%; WTI96.09 -0.4%; Gold3940.40 -0.7%.

The rally was narrow. Only four of the S&P 500’s 11 sectors rose – technology (+1.3%), communication services (+1.2%), industrials (+1.0%) and real estate (+0.1%) – while consumer staples dropped 2.1% and materials fell 2.0%, the day’s worst groups. Energy slid 0.8%, consumer discretionary 0.7%, financials 0.6%, utilities 0.6% and health care 0.3%.

Hormuz strike. U.S. forces carried out limited, defensive strikes on Iran’s Qeshm Island in the Strait of Hormuz after Iran’s Revolutionary Guard fired on a U.S. aircraft, the BBC reported. The IRGC said it shot down U.S. drones near the strait. Oil briefly rebounded on the news, then faded: WTI crude settled at $96.09 a barrel, down 0.4%, keeping most of Monday’s 7% collapse on hopes for a diplomatic deal. Gold settled down 0.7% at $3,940.40 an ounce.

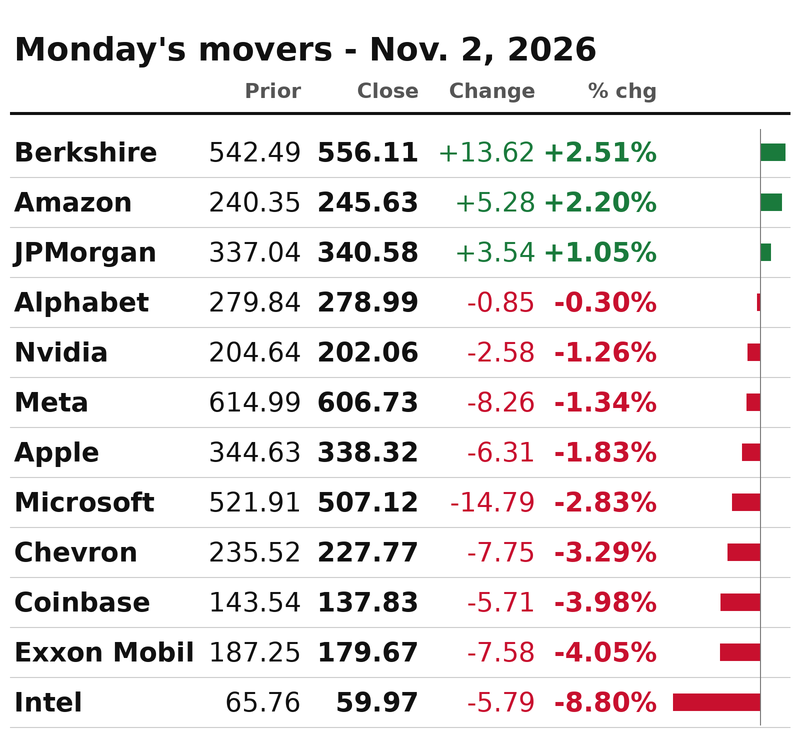
Tech rebounds. Microsoft rose 2.7%, Meta 2.4%, Nvidia 2.3% and Amazon 2.1%, leading the Nasdaq’s comeback. Intel added 1%, steadying after last week’s 35% two-session collapse.

AI hardware reports tonight. AMD jumped 3.7%, Arista Networks 3.5% and Super Micro Computer 3.1% ahead of their quarterly reports after Tuesday’s close – the market’s next test of the AI-infrastructure trade after Friday’s rout in the group.

Apple slips. Apple fell 1.9% as investors weighed its forecast for 7% to 10% December-quarter revenue growth, below the roughly 11% analysts expected, against a record $114.5 billion quarter. Palantir slid 1.7%, giving back part of its post-earnings after-hours pop.

Shopify sinks. Shopify tumbled 8.7% after its third-quarter revenue and gross merchandise volume missed estimates. Keurig Dr Pepper sank 5.7% after flagging slower fourth-quarter U.S. coffee profit growth, dragging consumer staples to the worst sector loss.

Eaton jumps. Eaton surged 7% after reporting record third-quarter results – organic sales up 19%, above the high end of its guidance – and raising its organic growth outlook.

The rest of the tape. Coinbase jumped 5.5% as bitcoin rose about 1.4% to roughly $77,800. The 10-year Treasury yield climbed about 7 basis points to 4.96%. The dollar index edged up 0.1% to 101.87. The VIX fell 1.5% to 20.84.

Tuesday November3 2026 stock movers: Eaton+7.00%, Coinbase+5.53%, AMD+3.65%, Arista+3.52%, SuperMicro+3.12%, Microsoft+2.74%, Meta+2.36%, Nvidia+2.27%, Amazon+2.06%, Apple-1.90%, Pfizer-2.18%, KeurigDrPepper-5.65%, Shopify-8.74%.

What to watch. AMD, Super Micro and Arista report after tonight’s close. Midterm election results come in overnight, with control of the House and Senate at stake. Berkshire Hathaway reports later this week, and the October jobs report lands Friday.

JBizNews Desk | Wall Street
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Exxon gas station in Washington DC in May 2024. Displayed prices are historical, not current.

Photo: Tony Webster / Wikimedia Commons

Americans are voting with the national average price of regular gasoline near $4.15 a gallon, the highest nominal level recorded on a congressional Election Day, according to AAA. Prices have eased over the past week but remain well above a year ago.

AAA’s November 3 price table put regular gasoline at $4.1493 a gallon nationally, compared with $4.2661 a week earlier and $3.0360 a year earlier.

In a Tuesday release, AAA Oregon/Idaho said the previous congressional Election Day high was about $3.80 a gallon in 2022. The comparison is in dollars paid at the time, without an inflation adjustment.

An Election Day record, not an all-time peak

The date-specific record does not mean gasoline has never cost more. AAA lists its all-time national regular-gasoline high at $5.0165 a gallon on June 14, 2022, substantially above Tuesday’s average. Nor does the Election Day comparison establish a record after accounting for inflation.

Different price trackers also produce slightly different readings. The Hill reported a GasBuddy average of about $4.11 Tuesday afternoon and cited a roughly $3.75 comparison for Election Day 2022. Those figures should not be mixed with AAA’s series; both accounts describe unusually high Election Day pump costs, not an all-time gasoline record.

Using AAA’s figures, a 15-gallon purchase at the national average costs about $62.24, compared with about $45.54 a year earlier. That is roughly $16.70 more for the same quantity, although the actual bill depends on the station, fuel grade and local taxes.

Recent relief has not erased the increase

AAA Oregon/Idaho attributed the latest weekly decline to less expensive winter-blend gasoline, refinery maintenance winding down and the seasonal drop in demand. Its public affairs director, Marie Dodds, said: “Filling up is packing less of a punch to family budgets as fuel prices fall.” She cautioned that elevated crude costs limit how far pump prices can decline.

The organization said the national average was $2.98 on February 28, when the U.S. and Israel launched airstrikes against Iran. It linked ongoing oil-market volatility to the conflict and shipping disruptions around the Strait of Hormuz, alongside the usual seasonal forces that affect refining and demand.

Diesel remains another source of pressure for businesses that move goods. AAA’s Tuesday table showed a national average of $6.2875 a gallon, down from $6.3521 a week earlier but up from $3.6800 a year earlier. That raises the fuel bill for users of diesel even as prices retreat from recent highs.

National averages also mask large regional differences. AAA Oregon/Idaho’s November 3 state table put California at about $5.89 for regular gasoline and North Carolina at about $3.38. A national headline therefore does not describe what every motorist pays.

The figures add a concrete household expense to the Election Day cost-of-living debate. They do not establish how any voter will cast a ballot or what effect fuel prices will have on the outcome. For drivers and businesses, the immediate question is whether the recent decline continues despite the risks to oil supplies.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Archive cryptocurrency exchange trading terminal with candlestick chart and order book.

Photo: Aldgodjer (CC BY-SA 4.0; illustrative HitBTC archive, 2016)

Tron founder Justin Sun is asking a court to sanction Trump-linked World Liberty Financial and its lawyers, alleging that the crypto venture failed to disclose United Arab Emirates ownership ties until months into his lawsuit over frozen tokens tied to a $45 million investment. The allegations are disputed, and no sanctions have been imposed in the reports.

The request adds a new procedural fight to the lawsuit Sun filed in April, rather than a new frozen-token lawsuit. CoinDesk’s Helene Braun reported at 11:55am EST Tuesday that Sun accused World Liberty of concealing its UAE ties. The Block’s Jason Shubnell separately reported the sanctions request at 11:08am EST.

Ownership disclosure at the center of the dispute

According to Sun’s account, cited by both outlets, World Liberty initially identified only itself in its ownership chain and listed Florida as its sole citizenship in the California federal court case. It later amended the disclosure to identify 22 entities in that chain and claim citizenship in Florida, Delaware, Puerto Rico and the UAE.

Sun says the change came after an August hearing at which a judge ruled that some claims could remain in public court while others should go to private arbitration. He alleges the company should have disclosed its foreign ownership earlier, before his lawyers spent months and hundreds of thousands of dollars opposing its arbitration request, CoinDesk reported.

The citizenship question matters because it could affect whether the federal court has authority to hear the dispute. World Liberty is arguing that its UAE citizenship prevents the case from proceeding there, according to CoinDesk. The Block reported that a company’s owners’ citizenship can affect federal diversity jurisdiction.

World Liberty’s lawyers said they learned of the UAE citizenship after the original disclosure was filed, according to Sun’s account in CoinDesk. The court has not found that the company intentionally concealed its ownership, and the sanctions request does not establish wrongdoing.

Frozen-token fight remains unresolved

Sun initially agreed to buy $30 million in WLFI tokens in November 2024, then increased his investment to $45 million, CoinDesk reported. He alleges World Liberty induced that investment through fraud and later unlawfully froze his holdings. Those are allegations in the existing dispute, not court findings.

World Liberty previously defended its decision to freeze Sun’s tokens and could not be reached by CoinDesk for comment on the latest allegations. The Block reported that the company countersued Sun in May, accusing him of a “meritless PR stunt” against the Trump-family-backed project.

Sun says he plans to refile his lawsuit in California state court after the sanctions motion is resolved, according to both outlets. That is a stated next step, not a completed refiling or a ruling returning the tokens to him.

The latest development concerns disclosure, jurisdiction and the costs of litigation. Neither report describes an order imposing sanctions, a finding that World Liberty concealed ownership intentionally, or a final decision on Sun’s underlying fraud and token-freeze claims.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Nasdaq MarketSite in Times Square, archive photo September 19, 2021, cropped.

Photo: Ajay Suresh / Wikimedia (archive; CC BY 2.0)

The Nasdaq rebounded in Tuesday’s midday trading as chipmakers rallied, while a decline in Apple kept the Dow Jones Industrial Average in the red.

In CNBC’s market report updated at 12:24pm EST on November 3, the Nasdaq Composite was up 0.8% and the S&P 500 had gained 0.4%. The Dow was down 217 points, or 0.4%. These figures reflect that report’s midday snapshot, not prices at the moment of publication.

Chipmakers lead the recovery

Advanced Micro Devices gained 4% ahead of its third-quarter earnings release, scheduled for after Tuesday’s closing bell. Broadcom rose more than 3%, while Micron Technology, Nvidia and Intel each gained nearly 3%, according to CNBC’s 12:24pm report.

The gains marked a reversal from Monday, when the Nasdaq fell more than 1% and both the Nasdaq Composite and S&P 500 extended their declines to a third consecutive session.

The Nasdaq-100, a separate index from the Nasdaq Composite, rose 0.6% in CNBC’s midday report. Even after that bounce, it remained more than 10% below its recent high, leaving it in correction territory.

Apple weighs on the Dow

Apple fell 2% after the iPhone maker issued a disappointing margin forecast late Monday and fiscal fourth-quarter iPad sales missed Wall Street estimates, CNBC reported. The stock’s decline helped keep the Dow lower even as semiconductor shares recovered.

The split showed that Tuesday’s technology rebound was uneven. Stronger chip stocks lifted the Nasdaq, but the recovery had not erased the recent losses or the concerns about financing the artificial-intelligence buildout.

Shawn Snyder, an economic strategist at Potomac Fund Management, told CNBC that concerns about the cost of capital and the debt financing needed for that buildout would persist. He also said the AI trade could be approaching oversold territory.

Investors were also awaiting U.S. midterm election results. The midday stock moves did not establish an election outcome, and AMD had not yet reported its quarterly results.

Earlier coverage: Dow Drops 300 Points as Election Day Trading Splits Wall Street. That opening report is a separate, earlier snapshot of Tuesday’s session.

JBizNews Desk | Wall Street
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Robotic assembly line at Tesla factory, June 6, 2012. Archive photograph by Steve Jurvetson.

Steve Jurvetson / Wikimedia Commons | CC BY 2.0 | Archive, 2012

New orders for U.S. manufactured goods rose 1.8% in September to $677.2 billion, beating forecasts as demand increased for a third consecutive month, the Census Bureau reported Tuesday.

The $12.2 billion monthly gain topped the 1.2% consensus forecast reported by Seeking Alpha. August’s increase was revised to 0.3% from 0.1%.

The Census Bureau’s full September report showed shipments rose 1.3%, or $8.8 billion, to $668.5 billion. Shipments have increased in 11 of the past 12 months.

Unfilled orders grew 0.9%, or $13.8 billion, to $1,623.8 billion, while inventories increased 0.4%, or $3.7 billion, to $976.0 billion. Inventories have risen for 12 consecutive months.

The inventories-to-shipments ratio edged down to 1.46 from 1.47 in August. The unfilled orders-to-shipments ratio also declined, to 6.84 from 6.86.

JBizNews Desk | Washington
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

The entrance and sign at the Commodity Futures Trading Commission in Washington, D.C.

Photo: G. Edward Johnson / Wikimedia Commons (CC BY 4.0)

WASHINGTON – Perpetual futures tied to individual stocks can begin trading on U.S. exchanges that meet joint federal registration requirements, CFTC Chairman Michael Selig said Tuesday, opening a regulated path for a trading model widely used in cryptocurrency markets.

The Commodity Futures Trading Commission’s statement applies to designated contract markets that are also registered with the Securities and Exchange Commission as notice-registered national securities exchanges for security futures products. It is not blanket permission for every exchange to offer the contracts.

The products, known as equity perpetual futures or equity perps, use the existing security-futures framework, with oversight from both the CFTC and SEC.

Unlike traditional futures, perpetual futures have no expiration date. They let traders take positions on an asset’s price without owning it and often use leverage, which can amplify losses as well as gains.

A regulated route for equity perps

Selig said bringing the products into regulated U.S. markets would give American investors and traders an alternative to offshore venues.

“I believe that bringing these types of innovative products into our regulated markets ensures that American investors and traders can access these products within the protections of the CFTC’s proven regulatory framework, rather than being forced to turn to offshore, and often unregulated, venues,” he said.

The chairman said the contracts build on the Commodity Futures Modernization Act of 2000 and the CFTC-SEC memorandum of understanding. Stock-based derivatives fall across the two agencies’ jurisdictions, making coordination part of the route to market.

Perpetual futures have become a major part of cryptocurrency trading, including on offshore exchanges and decentralized platforms, CoinDesk reported Tuesday. The equity contracts extend that model to individual stocks under the security-futures rules.

The CFTC statement did not name exchanges that would offer equity perps, identify the stocks to be covered or provide a specific launch schedule.

JBizNews Desk | Washington, D.C.
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Two empty chairs facing each other across an office table set for a job interview, a notebook and pen on the table.

U.S. job openings rose to 7.5 million in September, the Bureau of Labor Statistics reported Tuesday, topping the roughly 7.15 million economists had expected and up from an upwardly revised 7.2 million in August – a show of resilience in a labor market that had been cooling for months.

The openings rate was 4.5%. Hires changed little at 5.4 million, and total separations held at 5.3 million. Layoffs and discharges were little changed at 1.6 million, a 1.0% rate.

Quits – workers leaving jobs voluntarily, a widely watched gauge of confidence in finding something better – increased to 3.4 million, and are up 375,000 over the past year, the bureau said.

By industry, openings rose by 104,000 in state and local government outside education, while hiring picked up by 158,000 in accommodation and food services. Layoffs fell by 70,000 in health care and social assistance.

August’s figures were revised higher: openings by 111,000, hires by 79,000, and layoffs and discharges by 127,000, to 1.8 million.

The September reading is the strongest since May and ends a run of monthly declines that had taken openings from 7.6 million in the spring to about 7.1 million by summer’s end. Stocks added to early losses after the 10 a.m. release, with the Dow Jones Industrial Average down 342 points, or 0.7%, as of 10:02 a.m. EST, and the 10-year Treasury yield near 4.93%.

What it means for you: If you are looking for work or thinking about switching, 7.5 million open roles is a deep pool, and rising quits signal that other workers are confident enough to make a move – often the lever that wins better pay. Steady layoffs, at 1.6 million, mean there is no sign of a broad wave of job cuts. The soft spots are worth knowing too: hiring overall is not accelerating, so searches can still take time.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Bank of Korea historic main building in Seoul, photographed March2 2004. Archive photo by Otraff, CC BY-SA3.0. Full composition retained.

Photo: Otraff / Wikimedia Commons (archive; CC BY-SA 3.0)

South Korea’s central bank has asked 18 banks and 13 securities firms how a major crypto exchange hack could affect their businesses, with responses due November 4. The survey examines a hypothetical disruption, not a newly reported hack or a finding that financial stability risks have already materialized.

The Bank of Korea sent the questionnaire on October 23, CoinDesk reported Tuesday, November 3, citing Yonhap and other South Korean outlets. The institutions include KB Kookmin, Shinhan, Hana, Woori and NH NongHyup. The report described it as the central bank’s first survey of this kind.

One scenario asks what would happen if the country’s largest crypto exchange halted operations following a major hack. Other questions cover a sharp fall in crypto prices followed by a prolonged trading slump, and large crypto-related losses at another financial institution, according to local reporting summarized by CoinDesk.

The survey also seeks information about firms’ crypto teams, budgets, business plans and investments in domestic and overseas crypto companies. A central bank official told The Herald Business that existing business reports and information shared with the Financial Supervisory Service did not provide enough detail about those activities, CoinDesk reported.

The distinction between mapping exposure and announcing a crisis is important. An official told Alpha Economy that current laws still restrict financial firms’ crypto activities and that the Bank of Korea did not consider risks to financial stability to have materialized, according to CoinDesk. The exercise should not be read as confirmation of losses at the surveyed firms.

The central bank plans to use the responses as internal reference data, the report said. No sanctions or new rules have been decided. The October 23 dispatch date and November 4 response deadline describe the survey’s timetable, not the date of an exchange failure.

JBizNews Desk | Seoul, South Korea
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

A touchscreen card payment terminal with a blank screen on a retail counter beside a receipt printer in morning light.

Fiserv shares jumped about 8% Tuesday morning after the payments technology company topped third-quarter earnings and revenue estimates, doubled its cost-savings target to $1 billion and said it would resume buying back its stock with $500 million in repurchases planned this quarter.

The stock traded at $56.26, up $4.33, or 8.3%, as of 9:43 a.m. EST, after rising nearly 10% in premarket trading.

Fiserv said adjusted earnings were $1.75 a share for the quarter ended Sept. 30, above the roughly $1.72 analysts had expected, though down 14% from $2.04 a year earlier. Revenue slipped 1% to $5.20 billion. Adjusted revenue of $4.85 billion edged the roughly $4.847 billion analysts had expected. Organic revenue, which strips out currency moves and acquisitions, was flat – a 2% decline in its Merchant Solutions segment offset by a return to growth in Financial Solutions, up 2%.

The quarter included a $6.45 billion non-cash goodwill impairment charge following a sustained slide in the company’s share price, producing a GAAP loss of $11.17 a share. Adjusted operating margin narrowed to 31.2% from 37% a year earlier. Free cash flow for the first nine months was $2.04 billion, down from $2.88 billion.

“Our team is executing with urgency, and we are seeing meaningful progress,” Chief Executive Takis Georgakopoulos said in the release, pointing to banking-customer net attrition down more than 25% so far this year, major client wins now ramping and consistent underlying growth at Clover, the company’s small-business payments platform, where gross payment volume rose 11% and processing revenue increased 12%.

Fiserv raised the savings target under its Project Elevate efficiency program to $1 billion from $500 million after a portfolio review identified more efficiencies, and it reaffirmed its full-year outlook: organic revenue between a 1% decline and flat, and adjusted earnings of $7.20 to $7.40 a share – the midpoint above what analysts had forecast.

“Our second-half initiatives are on track to support the revenue acceleration we expect in the fourth quarter, and we are reaffirming our full-year guidance,” Chief Financial Officer Paul Todd said. “Our growing confidence also allows us to resume share repurchases earlier than anticipated, with $500 million planned in the fourth quarter.”

The company also completed the sale of its student-loan servicing business and formed MoneyPass Group, a joint venture around its ATM network businesses in which it keeps a minority stake.

What it means for you: Fiserv runs much of the plumbing behind everyday payments – its Clover terminals sit on the counters of millions of small businesses, and its software processes accounts for thousands of banks and credit unions. Tuesday’s announcement brings no price or fee changes for the merchants and consumers who use that plumbing. For investors, the message was that a company whose shares had been sliding is cutting costs harder and putting cash into buybacks, and the stock’s roughly 8% jump shows Wall Street welcomed it.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

A glass Apple retail store facade with a large illuminated Apple logo on an empty city plaza in morning light.

Wall Street opened split on Election Day Tuesday: the Dow Jones Industrial Average dropped more than 300 points while the Nasdaq Composite climbed, and Apple slid about 3% after its holiday-quarter outlook disappointed investors despite a record quarter.

As of 9:45 a.m. EST, the Dow was down 338 points, or 0.7%, at 51,646, while the Nasdaq was up 187 points, or 0.7%, at 25,351. The S&P 500 was little changed.

Apple traded at $328.53, down 2.9%, after falling nearly 4% in the opening minutes. In results reported after Monday’s closing bell, Apple said fiscal fourth-quarter revenue rose 12% to a record $114.5 billion, with earnings of $2.10 a share and iPhone revenue up 17% – but the company forecast holiday-quarter revenue growth of 7% to 10% and warned that rising memory-chip costs will squeeze margins.

Intel jumped about 4% to roughly $62, bouncing after a two-session slide of about 35% that had left the stock below $60 at Monday’s close. Palantir fell about 4% to around $171, extending Monday’s decline even after the data-analytics company reported third-quarter revenue up 96% to $2.31 billion – its first $2 billion quarter – and raised its full-year outlook.

Shopify sank about 9% to $142 after the e-commerce platform’s revenue missed analyst estimates for the first time since 2022, one of the morning’s biggest single-stock declines. Fiserv jumped about 6% after the payments company beat estimates, doubled its cost-savings target and restarted share buybacks.

In bond and commodity markets, the 10-year Treasury yield rose to about 4.93%. U.S. crude steadied near $96 a barrel after Monday’s 7.4% plunge, as traders weighed overnight U.S. strikes on Iran’s Qeshm Island – which officials described as defensive – against hopes for a diplomatic deal with Tehran. Gold slipped about half a percent to around $3,950 an ounce.

The split open comes as Americans vote in the midterm elections, with control of Congress at stake and polls closing this evening. Before that, the September job-openings report lands at 10 a.m. EST, and chipmaker AMD headlines earnings after the closing bell.

What it means for you: The 10-year Treasury yield near 4.93% keeps mortgage and loan rates in their recent range, still well below the roughly 5.3% touched a month ago – helpful if you are shopping for a home or car loan. U.S. crude’s drop from $104 on Friday to about $96 a barrel, roughly 7.5% in two days, points to some relief at the gas pump in the coming weeks if it holds. For retirement savers, a split open like this one is a reminder that a diversified 401(k) cushions single-stock hits like Apple’s. And Apple’s warning about memory-chip costs is the kind of squeeze that can show up in holiday gadget prices.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

A laptop on a small business packing desk showing an online store dashboard beside stacked cardboard shipping boxes and a tape dispenser.

Shopify shares sank about 9% in early trading Tuesday after the e-commerce platform reported third-quarter revenue that fell short of Wall Street estimates for the first time since 2022, overshadowing 32% sales growth and a holiday-quarter forecast that came in above expectations.

The stock traded at $141.76, down $14.46, or 9.3%, as of 9:38 a.m. EST, paring a premarket slide of about 15%.

Revenue rose 32% from a year earlier to $3.742 billion in the quarter ended Sept. 30, Shopify said in its earnings release Tuesday, just below the roughly $3.75 billion analysts had expected – the company’s first revenue miss against consensus estimates since 2022.

Gross merchandise volume, the total dollar value of orders sold through Shopify’s platform, grew 29% to $119.15 billion, also short of the roughly $120 billion analysts had projected. Subscription solutions revenue, the company’s recurring software business, rose 20% to $836 million, below the roughly $850 million expected, while merchant solutions revenue climbed 35% to $2.91 billion.

Gross margin narrowed to 47.6% from 48.9% a year earlier as lower-margin merchant services made up a larger share of the business.

The miss landed alongside otherwise strong results. Operating income jumped 66% to $568 million, net income rose to $462 million from $264 million a year earlier, and free cash flow reached $816 million – a 22% margin, up from 18%. Adjusted earnings of 49 cents a share topped analyst estimates.

“We extended our track record of consistent execution, with 32% revenue growth and a 22% free cash flow margin,” Chief Financial Officer Jeff Hoffmeister said in the release. “Delivering these results at our scale speaks to the strength of our model, our multiple growth drivers, and our expanding addressable market.”

President Harley Finkelstein said the company “powered $119 billion in GMV, while continuing to build commerce into every surface, every agent, and increasingly, everywhere.”

For the fourth quarter, Shopify forecast revenue growth in the low-thirties percentage range – above what analysts had penciled in for the holiday season, though a slower pace than the 34% growth it posted earlier this year – with gross profit expected to grow in the high-twenties percentage range.

Shopify provides the software backbone for millions of online stores, handling checkout, payments and shipping for everyone from first-time sellers to major brands. Its gross merchandise volume offers one of the broadest real-time reads on online shopping heading into the holidays.

What it means for you: The sell-off is about Wall Street’s expectations, not a pullback in online shopping – $119 billion worth of goods moved through Shopify-powered stores in the quarter, up 29% from a year ago. If you run a small business on the platform, the company announced no price or fee changes today. For investors, the drop reflects how much good news was already priced into the stock: even a narrow miss on revenue, paired with slightly slower growth ahead, was enough to knock about 9% off the shares at the open.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Central Bank of Paraguay building in Asuncion, photographed in 2010.

Photo: FF MM / Wikimedia Commons (2010 archive)

Paraguay central bank chief Carlos Carvallo submitted his resignation Tuesday after the bank began resolution proceedings for digital lender Ueno, Reuters reported Tuesday morning via Devdiscourse. Carvallo said he would remain in office while the proceedings were carried out.

The central bank said it had detected a shortfall in Ueno’s solvency ratio, a measure of its capital against risk-weighted assets. It said the resolution process was intended to protect depositors and preserve financial stability.

Carvallo and the central bank have faced scrutiny over their supervision of the lender and its political ties, Reuters reported. Carvallo had been Ueno’s president until August 2023.

“Stepping aside will help to quell the controversy surrounding the BCP,” Carvallo told a press conference after the proceedings were announced, according to Reuters. BCP is the Spanish abbreviation for the Central Bank of Paraguay.

He said his resignation would allow the central bank and the banking superintendent’s office to work without distraction from political and media disputes.

Ueno, majority-owned by Grupo Vazquez, has about 3 million customers and administers roughly $850 million in public funds in Paraguay, Reuters reported. The news agency said Grupo Vazquez and Ueno did not immediately respond to its requests for comment.

The central bank described the case as isolated and said it did not point to broader problems in the financial system. Those were the regulator’s assessments. It said the Superintendency of Banks would appoint auditors to verify Ueno’s assets as of the resolution date.

Several lawmakers had called in recent months for the dismissal of the central bank’s senior management after rejecting a report on Ueno that they considered incomplete, Reuters reported.

Archive photograph of the Central Bank of Paraguay, not Tuesday’s announcement. FF MM / Wikimedia Commons, CC BY-SA 3.0; displayed at reduced resolution without further edits.

JBizNews Desk
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

An offshore oil and gas platform moored in a Norwegian fjord.

Photo: W. Bulach / CC BY-SA 4.0 (archive photo)

U.S. crude oil fell below $95 a barrel on Tuesday morning, November 3, trading at $94.92 as of about 9:02 a.m. Eastern, down 1.6 percent from Monday’s official settlement of $96.46, according to CME Group prices. The December contract fell as low as $93.59 after rising as high as $98.82 overnight, a swing of more than 5 percent.

The drop unwound an overnight rebound that followed a reported U.S. strike on Iran’s Qeshm Island, as the United States and Iran continued reviewing proposals from Qatari mediators to bridge their differences.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

An offshore oil platform illuminated at dusk in the Gulf of Mexico.

Photo: GuavaTrain / CC0 (archive photo)

Updated: Oil later fell below $95 a barrel – read the latest.

U.S. crude oil steadied on Tuesday morning, November 3, trading at $97.26 a barrel as of about 8:24 a.m. Eastern, up 0.8 percent from Monday’s official settlement of $96.46, according to CME Group prices. The December contract traded between $96.12 and $98.82 overnight.

The gains followed a reported U.S. strike on Iran’s Qeshm Island and comments from a senior Iranian official that a deal to end the war remained distant, after U.S. crude fell 7.4 percent on Monday.

The United States and Iran are reviewing proposals to bridge their differences, Qatari mediators announced on Monday, though the Iranian official said Tehran would not accept what he called Washington’s “excessive demands.”

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

New York Stock Exchange facade and American flags, landscape archive photograph.

Photo: David Vives / Unsplash (archive)

Stock futures were mixed as Americans headed to the polls Tuesday morning. Yahoo Finance’s delayed quotes timestamped around 6:59 a.m. EST showed Dow futures down 0.85% and S&P 500 futures down 0.18%, while Nasdaq 100 futures rose 0.19%. These are timestamped snapshots, not live prices.

Apple was among the stocks under pressure. Reuters reported a premarket decline of about 4% in its report updated at 6:42 a.m., after management warned about pressure on holiday-quarter margins.

A record quarter, a stark warning

Apple reported September-quarter revenue of $114.5 billion, up 12%, record September-quarter iPhone revenue, an all-time high for Services, and diluted earnings of $2.10 a share. Fiscal-year revenue reached a record $479 billion. John Ternus, delivering his first earnings report as CEO, called the new iPhone Duo “the most transformational iPhone since the original.”

The warning was Apple’s own outlook, not a forecast by JBizNews. On the company’s November 2 earnings call, management projected December-quarter gross margin of 45% to 46%, with higher memory costs and the rollout of Siri AI weighing on margins, Reuters reported. CFO Kevan Parekh also forecast holiday-quarter Services growth of 8% to 9%, according to PYMNTS’s account of the call. Those projections are forward-looking and may change.

Even a 96% growth rate isn’t enough anymore

Palantir reported revenue up 96% to $2.313 billion, its first $2 billion quarter, with U.S. commercial revenue up 148%. Its shares fell anyway. As JBizNews reported earlier this morning, Benzinga’s 6:24 a.m. EST report put the shares down 8.15% at $163.80 in premarket trading, despite the earnings beat and higher outlook.

Monday’s regular session ended mixed: the S&P 500 closed down 0.51% at 7,541.40 and the Nasdaq Composite fell 1.07% to 25,164.36, while the Dow gained 0.41% to 51,983.98.

Election Day arrives

The midterm elections add political uncertainty to the earnings and interest-rate picture. Overseas, South Korea’s Kospi closed down 3.59%.

Brent crude futures were up 1.65% at $106.50 a barrel in Yahoo’s delayed quote timestamped 7:12 a.m. EST. The 10-year Treasury yield quote was 4.894%, but that figure was Monday’s closing reading, not a new Tuesday-morning move.

Monday brought one solid economic number: factory activity reached 55.5 on the ISM index in October, beating forecasts. Production was at its strongest since November 2021, though input prices remained high.

What it means for you

Oil prices, borrowing costs and device prices are the household-budget channels to watch. A decline in crude does not guarantee an immediate drop at the pump, and a Treasury-yield move does not automatically translate into the same change in mortgage or auto-loan offers. Apple’s outlook points to cost pressure on the company; it is not a promise of another retail price increase. Compare actual prices and loan terms rather than treating a market snapshot as a household saving.

What to watch today

At 10 a.m. Eastern time, the September job-openings report is scheduled for release. AMD reports after the market close, another test for chip stocks. Election results will be another focus as polls close this evening.

JBizNews Desk | Wall Street

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Financial market data on a screen, illustrative archive photograph, not Palantir share prices.

Photo: Daniel / Unsplash (illustrative archive)

Palantir Technologies shares fell about 8% in Tuesday’s premarket trading, extending the negative reaction to an earnings report that beat analyst estimates and came with a higher full-year revenue forecast.

The stock was down 8.15% at $163.80, according to Benzinga Pro data cited in Benzinga’s report published at 6:24 a.m. EST on Tuesday, November 3. That is the quote reported at that time, not a live price or the regular-session opening price.

The premarket move is a new development after JBizNews’s earlier coverage of Palantir’s third-quarter earnings and Monday’s after-hours reaction.

Strong earnings, weaker contract-growth rates

Palantir reported third-quarter revenue of $2.313 billion, up 96% from a year earlier. Adjusted earnings were 44 cents a share. Benzinga put analyst expectations at $2.18 billion in revenue and 41 cents a share.

Benzinga attributed the selling pressure to investor concern about slower contract growth and Palantir’s valuation, despite the earnings beat and stronger outlook.

The company’s earnings release showed total contract value of $2.918 billion, up 6% year over year. U.S. commercial total contract value was $1.463 billion, up 11% year over year.

Benzinga compared those growth rates with 49% for total contract value and 153% for U.S. commercial contract value in the previous quarter. The comparison is between growth rates reported in successive quarters. It does not mean contract value fell 6% or 11% from the prior quarter.

Contract value is also different from recognized revenue. U.S. commercial revenue rose 148% year over year to $984 million in the third quarter, according to Palantir’s release.

Higher revenue forecast

Palantir raised its 2026 revenue forecast to a range of $8.530 billion to $8.534 billion. For the fourth quarter, it forecast revenue of $2.649 billion to $2.653 billion.

Those figures left investors weighing rapid sales growth and a higher outlook against the pace of new contract activity. Tuesday’s quoted decline occurred before the regular U.S. stock-market session.

JBizNews Desk
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Oracle Austin Waterfront Campus illuminated at night, 2018 archive photograph.

Photo: DronePhotographer / Wikimedia (2018 archive)

Oracle has priced $20 billion in common-stock and senior-note offerings, setting a $116 share price and the terms of five bond maturities. The company announced the pricing in a release issued Monday, November 2, at 10:09 p.m. Eastern time.

The pricing is a new step after the preliminary filings covered in JBizNews’s earlier report on Oracle’s financing plan. Those filings left the final stock price and other offering terms open. Pricing does not mean the transactions have already closed.

Oracle said it is offering 86,206,897 common shares at $116 each. It expects approximately $9.9 billion in net proceeds from the stock offering after underwriting discounts and estimated expenses.

The senior-note offering has five parts:

  • $2 billion of 7.000% notes due in 2029.
  • $1.75 billion of 7.450% notes due in 2031.
  • $2.25 billion of 7.850% notes due in 2033.
  • $2.5 billion of 8.000% notes due in 2037.
  • $1.5 billion of 8.650% notes due in 2046.

The company expects approximately $10 billion in net proceeds from the notes after underwriting discounts and estimated expenses. The stated interest rates are the notes’ coupons, not a claim about their market yields.

Both offerings are expected to close Wednesday, November 4, subject to customary closing conditions. Neither depends on the other being completed, Oracle said.

Oracle said the proceeds, if the offerings close, will go toward general corporate purposes. Possible uses include capital spending, debt repayment, future investments or acquisitions, cash dividends and share repurchases. The release does not earmark all of the money for artificial intelligence spending.

BofA Securities is the sole global coordinator of the offerings, alongside a group of other underwriting banks. Oracle said the securities are being offered under a registration statement filed with the Securities and Exchange Commission.

JBizNews Desk
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

An oil pumpjack in France, used as an illustrative image for oil markets.

Photo: Snap Wander / Unsplash (illustrative)

Oil prices rebounded Tuesday after the United States struck Iran’s Qeshm Island and a senior Iranian official said a deal to end the war remained distant, Reuters reported via Investing.com.

As of 2:44 a.m. EST on November 3, Brent crude futures were up $1.84, or 1.76%, at $106.61 a barrel, while U.S. West Texas Intermediate crude was up $1.60, or 1.66%, at $98.06, according to Reuters. These are the report’s early-morning prices, not quotes at this article’s publication time.

Both benchmarks had fallen more than 7% on Monday as talks involving Iranian and Qatari officials raised hopes for an end to the conflict, Reuters reported.

A U.S. official said Monday that the United States had struck Qeshm Island. Some officials described the attacks as defensive and intended to prevent Iran from attacking commercial ships in the Strait of Hormuz, according to Reuters.

On Tuesday, a senior Iranian official told Reuters that the two countries were far from an agreement and Tehran would not accept Washington’s “excessive demands.” The renewed military activity and uncertain diplomatic outlook kept risks to energy supplies in focus, the report said.

JBizNews Desk
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Server racks in a November 2015 archive photograph illustrating computer infrastructure. Not a photograph from China.

Photo: Carl Lender / Wikimedia Commons (archive)

Institutional investors preparing to buy shares in Anthropic’s planned initial public offering are pressing for a valuation of roughly $1.5 trillion to $1.6 trillion, below figures approaching $2 trillion discussed in recent months, The Wall Street Journal reported Monday.

The Journal cited people familiar with the matter as saying investors had conveyed that view to the Claude developer and its advisers over the preceding several days. The reported range represents investor feedback, not a final valuation, an announced offering price or a completed transaction.

The push for a more cautious valuation followed a selloff in technology shares, the Journal reported. Its account described institutional buyers weighing the IPO amid renewed concern about technology-stock prices.

Offering terms remain preliminary

Anthropic’s amended SEC registration filing leaves the offering price and number of shares blank. No final price or offering size has been set in that filing. A valuation is the implied worth of the company, not the amount of money it would raise by selling shares.

The company has applied to list its Class A shares on Nasdaq under the symbol ANT. A preliminary registration does not establish that the offering has been completed, and the proposed terms can change.

The valuation discussion is a separate development from the financial results in the amended filing, covered in JBizNews’ earlier earnings report. That filing showed sharply higher revenue alongside a return to an operating loss as computing costs increased.

The Journal’s account does not establish that Anthropic has accepted the investors’ preferred range or that every prospective buyer shares it. The final terms will depend on the offering process and any subsequent company disclosures.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Reserve Bank of Australia Governor Michele Bullock. Official RBA archive portrait.

Photo: RBA (archive)

Australia’s central bank raised its cash rate target by a quarter percentage point to 4.85% from 4.60% on Tuesday, November 3, as it sharply worsened its inflation outlook despite signs that the economy is slowing. The Reserve Bank of Australia’s Monetary Policy Board voted six to three for the increase.

The new 4.85% target is the highest since 2008. The RBA’s historical table shows a peak of 4.75% from late 2010 through October 2011 and no higher target between 2009 and this decision. It last stood above 4.85% in November 2008, at 5.25%, before falling to 4.25% in December.

The RBA’s decision was announced at 2:30 p.m. Sydney time, equivalent to 10:30 p.m. Monday in New York. The bank’s rate overview lists November 4 as the effective date for the new target.

Inflation is now forecast to reach the top of the bank’s 2% to 3% target range only in late 2027, around three quarters later than previously expected. The board said price pressures remain broadly based and warned that higher inflation expectations could become embedded.

The bank pointed to higher fuel and commodity costs linked to the Middle East conflict, alongside domestic capacity pressures that are tighter than previously thought. It also said AI-related investment is driving rapid increases in prices for technology-related goods, while businesses report rising costs and plans to pass them on.

The decision adds pressure to an economy already feeling earlier rate increases. The RBA said economic growth is slowing, housing prices have fallen significantly and unemployment has risen. It expects output growth to slow further over the coming year as higher borrowing costs and weaker housing activity weigh on household consumption and dwelling investment.

The outlook is not uniformly weak. Business investment is expected to be stronger in the near term, including investment in data centres. Employment is forecast to keep growing, though unemployment is projected to rise more than the bank expected in August.

ABC News reported that this was the RBA’s fifth increase this year and that the new rate is the highest in 18 years. The three dissenting board members preferred to hold the target at 4.60%.

The board did not commit to a further increase at its next meeting. It said future decisions would depend on incoming data, the evolving outlook and risks to inflation and activity. The bank warned that unresolved Middle East supply disruptions could leave inflation higher and growth lower than forecast.

The cash rate is the overnight interbank rate targeted by the RBA, not a uniform mortgage rate charged to households. The bank says it influences lending and deposit rates across the economy. Its next scheduled cash-rate update is December 8 at 2:30 p.m. Sydney time.

JBizNews Desk | Sydney, Australia
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Seoul skyline at night with Lotte World Tower, October2016. Archive photo.

Photo: Joon Kyu Park / Wikimedia Commons (archive)

Asian stocks fell Tuesday as Wall Street’s technology selloff followed the region into Election Day in the United States, while a 7 percent crash in oil prices offered relief to Asia’s energy-importing economies. Tokyo’s market was closed for Culture Day, a national holiday.

South Korea’s Kospi was down 186.89 points, or 3.19 percent, at 5,672.19 at 9:06 a.m. Korean time Tuesday, Hankyung reported, as chip stocks extended their slide on doubts that heavy spending on artificial intelligence will pay off.

The drop followed a split session in New York. The Dow Jones Industrial Average rose 0.4 percent to 51,983.98 and eight of the S&P 500’s eleven sectors gained, but the Nasdaq Composite fell 1.1 percent to 25,164.32, its third straight decline, and the S&P 500 slipped 0.5 percent to 7,541.40. Intel tumbled another 8.8 percent to close below $60, stretching its two-day loss to about 35 percent.

After the closing bell, Apple reported record September-quarter revenue of $114.5 billion, up 12 percent, with iPhone sales up 17 percent, but forecast holiday-quarter growth of 7 to 10 percent and lower gross margins, citing rising memory-chip costs; the shares slipped in extended trading. Palantir said revenue rose 96 percent to $2.31 billion and raised its full-year outlook. Both reports test whether investors will keep paying for AI growth or keep punishing its cost.

Oil gave the region its brighter news. U.S. crude settled down 7.4 percent at $96.46 a barrel on the New York Mercantile Exchange, and Brent settled at $104.77. Early Tuesday in Asia, U.S. crude traded near $95.50, as diplomacy between Washington and Tehran kept deflating the conflict premium that pushed oil above $100 last week.

China delivered two conflicting readings on its factories. The private RatingDog manufacturing survey was 52.0 in October, with output growing at its fastest pace in six months, while the official gauge released over the weekend fell to 49.3, into contraction. The Shanghai Composite rose 1.1 percent Monday, and Hong Kong’s Hang Seng Index added 0.4 percent to close at 23,393.32; both markets reopen half an hour after this report is published.

In Japan, the Nikkei 225 was closed for the holiday after slipping 0.3 percent Monday to 63,081.86, according to index data. Trading resumes Wednesday.

For households, the oil drop is the number that matters most: cheaper crude usually means lower gasoline prices within a few weeks. The chip-stock slide can dent retirement and college savings accounts, especially funds heavy in technology. And Tuesday’s midterm elections decide which party controls Congress, which shapes the tax and spending policy that reaches family budgets.

Election results begin coming in after polls close Tuesday evening in the United States. Later in the week come Berkshire Hathaway’s results and Friday’s October jobs report.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Archive photo of an oil refinery.

Photo: Walter Siegmund / CC BY 2.5 (archive photo)

U.S. crude settled Monday, November 2, at $96.46 a barrel, down $7.66, or 7.4 percent, from Friday’s official settlement of $104.12, according to CME Group data, capping a day of heavy selling as signs of progress toward ending the U.S.-Iran conflict weighed on prices. In electronic trading after the settlement was fixed, the December contract held near $96.36 as of about 6:35 p.m. Eastern.

Brent crude, the global benchmark, fell about 6 percent to near $106.50 earlier Monday morning, Reuters reported. Friday’s settlement is the benchmark fixed during the afternoon session; in electronic trading after it was fixed, the U.S. contract had already slipped to $102.95 before the weekend break, CME data show.

The slide deepened as Iranian negotiators left the Qatar-mediated talks with a draft proposal circulating and a follow-up meeting possible, Reuters reported, citing an official briefed on the matter. No agreement has been announced. On Sunday, President Trump said the conflict would end “very soon,” through a deal or further action, and Iran said the Qatar-mediated talks were advancing.

The drop came even after a vessel was struck by an unknown projectile in the Strait of Hormuz on Sunday, and after OPEC+ producers met Sunday and held December output steady. Gold rose as oil fell.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Federal Hall, Wall Street, New York City in August 2017. Archive photograph.

Photo: Arild Vagen / Wikimedia Commons (archive photo)

Oil crashed 7% Monday on renewed hopes for U.S.-Iran diplomacy, splitting the tape in two: the Dow rose and eight of the S&P 500’s 11 sectors gained, but the Nasdaq fell for a third straight session as Intel sank below $60 and the chip rout deepened, hours before Apple and Palantir reported after the close.

The numbers. The Dow Jones Industrial Average rose 213.67 points, or 0.41%, to 51,983.98, snapping a two-day losing streak. The S&P 500 fell 38.67 points, or 0.51%, to 7,541.40, and the Nasdaq Composite dropped 272.68 points, or 1.07%, to 25,164.32 – both down a third straight day. The Russell 2000 slipped 5.96 points, or 0.21%, to 2,805.88. The VIX jumped 8.9% to 21.15. Nasdaq composite volume was about 8.0 billion shares, down from Friday’s heavy 9.1 billion.

Table: Dow, S&P 500, Nasdaq, Russell 2000, WTI crude and gold - prior close, close, change and percent change for Monday, Nov. 2

Source: NYSE, Nasdaq and NYMEX/COMEX closing data

Sectors: the rotation. Money left technology and energy and went almost everywhere else. Consumer discretionary led, up 2.41%, followed by financials at +1.86%, materials +1.76%, consumer staples +1.58%, industrials +1.38%, real estate +1.09%, utilities +0.55% and communication services +0.36%. The two losers that matter: energy, down 3.96% on the oil collapse, and technology, down 2.95% as the chip selloff rolled on. Health care eased 0.15%. Eight winners against three losers – but technology’s decline weighed heavily on the index.

The movers. Intel tumbled another 8.8% to $59.97, closing below $60 and stretching its loss over two sessions to about 35%, following Friday’s 28.6% crash on a weak holiday-quarter outlook. Microsoft fell 2.8%, Nvidia 1.3%, Meta 1.3% and Alphabet 0.3%. Apple slipped 1.8% to $338.32 ahead of its after-close report. On the winning side: Amazon rebounded 2.2% after Thursday’s post-earnings selloff, Berkshire Hathaway rose 2.5% ahead of its earnings report, and JPMorgan added 1.1% as financial stocks rose. The oil crash hit the majors – Exxon Mobil fell 4.1% and Chevron 3.3% – while Coinbase dropped 4.0% as crypto sagged.

Monday November 2, 2026 stock movers: prior close, close, change and percent change for Berkshire, Amazon, JPMorgan, Alphabet, Nvidia, Meta, Apple, Microsoft, Chevron, Coinbase, Exxon Mobil and Intel.

Source: Yahoo Finance daily closing prices

Oil’s collapse. U.S. crude settled at $96.46 a barrel, down 7.4% from Friday’s $104.12 settlement, after trading as much as 8% lower intraday, as traders priced the possibility that diplomacy between Washington and Tehran could defuse the conflict premium that drove oil above $100 last week. Gasoline futures sank with crude; lower crude prices could eventually ease pressure at the pump, though retail gasoline prices do not adjust immediately.

Gold, bonds, the dollar and bitcoin. Gold rebounded, settling at $3,969.60 an ounce, up $70.70, or 1.8%, from Friday’s $3,898.90 settlement after Friday’s 3.5% dump. The 10-year Treasury yield eased about 2 basis points to roughly 4.91%. The dollar index slipped 0.1% to 101.79. Bitcoin traded near $76,800, down from about $77,200 at Friday’s close.

After the close. Apple posted a record September quarter – revenue up 12% to $114.5 billion and earnings of $2.10 a share, both ahead of estimates, with iPhone sales up 17% – in John Ternus’s first report as CEO; management then forecast holiday-quarter revenue growth of 7% to 10%, below the 11.4% growth analysts polled by LSEG expected. Palantir nearly doubled revenue again, up 96% to $2.31 billion, beating estimates and raising its full-year outlook as U.S. commercial sales passed government sales for the first time. Both reports land as the market’s first big test this week of whether it will pay for AI growth or keep punishing its cost.

What to watch. The midterm elections Tuesday, Berkshire Hathaway’s results later this week, and the October jobs report Friday.

JBizNews Desk | Wall Street
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

New York Stock Exchange on Wall Street, July 2012 archive photograph.

Photo: Carlos Delgado; CC BY-SA (archive)

UDR raised its full-year adjusted funds-from-operations outlook, Valaris reported stronger sequential operating results as drillships returned to work, and trucking company PAMT reported a wider quarterly net loss in earnings releases issued Monday after the market close.

The reports cover different corners of the economy: apartment operations and property partnerships, offshore drilling demand, and freight rates facing higher costs. They also illustrate why headline profit figures and management’s adjusted measures need to be read separately.

UDR raises adjusted FFO outlook, but not every measure

Apartment owner UDR reported third-quarter net income of $0.67 per diluted share, up from $0.12 a year earlier. Funds from operations were unchanged at $0.62 per share, and FFO as adjusted was flat at $0.65.

UDR raised its full-year FFOA range to $2.54-$2.56 per share from $2.49-$2.57. That increased the midpoint by two cents to $2.55 while narrowing the range.

The revision was not an across-the-board increase. The company updated its FFO range to $2.48-$2.50 from $2.47-$2.55, lowering that midpoint by two cents to $2.49. Its net-income outlook increased to $1.58-$1.60 from $1.03-$1.11.

The full results followed preliminary figures released October 21. UDR said third-quarter total revenue declined 0.9% as property sales offset growth from same-store and acquired communities.

UDR also said it closed a $2 billion strategic partnership with Apollo, contributing 19 apartment communities containing 7,059 homes to a joint venture. It received $1.34 billion of equity capital, retained an approximately one-third interest and will continue to operate and manage the properties.

The company adjusted its same-store growth presentation to exclude those 19 communities. That portfolio change matters when comparing the new operating growth figures with older disclosures. FFO and FFOA are non-GAAP measures and are not interchangeable with net income.

Valaris adds backlog as drillship work increases

Offshore drilling contractor Valaris reported $594 million in operating revenue, $47 million in net income and $151 million in adjusted EBITDA for the third quarter.

Net income was in line with the second quarter, while adjusted EBITDA increased from $97 million. Revenue excluding reimbursable items rose to $556 million from $502 million, helped by more operating days and higher average daily revenue in the floater fleet.

Chief Executive Anton Dibowitz said all ten active drillships were on contract after the company returned four drillships to work this year following significant idle periods. Valaris added approximately $600 million of contract backlog since its second-quarter report, bringing the total to about $4.8 billion.

The company estimated that Middle East conflicts reduced quarterly adjusted EBITDA by about $24 million, compared with $30 million in the second quarter. It said the impact began to moderate as war-risk insurance costs fell and two jackups resumed bareboat charters.

Valaris said its pending combination with Transocean had received required regulatory approvals and was anticipated to close on or about December 1. That remains an expected closing, not a completed transaction.

PAMT revenue rises, but costs outweigh rate gains

Truckload carrier holding company PAMT reported third-quarter revenue of $162.5 million, up 8.2% from $150.3 million a year earlier. Its net loss widened to $8.1 million, or $0.38 per share, from $5.6 million, or $0.27 per share.

The operating loss narrowed to $5.0 million from $5.7 million. The distinction is important: a wider bottom-line loss did not mean the operating loss also widened.

President Lance Stewart said rate per mile improved 11% sequentially and 6% year over year. However, higher net fuel costs, driver recruitment and retention costs, and reduced gains on used-equipment sales offset those improvements.

PAMT said fuel surcharges typically lag changes in diesel prices by a week or more, leaving a timing mismatch when fuel prices rise quickly. It reported $102 million of available liquidity and $323.1 million in outstanding debt at September 30.

The three releases show distinct operating trends rather than a single market-wide earnings signal. UDR’s adjusted guidance improved, Valaris benefited from returning rigs to service, and PAMT’s pricing gains were not yet enough to produce a quarterly profit.

Stock reaction: verified quotes and limits

Valaris quote data showed $93.96 at 4:03 p.m. Eastern in Monday’s after-hours session, down $0.73, or 0.77%, from its $94.69 regular-session close. The stock had fallen 10.08% during regular trading, before the after-close report. The early extended-session snapshot is not a final after-hours price or proof that earnings alone caused the move.

A sufficiently reliable post-release stock reaction for UDR and PAMT could not be verified at this update. Available UDR quotes included pre-release intraday data, while PAMT sources showed conflicting or older prices. No earnings-reaction percentage is assigned to either company.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Tempus laboratory photograph provided in the company media library. This is not a Cipher facility.

Photo: Tempus

Tempus AI raised its full-year revenue outlook after reporting 23% quarterly sales growth, while Cipher Digital recorded its first high-performance computing lease revenue as it continued a transition away from bitcoin mining. IDEXX Laboratories also raised its annual outlook, while Krystal Biotech outlined later clinical milestones and a new share-buyback authorisation. Choice Hotels raised its room-revenue outlook but cut its GAAP profit guidance.

Tempus raises revenue guidance

Tempus reported revenue of $411.5 million for the three months ended September 30, up from $334.2 million a year earlier, according to its Monday results release. Diagnostics revenue rose 20% to $303.5 million, while Data and Applications revenue increased 33% to $108.1 million.

Oncology testing volume increased 32%. Minimal residual disease testing volume reached approximately 12,000, up 300%, the company said. Gross profit rose 27% to $266.7 million.

The company narrowed its net loss to $14.9 million, or 8 cents a share, from $80.0 million, or 46 cents a share, a year earlier. The latest quarter included $50.8 million in stock-based compensation and related payroll taxes as well as $42.8 million in unrealized gains on marketable securities.

Adjusted EBITDA increased to $25.6 million from $1.5 million. That adjusted measure excludes items included in the company’s GAAP results and is not a substitute for net income or loss.

Tempus increased its 2026 revenue guidance to $1.600 billion to $1.605 billion, representing approximately 25% annual growth. It continued to expect roughly $65 million in full-year adjusted EBITDA. The company ended the quarter with $854.4 million in cash and marketable securities.

Its pending acquisition of Personalis had cleared regulatory review, but the company said the shareholder meeting to approve it was planned for November 30. The acquisition had not been completed in the results announcement.

Cipher begins recognizing HPC lease revenue

Cipher Digital reported $26.7 million in total third-quarter revenue, down from $71.7 million a year earlier, in its business update and financial statements. Bitcoin mining revenue declined to $20.8 million from $71.7 million, while HPC leasing contributed $5.9 million for the first time.

The first HPC revenue followed the start of rent at Black Pearl. Cipher said additional data halls at Black Pearl and Barber Lake were scheduled to come online through year-end.

Its operating loss widened to $71.9 million from $37.6 million a year earlier. Adjusted EBITDA was negative $10.0 million, compared with positive $40.8 million in the prior-year period.

Cipher reported net income of $31.6 million, helped by a $127.2 million gain from a change in the fair value of warrant liabilities. Its financial statements nevertheless showed a diluted loss of 22 cents a share. The operating loss, warrant-related gain and adjusted EBITDA should be considered separately rather than treating one measure as a complete account of performance.

The company highlighted a previously announced extension of its Barber Lake lease to 20 years, increasing total contracted revenue to approximately $9.1 billion. That figure is contracted revenue over the lease’s life, not revenue earned in the quarter.

Cipher also said it received a conditional base-load classification for 1 gigawatt at Colchis and conditional studied-load classifications for another 1.6 gigawatts. These are conditional development milestones, not evidence that all that capacity is operating. Its pipeline totals approximately 5.9 gigawatts, the company said.

Both companies’ outlooks depend on future execution. Tempus’ guidance remains a forecast, while Cipher’s planned data-center capacity, lease deliveries and potential generation projects remain subject to construction, financing and other risks.

IDEXX lifts annual revenue and earnings outlook

IDEXX Laboratories reported third-quarter revenue of $1.214 billion, up 10% on both a reported and organic basis, and diluted earnings of $4.01 a share, up 18%, in its Monday results release. Companion Animal Group diagnostics recurring revenue increased 11% on both measures.

The veterinary diagnostics company placed more than 1,900 inVue Dx analyzers during the quarter, bringing the installed base to nearly 11,000. Operating margin reached 33.1%, up one percentage point from the prior-year period.

IDEXX raised its full-year revenue guidance to $4.741 billion to $4.767 billion, up $32 million at the midpoint, including $5 million related to its CoVet acquisition. It increased its diluted earnings outlook to $14.96 to $15.16 a share, up 25 cents at the midpoint.

The stronger sales and earnings forecast did not mean every outlook metric improved. IDEXX lowered its reported operating-margin forecast to 32.1% to 32.3%, including acquisition-related effects, from 32.3% to 32.5% previously.

Krystal’s product growth accompanies later clinical readouts

Krystal Biotech reported $127.3 million of third-quarter Vyjuvek net product revenue, up 30% from $97.8 million a year earlier, according to its financial and operating update. Net income was $63.1 million, or $2.05 a diluted share, compared with $79.4 million, or $2.66 a share, in the prior-year quarter. Cash, equivalents and investments totalled $1.2 billion.

Alongside the commercial results, Krystal said several trial milestones now fall in 2027. The last patient visit in the IOLITE study of KB803 is expected in February 2027, with top-line results shortly afterward. The company added patients to replace two who withdrew for reasons unrelated to safety and to provide additional supporting evidence.

Enrollment in the EMERALD-1 study of KB801 has been slower than initially anticipated, reflecting eligibility criteria and the difficulty of enrolling a placebo-controlled study where approved therapy exists. Krystal now expects to complete enrollment of approximately 60 patients and report top-line results in 2027. Interim results from its repeat-dose KB407 cystic-fibrosis study are now expected in the first half of 2027.

Krystal’s board also authorised repurchases of up to $400 million of common stock. Management expects opportunistic buying over two years, but the authorisation has no expiration date and does not oblige the company to purchase any amount. It is permission for future repurchases, not $400 million already spent.

Choice Hotels raises RevPAR outlook but cuts GAAP profit guidance

Choice Hotels reported Monday morning that third-quarter U.S. revenue per available room increased 3.8%, reflecting stronger occupancy and rates. Revenue was $458 million, compared with $447 million a year earlier, and adjusted diluted earnings were $2.33 a share.

Net income fell to $58 million from $180 million. The year-earlier quarter included a $100 million joint-venture acquisition gain, while the current quarter included a $24 million contract-termination charge and $6 million of hotel impairment charges. Those items were excluded from adjusted results.

Choice raised its 2026 U.S. RevPAR growth outlook to 1.5%-2.5%, from 0%-1.25%, but lowered its GAAP net-income outlook to $178 million-$185 million from $230 million-$241 million. The lower profit forecast reflects higher expected reimbursable marketing and reservation-system expenses, current charges, lower affiliate earnings and higher interest expense. The mixed revisions are not a blanket guidance increase.

How the stocks traded

The following are Monday, November 2 snapshots from Tempus, Cipher, IDEXX, Krystal and Choice Hotels quote data. Regular-session changes are measured against the prior close; after-hours changes are measured against Monday’s regular-session close, not the prior day’s close.

  • Tempus: $77.46 at 5:53 p.m. Eastern after hours, down $1.02, or 1.30%, from its $78.48 regular-session close. It had gained 8.67% during regular trading, before the after-close results.
  • Cipher: $6.95 at 5:29 p.m. Eastern after hours, up $0.09, or 1.31%, from its $6.86 close. Its regular-session decline was 5.90%.
  • IDEXX: closed at $671.64 at 4 p.m. Eastern, up $120.43, or 21.85%, following its morning results. It was quoted at $675.00 at 5:02 p.m. after hours, up another 0.50% from the close.
  • Krystal: closed at $295.90 at 4 p.m. Eastern, down $36.39, or 10.95%, following its earnings and clinical update. The 4:26 p.m. after-hours quote was unchanged at $295.90.
  • Choice Hotels: was quoted at $116.69 at 3:51 p.m. Eastern during regular trading, up $5.53, or 4.97%, following its morning report. This is a timed intraday snapshot, not a verified final closing price.

These snapshots describe trading around the reports, not proof that earnings alone caused every move. After-hours quotes can change.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Palantir stand at the NHS Confederation conference, June 2022. Archive photo.

Photo: Wikimedia Commons (archive photo)

Palantir Technologies nearly doubled third-quarter revenue to $2.313 billion and raised its full-year outlook Monday, as U.S. commercial sales overtook U.S. government revenue for the first time.

The software company reported revenue growth of 96% from a year earlier and 20% from the second quarter, crossing $2 billion in quarterly sales for the first time, according to its third-quarter earnings release.

Palantir raised its 2026 revenue guidance to $8.530 billion-$8.534 billion. It projected fourth-quarter revenue of $2.649 billion-$2.653 billion, making the outlook another measure of the pace management expects after the latest quarter.

Commercial sales lead the U.S. business

U.S. commercial revenue rose 148% from a year earlier and 29% sequentially to $984 million. U.S. government revenue increased 96% annually and 18% sequentially to $953 million.

Together, U.S. revenue reached $1.937 billion, up 119% year over year. The commercial business exceeding government revenue is a milestone in the company’s sales mix, though both operations continued to grow rapidly.

Chief Executive Alex Karp described demand for what he called “Sovereign AI” as a major force behind the business. That is management’s assessment of the opportunity, distinct from the financial results already recorded.

Profit and cash flow rise alongside sales

Palantir reported GAAP net income attributable to common stockholders of $1.128 billion, representing a 49% margin, and diluted earnings of 44 cents a share. Adjusted diluted earnings were also 44 cents a share.

GAAP operating income was $1.085 billion, a 47% margin. Adjusted operating income was $1.427 billion, a 62% margin. The adjusted figures exclude items included under generally accepted accounting principles and should not be treated as substitutes for the GAAP measures.

Cash from operations reached $1.205 billion. Adjusted free cash flow was $1.216 billion, while cash, equivalents and U.S. Treasury securities totaled $10.4 billion.

Contract growth is not the same as current revenue

The company closed 212 deals worth at least $1 million, including 107 worth at least $5 million and 64 worth at least $10 million. Those thresholds overlap; they are not separate groups to add together.

Total contract value closed during the quarter was $2.918 billion, up 6% year over year. U.S. commercial total contract value was $1.463 billion, up 11%. U.S. commercial remaining deal value reached $6.517 billion, up 79% annually and 4% sequentially.

Those contract measures describe business signed or remaining under the company’s definitions, rather than revenue recognized in the quarter. The gap between 96% revenue growth and 6% total contract value growth is a reason to read the measures separately rather than describing all bookings as having doubled.

A higher full-year forecast

Palantir’s revised outlook calls for U.S. commercial revenue above $3.559 billion in 2026, representing growth of at least 143%. The company raised adjusted operating-income guidance to $5.245 billion-$5.249 billion and adjusted free cash flow guidance to $4.8 billion-$5.0 billion.

For the fourth quarter, it forecast adjusted operating income of $1.640 billion-$1.644 billion. It continued to expect positive GAAP operating income and net income in each quarter of the year.

The outlook remains a forecast, not revenue or profit already earned. The stock reaction is reported separately below from verified market data.

Stock reaction after the report

Palantir traded at $171.76 at 5:56 p.m. Eastern in Monday’s after-hours session, down $6.58, or 3.69%, from its $178.34 regular-session close, according to market quote data. The move followed the earnings release and raised guidance. It was separate from the stock’s 3.13% decline during regular trading. Extended-session prices can continue to change.

JBizNews Desk | Miami
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Apple Fifth Avenue store in New York, December 2010 archive photograph.

Photo: Jorge Lascar / Wikimedia Commons (archive)

Correction and update, November 2 at 9:10 p.m. EST: The revenue-growth outlook is above the 6.1% LSEG estimate, not below an 11.4% estimate as previously stated. The gross-margin forecast trails estimates. The stock reaction has been updated to the after-hours closing price.

Apple forecast December-quarter revenue growth of 7% to 10% on its earnings call Monday, above the 6.1% growth analysts polled by LSEG expected, but its gross-margin outlook of 45% to 46% trailed the 46.3% estimate, according to CNBC. The mixed outlook followed record September-quarter sales of $114.5 billion.

Stock reaction: Apple shares ended Monday’s after-hours session at $328.81, down 2.81% from the regular-session close, after falling as low as $323.33, a 4.43% decline, according to 9to5Mac. CNBC reported that shares slid about 3% in extended trading as investors weighed the weak margin forecast. That post-earnings reaction was separate from Monday’s 1.83% regular-session decline.

Chief Financial Officer Kevan Parekh said the outlook reflects Apple’s best view of constrained supply. The growth guidance and analyst comparison emerged after the company released its quarterly results and during the call that began at 5 p.m. Eastern.

Apple reported record September-quarter revenue of $114.5 billion on Monday as iPhone sales climbed and Services reached an all-time high, delivering its first quarterly earnings report under Chief Executive John Ternus.

Diluted earnings per share rose 14% to $2.10 in the fiscal fourth quarter ended September 26. Revenue increased 12% from a year earlier. The results included a benefit from tariff refunds, which added $0.05 to earnings per share and approximately one percentage point to the company’s 47.9% gross margin.

The company’s release and accompanying financial statements show a strong finish to the fiscal year, although sales declined in iPad and Wearables, Home and Accessories.

iPhone and Services lead the quarter

iPhone revenue reached $57.583 billion, up about 17% from $49.025 billion a year earlier. The product remained Apple’s largest business and set a September-quarter sales record.

Services revenue rose to $31.573 billion from $28.750 billion, an increase of about 10%. Apple said the figure was an all-time record. The category’s growth gives the company a second large source of sales alongside its hardware business.

Mac revenue increased to $10.792 billion from $8.726 billion, up about 24%. By contrast, iPad revenue fell to $6.229 billion from $6.952 billion, while Wearables, Home and Accessories declined to $8.300 billion from $9.013 billion.

The differing category results make the quarter more specific than an across-the-board hardware rebound: iPhone and Mac grew, Services set a record, and two other product groups contracted.

China grows as Japan slips

Greater China revenue increased to $17.539 billion from $14.493 billion, up about 21%. The Americas rose to $48.680 billion from $44.192 billion, while Europe reached $32.008 billion from $28.703 billion.

Rest of Asia Pacific revenue increased to $9.710 billion from $8.442 billion. Japan was the exception among the reportable geographic segments, with revenue falling to $6.540 billion from $6.636 billion.

Profit rises, with a tariff-refund benefit

Net income increased to $30.711 billion from $27.466 billion. Operating income rose to $35.631 billion from $32.427 billion, according to the unaudited statements.

The tariff refunds are important when reading the earnings headline. Apple reported $2.10 in diluted earnings per share including the $0.05 favorable effect, rather than presenting the full increase as unrelated to that benefit. The release likewise identified the refund contribution to gross margin.

Research and development spending rose to $11.730 billion from $8.866 billion. Total operating expenses reached $19.189 billion, compared with $15.914 billion in the year-earlier quarter.

A record fiscal year

For fiscal 2026, Apple reported revenue of $478.834 billion, up from $416.161 billion in fiscal 2025. Full-year net income was $132.175 billion, compared with $112.010 billion, and diluted earnings per share rose to $8.98 from $7.46.

Chief Financial Officer Kevan Parekh said Apple generated $28 billion in operating cash flow during the quarter and returned $28 billion to shareholders. He also said the installed base of active devices reached a new all-time high across all major product categories and geographic segments.

The annual cash-flow statement showed $145.097 billion in operating cash flow and $86.390 billion in common-stock repurchases for the full fiscal year. Those annual totals are separate from Parekh’s quarterly figures.

Ternus points to the holiday lineup

Ternus said the company was entering the holiday season with a new lineup that included iPhone Duo, iPhone 18 Pro and Pro Max, new home hardware, Touch on Mac and Siri AI. Those remarks describe Apple’s current product push, not a claim that all the new devices contributed to the September-quarter results.

Apple’s board declared a cash dividend of $0.27 per common share, payable November 16 to shareholders of record at the close of business November 12. Management discussed the outlook on its results conference call Monday evening.

Revenue outlook tops estimates; margin forecast trails

On the call, Parekh said Apple expects total revenue to rise 7% to 10% year over year in the December quarter and still anticipates the highest quarterly revenue in the company’s history. The range is above the 6.1% analyst expectation compiled by LSEG, according to CNBC. Gross-margin guidance of 45% to 46%, however, is below the 46.3% average estimate.

According to a transcript of management’s prepared remarks, Parekh also forecast gross margin of 45% to 46%, citing higher memory costs and some costs associated with the ramp of Siri AI. He projected Services growth of 8% to 9% and operating expenses of $20.4 billion to $20.8 billion.

The outlook assumes global tariff rates, policies and their application remain as they were at the time of the call, and that the global macroeconomic outlook does not worsen. Those figures are management forecasts for the coming quarter, not results already achieved.

JBizNews Desk | Cupertino, California
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Federal Reserve Eccles Building in Washington, March 2011 archive photograph.

Photo: Federal Reserve (archive photo)

U.S. banks tightened lending standards for commercial real estate and small-business loans while demand for many types of borrowing weakened in the third quarter, according to the Federal Reserve’s October Senior Loan Officer Opinion Survey.

The Fed survey showed tighter standards and weaker demand in all three commercial real estate categories: construction and land development, nonfarm nonresidential properties and multifamily properties. For commercial and industrial loans, demand weakened among companies of all sizes.

The results describe changes over the preceding three months, generally the third quarter of 2026. They are not a reading of fourth-quarter conditions.

Small firms face tighter approval standards

Banks said approval standards for business loans to large and middle-market companies were basically unchanged, while standards for small companies tightened. The survey defines large and middle-market firms as those with annual sales of at least $50 million; small firms have sales below that threshold.

Most loan terms were eased or left basically unchanged, but banks increased premiums on riskier business loans across company sizes. For small firms, collateral requirements and the use of interest-rate floors also tightened.

Banks most frequently pointed to a less favorable or more uncertain economic outlook and worsening industry-specific problems as reasons for tightening.

Weaker demand for business borrowing reflected less customer investment in plant or equipment and a shift toward more attractive funding from other banks or nonbank lenders, respondents said.

Commercial property faces pressure on both sides

The combination of tighter approval standards and weaker demand extended across every commercial real estate category covered by the survey. That means the reported weakness was not confined to office or retail property: it also included construction and land development and multifamily lending.

The summary generally refers to domestic banks. U.S. branches and agencies of foreign banks reported a different demand picture, with stronger demand for commercial real estate and business loans. Foreign banks tightened commercial property standards but left business-loan standards basically unchanged.

Mortgage demand weakens, jumbo standards ease

Standards for most types of residential mortgages were basically unchanged. Banks eased standards for both qualified-mortgage jumbo loans and non-qualified-mortgage jumbo loans, while tightening standards for subprime mortgages.

Demand weakened across all surveyed residential mortgage categories. Standards and demand for home equity lines of credit were basically unchanged.

The survey measures lenders’ reported changes, not a count of loans issued or a forecast for home prices.

Credit cards and auto loans diverge

Banks reported stronger demand for credit card loans and weaker demand for auto loans. Demand for other consumer loans was basically unchanged.

Overall approval standards and most terms for consumer borrowing were broadly stable, but some conditions tightened. Banks reduced credit card limits, raised minimum required auto-loan credit scores and became less willing to make certain credit card and other consumer loans to borrowers below credit-score thresholds.

Special questions covering the past year found banks were more likely to approve credit card applications from prime and super-prime borrowers and less likely to approve subprime applications. Banks most often attributed stronger card demand to changes in consumers’ spending needs in response to the prices of goods and services.

Banks tighten lending to nonbank financial firms

Banks also tightened standards for every surveyed category of lending to nondepository financial institutions, including mortgage and business credit intermediaries, private equity funds and consumer credit intermediaries.

Respondents cited an uncertain economic outlook and weaker financial strength among those borrowers. Demand strengthened from business credit intermediaries and private equity funds, while remaining unchanged for the other categories.

The survey drew responses from 61 domestic banks and 18 U.S. branches and agencies of foreign banks. It was sent on September 21, with responses due October 5. Descriptions such as tighter standards or weaker demand refer to the balance of banks reporting changes, not to a claim that every bank moved in the same direction.

JBizNews Desk | Washington
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

United States Treasury building in Washington, DC, July 2015 archive photograph.

Photo: Wikimedia Commons (archive photo)

The U.S. Treasury on Monday lowered its estimate of privately held net marketable borrowing for the final quarter of 2026 to $618 billion, saying a larger cash balance at the start of the quarter reduced the amount it expects to raise.

The estimate is $10 billion below the projection issued in August and assumes Treasury will finish December with $850 billion in cash, according to the department’s November 2 borrowing announcement.

The headline reduction does not mean underlying financing needs have eased. Treasury said that, excluding the benefit from its higher-than-assumed opening cash balance, its October-December borrowing estimate is $24 billion higher than it projected in August.

Opening cash offsets higher needs

Treasury entered the quarter with $984 billion in cash, compared with the $950 billion it had previously assumed. That $34 billion difference lowered its expected need to borrow, while lower projected net cash flows partly offset the benefit, the department said.

The department kept its end-of-December cash assumption at $850 billion. The revised borrowing estimate therefore reflects both the larger starting cushion and the updated outlook for money flowing into and out of the government’s accounts.

These are quarterly financing estimates, not a new announcement of the sizes or maturity mix of individual debt auctions. Treasury said it will provide additional details in its quarterly refunding announcement at 8:30 a.m. Eastern time on Wednesday, November 4.

$800 billion projected for early 2027

For January through March 2027, Treasury estimates it will borrow $800 billion in privately held net marketable debt. That projection assumes an end-of-March cash balance of $1 trillion.

The next-quarter estimate is conditional on that cash target. It should not be read as an announced auction schedule or a measure of the federal deficit on its own: the release concerns Treasury’s financing requirements and cash balances.

Prior-quarter borrowing reached $742 billion

Treasury also reported that it borrowed $742 billion in privately held net marketable debt during July through September and finished the quarter with $984 billion in cash. Its August projection had called for $739 billion in borrowing and a $950 billion closing cash balance.

Excluding the higher-than-assumed closing cash balance, Treasury said actual borrowing for that quarter was $30 billion below the August estimate. The figures show why cash assumptions matter when comparing successive borrowing projections.

The department’s definition excludes rollovers of securities held in the Federal Reserve’s System Open Market Account, while including financing needed for redemptions from that portfolio. Monday’s release sets out the aggregate borrowing outlook; Wednesday’s refunding announcement is the next scheduled step for further financing details.

JBizNews Desk | Washington
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Aerial view of Meta headquarters in Menlo Park, California, January 2023 archive photograph.

Photo: Wikimedia Commons (archive photo)

Meta Platforms is considering raising at least $20 billion through potential cross-border bond offerings, according to a Monday Bloomberg report, adding another possible source of financing as the Facebook and Instagram owner builds out its artificial intelligence infrastructure.

Bloomberg reported, citing people familiar with the matter, that no final decision had been made and the size could grow depending on investor demand. Reuters separately relayed the report. The proposed borrowing has not been announced as a completed transaction.

The distinction is important for investors: exploring a debt sale is not the same as pricing bonds, receiving cash or locking in borrowing costs. The available report does not establish a final amount, interest rate or repayment schedule. Nor should the $20 billion starting point be treated as a firm ceiling.

Another part of a much larger funding effort

The potential bond deal follows JBizNews’s report on Meta’s equity-financing plans last week. Those plans included approximately $35 billion in public offerings and a possible future $60 billion share-sale program. They were proposals and financing arrangements, not a statement that the entire amount had already reached Meta’s bank accounts.

Bonds and stock offerings raise capital differently. A bond is money borrowed with an obligation to repay under agreed terms. Selling shares provides equity capital but can increase the number of shares among which future earnings are divided. The possible bond offerings are therefore a different financing channel, not another name for last week’s share sales.

The scale of the funding effort reflects the cost of the computing capacity behind Meta’s AI strategy. In its third-quarter financial results, Meta reported $96.873 billion of operating cash flow in the first nine months of 2026 and $83.055 billion in purchases of property and equipment over the same period. Those are historical cash-flow figures, not estimates of proceeds from the potential bond sale.

Credit concerns are part of the backdrop

The new report also follows scrutiny of Meta’s credit outlook. A Fortune article carried on JBizNews earlier Monday described S&P Global’s decision late Friday to move Meta’s outlook to negative while affirming its AA- rating. An outlook change signals concern about the direction of credit risk; it is not itself a downgrade.

That discussion is separate from whether investors ultimately buy a new bond issue and on what terms. Bloomberg described the possible offering as investment-grade borrowing, meaning debt in the higher-rated portion of the credit market. A large investment-grade issuer can still face questions about future cash needs and the pace at which new spending produces returns.

For now, the development is a financing plan under consideration. A formal offering announcement and pricing would establish the amount actually raised and its cost. Until then, the reported $20 billion or more remains a potential transaction whose final size could change.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Andy Jassy at AWS re:Invent in December 2024. Todd Bishop / GeekWire; archive; crop.

Photo: Todd Bishop / GeekWire (archive photo)

Amazon could spend $395 billion on capital investment in 2027 and $476 billion in 2028, JPMorgan analyst Doug Anmuth forecast in a note reported Monday, November 2, by Yahoo Finance, putting a new Wall Street estimate on the cost of the company’s artificial-intelligence expansion.

Those figures are JPMorgan’s forecasts, not spending guidance issued by Amazon. In its October 29 earnings release, Amazon maintained its expectation for approximately $220 billion in cash capital expenditures in 2026. The release did not provide the $395 billion or $476 billion figures.

“We do not expect capex growth to decelerate or slow next year,” Anmuth wrote, according to Yahoo Finance’s report. He projected $395 billion in 2027, followed by $476 billion in 2028. The latter figure approaches half a trillion dollars in a single year, but remains an analyst estimate rather than an approved company budget.

Amazon Chief Executive Andy Jassy said last week that the company expected to spend “meaningfully more” on capital investment in 2027 without assigning a dollar amount, Yahoo Finance reported. Anmuth’s note attempts to quantify that outlook as Amazon adds the computing infrastructure behind its cloud and AI services.

Anmuth argued that management’s visibility into demand gives it confidence to invest more aggressively in AI computing infrastructure. That is the bank’s assessment of the investment case, not evidence that the projected spending or its expected returns are guaranteed.

The cash cost behind the AI buildout

Amazon’s own results show the cash demands already involved. Free cash flow for the trailing twelve months ended September 30 was an outflow of $42.4 billion, compared with an inflow of $14.8 billion a year earlier. The company attributed the decline primarily to a $94.8 billion year-over-year increase in purchases of property and equipment, net of sales proceeds and incentives, mainly reflecting AI investment.

That cash-flow measure covers a full trailing year, not the third quarter alone. Amazon also reported $168.3 billion in operating cash flow over the same twelve-month period, up 29%. The gap shows why operating cash generation and free cash flow tell different stories when a company is building expensive infrastructure.

The demand side is growing as well. Amazon Web Services reported third-quarter sales of $46.0 billion, up 39% from a year earlier, and operating income of $17.8 billion. In the earnings release, Jassy projected AWS revenue growth above 40% in both 2027 and 2028. That company outlook is separate from JPMorgan’s spending forecasts.

For investors, the distinction is the central one: Amazon has confirmed a $220 billion cash-capex expectation for this year, while JPMorgan is modeling a much larger investment cycle over the next two years. Whether cloud growth turns those investments into lasting free cash flow remains a question to track, rather than a result established by the forecast.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

New York Stock Exchange entrance in June 2024. Kidfly182 / Wikimedia Commons, CC BY 4.0; crop.

Photo: Kidfly182 (archive photo)

Broadridge said Monday, November 2, that it plans to provide on-chain shareholder governance and digital transfer agency services for the New York Stock Exchange’s planned tokenized-securities platform, bringing proxy voting and issuer services into the exchange’s digital-stock project.

The platform is not live. In its announcement, Broadridge said the NYSE platform is scheduled to launch following regulatory approval. The announcement did not give a launch date or say that approval had been granted.

The planned integration addresses what happens after an investor acquires a tokenized share: how that ownership connects to shareholder communications, voting eligibility and the services a public company uses to maintain its stockholder records. Digital trading alone does not supply those connections.

Under the plan, NYSE will use Broadridge’s governance smart contracts to connect tokenized securities with meeting agendas, voting rules and verifiable results. The framework also supports distributing proxy materials and authenticating digital wallets against verified voting entitlements, according to Broadridge.

Investors would be able to use the on-chain governance services through supported wallets, broker interfaces or ProxyVote. Those access routes are part of the proposed service, not a statement that every wallet or every tokenized stock product is supported.

Connecting stock ownership with shareholder rights

“Broadridge is building the governance layer for tokenized equities, ensuring investors have access to trusted, institutional-grade governance,” Broadridge Chief Executive Tim Gokey said in the announcement. He said the company is bringing digital and traditional transfer agency services together with proxy voting so issuers can participate regardless of how shares are traded or held.

The digital transfer agency integration would enable NYSE-listed companies to tokenize their stock for trading on the planned platform, Broadridge said. It is intended to connect the issuer-facing services behind a stock with the digital infrastructure used to trade it.

“Tokenization has the potential to transform the manner in which issuers interact with their shareholders,” NYSE Group President Lynn Martin said. She described the partnership as a step toward connecting tokenized trading, clearing and shareholder governance.

The companies are describing infrastructure to support tokenized ownership, rather than announcing that investors can begin trading on the venue today. Regulatory approval and the platform’s launch remain the conditions to watch.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

A large PAMP gold bar and a smaller gold ingot on display at the Banque de France.

Photo: Ibex73 / CC BY 4.0 (archive photo)

Gold rose 2 percent on Monday morning, November 2, with the December contract trading at $3,976 an ounce as of about 11:22 a.m. Eastern, up $77.10 from Friday’s official settlement of $3,898.90, according to CME Group prices. The contract touched $3,976.80, its highest of the session.

Gold opened the overnight session at $3,890 an ounce and traded as low as $3,889 before climbing through the morning, CME data show. The rise came as oil prices plunged, with U.S. crude down nearly 7 percent to $97 a barrel.

JBizNews Desk | New York

© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

President Donald Trump presents the National Medal of Science to Elon Musk. Reuters via New York Post; archive, crop.

Photo: Reuters (archive photo)

President Donald Trump said he would protect Elon Musk if Democrats pursued the Tesla and SpaceX chief after the midterm elections, according to a New York Post report published Monday on his interview with Miranda Devine for the “Pod Force One” podcast.

Asked about the prospect of Musk being arrested, Trump dismissed the threat before giving a conditional pledge of support. “It won’t happen. It’s talk,” he said. “But if it is talk, we’ll have to protect them.”

The comments put Musk and the businesses he leads back at the center of the political debate before Tuesday’s congressional elections. The Post reported them at 6 a.m. Eastern on November 2; they were not an announcement of a new protection order or an issued pardon.

The interview touched on calls to target people who worked with the administration, as well as former Labor Secretary Robert Reich’s push for Democrats to lay the groundwork for nationalizing SpaceX. The report did not describe a completed move to seize the company or its assets.

Trump also said he would consider preemptive pardons for people who worked in his administration if Democrats followed through on threats to prosecute them. “I would if I needed to. Sure,” he told Devine. Asked whether that extended to everyone who had worked for him, he said, “I’d do it.”

The Musk answer did not specify a legal mechanism to protect Tesla or SpaceX, and Trump did not announce a pardon for Musk. His broader remarks about pardons were conditional, rather than a grant of immunity to his allies.

The Post noted that presidential pardons cover federal crimes, not state prosecutions, civil suits or impeachment. That distinction limits what a pardon could accomplish even if Trump chose to issue one.

Trump said the election results would soon settle the immediate political question. “We’ll know on Tuesday night,” he said.

JBizNews Desk | Washington
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

“A sustained correction in the AI trade is a major risk to the global economy,” BofA Global Research’s economists wrote Monday, the day before a midterm vote in which data centers are on the ballot in 10 states.

“Investors are increasingly concerned about the sustainability of the AI trade, and the more capex rises, the more risks loom,” they wrote. A slowdown would hit growth directly and through the wealth effect, as stock gains that have propped up spending reverse. They also tie some of the rise in interest rates to the borrowing needed to pay for the buildout.

Voters have their own complaints about the buildout. They will decide 41 local data-center ballot measures on Tuesday, from new requirements for developers to outright bans on construction, Axios reported, citing Ballotpedia. All six data-center measures already decided this year, in New Hampshire, Wisconsin, Michigan and California, went against development.

The backlash has reached the top of the ticket. In Texas, Gov. Greg Abbott halted new data-center approvals pending an audit after facing a backlash in rural communities, and his Democratic challenger, Gina Hinojosa, supports a moratorium. In Ohio, Sen. Jon Husted is on the defensive over his past support for data centers in a race that could help decide control of the Senate; the state has 21 data-center measures on Tuesday’s ballot.

Goldman Sachs expects attention to data centers to fade after Tuesday. Data centers “emerged as a theme in some campaigns this year,” Goldman’s Alec Phillips wrote in a Nov. 1 preview, but the issue ranks low among voter priorities, and he expects the focus to “fade somewhat” once governors stop campaigning. Congress might limit tax breaks for data centers, he wrote, but a national moratorium looks unlikely under any outcome.

The outcome itself looks less in doubt. Polling suggests national sentiment has swung about 10 to 11 points toward Democrats, and prediction markets imply they’ll win the House with around 236 seats, a wider margin than either party has held in several years, Phillips wrote. The Senate is a closer call.

The boom

The data centers are going up anyway. Spending on data-center construction hit a preliminary record annual rate of $84.95 billion in August, up 73% from a year earlier, according to the Census Bureau. J.P. Morgan Asset Management’s David Kelly told Fortune he expects the squeeze they put on construction workers and materials to intensify in 2027. AI-related hardware investment is now $613 billion above its 2022 level, about 1.9% of GDP, Goldman’s economists estimate. The biggest tech companies are on track to spend roughly $800 billion on capex this year, up 96%, and analysts expect $1.2 trillion next year, according to Goldman’s Ben Snider.

The rest of the stock market has started to pull its own weight. Since earnings season began, the S&P 500 has fallen 3% while the S&P 500 excluding AI stocks has risen 5%, Snider wrote.

BofA Global Research chart of contributions to U.S. GDP growth from AI capex, 2023 to 2026

The jobs

AI is also showing up in the job numbers. Some 24.6% of U.S. businesses now use AIin at least one business function, up 0.8 points in a month, and 28.6% expect to within six months, Goldman’s Sarah Dong and Joseph Briggs wrote, citing Census Bureau data. In information, professional services and finance, adoption is approaching half.

Goldman Sachs chart of the share of U.S. firms using AI, rising to 24.6% in October 2026

The labor market impact “has become increasingly visible in recent months,” they wrote. Industries with higher AI adoption now show weaker job growth and higher unemployment, a relationship Goldman calls statistically significant. Marketing, graphic design, customer service and some tech jobs are taking the hit. Layoffs attributed to AI reached 4,000 in September and 207,000 since May 2023.

The buildout hires its own workers. Construction jobs tied to data centers are up about 315,000 since 2022 relative to broader construction trends, Goldman estimates.

The rest of the economy

Outside AI, the order books are thinning. The Goldman Sachs Analyst Index, which surveys the bank’s own stock analysts on the companies they cover, fell 6.5 points to 49.1 in October, below 50 for the first time since April 2025. New orders fell 33 points to 29.5, the lowest since May 2020.

Asked about the top risks for 2027, the analysts named the war in Iran most often, including higher input costs and supply disruptions. AI spending and adoption came next.

After Tuesday

Tariffs go up, whoever wins. Democrats would likely target a few countries or products, such as Canada, but Goldman expects President Trump to announce new tariff increases after the election that more than offset them, raising the effective tariff rate by a little under 2 percentage points.

A Democratic House would focus on spending deadlines and the debt limit, with the Iran war, tariff rollbacks, reversing spending cuts and expanding health benefits at the top of its agenda, Goldman expects. Reversing last year’s cuts would add about 0.25% of GDP in spending in 2027.

In Congress, Phillips expects the AI fight to move from data centers to regulation, where Goldman sees room for a compromise on basic federal oversight and self-testing, and little appetite for anything restrictive.

Generative AI was used for research assistance and/or transcription of this article. The reporter independently reported and verified the factual claims in this article, and a human editor reviewed it before publication.

This story was originally featured on Fortune.com

This post was originally published here. 

Rivian assembly plant in Normal, Illinois, September 14, 2021 archive, illustrating US manufacturing. Rivian / Wikimedia Commons, CC BY-SA 4.0; crop.

Photo: Rivian (archive photo)

U.S. manufacturing expanded faster in October as production reached its strongest reading since November 2021, but purchasing managers continued to report rising prices and slower deliveries, the Institute for Supply Management said in its monthly report released Monday, November 2. The Manufacturing Purchasing Managers’ Index rose to 55.5 from 54.5 in September, marking a tenth consecutive month of expansion.

The production index increased to 59.0 from 56.7, while new orders edged up to 55.5 from 55.3. A reading above 50 signals expansion for those measures. The survey shows the direction and breadth of changes reported by manufacturers, not a percentage change in the volume of output.

The improvement in activity came with persistent cost pressure. The prices index eased to 75.2 from 77.9, meaning prices were still rising, though at a slower rate. It does not mean manufacturers reported falling input prices.

Supplier deliveries also slowed further. That index rose to 59.1 from 59.0; unlike most ISM indexes, a reading above 50 means deliveries are taking longer, not that supplier performance has improved.

Employment remained in expansion territory but grew more slowly, with its index slipping to 52.4 from 52.7. Inventories returned to growth at 51.4, up from 48.6. The backlog-of-orders index eased to 54.6 from 56.4.

Susan Spence, chair of ISM’s Manufacturing Business Survey Committee, said general sentiment worsened for a third consecutive month. Negative comments made up 66% of responses, versus 34% positive. Among the negative comments, 62% mentioned pricing volatility and 41% mentioned longer lead times; respondents could cite more than one issue.

Twelve manufacturing industries reported growth and three reported contraction. The report pairs stronger factory activity with complaints about supply constraints and costs. Those manufacturing survey results do not by themselves establish the pace of growth across the broader economy.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Anthropic CEO Dario Amodei at TechCrunch Disrupt, September 20, 2023 archive. Kimberly White / Getty Images for TechCrunch, CC BY 2.0; crop.

Photo: Kimberly White / TechCrunch (archive photo)

Anthropic reported $16.956 billion in third-quarter revenue but returned to a GAAP operating loss as compute costs climbed, according to an amended IPO registration filing submitted to the Securities and Exchange Commission on Monday, November 2. The Claude developer posted an operating loss of $567 million for the three months ended September 30, compared with operating income of $974 million in the June quarter.

Revenue rose from $1.382 billion in the same quarter a year earlier. Anthropic put the year-over-year increase at 1,127%. Revenue also increased from $11.555 billion in the June quarter, even as the cost of supplying and developing its AI models weighed on operating results.

Compute and infrastructure expense reached $9.863 billion in the September quarter, up from $5.558 billion in the preceding quarter. Management attributed the return to an operating loss primarily to $5 billion of compute under short-term commitments and about $2 billion in noncash charges tied to its donation-matching program.

The filing says short-term compute currently costs significantly more than comparable capacity secured under multiyear commitments. Anthropic expects its use of short-term compute to increase in the near term, putting pressure on both its GAAP operating margin and adjusted operating margin.

Adjusted operating income, a non-GAAP measure, was $2.463 billion, compared with $2.235 billion in the June quarter. The adjusted operating margin fell to 15% from 19%. The measure excludes stock-based compensation and noncash charitable contributions, so it is not the same as GAAP operating income.

Anthropic reported a GAAP net loss of $23.291 billion for the quarter. That included a $21.936 billion expense from changes in the fair value of convertible notes, derivative liabilities and simple agreements for future equity, or SAFEs. Those financing-related valuation changes are separate from the operating loss.

The amended Form S-1 remains a preliminary registration for a proposed initial public offering, not a completed listing. Its cover leaves the offering price and share count blank and says Anthropic has applied to list its Class A shares on Nasdaq under the symbol ANT. The filing says the securities cannot be sold until the registration statement becomes effective.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Peter Tuchman on the New York Stock Exchange floor, November 5, 2021 archive. Bear Bull Traders, CC BY 2.0; crop. Not a photograph of today’s trading.

Photo: Bear Bull Traders (archive photo)

The Dow Jones Industrial Average jumped more than 400 points at the open Monday as Wall Street tried to bounce back from its worst day since June, with technology shares leading the recovery ahead of Apple’s earnings report tonight.

By 9:34 a.m. Eastern time, the Dow was up 428 points, or 0.8%, at 52,198. The S&P 500 rose 0.5% to 7,620 and the Nasdaq composite gained 0.7% to 25,607, clawing back a piece of Friday’s rout, when fears over the cash cost of the artificial intelligence buildout knocked the Nasdaq down 2.9%.

Tech leads the bounce – except Intel

Amazon, one of last week’s biggest casualties, rose 2.3% to about $246. Apple added 1.7% to about $208 as investors positioned for its results after the closing bell, the last mega-cap report of the season. Nvidia edged down 0.4%.

The exception was Intel, which fell another 2.6% to about $64, extending the losses from Friday, when the chipmaker closed down 28.6% after forecasting fourth-quarter revenue of $15 billion to $16 billion and earnings of just 10 cents a share on a weak personal-computer market. In two sessions, the stock has lost nearly a third of its value.

Oil’s slide deepens – and drags the oil majors down

The other big move of the morning was crude: Brent fell 5.7% to $106.94 a barrel as of 9:24 a.m., deepening an overnight slide as talks between Iranian negotiators and Qatari mediators on ending the U.S.-Israeli war on Iran raised hopes that supply disruptions could ease. That reversed Friday’s energy trade – Exxon Mobil, which had rallied after beating profit expectations, fell 2.6% to about $182.

The 10-year Treasury yield slipped to 4.90%, while gold rose 1.3% to $3,949 an ounce. Bitcoin held near $78,000 after last week’s record $6.3 billion Binance hack.

What changed from the pre-market picture

Futures had pointed to a gain of about half a percent across the board, and the open delivered almost exactly that. The differences were in the details: Intel’s small premarket loss deepened once regular trading began, oil’s slide steepened from about 4% to nearly 6%, and the Dow, which held up better than the Nasdaq through last week’s tech turmoil, took the early lead as money moved back into blue chips.

What it means for you

Two pieces of this morning land directly in household budgets. First, relief at the gas pump is getting closer: oil has now fallen roughly $10 a barrel since Thursday, and cheaper crude works its way into fuel prices over the following weeks – though at $107, Brent remains far above where it started the year. Second, the 10-year Treasury yield that mortgage and auto-loan rates follow slipped to 4.90%, down from around 5.3% at the start of October, which takes some pressure off borrowing costs. For retirement savers, Monday’s bounce repaired part of Friday’s damage within the first hour – but with Apple reporting tonight and the jobs report Friday, the week is far from settled.

What to watch

At 10 a.m., the manufacturing sector’s activity and prices-paid readings offer the first economic data of a packed week. After the close, Apple’s results – and especially what it says about AI spending – will set up Tuesday’s session, when Americans also vote in the midterm elections. Any breakthrough or breakdown in the Iran talks moves oil, and with it, inflation math for the Federal Reserve.

JBizNews Desk | Wall Street
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.

Alan Konevsky, tZERO CEO, in a company-supplied office portrait published in 2024 by Haute Living; archive, crop.

Photo: tZERO / Haute Living (archive photo)

tZERO agreed on Monday, November 2, to go public through a business combination with FG Imperii Acquisition Corp., in a proposed transaction that values the tokenized-markets infrastructure company at $350 million before new financing.

The pre-money equity valuation includes up to $25 million tied to specified milestones, according to the companies’ announcement. The deal has not closed. The companies expect completion in early 2027, subject to shareholder approvals, regulatory requirements and other conditions.

FG Imperii is a Nasdaq-listed special purpose acquisition company. Following the proposed combination, the companies expect the combined business to trade on NYSE American under the symbol TZRO, subject to listing approval.

The transaction could provide access to up to approximately $231 million held in FG Imperii’s trust account. That figure is subject to public-shareholder redemptions and is before transaction expenses. It is not cash tZERO has already raised or a guaranteed amount available at closing.

A separate forward-purchase arrangement with FG Merchant Partners LP could cover up to 2.5 million shares. The companies said that arrangement remains subject to definitive documentation. An FG Imperii affiliate also provided additional capital to tZERO’s previously announced funding round; the announcement did not specify that contribution’s amount.

Neighborhood Intelligence said on November 2 that it owns approximately 38% of tZERO through direct and indirect interests and signed a stockholder support agreement dated October 31 to vote in favour of the proposed combination, subject to its terms. Its announcement describes support for the pending transaction, not completion of the merger.

Existing tZERO shareholders are expected to roll all their equity interests into the combined company. Both boards approved the proposed combination, and tZERO said shareholders representing about 62% of its capital on a fully diluted basis had signed support agreements.

tZERO provides infrastructure for issuing, trading, settling and holding tokenized assets through its technology platform and regulated subsidiaries. Its proposed uses for net proceeds include strengthening the balance sheet, expanding technology and regulated infrastructure, commercial growth, new products and general corporate purposes.

Chief Executive Alan Konevsky is expected to continue leading the business after closing. Completion remains conditional, including on the effectiveness of a Form S-4 registration statement and approval of the combined company’s stock listing. The parties cautioned that the transaction may not be completed on the expected schedule, or at all.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. Unauthorized reproduction or redistribution is strictly prohibited.