Artificial intelligence (AI) companies are attracting a disproportionate share of capital inflows compared with other private market sectors. More than 75% of limited partners (LPs) intend to allocate to AI in the next 12 months—more than four times that of blockchain—yet AI exit activity remains relatively subdued, a report from S&P found.

“We’re witnessing unprecedented investor conviction colliding with a closed exit window,” Ilja Hauerhof, New Product Development Director, Private Markets, S&P Global Market Intelligence told Benzinga.

Aside from xAI’s $250 billion acquisition by SpaceX, overall exit activity remains subdued, with funding flows operating on a different scale.

“Fresh capital is moving off the sidelines, supporting large AI funding rounds. The structural imbalance means capital is entering faster than it is leaving. Deployment is now decoupled from exit cycles, with LPs’ intentions reflecting a forward-looking commitment to AI as a transformative platform,” the report said.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Launches And Lawsuits: Texans Sue SpaceX Over Alleged Rocket-Induced Damage

This post was originally published here
On CNBC’s “Halftime Report Final Trades,” Bryn Talkington, managing partner of Requisite Capital Management, named Uber Technologies, Inc. (NYSE:UBER) as her final trade.

Supporting her view, Citizens analyst Andrew Boone, on April 28, reiterated Uber with a Market Outperform and maintained a $100 price target.

Last month, Uber agreed to a fleet partnership with Hertz Global Holdings, Inc‘s (NASDAQ:HTZ) Oro Mobility, an affiliated operating company that will provide fleet management services for an autonomous robotaxi program.

The service is expected to launch in the San Francisco Bay Area later this year, with potential expansion in 2027. 

Don’t forget to check out our premarket coverage here

Jim Lebenthal, partner at Cerity Partners, picked Exxon Mobil Corporation (NYSE:XOM).

On the earnings front, Exxon Mobil reported a decline in first-quarter earnings …

Full story available on Benzinga.com

This post was originally published here
During times of turbulence and uncertainty in the markets, many investors turn to dividend-yielding stocks. These are often companies that have high free cash flows and reward shareholders with a high dividend payout.

Benzinga readers can review the latest analyst takes on their favorite stocks by visiting Analyst Stock Ratings page. Traders can sort through Benzinga’s extensive database of analyst ratings, including by analyst accuracy.

Below are the ratings of the most accurate analysts for three high-yielding stocks in the materials sector.

Avient Corp (NYSE:AVNT)

  • Dividend Yield: 3.09%
  • Keybanc analyst Aleksey Yefremov downgraded the stock from Overweight to Sector Weight on March 4, 2026. This analyst has an accuracy rate of 64%
  • Wells Fargo analyst Michael Sison maintained an Overweight rating and raised the price target from $42 to $47 on Feb. 13, 2026. This analyst has an accuracy rate of 64%.
  • Recent News: On April 27, Avient promoted Giuseppe Di Salvo to CFO.
  • Benzinga Pro’s real-time newsfeed …

Full story available on Benzinga.com

This post was originally published here
Robinhood Markets Inc. (NASDAQ:HOOD) is pivoting from a volatile trading app to a recurring-revenue powerhouse, driven by a subscription tier that Cathie Wood‘s Ark Invest likens to the revolutionary impact of Amazon Prime.

The ‘Amazon Prime’ Of Finance

While Robinhood’s first-quarter results revealed softer transaction revenues due to weak trading activity, Wood’s Ark Invest urges the market to look past cyclical volume.

The real catalyst is Robinhood Gold, a $5-per-month subscription tier rapidly becoming the gateway to the company’s broader financial ecosystem.

According to a recent Ark Invest newsletter, “Parallels with Amazon Prime are instructive.” Just as Amazon.com Inc.‘s (NASDAQ:AMZN) Prime utilized free shipping to become the “gravitational center” of Amazon’s operations, Gold is designed to maximize platform adoption.

Ark notes it aims to transform “intermittent brokerage users into high-frequency financial users,” shifting Robinhood toward a lucrative recurring revenue model. Currently, Gold subscriptions generate approximately $100 million in annualized recurring revenue.

data-variant=”card”
data-news-mode=”manual”

This post was originally published here
The markets are mispricing the impact of escalating geopolitical tensions and rising macro risks, according to Peter Schiff, who suggests buying the dip in precious metals.

In a Monday post on X, Schiff said, “gold is down over $100 and silver is down over $2.50” as conflict with Iran intensifies, oil prices surge, bond yields climb, and equities weaken.

He framed the selloff as a disconnect, telling investors to “take advantage of their ignorance and buy the dip.”

Gold, Silver Fall Despite “Safe Haven” Status

Gold and silver, traditionally seen as safe-haven assets, have come under …

Full story available on Benzinga.com

This post was originally published here
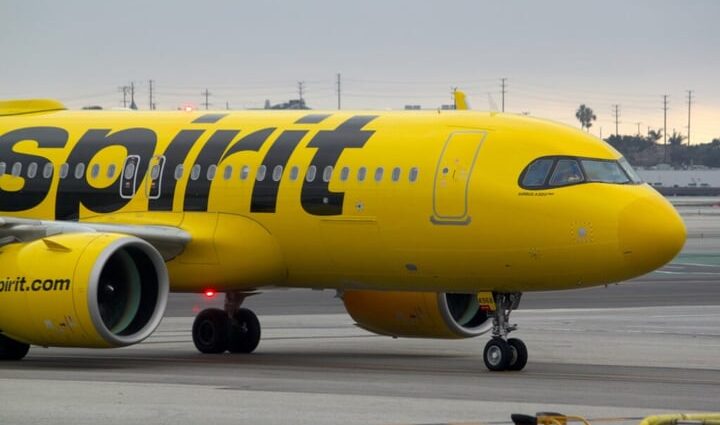
Governor Gavin Newsom (D-CA) criticized President Donald Trump and his handling of the Iran war on Sunday amid Spirit Aviation Holdings Inc.‘s (OTC:FLYYQ) grounding of its fleet over the weekend.

‘Affordability Is A Hoax,’ Says Newsom

In a post on the social media platform X on Monday, Newsom’s official Press Office handle quoted a post by NBC News, which shared that Spirit decided to cease operations because of geopolitical factors leading to increased fuel prices. “Wow. Trump destroyed America’s largest low cost carrier. Affordability is a hoax!” the post said.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Delta Airlines Cancels Several Flights Amid Crew, Scheduling Changes, Considers Scrapping Free Food Policy On Board: Report

This post was originally published here
Roundhill Investments has filed to launch the Roundhill Magnificent Seven Plus ETF. This fund would pair the dominant mega-cap tech stocks with a slate of newer AI and space contenders, according to a filing.

The proposed product is expected to trade under the ticker name MAGP. The expense ratio and official launch date have yet to be announced. As with all ETF filings, the fund remains subject to regulatory approval.

What’s Inside MAGP

The ETF Tracker reported Monday that Roundhill has filed to launch the $MAGP Roundhill Magnificent Seven Plus ETF.

The proposed ETF will track a basket of 11 companies. This would include the so-called “Magnificent Seven” — Alphabet Inc (NASDAQ:GOOGL) (NASDAQ:GOOG), Microsoft Corp (NASDAQ:MSFT), Amazon.com Inc (NASDAQ:AMZN), Meta Platforms Inc. (NASDAQ:

Full story available on Benzinga.com

This post was originally published here
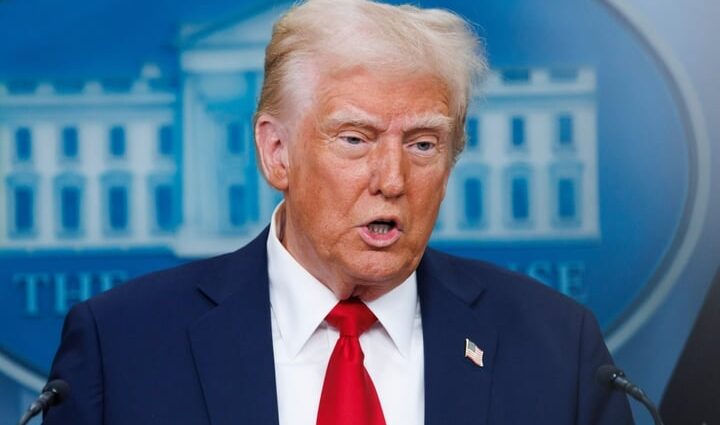
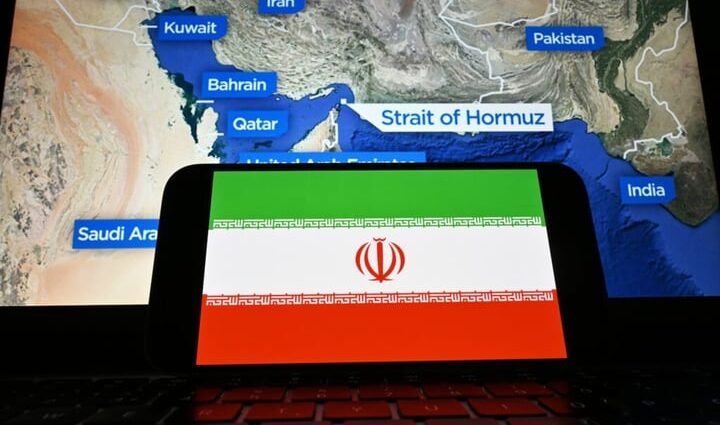
President Donald Trump has voiced his astonishment at the market’s resilience amid the ongoing war with Iran, contrary to his expectations of a significant downturn.

At the Small Business Summit on Monday, Trump said that he had assumed a 25% market slump as a result of the conflict with Tehran. He rationalized that the decline would have been “worth it” to counteract the risk of a nuclear-armed Iran.

Trump stressed that the Iranian regime should have been toppled “47 years ago”, a task that should have been executed by “many presidents or other countries.” Despite the war, he underscored that markets are hitting “new highs.”

Trump Stunned By Market Strength

Trump’s surprise at the market’s resilience echoes his comments to CNBC last month. He stated, “If you would have told me that the Dow is almost at 50,000, I’m looking at your screen right now, and that oil is at 90 instead of 200, I would have been frankly surprised.”

He further noted the adaptability of the market, …

Full story available on Benzinga.com

This post was originally published here
Tesla Inc. (NASDAQ:TSLA) CEO Elon Musk‘s $1 trillion pay package and ambitious 10 million active Full Self-Driving (FSD) subscriber goal could face possible hurdles as EU regulators have reportedly expressed concern about the technology following its approval.

Emails Express Concern Over FSD

According to a Reuters report on Tuesday, citing emails it accessed, regulators in the Netherlands, as well as Scandinavian countries like Sweden, Denmark, Norway and Finland, have flagged concerns about the technology’s safety in icy road conditions, as well as its tendency to speed up and its ability to circumvent the prevention of phone use.

Tesla did not immediately respond to Benzinga‘s request for comment.

The regulators also raised concerns about Tesla asking its supporters to urge the regulators to approve the technology in the region, the report said. A committee is set to hear from Dutch officials from the Netherlands Vehicle Authority (RDW) about the reasons why the Supervised FSD technology was approved.

For an EU-wide approval, the technology …

Full story available on Benzinga.com

This post was originally published here
A Peter Thiel-backed startup, Panthalassa, has secured $140 million in a funding round aimed at propelling its AI-powered sea technology.

Led by Thiel, the funding round witnessed participation from a mix of new and returning investors such as John Doerr, Marc Benioff‘s TIME Ventures, Max Levchin‘s SciFi Ventures, and Founders Fund. The funds will be channeled towards the completion of Panthalassa’s pilot manufacturing facility near Portland.

Founded in 2016, Panthalassa is working on a technology that merges wave power generated by floating orbs with onsite AI computing. The systems transmit data via low-Earth-orbit satellites. The Oregon-based startup has spent nearly a decade developing technologies in power generation, propulsion, autonomous operations, and computing.

Its co-founder and CEO, Garth Sheldon-Coulson, said that the company has developed offshore technology to harness high-energy waves into reliable, clean power, with Ocean-3 pilots launching this year and commercial rollout planned for 2027.

Meanwhile, Thiel said, “Extra-terrestrial solutions are no longer science fiction. Panthalassa has opened the ocean frontier.”

data-variant=”card”

This post was originally published here
In today’s rapidly changing and fiercely competitive business landscape, it is vital for investors and industry enthusiasts to carefully evaluate companies. In this article, we will perform a comprehensive industry comparison, evaluating Micron Technology (NASDAQ:MU) against its key competitors in the Semiconductors & Semiconductor Equipment industry. By analyzing important financial metrics, market position, and growth prospects, we aim to provide valuable insights for investors and shed light on company’s performance within the industry.

Micron Technology Background

Micron is one of the largest semiconductor companies in the world, specializing in memory and storage chips. Its primary revenue stream comes from dynamic random access memory, or DRAM, and it also has minority exposure to not-and or NAND, flash chips. Micron serves a global customer base, selling chips into data centers, mobile phones, consumer electronics, and industrial and automotive applications. The firm is vertically integrated.

Company P/E P/B P/S ROE EBITDA (in billions) Gross Profit (in billions) Revenue Growth
Micron Technology Inc 27.20 8.97 11.24 21.0% $18.48 $17.75 196.29%
NVIDIA Corp 40.51 30.66 22.53 31.11% $51.28 $51.09 73.21%
Broadcom Inc 81.19 24.69 29.68 9.12% $11.15 $13.16 29.47%
Advanced Micro Devices Inc 130.86 8.84 16.13 2.44% $2.86 $5.58 34.11%
Texas Instruments Inc 48.02 15.24 13.90 9.35% $2.42 $2.8 18.58%
Analog Devices Inc 72.58 5.74 16.71 2.46% $1.52 $2.04 30.42%
Qualcomm Inc 18.11 6.51 4.10 13.57% $2.82 $5.7 5.0%
Marvell Technology Inc 53.31 10 17.37 2.79% $0.75 $1.15 22.08%
Monolithic Power Systems Inc 112.46 21.02 25.87 4.95% $0.21 $0.41 20.83%
NXP Semiconductors NV 27.80 6.72 5.85 10.69% $1.7 $1.79 12.2%
ON Semiconductor Corp 351.86 5.23 7.01 2.33% $0.45 $0.55 -11.17%
GLOBALFOUNDRIES Inc 42.61 3.12 5.57 1.68% $0.73 $0.51 0.0%
Astera Labs Inc 164.96 25.28 42.39 3.41% $0.07 $0.2 91.77%
Credo Technology Group Holding Ltd 98.93 17.96 31.31 10.03% $0.16 $0.28 201.49%
Tower Semiconductor Ltd 110.74 8.30 15.58 2.78% $0.2 $0.12 13.69%
First Solar Inc 13.66 2.30 4.20 5.62% $0.51 $0.49 11.15%
MACOM Technology Solutions Holdings Inc 132 16.17 21.43 3.64% $0.07 $0.15 24.52%
Lattice Semiconductor Corp 6279 24.07 33.18 -1.08% $0.01 $0.1 24.16%
Average 457.56 13.64 18.4 6.76% $4.52 $5.07 35.38%

Full story available on Benzinga.com

This post was originally published here
In today’s fast-paced and competitive business landscape, it is essential for investors and industry enthusiasts to thoroughly analyze companies before making investment decisions. In this article, we will conduct a comprehensive industry comparison, evaluating Amazon.com (NASDAQ:AMZN) against its key competitors in the Broadline Retail industry. By examining key financial metrics, market position, and growth prospects, we aim to provide valuable insights for investors and shed light on company’s performance within the industry.

Amazon.com Background

Amazon is the leading online retailer and marketplace for third party sellers. Retail related revenue represents approximately 74% of total, followed by Amazon Web Services (17%), and advertising services (9%). International segments constitute 22% of Amazon’s total revenue, led by Germany, the United Kingdom, and Japan.

Company P/E P/B P/S ROE EBITDA (in billions) Gross Profit (in billions) Revenue Growth
Amazon.com Inc 32.54 6.62 3.97 5.43% $59.58 $94.06 13.63%
MercadoLibre Inc 46.03 13.62 3.18 8.62% $1.07 $3.78 44.56%
eBay Inc 25.25 11 4.37 11.31% $0.77 $2.29 14.97%
Coupang Inc 184.18 7.92 1.09 -0.56% $0.17 $2.54 10.92%
Dillard’s Inc 15.12 4.84 1.31 10.66% $0.3 $0.72 -3.03%
Global E Online Ltd 82.96 5.83 5.92 6.69% $0.13 $0.15 28.05%
Macy’s Inc 8.24 1.04 0.23 11.04% $0.9 $2.97 -1.14%
Ollie’s Bargain Outlet Holdings Inc 21.20 2.65 1.92 4.6% $0.13 $0.31 16.82%
Kohl’s Corp 5.96 0.39 0.10 3.13% $0.39 $1.85 -4.15%
Savers Value Village Inc 58.93 2.93 0.80 5.28% $0.07 $0.26 15.59%
Hour Loop Inc 48.80 12.27 0.60 -8.96% $-0.0 $0.03 3.03%
Average 49.67 6.25 1.95 5.18% $0.39 $1.49 12.56%

Full story available on Benzinga.com

This post was originally published here
The most oversold stocks in the financial sector presents an opportunity to buy into undervalued companies.

The RSI is a momentum indicator, which compares a stock’s strength on days when prices go up to its strength on days when prices go down. When compared to a stock’s price action, it can give traders a better sense of how a stock may perform in the short term. An asset is typically considered oversold when the RSI is below 30, according to Benzinga Pro.

Here’s the latest list of major oversold players in this sector, having an RSI near or below 30.

South Plains Financial Inc (NASDAQ:SPFI)

  • On April 28, South Plains Financial reported mixed first-quarter financial results. Curtis Griffith, South Plains’ Chairman and Chief Executive Officer, said, “We delivered solid first quarter results driven by strong profitability, improving credit quality, and continued discipline across our balance sheet.” The company’s stock fell around …

Full story available on Benzinga.com

This post was originally published here
As artificial intelligence (AI) fuels a massive memory storage shortage, CNBC’s Jim Cramer says top storage stocks still have massive upside, even if their valuations seem stretched.

Chasing The AI Memory Boom

Despite staggering year-to-date gains across the sector, Cramer believes the explosive rally in memory suppliers is far from over.

In a recent X post, he highlighted Western Digital Corp. (NASDAQ:WDC), SanDisk Corp. (NASDAQ:SNDK), and Seagate Technology Holdings PLC (NASDAQ:STX) as prime beneficiaries of an accelerating AI hardware rotation.

“Memory shortage stocks have to go to a higher place,” Cramer declared. Emphasizing the intense momentum behind the trade, he added, “It’s very difficult to imagine it, but stocks do gallop to where they should be… WDC, SNDK, STX, will be overheated until they get to where they have to go.”

Full story available on Benzinga.com

This post was originally published here
Celanese Corporation (NYSE:CE) will release earnings for its first quarter after the closing bell on Tuesday, May 5.

Analysts expect the Irving, Texas-based company to report quarterly earnings of 88 cents per share. That’s up from 57 cents per share in the year-ago period. The consensus estimate for Celanese’s quarterly revenue is $2.35 billion (it reported $2.39 billion last year), according to Benzinga Pro.

On April 15, Celanese declared quarterly dividend of 3 cents per share.

Shares of Celanese fell 0.7% to close at $68.74 on Monday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate analysts have rated the company in the …

Full story available on Benzinga.com

This post was originally published here
Lattice Semiconductor (NASDAQ:LSCC) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/o73e9jtw/

Summary

Lattice Semiconductor Corp reported a strong Q1 2026 with revenue of $170.9 million, marking a 42% year-over-year growth, driven by momentum in data center AI applications.

The company announced a planned acquisition of AMI, aiming to create a comprehensive secure management and control platform, enhancing long-term growth opportunities.

Guidance for Q2 2026 indicates revenue of $185 million at the midpoint, representing nearly 50% year-over-year growth, with EPS expected to grow by 80% year-over-year.

Operational highlights include a reduction in channel inventory from three months to close to two months, and a strategic focus on compute and communications markets.

Management expressed confidence in sustained above-market growth, highlighting strong demand trends across AI servers, networking, and industrial automation, with a robust backlog extending into 2027.

Full Transcript

OPERATOR

Ladies and gentlemen, greetings and welcome to The Lattice Semiconductor first quarter 2026 earnings conference call. At this time, all participants are in the listen only mode. A brief question and answer session will follow the formal presentation. If anyone requires operator assistance during the conference, please signal an operator by pressing Star and zero on your telephone keypad. As a reminder, this conference is being recorded. It is now my pleasure to introduce your Host for today, Mr. Rick Mushe, Vice President of Investor Relations. Please go ahead.

Rick Mushe (Vice President of Investor Relations)

Thank you Operator and good afternoon everyone. With me today are Ford Tamer, Lattice CEO Lorenzo Flores, Lattice’s CFO and Sanjoy Maite, AMI CEO will provide a financial and business review of the first quarter of 2026, an overview of the AMI acquisition and the business outlook for the second quarter of 2026. Both a copy of our earnings press release and the press release announcing our planned acquisition of AMI can be found at our Company website in the Investor Relations section at latticemi.com I would like to remind everyone that during our conference call today we may make projections or other forward looking statements regarding future events or the future financial performance of the Company. We wish to caution you that such statements are predictions based on information that is currently available and that actual results may differ materially. We refer you to the documents that the Company files with the SEC, including our 10-Ks, 10-Qs, and 8-Ks. These documents contain and identify important risk factors that could cause the actual results to differ materially from those contained in our projections or forward looking statements. This call includes and constitutes the Company’s official guidance for the second quarter of 2026.. If at any time after this call we communicate any material changes to this guidance, we intend that such updates will be done using a public forum such as a press release or publicly announced conference call. We will refer primarily to non GAAP financial measures during this call. By disclosing certain non GAAP information, Management intends to provide investors with additional information to permit further analysis of the Company’s performance and underlying trends for historical periods. We provided reconciliations of these non GAAP financial measures to GAAP financial measures that can be found on the Investor Relations section of our website@latticemi.com lastly, we’ve streamlined our financial reporting to better align with our strategic focus. Beginning this quarter, we’ll break out revenue across two primary end markets, compute and Communications and industrial and embedded. Our consumer business is now included within the Industrial and embedded end market. For comparability, we’ve recast all prior period results so you can make a direct apples to apples comparison with that I’ll turn the call over to our CEO Borg Tamer.

Ford Tamer (CEO)

Thank you Rick and welcome everyone to our first quarter earnings call. Lattice has delivered an excellent start to 2026 with results that underscore both strong market tailwinds and our disciplined execution against a clear strategy. Our first quarter performance exceeded expectations and our second quarter outlook reflect our expected continued momentum across the business. This is the seventh earnings call since I joined Lattice and I hope we have now demonstrated that we consistently say what we do and do what we say and these positive factors in aggregate provide the foundation for our proposed acquisition of AMI. This acquisition positions Lattice to create the industry’s most comprehensive secure management and control platform and enables us to deepen our customer relationships and expand our long term growth opportunity. Now turning to our results and outlook, revenue for the first quarter was $170.9 million representing 42% year over year growth with strength across all end markets. Our compute and communications end market achieved record revenue driven by continued momentum and data center AI application. In Q1, 62% of our revenue came from compute and communications products. With expanding opportunities ahead, as Rick highlighted in the safe harbor, we have now merged our industrial and automotive end market with our consumer end market into what we now term Industrial and Embedded. The revenue from our Industrial and Embedded end market grew more than 20% sequentially, reflecting improving market conditions and expanding adoption of Lattice solutions. As importantly, along with increased consumption channel inventory reduced from three months last quarter to close to two months of inventory on hand and we expect this trend to continue to under two months and Q2. As we anticipated, profitability grew faster than revenue. With EPS up 86% year over year, these results demonstrate the operating leverage in our model and our ability to scale efficiently. As revenue accelerates, demand trends continue to build across AI servers, networking, industrial automation and emerging physical AI applications. We are seeing accelerated bookings which now support a strong backlog that extends well into 2027. We’re also witnessing improved customer visibility and healthy design win momentum across our FPGA portfolio. Taken together, we’re confident that we’re in the early innings of a month to year growth cycle and in our ability to deliver sustained above market growth for the foreseeable future. Our results also highlight the progress we’ve made in evolving Lattice into a system level solutions company. Customers increasingly value Lattice not just for low power programmable hardware, but for complete solutions spanning connectivity, security, management and control. As system complexity increases, particularly in AI driven and advanced computing architectures, our customers are giving their highest priority to platforms that reduce integration risk, shorten development cycles and enable faster deployment at scale. These trends continue to expand Lattice’s role within customer systems, increase attach rates and drive higher value per design. We also continue to benefit from our everywhere companionship strategy, positioning Lattice broadly across the ecosystem. Rather than competing with CPUs, GPUs, or other processors, our low power FPGAs enable and enhance them, providing secure boot power sequencing, platform management, I O aggregation, sensor bridging and control. This approach allows Lattice to participate across hyperscale data centers, communication infrastructure, industrial automation, aerospace and defense, automotive, medical and emerging physical AI applications while remaining silicon agnostic and ecosystem neutral. Looking to the second quarter, our revenue guidance of $185 million at the midpoint represents nearly 50% year over year growth. This underscores our confidence in the accelerating momentum of the business. Our Midpoint eps outlook of $0.44 reflects roughly 80% year over year growth. It highlights the powerful operating leverage in our model and differentiated products we bring to market. We maintain a disciplined capital strategy and believe we’ll be able to consistently drive earnings growth that significantly outpaces revenue growth and we are committed to continue to do so. Turning now to the planned acquisition of AMI we announced earlier today, we are excited to have signed a definitive agreement to acquire AMI, a leader in firmware, orchestration and system level manageability. The combination of Lattice’s low power programmable hardware was AMI’s industry leading solutions including BIOS, BMC and Platform Security create the industry’s most complete secure management and control platform. Together we’ll enable customers to accelerate development, simplify system integration and bring increasingly complex platforms to market faster across AI servers, advanced compute, communication infrastructure and industrial applications. Strategically, this acquisition represents a pivotal milestone in advancing Lattice long term growth strategy. AMI’s firmware is expected to remain processor and silicon agnostic, preserving open ecosystems and customer choice, while lattice FPGAs provide a complementary hardware foundation, reinforcing our everywear companionship strategy. We expect this transaction to be accretive to gross margin, free cash flow and EPS on a non GAAP basis. It also supports our trajectory toward exceeding a $1 billion annual revenue run rate by the end of 2026. We look forward to welcoming the talented AMI team to Lattice and expect this combination to strengthen our system level roadmap and long term growth profile significantly. Looking forward, we’re encouraged by the continued durability of demand across our end markets, the depth of customer engagement and the expanding role Lattice plays in next generation system with a differentiated strategy, a scalable financial model and an increasingly complete platform spanning hardware, firmware, security, manageability and control. We are confident that Lattice is exceptionally well positioned for the future. With that, I’ll turn the call over to Lorenzo for a comprehensive review of our first quarter results.

Lorenzo Flores (CFO)

Lorenzo thank you Ford and good afternoon everyone. We will begin with an overview of our first quarter, 2026 financial performance and our second quarter outlook, followed by an overview of our planned AMI acquisition. With a quarter this good and guidance this strong, it is worth repeating some of what Ford said. Revenue reached $170.9 million, growing 42% year over year and 17% quarter over quarter. Earnings performance was even stronger as Q1 non GAAP EPS demonstrated the leverage in our model. EPS grew more than 80% year over year to 41 cents, a 30% increase quarter over quarter and above the high end of our guidance. We expect Q2 to continue this growth trend and I’ll detail our guidance in a few moments. Back to Q1 revenue growth was driven by a record performance in compute and communications, up 86% year over year and 15% sequentially. We continue to benefit from strong data center growth as Ford told you. Additionally, our industrial and embedded end market grew 21% quarter over quarter, primarily driven by increased demand in factory automation, robotics and medical applications. Q1 non GAAP gross margin was a little better than expected at 70% up 60 basis points quarter over quarter and 100 basis points year over year. Our gross margin continues to reflect the value and differentiation our products provide for our customers. Non GAAP operating expense was $60.8 million, up roughly 8% sequentially and 18% on a year over year basis. Much of the sequential increase is from performance based bonuses and commissions. As our revenue and profitability are exceeding expectations. We also continue to invest in order to capitalize on our near and long term opportunities. Our Q1 non GAAP operating margin expanded 370 basis points to 34.4% and our EBITDA margin increased 310 basis points to 39.6%. Both were a little better than expected. Q1 cash flow was impacted by last year’s annual bonus payout as well as revenue linearity in the quarter associated with our rapid growth. GAAP net cash flow from operating activities for the first quarter of 2026 was 50.3 million compared to 57.6 million in Q4. Free cash flow trended with operating cash flow in Q1 free cash flow was $39.7 million, down from $44 million in Q4. We expect a strong recovery of cash flow as we continue to grow. During Q1 we repurchased $15 million of stock. We ended the quarter with $140 million in cash and no debt. Now for our guidance, we are targeting closing the AMI acquisition in Q3. So this guidance reflects expectations for Lattice stand alone in Q2 2026. We expect revenues to grow in the range of $175 million to $195 million at the midpoint of this range. This is almost 50% growth from Q2 25 and 8% over Q1. We expect gross margin to be 70% plus or minus 1% on a non GAAP basis. We expect non GAAP operating expense to be between 64 and $67 million. Most of the growth in OPEX will be in R and D and reflects disciplined investments to drive long term sustained revenue growth. We expect income tax rate for Q2 to be between 4% and 6% on a non GAAP basis. We anticipate non GAAP EPS to be in the range of $0.42 per share and $0.46 per share. At the midpoint of this guidance, we expect that we would again exceed 80% year over year earnings growth as we continue to demonstrate the leverage in our model. Turning now to the AMI transaction, I am just as excited as for our Board of Directors and our leadership team that we have entered into a definitive agreement to acquire ami. AMI is a leader in platform firmware, secure boot device management and system control software. This acquisition represents a strategic expansion of Lattice’s capabilities to deliver system level solutions, further accelerating our growth. The total consideration of the deal is expected to be $1.65 billion with $1 billion of cash and $650 million of equity. This is approximately 5.4 million shares. Based on the closing price on May 1, we expect the acquisition to be equally compelling from a financial perspective. With ami, we expect our revenue to exceed an annual run rate of $1 billion by the end of this year. We anticipate AMI’s software centric asset light model will further enhance Lattice’s already strong business model. We expect that the transaction will be immediately accretive to gross margin, free cash flow and EPS on a non …

Full story available on Benzinga.com

This post was originally published here
Apple Inc. (NASDAQ:AAPL) is exploring potential partnerships with Intel Corp. (NASDAQ:INTC) and Samsung Electronics Co. Ltd. (OTC:SSNLF) to manufacture its processors in the United States, according to a report.

The talks are part of the company’s effort to diversify its chip supply chain beyond its reliance on Taiwan Semiconductor Manufacturing Co. Ltd. (NYSE:TSM), according to a Bloomberg report.

Early-Stage Talks, Site Visits

Apple executives have reportedly visited a Samsung facility being built in Texas and also had early conversations with Intel about using its foundry services. None of the talks has produced orders, and the work is still described as preliminary.

While these moves could provide Apple with additional manufacturing flexibility, the company is said to have concerns about adopting non-TSMC production technologies, particularly around reliability and the ability to scale output efficiently.

The report said Apple’s internal discussions are still in an early phase.

data-variant=”card”

Full story available on Benzinga.com

This post was originally published here
Shares of Sterling Infrastructure Inc (NASDAQ:STRL) rose in pre-market trading after the company reported better-than-expected first-quarter financial results and raised its FY26 guidance above estimates.

Sterling Infrastructure reported quarterly earnings of $3.59 per share which beat the analyst consensus estimate of $2.01 per share. The company reported quarterly sales of $825.675 million which beat the analyst consensus estimate of $603.577 million.

Sterling Infrastructure shares jumped 22.5% to $648.37 in pre-market trading.

Here are some other stocks moving in pre-market trading.

Gainers

  • 3 E Network Technology Group Ltd (NASDAQ:MASK) gained 69% to $2.45 in pre-market trading after the company announced it signed a 1.3 million convertible notes agreement with an institutional investor.
  • Sadot Group Inc (NASDAQ:SDOT) gained 60.3% to $0.42 in pre-market trading after dipping 45% on Monday.
  • Backblaze Inc (NASDAQ:BLZE) rose 41.4% to $6.56 in pre-market trading after the company reported better-than-expected first-quarter financial results and raised its FY26 sales guidance above estimates.
  • Inno Holdings Inc (NASDAQ:INHD) gained 21.6% to $2.14 in pre-market trading. Inno Holdings shares jumped around 14% on Monday after the company announced a year-over-year increase in its second-quarter financial results.
  • Regentis Biomaterials Ltd (NYSE:RGNT) rose 17.3% to $3.11 in pre-market trading after falling 8% on Monday.
  • EverQuote …

Full story available on Benzinga.com

This post was originally published here
Advanced Micro Devices Inc. (NASDAQ:AMD) is preparing to report first-quarter earnings on Tuesday. Investors are weighing whether its AI-fueled stock rally reflects genuine long-term growth or expectations that may have outpaced near-term financial reality.

AMD Earnings Preview: AI Ambitions Fuel Investor Optimism

On Monday, Futurum Group Chief Market Strategist Shay Boloor described AMD as one of the market’s most compelling rerating stories.

He noted that the company is shifting from a CPU-focused growth narrative toward becoming a broader AI infrastructure contender.

“I think Q1 should be strong,” Boloor said on X, while cautioning that AMD’s last month’s rally suggests investors may already be pricing in future AI success before substantial revenue fully arrives.

AMD shares have surged 55.12% over the past month, according to Benzinga Pro.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Lisa Su Hosts Howard Lutnick As Commerce Department Highlights ‘Gold Standard’ American Tech Stack: AMD CEO Appreciates The ‘Open Dialogue’

This post was originally published here
Tesla Inc.‘s (NASDAQ:TSLA) cumulative sales in multiple European markets showed growth in April as the Elon Musk-led EV maker charts a path back from sales declines.

Tesla Posts Positive Sales Growth In Most Markets

The automaker posted sales growth in markets like France, the Netherlands, Denmark and Sweden, but it fell in countries like Italy, Spain and Portugal, according to a report by Reuters on Tuesday. Sales grew 112% in France, while the Netherlands recorded a 23% growth. While Scandinavian nations Sweden and Denmark recorded a 111% and 102% growth, respectively, the report said.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Tesla Rivals Geely, BYD Report Double-Digit Profit Decline In First Quarter 2026 Amid Revenue Shortfall, Foreign Exchange Volatility

This post was originally published here
GameStop Corp. (NYSE:GME) CEO Ryan Cohen‘s behavior and bizarre answers raised concerns as he discussed the company’s $56 billion unsolicited bid to acquire eBay Inc. (NASDAQ:EBAY).

Cohen’s distracted, seemingly confused demeanor during the 16-minute CNBC interview on Monday left viewers and hosts perplexed. The CEO called the bid “an opportunity to build a much larger business,” but his lack of eye contact and rapidly changing facial expressions added to the strangeness of the interview.

Cohen’s Awkward Answers

When host Andrew Sorkin asked Cohen to explain the $16 billion gap in proposed financing and the acquisition price for eBay, the CEO responded, “It’s on our website…It’s half cash, half stock.” When pressed again for a detailed answer for viewers, Cohen replied, “We’ll see what happens.”

Sorkin questioned whether there have been direct talks with the company and what progress has been made so far. Cohen answered with a “No.” After a long gap, he added: “We’re just starting.”

Becky Quick took over from Sorkin and precisely asked again where the rest of the money would come from, Cohen snapped, “I don’t understand your question,” followed by an awkward silence. After telling Quick to refer to the website for details, Cohen said the company could issue new stock.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

This post was originally published here
With U.S. stock futures trading higher this morning on Tuesday, some of the stocks that may grab investor focus today are as follows:

  • Wall Street expects Pfizer Inc. (NYSE:PFE) to report quarterly earnings at 72 cents per share on revenue of $13.79 billion before the opening bell, according to data from Benzinga Pro. Pfizer shares rose 0.3% to $26.38 in after-hours trading.
  • Pinterest Inc. (NYSE:PINS) reported better-than-expected financial results for the first quarter and issued a strong revenue forecast for the second quarter. Pinterest posted first-quarter revenue of $1.01 billion, beating analyst estimates of $966.25 million, according to Benzinga Pro. The …

Full story available on Benzinga.com

This post was originally published here
Shopify Inc. (NASDAQ:SHOP) will release earnings for its first quarter before the opening bell on Tuesday, May 5.

Analysts expect the Ottawa, Canada-based company to report quarterly earnings of 33 cents per share. That’s up from 25 cents per share in the year-ago period. The consensus estimate for Shopify’s quarterly revenue is $3.09 billion (it reported $2.36 billion last year), according to Benzinga Pro.

On Feb. 11, Shopify reported better-than-expected fourth-quarter revenue and also authorized a $2 billion stock buyback.

Shares of Shopify fell 0.1% to close at $127.55 on Monday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate analysts have rated …

Full story available on Benzinga.com

This post was originally published here
The CNN Money Fear and Greed index showed a decline in the overall market sentiment, while the index remained in the “Greed” zone on Monday.

U.S. stocks settled lower on Monday, with the Dow Jones index falling more than 550 points during the session after an Iranian drone strike on a UAE oil facility sent Brent crude above $114 a barrel, increasing expectations of a Federal Reserve rate hike by March 2027.

In earnings, Norwegian Cruise Line Holdings Ltd. (NYSE:NCLH) posted upbeat earnings for the first quarter, but lowered its FY2026 forecast. Tyson Foods Inc. (NYSE:TSN) posted better-than-expected earnings for the second quarter on Monday.

On the economic data front, U.S. factory orders …

Full story available on Benzinga.com

This post was originally published here
Altimeter Capital has sold its Microsoft Corp. (NASDAQ:MSFT) holdings to aggressively fund positions in AI hardware giants like Nvidia Corp. (NASDAQ:NVDA) and SK Hynix, signaling a strategic rotation from software into the booming compute and memory supercycle.

Shifting Capital On AI Supercycle

Despite praising Microsoft’s leadership, Altimeter CEO Brad Gerstner explained, in a conversation with CNBC, that allocating capital in today’s market requires strict prioritization. With 80% of Altimeter’s capital now deployed in memory, logic, and compute, the firm had to pull funds from elsewhere.

“You have to make choices in this market. We only have so much capital,” Gerstner said. He noted that Microsoft was investing “a little less aggressively in capex” to drive future AI growth, while the broader market holds lingering “skepticism about software today.”

The pivot has already paid off. Gerstner pointed out that the stocks Altimeter rotated those dollars into, specifically memory manufacturer SK Hynix, have performed exceptionally well, making the rotation a highly profitable move.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

This post was originally published here
The yield on 30-year U.S. Treasury bonds has climbed above the key 5% threshold, levels not seen in nearly two decades. This has rekindled fears that government borrowing costs could spiral into a self-reinforcing shock, with traders bracing for a quicker surge as debt-service pressures intensify.

Schiff Warns of Faster Surge in Long-Term Yields

In Monday’s post on X, market commentator Peter Schiff warned that the pace of yield increases could accelerate significantly. He said, “The move from 5% to 6% will be much quicker than the move from 4% to 5%, and the move from 6% to 7% will be quicker still.”

Concerns Over Debt, Economic …

Full story available on Benzinga.com

This post was originally published here
Apple Inc. (NASDAQ:AAPL) asked the Supreme Court of the United States to halt a contempt ruling as it escalates its legal battle with Epic Games over App Store payment rules that could reshape the global app economy.

Apple Seeks Emergency Stay In Epic Games Case

On Monday, Apple filed an emergency request seeking a stay of a lower court decision that found the iPhone maker in contempt for failing to comply with a prior injunction in its dispute with Epic Games, reported The Hill.

“A stay is now needed before Apple is forced to litigate its commission rate under an erroneous and prejudicial contempt label—in proceedings that could reshape the global app market—before this Court can consider whether to grant review,” the company said in its filing.

Epic Games CEO Criticizes Apple

Epic Games CEO Tim Sweeney criticized Apple following its Supreme Court filing in the ongoing App Store legal battle, warning it could influence global regulation of app commissions.

In posts on X, Sweeney said Apple’s filing “threw a grenade into world app market,” arguing it effectively acknowledges that regulators worldwide are monitoring the case to determine acceptable commission rates outside the United States.

He also …

Full story available on Benzinga.com

This post was originally published here
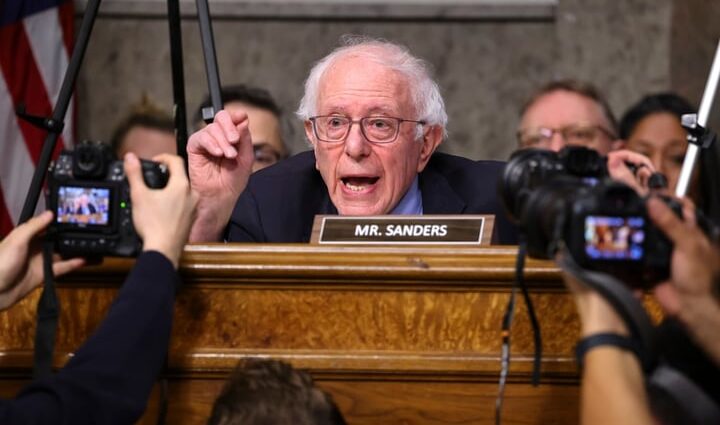
Sen. Bernie Sanders (I-VT) on Monday accused oil companies of profiting from the war in Iran amid an oil and gasoline price surge in the U.S.

Ripping Off Americans

Sanders, in a post on X, drew comparisons between crude oil and gasoline prices from 2026 and 2011. The Vermont independent outlined that oil prices on Monday were around the $105/barrel mark, while gas cost $4.46 per gallon in the U.S.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Congressman Buys Defense Stocks As Middle East Tensions Continues: Here Are The Companies

This post was originally published here
Delta Air Lines Inc. (NYSE:DAL) has reportedly canceled several flights amid changes to its schedule, as well as personnel, while also considering a possible end to free food on its flights.

Delta Cancels Flights

The airline canceled about 500 flights since Friday, according to a Business Insider report on Monday, which cited an internal memo from the airline. The flight cancellations come as the company’s pilots are taking on fewer extra flights, with acceptance rates tanking to 2% from 37%, leading to staffing woes, the report said.

Delta then adopted the 23.M.7 system, which isn’t intended for consistent use and reportedly incentivizes pilots to take on unstaffed trips, but can lead to gaps elsewhere, the report said. The memo cited by Business Insider said that the system was “being used 10 to 15 times more than last year.”

Delta has been increasing pilot reserves and accelerating pilot hiring, according to a statement by a spokesperson for the airline cited in the report.

No More Free Food?

The airline will also stop …

Full story available on Benzinga.com

This post was originally published here
On Monday, Ameresco (NYSE:AMRC) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://edge.media-server.com/mmc/p/gg877j2t/

Summary

Ameresco reported a 14% year-over-year revenue growth in Q1 2026, despite adverse weather conditions impacting some facilities.

The company announced a $400 million strategic investment from HASI in its biofuels business, creating a joint venture named Neogenics Fuels.

Leadership changes include promotions of Nicole Bulgarino and Lou Maltezzos to co-presidents, and the appointment of Mike Bakkett as CEO of Neogenics Fuels.

The company has a strong project backlog, with a 20% increase to $2.8 billion and total backlog reaching $5.3 billion.

Ameresco’s future outlook includes leveraging new partnerships and investments to drive growth, particularly in the biofuels and data center spaces.

Full Transcript

OPERATOR

Thank you for standing by. My name is Jordan and I’ll be your conference operator today. At this time I’d like to welcome everyone to the Q1 2026 Ameresco Inc. Earnings Conference Call. All lines have been placed on mute to prevent any background noise. After the speaker’s remarks, there will be a question and answer session. If you’d like to ask a question during this time, simply press STAR followed by the number one on your telephone keypad. If you’d like to withdraw your question, press STAR one again. Thank you. I would now like to turn the call over to Lela Dhillon, Chief Marketing Officer. Please go ahead.

George Sakellaris

Thank you and good afternoon everyone. We appreciate you joining us for today’s call. Our speakers on the call today will be George Sakellaris, Ameresco’s Chairman and Chief Executive Officer Mike Bakas, who will become the CEO of Neogenics Fuels Nicole Bulgarino and Lou Maltezzos, newly appointed co Presidents of Ameresco and Mark Chiplock, Chief Financial Officer. In addition, Josh Prue, our Chief Investment Officer, will also be available during Q and A to help answer questions. Before I turn the call over to George, I would like to make a brief statement regarding forward looking remarks. Today’s earnings materials contain forward looking statements including statements regarding our expectations. All forward looking statements are subject to risks and uncertainties. In particular, some of the commentary is predicated on the expected closing of the Neogenics Fuels transaction. Please refer to today’s earnings materials, the safe harbor language on slide 2 of our supplemental information and our SEC filings for a discussion of the major risk factors that could cause our actual results to differ from those in our forward looking statements. In addition, we use several non GAAP measures when presenting our financial results. We have included the reconciliations of these measures and additional information in our supplemental slides that were posted to our website. Please note that all comparisons that we will be discussing today are on a year over year basis unless otherwise noted. I will now turn the call over to George George thank you Lila and good afternoon everyone. I am pleased to report that we had a solid start to the year with the Ameresco team delivering 14% revenue growth despite experiencing adverse weather conditions impacting several of our RNG facilities. New business also remained Quite strong with 20% growth in awarded backlog against a backdrop of significant activity, especially with the federal government. We also announced several important corporate actions which we have taken to better position ourselves for substantial future growth opportunities while also maximizing shareholder value. Today, after the market closed we announced the signing of a transformational agreement with hasi for a $400 million strategic investment in our biofuels business. This agreement will create a newly formed joint venture named Neogenics Fuels. Ameresco has been a leader in the biofuels industry for the last 25 years. When completed, this transaction will enable us to monetize a portion of the $1.8 billion enterprise value that we have created in our biogas business. Of the $400 million commitment from HASI, 300 million will be directly invested in Neogenics Fuels to drive business growth and the $100 million will be direct compensation to Ameresco for the existing business which will be used for strategic opportunities, working capital and deleveraging throughout the year. I would like to turn the call over to Mike Backas, a member of of my management team for nearly 30 years and who will become Chief Executive Officer of Neogenics Fuels to comment on this exciting transaction.

Mike Bakas

Mike thank you George. Good afternoon everyone. First and foremost, I very much appreciate the confidence and trust that George and HASI leadership have bestowed on me to take the helm of what we see as a transformative business. As many of you are aware, I have been leading Ameresco’s biogas business since the founding of the company, helping to create one of the country’s largest greenfield developers of biogas projects. We are thrilled to be taking the next step in this evolution along with our long term partner HASI with the creation of Neogenics Fuels which will be 70% owned by Ameresco and 30% by Hassi. As part of the transaction, Ameresco will contribute its operating biogas assets along with one of the most robust development pipelines in the industry. The organization will be staffed by Ameresco’s seasoned team of biogas veterans. Both Ameresco and Hassi recognize a tremendous opportunities to deliver resilient energy and biofuel solutions while building the foundation for renewable molecules and next generation drop in fuels of the future. This transaction represents a combination of Ameresco’s proven history and expertise in successful Biogas development with HASI’s deep sector financial knowledge and scalable capital platform. We see this partnership as positioning Neogenics to to become a global industry leader in the next generation of fuels as our addressable market continues to expand. As noted, we have a signed agreement and expect a timely close to the transaction. George, I’ll turn the call back to you.

George Sakellaris

Thank you Mike. We are very excited about this transaction which I believe not only recognizes the tremendous tangible value of our energy assets but also positions Ameresco to better drive long term profitable growth. Also during the quarter we strengthened our corporate structure to position us to fully execute on our great growth opportunities. We recently promoted proven leaders Nicole Bulgarino and Lou Maltedros to co presidents of Ameresco and Peter Grisakis to Chief Operating Officer. Lou and Nicole both came to Ameresco 22 years ago with our successful excellent solutions acquisition. As co presidents, Nicole and Lou will work closely with me on Ameresco’s continued growth strategy while at the same time maintaining clear and distinct areas of operational focus. The easiest way to understand the operational alignment is to look at our current project business which is split evenly between energy infrastructure and building efficiency. Nicole is responsible for the energy infrastructure half of the business while continuing to guide the company’s federal solutions business. Lou focuses on the building efficiency side, overseeing the core non federal projects. Now I will ask each of them to comment on some of the market dynamics in their respective areas.

Lou Maltezzos (Co-President)

Nicole thank you George and good afternoon everyone. Ameresco’s federal business continues to be a core strength of the company. We see strong demand across our traditional federal programs including energy efficiency infrastructure modernization with long term ESPC and design build work. Ameresco’s military and civilian federal government customers remain focused on upgrading buildings, improving reliability, reducing life cycle cost and hardening critical facilities and I am pleased to note a nice uptick in federal government proposal activity over the last year. Ameresco’s long standing relationships, technical expertise and proven execution track record position us well to continue delivering strong results in this important market. In parallel, we are seeing great demand for our energy infrastructure solutions. We have built a strong pipeline of large and complex projects including transformational data center opportunities. This activity is being driven by growing demand for on site reliable power solutions where access to utility power is constrained or delayed. We are approaching this market with discipline, focusing on larger experienced developers and projects where Ameresco’s behind the meter capabilities can provide clear value while still disciplined. In that in what we advance, we are encouraged by the quality and the scope of opportunities we are pursuing and how they are progressing. I will now turn the call over to gleam. Thank you Nicole. It’s been a very exciting time for our project business with our long history and expertise in providing building efficiency solutions for many of our customers, energy represents one of their single largest operating expenditures. More and more our customers are experiencing spiking electricity prices leading to heightened interest in energy efficiency solutions. In addition to these challenges, many customers have older, often outdated buildings with limited capital budgets to pursue new construction. So upgrading their existing facility is not only the best economic option, but it’s often their only option. The cost savings generated from our energy efficiency upgrades can then be reinvested in a laundry list of facility improvements, all done by Ameresco. As electricity prices rise, energy efficiency investments drive much faster returns, allowing our customers to tackle more and more improvements. This enables Ameresco to execute larger, more comprehensive projects. As one of the largest energy services companies in North America, Ameresco should be a main beneficiary of increasing energy costs for years to come. I’ll now turn the call back over to George for a few brief comments before Mark covers our financials.

George Sakellaris

Thank you Lou. Before we turn to the financials, I want to step back and connect the themes you have heard over the last few minutes. We see the creation of Neogenics fuels with HASI as a clear validation of the scale and value we have created in our biofuels platform, while also bringing in a strong long term partner and incremental capital to accelerate the next phase of growth. At the same time, the leadership updates we announced reflect the depth of our bench and our focus on continuity and execution as we scale positioning Mike to lead Neogenics Fuels and elevating Nicole and Lu as Co President to sharpen execution across our energy infrastructure and building efficiency business. Together we see these actions strengthening our operating model, enhancing our ability to deploy capital and talent where returns are most attractive, and keeping Ameresco firmly on the same strategic path, delivering durable growth while creating long term shareholder value. With that, I will turn it over to Mark to walk through the quarter’s financial results and guidance reflecting the Neogenics Huels transaction.

Mark Chiplock (Chief Financial Officer)

Mark thank you George. We had a solid start to the year with total revenue of $401 million up 14% year over year, reflecting broad based growth across our core businesses and led by continued strength in projects in O and M. Project revenue increased 16% to $291 million driven by solid execution across federal and key geographies as well as continued demand for both building efficiency and energy infrastructure solutions. Importantly, business development activity remained very strong. Awarded project backlog grew 20% to $2.8 billion with over half a billion dollars of new awards during the quarter bringing our total project backlog to $5.3 billion. We continue to see a healthy pipeline of opportunities and strong proposal activity, particularly in the federal market. Energy asset revenue grew 7% to $61 million supported by the continued expansion of our operating portfolio. We did see some weather related impacts at certain RNG facilities during the quarter, but the underlying performance of the portfolio remains strong. Our operating energy asset base now stands at 838megawatts with 568megawatts in development and construction, positioning us well for continued long term growth. As we continue to scale this platform, we’re increasingly focused on both the operational performance and and the capital efficiency of our asset strategy. In line with that strategy and as George highlighted, we entered into an agreement to sell a 30% equity interest in our biofuels business. Of the $400 million commitment from HASI, $300 million will be directly invested in Neogenics Fuels to drive business growth and $100 million will be direct compensation to Ameresco for the existing business which will be used for strategic opportunities, working capital and deleveraging throughout the year. This transaction implies a post money enterprise value of approximately $1.8 billion and recognizes the tremendous value embedded within our energy asset portfolio. In addition, it will allow us to retain control of the platform and bring in a trusted partner to help fund future growth which will allow us to continue scaling the business in a capital efficient manner. Turning back to the financials, O and M had another strong quarter with revenue up 22% driven by the continued additions of new long term contracts. Our long term O and M backlog now exceeds $1.5 billion, reinforcing the visibility and durability of this revenue stream. Gross margin of 14.1% reflects project mix along with the impact from adverse weather conditions at certain RNG sites. We continued to make targeted investments in people, project development and execution capabilities to support future growth. These investments drove operating expenses to $46 million during the quarter. Net interest and other expenses were slightly higher than expected, driven primarily by $1.8 million of non cash mark to market impact and approximately $1 million in foreign exchange losses. Net loss attributable to common shareholders was $18.3 million with a GAAP EPS loss of $0.35 per diluted share and non GAAP loss per share of $0.33. …

Full story available on Benzinga.com

This post was originally published here
Paramount Skydance (NASDAQ:PSKY) held its first-quarter earnings conference call on Monday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/r43swb5e/

Summary

Paramount Skydance reported strong Q1 2026 results, highlighting nearly doubling their film slate and achieving financial goals, driven by top creative talent and operational transformation.

The company is focused on integrating platforms and leveraging AI for efficiency, with significant updates to its streaming services expected by mid-2026.

Paramount Skydance is progressing on a major transaction with Warner Bros. Discovery, aiming to finalize by September 2026, enhancing their competitive position in global media and entertainment.

UFC partnership has exceeded expectations, with significant viewer engagement and contribution to advertising revenue, attracting a younger audience.

Management emphasized a strategic focus on quality content and technology investments, while maintaining flexibility with content licensing, including partnerships with platforms like Netflix and Prime Video.

Full Transcript

Krista (Conference Operator)

Good afternoon. My name is Krista and I’ll be your conference operator today. I would like to welcome everyone to Paramount’s first quarter 2026 earnings conference call. At this time, all lines have been muted to prevent any background noise. After the speaker’s remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press Star followed by the number one on your telephone keypad. And if you’d like to withdraw your question, please press star one again. I would now like to turn the call over to Kevin Crichton, Paramount’s EVP of Corporate Finance and Investor Relations. You may now begin your conference call.

Kevin Creighton

Good afternoon and thank you for taking the time to join us for the Paramount Q1 2026 earnings call. I’m Kevin Creighton, EVP of Corporate Finance and Investor Relations. Joining me today is our Chairman and Chief Executive Officer David Ellison, our Chief Financial Officer Dennis Janelli, and our Chief Strategy and Operating Officer Andy Gordon. As a reminder, we will be making forward looking statements today that involve risks and uncertainties. Our remarks will also include non-GAAP financial measures. Reconciliations of these measures can be found in our earnings letter or in our trending schedules which contain supplemental information. These can be found on our investor relations website.

David Ellison (Chairman and Chief Executive Officer)

I’ll now turn it over to David Ellison for a few brief remarks before we take analyst questions. Thanks Kevin and good afternoon everyone. As you’ve seen in our first quarter results and most recent shareholder letter, we’re off to a strong start in our first full year as Paramount Skydance. The the progress we’ve made in just nine months is a testament to the amazing team we’ve assembled that has worked tirelessly and with great conviction to deliver on all areas of our business. We are executing deliberately against our priorities and seeing tangible results, attracting top creative talent, nearly doubling our film slate, delivering shows audiences love and green lighting dozens of new and returning series while achieving our financial goals. At the same time, we are transforming how we operate, unifying platforms, data and workflows and embedding advanced technology to drive efficiency, better serve our partners and elevate the overall consumer experience across the business. We are getting things done and it’s translating into real momentum. As a storytelling company, our top priority is and always will be delivering great films and television series from the world’s leading creators that resonate with broad global audiences. Recent highlights include Scream 7, which became the highest grossing installment in the franchise’s 30 year history, Landman, now the most watched series in Paramount Plus history and the continued strength of CBS, which has 13 of the top 20 primetime series, including all four of the top new series, an achievement no broadcast network has matched since the early 1990s on streaming and sports engagement remains strong with more than 10 million households watching over 100 million hours of UFC programming on Paramount Plus and CBS Sports delivering the most watched final round of the Masters in over a decade. These are just a few examples of the progress and growth taking place company wide. As I mentioned, we are also making meaningful strides improving our products to deliver more dynamic personalized experiences and superior monetization. New features such as enhanced mobile experiences, short form video and more advanced recommendations are helping us to better serve consumers. We’re also leveraging AI powered capabilities across the businesses including our Agentic Data Warehouse and Precision Plus our targeted and optimization platform, to move faster and operate with greater effectiveness and support of our advertising partners. While there is still significant work ahead, we remain confident in our strategy and the trajectory we are on. Finally, we continue to make steady progress towards completing the Warner Bros. Discovery transaction, which we believe will accelerate our transformation, strengthen our competitive position and enhance our ability to help shape the next era of entertainment. To date we have satisfied our US HSR obligations and there are no statutory impediments remaining and we continue to advance through European and other international regulatory approvals, several of which have already been secured. Earlier in April, we announced a broad syndication of the PIPE equity commitments to strategic investors, underscoring continued investor confidence, secured $10 billion in permanent financing and syndicated the remaining $49 billion of our bridge to a group of leading banks and institutional lenders. Additionally, on April 23, WBD shareholders voted to approve the transaction. We’re pleased with the momentum and will continue to take the necessary steps to bring this deal to completion. At every stage we remain guided by our strong conviction that the combination of these two iconic companies and their extraordinary teams will create a leading global media and entertainment company powered by storytelling and accelerated by technology that strengthens competition, better, serves the creative community and delivers even more compelling stories to audiences worldwide. We’re excited for all that’s ahead and look forward to the opportunities it will create. And with that, I’ll turn it back over to Kevin for your questions.

Kevin Creighton

Thanks David. Just a quick note before we open the line giving the pending transaction for WBD. We won’t be taking questions on the deal today beyond what we wrote in the shareholder letters. With that, Krista, we’ll go ahead and open up the line.

Krista (Conference Operator)

Please. Thank you. If you would like to ask a question, please press Star one on your Telephone keypad. To withdraw your question again, press Star one. We do ask that you limit yourself to one question. For any additional questions, please re queue. And your first question comes from Sean Difley with Morgan Stanley. Please go ahead.

Sean Difley (Equity Analyst)

Great. Thanks very much. I was hoping you could comment on business transformation early learnings as you converge your tech stacks between Paramount plus and Pluto and any things that you could apply to a larger asset base and then broadly how you see AI transforming the business. You mentioned on the ad tech front, but anything else that you think is notable to call out?

Andy Gordon (Chief Strategy and Operating Officer)

Yeah, sure. No, no, absolutely. So what I would say in terms of early learnings is really our ability to execute and move quickly in regards to the transformation. We’re on track, as we discussed previously, to really consolidate our three streaming services into one unified platform by really the middle of this year. Those learnings are going to be crucial as we get into basically the transaction with WBD. I think if you look at our ability to execute on our cost saves and efficiencies, we’ve had great learnings there and I think we’ve been delivering on what we said we were going to do regarding plan. So I do believe that what we’ve been executing at Paramount will be a good kind of accelerant in learning for everything we’re doing. WBD getting more specific into that. As Kevin said, we’re going to kind of stay a little bit away from the transaction today given we’re obviously still in the middle of the process. I’ll turn it over to Andy if there’s anything you want to add to that. Yeah, I would just say what we’re learning also is as we integrate BET plus Pluto and Paramount into one tech stack, it’s going to accelerate our ability to do the same when we close WBD and in particular when you see the consumer product that comes out this summer, I think you’ll be pretty pleased about how they all function together and create a better experience both for the free consumers on the fast channel business of Pluto, but also on the paid subscription businesses of Paramount both ad-supported and ad-free. So we’re pretty excited about what we’re doing and look to dive into more specifics on in terms of what we’re seeing on the platforms we’re operating. As we said, we remain on track for convergence. That obviously has significant benefits across personalizations and recommendations. You know, on the front end, we’re modernizing the consumer facing technology to create more dynamic personalized experiences. As of April, you’re able to see obviously short form video Clips, servicing trailers, sports highlights and library content in a curated, more personalized feed. We’re working on enhanced personalization across discovery including AI driven artwork. We’re also focusing on building other mobile optimized experience like live stats for live sports. All of these are really designed to deepen engagement across the platform for Pluto. Basically this summer Pluto is going to get the most significant update really since the inception of the platform. Other areas you’re really seeing us really utilize technology is across our tech and product org. Approximately 80% of our engineering organization is using code assisted technology which is driving meaningful production gains and really cutting approval times by more than in half. So again it’s really accelerating how we work across the business and these investments all support our long term D2C growth and are foundational to where we’re taking the business. And again, these are all great learnings that will prepare us for the transaction at the end of the third quarter. The only thing I’d add around AI transformation is we’re spinning up pods to go after AI based workflows in the back office. So think finance, HR operational functions and we’re really enabling both on the Paramount side and we think this sets us up for the combination people to go after AI based workflows and efficiency in the back office and we see that’s going to be a real benefit and so we’re doing that today with the teams that David talked about and that will set us up well in the future as well. Yeah, just one more thing to add is on Oracle Fusion, our ERP system, we made a major milestone in the first quarter with the remainder of that transformation to the Oracle Fusion system for Paramount standalone by early 27. So again that puts us in a much better spot as part of the closing of Warner Bros. Discovery as well.

Kevin Creighton

Great. Thanks Sean. Appreciate the question.

Jessica Reif Uhrlich (Equity Analyst)

Krista. Next question …

Full story available on Benzinga.com

This post was originally published here
On Monday, OSI Systems (NASDAQ:OSIS) discussed third-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://edge.media-server.com/mmc/p/esihax8t/

Summary

OSI Systems achieved a fiscal Q3 record with revenues of $453 million and non-GAAP earnings per diluted share of $2.60, despite challenging year-over-year comparisons.

The company reported strong security revenues, excluding Mexico, with a 25% year-over-year growth, and the optoelectronics and manufacturing division also saw a 10% increase.

A significant backlog of approximately $1.9 billion was noted, driven by a Homeland Defense award valued at around $235 million.

Operating cash flow was $14 million in Q3, but post-quarter collections of $74 million from Mexico are expected to boost Q4 cash flow.

The company maintained its fiscal 2026 guidance for revenues and non-GAAP earnings per share, despite potential impacts from the DHS shutdown and Middle East conflicts.

Management highlighted the potential for future growth in security solutions for upcoming major events and continued investments in R&D to foster innovation.

Full Transcript

OPERATOR

Ladies and Gentlemen, thank you for standing by. At this time, I would like to welcome everyone to the osi Systems Inc. Third quarter 2026 conference call. All lines have been placed on mute to prevent any background noise. After the Speaker’s remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press STAR followed by the number one on your telephone keypad. If you would like to withdraw your question, press star one again. Thank you. I will now turn the conference over to Alan Edrick, the Chief Financial Officer. You may begin.

Alan Edrick (Executive Vice President and CFO)

Thank you. Good afternoon and thank you for joining us. I’m Alan Edrick, Executive Vice President and CFO of OSI Systems, and I’m here today with AJ Mehra, OSI’s President and CEO. Welcome to the OSI Systems Fiscal 2026 third quarter conference call. We are pleased that you can join us as we review our financial and in our operational results. Before we discuss these results, I would like to remind everyone that today’s discussion will include forward looking statements and the Company wishes to take advantage of the safe harbor provisions of the Private Securities Litigation Reform Act of 1995 with respect to such forward looking statements. All forward looking statements made in this call are based on currently available information and the Company undertakes no obligation to update any forward looking statements based upon subsequent events, new information or otherwise. We will also reference both GAAP and non-GAAP financial measures. Applicable reconciliations are available. In today’s earnings release, we delivered solid third quarter financial results, setting fiscal Q3 records across multiple metrics. Despite facing the most challenging year over year comparison of fiscal 2026 primarily driven by our Mexico contracts, the Company’s revenues reached a fiscal Q3 record of $453 million million and non GAAP earnings per diluted share set a fiscal Q3 record of $2.60 per share. Importantly, excluding revenues generated by the large Mexico security contracts in both periods, security revenues grew 25% year over year. Our optoelectronics and manufacturing division also performed well, posting 10% growth and a Q3 record for that division. Bookings were strong with a 1.3 book to bill ratio driven by both security and opto, resulting in a record backlog highlighted by the previously announced Homeland Defense Award, about which AJ will provide more information shortly. On the cash side, we generated $14 million in fiscal Q3 operating cash flow despite limited collections in the quarter on the receivables in Mexico. Shortly after quarter end we collected approximately $74 million of the largest Mexico receivable, a strong start to Q4 cash flow. Before diving more deeply into our financial results and discussing our outlook for fiscal 26, I will turn the call over to AJ for our business and operational discussion.

AJ Mehra (President and CEO)

Thanks Alan and thank you everyone for joining us today. I’m pleased to be here to discuss our third quarter results for fiscal 2026. We delivered another quarter of solid execution and ended the quarter with a backlog of approximately 1.9 billion, the highest in the company’s history. We remain focused on execution, leveraging our strengths in key markets and utilizing our global operating model. As we finish Q4 and head into fiscal 2027, let’s turn our businesses to discuss Q3 performance in more detail, starting with security. As expected, Q3 performance was up against difficult year over year comparisons, primarily due to our Mexico programs transitioning from significant product sales to long term related service and support revenues. Despite that, Security performed well with solid bookings, top line growth and operating margin expansion. Furthermore, we continue to be very active with customers across aviation, ports and borders and defense related applications. Bookings were highlighted by a sizable award from Homeland Defense of an Undefinitized contract action or UCA with a not to exceed value of approximately 235 million for the production and integration of Homeland Defense over the Horizon Radar Transmit subsystem. We continue to build strong traction with our RF engineered solutions and are hopeful that there may be additional opportunities in this area of future business. In addition, these capabilities position us well to further support more Golden Dome initiative, the US Initiative to create an Integrated Missile Defense System. As you know, we are a participant in the 151 billion SHIELD IDIQ which we announced last quarter and we look forward to the opportunities that may arise from this initiative. During Q3, we also received several international awards for cargo and vehicle inspection systems and airport screening solutions. In addition, we were an integral part of the security at the Milan Winter Olympic Games, providing our products to screen participants, officials, fans as well as their baggage and cargo. Towards the latter half of Q3, we began to see initial impacts from conflict in the Middle East. Certain programs activities have been delayed by factors such as logistic constraints, travel restrictions and heightened security protocols. Certain customers in the region are facing pressure from disruptions tied to the conflict. If the situation persists, we could see further impact on the timing of order intake and project completion timelines. That said, once the region stabilizes, we could potentially see even stronger demand for security solutions in the us. The order activity for security products was impacted during the quarter by the shutdown at DHS which delayed the procurement of our products and services to support US Border initiatives. Now that the shutdown has ended, we are hopeful for order patents to normalize over the coming weeks and months and I want to emphasize here that these are timing related dynamics rather than changes in the underlying demand. In the US we’re also excited about the potential of our security solutions for high profile upcoming events such as the FIFA World Cup 26 soccer tournament and the 2028 Olympics. Furthermore, in the US the roughly 1 billion outlined in the One Big Beautiful Bill for NII equipment remains a significant growth opportunity. And of course during the shutdown the spending resulting from this bill was delayed in Q3. Turning to optoelectronics and manufacturing, Q3 performance was again strong as revenues increased 10% year over year with the book to bill ratio well exceeding one. In March, Opto received a $40 million award for the electronic sub assemblies from a medical OEM, a significant award in a division where most orders are under 5 million customers continue to value a vertically integrated model and global manufacturing footprint as it diversify supply chains and launch new products. A global manufacturing footprint across Malaysia, Indonesia, India, Canada, Mexico, the UK and the US Allows us to offer customers attractive combinations of value and scalability. Opto’s backlog remains at record levels, providing great long term visibility across aerospace, defense, medical, industrial and other end markets. And finally, our healthcare division which continues its path of improving operations and focusing on new product development in Q3 health care was adversely impacted by order timing, most notably in the US Resulting in lower sales and profitability. On the flip side, we did see growth in the EMEA region during the quarter. As you may know, healthcare’s products generally carry the highest contribution margins at osi, so even modest revenue growth has an outsized impact on profitability. Looking at OSI systems overall, our financial position remains strong. The robust and growing backlog year to date, cash flow generation and a healthy balance sheet give us continued confidence in the company’s prospects. In addition to large program opportunities highlighted earlier, we remain focused on increasing our mix of recurring revenues through expanded service and support agreements. As always, I would like to thank our employees, customers and stockholders for the continued support and dedication. With that, I will turn the call over to Alan to discuss our financial results in more detail before we open the call for questions. Thank you.

Alan Edrick (Executive Vice President and CFO)

Well, thank you aj. Now let’s review in greater detail the financial results for Q3. Let’s begin with a look into our revenues by Division security. division revenues in Q3 came in at $319 million million, driven by higher service revenues and increased contribution from the RF business, which has been effectively integrated into our overall operations and increased aviation product revenues.. As expected, revenues from our large Mexico security contracts decreased to 11 million in Q3 fiscal 26 from 69 million in Q3 of the prior year. Excluding the Mexico contracts, securities revenues surged 25% year over year, reflecting healthy growth across the broader security portfolio. Fiscal Q4 is expected to experience a reduced revenue impact from Mexico in comparison to Q3, with the magnitude of this headwind expected to largely roll off as the company enters fiscal 27. Our Opto electronics and manufacturing division had another excellent quarter. Opto sales, including Intercompany, increased 10% year over year to $111 million million, a new Q3 …

Full story available on Benzinga.com

This post was originally published here
Vertex Pharmaceuticals (NASDAQ:VRTX) held its first-quarter earnings conference call on Monday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://event.choruscall.com/mediaframe/webcast.html?webcastid=fH9sLE8H

Watch the full earnings call below:

Summary

Vertex Pharmaceuticals reported Q1 2026 total product revenue of $2.99 billion, reflecting an 8% year-over-year increase, driven by growth across its portfolio, particularly from new disease areas.

The company’s strategic focus includes expanding its cystic fibrosis (CF) treatments, progressing its nephrology franchise, and advancing its pipeline with multiple regulatory submissions and trials in areas such as sickle cell disease and beta thalassemia.

Vertex Pharmaceuticals reiterated its 2026 revenue guidance of $12.95 to $13.1 billion, with significant contributions expected from non-CF products like Casgevy and Journavix.

Operational highlights include the rapid regulatory submission for Povi in IGAN and label expansions for ALIFTREC and Trikaftor, enhancing patient eligibility and market reach.

Management emphasized the potential for its renal franchise to rival CF in size, with promising interim results for Povi in IGAN and planned studies in other B-cell mediated diseases.

Full Transcript

OPERATOR

Good day and welcome to the Vertex Pharmaceuticals first quarter 2026 earnings call. All participants will be in a listen only mode. Should you need assistance, please signal conference specialist by pressing the star key followed by zero. After today’s presentation there will be an opportunity to ask questions. Please note this event is being recorded. I would now like to turn the conference over to Ms. Susie Lisa. Please go ahead.

Susie Lisa (Senior Vice President of Investor Relations)

Good evening all. My name is Susie Lisa and as the Senior Vice President of Investor Relations, it is my pleasure to welcome you to our first quarter 2026 financial results conference call. On tonight’s call, making prepared Remarks, we have Dr. Reshma Kewalramani, Vertex’s CEO and President, Charlie Wagner, Chief Operating Officer and Chief Financial officer and Duncan McKechnie, chief commercial officer. We recommend that you access the webcast slides as you listen to this call. The call is being recorded and a replay will be available on our website. We will make forward looking statements on this call that are subject to the risks and uncertainties discussed in detail in today’s press release and in our filings with the securities and Exchange Commission. These statements including without limitation, those regarding Vertex’s marketed medicines for cystic fibrosis, sickle cell disease, beta thalassemia and moderate to severe acute pain. Our pipeline and Vertex’s future financial performance are based on management’s current assumptions. Actual outcomes and events could differ materially. I would also note that select financial results and guidance that we will review on the call this evening are presented on a non GAAP basis. I’ll now turn the call over to Reshma. Thanks Suzy. Good evening all and thank you for joining us on the call today. Vertex is off to a terrific start in 2026, which we see as a year defined by execution. Q1 revenue growth was strong across the portfolio as we reach more patients with more products and delivered total product revenue of 2.99 billion, reflecting 8% growth year on year. Importantly, we achieved key commercial milestones for each of the newer products since launch through end of Q1, Aliftrek exceeded 1 billion in cumulative revenue, more than 500 people have initiated their Kashgevi treatment journey and over 1 million prescriptions have been written for Journavix. Another highlight in Q1 was that products from the new disease areas, namely Kashevi and Journavix, drove approximately 25% of total product revenue growth. Execution in R and D was equally strong with multiple regulatory submissions recently completed and more anticipated. Combined with rapid progress across clinical trials and important advancement in research, let me spotlight a few accomplishments. First on POVI. The interim analysis results from the Phase 3 Rainier study in IGAN on efficacy and safety from top to bottom were sparkling and and further fueled our enthusiasm for POVI as a potentially best in class BAF April inhibitor. I was exceptionally pleased with the rapidity and quality of the recently submitted BLA filing for POVI in Igan. Indeed, at 27 days from database lock to regulatory submission, this was the fastest submission in Vertex history. Equally notable is the urgency with which the POVI primary membranous nephropathy and the POVI Myasthenia gravis programs are advancing in Membranous. The Phase two study has been fully enrolled and the Phase three program has already initiated. In addition, the Phase two Proof of concept Myasthenia gravis trial is underway. Second on Kasgevi I’m also very pleased with the rapidity and quality of this SBLA submission for Kashgevy in 5 to 11 year olds with sickle cell disease or beta thalassemia. The Kashgevi filing has been granted a Commissioner’s National Priority Voucher Review reflecting the importance of treating this younger age group before some of the most serious complications of the disease can begin. Overall, Vertex continues to extend its leadership in cf, drive growth with new product launches while building out our next disease area franchise in nephrology, accelerate programs in mid and late stage development and advance the earlier stage R and D pipeline. Tonight I’ll limit my R and D comments to CF as well as the pipeline programs with the most significant new information to share. Certain renal programs POVIne Myasthenia gravis and zamilacel in type 1 diabetes starting with CF.4 quick R& D updates for this quarter we recently reached a significant milestone in the US with label expansions for both ALIFTREC and trikaftor. With this expansion, patients with a clinical diagnosis of CF who have at least one variant in the CFTR gene they that is responsive based on clinical and or in vitro data are now covered by the ALIFTREC and Trikafta labels, reinforcing the impact of these medicines regardless of the location of the variant in the CFTR protein. This is a significant expansion of eligibility that reflects decades of investment, effort and a relentless pursuit of the science. It is also a great example of innovation using using results from clinical trials complemented by in vitro data to expand the benefit of Vertex CFTR modulators to about 95% of people with CF, including those with rare and even N of 1 genotypes. As we expand the ALIFTREC and Trikafta labels to additional mutations. We’re also expanding the labels to younger patients. We will soon submit for approval for ALIFTREC in patients 2 to 5 years of age, where you may recall our pivotal trial demonstrated of a remarkable 65% of children reaching normal levels of CFTR function, and we also plan to submit for Trikafta in children 1 to 2 years of age in the near term. In addition, we continue to advance our Next Generation 3.0 CFTR modulators, including VX828, which is currently in a study of patients with CF. We are on track to complete the study and share results in the second half of this year. Following closely behind VX828 in the family of Next Gen 3.0 are VX581 and VX272, both of which are currently in the clinic in Phase 1 Healthy Volunteer Studies. As we have consistently said, if it is possible to do better in cf, we’re committed to being the ones who do so. And finally, on VX522, the MRNA therapy we’ve been developing for people who produce no CFTR protein and therefore cannot benefit from our modulators. We we previously disclosed tolerability issues in this program. Despite actions we have taken in the trial to overcome these issues, we have not been able to do so and as such we have chosen to discontinue the program. Given this early termination, we will not be able to assess the efficacy or full safety of VX522. We will be working with CITES to close out the study in the coming weeks, moving on to our renal franchise, which continues to make quick progress and is rapidly establishing itself as Vertex’s fourth franchise along cf, heme and pain. In total, we have four programs in mid and late stage development in renal POVI in Igan, POVI in primary membranous nephropathy, Enoxaplin in AMKD and VX407 in 80 PKD. Tonight I’ll cover the first three programs starting with POVI and Igan recall. POVI’s differentiated potential best in Class profile stems from its specific design as an engineered tachy fusion protein with binding affinity, potency and PK properties that deliver optimal dual BAF April inhibition. The dual inhibition and engineering advantage is evident in both the interim analysis data of the Rainier study where we saw rapid, deep and sustained improvement in proteinuria, a favorable safety profile and consistency across all subgroups, as well as in three Key patient dosing benefits once monthly dosing, small volume and subcutaneous administration via an auto injector. Overall, the phase three interim analysis data represent a home run in terms of study design, execution and the results with POVEY achieving statistically significant and clinically meaningful results across all primary and secondary endpoints. Patients in this trial received excellent standard of care with high rates of background medicines including the highest rates of of SGLT2s seen in any IGAN study. Baseline characteristics were well matched to real world IGAN patients in terms of age, renal function and degree of proteinuria. In addition, as a measure of study quality, it’s important to look at discontinuations. In this study, treatment discontinuations were low and trial discontinuations were even lower at a rate of 1.5% in the placebo group and 0.8% in the POVI group. To replay the top line primary and secondary efficacy results for the primary endpoint, POVI achieved a 52% reduction from baseline in peritoneuria as measured by 24 hour UPCR. That’s a 49.8% reduction versus placebo. For the first secondary endpoint, POVI treatment led to a 77.4% reduction from baseline in serum GDIGA1 levels. That’s a 79.3% reduction versus placebo for the second secondary endpoint. Of those patients with hematuria at baseline, 85.1% of POVI treated patients achieved hematuria resolution which is a 61.7% reduction versus placebo. In addition, 42.2% of patients reach the exploratory endpoint of 24 hour UPCR of less than 0.5 grams per gram, an important clinical threshold. These are remarkable results and particularly noteworthy considering that at the time of the interim analysis, patients had received just 36 weeks of POV treatment. On safety, POV was generally safe and well tolerated. The majority of adverse events were mild to moderate and there were no serious adverse events related to pov. Importantly, in terms of infections, most were mild to moderate. The rate of SAEs of infection was low at 0.5% observed in both the placebo and POV groups. There were no opportunistic infections and no discontinuations related to POV overall, including no discontinuations due to infections. Lastly, on antidrug antibodies or adas, adas were observed as expected with biologics but had no impact on povi’s efficacy or risk profile. We look forward to sharing more details of the interim analysis results and anticipate doing so at upcoming medical meetings this fall. Shifting to POVI and primary membranous nephropathy I am pleased to share we have completed enrollment of the Phase 2 portion of the Olympus Phase 2.3study and have already initiated the Phase 3 portion ahead of our previously announced Mid2026 goal and finally on POVI as part of its pipeline in the product potential for B cell mediated diseases beyond renal I’m also pleased to share that the Phase two proof of concept study of POVI in generalized myasthenia is underway. This is a 30 patient study of people with GMG evaluating both the 80 and 240 mg dose for 12 weeks with the primary endpoints of safety and the percent change from baseline in IgG at week 12. The rationale for studying POV and myasthenia is compelling and it’s a serious B cell mediated disease with high morbidity affecting approximately 175,000 people in the US and Europe. There is high unmet need as current therapies have meaningful limitations, which means there’s room for improved efficacy, a better benefit risk profile and more patient friendly dosing and administration, which we have discussed in the context of IGAN as being critically important when considering a chronic biologics market. We believe povi’s mechanism of action, striking at the heart of autoantibody production with an engineered protein format provides best in class promise in myasthenia and we are excited to develop this opportunity. Shifting back to renal to finish up with enoxaplin in Apol1 mediated kidney disease or AMKD. First on amplitude, the pivotal phase 3 study of primary AMKD, that is to say patients with two Apol1 variants for nurture kidney disease and no other renal related comorbidities. We are on track to conduct the interim analysis which occurs after 48 weeks of treatment, and to share data from this Cohort in early 2027. If positive, we will be poised to file for potential accelerated approval in the US thereafter. Second, on amplified our Phase 2b study of enoxapline in separate populations, patients with 2 APOL1 variants, modest peritoneuria and no other kidney disease and patients with two APOL1 variants, moderate to severe peritoneuria and a second disease, type 2 diabetes that could impact the kidney. These two populations are not being studied in amplitude. We recently completed enrollment in the Amplified study which is a study of 13 weeks in duration. Given the clear differences in these populations, we made the decision early on to study them in separate trials. Emerging data in the field confirm the wisdom of this decision. We are excited to learn from the Amplified study and look forward to sharing results in the second half of this year. Finally, on type 1 diabetes, a reminder that Zamylacel has very strong clinical results to date, as detailed in last year’s New England Journal of Medicine. Among patients who received a full dose and had at least one year of follow up, 10 out of 12 patients who were insulin free. These results are unprecedented and are particularly noteworthy given that these patients are those with 20 plus years of type 1 diabetes, undetectable endogenous insulin production at baseline, taking 40 plus units of exogenous insulin per day and with two or more severe hypoglycemic events per year despite best available care. You may recall that in the second half of last year we paused dosing of the phase 1, 2, 3 study in order to conduct a manufacturing analysis which we have now completed. I am pleased to report that dosing in the study has resumed and multiple patients have been dosed with dosing now restarted. We will update you in the coming months on the revised timelines for study completion and regulatory filings. With that, I’ll turn the call over to Duncan for for a commercial update.

Reshma Kewalramani

Thanks very much Reshma. I’ll start with cf, which continues to perform very well year over year. Revenue growth was 6% globally, balanced nicely between US growth of 5% and international growth of 8% in quarter one. Global growth reflects continued ALIFTREC uptake as its once daily dosing and improved sweat chloride profile continue to resonate with the clinical and patient communities. As mentioned, a Liftrek has now surpassed $1 billion in cumulative global revenue since its approval in the U.S. in late December 2024 and Europe in July 2025. Outside the U.S. we have signed reimbursement agreements in 11 countries for ALIFTREC in quarter one alone, building on the access generated in the second half of last year. The tremendous scientific and regulatory achievements represented by the label expansions for elliftrek and Trikafta also also represent a meaningful incremental commercial opportunity of approximately 800 people in CF who are newly eligible in the U.S. this broad labeling is one of several key CF growth drivers for the remainder of 2026, along with the global rollout of a LiftRec treating younger patients and expanding into additional geographies. We have worked closely with the CF population for two decades and remain focused on continuing to serve the CF community and and expand our leadership across all genotypes, age groups and geographies shifting to heme. The rollout of Kashgevi continues to gather momentum across all three regions and I’m pleased to highlight another significant commercial milestone. Since launch, over 500 patients have now initiated the Kashgevi treatment journey. Hundreds have had their first cell collection and many patients have had their cells edited and are ready for infusion. During the first quarter we delivered $43 million in Kashgevi revenue. Importantly, we worked on securing a pricing agreement for Kashgevi in Germany in quarter one and are currently working through the implementation steps. This is a historic moment and we’re excited that German patients with sickle cell disease and TDT may soon be benefiting from long term access to Kashgevi at a sustainable price. Overall, we are very encouraged by the robust flow of patients in the US in in Europe and the Middle east moving from referral to cell collection and infusion. First quarter revenue reflects expected variability quarter to quarter as patients choose the timing for their infusion that suits them best for the full year 2026. The Kashgevi Outlook is very promising as we have built our ATC network, secured reimbursements …

Full story available on Benzinga.com

This post was originally published here
On Monday, Aviat Networks (NASDAQ:AVNW) discussed third-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://edge.media-server.com/mmc/p/9inczpqi/

Summary

Aviat Networks reported Q3 fiscal 2026 revenues of $100 million, a decrease from $112.6 million in the same period last year, impacted by project pushouts in the Middle East.

The company is optimistic about future growth due to increased visibility in U.S. markets, particularly in multi-dwelling units (MDU) and utility sectors driven by AI and broadband programs.

Gross margins were 29.3% GAAP and 29.4% non-GAAP, down from the previous year, mainly due to volume and product mix; however, margins are expected to recover in Q4.

Aviat Networks has lowered inventories by $4 million and improved its balance sheet by reducing unbilled receivables and accounts payable, signaling better cash management.

Fiscal 2026 guidance has been adjusted to revenues between $428 million and $440 million and adjusted EBITDA between $35 million and $40 million, factoring in geopolitical uncertainties.

Full Transcript

OPERATOR

Good Afternoon. Welcome to Aviat Networks’ third quarter fiscal 2026 earnings call. Currently, all participants are in a listen only mode. A question and answer session will follow the formal presentation. Please note this conference is being recorded. I will now turn the conference over to your host, Mr. Andrew Fredrickson, Vice President, Corporate Finance. Thank you, You may begin.

Andrew Fredrickson (Vice President, Corporate Finance)

Thank you and welcome to Aviat Networks’ third quarter fiscal 2026 results conference call and webcast. You can find our press release and updated investor presentation in the IR SECtion of our website at www.aviatnetworks.com along with a replay of today’s call. With me today are Pete Smith, Aviat’s President and CEO, who will begin with opening remarks on the Company’s fiscal quarter, followed by Andy Schmidt, CFO, to review the financial results for the quarter. Pete will then provide closing remarks on Aviat’s strategy and outlook followed by a question and answer session. Jonana Mikulenka, Aviat’s Chief Accounting Officer, is also with us on the call. As a reminder, during today’s call and webcast, management may make forward looking statements regarding Aviat’s business, including but not limited to statements relating to fiscal guidance, financial projections, business drivers, new products and expansions, and economic activity in different regions. These and other forward looking statements reflect the Company’s opinions only as of the date of this call and webcast, and involve assumptions, risks and uncertainties that could cause actual results to differ materially from those statements. Additional information on factors that could cause actual results to differ materially from the statements expressed or implied on this call can be found in our most recent filings with the SEC. The Company undertakes no obligation to revise or make public any revision of these forward looking statements in light of new information or future events. Additionally, during today’s call and webcast, management will reference both GAAP and non GAAP financial measures. Please refer to our press release which is available in the IR SECtion of our website at www.aviatnetworks.com and financial tables therein, which include a GAAP to non GAAP reconciliation and other supplemental financial information. At this time I would like to turn the call over to Aviat’s President and CEO Pete Smith.

Pete Smith (President and CEO)

Thanks, Andrew and good afternoon. Let’s review the Highlights from the third quarter Total revenues of $100.0 million Adjusted EBITDA of $4.4 million Non GAAP EPS of $0.06 Lowered inventories by $4.0 million versus the December quarter Maintained a trailing twelve month book to bill ratio greater than 1.0 Quarterly results were impacted by the conflict in the Middle east where we saw certain project pushouts and unfavorable end of quarter demand shifts and several tier one customers totaling approximately $9 million in revenue. Now let me talk more about our end markets and key developments in the U.S., we see reason for optimism in the quarters ahead as we gain increased visibility on timing of our multi dwelling unit or MDU opportunity, growing demand from utilities as they invest to meet increased power demand from artificial intelligence build outs and the nearing arrival of the Broadband Equity Access and Deployment or BEAD program on the MDU. We have increased confidence in the level of commitment to this project from our Tier one customer and we believe that we have secured a favored position as the supplier of choice. This is translating to increased visibility on timing for the markets we have won and opening the door to additional market areas for deployment for the projects in progress. We have installations occurring now and through the rest of Q4. These are still relatively small and we expect a larger step up during fiscal 2027. As the aviation installations progress and we compete for additional markets related to the MDU opportunity, we are seeing more prospects to provide services and other value added solutions to our Tier one customer. Overall, we are feeling better about this opportunity today than at any other previous point and believe we will have meaningful revenue contribution from this project in fiscal year 2027. Further, we have validated our next generation offering in this area should subscriber growth materialize. We anticipate demand for this next gen product in fiscal year 2028. Private networks remain Aviat’s largest segment today and within private networks, utilities are Aviat’s second largest customer group in this segment. Aviat has been strategically focused on growing our presence and offerings with utilities over the last several years with product innovations like our Ultra High powered 11 GHz radio and the 2024 acquisition of 4RF Networks. Even prior to the demand brought on by artificial intelligence and data center buildouts, there was a growing need for increased investment in America’s grid from a modernization and reliability standpoint. Today, the outlook for Aviat’s utilities is quite robust. Recent industry reports suggest that utilities will deploy 1.4 trillion on capital spending plans over the next five years. This forecast is up over 20% versus a year ago. Approximately half of this spend will go towards transmission and distribution where Aviat’s network hardware is critical for smart grid connectivity and management, substation monitoring and security, crew communications and wildfire detection. Power generation has become the primary constraint and a fundamental determinant of growth for artificial intelligence or AI. This build out of the grid lifts the importance of Michelin critical communication and Aviat is well positioned to capture increasing share of demand in this market. The utility segment is approaching 10% of our overall business. Our funnel of opportunity is strong and the discussions we are having with many of the largest utilities in the US signals that this growth opportunity will remain for several years ahead. Lastly, on the BEAD program, our customers continue to signal that purchase orders related to the program should begin in mid to late calendar 2026. This is consistent with the message we have told investors for approximately a year now. However, as final approvals are made, the set of opportunities is beginning to take shape. 46 of the 56 states and territories have signed have signed their final award agreement. The total funding for the approved deployment spend to date is approximately $20 billion. The size of Aviat’s opportunity depends on the allocation of BEAD funds towards fixed wireless access, which in our estimation stands between 10 and 15% of the award dollars. The allocation of funds to wireless has been increasing over time. Feedback from four of our wireless Internet service provider customers who have all won bead deployment projects signal that calendar 2027 will likely see the largest ramp purchase orders for Aviat, but we still remain very early in the fund deployment life cycle and will provide updates as available. Aviant stands at the ready to assist all of its customers with bid opportunities that, thanks to its Build America Buy America certifications, our E Commerce Aviat Store presence and our leading position in serving rural broadband needs. Apart from these growth drivers, we’ve invested in our roadmap. We’ve taken our North American all indoor radio to international markets. We are also bringing PasserLink radios to North America in early fiscal 2027. Both these represent installed base opportunities for an addressable market of over $250 million. I will now turn the call over

Andy Schmidt (Chief Financial Officer)

to Andy to go through the financial results. Thanks Pete and good afternoon everyone. Before going through the financial results, I would like to briefly introduce Joanna Mikolenka, who joined Aviat in January as our Chief Accounting Officer. She brings with our over 30 years of of accounting experience, including previously serving as Chief Accounting Officer and and Corporate Controller at other public companies. She’s already making a great impact to the overall Aviat team and will help us to achieve our goals. Welcome Janana. Now I’ll review some of our key fiscal 2026 third quarter results. Please note that the detailed financials can be found in our press release and all comparisons discussed are between the third quarter of the fiscal year 2026 and the third quarter of fiscal year 2025, unless otherwise noted. For the third quarter, we reported total revenues of 100 million as …

Full story available on Benzinga.com

This post was originally published here
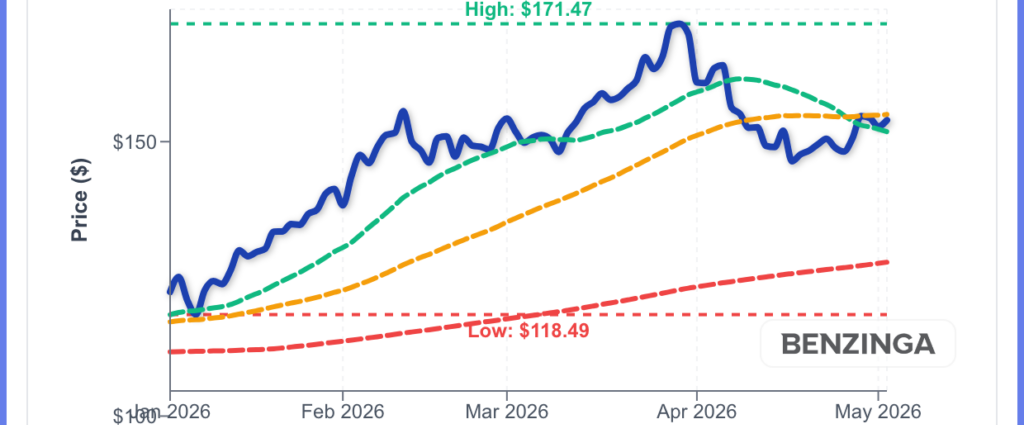
Wall Street’s first prediction market ETFs were set to debut this week, but the Securities and Exchange Commission has paused the rollout and asked for more disclosures.

The delay hits as Robinhood Markets (NASDAQ:HOOD) prints record prediction market revenue, signaling investor demand for the same boom these ETFs are trying to package.

ETF issuers Roundhill Investments, Bitwise and GraniteShares filed in February for more than two dozen funds combined.

The 75-day window that lets ETFs go live automatically was due to expire this week, and Bloomberg ETF analyst James Seyffart had said last week the launches looked imminent.

Two Dozen Funds In Limbo

The three issuers have filed for more than …

Full story available on Benzinga.com

This post was originally published here
On Monday, Backblaze (NASDAQ:BLZE) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://events.q4inc.com/attendee/290886121

Summary

Backblaze reported a strong Q1 2026 with $38.7 million in revenue, up 12% year-over-year, and B2 cloud storage growing 24%.

The company is seeing significant growth from AI-related customers, with a 76% increase in AI customer usage year-over-year.

Backblaze is focusing on the NEO cloud market, estimating a $14 billion opportunity by 2030, and has secured multiple six, seven, and eight-figure deals.

The company introduced new B2 pricing effective May 1, expected to positively impact revenue and margins.

Guidance for full-year 2026 revenue has been raised to $161.5 million to $163.5 million, with an adjusted EBITDA margin guidance increase to 23-25%.

Full Transcript

Abby (Conference Operator)

Ladies and Gentlemen, thank you for standing by. My name is Abby and I will be your conference operator today. At this time I would like to welcome everyone to the Backblaze first quarter 2026 earnings call. All lines have been placed on mute to prevent any background noise. After the speaker’s remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press followed by the number one on your telephone keypad. If you would like to withdraw your question, press star one again. Thank you and I would now like to turn the conference over to Mimi Kong, Head of Investor Relations. You may begin.
Mimi Kong (Head of Investor Relations)

Thank you. Good afternoon and welcome to Backblaze’s first quarter 2026 earnings call. On the call with me today are Gleb Budman, Co Founder, CEO and Chairperson of the Board, and Mark Sweden, Chief Financial Officer. Today, Backblaze will discuss the financial results that were distributed earlier. Statements on this call include forward looking statements about our future financial results, the impact of our go to market transformation, sales and marketing initiatives, cost saving initiatives, results from new features, the impact of price changes, our ability to compete effectively and manage our growth, and our strategy to acquire new customers, retain and expand our business with existing customers. These statements are subject to risks and uncertainties that could cause actual results to differ materially, including those described in our risk factors that are included in our most recent quarterly report on Form 10Q and our other financial filings. You should not rely on our forward looking statements as predictions of future events. All forward looking statements that we make on this call are based on assumptions and beliefs as of today and we undertake no obligation to update them except as required by law. Our discussion today will include non GAAP financial measures. These non GAAP measures should be considered in addition to and not as a substitute for our GAAP results. Reconciliation of GAAP to non GAAP results may be found in our earnings release which was furnished with our Form 8K filed today with the SEC. You can also find a slide presentation related to our comments in the webcast which will also be posted on our Investor Relations page after the call. Please also see our press release or presentation for definitions of additional metrics such as NRR gross customer retention rates and adjusted free cash flows. We will be participating in the Needham Technology Media and consumer conference on May 12th in New York. I hope to see many of you there. Thank you for joining us and I will now like to turn the call over to Cliff.
Cliff

Thank you Mimi and thank you everyone for joining us today. Q1 was a strong quarter. We beat revenue and adjusted EBITDA guidance, ending the quarter with 38.7 million in revenue up 12% year over year with B2 growing 24%. We more than doubled our average sales deal size and drove 72% year over year growth in our 50k port plus ARR cohort. As we continue to move up market and we are on track for our first full year of free cash flow positivity as a public company, what excites Me Most about Q1 goes beyond the numbers. AI is making storage increasingly important and our organization is gelling and executing better than ever to capture that opportunity. This is evidenced by more than 1/3 of all new bookings coming from AI and the number of AI customers using our platform growing by 76% year over year. We entered 2026 saying we would build a more scalable, more predictable growth engine that serves the AI opportunity. Q1 started to show what that looks like in AI. We are seeing demand from two parts of the market. One is companies building the infrastructure and tools that enable AI. The other is companies using that infrastructure to bring AI into products and workflows. We are winning in both. On the infrastructure side, there is a major re platforming happening in the market for the first time in about two decades. The traditional hyperscalers are not the only place companies are building, they’re also building on the Neo clouds. Synergy Research estimates that the NEO cloud market was $25 billion in 2025 and growing to about 400 billion by 2031. In order for these Neo clouds to support their customers AI workflows, they need to offer cloud storage. Some Neo clouds have offered cloud storage built on Flash. It was fast and it worked. But as these platforms have scaled and AI workloads have grown, the economics have become increasingly difficult. Flash is now about 10 times more expensive per terabyte than hard drives. It works well for use cases requiring the lowest latency for smaller data sizes, but becomes unsustainable as at an exabyte scale. As a result, NEO Clouds are now actively looking to introduce a cost efficient hard drive tiered time flash to manage both performance and economics across their infrastructure. At Backblaze, we built an Internet scale file system to optimize performance per dollar out of hard drives and thus believe Backblaze is ideally positioned to provide exactly what these Neo clouds need. We’ve seen support for that belief not only from the multiple signed Neo clouds where we provide this for them already, but also the active engagement we’re having with many of the top neoclouds. We estimate our opportunity to support neoclass at $14 billion by 2030, and with the success we’re seeing, we are aligning resources internally behind that opportunity. In addition to neopods, we’re seeing a significant opportunity for us supporting other AI infrastructure. For example, we are also seeing strong demand from companies supplying large data sets into the AI ecosystem because they need a place to store large data sets efficiently but also be able to move them where they need to go rapidly. One recent example is a training data provider serving AI use cases that selected V2 to store large volumes of video data. A hyper growth company, it was experiencing rate limits and bandwidth constraints with its existing provider and needed a solution that could scale quickly. Backblaze won on both economics and technical fit. The deal closed in just 11 days at nearly a million dollars of arrangement, underscoring how quickly these companies move when infrastructure becomes a constraint and how well Backblaze is suited to the infrastructure side of the AI opportunity. The other part of the AI market we’re seeing is companies using infrastructure like ours to bring AI into their products. As AI models move from text to multimodal, incorporating video, audio and images, the volume of data required to train and run those models grows by orders of magnitude. This is not a future trend, it’s happening now and it’s creating significant and growing need for storage that can handle it economically and at scale. With the generative AI customers we have today, we are finding that price and performance get us in the door, but it is the experience that keeps them and grows them transparent pricing, responsive support and a team that works with them rather than just selling to them. These customers are scaling fast and they do not have time to manage infrastructure problems with Backblaze. They don’t have to. A good example from Q1 is an AI powered video creation company that selected B2 to store data used to train its models. The customer had been running into cost and performance issues with its existing provider. The platform was difficult to manage and the economics were not working at its scale. Backblaze offered the best performance per dollar and a platform that was easy to use and easy to scale. The initial deployment represents nearly half a million dollars of ARR and creates a clear path to expand into higher performance workloads over time. These customer wins are just examples of where we won in Q1 and are reflective of opportunities we have in pipeline going forward. It’s clear that whether customers are building AI infrastructure or using AI in their products, they are scaling fast, the data is growing exponentially and they need infrastructure that is performant, open and cost efficient at scale. That is the moat we have spent 19 years building and AI is making it more valuable, not less, to be the leading storage platform for AI. We are also meeting developers where they already work. We are embedding backwards into the AI ecosystem by integrating directly into the tools developers already use. For Hugging face, which has 13 million users and over 2 million models, we shipped a tool that lets teams store and share model caches on B2 for ComfyUI, which recently raised at a $500 million valuation. We built a plugin to support generative AI workflows for cvat, which is used by tens of thousands of computer vision teams. B2 is now integrated as a backend for training Data and for MLflow, the most downloaded tool for taking AI projects from lab to production. With 60 million monthly downloads. B2 has now been added as an integrated artifact store. So the AI opportunity is making what we do increasingly critical. We’re also stepping up to meet it. A year ago we began a meaningful transformation of our go to market organization focused on three things increasing awareness, driving greater pipeline consistency and expanding revenue within our installed base. In Q1, we delivered progress on all three. On awareness, the Flamethrower startup program is gaining real traction. We have now welcomed approximately 100 companies in under three months, half the time it would typically take. We’ve been added to the A16Z Founder Resource Program, the Launch Startup Showcase and the Startup Grind Conference, all of which expand our reach with venture backed startups. On pipeline consistency, we have completed our core Go to Market systems upgrade, giving our team better visibility and a stronger foundation for a faster, more disciplined revenue motion. And within our installed base, pipeline sourced from existing customers has nearly doubled year over year, reflecting our growing ability to land and expand with our customers. To accelerate this next phase, we welcomed Anush Kumar as our Chief Revenue Officer. Anush has scaled go to market for cloud infrastructure and enterprise storage at NetApp, VMware, Red Hat and SUSE. He brings the pipeline discipline and execution rigor this phase of our growth requires and we believe his leadership will be a meaningful complement to the upmarket momentum we have already built. We also saw encouraging new customer momentum during the quarter across a range of data intensive use cases that included a healthcare data company who selected us for disaster recovery, a cloud gaming platform that chose B2 to store video across multi cloud environments, and an audio streaming platform migrating from self managed infrastructure to B2. These wins reinforce a broader point. Backwave is winning where data is valuable, active and operationally important and this is why I am excited about the opportunity ahead. The shift to multimodal AI is driving exponential data growth and the need for high performance, yet cost efficient storage has never been greater. The customers who are choosing Backblaze are exactly the kinds of customers that compound with us over time. We are stepping up to this opportunity with an up level team, a go to market transformation well underway and a platform we have spent nearly two decades building and optimizing. AI is making everything we have built more valuable and we are becoming the storage infrastructure that powers the AI economy. With that, I’ll turn it over to Mark.

Mark Sweden (Chief Financial Officer)

Thank you Gleb and good afternoon everybody. Our first quarter results reflect the strategy that we have been executing against. We exceeded the top end of both revenue and adjusted EBITDA guidance. Our Q1 outperformance reflects stronger sales execution and the EBITDA demonstrates the operating leverage in the model. Let me walk through the quarter and then cover our outlook. We finished Q1 with revenue of $38.7 million above the high end of our guidance of 38 million. The beat was broad based across both V2 cloud storage and computer backup, with B2 remaining the primary growth driver. B2 cloud storage grew 24% year over year to 22.4 million and ARR grew 28% year over year, reflecting the underlying strength and momentum of the business. The Q1 revenue outperformance was driven by higher customer data consumption on the B2 cloud platform and computer backup coming in slightly more favorable than our forecasted decline on bookings. which primarily affect revenue in future quarters. We closed multiple large deals for a strong quarter. We made several updates this quarter to improve the calculations of our ARR and RPO metrics. I will briefly walk through those changes as I cover the results. ARR increased by more than $5 million sequentially to $158 million with B2 growing 28% year over year. This quarter we updated our ARR methodology to improve comparability across periods and the change is defined in the earnings presentation posted on our Investor Relations website. Under both the new and previous methods, the sequential ARR improvement is approximately $5 million. We ended the quarter with 187 customers contributing over $50,000 in ARR, up 51% from a year ago reflecting continued strong progress upmarket. We also updated our RPO methodology this quarter and described the change in our earnings presentation. The change is aligned to our peer group and RPO is now a more important metric as we continue to move upmarket, signing both annual and multi year customer commitments. Under the updated methodology, RPO increased by $6 million sequentially and by $31 million from the prior year period. Our gross customer retention metrics remain very healthy with customers continuing to use both our B2 and computer backup solutions for nine years on average beginning this quarter. Our reported net revenue retention reflects an in quarter methodology which we believe provides a more current view of our customer expansion and retention trends. In B2, net revenue retention was 110% up from 105% a year ago, reflecting continued expansion within the customer base as a consumption business. V2 benefits from both the organic customer data growth and the cross sell upsell sales motion. Q1 gross margin was 61% versus 56% in the prior year. The year over year improvement shows strong operating leverage continuing to kick in as we tightly manage costs and also from the extension of the useful life of our fixed assets. Total operating expenses were $29 million in Q1, roughly flat compared to Q4 and improved by approximately 600 basis points from the prior year as a percentage of revenue, reflecting strong operating leverage. As we maintain our focus on Cost Management, Q1 adjusted EBITDA was $10 million or 26% of margin, up from $6 million or 18% in the prior year reflecting strong operating leverage as revenue scales sequentially. Margin declined modestly from 28% in Q4, primarily reflecting the one time benefits we referenced in our last earnings call. Adjusted free cash flow was negative $1.8 million in Q1, reflecting earlier payments in the quarter. We are also pulling forward a portion of 2027 CAPEX into 2026 in response to strong demand signals. Even with that pull forward, we …

Full story available on Benzinga.com

This post was originally published here

On Monday, Allison Transmission (NYSE:ALSN) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/k2c6e7qr/

Summary

Allison Transmission reported a 4% year-over-year decrease in first-quarter net sales to $733 million, largely due to a strong prior year period.

The company’s Defense end market showed significant growth with a 64% revenue increase, contributing positively to overall performance.

The Allison Off Highway business unit generated $673 million in sales, driven by strong demand in mining and construction markets.

Allison Transmission is focused on realizing $120 million in annual run-rate synergies from the integration of its business units.

The company reaffirmed its full-year 2026 guidance, expecting consolidated net sales between $5.575 billion and $5.925 billion, and adjusted EBITDA margins in the range of 27% to 29% over the next few years.

Management emphasized the importance of disciplined execution and synergies to drive future margin improvements and underscored strong cash flow and capital allocation towards debt reduction and shareholder returns.

Full Transcript

OPERATOR

Good afternoon. Thank you for standing by. Welcome to Allison’s first quarter 2026 earnings conference call. My name is Shamali and I will be your conference call operator today. At this time, all participants are in a listen only mode. After prepared remarks, Allison executives will conduct a question and answer session and conference call. Participants will be given instructions at that time. As a reminder, this conference call is being recorded. If anyone should require operating assistance during the conference, please press Star 0 on your telephone keypad. I would now like to turn the conference call over to Jackie Bowles, Executive Director of Treasury and Investor Relations. Please go ahead. Jackie.

Jackie Bowles (Executive Director of Treasury and Investor Relations)

Thank you. Shamali. Good afternoon and thank you for joining us for our first quarter 2026 earnings conference call. With me this afternoon are Dave Graziosi, our Chair, President and Chief Executive Officer Scott Mel, our Chief Financial Officer and Treasurer Fred Boley, Allison’s Chief Operating Officer and Allison Transmission Business Unit Leader and Craig Price, Allison Off Highway Business Unit Leader. As a reminder, this conference call, webcast and this afternoon’s presentation are available on the Investor relations SECtion of allisontransmission.com A replay of this call will be available through May 18th. As noted on slide 2 of the presentation, many of our remarks today contain forward looking statements based on current expectations. These forward looking statements are subject to known and unknown risks, including those set forth in our annual report on Form 10K for the year ended December 31, 2025. Should one or more of these risks or uncertainties materialize or should underlying assumptions or estimates prove incorrect, actual results may vary materially from those that we express today. In addition, as noted on slide three of the presentation, some of our remarks today contain non GAAP financial measures as defined by the SEC. You can find reconciliations of the non GAAP financial measures to the most comparable GAAP measures attached in this appendix to the presentation and to our first quarter 2026 earnings press release. Today’s call is set to end at 5:45pm Eastern Time. In order to maximize participation opportunities on the call, we’ll take just one question from each analyst. Please turn to Slide 4 of the presentation for the call agenda. During today’s call, Dave Graziosi will provide a business update and briefly review the company’s performance. Scott Mel will then discuss Allison’s segment reporting structure and Further review Allison’s first quarter 2026 financial performance and Allison’s full year guidance update prior to commencing the Q and A. Now I’ll turn the call over to Dave.

Dave Graziosi (Chair, President and Chief Executive Officer)

Thank you. Jackie, Good afternoon and thank you for joining us. Please turn to Slide 5 of the presentation for our first quarter business update. First, I want to recognize and thank our global employee base for all the work done so far this year. Our teams have been working diligently on integration and value capture within both Allison business units. Our execution has tracked closely with our planning and the integration process is proceeding in a disciplined and structured manner. Having said that, it has not been without a tremendous amount of effort by the Allison teams to arrive at where we are today. As our teams more closely coordinate efforts, we are beginning to see the initial phases of synergy realization take shape across several key areas and expect to begin to see financial benefits later in 2026. It’s been encouraging to see the groundwork laid prior to the transaction translate into real momentum and reaffirmed guidance in achieving our target of 120 million of annual run rates synergies. We remain confident in our acquisition thesis, accelerating sales growth through the strategic combination of the two business units, strengthening our localized production footprint and generating sustainable cost reductions that enhance long term shareholder value. Allison’s reach is now greatly expanded with our global operations, allowing for more localized production and opportunities for cost reductions. By leveraging increased purchasing scale and utilizing manufacturing in best cost countries, we expect to drive value creation and margin improvement across our business. I want to give another welcome to our new colleagues around the world and thank you for all that you do. It’s been a productive first quarter and exciting times for Allison as we enter this new chapter. Moving now to a brief update on first quarter sales, performance and end market outlooks for both of our business units, please turn to slide 6. Starting with our legacy Allison Transmission business first quarter net sales were $733 million a year over year decline of 4% when compared against a robust first quarter of 2025 for the North America on Highway end market. We continue to view the truck market with cautious optimism. Although order trends have shown strength and implies slight ramp throughout the year, we believe there is still uncertainty surrounding geopolitical impacts, including tariffs and final rulings on emissions regulations that are hindering end users new vehicle purchasing decisions. Continuing with the Allison Transmission business unit, the Defense end market had an extremely strong first quarter with revenue up 64% year over year. We continue to see strength from international customers primarily in track programs with both legacy and new products, including our 3040 MX cross drive transmission. We hold a favorable outlook for the Defense end market as national security becomes even more relevant to nations around the world, leading to increased budgets and new programs being funded. Please turn to Slide 7. The Allison Off highway business unit generated $673 million of sales in the first quarter with continued growth in the mining end market driven by elevated commodity prices including gold, copper and rare earth minerals. The construction and material handling end market also performed in the first quarter as global construction markets are seeing steadier investments and positive developments, particularly in Europe in the agriculture end market. While commodity prices remain a driving factor, there are early positive indicators in certain sub segments and regions, for example the low horsepower market in India, but overall a fairly muted environment even prior to the start of the conflict in the Middle East. On that topic, the conflict in the Middle east currently has undetermined impact and implications, both favorable and unfavorable for multiple end markets across Allison business units. While the duration of the conflict remains uncertain, we have not seen any material disruption to our business at this time. We recognize the potential for indirect impacts across our supply chains, energy markets and and broader macroeconomic conditions, and our teams are actively monitoring and maintaining close coordination. In summary, integration is progressing as expected and value capture is materializing. End markets, although impacted by uncertainty in some aspects, are steady if not showing signs of recovery. To everyone across our organization, thank you for the extraordinary commitment, resilience and teamwork you’ve shown. Your efforts have laid a strong foundation for Allison’s futures. To our investors, we are confidently positioned to unlock meaningful synergies, accelerate growth and create lasting value. Now I’ll pass the call over to Scott for a review of Allison’s segment reporting structure, first quarter 2026 financial performance and full year guidance update.

Scott Mel (Chief Financial Officer and Treasurer)

Scott, thank you Dave and thanks to those of you joining us on the call. Please turn to slide 8 of the presentation. Before we begin with segment and consolidated results, I want to quickly go over some housekeeping items and outline our new reporting structure. First quarter results now include segment reporting for Allison Transmission, Allison off highway and Allison Central Group. The Allison Transmission Business unit is the company’s legacy business excluding certain costs now accounted for within the Allison Central Group, while the Allison Off Highway Business unit reflects the business acquired from Dana at the beginning of the year. Allison Central Group is a centralized cost center which includes certain functional costs that support the Company’s global operations. Now on the left hand side of Slide 8, we provide sales, operating profit and adjusted EBITDA by segment. Segment operating income flows over to the consolidated table on the right with further detail down to net income and non GAAP financial measures of adjusted diluted EPS and consolidated adjusted ebitda. Please note that first quarter gross profit in the Allison off highway segment was negatively impacted by approximately $76 million of one time acquisition related purchase price accounting items on a consolidated basis. First quarter net income decreased year over year to $112 million driven by the addition of costs from the Allison off highway business unit including approximately $76 million of expenses related to the stepped up basis in inventory and incremental depreciation expense related to the stepped up basis in fixed assets and an additional $22 million of intangible asset amortization expense. The year over year decrease in net income was also driven by higher interest expense net along with approximately $17 million of one time acquisition related integration expenses. Moving down to per share earnings, first quarter diluted EPS was $1.33 when excluding the effect of non cash, non recurring, infrequent or unusual items. Including the costs associated with the acquisition of the Allison off highway business unit. Adjusted net income and adjusted diluted EPS were $216 million and $2.57 per share respectively. As a reminder, reconciliations for non GAAP financial measures can be found in the appendix of the first quarter earnings presentation and earnings press release. There will also be more detail provided in our 10Q to be published later this week. Please turn to Slide 9 of the presentation. First quarter adjusted diluted EPS of $2.57 increased 6% year over year and we expect the acquisition of the Allison off highway business unit to be accretive to earnings on a full year basis. Adjusted EBITDA for the first quarter was $362 million, increasing 22% year over year with adjusted EBITDA margin at 26% reflecting disciplined execution across our business units despite the less than ideal operating environment. As we have discussed previously, we believe that improving end market conditions in both business units will have a favorable impact on margins. Our value capture and synergy realization will also provide an uplift to our margins with our target for adjusted EBITDA margin in the 27 to 29% range. Cash generation continues to be a key attribute of Allison with the ability to generate substantial cash flow while successfully integrating the Allison off highway business unit and navigating uncertain end market environments including geopolitical policies and conflicts. Now I will briefly highlight our capital allocation priorities. We continue to invest for long term and sustainable growth across our business units with new products and initiatives targeting identified growth opportunities. We are also focused on debt reduction to achieve our near term leverage targets and while simultaneously returning capital to shareholders through share repurchases and our quarterly dividend. At the bottom of the slide you can see how we allocated capital in the first quarter during the quarter we repaid $150 million of the $300 million …

Full story available on Benzinga.com

This post was originally published here

Tactile Systems Tech (NASDAQ:TCMD) reported first-quarter financial results on Monday. The transcript from the company’s first-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://edge.media-server.com/mmc/p/jb5atvev/

Summary

Tactile Systems Tech reported Q1 2026 revenue of $75.3 million, a 23% year-over-year increase, with lymphedema revenue at $62.2 million and airway clearance revenue at $13 million.

Gross margins improved by 250 basis points to 76.5%, and adjusted EBITDA rose to $3.7 million, indicating strong operational execution and margin expansion.

The company updated its full-year 2026 revenue guidance to $360-$368 million, reflecting confidence in commercial execution and the inclusion of revenue from the Lymphotek acquisition.

Tactile Systems Tech accelerated its AI platform for Medicare prior authorization, demonstrating operational agility and readiness for new Medicare requirements.

Management expressed confidence in strategic initiatives, such as the launch of next-generation AfloVest and integration of Lymphotek’s technology, aimed at driving long-term growth.

Full Transcript

Sam Bensinger (Investor Relations)

Good afternoon and thank you for joining the call today. With me from Tactile’s management team are Sherry Dodd, Chief Executive Officer, and Elaine Berkemeyer, Chief Financial Officer. Before we begin, I’d like to remind everyone that our remarks and responses to your questions today may contain forward looking statements that are based on the current expectations of management and involve inherent risks and uncertainties. These could cause actual results to differ materially from those indicated, including those identified in the Risk Factors SECtion of our Annual report on Form 10K as well as our most recent 10Q filing to be filed with the SECurities and Exchange Commission. Such factors may be updated from time to time in our filings with the SEC, which are available on our website. We undertake no obligation to publicly update or revise our forward looking statements as a result of new information, future events or otherwise. This call will also include references to certain financial measures that are not calculated in accordance with Generally Accepted Accounting Principles or GAAP. We generally refer to these as non-GAAP financial measures. Reconciliations of those non-GAAP financial measures to Most comparable measures calculated and presented in accordance with GAAP are available in the Earnings Press release on the Investor Relations portion of our website. With that, I’ll now turn the call over to Sherry.

Sherry Dodd (Chief Executive Officer)

Thanks. Good afternoon everyone and welcome to our first quarter 2026 earnings call. Here with me is Elaine Berkemeyer, our Chief Financial Officer.

Elaine Berkemeyer (Chief Financial Officer)

Thanks, Sherry. Unless noted otherwise, all references to first quarter financial results are on a GAAP and year over year basis. Total revenue in the first quarter increased by $14 million, or 23% to $75.3 million by product line. Sales and rentals of lymphedema products, which includes our Flexitouch, Entre, Nimble and lymphotex systems, increased $11.7 million, or 23% to $62.2 million, and sales of our airway clearance products, which includes our AfloVest system increased $2.3 million, or 22% to $13 million. Growth was broad based and reflected strength across both volume and revenue per unit, including higher shipments, strong collections and a favorable mix across payer and product categories. Continuing down the P and L Gross margin was 76.5% of revenue compared to 74% in the first quarter of 2025. The increase in gross margin was attributable to primarily to lower manufacturing costs, stronger collections and favorable product and payer mix reflected in our revenue. Importantly, these improvements reflect structural enhancements in the business rather than temporary cost actions. First quarter operating expenses increased $9.3 million, or 19% to $59.1 million. The change in GAAP operating expenses reflected a $5.2 million increase in sales and marketing expenses, a $1 million increase in research and development expenses, and a $3 million increase in reimbursement, general and administrative expenses. As we discussed previously, we are annualizing investments made in 2025 while continuing to invest in IT infrastructure and automation to support long term growth. Despite these ongoing investments, operating loss decreased $3 million to 66% to $1.5 million. Interest income decreased $0.2 million or 26% to $0.7 million due to our decreased cash position. Interest expense decreased $0.4 million or 93% to $28,000. Income tax expense was $0.9 million compared to an income tax benefit of $1.1 million. Net loss decreased to $1.2 million or 41% to $1.8 million or $0.08 per diluted share compared to $3 million or $0.13 per diluted share. Adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) increased to $3.7 million compared to an adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) loss of $0.3 million in the prior year, with margin expanding to 4.9% from negative 0.4% reflecting a meaningful improvement in operating leverage. With respect to our balance sheet, we had $75 million in cash and cash equivalents and no outstanding borrowings at quarter end. This compares to $83.4 million in cash and no outstanding borrowings as of December 31, 2025. The change in cash during the quarter primarily reflects the LymphaTech acquisition share repurchases and normal seasonal items such as bonus payments. We continue to see improvement in working capital efficiency, including a meaningful reduction in days sales outstanding. Turning to review of our 2026 outlook for the full year 2026, we are raising our guidance and now expect total revenue in the range of 360 to $368 million, representing growth of approximately 9% to 12% year over year. This guidance assumes both our lymphedema and airway clearance businesses will grow in a similar overall range, with airway clearance growing modestly faster. The increase in guidance is driven by three primary factors. First, we continue to expect strength in the commercial execution across the business. Second, we have included the contribution from lymphoteg. Third, we have incremental early confidence in how the Macs are navigating the new prior authorization requirements we discussed on our last call. More broadly, we believe underlying demand remains durable and our tools and processes designed to support prior authorizations are tracking well against plan. While prior authorization approval data is still early and continuing to take shape, our outlook appropriately reflects discipline until we have a longer track record of consistent outcomes for modeling purposes. For the full year 2026, we expect our GAAP gross margins to be 76% to 77%, our GAAP operating expenses to increase 10 to 12% year over year. The increase relative to our prior outlook reflects one time acquisition and legal related costs, net interest income of approximately $3 million, a tax rate of 28%, and a fully diluted weighted average share count of approximately 22 to 23 million shares. We continue to expect to generate adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) of approximately 49 to $51 million in 2026. This outlook reflects the annualization of 2025 investments and continued strategic investments in 2026 which we believe are important to support long term growth and operating leverage. Our adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) expectation assumes certain non cash items including a stock compensation expense of approximately $9 million, intangible amortization of approximately $3.6 million, depreciation expense of approximately $3.2 million, litigation related expenses of approximately $1 million and one time acquisition related and integration cost of $1.3 million. With that, I’ll turn the call back to Sherri for some closing remarks. Sherry thank you Elaine.

Sherry Dodd (Chief Executive Officer)

We are encouraged by a strong balanced start to the year and the trajectory of our business. Our Q1 results demonstrated broad based performance and reflect disciplined execution, improving productivity from a fully built commercial organization and the increasing benefits from investments we have made in technology and infrastructure. As we look ahead, our focus remains on the fundamentals that matter most expanding access to care, innovating across our product portfolio and enhancing lifetime patient value. While we remain mindful of near term adjustments related to Medicare prior authorization. Ultimately, we believe this change reinforces our emphasis on clinical rigor, access, durability and long term reimbursement stability and we are well positioned to navigate it. We are operating from a position of strength supported by a resilient balance sheet, multiple growth levers in motion and a clear strategy to translate consistent execution into sustained growth over time. With that operator, we’ll now open the call for questions.

OPERATOR

Thank you. We will now be conducting a question and answer session. If you would like to a question,sk a question, question, please press Star one on your telephone keypad. A confirmation tone will indicate your line is in the question queue. You may press Star two if you would like to remove your question from the queue. For participants using speaker equipment, it may be necessary to pick up your handset before pressing the star keys again. That is Star one to ask a question and our first question will come from Ryan Zimmerman with btig.

Ryan Zimmerman (Equity Analyst)

Good afternoon and congrats on a nice start to the year here. I want to ask about some of the dynamics that are starting to occur in second quarter. Sherry, I think you called out some pull forward dynamic with lymphedema sales ahead of 2Q. And so one I think if I look at the beat versus where you’re raising guidance came in, there’s about a $1.7 million difference there. I just want to understand if that was the pull forward effect. And then just anecdotally kind of what you’re seeing with the Macs in 2Q, how they’re responding to this, how physicians …

Full story available on Benzinga.com

This post was originally published here

Firefly Aerospace (NASDAQ:FLY) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://edge.media-server.com/mmc/p/j83wnajm/

Summary

Firefly Aerospace reported record quarterly revenue of $81 million, with significant contributions from its Blue Ghost lunar lander and Electra spacecraft programs.

The company announced a new partnership with Nvidia to enhance its Ocula Lunar Imaging Service, enabling faster data processing in cislunar space.

Firefly Aerospace secured agreements with the US Space Force for the space-based interceptor program and continued progress on its reusable Eclipse rocket.

The company is scaling up its infrastructure, including expanding clean room facilities, to meet the increasing demand for lunar missions and other space ventures.

Management reiterated the 2026 revenue outlook of $420 million to $450 million, supported by strong demand signals from NASA and national security sectors.

Full Transcript

OPERATOR

Greetings. Welcome to The Firefly Aerospace First Quarter 2026 Financial Results Conference Call. At this time all participants are in a listen only mode. A question and answer session will follow the formal remarks. To ask a question during the session, you will need to press star 11 on your telephone. You will then hear an automated message advising your hand is raised to withdraw your question. Please press star 11 again. Please note this conference call is being recorded. I will now turn the conference over to Michael Sheets, Firefly Director of Investor Relations. Michael, you may begin.

Michael Sheets (Director of Investor Relations)

Thank you operator. Hello there and may the Fourth be with you. I’m Michael Sheets and welcome to Firefly’s first Quarter Financial Results Call. I’m pleased to be joined on the call by CEO Jason Kim and CFO Darren Ma as we report for the period ending March 31, 2026. Today’s call will include forward looking statements including, but not limited to, statements the company will make about its future financial and operating performance, growth strategy and market outlook. Actual results may differ materially from those contemplated by these forward looking statements. Factors that could cause the actual results and trends to differ materially are set forth in our annual and quarterly reports filed with the SEC. Firefly assumes no obligation to update any forward looking statements which speak only as of their respective dates. Also in this call we will discuss both GAAP and non GAAP financial measures. A reconciliation of GAAP to non GAAP measures is included in the first quarter 2026 earnings release. Unless otherwise stated, financial information referenced in this call will be non-GAAP. Our earnings press release, SEC filings and a replay of today’s call can be found on our investor relations websiteat investors.fireflyspace.com Now I’ll turn the call over to Jason.

Jason Kim (Chief Executive Officer)

Thank you Michael and Welcome to our first quarter 2026 earnings call. Firefly opened the year with strong execution and increasing momentum driven by major government programs that align directly with our core capabilities. We delivered record quarterly revenue of $81 million. The acceleration of the Artemis program combined with NASA’s moon base initiative calls for monthly robotic lunar landings and reinforces the demand signals we’ve been building toward. Our early investments to scale Blue Ghost production and our milestone as the first commercial company to land on the Moon successfully position us to be a critical commercial partner as NASA expands lunar operations. With three additional missions ahead, we’re already executing toward the goal. We also advanced our Ocular Lunar Imaging Service through a new partnership with NVIDIA, enabling on orbit processing for faster, more actionable data in cis-lunar space on the National Security Front Firefly subsidiary Saitek secured an agreement with the US Space Force to support the space based interceptor program under Golden Dome. We are concurrently delivering and improving the value of our AI enabled data processing through the US Space Force’s operational forged missile defense system within launch. The capacity constrained market is driving increased demand for Alpha following its successful return to flight. We also completed the Victus DM responsive launch demonstration and made steady progress on our reusable Eclipse rocket in the first quarter. The pace of change in the space economy is accelerating and Firefly is scaling up our existing revenue generating capabilities to meet the demand across every line of business for those new to Firefly. We are a space and defense company delivering innovative hardware and software to perform the hardest missions in space for national security, exploration and commercial technology. Our hardware is represented by four revenue generating products, our Blue Ghost Lunar Landers, Electra Satellite orbiters, Small lift Alpha rockets and Medium lift Eclipse rockets. Firefly’s software Portfolio falls under SciTech’s AI enabled defense systems which are proven in national security operations. The industry tailwinds behind artificial intelligence and data centers are fueling operational realities for our company as we deliver crucial no fail systems in support of the US and our allies. We are meeting the US Government’s call for commercial investment, speed and scale in defense and exploration. Our advanced technology products and funding of infrastructure include upgrades and expansion of Firefly’s co located spacecraft and rocket factories, clean rooms and test ends as well as our data centers and classified facilities. Now, turning to our business updates in the first quarter we completed new milestones across each of our product lines and services. The Lunar Opportunity is here. Recent milestones including the NASA moon base event, Artemis 2, successful lunar orbit and our Blue Ghost moon landing and surface operations ignited the industry and the world. The Moon is now a permanent destination. NASA’s moon based plan represents a dramatic acceleration of the Artemis program with a detailed pathway to irregular cadence emissions to the surface and persistent support from satellites in lunar orbit. Our prior growth strategy was to extend from one moon landing a year to multiple a year and now we have an amplified demand signal from NASA. The agency’s objective is to provide monthly robotic landings on the Moon’s surface starting next year, as well as larger lander missions to support the required lunar infrastructure for a permanent presence. The first two phases of the NASA Moon base architecture taking place over the next seven years represents a $20 billion program with multiple shots on goal opportunities for Firefly. When you combine Blue Ghost, the only commercial lander to operate successfully with our Electra spacecraft, we provide the ideal system to deliver and support many of the payloads and capabilities needed such as navigation, orbital communications, surface observation, power infrastructure, exploration drones, rovers, cargo and support systems for humans on the Moon. The Moon is a vastly untapped resource and Firefly is the tip of the spear in the routine deliveries and services that NASA needs to support a permanent presence on the Moon. Last week we heard NASA Administrator Isaac Mims request in a Congressional hearing to template Blue Ghost and launch with frequency. As stated earlier, we are already building towards this. In the first quarter we made significant progress on our new clean room which is four times the size of our existing clean room. This enables a production line of lunar landers for frequent missions. We are leveraging our vertical integration to scale up while also investing in our Blue Ghost supply chain. We are working closely with each major supplier to ensure they are ramping up with us through through long term agreements and strategic inventory in place to ensure quality, schedule and quantities of delivery. Meanwhile, assembly of our Blue Ghost lander and Electra orbiter is well underway for Blue Ghost Mission 2 and we’re on track to complete assembly and payload integration this summer. We named Blue Ghost Mission 2 riders to the dark as our team charges toward another historic milestone, conducting the first American landing on the Moon’s far side carrying both NASA and commercial payloads. We are making progress on our additional lander contracts with the blue Ghost Mission 3 Preliminary Design Review complete which verifies the vehicles designed to deliver payloads to the Moon’s Gruitheisen domes. The team is now preparing to complete the critical design review for Mission 3 while also getting ready to complete the preliminary design review for Blue Ghost Mission four to the Moon’s south pole. Moving to Electra we’re pleased to add NVIDIA as another Firefly partner with our first collaboration included as part of our Ocularr Lunar Imaging Service, NVIDIA’s Jetson module was embedded in the high resolution Lawrence Livermore National Laboratory telescopes and delivered to Firefly spacecraft facility for integration on our Electra Orbital Vehic. This Electra will first serve as a transfer vehicle and communications relay for Blue Ghost and then begin our Oculus service to support advanced lunar surface mapping, mineral detection and reconnaissance for five years in lunar orbit. Our Ocular data will be rapidly processed onboard Electra and autonomously transmitted back to Earth utilizing the NVIDIA Jetson module. Combined with Firefly scitech enabled AI software. This allows Firefly to mitigate downlink constraints from the Moon by processing data on orbit before it is transmitted to Earth as real time actionable insights for government and commercial customers. Firefly’s AI software will further enable advanced space domain awareness Our AI algorithms and data fusion technologies are already proven in critical national security missions in Earth orbit. Our software will enable Electra to leverage multiple data feeds on board to more accurately track objects and provide timely situational awareness of space operations occurring in the cislunar domain. These capabilities are transferable to Electra’s upcoming Space Domain Awareness mission for the Defense Innovation Unit Sinequan project. This mission also incorporates high resolution Lawrence Livermore National Laboratory telescopes just like the ones enabling our Oculus service. After completing the critical design review for the mission, the team has begun building and testing ELECTRO flight hardware. Additionally, in the first quarter, Firefly completed critical Electra test milestones for Blue Ghost Mission 2, including separation testing to demonstrate Electra’s mechanisms that will deploy the European Space Agency’s Lunar Pathfinder satellite following a separation from our Blue Ghost lander. This further highlights Electra’s ability to operate and deploy critical high mass payloads across cislunar space. The team also completed the initial interoperability testing to ensure our Electra orbiter communicates with Blue Ghost on the Moon’s far side and acts as a backup communications relay for NASA’s Lucy Night payload. This enables NASA’s radio telescope to operate for up to two years on the surface even without direct line of sight to Earth. This relay service on Electra is the pathway to our commercial offering, delivering alternative communications options that reduce blackout periods and strengthen connectivity for multiple future lunar missions for Firefly and our customers. As we saw at the recent space symposium event, there is growing demand for Electra’s robust capabilities combined with our AI powered software to support dynamic space operations for national security, space exploration and international missions. The demand includes space maneuverability to novel orbits, deorbit services for multiple spacecraft, and long haul communications. At the symposium, US Space Force Major General Purdy further emphasized the need for enhanced national security capabilities in cislunar space, including transportation, communications and navigation systems beyond Earth orbit. Once deployed, those assets require protection and continuous monitoring, which is best done from the moon as the ultimate high ground. Our electric vehicles are well positioned to enable these missions with high thrust, precision SPECTRE engines, ample fuel and payload capacity, and AI software. As General Saltzman said in his April 30 congressional testimony, speed, scale and clear demand signals are critical and Electra positions us to capture that with responsive on orbit capability. We’ll continue to scale up our Electra production line as demand steadily increases. Moving to our Saitek software offerings under our spacecraft business, we are pleased to be selected by the US Space Force to support the space based interceptor program under Golden Dome. In a Space Force press release just a week ago, this program was announced to develop a space based missile defense interceptor system that will demonstrate capability integrated into the golden dome architecture. By 2028. Space Force awarded a select group of companies including Firefly subsidiary SciTech with contracts totaling up to $3.2 billion. This critical program will enable next generation space based tracking and advanced interceptors integrated with artificial intelligence to counter the maneuverability and lethality of threats. As the prime contractor, we continue to execute on the operational US Space Force Forge system providing a modernized AI enabled missile warning and tracking architecture. We’re rapidly processing vast amounts of data from satellites across all orbits from LEO to MIO to GEO to deliver high quality mission critical information to our warfighters to defend against threats. After the Space Force operationally accepted our Forge system last year, in the first quarter we were awarded a 109 million dollar engineering change proposal to accelerate and expand data center delivery. This critical system processed thousands of threats in the first 30 days of the Iran conflict to help protect our war fighters. The team further completed the interim ground readiness review for the Space Development Agency. As part of our role in delivering the mission management and data fusion ground components for the proliferated warfighter Space architecture satellite constellation tranche 1 tracking layer. More recently, the Air Force Research Laboratory awarded us a contract to support development of the advanced algorithm R and D and verification architecture by implementing deep learning and advanced AI algorithms on small size, weight and power processors. This capability supports enhanced target detection, tracking and custody and is conducive to future on orbit processing missions. Last week we also heard Chairman of the Joint Chiefs of Staff General Kaine underscore in a congressional hearing the urgent need for critical investments in space based command and control, artificial intelligence and advanced surveillance and reconnaissance. This capability counters modern multi domain threats where operations are coordinated and synchronized across air, land, sea, space and cyber domains. Our proven AI software and …

Full story available on Benzinga.com

This post was originally published here

BWX Technologies (NYSE:BWXT) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://edge.media-server.com/mmc/p/7xp2ev8c/

Summary

BWX Technologies reported a strong start to 2026 with a 26% revenue increase, 11% of which was organic, a 14% rise in adjusted EBITDA, and a 22% growth in earnings per share, all surpassing expectations.

The company’s backlog reached $8.7 billion, up 77% year-over-year, supported by robust bookings in government and commercial sectors, providing clear visibility for future growth.

BWX Technologies announced the acquisition of Precision Components Group to expand its US commercial nuclear manufacturing capacity, with plans to establish a greenfield plant in Mount Vernon, Indiana.

Government operations saw a 4% revenue increase, driven by strong bookings and operational efficiencies, with a segment backlog approaching $7 billion.

Commercial operations exceeded expectations with a 121% revenue increase, driven by robust growth in commercial nuclear and medical sectors, and contributions from Connectrix.

The company increased its 2026 revenue guidance to at least $3.75 billion, with adjusted EBITDA guidance raised to $650 million to $665 million.

BWX Technologies plans to focus on margin expansion, cash generation, and capturing new high-value contracts across defense and commercial nuclear markets.

Management expressed confidence in meeting or exceeding medium-term financial targets and highlighted the importance of local manufacturing capacity in the US for future growth.

Full Transcript

OPERATOR

Ladies and gentlemen, welcome to BWX Technologies’ first-quarter 2026 earnings conference call. At this time, all participants are in listen only mode. Following the company’s prepared remarks, we will conduct a question and answer session and instructions will be given at that time. I would now like to turn the call over to our host, Chase Jacobson, BWXT’s vice president of Investor Relations. Please go ahead.

Chase Jacobson (Vice President of Investor Relations)

Thank you. Good evening and welcome to today’s call. Joining me are Rex Jebeden, President and CEO, and Mike Fitzgerald, Senior Vice President and CFO. On today’s call, we will reference the first quarter 2026 earnings presentation that is available on the Investors section of the BWXT website. We will also discuss certain matters that constitute forward looking statements. These statements involve risks and uncertainties including those described in the safe harbor provision found in the investor materials in the Company’s SEC filings. We will frequently discuss non GAAP financial measures which are reconciled to GAAP measures in the appendix of the earnings presentation that can be found on the Investors section of the BWXT website. I would now like to turn the call over to Rex.

Rex Jebeden (President and CEO)

Thank you Chase and good evening to all of you. We had a great start to 2026 with very strong first quarter results. Revenue grew 26%, 11% of which was organic adjusted, EBITDA grew 14% and earnings per share grew 22%, all ahead of expectations. Outperformance in the quarter was driven by improved throughput, favorable pacing of work and exceptional operational execution across our business lines. We ended the quarter with a backlog of 8.7 billion, up 77% year over year and 19% sequentially supported by robust bookings in government and consistent backlog and commercial, providing clear visibility to future growth. Demand for commercial nuclear power components and services continues to accelerate across the U.S. canada and Europe as projects launch. We believe that localized manufacturing capacity will increasingly differentiate bwxt, making the establishment of US Commercial manufacturing footprint to complement our Canadian operations a strategic priority. To that end, in April we announced the acquisition of Precision Components Group pcg, a U S based manufacturer of complex heat transfer components for the US naval and commercial nuclear markets. With two facilities in more than 400 highly skilled employees, PCG represents our first step toward building domestic US commercial nuclear manufacturing capacity. While most of PCG’s current revenue and backlog is related to cable programs, its facilities have immediately available capacity that we intend to utilize for the commercial market with products such as reactor internals, pressurizers, heat exchangers and reactor head assemblies. Beyond the PCG acquisition, we intend to expand our US Commercial manufacturing footprint, likely with a greenfield plant at our Mount Vernon, Indiana site on the Ohio River. This facility will be capable of producing larger heavy nuclear equipment including steam generators and reactor pressure vessels. Ultimately, our goal is to build scalable US Commercial nuclear manufacturing operations that can serve US and global SMR and large reactor projects. By adding domestic capacity, we are positioning BWXT to meet rising commercial demand while creating meaningful synergies with our existing US Operations. Beyond commercial power, we are making disciplined growth investments across the portfolio, supporting existing businesses, adding new technologies and capabilities, and pursuing opportunities in advanced nuclear and other national security applications. Turning to segment results and market outlook Government operations revenue was up 4% and adjusted EBITDA was up 1% in the quarter, slightly ahead of our expectations. We had strong bookings including 1.4 billion from the second portion of the pricing agreement for naval reactors awarded last year and long lead material procurement contracts for out year production. This led to segment backlog of nearly 7 billion, up 25% sequentially and 93% year over year. In naval propulsion. We are driving operational efficiencies in our plants which contributed to our good margin performance in the quarter. We anticipate continued revenue growth with a steady pace of Virginia class production, growth in the Columbia class and early work on the next board class ship set. The President’s FY27 budget request supports these programs and shipbuilding generally, further reinforcing our confidence in longer term growth rates and special materials. Our legacy programs delivered solid results and our Defense Fuels Enrichment and HPDU programs are progressing in line with early program schedules specific to Defense fuels enrichment. We completed construction of the Centrifuge Manufacturing Development facility earlier in the year and have begun prototyping the first units in April. We engaged with the NRC regarding our plans to build an H and U enrichment facility in Irwin, Tennessee. This engagement is an important milestone as it creates alignment with regulators in the NRC approval process for our new large HPDU contract. We are organizing the supply chain and preparing for construction of the new facility in Jonesboro, Tennessee. That program will ramp through 2026 and continue over the next several years before transitioning to commissioning and production. The growth potential in special materials is exciting and we continue to pursue new scopes with existing customers and evaluate entry points to new markets. Technical Services has delivered strong equity income growth over the past few years with multiple strategic wins. We are pursuing new opportunities in the DOE market and in other new markets with the next wave of contract awards expected over the next 12 to 18 months. Moving to Microreactors and advanced nuclear fuels. The market is evolving rapidly in land based defense, commercial and space markets. We continue to see strong demand across the board including for TRISO fuel for demonstration reactors and future commercial projects with multiple reactor developers. Of note, Kairos, with whom we have a collaboration agreement on TRISO, recently began construction of its Hermes 2 reactor for Google in Oak Ridge, Tennessee. Finally, we are continuing our close engagement with the army on the Janus program. Turning now to commercial operations Results in the quarter were well ahead of our expectations. Organic revenue grew 39% and total revenue rose 121% with robust double digit growth in commercial, nuclear and medical and contribution from Connectrix. While the outperformance was partially due to timing of outage work and progress on large component manufacturing. We also improved operational performance with accelerated throughput and reduced lead times following an 85% increase in backlog in 2025. Backlog was flat sequentially in the first quarter but still up 33% year over year, supporting our expectation for low teens organic growth in commercial power this year the outlook for new build nuclear projects remains very positive. Notably, the US and Japan announced plans to invest up to 40 billion to build up to 3 GW of GE Hitachi SMRs in the southeastern United States. Our role as the reactor vessel supplier on the first GE Hitachi BWRX300SMR in Canada puts us in a good competitive position for these future projects given BWX Technologies’ industrial scale and engineering and design capabilities. Customers are increasingly coming to BWXT to supply critical nuclear components for their current and future SMR and large scale nuclear projects which should lead to further backlog growth over the next 12 months. Connectrix continues to exceed the acquisition business case, having delivered another very strong quarter. A key highlight in the quarter was Conetrix being selected as the design and fabrication partner for a UK Tritium loop facility which will be the world’s largest and most advanced tritium fuel cycle facility. This presents an entry point for engineering, services and specialty equipment manufacturing in the exciting nuclear fusion market. With that, I will now turn the call over to Mike.

Mike Fitzgerald (Senior Vice President and CFO)

Thanks Rex and good evening everyone. I’ll begin with total company financial highlights on slide 4 of the earnings presentation. First quarter revenue was $860 million up 26% year over year with 11% organic growth. Strong performance in commercial operations was complemented by steady growth in government operations. Adjusted EBITDA was $148 million, up 14% year over year, driven by robust growth in commercial operations and modestly higher government operations. Partially offset by higher corporate expense relative to an unusually low level in last year’s first quarter. Adjusted earnings per share were $1.12, up 22% reflecting strong operating performance and approximately $0.08 of higher non operating contributions. Our adjusted effective tax rate for the quarter was 15.8%, benefiting from timing of stock compensation. Our updated full year tax rate guidance of less than 21.5% is modestly higher than last year’s rate, reflecting strong growth in international earnings, mainly from Canada. First quarter free cash flow was $50 million, a strong result for what is typically our seasonally weakest quarter. Reflecting solid earnings and effective working capital management, capital expenditures in the quarter were $43 million. We continue to expect our full year capital expenditures to be around 6% of sales. However, it is possible that CAPEX may exceed that level in future periods as we advance targeted growth investments including expansion of US Commercial nuclear manufacturing capacity and advanced nuclear and fuel capabilities. Given the significant business we expect to capture, we are carefully balancing these strategic investments with our financial return metrics as we evaluate the numerous growth initiatives across the business. Moving to the Segment Results on Slide 6 In government operations, first quarter revenue was up 4% with growth in special materials and naval propulsion offsetting lower microreactor volumes. Adjusted EBITDA in The segment was 118 million, up 1%, resulting in an adjusted EBITDA margin of 20.4% as better revenue, solid operating performance and timing of technical services income benefited margin. Given first quarter performance, we now expect government operations margins to exceed 19% for the year. Turning to commercial operations, revenue was up a robust 121%, including 39% organic growth, reflecting increases in both commercial power and medical and contribution from Connectrix. Growth exceeded expectations due to increased throughput on large commercial nuclear component projects mainly associated with a Pickering life extension and better than expected performance from Conetrix. Adjusted EBITDA in The segment was $36 million, up 162% from last year. Adjusted EBITDA margin in the quarter was 12.9%, with higher sales and strong execution offsetting the impact of growth investments as we continue to scale the business. Turning to our 2026 guidance on Slide 7 and 8 of the earnings presentation, which I will note does not include contribution from the recently announced PCG acquisition. We expect revenue of at least $3.75 billion, up high teens compared to 2025. In government operations, we expect low teens growth with over half coming from the defense fuels and HPDU contracts. In commercial operations, we increased our revenue growth expectation to approximately 30% driven by low teens growth in commercial power, high teens medical growth and a full year of contribution from Conetrix which as mentioned has outperformed our expectations to date. For adjusted EBITDA. We are increasing the guidance range by $5 million on each end resulting in revised adjusted ebitda guidance of $650 million to $665 million. Regarding the cadence of operating earnings, we continue to expect our full year results will be slightly more back half weighted than usual with about 55% of full year EBITDA anticipated in the second half and we expect second quarter EBITDA to be roughly in line with to slightly below first quarter levels. These assumptions lead to non GAAP earnings per share guidance of $4.60 to $4.75 with the increase driven by higher operating earnings. We expect free cash flow of $315 million to $330 million inclusive of mid to high teens operating cash flow growth supporting continued reinvestment and long term shareholder value creation. Regarding the recently announced acquisition of PCG, the business generated approximately $125 million of revenue with low double digit EBITDA margins in 2025 and we anticipate mid single digits revenue growth in 2026. The acquisition, which will be included in our commercial operations segment is expected to close in the second half of the year. As such, our annual financial guidance does not include contributions from PCG at this time. Overall, we’re off to a strong start in 2026. Our robust backlog provides us great visibility for the remainder of the year allowing us to focus on margin expansion, cash generation and capturing new high value contracts across the defense and commercial nuclear markets. With that, I will turn it back to Rex for closing remarks.

Rex Jebeden (President and CEO)

Thank you Mike. It is an exciting time at bwxt. We are delivering on our commitments to customers and shareholders and driving value through process optimization, technology adoption and disciplined growth investments. Our 2026 guidance supports meeting or exceeding the medium term financial targets we introduced at our Investor Day in February 2024. We look forward to providing an update at our next Investor Day this fall. As I wrote in a recent Washington Times op ed, BWXT is not betting on a horse, we are betting on the race. We participate across the nuclear value chain in defense and commercial markets and as a merchant supplier and a technology provider enabling us to win across a broad range of competitive outcomes. We have record backlog, unprecedented demand and the financial strength to continue investing for growth. We intend to build on our market leading position in nuclear solutions for defense and commercial nuclear markets, thereby Driving long term shareholder value. And with that, we look forward to your questions.

OPERATOR

We will now begin the question and answer session. Please limit yourself to one question and one follow up. If you would like to ask a question, please press star one to raise your hand. To withdraw your question, press star one. Again, we ask that you pick up your handset for better sound quality when asking question to allow for optimum sound quality if you are muted locally. Please remember to unmute your device. Please stand by while we compile the Q&A roster. Our first question comes from Matt Akers from BNP Paribas. Please go ahead.

Matt Akers (Equity Analyst)

Hey, good afternoon guys. Thanks for the question. I may have missed this, but did you say how much you’re planning to pay for pcg? And then I guess another question on the sort of footprint build-out. As you mentioned, this is sort of the first step toward building out the footprint and sort of how should we think about the remaining steps? Is it more kind of …

Full story available on Benzinga.com

This post was originally published here

Fabrinet (NYSE:FN) reported third-quarter financial results on Monday. The transcript from the company’s third-quarter earnings call has been provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://edge.media-server.com/mmc/p/j8jygw47/

Summary

Fabrinet reported record revenue of $1.214 billion for Q3 FY2026, a 39% year-over-year increase, driven by strong performance in telecom and interconnect revenue.

The company is actively working on narrowing the supply-demand gap in Datacom due to component shortages, with expectations for improvement over time.

Fabrinet has made strategic progress, including starting shipments for two Datacom transceiver programs to a hyperscale customer and preparing to ramp multiple merchant transceiver programs.

Non-optical communications also saw significant growth, with high-performance computing revenue up 25% from Q2, and the company is expanding its manufacturing capacity to meet demand.

Fabrinet made a minority investment in Raytech Semiconductor to enhance its capabilities in the co-packaged optics (CPO) space, positioning itself for future growth in advanced optical technologies.

The company expects Q4 revenue to be between $1.25 billion and $1.29 billion, with continued margin pressures due to FX headwinds and ramp costs, but remains optimistic about long-term growth.

Full Transcript

OPERATOR

Good afternoon. Welcome to Fabrinet’s financial results conference call for the third quarter of fiscal year 2026. At this time, all participants are in a listen only mode. Later, we will conduct a question and answer session and instructions on how to participate will be provided at that time. As a reminder, today’s call is being recorded. I would now like to turn the call over to Gaura Tumadanian, Vice President of Investor Relations. You may begin.

Gaura Tumadanian (Vice President of Investor Relations)

Thank you Operator and good afternoon everyone. Thank you for joining us on today’s conference call to discuss Fabrinet’s financial and operating results for the third quarter of fiscal year 2026 which ended March 27, 2026. With me on the call today are Seamus Grady, Chairman and Chief Executive Officer and Chavez Vera, Chief Financial Officer. This call is being webcast and a replay will be available on the Investor section of our website located@investor.fabrinet.com during this call we will present both GAAP and non GAAP financial measures. Please refer to the Investors section of our website for important information including our earnings press release and investor presentation which include our GAAP to non GAAP reconciliation as well as additional details of our revenue breakdown. In addition, today’s discussion will contain forward looking statements about the future financial performance of the company. Forward looking statements are subject to risks and uncertainties that could cause actual results to differ materially from management’s current expectations. These statements reflect our opinions only as of the date of this presentation and we undertake no obligation to revise them in light of new information or future events, except as required by law. For a description of the risk factors that may affect our results, please refer to our recent SEC filings, in particular the section captioned Risk Factors in our Form 10Q filed on February 3, 2026. We will begin the call with remarks from Seamus and Chava, followed by time for questions. I would now like to turn the call over to Fabrinet’s Chairman and CEO Seamus Grady.

Seamus Grady (Chairman and Chief Executive Officer)

Seamus thank you, Gaura Good afternoon everyone and thanks for joining our call. Today we delivered an outstanding financial performance in the third quarter along with several notable achievements that we believe can extend our strong growth Trends into the fourth quarter and fiscal year 2027. Revenue is above our guidance range at a record $1.214 billion, with year over year growth accelerating to an impressive 39%. Record non GAAP EPS of $3.7 also exceeded our guidance range, reflecting continued excellent execution. Looking at our quarter by product area, Optical Communications revenue growth increased to 35% from a year ago. This was driven by 55% year over year growth in telecom revenue, which was fueled by strong growth in a wide range of products within telecom datacenter. Interconnect revenue grew a robust 90% from a year ago and 38% from Q2 and we believe strong longer term Data Center Interconnect (DCI) growth trends remain firmly intact. This remarkable telecom performance more than offset softer than expected Datacom revenue, which grew 4% year over year but declined 6% from Q2. Underlying Datacom demand remains exceptionally strong. In fact, demand during the quarter far exceeded what we were able to ship, meaning our reported revenue does not fully reflect the true momentum of the business. Right now demand is outpacing the broader supply of certain components and we are actively working to narrow that gap. While we expect the supply demand imbalance to persist into the fourth quarter, we remain optimistic that supply conditions will improve over time. The strong demand we are seeing today positions us well as that improvement unfolds. As we have outlined, our Datacom strategy is to continue supporting the strong demand trends we are seeing with our largest customer while actively expanding into new high growth channels such as direct engagement with hyperscalers and partnerships with merchant vendors. With that in mind, we are happy to report that we have made meaningful tangible progress on both fronts. First, we’re excited to share that we have successfully completed qualification and have already begun shipping two Datacom transceiver programs directly to a hyperscale customer with initial ramp starting in the fourth quarter. We expect volumes to ramp steadily throughout fiscal 2027 with these programs becoming a meaningful contributor to our Datacom revenue over time. Second, building on the groundwork laid over the last several quarters, we are on track to qualify and ramp multiple merchant transceiver programs, including several for data center scale out applications with existing and new customers. We expect production to begin in the second half of the calendar year, aligning with the early part of fiscal 2027 with additional ramps progressing into the second half of the fiscal year. We expect this combination of hyperscale and merchant program wins to further diversify our Datacom revenue and provide multiple new growth vectors in the new year and beyond. In non optical communications, revenue jumped 52% year over year and 8% sequentially from Q2. This growth was driven primarily by high performance compute revenue which continues to ramp as we support our customers transition to their latest product generation. At the same time, we are seeing encouraging traction beyond the current ramp with new program wins and expanded scope across additional products that we will be manufacturing to support their accelerated computing infrastructure. We’re also increasing capacity to align with the customer’s ambitious growth plans, reflecting a deepening and increasingly strategic relationship. Automotive revenue moderated in the third quarter as anticipated with revenue decreasing modestly from Q2. This decline was more than offset by continued growth in industrial laser revenue which was up 9% from a year ago and 7% from Q2. An important area of strategic focus for us over the past several years has been CO packaged Optics or CPO. In this space we are deepening our engagement with customers across the CPO ecosystem including optical components, external laser source pluggables as well as other integrated precision optical packaging solutions. Building on our long standing silicon photonics expertise. CPO relies heavily on advanced semiconductor packaging technologies and we have been actively investing to expand our capabilities in this area with a focus on scalable, high quality manufacturing processes and broader system level integration. This includes leveraging and extending our in house silicon photonics expertise while also partnering with key technology providers to enhance our ability to deliver more integrated end to end manufacturing solutions. With that backdrop, we have made a minority investment in Ray Tech Semiconductor Semiconductor, a Taiwan based provider of advanced wafer level packaging technologies. As an ecosystem partner. We already serve a number of common customers and expect this collaboration to further strengthen our capabilities and extend our offering. This investment supports our continued evolution from silicon photonics into more advanced packaging and integration solutions, reinforcing our role as a key manufacturing partner within the CPO ecosystem. Looking at our business as a whole, we are very excited by both the number and size of customer engagements for our advanced manufacturing services. The breadth and depth of these projects provides us with significant opportunities to demonstrate our differentiation and expertise that we’ve established as a key enabler for the success of our customers. Most Advanced Products as you know, we have been expanding our capacity to support our accelerating growth trends. We continue to make progress in the construction of Building 10, which will add 2 million square feet to our current 3.7 million square feet of space. With plans to be fully completed around the beginning of the new calendar year, we are on track to have a portion of building 10 ready by next month consistent with what we described last quarter. In addition to that, with our accelerated construction timeline, we now expect to commission an additional floor in this five storey structure by the end of September, with the rest of the building still scheduled to be completed by January. Beyond Building 10, we have sufficient land available at our campus in Chonburi for two additional buildings of more than 1 million square feet each. While this means we expect to have ample capacity available for the next several years, we continue to think ahead. In that context, we have recently acquired a building and land in the Nawanakhore Industrial Estate in Thailand not far from our Pinehurst campus. We have already begun renovations to make the existing 200,000 square foot building a world class clean room factory with sufficient space on the 8 acre site for additional expansion at a later time. In summary, our success in the third quarter extends well beyond our strong financial performance. We are particularly encouraged by the multiple new growth vectors we are adding across our Datacom business, while our diversified telecom portfolio continues to show solid momentum and our non optical communications segment expands further. This combination of execution and strategic progress reinforces our confidence in sustaining our growth trajectory, extending our leadership position in the fourth quarter and carrying that momentum into fiscal year 2027. Now I’d like to turn the call over to CHABA for more details on our third quarter results and our outlook for the fourth quarter.

Chavez Vera (Chief Financial Officer)

CIABA thank you Seamus and good afternoon everyone. We delivered another record breaking performance in the third quarter of fiscal year 2026. Revenue of $1.214 billion exceeded our guidance range, with revenue growth accelerating to a remarkable 39% from a year ago and 7% from the prior quarter. Strong execution and FX evaluation tailwinds led to non GAAP EPS of $3.72 that also exceeded our guidance range. Turning to revenue by Market in the third quarter, optical communications revenue was $889 million with revenue growth accelerating to 35% from a year ago and 7% from Q2. Within optical communications, telecom revenue was a record $628 million, climbing 55% from a year ago and 13% from Q2. Within telecom, revenue from Data Center Interconnect Modules or DCI jumped to $197 million, growing 90% from a year ago and 38% from the second quarter. Datacom revenue of $260 million increased 4% from a year ago, but moderated 6% from Q2 due to broadening component and material supply constraints in the quarter. Turning to non optical communications revenue reached $326 million, growing 52% year over year and 8% sequentially from Q2. This strong performance was once again driven primarily by continued momentum in our HPC program which delivered $107 million in revenue, up 25% from Q2. Automotive revenue declined slightly as anticipated to $115 million while industrial laser revenue increased to $44 million. As I discussed, the details of our P and L all expense and profitability metrics will be presented on a non GAAP basis unless otherwise Noted gross margin in the third quarter was 12.1%, a 10 basis point improvement from a year ago and a 30 basis point decline from Q2. As anticipated primarily due to foreign exchange headwinds. We continue to demonstrate operating leverage with operating expenses declining to 1.4% of revenue. This resulted in an operating margin of 10.7%, a 50 basis point improvement from a year ago and 20 basis point decline from Q2. Interest income was $7 million and we saw a foreign exchange evaluation gain of $7 million in the quarter. Our effective GAAP tax rate for the quarter was 6.7%. We expect our tax rate to moderate in Q4 resulting in a mid single digit effective GAAP tax rate for the year. Net income was a record $135 million or $3.72 per diluted share. Turning to our balance sheet, we ended the third quarter with cash and short term investments of $946 million, down $16 million from the end of Q2. Operating cash flow for the quarter was $53 million. Capital expenditure spending of $64 million reflects continued accelerated construction of Building 10 as well as capacity expansions to support the rapid growth across the business. As a result, free cash flow was an outflow of $11 million in the quarter. Before getting into our guidance, I want to provide some additional color on our recent capital allocation decisions. As Seamus mentioned, we have made a minority investment in Ray Tech Semiconductor Semiconductor to support our efforts in advancing manufacturing solutions for CPO. In April we completed a private placement of approximately $32 million for 20 million shares of Ray Tech Semiconductor, representing approximately a 14% position. This investment deepens our partnership and supports our joint efforts toward bringing CPO technology to market at scale. Early in the fourth quarter, we expect to complete the purchase of an 8 acre campus in Nawanakhore Industrial Estate, Thailand. Located approximately 15 minutes from our Pinehurst campus, the Nawanakhore facility currently consists of a 200,000 square foot building with additional space on the site for future expansion. We have already initiated minor renovations to support world class green room manufacturing capabilities and we expect to begin utilizing the space early next quarter. The total purchase price of $11 million will be reflected in our fourth quarter financials. With our very strong balance sheet, we are well positioned to deploy capital efficiently, support our growth initiatives and continue to generate superior returns while remaining committed to returning surplus cash to shareholders through our share repurchase program. In the third quarter we did not repurchase a meaningful number of shares. However, our share repurchase program remains active and we ended the quarter with approximately $169 million available under our current authorization. Now turning to the details of our guidance, we expect revenue in all major product categories to increase in the fourth quarter despite a broader supply constrained environment with Datacom growth expected to be more measured as we continue to navigate component availability that is not keeping pace with strong demand. At the same time, we are excited by the number of new customer programs coming online, which we expect will contribute more meaningfully to our performance in fiscal year 2027 than in the fourth quarter. With that backdrop, we expect total revenue to be in the range of 1.25 to $1.29 billion, representing year over year growth of approximately 40%. At the midpoint, we expect gross margin dynamics to be similar to Q3 with continued operating leverage as top line growth continues. As a result, we expect non GAAP EPS to be in the range of $3.72 to $3.87. In summary, our third quarter results were exceptional with record revenue and earnings that exceeded our guidance. As growth continued to accelerate, we also made strong progress against our longer term strategic priorities, establishing additional vectors of sustainable growth that we expect to begin contributing as early as the fourth quarter, positioning us to extend our strong track record into fiscal 2027 and beyond. Operator, we are now ready to open the call for questions.

OPERATOR

Thank you ladies and gentlemen. To ask the question, please press START 11 on your telephone, then wait for your name to be announced. To withdraw your question, please press Star one one again. Please stand by while we compile the Q and A roster. Thank you. And our first …

Full story available on Benzinga.com

This post was originally published here

Inspire Medical Systems (NYSE:INSP) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://edge.media-server.com/mmc/p/rm8dfkqw/

Summary

Inspire Medical Systems reported a 1.6% increase in first-quarter revenue to $204.6 million, despite challenges related to coding and reimbursement uncertainties and the Wiser program, which negatively impacted revenue by approximately $20 million.

The company is revising its full-year revenue outlook to $825 million to $875 million, citing ongoing coding and reimbursement challenges as well as the Wiser program impact, with a total estimated adverse impact of $120 million to $150 million for the year.

Inspire Medical Systems is focused on improving the coding and reimbursement process, providing proactive education, and increasing its field reimbursement team to support patient access and minimize disruptions.

Operationally, the company is prioritizing revenue-generating activities, maintaining disciplined cost management, and making targeted investments in long-term growth areas such as marketing, R&D, and operational efficiencies.

Management mentioned that Medicare has created a C code for Inspire 5 procedures, and commercial payers are maintaining CPT code 64568, but challenges remain with coding and reimbursement consistency.

The company expects sequential improvement in revenue and adjusted operating income in the second half of the year, with the fourth quarter expected to be the strongest.

The company continues to monitor the impact of GLP1 therapies on patient behavior and revenue, although the primary focus remains on resolving coding and reimbursement issues.

Full Transcript

OPERATOR

Good afternoon. My name is d’Alem and I’ll be your conference operator today. At this time I’d like to welcome everyone to the Inspire Medical Systems’ first quarter 2026 conference call. All lines have been placed on mute to prevent any background noise. After the speakers’ remarks, there’ll be a question and answer session. I’ll now hand the conference over to your first speaker, Esgi Yaja, the Vice President of Investor Relations at Inspire. You may begin the conference.

Esgi Yaja

Thank you d’Alem, and thank you all for participating in today’s call. Joining me are Tim Herbert, Chairman and Chief Executive Officer, and Matt Osberg, Chief Financial Officer. Earlier today we released financial results for the three months ended March 31, 2026. A copy of the press release is available on our website. On this call, management will make forward looking statements within the meaning of the federal securities laws. All forward looking statements, including without limitation those relating to our operations, financial results and financial condition, investments in our business full year 2026 financial and operational outlook and changes in market access in different aspects of coding or reimbursement are based upon our current estimates and various assumptions. Forward looking statements involve material risks and uncertainties that could cause actual results or events to materially differ. Accordingly, you should not place undue reliance on these statements. For a discussion of these risks and uncertainties. Please see our filings with the securities and Exchange Commission, including our periodic reports on Form 10-K and 10-Q, as well as the Form 10-Q which we filed this afternoon with the SEC for the quarter ended March 31, 2026. Inspire Medical Systems disclaims any intention or obligation, except as required by law, to update or revise any financial projections or forward looking statements, whether because of new information, future events or otherwise. This conference call contains time sensitive information and speaks only as of the live broadcast today, May 4, 2026. With that, it is my pleasure to turn the call over to Tim Herbert.

Tim Herbert (Chairman and Chief Executive Officer)

Tim thank you Esgi and thanks everyone for joining us today on the call. Today I will start by providing some key takeaways of our first quarter results including an update on coding and reimbursement. I will also provide some insight into our revised outlook for the year and we’ll then turn it over to Matt who will provide additional insights on our first quarter and full year financials. We will then open up the call for questions. First, I want to highlight how pleased we are with the team’s execution in the first quarter despite challenges related to coding and reimbursement uncertainty as well as the Wiser program. The organization delivered revenue growth and improved adjusted operating income and operating cash flow compared to the prior year period. In this environment, it is critical that we focus on the factors within our control. Our first quarter results demonstrate this as well as our focus on prioritizing revenue generating activities and maintaining disciplined cost management while continuing to make targeted investments to support long term growth. We believe these actions position the company well both in the near and long term. As we progress through the first quarter, we saw many developments with respect to coding and reimbursement and we are diligently working to establish a consistent methodology to coding of the Inspire 5 procedure. In the short term, the long term solution is to establish a new CPT code for a single lead Inspire system. This is a long process and if approved, we expect this new CPT code to become effective on January 1, 2028. Therefore, we are establishing short term remedies for the various payers to bridge until the new CPT code is in place. For centers concerned with the Inspire 5 reimbursement, we have inventory of Inspire 4 which has proven itself to be an extremely effective therapy with clear coding and reimbursement. As for coding for Inspire 5 Systems, we are working with physicians, centers and payers to establish clear and consistent coding and reimbursement guidelines and there was progress in the first quarter for Medicare patients. The Centers for Medicare and Medicaid Services or CMS announced the creation of a C code to be used with Inspire 5 procedures and the Medicare Administrative Contractors or Macs are beginning to incorporate the C code into their local policies. This provides a reliable solution for hospitals and ambulatory surgical centers and importantly, the facility payment is equal to the Inspire 4 CPT code 64582. Staying with Medicare for Physicians currently the MACs lists the Inspire 4 CPT Code 64582 without the use of a modifier. As such, the majority of Medicare cases this year have been billed without the use of a modifier and we will continue to monitor this throughout the year. At this point, the commercial payers continue to list CPT code 64568 for Inspire 5 procedures. There is guidance provided by societies including a non binding newsletter from the American Hospital association recommending the use of an unlisted CPT code (specifically 64999), specifically 64999. However, the use of of an unlisted code requires manual reviews and additional support from centers. Because of of this, many centers and payers may be reluctant to adopt the use the use of of this unlisted code. The good news for commercial payers is each case is prior authorized meaning the billing code is approved in the prior authorization before the procedure, significantly reducing payment uncertainty for the center. Medicare Advantage is managed by commercial payers and we recommend consistent coding practices as defined by the payer and Medicare Advantage patients are also prior authorized. Although challenging, there has been progress in coding and reimbursement and we’ve seen initial billing practices being established by physicians and and centers in response to the changes in coding. However, we recognize that significant uncertainty remains and we will continue to support our customers as they navigate the path forward. This coding uncertainty has adversely impacted the number of patients in the pipeline, including the number of prior authorizations submitted to commercial payers as we moved through the first quarter. We expect this trend to reverse and improve in the remainder of the year as we continue to support prior authorizations and build confidence in the coding processes and guidelines. To further support patient access to therapy, we are increasing our assistance to customers by providing additional proactive education relating to prioritization and billing processes and we are adding to our field reimbursement team. Our goal is to provide as much clarity to our customers as possible to mitigate disruptions to patient access to care. Switching to the Wiser Program Wiser is a government initiative requiring AI reviewed prior authorization for Medicare cases and six pilot states and the program kicked off in mid January of 2026. During the first quarter, the Weiser program created prior authorization delays for traditional Medicare procedures in the six Weiser states resulting in a headwind to our first quarter revenue. As we continue to gain experience working with the new systems in these states, we anticipate the headwinds to abate in the remainder of the year. With the ongoing coding and reimbursement challenges and the Wiser program impact, we are revising our full year revenue outlook in light of our lower revenue outlook and as we demonstrated in the first quarter, we will continue to be disciplined with our spending and focus on prioritizing revenue generating activities while still making progress. Long term Growth Investments in addition to enhancing our support to customers for proactive education and assistance with prior authorization and billing processes, we are also prioritizing projects to drive and improved patient care pathway, enhanced marketing effectiveness, improved digital product experience, continued R and D for new product development and operational efficiencies, we believe that these projects in these areas can begin to deliver returns in the second half of 2026 and accelerate in 2027. We continue to remain focused on our commitment to put the patient first and deliver strong patient outcomes. We continue to believe that there is a large untreated population of people struggling with sleep apnea that can benefit from Inspire therapy and we continue to be encouraged by the strong adoption of Inspire 5 and the positive data we continue to collect at the upcoming Sleep Conference in Baltimore. In June, we will be presenting the full results from the Inspire 5 trial conducted in Singapore. While we have previewed some of the early data points including inspiratory overlap, this is the first time we will be showing the full trial results including the ability of the new accelerometer based sensing technology that and the safety and efficacy of the Inspire 5 implant. Additionally, the Inspire Adhere trial trial is now complete. The data from the 5,000 patient cohort will be presented at the Sleep conference. This is a real world cohort demonstrating the effectiveness of Inspire as it is delivered today and builds upon our previous safety and efficacy trials. We will further highlight the effects of Inspire therapy on cardiovascular outcomes, utilizing a large claims database to retrospectively examine incident cases of cardiovascular disease after Inspire implantation as compared to a matched group of patients receiving CPAP therapy and those not receiving treatment at the sleep conference. We will present this study on the cardiovascular outcomes along with two other independent studies using two different claims databases to compare the use of various claims databases in the demonstration of improved cardiovascular and respiratory outcomes associated with Inspire therapy. In addition, a third independent study from Virginia Commonwealth University was just published in a peer reviewed journal. The data demonstrated that the Inspire patient cohort had significantly lower odds of stroke, myocardial infarction, atrial fibrillation, acute heart failure, acute respiratory failure and hospitalization, to name a few, with at least two years follow up. These strong results suggest Inspire provides systemic cardiovascular and respiratory health benefits and reduces healthcare burden compared to cpap. We expect further studies to support these findings. We are happy to report that the Predictor manuscript manuscript has been accepted by your major medical journal and we look forward to the publication in the coming weeks. As you are aware, Predictor manuscript is the 600 patient study we conducted to demonstrate alternative screening options to replace the drug induced sleep endoscopy or DICE procedure procedure for a large subset of eligible patients, improving the patient experience and reducing the timeline to implant. Last but not least, last month we published our 2025 patient experience report patient experience report. Highlighted in the report is a continued improvement in our revision and explant rates, which were 1.7% and less than 1%, respectively, for full year 2024. In summary, we remain focused on providing the best therapy solution for patients and helping our customers navigate what we believe will be a temporary market disruption related to coding and reimbursement and the wiser program. We are actively addressing the challenges posed by this disruption and we remain excited about our product and the market opportunity to improve the lives of our patients as we’ve already done for over 135,000 patients since our inception. We will continue to take actions to position the company for long term profitable growth and we believe that we have the right strategies in place to drive long term stakeholder value. I’ll now turn the call over to Matt for his review of our financial performance.

Matt Osberg (Chief Financial Officer)

Thank you Tim and good afternoon everyone. First, I’ll begin with a review of the first quarter results and then follow with commentary on our outlook for the remainder of 2026. Revenue increased 1.6% to $204.6 million, primarily driven by increased market penetration. As Tim mentioned, in the first quarter we experienced disruption related to coding and reimbursement challenges and the Wiser program and we estimate that these items adversely impacted revenue by approximately $20 million. Operating margin and adjusted operating margin improved, primarily driven by gross profit expansion. Due to a higher sales mix of Inspire 5 systems, the effective tax rate increased to 571.2% primarily driven by tax shortfalls related to our stock based compensation which were created by a decline in our stock price at award vesting date compared to the stock price at grant date. Additionally, in the prior year period we maintained a full valuation allowance against federal and state deferred tax assets. The adjusted effective tax rate which removes the impact of stock based compensation was 25.7%. As we mentioned on our fourth quarter call, as we are in a situation where our pretax income is relatively small base, certain discrete tax charges can have a material impact on our tax rate. Due to the fact that we have a significant amount of stock based compensation outstanding and due to the volatility of our stock price, the tax impact of stock based compensation on our effective tax rate can be material and could have significant variability from year to year. We expect the tax impact from stock based compensation will be concentrated in the first quarter of the year as that is when the majority of our vesting of our RSUs and PSUs occur. Diluted EPS was a loss of $0.39 and adjusted diluted EPS was $0.10. For the quarter. Our adjusted EBITDA margin, which excludes the impact of stock based compensation improved 100 basis points to 17.5%. Turning to cash flow and the balance sheet operating cash flow was $12.8 million for the quarter, an improvement of $20 million compared to the first quarter of the prior year, primarily driven by improved working capital partially offset by higher net loss in the current period. Our balance sheet remains strong with no debt and $400 million in cash and investments at the end of the quarter. Our strong cash position allows us to remain focused on making investments to drive profitable growth. We ended the quarter with 284 U.S. territories and 288 U.S. field clinical representatives. We are being strategic in our approach to territory management and optimizing our model through targeted territory consolidation. We hired 13 field clinical reps in the quarter and are now at our goal of one territory manager to one field clinical rep. Turning now to our 2026 outlook, we are revising our full year revenue outlook to be in the range of $825 million to $875 million. This range incorporates updated assumptions of the expected impact on our full year results from continued coding and reimbursement uncertainty and the Wiser program. As I mentioned, our first quarter revenue was adversely impacted by coding and reimbursement challenges and the Wiser program by an estimated $20 million. We expect the adverse impact of these items to increase to approximately $40 million to $50 million in the second quarter as …

Full story available on Benzinga.com

This post was originally published here

On Monday, ON Semiconductor (NASDAQ:ON) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/62mp4a93

Summary

ON Semiconductor reported Q1 2026 revenue of $1.51 billion, with non-GAAP EPS of $0.64, both exceeding guidance midpoints.

The company experienced strong growth in AI data centers, automotive, and industrial segments, with AI data center revenue projected to double in 2026.

Gross margin expanded to 38.5%, marking the third consecutive quarter of improvement, and is expected to continue growing throughout the year.

Strategic initiatives include ramping Trio products across automotive and AI applications, with significant design wins in these areas.

Management highlighted a positive demand environment, with signs of recovery across key markets and ongoing investments in power and sensing technologies.

Full Transcript

OPERATOR

Good day and thank you for standing by. Welcome to the ON Semiconductor first quarter 2026 earnings conference call. At this time all participants are in a listen only mode. After the speaker’s presentation there will be a question and answer session. To ask a question during this session you will need to press star 11 on your telephone. You will then hear an automated message advising your hand is raised to withdraw your question. Please press star 11 again. Please be advised that today’s conference is being recorded. I would now like to hand the conference over to your speaker today, Parag Agarwal, Vice President of Investor Relations and Corporate Development. Please go ahead.

Parag Agarwal (Vice President of Investor Relations and Corporate Development)

Thank you. Daniel Good after and thank you for joining ON Semiconductor’s first quarter results conference call. I’m joined today by Hassan Al Khoury, our President and CEO and Thad Trent, our CFO. This call is being webcast on the Investor Relations section of our website@www.onsemi.com. a replay of this webcast along with our first quarter earnings release will be available on our website approximately one hour following this conference call and the recorded webcast will be available for approximately 30 days following this conference call. Additional information is posted on the Investor Relations section of our website. Our earnings release and this presentation includes certain non GAAP financial measures. Reconciliation of these non GAAP financial measures to the most directly comparable GAAP financial measures and a discussion of certain limitations when using non GAAP financial measures are included in our earnings release which is posted separately on our website in the Investor Relations section. During the course of this conference call, we’ll make projections or other forward looking statements regarding future events or the future financial performance of the company. We wish to caution that such statements are subject to risks and uncertainties that could cause actual events or results to differ materially from projections. Important factors that can affect our business, including factors that could cause actual results to differ materially from forward looking statements, are described in Our most recent Form 10K, Form 10-Qs and other filings with the securities and Exchange Commission and in our earnings release for the first quarter, our estimates or other forward looking statements might change and the Company assumes no obligation to update forward looking statements to reflect actual results, change assumptions or other events that may occur except as required by law. Now let me turn it over to Hassan.

Hassan Al Khoury (President and CEO)

Hassan thank you Parag Good afternoon to everyone on the call and thank you for joining us. This quarter marks a clear inflection point for onsemi. Improving demand signals, accelerating AI data center growth and sustained gross margin expansion demonstrate that the structural changes we made over the past several years are now translating into tangible financial results. We delivered revenue of $1.51 billion and non GAAP diluted earnings per share of $0.64, both above the midpoint of guidance. Driven by growth in AI data center, we expanded gross margin for the third consecutive quarter to 38.5% while returning meaningful capital to shareholders as volumes recover and new products ramp. Our focused portfolio and lean cost structure are driving the operating leverage we designed this model to deliver. Turning to the demand environment, we saw a clear improvement as the quarter progressed with strengthening order patterns and an increase in short lead time orders. Taken together, these signals give us confidence that this cycle has found its low point and we are now on a path to recovery. On the new products front, our execution on Treo continues to accelerate as the platform moves from product proliferation into ramping revenue and design wins. In the first quarter, revenue increased more than two and a half times sequentially and we saw broader adoption across high volume automotive, industrial and AI applications with Treo design wins supporting the transition to software defined vehicles. Programs in our funnel include zonal architectures built on 10BASE-T1S paired with smart FETs, auto ADAS park assist system using ultrasonic sensing, power management for AI client platforms and inductive position sensing for humanoids and advanced automation use cases. These wins reinforce Trio’s penetration as customers move to a more centralized compute model with zonor for a scalable software architecture and require a faster time to market. Our Trio based driver ICs and inductive position sensing combined with our Gallium Nitride products deliver high power density, efficiency and ease of use in humanoid applications, AI data centers and automotive. Our overall GAN Solutions design funnel which includes vertical GaN now exceeds $1.5 billion supported by a rich product portfolio spanning 40 to 1200 volts. 10 products already sampling with another 20 sampling in the second half of 2026. With a balanced model that combines internal GAN development and foundry partnerships, we have a differentiated roadmap and resilient supply chain that positions us to begin ramping in these markets with revenue starting in 2027. Diving deeper into automotive in the first quarter we began production shipments of our trio based 10BASE-T1S Ethernet solutions for a leading North American customer’s next generation zonal architecture. The platform integrates more than 30 trio devices enabling in zone connectivity. Higher energy costs are accelerating EV demand with cost optimized EV platforms driving increased adoption of IGBT based traction inverter solutions. Our latest generation IGBTs deliver a compelling balance of performance efficiency and cost complementing our silicon carbide wins, particularly in front axle applications. During the quarter, we were awarded a new IGBT based traction inverter program with a North American OEM that is transitioning to direct semiconductor sourcing as the industry transitions to 900 volt EV architectures led by Chinese OEMs. We are the preferred power solution and are already in production at customers in their next generation of EV platforms, enabling flash charging and higher efficiency for a longer drive range. Our China automotive revenue grew year over year in Q1 despite a decline in the China passenger vehicle market of 6% for the same period. Our silicon carbide share of new EV models deployed at the 2026 Beijing Auto show in April is approximately 55%. Recent expanded collaborations with Geely and NIO highlight our role in enabling these customers to scale globally with their next generation 900 volt platforms. The latest reports from the China association of Automobile Manufacturers highlight continued strength in new energy vehicle exports in the first quarter, supporting our view that EV adoption is extending beyond the China domestic market. With ongoing fuel supply disruption and elevated energy costs, we expect demand for high efficiency EV platforms and silicon carbide content to remain durable, supporting long term growth opportunities for onsemi in automotive power globally. Turning to AI data centers, our revenue grew more than 30% quarter over quarter, nearly double our expected growth rate entering the quarter driven by a broader adoption across the PowerTree. With multiple XPU vendors and all the leading hyperscalers looking ahead, we now expect our AI data center revenue to double year over year in 2026. As the only broad based US power semiconductor supplier, ONSEMI continues to build a leading position in AI data centers across the full set of power capabilities required to modernize the PowerTree, including high voltage conversion, intelligent power stages, protection and control and system level integration from the grid to the processor. As policymakers push for greater transparency in the US Data center energy use, it reinforces a trend we have been aligned with for some time. Onsemi’s power portfolio helps hyperscalers overcome power density and efficiency constraints, reducing losses from the grid to the processor. We are engaged with all major power supply vendors serving every major AI hyperscaler with flex power. For example, our partnership now spans more than 30 active programs across intermediate bus converters, power supplies, battery backup, super capacitors and next generation 800-volt DC architectures. The AI halo effect continues to drive incremental demand in adjacent infrastructure markets, particularly energy storage systems, as rising energy costs and declining battery prices accelerate. Project economics Driven by our differentiated SIC hybrid modules. We are seeing renewed growth in our string ESS and microgrid business globally from China to North America. We now expect to outpace the power semiconductor growth for this market in 2026 with more than 40% revenue growth year over year and a market share approaching 60% and are now ramping revenue for a large US OEM’s microgrid deployment. Our announcement with Sanang Electric highlights our hybrid power integrated modules combining ElitSiC technology and FS7 IGBTs enabling higher efficiency and higher power density for utility scale solar inverters and liquid cooled energy storage platforms. These solutions deliver the best system level electrical and thermal performance and reinforce our position as a technology partner of choice as customers scale next generation renewable and storage deployments. Turning to sensing, we are delivering a multimodal sensing capability that customers can deploy across industrial autonomous automotive sensing and emerging robotics applications. We secured a meaningful design win with a leading global robotics platform where our high resolution image sensor and indirect time of flight technology were selected to enable reliable depth perception and navigation in autonomous systems. Our roadmap spans complementary modalities including high resolution imaging depth and other sensing approaches like short-wave infrared (SWIR) that are designed to work together with automotive grade reliability and long lifetime performance. As we move forward, we are encouraged by improving market conditions and the momentum we are seeing across our highest value applications. Our continued evolution towards a product and solution centric portfolio combined with disciplined investment decisions and our fabright actions is strengthening our operating model and enhancing margin durability. We are executing a clear strategy with deeper customer intimacy and a portfolio aligned to the most important long term power and sensing transitions. This positions us well to deliver sustainable growth, expanding profitability and long term value creation.

Thad Trent

I’ll now turn it over to Thad to give you more details on our result and guidance for the second quarter. Thanks Hassan the improving market conditions are coming through in our financial results and outlook. As demand visibility improves this year, we expect the impact of the structural changes we have made to become increasingly visible in our results. With a leaner cost structure, a more focused portfolio and differentiated power and sensing investments, we have built a model that delivers strong operating leverage with incremental revenue driving expanded margins, earnings and free cash flow in the first quarter, Order patterns and improving backlog visibility indicate that we are moving away from the bottom of the cycle and we are on a path to recovery. We delivered revenue of $1.51 billion better than normal seasonality and non GAAP earnings per share of 64 cents, both above the midpoint of our guidance. We expanded non GAAP gross margin for the third consecutive quarter to 38.5% and we expect sequential gross margin expansion throughout the year and we returned $346 million to shareholders through Opportunistic share repurchases representing nearly 160% of free cash flow. Q1 revenue was $1.51 billion, down 1%, versus the fourth quarter and up 5% year over year. As expected, there was roughly $50 million of planned non core exits in the quarter. Turning to the end markets, Automotive revenue was $797 million in the first quarter, roughly flat quarter over quarter and grew nearly 5% year over year, marking the first year-over-year growth after seven quarters of decline. We continue to see stabilization in the automotive market and we now believe we’re shifting to natural demand. China Electric vehicle programs continue to outperform other regions driven by a strong export market. Industrial revenue was $417 million, down 6% sequentially but ahead of our expectations. We saw broad based strength across our traditional industrial business for the second consecutive quarter, partially offset by the typical Chinese New Year seasonality. Our AI Data center business is accelerating with Q1 revenue growing more than 30% quarter to quarter and doubling year over year reflecting platform ramps and expanding engagement across the PowerTree. We expect our 2026 AI data center revenue to double compared to full year 2025. For the first quarter. Total revenue for the other category was $299 million and increased 3% quarter over quarter due to AI data center strength. Looking at the first quarter split between the business units, revenue for the Power Solutions Group (PSG) was $737 million, an increase of 2% quarter over quarter and 14% year over year. Revenue for the Analog and Mixed Signal Group (AMG) was $540 million, a decrease of 3% quarter over quarter and 5% year over year. Revenue for the Intelligent Sensing Group OR ISG was $246 million, a 5% decrease quarter over quarter and a 1% increase over the same quarter last year. Moving to gross margin in the first quarter, GAAP and non GAAP gross margin of 38.5% increased sequentially in a seasonally down quarter. The improvement in gross margin is a result of the structural changes we have made over the last several years that have improved our manufacturing performance. Manufacturing utilization increased sequentially to 77% as we ramped production quickly to respond to stronger demand signals in the quarter. In Q2 we expect utilization to be flat to up slightly given the improving demand outlook and our ongoing FABRITE actions. We expect sequential gross margin expansion throughout the year. GAAP operating expenses were $637 million including $329 million in restructuring expenses. Non GAAP operating expenses were $294 million, a decrease of 7% from Q1 2025 driven by cost optimization actions. The GAAP operating margin for the quarter was negative 3.5% and non GAAP operating margin was 19.1%. Our The GAAP tax rate was 26.2% and non The GAAP tax rate was 15%. The diluted GAAP loss per share was $0.08 and non GAAP earnings per share was $0.64. The GAAP diluted share count was 394 million shares and non The GAAP diluted share count was 396 million shares. We opportunistically purchased $346 million of shares at an average price of $60.54. Turning to the balance sheet, cash and short term Investments was approximately $2.4 billion with total liquidity of 3.9 billion including $1.5 billion undrawn on a revolver. Cash from operations was 239 million and free cash flow was $217 million. Capital expenditures were $22 million or 1.4% of revenue. Inventory increased by $60 million to 201 days from 192 days in Q4. The sequential increase was a result of higher internal loadings and customer commitments. This includes 75 days of strategic inventory which is down from 76 days in Q4. As we continue to deplete this inventory over the next two years. Excluding the strategic builds, our base inventory Distribution inventory was flat at 10.8 weeks. Looking forward, let me provide the key elements of our non GAAP guidance for the second quarter of 2026. As a reminder, today’s press release contains a table detailing our GAAP and non-GAAP guidance. We anticipate Q2 revenue will be in the range of 1.535 billion to $1.635 billion. We expect to exit an incremental 30 million to 40 million of non core revenue in the second quarter. Excluding these exits, our revenue is expected to increase approximately 7% at the midpoint and be above seasonal. Our non-GAAP gross margin is expected to be between 38 and 40% which includes share-based compensation of $6 million. Non GAAP operating expenses are expected to be between 287 and $302 million and which includes share-based compensation of $28 million. We anticipate our non-GAAP other income to be a net benefit of $6 million. With our interest income exceeding interest expense, we expect our non-GAAP tax rate to be approximately 15% and our non-GAAP diluted share count is expected to be approximately 394 million shares. …

Full story available on Benzinga.com

This post was originally published here

On Monday, Paymentus Holdings (NYSE:PAY) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://edge.media-server.com/mmc/p/xzfeec5r/

Summary

Paymentus Holdings reported a record first-quarter revenue of $358.4 million, marking a 30.2% year-over-year increase, with an adjusted EBITDA of $42.4 million, reflecting a 41.5% growth.

The company announced the launch of Billio, an AI Native Service Commerce platform, and Bill Wallet, which are expected to transform service interactions and enhance long-term growth potential.

The full-year 2026 guidance was raised, with expected revenue between $1.425 billion and $1.44 billion, and adjusted EBITDA between $165 million and $172 million, reflecting continued confidence in business growth and strategic execution.

Full Transcript

OPERATOR

Good day and welcome to the first quarter 2026 Paymentus Holdings Earnings conference call. At this time all participants are in a listen only mode. After the speaker presentation there will be a question and answer session. To ask a question during the session you will need to press star 11 on your telephone. You will then hear an automated message advising your hand is raised to withdraw your question. Press star 11 again. Please be advised that today’s conference is being recorded. I would now like to hand the conference over to your speaker, Mr. David Hanover, investor Relations. Please go ahead.

David Hanover (Investor Relations)

Thank you. Good afternoon. Welcome and thank you for joining the webcast to review our first quarter 2026 results. Our earnings release documents are available on the investor Relations section of the paymentus.com website. They include the earnings presentation that we’ll make reference to during this webcast. This webcast is being recorded. I hope everyone’s had a chance to review those documents. Our Founder and CEO Dushan Sharma will make some opening remarks before Sanjay Khara, our cfo discusses the details of the first quarter and our guidance. Following our prepared remarks, we’ll take questions. Let me just remind you that we will make forward looking statements within the meaning of the Private Securities Litigation Reform act of 1995 and we refer to non GAAP financial measures during the webcast. Forward looking statements are based on management’s current expectations and assumptions that are subject to risks and uncertainties. Factors that may cause our actual results to differ materially from expectations are detailed in our earnings materials and in our SEC filings that are available on both the SEC and our websites. Information about non GAAP financials, including reconciliations to us GAAP can also be found in our earnings materials that are available on the website. With that, I’d like to turn the webcast over to Dushan Sharma. Dushan thanks David. We had a tremendous start of 2026 with record revenue and a strong growth exceeding our CAGR model across all key metrics. We believe these results underscore the durability and long term growth potential of our business model. That strength is driven by our platform, our ecosystem, our expertise and scale, our quality of service with support, security, availability and compliance frameworks along with a broad and continuously evolving innovation framework. In addition to our very strong financial results, we also announced an important product launch today that we believe will transform how service providers interact with their customers. Today’s agenda will proceed as follows. First, I’ll provide a brief overview of our results. Sanjay will then provide a detailed financial review and discuss our outlook and I’ll then come back and discuss the strategic product announcement we have made today. We’ll then answer any questions. Let me start with financial highlights as shown on slide 3, first quarter revenue was a record $358.4 million, an increase of 30.2% year over year. At the same time, Contribution profit was $109.7 million, up 25.2% year over year. Adjusted EBITDA was a record $42.4 million in the quarter, representing 41.5% growth year over year and a 38.7% margin. Once again, a majority of our year over year growth in contribution profit fell to our bottom line and we exceeded the rule of 40 for the quarter, again coming in at 64 versus 61 in Q4. This reflects our team’s solid execution and our focus on delivering consistent revenue growth alongside high quality earnings. These results are exciting for multiple reasons. Let me speak to two that will likely be on top of mind. First, they speak to the vertical diversification and our enhanced pricing strategy over the years whereby the impact of elevated Energy price index on our numbers has been materially reduced. Second, as we have shared in the past, we operate on a 2 fiscal year horizon. Therefore, this outperformance is not just about 1/4. It actually gives us confidence and additional visibility for the rest of the year and when combined with our backlog and bookings, we are also feeling good about 2027 with our additional visibility. Now on to our business Results on Slide 4, we continued our strong momentum in the first quarter with robust bookings and a very substantial pipeline. We also continue to expand and diversify our customer base by signing new clients in several industry verticals including Utilities, Insurance, Telecommunications, government Agencies, Property Management, Consumer Finance, Banking, Education and health care. Complementing this, we signed channel partners in Education and telecommunications verticals and likewise, onboarding of a substantial backlog remains a priority for us. Our team continues to demonstrate solid execution when it comes to onboarding activities. We also saw better than expected seasonal performance in the first quarter, largely from the large cohort of new customers that we added in the second half of last year. In addition, during the first quarter we onboarded clients throughout multiple verticals including utilities, consumer finance, government agencies, telecommunications, banking, insurance and education. With that, I’ll turn it over to Sanjay to review our financial results in more detail.

Sanjay Khara (Chief Financial Officer)

Thanks Dushan and thank you all for joining us today. Before I discuss our first quarter results and outlook, I’d like to remind everyone that the financial results I’d be referring to include non GAAP financial measures our Q1 press release and earnings presentation includes reconciliations of these non GAAP financial measures to their corresponding GAAP measures. Both of these are available on our website. Turning to slide 5 we delivered a strong start to the year with the first quarter results that came in much stronger than we had anticipated. Driven by higher transaction activity from both new and existing bidders. This helped drive strong double digit growth for revenue contribution profit adjusted EBITDA. This, combined with our strong bookings, sizable backlog and strong pipeline at quarter end supports our positive outlook for 2026. Our first quarter 2026 results included revenue of 358.4 million, contribution profit of 109.7 million and adjusted EBITDA of 42.4 million. On a rule of 40 basis, we came in at 64, which we consider a solid result and a record for the company. We are encouraged by this achievement, especially given the macro backdrop we are operating in. I’d like to also call out that we saw a sequential acceleration in the year over year growth rate for the number of transactions, revenue and contribution profit despite tough year over year comps and a challenging macroeconomic environment. Moreover, the sequential growth rate we saw for all of these three metrics in Q1 was greater than the sequential growth rate we saw during the same period last year. Simply put, both our annual and sequential growth rates accelerated in Q1 2026, boosting our confidence for the full year 2026 outlook. I’ll discuss the drivers of our outperformance and strong business momentum behind them shortly. These strong results also enabled us to once again exit the quarter with a much stronger cash position and gave us the flexibility to allocate capital with a continuous focus on longer term growth which also contributed to robust bookings. Now let’s review our first quarter financials in more detail. As I mentioned earlier, first quarter 2026 revenue was 358.4 million, up 30.2% year over year. This growth was largely driven by the launch of new billers over the past year as well as increased same store sales from existing billers. We also processed a higher number of transactions during the first quarter reaching 203.4 million, up 17.4% year over year. Our average revenue per transaction increased by approximately 11% to $1.76 in the first quarter compared to $1.59 in the prior year period. Continuing our robust trend of double digit annual growth rate of revenue per transaction over the past seven quarters. This was mainly due to the biller mix or more specifically the large enterprise billers that we launched during the second half of 2025 with higher average payment amounts. The first quarter guidance we previously provided did consider some of the anticipated upside from large enterprise accounts, but as you can see it still exceeded our expectations. First quarter 2026 contribution profit increased to 109.7 million up 25.2% year over year. This increase also reflected the launch of new billers and higher transactions from existing billers. Contribution margin was 30.6% for the first quarter compared to 31.8% in the prior year period. The year over year reduction reflects the increased mix of large high volume enterprise billers in our growing customer base. This change in contribution margin was largely offset by by a year over year reduction in operating expense margin which resulted in a record adjusted EBITDA margin of 38.7%. This is consistent with our continued focus on profitability. Contribution profit per transaction for the quarter was $0.54, an improvement from $0.51 from prior year period, demonstrating our ability to expand market share without sacrificing comparable contribution profit per transaction. As we have noted before, variables that are outside our control such as an increase in average payment amount or changes in the payment mix can affect contribution profit on a quarter to quarter basis and therefore we treat this as a secondary metric while our gross revenue and adjusted EBITDA remain primary metrics. First quarter 2026 adjusted gross profit was 92.4 million, up 27.3% year over year and ahead of our contribution profit growth rate as we achieve operational economies of scale. As we anticipated the first quarter 2026 non GAAP operating expenses increased 16.3% year over year to $53 million. This increase was primarily due to higher sales and marketing expenses. You may notice our OPEX year over year growth rate increased this past quarter. This is a positive leading indicator for our business as it means we are aggressively converting our substantial pipeline to bookings. We expect to make similar investments throughout the year as we continue to execute our go to market strategy, calibrate operating expenses with contribution profit expansion and deploy our growing cash balance to support further organic growth. These expectations are already incorporated into our guidance which I’ll review in More detail shortly. First Quarter 2026 Non GAAP net income was 26.9 million or $0.21 per share compared to Non GAAP net income of 17.6 million or $0.14 per share in the prior year period, reflecting an annual EPS growth rate of 50%. This EPS incorporates a non GAAP tax rate of 25%, which is based on our current expectation of our long term projected tax rate and is also reflected in our 2026 guidance. First quarter 2026 adjusted EBITDA increased 41.5% to 42.4 million compared to 30 million in the prior year period. Adjusted EBITDA also represented a record 38.7% of contribution profit, an annual improvement of 450 basis points compared to 34.2% in the prior year period. We believe the stronger adjusted EBITDA margin demonstrates the inherent operating leverage we have in the business. Please note our incremental adjusted EBITDA margin was approximately 56% related to this. Once again, we also exceeded the rule of 40 for the quarter, coming in at 64, a record. Now I’ll discuss our balance sheet and liquidity position on Slide 6. We ended the first quarter with total cash and cash equivalents of 342.1 million compared to 324.5 million at the end of 2025. The 17.6 million sequential increase was primarily comprised of 30.5 million of cash generated from operations, partially offset by 9.4 million used in investing activities primarily for capitalized software and 3.3 million spent in net settlement of employee RSUs. The company does not have any debt free cash flow generated during the quarter was 20.9 million. This was primarily driven by strong adjusted EBITDA in the quarter, offset by investments in working capital, primarily in accounts receivable. Driving organic growth continues to be our primary focus. Having said that, our strong cash position enables us to maintain financial flexibility to keep room for working capital investments as we scale. In addition, our ample liquidity allows us to explore attractive M and A opportunities that may arise in order to expand our growth prospects. Our day sales outstanding at the end of the first quarter was 29, comparable to 28 days at the end of the prior quarter and much better than our expected range. Working capital at the end of the first quarter was approximately 365.4 million, an increase of approximately 6.7%. Sequentially, we had 129.3 million diluted shares outstanding during the first quarter, pretty much comparable to the prior quarter. Now I’ll turn to slide 7 to discuss our second quarter and full year 2026 raised guidance for revenue contribution profit and adjusted EBITDA. Before discussing full year guidance, I want to mention that we are continuing to follow the same prudent approach to guidance that we have followed for the past three years, which has proven to be successful for us as shown on the slide. For Q2.26 we expect revenues in the range of 340 to to 350 million, contribution profit in the range of 108 to 111 million and adjusted EBITDA in the range of 38 to $40 million. On a rule of 40 basis for the second quarter of 2026, our guidance implies a range of 51 to 55 for the full year 2026, we now expect revenue in the range of 1.425 billion to 1.44 billion, an increase of 2.3% from midpoint of our previous guidance. This guidance now represents a 19.7% annual growth at midpoint and 20.4% annual growth at the high end. Contribution profit in the range of 450 to 457 million, up 1.5% from midpoint of our previous guidance and now representing 17.4% annual growth at midpoint and 18.3% annual growth at the high end. Adjusted EBITDA in the range of 165 to $172 million, up 4% from midpoint of our previous guidance and now representing 22.6% annual growth at the midpoint and 25.2% annual growth at the high end and a non GAAP tax rate of 25% on the Rule of 40 basis, our guidance implies a range of 53 to 56 for the full year 2026. During our past few earning calls, we provided long term growth targets for both revenue and adjusted ebitda, our two primary financial metrics. We stated that our goal was to grow revenue at approximately 20% and grow adjusted EBITDA between 20 to 30% the full year. Updated 2026 guidance range we have provided today reflects the expected achievement of these long term targets. In summary, we are very pleased with our strong start to 2026, reflecting the continued momentum we’ve shown across the past several quarters. During this time we have consistently demonstrated our ability to generate profitable growth. This enabled us to end the first quarter with a substantial backlog and pipeline. Given our solid footing and strong visibility, we continue to believe we are well positioned for further growth in 2026 and beyond. Thank you everyone for your attention today and now I’ll turn it back to Dushant for final remarks before we open up the call for questions.

Dushan Sharma (Founder and CEO)

Thanks Anjay. After seeing the impact of our state of the art platform and the ecosystem on the broader service economy, we find ourselves at an exciting juncture similar to what we experienced at our inception as we looked at the economy. Broadly, we realized that almost all investments in commerce have gone towards product or retail commerce with a focus on how to sell more to customers and having them check out quickly. This product commerce paradigm is also retrofitted in service commerce, which at its core is not transactional but instead relational. This mismatched paradigm has left service commerce to lag behind as enterprises spend millions of dollars on a myriad of mismatched components and tools. At Paymentus Holdings we realized that to truly solve the issue, we needed to bring about a paradigm shift with a full stack Purpose built AI Native Platform with Service Native components Even before our ipo. Employing our proactive …

Full story available on Benzinga.com

This post was originally published here

SanDisk Corp. (NASDAQ:SNDK) shares rocketed roughly 81% in April, dwarfing NVIDIA Corp.’s (NASDAQ:NVDA) modest 1.8% gain and delivering more than 45 times the return of the AI chip king, according to Benzinga Pro data.

The move highlights a sharp rotation inside the AI trade: investors are not walking away from Nvidia, but they are aggressively bidding up the memory side of the AI stack as NAND pricing and data center demand reset higher.

The Setup

The setup is straightforward: Nvidia remains the dominant force in AI accelerators, with unmatched scale, software lock-in and data center momentum.

But SanDisk has emerged as the purest way to play the storage shortage triggered by AI workloads, and …

Full story available on Benzinga.com

This post was originally published here

ADC Therapeutics (NYSE:ADCT) held its first-quarter earnings conference call on Monday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://app.webinar.net/9g7e18bVQx8

Summary

ADC Therapeutics SA reported first quarter 2026 net product revenues of $20 million, reflecting a 15% increase from the previous year, primarily due to quarter-to-quarter variability in customer ordering.

The company is focused on advancing its strategic initiatives, particularly around its drug Zenlonta, with multiple clinical trials expected to yield data within 2026 and 2027, potentially expanding its market reach into earlier lines of therapy.

ADC Therapeutics SA reduced operating expenses by 13% compared to Q1 2025, maintaining a healthy cash balance of $231 million, which supports a cash runway into 2028.

The company anticipates significant revenue growth starting in 2027, contingent upon positive clinical trial outcomes and subsequent regulatory approvals and compendium listings.

Management expressed confidence in Zenlonta’s potential to reach peak annual revenues of $600 million to $1 billion in the US, assuming successful trial outcomes and regulatory milestones.

Full Transcript

OPERATOR

Good morning ladies and gentlemen and welcome to The ADC Therapeutics Q1 2026 earnings conference call. At this time, all lines are in listen only mode. Following the presentation, we will conduct a question and answer session. If at any time during this call you require immediate assistance, please press star zero for the operator. This call is being recorded on Monday, May 4, 2026. I would now like to turn the conference over to Nicole Riley, Head of Investor Relations and Corporate Communications. Please go ahead.

Nicole Riley (Head of Investor Relations and Corporate Communications)

Thank you operator. Today we issued a press Release announcing our first quarter of 2026 financial results and business updates. This release and the slides we will use in today’s presentation are available on the Investors section of the ADC Therapeutics website. I’m joined on today’s call by our Chief Executive Officer Amit Malik. who will discuss our operational performance and recent business highlights, followed by our Chief Financial Officer Pepe Carmona. who will review our first quarter of 2026 financial results. We will then open the call to questions. Before we begin, I would like to remind listeners that some of the statements made during this conference call will contain forward looking statements within the meaning of the safe harbor provisions of the U.S. Private Securities Litigation Reform Act of 1995. These forward looking statements are subject to certain known and unknown risks and uncertainties and actual results, performance and achievements could differ materially. They are identified and described in the accompanying slide presentation and in the Company’s filings with the SEC, including Form 10-K, 10-Q, and 8-K. ADC Therapeutics is providing this information as of today’s date and does not undertake any obligation to update any forward looking statements contained in this conference call as a result of new information, future events or circumstances. Except as required by law, the Company cautions investors not to place undue reliance on these forward looking statements. Today’s presentation also includes non-GAAP financial reporting. These non-GAAP measures should be considered in addition to and not in isolation or as a substitute for the information prepared in accordance with GAAP. You should refer to the company’s first quarter of 2026 earnings release for information and reconciliation of historical non-GAAP measures to the comparable GAAP financial measures. I will now turn the call over to our CEO Amit Malik..

Amit Malik (Chief Executive Officer)

Amit thank you Nicole. We continue to make good Progress in the first quarter of 2026 as we advance towards multiple important milestones for Zinlanta over the remainder of the year, beginning with the expected Lotus 5 top line readout in the second quarter. From a commercial perspective, we continue to focus on execution and delivering on our commercial strategy maintaining Zinlanta as a differentiated treatment option for third line plus DLBCL patients. First quarter net product revenues were $20.0 million as compared to the prior year’s first quarter net product revenues of $17.4 million. The increase was driven primarily by normal quarter to quarter variability in customer ordering, with underlying demand broadly stable. Looking toward the second line plus setting where we believe the largest growth opportunity lies for Lotus 5, our phase 3 confirmatory trial of Zinlanta plus Rituximab, we expect to share top line data before the end of June, potentially bringing us another step closer to providing this combination to significantly more patients. While this timeline is rapidly approaching, I do want to highlight that we are currently still blinded to the Data. Turning to Lotus 7, we expect to complete enrollment of approximately 100 patients at the selected dose level of Zinlanta plus Clocitumab in the second quarter with full data anticipated by year end in indolent lymphomas. We continue to anticipate data publication between the end of 2026 and mid-2027 from the multicenter investigator initiated trials of Zinlanta in combination with rituximab to treat relapsed or refractory follicular lymphoma and of Zinlanta as a monotherapy to treat relapsed or refractory marginal zone lymphoma, we continue to pay close attention in the quarter to managing our cost base and optimizing our balance sheet on a non GAAP basis. We reduced our total operating expenses by 13% versus Q1 2025 and we ended the first quarter of 2026 with a healthy cash balance of $231 million. This maintains our expected cash Runway at least into 2028, enabling us to deliver against our strategy. We are building off the well established role of Zinlanta as a single agent therapy in third line plus dlbcl.

Amit Malik (Chief Executive Officer)

Whereas Inlanta has a profile of rapid, deep and durable efficacy as well as manageable safety with simple and convenient administration, we believe the relative stability we’ve seen in net product revenues over multiple quarters demonstrates that Xenlanta has a clear place in this market. This is just a starting point as we believe in the potential for Xenlanta to reach significantly more patients by expanding use into earlier lines of therapy in DLBCL and into indolent lymphomas. The data we’ve seen across these settings so far have been consistently encouraging with the potential to be highly differentiating through expansion into these settings in DLBCL and into indolent lymphomas. We are confident that Zinlanta has the potential to reach peak annual revenues of $600 million to $1 billion in the US assuming both compendia listing and regulatory approval. The upcoming Lotus 5 trial readout, if positive, will begin to unlock the value of our life cycle management efforts within the company.

Amit Malik (Chief Executive Officer)

Taken together with the upcoming data expected …

Full story available on Benzinga.com

This post was originally published here

Shark Tank star Kevin O’Leary isn’t hunting for the small equity business in 2026. The TV personality has firmly turned toward what he sees as the ultimate commodity of the current tech revolution – the physical infrastructure required to keep it going.

When Geopolitics Meet Finance

O’Leary’s key domestic project is the Stratos Project in Box Elder County, Utah. Spanning 40,000 acres, the site is designed to reach 9 GW of power—a figure the Wall Street Journal put as “equal to more than 20% of all data-center capacity currently operating in the U.S.”

Yet to avoid straining the national grid, O’Leary proposes burning natural gas on-site via the Ruby pipeline. The first phase would target 3GW, at a cost of roughly $45 billion.

“I think we’re in a competition with the Chinese on economic superiority and military superiority,” he noted, reasoning that the motivation is as much geopolitical as it is financial.

North of the border in his native Canada, O’Leary is doubling down with a proposed $70-billion, 7.5-gigawatt AI data center campus in Alberta. However, despite being exempt from provincial environmental impact assessment, the project still faces numerous local permits, including approval from the First Nation.

“The minute we get the permit, that triggers a whole bunch of other activities in terms of how we finance it, when we start engineering, design, everything …

Full story available on Benzinga.com

This post was originally published here

On paper, this should have been a clean win. Oil prices surged on geopolitical tensions around the Strait of Hormuz. Energy stocks looked like the obvious beneficiaries. And Exxon Mobil Corp (NYSE:XOM)—one of the world’s largest producers—should have been front and center.

Instead, the stock fell 9% in April, its worst month in a year.

That disconnect points to a bigger issue: higher crude prices don’t automatically translate into higher oil stock returns.

The Rally That Gave Back Gains

According to an April 29 note from JPMorgan, the energy trade has been more volatile than it appears. The firm said sector performance has “swung wildly” this year. Energy is still the top-performing sector year-to-date, up 26%, but has fallen since the market low—”effectively wiping out most of its …

This post was originally published here

SpaceX is in the hot seat after around 80 South Texas residents filed a lawsuit in the U.S. District Court for the Southern District of Texas, alleging that repeated sonic booms and shockwaves from Starship testing over the past two and a half years have damaged their homes.

In the complaint, filed in Brownsville, Texas, the residents allege damage linked to 11 Starship-related test flights carried out from April 2023 through October 2025, Reuters reported. 

The lawsuit describes exposure to “extraordinary amounts of acoustic energy, including noise, vibrations, and sonic ⁠booms.” 

Benzinga reached out to SpaceX and attorneys for the plaintiffs for comment.

The filing argues SpaceX did not sufficiently evaluate how these tests could affect nearby homes and kept moving forward even with what the plaintiffs describe as “foreseeable, yet inadequately modeled, peril.” It also alleges SpaceX proceeded with “conscious indifference to the rights, safety, or welfare of others, including plaintiffs.”

The complaint …

Full story available on Benzinga.com

This post was originally published here

Bill Ackman’s $5 billion Pershing Square IPO almost flopped on day one last week, but the billionaire is already deploying the cash into an AI trade led by Meta, Alphabet and Uber.

Pershing Square USA (NYSE:PSUS) closed 18% below its $50 IPO price on April 29. Ackman blamed the drop on his decision to give retail investors their full requested allocation, leaving many holding more shares than they could afford to settle.

He said those forced sales drove the day-one slump, and bought 500,000 PSUS shares plus 800,000 of asset manager Pershing Square Inc. (NYSE:PS) himself the next day.

The Financial Times attributed the slump to weak investor demand, with the combined listing raising $5 billion against an initial $10 billion target and well below the $25 billion Ackman sought in a pulled 2024 attempt.

Ackman told CNBC this morning that the closed-end fund …

Full story available on Benzinga.com

This post was originally published here

IREN Limited (NASDAQ:IREN) shares climbed on Monday. This move follows a massive power milestone in Texas and heavy investor positioning.

The Nasdaq is down 0.38% while the S&P 500 has shed 0.48%.

Sweetwater 1 Hits Grid Milestone

The company announced the successful energization of its 1.4 gigawatt (GW) Sweetwater 1 data center site. This connects the high-voltage substation to the ERCOT grid. This site serves as a foundation for the broader 2GW Sweetwater campus.

CEO On Infrastructure Execution

Management credited the “disciplined execution” of their vertically integrated model. Co-CEO Daniel Roberts stated, “Delivering Sweetwater 1 substation energization on schedule reflects our disciplined execution, the strength of our …

Full story available on Benzinga.com

This post was originally published here

Six months ago, the most powerful banker in America walked onto a quarterly earnings call and used a word that doesn’t usually come up when bank CEOs talk to Wall Street: cockroaches.

It was Oct. 14, 2025. JPMorgan Chase (NYSE:JPM) had just taken a $170 million hit from the bankruptcy of Tricolor Holdings, a subprime auto lender that, as it later emerged, had been making car loans to borrowers without credit scores or, in many cases, driver’s licenses. A few weeks earlier, an auto-parts maker called First Brands had collapsed under what investigators believe was an opaque borrowing scheme involving as much as $2.3 billion in undisclosed loans. The Department of Justice opened a criminal probe.

Then Jamie Dimon said the line that would echo across Wall Street for the rest of the year: “My antenna goes up when things like that happen. And I probably shouldn’t say this, but when you see one cockroach, there are probably more. Everyone should be forewarned on this one.”

More Credit Issues?

It was vintage Dimon — direct, memorable, and just a little bit alarming. The comment got picked up everywhere. Howard Marks, the Oaktree Capital co-founder famous for his memos on credit cycles, wrote an entire November note titled “Cockroaches in the Coal Mine” riffing on Dimon’s framing. The word stuck. 

He backed it up with a real-world view of where things were headed: “We’ve had a credit bull market now for the better part of since 2010. These are early signs there might be some excess out there. If we ever have a downturn, you’re going to see quite a few more credit issues.”

For investors, it landed at exactly the wrong moment. Bank stocks had been on a tear. Private credit — the world of non-bank lenders making loans to mid-sized companies …

Full story available on Benzinga.com

This post was originally published here

Zoom Video Communications Inc. (NASDAQ:ZM) shares gained 3.25% at $106.80 on Monday. The Nasdaq rose 0.22% and the S&P 500 gained 0.07%.

• Zoom Communications stock is challenging resistance. Why are ZM shares at highs?

AI-First Strategy Gains Momentum

The upward trend reflects confidence in Zoom’s pivot toward an AI-first ecosystem. Russell Dicker, a former Microsoft Corp. (NASDAQ:MSFT) veteran, recently joined as chief product officer to oversee this transition. Dicker noted, “With AI embedded across the platform, we have the opportunity to simplify how work gets done.”

Capturing the Business of One

On …

Full story available on Benzinga.com

This post was originally published here

Tesla Inc. (NASDAQ:TSLA) CEO Elon Musk threatened OpenAI’s Sam Altman and Greg Brockman two days before their trial began, warning they would become “the most hated men in America” if they refused to settle.

Musk sent the message on April 25 to gauge interest in a settlement, according to a court filing made Sunday.

When Brockman replied suggesting both sides drop their claims, Musk fired back: “By the end of this week, you and Sam will be the most hated men in America. If you insist, so it will be.”

OpenAI’s lawyers want the text entered into evidence as Brockman takes the stand Monday. The filing says the message tends to prove Musk’s motive and bias, and that his motivation for the lawsuit is to attack a competitor.

Kalshi …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks traded mostly lower midway through trading, with the Dow Jones index falling over 400 points on Monday.

The Dow traded down 0.90% to 49,052.82 while the NASDAQ fell 0.48% to 24,994.93. The S&P 500 also fell, dropping, 0.50% to 7,194.07.

Leading and Lagging Sectors

Energy shares jumped by 0.8% on Monday.

In trading on Monday, materials stocks fell by 1.3%.

Top Headline

Norwegian Cruise Line Holdings Ltd (NYSE:NCLH) posted upbeat earnings for the first quarter, but lowered its FY2026 forecast.

Norwegian Cruise Line reported quarterly earnings of 23 cents per share which beat the analyst consensus estimate of 14 cents per share. The company reported quarterly sales of $2.331 billion which missed the analyst consensus estimate of $2.357 billion.

The company also cut its FY2026 adjusted EPS guidance from $2.38 to $1.45-$1.79.

Equities Trading UP
           

  • CNS Pharmaceuticals Inc (NASDAQ:CNSP) shares shot up 298% to $9.19 after the company announced …

Full story available on Benzinga.com

This post was originally published here

Audax Private Debt has wrapped up a $1 billion continuation vehicle for private credit, with Pantheon, a global credit secondaries solutions investor serving as the lead investor.

The new fund, Audax Direct Lending Solutions Fund I CV, was formed to purchase a mix of first-lien, senior secured loans and related equity co-investments that previously sat in Audax Private Debt’s Direct Lending Solutions Fund I, according to a press release. That earlier fund collected $1.65 billion in commitments and closed in January 2019. Pantheon led and structured the CV transaction.

“We believe this transaction underscores the strength and stability of the DLS I portfolio, our commitment to underwriting discipline, and our longstanding credit-first approach, which have contributed to our performance across market and economic cycles,” noted Kevin Magid, CEO of Audax Private Debt.

“It also speaks to our ongoing efforts to deliver flexibility to our investors and optimize …

Full story available on Benzinga.com

This post was originally published here

RLJ Lodging (NYSE:RLJ) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/vs5hudrt/

Summary

RLJ Lodging reported a strong start to 2026, with a 4.8% RevPAR growth in Q1, outperforming the industry by 100 basis points, driven by urban markets and recent renovations.

The company achieved high single-digit EBITDA growth, margin expansion, and significant non-room revenue growth, emphasizing ROI initiatives and conversions.

RLJ Lodging remains optimistic about future performance, citing strong business travel demand, especially in technology and finance sectors, and expects continued growth despite macroeconomic uncertainties.

Strategic capital allocation includes completing major renovations and conversions, with a focus on ROI-driven projects, and maintaining a strong balance sheet by addressing debt maturities through 2029.

Management noted significant events like the World Cup and America’s 250th anniversary as potential tailwinds for urban market performance in 2026.

Full Transcript

OPERATOR

Greetings and welcome to the RLJ Lodging Trust first quarter 2026 earnings conference call. At this time, all participants are in a listen only mode. A brief question and answer session will follow the formal presentation. If anyone should require operator assistance during the conference, please press Star 0 on your telephone keypad. As a reminder, this conference is being recorded. It is now my pleasure to introduce your host, John Paul Austin, Director of Investor Relations, RLJ Lodging Trust. Thank you sir. You may begin.

John Paul Austin (Director of Investor Relations)

Thank you operator. Good morning and welcome to RLJ Lodging Trust’s 2026 first quarter earnings call. On today’s call, Leslie Hale, our President and Chief Executive Officer, will discuss key highlights for the quarter. Nikhil Bala, our Chief Financial Officer, will discuss the Company’s financial results. Tom Bardinette, our Chief Operating Officer, will also be available for Q&A. Forward looking statements made on this call are subject to numerous risks and uncertainties that may lead the Company’s actual results to differ materially from what has been communicated. Factors that may impact the results of the company can be found in the company’s 10-Q and other reports filed with the SEC. The company undertakes no obligation to update forward looking statements. Also, as we discuss certain non-GAAP measures, it may be helpful to review the reconciliations to GAAP located in our press release. Finally, please refer to our schedule of supplemental information which includes pro forma operating results for our current hotel portfolio. I’ll now turn the call over to Leslie Hale.

Leslie Hale (President and Chief Executive Officer)

Thanks John Paul Good morning everyone and thank you for joining us today. We are encouraged to see the lodging industry off to a strong start this year benefiting from the underlying strength of fundamentals with the acceleration of business transient demand, being a key driver. We are particularly pleased with our first quarter results as our urban centric portfolio outperformed the industry. Our favorable footprint with exposure to many top performing markets such as Northern California and South Florida among others allowed us to capture the broad based momentum in all segments of demand. Along with the ramp from our recent high impact renovations and conversions driving solid results ahead of our expectations. During the first quarter we achieved RevPAR, growth of 4.8% outperforming the industry by 100 basis points. We delivered robust non room revenue growth which exceeded our REVPAR performance by more than 300 basis points and we drove high single digit year over year EBITDA, growth and margin expansion. We also advanced our conversion pipeline and addressed all of our maturities through 2029. Our solid first quarter performance demonstrates the momentum in our urban markets and the growth embedded in our portfolio. While the ongoing execution of Our capital allocation and balance sheet initiatives position us to continue to drive outperformance relative to the industry and create long term shareholder value. Turning to our operating results, our first quarter RevPAR, growth of 4.8% was balanced between occupancy and ADR gains. Trends improved sequentially throughout the quarter with RevPAR, in February and March achieving healthy year over year growth of 6% and 9% respectively. Following January’s RevPAR, decline, both February and March were aided by a robust calendar of events as well as the favorable timing of holidays which bolstered demand. We were pleased to see this positive momentum carry into April. Our urban markets have been consistently performing well, disproportionately benefiting from positive trends across all demand segments. We were pleased to see our urban footprint outperform the broader industry urban markets with a number of our markets delivering high single digit RevPAR, growth. Notably, Northern California achieved outstanding RevPAR, growth of 27%, benefiting not only from the super bowl and the favorable shift of the RSA Conference to March this year, but also from the continued expansion of of the AI industry which is driving significant corporate investment and business travel demand broadly across this market. In addition to a better overall environment, New York City, was another noteworthy market during the quarter with our properties achieving over 8% RevPAR, growth driven by healthy corporate and leisure transient demand, a favorable events lineup and the ramp of our high occupancy renovations that we completed last year. As it relates to segmentation, business travel saw robust growth during the first quarter with our business transient revenues growing by 9% which was largely demand driven with room nights increasing by nearly 700 basis points. The momentum in business travel accelerated throughout the quarter underpinned by strong growth in business investment driven by AI related spending as well as record corporate profits. This is specifically fueling the ongoing strength in sectors such as technology, finance, aerospace and life sciences which is amplifying overall business travel (BT) demand. Leisure trends were strong across our portfolio with revenues growing by 5%. Demand remained resilient and we were encouraged to see rate growth of 3%. The leisure segment benefited from a compressed spring break as well as elevated demand at a number of our hotels as winter storms across the country drove additional leisure travel during peak season. Our urban leisure once again saw stronger relative performance as our hotels and live workplace submarkets are capturing robust demand around sports, concerts, dining, festivals and entertainment. Importantly, our geographically diversified portfolio continues to benefit year after year from the rotation of signature events within our footprint relative to our group segment, even with difficult comparisons from the inauguration in D.C. and the Austin Convention center booking trends remained healthy evidenced by our in the quarter for the quarter revenue pace increasing by 900 basis points and ADR increasing by 3% over last year. We were especially pleased to see a meaningful pickup in group bookings for the second quarter which saw pace improve by 400 basis points. We are encouraged by the increasing share of corporate bookings within our group mix which has positive implications for ADR and out of room spend. Our portfolio also generated outsized non room revenue growth of 8.2%, once again underscoring the momentum behind our ROI initiatives and the investments we have made in expanding ancillary revenue channels. These initiatives allowed us to increase our total revenues by 5.4%. This top line growth combined with disciplined cost management and a lean operating model contributed to our significant EBITDA, outperformance relative to our initial expectations and our margins expanding by 45 basis points over the prior year. Now, turning to capital allocation, our transformative renovations from last year as well as our completed conversions are delivering tangible results and contributed meaningfully to our outperformance relative to the industry. This is demonstrated by our four major renovations at high occupancy hotels completed last year achieving 9% RevPAR, and 10% EBITDA, growth during the quarter. Our conversions continue to deliver solid results with our seven completed conversions generating EBITDA, growth of 16%. Additionally, we made further progress towards our Renaissance Pittsburgh conversion and remain on track to relaunch the property under Marriott’s autograph collection. This summer we advanced preparation of our conversion of the Wyndham Boston Hotel which will join Hilton’s Tapestry collection, and we are on pace to begin construction later this year and we look forward to announcing our next conversion in the coming quarter. Collectively, these capital allocation initiatives supported by our strong balance sheet, position us for multiple years of growth in 2026 and beyond. Looking ahead, we recognize that the macro environment remains uncertain, driven by an evolving geopolitical backdrop which is giving rise to shorter booking windows and limiting visibility beyond the near term. To date, however, we have not observed a noticeable impact on our results. Our first quarter outperformance on both the top and bottom line is encouraging and we believe the setup continues to favor urban markets for the remainder of the year, supported by sustained strength in business, transient and robust demand for urban leisure experiences, trends that should disproportionately benefit our portfolio overall. We had already anticipated these healthy trends in our original guidance for the remainder of the year. However, given the current uncertainty, we will continue to monitor any shifts in demand. Our outlook assumes the continuing broad based strength in business travel (BT) supported by healthy corporate profits and growth across a number of industries, reinforcing our view that the recovery in this segment has further room to grow the resiliency of leisure demand and expectations for continued rate growth as we approach the peak summer travel season, especially in our urban markets which have an extensive lineup of events, sports, concerts and entertainment A positive group pace for the remainder of the year with ADR demonstrating pricing power and our expectations that even with a shortened booking window we will continue to see strong in the quarter for the quarter bookings a favorable footprint to capture upcoming catalysts including the World cup and America’s 250th anniversary the ongoing momentum in Northern California across all demand segments further validating the sustainability of this market’s recovery. Continued growth of non room revenues from our ROI initiatives as well as tailwinds from the ramp of our four significant renovations completed last year and our recently completed conversions which are well positioned to drive multiple years of growth. Our strong results are a direct outcome of the strategic repositioning of our portfolio over the past several years through asset recycling, targeted acquisition and high impact conversion. As we look ahead, we remain cautiously optimistic about the long term durability of the demand trends we are seeing and believe our well positioned portfolio will support continued strong relative performance and the creation of long term value for our shareholders. With that I will turn the call over to Nikhil.

Nikhil Bala (Chief Financial Officer)

Thanks Leslie to start, our comparable numbers include our 92 hotels owned at the end of the first quarter. Our reported corporate adjusted EBITDA and AFFO include operating results from all sold hotels during RLJ’s ownership period. Our first quarter results came in ahead of our expectations with Occupancy increasing by 2.6% to 70.8%, average daily rate increasing by 2.1% to $210 and our RevPAR of $149 increasing by 4.8% versus the prior year. Fundamentals strengthened throughout the quarter following January’s 1.9% RevPAR decline with growth accelerating to a robust 6.1% in February and 8.9% in March. These healthy trends carried into April which achieved preliminary RevPAR growth of approximately 4%. During the quarter we saw meaningful strength within our urban markets which achieved 4.4% RevPAR growth outperforming STR’s comparable markets by 110 basis points. This growth was broad based and balanced between approximately a 2 point increase in occupancy and a 2 point increase in ADR. Our strong urban portfolio performance was bolstered by double digit RevPAR growth in markets such as South Florida which grew RevPAR by approximately 10% and Houston and Denver which each achieved 14% RevPAR growth, additionally demonstrating that our portfolio benefits from seven days a week demand both weekdays and weekends saw mid single digit RevPAR growth. Our urban markets benefited from improvements in all segments of demand, notably business travel. The acceleration in BT demand that we are seeing has positive implications for the momentum in out of room spend which was evident in the robust growth of 8.2% in our non room revenues that we saw during the first quarter. We were especially pleased to see the strong revenue growth come on the heels of the robust 7.2% growth we achieved during the prior quarter. Our non room revenues generate strong margins which improved by 130 basis points during the quarter, underscoring the success of our ROI initiatives aimed at profitably growing food and beverage reconcepting underutilized spaces and growing other ancillary revenues. Overall, non room revenue growth led our first quarter total revenues to grow by 60 basis points ahead of our RevPAR growth. Turning to bottom line results, total operating expenses were up 2.1% on a PER occupied room basis, underscoring the benefits of our lean operating model and our disciplined approach to managing costs which allowed for strong flow to the bottom line. Although energy expenses were elevated due to the winter storms as well as disruption in the energy markets due to the war, these were more than offset by improvements in fixed costs driven by a double digit decline in property insurance due to a favorable renewal last year and other cost control initiatives. During the first quarter our portfolio achieved Hotel EBITDA of $89.9 million representing year over year growth of $6.1 million or 7.2% and Hotel EBITDA margins of 26.4% which expanded by 45 basis points over the prior year. These results translated to adjusted EBITDA of $80.9 million and adjusted FFO per diluted share of $0.33 for the first quarter with respect to our balance sheet. As previously announced, during the first quarter we executed a series of refinancing transactions which expanded our undrawn capacity by $500 million and created additional flexibility. We intend to use the additional capacity created by these refinancings to pay off our $500 million senior notes that mature on July 1 this year. Following this payoff, we will have no maturity due until 2029 and our weighted average maturity will be over four years. Our balance sheet remains well positioned with over $950 million of liquidity, including undrawn capacity of $600 million on our corporate revolver, 84 of our 92 hotels unencumbered by debt, an attractive weighted average interest rate of 4.6% and 75% of debt either fixed or hedged. We ended the first quarter with $2.2 billion of debt. In addition to proactively addressing our maturities, we continue to demonstrate our steadfast commitment to returning capital to shareholders by paying an attractive and well covered quarterly dividend of $0.15 per share. Now, turning to our full year outlook, we are pleased with the strong start to the year. At the same time, we remain mindful of the uncertainty in the overall macro environment. We have incorporated our strong first quarter outperformance into our revised guidance while keeping our expectations for the remainder of the year unchanged from our prior outlook for 2026. We now expect Comparable RevPAR growth to range between 1.5% and 3.5%, Comparable Hotel EBITDA between $356 million and $380 million, Corporate Adjusted EBITDA between $324 million and $348 million and Adjusted FFO per diluted share to be between $1.29 and $1.45. Our outlook assumes no additional acquisitions, dispositions or balance sheet activity beyond what has been completed to date. We continue to estimate capital expenditures will be in the range of $80 million to $90 million, cash GNA will be in the range of $32.5 million to $33.5 million and expect net interest expense will be in …

Full story available on Benzinga.com

This post was originally published here

Bitmine Immersion Technologies (NYSE:BMNR) acquired 101,745 Ethereum (CRYPTO: ETH) last week, pushing total holdings to 5.18 million tokens worth $12.1 billion.

Bitmine Now Holds 4.29% Of Total ETH Supply

Bitmine’s 5.18 million ETH represents 4.29% of Ethereum’s total 120.7 million supply, making it 86% of the way to the “Alchemy of 5%” goal in just 10 months. 

The company also holds 200 Bitcoin (CRYPTO: BTC), $200 million in Beast Industries, $83 million in Eightco Holdings (NASDAQ:ORBS), and $700 million cash for total crypto and cash holdings of $13.1 billion.

Bitmine has staked 4.36 million ETH worth $10.2 billion at $2,336 per coin, more than any other entity in the world. 

At full scale, projected ETH …

Full story available on Benzinga.com

This post was originally published here

Blackstone Inc. (NYSE:BX) and Goldman Sachs Group Inc. (NYSE:GS) are committing a combined $450 million to a new $1.5 billion joint venture with Anthropic that will deploy the Claude maker’s AI models directly inside mid-sized companies.

The deal, announced Monday, lands as Anthropic eyes a public listing as soon as this year.

Spending On Large Language Models Up 15-Fold

Anthropic, Blackstone and Hellman & Friedman are each anchoring the deal at $300 million apiece.

Goldman Sachs is putting in $150 million, with General Atlantic, Leonard Green, Apollo Global Management, GIC and Sequoia Capital filling out the consortium.

The new firm will embed Anthropic engineers directly inside customers to design and maintain AI deployments.

Initial target sectors include healthcare, manufacturing, financial services …

Full story available on Benzinga.com

This post was originally published here

Xanadu Quantum Technologies (NASDAQ:XNDU) shares are trading sharply lower on Monday. The sell-off follows the company’s filing of a resale prospectus with the U.S. Securities and Exchange Commission.

The registration covers the potential sale of up to 293,655,720 Class B subordinate voting shares by selling securityholders.

Details of the Resale Filing

The filing includes 254.7 million shares issuable upon the conversion of Class A multiple voting shares. It also registers 27.5 million PIPE shares from private placements entered into on Nov. 3. Additionally, the prospectus covers 157,960 shares issuable upon the exercise of warrants issued to the Royal Bank of Canada.

Proceeds and Selling Holders

Xanadu stated it will not receive proceeds from secondary sales. “We …

Full story available on Benzinga.com

This post was originally published here

Chevron (NYSE:CVX) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://event.webcasts.com/starthere.jsp?ei=1740948&tp_key=b288c096d9

Summary

Chevron Corp reported first-quarter 2026 earnings of $2.2 billion or $1.11 per share, with adjusted earnings of $2.8 billion or $1.41 per share, despite a $360 million charge related to legal reserves.

The company emphasized its disciplined execution despite geopolitical tensions, maintaining strong production and refining operations, with US production over 2 million barrels per day and significant integration benefits across its value chain.

Chevron maintains its 2026 guidance unchanged, expecting 7-10% production growth and consistent capital spending, while continuing to execute strategic projects in Venezuela and optimizing global supply chains.

Share repurchases were consistent with guidance at $2.5 billion, and the company anticipates improvements in working capital in the second half of the year, driven by commodity prices.

Management reiterated the importance of maintaining capital discipline, strong cash flow, and consistent shareholder returns, with a focus on long-term resilience and strategic growth opportunities, particularly in the Permian and Venezuela.

Full Transcript

OPERATOR

Good morning, my name is Katie and I will be your conference facilitator today. Welcome to Chevron’s first quarter 2026 earnings conference call. At this time, all participants are in a listen only mode. After the speaker’s remarks, there will be a question and answer session and instructions will be given at that time. If anyone requires assistance during the conference call, please press star then zero on your touchtone telephone. As a reminder, this conference call is being recorded. I will now turn the conference call over to the head of Investor Relations of Chevron Corporation, Jeanine Wei. Please go.

Janine Wei

Thank you, Kayte. Welcome to Chevron’s first quarter 2026 earnings conference call and webcast. I’m Janine Wei, Head of Investor Relations. Our Chairman and CEO Mike Wirth and CFO Eimear Bonner are on the call with me today. We’ll refer to the slides and prepared remarks that are available on Chevron’s website. Before we begin, please be reminded that this presentation contains estimates, projections and other forward looking statements. A reconciliation of non GAAP measures can be found in the appendix to this presentation. Please review the cautionary statement and additional information presented on slide 2. With that now I’ll turn it over to Mike.

Mike Wirth (Chairman and CEO)

All right, thanks Janine, and welcome to your new role. This quarter, Chevron delivered solid performance driven by disciplined execution and a resilient portfolio. Despite market volatility and heightened geopolitical tensions, our people remain focused on safely delivering the reliable energy the world needs. Our approach remains consistent. Maintain capital and cost discipline, generate strong cash flow and deliver superior shareholder returns. Chevron’s fundamentals are strong. We have a world class portfolio and upstream assets with peer leading cash margins. And we’re carrying strong momentum into the second quarter with US production over 2 million barrels of oil equivalent per day, Gorgon and Wheatstone LNG running at full rates, TCO producing above 1 million barrels of oil equivalent per day and US refineries operating at record crude throughput. The unique combination of Chevron’s industry leading refining complexity and our diverse waterborne equity crudes from TCO, Guyana, Permian, Venezuela and Argentina creates opportunities for value capture through integration. Our high quality upstream and downstream portfolios delivered significant integration benefits during the quarter. We maintained strong supply into tight markets and maximized margins across products including fuel oil, sulfur and other secondary products which saw significant price dislocations. We continue to optimize flows across our value chains to maintain high utilization and reliable supply into the market. In the second quarter, we expect global equity crude throughput to more than double to year over year to 40% in Asia. We anticipate over 80% refinery utilization moving to Venezuela. We continue to leverage our deep expertise and long standing position to create an option for the future. Two weeks ago we announced an asset swap with PDVSA. The agreement increases our position in the Orinoco Ayacucho 8 expands our continuous acreage position with PetroPiar offering operating and development synergies along with long term growth potential and optionality. Petroindependencia is a joint venture we’ve been in for more than 15 years where we’ve increased our equity stake to 49%. Current operations are running smoothly. We’re still in debt recovery mode and expect Venezuela to continue to represent 1 to 2% of cash flow from operations. This transaction is expected to improve resource depth and integration upside supporting potential growth into the future. Now over to EMER to discuss the financials.

Eimear Bonner

Thanks Mike for the first quarter, Chevron reported earnings of $2.2 billion or $1.11 per share. Adjusted earnings were $2.8 billion, or $1.41 per share. Included in the quarter was $360 million. Charge related to legal reserve foreign currency effects decreased earnings by $223 million. Organic capex was $3.9 billion this quarter, consistent with historical capex trends of lighter spending in the first half of the year. Inorganic capex was approximately $200 million. We expect to finish within full year. Capital guidance adjusted first quarter earnings were $440 million lower than last quarter. Adjusted upstream earnings increased due to higher realizations, lower depreciation, depletion, and amortization and favourable operating expenses and tax impacts. Adjusted downstream earnings decreased primarily due to unfavourable timing effects which were partly offset by higher refining margins. Unfavourable timing effects totalled around $3 billion for the quarter, reflecting a steep rise in commodity prices in March. The effect was evenly split between inventory valuation and mark to market accounting. On paper derivative positions linked to physical cargoes. We anticipate approximately $1 billion of the paper positions to unwind in the second quarter, with the majority of related cargoes delivered in April. Looking forward, we would expect additional timing effects when prices are rising and further unwinds when prices are falling. Chevron generated cash flow from operations, excluding working capital of $7.1 billion in the quarter. This includes unfavorable impacts from special items and timing effects totaling approximately $3 billion. Adjusted free cash flow was $4.1 billion for the quarter and included a $1 billion loan. Repayment from TCO. Share repurchases were $2.5 billion in line with guidance, working capital was impacted by sharp commodity price increases as well as a build in inventory. Consistent with historical trends, we expect an increase in working capital in the first half of the year and a release in the second half, the extent of which will be primarily driven by prices. Over the period. More than $5 billion in commercial paper was issued to manage liquidity and general business needs. About half has already been paid down in April and we expect these short term balances to climb further throughout the second quarter. First quarter 2026 oil equivalent production increased by approximately 500,000 barrels per day compared to the first quarter of 2025. This reflects the integration of legacy Hess assets in addition to continued organic growth across the portfolio. The conflict in the Middle east had a limited impact on production in the quarter. With less than 5% of our portfolio located in the region in the partition zone, we’re operating at near minimum rates to manage storage in the Eastern Mediterranean. Both Tamar and Leviathan are operating at full capacity. During the quarter, we continued to execute key expansion projects, completing the offshore scope for both the Tamar optimization project and the Leviathan Third Gathering Line. Let me close by reinforcing that. Despite changes in the external environment, we’re executing our plan with discipline, consistent with our long standing financial priorities. This disciplined approach gives us resilience during periods of volatility and the ability to invest and return cash to shareholders through the cycle, all while ensuring we maintain a balance sheet built for the long term. Chevron business is Strong and our 2026 guidance is unchanged. Capital spending and production outlooks are consistent with previous guidance and we’re on track to deliver our 3 to 4 billion dollars structural cost reduction target by year end. This consistency underpins our 2030 targets announced in November, including over 10% growth in adjusted free cash flow and earnings per share and 3% improvement in ROC, all at $70. Brent, these aren’t aspirational goals. They’re grounded in assets that are operating today, a more efficient organizational model and continued capital discipline. I’ll now hand it off to Janine.

Janine Wei

Okay, that concludes our prepared remarks. Thank you, Mike Emer As a reminder, additional guidance can be found in the appendix of the presentation as well as in the slides and other information that’s posted on chevron.com we’re now ready to take your questions. We ask that you please limit yourself to one question and we’ll do our best to get all of your questions answered. Katie, please open the lines.

OPERATOR

Thank you. If you have …

Full story available on Benzinga.com

This post was originally published here

Tyson Foods (NYSE:TSN) reported second-quarter financial results on Monday. The transcript from the company’s second-quarter earnings call has been provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://events.q4inc.com/attendee/759959591

Summary

Tyson Foods reported second quarter sales of $13.7 billion and an adjusted operating income of $497 million, indicating strategic success and momentum in their diversified protein-centric approach.

The company highlighted strong performance in its chicken segment with a 12.2% margin, driven by operational excellence and strategic customer partnerships, while genetics improvements are expected to further enhance future performance.

Prepared Foods saw a 4.8% sales increase with a 14% margin, gaining market share across several categories and benefiting from disciplined execution and innovation.

Beef segment faced challenges due to cattle cycle volatility but is expected to improve with footprint optimizations, while pork benefited from stable operations and balanced supply-demand dynamics.

The company raised its AOI guidance for the year, indicating confidence in continued robust demand for high-quality protein and operational improvements, despite external market pressures.

Full Transcript

OPERATOR

Good morning and welcome to the Tyson Foods second quarter 2026 earnings conference call. All participants will be in a listen only mode. Should you need assistance, please signal a conference specialist by pressing the Star key followed by zero. After today’s presentation there will be an opportunity to ask questions. To ask a question, you may press Star then one on your touchtone phone. To withdraw your question, please press Star then two. Please note this event is being recorded. I would now like to turn the conference over to John Cottle, vp, Investor Relations. Please go ahead.

John Cottle (Vice President, Investor Relations)

Good morning and welcome to Tyson Foods second quarter fiscal year 2026 earnings conference call. On today’s call, Tyson Foods President and Chief Executive Officer Donnie King, Chief Financial Officer Curt Callaway and Chief Operating Officer Devin Cole will provide prepared remarks. Following the prepared remarks, we will have a Q and A session. We have also provided a supplemental presentation which may be referenced on today’s call and is available on Tyson’s investor Relations website and via the link in our webcast. During today’s call we will make forward looking statements regarding our expectations for the future. These forward looking statements made during the call are provided pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Forward looking statements include all comments reflecting our expectations, assumptions or beliefs about future events or performance that do not relate solely to historical periods. These forward looking statements are subject to risks, uncertainties and assumptions which may cause actual results to differ materially from our current projections. Please refer to our forward looking statement disclaimers on Slide 2 as well as our SEC filings for additional information concerning risk factors that could cause our actual results to differ materially from our projections. We assume no obligation to update any forward looking statements. As we mentioned last quarter segment results are presented on a segment operating income level and will be discussed on an adjusted basis. The primary difference between segment operating income and the method used in previous quarters is that we no longer allocate corporate expenses and amortization down to the segment level. We have recast previously reported quarterly results for the previous three fiscal years to reflect the new format. The segment change has no impact on consolidated historical US GAAP financial results. The recast financial information is accessible through the Events and Presentation section of the Company’s investor relations website at ir.tyson.com Please note that references to earnings per share, segment operating income, operating income and operating margin in our remarks are on an adjusted basis for our fiscal periods unless otherwise noted. For reconciliations of these non GAAP measures to their corresponding GAAP measures Please refer to our earnings press release now. I will turn the call over to Donnie.

Donnie King (President and Chief Executive Officer)

Thank you John and thanks to everyone joining us today. Overall, I’m pleased with our performance in the second quarter and we are raising our AOI guidance for the year to incorporate better performance year to date and continued confidence in the future of our business. I’d like to reinforce what we’re building at Tyson, a diversified protein centric company positioned to capture growing demand for high quality protein. Animal protein remains top of mind for consumers and continues to gain momentum as a foundational part of a healthy diet. We are directly tied to and stand to benefit from this long term trend. We’re focused on disciplined execution, a diversified multi protein portfolio and a balanced approach to capital allocation. Our scale and operating capabilities support cash generation across cycles enabling us to reinvest in the business, reduce leverage over time and return capital to shareholders consistent with our capital priorities. We remain committed to our long term strategy that creates value for customers, consumers and shareholders and will continue to be transparent with our investors along the way. Our shift to segment operating income is working as intended. This change empowers our business leaders to pursue volume growth and enhance their decision making based on a more direct view of the impacts of those decisions without corporate expenses and amortization which are more fixed in nature. As stated previously, we will continue to focus on reducing spending and maximizing efficiencies in our corporate functions and see more Runway with both initiatives. Let me tell you more about the quarter and Devin and Kurt will elaborate. Our second quarter results with $13.7 billion in sales and $497 million in adjusted operating income demonstrate that our strategy is working and is gaining momentum for both Tyson Foods and and our customers. We remain focused on continuous improvement and our team is energized by the opportunities ahead within chicken. We delivered another impressive quarter with $523 million in segment operating income at a 12.2% margin while navigating a more normalized commodity environment and typical Q2 seasonality. Strong execution on the controllables and more efficient marketing and promotional spend drove improved performance. Demand remains robust and our customer centric approach is working. Overall, year over year chicken volume was up 1.7% with retail and food service volumes growing nearly three times faster than total volume, reflecting momentum with our strategic customers. Importantly, these results were not driven by broad price increases with base pricing being slightly lower in the quarter, but rather we saw improvements in product mix and executed well operationally. Our end to end chicken business, including our chicken genetics business, is performing at a high level as we continue to deliver on our commitments, but we see ample opportunities for more improvement and growth. This is another example of how our chicken business is outperforming compared to a commodity chicken business. Moving to prepared foods segment operating income increased to $352 million even as commodity costs were higher year over year and our margin expanded to 14% reflecting strong demand share gains and disciplined execution. Sales grew 4.8% and volume grew 0.4%. Importantly, we continue to drive innovation and our brands are winning in the marketplace. In Q2, we gained share in volume, dollars and units. Our brand strength and focus on customer relationships, along with improved promotional efficiency and targeted MAP investments are delivering strong return on investment. Turning to beef, our segment results reflected the expected volatility in the cattle cycle. We successfully completed the previously announced strategic decision to optimize our manufacturing footprint. As a result, our second quarter results reflect only a portion of these operational adjustments, which are intended to improve utilization and strengthen our cost position. Importantly, we’re staying focused on the levers we can control plant utilization, operating discipline, customer mix and execution, and we expect the benefits from these actions to build as we move through the year. Our outlook for the remainder of the year implies lower losses in the back half than the front half of the year. We continue to expect results below historical margin levels until cattle supplies normalize. Our pork segment performed well in a stable operating environment. All parts of the pork value chain, from hog supply pork production through retail and food service customers are in relative balance, allowing for more predictable and stable operating margins. Pork’s relative value to beef is likely to benefit revenue for the balance of the year. Finally, our international segment continued its momentum and had another good quarter. As we’ve discussed, there is increasing demand for protein, which helps us drive strong revenue and cash flow even through economic ups and downs. We also benefit from being a producer of several different animal proteins as the timing of these cycles can vary. This trend insulates us from an otherwise fragile macro environment. Consumer confidence recently fell to a record low while inflation is still elevated more than 3%. At the same time, food service traffic rebounded in the second quarter, reinforcing the value of our diversified portfolio across retail and food service. We also benefit from our scale as we can provide lower unit costs, better service levels and maintain a healthy market share as we produce approximately 1 in 5 pounds of US chicken, beef and pork. Our long history and strong position in the marketplace solidifies our business for the long run. Protein continues to be a priority for consumers. As a leading animal protein provider, we are well positioned to meet this demand with products that deliver complete nutrition, including all nine essential amino acids. This, along with our shift to simple ingredients like those found in your pantry, is resonating and gaining traction with consumers. Together, these factors support stronger returns through disciplined investment, expanding profitability and consistent cash return to shareholders. Consumers are choosing protein and they’re leaning into brands they trust for quality, taste and convenience. That plays directly to Tyson Foods strengths where we’re winning in chicken and prepared foods, driving share, volume and margin. According to Nielsen data, total food and beverage category retail volume declined 1% with dollars up 1.7% over the 13 weeks ending in March. In contrast, our Tyson retail branded products, which includes our national and regional brands, grew by 2.3% in volume and 3.6% in dollars, outperforming the broader categories. We are also winning in digital across key retailers. Our digital dollar growth is materially stronger than in store performance, reflecting our ability to compete and win in omnichannel shopping. A few examples include Tyson branded value added chicken up 6.5%, Adele’s dinner sausage increased by 9.7%, Hillshire lunch meat grew by 7.6% and Wright and Jimmy Dean bacon increased by 6.8%. Our Hillshire snack combos have also achieved double digit growth. In addition to the volume growth, all five categories grew dollars and share, reinforcing that we’re winning with consumers while improving the quality of our growth. We’re also performing well in food service with volume growth of 60 basis points. In terms of how we’re driving innovation in our portfolio, we are using AI driven insights that sharpen how we identify emerging preferences and translate them into action. This enables us to bring on trend consumer led products into the marketplace. In practice, the integration of AI allows us to better connect what consumers are telling us with what shows up on shelves and menus. The capability is accelerating our innovation pipeline, improving decisions around distribution and pricing and strengthening the effectiveness of marketing and new customer acquisition. One example of this is in our Jimmy Dean brand. Using these insights, we’re pioneering the next wave of higher protein breakfast. Our recent launch of a Jimmy Dean protein breakfast platform is off to a phenomenal start bringing higher protein versions of consumer traditional favorites like sandwiches and bowls that are showing stronger velocity and consumer takeaway. We’re pairing those core items with innovation like Jimmy Dean high protein waffles that is the new and incremental to our prepared foods business. Early consumer responses have been very positive and it’s bringing new and younger consumers to the brand. We have already begun to capture meaningful share at retail and we see a compelling Runway to build on this momentum. As we expand distribution and continue to innovate, our retail performance remains superior to that of our primary competitors in comparable business segments across the industry. Over the past 12 months, our prepared foods retail business has driven strong gains in volume, market share and profitability, outpacing our peers. However, our valuation continues to reflect discount relative to those peers. Investors who recognize the value today will benefit the most. This is why Tyson Foods is uniquely situated for success in today’s environment. Demand for our products continues to grow and we’re well positioned to capture this momentum. While some companies face challenges in generating demand, our share gains demonstrate both our strength and our expectation for further growth, an essential driver of our ongoing success. Our protein centric offerings combined with disciplined capital allocation enable us to capitalize on the opportunities that stem from strong performance and allow us to continue to thrive in the Marketplace. As a 90 year old American company, we provide trust and consistency across cycles. As you’ve heard us say many times, we’re not standing still. Overall, these strengths allow us to deliver lasting value to our customers, consumers, team members and shareholders. Looking ahead, the opportunities before us are more promising than ever and I’m very confident in our portfolio and in our strategy. With that, I’ll turn it over to Devin to take you through the segments in more detail.

Devin Cole (Chief Operating Officer)

Thank you Donnie and good morning. In the second quarter our team made progress toward our strategic objectives. We remain committed to holding ourselves accountable to our customers and consumers expectations. Now let’s review our segment performance. Prepared Foods delivered a strong quarter with sales up 4.8% versus last year and volume up 0.4%. Segment operating income was 352 million, up 7% year over year and margin expanded to 14%. Reflecting continued progress on our multi year plan to enhance profitability, we gained share in volume, dollars and units in the quarter. Volume share was up 70 basis points and dollar share was up 50 basis points driven by strong protein demand and our disciplined execution with notable wins in bacon, lunch, meat, dinner, sausage and snacking. Volume growth reflects distribution gains, innovation and improved promotional efficiency supported by targeted MAP investments as consumers prioritize convenient, nutritious, high protein solutions. Looking ahead, we expect continued growth in segment operating income for the full year and remain well positioned in this business for the long term. In chicken we delivered segment operating income of 523 million and a margin of 12.2% despite a more normalized pricing environment and the typical seasonality we see in Q2, sales were up 3.5% year over year driven by favorable mix and volume growth. With total chicken volume up 1.7%, retail and food service volumes grew nearly three times faster than total volume, reflecting strong consumer demand and momentum with our strategic customers. Our diversified pricing strategies and improved mix kept average selling prices stable even as base pricing was down. That stability and our bottom line results were driven by a better product mix tied to strategic customer growth and stronger operational performance. Execution continued to improve across the controllables live performance yield, asset utilization, labor productivity and end to end supply chain discipline, supporting our sixth consecutive quarter of year over year volume and net sales growth and reinforcing the consistency and predictability of our chicken business. We also wanted to highlight the success we are seeing in our chicken genetics business which is competing at a high level again. This has been driven by the hard work of our genetics and live production teams. Alongside family farmers who are the best at what they do, this business is delivering meaningful sustainable results and creating real economic value for our customers. Combined with our shift toward a more value added product mix, our strategic customer alignment and our chicken genetics business differentiates Tyson from commodity chicken competitors and strengthens the value proposition we deliver to customers and shareholders. Growth was strong across retail and food service with nearly all sub channels delivering positive volume growth. We are strengthening service and quality with our strategic customers while continuing to expand our value added and premium portfolio to meet demand for convenient high quality options. Taken together, our strategic customer partnerships and disciplined execution are strengthening our chicken business model. As it becomes more consistent and predictable, we see more Runway ahead in our beef segment. We remain committed to disciplined execution and the actions within our control as we operate in a dynamic market environment. Beef sales increased slightly in the second quarter compared to the prior year. Our updated operational footprint is aligning with lower cattle availability and we are seeing the benefits of a higher capacity utilization. While the quarter included variability in industry conditions, we believe the harvesting plan adjustments better position us to compete effectively this year and over the long term with the right size production footprint. We expect to see increasing benefits from these actions in the coming quarters. Segment operating income declined compared to the prior year as higher cattle costs more than offset higher cutout values even as consumer demand remains strong. As we navigate the current cycle, we remain …

Full story available on Benzinga.com

This post was originally published here

BrightSpring Health Services (NASDAQ:BTSG) on Friday reported strong first-quarter results and increased its full-year guidance.

The home health care service provider reported first-quarter adjusted earnings of 39 cents per share, beating the analysts’ estimate of 31 cents.

Sales jumped 35.6% to $3.61 billion, surpassing the consensus of $3.39 billion. Adjusted EBITDA of $190 million rose 44.8% compared to $131 million a year ago.

BrightSpring Health Services increased its fiscal 2026 sales guidance from $14.45 billion-$15 billion to $14.73 billion-$15.23 billion compared to the consensus of $14.85 billion. Total Adjusted EBITDA is expected to be …

Full story available on Benzinga.com

This post was originally published here

Editor’s Note: This article has been updated to correct the name of QNX’s president.

BlackBerry Ltd. (NYSE:BB) no longer sells the phones that once defined its brand, but its software story is getting harder for investors to ignore.

The company’s QNX technology now runs quietly inside 275 million vehicles, making BlackBerry far more relevant than many consumers realize, The Wall Street Journal reports.

Profitability Turnaround

Last month, BlackBerry posted its fourth straight profitable quarter, marking its first such streak in about a decade. That gives the turnaround story more weight beyond nostalgia for its keyboard-phone era.

The company reported fourth-quarter revenue of $141.7 million, topping guidance. QNX revenue reached $65.8 million, while Secure Communications revenue came in at $67.3 million.

QNX Momentum

CEO John Giamatteo said QNX continues to win business with automakers and suppliers. The company’s royalty backlog grew to about $865 million, signaling stronger future revenue potential.

Hidden Auto Play

QNX powers safety-critical software across automotive, medical, industrial, rail and robotics markets. “On a car, you’ll never see QNX’s logo,” said QNX President John Wall, The Wall Street Journal added. “What you will see …

Full story available on Benzinga.com

This post was originally published here

A Wall Street Journal investigation published Sunday found that just 0.1% of Polymarket accounts have taken home 67% of all profits on the platform, while more than 70% of users have lost money.

The analysis covered 1.6 million accounts dating back to November 2022, with the bottom 10% of traders down an average of $4,000 each. A typical user is somewhere between $1 and $100 in the red.

The numbers echo a recent academic study finding that 68.8% of Polymarket users lost money, with the top 1% capturing 77% of gains.

Kalshi shows similar patterns.

Spokeswoman Elisabeth Diana told the Journal there are 2.9 unprofitable users for every profitable one, based on data from the past month.

Kalshi Pushes Back On The Framing

Kalshi co-founder Luana Lopes Lara fired back on X, rewriting the WSJ’s headline herself: “People win more on prediction markets than sportsbooks and equities.”

Diana also …

Full story available on Benzinga.com

This post was originally published here

Hess Midstream (NYSE:HESM) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://edge.media-server.com/mmc/p/ozzfui9j/

Summary

Hess Midstream reported solid operational performance and achieved its guidance despite severe winter weather impacting the first quarter of 2026.

The company completed a $60 million share and unit repurchase and increased its distribution by 2% for Class A shares.

Throughput volumes were lower due to winter weather but are expected to grow for the rest of the year, with a minor impact from planned maintenance in Q2.

Capital expenditures were reduced by a third to approximately $100 million for 2026, with adjusted free cash flow guidance increased to $910-$960 million.

Net income for Q1 2026 was $158 million, with adjusted EBITDA at $300 million, slightly down from Q4 2025 due to weather-related lower revenues.

The company remains focused on safe, reliable operations and leveraging infrastructure for significant free cash flow, supporting shareholder returns and debt reduction.

Hess Midstream expects to maintain its financial strategy with conservative leverage targets and a focus on incremental shareholder returns and debt repayment.

The company reported a strong performance in terminaling revenues due to tariff adjustments, expecting stability for the remainder of the year.

Management emphasized ongoing operational collaboration with Chevron and a strategic focus on optimizing efficiencies and productivity in the Bakken.

Full Transcript

OPERATOR

Good day ladies and gentlemen and welcome to the first quarter 2026 Hess midstream conference call. My name is Kevin. I’ll be your operator for today. At this time, all participants are in a listen only mode. After the speaker’s presentation, there will be a question and answer session. To ask a question during the session, you’ll need to press star 11 on your telephone. You will then hear an automated message device and your hand is raised to withdraw your question. Please press star 11 again. Please be advised today’s conference is being recorded for replay purposes. I would now like to turn the conference over to Jennifer Gordon, Vice President of Investor Relations. Please proceed.

Jennifer Gordon (Vice President of Investor Relations)

Thank you Kevin. Good morning everyone and thank you for participating in our first quarter earnings conference call. Our earnings release was issued this morning and appears on our website, www.hessmidstream.com. Today’s conference call contains projections and other forward looking statements within the meaning of the federal SECurities law. These statements are subject to known and unknown risks and uncertainties that may cause actual results to differ from those expressed or implied in such statements. These risks include those set forth in the risk factors SECtion of Hess Midstream’s filings with the SEC. Also on today’s conference call, we may discuss certain GAAP financial measures. A reconciliation of the differences between these non GAAP financial measures and the most directly comparable GAAP financial measures can be found in the earnings release. With me today are Jonathan Stein, Chief Executive Officer and Mike Chadwick, Chief Financial Officer. I’ll now turn the call over to Jonathan Stein.

Jonathan Stein (Chief Executive Officer)

Thanks Jennifer. Welcome everyone to our first quarter 2026 earnings call. Today I will discuss our first quarter performance and outlook for the remainder of the year and then I’ll hand the call over to Mike to review our financials. In the first quarter, we continued to execute our operational priorities and deliver our financial strategy. We delivered solid operational performance and achieved our guidance which included the impact of severe winter weather in January and February. In March we completed an accretive $60 million share and unit repurchase on the public, our sponsor, and last week we increased our distribution 2% or approximately 8% on an annualized basis for Class A shares. This increase included our targeted 5% annual increase for Class A shares and a distribution level increase following our repurchase that maintains our total distributed cash on a lower share and unit count. Turning to our results, during the quarter, throughput volumes averaged 430 million cubic feet per day for gas processing, 119,000 barrels of oil per day for crude terminaling and 115,000 barrels of water per day for water gathering. In line with our guidance, throughput volumes were down compared to the fourth quarter, primarily due to severe winter weather in January and February, partially offset by recovery in March as well as capture of additional third party gas volumes. Consistent with our annual guidance, we continue to expect volumes to grow the rest of the year, excluding the impact of planned maintenance at Tioga Gas Plant in the second quarter. That is expected to reduce volumes by 5 to 10 million cubic feet per day for the quarter. Turning to Hess Midstream’s capital program in the first quarter, we safely brought online the second of two new compressor stations after completing it in the fourth quarter of 2025. In the first quarter, capital expenditures were $10 million seasonally lower than the fourth quarter of 2025 as severe winter weather restricted activity levels. We expect our capital spend to be seasonally higher in the second and third quarters as we continue to execute our program, including completion of greenfield high pressure gathering pipeline infrastructure that we started in 2025. However, with the second compressor station online and reflecting Chevron’s strategy to adopt longer laterals which reduces well connect CapEx for Hess Midstream, we have now reduced our 2026 estimated capital expenditure by a third to approximately $100 million. As a result of this reduction and together with the deferral of cash taxes, we are increasing our 2026 adjusted free cash flow guidance to 910 to $960 million, reflecting a 20% increase year over year. At the midpoint, Hess Midstream remains a leader in shareholder cash returns with one of the highest free cash flow yields across our peer set. In summary, we remain focused on executing safe and reliable operations while leveraging our historical investment in existing infrastructure to continue generating significant adjusted free cash flow, allowing us to equally provide returns to our shareholders through growing distributions and incremental share repurchases while simultaneously continuing to reduce our debt leverage. With that, I’ll hand the call over to Mike to review our financial performance for the first quarter and guidance.

Mike Chadwick (Chief Financial Officer)

Thanks Jonathan and good morning everyone. Today I’ll discuss our financial results for the first quarter of 2026 and provide an update on our second quarter financial guidance and outlook for 2026. Turning to our results for the first quarter of 2026, net income was $158 million compared to approximately $168 million in the fourth quarter of 2025. Adjusted EBITDA for the first quarter of 2026 was $300 million compared with $309 million in the fourth quarter. The decrease was primarily due to lower revenues primarily caused by severe winter weather in January and February, total revenues, including pass through revenues decreased by approximately 15 million, resulting in segment revenue changes as follows. Gathering revenues decreased by approximately 14 million. Processing revenues decreased by approximately 6 million, while terminalling revenues increased by approximately 5 million. Total cost and expenses excluding depreciation and amortization. Pass through costs and net of our proportional share of LM4 earnings decreased by approximately $6 million, primarily from lower seasonal maintenance and lower third party offloads, resulting in adjusted EBITDA for the first quarter of 2026 of $300 million. Our gross adjusted EBITDA margin for the first quarter of 2026 was maintained at approximately 83% above our 75% target, highlighting our continued strong operating leverage. First quarter of 2026 capital expenditures were approximately $10 million, significantly lower than in the fourth quarter of 2025 as severe winter weather limited activity. Net interest excluding amortization of deferred finance costs was approximately $53 million, resulting in adjusted free cash flow of approximately $237 million, an increase of 14% from the fourth quarter of 2025. We had a drawn balance of 343 million on our revolving credit facility at the end of the first quarter of 2026. For the second quarter of 2026, we expect net income to be approximately $150 million to $160 million and adjusted EBITDA to be approximately flat with the first …

Full story available on Benzinga.com

This post was originally published here

Palantir Technologies Inc. (NASDAQ:PLTR) reports first-quarter earnings after the bell today.

Palantir has routinely beaten earnings estimates, which explains the 96% chance Polymarket gives it of topping the $0.28 non-GAAP consensus.

The more interesting action is on Kalshi, where traders are betting on which words Alex Karp will say on the 5:00 p.m. ET call.

What Kalshi Predicts

“Foundry” is at 99%. Foundry is Palantir’s commercial data and analytics platform, the software that paying enterprise customers actually use.

“Warp Speed” is at 93%. Warp Speed is Palantir’s manufacturing operating system, with a cohort that now spans Anduril Industries, L3Harris Technologies Inc. (NYSE:LHX), Shield AI, Saronic and Epirus.

It is the centerpiece of Palantir’s reindustrialization pitch and a recurring Karp set piece.

“USDA” is at 80%. Palantir signed a $300 million blanket purchase agreement with the Department of Agriculture on April 22 to implement the “One Farmer, One File” program. Fresh, named, and exactly the kind of …

Full story available on Benzinga.com

This post was originally published here

The Marzetti (NASDAQ:MZTI) reported third-quarter financial results on Monday. The transcript from the company’s third-quarter earnings call has been provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://edge.media-server.com/mmc/p/h7f8qyxz/

Summary

The Marzetti successfully completed the acquisition of Bachan’s, a growing Japanese American barbecue sauce brand, enhancing their portfolio and growth potential.

Consolidated net sales declined 1% to $453 million, while adjusted net sales decreased 0.91%. However, the company achieved a record third-quarter gross profit of $107.2 million.

The Foodservice segment saw a 1.8% growth in adjusted net sales, driven by strong demand from national chain restaurant customers.

The company anticipates future growth from new product introductions and continued expansion in both retail and foodservice segments.

Management remains optimistic about the integration of Bachan’s and the potential for further acquisitions in the authentic flavors space.

Full Transcript

Dede (Conference Call Facilitator)

Good morning. My name is Dede and I will be your conference call facilitator today. At this time I would like to welcome everyone to the Marzetti company’s fiscal year 2026 third quarter conference call. Conducting today’s call will be Dave Szeczynski, President and CEO, and Tom Pigott, CFO. All lines have been placed on mute to prevent any background noise. After the speakers have completed their prepared remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press Star 11 on your telephone keypad. If you would like to withdraw your question, please press Star 1 again. Thank you. And now to begin the conference call, here is Dale Ganobc, Vice President of Corporate Finance and Investor Relations for the Marzetti Company.

Dale Ganobc (Vice President of Corporate Finance and Investor Relations)

Good morning everyone and thank you for joining us today for the Marzetti Company’s fiscal year 2026 third quarter conference call. Our discussion this morning may include forward looking statements which are subject to the safe harbor provisions of the Private Securities Litigation Reform act of 1995. These statements are subject to a number of risks and uncertainties that could cause actual results to differ materially from and the Company undertakes no obligation to update these statements based upon subsequent events. A detailed discussion of these risks and uncertainties is contained in the Company’s filings with the SEC. Also note that the audio replay of this call will be archived and available on our website investors.marzetti company.com later today for today’s call, Dave Szeczynski, our President and CEO, will begin with an update on our Bachanz acquisition that was successfully completed on Friday, May 1, along with a business update and highlights for the quarter. Tom Pigott, our CFO, will then provide an overview of the financial results. Dave will then share some comments regarding our current strategy and outlook. At the conclusion of our prepared remarks, we’ll be happy to respond to any of your questions. Once again, we appreciate your participation this morning. I’ll now turn the call over to the Marzetti Company’s President and CEO, Dave Szeczynski.

Dave Szeczynski (President and CEO)

Dave thanks Dale and good morning everyone. It’s a pleasure to be here with you today as we review our third quarter results for fiscal year 2026. I would like to start today’s call by providing you with some insights specific to our acquisition of Bachan’s, the fast growing Japanese American barbecue sauce brand known for its delicious authenticity clean label products. I’m happy to share that in advance of last week’s closing of the transaction, we have been collaborating closely with the Bachan’s team on our future plans for the business. Everything we’ve learned has made us even more convinced about what a great addition this is to our family of brands. Since our announcement, the Bachan’s business has continued on a path of strong growth, with Circana’s data for the quarter ending March 31st showing strong sales growth of over 25% and TDPs up over 50%. This growth has resulted in share gains for Bachan’s in the barbecue sauce category, positioning them as the second leading retail brand. Consumers love both the brand and the products, as evidenced by its broad usage across a wide variety of proteins, food types and meal occasions. We believe this brand has tremendous potential and is the perfect fit for our S.O.S. portfolio. Our thoughtful plans for the Bachon’s integration are fully on track. They will remain based in California with their very strong team retained to lead the business. We are also delighted that Bachan’s founder Justin Gill has agreed to continue working with us on product development and marketing strategy. At the same time, we are developing plans to provide this team with the opportunity to draw from Marzetti’s resources, including our go to market capabilities, culinary expertise, procurement capabilities and supply chain expertise to support both their continued growth and cost synergies. Over time, we anticipate additional opportunities for Bachan’s to more fully leverage Marzetti’s supply chain network. We believe our light touch integration approach will allow Bachan’s to continue its strong growth trajectory and we look forward to a bright future with the Bachan’s team. This acquisition strategically expands our portfolio of leading sauces, dressings and DIP brands that now represent two thirds of our consolidated net sales. It also specifically strengthens our portfolio of sauces which alone account for nearly 40% of our consolidated net sales. In the era of M&A and GLP-1s, we believe consumers will continue to seek flavor enhancements for their meals. We believe our deep culinary expertise and focused scale in these categories positions us well to support the continued growth of Bachan’s as well as our other brands. Moving on to the Marzetti Company’s results for our fiscal third quarter which ended March 31, consolidated net sales declined 1% to $453 million, excluding non core sales attributed to the temporary supply agreement or TSA. Adjusted net sales decreased 0.91% to 452 million. Despite the lower sales, we were pleased to report record third quarter gross profit of 107.2 million, an increase of 1.2% driven by our cost savings programs in Our retail segment net sales declined 3.2% while volume measured in pounds shipped declined 5.6%. Our category leading frozen bread brands were a bright spot as sales of our New York Bakery frozen garlic bread products continued to grow and increased market share. While sales of our sister Schubert dinner rolls benefited from the pull forward of demand due to the earlier Easter holiday, these sales gains were more than offset by the impacts of category softness and reduced sales into the Club Channel. We have initiatives in place with our Club Channel partners to pursue future growth for both our Chick-fil-A sauces and Olive Garden dressings. Circana’s scanner data for the quarter ending March 31 showed sales of our core brands and licensed items up 2/10 of 1%. In the frozen garlic bread category, our category leading New York bakery brand grew sales 4.4% adding 260 basis points of market share for a category leading share of 46.7%. In the frozen dinner roll category, our own sister Schubert’s brand and our licensed Texas Roadhouse brand combined to grow 10.1% for a category leading market share of 61%. In the shelf Stable Sauces and condiments category, sales of our licensed Chick Fil a sauces grew 4.4% resulting in a 5 basis points growth of share. In the crouton category, our branded croutons added 40 basis points of market share for a category leading 28.5%. In the Foodservice segment. Excluding the non core TSA sales, adjusted net sales grew 1.8% while volume measured in pound shipped improved 0.81%. In addition to the benefit of inflationary pricing, the increase in foodservice segment net sales reflects increased demand from several of our core national chain restaurant customers. We were pleased to report record third quarter gross profit of $107 million with reported gross margin of 50 basis points. Our focus on supply chain productivity, value engineering and revenue management all remain core elements to further improve our margins and financial performance. I’ll now turn the call over to Tom Pigott, our CFO for his commentary

Tom Pigott (Chief Financial Officer)

on our third quarter results. Tom? Thanks Dave. Overall, the company delivered improved gross profit performance despite a modest decline in revenue. In addition, investments were made to Support future growth. Third quarter consolidated net sales decreased by 1% to $453.4 million. The revenue performance was primarily driven by a decline in core volume and product mix of 120 basis points. This decline was partially offset by net pricing which was accretive by by approximately 30 basis points. Despite the decline in revenue, consolidated gross profit increased by $1.3 million or 1.2% versus the prior year quarter to $107.2 million and reported gross margin expanded by 50 basis points. The gross profit growth was driven by our productivity program where we benefited from cost savings across a number of areas including procurement, manufacturing, value engineering and distribution. This quarter marked the 11th straight quarter of gross margin improvement versus the prior year. This accomplishment is a reflection of the many cost savings initiatives, network restructuring programs, revenue growth management projects and the ongoing pricing net of commodities management program that the company has successfully implemented. Selling general and administrative expenses grew $5.4 million or 9.5%. The increase was primarily driven by a net increase in acquisition related costs, higher IT expenses and personnel related costs. As we invested to support continued growth, consolidated reported operating income decreased $3.3 million. The gross profit growth was offset by the higher investments made in SG&A. Our tax rate for the quarter was 23.3% versus 20.7% in the prior year quarter. We estimate our tax rate for the fourth quarter fiscal 26 to be 23%. Third quarter diluted earnings per share decreased $0.14 or 9.4% to $1.35 driven by the reduced operating income and higher tax rate. Turning to the balance sheet and cash flow, the company had strong cash flow generation during the quarter and year to date. Operating cash flow is up over $55 million versus the prior year. Year to date payments for Property additions totaled $54.6 million. For the full year fiscal 26. We are forecasting total capital expenditures of $80 million. We will continue to invest in both cost savings projects and other manufacturing improvements as well as the Atlanta facility we acquired to support future growth. In addition to investing in the business, we also return funds to shareholders. Our quarterly cash dividend of $1 per share paid on March 31 represented a 5% increase from the prior year’s amount. Our enduring streak of annual dividend increases stands at 63 years as we’ve completed 3/4 of the year. We are pleased to report growth across a number of metrics in a difficult operating environment. Reported and adjusted net sales increased 2.2% and 0.9% respectively. Reported and adjusted gross margin reflected increases of 40 and 80 basis points, respectively. Reported operating income was flat while adjusted operating income increased 1%. In addition, operating cash flow grew by 32%. We finished the quarter with a debt-free balance sheet and over $218 million in cash. As was previously announced, we closed on the $400 million acquisition of Bachan’s on May 1. The transaction was funded by a $200 million term loan and cash on the balance sheet. The interest rate on the debt is currently less than 5%. The company’s strong cash generating capabilities and low debt levels put us in a position to continue to invest further growth and return funds to our shareholders. So to wrap up my commentary, our results demonstrate strong execution across a number of areas and we continue to invest to support the future growth of our business and return funds to our shareholders. I’ll now turn it back over to Dave for his closing remarks. Thank you.

Dave Szeczynski (President and CEO)

Thanks Tom. Going forward, the Marzetti Company will continue to leverage the combined strength of our team, our operating strategy and our balance sheet in support of the three simple pillars for our growth plan to 1 accelerate core business growth 2 to simplify our supply chain to reduce our cost and grow …

Full story available on Benzinga.com

This post was originally published here

AMC Entertainment Holdings Inc (NYSE:AMC) shares are trading higher on Monday. The surge comes just one day before the theater giant reports its first-quarter earnings on Tuesday.

Netflix Partnership Hits High Gear

The rally follows a Saturday announcement from CEO Adam Aron regarding a landmark deal with Netflix Inc (NASDAQ:NFLX).

Aron revealed the streaming giant authorized a wide global release for Greta Gerwig’s Narnia on Feb. 12.

Crucially for investors, the film will carry a traditional 49-day exclusive theatrical window.

Aron noted on X, “It should not be lost on anyone the significance of Netflix trying …

Full story available on Benzinga.com

This post was originally published here

This week, the Bank of Japan wrecked havoc on the foreign exchange market. What’s the Yen Carry Trade, how does an intervention work, and what does it all mean?

Yen Carry Trade – A Massive Money Printer

Years ago, a massive money printer emerged out of Japan. It was called “The Yen Carry Trade”, and it provided trillions of dollars of capital that would flow into US Treasuries, stocks, and other financial assets.

To deal with the enormous economic pain that Japan was suffering after the 1990 bubble burst, the Bank of Japan took its overnight interest rate to 0.0%, and from 2016-2024, even negative.

Japanese overnight interest rate, 1990-present

Remember, the central bank’s overnight interest rate is the price of money. In this case, they made the Yen not just free, but for a brief period, they were paying you to take out Yen loans.

It worked.

Trillions of dollars worth of Yen-denominated loans were taken out. But due to the historically easy monetary policy of ZIRP/NIRP, people didn’t want to hold onto a currency whose value was being crushed. Therefore, people immediately sold the Yen they had just gotten and bought dollars.

Overnight rate versus JPY/USD exchange rate

This selling pressure, coupled with poor economic growth and easy monetary policy, led to an immense amount of weakness for the Yen. In the past 15 years, the Yen has lost 49% of its value versus the dollar.

Taking out Yen loans at 0%, buying dollars and just waiting for the currency to weaken (which already would have yielded a positive return), was not enough-

Investors took out JPY at 0%, sold the Yen/bought dollars, then put those dollars into positive yielding instruments like US Treasuries, Mortgage Backed Securities, and even stocks. Not only were they making money from the dollar strengthening (meaning over time, fewer dollars would be required to pay their Yen loan back), but they also had a positive return from the dollar investment into bonds, stocks, etc.

What could go wrong?

The Problem

There was one small problem- the Yen couldn’t be allowed to weaken too much, or else Japan would suffer from the problem of domestic inflation given their reliance on food and energy imports.

This wasn’t too much of a concern for much of the last two decades (as GDP, inflation and wages were occasionally even negative), …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Morgan Stanley analyst Nigel Dally downgraded Prudential Financial Inc (NYSE:PRU) from Equal-Weight to Underweight and slashed the price target from $106 to $92. Prudential Financial shares closed at $98.62 on Friday. See how other analysts view this stock.
  • Baird analyst David Rodgers downgraded Alexandria Real Estate Equities, Inc (NYSE:ARE) from Outperform to Neutral and cut …

Full story available on Benzinga.com

This post was originally published here

L.B. Foster (NASDAQ:FSTR) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://edge.media-server.com/mmc/p/zt5gytqb/

Summary

L.B. Foster reported robust Q1 2026 financial performance with a 23.9% increase in net sales, primarily driven by a 38.4% growth in the rail segment.

The company achieved a significant improvement in profitability, with EBITDA up 183% and gross margins improving by 60 basis points to 21.2%.

Strategic focus remains on organic growth within the precast concrete business, with capital investments targeted to support this area.

Despite a seasonal increase in total debt by $16.9 million, the company reduced its overall debt by $22.8 million compared to last year, improving its leverage ratio to 1.2 times.

Management reaffirmed its full-year financial guidance, expressing optimism for continued growth, supported by a strong order intake in April and a robust bidding environment.

Full Transcript

OPERATOR

Good day and thank you for standing by. Welcome to the Q1 2026 LB Foster Earnings Conference call. At this time, all participants are in a listen only mode. After the speaker’s presentation, there will be a question and answer sess. To ask a question during the session, you will need to press star 11 on your telephone. You will then hear an automated message advising that your hand is raised to withdraw your question. Please press star 11 again. Please be advised that today’s conference is being recorded. I would now like to hand the conference over to your first speaker today, Lisa Durante, Director of Financial Reporting and Investor Relations. Please go ahead.

Lisa Durante (Director of Financial Reporting and Investor Relations)

Thank you operator. Good morning everyone and welcome to L.B. Foster’s first quarter of 2026 earnings call. My name is Lisa Durante, the company’s Director of Financial Reporting and Investor Relations. Our President and CEO Jon Castle and our Chief Financial Officer Bill Tallman will be presenting our first quarter operating results, market outlook and business developments this morning. We’ll start the call with John providing his perspective on the company’s first quarter performance. Bill will then review the company’s first quarter financial results. John will provide perspective on market developments and company outlook in his closing comments. We will then open up the session for questions. Today’s slide presentation along with our earnings release and financial disclosures were posted on our website this morning and can be accessed on our Investor Relations page at lbfoster.com our comments this morning will follow the slides in the earnings presentation. Some statements we are making are forward looking and represent our current view of our markets and business today. These forward looking statements reflect our opinions only as of the date of this presentation and we undertake no obligation to revise or publicly release the results of any revisions to these statements in light of new information, except as required by securities laws. For more detailed risks, uncertainties and assumptions relating to our forward looking statements, please see the disclosures in our earnings release and presentation. We will also discuss non-GAAP financial metrics and encourage you to carefully read our disclosures and reconciliation tables provided within today’s earnings release and presentation as you consider these metrics. So with that, let me turn the call over to John.

Jon Castle (President and CEO)

Thanks Lisa and hello everybody. Thanks for joining us today for our first quarter earnings call. I’ll begin with slide 5 covering the key drivers for our results of the quarter. As you can see from earnings release, we carry positive momentum generated at the end of last year into the first quarter, delivering strong results across the board. Robust sales growth in Q1 was as expected of 23.9% over last year. The growth was highest in the rail group which was up 38.4% over last year with all business units delivering significant improvements. Sales for infrastructure segment were also up 5.9% driven by continuing demand on our precast concrete business. The strong sales growth translated into significant improvement in profitability, with EBITDA up 183% over last year. Improved profitability was realized within our margins with gross profit up 27.5% and gross margins improving 60 basis points to 21.2%. We also continue to leverage our operating structure with SG&A as a percent of sales declining 240 basis points compared to last year. Our normal working capital cycle increased total debt $16.9 million during the quarter as we prepared to support our customers construction season. However, disciplined capital allocation approach reduced total debt $22.8 million compared to last year, coupled with significant improvement in profitability during the quarter. Our gross leverage was cut in half from 2.5 times last year to 1.2 times at quarter end. So in summary, we’re really pleased with the strong start to the year and we remain optimistic about our prospects for continued progress in 2026. I’ll cover the market outlook and our financial guidance for the year after Bill runs through the financial details for the quarter. Over to you Bill.

Bill Tallman (Chief Financial Officer)

Thanks John and good morning everyone. I’ll begin my comments on Slide 7 covering the consolidated results for the first quarter. Reconciliations for non GAAP information and other financial details are included in the appendix of the presentation. Net sales for the quarter were $121.1 million, up 23.9% over last year, primarily due to the strong growth in the rail segment. As a reminder, last year sales in rail were weaker than normal due to a pause in government funding programs that delayed customer project work. As John mentioned, the consolidated gross profit was up 27.5% in the quarter, with gross margins improving 60 basis points to 21.2%. Both segments realized double digit increases in gross profit in the quarter, highlighting the broad improvement realized in our results. I’ll provide more color on segment sales and margins later in the presentation. SG&A expenses totaling $23 million were up $2.1 million or 9.9% compared to last year. The primary driver was higher employment costs, including a $1.2 million increase in incentive compensation expense with the improved results in Q1 compared to last year. This year’s incentive expense also includes $0.7 million in accelerated stock compensation expense associated with annual incentive plan grants awarded to retirement eligible employees. Despite the higher expenses year over year, The SG&A percent of sales improved 240 basis points to 19%. EBITDA was $5.2 million, up 183% versus last year driven by the sales growth and improved gross profit. First quarter cash flow improved over last year with operating cash flow favorable 15.7 million million on improved profitability and lower working capital needs. And lastly, consolidated orders and backlog were both lower compared to last year, 4.7% and 11.7% respectively. I’ll cover segment specific drivers later in the presentation. The financial profile of Our results on slide 8 highlights the seasonality in the business over the last three years. We’re entering the construction season for our customers, which typically translates to higher sales and profitability. During our second quarter third quarters last year, First quarter sales were unusually low due to a pause in government funding impacting rail demand early in the year. These delays were resolved throughout 2025 resulting in an unusually strong fourth quarter last year. So while 2025 looks relatively normal compared to the averages, the quarterly splits last year were far from normal. This year’s first quarter results represent a typical level of demand and we expect the phasing of business to follow a more normal pattern in 2026. I’ll cover the segment specific performance on the next couple of slides starting with rail on slide 9, first quarter revenues were 74.8 million, up 38.4% compared to last year’s soft start primarily in rail products. The improvement was strongest for Rail products with sales up 40.8% due to higher demand for rail distribution and transit products. Global Friction Management sales were up 39.5% as this growth platform continues to perform well. Technology, services and solutions sales were also up 29.1% due to short term project work. In our UK business, rail margins of 21.6% were down 70 basis points driven primarily by unfavorable sales mix with the higher rail distribution volumes this year. Turning to rail orders and backlog, Q1 orders were down 3.2% due to lower orders for Friction Management after a very strong level attained last year. Rail product and TS and S orders were relatively flat compared to last year and the rail backlog was up 11.3% due to a large multi year order secured in our UK business late last year. Turning to Infrastructure Solutions On Slide 10, net sales increased $2.6 million or 5.9%. The improvement was realized in precast …

Full story available on Benzinga.com

This post was originally published here

Axsome Therapeutics (NASDAQ:AXSM) held its first-quarter earnings conference call on Monday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://event.choruscall.com/mediaframe/webcast.html?webcastid=tczjFX9Q

Summary

Axsome Therapeutics Inc reported strong financial growth, with total revenue for their three marketed products reaching $191 billion, a 57% increase year-over-year.

The company received FDA approval for Ovelity for treating agitation in Alzheimer’s disease, marking a significant milestone.

The company expanded its sales force and improved coverage for their products to support continued growth.

Forward-looking statements highlight the planned expansion of their pipeline, including new trials and submissions for regulatory approval.

Management expressed confidence in achieving robust growth and updated peak sales estimates, forecasting Ovelity to potentially generate at least $8 billion in annual revenue.

Operating expenses increased due to product launch preparations and sales force expansion, but the company expects revenue growth to outpace these costs.

Axsome Therapeutics Inc ended the quarter with $305 million in cash, supporting operations into cash flow positivity.

Full Transcript

OPERATOR

Good morning and welcome to Axsome Therapeutics Inc first quarter 2026 earnings conference call. My name is Kevin and I’ll be your operator for today’s call. At this time all participants are in listen only mode. Later there will be a question and answer session and instructions will be given at that time. Please note this call is being recorded. I will now turn the call over to Ashley Dong, Senior Director of Investor Relations. Ashley, please go ahead.

Ashley Dong (Senior Director of Investment Relations)

Thank you. Good morning and thank you for joining Axsome Therapeutics Inc’s first quarter 2026 earnings conference call. With us today are Dr. Ario Tabuto, our Chief Executive Officer, Nick Pizzi, our Chief Financial Officer and Ari Maisel, our Chief Commercial Officer, who will begin our call with prepared remarks. Mark Jacobson, our Chief Operating Officer and Hunter Murdock, our General Counsel will also be available for Q and A. Please note that today’s discussion includes forward looking statements regarding our financial performance, commercial strategy and operational plans, including research, development and regulatory activities. These statements are based on current expectations and assumptions and are subject to risks and uncertainties that may cause actual results to differ materially. Please refer to our SEC filings, including our quarterly and annual reports, for a description of these and other risks. You are cautioned not to rely on these forward looking statements which are made only as of today and the company disclaims any obligation to update such statements. And with that, I’ll hand it over to Ariel.

Ario Tabuto

Thank you Ashley and good morning everyone. In the first quarter of 2026, Axsome delivered strong year over year growth and execution across the business. This performance was driven by our commercial products and the advancement and expansion of our R and D pipeline which is now composed of six innovative, potentially first in class or best in class product candidates. Starting with our commercial business, total revenue for our three marketed products was $191 billion representing year over year growth of 57% driven by Ovelity and Cenozzi with contribution from Simbravo. Building on the strong clinical profile of our marketed products in the quarter, we substantially expanded the sales force for Ovelity, finalized plans for the expansion of the Simbravo sales force and increased covered lives and quality of coverage for all of our marketed products. These initiatives will support continued strong revenue growth of the base business this year and beyond. Last week we received FDA approval of availability for the treatment of agitation associated with Alzheimer’s disease, an indication which received FDA Breakthrough Therapy designation and priority review. This approval introduces a first in class treatment option for this highly prevalent, debilitating and critically underserved neuropsychiatric condition. As such, it marks an important milestone for the millions of patients living with Alzheimer’s disease, their families and their caregivers. Ovelity has now been approved in two indications that received FDA Breakthrough Therapy designation and were granted FDA Priority Review. The approval in Alzheimer’s disease agitation combined with the health of the MTD business and the recent augmentation of the Ovelity commercial infrastructure provide us with a clear line of sight to Ovelity’s market potential. ARI will provide an update to our peak sales estimate for the Ovelity franchise based on these developments. The approval in Alzheimer’s disease agitation is a testament to our research and development productivity. Since the start of this year we have continue to advance and expand the rest of our industry leading pipeline with a focus on developing first in class and best in class products. On the regulatory front. Following the FDA approval of Ovelity last week, we are pleased to share that we have submitted Our NDA for AXS12 for the treatment of cataplexy and narcolepsy. Clinically, our ongoing trials continue to progress and we will be starting multiple phase 3 trials within the next few months. Finally, we recently expanded our pipeline further with the addition of AXS20, a potentially first in class pre phase 3 PDE10A inhibitor for schizophrenia and Tourette Syndrome. I will discuss each of these developments in detail later in the call. All in all, Axsome is advancing the commercialization of three differentiated marketed medicines across four highly prevalent indications, as well as an innovative pipeline of potentially first in class and best in class medicines that includes six product candidates targeting 10 different highly burdensome conditions in psychiatry and neurology. Looking ahead, Axsome is well positioned to realize robust growth driven by execution across our commercial portfolio, the long term ability in Alzheimer’s disease agitation and the advancement of the rest of our neuroscience pipeline. With that, I’ll hand the call over to Nick to review our financial results for the quarter.

Nick Pizzi (Chief Financial Officer)

Thanks Dario and good morning everyone. Our financial performance in the first quarter was strong with our three commercial products delivering continued double digit revenue growth. Total revenue for the quarter was $191.2 million, a 57% increase compared to 1Q25. We expect revenue growth to continue in 2026. Ovelity achieved net product revenue of $153.2 million in the quarter, up 59% compared to the first quarter of 2025. The Cenosi net product revenue for the quarter was $33.9 million, a 34% increase compared to the first quarter of 2025. Cenosi revenue consisted of $32.6 million in net product sales and $1.3 million in royalty revenue associated with CECenosi sales in out licensed territories. Net sales for Simbravo were $4.1 million in the quarter. Ovelity and CENOS gross to net Discounts for the first quarter of 2026 were both in the low to mid-50s range. We anticipate the gross and net discounts for both products to improve throughout the year consistent with prior year trends. Cimbravo gross net discount for the quarter was in the high 70% range and we continue to expect it to remain elevated over the near term as access continues to evolve and awareness continues to build. Turning now to expenses, total costs of revenue were $14.7 million compared to $9.8 million for the first quarter of 2025. Our research and development expenses were $52.7 million in the quarter compared to $44.8 million for the first quarter Of 2025. The increase in R and D spend primarily reflects a one time acquisition related expense booked in the quarter. Our selling, general and Administrative expenses were $185 million for the quarter compared to $120.8 million for the first quarter of 2025. The increase was primarily driven by the acceleration of prelaunch activities for Ovelity in Alzheimer’s disease agitation and commercialization activities for Ovelity which included the National Direct to consumer advertising campaign and Salesforce expansion along with commercial activities for some Bravo. Net loss for the quarter was $64.5 million or $1.26 per share compared to a net loss of $59.4 million or $1.22 per share for the first quarter of 2025. The $64.5 million net loss in the quarter includes $23.4 million in stock based compensation expense. Our balance sheet remains strong. We ended the first quarter with $305 million in cash and cash equivalents compared to $323 million as of the end of last year. Our overall financial performance reflects continued top line revenue growth and improving operating leverage driven by disciplined commercial execution. We anticipate that our current cash balance is sufficient to fund our operations into cash flow positivity based on our current operating plan. And with that I’d like to turn the call over now to Ari who will provide additional details on the key drivers behind our medicines and the broader commercial performance of the business.

Ari Maisel (Chief Commercial Officer)

Thank you Nick the first quarter of 2026 was a pivotal period for Axiom’s brand reflected an ongoing demand for our medicines, meaningful improvements in payer coverage and salesforce expansion activities. Our promotional efforts across HCP and patient audiences, combined with a broadening commercial infrastructure will support Axome sales objectives throughout 2026. Starting with Ovelity, more than 223,000 prescriptions were written in the quarter, representing 35% year over year growth and remaining consistent with the prior quarter. By comparison, the antidepressant market grew 1% year over year and declined by 1% compared to Q4 2025. Ovelity performance in the quarter was highlighted by a continued shift toward earlier line use, with first line first switch prescriptions increasing to 56% of overall demand. Primary care adoption also expanded in the quarter, now representing 35% of total ovelity prescribers. These trends reflect meaningful improvements in market access over the last two years, broadened awareness of the brand driven by our national direct to consumer campaign and our concentrated effort in expanding use among primary care providers, a key driver of earlier line utilization and an important foundation to support early trial in connection with the upcoming Alzheimer’s disease agitation launch. Additionally, more than 5,500 new prescribers were activated in the quarter, bringing the total number of unique prescribers for Ovelity since launch to approximately 60,000. We continue to make important progress with formulary access for Ovelity. Commercial coverage is at 78% and alongside Medicare and Medicaid coverage at 100%. Total coverage is now at 86% of all lives across channels, establishing a strong foundation of access for Ovelity in advance of the launch in Alzheimer’s disease agitation. We expect both the quantity and quality of coverage to continue to expand and improve. Ovelity’s growth to date in the depression market continues to reflect its compelling clinical profile highlighted by rapid and durable symptom improvement and a distinctly favorable safety and tolerability profile. Last week’s FDA approval of Ovelity as a treatment for agitation associated with dementia due to Alzheimer’s disease is a significant advancement for patients and a major milestone for the brand. We are very pleased with the product label which provides compelling clinical information regarding Ovelity’s impact on agitation for Alzheimer’s patients. Ovelity is a first in class treatment for this patient population demonstrating rapid and durable symptom improvement with a favorable safety and tolerability profile. Ovelity is the only approved treatment for Alzheimer’s disease agitation with efficacy on symptom relapse death demonstrated in long term trials in a short term study. The most Common adverse reactions were dizziness and dyspepsia and only 1.3% of patients discontinued treatment due to an adverse reaction, the same rate as placebo in market research. HCPs rate ovelity’s clinical profile in Alzheimer’s disease agitation as highly compelling from both an efficacy and safety perspective with clear potential for first line use in appropriate patients. We are expanding the all validity sales team to approximately 630 representatives enabling Axome to reach 68,000 HCP targets across primary care, psychiatry, neurology and geriatric specialists who treat both MDD and Alzheimer’s agitation patients across community and long term care settings. Our expansion efforts are substantially complete, positioning us well for the commercial launch in June. We believe Ovelity has the potential to play a significant role in the treatment of Alzheimer’s agitation and together with the MDD indication further broadens its use across serious neuropsychiatric conditions. Ovality’s expanded sales force and strong foundation of coverage position the brand to drive growth across both indications throughout the second half of 2026. Taking into account the recent label expansion in Alzheimer’s disease agitation, the clinical profile in this indication, the health and trajectory of the MDD business and recent investments in our sales infrastructure, we are now able to update our peak sales outlook for the product. We now believe Ovelity has the potential to generate at least $8 billion in annual revenue at peak with approximately equal contribution from each indication over the extended life of the product. We see a clear path to achieving this growth potential supported by the underlying fundamentals of the business as we continue to scale. Turning now to Simbravo, more than 17,000 total prescriptions were written in the quarter representing 36% growth versus Q4 2025. More than 5,000 new patients started Simbravo treatment in the quarter. Neurology specialists accounted for approximately 60% of total writers in the quarter with primary care representing approximately 32%, an increase from 20% in the first quarter of launch. While headache specialists will remain a critical prescriber segment for Simbravo, the increase in primary care prescribing is an encouraging signal of Simbravo’s potential and reinforces the early experience with Simbravo as a safe and tolerable acute migraine treatment that provides fast migraine pain improvement sustained through 24 and 48 hours. Based on Simbravo’s growth within its launch year and increasing demand for education of the only branded multi mechanistic acute migraine treatment in the market, we are increasing the Simbravo sales team by approximately 50 representatives. Our expanded Simbravo sales force of 150 representatives will support broader reach in the primary care market while deepening engagement with headache specialists and neurologists throughout the country. We are also pleased to announce a major commercial payer contract for Simbravo, effective this month, securing coverage for approximately 17 million lives. The agreement reflects Simbravo’s compelling clinical profile and its potential to address the needs of patients with inadequate response to triptans. Overall payer coverage for Simbravo is approximately 57%, representing 56% in the commercial channel and 57% in government channels. We expect coverage for Simbravo to expand and evolve throughout 2026 and finally, in Q1, approximately 54,000 Cenoze prescriptions were written, representing 16% year over year growth and a 3% decline sequentially. By comparison, the wake promoting agent market grew 1% year over year and declined by 5% versus Q4 2025. Nearly 500 new clinicians prescribed Cenozy in the quarter, bringing the total cumulative prescriber base to more than 16,500 since launch. Payer coverage for Cenozy remains steady at approximately 83% of lives covered across channels. Overall, the first quarter of 2026 was marked by significant progress across Axome’s commercial business, including strong demand for our products, key advancements in market access, launch preparations for ovality and Alzheimer’s disease agitation, and disciplined organizational growth designed to maximize the potential of our singular CNS portfolio. Looking ahead, ACSUM is well positioned to deliver on our commercial objectives across our innovative portfolio through the balance of the year. We look forward to sharing our continued progress with you over the coming months. I will now turn the call back to ARIO to discuss our singular CNS pipeline.

Ario Tabuto

Thank you Ari. I will now touch on recent developments and upcoming milestones for the rest of our pipeline, starting with AXS12. As I mentioned, we recently submitted our NDA for AXS12 for the treatment of cataplexy in patients with narcolepsy. Narcolepsy is a rare and debilitating neurological condition that affects approximately 185,000 people in the U.S. we are excited by the potential of AXS12 to provide a new and differentiated treatment option to patients living with narcolepsy. We look forward to announcing the FDA’s decision on the acceptance of the filing. Beyond AXS12 and narcolepsy, we are also developing the full suite of clinical programs in our leading neuroscience pipeline. Starting with AXS05. We we are on track to initiate a pivotal phase 2.3trial in smoking cessation this quarter. Moving on to Solriamfetol, our phase three programs for this molecule continue to progress. These include adhd, binge eating disorder, MDD with symptoms of excessive daytime sleepiness and excessive sleepiness, and shift work disorder for adhd. We are on track to initiate two pediatric phase three trials, one in children and one in adolescents this quarter. For mdd, we recently initiated the Clarity study, a phase three double blind placebo controlled randomized withdrawal trial. In the trial, patients who achieve a sustained response during the open label period will be randomized to continue Solrian Vetol or switch to placebo. The primary endpoint of that trial is is time to relapse the depressive symptoms with binge eating disorder. Our Engage Phase 3 double blind randomized controlled trial is …

Full story available on Benzinga.com

This post was originally published here

Palantir Technologies Inc. (NASDAQ:PLTR) shares are gaining momentum Monday. Investors are positioning themselves ahead of the company’s first-quarter 2026 earnings release after the closing bell.

Bullish Expectations For Q1

Wall Street expects revenue of $1.54 billion and earnings per share of 27 cents. Palantir has beaten EPS estimates for three consecutive quarters.

Wedbush analyst Dan Ives maintains an Outperform rating and a $230 price forecast. In a recent note, Ives called current revenue estimates “beatable.” He expects “another robust quarter” driven by the company’s Artificial Intelligence Platform …

Full story available on Benzinga.com

This post was originally published here

The United Arab Emirates (UAE) has been in talks with the U.S. about the possibility of establishing a currency swap line, as revealed by the Middle East nation’s trade minister.

On Monday, Thani Al Zeyoudi, the UAE’s Trade Minister, unveiled the ongoing discussions during a conference in Abu Dhabi on Monday. Al Zeyoudi said, as per Reuters, that the U.S. “swap policy” is currently limited to a small group of only five countries, and is part of ongoing discussions with an elite set of partners.

The minister highlighted that the currency swap line is a reflection of the significant level of trade and investment between the two countries, making such an arrangement necessary.

However, he gave no further details on the discussions or any timeline for a possible currency swap agreement with the U.S.

The UAE has exited OPEC and OPEC+ effective May 1.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Russia Says UAE’s OPEC Exit Could Trigger Oil Glut And Price Drop— But Not Until This Happens

This post was originally published here

(Editor’s note: The headline and story has been updated to include Anthropic’s announcement)

Anthropic has sealed a joint venture with several top Wall Street firms, including Blackstone (NYSE:BX) and Goldman Sachs (NYSE:GS), the companies announced on Monday.

The companies did not disclose financial details on the deal. However, Anthropic, Blackstone, and Hellman & Friedman are expected to be the main investors, each contributing about $300 million, the Wall Street Journal earlier reported.

Goldman Sachs is also expected to be a founding investor, with a contribution of around $150 million, as per the report. Other firms, including General Atlantic, are part of the deal, bringing the total expected investment to about $1.5 billion.

The investors aim to establish a company that will act as a consulting arm for Anthropic. This new entity will help businesses, including the private-equity firms’ portfolio companies, integrate AI …

Full story available on Benzinga.com

This post was originally published here

Krystal Biotech (NASDAQ:KRYS) reported first-quarter financial results on Monday. The transcript from the company’s first-quarter earnings call has been provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://www.webcaster5.com/Webcast/Page/3018/53916.

Summary

Krystal Biotech Inc reported Q1 2026 net revenue of $116.4 million, marking a 9% sequential growth and a 32% year-over-year increase, driven by strong sales of Vyjuvec, particularly in Europe and Japan.

The company maintained a gross margin of 95% and recorded its 11th consecutive quarter of positive EPS, with net income of $55.9 million.

Krystal Biotech Inc highlighted the progress of its pipeline, including two upcoming registrational study readouts expected in 2026 and additional pipeline advancements, particularly in CF and Haley-Haley disease.

The company is actively expanding Vyjuvec’s market presence, planning launches in Italy and Spain in the latter half of 2026, with ongoing pricing negotiations in Germany and France.

Management expressed confidence in their strategic positioning and financial health, supported by a robust cash position exceeding $1 billion, enabling continued pipeline development and market expansion.

Full Transcript

OPERATOR

Thank you for standing by and welcome to the Krystal Biotech Inc first quarter 2026 conference call. this time, all participants have been placed on a listen only mode. After the speaker’s presentations, there will be a question and answer session. As a reminder, today’s conference is being recorded. I would now like to hand the conference over to your host, Stephane Paquette, Vice President of Corporate Development. Please begin.

Stephane Paquette (Vice President of Corporate Development)

Good morning and thank you all for joining today’s call. Earlier today we released our financial results for the first quarter of 2026. The press release is available on our website at www.krystalbio.com. we also filed our earnings 8K and 10Q with the SEC earlier today. Joining me today will be Krish Krishnan, Chairman and Chief Executive Officer Suma Krishnan, President of Research and Development Duran Gooks, Executive Vice President and General Manager for Europe Christine Wilson, Senior Vice President and head of U.S. commercial and Kate Romano, Chief Accounting Officer. This conference call will and our responses to questions may contain forward looking statements. You are cautioned not to rely on these forward looking statements which are based on current expectations, using the information available as of the date of this call and are subject to certain risks and uncertainties that may cause the company’s actual results to differ materially from those projected. A description of these risks, uncertainties and other factors can be found in our SEC filings. With that, I will turn the call over to Krish.

Krish Krishnan (Chairman and Chief Executive Officer)

Good morning. It’s now been 10 years since we founded Crystal and in that time we have worked to change the lives of DEB patients globally for the better, while building a durable, fully integrated company with the financial strength to continue delivering value for both patients and shareholders. We have done this with discipline. We’ve not accessed the capital market since 2022. 2022 is six years from when the company was founded. We maintain a strong balance sheet and we continue to generate meaningful operating leverage. Yet more importantly, somewhat ironically, we believe the next 12 to 24 months represent one of the most exciting periods in Crystal’s history. We are positioned for two registrational readouts this year and two more next year. I sincerely want to thank our employees for the dedication and execution that have brought us to this point. Now turning to Vyjuvec, we delivered another quarter of global revenue growth with net revenue of $116.4 million in the queue. This brings cumulative net Vyjuvec revenue since launch to more than $846 million. We are particularly pleased with this performance which represents a 9% sequential growth versus 4Q 2025 despite a higher than usual level of insurance changes, which happens, by the way, not just to us but many biotech commercial companies. In one queue. Gross margin was 95% and we delivered our 11th consecutive quarter of positive EPS outside the U.S. we’re still early in the Vyjuvec launch in Europe and Japan and I’m pleased with the progress overseas. We’re also working to add two additional major European markets, Italy and Spain, later this year. Laurent and Christine will provide more detail on Vysuvec Commercial Dynamics and the opportunity ahead in a moment. FDA has now granted Platform Technology Designations to both KB 407 for CF and KB 111 for Haley Haley. This is in addition to receiving the same designation for Our NK program, KB801 last year. These designations have a profound implications for Crystal at the program level. These designations allow us to streamline our interactions with the agency and our development plans. We’ve already seen the benefits with KB801 as the designation allowed us to rapidly advance KB801 into a registrational study. The platform implications are also powerful. These designations bring a compounding advantage. Each developmental milestone on our pipeline strengthens our collective regulatory data set and reduces development risk, cost and time for the next program we bring to the clinic. This advantage is presently unique to Crystal and one we intend to leverage to its full potential. You’ll hear more about our development plans from Sooma. I’ll now turn it over to the team to provide details on the commercial launch and the clinical pipeline.

Laurent

Laurent thank you Krish. We are very encouraged by the progress we are seeing outside the United States, where Vyjuvec is beginning to establish itself as an important new treatment option for DEB patients in key international markets. When we think about the international launch, the story is not just one of geographic expansion. It is a story of building trust across cultures with physicians, with treatment centers, with payers, and ultimately with the entire EB community who have been waiting for new options. There are nuances in every country we launch, and sometimes within a country by region. That said, across Europe and Japan we are seeing strong word of mouth and increasing engagement from key centers, that is Raising awareness of Vyjuvec and helping translate physician interest into real patient demand. Importantly, our prescriber base continues to broaden. This gives more patients the opportunity to start treatment closer to home while also creating a more durable and resilient foundation for the launch. We estimate that more than 140 DEB patients have been prescribed Vyjuvec across Germany, Japan and France. We believe this reflects both strong execution by our international team and growing physician confidence in Vaijuvec in the early launch market. This early momentum is also beginning to Show Financials European market plus Japan contributed to $28.9 million in net revenue, demonstrating the meaningful role these regions can play in the growth of Vyjuvec over time. Looking ahead, our focus is clear. We are working to deepen penetration in our current launch market, secure positive access and reimbursement outcomes, and expand it to additional major European markets. In Germany and France, pricing negotiations remain ongoing. We continue to expect a decision in Germany in the second half of 2026. In France, we continue to expect a decision in 2027 which would further support broader access and reimbursement stability. We are also advancing discussions with reimbursement authorities in Italy and are actively preparing for potential launch in the second half of 2026 pending the outcome of those negotiations. And in Spain, I’m pleased to report that our discussions with authorities have accelerated. Based on our latest interactions, we now see a potential opportunity to launch in Spain in the second half of the year, again pending the outcome of negotiations. In the interim, we are also responding to opportunities to start patients on Vyjuvec through early reimbursement access pathways. Overall, we are very encouraged by the early tractions we are seeing internationally. The launch is progressing market by market, physician by physician and patient by patient. We remain focused on disciplined execution of our global commercialization strategy and on bringing Vyjuvec to more BEB patients around the world. I will now hand the call off to Christine to share updates on Vijuvec launch in the U.S. christine, thank you Laurent.

Christine Wilson (Senior Vice President and Head of U.S. Commercial)

Our team has been making great progress in recent months, building on our leadership position and delivering transformational outcomes for patients across the United States. Strong salesforce execution is expanding our community reach and allowing us to meet patients wherever they seek care, whether that is at the center of Excellence with a pediatric dermatologist or in a family practice office in the community. By bridging this gap, we have now been able to secure over 695 reimbursement approvals for DEB patients nationwide. Even as access teams were navigating a higher volume of insurance switchovers, upstream demand metrics are even better, with over 60 new prescribers in the first quarter and over 570 unique prescribers since launch, underpinning a strong patient approval outlook for the rest of the year. Net Vyjuvec revenues for the United States were $87.5 million for the quarter. Revenues were impacted by insurance switchovers in the quarter, which are now behind us as well as the start stop treatment cadence characteristics of a patient population shifting towards maintenance treatment regimen. With Vyjuvec now on the market in the United States for nearly three years, a growing number of patients have been able to achieve dramatic and transformational wound closure outcomes. Patients have been able to take control of their disease and their lives, opening up new opportunities and autonomy never before possible. These quality of life gains made possible by the robust efficacy and safety profile of Vyjavac are deeply motivating and the foundation for the long term trust based relationships we are building with the DEB patient community. These improvements are also a natural and anticipated evolution of the launch as patient motivations and support needs shift to reflect their newfound autonomy. This is where the flexibility of Vyjuvec administration and last year’s label updates are especially valuable, providing patients with the option to self administer or receive nurse support where and when they want it. To this end, we have launched patient support initiatives to communicate and educate around recent Vyvac legal updates which provide greater administration flexibility and help DEB patients and their families conveniently integrate Vyjuvec into lifelong wound healing routines as part of their standard of care. Our goal is to establish long term relationships with Vyvac patients, ensuring ongoing connectivity and ease of use throughout throughout their lifelong treatment journey, skin cells do turn over and wounds eventually reopen, particularly as patients get more active. As patients transition into these start and stop phases, we are focused on enabling timely access to Vyjorvec whenever it is needed. This focus is driving continued assessment of our infrastructure to better support patients where they are in their journey and to further enhance the ease of delivering Vyjavec across the United States. At the recent American Academy of Dermatology Conference, key opinion leaders underscored their appreciation for Vyjavec and the positive outcomes achieved by their treated patients in a patient population where prior to Vyjavec’s approval there were no treatment options beyond palliative wound care, Vyjuvec represents a meaningful advancement and fueling an increased focus on the long term clinical and quality of life benefits that that might come with long term Vyjuvec therapy. As we progress in our launch, we are excited about the opportunity ahead. There are still hundreds of known diagnosed patients we hope to bring to therapy and many more not yet identified that we believe could benefit from Vyjuvec. By driving new patient starts and maximizing convenience for patients already on therapy, we see an opportunity to deliver significant growth in the years ahead. With that, I’ll Turn the call over to Suma to share the latest on our development pipeline.

Suma Krishnan (President of Research and Development)

Summa thank you Christine and good morning everyone. I am excited to share that we are faced with two registrational study readouts expected later this year and two more in 2027. With respect to the ophthalmology registrational readouts this year, we are excited to announce the completed enrollment in our registrational study evaluating KB803 for the treatment and prevention of corneal abrasions in DEB patients. A total of 16 patients were enrolled in the study. IOLITE study is randomized intra patient double blind decentralized placebo controlled study with crossover design in which patients are randomized one to one to receive KB803 three times weekly for 12 weeks followed by placebo three times weekly for 12 weeks or vice versa. The primary efficacy endpoint, the change from baseline in the average number of days per month with symptoms will be assessed at 24 weeks, putting us on a path for a readout in the fourth quarter of this year. This is an exciting milestone for our team and the many dead patients suffering from ocular complications of this terrible disease. Our second registration study evaluating KB801 for the treatment of neurotropic keratitis is also progressing well. Our focus here is operational, supporting our trial sites, expanding our network and driving enrollment. This is an eight week study. We expect to enroll 60 patients and are on track for a data readout later this year. We are moving quickly on our broader pipeline as well, including the initiation of two open label studies evaluating repeat dose KB407 and KB111 which we expect to read out later this year based on FDA interactions. We are initiating an open label single arm study to evaluate safety of repeat dose KB407 for 24 weeks in 5 patients with CF who are ineligible for, do not tolerate or do not benefit from modular therapy dosing …

Full story available on Benzinga.com

This post was originally published here

Norwegian Cruise Line (NYSE:NCLH) held its first-quarter earnings conference call on Monday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://event.choruscall.com/mediaframe/webcast.html?webcastid=nrlnZej1

Summary

Norwegian Cruise Line reported a mixed financial performance for Q1 2026, with net yield down 1% but adjusted EBITDA exceeding guidance at $533 million.

The company is undertaking significant strategic initiatives, including cost reductions in SG&A by $125 million annually and optimizing its revenue management and marketing systems.

Future outlook includes challenges due to geopolitical tensions and internal missteps, particularly in Europe, leading to a reduced full-year guidance with net yields expected to decline by 3 to 5%.

Operational highlights include the christening of Norwegian Luna and the upcoming opening of Great Tides Water Park, expected to drive demand in 2027.

Management emphasized the focus on internal improvements, leveraging strong brand assets, and reducing leverage as top priorities, despite a challenging macroeconomic environment.

Full Transcript

OPERATOR

Good morning. Welcome to the Norwegian Cruise Line holdings first quarter 2026 earnings conference call. My name is Rob and I’ll be your operator at this time. All participants are in listen only mode. Later, we’ll conduct a question and answer session and instructions for the session will follow at that time. If anyone should require operator assistance during the conference, please press Star zero on your touchstone telephone. As a reminder to all participants, this conference call is being recorded. I’ll now turn the conference over to your host, Sarah Inman. Ms. Inman, please proceed.

Sarah Inman

Thank you and good morning everyone. Thanks for joining us for our first quarter 2026 earnings call. I’m joined today by John Chidze, Chairperson and CEO of Norwegian Cruise Line holdings and Mark Kempa, Executive Vice President and Chief Financial Officer. As a reminder, this conference call is being simultaneously webcast on the company’s investor relations website. We will be referring to a slide presentation during this call which can also be found on our website. Both the conference call and presentation will be available for replay for 30 days following today’s call. Before we begin, I would like to cover a few items. Our Press release with first quarter 2026 results was issued this morning and is also available on our investor relations site. This call includes forward looking statements that involve risks and uncertainties that could cause our actual results to differ materially from such statements. These statements should be considered in conjunction with the cautionary statement contained in our earnings release. Our comments may also reference non GAAP financial measures. A reconciliation to the most directly comparable GAAP financial measure and other associated disclosures are contained in our earnings release and presentation. Unless otherwise noted, all references to 25 and 26 net yield and adjusted net cruise cost, excluding fuel per capacity day are on a constant currency basis and comparisons are to the same period in the prior year. With that, I’d like to turn the call over to John.

John Chidze (Chairperson and CEO)

Thanks everyone for joining the call. It’s my pleasure to be joined by Mark today as we discuss our first quarter results. I’ve now been in the seat for roughly three months. I’m going to start the call by spending a few minutes covering what I’m seeing so far across the business and then we’ll update you on the actions we are taking to position the business for long term success. It has been a very active start. I have spent a meaningful amount of time meeting with various stakeholders including shareholders, travel partners, guests and team members, listening carefully to their perspectives on the business. Our proactive work this quarter is setting the tone for the remainder of 2026. My key focus is on driving sustainable improvement at NCLH and that starts with disciplined execution, operational rigor and a clear focus on the fundamentals. I continue to believe that NCLH is a special company with strong brands, world class assets and dedicated guests. This was especially evident at the christening of Norwegian Luna that was held about a month ago. The excitement on board from travel partners and guests was palpable at Great Stirrup Cay. We witnessed the significant progress being made on the island, particularly at the Great Tides Water park which remains on track to open later this summer. This water park will be a demand driver moving into 2027. It will elevate the island’s offerings and enhance the guest experience. Experiencing our newest ship and upgraded private island amenities firsthand brought to light the strength of our brands and the size of the opportunity ahead of us. It also reinforced my view that cruising remains one of the most attractive propositions in travel. Day in and day out, we offer a differentiated vacation experience across multiple destination, focusing on convenience and quality to deliver enhanced value for our guests. As cruising continues to benefit from healthy industry fundamentals, including record passenger volumes and encouraging indicators of both repeat and first time cruise demand, I am confident in the industry’s long term trajectory. We are focused now more than ever on where we need to enhance operations so that NCLH can capitalize on these broader industry trends from a position of strength. To that end, I now have a good sense of the core areas where we will be dedicating the most focus to drive the most meaningful impact in the near term. Since stepping into the CEO role in February, one of my top priorities has been strengthening our internal culture across the organization. This includes building a greater sense of urgency, sharpening accountability in fostering a one team mindset across our operational segments. Of course strategy matters, but my turnaround experience has reinforced that culture is essential to improving how we operate, how we make decisions, how we deliver results and the speed at which we do it. We are already taking steps to build and enhance a cohesive culture, including our recently completed search for a new Chief People Officer whom we expect to officially welcome to the team soon. On the cost side, we are working efficiently and effectively to optimize our SGA structure, streamline the organization and better align resources with the areas that matter most to drive performance and long term value creation. While ship operating costs have remained relatively consistent over the past several years, we see a meaningful opportunity to reduce shoreside cost. As part of that effort, we are streamlining the shoreside organization and making targeted role and position adjustments to improve efficiency and better align resources. As a result, we expect our salary and benefits costs to decrease by approximately 15% on an annualized basis. Actions like these are never easy, but are intended to better align resources, improve productivity and strengthen execution across the business. As part of these efforts, we are also exploring additional opportunities to improve efficiency in our operating model and drive incremental savings over time. For example, we have started to pilot select offshoring initiatives across different areas of the company. These efforts are in their early stages and we are testing and learning as we go. We plan to utilize this lever as we move ahead, expanding upon and scaling our efforts where and when appropriate and most beneficial to the business. We are also taking a hard look at other spend across the business, including marketing and advertising, and we see an opportunity to not only improve effectiveness but also efficiency from a marketing perspective. Our focus is on correcting missteps we have made in recent years as we enhance our ability to target the right consumer with the right message through the right channels, while ensuring that our spend is translating into demand returns. In line with this focus, we are planning to reduce our marketing spend in 2026 while sharpening the effectiveness of that spend. As a result of the marketing spend reductions as well as organizational optimizations, we expect to reduce our SGA by $125 million on an annualized basis. These are long term structural actions that we believe will help offset near term pressures and position the business for stronger performance over time. Beyond this, we have been evaluating our bundled AIR program through the same lens of discipline and return on investment, and we have continued to make targeted changes to improve economics. In many cases, this program has effectively served as a promotional tool but hasn’t always delivered returns commensurate with its cost. We will continue to assess these offerings to ensure they remain commercially sound while offering convenience to our guests. I am confident in the efforts underway to capitalize on opportunities we are identifying on the cost side, and while the revenue side of the equation is more complex, I recognize that it undoubtedly represents our greatest opportunity from a revenue management perspective. As you know, this is not a function that changes overnight, but we are actively taking steps to strengthen it. To that end, we recently implemented Phase one of a new revenue management system, and while its capabilities are meaningfully stronger than our prior tools, its effectiveness will depend on correctly calibrating the underlying data, refining and turning it to better align with our deployment. A system like this is also only as strong as the people using it, and we are continuing to build out the team and capabilities needed to fully leverage it. We are also continuing to refine and tune the system to better align with our deployment. Additionally, for revenue management to be effective, we need to generate stronger demand at the top of the funnel. As clearly evidenced by our shortfall in occupancy for this year. Our marketing function has not been operating as effectively as it needs to and we have to get those fundamentals right in order to drive demand more consistently and and put ourselves in a better position to optimize pricing. As I mentioned earlier, we have had missteps over the last few years where we were not consistently and effectively speaking to our core customer. We were not always putting the right commercial support behind the itineraries we were trying to fill and our marketing was not as demand generative as it needed to be. To address that, we are looking to bring in new leadership and marketing at NCL and better align that function with revenue management, deployment and sales. This work is critical and will strengthen the business over time, but it may result in some near term variability in top line performance as we work through these initiatives. While we’ve identified key internal priorities and are making progress addressing areas of underperformance, the external operating environment has turned more challenging. We entered the year behind our ideal booking curve in certain areas and recent geopolitical developments have added pressure to an already challenged backdrop, particularly in our European market this summer and demand for close in bookings. Rest assured, we are monitoring this closely and making adjustments to our business model when and where needed. I want to be clear, while the macro environment continues to rapidly shift and evolve beyond our control, many of the issues we are addressing are internal and fixable. They come back to execution, alignment and discipline. As I noted at the outset of this call, Mark will go into our guidance for the year, but we recognize that our 2026 outlook is below expectations. We are not satisfied with that and I know our shareholders aren’t either. I stepped into this role to address these issues and we are here to do just that with the support of our talented team. We have the assets, we have the brands and now we have the focus. Our job is to execute better, operate with more discipline and build a stronger, more cohesive organization. While progress will take time, I am confident we are moving in the right direction to deliver stronger, more sustainable performance over time. With that, let me turn it over to Mark.

Mark Kempa (Executive Vice President and Chief Financial Officer)

Thank you John and good morning everyone. I’ll begin with our first quarter results on Slide 6 which were in line with our expectations. Net Yield in the first quarter was down 1% which is above our guidance adjusted Net cruise cost ex fuel of $168 was slightly better than guidance, declining 1% driven by strong cost controls which ultimately drove adjusted EBITDA of 533 million exceeding our guidance. Lastly, adjusted net income for the quarter benefited from below the line foreign currency exchange and was 108 million or an adjusted EPS of 23 cents. Turning to slide 8, you can see our second quarter and full year guidance. Our outlook reflects an extremely challenging backdrop for the balance of the year. Keep in mind our prior guidance did not include any impacts from the disruptions in the Middle east which is creating incremental headwinds including pressure on the top line and higher fuel expense. These external pressures are occurring as we continue to calibrate our revenue management system, improve commercial execution including marketing and demand generation, and work through the impact of entering the year behind our targeted booking curve. As a result, we are reducing our full year guidance for net yield, adjusted EBITDA and adjusted earnings per share. Starting with net Yield in the second quarter, we expect a decline of 3.6%. This reflects pressure mainly on our European sailings, which represent approximately 26% of our deployment in the quarter as well as weaker than anticipated domestic demand as consumers reevaluate travel plans. In the current macroeconomic environment. Looking to the full year, we expect net yields to decline 3 to 5%. This updated guidance reflects both the impact of the macroeconomic environment and the extent to which those pressures have compounded the execution and commercial challenges already facing our business. In terms of pacing through the quarters, we currently expect the third quarter to be significantly weaker than the second quarter, reflecting our greater exposure to Europe, which represents approximately 38% of our deployment in the quarter and as well as continued softness in markets such as Alaska, which we discussed last quarter. Looking to the fourth quarter, we are assuming the consumer environment remains pressured, although net yields should improve from Q3, supported in part by the opening of Great Tides Water park at Great Stirrup Cay by the end of the third quarter. Moving to Cost John discussed earlier in the prepared remarks, we have made great strides to take quick and decisive action on the cost management side of the equation. I will go into this in a bit more detail, but we now expect our adjusted NCCX fuel to be approximately flat for the full year and up 1% in the second quarter due to the timing of certain costs. Moving to fuel, we now expect fuel expense to be approximately 800 million based on the current spot prices. However, fuel expense would be approximately 6% lower if rates were based on the forward curve as a result of softer than expected top line performance and higher fuel costs partially offset by better cost performance. We are reducing our full year adjusted EBITDA guidance to between 2.48 and 2.64 billion and our adjusted EPS guidance to between $1.45 and $1.79. We recognize these results are significantly below expectations. That said, we have moved quickly to focus on what we can control, particularly on the cost side which I will detail on slide 9. We have taken swift action within SGA to drive efficiencies and identify savings. To start, we are taking steps to optimize our organization and reduce our marketing spend which combined are expected to generate annualized run rate savings of 125 million in 2026. These efforts will result in an expected approximate 2 percentage point reduction in adjusted net cruise cost ex fuel. Unfortunately, a meaningful portion of these savings is being offset by incremental direct costs related to the conflict in the Middle east, including higher crew airfare and increased logistics costs. Together, these impacts represent an approximate 1% increase in adjusted net cruise cost ex fuel. As a result, we now expect full year adjusted net cruise cost ex fuel to be approximately flat for the year. The important point to keep in mind is that while these savings are being partially offset by war related impacts in 2026, the actions we have taken are structural in nature. On a run rate basis, we expect to carry these savings forward and see a benefit in adjusted net cruise cost ex fuel as we move into 2027. As shown on slide 10. These actions position us to keep adjusted net cruise cost ex fuel sub inflationary and in fact 1% or lower in 2026 for a third straight year despite the current macroeconomic headwinds while also meaningfully exceeding our cumulative three year savings target of 300 million. We are now approaching 400 million in savings between our shipboard efforts over the last three years. Combined with our recent shoreside cost savings. We expect these actions to continue to benefit the business over time, supporting margin expansion as top line performance begins to recover in 2027. It’s also important to note that our work here is not done. We continue to see additional savings opportunities across the business both within SGA and on the shipboard side and we expect to build on these efforts going forward. The reduction in our 2026 adjusted EBITDA outlook has also impacted our expected year end net leverage. Reducing net leverage remains our top financial priority and we remain confident that leverage will improve over the coming years as earnings grow, capital spending moderates and cash flow strengthens as we turn around the business turning to Slide 11 our gross new build and growth CapEx detail highlights that we are beginning to move beyond a period of elevated capital spending. Over the last several years, we have invested heavily in our fleet, adding two to three ships annually and driving strong capacity growth, with capacity days expected to increase 7% in 2026. We will continue to take delivery of new ships over the next two years with two ships in 2026 and another two in 2027 beginning in 2028 and 2029, however, that pace moderates meaningfully with only one ship scheduled for delivery in each of those years. As a result, we expect Gross New build and growth capex to decline by nearly 1 billion per year, which should materially improve free cash flow generation. We view this as an important inflection point for the business and a meaningful opportunity to accelerate deleveraging. Also important to note, as shown on Slide 12, our debt maturity profile remains manageable with no significant debt maturities until 2030. That gives us added financial flexibility and supports our ability to focus on deleveraging over the next several years. With that, I’ll turn it back to John for closing remarks.

John Chidze (Chairperson and CEO)

Thanks, Mark. Before we open the line for …

Full story available on Benzinga.com

This post was originally published here

U.S. stocks traded lower this morning, with the Dow Jones index falling more than 150 points on Monday.

Following the market opening Monday, the Dow traded down 0.36% to 49,321.96 while the NASDAQ slipped 0.02% to 25,109.76. The S&P 500 also fell, dropping, 0.09% to 7,223.30.

Leading and Lagging Sectors

Consumer discretionary shares jumped by 0.4% on Monday.

In trading on Monday, energy stocks fell by 1%.

Top Headline

Tyson Foods (NYSE:TSN) posted better-than-expected earnings for the second quarter on Monday.

The company posted adjusted EPS of 87 cents, beating market estimates of 78 cents. The company’s sales came in at $13.653 billion versus expectations of $13.611 billion.

Equities Trading UP
           

  • CNS Pharmaceuticals Inc (NASDAQ:CNSP) shares shot up 319% to $9.69 after the company announced a $22.5 million private placement of 650,000 shares at $2.30 …

Full story available on Benzinga.com

This post was originally published here

As of May 4, 2026, three stocks in the health care sector could be flashing a real warning to investors who value momentum as a key criteria in their trading decisions.

The RSI is a momentum indicator, which compares a stock’s strength on days when prices go up to its strength on days when prices go down. When compared to a stock’s price action, it can give traders a better sense of how a stock may perform in the short term. An asset is typically considered overbought when the RSI is above 70, according to Benzinga Pro.

Here’s the latest list of major overbought players in this sector.

Avanos Medical Inc (NYSE:AVNS)

  • On April 14, Avanos Medical announced a going-private deal. American Industrial Partners will buy the medtech company in an all-cash transaction at an enterprise value of approximately $1.272 billion. The company’s stock gained around 78% over the …

Full story available on Benzinga.com

This post was originally published here

Within the semiconductor space, Texas Instruments Inc. (NASDAQ:TXN) is riding the coattails of a massive sector-wide rally to post a staggering 61.94% year-to-date gain.

As investors scramble to identify the true beneficiaries of the artificial intelligence (AI) boom, TXN’s stock has officially joined the top tier of Benzinga Edge’s momentum rankings.

Surging Momentum Meets Price Trend Strength

The stock’s recent breakout is heavily underscored by its Benzinga Edge’s Stock Rankings. TXN boasts a near-perfect momentum score of 91.86, a metric that measures the stock’s relative strength based on price movement patterns and volatility over multiple timeframes.

Additionally, the stock’s quality score—which evaluates historical profitability and operational efficiency—stands at an impressive 92.13. Texas Instruments is also showing distinctly positive upward price trends across short, medium, and long-term horizons. Furthermore, it carries a solid growth score of 75.05.

Benzinga Edge's Stock Rankings for TXN.

data-variant=”card”
data-news-mode=”manual”

This post was originally published here

Transamerica Structured Index Advantage® Income Annuity (TSIA Income) adds new options to help create protected, nonreducing* lifetime payments with flexibility to support evolving retirement and legacy goals

BALTIMORE, May 4, 2026 /PRNewswire/ — Transamerica today introduced TSIA Income, a new registered index-linked annuity (RILA) designed to help individuals create protected lifetime income while remaining connected to market opportunity and maintaining flexibility as retirement needs evolve.

As responsibility for retirement income continues to shift to individuals, many Americans are looking for ways to turn savings into predictable, reliable payments. TSIA Income is designed to help address this challenge by providing guaranteed lifetime income, offering a dependable stream of payments while still allowing for flexibility and continued participation in market opportunities.

“Today’s retirees want confidence their income can last, along with flexibility as their needs evolve,” said Liza Tyler, head of Annuity Solutions at Transamerica. “As more Americans recognize the value annuities can offer in helping turn savings into protected income, TSIA Income represents the next evolution of Transamerica’s annuity offerings—combining protected lifetime income with added flexibility that gives people greater control over when income begins and how they plan ahead.”

As an added benefit, Transamerica now offers Performance Lock+ at no additional cost on all new and existing Transamerica registered index‑linked annuity (RILA) contracts. Performance Lock+ provides added flexibility by allowing clients to lock in Index Account Option gains during a Crediting Period and move those gains into a Performance Lock Account, helping to protect progress along the way. Clients also have monthly opportunities, prior to the Allocation Anniversary, to re‑enter their original Index Account Option, giving advisors and investors greater control as market conditions and goals evolve.

TSIA Income offers multiple ways to tailor how and when lifetime income begins, including:

A no explicit fee income option
TSIA Income includes a no explicit fee RILA income option, designed for investors who want protected lifetime income in a cost-efficient way. Income can begin immediately or be deferred, with Rider …

Full story available on Benzinga.com

This post was originally published here

Twist Bioscience (NASDAQ:TWST) released second-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://edge.media-server.com/mmc/p/epdbxrqp/

Summary

Twist Bioscience reported a 19% year-over-year revenue growth for Q2 2026, reaching $110.7 million, marking the 13th consecutive quarter of sequential revenue growth.

The company highlighted its semiconductor-based DNA synthesis platform as a key competitive advantage, enabling cost-effective synthesis and rapid product innovation.

Twist Bioscience announced collaboration with Amazon Web Services for AI-powered drug discovery, showcasing its DNA synthesis and protein solutions capabilities.

The company is on track to achieve adjusted EBITDA breakeven in Q4 2026, with a focus on expanding gross margins and disciplined investment in growth opportunities.

Management noted strong growth in DNA synthesis and protein solutions, particularly driven by AI-enabled drug discovery, while NGS applications grew 12% year over year.

Full Transcript

OPERATOR

Welcome to Twist Bioscience 2026 Second Quarter Financial Results Conference Call. At this time all participants are in listen only mode. After the speaker’s presentation there will be a question and answer session. To ask a question you will need to press star 1-1. In the interest of time we ask that you please limit yourselves to one question. Also note this call is being recorded. I would like to turn the call over to Angela Bidding, SVP of Corporate Affairs. Please go ahead.

Angela Bidding (SVP of Corporate Affairs)

Thank you Operator Good morning, everyone. I would like to thank you for joining us for Twist Biosciences conference call to review our fiscal 2026 second quarter financial results and business progress. We issued our financial results press release before the market and it is available at our website at www.twistbioscience.com. with me on the call today are Dr. Emily Leproust, CEO and Co Founder of Twist, Adam Lapidus, CFO of twist and Dr. Patrick Finn, President and COO of Twist. Today we will discuss our business progress, financial and operational performance as well as growth opportunities. We will then open the call for questions. We ask that you limit your questions to only one and then re queue. As a courtesy to others on the call, this call is being recorded. The audio portion will be archived in the Investor section of our website and will be available for two weeks. During today’s presentation we will make forward looking statements within the meaning of the US Federal securities laws. Forward looking statements generally relate to future events or future financial or operating performance. Our expectations and beliefs regarding these matters may not materialize and actual results and financial periods are subject to risks and and uncertainties that could cause actual results to differ materially from those projected. These risks include those set forth in the press release we issued earlier today as well as those more fully described in our filings with the securities and Exchange Commission. The forward looking statements in this presentation are based on information available to us as of the date hereof and we disclaim any obligation to update any forward looking statements except as required by law. We’ll also discuss adjusted ebitda, a financial measure that does not conform with Generally Accepted Accounting principles. Information may be calculated differently than similar non GAAP data presented by other companies when reported. A reconciliation between GAAP and non GAAP financial measures will be included in our earnings documents which can be found on the Investor section of our website. With that, I will now turn the call over to our CEO and co Founder Emily La Proust.

Emily La Proust (CEO and Co-Founder)

Thank you Angela and good morning everyone. Twist Bioscience delivered another strong quarter and extended our track record of consistent execution, posting our 13th quarter of sequential revenue growth we have outperformed the broader life science tools market with a model that scales efficiently and drives increasing value creation. Twist Bioscience Core Technology Advantage is a semiconductor based DNA synthesis platform that provides a structural advantage in cost, scale and speed that feeds into every product and service we offer. The same platform also enables a highly efficient new product introduction engine, allowing us to rapidly translate customer demand into scalable offerings and continuously expand our portfolio. As we increase volume on the silicon chip, we expand our wallet share, accelerate product innovation and further strengthen our competitive advantage. The model works exactly as designed. We have delivered sustained revenue growth, expanded gross margin above 50 percent, invested strategically to drive continued return on that investment, and we remain firmly on track to achieve adjusted ETA breakeven in the fourth quarter of fiscal 2026. Focusing on our results for the second quarter of fiscal 2026, we grew total revenue to $1.7 million, up more than 19% year over year. DNA synthesis and protein solutions grew 28%. Powered by continued strength in AI enabled drug discovery, NGS applications grew 12% year over year and 9% sequentially. Diving deeper into DNA synthesis and protein solutions, we continue to see robust growth. Last month Amazon Web Services announced Twist Bioscience as a wet Lab partner for Amazon BioDiscovery, its AI powered drug discovery application. This is an exciting validation of our DNA synthesis, protein solutions and biologics capabilities. In advance of the launch, Twist Bioscience has been working with AWS team for several months providing wet lab services for the application’s scientific launch partners including Memorial Sloan Kettering Cancer center and the Gray Lab at Johns Hopkins University. The objective for researchers using Amazon BioDiscovery is to deploy AI models to design and optimize antibody candidates faster. We’re here to support them with products and services that accelerate that pathway. By staying in close contact with our customers, we identified this emerging category of AI enabled drug discovery early and invested ahead of the market acceleration with increasing adoption across pharma, dry lab and big tech companies. Importantly and on balance, the growth of AI enabled drug discoveries complements our work with customers pursuing traditional drug discovery, which remains a robust area of our business. Regardless of approach. Our customers for DNA synthesis and protein solutions are all working through the same fundamental design, build, test, learn cycle. What differs is how they execute against that framework. There is no one size fits all model. Each program is tailored to the customer, scientific approach, resources and stage of discovery. What remains constant across every engagement is the Foundation Twist Bioscience Silicon platform, which enables cost effective synthesis of hundreds of thousands of unique sequences. In parallel, that unique and preparatory capability is what makes speed at scale possible? No matter where the customer enters the workflow, no two orders are identical, so we see consistent patterns in how these campaigns are structured on Slide 6. To give you some context, one example is our work with Memorial Sloan Kettering and Amazon, where the team ordered approximately 100,000 specific DNA sequences as a pooled library. This approach is highly efficient precisely because of how our platform is built. Pooled DNA can be manufactured collectively rather than individually cloned and processed, driving down cost per sequence dramatically. And with this DNA provider, we can deliver hundreds of thousands of specific sequences pooled at speed and scale. Once at the pool, DNA either twists other customers, then screens that library to identify promising candidates, selects the most relevant sequences, and advances those into individual synthesis, protein expression, and characterization. Through iterative cycles, this process yields validated antibody leads. The second model involves customers ordering hundreds to thousands of gene fragments and executing downstream workflow internally. Here again, TWIST Platform delivers an edge in the ability to synthesize diverse sequence sets quickly and at accessible cost, meaning customers can explore broader design spaces. In these cases, customers convert fragments into clonal genes, express proteins, and perform characterization assays within their own laboratories. Others choose to start further downstream, purchasing clonal genes or antibodies and binding proteins such as IgG, ScFv, DHH, and others to focus their internal efforts on functional characterization and validation. Even at this entry point, the advantage traces back upstream. The parallel synthesis capability underpinning our platform ensures the sequences they receive reflect the speed at scale. That alternative cannot match. We have a growing segment of customers. We rely on TWIST as an end to end partner in these engagements. We handle DNA synthesis, clonal gene constructions, protein expression, and characterizations. Our platform’s ability to run large, complex sequence sets in parallel accelerates every stage of that workflow, and we deliver high quality experimental data that enables customers to focus on critical analysis, decision making, and iterative design. We also have a number of customers who give us a biological target and ask us to do all of the work through in vivo, in vitro, and our AI ML discovery approaches. Across all of these models growth scales with the scope and complexity of the workflow, ranging from smaller exploratory programs to multimillion dollar discovery efforts. Our role is to provide flexibility across the spectrum. Because our platform was purse built for parallel synthesis at scale, we can meet customers where they are. Whether they need a pool libraries of hundreds of thousands of sequences or a fully managed discovery program, we support them as their research advances. On Slide 7, you’ll see our portfolio for DNA synthesis and protein solutions serving customers across the biological continuum. Building on our success in serving therapeutic discovery customers, in February we licensed the BBODY Bispecific platform to expand our capabilities in this rapidly growing modality. We now enable high throughput discovery in bispecifics, an area that has historically been limited by scale. We have already received our first orders for this platform with a robust funnel. Looking Forward moving to slide 8 and NGS growth re accelerated in the second quarter our NGS tools business remains a durable and growing part of the portfolio with particular strengths in oncology diagnostics. We operate at a critical part in the workflow between the sample and the sequencer. Where our products support precision and customization at scale, our target enrichment and laboratory preparation solutions deliver the uniformity and on target performance required for high sensitivity applications. This is especially relevant in the continuum of cancer care on slide nine where we are seeing increasing adoption in commercial diagnostic tests including initial momentum in molecular or minimal residual disease or mrd. These applications demand extremely high accuracy and reproducibility faster on times and our chemistry is well aligned to these requirements. Specifically on slide 10, as MRD testing transitions from early clinical adoption into scale deployment across oncology diagnostics, the technical and operational requirements become significantly more demanding. These assays are pushing the limit of sensitivity, often requiring detection of variant at extremely low allele frequencies. That places a premium on panel design as well as the entire workflow to ensure uniform coverage and reproducibility across run. In this environment, success depends on the ability to deliver highly customized target enrichment panels, library preparation enabled by novel enzymes as well as the buffer, be, gdi, umis and other components optimized for specific indications and evolving clinical needs. Equally important is speed. As these tests move into broader clinical workflows, laboratories and diagnostic developers need rapid turnaround on panel design, synthesis and deployment to support asset development timelines and commercial scale. Up at wiz, we combine high super DNA synthesis with precision probe design and manufacturing at scale, enabling fast, reliable delivery of customized panels with consistent performance characteristics that allows our customers to move quickly from development to validation commercialization without compromising on data quality and importantly securing and future proofing their stable supply chain for bespoke or tumor informed MRD panels. Like all of our NGS panels, this is a consumable driven workflow that scales with test volume supporting recurring revenue as these applications expand. This time I’d like to turn the call over to Paddy to expand further on our growth initiative around the coming product offering.

Paddy

Thank you Emily. Halfway through our fiscal year, the results are strong and we believe the road ahead is stronger. Everything we do in protein solutions and AI enabled discovery runs on one foundation, our DNA synthesis platform. It’s a structural advantage for cost, scale and speed. Full stop. And we continue to advance and strengthen this platform to enhance customer experience even more. Today we accept the vast majority of DNA sequences as we know we can manufacture them. We have an algorithm embedded in our e-commerce system to inform a customer immediately if they have uploaded a sequence that may be difficult to manufacture. This notification improves the user experience for customers as some sequences present manufacturing challenges Repeat regions hairpins extreme GC content Three years ago we accepted about 96% of clonal genes and could manufacture about 97.5% of clonal genes and about 98% of DNA sequences more broadly, including oligopools, DNA libraries, gene fragments. Today we accept about 97% of clonal genes and can manufacture approximately 98.5% of clonal genes, about 99% of DNA requests more broadly. That’s not theoretical capability, that’s production reality at scale. We routinely deliver clonal genes and fragments up to 5,000 base pairs, oligopools up to 300 bases, multiplex gene fragments up to 500 base pairs across a …

Full story available on Benzinga.com

This post was originally published here

GameStop Corp. (NYSE:GME) has launched a historic $56 billion takeover bid for e-commerce giant eBay Inc. (NASDAQ:EBAY), setting the stage for a dramatic corporate battle as CEO Ryan Cohen threatens a hostile approach if the board refuses to engage.

A ‘Massive’ David vs. Goliath Play

The video game retailer announced a formal proposal to acquire 100% of eBay for $125.00 per share, evenly split between cash and stock.

Chief Market Strategist Shay Boloor highlighted the staggering scale of the David-and-Goliath bid, pointing out that the offer is “massive relative to GameStop’s ~$12B market cap.”

GameStop has already quietly built a 5% economic stake in eBay over the past three months and secured up to $20 billion in third-party acquisition financing from TD Securities to make the math work.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Ryan Cohen Is The Next Warren Buffett? Michael Burry Thinks So

This post was originally published here

Pinterest, Inc. (NYSE:PINS) will release earnings for its first quarter after the closing bell on Monday, May 4.

Analysts expect the San Francisco, California-based company to report quarterly earnings of 22 cents per share, down from 23 cents per share in the year-ago period. The consensus estimate for Pinterest’s quarterly revenue is $968.12 million (it reported $854.99 million last year), according to Benzinga Pro.

On March 3, Pinterest announced a significant $1 billion strategic investment from Elliott Investment Management.

Pinterest shares gained 2.9% to close at $20.22 on Friday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate analysts have rated the …

Full story available on Benzinga.com

This post was originally published here

Superior Gr of Cos (NASDAQ:SGC) released first-quarter financial results and hosted an earnings call on Monday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://event.choruscall.com/mediaframe/webcast.html?webcastid=8WHfrg1X

Summary

Superior Gr of Cos reported a 3% increase in first-quarter revenue, with a gross margin improvement of 30 basis points and EBITDA rising to $4.8 million from $3.5 million last year.

Branded Products, the largest segment, saw a 5% revenue growth driven by volume gains, while Healthcare Apparel also grew 5%, aided by a new leadership strategy.

Contact Centers experienced an 8% revenue decline due to prior client attrition, but sequential improvement was noted, and the opportunity pipeline remains strong.

The company maintains a strong balance sheet with $23 million in cash and expects further growth across all segments, projecting 2026 net sales of $572 million to $585 million and EPS of $0.54 to $0.66.

Management expressed confidence in navigating uncertain environments, with a focus on execution, AI implementation, and potential M&A opportunities in Contact Centers.

Full Transcript

OPERATOR

Good morning and welcome to the Superior Gr of Cos First Quarter 2026 Conference Call with us today are Michael Benstock, Chief Executive Officer, and Mike Kempel, President and Chief Financial Officer. Jake Himmelstein, President of the Company’s Branded Products segment, will join today’s call for the Q and A session. As a reminder, this conference call is being recorded. This call may contain forward looking statements regarding the Company’s plans, initiatives and strategies and the anticipated financial performance of the Company including but not limited to sales and profitability. Such statements are based on management’s current expectations, projections, estimates and assumptions. Words such as expect, believe, anticipate, think, outlook, hope and variations of such words and similar expressions identify such forward looking statements. Forward looking statements involve known and unknown risks and uncertainties that may cause future results to differ materially from those suggested by the forward looking statements. Such risks and uncertainties are further disclosed in the Company’s periodic filings with the Securities and Exchange Commission, including but not limited to, the Company’s most recent Annual report on Form 10-K and quarterly reports on Form 10-Q. Shareholders, potential investors and other readers are urged to consider these factors carefully in evaluating the forward looking statements made herein and are cautioned not to place undue reliance on such forward looking statements. The Company does not undertake to update the forward looking statements except as required by law. And now I’ll turn the call over to Michael Benstock.

Michael Benstock (Chief Executive Officer)

Thank you Operator. Good morning and thanks everyone for joining us. We had a good start to the year. First quarter revenue was up 3%, gross margin rate improved by 30 basis points, SG&A came down as a percent of sales by nearly a full point and EBITDA increased to $4.8 million from $3.5 million last year. EPS was $0.06 compared to a $0.05 loss in the first quarter of 2025. What I’m pleased with is that the improvement didn’t come from just one place. We saw progress across the business and that tells us the work we’re doing is starting to show up in a mean that the environment is still uncertain, including the added uncertainty around the Iran conflict. But we’re staying focused on execution and we’re encouraged by what we’re seeing. Overall, the company is in a strong position. We have a broad business mix, good customer relationships and supply chain flexibility. Those are all important in a market like this and that gives us confidence in our underlying strategies. Starting with branded products which is our largest segment, revenue grew 5% year over year for the second quarter in a row driven by volume gains within existing customer accounts. We also improved gross margin and held SG&A near 27% of sales which helped EBITDA grow nicely versus last year. Our pipeline and backlog remains strong and we’ll keep investing in sales, talent and technology to support growth in this part of the business. Moving to Healthcare Apparel, I want to welcome Chris Hein who recently joined us as President of that segment. Chris has deep multichannel apparel experience and a strong history of building successful teams and driving results. We’re excited to have him with us and look forward to what he brings to the business. In healthcare apparel, revenue grew 5% versus last year’s first quarter. That was driven by volume growth in existing wholesale accounts and continued progress in direct to consumer. Mike will discuss in more detail our lower EBITDA for the quarter. We continue to see good potential in the segment and are focused on improving execution from here with new strategies and leadership in place. Turning to Contact Centers, revenue was down 8% versus the first quarter 2025 mainly because of prior year client attrition. On the other hand, revenue did improve sequentially from the fourth quarter, helped by existing customer expansion. The Opportunity pipeline is still at a historical high and with easier comparisons ahead, we’re focused on converting the pipeline into year over year growth. We also made real progress on the cost side with SG&A down more than 200 basis points as a percent of sales compared to the year ago quarter. This reflects the benefits of last year’s cost reduction work, including our continued focus on implementing AI and other technologies. As a result, Contact Center’s EBITDA was down only slightly year over year, but the margin rate improved which should help profitability going forward. We also maintained a strong balance sheet which gives us the flexibility to keep investing where it makes sense while also repurchasing shares when we see the opportunity. So overall this was a solid start to the year. We’re encouraged by the progress we made and we think the work underway across the business is putting us in a better position as we move through the year. With that, Mike will walk you through the first quarter financial results and then we’ll open it up for questions.

Mike Kempel (President and Chief Financial Officer)

Thank you Michael and thanks everyone for joining us today. We grew consolidated revenue by 3% in the first quarter to $141 million. As we have mentioned before, our business is typically back half weighted with sequential improvement through the year and that’s reflected in our 2026 guidance looking at the segments branded products, our largest segment grew 5% year over year to $91 million. Healthcare apparel, our second largest segment also grew revenue by 5% to $29 million. Contact centers revenue declined 8% year over year as anticipated to $22 million. But we did see improvement sequentially from the fourth quarter and we expect that to continue as the …

Full story available on Benzinga.com

This post was originally published here

Fabrinet (NYSE:FN) will release earnings for its third quarter after the closing bell on Monday, May 4.

Analysts expect the company to report quarterly earnings of $3.56 per share, up from $2.52 per share in the year-ago period. The consensus estimate for Fabrinet’s quarterly revenue is $1.19 billion (it reported $871.8 million last year), according to Benzinga Pro.

On Feb. 2, Fabrinet reported second-quarter earnings of $3.36 per share, which beat the consensus estimate of $3.25.

Fabrinet shares gained 3.4% to close at $706.53 on Friday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating …

Full story available on Benzinga.com

This post was originally published here

Wall Street is bracing for a leadership transition. As Jerome Powell’s term as a Fed Chairman ends on May 15, the market is starting to adjust to a new leadership, likely under Kevin Warsh.

Historically, changing the guard triggers market anxiety, as investors fear a shift in the “reaction function” of the world’s most powerful central bank.

While volatility seems inevitable as markets “test” the new Chair, research suggests investors are pricing in the inherited environment rather than the man behind the desk. However, historical data suggests that significant market underperformance typically accompanies these transitions.

The Replacement Illusion vs. Macro Reality

Dr. Dejan Kovač, a Harvard postdoc fellow, analyzed Fed transitions over the last 50 years. He looked at data from the Burns-to-Miller handover in 1978 to Powell’s arrival in 2018. The period following these transitions is clear – markets, on average, underperform by 7.7 percentage points in the year following a leadership change.

However, Kovač’s study also reveals a replacement illusion. After controlling for macro factors like CPI, the Fed Funds rate, …

Full story available on Benzinga.com

This post was originally published here

During times of turbulence and uncertainty in the markets, many investors turn to dividend-yielding stocks. These are often companies that have high free cash flows and reward shareholders with a high dividend payout.

Benzinga readers can review the latest analyst takes on their favorite stocks by visiting Analyst Stock Ratings page. Traders can sort through Benzinga’s extensive database of analyst ratings, including by analyst accuracy.

Below are the ratings of the most accurate analysts for three high-yielding stocks in the information technology sector.

Amdocs Ltd (NASDAQ:DOX)

  • Dividend Yield: 3.52%
  • Stifel analyst Shlomo Rosenbaum maintained a Buy rating and cut the price target from $97 to $88 on Feb. 4, 2026. This analyst has an accuracy rate of 63%
  • Wolfe Research analyst George Notter downgraded the stock from Outperform to Market Perform on Nov. 13, 2025. This analyst has an accuracy rate of 82%.
  • Recent News: On March 23, Amdocs announced the appointment of Shimie Hortig to the board of directors upon Shuky Sheffer’s retirement as …

Full story available on Benzinga.com

This post was originally published here

Advanced Micro Devices Inc. (NASDAQ:AMD) shares are trading lower Monday as investors exercise caution ahead of the company’s first-quarter 2026 earnings report.

The stock faced downward pressure during premarket action, following a period of broader tech sector profit-taking.

Earnings Expectations Loom

The semiconductor giant is scheduled to release its first-quarter results on Tuesday. According to analyst estimates, the market anticipates earnings per share of $1.24. Revenue expectations currently sit at $9.88 billion.

Analyst Price Forecasts

On May 1, RBC Capital maintained a Sector Perform rating on AMD. However, the firm notably raised its price forecast to $325.00. The …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades and downgrades, please see our analyst ratings page.

  • BTIG raised the price target for Brightspring Health Services Inc (NASDAQ:BTSG) from $55 to $65. BTIG analyst David Larsen maintained a Buy rating. Brightspring Health shares closed at $52.58 on Friday. See how other analysts view this stock.
  • Needham raised Celcuity Inc (NASDAQ:CELC) price target from $122 to $157. Needham analyst Gil Blum maintained a Buy rating. Celcuity shares closed at $125.65 on Friday. See how other analysts view this stock.
  • Piper Sandler raised price target for Essex Property Trust Inc (NYSE:ESS) from $275 to $310. Piper Sandler analyst Alexander Goldfarb upgraded the stock from Neutral to Overweight. Essex Property Trust shares closed at $263.35 on Friday. See how other analysts view this stock.
  • HC Wainwright & Co. raised the price target for Corcept Therapeutics …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Piper Sandler analyst Alexander Goldfarb upgraded Essex Property Trust Inc (NYSE:ESS) from Neutral to Overweight and raised the price target from $275 to $310. Essex Property Trust shares closed at $263.35 on Friday. See how other analysts view this stock.
  • Stifel analyst W. Andrew Carter upgraded SiteOne Landscape Supply, Inc. (NYSE:SITE) from Hold to Buy and maintained the price target of $157. SiteOne …

Full story available on Benzinga.com

This post was originally published here

Top Wall Street analysts changed their outlook on these top names. For a complete view of all analyst rating changes, including upgrades, downgrades and initiations, please see our analyst ratings page.

  • Mizuho analyst Dan Dolev initiated coverage on Federal National Mortgage Association (OTC:FNMA) with an Outperform rating and announced a price target of $10. Federal National Mortgage shares closed at $8.15 on Friday. See how other analysts view this stock.
  • Piper Sandler analyst Yasmeen Rahimi initiated coverage on First Tracks Biotherapeutics Inc (NASDAQ:TRAX) …

Full story available on Benzinga.com

This post was originally published here

On CNBC’s “Halftime Report Final Trades,” Jim Lebenthal, partner at Cerity Partners, named Apollo Global Management, Inc. (NYSE:APO) as his final trade.

Apollo-managed funds, on April 27, acquired the Interiors Business Group of Forvia SE (OTC:FURCF) in a carve-out transaction. Deal terms remain undisclosed.

Kevin Simpson, Capital Wealth Planning founder and CIO, picked Archer-Daniels-Midland Company (NYSE:ADM) ahead of quarterly earnings.

ADM said it will release first-quarter financial results on Tuesday, May 5. Analysts expect the company to report quarterly earnings at 66 …

Full story available on Benzinga.com

This post was originally published here

Hedge funds are rapidly dialing back their exposure to U.S. technology stocks, marking the most aggressive pullback in over a decade, according to market commentary from The Kobeissi Letter.

Largest Two-Week Reduction in Years

In a Sunday post on X, the letter stated that hedge funds have recorded their biggest two-week reduction in U.S. information technology exposure in the past 10 years, excluding the extraordinary volatility seen during the meme stock frenzy in early 2021.

The letter said the shift was “driven by long sales outpacing short covers at a ratio of 1.5 to 1.” It marked the move as profit-taking, with funds “cashing-in massive profits in tech.”

Sell-Off Mirrors Michael Burry Move

The trend aligns with …

Full story available on Benzinga.com

This post was originally published here

On CNBC’s “Mad Money Lightning Round,” Jim Cramer recommended buying RTX Corp (NYSE:RTX), saying it is a “monster” right here.

“It’s down a lot. It makes no sense,” he added. “It’s because there’s not enough aircraft servicing, because people feel that people aren’t going to fly anymore. Wrong!”

RTX, on April 30, raised its quarterly dividend from 68 cents to 73 cents per share.

Aurora Innovation, Inc. (NASDAQ:AUR) is a “worthy” spec, Cramer said. “I’m not sure …

Full story available on Benzinga.com

This post was originally published here

Pfizer Inc. (NYSE:PFE) will release earnings for its third quarter before the opening bell on Tuesday, May 5. Analysts expect the pharmaceutical company to report quarterly earnings of 72 cents per share. That’s down from 92 cents per share in the year-ago period.

Benzinga Pro puts the consensus estimate for Pfizer’s quarterly revenue at $13.8 billion. Pfizer reported $13.71 billion last year.

With the recent buzz around the company, some investors are eyeing potential gains from its dividends. Currently, Pfizer has an annual dividend yield of 6.53%. That’s a quarterly dividend amount of 43 cents per share ($1.72 a year).

To figure out how to earn $500 monthly from PFE, we start with the yearly target of $6,000 ($500 x 12 months).

Next, we divide this amount by Pfizer’s $1.72 dividend: $6,000 / $1.72 = 3,488 shares.

So, an investor …

Full story available on Benzinga.com

This post was originally published here

A Spirit Aviation Holdings Inc. (OTC:FLYYQ) fan kicked off a crowdsourcing endeavor to buy the budget airline operator after it ceased its operations as creditors refused to support a government-backed $500 million rescue plan.

Green Bay Packers Models

Hunter Peterson, a fan of the airline, kicked off the fundraiser as a joke, according to a Business Insider report on Sunday, which has since gathered steam. The official website, dubbed “Spirit 2.0,” shared that over $88,071,428 had been unverified pledges had been made to the fundraiser before it crashed.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Sean Duffy Says Spirit Collapse Was ‘Self-Made,’ Rejects Iran War Blame

This post was originally published here

Expanded suite designed to support the savings goals and retirement readiness of Canadian employees 

TORONTO, May 4, 2026 /CNW/ – Today, SLGI Asset Management Inc. (“Sun Life Global Investments”) announced the expansion of its Granite solutions with Sun Life Granite Index+ Target Date Funds (Granite Index+). As the largest Canadian-based target date fund manager,1 Sun Life Global Investments is responding to the growing demand for more differentiated target date funds that support long‑term retirement outcomes for Canadian plan members.

Sun Life Granite Target Date Funds, a flagship retirement solution for more than 15 years, were built for Canadian employers who want a highly diversified solution and believe active management adds value over time. As Canadians’ financial needs have evolved, Granite Index+ was introduced to offer another choice: a simpler, predominantly passive option that still provides broad diversification and access to private markets, at a competitive fee. Together, the Granite lineup gives employers more flexibility to choose a default solution that fits their plan’s goals, governance model and fee budgets.

“We’re seeing the needs and preferences of Canadian employers evolve, and we’re focused on creating solutions that meet them where they are,” said Anne Meloche, Head of Institutional Business, Sun Life Global Investments. “With target date funds serving as the default choice for 81% of workplace plans,2 it’s critical that companies have options that align with their investment preferences, fee budget and fiduciary responsibilities to better support their members being retirement ready.”

Redefining the retirement landscape with resilient portfolios

Granite Index+ is managed by the Canadian-based …

Full story available on Benzinga.com

This post was originally published here

U.S. stock futures were lower this morning, with the Dow futures falling around 200 points on Monday.

Shares of Norwegian Cruise Line Holdings Ltd (NYSE:NCLH) fell in pre-market trading following first-quarter results.

Norwegian Cruise Line reported quarterly earnings of 23 cents per share which beat the analyst consensus estimate of 14 cents per share. The company reported quarterly sales of $2.331 billion which missed the analyst consensus estimate of $2.357 billion.

The company also cut its FY2026 adjusted EPS guidance from $2.38 to $1.45-$1.79.

Norwegian Cruise Line shares dipped 4.9% to $17.89 in pre-market trading.

Here are some other stocks moving lower in pre-market trading.

  • Xanadu …

Full story available on Benzinga.com

This post was originally published here

Billionaire entrepreneur Mark Cuban is sounding the alarm on the future of enterprise artificial intelligence (AI), warning that fragmented AI models from tech giants like Microsoft Corp. (NASDAQ:MSFT) and Alphabet Inc. (NASDAQ:GOOG) (NASDAQ:GOOGL) will create overwhelming corporate complexity and turn business scale into a massive liability.

‘Walled Garden’ Dilemma

In an assessment of the current AI landscape, Cuban cautioned that the fierce competition among foundational tech giants is creating an unsustainable, highly fragmented environment for large corporations.

“Every LLM is a walled garden in a race to beat the hell out of the next foundational model,” Cuban stated. He noted that corporate IT departments will face relentless stress deciding when to adopt, run parallel, or abandon these rapidly shifting technologies.

Because these distinct models do not seamlessly integrate, Cuban offered a blunt forecast: “In the next 5 years enterprise AI is going to be a mess, with all the different implementations and flavors and sources and models.”

This post was originally published here

With U.S. stock futures trading mixed this morning on Monday, some of the stocks that may grab investor focus today are as follows:

  • Wall Street expects Tyson Foods Inc. (NYSE:TSN) to report quarterly earnings at 78 cents per share on revenue of $13.61 billion before the opening bell, according to data from Benzinga Pro. Tyson Foods shares fell 0.3% to $63.50 in after-hours trading.
  • Analysts are expecting Williams Companies Inc. (NYSE:WMB) to post quarterly earnings at 62 cents per share on …

Full story available on Benzinga.com

This post was originally published here

U.S. stock futures mostly advanced on Monday, as President Donald Trump announced “Project Freedom” to guide ships of neutral countries stranded in the Strait of Hormuz out of restricted waters.

S&P 500 futures gained 12.25 points, or 0.17%, to 7,270.25 and Nasdaq 100 futures advanced 100.25 points, or 0.36%, to 27,936.00 as of 2:11 a.m. EST, while futures tied to the Dow Jones Industrial Average eased 16 points, or 0.032%, to 49,630.00.  

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Sean Duffy Says Gas Prices Could Drop Fast If Strait Of Hormuz Reopens: ‘You’ll See Prices Come Down…Immediately’

This post was originally published here

The CNN Money Fear and Greed index showed almost no change in the overall market sentiment, while the index remained in the “Greed” zone on Friday.

U.S. stocks settled mixed on Friday, with the S&P 500 settling at a fresh record high level during the session.

Crude oil prices fell on Friday as Iran routed a fresh Hormuz reopening proposal through Pakistani mediators.

In earnings, shares of Apple Inc. (NASDAQ:AAPL) gained more than 3% after the company posted better-than-expected fiscal second-quarter earnings and revenue. Atlassian Corp. (NASDAQ:TEAM) shares surged almost 30% after the company reported better-than-expected third-quarter financial results. Exxon Mobil Corp. (NYSE:XOM) reported better-than-expected results for the first quarter.

On the economic data front, the ISM manufacturing PMI came in unchanged at 52.7 …

Full story available on Benzinga.com

This post was originally published here

A fresh debate over the state of the U.S. economy is gaining traction on social media, after Anthony Pompliano declared a “manufacturing boom” underway, while The Kobeissi Letter is fueling renewed concerns that underlying stagflation pressures may be building.

Manufacturing Momentum Picks Up

In an X post on Sunday, investor and commentator Pompliano pointed to what he described as a “manufacturing boom” underway in the United States.

Supporting the view, the latest data showed the U.S. manufacturing sector continued to expand in April, with the ISM Manufacturing PMI holding steady at 52.7, matching March’s reading and marking a fourth consecutive month of growth.

The New Orders Index rose to 54.1, while production and supplier deliveries remained in expansion territory. However, employment and inventories stayed in contraction, highlighting ongoing labor market softness despite broader economic momentum.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

GameStop Proposes To Acquire eBay For $55.5 …

This post was originally published here

Macro investor and the founder and CEO of Azuria Capital LLC, Otavio Costa, is slamming the Federal Reserve‘s latest inflation narrative, accusing the central bank of using curated data to justify premature interest rate cuts while actual living costs continue to soar.

‘Useless’ Metric

The controversy centers on the St. Louis Fed’s recent promotion of the Trimmed-Mean PCE inflation rate—a metric closely associated with former Fed Governor Kevin Warsh. Data released for March 2026 showed this measure ticking up only slightly to 2.36%.

However, critics argue this alternative measure of core inflation intentionally masks the reality of surging prices by stripping out extreme price fluctuations from the data.

“The St. Louis Fed now posting Kevin Warsh’s useless inflation metric,” Costa stated recently on social media. “That’s how far these guys have to go to justify cutting rates while inflation is picking back up.”

Costa highlighted a stark market divergence to prove his point: while the trimmed-mean metric paints a picture of stabilizing prices, the broader commodities sector is experiencing a massive upward spike.

By actively ignoring volatile categories—which invariably affect essential consumer goods—critics argue the metric fails to reflect the true economic pressures facing everyday households.

Full story available on Benzinga.com

This post was originally published here

Demand for used EVs surged in the U.S. as gas prices continue to rise amid the U.S.-Israel and Iran war, with sales seeing double-digit increases on the used market.

A Surge In Demand

Used EV sales jumped nearly 28% in March this year, CNBC reported, citing data from Cox Automotive on Sunday. One of the reasons outlined is the end of leases for EVs, which has led to an influx on dealership lots, according to analyst Joseph Yoon from market research firm Edmunds, cited in the report.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Gavin Newsom Slams Trump’s ‘Iran War Tax’ As California Gas Price Breaks $6/Gallon Threshold

This post was originally published here

Palantir Technologies Inc. (NASDAQ:PLTR) will release earnings for its first quarter after the closing bell on Monday, May 4.

Analysts expect the Aventura, Florida-based company to report quarterly earnings of 28 cents per share. That’s up from 13 cents per share in the year-ago period. The consensus estimate for Palantir’s quarterly revenue is $1.54 billion (it reported $883.86 million last year), according to Benzinga Pro.

On April 28, Cleveland-Cliffs signed a three-year partnership with Palantir to deploy AI across its operations and commercial functions.

Shares of Palantir gained 3.6% to close at $144.07 on Friday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or other variables.

Let’s have a look at how Benzinga’s most-accurate …

Full story available on Benzinga.com

This post was originally published here

Denmark’s temporary halt on new grid connections for data centers underscores how soaring AI and cloud infrastructure demand is forcing even renewable-rich nations to reconsider energy priorities.

Denmark’s Grid Strain Forces Data Center Pause

Denmark has paused new grid connection agreements after requests surged far beyond available capacity, CNBC reported on Monday.

State-owned grid operator Energinet said roughly 60 gigawatts of projects are awaiting access — dramatically above the country’s peak electricity demand of about 7 gigawatts.

Data centers account for nearly a quarter of pending requests, intensifying concerns over whether critical infrastructure, local industries and public services could face tougher competition for electricity.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

US Utility Spending To Hit $1.4 Trillion By 2030 As AI, Data Centers …

This post was originally published here

Ford Motor Co. (NYSE:F) CEO Jim Farley says making vehicles more affordable must become a priority for the auto industry, arguing that Ford is already preparing lower-priced models as new-car costs strain U.S. households.

Farley Says Ford Must Lower Prices

In a CBS News interview on Friday, Farley was asked whether Americans can afford new cars today. “Some Americans can,” he said. “But we need to do a great job as a brand and as an industry to make our vehicles more affordable. I think you’re certainly going to see that at Ford over the next couple of years.”

Farley said Ford wants to offer more new models at about $40,000 or less. “Most of our new models are going to be more affordable versions,” he said, adding that Ford will offer more choices, “around $40,000, less than $40,000.” He said the challenge is building them in America while …

Full story available on Benzinga.com

This post was originally published here

A surge in capital expenditure related to artificial intelligence could enhance earnings per share estimates for the S&P 500 in the years 2026-27, according to short-seller Jim Chanos.

AI Capex Could Boost S&P 500 EPS

A significant rise in AI-related capital expenditure (capex) is expected to elevate S&P 500 earnings per share (EPS) estimates.

Chanos highlighted that the accounting practices for AI investments create a disparity between immediate revenue and profit recognition and the capitalization of costs. This discrepancy is anticipated to result in a profits “magic” during periods of increased capital spending, Chanos added.

The boost in EPS estimates stems from the way AI-related …

Full story available on Benzinga.com

This post was originally published here

Equity ETFs tied to the S&P 500 Index attracted massive inflows last week, as investors poured billions into broad U.S. equity exposure despite a noisy macro backdrop.

In a post on X, The ETF Tracker wrote, “Here is where ETF investors put the most of their money last week.”

S&P 500 Giants Lead The Charge

The iShares Core S&P 500 ETF (NYSE:IVV) topped the inflow charts, pulling in $7.08 billion in capital. This was followed by inflows of $5.36 billion in Vanguard S&P 500 ETF (NYSE:VOO) and $ 4.46 billion in SPDR S&P 500 ETF Trust (NYSE:SPY).

These three inflows imply roughly $16.9 billion combined for the week. The ETF Tracker attributed the data to ETF Central.

All three ETFs track the S&P 500 Index. VOO is the biggest among …

Full story available on Benzinga.com

This post was originally published here

Norwegian Cruise Line Holdings Ltd. (NYSE:NCLH) will release earnings for its first quarter before the opening bell on Monday, May 4.

Analysts expect the Miami, Florida-based company to report quarterly earnings of 14 cents per share. That’s up from 7 cents per share in the year-ago period. The consensus estimate for Norwegian Cruise Line’s quarterly revenue is $2.36 billion (it reported $2.13 billion last year), according to Benzinga Pro.

On March 2, Norwegian Cruise Line reported fourth-quarter results that topped earnings expectations but missed on revenue and included a cut to its full-year 2026 adjusted profit outlook.

Shares of Norwegian Cruise Line gained 3.5% to close at $18.81 on Friday.

Benzinga readers can access the latest analyst ratings on the Analyst Stock Ratings page. Readers can sort by stock ticker, company name, analyst firm, rating change or …

Full story available on Benzinga.com

This post was originally published here

Governor Gavin Newsom (D-CA) slammed President Donald Trump on Saturday as gas prices continued to surge amid escalating tensions in the Middle East due to the ongoing U.S.-Israel and Iran war.

Trump Iran War Tax

In a post on the social media platform X, Newsom’s official Press Office handle delivered sharp criticism of Trump, saying that the war in Iran had “driven U.S. gas prices up 44% to a four-year high.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Elizabeth Warren Says Trump’s Iran War Was Final ‘Nail In The Coffin’ For Spirit Airlines: ‘Spiking Fuel Prices…’

This post was originally published here

Sen. Elizabeth Warren (D-Mass) criticized President Donald Trump on Saturday for prolonging the conflict in Iran, which has led to a surge in oil prices and, in turn, resulted in budget airline Spirit Aviation Holdings Inc. (OTC:FLYYQ) ceasing operations.

Iran War Final ‘Nail In The Coffin,’ Elizabeth Warren Says

In a post on X, Warren slammed the administration’s participation in the war. “Spiking fuel prices from Trump’s war was the nail in the coffin for twice-bankrupted Spirit airline,” she said. Warren added that the proposed merger with JetBlue Airways Corp (NASDAQ:JBLU) fell through because a judge appointed by former President Ronald Reagan deemed the merger “illegal.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Trump’s Take On Iran Proposal, Tariffs On EU Cars And More: This Week In Politics

This post was originally published here

SpaceX CEO Elon Musk on Sunday said that the importance of reusable rockets was crucial for humans to become a multiplanetary civilization amid the billionaire’s Mars colonization goals.

Cannot Become Multiplanetary Without Reusable Rockets

Responding to a post by Tesla Owners Silicon Valley, which shared that SpaceX had reduced costs per kg to orbit by 500x from approximately “$54,500 (Shuttle era) to ~$1,500.”

Musk said that the assessment of a technology lies in calculating how “it improves fundamental metrics,” adding that to achieve multiplanetary status without reusable rockets “is impossible.”

He then drew parallels to the colonial powers reaching America, saying that it would’ve been “impossible to colonize America with expendable boats.”

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Tesla’s Week Explained: Elon Musk’s $158 Billion Payout, Semi …

This post was originally published here

GameStop Corp. (NYSE:GME) on Sunday proposed to acquire eBay Inc. (NASDAQ:EBAY) for $125 per share in a cash-and-stock transaction, valuing the video game retail chain at approximately $55.5 billion.

The offer represents a 20% premium to eBay’s closing price on Friday.

This move by GameStop follows reports that the company has been quietly building a stake in the e-commerce firm, aiming to increase its market value significantly, with CEO Ryan Cohen expressing ambitions to reach a $100 billion valuation.

Deal Structure, Financing

Under the proposed terms, eBay shareholders would receive consideration split evenly between cash and GameStop stock, with the ability to elect their preferred mix, subject to pro-rata allocation. GameStop disclosed it has already assembled a 5% economic interest in eBay through a combination of derivatives and direct share ownership.

The company plans to fund the cash portion using its existing balance sheet, about $9.4 billion in cash and liquid investments as of Jan. 31, 2026, alongside third-party financing. It has secured a “highly confident” financing letter from TD Securities for up to $20 billion.

GameStop added that it plans to submit a Schedule 13D and make an HSR filing on …

Full story available on Benzinga.com

This post was originally published here

Jim Cramer on Sunday argued that the latest wave of Big Tech earnings proves aggressive artificial intelligence (AI) and data center spending is fueling competitive advantage rather than creating a dangerous market bubble.

Cramer Rejects AI Bubble Narrative After Big Tech Earnings

In a detailed analysis published on CNBC, Cramer pushed back against mounting concerns that hyperscaler spending on AI infrastructure is overheated, saying the latest quarterly results show the opposite.

“I am growing tired of the endless bubble talk about all of the data center spending,” Cramer wrote. “This was the quarter where we realized that if you didn’t spend, you were already behind the 8-ball.”

Cramer pointed to strong market performance from Alphabet Inc. (NASDAQ:GOOG) (NASDAQ:GOOGL), Amazon.com Inc. (NASDAQ:AMZN) and Apple Inc. (NASDAQ:AAPL) over the past five days, arguing investors are rewarding companies whose AI investments are producing measurable returns.

Over the past five days, Alphabet Class A shares surged 11.32% to $385.69, while Class C shares increased by 11.43% to $383.22.

Apple climbed to $280.25, …

Full story available on Benzinga.com

This post was originally published here

The tech industry has witnessed a massive surge in layoffs amid soaring investments in AI infrastructure, with over 81,000 jobs slashed in the first quarter of 2026. This marks a dramatic increase compared to previous quarters, highlighting the ongoing challenges faced by the sector.

Highest Quarterly Layoffs In 2 Years

According to The Kobeissi Letter, tech companies have announced a staggering 81,747 layoffs in the first quarter of 2026. This marks the highest quarterly total since at least the first quarter of 2024.

Layoffs in the tech sector have more than doubled compared to the previous quarter, showing a dramatic increase of 580% since the fourth quarter of 2025. March alone accounted for 45,800 job cuts, making it the worst month for tech layoffs in over two years, as reported by Kobeissi Letter.

Full story available on Benzinga.com

This post was originally published here

Momentum cracked across pockets of the market as earnings misses and cautious outlooks shook investor confidence.

From tech to fintech, big names stumbled as disappointing results and guidance resets weighed on sentiment.

These ten large-cap stocks were the worst performers last week. Are they a part of your portfolio?

Rambus, Inc. (NASDAQ:RMBS) slumped 28.47% last week after the company reported worse-than-expected first-quarter adjusted EPS results.

Summit Therapeutics Inc. (NASDAQ:SMMT) fell 27.82% this week. The company reported Q1 financial results.

Roblox Corporation (NYSE:RBLX) dipped 19.64% this week after the company reported first-quarter financial results and cut its FY26 adjusted sales guidance below estimates. Also, …

Full story available on Benzinga.com

This post was originally published here

April didn’t just rally — it rewrote the playbook for Wall Street momentum with the biggest tech earnings on a spree.

AI euphoria, blockbuster earnings, and relentless dip buying turned skeptics into believers.

But beneath the surge, soaring capex and execution risks are starting to test the narrative.

Earnings Snapshot

Microsoft Corporation (NASDAQ:MSFT) announced third-quarter financial results on Wednesday after market close. Company reported third-quarter revenue of $82.9 billion, up 18% year-over-year. The revenue total beat a Street consensus estimate of $81.39 billion according to data from Benzinga Pro.

Amazon.com Inc (NASDAQ:AMZN) reported first-quarter revenue of $181.52 billion, beating the consensus estimate of $177.30 billion.

Alphabet Inc. (NASDAQ:GOOGL(NASDAQ:GOOG) reported quarterly earnings of $5.11 per share, which blew past the analyst consensus estimate of $2.62 by 95.04%.

Meta Platforms Inc (NASDAQ:META) reported financial results for the first quarter on Wednesday after the bell. Meta expects second-quarter revenue to be in the range of $58 billion to $61 billion versus estimates of $59.50 billion.

Apple Inc. (NASDAQ:AAPL)  reported revenue of $111.18 billion, up 17% year over year and above analyst estimates of $109.66 billion, while earnings came in at $2.01 per share versus estimates of $1.94.

Roblox Corp. (NYSE:RBLX) reported quarterly losses of 35 cents per share, which beat the analyst estimate for losses of 39 cents, according to Benzinga Pro data. 

Spotify Technology S.A. (NYSE:SPOT) reported …

Full story available on Benzinga.com

This post was originally published here

Wall Street’s winners list is getting crowded, and momentum is doing the talking.

From tech to telecom, big names are catching fire as earnings beats and bold moves fuel investor buzz.

These ten large-cap stocks were top performers last week. Are they a part of your portfolio?

Centene Corporation (NYSE:CNC) gained 25.68% in the last week after the company reported better-than-expected first-quarter financial results. Also multiple analysts raised their price forecast on the stock.

Twilio Inc. (NYSE:TWLO) jumped 27.36% in the last week after the company reported better-than-expected first-quarter financial results and issued second-quarter guidance above estimates. Also, the company raised its FY26 sales guidance above estimates.

Nokia Corporation (NYSE:NOK) gained 24.3% in the last week. Investors are reacting to Nokia’s decision to offload its …

Full story available on Benzinga.com

This post was originally published here

From a semi-truck production ramp to concerns about the company’s valuation, as well as a $500 million windfall in the form of SpaceX and xAI, here’s a look at the major events in Tesla Inc.‘s (NASDAQ:TSLA) week.

Over $500 Million From SpaceX, xAI

Tesla reportedly made over $573 million selling vehicles and battery technology to Musk’s other businesses, SpaceX and xAI, according to regulatory filings on Thursday. The company sold $430 million worth of energy storage systems, while $143 million was from vehicles sold to SpaceX.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Elon Musk’s Tesla Invested $2 Billion Into SpaceX, Q1 2026 Earnings Show

This post was originally published here

Seven OPEC+ producers said on Sunday they will dial back part of their extra voluntary cuts by 188,000 barrels per day starting in June 2026, framing the move as a calibrated step aimed at keeping the oil market steady. The decision lands as the United Arab Emirates announced it will withdraw from OPEC and OPEC+ effective May 1, a break with the group’s coordinated approach as crude traded above $100 a barrel Tuesday morning.

The shared reader stake is market stability: both the OPEC+ supply plan and the UAE’s departure can shift fuel costs and price expectations for consumers and businesses.

Why UAE’s Exit Signals A Market Shift

UAE’s exit ends nearly 60 years of membership and points to a future where at least one major Gulf producer sets output policy on its own. The UAE state news agency WAM said the country plans to lift production toward 5 million barrels per day by 2027, from about 3.4 million currently.

The UAE’s energy minister described the move as a sovereign call tied to a long-term strategy, while also arguing the timing was chosen to avoid adding stress to markets constrained by the Strait of Hormuz. The announcement came only hours before OPEC was scheduled to meet in Vienna.

According to OPEC+ statement, Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman explained that they met virtually Sunday and agreed to a June 2026 production increase of 188,000 barrels per day by unwinding a slice of the extra voluntary cuts first outlined in April 2023.

The group also kept the door open to changing course, saying the voluntary reductions could be brought back partly or fully depending on …

Full story available on Benzinga.com

This post was originally published here

Gerber Kawasaki Wealth & Investment Management CEO Ross Gerber has accused large private-market players of keeping troubled private credit and private equity marked at inflated levels, then said wirehouses are still collecting management fees as if those assets were worth full price, a setup he likened to the run-up to the 2008 mortgage blowup.

He has also argued that inflation pressures are being reignited by tariffs and war, warning in tariffs and war pushing living costs up that once price momentum takes hold it can be hard to unwind, which can make already-opaque valuations even harder for investors to judge.

In a series of posts on X, Gerber wrote that private-market transparency is essential because weak assets are not being written down, and he called for stricter accounting at major private equity firms.

Why Private-Market Valuations Need Urgent Reform

Gerber’s sharper allegation centered on fee mechanics: he said wirehouses are billing clients in managed accounts based on unchanged values, even when the underlying private holdings are deteriorating.

He compared that dynamic to the incentives that, in his view, helped drive the 2008 housing-finance disaster, where compensation kept flowing while risk accumulated.

data-variant=”card”
data-news-mode=”manual”

This post was originally published here

It’s been an eventful week for Apple Inc. (NASDAQ:AAPL) and its leadership. Here’s a quick roundup of the major stories that unfolded over the week.

Buffett: Apple’s Leadership Shift Could Reshape Shareholder Returns Strategies

Warren Buffett shared insights into Apple’s leadership shift and its potential impact on shareholder returns strategies. The Berkshire Hathaway Inc. (NYSE:BRK) veteran’s remarks came during the company’s annual meeting.

Buffett revealed that Berkshire Hathaway had effectively invested around 10% of its resources in Apple. This investment, despite not being treated as a forever asset, remains the conglomerate’s largest holding.

He also highlighted Apple’s 50th anniversary, noting that the company still feels young. Buffett contrasted the public’s familiarity with Steve Jobs with the relative anonymity of Tim Cook when he took over as CEO after Jobs’ passing.

Read the …

Full story available on Benzinga.com

This post was originally published here

The week saw significant developments in the U.S. economy, with the GDP growth rate for the first quarter of 2026 soaring, gas prices, and a dip in President Trump’s approval rating. Here’s a quick recap of the weekend’s top stories.

US GDP Grows 2%, Core PCE Inflation Jumps 3.2% In March

The U.S. economy experienced a 2% annualized growth rate in the first quarter of 2026, as per the advance estimate released on Thursday. This figure was higher than the previous 0.5% pace but fell short of economists’ 2.3% expansion expectations. The Core PCE inflation rate for March also rose to 3.2%.

Alphabet Inc. (NASDAQ:GOOG) (NASDAQ:GOOGL) and Meta Platforms Inc. (NASDAQ:META) were among the companies affected by this news. 

Read the full article here.

Fed …

Full story available on Benzinga.com

This post was originally published here

Nvidia Corp. (NASDAQ:NVDA) CEO Jensen Huang pushed back Thursday against high-profile warnings that artificial intelligence will gut white-collar work, calling the most extreme forecasts counterproductive.

In the same debate over whether AI will meaningfully displace workers, Kalshi traders are siding with him, pricing a 34% chance that U.S. unemployment tops 5% in 2026.

Responsible Framing

In remarks from the “Memos to the President” podcast, Huang said leaders in the industry should watch how they frame AI’s stakes and stick to evidence. He aimed at executives, making sweeping claims about job destruction and broader societal collapse. 

Those warnings have shown up in betting markets as a measurable question: Will unemployment jump sharply as AI spreads through offices? On Kalshi, the odds fall quickly beyond the 5% line, with contracts implying 15.7% for unemployment above 6%, 12.9% above 7%, and 6.2% above 8% in 2026.

data-variant=”banner”
data-news-mode=”manual”

>


Read Also:

Nvidia CEO Jensen Huang Calls AI …

This post was originally published here

Lockheed Martin Corp. (NYSE:LMT) and Boeing Co. (NYSE:BA) are set to supply Israel with two additional fighter squadrons after Israel’s defense ministry said on Sunday it signed off on a large aircraft-buy plan.

The ministry framed the move as an early step in a broader military modernization push meant to prepare for what it called a tougher security environment over the next decade.

$119 Billion Purchase

According to a Reuters report, the procurement committee’s approval supports a $119 billion (350 billion shekel) program and includes a fourth F-35 squadron from Lockheed Martin plus an additional squadron of Boeing’s F-15IA jets.

The ministry said the aircraft are intended to anchor long-range force planning and help Israel maintain air dominance.

data-variant=”card”
data-news-mode=”manual”

>


This post was originally published here

After days of sparring in a federal courtroom, Sam Altman used a Saturday post on social media to extend a small olive branch to rival Elon Musk, saying Musk “can come if he wants” to a limited OpenAI gathering tied to the May 5 rollout of GPT-5.5.

The gesture landed as Musk testified he didn’t read OpenAI’s for-profit fine print and pressed for major governance changes and $150 billion in damages.

Altman’s invite came as OpenAI circulated an online RSVP form for a small GPT-5.5 release celebration, with Codex set to help pick attendees from responses, reported Business Insider.

Non-Profit Built For Humanity

On Thursday in a California court, Musk argued he put millions behind OpenAI, expecting a nonprofit built for humanity, then watched the value concentrate in a for-profit structure.

In his post, Altman added, “The world needs more love,” even as the judge overseeing the case warned both leaders to …

Full story available on Benzinga.com

This post was originally published here

Tesla Inc. (NASDAQ:TSLA) recently ramped up its Robotaxi operations in Texas, providing unsupervised Robotaxi rides in Dallas and Houston, while it was already providing rides in Austin. While the ramp-up in Cybercab production could provide another boost in its Robotaxi exploits, Tesla remains far behind its rival Alphabet Inc.‘s (NASDAQ:GOOGL) (NASDAQ:GOOG) Waymo.

Tesla Vs Waymo

On Thursday, Electrek reported that Tesla had increased the size of its unsupervised Robotaxi fleet to 25 across the three Texan cities, citing the Robotaxi tracker. The increase represents a sign of growth in the service, which has struggled to replicate the successes of Waymo, almost a year after it was launched in June 2025 with an onboard safety driver.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Alphabet-Backed Waymo Issues Software Update For Fleet Following PG&E San Francisco Outage

This post was originally published here
Former White House AI and Crypto Czar David Sacks said he agrees with Elon Musk that training artificial intelligence to push ideological biases is dangerous and could ultimately enable AI to deceive users about its own actions.

Sacks Draws The Line On AI Truthfulness

“If you teach the AI to lie… that’s very dangerous because then the AI can lie to us about what it’s doing,” Sacks said while speaking to Dasha Burns on a Politico podcast released Friday, referencing Musk’s warnings against embedding so-called “woke” values into AI models.

The debate over AI bias predates Sacks’ remarks. Musk previously criticized OpenAI‘s ChatGPT for biased responses, citing instances where the chatbot declined to write a positive poem about Donald Trump while doing so freely for Joe Biden, a concern Sacks said …

Full story available on Benzinga.com

This post was originally published here

On Saturday, Warren Buffett warned that financial markets are increasingly being driven by speculation rather than long-term investing, saying he has “never had people in a more gambling mood than now.”

Buffett Warns Of Surge In Market Speculation

Speaking in a CNBC interview during Berkshire Hathaway Inc.’s (NYSE:BRK(NYSE:BRK) annual shareholders meeting, the longtime investor criticized the surge in short-term trading behavior, particularly the rise of options trading and prediction-style bets.

He described modern markets as resembling “a church with a casino attached,” adding that the casino side has become far more prominent.

Buffett said, “That’s not investing. It’s not speculating. It’s gambling, just totally,” referring to one-day options trading and other high-frequency strategies gaining popularity among retail investors.

He also noted that over six decades in markets, only a small number of years offered meaningful investment opportunities.

As a result, Berkshire Hathaway has accumulated nearly $400 billion in cash, as Buffett continues to find assets …

Full story available on Benzinga.com

This post was originally published here

Transportation Secretary Sean Duffy pushed back Saturday on claims that the U.S.-Iran war caused Spirit Airlines(OTC:FLYYQ) collapse, calling the carrier’s financial troubles pre-existing and structural.

Spirit’s Collapse Was Self-Made

“Spirit was in dire straits long before the war with Iran,” Duffy said at a New Jersey press conference. “Multiple times, they filed for bankruptcy. Their model wasn’t working.”

Spirit announced Saturday it was “winding down its global operations, effective immediately,” marking its second bankruptcy in 12 months.

CEO Dave Davis told The Wall Street Journal that surging jet fuel costs, driven by the Iran conflict, doomed the airline’s recovery plan.

Government Not Writing Blank Checks

Several budget carriers have since requested a $2.5 billion federal bailout through …

Full story available on Benzinga.com

This post was originally published here

On Friday, President Donald Trump said the European Union is violating a trade agreement and announced plans to raise tariffs on imported automobiles and commercial vehicles.

EU Faces 25% Auto Tariff Hike

In a Truth Social post, Trump said he would increase tariffs on cars and trucks coming from the EU to 25%, citing what he described as noncompliance with a previously agreed trade deal.

“I am pleased to announce that, based on the fact the European Union is not complying with our fully agreed to Trade Deal, next week I will be increasing Tariffs charged to the European Union for Cars and Trucks coming into the United States,” he wrote.

Trump added that vehicles produced in the U.S. would be exempt. “It is fully understood and agreed that, if they produce Cars and Trucks in U.S.A. Plants, there will be NO TARIFF,” he said.

He also pointed to what he called a surge in domestic investment, claiming “over 100 Billion Dollars” is being invested in new auto plants across the country.

This post was originally published here

U.S. gas prices surged to $4.43 per gallon, up 61% since December, as oil briefly hit $126 a barrel on Thursday, its highest level since the Iran war began.

According to The Kobeissi Letter, Americans will spend roughly $90 billion more on gasoline in a year than they would at $3/gallon.

Iran Escalation Fears Rattle Oil Markets

President Donald Trump on Saturday said he was reviewing a new Iranian proposal while nuclear talks remained stalled, after rejecting Tehran’s earlier offer on Friday as failing to meet U.S. demands, leaving the status of the Strait of Hormuz and …

Full story available on Benzinga.com

This post was originally published here

On Saturday, Warren Buffett used Berkshire Hathaway Inc. (NYSE:BRK) (NYSE:BRK) annual meeting stage to highlight the leadership handoff that executives described as a clean win, with the board’s succession choice approved without dissent and Greg Abel already running the playbook. The shift puts fresh attention on whether Abel can deploy a cash hoard that has topped $350 billion, a challenge outlined in the pressure to put the cash to work as investors weigh buybacks, deals, or even a dividend.

During the shareholder meeting, Buffett explained that the company pointed to what it called a board “refreshment” and said the directors’ vote on the change was unanimous. He said that the internal transition has been “100% successful,” adding that Abel is handling the job at a higher level than before.

‘It was a surprise to all the board when I announced it last year and that’s been 100% successful. Greg is doing everything I did and then some, and he’s doing it better in all cases, and he’s got, he’s the right person,” Buffett said about Abel.

That same meeting also framed the change as more than a title swap, because Abel’s remit includes the day-to-day of Berkshire’s operating companies and major capital calls. Beyond insurance, he previously ran Berkshire’s non-insurance operations, a background that now intersects with oversight of units such as Geico and the conglomerate’s roughly $300 billion equity portfolio.

Is Berkshire Hathaway’s Cash Pile A Boon Or Bane?

The shared reader stake is straightforward: Berkshire’s capital-allocation calls can directly affect shareholder returns through buybacks, acquisitions, or dividends. With cash …

Full story available on Benzinga.com

This post was originally published here

Apple Inc. (NASDAQ:AAPL) was highlighted on Saturday after Warren Buffett described how Berkshire Hathaway’s roughly $35 billion bet on the iPhone maker a decade ago ballooned to about $185 billion on a pre-tax basis, counting dividends and gains, largely under CEO Tim Cook. The backdrop is that Apple is also adjusting its internal playbook as Cook prepares to step down, including a pullback in buybacks and a sharp increase in research spending as John Ternus is lined up to take over.

In the remarks explained during Berkshire Hathaway’s annual meeting, Buffett said Berkshire effectively committed about 10% of its resources to Apple by buying shares and letting Apple’s management do the heavy lifting. He said the position remains Berkshire’s biggest holding, even though the conglomerate does not treat every stock as a forever asset.

Buffett’s $35 Billion Investment Transformation

During the meeting shared by CNBC, Buffett also pointed to Apple’s 50th anniversary, saying the company can still feel young despite the milestone. He contrasted the public’s familiarity with Steve Jobs with how few investors knew Cook’s name when he took the top job after Jobs’ death.

“I think just within the last week …

Full story available on Benzinga.com

This post was originally published here

Renowned economist Gary Shilling has reportedly issued a stark warning about an impending recession in the U.S., forecasting a significant downturn in the stock market.

S&P 500 Could See A Major Correction, Warns Shilling

According to a report by Business Insider, Shilling predicts that the S&P 500 could drop by as much as 30% by the end of the year.

Shilling attributes the potential recession to ongoing economic vulnerabilities, noting that only a substantial increase in fiscal stimulus or strong consumer spending could prevent it.

However, he views both scenarios as unlikely. The housing market is sluggish due to high interest rates, and capital expenditures have sharply declined, despite a rise in AI-related investments.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

Trump Renews Powell Attack, Offers Warsh Half The Oval Office

This post was originally published here
Voice AI is having a moment, and SoundHound AI, Inc. (NASDAQ:SOUN) is right in the spotlight.

Shares of the conversational AI player have been trending as fresh commentary from Twilio Inc. (NYSE:TWLO)
reignited investor interest in the voice AI theme. Twilio’s strong first-quarter results and bullish outlook on AI-driven voice demand appear to have added momentum to SoundHound’s narrative, alongside its own strategic moves.

“In Q1, we continued to see unprecedented demand for voice, reimagined through the lens of AI,” said Twilio CEO Khozema Shipchandler, highlighting voice as a growing entry point for both AI-native firms and enterprises. The company’s voice channel revenue rose 20% year over year, reinforcing the view that conversational AI is rapidly scaling across industries.

Speculations are – this optimism on voice AI has spilled over to SoundHound, which recently announced plans to acquire LivePerson to deepen its presence in AI-driven customer service. The deal, expected to close in the second half of 2026, aims to combine SoundHound’s voice AI capabilities with LivePerson’s messaging platform to create a more comprehensive offering.

Meanwhile, an exchange filing shows that SoundHound AI’s shares are 5.21% owned by Vanguard Capital Management, which reported beneficial ownership of 20.35 million shares with sole voting power over about 2.96 million shares. The filing noted the stake is held in the ordinary course of business and is not intended to influence control of the company.

The broader Technology sector gained 1.49% on the day, underscoring strong momentum in AI-linked names, even as SoundHound’s stock movement suggested investors are reacting to a mix of company-specific developments and …

Full story available on Benzinga.com

This post was originally published here
Berkshire Hathaway Inc. (NYSE:BRK) (NYSE:BRK) said Saturday that first-quarter 2026 net earnings attributable to shareholders climbed to $10.106 billion, more than double the $4.603 billion posted a year earlier, as operating profit rose despite investment-market swings. The results arrive as a $373 billion cash pile takes center stage and the stock has lagged: Berkshire is down 11.19% year over year while the S&P 500 gained 29.5%.

According to Berkshire Hathaway’s earning report, operating earnings of $11.346 billion for the quarter, up from $9.641 billion, while investment gains and losses were a $1.240 billion drag versus a $5.038 billion hit in the prior-year period. Net earnings per average equivalent Class A share were $7,027 and Class B were $4.68, compared with $3,200 and $2.13, respectively, a year earlier.

That gap between business performance and share performance has become part of the investor conversation, with some shareholders looking for CEO Greg Abel to demonstrate his approach before adding exposure. Lawrence Cunningham, a University of Delaware governance professor, said some buyers may want to see Abel “prove himself in his job,” even as he described the market as “expressing caution.”

Berkshires Earnings: What Lies Beneath?

According to the earning report, Berkshire also cautioned that quarterly net income can be distorted by GAAP rules that route unrealized equity moves through earnings, and it argued those figures can mislead investors who don’t follow the accounting details. According to Berkshirehathaway, investment results included about $7.0 billion of losses tied to shifts in unrealized gains on equity holdings during the quarter, along with $5.8 billion of after-tax realized gains from selling investments.

Within operating earnings, insurance underwriting contributed $1.717 billion, up from $1.336 billion, while insurance investment income slipped to $2.679 billion from $2.893 billion. BNSF generated $1.377 billion versus $1.214 billion, Berkshire Hathaway Energy delivered $1.114 billion versus $1.097 billion, …

Full story available on Benzinga.com

This post was originally published here
Warren Buffett once offered a rare glimpse into why Greg Abel is his chosen successor at Berkshire Hathaway Inc. (NYSE:BRK) (NYSE:BRK), highlighting that long-term discipline, cultural fit and discovering one’s true calling matter far more than brilliance alone.

Buffett Says Berkshire Future Depends On Culture, Not Celebrity

During Berkshire Hathaway’s annual shareholder meeting in 2025, Buffett made clear that Abel’s value lies not in flashy leadership traits but in his ability to preserve the company’s unique culture of trust, disciplined capital allocation and long-term thinking.

Buffett described Berkshire as an extraordinary business ecosystem built over decades, one that cannot easily be replicated.

“You can’t even dream all the dreams that you could have about a place like Berkshire,” Buffett said, underscoring the rare foundation Abel will inherit.

Rather than portraying Abel as a larger-than-life figure, Buffett suggested his successor’s strength comes from understanding Berkshire’s principles and protecting what has already been built.

data-variant=”card”
data-news-mode=”manual”

>


Read Also:

This post was originally published here
Billionaire hedge fund manager Bill Ackman has that he was clarifying why his newly listed closed-end funds, Pershing Square USA (PSUS) and Pershing Square Inc. (PS), slid after listing, pointing to how late-day trading mechanics collided with an unusually retail-heavy allocation. The explanation came as investors digested details of a combined IPO targeting $5 billion at $50 a share that included special terms for cornerstone buyers and a dual-ticker debut.

In a post on X, Ackman shared that his team gave retail buyers full allocations while trimming institutional fills, a reversal of the typical pecking order in new issues.

In the same combined offering, the new fund was structured so buyers would receive one Pershing Square Inc. share for every five shares purchased in Pershing Square USA, while cornerstone participants were set to receive 1.5 Pershing Square Inc. shares for every five PSUS shares.

Retail Investors Caught In IPO Timing Trap

The shared reader stake is settlement-driven liquidity risk, because both accounts describe how allocation size and trading timing can force sales that pressure prices.

Ackman said the stocks didn’t open until 1:55 p.m., leaving a narrow window for investors who wound up with more …

Full story available on Benzinga.com

This post was originally published here
Lockheed Martin (NYSE:LMT) on Friday was awarded U.S. Space Force contracts to develop capabilities for the Space-Based Interceptor program.

The firm has been selected by the U.S. Space Force to enhance its missile defense capabilities through the Space-Based Interceptor program, which aims to provide an additional layer of protection against emerging missile threats.

This development is part of a broader initiative to integrate advanced technologies and deliver an integrated demonstration by 2028.

The broader market experienced slight gains, with the Nasdaq rising 0.87% and the S&P 500 up 0.19%. Meanwhile, Lockheed Martin’s stock performance contrasts with the Dow Jones, which closed down 0.43%, suggesting that the stock is moving in line with positive company-specific news despite mixed market conditions.

Technical Analysis

Lockheed Martin is currently trading within its 52-week range, which has seen a high of $692.00 and a low of $410.11. The stock is trading 10.6% below its 20-day simple moving average (SMA) and 16.4% below its 50-day SMA, indicating a bearish short-term trend.

The relative strength index (RSI) is at 22.03, suggesting the stock is oversold, which could indicate potential for a rebound. This level of RSI typically reflects significant selling pressure, …

Full story available on Benzinga.com

This post was originally published here
As the S&P 500 seeks the next leg higher, smart money might be moving toward healthcare, a sleeper sector of 2026.

While technology valuations trade at a premium to historical averages, healthcare has remained a relative laggard. Despite BlackRock’s optimism in January, after the first third of the year, the sector has underperformed. The Vanguard Health Care Index Fund (NYSE:VHT) is down 5.50% year-to-date.

Still, the series of earnings upgrades, coupled with an AI-driven drug-discovery tailwind, suggests the sector is no longer just a defensive play. It is shaping into a growth engine that the broad market is yet to fully acknowledge.

The April Surge

The latest earnings cycle confirms the shift. On Tuesday, UnitedHealth (NYSE:UNH) raised full-year guidance following a strong first quarter. Despite short-term pressure, the fundamental outlook for the leading insurer continues to strengthen as it integrates advanced analytics into its claim processing.

Meanwhile, on Thursday, Eli …

Full story available on Benzinga.com

This post was originally published here
Software provider Cloudera is being sued by the U.S. Department of Justice’s Civil Rights Division for alleged intentional discrimination against U.S. workers in favor of those with temporary visas.

The case was filed under the Immigration and Nationality Act and was lodged with the Office of the Chief Administrative Hearing Officer, according to a press release.

• KKR stock is trading near recent lows. What’s next for KKR stock?

The department detailed allegations that Cloudera, which is co-owned by KKR & Co. Inc (NYSE:KKR) and Clayton Dubilier & Rice, set up a parallel recruiting track that discouraged U.S. applicants and failed to seriously evaluate them for certain positions, the lawsuit stated. The filing also claims the company used an email inbox that blocked messages from outside senders, yet still …

Full story available on Benzinga.com

This post was originally published here
Spirit Airlines (OTC:FLYYQ) stopped flying on Saturday after its creditors wouldn’t back a U.S. government rescue plan, leaving the carrier to liquidate as the Iran war sent jet fuel costs sharply higher.

The failure lands in the middle of a fierce bailout debate, with transportation policy analyst Marc Scribner arguing in a push against using public funds for bailouts that Spirit’s risks belong with shareholders and lenders rather than taxpayers.

According to a report by Reuters, Spirit’s board concluded Friday negotiations without securing a viable solution, according to sources familiar with the discussions. The airline subsequently grounded its entire operation and warned passengers to stay home.

Why Spirit Airlines’ Liquidation Signals Market Shifts

Scribner has framed a federal backstop as a “bad investment,” warning that even a loan can shift airline downside to the public and that outright ownership would deepen that transfer. He also pointed to long-running losses at Amtrak and the U.S. Postal Service as examples he says show how poorly government can perform as an operator.

Spirit’s failure marks a political blow for President Donald Trump, whose $500 million rescue plan faced pushback from Republican allies and advisers before ultimately collapsing. Trump said on Friday the White House delivered what he described as a last proposal, adding that any help had to be on terms that put the U.S. first.

Spirit’s shutdown removes a major discount competitor that at one point accounted for about 5% …

Full story available on Benzinga.com

This post was originally published here
Retail investors talked up five hot stocks this week (April 27 to May 1) on X and Reddit’s r/WallStreetBets, driven by retail hype, Iran war, earnings, AI buzz, and corporate news flow.

Apple Inc. (NASDAQ:AAPL), Alphabet Inc. (NASDAQ:GOOG) (NASDAQ:GOOGL), Robinhood Markets Inc. (NASDAQ:HOOD), Meta Platforms Inc. (NASDAQ:META), and Eli Lilly And Co. (NYSE:LLY), hardware, semiconductors, cloud, fintech, social media, AI, and pharmaceutical, reflected diverse investor interests.

Apple

  • Apple reported strong second-quarter fiscal 2026 earnings on April 30, posting record March-quarter revenue of $111.2 billion and EPS of $2.01. iPhone revenue showed solid growth, Mac and Services hit highs, while gross margins expanded; the company also authorized another $100B in buybacks and raised its dividend 4% to $0.27/share. This marked Tim Cook‘s final earnings call as CEO before transitioning to executive chairman, with John Ternus taking over as CEO later in 2026.
  • Some retail investors were appreciating AAPL’s approach of not investing heavily in AI as compared to its Magnificent 7 peers.
Source: Reddit
  • The stock had a 52-week range of $193.25 to $288.62, trading around $270 to $279 per share, as of the publication of this article. It rose 27.69% over the year, but declined by 0.02% and 0.19% over the last six months and year-to-date, respectively.
  • AAPL had a strong price trend in the medium, short and long term, with a poor value ranking, as per Benzinga’s Edge Stock Rankings.

Alphabet

  • Alphabet reported strong first-quarter 2026 earnings, with consolidated revenue rising 22% YoY to $109.9 billion, driven by robust Google Search/YouTube ads and especially Google Cloud revenue surging 63% to over $20 billion for the first time. Net income jumped 81% to $62.6 billion, aided by operating margin expansion to 36.1% and unrealized gains on equity …

Full story available on Benzinga.com

This post was originally published here
Benzinga examined the prospects for many investors’ favorite stocks over the last week — here’s a look at some of our top stories.

U.S. stocks extended their powerful April rally as cooling inflation concerns, resilient earnings and renewed enthusiasm around artificial intelligence pushed major indexes to fresh record highs. The S&P 500 and Nasdaq Composite posted their strongest monthly gains since 2020, while the Dow Jones Industrial Average also advanced sharply as investors looked past lingering geopolitical risks and focused on strong corporate performance. Market sentiment improved further after softer oil prices eased fears of another inflation spike tied to Middle East tensions.

Technology and semiconductor stocks remained the primary drivers of the rally, with chipmakers benefiting from continued optimism around AI infrastructure spending. Strong results and upbeat commentary from companies such as Alphabet and major semiconductor firms reinforced confidence that demand for AI computing power remains robust despite concerns earlier this year about excessive capital spending.

Even with the strong momentum, investors remain cautious ahead of another wave of earnings reports and key economic data, including the monthly jobs report and further inflation readings. Federal Reserve officials have continued signaling concern about inflation persistence, leading traders to reassess expectations for near-term rate cuts even as equity markets push higher.

Benzinga provides daily reports on the stocks most popular with investors. Here are a few of this past week’s most bullish and bearish posts that are worth another look.

The Bulls

Apple Posts Double Beat In Q2 As Active Installed Base Hits All-Time High — ‘Our Best March Quarter Ever’,” by Adam Eckert, reports that Apple Inc. (NASDAQ:AAPL) delivered a fiscal second-quarter earnings and revenue beat with EPS of $2.01 on revenue of $111.18 billion, both topping Wall Street estimates, as CEO Tim Cook called it the …

Full story available on Benzinga.com

This post was originally published here
Iran has reportedly lost about $4.8 billion in oil revenue since the U.S. naval blockade took effect on April 13, the Pentagon estimated Friday, as nuclear negotiations remain at a stalemate.

A Pentagon official familiar with the assessment confirmed the figure to The Hill, first reported by Axios.

“We are inflicting a devastating blow to the Iranian regime’s ability to fund terrorism,” acting Pentagon press secretary Joel Valdez said Friday.

Speaking at the White House on Friday about Iran’s latest peace …

Full story available on Benzinga.com

This post was originally published here
Tesla (NASDAQ:TSLA) spent about $4.8 million on Elon Musk‘s security in 2025, up from $2.8 million a year earlier, according to its Thursday Securities and Exchange Commission filing.

Rising Executive Security Costs Reflect Broader Threat Concerns

Security spending for Elon Musk, who is also CEO of SpaceX and xAI, more than doubled through February, rising to $1.3 million from $500,000 during the same period a year earlier.

These figures do not represent the total cost of Musk’s security, as his other companies also contribute to managing the risks associated with his high profile.

Last year, responding to a post, Musk said on X that he “definitely need[s] to enhance security.”

The rise comes as companies face increased security concerns for top executives. In …

Full story available on Benzinga.com

This post was originally published here
Apple beat at $111.2B with a $100B buyback. Meta got hit. Powell’s last press conference brought the most divided Fed since 1992.

$710 billion. That’s what Amazon (NASDAQ:AMZN) , Microsoft (NASDAQ:MSFT), Google (NASDAQ:GOOGL) (NASDAQ:GOOG), and Meta (NASDAQ:META) just told the market they (NYSE:MAGS) will spend on AI CapEx in 2026. Pichai said the quiet part out loud: “We are compute-constrained.”

The S&P closed Friday at a fresh record 7,230 (+0.3%), the Nasdaq at a record 25,114 (+0.9%), both posting their best month since 2020. Apple did most of the Friday lifting after a $111.2B revenue beat. The Dow slipped 153 points to 49,499. WTI cooled to $102.28 (-2.7%) on Iran de-escalation signals, but the national gas average still hit $4.39, up from $4.06 a week ago.

THE RUNDOWN

CapEx › THE $710B SHOCK › Amazon at $200B. Microsoft at $190B. Google at $185B. Meta at $135B. Every one of them raised guidance this week, and Pichai’s “we are compute constrained” line was the most consequential CEO sentence of the quarter. The signal isn’t just the size; it’s the dispersion. Stocks that turn CapEx into revenue today (AAPL, AMZN, GOOGL) ripped. Stocks where the spend is still a 2027 story (META -8.6% Wednesday, MSFT -3.9%) got punished.

APPLE › $111.2B AND A $100B BUYBACK › Apple delivered Q2 revenue of $111.18B vs …

Full story available on Benzinga.com

This post was originally published here
Meta Platforms (NASDAQ:META) acquired Assured Robot Intelligence, a humanoid robotics startup, for an undisclosed sum on Friday, adding the team to its Superintelligence Labs research division as it advances its humanoid robotics ambitions.

The deal positions Meta directly in a rapidly commercializing humanoid robotics sector, where big tech, automakers and well-funded startups are competing to deploy physical AI at scale.

Founders With Deep Robotics Pedigree

ARI co-founder Lerrel Pinto previously taught at New York University and co-founded Fauna Robotics, a startup specializing in developing approachable, small-scale humanoid robots, which Amazon (NASDAQ:AMZN) acquired in March.

Co-founder Xiaolong Wang is an associate professor at UC San Diego and was previously a researcher at Nvidia (NASDAQ:NVDA).

Meta Superintelligence Labs head Alexandr Wang welcomed the ARI team on X, underscoring the division’s push into physical AI, an area Meta has been building toward for years.

Full story available on Benzinga.com

This post was originally published here
TPG Inc. (NASDAQ:TPG) CEO Jon Winkelried stated that the firm’s performance in Q1 was “particularly notable given the complex macro backdrop.”

“The convergence of AI disruption, private credit stress, and geopolitical conflict has created significant market uncertainty… We’ve delivered some of our best-performing vintages during periods of dislocation,” he said on the Q1 earnings call with analysts.

The CEO added that the firm views the current environment as “an opportunity,” and has “never felt more confident in the positioning of our franchise and our ability to successfully execute on our growth drivers.”

TPG’s fee-related earnings exceeded $1 billion in the last 12 months for the first time, reflecting a 31% annualized growth rate since its initial public offering (IPO).

In credit, the firm raised $4.4 billion, adding commitments from several new partnerships. Winkelried  noted that “While the asset class has been under heightened scrutiny more recently, our credit portfolios are healthy, and we have strong conviction in the long-term growth outlook for our business.”

This post was originally published here
U.S. stocks traded mixed toward the end of trading, with the Dow Jones index falling around 0.1% on Friday.

The Dow traded down 0.09% to 49,608.95 while the NASDAQ surged 1.06% to 25,157.20. The S&P 500 also rose, gaining, 0.50% to 7,245.21.

Leading and Lagging Sectors

Information technology shares jumped by 1.6% on Friday.

In trading on Friday, energy stocks fell by 1.3%.

Top Headline

Chevron Corporation (NYSE:CVX) reported mixed first-quarter results on Friday.

The company posted earnings of $2.2 billion, or $1.11 per share, down from $3.5 billion a year earlier. Adjusted EPS of $1.41 beat the $0.95 estimate, while revenue of $48.61 billion missed the $52.08 billion estimate.

Equities Trading UP
           

  • Esperion Therapeutics Inc (NASDAQ:ESPR) …

Full story available on Benzinga.com

This post was originally published here
Willis Towers Watson PLC (NASDAQ:WTW) posted mixed results for the first quarter on Thursday.

The company posted adjusted EPS of $3.72, beating market estimates of $3.67. The company’s sales came in at $2.412 billion missing expectations of $2.428 billion.

“WTW delivered first quarter results that demonstrate our strong operating discipline and continued progress of our strategy,” said Carl Hess, WTW’s Chief Executive Officer. “Our ongoing focus on enhancing efficiency drove margin expansion and significant EPS growth, despite a more challenging global market that created near-term headwinds to organic growth. Our investments in talent, AI and innovation to accelerate performance continue driving client value, and we remain confident in delivering our full-year commitments.”

Willis …

Full story available on Benzinga.com

This post was originally published here
FMC Corp (NYSE:FMC) reported better-than-expected second-quarter financial results and reaffirmed its FY2026 guidance, after the closing bell on Wednesday.

FMC reported quarterly losses of 2 cents per share which beat the analyst consensus estimate of losses of 33 cents per share. The company reported quarterly sales of $758.600 million which beat the analyst consensus estimate of $744.406 million.

FMC affirmed its FY2026 adjusted EPS guidance of $1.63-$1.89 and sales guidance of $3.600 billion-$3.800 billion.

FMC shares fell 4.2% to trade at $14.71 on Friday.

These analysts made changes to their price targets on …

Full story available on Benzinga.com

This post was originally published here
T Rowe Price Group Inc (NASDAQ:TROW) reported better-than-expected earnings for the first quarter on Thursday.

The company posted quarterly earnings of $2.52 per share which beat the analyst consensus estimate of $2.35 per share. The company reported quarterly sales of $1.857 billion which missed the analyst consensus estimate of $1.858 billion.

T. Rowe Price shares rose 0.6% to trade at $103.50 on Friday.

These analysts made changes to their price targets on T. Rowe Price following earnings announcement.

  • Evercore ISI Group analyst Glenn Schorr maintained the stock with an In-Line rating and raised the price target …

Full story available on Benzinga.com

This post was originally published here
International Paper Co (NYSE:IP) on Thursday reported mixed results for the first quarter.

The company posted quarterly earnings of 15 cents per share which beat the analyst consensus estimate of 14 cents per share. The company reported quarterly sales of $5.970 billion which missed the analyst consensus estimate of $6.014 billion.

“This quarter, we delivered meaningful progress across the business. In North America, our commercial actions are gaining traction and helping us outgrow the market, while we advance cost-out efforts and make solid gains in mill and box plant productivity. In EMEA, we’re accelerating commercial and cost initiatives while a small core team is focusing on the planned separation,” said …

Full story available on Benzinga.com

This post was originally published here
Clorox Corporation (NYSE:CLX) posted upbeat third-quarter results and updated full-year guidance on Thursday.

Clorox reported third-quarter revenue of $1.67 billion, flat versus the same period year-over-year. Organic sales were down 1% year-over-year in the quarter.

The company’s revenue total beat a Street consensus estimate of $1.667 billion, according to data from Benzinga Pro. Clorox reported third-quarter earnings per share of $1.64, beating a Street consensus estimate of $1.55.

“Our third-quarter results were mixed, with continued momentum in some parts of our portfolio and slower-than-anticipated market share recovery in others,” Clorox CEO Linda Rendle said.

Updated guidance for Clorox calls for net sales to be down 6% year-over-year in fiscal 2026. The company lowered its adjusted earnings per share guidance for the full fiscal year …

Full story available on Benzinga.com

This post was originally published here
U.S. equities extended their record run on Friday as Apple Inc.’s (NASDAQ:AAPL) blowout second-quarter earnings powered a broad-based technology rally, lifting the S&P 500 and Nasdaq 100 to fresh all-time highs.

Crude oil sank more than 3% as Iran routed a fresh Hormuz reopening proposal through Pakistani mediators.

President Donald Trump announced he is increasing tariffs on European cars and trucks coming into United States to 25%.

Across U.S. equity markets by midday Friday, gains were broad-based but tilted toward Big Tech. The S&P 500 advanced 0.7% to 7,262, while the Dow Jones Industrial Average added 65 points or 0.1% to 49,729.

The Nasdaq 100 rose 1.1% to 27,743, with Apple’s 5.1% surge lifting the broader complex.

Within other Magnificent Seven stocks, Microsoft Corp. (NASDAQ:MSFT) climbed 2.1%, Amazon.com Inc. (NASDAQ:AMZN) rose 1.9%, Tesla Inc. (NASDAQ:TSLA) gained 3.6%, while Nvidia Corp. (NASDAQ:NVDA) and Alphabet Inc. (NASDAQ:GOOGL) edged 0.2% lower.

The Russell 2000 added 0.3% to 2,807.

Friday’s Performance In Major US Indices

Index Last % Change
S&P 500 7,262.62 +0.7%
Dow Jones 49,729 +0.1%
Nasdaq 100 27,743 +1.1%
Russell 2000 2,807 +0.3%
Updated by 12:00 PM ET

According to the Benzinga Pro platform:

  • The Vanguard S&P 500 ETF (NYSE:VOO) rose 0.7%.
  • The SPDR Dow Jones Industrial Average ETF Trust (NYSE:DIA) ticked 0.1% higher.
  • The Invesco QQQ Trust (NASDAQ:QQQ) climbed 1.1%.
  • The iShares Russell 2000 ETF (NYSE:IWM) added 0.3%.

Apple Blowout Lifts Tech

The Technology Select Sector SPDR Fund (NYSE:XLK) led S&P 500 sectors with a 1.5% gain, followed by the Consumer Discretionary Select Sector SPDR Fund (NYSE:XLY) up 1.0%.

The clear laggard was the Energy Select Sector …

Full story available on Benzinga.com

This post was originally published here
Elon Musk’s SpaceX is due to fly a Falcon 9 rocket later today from Cape Canaveral, sending 29 Starlink satellites into low-Earth orbit.

The launch comes just weeks before the company’s IPO roadshow is expected to open, with bettors pricing in what may become the largest public offering in history.

Liftoff for the Starlink 10-38 mission is targeted for 1:35 p.m. ET, with a backup window stretching until 5:33 p.m. The Falcon 9 booster will land on the drone ship A Shortfall of Gravitas hundreds of miles downrange.

Inside “Project Apex”

SpaceX held a three-day analyst meeting last week as part of preparations for the offering, which Reuters has reported is internally codenamed Project Apex.

Morgan Stanley, Goldman Sachs, Bank of America, Citi and JPMorgan are leading the deal as active bookrunners, with a $75 billion raise targeted at …

Full story available on Benzinga.com

This post was originally published here
On Friday, Ensign Group (NASDAQ:ENSG) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://events.q4inc.com/attendee/736338497

Summary

Ensign Group reported strong financial performance with a Q1 revenue increase of 18.4% and raised its annual 2026 earnings guidance to $7.48-$7.62 per diluted share.

The company highlighted record occupancy rates and growth in skilled nursing operations, with consistent demand despite concerns about managed care volumes.

Ensign Group has acquired 22 new operations, primarily in Texas, and expects continued growth supported by demographic trends and strategic acquisitions.

Operational excellence was demonstrated by improved clinical outcomes and low turnover rates, with 85% of operations achieving a four or five-star quality rating.

Management emphasized the company’s decentralized model and strong local leadership as key drivers of its success, with a focus on clinical excellence and community trust.

Full Transcript

OPERATOR

Our earnings press release yesterday and it is available on the Investor Relations section of our website at ensigngroup.net a replay of this call will also be available on our website until 5pm Pacific on May 29, 2026. We want to remind anyone that may be listening to a replay of this call that all the statements made are as of today May 1, 2026 and these statements have not been or will be updated subsequent to today’s call. Also, any forward looking statements made today are based on management’s current expectations, assumptions and beliefs about our business and the environment in which we operate. These statements are subject to risks and uncertainties that could cause our actual results to materially differ from those expressed or implied on today’s call. Listeners should not place undue reliance on forward looking statements and are encouraged to review our SEC filings for a more complete discussion of factors that could impact our results. Except as required by Federal securities laws, Ensign and its independent subsidiaries do not undertake to publicly update or revise any forward looking statements where changes arise as a result of new information, future events, changing circumstances or for any other reason. In addition, the Ensign Group, Inc. Is a holding company with no direct operating assets, employees or revenues. Certain of our independent subsidiaries, collectively referred to as the Service center, provide accounting, payroll, human resources, information technology, legal risk management and other services to the other independent subsidiaries through contractual relationships. In addition, our Captive Insurance subsidiary, which we refer to as the Insurance Captive, provides certain claims made coverage to our operating companies for general and professional liability as well as for workers compensation insurance liabilities. Ensign also owns Standard Bearer Healthcare reit, which is a captive real estate investment trust that invests in healthcare properties and enters into lease agreements with certain independent subsidiaries of Ensign, as well as third party tenants that are unaffiliated with the Ensign Group. The words Ensign, Co. We, our, and us refer to the Ensign Group, Inc. And its consolidated subsidiaries. All of our independent subsidiaries, the Service Center, Standard Bearer Healthcare REIT and the Insurance Captive are operated by separate, independent companies that have their own management, employees and assets. References herein to the consolidated company and its assets and activities, as well as the use of the words we, us, our and similar terms are not meant to imply, nor should it be construed as meaning, that the Ensign Group has direct operating assets, employees or revenue or that any of the subsidiaries are operated by the Ensign Group. Also, we supplement our GAAP reporting with non GAAP metrics. When viewed together with our GAAP results, we believe that these measures can provide a more complete understanding of our business, but they should not be relied upon to the exclusion of GAAP reports. A GAAP to Non-GAAP Reconciliation is available in yesterday’s press release and is available in our Form 10Q and with that I’ll turn the call over to Barry Bourke, our CEO.

Barry Bourke (Chief Executive Officer)

Barry, Our local leaders and their teams continue to be an example of excellence in healthcare services as they earn the trust of patients, families and their local healthcare communities through high quality outcomes. As each operation solidifies its reputation respective markets, they’re not only seeing more patients, but they’re also being entrusted to care for increasingly complex cases, including a larger share of Medicare managed care and other skilled patients. This is only possible because of the extraordinary clinical outcomes achieved by our dedicated and talented caregivers. As we’ve said many times, our consistent financial performance is a direct reflection of a relentless patient focused culture, one that empowers our frontline teams to deliver exceptional care in a family like environment where people genuinely care about one another. On the census front, our same store and transitioning occupancy reached new record highs during the quarter of 84.3% and 85.1% respectively. On the skilled mix front, our same store and transitioning operations, skilled revenue and days increased by 9.6% and 5.1% respectively over the prior year quarter and Medicare revenue increased by 9.8% and 9.2% respectively. We also wanted to comment on some of the recent noise around managed care volumes. What we are seeing in Ensign affiliated operations does not support the concern of a broad based slowdown in skilled nursing demand. While hospital and managed care volumes may ebb and flow as patients move through the system, that volatility tends to normalize for us, resulting in consistently strong occupancy and skilled mix trends as demonstrated by our current and recent quarter results. In fact, between Q4 and Q1 we saw growth across all skilled payers. Our same store and transitioning managed care and Medicare census increased sequentially by 6.2% and 8.3% respectively. The primary driver of these improvements continues to be the expanding trust from the communities we serve earned through consistent high quality outcomes. Likewise, regarding commentary around increased clinical reviews and heightened scrutiny of post acute utilization, this is not new. Our experience over many years is that this dynamic refines demand rather than reduces it. Our admission trends have remained consistently strong as patient acuity continues to rise and payers look to move patients efficiently to lower cost settings. We have not seen any meaningful system wide reduction in admissions or skilled mix. The patients who truly need skilled nursing are still coming we’re simply seeing a continued shift towards higher acuity admissions which plays directly into our strengths. We have built our model around being the provider of choice in our local markets through strong clinical capabilities, deep hospital relationships and the ability to care for more complex patient types. As payers become more disciplined, that does not reduce our volume. In fact, in many cases it shifts volumes, more specifically higher acuity volume towards operators who can deliver outcomes. It is also important to remember that Ensign’s model is highly diversified across many geographies, payers, referral sources and local community partners. We are not dependent on any single payer region or utilization trend. Even when one plan tightens in a specific market, we have consistently offset that through other market share gains, stronger referral relationships, higher acuity admissions, and growth across other channels. Our clinical leaders also continue to drive outstanding outcomes, which is particularly impressive given our growth over the past several years. According to the most recently published CMS data, same store affiliated facilities outperformed their peers in annual survey results by 22% at the state level and 31% at the county level. This is especially notable given that many of these facilities were one or two star at acquisition. Additionally, our same store operations outperformed industry peers in five star quality measures by 24% nationally and 20% at a state level. In fact, we ended the quarter with 85% of all of our operations at four or five star quality measures. These results reinforce our position as the provider of choice in our markets and demonstrate our ability to create long term value through sustained clinical excellence. This clinical strength depends on attracting and retaining exceptional talent. We are encouraged by the depth of talent continuing to join our organization. On the retention side, we’re seeing improvements in turnover, stable wage growth and reduced reliance on agency staffing. Even with increased occupancy, we are especially proud of the exceptionally low turnover among our directors of nursing which has declined by 32% over the past two years. This level of leadership stability is a key driver of consistent high quality care. In addition, we continue to acquire new operations with significant long term upside and expect to maintain a healthy pace of growth. Since 2024, we have successfully sourced, underwritten and closed and transitioned 99 new operations across several markets, many of which are already performing at or above expectations. We also continue to benefit from powerful demographic tailwinds which we expect to further support census momentum that we are seeing across our portfolio. While we’re pleased with our current record same store occupancy, we are equally excited about the remaining organic growth opportunity at 84% occupancy we still have meaningful Runway with many of our most mature operations consistently achieving occupancy rates in the mid 90% range. This embedded growth remains one of the most compelling drivers of our long term performance. Due to the strength of the first quarter and the acquisitions we announced yesterday, we are increasing our annual 2026 earnings guidance to $7.48 to $7.62 per diluted share, up from our original guidance of $7.41 to $7.61. We are also increasing our annual revenue guidance to 5.81 billion to to 5.86 billion, up from 5.77 billion to 5.84 billion. The midpoint of our earnings guidance represents a 15% increase over 2025 and 37% growth over 2024. We remain highly confident in 2026 and expect our local teams to continue executing, innovating and integrating new operations while delivering strong results. Next, I’ll ask Chad to add some additional insights regarding our recent growth.

Chad

Chad thank you Barry. During the quarter and since, we accelerated our growth by adding 22 new operations including 21 real estate assets, bringing the number of operations acquired during 2025 and since to 71. These recent additions include 20 in Texas, one in Arizona and one in Wisconsin. In total, we added 2,662 new skilled nursing beds, 100 senior living units and 55 independent living units across three states. This growth brings the number of operations in our recently acquired group of operations to 17.4% of our entire portfolio. We were thrilled to complete these acquisitions and to expand our presence in some key markets in each of these states, particularly in Texas. Like in the recent Stonehenge acquisition we closed in Utah. This Texas portfolio is made up of very new, high quality construction and populated and growing metro areas. As we’ve discussed in our recent past, in certain strategic situations paying higher prices can be justified for performing assets that have newer physical plants. And while some of those deals may take a bit longer to generate the returns we expect, we’ve seen these deals pay off over time as our leaders implement the proper adjustments to key clinical and financial systems. Along with establishing a culture of ownership and accountability, we continue to learn from and improve our transition process and believe that those lessons are showing through in the performance of our recently acquired acquisitions. In particular, as we continue to scale, we have leadership spread across many mature markets enhancing ability to to make larger deals smaller by breaking them into bite sized pieces, transitioning in the traditional ensign way but with a local cluster driven plan that gives each operation the time and attention they deserve. The performance of our newly acquired operations, particularly in the last few years, shows that our building by building approach to transitions works for single operations, small portfolios and larger portfolios, particularly when the larger deal spans several markets and geographies. While we will certainly continue to evaluate consider any deal that’s out there, we are also very comfortable growing the way we’ve grown over the last few quarters with lots of transactions across many states, including small deals to larger portfolios and where it makes sense, higher priced strategic assets. As we look at the current pipeline, we continue to see opportunities that include everything from larger portfolios, landlords looking to replace current tenants, nonprofits looking to divest of their post acute assets and a steady flow of traditional onesie twosies. We have several new additions lining up for Q2 and Q3 of 2026 as our local leadership teams and their partners at the Service center work together to source, underwrite and carefully select the right opportunities. We continue to have a lot of success in closing deals with sellers who are not just interested in receiving top dollar. They care deeply about the quality and reputation of the company they select to inherit their legacy and they choose us because they believe in our mission to Dignify post acute Care during the quarter we were pleased to complete the construction of a replacement facility of one of our high performing skilled nursing operations in San Diego County, Grossmont Post Acute in La Mesa, California, which is located next to Sharp Grossmont Hospital, which was housed in an aging building that the landlord decided to replace with a new medical office space. After several years on lots of hard work, we successfully completed the construction and have moved all the patients and staff to a brand new state of the art building while also …

Full story available on Benzinga.com

This post was originally published here
Church & Dwight Co., Inc. (NYSE:CHD) reported first-quarter 2026 results that topped Wall Street estimates on Friday, driven by stronger organic sales growth, margin expansion and continued demand across its consumer portfolio.

The consumer products company posted adjusted earnings of 95 cents per share, beating the consensus estimate of 93 cents. Revenue rose 0.2% year over year to $1.469 billion, ahead of estimates of $1.456 billion.

Organic sales grew 5.0%, above the company’s prior outlook of 3%, supported by volume growth of 5.3% across all three divisions. Domestic organic sales increased 5.4%, while international organic sales rose 3.7%.

Margin Expansion And Profitability

Adjusted gross margin expanded 130 basis points to 46.4%, driven by higher volumes, productivity gains and favorable product mix, partially offset by inflation and tariff costs.

Reported earnings per share were 91 cents, up from 89 cents a year earlier, while adjusted EPS increased 4.4% year over year.

Operating income totaled $291 million, with adjusted operating income of …

Full story available on Benzinga.com

This post was originally published here
On Friday, Xenia Hotels & Resorts (NYSE:XHR) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://events.q4inc.com/attendee/934224251

Summary

Xenia Hotels & Resorts reported strong Q1 2026 results, with net income of $19.8 million and adjusted EBITDA RE of $81.4 million, marking a 12% increase from last year.

Same property RevPAR grew by 7.4%, with significant contributions from the Grand Hyatt Scottsdale Resort and broad-based strength across the portfolio.

The company raised its full-year 2026 adjusted EBITDA RE guidance by $6 million to $266 million at the midpoint, reflecting confidence in continued performance.

Capital expenditures for the year are expected between $70 and $80 million, with significant projects completed, including the W Nashville food and beverage reconcepting.

Management highlighted a robust transaction market and potential for acquisitions, while maintaining a balanced approach to capital allocation, including debt reduction and share repurchases.

Full Transcript

Reagan (Moderator)

Good afternoon everyone and thank you for joining the Xenia Hotels & Resorts, Inc. Q1 2026 earnings conference call. My name is Reagan and I’ll be your moderator today. All lines will be muted during the presentation portion of the call with an opportunity for questions and answers at the end. And if you like to ask a question, you may do so by pressing Star one on your telephone keypad. I would now like to pass the conference over to our host, Abdul Martinez, Director of Finance. Please proceed.

Abdul Martinez (Director of Finance)

Thank you Reagan and welcome to Xenia Hotels & Resorts First Quarter 2026 Earnings Call and webcast. I’m here with Marcel Verbas, our Chair and Chief Executive Officer, Barry Bloom, our President and Chief Operating Officer and Atish Shah, our Executive Vice President and Chief Financial Officer. Marcel will begin with a discussion on our performance, Barry will follow with more details on operating trends and capital expenditure projects and Atish will conclude today’s remarks on our balance sheet and outlook. We will then open up the call for Q and A. Before we get started, let me remind everyone that certain statements made on this call are not historical facts and are considered forward looking statements. These statements are subject to numerous risks and uncertainties as described in our annual report on Form 10K and other SEC filings which could cause our actual results to differ materially from those expressed in or implied by our comments. Forward looking statements in the earnings release that we issued this morning along with the comments on this call are made only as of today May 1, 2026 and we undertake no obligation to publicly update any of these forward looking statements as actual events unfold. You can find the reconciliation of non GAAP financial measures to net income and definitions of certain items referred to in our remarks in our first quarter earnings release which is available on the Investor Relations section of our website. The property level information we’ll be speaking about today is on a same property basis for all 30 hotels unless specified otherwise. An archive of this call will be available on our website for 90 days. I will now turn it over to Marcel to get started.

Marcel Verbas (Chair and Chief Executive Officer)

Thanks hello and good afternoon everyone. We are pleased to report strong first quarter 2026 results that exceeded our expectations across all key metrics. Our portfolio delivered exceptional first quarter performance driven by strength in both the group and transient demand segments, especially in the month of March. We also saw highly encouraging results at Grand Hyatt’s Scottsdale Resort as it continues on its path towards stabilization following the completion of its transformative renovation. For the first quarter of 2026 we reported net income of $19.8 million, adjusted EBITDAre of $81.4 million, an increase of nearly 12% to last year, and adjusted FFO per share of $0.63 which was 23.5% higher than the first quarter of 2025. For the first quarter, our same property RevPAR grew 7.4% with occupancy increasing 180 basis points, an average daily rate increasing 4.8% compared to the first quarter of 2025. Additionally, we continue to benefit from strong growth in non rooms revenues as evidenced by our same property total RevPAR for the quarter growing to $370.13 reflecting an increase of 7.2% as compared to the same quarter last year. Food and beverage revenues increased 6.2% on a same property basis reflecting continued growth in banquet and catering revenues as well as our ongoing focus on outlet optimization efforts, while other revenues were up nearly 11% for the quarter. Same property hotel EBITDA for The quarter was $87.8 million, an increase of almost 18% compared to the same period last year. Significant growth in rooms revenues, a large portion of which consisted of rate growth combined with disciplined expense management drove an improvement in same property hotel EBITDA margin from 27% in the first quarter of 2025 to 29.7% this year, an expansion of 270 basis points. At Grand Hyatt Scottsdale Resort, record revenues and hotel EBITDA were achieved for the first quarter as the ramp up of the overall resort continues. The resort has seen successful execution of occupancy driven ramp up plans that have produced significant transient business volumes to supplement the growing base of group demand. These improvements have translated throughout the operation into record food and beverage outlet, spa, recreation, parking and miscellaneous revenues. Expenses have grown at a slower pace as much of the occupancy gains have required relatively limited incremental cost. As a result, the resorts hotel EBITDA margin improved significantly during the first quarter. While Grand Hyatt Scottsdale was a significant driver of our first quarter outperformance, we experienced broad based strength across our portfolio of luxury and upper upscale hotels and resorts. Increased group and transient demand contributed to revar and total RevPAR increases in 15 of our 22 markets. In addition to the Phoenix Scottsdale market, we experienced double digit percentage total revpar growth in Salt Lake City, Birmingham, Portland, Santa Clara, Santa Barbara and Houston which is indicative of the range of markets and demand segments that contributed to our strong performance for the quarter. Our weakest performance for the quarter on a year over year basis were as anticipated as these properties either benefited from one time events last year such as the super bowl in New Orleans and the Presidential inauguration in Washington D.C. or experienced some disruption due to capital projects, specifically Fairmont Pittsburgh and W Nashville. W Nashville also was impacted by several weather events that negatively impacted performance for the quarter. We continue to benefit from our portfolio’s favorable positioning and diversification as it relates to the various demand segments. Group rooms revenues increased in excess of 7% for the quarter as compared to the same period last year, bolstering our performance. Transient rooms revenues also grew approximately 7% for the quarter, primarily driven by extremely strong performance in March as the timing of Easter in early April appeared to compress high levels of corporate transient leisure demand into the month of March. Now turning to capital expenditures, we continue to expect to spend between 70 and 80 million dollars on property improvements during the year. During the first quarter we completed the renovation of the M Club at Marriott Dallas Downtown and the guest room renovation at Fairmont Pittsburgh which was completed as planned with limited disruption on budget and in advance of the NFL draft that took place in Pittsburgh last week. With record attendance on our last couple of earnings calls, we expressed our excitement about the reconcepting of the food and beverage outlets at W Nashville. We are pleased to report that all outlets have opened for business and were completed on time and within budget. The new outlets are tremendous, new amenities for the hotel and initial feedback from customers has been extremely positive. Barry will provide additional details on our capital projects including the Nashville food and beverage reconcepting during his remarks. Looking ahead to the second quarter, we are encouraged by the continuation of the positive momentum our operators are reporting for April. While calendar shifts related to Easter timing and spring breaks contributed to our outstanding results in the month of March, we estimate that April same property RevPAR increased nearly 6% as compared to April 2025. The estimated RevPAR growth of over 10% that our portfolio experienced during the combined months of March and April is a reflection of strong demand in our markets when eliminating the impact of the timing of Easter compared to last year, with our largest resorts benefiting a bit due to safety concerns in Mexico and weather conditions in Hawaii. Turning to our outlook for the remainder of the year, given the Stronger than projected first quarter results, we have raised our full year 2026 adjusted EBITDA RE guidance by $6 million to $266 million at the midpoint. Our guidance for adjusted FFO per share for full year 2026 is now $1.94 at the midpoint this would represent an increase of approximately 10% over 2025. While we are encouraged by our first quarter performance as well as demand trends in April, a significant amount of overall market and geopolitical uncertainty continues to exist as we look ahead to the remainder of the year. As such, we have not changed our outlook for the balance of the year when compared to our previously issued guidance. Atish will walk through all of our current 2026 guidance items in more detail, including our updated views of the anticipated demand lift from one time events such as the FIFA World cup and America 250. Although we have not completed any transactions since the sale of Fairmont Dallas last year, we have significantly improved our portfolio through robust acquisition and disposition activities since our listing in 2015. We continue to evaluate potential transactions with an eye toward further portfolio improvement and sustainable earnings growth in the years ahead. The transaction market and opportunity set appear to be a bit more robust than they have been in the last couple of years and we will continue to evaluate these opportunities while being mindful of our balance sheet and other capital allocation priorities. While the macroeconomic environment remains fluid and uncertain, we continue to believe our portfolio is very well positioned for continued earnings growth. The quality of our luxury and upper upscale hotels and resorts in top 25 and key leisure markets, combined with our experienced operating partners and a favorable supply backdrop for the next several years provide a solid platform for continued outperformance in 2026 and in the years ahead. I will now turn the call over to Barry to provide more details on our first quarter operating results and our capital projects.

Barry Bloom (President and Chief Operating Officer)

Thank you Marcel Good afternoon everyone. For the first quarter our 30 same property portfolio RevPAR was $205.93, an increase of 7.4% as compared to the first quarter in 2025 based on occupancy of 71.4% at an average daily rate of $288.62. Properties achieving double digit Revpar growth as compared to the first quarter of 2025 included Grand Hyatt Scottsdale RevPAR up 46.2% Kimpton Hotel Monaco Salt Lake City 27.2% Andaz Savannah up 16.4% Hyatt Regency Santa Clara up 14.7% Grand Bohemian Hotel Mountain Brook up 13.9% and Kimpton Canary Hotel Santa Barbara up 12%. Growth at these properties was due to a variety of factors including increased citywide demand, stronger leisure demand in drive two markets and one off major events. Properties with softer performance in Q1 this year included Lowe’s New Orleans which hosted the Super bowl in Q1 of 2025 Ritz Carlton Pentagon City, which lapped last year’s presidential inauguration and W Nashville due to poor weather and anticipated disruption. The Jose Andres Food and Beverage Relaunch Looking at each month of the quarter, January RevPAR was $163.59 of 1.4% to January 2025 with occupancy flat and ADR of 1.4%. February RevPAR was $216.11, up 4.8% compared to February 2025 with occupancy down 40 basis points and ADR up 5.4%. March was the strongest month of the quarter across all three metrics with RevPAR of $239.08 up 14.3% compared to March 2025 with occupancy up 540 basis points and ADR up 6.5%. Group business continued to maintain its recent strength during the quarter with group rooms revenue up over 7%, reflecting strength in group business that is expected to continue to improve throughout the rest of the year. Overall for the quarter, group nights were up 2.5% with ADR up 4.4%. Business levels grew for each night of the week during the quarter compared to the first quarter of 2025. Occupancies grew by 210 basis points on weekdays and 110 basis points on weekends with ADR growth of 4.5% on weekdays and 5.3% on weekends. RevPAR on Wednesday nights was up a notable 11% for the quarter. Leisure business during the quarter was consistent across the large resorts in the portfolio with significant increase in leisure business at Grand Hot Scottsdale and Henry C Grand Cypress as well as Strength the Park Hot Aviarra, which lapped a difficult comparison to the first quarter of 2025 at our smaller leisure focused hotels. Leisure business grew significantly at Andaz, Savannah, Royal Palms and Kimpton Canary Hotel Santa Barbara now turning to expenses and profit first quarter same property hotel EBITDA was $87.8 million, an increase of 17.9% driven by a total revenue increase of 7.3% compared to the first quarter of 2025, resulting in 270 basis points of margin improvement. Our operators are now able to better control expenses in a more stable occupancy and a growing rate environment for the 30 same property portfolio. Food and beverage revenues increased 6.2% in the quarter as a result of nearly 11% growth in banquets, while outlet growth declined slightly primarily as a result of outlet closures at W Nashville during the quarter. Other operating department income including parking, spa and golf revenues grew by approximately 13%. Rooms expenses were well controlled, increasing 2.3% on a per occupied room basis while FMB profit margin improved by approximately 150 basis points. Ang grew by approximately 4.5% while sales and marketing expenses remained flat during the quarter. In line with recent trends, the strategies have been refined and focused across the portfolio. Property operations and maintenance expenses grew by just 1.3% due primarily to lower general expenses, while energy expenses across the portfolio grew at over 9% due to significant winter storms which drove higher costs, especially for gas turning to CapEx during the first quarter we invested $15.2 million in portfolio improvements. We completed two projects during the first quarter including the completion of a Guest Stream renovation at Fairmont Pittsburgh and a renovation of the M Club at Marriott Dallas Downtown. More significantly, we reconcepted the food and beverage facilities at W Nashville pursuant to our previously announced agreements with Jose Andres Group, which JAGDO operates, and our licenses to potentially all of the hotel’s food and …

Full story available on Benzinga.com

This post was originally published here
NCS Multistage Holdings Inc. (NASDAQ:NCSM) shares plummeted on Friday, extending a sharp downward trend after the company posted disappointing first-quarter financial results.

The Houston-based oilfield services provider reported quarterly losses of 14 cents per share. This performance marks a significant reversal from the earnings of $1.51 per share recorded during the same period last year.

Sales Figures Fall Short

Top-line results failed to meet Wall Street expectations. The company reported quarterly sales of $45.637 million. This figure missed the analyst consensus estimate of $51.215 million. It also …

Full story available on Benzinga.com

This post was originally published here
Shares of Magnachip Semiconductor Corp (NYSE:MX) climbed Friday. The move follows a volatile week for South Korean chipmaker marked by a sharp post-earnings selloff.

Recovery From Earnings Dip

The stock fell nearly 30% Wednesday after the company issued in-line second-quarter guidance. Magnachip Semiconductor projects second-quarter sales between $44.5 million and $48.5 million. This range sits right against the $46.5 million analyst consensus.

First-quarter results beat expectations. The company reported a loss of 11 cents per share. This outperformed the 22-cent loss predicted by analysts.

Quarterly sales reached $46.208 million, also topping estimatesn, according to Benzinga Pro.

Critical Levels To Watch for …

Full story available on Benzinga.com

This post was originally published here
Newell Brands Inc. (NASDAQ:NWL) shares surged Friday after the company reported a narrower-than-expected first-quarter loss and improving margins, offsetting continued softness in demand.

The consumer products company said pricing discipline and portfolio strength helped it navigate a choppy sales environment.

Quarterly Details

Newell posted an adjusted loss of 5 cents per share, beating analysts’ estimates of a 9-cent loss. Revenue totaled $1.549 billion, down 1.1% year over year but above the consensus estimate of $1.507 billion. Core sales declined 3.5%.

The Home & Commercial Solutions segment reported net sales of $780 million, with core sales down 6.9%. The Learning & Development segment generated $594 million in net sales, …

Full story available on Benzinga.com

This post was originally published here
Eldorado Gold (TSX:ELD) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://event.choruscall.com/mediaframe/webcast.html?webcastid=VbJHuSmZ

Summary

Eldorado Gold reported a 13% year-over-year decrease in gold production for Q1 2026, with total revenue increasing by 50% to over $532 million due to higher gold prices.

The company is advancing two major projects—Scouries in Greece and Macavena Bay in Saskatchewan—with anticipated production starting in Q3 2026.

Earnings per share from continuing operations increased to 69 cents, with adjusted net earnings at 95 cents per share.

All-in sustaining costs rose due to higher royalty expenses and labor inflation, particularly in Turkey.

CEO George Burns announced his retirement, with Christian Milao set to succeed him, ensuring continuity in leadership.

The company has increased its exploration budget significantly, focusing on high-potential targets at Macavena Bay and other locations.

Capital costs at Scouries have increased by $155 million due to additional workforce requirements for electrical and instrumentation work.

Management remains confident in maintaining operational and financial performance, with a focus on strategic growth and shareholder returns.

Full Transcript

OPERATOR

Thank you for standing by. This is the conference Operator. Welcome to the Eldorado Gold first quarter 2026 results conference call. As a reminder, all participants are in listen only mode and the conference is being recorded. After the presentation, there will be an opportunity to ask questions. To join the question queue, you may press Star then one on your telephone keypad. Should you need assistance during the conference call, you may reach an operator by pressing STAR and zero. I would now like to turn the conference over to Lynette Gould, Vice President, Investor Relations, Communications and External affairs. Please go ahead, Ms. Gould. Thank you Operator and good morning everyone. I’d like to welcome you to our conference call to discuss our first quarter 2026 results. Before we begin, I would like to remind you that we will be making forward looking statements and and referring to non IFRS measures during the call. Please refer to the cautionary statements included in the presentation and the disclosure on non IFRS measures and risk factors in our management’s discussion and analysis. Joining me on the call today we have George Burns, Chief Executive Officer, Christian Milao, President, Paul Fernyhough, Executive Vice President and Chief Financial Officer and Simon Hilley, Executive Vice President and Chief Operating Officer. Our release Yesterday details our first quarter 2026 financial and operating results. The release should be read in conjunction with our Q1 2026 financial statements and management’s discussion and analysis, both of which are available on our website. They have also both been filed on SEDAR plus and NGIRs. All dollar figures discussed today are US Dollars unless otherwise stated. We will be speaking to the slides that accompany this webcast which can be downloaded from our website. After the prepared remarks, we will open the call for Q and A at which time we will invite analysts to queue for questions. I will now turn the call over to George.

George Burns (Chief Executive Officer)

Thank you Lynette and good morning everyone. I’ll begin with an overview of our first quarter and provide brief updates on Makavena Bay and Skouries. I’ll then hand the call over to Paul to review the financials and then to Simon with an update on our operations. Following that, Christian will make some concluding remarks before opening up the call for questions. We’ve had a very busy and solid start to 2026 with performance in the quarter tracking in line with our expectations and full year guidance. This year production is back half weighted as two mines come into production and several other operations deliver stronger results later in the year. 2026 is an important year for El Dorado as we continue to advance two high quality growth projects Scurias in Greece and Maca Bay in Saskatchewan. Maca Bay is nearing first concentrate production followed by first concentrate at Skouries in Q3. Once in operation, both assets will meaningfully enhance our production profile and cash flow generation starting in the third quarter of 2026. To provide greater transparency as these polymetallic assets come online, we plan to enhance our disclosure by reporting copper assets on a dollar per pound co product basis for Skouries and Mac Bay. Before getting into the project updates, I want to note that as previously announced, I plan to retire as CEO later this year as we ramp up Skouries towards commercial production. Christian, who joined us last September, has been deeply involved across the business and is set up to seamlessly step into the role at that time. I’m pleased to remain on the board to support continuity and Dan Meyerson has joined the board as Deputy Chair providing important continuity from the foreign side. I want to take a moment to recognize the achievement of our colleagues at the Mock. In March they received the TSM Gold Leadership Award, a special recognition for mining operations who achieved Level aaa, the highest possible rating across all applicable TSM performance indicators. This recognition reflects the dedication of our employees and our unwavering commitment to responsible mining in Quebec and across our global operations where TSM protocols are applied as a matter of practice under El Dorado’s Sustainability Integrated Management System. Well done Lamaque team. The foreign transaction represents a significant milestone for Eldorado at Mac Bay. We have now begun integration activities and are working closely with the existing team as the project nears first concentrate production. Following the close, members of our management team visited Saskatchewan and the macpay Project to welcome the team to El Dorado, see progress firsthand and engage with our stakeholders in Saskatchewan. What stood out was the enthusiasm of our new team, the capabilities supporting the operation and the clear focus on safety, collaboration and responsible execution. Now that Mac Bay is part of our portfolio, we expect to provide the following with our second quarter results, Mac Bay production and cost outlook for 2026 timing for an expansion study and progress on a study for potential lead Silver circuit Following the close of the transaction, we have already approved approximately $17 million spend on exploration for the remainder of 2026, reflecting the target rich environment in our view that continued exploration success has the potential to drive meaningful long term value. The quality of Mac Bay and its exploration potential reinforce our confidence that it will become a long term cornerstone asset within our portfolio, delivering near term growth while adding copper exposure in a stable top three global mining friendly jurisdiction. Turning to Skouries in Greece on slide 6. Construction activities continue to progress well across all major areas. The team remains focused on disciplined safe execution as we move through the final construction phase at the end of the quarter. Overall project progress was approximately 94%, steadily advancing towards first concentrate production as execution activities have progressed and the project advances toward construction completion on schedule, we have updated our forecast to complete and have revised our total project capital to $1.315 billion, an increase of approximately 155 million from the prior estimate. The primary driver was an increase related to construction workforce levels to support sustained final construction momentum. Total workforce has increased from 2350 in Miguel 1 to approximately 3200 which includes about 490 in operations. Advancing scurries in safe production in the current metal environment is a key driver of value creation. This incremental capital reflects our continued focus on maintaining momentum and towards first and first concentrate production. Accelerated operational capital at securities is now expected to be approximately 260 million, reflecting an incremental 82 million to expand pre commercial mining and site works. This supports open pit mining and advancing underground development ahead of first production. We’re well positioned for startup with more than 2.8 million tons of horse stockpiled which provides the entire planned mill tonnage for 2026 overall. This investment supports a smoother ramp up into production. On the process plant. Work remains focused on final mechanical installations, piping cable tray cabling as we prepare for first or with respect to the damage cyclone feed pump variable speed drives. Temporary replacement equipment is expected to be installed in Q2 high and medium voltage electrical distribution for multiple substations is progressing. The process control building structure is complete and electrical rooms are being progressively handed over to commissioning on the power line and substations. The 150kV power line and primary substation continue to advance to start up in Q3 ahead of grinding area or commissioning. Final electrical regulatory authority approval will require completion of inspection and energization protocols. Power line construction is progressing with the transmission tower assembly complete and pilot wire pulling now underway along the transmission line. The primary substation is advancing through ongoing assembly of the substation structures and control building structural completion. Pre commissioning is now underway starting with the substations that feed the process plant, filter plant, the primary crusher. While commissioning continues across fire, utility and process water systems in parallel. We’ve begun pre commissioning and flotation …

Full story available on Benzinga.com

This post was originally published here
Eldorado Gold (NYSE:EGO) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://event.choruscall.com/mediaframe/webcast.html?webcastid=VbJHuSmZ

Summary

Eldorado Gold reported a 13% decrease in gold production for Q1 2026 year-over-year, with total revenue exceeding $532 million due to significantly higher gold prices.

The company is advancing two major growth projects: Scouries in Greece and Macavena Bay in Saskatchewan, expecting both to enhance production and cash flow in the second half of 2026.

A 155 million USD increase in capital expenditure for Scouries was announced, primarily due to additional labor costs associated with completing electrical and instrumentation work.

Eldorado Gold expects to commence copper production from Macavena Bay and Scouries, diversifying its portfolio with exposure to copper in stable jurisdictions.

George Burns announced his retirement as CEO, with Christian Milao set to take over, ensuring leadership continuity as the company transitions through key operational milestones.

Full Transcript

George Burns (Chief Executive Officer)

Thank you Lynette and good morning everyone. I’ll begin with an overview of our first quarter and provide brief updates on Makavena Bay and Scourias. I’ll then hand the call over to Paul to review the financials and then to Simon with an update on our operations. Following that, Christian will make some concluding remarks before opening up the call for questions. We’ve had a very busy and solid start to 2026 with performance in the quarter tracking in line with our expectations and full year guidance. This year production is back half weighted as two mines come into production and several other operations deliver stronger results later in the year. 2026 is an important year for El Dorado as we continue to advance two high quality growth projects Scurias in Greece and Macavena Bay in Saskatchewan. Macaquena Bay is nearing first concentrate production followed by first concentrate at Skouries in Q3. Once in operation, both assets will meaningfully enhance our production profile and cash flow generation starting in the third quarter of 2026. To provide greater transparency as these polymetallic assets come online, we plan to enhance our disclosure by reporting copper assets on a dollar per pound co product basis for Skouries and Macaquena Bay. Before getting into the project updates, I want to note that as previously announced, I plan to retire as CEO later this year as we ramp up Skouries towards commercial production. Christian, who joined us last September, has been deeply involved across the business and is set up to seamlessly step into the role at that time. I’m pleased to remain on the board to support continuity and Dan Meyerson has joined the board as Deputy Chair providing important continuity from the foreign side. I want to take a moment to recognize the achievement of our colleagues at the Macaquena. In March they received the TSM Gold Leadership Award, a special recognition for mining operations who achieved Level aaa, the highest possible rating across all applicable TSM performance indicators. This recognition reflects the dedication of our employees and our unwavering commitment to responsible mining in Quebec and across our global operations where TSM protocols are applied as a matter of practice under El Dorado’s Sustainability Integrated Management System. Well done Macaquena team. The foreign transaction represents a significant milestone for Eldorado at Macaquena Bay. We have now begun integration activities and are working closely with the existing team as the project nears first concentrate production. Following the close, members of our management team visited Saskatchewan and the macpay Project to welcome the team to El Dorado, see progress firsthand and engage with our stakeholders in Saskatchewan. What stood out was the enthusiasm of our new team, the capabilities supporting the operation and the clear focus on safety, collaboration and responsible execution. Now that Macaquena Bay is part of our portfolio, we expect to provide the following with our second quarter results, Macaquena Bay production and cost outlook for 2026 timing for an expansion study and progress on a study for potential lead Silver circuit Following the close of the transaction, we have already approved approximately $17 million spend on exploration for the remainder of 2026, reflecting the target rich environment in our view that continued exploration success has the potential to drive meaningful long term value. The quality of Macaquena Bay and its exploration potential reinforce our confidence that it will become a long term cornerstone asset within our portfolio, delivering near term growth while adding copper exposure in a stable top three global mining friendly jurisdiction. Turning to Scurries in Greece on slide 6. Construction activities continue to progress well across all major areas. The team remains focused on disciplined safe execution as we move through the final construction phase at the end of the quarter. Overall project progress was approximately 94%, steadily advancing towards first concentrate production as execution activities have progressed and the project advances toward construction completion on schedule, we have updated our forecast to complete and have revised our total project capital to $1.315 billion, an increase of approximately 155 million from the prior estimate. The primary driver was an increase related to construction workforce levels to support sustained final construction momentum. Total workforce has increased from 2350 in Miguel 1 to approximately 3200 which includes about 490 in operations. Advancing scurries in safe production in the current metal environment is a key driver of value creation. This incremental capital reflects our continued focus on maintaining momentum and towards first and first concentrate production. Accelerated operational capital at securities is now expected to be approximately 260 million, reflecting an incremental 82 million to expand pre commercial mining and site works. This supports open pit mining and advancing underground development ahead of first production. We’re well positioned for startup with more than 2.8 million tons of horse stockpiled which provides the entire planned mill tonnage for 2026 overall. This investment supports a smoother ramp up into production. On the process plant. Work remains focused on final mechanical installations, piping cable tray cabling as we prepare for first or with respect to the damage cyclone feed pump variable speed drives. Temporary replacement equipment is expected to be installed in Q2 high and medium voltage electrical distribution for multiple substations is progressing. The process control building structure is complete and electrical rooms are being progressively handed over to commissioning on the power line and substations. The 150kV power line and primary substation continue to advance to start up in Q3 ahead of grinding area or commissioning. Final electrical regulatory authority approval will require completion of inspection and energization protocols. Power line construction is progressing with the transmission tower assembly complete and pilot wire pulling now underway along the transmission line. The primary substation is advancing through ongoing assembly of the substation structures and control building structural completion. Pre commissioning is now underway starting with the substations that feed the process plant, filter plant, the primary crusher. While commissioning continues across fire, utility and process water systems in parallel. We’ve begun pre commissioning and flotation focused on air and instrumentation as well as a sag and ball mill, instrumentation, electrical and control systems and we started wet commissioning in the process water pumps and tailing thickeners together, scouries at Macavena Bay represent a step change for Eldorado in scale and portfolio diversification across jurisdictions and metals. With that, I’ll turn it over to Paul to review the financial results.

Paul Fernyhough (Executive Vice President and Chief Financial Officer)

Thank you, George and good morning. I’ll start on slide 7. In Q1 2026, we produced 100,358 ounces of gold, a 13% decrease year over year, primarily reflecting lower tonnes at stacked grades at Kisladag and lower grades at Efemçukuru, partially offset by higher grades and improved recoveries at Olympias and Lamaque. Gold sales totalled 100,619 ounces ounces at an average realized gold price of $4,891 per ounce, generating total revenue in excess of $532 million, a 50% increase from $355 million in the comparable quarter last year, driven by significantly higher gold prices. Production costs were $188 million, up from just over $148 million, driven primarily by royalty expense in Turkey and Greece, which accounted for approximately 70% of the increase, with the balance largely attributable to labour inflation in Turkey and incremental labour and contractor costs associated with continued development of the Lamaque complex. Royalty expense increased to $50 million from $22 million last year, reflecting higher realized gold …

Full story available on Benzinga.com

This post was originally published here
Wabash National (NYSE:WNC) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://events.q4inc.com/attendee/310958583

Summary

Wabash National reported first-quarter 2026 revenue of $303 million, slightly below guidance, with an adjusted non-GAAP EBITDA of negative $38 million due to lower production volumes.

The company is focusing on strategic initiatives such as digital enablement, parts and services expansion, and operational efficiency improvements to position for market recovery.

Wabash National expects revenue growth in Q2 2026 to range between $380 million and $400 million with adjusted EPS guidance between negative $0.40 and negative $0.60, indicating recovery from Q1 lows.

Despite current market softness, there is optimism for 2027 as freight indicators improve and customer engagement increases, suggesting readiness for capital spending.

Operational highlights include a 19% increase in backlog sequentially, improved safety metrics, and ongoing investment in digital tools and AI to enhance customer experience and operational efficiencies.

Full Transcript

OPERATOR

Thank you and good afternoon everyone. We appreciate you joining us on this call. With me today are Brent Yeage, President and Chief Executive Officer, and Pat Kesslin, Chief Financial Officer. Before we get started, please note that this call is being recorded. I’d also like to point out that our earnings release, the slide presentation supplementing today’s call, and any non GAAP reconciliations are available at ir.wabash.com Please refer to slide 2 in our earnings deck for the company’s Safe harbor disclosure addressing forward looking statements. I’ll now hand it off to Brent Thanks John. Before we begin, I want to recognize Mike Pettit who as of April 8th is transitioning out of Wabash. Mike has been a meaningful contributor to

Brent Yeage (President and Chief Executive Officer)

Wabash for 14 years and has played an important role in shaping our culture and our strategy. His impact on the organization is lasting and we are grateful for his leadership and commitment to Wabash. We wish him all the best as he enters this new chapter of his life. As we entered the first quarter, we did so with a clear eyed view of the environment in front of us. Freight markets were uncertain and customers continued to act cautiously. Order patterns were uneven, asset utilization inconsistent and capital decisions across the industry were being evaluated carefully. At the same time, we were encouraged by early signs of stabilization and improving fundamentals that typically precede a broader recovery. Now, as we move into the second quarter of 2026, both our customers and our visibility continues to improve and it shows an environment that is building to set up for a constructive 2027 as spot rates, contract rates, capacity and demand all are coming together to drive back to replacement demands for equipment and possibly beyond as fleets begin to plan more confidently. Against that backdrop, our priorities have not changed. We are focused on controlling what we control, protecting margins through the cycle and executing against our long-term strategy. That means aligning costs to demand, maintaining pricing discipline and continuing to invest in areas that differentiate Wabash, particularly parts and services, digital-enablement and our manufacturing operations. The actions we have taken positions us favorably for the market’s return versus prior down cycles. We are deploying capital more effectively, more efficiently and at levels above what has been historically possible, managing liquidity with discipline and building a business that will emerge from this cycle stronger, more resilient and better positioned to perform as market growth accelerates. Execution remains the focus in Q1. Key operating metrics, including on time to promise first time quality and total recordable incident rates, continue to improve and set new benchmarks. That performance reflects the experience, commitment and capability of our team and I want to recognize our employees for their continued focus and discipline. Market conditions in the first quarter were largely consistent with what we saw exiting last year. We are encouraged by the progress beginning to take shape across several underlying indicators. Improvements in spot rates and manufacturing activity, for example, are increasing visibility into recovery as evidenced by the 19% increase in backlog versus prior quarter to 837 million. While geopolitical uncertainty continues to influence customer behavior at present, with fleets remaining conservative, extending asset lives and prioritizing flexibility over expansion, the tone is shifting quickly and customers are increasingly engaging to discuss their future needs. As expected, the early stages of this recovery continue to be supply driven. Capacity continues to contract and as enhanced driver eligibility enforcement designed to improve safety across the industry, improves freight rates and begins to restore carrier profitability. At the same time, key freight indicators are exhibiting some of the strongest year over year performance, including the ATA for Hire Truck Tonnage Index having its largest year over year increase since October of 2022, and the logistics managers index increasing 4.2 points sequentially the fastest level of expansion since May of 2022. As this recovery builds, capital spending will follow. Wabash is well positioned to respond with the capabilities, capacity and customer relationships to support increased demand and increased market share. Looking ahead, our near term demand outlook remains balanced as customers convert improving profitability into capital spending decisions. Beyond that, the outlook is increasingly constructive as we move into 2027, multiple leading indicators continue to trend positively, customer conversations are becoming more optimistic and the very positive impact of the recent change in section 232 tariffs and the forthcoming positive progression of the anti dumping and counter daily duty process further supports our confidence as we approach the Q3 and Q4 bid season for 2027. While we prepare to exit this stage of the market cycle, operational discipline and cost management remains foundational to how we run the business for both near term assuredness and long term improved profitability. That means staying disciplined on costs, protecting liquidity and remaining ready for multiple scenarios. The plant idling actions announced in our January 2026 call are progressing as planned with 3 million of the costs referenced in our prior call recognized in Q1 2026 and in line with projections. Beyond those actions, we continue to evaluate opportunities to rationalize our portfolio and right size fixed costs while remaining committed to our strategy of delivering industry leading supply chain solutions from first to final line. Our objective is straightforward renew costs in a sustainable way that protects margins and liquidity today and creates leverage for improved profitability and cash generation as volumes recover. We remain agile and prepared to adjust spending including capital expenditures as conditions evolve. At this time, we have been deliberate about what we do not Investments in safety, quality and customer support remain non negotiable. We continue to fund initiatives that expand recurring revenue and strengthen customer relationships, particularly …

Full story available on Benzinga.com

This post was originally published here
FatPipe Inc. (NASDAQ:FATN) shares are trading sharply higher this Friday. The move follows the company’s preliminary fourth-quarter fiscal 2026 business update released Thursday.

The Nasdaq is up 1.17% while the S&P 500 has gained 0.68%.

• Fatpipe stock is among today’s top performers. Why is FATN stock up today?

Massive Revenue Growth

The SD-WAN pioneer expects fourth-quarter revenue between $6.6 million and $7 million. This range represents approximately 79% year-over-year growth at the midpoint. This jump highlights increasing demand for its enterprise-class networking and cybersecurity solutions.

Adjusted EBITDA Skyrockets

Profitability metrics showed even more dramatic …

Full story available on Benzinga.com

This post was originally published here
Ares Management (NYSE:ARES) raised roughly $30 billion in new capital in the first quarter, a company record that signals big investors are still allocating to private credit despite months of skeptical commentary about the space.

Ares credit business accounted for the largest share of the quarter’s haul, raising $20.4 billion, while its real assets platform brought in $6.2 billion.

“We are on track for another record year of fundraising as we continue to see broad-based investor demand across our platform. We also continue to see strong fundamental performance across our investment portfolios despite the volatile market environment,” said CEO Michael Arougheti in a press release.

Ares finished the quarter with $158.1 billion of uninvested capital, up 11% from the prior year. The firm said it deployed $32.3 billion during the period across U.S. and European direct lending, real estate, and alternative credit strategies.

data-variant=”card”

This post was originally published here
Summit Hotel Properties (NYSE:INN) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/2oxvw6qi/

Summary

Summit Hotel Properties reported a 0.2% year-over-year increase in RevPAR for Q1 2026, driven by a 5.6% increase in average rates, particularly in March.

The company successfully closed the sale of a Hilton Garden Inn and is in the process of selling two more hotels, aligning with its strategy to recycle capital from lower-growth assets.

Summit Hotel Properties raised its full-year guidance for key operating and financial metrics, reflecting an improved outlook driven by strong demand trends expected to continue into the second quarter.

Operational highlights include strong performance in urban markets like San Francisco and Miami, with significant RevPAR growth driven by high-impact events.

Management remains focused on optimizing profitability, prudent capital allocation, and maintaining a strong balance sheet, with no debt maturities until 2028.

Full Transcript

OPERATOR

Ladies and Gentlemen, thank you for standing by. Welcome to the Summit Hotel Properties first quarter 2026 conference call. At this time all participants are in a listen only mode. After the speaker’s presentation there will be a question and answer session and to ask a question during the session you would need to press Star 11 on your telephone and you will then hear an automated message advising your hand is raised and to withdraw your question please press star 11 again. Please be advised that today’s conference is being recorded. I would like now to turn the conference over to Kevin Mellotta. Please go ahead.

Kevin Mellotta

Thank you operator and good morning. I am joined today by Summit Hotel Properties President and Chief Executive Officer John Stanner and Executive Vice President and Chief Financial Officer Trey Conklin. Please note that many of our comments today are considered forward looking statements as defined by federal securities laws. These statements are subject to risks and uncertainties both known and unknown as described in our SEC filings. Forward looking statements that we make today are effective only as of today May 1, 2026 and we undertake no duty to update them later. You can find copies of our SEC filings inearnings release which contain reconciliations to non-GAAP financial measures referenced on this call on our website at www.shpreit.com. Please welcome Summit Hotel Properties President and Chief Executive Officer John Stanner. Thank you Kevin and good morning everyone. Thank you for joining us today for our first quarter 2026 earnings conference call. We are pleased with our first quarter financial results which were driven by a meaningful sequential improvement in operating fundamentals throughout the quarter. RevPAR in our pro forma portfolio inflected positive in the first quarter, increasing 20 basis points year over year which exceeded expectations communicated during our fourth quarter 2025 earnings call by over 200 basis points. Importantly, operating strength was broad based across the portfolio, particularly in March with growth in multiple high rated demand segments driving increases in average rates and RevPars. In many of our markets, operating fundamentals improved each month as the quarter progressed. While RevPAR declined in January and February, those declines were more than offset by 4.1% RevPAR growth in March which was driven by a robust 5.6% increase in average rate. We were especially encouraged with March results which represented a relatively clean calendar comparison for our portfolio despite the lingering government shutdown and highly publicized TSA wait times. We believe March trends are more indicative of the underlying demand strength in our business and have been pleased to see these trends continue in April. While demand strength and pricing power were broad based across our portfolio, our best performing demand segments were our highest rated segments which allowed us to yield out a portion of lower rated business in a reversal of the prevailing pricing trends we experienced for most of last year. In particular, the ongoing recovery in business transient travel is driving better midweek performance as RevPAR growth increased 3% for the quarter and 10% in March in our negotiated segment. This helped drive double digit RevPAR growth in a dozen of our markets in March, including urban centric markets such as Baltimore, Charlotte, Cleveland, Miami, Pittsburgh, San Francisco and Washington dc. As a reminder, we expected our first quarter to be the most challenging of the year given multiple headwinds faced in our portfolio, notably a difficult super bowl comparison in New Orleans where we own six hotels and continued weakness in government demand with Doge related travel cuts not lapping year over year comparisons until the March April timeframe. In addition, disruption related to winter Storm Fern and civil unrest in Minneapolis further reduced first quarter reported RevPAR growth. In total, these events created an approximately 140 basis point headwind to our first quarter RevPAR growth, most significantly in January and February. Our outlook for the remainder of the year has improved driven by strengthening demand trends that have persisted into the second quarter. We are also approaching what is expected to be a robust summer of special events driven demand. We expect April RevPAR to increase approximately 3.5% and our second quarter revenue pace is currently trending approximately 4% ahead of the same time last year. Pace trends in June are particularly strong supported by a favorable event calendar highlighted by our significant exposure to major demand catalysts including the 2026 FIFA World cup where we have exposure to six US host markets representing approximately 1/3 of our total room count and 44 scheduled matches. In addition, we expect strong incremental demand from the US 250th anniversary celebrations in Boston, Washington D.C. and Baltimore as well as several other major summer travel and event driven demand drivers. As we’ve discussed on previous calls, government and government related demand has been a significant headwind for our portfolio since the creation of DOGE in the first quarter of last year and the lapping of these comparisons is expected to improve our year over year growth rates going forward. While first quarter government related demand declined 12% year over year, this represented a meaningful improvement from the 20% plus declines we experienced through most of 2025. Encouragingly, March government revenue increased approximately 3% and our outlook for this demand segment has improved, demonstrated by second quarter government pace currently trending up mid single digits. Government demand represents approximately 5% to 7% of our total guest room and revenue mix and we believe this could serve as a potential modest tailwind to our year over year growth rates in the last three quarters of the year. Given our strong first quarter results and our improved outlook for the remainder of the year, we’ve increased the guidance ranges for our key operating and financial metrics which were outlined in our earnings release yesterday. Trey will provide more details on our updated guidance ranges later in the call, but we believe the revised ranges strike the appropriate balance of reflecting a more positive outlook and while acknowledging that our most meaningful quarters are still ahead and macro and geopolitical uncertainty persists while near term performance trends are driving our improved outlook. Longer term lodging fundamentals suggest an improved demand environment has the potential to create an extended period of attractive top line growth. More specifically, supply growth remains meaningfully below historical averages and still elevated construction and financing costs create an impediment to a meaningful near term recovery. Acceleration in construction starts. In addition, consumer prioritization of travel and experiences remains paramount which has driven resilient leisure demand finally, improved industry demand has increasingly been driven by the ongoing recovery and acceleration of business travel which uniquely benefits our urban centric portfolio. We believe these dynamics create a favorable operating environment as as we move through the balance of 2026 and beyond from a capital allocation standpoint in the first quarter we successfully closed on the previously announced sale of the 122 room Hilton Garden Inn in Longview, Texas, a non core asset owned in our joint venture with GIC. The hotel was sold for $12.3 million representing a 6.8% capitalization rate based on trailing twelve month net operating income. After consideration of foregone near term capital expenditures. In April we entered into an agreement to sell our wholly owned courtyard and residence in Dallas Arlington South Hotels for a combined sale price of $19 million. The two hotels total 199 guest rooms and the transaction reflects a 5% capitalization rate based on trailing 12 month NOI. After factoring in near term capital expenditures that we would otherwise have been required to, we expect the Arlington transaction to close in the third quarter which will allow us to capture the demand generated from the FIFA matches in the market. These dispositions are consistent with our ongoing strategy to selectively recycle capital out of lower growth assets, reduce future capital requirements, enhance the overall quality and growth profile of our portfolio. Proceeds from asset sales support our broader capital allocation priorities including enhancing liquidity, reducing leverage, repurchasing shares and maintaining the physical condition of our portfolio. During the first quarter we remained active under our share repurchase program, repurchasing 1.4 million common shares for an aggregate purchase price of $6 million or a weighted average price of approximately $4.17 per share. As of March 31, 2026, we had approximately $29 million of remaining capacity under the program. Since launching the program in 2025, we’ve repurchased approximately 5 million shares, representing roughly 4% of total shares outstanding at an average price of $4.26 per share. We believe these repurchases represent an attractive use of capital and reflect our continued confidence in the intrinsic value of the portfolio and the long term earnings power of the business. In summary, we’re encouraged by the start to the year and remain optimistic about the improved outlook for our industry broadly and our company specifically. While the operating environment remains dynamic, the breadth of demand improvement we are seeing across the portfolio combined with favorable industry supply conditions reinforces our confidence in Summit’s ability to outperform its fundamentals Strengthen Our priorities are unchanged. We remain intensely focused on optimizing profitability at the property …

Full story available on Benzinga.com

This post was originally published here
Xerox Holdings Corp (NASDAQ:XRX) shares continued their upward trajectory on Friday.

The stock rose nearly 18% in early trading following a significant revenue beat. This rally builds on momentum from Thursday’s session.

The Nasdaq is up 1% while the S&P 500 has gained 0.61%.

Revenue Beats And Short Interest

Xerox reported first-quarter sales of $1.846 billion. This figure surpassed the analyst consensus estimate of $1.747 billion.

This performance marks a sharp increase from $1.457 billion in the prior-year period.

Despite the revenue win, the company reported an adjusted loss of 43 cents per …

Full story available on Benzinga.com

This post was originally published here
Weyerhaeuser (NYSE:WY) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://app.webinar.net/LywvYzE8PZe

Summary

Weyerhaeuser Co reported first quarter GAAP earnings of $156 million on net sales of $1.7 billion, with adjusted EBITDA totaling $308 million, marking a 120% increase over the previous quarter.

The company completed the divestiture of non-core Timberlands in Virginia for $192 million and continued to focus on its wood products growth strategy, introducing new products such as Aerostrand and Propanel.

Weyerhaeuser Co expanded its distribution network, opening new locations in Billings, Montana and Gallatin, Tennessee, to support growth in underpenetrated markets.

Future outlook includes stable second-quarter earnings expectations, with continued focus on operational excellence and strategic growth initiatives, despite ongoing macroeconomic uncertainties.

Management highlighted challenges due to increased transportation and raw material costs and expressed optimism in long-term housing market fundamentals despite current headwinds.

Full Transcript

OPERATOR

Greetings and welcome to the Weyerhaeuser first quarter 2026 earnings conference call. At this time all participants are in a listen only mode. After the speaker’s remarks, there will be a question and answer session. To ask a question, please press star one on your telephone keypad. Confirmation tone will indicate your line is in the question queue. If anyone should require operator assistance during the conference, please press star zero. As a reminder, this conference is being recorded. It is now my pleasure to introduce Andy Taylor, Vice President of Investor relations. Thank you Mr. Taylor. You may begin. Thank you. Good morning everyone. Thank you for joining us today to discuss Weyerhaeuser’s first quarter 2026 earnings. This call is being webcast at www.weyerhaeuser.com. Our earnings release and presentation materials can also be found on our website. Please review the warning statements in Our earnings release and on the presentation slides. Context concerning the Risks associated with Forward looking Statements as forward looking statements will be made during this conference call, we will discuss non GAAP financial measures and a reconciliation of GAAP can be found in the earnings materials on our website. On the call this morning are Devin Stockfish, Chief Executive Officer and Davey Wold, Chief Financial Officer. I will now turn the call over to Devin Stockfish.
Devin Stockfish (Chief Executive Officer)

Thanks, Andy. Good morning everyone and thank you for joining us. Yesterday, Weyerhaeuser reported first quarter GAAP earnings of $156 million, or 22 cents per share. On net sales of $1.7 billion, excluding special items, we earned $77 million or 11 cents per share. Adjusted EBITDA totaled $308 million, a 120% increase over the fourth quarter. These are solid results and I’d like to thank our teams for their continued focus and operational performance. Through their efforts, adjusted EBITDA improved across each of our business segments compared to the prior quarter, a notable achievement against a backdrop of elevated macroeconomic uncertainty. Before getting into the business results, I’ll provide a quick update on previously announced actions to optimize our portfolio. In February we completed the divestiture of non core Timberlands in Virginia for $192 million, and in April we received $22 million in proceeds following the transfer of our timber licenses in British Columbia to the buyer of our Princeton Mill. This represents the final proceeds associated with the Princeton transaction. I’ll also highlight some recent advancements associated with our wood products growth strategy. First, we were excited to preview two new products, AeroStrand and ProPanel, at the International Builder show in February. We’re committed to delivering products that meet the evolving needs of our customers, and these represent the first of many new and innovative products that we intend to introduce over the next several years. Feedback thus far has been overwhelmingly positive and we expect strong demand for both products as we bring them to market. And finally, we expanded our distribution footprint in the first quarter, opening a new location in Billings, Montana and announcing a new facility in Gallatin, Tennessee near Nashville, which will be operational by year end. Both sites support our strategy for continued growth of Weyerhaeuser’s proprietary products in strong and under penetrated markets. With these new facilities, our distribution Network expands to 22 locations and as we laid out at our Investor day, we see opportunities for additional growth through 2030. Turning now to our first quarter business results, I’ll start with Timberlands on pages six through nine of our earnings slides, excluding a special Item, Timberlands contributed $57 million to first quarter earnings. Adjusted EBITDA was $120 million, a 5% increase compared to the fourth quarter. In the west, adjusted EBITDA was $58 million, a $13 million increase over the prior quarter, largely driven by higher sales volumes and seasonally lower costs. Starting with the Western domestic market, log demand and pricing improved in the first quarter as mills responded to strengthening lumber prices and seasonally lower log supply. As a result, our average domestic sales realizations increased moderately compared to the fourth quarter. Our fee harvest volumes were slightly higher and per unit log and haul costs decreased as we made the seasonal transition to lower elevation and lower cost harvest operations. Forestry and road costs were seasonally lower. Moving to our Western export business, log markets in Japan were muted in the first quarter in response to ongoing consumption headwinds in the Japanese housing market. As a result, our customers finished goods inventories remained elevated and log prices decreased. Despite this dynamic, our customers remain well positioned relative to imported European lumber, which continues to face headwinds in the Japanese market. For the quarter, our average sales realizations for export logs to Japan were moderately lower and our sales volumes were moderately higher, largely due to the timing of vessels turning briefly to China. We remain in the early stages of re establishing our log export program to strategic customers in the region. However, our shipments have been limited to date, largely driven by ongoing weakness in the Chinese real estate sector and the seasonal slowing of construction activity around the Lunar New Year holiday. For the first quarter, we delivered one vessel to China which was comparable to the prior quarter. Turning to the south, adjusted EBITDA for Southern Timberlands was $62 million, a $7 million decrease compared to the fourth quarter. Despite improved pricing and takeaway of lumber. Southern sawlog markets remained subdued in the first quarter as log supply outpaced demand given drier than normal weather conditions. With respect to southern fiber markets, demand and pricing moderated in the first quarter as mills reduced consumption ahead of spring maintenance outages and in response to lower takeaway of finished goods. On balance, demand for our logs remained steady given our delivered programs across the region and our average sales realizations were comparable to the fourth quarter. Our per unit logging haul costs were also comparable and forestry and road costs were higher. Our fee harvest volumes were slightly lower in the first quarter. In the north, adjusted EBITDA was comparable to the fourth quarter turning now to Strategic Land Solutions on pages 10 and 11 as a reminder, this is the new name for our Real Estate, Energy and Natural Resources segment. Starting this quarter, we’re expanding our disclosure for this segment to three business Real Estate, Natural Resources, and Climate Solutions. The new name reflects our broadening scope and growth focus across these businesses, and the new reporting structure enhances the cadence of disclosure for our climate solutions activities. In the first quarter, Strategic land Solutions contributed $169 million to earnings. Adjusted EBITDA was $193 million, a $98 million increase compared to the fourth quarter. This reflects a very strong quarter for the segment, largely driven by the timing and mix of real estate sales and the completion of a $94 million conservation easement transaction in Florida. As we discussed last quarter, the conservation transaction conveyed approximately 61,000 acres of Weyerhaeuser timberlands to a larger wildlife corridor, restricting future development and protecting habitat for a variety of species. Notably, the easement allows Weyerhaeuser to retain ownership of the land for continued sustainable forest management. As for the rest of the segment, real estate markets have remained solid year to date, and we continue to capitalize on steady demand and pricing for HBU properties with significant premiums to timber value for the quarter. Our results reflect a sizable increase in real estate acres sold, which is a typical trend for this business. In the first quarter, our average price for real estate sales declined from the record level achieved last quarter, which benefited from several high value development transactions in South Carolina. Now moving to Wood products on pages 12 through 14. Excluding a special item, wood products contributed $14 million to first quarter earnings. Adjusted EBITDA was $71 million, a $91 million improvement compared to the fourth quarter, largely driven by an increase in lumber and OSB pricing. Starting with lumber first quarter, adjusted EBITDA was $27 million, an $84 million increase from the Prior Quarter the framing lumber composite strengthened in the first quarter as buyers work to replenish lean inventories into the spring building season but face supply constraints from previously enacted curtailments and closures. While this dynamic was felt across the North American market, it was most acute in southern yellow pine, which experienced a significant price increase during the quarter. For our lumber business, average sales realizations increased by 13% compared to the fourth quarter. Our production volumes increased as we returned to a more normal operating posture following market related production adjustments in late 2025. As a result, our sales volumes increased slightly and unit manufacturing costs were lower. Log costs were comparable to the prior quarter. Now turning to OSB, first quarter adjusted EBITDA was $3 million, a $13 million increase compared to the fourth quarter. OSB Composite pricing entered the year on an upward trajectory as demand improved slightly leading into the spring building season. By February, pricing stabilized and remained steady for the balance of the quarter. As a result, our average sales realizations increased by 8% compared to the fourth quarter. Our production and sales volumes were slightly lower, largely driven by temporary winter weather disruptions. Early in the quarter, unit manufacturing costs were slightly lower and fiber costs were slightly higher. Adjusted EBITDA for engineered wood products was $39 million, a $10 million decrease compared to the fourth quarter, primarily due to lower average sales realizations for most products and higher raw material costs, most notably for OSB Web stock. Our sales volumes for solid section products increased slightly while I joist volumes were comparable to the prior quarter. Unit manufacturing costs were also comparable. Although EWP sales volumes and pricing held up reasonably well, demand was softer than our initial expectations early in the first quarter. That said, we saw a slight uptick in order files in March, and we expect our sales volumes to increase seasonally in the second quarter. Moving forward, demand for EWP products will remain closely aligned with new home construction activity, particularly in the single family segment. In distribution, adjusted EBITDA improved by $7 million compared to the fourth quarter, largely due to higher sales volumes. With that, I’ll turn the call over to Davey to discuss some financial items and our second quarter outlook.
Davey Wold (Chief Financial Officer)

Thanks, Devin, and good morning everyone. I’ll begin with key financial items, which are summarized on Page 16. We ended the quarter with approximately $300 million of cash and total debt of $5.4 billion. During the quarter, we repaid our $150 million 7.7% notes at maturity. We returned $151 million to shareholders through the payment of our quarterly base dividend and approximately $10 million through share repurchase activity in the first quarter.

Davey Wold (Chief Financial Officer)

Capital expenditures were $112 million in the first quarter, which includes $30 million related to the construction of our EWP facility in Arkansas. As we previously communicated, we anticipate approximately $300 million of investments for Monticello in 2026, and as a reminder, CAPEX associated with this project will be excluded for purposes of calculating adjusted FAD as used in our cash return framework.

Davey Wold (Chief Financial Officer)

During the first quarter we generated $52 million of cash from operations. It’s worth noting that first quarter is usually our lowest operating cash flow quarter due to seasonal inventory and other working capital Build first quarter results for our unallocated items are Summarized on Page 15.

Davey Wold (Chief Financial Officer)

Adjusted EBITDA for this segment decreased by $27 million compared to the fourth quarter, primarily attributable to changes in intersegment, Profit Elimination, and LIFO. Looking forward, key outlook items for the second quarter are presented on page 18. In our Timberlands business, we expect second quarter earnings before special items and adjusted EBITDA to be comparable to the first quarter of 2026. Turning to our Western Timberlands operations, we expect steady log demand in the domestic market in the second quarter as mills respond to improving lumber takeaway through the spring building season and build log inventories ahead of fire season. At the same time, log supply is expected to increase as weather conditions improve seasonally. On balance, this should translate to a fairly stable domestic log market.

Davey Wold (Chief Financial Officer)

We anticipate our average domestic sales realizations will be slightly higher than the first quarter as price increases in April are expected to hold steady through quarter end given seasonally favorable operating conditions in the second quarter, our fee harvest volumes and forestry and road costs are expected to be higher and per unit loggin haul costs are expected to increase as we move to higher elevation sites and in response to elevated fuel costs. Moving to our Western export program, we anticipate log markets in Japan and China will remain relatively stable in the second quarter, albeit at reduced levels. As a result, our log shipments and pricing are expected to be comparable to the first quarter. That said, export costs have increased in response to the Middle east conflict.

Davey Wold (Chief Financial Officer)

Turning to the south, log inventories were elevated at the outset of the second quarter and log supply is expected to increase seasonally as the quarter progresses. We anticipate relatively stable sawlog demand while fiber demand remains soft in response to spring maintenance outages and lower takeaway of finished goods.

Davey Wold (Chief Financial Officer)

On balance, takeaway for our logs is expected to remain steady given our delivered programs across the region, and we anticipate our sales realizations will be comparable to the first quarter. Our fee harvest volumes and forestry and road costs are expected to be higher due to drier weather conditions that are typical in the second quarter and we anticipate moderately higher per unit logging haul costs largely due to increased fuel costs.

Davey Wold (Chief Financial Officer)

In the north, our average sales realizations are expected to be moderately higher than the first quarter due to mix and fee harvest volumes are expected to be significantly lower given spring breakup conditions. Moving to Strategic Land Solutions or sls, we continue to expect full year adjusted ebitda of approximately $425 million and given our new segment disclosure framework basis is now provided as a percentage of total SLS sales and is expected to be between 20 to 30% for the year. Real estate markets have remained solid year to date and we expect a consistent flow of transactions with significant premiums to timber value as the year progresses.

Davey Wold (Chief Financial Officer)

Additionally, we expect to deliver steady growth from our climate Solutions business in 2026.

Davey Wold (Chief Financial Officer)

For the second quarter, we expect SLS adjusted EBITDA will be approximately $70 million lower and earnings will be approximately $80 million lower than the first quarter of 2026 driven by the sizable conservation easement transaction in the first quarter, we expect this to be partially offset by stronger results from our real estate business due to timing and mix.

Davey Wold (Chief Financial Officer)

For our wood products segment, we expect second quarter earnings before special items and adjusted EBITDA to be comparable to the first quarter of 2026 excluding the effect of changes in average sales realizations for lumber and osb. Notably, we expect improved sales volumes across all wood products businesses as we get deeper into the building season.

Davey Wold (Chief Financial Officer)

This will be offset by higher costs in the second quarter, largely driven by inflationary pressures related to transportation and certain raw materials, as well as planned annual maintenance outages at three of our OSB mills. As for product pricing, we’re encouraged by the recent upward momentum in lumber.

Davey Wold (Chief Financial Officer)

As shown on page 19, our current and quarter to date average sales realizations for lumber are significantly higher than the first quarter average, while OSB realizations are slightly higher. For our lumber business, we anticipate higher sales volumes and slightly higher log costs in the second quarter. Our unit manufacturing costs are expected to be comparable to the prior quarter. For our OSB business, we expect higher sales volumes and moderately higher fiber costs in the second quarter. Our unit manufacturing costs are expected to increase largely due to the previously mentioned planned outages and higher prices for resin. For our engineered wood products business, we anticipate higher sales volumes for all products in the second quarter and comparable average sales realizations.

Davey Wold (Chief Financial Officer)

Raw material costs are expected to be slightly higher. For our distribution business. We expect adjusted EBITDA to be slightly higher compared to the first quarter as sales volumes increase seasonally. With that, I’ll now turn the call back to Devin and look forward …

Full story available on Benzinga.com

This post was originally published here

On Friday, TC Energy (TSX:TRP) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://www.gowebcasting.com/events/tc-energy-corporation/2026/05/01/2026-first-quarter-financial-results/play

Summary

TC Energy Corp reported a 14% year-over-year increase in comparable EBITDA, reaching over $3 billion, marking its best safety performance in six years.

The company announced a $1.5 billion investment in the Appalachia Supply Project on its Columbia Gas system, supported by a 20-year take-or-pay contract, expected to be in service by 2030.

TC Energy Corp reaffirmed its 2026 and 2028 EBITDA outlook, with a target of $11.6 to $11.8 billion for 2026 and $12.6 to $13.1 billion for 2028, supported by a robust project development pipeline.

In Canada, the company reached new commercial agreements for Coastal GasLink Phase 2 and is exploring a new investment framework for NGTL expansions.

The US Heartland region represents a significant growth opportunity, with natural gas demand expected to grow 40% through 2035, driven by power generation and data center expansion.

Full Transcript

OPERATOR

Thank you for standing by. This is the conference operator. Welcome to the TC Energy first quarter 2026 results conference call. As a reminder, all participants are in listen only mode and the conference is being recorded. After the presentation, there will be an opportunity to ask questions. To join the question queue, you may press star, then one on your telephone keypad. Should you need assistance during the conference call, you may reach an operator by pressing STAR and then zero. I would now like to turn the conference over to Gavin Miley, Vice President, Investor Relations. Please go ahead.

Gavin Miley (Vice President, Investor Relations)

Thank you. I’d like to welcome you to TC Energy’s first quarter 2026 conference call. Joining me are Francois Poirier, President and Chief Executive Officer, Sean o’, Donnell, Executive Vice President, Chief Financial Officer, along with other members of our senior leadership team. Sean will begin today with some comments on our financial results and operational highlights. A copy of the slide presentation is available on our website under the Investors section. Following the remarks, we’ll take questions from the investment community. We ask that you please limit yourself to two questions and if you are a member of the media, please contact our media team. Today’s remarks will include forward looking statements that are subject to important risks and uncertainties. For more information, please see reports filed by TC Energy, with Canadian securities regulators and with the U.S. Securities and Exchange Commission. Finally, we’ll refer to certain non GAAP measures that may not be comparable to similar measures presented by other entities. A reconciliation is contained in the appendix of this presentation. With that, I’ll now turn the call to Francois.

Francois Poirier (President and Chief Executive Officer)

Thanks Gavin and good morning everybody. We entered 2026 with strong momentum, delivering against a clear and consistent set of strategic priorities. First and foremost, we had our best safety performance in six years. We generated over $3 billion of comparable EBITDA up 14% year over year, demonstrating strong stable results amid ongoing market and geopolitical volatility. We reached settlement agreements with customers on our Canadian Mainline, ANR and Great Lakes assets with outcomes largely in line with expectations, further supporting our comparable EBITDA outlook. Today I’m pleased to announce a strategic investment on our Columbia gas system, the US $1.5 billion Appalachia supply project, which extends our reach into a high demand corridor and creates a scalable platform for future growth. Customer demand continues to validate our strategy with consecutive open seasons in Ohio and on our Crossroads system seeing strong response supporting incremental growth visibility. In Canada, we reached an important milestone with new commercial agreements for Coastal GasLink Phase 2 under a disciplined risk allocation framework while execution of the Bruce Power MCR program remains firmly on track. These outcomes reinforce our confidence in delivering on our 2026 comparable EBITDA outlook, maintaining disciplined capital spending and preserving balance sheet strength as we continue to deliver solid growth, low risk and repeatable performance. The US Heartland is one of the most strategically important regions in our portfolio and one where we have a clear competitive advantage. With over 27,000 miles of pipeline infrastructure, we operate more natural gas pipeline and storage in the region than any other company, offering unmatched access to low cost supply and key demand markets. Today, the heartland represents approximately 3/4 of our US deliveries with natural gas demand expected to grow an additional 40% through 2035. Driven by diversified demand from power generation including data centers, LDCs and LNG exports. Our ANR system sits at the core of our Heartland footprint and exemplifies the strength of our incumbent position in the US Midwest. Including our Heartland and Northwoods projects. We’ve announced nearly $3 billion of investment on ANR over the last six years, adding more than 1.1 bcf per day of incremental capacity by leveraging existing rights of way and infrastructure on our Columbia Gas system. Natural gas demand across the footprint has increased by approximately 50% and we expect an additional 4 BCF a day of incremental demand by 2035. We expect this momentum to continue to unlock additional accretive growth opportunities to further reinforced by the strategic investment being made today in our Appalachia Supply project. This project further extends our reach into this high value high growth market. The US $1.5 billion expansion project on our Columbia Gas system is supported by a long term 20 year take or pay contract backed by an investment grade utility and is expected to deliver solid risk adjusted returns and a 7.3 times build multiple. The project will add 0.8 BCF per day of capacity to support new power generation development with an anticipated in service date of 2030. But importantly, the project will be capable of up to 2bcf a day of total capacity through future expansions creating line of sight for capital efficient growth projects relating to overall economic development demand from data centers and as broader electrification continues to scale. This strategic investment reinforces the strength of the Columbia Gas system while positioning us for several potential follow on accretive opportunities. Accelerating power related load growth is driving customer demand across our footprint and it’s reflected in the results of our two most recent open seasons. As we noted in our previous quarter earnings call, the Columbus, Ohio open season was approximately three times oversubscribed. This strong response reflects Ohio’s projected natural gas demand growth of more than 30% over the next decade, the largest increase nationally outside of LNG exporting states. Growth is being driven by power generation, industrial expansion and grid reliability needs, including significant incremental load from more than 40 new data centers, positioning Ohio as a top five US data center market. Our Crossroads open season received a similarly strong response with bids exceeding two and a half times the capacity offering. What’s important is not just the level of demand we’re seeing, but how we’re well positioned to capture it. We are intentionally strengthening connections across our systems, linking assets with access to premium low cost supply such as Columbia Gas to systems serving high quality long duration demand such as A and R in corridor expansion. Opportunities on established systems like Crossroads allow us to respond quickly to customer needs, deploy capital efficiently and meaningfully, reduce execution risk Turning to Bruce Power, the MCR program continues to execute safely, reliably and with improving economics. We’ve seen successive MCR costs come down by applying lessons learned and using new tools like robotics for removal and installation activities. That execution excellence underpins the long term visibility of cash flows from the asset. By 2030 distributions will begin to meaningfully exceed capital spend and by 2032 Bruce is expected to generate approximately $1 billion of annual free cash flow, increasing to approximately $2 billion once the MCR program is complete in 2035. Strong execution reinforces confidence in the team’s ability to deliver significant free cash flow growth from Bruce Power. That creates further optionality supporting growth across our entire portfolio as well as the potential expansion of of Bruce C and

Sean

with that I’ll turn it over to Sean to walk through the numbers. Thanks Francois Good morning, everybody. Turning to our first quarter performance, TC delivered 14% year over year growth in comparable EBITDA, marking a very strong start to 2026 from each of our four business units. Both our Canadian and US natural gas pipeline businesses continued to perform exceptionally well, setting seven new all time delivery records during the quarter. The results underscore the strength of our footprint and the value that our highly contracted in corridor assets provide to our customers. In the power and energy solutions business, Bruce Power achieved 88% availability in the quarter, which is in line with our plan and which also includes the planned outage on unit 8 for full year 26. We continue to expect Bruce’s availability to be in the low 90% range which is consistent with 2025. Our Alberta cogeneration fleet also delivered exceptional performance, achieving 99.5% availability. On the right hand side of the page we summarize our quarterly EBITDA performance.

Sean

I would highlight that this was a record quarter, marking the first time that we generated more than $3 billion of comparable EBITDA from continuing operations in a single quarter. Growth was led by our Mexico and U.S. natural gas businesses who placed over $8 billion of new assets into service in 2025. Canadian natural gas pipelines benefited from higher flow through depreciation and NGTL incentive earnings, while Power and Energy Solutions SAw higher contributions from Bruce Power.

Sean

These results reflect strong execution across each of our lines of business and reinforce the momentum that underpins our financial outlook for the portfolio this year. Looking ahead, we’re reaffirming both our 2026 and 2028 comparable EBITDA outlook which reflects our customers steady demand for access to our assets under our unique long term, low risk, take or pay and rate regulated commercial constructs. For 2026, our comparable EBITDA outlook remains at 11.6 to 11.8 billion, which represents roughly a 7% actual to midpoint increase relative to an exceptional performance in 2025 and it represents an 8% actual to midpoint annualized increase

Sean

relative to 2024. Looking out to 2028, we continue to target comparable EBITDA of 12.6 to 13.1 billion, implying a 6% actual to midpoint 3 year annualized growth rate that is fully underpinned by SAnctioned projects advancing towards in service dates. Moving to the right hand side of the page, we summarize several additional factors that could influence our EBITDA outlook over time. While our EBITDA is highly contracted, we have ongoing revenue enhancement initiatives and cost and capital optimization programs across the organization that are in flight, each of which have the potential to drive incremental upside. We’ve added a Project Execution Dashboard to provide a unique level of visibility on the key projects that are driving EBITDA growth over the next few years. Collectively, these projects account for the majority of our capital allocation and expected EBITDA growth. You’ll note that we have a clear line of sight to our in service base and our build multiples, similar to 2025 where we placed over $8 billion of projects into service on time and 15% below budget.

Sean

The team is carrying that momentum into 2026 where our projects are tracking on schedule and on or under budget. We’re providing a lot of detail on this slide, but you’ll note that the majority of investment activity is concentrated in the US where we are seeing commercial and regulatory tailwinds that are supporting a weighted average build multiple of 6.2x. Notwithstanding the attractive positioning of the portfolio today, project execution continues to be a strong focus given how critical it is to our continued growth.

Sean

Strong execution is a direct reflection of the discipline embedded in our low risk project selection process and the strength of our cross functional project delivery capabilities. It is this consistency in our team’s execution excellence year in and year out that is foundational to our ability to deliver the financial outlook we provide and also reinforces the confidence we have in both our near term forecasts and our longer term growth trajectory.

Sean

I’ll wrap this slide up by underscoring that the visibility we are sharing on our next wave of projects continues to validate the quality, repeatability and low risk nature of our project backlog. It’s that backlog and our team’s ability to execute that underpin our EBITDA outlook and continued shareholder value proposition. I’d like to turn to our investment outlook with our updated capital Allocation Dashboard. This chart further demonstrates the depth, diversity and continued growth of our project portfolio through the end of the decade.

Sean

With today’s announcement of the Appalachia Supply project, we converted approximately $2.2 billion of investment capital from pending approval into SAnctioned last quarter. We also added over 2 billion of new high conviction substantially de risked projects to our pending approval bucket which continues to support near term project announcements. Beyond the project portfolio on this slide we have about $15 billion of additional projects in origination that are competing for capital allocation this decade.

Sean

To give you a sense for where some of this $15 billion backlog stands and our confidence in converting them to SAnctioned capital over the next year or two, Francois mentioned that we recently conducted two open seasons in the US that were substantially oversubscribed that we’re extremely excited about. Similarly, in Canada we’ve launched the first in a series of expected new offerings on NGTL while continuing to advance parallel discussions on a new growth investment framework with customers.

Sean

I’ll wrap this slide up with a few comments about how we are thinking about capital allocation going forward. Over the next couple of years we will continue to look to optimize and bring forward capital to support up to $6 billion of annual net capital deployment as we look after the latter part of the decade and are considering the project backlog we discussed. It is this high value largely in Carter opportunity set that will define our level of net investment. We remain committed to maintaining the balance sheet strength and our 4.75 times leverage target and we will continue to execute projects with excellence. These guide rails are fundamental to our risk and capital allocation screening process which supports the ability to exceed the $6 billion annual level, particularly as we near the conclusion of the Bruce mcr program post 2030. As Francois highlighted earlier, that is the scenario which is now in our planning window that sets us up very well for continued ebitda growth towards 2030 and beyond.

Sean

With that update, I’ll pass the call back to Francois.

Francois Poirier (President and Chief Executive Officer)

Thanks Sean. We’ve got an exciting year ahead and our strategic priorities remain clear and firmly in place. We’ll continue to maximize the value of our assets through safety and operational excellence while leveraging commercial and technological innovation. We will prioritize low risk, high return growth. More announcements are expected throughout this year and thirdly, we will maintain our financial strength and agility to support long term value creation.

OPERATOR

Operator we are now ready to take questions.

OPERATOR

Thank you. To join the question queue you May press star then 1. On your telephone keypad you will hear a tone acknowledging your request. Please limit your questions to two and if you should have additional questions, please re enter the queue. If you’re using a speakerphone, please pick up your handset before pressing any keys. To withdraw your question, Please press star then 2. The first question comes from Praneet Satish with Wells Fargo. Please go ahead.

OPERATOR

The first question comes from Aaron McNeil with TD Cowen. Please go ahead.

Aaron McNeil (Equity Analyst at TDCON)

Good morning all, Thanks for taking my questions. Appreciating the implication that the Appalachia Supply Project arguably has a bit of pre spend for future growth, can you give us a sense of what the economics of a fully loaded project at 2 BCF might look like from a build multiple perspective? And then what needs to happen to get to 2 BCF per day and when do you think that could happen by?

Tina Ferraco

Good morning Erin. This is Tina Ferraco. I’ll kick off with a response to that question. We’re really excited to about announcing our Appalachian Supply Project this morning. For many reasons over and above the headlines that we talked about, when we make capital allocation decisions we look many years ahead and the scenarios around placing this line into service gives us a strong long term growth trajectory. So the nature of these facilities in terms of pipeline extension and compressor modifications is an opportunity for …

Full story available on Benzinga.com

This post was originally published here

Minerals Technologies (NYSE:MTX) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://event.choruscall.com/mediaframe/webcast.html?webcastid=2A6Ds1r6

Summary

Minerals Technologies reported strong first-quarter sales of $547 million, an 11% increase year-over-year, driven by growth in both the consumer and specialty, and engineered solutions segments.

Strategic growth investments, including expansions in cat litter and natural oil purification facilities, are contributing to revenue growth, with a target of $100 million in incremental sales for 2026.

Despite geopolitical challenges, the company managed to avoid significant disruptions but faced increased energy and freight costs, addressing these with pricing actions and temporary surcharges.

Operating income increased by 7% to $68 million, with earnings per share rising 21% to $1.38, indicating strong financial performance despite cost pressures.

Management expressed confidence in achieving mid-single-digit sales growth for 2026, bolstered by strategic investments and improving market trends, but remained cautious of macroeconomic uncertainties.

Full Transcript

OPERATOR

Good morning and welcome to Minerals Technologies first quarter 2026 earnings conference call. All participants will be in listen only mode. Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today’s presentation, there will be an opportunity to ask questions. To ask a question, you may press star then one on your telephone keypad. To withdraw your question, please press star then two. Please note this event is being recorded. I would now like to turn the conference over to Lydia Kopalova, Head of Investor Relations. Please go ahead.

Lydia Kopalova (Head of Investor Relations)

Thank you, Gary. Good morning everyone and welcome to our first quarter 2026 earnings conference call. Today’s call will be led by Chairman and Chief Executive Officer Doug Dietrich and Chief Financial Officer Eric Alduck. Following Doug and Eric’s prepared remarks, we’ll open it up to questions. As a reminder, some of the statements made during this call may constitute forward looking statements within the meaning of the federal securities laws. Please note the cautionary language about forward looking statements contained in our earnings release and on the slides. Our SEC filings disclose certain risks and uncertainties which may cause our actual results to differ materially from these forward looking statements. Please also note that some of our comments today refer to non GAAP financial measures. A reconciliation to GAAP financial measures can be found in our earnings release and in the appendix of this presentation, which I’ll post on our website. Now I’ll open it up to Doug.

Doug Dietrich (Chairman and Chief Executive Officer)

Thanks, Lydia. Good morning everyone and thank you for joining today. As usual, I’ll provide a quick review of our first quarter financials. Then I’ll give an update on our outlook for the remainder of 2026, including an overview of the impact that current events are having on our business and the progress we’ve been making on our growth projects. Eric will then take you through the detailed financials and provide our outlook. After that we’ll open up the call to questions. Before we get into the details, let me start with the headline. We delivered a strong first quarter with broad based double digit growth and we’re seeing early proof that our strategic growth investments are paying off. First quarter sales came in at $547 million up 11% from prior year. Sales growth was broad based and from both of our segments we saw an 11% year over year increase in our consumer and specialty segment driven by household and personal care which grew 16% and specialty additives which grew 6%. Our engineered solutions segment sales increased 12% over last year with high temperature technologies up 8% and environmental and infrastructure up 24%. A portion of this growth is tied to the specific investments we made last year in support of our strategic growth initiatives to expand into higher margin consumer markets and into higher growth geographies. If you recall, we projected that these initiatives would drive $100 million in annualized revenue beginning this year and this quarter we delivered the first portion of that growth from a market perspective. We saw small improvements in demand at the start of the year, which then trended stronger in March. The stronger trend has continued here. In the second quarter, operating income was $68 million excluding special items, up 7% from last year. Earnings per share were $1.38, up 21%, and both operating and free cash flows improved significantly compared to last year. Like most companies, we felt the impact this quarter from the rapidly changing environment caused by the recent geopolitical events, and I’ll talk about that more on the next slide. Let’s start on the left side of this slide with some points about the impact Current Events in the Middle East Overall, we’ve avoided any material impact on sales or operations to date. Where we have seen an impact is with higher energy and freight costs, which we are addressing through pricing actions and temporary surcharges. In terms of our operating and sales footprint, we only have a small presence in the region, primarily consisting of refractory sales to Middle East steel producers and a long standing joint venture in our energy services business. We did encounter some challenges with shipments that were in the Persian Gulf when the conflict started, but we managed to redirect those shipments to ensure delivery to our customers. Our team responded quickly to the changing environment, much as we did last year with tariffs, and I want to thank our employees for their agility and creativity in identifying solutions for our customers. Our biggest current challenges are higher energy prices at our facilities, increased fuel cost for our heavy equipment, and higher transportation and freight costs. Once these impacts became apparent, we implemented price actions, some of which could be implemented quickly and others which will take effect over the next 90 days due to contractual terms. We are of course closely monitoring the evolving conditions and are prepared to implement further actions as needed. We’ve had minimal supply disruptions as a result of the conflict, and I’d like to point out that from a broader supply chain and logistics standpoint, we benefit from the geographically diverse structure of our business and the localization of our operations. We typically produce our products within the same region or country where we sell them. I believe that this operating structure is one of MTI’s key differentiators as it limits the impact that global supply chain disruptions have on us. This structure will further demonstrate its value as the trend for locally produced minerals and mineral based products increases. Now let me turn to the right side of the slide to update you on our growth projects, the progress we’re making and the associated timing of the expected sales, as well as some market updates. There are a number of positive elements here, all contributing to what we see as strong sales momentum this year. I’ll start with our consumer and specialty segment. In our household and personal care product line, we’ve been upgrading and expanding several of our facilities. The cat litter facility expansions that we completed late last year in North America are fully online. We’ve been ramping up the new business we’ve secured for them from customers in the US and Canada. In fact, this is a record sales quarter for cat litter which grew 19% over last year. Our new cat litter facility in China also continues to ramp up and should be fully functional by the second half of the year. With new business orders already secured. Last year we announced a capacity expansion for our natural oil purification facility. We expect to have this fully online late in the second quarter, enabling us to meet the rapidly growing demand we are seeing for renewable fuels, specifically sustainable aviation fuel. Our high performing products are uniquely capable of meeting the challenging specification for these applications. This quarter. Sales of These products grew 14% over last year and we expect this pace to accelerate once the expansion is fully operational. Elsewhere in our specialties business, our animal health business is trending nicely with sales up 9% over last year, and we’re anticipating strong volume growth in Fabricare starting in the second half with the introduction of a new technology in our specialty additives product line. We previously announced the ramp up of several new satellites in our paper and packaging business, as well as capacity expansions at others, all of which remain on track for the second half of this year. One area where we’ve not seen much improvement is in the North America residential construction market, which remains relatively slow. Turning to our engineered solutions segment in the high Temperature technologies product line, the MinScan installations we previously announced all remain on track. We are seeing higher refractory product demand from stronger steel markets in North America as well as from the share gains we’ve captured as a result of our MinScan installations. Europe steel production, on the other hand, remains soft. Our metal casting business remains stable with no major inflections. We’re seeing some strength in municipal foundry applications and the North America heavy truck market is showing signs of potential recovery, but we continue to see slow demand from the agricultural equipment market. Foundry markets in Asia remain stable and demand for our engineered foundry blends continues to expand, with sales growing 9% in the first quarter over last year. In environmental and infrastructure, we’re seeing the potential beginnings of demand improvement mainly through environmental lining project activity, which has increased of late. We’re also on track for 10 or possibly more new water utility implementations for our FluoroSorb PFAS remediation product in the second half, and demand for our infrastructure drilling products remains robust in both North America and Europe. Let me summarize all this for you. First, I’m pleased with how our growth investments are performing and we’re on track to deliver $100 million of incremental sales. We’re off to a strong start to the year and we still have several new growth projects ramping up over the next two quarters. In addition, we’re seeing improving trends in many of our end markets. At the same time, we’re mindful of continued macro uncertainty, particularly around energy costs. But even with that backdrop, the momentum we’ve established from these well time investments and the positions we’ve established in durable and growing end markets puts us on track for a solid growth year. Our current projection is for mid single digit sales growth in 2026 and this could inflect higher if the market strength we are currently seeing continues. Now let me turn the call over to Eric who can take you through our financials and provide more details.

Eric Alduck (Chief Financial Officer)

Eric thanks Doug and good morning everyone. I’ll start by providing an overview of our first quarter results followed by a review of the performance of our segments and I’ll wrap up with our outlook for the second quarter. Following my remarks, I’ll turn the call over for questions. Now let’s review our first quarter results. We had a strong start to the year. first quarter sales were $547 million, up 5% sequentially and up 11% from prior year with solid growth across all product lines. In the sequential sales bridge on the upper left, you can see that sales in the consumer and specialties segment grew 22 million from the the prior quarter or 8% driven by strong growth in both household and personal care and specialty additives. Sales in the engineered solutions segment were up $5 million from the prior quarter driven by High Temperature technologies. Operating income was $68 million in the first quarter, up $1 million from the fourth quarter driven by higher volumes and improved productivity in the consumer and specialties segment. Turning to the year over year bridges, you can see that sales were well above prior year in all four of our product lines, excluding favorable foreign Exchange our sales grew 8%, driven by higher volumes in several of our businesses. We also benefited from a few extra days in the quarter relative to last year. We estimate that underlying growth excluding FX and the few extra days was 5 to 6%. In consumer and specialties sales in household and personal care were up $19 million or 16%, and specialty additives sales increased $9 million or 6% from prior years. In engineered solutions, sales in high temperature technologies grew $14 million or 8% versus prior year and environmental and infrastructure sales grew $13 million or 24%. Operating income improved 7% from prior year with increases from the segments totaling $8 million. Operating income and margin would have been stronger if not for the rapid shift in freight and energy costs we experienced during the quarter as well as higher corporate expense due to the change in stock price during the quarter and the resulting mark to market impact on stock based compensation. Recall that our guidance for the first quarter assumed 2 to 3 million from thears of higher energy and mining costs. We actually incurred about $5 million of higher costs in the quarter. While we do hedge a large portion of the energy we consume at our plants, the increases we experienced in the quarter were mostly in the form of higher freight expenses due to the increase in fuel costs. We expect to fully offset these higher input costs through pricing and other actions as we move through the year. However, we are anticipating a timing lag of up to 90 days, in some cases based on contractual pricing arrangements. All in all, it was a good start to the year with solid growth above our initial expectations. We are managing through some new cost challenges and we are working diligently and quickly to overcome them, just as we’ve done in previous inflationary periods. Despite these higher costs, our earnings per share, excluding special items, grew 21% from last year, setting us up for a strong year in 2026. Now let’s turn to a review of our segments beginning with consumer and specialties first quarter sales in the consumer and specialties segment were $297 million, up 11% from prior year. In household and personal care, sales of $142 million were up 16% year over year. Cat litter sales continued to build on the momentum we saw in the second half of last year. The new business we secured ramped up ahead of schedule in the first quarter, which helped drive cat litter sales up 19%. Sales of bleaching earth for edible oil and renewable fuel purification remained on a solid growth track, up 14% from prior year and commissioning is underway with our capacity expansion for this product line to serve our expanding order book. Our capacity investments are also progressing well for animal health and fabric care, which grew 9% and 13% respectively in the first quarter, and we expect sales from these investments to ramp up beginning in the second half. Sales in specialty additives grew 6% from prior year to $154 million. Our volume to paper and packaging customers in Asia was up 21% including the ramp up of our newest satellites there. This growth was partly offset by slower sales into residential construction. We did see an improvement in residential construction volumes from the fourth quarter as expected. However, this end market remains soft compared to prior years. Operating income for the segment increased by 8% from last year to $33 million. Operating margin improved by 40 basis points sequentially despite the rapid increases in freight and energy costs we saw in the first quarter, and we expect operating margin to continue to build throughout the year as we work with our customers to pass through these incremental costs and as we gain leverage from our growth initiatives. Looking ahead to the second quarter, we expect segment sales to be similar sequentially and up 4 to 5% from prior year. Sales in household and personal care are expected to remain strong up mid …

Full story available on Benzinga.com

This post was originally published here

Civeo (NYSE:CVEO) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://edge.media-server.com/mmc/p/fusxhf9y/

Summary

Civeo reported a strong start to 2026 with consolidated revenue up 20% and adjusted EBITDA up 78%, driven by improved occupancy in Canadian assets and growth in Australian services.

The company raised the lower end of its revenue guidance for 2026, indicating an expected 8% growth, while maintaining adjusted EBITDA guidance due to potential inflationary impacts from global energy disruptions.

Civeo continues to focus on disciplined capital allocation, repurchasing shares and extending credit agreements to enhance financial flexibility and support future growth opportunities.

Operational highlights include strong performance in Australia due to acquisitions and integrated services growth, and improved occupancy and margins in Canada.

Management remains confident in future opportunities, especially in North America, with a robust bid pipeline and potential infrastructure projects, although final investment decisions remain a key factor.

Full Transcript

OPERATOR

Greetings and welcome to the Civeo Corporation first quarter 2026 earnings call. At this time, all participants are in a listen only mode. A question and answer session will follow the formal presentation. If anyone should require operator assistance, please press Star zero on your telephone keypad. As a reminder, this conference is being recorded. It is now my pleasure to introduce Regan Nielsen, Vice President, Corporate Development and Investor Relations. Please go ahead.

Regan Nielsen (Vice President, Corporate Development and Investor Relations)

Thank you and welcome to Civio’s first quarter 2026 earnings conference call today. Our call will be led by Bradley Dodson, Civeo’s President and Chief Executive Officer and Colin Gary, Civio’s Chief Financial Officer and Treasurer. Before we begin, we would like to caution listeners regarding forward looking statements. To the extent that our remarks today contain anything other than historical information, please note that we’re relying on the safe harbor protections afforded by federal law. These forward looking statements speak only as of the date of our earnings release and this conference call. We undertake no obligation to update or revise these statements except as required by law. Any such remarks should be read in the context of the many factors that affect our business, including risks and uncertainties disclosed in our Forms 10K, 10Q and other SEC filings. I’ll now turn the call over to Bradley. Thank you Reagan and thank you all for joining us today on our first quarter 2026 earnings call. I’ll start with some key takeaways for the quarter and summarize our consolidated and regional performance. After that, Colin will provide further financial and segment level detail and I’ll conclude prepared remarks with our outlook for 2026. We will then open the call for questions. There are four key takeaways from the call today. First, we delivered a strong start to 2026, outperforming our expectations for the quarter. Consolidated revenue was up 20% and adjusted EBITDA was up 78%. Revenue growth was driven by a mixture of improved occupancy across the Canadian assets in both the oil sands and LNG markets, continued growth in our Australian integrated services business, contributions from acquired villages in Australia, improvements in our mobile camp fleet utilization. We also benefited from foreign currency improvements. This was all complemented by strong incremental margins in Canada as a result of our cost reduction initiatives that we took last year. The second key takeaway is we continue to execute on our disciplined and balanced capital allocation strategy, returning capital to shareholders while enhancing Civeo’s financial flexibility. Third, we remain confident in the revenue trajectory of the business as a whole and are raising the lower end of our revenue guidance. The midpoint of the Revised guidance implies 8% revenue growth for the year. Our confidence stems from continued momentum in the Australian Integrated Services platform and an increasingly robust bid pipeline from North America. Asset and Service Deployment as of today, we are actively bidding on projects with total contract values in excess of $1.5 billion, which is the strongest we’ve seen today. While much of this growth is dependent on customer reaching final investment decisions which is outside of our control, we are excited about the opportunities that these present for later in 2026 and going into 2027. The last key point, the cost impacts of the ongoing conflict in Iran and associated dislocations of the global energy and raw materials trade will likely have an impact on our margins. Australia is highly dependent on normalized global seaborne energy trade for diesel and other fuels. As a result of this, the potential associated impact on inflation, energy prices and the impacts of those variables on our customers activity, we are anticipating temporary inflationary impacts to our adjusted EBITDA. Thus, we are maintaining our initial guidance of $85 million to $90 million of adjusted EBITDA for 2026. I’ll start with some operational results for the quarter On a consolidated basis, our first quarter results reflect strong year over year growth with revenues increasing 20% and adjusted EBITDA increasing 78% compared to the prior year period. In Australia, performance was strong for the first quarter, supported by the full quarter contribution from the villages we acquired in May 2025 as well as continued revenue growth in our integrated services business. In Canada, we delivered strong year over year improvement with higher occupancy across key lodges and meaningful margin expansion. Importantly, this reflects both improved activity levels and the continued benefit of structural cost improvements we implemented last year. From a macro perspective, our operating environment remains dynamic. Mining prices, including oil and metallurgical coal have been volatile and customer spending remains disciplined in both Australia and Canada. We are focused therefore on maintaining our flexibility as conditions continue to evolve. In Australia, met coal prices currently in the $230 per ton range, which is up approximately 25% from the second half of last year. Last quarter we were optimistic that healthy commodity prices would drive higher occupancy in our villages in the back half of 2026. However, the ongoing disruption to global supply chains as a result of the war in the Middle east has likely shifted the timing of any such uplift into 2027. On the oil side, prices are undoubtedly higher, but activity levels have not changed as our customers planning requires much longer term perspectives in terms of improved oil prices to adjust their activity levels. Said differently there’s too much uncertainty in the oil market for our customers to change spending plans at this time, and as such, cost discipline remains their priority. From a timing perspective, we will likely see a deferral of turnaround activity in Canada from what normally occurs in the second quarter into later in this year. Turning to capital allocation, during the quarter we repurchased approximately 500,000 shares representing approximately 4% of Sevilla’s shares outstanding at year end 2025. We have now completed approximately 96% of our current authorization and remain committed to completing it as soon as practicable. As a reminder, upon the completion of this current authorization, we have an additional authorization in place to repurchase up to 10% of the company’s outstanding shares. Also during in April, we amended and extended our credit agreement, increasing the company’s total revolving capacity and extending the maturity of our bank agreement to April 2030. This further enhances civilization’s liquidity and provides additional flexibility as we evaluate capital deployment opportunities going forward. Stepping back Before I turn it over to Colin, I want to reiterate my tremendous confidence in Civio’s future. The bid pipeline in North America is robust with levels of inbound inquiries for beds and services that I haven’t seen since oil sands days of the early 2000s. Like then, this demand is highly dependent on highly project dependent, meaning dependent on positive final investment decisions. However, unlike the 2015-2020 timeframe when North America growth was almost exclusively dependent on on one major LNG project, this time is especially exciting given the variety and volume of different projects. While we recognize growth will not be linear, we are confident in our ability to weather the changes as they arise. Just as we are navigating today’s energy dislocation. I am confident that our values of service quality and excellence coupled with our world class asset base and asset availability position Civio well for the opportunities ahead, what we do best is take care of people. If the industry demand materializes to even a fraction of what’s outstanding today, there’ll be a lot more people for us to take care of. This is an exciting time for Civeo. We are more confident than ever in our actions, positioning and prospects for growth and value creations. With that, I’ll turn it over to Tom.

Colin Gary (Chief Financial Officer and Treasurer)

Thank you Bradley. Thank you all for joining us this morning. Turning to the income statement, today we reported total revenues first quarter of $172.7 million compared to $144 million in the first quarter of 2025, an increase of approximately 20%. Net loss for the quarter was 3.8 million or $0.34 per diluted share compared to a net loss of 9.8 million or $0.72 per diluted share in the prior year period. During the quarter we had generated adjusted EBITDA of 22.5 million compared to 12.7 million in the first quarter of 2025, an increase of 78%. Operating cash flow in the quarter was negative $9.7 million, primarily reflecting expected seasonal working capital outflows in the first quarter. The year over year increase in revenue was primarily driven by higher activity levels in both Australia and Canada including the contribution from the villages we acquired in May 2025 in Australia and higher occupancy across key lodges in Canada. Year over year increase in adjusted EBITDA was primarily driven by higher occupancy and improved margins in Canada as well as increased contributions from the Australian villages acquired in May of 2025. Looking at Australia specifically, first quarter revenues were $123 million up 19% from $103.6 million in the prior year quarter. Adjusted EBITDA was 21.8 million compared to 19 million in the prior year period. The increase in revenues was probably primarily driven by the contribution from the villages acquired in May 2025 as well as continued growth in our integrated services business. These gains were partially offset by modest …

Full story available on Benzinga.com

This post was originally published here

Tokenization holds a lot of promise but its realization is likely still some ways away, according to JPMorgan Chase’s. (NYSE:JPM) global ETF product chief. 

Tokenization will reshape financial markets, “but we’re a couple of years away from some good use cases,” Ciarán Fitzpatrick said in a post on April 24.

Fitzpatrick pointed to JPMorgan’s efforts to tokenize ETFs through its Kinexys blockchain platform, saying the bank is still in proof-of-concept. 

Don’t Miss:

Fitzpatrick’s remarks came after JPMorgan CEO Jamie Dimon said in his annual letter last month that the bank’s continued success hinges on how it can adopt blockchain and AI, adding that it needed to move quickly.

One potential benefit of tokenization is cutting costs both for institutions and users by eliminating operational friction and intermediaries, Fitzpatrick said in his post.

Tokenization has become all the rage on Wall Street over the past year, under a warming regulatory environment under the Trump administration.

The Securities and Exchange Commission in January issued a statement clarifying its position on tokenized securities, saying traditional rules of registration and disclosure still apply. SEC Commissioner Hester Peirce in March encouraged companies considering tokenization to speak with the regulator.

Trending: Investors With $1M+ Often Use Advisors for Tax Strategy — This Tool Matches You With One in Minutes  

“We want to work with you toward being able to experiment to see whether the market wants your products,” Peirce said.

Peirce’s remarks came shortly after the SEC approved a rule change allowing the trading of tokenized shares on Nasdaq.

Against this backdrop, institutions such as BlackRock (NYSE:BLK) and Fidelity continue to dip their toes into the space with tokenized money market funds. 

Read Next: 

Building Wealth Across More Than Just the Market

Building a resilient portfolio means thinking beyond a single asset or market trend. Economic cycles shift, sectors rise and fall, and no one investment performs well in every environment. That’s why many investors look to diversify with platforms that provide access to real estate, fixed-income opportunities, professional financial guidance, precious metals, and even self-directed retirement accounts. By spreading exposure across multiple asset classes, it becomes easier to manage risk, capture steady returns, and create long-term wealth that isn’t tied to the fortunes of just one company or industry.

Rad AI

RAD …

Full story available on Benzinga.com

This post was originally published here

AutoNation, Inc. (NYSE:AN) shares rose Friday after the company reported first-quarter 2026 results, as strong profitability in higher-margin segments helped offset weaker sales.

The auto retailer leaned on financing and after-sales operations to support performance amid softer demand.

Quarterly Details

AutoNation reported first-quarter adjusted earnings of $4.69 per share, beating analysts’ estimates of $4.51. Revenue totaled $6.552 billion, down 2% from a year earlier and below the consensus estimate of $6.651 billion.

Gross profit declined 1% year over year to $1.21 billion, while operating income fell 6% to $314.3 million.

Same-store revenue decreased 4% to $6.40 billion, and same-store gross profit dropped 2% to $1.18 billion.

“We are pleased to report our strong first-quarter results highlighted by record …

Full story available on Benzinga.com

This post was originally published here

Hudbay Minerals (TSX:HBM) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

The full earnings call is available at https://event.choruscall.com/mediaframe/webcast.html?webcastid=hcYqCUqf

Summary

Hudbay Minerals reported record quarterly revenue of $757 million, adjusted EBITDA of $422 million, and adjusted net earnings of $159 million for Q1 2026.

The company highlighted its strong cash position, ending the quarter with over $1 billion in cash, and emphasized its focus on cost control and maintaining low consolidated cash costs.

Hudbay Minerals plans to advance the development of the Copper World project and has received $420 million from Mitsubishi as part of a joint venture, enhancing financial flexibility.

Operational highlights included record mill throughput in Peru and strategic advancements in Manitoba and British Columbia, with all operations on track to meet 2026 production guidance.

The company maintained a positive outlook on copper and gold production growth, expecting a 24% increase in copper output over the next three years and a pathway to 500,000 tonnes of copper production by the mid-2030s.

Management expressed confidence in managing external cost pressures, such as fuel price increases, and indicated that the company is well-positioned to handle potential political changes in Peru.

Hudbay Minerals is advancing its U.S. copper growth pipeline, with significant progress in Copper World and an acquisition of Arizona Sonoran, aiming for long-term growth and increased production.

Full Transcript

OPERATOR

Good morning ladies and gentlemen. Thank you for standing by. Welcome to the Hudbay Minerals Inc. First Quarter 2026 Results Conference Call. At this time all participants are in listen only mode. Following the presentation, we will conduct a question and answer session. To join the question queue, you may press Star then one on your telephone keypad. You’ll hear a tone acknowledging your request. Should you need assistance during the conference call, you may reach an operator by pressing Star then zero. I would like to remind everyone that this conference call is being recorded on May 1, 2026 at 11:00am Eastern Time. I would now like to turn the conference over to Candace Brulee, Senior Vice President, Capital Markets and Corporate Affairs. Please go ahead. Thank you Operator. Good morning and welcome to Hudbay Minerals’ first quarter 2026 results conference call. Hudbay Minerals’ financial results were issued this morning and are available on our website at www.hudbay.com. a corresponding PowerPoint presentation is available in the Investor Events section of our website and we encourage you to refer to it during this call. Our presenter today is Peter Kokilski, Hudbay Minerals’ President and Chief Executive Officer. Accompanying Peter for the Q and A portion of the call will be Eugene Lee, our Chief Financial Officer, and Andre Lauzon, our Chief Operating Officer. Please note that comments made on today’s call may contain forward looking information and this information by its nature is subject to risks and uncertainties and as such actual results may differ materially from the views expressed today. For further information on these risks and uncertainties, please consult the company’s relevant filings on SEDAR+ and EDGAR. These documents are also available on our website. As a reminder, all amounts discussed on today’s call are in US Dollars unless otherwise noted. And now I’ll pass the call over to Peter Kukilski.

Peter Kukilski

Thank you. Candace Good morning everyone and thank you for joining us on today’s call. We’ve had a great start to the year, achieving several key operational, financial and growth milestones. Hudbay delivered another quarter of record revenue, record adjusted EBITDA and record adjusted earnings in the first quarter. This was driven by steady operating performance, our focus on cost control and the continued benefit from margin expansion with our unique mix of copper and gold exposure. Our leading operating cost performance resulted in record low consolidated cash costs in the first quarter which contributed to continued strong free cash flow generation. With the strong performance in the quarter, all our operations are on track to achieve 2026 production and cost guidance. Building on our commitment to prudent balance sheet management we ended the quarter with over $1 billion in cash and cash equivalents benefiting from $420 million received from Mitsubishi for their initial cash contribution on closing of the Copper World Joint venture transaction in January. Our enhanced financial flexibility has positioned us well to continue advancing the development of Copper World, reinvest in high return opportunities at each of our operations and de risk the Cactus project upon completion of the acquisition of Arizona Sonoran to deliver attractive growth and maximize long term risk adjusted returns at each of our operations for stakeholders. Slide 3 provides an overview of our first quarter operational and financial performance. The first quarter demonstrated strong operating performance with higher mill throughput across the three operations compared to the previous quarter, delivering consolidated copper production of 28,000 tonnes and consolidated gold production of 62,000 ounces. We achieved record quarterly revenues of $757 million and record adjusted EBITDA of $422 million in the first quarter. Cash generated from operating activities was $211 million, remaining relatively consistent with the fourth quarter as a result of favorable changes in non cash working capital. First quarter adjusted net earnings was a record of $159 million or $0.40 per share, reflecting higher realized metal prices and strong cost control across the operations resulting in higher gross profit margins. During the first quarter we continued to demonstrate industry leading cost performance, delivering record low consolidated cash costs of negative $1.80 per pound of copper and sustaining cash costs of $0. This incredible cost performance was partially driven by higher gold by product credits reflecting the benefits of Hudbay’s unique commodity diversification. Turning to Slide 4, Hudbay has delivered several quarters of significant free cash flow generation as a result of steady operating performance, expanding margins from strong copper and gold exposure and our cost control efforts. With our enhanced balance sheet and diversified free cash flow generation, we are well positioned to fund our attractive growth pipeline. Our cost control efforts are focused on navigating emerging external cost pressures such as higher fuel prices and short term labor challenges. We have not experienced any disruption to fuel availability and have been able to mitigate the cost pressures through initiatives to further improve throughput and enhance operating efficiencies. We are well insulated from external cost pressures due to our diversified platform with significant byproduct credits from gold production and the polymetallic nature of our ore deposits. While most of our revenues continue to be derived from copper, revenue from gold represents a meaningful portion of total revenues with 39% of gross revenues from gold in the first quarter. After accounting for our sustaining capital investments but before growth investments, we generated $102 million in free cash flow during the quarter, bringing our trailing 12 month free cash flow generation to approximately $400 million. As mentioned earlier, we ended the first quarter with over a billion dollars in cash and cash equivalents and as of March 31st our total liquidity was $1.4 billion. Our net debt at the end of the quarter was nearly zero, bringing our net debt to EBITDA ratio to its lowest point in more than a decade. Consistent with our prudent balance sheet management and focus on cost of capital following the quarter, we repaid our outstanding 2026 Senior Unsecured Notes on maturity on April 1st. We used a combination of cash on hand and a $272 million draw on our low cost revolving credit facilities. After giving effect to this repayment, Hudbay’s total liquidity decreased by $473 million to $957 million. This continues to provide us with significant financial flexibility as we advance Copper World towards a sanctioning decision later this year. Turning to Slide 5, the Peru operations continued to demonstrate steady operating performance with production and costs in line with expectations. The operations produced 21,000 tonnes of copper, 9,000 ounces of gold, 530,000 ounces of silver and 380 tonnes of molybdenum during the first quarter. Production of copper and gold were lowered in the fourth quarter due to the depletion of the higher grade pampacuntu ore in late 2025. Mill throughput levels averaged approximately 90,700 tons per day in the first quarter of 2026, achieving a new quarterly record. The team’s efforts to increase mill throughput align with the Peru Ministry of Energy and Mines regulatory change to allow mining companies to operate up to 10% above permitted levels. On March 6, Hudbay received a permit approval to increase annual mill throughput capacity to 31.1 million tons from 29.9 million tonnes, setting a new base for the 10% permitted allowance. We continue to advance the installation of pebble crushers later this year to further increase mill throughput rates in the second half of 2026 and we are on track to achieve 2026 production guidance for all metals in Peru. First quarter cash costs in Peru were $0.70 per pound of copper, a 23% increase compared to the fourth quarter due to lower byproduct credits offset by lower profit sharing, lower power costs and lower treatment and refining charges. Cash costs in the quarter outperformed the low end of the annual guidance range as a result of strong operating cost performance and temporarily higher gold by product sales from Pampacancha. Despite emerging external cost pressures, we are well positioned to achieve the full year cost guidance range in Peru during the quarter. Constancia was recognized as the safest open pit operation in Peru during the National Mining Safety Contest for our performance in 2025. This reflects our company’s unwavering commitment to safety and validates Constancia’s compliance with the highest operational safety and regulatory standards. Moving to our Manitoba Operations on slide 6, the first course demonstrated strong operational agility in mitigating lower equipment utilization and labor availability at the Lalor mine while continuing to prioritize gold ore feed for the new Britannia mill. This strategy successfully maintained strong gold production in the first quarter supported by higher mill recoveries compared to the fourth quarter of 2025. Our Manitoba operations produced 48,000 ounces of gold, 2,500 tons of copper, 5,000 tonnes of zinc and 213,000 ounces of silver in the quarter. Production of gold was higher than in the fourth quarter due to higher gold recoveries and higher mill throughput while all other metals were lower, primarily due to lower grades. Production in the second half of 2026 is expected to be higher than the first half of 2026 due to grade sequencing and and higher ore output from Lalor. With solid operating Results in the first quarter, we are on track to achieve 2026 production guidance for all metals in Manitoba. The Lalor mine hoisted an average of 3,900 tons of ore per day in the first quarter, strategically prioritizing gold zones to secure optimal feed for the new Britannia mill. Total ore mined was lowered in the prior quarter because of lower effective utilization of equipment to due to reduced workforce availability. This was offset by successfully onboarding nearly 80 new employees as recruitment and upskilling of employees are underway to increase proficiency of frontline employees. The new Britannia mill averaged approximately 2,000 tons per day in the first quarter and benefited from continuous improvement initiatives to unlock future throughput capacity. Gold recoveries of 90% at the new Britannia mill reflects ongoing optimization efforts. Similarly, the Stall mill achieved improved gold recoveries of 73% in the first quarter, reflecting process optimisation and enhanced gold recovery initiatives. The 1901 deposit delivered 11,000 tonnes of development ore in the first quarter. The team continues to advance haulage and exploration drifts to further delineate the ore body and support ongoing infrastructure projects. Looking ahead, we plan to prioritize exploration definition, drilling ore body access and establish critical infrastructure at 1901 in preparation for full production in 2027 Manitoba gold cash costs in the first quarter were $408 per ounce, outperforming the low end of the guidance range. We are well positioned to achieve our 2026 cash cost guidance range in British Columbia. We continue to focus on advancing our multi year optimization plans, achieving significant milestones in both mining productivity and project permitting in the first quarter, and remain on track to deliver the benefits of the stripping program and unlock higher grade ore later this year. As shown on slide 7, Copper Mountain produced 4.8 thousand tons of copper, 5.2 thousand ounces of gold and 43,000 ounces of silver in the first quarter. In line with our guidance and planned mine sequencing. Production was supported by a higher mill throughput offset by lower grades compared to the fourth quarter. We remain on track to achieve our 2026 production guidance expectations for all metals in British Columbia, with higher production expected in the second half of the year as mill improvements take effect. Mining activities reached a record total material movement of over 25 million tonnes in the first quarter, driven by an optimized mining sequence in the main pit and increased contributions from the north pit. This ramp up was supported by the successful commissioning of a new production loader in January to further bolster the equipment fleet and add to this momentum, a new shovel has been recently commissioned. Drilling throughput benefited from the completion of the second SAG mill and the mill optimization initiatives implemented in late 2020 resulting in increased mill throughput in the first quarter of 2026. The second SAG mill achieved increased throughput in the quarter and averaged 10,000 tonnes per day in March. The primary sag mill continues to operate under a reduced load and is being rigorously monitored prior to the head replacement scheduled for late June and into July. The mill remains on track to achieve its permitted capacity of 50,000 tonnes per day in the second half of 2026. British Columbia cash costs were lower than the prior quarter, delivering cash costs of $2.41 per pound of copper as a result of higher gold byproduct credits and resolving the unplanned maintenance downtime issues experienced in the prior quarter. First quarter cash costs were within the guidance range and despite emerging external cost pressures, we remain on Track to achieve 2026 cash cost guidance in British Columbia during the quarter. The new Ingabel project reached a major milestone in February with the receipt of the Mines act and the Environmental Management act amended permits from provincial regulators. The new Ingabel project supports continued copper production, increased gold production and further mine life extensions. The project is designed to access higher grade mineralization while improving operational efficiency with a stripping ratio approximately three times lower than current mining areas. With these permit approvals, we are advancing critical infrastructure required for the expansion. This includes the construction of an access road, a bridge across the Similkameen river and the development of an East Hall Road link to New Ingabel with existing operations. A large drill program was initiated during the first quarter at Newingerbell to improve resource definition and expansion. We are pleased to receive the news this week that the B.C. government has added the New Ingabel project to the province’s list of priority resource projects. This list highlights the acceleration of major projects that strengthens economic growth, support resource development and create jobs and long term value. Turning to Slide 8, we announced our annual mineral reserve and resource update along with an improved three year production outlook. During the quarter we extended Snow Lake’s mine life by four years to 2041, maintained Constancia’s mine life to 2040 and extended Copper Mountain’s mine life by two years to 2045. Consolidated copper production is expected to average 147,000 tonnes per year over the next three years, representing a 24% increase from 2025. This growth is driven by higher expected copper production in British Columbia from the mill throughput ramp up in 2H20, higher grades in British Columbia in 2027, from …

Full story available on Benzinga.com

This post was originally published here

TORONTO, May 1, 2026 /CNW/ – 1832 Asset Management L.P. today announced fund changes, which are designed to enhance flexibility, improve consistency, and help support long-term investor outcomes.

Portfolio management enhancements

Effective today, the Multi-Asset Management team at 1832 Asset Management L.P. will assume from State Street Global Advisors Ltd.  direct portfolio management responsibility for the following aspects of Tangerine Balanced Income Portfolio, Tangerine Balanced Portfolio, Tangerine Balanced Growth Portfolio, Tangerine Equity Growth Portfolio, and Tangerine Dividend Portfolio (collectively, the “Tangerine Core Portfolios”):

  • asset allocation across all Tangerine Core Portfolios
  • management of the Canadian bond component for each of Tangerine Balanced Income Portfolio, Tangerine Balanced Portfolio and Tangerine Balanced Growth Portfolio
  • management of a portion of the equity investments for each …

Full story available on Benzinga.com

This post was originally published here

Park Hotels & Resorts (NYSE:PK) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://viavid.webcasts.com/starthere.jsp?ei=1752378&tp_key=1b20bde68a

Summary

Park Hotels & Resorts announced a $96 million renovation project for the Ali’ I Tower at Hilton Hawaiian Village, which will impact 2026 financials slightly.

The company has strengthened its balance sheet with $2 billion liquidity and significant progress on refinancing 2026 maturities, including a new $700 million loan.

RevPAR growth guidance for 2026 increased by 50 basis points to a range of 0.5% to 2.5%, with adjusted EBITDA guidance raised by $7 million.

Royal Palm is set to reopen in June, with expectations for substantial operational improvements and potential benefits from the World Cup.

Management is actively working to dispose of 12 non-core assets and expressed confidence in progress by year-end.

Hawaii market is expected to perform well, with potential benefits from global travel shifts and investment in property upgrades.

Group demand is strong, particularly for June, with significant growth in key markets like New York, Orlando, and Hawaii.

Operational focus includes managing labor costs, insurance reductions, and real estate tax appeals to optimize expenses.

Full Transcript

OPERATOR

Palm and the launch of the Ali’ I Tower renovation at Hilton Hawaiian Village. This project will encompass all 351 guest rooms, the tower lobby, its private pool and the addition of three new keys. Total investment for the project is expected to be approximately $96 million. We expect renovation related disruption at Hilton Hawaiian Village to have a modest impact in 2026 with the towers closure expected to have less than a $2 million impact on 2026 Hotel Adjusted EBITDA and representing just a 10 basis point impact to portfolio RevPAR. Once complete, nearly 80% of the resort’s rooms will be newly renovated, significantly enhancing the iconic hotel’s long term competitive positioning. Turning to the balance sheet, our liquidity at the end of the first quarter was approximately $2 billion including $156 million of cash plus $1.8 billion of available capacity under our $1 billion revolving credit facility and $800 million delayed draw term loan. With respect to our 2026 maturities, we have made significant progress over the past two months to raise a $700 million floating rate delayed draw mortgage on Bonnet Creek which is expected to close this week. The loan, which was upsized $50 million based on the complex strong results, will bear interest at SOFR 225 basis points. When combined with the $800 million delayed draw term loan, this $1.5 billion of new debt capital commitments provide us with certainty while also allowing for the flexibility to fund within par prepayment windows and closer to the maturities. Accordingly, we expect to execute a partial draw under the delayed draw term loan and in June to fully repay the $121 million Hyatt Regency Boston mortgage which matures in July. We then expect to draw the remaining capacity in September along with fully drawing proceeds from the Bonnet Creek mortgage financing, to fully repay the $1.275 billion CMBS loan on the Hilton Wine Village which matures in early November with additional proceeds to be used for corporate purposes. We are grateful for the continued support of our bank group whose confidence in Park’s credit profile and strength of our portfolio has been instrumental in executing these transactions. Their commitment is a clear validation of our balance sheet strategy and underscores our ability to address all 2026 debt maturities in a comprehensive and highly effective manner. Upon completion of these transactions, we will have meaningfully enhanced our financial flexibility unencumbering the Hilton Hawaiian Village, extending our weighted average debt maturity to nearly four years and eliminating any significant maturities for approximately two years on an annualized basis. These refinancings are expected to increase interest expense by approximately $28 million, with roughly $13 million reflected in our 2026 AFFO guidance,. Based on the timing of these transactions with respect to our dividend, on April 15th, we paid our first quarter cash dividend of $0.25 per share. On April 24th, our board of directors approved a second quarter cash dividend of $.25 per share to be paid on July 15th to stockholders of record as of June 30th. The dividend currently translates to an annualized yield of approximately 9% based on recent trading levels. Turning to Guidance While we remain mindful of the geopolitical uncertainties and the potential impact of higher oil prices on both business and leisure travel, we were very encouraged by the strength observed in Q1. With solid demand trends continuing into the second quarter April, RevPAR is expected to be flat but up 3% excluding Miami, with performance led by continued strength in Hawaii, Bonnet Creek and Key west, as well as solid Spring Break leisure transient demand in Santa Barbara. And while we expect performance to modestly soften in May, June looks very strong, driven by strong group demand up nearly 10% and favorable year over year comparisons across several key markets including Hawaii, Orlando, Key west and New York. Overall, we expect Q2 RevPAR to come in around the midpoint of our guidance range with roughly a 100 basis point drag from Miami for the year. With Q1’s outperformance, we are increasing our RevPAR growth guidance by 50 basis points at the midpoint to a new range of 0.5% to 2.5% and Adjusted EBITDA guidance by $7 million at the midpoint to a new range of $587 million to $617 million. While AFFO increases by a penny at the midpoint to a new range of $1.74 to $1.90 per share. It is also worth noting that the recently sold Hilton Seattle Airport Hotel was expected to contribute approximately $3 million in EBITDA for the remainder of the year. This concludes our prepared remarks. We will now open the line for Q&A. To address each of your questions, we ask that you limit yourself to one question and one follow up. Operator, May we have the first question, please? We’ll now be conducting a question and answer session. If you’d like to ask a question, please press Star one on your telephone keypad. The confirmation tone will indicate your line is in the question queue. For participants using speaker equipment, it may be necessary to pick up the handset before pressing the star keys. One moment please, while we poll for questions. Thank you. Our first question is from Flores Van Dykem with Ladenburg Thalman.

Flores Van Dykem (Equity Analyst)

Hey, Dr. Flores. Thanks. Morning, Tom. Glad to be on these calls again with you guys. If you can give us a little bit more of an update on the disposition. One of the key things I think the market is having some trouble understanding is the quality of the portfolio that’s being shielded by the lower 10% of your assets. If you can talk a little bit about where I know that you have pretty much all of those presumably in the market, what’s the status on that? Are you having some detailed discussions? What’s the pushback that you’re getting from the market and are you going to hold out for the last dollar on those assets?

Tom Baltimore

Well, Flores, it’s great to have you back and appreciate the question. If I could sort of frame it for a second. Keep in mind, if you think about the remaining 12 assets that we have, we currently have 33 assets in the portfolio. We have sold or disposed of 52 assets. As I said in the prepared remarks for over $3 billion, we have 12 assets that we’re defining as sort of non core. Three of those assets obviously rest with the dispute with Safehold, which will resolve itself, if not this year, certainly next year. The EBITDA from those assets is about $16 million plus or minus the remaining nine assets account for about $41 million in EBITDA and candidly, probably 45% of that relates to one asset in Florida. So, you know, we’re generally dealing with eight assets that are small. Some have short term ground leases, some are joint venture, some have various challenges. And I would say obviously the last mile is often the most difficult. I would hope the market would give us credit for the perseverance, the discipline, our ability to reshape, the portfolio over the last nine years. We are very confident we’re going to make substantial progress this year on those non core assets. And our collective team are working their tails off. We have work streams underway on all of them and it’s going to be a little lumpy and choppy. I think you’ll see more reported as the year unfolds. And believe me, no shortage of effort and focus. We realize it’s while a small overhang. It’s an overhang. It clearly is less if you look at the 41 million, certainly less than 5, 6% of overall EBITDA. But it is a drain when you think about operating metrics. And so we’re working hard to get the assets sold as quickly as we can. We’re not holding out for, the last dollar, but we certainly want to have counter parties who can execute and who can move through the process. And we certainly are always focused on creating value for shareholders.

Flores Van Dykem (Equity Analyst)

Thanks. Maybe a follow up question on the World Cup. I know that your Royal Palm asset I think is opening up in June. Is that. And that is a market potentially that could get impacted by the demand for the World Cup. If you can talk broadly about what the impact is going to be or are you seeing so far, I think it’s everybody’s sort of muted on the World cup impact, but if you can give us a little bit more color on that, that would be great.

Tom Baltimore

Yeah, it’s a lot to unpack there, Flores, but I’m happy to take it. I think most importantly, if we step back and think about the Royal Royal Palm at 15th and Collins 393 Keys, we’re expanding to 404, putting in approximately $112 million. We could not be more excited. We could not be prouder. We had obviously a group there. We can’t wait to get more analysts and more investors in. I couldn’t be more grateful to Carl Mayfield, who heads our design and construction team, who is literally spending three or four days of his week in Miami leading. And we also have the operator, lead operator from Davidson who’s been on site since we launched construction in last May. As of this morning, we had 417 men and women on site. And that includes from owners reps to general contractor to subs to owners teams to operations folks. And we are currently targeting that construction will be substantially complete by early June. And what we would call the stocking and training TCO would begin and target sort of in mid May. You’ve got a few weeks of testing all the fire alarm and life safety issues that have got to work through. And we’re probably looking at a target public occupancy TCO and hoping for sort of mid June. So when you think about where that all unfolds as it relates to the World Cup, we have included in our guidance that Shawn outlined in his prepared remarks. We have no contribution coming from Miami in that process at this time. So if we are able to get open, I think the two prominent games in Miami will be July 11 and July 18. We are cautiously optimistic that we should be open in time for those. And that’s what we’re all working our tails off to make sure that that occurs again. We don’t have anything in the current guidance. So we’ve been quite conservative in that intentionally, just given all of the geopolitical, but also the complexity of the inspection and regulatory process as we close out the job. But you may recall other projects and the months and in some cases years, I think that this, again speaks to the core competency, the leadership that we have at park, our experience, the extraordinary success that we’re having obviously at Bonnet Creek, and also what we’re seeing also in Key West. And we feel the same way about Royal Palm as we look out. So we’re very, very bullish and excited about this project and think we’re going to have a tremendous success there over time. Thanks to. Thank you.

OPERATOR

Our next question is from Smedes Rose with Citi.

Smedes Rose (Equity Analyst)

Hi. Thank you. I just wanted to ask you. Hi. I wanted to ask you, in your guidance, it looks like the expense expectations moved up around 40 basis points versus your prior guidance. And I was just kind of wondering what was behind that.

Shawn

Yes, Mead. Shawn, we obviously in Q1, we had some outperformance top line. A lot of that was occupancy based. So we certainly naturally see while cost per room solid in terms of, you know, basically 50 basis points or so growth, you know, with the extra occupancy expense growth was a little more than expected as well. So we’re kind of carrying that through much like we’re doing with the top line into the expense. Certainly expected …

Full story available on Benzinga.com

This post was originally published here

On Friday, Portland Gen Electric (NYSE:POR) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

Access the full call at https://edge.media-server.com/mmc/p/f22aee7q/

Summary

Portland Gen Electric reported Q1 GAAP net income of $45 million or $0.38 per diluted share, with non-GAAP net income of $68 million or $0.58 per share.

The company experienced a 10% year-over-year growth in industrial customer demand, despite mild winter weather affecting residential and small commercial usage.

Portland Gen Electric reiterated its full-year earnings guidance of $3.33 to $3.53 per diluted share and long-term earnings and dividend growth guidance of 5% to 7%.

The company is progressing on strategic priorities, including regulatory filings for the Washington acquisition and clean energy resource procurement, targeting a mid-2027 close for the Washington transaction.

Management discussed advancements in cost management initiatives to mitigate weather impacts and affirmed commitment to maintaining operational excellence.

Portland Gen Electric anticipates a regulatory approval process for the Washington acquisition to take about a year, with discussions on potential customer benefits ongoing.

The company is focusing on capital investments to support customer growth, clean energy, and long-term reliability, with plans to manage volatility in energy usage and power costs through engagement with regulators.

Full Transcript

OPERATOR

Good morning everyone and welcome to today’s conference call with Portland General Electric. Today is Friday, May 1, 2026. This call has been recorded and all lines have been placed on mute to prevent background noise. After the speaker’s remarks, there will be a question and answer period. If you would like to ask a question during this period, press star then the number is 11 on your telephone keypad. To withdraw your question, please press star 11. Again. If you do intend to ask the question, please avoid the use of speakerphones for opening remarks. I will turn the conference over to Portland Gen Electric Senior Manager of Investor Relations, Ern Swartz. You may begin.

Ern Swartz (Senior Manager of Investor Relations)

Thank you, Tawanda, good morning everyone and thank you for joining us today. Before we begin, I would like to remind you that we issued a press release this morning and have prepared a presentation to supplement our discussion, which we will be referencing throughout the call. The press release and slides are available on our website at investors.portlandgeneral.com referring to slide 2 some of our remarks this morning will constitute forward looking statements. We caution you that such statements involve inherent risks and uncertainties and actual results may differ materially from our expectations. For a description of some of the factors that could cause actual results to differ materially, please refer to our press release and our most recent periodic reports on Forms 10-K and 10-Q, which are available on our website. Turning to Slide 3 leading our discussion today are Maria Pope, President and CEO, and Joe Terpik, Senior Vice President of Finance and CFO. Following their prepared remarks, we will open the line for your questions. Now I will turn things over to Maria.

Maria Pope (President and CEO)

Good morning. Thank you, Erin. Thank you all for joining us today. The first quarter delivered another stretch of warm winter weather, 10% year over year, industrial customer demand growth and continued maturity of our cost management initiatives. Beginning with slide 4, I will speak to our financial results and key drivers. For the first quarter we reported GAAP net income of 45 million or 38 cents per diluted share and non GAAP net income of 68 million or 58 cents per share. Our non GAAP results exclude the previously disclosed deferral adjustments related to the January 2024 storm restoration and reliability contingency event and business transformation, optimization and acquisition expenses. Our results reflect extremely mild weather, particularly in February and March, and lower seasonal usage from residential and small commercial customers, which Joe will cover in more detail. We will be engaging with our regulator to explore frameworks to help mitigate weather and other volatility impacting both revenue and power costs. Greater predictability is good for both customers and shareholders and we recognize that this will be multi year work. Despite weather and usage impacts, our team delivered a quarter of strong operational execution including overcoming inflationary pressure and advancing our cost management program, adapting to power market conditions, positioning our portfolio and generations fleet to deliver optimal value and executing on our robust capital investment plan to support customer growth, clean energy and long term reliability. On recent calls you have heard us highlight the company wide work to optimize our cost structure. We are using our operational strength, which we’ve built over multiple years to mitigate the impact of recent weather challenges by accelerating our cost management work. Our teams are squarely undertaking the challenge and we are committed to delivering strong results. As such, we are reiterating our full year Earnings guidance of $3.33 to $3.53 per diluted share and our long term earnings and dividend growth guidance of 5 to 7%. Turning to Slide 5 for updates on our five key strategic priorities. First, our teams made progress on the Washington acquisition and other key regulatory filings. In late March and early April, we filed applications with the Washington Utilities and Transportation Commission and the Oregon Public Utility Commission for approval of the Washington transaction. We anticipate the regulatory approval process to take about a year and continue to target a mid-2027 close. PGE’s holding company proposal continues to advance. The docket’s procedural schedule has been modestly extended to prioritize timely resolution of the holding company. We have paused the transmission company. That said, formation of a transmission company remains part of our long term strategy. We appreciate the ongoing collaboration and expect to engage with parties in the near future. Having just received reply testimony late yesterday, many issues have been resolved with a few key items remaining. The process is on course with a target final order date probably in August. Second, building upon our 2025 O&M cost management work, we continued driving efficiencies and improving productivity. We are accelerating this work, even the very warm winter weather and first quarter results. Importantly, our large load tariff proposal UM 2377 is in the final stages of review with the OPUC and we expect an order in the next several weeks. A transparent, predictable tariff for new and existing data centers strengthens protections for existing customers while supporting economic development in our region. Our proposed rate structure under consideration, enabled by Oregon’s recent legislation includes a a 26% increase in data center prices which will help reduce the cost born by residential and small business customers. Third, as I noted, industrial demand growth is accelerating in our service area. We foresee robust energy usage from data centers and high tech customers with large customer capacity growing by about 10% compounded annually through 2030. This growth forecast is driven by existing customers and contracts already executed with new customers customers companies that own property and have civil work underway. Compared to Q1 last year, our data center customer load growth grew by 10%. Fourth, progress towards additional clean energy resource procurement we filed our 2025 RFP final shortlist with the OPUC in February as we aim to procure approximately 2,500 megawatts. The shortlist is composed of a diverse mix of projects and technologies to support our existing portfolio and growing customer demand. We look forward to working collaboratively with stakeholders to achieve commission acknowledgment in the coming months and fifth, our year round risk based wildfire mitigation work remains on track as we prepare for the summer months. In parallel, regulators and policymakers are engaged in this critical topic. The opuc, in coordination with the Oregon Department of Energy, has hired experts on wildfire liability policy options that balance customer needs for essential services, support for wildfire victims and financial help of utilities. We expect the study’s findings will help inform policymakers in advance of the 2027 legislative session. In December, we filed our 2026 through 2028 wildfire mitigation plan which represents a significant evolution moving from an annual update to a forward looking three year strategic framework. As we progress through 2026, our focus continues to be on executing on our core priorities solid operational performance, meeting growing energy demands, expanding into Washington State and advancing customer driven clean energy investments. With the first quarter behind us, opportunities are significant. We are focused on achieving solid financial results and delivering value for customers, communities and shareholders.

Joe Terpik (Senior Vice President of Finance and CFO)

With that, I’ll turn it over to Joe. Thank you Maria and good morning everyone. Turning to slide 6, our Q1 results reflect strong energy demand from our industrial customers and ongoing System Investments. Total Q1 2026 loads were flat as compared to Q1 2025 and changes in demand between our customer classes were largely offsetting. Industrial demand increased 10% on a nominal and weather adjusted basis. The industrial customer class is expected to continue growing at a strong pace, highlighting the strength of our large customer pipeline and the attractiveness of our service area to data centers and high tech customers. Commercial load decreased 2.9% or 2.3% weather- adjusted and residential load decreased 6.2% or 4.6% weather-adjusted. PGE has seen seasonal shifts in residential and small commercial average uses in recent years with rooftop solar adoption and energy efficiency growth. While not considered in our 2026 plan, deviations of this magnitude are not unprecedented and we are adapting to manage through this. Historically, demand has been winter peaking, but our region has been transitioning to a dual peaking profile with customers increasing their cooling demand as air conditioning becomes more widespread in our region. After considering the recent trends in customer usage, we now anticipate weather adjusted load growth upgrade 1.5% to 2.5% this year. In the last 12 months, our organization has evolved tremendously in the ability to adapt through cost management. We have a well defined plan in place for the balance of the year to solve for the load impacts experienced this quarter which I will discuss shortly. Now I will cover our quarter over quarter earnings drivers. We experienced a 7-cent increase in retail revenues, including a 9 cent increase from additional cost recovery largely from the inclusion of our seaside battery asset in customer rates beginning in November 2025. A 9-cent increase driven by higher industrial demand offset by 11 cents due to lower residential demand A decrease from power cost of $0.15 driven by $0.09 from power cost performance in 2025 that reverses for this comparison and $0.06 from current year power cost performance driven by less favorable wholesale and environmental credit market conditions. A 16-cent decrease from other capital and financing costs in support of our ongoing rate base investments made up of $0.10 of higher depreciation and amortization, $0.05 of dilution and $0.01 of additional interest cost a $0.09 decrease from other items, primarily the timing of tax credits and O and M costs $0.10 from deferral reductions related to the January 2024 storm and reliability contingency event reflecting the outcome of the final OPUC order received In March, a 10 cent decrease from business transformation optimization expenses and acquisition costs. This brings us to our GAAP EPS of $0.38 per diluted share. After adjusting for the 2024 regulatory disallowance and our business transformation expense, we reach our Q1 2026 non GAAP EPS of $0.58 per diluted share. On to Slide 7 for our 5 year capital forecast which includes 2026 and 2027 spend for the incoming 2023 RFP projects. I will note this view does not contemplate CAPEX from the ongoing 2025 RFP or the Washington Utility business. Given our ongoing investment in critical systems and assets, serving our customers and other policy priorities, we remain engaged with stakeholders as we consider our next regulatory steps. We will keep you informed as this progresses in line with our usual practice. Onto slide 8 for liquidity and Financing Summary Total liquidity at the end of the quarter was 954 million. Our investment grade credit ratings remain unchanged. We will continue to maintain strong cash flow metrics with an estimated 2026 CFO to debt metric above 19% in the first quarter, we executed a $550 million equity forward to address our 2026 base equity needs and fund the 2023 RFP project this quarter. We also entered into two unsecured credit agreements, a $350 million term loan facility maturing in March 2028 to fund capital expenditures including those related to our 2023 RFP and general corporate needs, and a 680 million delayed draw term loan intended to finance the Washington acquisition related cost. The loan is available until specific milestones tied to the acquisition are achieved and matures 364 days after funding. Lastly, in April, the Board of Directors declared a quarterly common stock dividend of 55.125 …

Full story available on Benzinga.com

This post was originally published here

Forum Energy Technologies (NYSE:FET) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

View the webcast at https://edge.media-server.com/mmc/p/wdz4bmk5/

Summary

Forum Energy Technologies reported a strong first quarter with an 8% increase in revenue, 14% rise in EBITDA, and a 300% boost in net income year-over-year, driven by their ‘beat the market’ strategy.

The company achieved a book-to-bill ratio of 106% and increased its backlog by 44% compared to the previous year, reaching the highest level in 11 years.

Future guidance is optimistic with a forecasted second-quarter EBITDA of $24 to $30 million, and the company has raised its full-year EBITDA guidance midpoint to $103 million, anticipating market share gains and backlog conversion.

Operational highlights included the commercialization of innovative products like Duracoil 95, Unity ROV operating system, and Duralide manifold system, along with advancements in rig floor automation with the FR120 iron roughneck.

Management emphasized the strategic execution of cost savings, achieving $15 million in annualized savings, and continued share repurchase activities, indicating a strong balance sheet with extended credit facilities.

Full Transcript

OPERATOR

Good morning ladies and gentlemen and welcome to the Forum Energy Technologies first quarter 2026 earnings conference call. My name is Daniel and I will be your coordinator. For today’s call, there is a process for entering the question and answer queue. To ask a question during the session, you will need to press star 11 on your telephone. You will then hear an automated message advising. Your hand is raised to withdraw your question. Please press star 11 again. At this time, all participants are in a listen only mode and all lines have been placed on mute to prevent any background noise. This conference call is being recorded for replay purposes and will be available on the company’s website. I will now turn the conference over to Rob Kukla, Director of Investor Relations. Please proceed, sir.

Rob Kukla (Director of Investor Relations)

Thank you, Daniel. Good morning everyone and welcome to Forum Energy Technologies’ first quarter 2026 earnings conference call. With me today are Neil Lux, our President and Chief Executive Officer and Lyle Williams, our Chief Financial Officer. Yesterday we issued our earnings release which is available on our website. Today we are relying on federal safe harbor protections for forward looking statements. Listeners are cautioned that our remarks today will contain information other than historical information. These remarks should be considered in the context of all factors that affect our business, including Those disclosed in Forum Energy Technologies’ Form 10-K and other SEC filings. Finally, management’s statements may include non-GAAP financial measures. For reconciliation of these measures, please refer to our earnings release and website. During today’s call, all statements related to EBITDA refer to adjusted EBITDA and unless otherwise noted, all comparisons are first quarter 2026 to fourth quarter 2025. I will now turn the call over to Neil.

Neil Lux (President and Chief Executive Officer)

Thank you Rob and good morning everyone. Our first quarter results reinforced our confidence in the path we presented with FET 2030. Year over year we increased revenue 8%, EBITDA 14% and net income 300%. The execution of our Beat the Market strategy drove these results impressively. We grew revenue per global rig 12% from a year ago and positioned our company for future gains with strong bookings. Orders were up 10% year over year with a book to bill of 106%. We entered the year with our highest backlog in 11 years and we grew that backlog again. Compared to the first quarter of last year, our backlog is up 44%. Also, following the completion of our structural cost saving initiatives, we are now a more efficient organization. These efforts have achieved 15 million of annualized savings. In addition, we continued our share repurchase program and strengthened the balance sheet by extending our credit facilities maturity to 2031. Overall, this was the kind of start we wanted to see providing momentum into the second quarter and beyond. Looking ahead, our results should increase substantially driven by market share gains, backlog conversion and cost savings. We are forecasting second quarter EBITDA between 24 and 30 million, which at the midpoint is up 32% from a year ago. These results would deliver incremental margins of 51% with EBITDA margin approaching 13%. This sequential improvement is driven solely by the execution of our plan. Turning to the full year, we are raising the midpoint of our EBITDA guidance to 103 million, up 20% compared with 2025. Importantly, while we are seeing signs of increased activity which is consistent with some analysts expectations, our forecast conservatively assumes a flat market. Should the market pick up, I would expect to see further upside to our forecast. During the first quarter we continued gaining market share through innovation and new customer adoption. This is a key part of our strategy. So let me provide an update on a few products we have recently commercialized. First, Duracoil 95 coil tubing for sour service environments is continuing to gain traction and is now active on three continents. This is an ideal product for Venezuela and the Middle East, especially if workover activity accelerates to bring production back online. Another innovation I want to mention is Unity, our next generation operating system for remote ROV operations. We recently had the opportunity to showcase this technology at a large international trade show. In a real time demonstration, our customers were able to control an ROV positioned hundreds of miles away from a terminal in our booth. It was a powerful demonstration of Unity’s capabilities and and has ignited interest in our product. The next product I want to highlight is Duraline, our manifold system for multi well frac applications. Compared to our competition, Duraline is significantly safer and more efficient. Also, it is a great example of technology developed for US Shale applications that can be exported to international locations. In the first quarter we received a significant order for multiple systems to be deployed in Argentina this year. Another innovative area for FET is rig floor automation. We have developed patent pending software for the FR120 iron roughneck that automates the drill pipe makeup and breakout process with the push of a button. Our solution dramatically simplifies rig floor operations, reduces non productive time and increases drilling efficiency by 30%. This software will be packaged with new iron roughnecks and sold as an upgrade to existing ones. I am very excited about this development. Shifting to the power generation and data center markets, we have seen increased interest in the cooling solutions offered by our global heat transfer product family. Based on customer feedback, we have developed a stationary power cooling solution. This new design gives us an opportunity to address a bigger part of the market and since its introduction we have developed a strong commercial funnel. These innovations are great examples of how our product pipeline is supporting both near term share gains and the long term ambitions of FET 2030 Shifting to the Middle East Conflict and its Impact first and foremost, I am thankful all our employees in the region are safe. That is our primary concern. Also, operationally we have not suffered any facility damage. We have experienced some disruptions that are having a slight impact on our business, particularly around logistics and freight costs. However, our teams did an excellent job finding creative solutions to these challenges and we were able to increase revenue in the Middle East during the quarter. While uncertainty remains high, we are not forecasting any material negative impact from the conflict. For context, Middle East revenue is only 10% of our total, limiting the company’s exposure. At the same time, this conflict is creating medium to longer term tailwinds for our industry. A significant portion of the world’s oil and gas supply has been disrupted for 62 days and counting. Even if oil shipments through the Strait of Hormuz resume quickly, global oil inventories will be meaningfully reduced. Barring a material downturn in global demand, we expect investment in oil and gas production to increase over time to replace depleted inventories and support energy security. Some analysts have suggested that our industry will experience a prolonged upcycle beginning later this year or early 2027. This up cycle aligns with the growth market scenario of our Forum Energy Technologies 2030 vision. Under this scenario, our addressable markets grow at a rate of 9% annually and we expand our market share to 22% by 2030. The combination of market expansion and share gains doubles revenue to 1.6 billion, quadruples EBITDA and nearly triples free cash flow in that time frame. This scenario underscores our strategy’s long term value creation potential while our near term focus remains on disciplined execution and cash flow generation. Now, to provide more detail on our first quarter results and near term financial outlook, I will turn the call over to Lyle.

Lyle Williams (Chief Financial Officer)

Thank you Neil. Good morning. I will begin with first quarter results and our guidance, then shift to a discussion of cash flow and our capital allocation strategy. First quarter revenue of 209 million came in near the top end of our guidance. Growth in offshore and international markets led the revenue increase of 3%, outpacing global rig count. Our international revenue was up 7% with Canada, Europe and Latin America, each delivering double digit gains. This is the third consecutive quarter when international exceeded US revenue and offshore revenue expanded 10% driven by a 20% increase in our subsea product line as the team begins to execute orders secured last year. Adjusted EBITDA for the quarter was 23 million in line with our guidance as cost savings benefits were largely offset by product mix. Adjusted net income of 6 million increased 11% on favorable income tax expense rate that benefited from geographic income mix. We grew backlog again in the first quarter even after very strong bookings in 2025, both segments posted a book to bill ratio greater than 100%. We saw higher demand for capital equipment in the stimulation and intervention and the drilling product lines and increased demand for wireline cables. Valve orders increased nicely bouncing back from tariff related impacts throughout 2025. Let me continue with additional color on our segment results. Drilling and completions revenue was 127 million flat with the previous quarter. The subsea product line increased 20% as we recognized revenue on ROVs and the rescue submarine project. The stimulation and intervention product line increased 7% supported by power end and wireline cable demand. And to note, our Quality Wireline product family set a new record this quarter in revenue and in Greeceless cable sales. Coil tubing revenue was down 17% coming off strong US sales last quarter and due to customer requested delivery pushouts into the second quarter. Despite flat revenue segment EBITDA was up 6%, benefiting from cost savings and improved plant utilization related to our facility consolidations. Artificial lift and downhole revenue was 82 million, up 9% with increased sales volumes across all three product lines. EBITDA was roughly flat reflecting a combination of product mix, timing of incentive expense and lower absorption at one facility which we expect to improve in the coming quarters. Consolidated free cash flow was $1 million, consistent with our guidance. As a reminder, our free cash flow is typically back half weighted. For example, roughly 2/3 of our free cash flow was generated in the second half of 2025. Despite the seasonally lower free cash flow, we still remained active on share buybacks. We repurchased almost 93,000 shares for approximately $5 million under our share repurchase authorization. These purchases averaged $49 per share, about 20% lower than our stock price at yesterday’s close. In addition, we paid $9 million for withholding taxes associated with our stock based compensation program, avoiding the issuance of roughly 180,000 shares and ultimately benefiting our shareholders. These payments, along with transaction costs associated with the credit facility amendment resulted in a Modest and temporary increase in net debt. We ended the quarter with net debt of 121 million with a net leverage ratio still at a comfortable level of under 1.4 times. While this is higher than where we ended last year, we expect net leverage to decline to under 1 times by the end of the year. Liquidity of 91 million remains strong with 54 million available under our revolving credit facility. During the quarter, we extended our credit facility maturity to February 2031 with improved pricing and greater letters of credit capacity. This amendment combined with our strong balance sheet provides significant flexibility for FET to fund strategic initiatives including long term debt, retirement, organic growth and acquisitions. Now turning to our guidance for the second quarter. As Neil mentioned earlier, our our results should increase substantially, driven primarily by backlog conversion, cost savings and market share gains. We are forecasting revenue between 200 and 225 million and EBITDA between 24 to 30 million, which at the midpoints are up 6% and 32% from a year ago. Adjusted net income expected for the second quarter is between 6 and $11 million. Our free cash flow. Our full year guidance issued in February assumed relative flat market activity compared to the back half of 2025. Now, …

Full story available on Benzinga.com

This post was originally published here

Bitcoin is the best asset to protect your wealth against inflation, according to billionaire hedge fund manager Paul Tudor Jones.

“Bitcoin is unequivocally the best inflation hedge that there is—more than gold,” the Tudor Investment Corporation founder said on an episode of the “Invest Like The Best” podcast released Wednesday. 

Jones cited Bitcoin’s 21 million hard cap and its decentralization, adding that gold’s supply increased every year.

Don’t Miss:

“In that sense [Bitcoin] has the greatest scarcity value of anything,” he said.

Jones touted Bitcoin’s potential as an inflation hedge while recounting his motivation for adding the asset to his portfolio in 2020. He said following fiscal interventions by the Federal Reserve and the Treasury Department that year, he was convinced “that the inflation trades were going to take off,” adding, “the best one at that point in time? It was Bitcoin.”

However, Jones said Bitcoin faces some unique risks due to its digital nature.

“The problem with it as an inflation hedge is if you got into kinetic exchange, there’s clearly going to be cyber warfare and anything that you have to deal with electronically is going down, including Bitcoin,” he said on the podcast.

Trending: Investors With $1M+ Often Use Advisors for Tax Strategy — This Tool Matches You With One in Minutes 

Jones also cited quantum computing as another potential threat to Bitcoin, saying that with the advent of AI, the protocol could be exploited sometime in the future.

Jones has not advocated for holding Bitcoin alone but as part of a diversified portfolio. In 2020, he recommended a 1%-2% allocation, a recommendation he maintained in remarks to Bloomberg last June.

Jones’ most recent remarks come even as Bitcoin trades around $76,000, about 40% below its record price of $126,000 reached in October.

Read Next: 

Building Wealth Across More Than Just the Market

Building a resilient portfolio means thinking beyond a single asset or market trend. Economic cycles shift, sectors rise and fall, and no one investment performs well in every environment. That’s why many investors look to diversify with platforms that provide access to real estate, fixed-income opportunities, professional financial guidance, precious metals, and even self-directed retirement accounts. By spreading exposure across multiple asset classes, it becomes easier to manage risk, capture steady returns, and create long-term wealth that isn’t tied to the fortunes of just …

Full story available on Benzinga.com

This post was originally published here

Mohawk Industries (NYSE:MHK) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://edge.media-server.com/mmc/p/zseygt3s/

Summary

Mohawk Industries reported Q1 2026 adjusted EPS of $1.90, up 25% from the previous year, with net sales of $2.7 billion, an 8% increase.

The company is implementing productivity and restructuring actions to enhance results, repurchasing 607,000 shares for $64 million, and preparing for potential further price increases due to escalating energy costs from Middle East conflicts.

Guidance for Q2 2026 expects adjusted EPS between $2.50 and $2.60, with the company focused on cost control, product innovation, and maintaining flexibility amid challenging market conditions.

Full Transcript

OPERATOR

Good morning everyone and welcome to Mohawk Industries first quarter 2026 earnings conference call. All participants will be in a listen only mode. Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today’s presentation, there will be an opportunity to ask questions. To ask a question, you may press star and then one on your touchtone telephones. To withdraw your questions, you may press star and two. Please also note today’s event is being recorded. At this time, I’d like to turn the floor over to Nick Manthy, Chief Financial Officer. Please go ahead.

Nick Manthy (Chief Financial Officer)

Thanks, Jamie. Good morning everyone and welcome to Mohawk Industries Quarterly Investor Conference Call. Joining me today on the call are Jeff Lorberbaum, Chairman and Chief Executive Officer and Paul De Kock, President and Chief Operating Officer. Today we’ll update you on the company’s first quarter performance and provide guidance for the second quarter of 2026. I’d like to remind everyone that our press release and statements that we make during the call may include forward looking statements as defined in the Private Securities Litigation Reform Act of 1995, which are subject to various risks and uncertainties, including but not limited to, those set forth in our press release and our periodic filings with the securities and Securities and Exchange Commission. This call may include discussion of non GAAP numbers. For a reconciliation of any non GAAP to GAAP amounts, please refer to our Form 8K and press release in the Investors section of our website. I’ll now turn the call over to Jeff for his opening remarks.

Jeff Lorberbaum

Thank you, Nick. Our performance for the first quarter was in line with our expectations despite a challenging environment. Our adjusted EPS was $1.90, up approximately 25% versus the prior year. Our results include benefits from productivity restructuring and product mix offset by inflation and volume. Last year was impacted by the system conversion and had four fewer days. Our net sales were approximately 2.7 billion, an increase of 8% as reported or decreases 2.6% on a constant basis across our regions. The commercial sector continued to outperform residential new home construction remains soft and consumers continue to defer home purchases and remodeling projects due to economic uncertainty. We’re implementing productivity actions and executing our previously announced restructuring projects to enhance our results during the quarter, we repurchased 607,000 shares of stock for $64 million as part of our current stock buyback authorization. Our strong balance sheet provides strategic and operational flexibility to take advantage of opportunities that arise at the end of February. The conflict in the Middle East intensified increasing volatility in global energy markets. The full impact of the conflict is unpredictable given the disruption to the worldwide supply of oil and natural gas. Higher gasoline and diesel prices were the fastest and most visible impact of supply disruptions and are contributing to a more cautious consumer outlook. Energy prices as well as the cost of oil and natural gas derivatives are also increasing which affects the costs of many of our products. Depending on the duration of the conflict, the economic impact will vary across our markets with increased inflation reducing consumer sentiment and discretionary spending. U.S. natural gas prices have been less impacted due to the significant domestic production, though oil prices in the U.S. have risen as they follow worldwide trends. In the US 10 year treasury yields have increased creating a corresponding rise in mortgage rates. The European continent, will be more affected due to the dependence on oil and gas from the Middle East and we have made forward purchases to limit our exposure. European governments are reviewing initiatives to lessen the impact on businesses and consumers such as cutting energy taxes, implementing fuel price caps and coordinating European gas storage.. The energy markets will remain volatile until the global supply normalizes. We’re implementing price increases across many products and geographies and further price increases could be required. The impact of higher cost of raw materials will be greater in the second half of the year due to our flow through of our inventory. We are continuing to launch new product collections with industry leading designs and features to enhance our sales and margins. We’re implementing operational strategies that we’ve used to navigate past disruptions which prioritize adaptability and cost control. We’re maintaining flexibility to align with evolving demand, supply, availability and volatile costs. We’re focused on the controllable parts of our business including sales initiatives, inventory levels and discretionary spending and investments. Now Nick will provide the details of our financial performance for the quarter. Thanks Jeff.

Nick Manthy (Chief Financial Officer)

Looking at our Q1 2026 financial results, net sales for the quarter were $2.7 billion, up 8% as reported and a decrease of 2.6% on a constant basis. Our global ceramics segment delivered stronger mix and we lapped the impact of the order management system conversion in flowing North America which partially offset the slower market conditions across our markets. Gross margin was 23.5% as reported and 24.8% on an adjusted basis. This is up 70 basis points from prior year as the benefit of restructuring and productivity initiatives of $32 million and favorable FX of 20 million offset the increased input costs of $28 million. SG&A expenses were 19.4% as reported and 19.3% excluding charges in line with prior year levels. That gave us an operating Income as reported of $112 million or 4.1% of net sales. We had $38 million in nonrecurring charges, primarily related to our restructuring actions initiated last year. Our adjusted operating income was $149 million or 5.5% of sales. That’s an increase of 70 basis points versus prior year. The benefits of lapping the prior year order management system conversion of $30 million and our restructuring and productivity initiatives of 36 million were partially offset by increased input costs of $38 million. Lower volumes given the weaker market conditions were offset by extra days in the quarter. Interest expense was $2 million, a decrease compared to prior year due to the reduction in short term debt and the benefit of increased interest income. Our adjusted tax rate was 19.4% and we are forecasting the full year tax rate for 2026 to be between 19 and 20%. That gave us an earnings per share on both a reported and adjusted basis of $1.90. Turning to the segments, Global Ceramics had net sales just under $1.1 billion. That’s a 10.4% increase as reported and basically flat on a constant basis. The ceramic business delivered positive price mix given strength in the commercial channel and continued success in the countertop business, offset by lower volumes in the residential channel. Adjusted operating income was 55 million or 5% of sales. That’s an improvement of 20 basis points compared to the prior year as the combination of productivity initiatives of 21 million and positive price mix of 13 million were only partially offset by an increase in input costs of $30 million. Flooring North America, net sales were $880 million. That’s a 2% increase as reported or a 4.1% decrease on a constant basis as sales were impacted by slower conditions in both new residential construction and residential remodeling. We had an adjusted operating income of 35 million or 4% of sales. That’s an improvement of 100 basis points compared to prior year as we lapped the impact of the order management system conversion of $30 million which was partially offset by increased input costs of 13 million and the net impact of lower volumes. In Flooring Rest of the World, we had sales of $751 million as reported. That’s a 12.2% increase or a decrease of 4.4% on a constant basis. With the decrease in volumes in the residential remodeling market impacting our flooring categories, partially offset by volume growth in both our panels and insulation businesses. Adjusted operating income was $74 million or 9.8% of sales. That’s an improvement of 70 basis points compared to prior year as the combination of productivity gains and lower input costs of 14 million were more than enough to offset negative price mix. Corporate expenses and eliminations were 14 million in the quarter and we estimate the full year 2026 expenses to be between 52 and 55 million. And now looking at the balance sheet, cash and cash equivalents ended the quarter at 872 million. We had free cash flow of 8 million in the quarter which is in line with seasonal trends. Inventories were just shy of 2.7 billion, up less than 1% compared to prior quarter due to inflation. Property, plant and equipment ended the quarter at just under 4.7 billion. Capex spending in the quarter was $102 million and we plan to invest approximately 480 million in 2026. Focused on cost reduction initiatives, product innovation and maintenance. The balance sheet remains in a very strong position with NET debt of $1.2 billion and a net debt to EBITDA ratio of 0.9. In summary, our strong balance sheet provides us flexibility to navigate a challenging macro environment while staying positioned to pursue opportunities as the market recovers. Now Paul will review our Q1 operational performance.

Paul De Kock (President and Chief Operating Officer)

Thank you Nick Our global ceramics segment delivered improved sales and profitability year over year. Our regions are responding to their local markets with new styles and sizes that are improving our average price and distribution in both residential and commercial. Our premium collections increased our mix with advanced technologies that enhance the visuals. Across our regions, productivity improvements and restructuring actions are improving our results. In the U.S. we benefited from stronger commercial sales and increased retail partnerships which offset ongoing weakness in the builder channel. In March, we introduced our spring collection which emphasizes higher end decorative wall tile and large polished floor tile. To enhance our mix, we announced price increases on ceramic tile and quartz countertops to offset the higher material and transportation cost. We continue to expand our countertop business with quartz volume growing as we ramp up our new production and introduce higher value products. The U.S. International Trade Commission recently ruled that imported quartz countertops from around the world are harming domestic production and the Commission is determining tariffs and quotas to safeguard the industry. In our European ceramic business, we delivered solid sales and margin improvement with investments in sales, personnel, showrooms and new collections in the region. We have greater participation in the commercial channels which is outperforming the residential markets. The industry has announced limited price increases at this point given the market softness. We have purchased a portion of our natural gas requirements this year which will reduce the impact of higher energy prices. Our Latin American ceramic businesses have been less impacted by the conflict. We are raising prices in Mexico and Brazil in response to increasing natural gas and transportation costs in Mexico. Our volume improved as we expanded distribution, improved service times and grew sales with large size polished porcelain collections in Brazil. Our new product introductions are improving our mix with growth in the higher value porcelain category. U.S. reciprocal tariffs on Brazil were significantly reduced which will improve our export volumes to the United States. Brazil’s economy remains sluggish and the central bank is now cutting interest rates to stimulate growth. Our flooring rest of the world segments result were driven by productivity, cost improvements and additional days in the period. As the new year began, the European market was showing some improvement after multiple central bank rate cuts and lower inflation. With the war in Iran, consumer confidence declined as fuel and energy cost increased. We are implementing price increases to offset the higher costs impacting our business in the quarter. Our laminate sales benefited from growing retail partnerships and the success of our new collections which combined elevated style and performance. We updated our LVT designs, added offerings at new price points and expanded our retail distribution. Our sheet vinyl sales to the Middle East were disrupted and alternative transport options are improving shipments. Our panels business improved sales and margins with our premium products and we implemented price increases. We have since announced additional price increases to cover further inflation. Our new MDF recycling plant is expanding production and will further benefit our costs. Our insulation business performed well and improved our costs by re engineering our products. We’re growing our insulation sales in Germany and Eastern Europe to support the startup of our manufacturing facility in Poland. Our businesses in Australia and New Zealand improved results with favorable pricing mix and cost. Our new carpet collections, national promotions and increased participation in the new construction channel enhanced our performance. Our flooring North America segment remained slow during the quarter given lower remodeling and new construction activity and inventory reductions in the channel. Our results were positively impacted by restructuring system improvements and additional days in the period partially offset by lower volume and inflation. Commercial continued to outperform residential and we are improving our position in retail and new construction channels. During the quarter, we announced pricing actions in response to material, energy and transportation increases. Mortgage rates rose almost half a point in March leading to slower new home sales and declining builder sentiment. While new home sales softened, we have increased our presence in the top national and regional builders. We improved our hard surface mix with our best in class laminate, hybrid and LVT collections. Our proprietary accessories coordinate with our hard surface offering increasing complementary sales. Our new carpet introductions are being well received with a focus on our premium polyester and Smart Strand collections. In February, we launched the industry’s first carpet collections, certified by the Asthma and Allergy foundation to significantly reduce household allergens using natural probiotics. Our commercial order backlog has seasonally improved with our carpet tile collections outperforming. Our recently acquired rubber flooring products are being embraced by architects and designers and are creating additional specification opportunities for our other commercial products and I will now return the call to Jeff.

Jeff Lorberbaum

Thank you Paul One month into the second quarter, we continue to adapt our business to changes caused by the Middle east conflict. Thus far, we’ve announced price increases across much of our portfolio due to inflation and our order backlog has continued to grow across our regions. The commercial channel remains solid while residential remodeling and new home construction could be impacted by lower consumer confidence. Our high end collections are performing better in the market and our new products are enhancing our mix. We’re maximizing our flexibility to react to changes in our supply chain, operating costs and market demand. Presently, we’re containing cost, reengineering products and limiting capital expenditure. We’ll not see the full impact of our pricing actions and rising costs until the third quarter. The degree to which the Middle east conflict will impact our markets depends on the duration of the disruptions and the inflationary pressure. Given these factors and one less shipping day in the second quarter, we expect our adjusted EPS to be between $2.50 and $2.60, excluding restructuring or other one time charges. We are managing all aspects of the business we can control and responding to market changes as they arise. In the past, Mohawk has adapted to cyclical changes as well as dramatic market disruptions while enhancing our business for …

Full story available on Benzinga.com

This post was originally published here

Micron Technology Inc. (NASDAQ:MU) shares rose on Friday. This follows earnings commentary from hyperscalers, which confirms that memory is now a primary cost driver in the AI arms race.

• Micron Technology stock is at critical resistance. What’s driving MU to record levels?

While Big Tech faces margin pressure, memory suppliers are reaping the benefits of skyrocketing prices.

The Nasdaq is up 0.71% while the S&P 500 has gained 0.49%.

Hyperscalers Face Rising Costs

Meta Platforms Inc. (NASDAQ:META) raised its 2026 capital expenditure outlook to a range of $125 billion to $145 billion. CEO Mark Zuckerberg noted “most” …

Full story available on Benzinga.com

This post was originally published here

Colgate-Palmolive Company (NYSE:CL) shares rose Friday after the consumer products maker reported first-quarter results that beat Wall Street expectations, as steady demand and category leadership helped offset margin pressure and mixed regional performance.

The company reported adjusted earnings of 97 cents per share, topping analyst estimates of 94 cents. Revenue came in at $5.324 billion, ahead of the $5.215 billion consensus.

Sales Growth And Market Leadership

Net sales increased 8.4%, while organic sales rose 2.9%, including a 0.6% headwind from lower private-label pet food sales. Colgate-Palmolive said it maintained global leadership, with a 41.1% share in toothpaste and 32.6% in manual toothbrushes year to date.

Performance varied by region. North America net sales declined 1.8%, with operating profit falling 28% to $141 million. Latin America net sales rose 14.8%, with operating profit up 15% to $401 million. Europe, Middle East and Africa posted an 11.9% increase in net sales and a 20% rise in operating profit to $266 million.

“These results underscore the resilience of our business model as we are able to execute against our long-term …

Full story available on Benzinga.com

This post was originally published here

OFS Capital (NASDAQ:OFS) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://event.choruscall.com/mediaframe/webcast.html?webcastid=yklVOILv

Summary

OFS Capital reported a net investment income of $0.18 per share for Q1 2026, covering the distribution of $0.17 per share, despite a $0.02 decline from the previous quarter due to lower net interest margins.

The company’s net asset value decreased to $8.16 per share from $9.19, primarily due to unrealized depreciation in CLO equity holdings and market sentiment affecting loan prices.

OFS Capital has extended its debt maturities to 2028 and beyond, reducing its total debt by $45.6 million over the last four quarters, and entered a new credit facility with Natixis.

The company is focused on monetizing its equity position in Fansteel, which has yielded substantial returns, to improve net investment income and reduce portfolio concentration.

Despite macroeconomic uncertainties, OFS Capital maintains a resilient loan portfolio with a focus on senior secured loans and limited exposure to sectors affected by AI disruptions.

Full Transcript

OPERATOR

Good day and welcome to the OFS Capital Corporation First Quarter 2026 Earnings Conference Call. All participants will be in listen only mode. Should you need assistance, please signal a conference specialist by pressing the star key followed by zero. After today’s presentation, there will be an opportunity to ask questions. To ask a question, you may press star then one on your telephone keypad. To withdraw your question, please press star then two. Please note this event is being recorded. I would now like to turn the conference over to Steve Altobrando. Please go ahead.

Steve Altobrando

Good morning everyone and thank you for joining us. Also on the call today are Bilal Rashid, our Chairman and Chief Executive Officer, and Kyle Spina, the company’s Chief Financial Officer and Treasurer. Before we begin, please note that the statements made on this call and webcast may constitute forward looking statements as defined under applicable SECurities laws. Such statements reflect various assumptions, expectations and opinions by OFS Capital Management concerning anticipated results, are not guarantees of future performance, and are subject to known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from such statements. The uncertainties and other factors are in some way beyond management’s control, including the risk factors described from time to time in our filings with the SEC. Although we believe these assumptions are reasonable, any of those assumptions could prove incorrect and as a result the forward looking statements based on those assumptions also could be incorrect. You should not place undue reliance on these forward looking statements. OFS Capital undertakes no duty to update any forward looking statements made herein and all forward looking statements speak only as of the date of this call. With that, I’ll turn the call over to Chairman and Chief Executive Officer.

Bilal Rashid (Chairman and Chief Executive Officer)

Thank you Steve. Yesterday afternoon we reported our first quarter results. Net investment income totaled $0.18 per share, covering our distribution of $0.17 per share. Despite being down $0.02 per share from the prior quarter. The decline was again primarily driven by a lower net interest margin. This reflects the higher interest costs on our unsecured notes issued last year, which replaced debt issued in a historically low rate environment. That said, this new debt has allowed us to meaningfully extend our debt maturities. In addition, benchmark rate reductions by the Fed last year have lowered yields across our loan portfolio, further impacting our net interest margin. Our net asset value at quarter end was $8.16 per share, compared to $9.19 per share in the prior quarter. The decrease was primarily due to unrealized depreciation on our CLO equity holdings driven by spread tightening in the underlying loan collateral as well as a decrease in loan prices due to overall market sentiment. Overall, our non accrual investments as a percentage of our total portfolio at fair value decreased slightly quarter over quarter by 0.7% during the quarter we exited one of our long time non accrual loans. In addition, we placed one small loan representing just 0.3% of the total portfolio at fair value on non accrual status. Despite this borrower remaining current on its interest payments, the loan was placed on non accrual status due to an internal credit rating downgrade. We remain focused on improving our net investment income over the long term. As discussed on prior calls. This includes our ongoing efforts to monetize our minority equity position in Fansteel, the largest position in our portfolio which had a fair value of approximately $80.4 million at quarter end. We continue to be encouraged by the company’s operational momentum and believe its long term outlook remains compelling. A successful exit could increase the likelihood of improved net investment income and reduced portfolio concentration. At the same time, we remain disciplined in balancing the timing of a potential exit with the realization value of the asset in order to maximize our overall returns. Since our initial $200,000 investment in 2014, our position …

Full story available on Benzinga.com

This post was originally published here

On Friday, Alliant Energy (NASDAQ:LNT) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://events.q4inc.com/attendee/225617875

Summary

Alliant Energy reported strong first quarter 2026 earnings, achieving approximately 25% of their full-year guidance midpoint despite mild temperatures.

The company announced a new 370 megawatt electric service agreement in Iowa and plans for a simple cycle natural gas facility to support growth.

Alliant Energy reaffirmed its 2026 earnings guidance and expects a compound annual earnings growth rate of 7% plus from 2027 to 2029.

The company secured five data center agreements totaling 3.4 gigawatts of demand, with three projects under construction.

Alliant Energy plans to finance growth with a balanced mix of equity and debt, maintaining a resilient financial profile.

The regulatory framework in Iowa allows for stable electric rates through at least 2030, with large users funding necessary infrastructure.

Management highlighted their strategic focus on economic development, affordability, and long-term value creation.

First quarter 2026 GAAP and ongoing earnings were $0.87 and $0.82 per share respectively, with higher revenue requirements offset by increased expenses.

The company plans up to $800 million in long-term debt issuances for 2026 and has raised $1.3 billion through forward equity agreements.

Alliant Energy’s four-year capital plan is funded through a mix of cash from operations, tax credit monetization, and new financings.

Full Transcript

OPERATOR

Hello, thank you for holding and welcome to Alliant Energy’s first quarter 2026 earnings conference call. At this time, all lines are in a listen only mode. Today’s conference call is being recorded. I would now like to turn the call over to your host, Susan Gill, Investor Relations Manager at Alliant Energy.

Susan Gill (Investor Relations Manager)

Good morning and thank you for joining Alliant Energy’s program for the first quarter 2026 financial results conference Call Joining me today are Lisa Barton, President and Chief Executive Officer, and Robert Durian, Executive Vice President and Chief Financial Officer. Following their prepared remarks, we will have time to take questions from the investment community. Last night we issued a news Release announcing our first quarter 2026 results and reaffirmed 2026 full year earnings guidance. That release, along with our earnings presentation will be referenced during today’s call and is available on the Investors section of our website at www.alliantenergy.com. before we begin, please note that today’s remarks and responses will include forward looking statements. These statements are subject to risks and uncertainties that could cause actual results to differ materially. Those risks are described in last night’s earnings release and in our filings with the securities and Exchange Commission. We disclaim any obligation to update these forward looking statements. In addition, this presentation contains references to ongoing earnings per share which is a non-GAAP financial measure. Reconciliation to GAAP results are provided in the earnings release available on our website. At this point, I will turn the call over to Lisa.

Lisa Barton (President and Chief Executive Officer)

Thank you, Sue. Good morning everyone. I appreciate you joining us today. 2026 is off to an excellent start. First quarter ongoing earnings delivered approximately 25% of the midpoint of our full year guidance. Despite very mild temperatures across our service territory, we remain firmly on track to achieve our 2026 earnings targets while executing on our strategic priorities. At Alliant Energy, our focus is straightforward, unlocking the potential of our customers and communities, prioritizing affordability while delivering long term value for investors. As I have shared previously, we remain committed to driving economic development and prosperity across the states we serve. Today I am pleased to share our progress on our 2-4 gigawatts of large load opportunities. In April we executed a new 370 megawatt electric service agreement with a hyperscale customer in Iowa with a full load ramp expected by the end of 2030. To support this growth, we ventured into an agreement with a high quality counterparty to construct a simple cycle natural gas facility. Our third quarter update will include a refreshed Iowa Resource Plan reflecting any incremental load beyond the 3 gigawatts already in our plan, as well as the impact of updated MISO accreditation assumptions. We expect to finance these incremental investments with a balanced mix of equity and debt to maintain a resilient financial profile. We now have five fully executed data center agreements representing approximately 3.4 gigawatts of contracted demand, with three of these projects under active construction. Importantly, we have secured the generation resources needed to reliably serve this load, which represents now more than a 60 percent increase in our current peak demand. And looking ahead, we continue to make strong Progress on the 2-4 gigawatts of future large load opportunities we first announced six months ago. Our commitment has remained consistent, creating wins for existing customers and communities, a win for new customers and a win for our investors. We are strategically positioning our company and the states we serve for sustainable long term growth while keeping customer costs as low as possible. Our approach ensures we remain a trusted partner to customers and communities by delivering reliable, affordable energy solutions that support their long term ambitions. Evidence of this strategy in action shown through last week when we joined the QTS leadership in Cedar Rapids to welcome US Secretary of Energy Chris Wright and Iowa legislators to tour the site. This $10 billion development, the largest economic investment in Iowa’s history, underscores our role in enabling innovation, job creation and long term economic diversification in the communities we serve. This is the alliant energy advantage, a disciplined, solutions oriented approach to growth. We guide data center customers to low cost transmission ready sites in our service territories. And because our more recent electric service agreements are capacity only, the investments required to serve this load are primarily energy storage and natural gas combustion turbines. This approach creates strong alignments between capital investments and revenue growth while preserving flexibility to serve future energy needs. As demand for capacity and energy continues to evolve, economic growth drives job creation, expands tax base and strengthens communities. It also benefits customers by increasing load which helps us maintain cost cost competitiveness for all customers. As electricity sales grow, we can spread fixed system costs over more kilowatt hours in Iowa. Our regulatory framework enables us to keep base electric rates stable through at least the end of the decade, that is at least four more years of no retail electric base rate reviews in Iowa while earning our authorized return through retaining tax credits and energy margins from new generation investments. A foundational principle of utility regulation is cost responsibility. At Alliant Energy, our policy is clear. Customers driving large incremental demand are responsible for funding the infrastructure required to serve them through individual customer rates. Large users fund transmission interconnections, system upgrades and incremental investments protecting affordability for all customers. In closing, I want to thank our employees. Their dedication and solutions oriented execution are the foundation of our operational excellence and the driving force behind the progress we continue to make. I would also like to recognize the outstanding efforts of our field teams in restoring service for following recent storm activity across our service territory. Despite the heavy storm activity, we achieved strong reliability and safety statistics through the first part of 2026, which is a testament to the quality of the work by the field organization. I will now turn the call over to Robert for details on our financial results, financing plan and regulatory activity.

Robert Durian (Executive Vice President and Chief Financial Officer)

Thank you, Lisa Good morning everyone. Yesterday we announced solid first quarter 2026 Generally Accepted Accounting Principles (GAAP) and ongoing earnings of $0.87 and $0.82 respectively. As shown on slide 5. Our ongoing earnings year over year change was primarily due to higher revenue requirements and Allowance for Funds Used During Construction (AFUDC) from capital investments at our Iowa and Wisconsin utilities. These positive drivers were offset by higher operations and maintenance expenses related to new energy resources and planned maintenance at existing generating facilities as well as higher depreciation and financing costs. Temperatures in the first quarter of 2026 reduced electric and gas margins by approximately $0.04 per share compared to a reduction of $0.03 in the prior year. Excluding the impacts of temperatures, electric sales in the first quarter were essentially even year over year. First quarter ongoing earnings exclude a 5 cent benefit from the remeasurement of deferred tax assets reflecting updated state income tax apportionment assumptions driven by higher projected electric utility revenues from commercial and industrial customers, including data centers. We are reaffirming our 2026 earnings guidance with Slide 6 reflecting several of our key 2026 assumptions. Our longer term earnings outlook remains intact and based on our current plan, we expect our compound annual earnings growth rate across 2027 through 2029 to be 7% plus. We will continue to assess our long term earnings growth potential as we execute our data center expansion and update our capital expenditure plans later this year. Turning to financing as shown on slide 7, during the first quarter of 2026 we had parent level and aligned energy finance maturities of $1.1 billion and we retired these maturities with available cash and new debt issuances including a $400 million term loan. Our remaining 2026 debt financing plans include up to $800 million of long term issuances consisting of up to $300 million at WPL and up to $500 million at IPL. We are continuously working to capture low cost capital for new infrastructure investments to help lower costs for our customers and have 2 positive developments at IPL in the first quarter. First, we increased the capacity of our sale of the receivable program at IPL from 110 to $180 million and second, janitor Poor’s upgraded IPL’s credit rating from BBB plus to A minus. As a reminder, our four year capital plan is funded through a balanced mix of cash from operations including proceeds from ongoing tax credit monetization and new financings including debt, IBIT instruments and common equity as shown on Slide 8 of the approximately $2.4 billion of expected common equity needs over the next four years, we have already raised approximately $1.3 billion through forward equity Agreement. These forward Equity agreements take care of planned equity needs through 2027. This leaves approximately $1 billion of remaining equity to be raised through 2029, excluding equity expected to be raised under our …

Full story available on Benzinga.com

This post was originally published here

MasTec (NYSE:MTZ) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/i3g4g2jb/

Summary

MasTec reported a strong first quarter with revenue reaching $3.829 billion, a 34% increase year-over-year, and adjusted EBITDA at $284 million, marking a 73% increase.

The company set new records in backlog at $20.3 billion, reflecting a $1.4 billion sequential increase, demonstrating robust demand across its end markets.

MasTec raised its full-year 2026 guidance, expecting revenue of $17.5 billion and adjusted EBITDA of $1.5 billion, indicating continued confidence in market opportunities and operational execution.

Strategic positioning in critical infrastructure sectors, such as AI-driven data centers and telecom, supports MasTec’s long-term growth, with telecom revenue projected to reflect significant growth due to increased data usage.

Management expressed optimism about the company’s ability to manage demand through organic growth and potential M&A, highlighting a strong workforce expansion and strategic focus on high-growth segments.

Full Transcript

OPERATOR

Thank you for standing by and welcome to MasTec’s first quarter 2026 financial results conference Call. I want to remind participants that today’s call is being recorded. I’d now like to turn the call over to Mark Lewis for some opening comments.

Mark Lewis

Thank you Lisa and good morning everyone and thanks for joining us for MasTec’s first quarter conference call. Joining me today are Jose Mas, Chief Executive officer and Paul DeMarco, our CFO. We have prepared slides to supplement our remarks today which are posted on MasTec’s website under the Investors tab and through the webcast link. This morning there is also a companion document with information analytics on the quarter and a guide summary to assist in financial modeling. Please read the forward looking statement disclaimer contained in the slides accompanying this call. During this call we’ll make certain forward looking statements regarding our plans and expectations about the future as of the date of this call. Because these statements are based on current assumptions and factors that involve risks and uncertainties, our actual performance and results may differ materially from our forward looking statements. Our Form 10K as updated by our current and periodic reports and filings includes a detailed discussion of risks and uncertainties that may cause such differences. Additionally, in today’s remarks we’ll be discussing adjusted financial metrics reconciled in yesterday’s press release and supporting schedules. We may also use certain non GAAP financial measures on this call. A reconciliation of any non GAAP financial measures not reconciled in these comments to the most comparable GAAP financial measure can be found in our earnings press release slides or companion documents. We had another great quarter to start the year and let’s get into it. I’ll now turn the call over to Jose.

Jose Mas (Chief Executive Officer)

Jose Thanks Mark. Good morning and welcome to MasTec’s 2026 first quarter call. Today I’ll be reviewing our first quarter results as well as providing my outlook for the markets we serve. First, some first quarter highlights. Revenue for the quarter was 3,829,000,000 up 34% year over year. Adjusted EBITDA was 284,000,000, a 73% year over year increase. Adjusted earnings per share was $1.39, a 174% year over year increase and backlog at quarter end was $20.3 billion, a $1.4 billion sequential increase and a new record level. In summary, we delivered a great quarter, in fact the strongest first quarter in our history, setting new highs across virtually every key metric. Revenue, EBITDA and EPS were all above guidance with strong year over year double digit growth, EBITDA margins improved 170 basis points versus last year first quarter and total company book to bill was 1.4 times, setting yet another backlog record. 2026 should be a great year and I’m excited about the momentum we are building as we look ahead to 2027 beyond. Maybe more importantly, when you step back from the quarter, what we’re seeing across our end markets continues to reinforce our confidence in the longer term. Opportunity in front of us the amount of investment going into critical infrastructure right now is significant and is being driven by some very durable trends. Whether that’s AI in data centers, grid reliability, energy demands, critical infrastructure or connectivity and the way we’re positioned at MasTec, we’re right in the middle of all of that. On the telecom side, we feel really good about where we are. The fundamentals continue to improve driven by strong growth in total data usage. Aggregate U.S. data consumption is estimated to almost double by 2030. This growth is fueled by increasing demand for streaming video, cloud computing, gaming and connected devices. The rapid expansion in total network traffic underscores durable demand and significant long term growth potential. At the same time, you’ve got the next wave of investment coming from bead funding which will support rural broadband and middle mile builds over the next several years. But the biggest shift we’re seeing is around data center interconnectivity. AI is driving a level of demand for fiber capacity, redundancy and low latency that we haven’t seen before. Connecting data centers, both long haul and Metro is becoming a major driver of spending and we think that creates a multi year opportunity measured in the tens of billions of dollars in power delivery. The visibility remains strong. We’re in the middle of a multi year investment cycle in the grid. Utilities are spending heavily on transmission system hardening and reliability and that’s being driven by both aging infrastructure and increasing demand. A big part of that demand is coming from AI and data centers, which could drive up to 12% of total US electricity consumption by the end of the decade. That kind of growth requires significant expansion of the grid, new transmission lines, substations and upgrades across the system. So when you combine load growth, resilience and energy transition, it creates a long duration, highly visible opportunity set and we

Paul DeMarco (Chief Financial Officer)

think we’re really well positioned there. Power delivery revenue for the quarter was up 16% and EBITDA was up 40% and book to bill was 1.6 times with backlog increasing over $600 million sequentially. In clean energy and infrastructure, what’s really making a difference is the platform we built across renewables, civil, industrial and general building. Our renewable revenue was up over 60% year over year and margins improved 70 basis points. In our industrial and infrastructure markets we’re seeing significant opportunities tied to critical infrastructure including gas fire generation, civil construction and general building. For mission critical projects, data center development is a big part of that. Each one of those projects requires significant site work, power infrastructure and ongoing expansion and that plays directly into our capabilities. Our recent Turnkey Data center award is progressing very well. The demand for both the skill set that MASTIC has developed in construction management coupled with the capabilities we have in civil power, telecom and maintenance provides us the opportunity to exponentially grow this part of our business. As the opportunity for full turnkey services matures, we continue to look for ways to increase our self perform capabilities and improve margins. Clean energy and infrastructure segment revenues increased 45% year over year, EBITDA was up 56% and segment backlog increased sequentially by over $770 million, representing a book to bill of 1.6 times. On the pipeline side, the fundamentals are also very solid for the quarter pipeline Segment revenue was up 92% year over year and EBITDA more than tripled. There’s a growing need for natural gas infrastructure, particularly to support gas fired generation which remains critical for reliability as power demand increases and at the same time, global LNG demand continues to grow, driving investment in export, infrastructure and related pipelines both domestically and and internationally. So we see this as a business with good visibility and steady demand going forward. Our reported backlog is not fully representative of the potential as it only includes signed contracts based on current negotiations and verbal awards. Our visibility in this segment is as strong as it’s ever been and we expect strong long term growth. In closing, we delivered an exceptional start to 2026 with record performance across revenue, profitability and backlog. These results reflect strong execution across the business and the strength of our diversified platform. More importantly, the long term fundamentals across all of our end markets remain highly compelling. From AI driven data center growth and telecom demand to grid modernization, energy infrastructure and pipeline opportunities, the scale and durability of investment continue to grow. We believe MASTIC is uniquely positioned at the center of these critical infrastructure trends with the capabilities, customer relationships and backlog to drive sustained growth. Given our strong performance and momentum, we are increasing our full year guidance. We now expect revenue of 17.5 billion, adjusted EBITDA of 1.5 billion and earnings per share of $8.79 representing year over year growth of 22%, 30% and 34% respectively. With strong visibility, accelerating demand and meaningful momentum across our segments, we are confident in our outlook for 2026 and increasingly optimistic about the opportunities ahead in 2027 and beyond. I’d like to take a moment to thank the men and women of mastic. It is both an honor and a privilege to lead such an outstanding team. Our people are deeply committed to the values that define us safety, environmental stewardship, integrity and honesty while consistently delivering high quality projects at the best possible value for our customers. These principles have not gone unnoticed. Our customers recognize and appreciate the dedication and excellence our team brings to every project. It is through the hard work and commitment of our people that we have positioned ourselves for continued growth and long term success. I’d like to thank you for your continued support and I’ll now turn the call over to Paul for our financial review. Paul thank you Jose and good morning. We are pleased with the momentum built by our first quarter results and the continued trend of improved first quarter performance. This has been a focused effort in recent years and 2026 marks the best first quarter in Mostech’s history. Off of our strong start, we now expect to generate almost 45% of our full year EBITDA in the first half of 2026, implying markedly lower seasonality than our business has experienced historically. Our Q1 results represent record levels of first quarter revenue, adjusted EBITDA, EPS and backlog. Year over year, we drove meaningful growth with revenue up 34%, adjusted EBITDA up 73%, EPS 174% and backlog by 28%. We continue to see strong customer demand for Mostch’s broad service offerings and expertise to meet their infrastructure development goals. Our customers continue to show high confidence in Mostek, seeking deeper integration and partnership through alliance agreements, sole sourced contracts and a desire for Mastec to provide turnkey services on strategic infrastructure builds. This is particularly apparent when speed and execution certainty are critical. Our scale, expertise and focus on mutually beneficial outcomes are key components driving this confidence. Now I’ll share some further details on our first quarter segment performance and our outlook. Our communications segment had a good start to the year, generating revenue of $802 million, growing 18% year over year and 7% ahead of expectations. EBITDA margins were about 100 basis points below last year’s first quarter, negatively impacted by cost to exit certain markets in our DIRECTV fulfillment business. Communications backlog in the first quarter was up slightly from year end and 12% year over year to another record level. We continue to see strong broad based demand for wireline services with customers engaging for multiyear turnkey opportunities. Our second quarter communications outlook calls for $875 million of revenue with EBITDA margins slightly higher than 2025 in the low double digits. We also expect to achieve double digit EBITDA margins for the remainder of the year resulting in approximately 70 basis points of margin expansion versus 2025. First quarter power delivery results exceeded our guidance by 10% on revenue and 21% on EBITDA with solid execution to start the year resulting in 120 basis points of EBITDA margin expansion year over year. Most notable in the quarter was the continued backlog strength with a 1.6 times book to bill driving backlog to a new record of 6.2 billion. We saw a number of new contracts executed in Q1 as well as expanded scope on some existing projects. Regarding Greenlink, our client resolved the transmission permitting review earlier than anticipated and we are now operating across the full contractual scope. This is one of the factors driving our revenue guidance higher to approximately 4.8 billion or 14% year over year growth Full year EBITDA margins remain on track to approach double digits and are trending higher than our prior guidance. We continue to expect year over year margin expansion in each quarter for power delivery with 60 to 70 basis points of margin expansion for Q2. Specifically, our pipeline segment had a terrific first quarter generating $682 million of revenue, almost doubling year over year with EBITDA margins of 21%. Margins exceeded our guidance by 165 basis points and increased 270 basis points sequentially. It is important to note that broader pipeline construction demand is still developing and we are generating these margin results in a competitive environment. Unquestionably, we are executing at a high level, delivering high quality projects ahead of schedule for our clients. These positive outcomes further illustrate Mastic’s position as the leader in this space and will continue to be a differentiating factor as the cycle develops. For the second quarter we expect revenue of 600 million with EBITDA margins in the high teens slightly below the first quarter result. Full year margins are still forecasted in the mid teens but trending higher with the first half performance. We are currently taking a conservative view around second half project timing and productivity. While we firm up specific resource allocations longer term we continue to see an unprecedented level of project activity and remain very bullish on the opportunity set for this segment in the years ahead. Clean Energy and infrastructure also started the year off Strong delivering over $1.3 billion of revenue up 45% year over year, almost 10% ahead of our guidance. EBITDA margins of 6.7% expanded 50 basis points from Q1 of 2025 and we generated 56% EBITDA growth. Renewables and general buildings both contributed to the revenue beat with year over year growth of 63% and 166% respectively. While our recent acquisitions were solid contributors to the quarter organically, we still generated over 30% year over year growth backlog continued to develop nicely, reaching another record level of 7.3 billion. This represents a total book to bill of 1.6 times inclusive of 1.3 times organically. Infrastructure led the backlog development, but renewables also extended its streak to 11 consecutive quarters of backlog growth. Demand continues to be robust across the business verticals, leading us to increase our full year revenue guidance to approximately 6.7 billion, up 325 million or 5% higher than previous forecasts. EBITDA margins are still forecasted in the high single digits comparable year over year, largely due to the higher mix of general buildings activity in 2026. Q2 revenue is expected to increase almost 50% year over year to 1.7 billion, with EBITDA margins also comparable to 2025 second quarter. We generated cash flow from operations of 99 million in the first quarter with higher revenue levels versus guidance driving additional working capital investment. We also saw DSOs increase to 72 days versus 65 days at year end, resulting in lower cash conversion than anticipated. We expect DSOS to trend back to the mid-60s over the course of the year. Our liquidity stands at approximately 1.8 billion and net leverage of 1.8 times is well within the terms of our financial policy and criteria to maintain our investment grade ratings. Our improved Q1 performance coupled with continued capital efficiency led to further growth of return on invested capital, expanding almost 100 basis points from year end to over 10%. We expect this trend to continue and we’ll share more thoughts regarding ROIC targets at our upcoming Investor Day. Moving to our consolidated 2026 guidance, we are raising our full year guidance to reflect the first quarter beat and our improving outlook for the remainder of 2026. We now expect revenue of $17.5 billion or 22% growth year over year and 3% higher than our prior forecasts for adjusted EBITDA. We are now forecasting $1.5 billion or an 8.6% margin, with a $50 million increase representing a 10% margin flow through on the increased revenue outlook. Adjusted EPS is forecasted to be $8.79, an increase of almost 35% year over year and 5% ahead of our prior guidance. Our cash flow from operations outlook remains unchanged, expecting to exceed $1 billion for 2026. We are increasing our net cash capital expenditure forecast to about $220 million to

OPERATOR

support the additional revenue growth. Our second quarter outlook reflects another strong quarter of year over year growth across all of our major financial metrics, with revenue adjusted EBITDA and eps growth growing 21, 38 and 47% respectively. Adjusted EBITDA margins are expected to expand by over 100 basis points compared to the second quarter of 2025. Lastly, I wanted to remind you that MAASDAQ will be hosting Investor Day on May 12, which will also be webcast live via a link on Mostec’s investor site. We are excited to introduce additional members of our operational management team to the investment community and provide a medium term financial outlook. This concludes our prepared remarks. I’ll now turn the call over to the operator for Q and A. Thank you. If you would like to ask a question, please press star 11 on your telephone. You will then hear an automated message advising your hand is raised. If you would like to remove yourself from the queue, press star 11 again. We also ask that you would please limit yourself to one question and one follow up on the same subject and then if you have more questions, you can always return back to the queue by pressing star 11 again. Please wait for your name and company to be announced before proceeding with your question. One moment while we compile the Q and A roster and our first question today will be coming from the line of Alex Riegel of Texas Capital Securities. Your line is open.

Alex Riegel

Jose, Congratulations to you and your team on another outstanding quarter. Thank you Alex. Good morning. Good morning. In the context of profit margins, growth at Mastec has been very impressive. And now with backlog up 28% year over year, can you talk about how pricing and or contract terms are changing and is there a point where price and contract terms become more important to the company rather than volume? So Alex, I think it’s a great question. I think we’ve been talking about the momentum of the business over the course of the last year. We’ve obviously seen it in our backlog growth, right? If you I think backlog in 25 was up about 4.5 billion. We’re up another 1.4 billion this quarter. I think in the last two quarters alone we’re up around 3.5 billion. So I would argue that you know, a lot of the improvements that we’ve seen in the business from a pricing perspective, obviously from a growth perspective, haven’t really even started hitting our financials yet. Right. I think we’re just at the beginning of seeing some of the improvements that we saw in 25 relative to backlog …

Full story available on Benzinga.com

This post was originally published here

On Friday, Church & Dwight Co (NYSE:CHD) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

The full earnings call is available at https://events.q4inc.com/attendee/339105132

Summary

Church & Dwight Co reported a strong Q1 2026 with net sales up 0.2% and organic sales growing 5%, driven by volume. Adjusted EPS was $0.95, surpassing the $0.92 outlook.

The company’s US consumer business saw a 5.4% increase in organic sales, led by brands like Therabreath, Arm and Hammer, Hero, and Oxiclean. Online sales now account for 24% of total consumer sales.

Church & Dwight Co reiterated its 2026 outlook for 3-4% organic growth and 5-8% EPS growth, despite potential inflation pressures from the Middle East conflict, which are expected to add $25-$30 million in costs.

Full Transcript

OPERATOR

Good morning ladies and gentlemen and welcome to the Church & Dwight Co’s first quarter 2026 earnings conference call. Before we begin, I have been asked to remind you that on this call the Company’s management may make forward looking statements regarding, among other things, the Company’s financial objectives and forecast. These statements are subject to risks and uncertainties and other factors that are described in detail in the Company’s SEC filings. I would now like to introduce your host for today’s call, Mr. Rick Durkee, President and Chief Executive Officer of Church and Dwight. Please go ahead, sir.

Rick Durkee

All right, thank you. Good morning everyone. Thanks for joining the call. We had a fantastic quarter. I want to start off by thanking all of our Church & Dwight Co employees around the world on executing so well in a volatile environment. I’ll begin with some thoughts on the macro environment and then a review of our Q1 results. Then I’ll turn the call over to Lee McChesney, our CFO, and when Lee is done we’ll open it up for questions starting with the broader environment. Conditions remain dynamic and the consumer backdrop continues to be mixed. Consumer sentiment remains pressured by inflation, borrowing costs and geopolitical uncertainty related to the Middle East, which as you know, is also contributing significant inflation in commodities and transportation costs. That said, the consumer remains resilient, employment remains stable and Our largest categories grew 3% in the quarter. Our portfolio, with its beautiful balance of value and premium offerings, continue to perform well in this type of environment, supported by strong brands and innovation. Turning to the Q1 results, we delivered a strong start to the year and exceeded our outlook across key metrics. Net sales increased 0.2% ahead of our expectation for a decline and organic sales grew 5%, well above our 3% outlook. This growth was driven by volume. Adjusted Gross margin expanded 130 basis points to 46.4% and adjusted EPS was 95 cents, up 4.4% year over year and above our 92 cent outlook. Overall, this was a high quality beat driven by strong execution across the business. Now I’m going to turn my comments to each of the three divisions. First up is the US consumer business. Organic sales increased 5.4% which was primarily all volume. Across the portfolio. Our brands continue to perform exceptionally well. Growth in the quarter was led by Therabreath, Arm and Hammer, Hero and Oxiclean, supported by strong innovation and distribution gains across all classes of trade. Global E Comm also remained a key contributor with online sales now representing approximately 24% of total consumer sales. Innovation and distribution gains continue to be key drivers of our performance and the first quarter of this year is no different. We’re confident that our relentless focus on innovation will continue to drive industry leading growth. Distribution Gains at Shelf and Market Share expansion. In fact, we are just finishing tabulating all the distribution gains looking forward and I’m proud to say Church and DWight was number one across all of CPG on total distribution points gained year over year. New product launches this year are expected to account for half of our organic growth as we innovate in key categories across our portfolio of industry leading everyday products. The Arm Hammer brand had another quarter of growth with laundry hitting record shares across total laundry detergent. Arm and Hammer laundry Detergent consumption grew 4.1% in the quarter compared to category growth of 2.7%. The value segment of laundry continues to grow. Arm and hammer laundry grew despite a lower level of promotion in the quarter. Our newest innovation in laundry is Arm and Hammer baking soda fresh with 10 times the amount of baking soda and is off to a great start with a 4.9 consumer rating where most laundry items are around 4.5. our Arm and Hammer laundry sheets also continue to do well growing consumption by 30%. We like the category building potential of EVO and we are well positioned to win in value. Next up is litter. Fantastic results as Arm and Hammer cat litter consumption grew a robust 6.8% and share increased 0.4 points to reach 24.6%. While category promotional levels remain elevated, they did decline sequentially from Q4. OxiClean share declined in the quarter as we continue to be impacted by distribution loss and lapping that from a large club retailer a year ago. The good news is that the trends on Oxiclean improved throughout the quarter and sales growth surpassed our expectations. Hero and Therabreath continue to contribute considerably to overall performance. Therabreath achieved another quarter of record share gains 3.5 points to 24.1 and further solidifying our number two position in total mouthwash. Household penetration remains low relative to the category. In fact, even with these great distribution gains recently we still have less than 20% of the shelf so more room to run even in mouthwash early days. But the Therapreath toothpaste launch is off to a great start. Hero consumption growth also outpaced the category leading to share gains and remains the share leader two times larger than the next competitor. Hero’s growth was driven by distribution expansion, strong Q1 activations led by Brand Ambassador and Jordan Chiles on Mighty Patch Original and mighty shield innovation. Mightyshield is already achieving retailer hurdle rates. Finally, Touchland in Q1 consumption continued to grow low double digits but sales were impacted by a strong Q4 holiday multi pack sell through Recent consumption has slowed as we lapped year ago launches. Internally we are hard at work on integration and innovation. Turning to international Our international business delivered organic sales growth of 3.7% driven by our GMG and our subs. Growth was led by Therabreath, Hero and Batiste brands and partially offset by lower Middle East regional sales. Of note, in April we went live with our upgraded ERP system. Our project leader Nicole said it best our customers did not notice the transition. Thank you to the entire team. I’ll close by saying that we are very pleased with our start to the year. Our brands remain strong, our portfolio is well positioned and our strategic actions continue to support long term growth. I’m proud of our Church & Dwight Co team as we perform well in a volatile environment. As we look forward, our TSA agreement with the VMS business is winding down and that organizational time that has been freed up is being spent on our forward looking growth initiatives. We’re laying the groundwork for Arm and Hammer expansion, Oral Care growth behind Therabreath and International M and A and with that I’ll turn the call over to Lee for more detail on the quarter.

Lee McChesney (Chief Financial Officer)

Thank you Rick and good day everyone. Back in January at our 2026 Investor Day, we shared an industry leading outlook for 2026. The highlights of that outlook included organic sales growth of 3 to 4% and EPS growth of 5 to 8% in line with our evergreen model. As we now share results in the first quarter, we’re delighted with the execution of our Church & Dwight Co team members across the globe. The first quarter highlights once again the many strengths of our portfolio and the team’s execution capabilities. Let’s jump into the details and provide you an update on our views for the year. We’ll start with EPS. First quarter adjusted EPS is $0.95 up 4.4% from the prior year. $0.95 was better than our $0.92 outlook and was driven by higher volume and gross margin results. Organic sales in 1Q were up 5% above our outlook of 3% and organic sales are broad based across the globe with volume growth of 5.3% partially offsetting a negative price and mix of 0.3%. Our organic growth was fueled by a steady stream of market leading innovation and strong distribution wins with our commercial partners. The organic results also drove our reported revenue up to 0.2% versus our original outlook of negative one back in January. I want to put our reported results in perspective. Due to our portfolio actions, our reported sales results would naturally be down 8%. However, our organic growth of 5%, our touch on acquisition and some FX favorability fully closed the gap. The first quarter, fueled by volume growth was certainly a strong start to the year. Our first quarter adjusted margin was 46.4%, a 130 basis point increase from a year ago. Our results versus last year were driven by 150 basis points from productivity programs, 110 basis points from higher margin acquisitions. Combined with the impact of the strategic portfolio actions, 50 basis points from the combination of volume, price and mix and 10 basis points from FX. These factors offset 190 basis points of inflation and tariff costs. Let’s jump to our investments in marketing. Our market expense as a percentage of sales was 9.5% or 20 basis points higher than the first quarter of last year. Looking forward, we’re continuing to target investments at approximately 11% of net sales. In line with our Evergreen model, Q1 adjusted SGA increased 110 basis points year over year. As we noted in our January Investor Day, SGA in the first half of the year is primarily growing versus last year due to the inclusion of Touchland’s SGA and amortization expense. Adjusted other expense increased by $5.2 million due to a lower interest income compared to the last year in Q1. Our adjusted tax rate was 20.3% compared to 21.8% in Q1 of 2025. 150 basis point year over year decrease and our expected adjusted effective tax rate for the year remains at 21.5%. Let’s now turn to cash flow. We delivered strong cash results in the quarter as cash flow from operations was 174.8 million. Our higher year over year cash earnings were partially offset by an increase in working capital and supported growth and capital expenditures for the period were 31.9 million and we continue to expect full year capital expenditures to be approximately 2% of sales. Let’s now turn to our 26 outlook. While the macro environment remains dynamic, we remain encouraged with our path forward. The strength of our brands, our strategic portfolio actions in 2025 and our growth initiatives continue to provide us confidence. And as we noted in our press release, the situation in the Middle East is fluid and is creating some incremental volume and inflationary pressure on commodities and transportations. For example, we are currently estimating 25 to 30 million dollars of incremental inflation pressure. Our Teams across the globe are responding to these developments and are taking actions across the P and L. As a result of our mitigating actions, we are reiterating our full year 2026 outlook. We remain on track to deliver full year organic growth of approximately 3 or 4% and we continue to expect reported sales growth to decline approximately 1.5 to 0.5% as a result of the strategic portfolio actions taken in 2025. We continue to expect full year gross margin expansion of approximately 100 basis points versus 2025 and this outlook reflects the breadth of actions we discussed in January and the balance of incremental headwinds and actions that we’ve identified since the Middle East conflict began. Marketing as a percentage of sales remains at approximately 11%. SGA as a percentage of sales will be higher than last year, reflecting the impact of the Touchland acquisition in the …

Full story available on Benzinga.com

This post was originally published here

Virtus Inv (NASDAQ:VRTS) released first-quarter financial results and hosted an earnings call on Friday. Read the complete transcript below.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

View the webcast at https://edge.media-server.com/mmc/p/bp6f2sjd/

Summary

Virtus Inv reported an 8% increase in sales, driven by U.S. retail funds, separate accounts, and global funds, despite overall net outflows of $8.4 billion.

The company expanded into Private Markets through its investment in Keystone National Group, enhancing its asset-centric private credit capabilities.

Assets under management decreased to $149 billion, a decline from $159 billion, primarily due to net outflows and market performance.

The operating margin was reported at 24%, with adjusted earnings per share at $5.38, affected by seasonal employment expenses.

Future initiatives include launching new ETFs and expanding distribution of diverse investment strategies, with a focus on improving net flows and capitalizing on quality-oriented equity strategies returning to favor.

Full Transcript

OPERATOR

Good morning. My name is Dede and I will be your conference operator today. I would like to welcome everyone to the Virtus Investment Partners Quarterly Conference call. The slide presentation for This call is available in the Investor Relations section of the Virtus website at www.virtus.com. This call is being recorded and will be available for replay on the Virtus website. At this time. All participants are in a listen only mode. After the speaker’s remarks there will be a question and answer period and instructions will follow at that time. I will now turn the conference to your host, Shawn Roark.

Shawn Roark (Host)

Thanks Dede and good morning everyone. Welcome to Virtus Investment Partners discussion of our first quarter 2026 financial and operating results. Joining me today are George Elward, our President and CEO, and Mike Engerthal, our Chief Financial Officer. After their prepared remarks, we will open the call for questions. Before we begin, I’ll refer you to the disclosures on slide 2. Today’s comments may include forward looking statements which involve risks and uncertainties described in our news release and SEC filings. Actual results may differ materially. We will also reference certain non GAAP financial measures. Reconciliations of the most directly comparable GAAP measures are available in today’s news release and financial supplement on our website. Now I’d like to turn the call over to George thank you Sean and good morning everyone. I’ll start today with an overview of the results we reported this morning and then Mike will provide more detail. Although the first quarter was challenging from a net flow perspective, reflecting our meaningful exposure to quality oriented equity strategies which have remained out of favor with several areas of strength during the quarter that were overshadowed and we also advanced key growth initiatives. Key highlights of the quarter included an 8% increase in sales with growth in U.S. retail funds, separate accounts and global funds Positive net flows in several strategies including high conviction growth equity, multi sector fixed income listed real assets and event driven positive net flows in ETFs and global funds. Expansion into Private Markets with our investment in Keystone National Group and continued return of capital including 10 million of share repurchases, we remained active in broadening our product offerings to meet the evolving client demand and expand our growth opportunities over time. The investment at Keystone on March 1 added a differentiated asset centric private credit capability and our sales teams are actively focused on expanding distribution of their compelling strategies to retail and institutional clients. Keystone focuses on senior secured amortizing fixed rate financings backed by tangible assets. We believe their approach offers attractive stability and defensive characteristics for investors seeking a private credit allocation or a broader income oriented solution with a different risk profile than many traditional direct lending vehicles. Keystone expands our private market capabilities which also include those of Crescent Cove as well as our overall alternative offerings that include managed futures and event driven strategies. We continue to launch attractive actively managed ETFs including emerging markets dividend ETF from our systematic team, a real estate income ETF from Duff and Phelps and a growth equity ETF from Sylvan. We expect to continue to be active in developing and introducing new products over the upcoming quarters. Looking at our first quarter results, assets under management were $149 billion at March 31, down from $159 billion due to net outflows and market performance, total sales increased 8% to $5.8 billion with a 26% increase in sales of equity strategies in large part from some of our strategies that do not have a quality orientation by product. We had higher sales of US Retail funds, retail separate accounts and global funds. Retail separate account sales increased 19% with higher sales in each month of the quarter and on April 1st we reopened this mid cap core strategy that had been soft closed in 2024. Total net outflows were 8.4 billion and across products the outflows were almost entirely driven by equities. I would note that the majority over 80% of the net outflows were in the first two months of the quarter as net outflows improved significantly in March. Looking at flows across asset classes, the equity net outflows largely reflected the continued style headwind for quality oriented strategies including a meaningful institutional global equity redemption and the previously disclosed rebalancing of a lower fee retail separate account model only mandate to a passive strategy. Fixed income net flows were essentially breakeven for the quarter as positive net flows in multi sector convertibles and preferreds were offset by net outflows in investment grade and leveraged finance. Multi asset strategies were also essentially breakeven while alternative strategies had net outflows of $0.4 billion primarily driven by managed futures. In terms of what we saw in April, as previously mentioned, overall trends improved over the course of the first quarter and April flows were more similar to March for US Retail funds, both sales and flows improved in April over March and HTF sales and net flows were at their highest level since September for retail separate accounts. While we do not have as much transparency given a large portion is model only, we do anticipate better flows in the second quarter and are pleased to have recently reopened the SMID Cap core strategy on the institutional side, known wins actually modestly exceed known redemptions for the first time in a long time. Though as always, institutional flows can be very lumpy and hard to predict. Turning now to our financial results, the operating margin was 24% and reflected the impact of seasonally higher employment expenses. Excluding those items, the operating margin was 30.3%. Earnings per share as adjusted, a $5.38 declined from the fourth quarter, primarily due to $1.26 per share of seasonal employment expenses. Excluding those items, earnings per share as adjusted declined 6%. Turning to investment performance, as we previously discussed, recent performance reflects our overweight and quality equity. However, we did see improving relative performance in the first quarter in our equity strategies. Fixed income and alternative strategies have consistently strong performance with 78 and 71% respectively, beating benchmarks for the three year period. Over the longer ten year period, 54% of our equity, 73% of our fixed income and 71% of alternative strategies beat their benchmarks. In terms of our balance sheet and capital, we ended the quarter with cash and equivalents of $137 million. Other investments of $269 million and $200 million …

Full story available on Benzinga.com

This post was originally published here

Coinbase Global (NASDAQ:COIN) are Robinhood Markets (NASDAQ:HOOD) are backing a rule banning prediction markets from offering slot machines, roulette and other casino games.

A Calculated Concession

Casino games are “entertainment products, generally played against the casino itself” with no price discovery function, the Coalition for Prediction Markets members told the CFTC on Thursday.

Prediction markets “facilitate price discovery, providing useful information about the probability of future events.”

The framing matters. Sports made up close to 90% of Kalshi’s volume in the year ending in February, according to the Congressional Research Service.

U.S. legal sports betting hit a record $167 billion in 2025, up 11% year-over-year, according to the American Gaming Association. By ceding slot machines, the Coalition is asking the CFTC to formalize a distinction that protects access to that lucrative market.

Polymarket traders think there is only a …

Full story available on Benzinga.com

This post was originally published here

Huntsman (NYSE:HUN) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

This content is powered by Benzinga APIs. For comprehensive financial data and transcripts, visit https://www.benzinga.com/apis/.

Access the full call at https://event.choruscall.com/mediaframe/webcast.html?webcastid=CrqpAfyY

Summary

Huntsman reported stronger than expected demand and successful price increases to offset rising costs, particularly influenced by seasonality and supply chain disruptions.

The company plans to continue managing costs and expanding margins while focusing on stable and long-term demand trends to normalize margins.

Operational performance in the first quarter was strong, with high capacity utilization rates, particularly in the MDI and polyurethanes segments.

Management expressed cautious optimism about future demand sustainability, noting potential challenges from inflationary pressures and geopolitical uncertainties.

The company is seeing positive trends in advanced materials, driven by aerospace and power sectors, and expects continued traction in these areas.

Full Transcript

OPERATOR

Greetings. Welcome to Huntsman’s first quarter 2026 earnings call. This time all participants are in listen only mode. A question and answer session will follow today’s formal presentation. If anyone should require operator assistance during the conference, please press Star zero from your telephone keypad. Please note this conference is being recorded at this time. I’ll turn the conference over to Ivan Marcuse, Vice President of Investor Relations and Corporate Development. Thank you. You may now begin.

Ivan Marcuse (Vice President of Investor Relations and Corporate Development)

Thanks, Rob and good morning everyone. Welcome to Huntsman’s first quarter 2026 earnings call. Joining us on the call today are Peter Huntsman, Chairman, CEO and President, and Phil Lister, Executive Vice President and CFO. Yesterday, April 30, 2026, we released our earnings for the first quarter 2026 via press release and posted to our website, huntsman.com. we also posted a set of slides and detailed commentary discussing the first quarter 2026 on our website. Peter Huntsman will provide some opening comments shortly and we will then move to the question and answer session for the remainder of the call. During this call, let me remind you that we may make statements about our projections or expectations for the future. All such statements are forward looking statements and while they reflect our current expectations, they involve risks and uncertainties and are not guarantees of future performance. You should review our filings with the SEC for more information regarding the factors that could cause actual results to differ materially from these projections or expectations. We do not plan on publicly updating or revising any forward looking statements during the quarter. We will also refer to non GAAP financial measures such as adjusted ebitda, adjusted net income or loss and free cash flow. You can find reconciliations to the most directly comparable GAAP financial measure in our earnings release which has been posted to our website@huntsman.com. I’ll now turn the call over to Peter Huntsman, our Chairman and President.

Peter Huntsman (Chairman, CEO and President)

Ivan thank you very much. Thank you all for taking the time to join us this morning. Before I begin my remarks about our company and recent events, I want to simply say that I hope there is a quick and peaceful resolution to the ongoing conflict in the Middle east. Over the past 40 years, I’ve had the opportunity to visit every country bordering the Persian Gulf with the exception of Iraq. I have always been treated warmly and fairly by the people I’ve encountered. I hope that my comments do not come across as being callous in any way to the suffering and fear emanating from this region. As I address the economic impact of these events to our bottom line and industry. From the first hours of this conflict, our number one commercial priority has been to increase prices enough to offset rising costs. I believe we’ve been successful in doing this. This will require continued communications with our customers and suppliers and also the discipline to make sure that we are not a shock absorber between raw material costs and finished product pricing. Our next priority is operating our plants in a reliable manner to make sure that we have the product to meet our demand. Our operations during the first quarter and going into the second quarter have been excellent. From a sales perspective, we’re seeing stronger than expected demand going well into the second quarter. I would say that this is being brought about by three factors. Number one seasonality as we move into the second quarter and the building season resumes across North America, Europe and Asia. Number two customers who are buying ahead of the expected price increases that are being announced and number three disruptions that have been seen in certain trade flows that have impacted supply. An example of this would be some of our Malaysian customers in Europe who have become overly dependent on Chinese supplied maleic have seen a disruption in supply as raw materials and shipping costs have increased from that region. These three factors are also happening at a time when most inventory levels are very low across many supply chains. These improved order patterns are being seen as we enter into the second quarter in most of our regions and across many of our products. The obvious countervailing point to all of this is how long does it continue? I can’t see order patterns that go through the month of June, but the guidance that we have shared from each division in Q2 reflect what we’ve seen to date today. That visibility is less clear as we look further into the quarter. I struggle to see how inflationary pressures, particularly in areas reliant on imported energy like much of Asia and Europe, will not see an inevitable downward pressure later in the year as consumer spending gradually shifts towards higher prices. To what degree this occurs is yet to be seen. I am heartened to see the housing starts and durable good orders in the United States better than expected for the month of March. But I’m also keeping an eye on residential permits. A step that precedes Construction starts down 11% for the month of March. There will also be some longer term dislocation of traditional economics. If you were a producer that enjoyed discounted raw materials coming out of Venezuela, Iran and Russia a few months ago, it is likely that you’re not seeing such discounts today, and I highly doubt you’ll see them in the foreseeable future. Many customers are looking for closer and more secure sources of supply. Supply chains are shifting and being reassessed. I believe there will be some lasting impact for certain regions and products that may not seem too apparent today. It is simply too early to know how lasting some of these will be. In short, we are aggressively raising our prices to both cover our cost of our raw materials while also expanding margins from the trough economics that we’ve been experiencing for the past three years. We will continue to manage our costs and deliver these objectives on budget. We will be focused on volumes and make sure that spot buying also comes with longer term volumes and obligations. I’m glad to see the trends that we’re seeing in the second quarter, but we still have a ways to go to get to our normalized margin levels. This will require stable and longer term demand trends to continue. I feel that we are in a strong position today to capitalize on such changes going forward. Thank you operator with that will open the time up for Q and A.

OPERATOR

Thank you. We’ll now be conducting a question and answer session. We ask you please limit yourself to one question and one follow up. If you’d like to ask a question, please press Star one on your telephone keypad and a confirmation tone will indicate your line is in the question queue. You may press star 2 if you’d like to remove your question from the queue. For participants who are using speaker equipment, it may be necessary to pick up your handset before pressing the star keys. Thank you. And our first question is from the line of Patrick Cunningham with Citi. Please proceed with your questions.

Patrick Cunningham (Equity Analyst)

Hi, good morning. In the release you talked about the potential for a more durable return to mid cycle profitability. This likely depends on both supply and demand side at this point, but can you give us the latest view on what this crisis may do in terms of supply side rationalization for MDI and polyurethanes?

Peter Huntsman (Chairman, CEO and President)

How do you see this playing out in terms of structural energy cost, pressure, feedstock availability or potential closures? At this point I don’t see a great deal of structural change. As we look at mdi, I do see pressures continuing in Europe. If you’re a European producer now having to put up with natural gas that’s priced somewhere in the mid teens versus where we are today. I noticed in the Houston ship channel price this morning was under $2 per MMBtu. These are real material gaps and shifts. I can’t help but think that there’s going to be continued pressure on petrochemical producers across the board and in MDI across Europe. But having said that, I also think that there are probably some structural issues that may make Chinese exports in certain products. I won’t get into exactly which products those are, but I think that they’re varied across the board. If you’re relying on coal as a raw material in China, you’re probably doing quite well. If you’re integrated into a world scale refinery and integrated system in China, you’re probably doing quite well. If you’re part of what they call the teapot refineries of refineries integrated into export bound chemical facilities, you may be under some cost pressures as you see some of the discounted crude products. So it’s not just what we see from a competitive point of view. It’s also what we see from the raw material that many of our customers and many of our competitors and the industry in general will be facing. And I think those are some of the longer term issues that we’ll be dealing with even after the Strait of Hormuz hopefully opens soon here. Very helpful. And could you talk about some of the sustainability of the positive trends you’re seeing in advanced materials, particularly interested in line of sight into aerospace and power order books and what that potentially means for segment profitability in 2026? I think and I don’t want to get too much into our numbers as to where we planned and where we saw a lot of upside since the beginning of the war, but my CFO will start kicking me on the side here. But what we the performance we’re seeing in advanced materials is largely what we expected a quarter ago. We may have seen a little bit of impetus there in pricing, but remember that business is not reliant on any one major raw material as you would see for instance in benzene going into MDI or some of the raw materials caustic and chlorine prices and so forth into some of our performance products materials. And so as you look at our advanced material section, that continues as we see as we’ve said now the last couple of quarters, we see the recovery continue with aerospace power, these better than GDP growth businesses. That business is just going to continue to get traction and I’m not sure the results this quarter. In the second quarter where we finished the first quarter, I’m not sure that would be materially different from where we’d be without the Gulf conflict.

OPERATOR

Our next questions are from the line of Kevin McCarthy with vertical research Partners. Please proceed with your questions.

Kevin McCarthy (Equity Analyst)

Thank you and good morning. Peter, can you speak to operating rates in MDI both for Huntsman and also what you’re observing at the Industry level and related to that, you know, how are things changing post war versus pre war?

Peter Huntsman (Chairman, CEO and President)

I think that as we look at the industry in general, you’re probably looking at at the low to mid-80s. And I think now from where we are, we would be in the high 80s. We’re sold out completely in our Chinese operation, our US operation for the most part is sold out. Europe, as we said when we announced our first quarter earnings before the Middle east conflict, we’re starting to see some green shoots there. We continue to see some opportunities in Europe and I would say that we’re operating at pretty good levels across the board. There have been a number of outages and I would say short term and also planned disruptions in the industry. Not to be too unexpected. When you go have an industry that’s been operating kind of at a lower probably 70, 80% for the last couple of years and now all of a sudden you see an increase in demand and pull through, you typically have operating issues. …

Full story available on Benzinga.com

This post was originally published here

GrafTech International (NYSE:EAF) held its first-quarter earnings conference call on Friday. Below is the complete transcript from the call.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

The full earnings call is available at https://events.q4inc.com/attendee/833501560

Summary

GrafTech International reported a net loss of $43 million for Q1 2026, with adjusted EBITDA at negative $14 million, primarily due to a decline in average pricing.

The company announced a price increase for graphite electrodes by $600 to $1,200 per metric ton, aiming to restore pricing levels and safeguard supply continuity.

Despite geopolitical uncertainties, the company maintains strong liquidity of $329 million and expects modest year-over-year improvement in cash costs.

GrafTech is actively engaged in supporting trade cases in the U.S. related to unfairly priced imports, with potential rulings expected by mid-2026.

The company is positioning itself for long-term growth, capitalizing on trends like decarbonization and the shift to electric arc furnace steelmaking.

Full Transcript

JL (Operator)

Thank you for standing by. My name is JL and I will be your conference operator today. At this time I would like to welcome everyone to the GrafTech International’s first quarter 2026 earnings conference call and webcast. All lines have been placed on mute to prevent any background noise. After the speaker’s remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press Star followed by the number one on your telephone keypad. If you would like to withdraw your question, simply press Star one again. I would now like to turn the conference over to Mike Dillon, Vice President of Investor Relations and Treasurer. You may begin.

Mike Dillon (Vice President, Investor Relations and Treasurer)

Good morning and welcome to GrafTech International’s first quarter 2026 earnings call. Thank you for joining us. Joining me on the call are Tim Flanagan, Chief Executive Officer and Rory O’Donnell, Chief Financial Officer. Tim will begin with opening comments on our first quarter performance and key strategic initiatives. Rory will then provide more details on our quarterly results and other financial matters. After brief closing comments by Tim, we will then open the call to questions turning to our next slide. As a reminder, our comments today may include forward looking statements regarding, among other things, performance trends and strategies. These statements are based on current expectations and are subject to risks and uncertainties. Factors that could cause actual results to differ materially from those indicated by forward looking statements are shown here. We will also discuss certain non GAAP financial measures and these slides include the relevant non GAAP reconciliations. You can find these slides in the Investor Relations section of our website at www.GrafTechh.com. a replay of the call will also be available on our website. I’ll now turn the call over to Tim. Good morning and thank you for

Tim Flanagan (Chief Executive Officer)

joining Graftech’s first quarter earnings call. While the graphite electrode industry continues to navigate a period of transition, we are starting to see signs of improvement and GrafTech is well positioned to capitalize on the recovery ahead. At the same time, geopolitical conflicts are generating macro uncertainty and energy market volatility. Against this backdrop, our priorities remain clear, drive disciplined commercial execution, continue improving our cost structure, maintain strong liquidity, operate safely, and position GrafTech for long term value creation. In all of these areas, we’ll continue to take decisive actions to support the long term viability of our business. To that end, let me provide an update on several of our key strategic initiatives that leverage the commercial, operational and financial progress that we’ve made over the past couple of years. Starting on the commercial front, for some time we’ve been clear that pricing levels have not reflected the indispensable nature of a graphite electrode nor the level of investment required to maintain a stable, reliable supply for the steel industry. That’s happened even as steel makers in the US And Europe have announced cumulative price increases over the past five quarters for finished steel products of approximately 50 and 25% respectively, reinforcing the disconnect between value creation in the steel industry and the pricing environment for graphite electrodes. A Mission critical consumable in response, we are actively pursuing both market based and policy driven solutions as part of our disciplined approach to addressing this condition. On March 26, we announced that we’re increasing our graphite electrode prices by by a minimum of 600 to $1,200 per metric ton, depending on the region. From a customer’s perspective, this represents a 1 to $2 increase, or less than 1/2 of 1% of the cost to produce a ton of steel. This increase will only apply to volume that was not yet committed as of that date. This price increase represents only a first step to restoring pricing to levels that safeguard regional graphite electrode production and continuity of supply for our customers. And as we remain focused on value over volume, we’ll continue to walk away from volume opportunities that do not meet our margin requirements. So still early on, we’ve been encouraged by our customers reaction to the price announcement and the reflection of the price increase in recent tenders. As of Today, more than 85% of our anticipated volume is committed in our order book, mostly at price points that reflect market pricing at the end of the fourth quarter of 2025. However, we’re pleased to see the positive pricing momentum which will lay a critical foundation as we begin the 2027 price negotiations later this year. To further support these efforts, we are actively engaged in advocating for GrafTech in our key commercial jurisdictions as part of our commitment to fair trade and market stability in the U.S. this includes our support of trade cases filed earlier this year related to the imports of large diameter graphite electrodes at unfair prices. In April, the International Trade Commission announced the preliminary determination that there is a reasonable indication that the domestic industry is being materially injured by imports from China and India that are being sold in the US at far less than fair value and subsidized by those governments respectively. As a result of this determination, the U.S. department of Commerce will continue its investigation. We’re very encouraged by these developments and remain confident that the Commerce and that the ITC will complete a thorough investigation and take the necessary actions to address these unfair trade practices. As we assess progress towards constructive pricing and supportive trade actions, we continue to evaluate the level of production capacity we need to maintain and the level of volume we will deliver to the market, reflecting our commitment to take decisive actions and support the long term viability of our business. We also continue to assess the industry wide impact of recent geopolitical developments, particularly the effect on key graphite electrode inputs including oil based raw materials, energy and logistics. Disruptions in the production and transportation of oil out of the Middle east are having a significant impact on the global oil market. This in turn has translated into higher decan oil prices, the key raw material for petroleum, needle coke. While the needle coke market has been relatively flat for the past two years, we anticipate that higher input costs and potential disruptions in decan oil availability for certain needle coke producers will provide a catalyst for needle coat pricing. In addition, shipping disruption and rising geopolitical risk continue to reinforce the need for supply chain security. We are beginning to see a shift in sourcing behavior for certain steel producers with an increased focus on regional production and surety of supply to safeguard continuity of their operations. In this regard, we’re well positioned to meet the needs of our customers. Our strategically positioned global manufacturing footprint provides a competitive advantage given its proximity to large EAF steelmaking regions. Further, we have surety of needle coke supply through our vertical integration with Seadrift which sources all of its decan oil needs from domestic producers. Lastly, regarding the impact of the conflict on Graftex cost structure, our efforts over the past several years have created a more agile, more efficient manufacturing footprint that positions us well to control production costs while navigating a dynamic macro environment. We expect incremental improvement through operational efficiencies and disciplined production management. As a result, our current expectation is that we’ll achieve a modest year over year reduction in cash cogs consistent with our guidance at the beginning of the year. However, the extent and duration of the conflict in the Middle east and the resulting longer term impact on the oil and energy markets remains uncertain. Ultimately, sustained increases in our key input costs will require us to take further action on electrode pricing. Stepping back as it relates to the graphite electrode and needle coke industries, we are seeing an inflection point take shape. The near term pricing environment is improving and the long term fundamentals remain firmly intact. Electric arc furnace steelmaking continues to gain share globally driven by decarbonization trends and structural shifts in steel production. This transition supports long term demand for graphite electrodes and and in turn petroleum needle coke. We expect further synthetic graphite and petroleum needle coke demand to result from the building of Western supply chains for battery needs, whether for electric vehicles or energy storage applications. We applaud the efforts of policymakers both in the US and the EU as begin to develop a joint Critical Minerals Action Plan. This action plan establishes a framework for the two trading partners to coordinate policies to ensure supply chain resiliency for critical minerals such as synthetic graphite as they explore potential trade mechanisms including order adjusted price floors. Furthermore, there’s overwhelming evidence in trade cases across multiple jurisdictions that whether it’s to support the establishment of a supply chain that doesn’t exist outside of China today, or to protect those industries that do, pricing sport for materials that are critical for national and economic security are an absolute must. Against this backdrop, graphtec continues to take proactive measures that seek to capitalize on these emerging opportunities. These include ongoing engagement with the US Administration at various levels to help inform and shape critical mineral policies as it relates to graphite electrodes as well as battery materials within the eu, supporting the ongoing efforts of the European Carbon and Graphite association as they advocate for stronger European steel and graphite electrode industries and demonstrating our technical capabilities through partnership and engagement with various agencies, research institutions and companies. Let me pivot to our current thoughts on the steel industry trends as context for the rest of our discussion. Our Performance and Outlook Global steel production outside of China was 212 million tons in the first quarter, up approximately 1% compared to the prior year, with a global utilization rate of approximately 67% for the quarter. Looking at some of our key commercial regions, using data recently published in the World Steel association for North America, steel production was up 2% in the first quarter compared to the prior year, driven by 6% year over year growth in the United States and we’re seeing this Trend continue into Q2 with the AISI reporting that weekly US capacity utilization rate hit 80% for just the second time in the past two years. This is a clear signal that EAF steelmaking activity and therefore demand for our electrodes is gaining momentum in an important commercial region. Conversely, in the EU, steel output for the first quarter remained depressed, declining 3% compared to the prior year. However, as we’ve noted previously, indicators of a rebound in the steel market have started to appear both in the EU and globally. Turning to the next slide and extent expanding on this point, in April, World Steel published their latest short range outlook for steel demand globally. Outside of China, World Steel is projecting 2026 steel demand to grow 1.9% year over year for the US World Steel is projecting 1.7% steel demand growth in 2026. Along with this demand growth, favorable trade policies are expected to further support U.S. steel production. For Europe, World Steel is projecting a return of steel demand growth in the near term, forecasting demand growth of 1.3% for 2026. This reflects some of the demand drivers we’ve discussed in the past earnings calls, including initiatives to increase infrastructure investment defense spending representing key steel incentive industries. In addition, key policy initiatives in the EU are expected to support higher levels of steel production in this important commercial region for Graftec. Specifically, provisions within the Carbon Border adjustment mechanism, or CBAM, implemented in early 2026 will make certain steel imports into the EU less competitive. Further, in April, the EU approved the proposal initially made by the European Commission in 2025 to to significantly increase trade protections on steel. These new measures, which will be effective at the beginning of July, will cut tariff free steel import quotas nearly in half, double the above quota duties to 50%, and introduce melt and pour disclosure rules to prevent circumvention. All this is expected to boost domestic steel production, with some analysts projecting capacity utilization rates in the EU could increase from current levels around 60% to potentially 80% over time. Overall, we continue to project that globally outside of China, demand for graphite electrodes will increase in 2026, with all major regions expected to contribute. Graphtex is uniquely positioned to capture a disproportionate share of that growth. Before I hand the call over to Rory, I want to circle back on one of the key priorities I mentioned in my opening comments, operating safely. Our team continues to do just that and I want to thank them for their efforts. For the first quarter, our total recordable insert rate was 0.35, a further improvement over the full year rate for 2025. Sustaining this momentum will remain a critical focus as we work relentlessly towards our goal of zero injuries. But with that, I’m going to turn it over to Rory, who will provide more color …

Full story available on Benzinga.com

This post was originally published here

On Friday, Real Matters (TSX:REAL) discussed second-quarter financial results during its earnings call. The full transcript is provided below.

Benzinga APIs provide real-time access to earnings call transcripts and financial data. Visit https://www.benzinga.com/apis/ to learn more.

View the webcast at https://edge.media-server.com/mmc/p/fmjc66e5/

Summary

Real Matters reported strong financial performance in Q2 2026 with consolidated revenues of $47.2 million, up 27% year-over-year, and consolidated net revenue increasing 35% to $13.6 million.

The company launched seven new clients, including one of the largest non-bank servicers in US title, and saw significant increases in US appraisal and title origination volumes.

Real Matters’ adjusted EBITDA improved to $0.9 million from a $1.9 million loss in the prior year, highlighting robust revenue growth and operational efficiency.

The company is approaching an inflection point in the US title business, requiring investments in capacity to onboard new clients and scale operations.

Management expressed optimism about future growth, emphasizing client growth, market share expansion, and the potential for increased refinance volumes due to the current distribution of mortgage interest rates.

Full Transcript

OPERATOR

Good day and thank you for standing by. Welcome to Real Matters second quarter 2026 earnings conference call. At this time, all participants are in a listen only mode. After the speaker’s presentation, there will be a question and answer session. To ask a question during the session, you’ll need to press star 1-1 on your telephone. You will then hear an automated message advising your hand is raised to withdraw your question. Please press star 1-1 again. Please be advised that today’s conference is being recorded. I’d now like to hand the conference over to Lynn Beauregard, Vice President, Investor Relations and Corporate Communications. Please go ahead.

Lynn Beauregard (Vice President, Investor Relations and Corporate Communications)

Thank you Operator and good morning everyone. Welcome to Real Matters Financial Results Conference call for the second quarter ended March 31, 2026. With me today are Chief Executive Officer Brian Lang and Chief Financial Officer Rodrigo Pinto. This morning before Market Open, we issued a news release announcing our results for the three and six months ended March 31, 2026. The release accompanying slide presentation as well as the financial statements and MD and A are posted in financial sections of our website at realmatters.com during the call we may make certain forward looking statements which reflect the current expectations of management with respect to our business and the industry in which we operate. However, there are a number of risks, uncertainties and other factors that could cause our results to differ materially from our expectations. Please see the slide titled Cautionary Note regarding Forward looking Information in the accompanying slide presentation for more details. You can also find additional information about these risks in the Risk Factors section of the Company’s Annual Information form for the year ended September 30, 2025, which is available on SEDAR+ and in the Financial section of our website. As a reminder, we refer to non-GAAP measures in our slide presentation including Net Revenue, Net Revenue Margins Adjusted Net Income or Loss Adjusted Net Income or Loss per Diluted share Adjusted EBITDA Adjusted EBITDA margins Non GAAP measures are described in your MD&A for the three and six months ended March 31, 2026, where you will also find reconciliations to the nearest IFRS measures. With that, I’ll turn the call over to Brian.

Brian Lang (Chief Executive Officer)

Thank you Lynn Good morning everyone and thank you for joining us on the call today. Our second quarter results built on the strong momentum we saw in the first quarter as we reported consolidated revenues of $47.2 million, up 27% year over year and consolidated net revenue increased 35% to $13.6 million. Real Matters delivered its strongest consolidated adjusted EBITDA results in seven quarters in Q2 generating a profit of $0.9 million, a notable improvement from a $1.9 million loss in the prior year quarter reflecting robust revenue growth and enhanced operating leverage across the U.S. appraisal and U.S. title segments. We launched seven new clients in the second quarter, including one of the largest non bank servicers in U.S. title. Our US appraisal origination transaction volumes increased by 22% year over year and our origination volumes more than tripled in U.S. Title. Our financial performance in the second quarter continued to reflect the positive effects of new client launches, increased market share and enhanced operational efficiencies. We also benefited from moderate market tailwinds in the first half of the quarter. These outcomes underscore our business model’s capacity to deliver considerable operating leverage as transaction volumes grow in U.S. appraisal. We maintain leading positions on lender scorecards and we demonstrated strong operating leverage as an 18% increase in net revenue drove 41% year over year growth in adjusted EBITDA. We also recorded significant improvements in our home equity and other revenues driven by market share gains with existing clients. U.S. title origination volumes were up 268% year over year, driven by net market share gains with existing clients, new clients and moderate refinance market tailwinds. To put this in perspective, U.S. Title refinance origination volumes for the second quarter were equivalent to the total volume we processed in each of fiscal 2023 and fiscal 2024. We posted an adjusted EBITDA loss of $400,000 in U.S. title, putting the path to profitability in this segment well within our sights. We launched four new title clients in the second quarter, including one of the largest non bank servicers. And subsequent to the end of the quarter we launched our third tier one lender and another top 100 lender. The momentum we have built in U.S. title with a growing client base that now includes three tier one lenders and one of the largest non bank servicers, positions this segment as an increasingly important growth engine for the company. With this increase in our title volume, run rate and anticipated sales pipeline momentum, we are approaching an inflection point in the title business that will require us to invest in capacity to onboard new clients and scale up. Turning to Canada, the business launched three new clients in the second quarter. We delivered modest revenue and net revenue growth despite a decline in mortgage market volumes and Canadian net revenue margins reached a record high of 19.9%. With that, I’ll hand it over to Rodrigo.

Rodrigo Pinto (Chief Financial Officer)

Rodrigo thank you Brian and good morning everyone. The U.S. Mortgage market experienced robust momentum at the beginning of our second fiscal quarter, supported by declining interest rates and narrower mortgage spreads. The pace of activity then decelerated in March as geopolitical tensions surfaced and interest rates edged higher. The 30 year mortgage rate opened the quarter at 6.15% and reached an intra quarter low of 5.98%. However, mortgage rates reversed sharply in March, closing the quarter at 6.4% driven by upward pressure on the US 10 year treasury yield slowing origination growth. Lastly, the average 10 year yield and 30 year mortgage spread narrowed to below 200 basis points during the quarter. The modest decrease in mortgage rates mid quarter prompted growth in refinance market originations, although from a low base. Meanwhile, purchase market origination volume experienced only modest growth, consistent with industry estimates. Turning to our second quarter financial performance, I’ll start with our U.S. appraisal segment where we recorded revenues of 33.7 million, up 26% from the same period last year. Revenues from mortgage originations increased 24% year over year. Home equity revenues increased 30% year over year and accounted for 26% of the segment’s revenues, reflecting a higher addressable market for home equity transactions and net market share gains with existing and new clients. Another revenue increased 61% year over year due to continued net market share gains. U.S. appraisal net revenue was 8.6 million, up 18% from the second quarter of fiscal 2025. Net revenue margins decreased by 170 basis points year over year, primarily due to the distribution of transactions volumes as it relates to geographies, clients and product mix. Second quarter U.S. appraisal operating expenses increased 6% year over year to 5 million, driven mainly by higher salaries and benefit costs. We generated U.S. appraisal adjusted EBITDA of 3.6 million, up 41% from the prior year quarter and adjusted EBITDA margins expanded by 670 basis points to 41.1%, reflecting strong operating leverage as volumes increased. Turning to our U.S. title segment, second quarter revenues increased 127% year over year to 5% million, driven mainly by refinance origination revenues which increased 271% due to market share gains with existing and new clients as well as higher market refinance volumes. Home Equity revenues increased 54% supported by market share gains with existing clients and growth in reverse mortgage transactions with new clients. U.S. title net revenue was 3.3 million, up 176% from the second quarter last year and net revenue margins improved to 63.3% from 52.1% in the second quarter of 2025. This margin expansion was driven by higher volume serviced, which diluted our fixed costs and a higher proportion of incoming order volumes that closed. U.S. title operating expenses increased 12% year over year, primarily due to additional hires to accelerate the deployment of new title clients and to a lesser extent, salary increases and higher benefit costs. We reported an adjusted EBITDA loss of 0.4 million for the U.S. title segment, a significant improvement compared to the 2.1 million loss in the second quarter of fiscal 2025, consistent with prior periods. More than 85% of incremental net revenue generated during the quarter flowed to the bottom line, demonstrating the operating leverage inherent in business as volumes scale. In Canada, second quarter revenues were 8.4 million, consistent with the prior year as lower mortgage market volumes were largely offset by foreign exchange. Net revenue increased 5% to $1.7 million, driven by improved net revenue margins, which hit a record high of 19.9%, while adjusted EBITDA increased to 1.1 million. Adjusted EBITDA margins decreased slightly due to modestly higher operating expenses. Overall in the second quarter, consolidated revenue increased 27% year over year to 47.2 million and consolidated net revenue increased 35% to 13.6 million, primarily driven by continued strength in our U.S. appraisal and U.S. title segments. We delivered positive consolidated …

Full story available on Benzinga.com

This post was originally published here

On Friday, Gates Industrial Corp (NYSE:GTES) discussed first-quarter financial results during its earnings call. The full transcript is provided below.

This transcript is brought to you by Benzinga APIs. For real-time access to our entire catalog, please visit https://www.benzinga.com/apis/ for a consultation.

Access the full call at https://events.q4inc.com/attendee/933052327

Summary

Gates Industrial Corp reported first-quarter sales of $851 million, a core sales decrease of 2.9%, impacted by ERP implementation and fewer working days.

Adjusted EBITDA was $177 million with a margin of 20.8%, down 130 basis points year-over-year due to ERP inefficiencies and fewer working days.

The company reiterated its 2026 financial guidance, projecting improved core growth and adjusted EBITDA margin in the second half of the year.

Notable operational highlights include the successful ERP transition in Europe, which temporarily increased operating costs but is expected to stabilize.

Gates Industrial Corp announced the acquisition of Timken’s Industrial Belt business, expected to enhance its power transmission position in North America.

Full Transcript

OPERATOR

Good morning and welcome everyone to the Gates Industrial Corp first quarter 2026 earnings call. Today’s conference is being recorded. All lines have been placed on mute to prevent any background noise. After the speaker’s remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press the star key followed by the number one on your telephone keypad. If you would like to withdraw your question, press star one again. At this time I would like to turn the conference over to Rich Quozzo, Senior Vice President, Investor Relations. Please go ahead.

Rich Quozzo

Greetings and thank you for joining us on our first quarter 2026 earnings call. I’ll briefly cover our non GAAP and forward looking language before passing the call over to our CEO Ivo Yorick, will be followed by Brooks Mallard, our CFO. Before the market opened today, we published our first quarter results. Copy of the release is available on our website at investors.gates.com our call this morning is being webcast and is accompanied by a slide presentation. On this call we will refer to certain non GAAP financial measures that we believe are useful in evaluating our performance. Reconciliations of historical non GAAP financial measures are included in our earnings release and the slide presentation, each of which is available in the Investor Relations section of our website. Please refer now to slide 2 of the presentation which provides a reminder that our remarks will include forward looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward looking statements are subject to risks that could cause actual results to be materially different from those expressed in or implied by such forward looking statements. These risks include, among others, matters that we’ve described in our most recent Annual report on Form 10-K and in other filings we make with the SEC, including our annual report on Form 10-K that was filed in February 2026. We disclaim any obligation to update these forward looking statements. We’ll be attending several conferences over the coming weeks and look forward to meeting with many of you. And before we start, please note all comparisons are against the prior year period unless stated otherwise. Now I’ll turn the call over to Ivo.

Ivo Yorick (Chief Executive Officer)

Thank you Rich and Good morning, everyone. We appreciate your participation on our call today. I will start on slide 3 with a brief recap of the first quarter. Our team executed well on our business priorities during the first quarter, navigating successfully through a fair level of business transition. In particular, our Europe team successfully implemented a new Enterprise Resource Planning (ERP) system and achieved higher efficiency rates as the quarter progressed. Exiting the quarter, our Europe business had stabilized and was delivering revenues on par with prior three Enterprise Resource Planning (ERP) implementation periods, although with still somewhat above normal operating costs. We anticipate our operational efficiency in Europe to stabilize further during the second quarter. On a global basis, our sales dollars and margin rate, were broadly consistent with expectations we have outlined in February, excluding the impact of the anticipated headwinds from the Enterprise Resource Planning (ERP) transition and the two fewer working days that affected the first two months of the quarter. Overall demand trends improved during the quarter. Core sales growth approximated mid single digits year over year. In March, we finished the quarter with a book-to-bill solidly above one. As we sit here today and based on our present run rates, we feel good about our core sales growth prospects for the year absent of any additional potential escalation of the conflict in the Middle East. In addition, we do not anticipate any material financial impact from the recent revisions in Section 232 tariffs,. As such, we are reiterating our 2026 financial guidance. Please turn to slide 4. Our first quarter sales were $851 million, representing a core sales decrease of 2.9% relative to our core sales guidance provided in February. We experienced some small incremental distribution inefficiencies associated with the Enterprise Resource Planning (ERP) transition which led to a build of past due backlog as we exited the quarter. We expect to recover these sales in the second quarter and Brooks will go into more detail later on the call. The European Enterprise Resource Planning (ERP) transition and fewer working days relative to a prior year period combined represented approximately a 600 basis points headwind, to our core sales. Entering 2026 we experienced a positive inflection in industrial OEM orders and that trend has continued. Adjusted EBITDA was $177 million in line with expectations, resulting in an adjusted EBITDA margin, of 20.8% down 130 basis points year over year. The decrease was primarily driven by inefficiencies related to the Enterprise Resource Planning (ERP) transition and the impact of having too fewer working days compared to prior year period. Our adjusted gross margin was 40.5%, down approximately 20 basis points. Our adjusted earnings per share was 35 cents and down slightly. The fewer working days in a quarter and Enterprise Resource Planning (ERP) transition combined to represent a 7 cent headwind to adjusted EPS. Operational performance and a lower adjusted tax rate were modest Benefits. On slide 5, I will cover segment highlights all year over year. Comparisons were substantially impacted by the Enterprise Resource Planning (ERP) conversion as well as the fewer working days. Looking past these items, we saw a very solid strength across both of our segments with noted underperformance in commercial on highway production common to both in the Power Transmission segment, we generated revenues of $533 million in the quarter, a decrease of approximately 2.5% on a core basis, primarily driven by the fewer working days and Enterprise Resource Planning (ERP) transition In Europe. The Power Transmission segment realized accelerating order trends during March, personal mobility expanded 6% and our growth rate, was affected by project timing as well as the Enterprise Resource Planning (ERP) transition. In Europe, the region with the largest exposure to personal mobility. We anticipate a return to our normalized levels in personal mobility starting in Q2. Additionally, the construction end market continued to improve and the ag market is recovering. In a fluid power segment, our sales were $318 million with a decrease in core sales of approximately 3.5%. Fewer working days and the Europe Enterprise Resource Planning (ERP) implementation again contributed to the decline. We realized strong double digit growth in Asia-Pacific (APAC) during the quarter. Broadly, order intake was strong exiting the quarter. I would note that the commercial on highway was relatively weak in a quarter. That said, North American orders have inflected positively to start 2026. Our data center business continues to perform in line with our expectations and revenue grew approximately 700% from a low base in the prior year period. I’ll now pass the call over to Brooks for further comments on our results.

Brooks Mallard (Chief Financial Officer)

Thank you Ivo. I’ll begin on slide 6 and discuss our core sales performance by region. In the Americas, core sales declined approximately 2.6% in the first quarter. Two fewer working days in our first quarter relative to the prior year period had an unfavorable impact on growth. North America core sales were down a little less than 2%. Excluding the working days impact, North America core sales would have increased compared to the prior year. In EMEA, core sales declined approximately 8.5% year over year, most of which was incurred in February. While production outpaced targets, finished goods shipping lagged production output in February and through the first part of March. This led to slightly lower than expected revenues of around 4 million and higher pass through backlog than normal as we exited Q1. Overall, we were pleased with our improvement through the quarter. We delivered positive core growth in EMEA in March and that trend has continued through the early stages of Q2. We expect to further improve our distribution efficiencies through the second quarter and exit at normalized levels of shipping output and past due backlog. Our Asia-Pacific (APAC) region grew almost 4%. Industrial OEM and auto aftermarket both grew nicely and fueled the performance. slide 7 shows the components of our year over year change to adjusted earnings per share on a combined basis, the temporary headwinds of the Enterprise Resource Planning (ERP) transition and fewer working days represented a $0.07 headwind to adjusted earnings per share. Underlying operating performance contributed $0.02 per share. Other items, including a lower tax rate and share count, represented a 2 cent benefit. Slide 8 provides an overview of our free cash flow and balance sheet position over the last 12 months. We delivered free cash flow conversion of approximately 101%. Stronger operating cash flow drove positive free cash flow for the quarter. We continue to strengthen the balance sheet, exiting the quarter with net leverage at 1.9 times, representing an improvement of approximately 0.4 turns compared to the first quarter of 2025. Our capital allocation approach remains balanced and we repurchased additional shares in the first quarter. In late February, we received a credit rating upgrade from Moody’s to Ba2 from Ba3. Our return on invested capital remains strong while incurring margin headwinds associated with the Enterprise Resource Planning (ERP) transition and continuing to make investments in our key process and growth initiatives. Turning to Slide 9, we have reiterated our full year 2026 financial guidance. We anticipate core growth to improve over the course of the year. For the second quarter, we are guiding revenues to a range of $905 million to $945 million at the midpoint. Core growth is estimated to be approximately 3.5% year over year. We project adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) margin to decline 30 basis points compared to the prior year period influenced by temporary impacts from the Enterprise Resource Planning (ERP) transition and our footprint optimization projects, which we expect to benefit adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) margin performance in the second half of this year. I’ll now turn it back to Ivo for closing thoughts.

Ivo Yorick (Chief Executive Officer)

Thanks Brooks on slide 10, let me summarize our key messages. First, our team executed well and showed a great degree of resiliency during a period of significant business transition. We delivered slightly better adjusted EBITDA margin than expected and solid free cash flow on a seasonal basis. Our European business is operating as expected post the Enterprise Resource Planning (ERP) transition and our team is highly focused on driving incremental efficiencies. With a new system in place, we have shifted our operational focus to optimizing customer service fill rates to pre Enterprise Resource Planning (ERP) implementation levels which were at world class. Second, we continue to see improving demand trends across most of our end markets. Industrial OEM orders are gaining momentum and we experience good demand trends in April in emea. Our revenue is trending nicely above expectations to start the quarter. As such, we have good confidence in achieving our core revenue growth guidance with where we sit today.. Third, we believe our Business is in a strong position. We are executing on our footprint optimization projects and anticipate achieving an adjusted ebitda margin approaching 23.5% in the second half of the year. In addition, our balance sheet is in a strong shape. We announced a small acquisition today acquiring Timkens Industrial Belt business which we expect to close in the third quarter. The acquisition augments our part transmission position in North America and should supplement growth moving forward. We intend to remain opportunistic, deploying capital to enhance shareholder returns. Before taking your questions, I want to thank all of our global Gates Associates for their diligence and effort, supporting our customers needs and executing on our strategic goals. With that, I will now turn the call back to the operator for Q and A.

OPERATOR

Thank you. We will now begin the question and answer session. If you have dialed in and would like to ask a question, please press Star one on your telephone keypad to raise your hand and join the queue. If you would like to withdraw your question, simply press Star one. Again, we ask that you please limit yourself to one question and one follow up to allow everyone an opportunity to ask a question. We’ll take our first question from Michael Holloran at Baird.

Michael Holloran (Equity Analyst at Baird)

Hey, morning everyone. Maybe we just start where you were leaving off there a little bit. Ivo. So it sounds like core growth would have been positive in the quarter excluding Enterprise Resource Planning (ERP) and some of the days issues. Feels like the trajectory is what you’re wanting to see, exiting Q1 into Q2 holistically, maybe just confidence in the sustainability. As we sit here today, any areas of concern? What are your customers saying? Just kind of generically help us understand how you think this tracks to the year.

Ivo Yorick (Chief Executive Officer)

Yeah, Mike, good morning and thank you for the question. Look, we actually had a terrific quarter. You know, taking into account the quantified issues that we have highlighted on our Q3 earning call last year outlining that we have a major Enterprise Resource Planning (ERP) upgrade that we are going to do on basically 24% of the global company’s revenues in a Big Bang type event. And we have executed in an amazing way. I’m super proud of our Europe team. They have done a fantastic job and the business performed as we have anticipated. The business continues to behave in a very strong fashion. Net of the two less selling days than the Enterprise Resource Planning (ERP), we would have been basically up 300 basis points on core, which is right in line with what we have expected for the year and is basically trending towards the midpoint of our annual guidance. April,, we have exited in a very strong position as well. The Order flow is very solid. We have highlighted on last couple of calls that we have seen a very nice inflection in the industrial OEM order flow that remained throughout Q1 and into April,. So as far as I, you know, as far as I, you know, as I see it today, I feel quite confidently that we are in a very good position to be able to achieve our annual guidance and, and, you know, we’ve actually put the business in a position to be able to do really well as, you know, as the revenue generation capabilities and the end market stabilize. So we’re in a very good shape.

Michael Holloran (Equity Analyst …

Full story available on Benzinga.com

This post was originally published here