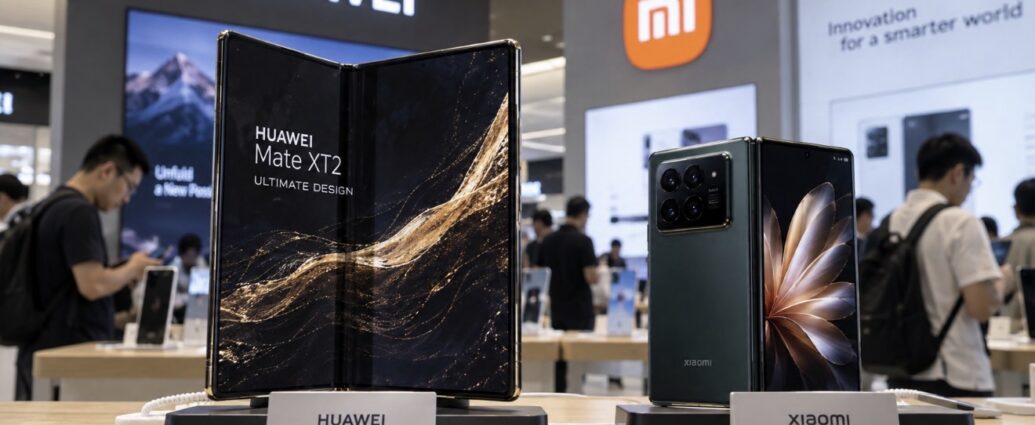
Huawei and Xiaomi Launch New Foldables as China Turns Up Pressure on Apple
SHENZHEN, China — Huawei and Xiaomi unveiled new premium foldable smartphones Monday, sharpening competition with Apple just as the U.S. company prepares for one of the most important product weeks of its year.
Huawei introduced its latest Mate XT2, a twice-folding smartphone priced from roughly $2,980, while Xiaomi launched a new foldable device starting at about $1,540.
The launches matter because Chinese smartphone makers are no longer competing only on price.
They are increasingly trying to lead on design, hardware and advanced features — especially in premium devices that directly challenge the most profitable part of Apple’s business.
Huawei’s new phone expands on its unusual tri-fold design, which opens into a much larger tablet-like screen while still folding down into a handheld device.
Xiaomi, meanwhile, is pushing its own premium foldable lineup as it seeks to move further beyond the lower-cost segment where Chinese brands first built their global market share.
The timing is significant.
Apple is entering its annual fall product cycle while Chinese manufacturers are trying to capture more attention in the world’s largest smartphone market.
China has become one of Apple’s most difficult regions.
Local competitors have improved rapidly, especially in cameras, battery technology, artificial-intelligence features and foldable designs.
Huawei’s comeback has been particularly important.
The company was heavily constrained by U.S. export restrictions that cut its access to advanced Western semiconductor technology.
But Huawei has increasingly rebuilt its smartphone business around domestically developed chips and Chinese suppliers.
That has turned the company into something more than a consumer-electronics competitor.
It has become a symbol of China’s effort to reduce dependence on American technology.
Xiaomi is following a similar broader trend by increasing the amount of proprietary hardware and software inside its devices.
That puts pressure on Apple from two directions.
First, Chinese brands are offering features — such as advanced folding screens — that Apple currently does not sell.
Second, they are becoming less dependent on the same foreign technology ecosystem Apple and other Western companies use.
The commercial implications are significant.
Premium smartphones carry some of the highest profit margins in consumer electronics.
If Huawei, Xiaomi and other Chinese manufacturers continue taking share from Apple in that category, the impact could extend beyond phone sales into app revenue, services, accessories and the broader Apple ecosystem.
Foldable phones are still a relatively small part of the global smartphone market.
But they have become strategically important because they allow manufacturers to differentiate their products in an industry where traditional smartphones increasingly look and function alike.
Huawei’s nearly $3,000 starting price also sends a strong signal.
Chinese brands are no longer trying only to undercut Western competitors.
They increasingly believe consumers will pay luxury-level prices for Chinese technology.
That could be one of the biggest changes happening in the global smartphone market.
For years, Apple competed against Chinese companies primarily on the assumption that it owned the premium end.
Huawei and Xiaomi are increasingly challenging that assumption.
JBizNews Desk | Shenzhen, China
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Trump Says Canada’s Dollar ‘Imbalance’ With U.S. Is Unacceptable, Opening New Front in Trade Fight
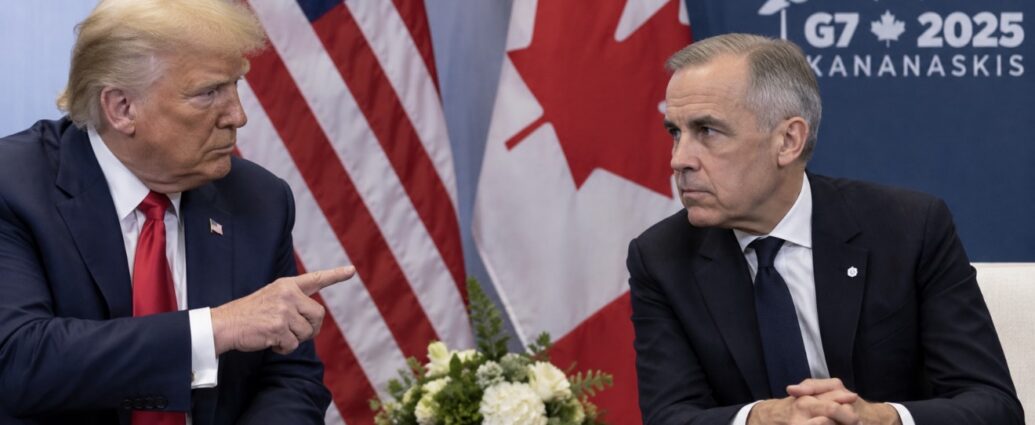
President Donald Trump is taking aim at the Canadian dollar, declaring the long-standing difference between the two countries’ currencies unacceptable as Washington and Ottawa move deeper into an escalating trade confrontation.
President Donald Trump opened a new front in the U.S.-Canada economic dispute Sunday, criticizing the value of Canada’s currency relative to the U.S. dollar and signaling that exchange rates could become another issue in already-fractured trade negotiations.
“Canada’s Dollar imbalance with the U.S. is unacceptable,” Trump wrote Sunday, adding that the situation had existed for years but would no longer be tolerated.
Trump did not announce a specific currency action or explain what exchange rate he believes would be appropriate.
But the statement immediately raises the possibility that Washington could begin pressing Ottawa over the Canadian dollar as part of broader trade negotiations.
The Canadian dollar recently traded around C$1.38 for one U.S. dollar, meaning one Canadian dollar buys roughly 72 U.S. cents.
That difference itself is not unusual.
Currencies trade at different nominal values for many reasons, including interest rates, inflation expectations, economic growth, commodity prices and investor demand.
What matters economically is whether a government is deliberately keeping its currency artificially weak to make exports cheaper.
Trump’s remarks suggest the administration may increasingly view Canada’s exchange rate through the same lens it has used when criticizing trade imbalances with other countries.
The comments arrive at an especially sensitive moment.
U.S.-Canada trade negotiations recently broke down after Ottawa rejected American demands it considered unacceptable.
The United States has already imposed 50% tariffs on tens of billions of dollars of Canadian goods, while Canada is preparing to retaliate with its own tariffs beginning September 8.
Ottawa says its countermeasures will cover C$27.6 billion of U.S. imports, with tariffs ranging from 15% to 50%.
Products affected include steel, dairy goods, appliances, agricultural equipment, pulp and paper, plastics and electronics.
The currency dispute could make finding a compromise even harder.
Canada sends roughly two-thirds of its exports to the United States, making the U.S. market enormously important to Canadian manufacturers, energy companies and agricultural producers.
A weaker Canadian dollar can help exporters because their goods become cheaper for American buyers.
But it also makes U.S. products more expensive for Canadians and raises the cost of imported equipment and materials.
The latest Canadian trade numbers already show the pressure building.
Canada’s merchandise trade surplus fell sharply to C$769 million in July from C$4.2 billion in June, while exports to the United States dropped 6.6%.
The Canadian dollar has also been under pressure because of the escalating trade dispute.
Foreign-exchange strategists surveyed recently expect the currency to remain relatively weak in the near term, although many believe it could strengthen if tensions with Washington eventually ease.
What It Means for You
This could become much bigger than a disagreement over whether one dollar is worth more than another.
If the White House formally makes the Canadian dollar part of trade negotiations, Washington could begin demanding policies intended to strengthen Canada’s currency or compensate American companies for what it considers an exchange-rate disadvantage.
That could affect autos, steel, lumber, agriculture, energy and manufacturing — industries where U.S. and Canadian supply chains are deeply interconnected.
For American consumers, the risk is straightforward.
More tariffs or currency-related trade restrictions can increase the cost of Canadian products entering the United States.
For Canadian companies, a stronger currency could make exports less competitive just as they are already dealing with sharply higher U.S. tariffs.
And for investors, Trump’s statement introduces another variable into one of the world’s largest trading relationships.
The U.S.-Canada dispute began with tariffs.
It expanded into autos, banking and government procurement.
Now the Canadian dollar itself is on the table.
That means the economic fight between America and its largest northern trading partner may be entering a new — and potentially more complicated — phase.
JBizNews Desk | New York
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Finland Cuts Off UNRWA as U.S. Blacklists 108 Staff
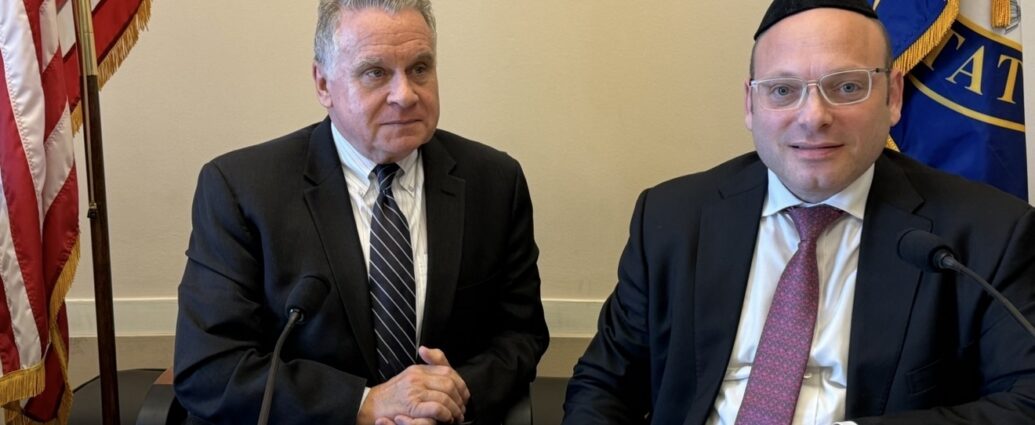
Helsinki joins Washington and Stockholm in ending direct support for the U.N. agency — extending a shift that gained force at the first post-Oct. 7 congressional hearing on UNRWA, where testimony from Orthodox Jewish Chamber of Commerce founder Duvi Honig entered the permanent record.
A third Western government has decided it can help Palestinians without paying UNRWA.
Finland will stop financing the U.N. Relief and Works Agency for Palestine Refugees when its current agreement expires at the end of 2026, Foreign Trade and Development Minister Ville Tavio announced on Aug. 27, ending contributions of €5 million a year and declining to negotiate a replacement. Tavio said Finnish aid to Palestinian territories will not fall, only move to other channels such as the World Food Programme, with the U.N.‘s new Palestine reconstruction fund under consideration. Israel’s Foreign Ministry welcomed the move, calling the agency a hotbed of terrorism.
Washington moved first and hardest. The United States suspended funding in January 2024 after allegations that agency staff took part in the Oct. 7 attacks, Congress then barred further money, and President Trump directed federal agencies in February 2025 to make no contribution, grant or payment. Sweden ended core support that December while continuing Gaza aid through other bodies. Finland had suspended its own payments in January 2024, then restored them two months later after reviewing the agency’s risk controls. This time it is not renewing at all.
American investigators, meanwhile, have gone from allegations to names. The USAID Office of Inspector General, a law enforcement body separate from the shuttered aid agency, has referred 108 current or former UNRWA employees to the State Department for suspension or exclusion from U.S.-funded work, and roughly 1,500 staff remain under investigation for ties to terrorist organizations in Gaza. Three more were recently proposed for debarment, among them a former UNRWA teacher accused of receiving and holding civilian hostages beginning on Oct. 7.
The case against the agency is not only about individuals. Those referred include school principals, teachers, security personnel, counselors and medical staff — a deputy principal serving as a Hamas company commander, a teacher with sniper training, another who tracked explosive device assignments, and a principal assigned to a Hamas weapons manufacturing unit whose school sat above three anti-tank positions and a tunnel shaft. A 2023 review by UN Watch and Impact-SE identified 133 UNRWA educators promoting hate and violence, plus 82 staff across 30 schools producing hateful material for students. Underpinning it all is a structural fact laid out in congressional testimony: the United Nations does not designate Hamas or Hezbollah as terrorist organizations, so U.N. resources can and regularly do reach their members. A humanitarian body on paper had become a payroll, a classroom system and, in places, physical cover for a terror organization.
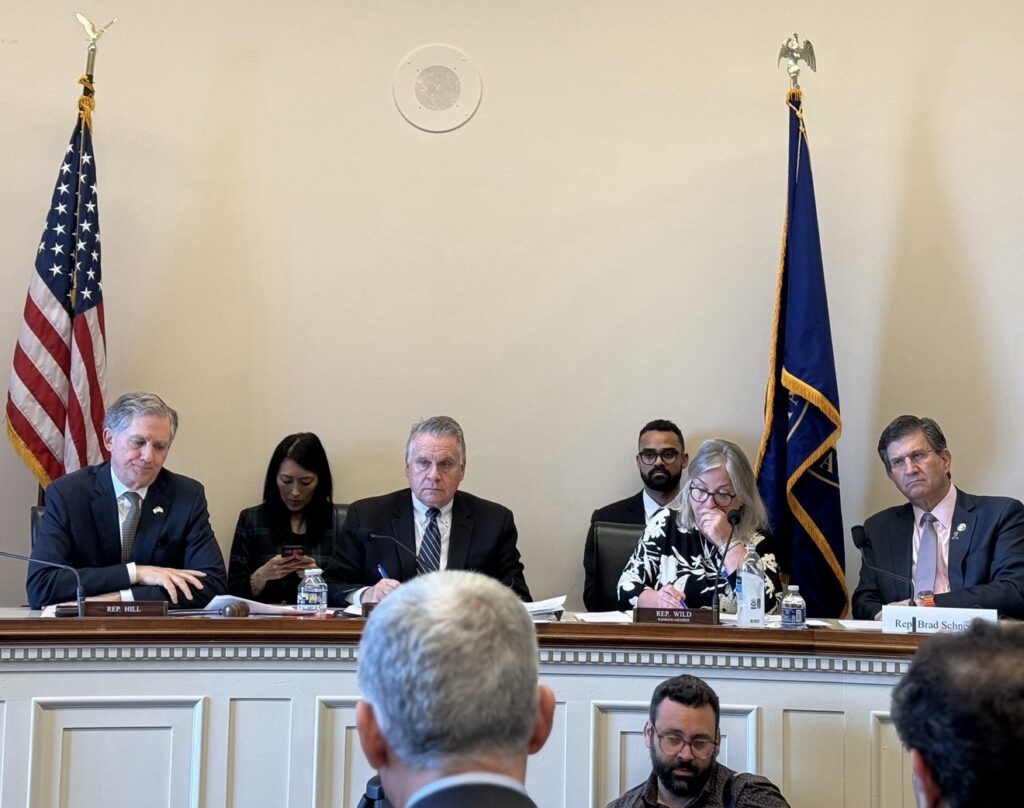
That argument was first pressed in a hearing room. On Nov. 8, 2023, one month after the attacks, Rep. Chris Smith convened a hearing on UNRWA’s schools, antisemitism and American funding. Smith entered testimony submitted by Duvi Honig, founder and CEO of the Orthodox Jewish Chamber of Commerce, into the permanent congressional record. Honig worked with Smith before the hearing on its direction and afterward on its takeaways. Smith went on to chair three more UNRWA hearings within twelve months and advanced the Stop Support for UNRWA Act, which cleared the Foreign Affairs Committee in February 2024.
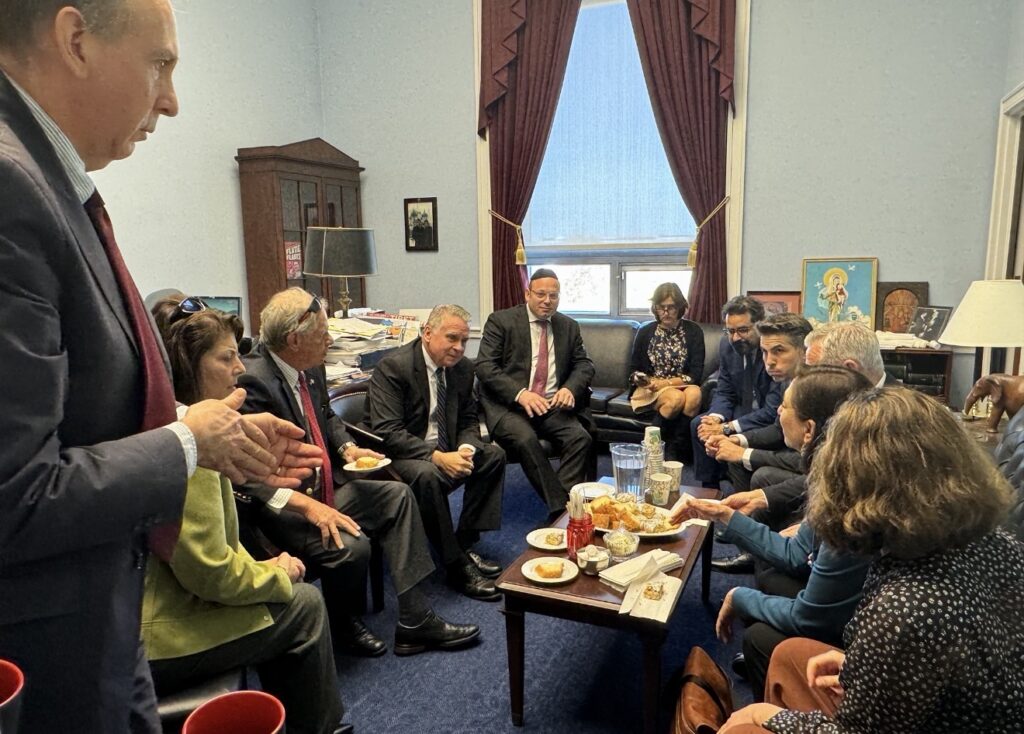
“I’m proud and honored to have helped build this foundation from the beginning — working with Congressman Chris Smith before that historic hearing, helping shape its direction, testifying and putting our position into the permanent congressional record, and then working through the takeaways afterward as we pushed this from exposure toward action,” Honig said.
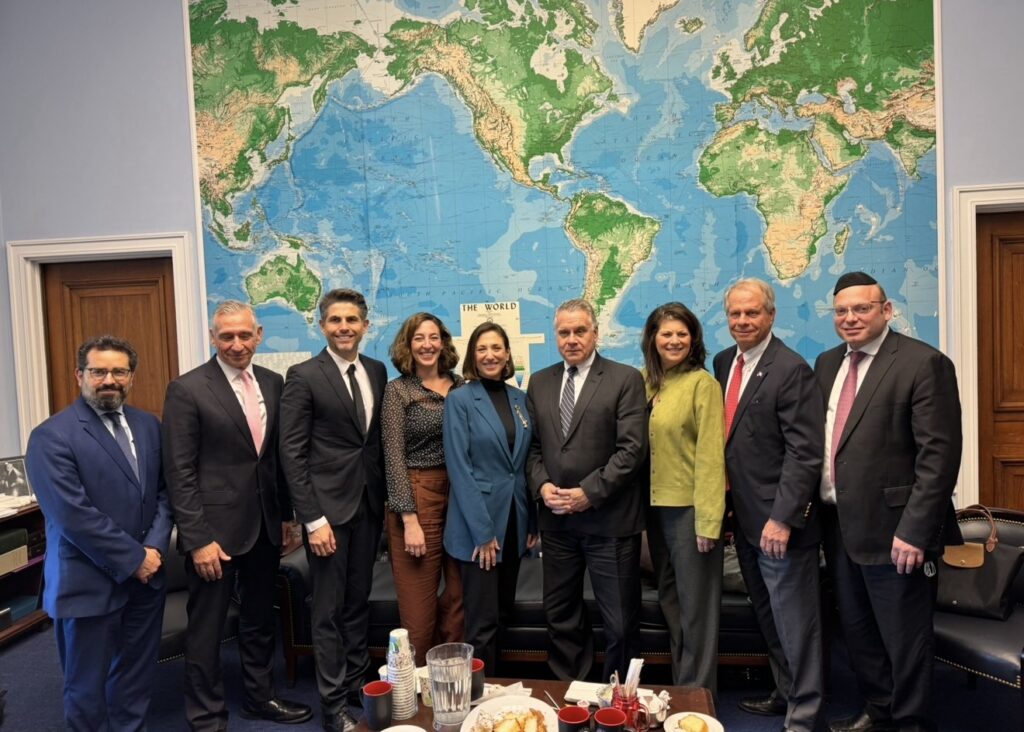
“The principle was clear from day one: taxpayer dollars intended to help innocent people should never be allowed to support terror, radicalization or institutions exploited under the disguise of humanitarian assistance. Protecting Jewish lives and protecting Palestinian lives both require making sure humanitarian funding reaches the people who need it.”
Honig credited Smith directly. “He is second to none on Capitol Hill in fighting antisemitism, hate and injustice, and he has repeatedly been willing to stand at the forefront when others would rather look away.”
For seven decades UNRWA rested on one assumption: that funding Palestinians and funding the agency were the same act. Three governments have now separated them. The United States alone sent the agency $344 million in 2022. It sends nothing today.
JBizNews Desk | Washington
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
United Returns to Israel Tomorrow With Two Daily Newark–Tel Aviv Flights
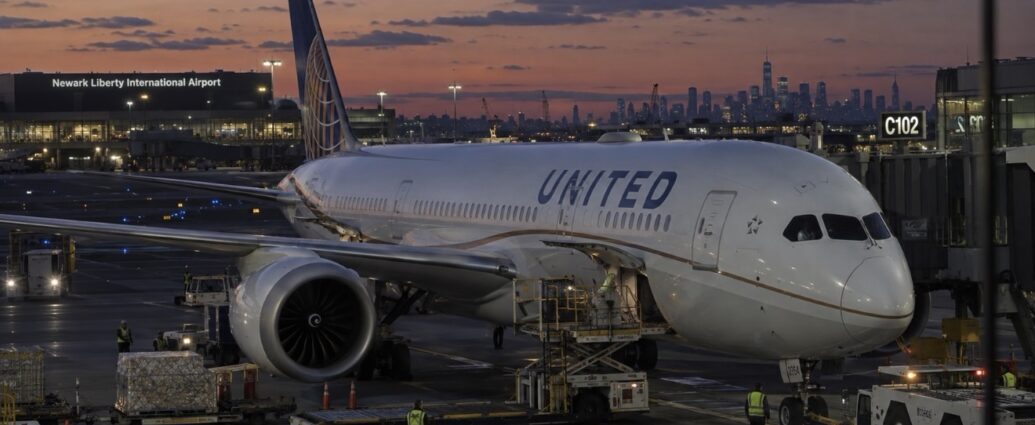
NEWARK, N.J. — United Airlines is set to restore one of the most important U.S.–Israel air links Tuesday, September 8, with two daily nonstop flights from Newark Liberty International Airport to Tel Aviv, bringing substantial new capacity back to the market just ahead of the Jewish High Holiday travel season.
The restart remained on the published schedule Monday, September 7, with both United flights showing service beginning September 8.
United Flight 84 is scheduled to depart Newark at 3:25 p.m. and arrive at Tel Aviv’s Ben Gurion Airport at 8:55 a.m. the following morning. The flight is scheduled on a Boeing 787-10 Dreamliner.
United Flight 90 is scheduled to leave Newark at 10:50 p.m., arriving in Tel Aviv at 4:20 p.m. the following day.
That means United is not returning cautiously with a limited or occasional schedule. It is moving directly back to two flights a day from Newark, restoring a major portion of the airline capacity that travelers between the United States and Israel lost during the latest Middle East disruption.
The timing matters.
September is one of the most important travel periods of the year for the Orthodox Jewish community and the broader U.S.–Israel market, as thousands of travelers prepare to head to Israel for Rosh Hashanah, Yom Kippur and Sukkot.
United’s Newark hub is particularly important for that traffic because passengers do not have to originate in the New York area. Travelers from cities across the United States can connect through Newark and continue directly to Tel Aviv on the same airline.
For New Jersey, New York and the large Jewish communities surrounding Newark, the restoration is even more significant. Newark has historically been one of the principal gateways between the United States and Israel, and United has long been one of the largest U.S. carriers serving the route.
The airline’s return also represents another sign that American carriers are gradually rebuilding their Israel networks after months of instability.
Delta Air Lines resumed its own New York-JFK to Tel Aviv service on September 6, meaning two of the largest U.S. airlines are again competing for nonstop New York-area traffic to Israel.
The difference is capacity: United’s planned Newark schedule provides two daily flights, while Delta restarted with one daily JFK flight.
United’s return therefore adds hundreds of seats each day in each direction and gives travelers considerably more flexibility in departure times, connections and premium-cabin availability.
The afternoon Flight 84 departure is particularly useful for passengers connecting into Newark from other U.S. cities earlier in the day, while Flight 90 provides a late-evening option that allows travelers to complete much of a normal workday before heading to the airport.
The Boeing 787-10 scheduled for Flight 84 is among the largest aircraft in United’s Dreamliner fleet. Published configuration information shows approximately 318 seats, including business class, premium economy and economy cabins.
The return also carries broader importance for airfare competition.
When major U.S. carriers suspend Israel flights, the reduction in available seats can place significant pressure on fares, particularly during periods of strong demand. Restoring several hundred United seats every day gives travelers another major option and reduces reliance on Israeli carriers and connecting itineraries through Europe.
For businesses, the route is also more than a leisure or family-travel connection.
New York and New Jersey maintain deep commercial relationships with Israel in technology, finance, health care, real estate, venture capital and professional services. The ability to travel nonstop between the New York metropolitan area and Tel Aviv is therefore an important piece of business infrastructure.
United has repeatedly had to adjust its Israel operation since October 2023 as security conditions changed. Airlines have suspended, resumed and again suspended service as conflict spread across the region and airspace conditions shifted.
That history is why travelers have been watching this particular restart closely.
As of Monday, however, the September 8 restart remained intact in published schedules. UA84 is listed beginning September 8 at 3:25 p.m., while UA90 is likewise scheduled to begin September 8 with its 10:50 p.m. Newark departure.
There has been no newly announced postponement of those flights.
The next important test comes Tuesday afternoon, when UA84 is scheduled to push back from Newark and begin the roughly 10½-hour journey to Ben Gurion.
If both flights operate as planned, September 8 will mark the return of a major piece of the U.S.–Israel aviation network — and, for thousands of travelers preparing for the coming holiday season, a return of something that has been increasingly difficult to count on: two daily United departures from Newark directly to Israel.
JBizNews Desk | Newark, New Jersey
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
There’s a Legal Fight Brewing at Oktoberfest
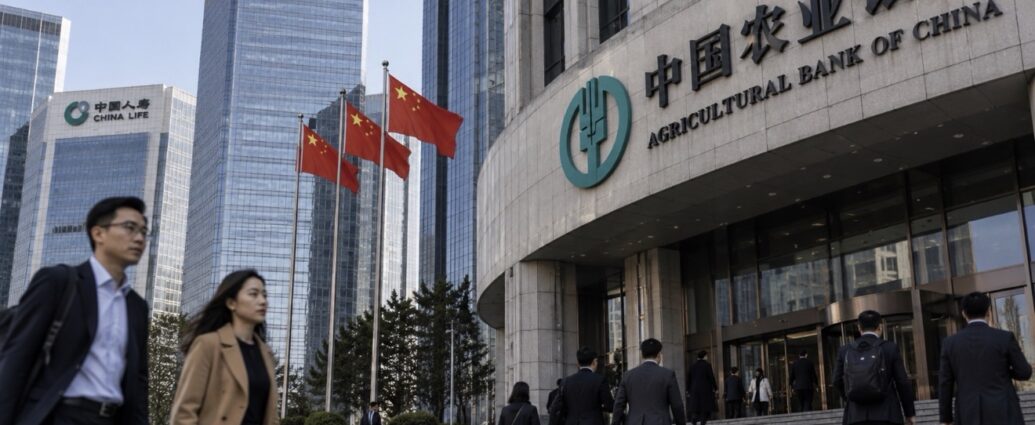
China Pumps $54 Billion Into Banks and Insurers in Major Financial-System Boost
Beijing is injecting tens of billions of dollars into some of China’s biggest financial institutions, strengthening their balance sheets as the government pushes banks to keep lending and support economic growth.
China is moving roughly $54 billion into major state-owned banks and insurance companies, one of Beijing’s most significant recent efforts to reinforce the financial system and give lenders more room to support the economy.
The capital push announced Sunday centers on three state financial institutions receiving a combined 290 billion yuan, or about $43 billion, while another group of major state-controlled insurers will receive additional capital.
Agricultural Bank of China plans to raise up to 160 billion yuan, approximately $24 billion, through a private placement of shares.
Industrial and Commercial Bank of China, the country’s largest commercial lender by assets, plans to raise another 100 billion yuan, or roughly $15 billion.
The Export-Import Bank of China is set to receive a further 30 billion yuan.
The money is intended to strengthen what regulators call core Tier 1 capital — essentially the highest-quality financial cushion banks maintain to absorb losses and continue lending during periods of economic stress.
China is also putting billions of dollars into its insurance sector.
China Life Insurance is set to receive 35 billion yuan, while China Taiping Insurance will receive 7 billion yuan. Other state-backed insurers are also receiving additional capital through separate transactions.
The broader message from Beijing is clear: China wants its largest financial institutions strong enough to continue providing credit even as parts of the economy remain under pressure.
Loan demand has been uneven, property-sector problems continue to weigh on activity, and Chinese banks have faced pressure on profitability as interest rates remain low.
At the same time, Beijing is asking banks to finance strategic industries, infrastructure, manufacturing and other areas the government views as important to long-term economic growth.
That creates a balancing act.
Banks are expected to lend more aggressively while also protecting themselves against bad loans and maintaining sufficient capital.
The new government money gives them additional room to do both.
China has already been using special government bonds to reinforce its banking system. Earlier government disclosures showed that 500 billion yuan in special treasury bonds had previously been issued to help several major banks replenish core capital.
The latest round extends that strategy to additional financial institutions.
What It Means for You
This is not simply a bank bailout.
It is Beijing using government money to make sure its financial system has enough firepower to keep lending.
That matters globally because Chinese banks finance enormous portions of manufacturing, infrastructure, exports and industrial investment.
More bank capital can translate into more credit for factories, technology projects and Chinese companies competing in global markets.
It also shows that Beijing remains concerned enough about economic conditions to strengthen financial institutions before problems become larger.
For investors and businesses, the most important question is what happens next.
If the additional capital produces stronger lending and investment, it could support Chinese growth and global demand for commodities and industrial goods.
If banks remain reluctant to lend — or companies remain reluctant to borrow — then even tens of billions of dollars in new capital may have limited impact.
Either way, China has just made another major government-backed move to keep its financial system capable of supporting the world’s second-largest economy.
JBizNews Desk | New York
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Opinion | The AfD Rises on the German Right
Europe Gets a New Commercial Route to Orbit as Isar Aerospace Makes History
A German space company has successfully carried satellites into orbit from Norway, giving continental Europe a new privately developed launch capability and marking a major breakthrough for its commercial space industry.
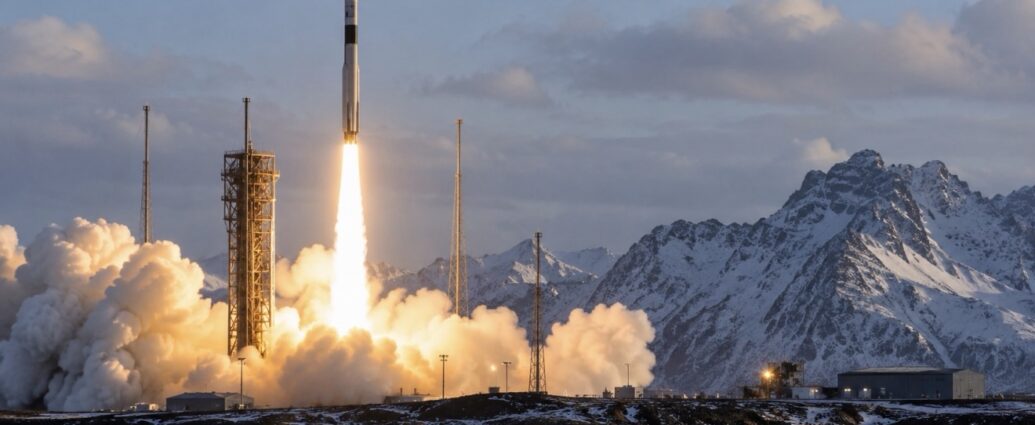
Isar Aerospace successfully reached orbit Saturday with its Spectrum rocket, deploying satellites from the company’s dedicated launch complex at Andøya Space in northern Norway.
The mission, called “Onward and Upward,” lifted off at 10:12 p.m. Central European Summer Time on September 5 and successfully delivered its payloads into orbit.
It was only Spectrum’s second flight.
That makes the achievement particularly significant.
Isar Aerospace says it has become the first commercial space company from Europe to successfully deliver satellites into orbit, while Andøya Space described the flight as the first successful satellite launch from mainland Europe.
The rocket carried five CubeSats and one experimental payload, with the mission designed not only to deliver satellites but also to continue qualifying Spectrum’s systems under real operating conditions.
The successful flight comes after a much more difficult first mission.
Spectrum’s first test flight did not reach orbit, making Saturday’s success an important demonstration that the company was able to identify problems, improve the vehicle and move quickly toward a functioning commercial launch system.
For Europe, the business implications are substantial.
European governments, defense agencies and private satellite companies have faced a shortage of domestic launch capacity as demand for small-satellite launches has expanded.
For years, much of the global commercial launch market has been dominated by a relatively small number of companies, particularly SpaceX.
Isar Aerospace is trying to build a European alternative.
The company has already raised more than €500 million in private capital and employs more than 400 people from nearly 50 countries.
Its Spectrum rocket is designed specifically for small and medium-size satellites, allowing customers to purchase dedicated launches or share space with other payloads.
Isar is also building a commercial pipeline beyond Europe.
Earlier this month, the company signed an agreement with Astroscale Japan to launch a future satellite designed to remove space debris. That mission is targeted for 2027 or 2028.
Andøya Space is preparing for much larger launch volumes as well.
The Norwegian spaceport says it ultimately wants the capacity to support up to 30 satellite launches annually within the next several years.
What It Means for You
This is not simply another rocket launch.
It is about who controls access to space.
Satellites now support communications, navigation, defense, agriculture, weather forecasting, financial systems and an increasingly large part of the global digital economy.
Countries that cannot launch their own satellites remain dependent on someone else to get critical infrastructure into orbit.
Europe has been trying to reduce that dependence.
Saturday’s successful Spectrum mission shows that privately funded European companies may finally be able to help fill that gap.
For Isar Aerospace, reaching orbit transforms the company from a promising rocket developer into something far more valuable:
A company that has demonstrated it can actually put customers into space.
And in the rapidly expanding commercial space economy, that distinction can be worth billions.
JBizNews Desk | New York
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
OPEC+ Holds Oil Supply Steady as Iran Conflict Pushes Crude Toward $100
Global energy markets enter the new week under renewed pressure after the oil alliance declined to add more barrels while fighting around the Strait of Hormuz continues to threaten one of the world’s most important shipping routes.
OPEC+ agreed Sunday to keep its oil-production policy unchanged for October, choosing not to increase supply further as the continuing U.S.-Iran conflict disrupts shipping through the Strait of Hormuz and pushes crude prices toward levels not seen in months.
The decision means the group will maintain October production at September levels after six consecutive months of increases.
The timing is especially important.
Brent crude finished Friday at $96.28 a barrel, gaining approximately 7.6% for the week, while U.S. West Texas Intermediate crude settled at $91.48, up nearly 10% for the week.
Oil markets were already dealing with restricted shipping through the Strait of Hormuz before another round of military escalation over the weekend.
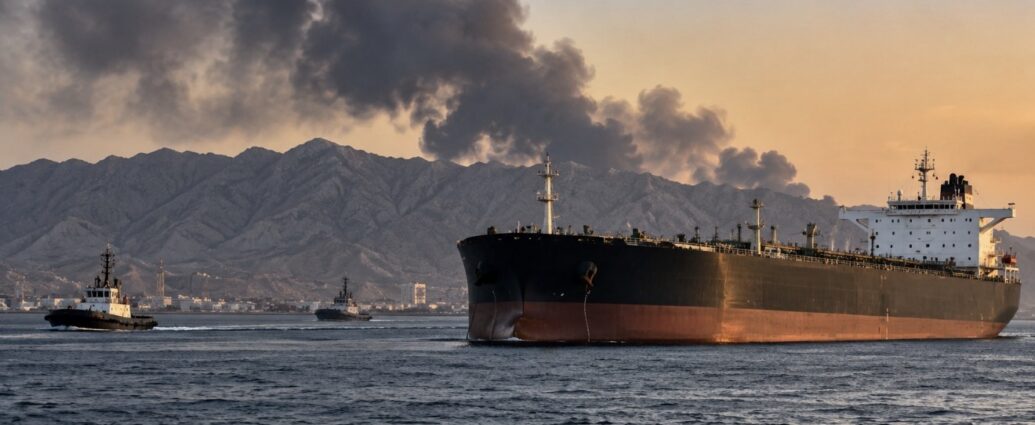
U.S. forces struck three Iranian oil tankers after Iran launched missiles toward American naval vessels, adding another layer of uncertainty before global crude trading resumes.
For businesses, the danger extends far beyond the price of oil itself.
Higher crude prices feed directly into gasoline, diesel, jet fuel, trucking, shipping, agriculture and manufacturing costs. U.S. diesel prices have already climbed to record territory, putting additional pressure on companies that move physical goods.
That makes the OPEC+ decision significant.
Normally, higher prices could encourage major producers to put more barrels onto the market. But the current problem is increasingly about whether oil can physically move through the region rather than simply how much producers are willing to pump.
The Strait of Hormuz is the narrow maritime passage connecting the Persian Gulf with global markets and is one of the most important energy chokepoints in the world. Continued disruption there can affect oil and liquefied natural gas supplies regardless of official production quotas.
OPEC+ also faces its own limitations. Several members have struggled to reach their assigned production targets, meaning a higher quota would not necessarily translate into the same amount of additional oil reaching global buyers.
The seven OPEC+ countries participating in Sunday’s decision include Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman.
The group had been gradually restoring production that was removed from the market through earlier voluntary cuts. September’s increase of approximately 188,000 barrels per day completed another stage of that process.
But for October, producers are stopping there.
The next OPEC+ meeting is scheduled for October 4, when members are expected to consider November production.
What It Means for You
The number to watch now is $100 oil.
If Brent crude breaks decisively above that level, the consequences could begin appearing throughout the economy — at gas stations, in airline fares, freight bills and ultimately consumer prices.
That creates an additional problem for the Federal Reserve.
The Fed is already confronting stronger-than-expected employment data and renewed concerns that inflation may remain stubborn. Another sustained energy-price increase could make lowering interest rates considerably more difficult — and could even strengthen the argument for keeping monetary policy tighter.
For businesses, the equation entering the new week is becoming increasingly clear:
The Middle East conflict is no longer simply a geopolitical story.
It is becoming an inflation, transportation, interest-rate and economic-growth story — and OPEC+ just decided it will not provide additional oil to soften the impact, at least for now.
JBizNews Desk | New York
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
India Clears National Stock Exchange for Long-Delayed IPO After Nearly a Decade of Regulatory Battles
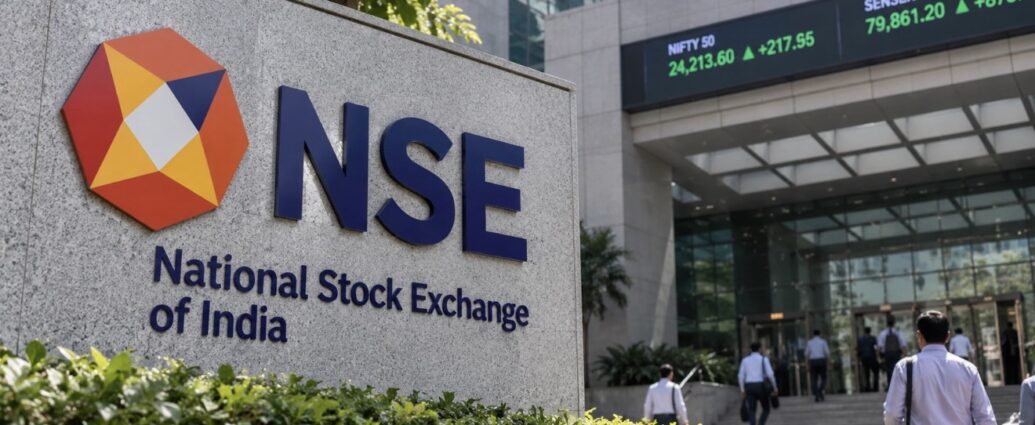
India’s National Stock Exchange has finally received regulatory clearance to move ahead with its long-awaited initial public offering, removing one of the biggest obstacles to what could become one of the country’s largest stock-market listings.
India’s market regulator, SEBI, cleared the IPO Friday after years of delays tied to legal and compliance disputes involving the exchange.
The timing is significant.
India’s Supreme Court also dismissed a major case tied to allegations that some high-frequency traders received unfair access to NSE’s systems, removing another major legal overhang as the exchange prepares to go public.
For investors, the simple story is this:
One of the most important stock exchanges in the world is finally preparing to become a publicly traded company itself.
Why NSE Matters
The National Stock Exchange is not a small regional marketplace.
It operates India’s benchmark Nifty 50 index and dominates the country’s equity-derivatives market.
By the number of derivative contracts traded, NSE is the most active derivatives exchange in the world.
That gives it a powerful position at the center of India’s rapidly expanding capital markets.
Every time investors trade stocks, futures or options through the exchange, NSE can generate revenue through transaction fees, technology services, data and other market infrastructure.
As India’s economy and investor base grow, that activity becomes increasingly valuable.
A Potential $55 Billion Company
NSE has been valued at roughly $55 billion in India’s unlisted share market.
At that valuation, it could rank among India’s ten most valuable publicly traded companies once listed.
That does not mean the IPO itself will raise $55 billion.
The offering is expected primarily to be an offer for sale, meaning existing shareholders will sell some of their stakes to public investors.
The exchange itself would not receive most of the proceeds.
But the listing would finally give investors a transparent public-market price for one of India’s most important financial institutions.
Why It Took So Long
NSE has been trying to go public for nearly a decade.
The major obstacle was regulatory controversy.
Authorities investigated whether certain high-frequency trading firms received faster or preferential access to the exchange’s trading infrastructure through systems involving co-location servers and specialized network connections.
In simple terms, regulators were examining whether some traders effectively got a technological head start over everybody else.
In markets where trades happen in fractions of a second, even tiny speed advantages can be worth enormous amounts of money.
Those allegations created years of legal battles and prevented NSE from moving forward with its listing.
The Legal Cloud Is Finally Lifting
The Supreme Court’s dismissal of the regulatory case removes a major hurdle.
NSE previously agreed in principle to pay roughly $155 million to settle outstanding issues connected to the dispute.
That allows regulators and the exchange to move toward closing a chapter that has hung over NSE since the middle of the last decade.
For investors, regulatory certainty matters almost as much as financial performance.
A company preparing for an IPO needs buyers to understand the risks they are purchasing.
A decade-old dispute involving the integrity of the exchange itself was a particularly serious problem.
Removing it makes NSE much easier to value.
India’s Capital Markets Are Becoming a Global Force
The IPO also reflects something bigger happening in India.
More Indian households are investing in stocks.
Domestic mutual funds are growing.
Foreign investors are increasingly active.
Companies are raising more money through Indian capital markets.
And India has become one of the world’s busiest IPO markets.
That creates a powerful business model for an exchange.
NSE does not have to guess which individual company will succeed.
It earns money from the infrastructure investors use to trade all of them.
The more active India’s markets become, the more valuable that infrastructure can become.
Why the IPO Could Draw Huge Interest
Stock exchanges can be unusually attractive businesses.
They often benefit from:
High margins.
Recurring trading activity.
Market-data revenue.
Technology fees.
Strong network effects.
And significant barriers to new competitors.
Once investors and brokers concentrate on one major exchange, it becomes difficult for a newcomer to recreate that liquidity.
NSE already has that scale.
That is why the IPO could attract substantial interest from domestic and international investors.
What It Means for Businesses
For Indian companies, a stronger and more transparent public exchange can deepen access to capital.
For global investors, the listing provides another way to invest directly in the growth of India’s financial markets rather than choosing individual banks, technology companies or manufacturers.
And for India itself, the IPO marks another step in the maturation of its capital-market system.
The irony is difficult to miss.
For years, millions of companies and investors have relied on NSE to buy and sell shares.
Now investors are preparing to buy shares in the exchange itself.
After nearly a decade of regulatory battles, one of the world’s busiest financial marketplaces is finally moving toward becoming a publicly traded company.
JBizNews Desk | Mumbai
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Trump Warns U.S. Could Strike Iran’s Pickaxe Mountain Nuclear Site ‘Very Soon’
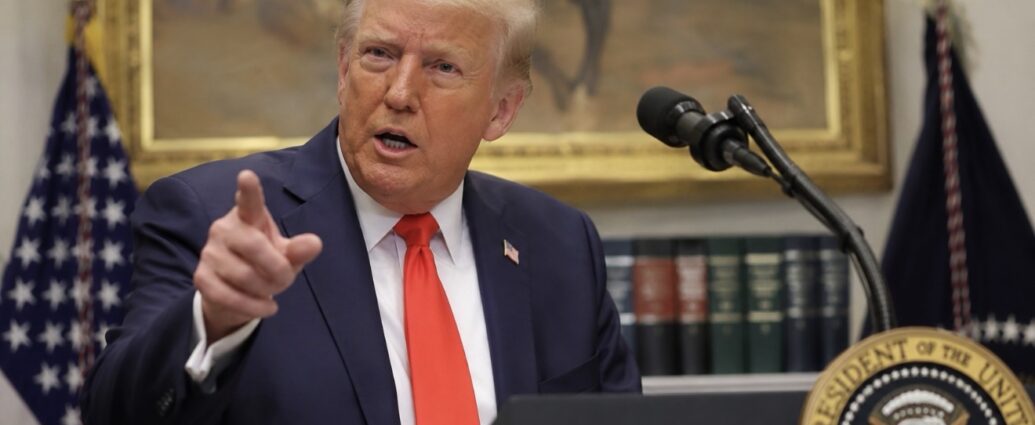
WASHINGTON — President Donald Trump warned Friday that the United States could soon strike Iran’s heavily fortified Pickaxe Mountain facility if Washington determines Tehran is continuing nuclear activity there, putting one of Iran’s most protected sites directly on notice.
“Iran will not have a nuclear weapon,” Trump told reporters in the Oval Office, adding that the United States “may hit Pickaxe very soon” if there is evidence of activity at the facility.
The warning comes as the United States has resumed attacks against Iranian targets after a period of reduced military activity, marking a renewed escalation in the confrontation between Washington and Tehran.
Trump said the United States carried out what he described as a “very heavy attack” against Iran Thursday night and remains prepared to launch additional strikes whenever necessary. He also suggested Iran may have limited ability to withstand continued American military pressure.
The President, however, stopped short of describing the confrontation as a full-scale war. Instead, he called it a limited “military conflict,” echoing comments from Vice President JD Vance that the renewed fighting should not necessarily be characterized as a war.
The focus on Pickaxe Mountain is especially significant because of its reported role in Iran’s nuclear infrastructure. A strike on a heavily fortified nuclear-related facility would signal that Washington is prepared to continue targeting sites Tehran may have believed were protected from conventional attacks.
Trump’s message also reinforces the central U.S. position driving the confrontation: Iran will not be permitted to obtain a nuclear weapon, regardless of how deeply its nuclear infrastructure is buried or fortified.
For Tehran, the warning creates a stark calculation. Continuing activity at Pickaxe Mountain could bring another direct U.S. attack, while halting operations would demonstrate the growing effect of American military pressure.
For markets and businesses, renewed strikes on Iranian nuclear infrastructure would also raise the risk of further instability across the Middle East, including potential disruptions involving Gulf energy production, shipping routes and global oil prices.
Trump indicated that he does not expect the current escalation to continue for an extended period, saying Thursday that he did not believe Iran could withstand American attacks much longer.
But Friday’s warning made clear that Washington is not declaring the operation finished.
If activity continues at Pickaxe Mountain, the next phase could come quickly.
JBizNews Desk | Washington
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Revolut Moves Closer to Becoming a Full U.S. Bank
STAMFORD, Conn. — Revolut took a major step toward becoming a full-service American bank after receiving conditional approval from the Office of the Comptroller of the Currency for a national bank charter.
The British financial-technology company still needs approvals from the Federal Deposit Insurance Corporation and the Federal Reserve before it can fully launch banking operations in the United States.
But the OCC decision moves Revolut significantly closer.
The company has approximately 80 million customers worldwide and has built much of its growth around mobile banking, foreign-exchange services, multicurrency accounts and international payments.
Revolut plans to base its U.S. bank in Stamford, Connecticut, where it expects to invest approximately $95 million in capital and employ roughly 160 people.
Its planned U.S. products include checking accounts, installment loans, credit cards, foreign-exchange services and eventually a stablecoin.
That matters because Revolut would no longer simply be a financial app relying on another bank’s infrastructure.
A banking charter would allow it to move much deeper into deposits, lending and payments.
It would also give Revolut more control over the economics of its U.S. business.
Fintech companies traditionally earn fees by sitting on top of traditional banks. Once they become banks themselves, they can potentially capture more of the revenue from deposits, lending and transaction activity.
For small and midsize businesses, the most important part may be Revolut’s international reach.
Companies increasingly operate across borders, paying vendors overseas, employing remote workers, buying inventory in foreign currencies and receiving payments from customers in different countries.
Traditional banking services can make those transactions expensive and slow.
Revolut has built much of its brand around making multicurrency banking simpler and cheaper.
If it connects a U.S. bank directly into its existing European and Latin American infrastructure, it could become a more serious competitor for businesses that regularly move money across borders.
The bigger story is what is happening to banking itself.
For years, fintech companies competed with banks by building better apps.
Now some of those companies are trying to become the bank.
That puts pressure on traditional institutions not only to improve digital products, but also to compete on fees, foreign-exchange pricing and ease of use.
The remaining regulatory approvals are still important, and conditional OCC approval does not guarantee a final launch.
But Revolut’s move shows that the line between fintech and traditional banking is disappearing quickly.
For consumers and businesses, that could mean more competition.
For established banks, it means another global rival is getting closer to entering their core business.
JBizNews Desk | Stamford
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Unexpected WhatsApp Bans Leave Businesses Locked Out and Cut Off From Customers
WhatsApp users in Israel and elsewhere are reporting sudden account suspensions that can leave them locked out without warning — cutting off access to customers, employees, vendors and years of important conversations.
For an individual user, that is frustrating.
For a business, it can become an immediate operational problem.
WhatsApp has become a major communications tool for small businesses around the world. Companies use it for customer service, sales, scheduling, orders, supplier communication and internal messaging.
That means losing an account can feel almost like losing access to email, a company phone system and part of a customer database at the same time.
What Is Happening
Users have reported receiving messages saying their accounts were banned for violating WhatsApp’s terms even when they say they were not given a clear explanation of what triggered the decision.
Some users have later regained access after requesting a review.
WhatsApp has previously acknowledged technical issues that caused certain accounts to be banned incorrectly.
That raises a bigger question for businesses:
How much of a company’s daily operation should depend on a communications platform controlled by someone else?
Why Businesses Are Especially Exposed
A small business may build much of its customer communication around one WhatsApp number.
Customers know that number.
Employees use it.
Orders come through it.
Photos, invoices, delivery information and customer conversations may all live there.
If the account is suddenly disabled, the business does not simply lose access to an app.
It can temporarily lose access to the people it depends on.
That is the real business risk.
The company may own the customer relationship, but Meta controls the platform connecting the two.
Automated Enforcement Can Make Mistakes
WhatsApp operates at enormous scale.
That means Meta relies heavily on automated systems to detect spam, fraud, abuse and other violations.
Those systems are necessary.
But automated enforcement is not perfect.
A business sending many similar messages can sometimes resemble spam.
An unusual increase in activity can look suspicious.
Accounts can also be reported by other users.
When automated systems combine those signals, legitimate accounts can sometimes be caught alongside actual scammers.
The bigger problem comes when users do not understand why they were banned or how quickly they can get their account restored.
Being Locked Out Can Cost Real Money
For businesses, even a temporary suspension can have financial consequences.
A retailer can miss orders.
A service business can miss appointments.
A contractor can lose contact with customers.
A salesperson can lose access to leads.
An employer can suddenly lose an internal communication channel.
And customers may have no idea the account was suspended.
They may simply assume the business stopped responding.
That can damage trust even after access is eventually restored.
The Risk Is Bigger for Small Businesses
Large companies usually have multiple systems.
They have email.
Customer-service software.
Phone systems.
Websites.
Databases.
Backup communications.
A small business may have none of that.
For many small operators, WhatsApp has become the system.
That makes the convenience enormous.
But it also creates a single point of failure.
If the account disappears, there may be no immediate backup.
Meta Wants More Businesses on WhatsApp
This creates an important issue for Meta itself.
WhatsApp is increasingly becoming a commercial platform.
Meta is expanding paid business messaging, customer-service tools and commerce features designed to make WhatsApp more important to companies.
That strategy depends on trust.
Businesses will be reluctant to rely even more heavily on WhatsApp if they believe their account can suddenly be disabled without a clear explanation.
For commercial users, reliability does not only mean the app stays online.
It also means legitimate businesses need confidence that their access will remain stable.
And if something goes wrong, there needs to be a fast and understandable appeals process.
What Businesses Should Do
The lesson is not that businesses should stop using WhatsApp.
For many companies, it remains one of the easiest and most effective ways to communicate with customers.
The lesson is not to let WhatsApp become the only place where critical business relationships exist.
Businesses should maintain independent customer contact records.
Important documents and order information should be stored elsewhere.
Customers should have another way to reach the company, whether through email, SMS, a website or another messaging service.
The goal is simple:
If WhatsApp locks the account tomorrow, the business should still be able to operate.
What It Means for Businesses
Digital platforms have given small businesses access to tools that once required expensive software and communications systems.
But they have also created a new kind of dependency.
A business can build thousands of customer relationships through a platform it does not control.
Everything works extremely well — until the account is suddenly locked.
For businesses increasingly dependent on WhatsApp, the latest complaints are a reminder of a basic digital-business rule:
Own the relationship with your customer, and never let one outside platform become the only door connecting you to them.
JBizNews Desk | Tel Aviv
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
South Korea Gets Trump’s Message — Seoul Moves Toward Hormuz Mission After U.S. Scales Back Joint Drills
South Korea is moving toward a possible military deployment to the Strait of Hormuz just weeks after President Donald Trump publicly tied reduced U.S.-South Korea military exercises to Seoul’s refusal to assist Washington in the war against Iran.
The timing is difficult to miss.
South Korean media, citing government and military sources, report that Seoul is preparing to seek parliamentary approval for a mission aimed at protecting freedom of navigation through the Strait of Hormuz.
Options under consideration reportedly include a maritime patrol aircraft, a logistics support vessel and a mine-clearing unit.
South Korea has also been discussing the possible mission with the United States, Britain and France.
The government has not made a final deployment decision, and the South Korean presidential office has pushed back against reports suggesting the mission is already approved.
But Seoul is clearly considering a contribution that looks very different from the position it held only weeks ago.
The Message From Washington
Last month, Trump announced that he was reducing the scale of joint U.S.-South Korea military exercises.
He cited his relationship with North Korean leader Kim Jong Un as one reason.
But Trump also specifically pointed to South Korea’s refusal to assist the United States in the conflict with Iran.
That made the decision more than a military scheduling issue.
It became a message about burden-sharing.
The United States has tens of thousands of troops stationed in South Korea and has spent decades providing a major security umbrella against North Korea.
Trump’s position was essentially that allies benefiting from American military protection should also be willing to assist the United States when critical global shipping routes and American interests are under threat.
Now Seoul is considering exactly the kind of maritime contribution Washington had been seeking.
Why Hormuz Matters to South Korea
There is also a powerful economic reason for Seoul to care.
South Korea is one of the world’s largest energy importers.
It depends heavily on oil and natural gas moving out of the Middle East.
The Strait of Hormuz is the gateway for a major share of those supplies.
If shipping through the strait becomes unreliable, South Korea does not simply have a foreign-policy problem.
It has an energy problem.
Higher oil and gas prices hit Korean manufacturers, airlines, shipping companies and consumers.
That gives Seoul a direct economic interest in keeping the waterway open.
This Is Not Yet a Deployment
That distinction is important.
South Korea’s presidential Blue House says discussions are still focused on practical ways to contribute to freedom of navigation.
It has rejected reports that a final decision to deploy forces has already been made.
The government is reportedly considering submitting a consent motion to parliament after a cabinet review.
So the next step is political.
Seoul has to decide whether it wants to formally commit military assets and then secure the necessary domestic approval.
Why the Mine-Clearing Option Matters
One of the most important options being discussed is a mine-clearing unit.
That is not symbolic.
Mines can close or severely restrict commercial shipping without requiring Iran to directly attack every vessel passing through the strait.
Clearing them requires specialized ships, equipment and trained personnel.
A South Korean contribution in that area could therefore have real operational value for maintaining commercial traffic.
The same is true of maritime patrol aircraft, which can monitor shipping lanes and identify potential threats.
What It Means for Businesses
For global businesses, this is ultimately about keeping one of the world’s most important energy corridors functioning.
Oil markets do not need the Strait of Hormuz to be completely closed before prices rise.
Even the threat of disruption can increase:
- Oil prices
- Marine insurance
- Freight costs
- Shipping delays
- Energy prices
South Korea has more at stake than most countries because of its dependence on imported energy and its enormous manufacturing economy.
That makes participation in a Hormuz mission both a military decision and an economic one.
The Bigger Alliance Message
The broader lesson may be even more important.
Trump has repeatedly argued that American allies should contribute more directly when U.S. forces are carrying the burden of protecting shared economic and security interests.
South Korea initially stayed out of the Iran conflict.
Washington responded by reducing military cooperation.
Now Seoul is actively discussing sending assets toward the very region where the United States wanted help.
South Korean officials have not said the two decisions are directly connected.
But the sequence is clear.
Washington applied pressure. Seoul heard the message. And South Korea is now considering putting military assets into the Strait of Hormuz.
For America’s other allies, that sequence will be closely watched.
JBizNews Desk | Seoul
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
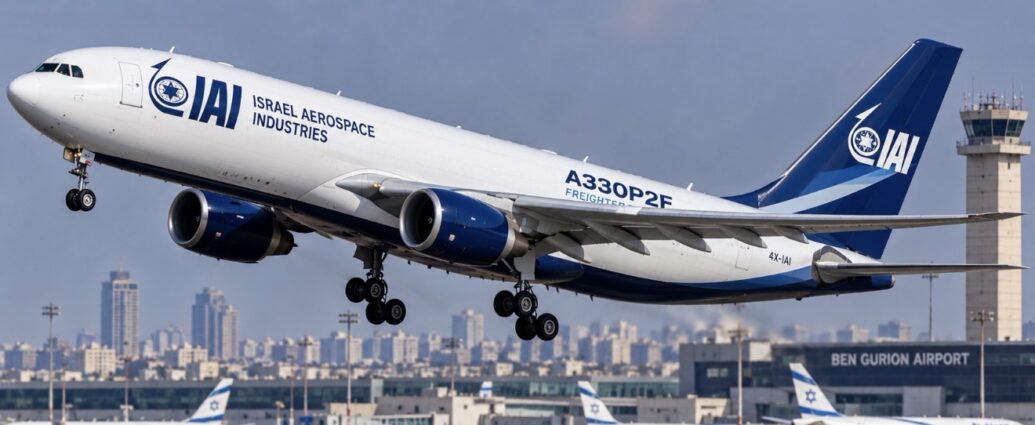
Israel Aerospace Industries Flies First Converted Airbus A330 Freighter, Expanding Global Cargo Business
Israel Aerospace Industries has completed the maiden flight of its first converted Airbus A330-300 freighter, marking a major milestone in the company’s push to expand deeper into the global air-cargo market.
The aircraft began life as a passenger jet.
IAI has now converted it into a dedicated freighter capable of carrying up to 61 tons of cargo and accommodating as many as 30 cargo containers.
That turns an older passenger aircraft into a new commercial asset instead of sending it toward retirement.
Why This Matters
Passenger-to-freighter conversions have become a major business for airlines and aircraft lessors.
A new cargo aircraft can cost tens of millions of dollars.
Converting an existing passenger jet can be significantly cheaper.
The economics are straightforward.
An airline or leasing company takes an aircraft that may no longer be attractive for passenger service, removes the cabin interior, reinforces the floor, modifies the structure, installs a large cargo door and converts the aircraft for freight operations.
That can add many more years of useful service.
For aircraft owners, it can dramatically increase the value of an aging jet.
IAI Is Already a Major Player
Israel Aerospace Industries has decades of experience converting passenger aircraft into freighters.
Its work has historically centered heavily on Boeing aircraft, including widebody platforms used by cargo operators around the world.
The A330 program changes that.
IAI is now positioning itself as one of the relatively few aerospace companies capable of converting both Airbus and Boeing widebody aircraft.
That gives it access to a much larger pool of aircraft.
Thousands of Airbus A330s have been delivered worldwide.
As passenger versions age, many will eventually become candidates for conversion.
The A330 Is Well Suited for Cargo
The Airbus A330 is already widely used by passenger airlines.
It has strong range, a large fuselage and relatively efficient operating economics.
The converted A330-300 is aimed primarily at regional and medium-haul freight operations.
Its capacity of up to 61 tons gives operators a middle ground between smaller narrowbody freighters and much larger long-haul cargo aircraft.
That can make it attractive for routes where airlines need significant capacity but do not need the size of a Boeing 747 freighter.
The Maiden Flight Is Only One Step
The successful flight does not mean the aircraft is ready for commercial service tomorrow.
The program still has to complete flight testing and regulatory certification.
That process is designed to prove that the structural modifications, cargo systems and aircraft performance meet aviation-safety standards.
Once certification is completed, IAI can begin delivering converted aircraft to customers.
That is when the program moves from engineering project to revenue-generating business.
Why Air Cargo Still Matters
The air-freight market experienced extraordinary demand during the pandemic, when passenger flights collapsed and companies struggled to move goods.
Demand has since normalized.
But long-term structural drivers remain.
E-commerce continues to grow.
Pharmaceuticals rely heavily on air cargo.
Semiconductors, electronics, automotive parts and high-value industrial components often need rapid transportation.
Supply-chain disruptions also remind companies that speed can sometimes be worth paying for.
That keeps freighter aircraft strategically important even when the broader shipping market slows.
There Is Also a Huge Aircraft-Supply Opportunity
Many older passenger jets are reaching the point where airlines have to decide what to do with them.
They can sell them.
Store them.
Scrap them.
Or convert them.
For aircraft leasing companies, conversion can be particularly attractive.
A plane that has become less valuable in passenger service can potentially earn revenue for many additional years carrying freight.
That creates business for conversion specialists such as IAI.
What It Means for Israel
This is also an important aerospace-export story.
IAI is one of Israel’s largest industrial and defense companies.
Commercial aircraft conversion gives it a revenue stream outside traditional military systems.
The company sells engineering expertise to global airlines, lessors and cargo operators.
That means the value created in Israel is exported around the world.
It also strengthens Israel’s position in a highly specialized corner of the global aerospace industry where only a limited number of companies have the technical capability and regulatory experience to compete.
What It Means for Businesses
For cargo airlines and aircraft owners, the A330 conversion offers another option for adding capacity without purchasing a brand-new freighter.
For IAI, it expands the addressable market dramatically.
For the aerospace industry, it reinforces a broader trend:
Older passenger aircraft are increasingly being viewed not as obsolete assets, but as raw material for the next generation of cargo fleets.
The first flight is therefore about more than one aircraft.
It is proof that IAI’s Airbus conversion program has moved from the drawing board into the air.
If certification proceeds as planned, that could open a significant new commercial market for the Israeli aerospace company.
JBizNews Desk | Tel Aviv
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Belgian Union Threatens Brussels Airlines Strike Over Israel Flights
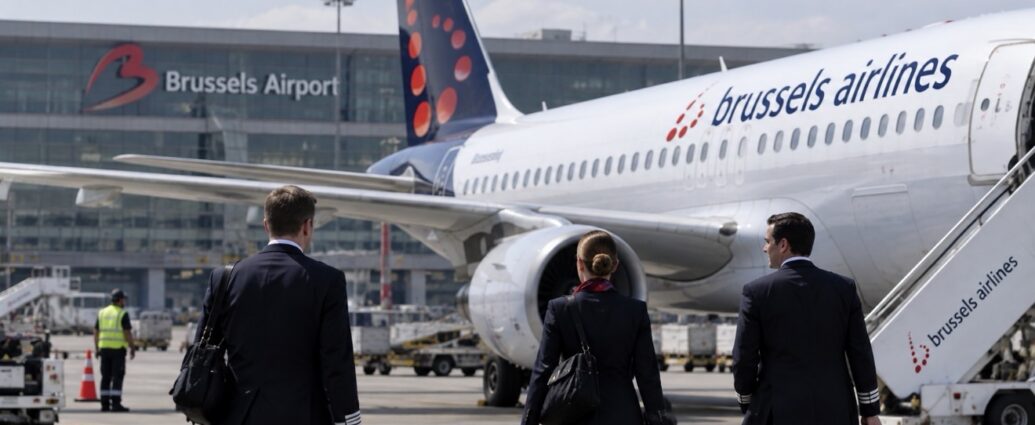
Brussels Airlines is facing a growing labor dispute over flights to Tel Aviv, with a Belgian union threatening strike action unless crew members are allowed to refuse assignments to Israel on safety or conscientious grounds.
The dispute centers on a question that goes far beyond one airline:
Can airline employees decline to work a specific international route because they object to the destination or believe it is unsafe?
Brussels Airlines resumed service to Tel Aviv on August 3 after a five-month suspension and is currently operating three flights a week.
The union representing flight crews says employees who object to flying to Israel should be allowed to refuse those assignments without losing pay or facing disciplinary action.
The airline disagrees.
Brussels Airlines says safety is its top priority and that route decisions are based on security assessments, operational conditions and passenger demand.
It also says employees are expected to carry out assigned duties under the terms of their employment.
Why This Matters
This is not simply a labor dispute.
It is a business-risk issue for airlines operating routes into politically sensitive or conflict-affected regions.
Airlines already have to manage:
- Security assessments
- Insurance costs
- Crew availability
- Passenger demand
- Airspace restrictions
- Government travel guidance
If employees also gain broad discretion to refuse specific destinations for political or ethical reasons, staffing could become much more difficult.
That could force airlines to cancel flights even when regulators and company security teams consider the route safe to operate.
The Volunteer Question
The union says Brussels Airlines previously relied more heavily on volunteers for Israel flights.
It argues that the company has moved away from that system because it could not find enough employees willing to operate the route.
Brussels Airlines disputes that characterization.
That disagreement is central to the dispute.
If enough crew members refuse assignments, the airline may not have enough staff to maintain its schedule.
And once staffing becomes unreliable, the financial consequences can grow quickly.
Cancelled flights mean refunds.
Aircraft may sit idle.
Passengers need to be rebooked.
Hotels and compensation costs can rise.
And travelers may begin booking with competitors instead.
A Broader Precedent for European Airlines
The larger concern is precedent.
Airlines operate routes to countries facing political controversy, war, sanctions, protests and security concerns all over the world.
If workers can decline assignments based on personal political or ethical objections, airlines could face similar disputes on many routes.
That would create a difficult line for management.
Safety concerns can be assessed through intelligence, government guidance and aviation-security professionals.
Political objections are much harder to standardize.
One employee may object to one country.
Another may object to another.
An airline cannot operate a global route network if every destination effectively becomes optional.
What It Means for Travelers
For passengers traveling between Belgium and Israel, the immediate risk is disruption.
If the union follows through with strike action, Brussels Airlines could be forced to cancel or reduce flights.
That would tighten capacity on a route that has already experienced repeated suspensions and resumptions because of regional security conditions.
Less capacity generally means higher fares and fewer backup options when flights are disrupted.
For business travelers, that unpredictability can be especially costly.
What It Means for Airlines
The dispute highlights how geopolitical conflict increasingly reaches directly into airline operations.
A route can be technically open.
Airports can be functioning.
Demand can exist.
But if crews do not want to fly it, the airline still has a problem.
That can affect staffing models, employment contracts and labor negotiations far beyond Brussels Airlines.
The commercial question is straightforward:
Who ultimately decides whether a route should be flown — airline management and safety professionals, or individual employees assigned to operate it?
Brussels Airlines is now being forced to answer that question in real time.
And if the dispute escalates into a strike, other European carriers will be watching closely.
JBizNews Desk | Brussels
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Norway’s $2.3 Trillion Wealth Fund Weighs Major Cut to U.S. Treasury Holdings
One of the world’s largest pools of investment capital is considering a major reduction in its exposure to U.S. government debt.
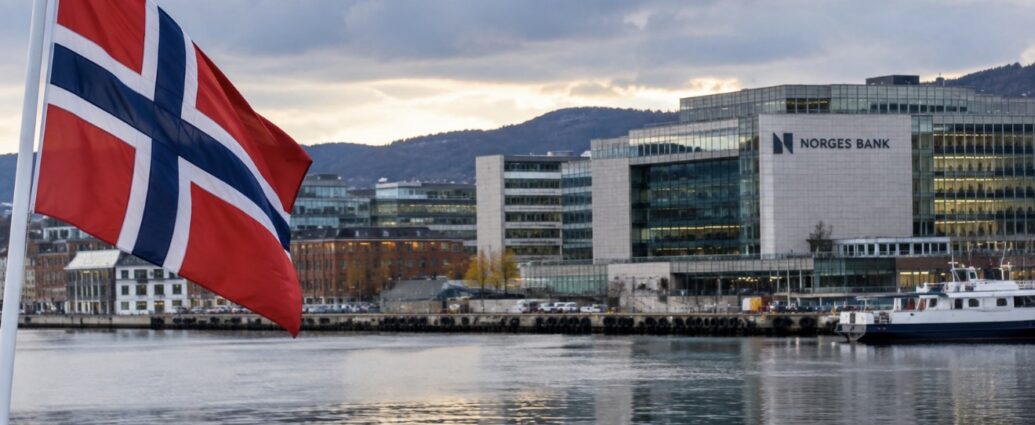
The manager of Norway’s roughly $2.3 trillion sovereign wealth fund is proposing changes to its bond benchmark that could sharply reduce the fund’s holdings of U.S. Treasuries.
The proposal would lower the share of government bonds in the fund’s fixed-income benchmark from 70% to 50% and shift more money toward other types of bonds.
Based on the fund’s current holdings and Reuters calculations, that could eventually mean roughly $80 billion less in U.S. Treasury exposure.
Nothing has been sold yet.
This is a proposal, not an executed trade.
But because Norway’s fund is so large, even a strategic change in how it allocates bonds can matter to global markets.
Why This Matters
U.S. Treasuries are the foundation of the global financial system.
Banks hold them.
Central banks hold them.
Insurance companies hold them.
Pension funds and sovereign wealth funds hold them.
They are used as collateral throughout financial markets and are generally treated as one of the safest and most liquid assets in the world.
So when a fund as large as Norway’s begins discussing a meaningful reduction in government-bond exposure, investors pay attention.
The issue is not that Norway suddenly believes the United States will not repay its debt.
The concern is more about portfolio construction.
Government bonds have become less attractive relative to other fixed-income investments because yields, inflation risk, fiscal deficits and debt issuance have all changed.
The Fund Is Looking for Better Balance
Norway’s sovereign wealth fund owns stocks, bonds, real estate and infrastructure around the world.
Its job is to invest the country’s oil wealth for future generations.
That means it is constantly trying to balance safety, returns and diversification.
Under the current structure, government debt represents a very large share of the fund’s bond portfolio.
The proposed change would reduce that concentration.
Instead, the fund could allocate more money toward corporate bonds, securitized debt and other fixed-income assets.
That could provide higher returns, though usually with somewhat more risk.
Why Treasuries Are Under More Scrutiny
The United States is borrowing enormous amounts of money.
That means the Treasury Department has to issue a huge supply of new bonds to finance federal spending.
At the same time, investors are demanding higher yields to hold longer-term debt.
That has pushed Treasury yields significantly higher than they were several years ago.
Higher yields can make Treasuries more attractive because investors earn more interest.
But they also mean bond prices can be more volatile.
If inflation stays high or markets expect interest rates to rise further, existing bonds can lose value.
For a massive long-term investor, that creates a reason to ask whether too much capital is concentrated in sovereign debt.
Why an $80 Billion Shift Matters
The U.S. Treasury market is enormous, so an $80 billion reduction would not by itself destabilize it.
But the symbolism matters.
Norway is not a hedge fund making a short-term trade.
It is one of the largest and most conservative institutional investors in the world.
If it concludes that government bonds should occupy a smaller share of its portfolio, other pension funds and sovereign investors may ask similar questions.
And if several large global investors reduce Treasury demand at the same time, the U.S. government may have to offer higher yields to attract buyers.
Higher Treasury yields eventually affect almost everything else.
Mortgage rates.
Corporate borrowing.
Auto loans.
Commercial real estate.
Stock valuations.
This Is About More Than America
The proposal does not target U.S. Treasuries specifically.
It would reduce government-bond exposure more broadly.
But because the United States represents such a large portion of global sovereign debt markets, Treasuries would naturally be heavily affected.
Norway’s fund currently holds roughly $215 billion in U.S. government debt, making the United States one of its most important bond exposures.
That means any benchmark change could move tens of billions of dollars.
What It Means for Businesses
For American businesses, the important number to watch is not Norway’s portfolio by itself.
It is Treasury yields.
If foreign investors become less willing to hold U.S. government debt, borrowing costs can rise.
Corporate loan rates are often priced relative to Treasury yields.
So are mortgages and many other forms of credit.
That means what looks like a technical portfolio decision in Oslo can eventually affect the cost of financing a warehouse, buying a home or issuing corporate debt in the United States.
Again, Norway has not announced an $80 billion Treasury sale.
The fund manager is proposing a strategic change that could lead to a substantial reduction over time.
But the proposal arrives at an important moment.
The United States is issuing enormous amounts of debt.
Long-term yields are already elevated.
And one of the world’s biggest investors is asking whether government bonds should continue occupying such a large share of its portfolio.
That is a question Wall Street — and Washington — will be watching closely.
JBizNews Desk | Oslo
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. Trade Gap Jumps 24% as Businesses Load Up on Computers, Chips and Capital Equipment
WASHINGTON — America’s trade deficit widened sharply in July, but the reason matters: U.S. businesses were importing billions of dollars more in computers, semiconductors and other capital equipment as corporate investment — particularly around artificial intelligence and technology infrastructure — continued to accelerate.
The U.S. trade deficit increased 24.4% in July to $88.6 billion, up from a revised $71.2 billion in June.
Exports fell 2.1% to $310.7 billion, while imports rose 2.8% to $399.3 billion.
At first glance, the widening deficit looks like another sign that America is buying significantly more goods from overseas than it is selling abroad.
But underneath the headline was a particularly important development for businesses.
Imports of capital goods surged by $14.4 billion in a single month.
Computer imports increased $6.9 billion. Imports of computer accessories jumped another $6.6 billion, while semiconductor imports increased approximately $1.2 billion.
That means much of the increase was not simply American consumers buying additional clothing, televisions or household products.
Businesses were buying equipment.
That distinction matters.
When a company imports a computer server, semiconductor or other piece of capital equipment, it is generally purchasing something intended to produce future revenue.
The July numbers fit directly into the enormous investment boom surrounding artificial intelligence, cloud computing, data centers and semiconductor manufacturing.
Technology companies and corporations across the economy are purchasing increasingly sophisticated computing equipment as they build AI infrastructure and modernize existing operations.
The result can make the trade deficit look worse today while potentially increasing productive capacity tomorrow.
There was still weakness elsewhere in the report.
U.S. exports declined by $6.6 billion, with exports of industrial supplies and materials falling approximately $8.7 billion.
A larger trade deficit can also weigh on gross domestic product because imports subtract from GDP calculations when they grow faster than exports.
But the longer-term trade picture remains considerably different from the monthly headline.
Through July, the U.S. goods and services deficit was approximately $188.4 billion, or 29.6%, smaller than during the same period last year.
Exports during the first seven months of the year increased roughly 12%, while imports rose only about 1.9%.
For business owners and investors, July’s report therefore sends two messages at once.
America is again importing substantially more than it exports.
But businesses are also pouring money into the equipment they believe they will need for the next stage of economic growth.
The question now is whether those billions of dollars being spent on computers, chips and infrastructure generate enough productivity and revenue to justify the investment.
That will ultimately matter much more than one month’s trade deficit.
JBizNews Desk | Washington
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.