By JBizNews Desk

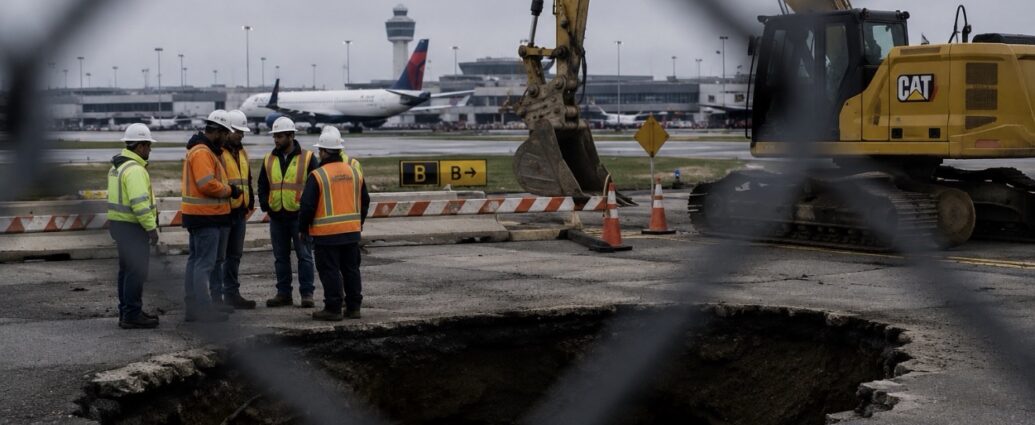
NEW YORK — The U.S. Department of Transportation (DOT) has officially activated its most aggressive consumer-protection enforcement campaign in aviation history as millions of Tri-State travelers prepare for the summer holiday travel cycle. Operating under newly finalized federal mandates, transportation officials confirmed that commercial airlines are now legally required to issue immediate, automatic cash refunds to passengers when flights are canceled or significantly delayed, dismantling the industry’s long-standing reliance on restrictive travel vouchers.

The emergency oversight is landing directly on major regional transportation hubs including Newark Liberty International Airport, JFK International Airport, and LaGuardia Airport, where seasonal congestion routinely creates delays and cancellations during peak travel months.

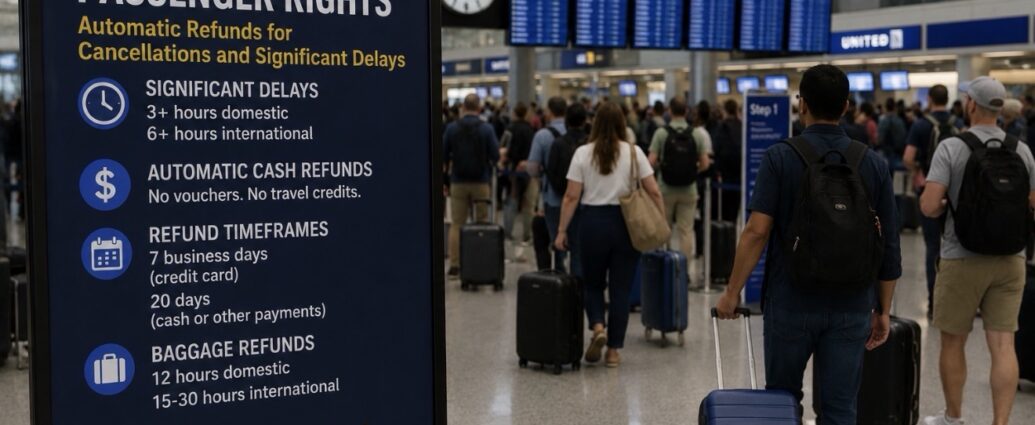
Under the DOT’s updated rules, a delay becomes officially “significant” once it exceeds three hours for domestic flights or six hours for international itineraries. If an airline cancels a flight or pushes departure times beyond those thresholds and the passenger rejects the carrier’s alternative itinerary, the airline must automatically process a full refund back to the customer’s original form of payment.

The move represents one of the most consequential shifts in consumer air-travel protections in decades.

Previously, airlines often issued future travel credits or promotional vouchers instead of direct refunds, forcing passengers to navigate expiration dates, blackout periods, and rebooking restrictions. The new federal mandates eliminate that flexibility entirely.

Under the updated framework, airlines must process refunds within seven business days for credit-card purchases and within 20 days for cash or alternative-payment transactions.

The timing is especially important for household budgets as airfare prices remain elevated following months of fuel-market volatility and strong post-pandemic travel demand.

The consumer protections also extend beyond canceled flights themselves. Passengers are now entitled to refunds for checked baggage fees if luggage is not delivered within 12 hours on domestic routes or within a specified 15-to-30-hour window on international flights.

Refund requirements also apply to paid services travelers never receive during transit, including onboard Wi-Fi, upgraded seating packages, and certain cabin amenities.

Transportation officials say the goal is to create a standardized national refund framework that prevents travelers from becoming trapped in customer-service disputes during periods of operational disruption.

Regional consumer advocacy groups are encouraging travelers throughout New York and New Jersey to monitor airline apps and booking platforms carefully as summer traffic accelerates.

Federal transportation investigators are also expected to increase monitoring at major airport hubs during the peak summer season to ensure airlines comply with the new requirements.

Major carriers including Delta Air Lines, United Airlines, American Airlines, JetBlue Airways, and Southwest Airlines have publicly stated they are adjusting operational and refund systems to align with the updated rules.

For everyday travelers, the regulations provide a major financial safeguard at a time when flight disruptions remain common and family travel costs continue climbing.

The message from Washington is increasingly straightforward: if an airline fails to provide the transportation service purchased, consumers are entitled to receive their money back automatically — not credits, points, or future travel promises.

JBizNews Desk | New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

Cairo — May 26, 2026 — Egypt has launched its first nationwide airborne geophysical mineral survey in more than four decades, a major strategic push aimed at transforming the country into a regional mining powerhouse and attracting billions of dollars in foreign investment tied to gold, phosphate, copper and critical minerals.

The announcement was made Sunday by Karim Badawi, Egypt’s Minister of Petroleum and Mineral Resources, during a visit to the country’s flagship Sukari gold mine in the Eastern Desert.

The survey — Egypt’s first comprehensive aerial mineral mapping program since 1984 — comes as Cairo attempts to triple mining’s contribution to national GDP by 2030 while positioning itself as a rising competitor to Saudi Arabia in the global race for strategic mineral supply chains.

Egypt signed the mapping agreement with Spain-based Xcalibur Smart Mapping, one of the world’s leading airborne geophysics firms, under a contract covering six major geological regions stretching across the Eastern Desert, Sinai, the Western Desert and the Bahariya-Abu Tartour corridor.

The project will deploy specialized aircraft equipped with high-resolution magnetic and radiometric sensors capable of identifying underground mineral structures at depths and accuracy levels far beyond Egypt’s existing geological database.

Officials said the resulting data will become the foundation for future international licensing rounds and will headline the revamped Egypt Mining Forum scheduled for September 28–29 in the New Administrative Capital.

The timing reflects a broader strategic shift underway inside Egypt’s economy.

Despite holding significant mineral reserves — including an estimated 9 million ounces of gold and some of the world’s largest phosphate deposits — mining currently contributes less than 1% of Egyptian GDP.

Badawi has publicly committed to raising that figure to approximately 6% by the end of the decade.

The government increasingly sees mining as a critical pillar of foreign direct investment, export revenue and hard-currency generation at a time when Egypt continues operating under an International Monetary Fund stabilization program and faces ongoing pressure on its external finances.

The country has repeatedly devalued the Egyptian pound since 2022 while aggressively seeking new sources of foreign capital.

A modern investor-grade geological database is viewed inside Cairo as one of the key missing ingredients that prevented Egypt from competing effectively with faster-moving mining jurisdictions across the Gulf and Africa.

For years, global exploration firms complained that Egypt’s geological records remained fragmented, outdated and largely unusable for modern resource modeling.

The new airborne survey is designed to change that.

The commercial implications could be significant.

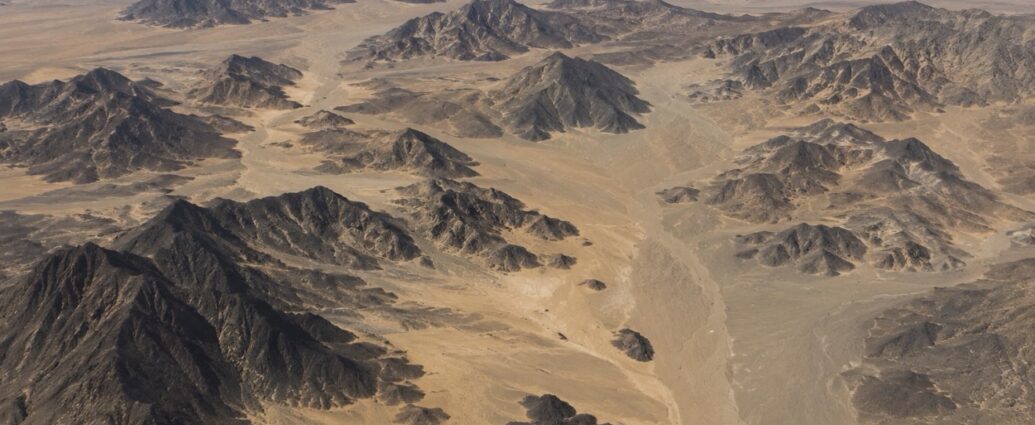
Egypt’s Eastern Desert — particularly the so-called “golden triangle” corridor linking Safaga, Quseir and Qena — is believed to contain extensive reserves of gold, copper, zinc, lead, phosphate and industrial minerals essential to fertilizer production and electric-vehicle battery supply chains.

Global mining companies are already beginning to position themselves.

AngloGold Ashanti entered as a strategic partner in Egypt’s Sukari gold operation, which produced more than 500,000 ounces of gold in 2025 and remains the country’s largest operating mine.

Meanwhile, Chinese industrial giant Hubei Xingfa Chemicals Group has reportedly been negotiating a nearly $2 billion phosphate investment tied to Egypt’s mineral corridor, according to disclosures made earlier this year by Badawi.

The phosphate angle is particularly important because phosphate is a critical input not only for fertilizers but also for lithium iron phosphate battery technology increasingly used across electric vehicles manufactured by companies including Tesla, BYD, Ford and major Chinese battery producers.

Egypt is also attempting to reposition itself legislatively to compete for global exploration capital.

Parliament approved reforms in 2025 converting the former Egyptian Mineral Resources Authority into the more commercially structured Mineral Resources and Mining Industries Authority (MRMIA).

The restructuring gives the authority significantly greater autonomy over contracts, revenue retention and project governance while allowing Egypt to move away from rigid production-sharing frameworks that long discouraged foreign operators.

Badawi has openly acknowledged that Egypt’s previous mining structure left the country uncompetitive compared with jurisdictions such as Saudi Arabia, Australia and Canada.

Saudi Arabia remains Egypt’s clearest regional competitor.

Under Crown Prince Mohammed bin Salman’s Vision 2030 initiative, Riyadh has aggressively expanded its own mining ambitions, unveiling mineral wealth estimates exceeding $2.5 trillion while positioning the Kingdom as a global critical-minerals hub through the Future Minerals Forum and state-backed investments tied to Ma’aden and Manara Minerals.

Egypt is now attempting to market itself as a complementary lower-cost regional alternative with direct access to Red Sea logistics corridors and Suez Canal shipping infrastructure.

The Xcalibur survey is expected to produce detailed mineral mapping data that officials hope will underpin Egypt’s first major international licensing round under the new mining framework.

For commodity markets, fertilizer producers, battery manufacturers and global mining investors, the survey represents more than a technical geology project.

It signals that one of the Middle East and North Africa’s largest untapped mineral jurisdictions is finally opening itself to large-scale competitive development.

After 42 years, Egypt is rewriting its mining maps — and preparing to put its underground wealth on the global auction block.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

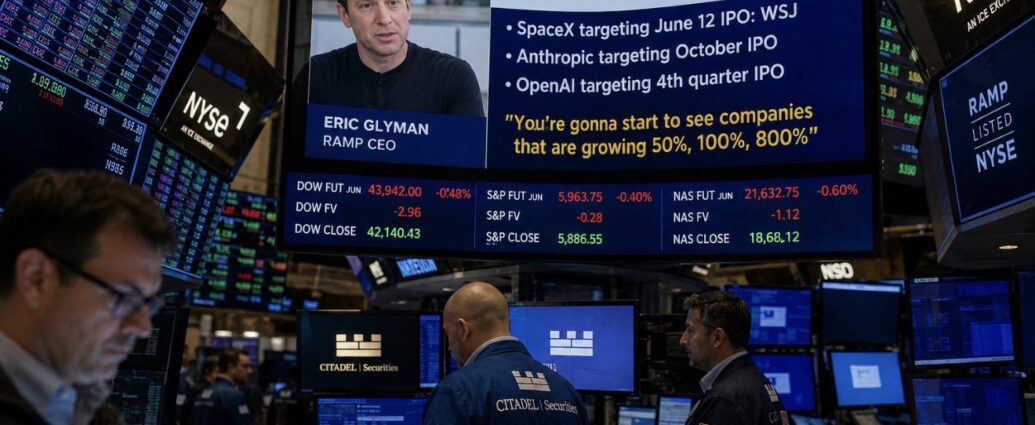
Elon Musk’s SpaceX warned investors in its IPO filing that global shortages of advanced artificial intelligence chips could slow or limit the company’s ambitious plan to build massive AI data centers in space.

The disclosure appeared in the company’s S-1 registration filing submitted to the Securities and Exchange Commission as SpaceX prepares for what could become the largest public offering in financial history.

The company is reportedly targeting a valuation approaching $1.75 trillion ahead of its planned Nasdaq debut under the ticker symbol SPCX.

At the center of the filing is a major strategic shift:
SpaceX is no longer presenting itself simply as a rocket-launch company.

Instead, the company increasingly describes itself as a vertically integrated AI infrastructure platform spanning rockets, satellites, chip manufacturing, orbital computing, broadband communications, and artificial intelligence systems.

The filing repeatedly references “orbital AI” and outlines plans to eventually deploy large-scale AI compute systems directly into orbit.

But SpaceX also acknowledged a major obstacle:
the world may not have enough advanced chips available to support those plans.

To reduce dependence on outside suppliers, SpaceX disclosed that it is working on a chip-manufacturing initiative known internally as “Terafab,” designed to help produce specialized AI hardware for future orbital computing systems.

The filing states that Tesla and Intel are involved through framework agreements tied to the effort.

However, SpaceX also warned investors that neither company is obligated to complete the project and that the factory may not become operational within expected timelines.

That caution matters because AI chips have become one of the most supply-constrained technologies in the global economy.

Demand for advanced processors used in artificial intelligence systems has surged over the past two years as companies race to build massive AI infrastructure platforms.

SpaceX’s vision goes even further than terrestrial AI expansion.

The company plans to begin launching AI compute satellites into sun-synchronous orbit as early as 2028, with long-term ambitions involving what it describes as “orbital AI at scale.”

According to the filing, the ultimate objective would involve deploying up to 100 gigawatts of orbital compute capacity annually — a staggering figure requiring thousands of launches and unprecedented payload volumes.

SpaceX described the effort in the filing as “an incredibly difficult technical challenge.”

The idea behind orbital AI infrastructure is that space-based data centers could eventually operate with access to continuous solar energy while avoiding some of the cooling and land constraints faced by Earth-based facilities.

Musk has publicly promoted the concept for months.

At the World Economic Forum in Davos earlier this year, he argued that space could become the cheapest place in the world to operate AI computing systems within only a few years.

The IPO filing, however, takes a noticeably more cautious tone than Musk’s public comments.

While Musk has often projected confidence about rapid deployment timelines, the S-1 repeatedly highlights technical, manufacturing, and supply-chain risks that could delay execution.

Competition in the sector is also intensifying quickly.

Google-backed projects, Nvidia orbital-compute initiatives, Blue Origin satellite proposals, and multiple venture-funded startups are all pursuing various forms of space-based computing infrastructure.

The race is increasingly viewed inside Silicon Valley and Wall Street as a new frontier tied directly to the global AI boom.

Financially, the filing reveals a company in transition.

SpaceX generated approximately $18.7 billion in revenue during 2025, largely from its Starlink satellite broadband business.

At the same time, the company posted significant losses as it ramped spending on AI-related infrastructure and orbital-compute development.

The filing states that more than three-quarters of recent capital expenditures were directed toward AI infrastructure initiatives.

The broader SpaceX empire has also expanded dramatically following Musk’s merger earlier this year between SpaceX and his artificial-intelligence company xAI.

The combined organization now spans:

  • Rockets
  • Satellite broadband
  • AI models
  • Social media platforms
  • Developer software tools
  • Planned orbital computing systems

Investors evaluating the IPO are effectively being asked to fund one of the most ambitious infrastructure bets ever attempted in the technology sector.

The core question for Wall Street is becoming increasingly clear:
Can Starlink’s profitable satellite business generate enough cash flow to finance Musk’s much larger orbital AI vision before competitors catch up or supply constraints slow the effort?

The filing suggests SpaceX itself recognizes that answer remains uncertain.

When Musk speaks publicly, the future often sounds inevitable.

When SpaceX lawyers write disclosures for regulators and investors, the risks become harder to ignore.

That gap between ambition and execution may ultimately define the company’s IPO story.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Consumers squeezed by inflation are increasingly pulling back from premium coffee chains and shifting toward faster, lower-cost alternatives — and one of the fastest-growing winners is 7 Brew Coffee, the Arkansas-based drive-thru chain now racing to expand across the United States.

The privately held company, known for compact drive-thru-only locations and lower-priced beverages, has rapidly emerged as one of the hottest growth stories in the American quick-service restaurant industry. Industry data compiled this month by restaurant analytics firms including Technomic and Placer.ai shows 7 Brew continuing to post some of the strongest customer traffic growth in the coffee sector as value-conscious consumers search for cheaper daily routines without fully giving up specialty coffee purchases.

Founded in Rogers, Arkansas, the chain has expanded from a regional operator into a national growth platform in just a few years. 7 Brew now operates hundreds of locations across more than 30 states and has continued opening stores at a pace that rivals some of the largest restaurant growth stories in the country.

Unlike traditional coffeehouse models built around indoor seating and long customer dwell times, 7 Brew focuses almost entirely on speed, convenience, and lower operating costs. Most locations are compact double-lane drive-thru units with minimal indoor space, allowing stores to serve large volumes of customers with lower real-estate expenses and smaller staffing requirements.

That operating model is becoming increasingly attractive in the current economy.

Consumers across the country continue facing elevated prices for housing, insurance, groceries, and utilities, forcing many households to trade down from premium purchases while still seeking small affordable indulgences. Analysts say coffee remains one of the last discretionary habits consumers are reluctant to fully eliminate, creating opportunities for lower-priced operators.

The pricing gap has become especially noticeable against premium coffee chains where customized drinks can now regularly exceed $7 or $8 in major metropolitan markets.

Restaurant analysts say 7 Brew has benefited by positioning itself between fast-food coffee and high-end specialty chains, offering flavored drinks, energy beverages, teas, and espresso products at lower average ticket prices while emphasizing speed and convenience.

The company’s expansion is also occurring during a broader transformation inside the U.S. coffee industry.

Major chains including Starbucks and Dutch Bros have increasingly leaned into drive-thru service, mobile ordering, and labor-efficiency strategies as consumer traffic patterns shifted following the pandemic. But 7 Brew’s simplified operating structure has allowed it to expand aggressively into suburban and secondary markets where construction costs and labor expenses remain lower.

Private equity investors have also poured money into the sector.

Industry observers increasingly compare 7 Brew’s growth trajectory to the early national expansion years of chains like Dutch Bros, Raising Cane’s, and Chipotle Mexican Grill, all of which leveraged highly focused operating models into massive national footprints.

The company’s expansion has accelerated particularly across the South, Midwest, and Sun Belt states, regions experiencing strong population growth and relatively lower commercial development costs.

The strategy comes at a moment when consumers are becoming more price-sensitive across the broader restaurant industry.

Recent earnings reports from multiple fast-food and casual dining chains have shown customers increasingly reducing discretionary spending, visiting restaurants less frequently, or trading down toward value-oriented brands. Coffee chains have proven somewhat more resilient than full-service restaurants, but even premium operators are seeing pressure from consumers seeking cheaper alternatives.

For 7 Brew, that environment has created a major opening.

The company’s rapid expansion is also reshaping competition within local beverage markets, placing pressure on independent coffee shops and regional operators already dealing with higher labor costs, elevated rents, and rising ingredient prices.

Industry analysts expect consolidation and competitive pressure within the beverage sector to intensify through 2026 as chains race to capture customers looking for lower-cost convenience options.

Whether 7 Brew can sustain its breakneck growth pace nationally remains an open question, particularly as expansion eventually moves into denser urban markets where drive-thru-heavy formats become harder to scale.

But for now, the company is emerging as one of the clearest examples of how inflation and changing consumer habits are reshaping the American restaurant industry — one drive-thru lane at a time.

JBizNews Desk — Midwest

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

WASHINGTON, May 26, 2026 — Newly sworn-in Federal Reserve Chair Kevin Warsh signaled at his East Room swearing-in ceremony on Friday that he intends to model his leadership of the central bank after former Fed Chair Alan Greenspan, invoking the architect of the 1990s economic boom as he laid out a vision for a more restrained, less talkative and more discretionary Federal Reserve.

Warsh, who officially became the 17th chair of the Federal Reserve after taking the oath from Supreme Court Associate Justice Clarence Thomas, told guests that Greenspan was the first Fed chair to show him “what this role demands” and pledged to fill the office “with energy and purpose, just the way Chairman Greenspan did.” Standing alongside his wife, Jane Lauder, Warsh formally succeeded Jerome Powell, ending Powell’s eight-year run atop the central bank.

The reference to Greenspan was not simply ceremonial. Warsh assumes control of the Fed at a moment when inflation has remained above the central bank’s 2% target for more than five years, oil prices have surged following the Iran conflict, and the White House has openly pressured the Fed to lower interest rates. By repeatedly invoking Greenspan’s 1990s-era approach — when the Fed largely held rates steady during the technology boom on the belief that productivity gains were containing inflation — Warsh offered markets their clearest indication yet of how he intends to govern monetary policy.

President Donald Trump, hosting the ceremony at the White House, praised Warsh as a future “great chairman” and renewed his argument that lower borrowing costs would allow the U.S. economy to expand faster without reigniting inflation while simultaneously reducing federal debt-servicing costs. Trump also publicly encouraged Warsh to “do his own thing,” a line widely interpreted as an attempt to calm investor fears that the new Fed chair would operate under direct political pressure from the administration.

Treasury Secretary Scott Bessent, one of Warsh’s strongest backers inside the administration, has spent months building the intellectual case for a Greenspan-style Fed. In a January speech, Bessent described Greenspan as “the open-minded maestro” and argued that central banks should avoid prematurely tightening policy during periods of major technological transformation. He repeatedly pointed to the late 1990s as evidence that productivity booms can absorb inflationary pressures without requiring aggressive rate hikes.

Warsh himself has been laying out a similar framework for more than a year. He has argued publicly that artificial intelligence and automation will lift productivity, reduce structural inflationary pressures and eventually create room for lower rates. During his Senate Banking Committee confirmation hearing in April, Warsh also signaled that he wants the Fed to communicate less frequently, scale back forward guidance and stop telegraphing policy moves months in advance.

Most notably, Warsh declined to commit to holding a press conference after every Federal Open Market Committee meeting — a practice institutionalized by Powell that turned Fed communication into one of Wall Street’s primary policy signals.

That potential shift matters enormously for markets. Under Powell, the Fed used communication itself as a policy tool, conditioning investors through speeches, forecasts and repeated signaling. Under Warsh, the institution appears headed toward a more opaque model where fewer public remarks carry greater weight — echoing Greenspan’s famously cryptic approach, when markets often dissected every sentence from the chair for clues about future policy.

The economic backdrop, however, is far more complicated than the one Greenspan managed during the 1990s expansion.

Minutes from the Federal Reserve’s most recent meeting show that many policymakers remain deeply concerned about persistent inflation pressures tied to elevated oil prices, tariffs and supply-chain disruption. Several Fed officials indicated they now expect rates to remain elevated longer than anticipated earlier this year, while some suggested additional tightening could become necessary if inflation fails to ease.

Fed Governor Christopher Waller, widely viewed as one of the central bank’s more dovish members and another Trump appointee, said Friday that while he currently supports holding rates steady, he would not rule out hikes if rising oil prices create a longer-lasting inflation shock.

Markets are now pricing in the likelihood that the Fed will remain on hold through much of 2026, with some traders increasingly assigning probability to possible hikes in early 2027 — a stance that clashes both with Trump’s push for lower rates and with Warsh’s own optimism that technological productivity gains will ultimately suppress inflation.

In his prepared remarks Friday, Warsh framed the Fed’s mission in straightforward terms.

“Our mandate at the Fed is to promote price stability and maximum employment,” Warsh said. “When we pursue those aims with wisdom and clarity, independence and resolve, inflation can be lower, growth stronger, real take-home pay higher.”

He also pledged to oversee what he called a “reform-oriented Federal Reserve” capable of moving beyond “static frameworks and models” — language that aligns closely with his push for a more flexible and less communication-heavy central bank.

The symbolism of the ceremony itself also stood out. The East Room audience included Cabinet officials, Supreme Court Justices Clarence Thomas and Brett Kavanaugh, House Speaker Mike Johnson, National Economic Council Director Kevin Hassett, and Treasury Secretary Bessent. Federal Reserve chairs are traditionally sworn in at the Fed’s Eccles Building in Washington. The last chair to take the oath at the White House was Greenspan himself — a detail Warsh deliberately highlighted.

For businesses and investors, the message from Friday’s ceremony was increasingly clear: a Warsh-led Federal Reserve is likely to speak less, reveal less and rely more heavily on discretion than the Powell Fed that preceded it.

If Warsh’s thesis about artificial intelligence-driven productivity proves correct, that approach could allow inflation to cool without requiring another painful tightening cycle. But if energy costs, tariffs and geopolitical disruptions keep inflation stubbornly elevated, the same communication-light strategy may leave markets with less warning before future rate increases.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Europe’s financial markets are no longer treating the war in Ukraine as a regional conflict. They are treating it as the opening phase of a broader security and economic realignment that could redefine the continent’s budgets, debt markets and industrial priorities for the next decade.

That shift became more visible Sunday after Russia launched one of its largest aerial attacks on Kyiv this year, firing roughly 600 drones and 90 missiles overnight, including the nuclear-capable Oreshnik hypersonic missile. Ukrainian President Volodymyr Zelensky said Kyiv absorbed the heaviest strikes, while Mayor Vitali Klitschko reported damage across every district of the capital. European Union foreign policy chief Kaja Kallas described Moscow’s use of the Oreshnik as reckless nuclear brinkmanship intended to intimidate Europe politically as much as militarily.

The strike came just days after Moscow announced plans to file a case at the International Court of Justice accusing Estonia, Latvia and Lithuania of discriminating against Russian-speaking minorities — language European officials immediately recognized from the Kremlin’s playbook before the annexation of Crimea in 2014 and before Russia’s full-scale invasion of Ukraine in 2022.

For European governments, the issue is no longer whether Russia poses a threat. The question now is how much economic capacity Europe must permanently dedicate to deterring it.

That answer is already showing up in defense budgets.

Estonian Defense Minister Hanno Pevkur said this month that Estonia plans to allocate roughly 5.4% of GDP annually to defense between 2026 and 2029, while Lithuanian President Gitanas Nausėda announced plans to push Lithuanian defense spending toward 5% to 6% of GDP. Poland is already spending roughly 4.5% of GDP on defense, one of the highest levels in NATO.

The broader trend is striking. European Union defense spending has climbed from approximately €218 billion in 2021 to a projected €381 billion in 2025. At NATO’s summit in The Hague, alliance members — with the exception of Spain — backed a framework targeting 3.5% of GDP for core military spending plus another 1.5% for security-related investment.

If fully implemented, Europe’s combined defense spending could approach €800 billion annually by the end of the decade.

That figure is extraordinary when compared to Europe’s own central budget. The EU’s annual institutional budget remains under €200 billion. In practical terms, Europe is preparing to spend roughly four times its collective administrative budget on defense every year because policymakers increasingly believe the Ukraine war may not remain geographically contained.

Financial markets have been pricing in that possibility for months.

German defense giant Rheinmetall AG has become one of Europe’s biggest market winners since Russia’s invasion of Ukraine, with shares rising more than twelvefold. The company expects 2026 sales growth of 40% to 45% after reporting a massive €64 billion order backlog. Rheinmetall is now expanding artillery shell production from roughly 70,000 units in 2022 toward a targeted 1.5 million annually by 2030.

Investors are treating Europe’s defense sector less like a cyclical trade and more like a long-duration structural growth industry.

The STOXX Europe Aerospace and Defense Index now trades at roughly 43 times projected 2026 earnings, more than double the broader STOXX Europe 600 valuation. Norway’s Kongsberg Gruppen is projected to post annual growth above 20%, while Britain’s BAE Systems continues forecasting sustained multi-year expansion tied to NATO rearmament.

But despite the spending surge, analysts warn Europe still faces major structural weaknesses.

A February defense assessment from McKinsey found that European NATO countries remain below pre-2021 military equipment stockpile levels even after NATO Europe and Canada spent more than $482 billion on defense in 2024. One major reason is fragmentation. European NATO members currently operate 12 separate main battle tank platforms, compared with just one used by the United States military.

That fragmentation increases procurement costs, slows scaling and limits interoperability during an actual conflict scenario.

The strategic concern underlying much of the spending is the Baltic region.

A recent Harvard Belfer Center scenario study examined the risk of a Russian move aimed at isolating Estonia, Latvia and Lithuania through the Suwałki Gap — the narrow corridor between Belarus and the Russian enclave of Kaliningrad that connects the Baltic states to the rest of NATO territory.

While European officials publicly insist they do not view war with NATO as imminent, defense planning assumptions across the continent increasingly reflect the possibility that Moscow could eventually test alliance cohesion through hybrid operations, limited territorial incursions or coercive pressure against NATO’s eastern flank.

That fear is now embedded not only in military planning, but in sovereign borrowing costs, industrial policy and equity markets.

The bond spreads, the weapons orders and the emergency defense appropriations are all pointing toward the same conclusion: Europe is preparing financially for a world in which deterrence may become a permanent economic sector.

If Russia never expands the conflict beyond Ukraine, Europe will have built one of the largest defense spending programs in modern peacetime history. If Moscow eventually tests NATO directly, policymakers increasingly believe the current spending wave may only represent the beginning.

Europe’s markets appear to have already made their bet.

Europe — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Walmart is warning that rising gasoline prices are beginning to pressure even the lower-income shoppers who have historically formed the backbone of the retailer’s customer base.

The warning came from Walmart executives during recent earnings discussions and signals growing strain across large segments of the American consumer economy as fuel and food costs continue climbing.

John David Rainey, Walmart’s chief financial officer, said wealthier consumers continue spending steadily, but lower-income households are becoming increasingly cautious and financially stressed.

“The high-income consumer is spending with confidence in many categories, whereas the low-income consumer, we can tell, is more budget-conscious,” Rainey said.

One number stood out sharply.

Walmart executives said many customers are now purchasing fewer than 10 gallons of gasoline per visit at Walmart fuel stations — something the company says it has not seen consistently since 2022.

That shift may sound small, but retailers view it as a major economic signal.

Consumers are increasingly buying only enough gas to get through the immediate week rather than filling their tanks completely, a behavior often associated with tighter household cash flow.

The backdrop is rising fuel costs tied to global energy disruptions.

According to AAA, the national average for regular gasoline has climbed above $4.50 per gallon following months of volatility linked to the Middle East conflict and ongoing disruptions tied to the Strait of Hormuz, one of the world’s most important oil shipping routes.

Higher fuel costs are now filtering through nearly every part of household spending.

Walmart’s U.S. chief executive, John Furner, said elevated fuel costs reduced company profit by roughly $175 million during the most recent quarter alone.

The retailer still posted strong sales growth.

Comparable U.S. sales excluding fuel rose 4.1%, while e-commerce growth remained robust.

But Walmart’s forward guidance came in weaker than some analysts expected, reflecting concerns that consumers are becoming more selective with discretionary spending.

Executives also warned that if elevated transportation and fuel costs continue, shoppers could begin seeing additional retail price inflation during the second half of the year.

That matters because Walmart has increasingly become one of the country’s primary economic barometers.

Over the past several years, middle-income consumers increasingly shifted spending toward Walmart in search of lower prices as inflation pressured household budgets.

That trade-down trend helped Walmart outperform many competitors across the retail sector.

Now the company is signaling that financial stress is moving deeper into lower-income households as well.

The pressure extends beyond gasoline.

The U.S. Department of Agriculture forecasts overall food prices will continue rising during 2026, with categories like beef and fresh produce seeing particularly sharp increases.

For many Walmart shoppers, groceries and gasoline make up the largest portions of monthly spending.

When both rise simultaneously, households often reduce restaurant visits, discretionary shopping, travel, and entertainment first.

Other companies are already seeing similar patterns.

Fast-food chains, discount retailers, and consumer lenders have all recently pointed to softer spending trends among lower-income consumers.

Federal retail data still shows headline consumer spending remaining positive overall, but much of the increase is being driven by higher prices rather than significantly larger purchasing volumes.

Walmart says it is attempting to offset some of the pressure through aggressive pricing initiatives, including thousands of rollback promotions across stores nationwide.

The retailer may also benefit from tariff-related refunds tied to recent court rulings overturning portions of earlier trade tariffs, potentially giving the company additional flexibility on pricing later this year.

Even so, Walmart’s broader message to Wall Street was clear:
American consumers are becoming more financially selective as inflation continues weighing on household budgets.

Importantly, Walmart itself is not struggling financially.

The company maintained full-year guidance and continues expanding delivery capabilities, e-commerce infrastructure, and logistics operations nationwide.

But the behavior of the shoppers walking through Walmart stores is changing.

When the nation’s largest retailer starts warning that its core lower-income customers are buying smaller amounts of gas, eating out less frequently, and watching every dollar more carefully, investors across the broader economy tend to pay attention.

As summer travel season begins, Walmart is signaling that many American families may be preparing for a more cautious spending environment than Wall Street had expected only a few months ago.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

The people cleaning hotel rooms in New York City are on track to become some of the highest-paid hospitality workers in the United States.

Under a new tentative eight-year labor agreement reached between the Hotel and Gaming Trades Council and the Hotel Association of New York City, nearly 30,000 union hotel workers across more than 250 properties in the five boroughs secured what union leaders are calling the largest wage increase in the organization’s nearly century-long history.

By the end of the contract in 2034, the average New York City hotel housekeeper is projected to earn more than $100,000 annually, with hourly wages climbing from roughly $40 today to more than $61 per hour under the final years of the agreement.

Non-tipped hotel employees will see hourly compensation rise by approximately $21.20 over the life of the contract, representing average annual increases exceeding 5% per year — more than double the pace of raises in the prior agreement.

The contract was ratified by hotel operators on May 18 and approved by union members later that week, eliminating what hotel executives feared most: a labor disruption during the 2026 FIFA World Cup, which is expected to flood the New York metropolitan region with international tourists and drive hotel occupancy to near-record levels throughout the summer.

But the significance of the deal stretches far beyond organized labor.

It is also a direct test of how much additional cost the New York tourism economy can absorb before consumers begin pushing back.

The economics behind the agreement are unusually straightforward because both labor leaders and hotel operators effectively acknowledged the same reality: the bill eventually reaches the guest.

New York City already operates one of the most expensive hotel markets in the world, with average room rates hovering around $335 per night and occupancy levels near 84%, among the highest urban occupancy rates in the United States.

That pricing strength gave hotel operators confidence they could ultimately pass much of the labor increase into future room rates.

Mayor Zohran Mamdani described the agreement as a victory for “our hospitality industry, our economy, and for a city that works best when the people who keep it running can afford to live here too.” City Council Speaker Julie Menin similarly framed the deal as an economic-stability measure for workers and the broader city economy.

Behind the political messaging sits a simpler business calculation.

Hotel inventory is perishable. Every unsold room night disappears permanently once the night passes, creating powerful incentives for operators to continuously test how high prices can rise before demand weakens.

And right now, the ceiling appears unusually high.

American Express Global Business Travel’s Hotel Monitor 2026 had already forecast New York hotel prices rising roughly 4% this year before the union contract was finalized. Industry participants now expect actual pricing increases to exceed those projections.

Hotel owners themselves are openly acknowledging the pressure.

Hotelier John Born told The Real Deal that the agreement would “absolutely, positively” affect hotel profitability, adding that operators would rely on future room-rate increases to offset escalating payroll obligations.

“The raises are substantial and they compound over time,” Born said.

That may be the clearest explanation of what travelers booking New York hotel rooms are about to experience.

The labor agreement extends far beyond wages alone.

The contract preserves fully employer-funded healthcare coverage for roughly 27,000 workers and their families, while increasing hotel contributions to the union’s Health Benefits Fund from 27.25% to 30.25% of payroll — representing nearly $65 million annually in additional employer healthcare spending.

The deal also creates new employer-funded housing and childcare programs, expands paid time off, increases pension contributions, guarantees paid family leave for new parents and establishes paid leave for workers to vote in elections.

None of those expenses appear directly on a hotel invoice.

Eventually, all of them become embedded in nightly room pricing.

For the broader hospitality industry, the New York agreement is now viewed as a national benchmark.

Union organizers in Los Angeles, Chicago, Boston, San Francisco and Las Vegas have already begun citing the NYC contract in their own negotiations, according to industry participants and labor analysts. Hotel executives privately acknowledge the agreement will likely reset wage expectations across unionized hospitality markets nationwide.

That makes the New York contract more than a local labor story.

It is increasingly being viewed as the beginning of a broader wage repricing across the U.S. hospitality sector.

There is also a significant small-business angle often overlooked in the headline numbers.

While some of the city’s largest luxury properties fall under the agreement, many of the roughly 250 covered hotels are mid-market and independently operated businesses with thinner margins and far less flexibility to absorb rising labor costs.

Industry participants credited advocacy from the Multicultural Business Coalition, which worked alongside the Hotel Association of New York City during negotiations and pushed for phased wage increases designed to give smaller operators more time to adapt pricing structures and operating models before the highest-cost years of the agreement arrive.

The reason this contract matters beyond tourism is because it captures one of the defining tensions inside the broader American economy right now: organized labor is demanding larger gains in high-cost cities at the same moment consumers are already struggling with inflation-sensitive pricing.

The hotel worker earning six figures is the same New Yorker city leaders argue deserves the ability to live in the city they help operate.

The tourist paying $400 for a Manhattan hotel room is the same consumer whose spending supports the city’s restaurants, theaters, retail stores and service economy.

Both numbers are now rising together.

And for the next eight years, the answer to the question “Who pays for the raise?” increasingly points to the same person every time they check into a hotel.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. construction industry is entering peak building season warning that a worsening labor shortage is delaying major infrastructure projects, increasing costs, and threatening the rollout of federally funded roads, bridges, semiconductor plants, power systems, and artificial intelligence data centers across the country.

Economists and trade groups tracking the sector say the shortage is becoming one of the biggest bottlenecks facing the broader American economy.

Anirban Basu, chief economist at the Associated Builders and Contractors, said the industry needs approximately 349,000 net new workers in 2026 simply to keep labor supply and demand balanced. That gap is expected to widen further to roughly 456,000 workers by 2027 as construction spending continues expanding.

Without those workers, Basu warned, labor shortages will intensify across multiple regions and specialized trades, pushing project costs even higher.

The warning arrives as total U.S. construction spending approaches roughly $2.05 trillion, fueled by the AI infrastructure boom, semiconductor manufacturing expansion, renewable-energy projects, and billions of dollars still flowing from the 2021 bipartisan infrastructure law.

According to ABC economic models, every $1 billion in construction spending generates roughly 3,450 to 3,550 construction-related jobs, meaning even modest spending increases create enormous labor demand.

Aging demographics are now colliding directly with that expansion.

Industry data shows roughly one in five U.S. construction workers is already over the age of 55, while the National Center for Construction Education and Research projects approximately 41% of the current construction workforce could retire by 2031.

Basu said much of the hiring demand now stems not from entirely new projects, but simply from replacing workers leaving the industry through retirement.

Mike Bellaman, president and chief executive of ABC, said the labor squeeze is hitting nearly every major growth segment of the economy simultaneously.

“The macrodynamics at play include an aging and retiring workforce, immigration enforcement, high materials prices, tariffs, office vacancies and rapidly evolving technologies,” Bellaman said in recent remarks addressing the industry outlook.

Specialized skilled trades are facing the most severe shortages.

Electricians, heavy-equipment operators, welders, and advanced industrial technicians are increasingly difficult to recruit as AI-driven data center construction accelerates nationwide. Industry forecasts estimate roughly $86 billion in data center spending alone this year, creating intense competition for highly specialized electrical labor.

The shortages are especially visible around semiconductor manufacturing hubs in Arizona, Ohio, Texas, and New York, where massive fabrication plants backed by the CHIPS Act are already competing for limited labor pools.

Contractors say the strain is now translating directly into delayed projects.

A nationwide workforce survey conducted by the Associated General Contractors of America and NCCER found that 92% of contractors are struggling to fill open positions, while nearly half report labor shortages are actively delaying projects already underway.

Approximately 88% of surveyed firms reported unfilled openings for craft workers, while 80% said they lacked enough salaried project-management staff.

Ken Simonson, chief economist at AGC, said labor shortages are affecting virtually every major category of construction simultaneously, including housing, transportation, manufacturing, energy infrastructure, and data centers.

Federal immigration enforcement has further complicated hiring efforts.

AGC survey data showed roughly 28% of construction firms reported direct or indirect workforce disruption tied to immigration enforcement activity over the past six months. Some contractors reported workers failing to appear at job sites following rumored immigration actions, while others said subcontractors lost substantial portions of their labor force.

The impact has varied heavily by state, with firms in Georgia, Virginia, Alabama, Nebraska, and South Carolina reporting some of the largest disruptions.

Construction companies are responding by aggressively raising wages and increasing training investments.

Industry surveys show roughly 95% of contractors increased base pay during the past year, while many firms also expanded apprenticeship programs and workforce-training initiatives. Larger contractors are investing heavily in prefabrication, modular construction, automation tools, and AI-driven scheduling systems to maximize productivity from limited labor pools.

Industry groups are also lobbying Congress for immigration reforms targeted specifically at construction labor.

AGC Vice President Brian Turmail said the organization is pushing for a construction-specific visa program and expanded legal pathways allowing undocumented workers already employed in the sector to remain active legally.

Industry leaders argue that without a major workforce solution, much of Washington’s infrastructure agenda risks running into delays, cost overruns, and incomplete projects despite the availability of federal funding.

The labor shortage is also colliding with broader cost pressures.

Contractors continue facing elevated prices for steel, aluminum, copper, lumber, transformers, and electrical equipment, while tariffs tied to ongoing trade disputes have added additional volatility to materials costs. Lead times for critical grid equipment and industrial electrical systems now stretch between two and four years in some cases.

For policymakers, the warning from the construction sector is increasingly blunt: the United States has approved the money, announced the factories, and launched the projects — but may not have enough workers available to build them all on schedule.

JBizNews Desk — Midwest

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Chinese President Xi Jinping’s government implemented its zero-tariff policy for 53 African countries on May 1, 2026, formally opening China’s 1.4 billion-consumer market to duty-free imports from nearly the entire African continent — a sweeping trade move widely viewed by analysts as a direct geopolitical and economic counter to President Donald Trump’s tariff-heavy trade strategy.

The policy, first announced by Xi Jinping on February 14, was confirmed by China’s State Council and the Chinese Ministry of Commerce and has now been fully active for more than three weeks. Under the arrangement, all goods entering China from the 53 African nations that recognize Beijing instead of Taiwan now face zero customs duties.

The lone exception is Eswatini, the small Southern African kingdom that still maintains diplomatic ties with Taipei. Beijing excluded the country entirely, reinforcing China’s broader “One China” pressure campaign.

The scale of the move is historic.

The new tariff-free framework covers Africa’s largest economies, including South Africa, Nigeria, Egypt, Algeria, Kenya, Ethiopia, Ghana, Tanzania, Morocco, and Angola. It expands China’s earlier December 2024 decision that granted zero tariffs only to 33 least-developed African nations.

Now, virtually the entire continent has free access to the world’s second-largest economy.

For African exporters, the financial impact is immediate and massive.

A South African wine producer that previously paid a 14% import tariff to sell bottles in Shanghai now pays nothing. Nigerian cocoa exporters, Kenyan coffee growers, Egyptian cotton suppliers, Ethiopian sesame farmers, and Ghanaian cashew producers suddenly become significantly more competitive inside China’s enormous consumer market.

The timing is not accidental.

The policy arrives just as African exports to the United States are facing new tariffs under the Trump administration, while Washington’s long-standing Africa trade framework has weakened dramatically. The African Growth and Opportunity Act (AGOA) — the cornerstone of U.S.-Africa trade relations since 2000 — technically remains alive through December 31, 2026 after a temporary reauthorization, but confidence in Washington’s long-term commitment has sharply deteriorated.

At the same time, the Trump administration dismantled major portions of USAID, scaled back parts of the Export-Import Bank, and reduced development financing programs that historically helped anchor American influence across Africa.

China moved quickly to fill the vacuum.

According to official Chinese government data, China-Africa trade reached a record $295.6 billion in 2024, making China Africa’s largest trading partner by a wide margin. First-quarter 2025 trade totaled another $72.6 billion, up 2.7% year-over-year even before the full tariff elimination took effect.

Trade analysts now expect those numbers to accelerate sharply through the second half of 2026.

The bigger story is minerals.

Africa holds some of the world’s most important strategic resources: roughly 70% of global cobalt production, nearly half of known manganese reserves, major lithium deposits, rare earth elements, uranium, copper, platinum, graphite, and chromium — the raw materials powering the global race for artificial intelligence infrastructure, semiconductors, electric vehicles, defense systems, batteries, and renewable energy technology.

China’s new policy effectively gives African producers a stronger financial incentive to send those materials directly into Chinese supply chains rather than Western ones.

Companies positioned to benefit include CATL, BYD, CMOC Group, Zijin Mining, China Molybdenum, Ganfeng Lithium, Huayou Cobalt, and Tsingshan Holding Group, all of which already operate deep inside African mining and processing networks.

The move directly undercuts years of U.S. industrial strategy.

The Inflation Reduction Act, the CHIPS and Science Act, and U.S.-backed infrastructure projects like the Lobito Corridor rail network were all designed to reduce Western dependence on Chinese-controlled supply chains. China’s tariff elimination weakens the economics of those alternatives almost overnight.

For African governments, the appeal is simple: China is offering real market access with few political conditions attached.

There are no governance requirements, labor-rights benchmarks, or democratic reforms tied to the tariff removal. Leaders including South African President Cyril Ramaphosa, Nigerian President Bola Tinubu, Egyptian President Abdel Fattah el-Sisi, Kenyan President William Ruto, and Ethiopian Prime Minister Abiy Ahmed have publicly welcomed the deal.

China has also pledged financing support, exporter training, logistics coordination, and marketing assistance through what Beijing calls its “green channel” trade system.

The geopolitical signal is equally clear.

By excluding Eswatini, China demonstrated that diplomatic recognition of Taiwan now carries direct economic consequences. African nations considering closer relations with Taipei can now see exactly what they stand to lose.

For the United States, the policy represents a growing strategic problem.

American industrial giants including Caterpillar, John Deere, General Electric, Honeywell, Boeing, Cummins, and Bechtel now compete in African markets where Chinese companies can bundle infrastructure deals, financing, and guaranteed access to the world’s largest manufacturing ecosystem.

Meanwhile, cheaper African raw materials flowing into Chinese factories will help Beijing lower production costs for batteries, electronics, electric vehicles, magnets, and solar equipment — goods that still eventually reach global markets, including the United States.

Even Trump’s tariffs cannot fully block that dynamic.

Chinese goods can still enter global supply chains indirectly through countries like Mexico, Vietnam, Indonesia, and Malaysia, lowering the effectiveness of Washington’s tariff wall over time.

For everyday Africans, however, the benefits are immediate and tangible.

Workers in Lagos, Nairobi, Cairo, Addis Ababa, Johannesburg, Accra, and Lusaka stand to gain from rising exports, stronger currencies, higher commodity demand, and improved trade balances. Governments across the continent are expected to see increased foreign exchange reserves and stronger fiscal positions.

For Washington, the uncomfortable reality is becoming harder to ignore.

China spent two decades building the infrastructure, ports, rail systems, trade relationships, scholarships, diplomatic ties, and financing channels necessary to make a policy like this credible. The Belt and Road Initiative was not just about roads and bridges — it was about building long-term commercial dependence.

Now Beijing is cashing in on that investment.

The Trump administration has bet that tariffs and bilateral pressure can rebuild American industrial power. China has bet that opening its market to the developing world will buy lasting influence and strategic dominance.

Africa has become the first major battleground testing which model works better.

So far in 2026, the scoreboard favors Beijing.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

AutoZone beat Wall Street earnings expectations Tuesday, but investors focused instead on shrinking profit margins and weaker-than-expected international performance, sending shares of the auto-parts retailer sharply lower.

The company’s stock fell roughly 9.6% after reporting fiscal third-quarter results for the period ending May 9.

Phil Daniele, AutoZone’s president and chief executive officer, said the company remains focused on “a disciplined approach of increasing earnings and cash flows to drive shareholder value,” but the details inside the earnings report raised concerns across Wall Street.

AutoZone earned $641.5 million during the quarter, equal to $38.07 per share, beating analyst expectations of roughly $36.18 per share.

Revenue rose 8.4% to $4.84 billion, though that figure came in slightly below forecasts.

The biggest issue was margins.

Gross margin fell to 52.2%, down 57 basis points from a year earlier. Much of the decline came from a large accounting-related inventory charge tied to the company’s use of LIFO accounting — short for “last in, first out.”

Under LIFO accounting, the newest and often most expensive inventory costs are recognized first during inflationary periods, reducing reported profit margins.

AutoZone said the LIFO adjustment alone reduced quarterly gross margin by 77 basis points.

The pressure is expected to continue.

Jamere Jackson, the company’s chief financial officer, warned analysts during the earnings call that another significant LIFO-related hit is likely in the current quarter, with an estimated $30 million impact on operating profit.

That guidance disappointed investors who had hoped the inventory-related pressure would begin easing.

International operations also weakened.

AutoZone reported softer-than-expected results in Mexico and Brazil, two markets the company has increasingly relied upon to support long-term growth outside the United States.

Management maintained that the company continues gaining market share internationally, but slower growth in Latin America raised concerns about the pace of expansion abroad.

Domestic operations, however, remained relatively solid.

Comparable U.S. store sales rose 4.1%, with both do-it-yourself customers and commercial repair-shop demand holding up well.

The company opened 82 new stores during the quarter, including:

  • 57 in the United States
  • 20 in Mexico
  • 5 in Brazil

AutoZone now operates nearly 7,900 stores across North and South America.

Management reaffirmed plans to open approximately 350 to 360 stores during the current fiscal year.

The company also continued aggressively repurchasing its own stock.

AutoZone spent roughly $586 million buying back shares during the quarter and still has approximately $800 million remaining under its current authorization program.

Share repurchases have long been one of the company’s major drivers of earnings-per-share growth.

Despite the earnings beat, investors reacted strongly because AutoZone has historically traded as one of Wall Street’s most consistent and predictable retail performers.

When highly valued companies show any signs of margin pressure or slowing international growth, stock reactions often become amplified.

The broader backdrop remains mixed for the auto-parts industry.

Historically, companies like AutoZone benefit when consumers delay buying new vehicles and instead spend more maintaining older cars.

That trend still appears intact across much of the United States.

But inflation pressures, accounting impacts, and uneven overseas performance are now complicating the story.

Daniele also addressed concerns tied to rising global energy prices and supply disruptions surrounding the Middle East conflict, telling analysts the company does not currently view lubricant or inventory supply issues as materially disruptive to operations.

AutoZone maintained its broader fiscal 2026 outlook and said management still expects continued growth domestically and internationally.

Still, Tuesday’s sharp selloff reflected a broader reality on Wall Street:
even companies known for consistency can face significant investor backlash when profit pressures, elevated expectations, and international uncertainty collide in the same quarter.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The European Central Bank issued a sharp warning Tuesday: if the fast-growing private credit market runs into trouble, insurance companies could take the biggest hit — not banks.

The warning came in a financial stability report published in Frankfurt, but the risks reach far beyond Europe. The same trend has spread rapidly across the United States, especially through retirement and annuity products owned by millions of Americans.

Private credit has become one of the fastest-growing areas on Wall Street.

Instead of traditional banks making loans directly to companies, giant investment firms including Apollo Global Management, Blackstone, KKR, Blue Owl Capital, and Ares Management now raise money from investors and lend it out themselves.

The market has exploded in size over the past decade and is now estimated globally at between $1.5 trillion and $2 trillion.

Most ordinary consumers have never heard of private credit.

But many are already deeply connected to it through life insurance and retirement products.

When consumers buy annuities or retirement-focused insurance products, insurance companies invest those funds in order to generate returns over time. Increasingly, those insurers are putting large portions of that money into private credit loans.

According to the ECB, insurance companies and pension funds now account for roughly 70% of all money invested globally in private credit funds.

European insurers alone hold approximately €211 billion in private credit exposure, while pension funds hold another €52 billion.

The same pattern has accelerated across the United States.

Apollo owns Athene, one of the country’s largest annuity businesses with roughly $344 billion in assets. Athene now represents about half of Apollo’s overall business model.

KKR owns Global Atlantic. Blue Owl owns Kuvare, parent company of Guaranty Income Life and United Life. Blackstone manages significant insurance-related assets through partnerships including Corebridge Financial, formerly part of AIG.

Earlier this year, F&G Annuities & Life disclosed that roughly 20% of its investment portfolio is tied to private credit strategies managed by Blackstone.

U.S. regulators are increasingly paying attention.

In April, the Federal Reserve reportedly began asking major banks for detailed information regarding their lending exposure to private credit firms. Regulators are trying to determine how large the risks could become if defaults begin rising across the sector.

The international Financial Stability Board warned earlier this month that global banks currently maintain roughly $220 billion in direct credit lines to private credit funds, though some private estimates place the figure far higher.

Why the concern now?

Several warning signs have started appearing across the industry.

This spring, investors began withdrawing money from certain funds operated by Blackstone and Blue Owl. Shares of Apollo have also fallen sharply from late-2024 highs.

At the same time, ratings agency Moody’s noted earlier this year that private credit and insurance businesses now account for more than half of the combined operations at Apollo, Blackstone, KKR, and Carlyle.

That growing interconnection means stress in one part of the system could quickly affect the others.

The ECB also highlighted another risk: leverage.

Private credit funds often borrow money themselves in order to make larger loans and boost returns. According to the ECB, European private credit funds borrow roughly 40 cents for every dollar of investor capital, while U.S. funds average closer to 30 cents on the dollar.

That leverage magnifies profits when markets remain stable — but can also accelerate losses when borrowers struggle.

Some investors are warning that ordinary retirees may not fully understand how much exposure their retirement savings now have to private credit markets through annuities and insurance products.

There are also concerns about transparency.

The ECB said banks and regulators often cannot fully see when the same company owes money both to traditional banks and to private credit lenders simultaneously. U.S. regulators including the Treasury Department’s Office of Financial Research have raised similar concerns about visibility into insurance-company holdings.

Despite the growing worries, the private credit industry still has enormous amounts of capital available to lend.

According to the ECB, private credit funds held approximately €507.7 billion in committed but unspent capital as of last September, on top of more than €1.13 trillion already invested.

Wall Street firms continue pushing back against the concerns.

The firms argue their loans are generally backed by company assets and that insurance-company money is naturally suited for long-term lending because insurers do not face the same short-term withdrawal pressures as banks or mutual funds.

The ECB acknowledged that insurers may be structurally better positioned than many investors to hold illiquid long-term loans.

Still, the central bank’s warning Tuesday was direct.

If losses begin building across private credit markets, insurance companies may absorb the damage first — and millions of retirement savers could ultimately sit on the other side of that exposure.

Shares of Apollo, Blackstone, KKR, Ares, and Blue Owl all remain publicly traded on the New York Stock Exchange and have pulled back significantly from their highs reached during the peak of the private-credit boom.

For regulators, investors, and retirees alike, the question is no longer whether risks exist inside private credit.

The question is where the first cracks will appear.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

LONDON — A historic early-season heat wave is sweeping across Western Europe, smashing temperature records in the United Kingdom and France and placing an estimated $11.8 trillion in economic activity under extreme stress before summer has officially begun.

The United Kingdom recorded its hottest May day ever on Tuesday, with temperatures at Kew Gardens in Greater London reaching 34.8 degrees Celsius (94.6 Fahrenheit) — shattering the previous national May record by roughly two degrees.

France’s national weather agency confirmed Monday was the country’s hottest May day ever recorded. Temperatures in Portugal are approaching 40 degrees Celsius (104 Fahrenheit), while parts of Spain are forecast to reach 38 degrees Celsius. Belgium is also on track to break historic May heat records.

Meteorologists say the event is being driven by a massive “heat dome” — a powerful high-pressure system trapping hot air from North Africa over Western Europe while blocking the cooler weather systems that would normally moderate temperatures.

In practical terms, the atmosphere has effectively placed a lid over Europe, allowing temperatures to climb 10 to 15 degrees Celsius (18 to 27 Fahrenheit) above seasonal averages across much of the region.

The economic exposure is enormous.

Researchers at the ClimaMeter consortium estimate roughly 242 million people across Western Europe are now living under heat conditions intensified by climate change in regions representing approximately $11.85 trillion in economic activity.

Of that total, roughly $5.89 trillion lies in the highest-intensity heat zone currently facing the most severe temperatures.

Those figures are not direct damage estimates. They reflect the size of the economies operating under elevated heat stress — including agriculture, transportation, retail, manufacturing, tourism and energy infrastructure.

The business consequences are already appearing across multiple sectors.

Agriculture Faces Accelerated Crop Stress

Farmers across France, Spain and southern Europe are reporting accelerated harvest cycles as crops ripen too quickly under the intense heat.

That may sound beneficial, but rapid ripening often reduces crop quality and lowers overall yields.

The European Environment Agency estimates that extreme weather events — including drought, heat, frost and hail — now account for roughly 80% of agricultural losses across the European Union, with drought alone responsible for 54%.

Wheat, corn, fruit and vegetable production are particularly vulnerable if the heat persists into June.

Agricultural traders are already watching European grain markets closely, with both Euronext milling wheat futures and U.S.-linked commodity contracts potentially vulnerable to price spikes if crop stress worsens.

Power Grids Are Coming Under Pressure

Heat waves strain electricity systems from both directions at once.

Demand surges as households and businesses increase air-conditioning usage, while power generation itself can weaken because rivers used for hydropower and nuclear-reactor cooling become warmer and run lower.

France’s nuclear fleet — which normally supplies roughly two-thirds of the country’s electricity — has historically been forced to reduce output during severe heat waves when river temperatures become too high to safely cool reactor systems.

Parts of Italy have already introduced restrictions on outdoor work during peak heat hours, while hundreds of homes in southeast England temporarily lost water service earlier this week after demand surged.

Retail, Labor and Tourism Are Being Disrupted

Extreme heat also hits labor productivity directly.

Outdoor construction crews, delivery networks, agricultural fieldwork and hospitality businesses all face operational slowdowns once temperatures climb above roughly 35 degrees Celsius.

Retailers face separate challenges including higher refrigeration costs, faster spoilage of fresh food and damage to temperature-sensitive goods.

Tourism patterns are shifting as well.

Coastal regions in southwest France and southern Europe have seen beaches fill unusually early, boosting some seasonal tourism businesses. But inland city centers, shopping districts and restaurant corridors are reporting weaker foot traffic as consumers stay indoors.

Wildfire and Insurance Risks Are Rising

The heat is also elevating wildfire risk across multiple countries.

A wildfire broke out near Arthur’s Seat, the well-known hill overlooking Edinburgh, Scotland, earlier this week. Similar heat patterns have historically preceded larger wildfire outbreaks across the Iberian Peninsula and southern France later in the summer.

The insurance industry is paying close attention.

Major European reinsurers including Munich Re, Swiss Re and Hannover Re, along with the Lloyd’s of London market, have steadily raised climate-related pricing in recent years as heat waves, droughts and wildfire losses become recurring annual events rather than isolated disasters.

Europe Is Warming Faster Than Most of the World

The broader trend worries climate scientists as much as the individual event itself.

According to the Copernicus Climate Change Service and the World Meteorological Organization, Europe is now warming at roughly twice the global average rate, making it the fastest-warming continent on Earth.

The continent’s 2024 heat waves were linked to more than 62,700 heat-related deaths, while the summer of 2025 produced record temperatures across parts of Spain.

This year’s heat event is arriving earlier and intensifying faster than last year’s.

American Companies and Investors Are Watching Closely

The implications extend well beyond Europe.

U.S.-listed air-conditioning and cooling manufacturers including Carrier Global, Trane Technologies and Lennox International are expected to benefit from growing European demand for residential cooling systems.

Historically, much of Western Europe had relatively low air-conditioning penetration compared with the United States. Repeated heat waves are rapidly changing that equation.

Energy utilities with heavy European exposure — including EDF, Enel, Iberdrola and RWE — face pressure balancing higher electricity demand against constrained generation capacity.

Commodity traders are monitoring grain markets closely, while global insurers and reinsurers are again confronting the reality that European climate exposure is becoming a structural cost issue rather than a seasonal anomaly.

The political timing also matters.

European governments are already managing pressure tied to high energy prices, food inflation, immigration tensions and elevated oil prices linked to the ongoing Middle East conflict.

A prolonged summer heat crisis would place additional strain on household budgets and public infrastructure at exactly the moment governments are already facing political fatigue.

For now, the immediate story is the records themselves.

Britain has never recorded a hotter May day. France’s weather agency is calling conditions “unprecedented.” Schools, hospitals, transit systems and outdoor workplaces across Western Europe are already operating under emergency protocols normally associated with peak summer conditions.

And forecasters warn the heat dome may intensify further before it finally breaks.

Summer, in effect, has arrived in Europe a month early.

The economic consequences are only beginning to emerge.

Europe — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

ANTWERP — Belgium is moving toward a prosecution that Jewish leaders across Europe say could fundamentally reshape the future of Jewish religious life on the continent — while also threatening one of Belgium’s most historically important business communities and export ecosystems.

On June 18, a Belgian court is expected to decide whether two mohels — Jewish ritual circumcisers — will stand trial on charges of “intentional assault or bodily harm with premeditation against minors” and the “unlawful practice of medicine.”

The case stems from police raids conducted last year in Antwerp’s historic Jewish quarter, where investigators reportedly seized circumcision instruments and demanded lists of recently circumcised infants.

For Belgium’s Jewish community, the issue extends far beyond a legal dispute.

Brit milah, ritual circumcision performed on the eighth day after birth, is among the oldest and most central practices in Judaism, observed continuously for thousands of years. Prosecuting mohels for carrying out the ritual is viewed by many Jewish leaders not as a regulatory matter, but as an attempt to criminalize a core religious obligation.

And because the case is unfolding in Antwerp, the economic implications are significant.

Antwerp has long served as the global center of the rough diamond trade, a business historically built and dominated by the city’s Orthodox Jewish community. For decades, the Antwerp diamond district handled the overwhelming majority of the world’s rough diamonds while supporting an interconnected ecosystem of trading firms, logistics providers, insurers, financiers, textile businesses, food suppliers and real estate operators.

At its peak, the broader trade was estimated in industry analyses at roughly $40 billion annually.

Jewish-owned businesses remain deeply embedded throughout those networks, even as the industry faces growing competition from Dubai, Mumbai and synthetic diamonds.

Now, many within the community see the prosecution as part of a broader pattern of pressure on Jewish religious life in Europe.

Earlier this week, 45 Jewish community leaders from across Europe signed an open letter accusing Belgian prosecutors of “effectively criminalizing the act of circumcision” and warning that the case was “reminiscent of efforts taken in Europe against Jewish practice prior to the Second World War.”

The letter, organized by the European Jewish Association, stated bluntly that “Belgian Jews are now second-class citizens with limited rights.”

Rabbi Menachem Margolin, chairman of the European Jewish Association, described the prosecution as “a clear attempt to misuse irrelevant constitutional provisions in order to effectively ban circumcision.”

“This is not borderline and not ambiguous — this is antisemitism,” Margolin said.

The dispute has already drawn international diplomatic attention.

Bill White, the United States ambassador to Belgium, publicly criticized the prosecution, calling it “a shameful stain on Belgium.” Earlier this year, White urged Belgian authorities to “stop this unacceptable harassment of the Jewish community.”

Israeli Foreign Minister Gideon Sa’ar called the case “a scarlet letter on Belgian society” and accused Belgium of joining “a short and shameful list” of countries using criminal law to target Jewish religious practice.

The economic pressure campaign escalated further Tuesday when Duvi Honig, founder and CEO of the Orthodox Jewish Chamber of Commerce and co-founder and secretary of the Multicultural Business Coalition, announced plans for a coordinated international response if the prosecutions move forward.

Honig described the Antwerp case as “a self-inflicted economic war by Belgium against its own Jewish business community, dressed up as medical regulation.”

He compared the situation to historical expulsions and restrictions on Jewish economic life in Europe, arguing that countries targeting longstanding Jewish communities often underestimate the economic consequences.

“The dressing has changed. The underlying act has not,” Honig said. “And the economic outcome will not change either.”

Honig said the Orthodox Jewish Chamber of Commerce would explore international boycott efforts targeting key Belgian export sectors, particularly pharmaceuticals and medical products, if the case proceeds.

The economic exposure is meaningful.

Belgium’s pharmaceutical sector is the country’s largest export industry, generating approximately $80.8 billion in exports in 2025, according to international trade data. Major global pharmaceutical companies including Pfizer, Johnson & Johnson, GSK Biologicals and Baxter maintain major operations in Belgium whom the Orthodox Jewish Chamber of Commerce has close working relationship with.

The Wallonia region alone reportedly derives more than one-third of its exports from pharmaceuticals, supporting tens of thousands of jobs directly and indirectly.

Honig argued that any boycott effort would focus not only on public pressure but also on reputational and procurement risks tied to Belgium’s treatment of religious minorities.

The broader concern inside the Jewish community is demographic and economic.

Belgium’s Jewish population has already faced growing security pressures amid rising antisemitic incidents across Europe. If families begin concluding they cannot freely practice core religious traditions inside Belgium, some leaders fear migration out of the country could accelerate.

For Antwerp, that would carry implications beyond religion alone.

The city’s Jewish business infrastructure is deeply intertwined with industries built on multigenerational trust networks, including diamonds, finance, trade logistics and specialty import-export sectors.

Those ecosystems are difficult to replace once they begin unwinding.

The issue also appears to be spreading.

Jewish organizations say authorities in Austria and Switzerland have begun examining similar legal theories surrounding ritual circumcision, raising fears that the Belgian case could become a broader European precedent.

For European governments already grappling with weak economic growth, high energy costs and political fragmentation, the prospect of alienating established business communities carries growing sensitivity.

The Antwerp hearing on June 18 will determine whether the two mohels formally stand trial.

But regardless of the court’s decision, many Jewish leaders say the signal has already been sent — not only to Belgium’s Jewish population, but to Jewish business communities across Europe watching closely to see whether longstanding religious practices can still be protected under modern European law.

Europe — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Mastercard has walked away from a planned investment in crypto firm Zerohash as the company moves aggressively ahead with its $1.8 billion acquisition of stablecoin infrastructure company BVNK, marking one of the biggest moves yet by a traditional payments giant into blockchain-based finance.

The decision positions Mastercard as the first major global card network to use a multibillion-dollar acquisition to establish a direct foothold in the rapidly growing stablecoin market.

The deal, originally announced by Mastercard Chief Product Officer Jorn Lambert on March 17, 2026, is expected to close by the end of the year pending regulatory approvals.

The broader significance is clear: major financial companies are no longer experimenting cautiously with stablecoins. They are now spending billions to own the infrastructure behind them.

Stablecoins are digital currencies tied directly to traditional currencies like the U.S. dollar. Unlike volatile cryptocurrencies such as Bitcoin, stablecoins are designed to maintain a fixed value, making them more practical for payments, international transfers, and commercial transactions.

That is exactly why companies like Mastercard, Visa, PayPal, and Stripe are racing into the sector.

BVNK, founded in London in 2021 by CEO Jesse Hemson-Struthers, builds payment technology allowing businesses to send, receive, and manage stablecoin transactions globally.

The company currently processes roughly $30 billion in annual payment volume and works with firms including Worldpay, Deel, Rapyd, and Flywire.

Under the terms of the agreement, Mastercard will pay approximately $1.5 billion in cash upfront, with another $300 million tied to future performance targets.

The acquisition surpasses Stripe’s $1.1 billion purchase of Bridge in 2024 and becomes the largest stablecoin infrastructure acquisition completed so far.

According to reporting first published by CoinDesk, Mastercard also decided to abandon ongoing investment discussions with rival crypto infrastructure provider Zerohash, choosing instead to consolidate around a single stablecoin strategy centered on BVNK.

The company plans to integrate BVNK’s technology directly into Mastercard Move, its existing cross-border payment platform.

That would eventually allow businesses operating on Mastercard’s network to move stablecoin payments globally using Mastercard infrastructure.

For consumers and businesses, the appeal is speed and cost.

Traditional international bank transfers can take multiple days and often involve significant fees. Stablecoin transactions can settle within minutes while costing only a fraction as much.

The competitive pressure across the financial sector is intensifying quickly.

Visa invested in BVNK before Mastercard moved to acquire the company outright. PayPal launched its own stablecoin product known as PYUSD. Stripe bought Bridge. Large banks including JPMorgan Chase continue expanding blockchain-based payment systems internally.

The industry increasingly sees stablecoins not as speculative crypto products but as a possible future layer of the global payments system.

Regulation has also shifted dramatically.

The Trump administration has taken a more crypto-friendly approach than previous administrations, while Congress earlier this year passed stablecoin legislation establishing clearer legal frameworks for digital-dollar infrastructure providers.

That regulatory clarity is encouraging large financial firms to move faster.

For Mastercard, buying BVNK rather than building internally also saves time.

Executives said recreating BVNK’s licensing network and payment infrastructure independently would likely take years. The acquisition immediately gives Mastercard access to a global stablecoin payment framework already operating across more than 130 countries.

The transaction still faces regulatory review across multiple jurisdictions, including Europe, where BVNK recently secured approval under the European Union’s new Markets in Crypto-Assets (MiCA) regulatory framework.

Existing BVNK customers are expected to continue operating normally throughout the approval process.

The acquisition reflects a much larger transformation underway across global finance.

Only a few years ago, many traditional payment companies treated cryptocurrency cautiously and often distanced themselves publicly from blockchain-based finance.

Now the world’s largest payment firms are spending billions to secure ownership positions inside the stablecoin ecosystem before adoption expands further.

The race is no longer about whether stablecoins will matter.

It is about who controls the infrastructure when they do.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump’s administration is giving roughly $2 billion in federal funding to nine American quantum computing companies while taking ownership stakes in each business, marking one of the most aggressive industrial-policy moves yet in the emerging quantum technology race.

The funding package, announced by Commerce Secretary Howard Lutnick on May 21, 2026, represents a major shift in how Washington supports strategic industries.

Instead of simply issuing grants, the federal government is now becoming a shareholder.

The largest recipient is IBM, which will receive approximately $1 billion tied to quantum computing manufacturing and infrastructure expansion in the United States.

GlobalFoundries will receive roughly $375 million, while companies including D-Wave Quantum, Rigetti Computing, Quantinuum, and Infleqtion are each expected to receive around $100 million.

Additional funding is being distributed among smaller quantum startups and infrastructure firms.

Quantum computing is widely viewed as one of the next major technology frontiers after artificial intelligence.

Unlike traditional computers, which process information using binary bits, quantum computers use quantum bits known as qubits that can process enormous combinations of calculations simultaneously.

The technology remains early and highly experimental, but researchers believe it could eventually transform:

  • Drug discovery
  • National security
  • Materials science
  • Logistics
  • Financial modeling
  • Encryption systems

The administration’s move reflects growing concern in Washington over technological competition with China, which has invested billions into national quantum research programs.

The White House now classifies quantum computing alongside semiconductors, artificial intelligence, and rare earth minerals as core national-security technologies.

The structure of the funding package is what makes the announcement especially significant.

The federal government is not just subsidizing development.

It is taking equity ownership in the companies receiving taxpayer support.

That model mirrors the administration’s earlier investment strategy involving companies including:

  • Intel
  • MP Materials
  • Lithium Americas
  • Critical Metals

Supporters argue taxpayers should benefit financially if government-backed technologies become highly valuable.

The administration frequently points to its earlier investment in Intel, where government-owned shares appreciated substantially after the company’s recovery.

Critics argue government ownership creates conflicts of interest when regulators also become shareholders in the same companies they oversee.

IBM confirmed it will match federal support with an additional $1 billion private investment focused on building advanced quantum chip manufacturing infrastructure in the United States.

The company clarified the federal government’s ownership stake applies to a dedicated quantum subsidiary rather than the broader IBM corporation.

Markets reacted immediately after the announcement.

Shares of publicly traded quantum firms including D-Wave Quantum and Rigetti Computing surged sharply following the news as investors interpreted the funding as major federal validation of the sector.

The technology itself still faces enormous challenges.

Quantum computers today remain highly unstable and error-prone.

Most quantum systems require complex error-correction layers simply to maintain calculations long enough to complete useful tasks.

Researchers still debate how quickly commercially viable quantum systems can emerge at scale.

But Washington increasingly views the race itself as strategically important regardless of the exact commercialization timeline.

The funding originates from the CHIPS and Science Act, originally signed into law in 2022.

Under the original framework, most of the money would have been distributed as traditional grants.

The Trump administration restructured the program to require ownership participation in return for federal capital.

Industry leaders largely welcomed the move.

Rebecca Krauthamer, founder of Quantum Thought and CEO of QuSecure, said the announcement reflects a major shift in Washington’s approach to quantum technology.

“The administration’s $2 billion equity stake across nine quantum companies marks the moment Washington stopped treating quantum as a speculative bet and started treating it as critical national infrastructure,” Krauthamer said.

The announcement also signals how aggressively governments globally are now intervening in advanced technology markets.

The United States, China, Europe, and parts of the Middle East are increasingly treating strategic technologies not simply as commercial sectors but as geopolitical assets.

For investors, the move gives the quantum industry significantly stronger financial backing at a time when many companies in the sector remain years away from profitability.

But it also introduces new political considerations into future mergers, acquisitions, and strategic partnerships involving government-backed firms.

The broader message from Washington is becoming increasingly clear.

Quantum computing is no longer viewed as a speculative science experiment.

It is now officially part of American industrial policy.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Picture this. A regime that was broke three months ago is sitting in a hotel suite in Doha, Qatar, talking about getting $100 billion back. Their currency had collapsed. Their oil exports were near zero. Their people were furious about food prices.

And now they are about to walk away with a deal.

How did that happen? Let’s walk through it.

Who is at the table?

On the Iranian side, the chief negotiator is Mohammad-Bagher Ghalibaf, the Speaker of Iran’s Parliament. He flew to Qatar on Monday, May 25, 2026, and met with Qatari Prime Minister Sheikh Mohammed bin Abdulrahman Al Thani. He flew home to Tehran on Tuesday. With him in Doha were Iranian Foreign Minister Abbas Araghchi and Central Bank Governor Abdolnaser Hemmati. The central bank governor being in the room tells you everything. This is about money.

On the American side, President Donald Trump’s Middle East envoy Steve Witkoff is running point.

What does Iran want?

Two things, and Iranian officials are openly telling Arab mediators what they are. First, they want their money back — roughly $100 billion in assets that the West froze. Second, they want to sell oil on the world market again.

But there is a third goal, and this is the one that should make every American pay attention. Iranian officials told the mediators they want to give up just enough on their nuclear program to get the money — but not enough to let President Trump stand up and say he won.

In plain English: Iran wants the cash, but it does not want Trump to look like a winner.

What is America getting?

Here is where the story gets uncomfortable. The U.S. wants Iran to reopen the Strait of Hormuz, the narrow waterway where roughly one out of every five barrels of the world’s oil normally passes through. Iran mined it during the war. Ships cannot move. American drivers are paying more at the pump. That is the pressure squeezing the White House right now.

In exchange for reopening the Strait, Trump is offering Iran a 60-day window where sanctions get lifted, oil sales restart, and the frozen money starts moving.

What about Iran’s nuclear weapons program? That is supposed to get negotiated during those 60 days. Over the weekend, Trump softened one of his biggest demands. He had wanted Iran to ship its enriched uranium to the United States. Now he says he would accept Iran destroying it or sending it to another country.

That is a big walkback. Iran is sitting on 440.9 kilograms of uranium enriched to 60% purity, according to the International Atomic Energy Agency. That is one technical step away from a bomb.

Did they really keep talking while shooting at each other?

Yes. And this part tells you how desperate the regime is.

Late Monday night, U.S. Central Command struck Iranian speedboats it said were laying mines in the Strait of Hormuz. Iran fired on U.S. planes. The U.S. hit back at missile-launch sites in southern Iran. Several Islamic Revolutionary Guard Corps fighters were killed.

And what did Tehran do? It delayed announcing the deaths of its own soldiers so the talks in Doha would not blow up. Think about that. The regime would rather hide its own casualties from its own people than walk away from this deal. That is how badly Iran needs the money.

Why is Iran so desperate?

Because the regime is broke. Inflation hit 48.6% in October 2025 and 42.2% in December. The rial collapsed. Trump’s maximum-pressure order in February 2025 cut Iran’s oil exports to almost nothing. Then the war in February 2026 shut down the Strait. The regime ran out of room.

What does Israel think?

Israel hates this deal. A senior Israeli official told reporters this week that the agreement “is bad because it signals to the Iranians that they possess a weapon no less effective than a nuclear one, and that is the Strait of Hormuz.”

That is the Israeli argument in one sentence. Iran just learned that if it chokes the world’s oil supply, the United States will rush to the table and write a check. Why would Iran ever give that lever up?

Another person familiar with the talks told reporters that Israel is “very unhappy” with the deal and “angry” at Witkoff for “pushing a deal at any cost.”

What does the market think?

The market thinks something is coming. Brent crude dropped as much as 6.4% on Monday to $96.90 a barrel. WTI traded near $91. Charu Chanana, chief investment strategist at Saxo Markets in Singapore, told clients the two sides may be closer on a ceasefire but they are still far apart on sanctions and on the nuclear program. The market, she said, has priced in relief — but not a real fix.

According to the International Energy Agency’s May 2026 oil report, Brent has swung from a high of $144 a barrel all the way down below $100 and back up to about $110. More than 14 million barrels a day of Gulf oil has been shut in. The world has already lost more than one billion barrels of supply since the war began.

So yes, getting oil flowing again would help every American. That is real. That matters at the gas pump.

So what is the catch?

The catch is this. Iran gets oil sales, frozen funds, and a sanctions break. America gets verbal promises and a 60-day window to figure out the nuclear file. There is no signed cap on Iran’s uranium enrichment. There is no signed inspection deal. There is no signed plan to destroy the stockpile before the cash flows.

And in Tehran, lawmaker Ebrahim Rezaei, a spokesman for the parliament’s National Security and Foreign Policy Commission, posted on X this week that the Iranian delegation in Doha “must negotiate from a position of victorious power” and “not whitewash the red lines.” He called Iran “the definitive victor of the war.”

That is the message the regime is sending to its own people. They won. America blinked.

So who actually wins?

If the deal goes through, oil prices fall and gas gets cheaper. That helps Trump. That helps American families heading into summer.

But strategically? Iran is the regime that came in needing this. Iran is the regime that gets to keep its uranium. Iran is the regime that learned how powerful the Strait of Hormuz is as a weapon. And Iran is the regime that is privately telling Arab mediators that the whole goal is to walk away with the money — without giving Trump a clean win.

Secretary of State Marco Rubio said this week the Strait of Hormuz “will open one way or the other.” He is right that it will open.

The harder question is on whose terms.

For now, it looks like Tehran’s.

JBizNews Desk — Middle East

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — The S&P 500 and Nasdaq Composite closed at fresh all-time highs Tuesday as investors poured back into artificial intelligence and semiconductor stocks following the Memorial Day holiday, pushing technology shares sharply higher while more traditional consumer companies struggled.

The standout move came from Micron Technology, which surged nearly 20% and crossed a $1 trillion market value for the first time after a major Wall Street upgrade tied to exploding demand for AI memory chips.

The split between soaring technology names and weakness in consumer-focused companies defined the entire trading session.

The Closing Numbers

  • S&P 500: 7,519.12, up 0.61%, record close
  • Nasdaq Composite: 26,656.18, up 1.19%, record close
  • Dow Jones Industrial Average: 50,461.68, down 0.23%
  • Russell 2000: Broke above 2,900 for the first time ever

Technology stocks dominated the rally.

Sixteen of the top 20 gainers in the S&P 500 came from semiconductor or computer hardware companies as investors continued betting heavily on artificial intelligence infrastructure demand.

Micron Leads The Market

Micron Technology jumped 19.3% after UBS analyst Timothy Arcuri sharply raised his price target on the stock, citing overwhelming demand for high-bandwidth memory chips used inside AI systems.

The chips are essential for powering advanced AI processors built by companies like Nvidia, and demand has accelerated as hyperscale data center construction continues globally.

UBS said Micron’s production capacity for AI memory products is effectively sold out through the end of 2026.

The rally pushed Micron into the trillion-dollar market-cap club alongside:

  • Apple
  • Microsoft
  • Nvidia
  • Amazon
  • Alphabet
  • Meta
  • Tesla
  • Broadcom

The stock has risen roughly 700% over the past year.

Why The Dow Fell

While the Nasdaq and S&P hit records, the Dow Jones Industrial Average moved lower largely because of a sharp decline in AutoZone shares.

AutoZone fell 9.6% after reporting earnings that beat Wall Street estimates but revealed pressure on profit margins and softer international performance.

Because the Dow is price-weighted and AutoZone’s stock trades above $3,500 per share, the decline had an outsized impact on the index.

Walmart also weighed on the Dow after recent warnings from executives that higher gasoline prices are squeezing lower-income shoppers.

Quantum Stocks Stay Strong

Quantum computing companies continued climbing following last week’s announcement that the Trump administration will invest roughly $2 billion into nine American quantum firms in exchange for government ownership stakes.

Shares of:

  • D-Wave Quantum
  • Rigetti Computing
  • IonQ

all traded higher.

IBM, which is receiving the largest federal quantum grant, also gained.

Intel Slips After Downgrade

Intel moved lower after analysts at Northland Capital Markets downgraded the stock, warning that future spending by large cloud providers could slow as AI infrastructure costs continue rising.

The downgrade highlighted growing concerns that some technology companies may eventually hit limits on how much capital they can continue pouring into AI expansion.

Consumer Confidence Weakens

Markets also digested fresh economic data Tuesday.

The Conference Board reported that U.S. consumer confidence slipped in May as Americans expressed increasing concern over inflation and economic conditions tied to the Middle East conflict and higher fuel prices.

At the same time, a new Case-Shiller housing report showed home-price growth slowing sharply nationwide, with more than half of major U.S. cities now showing year-over-year price declines.

Treasury Yields Ease

The benchmark 10-year Treasury yield moved lower during the session.

Lower yields generally help technology valuations because future earnings become more attractive when borrowing costs decline.

Investors increasingly believe the Federal Reserve could still cut interest rates later this year despite elevated energy prices and geopolitical tensions.

Oil Remains Volatile

Oil prices remained elevated as investors monitored developments involving Iran and the Strait of Hormuz.

WTI crude traded above $90 per barrel during the session after new comments from Iran’s Revolutionary Guard raised concerns about potential retaliation tied to ceasefire negotiations.

Energy markets continue reacting sharply to any developments involving the region because roughly one-fifth of global oil shipments move through the Strait of Hormuz.

Space Stocks Rally Again

Several space-related companies also surged as enthusiasm surrounding the upcoming SpaceX IPO continued spreading across the sector.

Rocket Lab, Redwire, and AST SpaceMobile all posted strong gains.

SpaceX is expected to launch what could become the largest IPO in history next month with a targeted valuation near $1.75 trillion.

The Week Ahead

Investors are now focused on:

  • Friday’s Personal Consumption Expenditures inflation report
  • First-quarter GDP revisions
  • Upcoming earnings from Salesforce, Dell Technologies, and Zscaler
  • Multiple Federal Reserve speeches scheduled this week

Markets remain caught between two competing forces:
explosive AI-driven growth in technology and mounting pressure on consumers from higher prices and slowing affordability.

For now, the technology rally continues to overpower everything else.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Pentagon is running side-by-side tests of competing artificial intelligence models with 25 of the department’s designated “power users” to determine which system could replace Anthropic’s Claude across U.S. military operations, according to a Bloomberg report published Thursday morning.

The trials began in early March, days after Defense Secretary Pete Hegseth designated Anthropic a “supply-chain risk” to national security and ordered the federal government to stop doing business with the company over its refusal to permit the use of Claude for fully autonomous weapons systems and mass domestic surveillance.

Anthropic has since filed challenges in federal courts in San Francisco and Washington seeking to overturn the designation, arguing that the blacklist could cost the company billions of dollars in lost government and commercial business if allowed to stand.

Cameron Stanley, the Pentagon’s chief digital and AI officer, told Bloomberg earlier this year that the Defense Department would require more than a month to begin transitioning away from Anthropic products already embedded inside U.S. military operations tied to the Iran conflict.

More than two months later, that transition has evolved into an active competitive evaluation process. The 25 military “power users” participating in the testing are drawn from combatant commands and intelligence operations that rely heavily on large language models for battlefield analysis, planning and operational decision support.

The companies positioned to absorb the lost Anthropic business are already emerging. On May 1, the Department of Defense announced agreements with seven major AI firms to deploy systems across classified Pentagon networks: SpaceX, OpenAI, Google, Nvidia, Reflection, Microsoft, and Amazon Web Services. Anthropic was notably absent from the group.

According to the Pentagon, the participating companies share “the conviction that American leadership in AI is indispensable to national security.”

At the center of the dispute are Anthropic’s restrictions on how Claude can be used by military and government agencies. The company has maintained that it will not permit its models to be used for fully autonomous lethal targeting or mass surveillance of American citizens.

Senior Pentagon officials, including Hegseth, have argued those restrictions are incompatible with the operational demands of modern warfare.

Hegseth wrote earlier this year on X that “effective immediately, no contractor, supplier, or partner” doing business with the Pentagon could engage in commercial activity with Anthropic — an unusually sweeping designation that extended beyond direct government contracts into broader vendor relationships.

Anthropic chief executive Dario Amodei later met with White House Chief of Staff Susie Wiles and other administration officials on April 17 in what was widely viewed as an effort to ease tensions with the administration.

Following the meeting, President Donald Trump told CNBC that a deal with Anthropic remained “possible.”

“They’re very smart, and I think they can be of great use,” Trump said.

No formal resolution has emerged, and the legal fight remains active.

The financial stakes are substantial. Roughly $200 million in federal business is reportedly in question, while the administration has established a six-month timeline for agencies to migrate away from Anthropic systems.

Anthropic has also revised parts of its internal AI safety framework in recent months, shifting from binding internal scaling commitments toward a more flexible model the company says better reflects competitive realities in the global AI race.

Critics have characterized the changes as a concession designed to remain commercially competitive, while Anthropic argues that unilateral restraint by responsible developers does not prevent rivals from advancing more aggressively.

At present, Claude remains the only large language model authorized for certain classified U.S. military systems through Anthropic’s partnership with Palantir Technologies.

Competing systems including OpenAI’s ChatGPT, Google’s Gemini and xAI’s Grok are currently available inside unclassified Pentagon environments and have reportedly agreed to modified safeguard terms under their government access arrangements.

The Pentagon’s current testing process will help determine which of those systems — or combination of systems — ultimately fills Anthropic’s classified role.

The broader implications extend well beyond a single defense contract.

The Pentagon’s position effectively establishes that AI suppliers seeking government business must accept military-defined use cases without negotiating operational restrictions on a case-by-case basis.

That precedent is now forcing every major American AI developer to decide how far it is willing to go in balancing commercial opportunity, national-security cooperation and publicly stated safety commitments.

OpenAI announced its own Pentagon partnership on the same day the administration blacklisted Anthropic, with chief executive Sam Altman describing the arrangement as including “technical safeguards” accepted by the government. The specific details of those safeguards have not been publicly disclosed.

For the AI industry, the Anthropic dispute is becoming the first major test of what happens when a frontier AI company attempts to hold a published safety line against the largest government customer in the world.

If Anthropic succeeds in court, the outcome could strengthen the ability of AI firms to negotiate operational restrictions with government agencies. If the Pentagon prevails, the message to Silicon Valley will be that access to federal contracts comes on government terms — and that companies willing to remove restrictions will gain the advantage.

The Pentagon’s 25-user evaluation group is expected to issue recommendations in the coming weeks. The company ultimately selected will inherit one of the most consequential AI contracts in the federal government, while Anthropic’s path back may depend on whether the courts decide the blacklist can stand.

JBizNews Desk

© 2026 JBizNews. All rights reserved.

By JBizNews Desk

May 25, 2026 — Alaska’s long-dormant oil sector is experiencing its sharpest revival in nearly two decades as major discoveries, surging lease demand, elevated oil prices and accelerated federal permitting under the Trump administration pull capital and drilling activity back into the American Arctic.

Operators including ConocoPhillips, Santos Ltd., Repsol SA, Exxon Mobil Corp., Shell Plc and privately held Armstrong Oil & Gas are ramping up exploration and development programs across Alaska’s North Slope after a series of discoveries and lease sales reignited industry expectations for long-term production growth in the region.

The momentum accelerated in March when a lease auction inside the National Petroleum Reserve-Alaska (NPR-A) generated a record $164 million in winning bids, one of the strongest federal Arctic lease sales in modern history.

The revival marks a dramatic reversal for a basin many energy analysts believed was entering permanent decline.

Instead, the combination of new discoveries, stronger oil economics, geopolitical instability and aggressive permitting reforms is increasingly positioning Alaska once again as a strategic pillar of long-term American energy supply.

The clearest signal arrived May 18, when Australia-based Santos confirmed first oil production at its long-awaited Pikka development on Alaska’s North Slope — the first major new oil field brought online in the region in roughly twenty years.

Santos, which operates the project with a 51% stake alongside partner Repsol, is targeting plateau production of approximately 80,000 barrels per day later this year. Oil from Pikka flows through a newly constructed 22-mile pipeline connecting into the broader Trans-Alaska Pipeline System.

The company also confirmed successful appraisal drilling at its nearby Quokka discovery, which executives believe could eventually rival Pikka in production scale.

The discoveries are reviving optimism around Alaska’s broader resource base.

The U.S. Geological Survey estimates the NPR-A alone may contain roughly 8.8 billion barrels of technically recoverable oil — far more than many industry models assumed even a decade ago.

That resource potential is now intersecting with a dramatically more favorable political environment.

Under Interior Secretary Doug Burgum, the Trump administration has aggressively moved to accelerate energy permitting timelines throughout Alaska’s Arctic regions as part of its broader “American Energy Dominance” strategy.

Interior Department officials are developing a streamlined framework designed to allow qualifying North Slope projects to complete portions of environmental review and permitting in as little as 30 days through standardized programmatic analysis covering roads, well pads, pipelines and processing infrastructure.

The accelerated structure is expected to benefit projects including ConocoPhillips’ Willow development, additional Santos expansion phases and future drilling tied to acreage secured during the March lease sale.

The administration is also preparing a new offshore leasing framework through the Bureau of Ocean Energy Management that would reopen portions of Arctic territory previously restricted under both the Obama and Biden administrations.

The policy shift arrives at a moment when geopolitical instability has sharply increased strategic pressure for additional North American oil production.

The U.S.-Iran conflict and ongoing tensions surrounding the Strait of Hormuz have tightened global spare production capacity, revived energy-security concerns and pushed governments and investors to reassess the long-term importance of domestic supply.

Alaska’s revenue outlook has already improved materially as a result.

The Alaska Department of Revenue now forecasts Alaska North Slope crude prices averaging approximately $75 per barrel during fiscal 2026, including war-driven price spikes above $90 earlier this spring. Those assumptions translate into significantly higher royalty and severance-tax revenues for the state government after years of fiscal pressure tied to declining throughput in the Trans-Alaska Pipeline System.

For major operators, the opportunity is increasingly becoming difficult to ignore.

ConocoPhillips — currently the largest integrated producer on Alaska’s North Slope — said during first-quarter earnings that its massive Willow project reached roughly 50% completion during the winter construction season, with first production targeted for 2029.

Chief Executive Officer Ryan Lance also confirmed the company completed a four-well winter exploration program while securing what management described as “high-priority acreage” during the March NPR-A auction.

Combined with Pikka, Quokka and other adjacent discoveries, the projects could significantly reverse the long-running decline in North Slope production that has weighed on the Trans-Alaska Pipeline System for decades.

TAPS throughput has fallen from a peak above 2 million barrels per day in 1988 to roughly 475,000 barrels per day in recent years, forcing pipeline operators to engineer around low-flow risks including freezing and viscosity challenges.

New production from Willow, Pikka and future NPR-A developments could potentially push pipeline throughput back above 500,000 barrels per day for the first time in years while materially extending the system’s long-term economic viability.

The industry optimism, however, is colliding with growing legal and environmental resistance.

Groups including the Natural Resources Defense Council, Center for Biological Diversity, Friends of the Earth and several Alaska Native organizations have filed multiple lawsuits challenging expanded Arctic leasing and drilling approvals.

Community leaders in the Iñupiat village of Nuiqsut, located near several major development areas, have warned that expanded drilling activity threatens caribou migration routes and traditional subsistence resources.

Environmental groups also argue the broader revival narrative may be overstated, noting that several major oil companies reduced or exited portions of their Alaska portfolios over the past decade, including Shell’s retreat from offshore Arctic drilling and BP’s sale of Alaska assets to Hilcorp Energy.

But industry executives increasingly counter that the problem was never geology.

It was access.

Now, with elevated oil prices, stronger federal support, revived lease activity and multiple commercially viable discoveries coming online simultaneously, Alaska is once again drawing serious long-term capital back into the Arctic.

The strategic implications extend far beyond the state itself.

With Russian crude increasingly isolated from Western markets, Middle East shipping lanes vulnerable to disruption and global spare production capacity tightening, Alaska’s Arctic reserves are once again being viewed in Washington and across energy markets as a critical strategic asset rather than a stranded one.

Whether the industry can fully overcome the region’s legal battles, infrastructure costs and extreme operating conditions remains uncertain.

But for the first time since the glory years of the original Trans-Alaska Pipeline buildout, the discoveries, the capital, the policy environment and the global market signals are all moving in the same direction.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

More Americans are working two or more jobs than at almost any other point in modern history, as families struggle to keep up with rising costs for housing, groceries, insurance, and everyday necessities.

The latest data from the U.S. Bureau of Labor Statistics, released as part of the April 2026 employment report, shows roughly 8.5 million Americans currently hold more than one job. That follows a record 9.47 million multiple-job workers recorded in November 2025 — the highest number since the government began tracking the data in 1994.

In practical terms, roughly one out of every twenty working Americans now depends on more than one paycheck to make ends meet.

The percentage of workers holding multiple jobs has climbed to approximately 5.7%, the highest level in a quarter century.

The economic pressures driving the trend are increasingly straightforward: everyday costs have risen faster than wages.

According to federal inflation data, housing costs have increased roughly 28% over the past five years, while average wages have grown closer to 24% during the same period. Prices for groceries, utilities, insurance, child care, and transportation have also climbed sharply, leaving many households struggling to close the gap between earnings and expenses.

For millions of workers, taking a second job has become the only realistic solution.

The trend is no longer concentrated among lower-income workers alone.

A recent report from the Federal Reserve Bank of St. Louis found that more than half of Americans working multiple jobs now hold college degrees — a major shift from earlier decades when second-job workers were concentrated primarily in lower-wage service industries.

Today, teachers, nurses, accountants, software engineers, office managers, and corporate employees are increasingly supplementing their primary income through gig work, freelancing, consulting, evening retail shifts, rideshare driving, and remote contract work.

The number of Americans simultaneously working two full-time jobs has also surged.

The latest BLS figures show approximately 476,000 Americans currently hold two full-time jobs at the same time, the second-highest total ever recorded behind the December 2025 peak of 488,000. The number has more than doubled since 2020.

Financial planners and labor economists say the pattern reflects growing pressure on middle-class households rather than traditional unemployment distress.

Certified financial planner Carolyn McClanahan has publicly warned that many families now require substantial additional income simply to maintain what was once considered a standard middle-class lifestyle, including housing, transportation, child care, and healthcare coverage.

Julia Pollak, chief economist at ZipRecruiter, has also noted that some workers are taking second jobs after employers reduced hours or slowed salary growth amid broader economic uncertainty.

The expansion of remote work has accelerated the phenomenon further.

With millions of white-collar employees now working from home at least part-time, some workers have quietly taken on overlapping second positions — a trend often referred to online as “overemployment.”

Major corporations including JPMorgan Chase, Meta Platforms, and Amazon have publicly warned employees against secretly working multiple full-time jobs simultaneously, saying violations could lead to termination.

The broader financial strain is increasingly visible across the economy.

According to the Federal Reserve Bank of New York, U.S. credit card debt reached a record $1.21 trillion at the end of last year. Personal savings rates remain below pre-pandemic norms, while delinquencies on auto loans and credit cards continue rising, particularly among households earning under $75,000 annually.

Inflation has eased from its peak but remains elevated relative to wage growth.

The Consumer Price Index increased roughly 3% over the past year, while wage growth has slowed closer to 3.5%, leaving many workers feeling little real improvement in purchasing power.

The Trump administration has argued that deregulation, tax policy, and lower energy costs will eventually ease pressure on household finances. Treasury Secretary Scott Bessent has said economic growth and lower interest rates should gradually improve affordability conditions.

Critics, including economists at the Center for Economic and Policy Research, argue the continued rise in multiple-job workers reflects a labor market where incomes still have not fully caught up with years of elevated living costs.

The pressure spans both urban and rural America.

States with high living costs including California, New York, Massachusetts, and Hawaii report elevated levels of multiple-job workers, while lower-wage rural states continue facing similar strain because a single paycheck often no longer covers basic expenses.

Despite strong headline employment numbers and relatively low unemployment, economists increasingly say the multiple-job trend reveals a more complicated picture underneath the surface of the labor market.

Millions of Americans are technically employed — but are working longer hours than ever simply to maintain financial stability.

For policymakers, employers, and investors, that may be one of the clearest warning signs hiding beneath an otherwise resilient economy.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

NEW YORK, May 26, 2026 — Retiring Representative Jerry Nadler announced in September 2025 that he would not seek a 17th term, opening New York’s 12th Congressional District for the first time in more than three decades and triggering what has quickly become the most expensive open-seat House race in the country.

The district — covering Manhattan’s Upper East Side, Upper West Side, Midtown, Hell’s Kitchen, Chelsea and Stuyvesant Town — is the wealthiest congressional district in New York State, one of the wealthiest in America, and among the most politically influential donor bases in the country. The June 23 Democratic primary is widely viewed as the real election in the heavily Democratic seat.

What makes the race extraordinary is not just the candidates. It is the money, the industries and the power centers lining up behind them.

Former New York Mayor Michael Bloomberg is preparing to spend roughly $5 million through allied outside groups backing Assemblyman Micah Lasher, according to NY1, marking one of the largest single-donor interventions in a House primary this cycle. Lasher previously worked for both Nadler and Bloomberg and is widely viewed inside Manhattan political circles as the establishment favorite.

For the business community, the race carries weight far beyond Manhattan politics.

Wall Street spent much of the past year reacting nervously to Mayor Zohran Mamdani’s political rise, with several finance executives warning publicly that New York’s competitiveness was under pressure. Pershing Square founder Bill Ackman became one of the most outspoken voices arguing that the city’s business climate was deteriorating. Inside finance circles, the NY-12 race is increasingly viewed as the next test of how Manhattan’s economic leadership wants to be represented in Washington.

Nadler himself endorsed Lasher in February, calling him the candidate best positioned to carry forward the district’s long-established political tradition. Lasher has raised roughly $2 million directly through the latest Federal Election Commission filing period, with his campaign emphasizing that most of his donations come from Manhattan itself.

But Lasher is far from alone.

Attorney and political commentator George Conway has turned the race into a nationalized anti-Trump fundraising machine, raising more than $3 million in the first quarter of 2026 alone, fueled heavily by national Democratic donors familiar with his television appearances and public criticism of President Donald Trump.

Then there is Alex Bores, the East Side assemblyman and former Palantir Technologies employee who has emerged as the race’s most important technology and artificial intelligence candidate.

Bores has centered much of his campaign around AI regulation and tech policy, triggering an unusual Silicon Valley proxy battle inside a New York congressional race. Pro-Bores outside groups funded by AI-industry executives are spending heavily to support him, while separate AI-aligned super PACs are simultaneously funding opposition efforts against him, according to campaign-finance filings reviewed by City & State New York.

The fight reflects growing tension inside the technology industry itself over how aggressively artificial intelligence should be regulated as AI becomes one of the largest investment themes in modern economic history.

Bores has raised nearly $2.9 million according to some campaign tallies, though critics note that much of his donor support comes from outside New York City, including substantial fundraising from California technology circles.

The race also includes one of America’s most recognizable political names.

Jack Schlossberg, the grandson of President John F. Kennedy, entered the race in November and quickly converted his social-media following into roughly $2 million in campaign fundraising. Schlossberg has leaned heavily into younger, digital-first campaigning styles and positioned himself as a generational-change candidate for Manhattan Democrats.

The broader stakes are enormous because NY-12 is not simply another congressional district.

The district’s donor ecosystem includes hedge fund managers, private-equity executives, major law-firm partners, real-estate developers, investment bankers and corporate executives who routinely finance national Democratic campaigns across the country. Whoever wins the seat inherits not only Nadler’s congressional position, but one of the most powerful fundraising networks in American politics.

Political observers increasingly see the race as a live proxy battle between several competing visions of elite Democratic power.

A Lasher victory would reinforce the Bloomberg-Nadler institutional establishment backed by Wall Street and traditional Manhattan political networks.

A Conway win would elevate a nationally known anti-Trump voice with crossover centrist appeal.

A Bores victory would hand Silicon Valley-aligned AI policy advocates a major platform inside Congress at the exact moment Washington is beginning to wrestle seriously with artificial intelligence regulation.

And a Schlossberg upset would instantly reshape the role celebrity, dynasty and social-media politics play inside modern House campaigns.

The filing deadline closed in April. Ten Democrats remain on the ballot. Early voting begins June 13.

For Wall Street, Silicon Valley and New York’s political establishment, the race is no longer just about replacing Jerry Nadler.

It is becoming a fight over who represents the future power structure of Manhattan itself.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

NEW YORK — A newly disclosed SpaceX S-1 filing, surfaced this week ahead of what is shaping up to be the largest initial public offering in history, shows that Antonio Gracias, the founder of Valor Equity Partners and one of Elon Musk’s closest longtime associates, is positioned to capture a fortune estimated between $90 billion and $140 billion from the deal, while his firm is simultaneously owed nearly $20 billion by SpaceX under a series of related-party equipment lease agreements that have already triggered scrutiny from auditors and corporate governance specialists.

According to the filing, dated Monday, May 25, 2026, Valor-affiliated entities collectively control more than 500 million shares of SpaceX Class A stock, representing roughly 7.3% of the company. The disclosure effectively makes Gracias the second-largest individual shareholder in SpaceX behind Musk himself. At the roughly $1.75 trillion valuation reported by Bloomberg and Reuters, the stake would be worth approximately $90 billion. At a $2 trillion valuation — a figure floated by some early investors — the holdings would exceed $140 billion, instantly placing Gracias among the wealthiest individuals in the world.

Gracias, 55, founded Valor Equity Partners in Chicago and has spent more than two decades inside Musk’s business orbit. He reportedly lent Musk approximately $1 million during Tesla’s earliest days, later served eight years as Tesla’s lead independent director, and held board positions across several Musk-controlled companies, including SpaceX, SolarCity, Neuralink, and The Boring Company. Valor also became one of the earliest institutional investors across Musk’s expanding corporate network.

But the new filing reveals a second and far more controversial layer to the relationship.

According to the S-1, an xAI subsidiary called CTC entered into a series of equipment lease agreements with Valor beginning in October 2025 for high-performance Nvidia GPU infrastructure used in artificial intelligence data centers. Additional agreements followed in January and April 2026. Together, the three transactions obligate SpaceX to make nearly $20 billion in payments to Valor-linked entities over the life of the agreements.

At the time the first lease was executed, xAI remained a separate Musk-controlled company before later being folded into SpaceX earlier this year. The filing states that SpaceX has now guaranteed the obligations tied to the agreements.

The structure quickly attracted accounting scrutiny from PricewaterhouseCoopers, SpaceX’s outside auditor. According to the filing, PwC determined the agreements function economically more like financing arrangements or loans than traditional sale-leaseback transactions because CTC retained operational control over the GPU infrastructure while Valor effectively acted as a secured lender.

As a result, PwC required SpaceX to classify approximately $9 billion of the obligations as related-party debt directly on the company’s balance sheet rather than allowing the transactions to remain off-balance-sheet lease structures.

The disclosure also revealed that xAI separately carried secured senior notes priced at an unusually high 12.5% interest rate — a level corporate finance analysts typically associate with distressed or high-risk borrowers. Analysts say the aggressive financing terms help explain why SpaceX guarantees were necessary to complete the Valor transactions.

Once SpaceX becomes publicly traded, those obligations effectively transfer to incoming retail and institutional shareholders, who would inherit billions in liabilities negotiated while the company operated privately and outside standard public-market disclosure requirements.

The pace of payments has already accelerated rapidly. SpaceX reported approximately $885 million in payments to Valor-linked entities during 2025 and an additional $857 million during just the first two months of 2026, according to the filing. The figures illustrate how central Valor has become to Musk’s AI infrastructure expansion strategy.

Neither Valor Equity Partners nor SpaceX publicly responded Monday to questions regarding the structure of the transactions. Governance experts reviewing the filing raised concerns about the concentration of influence surrounding Gracias, who simultaneously serves as a major shareholder, board-level insider, and one of the company’s largest related-party creditors.

Institutional investors are expected to press management heavily on the issue during the eventual IPO roadshow, particularly as public-market scrutiny intensifies around related-party transactions, governance safeguards, and Musk’s increasingly interconnected corporate empire.

The Valor disclosures also arrive amid a broader financing push tied to AI infrastructure demand. The filing references efforts to secure up to $20 billion in additional GPU-related financing involving Apollo Global Management, Nvidia, and other lenders connected to large-scale data-center buildouts. Apollo separately announced a $3.5 billion financing arrangement for Valor Compute Infrastructure supporting a $5.4 billion hardware acquisition and leaseback strategy.

Gracias briefly followed Musk into government service last year through a role connected to the Department of Government Efficiency, before later stepping down amid scrutiny tied to his simultaneous oversight of public pension assets.

For Gracias, the SpaceX IPO could convert decades of loyalty to Musk into one of the largest fortunes ever created by a venture investor. For incoming shareholders, however, the filing raises a more immediate question: whether the web of insider financing relationships exposed in the S-1 can withstand the discipline and transparency demanded by public markets.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Hartford, Conn. — May 26, 2026 — Employers across New York, New Jersey and Connecticut are entering one of the most aggressive labor-compliance expansions in years as new warehouse regulations, wage-and-hour rulings, clawback restrictions and worker-protection laws begin reshaping payroll exposure and employment practices throughout the tri-state economy.

The changes span multiple states and industries simultaneously, forcing companies to rework employment agreements, scheduling systems, productivity metrics and compensation policies heading into the second half of 2026.

Connecticut has emerged as one of the latest states targeting warehouse productivity systems tied to algorithmic performance monitoring.

A new law approved by the Connecticut General Assembly and taking effect July 1 regulates productivity quotas used by warehouse and logistics operators, joining similar frameworks already enacted in California, New York and Minnesota.

The statute requires employers to disclose productivity quotas in writing, prohibits quota structures that interfere with legally required meal or bathroom breaks and creates new legal pathways for workers disciplined under undisclosed performance systems.

The law directly affects distribution operations tied to companies including Amazon, FedEx, UPS and a rapidly expanding network of third-party logistics firms operating across the Bridgeport, Hartford and New Haven corridors.

At the same time, the Connecticut Supreme Court unanimously ruled in February that employees must be compensated for time spent undergoing mandatory pre-shift security screenings conducted on employer property.

The ruling immediately expanded wage-and-hour exposure for casinos, warehouse operators, retailers and distribution employers across the state.

Operators including Foxwoods Resort Casino, Mohegan Sun and major retail centers are now facing both prospective payroll increases and potential retroactive litigation tied to uncompensated screening time.

Plaintiffs’ attorneys reportedly began filing test cases within weeks of the ruling.

New York employers are confronting a separate but equally significant regulatory shift.

The state recently enacted new restrictions limiting the use of employer clawback clauses tied to signing bonuses, training expenses and relocation packages.

The law narrows employers’ ability to demand repayment from workers who voluntarily resign under ordinary circumstances, while still preserving more limited clawback authority tied to misconduct or cause-based termination.

The changes are already forcing reviews of standard employment agreements across Wall Street, private equity, technology and biotech sectors.

Major firms including JPMorgan Chase, Goldman Sachs, Morgan Stanley, Citigroup, Pfizer and Regeneron Pharmaceuticals are reportedly reassessing portions of existing compensation and retention structures in response to the new framework.

The broader labor-regulation map across the tri-state region is also continuing to expand.

New York City has broadened paid sick and safe leave rules, added new paid prenatal leave requirements and tightened restrictions surrounding employer use of consumer credit history in hiring decisions.

Meanwhile, the New York City Council continues debating a proposal supported by Mayor Zohran Mamdani that would raise the city’s minimum wage to $30 per hour — potentially the highest municipal wage floor in the United States.

New Jersey is simultaneously expanding transparency rules, anti-discrimination standards and pay-data reporting obligations through the state Department of Labor and Workforce Development.

Governor Mikie Sherrill’s administration has also signaled support for additional worker-protection legislation during the 2026 session.

At the federal level, the National Labor Relations Board recently reinstated the narrower pre-Biden joint-employer standard first adopted in 2020, modestly easing employer exposure tied to staffing agencies, contractors and franchise relationships.

But for most companies, state-level regulation is increasingly driving the larger compliance burden.

Insurance and risk-management firms say the complexity is accelerating quickly.

Acrisure warned in a recent 2026 compliance briefing that even a single remote employee working from another jurisdiction can expose an employer to an entirely different state’s labor requirements and litigation standards.

For businesses operating across New York, New Jersey, Connecticut and Pennsylvania, the practical implications are becoming unavoidable.

Employment contracts, leave policies, productivity systems, payroll practices, screening procedures and wage forecasting models all increasingly require state-by-state restructuring.

The cost of compliance is rising rapidly.

The cost of getting it wrong is rising even faster.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Facing persistent food inflation and increasingly cost-conscious consumers, a growing number of U.S. restaurants are experimenting with pay-what-you-want pricing models as operators search for ways to keep dining rooms full without driving customers away with higher menu prices.

One of the most visible experiments is unfolding in New York City at HAGS, the acclaimed Lower East Side restaurant run by James Beard-nominated chef Telly Justice and wine director Camille Lindsley.

The restaurant has spent several years operating pay-what-you-can weekend brunches and is now expanding the concept nationally through a new dinner series launching with partner restaurants in Philadelphia, New Orleans, and Charlotte.

The structure is simple but unusual for modern American dining: guests pay whatever they can afford rather than a fixed menu price.

At a time when tasting menus in major cities routinely exceed $200 per person, the model is gaining attention as independent restaurants struggle to navigate rising costs and weakening consumer demand.

Justice said the concept reflects growing pressure on diners who increasingly feel priced out of full-service restaurants altogether.

The model depends heavily on a mix of loyal regular customers, diners willing to pay above-average amounts, and enough overall traffic to offset lower individual payments from guests with tighter budgets.

Several restaurants testing the approach have adopted suggested pricing tiers tied loosely to income levels or financial flexibility. Diners are encouraged to pay more if they can afford it, pay approximately the actual cost if comfortable, or contribute a reduced amount if they otherwise would not dine out at all.

Restaurant owners say the structure helps remove some of the social awkwardness around deciding what feels “fair” while preserving accessibility.

The economic pressure driving these experiments is significant.

A nationwide consumer survey released earlier this year by restaurant technology firm Popmenu found roughly 68% of Americans are reducing restaurant spending in 2026 and prioritizing affordability and convenience more heavily than in prior years.

Average weekly restaurant spending declined to approximately $90 earlier this year from roughly $115 during mid-2025, according to the survey.

At the same time, 71% of restaurant operators said they planned additional menu-price increases this year as labor, rent, insurance, and food costs continue climbing.

Independent restaurants in cities like New York are facing especially intense pressure.

Operators are dealing with rising commercial rents, elevated wage costs, congestion pricing impacts, and ingredient inflation that the National Restaurant Association says remains roughly 30% above pre-pandemic levels.

At the same time, the financial gap between cooking at home and dining out has narrowed substantially as grocery inflation remains elevated.

The pay-what-you-want trend is also spreading beyond New York.

In Austin, Texas, Italian restaurant L’Oca d’Oro has drawn national attention for its “Pay What You Will Tuesdays,” which ownership says are generating stronger midweek traffic and higher overall revenue than traditional pricing previously produced on slower nights.

According to interviews with NPR, most diners still pay a substantial portion of the standard bill, while beverage sales and service charges continue generating stable revenue streams for the business.

Restaurant owners experimenting with the model say the goal is not charity but traffic preservation and customer retention during a period when consumers increasingly hesitate before spending on discretionary dining.

Large chains, however, remain skeptical.

Panera Bread famously experimented with a pay-what-you-want concept through its “Panera Cares” cafes beginning in 2010 before ultimately shutting the initiative down after years of financial losses.

That experience continues serving as a cautionary example throughout the industry and helps explain why most current experiments are concentrated among smaller independent operators rather than national chains.

The broader economics of the restaurant business remain difficult.

Industry analysts estimate operating costs across the U.S. restaurant sector remain roughly 30% above 2019 levels, while margins for many full-service restaurants continue hovering in the low single digits.

Food and beverage inflation is expected to continue rising through the remainder of 2026, while labor expenses remain elevated following years of wage increases across hospitality industries.

Consumer behavior is also shifting in ways that complicate traditional restaurant pricing strategies.

Cristin O’Hara, head of Bank of America Global Commercial Banking’s Restaurant Group, recently noted that many consumers who previously traded down toward fast-food chains for value are now reducing restaurant visits altogether or seeking visible affordability even at casual dining establishments.

Industry consultants say price sensitivity now cuts across nearly every income level.

For restaurants, that creates a difficult balancing act: raise prices too aggressively and traffic falls, but absorb inflation entirely and already-thin margins disappear.

The Trump administration’s tariffs on imported food products and packaging materials have added additional pressure across parts of the industry, particularly for restaurants dependent on imported seafood, produce, coffee, and specialty ingredients.

Few analysts believe pay-what-you-want pricing will become a mainstream national model.

But the fact that respected independent restaurants are experimenting with it — and in some cases generating stronger traffic and customer loyalty — highlights how dramatically consumer dining habits are changing under prolonged inflation pressure.

For restaurant owners across the country, the message is becoming increasingly clear: affordability is no longer just a marketing strategy. It is becoming central to survival.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

New York — May 26, 2026 — The New York State Public Service Commission has approved Consolidated Edison’s latest long-running rate case settlement, authorizing electric-rate increases averaging approximately 3.5% in 2026 alongside additional increases through 2028 as New York businesses and households continue grappling with rising utility affordability pressure.

Natural gas rates are also set to rise by roughly 4.4% under the agreement.

ConEd President Matthew Ketschke has argued the increases are necessary to fund critical grid modernization projects, reliability upgrades and infrastructure investments tied to New York State’s broader electrification mandates under the Climate Leadership and Community Protection Act.

PSC officials emphasized the approved settlement represented a substantial reduction from ConEd’s original request.

James Denn, director of public affairs at the Public Service Commission, said regulators reduced the utility’s initial proposal by approximately 87%.

Even so, the impact on commercial users is expected to be significant.

Small businesses are projected to see summer electric bills rise by approximately 8%, while larger commercial accounts with higher electricity demand profiles could face increases approaching 9.8%.

ConEd serves more than 9 million customers and approximately 350,000 businesses across New York City and Westchester County, including roughly 183,000 small businesses.

The rate case became one of the region’s most politically charged utility battles over the past year.

ConEd originally sought roughly $1.6 billion in additional electric revenue and another $440 million in gas revenue through its initial filing, prompting fierce opposition from local officials, county governments and consumer advocates across the metropolitan region.

Westchester County Executive Ken Jenkins, the Westchester County Board of Legislators and elected officials across all five boroughs publicly challenged the proposal, arguing New Yorkers were already facing unsustainable housing and living costs.

Mayor Zohran Mamdani, then mayor-elect, reportedly raised ConEd affordability concerns directly during a post-election transition discussion with President Donald Trump.

The broader financial backdrop for ratepayers remains increasingly strained.

Nearly 414,000 ConEd customers entered 2026 at least 60 days behind on utility payments, with total arrears approaching approximately $871 million according to utility filings.

ConEd also disconnected nearly 88,000 households during the first half of 2025 alone, figures consumer advocates say reflect a deepening affordability crisis across one of the country’s most expensive metropolitan utility markets.

At the same time, ConEd’s financial performance has remained strong.

The company reported nearly $13 billion in operating revenue during the first nine months of 2025, roughly 12% above comparable 2024 levels.

ConEd says it provided approximately $244 million in utility bill discounts through its Energy Affordability Program last year, assisting roughly 530,000 customers, while also planning further expansion of the program during 2026.

The infrastructure spending tied to the rate increases is substantial.

ConEd has invested more than $2.35 billion since mid-2024 into substation upgrades, transmission hardening and distribution-system modernization as New York pushes toward increased electrification of transportation, heating and data infrastructure.

The utility argues those investments are essential to maintaining reliability across a city increasingly dependent on uninterrupted electricity flows.

For businesses across the tri-state region, however, the rate hikes arrive during an already difficult operating environment.

Commercial property taxes remain elevated, wage-and-hour liabilities are increasing, labor regulations continue tightening and broader inflation pressures are still filtering through supply chains and payroll costs.

Restaurant operators, retailers and light-industrial businesses with heavy summer cooling demand are expected to absorb the largest near-term impact from the utility increases.

The settlement still awaits final procedural implementation approval by regulators, and some customers could face retroactive adjustments depending on final billing timelines.

For many small businesses already operating on compressed margins, the bigger concern is no longer whether utility costs will rise.

It is how much additional cost increases the regional economy can absorb before the pressure begins showing up in closures, staffing cuts and reduced investment.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

A bipartisan coalition of state attorneys general is rapidly emerging as one of the most aggressive forces in American antitrust enforcement, moving to challenge major media and entertainment consolidation efforts as the Trump administration’s Justice Department scales back several high-profile merger fights.

The shift accelerated after a landmark April 15 jury verdict in the U.S. District Court for the Southern District of New York, where 33 states and the District of Columbia defeated Live Nation Entertainment and its Ticketmaster subsidiary on monopolization claims after the Department of Justice settled mid-trial without securing a breakup of the company.

The verdict is now reshaping expectations across Wall Street, corporate boardrooms, and the media industry.

California Attorney General Rob Bonta and New York Attorney General Letitia James led the coalition that refused to accept the DOJ settlement and instead pressed forward independently. The jury ultimately found that Live Nation unlawfully monopolized primary ticketing and amphitheater services while also illegally tying amphitheater access to concert promotion contracts.

Pennsylvania Attorney General Dave Sunday, a Republican, criticized the federal settlement as inadequate, saying it “falls far short of protecting consumers.” North Carolina Attorney General Jeff Jackson, a Democrat, called the DOJ’s approach “barely a slap on the wrist.”

The bipartisan push marked a significant moment in the balance of antitrust power between Washington and the states.

The remedies phase in the Live Nation case is still ongoing, with states seeking broad structural relief that could ultimately include a forced divestiture of Ticketmaster — a remedy federal officials declined to pursue. Live Nation Chief Executive Michael Rapino has repeatedly defended the company’s business model as procompetitive and consumer-friendly, but the jury rejected those arguments across the central claims presented at trial.

Attention is now shifting toward two major pending media transactions that state officials appear increasingly willing to challenge independently.

On April 17, Chief Judge Troy L. Nunley of the U.S. District Court for the Eastern District of California granted a preliminary injunction blocking further integration between Nexstar Media Group and Tegna, siding with an eight-state coalition led by California and New York.

The states argued the combination would substantially reduce competition across more than 30 local television markets and raise retransmission fees ultimately passed on to cable and satellite customers. Under the ruling, Nexstar must continue operating Tegna as an independent company pending final judgment.

Nexstar Chief Executive Perry Sook has argued the merger is necessary to compete against streaming giants and digital advertising platforms, but state enforcers contend the concentration in local broadcasting markets remains too severe.

The next major flashpoint may become the proposed Paramount Skydance Corporation acquisition of Warner Bros. Discovery, announced February 27 in a transaction valued at roughly $110 billion including debt.

Although the deal cleared the federal Hart-Scott-Rodino waiting period earlier this year, several attorneys general have signaled privately and publicly that federal clearance may no longer guarantee completion.

The transaction, backed by David Ellison and the Ellison family investor consortium, is being framed by executives as a necessary scale response to streaming competition from Netflix, Amazon, Disney, and YouTube. Paramount Chief Legal Officer Makan Delrahim, himself a former Trump-era DOJ antitrust chief, has defended the merger as procompetitive.

But after the Live Nation verdict, corporate advisers increasingly fear states could adopt the same litigation strategy against large media combinations even when federal regulators step aside.

The broader concern for corporate America is that states are no longer merely supplementing federal antitrust enforcement — they are increasingly replacing it.

Several consumer advocacy organizations and former enforcement officials have criticized the Trump administration’s merger posture, arguing that behavioral settlements and negotiated conduct remedies have replaced structural breakups that historically defined major antitrust cases.

The Live Nation case crystallized those frustrations and emboldened states to assert authority under both federal and state competition laws.

At the same time, states are building new procedural tools to expand oversight. California, Washington, and Colorado have already enacted state-level “mini-HSR” laws requiring merger notifications at the state level, while similar legislation is advancing in multiple additional states. The measures effectively create a second layer of merger review beyond Washington, significantly increasing regulatory complexity and closing risk for large transactions.

Markets are already reacting to the new environment.

Shares of Nexstar have underperformed since the California injunction, while merger arbitrage spreads tied to the Paramount-Warner Bros. Discovery transaction have widened amid growing uncertainty over potential state litigation. Live Nation shares also remain under pressure as investors wait to see whether courts ultimately order structural remedies involving Ticketmaster.

For corporate executives, private equity firms, and investment bankers, the lesson from the past several months is becoming increasingly clear: federal approval alone may no longer be enough to close transformative mergers in the United States.

State attorneys general — operating with growing legal sophistication, bipartisan political cover, and increasingly favorable court precedents — are now prepared to litigate national-scale antitrust battles on their own.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

New York — Mid-market consumers across the Tri-State area are navigating a steep divergence in transportation costs as summer approaches. While localized dealership inventories show a minor 0.2% cooling in new vehicle sticker prices following a holiday weekend sales push, regional auto insurance premiums continue an aggressive upward climb, creating a compounding fixed cost for commuting households.

Regulatory Pressures Drive Local Premiums Higher

Data from regional regulatory filings indicates that the New York-New Jersey metropolitan area remains one of the most expensive corridors in the nation for automotive coverage. According to recent disclosures from the New York Department of Financial Services (DFS), New York drivers are now averaging just over $4,000 annually for comprehensive coverage, sitting nearly $1,500 above the baseline national average.
The regional spikes are a trailing reaction to severe underwriting losses from previous fiscal quarters, driven heavily by skyrocketing repair overhead for digital vehicle components, like bumper sensors and built-in camera arrays. Furthermore, state officials note that systemic issues like litigation bottlenecks, medical claim severity under the state’s no-fault system, and organized insurance fraud loops have added an estimated $300 premium penalty to every single driver’s annual policy.

Mandated Statutory Floor Hikes Hit New Jersey

Across the Hudson River, the New Jersey Department of Banking and Insurance (DOBI) is overseeing an equally sharp shift in baseline driver expenses. On January 1, 2026, the state officially executed Phase II of its mandatory auto insurance modernization reform under public law. This statutory change automatically raised the legal floor for bodily injury liability coverage from $25,000 to $35,000 per person, and from $50,000 to $70,000 per accident.
While the policy expansion was designed to shield crash victims from out-of-pocket medical debt caused by modern economic inflation, the higher legal baseline has automatically trickled down into standard monthly premium adjustments for budget-tier policyholders. Tri-State families renewing basic, state-minimum policies this season are encountering automatic rate hikes as carriers realign their baseline underwriting rules to match the new statutory thresholds.

Consumers Adjust Strategies to Dodge Price Volatility

For the everyday consumer, the shifting pricing structure is altering vehicle purchasing and maintenance strategies. Regional consumer protection panels report a significant increase in drivers opting for higher deductibles—shifting from a standard $500 to $1,000 threshold—in an immediate effort to suppress monthly premium bills.
However, local insurance analysts warn this exposure leaves working household budgets vulnerable to sudden out-of-pocket liabilities if minor accidents occur on dense commuter corridors like the Garden State Parkway or the Long Island Expressway. To offset the crunch, consumer advocates are urging drivers to aggressively audit their existing policy profiles by requesting multi-policy bundles or opting into telematics tracking applications, as individual zip-code pricing formulas vary wildly between metropolitan neighborhoods.

JBizNews Desk | New York
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

East Rutherford, N.J. — May 26, 2026 — New Jersey Governor Mikie Sherrill has secured another reduction in NJ Transit’s controversial 2026 FIFA World Cup fare pricing, cutting round-trip service from New York Penn Station to MetLife Stadium to $98 after the original $150 price triggered widespread backlash across the tri-state region.

The governor announced earlier this month that the latest reduction — down from an interim $105 fare — was achieved through a corporate sponsorship package funded by DoorDash, Audible, FanDuel, DraftKings, PSE&G, South Jersey Industries, and American Water, which she emphasized would come “without New Jersey taxpayer money.”

The pricing battle quickly became one of the most politically sensitive operational issues surrounding the 2026 World Cup buildup.

NJ Transit Chief Executive Officer Kris Kolluri had defended the original $150 round-trip fare as a necessary cost-recovery mechanism tied to roughly $48 million in tournament operating expenses and an estimated $6 million logistics bill per match day needed to move approximately 40,000 fans through the Meadowlands rail network during each of the tournament’s eight matches at MetLife Stadium.

The comparison to ordinary commuter pricing fueled the outrage.

A standard round-trip fare between New York Penn Station and MetLife Stadium currently costs approximately $12.90, meaning the original World Cup pricing represented an effective 11-times premium over normal transit service.

Criticism escalated rapidly after the April announcement, with local officials, transit advocates and commuters accusing NJ Transit and state officials of turning public infrastructure into a FIFA profit center at the expense of residents.

The sponsorship model ultimately became the political solution.

By replacing taxpayer subsidy with private corporate underwriting, Sherrill effectively repositioned the fare reduction from a government bailout into a high-profile public-private partnership tied to what is expected to become the largest sporting event ever hosted in North America.

For the sponsors, the economics are equally clear.

DoorDash, Audible, FanDuel and DraftKings gain massive global brand exposure tied to World Cup transportation and fan mobility infrastructure, while regulated utilities including PSE&G, South Jersey Industries and American Water strengthen goodwill with Trenton policymakers at a time when infrastructure approvals, energy-transition investments and future rate cases remain front and center across New Jersey politics.

The fare rollback also reflects growing coordination between New Jersey and New York officials seeking to maximize the economic impact of the World Cup across the broader metropolitan region.

New York Governor Kathy Hochul separately reduced MTA special-event bus pricing to $20 from $80 for New York City fans traveling to MetLife Stadium, reinforcing a broader tri-state strategy focused on visitor spending, tourism capture and regional transportation capacity.

Tourism officials across New York and New Jersey estimate the tournament could generate several billion dollars in combined economic activity across hospitality, retail, transportation and entertainment sectors during the June-through-July tournament window.

Operationally, however, the transportation challenge remains enormous.

NJ Transit’s board has already approved a contract worth up to $3.4 million with A Yankee Line, Inc. to provide emergency backup bus capacity, with 100 buses on standby during standard match days and 125 buses reserved for the July 19 World Cup final.

The pressure on the rail and bus system will intensify further because private parking at MetLife Stadium will largely be prohibited during match days, while ride-share access will also face significant restrictions designed to reduce roadway congestion and security risks.

That effectively forces tens of thousands of spectators directly onto the public transportation network.

The first World Cup match at MetLife Stadium is scheduled for June 13, with the venue hosting eight total matches, including the tournament final.

Ticket pricing itself has already underscored the event’s massive economic scale.

Early group-stage seats have started around $60, while premium Category 1 tickets for the final have exceeded $10,000 before resale markups, with secondary-market pricing in some cases already climbing far higher.

For Governor Sherrill, the fare reduction represents more than a transportation adjustment.

It converts what had become a politically damaging narrative around transit price gouging into a corporate-sponsored affordability initiative she can carry into the broader fiscal and infrastructure debates ahead of the 2026 election cycle.

The operational test, however, still lies ahead.

Once the crowds arrive next summer, the success or failure of the entire strategy may ultimately depend less on the ticket price — and more on whether the trains actually move.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Governor Mikie Sherrill is announcing a new small-business rewards initiative tied to the FIFA World Cup 2026 as New Jersey intensifies efforts to steer tournament spending toward local shops, restaurants, and neighborhood commercial corridors ahead of the games beginning June 11.

The announcement Tuesday builds on the broader Welcome World Rewards Program unveiled earlier this year by the New York New Jersey Host Committee, with backing from both Sherrill and New York City Mayor Zohran Mamdani.

The program is designed to encourage World Cup visitors to spend money at participating local businesses instead of limiting activity to stadiums and major tourist hubs.

Under the system, fans check in digitally at participating businesses, earn reward points, and become eligible for prizes through a centralized online platform. Participation is free for consumers.

State officials say the goal is to spread tournament traffic across smaller business districts throughout New Jersey and New York.

Alex Lasry, chief executive of the NYNJ Host Committee, previously described small businesses as central to the region’s economic strategy surrounding the tournament.

The economic stakes are enormous.

Tournament organizers and regional officials estimate the World Cup could generate between $3.3 billion and more than $4 billion in combined regional economic impact across New York, New Jersey, and nearby markets.

State officials have spent months building programs aimed at ensuring local businesses capture part of that spending.

Pressure for inclusion intensified after criticism surrounding the 2014 Super Bowl hosted in New Jersey, when many minority-owned and smaller local businesses argued they saw little direct benefit from the event despite the massive overall spending surrounding it.

The Sherrill administration has since rolled out multiple programs tied to World Cup preparations.

Earlier this year, the governor launched a $5 million NJ World Cup Community Initiative through the New Jersey Economic Development Authority, funding fan festivals, watch parties, cultural events, and local tourism activations connected to the tournament.

On May 6, the administration announced grants to 34 organizations statewide, including chambers of commerce, tourism boards, municipalities, and community groups.

Recipients included:

  • Visit South Jersey
  • The African American Chamber of Commerce of New Jersey
  • Visit Atlantic City
  • Meadowlands Regional Chamber & CVB
  • Greater Asbury Park Chamber of Commerce
  • Somerset County
  • Fort Lee officials
  • Multiple regional tourism organizations

Officials say many of those events will integrate directly into the Welcome World Rewards platform, giving visitors a centralized digital map of participating businesses and activities.

The state has also adjusted hospitality policies ahead of the tournament.

Earlier this month, Sherrill supported expanded bar and restaurant operating hours during World Cup match days to help restaurants and nightlife venues handle expected crowds.

The World Cup preparations have not been entirely smooth.

Sherrill has publicly pushed FIFA to absorb more transportation-related costs connected to the tournament after concerns emerged surrounding NJ Transit pricing and infrastructure demands.

State officials have argued that New Jersey taxpayers should not shoulder the full burden while FIFA is projected to generate billions in tournament revenue globally.

MetLife Stadium in East Rutherford — branded during the tournament as New York/New Jersey Stadium — will host eight matches, including the World Cup Final on July 19.

Additional activity tied to national-team training bases and regional fan tourism is expected across New Jersey throughout the tournament period.

Training sites include:

  • Haiti at Stockton University
  • Morocco at The Pingry School
  • Senegal at Rutgers University
  • Brazil in Morris Township

Hospitality businesses are watching closely.

While state officials continue projecting major tourism inflows, some hotel operators have expressed concerns that reservations in certain markets remain softer than initially expected.

That has increased pressure on the rewards platform and local activation strategy to drive actual neighborhood-level spending once fans arrive.

Businesses across New Jersey and New York can currently register to participate through the NYNJ Host Committee rewards platform and related tourism portals.

With the tournament now just over two weeks away, the success of New Jersey’s strategy will soon move from planning stages into real-world testing as millions of visitors begin arriving across the region.

JBizNews Desk — New Jersey

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

NEW YORK — May 24, 2026

Anthropic is in early discussions with Microsoft Corp. to run its Claude artificial intelligence models on Microsoft’s proprietary Maia 200 AI chips, a move that would transform a financial partnership into a direct infrastructure alliance and give Microsoft its first major external customer for its in-house silicon platform.

The talks, first reported Thursday by The Information and later confirmed by CNBC through a person familiar with the matter, remain preliminary and no agreement has been finalized. Anthropic declined to comment publicly, while Microsoft did not issue a statement. Microsoft shares traded little changed Thursday.

The negotiations arrive just six months after Microsoft committed up to $5 billion to Anthropic in a strategic funding arrangement that also included a separate $10 billion investment commitment from Nvidia Corp., valuing the AI startup near $350 billion.

As part of that deal, Anthropic agreed to spend approximately $30 billion on Microsoft’s Azure cloud infrastructure over time, while continuing to maintain major compute relationships with Amazon Web Services and Google Cloud.

At the center of the discussions is Microsoft’s Maia 200, the company’s newest custom AI processor unveiled earlier this year. Built on Taiwan Semiconductor Manufacturing Co.’s advanced 3-nanometer process, Maia 200 is optimized primarily for AI inference — the process of generating responses from already-trained models — rather than for large-scale training.

Microsoft Chairman and CEO Satya Nadella told investors during the company’s April earnings call that Maia 200 delivers more than 30% better tokens-per-dollar economics compared with leading chips currently deployed inside Microsoft’s infrastructure fleet. The company has already confirmed the chip powers portions of its Copilot ecosystem and will support OpenAI’s GPT-5.2 deployments.

Until now, however, Maia 200 has largely remained an internal Microsoft product.

A deal with Anthropic would mark the first significant use of Microsoft’s custom silicon by an outside frontier AI lab, placing Azure more directly into competition with Amazon’s Trainium platform and Google’s Tensor Processing Units, both of which already serve external AI developers.

For Anthropic, the motivation is straightforward: compute demand.

Usage of Claude and Anthropic’s fast-growing Claude Code developer tools has surged throughout 2026, forcing the company into a global race for processing capacity across multiple cloud and hardware providers.

In April, Anthropic signed a massive 10-year infrastructure arrangement with AWS reportedly worth more than $100 billion centered around Amazon’s Trainium chips. The company also expanded TPU commitments with Google last year, while continuing to rely heavily on Nvidia GPUs for both training and deployment workloads.

Earlier this week, SpaceX disclosed that Anthropic will pay approximately $1.25 billion per month through 2029 for compute infrastructure tied to Elon Musk’s expanding AI data-center network.

Against that backdrop, Maia 200 would likely serve as a dedicated inference engine rather than a training system.

That distinction matters financially.

Training frontier AI models remains dominated by Nvidia’s Hopper and Blackwell architectures along with Google’s TPU systems. But inference — the actual day-to-day generation of responses for users — increasingly represents the largest operating expense for AI labs at scale.

Every Claude API call, enterprise integration, coding request and chatbot response consumes inference capacity.

Reducing the cost of those workloads by even modest percentages could materially improve Anthropic’s gross margins as usage accelerates globally.

For Microsoft, the strategic importance is potentially even greater.

Azure has spent years trying to close the gap with AWS and Google in proprietary AI silicon, while simultaneously attempting to reduce dependence on Nvidia’s expensive GPU supply chain.

If Anthropic adopts Maia 200 meaningfully, Microsoft would gain a marquee external validation of its chip economics and demonstrate that Azure can compete not just as a cloud reseller of Nvidia hardware, but as a vertically integrated AI infrastructure platform.

The talks also deepen the increasingly complicated relationships among Microsoft, OpenAI and Anthropic.

Microsoft remains OpenAI’s largest strategic partner and investor, with roughly $13 billion committed to the ChatGPT creator. Yet over the past year Microsoft has simultaneously expanded ties with Anthropic, integrating Claude models into portions of its enterprise software stack, including Office and Copilot workflows.

A Maia 200 compute partnership would further solidify that relationship.

Industry executives also believe Anthropic could seek influence over future Maia chip designs if an agreement progresses — similar to the collaborative design relationships Anthropic already maintains with Amazon on Trainium and Nvidia on next-generation AI systems.

That type of long-term co-design arrangement would make Anthropic not merely a Microsoft customer, but a strategic infrastructure partner.

The broader significance extends beyond the two companies themselves.

The AI infrastructure landscape is increasingly evolving into a tightly interconnected system where hyperscalers, chipmakers and frontier AI labs simultaneously act as investors, suppliers, customers and competitors.

Anthropic now buys infrastructure from nearly every major player in the ecosystem: AWS, Google Cloud, Nvidia, CoreWeave, SpaceX and potentially Microsoft’s Maia platform.

OpenAI has followed a similar path across Microsoft, Oracle, Nvidia and AWS.

For investors, Thursday’s market reaction remained relatively muted because negotiations remain early-stage and no commercial agreement has yet been signed.

But the underlying signal is larger than one deal.

Microsoft is moving its custom AI silicon strategy from internal experimentation toward commercialization, while Anthropic’s willingness to test Maia 200 suggests growing confidence that alternative chips can meaningfully compete with Nvidia in high-volume inference workloads.

If the partnership materializes, the AI infrastructure race shifts another step away from Nvidia’s near-monopoly dominance and toward a more fragmented, full-stack competition among the world’s largest cloud providers.

Whether the talks ultimately result in a finalized agreement remains uncertain.

But six months after Microsoft wrote a $5 billion check into Anthropic, the relationship is clearly evolving beyond capital — and increasingly into the hardware foundation powering the next generation of artificial intelligence itself.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Two closely watched reports released Tuesday painted a weaker picture of the American consumer as higher energy prices tied to the Middle East conflict continue pressuring household budgets and the U.S. housing market loses momentum across much of the country.

The Conference Board reported Tuesday morning that its Consumer Confidence Index slipped to 93.1 in May, down from a revised 93.8 in April. The survey period covered May 1 through May 19 and captured growing concern over inflation tied to the ongoing war in the Middle East.

Less than an hour earlier, S&P Dow Jones Indices released new housing data showing national home-price growth slowed further in March, while more than half of major U.S. metro markets posted outright year-over-year declines.

Together, the reports point to an American consumer growing more cautious as energy costs rise, borrowing remains expensive, and household affordability pressures intensify.

Dana M. Peterson, chief economist at The Conference Board, said consumers grew more concerned during the survey period about current business conditions, employment prospects, and inflation pressures linked to the Middle East conflict.

The details inside the confidence report were mixed but generally soft.

The Present Situation Index, which measures how Americans view current economic and labor-market conditions, fell 3.2 points to 121.2. Consumers reported jobs becoming harder to find and business conditions appearing less favorable than a month earlier.

The Expectations Index, which measures how consumers view the next six months, rose slightly to 74.4 but remained well below the key 80 level historically associated with recession risk.

The index has now remained below 80 for several consecutive months.

Consumers are also becoming more selective with discretionary spending.

The Conference Board survey showed weaker plans for vacations, hotels, motels, and personal travel. Interest in major purchases also softened.

Categories tied to necessities — including utilities and healthcare — rose in importance, replacing hotels and travel among the top spending priorities households expect over the coming months.

Dining out, streaming subscriptions, and beauty-related spending held up better than travel but still weakened modestly from prior readings.

Pet-care spending was one of the few categories showing improvement.

The pressure is increasingly tied to inflation expectations.

Higher oil prices tied to instability in the Middle East continue feeding into gasoline, transportation, shipping, and food costs. For many households, rising gas prices remain one of the most immediate visible reminders of inflation.

The housing data released Tuesday reflected similar affordability strain.

According to the S&P CoreLogic Case-Shiller National Home Price Index, national home prices rose just 0.7% in March from a year earlier, slowing again from February’s already-weak 0.8% annual increase.

The 10-city composite index rose 1.4%, while the broader 20-city index increased only 0.8%.

More notably, more than half of the major metro areas tracked by the index recorded year-over-year price declines.

Nicholas Godec, head of fixed income tradables and commodities at S&P Dow Jones Indices, described the slowdown as both broadening and deepening across the housing market.

Regional performance varied sharply.

Chicago, New York, and Cleveland led the country in home-price gains, while Denver and Tampa experienced some of the steepest declines. Los Angeles and Washington, D.C. also turned negative year over year.

Mortgage rates remain a major obstacle.

With rates hovering near 6%, many potential buyers remain priced out of the market, while existing homeowners continue holding onto lower-rate mortgages secured during earlier years. That combination has slowed transactions and reduced upward price pressure.

Inflation-adjusted home values have now declined for roughly ten consecutive months.

Markets, however, were trading higher Tuesday morning despite the softer economic data.

The S&P 500 rose approximately 0.8% in morning trading, led by technology shares, while the Nasdaq Composite climbed roughly 1.3%. The Dow Jones Industrial Average traded near flat levels.

Shares of Micron Technology surged about 15% after UBS projected significant upside tied to long-term semiconductor supply agreements and continued AI-related demand growth.

Investors are also closely watching diplomatic developments surrounding the conflict involving Iran, with traders increasingly weighing the possibility of negotiations that could ease pressure on global oil markets.

The market rally follows a strong previous week on Wall Street.

The Dow Jones Industrial Average closed Friday at a record 50,579.70, while the S&P 500 completed its eighth consecutive weekly gain — its longest winning streak since 2023. The Nasdaq also ended last week at record highs.

Attention now shifts toward several major economic releases later this week.

The Bureau of Economic Analysis is scheduled to release the Personal Consumption Expenditures price index Friday, the Federal Reserve’s preferred inflation measure. Updated GDP, consumer spending, and personal income figures are also expected.

Corporate earnings from Salesforce, Dell Technologies, and Zscaler are scheduled in coming days as investors continue assessing both economic conditions and AI-related growth trends.

For consumers, however, Tuesday’s data carried a simpler message: prices remain elevated, confidence is softening, and households are becoming increasingly cautious about the months ahead.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Mayor Zohran Mamdani is preparing to announce a major exemption to his proposed rent-freeze plan, allowing owners of certain distressed affordable-housing buildings to raise rents on vacant apartments even if a citywide rent freeze takes effect later this year.

The announcement, expected Tuesday, marks the first significant modification to Mamdani’s signature housing pledge and highlights growing financial pressure inside New York City’s rent-stabilized housing market.

According to comments made by Dina Levy, commissioner of the city’s Department of Housing Preservation and Development, the exemption would apply only to certain city-financed affordable-housing properties and only when apartments become vacant.

“The reality is, they will all remain affordable,” Levy said in remarks reported Tuesday.

The move represents the clearest sign yet that City Hall is responding to mounting warnings from landlords, lenders, and housing analysts that a blanket rent freeze could push already-fragile buildings deeper into financial distress.

Under the proposal, roughly 300,000 apartments tied to city housing-finance programs could become eligible for one-time rent increases upon tenant turnover. Any increases would remain capped under existing affordable-housing income guidelines and would be reviewed individually on a building-by-building basis.

The apartments represent roughly one-third of the city’s overall rent-stabilized housing stock and include properties owned by large affordable-housing operators including Related Companies and other major developers participating in city subsidy programs.

City officials say only a limited number of apartments are expected to receive immediate increases under the carve-out.

The exemption is part of a broader housing stabilization package the administration is preparing to roll out, including expanded repair financing, tax relief, assistance resolving housing-code violations, and a new $5 million loan program aimed at helping landlords recover unpaid rent and avoid foreclosure or eviction-related distress.

The policy shift reflects growing pressure from owners of older rent-stabilized buildings, particularly in parts of the Bronx and Brooklyn, where rising insurance costs, utilities, labor expenses, taxes, and debt payments have increasingly outpaced rental income growth.

Kenny Burgos, chief executive of the New York Apartment Association, warned regulators earlier this month that many fully stabilized buildings are already operating under severe financial strain and could face growing mortgage-default risks if rents remain frozen.

A recent report from New York University’s Furman Center also concluded that a large share of the city’s regulated housing stock is trending toward financial distress under current conditions.

The political balancing act for Mamdani is becoming increasingly complicated.

The mayor campaigned heavily on a promise to freeze rents for approximately one million rent-stabilized apartments throughout his four-year term and appointed a new majority to the city’s Rent Guidelines Board earlier this year.

In May, the board voted preliminarily to keep a full rent freeze under consideration for one-year leases ahead of a final decision expected next month.

Tenant advocates continue pushing for a complete freeze without exemptions, arguing that affordability pressures on renters remain severe across the city.

Landlord groups, meanwhile, say the new carve-out only addresses a small portion of the broader financial problems facing the rent-stabilized housing system.

Some real-estate organizations have also publicly explored potential legal challenges against a full rent freeze.

Real-estate attorney Scott Mollen, a former Rent Guidelines Board chair, has argued that aggressive political involvement by City Hall could expose the board’s decisions to legal scrutiny if judges conclude the process became politically predetermined.

By creating a limited exemption tied specifically to distressed affordable-housing properties, the administration may also be attempting to strengthen its legal position ahead of the final Rent Guidelines Board vote.

For tenants currently living in affected buildings, the immediate impact remains limited.

The exemption would apply only when units become vacant. Existing tenants would not face immediate increases under the carve-out, though new tenants moving into qualifying apartments could face higher rents within city affordability caps.

The broader housing plan expected later this week is also anticipated to include additional measures tied to affordable-housing construction, tenant protections, and code enforcement initiatives.

With the final Rent Guidelines Board vote approaching in June, the debate over affordability, landlord solvency, and the future of New York’s rent-stabilized housing system is likely to intensify sharply in the weeks ahead.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Delta Air Lines is hiring more pilots and rebuilding the teams that schedule its flight crews after internal staffing-system breakdowns pushed cancellations sharply above much of the U.S. airline industry, according to company memos and comments from senior executives this month.

The operational strain comes at a critical moment for the carrier as the summer travel season begins ramping up.

“Our challenges, while not systemic, highlight where we must sharpen our operational edge,” Dan Janki, Delta’s chief operating officer, wrote in an internal employee memo addressing the situation.

At the center of the problem is Delta’s ability to quickly locate replacement pilots when original crew assignments become unavailable.

In an April 24 memo first reported by USA Today, Ryan Gumm, Delta’s senior vice president of flight operations, told employees that cancellations tied directly to pilot availability are running more than ten times historical norms and now account for approximately 35% of Delta mainline cancellations, up sharply from roughly 7% in 2024.

For certain aircraft types, Gumm said, it can now take Delta as long as 12 hours to secure a pilot replacement for a single flight.

A major factor behind the breakdown is that pilots are increasingly refusing additional trip assignments.

According to Gumm’s memo, pilot acceptance rates for uncovered flights have collapsed to roughly 2% this year, compared with approximately 37% a year ago. With fewer pilots volunteering to cover open trips, Delta has increasingly relied on an emergency contract mechanism known internally as “23.M.7” to fill last-minute scheduling gaps.

The system was originally designed for isolated operational emergencies — not daily usage across a large airline network.

Gumm acknowledged in the memo that Delta is now using the emergency scheduling tool between 10 and 15 times more frequently than last year, often creating cascading disruptions as reassigned pilots leave later flights short-staffed.

The operational weakness became highly visible during the first weekend of May when Delta canceled hundreds of flights despite relatively modest weather disruptions across parts of the country.

Competing airlines including American Airlines, United Airlines, and Southwest Airlines largely maintained stable operations during the same period.

According to aviation analytics firm Cirium, Delta’s domestic cancellation rate has remained above the overall U.S. airline average for much of 2026, with notable spikes in January and March before modest improvement during April and May.

The problems represent a rare stumble for an airline long viewed as the operational benchmark of the U.S. industry.

Delta’s reputation for reliability has supported premium pricing, strong customer loyalty, and some of the strongest profit margins in the airline sector for years.

Chief Executive Ed Bastian acknowledged during Delta’s recent first-quarter earnings call that changes to pilot-routing and scheduling systems under the current labor agreement contributed to recent operational stress.

Bastian said the company is devoting significant attention to restoring consistency and admitted recovery performance following weather disruptions had not always met Delta’s internal standards.

Pilot representatives have sharply criticized management’s handling of the situation.

The Air Line Pilots Association, which represents Delta pilots, told USA Today that the disruptions reflect “mismanagement of resources, lack of proper tools and training for crew schedulers, and numerous misguided attempts to pinch pennies.”

Pilots have also argued the company bypassed portions of the contractual trip-assignment process, contributing to frustration among senior pilots and reducing willingness to voluntarily pick up additional flights.

The labor tension arrives ahead of upcoming contract negotiations, with Delta’s current pilot agreement becoming amendable at the end of this year.

Delta says it is now accelerating hiring, expanding reserve-pilot pools, and adding additional staffing to crew scheduling and tracking departments in an effort to stabilize operations before peak summer demand.

According to Gumm, Delta currently employs approximately 20% more pilots than it did before the pandemic in 2019, and pilot hiring has outpaced overall flight-hour growth.

The airline also accelerated application reviews for pilots formerly employed by Spirit Airlines, which ceased operations earlier this month, while offering free standby travel to displaced Spirit employees.

Despite the recent turbulence, Delta’s broader financial position remains strong.

The company reaffirmed its full-year guidance during its first-quarter earnings call, citing resilient premium-cabin demand and continued growth in its lucrative SkyMiles partnership with American Express.

Wall Street analysts continue monitoring operational metrics closely as summer travel volumes rise and thunderstorm season approaches.

This is also not Delta’s first major operational technology setback in recent years.

The carrier faced heavy criticism during the 2024 CrowdStrike outage, when faulty cybersecurity software disrupted millions of Microsoft Windows systems globally. Delta’s recovery lagged behind several competitors, sparking public disagreements between Delta, CrowdStrike, and Microsoft over responsibility for the prolonged disruptions.

Industry-wide pressures remain significant as airlines continue navigating strained air-traffic-control staffing, weather volatility, and elevated operating costs.

But analysts note that Delta’s current problems appear driven primarily by internal scheduling systems and labor-management issues rather than broader external disruptions.

For investors and travelers alike, the key question now is whether Delta can stabilize operations before the busiest travel stretch of the year intensifies pressure across the network.

With peak summer travel approaching rapidly, Delta’s performance will likely be judged less by internal memos and more by what passengers ultimately see on airport departure boards.

JBizNews Desk — Atlanta

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

May 26, 2026 — Bond strategists at ING Bank NV, Goldman Sachs Group Inc., Barclays Plc and Deutsche Bank AG warned Sunday that the sharp rise in long-term Treasury yields triggered during the U.S.-Iran conflict is unlikely to meaningfully reverse even if the war ends, signaling what many on Wall Street increasingly view as a structural reset in global borrowing costs rather than a temporary oil-shock distortion.

The benchmark 10-year Treasury yield traded near 4.67% late last week — its highest level since January 2025 — after beginning the year below 4%. The 30-year Treasury bond yield climbed above 5.17%, approaching levels last seen before the 2008 financial crisis, while sovereign yields across Europe and Japan have moved sharply higher in parallel.

The message emerging from strategists is increasingly clear: the bond market’s problem is no longer just inflation. It is confidence.

In a Bloomberg analysis published Sunday, strategists argued that “real yields” — Treasury yields adjusted for inflation expectations — are now driving most of the selloff, suggesting investors are demanding materially higher compensation to finance swelling government deficits, escalating defense spending, heavy AI-related debt issuance and the growing possibility that the Federal Reserve under new Chair Kevin Warsh could still raise rates later this year rather than cut them.

“The argument that duration is selling off globally due to inflation fears is hard to square with market pricing of medium- and long-term inflation risk,” wrote Jonathan Pingle in commentary cited by Bloomberg, framing the move as a deeper repricing of fiscal and policy risk rather than a short-term energy spike.

At Goldman Sachs, Phillip Lee, head of real-money rate sales, said on a firm podcast that persistent deficits, expanding Treasury issuance and rising concerns over debt sustainability are increasingly forcing investors to demand higher compensation for holding long-dated government bonds.

“I think rates are going higher,” Lee said bluntly.

The shift marks a major change in how Wall Street is interpreting the bond market. Earlier in the Iran conflict, many investors viewed rising yields primarily as a response to surging crude prices and inflation fears tied to disruptions in the Strait of Hormuz. Increasingly, strategists believe the war merely accelerated pressures that were already building beneath the surface.

Ajay Rajadhyaksha, global chairman of research at Barclays, warned that the forces now driving the bond selloff are not temporary.

“Fiscal deterioration, defense spending, sticky inflation and central bank paralysis are not resolving next week,” Rajadhyaksha wrote. “They are getting worse.”

That view directly clashes with the more optimistic outlook being advanced by Treasury Secretary Scott Bessent, who told Reuters during last week’s G7 finance meetings in Paris that elevated inflation and bond yields remain “transient” and should ease once the conflict subsides.

Bessent argued oil markets themselves are signaling expectations for eventual stabilization, pointing to Brent crude trading near $105 for near-term delivery but closer to $88 for December contracts.

“I think headline will be high as long as the conflict’s going,” Bessent said. “I don’t think that will leak into core through three or four months out.”

Markets increasingly appear unconvinced.

Traders who entered 2026 expecting multiple Federal Reserve rate cuts have rapidly reversed course. Interest-rate futures now imply rising odds of at least one Fed hike before year-end despite slowing portions of the economy and leadership changes at the central bank.

Jim Reid, research strategist at Deutsche Bank, described the recent bond-market move as “aggressive,” while separate Deutsche Bank analysis warned yields could climb even higher if the U.S.-Israeli conflict with Iran triggers further economic disruption or prolonged fiscal spending increases.

A second major driver now compounding the selloff is the artificial-intelligence investment boom reshaping corporate capital markets.

While AI is widely expected to improve long-term productivity, strategists increasingly believe its near-term economic impact is inflationary. Technology giants including Microsoft, Meta Platforms, Alphabet, Amazon and Oracle are collectively spending hundreds of billions of dollars on AI infrastructure, data centers and semiconductor capacity — much of it financed through bond markets already absorbing historically large Treasury issuance.

The result is an extraordinary simultaneous demand for capital from both governments and corporations.

Stronger AI-driven economic growth could also reinforce higher yields by encouraging investors to favor equities over fixed income, forcing bond markets to offer increasingly attractive returns to remain competitive.

At the same time, sovereign debt burdens continue worsening across much of the developed world.

The U.S. federal deficit remains near record peacetime levels even before accounting for war-related military spending and higher interest costs. Treasury issuance is projected to continue climbing into 2027, while major economies including the United Kingdom, Japan, Germany and France face similar financing pressures.

Strategists increasingly believe the traditional buyer base — foreign central banks, commercial banks and institutional asset managers — is no longer willing to absorb that volume of debt at prior yield levels.

That repricing is beginning to ripple far beyond Wall Street trading desks.

Long-term Treasury yields directly influence mortgage rates, auto loans, corporate borrowing costs, credit-card refinancing and small-business lending across the U.S. economy. Mortgage rates have already resumed climbing alongside the 10-year yield, worsening affordability pressures throughout the housing market and placing additional strain on consumers already contending with elevated insurance, transportation and food costs.

For the Trump administration, the bond market is increasingly becoming the central economic constraint.

The White House’s hope that a diplomatic resolution with Iran could rapidly cool inflation and stabilize markets now collides with a growing strategist consensus that long-term borrowing costs are rising for deeper structural reasons that no ceasefire alone can solve.

If that view proves correct, the American economy may remain trapped in a world of elevated financing costs well into 2027 — regardless of what happens next in the Strait of Hormuz.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

JERUSALEM — The Bank of Israel’s Monetary Committee, led by Governor Prof. Amir Yaron, voted Monday, May 25, 2026, to lower the benchmark interest rate by 0.25 percentage points to 3.75% from 4.00%, citing easing inflation, a sharply stronger shekel, and resilient economic data that gave policymakers room to resume monetary easing despite ongoing regional instability.

The decision marks the central bank’s third cut since November 2025 and matched expectations from most economists and financial markets. The Bank of Israel had paused at its previous two meetings amid uncertainty surrounding the war with Iran, after delivering consecutive 0.25-point cuts in November and January.

In its policy statement, the Monetary Committee acknowledged that inflation has stabilized near the midpoint of the government’s official 1%–3% target range but warned that geopolitical and global inflationary pressures remain elevated. The committee said geopolitical uncertainty remains significant both domestically and globally, adding that while Israeli inflation has moderated, there has been a sharp increase in the global inflation environment since the previous rate decision.

Officials cautioned that risks remain for renewed inflation acceleration, citing energy prices, supply constraints, fiscal pressures, and regional developments tied to ongoing security concerns. At the same time, policymakers emphasized that the shekel’s rapid appreciation is helping offset inflationary pressures by lowering import costs and easing pressure on consumer prices.

The currency move has been dramatic. Since the previous interest-rate decision, the shekel strengthened 8.3% against the U.S. dollar, 7.2% against the euro, and 7.4% on a nominal effective exchange-rate basis, according to Bank of Israel data. The stronger currency has become one of the central bank’s most important disinflationary forces and a major factor allowing policymakers to continue cutting rates without triggering renewed price instability.

The central bank also addressed the economic impact of Operation Roaring Lion, Israel’s recent military campaign against Iran and Iranian-linked targets. According to the Bank of Israel, first-quarter 2026 GDP contracted at an annualized rate of 3.3%, reflecting disruptions tied to the operation and wartime economic conditions.

Still, officials emphasized that the downturn was milder than many economists had feared and less severe than the contraction experienced during Operation Rising Lion in June 2025. The committee said current indicators of economic activity point to recovery following Operation Roaring Lion. Officials noted that credit-card spending data, which declined during the military operation, has since rebounded and now sits slightly above the long-term trend line, signaling improving domestic demand and consumer activity.

The 0.25-point rate cut comes as central banks globally face increasingly difficult tradeoffs between slowing economic growth and persistent inflation concerns tied to energy markets and geopolitical disruptions. Israel’s situation has become particularly complex because the country is simultaneously managing wartime fiscal pressures, strong capital inflows, and a rapidly appreciating currency.

Markets reacted positively to the decision, with Israeli government bonds rising modestly and traders increasing expectations for at least one additional rate cut later this year if inflation continues cooling and geopolitical conditions stabilize.

Analysts say the Bank of Israel is attempting to engineer a delicate balancing act: supporting economic recovery after months of military disruptions while avoiding renewed inflation pressure from energy costs and wartime spending.

Governor Amir Yaron has repeatedly emphasized that future policy decisions will remain highly data dependent and closely tied to developments in both the security environment and global inflation trends.

For now, the central bank appears increasingly confident that the shekel’s strength and moderating domestic inflation are giving policymakers room to cautiously support growth — even as the broader Middle East remains on edge.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Kevin Warsh, sworn in by President Donald Trump at the White House on Friday, May 22, 2026, as the new chair of the Federal Reserve, has openly vowed to bring “regime change” to the central bank. In speeches and interviews leading up to his confirmation, Warsh has called for shrinking the Fed’s $6.7 trillion balance sheet, removing forward guidance from Fed communications, encouraging more open dissent at policy meetings — what he has called “a good family fight” — and changing the data the Fed bases its decisions on. He blames “policy errors” by the Fed in 2021 and 2022 for the high inflation that followed.

The ambition is enormous. The catch, according to former Fed officials, ex-staffers, and central bank watchers interviewed over the weekend, is that Warsh cannot deliver any of this on his own. The Federal Reserve is a consensus-driven institution. On every major decision — interest rates, balance sheet policy, regulatory rules, communications frameworks — Warsh will need the backing of the Federal Open Market Committee, the 12-member body that includes the seven Fed governors and five voting reserve bank presidents.

“One of his primary things he’s going to be doing is presumably trying to build a consensus, when appropriate, to lower interest rates,” said Jon Faust, who previously worked as an adviser to former chairs Jerome Powell, Janet Yellen, and Ben Bernanke. The challenge for Warsh is that the rest of the FOMC does not necessarily share his views on either the magnitude or the urgency of the changes he wants.

Randall Kroszner, who served alongside Warsh as a Fed governor from 2006 to 2009 and now teaches at the University of Chicago, said the new chair’s power lies in persuasion rather than direct authority. “The chair has the power to persuade. And they’re in a very strong position to be able to persuade. But they still need to persuade.” Kroszner described Warsh as a “long-run strategic thinker” who “wants to bring people along” and added that he “understands that to get things done, you need to build a consensus around things.”

The most pivotal decisions — interest rates and the balance sheet — require FOMC votes. Warsh can chair the meetings, set the agenda, and shape the discussion, but he gets one vote like every other member. Jerome Powell, notably, is planning to remain on the Fed board even after his term as chair expired May 15. The Justice Department launched a controversial criminal probe into Powell earlier this year, then withdrew it. Powell’s decision to stay on the board means Warsh will sit across the table from his predecessor at every meeting — a dynamic with little precedent in modern Fed history.

The FOMC has historically functioned as a deliberative body where political considerations are explicitly left at the door. “I was going to FOMC meetings when Alan Greenspan was chair, so that’s a long time. Politics never enters that room,” said Loretta Mester, the former Cleveland Fed president. That tradition will be tested as Warsh navigates between Trump’s demands for lower rates and the committee’s independent assessment of an economy facing both elevated inflation from the U.S.-Iran war and slowing growth from tighter credit conditions.

There are areas where Warsh has clear unilateral authority. As Fed chair, he can choose how frequently he holds press conferences, how often he speaks publicly, and what he says. He sets the tone for Fed communications strategy. He chairs FOMC meetings and can change how they are structured. He represents the Fed publicly with Congress, foreign central banks, and global markets. None of those areas require committee approval.

But on bigger structural questions — like whether to eliminate or scale back the quarterly Summary of Economic Projections, the Fed communications tool that publishes policymakers’ forecasts for growth, unemployment, and inflation, or the “dot plot” showing officials’ projections for the federal funds rate — even an aggressive chair traditionally seeks broad input first. David Wilcox, former head of the Fed’s Division of Research and Statistics and now at Bloomberg Economics, recalled that when Ben Bernanke introduced the SEPs in 2007, “there was absolutely nobody on the committee who could say their views hadn’t been heard and carefully considered.”

If Warsh chooses to push through major changes without broad support, former Fed staffers warn he could find himself isolated when he most needs allies. Claudia Sahm, the former Fed economist behind the widely watched Sahm Rule recession indicator, said Warsh “should know better” than to push too hard against consensus. “When I disagree with him on a lot of things, I don’t think he is an agent of chaos,” Sahm said. “I think he wants the Fed to innovate and improve and do policy well. That should lead him to meet the committee where they are, and try to shift things gradually.”

The political pressure on Warsh is substantial. Trump repeatedly attacked Powell during his second term, publicly nicknaming him “Too Late” and threatening to fire him over the Fed’s reluctance to cut rates. At Friday’s swearing-in ceremony, Trump said directly: “I want Kevin to be totally independent. Don’t look at me, don’t look at anybody.” The fact that the ceremony was held at the White House at all — the first time a Fed chair has been sworn in there since Greenspan in 1987 — has raised bipartisan concerns about executive influence over the historically independent central bank.

Warsh’s real “regime change” may ultimately happen in less visible parts of the Fed. Loretta Mester noted that the central bank has struggled for years to clearly explain when it uses asset purchases to support markets versus when it uses them for broader monetary policy purposes. “The Fed hasn’t done a very good job, I think, over time of distinguishing and explaining when it’s using asset purchases for a monetary policy reason,” she said. Warsh could reshape expectations that the Fed will always step in whenever markets wobble — a belief that has defined Wall Street behavior since the financial crisis.

He has also expressed support for deregulatory efforts led by Fed Vice Chair for Supervision Michelle Bowman, including revisions to bank reserve rules and liquidity treatment during periods of stress. Dallas Fed President Lorie Logan recently praised those efforts publicly, suggesting Warsh may have more room to move on regulatory “plumbing” than on headline interest-rate decisions.

For markets, the immediate signal is patience. Most analysts expect the Fed to keep rates steady over the next several months while Warsh builds support within the committee. The federal funds rate currently sits between 3.5% and 3.75%, where it has remained since the Fed’s late-2025 rate cut. Trump’s push for aggressive reductions collides with the reality that inflation expectations are still climbing — the University of Michigan’s May survey showed year-ahead inflation expectations rising to 4.8%, with long-run expectations at 3.9% — while energy prices remain elevated because of the Iran conflict.

Cutting rates aggressively into that environment risks reigniting the same inflation cycle Warsh has spent years criticizing.

For consumers and businesses, the practical message is straightforward. Mortgage rates, auto loans, credit cards, small business lending costs, and savings account yields are unlikely to change dramatically through the summer. Any economic relief tied to lower Fed rates will almost certainly arrive slower than the White House hopes.

The early signs suggest Warsh understands this institutional reality. David Wessel, senior fellow at the Brookings Institution, said Warsh has “outlined a wide-ranging agenda” but cautioned that observers should “watch what he does, not what he has said.” Wessel added that Warsh “will not simply be able to impose his will on the central bank, and will have to work with his fellow policymakers.”

For investors, banks, businesses, and homeowners, the takeaway is important but measured. Warsh brings a different philosophy, communication style, and set of priorities than Powell. But the institution he now leads is designed to move slowly and deliberately.

Real “regime change” at the Federal Reserve does not happen in a quarter. It happens over years.

If Warsh builds credibility gradually, persuades colleagues carefully, and saves political capital for the moments that matter most, he could leave the Fed meaningfully changed by the end of his term. If he moves too quickly, he risks becoming isolated inside the very institution he wants to reform.

The next 90 days will tell Wall Street which path he chooses.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Shares of Delivery Hero SE surged Tuesday after reports emerged that Uber Technologies Inc. is exploring a potential takeover of the German food-delivery giant, a move that could reshape the global online delivery industry and trigger one of the largest consolidation deals the sector has seen since the pandemic-era boom.

Delivery Hero shares jumped sharply in Frankfurt trading following the reports, adding billions of dollars in market value as investors reacted to speculation that Uber may be positioning itself to expand deeper into Europe, the Middle East, and Asia through a large-scale acquisition.

The reports come at a pivotal moment for the global delivery sector, where slowing growth, rising labor costs, and investor pressure for profitability have intensified consolidation expectations across the industry.

Delivery Hero operates food-delivery platforms in more than 70 countries and maintains particularly strong positions across Europe, the Middle East, Latin America, and parts of Asia. The company also holds stakes in several regional delivery businesses and quick-commerce operations.

Uber, meanwhile, has spent years aggressively expanding beyond ride-sharing into food delivery, grocery delivery, freight logistics, and broader local commerce services through its Uber Eats platform.

Industry analysts say a combination between Uber and Delivery Hero would dramatically expand Uber’s international delivery footprint while strengthening its position against competitors including DoorDash, Just Eat Takeaway, Meituan, Deliveroo, and Prosus-backed food delivery businesses.

The strategic logic behind such a transaction is increasingly clear.

Global food-delivery growth has slowed materially from the explosive levels seen during the COVID-19 pandemic, forcing companies to focus more heavily on scale, logistics efficiency, and profitability rather than pure customer acquisition. Investors have increasingly pushed management teams to reduce subsidies, cut marketing costs, and improve margins after years of aggressive expansion spending.

For Uber, acquiring Delivery Hero could provide instant scale in markets where Uber Eats remains weaker or fragmented, particularly across continental Europe and emerging international markets.

The potential deal would also likely attract heavy regulatory scrutiny.

Competition authorities in the European Union, the United Kingdom, and multiple international jurisdictions have already taken a far more aggressive stance toward technology mergers and platform consolidation over the past two years. Any large-scale Uber acquisition involving major delivery-market overlaps would likely face lengthy antitrust review processes.

Investors nevertheless reacted positively to the reports, viewing consolidation as one of the clearest paths toward stronger profitability in a sector that continues struggling with thin margins and intense promotional competition.

Delivery Hero has faced mounting pressure in recent years to improve financial performance after aggressive expansion into rapid grocery delivery and quick-commerce operations weighed heavily on earnings. The company has since pulled back from several markets and shifted more aggressively toward cash-flow improvement.

Uber Chief Executive Dara Khosrowshahi has repeatedly emphasized that the company is prioritizing profitable growth and operational scale following years of investor concern over cash burn and subsidy-heavy expansion strategies.

The broader market backdrop is also fueling takeover speculation.

Technology and platform companies globally are increasingly exploring acquisitions as lower interest-rate expectations, stabilizing capital markets, and pressure to accelerate growth encourage renewed merger activity.

For Europe specifically, a potential Uber-Delivery Hero transaction would represent one of the largest technology consolidation efforts in years and could significantly reshape the competitive balance across digital commerce, logistics, and local delivery infrastructure.

Neither Uber nor Delivery Hero publicly confirmed takeover discussions Tuesday.

Still, the sharp market reaction highlights how strongly investors believe further consolidation across the global food-delivery sector has become almost inevitable.

After years of expansion fueled by cheap capital and rapid pandemic growth, the industry is increasingly entering a new phase defined by scale, efficiency, and survival.

JBizNews Desk — Europe

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

America’s biggest banks are about to get significantly more powerful — and consumers, businesses, and investors are likely to feel the effects quickly.

Federal Reserve Vice Chair for Supervision Michelle Bowman outlined the administration’s direction in a February 19 speech at the Federal Reserve Bank of Atlanta and in congressional testimony the following week: Washington is rolling back a series of post-2008 banking rules that have constrained lending capacity for more than a decade.

According to consulting firm Alvarez & Marsal, the changes could ultimately unlock roughly $2.6 trillion in additional lending capacity across the U.S. banking system — capital that has largely remained trapped on bank balance sheets since the global financial crisis.

The figure is enormous. It exceeds the annual economic output of many developed nations and represents one of the largest structural shifts in American banking policy since the aftermath of 2008.

The core of the deregulation effort centers around changes to the supplementary leverage ratio, one of the key post-crisis rules requiring large banks to maintain sizable capital cushions against potential losses. The Federal Reserve, the Office of the Comptroller of the Currency, and the Federal Deposit Insurance Corporation finalized a looser version of the framework late last year.

Alvarez & Marsal estimates the immediate impact alone could free approximately $140 billion in deployable capital at the eight largest U.S. banks. Additional revisions targeting stress-testing procedures, mortgage regulations, and portions of the broader Basel III banking framework are expected to follow.

The banking industry has openly welcomed the shift.

JPMorgan Chase Chief Executive Jamie Dimon, whose bank now holds roughly $4.42 trillion in assets, has argued for years that U.S. regulators overcorrected after the financial crisis and placed American lenders at a competitive disadvantage versus European and Asian rivals.

Goldman Sachs Chief Executive David Solomon publicly praised Bowman’s appointment last year, while Bank of America Chief Executive Brian Moynihan described the regulatory pivot as a meaningful boost for bank profitability and lending flexibility.

The question now is where the money goes.

A significant portion is expected to flow directly into artificial intelligence infrastructure. Until now, large banks have largely watched from the sidelines as private credit firms financed the rapid buildout of AI data centers, semiconductor facilities, cloud infrastructure, and energy projects tied to companies such as Microsoft, Amazon, Alphabet, Meta Platforms, and Nvidia-linked suppliers.

With more balance-sheet flexibility, major banks are now positioning themselves to finance billions of dollars in new AI-related infrastructure projects.

Mortgage lending is another major target.

Speaking at the American Bankers Association community banking conference in Orlando earlier this year, Bowman previewed regulatory adjustments designed to make mortgage origination and servicing less expensive for traditional banks.

For years, many banks gradually retreated from the mortgage business as compliance burdens increased, allowing nonbank lenders to capture significant market share. Regulators now appear eager to reverse that trend in hopes of increasing credit availability for homebuyers.

The broader small-business economy could also benefit. Mid-sized manufacturers, regional businesses, and acquisition financing markets are expected to see expanded access to traditional bank credit after years in which private credit funds increasingly filled the gap.

The rise of private credit itself became one of the clearest signs that post-crisis banking rules had fundamentally reshaped corporate finance.

Critics, however, warn that the rollback carries real risks.

Former Federal Reserve Vice Chair for Supervision Michael Barr, who previously held Bowman’s role, has argued that weaker capital standards could leave the banking system more vulnerable during future periods of stress. Critics point to the collapses of Silicon Valley Bank, Signature Bank, and First Republic Bank in 2023 as evidence that banking instability remains a genuine threat even after years of reform.

Bowman has rejected that argument, contending that U.S. banks remain substantially better capitalized than they were before the 2008 crisis and that excessive regulation has become a greater threat to growth than bank fragility itself.

The Trump administration has aligned closely with that view.

Treasury Secretary Scott Bessent has framed the banking-rule rollback as part of a broader strategy to stimulate economic growth without relying entirely on Federal Reserve rate cuts. The logic is straightforward: if banks lend more aggressively, economic activity accelerates without requiring monetary policy alone to support growth.

Wall Street is already responding.

Bank stocks have broadly outperformed the wider market since Bowman assumed the Fed supervision role last June. The Financial Select Sector SPDR Fund and the SPDR S&P Bank ETF have both gained faster than the S&P 500 over the past year as investors anticipate larger dividends, expanded share buybacks, and stronger lending growth.

International regulators are now watching closely as well. European and Asian policymakers face increasing pressure to determine whether they should follow Washington’s lead or risk placing their own financial institutions at a competitive disadvantage globally.

For everyday Americans, the implications are increasingly direct.

The nation’s largest banks are about to have significantly more money available for mortgages, business loans, infrastructure financing, and corporate expansion. That could support economic growth, improve credit availability, and accelerate investment across sectors ranging from housing to artificial intelligence.

It could also mean operating with thinner safety margins than the system maintained during much of the post-2008 era.

Whether that trade-off ultimately strengthens the economy or creates new long-term financial vulnerabilities may define the next chapter of American banking.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Taiwan has officially overtaken India to become the fifth-largest stock market in the world, a remarkable shift driven almost entirely by the global artificial intelligence boom and the explosive rise of semiconductor giant Taiwan Semiconductor Manufacturing Company (TSMC).

Bloomberg market data published Monday showed Taiwan’s total stock-market capitalization reached approximately $4.95 trillion, narrowly surpassing India’s $4.92 trillion. Taiwan’s benchmark TAIEX index climbed to a record 44,097 points Tuesday morning, cementing the island’s new position behind only the United States, China, Japan, and Hong Kong in global equity-market rankings.

The reversal is extraordinary given the scale difference between the two economies.

Taiwan has a population of roughly 23 million people and an economy worth under $1 trillion. India has approximately 1.4 billion people and an economy more than four times larger. Yet Taiwan’s market has surged ahead because of one company dominating the center of the AI economy.

TSMC alone now represents roughly 42% of Taiwan’s total stock market value.

The company’s shares have surged nearly 50% this year as investors continue pouring money into businesses tied to artificial intelligence infrastructure. TSMC manufactures the advanced semiconductors powering AI systems used by companies including Nvidia, Apple, Advanced Micro Devices, Broadcom, Qualcomm, Amazon, Microsoft, and Meta Platforms.

The company is widely estimated to produce roughly 90% of the world’s most advanced chips — semiconductors essential for AI data centers, cloud computing, smartphones, autonomous systems, and advanced defense technologies.

As global AI spending accelerates, demand for TSMC’s manufacturing capacity has exploded alongside it.

TSMC Chief Executive C.C. Wei has repeatedly said the company remains effectively sold out at the high end of production, with customer demand continuing to exceed available supply despite aggressive expansion efforts.

The company is currently building or expanding manufacturing facilities in Arizona, Japan, and Germany, backed by billions of dollars in incentives and industrial-support programs from governments eager to secure domestic semiconductor production.

Even so, the most advanced chips in the world continue to be produced overwhelmingly inside Taiwan itself.

Taiwan’s government has also actively supported the rally.

Last month, Taiwan’s Financial Supervisory Commission relaxed concentration rules for domestic mutual funds, allowing investment funds focused on Taiwanese equities to allocate up to 25% of assets into a single stock if that company represents more than 10% of the broader market.

At present, TSMC is the only company qualifying under the revised rules.

Analysts at JPMorgan Chase estimated the regulatory change alone could attract more than $6 billion in additional inflows into Taiwanese equities over the coming months, further strengthening demand for TSMC shares.

India, meanwhile, has moved in the opposite direction.

According to Bloomberg data, foreign investors have withdrawn roughly $24 billion from Indian equities so far this year amid slowing corporate earnings growth, weakness in the rupee, and the global rotation toward AI-linked investments concentrated in semiconductor-heavy markets like Taiwan and South Korea.

The reversal has been rapid. Just two years ago, India’s stock market was nearly three times the size of Taiwan’s.

TSMC itself is now valued at more than $1 trillion, placing it among the most valuable companies in the world and reinforcing how deeply the AI boom has concentrated market gains into a relatively small number of semiconductor leaders.

But Taiwan’s success also exposes its greatest vulnerability.

Because such a large share of the country’s stock market depends on one company and one industry, any slowdown in AI spending, production disruption, or geopolitical instability could trigger severe market volatility.

The geopolitical risk remains especially significant given tensions between Taiwan and China.

Beijing continues to claim Taiwan as part of its territory and has never ruled out the use of force to achieve reunification. Semiconductor security and U.S. support for Taiwan remained a major topic during recent meetings between President Donald Trump and Chinese President Xi Jinping earlier this month in Beijing.

Taiwanese officials have publicly welcomed the market milestone while also acknowledging the risks of excessive dependence on semiconductors.

Premier Cho Jung-tai has urged policymakers to accelerate investment in industries including electric vehicles, biotechnology, and green energy in an effort to broaden Taiwan’s economic base beyond chips.

Those diversification efforts, however, remain in relatively early stages.

For India, the loss of fifth place arrives at a politically difficult moment.

Prime Minister Narendra Modi’s government has aggressively promoted manufacturing expansion and semiconductor investment initiatives aimed at reducing reliance on imports and building a domestic chip ecosystem. But replicating Taiwan’s semiconductor infrastructure — built over four decades with deep engineering specialization and global supply-chain integration — remains enormously difficult.

India’s stock market still ranks among the world’s largest emerging-market exchanges, but momentum has increasingly shifted toward AI-linked economies and semiconductor-heavy markets tied directly to the global computing buildout.

TSMC shares are expected to resume trading Wednesday in Taipei following Tuesday’s record close.

For now, the rise of a single company has fundamentally reshaped global stock-market rankings — and transformed Taiwan into one of the central financial winners of the artificial intelligence era.

JBizNews Desk — Asia

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump signed an executive order before the Memorial Day weekend titled “Integrating Financial Technology Innovation Into Regulatory Frameworks,” directing the Federal Reserve and other federal financial regulators to review and ease rules that have long kept fintech companies and cryptocurrency firms from gaining direct access to the Federal Reserve’s payment system. According to the official White House fact sheet released the same evening, the order is intended to “streamline regulatory processes, reduce unnecessary barriers to entry, and encourage collaboration between fintech firms, federally regulated financial institutions, and Federal financial regulators.”

“The Federal Government must update regulations to allow integration of digital assets and innovative technology into traditional financial services and payment systems,” Trump said in the executive order. The directive specifically targets what the order calls “overly burdensome and fragmented regulations and supervisory practices that form barriers to entry and primarily benefit incumbent financial services firms” — language that effectively puts traditional banks directly in the administration’s crosshairs.

The executive order establishes two parallel review processes with firm deadlines. Federal financial regulators — including the Consumer Financial Protection Bureau, Commodity Futures Trading Commission, Federal Deposit Insurance Corporation, Office of the Comptroller of the Currency, National Credit Union Administration, and Securities and Exchange Commission — must conduct a review within 90 days, by August 17, 2026, to identify regulations, supervisory practices, guidance, and application procedures that “unduly impede fintech firms” from partnering with federally regulated institutions or obtaining bank charters themselves. Within 180 days, by November 15, 2026, those agencies must take concrete action based on their findings.

The order separately directs the Federal Reserve Board to complete its own review within 120 days examining whether “covered firms” — including uninsured depository institutions, fintech firms, stablecoin issuers, and cryptocurrency companies — should gain broader access to Federal Reserve payment accounts and settlement services. The Fed must also evaluate the legal pathways for expanding such access “to the extent permitted by law, subject to appropriate risk management requirements.”

At the center of the battle is something known inside the industry as a Federal Reserve master account. A master account gives a financial institution direct access to the Fedwire settlement network and the broader Federal Reserve payment system. Traditional banks use these accounts to move money instantly across the U.S. financial system. Without one, fintech and crypto firms must route transactions through partner banks, adding delays, fees, and dependence on incumbents.

For decades, those accounts have effectively been reserved for federally chartered banks. That wall has started to crack. In March 2026, the Federal Reserve Bank of Kansas City approved a limited-purpose master account for Payward, the parent company of crypto exchange Kraken, marking one of the first major openings of Federal Reserve payment access to a crypto-related entity. Trump’s order now accelerates the broader review process and forces regulators to publicly justify any future denials.

The implications for the fintech and crypto industries are enormous. Direct Federal Reserve access could dramatically reduce payment costs and settlement friction for stablecoin issuers, tokenization platforms, digital asset custodians, and instant-payment providers. Companies positioned to benefit include Circle Internet Group, issuer of the USDC stablecoin; Coinbase Global; Kraken; Anchorage Digital; Paxos; Fidelity Digital Assets; and fintech firms including Block, PayPal Holdings, Stripe, Plaid, Chime Financial, SoFi Technologies, Robinhood Markets, and Brex.

For Wall Street’s biggest banks, the order represents a direct competitive threat. JPMorgan Chase, Bank of America, Wells Fargo, Citigroup, U.S. Bancorp, and PNC Financial Services have long benefited from privileged access to the Federal Reserve’s payment rails. Lowering those barriers would force banks to compete more aggressively on fees, speed, technology, and customer experience against well-funded fintech challengers. Community and regional banks that generate revenue from correspondent banking relationships could feel even greater pressure.

For consumers, the long-term impact could be meaningful. If stablecoin issuers receive direct Federal Reserve settlement access, dollar-backed digital tokens could become faster and cheaper for online commerce, international transfers, and remittances. If fintech firms like Chime, Cash App, and SoFi gain easier access to banking infrastructure or charters, consumers could see more competitive interest rates, lower overdraft fees, and faster movement of money between accounts, brokerages, and payment apps.

The political backdrop is equally important. Trump’s administration has consistently embraced a fintech- and crypto-friendly stance since returning to office, sharply reversing what many in the industry described as the Biden administration’s “Operation Choke Point 2.0” approach toward crypto banking access. Treasury Secretary Scott Bessent and SEC Chairman Paul Atkins have both publicly supported greater fintech integration into the banking system.

Capital Alpha analyst Ian Katz wrote in a research note that “we don’t expect the order will be ignored by incoming Fed Chair Kevin Warsh,” referring to the former Federal Reserve governor widely viewed as the leading candidate to replace Jerome Powell, whose term expires on May 15, 2026.

Trump signed a second executive order the same evening directing regulators to strengthen Bank Secrecy Act enforcement against undocumented workers using unregistered payment services and peer-to-peer platforms to bypass tax reporting requirements. Together, the two orders outline a broader strategy: open the financial system to legitimate digital innovation while tightening enforcement against off-the-books financial activity.

Critics immediately raised concerns about Federal Reserve independence. Fed officials have historically resisted political pressure over master account access, arguing that opening payment rails to uninsured or lightly regulated firms creates financial stability and anti-money-laundering risks. But the administration’s hard deadlines now force regulators to publicly defend any refusal to broaden access.

The crypto industry reacted enthusiastically. Cardano ecosystem executive Bipananda Dadybayo said firms focused on tokenized treasuries, blockchain settlement systems, and digital payments could “benefit disproportionately” if the order leads to broader integration with the Federal Reserve system.

“For most of crypto’s history, the industry built systems outside traditional financial infrastructure,” Dadybayo said. “This potentially marks the beginning of a different phase — from crypto outside the system to crypto inside the rails.”

The move also ties directly into the larger global battle over digital money. As China, India, Brazil, and other BRICS countries push forward with central bank digital currencies designed partly to reduce dependence on the dollar, the Trump administration is making a different bet: that private-sector dollar stablecoins and fintech innovation can extend America’s monetary dominance into the digital age without creating a U.S. government-controlled digital currency.

The executive order does not immediately grant any fintech or crypto company new access. But it starts the clock. By August 17, regulators must report findings. By November 15, they must act. And by mid-September, the Federal Reserve must complete its own review.

For the first time in generations, the American financial system’s definition of who gets access to the core payment infrastructure — and who gets to compete with banks themselves — is formally being reconsidered.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JbizNews —Frankfurt — The European Central Bank must proceed with an interest rate hike at its upcoming June monetary policy meeting regardless of whether ongoing diplomatic negotiations yield a peace deal in the Middle East, according to an explicit policy directive issued on May 26, 2026. ECB Executive Board Member Isabel Schnabel warned that the protracted geopolitical conflict in Iran has inflicted structural damage on the continent’s commercial pipeline, forcing a sharp upward revision in long-term inflation modeling. The central bank’s hardening stance signals that policymakers are preparing to prioritize structural price stability even as external energy shocks rapidly depress corporate profitability and squeeze aggregate consumer demand across the currency bloc.

The hawkish policy maneuver arrives on the heels of the European Commission’s official Spring 2026 Economic Forecast, which systematically downgraded Eurozone gross domestic product (GDP) expansion metrics while accelerating inflation targets. Under the newly calibrated baseline, real GDP growth across the EU is projected to contract to a sluggish 1.1% this year, while the core Eurozone is expected to post a meager 0.9% expansion. Simultaneously, widespread commodity volatility has driven projected headline inflation up by a full percentage point to 3.1% for the current calendar year. This restrictive macroeconomic environment is being directly exacerbated by a severe supply-side disruption following the closure of the Strait of Hormuz, which triggered a 50% spike in regional wholesale natural gas prices and a 65% surge in crude oil baselines between late February and the end of April.

For institutional market participants, the intersection of rising borrow costs and sticky input liabilities is triggering a notable contraction in industrial capital expenditure. European Commission forecasters noted that elevated sovereign yields are compounding corporate debt service burdens, pushing multi-national enterprises to alter near-term hiring and capital expansion plans. While nominal wage pressure remains highly elevated as regional labor unions seek compensation for eroding purchasing power, corporate operating margins are contracting under the weight of utility overhead. Commercial analysts at MUFG Research underscored that because domestic household savings buffers have been largely exhausted over the prior cyclical cycle, private consumption can no longer be relied upon to insulate corporate revenues from broader macroeconomic compression.

The structural fiscal health of member state governments is also fracturing under the financial burden of managing national energy grid interventions. Aggregate public sector deficits across the trading bloc are now anticipated to expand from 3.1% of GDP last year to 3.6% over the medium term. This widening budgetary mismatch is set to push the total EU debt-to-GDP ratio from 82.8% to 84.2% before the conclusion of the fiscal year, with core sovereign weights in the Eurozone hitting a more severe 90.2%. The expanding debt load is being further aggravated by an unfavorable, widening interest-growth differential that increases the long-term cost of rolling over outstanding government securities.

On the commercial labor front, the protracted tightening of the continental labor market has officially peaked. Institutional payroll modeling indicates that aggregate employment growth across the European Union will decelerate sharply to 0.3% this year, a noticeable decline from the 0.5% pace recorded during the prior expansionary leg. Total unemployment is projected to solidify at 6.0%, effectively halting a multi-year downward trajectory that had previously acted as a key pillar of support for corporate services and domestic retail spending.

Despite the prevailing headwinds, certain counter-cyclical sectors are showing strong structural resilience. Public sector capital outlays directed toward defense procurement and localized green energy infrastructure grids are expected to remain highly robust, partially mitigating the capital flight observed in private commercial real estate and residential construction markets. Furthermore, corporate investments into advanced generative artificial intelligence platforms are being cited by institutional economists as a primary supply-side tailwind that could unlock latent industrial productivity, provided that private enterprise implementation can bypass building regulatory friction within the Brussels legislative apparatus.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

SINGAPORE — Jeff Currie, chief strategy officer of energy pathways at Carlyle Group and co-chairman of Abaxx Markets, warned Monday, May 25, 2026, that Asian oil inventories have now fallen to so-called minimum operating levels and that Europe is likely only weeks behind, with the United States potentially facing meaningful physical supply shortages by July as the war with Iran continues to disrupt shipping through the Strait of Hormuz.

Speaking to CNBC on the sidelines of the UBS Wealth Conference in Singapore, Currie said headline global inventory figures are giving markets a false sense of security because a significant portion of stored crude oil cannot actually be used. Much of the world’s inventory, he said, is operational oil required to keep pipelines, terminals, storage caverns, and refining systems functioning safely.

“Asia is already at tank bottoms,” Currie said, describing a situation where inventories have effectively reached minimum operating requirements. Europe, in his view, is roughly four weeks behind, while the United States — still temporarily insulated by Strategic Petroleum Reserve flows and strong domestic production — could begin feeling genuine physical tightness by July.

Currie, formerly the longtime global head of commodities research at Goldman Sachs Group Inc., remains one of the most closely watched voices in global energy markets after helping shape Wall Street’s understanding of the post-2020 commodity supercycle.

The stress is already becoming visible inside refined-product markets. Currie noted that jet fuel prices surged first before easing, only for diesel prices to move sharply higher afterward. Diesel in Singapore is now trading above jet fuel, reflecting how refiners are struggling to allocate shrinking crude supplies across transportation, industrial, and aviation demand heading into peak summer consumption season.

The sequencing he outlined presents a stark picture of the next several weeks: Asia is already depleted, Europe is approaching similar conditions, and the United States could begin seeing tighter physical balances just as summer driving demand accelerates.

Currie’s warning came despite a sharp decline in crude prices Monday. Brent crude fell roughly 5% to around $97.61 per barrel amid renewed hopes for a diplomatic breakthrough between Washington and Tehran. But Currie argued that financial markets are focusing excessively on headlines while ignoring the slower-moving physical reality underneath.

“The market is trading diplomacy while inventories continue drawing down,” one commodities trader attending the conference summarized afterward.

The broader geopolitical backdrop remains highly unstable. Iran’s foreign ministry said Monday that no agreement with the United States was close, despite President Donald Trump signaling that negotiations were progressing constructively. Trump also confirmed that the U.S. naval blockade targeting Iranian shipping would remain fully in place until any agreement is formally signed and verified.

The International Energy Agency had previously assumed a reopening of the Strait of Hormuz by late May under its baseline market projections — a timetable that has now quietly passed without resolution.

The implications extend far beyond crude oil prices themselves. European refiners have increasingly depended on accelerated imports of U.S. crude exports to offset shortages tied to Hormuz disruptions. But Currie warned those temporary flows cannot continue indefinitely if U.S. domestic inventories begin tightening simultaneously.

Once Strategic Petroleum Reserve drawdowns slow and domestic inventories tighten further, Europe could rapidly face the same structural shortages already emerging in Asia.

The result could be mounting pressure across diesel, jet fuel, gasoline, shipping costs, and refining margins through the second half of the summer.

Currie’s comments also landed at a delicate moment for global central banks. Earlier Monday, the Bank of Israel cut interest rates by 0.25 percentage points to 3.75% while warning that global inflationary pressures tied to energy markets remain elevated. The Federal Reserve, European Central Bank, and Bank of England have each acknowledged in recent weeks that another sustained energy shock could complicate expected rate-cut paths later this year.

For oil markets, Currie’s framework increasingly suggests the coming months may be driven less by speculative positioning and more by simple physical availability.

If Asia is already operating at minimum inventory levels, Europe is only weeks behind, and the United States begins tightening by July, the global energy system could enter peak summer demand with very little operational cushion remaining.

The question now is whether diplomacy can move quickly enough to stabilize flows before physical shortages begin forcing prices materially higher again.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

12:40am EST – By JBizNews Desk

NEW YORK — U.S. equity futures traded firmly higher Monday night, May 25, 2026, signaling a strong open when Wall Street returns from the Memorial Day holiday Tuesday, as oil prices tumbled and President Donald Trump said talks with Iran to end the three-month war are “proceeding nicely.” Dow Jones Industrial Average futures jumped as much as 441 points earlier in the evening before settling up 0.6% as of 9:12 p.m. Eastern, while S&P 500 futures gained 0.6% and Nasdaq-100 futures climbed 0.8%, according to CME Group data. West Texas Intermediate crude dropped roughly 5%, slipping back below the psychologically critical $100-a-barrel threshold.

The opening bell rings at 9:30 a.m. Eastern Tuesday at both the New York Stock Exchange and Nasdaq, with Treasury markets also returning to full trading after the Memorial Day closure. Wall Street enters the shortened four-day week with momentum, but traders face one of the heaviest macro calendars of the quarter — a week packed with inflation data, GDP revisions, retail earnings, and a fragile geopolitical backdrop that continues to swing oil prices and bond yields almost daily.

President Donald Trump told reporters Monday that negotiations with Tehran were advancing while reiterating that the United States could “go on the offensive” if diplomacy collapsed. Iranian officials reportedly traveled to Qatar for consultations tied to a potential framework agreement. The market response was immediate: energy prices fell, Treasury yields eased, and futures rallied as investors increasingly priced in the possibility that the Strait of Hormuz could reopen in the coming weeks.

Oil remains the market’s central macro variable. Brent crude settled just above $100 a barrel Friday after briefly surging as high as $140 earlier this spring. JPMorgan analysts continue forecasting an average Brent price near $97 through the remainder of 2026 if shipping traffic through Hormuz resumes by early summer. AAA said this Memorial Day weekend marked the most expensive for U.S. drivers in four years, with national gasoline prices averaging $4.51 per gallon — up roughly 51% since the conflict began on February 28. Saudi Aramco CEO Amin Nasser warned earlier this month that full normalization of global oil flows may not occur until 2027 if disruptions persist.

Stocks nevertheless continue to push higher. The Dow Jones Industrial Average closed Friday at a record 50,285.66 after gaining nearly 300 points. The S&P 500 remains near 7,445 while the Russell 2000 has recently outperformed amid investor rotation into economically sensitive small-cap names. The Dow advanced 2.13% last week, the S&P 500 gained 0.88%, and the Nasdaq Composite rose 0.45%.

The defining event of the week arrives Thursday morning at 8:30 a.m. Eastern when the Bureau of Economic Analysis releases the April Personal Consumption Expenditures Index, the Federal Reserve’s preferred inflation gauge. The release also includes personal income, personal spending, the second estimate of first-quarter GDP, durable goods orders, and weekly jobless claims — creating one of the densest economic report windows of the year.

The PCE report takes on outsized importance after April’s hotter-than-expected Consumer Price Index rattled markets earlier this month and reignited concerns that inflation tied to energy and supply chains could remain sticky well into the second half of 2026. Investors are now watching whether inflation continues cooling or whether oil-driven price pressures force the Federal Reserve into a prolonged higher-for-longer stance.

The policy backdrop became even more consequential Friday when Kevin Warsh officially assumed the role of Federal Reserve Chair. Warsh is viewed as significantly more hawkish on inflation than his predecessor, and several Fed officials have recently signaled diminishing appetite for near-term rate cuts. Markets are now increasingly debating whether the Fed’s next move could eventually shift back toward tightening if inflation accelerates further.

Tuesday itself brings several notable releases, including the Conference Board Consumer Confidence Index at 10 a.m. Eastern, the Philadelphia Fed Non-Manufacturing Survey at 8:30 a.m., and the Dallas Fed Manufacturing Survey later in the morning. Wednesday adds new home sales and the Richmond Fed Survey of Manufacturing Activity, while Friday closes the week with the Chicago Purchasing Managers’ Index, trade data, and wholesale inventory figures.

The final major wave of earnings season also arrives this week. AutoZone headlines Tuesday’s calendar alongside reports from Box, Champion Homes, Semtech, Elbit Systems, and Modine Manufacturing. Wednesday brings the most closely watched session, featuring results from Salesforce, HP Inc., Marvell Technology, Snowflake, Synopsys, Agilent Technologies, Abercrombie & Fitch, Bath & Body Works, and DICK’S Sporting Goods. Thursday includes reports from Dell Technologies, Autodesk, Best Buy, and Burlington Stores.

Wall Street will pay especially close attention to Salesforce and Marvell Technology as gauges for the artificial intelligence economy. Investors increasingly want proof that enterprise software companies can generate sustainable monetization from AI products rather than simply rebranding existing offerings. Marvell, Synopsys, and HP are also expected to provide insight into AI infrastructure spending, semiconductor demand, and broader enterprise technology budgets following Nvidia’s closely watched earnings report last week.

Nvidia reported record quarterly revenue of $81.6 billion, up 85% year over year, driven primarily by explosive growth in its data-center division, which generated $75.2 billion in sales. Yet despite the strong numbers, the stock failed to spark the type of euphoric post-earnings rally that has defined much of the AI trade over the past two years — a sign that investor expectations remain extraordinarily elevated.

Elsewhere, speculative growth names also continued attracting attention Monday night. BlackBerry shares jumped more than 8% amid renewed enthusiasm around its QNX automotive platform. Quantum-computing company Infleqtion rose after follow-through buying tied to last week’s federal funding announcement, while AST SpaceMobile gained sharply on progress tied to direct-to-cell satellite deployment.

The market’s risks remain straightforward but substantial. Any breakdown in Iran negotiations — or another sudden escalation in the Strait of Hormuz — could rapidly reverse the current futures rally. Reuters reported last week that Iran’s supreme leader instructed negotiators to keep enriched uranium inside the country, a position that could complicate any final agreement with Washington.

For now, however, traders appear willing to extend the same thesis that has powered equities throughout May: that AI-driven earnings growth, easing geopolitical premiums, and eventually lower oil prices will outweigh inflation fears and keep risk assets climbing. Whether Thursday’s PCE data validates that narrative — or undermines it — may determine the direction of Wall Street for the remainder of the summer.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

President Donald Trump’s latest financial disclosure, filed with the U.S. Office of Government Ethics and detailed in a Bloomberg analysis published May 23, revealed 3,711 trades executed during the first quarter of 2026 — a volume and scale of activity without precedent for a sitting American president.

The disclosures, filed through two OGE Form 278-T reports, show transaction activity spanning technology, defense, aviation, banking, energy and consumer stocks, with estimated total trading volume ranging between roughly $220 million and $750 million during the three-month period.

The Trump Organization said the trades were executed by outside financial firms operating under standing portfolio-management mandates and that neither Trump, his family nor company executives directed individual buy-and-sell decisions.

Still, the sheer size of the activity — combined with the timing of several trades surrounding the U.S.-Iran conflict — is reigniting ethics debates across Washington and Wall Street over presidential market exposure, disclosure rules and the growing overlap between political power and financial markets.

Unlike most recent presidents, who broadly relied on blind trusts or diversified mutual funds, Trump’s filings show extensive single-stock trading across hundreds of publicly traded companies, many directly affected by federal policy decisions.

The disclosures were filed under the STOCK Act, the 2012 law requiring the president, vice president and members of Congress to report securities transactions exceeding $1,000 within 45 days. The filings disclose value ranges rather than exact amounts and do not reveal gains or losses tied to individual positions.

A Bloomberg review of the filings — alongside analysis from outside investment experts — suggests much of the activity reflects highly automated wealth-management strategies increasingly common among ultra-high-net-worth investors.

Several trades appear consistent with direct indexing, algorithmic portfolio rebalancing and tax-loss harvesting systems designed to scan large portfolios continuously for opportunities to offset gains and optimize taxes.

“Tax-loss harvesting is probably the single most common portfolio strategy we see among high-net-worth and ultra-high-net-worth investors today,” Samir Vasavada, co-founder of investment platform Vise, told Bloomberg. “When you’re holding hundreds or thousands of individual positions and the system is scanning for losses to harvest every day, you end up with a lot of trades.”

That explanation aligns with patterns throughout the filing.

A number of stocks repeatedly appear on both the buy and sell side within the same trading sessions — behavior more characteristic of automated portfolio-management systems than discretionary trading by a single investor. Trading spikes also appeared around key inflation releases from the Bureau of Labor Statistics earlier this year, suggesting portions of the portfolio may be operating under quantitative models tied to macroeconomic events.

But the trades drawing the greatest scrutiny are the ones that do not appear systematic.

Of the 3,711 trades disclosed, approximately 625 were labeled “unsolicited” by brokers — indicating they were not initiated by the brokerage firms themselves. Nearly all clustered during March, particularly immediately following U.S. military strikes against Iran.

More than 2,000 trades occurred during March alone as markets swung violently around wartime developments, with many of the unsolicited purchases concentrated in sectors directly exposed to geopolitical escalation, including defense contractors, aerospace companies, semiconductors and energy firms.

That timing is already attracting attention from ethics watchdogs and lawmakers.

“If you’re in the business of predicting contract awards, for example, then there might be some information embedded in these kinds of disclosures,” William Cassidy, an assistant finance professor at Washington University in St. Louis, told Bloomberg.

Cassidy did not allege insider trading, and no accusations or charges have been filed. But the disclosures are likely to intensify calls from both parties for tighter restrictions on securities trading by senior elected officials and executive-branch leadership.

The filings reveal extensive exposure to many of the market’s most influential technology and AI-linked companies.

Purchases of Nvidia, Microsoft, Broadcom, Amazon, Apple and Meta Platforms each ranged between $1 million and $5 million in disclosed value bands. Other positions included AMD, Intel, Goldman Sachs, Alphabet, Airbnb, DoorDash, Micron Technology, Oracle, Bank of America and Bloom Energy.

One Nvidia purchase in the $500,000-to-$1 million disclosure range reportedly occurred roughly one week before the Commerce Department approved additional Nvidia chip sales to China — a sequence congressional critics and outside analysts quickly highlighted after the filings became public.

According to Yahoo Finance analysis cited by MSNBC’s Stephanie Ruhle, the so-called “Magnificent Seven” technology stocks appeared in at least 94 separate transactions during the quarter.

A separate reconstruction by Euronews estimated several disclosed positions — including AMD, Intel, Marvell Technology, SanDisk, Seagate Technology, Bloom Energy and Intuitive Machines — had appreciated more than 100% by the end of March.

The Trump Organization has repeatedly emphasized that the president himself is not actively directing the portfolio.

While Trump family assets remain overseen operationally by Donald Trump Jr. and Eric Trump, portions of the filing indicate substantial third-party broker involvement operating independently under predefined mandates and investment rules.

The filings themselves do not specify how the mandates are structured, which accounts are managed externally or whether Trump receives real-time reporting regarding portfolio activity.

For markets, however, the disclosures are already becoming a roadmap for retail traders, political analysts and financial commentators attempting to identify signals tied to defense spending, AI investment trends and wartime sector rotations.

For Washington, the filings may revive legislative efforts that stalled several years ago to ban or heavily restrict individual stock trading by members of Congress, presidents and senior executive officials.

Sen. Josh Hawley, Sen. Jon Ossoff and former Rep. Abigail Spanberger have all introduced variations of such legislation in recent years, though none advanced into law.

The latest disclosures now provide reform advocates with the most extensive real-world example yet of how deeply modern political leadership can intersect with active financial-market exposure.

More broadly, the filings illustrate how the presidency itself increasingly sits inside the same high-frequency market ecosystem as institutional investors, hedge funds and ultra-wealthy portfolios — where every policy signal, geopolitical shock and economic data release can ripple immediately into asset prices.

And under the STOCK Act, the public now gets to watch those ripples appear — 45 days at a time.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

NEW YORK — The death of Toshifumi Suzuki, the Japanese retail pioneer who transformed 7-Eleven into the world’s dominant convenience-store chain, arrives at a defining moment for the company’s American operations — one marked by a delayed IPO, leadership uncertainty, store closures, and the lingering fallout from a failed multibillion-dollar takeover battle that nearly shifted control of one of America’s most recognizable retail brands to a Canadian rival.

Seven & i Holdings Co. confirmed Monday, May 25, 2026, that Suzuki died of heart failure on May 18 at age 93. The executive who introduced the American 7-Eleven concept to Japan in 1974 and later orchestrated the rescue of the bankrupt U.S. parent company, Southland Corp., in 1991 leaves behind a U.S. business now grappling with the same strategic challenge he spent decades solving: how to make convenience retail indispensable to daily life.

Today, 7-Eleven, Inc., headquartered in Irving, Texas, operates more than 9,000 stores across the United States and Canada and employs roughly 135,000 people. The chain remains the largest convenience retailer in North America by a wide margin. Yet the U.S. division has increasingly become the pressure point inside Suzuki’s global empire as inflation, changing consumer behavior, and declining cigarette sales reshape the economics of the sector.

The company is also navigating a major leadership transition. Longtime U.S. chief executive Joseph DePinto, who led the American business for more than two decades, retired at the end of 2025. Stan Reynolds and Douglas Rosencrans are currently serving as co-chief executives while parent-company CEO Stephen Hayes Dacus — the first foreign-born chief executive in Seven & i history — searches for a permanent successor to oversee the North American business.

That uncertainty is unfolding alongside a sweeping restructuring effort. Last year, 7-Eleven announced plans to close roughly 450 underperforming North American stores and raise approximately $750 million through sale-leaseback transactions after executives warned that “inflation-weary and pressured U.S. consumers” were reducing discretionary purchases. Since then, the company has expanded the effort to roughly 645 locations slated for closure or franchise conversion during 2026 while simultaneously investing in a major redesign of its U.S. stores modeled after the high-efficiency Japanese “konbini” concept Suzuki pioneered decades ago.

The company’s long-anticipated American IPO — expected to be one of the largest retail listings in years — has also been pushed back. Seven & i had targeted a second-half 2026 public offering for 7-Eleven Inc. on a U.S. exchange, but executives recently delayed the timeline, citing market conditions and the need to demonstrate sustained recovery in same-store sales before moving forward.

Suzuki’s influence remains embedded throughout the American business he rescued. When he engineered Ito-Yokado’s acquisition of Southland Corp. out of bankruptcy in 1991, he inherited a heavily indebted U.S. operator struggling under the weight of a failed leveraged buyout. He rebuilt it using operational systems developed in Japan: computerized point-of-sale tracking, real-time inventory analysis, rapid fresh-food rotation, and tightly monitored franchise accountability. Those systems now form the operational backbone of modern American convenience retail.

The strategic importance of Suzuki’s U.S. network became especially clear during the takeover battle that consumed the company through 2024 and 2025. Canadian retail giant Alimentation Couche-Tard, owner of Circle K, pursued Seven & i with a bid valued at roughly $47 billion before talks ultimately collapsed last year. Couche-Tard publicly accused Seven & i leadership of orchestrating a “calculated campaign of obfuscation and delay” during negotiations. A separate management-led buyout attempt spearheaded by Junro Ito also failed after financing efforts fell short.

The failed transactions forced Seven & i into a broader restructuring strategy centered around its American convenience-store business. The company installed Dacus as CEO, accelerated plans for the U.S. IPO, and agreed to sell supermarket and restaurant operations to Bain Capital in order to focus almost entirely on convenience retail — the business Suzuki built into a global powerhouse.

For U.S. consumers, the most visible manifestation of Suzuki’s legacy is the gradual transformation of American 7-Elevens into food-oriented neighborhood hubs modeled after Japanese convenience stores. The company has expanded fresh-food selections, introduced kids’ meals, catering options, and promotional “Slurpee happy hour” campaigns while redesigning stores under its “New Standard” concept in an attempt to replicate the high-frequency customer traffic that defines Japanese konbini culture.

Whether that strategy succeeds may ultimately determine the valuation of the eventual IPO — and whether the next American CEO inherits a growth platform or a difficult turnaround story.

Retail analysts say the timing of Suzuki’s death carries symbolic weight. The architect of modern convenience retail is gone just as the company he built faces a defining test of whether his operating philosophy can sustain the business into its next century without him as the guiding force.

What remains undeniable is the scale of Suzuki’s impact on American retail. The thousands of 7-Eleven stores he helped rescue from bankruptcy now represent the largest convenience-store network in the United States. Every late-night Slurpee run, every taquito warmer, every quick stop for coffee or gasoline traces back, in some measure, to the Japanese executive who was once told an American convenience-store concept could never succeed in Tokyo — and who later returned to save the American original itself.

The company he built now enters its next chapter without him.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.


Crude oil prices surged Monday, May 25, 2026, after the U.S. military destroyed two Islamic Revolutionary Guard Corps vessels caught laying naval mines in the Strait of Hormuz and struck a surface-to-air missile battery at Bandar Abbas that had targeted American warplanes, raising fresh fears that a U.S.-Iran agreement to end the three-month war could slip away just as it appeared within reach. Senior U.S. defense officials briefing reporters Monday afternoon confirmed the strikes, which arrived mid-session and forced traders to abandon what had been one of the steepest single-day collapses in crude prices since the war began.

The reversal was violent. International benchmark Brent crude had earlier plunged roughly 7% to trade near $96 a barrel and West Texas Intermediate had skidded to roughly $90 a barrel after President Donald Trump posted on Truth Social that negotiations with Tehran were “proceeding nicely” and disclosed he had pressed Saudi Arabia, Qatar, Pakistan, Turkey, Egypt and Jordan to join the Abraham Accords as part of a wider regional settlement. The Monday slide had extended last week’s drop of more than 5% in Brent and over 8% in WTI, unwinding much of the war premium that had carried Brent above $114 just three weeks ago. The afternoon strikes erased a meaningful portion of the day’s losses and reignited the volatility that has defined the conflict.

The mine-laying operation was caught in real time. According to reporting from Fox News national security correspondent Jennifer Griffin citing a senior U.S. official, American forces tracked the two IRGC craft as they were depositing mines into the shipping lane and engaged them before the devices could be fully positioned. Both vessels were destroyed. U.S. Central Command considers them eliminated. The episode is the precise scenario American commanders have warned about for months: Tehran deploying small, fast-moving craft from its “mosquito fleet” to seed the world’s most critical oil chokepoint with naval mines, a tactic that could close the strait to commercial shipping for weeks even after a ceasefire is signed.

The second engagement followed almost immediately. A SAM site at Bandar Abbas — the southern Iranian port city that serves as the IRGC Navy’s primary operational hub and the inspection point through which Iran routes vessels transiting the strait — locked onto U.S. warplanes operating in the area. American forces struck the battery in response. Iran’s Mehr News Agency acknowledged sounds of explosions east of Bandar Abbas but said the situation in the city itself was normal. Separately, OSINT monitors and regional wire feeds reported large fires on Kharg Island, the terminal that handles roughly 90% of Iran’s crude exports, though U.S. officials have not confirmed American responsibility for that incident.

Pentagon officials, through Griffin’s reporting, were emphatic about the framing: the strikes were defensive in nature, not offensive, and not an attempt to break the ceasefire. U.S. officials said the operation is finished for now. That language is deliberate and aimed squarely at oil traders and at the Iranian negotiating team. The White House is signaling that mine-laying in the strait crosses a hard red line — even during active peace talks — but that American forces will not expand the engagement beyond the immediate threat. Whether Tehran accepts that distinction will determine the next 48 hours in the energy market.

The diplomatic track had been gathering real momentum before the strikes. U.S. Secretary of State Marco Rubio said last week there were “good signs” an agreement to end the war was within reach, while warning any deal would be “unfeasible” if Iran insists on permanent control over Hormuz shipping. A Pakistani mediator separately briefed Beijing that an accord was nearing. The framework under discussion would extend the existing ceasefire for roughly two months, during which Washington would lift its naval blockade of Iranian ports — in place since April 13 — and Tehran would reopen the strait to international shipping. Through that chokepoint normally moves about one-fifth of the world’s seaborne oil and 20% of global liquefied natural gas, flows that have been effectively halted since the war began February 28.

Two fault lines remain unresolved and both were on display Monday. Iran’s enriched uranium stockpile continues to be the central nuclear sticking point — Trump posted that the material will either be turned over to the United States and destroyed or handled in coordination with Tehran. The second is Iran’s demand to retain authority over maritime traffic through Hormuz and to collect tolls reported to exceed $1 million per ship. The mine-laying activity that triggered Monday’s American strikes underscores how far the two sides remain from operational normalization of the waterway, regardless of progress at the negotiating table.

Energy executives are bracing for a prolonged tail. A recent note from MUFG told clients that full normalization of Middle East oil supply may not occur until 2027 given infrastructure damage and dislocated shipping insurance markets. Chevron Chief Executive Mike Wirth told CNBC’s David Faber at the Milken Institute Global Conference earlier this month that fuel shortages are now a growing concern in parts of the world dependent on Gulf product flows, particularly naphtha, LPG and jet fuel. A Goldman Sachs note to clients flagged accelerating drawdowns in easily accessible refined-product buffers, while OPEC+ is weighing an output increase that analysts at Wood Mackenzie warn cannot offset Hormuz disruption in the near term.

The market is left holding two contradictory data points from the same Monday session: a president signaling diplomatic breakthrough and a U.S. military operation that destroyed Iranian warships in the strait. Traders are pricing both, and the next move belongs to Tehran.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.


Let me know if you need a formatted version, summary, analysis, or anything else related to it.

JBizNews — Monday, May 25, 2026

A rare convergence of Jewish American religious leaders, civic organizations, business executives, and foreign diplomats gathered on Capitol Hill on May 19 during Jewish American Heritage Month to recognize Nobel laureate Dr. Harvey J. Alter — whose discovery of the hepatitis C virus and the screening protocols it spawned have saved millions of lives — underscoring the urgency of scientific preparation at a moment when the Bundibugyo strain of Ebola is spreading rapidly across the Democratic Republic of the Congo and Uganda, prompting major airlines to suspend or reduce service to affected regions.

The event, the annual Jewish American Heritage Month celebration organized by Ezra Friedlander’s Project Legacy, drew nine U.S. Senators, three U.S. Representatives, and ambassadors and trade ministers from Canada, Bahrain, Morocco, Egypt, Germany, and South Korea. The gathering was co-chaired by Malcolm Hoenlein, CEO Emeritus of the Conference of Presidents of Major American Jewish Organizations, and Eric J. Gertler, Executive Chairman of U.S. News & World Report. Held in the historic Kennedy Caucus Room of the Russell Senate Office Building, the event demonstrated the depth of Jewish American institutional reach across government, finance, philanthropy, religious life, and international commerce.

The timing is acute. As of May 24, the World Health Organization had recorded more than 1,000 suspected and confirmed Ebola cases and at least 231 deaths in the outbreak. Airlines including American Airlines, United Airlines, and Air France have suspended or sharply reduced flights to Kinshasa and other Central African hubs, citing operational and safety concerns. The flight suspensions are already disrupting trade and threatening to isolate the region from international commerce and medical supply chains.

The honorees — Dr. Alter, entrepreneur Elliott Broidy, and Rabbi David Baron — represented the breadth of Jewish American institutional contribution. Dr. Alter, the 2020 Nobel laureate in Physiology or Medicine for identifying the hepatitis C virus, embodied the Jewish American role in science and public health. His decades of work at the National Institutes of Health in the 1970s and 1980s proved that an unknown virus was driving post-transfusion hepatitis. The screening systems his research enabled have driven transfusion-transmitted hepatitis in the United States to near zero. His discovery spawned pharmaceutical franchises at Gilead Sciences, Merck, AbbVie, and Bristol Myers Squibb. Broidy, recipient of the Visionary Award, reflected the Jewish American entrepreneurial and philanthropic tradition. Rabbi David Baron of the Temple of the Arts in Beverly Hills, honored with the Creativity in the Jewish Community Award, represented the religious and cultural institutions anchoring the community’s identity.

The religious leadership present was notably diverse and unified. Rabbi Pini Dunner of Young Israel of Beverly Hills, Chairman of the Orthodox Jewish Chamber of Commerce West Coast, delivered remarks alongside Rabbi Mordechai Suchard of The Gateways Organization and Rabbi Levi Shemtov, Executive Vice President of American Friends of Lubavitch. This constellation — Orthodox, Modern Orthodox, and Lubavitch leadership appearing together on a Capitol Hill stage — demonstrated institutional cohesion across religious movements.

U.S. Senators Richard Blumenthal, John Fetterman, Tim Sheehy, John Hickenlooper, Elissa Slotkin, Ron Wyden, James Lankford, Jacky Rosen, and Pete Ricketts addressed the gathering, alongside Representatives Randi Fine, Ken Calvert, and Jeff Merkley. Senator Blumenthal emphasized that Dr. Alter could have monetized his hepatitis C discovery for enormous personal gain but instead released findings to the public-health system. Senator Fetterman delivered what attendees described as an unusually passionate bipartisan statement of support for the Jewish American community. Senator Sheehy framed scientific generosity as a uniquely American strength. The bipartisan presence — nine senators from both parties — signaled political consensus around the value of Jewish American institutional power.

Jewish American Heritage Month, observed each May since 2006, traces to 1980 when Congress designated April 21-28 as Jewish Heritage Week through conversations between Malcolm Hoenlein, President Ronald Reagan, and Nobel laureate Elie Wiesel. President George W. Bush expanded it to a full month of May in 2006, recognizing over 370 years of Jewish American contribution to science, business, law, and public service since 1654. The Weitzman National Museum of American Jewish History now stewards the observance with more than 200 organizations.

Ezra Friedlander, organizer of the event through Project Legacy, said: “This year’s honorees reflect a deep commitment to public service, innovation, philanthropy, and the fight against hatred and intolerance.”

The commercial dimension was substantial. Duvi Honig, Founder & CEO of the Orthodox Jewish Chamber of Commerce and co-founder and secretary of the Multicultural Business Coalition, who chaired World Trade Week NYC on Wednesday, spoke to the gathering’s purpose. “Building bridges through unity is what speaks to me most,” Honig said. “Each attendee walked away with new or reinforced relationships to help build a better tomorrow.” The ambassadors and trade ministers represented nations with which the United States maintains multi-billion-dollar trade flows in life sciences, defense, semiconductors, energy, agriculture, and finance.

Elliott Broidy, in accepting the Visionary Award, reflected on lessons from his parents about the responsibility that accompanies success. He praised Dr. Alter as an embodiment of tikkun olam — the Jewish concept of repairing the world — for identifying hepatitis C. Broidy framed the luncheon as a reaffirmation of shared responsibility to confront hatred and protect the values of tolerance, democracy, and human dignity at a moment when antisemitism has risen sharply.

The Capitol Hill gathering serves a dual purpose: honoring specific achievements, but also functioning as a high-level networking forum where ambassadors, senators, business leaders, and religious figures reinforce relationships that undergird international commerce, diplomatic coordination, and policy alignment. For the Jewish American community, the event demonstrates that institutional unity across Orthodox and non-Orthodox Judaism, business and nonprofit sectors, and civic and religious leadership remains a competitive advantage.

The recognition of Dr. Alter arrives as the global health system confronts the Ebola outbreak, making his innovation as a Jewish American leader who helped save millions of lives through epidemic-related medical breakthroughs even more meaningful amid the growing health and commercial disruption now unfolding. His career — patient, federally funded basic research conducted over decades for public good — produced breakthroughs that created entire pharmaceutical industries and prevention systems now viewed as essential global infrastructure. It also reflects the very purpose of Jewish American Heritage Month: recognizing the extraordinary contributions Jewish Americans have made to science, medicine, public service, innovation, and humanity as a whole.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

MARANELLO, Italy — Ferrari NV officially unveiled the Luce, its first fully electric production vehicle, marking the most dramatic transformation in the company’s modern history and signaling that even the world’s most iconic combustion-engine brand is now betting heavily on the future of electric performance.

The new four-door, four-seat electric supercar carries a starting price of approximately €550,000 ($640,000), making it the most expensive regular-production Ferrari ever introduced. The vehicle was developed through a five-year collaboration with LoveFrom, the design collective founded by former Apple design chief Sir Jony Ive, the architect behind products including the iPhone, iMac, Apple Watch, and iPod.

For Ferrari, the launch represents far more than a new model.

For decades, the Italian automaker insisted it would never fully abandon the emotional identity tied to internal-combustion engines. Ferrari CEO Benedetto Vigna reversed that philosophy last year, and the Luce now becomes the centerpiece of Ferrari’s long-term strategy to prove that luxury electric vehicles can command Ferrari-level prestige, pricing, and margins despite a broader slowdown in global EV demand.

The Luce — Italian for “light” or “illumination” — enters production immediately and sits above Ferrari’s current lineup, including the approximately $430,000 Purosangue SUV.

Under the hood — or more accurately beneath the chassis — Ferrari built one of the most technically ambitious electric drivetrains ever placed into a production vehicle.

The Luce uses:

  • Four electric motors
  • More than 1,000 horsepower
  • A 122-kWh battery pack
  • 0-to-60 mph in 2.5 seconds
  • Approximately 330 miles of range
  • An 800-volt electrical architecture
  • Advanced independent torque vectoring on all four wheels

Ferrari engineers said the platform delivers levels of handling precision impossible to achieve through traditional mechanical differentials.

The vehicle also introduces the largest wheel setup ever used on a production Ferrari, with 23-inch front wheels and 24-inch rear wheels.

But the headline of the launch is not just electrification.

It is design.

Ferrari granted an unusually high level of creative control to Ive and LoveFrom — something virtually unprecedented in Maranello’s history. The result is a dramatically minimalist Ferrari with smooth shell-like bodywork, floating aerodynamic elements, extensive glass integration, and an interior built around physical craftsmanship rather than touchscreen dominance.

The cabin includes:

  • Precision-machined aluminum controls
  • Custom OLED displays developed with Samsung Display
  • A steering wheel made from recycled aluminum
  • A Gorilla Glass key embedded with E Ink display technology

In a direct contrast to Tesla’s touchscreen-heavy interior philosophy, Ive openly criticized the industry trend toward removing physical controls from vehicles.

“The reason we developed touch for the iPhone was to solve a specific problem,” Jony Ive said during the launch. “I never would have used touch in a car for the main controls because it requires you to look away from the road.”

The comment immediately positioned the Luce not only as Ferrari’s first EV, but also as a philosophical counterpoint to the minimalist interface approach pioneered by Tesla.

The stakes for Ferrari are enormous.

The company currently sells only around 14,000 vehicles annually, yet consistently generates some of the highest profit margins in the automotive industry. By introducing the Luce as a full production model rather than a limited-edition showcase car, Ferrari is testing whether ultra-luxury buyers will embrace electric drivetrains at the very top of the market.

Competitors including Lamborghini and Aston Martin have delayed portions of their own EV rollouts amid cooling luxury EV demand and continued buyer attachment to traditional engine sound and mechanical driving feel.

Ferrari is betting that exclusivity, design prestige, and technological sophistication can overcome those concerns.

For LoveFrom, the project also marks the largest physical product collaboration in the firm’s history since Ive left Apple in 2019. The partnership gives Ferrari access to one of the most influential consumer-product designers of the modern era — a marketing and branding advantage few competitors can replicate.

Wall Street is watching closely.

Ferrari shares (NYSE: RACE) have significantly outperformed much of the global automotive sector over the last several years, supported by the company’s strict production discipline, long customer waitlists, and ultra-premium pricing strategy.

Analysts at firms including Morgan Stanley and Bernstein have already identified the Luce as one of Ferrari’s most important long-term growth drivers heading into 2027 and beyond.

The larger question now facing Ferrari is whether it can achieve something the broader EV market has struggled with:

Making electric power feel aspirational rather than compromised.

That test begins now.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
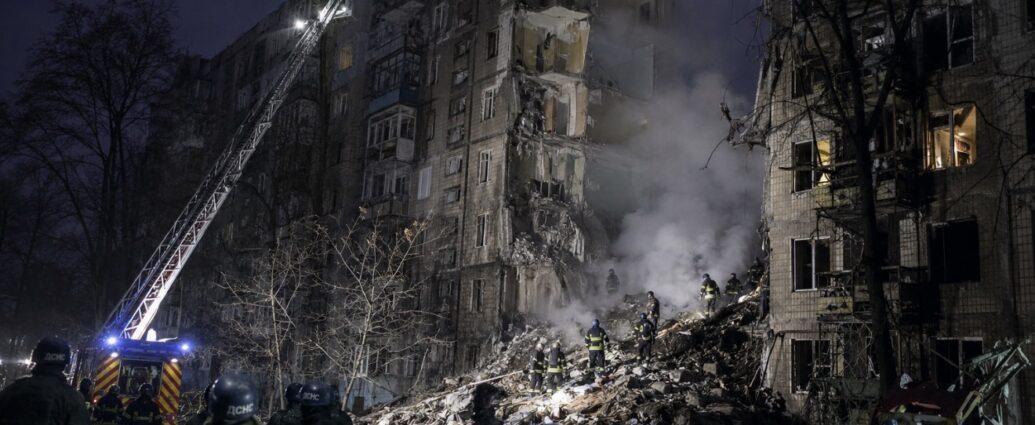
By JBizNews Desk

New York — May 25, 2026 — Manhattan’s commercial real estate market opened 2026 with strengthening demand for premium office space, declining vacancies in top-tier buildings and rising leasing activity across finance and technology corridors, directly challenging predictions that New York City would suffer a major corporate exodus following Mayor Zohran Mamdani’s election victory.

New first-quarter data compiled by JLL show leasing momentum accelerating in trophy Class A office product across Midtown Manhattan, Hudson Yards and parts of Downtown, with institutional landlords reporting tightening availability in the city’s strongest submarkets.

Separate market analysis published by Cushman & Wakefield this spring tracked similar trends, identifying rising absorption across premier Manhattan office assets while industrial demand continued strengthening throughout northern New Jersey’s logistics corridor tied to the Port of New York and New Jersey.

The data sharply undercut widespread predictions from segments of the financial press and political commentators who forecast that high-income residents, major employers and institutional capital would rapidly flee New York after Mamdani’s November election.

To date, the broad corporate retreat has not materialized in the leasing numbers, migration data or tax-revenue forecasts released so far in 2026.

The New York City Council’s December economic outlook projected fiscal-year 2026 and 2027 tax revenues above earlier Office of Management and Budget expectations, while the New York City Economic Development Corporation continues describing Manhattan as a magnet for younger educated workers and high-value employers.

The office market, however, is increasingly splitting into two entirely different realities.

Top-tier Class A buildings near major transit hubs are outperforming aggressively, with some premier towers effectively becoming waitlisted as financial firms, law firms and technology tenants compete for limited premium inventory.

Meanwhile, aging Class C office buildings continue deteriorating as viable commercial assets.

Industry executives now openly describe much of the older office inventory across Manhattan and the broader metropolitan area as functionally obsolete.

Executives surveyed earlier this year by New Jersey Business Magazine predicted large portions of the Class C market could disappear entirely within the next two years as properties migrate into residential conversion pipelines, light-industrial redevelopment projects or demolition plans.

That bifurcation is spreading across the region.

In New Jersey, Class A demand remains strongest in Newark, Jersey City, New Brunswick and the broader HELIX innovation corridor, where life-science, healthcare and institutional developments continue attracting tenants and capital.

South Jersey office inventory remains the weakest segment of the state’s office market, while Central Jersey is seeing more measured Class A expansion tied to pharmaceutical, logistics and technology employers.

Industrial real estate continues leading institutional investment flows across both sides of the Hudson River.

The Port Newark-Elizabeth Marine Terminal complex, Meadowlands logistics corridor and last-mile distribution hubs in Edison, Carteret and Linden remain among the strongest-performing industrial markets on the East Coast as e-commerce growth and reshoring strategies continue supporting warehouse demand.

Major institutional investors including Blackstone, Prologis, KKR and Brookfield Asset Management remain active buyers throughout the region’s industrial and multifamily sectors.

The macroeconomic backdrop has also become more supportive for commercial real estate than many analysts anticipated late last year.

Interest rates have moderated during the first half of 2026, while major financial institutions including JPMorgan Chase, Goldman Sachs, Morgan Stanley and Citigroup have tightened return-to-office mandates, increasing demand for high-quality office space close to transportation infrastructure and corporate amenities.

Capital markets have also stabilized.

Acquisition activity, refinancing volume and development financing have all improved materially year over year for institutional-quality projects, particularly in multifamily, logistics and top-tier office product.

The political risk premium that briefly entered New York commercial real estate pricing immediately after the mayoral election has therefore compressed substantially.

That does not mean concerns have disappeared.

Investors, landlords and corporate tenants remain closely focused on how the Mamdani administration handles fiscal policy, commercial taxation, the ongoing PTET credit debate and broader business regulation heading into the city’s fiscal 2027 budget cycle.

But for now, the leasing data tell a much different story than the one many expected six months ago.

Rather than empty towers and fleeing corporations, Manhattan’s strongest buildings are seeing rising competition for space.

The exodus narrative, at least so far, has run into a stubborn obstacle: the actual market.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 24, 2026 — The man responsible for managing the retirement savings of millions of Canadians just delivered one of the clearest warnings yet about the artificial-intelligence stock boom driving global markets higher.

John Graham, chief executive of CPP Investments, said Thursday that he is increasingly concerned U.S. equity markets have become too concentrated around a small group of artificial-intelligence winners whose valuations may be running ahead of business fundamentals.

The comments came as CPP Investments reported strong annual results. The pension giant, one of the world’s largest institutional investors, said assets climbed to approximately $793 billion, generating a 7.8% net annual return and an 8.8% annualized return over the past decade.

Most pension executives would have used the moment to celebrate performance.

Graham instead used it to caution investors.

He said CPP Investments remains “knowingly underweight” artificial-intelligence exposure within its U.S. equity portfolio because of what he described as growing concentration risk surrounding the market’s largest technology companies.

That stance has carried a cost.

The so-called Magnificent Seven technology stocks — including Nvidia Corp., Microsoft Corp., Amazon.com Inc., Meta Platforms Inc., and other AI-linked megacaps — have continued powering indexes toward record highs throughout 2026, leaving more defensive institutional investors trailing benchmark performance.

Graham acknowledged the underweight position has been “super painful” while markets continue rallying.

But he also framed the AI debate in unusually direct terms for a pension-fund chief executive.

“Technology can change the world and be overvalued,” Graham said. “It can be both.”

The statement captures the increasingly uncomfortable tension sitting underneath the AI boom now dominating global markets. Many institutional investors believe artificial intelligence will fundamentally reshape industries, corporate productivity, and economic growth over the next decade. The question is whether current stock prices already assume too much future success too quickly.

Graham said the fund is not attempting to predict a market crash or call the top of the AI cycle. Instead, CPP is positioning itself around uncertainty.

“We actually don’t know” whether a bubble is forming, he said.

That uncertainty has shaped how the Canadian pension giant is allocating capital. Rather than aggressively chasing the highest-profile AI software and semiconductor names, CPP Investments has increasingly focused on what Graham described as the “picks and shovels” behind the AI buildout — infrastructure assets such as power systems, energy generation, data centers, land, cooling systems, and transmission capacity.

The strategy reflects a broader institutional shift now emerging among some of the world’s largest long-term investors.

Regardless of which AI platforms ultimately dominate, the underlying infrastructure powering artificial intelligence is expected to require enormous amounts of electricity, computing capacity, physical real estate, and network connectivity. Pension funds increasingly view those assets as more stable and less dependent on speculative equity valuations.

Several major global retirement systems are now signaling similar concerns.

Australia’s Aware Super, which manages roughly A$210 billion, recently warned about “orange lights” appearing inside portions of the AI financing ecosystem, particularly around circular funding arrangements in which companies indirectly finance demand for each other’s services.

AustralianSuper, one of the country’s largest pension managers, has also indicated plans to reduce portions of its global equity exposure heading into the second half of 2026.

The caution stands in sharp contrast to broader market momentum.

The Dow Jones Industrial Average closed at a record high Thursday above 50,000. The S&P 500 remains near historic highs, driven largely by continued investor enthusiasm surrounding AI-related spending and earnings growth.

At the same time, valuation measures are becoming increasingly stretched.

The S&P 500’s cyclically adjusted price-to-earnings ratio, one of Wall Street’s longest-running valuation gauges, has climbed toward levels historically associated with elevated future downside risk. Several prominent investors and policymakers have begun publicly discussing bubble conditions.

Federal Reserve Governor Lisa Cook recently warned she would not be surprised by “outsized asset price declines” if investor expectations eventually disconnect from economic fundamentals.

Bridgewater Associates founder Ray Dalio has similarly described artificial intelligence as being in the “early stages of a bubble,” comparing current investor enthusiasm to earlier periods of speculative excess.

Still, there remains a strong bullish argument supporting current valuations.

Artificial-intelligence spending has become one of the most powerful growth engines inside the U.S. economy. Analysts estimate AI-related capital expenditures contributed materially to U.S. GDP growth throughout 2025, while many of the companies leading the boom continue posting exceptionally strong revenue and profit expansion.

Unlike portions of the late-1990s dot-com bubble, today’s dominant AI companies are already highly profitable businesses generating enormous cash flow.

The debate, increasingly, is not whether AI changes the world.

It is whether the stock market has already priced in too much of that transformation too early.

That distinction explains why pension funds like CPP Investments are becoming more selective even while remaining invested overall. Graham and others are not abandoning markets. They are quietly shifting exposure toward assets they believe can survive multiple economic scenarios rather than relying entirely on continued multiple expansion in a handful of technology giants.

For long-duration investors managing retirement liabilities decades into the future, protecting against concentration risk matters more than outperforming over a single quarter or year.

And that may be the deeper message behind Graham’s warning.

The institutions with the longest investment horizons in the world are becoming more cautious precisely as public-market optimism reaches its highest levels.

That gap between rising market euphoria and increasingly defensive pension positioning is becoming one of the defining stories underneath the AI rally itself.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 24, 2026 — For decades, one rule defined global finance during geopolitical crises: when war broke out, investors bought U.S. Treasury bonds.

That rule is now being tested in ways Wall Street has not seen in a generation.

Instead of rallying during the Iran conflict, the Treasury market has sold off sharply. Bond prices have fallen, yields have surged, and the world’s largest safe-haven asset class is suddenly behaving less like a shelter and more like an inflation trade.

The reason is straightforward but deeply consequential: investors no longer fear recession first. They fear inflation first.

The 10-year U.S. Treasury yield, the benchmark interest rate underpinning nearly every major borrowing cost in the American economy, climbed to roughly 4.60% this week after briefly touching a 16-month high near 4.7%. Since the Iran war escalated in late February, yields have risen approximately 70 basis points — an unusually large move for sovereign debt markets.

Historically, wars triggered the opposite reaction. Investors typically fled into Treasuries during global instability, pushing yields lower as bond prices rose. That relationship held through the Gulf War, the Iraq invasion, the September 11 attacks, the European debt crisis, and much of the pandemic era.

This time, the inflation shock is overpowering the traditional safety trade.

Energy markets sit at the center of the disruption. A substantial share of global oil and fertilizer shipments move through the Strait of Hormuz, and continued instability surrounding the corridor has amplified fears of prolonged supply disruptions and structurally higher energy costs.

The economic consequences are already spreading globally. Airlines across Europe have reduced or rerouted flights due to elevated fuel costs and regional security concerns. American consumers have spent tens of billions more on gasoline this year compared with prewar expectations. Agricultural markets across Asia are dealing with rising fertilizer uncertainty that could ultimately feed back into global food inflation.

Every one of those pressures flows into the same market calculation: persistent inflation reduces the Federal Reserve’s ability to lower interest rates.

That concern is now clearly visible in inflation-expectation markets. The one-year Treasury breakeven inflation rate has climbed above 3%, while medium-term inflation expectations remain materially above the Federal Reserve’s formal 2% target.

Translated into everyday terms, bond investors increasingly believe the inflation environment of the early 2020s is not fully gone.

That matters far beyond Wall Street.

The 10-year Treasury yield directly influences mortgage rates, auto financing, corporate borrowing costs, commercial real estate lending, and the federal government’s own debt-service expenses. When yields rise and remain elevated, borrowing costs throughout the economy reset higher.

The housing market has already absorbed much of the impact. Freddie Mac’s average 30-year mortgage rate has remained above 7% for most of 2026, contributing to one of the slowest housing turnover environments in years. Home affordability has deteriorated sharply, refinancing activity has collapsed, and existing homeowners remain reluctant to sell properties tied to older low-rate mortgages.

The Federal Reserve has also become increasingly constrained.

Minutes from the Fed’s latest policy meeting showed policymakers remain concerned that inflation could reaccelerate if energy prices remain elevated through the second half of the year. Interest-rate futures markets now reflect rising expectations that the central bank may need to maintain restrictive policy longer than investors anticipated only months ago.

At the start of 2026, traders debated how quickly the Fed might begin easing. The conversation has shifted toward whether another rate increase could eventually become necessary.

The pressure extends beyond inflation alone.

Governments worldwide are issuing record amounts of debt at the same moment central banks are no longer acting as dominant buyers. According to OECD estimates, member governments issued roughly $17 trillion in sovereign debt during 2025, with issuance expected to rise further in 2026. U.S. federal debt has now crossed $39 trillion.

That creates a structural supply problem inside global bond markets: more debt must be absorbed by private investors precisely when inflation uncertainty is increasing the compensation investors demand to hold long-duration bonds.

Foreign reserve managers are also behaving differently than in past crises.

For much of the modern era, geopolitical instability automatically strengthened demand for U.S. Treasuries and the dollar. While the dollar remains dominant globally, reserve diversification has accelerated in recent years. Gold prices have repeatedly reached record highs during the Iran conflict, while several foreign central banks have gradually reduced reliance on long-dated U.S. government debt.

China’s sovereign bond market, notably, has remained comparatively stable during the conflict, underscoring how fragmented global capital flows have become compared with prior decades.

Markets increasingly view the path of oil prices as the key variable determining whether Treasuries can stabilize.

President Donald Trump has repeatedly argued that a negotiated Iran framework capable of restoring normal energy flows through Hormuz would rapidly ease inflation pressures. Administration officials have signaled that discussions remain active, though no finalized agreement has yet emerged.

If energy prices retreat materially, inflation expectations could ease and Treasury markets may begin behaving more traditionally again, with yields stabilizing or falling as geopolitical risk subsides.

If not, bond investors appear increasingly willing to price a world defined by structurally higher inflation, tighter monetary policy, and permanently elevated borrowing costs.

What makes the moment historically significant is not simply the Iran war itself.

It is the possibility that the foundational assumption underpinning modern finance — that U.S. Treasuries automatically function as the ultimate global refuge during crises — is no longer operating as reliably as it once did.

For now, the bond market’s message is clear: inflation risk has become powerful enough to overpower fear itself.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

Elon Musk stands to collect roughly $1.8 trillion in equity awards across Space Exploration Technologies Corp. and Tesla Inc. if his companies hit the production, market-value, and operational targets attached to his stacked compensation deals — a sum larger than the annual economic output of nearly every country on Earth except the United States, China, Germany, Japan, India, and the United Kingdom. The disclosure surfaced in SpaceX’s S-1 filing submitted to the Securities and Exchange Commission last Wednesday ahead of what is expected to become the largest initial public offering in history.

To put $1.8 trillion into perspective, it approaches the annual GDP of Spain ($1.8 trillion) and exceeds the economies of South Korea ($1.95 trillion), Mexico ($1.85 trillion), Russia ($2.1 trillion), Brazil ($2.2 trillion), and Italy ($2.4 trillion). It also rivals much of the economic output of France ($3.2 trillion). Were Musk to fully realize the payout, his personal fortune would exceed the combined GDP of every country in Central America, nearly all nations across Africa, and much of Eastern Europe outside Russia. No private executive in modern history has ever been attached to compensation opportunities at this scale.

The S-1 filing by Space Exploration Technologies Corp., led by founder and CEO Elon Musk, revealed that Musk could receive more than 1.3 billion shares if the company reaches specific market capitalization and operational milestones. The SpaceX portion alone is estimated to be worth approximately $760 billion at the highest valuation targets, according to calculations tied to the Bloomberg Billionaires Index. Combined with Tesla’s restored 2018 compensation package and the company’s 2025 “Mars Shot” incentive structure, Musk’s potential payout becomes the first executive compensation framework in history to cross the trillion-dollar threshold.

The Tesla package operates over a 10-year horizon. Under the structure, the first earned tranches vest around 2033 for milestones achieved during the first half of the plan, while additional tranches vest around 2035 if Tesla reaches targets during years six through ten. Full vesting would require Tesla’s market capitalization to climb from roughly $1.54 trillion today to approximately $8.5 trillion, alongside cumulative delivery of 20 million vehicles, operation of one million robotaxis, deployment of one million Optimus humanoid robots, and generation of up to $400 billion in core profits.

The SpaceX compensation package has no fixed timeline. According to the filing, Musk must remain employed at SpaceX, where he has reportedly maintained a nominal salary of $54,080 annually since 2019. One of the most ambitious requirements calls for the establishment of a permanent human colony on Mars containing at least one million inhabitants. Another tranche would vest only if SpaceX successfully operates space-based data centers capable of at least 100 terawatts of compute capacity — equivalent to roughly 100,000 one-gigawatt nuclear reactors operating simultaneously.

Scientists remain skeptical. Paul Sutter, a NASA advisor and research scientist at Johns Hopkins University, previously wrote that Musk’s Mars timeline “doesn’t correspond to a real plan.”

In practical terms, Musk is likely to begin receiving Tesla-related equity first, potentially beginning in the 2033 vesting period, while the larger open-ended SpaceX awards remain dependent on technological breakthroughs and interplanetary colonization efforts that many scientists believe remain decades away — if achievable at all.

According to reports surrounding the anticipated IPO, SpaceX is targeting a valuation near $1.75 trillion, which alone would place the company among the ten most valuable corporations in the world immediately upon listing. At that valuation, Musk’s current pre-package ownership stake in SpaceX could already exceed $700 billion before any additional performance awards vest.

“The awards are obviously unprecedented and it’s kind of hard to wrap your brain around it,” said Jason Schloetzer, associate professor of accounting at Georgetown University’s McDonough School of Business.

The broader impact on Musk’s wealth would be historic. Forbes currently estimates Musk’s net worth near $811 billion, while the Bloomberg Billionaires Index places it closer to $636 billion. Musk also maintains significant ownership stakes in Neuralink Corp. and The Boring Company, alongside his holdings in Tesla and SpaceX.

If every milestone across Tesla and SpaceX were ultimately achieved, Musk’s combined business empire — including public, private, and contingent equity — could reach between $2.6 trillion and $2.8 trillion, a figure approaching the economic output of India and rivaling that of France.

The compensation structures are also raising major governance concerns ahead of the SpaceX listing. The filing confirms Musk controls approximately 85% of voting power, and the company plans to utilize governance exemptions that reduce certain independent oversight requirements commonly applied to newly public companies. The filing further states that Musk “can only be removed” from leadership positions through votes controlled by holders of super-voting shares that he himself controls.

That governance concentration has already drawn criticism from institutional investors. Norges Bank Investment Management, which oversees Norway’s roughly $2 trillion sovereign wealth fund, previously opposed Tesla’s compensation structure, citing the size of the award, dilution concerns, and concentration of executive power.

For Wall Street banks, the underwriting opportunity itself is historic. A SpaceX IPO valued near $1.75 trillion would eclipse the scale of Saudi Aramco’s 2019 public offering and instantly rank among the largest listings in financial history. Firms including Goldman Sachs, Morgan Stanley, and JPMorgan Chase are reportedly competing for lead underwriting roles.

The larger question now confronting corporate boards and compensation committees is whether the Musk model — compensation packages measured in trillions and tied to outcomes ranging from autonomous transportation to planetary colonization — becomes the new benchmark for founder-led companies or remains a once-in-history anomaly.

For now, no other executive on Earth operates under contracts remotely approaching Musk’s scale. Whether he ultimately collects depends not only on electric vehicles, artificial intelligence, and robotics — but potentially on humanity’s ability to establish life on another planet.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
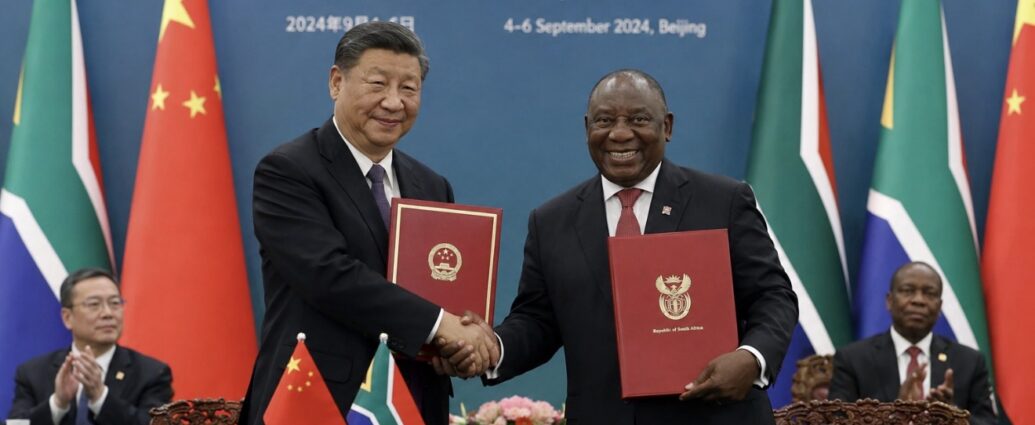
By JBizNews Desk

VATICAN CITY — May 25, 2026 — Pope Leo XIV declared Monday that artificial intelligence must be “disarmed” to protect humanity from its dangers, escalating a global debate that could reshape how the world’s largest technology companies build, deploy, regulate, and profit from the fastest-growing industry of the decade.

The warning came in Magnifica Humanitas, the first encyclical issued by Leo XIV and the highest-authority pastoral document a pope can release. The roughly 42,000-word document was unveiled at the Vatican’s Synod Hall alongside Christopher Olah, co-founder of Anthropic and head of the company’s interpretability research team — a striking signal that the Vatican intends to play an active role in the global AI policy fight rather than simply commenting from the sidelines.

“To disarm does not mean rejecting technology, but preventing it from dominating humanity,” Pope Leo XIV wrote in the document, arguing that artificial intelligence “must be disarmed, welcoming and accessible.” The pope warned against what he described as an escalating “economic and cognitive arms race” among governments and major technology companies competing to dominate the AI sector.

The encyclical immediately places the Vatican on a collision course with much of Silicon Valley and the increasingly aggressive AI expansion strategy unfolding across the United States. Leo XIV, the first American pope, has already publicly clashed with the Trump administration over immigration policy and broader deregulatory approaches to emerging technologies. Monday’s encyclical deepened that divide by openly criticizing concentrated AI ownership and calling for stronger international oversight frameworks.

The pope’s language lands at a sensitive moment for the AI industry. The global AI market has rapidly consolidated around a handful of dominant players, including Microsoft-backed OpenAI, Amazon-backed Anthropic, Google DeepMind, Meta Platforms, and Elon Musk’s xAI, with investors pouring hundreds of billions of dollars into data centers, chips, infrastructure, and military applications tied to artificial intelligence.

Leo warned that AI ownership “concentrated in the hands of a few” risks creating dangerous imbalances of power over information, economics, labor, and human behavior. He called for independent international legal structures governing AI development and argued that data — the core fuel behind modern AI systems — should not be treated solely as a private commercial asset.

The Vatican’s position aligns more closely with Europe’s regulatory approach, including the European Union’s AI Act, than with Washington’s current market-driven strategy. Earlier this year, President Donald Trump signed executive actions significantly reducing federal AI oversight requirements in an effort to accelerate U.S. competitiveness against China.

The pontiff reserved especially strong criticism for military AI systems and autonomous weapons, declaring that traditional “just war” theory is increasingly obsolete in an era where machines can independently identify and attack targets with minimal human oversight.

“The growing ease with which autonomous weapons systems can be deployed makes war more feasible and less subject to human control,” the encyclical stated.

The comments arrive as defense technology companies tied to AI and autonomous systems — including Palantir Technologies, Anduril Industries, RTX, and Lockheed Martin — have benefited from surging military spending tied to the ongoing U.S.-Iran conflict and broader geopolitical tensions. Investors have pushed many defense-AI firms to record valuations amid expectations that autonomous systems will become central to future warfare.

Leo also widened the debate beyond military use, attacking the broader labor and economic structure underpinning the AI boom. The encyclical criticized exploitative data-labeling workforces, the use of copyrighted materials in AI training, and the extraction of rare-earth minerals needed for advanced chips and computing infrastructure.

In one of the document’s most striking passages, the pope connected modern AI supply chains to historical systems of exploitation and colonialism, warning against what he called “new forms of slavery” emerging through data extraction, labor outsourcing, and resource dependency.

The remarks carry major implications for the media and entertainment industries, where lawsuits over AI training data are rapidly escalating. The New York Times remains in active litigation against OpenAI and Microsoft over copyrighted content, while companies including Disney and Universal have pursued legal action against AI image-generation firms.

By publicly endorsing stronger consent and compensation standards, the Vatican strengthened growing global pressure to force AI developers into licensing agreements that could significantly increase costs across the industry.

For investors, the encyclical may not immediately move markets, but analysts increasingly view regulation, copyright exposure, labor scrutiny, and reputational pressure as major long-term risks to AI profitability. With approximately 1.4 billion Catholics worldwide and deep political influence across Europe, Latin America, Africa, and parts of Asia, the Vatican’s intervention could shape public policy conversations well beyond religious circles.

Leo XIV’s decision to make AI the centerpiece of his first encyclical signals that the Catholic Church intends to become an organized and sustained voice in the global AI debate — not simply a moral observer.

For executives in Silicon Valley, Wall Street, and Washington, Magnifica Humanitas may ultimately prove less significant as theology and more important as an early framework for the next generation of global AI regulation.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Federal Bureau of Investigation’s Boston field office has just announced, that it has dismantled an India-based call center fraud operation that targeted elderly Americans through fake tech support scams, while two U.S. technology executives who helped route the scam calls have pleaded guilty to federal charges.

The case closes out a six-year investigation that has now produced convictions involving seven people across the United States and India — and highlights how a multibillion-dollar global scam industry continues draining retirement savings from older Americans.

The two U.S. executives identified by the FBI are Adam Young and Harrison Gevirtz, who served as chief executive officer and chief strategy officer of a call-tracking and analytics company that prosecutors say knowingly helped route scam calls from India to victims in the United States. According to federal prosecutors, the pair learned their customers were operating fraudulent tech support schemes but failed to report the activity between 2017 and April 2022.

Both men are scheduled to be sentenced on June 16, 2026.

“What the CEO and CSO of this well-known call tracking and analytics company did was downright despicable,” said Ted E. Docks, special agent in charge of the FBI’s Boston division. “By their own admission, they willfully profited from telemarketing and tech support scammers, here and abroad, who preyed on the elderly, exploited the vulnerable, and drained victims of their life savings and peace of mind.”

Federal authorities say the India-based scammers posed as representatives from companies such as Microsoft, Amazon, and government agencies, convincing victims their computers or bank accounts had been compromised. Victims were then pressured into sending money through gift cards, wire transfers, or cryptocurrency.

The five India-based defendants previously convicted in the case include Sahil Narang, Chirag Sachdeva, Abrar Anjum, and Manish Kumar, along with a former employee of the U.S. call-routing company. Prosecutors said the network defrauded Americans of millions of dollars, primarily targeting elderly victims.

The case reflects a much larger problem. According to the FBI’s Internet Crime Complaint Center (IC3), Americans lost roughly $2.1 billion to tech support scams in 2025 alone. Elderly Americans accounted for a disproportionate share of those losses.

Data from the Federal Trade Commission show Americans over age 60 lost $214 million in business and government impersonation scams involving losses between $10,000 and $100,000 during 2024. Victims reporting losses above $100,000 collectively lost another $445 million.

Older Americans are especially vulnerable because scammers often target retirees with savings accounts, home equity, or retirement funds. Fraud experts say many victims are manipulated through fear, confusion, and isolation.

The scams themselves have become highly organized businesses. Authorities earlier this year shut down three additional India-based call centers tied to nearly $49 million in losses involving more than 660 U.S. victims. Those operations were dismantled with assistance from India’s Central Bureau of Investigation after cooperation between U.S. and Indian law enforcement agencies intensified.

For the American technology industry, the case sends a warning well beyond one company.

Call-routing software, cloud phone systems, analytics tools, and customer-service platforms are legitimate multibillion-dollar businesses used daily by companies across the economy. Firms including Twilio, RingCentral, Five9, Cisco Systems, Microsoft, NICE Ltd., and Genesys provide communications infrastructure that powers customer support operations worldwide.

Federal prosecutors are now signaling that technology providers may face criminal exposure if they knowingly allow their systems to facilitate fraud.

That shift is drawing close attention from compliance officers and legal departments across the telecom and software industries, particularly companies involved in call routing, online advertising, customer analytics, and payment processing.

Banks and retailers are also deeply exposed. Fraud proceeds are often moved through Western Union, MoneyGram, gift cards sold at major retailers, and increasingly through cryptocurrency exchanges such as Coinbase, Kraken, and Binance.US.

Retailers including Walmart, Target, and Amazon have introduced warning signs and employee training programs aimed at helping consumers identify gift-card scams before money is lost. Financial institutions have also increased monitoring for suspicious transfers involving elderly customers.

The scams are creating broader economic consequences as well. AARP has repeatedly warned that elder fraud is becoming both a financial and public health issue. Victims often suffer depression, stress, and long-term financial insecurity after losing retirement savings.

For India, the reputational stakes are significant. The country’s business-process outsourcing industry generates more than $280 billion annually and employs millions of workers through legitimate companies such as Infosys, Tata Consultancy Services, Wipro, HCL Technologies, and Tech Mahindra.

Indian authorities have stepped up enforcement in recent years under pressure from Washington, but scam operations continue resurfacing because of low operating costs, high dollar-based profits, and historically inconsistent prosecutions.

The case also fits into the Trump administration’s broader focus on elder fraud enforcement and closer law-enforcement cooperation with the government of Prime Minister Narendra Modi. Attorney General Pam Bondi has made consumer fraud and elder exploitation a priority issue for the Department of Justice.

For ordinary Americans, investigators say the warning signs remain simple: unexpected calls claiming to be from tech support, the IRS, Social Security, Amazon, or a bank should immediately raise suspicion — especially if payment is requested through gift cards, wire transfers, or cryptocurrency.

The FBI urges victims to report scams through its IC3.gov reporting portal.

The broader reality is sobering. The money Americans lost to tech support scams last year alone exceeds the annual economic output of some small countries. And while this investigation shut down one network, authorities acknowledge that new scam operations continue appearing almost as quickly as old ones disappear.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Volvo Group said that it will pay $197 million to settle a California investigation into heavy-duty diesel truck engines that regulators said emitted more pollution than allowed under state rules.

The settlement, announced jointly by the California Air Resources Board (CARB) and Volvo, covers more than 10,000 heavy-duty diesel engines sold in California between the 2010 and 2016 model years. Regulators said Volvo failed to properly disclose certain emissions-control software systems that affected how the engines handled pollution under different driving conditions.

California officials stressed that the case is not comparable to the intentional “cheat device” scandal that engulfed Volkswagen in 2015. Instead, the dispute centered on software disclosure and emissions calibration issues. CARB said Volvo cooperated fully with the investigation and acted “transparently and in good faith.”

Volvo said the settlement does not include any admission of wrongdoing.

The money will be split several ways. Volvo will pay $13 million in civil penalties, contribute $71 million to California’s Air Pollution Control Fund, spend $108 million on emissions-reduction projects across the state, and reimburse roughly $5 million in investigative costs. The company also agreed to provide software updates and extended warranty coverage for approximately 7,200 trucks still operating in California.

For Volvo, the financial hit is meaningful but manageable. The Sweden-based truckmaker said it will book the full amount as a second-quarter charge when it reports earnings on July 17. About $89 million of the impact will hit cash flow immediately, while the rest will be spread over the next five years.

The settlement involves Volvo Group, the commercial truck and equipment company that owns Volvo Trucks, Mack Trucks, Renault Trucks, and UD Trucks. It is separate from Volvo Cars, the passenger-car company owned by China’s Geely Holding Group.

The case highlights how powerful California has become in shaping the future of the trucking industry. The state has some of the strictest vehicle emissions rules in the world, and truckmakers that want access to California’s massive freight market must comply with CARB standards. The ports of Los Angeles and Long Beach together handle more than 40% of U.S. container imports, making California impossible for major truck manufacturers to ignore.

At the center of the dispute were “auxiliary emission control devices,” essentially software systems that adjust engine behavior depending on factors like temperature, altitude, and driving load. California rules require manufacturers to fully disclose how those systems work. Regulators said Volvo’s disclosures were incomplete and that some engine configurations exceeded permitted pollution limits.

The settlement lands as the trucking industry faces mounting pressure to move toward cleaner vehicles. California’s Advanced Clean Trucks rule requires manufacturers to steadily increase sales of zero-emission trucks through 2035, pushing companies including Volvo, Daimler Truck, Paccar, Navistar, and Tesla to accelerate electric and hydrogen-powered truck development.

For trucking companies, stricter emissions rules increasingly mean higher costs. Fleet operators including J.B. Hunt, Knight-Swift, Schneider National, Old Dominion, and XPO depend heavily on manufacturers like Volvo for their truck fleets. Software updates, warranty work, and compliance changes can affect maintenance schedules, fuel economy, and operating costs — especially for smaller trucking firms already dealing with tight profit margins.

Wall Street largely took the settlement in stride. Volvo Group generated roughly $48 billion in revenue and nearly $5 billion in net income last year, making the penalty financially absorbable. Analysts at Morgan Stanley, JPMorgan Chase, and UBS have repeatedly warned investors that emissions compliance costs are becoming a permanent expense across the global trucking sector.

The settlement also sends a message to the rest of the industry: California regulators are willing to negotiate with companies that cooperate, but enforcement pressure is only increasing. In recent years, Daimler Truck reached a separate emissions settlement with CARB, while diesel-engine giant Cummins agreed to pay roughly $2 billion in penalties tied to emissions violations involving Ram pickup trucks built by Stellantis.

For Volvo chief executive Martin Lundstedt, resolving the case removes a regulatory cloud hanging over the company ahead of a critical earnings cycle. For California regulators, the agreement adds another major enforcement victory as the state pushes aggressively toward a lower-emissions freight system.

For consumers, the bigger takeaway is simpler: the cost of meeting tougher environmental rules is increasingly becoming part of the price of moving goods across America.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
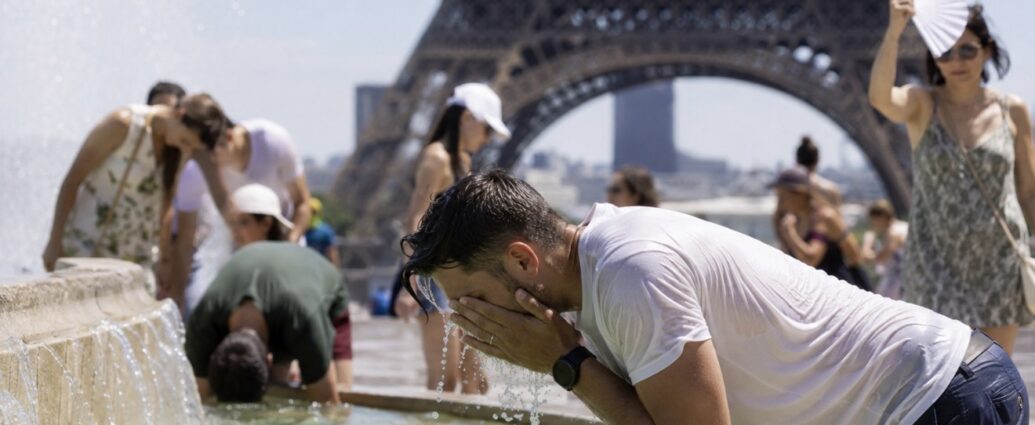
By JBizNews Desk

NEW YORK, May 24, 2026 — The late Charlie Munger’s blunt warning about the American healthcare system is aging uncomfortably well.

The longtime Berkshire Hathaway vice chairman argued years ago that if insured families still had to pay thousands of dollars just to have a baby, then they did not really have insurance at all. Today, the numbers suggest the problem has only grown worse.

According to the Peterson-KFF Health System Tracker, using data from the Merative MarketScan Encounter Database, the average pregnancy, childbirth and postpartum care bill for women covered by employer-sponsored insurance now reaches $20,416, with families paying an average of $2,743 out of pocket even after insurance.

That does not include many of the costs that come afterward.

Newborn care adds another $5,820 in average medical spending during the baby’s first months, while cumulative healthcare costs for mother and child during the first two years now approach roughly $37,000 per family, according to KFF analysis. Families directly pay more than $4,200 of that amount themselves.

Munger saw the problem years ago.

In a widely discussed 2019 Yahoo Finance interview, Munger argued that a young couple facing a $5,000 deductible to deliver a baby effectively held an insurance product that failed its most basic purpose.

“If you have a policy with a huge deductible and you still can’t afford childbirth,” Munger said at the time, “what exactly are you insured for?”

The Berkshire executive went further, describing the broader U.S. healthcare system as something that had “grown like Topsy by accident” through decades of overlapping government intervention, private-sector inefficiency and distorted incentives.

His criticism was not ideological as much as economic.

Munger repeatedly pointed to Singapore as a model, arguing the country achieved better health outcomes at a fraction of America’s cost through mandatory medical savings accounts, universal coverage and strict cost controls. In his view, America’s healthcare system had become a hidden tax on workers, businesses and manufacturers that quietly weakened U.S. competitiveness.

The gap has only widened since then.

Federal out-of-pocket maximums under Affordable Care Act-compliant plans climbed to $9,200 for individuals and $18,400 for families in 2025. In 2026, those caps rise again to $10,600 and $21,200, according to federal guidance.

For many families, childbirth alone is enough to hit those limits.

The average allowed charge for a Cesarean-section birth now reaches roughly $28,998, compared with $15,712 for a vaginal delivery, according to Health Care Cost Institute and KFF data. About 32% of U.S. births now occur by C-section.

Many parents also get caught by timing.

Pregnancies often span two insurance-plan years, meaning families can hit deductibles and out-of-pocket maximums twice during a single pregnancy and delivery cycle.

The financial pressure arrives at exactly the moment household budgets are already under strain.

One parent often takes unpaid leave or reduced work hours while childcare, housing and basic living costs continue climbing. Industry analysts note that pregnancy remains the single most common cause of hospitalization for Americans covered by employer-sponsored insurance, making maternity costs one of the clearest stress points in the modern benefits system.

The issue has started attracting bipartisan political attention.

Lawmakers introduced legislation in 2025 that would eliminate cost-sharing for maternity care under employer-sponsored insurance plans, similar to how preventive services are currently treated under the Affordable Care Act. The proposal has not advanced, but its introduction reflected growing concern that high-deductible insurance models have shifted too much financial risk onto middle-class families.

Major corporations have spent years trying to address the problem themselves.

Companies including Walmart, JPMorgan Chase, and other large employers have experimented with direct healthcare contracting, bundled maternity-payment systems and employer-run clinics in an effort to reduce healthcare spending. So far, none have meaningfully changed the broader national cost trajectory.

U.S. healthcare spending surpassed 17% of GDP in 2024 — by far the highest level in the developed world — even as American life expectancy continues to lag behind many peer nations.

For Wall Street and corporate America, Munger’s argument still resonates because healthcare costs ripple through nearly every part of the economy.

Rising medical expenses feed directly into wage pressure, consumer spending patterns, government deficits, insurance premiums and employer labor costs. Families paying thousands of dollars out of pocket to have children are not just facing a healthcare issue — they are facing a broader affordability problem affecting everything from home purchases to retirement savings.

That was the core of Munger’s warning.

The question he posed in 2019 remains unresolved in 2026:

If insurance does not meaningfully protect families from the cost of having a child, what exactly is it protecting them from?

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
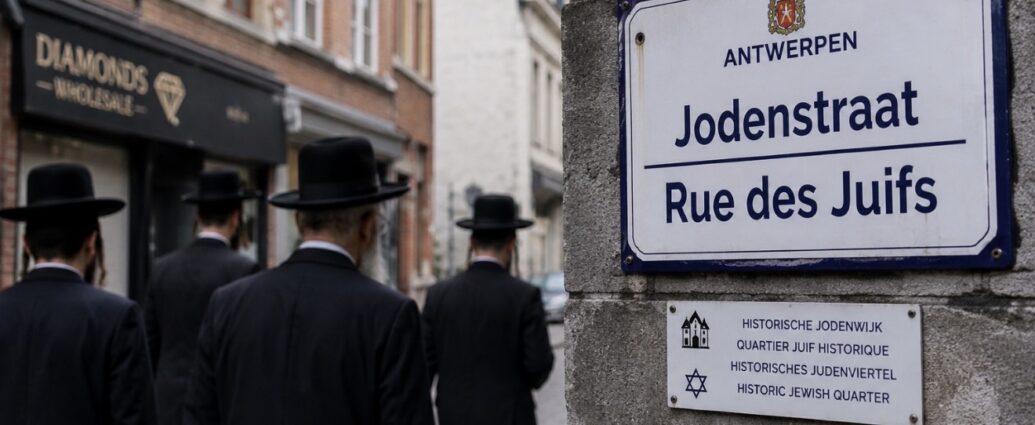
President Donald Trump abruptly postponed the signing of a long-anticipated executive order on artificial-intelligence oversight Thursday afternoon, telling reporters in the Oval Office that he yanked the order off his desk because he feared it could slow the United States in its race against China to dominate the technology.

“I didn’t like what I was seeing,” Trump told reporters during an unrelated event with Environmental Protection Agency Administrator Lee Zeldin, according to remarks confirmed by multiple outlets present in the room. “We’re leading China, we’re leading everybody, and I don’t want to do anything that’s going to get in the way of that lead. I really thought that could have been a blocker.”

The signing ceremony had been scheduled for later in the afternoon, and the White House had already sent invitations to executives from leading AI companies. Representatives from Anthropic, OpenAI, Google, xAI and major industry trade groups had been briefed earlier in the week on the contents of the order. Trump added that AI is “causing tremendous good” and reiterated that he did not want federal action to interfere with American competitiveness.

The shelved order would have established a voluntary government review process for so-called frontier AI models before public release, giving federal agencies a window of up to 90 days to evaluate the most powerful new systems for cybersecurity and national-security risks. The framework was reportedly modeled in part on the United Kingdom’s approach, which distributes safety responsibilities across multiple agencies, with the Treasury Department taking a lead role in a proposed clearinghouse for identifying and patching flaws in unreleased AI systems.

The trigger for the policy push, according to people briefed on the discussions, was the emergence of a new generation of cybersecurity-capable models — including Anthropic’s Mythos system, which the company has declined to release publicly because of its ability to identify and exploit software vulnerabilities at unprecedented speed. OpenAI has acknowledged that its newest system has similarly powerful capabilities. Both companies have been quietly partnering with banks, hospital systems and federal agencies to test defensive uses of the technology rather than open the models to the broader public.

The decision to pull the order marks a significant victory for the business-aligned wing of the Trump administration, led by White House AI and Crypto Czar David Sacks, the venture capitalist and Craft Ventures founder who has consistently pressed for a light federal touch on AI development. Sacks has argued publicly that heavy compliance regimes would crush smaller AI startups and that the United States needs a single national framework rather than a patchwork of rules. In December, Trump signed a separate executive order directing the Justice Department to challenge state-level AI laws deemed onerous to the industry — an order Sacks helped shape.

For the AI industry, the postponement removes — for now — what would have been the most significant federal oversight measure since the administration revoked former President Joe Biden’s 2023 AI executive order on its first day in office. That earlier Biden directive had required leading AI developers to share safety test results with the federal government. Since then, the Trump administration’s posture has been almost exclusively pro-deployment, including scrapping the so-called AI Diffusion framework on chip exports and announcing the Stargate infrastructure project alongside OpenAI and partners.

The reversal also lands in a sensitive market moment. Investors had been watching the planned order closely because of its potential impact on Nvidia, the dominant supplier of graphics processors used to train frontier models, as well as on Meta Platforms, Alphabet and Microsoft, all of which have heavy exposure to the pace of AI model releases. A mandated pre-release review window of up to 90 days would have lengthened product cycles across the ecosystem and complicated the open-weight release strategy that Meta has used for its Llama family of models.

Critics inside the administration’s own coalition had pushed back hard in recent days. Parts of the MAGA movement that distrust large technology companies argued that any voluntary federal framework, even one rooted in cybersecurity, would calcify into a regulatory regime that favors incumbents over smaller competitors. Sacks himself faced renewed scrutiny in December over ethics waivers tied to more than 400 investments his firm holds in technology companies with AI exposure, a controversy that has shadowed his role in shaping the now-delayed order.

A White House spokesperson, asked for further comment on the timing or substance of the postponement, referred reporters to Trump’s public remarks. The president did not give a new target date for the signing, and it remains unclear whether the order will be reworked, narrowed to focus strictly on cybersecurity, or shelved entirely. The order has already been pushed back several times since planning began earlier this spring.

For now, the message from the Oval Office is the one that Silicon Valley wanted to hear: federal Washington is once again standing aside while the largest AI labs continue to set the pace.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews — May 25, 2026

Abu Dhabi National Oil Co. is quietly ferrying oil and gas cargoes out of the Persian Gulf using its own fleet, threading vessels past both the Iranian navy and U.S. warships to reach energy-starved buyers, according to vessel-tracking data and people with direct knowledge of the operations cited Sunday by Bloomberg. The state producer, known as Adnoc, has leaned on “dark transits” — sailing the Strait of Hormuz with transponders switched off — to emerge as the most successful exporter operating out of the Middle East nearly three months into the U.S.-Iran war that has paralyzed the world’s most important oil chokepoint.

The disclosure marks a turning point in a conflict that has frozen roughly a fifth of global liquefied natural gas supply and a sizable share of seaborne crude since late February. According to IMF PortWatch data, only two vessels transited Hormuz on May 17, the latest published day, against a pre-crisis baseline of roughly 95 per day — leaving the waterway functionally closed even as Tehran signals a conditional reopening tied to stalled peace talks with Washington.

Adnoc’s edge, traders and shipping executives say, lies in fleet control. While most Gulf producers and Western commodity houses lease tonnage and are hemmed in by owners’ risk appetite, Adnoc has been moving cargoes on vessels controlled by Navig8, majority owned by its shipping and logistics arm, and by joint-venture partner Wanhua Chemical Group. The shipments span crude, clean petroleum products and gas carriers. After clearing Hormuz, vessels typically transfer cargo to client tankers in safer waters or sail directly to India’s west coast before returning to the Gulf for fresh loadings — a short-haul rotation that maximizes proximity to the strait. Adnoc’s Upper Zakum crude loads at Zirku Island, while naphtha and LPG move from the Ruwais mega-refinery.

“With the UAE leaving OPEC and finding ways to send ships through Hormuz in the dark, Adnoc has been willing to take more risks in order to get their oil out,” said Matt Wright, senior freight analyst at Kpler. The UAE officially exited the Organization of the Petroleum Exporting Countries on May 1, freeing Adnoc from production discipline at precisely the moment its storage was filling up and its independent commercial posture was hardening.

Qatar, the world’s third-largest LNG supplier, is now following a similar playbook. The Al Rayyan LNG carrier was spotted north of Muscat, Oman, on Monday after clearing Hormuz en route to top customer China, ship-tracking data reviewed by Bloomberg show. The vessel had stopped broadcasting its signal around May 22 while idling near QatarEnergy’s Ras Laffan export plant. A second Qatari tanker loaded in late March also transited the strait between Sunday and Monday. The covert runs follow the May 10 transit of the Al Kharaitiyat, Qatar’s first successful LNG shipment through Hormuz since the war began. QatarEnergy had previously declared force majeure on contracted deliveries after Iranian strikes forced Ras Laffan offline in March.

Antonia Syn, gas and LNG research analyst at Rystad Energy, said the divergence between the two producers reflects strategy as much as luck. “Adnoc hasn’t declared force majeure, unlike QatarEnergy,” she said, noting that invoking the clause “formally reduces commercial pressure to attempt risky transits, and Adnoc appears determined to avoid fully conceding that gulf LNG is stranded.” The Emirati carriers currently slipping through the strait are older vessels of the same generation as sister tankers scrapped last year, Syn added — a sign Adnoc is putting its most expendable hulls on the front line.

The volumes remain a fraction of pre-war flows. Kpler and satellite-analysis firm SynMax data show Adnoc exported at least 6 million barrels of crude on four tankers from inside-Gulf terminals in April, against pre-war shipments that ran several times that level. Pre-conflict, the Persian Gulf routinely sent three LNG cargoes a day through Hormuz. Saudi Aramco has rerouted shipments entirely through the Red Sea, while Iraq and Kuwait have either halted sales or slashed prices to lure buyers willing to absorb the risk.

War-risk premiums and freight rates have surged in tandem. VLCC rates from the Gulf to China jumped 24% in a single session earlier in the conflict to $1.67 per barrel, the steepest one-day move of the year, Kpler reported. Insurers have layered additional war-risk charges on every cargo, and electronic interference around Iran’s Bandar Abbas port — flagged by the U.S.-led Joint Maritime Information Centre — has disrupted navigation systems, pushing the Baltic and International Maritime Council to advise members to avoid the Arabian Gulf entirely where possible.

For buyers in China, India, Japan and Pakistan, the dark-transit cargoes represent the thin lifeline keeping Asian LNG and crude inventories from buckling. For Adnoc, they represent something more strategic: a demonstration that an OPEC defector with its own ships, its own refineries and its own appetite for risk can keep the lights on in customer countries when its larger neighbors cannot. The longer Hormuz stays effectively shut, the more that capability looks like a structural shift in Gulf energy power.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
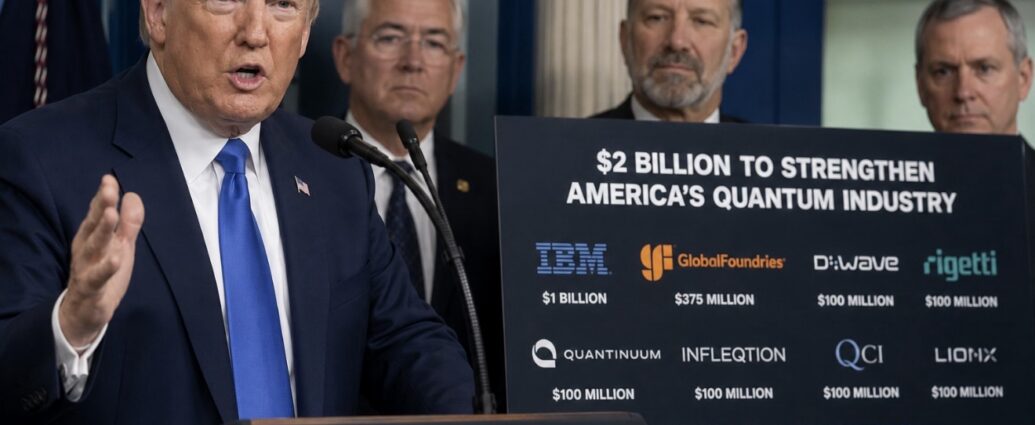
May 25, 2026 — A wave of new immigration barriers and a stalled entry-level hiring market are pushing tens of thousands of foreign graduates of U.S. universities toward the exits, with students, career counselors and labor-market data all pointing to the sharpest erosion of the post-graduation work pipeline in a generation.

The Federal Reserve Bank of New York reported on May 5 that the unemployment rate for recent college graduates ages 22 to 27 held at 5.6% through the first quarter of 2026 — well above the 3.1% rate for all college graduates and the 4.2% rate for all workers — as hiring across white-collar sectors continues slowing amid corporate cost-cutting, artificial-intelligence automation and mounting economic uncertainty.

At the same time, a Trump administration proclamation signed September 19, 2025, imposing a $100,000 fee on new H-1B petitions filed from abroad has dramatically narrowed the work-visa runway international students traditionally relied on after graduation.

Together, the two forces are reshaping one of America’s most important talent pipelines.

Approximately 84,000 international students are projected to earn bachelor’s degrees from U.S. universities this spring, according to an Economic Innovation Group analysis of National Center for Education Statistics data. Layered on top are roughly 306,000 master’s candidates and 153,000 doctoral students counted in the latest Open Doors survey sponsored by the U.S. Department of State.

Most are graduating into what the New York Fed describes as a “low-hire, low-fire” labor market — one where companies are slowing recruitment, preserving cash and reducing entry-level openings even as layoffs moderate.

For international students, the slowdown is colliding with visa restrictions at exactly the worst moment.

Erica Ford, an international career development coach at Cornell University who advises roughly 300 foreign students annually, told CNBC that STEM graduates who previously expected multiple offers are now relieved to secure even one. Doctoral candidates are pivoting away from academic research toward industry roles as university funding tightens, while nonprofit employers once considered viable alternatives are shedding staff and freezing hiring.

The pressure is especially severe because international graduates operate under visa deadlines domestic students do not face.

President Donald Trump’s September H-1B overhaul fundamentally changed the economics of sponsorship. The proclamation requires employers to pay a $100,000 surcharge on new H-1B petitions filed for workers outside the United States while shifting the system toward a wage-weighted lottery that favors higher-paid applicants over the previous random selection process.

U.S. Citizenship and Immigration Services later clarified that the fee does not apply to F-1 students adjusting status from inside the country — a carve-out that has slightly improved odds for graduates already working under Optional Practical Training programs because fewer overseas applicants are entering the system.

But the relief is narrow.

The wage-weighted structure still favors senior-level, highly paid positions, leaving entry-level international graduates competing for a shrinking pool of sponsorship-capable employers. Reid Hoffman, the LinkedIn co-founder and venture investor, has publicly urged the administration to create lower-fee exemptions for startups, warning that the current structure effectively pushes high-skilled immigrants toward only the largest corporations capable of absorbing the cost.

Recruiters across startup, venture-backed and small-business sectors report hiring pipelines drying up almost immediately after the fee took effect.

The student experience increasingly reflects that collapse.

Sid Chakravarthy, a 21-year-old mathematics and economics graduate of Boston University raised in Dubai, told The New York Times he submitted more than 700 job applications, receiving automatic rejections for roughly the first 500 despite meeting qualifications for many of the roles. Sakshi Patel, who completed a master’s degree last year and is pursuing finance positions, described interview processes that abruptly stall once sponsorship requirements surface.

Career offices at major research universities report a sharp increase in international students simultaneously applying for jobs in Canada, the United Kingdom, Germany and Ireland — countries now aggressively marketing simpler post-study immigration pathways to graduates who once overwhelmingly prioritized the United States.

The enrollment numbers are already beginning to reflect the shift.

International graduate enrollment fell roughly 6% — nearly 10,000 students — during the autumn 2025 term, according to National Student Clearinghouse Research Center data released in January. It marked the first decline in three years after international graduate enrollment surged more than 50% between 2020 and 2024.

Meanwhile, the U.S. State Department issued 15% fewer student visas globally between October 2024 and March 2025. The sharpest decline came from India — historically the single largest source of U.S. graduate students — where visa issuance dropped 43.5%.

NAFSA: Association of International Educators now projects a meaningful contraction in the number of jobs created or supported by international students during the 2025-2026 academic year after the category peaked in 2023-2024.

Business groups, universities and immigration attorneys warn the broader consequences could extend well beyond campus enrollment.

For decades, international graduates have formed a critical talent base for American technology firms, research labs, financial institutions, healthcare systems and startup ecosystems. A growing combination of H-1B costs, visa uncertainty, security reviews, processing delays and weak entry-level hiring conditions now risks redirecting portions of that talent pipeline toward competing economies.

The administration argues the overhaul protects American workers, raises wage standards and prevents employers from undercutting domestic labor markets through lower-cost foreign hiring.

But critics warn the long-term effect may be to weaken one of America’s most successful competitive advantages: attracting and retaining global talent.

Eva Yao, founder of Colorado-based Flari Tech and herself a former H-1B visa holder, told CNBC she now advises foreign graduates to focus almost exclusively on large corporations with the financial scale to absorb the new fees and compliance costs — guidance that runs directly against decades of policy designed to encourage entrepreneurial immigration and startup formation.

For now, the path remains open.

But it is becoming narrower, slower, more expensive and significantly more selective than at any point in the post-1990 era.

And a generation of international graduates is beginning to recalibrate its future around that reality.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 25, 2026 — If you want to understand where Meta Platforms is spending its money, look at Alexandr Wang.

The 28-year-old founder of Scale AI is the executive Mark Zuckerberg has placed at the center of the biggest transformation in Meta’s history — and one of the most expensive bets in Silicon Valley. Wang is Meta’s first-ever Chief AI Officer, the head of a newly created division called Meta Superintelligence Labs, and the youngest Chief AI Officer at any Fortune 50 company. Nearly everything Meta is now doing in artificial intelligence runs through him.

The deal that brought him into the company stunned Wall Street.

In June 2025, Zuckerberg agreed to pay roughly $14.3 billion for a 49% stake in Scale AI, the data-labeling company Wang started from a Y Combinator house in 2016. The price bought Meta nearly half the company — but more importantly, it brought Wang directly into Meta’s executive ranks.

He entered as Chief AI Officer, immediately took control of a brand-new AI division built around him, and was given authority over Meta’s top AI leadership teams.

The assignment is massive.

Meta expects to spend between $115 billion and $135 billion in 2026 alone, much of it tied to AI infrastructure, chips and data centers. Zuckerberg has repeatedly told investors the company’s mission is to build what he calls “personal superintelligence for everyone.”

Wang is the executive responsible for turning that slogan into a real business.

His rise reads like a Silicon Valley movie script.

Born in New Mexico to Chinese immigrant physicists, Wang left MIT at 19 to build Scale AI alongside co-founder Lucy Guo. The pair reportedly slept on air mattresses while trying to grow the business. Within less than a decade, Scale AI became one of the most important hidden companies in the technology industry, supplying the labeled data used to train AI systems across Silicon Valley.

OpenAI, Microsoft, Google and Meta all became customers.

When Zuckerberg concluded Meta was falling behind in the AI race, he did not simply invest in Scale AI — he hired the founder running it.

Since arriving at Meta, Wang has moved aggressively.

He dismantled Meta’s older AGI Foundations structure, reorganized the company’s AI operations into four new groups under Meta Superintelligence Labs, and made one of the boldest strategic shifts in the company’s modern history: pulling back from Meta’s open-source AI identity.

For years, Meta’s Llama models had become the company’s flagship AI product and a centerpiece of Zuckerberg’s open-source strategy. Under Wang, Meta pivoted sharply. On April 8, 2026, the company released Muse Spark, its first major proprietary foundation model under the new structure.

The decision signaled a dramatic shift away from Meta’s prior philosophy and immediately sparked debate across Silicon Valley.

Not everyone inside Meta agreed with Wang’s direction.

Yann LeCun, the Turing Award-winning AI pioneer who led Meta’s FAIR research division for years, departed the company in late 2025 after publicly criticizing Wang as “young and inexperienced.” Months later, LeCun raised more than $1 billion for his own AI startup, setting up what many inside the industry now view as a philosophical rivalry over the future of artificial intelligence.

Reports have also suggested tension between Wang and Zuckerberg himself.

The Financial Times reported in late 2025 that Wang privately complained about the level of oversight Zuckerberg maintained over AI operations. Then in March 2026, new reports claimed Zuckerberg had quietly reduced Wang’s authority by creating a parallel AI engineering organization under Meta CTO Andrew Bosworth and executive Maher Saba.

Meta publicly rejected the idea.

Company spokesperson Andy Stone responded on X that Wang “still runs MSL” and continues to hold “growing, not waning influence” inside the company.

For investors, however, the internal politics matter less than the broader direction of Meta itself.

On May 20, Meta announced roughly 8,000 layoffs even as the company continued accelerating its AI spending plans. The contrast captured Zuckerberg’s current strategy clearly: reduce labor costs where possible while pouring tens of billions of dollars into artificial intelligence infrastructure.

To Meta’s leadership, AI is no longer a side business. It is the future of the company.

The financial stakes are enormous.

Meta’s advertising machine — powered by Facebook, Instagram, WhatsApp and Messenger — generated roughly $46.6 billion in quarterly ad revenue last year while serving more than 3.5 billion daily users across its platforms.

If Wang successfully uses AI to improve ad targeting, recommendation systems, creator tools and user engagement, the return on Meta’s investment could be enormous. If he fails, the company will have spent more building its AI strategy than the total value of many public corporations.

For now, Zuckerberg appears fully committed.

The Meta CEO reportedly spends between five and 10 hours a week personally coding AI-related projects and is said to be building his own internal AI assistant to help manage the company more efficiently.

The message to Meta employees and investors has become increasingly clear: artificial intelligence is no longer just another Meta initiative.

It is the company’s entire future.

And the person Zuckerberg has chosen to lead that future is Alexandr Wang.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 24, 2026 — A new cancer therapy being developed by Merck & Co. and China’s Sichuan Kelun-Biotech has produced one of the strongest oncology trial results of the year, cutting the risk of tumor progression or death by as much as 65% in a late-stage lung cancer study ahead of the annual American Society of Clinical Oncology conference.

The drug, known as sac-TMT, belongs to one of the fastest-growing and most closely watched categories in cancer medicine: antibody-drug conjugates, or ADCs. These therapies are designed to function like precision-guided weapons against tumors — using antibodies to identify cancer cells before delivering targeted chemotherapy payloads directly into them while limiting damage to surrounding healthy tissue.

The latest results come from a Phase 3 trial known as OptiTROP-Lung05, where researchers tested sac-TMT in combination with Keytruda, Merck’s blockbuster immunotherapy drug, against Keytruda alone in patients with advanced non-small-cell lung cancer.

According to data scheduled for presentation at the ASCO annual meeting in Chicago beginning May 29, the combination achieved what researchers described as a statistically significant and clinically meaningful improvement in progression-free survival, meaning patients lived substantially longer without their cancer worsening.

The results add to a growing string of major wins for sac-TMT across multiple tumor types.

In a separate late-stage breast cancer study last year, the drug reduced the risk of progression or death by roughly 65% compared with conventional chemotherapy. Another lung cancer study showed the therapy lowered the risk of death by approximately 40% in heavily pretreated patients whose disease had stopped responding to prior therapies.

The consistency across different cancers and treatment settings is one of the reasons sac-TMT is increasingly viewed as one of the most important pipeline assets inside Merck’s future oncology strategy.

The drug targets a protein called TROP2, which appears on the surface of many common solid tumors, including lung, breast, ovarian, and several gastrointestinal cancers. Because the target exists across multiple cancer types, successful TROP2 therapies potentially represent multibillion-dollar franchises capable of treating millions of patients globally.

For Merck, the timing is critical.

The company’s dominant cancer medicine, Keytruda, generates more than $25 billion annually but faces major patent expirations beginning later this decade. Investors and analysts have spent years asking how Merck intends to replace that revenue stream once generic competition emerges.

Sac-TMT is rapidly becoming one of the clearest answers.

Merck is currently running at least five global Phase 3 lung cancer trials involving the drug, alongside additional studies in breast, ovarian, and other solid tumors. The company originally secured worldwide rights outside greater China through a massive licensing agreement signed with Kelun-Biotech in 2022 worth roughly $1.4 billion upfront and potentially up to $9 billion in milestone payments.

At the time, some investors questioned whether the deal was overly aggressive.

The latest ASCO data is making the transaction look increasingly strategic.

The lung cancer findings may also represent a broader scientific milestone beyond Merck itself.

According to researchers involved in the study, OptiTROP-Lung05 is believed to be the first successful Phase 3 trial showing that combining an antibody-drug conjugate with an immune checkpoint inhibitor improves first-line lung cancer outcomes versus immunotherapy alone.

That matters because pharmaceutical companies worldwide have been racing to determine whether ADCs can work synergistically with immune therapies like Keytruda, Opdivo, and Tecentriq.

If successful, the combination approach could fundamentally reshape standard treatment regimens across several major cancers.

There are important limitations investors and physicians are watching closely.

The OptiTROP-Lung05 study was conducted entirely in China and compared sac-TMT plus Keytruda against Keytruda alone. In the United States, frontline lung cancer treatment more commonly includes Keytruda combined with chemotherapy rather than as a standalone therapy.

As a result, the trial itself is unlikely to directly support U.S. regulatory approval.

Instead, analysts are focused on ongoing multinational studies testing sac-TMT against the broader global standard of care. Those results, expected over the next 18 to 24 months, will likely determine whether the therapy becomes a worldwide commercial breakthrough.

Even so, regulatory momentum is already building.

Kelun-Biotech has filed for approval in China, where regulators have accepted the application for review, while the U.S. Food and Drug Administration has already granted sac-TMT breakthrough therapy designation for certain lung cancer settings, potentially accelerating future review timelines.

The implications extend beyond one company or one drug.

Antibody-drug conjugates were once viewed as a niche technology area plagued by toxicity problems and repeated late-stage clinical failures. That perception changed dramatically after the success of AstraZeneca and Daiichi Sankyo’s Enhertu, which transformed treatment expectations in breast cancer.

Now nearly every major pharmaceutical company is racing to establish leadership in ADCs.

Pfizer, Roche, AstraZeneca, Gilead Sciences, and Merck have collectively committed tens of billions of dollars toward acquisitions, licensing deals, and research partnerships tied to the category.

For patients, the stakes are far more personal than market share.

Lung cancer remains the deadliest form of cancer globally, causing approximately 1.8 million deaths annually worldwide. Survival rates remain stubbornly low despite years of advances in immunotherapy and targeted medicine.

A treatment capable of significantly delaying tumor progression — particularly in earlier lines of therapy — represents the kind of advance oncologists believe could gradually shift long-term survival curves over time.

For Merck investors, the central question is becoming increasingly straightforward.

The company no longer simply needs to defend Keytruda.

It needs to prove it can build the next generation of oncology leadership before Keytruda’s patent clock expires.

And based on the latest data emerging ahead of ASCO, sac-TMT is beginning to look like one of the company’s strongest candidates to do exactly that.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Target delivered a first-quarter result Wednesday that few on Wall Street expected, posting earnings per share of $1.71 against the $1.46 consensus estimate, revenue of $25.44 billion against expectations of $24.66 billion, and the company’s first positive comparable-sales quarter in more than a year.

Comparable sales rose 5.6%, store traffic increased 4.4%, and chief executive Michael Fiddelke raised the company’s full-year outlook for both revenue and earnings, signaling growing confidence that Target’s turnaround strategy is beginning to gain traction.

The surprise was not only the earnings beat but the breadth of the improvement. Target said sales increased across all six major merchandise categories, led by beauty, hardlines and food. Both digital and in-store traffic improved, and the gains were spread across geographic regions and demographic groups.

“First quarter financial results were stronger than expected, providing encouraging early signs that our clarified strategy is resonating with our guests and driving broad-based growth across our business,” Fiddelke said in the earnings release.

Speaking with analysts after the report, Fiddelke said the company is seeing consumers respond positively in categories where Target emphasizes “style, design, and value,” particularly across its private-label brands.

The company raised its full-year sales growth forecast to approximately 4%, double the roughly 2% growth guidance it issued earlier this year. Operating margin is now expected to exceed the 4.6% adjusted margin Target posted in 2025, while earnings per share are projected to land near the high end of the previously guided $7.50 to $8.50 range — above the $8.14 Wall Street consensus.

The results stand in sharp contrast to the broader narrative that the American consumer is slowing sharply. Lowe’s described the housing market this week as the weakest since the financial crisis, while home-improvement spending remains under pressure from elevated mortgage rates. Walmart has continued leaning aggressively on price competition. Home Depot has relied heavily on professional contractor demand.

Target, which had been viewed as the laggard among major big-box retailers for nearly two years, suddenly delivered numbers that looked far closer to Costco than to its own recent history.

Gross margin expanded to 29.0% from 28.2% a year earlier, helped by supply-chain efficiencies, higher advertising revenue from the company’s Roundel media business and lower markdown activity. Selling, general and administrative expenses also increased, which initially pressured the stock in premarket trading despite the earnings beat, though shares later stabilized.

Fiddelke’s strategy has focused heavily on repositioning Target around what management calls “busy families,” emphasizing private-label brands such as Cat & Jack, A New Day and Threshold while reducing less productive inventory categories.

The company has also continued prioritizing digital fulfillment, particularly same-day Drive Up services, which management sees as a major long-term growth driver.

The broader economic takeaway from the quarter is more nuanced than a simple retail rebound. Target’s customer base skews somewhat more affluent and suburban than the national average, and much of the strength came from discretionary categories such as beauty, apparel and home décor.

That reinforces the “split-economy” thesis that has increasingly defined corporate earnings over the last 18 months: higher-income consumers continue spending relatively freely, while lower-income households remain under pressure from inflation, housing costs and elevated borrowing rates.

For investors who had largely written off Target after five consecutive quarters of negative comparable sales, the earnings report marks the first meaningful evidence that Fiddelke’s turnaround strategy may be working.

The next challenge will come during the summer months, particularly if oil prices remain above $100 per barrel and rising gasoline costs begin to eat into discretionary household budgets.

Still, management’s decision to project sales growth in every quarter of 2026 suggests Target believes the momentum is durable rather than temporary.

JBizNews Desk

© 2026 JBizNews. All rights reserved.

The U.S. housing market is showing its clearest signs of stabilization in nearly four years, according to two major industry reports released Thursday, May 21, 2026. Redfin said home purchase cancellations declined slightly in April, while Realtor.com reported contract signings climbed to their strongest level in three years — a sign that both buyers and sellers are slowly returning to the market after a prolonged housing slowdown.

Redfin said just over 47,000 home purchase agreements fell through in April, equal to 13.4% of homes that went under contract during the month. That was slightly lower than March and tied with January for the lowest cancellation rate since September 2024.

At the same time, Realtor.com’s Spring 2026 Housing Market Progress Report found contract signings rose 4.5% year-over-year in April, marking the strongest annual increase since 2022.

Taken together, the reports suggest the housing market may finally be finding balance after several difficult years shaped by high mortgage rates, affordability pressures, and economic uncertainty.

“We’re seeing some buyers cancel purchase agreements, but no more than usual, and when buyers do back out, it’s typically because of post-inspection repair costs and appraisals,” said Timothy Hourigan, a Redfin Premier agent in Syracuse, New York.

For buyers, the market is beginning to feel more manageable.

Sellers who spent much of 2023 and 2024 pricing homes aggressively are increasingly adjusting expectations. More homes are being listed closer to realistic market value from the beginning, reducing the number of deals collapsing after inspections or financing negotiations.

Mortgage-rate stability has also helped.

While rates remain elevated compared with pandemic-era lows, buyers are adapting to the new environment. The average 30-year fixed mortgage rate fell for several weeks in April before rebounding modestly in May as inflation and geopolitical tensions pushed bond yields higher again.

Industry analysts say stable rates matter almost as much as lower rates because buyers gain confidence when financing costs stop swinging wildly week to week.

The recovery is not happening evenly across the country.

The strongest momentum is currently concentrated in the Midwest.

According to Realtor.com, Kansas City posted a 12.5% increase in new listings alongside a 20.7% jump in contract signings. Louisville saw listings rise 13.6% while contract signings climbed 18.9%. Indianapolis, Columbus, and Cincinnati also showed strong buyer and seller activity simultaneously.

Across the 50 largest U.S. metropolitan markets, 34 cities recorded higher contract signings this year compared with the same period in 2025.

The Sun Belt tells a slightly different story.

Markets such as Phoenix, Austin, Jacksonville, and parts of Florida are seeing contract signings improve even while new listings decline. Analysts say that is largely because home prices in those markets have already corrected significantly over the past 18 months, finally attracting buyers back into the market.

In Phoenix, new listings dipped slightly while contract signings rose more than 8%. Austin saw listings fall but buyer activity rise nearly 8% as well.

The cancellation picture also varies sharply by city.

Atlanta currently has the highest cancellation rate among major U.S. markets, with nearly 1 in 5 home contracts failing to close in April. Other high-cancellation markets include San Antonio, Jacksonville, and parts of Florida, where affordability pressure and insurance costs continue affecting buyers.

Meanwhile, San Francisco posted the lowest cancellation rate in the country, helped partly by renewed demand tied to the artificial intelligence technology boom and a rebound in high-income hiring.

For buyers, the market now offers more negotiating power than at any point in years.

In many markets, sellers are increasingly agreeing to price reductions, repair credits, and closing-cost assistance in order to keep deals together. Buyers are also regaining the ability to include inspection contingencies and financing protections — terms that largely disappeared during the ultra-competitive housing frenzy of 2021 and early 2022.

For sellers, the message is becoming clearer as well: homes priced realistically are still selling, while overpriced homes are sitting longer and attracting weaker offers.

The improving stability is also important for mortgage lenders and real estate companies.

When home deals collapse, lenders lose money on underwriting, appraisals, staffing, and processing costs. Stabilizing contract completion rates help companies including Rocket Mortgage, United Wholesale Mortgage, loanDepot, Guild Mortgage, and major bank lenders improve operational efficiency.

Real estate brokerages and platforms including Zillow, Redfin, Compass, eXp World Holdings, and Anywhere Real Estate also benefit when transaction volumes increase after several difficult years for the industry.

Nationally, housing inventory continues improving gradually.

New listings are now roughly 22% above the lows reached in 2023, though supply remains well below pre-pandemic levels in many regions. Analysts say the market is no longer deteriorating — it is slowly normalizing.

The housing market still looks very different from the boom years of 2021 and early 2022, when bidding wars, waived inspections, and all-cash offers dominated the market. Mortgage rates remain elevated, affordability remains challenging, and many first-time buyers are still struggling with down payments and monthly payment costs.

But for the first time in years, both buyers and sellers are beginning to move again instead of waiting on the sidelines.

For everyday Americans considering buying or selling a home, the message from the latest data is relatively simple: inventory is improving, sellers are negotiating again, and the market is becoming more balanced than it has been in years.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 24, 2026 — Japan’s Nikkei 225 crossed 65,000 for the first time in history Monday while the Dow Jones Industrial Average held above 50,000 and oil prices fell sharply on hopes the Strait of Hormuz may reopen soon — a combination that would have sounded almost impossible during the 2008 financial crisis, when soaring oil prices and collapsing financial markets nearly broke the global economy.

The Nikkei surged past the 65,000 mark in early Asia trading as Brent crude fell more than 4% to below $99 a barrel and West Texas Intermediate dropped toward $92 after President Donald Trump said negotiations with Iran were “proceeding in an orderly and constructive manner.” Trump also said he instructed negotiators “not to rush into a deal” because “time is on our side,” while keeping his threat of renewed military strikes against Iran on the table if talks fail.

The Dow sat above 50,000 after Friday’s record close at 50,579.70, while the S&P 500 closed at 7,473.47 and the Nasdaq Composite ended at 26,343.97 — all near historic highs despite a Middle East war that has kept global oil markets under extreme stress for nearly three months.

For most investors and consumers, the obvious question is simple: how?

The world in 2008 looked nothing like the world today. That September, Lehman Brothers collapsed. Bear Stearns had already failed. AIG, Fannie Mae and Freddie Mac were taken over by the U.S. government. Citigroup and Bank of America survived only on federal lifelines. The Dow crashed below 6,600. Oil had touched nearly $147 a barrel that July before collapsing as the global economy froze. Credit markets seized. Home values evaporated. Unemployment doubled. And the consensus view, voiced from Davos to Washington, was that American financial dominance was finished, that emerging markets would lead the next era, and that the U.S. consumer was permanently broken.

If anyone had told a trader in October 2008 — staring at a 6,500 Dow and $147 oil still ringing in their ears — that 18 years later the Dow would be above 50,000, the Nikkei would be at 65,000, oil would be elevated again on a new Middle East war, and markets would be hitting records anyway, that trader would not have believed it. Nobody would have. The world that produced today’s prices had to be built, piece by piece, and most of the construction happened quietly.

The U.S. transformation started with energy. In 2008, the United States was the world’s largest oil importer, sending hundreds of billions of dollars overseas every year to pay for crude. The shale revolution changed that completely. New drilling and fracking technology unlocked the Permian Basin in Texas, the Bakken in North Dakota, the Marcellus in Pennsylvania, and the Eagle Ford in south Texas. By 2018 the U.S. had become the world’s largest oil producer. By 2020 it had become a net energy exporter. Today, when Brent trades at $99, much of that money flows to ExxonMobil, Chevron, ConocoPhillips, Pioneer Natural Resources and hundreds of independent American producers — not to OPEC. In 2008 a $100 oil price drained the U.S. economy. In 2026 it is closer to a wash.

The second transformation was the rebuilding of the banking system. The 2008 crash was not really about oil. It was about leverage. American banks had stacked a pyramid of mortgage-backed securities on top of subprime loans, and when housing turned, the whole credit system collapsed. After the crisis, the Dodd-Frank Act, the Federal Reserve’s annual stress tests, and tighter international capital rules forced banks to hold far more capital and far less risk. Today JPMorgan Chase, Bank of America, Citigroup, Goldman Sachs, Morgan Stanley and Wells Fargo are among the strongest-capitalized banks in the world. Energy shocks now hurt margins. They do not detonate the financial system.

The third transformation was the rise of the technology economy. The companies leading the Dow and the S&P 500 today are not the companies that led them in 2008. General Motors went bankrupt. General Electric was broken up. AIG, Citigroup, Bank of America and Kraft were removed from the Dow or restructured almost beyond recognition. In their place came Apple, Microsoft, Nvidia — added to the Dow in November 2024 — Amazon, added in February 2024, plus Visa, Salesforce, and UnitedHealth. These are software-margin businesses with very little direct exposure to the price of oil. Nvidia, Microsoft, Apple, Alphabet, Amazon, Meta Platforms and Broadcom alone now make up roughly a third of the S&P 500’s market capitalization, and they are growing earnings on a structural AI capital-spending wave that has no real 2008 parallel. Meta has committed to $115 billion to $135 billion in 2026 capital expenditures, almost all of it on AI data centers. That kind of spending becomes someone else’s revenue — and most of it flows straight back into the U.S. corporate sector.

The fourth transformation is the economy underneath all of it. The U.S. economy of 2008 was still heavily industrial. The U.S. economy of 2026 is roughly 80% services. Software, healthcare, financial services, entertainment, professional services — none of them care much about the price of crude. A barrel of oil at $100 is a meaningful input cost for an airline, a chemical company or a trucker. It is a rounding error for a software company billing $50,000 per seat or an asset manager charging fees on $5 trillion in AUM.

Asia’s transformation runs in parallel — and the Nikkei story is the clearest example. For most of the period after 2008, Japan was written off. The country’s stock market spent more than three decades trying to climb back from its 1989 bubble peak of 38,915. It did not break that record until 2024. The consensus view was that Japan was structurally finished — aging population, deflationary economy, frozen corporate culture, government debt over 250% of GDP. The country was a global cautionary tale.

Then the rebuild happened, also quietly. The Tokyo Stock Exchange forced listed companies to improve return on equity, unwind cross-shareholdings, and treat shareholders as actual owners — a corporate governance revolution that took a decade to play out and is still going. Warren Buffett’s Berkshire Hathaway publicly invested in Mitsubishi Corp., Mitsui & Co., Sumitomo Corp., Itochu Corp. and Marubeni Corp., signaling to the world that Japanese trading houses were undervalued cash machines. A weaker yen turbocharged Japanese exporter earnings. And then artificial intelligence arrived — and Japan turned out to own essential pieces of the AI supply chain.

Japanese companies supply the equipment, materials and precision components that make modern AI chips possible. Tokyo Electron, Advantest, Disco Corp., Lasertec, Shin-Etsu Chemical, SUMCO, Fujikura and Furukawa Electric are now essential vendors to Nvidia, TSMC, Samsung Electronics and the broader global semiconductor industry. The Nikkei’s 24% year-to-date gain in 2026 is the world’s strongest among major equity indices and is being driven by the same AI capital expenditure wave lifting U.S. tech — except Japan gets it twice, because falling oil prices also reduce the country’s enormous energy import bill. Nomura Securities senior strategist Takashi Ito put it plainly: “even a modest easing of inflation can provide meaningful relief.”

The Federal Reserve’s position has also changed dramatically since 2008. Back then, the Fed under Ben Bernanke was slashing rates to stop the financial system from collapsing, eventually pushing them to near zero and launching quantitative easing. Today, newly sworn-in Fed Chair Kevin Warsh is holding rates elevated to fight inflation that has stayed above the central bank’s 2% target for years. Markets are climbing despite high interest rates, not because of cheap money — a fundamentally different and arguably healthier dynamic. Fed Governor Christopher Waller said Friday he wants to hold rates steady but would not rule out hikes if energy-driven inflation proves durable. A Hormuz reopening cuts directly against that risk and reopens the path to the rate cuts Warsh has signaled he prefers.

Why are markets rising to new heights in a time like this, instead of crashing? Because the modern economy is built on a different foundation. The U.S. is energy-independent. Banks are over-capitalized. The largest companies sell software, not steel. Earnings are growing on an AI capital expenditure wave measured in hundreds of billions of dollars. Japan has rebuilt itself into a core AI supplier. And the financial system has the shock absorbers it lacked in 2008. The same headlines that crushed the world 18 years ago — Middle East war, $100 oil, central banks under pressure — are now hitting an economy designed to absorb them rather than buckle under them.

None of this means markets are risk-free. Iran’s Supreme Leader Mojtaba Khamenei has ordered enriched uranium reserves to stay inside the country, contradicting Washington’s central demand. Tehran is reportedly working with Oman on a permanent toll system for the Strait of Hormuz, which Trump has rejected outright. The U.S. blockade of Iranian ports remains in place. Goldman Sachs head of oil research Daan Struyven estimates every additional month the strait stays shut adds roughly $10 to the year-end oil price. The math runs in both directions, and the gap between Trump’s threat to strike and his “time is on our side” patience is the gap traders will reprice the moment the next Truth Social post lands.

But the bigger story is the one most investors lived through without quite noticing. The world that made the Dow at 50,000, the Nikkei at 65,000, and oil at $99 impossible in the same sentence has been replaced by a different world entirely. In 2008, nobody would have believed it. In 2026, it is the tape.

— JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

Bunia, Democratic Republic of the Congo — May 24, 2026 — Hospitals across eastern Congo are “fighting with no tools at all,” according to Dr. Jean Kaseya, Director-General of the Africa Centres for Disease Control and Prevention, as a fast-moving outbreak of Bundibugyo ebolavirus spreads across one of Africa’s most strategically important mining corridors and begins rippling through the pharmaceutical, aviation, insurance and global commodities sectors.

The Democratic Republic of the Congo’s Ministry of Public Health, working alongside the World Health Organization and Africa CDC, has confirmed 968 suspected cases and 216 deaths across Ituri, North Kivu and South Kivu provinces, while neighboring Uganda has reported five imported cases in Kampala, the country’s capital and commercial hub.

The outbreak has already triggered emergency travel measures, intensified supply-chain monitoring and reignited fears of a broader regional disruption across Central Africa.

On May 18, the U.S. Centers for Disease Control and Prevention and the Department of Homeland Security imposed enhanced travel screening and routing restrictions for travelers recently transiting the DRC, Uganda or South Sudan. American citizens and permanent residents leaving affected areas are now being funneled through designated U.S. airports in Virginia, Texas and Georgia for additional screening procedures.

The measures are complicating operations for international carriers including Delta Air Lines, United Airlines, Air France-KLM and Brussels Airlines, the latter long serving as one of the primary Western aviation links into Kinshasa.

The outbreak is also colliding with a growing funding crisis inside global public health systems.

The WHO and Africa CDC have jointly requested more than $314 million in emergency funding for containment, treatment and surveillance operations, including roughly $54 million earmarked for neighboring high-risk countries such as Rwanda, Kenya, Tanzania, Angola, Burundi and South Sudan.

The United States has pledged approximately $50 million toward frontline response efforts, while Congo and Uganda are seeking a combined $320 million in additional support.

Kaseya warned this week that donor fatigue is rapidly becoming as dangerous as the virus itself.

International health assistance to African response systems has fallen sharply over the past five years, according to Africa CDC estimates, with several programs weakened further by recent aid reductions and shifting budget priorities across Western governments.

For pharmaceutical companies, the outbreak presents a uniquely difficult challenge: there is currently no approved vaccine or targeted therapeutic for the Bundibugyo strain now spreading across eastern Congo.

Merck & Co.’s Ervebo, the only FDA-approved Ebola vaccine, targets the Zaire strain of the virus and has not been approved for Bundibugyo. The company said existing cross-protection research remains limited and largely untested in human trials.

Regeneron Pharmaceuticals’ Inmazeb antibody treatment is also designed specifically for Zaire ebolavirus and is not approved for Bundibugyo infections.

Drugmakers including Johnson & Johnson and Bavarian Nordic are now evaluating whether experimental candidates can be accelerated into cross-strain testing, but WHO officials warned this week that any targeted vaccine rollout remains months away.

The timing is especially sensitive because the outbreak’s epicenter overlaps directly with one of the world’s most important critical-minerals regions.

Ituri Province sits near major gold, cobalt and coltan transport corridors central to global electric-vehicle and battery supply chains. The Democratic Republic of the Congo produces more than 70% of the world’s cobalt supply, a strategic material used by manufacturers including Tesla, Ford Motor Co., General Motors and major Chinese battery producers.

Mining companies including Glencore, CMOC Group and Barrick Mining have not yet announced operational suspensions, but previous Ebola outbreaks triggered widespread staff evacuations, travel restrictions and production disruptions throughout the region.

The WHO has already identified mining-related population movement as a major transmission risk.

The outbreak also raises concerns for regional banking, trade and logistics infrastructure.

Kampala, where imported cases have now been confirmed, serves as a key financial and transportation hub for East African institutions including Equity Group Holdings, KCB Group and Standard Bank. Kenya and Tanzania have intensified airport health screening procedures at Nairobi’s Jomo Kenyatta International Airport and Dar es Salaam’s Julius Nyerere International Airport.

Meanwhile, major insurers and reinsurers including Allianz, AXA and Marsh McLennan are reportedly reviewing pandemic-related exposure across African travel, trade-credit and logistics policies.

The broader market fear is not simply the current outbreak itself.

It is the possibility that the outbreak escapes containment and evolves into a larger regional emergency similar to the 2014–2016 West African Ebola crisis, which caused an estimated $53 billion in economic losses across Guinea, Liberia and Sierra Leone while severely disrupting mining operations and international investment flows.

Several warning signs are already intensifying concern among health officials and multinational operators.

The outbreak reportedly went undetected for nearly four weeks, healthcare workers have already died treating infected patients at Mongbwalu General Referral Hospital, and ongoing armed conflict across eastern Congo continues restricting medical access and surveillance operations.

With no approved Bundibugyo-specific treatment available and hospitals already overwhelmed, executives across pharmaceuticals, mining, aviation and global logistics are increasingly treating the outbreak not just as a humanitarian crisis but as a growing commercial and supply-chain risk.

The next major turning point may ultimately come down to funding speed.

If the WHO–Africa CDC emergency appeal is funded quickly, the outbreak may remain primarily a logistics and containment challenge.

If donor fatigue prevails, the crisis risks spreading deeper into regional trade routes, aviation corridors and critical-minerals supply chains already strained by geopolitical instability and global commodity competition.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 24, 2026 — Oil prices and the U.S. dollar fell sharply Sunday night while stock futures and Asian markets moved higher after new signs that the United States and Iran may be inching toward a deal to reopen the Strait of Hormuz — a breakthrough that could eventually lower gasoline prices, ease inflation pressure and reduce the risk of future Federal Reserve rate hikes.

Brent crude dropped more than 4% in early electronic trading, while futures tied to the S&P 500, Dow Jones Industrial Average and Nasdaq climbed ahead of Tuesday’s Wall Street reopen. The U.S. dollar also weakened as investors moved back into riskier assets and away from the safe-haven trades that have dominated markets during the Middle East conflict.

The market reaction came even as President Donald Trump publicly told his negotiating team not to rush into a final agreement.

“Time is on our side,” Trump wrote Sunday on Truth Social, while criticizing opponents of the developing framework as “losers.” The comment followed his statement Saturday that a deal with Iran was already “largely negotiated,” though Trump also repeated his warning that military strikes could resume “at a much higher level and intensity” if negotiations collapse.

Secretary of State Marco Rubio, speaking Sunday in an interview with The New York Times from New Delhi, also cooled expectations for an immediate breakthrough.

“A deal like this cannot be done in 72 hours on the back of a napkin,” Rubio told the paper, signaling that negotiations may continue for weeks even as markets already begin pricing in a reopening.

Still, traders heard enough optimism to spark a major overnight move.

Because U.S. stock markets are closed Monday for Memorial Day, the first major reactions came from Asia and overnight futures trading. Markets in Tokyo, Seoul, Sydney, Shanghai and Taiwan all opened higher as investors bet that the worst-case energy scenario of 2026 may finally begin easing.

The reason is simple: the Strait of Hormuz matters to almost everything people buy.

The narrow waterway normally carries about 20% of the world’s oil and liquefied natural gas. Since fighting erupted in late February, its near-shutdown has driven gasoline prices higher, pushed up shipping costs, fueled inflation and added pressure to everything from airline tickets to groceries.

Even after Sunday night’s drop, oil prices remain dramatically elevated. Brent crude settled Friday at $103.54 a barrel and West Texas Intermediate crude closed at $96.60 — both still far above where they traded before the war began.

Analysts at Goldman Sachs estimate that every extra month Hormuz stays restricted adds roughly another $10 to oil prices. That is why even the possibility of reopening the route is enough to send markets moving sharply.

The falling dollar is another sign investors are becoming less fearful about the global economy.

During wars and financial shocks, investors often rush into the U.S. dollar for safety. As tensions ease, money tends to move back into stocks, commodities and foreign currencies. Sunday night’s decline in the dollar reflected growing belief that the worst-case economic scenario may be fading.

For American consumers, cheaper oil would matter immediately.

Lower crude prices would eventually filter into gasoline stations, transportation costs, manufacturing prices and consumer goods across the economy. It would also ease pressure on the Federal Reserve, which has spent years struggling to contain inflation.

That puts the spotlight directly on new Federal Reserve Chair Kevin Warsh, who was sworn in Friday at the White House.

Fed officials recently warned that high oil prices and tariffs could force them to keep interest rates elevated longer — or even raise rates again — if inflation refuses to cool. A drop in energy prices would make that much less likely and could reopen the door to eventual rate cuts later this year.

Some of the market winners and losers are already becoming clear.

Airlines, transportation companies, delivery firms and technology stocks generally benefit when fuel costs fall and interest-rate pressure eases. Energy giants like Exxon Mobil, Chevron, and ConocoPhillips, which surged during the oil spike, could face pressure if crude prices continue falling.

Defense companies that rallied during the conflict, including Lockheed Martin and Northrop Grumman, may also lose momentum if investors begin betting the war is winding down.

But the risks are far from gone.

Iran’s Supreme Leader Mojtaba Khamenei has reportedly insisted that enriched uranium remain inside the country, conflicting with one of Washington’s core demands. Iran is also discussing possible toll systems tied to Hormuz shipping traffic — an idea Trump has rejected outright.

The U.S. blockade of Iranian ports also remains in place, and military tensions in the Gulf have not disappeared.

That is why traders remain cautious about declaring victory too early.

Sunday night’s rally reflects growing belief that a deal may be coming. Trump’s actual message, however, was more complicated: negotiations are progressing, but Washington does not appear ready to finalize an agreement quickly.

That difference matters.

If talks break down or fighting resumes, oil prices could surge again almost immediately — and the same markets rallying Sunday night could reverse just as fast.

For now, though, global investors are betting on the possibility that the biggest economic shock of 2026 may finally begin easing.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The decade-long hard seltzer boom that reshaped the American beverage aisle is losing momentum, and beverage executives, distributors and consumer-data firms increasingly believe the industry’s next major growth wave will come from still, non-carbonated drinks — from ready-to-drink teas and flat cocktails to functional waters and healthier energy beverages.

New data from Circana for the 52 weeks ended April 26 show malt-based hard seltzers — the category dominated by White Claw and Boston Beer Co.’s Truly — declining 1.1% in volume year over year, even as ready-to-drink premixed cocktails surged 46.4%, fueled by rapid growth from brands including Surfside, Sun Cruiser, BuzzBallz and Cutwater Spirits.

The shift is increasingly being driven by Generation Z consumers, whose beverage preferences are diverging sharply from the millennial-driven drinking trends that powered the seltzer explosion between 2018 and 2021.

“We’re seeing a lot of promiscuity within consumption and alcohol around new products,” Scott Scanlon, executive vice president of alcoholic beverages at Circana, said in remarks reported Sunday. “White Claw and Truly were the breakout brands eight years ago. Now you’re seeing Surfside and Sun Cruiser capturing that rotation.”

Industry consultants say the trend extends well beyond alcohol.

Randy Burt, Americas director of consumer products at AlixPartners, said consumer demand has decisively shifted toward still beverages across both alcoholic and non-alcoholic categories as younger consumers increasingly prioritize variety, tea-based drinks, lower carbonation and “better-for-you” positioning.

“Gen Z is a lot more likely to order tea-based beverages at happy hour,” Burt said. “They’re moving away from carbonated seltzers as the default healthier option.”

The growth differential is already beginning to reshape corporate strategy across the nearly $400 billion U.S. beverage industry.

According to BrewBound industry data, Stateside Brands’ Surfside and Boston Beer’s Sun Cruiser both posted triple-digit growth during the latest reporting period. Anheuser-Busch InBev’s Cutwater Spirits, which sells both sparkling and still cocktails, recorded strong double-digit gains, while BuzzBallz — acquired by Sazerac in 2024 — continues rapidly expanding into grocery and convenience-store distribution.

The non-alcoholic market is moving in the same direction.

Liquid Death, the fast-growing canned-water and iced-tea company valued above $1.4 billion in its latest funding round, has aggressively expanded its still-drink portfolio while preparing to enter the better-for-you energy category in 2026. The company said its ready-to-drink tea business is now growing roughly 20 times faster than the broader tea category itself.

Even within Liquid Death’s own lineup, still beverages are increasingly outpacing sparkling offerings.

The shift reflects a broader generational change in how younger consumers approach beverages altogether.

Gen Z consumers grew up during a period when soda consumption steadily declined from its late-1990s peak, reusable water bottles became lifestyle accessories and beverage shelves fragmented into hundreds of specialized categories built around wellness, functionality, caffeine, hydration and flavor experimentation.

Rather than locking into a single category the way prior generations often did, younger consumers increasingly rotate between teas, flavored waters, mocktails, energy drinks, cocktails and functional beverages depending on the occasion.

That fragmentation is forcing beverage companies to rethink product development, marketing and shelf allocation.

PepsiCo, which acquired prebiotic soda maker Poppi for nearly $2 billion last year, has been rapidly expanding its presence across healthier soda alternatives, hydration drinks and still functional beverages. The Coca-Cola Co. continues pouring investment into brands including Fairlife, BodyArmor and its broader still-water portfolio as growth in traditional carbonated soft drinks moderates.

Industry reports from Mintel, Circana and Tastewise have consistently shown younger consumers favoring beverages positioned around wellness, lower sugar, functionality and ingredient transparency. Tastewise data cited by industry analysts pointed to roughly 42% year-over-year growth in consumer interest surrounding “healthy soda” products.

The result is an increasingly crowded battle for what beverage executives call “share of throat” — the portion of consumer consumption captured by any given category.

Hard seltzer is not disappearing. But its role inside the industry appears to be changing from explosive-growth engine to mature category.

That transition carries major implications for retailers, distributors and investors.

Boston Beer Co., which rode Truly’s meteoric growth to record valuations before suffering through the seltzer slowdown, has increasingly leaned into Twisted Tea and Sun Cruiser, both positioned more directly around tea-based consumption trends. Molson Coors, after scaling back efforts tied to Vizzy and Topo Chico Hard Seltzer, is reallocating attention toward non-alcoholic and still-adult beverage categories.

Meanwhile, major spirits companies including Diageo, Brown-Forman and Constellation Brands are expanding ready-to-drink lineups centered around spirit-forward still formats rather than sparkling seltzer imitators.

For beverage executives, the message emerging from the latest sales data is increasingly difficult to ignore: the next era of category growth may belong less to bubbles and more to hydration, tea, wellness and flavor experimentation.

The bubble era is not over.

But the leadership of the bubble era increasingly appears to be changing.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Crude carriers shifted into position near the Strait of Hormuz on Sunday, May 24, 2026, after President Donald Trump declared over the weekend that a framework deal with Iran to reopen the world’s most consequential energy corridor has been “largely negotiated” and will be unveiled imminently — even as Tehran publicly contested his version of events and tanker operators kept crews on hold pending a formal end to hostilities.

In a Saturday social-media post, Trump described the agreement as “subject to finalization between the United States of America, the Islamic Republic of Iran, and the various other Countries.” Iran’s Foreign Ministry said the two sides had locked in a memorandum of understanding as a first phase, with deeper negotiations to unfold over the following 30 to 60 days. A senior Iranian official, outlining the first-phase terms, said Tehran will return the Strait of Hormuz to pre-war operating conditions, underwrite shipping security through the waterway, give assurances that it will not pursue nuclear weapons, and resume exports of its own fuel and crude. The same official stressed that Iran has not agreed to hand over its enriched uranium stockpile, and that the nuclear question has been carved out for phase two.

Tehran’s counter-messaging muddied the picture almost instantly. Fars news agency reported that the Strait of Hormuz will stay under Iranian management and dismissed Trump’s framing as “incomplete and inconsistent with reality.” Iran’s chief negotiator Mohammad Bagher Ghalibaf struck a similar note after the latest round of talks, warning that Tehran “will not back down from the rights of our nation and country — especially when dealing with a party that has never shown sincerity.” Traders have seen this movie before: at least two prior reopening declarations during the war unraveled within days.

The Strait of Hormuz has been functionally closed to commercial transit since late February, when U.S. and Israeli strikes on Iran set off a cascade of Iranian retaliatory measures that throttled tanker movement to roughly five percent of its normal pace. The corridor moves about a fifth of the world’s daily crude shipments and a comparable slice of global LNG. General Dan Caine, Chairman of the Joint Chiefs of Staff, confirmed earlier this month that 22,500 mariners are stranded on more than 1,550 commercial ships trapped in and around the Gulf. Maersk, MSC, CMA CGM and Hapag-Lloyd halted transits in the conflict’s opening days and have yet to resume full service.

Vessel-tracking firm Kpler said crude carriers idling north of Dubai and Fujairah began nudging toward the chokepoint within hours of the weekend announcement — a near-repeat of April’s aborted reopening, when at least eight tankers advanced before the corridor refroze. Roughly 130 million barrels of crude and 46 million barrels of refined fuels are currently floating on some 200 tankers across the region, according to Kpler data, a backlog that would surge into global markets the moment flows truly restart.

Futures markets are already pricing the optionality. Brent crude has swung in a band between roughly $100 and $144 a barrel for nearly three months, settling near $105 last week, while North Sea Dated changed hands around $110 in early May. JPMorgan analysts, who had penciled in a June restart, now project oil will average $97 a barrel for the balance of 2026 if the strait reopens on track. Citigroup energy strategists Anthony Yuen and Eric Lee had earlier flagged that any closure would deliver a sharp but compressed spike, since every major economy is incentivized to restore flows. Michael Green, chief strategist at Simplify Asset Management, notes that Brent historically needs to hold near $60 a barrel before U.S. pump prices retreat to roughly $3 a gallon — a level still well south of where the market is trading.

The operational hurdle is steeper than the diplomatic one. Matt Wright, principal freight analyst at Kpler, said shipowners remain unwilling to send crews back into the corridor on a political signal alone. War-risk insurance premiums, which ran at about 0.25 percent of hull value before the conflict, have leapt to between three and eight percent — equating to $3 million to $8 million in coverage costs for a single very large crude carrier transit, according to Marsh Risk war leader Dylan Saunders-Mortimer. VLCC freight rates from the Gulf to China have spiked in recent sessions, with Kpler clocking a 24 percent single-day jump to $1.67 per barrel — the steepest move of the year. The U.S. International Development Finance Corporation has been assembling a $20 billion reinsurance facility intended to draw tanker operators back, but the program’s terms remain unsettled.

Secretary of State Marco Rubio, speaking in New Delhi on Saturday, reiterated that any final accord must reopen Hormuz toll-free, halt Iran’s nuclear weapons pursuit, and secure the transfer of enriched uranium. “This problem will be solved, as the president’s made clear, one way or the other,” Rubio said.

For corporate America, even a partial restart would ease pressure that has bled into every corner of the consumer economy. U.S. inflation has held at multi-year highs since the conflict began, gasoline prices have spiked, ocean-freight costs have lifted everything from manufacturing inputs to imported food, and supply chains have absorbed a parallel hit from the Red Sea. OPEC trimmed its 2026 global demand growth forecast to 1.17 million barrels per day in its May report, down from 1.38 million, citing the conflict’s drag on trade.

Even under the cleanest possible path — a finalized phase-one accord, Iranian compliance on safe passage, sustained U.S. and allied naval reassurance, and tanker operators willing to put crews and hulls back in harm’s way — the International Energy Agency and Wall Street energy desks expect Hormuz throughput to stay below pre-war norms well into the third quarter. Stranded barrels will hit the market first; restoring production at Saudi, Emirati, Iraqi and Kuwaiti loading facilities, and rebuilding the depleted floating-storage and onshore inventories the war has burned through, will take months, not weeks.

The next 72 hours will tell the market whether this is, at last, the real reopening — or another false start in a war that has produced several already.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Newark, N.J. — May 24, 2026 — New Jersey’s suburban housing market has entered an increasingly extreme phase of bidding competition as inventory shortages, migration from New York City and land scarcity collide across the state’s highest-demand commuter corridors.

The pressure became visible this month after New Jersey real estate agent Amanda Cruz posted a viral social-media video describing how a client lost a home despite offering $150,000 above the asking price.

“Someone else came in much higher than us,” Cruz said. “Like, we weren’t even in the ballpark.”

The video quickly became a symbol of the broader affordability and supply crisis unfolding across Bergen, Essex, Morris, Hudson and Union counties, where buyers continue competing aggressively for limited single-family inventory near Manhattan.

The structural imbalance is increasingly straightforward: demand continues rising while buildable land for new detached housing has effectively disappeared across many of New Jersey’s wealthiest suburban markets.

As a result, inventory turnover now depends largely on existing homeowners deciding to sell rather than meaningful new supply entering the market.

The migration dynamics are accelerating the pressure further.

Analysts increasingly expect New York Governor Kathy Hochul’s proposed second-home tax targeting pied-à-terre owners and investment properties to push additional high-income households toward permanent residency in New Jersey rather than maintaining part-time Manhattan ownership.

That migration pressure is concentrating heavily in transit-oriented suburbs with direct access to New York City.

Montclair, Maplewood, South Orange, Summit, Millburn, Short Hills, Tenafly, Englewood Cliffs and Hoboken are now routinely seeing multiple-offer scenarios on homes priced below roughly $2.5 million, particularly those located within thirty minutes of Manhattan commuter access.

Similar patterns are emerging across parts of lower Fairfield County, Connecticut, including Greenwich, Westport and New Canaan.

The buyer pool itself is increasingly splitting into distinct tiers.

Younger professional families priced out of Brooklyn Heights, Cobble Hill, Park Slope and Williamsburg are moving into Jersey City, Hoboken, Montclair and Maplewood, while higher-net-worth buyers exiting Manhattan neighborhoods such as Tribeca, the Upper East Side and the Upper West Side are concentrating in Short Hills, Greenwich and Bronxville.

All-cash offers are becoming increasingly common across premium listings, particularly among finance and technology professionals already established in suburban markets and now seeking larger homes or school-district upgrades.

At the same time, institutional capital continues shifting heavily into multifamily and build-to-rent development projects across the state.

Transit-oriented housing remains one of the strongest-performing sectors in New Jersey real estate, with major developers including Roseland Residential Trust, Veris Residential, Mack-Cali and Toll Brothers Apartment Living expanding aggressively throughout key suburban corridors.

Recent projects include a 150-unit condominium development in Robbinsville launched by Sharbell Development Corp., blending market-rate and affordable housing components.

The broader policy environment is also shaping migration and investment flows.

Mayor Zohran Mamdani’s proposed rent freeze covering approximately one million rent-regulated apartments in New York City is increasingly cited by commercial real estate analysts as another factor encouraging both households and capital to shift toward New Jersey, where free-market multifamily economics remain significantly more flexible.

Meanwhile, Governor Mikie Sherrill’s discussions around utility-rate stabilization and affordability have so far done little to slow inbound residential demand.

The core issue remains supply.

Affordable-housing legislation has expanded multifamily development pipelines across the state, particularly in Hudson and Essex counties, but meaningful new single-family construction remains severely constrained by zoning, land scarcity and infrastructure limitations.

That imbalance is forcing many first-time buyers to fundamentally reset expectations.

Real estate brokers across Bergen, Essex and Morris counties increasingly report advising clients to raise target budgets by 15% to 25% compared with late-2025 pricing assumptions simply to remain competitive.

For many households, the question is no longer whether New Jersey housing is expensive.

It is whether there will be anything left to buy at all.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
May 24, 2026 — President Donald Trump slowed momentum toward a potential Iran agreement Sunday, warning negotiators not to rush into a deal as oil markets, inflation fears and mounting Republican backlash collided with White House efforts to stabilize the global economy before the 2026 midterms.

“The negotiations are proceeding in an orderly and constructive manner, and I have informed my representatives not to rush into a deal — time is on our side,” Trump wrote Sunday morning on Truth Social, a sharp change in tone from Saturday’s declaration that an agreement with Tehran had been “largely negotiated, subject to finalization.”

Trump also confirmed that the U.S. naval blockade on Iranian ports, imposed April 13 after Iran threatened commercial shipping lanes, “will remain in full force and effect until an agreement is reached, certified, and signed.”

“Both sides must take their time and get it right,” the president wrote. “There can be no mistakes!”

The reversal immediately eased concerns among Republican national-security hawks who feared the administration was moving too quickly toward an agreement that would leave Iran financially and militarily intact in exchange for temporary market stability and lower oil prices heading into the election season.

According to Axios, the proposed framework under discussion would include a 60-day ceasefire extension, the reopening of the Strait of Hormuz, renewed Iranian oil exports, sanctions relief and the release of tens of billions of dollars in frozen Iranian assets. Iranian outlet Tasnim reported the U.S. naval blockade itself could be dismantled within 30 days under the first phase of the agreement.

Trump moved Sunday to distance the negotiations from former President Barack Obama’s 2015 nuclear deal, calling the JCPOA “one of the worst deals ever made by our Country” and “a direct path to Iran developing a Nuclear weapon.” The current negotiations, he said, are “THE EXACT OPPOSITE.”

The Strait of Hormuz — the narrow passageway connecting the Persian Gulf to global shipping lanes — handles roughly 20% of the world’s seaborne oil supply, making the negotiations one of the most consequential economic flashpoints in the world economy. Since the war intensified this spring, energy traders, manufacturers, shipping companies and central banks have been bracing for a prolonged disruption capable of pushing inflation sharply higher worldwide.

Iran’s Revolutionary Guard told Fars News Agency on Sunday that only 33 vessels passed through Hormuz during the prior 24 hours, far below the prewar daily average of roughly 140 ships. Fars also reported that approximately 240 vessels remain queued awaiting Iranian authorization to transit the waterway, underscoring Tehran’s continuing leverage over one of the world’s most important energy chokepoints despite the American blockade on Iranian ports.

Brent crude has already fallen nearly 5% over the past week while West Texas Intermediate has dropped more than 7%, with traders rapidly unwinding wartime risk premiums that had built up earlier this month. Brent settled Friday near $103.82 per barrel while WTI closed near $97 as markets increasingly priced in a possible de-escalation scenario.

The pullback has already started easing pressure on American consumers after gasoline prices surged to wartime highs of roughly $4.48 per gallon earlier this month. But the inflation shock from the conflict continues rippling through supply chains, transportation costs and manufacturing inputs, keeping pressure on the Federal Reserve as headline inflation climbed to 3.3% in March, its highest reading since May 2024.

With midterm elections now just months away, the administration is balancing military leverage against growing voter anxiety over energy costs, inflation and recession fears. Goldman Sachs recently raised its recession probability outlook to 30%, while JPMorgan placed the odds even higher at 35%.

Secretary of State Marco Rubio acknowledged Thursday there were “good signs” negotiations were progressing but warned any arrangement would become “unfeasible” if Iran seeks permanent control over shipping through Hormuz, including the possibility of imposing transit tolls on commercial traffic.

The unresolved disputes over Hormuz transit authority, sanctions relief and Iran’s enriched uranium stockpile remain the largest obstacles to any final agreement.

Pressure inside Washington intensified dramatically over the weekend as Republican national-security hawks openly warned that Tehran could emerge from the conflict strategically stronger despite months of military strikes.

Sen. Ted Cruz called the reported framework a “disastrous mistake” in an X post that generated more than 6.3 million views within seventeen hours, warning that the administration risked allowing a regime still chanting “death to America” to emerge from the war with renewed oil revenue, sanctions relief and continued nuclear capability.

Sen. Lindsey Graham warned that any agreement leaving Iran effectively controlling the Strait of Hormuz would result in Tehran being viewed globally as “a dominate force.” Senate Armed Services Committee Chairman Roger Wicker called the proposed ceasefire structure “a disaster” that would render the gains of the U.S.-Israeli military campaign “for naught,” while Senate Intelligence Chairman Tom Cotton amplified Graham’s warning through official Senate Republican channels.

The criticism reflects growing fears among conservative national-security voices that Tehran is pursuing the same strategy it has relied on for decades: absorb military punishment, survive politically, regain access to capital markets and rebuild over time.

Iran’s missile infrastructure remains largely intact despite months of strikes, and Western intelligence officials continue monitoring reports that Tehran is rebuilding portions of its ballistic missile arsenal while deepening military coordination with China, including discussions involving anti-ship missile systems and advanced satellite-guidance technology.

For now, Trump appears determined to avoid rushing into an agreement that could fracture his political coalition while giving Tehran economic breathing room without permanently dismantling its nuclear and missile capabilities.

Whether Iran is willing to negotiate under a slower timetable — particularly with the naval blockade still fully operational — now becomes the central question heading into the week ahead.

For global markets, the stakes extend far beyond diplomacy. The outcome of the negotiations will shape oil prices, inflation trends, shipping flows, central-bank policy and the broader direction of the world economy through the second half of 2026.

For now, the blockade remains in place. Oil continues moving cautiously through Hormuz. And traders, businesses and governments worldwide remain suspended between the possibility of stabilization and the risk of another major escalation.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK, May 21, 2026 — The economic data says the U.S. labor market is healthy. Employers are still adding jobs, unemployment remains relatively low at 4.3%, consumer spending has not collapsed, and corporate earnings continue beating expectations. By traditional economic definitions, the United States is still operating inside what policymakers hoped would become a soft landing.

For millions of Americans graduating from college this spring, it does not feel that way at all.

The unemployment rate for recent college graduates has remained above the national unemployment rate for five consecutive years, according to data from the Federal Reserve Bank of New York, a reversal from the decades before the pandemic when college graduates almost always enjoyed materially lower unemployment than the overall workforce. In the first quarter of 2026, unemployment among recent graduates stood near 5.7%, while underemployment — graduates working jobs that do not require a four-year degree — remained above 41%.

In practical terms, more than four out of every ten employed recent graduates are now working positions beneath the education level they were told would unlock opportunity.

Beneath those headline numbers sits a structural shift that economists, universities, and employers are only beginning to fully understand. Entry-level white-collar hiring has slowed sharply since the generative AI boom accelerated in 2023, with companies increasingly automating the routine analytical, administrative, coding, and research tasks that historically served as the first rung on the corporate ladder.

Labor-market tracking data shows entry-level job postings have fallen roughly 35% since early 2023. The industries historically responsible for absorbing large waves of graduates — consulting, technology, finance back-office operations, media, marketing, and advertising — are among the sectors pulling back the hardest.

The result is an economy producing a deeply unusual contradiction: businesses are still profitable, still hiring selectively, and in many cases still growing, while simultaneously reducing the number of junior workers they bring into the system.

The National Association of Colleges and Employers, or NACE, initially projected that hiring for the graduating Class of 2026 would rise just 1.6% from the previous year, effectively flat once adjusted for population growth. But a spring revision showed employers now expect hiring to rise 5.6%, an improvement driven by more than one-third of surveyed companies increasing planned graduate recruitment.

Even that improvement came with an important caveat. The rebound is not broad-based. Hiring growth is concentrated in engineering, information services, construction, logistics, and specialized professional services rather than the traditional office-heavy sectors many graduates spent years preparing to enter.

Mary Gatta, NACE’s director of research and public policy, described the trend as less of a recovery and more of a recalibration. Companies that initially believed AI would allow them to dramatically shrink junior staffing are beginning to realize they still need employees capable of operating, supervising, and integrating AI systems into workflows.

But needing fewer entry-level workers than before is still not the same thing as needing none.

That distinction is now reshaping the bottom layer of the American white-collar workforce.

Research published by the Stanford Digital Economy Lab found employment among workers aged 22 to 25 in AI-exposed occupations has fallen 13% since late 2022. Junior software developer employment dropped roughly 20% during the same period, while older workers in comparable positions actually saw gains.

A separate study released by Harvard researchers in February 2026, analyzing more than 62 million workers, found companies adopting generative AI reduced junior staffing by roughly 9% to 10% while largely preserving senior-level positions.

The emerging pattern is becoming increasingly visible across corporate America: firms are not eliminating experienced workers. They are reducing intake at the bottom.

BlackRock Chief Executive Larry Fink warned earlier this year that the graduating class of 2026 could face one of the most difficult entry-level hiring environments in years because artificial intelligence is replacing portions of junior-level office work faster than the labor market can create new pathways.

Economists increasingly describe the current environment as a “no-hire, no-fire” labor market. Companies are reluctant to lay off experienced workers because skilled labor remains expensive and difficult to replace. At the same time, they are slowing or freezing the hiring pipelines that traditionally replenished future mid-level talent.

That dynamic helps explain why the labor market feels far weaker to young workers than broader economic indicators suggest.

The graduates themselves are adapting in real time. Data from ZipRecruiter’s 2026 Graduate Report shows roughly one in five employed graduates now believes they are overqualified for their current role, while a similar percentage said they deliberately applied for jobs below their education level simply to secure income and experience.

Student debt pressures are intensifying the situation. Higher-education expert Mark Kantrowitz estimates roughly 160,000 federal student-loan borrowers entered unemployment deferment programs during the first quarter of 2026 alone, with interest continuing to accrue for many borrowers despite paused payments.

There are important exceptions to the broader trend.

International Business Machines Corp. said this year it plans to triple entry-level hiring across parts of its U.S. workforce. IBM Chief Executive Arvind Krishna has argued that younger employees often adapt to AI-assisted workflows faster than mid-career workers because they have fewer legacy habits and are more comfortable collaborating directly with machine-learning systems.

The company says junior developers now spend less time performing repetitive coding tasks and more time interfacing directly with customers while AI handles foundational programming work underneath them.

Whether IBM’s approach becomes a blueprint for corporate America or remains an isolated strategy could become one of the defining workforce questions of the next several years.

Universities and workforce researchers are also experimenting with what some are beginning to call “AI apprenticeships” — entry-level programs where graduates use generative AI systems to perform at productivity levels once associated with more experienced workers while still receiving junior-level pay and training.

Supporters argue the model could preserve pathways into white-collar careers. Critics warn it may permanently compress entry-level employment and wages by allowing companies to operate with fewer people overall.

For now, the numbers tell the immediate story clearly: the entry-level labor market has frozen even as the broader economy remains relatively stable.

And beneath that freeze sits a longer-term risk for corporate America itself.

A labor market that automates away too much of the bottom rung may eventually discover there is nobody left prepared to fill the middle one.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
HOUSE ADVANCES PERMANENT DAYLIGHT SAVING TIME BILL AS TRUMP BACKS END TO CLOCK CHANGES, WITH RETAILERS, RESTAURANTS AND WORKFORCE POISED FOR ECONOMIC BOOST

By JBizNews Desk

May 23, 2026 — The House Energy and Commerce Committee on Thursday, May 22, voted 48-1 to advance the Sunshine Protection Act, folding the long-stalled measure into the broader Motor Vehicle Modernization Act and sending it to the House floor in what Congressional sponsors are billing as the most serious push in four years to lock the United States into permanent daylight saving time. President Donald Trump endorsed the vote Thursday evening on Truth Social, writing that “Hundreds of Millions of Dollars are spent every year by people, Cities, and States, being forced to change their Clocks,” and pledging to “work very hard” to see the bill signed into law.

The legislation, originally introduced by Sen. Rick Scott (R-Fla.) and Rep. Vern Buchanan (R-Fla.), would permanently advance the nation’s clocks forward one hour, ending the twice-yearly springing forward and falling back that has governed American timekeeping for decades. Buchanan’s office confirmed the bill carries 32 bipartisan cosponsors in the House, with the Senate companion measure carrying 18 cosponsors. States such as Hawaii and most of Arizona that currently opt out of daylight saving would retain that flexibility under the bill’s framework.

For American businesses, the economic stakes are substantial. Chambers of Commerce across the country have historically backed permanent daylight saving time, citing extended evening daylight as a proven driver of after-work foot traffic into restaurants, retail centers, sporting venues and entertainment districts. Analysis from the JPMorgan Chase Institute has previously documented that the fall switch back to standard time triggers card-spending declines of between 2.2% and 4.9% depending on metro area, with supermarkets absorbing per-capita retail drops of nearly 6%. Locking in permanent daylight time would, in effect, eliminate that recurring autumn drag on consumer activity, delivering what one Orrin G. Hatch Foundation policy director previously described as “a stimulus package all on its own.”

Hospitality stands to be a primary beneficiary. PNC economist Kurt Rankin has noted that restaurants, hotels, golf operators, fuel retailers and outdoor recreation businesses capture outsized sales lifts from extended evening daylight, sectors that collectively employ tens of millions of American workers and remain central to small-business job creation. The National Retail Federation has historically backed daylight saving time as a tailwind for member sales, and the trade group has been actively examining the implications of a permanent shift on the broader retail economy.

The workforce productivity case is equally direct. University-based research has long documented that the spring-forward transition costs the average American worker roughly 40 minutes of sleep, producing measurable spikes in workplace errors, injuries and absenteeism in the days that follow. A 2014 University of Colorado Boulder study tied a 17% jump in traffic fatalities to the spring transition, while other peer-reviewed work has linked the biannual disruption to elevated heart attack and stroke risk in the immediate aftermath. Employers across manufacturing, logistics, healthcare and corporate sectors absorb those costs through lost output, higher insurance claims and degraded performance, a recurring annual tax on American labor productivity that the Sunshine Protection Act would eliminate outright.

Compliance and operational costs would also fall. Cities, school districts, transit systems, broadcasters and Fortune 500 IT departments collectively spend significant sums each year reconfiguring scheduling systems, signage, public clocks and software for the twice-annual shift, costs Trump highlighted in his Thursday statement, noting that “many of these Clocks are located in Towers, and the cost of renting, or using, Heavy Equipment to do this twice a year is prohibitive.” For multinational corporations coordinating across U.S. time zones, a fixed national clock simplifies meeting logistics, payroll cycles and supply-chain coordination with international partners.

The bill’s prospects on the House floor remain uncertain. The Senate unanimously passed an earlier version of the Sunshine Protection Act in March 2022 only to see it stall in the House, and Senate Commerce Committee Chair Ted Cruz has previously cautioned that there are “very real and complicated issues and countervailing arguments on both sides,” with sleep scientists and pediatric medicine groups continuing to lobby in favor of permanent standard time rather than permanent daylight time. But the 48-1 committee vote, the bipartisan cosponsor roster and direct White House backing mark the most favorable alignment for the measure since 2022.

For Congress, the calculation is increasingly an economic one. With the U.S. consumer economy representing roughly two-thirds of gross domestic product and small businesses driving the majority of net new job creation, even modest, durable tailwinds for retail and hospitality spending carry real macroeconomic weight. Eliminating the recurring productivity hit on the American workforce — across factories, offices, hospitals and the federal payroll itself — represents a rare piece of legislation with the potential to deliver measurable gains to GDP, employment and consumer activity without expanding the deficit. Whether the House converts this momentum into final passage will shape the daylight, and the economic rhythm, of every American workday going forward.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
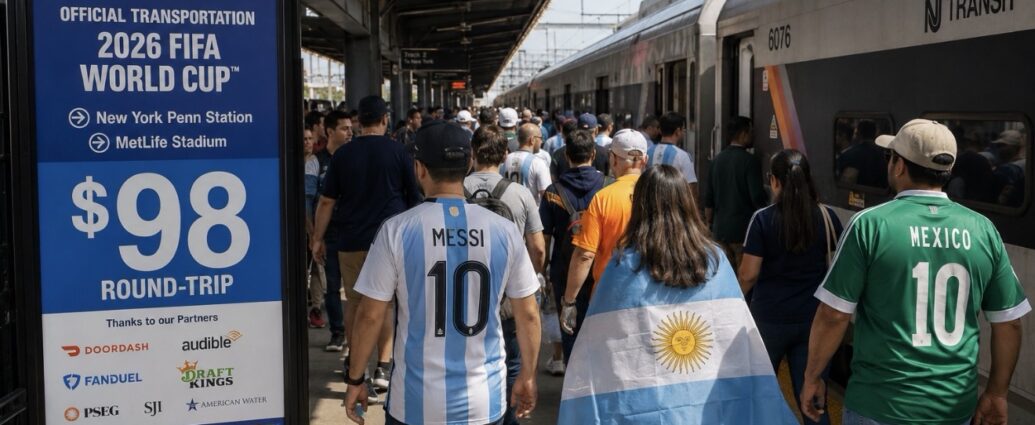
JBizNews Desk
PARIS — Sunday, May 24, 2026

A Paris appeals court on Thursday found Airbus and Air France guilty of involuntary manslaughter over the 2009 crash of a Rio-to-Paris flight that killed 228 people, overturning a lower-court acquittal that had stood for nearly three years and reopening one of the most contested corporate-liability cases in European aviation.

The Paris Court of Appeal ruled that the French flag carrier and Europe’s largest aerospace manufacturer were “solely and entirely responsible,” ordering each company to pay 225,000 euros — roughly $261,000 — the maximum criminal fine allowed under French law for corporate manslaughter.

The financial penalties are relatively minor for companies of that scale, but the criminal convictions themselves are highly consequential: a rare instance of both an airline and an aircraft manufacturer being held criminally liable for a commercial aviation disaster.

Flight AF447, an Airbus A330 operating between Rio de Janeiro and Paris, crashed into the Atlantic Ocean on June 1, 2009, killing all 216 passengers and 12 crew members aboard. The victims included 72 French citizens and 58 Brazilians. The aircraft’s black boxes were not recovered until 2011 following a deep-ocean search operation costing tens of millions of dollars.

Investigators later determined that the chain of events began when ice crystals blocked the aircraft’s pitot tubes — external sensors used to measure airspeed — causing unreliable speed readings during severe turbulence at high altitude.

The aircraft’s autopilot disconnected automatically when the data became inconsistent, forcing the pilots to fly manually under deteriorating conditions. Investigators concluded that the crew inadvertently placed the aircraft into an aerodynamic stall after pulling the nose upward, causing the wings to lose lift before the aircraft descended into the ocean.

The technical sequence itself has long been established. Thursday’s ruling instead focused on whether Airbus and Air France failed to adequately address the risks associated with the system failure.

The appeals court concluded that Airbus underestimated the dangers linked to pitot tube malfunctions and failed to provide sufficient warnings to airlines regarding the severity of the risk. Air France was separately found to have inadequately trained pilots to respond to high-altitude instrument failures and emergency manual-flight conditions.

The verdict marks a sharp reversal from the companies’ acquittal in 2023, when a lower French court ruled there was insufficient evidence proving a direct causal link between corporate decisions and the crash itself. While civil liability had already been established previously, criminal responsibility had been rejected.

Families of the victims, led by the association Entraide et Solidarité AF447 and its president Danièle Lamy, appealed the acquittal and secured the retrial that ultimately produced Thursday’s ruling.

Airbus moved quickly Thursday to signal that the legal battle is far from over.

In a statement issued from Toulouse, the company acknowledged the ruling while emphasizing that the appeals court’s decision contradicted both the earlier acquittal and prior conclusions reached by French investigating magistrates and prosecutors.

Airbus said it would immediately appeal to the Court of Cassation, France’s highest court for criminal and civil matters. Air France is widely expected to pursue the same course.

Any further proceedings will focus less on the facts of the crash itself and more on the legal standards and reasoning used by the appeals court in assigning criminal responsibility.

For investors, the market reaction reflected the broader reputational implications more than the direct financial cost. Airbus shares fell roughly 4.3% in Paris trading Thursday, while Air France-KLM shares declined nearly 1%.

The AF447 disaster already reshaped global aviation standards years ago. Regulators and airlines revised pitot tube specifications, expanded pilot training for unreliable airspeed events and increased emphasis on manual handling of aircraft during automation failures.

The crash became one of the most heavily studied incidents in modern pilot training programs, particularly around how crews respond when automated systems unexpectedly transfer control back to humans during high-stress emergencies.

What changed Thursday was not aviation procedure but the legal record.

After 17 years, multiple investigations, two major trials and a sustained campaign by victims’ families, a French court has now placed criminal responsibility directly on both the aircraft manufacturer and the airline operator.

Whether those convictions ultimately survive the next round of appeals will determine whether AF447 is remembered primarily as a tragedy that transformed aviation safety — or as one of the rare cases where Europe’s aviation establishment was criminally held to account.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Walmart Inc. confirmed in internal memos circulated to staff on Friday, May 22, 2026, that two of its senior executives are departing the company. Tom Ward, chief operating officer of warehouse-club arm Sam’s Club, is retiring, and Cedric Clark, executive vice president of U.S. store operations, is leaving the business altogether. The memos, distributed from Walmart’s Bentonville, Arkansas headquarters, mark the first major leadership turnover under new chief executive John Furner, who succeeded Doug McMillon in February as Walmart’s sixth chief executive in company history.

The internal communications said a replacement for Clark will be named in the “coming weeks.” The timing of Ward’s succession at Sam’s Club has not been disclosed. Both departures come roughly four months into Furner’s tenure and follow the four senior executive elevations he announced in January when he took the top job.

The leadership turnover arrives during a period of sustained operational strength at Walmart. The company reported fiscal first-quarter earnings on Thursday, May 21, with mixed results, telling investors its business remains strong despite consumer pressures from elevated gas prices and the lingering economic strain of the U.S.-Iran war. Walmart’s e-commerce and delivery network now reaches 95% of U.S. households in under three hours, a capability the company has built through aggressive investment in supply chain technology and fulfillment automation.

Furner, a 32-year Walmart veteran who previously ran Walmart U.S. and Sam’s Club U.S., has signaled from the outset that his agenda centers on consolidating decision-making and harnessing artificial intelligence across retail operations. In a January statement, Furner said: “As AI rapidly reshapes retail, we are centralizing our platforms to accelerate shared capabilities, freeing up our operating segments to be more focused on and closer to our customers and members.”

That centralization push is the strategic context for the latest departures. Walmart has invested heavily in generative AI shopping tools, automated fulfillment, and a platform consolidation strategy that pulls historically separate operating units — Walmart U.S., Sam’s Club, and Walmart International — onto shared digital infrastructure. The reorganization has elevated technologists and platform leaders while compressing the traditional store-operations hierarchy that Clark oversaw.

Furner’s January reshuffle installed Daniel Guggina as the new chief operating officer of Walmart U.S., replacing Furner himself in that role. Chris Nicholas, formerly chief executive of Sam’s Club U.S., was promoted to president and chief executive of Walmart International, succeeding Kathryn McLay, who departed the company on April 30, 2026, after a decade of service. Latriece Watkins stepped up to lead Sam’s Club U.S. The company also added Shishir Mehrotra, chief executive of Superhuman and former leader at Grammarly, to its board of directors in January, deepening the technology bench at the governance level.

The board has telegraphed strong support for the transition. Lead independent director Randall Stephenson noted in Walmart’s 2026 proxy statement that the succession has been “seamless” and that the board “remains highly engaged in talent development and succession planning.” Chairman Greg Penner, a member of the Walton family that founded the company, has publicly endorsed the centralization strategy.

The financial backdrop is robust. Walmart returned $15.6 billion to shareholders through dividends and share repurchases in fiscal 2026 and authorized a new $30 billion share repurchase program. The company posted $483 billion in U.S. net sales and more than $713 billion in total revenue. Its market capitalization places it among the most valuable U.S. companies by enterprise scale, behind only the largest Magnificent 7 technology names.

The departing executives leave substantial legacies. Tom Ward, a longtime Walmart veteran, was central to building out Sam’s Club’s member experience and supply chain capabilities during a period of intensifying rivalry with Costco. Cedric Clark oversaw store operations across Walmart’s roughly 4,600 U.S. stores, responsible for execution at the physical heart of the business — the in-store experience that still generates the majority of company revenue despite the rapid growth of e-commerce.

The pattern of senior departures and internal promotions suggests Furner is consolidating authority around a smaller, more technology-focused leadership group. That mirrors the playbook used by other large-cap retailers — including Target under chief executive Brian Cornell and Amazon under chief executive Andy Jassy — as they reorganize around AI-enabled supply chain, merchandising, and customer-service capabilities.

For investors, the leadership churn at Walmart is being read as confirmation that Furner intends to move quickly. The company has long been seen as a deliberate, slow-changing institution under Doug McMillon’s 11-year tenure. Furner’s willingness to reshape his executive bench within four months marks a notable shift in pace. Whether that velocity translates into accelerated earnings growth, faster e-commerce gains against Amazon, and stronger differentiation against Costco and Target will be the central question heading into the company’s fiscal second-quarter results later this summer.

For Walmart’s more than two million U.S. associates and its global workforce, the message from the top is clear. The company that has dominated American retail for two decades is preparing for a different kind of next decade, and the leadership team being assembled in Bentonville reflects that bet.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The cost of buying a home in America just got sharply more expensive. Freddie Mac reported Thursday morning that the average 30-year fixed-rate mortgage climbed to 6.51% for the week ending May 21, up from 6.36% a week earlier and the highest level in roughly nine months. A year ago, the same rate stood at 6.86%.

The jump, announced in Freddie Mac’s weekly Primary Mortgage Market Survey, lands at the worst possible moment for the housing market. Spring is the season when most American families try to close on a home before summer moves and the new school year. Instead, buyers are watching their monthly payments climb week by week with no clear ceiling in sight.

Sam Khater, chief economist at Freddie Mac, framed the shift bluntly in the release accompanying the data. He urged aspiring buyers to shop multiple lenders, noting that comparing quotes can save thousands as rates fluctuate. It was a quiet acknowledgment that the friendly rate environment many had banked on for 2026 has slipped away.

Other industry trackers showed conditions even tighter than Freddie Mac’s headline figure suggests. The Mortgage Bankers Association put the average 30-year rate at 6.56% through last Friday, a seven-week high. Mortgage News Daily, which tracks daily lender pricing rather than weekly averages, showed rates around 6.65% to 6.67% mid-week. Zillow’s lender survey pegged the average closer to 6.73%.

The driver is no mystery. The 10-year Treasury yield, the benchmark mortgage rates track most closely, has jumped roughly 15 basis points over the past week to about 4.6%. Bond investors are pricing in two related shocks at once: persistent inflation, after the April consumer price index showed prices rising 3.8% annually, and the economic fallout from the ongoing U.S.-Iran war, which has pushed oil prices sharply higher and rippled through the cost of everything from gasoline to manufactured goods.

Bob Broeksmit, president and CEO of the Mortgage Bankers Association, said higher Treasury yields continued to push mortgage rates higher through the prior week, weighing on affordability and application activity. Purchase applications have softened in step with the climb.

Inside the Federal Reserve, the calculation has flipped. Just months ago, futures markets were pricing in cuts to the federal funds rate before year-end. Now, traders see essentially no chance of a 2026 cut and rising odds that the Fed’s next move could be a hike. That marks one of the more dramatic policy reversals of the cycle and reflects how seriously policymakers are taking the inflationary pressure from the oil-price spike tied to the Middle East conflict.

For households, the math is unforgiving. At 6.51%, the monthly principal-and-interest payment on a $400,000 loan runs about $2,529, versus $2,492 at 6.36% just one week earlier and $2,624 had rates climbed to 7%. Mortgage originators say a return to the 5% range is what would actually unlock the sidelined buyers who have been waiting since 2022. That five-handle now looks distant.

The supply side offers little relief. Lawrence Yun, chief economist at the National Association of Realtors, said following the trade group’s latest existing-home sales release that inventory remains tight at a 4.4-month supply — well below the six months considered balanced. Existing-home sales ticked up just 0.2% in April to a 4.02 million annual pace, with the median price up 0.9% year over year to $417,800. Yun warned that unless supply meaningfully increases, home price growth could outpace wage growth and further erode the homeownership rate.

That leaves first-time buyers caught in the familiar squeeze: prices that won’t come down because inventory won’t come up, and financing costs that won’t come down because inflation won’t come down. Many are simply waiting. Nicholas Barta, division president at Security First Financial, said borrowers have psychologically adjusted to the mid-to-high-six range in a way they had not during the 2022–2023 spike, but the qualification math at 7% remains punishing.

For the spring season, the damage may already be done. Buyers who started shopping in March on the assumption that the Federal Reserve would soon cut, and that the 30-year would drift back into the high fives, are recalibrating in real time. Sellers are recalibrating too. Listings that sat through April at aspirational prices are starting to see cuts, particularly across parts of the South and West where inventory has loosened the most.

The path forward depends on factors well outside the housing market. A de-escalation in the Iran conflict and a meaningful drop in oil prices would pull Treasury yields lower and pull mortgage rates with them. A second inflation surprise in the May CPI report, due next month, would do the opposite. For now, the housing market is once again hostage to forces playing out thousands of miles away.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Major U.S. and global commercial real estate lenders, including Goldman Sachs Group and Deutsche Bank, have started aggressively unloading troubled property loans at steep discounts — in some cases taking losses of up to 85% — signaling that the long-running strategy known across the industry as “extend and pretend” is finally breaking down.

For the past three years, many banks avoided recognizing losses by repeatedly extending commercial real estate loans instead of forcing borrowers into default. Now, with interest rates still elevated, office buildings sitting half-empty, and hundreds of billions of dollars in debt coming due, lenders are beginning to accept painful losses rather than continue pretending troubled properties will recover quickly.

The shift is becoming visible across major U.S. cities.

In Manhattan, Shanghai Commercial Bank reportedly sold debt tied to a stalled condo conversion project at 335 W. 35th Street at roughly an 85% discount to the loan’s payoff amount. In Los Angeles, lenders led by Goldman Sachs seized control of the historic Radford Studio Center, with Netflix now reportedly negotiating to buy the property at a fraction of its previous valuation.

In San Francisco, investors tied to a $240 million commercial mortgage-backed securities (CMBS) deal backed by the office tower at 600 California Street absorbed major losses after the underlying loan sale generated only about $101 million for bondholders.

Meanwhile, in Downtown Los Angeles, Brookfield Property Partners and its lenders are trying to offload nearly 5 million square feet of office space tied to distressed buildings — roughly 18% of the entire downtown office market.

The numbers behind the crisis are staggering.

According to Trepp, the commercial real estate data firm, the delinquency rate for office loans packaged into CMBS securities surged to a record 12.34% earlier this year — higher than the worst periods of the 2008 financial crisis. The overall CMBS special servicing rate climbed to 11.38% in April, with office buildings driving most of the distress.

The biggest problem is refinancing.

During the ultra-low interest-rate years of 2020 and 2021, many office landlords borrowed money at rates near 3% or 4%. Those same borrowers are now trying to refinance loans at rates closer to 6% or 7%, while simultaneously dealing with lower occupancy rates caused by remote and hybrid work.

Many buildings simply no longer generate enough rent to support the new financing costs.

Nationwide office occupancy remains stuck around 80%, according to CommercialEdge, well below the levels many buildings need to break even.

The scale of debt coming due is enormous.

The Mortgage Bankers Association estimates roughly $875 billion in commercial real estate loans will mature during 2026 alone. Banks hold nearly half of that exposure.

Regional banks remain especially vulnerable because many concentrated heavily in commercial property lending during the low-rate era.

Bank analysts have repeatedly flagged institutions including New York Community Bancorp, Valley National Bancorp, Western Alliance, Zions Bancorporation, and Cullen/Frost Bankers as among the most exposed to commercial real estate stress.

The issue matters far beyond Wall Street or large office towers.

When regional banks absorb losses, they often tighten lending across the board. That means small business owners, restaurant operators, doctors, contractors, and families seeking home equity loans can all face tougher borrowing conditions.

Banks in stressed markets are already demanding larger down payments, shortening loan terms, and raising financing requirements for small-business and commercial borrowers.

The crisis is also reshaping cities themselves.

Empty office towers in San Francisco, Chicago, Los Angeles, Houston, Washington, D.C., and parts of New York City are reducing property-tax revenue that local governments rely on to fund schools, police, transit systems, and city services.

San Francisco officials have already warned of structural budget gaps tied partly to collapsing downtown office values. Chicago and New York are facing similar pressures.

Politicians are increasingly pushing office-to-apartment conversions as a solution.

Congress recently advanced bipartisan legislation designed to encourage developers to convert older office buildings into housing as the U.S. faces an estimated 4.7 million-home shortage.

But the reality is more complicated.

Many office towers are difficult or prohibitively expensive to convert because of plumbing layouts, window spacing, elevator configurations, and zoning rules. Industry experts say only a relatively small percentage of distressed office buildings are actually suitable for residential conversion.

While banks are taking losses, large investment firms are moving in aggressively.

Private equity giants including Blackstone, KKR, Apollo Global Management, Brookfield, Starwood Capital Group, and Carlyle Group have raised billions of dollars specifically to buy distressed commercial real estate loans at discounted prices.

Executives including Goldman Sachs CEO David Solomon, JPMorgan CEO Jamie Dimon, and Morgan Stanley CEO Ted Pick have all described distressed commercial real estate as one of the biggest investing opportunities of the current cycle.

The basic strategy is simple: buy distressed assets cheaply, wait for markets to stabilize, and eventually profit when values recover.

There are early signs the worst may eventually pass.

Industry analysts say the market cannot recover until losses are finally recognized and bad loans clear through the system. Banks taking losses today may actually help reset the market faster by allowing new investors and new uses for old properties to emerge.

But the pain is unlikely to end quickly.

The more than $130 billion in distressed commercial real estate debt already circulating through the financial system is expected to continue pressuring banks, property owners, and city budgets well into 2027.

The lesson of the current cycle is becoming increasingly clear: the lenders who accepted smaller losses early are moving forward. The ones who waited the longest are now absorbing the deepest pain.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. Southern Command, the Pentagon combatant command responsible for military operations in Central and South America and the Caribbean, announced on Wednesday, May 20, 2026, that the USS Nimitz aircraft carrier strike group has entered the Caribbean Sea as the Trump administration intensifies its economic, judicial, and diplomatic campaign against the Cuban government. The announcement, made through an official SOUTHCOM statement and a video posted to its X account, called the deployment “the epitome of readiness and presence, unmatched reach and lethality, and strategic advantage.”

The USS Nimitz is a nuclear-powered U.S. Navy aircraft carrier, effectively a floating military airbase capable of carrying dozens of fighter jets, surveillance aircraft, helicopters, and thousands of sailors and Marines. The broader carrier strike group includes guided-missile destroyers, support ships, radar systems, and combat aircraft designed to project American military power anywhere in the world without relying on foreign bases.

The strike group, deployed as part of the multinational Southern Seas 2026 maritime exercise, includes the carrier USS Nimitz (CVN 68), the embarked Carrier Air Wing 17 of nine squadrons flying F/A-18C/E/F Super Hornets, EA-18G Growlers, E-2D Hawkeyes, C-2A Greyhounds, and MH-60R/S Sea Hawks, the guided-missile destroyer USS Gridley (DDG 101), and the fleet oiler USNS Patuxent (T-AO 201). The carrier had recently completed joint naval exercises with the Brazilian Navy off Rio de Janeiro before transiting into SOUTHCOM’s area of responsibility.

The timing carries unmistakable political weight. The carrier’s arrival coincided with three coordinated moves by Washington the same day. The U.S. Department of Justice unsealed a federal criminal indictment against 94-year-old former Cuban leader Raúl Castro in connection with the 1996 shootdown of two civilian aircraft operated by the Miami-based exile group Brothers to the Rescue, in which four people were killed. Secretary of State Marco Rubio, the Florida Republican and son of Cuban immigrants, released a Spanish-language video urging Cubans to reject what he called the island’s communist leadership. And President Donald Trump posted a presidential statement linking Cuba to the captured former Venezuelan leader Nicolás Maduro, writing that the indictment and removal of Maduro “sent a clear message to his socialist allies in Havana: this is our hemisphere, and those who destabilize it and threaten the United States will face consequences.”

For business and markets, the deployment reads as the climax of a months-long pressure campaign that has already reshaped the regional economic landscape. According to U.S. Treasury and State Department records, the Trump administration has imposed more than 240 sanctions on Cuba since January 2026. U.S. Navy and Coast Guard assets have intercepted at least seven oil tankers carrying fuel destined for the island. Trump signed an executive order on May 1 expanding restrictions on Cuba’s energy, defense, mining, and financial services sectors. The cumulative result, according to regional energy analysts, is an 80% to 90% collapse in Cuban energy imports, triggering blackouts lasting up to 25 hours per day across more than 55% of the island’s territory.

The economic implications stretch well beyond Cuba’s borders. The Caribbean is one of the most important commercial corridors in the Western Hemisphere, anchoring trade flows between the Port of Houston, Port of New Orleans, Port of Miami, and Latin American export hubs. Roughly 40% of U.S. waterborne foreign trade transits through the region. Major shipping lines including A.P. Moller-Maersk, Mediterranean Shipping Company, Hapag-Lloyd, CMA CGM, and Crowley Maritime route container traffic through nearby waters. Any sustained military presence raises insurance, routing, and compliance costs for commercial operators, even without direct military conflict.

Cruise operators are especially exposed. Royal Caribbean Cruises, Carnival Corporation, Norwegian Cruise Line Holdings, and MSC Cruises all run major Caribbean itineraries, including stops in Jamaica, the Bahamas, the Cayman Islands, Aruba, and the Dominican Republic. The Caribbean cruise market generates roughly $30 billion annually in passenger spending across the region. Cruise stocks briefly fell last year when the USS Gerald R. Ford deployed to the Caribbean during the operation that resulted in Maduro’s capture. Investors are now watching closely for a similar market reaction tied to the Nimitz deployment.

The pressure campaign has also disrupted regional energy markets. With Cuba’s imports collapsing, fuel flows from Venezuela — historically Havana’s main supplier through subsidized oil agreements — have sharply declined. PDVSA, Venezuela’s state oil company now operating under a transitional government after Maduro’s removal, has reduced shipments to Cuba. The shift has tightened diesel and heavy fuel oil supplies across parts of the Caribbean and Central America, raising costs for utilities, freight operators, and businesses dependent on imported energy.

Financial institutions are also feeling the impact. Cuba has been largely cut off from U.S. banking channels since the 1960s, but some European and Canadian banks have continued facilitating trade and remittance flows. Trump’s May 1 executive order expanded restrictions on financial services tied to Cuban entities, increasing compliance pressure on banks including Banco Santander, BNP Paribas, and Royal Bank of Canada. Money-transfer channels used by Cuban families are facing increased scrutiny as Washington tightens enforcement.

The Cuban-American business community in South Florida, centered in Miami-Dade County, has emerged as one of the strongest supporters of the administration’s hardline approach. The community includes major real estate, hospitality, banking, and trade interests that have long favored stronger pressure on Havana. Rubio, before becoming secretary of state, was one of the most influential advocates of that position in Washington. Florida Governor Ron DeSantis has also aligned the state’s economic and political agenda with the administration’s broader Caribbean strategy.

CIA Director John Ratcliffe met with Cuban officials last week, warning that negotiations would not remain open indefinitely. The administration is reportedly seeking concessions involving political prisoners, migration controls, and counternarcotics cooperation. Cuban President Miguel Díaz-Canel rejected the indictment against Castro, calling it “a political maneuver, devoid of any legal foundation.”

For defense contractors, the deployment is quietly positive. Companies including Lockheed Martin, Northrop Grumman, RTX, General Dynamics, and Huntington Ingalls Industries benefit from ongoing carrier operations, maintenance cycles, munitions demand, and naval support contracts. Huntington Ingalls, which built all active Nimitz-class aircraft carriers, is also constructing the Navy’s next-generation Gerald R. Ford-class fleet. The USS Nimitz, commissioned in 1975, is scheduled for retirement in March 2027 following this deployment, making this one of its final major operations.

Regional governments are now navigating increasingly difficult trade and diplomatic calculations. Countries including Mexico, Jamaica, Colombia, and the Dominican Republic maintain significant migration, trade, tourism, and remittance ties with both Washington and Havana. Many are now assessing whether the administration’s tougher Cuba posture could expand more broadly across the hemisphere.

The Nimitz will eventually return to Naval Station Norfolk in Virginia after completing its Caribbean mission. But the message sent by its arrival — to Havana, Caracas, Beijing, and global markets — is likely to outlast the carrier itself.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
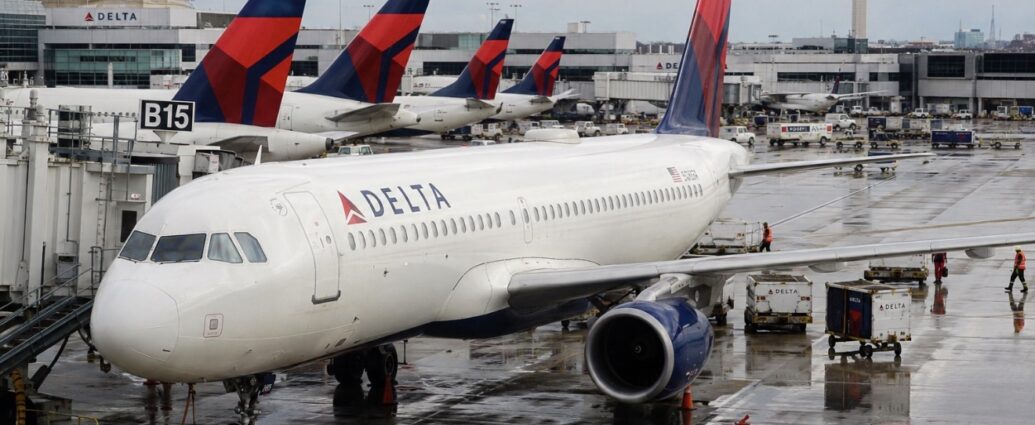
By JBizNews Desk

NEW YORK, May 24, 2026 — Nearly every American has received one at this point: the fake IRS call, the text claiming a package cannot be delivered, the urgent message pretending to come from a bank, hospital, or even a family member in distress.

Congress now says the problem has become large enough to demand answers directly from the country’s biggest telecommunications companies.

Representative David Schweikert, the Arizona Republican who chairs the Joint Economic Committee, and Senator Maggie Hassan, the New Hampshire Democrat serving as the committee’s senior member, sent a bipartisan letter Wednesday to AT&T Inc., Verizon Communications Inc., and T-Mobile US Inc. demanding detailed explanations of what the carriers are actually doing to detect, block, and prevent fraudulent calls and text-message scams moving through their networks.

The request comes as financial losses tied to scams continue rising sharply across the United States.

According to figures cited by the committee, scams cost Americans an estimated $200 billion during 2024. The Federal Trade Commission separately reported $16.6 billion in officially confirmed fraud losses last year, up roughly 33% from the prior year, while outside estimates suggest the true scale may be dramatically higher because many victims never report losses.

The financial damage has increasingly become concentrated among older Americans.

The FBI reported that seniors lost more than $4.8 billion to fraud schemes in 2024 alone, with many cases involving life savings wiped out through phone-based impersonation scams, investment fraud, romance scams, or fake emergency requests targeting retirees.

Lawmakers from both parties have spent the past year escalating scrutiny of what they increasingly describe as a highly organized international scam economy tied to criminal networks operating across Southeast Asia and other overseas jurisdictions.

The bipartisan nature of the congressional letter is itself notable in Washington.

Schweikert and Hassan rarely align publicly on major economic or regulatory issues, but both lawmakers argued the burden of scam detection has fallen too heavily on ordinary consumers rather than the communications companies transmitting the fraudulent traffic.

“Consumers need to be able to trust that the calls and texts they receive — from their doctor’s office or their child’s school, for example — are authentic,” the lawmakers wrote. “Scam communications, however, are increasingly difficult to distinguish from legitimate messages, and too much of the burden of detection is falling on customers.”

The committee is requesting detailed information from AT&T, Verizon, and T-Mobile regarding how they identify suspicious activity, how many scam calls and texts they block, how they coordinate with law enforcement, and what actions are taken against bad actors once fraudulent traffic is detected.

The letter effectively asks the carriers to prove their anti-scam systems are working at a time when reported fraud losses continue climbing.

The pressure on telecom providers has been building since Congress passed the TRACED Act in 2019, legislation aimed at combating robocalls and spoofed phone numbers. The law authorized the Federal Communications Commission to require carriers to implement authentication technology known as STIR/SHAKEN, designed to verify whether incoming calls are actually originating from the numbers displayed on caller ID.

While the technology has reduced portions of spoofed traffic, enforcement gaps remain — particularly involving smaller carriers, international routing systems, and increasingly sophisticated scam operations capable of adapting around detection systems.

Congressional investigators now appear increasingly skeptical that the existing protections are enough.

The telecom industry is also not the only target.

Lawmakers have recently expanded scam-related investigations into social media platforms, artificial-intelligence companies, online dating services, and digital advertising systems increasingly used by criminal networks to locate victims and distribute fraudulent content.

Earlier this year, members of the bipartisan Stop Scams Caucus sent a similar letter to Meta Platforms Inc. Chief Executive Mark Zuckerberg after reports suggested Meta-owned platforms may have played a significant role in distributing scam advertisements and fraudulent content targeting American consumers.

Several lawmakers are also pursuing legislation aimed at disrupting the overseas criminal organizations orchestrating many of the operations.

For AT&T, Verizon, and T-Mobile, the political implications extend beyond consumer complaints alone.

Telecommunications companies rely heavily on federal regulators and congressional support for spectrum access, merger approvals, infrastructure policy, and universal-service funding decisions. Sustained bipartisan criticism that consumers are losing billions through scams delivered across carrier networks could eventually lead to tougher reporting requirements, enforcement standards, or financial penalties.

At the moment, however, Congress is still primarily demanding transparency.

For consumers, the guidance from regulators and law enforcement remains consistent: government agencies, banks, hospitals, and legitimate businesses generally do not demand immediate payment through gift cards, cryptocurrency, wire transfers, or urgent threats delivered over unsolicited calls or text messages.

Security experts continue advising Americans to independently verify any suspicious communication by contacting institutions directly through official phone numbers rather than responding through incoming messages.

The broader issue now confronting Washington is larger than individual scams themselves.

The United States has built one of the world’s most advanced communications infrastructures, yet criminal networks continue exploiting those systems at industrial scale to target ordinary Americans.

Congress is now asking the telecom industry a direct question: if the carriers possess the data, network visibility, and technical tools to identify fraudulent traffic, why are the losses still accelerating?

The answers may shape the next phase of federal regulation surrounding America’s phone networks — and determine how aggressively telecom companies are ultimately required to police the systems they operate.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A proposed New York tax on all-cash home purchases above $1 million in New York City is likely to be dropped from the final state budget, according to people familiar with negotiations in Albany, marking a significant setback for Mayor Zohran Mamdani’s effort to close a multibillion-dollar city budget gap without raising broad income or corporate tax rates.

Bloomberg first reported the likely collapse Thursday morning, citing officials involved in the negotiations. The proposal would have imposed a 1% levy on buyers purchasing residential properties in cash above the $1 million threshold and was projected to generate roughly $160 million annually for New York City.

The measure formed part of the broader $8 billion state aid framework Gov. Kathy Hochul unveiled earlier this month in support of Mamdani’s proposed $124.7 billion city budget for the fiscal year beginning July 1.

Assembly Speaker Carl Heastie confirmed last week that the proposal was “part of the plan to help close the city’s deficit,” while State Senator James Skoufis, a member of the Senate Finance Committee, acknowledged the levy had become part of the wider budget negotiations.

But more than six weeks after the April 1 budget deadline, lawmakers familiar with negotiations now say the proposal is unlikely to survive the final vote as resistance from real estate interests and moderate Democrats intensified.

The policy argument behind the tax centered on how New York currently treats cash buyers versus financed buyers.

According to the nonprofit Center for New York City Neighborhoods, more than 60% of the nearly 18,000 home sales completed in New York City during the first half of 2025 were all-cash transactions, with a median purchase price of roughly $939,000.

In Manhattan’s luxury market, nearly nine out of every ten transactions above $3 million closed entirely in cash.

Mamdani’s office and progressive lawmakers argued that wealthy cash buyers — often institutional investors, second-home owners or foreign purchasers — effectively avoid the city’s mortgage-recording tax, which generates approximately $812 million annually but applies only to financed transactions.

The opposition came swiftly from the real estate industry, brokerage firms and centrist Democrats increasingly wary of Mamdani’s broader tax posture.

James Whelan, president of the Real Estate Board of New York, warned earlier this month that the city’s budget problems “will not be solved by more taxes,” adding that increasing transaction costs would discourage sales activity and potentially reduce overall revenue collected by the city, state and MTA.

Lobbying from broker associations and real estate trade groups intensified over the past two weeks as lawmakers weighed the proposal’s economic impact against the city’s fiscal needs.

The collapse also arrives during a broader wave of pushback against Mamdani’s economic agenda.

Earlier Thursday, JPMorgan Chase chief executive Jamie Dimon warned on Bloomberg Television that the mayor’s broader tax proposals risk damaging New York’s competitiveness as a business center.

“People think that somehow being anti-business is going to help the city, it’s not,” Dimon said.

Jeff Bezos separately criticized the administration this week on CNBC over New York City’s $43 billion school budget and broader spending structure.

Meanwhile, the Multicultural Business Coalition, an immigrant-led organization representing more than 50 chambers of commerce, has assembled a war chest exceeding $1 million to oppose Mamdani’s proposed city-owned grocery store initiative and is weighing legal action against the city.

The likely demise of the cash-purchase tax leaves another major proposal still alive inside negotiations: the pied-à-terre surcharge outlined by Hochul last week.

That measure would impose annual surcharges ranging from 0.8% to 1.05% on one- to three-family homes valued above $5 million, along with higher assessments on luxury condos and co-ops beginning at $1 million in market value. State officials estimate the proposal could generate roughly $500 million annually if approved.

The practical implications now move in two directions.

For City Hall, the loss of $160 million is not catastrophic on its own, but it reinforces a broader problem confronting Mamdani’s fiscal strategy. Each revenue proposal rejected in Albany increases pressure on the remaining tax measures — including the proposed 11.5% corporate tax rate and the 2% surcharge on residents earning more than $1 million annually.

Every failed revenue line eventually forces a choice between spending cuts, additional borrowing or new taxes elsewhere.

For the real estate market, however, the retreat is likely to produce short-term relief.

Luxury brokers said transaction activity slowed in March and April as buyers waited to see whether the levy would become law. With the proposal now appearing unlikely to survive, analysts expect some sidelined purchasers to move forward with transactions before future versions of the tax potentially re-emerge.

The Hamptons, Hudson Valley and several upstate luxury markets that had also been discussed in potential statewide expansions of the levy could similarly benefit from a rebound in transaction activity.

Politically, the episode reveals the limits of Mamdani’s support inside Albany even on comparatively targeted tax measures.

Unlike broader income or corporate tax increases, the cash-purchase levy focused almost exclusively on wealthy buyers and sought to address what supporters viewed as an imbalance in the existing mortgage-tax system.

That even this narrower proposal appears headed for defeat underscores how cautious the center of New York’s Democratic establishment remains toward large-scale tax expansion tied to Mamdani’s agenda.

The final state budget is expected before the end of May.

Neither Mamdani’s office nor Hochul’s office had publicly commented on the apparent collapse of the proposal by Thursday afternoon.

JBizNews Desk

© 2026 JBizNews. All rights reserved.

Bitcoin is closing one of its toughest stretches of the year as a rare convergence of macro, institutional, and technical headwinds bears down on the world’s largest cryptocurrency. The coin briefly broke below the key $75,000 support level this past week before paring losses to trade near $77,500 as of the Friday ETF market close, capping a multi-day slide that has erased more than $126 billion in crypto market value since mid-month.

The most striking signal came from the institutional side. U.S. spot Bitcoin ETFs bled $1.26 billion last week, the steepest weekly drawdown since late January, according to data cited by The Block. The exodus marked a six-day outflow streak that began May 15 and snapped what had been a six-week run of positive inflows. BlackRock’s iShares Bitcoin Trust (IBIT) posted $448 million in outflows on Monday alone — its second-largest single-day redemption of 2026 — followed by Ark Invest and 21Shares’ ARKB at $109.6 million and Fidelity’s FBTC at $63.4 million. Smaller outflows continued through Friday, when IBIT shed another $68 million and FBTC another $36 million, per Benzinga data.

The asymmetry has become sharp at the issuer level. BlackRock’s IBIT closed Friday with $61.1 billion in net assets against $64.8 billion in cumulative net inflows, meaning current market value now sits roughly $3.7 billion below the dollars investors have put into the fund. Fidelity’s FBTC, by contrast, still carries about a $3.2 billion cushion of net assets over cumulative inflows. IBIT alone accounts for roughly 4% of Bitcoin’s circulating supply, making its flows a closely watched proxy for institutional sentiment.

The macro backdrop has turned sharply against risk assets. April Producer Price Index data released by the Bureau of Labor Statistics showed wholesale inflation surging to 6% year-over-year, well above the 4.9% consensus and the highest reading since January 2023. Core PPI climbed to 5.2%, also above the 4.3% estimate. Both CPI and PPI now sit at three-year highs, driven in part by the energy spike tied to the U.S.-Iran war and lingering tariff pass-through from earlier in the year. The Cleveland Fed’s Inflation Nowcasting tool projects another 38-basis-point jump in trailing-twelve-month inflation to 4.18% by month-end.

Markets have responded by repricing the Federal Reserve’s path. CME FedWatch Tool data through late March showed roughly a 30% probability of a rate hike by year-end, with the odds of a cut collapsing to under 3%. The Atlanta Fed’s Market Probability Tracker placed rate-hike odds above rate-cut odds within a three-month window for the first time in this cycle. JPMorgan Chase projects the Fed’s next move will be an increase, though it expects the hike to come in the third quarter of 2027. Federal Reserve Chair Jerome Powell, whose term expires May 15, 2026, has thus far resisted calls to tighten in response to the energy shock, but markets are no longer pricing in the rate cuts that fueled the early-year crypto rally.

Bitcoin’s technical picture has weakened in step. The coin cleared $80,000 on May 4 and tested its 200-day moving average near $82,000 before stalling. The 20-day exponential moving average has now flipped from support to resistance near the $78,000 mark. Aggregate cumulative volume delta on Bitcoin’s spot order books ran negative for nine consecutive sessions through May 19, the longest sustained net-selling stretch of 2026, according to a Nexo note cited by The Block. Total crypto liquidations reached roughly $657 million in a single 24-hour window on Monday, with $584 million — about 89% — coming from long positions, per Glassnode and Bitcoin Magazine Pro data.

Spot Ether ETFs have fared even worse. The category logged a tenth consecutive day of outflows on Friday, the longest negative streak since March 2025, with Ether trading near $2,130 at the ETF close.

Bulls argue the structural picture remains intact. Despite the week’s losses, spot Bitcoin ETFs still hold $57.1 billion in cumulative net inflows and $98.9 billion in total net assets across all 12 funds, with year-to-date inflows still above $65 billion. The $1.26 billion in weekly outflows represents less than 2% of that cumulative base. Bloomberg ETF analyst Eric Balchunas has argued that even amid 2026’s redemption periods, “the overarching trend continues to be historically favorable” and that spot BTC ETFs have “substantially exceeded initial market forecasts” for inflows.

Some analysts read the rotation as healthy. FXTM senior market analyst Lukman Otunuga wrote in a recent note that “despite a difficult 2025, bitcoin may stage a comeback in 2026,” citing the prospect of lower rates and thinning active supply as eventual tailwinds. Whether the Fed’s rate path delivers those cuts is now the central question hanging over both crypto and broader risk assets.

The next catalysts will come from the macro calendar. May CPI data due in early June, the Fed’s June FOMC meeting, and any progress in the U.S.-Iran negotiations announced this weekend — which could pull oil sharply lower and ease inflation pressure — will all weigh heavily. A signed deal with Iran that reopens the Strait of Hormuz and brings Iranian crude back to global markets would be unambiguously bullish for Bitcoin, removing the energy-led inflation impulse currently driving hawkish Fed repricing.

For now, traders are watching $75,000 as the line in the sand. A clean break below that level, accompanied by accelerating ETF redemptions, would mark the most material crypto drawdown of the year. A hold and a rebound, particularly if paired with an Iran peace announcement and softer inflation data, could quickly reverse the narrative. Bitcoin, as always, sits at the intersection of macro, flow, and sentiment — and right now all three are pulling the same direction.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Imagine for a moment that two countries are at war. One is firing missiles at the other. People are dying. Cities are being hit. And yet, in the middle of all of this, the country being attacked opens its doors to 30,000 citizens of the country attacking it — and welcomes them in to spend a week praying at its holiest religious site.

That is exactly what is happening right now in Saudi Arabia. The Iranian Hajj and Pilgrimage Organization confirmed through Iran’s state news agency IRNA on Friday, May 22, 2026, that roughly 30,000 Iranian pilgrims have safely arrived in Saudi Arabia for the annual Hajj — the once-in-a-lifetime religious journey that all Muslims with the means must make at least once in their lives. The Saudi Ministry of Hajj and Umrah, headed by Hajj Minister Tawfiq Al Rabiah, confirmed that more than 1.2 million total pilgrims from around the world have arrived in the kingdom, with 1.8 million expected by the time the rites begin Monday, May 26.

The natural question is the obvious one. Iran has been firing drones and missiles at Saudi Arabia for months. The Saudi air defense system, the PAC-3 interceptor network supplied by the United States, is down to about 14% of its pre-war stockpile because of how many incoming Iranian threats it has had to shoot out of the sky. The U.S. Embassy in Riyadh issued its first-ever Level 3 “Reconsider Travel” warning specifically targeting the Hajj.

So why on earth would Saudi Arabia open the gates to thousands of Iranian citizens right now?

The answer comes down to three things: money, religion, and a careful business decision both governments have quietly made.

The money is enormous.

The Hajj is not just a religious event. It is one of the largest annual businesses in the entire Arab world. According to Saudi General Authority for Statistics data, the Hajj and year-round religious tourism generate roughly $12 billion every year for the Saudi economy. That is more than the entire annual gross domestic product of dozens of countries.

That $12 billion supports more than 1 million jobs in Saudi Arabia. Hotels in Mecca and Medina. Restaurants. Taxi drivers. Bus operators. Airline workers at Saudia. Doctors and nurses staffing pilgrimage hospitals. Construction workers. Cleaners. Security guards. Telecommunications workers at STC, Mobily, and Zain Saudi Arabia. The Hajj is the lifeblood of an entire layer of the Saudi economy that has nothing to do with oil.

Crown Prince Mohammed bin Salman’s Vision 2030 plan is built on growing this number, not shrinking it. The kingdom wants to bring 30 million annual religious visitors to Saudi Arabia by 2030, generating an additional $13.32 billion in government revenue on top of what the Hajj already produces. Blocking Iranians from coming this year would mean publicly admitting that the religious tourism business can be turned off by war — which is the last message Mohammed bin Salman wants the world to hear.

The religion matters even more.

Saudi Arabia’s king holds a special title: Custodian of the Two Holy Mosques. That title gives the kingdom religious authority across the entire Muslim world — about 1.9 billion people. It is the foundation of Saudi Arabia’s soft power and a major reason the kingdom carries diplomatic weight far beyond what its size and population would normally justify.

If Saudi Arabia were to ban Iranian pilgrims because of the war, it would essentially be saying: we will deny Muslims their religious obligation because of politics. That is exactly the accusation Iran’s leadership has spent decades trying to make stick. Banning Iranians would hand Tehran a propaganda victory worth more than anything Iran could win on the battlefield. It would also alienate Shia Muslim populations across Iraq, Lebanon, Bahrain, Pakistan, and India — many of whom Saudi Arabia is actively trying to court diplomatically.

So Saudi Arabia does the opposite. It welcomes the Iranians in. It deploys security to protect them. It coordinates their entry with Iraqi authorities, who escort the pilgrims through border crossings in overland convoys. Crown Prince Mohammed bin Salman has personally ordered, according to Gulf News, the “full mobilization of operational, security, and preventive plans” to make sure the pilgrimage goes smoothly. Neither MBS nor Hajj Minister Al Rabiah mentioned Iran or the war by name in their public statements. The silence is the message: the Hajj is bigger than the war.

Iran needs this too.

For Iran, the calculation is just as cold and just as practical. Supreme Leader Ayatollah Mojtaba Khamenei could have ordered an Iranian boycott of the Hajj, as Iran did between 1988 and 1990 after a deadly clash in Mecca. Boycotting would have sent a powerful political message.

But it would have also denied tens of thousands of Iranian Muslims their religious obligation, particularly older pilgrims for whom the Hajj is the spiritual goal of a lifetime. It would have meant that Iran’s government was telling its own faithful: politics matters more than your Hajj. That is a message no leader of an officially Islamic republic wants to deliver to their population.

So instead, Iran quietly sent 30,000 pilgrims through Iraqi territory, coordinated with Saudi authorities through diplomatic back-channels, and called it a wartime compromise. The normal Iranian quota is 86,700. This year is about a third of that. Iran can claim it stayed religiously faithful. Saudi Arabia can claim it kept the holy sites open to all Muslims. Both governments get what they need.

How the system actually works.

The 2023 China-brokered deal that restored diplomatic relations between Saudi Arabia and Iran is the quiet machinery making all of this possible. That agreement, negotiated by Chinese President Xi Jinping’s team, reopened embassies in both capitals and established working channels between the two foreign ministries. The war has bent that relationship, but it has not broken it.

Iraq has taken a practical middleman role. Its Interior Minister, Lieutenant General Abdul Amir al-Shamari, announced Iraqi authorities are escorting Iranian pilgrim convoys through border crossings and coordinating directly with both Tehran and Riyadh. Ali Reza Rashidan, head of Iran’s Hajj Committee, confirmed direct discussions with the Saudi Ministry of Hajj and Umrah. Iranian Ambassador to Riyadh Ali Reza Enayati announced the safe arrival of the first pilgrim group on Saudi soil.

For pilgrims themselves, the experience is largely unchanged. “We know we are at the safest place in the world,” Fatima, a 36-year-old German housewife traveling with her family, told AFP reporters in Mecca. Mecca’s hotels are sold out. Jeddah’s restaurants are packed. Saudia is running additional flights. Pilgrimage infrastructure built over decades is operating at full capacity.

The lesson for the rest of the world.

The Hajj is teaching everyone a quiet lesson right now. Even in war, certain institutions are too valuable to break. Saudi Arabia earns $12 billion, preserves its religious authority over 1.9 billion Muslims, and maintains a diplomatic channel with its largest regional rival. Iran delivers its citizens’ religious obligation, preserves its own Islamic credentials, and keeps a working line of communication with Riyadh open.

Both countries are doing the math, and both are reaching the same conclusion. Block the pilgrimage and everyone loses. Allow it to happen and everyone wins something — including the pilgrims who just want to pray.

For everyday Americans, the takeaway is simple. The headlines about war suggest a region in chaos. The reality on the ground is more complicated. Countries that are firing missiles at each other can still find ways to keep oil flowing, ports running, planes in the air, and religious pilgrims moving across borders. The global economy holds together not because nations love each other, but because the cost of letting it fall apart is higher than anyone is willing to pay.

The pilgrimage runs through Friday, May 29. By then, several hundred thousand more Iranian and other pilgrims will have entered and exited the kingdom. If the rites pass without major incident — and Saudi Arabia is working overtime to make sure they do — both Riyadh and Tehran will quietly count it as a win. Neither will say so publicly. That, too, is part of how the system works.

— JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
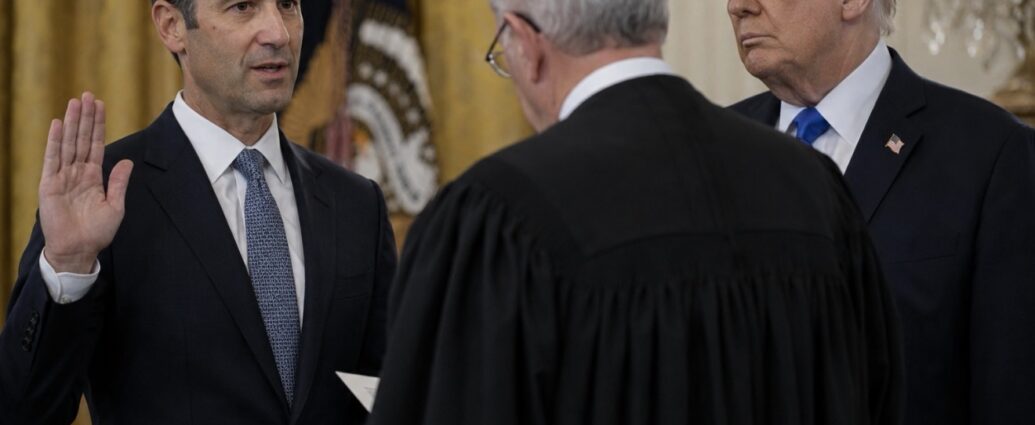
Walmart chief financial officer John David Rainey confirmed on Thursday, May 21, 2026, that the world’s largest retailer has formally applied to recover money it paid under the International Emergency Economic Powers Act tariffs that the U.S. Supreme Court ruled illegal in a 6-3 decision on February 20, 2026. Speaking during Walmart’s fiscal first-quarter earnings discussion, Rainey said the filing places Walmart alongside Apple, Home Depot, General Motors, John Deere, FedEx, and Costco in defying President Donald Trump’s April 21 warning that he would “remember” companies that sought refunds.

“We have availed ourselves of the option to participate in those refunds. For us, it’s a relatively small part of our overall business,” Rainey said. He clarified that Walmart is the importer of record on roughly half of 1% of its U.S. sales — a figure that translates to about $2.42 billion in potentially eligible imports against the $483 billion in U.S. net sales the company posted in fiscal 2026.

The scale of the refund pool is staggering. U.S. Customs and Border Protection opened a portal in April for importers to claim more than $160 billion in refunds tied to the voided tariffs. Trump responded by telling reporters he would “fight” having to pay the money back and that companies would be “brilliant” not to seek refunds. His “I’ll remember” line was interpreted across corporate America as a thinly veiled threat to retaliate through future regulatory, procurement, or trade decisions.

For several weeks, the threat appeared to work. Apple, Amazon, and other politically exposed firms initially held off filing, over concerns about White House retaliation. That posture has now collapsed. Apple has confirmed it is seeking refunds. Levi Strauss chief financial officer Harmit Singh told investors earlier in May that the apparel maker expects to receive roughly $80 million in refunds for duties paid on denim and other imports. Gap Inc. chief financial officer Katrina O’Connell said in March that “the tariff impact has been significant to our performance,” signaling Old Navy, Banana Republic, Athleta, and the namesake Gap brand will all benefit.

Smaller companies are already receiving checks. Oshkosh Corporation chief financial officer Matt Field confirmed earlier this month that the truck and military vehicle manufacturer has begun receiving payments. “Following acceptance of our initial filing, we have begun receiving payments on our tariff refund claims, representing an initial portion of our total claims submitted,” Field said. Basic Fun, the toymaker behind Care Bears and Tonka trucks, has also started receiving funds. Chief executive Jay Foreman said the initial refunds represent about 5% of the company’s total claim. “We will utilize the refund dollars to help support our 2026 cash flow and invest in our team. This is the toughest time of the year for toy companies,” Foreman said. He added that the company will use the funds to increase salaries and announce promotions.

Logistics giants UPS, FedEx, and DHL have committed to filing refund claims on behalf of customer shippers who paid duties through their networks, requiring no further action from those importers. FedEx earlier sued the U.S. government in the U.S. Court of International Trade, seeking a full refund and citing “injury” from the duties.

The National Retail Federation, which represents retailers from Walmart down to small brands and manufacturers, has called for “a seamless process to refund the tariffs to U.S. importers,” arguing the refunds “will serve as an economic boost and allow companies to reinvest in their operations, their employees and their customers.”

The political backdrop remains tense. Trump has complained that the Supreme Court ruling did not include language barring refunds for tariffs already collected. “I’m not happy with the Supreme Court, I’ll be honest with you,” he told reporters in April. The president has separately floated using tariff revenue to fund direct “tariff dividend” checks to Americans, though any such program would require Congress to pass legislation.

Several refund-related bills are now sitting in committee. Senator Josh Hawley, Republican of Missouri, introduced the American Worker Rebate Act of 2025, proposing stimulus checks funded by tariff revenue. Senator Martin Heinrich, Democrat of New Mexico, introduced a separate March 2026 bill for tax rebates tied to tariff-driven price increases. Representative Tim Burchett, Republican of Tennessee, introduced the Trump Tariff Rebate Act, and Representative Henry Cuellar, Democrat of Texas, introduced the American Consumer Tariff Rebate Act of 2026. All four remain stalled.

“The likelihood of tariff refunds passing in Congress still seems remote,” Bankrate financial analyst Stephen Kates said. “A Republican-backed bill would all but admit that tariffs were a policy mistake.”

Consumers hoping for lower prices are likely to be disappointed. A survey by the CNBC CFO Council found that of 25 chief financial officers polled, 12 said their companies planned to apply for refunds, but none said they intended to pass the savings directly to customers. The funds, instead, are being earmarked for cash flow, capital expenditure, share buybacks, and worker compensation.

For investors, refund flows could become a meaningful near-term earnings tailwind for retailers and manufacturers that absorbed tariff costs without fully passing them through. Many large retailers, including Walmart and Gap, have not yet factored the Supreme Court ruling or potential refunds into their forward guidance, leaving room for upside revisions as checks arrive. Apparel companies, toymakers, automakers, logistics-heavy importers, and home improvement chains stand to benefit most.

The broader question hanging over corporate America is whether Trump will follow through on his retaliatory rhetoric. The fact that Walmart, the nation’s largest private employer, has now publicly disclosed its filing suggests the math has been done — and the financial upside has won.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

WASHINGTON — May 24, 2026

The U.S. Department of the Treasury on Thursday sanctioned nine individuals it accuses of helping Hizballah deepen its influence inside Lebanon’s political, military and security institutions, widening Washington’s financial pressure campaign even as fragile Lebanese-Israeli ceasefire talks continue under U.S. mediation.

The designations were issued by Treasury’s Office of Foreign Assets Control (OFAC) under Executive Order 13224, the post-9/11 counterterrorism authority long used against Hizballah and Iran-linked networks.

Treasury Secretary Scott Bessent said the administration would continue targeting officials and operatives who enable Hizballah’s activities inside the Lebanese state apparatus, calling for the group’s complete disarmament.

“Hizballah is a terrorist organization,” Bessent said in Treasury’s statement. “The United States will continue to expose and disrupt individuals who abuse Lebanon’s institutions to support Hizballah and Iran’s destabilizing agenda.”

The sanctions package reaches unusually deep into Lebanon’s governing structure.

Treasury targeted four sitting members of Lebanon’s parliament aligned with Hizballah, including Mohamed Abdel-Mottaleb Fanich, described by OFAC as head of Hizballah’s executive council, along with lawmakers Hassan Fadlallah, Ibrahim al-Moussawi, and Hussein al-Hajj Hassan.

According to Treasury, the group played central roles in preserving Hizballah’s control and influence across key Lebanese state institutions while coordinating politically with Iran-backed networks.

The action also penetrates Lebanon’s official security establishment.

OFAC designated Col. Samir Hamadi, identified as chief of the Lebanese Armed Forces Intelligence Directorate’s Dahiyah branch, and Brig. Gen. Khattar Nasser al-Din of Lebanon’s Internal Security Forces General Security Directorate.

Treasury accused both officials of providing intelligence support and operational coordination to Hizballah during the ongoing regional conflict.

The sanctions extended further into the Amal Movement, the Shiite political and militia organization allied closely with Hizballah.

Treasury designated Ahmad Asaad Baalbaki, Amal’s security director, alleging he deployed joint forces alongside Hizballah against domestic political opponents, and Ali Ahmad Safawi, described as commander of Amal militia operations in southern Lebanon, whom OFAC accused of taking operational orders from Hizballah for coordinated attacks against Israel.

The most diplomatically sensitive designation was that of Mohammad Reza Sheibani, Iran’s ambassador-designate to Lebanon.

Lebanese authorities had already reportedly declared Sheibani persona non grata over allegations of political interference. Thursday’s U.S. sanctions formally place Tehran’s diplomatic channel into Beirut under the same terrorism-financing framework Washington uses against Hizballah operatives and military facilitators.

For Lebanon’s financial system, the implications are immediate.

Under Executive Order 13224, all property and interests in property tied to the designated individuals that fall under U.S. jurisdiction are blocked, and U.S. persons are generally prohibited from engaging in transactions with them.

The measures also increase secondary-sanctions exposure for foreign financial institutions and businesses that continue processing transactions linked to the named individuals or their associated entities.

That poses renewed pressure on Lebanon’s banking sector, which has struggled for years to rebuild international correspondent relationships following the country’s catastrophic 2019 financial collapse.

Banks across the Gulf and Europe are expected to immediately reassess compliance exposure tied to Lebanese political and security-sector clients.

Treasury’s action follows a broader escalation in Washington’s sanctions campaign throughout 2026, including earlier moves targeting Hizballah-linked gold trading operations, Iranian oil transport networks and regional financing channels tied to Tehran’s proxies.

The timing of Thursday’s designations is particularly notable.

The sanctions arrive while U.S.-brokered discussions between Lebanese and Israeli officials remain underway in Washington. Lebanese Prime Minister Nawaf Salam recently said additional negotiation rounds were expected following the latest extension of the ceasefire framework.

Senior U.S. officials signaled that the sanctions are intended to strengthen Lebanon’s legitimate state institutions while isolating actors accused of operating on Hizballah’s behalf from within the government itself.

The State Department said in a parallel statement that Washington remains committed to supporting Lebanon’s sovereignty and official institutions while combating terrorist infiltration inside the state.

Hizballah dismissed the measures shortly after their release, saying the sanctions would have “absolutely no effect” on the group’s operational posture amid continued Israeli military activity near the Lebanese border.

Still, the financial consequences for the designated individuals are substantial.

The sanctions sharply restrict access to dollar-denominated assets, global banking systems, insurance markets, and international travel channels tied to U.S.-linked financial infrastructure.

For multinational firms and investors with remaining exposure to Lebanon, the broader signal from Washington is difficult to ignore.

By sanctioning sitting parliamentarians, security officials and an accredited Iranian diplomat in the same package, the Trump administration is demonstrating a willingness to use OFAC authorities not only against armed groups, but against political and institutional actors accused of enabling them.

That escalation is likely to trigger another wave of compliance reviews across banking, telecommunications, shipping, commodities and infrastructure sectors with exposure to Lebanon or Iranian-linked networks.

Treasury officials indicated Thursday’s action is not expected to be the final round.

The administration framed the measures as part of an ongoing campaign aimed at pressuring Hizballah financially, diplomatically and politically while pushing Beirut toward broader state consolidation and eventual disarmament talks.

Whether that pressure changes realities on the ground — or simply hardens the region’s divisions further — now becomes the next test for Washington’s strategy in Lebanon.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
For a long time, the U.S. dollar has been the most important money in the world. Almost every country uses it to buy and sell things across borders. Oil is priced in dollars. Big international loans are made in dollars. Even when two countries that don’t speak English want to trade with each other, they usually agree to use dollars in the middle. People call the dollar the world’s “reserve currency” — like the main money everyone else trusts and saves.

But something is changing. People are using less and less paper money. Walk into a coffee shop in New York, London, or Tel Aviv and most people pay with their phone, a card, or a tap. Cash is slowly disappearing. And as money becomes digital, big countries are starting to ask a simple question: if money is just numbers on a screen now, why do we have to use America’s numbers? Why can’t we use our own?

This is the heart of the story. The world is moving to digital money, and the United States has to decide how to keep the dollar on top.

Here is the simple picture. Imagine the global economy as a giant playground. For 80 years, every kid who wanted to trade snacks had to first swap their snacks for dollar tokens. America made the tokens. America counted the tokens. If America didn’t like you, it could stop you from using the tokens — that’s what economic sanctions are. Now imagine the kids start saying, “Let’s just trade snacks directly. Or let’s make our own tokens.” That’s exactly what countries like China, Russia, India, Brazil, and others are starting to do.

The way they’re doing it is through something called a central bank digital currency, or CBDC. Think of it as official digital money made by a country’s central bank. China has one called the digital yuan or e-CNY. India has one called the e-rupee. Brazil has one called Drex. Europe is building one called the digital euro. The numbers are already big. China’s digital yuan has been used in more than 3.4 billion transactions worth about $2.3 trillion. India’s e-rupee has roughly 7 million users. These aren’t toys anymore.

A group of countries called BRICSBrazil, Russia, India, China, South Africa, plus newer members like the UAE, Iran, and Indonesia — is now trying to link all their digital currencies together. The plan is simple. If an Indian company wants to buy something from a Brazilian company, they could do it directly in e-rupees and Drex without ever touching a dollar. India, which is hosting the 2026 BRICS summit, has formally proposed this idea, led by its central bank, the Reserve Bank of India.

For the dollar, this is a real threat — at least in theory. If enough world trade moves off dollar rails, the U.S. loses some of its power.

So what is America doing about it? Here’s where the story gets interesting.

Most countries are responding by building their own government digital money. America has decided to do the opposite. President Donald Trump signed an executive order banning a U.S. central bank digital currency. Federal Reserve Chair Jerome Powell, whose term ended May 15, 2026, told Congress he would not pursue one either. The reason is mostly political. Many Americans, on both the right and left, don’t want the government to be able to track every dollar they spend. Banks don’t want it either, because it could pull money out of the banking system.

Instead, Washington has placed a bet on something called stablecoins. A stablecoin is digital money made by a private company, but each coin is backed by a real U.S. dollar — or by U.S. government bonds, which are basically promises from the U.S. Treasury. The two biggest are Tether (USDT) and Circle’s USDC. Together with smaller ones, the global stablecoin market is now worth about $200 billion.

Here’s the clever part. When someone in Argentina, Nigeria, Turkey, or Vietnam uses a dollar-backed stablecoin to save money or send a payment, they are — without thinking about it — buying dollars. The stablecoin company has to hold real dollars or U.S. Treasuries in the background to back the coin. Tether alone now holds about $100 billion in U.S. Treasuries, making it one of the biggest buyers of American government debt in the world.

So while China is building its own digital money to escape the dollar, America is letting private companies spread the dollar to every smartphone on the planet. It’s a different strategy with the same goal: keep the dollar on top.

Congress has been helping. The GENIUS Act, signed into law in July 2025, set the rules for how stablecoin companies have to operate in the United States. It banned them from paying interest to users, which protects American banks from losing deposits. House Financial Services Committee Chairman French Hill has said openly that growing the stablecoin market will “extend the reserve currency status” of the dollar around the world. That’s the official strategy in Washington.

The numbers behind dollar dominance still look strong. The U.S. dollar is on one side of 89% of all foreign exchange trades worldwide, compared to 29% for the euro and just 10% for the yuan. About 58% of global foreign-exchange reserves are still held in dollars. Oil, gold, and most major commodities are still priced in dollars. Even Saudi Arabia, despite years of speculation about it switching to yuan, still sells most of its oil in dollars.

But there are warning signs. Saudi Arabia, the UAE, Thailand, and Hong Kong are quietly testing a multi-country digital currency network called Project mBridge that can settle trades without dollars. Russia has been pushed off dollar rails by sanctions over the war in Ukraine and has been trading oil with China and India in local currencies. Iran, similarly cut off by sanctions, has joined the same effort. Argentina, Egypt, and parts of Africa are seeing huge growth in stablecoin use — which is good for the dollar — but they’re also exploring CBDC alternatives.

What does it all mean for normal people and investors?

A few simple things. First, the dollar isn’t disappearing anytime soon. The global system runs on it, and even the people trying to build alternatives know that replacing 80 years of dollar plumbing takes decades, not years. Second, the dollar is changing form. Less of it will be paper. More of it will be stablecoins on phones, instant payments through the Federal Reserve’s FedNow system, and digital tokens on bank apps. Third, the competition is real. China’s digital yuan and a future BRICS digital network are not going to overtake the dollar overnight, but they will chip away at its share — especially in regions like Africa, Latin America, and parts of Asia where America has less influence.

For U.S. companies, the cashless shift is mostly good news. Visa, Mastercard, PayPal, Block, Stripe, Coinbase, Robinhood, and the big banks all benefit when payments move to digital rails. U.S. Treasury demand from stablecoin issuers helps keep American borrowing costs lower than they would otherwise be. For foreign companies trying to escape the dollar, the path is harder than it looks — building parallel payment systems takes years and trust, and trust is something the dollar still has by default.

The bottom line is this. The world is going cashless, but cashless does not automatically mean dollar-less. The form of the money is changing, but the dollar’s role at the center of the global system is still mostly intact — for now. Washington’s bet is that stablecoins will carry the dollar into the digital age the same way Treasury bills carried it through the analog one. Beijing, New Delhi, and Brasília are betting the opposite. The race is on, and the next ten years will tell us who was right.

The dollar has been king for a long time. It still wears the crown. But for the first time in a generation, there are other players on the board.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Port Authority of New York and New Jersey announced on Friday, May 22, 2026, that Runway 4/22 at LaGuardia Airport reopened at 7:45 p.m. local time, ending a two-and-a-half-day closure that snarled travel during the unofficial kickoff to the Memorial Day weekend and exposed how a single piece of damaged airfield pavement can cascade through the U.S. aviation system. “Following a thorough inspection of LaGuardia’s airfield pavement using ground-penetrating radar, areas of concern were identified and proactively repaired. Those repairs are now complete, and Runway 4/22 has reopened. Our investigation into the cause of the sinkhole is ongoing,” the Port Authority said in a statement.

The sinkhole was first spotted at approximately 11 a.m. Wednesday, May 20, during a routine morning inspection of the airfield. The opening developed on taxiway Bravo, near but not directly on Runway 4/22, in an area where a new underground fuel pipeline had been constructed to bring jet fuel closer to aircraft and reduce the need for fuel trucks crossing the airfield. The runway was immediately taken out of service while engineers conducted core samples and sonar scans to check for additional weak points underground.

The business cost piled up quickly. According to flight-tracking service FlightAware, nearly 290 flights were canceled and more than 310 were delayed at LaGuardia on Wednesday alone, compounded by severe evening thunderstorms. Thursday saw another 51 cancellations. Friday delivered the biggest hit yet as the airport headed into the long weekend with one runway still down: by mid-morning Friday, 130 flight delays and five cancellations were already on the board, and the numbers grew through the day.

For the airlines that anchor LaGuardia — primarily Delta Air Lines, American Airlines, United Airlines, JetBlue Airways, Southwest Airlines, and Spirit Airlines — the disruption translates directly into real money. Industry estimates put the cost of a single canceled domestic flight at between $20,000 and $40,000 when factoring in crew repositioning, passenger compensation, hotel vouchers, rebooking expenses, and lost revenue. A three-day operational hit at one of the busiest domestic hubs in the country can push aggregate airline losses into the tens of millions of dollars before any indirect costs are counted.

LaGuardia, which mostly handles domestic travel, runs about half the daily traffic of nearby John F. Kennedy International Airport, but its location in Queens makes it the preferred gateway for business travelers heading to Manhattan. A disruption at LGA ripples outward to Boston Logan, Reagan National, Chicago O’Hare, Atlanta Hartsfield-Jackson, and other connected hubs, since aircraft and crews scheduled to fly in and out are forced to reposition. The Federal Aviation Administration advised travelers throughout the closure to check directly with carriers and posted real-time updates at fly.faa.gov.

Travelers absorbed the brunt. Sally Marchetto and her family, flying home to St. Louis, ended up rebooking onto separate flights and staying in an Airbnb in Queens. “Tomorrow, I’m leaving at 9 a.m., and my 80-year-old parents will have to go at like 2:30,” she told local reporters. Ossining resident Lee Weinberg lost a full day getting to Kansas City after Delta canceled his flight at 9:30 p.m. the night before. Olijuah Williams of Queens, headed to Atlanta, had his flight scrapped entirely. The stories repeated across hundreds of stranded passengers, many of whom turned to Airbnb, Marriott, Hilton, and Hyatt properties around the airport — a small windfall for hospitality businesses in East Elmhurst, Astoria, and Long Island City at the expense of the airlines.

For LaGuardia itself, the timing was awful. The airport has spent more than $8 billion over the past decade on a comprehensive redevelopment, replacing the aging terminals that former Vice President Joe Biden once compared to a “third-world country.” The new Terminal B and renovated Terminal C, anchored by Delta, were meant to symbolize a modern, reliable LGA. A sinkhole and a runway shutdown undercut that narrative in the worst possible week.

The episode also highlights a broader business concern: aging U.S. airport infrastructure. LaGuardia’s runway and taxiway system, like much of the nation’s airfield pavement, dates in parts to the mid-twentieth century. The American Society of Civil Engineers in its most recent infrastructure report card gave U.S. aviation a “D+” grade, citing deferred maintenance, capacity constraints, and outdated ground systems. The Bipartisan Infrastructure Law signed in 2021 allocated $25 billion for airport improvements, but disbursement has lagged demand, and large hubs like LGA continue to operate at or near full capacity with limited margin for surprise repairs.

This was not LaGuardia’s only operational crisis of 2026. The same runway was the site of a fatal collision in March between an Air Canada Express CRJ-900 regional jet operated by Jazz Aviation and an airport fire truck. Two pilots were killed. The National Transportation Safety Board, chaired by Jennifer Homendy, found that the airport’s ground surveillance system failed to generate a proximity alert and that the fire truck lacked a transponder to broadcast its location to air traffic control. That investigation remains open and has put fresh pressure on the Port Authority to upgrade ground-movement safety technology — a multimillion-dollar capital expenditure now likely to accelerate.

For investors, the larger story is exposure. Airline shares are tightly correlated to operational reliability at the major hubs. Delta, which has its largest New York presence at LGA, is most exposed to repeat disruptions. American Airlines and JetBlue carry significant LaGuardia schedules as well. Suppliers to airport modernization — including engineering and construction firms AECOM, Skanska, Turner Construction, and Jacobs Solutions — stand to benefit from any acceleration of infrastructure spending triggered by the year’s incidents.

Travelers will see residual delays through the weekend, the Port Authority warned, and the cause of the sinkhole remains under investigation. For the airlines, the airport, and the 70,000-plus passengers who pass through LaGuardia each day, the message from the past 72 hours is simple: in modern aviation, a single soft spot in the pavement can cost the industry millions and remind everyone how fragile the system really is.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
If you filled up your tank this weekend, you already know: gas is expensive again.

The American Automobile Association (AAA) said Thursday, May 21, 2026, that the national average price for regular gasoline has climbed to $4.56 a gallon — the highest Memorial Day weekend level in four years and $1.38 more than last year. By Sunday, millions of Americans were feeling it firsthand as a record 45 million people hit the highways for the holiday weekend.

A normal 15-gallon fill-up that cost around $48 last Memorial Day now costs roughly $68.

For families driving from New York to the Jersey Shore, Chicago to a lake house, or Los Angeles to San Diego, that difference adds up fast. A road trip that once felt affordable suddenly costs noticeably more before the vacation even begins.

“Travel demand remains strong, and despite higher fuel prices, many people are prioritizing leisure travel,” said Stacey Barber, vice president of AAA Travel.

People are still traveling. They’ve waited months for the holiday weekend. But many are watching every dollar more closely.

The current national average sits just below the all-time Memorial Day record of $4.61 per gallon, set in 2022 after Russia’s invasion of Ukraine disrupted global oil markets.

This time, the cause is different.

Gas prices have surged more than 50% since late February, when the U.S.-Iran conflict escalated and shipping through the Strait of Hormuz — one of the world’s most important oil routes — became heavily disrupted. Roughly 20% of the world’s oil supply normally passes through the strait, meaning instability there quickly affects fuel prices everywhere.

For the first time in nearly three years, every U.S. state is now averaging above $4 a gallon.

Drivers in California are paying the most, with average prices around $6.14 per gallon, meaning a standard fill-up can cost more than $90. Washington ($5.78), Hawaii ($5.64), Oregon ($5.35), Alaska ($5.27), Nevada ($5.27), Illinois ($5.01), Arizona ($4.81), Colorado ($4.76), and Ohio ($4.76) are also among the most expensive states.

Drivers in the Gulf Coast and Southeast are paying slightly less, though prices are still historically high. Mississippi currently has the cheapest average at $4.01, followed by Georgia, Louisiana, Texas, Oklahoma, Arkansas, Alabama, and South Carolina.

According to GasBuddy petroleum analyst Patrick De Haan, at least 19 states are expected to post record-high Memorial Day gas prices this weekend.

The pain is hitting working families hardest.

Research from Bank of America shows roughly 1 in 10 lower-income households are now spending more than 10% of monthly income on gasoline alone. Economists at Brown University’s Climate Solutions Lab estimate American households have spent an extra $24 billion on gasoline since the Iran conflict began earlier this year — roughly $200 extra per household.

For many families, that money would normally go toward groceries, utility bills, summer camps, or savings.

Americans are already changing habits to cope.

Costco, Sam’s Club, BJ’s Wholesale Club, Walmart, and Kroger discount fuel stations are seeing heavier traffic as drivers search for cheaper prices. Gas price apps are surging in popularity. More commuters are carpooling, combining errands, or working remotely extra days to avoid filling up as often.

Some families are shortening vacations altogether, replacing longer road trips with closer regional getaways.

Small businesses are under pressure too.

Contractors, landscapers, delivery drivers, plumbers, electricians, rideshare drivers, and trucking companies are all absorbing sharply higher fuel costs. Many are adding fuel surcharges or raising prices, which then pushes costs higher across the broader economy — from food delivery to home repairs.

Industry analysts warn prices may climb further.

GasBuddy projects the national average could approach $4.80 per gallon during peak summer travel season. If tensions in the Middle East worsen or the Strait of Hormuz remains partially closed deep into the summer, analysts say the all-time U.S. record of $5.02 per gallon set in June 2022 could come back into play.

The U.S. Energy Information Administration says gasoline demand is still rising while inventories are tightening, leaving little room for additional supply disruptions.

There is one possible relief valve.

The Trump administration is currently engaged in negotiations with Iran through mediators in Oman and Pakistan, and reports this weekend suggest Tehran may agree to surrender part of its enriched uranium stockpile as part of a broader agreement that could reopen the Strait of Hormuz.

If a deal is finalized, oil prices could fall quickly — and gasoline prices would likely follow. If negotiations collapse, drivers could face another leg higher at the pump.

For now, AAA says travelers should plan carefully: fill up in cheaper states when possible, monitor gas-price apps, avoid speeding, and check tire pressure to improve fuel economy.

For millions of Americans heading home from the holiday weekend, one thing is clear: the Iran conflict is no longer just a geopolitical story happening overseas. It is now directly shaping household budgets across the country every time drivers stop for gas.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
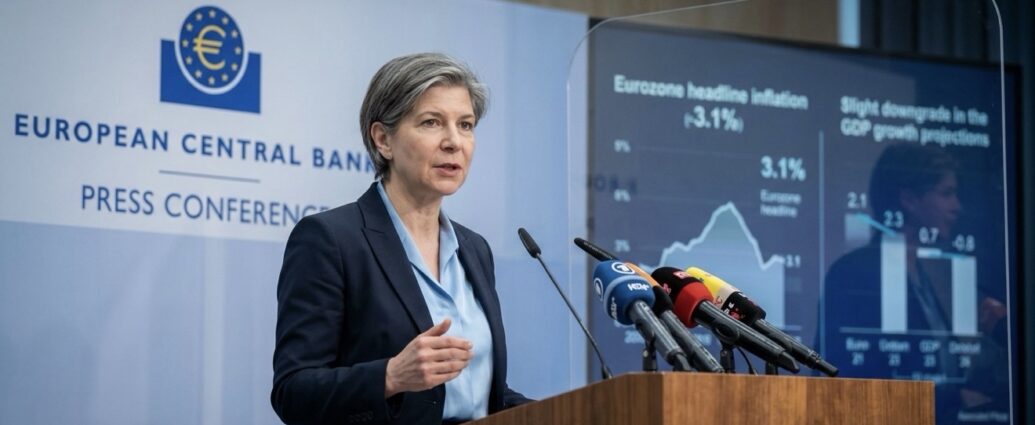
SpaceX successfully launched its upgraded Starship V3 rocket on Friday, May 22, 2026, from its Starbase facility in South Texas, deploying 20 mock Starlink satellites in space and executing a controlled splashdown in the Indian Ocean — a critical milestone for Elon Musk’s company just two days after SpaceX filed its prospectus with regulators to take the company public in what is expected to be the largest initial public offering in history. The test, the 12th major flight of the Starship program and the debut of the redesigned V3 version, lifted off at 5:30 p.m. local time from the southern tip of Texas and stretched halfway around the world during its hour-long flight.

The flight achieved most of its major objectives despite minor anomalies. One of the six engines on the Starship upper stage shut down early during ascent, and the Super Heavy booster spun out of control and broke apart over the Gulf of Mexico after the booster’s controlled re-entry burn failed. SpaceX lost communications with the booster moments before splashdown, indicating it likely disintegrated. But the Starship upper stage itself reached space, deployed its entire payload, scanned its own heat shield with two specialized companion satellites, and made a controlled re-entry through the atmosphere before splashing down upright in the Indian Ocean under what appeared to be full control. The vehicle then toppled over and ignited, as expected.

“It’s pretty incredible to see this happening live from space now,” SpaceX employee Kate Tice told viewers on the company’s livestream as applause and chants of “USA, USA” erupted from employees in the Starbase control room. Musk later called the launch and landing “an epic” event on his X social media platform.

The successful payload deployment is a critical commercial validation. The 20 mock satellites were designed to mimic the size, weight, and release mechanics of next-generation Starlink satellites — the larger, more powerful units that SpaceX plans to deploy at a much higher cadence once Starship enters operational service. Two additional modified satellites that Starship deployed scanned the spacecraft’s heat shield and transmitted data back to ground operators during the vehicle’s descent, providing real-time engineering data that will inform future flights. All of the satellites are expected to fall back to Earth and burn up in the atmosphere.

For SpaceX and its investors, the timing could not have been better. Musk announced earlier in the week that the company had filed its S-1 registration statement with the U.S. Securities and Exchange Commission, setting the stage for an IPO expected next month. Industry analysts estimate SpaceX could be valued at between $400 billion and $500 billion at the time of the offering, which would make it the largest U.S. IPO in history, eclipsing Saudi Aramco’s $25.6 billion offering in 2019 and Alibaba’s $25 billion raise in 2014. Investors are already getting exposure to the rocket company through exchange-traded funds, with shares of publicly traded space sector ETFs including ARKX rallying sharply this week on the IPO news and Friday’s successful test.

The financial stakes of Friday’s test were enormous. A spectacular failure, especially of the highly publicized V3 debut, would have raised hard questions for IPO underwriters about whether the Starship program is ready for the commercial cadence SpaceX has been promising. Back-to-back Starship test failures in January and March 2025 ended in midair explosions that rained debris into the Atlantic. The ninth test in May 2025 also failed. The tenth test in August 2025 became the first to successfully deploy mock satellites and execute a controlled splashdown. Friday’s flight took that progress and built on it with the larger, more powerful V3 design.

The new Starship V3 is significantly bigger and more capable than earlier versions. The fully stacked vehicle stands roughly 400 feet tall — taller than the Statue of Liberty including its pedestal. The Super Heavy booster generates more thrust at liftoff than any rocket ever built, surpassing NASA’s legendary Saturn V that sent astronauts to the moon in the 1960s and 1970s. V3 features upgraded engines, larger and stronger booster fins for stability, and a refined heat shield that SpaceX has been iteratively rebuilding flight after flight. The company’s stated goal is to ultimately catch the booster mid-air with the launch tower’s robotic “chopsticks” arms, fully reusing the rocket within hours of landing.

The commercial logic behind Starship is staggering. SpaceX intends to use the rocket to deploy thousands of next-generation Starlink satellites, which deliver internet service to consumers and enterprises in places where terrestrial broadband cannot reach. Starlink currently serves more than 5 million subscribers in over 100 countries, and the V3 Starlink satellites that Starship will eventually carry are designed to provide direct-to-cell service to standard smartphones — eliminating dead zones for T-Mobile, Verizon Communications, AT&T, and other partner carriers. The satellite communications market is projected to grow to more than $100 billion annually by 2030, and SpaceX is positioned to capture a dominant share.

NASA is equally invested. The U.S. space agency has ordered two Starships to serve as the lunar lander for its Artemis program, which intends to return American astronauts to the moon later this decade. NASA Administrator Sean Duffy has publicly emphasized Starship’s importance to U.S. space leadership, particularly as China accelerates its own crewed lunar program with the goal of landing Chinese astronauts on the moon by 2030. Every successful Starship test moves the Artemis timeline closer to reality.

Musk’s ultimate ambition extends much further. The Starship program is explicitly designed to enable human missions to Mars. SpaceX has been transparent about its intention to use the rocket to land cargo and eventually crew on the Red Planet within the next decade. Friday’s successful payload deployment is one small step in that long-term technology development, but every successful flight reduces the technical risk and validates the underlying engineering.

For investors, the story is even bigger than rockets. Musk has been openly framing SpaceX as an integrated artificial intelligence and satellite communications company, not just a launch provider. The Starlink subscriber base generates recurring revenue. The launch business generates contracted revenue from NASA, the U.S. Department of Defense, commercial satellite operators, and international space agencies. The data and connectivity layer Starlink provides enables a new generation of AI applications, autonomous vehicles, Internet of Things deployments, and global enterprise communications. Investors buying into the SpaceX IPO are buying exposure to all of those revenue streams at once.

The competition is intensifying. Jeff Bezos’s Blue Origin is developing its own large-class New Glenn rocket, which has flown several successful missions and is now positioning to compete for both NASA and commercial contracts. Boeing, Lockheed Martin, and the United Launch Alliance continue to dominate certain national security launches but face cost disadvantages against SpaceX. Rocket Lab, Relativity Space, Stoke Space, and other smaller competitors are pursuing niche segments. China’s State-Owned Long March rockets and the privately backed LandSpace are accelerating launch cadence at lower price points. The competitive pressure is real, but SpaceX’s lead in reusable rocketry — the technology that fundamentally lowers per-launch costs — remains substantial.

For everyday Americans, the SpaceX IPO will be one of the most-watched financial events of the year. Investment advisors at Charles Schwab, Fidelity Investments, Vanguard Group, Morgan Stanley, Edward Jones, and Merrill Lynch are already fielding client questions about how to get access. The IPO is expected to be heavily oversubscribed, with institutional allocations dominating early share distributions. Retail investors will likely need to wait for the secondary market for meaningful access, though some brokers including Robinhood Markets and SoFi Technologies have built IPO access tools that have democratized retail participation in earlier high-profile offerings.

The political backdrop is also significant. Musk’s complicated relationship with President Donald Trump — including Musk’s brief role leading the Department of Government Efficiency before his very public falling-out with the administration earlier this year — has not slowed SpaceX’s federal contracting. Starship’s central role in the Artemis program and SpaceX’s dominant share of U.S. national security launches make the company effectively too important to U.S. space and defense capabilities to be politically sidelined. Musk has also drawn renewed criticism for his political activities and X platform statements, but SpaceX the company has continued executing through the noise.

For the broader space economy, Friday’s test is a clear signal that the next phase of orbital commerce is real and arriving on a faster timeline than skeptics expected. Satellite internet, lunar logistics, in-space manufacturing, asteroid mining, space tourism, and eventually interplanetary cargo and crew transportation all depend on a working heavy-lift reusable rocket. Starship V3 is now closer than ever to delivering that capability.

The SpaceX IPO timeline appears intact. The Starship program is back on track. The Starlink business continues to grow. NASA’s moon program is moving forward. Musk’s Mars ambitions remain wildly aspirational, but each successful test brings them incrementally closer to credible.

For Wall Street, the practical message is straightforward. SpaceX just demonstrated that its next-generation rocket can fly, deploy payload, and return controlled — three weeks before its public offering. Investors will price that in.

— JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
John Doerr, the Kleiner Perkins chairman who wrote the 1999 check that turned Google into a $3.89 trillion company, said in a Wall Street Journal interview published Saturday, May 23, 2026, that artificial intelligence is the “biggest thing ever, since everything” and that the technology, far from being overhyped, “has been underhyped.”

The comments cut directly against a growing chorus of skeptics on Wall Street.

Doerr, 74, has tracked what he calls innovation “tsunamis” through five decades in venture capital. His timeline runs from the 1980 personal computer and microchip revolution, to the 1990s internet and browser wave, to the iPhone and cloud era of the late 2000s. By his reckoning, the tsunamis arrive roughly every 13 years. The current AI wave, he told the Journal, is bigger than all of them.

“We don’t know how AI is going to shape the new world of education, employment, healthcare — life as we know it,” Doerr said. “There is an insatiable hunger and appetite for electrons, and as in previous tsunamis, there will be winners and there will be losers.”

The interview lands at a tense moment in markets. Microsoft has guided to roughly $80 billion in AI-related capital spending in fiscal 2025, Alphabet to about $75 billion, Meta Platforms to as much as $65 billion, and Amazon to more than $100 billion. Nvidia, the chipmaker powering most of that buildout, has added trillions of dollars in market capitalization since OpenAI launched ChatGPT in late 2022. MIT economist Daron Acemoglu and Goldman Sachs head of global equity research Jim Covello have argued AI’s productivity payoff is being overestimated and that current spending resembles a classic late-cycle bubble. Doerr’s “underhyped” call comes from the investor who made the same contrarian bet on the internet in the late 1990s and was vindicated despite the dot-com crash.

Doerr backed his AI thesis with a striking adoption number. Three years after ChatGPT’s launch, 50% of Americans now say they use generative AI — a curve that has compressed into roughly half the time the consumer internet took to reach comparable scale. “The value creation is off the charts,” he told the Journal.

His current investing focus, he said, is funding entrepreneurs using AI in two areas: the climate transition and healthcare. He has invested in both sectors for nearly two decades, first through Kleiner Perkins, where he became chairman in 2016, and now also through his family office. His most recent disclosed AI investment, Hippocratic AI, a medical large language model company, closed a Series C round in November 2025. He remains on the board of Alphabet.

The interview produced Doerr’s sharpest line yet on what venture capital actually is. “At its heart, the venture-capital business is a human-capital business,” he said. That framing, he explained, is why he stayed out of cryptocurrency. He did not see human capital “playing a powerful role in the kind of innovation and market development.” He added that “there is still plenty of time for me to be wrong in that judgment.”

Doerr was also frank about his misses. After backing both the Segway and the failed electric-car maker Fisker, he said his partners reminded him of a venture saying: “never invest in anything with wheels.” He missed Tesla, now the world’s most valuable automaker under chief executive Elon Musk. But he reframed the lesson in the asymmetric math of venture investing. “You can only lose one time your money. You can make many times it if you get it right.”

The Google story remains the defining moment of his career. Doerr met Larry Page and Sergey Brin in 1999 at Google’s birthplace, a garage in Menlo Park. He wrote a $12 million check for 12% ownership at a $100 million valuation — at the time, the largest check at the highest price his firm had ever written. The investment is now worth nearly $470 billion on paper at Alphabet’s current market capitalization. “What made me fall off my chair was how big Larry and Sergey thought improving search could be,” Doerr told the Journal. “They saw something the rest of us hadn’t yet.”

That ability to back founders who see further is, in Doerr’s view, the entire job. The most amazing entrepreneurs, he said, “see the world differently than everyone else. They are fluent in using technology to change that world.” They are good recruiters and even better sellers — selling their vision to teammates, to customers, and to investors. His first filter when meeting a founder: “Would I mind getting into trouble with them?” Because no matter how successful a venture looks from the outside, “you take the lid off the can and inside it’s a can of worms.”

Doerr also made the broader economic case for venture capital. Over the last half-century, he noted, venture-backed companies accounted for 81% of patents issued to U.S. public companies by the U.S. Patent and Trademark Office. There were 5.3 million jobs at VC-backed companies in 2022 alone. “That isn’t an accident,” he said. “That’s a structural phenomenon that America enjoys.”

For investors, the immediate signal from the WSJ interview is not a trading call. Doerr’s comments will not move single names the way an analyst upgrade does. But the message will land in capital-allocation rooms. Major endowments, sovereign wealth funds, and pension plans take cues from venture capital legends in setting long-horizon technology weights. PitchBook data show U.S. venture deployment to AI startups held at record levels through the first quarter of 2026, with OpenAI, Anthropic, xAI, Mistral AI, and Perplexity all attracting multibillion-dollar rounds.

The political dimension is also live. Doerr has been an active voice in Washington, urging more federal AI research funding and faster deployment across U.S. industry. White House AI czar David Sacks has echoed parts of that framing, warning the U.S. risks losing the global AI race through what he calls “pessimism.” International Monetary Fund managing director Kristalina Georgieva in January separately warned of an AI “tsunami” coming for young workers and entry-level jobs. The same word now spans both bullish and cautionary takes on the technology.

Doerr bet against consensus on the internet in the 1990s, and the consensus was wrong. He has now placed the same bet on AI. Wall Street will spend the rest of this decade finding out whether the man who saw Google first has seen this one too.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
DEVELOPING — Saturday, May 23, 2026. A damaged chemical tank at the GKN Aerospace plant in Garden Grove, California has forced as many as 50,000 people from their homes across four Orange County cities and shut down a critical defense and commercial aerospace factory, after emergency crews concluded the tank can no longer be safely controlled and will either crack open or explode.

Garden Grove, a city of more than 170,000 residents in Southern California’s Orange County, sits roughly 30 miles from downtown Los Angeles and just five miles from Disneyland in neighboring Anaheim. Disneyland officials said Saturday the situation is not affecting their resorts and theme parks, which remain open to visitors.

The plant, at 12122 Western Avenue, is GKN Aerospace’s main U.S. transparencies facility. It is the sole producer of cockpit canopies for the Lockheed Martin F-35 Lightning II, the backbone of American and allied air power. The same factory also makes cockpit windshields and passenger cabin windows for the Boeing 787 Dreamliner, Boeing 737, Airbus A350, HondaJet, and Bombardier C-Series, according to GKN’s corporate website. That places the incident at the intersection of national security supply chains and global commercial aviation.

Orange County Fire Authority Division Chief Craig Covey said at a news conference Friday afternoon that the 34,000-gallon tank — still holding roughly 6,000 to 7,000 gallons of methyl methacrylate, a highly flammable acrylic chemical — cannot be drained or neutralized because of a faulty valve blocking access. “This thing is going to fail, and we don’t know when,” Covey said. Speaking separately to CBS Los Angeles, he added, “This is as bad as I’ve ever seen.”

The crisis began around 3:30 p.m. Thursday when the tank overheated and began venting toxic vapors. Evacuations were ordered, then briefly lifted Thursday night after crews believed cooling efforts were working. Early Friday morning, the tank destabilized again. By Saturday, the mandatory evacuation zone had expanded across Garden Grove, West Anaheim, Cypress, and Stanton, with ABC7 Los Angeles reporting roughly 50,000 residents displaced and CBS Los Angeles placing the figure above 44,000. Schools have closed, roads are shut, and regional events have been canceled.

California Governor Gavin Newsom declared a state of emergency for Orange County on Saturday, unlocking additional response resources and opening state-owned properties as shelter space. “We are mobilizing every state resource available to support local responders,” Newsom said. Evacuation centers at Savanna High School in Anaheim, Ocean View High School in Huntington Beach, John F. Kennedy High School in La Palma, and Freedom Hall at Mile Square Regional Park in Fountain Valley have absorbed displaced residents, with Freedom Hall reaching capacity Friday night.

A GKN Aerospace spokesperson said specialized hazardous-materials teams are assessing the situation and that “there are no reports of injuries at this time and our priority remains the safety of our employees, responders, and the surrounding community.” The company said it is “fully focused on working with emergency services and the relevant authorities.”

The business stakes are significant. GKN Aerospace, now part of Dowlais Group after being spun out of Melrose Industries in 2023, describes itself as “the world-leading supplier of cockpit transparencies and passenger cabin windows.” The Garden Grove site is qualified to build the F-35 canopy — a complex stealth-coated piece essential to the jet’s low-observable design — as well as transparencies for the F-22 Raptor, Boeing F-15 Eagle, F/A-18 Hornet, and AV-8B Harrier II.

For Lockheed Martin, the world’s largest defense contractor, any extended shutdown of canopy supply would add to existing pressure on the F-35 program, which has battled engine, sustainment, and parts-availability problems through the spring. Lockheed Martin shares closed Friday at elevated levels on heightened defense spending expectations tied to the Iran conflict; investors will be watching closely Monday for any guidance on production continuity. The Pentagon has historically kept only limited backup sourcing for military transparencies. PPG Industries runs a parallel canopy line at its Sylmar, California plant for the F-35A and F-35C variants, but qualification work on the F-35B short-takeoff version remains in progress, leaving GKN the dominant qualified supplier for parts of the fleet.

On the commercial side, the timing is rough for both Boeing and Airbus. Boeing, still working through 737 MAX certification and quality issues under chief executive Kelly Ortberg, relies on GKN’s Garden Grove output for windshield and cabin window assemblies on the 787 and 737 programs. Airbus, led by chief executive Guillaume Faury, sources transparencies for the A350 wide-body line from the same site. Both manufacturers are working through multi-year backlogs of thousands of aircraft, and supplier interruptions of even a few weeks have historically caused delivery delays, customer compensation claims, and disruption to airline fleet plans.

Beyond aerospace, the incident has revived broader questions about U.S. industrial safety, aging chemical storage infrastructure, and the concentration of defense-critical manufacturing in dense suburban areas. Methyl methacrylate is a known respiratory irritant; Orange County health officer Dr. Regina Chinsio-Kwong warned that vapor exposure can cause respiratory issues, eye irritation, nausea, and headaches. Crews have built sandbag containment barriers around the plant to prevent any chemical spill from reaching storm drains, creeks, or the nearby Pacific coast.

Wall Street will scrutinize Dowlais Group’s disclosures in the coming days for the financial impact, including potential damages, lost production, business interruption insurance recoveries, and any liability tied to the faulty valve at the heart of the failure. Analysts at major brokerages have not yet published formal notes on the incident, but defense and aerospace supply chain specialists are likely to flag the event as a case study in single-point-of-failure risk across high-value manufacturing.

For residents, the immediate concern is when they can return home. Chief Craig Covey and OCFA Chief TJ McGovern have offered no timeline, with McGovern acknowledging Friday, “We understand how disruptive and frightening this is to the public, particularly for the residents who have been asked to leave their homes for their own safety.” For investors, customers, and Pentagon planners, the more difficult question is how quickly the Garden Grove plant — and the strategic flow of canopies, windshields, and cabin windows it supplies — can be brought back online once the tank crisis is finally resolved.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
DEVELOPING — Saturday, May 23, 2026. Iran has agreed to relinquish its entire stockpile of highly enriched uranium as part of a framework agreement with the United States to end the months-long war, two senior U.S. officials told the New York Times on Saturday, marking a significant nonproliferation concession from Tehran and setting the stage for a meaningful repricing across global energy, equity, and shipping markets.

The breakthrough disclosure landed hours after President Donald Trump announced earlier Saturday that an agreement with Iran “has been largely negotiated,” telling reporters that calls he held overnight with Prime Minister Benjamin Netanyahu and a separate group of Middle Eastern leaders had gone well. Trump indicated the framework includes the reopening of the Strait of Hormuz — the critical maritime artery Tehran has largely blocked since the war’s outbreak roughly three months ago — and said a formal announcement could come “shortly.”

Trump had confirmed the contours of the uranium arrangement Thursday outside the White House, telling reporters, “We will get it. We don’t need it, we don’t want it. We’ll probably destroy it after we get it, but we’re not going to let them have it.” The 970-pound stockpile of uranium enriched to 60 percent purity — roughly 440 kilograms, just short of the 90 percent threshold required for weapons-grade material — has been the central sticking point in mediated negotiations conducted through Oman and Pakistan. Iran’s Parliament Speaker Mohammad Bagher Ghalibaf met with Pakistan Army Chief Syed Asim Munir in Tehran on Saturday, underscoring Islamabad’s role as a back-channel mediator.

According to the U.S. officials cited by the Times, Iran has committed only in a general statement to giving up the uranium, with the precise mechanism for transfer or downblending to be worked out in negotiations expected to follow a formal cessation of hostilities. The development comes despite a directive issued earlier in the week by Iran’s supreme leader, Ayatollah Ali Khamenei, that the near-weapons-grade material should not be sent abroad — a position that had whipsawed crude markets and rattled traders through Friday’s session. Iranian state media on Saturday also publicly contradicted Trump’s characterization of the Hormuz terms, insisting the waterway will remain under Iranian management, raising fresh questions about the durability of the framework.

Oil futures had already begun pricing the diplomatic thaw before Saturday’s reports. International benchmark Brent crude futures settled at $103.54 per barrel Friday, while U.S. West Texas Intermediate closed at $96.60, capping a week in which Brent lost more than 5 percent and WTI shed more than 8 percent. The declines followed Trump’s announcement Monday that he had called off imminent strikes on Iran at the request of U.S. Gulf Arab allies to give diplomacy additional runway.

U.S. Secretary of State Marco Rubio said Thursday there were “good signs” that an agreement to end the conflict is in sight, though he warned any deal would be “unfeasible” if Iran pursues measures to permanently control shipping through the Strait of Hormuz. The waterway, through which roughly a fifth of global crude transits, remains the second major sticking point. Tehran is reportedly working with Oman on a framework for a permanent toll system that would formalize Iranian control over maritime traffic — a proposal Trump has flatly rejected, insisting the strait remain open, free, and untolled.

The economic stakes of a final agreement are substantial. Analysts at SEB have estimated that sanctions relief tied to a nuclear accord could unlock an additional 800,000 barrels per day of Iranian crude for global markets, a development SEB analyst Ole Hvalbye called “undeniably bearish” for prices. Combined with the prospective reopening of the Strait of Hormuz to unimpeded traffic, a sustained agreement could pull Brent well below the $90 mark and ease the inflationary pressure that has dogged the Federal Reserve’s rate path through the spring.

Equity markets, particularly transportation, airline, refining, and consumer discretionary sectors hammered by elevated fuel costs since the war’s outbreak in February, stand to benefit from any durable de-escalation. Delta Air Lines, United Airlines, and American Airlines have all flagged jet fuel as a material drag on quarterly margins, while shipping giants A.P. Moller-Maersk and Hapag-Lloyd have absorbed surcharges and rerouting costs tied to Hormuz disruption. Conversely, U.S. shale producers including ExxonMobil, Chevron, ConocoPhillips, Pioneer Natural Resources, and Diamondback Energy, which have enjoyed a war-driven premium on every barrel, face compressed realized prices if Iranian supply returns at scale.

The proposed framework, according to multiple reports citing officials with knowledge of the talks, contemplates an immediate end to hostilities followed by a two-month negotiating window on the technical specifics of Iran’s nuclear program. The Financial Times reported that Trump is also demanding Iran dismantle its three principal nuclear sites — Natanz, Fordow, and Isfahan — all of which were struck by U.S. B-2 bombers in the opening phase of the war. CBS News reported that the proposal additionally includes the release of certain Iranian assets currently frozen in foreign banks, a concession likely to draw scrutiny from congressional hawks. Senior GOP senators on Saturday publicly criticized the reported terms as a “nightmare for Israel.”

For Iran, the economic case for capitulation is acute. The country’s oil exports, refining capacity, and banking sector have been crippled by both kinetic strikes and tightened secondary sanctions, and reopened access to international markets would deliver an immediate fiscal lifeline to a regime under sustained pressure. Oman Foreign Minister Badr al-Busaidi said earlier in the negotiations that Iran had effectively accepted the principle of “zero stockpiling” and that the existing material would be “downblended to the lowest level possible” and converted into irreversible reactor fuel.

Skeptics caution that prior Iranian commitments on enrichment have repeatedly unraveled and that the absence of detailed transfer protocols leaves room for backsliding. The Washington Post noted that Tehran’s pledge not to seek a nuclear weapon carries limited weight given its longstanding insistence that its program was never weapons-oriented to begin with. Israeli officials have warned that anything short of physical removal of the 440-kilogram stockpile would render the war, in the words of one senior Israeli military official, “one big failure.”

For markets, the asymmetry of outcomes is stark. A signed agreement removing both the nuclear overhang and the Hormuz chokepoint could trigger a sharp decline in crude prices, with knock-on relief for equities, bonds, and the dollar. A breakdown — particularly one driven by Khamenei’s reported intransigence on physical transfer, or Iranian state media’s Saturday repudiation of Trump’s Hormuz characterization — would send Brent sprinting back toward the highs above $115 per barrel that WTI touched in early April when Trump’s initial ultimatum expired.

Traders will return Tuesday from the U.S. holiday weekend to a market priced for cautious optimism but acutely sensitive to any signal — from Tehran, Washington, or the mediators in Muscat and Islamabad — that the framework is either firming or fraying. The next 72 hours of headlines will likely set the tone for crude, equities, and the inflation trajectory through the second half of the year.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Intuit is cutting roughly 3,000 employees — about 17% of its full-time workforce — and lowering its annual TurboTax revenue forecast, in one of the clearest signals yet that artificial intelligence is restructuring the consumer software industry from the inside out.

The company announced the cuts after the market closed Wednesday alongside fiscal third-quarter earnings. Shares fell roughly 13% in after-hours trading before stabilizing Thursday morning.

Chief executive Sasan Goodarzi told employees in an internal memo that Intuit needs to move with “far greater velocity, urgency, and discipline” as it builds what he called an “AI-native platform” across TurboTax, Credit Karma, QuickBooks and Mailchimp.

The company will close offices in Reno, Nevada, and Woodland Hills, California, with most affected U.S. employees exiting by July 31. Severance packages include 16 weeks of base pay plus two additional weeks for every year of service, along with July restricted stock unit vesting and bonus eligibility.

Intuit lowered its fiscal 2026 TurboTax revenue guidance to between $5.277 billion and $5.282 billion, down from a previous projection of $5.305 billion to $5.330 billion.

Goodarzi told analysts on the earnings call that the overall tax-filing industry contracted this season, with total IRS filings projected to decline by roughly 2 million versus broader economic forecasts — the steepest industrywide drop since the immediate post-COVID period.

The company expects to incur between $300 million and $340 million in restructuring charges, primarily in the fiscal fourth quarter ending July 31.

Importantly, the layoffs are not tied to collapsing business performance. Revenue rose 17% year-over-year to $4.7 billion in the latest quarter, GAAP operating income jumped 44%, and earnings per share increased 49%.

Instead, the cuts reflect a strategic decision to replace layers of human workflow with AI-powered systems.

“Operate as a single, unified team and platform,” Goodarzi wrote in the memo.

He also acknowledged that Intuit will “pull back” portions of Mailchimp operations, an implicit recognition that the company’s $12 billion acquisition of the email-marketing platform in 2021 has failed to produce the expected growth trajectory.

The move places Intuit squarely inside a broader corporate restructuring wave tied to artificial intelligence.

Meta Platforms is reassigning roughly 7,000 employees into AI-focused roles. Cisco Systems recently announced cuts of fewer than 4,000 jobs. Standard Chartered is eliminating nearly 8,000 support roles over four years. Oracle has already laid off more than 10,000 workers and is expected to reach 30,000 by year-end.

According to the 2026 layoff tracker maintained by Intellizence, more than 1,600 companies have announced mass workforce reductions since January, with AI increasingly cited as the rationale.

For workers, the Intuit announcement underscores a growing disconnect in corporate America: healthy earnings no longer guarantee job stability.

The company is profitable, growing and raising guidance in parts of the business — yet it is still eliminating nearly one-fifth of its workforce because executives believe AI systems can perform many tasks faster and cheaper.

For the roughly 30 million Americans who use TurboTax each year and the millions of small businesses operating on QuickBooks, the customer-facing changes may appear subtle at first. But behind the screen, fewer human accountants and support representatives will be available, while more interactions are expected to be handled by large language models trained on tax law and accounting workflows.

Whether that ultimately creates a better product, a cheaper product or both is the bet Intuit is now making.

JBizNews Desk

© 2026 JBizNews. All rights reserved.

By JBizNews Desk

ABU DHABI — May 23, 2026

Anwar Gargash, Diplomatic Adviser to the President of the United Arab Emirates, on Thursday delivered the UAE’s sharpest public rebuke yet of Iran’s latest attempt to assert authority over the Strait of Hormuz, dismissing Tehran’s newly declared maritime jurisdiction as a fantasy born of military defeat and accusing the Islamic Republic of decades of regional “bullying” that destroyed Gulf trust.

The immediate trigger was a newly published Iranian maritime map. Iran’s Persian Gulf Strait Authority — a body established by Tehran on May 5 during the current ceasefire with the United States — released what it described as an official “regulatory jurisdiction” zone governing traffic through the Strait of Hormuz. The map outlined an area stretching from the Iranian coast near Kuh-e Mubarak to southern Fujairah in the UAE on the eastern side, and from Qeshm Island toward Umm Al Quwain on the western side. Tehran declared that vessels moving through the corridor must coordinate passage with Iranian authorities.

The claim directly overlaps with Emirati maritime space and places shipping approaches to Fujairah’s strategic oil infrastructure — designed specifically to bypass Hormuz chokepoints — under asserted Iranian oversight.

Gargash responded publicly within hours on X, writing in Arabic that Iran was attempting to “solidify a new reality born from an obvious military defeat.” He called Iranian ambitions to dominate the strait or infringe on UAE sovereignty “nothing but pipe dreams,” adding that Gulf states had endured Iranian “bullying” for decades while Tehran simultaneously issued contradictory messages of friendship.

He said restoring trust would require genuine respect for sovereignty, responsible rhetoric, and a true commitment to regional neighborliness.

The remarks significantly escalate the diplomatic language coming from Abu Dhabi and underscore how seriously Gulf governments are treating Tehran’s latest maritime claims following months of regional conflict and disruption to global energy flows.

The UAE Ministry of Foreign Affairs had already rejected Iranian accusations that Abu Dhabi participated directly in the war, while Khalifa Shaheen Al Marar, the UAE Minister of State, warned at the BRICS Foreign Ministers’ Meeting that using the strait as a mechanism of economic coercion amounted to piracy under international norms.

Al Marar also invoked Article 51 of the United Nations Charter, declaring that the UAE retains the sovereign right to defend its territory, residents, infrastructure, and shipping lanes.

The confrontation has rapidly expanded beyond bilateral rhetoric into an organized Gulf diplomatic campaign.

According to Bloomberg, five Gulf states — Saudi Arabia, the United Arab Emirates, Bahrain, Kuwait, and Qatar — jointly submitted a formal letter to the International Maritime Organization instructing commercial operators not to recognize Iran’s Persian Gulf Strait Authority or comply with Tehran-designated transit routes through Hormuz.

The IMO had already convened an extraordinary session earlier this month in which more than 115 member states co-sponsored a resolution condemning Iranian threats against international shipping and opposing any attempted closure or unilateral control of the strait. UAE officials described the resolution as the largest show of support in the organization’s history on a Gulf maritime issue.

The stakes extend far beyond regional politics.

The Strait of Hormuz remains one of the most economically sensitive waterways on earth, carrying roughly one-fifth of global oil supplies along with major volumes of liquefied natural gas, petrochemicals, and fertilizer shipments. Since the outbreak of the U.S.-Israeli conflict with Iran on February 28, insurance costs, shipping rates, and naval tensions throughout the Gulf have surged sharply.

Reuters previously reported that Iran has begun implementing a layered clearance process for commercial ships moving through Hormuz, including extensive vetting procedures, state-level approvals in some cases, and fees tied to secure passage guarantees.

That creates an increasingly dangerous operational reality for global shipping companies and energy traders.

Commercial vessel owners are now caught between competing sovereign claims over the same strategic waterway: Gulf governments and the broader international maritime community rejecting Iran’s authority, while Tehran attempts to impose de facto enforcement on the water itself.

For Gulf leaders, the dispute is increasingly about who defines the post-war balance of power in the region.

For energy markets, it is about whether one of the world’s most critical trade arteries can continue functioning without military escalation.

And for global shipping operators, the unresolved question remains immediate and practical: whether vessels can safely navigate Hormuz without becoming entangled in a widening geopolitical confrontation between Iran and its Gulf neighbors.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Dow Jones Industrial Average climbed 294.04 points, or 0.58%, to a fresh all-time closing high of 50,579.70 on Friday, May 22, 2026, according to closing data from the New York Stock Exchange, capping the S&P 500’s eighth consecutive weekly gain — its longest winning streak since 2023. The S&P 500 rose 27.75 points, or 0.37%, to 7,473.47, inching closer to its all-time high set May 14. The Nasdaq Composite added 50.87 points, or 0.19%, to 26,343.97. The Russell 2000 gained 25.77 points, or 0.91%, to 2,869.23.

The rally extended into the Memorial Day weekend on twin tailwinds: easing oil prices and growing optimism that President Donald Trump’s mediated negotiations with Iran through Oman and Pakistan may yield a framework deal in the coming days. WTI crude settled at $96.60 per barrel and Brent crude at $100.21, both well off the recent highs that had spooked equity markets through the spring. The 10-year Treasury yield eased, the Cboe Volatility Index slipped to 16.70, and gold pulled back $19.30 to $4,523.20 per ounce as investors rotated out of safe havens.

The market gains came against a striking backdrop. The University of Michigan’s May Survey of Consumers showed household sentiment hitting a new low, with year-ahead inflation expectations climbing to 4.8% from 4.7% last month and long-run inflation expectations jumping to 3.9% in May from 3.5% in April. Both readings sit well above the 3.4% seen in February before the U.S.-Iran war began. The split between Wall Street optimism and Main Street pessimism is now as wide as it has been in years.

Earnings drove most of the day’s biggest movers. Ross Stores jumped 8.1% after the off-price retailer reported first-quarter profit and revenue that easily beat analyst expectations. The company raised its comparable sales forecast and full-year earnings guidance. Chief executive Jim Conroy said the retailer saw strong customer traffic during the quarter, with some boost likely tied to households spending tax refunds. Ross Stores has now decoupled from broader consumer concerns, with its value proposition resonating particularly well as inflation pressures intensify.

Workday surged 12.02% after the human-resources and finance software provider reported quarterly earnings of $2.66 per share, beating the $2.51 consensus by 5.98%, on revenue of $2.54 billion against an expected $2.52 billion. The company raised its full-year margin outlook. Co-founder Aneel Bhusri has returned as chief executive, a transition investors cheered for restoring founder-led strategic focus at a company facing intense competition from Microsoft and Oracle in enterprise software.

Zoom Communications jumped 9.2% after delivering a stronger-than-expected quarterly profit report, signaling that the video conferencing company is successfully pivoting from its pandemic-era growth model toward enterprise communications software and AI-powered productivity tools.

Qualcomm rallied more than 11% in midday trading on Friday and ended the week up 18%. The chipmaker has surged more than 50% since April 29 on the back of its fiscal second-quarter earnings beat and renewed investor enthusiasm for the artificial intelligence chip trade. SoftBank Group extended its scorching rally to a second day, rising more than 11% after closing up 20% Thursday on momentum from Nvidia’s blockbuster earnings, adding over $35 billion to its market capitalization in two sessions.

Estée Lauder jumped 11.9% after announcing it was no longer pursuing a possible merger with Puig, the Spanish fragrance and beauty products company. Puig shares plunged in Madrid trading on the news.

Take-Two Interactive rose 7% after a small revenue beat, with the company confirming Grand Theft Auto VI remains on track for a November launch — a release that Wall Street analysts have called the most important consumer technology launch of the year.

On the downside, Guzman y Gomez rose as much as 20.58% in Sydney trading after the Mexican-themed fast-food chain announced it would exit the U.S. market and refocus on Australia. Founder and co-chief executive Steven Marks said, “Having spent the last 3 months in the US, I realized this was going to take significantly more time and capital than we had expected,” adding that current U.S. performance “could not justify continued investment of shareholder capital.” The exit highlights how challenging the American restaurant market has become for international entrants competing against Chipotle Mexican Grill, Qdoba, and a fragmented field of regional Mexican-food chains.

The political and policy backdrop is reshaping itself in real time. President Donald Trump led a swearing-in ceremony Friday morning for Kevin Warsh as the new chair of the Federal Reserve, replacing Jerome Powell, whose term expired May 15. The ceremony took place in the East Room of the White House — the first time a Fed chair has been sworn in there since Alan Greenspan in 1987. “I want Kevin to be totally independent,” Trump said. “Don’t look at me, don’t look at anybody.” The president’s unprecedented public role in Warsh’s installation drew bipartisan concern about executive influence over the historically independent central bank.

Warsh inherits a central bank navigating an extraordinarily complex set of pressures: persistent inflation driven by the Iran war, elevated long-run inflation expectations, a rapidly rising private-credit default rate, the highest Memorial Day gas prices in four years, and a president with very specific expectations about interest rates. Goldman Sachs strategists this week warned of a growing risk that rising Treasury yields and inflation could trigger a stock market correction, even as the indexes sit at or near record highs.

For the week, the rally was broad. The S&P 500 rose 0.9% despite a rough Monday start, with concerns about persistent inflation and renewed Fed rate-hike risk giving way midweek to optimism on the Iran front. The index has now been above its 50-day moving average since April 8 and above its 200-day moving average for the same period. The 50-day moving average has been above the 200-day moving average since July 1, 2025 — a technical configuration known as a “golden cross” that historically supports continued upside.

For consumers, the disconnect between the stock market and household budgets continues to define the moment. 401(k) and IRA balances are at or near record highs for Americans with retirement accounts, providing a real boost to household wealth. At the same time, AAA reported the highest Memorial Day gas prices in four years at $4.56 a gallon, mortgage rates remain elevated, and grocery, restaurant, and service costs continue to climb. The Federal Reserve under new chair Warsh will be navigating between a stock market that does not appear to need help and a Main Street economy that may.

U.S. markets are closed Monday for Memorial Day. Traders return Tuesday to a calendar packed with macro data — including PCE inflation, durable goods orders, consumer confidence, and second-tier housing data — and continued attention to whether the Iran framework can be finalized into a signed agreement that reopens the Strait of Hormuz and pulls oil prices sharply lower.

For now, the trend is the bulls’ friend. Eight straight weekly gains is the longest streak in nearly three years. The Dow has crossed 50,000. The S&P 500 is within reach of fresh highs. But the cracks beneath the surface — consumer sentiment at record lows, private credit defaults at record highs, gas at a four-year peak, and inflation expectations climbing — remain.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

WASHINGTON — May 22, 2026

The federal government is no longer just funding America’s quantum computing industry. It is buying into it.

Commerce Secretary Howard Lutnick announced Thursday that the U.S. Department of Commerce has signed letters of intent to provide more than $2 billion in federal incentives under the CHIPS and Science Act to nine quantum computing companies — and, in exchange, Washington will take minority, non-controlling equity stakes in each recipient.

The structure mirrors the Trump administration’s increasingly aggressive industrial-policy model already used with Intel Corp. and MP Materials, transforming the federal government from grant provider into direct shareholder across industries deemed strategically critical to U.S. national security and technological leadership.

At the center of Thursday’s package is IBM Corp., which will receive $1 billion to launch what the company describes as America’s first purpose-built quantum chip foundry.

The new entity, named Anderon, will be headquartered in Albany, New York, and operate as a 300-millimeter quantum wafer manufacturing facility designed to serve both IBM and external industry customers developing next-generation quantum hardware.

IBM Chairman and CEO Arvind Krishna said the project would position the United States at the center of the emerging global quantum supply chain while accelerating domestic manufacturing capacity.

“Anderon will be well-positioned to fuel America’s fast-growing quantum technology industry,” Krishna said Thursday.

IBM is matching the federal incentive dollar-for-dollar, committing another $1 billion in cash alongside intellectual property, infrastructure assets and staffing commitments. IBM shares rose roughly 4% in early trading following the announcement.

The remaining federal funding will be distributed across a broad range of quantum architectures and technologies, reflecting Washington’s strategy of diversifying bets across competing approaches to quantum computing.

GlobalFoundries is slated to receive approximately $375 million to establish a secure domestic quantum foundry capable of manufacturing chips across multiple architectures, including superconducting, trapped-ion, photonic, silicon-spin and topological systems.

Additional awards include up to $100 million each for D-Wave Quantum, Rigetti Computing, Infleqtion, Atom Computing, PsiQuantum, and Quantinuum.

The smallest disclosed allocation — roughly $38 million — will go to Australian-American startup Diraq.

Commerce officials said the funding will target some of the industry’s most difficult engineering bottlenecks, including quantum error correction, cryogenic integration, photonic packaging and large-scale qubit control systems.

Those technical hurdles remain the primary obstacle preventing quantum computing from moving from experimental research into commercially scalable machines.

Markets reacted immediately.

Shares of D-Wave Quantum surged roughly 19% in premarket trading, while Rigetti Computing gained 15%. IonQ, which was not included in Thursday’s funding package, climbed 9% on expectations of broader sector support.

Smaller speculative quantum names rallied sharply as well, with Arqit Quantum jumping more than 25% and Quantum Computing Inc. gaining nearly 20%.

The political framing from the administration was unmistakable.

“With today’s CHIPS Research and Development investments in quantum computing, the Trump administration is leading the world into a new era of American innovation,” Lutnick said.

He described the initiative as critical for securing domestic manufacturing, protecting U.S. technological leadership and creating high-paying American jobs tied to advanced computing infrastructure.

The announcement further expands the administration’s evolving industrial strategy, which increasingly blends subsidies, tariffs, direct investment and federal ownership stakes across industries viewed as strategically vital.

Last year, the government converted nearly $9 billion in Intel support into an equity position approaching 10% of the semiconductor giant.

That precedent now appears to be extending into quantum hardware.

The economic stakes behind Washington’s move are potentially enormous, though still highly speculative.

IBM estimates the quantum industry could generate as much as $850 billion in economic value globally by 2040.

Consulting firm McKinsey & Company has projected that sectors including automotive manufacturing, chemicals, financial services and life sciences could collectively unlock more than $1.3 trillion in value from quantum applications by 2035.

But the industry remains far from commercial maturity.

Quantum systems are extraordinarily sensitive to environmental disruption, including heat, electromagnetic interference and vibration. No company receiving Thursday’s funding has yet demonstrated a commercially practical, fully fault-tolerant quantum computer capable of outperforming conventional systems at scale.

What Thursday’s announcement changes is not the underlying physics challenge.

It changes the capital structure around the companies trying to solve it.

By taking direct equity stakes alongside providing billions in funding, Washington is signaling to private investors that the federal government intends to remain deeply embedded in the future of quantum computing — both financially and strategically.

The Commerce Department has not yet disclosed the exact size of the ownership stakes it will receive in each company, and the agreements still require finalization.

But the broader direction is increasingly clear.

After semiconductors, rare earths and energy infrastructure, quantum computing has now joined the growing list of industries Washington considers too strategically important to leave entirely to market forces or foreign supply chains.

For IBM, Anderon and the broader quantum sector, Thursday’s announcement marks the beginning of a far more consequential phase: not simply proving the science works, but proving that America intends to own the industrial foundation beneath it.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
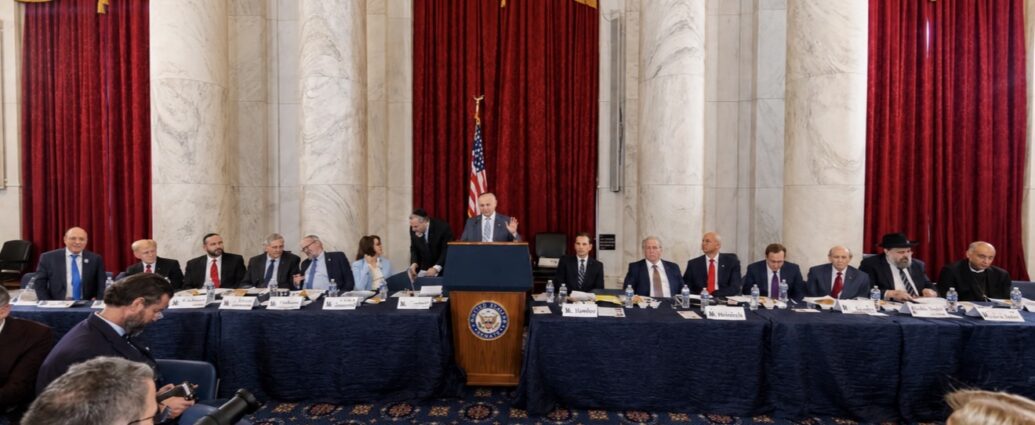
The Justice Department says four of the world’s biggest shipping container manufacturers secretly worked together during the COVID-19 pandemic to drive up prices on the metal containers used to move goods around the world — a scheme prosecutors say ultimately cost American consumers billions of dollars.

Federal prosecutors on Tuesday charged four major Chinese-linked container companies and seven executives with running what officials described as a global price-fixing cartel that controlled roughly 95% of the world’s standard shipping container supply.

For everyday Americans, the case matters because shipping containers are at the center of nearly everything sold in stores — from furniture and electronics to toys, clothing and appliances. When container prices surged during the pandemic, those costs flowed directly into higher prices for consumers.

According to the DOJ, the companies allegedly agreed to limit production beginning in late 2019, just before the pandemic disrupted global supply chains. By artificially restricting the number of containers available, prosecutors say the companies were able to push prices sharply higher as demand exploded.

Container prices more than doubled between 2019 and 2021, according to court filings.

The government says the companies made enormous profits during the period while businesses and consumers paid the price through shortages, shipping delays and rising inflation.

“Global price-fixing cartels strike at the heart of our economic liberty,” Associate Attorney General Stanley Woodward said Tuesday. “The defendants held hostage the world’s supply of ocean shipping containers during the Covid pandemic when our supply chains needed it the most.”

One company allegedly went from losing $110 million before the pandemic to making more than $180 million in profit by 2021. Another reportedly saw profits explode from roughly $20 million to nearly $1.75 billion.

In one of the more striking allegations, prosecutors say the companies even installed surveillance cameras inside one another’s factories to make sure no participant secretly produced more containers than agreed under the alleged cartel arrangement.

The four companies charged are:

  • China International Marine Containers Co. (CIMC)
  • Dong Fang International Container Co.
  • CXIC Group Containers Co.
  • Singamas Container Holdings Ltd.

Together, the firms dominate global container manufacturing and supply many of the world’s largest shipping companies.

Federal officials say the alleged conspiracy worsened supply chain chaos during the pandemic at a time when businesses were already struggling with factory shutdowns, labor shortages and transportation bottlenecks.

Consumers ultimately absorbed much of the damage through higher prices across the economy.

Shipping costs surged to record levels during the pandemic, with some freight routes increasing several-fold compared with pre-pandemic prices. Retailers and manufacturers often passed those higher transportation costs directly to shoppers.

The DOJ says one executive, Vick Nam Hing Ma, was arrested in France and is awaiting extradition to the United States. Six additional executives remain in China and are not currently in U.S. custody.

The criminal case could eventually lead to massive financial penalties. Under federal antitrust law, corporations can face fines reaching twice the profits gained from illegal conduct, potentially pushing total penalties into the billions of dollars.

Legal experts also expect major civil lawsuits to follow from shipping companies, retailers and importers seeking damages tied to inflated container prices.

The case arrives as Washington continues taking a tougher stance toward China on trade, supply chains and pandemic-era accountability.

It also highlights how heavily the global economy depends on a small number of overseas manufacturers for critical infrastructure used in global commerce.

For consumers still dealing with elevated prices years after the pandemic began, the case offers a new explanation for why goods became so expensive so quickly — and how a shortage of something as simple as steel shipping containers may have helped fuel one of the worst inflation spikes in decades.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Singapore is once again Southeast Asia’s biggest stock market, overtaking Indonesia after a sharp rally in Singapore shares and a difficult year for Indonesia’s markets and currency.

For everyday readers, the shift highlights how quickly global investors move money between countries when concerns about political stability, economic policy and financial markets begin to grow.

Singapore’s benchmark stock index, the Straits Times Index, climbed to a new record Tuesday, helping push the city-state ahead of Indonesia in total market value for the first time in years.

The rally has been fueled by investors looking for safer places to park money during growing global uncertainty tied to the Iran war, rising oil prices and volatility across emerging markets.

Singapore has increasingly benefited from its reputation as one of Asia’s most stable financial centers.

Its stock market is dominated by large banks, real estate firms and dividend-paying companies that investors often view as safer during turbulent periods.

The Singapore dollar has also remained relatively strong compared with many other Asian currencies, making Singapore assets more attractive to international investors.

Indonesia, meanwhile, has faced mounting pressure on several fronts.

Its stock market has struggled this year, while the Indonesian rupiah has hovered near record lows against the U.S. dollar. Foreign investors have also become increasingly worried about government policy, central bank independence and corporate governance standards.

Those concerns intensified after Indonesian President Prabowo Subianto appointed his nephew to a senior central bank role earlier this year, raising questions among investors about political influence over monetary policy.

Global index provider MSCI later warned Indonesia could risk losing its “emerging market” status if governance concerns are not addressed.

That matters because many large investment funds automatically buy or sell stocks based on those global index classifications.

If Indonesia were downgraded, billions of dollars could eventually flow out of the country’s stock market as index funds adjust their holdings.

Indonesia’s economy is also being hurt by high energy prices.

Although the country exports many commodities, it still imports large amounts of oil. Rising energy costs tied to Middle East instability have increased pressure on inflation and the country’s currency.

Meanwhile, slowing growth in China — one of Indonesia’s biggest trading partners — has added further economic strain.

Singapore’s rise reflects a broader trend happening globally:
during uncertain periods, investors often move money toward countries seen as politically stable, financially predictable and institutionally strong.

That has helped Singapore attract capital not only into its stock market, but also into private banking, real estate, hedge funds and family offices over the past several years.

The competition between Singapore and Indonesia has become symbolic of two very different investment stories in Southeast Asia.

Indonesia has traditionally offered faster economic growth and access to natural resources and consumer expansion.

Singapore, by contrast, offers stability, strong financial regulation and global investor confidence.

In strong economic periods, investors often favor faster-growing emerging markets like Indonesia.

During periods of global stress, many rotate back toward safer financial hubs like Singapore.

Analysts say that dynamic has accelerated sharply in 2026.

Despite Singapore reclaiming the top spot regionally, Southeast Asia’s markets remain relatively small compared with the world’s biggest companies and exchanges.

Several U.S. technology giants individually hold larger market values than entire Southeast Asian stock markets.

Still, the regional battle matters because global investors increasingly view Southeast Asia as an important long-term growth region amid slowing growth in China and higher valuations in India.

For Indonesia, regaining investor confidence may depend on restoring trust in economic management and avoiding further governance controversies.

For Singapore, the latest rally reinforces its position as Southeast Asia’s financial capital at a moment when investors globally are prioritizing stability over risk.

And in today’s market environment, stability is commanding a premium.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

America’s two largest publicly traded apartment landlords are nearing a massive merger that would place roughly 180,000 apartments under one corporate umbrella at a moment when rent has become one of the biggest financial pressures crushing American households.

AvalonBay Communities Inc. and Equity Residential are close to finalizing a deal that could be announced as soon as Thursday, according to people familiar with the matter. Under the structure being negotiated, AvalonBay shareholders would own more than 51% of the combined company and receive approximately 2.793 shares of Equity Residential stock for each AvalonBay share.

The companies are led by Benjamin Schall, chief executive of AvalonBay, and Mark Parrell, chief executive of Equity Residential.

Combined, the companies carry an estimated market value approaching $50 billion, while the real estate itself could be worth more than $78 billion, according to estimates from J.P. Morgan analysts. If completed, the transaction would rank among the largest real-estate mergers in American history.

The timing is not random.

Housing affordability has become one of the defining economic issues in the United States. In many major cities, rent now consumes well over a third of household income for middle-class families, while younger Americans increasingly struggle to buy homes because elevated mortgage rates and high prices have locked them into the rental market longer than previous generations.

At the same time, apartment owners themselves are under pressure from higher interest rates, rising insurance costs, labor expenses, taxes, maintenance costs, and growing political fights over rent regulation and affordable housing mandates.

The merger is designed to give the companies more scale to handle those pressures.

By combining operations, the firms can reduce overlapping corporate expenses, centralize leasing and technology systems, negotiate financing more efficiently, and potentially accelerate future apartment development projects.

Analysts Alexander Goldfarb and Connor Mitchell of Piper Sandler described the transaction as a true “merger of equals,” adding that it could trigger a broader consolidation wave across the apartment industry.

But for ordinary renters, the immediate question is much simpler: does this actually lower rent?

Probably not anytime soon.

Critics of large corporate landlords argue that mergers like this often strengthen pricing power and political influence while giving renters fewer alternatives in already expensive housing markets. Tenant advocates have increasingly targeted institutional landlords in cities including New York, Los Angeles, San Francisco, Seattle, and Washington as frustration over affordability continues rising.

Supporters of the merger argue the opposite — that larger apartment companies are better positioned to finance and build new housing supply, which could eventually help slow rent growth if enough units are added to the market.

That debate now sits at the center of the American housing crisis.

People familiar with the discussions said the combined company is expected to emphasize affordable-housing development, aligning with one of the Trump administration’s major domestic priorities as Washington searches for ways to increase housing inventory without dramatically expanding federal spending.

Even at this size, analysts estimate the merged company would still control only about 2% of apartment units across its markets, limiting arguments that it would dominate rental pricing nationally.

Still, the merger would create one of the most politically influential housing companies in America, with major exposure across New York, Boston, Washington, Los Angeles, Seattle, Miami, and multiple fast-growing Sun Belt regions.

The financial backdrop also explains why the companies may feel pressure to act now.

AvalonBay shares have fallen roughly 11% over the past year, while Equity Residential shares are down approximately 6%, with both companies trading below estimates of their underlying real-estate value.

During a February earnings call, Parrell acknowledged that rising costs and slowing rent growth created a difficult environment for apartment owners throughout 2025.

Meanwhile, the massive apartment-building boom that flooded many Sun Belt markets after the pandemic is beginning to slow, helping occupancy rates and pricing stabilize again after several softer quarters.

The two firms are also no strangers to each other.

In 2013, AvalonBay and Equity Residential partnered to divide the massive $9 billion acquisition of Archstone, one of the largest apartment transactions ever completed in the United States. Wall Street analysts have speculated for years that the relationship could eventually evolve into a full merger.

Now it appears that moment may have arrived.

For renters, leases are unlikely to change immediately if the transaction closes. Buildings will continue operating normally, and most tenants may not initially notice much difference.

Longer term, however, the combined company would gain substantially greater influence over apartment development, financing, lobbying efforts, and housing-policy debates in some of the most expensive cities in America.

The deal could also accelerate consolidation across the broader apartment REIT sector, potentially pressuring competitors including Camden Property Trust, Mid-America Apartment Communities, UDR Inc., and Essex Property Trust Inc. to explore mergers of their own.

Neither AvalonBay nor Equity Residential publicly commented on the discussions Wednesday.

If the merger is announced as expected, America may wake up Friday with a new dominant force in rental housing — and a much larger national conversation about whether corporate scale is helping solve the housing crisis or helping drive it.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Japanese exports surged 14.8% year over year in April, marking the fastest monthly growth pace since January and significantly exceeding the 9.3% increase economists surveyed by Reuters had expected, according to data released Wednesday by Japan’s Ministry of Finance.

The strength came overwhelmingly from semiconductors and AI-linked industrial demand.

Semiconductor exports jumped 41.6% from a year earlier, reinforcing the view among investors and economists that the global artificial-intelligence infrastructure buildout continues accelerating despite tariffs, geopolitical tensions, and higher energy prices.

Exports to China, Japan’s largest trading partner, rose 15.5%, while exports to the United States climbed 9.5%, recovering after months of tariff-related weakness earlier this year.

Imports increased 9.7%, also above forecasts, while Japan’s monthly trade deficit narrowed to 301.9 billion yen from 643 billion yen in March. The yen strengthened modestly following the release, trading near 158.88 per dollar.

The report underscores Japan’s growing importance in what many analysts now describe as the global “AI Giga-Cycle” — the massive multiyear expansion in spending on data centers, semiconductor fabrication plants, AI chips, and supporting industrial infrastructure.

Japanese companies sit directly at the center of that supply chain.

Firms including Tokyo Electron, Screen Holdings, Disco Corp., Advantest, and Renesas Electronics manufacture many of the advanced tools and testing systems required by chipmakers such as Taiwan Semiconductor Manufacturing Co., Samsung Electronics, SK Hynix, Micron Technology, and Intel Corp.

Demand for lithography, etching, deposition, wafer testing, and advanced semiconductor packaging equipment has surged alongside spending by U.S. technology giants racing to expand AI capacity.

The Tokyo Stock Exchange’s semiconductor-related shares have rallied sharply this year as investors increasingly view Japanese industrial suppliers as one of the clearest global beneficiaries of AI infrastructure spending.

Still, economists warn the export boom may not fully shield Japan’s broader economy.

Norihiro Yamaguchi, lead Japan economist at Oxford Economics, told CNBC this week that while “gains in exports due to robust IT demand could provide some short-term support,” elevated energy costs and geopolitical uncertainty continue weighing on household spending and business investment.

Japan’s economy grew at an annualized 2.1% pace in the first quarter, above the 1.7% Reuters consensus forecast. But the Bank of Japan has simultaneously cut its full-year fiscal 2026 growth outlook to 0.5% from 1.0% while sharply raising its core inflation forecast to 2.8% from 1.9%, citing the economic shock from the Iran conflict and rising global energy costs.

The trade data also reflects a broader shift in global commerce.

Over the past year and a half, Japanese exports have become increasingly tied to Asian industrial demand rather than traditional Western consumer spending. Shipments to China, Taiwan, South Korea, and Southeast Asia are now deeply connected to semiconductor-fabrication expansion tied directly to AI-related infrastructure investment.

At the same time, the Trump administration’s revised trade arrangement with Japan appears to be stabilizing export flows to the United States.

Earlier this year, Japanese exports to the U.S. had declined as much as 5% amid tariff tensions before rebounding after Washington finalized a bilateral trade framework capping Japanese auto and industrial tariffs at 15%.

That agreement also included a massive Japanese investment commitment into the United States.

Japan pledged approximately $550 billion in U.S. investment under the framework, with an initial $36 billion tranche approved for projects including energy infrastructure, semiconductor-related synthetic-diamond production, and natural-gas export facilities.

Commerce Secretary Howard Lutnick has repeatedly described the arrangement as a model for future bilateral trade negotiations designed to attract foreign industrial capital into American manufacturing.

For U.S. investors, the Japanese export surge carries direct implications for the AI trade dominating equity markets.

Strong semiconductor-equipment exports to China and Taiwan signal that capital spending by hyperscalers including Microsoft Corp., Alphabet Inc., Amazon.com Inc., Meta Platforms Inc., and Oracle Corp. remains elevated. Combined AI-related capital expenditures among those firms are projected near $725 billion in 2026, up sharply from roughly $410 billion a year earlier.

That spending supports not only Japanese suppliers but also U.S.-listed semiconductor-equipment firms including Applied Materials Inc., Lam Research Corp., KLA Corp., and ASML Holding NV, along with the broader Philadelphia Semiconductor Index.

The largest near-term risk remains energy.

Japan imports nearly all of its crude oil, much of which historically passes through the Strait of Hormuz. President Donald Trump said earlier this week that he postponed potential military action against Iran to allow diplomatic negotiations to continue.

WTI crude traded near $98.96 per barrel Wednesday, while Brent crude remained near similar levels.

For Japanese households, the export surge offers mixed news. Stronger semiconductor demand is helping support corporate profits and the yen, potentially easing imported inflation pressures. But rising energy costs continue weighing heavily on consumer budgets, food prices, and household purchasing power.

For American businesses and investors, however, the signal from Tokyo is clearer.

The AI infrastructure buildout powering global equity markets is still accelerating. Semiconductor bottlenecks that worried investors a year ago — including wafer capacity, advanced packaging, and equipment shortages — are increasingly being addressed through expanding industrial output across Japan and Asia.

The data also provides a political boost for the White House’s trade strategy.

Japan’s 9.5% export increase to the United States occurred under the revised tariff framework, giving the Trump administration a concrete example it can point to as it negotiates trade arrangements with the European Union, South Korea, and India.

For now, the message from Tokyo remains straightforward: global AI demand continues pulling aggressively on every supply chain connected to semiconductor production — and Japan remains one of the most critical links in that chain.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

NEW YORK, May 21, 2026 — The Dow Jones Industrial Average closed at a fresh record Thursday, overcoming a sharp midday selloff as crude oil prices reversed lower on renewed hopes that Washington and Tehran could still reach a diplomatic framework over Iran’s nuclear program. The blue-chip index gained 276.31 points, or 0.55%, to finish at 50,285.66, marking the highest closing level in its history. The S&P 500 added 0.17% to 7,445.72, while the Nasdaq Composite rose 0.09% to 26,293.10.

Markets spent most of the session reacting to a geopolitical headline rather than earnings or economic data. Reuters reported that Iran Supreme Leader Ayatollah Ali Khamenei issued an internal directive insisting that Iran’s stockpile of enriched uranium remain inside the country under any future agreement — a stance directly conflicting with Israeli officials’ assertions that President Donald Trump privately committed to requiring all enriched material be removed from Iranian territory as part of a final settlement.

The report initially sent energy markets sharply higher and pressured equities through midday trading as traders feared negotiations could deteriorate. Treasury yields climbed and defensive positioning accelerated before sentiment abruptly reversed later in the afternoon as investors concluded negotiations had not collapsed and that a diplomatic off-ramp still remained possible.

By settlement, the oil spike had fully unwound. West Texas Intermediate crude fell nearly 2% to $96.35 per barrel, while Brent crude dropped more than 2% to $102.58. The reversal eased pressure on yields and helped industrial, financial, and cyclical shares lead the Dow to a record finish.

The day’s most significant corporate mover came from Spotify Technology SA, which staged its first Investor Day since 2022 and delivered an aggressive long-term growth roadmap that energized growth investors. Shares surged 12.88% to close at $489.04, making Spotify one of the strongest performers in the S&P 500.

Spotify Chief Executive Daniel Ek told investors the company is targeting compounded annual revenue growth in the mid-teens, gross margins between 35% and 40% by 2030, and operating margins exceeding 20% within four years. Management also outlined a longer-term ambition of reaching 1 billion subscribers and generating $100 billion in annual revenue by the end of the decade.

The company simultaneously announced a licensing partnership with Universal Music Group that will allow Spotify to launch generative AI-powered music creation tools for premium subscribers. The agreement is viewed across the industry as one of the first large-scale frameworks attempting to address how artists, labels, and streaming platforms will monetize consumer-facing AI music products while protecting royalty economics.

The move immediately reignited debate across the entertainment and technology sectors over whether AI-generated music will become a subscription-growth driver or a disruptive threat to traditional recording economics.

Industrial names also contributed to Thursday’s rally. Deere & Co. posted a stronger-than-expected fiscal second-quarter report, while Bloom Energy Corp. surged more than 12% after announcing a partnership with European AI cloud operator Nebius Group, which itself jumped more than 16%.

The agreement underscored one of Wall Street’s newest AI investment themes: power generation. Analysts increasingly argue that electricity availability — rather than semiconductor supply — is becoming the primary bottleneck in expanding hyperscale artificial-intelligence infrastructure. Distributed gas-fired generation and energy resiliency providers are now emerging as secondary beneficiaries of the AI boom alongside chipmakers.

Speculative corners of the market also saw heavy momentum buying. The quantum-computing sector posted another outsized session, with Rigetti Computing Inc. soaring more than 30%, D-Wave Quantum Inc. climbing 22%, and Quantum Computing Inc. advancing 13%. IonQ Inc. gained 9%, while International Business Machines Corp. rose 7% and GlobalFoundries Inc. added 11%.

Rare-earth and strategic-mineral names extended gains as well. USA Rare Earth Inc. climbed 7% after announcing $19.3 million in funding support from the U.S. Department of Energy for pilot-scale rare-earth element separation development, reflecting continued federal emphasis on domestic critical-mineral supply chains.

Despite the Dow’s record finish, underlying breadth remained uneven for much of the session. At one point during afternoon trading, fewer than 180 stocks in the S&P 500 were advancing, according to data cited by TheStreet, before the late-session reversal in crude prices improved sentiment across broader indexes.

Looking ahead to Friday’s shortened pre-holiday session, futures pointed modestly lower late Thursday evening. S&P 500 futures were down roughly 0.22%, Dow futures declined 0.18%, and Nasdaq futures slipped 0.29%.

The corporate earnings calendar becomes lighter heading into Memorial Day weekend but still includes several closely watched reports. Booz Allen Hamilton Holding Corp. is expected to report fiscal fourth-quarter earnings before Friday’s opening bell, with Wall Street forecasting approximately $1.34 per share in earnings on $2.87 billion in revenue. Investors are closely watching whether the government consulting giant can stabilize margins after the stock lost more than 40% since the start of 2025 amid weakness in federal-services spending.

BJ’s Wholesale Club Holdings Inc., Frontline Ltd., Hub Group Inc., and Global Ship Lease Inc. are also scheduled to report Friday morning.

With the U.S. economic calendar relatively quiet, traders are entering the holiday weekend focused primarily on geopolitical risk. Markets remain highly sensitive to any additional statements from Tehran, Washington, or Israeli officials regarding uranium enrichment terms and the shape of a possible Iran agreement.

For now, however, Wall Street closes the week with a simple headline: the Dow at all-time highs, oil volatility unable to derail the rally, and Spotify unexpectedly emerging as one of the defining AI stories of the year.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
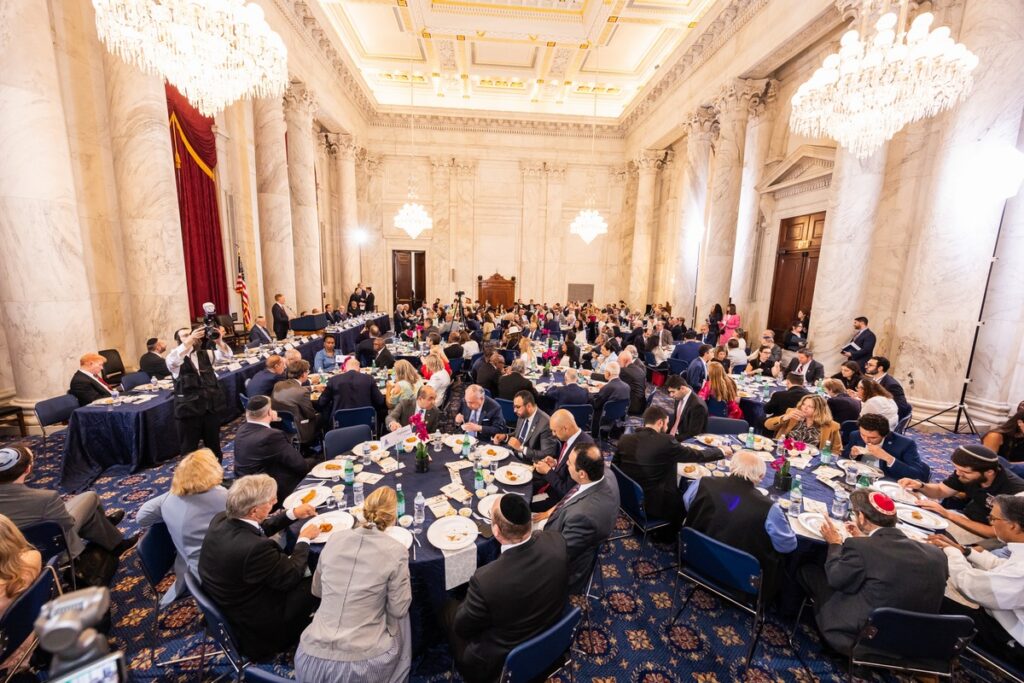
By JBizNews Desk
New York, Thursday, May 21, 2026

Oil prices spiked and U.S. stocks turned lower in midday trading Thursday after Reuters reported that Iranian Supreme Leader Ayatollah Mojtaba Khamenei issued a directive ordering that the country’s stockpile of near-weapons-grade enriched uranium cannot be shipped outside Iran, a hard line that directly contradicts the central American demand for ending the war.

Two senior Iranian sources confirmed the directive to Reuters. The White House has repeatedly told mediators that the removal of Iran’s enriched uranium stockpile is a non-negotiable condition for any peace deal, and President Donald Trump has personally assured Israeli officials that any agreement would include the transfer of the material out of Iranian hands.

West Texas Intermediate crude jumped as much as 4% in early trading, crossing $102 per barrel before pulling back to roughly $101.04, up about 2.9% on the day. Brent crude rose as much as 3.5% to $108.50 before settling near $107.36, a gain of 2.3%. The S&P 500 fell 0.45%, the Dow Jones Industrial Average dropped 0.48%, and the Nasdaq slid 0.50%. The Russell 2000 was the only major U.S. equity index in positive territory, up 2.56%, as small-cap energy names rallied on the crude move.

Trump told reporters at Joint Base Andrews on Wednesday that he was prepared to resume military action against Iran if the regime did not provide “100 percent good answers” in the current round of talks, but said he was willing to give diplomacy “a couple more days.”

“We’re all ready to go,” Trump said, referring to U.S. military assets in the region.

Earlier in the week, Trump said he called off an imminent strike package against Iranian targets at the request of Gulf Arab allies.

The market reaction was sharpened by a parallel warning from the International Energy Agency. Executive director Fatih Birol told reporters Thursday that the global oil market will enter a “red zone” this summer if the Strait of Hormuz does not reopen, with global crude inventories set to deplete as travel and air-conditioning demand picks up.

Iran has held the strait closed since early March, cutting traffic by more than 95% and pushing global oil supply chains into the worst disruption on record.

“Meanwhile, the Strait of Hormuz remains shut, another 14 million barrels of oil has failed to make it to market, and the first two months on the Brent curve are trading over $100,” said Robert Yawger, director of energy futures at Mizuho.

The combination of physical supply loss, a hawkish nuclear posture from Tehran and the IEA warning is rebuilding the geopolitical risk premium in crude that had been quietly fading over the past two weeks amid tentative ceasefire optimism.

Also weighing on equities was a 1.6% drop in shares of Nvidia, despite the chipmaker’s blockbuster earnings report Wednesday evening. Nvidia forecast second-quarter revenue of $91 billion and announced an $80 billion share repurchase authorization, but investors used the post-earnings strength to take profits. Treasury yields also rose across the curve, with the 10-year yield climbing on inflation concerns tied to higher oil prices.

For consumers, the math is straightforward and unwelcome. Every dollar increase in WTI crude typically translates to roughly 2.5 cents at the gas pump within two to three weeks. The move from $97 to $102 in a single session could add another 12 to 13 cents per gallon to gasoline prices by early June.

Airlines, trucking companies and food distributors that hedged jet fuel and diesel at lower levels in April are now watching those hedges expire into a higher-cost environment, with the pass-through to summer airfares and grocery prices already becoming visible.

Iranian officials are reportedly preparing a response to the latest American proposal, which Tehran’s ILNA news agency described as having “narrowed the gaps to some extent.” Whether that response includes any flexibility on the uranium question — the core issue in the negotiations — will determine whether markets are pricing in a genuine ceasefire path or a longer summer of $100-plus oil and renewed inflation pressure.

JBizNews Desk

© 2026 JBizNews. All rights reserved.

Ram Trucks unveiled three new Hemi V-8 pickups Wednesday in Chelsea, Michigan, marking the most aggressive return to large-displacement gasoline performance by a Detroit automaker in more than a decade — and a direct bet by Stellantis NV that American truck buyers still want power, speed, and high-end performance even with crude oil trading near $99 a barrel.

The new lineup, branded the Ram 1500 Rumble Bee, will launch in late 2026 with a 5.7-liter Hemi V-8 model, followed by the Rumble Bee 392 and a flagship Rumble Bee SRT during the first half of 2027.

The reveal was led by Tim Kuniskis, chief executive officer of Ram and the executive overseeing Stellantis’s U.S. brand strategy. Kuniskis acknowledged elevated fuel prices remain a risk but said the company expects gasoline costs to moderate before the trucks reach showrooms.

“We chased electrification, and that tide changed,” Kuniskis said, according to reporting from The Detroit News and CNBC. “This tide will change as well. I would like to believe by the time this thing’s sitting on a showroom floor, I would like to believe that the gas prices will be back in line.”

Stellantis declined to release official pricing but indicated the vehicles will begin arriving at U.S. dealerships starting this fall.

Kuniskis compared the entry-level Hemi truck to a heavily equipped current Ram Big Horn, which can already exceed $60,000, while suggesting the top-end Rumble Bee SRT could sit above the existing $100,000 Ram TRX performance truck.

Behind the muscle-truck branding sits a broader profitability strategy.

Kuniskis said high-performance vehicles typically generate roughly “three times the margin than an average vehicle,” despite accounting for a relatively small share of total unit sales. Those vehicles also function as “halo” products designed to drive attention and showroom traffic across the broader brand lineup.

That matters for Stellantis because the company has struggled to maintain momentum in North America.

The automaker’s operating margins have compressed over the past two years as Ford Motor Co. gained market share in full-size pickups and General Motors Co. strengthened its position in heavy-duty trucks. Ram sales declined during 2024 and again during the early months of 2025, prompting Kuniskis to launch what he has publicly described as a 25-product, 18-month offensive aimed at rebuilding the brand.

The Rumble Bee lineup is now the centerpiece of that effort.

The trucks will be manufactured at Stellantis’s plant in Saltillo, Mexico, adding another layer of complexity to the economics.

The revised USMCA trade framework and broader U.S. tariff policies have increased cost pressure for vehicles crossing the U.S.-Mexico border. Stellantis has previously disclosed material tariff-related costs tied to Mexican production, raising questions about whether the company can fully preserve margins on trucks expected to begin near the $60,000 range.

The timing also ties directly into the global energy market.

The launch came as West Texas Intermediate crude traded near $98.96 per barrel Wednesday afternoon, while Brent crude remained near similar levels. Oil markets continue reacting to tensions tied to the Iran conflict and uncertainty surrounding the Strait of Hormuz, one of the world’s most critical energy shipping corridors.

President Donald Trump said earlier this week that he postponed potential military action against Iran while diplomatic negotiations continue.

Any renewed escalation could quickly push gasoline prices higher — directly affecting the same middle-income recreational truck buyers Ram hopes to attract.

Kuniskis, however, has argued that emotional appeal matters more than fuel economy for the target customer.

“Data be damned — we raise our flag and let our HEMI ring free again,” he said previously when Ram announced the broader return of the Hemi engine to the Ram 1500 lineup.

The current 2026 Ram 1500 Hemi produces 395 horsepower and 410 pound-feet of torque, paired with an eTorque mild-hybrid system and an eight-speed automatic transmission. The upcoming Rumble Bee 392 will feature the larger 6.4-liter Hemi V-8, while the SRT variant is expected to anchor the lineup with the highest output.

The strategy also aligns with a broader brand-marketing push.

Ram returned to NASCAR’s Craftsman Truck Series for the 2026 season after a 13-year absence, unveiling its race truck at Michigan International Speedway last year. Stellantis cited industry research showing more than 40% of NASCAR fans own trucks, positioning the racing return as part of a larger campaign internally branded “Ram-Demption.”

For the broader auto industry, the launch may signal a new phase in Detroit’s strategy.

While automakers continue investing tens of billions into electric vehicles and battery platforms, Ram’s move suggests internal-combustion performance vehicles still command strong pricing power and customer loyalty.

Ford has not announced a major expansion beyond the current F-150 Raptor R, while General Motors has yet to unveil an equivalent muscle-truck strategy for the Chevrolet Silverado or GMC Sierra lines. Meanwhile, Toyota Motor Corp. continues gaining share with the Tundra and Tacoma platforms.

If the Rumble Bee lineup achieves strong margins and customer demand, analysts expect competing automakers could respond with similar performance-oriented trucks within the next 12 to 18 months.

For consumers, the launch sends two clear messages.

First, gasoline-powered performance trucks are not disappearing from the American market despite the industry’s aggressive electrification push.

Second, pricing across the performance-truck segment is likely heading even higher. A six-figure Rumble Bee SRT effectively raises the ceiling for what automakers believe truck buyers are willing to spend on premium recreational vehicles.

Stellantis shares traded mixed Wednesday in both Milan and New York.

The longer-term question may ultimately come down to oil prices.

If gasoline costs retreat toward the $70-per-barrel environment many automakers privately hope for, Ram’s timing could look highly strategic. If energy prices remain closer to current levels, Stellantis will be asking consumers to embrace high-horsepower trucks during one of the most expensive fuel environments in years.

The trucks are coming either way.

The fuel market will determine how many buyers follow.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
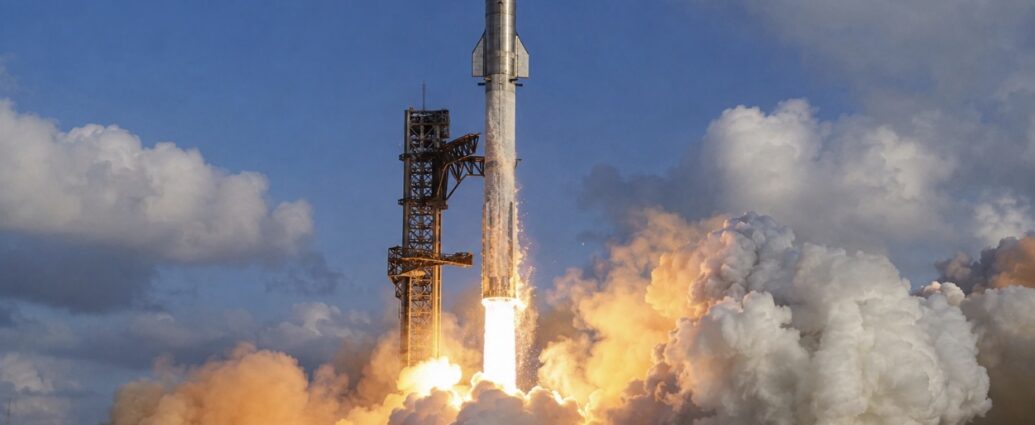
By JBizNews Desk
New York, Thursday, May 21, 2026

Jeff Bezos turned a CNBC sit-down into the bluntest indictment yet of Mayor Zohran Mamdani’s management of New York City, telling Andrew Ross Sorkin on Wednesday’s “Squawk Box” that if Amazon were run the way the city runs its $43 billion school system, packages would arrive six weeks late, cost a hundred dollars to ship, and contain the wrong item.

The line landed because the numbers behind it are not rhetorical. New York City is spending roughly $44,000 per student, about thirty percent more than Los Angeles or Chicago, while enrollment has dropped by close to 70,000 students since 2020 and math and reading proficiency continue to trail national benchmarks. The Citizens Budget Commission projects full per-student spending will reach $43,778 in fiscal year 2026, the highest of any major American school system. The Department of Education’s budget has climbed from $34.5 billion to about $44.6 billion in recent years even as the student count fell, with the city spending about $1.6 billion on a hold-harmless policy that kept school budgets flat as classrooms emptied.

Bezos, whose net worth sits near $269 billion, did not stop at the spending figure. He argued that almost none of the money is reaching teachers, and that doubling his own tax bill would not change that arithmetic because the dollars are absorbed by a management-heavy bureaucracy long before they get to a classroom in Queens or the Bronx.

“None of this money is getting to the teachers, I promise you,” Bezos said. “If you’re charging $44,000 per student, how much of that money do you think is trickling down to teachers? Not much.”

He also pushed back on Mamdani’s broader tax agenda, including proposals to raise rates on high earners and target luxury second homes, framing the mayor’s approach as a search for new revenue to feed a system that is already failing on the inputs it has. Bezos described Amazon’s internal management technique of asking “the five whys” to trace problems to root causes, contrasting it with what he characterized as a New York City reflex to point fingers and request more funding.

Mamdani responded within hours on X, writing, “I know a few teachers in Queens who would beg to differ,” a line his allies amplified as a defense of the city’s educators. The mayor did not dispute the budget figure or the per-pupil spending number.

The timing of Bezos’s broadside is what makes it more than a celebrity soundbite. The Bezos family pledged $150 million to early childhood education initiatives in New York earlier this year, giving the Amazon founder a standing claim to a seat in the city’s education debate that goes beyond a billionaire firing off opinions from Miami. He is, in effect, arguing that he is putting private capital directly into the same children the city’s $43 billion is failing to serve — and that the contrast tells the story.

The critique also lands as Mamdani’s management credibility is being challenged on a second front. Earlier Thursday, leaders of the Multicultural Business Coalition met with New York City Council Speaker Julie Menin and members of her staff to raise concerns that the mayor’s proposed city-owned supermarket initiative could undermine independently operated neighborhood supermarkets, threaten thousands of local jobs and place taxpayer-subsidized competition directly against small family-owned grocers already operating on thin margins.

The Multicultural Business Coalition — an immigrant-led nonprofit made up of more than 50 chambers of commerce representing Asian, African, Caribbean, Hispanic, Middle Eastern and Jewish-owned businesses in New York — has assembled a war chest north of $1 million to oppose the mayor’s proposed $70 million city-owned grocery store initiative ahead of a City Council Economic Development Committee hearing tentatively slated for May 29.

Coalition leaders argue the proposal would unfairly place taxpayer-backed, rent-subsidized and publicly financed grocery stores in direct competition with existing neighborhood supermarkets, bodegas and small family-owned retailers, threatening thousands of local jobs and the survival of independently operated stores already struggling with inflation, labor costs and razor-thin margins.

The coalition is in talks for a $1 million commitment from a single backer and is raising roughly $100,000 a week from individual donors and small and mid-size businesses, according to chairman Frank Garcia.

“We will be at the hearing in force,” Garcia told the New York Post. “We don’t want to hurt the mayor, but we are not going to let him hurt us.”

Garcia warned that if the coalition is brushed off, the group “will go after the mayor and his candidates and make sure he is a one-time mayor.” The coalition also opposes Mamdani’s proposed $30-an-hour minimum wage plan.

Ken Roldan, the coalition’s president and a former lawyer in the state attorney general’s civil rights bureau, said the group is weighing legal action against the city over the public supermarket proposal.

“We wouldn’t shy away from a lawsuit by any means,” Roldan told the Post.

Duvi Honig, founder of the Orthodox Jewish Chamber of Commerce and co-founder and secretary of the coalition, told the New York Post that it is the first time so many disparate immigrant business communities have aligned under one umbrella and that politicians are taking notice.

The Multicultural Business Coalition and Bezos’s CNBC appearance converge on the same underlying point from opposite ends of the economic spectrum. The immigrant grocers warn that a city government that has not demonstrated competence running housing, hospitals or schools should not be opening a tax-free, rent-free, capital-subsidized retail business across the street from bodegas and supermarkets that pay full freight.

Bezos is making the same argument in simpler language: a system that absorbs $44,000 per student and produces declining outcomes is not suffering from a funding problem — it is suffering from a management problem, and additional taxes will not solve it.

The political stakes for Mamdani are sharper than a viral exchange suggests. The mayor took office in January on a platform of using municipal power to lower costs for working New Yorkers, and the school budget and grocery initiative are now the two largest live tests of that theory. If Bezos’s critique gains traction and Roldan’s lawsuit threat materializes, the mayor enters his first full budget cycle defending both the highest per-pupil education spending in the country and a publicly subsidized grocery rollout, with critics emerging from the right, the center and within parts of the city’s immigrant business base.

City Hall has not yet engaged substantively with the management critique. Mamdani’s response to Bezos was limited to a one-line social media reply, and the mayor’s office did not respond to requests for comment on the coalition. The administration has yet to release detailed plans for the stores, but Nelson Eusebio, director of government relations for the National Supermarket Association, told the Post that members were told the city is spending too much money on the Harlem pilot location and questioned why those funds are not instead being invested into existing neighborhood supermarkets.

What Bezos said on CNBC is likely to follow the mayor through the rest of budget season. The “six weeks late and a hundred dollars to ship” comparison is the kind of image that survives beyond a single news cycle because it translates a sprawling bureaucracy into a customer experience every New Yorker can immediately picture.

Mamdani now has the rest of the spring to come up with a more substantive answer than knowing a few teachers in Queens.

JBizNews Desk

© 2026 JBizNews. All rights reserved.

President Donald Trump will travel to the Group of Seven leaders’ summit in Évian-les-Bains, France, next month, a White House official confirmed Tuesday, ending weeks of speculation about whether the U.S. president would attend amid the sharpest transatlantic rift in years over the U.S. war with Iran, tariffs and the future of the global trading order.

The White House official told Axios, which first reported the announcement, that Trump intends to use the June 15–17 gathering at the French Alpine lakeside resort to press allies on a sweeping commercial agenda: linking U.S. foreign aid to trade deals, accelerating the global adoption of American-developed artificial intelligence platforms, breaking China’s stranglehold on critical mineral supply chains, fighting drug trafficking and illegal immigration, and lifting regulatory barriers to boost U.S. exports and fossil fuel production.

The official said the summit itself is not expected to produce finalized agreements but instead establish the framework for future trade and industrial partnerships among Western allies.

The confirmation lands at a moment of unusual strain between Washington and several of its closest allies. Trump’s attendance had remained uncertain amid growing frustration with G7 members including France, Germany, Italy and the United Kingdom over what the administration views as insufficient support for the U.S.-led campaign against Iran and the broader effort to secure global energy shipping routes.

Trump has repeatedly criticized European NATO members for relying on U.S. military force while failing to contribute meaningfully to operations protecting cargo vessels transiting the Strait of Hormuz, one of the world’s most critical energy chokepoints. European leaders have argued privately that they remain cautious about becoming directly entangled in the conflict, though several governments have indicated willingness to provide logistical or reconstruction support once hostilities subside.

French President Emmanuel Macron, whose government currently holds the rotating G7 presidency, has worked aggressively behind the scenes to ensure Trump attends the summit despite the tensions. Macron reportedly offered the American president a formal post-summit dinner at the Palace of Versailles — a highly symbolic gesture aimed at appealing to Trump’s appreciation for historic grandeur and state ceremony.

The summit schedule itself was adjusted earlier this year to accommodate Trump’s calendar, including events surrounding his 80th birthday celebrations in Washington on June 14.

For financial markets and corporate executives, however, the summit’s most important agenda item may not be diplomacy at all — but critical minerals.

Treasury Secretary Scott Bessent told reporters during preparatory meetings in Paris this week that the United States is pushing G7 nations to coordinate more aggressively against what he described as China’s dominance over strategic mineral supply chains. Bessent said the group is discussing shared inventory reserves, pricing floors and industrial policies designed to reduce Western dependence on Chinese-controlled rare earths and battery materials.

The issue has become central to U.S. industrial strategy as the artificial intelligence, electric vehicle, semiconductor and defense sectors compete for access to lithium, cobalt, nickel, graphite and rare earth elements required for advanced manufacturing.

French Finance Minister Roland Lescure framed the challenge in unusually blunt terms.

“We are facing significant challenges — war in the Middle East, multilateral imbalances that are not sustainable, and the stakes regarding rare earths and critical materials,” Lescure said ahead of the meetings.

The minister warned that no single country should again be allowed to dominate the supply of materials essential to modern industrial economies — a direct reference to China’s overwhelming market share across several critical mineral categories.

The AI component of the summit is equally significant for Wall Street.

The Trump administration is expected to push allies toward broader adoption of American-developed AI systems, cloud infrastructure and semiconductor technologies as Washington increasingly treats artificial intelligence leadership as a geopolitical and economic priority. Such efforts would effectively support U.S. technology giants including Nvidia, Microsoft, Alphabet, Meta Platforms, Oracle and Amazon as they compete globally against Chinese and European rivals.

The strategy aligns with the administration’s broader view that AI leadership is not simply a commercial race but a national-security imperative.

Iran will loom over every conversation.

Speaking at the “No Money for Terror” conference in Paris, Bessent urged allies to intensify sanctions enforcement against Tehran’s financial and shipping networks. He credited the administration’s “Operation Economic Fury” sanctions architecture with disrupting tens of billions of dollars in projected Iranian oil revenue and weakening Tehran’s ability to finance military and nuclear operations.

The Treasury Secretary specifically called on European governments to strengthen banking enforcement measures while urging Asian allies to crack down on Iran’s shadow tanker fleet used to circumvent sanctions.

But divisions inside the G7 remain substantial.

The United States recently extended a waiver allowing some purchases of Russian seaborne oil to support energy-vulnerable economies affected by the Iran conflict, frustrating several European officials who believe the move weakens broader sanctions pressure on Moscow.

European Economic Commissioner Valdis Dombrovskis acknowledged the disagreements publicly, saying G7 countries are “not always 100% aligned on everything.”

The economic backdrop heading into the summit remains fragile.

Global bond markets have been rattled by rising inflation tied to energy prices, while central banks across the developed world face increasing pressure over whether interest rates may need to remain elevated longer than previously expected. IMF Managing Director Kristalina Georgieva warned ministers in Paris against policies that could worsen economic instability, while European Central Bank President Christine Lagarde acknowledged persistent concern over inflation and financial conditions.

For investors, the summit carries unusually direct implications.

Any coordinated Western strategy around critical minerals could reshape supply chains across the electric vehicle, semiconductor, aerospace and defense industries. Expanded international adoption of U.S. AI infrastructure would strengthen the revenue outlook for America’s largest technology firms. And any shift in energy coordination or sanctions policy could materially affect oil markets already strained by the ongoing Iran conflict.

The geopolitical wildcard remains whether the war itself escalates or cools before leaders arrive in France.

A diplomatic breakthrough between Washington and Tehran could dramatically lower tensions and stabilize energy markets. A further escalation — particularly involving disruptions to Gulf shipping lanes or energy infrastructure — would likely dominate the summit entirely and overshadow the broader trade and technology agenda.

What is already clear is that Trump is approaching the summit less as a traditional alliance-building exercise and more as a transactional negotiation.

The administration’s message to allies has been increasingly explicit: buy more American goods, support American AI leadership, reduce dependence on China, and align more aggressively with U.S. sanctions and energy policies.

Whether the rest of the G7 is politically willing — or economically able — to follow remains the defining question heading into what could become one of the most consequential global summits of Trump’s second term.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Sultan Ahmed Al Jaber, chief executive of Abu Dhabi National Oil Co., said Wednesday that the United Arab Emirates’ new crude-oil pipeline designed to bypass the Strait of Hormuz is now nearly 50% complete, underscoring how the Iran conflict is permanently reshaping global energy infrastructure and oil-export routes.

Speaking during a live-streamed event hosted by the Atlantic Council in Washington, Al Jaber said the so-called West-East Pipeline — designed to expand UAE crude exports through the port of Fujairah on the Gulf of Oman — is being accelerated toward completion in 2027.

“Today, it’s already almost 50% complete, and we are accelerating its delivery toward 2027,” Al Jaber said.

According to the Abu Dhabi Media Office, UAE Crown Prince Sheikh Khaled bin Mohamed bin Zayed Al Nahyan directed ADNOC to fast-track the project following the worsening regional energy crisis triggered by the Iran war.

The announcement carries major implications for global oil markets because Iran has effectively kept the Strait of Hormuz closed to most non-Iranian shipping since U.S. and Israeli strikes launched on Feb. 28.

The Strait historically handled roughly 20% of global seaborne crude shipments, making it the single most important oil chokepoint in the world.

Al Jaber described the disruption as “the most severe energy supply disruption in history.”

According to the ADNOC chief, more than 1 billion barrels of oil supply have already been lost because of the closure, with nearly 100 million additional barrels disrupted every week the strait remains inaccessible.

He also warned that even if the conflict ended immediately, global oil flows would not normalize quickly.

Al Jaber estimated it would take at least four months for shipping volumes through Hormuz to recover to roughly 80% of prewar levels, while full normalization may not occur until sometime in 2027.

“Once you accept that a single country can hold the world’s most important waterway hostage, freedom of navigation as we know it is just finished,” he said. “If we don’t defend this principle today, we will spend the next decade defending against the consequences.”

The business implications stretch across the global energy system.

ADNOC’s existing Abu Dhabi Crude Oil Pipeline already transports up to 1.8 million barrels per day from inland oil fields directly to Fujairah, bypassing Hormuz entirely. The new West-East Pipeline is designed to roughly double that export capacity.

That increase would effectively add export flexibility equivalent to the total production of a mid-sized OPEC member nation.

For commodity traders including Vitol, Trafigura, and Glencore, as well as oil majors such as Exxon Mobil Corp., Chevron Corp., and ConocoPhillips, the project significantly changes the long-term geopolitical risk profile attached to Gulf crude.

Infrastructure that bypasses Iran’s naval reach effectively lowers future supply-disruption risk premiums built into oil prices.

The project also follows another major strategic shift by the UAE.

Al Jaber confirmed during the same event that the UAE formally exited the Organization of the Petroleum Exporting Countries on May 1, ending decades of participation in the Saudi-led oil cartel.

He described the decision as a sovereign strategic move reflecting what he called the world’s growing need for additional energy supply.

Without OPEC production quotas, the UAE can now increase output based entirely on its infrastructure capacity — making the pipeline expansion central to the country’s future energy strategy.

Oil prices remain elevated despite easing modestly from spring highs.

West Texas Intermediate crude traded near $98.96 per barrel Wednesday afternoon, while Brent crude remained near similar levels. Prices have stabilized somewhat in recent weeks as traders increasingly price in alternative Gulf export routes, expanding Saudi pipeline capacity, and additional U.S. shale production.

For American consumers, the implications are immediate.

Every additional barrel of Gulf oil that can reach global markets without transiting Hormuz helps reduce the geopolitical risk premium embedded in gasoline, diesel, and jet-fuel prices.

U.S. gasoline prices have remained above roughly $4.10 per gallon through much of the spring, pressuring household budgets and weighing on discretionary spending.

Airlines including Delta Air Lines Inc., United Airlines Holdings Inc., and American Airlines Group Inc. have cited elevated fuel expenses in recent earnings reports, while logistics and transportation companies including FedEx Corp., United Parcel Service Inc., Old Dominion Freight Line Inc., and J.B. Hunt Transport Services Inc. continue facing higher operating costs.

The pipeline expansion also carries major implications for energy infrastructure investors.

Pipeline operators, storage companies, and export-terminal businesses tied to Gulf energy logistics are expected to benefit from long-term rerouting of oil and natural-gas flows.

U.S. liquefied-natural-gas exporters including Cheniere Energy Inc., Sempra, and Venture Global LNG have also gained market share as European and Asian buyers diversify away from shipping routes exposed to Iranian disruption.

Meanwhile, defense contractors including Lockheed Martin Corp., RTX Corp., Northrop Grumman Corp., General Dynamics Corp., and L3Harris Technologies Inc. continue benefiting from expanded Gulf maritime-security spending tied to the conflict.

The broader geopolitical situation remains unresolved.

President Donald Trump said earlier this week that he postponed a planned military strike against Iran while diplomatic negotiations continue, temporarily easing fears of immediate escalation but doing little to reopen the strait itself.

Secretary of State Marco Rubio and National Security Adviser Mike Waltz continue coordinating with Gulf allies including the UAE and Saudi Arabia regarding maritime-security responses.

The U.S. Fifth Fleet, headquartered in Bahrain, continues escorting limited commercial traffic outside the strait, though insurance markets remain highly restrictive for vessels attempting passage through the area.

The economic effects have spread far beyond energy markets.

The International Energy Agency has warned that prolonged Hormuz disruption could reduce global GDP growth during 2026, while the International Monetary Fund recently raised its inflation forecasts partly because of sustained energy-price pressures tied to the conflict.

Minutes released Wednesday from the Federal Reserve’s latest policy meeting also reflected continued concern among policymakers regarding energy-driven inflation risks.

Al Jaber argued the crisis demonstrates a broader structural vulnerability within the global energy system.

“Right now, too much of the world’s energy still moves through too few chokepoints,” he said.

That logic is already influencing infrastructure planning across the Gulf region.

Saudi Arabia is studying additional expansion of its East-West Pipeline linking eastern oil fields to the Red Sea. Iraq is revisiting dormant export routes through Turkey and Jordan. Oman is positioning its Duqm port on the Arabian Sea as a future regional export hub outside the Strait of Hormuz entirely.

For the UAE, the pipeline is more than an industrial project.

It is a strategic declaration that the country no longer intends to let its economic future depend entirely on stability inside the Persian Gulf.

For global markets, it represents one of the first major pieces of physical infrastructure being built specifically to reduce the long-term financial cost of Gulf instability.

Every mile of pipeline completed between Abu Dhabi and Fujairah slightly changes the global energy equation.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Israeli intelligence has compiled a target list containing thousands of names and is systematically tracking down participants in the Oct. 7, 2023 Hamas attack, relying on facial recognition, intercepted communications, biometric matching, and location intelligence to identify suspects across Gaza and beyond, according to a Wall Street Journal investigation published this week.

The operation continued even after the U.S.-brokered cease-fire signed in October 2025 and reached one of its highest-profile targets on May 15, when senior Hamas military commander Izz al-Din al-Haddad was killed in a targeted Israeli airstrike in Gaza City.

Israel Defense Forces Chief of Staff Lt. Gen. Eyal Zamir confirmed the strike on May 16, describing it as a “significant operational achievement” and stating that Israel would “continue to pursue our enemies, strike them and hold accountable everyone who took part in the October 7th massacre.”

Hamas spokesman Hazem Qassem separately confirmed Haddad’s death.

At the center of the operation is a specialized Shin Bet task force known as NILI, a Hebrew acronym translating roughly to “The Eternity of Israel Will Not Lie.” The unit was reportedly established specifically to identify and eliminate members of Hamas’s elite Nukhba commando force involved in the Oct. 7 border assault.

The business implications of the campaign extend far beyond military operations.

Israeli intelligence agencies are heavily dependent on a network of domestic cybersecurity, surveillance, digital-forensics, and artificial-intelligence firms whose technologies are increasingly being marketed worldwide to governments, police agencies, border authorities, and large corporations.

Among the most prominent is Cellebrite Software Ltd., the Nasdaq-listed digital-forensics company headquartered in Petah Tikva. Cellebrite reported 2025 revenue of approximately $475.7 million, up 19% year over year, while annual recurring revenue reached $480.8 million, a 21% increase. The company supplies mobile-device extraction and investigative software widely used by U.S. federal, state, and local law-enforcement agencies.

Chief Executive Thomas Hogan, who assumed the role in 2025, has publicly emphasized expanding the company’s AI-driven investigative capabilities for both government and enterprise clients.

Other major Israeli firms tied to the surveillance and intelligence ecosystem include Cognyte Software Ltd., which develops communications intercept and analytics systems used by foreign intelligence agencies; Corsight AI, a facial-recognition company focused on border and security applications; and Oosto, formerly known as AnyVision, which builds biometric video-analysis platforms.

NSO Group, developer of the controversial Pegasus mobile-intrusion software, remains under U.S. Commerce Department sanctions but continues operating internationally.

The broader industry has become one of Israel’s most important economic sectors.

Israeli cybersecurity exports reached roughly $14 billion in 2025, according to figures published by the Israel Innovation Authority and the Israel National Cyber Directorate. Defense exports overall hit a record $14.7 billion in 2024, according to the Israeli Ministry of Defense, with analysts expecting another record in 2025 once final numbers are released.

The technological dataset supporting Israel’s Oct. 7 manhunt is unusually extensive.

Many Hamas militants recorded the attacks using body cameras and uploaded footage to social media in real time. Israeli authorities also gathered hostage cellphone recordings, surveillance-camera footage from locations including the Nova music festival near Re’im, intercepted Telegram communications, and other digital evidence.

Israeli officials have described the resulting archive as one of the largest biometric datasets ever assembled on an attacking force during an active conflict.

In May, researchers affiliated with the Foundation for Defense of Democracies’ Long War Journal reported identifying previously unnamed attackers using Amazon Rekognition facial-recognition technology matched against publicly available social-media profiles. One identification reportedly returned a 99.9% similarity score.

Israel’s defense spending has expanded sharply since the war began.

Military expenditures now account for roughly 6.5% of Israeli GDP, according to data from the Bank of Israel and Israeli Finance Ministry budget documents, compared with approximately 4.5% before the conflict. The increase has widened fiscal pressures, weighed on the shekel, and increased sovereign borrowing costs, although ratings agencies including Moody’s Investors Service and S&P Global Ratings have maintained Israel’s investment-grade status.

The strike that killed Haddad reportedly involved days of continuous surveillance.

According to Israeli security officials, the operation was approved roughly 10 days before execution. Israeli Air Force commanders allegedly conducted what one senior official described as a “deception operation” designed to mask unusual military activity and reduce Hamas alert levels before the strike.

The attack targeted a residential structure in Gaza City’s Rimal neighborhood. Gaza emergency authorities reported at least seven deaths and more than 50 injuries.

Haddad had assumed leadership of Hamas’s military wing in May 2025 following the killing of his predecessor, Mohammed Sinwar.

Former hostages Romi Gonen and Emily Damari had previously identified Haddad in televised interviews as one of the commanders involved in their captivity inside Hamas tunnel networks.

For Israel’s cybersecurity and surveillance sector, the war has effectively become a large-scale real-world demonstration of operational capability.

Industry executives and investors have increasingly pointed to the conflict as proof that Israeli-origin intelligence systems can function under live battlefield conditions at scale. Since 2023, purchases of Israeli surveillance, digital-forensics, and AI-security tools have expanded among Western police departments, Gulf-state security agencies, European border authorities, and private-sector corporate-security teams.

The cease-fire signed last year remains fragile.

Israeli officials have indicated the target list assembled after Oct. 7 is still active — and not yet complete.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Dispute Over Security Funding and Iran Policy Exposes Growing Republican Divisions Ahead of Midterms

WASHINGTON — President Donald Trump is facing growing resistance from several Senate Republicans as disputes over a proposed White House ballroom funding provision, Iran policy, and broader spending priorities complicate efforts to advance a major Republican reconciliation package carrying significant implications for defense contractors, border-security firms, and the broader business community.

Senate Majority Leader John Thune acknowledged Wednesday that Republicans do not yet appear to have enough support to preserve roughly $1 billion in U.S. Secret Service-related funding tied in part to security adjustments surrounding Trump’s planned White House ballroom project, an issue that has become increasingly contentious inside the GOP conference.

The funding was included inside a broader roughly $70 billion Republican reconciliation package focused heavily on immigration enforcement, including expanded funding for Immigration and Customs Enforcement and Customs and Border Protection through the remainder of Trump’s term.

The dispute now threatens to complicate the broader legislation, which carries major implications for defense contractors, surveillance firms, immigration-services vendors, logistics operators, and border-security technology companies positioned around expanded federal spending.

The funding language, released through Senate Judiciary Committee materials tied to Chairman Chuck Grassley, includes money connected to security modifications surrounding the White House East Wing modernization project and broader Secret Service operational upgrades.

The White House has repeatedly argued that the ballroom itself would primarily rely on private support rather than direct taxpayer construction funding.

White House spokesman Davis Ingle told reporters the security-related funding follows heightened concerns surrounding presidential protection after last year’s assassination attempt targeting Trump.

Trump himself has repeatedly stated publicly that the ballroom project would not rely on direct taxpayer financing for construction.

The internal Republican disagreement intensified after Secret Service Director Sean Curran briefed Senate Republicans behind closed doors earlier this month, outlining the breakdown of the requested funding.

According to lawmakers familiar with the discussion, roughly 20% of the allocation would go toward East Wing-related security upgrades, while the remainder would support broader Secret Service technology modernization and protective operations.

Several Republican senators, including Susan Collins, Rand Paul, Jim Justice, and Thom Tillis, have raised concerns about the provision and broader spending priorities tied to the package.

The political tension comes amid widening divisions inside the Republican conference over both fiscal policy and Trump’s increasingly aggressive pressure campaign against GOP critics and dissenters.

Earlier this week, Trump endorsed Texas Attorney General Ken Paxton over incumbent Sen. John Cornyn in Texas’ Republican Senate primary runoff, intensifying political pressure on one of the Senate’s longtime Republican dealmakers.

Meanwhile, several Republican senators have also begun publicly distancing themselves from parts of the administration’s foreign-policy agenda following debate over U.S. involvement in the Iran conflict.

Sen. Bill Cassidy joined Sens. Rand Paul, Susan Collins, and Lisa Murkowski in supporting a war-powers resolution tied to military operations involving Iran, highlighting a growing willingness among some Republicans to publicly break with the administration.

For corporate America and major lobbying groups, the growing divisions create increasing uncertainty around tax policy, federal spending, trade legislation, border-security contracts, and broader regulatory priorities heading into the 2026 midterm cycle.

The business stakes tied to the reconciliation package are substantial.

The legislation would expand funding tied to immigration enforcement, detention operations, surveillance systems, biometric identity programs, staffing contracts, logistics infrastructure, and federal facility support across the southern border.

Companies operating in the national-security and government-services sectors — including firms tied to detention management, data analytics, logistics, and defense technology — have closely monitored the legislation for months given the scale of potential contract opportunities.

A prolonged delay or collapse of the package could push portions of that federal contracting pipeline further into 2027, creating uncertainty for companies and investors positioned around expanded immigration-enforcement spending.

The ballroom controversy has also become entangled with broader consumer and political frustrations surrounding inflation and government spending priorities.

Senate Minority Leader Chuck Schumer criticized the proposal Wednesday, arguing Republicans were prioritizing high-profile White House projects while many households continue struggling with elevated costs tied to energy prices, borrowing rates, and inflation.

Recent polling has also suggested growing public skepticism surrounding portions of Trump’s second-term agenda, particularly regarding foreign policy and federal spending priorities.

The political implications extend well beyond the ballroom dispute itself.

Several Republican senators central to past bipartisan negotiations on health care, appropriations, taxes, and trade are either retiring, facing difficult reelection fights, or increasingly distancing themselves from parts of the administration’s agenda.

That shift is creating growing concern among business groups, trade associations, hospital systems, and corporate lobbying organizations that the Senate could become significantly less predictable heading into the second half of Trump’s term.

Democrats are already targeting several potentially competitive Republican-held seats in states including North Carolina, Maine, Texas, and Louisiana, while business groups continue evaluating how shifting Senate dynamics could affect tax policy, tariffs, energy permitting, financial regulation, and future spending legislation.

For now, negotiations over the reconciliation package remain ongoing while Senate procedural officials continue reviewing whether portions of the disputed funding language comply with reconciliation rules.

Democrats have also signaled plans to force additional votes tied to the White House funding controversy in the weeks ahead.

For Trump and Senate Republicans alike, the coming weeks are increasingly shaping into a major test of whether the administration can maintain enough internal party unity to move one of its largest domestic spending and immigration packages through Congress.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Houston Hospital Ends Pediatric Gender Procedures, Terminates Five Physicians and Will Open Detransition Clinic; Both Parties Deny Liability as Federal Probe Sweeps Major U.S. Health Systems

By JBizNews Desk

HOUSTON, May 21, 2026 — The largest pediatric hospital system in the United States agreed to pay $10 million and overhaul a major clinical line under a settlement with the U.S. Department of Justice and the Texas Attorney General’s office, in a deal that signals materially higher federal compliance exposure for U.S. hospital systems that have billed Medicaid or private insurers for pediatric gender-transition care.

Texas Children’s Hospital (TCH) announced on May 15 that it had resolved a multi-year federal and state investigation into its billing of Texas Medicaid for pediatric gender-transition procedures. Under the agreement, TCH will pay $10 million in damages and civil penalties, terminate the hospital privileges of five physicians who performed the procedures, end administration of puberty blockers and cross-sex hormones to minors, and build a first-in-the-nation detransition clinic to provide restorative care. The settlement resolves allegations that the hospital violated the False Claims Act, the Federal Food, Drug, and Cosmetic Act, and federal fraud and conspiracy statutes by submitting false billings to public and private payors. Neither party admitted liability, and TCH stated it had been “compliant with all laws” and characterized the resolution as a decision to avoid further legal costs.

A Sector-Wide Federal Probe

The TCH settlement is the first resolution under what the DOJ has described as an ongoing national investigation. Acting U.S. Attorney General Todd Blanche said in the department’s announcement that “the Justice Department will use every weapon at its disposal to end the destructive and discredited practice of so-called ‘gender-affirming care’ for children.” Assistant Attorney General Brett A. Shumate confirmed the settlement is the first in a series. NYU Langone Health, one of the nation’s largest academic medical centers, has confirmed it received a federal grand jury subpoena related to its provision of gender-affirming care — a signal that DOJ is moving aggressively against hospital systems that have billed federal and state health programs for these services.

The probe creates direct financial exposure for U.S. hospital systems. Healthcare-sector False Claims Act settlements have historically reached tens of millions of dollars per institution — Children’s National Medical Center paid $12.9 million in 2015 to resolve unrelated False Claims Act allegations, and Citizens Medical Center of Victoria, Texas paid $21.75 million that same year for separate Stark Law violations. The TCH agreement establishes a new template combining monetary penalties, terminated clinical lines, terminated physician privileges, and mandated new services — significantly expanding the operational and reputational impact of a single federal resolution.

What TCH Is Paying For

The $10 million payment specifically resolves allegations that Texas Children’s coded gender-transition procedures under different diagnosis codes in order to obtain Texas Medicaid reimbursement for services the state’s Medicaid program does not cover. Texas Attorney General Ken Paxton’s office described the conduct as “unallowable and illegal ‘gender-transition’ interventions.” The DOJ said TCH “took significant steps entitling it to credit for cooperation” during the investigation, including turning over more than five million documents over a five-year probe. The five terminated physicians will be permanently barred from re-hire and credentialing at the hospital.

The probe began in 2023 after a TCH-affiliated surgeon, Dr. Eithan Haim, publicly disclosed that the hospital had continued performing the procedures after publicly announcing it had stopped them in response to a new Texas law. Haim was subsequently indicted by the Biden Justice Department for HIPAA-related allegations tied to the disclosures, and the case against him was later dismissed.

Counter-Perspectives

Legal advocates for the hospitals under federal probe have publicly challenged the legitimacy of the DOJ’s administrative subpoenas. According to coverage by the Washington Blade, attorney Loewy, representing trans-rights legal groups, said that “every court that has considered those subpoenas has found them illegitimate and issued for an improper purpose, or at least narrowed them really dramatically.” Medical professionals interviewed by NBC News, including Dr. Morissa Ladinsky, a clinical professor of pediatrics at Stanford University School of Medicine, questioned the settlement’s requirement that the hospital fire the physicians who previously provided transition care — arguing they would have been the most clinically equipped to staff a detransition clinic.

Hospital-Sector Implications

For hospital-system CFOs, the TCH settlement establishes three new realities. First, federal False Claims Act exposure on pediatric gender care is no longer theoretical. Second, the DOJ resolution template includes operational mandates — clinical-line closure, physician terminations, and new-service buildouts — that materially exceed a standard monetary penalty. Third, the broader probe sweeping NYU Langone and other major academic medical centers suggests sector-wide reserve adjustments and compliance reviews are likely to follow.

DOJ officials have signaled additional resolutions are expected. Investors and healthcare-sector analysts should expect further announcements from the department’s national investigation, with implications for hospital-system financial reporting, physician-credentialing policies, and insurance-billing compliance across the U.S. healthcare industry.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. This article may not be reproduced, distributed, or republished in whole or in part without the express written permission of JBizNews.

New Federal Advisory Urges Parents to Cut Daily Screen Exposure, Putting Pressure on Tech Platforms While Boosting Demand for Offline Activities

WASHINGTON — The U.S. Department of Health and Human Services on Wednesday issued a new surgeon general’s advisory urging families to significantly reduce children’s screen time, escalating federal concerns over how phones, tablets, gaming, and social media are affecting childhood development, sleep, mental health, and learning.

The advisory, released by the Office of the Surgeon General under Health and Human Services Secretary Robert F. Kennedy Jr., recommends no screen exposure for children younger than 18 months and limiting recreational screen use to no more than two hours daily for children and teenagers.

For many parents, the message was simple and direct: children are spending too much time on screens, and the federal government now believes the long-term consequences may be more serious than many families realize.

The advisory cited growing concerns surrounding sleep disruption, reduced attention spans, anxiety, behavioral issues, academic struggles, social-development challenges, and declining physical activity among children and teenagers heavily exposed to screens for long periods of time.

Federal officials said screen use now often begins before children turn one year old and steadily increases throughout childhood and adolescence.

The average American teenager now spends roughly four or more hours daily on recreational screen activities, according to data referenced in the advisory — including social media, gaming, YouTube, streaming video, texting, and other app-based entertainment.

For parents already struggling to manage devices inside the home, the report effectively formalizes what many families, pediatricians, and teachers have increasingly worried about for years.

The advisory encourages parents to create screen-free routines, reduce device usage during meals and before bedtime, encourage outdoor activity and face-to-face interaction, and more actively monitor how children use social media and digital platforms.

Schools, pediatricians, and local governments were also urged to help families establish healthier technology habits.

The warning also places growing pressure on some of the largest companies in the technology industry.

Social-media companies including Meta Platforms, TikTok parent ByteDance, Snap, and YouTube parent Alphabet have increasingly faced criticism from lawmakers, educators, and parents over whether platform features such as autoplay, endless scrolling, notifications, and algorithm-driven recommendations are designed to maximize engagement among younger users.

Gaming companies and app developers are also likely to face increased scrutiny as policymakers continue debating youth online safety, social-media restrictions, and screen-time regulation.

The advisory arrives as several states, including Florida and Utah, have already moved to restrict certain forms of social-media access for minors.

For parents and families, however, the issue often feels less political and more personal.

Many families say screens have become deeply embedded into everyday routines — from schoolwork and entertainment to communication and social interaction — making limits increasingly difficult to enforce.

The rapid expansion of smartphones, tablets, streaming platforms, gaming systems, and social media over the past decade has dramatically reshaped how children spend free time, interact with friends, consume information, and even relax before sleep.

The business implications are also significant.

Technology companies derive enormous value from user engagement, particularly among younger demographics who spend large portions of their day online. Reduced screen time could ultimately impact advertising revenue, app engagement, gaming purchases, and subscription activity across portions of the digital economy.

At the same time, industries tied to offline activities could benefit if families begin shifting more time away from screens.

Toy makers, youth sports programs, tutoring centers, summer camps, arts-and-crafts retailers, children’s publishing companies, and outdoor recreation businesses could all see stronger demand as parents search for alternatives to constant digital engagement.

Companies selling parental-control software, family safety tools, educational products, and sleep-related products may also benefit from increased awareness around healthy screen habits.

Some technology companies have already attempted to respond to growing parental concern.

Apple, for example, has expanded Screen Time and parental-control features across its devices, while other platforms have introduced teen safety settings, content restrictions, and time-management tools.

Still, critics argue those measures remain insufficient given how heavily digital platforms compete for user attention.

For schools, the advisory may reopen broader debates about classroom technology use following the major expansion of laptops and tablets during the pandemic years.

Many districts that adopted one-device-per-student programs are now facing growing questions from parents and health experts about how much screen exposure is appropriate during the school day.

For businesses serving families, the federal warning could reshape marketing, product development, and consumer behavior over time.

For parents, though, the issue is likely far more immediate.

The central message from Wednesday’s advisory was not that technology itself is inherently harmful, but that balance, moderation, sleep, physical activity, in-person interaction, and healthy development increasingly risk being crowded out by excessive screen exposure during childhood.

The advisory signals that federal health officials now view excessive screen time not simply as a parenting challenge, but as a growing public-health issue likely to remain at the center of future policy, education, and technology debates.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
NEW YORK, May 21, 2026 — Consul generals, ambassadors, U.S. trade officials and senior business executives gathered in Times Square on May 20 for the closing summit of World Trade Week NYC, days after President Donald J. Trump issued the 2026 Presidential Message reaffirming the federal observance he proclaimed last year through Proclamation 10944. The summit convened as the United States moves through the most active tariff and trade-deal cycle in a generation.

The summit was hosted by the Greater New York Chamber of Commerce and co-hosted by the Orthodox Jewish Chamber of Commerce, both appointed to the World Trade Week NYC Committee Leadership by the U.S. Department of Commerce. It is the only federally appointed convening of its kind in the country, and the chambers’ work in that role has drawn a Certificate of Special Congressional Recognition from the U.S. Congress and proclamations from New York Governor Kathy Hochul. Prior summits have produced on-site memorandums of understanding between the chambers and the governments of India and South Korea, signed in the presence of foreign trade ministers and U.S. officials.

L-R: Frank Garcia | Duvi Honig | Howard Teich | Dr. Vladimir Božović (Serbia) | Karel Smekal (Czech Republic) | Dadhiram Bhandari (Nepal) | Adalnio Senna Ganem (Brazil) | Marcos Bucio (Mexico) | Mark Jaffe | Jarmo Sareva (Finland) | Helana Natt | Amit Shah | James Kim (American Korean American Chamber of Commerce)

The economic backdrop is unprecedented. U.S. exports of goods and services reached a record $3.43 trillion in 2025, according to the Bureau of Economic Analysis — the largest export economy in U.S. history. The International Trade Administration estimates exports support nearly 9.8 million American jobs, and the U.S. trade-to-GDP ratio is running near 27 percent. The 2026 observance comes against tariff actions under Section 122 of the Trade Act of 1974, more than 20 new bilateral trade agreements reached over the past year, and the USMCA review scheduled for July.

In the 2026 Presidential Message issued from the White House this week, Trump said “America has built the world’s most powerful economy through the strength of our industries, the genius of our innovators, and the promise of fair and reciprocal trade,”  citing “over 20 new trade deals with major world partners, opening new markets for American goods.”  In Proclamation 10944 last year, he committed to “redoubling our efforts to combat unfair trade practices for every American.”  The argument is one his predecessors have made under the same federal observance. President George W. Bush, in 2006, called free and fair trade “a powerful engine for growth and job creation.”  President Bill Clinton, in 1997, noted that “95 percent of the world’s consumers live outside the United States.”

Featured diplomatic speakers represented trillions of dollars in annual goods trade with the United States. Marcos Bucio, Consul General of Mexico, represented the largest U.S. trading partner at $976.1 billion in total goods and services trade  in 2025. Tom Clark, Consul General of Canada, represented the second-largest at $719.5 billion  in U.S. goods trade. Binaya Srikanta Pradhan, Consul General of India, anchored $149.4 billion in U.S. goods trade . Adalnio Senna Ganem, Consul General of Brazil, represented the source of a $14.4 billion U.S. goods surplus. Karel Smekal of the Czech Republic represented roughly $12 billion in annual U.S. bilateral goods trade; Jarmo Sareva of Finland a key transatlantic partner in machinery and clean energy; Dr. Vladimir Božović of Serbia, who also serves as Vice President of the Society of Foreign Consuls in New York, the world’s largest diplomatic organization ; Aamer Ahmed Atozai of Pakistan, anchoring the U.S.-Pakistan Trade and Investment Framework Agreement; and Dadhiram Bhandari of Nepal.

Past summits convened by the chambers have drawn senior federal trade leadership across the full U.S. trade-enforcement and trade-facilitation chain. James McCament, then-acting chief operating officer of U.S. Customs and Border Protection , has keynoted. Troy A. Miller, who served as Commissioner of U.S. Customs and Border Protection, has been honored. Susan S. Thomas, the Acting Executive Assistant Commissioner for U.S. Customs and Border Protection, Office of Trade, responsible for designing and implementing U.S. tariff policies for the Trump Administration , addressed the 2025 summit on tariff enforcement. Danielle Outlaw, Deputy Chief Security Officer of the Port Authority of New York and New Jersey; Tenavel Thomas, Customs and Border Protection Port Director for Newark/NY; and Edward Mermelstein, New York City Commissioner of International Affairs, have all participated. Foreign delegations across years have included Israel, India, South Korea, China, Turkey, Pakistan, Germany, Morocco, Azerbaijan, Bahrain, Poland, Guatemala, Peru, Thailand, Canada, Bangladesh, Malaysia and the Philippines .

The chambers’ South Korea MOU, signed at a prior summit, has since produced the Orthodox Jewish Chamber’s South Korea chapter, opened at Seoul City Hall under the host of the Deputy Mayor of Economy. At last year’s summit, Korean Air received the Global Investment Impact Award for its $32 billion investment commitment in the United States . The Korean government separately recognized Duvi Honig, the Orthodox Jewish Chamber’s founder and CEO, as Trade Ambassador for the World Korean Business Convention 2025.

The summit’s headline panel, “Growing Global Trade & Investment Through Diplomacy,” was moderated by Howard Teich, Chair of the Greater New York Chamber, and Mark Jaffe, the Chamber’s President and CEO. It was joined by the Global New York Team of Empire State Development, the New York State governor’s international trade and investment office, represented by senior member Brian Teubner.

“Our members export billions of dollars of products and services to dozens of countries around the world,” Jaffe said . “World Trade Week NYC demonstrates how partnerships between governments, business leaders and economic organizations continue driving investment and economic opportunity throughout the United States.”

“Hosting this on behalf of the world’s biggest economy is a true honor,” Honig said. “It stimulates economic growth and builds bridges that unite the world through commerce. When business leaders, diplomats and government officials come together in one room, relationships are built that lead directly to investment, partnerships, job creation and long-term economic expansion.”

World Trade Week was launched in 1926 by Stanley T. Olafson of the Los Angeles Area Chamber of Commerce during what the Chamber describes as “a time of isolationism and under the conditions prevailing during the heyday of the restrictive Smoot-Hawley Tariff Act.”  President Franklin D. Roosevelt formally proclaimed it a national observance in 1935 , embedding it in the federal calendar as he dismantled the Smoot-Hawley tariff structure through the Reciprocal Trade Agreements Act of 1934. Every president since has reaffirmed it.

The summit’s International Trading Partners Awards recognized Brian Teubner of Empire State Development’s Global New York Team; Dr. Dana York, scientist and international AI leader; Ruben Luna of Key Food / Luna Group; and Frank Garcia of the Multicultural Business Coalition. Additional honorees were recognized at the Asian American Pacific Islanders Awardees ceremony. The 2026 Dr. Lucio Caputo Statesman Award was presented to Angelo Vivolo, President of the Columbus Citizens Foundation, by Marion Pardo, the Foundation’s former President and Chair.

As governments and corporations continue repositioning supply chains and competing for investment, business leaders at the summit said direct diplomatic engagement and international economic cooperation remain essential to sustaining American competitiveness, expanding exports and driving long-term economic growth.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. This article may not be reproduced, distributed, or republished in whole or in part without the express written permission of JBizNews.

Dow Slides Over 250 Points as Treasury Yields Rebound; Eli Lilly Pops on Obesity-Drug Breakthrough; Small Caps Buck the Sell-Off

NEW YORK, May 21, 2026 — American consumers got their clearest signal yet this earnings season that the nation’s largest retailer is bracing for a tougher spending environment. Walmart Inc. shares tumbled more than 6% on Thursday after the company paired in-line first-quarter results with cautious annual guidance, dragging the broader market lower as oil prices ripped past $100 a barrel on fresh tensions with Iran and Treasury yields climbed once again.

The S&P 500 declined 0.45%, the Dow Jones Industrial Average lost 0.48%, and the Nasdaq Composite fell 0.50%. The Dow shed roughly 252 points in afternoon trading, with Walmart (-6.43%), Salesforce (-4.27%) and Sherwin-Williams (-2.20%) leading the losses, while IBM (+3.69%), Honeywell International (+0.99%) and Chevron (+0.97%) held the index from a steeper decline. The Russell 2000 bucked the trend with a 2.56% gain, signaling rotation into domestically focused small caps less exposed to oil prices and rate risk.

Crude jumped on a Reuters report that Iran’s Supreme Leader Ayatollah Ali Khamenei issued a directive that the country’s near-weapons-grade enriched uranium must remain inside Iran — a development that complicates U.S.-Iran de-escalation efforts and revived inflation concerns just as Treasury yields rebounded. West Texas Intermediate crude rose $2.86 to $101.14 a barrel intraday, with Brent climbing toward $107. The move reversed two sessions of softening energy prices built on hopes for a diplomatic resolution. The 10-year Treasury yield sits near a one-year high, and gold slipped about $20 to roughly $4,512. The VIX ticked up to 17.62.

Walmart’s Caution Signals a Frugal American Consumer

Walmart (NYSE: WMT) posted first-quarter revenue of $177.8 billion, up 7.3% year-over-year and slightly above the $176.7 billion Wall Street consensus. Non-GAAP earnings per share of $0.66 met estimates. The problem was the forward look: management guided next-quarter revenue to $185.4 billion, roughly 0.5% below analyst expectations, and reaffirmed cautious annual guidance citing rising fuel costs, tariff pressures and what the company has flagged as more frugal consumer behavior. The sell-off came despite 26% e-commerce growth and 37% growth in advertising revenue — underlying strengths that ordinarily would have been celebrated. Walmart shares remain up roughly 19% year-to-date, but Thursday’s drop wiped out a portion of that gain in a single session and gave investors a real-time read on how America’s biggest retailer sees U.S. consumer spending heading into the summer.

Deere Reports Into a Tariff Headwind

Deere & Company (NYSE: DE) reported second-quarter fiscal 2026 results today against Wall Street expectations of $5.74 EPS on $11.50 billion in revenue, with the agricultural-equipment maker absorbing $1.2 billion in pretax tariff costs this fiscal year. New Chief Financial Officer Brent Norwood, who stepped into the role May 1 after more than two decades inside the company, took his first earnings call as investors pressed on margin trajectory and dealer-inventory levels. Deere shares had entered the print down roughly 15% from their all-time high.

Eli Lilly Pops on Obesity Drug Breakthrough

Eli Lilly (NYSE: LLY) shares rose 1.05% after the drugmaker said its next-generation obesity drug retatrutide cleared a crucial late-stage trial. In the highest-dose cohort, patients lost an average of 28.3% of body weight — roughly 70.3 pounds over 80 weeks — compared with 2.2% for placebo, according to CNBC’s coverage of the results. The data brings Lilly meaningfully closer to seeking approval for the weekly injection, which works differently from existing GLP-1 therapies from Lilly and Novo Nordisk and may offer stronger efficacy. The development carries direct consumer implications across U.S. healthcare costs and the broader obesity-treatment category, which is reshaping pharmaceutical and grocery economics simultaneously.

Analyst Calls and Sector Moves

Earlier this week, Home Depot (NYSE: HD) reported better-than-expected first-quarter earnings. Morgan Stanley analyst Simeon Gutman, who carries an overweight rating, told clients “The housing backdrop appears static and HD continues to execute well in a relatively ‘growthless’ environment,”  arguing the stock is not pricing in a housing recovery and that any “glimmer of inflection” in home-improvement end markets should be a positive. The session followed Wednesday’s broad rally on Nvidia (NASDAQ: NVDA) earnings, in which the AI chip leader posted April-quarter revenue topping $81 billion and a July-quarter outlook of $91 billion that fell shy of the most bullish analyst expectations. Nvidia declined to forecast any China sales despite CEO Jensen Huang’s recent Beijing visit. Nvidia shares hovered near the flatline Thursday as energy and yields took over the narrative.

What’s Next

Investors now turn to additional earnings tonight from Take-Two Interactive (TTWO), Workday (WDAY), Zoom Communications (ZM), Ross Stores (ROST), Ralph Lauren (RL) and Deckers Outdoor (DECK). With WTI above $100, the 10-year Treasury yield near one-year highs, and the Iran uranium standoff unresolved, the market enters Friday with two converging pressures — energy-led inflation and rate-driven valuation compression — that have, for now, overtaken the AI-earnings tailwind that defined the prior session.

JBizNews Desk

© 2026 JBizNews. All Rights Reserved. This article may not be reproduced, distributed, or republished in whole or in part without the express written permission of JBizNews.

OpenAI is about to do something almost no company in American history has been positioned to do. The maker of ChatGPT, last valued at roughly $852 billion, is preparing to confidentially file paperwork for an initial public offering in the coming weeks, with a target of going public as early as September. If it lands at anything close to its current private valuation, it will be one of the largest stock market debuts ever — bigger than Facebook, bigger than Alibaba, in the same conversation as Saudi Aramco. And it would mark the moment artificial intelligence stops being a venture-capital story and becomes a permanent piece of millions of Americans’ retirement portfolios.

The trigger was a courtroom in San Francisco.

On Monday, a judge dismissed the lawsuit that Elon Musk had been waging against OpenAI and Chief Executive Sam Altman for more than two years. Musk, who co-founded OpenAI in 2015 and later left, argued that Altman betrayed the company’s founding promise to operate as a nonprofit research lab for the benefit of humanity when OpenAI restructured into a for-profit business backed by Microsoft Corp.

Inside OpenAI, the case was widely viewed as an existential threat — not necessarily because Musk was likely to win outright, but because the litigation cloud made an IPO extraordinarily difficult. Investors rarely want to buy shares in a company whose corporate structure is actively being challenged in court by one of the world’s most aggressive litigants. With Monday’s dismissal, that cloud suddenly lifted. By Wednesday, the IPO machinery was already moving.

OpenAI is now working with Goldman Sachs Group Inc. and Morgan Stanley to prepare a confidential draft prospectus, according to people familiar with the plans. The confidential filing process allows companies to negotiate privately with regulators before publicly disclosing detailed financials and risk factors.

The timing is strategic.

Later Wednesday, SpaceX was also expected to move toward its own public-market preparations — a potential deal that could reportedly value the company near $1.5 trillion and raise up to $30 billion, potentially surpassing Saudi Aramco’s 2019 debut as the largest IPO in history. By moving alongside SpaceX, OpenAI gains two advantages: it diffuses some of the regulatory and media spotlight that would otherwise focus entirely on its own listing, and it reframes the public narrative away from Musk’s lawsuit and toward a broader race over the future of technology.

The reason OpenAI is pursuing public markets is straightforward: it needs enormous amounts of capital.

The company reportedly raised approximately $122 billion earlier this year, likely one of the largest private funding rounds in Silicon Valley history, yet the cash demands of frontier AI development continue to escalate. Training advanced AI systems requires massive data centers, enormous fleets of Nvidia chips, vast electricity consumption, and some of the most expensive engineering talent in the world.

Even Microsoft — OpenAI’s primary strategic backer — cannot indefinitely finance the company’s ambitions alone.

Going public unlocks access to the deepest capital pool on earth: the American stock market. Pension funds, mutual funds, ETFs, retirement plans, and ordinary retail investors would finally gain direct ownership exposure to the company that ignited the modern generative AI boom.

But the easy part may now be over.

OpenAI no longer dominates the AI landscape as completely as it appeared to a year ago. Anthropic, maker of the Claude AI platform, has emerged as a major enterprise rival and is reportedly discussing fundraising at valuations north of $900 billion. Meanwhile, Alphabet Inc. has aggressively accelerated development of its Gemini AI systems after initially appearing behind in the race, prompting OpenAI to internally declare a “code red” response effort late last year.

ChatGPT still commands more than 900 million weekly active users and over 50 million paying subscribers, but public investors will demand something private investors largely tolerated without scrutiny: detailed financial transparency.

Wall Street will want hard answers about revenue growth, operating losses, customer retention, infrastructure spending, and long-term profitability.

There is also the lingering question surrounding Sam Altman himself.

Although Musk’s lawsuit has now been dismissed, pretrial proceedings surfaced testimony from former OpenAI executives raising concerns about Altman’s management style and governance practices — issues that echoed the internal conflict that briefly led to Altman’s firing by OpenAI’s board in November 2023 before employees and investors forced his reinstatement days later.

As a public company, OpenAI will be required to formally disclose every material risk factor facing the business. That includes governance concerns, executive concentration risk, dependence on Altman’s leadership, and the operational tensions between OpenAI’s nonprofit origins and its rapidly expanding commercial ambitions.

Altman himself has openly admitted in past interviews that becoming a public-company CEO sounds “really annoying,” acknowledging that life under Wall Street’s quarterly scrutiny is fundamentally different from operating under the patient capital of Silicon Valley venture firms.

The broader implications for corporate America are enormous.

An OpenAI IPO anywhere near its reported valuation would instantly create one of the largest publicly traded companies in the United States, placing it alongside Apple Inc., Microsoft Corp., Nvidia Corp., Alphabet, Amazon.com Inc., and Meta Platforms Inc. among the most valuable firms on earth.

It would also become the first true public-market test of whether trillion-dollar AI valuations can survive exposure to ordinary investors, institutional scrutiny, and quarterly earnings pressure.

The outcome will likely shape the future decisions of nearly every major AI startup still waiting on the sidelines, including Anthropic, xAI, Perplexity, and others weighing whether to remain private or follow OpenAI into public markets.

For consumers, ChatGPT will likely look the same tomorrow morning.

But OpenAI itself would fundamentally change.

A public OpenAI would answer to shareholders, analysts, pension funds, and quarterly earnings expectations. It would face constant pressure to accelerate growth, increase monetization, and justify the extraordinary sums being invested into artificial intelligence infrastructure.

The mission to “benefit humanity” — the founding principle Musk spent years arguing OpenAI abandoned — would no longer be debated primarily inside courtrooms or boardrooms.

It would be tested every quarter on Wall Street.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Nvidia Corp. just reported the largest quarterly revenue in its history — $81.6 billion, up 85% from a year ago — beat Wall Street on every meaningful line, raised its dividend, added $80 billion to its buyback program, and guided to $91 billion for the current quarter. And then the stock fell.

Shares slipped roughly 1.3% in after-hours trading Wednesday to around $220.64, after closing the regular session at $223.47. To anyone reading the headlines, it makes no sense. The company is printing money at a pace almost without precedent in American corporate history. Data center revenue alone hit $75.2 billion in three months — more than the annual revenue of most Fortune 100 companies. Non-GAAP earnings per share came in at $1.87, beating the $1.76 Wall Street consensus. Operating cash flow reached $50.3 billion in a single quarter.

The answer says more about how Wall Street works than about how Nvidia is doing. When a company is priced for perfection, even spectacular results can disappoint. Nvidia entered the report valued near $5.4 trillion, the largest market capitalization of any company in history. At that size, investors are no longer asking whether Nvidia is growing. They are asking whether it can keep growing at the pace already baked into the price.

This is where Chief Executive Jensen Huang stepped in. On the analyst conference call Wednesday evening, he addressed the skepticism directly. The bear case on Nvidia has hardened around one core worry: that the company depends too heavily on a small handful of cloud giants — Microsoft, Amazon, Alphabet, and Meta Platforms — whose combined AI spending is now tracking near $725 billion for 2026.

Huang argued that concern is already outdated.

“The world is rebuilding computing for agentic AI and robotic physical AI, and Nvidia sits at the center of it all,” Huang told analysts, describing what he called a rapidly expanding “second cluster” of enterprise and government customers growing outside the hyperscalers.

To reinforce the point, Chief Financial Officer Colette Kress unveiled a new reporting structure breaking data center revenue into two segments: Hyperscale and ACIE — short for AI Clouds, Industrial and Enterprise. In the quarter just reported, Hyperscale generated roughly $37.4 billion while ACIE came in slightly higher at $37.9 billion.

In other words, more than half of Nvidia’s data center business is already coming from customers outside the four dominant cloud giants Wall Street focuses on. Hospitals, factories, telecom carriers, regional cloud providers, and national governments are increasingly buying Nvidia chips at massive scale.

Sovereign AI — systems sold to governments building domestic AI infrastructure — crossed $30 billion in fiscal 2026, more than triple the prior year, according to Kress. Customers now include the United Kingdom, France, the Netherlands, Canada, Singapore, and India, with India alone signing a reported $1 billion sovereign AI initiative.

She compared the spending trend to the buildout of power grids and interstate highways: governments now see AI infrastructure as strategic national infrastructure, not optional technology spending.

Investors, however, were looking for one more thing: clarity on China.

Nvidia’s data center business in China remains constrained by U.S. export restrictions, and the company continues absorbing roughly $5.5 billion tied to H20 inventory and related charges. Huang said he hoped a broader Trump-Xi framework could eventually restore access, but he offered no timeline or concrete guidance. That uncertainty appeared enough to keep traders from aggressively bidding shares higher after the report.

Beyond the stock reaction, Nvidia’s earnings highlighted how quickly AI is moving into the real economy.

Huang revealed that physical AI revenue — chips powering robots, autonomous systems, and industrial machines — has already reached approximately $9 billion, a business category that barely existed two years ago. Edge computing revenue, spanning gaming, AI-enabled PCs, robotics, telecom infrastructure, and automotive systems, generated $6.4 billion in the quarter, up 29% year over year.

The company also continues pushing aggressively into enterprise computing. Huang said Nvidia’s new Vera CPU platform opens what the company estimates is a $200 billion opportunity in the broader server market, placing Nvidia into more direct competition with Intel Corp. and Advanced Micro Devices Inc.

The labor and economic implications are becoming increasingly tangible. Nvidia highlighted partnerships powering robotaxi deployments, industrial automation systems, warehouse robotics, and humanoid robotics platforms — technologies expected to reshape transportation, logistics, and manufacturing over the next several years.

Gross margin held at 75%, matching expectations and signaling that Nvidia’s pricing power remains intact despite growing competition and custom AI chip programs from Alphabet, Amazon, and Microsoft. Huang also told analysts the company expects to remain supply constrained throughout the rollout of its next-generation Vera Rubin systems, meaning demand continues to outpace Nvidia’s ability to manufacture chips fast enough.

For investors, the modest aftermarket dip was a reminder that at Nvidia’s valuation, even record-breaking quarters may not satisfy every expectation already embedded in the stock price.

For the broader economy, though, Wednesday’s message was much larger: AI is no longer confined to Silicon Valley experiments or cloud computing budgets. It is rapidly becoming embedded into factories, vehicles, government infrastructure, healthcare systems, and consumer technology — and the businesses that adapt fastest may define the next decade of economic winners and losers.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Target Corp. delivered its strongest sales quarter since the pandemic boom on Wednesday, but the cautious tone from new Chief Executive Michael Fiddelke said almost as much as the numbers themselves. Comparable sales jumped 5.6% in the first quarter, ending four consecutive quarters of declines, while the Minneapolis-based retailer raised its full-year sales outlook to roughly 4%, double what management projected just two months ago.

Yet despite the strong quarter, Target shares still fell nearly 4%.

The reason says a lot about how Wall Street views retail turnarounds in 2026: investors are no longer rewarding one good quarter. They want proof the recovery can last.

Fiddelke, who officially took over as CEO on Feb. 1, made clear he understands that pressure.

“To be clear, a single good quarter has never been our goal,” Fiddelke told investors. On the company’s media call, he added: “We will not confuse this progress with potential. Our focus is on delivering consistent growth, not just in 2026, but for decades to come.”

In plain English: after more than a year of weak traffic, inventory problems, and slipping customer loyalty, management knows one strong quarter is not enough to declare victory.

Still, the underlying numbers were far stronger than analysts expected.
Net sales rose to $25.4 billion, up 6.7% from a year earlier. Gross margin expanded 80 basis points to 29%. Adjusted earnings per share climbed to $1.71, a 32% increase from the prior year.

Most importantly for retail analysts, customer traffic — one of the hardest metrics to artificially inflate — increased 4.4%, with gains across all six of Target’s core merchandise categories.

Digital sales stood out as a major driver.

Store-originated comparable sales rose 4.7%, while digital comparable sales jumped 8.9%. Same-day delivery through Target Circle 360 surged more than 27%, providing some of the clearest evidence yet that Target’s aggressive investment strategy is finally beginning to translate into measurable consumer engagement.

That matters because the company is spending heavily.

Target plans approximately $5 billion in capital expenditures this year — more than $1 billion above the prior fiscal year — as it pours money into store remodels, fulfillment systems, technology upgrades, staffing, and merchandising resets designed to rebuild the company’s “cheap chic” reputation.

But Wall Street’s hesitation centers on what comes next.

The second half of the year now becomes a major execution test.

Chief Merchandising Officer Cara Sylvester is overseeing what Target calls its largest food-and-beverage reset in more than a decade. At the same time, Chief Operating Officer Lisa Roath is expanding the company’s Target Beauty Studio concept into more than 600 stores while simultaneously revamping roughly 75% of decorative home assortments.

Each initiative individually would represent a significant operational challenge. Launching all of them simultaneously while consumers remain highly price-sensitive creates the kind of retail execution risk that has hurt Target before.

There is also the tariff issue.

Chief Financial Officer Jim Lee acknowledged the company is still “working through the process” of applying for tariff refunds while warning the tariff environment remains fluid. Because Target sources a substantial share of its apparel, home, and seasonal merchandise internationally, higher tariffs pressure margins long before reimbursement programs offset the impact.

That dynamic helps explain why management’s updated guidance — although stronger — still sounded restrained.
Fiddelke himself described the company’s more measured forecasting approach as a “lesson learned” from prior years when management grew overly optimistic and later had to walk expectations back.

The broader question facing investors is whether Target can fully reclaim the identity that once made it one of America’s most admired retailers.

For years, the company built a loyal customer base around fashionable but affordable merchandise — earning the nickname “Tarzhay” among shoppers who viewed it as a higher-end alternative to Walmart. But inflation, staffing issues, inventory disruptions, and inconsistent store experiences damaged that image over the last two years.

Fiddelke’s strategy is essentially an attempt to restore the brand’s original formula: stronger merchandising authority, cleaner stores, better staffing, improved technology, and a more enjoyable in-store experience.

The quarter Target reported Wednesday is the first substantial evidence that strategy may finally be working.

If the company’s food, beauty, and home resets perform well through the summer and back-to-school season, investors may begin viewing Target as a legitimate turnaround story again rather than a retailer merely bouncing off depressed comparisons.

If execution slips, however, the pressure will return quickly — especially with competitors like Walmart Inc. and Costco Wholesale Corp. continuing to gain market share.

The report also offered a broader read on the American consumer.

Sales growth in beauty, home goods, and discretionary categories suggests middle-income shoppers still have enough financial flexibility to spend on comfort and lifestyle purchases even amid elevated interest rates and inflation pressures.

At the same time, Target’s own guidance repeatedly referenced weakening consumer sentiment, signaling management remains cautious about the second half of the year and the broader economic backdrop.

A strong quarter helped restore confidence.

But even Target’s own leadership is not ready to call it a full turnaround yet.

For now, Wall Street appears to agree.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.
Paul Atkins, the Chairman of the U.S. Securities and Exchange Commission, just slowed down what was expected to become one of the biggest ETF product launches of the year. On Wednesday, he announced that fund sponsors had agreed to delay a wave of more than two dozen exchange-traded funds tied to prediction markets while the SEC opens a formal public comment process before allowing them to launch.

Atkins, a longtime Republican securities lawyer and former SEC commissioner under President George W. Bush, now leads the federal regulator responsible for approving investment products, enforcing disclosure rules, and protecting investors in U.S. financial markets. When the SEC Chairman decides a product needs additional review, it does not move forward.

The products in question were filed earlier this year by Roundhill Investments, GraniteShares, and Bitwise Asset Management. The firms proposed ETFs that would allow Americans to effectively bet on real-world outcomes — including elections, recessions, layoffs, sports events, and economic data — through ordinary brokerage accounts.

The funds would rely on contracts tied to prediction-market platforms such as Kalshi and Polymarket, where users wager on yes-or-no questions about future events. Prediction markets generated roughly $63.5 billion in trading activity last year and have rapidly evolved from niche internet platforms into a growing corner of Wall Street speculation.

Had the ETFs launched, the products would have become available through mainstream investment accounts at firms such as Charles Schwab, Fidelity Investments, and Vanguard Group, potentially placing them inside retirement portfolios and 401(k) plans used by millions of ordinary Americans. Several of the funds were expected to begin trading as early as May 21.

“Novel products raise novel questions,” Atkins said in a statement Wednesday, adding that the SEC must proceed “in a transparent and thoughtful manner” before approving the products.

Behind the delay are several major concerns.

First, prediction markets historically fall under the authority of the Commodity Futures Trading Commission, not the SEC. But Atkins previously told the Senate Banking Committee that some of the contracts increasingly resemble securities products, potentially placing them under SEC oversight instead.

Second, federal investigators are examining whether prediction markets could create opportunities for insider trading and market manipulation. Earlier this year, users on Polymarket placed unusually well-timed bets shortly before President Donald Trump authorized military actions involving Iran and Venezuela. Jay Clayton, the U.S. Attorney for the Southern District of New York and former SEC Chairman, confirmed his office is investigating aspects of the prediction-market industry for possible fraud and misconduct.

Third, courts in Massachusetts and Nevada are still debating whether some prediction-market contracts amount to illegal gambling under state law.

For now, Atkins has already succeeded in slowing the industry’s expansion. The ETFs will not launch this week, and the SEC’s public-comment process could delay approvals for months. The agency has broad authority to demand additional disclosures, request structural changes, or refuse approval entirely.

Notably, the issuers themselves agreed to pause the launches voluntarily, signaling that they are unlikely to challenge the SEC publicly while the review process unfolds.

The longer-term fight, however, may ultimately move beyond the SEC and into Congress.

Lawmakers including Sen. Adam Schiff and Sen. John Curtis are backing legislation known as the “Prediction Markets are Gambling Act,” which would ban sports-related prediction contracts outright. Meanwhile, Rep. French Hill, chairman of the House Financial Services Committee, acknowledged Wednesday that many lawmakers still do not fully understand how the rapidly growing market functions.

Atkins’ move is ultimately aimed at protecting ordinary investors — particularly retirees, working families, and retail traders who could easily mistake prediction-market ETFs for traditional investment products.

Unlike buying shares in a company that produces goods, hires workers, and generates profits, prediction-market contracts are fundamentally wagers on whether specific events will occur. Wrapped inside an ETF structure, those bets could suddenly appear alongside conventional stock and bond funds in retirement accounts across the country.

The SEC chairman is also attempting to protect confidence in the broader securities market itself. If products vulnerable to manipulation or insider-information risks receive the SEC’s approval through the ETF structure, it could undermine trust in the wider regulatory system overseeing Wall Street.

The stakes extend far beyond Washington regulators.

Intercontinental Exchange, owner of the New York Stock Exchange, recently committed up to $2 billion to Polymarket at an estimated $8 billion valuation. Investors including Sequoia Capital, Andreessen Horowitz, CapitalG, Paradigm Ventures, and Coinbase Ventures have poured money into Kalshi at valuations reportedly reaching $5 billion. Donald Trump Jr. also serves as an adviser to both companies.

Those investments were made under the assumption that prediction markets were on the verge of becoming a mainstream financial product embedded directly into the U.S. investment system.

Atkins’ decision does not end that possibility. But it makes clear that before prediction markets reach retirement accounts and everyday brokerage portfolios, the SEC intends to move far more carefully than the industry hoped.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Most of Wall Street will spend Thursday morning focused on chip stocks and artificial-intelligence names after Nvidia’s earnings. The more consequential signal for the broader U.S. economy may arrive 90 minutes before the opening bell from Moline, Illinois.

Deere & Co. reports fiscal second-quarter earnings Thursday morning, and analysts are preparing for a rare combination: higher revenue paired with sharply lower profit — a split that increasingly reflects the pressure tariffs and weak farm economics are placing on American agriculture.

Consensus estimates compiled from 17 analysts call for earnings of roughly $5.74 per share on revenue of approximately $11.5 billion. That would represent an estimated 11% increase in revenue year over year alongside roughly a 14% decline in earnings.

For a company with Deere’s dominant market position, that divergence points directly to rising costs and weakening customer conditions.

The tariff impact has already been quantified by management.

During Deere’s earlier quarterly earnings call, Chief Financial Officer Joshua Beal said the company expects approximately $1.2 billion in pretax tariff costs during fiscal 2026. Deere plans to offset part of that pressure through pricing increases, production efficiencies, and operational adjustments across its agriculture and construction businesses.

Whether those offsets hold is now the central question.

The underlying customer base — particularly U.S. row-crop farmers — remains under significant financial pressure after several difficult seasons marked by lower crop prices, elevated financing costs, and softer equipment demand.

Deere’s own guidance reflects that environment. Management expects its Production and Precision Agriculture division — the segment responsible for large tractors, combines, and planting equipment — to decline between 15% and 20% during fiscal 2026.

Large-equipment inventories across North America reportedly fell to multi-year lows late last year, yet Deere still chose to restrain production rather than aggressively ramp manufacturing — a sign management does not expect a rapid demand rebound.

The implications extend far beyond Deere itself.

A broad network of publicly traded companies now depends on the same stressed agricultural balance sheet.

CNH Industrial, maker of the Case IH and New Holland brands, previously cut profit guidance while citing expanded steel and aluminum tariffs as a growing cost exposure. Companies including AGCO Corp., Lindsay Corp., Titan Machinery, Tractor Supply Co., CF Industries, Nutrien, and Mosaic all remain exposed to the same underlying pressures tied to crop economics and rural spending.

Regional agricultural lenders and farm-credit-linked financial institutions are also closely tied to the sector’s health.

At the same time, another major earnings theme is emerging Thursday morning: the condition of the American consumer.

Walmart Inc. reports earnings before the bell, with Chief Executive John Furner and Chief Financial Officer John David Rainey scheduled to host the company’s earnings call early Thursday morning.

Analysts expect earnings of roughly $0.65 per share on approximately $174.65 billion in revenue, with U.S. comparable sales excluding fuel projected near 3.9%.

But the critical data point may not be the headline numbers themselves.

Investors are increasingly focused on whether consumers continue prioritizing essentials like groceries while pulling back on discretionary categories such as apparel, home goods, and electronics — a pattern already highlighted by Target Corp. in its own earnings report Wednesday.

If Walmart confirms similar trends, it would suggest two of America’s largest retailers are seeing the same consumer caution emerge simultaneously.

The off-price retail sector may provide another important read.

Ross Stores reports after Thursday’s close, while TJX Companies continues trading on Wednesday’s earnings reaction. Investors are watching closely for evidence that middle-income consumers continue “trading down” from traditional retailers toward discount chains.

A strong report from Ross could reinforce the idea that financial pressure on households is intensifying. A weak report could signal something more concerning: consumers may simply be buying less overall.

Higher-income spending patterns are also under scrutiny.

Deckers Outdoor Corp., parent of Hoka and UGG, reports after the close, while Ralph Lauren Corp. reports before the bell. Hoka in particular has become one of the stronger premium consumer brands during the recent economic slowdown, making its earnings a closely watched indicator for upper-middle-income discretionary spending.

The broader geopolitical backdrop remains largely unchanged.

President Donald Trump said earlier this week that he postponed potential military action against Iran while diplomatic negotiations continue. Oil prices eased modestly following those comments, with West Texas Intermediate crude trading near $98.96 per barrel late Wednesday and Brent crude moving similarly lower.

Any escalation in Middle East tensions could quickly reverse that trend and immediately lift defense contractors including Lockheed Martin, RTX Corp., Northrop Grumman, and General Dynamics.

Meanwhile, bond markets will continue digesting minutes released Wednesday from the Federal Reserve’s latest policy meeting. Investors are watching closely for signs of internal support around Fed Chair Kevin Warsh’s softer interest-rate posture and whether policymakers remain comfortable with inflation trends tied to energy prices and tariffs.

Treasury yields, regional banks, homebuilders, and broader rate-sensitive sectors are all likely to react to that interpretation throughout Thursday’s session.

Taken together, Thursday’s market narrative centers on a single economic question: how much pressure can both the American producer and the American consumer absorb before broader economic growth begins to weaken more meaningfully?

Deere provides the answer for the farmer.

Walmart provides the answer for the household.

Ross Stores measures the consumer already trading down.

Deckers and Ralph Lauren test whether higher-income spending remains resilient.

By the time markets open at 9:30 a.m., much of Wall Street’s real story may already be clear.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Wall Street investors may be getting a little too confident.

Bank of America warned Tuesday that professional money managers have become so heavily invested in stocks that the bank’s closely watched “sell signal” has officially triggered — a warning that markets could soon face a pullback after months of strong gains.

For everyday investors, the message is simple: when almost everyone is already bullish and fully invested, there may not be enough new buyers left to keep pushing stocks higher.

The warning comes after cash levels held by major fund managers dropped below 4% for the first time in months — a threshold Bank of America historically views as a sign investors have become overly optimistic.

At the same time, professional investors sharply increased their stock exposure in May, making one of the biggest monthly moves into equities ever recorded in the bank’s survey history.

“Bull capitulation almost complete,” Bank of America strategist Michael Hartnett wrote in a note to clients.

In plain English, that means many investors who had been cautious finally rushed back into the market — often a sign that optimism may be peaking.

The stock market has staged a powerful rally since March, driven largely by enthusiasm around artificial intelligence, strong earnings from major tech companies and hopes the economy could avoid recession despite rising oil prices and global tensions.

Much of the buying has flowed into giant technology companies including:

  • Nvidia
  • Apple
  • Microsoft
  • Amazon
  • Meta
  • Alphabet
  • Tesla

Those seven companies — often called the “Magnificent Seven” — have powered much of the broader market’s gains over the past few years.

But Bank of America now says that trade has become extremely crowded.

The concern is not necessarily that a major crash is imminent. Historically, the bank’s sell signal has often been followed by relatively modest pullbacks.

Still, the indicator suggests markets may be vulnerable because investors have already deployed much of their available cash.

If bad news hits — such as rising inflation, higher interest rates, weak earnings or geopolitical escalation — there may be fewer buyers ready to step in and support prices.

The timing of the warning is especially notable because several major risks remain hanging over markets:

  • Oil prices remain elevated because of the Iran war
  • Treasury yields have surged to multi-year highs
  • The Federal Reserve may keep rates higher for longer
  • Investors are increasingly worried about inflation returning

Long-term Treasury yields briefly climbed above 5.19% Tuesday, their highest levels in nearly two decades.

Higher bond yields often pressure stocks because they increase borrowing costs and make safer investments like bonds more attractive relative to equities.

Ironically, many investors surveyed by Bank of America said they expect yields to continue rising — while simultaneously remaining heavily invested in stocks.

That contradiction is part of what worries strategists.

The survey also found only 4% of fund managers expect a severe economic slowdown, showing how optimistic Wall Street has become despite ongoing global uncertainty.

Historically, markets tend to become more fragile when nearly everyone expects good news.

Hartnett specifically pointed to early June as a possible period for profit-taking, especially with the Federal Reserve’s next policy meeting approaching and Nvidia earnings due this week.

For everyday investors, analysts say the warning does not necessarily mean panic-selling stocks.

Instead, it may simply suggest being more cautious after a strong rally:

  • Reviewing portfolio risk
  • Avoiding excessive speculation
  • Rebalancing overly concentrated positions
  • Keeping some cash available for future opportunities

The broader economy still appears relatively strong, corporate profits remain healthy and AI optimism continues driving massive investment flows into technology.

But Bank of America’s message is that markets may now be priced for near perfection — leaving less room for disappointment.

And when almost everyone is already bullish, even small negative surprises can sometimes trigger outsized market reactions.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Foreign governments sharply reduced their holdings of U.S. Treasurys in March as the economic fallout from the Iran war forced central banks across Asia and the Middle East to defend their currencies and stabilize local markets.

Japan, the largest foreign owner of U.S. government debt, cut roughly $47.7 billion from its Treasury holdings, lowering its position to about $1.19 trillion, according to data released Monday by the U.S. Treasury Department. China also reduced its holdings, bringing them down to roughly $652 billion — the country’s lowest level since 2008.

For everyday Americans, the story matters because foreign demand for U.S. government debt directly affects borrowing costs across the economy, including mortgages, credit cards, auto loans and business financing.

When countries buy fewer Treasurys, the U.S. government often has to offer higher interest rates to attract buyers. Those higher rates can ripple through the entire financial system.

The selloff comes after the U.S.-Iran conflict triggered a major surge in global oil prices earlier this year, putting enormous pressure on countries that rely heavily on imported energy. Japan and several Asian economies saw their currencies weaken sharply as energy costs climbed, forcing central banks to step in and support their financial systems.

To do that, many governments sold dollar reserves — including U.S. Treasury bonds — and used the cash to buy their own currencies.

Analysts say the moves were driven more by financial defense than by politics.

“Given increased financial volatility since the start of the war in the Gulf, and resultant pressure on exchange rates, especially in Asia, it is not a surprise that U.S. Treasury holdings by central banks have fallen,” said Frederic Neumann, chief Asia economist at HSBC.

Japan faced some of the most severe pressure as the yen weakened past the key 160-per-dollar level, alarming policymakers in Tokyo. The Bank of Japan reportedly intervened in currency markets in late March and early April to slow the collapse.

China’s reduction, meanwhile, continues a much longer trend that has been unfolding for more than a decade. Beijing has steadily reduced its direct Treasury exposure since peaking near $1.3 trillion in 2013, although analysts believe China still indirectly holds large amounts of U.S. debt through financial centers such as Belgium and Luxembourg.

The Treasury market was also hit by rising inflation fears tied to the war and higher oil prices. Bond prices fell sharply in March as investors worried the Federal Reserve may delay future interest-rate cuts.

That matters because when bond prices fall, yields rise — increasing borrowing costs for the U.S. government.

Treasury yields have climbed back toward levels last seen before the 2008 financial crisis, and several government debt auctions earlier this year saw weaker-than-expected demand from investors.

The pressure is becoming increasingly important for Washington because the federal government is already paying close to $1 trillion annually in interest expenses on the national debt.

At the same time, foreign central banks have slowly become less dominant buyers of Treasurys in recent years. More hedge funds and private investors are now stepping into the market instead, a shift analysts say can create sharper swings and more volatility.

Not every country pulled back. The United Kingdom actually increased its Treasury holdings by nearly $30 billion during the month, helping offset part of the broader decline.

Overall, foreign private investors continued buying U.S. assets aggressively even as governments and central banks reduced exposure. Analysts say that suggests confidence in the U.S. economy itself remains relatively strong, even as official institutions focus more heavily on protecting their own currencies and economies from the global energy shock.

Investors are now watching closely for April Treasury data, which will show whether the March selling was a temporary reaction to the war-driven oil spike or the beginning of a broader global shift away from U.S. government debt.

For now, the message from foreign governments is increasingly clear: stabilizing their own economies is taking priority over supporting the global dollar system that has dominated world finance for decades.

— JBizNews Desk

© JBizNews.com. All rights reserved.

Anthropic has hired one of the most respected names in artificial intelligence: Andrej Karpathy, the former Tesla AI chief and OpenAI co-founder whose work helped shape today’s AI boom.

For everyday readers, the move highlights how intense — and expensive — the fight for top AI talent has become as companies race to dominate the next generation of artificial intelligence.

Karpathy announced Tuesday that he is joining Anthropic, the fast-growing AI company behind the Claude chatbot, to work on developing future large language models and advanced AI systems.

“I think the next few years at the frontier of LLMs will be especially formative,” Karpathy wrote in a post on X.

Inside the tech industry, the hire is being viewed as a major win for Anthropic and a blow to rivals including OpenAI, Tesla and Elon Musk’s xAI.

Karpathy is widely considered one of the most influential AI researchers of the modern era.

He was part of the original founding team at OpenAI alongside Sam Altman, Elon Musk, Ilya Sutskever and others back in 2015, before leaving to lead Tesla’s artificial intelligence efforts.

At Tesla, Karpathy helped build the computer vision systems behind Autopilot and the company’s Full Self-Driving technology.

He later became one of the most recognizable public educators in AI, helping explain complex technologies like neural networks and large language models to millions of engineers, developers and students online.

He also coined the now-popular phrase “vibe coding,” referring to the growing trend of developers describing what they want while AI generates the code automatically.

Anthropic says Karpathy will join its “pretraining” team — the group responsible for building the foundational intelligence of future AI models.

That stage of AI development is among the most expensive and competitive areas in technology today because it requires enormous amounts of computing power, data and highly specialized researchers.

In simple terms, these are the teams trying to create the next generation of ChatGPT-like systems before they are later refined into consumer products.

The hire comes at a pivotal moment in the AI race.

Anthropic has rapidly emerged as one of OpenAI’s biggest competitors, especially in enterprise AI and coding tools. The company recently reached a private valuation approaching $1 trillion and is widely expected to pursue an IPO in the near future.

Meanwhile, AI companies are battling aggressively for a very small pool of elite researchers capable of pushing frontier models forward.

Compensation packages for top AI talent have exploded, with some companies reportedly offering deals worth tens or even hundreds of millions of dollars.

The move is also notable because Karpathy had previously been linked to possible future projects with Elon Musk.

Musk reportedly tried to recruit him back to Tesla last year for work on the company’s Optimus humanoid robot initiative.

Instead, Karpathy chose Anthropic — a company founded largely by former OpenAI employees and increasingly seen as one of the strongest challengers in the AI industry.

The timing adds another layer of drama.

Karpathy’s hiring comes just one day after Musk lost a major legal battle against OpenAI and Sam Altman over claims tied to OpenAI’s transition into a for-profit company.

For Anthropic, landing Karpathy sends a clear message to competitors and investors: the company intends to compete aggressively at the very highest level of AI development.

The broader industry implications are enormous.

As AI systems become more powerful, experts increasingly believe the biggest advantage may not simply be who has the most computer chips or money — but who can attract the smartest researchers capable of improving models faster than rivals.

That makes people like Karpathy extraordinarily valuable.

For consumers, the escalating talent war could accelerate advances in AI tools used for coding, search, education, automation and business productivity.

It could also further intensify competition between major AI players including OpenAI, Google, Meta, Anthropic and Musk’s xAI as each races to build more capable systems.

And increasingly, the battle is no longer just about technology.

It is about who can convince the people building the future of AI where they want to work.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Jeff Bezos, the founder of Amazon.com Inc. and one of the wealthiest people in the world, said Wednesday that the bottom half of American earners should pay no federal income tax at all — arguing that politicians targeting billionaires are avoiding the more important economic question of how to strengthen working households.

Speaking on CNBC’s Squawk Box from Blue Origin’s facility in Merritt Island, Florida, Bezos told anchor Andrew Ross Sorkin that the current federal tax structure places unnecessary pressure on ordinary Americans while generating relatively little revenue from lower-income households.

“I don’t think it should be 3%,” Bezos said, referring to the roughly 3% of total federal income taxes paid by the bottom half of earners. “I think it should be zero.”

He expanded further: “I don’t want to reduce it, I want to eliminate it. I think there’s something very powerful about zero. Zero is a better number than $1.”

To illustrate the argument, Bezos repeatedly pointed to what he described as a nurse in Queens, New York, earning approximately $75,000 a year while sending more than $1,000 a month to Washington in federal taxes.

“We shouldn’t be asking this nurse in Queens to send money to Washington,” Bezos said. “They should be sending her an apology. It really makes no sense.”

The remarks immediately inserted one of America’s richest individuals into the center of the country’s escalating debate over wealth taxes, inequality, and the role of consumer spending in the broader economy.

Bezos, 62, founded Amazon in 1994, stepped down as chief executive in 2021, and now serves as executive chairman. He also owns Blue Origin and The Washington Post. His estimated net worth stands near $279 billion, according to the Bloomberg Billionaires Index.

The proposal itself was broad rather than technical.

Bezos did not offer a detailed funding mechanism or legislative blueprint, but instead reframed the tax discussion around lower-income households rather than high-income earners.

According to data from the Tax Foundation based on Internal Revenue Service statistics, the bottom half of American taxpayers reported adjusted gross income averaging roughly $54,000 in 2023. That group earned about 12% of total national income while paying approximately 3% of total federal income taxes.

By comparison, the top 1% earned roughly 21% of national income and paid approximately 38% of federal income taxes.

Bezos argued that the federal revenue collected from lower-income households is relatively small in the context of the overall federal budget but highly meaningful to individual families trying to absorb inflation, housing costs, food prices, and higher interest rates.

The economic implications could be substantial for consumer-facing businesses.

Retailers including Walmart Inc., Target Corp., Costco Wholesale Corp., Dollar General Corp., Dollar Tree Inc., TJX Companies Inc., and Ross Stores Inc. derive a large share of their revenue from middle- and lower-income consumers.

Economists estimate that eliminating federal income taxes for households below roughly the median income threshold could return between $80 billion and $100 billion annually to consumers depending on how eligibility is structured.

That disposable income would likely flow directly into everyday spending categories including groceries, fuel, restaurants, clothing, household goods, and automotive purchases.

Restaurant operators such as McDonald’s Corp., Chipotle Mexican Grill Inc., and Yum! Brands Inc. have repeatedly warned during recent earnings calls about pressure on lower-income traffic and shrinking discretionary spending.

Housing-related companies including D.R. Horton Inc., Lennar Corp., and PulteGroup Inc. could also benefit modestly if households retain more after-tax income for down payments and mortgage qualification.

The timing of Bezos’s comments appears closely tied to the broader political climate surrounding billionaire wealth.

Several new wealth-tax proposals have emerged in recent months.

Supporters of a proposed California ballot initiative imposing a one-time 5% tax on residents with net worth exceeding $1 billion recently gathered enough signatures to place the measure before voters in November.

In March, Sen. Elizabeth Warren reintroduced the Ultra-Millionaire Tax Act of 2026, proposing an annual 2% tax on households and trusts worth more than $50 million, an additional surtax on billionaire wealth, and a 40% exit tax on ultra-wealthy Americans who renounce U.S. citizenship.

New York lawmakers are also weighing expanded taxes on luxury second homes that could directly affect high-net-worth property owners including Bezos.

Bezos addressed those efforts directly during the interview.

“Politicians are using this age old technique of picking a villain and pointing fingers, but the problem is that doesn’t solve anything,” he said.

He added that he already pays billions in taxes and contributes billions more through philanthropy, while arguing that public policy should focus more heavily on lifting lower-income households rather than penalizing wealth creation.

Whether the proposal has a realistic legislative path remains uncertain.

Eliminating federal income taxes for roughly half of American earners would require either offsetting revenue increases, spending reductions, larger deficits, or some combination of all three.

Still, Bezos’s comments may matter politically because they shift the debate away from whether billionaires should pay more and toward whether working-class Americans should pay less.

That framing creates room for both parties to engage around expanded earned-income tax credits, child-tax-credit expansions, or income exemptions that could achieve versions of what Bezos described without fully eliminating taxes outright.

For the broader economy, the underlying issue remains consumer spending.

Household consumption accounts for roughly two-thirds of U.S. gross domestic product. Any policy that materially increases after-tax income for lower- and middle-income households would likely move quickly through retailers, restaurants, service businesses, banks, and housing markets.

In practical terms, that means stronger traffic at Walmart, more spending at gas stations and grocery stores, higher credit-card activity tracked by JPMorgan Chase & Co. and Bank of America Corp., and potentially stronger sales growth across the broader consumer economy.

Whether Congress acts on Bezos’s proposal is one question.

Whether one of America’s wealthiest business figures has now reframed the public tax debate around the working class instead of the billionaire class may prove equally important.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

For the last three years, Wall Street has operated on one basic rule: when Nvidia Corp. reports earnings, the market stops everything else and watches.

On Wednesday night, Nvidia delivered another massive quarter — and the market barely reacted.

The reason arrived hours earlier, when Elon Musk’s SpaceX confidentially filed paperwork for what could become the largest initial public offering in the history of global markets.

The targeted valuation: between $1.75 trillion and $2 trillion.

The expected raise: as much as $75 billion, more than double the size of Saudi Aramco’s record $29.4 billion IPO in 2019.

In plain English, a private rocket company may be about to become one of the most valuable publicly traded companies on earth.

And suddenly, even Nvidia’s staggering earnings looked almost routine.

On paper, Nvidia delivered exactly the kind of quarter that normally dominates global markets. The company reported first-quarter revenue of $81.62 billion, beating Wall Street estimates of $79.19 billion. Adjusted earnings per share came in at $1.87, above the $1.76 consensus. Gross margins held near 75%. Revenue guidance for the current quarter topped expectations again, ranging between $89.18 billion and $92.82 billion.

The company also announced an additional $80 billion share buyback, raised its dividend, and extended one of the most dominant earnings streaks in modern corporate history.

And yet Nvidia shares barely moved in after-hours trading.

The reason is simple: investors no longer view Nvidia as a surprise. They view it as infrastructure.

The market already assumes AI spending will remain enormous. The debate has moved beyond the chip supplier and toward the companies building entire ecosystems around artificial intelligence, satellites, broadband networks, and supercomputing infrastructure.

That is where SpaceX enters the story.

According to the filing, SpaceX generated roughly $4.694 billion in revenue during the quarter ended March 31. The business now spans three major divisions: rocket launches, the Starlink satellite-internet network, and a rapidly growing AI infrastructure operation tied to Musk’s acquisition of xAI earlier this year.

That AI segment includes the massive Colossus compute cluster, which houses more than 220,000 Nvidia GPUs and has already been tapped by companies including Anthropic for AI processing capacity.

In effect, SpaceX is becoming both a customer and competitor within the AI ecosystem at the same time.

The company is also attempting to turn the IPO into a public event rather than a traditional Wall Street offering.

SpaceX plans a 5-for-1 stock split ahead of the listing, reducing the implied per-share price from roughly $526 to about $105, according to documents reported by Bloomberg. The company has also discussed allocating as much as 30% of IPO shares to retail investors — an unusually large portion for an offering of this scale.

The strategy is politically and financially smart.

It turns the IPO into something ordinary Americans can participate in directly instead of watching from the sidelines while institutional investors dominate the allocation.

Still, the risks are enormous.

At a valuation approaching $2 trillion, SpaceX would debut at more than 100 times annual sales, far above the multiples at which even companies like Meta Platforms or Nvidia traded during peak growth periods.

The company also reportedly lost roughly $5 billion last year.

Critics argue the valuation reflects investor excitement around Musk more than traditional financial fundamentals.

But supporters counter that no company in the world controls a comparable combination of launch dominance, satellite broadband infrastructure, military contracts, and AI computing power.

Starlink alone is estimated by some analysts to be worth between $150 billion and $250 billion as a standalone business. SpaceX also launches the majority of satellites entering orbit globally and remains deeply embedded in U.S. military and intelligence infrastructure.

For everyday Americans, however, the bigger story is what this IPO represents.

For the first time, ordinary investors may soon own shares in the company controlling much of the world’s access to space, satellite communications, and rapidly expanding AI infrastructure.

The IPO also deepens the connection between Musk’s businesses and Washington. SpaceX depends heavily on federal contracts, regulatory approvals, and broadband subsidies. Once public, those political relationships become directly tied to the retirement accounts and brokerage portfolios of millions of investors.

Most importantly, the IPO signals something larger about the AI economy itself.

The market’s center of gravity is shifting.

Nvidia remains the backbone of AI hardware. But investors are now chasing the companies building the infrastructure that consumes Nvidia chips at massive scale — orbital internet systems, hyperscale compute clusters, and AI-powered communications networks.

That is why an $81 billion Nvidia quarter suddenly felt almost ordinary.

The AI economy has become so large that even Nvidia is no longer the whole story.

And by the time SpaceX executives begin meeting institutional investors ahead of the June roadshow, the question for many Americans may no longer be whether they should own Nvidia.

It may be whether they are willing to buy into Elon Musk’s vision of space, broadband, and artificial intelligence — at whatever price Wall Street decides the future is worth.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Something strange is happening in two stock markets most American investors barely glance at. South Korea’s Kospi is up roughly 70% this year. Taiwan’s Taiex is up about 41%. By contrast, the S&P 500 has gained a fraction of that. And the explanation is not a Korean economic miracle, a Taiwanese export boom, or a sudden flood of foreign investment chasing cheap valuations. The explanation is three companies — Samsung Electronics, SK Hynix, and Taiwan Semiconductor Manufacturing Co. — and one product they all make.

That product is the chip inside the artificial intelligence machines being built at a pace the global economy has not seen since the early internet.

To understand what is going on, start with how lopsided these two markets have become. TSMC alone now accounts for more than 40% of Taiwan’s entire stock market, according to UOB. In South Korea, Samsung and SK Hynix together make up a record 42.2% of the Kospi, according to Manulife Investment Management. That is the equivalent, in American terms, of Apple by itself being worth nearly half the S&P 500. June Chua, head of Asia equities at Manulife Investment Management, summed it up bluntly: both indexes have effectively become AI and semiconductor proxies. Tim Moe, chief regional equity strategist for Asia-Pacific at Goldman Sachs, agreed, telling CNBC the AI hardware theme is what is clearly propelling things.

So why has this become a Korea-and-Taiwan story rather than an America story? After all, the AI companies driving the demand — Nvidia, Microsoft, Google, Amazon, Meta — are all American.

Here is where the plain logic kicks in. The American giants design the AI. They write the software, train the models, run the cloud platforms. But every single one of them needs a physical chip to actually do the computing. And the world has exactly one company that can manufacture the most advanced versions of those chips: TSMC. The world has exactly two companies that can produce the high-bandwidth memory, known as HBM, that those chips need to function: Samsung and SK Hynix. Three companies. Two countries. Zero serious competitors at the cutting edge.

When Microsoft announces it will spend $80 billion on AI infrastructure, that money does not stop in Redmond. It flows to Nvidia. Nvidia then sends it to TSMC in Hsinchu and SK Hynix in Icheon. The cash arrives in Asia. The earnings show up on Asian balance sheets. The stock prices rise in Seoul and Taipei.

This is why the rally feels detached from ordinary economic news. The Kospi climbed from 5,000 to 8,000 in a single year — a move that took the index more than 18 years the first time around, from 1,000 to 2,000. On May 6, Samsung shares jumped almost 15% in a single session, vaulting the company past a $1 trillion market capitalization and making it the second Asian company ever, after TSMC, to cross that threshold. SK Hynix is up more than 146% so far this year. JPMorgan has lifted its bull-case target for the Kospi to 10,000 points.

Now the harder question. Is this real, or is this a bubble?

The honest answer is that it is both — depending on the time horizon.

On the short-term side, there are warning lights flashing. Kospi stocks have already pulled back more than 9% from their record high. Taiex has dropped about 4%. Concentration risk is now part of the conversation in every Asia portfolio meeting. Herald van der Linde, head of equity strategy for Asia-Pacific at HSBC, warned that Asian portfolios are reaching levels where too much exposure to too few stocks could limit further upside. Charu Chanana, chief investment strategist at Saxo Markets, said Korea and Taiwan had become very crowded expressions of the AI infrastructure boom, and once US inflation concerns nudged bond yields higher and US tech momentum wobbled, investors took profits where gains had been largest. Valuations on Taiex now sit at 18.2 times forward earnings, above the five-year average. When a single stock can move an entire national market by 3% in a session, the market is no longer really a market. It is a leveraged bet on one trend.

On the long-term side, the trend is very real. AI capital spending is on track to exceed $600 billion in 2026 alone. Samsung and SK Hynix have locked in multi-year supply agreements with Nvidia for the next generations of HBM memory chips. TSMC is the manufacturing chokepoint for nearly every advanced AI processor on earth. Even if the stock prices correct sharply, the underlying business of making AI hardware is not slowing down. It is accelerating.

For everyday Americans, the takeaway is bigger than a foreign stock ticker. The Korean and Taiwanese rallies are flashing a signal about where industrial power in the AI age actually lives. The brand names belong to Silicon Valley. The physical production sits across the Pacific. That has profound implications for trade policy, for the Trump administration’s push to bring chipmaking onshore, for the future of the CHIPS Act, and for any American company whose business model depends on AI hardware showing up on time and at price. When the Strait of Hormuz flares up, Americans feel it at the gas pump. When something flares up in the strait between Taiwan and the Chinese mainland, Americans will feel it in everything from cloud bills to laptop prices to the cost of running an AI customer service bot at a regional bank.

Short-term, the Korean and Taiwanese rallies will swing. Profits will get taken, narratives will shift, and someday the parabolic chart will break. Long-term, the structural shift is what matters: the most important factories in the world economy now sit on two islands and one peninsula in East Asia, and global stock markets are finally pricing that in.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Zuckerberg Redirects Thousands of Workers Into AI Roles as Meta Accelerates $145 Billion Infrastructure Push

NEW YORK — Meta Platforms Inc. began the largest companywide layoff in its history on Wednesday, eliminating approximately 8,000 positions — roughly 10% of its global workforce — while reassigning another 7,000 employees into new artificial-intelligence-focused roles, in a sweeping restructuring that Chief Executive Officer Mark Zuckerberg has framed as necessary to compete in the accelerating global AI infrastructure race.

The cuts, confirmed internally through a memo from Janelle Gale, Meta’s head of human resources, impacted divisions including Reality Labs, Facebook operations, recruiting, sales, and global business operations.

Notification emails began rolling out at approximately 4 a.m. local time, starting in Singapore before expanding into Europe and the United States later in the day.

California WARN filings showed additional layoffs at Meta facilities in Burlingame and Sunnyvale, while the broader cuts span Meta’s global workforce of roughly 78,865 employees.

The restructuring marks Meta’s largest reduction since Zuckerberg’s earlier “Year of Efficiency” campaign in 2022 and 2023, when the company eliminated approximately 21,000 positions.

Combined with the newest cuts, Meta has now reduced its workforce by roughly 25,000 employees since 2022, with additional reductions reportedly still under consideration later this year.

The business rationale is increasingly centered around one word: AI.

Meta raised its 2026 capital expenditure forecast last month to as much as $145 billion, up from prior guidance between $115 billion and $135 billion, as the company races to build massive artificial-intelligence infrastructure across the United States and globally.

The company told employees the restructuring is intended to “allow us to offset the other investments we’re making” while operating more efficiently.

The 7,000 reassigned workers will reportedly move into four newly structured AI-focused organizations under Chief AI Officer Alexandr Wang, who joined Meta following the company’s major investment in Scale AI.

Internal company materials describe the new groups as “AI-native design structures” with flatter management hierarchies and significantly heavier concentration around AI products, research, infrastructure, and automation.

The restructuring highlights one of the clearest trends emerging across corporate America: major companies are no longer simply adding AI capabilities — they are actively redesigning workforces around artificial intelligence itself.

Meta reported record quarterly revenue of $56.31 billion, meaning the layoffs are not being driven by collapsing business conditions or weakening advertising demand.

Instead, the company is reallocating resources away from traditional staffing expansion and toward AI compute power, data-center construction, networking infrastructure, and high-end AI engineering talent.

The compensation disparity inside Meta also underscores the broader shift now occurring across the technology sector.

While median employee compensation reportedly declined year-over-year and portions of stock-based compensation were reduced, Zuckerberg has simultaneously pursued elite AI researchers with compensation packages reportedly reaching $100 million in certain cases.

Meta’s restructuring also carries significant implications beyond Silicon Valley itself.

The eliminated jobs are concentrated primarily in high-income metro regions including San Francisco, Seattle, New York, and London, potentially impacting housing demand, restaurant spending, luxury retail, travel, and broader local economic activity tied to highly compensated technology workers.

Recruiting firms, staffing agencies, and job-platform operators also face secondary effects as Meta simultaneously eliminates positions while reducing future hiring demand.

At the same time, there are clear winners emerging from the shift.

Companies supplying AI infrastructure — including Nvidia Corp., Advanced Micro Devices Inc., Broadcom Inc., Taiwan Semiconductor Manufacturing Co., and SK hynix Inc. — stand to benefit directly from Meta’s rapidly expanding AI spending.

Utilities, construction firms, data-center developers, fiber providers, and power-equipment companies tied to large-scale AI campuses are also increasingly tied to the technology industry’s next growth cycle.

Meta has committed to massive long-term infrastructure expansion across the United States as demand for AI computing capacity continues accelerating.

For smaller businesses and employers, the message is increasingly complicated.

Some companies struggling to compete with Big Tech compensation packages may now gain access to experienced engineering and operational talent entering the labor market.

At the same time, Meta’s restructuring reinforces growing concerns throughout the business community that artificial intelligence is beginning to permanently reshape white-collar employment structures across industries ranging from technology and finance to marketing, operations, administration, customer service, and recruiting.

The broader implication is becoming increasingly difficult for corporate America to ignore:

The same AI boom powering record infrastructure spending, soaring semiconductor demand, and historic stock-market gains is simultaneously driving one of the largest workforce restructurings in modern technology history.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

AbbVie and Regeneron Remain Among Final Major Holdouts as Administration Pushes Drugmakers Toward Lower U.S. Prices and Domestic Manufacturing

WASHINGTON — President Donald Trump’s new 100% tariff framework on patented pharmaceutical imports is intensifying pressure on the remaining holdouts in the drug industry, with AbbVie Inc. and Regeneron Pharmaceuticals Inc. now among the final major manufacturers that have not yet agreed to pricing and manufacturing terms sought by the administration.

The tariff structure, established through an executive order signed earlier this year, ties tariff relief directly to whether pharmaceutical companies agree to two major conditions: participation in a “most-favored-nation” drug pricing arrangement tied to U.S. prices and commitments to expand pharmaceutical manufacturing capacity inside the United States.

Under the administration’s framework, companies agreeing to both conditions can avoid tariffs entirely, while firms expanding domestic manufacturing without pricing agreements face escalating tariff exposure over several years. Companies declining both conditions face the full 100% tariff on covered patented pharmaceutical imports.

The strategy has rapidly reshaped negotiations across the pharmaceutical industry.

Major manufacturers including Pfizer Inc., AstraZeneca Plc, Eli Lilly & Co., Novo Nordisk, Johnson & Johnson, Merck & Co., GSK Plc, Novartis AG, Sanofi SA, Amgen Inc., Bristol Myers Squibb Co., Gilead Sciences Inc., and others have already entered agreements with the administration tied to pricing concessions, domestic manufacturing expansion, or both.

That leaves AbbVie and Regeneron increasingly isolated as negotiations continue.

The administration argues the policy is intended to lower prescription drug costs for American consumers while simultaneously rebuilding domestic pharmaceutical manufacturing capacity after decades of overseas dependence.

The pricing agreements are tied in part to the administration’s new TrumpRx.gov platform, which is designed to help consumers access discounted medications directly through participating pharmaceutical manufacturers.

Officials say certain medications under the agreements could eventually see discounts ranging from roughly 50% to as high as 85% depending on the product and purchasing structure.

The administration has framed the broader tariff threat as leverage rather than purely punitive trade policy.

Commerce Secretary Howard Lutnick has indicated the White House remains engaged in ongoing negotiations with companies that have not yet signed agreements, suggesting the tariff structure is intended primarily to force concessions around pricing and domestic production.

For the pharmaceutical industry, however, the financial implications are enormous.

The United States remains by far the world’s most profitable pharmaceutical market, with Americans paying substantially higher prices for many branded medications than consumers in other developed countries.

Industry groups including PhRMA have strongly criticized the administration’s approach, arguing tariffs and pricing controls could ultimately increase costs, disrupt supply chains, reduce innovation incentives, and complicate long-term research and development investment.

Stephen J. Ubl, Chief Executive Officer of PhRMA, warned that tariffs on advanced medicines could threaten billions of dollars in existing and future U.S. investment tied to pharmaceutical development and manufacturing.

Investors are now closely watching AbbVie and Regeneron to determine whether the companies ultimately agree to pricing terms, expand U.S. manufacturing commitments, or attempt to challenge portions of the framework politically or legally.

AbbVie, headquartered in North Chicago, manufactures major blockbuster drugs including Humira, Skyrizi, and Rinvoq, while Regeneron, based in Tarrytown, New York, is known for products including Eylea and its partnership with Sanofi on the asthma treatment Dupixent.

Because portions of their manufacturing and supply chains remain tied to facilities outside the continental United States, prolonged tariff exposure could create pressure on pricing, margins, manufacturing strategy, or future investment decisions.

The broader business implications extend far beyond pharmaceutical companies themselves.

Domestic manufacturing firms, construction contractors, logistics providers, chemical suppliers, packaging companies, and industrial real-estate developers all stand to benefit if more drugmakers accelerate U.S.-based production expansion in response to tariff pressure.

At the same time, pharmacy chains including CVS Health, Walgreens Boots Alliance, and Walmart could see changes in prescription purchasing behavior if discounted direct-purchase drug programs gain traction among consumers.

Pharmacy benefit managers including CVS Caremark, Express Scripts, and OptumRx may also face pressure as the pricing landscape evolves under the administration’s framework.

For consumers, the potential outcome remains mixed.

Some Americans paying cash for medications could see immediate savings through direct-discount programs tied to participating manufacturers.

Others, however, may still face higher prices elsewhere if companies attempt to offset lower prices on certain drugs by raising prices on products outside the agreements or passing along supply-chain costs tied to tariffs.

The legal foundation of the pharmaceutical tariffs also differs from several of Trump’s earlier trade actions.

Administration officials have argued the pharmaceutical measures fall under Section 232 national-security authority, which historically gives the executive branch broader power to impose tariffs tied to national security concerns surrounding supply-chain dependence and industrial capacity.

That distinction may make the pharmaceutical tariffs more legally durable than some previous tariff actions challenged in court.

For now, Wall Street and the broader health-care industry are watching one central question:

Whether the remaining holdouts ultimately negotiate agreements with the administration — or whether the White House moves forward with fully imposing one of the most aggressive pharmaceutical tariff regimes in modern U.S. history.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A new government-backed savings account for children called “Trump Accounts” is launching this summer, giving families another way to invest for their kids’ futures. But financial planners say many parents may still be better off using a tool that has existed for decades — the 529 college savings plan.

The bigger surprise: most American families aren’t using either one.

According to a recent Edward Jones report, only about 23% of parents currently use a 529 savings plan, despite its major tax benefits.

For everyday families, the issue comes down to something simple: how to save money for children in a way that grows over time without getting heavily taxed.

Starting July 4, 2026, children born between January 1, 2025 and December 31, 2028 will automatically qualify for the new Trump Accounts program. Eligible children will receive a one-time $1,000 deposit from the federal government to help jump-start savings.

Parents can then contribute up to $5,000 per year until the child turns 18.

The accounts are designed somewhat like retirement accounts for children. The money can grow through investments over many years, potentially helping with future expenses such as buying a home, retirement or other long-term needs.

But financial planners say 529 plans still offer stronger tax advantages if the primary goal is saving for education.

Here’s the key difference:

With a Trump Account:

  • Parents contribute after-tax money.
  • Investments grow over time.
  • Withdrawals later are taxed as ordinary income.

With a 529 plan:

  • Parents also contribute after-tax money.
  • Investments grow tax-free.
  • Withdrawals used for qualified education expenses are completely tax-free.

That distinction can make a huge difference over 10 to 20 years of investment growth.

“At its core, 529 plans are one of the best tax-advantaged ways for families to save for college,” said Andy Esser, a Certified Financial Planner at Edward Jones.

529 plans can typically be used for:

  • College tuition
  • Private K-12 education
  • Apprenticeship programs
  • Student loan repayment

Many states also offer additional tax deductions or credits for contributions to 529 accounts.

Still, Trump Accounts have one major advantage that immediately grabs attention: free government money.

“A free $1,000 for newborns makes Trump accounts a no-brainer,” JPMorgan wealth advisors wrote in guidance to clients.

Financial planners increasingly say the ideal setup for families who can afford it may be using both:

  • A 529 plan for education savings
  • A Trump Account for broader long-term wealth building

The challenge is that many families struggle to save consistently at all.

Rising housing costs, childcare expenses, inflation and retirement pressures often leave little money available for long-term child savings accounts.

That’s one reason participation in 529 plans remains surprisingly low despite decades of availability.

The new Trump Accounts program is also receiving criticism from both sides politically.

Some conservatives argue the government is creating another unnecessary savings program when existing options already exist.

Some progressives argue wealthier families will benefit most because they are the ones most likely to afford the additional annual contributions.

Financial advisors acknowledge that reality.

Families with higher incomes and the ability to consistently invest thousands of dollars annually are likely to see the greatest long-term gains from either program.

There are also investment differences between the accounts.

529 plans generally offer a wide variety of investment options, including age-based funds that automatically become more conservative as children approach college age.

Trump Accounts are expected to be more limited, with investments largely tied to broad stock index funds.

Some planners say that makes 529s easier for families specifically targeting college savings timelines.

Still, many advisors say the Trump Accounts could help introduce more Americans to long-term investing — especially families who otherwise might never open a dedicated savings account for their children.

The $1,000 federal deposit guarantees every eligible child begins life with at least some invested savings, regardless of family income.

Whether families continue contributing beyond that initial deposit may ultimately determine how meaningful the program becomes.

For now, financial planners say the main takeaway for parents is straightforward:

  • If college savings is the priority, 529 plans usually provide the strongest tax benefits.
  • If families want broader long-term savings flexibility, Trump Accounts may add value.
  • And for many households, simply starting to save consistently matters more than choosing the “perfect” account.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Wall Street banks are moving to clean up billions of dollars in debt tied to Warner Bros. Discovery as Paramount’s massive takeover of the company moves closer to completion.

For everyday consumers, the story is really about how expensive today’s media industry has become — and how streaming wars, mergers and rising interest rates are forcing entertainment giants to constantly refinance huge piles of debt just to keep growing.

JPMorgan Chase and a group of major banks launched a $6.2 billion loan sale Tuesday tied to Warner Bros. Discovery, the parent company of HBO, CNN, Discovery Channel and Warner Bros. studios.

The money will help refinance existing loans and prepare for Paramount Skydance’s planned acquisition of Warner Bros. Discovery, a deal that could create one of the largest entertainment companies in the world.

If completed, the merger would combine brands including:

  • HBO
  • CNN
  • Warner Bros.
  • DC Studios
  • Paramount Pictures
  • CBS
  • Showtime
  • Nickelodeon
  • MTV

The combined company would instantly become one of the biggest competitors to Netflix and Disney in streaming and entertainment.

But the deal also comes with enormous debt.

Warner Bros. Discovery alone already carries roughly $33 billion in debt, much of it left over from the company’s earlier merger between Discovery and WarnerMedia in 2022.

That debt has weighed heavily on the company for years, forcing cost cuts, layoffs, canceled projects and aggressive spending reductions across parts of the media business.

The new financing effort is designed to spread out repayment obligations over a longer period and reduce short-term pressure ahead of the merger closing.

The timing is important because borrowing money has become much more expensive.

Interest rates have surged over the past two years as inflation and global economic uncertainty pushed bond yields sharply higher. On Tuesday, long-term U.S. Treasury yields briefly hit their highest levels in nearly two decades.

That means companies now pay far more to borrow than they did during the ultra-low-rate years when many media mergers were originally structured.

Banks appear eager to lock in financing now before conditions potentially worsen further.

The broader entertainment industry is still struggling to adjust after years of rapid streaming expansion.

Media companies spent enormous amounts of money launching streaming platforms to compete with Netflix, but many underestimated how difficult it would be to make those services profitable.

As a result, several major entertainment companies are now under pressure to consolidate, cut costs and reduce debt.

Supporters of the Paramount-Warner deal argue the merger could create enough scale to compete more effectively against tech giants and streaming leaders.

Critics worry combining so many major media assets could reduce competition and increase concentration across television, film production and streaming.

The Justice Department is still reviewing the merger for potential antitrust concerns.

Regulators are expected to focus heavily on how much power the combined company would hold across movies, cable television, sports rights and streaming content.

Meanwhile, investors are closely watching whether banks can successfully sell the new loans at attractive rates.

A strong investor response would signal confidence that large media companies can still manage their debt burdens despite higher rates and industry uncertainty.

A weaker response could raise concerns about how much appetite investors still have for heavily leveraged entertainment companies.

For consumers, the merger itself may eventually affect everything from streaming prices and content availability to which shows and sports rights remain on which platforms.

For now, though, the immediate challenge is financial: cleaning up billions of dollars in debt before one of the biggest media mergers in years can officially close.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The British government is quietly exploring a new “invite-only” visa program aimed at attracting wealthy foreigners willing to invest at least £5 million — roughly $6.7 million — into the UK economy, as officials try to reverse a growing exodus of millionaires and global investors from London.

For everyday readers, the proposal highlights a growing reality facing governments worldwide: countries are increasingly competing for wealthy individuals, entrepreneurs and investment dollars as economic growth slows and public finances tighten.

Under the plan being discussed, wealthy foreigners who invest £5 million into approved British businesses or priority industries could receive residency rights and potentially qualify for permanent settlement after three years.

Unlike Britain’s old “golden visa” system, the new version would reportedly be far more selective.

Officials are considering an “invite-only” model where the government actively approaches approved investors through wealth advisers and family offices rather than opening applications broadly to anyone with enough money.

The proposal is still under discussion, but the shift marks a major reversal from Britain’s previous stance.

The UK shut down its earlier investor visa program in 2022 amid concerns that it allowed questionable foreign money — particularly from Russian oligarchs — to flow into British assets with limited oversight.

Now, however, British officials are increasingly worried about something else: wealthy people leaving the country.

The pressure intensified after the government abolished the UK’s long-standing “non-dom” tax system, which had allowed many wealthy foreign residents to shield overseas income from British taxes for years.

Since those tax changes took effect, advisers say many affluent individuals and business owners have relocated assets and residences to places like Dubai, Switzerland, Italy, Singapore and Portugal.

That outflow has raised concerns inside government about losing investment, spending, tax revenue and global talent.

The proposed investor visa appears designed to slow that trend while avoiding some of the political backlash tied to the earlier program.

Property purchases would reportedly not qualify under the new system, meaning investors would need to place money into businesses, infrastructure or other targeted sectors instead of simply buying luxury London real estate.

That distinction is important because soaring housing prices became one of the biggest criticisms of “golden visa” programs across Europe.

Several countries — including Spain, Portugal and Ireland — have recently scaled back or eliminated similar residency-by-investment programs after public anger over housing affordability and concerns about wealthy foreigners buying access to residency.

Britain’s proposed £5 million threshold would also rank among the highest in the world.

For comparison:

  • The U.S. EB-5 investor visa requires roughly $1 million.
  • Portugal’s program starts around €500,000.
  • Greece ranges from roughly €250,000 to €800,000.

At £5 million, Britain would clearly target ultra-high-net-worth individuals rather than a broader investor market.

Supporters argue the UK still holds major advantages for wealthy global investors, including London’s financial system, elite schools, strong legal protections and extensive international business connections.

Critics, however, say offering special residency paths to the ultra-wealthy while tightening immigration rules for everyone else could become politically explosive.

The UK has simultaneously moved toward stricter immigration requirements for many workers and migrants, including tougher language rules and longer timelines for permanent residency.

That contrast could make the proposed investor visa highly controversial if formally introduced.

Still, economic pressures may be pushing policymakers toward compromise.

Britain’s economy has struggled with slower growth, rising debt pressures and weaker business investment in recent years. Officials increasingly fear that losing wealthy residents and entrepreneurs to competing countries could worsen those problems.

For now, the investor visa remains under review, and no final legislation has been introduced.

But the discussions themselves signal how aggressively governments are now competing for global wealth — especially as mobile millionaires gain increasing leverage over where they choose to live, invest and pay taxes.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Jensen Huang Calls AI Buildout “Largest Infrastructure Expansion in Human History” as Nvidia Extends Dominance Across Global AI Market

NEW YORK — Nvidia Corp. delivered another massive earnings beat Wednesday after the closing bell, reporting fiscal first-quarter revenue of $81.62 billion and forecasting second-quarter sales of approximately $91 billion, well ahead of Wall Street expectations as demand for artificial-intelligence infrastructure continued accelerating across the global economy.

The results reinforced Nvidia’s position at the center of the AI investment boom now reshaping technology, cloud computing, enterprise software, and global infrastructure spending.

According to the company’s quarterly earnings release issued Wednesday afternoon, revenue surged 85% year-over-year from $44.06 billion, topping analyst expectations near $79 billion.

Adjusted earnings came in at approximately $1.87 per share, above Wall Street estimates that had generally clustered between $1.77 and $1.78 per share.

The company’s all-important Data Center division generated $75.2 billion in revenue, significantly exceeding analyst forecasts and continuing to confirm extraordinary demand for Nvidia’s AI chips, networking systems, and rack-scale computing infrastructure.

Nvidia also announced an additional $80 billion share repurchase authorization and raised its quarterly dividend to $0.25 per share, signaling growing confidence from management that the current AI spending cycle remains in its early stages.

The biggest headline for Wall Street, however, was Nvidia’s forward guidance.

The company projected second-quarter revenue of approximately $91 billion, plus or minus 2%, far above consensus forecasts that had settled near $87 billion.

Even some of the market’s most bullish projections had struggled to reach the $91 billion level, making the guidance one of the strongest signals yet that AI infrastructure spending continues accelerating faster than many investors expected.

“The buildout of AI factories — the largest infrastructure expansion in human history — is accelerating at extraordinary speed,” said Jensen Huang, Nvidia’s founder and chief executive officer.

“Agentic AI has arrived, doing productive work, generating real value and scaling rapidly across companies and industries,” Huang added.

The results answered one of Wall Street’s biggest questions surrounding the AI trade: whether the enormous capital expenditures announced by major technology companies are fully translating into real revenue growth for Nvidia.

The answer appears to be yes.

Major cloud providers including Microsoft Corp., Amazon.com Inc., Alphabet Inc., and Meta Platforms Inc. are collectively expected to spend hundreds of billions of dollars on AI infrastructure, chips, networking, and data-center expansion over the coming years.

Wednesday’s report strongly suggested that spending wave is not slowing.

One particularly strong area inside the earnings report was Nvidia’s networking business.

Networking revenue surged to approximately $14.8 billion, significantly above analyst expectations, reflecting soaring demand for Nvidia’s NVLink systems and AI networking infrastructure used to connect massive GPU clusters powering generative AI systems.

The report also showed Nvidia increasingly evolving beyond simply selling chips.

Wall Street analysts have increasingly viewed Nvidia as an end-to-end AI infrastructure company supplying complete AI computing systems, networking fabrics, rack-scale architectures, and software ecosystems rather than only GPUs.

That broader positioning continues strengthening Nvidia’s competitive advantage across the AI industry.

The company’s commentary surrounding its upcoming Vera Rubin platform also drew major investor attention.

Huang has repeatedly emphasized that demand for Nvidia’s next-generation AI systems continues building rapidly as corporations, governments, and cloud providers race to expand AI capabilities.

At Nvidia’s GTC conference earlier this year, Huang projected combined demand across Nvidia’s Blackwell and Vera Rubin product cycles could eventually reach roughly $1 trillion over multiple years — one of the most aggressive infrastructure forecasts ever issued by a major technology executive.

China remained one of the few unresolved areas inside the report.

Nvidia continues facing restrictions tied to advanced AI-chip exports into China following U.S. government export controls, and the company said current guidance still assumes minimal contribution from the Chinese data-center market.

Any future loosening of export restrictions could provide additional upside beyond current forecasts.

Despite the strong report, Nvidia shares initially traded lower in after-hours trading before stabilizing as investors absorbed the guidance, buyback announcement, and margin outlook.

The temporary volatility reflected growing investor expectations surrounding Nvidia earnings after the company repeatedly exceeded Wall Street forecasts throughout the AI boom.

The broader implications extend far beyond Nvidia itself.

Suppliers including Taiwan Semiconductor Manufacturing Co., Micron Technology, SK Hynix, and Broadcom Inc. stand to benefit directly from continued AI infrastructure demand, while utilities, data-center developers, construction firms, fiber providers, and power-equipment companies are also increasingly tied to the AI expansion cycle.

The spending boom is also beginning to affect the broader labor market and real economy.

Construction of AI data centers across states including Texas, Virginia, and Arizona is driving demand for electricians, HVAC specialists, fiber installers, engineers, security personnel, and skilled construction workers as companies race to build the physical infrastructure required to support next-generation AI systems.

At the same time, rising power consumption tied to AI infrastructure is beginning to place additional strain on utility grids and long-term energy planning across multiple regions.

For investors, Wednesday’s earnings report reinforced the central market narrative driving much of the current technology rally: the global AI infrastructure cycle not only remains intact, but may still be accelerating.

The next major focus for Wall Street now shifts toward Nvidia’s conference call commentary surrounding production capacity, Blackwell rollout timing, enterprise AI demand, networking growth, and any potential developments tied to China export policy.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Stocks Rally, Oil Slides as Iran Talks Advance and Markets Brace for Nvidia Earnings After the Bell

NEW YORK — U.S. stocks rallied sharply Wednesday while oil prices fell as investors reacted to signs of progress in negotiations with Iran, easing fears of prolonged energy-market disruption and shifting Wall Street’s focus toward Nvidia Corp.’s closely watched earnings report due after the closing bell.

The Dow Jones Industrial Average surged more than 645 points, or 1.31%, while the S&P 500 gained 1.08% and the tech-heavy Nasdaq Composite climbed 1.54%, according to market data Wednesday afternoon. The broad rally snapped a recent stretch of market weakness driven by surging Treasury yields, geopolitical uncertainty, and concerns over the Federal Reserve’s policy outlook.

Oil prices posted one of their sharpest declines in recent weeks as traders grew more optimistic that tensions surrounding shipping routes through the Strait of Hormuz could ease if diplomatic negotiations continue progressing.

West Texas Intermediate crude fell 5.66% to settle near $98.26 per barrel, while Brent crude dropped 5.63% to approximately $105.02 per barrel.

The move marked a sharp reversal from earlier this week, when fears surrounding the Iran conflict and shipping disruptions pushed energy prices higher and added renewed inflation concerns across global markets.

Treasury yields also eased Wednesday after climbing earlier in the week to some of their highest levels in months. The benchmark 10-year Treasury yield pulled back after recently pushing above 4.13%, helping stabilize broader equity sentiment.

Wall Street’s attention now shifts almost entirely to Nvidia Corp., one of the world’s most valuable companies and the central driver of the artificial-intelligence investment boom that has powered markets over the past two years.

Nvidia is scheduled to report fiscal first-quarter earnings after the closing bell, with investors closely watching both revenue growth and forward guidance tied to AI infrastructure spending.

Options markets are implying one of the largest post-earnings swings in corporate history, with traders pricing in hundreds of billions of dollars in potential market-value movement following the report.

Analysts expect Nvidia to report approximately $78.8 billion in revenue alongside adjusted earnings of roughly $1.77 per share, driven primarily by continued explosive demand for AI chips and data-center infrastructure.

Wall Street remains focused on the company’s Blackwell architecture and future Vera Rubin platform, both viewed as critical to the next phase of enterprise AI expansion.

Jensen Huang, Nvidia’s founder and chief executive officer, has repeatedly emphasized that demand for AI infrastructure continues significantly outpacing supply as corporations, governments, and cloud providers race to expand computing capacity.

Shares of Nvidia rose roughly 2% during Wednesday’s regular trading session ahead of the report.

The retail sector also helped support market sentiment.

Lowe’s Cos. reported quarterly results ahead of Wall Street expectations, posting first-quarter revenue of approximately $23.1 billion and adjusted earnings per share of $3.03, topping analyst forecasts.

“Strong spring execution and continued momentum in Pro, Appliances, Online, and Home Services supported a solid start to the year,” said Marvin R. Ellison, Lowe’s chairman, president and CEO.

Comparable sales rose modestly while online sales jumped more than 15%, signaling continued resilience in consumer spending despite elevated borrowing costs and inflation pressure.

Target Corp. also exceeded expectations, reporting stronger-than-expected quarterly earnings and raising portions of its full-year outlook, adding to optimism surrounding consumer demand.

The strong retail earnings helped counter concerns that elevated energy prices and higher interest rates were severely weakening household spending.

Meanwhile, Federal Reserve policy remained a major focus for investors throughout the session.

Minutes released Wednesday from the Federal Open Market Committee’s April meeting showed several policymakers discussing the possibility that additional interest-rate increases could become necessary if inflation remains persistently above the Fed’s 2% target.

The minutes revealed growing divisions inside the central bank, with some officials favoring a more hawkish policy posture due to elevated energy prices, tariffs, and inflation risks tied to geopolitical instability.

Markets have increasingly scaled back expectations for near-term rate cuts as inflation remains stubbornly above target and labor-market conditions continue holding relatively firm.

Several Wall Street firms have recently revised forecasts, now expecting the Federal Reserve to maintain restrictive policy for longer than previously anticipated.

Cross-asset trading reflected the broader shift in sentiment Wednesday.

The U.S. dollar remained firm following the Fed minutes, while gold continued attracting safe-haven demand despite the broader equity rally. Bitcoin traded relatively stable as risk appetite improved across financial markets.

For consumers and businesses, Wednesday’s market action delivered mixed but important signals.

Falling oil prices could eventually provide some relief at the gasoline pump if geopolitical tensions continue easing and global shipping routes stabilize. At the same time, the Federal Reserve’s increasingly hawkish tone suggests borrowing costs for mortgages, credit cards, auto loans, and business financing are unlikely to decline meaningfully in the near future.

The next major test for markets now rests almost entirely on Nvidia’s earnings report and forward guidance.

A strong beat-and-raise from Nvidia could reinforce investor confidence in the broader artificial-intelligence trade and potentially drive another leg higher in technology stocks. A weaker-than-expected outlook, however, could test a market already navigating elevated interest rates, geopolitical uncertainty, and increasingly cautious Federal Reserve messaging.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

FOMC Record Reveals Growing Divide Over Policy Path as Energy Prices and Tariffs Keep Inflation Risks Elevated

WASHINGTON — Federal Reserve officials warned during their April policy meeting that additional interest-rate increases could become necessary if inflation remains persistently above the central bank’s 2% target, according to minutes released Wednesday that revealed growing divisions inside the Federal Open Market Committee over the future direction of monetary policy.

The minutes from the Fed’s April 28–29 meeting showed several policymakers pushing to remove language in the post-meeting statement that implied an easing bias, while others argued rate cuts could still become appropriate if inflation cools as expected.

“A number of participants indicated that upward adjustments to the target range for the federal funds rate could be appropriate if inflation remained above-target levels,” the minutes stated, reflecting a more hawkish tone than many investors had anticipated.

The committee voted at that meeting to keep the benchmark federal funds rate unchanged at 3.50% to 3.75%, extending the Fed’s holding pattern as officials continue balancing stubborn inflation pressures against slowing areas of the economy.

The minutes revealed one of the sharpest internal policy divides on the committee in years.

Several officials argued the Fed should remove language suggesting future easing bias from official statements, citing ongoing inflation risks tied to elevated global energy prices, persistent tariff pressures, and uncertainty surrounding the economic fallout from the escalating U.S.-Iran conflict.

Others on the committee maintained that inflation could gradually cool over time and said future rate cuts may still become appropriate if economic conditions weaken and price pressures ease.

The debate underscores how significantly the inflation outlook has shifted in recent months.

Fed officials repeatedly cited higher energy prices and geopolitical instability as key concerns, particularly as tensions in the Middle East continue placing pressure on global oil markets and supply chains. Policymakers also discussed the inflationary effects of tariffs and broader trade-policy uncertainty, warning that prolonged price shocks may become more deeply embedded across the economy.

The minutes suggested some officials are increasingly concerned that the Fed may need to keep monetary policy restrictive for longer than markets currently expect.

One of the clearest signs of the shift came in discussions surrounding the committee’s forward guidance. Several policymakers reportedly favored adopting more “two-sided” language that would explicitly acknowledge the possibility of future rate hikes if inflation fails to moderate.

Markets reacted cautiously following the release.

Treasury yields remained elevated while traders trimmed expectations for future rate cuts. Currency markets also reflected the more hawkish tone, with the U.S. dollar strengthening as investors reassessed the likelihood of policy easing over the coming year.

The release comes as Wall Street increasingly debates whether the Fed’s next move will ultimately be another rate cut — or whether persistent inflation could force policymakers back toward tightening.

Recent inflation data has complicated the outlook.

Consumer prices have remained above the Fed’s target despite slowing from peak levels reached during earlier inflation surges. Elevated energy prices tied to instability in the Middle East, alongside lingering tariff-related pressures and resilient consumer spending, have made it more difficult for officials to declare victory over inflation.

At the same time, labor-market conditions have remained relatively stable, reducing urgency for immediate easing. Unemployment has remained near historically low levels while wage growth and consumer demand continue supporting broader economic activity.

The minutes also highlighted concerns surrounding the inflationary impact of trade policy.

Officials noted that tariff-related cost pressures may be lasting longer than initially expected, complicating the Fed’s traditional approach of looking through temporary price shocks. Some policymakers warned that sustained increases in energy and goods prices could begin feeding more broadly into services inflation and long-term inflation expectations.

Research analysts and economists increasingly say the central bank faces a more difficult balancing act than previously anticipated.

Several Wall Street firms have already revised forecasts for future rate cuts, with some now projecting the Fed could remain on hold well into next year if inflation remains elevated.

For consumers and businesses, the implications are significant.

Mortgage rates, auto loans, commercial borrowing costs, and credit-card APRs remain elevated under the Fed’s restrictive policy stance, and any renewed discussion of future hikes could keep financing conditions tight for households and businesses alike.

The next major tests for policymakers will come from upcoming inflation, GDP, and labor-market reports, which are expected to heavily influence the tone of the Fed’s next meeting and shape expectations for the remainder of the year.

For now, Wednesday’s minutes made one point increasingly clear: while markets have spent months focusing on when the Federal Reserve may eventually cut rates, a growing number of policymakers are no longer ruling out the possibility that inflation could force the conversation back toward hikes.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The Pentagon is rapidly shifting toward a new kind of warfare: cheaper, AI-powered attack drones that can overwhelm enemies in large numbers instead of relying only on billion-dollar weapons systems.

The Defense Department announced Tuesday that it selected defense startup Shield AI to provide the autonomous software for a new low-cost drone program designed around swarms of expendable attack drones that can operate together with limited human control.

For everyday Americans, the story highlights how modern wars are changing — and why the U.S. military is increasingly investing in artificial intelligence and lower-cost weapons after seeing how devastating cheap drones have become in the Iran conflict.

The new Pentagon system, called LUCAS, is built around small one-way attack drones costing roughly $35,000 each. That is dramatically cheaper than traditional American missiles, some of which cost more than $1 million per shot.

Shield AI’s software, known as Hivemind, acts like an “AI pilot,” allowing groups of drones to coordinate attacks, avoid threats and continue missions even if communications are jammed or disrupted.

“It’s cheaper to destroy a target, but it’s also keeping our war fighters safer,” Shield AI co-founder Brandon Tseng said in an interview with CNBC.

The push comes after the Iran war exposed a major military reality: inexpensive drones can inflict enormous damage against far more expensive systems.

Iran’s Shahed drones — low-cost exploding drones used heavily throughout the conflict — have successfully struck military installations, infrastructure and energy facilities across the Middle East. Some attacks caused billions of dollars in damage using weapons that cost only a tiny fraction of the targets they hit.

That has forced Pentagon planners to rethink decades of military strategy.

Instead of depending mostly on advanced fighter jets, destroyers and high-end missiles, the military is increasingly preparing for future conflicts where thousands of smaller autonomous systems flood battlefields simultaneously.

The Pentagon reportedly moved unusually fast on the LUCAS program, taking it from development to combat deployment in less than a year — far quicker than traditional military procurement timelines that often take many years.

The shift is also transforming the defense industry itself.

For decades, giant contractors like Lockheed Martin, RTX and Northrop Grumman dominated Pentagon spending. Now venture-backed technology startups like Shield AI and Anduril are rapidly gaining ground by focusing on AI software, autonomous drones and lower-cost weapons.

Shield AI recently reached a valuation of roughly $12.7 billion as investor interest in military AI companies surged following the Iran conflict.

The Pentagon has also announced additional contracts tied to low-cost missile and drone systems as military leaders race to expand production capacity.

Analysts say the economic logic behind the shift is difficult to ignore.

A swarm of cheap autonomous drones can potentially overwhelm air defenses and destroy targets at a fraction of the cost required to stop them. That creates a dangerous imbalance where defending against attacks may become far more expensive than launching them.

The U.S. military now appears determined to build that capability for itself rather than risk falling behind adversaries already deploying large numbers of autonomous systems.

The Trump administration has strongly backed the effort, including through expanded missile defense and drone initiatives designed to speed up weapons development and manufacturing.

Supporters argue AI-powered systems could reduce risks to American troops while allowing the military to respond faster and more cheaply during future conflicts.

Critics, however, continue warning about the growing role of artificial intelligence in warfare, especially systems capable of making battlefield decisions with reduced human oversight.

Still, momentum inside the Pentagon is clearly accelerating.

Defense experts say the battlefield lessons from Iran, Ukraine and other recent conflicts have convinced military planners that autonomous drone warfare is no longer experimental technology — it is becoming the future of combat.

And for companies like Shield AI, the war-driven demand surge is rapidly turning Silicon Valley defense startups into some of the most important new players in the global arms industry.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Stocks may still have room to climb even if the Federal Reserve raises interest rates again — at least according to one closely watched market technician who says the AI-driven rally has not yet broken down.

Todd Gordon, founder of Inside Edge Capital and longtime CNBC market analyst, said Tuesday that the stock market’s biggest risk right now is not necessarily a small Fed rate hike itself, but whether inflation expectations spiral higher because of the Iran war and rising oil prices.

For everyday investors, the message is important: Wall Street is debating whether the current AI boom can continue even in a higher-interest-rate environment.

Markets have become increasingly nervous in recent weeks as Treasury yields surged sharply higher. The 30-year Treasury yield briefly climbed above 5.19% Tuesday — its highest level in nearly two decades — while investors have largely abandoned hopes for Fed rate cuts this year.

Higher yields matter because they increase borrowing costs throughout the economy, including mortgages, credit cards, business loans and corporate financing. They also tend to pressure high-growth technology stocks, whose valuations often rely on expectations of future earnings.

Despite that, Gordon believes the broader bull market remains intact for now.

His analysis focuses heavily on inflation expectations, especially a market measure known as the two-year breakeven inflation rate. According to Gordon, the critical line is roughly 2.98%.

If inflation expectations stay below that level, he believes the market can likely handle modest additional tightening from the Federal Reserve without collapsing the AI-driven rally.

“If expected inflation remains contained, I see little reason to expect the growth trade to break down,” Gordon wrote in a note for CNBC Pro.

Much of the debate centers on oil prices and the Iran conflict.

Since the war began earlier this year, crude oil prices have remained elevated, fueling concerns that inflation could reaccelerate just as the Federal Reserve hoped price pressures were cooling.

If tensions ease and oil prices fall back toward more normal levels, analysts believe inflation fears could fade and allow stocks — especially AI and technology companies — to continue climbing.

But if the conflict escalates further and oil prices spike again, investors worry the Fed could be forced into a tougher stance that would hurt markets more broadly.

Gordon’s bullish case also rests on a major technical chart pattern involving the Nasdaq and S&P 500.

He noted that the Nasdaq-to-S&P ratio is testing a key resistance level that has only appeared twice before in modern market history — once during the dot-com bubble in 2000 and again before the 2022 tech selloff.

Technical analysts often view repeated tests of major market levels as signals that a powerful breakout could eventually occur.

Gordon believes the current setup could potentially resolve upward if inflation pressures stabilize.

Still, there are warning signs.

Some growth indicators are no longer rising as strongly as major AI stocks themselves, suggesting parts of the rally may be narrowing beneath the surface. Analysts say that can sometimes happen late in strong bull markets.

Meanwhile, other economists argue the real danger may not come directly from the Fed, but from growing stress inside the bond market itself.

Foreign governments including Japan and China recently reduced their holdings of U.S. Treasurys as they defended their own currencies against rising energy costs tied to the war. Weak demand at several recent Treasury auctions has also pushed yields higher.

That creates a separate challenge for markets because borrowing costs can continue rising even without direct Fed action.

Some analysts now warn the Fed risks losing control of inflation expectations if it appears too slow to respond to higher energy-driven inflation.

For investors, the next major test arrives this week with Nvidia’s earnings report, one of the most closely watched events in global markets because Nvidia has become the centerpiece of the AI boom driving much of the stock market’s gains.

Strong results could reinforce the bullish AI narrative and help stocks recover despite rising rates. Weak guidance, however, could increase fears that the market has become too dependent on a handful of technology giants.

For now, Wall Street remains caught between two powerful forces: surging enthusiasm around artificial intelligence and growing fears that inflation and higher interest rates may eventually slow the rally down.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Federal tax returns filed by President Donald Trump, his family, the Trump Organization, and related entities are now shielded from future Internal Revenue Service enforcement tied to past filings under a newly revealed addendum to the administration’s controversial $1.8 billion settlement with the Justice Department.

The one-page document, signed Monday by Acting Attorney General Todd Blanche — Trump’s former criminal defense attorney — bars the IRS and Treasury Department from “prosecuting or pursuing any and all claims” tied to tax returns filed before the agreement took effect.

The language extends far beyond Trump personally.

According to the addendum, protections apply not only to Trump, Donald Trump Jr., Eric Trump, and the Trump Organization, but also to related trusts, affiliates, subsidiaries, and associated companies. The agreement further references protections against claims tied to alleged “Lawfare and/or Weaponization,” language closely aligned with Trump’s long-running accusations that federal agencies were politically weaponized against him.

The addendum emerged publicly Tuesday after initial reporting by Politico and immediately intensified criticism surrounding the broader settlement announced earlier this week.

The Justice Department has defended the arrangement as standard settlement practice.

A DOJ spokeswoman told CNBC the protections apply only to audits or enforcement actions tied to existing tax matters already under review prior to the settlement date, not future tax filings.

“As is customary in settlements, both sides executed waivers covering claims that could have been pursued previously,” the spokeswoman said, arguing the agreement was designed to fully resolve ongoing disputes rather than leave either side vulnerable to additional litigation tied to the same underlying issues.

Still, former IRS officials and ethics experts say the arrangement appears unprecedented in scope.

Former IRS Commissioner Daniel Werfel, who led the agency during the Biden administration, said he was unaware of any modern example in which the IRS permanently agreed to halt examination or enforcement activity involving previously filed returns tied to a sitting president or major business organization.

“Whether you are the president or Joe the Plumber, people expect the same tax rules and enforcement framework to apply to everybody,” Werfel told reporters.

The tax protections significantly expand the known scope of the broader agreement disclosed Monday.

Under that deal, the Justice Department agreed to resolve Trump’s massive lawsuit against the federal government while establishing a $1.776 billion “Anti-Weaponization Fund,” named symbolically after the year 1776. The fund is intended to compensate individuals the administration argues were victims of politically motivated investigations or prosecutions during prior administrations.

Trump himself will reportedly receive a formal government apology but no direct personal payment.

The origins of the case trace back to the leak of Trump’s confidential tax returns by former IRS contractor Charles Littlejohn, who was sentenced in 2024 after admitting he provided tax records to The New York Times and ProPublica. Thousands of additional taxpayers were also affected by the broader leak.

Trump filed the original lawsuit earlier this year as a private citizen, alleging the IRS and Treasury Department failed to safeguard confidential taxpayer information.

The newly disclosed settlement language has triggered immediate backlash from Democrats and government watchdog organizations.

Senate Minority Leader Chuck Schumer called the arrangement “a get-out-of-jail-free card,” arguing Trump effectively used the Justice Department he now oversees to secure extraordinary protections for himself and his family.

Citizens for Responsibility and Ethics in Washington President Donald K. Sherman described the agreement as “the most brazen act of self-dealing in the history of the presidency,” arguing it could potentially violate constitutional ethics restrictions governing presidential financial benefit.

A group of 93 Democratic lawmakers has already moved to intervene in the case, warning in court filings that the settlement could improperly direct taxpayer funds toward political allies and entities connected to the president.

U.S. District Judge Kathleen Williams, who oversaw the litigation in federal court in Florida, formally closed the case Monday but openly questioned the unusual process surrounding the settlement.

In court remarks, Williams noted that federal agencies involved in the dispute had not submitted traditional settlement-review documents establishing whether the agreement appropriately resolved an active legal controversy.

Trump’s legal team argued the dismissal was “self-executing” and did not require further judicial review.

The political controversy expanded further Tuesday when Blanche, appearing before a Senate subcommittee, declined to rule out that the Anti-Weaponization Fund could potentially compensate individuals convicted in connection with the Jan. 6 Capitol riot.

Asked separately whether members of his own family could ultimately benefit from the fund, Trump told CBS News the decision would be determined by a committee overseeing distributions.

Some Republicans have publicly defended the concept.

Sen. Ron Johnson (R-Wis.) said he supports compensation for individuals harmed by government misconduct, arguing the federal government should be held financially accountable when agencies improperly target citizens.

Other Republicans have been more cautious, requesting additional details about how the fund would operate and who could ultimately qualify for compensation.

The broader legal posture of the Trump administration has already produced substantial settlements involving former Trump allies.

Former National Security Adviser Michael Flynn reportedly received more than $1 million under a separate settlement tied to FBI conduct allegations, while former Trump campaign adviser Carter Page also reached a surveillance-related settlement earlier this year.

But the scale and structure of the new agreement involving Trump’s own family and business empire remains without modern precedent.

For nearly a decade, Trump’s tax returns have remained one of the most politically contentious issues in American politics, fueling investigations, congressional battles, media scrutiny, and repeated accusations of unequal treatment by both supporters and critics.

Now, the debate is shifting from whether Trump’s returns should have been investigated — to whether a sitting president can effectively shield his own family and business network from future IRS enforcement tied to past filings.

The Justice Department did not immediately respond to additional requests for comment Tuesday evening.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Saks Global, the company that owns Saks Fifth Avenue, Neiman Marcus and Bergdorf Goodman, says it expects to emerge from bankruptcy next month after slashing stores, cutting jobs and securing new financing aimed at stabilizing one of America’s largest luxury retail groups.

For everyday shoppers, the story is less about Wall Street restructuring and more about what it means for the future of luxury department stores in the U.S.

The company plans to exit Chapter 11 bankruptcy protection in late June with roughly $700 million in available liquidity and a much smaller retail footprint, according to CEO Geoffroy van Raemdonck.

Saks Global filed for bankruptcy in January after mounting debt problems and inventory shortages left stores struggling to keep merchandise on shelves. Vendors had stopped shipping products because they feared the company would not be able to pay its bills.

Now the company says most major luxury brands have resumed shipments, helping stores refill inventory ahead of a critical second half of the year.

Nearly 720 brands are once again shipping products to Saks Global, including luxury labels tied to Gucci owner Kering, Chanel and LVMH.

The turnaround comes with major downsizing.

Saks Global is shutting down 20 Saks Fifth Avenue stores, four Neiman Marcus locations and most Saks Off 5th discount stores. More than 1,800 jobs have been eliminated across stores, warehouses and corporate offices.

Bergdorf Goodman’s flagship Manhattan stores will remain open.

The company says the goal is to focus on fewer, more profitable luxury locations instead of trying to operate a massive nationwide footprint.

“What the business plan will show is that we have a plan of action to drive sales, to grow from a smaller footprint, and to be significantly more profitable,” van Raemdonck said in a recent interview with Women’s Wear Daily.

The restructuring marks a dramatic reversal for what was supposed to become a dominant American luxury retail empire.

In 2024, former Hudson’s Bay Chairman Richard Baker combined Saks and Neiman Marcus into a single luxury giant in a deal valued at roughly $2.7 billion. The strategy was designed to help U.S. department stores compete against increasingly powerful European luxury brands and online shopping trends.

But slowing luxury demand, heavy debt and weakening consumer spending quickly overwhelmed the company.

By early 2025, suppliers had frozen shipments, inventory dried up and bankruptcy became unavoidable.

The restructured Saks Global now hopes to rebuild around full-price luxury shopping instead of heavy discounting and outlet-style retail.

That shift reflects broader changes happening across the luxury industry. Many high-end fashion brands increasingly prefer selling directly to wealthy consumers through their own stores and websites rather than relying heavily on department stores that frequently discount merchandise.

The company’s long-term financial goals remain ambitious.

Court filings project Saks Global could eventually reach roughly $9 billion in annual merchandise sales and return to profitability within several years if the restructuring succeeds.

Still, the environment remains difficult.

Luxury retailers are facing slowing global demand, rising import costs and growing economic uncertainty. While wealthier consumers have generally remained more resilient than middle-income shoppers, analysts say luxury spending often weakens later in economic downturns.

The company is also betting that affluent customers will continue shopping in physical stores despite years of consumer migration toward online retail.

For now, the immediate focus is survival.

If Saks Global successfully exits bankruptcy in June, it would mark one of the fastest major retail restructurings in recent years and give the company a chance to rebuild before the critical holiday shopping season later this year.

Whether shoppers fully return — and whether luxury brands maintain confidence in the company long term — will likely determine whether the Saks-Neiman Marcus combination ultimately becomes a successful turnaround story or another cautionary tale in the changing American retail landscape.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Elon Musk said this week that Tesla’s driverless ride-hailing service will be “widespread in the U.S. by the end of this year,” reviving one of the company’s most ambitious — and repeatedly delayed — promises. But the traders risking real money on those timelines are increasingly betting against him.

Prediction markets tracking Tesla’s autonomy rollout continue pricing low odds that the company can deliver fully unsupervised robotaxi service at meaningful scale within the timeframes Musk publicly describes.

On Polymarket, one of the largest prediction platforms, traders currently assign Tesla roughly a 13% chance of launching unsupervised robotaxi operations in California by June 30. Another contract tied to a nationwide unsupervised Full Self-Driving rollout by the same deadline has generated more than $1 million in trading volume, with bettors sharply divided over whether Tesla can achieve the milestone.

The divide reflects a growing disconnect between Musk’s public optimism and the regulatory, technical, and operational hurdles still facing Tesla’s autonomous-driving ambitions.

At the center of the skepticism is California.

Tesla has not yet filed for the autonomous deployment permits required by the California Department of Motor Vehicles for fully driverless commercial ride-hailing operations. Under current state rules, companies must complete tens of thousands of supervised autonomous testing miles before qualifying for broader deployment approval.

Public records currently show no such qualifying Tesla miles reported under California’s driverless permitting system.

Tesla’s limited Bay Area transportation service launched earlier this year operates under a Transportation Charter Permit — the same regulatory category used for traditional human-driven car services — rather than a driverless autonomous permit.

California regulators are also tightening oversight beginning July 1, when new rules allowing police officers to directly cite autonomous vehicles for violations take effect.

That combination of regulatory delay and operational complexity has fueled growing skepticism among investors and industry analysts about how quickly Tesla can scale.

Even Tesla’s own filings have become more cautious.

The company’s first-quarter shareholder materials quietly softened earlier promises regarding robotaxi expansion. Several cities previously expected to launch autonomous operations during the first half of 2026 — including Phoenix, Miami, Orlando, Tampa, and Las Vegas — were shifted into a broader “preparations underway” category rather than firm rollout deadlines.

Only Dallas and Houston currently operate limited unsupervised Tesla robotaxi service.

And even there, scale remains relatively small.

Public tracking estimates suggest Tesla currently operates fewer than 40 unsupervised robotaxis across Austin, Dallas, and Houston combined, up from fewer than 10 vehicles at the start of April.

The growth trajectory is notable, but still far below what most investors would consider a nationwide rollout.

By comparison, Waymo, the autonomous-driving company backed by Alphabet, already operates fully driverless commercial ride services across multiple major U.S. cities, including Phoenix, San Francisco, Los Angeles, Miami, and Austin.

Tesla executives themselves have acknowledged that major scaling may depend on future software generations that are not yet available.

During the company’s latest earnings call, Musk pointed investors toward the next-generation Full Self-Driving platform, known internally as version 15, as a critical milestone for broader robotaxi deployment. He suggested the software could become available by early 2027.

Chief Financial Officer Vaibhav Taneja also tempered expectations, warning investors that robotaxi revenue would likely remain immaterial through much of 2026 while capital expenditures continue rising sharply.

Tesla expects to spend more than $25 billion this year while continuing to generate negative free cash flow.

Insider trading activity has also reflected a more cautious posture than Musk’s public messaging.

Tesla director Kathleen Wilson-Thompson sold shares during multiple periods since February, while Taneja also sold stock earlier this year near recent highs.

The financial stakes surrounding autonomy are enormous.

Tesla’s valuation increasingly depends less on its traditional vehicle business and more on investor belief that the company can dominate autonomous transportation and robotics.

Shares recently traded near $428, leaving Tesla with valuation multiples far above nearly every major automaker globally. Analysts estimate that a large portion of Tesla’s current market capitalization reflects expectations tied specifically to robotaxis and the company’s Optimus humanoid robotics program rather than its existing automotive operations alone.

That dynamic helps explain why autonomy timelines matter so much to investors.

If Tesla successfully scales driverless transportation nationally, the financial upside could be massive. Morgan Stanley estimates the broader autonomous vehicle economy could eventually generate trillions of dollars in annual revenue globally.

But the market for commercial robotaxis remains extremely early and highly uncertain.

The widening gap between Musk’s timelines and prediction-market odds has become so common inside Silicon Valley that it has earned its own nickname: “Elon Time.”

Musk himself has acknowledged the criticism before, once describing himself as “pathologically optimistic with time.”

The pattern stretches back years.

In 2019, Musk told investors he was “very confident” Tesla would deploy fully autonomous vehicles by 2020. Similar timelines were repeated repeatedly through 2025 before Tesla’s first limited robotaxi rollout eventually arrived in Austin last year under far more restricted conditions than initially promised.

Many prediction-market traders appear increasingly unwilling to take Musk’s deadlines at face value.

Last year, bettors reportedly lost millions wagering on earlier Tesla autonomy timelines after Musk publicly encouraged confidence in the company’s progress.

This time, many appear to be betting against him instead.

Tesla did not respond to requests for comment regarding the prediction-market skepticism or its broader rollout timeline.

The company’s next major test with investors will likely arrive alongside second-quarter delivery results, where analysts remain closely focused on slowing EV demand, shrinking margins, rising competition, and whether Tesla can continue convincing Wall Street that its future ultimately lies not in cars — but in autonomy.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Google is changing the internet’s most famous search bar.

At its annual developer conference Tuesday, the company unveiled the biggest redesign of Google Search in years, transforming the simple search box millions use every day into something much closer to an AI assistant that can answer questions, complete tasks and even work on projects for users automatically.

For everyday consumers, the shift signals a major change in how people may use the internet going forward — and how aggressively Google is trying to compete with ChatGPT, Claude and other AI tools that are rapidly changing online behavior.

Instead of typing a few keywords and getting a list of blue links, users will increasingly interact with Google more like they chat with an AI assistant.

The new search experience allows people to ask longer, conversational questions, create AI “agents” that track tasks over time and even delegate ongoing work directly through Google.

The overhaul is powered by Google’s newest AI model, Gemini 3.5 Flash, which is becoming the core engine behind the company’s expanding AI features.

Google executives framed the redesign as the next evolution of search itself.

The company is betting that people increasingly want answers and completed tasks — not just links to websites.

Some examples of what the new AI-powered Google can do:

  • Monitor topics over time
  • Summarize emails and documents
  • Create to-do lists
  • Research products
  • Track recurring tasks
  • Work across Gmail, Google Docs and Slides
  • Continue working even after users close their devices

Google is also introducing a feature called “Spark,” which acts more like a persistent digital assistant capable of operating in the background over extended periods.

The changes reflect how quickly the AI race has intensified.

For the first time in its history, Google faces a serious threat to its core search business from AI competitors.

OpenAI’s ChatGPT, Anthropic’s Claude and AI-native search startups like Perplexity have increasingly pulled users away from traditional Google searches, especially for research, coding and information-heavy questions.

That has created enormous pressure inside Google to reinvent search before competitors redefine how people access information online.

Despite those threats, Google says overall search activity continues growing.

Still, the company clearly recognizes that the format of search is changing rapidly.

For decades, Google made money by showing users links alongside advertisements. AI-generated answers could disrupt that model because users may no longer need to click through to websites as often.

That creates a delicate balancing act for Alphabet, Google’s parent company:

  • Push aggressively into AI
  • While protecting the advertising business that generates most of its profits

The company also faces another challenge: trust.

AI assistants remain imperfect and can still make mistakes, misunderstand requests or provide incorrect information.

Even Google executives acknowledged the technology is not yet fully reliable enough for users to completely trust autonomous AI agents with important tasks.

Still, the industry is moving rapidly in this direction.

OpenAI, Google, Anthropic and Microsoft are all racing to create AI systems that function more like full digital assistants rather than standalone chatbots.

The companies increasingly envision a future where AI continuously helps manage schedules, communications, research, shopping and everyday work in the background.

For consumers, that could eventually make computers and phones feel less like tools people manually operate — and more like systems actively helping them complete tasks automatically.

The speed of competition has become extreme.

Google executives said some internal AI teams now release updates nearly every day to keep pace with rivals.

The pressure is especially intense because whoever becomes the dominant AI assistant platform could control the next generation of internet behavior — much like Google Search dominated the last one.

The rollout of Google’s new AI search features will happen gradually over the coming months, with some advanced capabilities initially limited to paying subscribers.

But Tuesday’s announcement makes one thing clear:
the simple Google search bar that defined the internet for nearly 30 years is rapidly evolving into something very different.

And the battle over what replaces it is becoming the biggest fight in technology.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Toll Brothers, the country’s largest luxury-home builder, says wealthy Americans are still buying expensive homes despite high mortgage rates and growing worries about the housing market.

The company reported Tuesday that orders for new homes reached their highest level in two years, helping push shares higher after earnings topped Wall Street expectations.

For everyday consumers, the results highlight a growing split in the U.S. housing market: middle-class buyers are struggling with high monthly payments, while wealthier buyers continue purchasing million-dollar homes with far less pressure from interest rates.

Toll Brothers signed contracts for 2,834 homes during its latest quarter, up 7% from a year ago. The average selling price topped $1 million per home.

CEO Douglas Yearley Jr. said the company continued to perform well despite what he called a “challenging market,” adding that demand at the high end of the housing market remains strong.

The results stand out because much of the broader housing market has slowed sharply.

Mortgage rates remain near their highest levels in years, with the average 30-year fixed mortgage climbing close to 6.7%. Higher Treasury yields — which heavily influence mortgage rates — have continued rising amid inflation fears tied to the Iran war and energy prices.

For many Americans, that has made buying a home increasingly unaffordable.

Monthly mortgage payments on a typical U.S. home are now hundreds of dollars higher than they were just a few years ago. Many homeowners who locked in low 3% mortgage rates during the pandemic are also refusing to sell, creating a shortage of homes on the market.

But Toll Brothers operates in a very different part of the market.

Its customers are typically wealthier buyers who often make larger down payments, carry smaller mortgages relative to home values, or pay cash entirely. That makes them less sensitive to rising interest rates compared with first-time or middle-income buyers.

The company said many of its luxury communities are still raising prices, showing that demand at the top end of the market remains healthy even as entry-level housing slows.

Toll Brothers also raised its forecast for the rest of the year, signaling confidence that wealthy buyers will continue spending despite economic uncertainty.

The company ended the quarter with more than $1 billion in cash and continued buying back its own stock while increasing its dividend to shareholders.

The strong earnings report adds to growing evidence that the U.S. economy is increasingly splitting into two different realities.

Higher-income Americans have continued benefiting from strong stock markets, rising asset values and accumulated wealth from recent years. Many can still comfortably afford luxury homes even with elevated interest rates.

Meanwhile, many middle-class families are finding it harder to qualify for mortgages or afford monthly payments at current prices.

Housing analysts say that divide has become one of the defining trends of today’s real estate market.

Existing home sales across the country remain near multi-decade lows, while builders targeting first-time buyers have increasingly relied on incentives and mortgage-rate discounts to attract customers.

Luxury builders like Toll Brothers, however, continue seeing stronger demand than much of the industry.

For now, the company’s latest results suggest wealthy buyers are still willing to spend — even as much of the rest of the housing market remains under pressure.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

NATO is actively discussing a potential military escort mission through the Strait of Hormuz if the waterway remains blocked into July, a major escalation in the alliance’s posture toward the U.S.-Iran conflict that is already reshaping calculations across global energy, shipping, insurance, and defense markets.

The possibility was confirmed Tuesday by General Alexus Grynkewich, NATO’s Supreme Allied Commander Europe, who acknowledged during a press conference in Brussels that alliance leaders are evaluating operational plans should the crisis continue.

Asked directly whether NATO is considering a Hormuz mission, Grynkewich answered: “Absolutely.”

The remarks marked the first public confirmation that a formal NATO-led maritime operation is under active discussion as the conflict surrounding Iran and the Gulf deepens.

According to officials briefed on the discussions, several NATO member states support the proposal, though unanimous approval — required for a formal alliance operation — has not yet been secured. Alliance leaders are expected to revisit the issue during a major NATO gathering in Ankara on July 7-8, now emerging as a potential decision point for Western intervention.

For markets, the implications are enormous.

The Strait of Hormuz normally handles roughly one-fifth of global oil and liquefied natural gas shipments. The disruption triggered by the war and subsequent closure of major shipping lanes has produced one of the largest energy supply shocks in modern history.

The International Energy Agency estimates roughly 14 million barrels per day of crude exports remain disrupted or stranded behind the chokepoint.

Brent crude has traded above $100 per barrel for most of the conflict, briefly nearing $120 during peak panic buying before easing modestly this week after President Donald Trump confirmed he had postponed a planned strike following appeals from Gulf leaders seeking additional time for negotiations.

QatarEnergy has already declared force majeure on exports, while oil production across Saudi Arabia, Kuwait, Iraq, and the United Arab Emirates reportedly fell by more than 10 million barrels per day during the worst phase of the March disruption.

The political backdrop behind NATO’s discussions is increasingly tense.

Several European alliance members have resisted Trump administration pressure to directly participate in efforts to reopen Hormuz militarily. The White House recently announced plans to withdraw thousands of U.S. troops from Germany following disputes over burden-sharing and Gulf operations.

Spain has been among the most vocal opponents of direct military involvement, restricting the use of Spanish airspace and facilities for Iran-related strikes. Other European governments have quietly provided logistical support while avoiding formal military commitments.

At the same time, France and the United Kingdom have reportedly been coordinating separate maritime-security contingency plans for the Gulf should active hostilities eventually subside.

What changed Tuesday was NATO itself publicly acknowledging that alliance-level intervention is now being openly debated even while the war remains active.

Shipping markets are already operating under extreme strain.

The International Maritime Organization estimates approximately 20,000 mariners aboard nearly 2,000 commercial vessels remain stranded across Gulf waters. IMO officials say there is little precedent for disruptions affecting such a large concentration of commercial shipping simultaneously.

Earlier U.S.-led efforts to reopen transit routes under the Trump administration’s “Project Freedom” initiative failed within days despite overwhelming American naval superiority.

The U.S. Navy destroyed several Iranian attack boats during the operation, but Iran retaliated with missile and drone strikes targeting Gulf infrastructure, forcing insurers and major shipping operators to continue avoiding the route.

Only a handful of U.S.-flagged vessels successfully completed escorted transits before broader commercial traffic effectively stopped again.

Labor unions representing international seafarers have warned shipping companies not to interpret military escort proposals as guarantees of safety without explicit Iranian assurances.

The financial impact is already spreading far beyond energy.

War-risk insurance premiums for tankers entering Gulf waters have surged dramatically since February. Asian commodity buyers remain scrambled for replacement fertilizer and petrochemical supplies previously sourced through the Gulf.

According to shipping and commodity data from Kpler, Asian buyers receive a significant share of global urea, sulfur, and ammonia exports through the region, much of which remains disrupted.

Food supply chains across Gulf Cooperation Council countries are also under mounting stress.

Retailers including Lulu Retail have reportedly resorted to airlifting staple goods into Gulf markets that rely heavily on imports transiting Hormuz. Consumer food prices across parts of the region have surged sharply as shipping disruptions persist.

The crisis is becoming especially dangerous for Europe.

Qatar supplies roughly 12% to 14% of Europe’s liquefied natural gas imports, nearly all of which transit Hormuz. With Europe still heavily dependent on LNG following the collapse of Russian pipeline supplies after 2022, prolonged Gulf disruption threatens renewed industrial shutdowns and energy shortages across Germany, Italy, and other manufacturing-heavy economies.

That strategic pressure is increasingly driving NATO’s internal debate.

Every additional week of disruption raises the political and economic cost of inaction for European governments already struggling with elevated energy prices and slowing industrial production.

Meanwhile, the military risks continue escalating.

Trump has instructed the Pentagon to remain prepared for renewed large-scale strikes on Iran if negotiations fail. Sen. Lindsey Graham (R-S.C.) has publicly urged the administration to target Iranian energy infrastructure directly in future attacks — a move analysts warn would almost certainly prolong the closure of Hormuz through the summer.

Adding further pressure, the U.S. Senate voted 50-47 on Tuesday to advance a war powers resolution challenging Trump’s military authority over Iran, the first successful procedural breakthrough for congressional critics since the conflict escalated.

Markets are now confronting the possibility of simultaneous escalation on multiple fronts: renewed U.S. strikes, deeper Iranian retaliation, and a formal NATO naval operation entering the Gulf.

Such a scenario would represent the broadest coordinated Western military presence in the Persian Gulf since the Gulf War era.

For now, NATO officials are making clear that the alliance’s patience is narrowing as the economic damage spreads.

The longer Hormuz remains effectively closed, the more likely military intervention becomes.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

OpenAI is now offering businesses something that has become incredibly valuable in the artificial intelligence boom: guaranteed access to computing power.

The company announced Tuesday a new “Guaranteed Capacity” program that allows enterprise customers to lock in AI computing access for one, two, or three years at a time, giving businesses more certainty that they will be able to run AI products without interruptions as demand for advanced chips and data centers continues exploding worldwide.

For everyday readers, the bigger story is this: the AI industry is running so short on computing power that companies are now reserving AI capacity years in advance — almost like airlines locking in jet fuel or retailers reserving shipping containers before the holiday season.

OpenAI CEO Sam Altman said demand for AI infrastructure is outpacing supply and likely will for years. “Customers are increasingly asking us for certainty on capacity,” Altman wrote Tuesday on X. He added that the company expects the world to remain “capacity-constrained for some time” as AI models become more powerful.

The new program allows companies to reserve access across OpenAI’s major products, including ChatGPT Enterprise, its developer API, and Codex, the company’s AI coding assistant. Businesses that commit to larger and longer contracts will receive discounts.

The launch highlights one of the biggest realities behind the AI boom: there simply are not enough Nvidia chips, data centers, or electrical power supplies available globally to keep up with demand.

Training and running advanced AI systems requires enormous amounts of energy and computing infrastructure. Tech companies are now racing to secure long-term access to both. In some regions, AI firms are even competing directly with utilities and industrial companies for electricity.

OpenAI has become one of the largest buyers of AI computing infrastructure in the world. The company previously told investors it expects to spend roughly $600 billion on compute infrastructure by 2030. Earlier this month, OpenAI said it had already surpassed key targets tied to its Stargate infrastructure initiative, which is building massive AI-focused data center capacity across the United States.

The Guaranteed Capacity program also helps solve another growing question on Wall Street: how OpenAI plans to finance such enormous infrastructure expansion.

By getting customers to commit to long-term contracts upfront, OpenAI creates a more predictable stream of future revenue that can help support borrowing, infrastructure construction and investor confidence. Analysts say those long-term agreements could eventually become an important part of any future IPO filing.

The company is widely expected to pursue a stock market debut in the near future. OpenAI was recently valued at more than $850 billion by private investors following a massive fundraising round earlier this year.

The move also increases pressure on rivals including Anthropic and Google DeepMind. Once a large company signs a multi-year AI infrastructure agreement, competitors may struggle to win that business away for years.

Industry analysts increasingly compare the current AI market to an early “land grab,” where companies are racing to secure customers, computing power and infrastructure before the industry fully matures.

For businesses, the decision comes with risk.

Locking into OpenAI now could guarantee access to critical AI tools during future shortages. But it also means potentially committing heavily to one provider in an industry evolving at extraordinary speed, where today’s market leader could face new competition within months.

Still, OpenAI appears confident many companies will prioritize reliability over flexibility — especially as AI becomes more deeply embedded into customer service systems, software development, finance, healthcare and everyday business operations.

The announcement underscores how quickly artificial intelligence is shifting from an experimental technology into a core global infrastructure business — one increasingly shaped not just by software innovation, but by physical limits involving chips, electricity and data centers.

— JBizNews Desk

© JBizNews.com. All rights reserved.

House Republicans are moving this week to approve a revised version of the Senate’s sweeping housing package while stripping out one of its most controversial provisions — a forced-sale requirement targeting large institutional single-family landlords — setting up a direct clash with Senate leaders and threatening one of Washington’s largest bipartisan housing efforts in years.

House Financial Services Committee Chairman French Hill (R-Ark.) and Ranking Member Maxine Waters (D-Calif.) are preparing the amended legislation for a fast-track vote under suspension of the rules before lawmakers leave Washington for Memorial Day recess. That procedure requires a two-thirds majority, leaving little room for defections from either party.

The dispute centers on the Senate-passed version of the “21st Century ROAD to Housing Act,” which cleared the upper chamber in March by an overwhelming 89-10 margin after months of bipartisan negotiations led by Senate Banking Committee Chairman Tim Scott (R-S.C.), Senate Majority Leader John Thune (R-S.D.), Sen. Bernie Moreno (R-Ohio), and Sen. Elizabeth Warren (D-Mass.).

President Donald Trump publicly endorsed the Senate version earlier this month, calling housing affordability a national crisis and praising Scott and Moreno for advancing restrictions aimed at institutional ownership of single-family homes.

But the House’s revised text released May 14 removes the provision that had triggered alarm across the single-family rental industry and among large homebuilders.

Under the original Senate language, institutional investors owning at least 350 single-family homes would have been required to sell newly acquired build-to-rent properties to individual buyers within seven years. Renters would have received a right of first refusal and a 30-day exclusive purchase window before homes could be sold elsewhere. Violations carried civil penalties of up to $1 million per property or triple the home’s purchase price.

The House rewrite eliminates the forced-sale requirement entirely and explicitly states that no institutional landlord would be required to divest homes acquired either before or after the law’s enactment.

The rollback immediately won support from builders, multifamily developers, and housing lenders who argued the Senate version had effectively frozen financing for build-to-rent projects nationwide.

The National Association of Home Builders, the National Multifamily Housing Council, and the Community Home Lenders of America all backed the House changes within hours of release.

NAHB Chairman Bill Owens said the revisions restore certainty needed for developers to continue building rental inventory during a nationwide housing shortage. Sharon Wilson Geno, president of the National Multifamily Housing Council, said lawmakers had recognized that the original language threatened the long-term economics of the build-to-rent sector.

Industry groups say financing activity slowed sharply after the Senate approved its original bill in March because investors feared mandatory liquidation timelines would undermine long-duration rental business models.

But the House revisions have triggered growing resistance inside the Senate.

Warren has warned publicly that removing the investor restrictions could “kill the bill” entirely and accused House Republicans of watering down a key affordability measure that even Trump had endorsed. Senate Republicans involved in the negotiations are also signaling frustration that the House is reopening a package many lawmakers believed had already reached final compromise.

One senior Senate Republican aide told reporters the House rewrite risks collapsing the bipartisan coalition that delivered nearly 90 Senate votes, potentially pushing support below the 60-vote threshold needed to survive another Senate filibuster fight.

Sen. John Kennedy (R-La.), a member of the Senate Banking Committee, described widespread frustration among Senate Republicans who view the House revisions as a unilateral rewrite of carefully negotiated legislation.

The politics inside the House remain complicated as well.

Because the bill is moving under suspension of the rules, leadership needs broad bipartisan backing. Members of the conservative House Freedom Caucus, including Rep. Anna Paulina Luna (R-Fla.) and Rep. Eric Burlison (R-Mo.), have already raised objections tied to separate provisions involving a temporary Federal Reserve central bank digital currency ban and broader concerns over federal involvement in private housing markets.

At the same time, House Republicans argue the Senate drifted too far from the original supply-side housing framework approved overwhelmingly by the lower chamber earlier this year.

Rep. Mike Flood (R-Neb.), chairman of the Main Street Caucus, defended the revisions by noting the House’s original “Housing for the 21st Century Act” passed 390-9 before Senate negotiators added what some House members viewed as more aggressive market intervention measures.

Despite the investor fight, much of the broader housing package remains intact.

The House version still expands the public welfare investment cap for banks investing in affordable housing from 15% to 20% of risk-adjusted capital, a provision many housing lenders consider one of the bill’s most important supply-side reforms.

The legislation also streamlines HUD environmental reviews, modernizes manufactured housing standards, preserves rural rental units tied to expiring USDA mortgage programs, creates a new “Moving to Work” housing cohort, and speeds up Housing Choice Voucher inspection timelines.

Housing advocates say the package still represents one of the most significant federal housing efforts in decades even without the forced-sale language.

The timeline now adds pressure to both chambers.

If the House passes the amended bill this week, the legislation returns to the Senate, where Thune and Senate leaders must decide whether to accept the House revisions, negotiate a conference committee, or attempt to force the original Senate version back through the lower chamber.

Republicans have increasingly framed the housing legislation as a cornerstone of their affordability agenda heading into the 2026 midterm elections. Failure to deliver the package after months of bicameral negotiations would eliminate one of the few major bipartisan domestic-policy achievements still moving through Congress this year.

For now, builders, lenders, and institutional landlords are lining up behind the House version.

The Senate lawmakers who wrote the original bill are not.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

U.S. stocks pointed to a higher open Wednesday after three straight losing sessions, with Target Corp. surging on a blowout first quarter, Lowe’s Cos. ahead of the bell and the entire market positioned for Nvidia Corp.’s post-close earnings — even as the 10-year Treasury yield climbed to a 16-month high and President Donald Trump warned that the United States may resume strikes on Iran within “two or three days” if Tehran rejects Washington’s peace terms.

S&P 500 futures rose 0.3% before the opening bell, while Nasdaq futures advanced modestly as investors attempted to stabilize markets rattled by surging bond yields, rising oil prices and fears the Federal Reserve could eventually return to rate hikes if inflation accelerates further.

The biggest premarket mover was Target.

The Minneapolis-based retailer reported first-quarter results that sharply exceeded Wall Street expectations and raised full-year guidance, marking the company’s strongest quarter in more than a year and signaling that American consumers are still spending despite high interest rates and inflation pressure.

Net sales rose 6.7% to $25.4 billion, driven by 5.6% comparable sales growth and a 4.4% increase in customer traffic. Digital sales climbed nearly 9%, fueled by rapid growth in same-day delivery and advertising revenue. Adjusted earnings per share came in at $1.71, well ahead of analyst expectations.

Management also raised its 2026 forecast, now expecting annual sales growth around 4% and stronger operating margins.

Shares surged in premarket trading as investors interpreted the results as evidence that consumer demand remains more resilient than feared.

Lowe’s, the home improvement giant, was scheduled to report before the open, with analysts expecting earnings of $2.96 per share on revenue of roughly $22.9 billion. Retailer TJX Cos., parent company of T.J. Maxx and Marshalls, was also due to release earnings before the bell.

The semiconductor sector rebounded after a bruising three-session selloff tied to rising bond yields and profit-taking across artificial intelligence stocks.

Intel climbed more than 4% in premarket trading, while Advanced Micro Devices rose over 2% after Citi raised its price target on the stock. Micron Technology also moved higher as investors positioned ahead of Nvidia’s highly anticipated earnings report after the closing bell.

Nvidia remains the single most important stock in the market right now.

The AI chipmaker has become the world’s most valuable company and is widely viewed as the primary barometer for artificial intelligence spending globally. Traders expect the earnings report to determine whether the AI-driven rally that powered markets for much of the past year still has momentum — or whether valuations have become stretched.

The stakes are unusually high because Nvidia’s results now influence not only semiconductor stocks, but the broader Nasdaq, cloud computing firms, data center operators and even power utilities tied to AI infrastructure growth.

Cybersecurity stocks came under pressure despite solid earnings from Palo Alto Networks.

The company beat expectations and raised full-year guidance, but shares still fell nearly 4% after hours as investors focused on softer gross margins. The weakness spilled into peers including CrowdStrike and Zscaler.

Homebuilders, meanwhile, received a boost from strong results at Toll Brothers.

The luxury-home builder reported earnings and revenue well above analyst forecasts, benefiting from resilient high-income buyers despite elevated mortgage rates. Shares rose more than 5% in extended trading after the release.

But beneath the earnings optimism, the bond market continues to dominate investor psychology.

The 10-year Treasury yield hovered near 4.67% Wednesday morning, the highest level in roughly 16 months, as markets increasingly price in the possibility that inflation could remain elevated well into 2027 because of the Iran war and sustained energy-price shocks.

Oil prices remain elevated as the Strait of Hormuz — one of the world’s most critical shipping lanes — continues operating under severe disruption amid the ongoing conflict with Iran.

Trump intensified concerns Tuesday when he warned the United States could resume military strikes within days if Tehran rejects Washington’s terms.

The prolonged instability has pushed gasoline prices higher, increased freight and shipping costs globally and forced investors to reassess assumptions that the Federal Reserve would eventually move toward lower interest rates.

Markets now see meaningful odds of another Fed rate hike by late 2026 or early 2027.

Investors will closely analyze Wednesday afternoon’s release of the Federal Reserve’s latest meeting minutes for any indication policymakers are becoming more concerned about persistent inflation driven by energy and geopolitical instability.

Treasury Secretary Scott Bessent, speaking from G7 finance meetings in Paris, added further pressure by urging allies to strengthen sanctions on Iran while coordinating policies around critical minerals and trade protections against China.

Bessent warned European officials that excess Chinese industrial exports could damage Western manufacturing sectors if coordinated protections are not implemented.

Among other notable market movers, UnitedHealth Group fell after an HSBC downgrade, while Wolfspeed plunged on reports the semiconductor materials company may face bankruptcy risk within weeks. Chinese electric-vehicle maker Xpeng rose more than 5% after posting a smaller-than-expected quarterly loss and stronger delivery guidance.

The remainder of the week remains packed with market-moving catalysts.

In addition to Nvidia, companies including Intuit, Williams-Sonoma, Walmart, Deere, Ross Stores, Zoom, and Deckers Outdoor are scheduled to report earnings over the next two sessions. Investors will also watch Friday’s University of Michigan consumer sentiment reading for additional clues about household spending and inflation expectations.

For consumers, however, the market story increasingly comes down to something simpler than earnings or AI valuations.

Higher Treasury yields mean more expensive mortgages, car loans and credit cards. Higher oil prices mean more expensive gasoline, airfare and shipping costs.

And as long as the Iran conflict keeps pressure on global energy markets, those costs are likely to remain elevated regardless of whether stocks bounce for a day or continue sliding.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The collapse of Cuba’s economy under a tightening American pressure campaign has shifted from a geopolitical story into a business story, with U.S. investors, Cuban-American executives, and global mining, tourism, and telecom interests openly modeling what a post-Castro island opening could mean for capital flows just 90 miles off the Florida coast.

Secretary of State Marco Rubio, in remarks delivered this month after President Donald Trump signed Executive Order 14404 on May 1, framed the administration’s endgame in explicit commercial terms. Rubio said Cuba “would enjoy an enormous expatriate community, Cuban Americans that would go back and invest,” while pointing to the island’s tourism industry, fertile farmland, and strategic mineral reserves, including rare earth deposits critical to modern technology supply chains.

“Cuba should not be a poor country,” Rubio said. “Its people should not be starving. Its people should be prosperous.”

That investment thesis collided this week with the reality unfolding across the island.

Cuban Energy Minister Vicente de la O Levy acknowledged on state television that Cuba has effectively run out of crude oil, diesel, and fuel oil, leaving only domestically produced natural gas keeping portions of the power grid alive. Blackouts in Havana are now lasting as long as 20 to 22 hours a day, according to government statements, as the Trump administration’s escalating pressure campaign cuts off fuel shipments and financial lifelines to the communist government.

The economic collapse is becoming increasingly visible. Food shortages have intensified, transportation networks have deteriorated, and factories across the island are operating intermittently or shutting down entirely because of power outages and fuel scarcity.

At the same time, Washington’s posture toward Havana is hardening.

CIA Director John Ratcliffe traveled to Havana last week in the most senior U.S. intelligence visit to Cuba in decades. Ratcliffe reportedly met with senior Cuban security officials and delivered a direct message from President Trump that the United States is prepared to discuss economic normalization and security cooperation only if Cuba undertakes “fundamental changes,” according to officials cited by the Associated Press.

The administration is simultaneously escalating legal and financial pressure on the regime.

Federal prosecutors in Miami are reportedly examining potential charges tied to senior Cuban officials connected to the 1996 shootdown of planes operated by the exile group Brothers to the Rescue. While Trump declined to confirm potential indictments, he signaled the administration views the Cuban government as vulnerable.

“They need help,” Trump told reporters aboard Air Force One. “You talk about a declining country — they are really a nation in decline.”

For financial markets and multinational corporations, the most consequential move came through the State Department’s sanctions escalation under Executive Order 14404.

Rubio announced sanctions against GAESA, the military-controlled conglomerate that dominates much of Cuba’s economy, alongside Moa Nickel S.A., one of the island’s most strategically important mining operations. The State Department described GAESA as the core financial engine of Cuba’s communist system, estimating the organization controls more than 40% of the country’s economy through tourism, retail, banking, transportation, and industrial assets.

The move immediately rattled one of Cuba’s largest foreign corporate partners: Canada’s Sherritt International.

Sherritt, which owns a 50% stake in the Moa nickel joint venture and major energy assets on the island, initially announced plans to suspend participation in Cuban operations and began withdrawing expatriate employees after the sanctions announcement. Several company directors resigned shortly afterward.

But in a notable reversal this week, Sherritt said it was reconsidering dismantling its Cuban operations after consultations with advisers and government officials, citing what it called a “potential value-preserving opportunity.”

That language immediately caught Wall Street’s attention.

Analysts increasingly believe some foreign investors are quietly positioning for a possible post-Castro opening rather than abandoning Cuban assets entirely. The logic is straightforward: maintain strategic exposure now in hopes of benefiting from a future transition that could unlock billions of dollars in tourism, infrastructure, telecom, agriculture, and mining investment.

The opportunity is substantial.

Cuba possesses some of the world’s largest undeveloped nickel and cobalt reserves — materials essential to electric vehicle batteries and advanced defense technologies. With Washington aggressively seeking alternatives to China-dominated mineral supply chains, Cuba’s resource base has suddenly taken on greater geopolitical significance.

The island also sits directly adjacent to one of the wealthiest consumer markets on earth.

Before the revolution, Cuba was among the Caribbean’s premier tourism destinations. American hotel operators, airlines, cruise lines, telecom providers, and agricultural exporters have spent decades studying what a reopening could look like. Some estimates from prior U.S. trade studies projected billions of dollars in annual economic activity if restrictions were normalized.

But the same sanctions designed to pressure Havana are simultaneously increasing the risks for companies attempting to move too early.

Executive Order 14404 significantly expands the threat of secondary sanctions against foreign firms and financial institutions doing business with sanctioned Cuban entities. European banks, Canadian miners, and Latin American conglomerates that previously operated under older sanctions frameworks now face far greater legal and financial exposure if they continue transactions linked to GAESA or other targeted sectors.

For ordinary Cubans, the geopolitical and financial maneuvering translates into worsening daily hardship.

The Wall Street Journal reported this week that blackouts lasting nearly an entire day are fueling unrest across the island, with protests increasingly breaking out in Havana and other cities as shortages deepen. Inflation continues eroding purchasing power while the peso weakens further against the dollar.

The next key deadline arrives June 5, when the Treasury Department’s temporary wind-down period for foreign companies connected to GAESA-related transactions expires. After that date, enforcement risks rise sharply for multinational corporations still operating on the island.

For investors and policymakers alike, the stakes are becoming clearer.

If the pressure campaign succeeds in forcing meaningful political and economic reform, Cuba could become one of the most significant untapped emerging-market opportunities in the Western Hemisphere. If it fails, companies maintaining exposure risk being trapped inside a collapsing economy facing deeper isolation, fuel shortages, and intensifying political instability.

Either way, the business landscape of the Caribbean is changing rapidly — and global capital is already preparing for what comes next.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Alphabet Chief Executive Sundar Pichai unveiled Gemini Spark on Tuesday, a new always-on personal AI agent designed to autonomously draft emails, manage inboxes, compile documents and eventually complete purchases on a user’s behalf, marking Google’s clearest attempt yet to dominate the fast-emerging “agentic AI” market now being contested by OpenAI, Anthropic, Microsoft, and Apple.

The launch, announced during Google I/O in Mountain View, California, positions Gemini Spark as far more than a chatbot. Unlike traditional assistants that respond only when prompted, Spark operates continuously in the background on dedicated Google Cloud virtual machines, allowing it to continue performing tasks even after a user closes a laptop or locks a phone. The product will initially roll out next week to subscribers of Google AI Ultra, Alphabet’s new $100-per-month premium tier, before expanding into a wider U.S. beta.

“We’re super focused on bringing that frontier capability of agents safely and securely to consumers so that they work for everyone,” Pichai told reporters during a pre-briefing ahead of the keynote, framing the product as a digital assistant capable of acting independently under user direction rather than simply answering questions.

The unveiling immediately escalated Silicon Valley’s AI arms race, shifting competition away from chat interfaces and toward autonomous software agents that can execute workflows across apps, documents, and enterprise systems. Spark integrates directly with Gmail, Google Docs, Sheets, Slides, and the broader Workspace ecosystem while also connecting to third-party services through the emerging Model Context Protocol standard. Launch partners include Canva, Instacart, and OpenTable.

During the live demonstration, Josh Woodward, vice president of the Gemini App and AI Studio at Google Labs, showed Spark pulling information from emails and documents to automatically draft management updates and monitor customer-service inquiries for small businesses. The system runs on Google’s newly introduced Gemini 3.5 Flash model paired with the company’s “Antigravity” agentic framework, which coordinates multiple AI agents simultaneously.

Koray Kavukcuoglu, chief technology officer of Google DeepMind and Google’s chief AI architect, said the company’s newest model was specifically optimized for autonomous workflows. “3.5 Flash is especially good when deploying multiple agents simultaneously and completing long-running tasks,” Kavukcuoglu said, adding that Google had internally tested AI agents capable of building a functioning operating system from scratch.

Underneath the product reveal sits a major economic and infrastructure strategy.

Google claims Gemini 3.5 Flash outperforms its previous flagship Gemini 3.1 Pro model across most benchmarks while operating roughly four times faster than comparable frontier systems in token output speed. Google executives said an optimized Antigravity configuration can run up to 12 times faster in certain enterprise environments, potentially allowing customers to sharply reduce AI infrastructure costs.

Pichai told reporters that enterprise clients processing roughly one trillion AI tokens per day on Google Cloud could theoretically save more than $1 billion annually by shifting workloads toward a combination of Flash and the larger Gemini 3.5 Pro model, which is scheduled for broader release next month.

Internal demand growth inside Google itself has become staggering. According to executives, Google’s systems were processing roughly half a trillion tokens daily in March. That figure has now surpassed three trillion daily tokens and continues doubling every several weeks as AI adoption accelerates across products and enterprise workloads.

The launch arrives during an increasingly aggressive battle among major AI labs to dominate the emerging market for digital agents that can act independently across software ecosystems.

Anthropic recently introduced Claude Cowork, a desktop AI agent capable of operating directly on a user’s machine. OpenAI has been expanding browser-based ChatGPT agent functionality. Microsoft continues embedding AI agents across Office 365 and Windows. Meanwhile, Apple is expected to unveil a significantly upgraded Siri during next month’s WWDC conference, positioning the assistant as a cross-application agent capable of carrying out complex tasks autonomously.

Ironically, Google itself is expected to help power Apple’s upgraded Siri through a multi-year agreement reportedly valued near $1 billion annually, further underscoring how intertwined the AI infrastructure race has become even among fierce competitors.

Google’s competitive advantage may ultimately come from the enormous amount of user context already stored across its ecosystem. Unlike newer entrants, Gemini Spark can access years of emails, documents, calendars, spreadsheets, and browsing behavior already sitting inside Google accounts.

That deep integration is central to Google’s strategy.

“Your inbox is effectively a memory system competitors don’t have,” one developer attending the event remarked after the keynote, echoing a broader industry belief that long-term user context may become the defining moat in the AI-agent race.

The AI rollout also intersects with a parallel strategic shift underway inside Alphabet’s hardware business.

Earlier this month, Pichai disclosed during Alphabet’s first-quarter earnings call that Google will begin selling its custom Tensor Processing Unit chips directly to enterprise customers for deployment inside their own data centers — a sharp break from Google’s previous cloud-only hardware model.

“As TPU demand grows from AI labs, capital markets firms, and high-performance computing applications, we’ll begin delivering TPUs directly to select customers,” Pichai told investors.

The move represents one of the first credible long-term challenges to Nvidia’s dominance of AI accelerator hardware. Nvidia currently controls the overwhelming majority of the global AI-chip market and carries a market capitalization approaching $5 trillion.

Google has already signed large-scale TPU agreements with Anthropic, while reports indicate the company is negotiating additional multibillion-dollar chip arrangements with Meta Platforms and other hyperscale buyers.

The broader financial backdrop has given Alphabet room to aggressively pursue the AI expansion.

Google Cloud generated more than $20 billion in first-quarter 2026 revenue, up 63% year over year, while cloud operating income tripled to $6.6 billion. Alphabet also disclosed a backlog of roughly $460 billion in future contracted cloud business, nearly doubling from the prior quarter.

At the same time, Alphabet raised its projected 2026 capital expenditures to between $180 billion and $190 billion as the company races to build enough infrastructure to support growing AI demand.

Investors remain divided on whether the spending surge will ultimately generate meaningful profits. Alphabet shares have climbed roughly 23% year-to-date as investors embraced Google’s accelerating AI position, though the stock fell modestly following Tuesday’s keynote as Wall Street weighed the enormous infrastructure costs required to scale agentic systems globally.

For now, Pichai is making a much broader strategic bet than simply launching another chatbot. Google is positioning itself as the only major AI player controlling the entire vertical stack simultaneously — the AI model, the chips, the cloud infrastructure, the productivity suite, and the consumer interface.

Whether consumers ultimately pay $100 per month for a persistent AI agent embedded across their digital lives may determine whether Gemini Spark becomes one of the most important software launches of the decade — or another costly experiment in Silicon Valley’s increasingly expensive AI arms race.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A gigantic oil market bet placed Tuesday has traders across Wall Street asking the same question: did someone know something the rest of the market didn’t?

The trade — tied to roughly 134 million barrels of Brent crude oil — wagered that oil prices could suddenly collapse within days, despite the ongoing Iran war that has pushed global energy prices sharply higher for months.

For everyday consumers, the story matters because oil prices directly affect gasoline costs, airline tickets, shipping prices, inflation and even grocery bills.

The unusual trade immediately raised concerns because it comes as federal regulators are already investigating several other suspicious oil wagers placed shortly before major Iran-related announcements earlier this year.

According to Bloomberg data, the trader placed a massive options bet that would become highly profitable if Brent crude falls below roughly $90 a barrel by next week. Brent was trading near $112 when the trade appeared, meaning oil would need to plunge almost 20% in just days for the position to fully pay off.

If that happens, the trade could generate as much as $129 million in profit.

Oil traders say bets this large are extremely rare — especially during a war-driven energy crisis where prices have been moving violently on geopolitical headlines.

The timing is what especially alarmed the market.

Federal regulators are already reviewing several earlier trades that appeared shortly before major developments involving Iran and the Strait of Hormuz, one of the world’s most important oil shipping routes.

In March, traders reportedly placed hundreds of millions of dollars in bearish oil bets shortly before President Donald Trump delayed threatened military strikes on Iran. Similar trades later appeared before temporary ceasefire announcements and statements tied to reopening Gulf shipping routes.

The Commodity Futures Trading Commission and the Department of Justice are now reportedly investigating whether traders may have received advance information before placing those positions.

Tuesday’s trade added fresh fuel to those concerns because no public policy announcement had yet occurred when the position appeared.

That left traders scrambling to figure out whether the investor simply made a highly aggressive gamble — or expects a major geopolitical surprise in the coming days.

Oil markets have become extremely difficult to predict since the conflict began earlier this year.

Prices initially exploded higher after fears that the Strait of Hormuz could close and disrupt global oil supplies. Since then, traders have been forced to react to a nonstop stream of military developments, diplomatic signals and rumors of possible ceasefires.

The broader economic stakes are enormous.

Higher oil prices have already pushed gasoline prices upward and complicated the Federal Reserve’s inflation fight. Airlines, trucking companies and manufacturers are all dealing with higher fuel and transportation costs that eventually flow down to consumers.

Analysts say even relatively small swings in oil prices now have outsized effects on the economy because global supply chains remain fragile after years of inflation and geopolitical disruptions.

Despite those risks, U.S. stock markets have remained surprisingly calm, with investors continuing to push major indexes higher even as oil volatility surged.

Some energy analysts warn Wall Street may be underestimating the seriousness of the situation.

“This is a massive, massive energy crisis,” Amrita Sen, founder of Energy Aspects, recently said on CNBC, warning that investors appear overly optimistic about the conflict’s long-term impact.

At the center of Tuesday’s drama is one key reality: for the trade to work, oil prices would likely need a major positive geopolitical shock very quickly — such as a ceasefire breakthrough or a major reopening of Middle East oil routes.

Without that, many traders believe oil prices are unlikely to fall fast enough before the options expire next week.

Now regulators, hedge funds and energy traders around the world are watching closely for what happens next — both in the Middle East and inside the futures markets themselves.

For consumers already paying elevated prices at the pump, the outcome could help determine whether fuel prices finally ease this summer — or climb even higher.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A fierce split has opened among chief executives, economists, and labor researchers over what artificial intelligence is doing to entry-level work. One camp says AI is gutting the bottom rung of the corporate ladder and warns of a generation locked out of white-collar careers. The other says AI is reviving early-career roles by making junior employees productive faster than ever before. Both sides have data, named advocates, and real-world hiring decisions behind them — and the gap between them is now wide enough that new graduates need to understand exactly where each argument comes from to navigate the market.

The elimination camp is led publicly by Dario Amodei, chief executive of Anthropic, who told Fox News that AI capability is advancing faster than workforce planners assumed and is closing in on the tasks that define early-career white-collar work. “Two years ago, it was at the level of a smart high school student; now it’s probably at the level of a smart college student and reaching beyond that,” Amodei said, warning that summarizing documents, brainstorming, drafting reports, and routine research — the daily work that once trained junior employees in finance, consulting, law, and technology — are precisely the functions AI is learning to perform.

The labor data backing that argument has become difficult for executives to ignore. Entry-level job postings in the United States have fallen 35% since 2023, according to labor-research firm Revelio Labs. A study led by Stanford economist Erik Brynjolfsson, using ADP payroll data, found employment for workers ages 22 to 25 in the most AI-exposed occupations declined between 12% and 15% from the third quarter of 2022 through the second quarter of 2025 — roughly 150,000 fewer early-career jobs. The researchers found the decline came overwhelmingly from fewer hires rather than mass layoffs, suggesting companies are simply replacing junior recruitment pipelines with software before workers ever enter the building.

Consulting firms are beginning to map which jobs are most exposed. Boston Consulting Group, in an April analysis, estimated that roughly 12% of current U.S. jobs fall into a category where AI directly substitutes for human labor in core tasks, leading to net job losses and wage pressure on the remaining positions. Financial-analysis support roles, basic coding, document review, and call-center functions ranked among the most vulnerable. A separate global survey highlighted by Fast Company found two-fifths of executives said entry-level roles have already been reduced due to AI-driven efficiency gains, while 43% expect additional cuts over the next year.

Yet the opposite side of the debate has become equally vocal — and it is being driven by some of the world’s largest employers.

Marc Benioff, chief executive of Salesforce, said the company plans to hire 1,000 new graduates and interns to help build its Agentforce and Headless360 AI-agent platforms, framing the move as a direct rebuttal to the idea that AI eliminates junior opportunity. Arvind Krishna, chief executive of IBM, told investors the company expects to hire more college graduates over the next year than it has in several years. Matt Garman, chief executive of Amazon Web Services, said Amazon plans to bring on roughly 11,000 software-engineering interns in 2026, broadly in line with prior hiring levels, because demand for AI-related development work continues to expand.

The hiring momentum is reinforced by corporate survey data. SAP and Wakefield Research, polling chief human resources officers at companies generating more than $500 million in annual revenue, found 88% of CHROs said AI is making early-career employees productive faster than previous generations of workers. Seventy-nine percent said new hires receive enterprise AI tools within their first month on the job, while 87% said companies now expect incoming employees to either arrive AI-fluent or learn the systems almost immediately. More than half reported measurable productivity gains and higher confidence levels among workers using AI-assisted systems.

Even the government data complicates the apocalyptic narrative. Unemployment among Americans ages 20 to 24 has fallen sharply from last year’s peak and currently stands near 5.6%, according to data tracked by the Federal Reserve Bank of St. Louis. Meanwhile, demand for AI-related skills is accelerating across entry-level recruiting pipelines. As of March 2026, more than 10% of internship postings on the early-career platform Handshake referenced AI-related skills or tools, nearly double the share from a year earlier.

In reality, both camps are describing different parts of the same labor-market transformation.

AI is eliminating execution-heavy entry-level work — repetitive coding, data entry, first-draft writing, ticket routing, routine research, and standardized reporting. Those functions historically formed the training ground for junior workers. At the same time, AI is creating an entirely new category of entry-level employment focused on deploying, monitoring, integrating, auditing, and managing AI systems themselves.

Hugo Malan, president of the science, engineering, technology, and telecom division at staffing firm Kelly Services, described the shift as “a tectonic realignment” rather than a one-for-one replacement cycle. Andrew McAfee, principal research scientist at the Massachusetts Institute of Technology and co-leader of its Initiative on the Digital Economy, warned companies that removing junior employees entirely could damage their own future leadership pipelines. “How else are people going to learn to do the job except via on-the-job learning and training apprenticeship?” McAfee told Harvard Business Review.

Inside corporate America, the new hiring focus is becoming increasingly clear. Aaron Levie, chief executive of Box, told The Wall Street Journal that banks, pharmaceutical companies, healthcare systems, and large enterprises are now aggressively hiring engineers and operations staff capable of implementing AI-agent systems across their organizations. The market is shifting away from workers who simply execute tasks and toward workers who supervise, refine, troubleshoot, and operationalize AI itself.

For younger workers, the practical implications are increasingly straightforward.

The first advantage is demonstrating real AI fluency rather than vague familiarity. Employers are no longer impressed by resumes that simply mention “AI experience.” Hiring managers increasingly want evidence of actual implementation — which tools were used, what workflows were automated, what content or systems were built, and what productivity gains resulted.

Second, workers increasingly need to pursue augmentation roles rather than substitution roles. The positions showing the strongest growth are implementation engineering, AI operations, workflow automation, prompt architecture, AI compliance, quality control, and human oversight functions. The positions under the greatest pressure remain repetitive coding, basic research, tier-one customer support, and standardized financial analysis.

Third, graduates are benefiting most from joining firms publicly expanding junior hiring pipelines around AI adoption. Companies scaling AI products still require large cohorts of younger workers to build infrastructure, manage deployment, and support enterprise adoption. By contrast, companies using AI primarily as a headcount-reduction strategy are creating narrower entry points and steeper internal competition.

Fourth, judgment is becoming more valuable than raw production ability. The new entry-level role increasingly centers on verifying AI outputs, identifying mistakes, escalating complex situations, and translating machine-generated insights into decisions senior executives can trust. Knowing when AI is wrong may ultimately become more valuable than producing the first draft yourself.

Finally, the broader AI economy is also reviving demand for non-office labor that many white-collar graduates have ignored. Nvidia chief executive Jensen Huang recently described the AI expansion as “the largest infrastructure buildout in human history,” requiring massive numbers of electricians, plumbers, HVAC technicians, steel workers, installers, network specialists, and equipment operators. AT&T chief executive John Stankey said the company is paying substantial bonuses to recruit and retain field technicians as AI infrastructure construction accelerates nationwide.

The bottom line emerging from the debate is that both camps are correct — but only partially. The traditional execution-based entry-level job is unquestionably shrinking. But a new generation of entry-level work centered on AI deployment, oversight, and operational judgment is expanding rapidly, often at higher wages than the jobs being replaced.

The graduates who treat AI as something to compete against risk being displaced by it. The workers who learn how to direct, supervise, and build alongside it are increasingly positioning themselves on the winning side of the divide.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Elon Musk, the world’s wealthiest individual and chief executive of Tesla and SpaceX, declared Israel the global leader in innovation per capita during a virtual address Monday to a major technology conference in Tel Aviv — comments that drew immediate amplification from Israeli Prime Minister Benjamin Netanyahu and arrived just days before what is expected to be the largest initial public offering in U.S. history.

“I’m a huge admirer of the innovation coming out of Israel,” Musk said in video remarks delivered to the Samson International Smart Mobility Summit at Expo Tel Aviv. “I think it is objectively true that Israel punches high above its weight for population. My hat is off to Israel for just how much incredible innovation. I’d say innovation per capita, Israel must be number one in the world.”

Asked specifically to share a message with Israeli innovators in the audience, Musk added: “Innovation per capita, Israel is by far number one in the world.”

Israeli Prime Minister Benjamin Netanyahu shared video of the remarks Tuesday on X, calling Musk “the world’s leading man in innovation.” The endorsement, delivered at a government-hosted conference during a period of heightened geopolitical tension, gave Israel’s technology sector a major public boost from one of the world’s most influential business leaders.

Musk had originally been scheduled to appear in person at the summit earlier this year before the conference was postponed following the outbreak of the U.S.-Israeli military operation against Iran. Speaking remotely from Austin, Texas, Musk apologized for not attending physically and pointed to the pending SpaceX IPO as the reason.

“I would be there in person, but this is IPO, you know, going to get the IPO, SpaceX IPO going pretty soon, I think,” Musk said.

The SpaceX public offering, expected as soon as June, is projected to become the largest IPO in history, potentially valuing the combined SpaceX-xAI business at nearly $2 trillion.

Musk’s comments reinforced a long-standing narrative surrounding Israel’s technology ecosystem.

Despite a population of only around 10 million people, Israel consistently ranks among the world’s top countries in venture capital investment, startup density, research and development spending, cybersecurity innovation and artificial intelligence development.

According to the World Intellectual Property Organization’s Global Innovation Index, Israel ranks among the global leaders in:

  • R&D spending as a percentage of GDP
  • Venture capital investment
  • University-industry collaboration
  • Startup activity
  • Unicorn company creation

Israel has produced globally recognized technology firms and innovations including:

  • Mobileye
  • Waze
  • Check Point Software
  • ICQ
  • Key Intel chip architectures
  • Major cybersecurity platforms
  • Autonomous driving systems
  • Water and agricultural technologies

The conference itself focused heavily on artificial intelligence, autonomous vehicles and the future of transportation.

Musk reiterated his belief that AI-powered autonomous driving will eventually become safer than human driving and predicted that fully autonomous Tesla vehicles could become widely available in the United States before the end of the year.

“The vehicle will feel human, you will really be able to sense the entity inside the vehicle,” Musk said. “It feels alive.”

He also forecast rapid expansion in robotics and AI-driven productivity over the next decade, including major advances tied to Tesla’s Optimus humanoid robot project.

“Within five to ten years, 90% of all transportation will be powered by artificial intelligence,” Musk said.

The remarks come as Israel continues positioning itself as a global AI and defense technology hub during the ongoing regional conflict with Iran. The country’s technology and cybersecurity sectors have remained among the strongest-performing parts of the Israeli economy despite geopolitical instability.

Musk’s relationship with Israel has drawn significant attention since his November 2023 visit following the Oct. 7 Hamas attacks, when he toured Kibbutz Kfar Aza alongside Netanyahu and met with hostage families and victims.

Starlink, Musk’s satellite internet company, later expanded operations into Israel, providing connectivity support for government agencies and critical infrastructure.

For Netanyahu, the timing of Musk’s praise was politically valuable.

The Israeli prime minister has faced sustained international scrutiny over military operations and regional tensions tied to the Iran war. A high-profile endorsement from Musk shifted attention back toward Israel’s innovation economy and global technology leadership.

For Musk, the appearance also reinforced the future-focused narrative surrounding SpaceX, artificial intelligence and autonomous technologies just weeks ahead of the company’s anticipated IPO.

The remarks closed with Musk thanking the Israeli audience and expressing hope that he would visit Israel again after the SpaceX listing is complete.

For now, one of the world’s most influential technology entrepreneurs has publicly reinforced a claim Israel’s startup ecosystem has promoted for decades:
that few countries produce as much innovation relative to their size.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

SpaceX has chosen Goldman Sachs for the top banking role on what could become the biggest stock market debut in history, according to reports from CNBC and The Wall Street Journal.

Morgan Stanley, Bank of America, Citigroup and JPMorgan Chase are also expected to help lead the offering, which could value Elon Musk’s company at as much as $2 trillion and raise roughly $75 billion from investors.

For everyday consumers and investors, the headline is simple: Wall Street is betting that SpaceX could become one of the most valuable and influential companies ever to go public.

The company behind the Falcon rockets and Starlink internet satellites has grown far beyond the space industry. Starlink alone now serves millions of customers globally, while SpaceX’s launch business dominates commercial rocket launches in the United States. Earlier this year, Musk also merged his artificial intelligence company xAI into the broader SpaceX business, turning the company into a mix of space, internet and AI technology under one roof.

That combination is a major reason investor demand is expected to be enormous.

The IPO would easily surpass Saudi Aramco’s 2019 debut as the largest offering ever recorded. Analysts believe the deal could become one of the most heavily traded and closely watched stocks on Wall Street the moment shares begin trading.

But the offering is also generating debate.

Reports suggest SpaceX plans to reserve as much as 30% of the shares for everyday retail investors instead of mainly large Wall Street institutions. Supporters say that gives ordinary Americans a rare opportunity to buy into one of the world’s most sought-after private companies. Critics argue small investors could end up buying at extremely high valuations before fully understanding the company’s risks and finances.

Some analysts also warn the stock could swing sharply after launch because only a limited number of shares are expected to trade publicly at first. Musk, employees and longtime investors are still expected to control most of the company.

Another concern is debt. Reports indicate SpaceX and xAI took on billions of dollars in obligations tied to their merger, meaning part of the IPO money could go toward paying lenders rather than directly funding future expansion.

Still, enthusiasm around the company remains strong.

Starlink’s rapid growth has turned it into one of the world’s fastest-growing internet businesses, while the AI side of the company gives investors exposure to the booming artificial intelligence market that continues driving Wall Street higher.

The IPO also arrives as investors increasingly look for the next major AI-related stock after Nvidia’s massive run. OpenAI and Anthropic are both reportedly exploring future public offerings as the AI race accelerates.

For Goldman Sachs, winning the lead role on the deal is a major Wall Street victory. The position gives Goldman the top placement on the IPO paperwork and the largest share of underwriting fees, which analysts estimate could total close to $1 billion across all banks involved.

SpaceX has not officially confirmed the timing, but reports suggest public filing documents could arrive within days, with trading potentially beginning as soon as June.

If the offering moves forward at the valuations currently being discussed, it would mark one of the biggest moments in modern financial market history — and another massive expansion of Elon Musk’s business empire.

— JBizNews Desk

© JBizNews.com. All rights reserved.

WASHINGTON — Judge Karen LeCraft Henderson of the U.S. Court of Appeals for the D.C. Circuit sharply criticized the Pentagon on Tuesday over its decision to label artificial-intelligence company Anthropic a national-security supply-chain risk, calling the move “a spectacular overreach” during a high-stakes hearing that could reshape the federal government’s power over AI contractors.

“To me, this is just a spectacular overreach by the Department,” Henderson said during nearly two hours of oral arguments. “For the life of me, I do not see any evidence of maliciousness.”

Henderson was referring to the Pentagon’s March designation of Anthropic — maker of the Claude AI platform — as a supply-chain threat to U.S. national security, an extraordinary label historically associated with foreign adversaries or hostile overseas suppliers. The designation triggered a broader Trump administration order directing federal agencies to stop using Anthropic technology and gave the Defense Department six months to remove the company’s systems from military infrastructure.

The hearing before the three-judge D.C. Circuit panel marks the most consequential legal test yet in the escalating standoff between the Pentagon and one of Silicon Valley’s most powerful AI firms.

Anthropic attorney Kelly Dunbar argued the Pentagon illegally weaponized national-security authorities during what was fundamentally a contract dispute. “For the first time ever,” Dunbar told the court, “the secretary turned a powerful national security authority against an American company.”

Dunbar argued the Pentagon bypassed congressionally mandated procedures, exceeded statutory authority, and violated constitutional protections by invoking emergency-style supply-chain powers against a domestic AI developer rather than simply ending negotiations or refusing to award contracts.

At the center of the dispute are disagreements over how Anthropic’s models could be used inside military systems. According to court filings, the Defense Department sought unrestricted access to Anthropic’s AI technology for all lawful military purposes, while Anthropic insisted on maintaining safeguards prohibiting use of its systems for fully autonomous weapons or domestic mass-surveillance operations.

When negotiations collapsed, Defense Secretary Pete Hegseth issued the supply-chain designation and publicly attacked the company online, accusing it of obstructing critical national-security operations. Anthropic CEO Dario Amodei later said the company had “no choice” but to sue.

Justice Department attorney Sharon Swingle, representing the Pentagon, defended the designation by arguing the Defense Department had legitimate concerns about vendor reliability and the operational risks associated with deploying advanced AI inside military environments.

“It is clear that Anthropic has the technical capability to interfere with and even prevent the Department of War’s use of its AI model for critical military operations,” Swingle told the panel, warning that AI system failures during active military deployments “could have catastrophic national-security consequences.”

The Pentagon’s argument focused heavily on unpredictability rather than malicious intent — a distinction that drew extensive questioning from the appellate judges.

Judge Neomi Rao pressed Anthropic’s legal team on whether courts should second-guess national-security determinations made by defense officials. “It’s about risk,” Rao said, framing the issue around whether the Pentagon could reasonably conclude the company’s systems posed operational uncertainty.

Judge Gregory Katsas echoed that concern, telling Anthropic’s attorney that even if Pentagon rhetoric surrounding the company was excessive, “they still have this concern, right? The model is unpredictable.”

Both Rao and Katsas were appointed by President Donald Trump.

The legal posture surrounding the case has become increasingly unusual. Last month, a federal judge in California sided with Anthropic and temporarily blocked the Pentagon from enforcing the supply-chain designation, while the D.C. Circuit previously declined to issue a similar injunction. As a result, Anthropic can continue servicing many non-Pentagon federal contracts while broader litigation continues, though new Defense Department agreements remain frozen.

The D.C. Circuit agreed to expedite proceedings, with another hearing scheduled for June 5 and a ruling potentially arriving within weeks.

Beyond the courtroom drama, the dispute is emerging as one of the defining battles over how the federal government will regulate advanced artificial intelligence systems and the extent to which national-security authorities can be used against domestic technology firms.

Despite the blacklisting, reports indicate the Defense Department continued using Anthropic’s models during military operations tied to the Iran conflict, highlighting how deeply embedded advanced AI systems have already become inside portions of the national-security apparatus.

President Donald Trump has also recently softened his public tone toward the company. During an interview last month on CNBC’s “Squawk Box,” Trump suggested a future compromise with Anthropic remained possible. “It’s possible,” Trump said. “We want the smartest people.”

The president’s remarks followed a White House meeting with Amodei focused on cybersecurity cooperation, AI competitiveness against China, and broader U.S. technology leadership — conversations that appeared notably more conciliatory than the administration’s courtroom posture.

For Anthropic, the stakes extend far beyond lost government revenue. The company argues the supply-chain label effectively brands it as a national-security threat across the broader contractor ecosystem, potentially damaging relationships with commercial customers, investors, and global partners.

The case arrives at a pivotal moment for the company itself. Anthropic is reportedly in discussions to raise additional capital at valuations approaching $900 billion, making it one of the most valuable private companies in the world and a central player in the escalating global AI race.

A ruling from the D.C. Circuit in the coming weeks could ultimately determine whether the U.S. government can treat one of America’s leading AI firms as a national-security liability — or whether the Pentagon exceeded its authority in attempting to do so.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Russian President Vladimir Putin arrived in Beijing late Tuesday for a two-day state visit with Chinese President Xi Jinping, just one week after President Donald Trump wrapped his own high-stakes visit to the same capital — a back-to-back diplomatic sequence that has placed China at the center of competing efforts by Washington and Moscow to shape the post-Iran-war global order.

Putin was greeted at Beijing Capital Airport by Chinese Foreign Minister Wang Yi in a state-level ceremony that mirrored the diplomatic pomp Xi afforded Trump the previous week. China’s Foreign Ministry said it is Putin’s 25th visit to the country. The trip commemorates the 30th anniversary of the China-Russia strategic cooperative partnership and the 25th anniversary of the 2001 Sino-Russian Treaty of Friendship.

The timing itself has drawn global attention.

Within a span of days, Xi hosted both Trump and Putin in Beijing — reinforcing China’s increasingly central role in global diplomacy at a moment of growing geopolitical instability. Chinese state media portrayed the sequence as evidence Beijing has become an indispensable power broker between rival global blocs.

The core focus of Putin’s visit is energy.

At the top of the agenda is the long-delayed Power of Siberia 2 natural gas pipeline, a proposed project that would transport massive volumes of Russian gas into China. Moscow urgently needs new long-term buyers after losing much of its European energy business following the Ukraine war, while Beijing continues leveraging its position to negotiate favorable pricing and terms.

The Iran war has only increased the strategic importance of that relationship.

With instability disrupting Middle Eastern energy flows and pressure mounting around the Strait of Hormuz, China has relied increasingly on discounted Russian oil and gas imports. Russia has simultaneously become more dependent on Chinese trade, financing and industrial support as Western sanctions continue weighing on its economy.

Russian oil exports to China reportedly surged roughly 35% during the first quarter of 2026, according to Kremlin foreign policy adviser Yuri Ushakov.

Ahead of the trip, Putin praised what he called the “unprecedented level” of cooperation between Moscow and Beijing, saying the two countries support each other on issues involving sovereignty and strategic interests.

Chinese state media echoed the message, describing the partnership as “unshakable” despite mounting global tensions.

Beyond energy, analysts say Putin is also likely seeking insight into Trump’s recent discussions with Xi — particularly surrounding Ukraine and possible future negotiations involving Russia and the West.

The Trump administration has pursued intermittent diplomatic talks aimed at eventually ending the Ukraine war, though little concrete progress has emerged publicly.

“Putin may want to know Trump’s latest thinking on Ukraine and potential peace negotiations,” said Natasha Kuhrt, senior lecturer in war studies at King’s College London, in comments cited by NBC News.

Analysts say the visit also highlights a growing imbalance in the China-Russia relationship.

While Moscow still presents itself publicly as a global power equal to Beijing, many observers believe Russia now enters negotiations increasingly from a weaker position economically and diplomatically. China, meanwhile, has gained leverage by becoming one of the few major economies willing to maintain deep trade ties with Moscow despite Western sanctions.

Trump’s own Beijing visit last week produced limited public breakthroughs but avoided major escalation between Washington and Beijing. The two sides discussed trade, technology restrictions, Taiwan and critical minerals, while both governments signaled willingness to continue dialogue.

Xi warned during Trump’s visit that mishandling Taiwan could “push the two countries into conflict,” underscoring how fragile U.S.-China relations remain despite renewed diplomacy.

Putin’s visit is being framed differently.

Rather than negotiating a reset, Moscow and Beijing are portraying the trip as a reaffirmation of an already established strategic partnership — one built increasingly around energy, trade and mutual resistance to Western pressure.

Still, China continues walking a careful line.

Beijing has supported economic ties with Russia while trying to avoid becoming directly entangled in Western sanctions. Chinese banks and corporations have periodically limited certain Russian transactions to reduce exposure to secondary sanctions from the United States and Europe.

That balancing act reflects Beijing’s broader strategy: maintaining leverage and relationships with both Washington and Moscow without fully aligning with either side.

The back-to-back Trump and Putin visits underscore a larger reality emerging in global politics — nearly every major power now sees Beijing as a relationship it cannot afford to ignore.

Whether Xi ultimately positions China as a neutral mediator, a strategic partner to Russia, or a rival to the United States remains less clear.

For now, though, one image stands out above the rest:
Putin in Beijing days after Trump left — with Xi at the center of both meetings.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The AI bellwether reports Q1 results after the bell, with $725 billion in hyperscaler capital spending and the future of the U.S. market rally riding on the answer.

NEW YORK — Nvidia Corp. is scheduled to release its fiscal first-quarter 2027 earnings results after the market close Wednesday in what Wall Street strategists increasingly describe as the single most important corporate earnings report of the year — a print that could either validate or destabilize the artificial intelligence trade that has carried U.S. markets through tariffs, elevated inflation, geopolitical turmoil and slowing global growth.

According to Bloomberg consensus estimates, Nvidia is expected to report earnings per share of roughly $1.76 on revenue approaching $79 billion, more than 75% above the year-ago period. The Philadelphia Semiconductor Index, the broadest benchmark for the U.S. chip sector, has already surged roughly 64% year to date in 2026, dramatically outperforming the broader S&P 500.

But tonight’s report is no longer simply about one company.

It has become a referendum on the entire technology industry.

Because the American technology sector is now undergoing one of the largest structural transformations since the rise of the internet itself, as artificial intelligence, cybersecurity, cloud computing, semiconductors, energy infrastructure and geopolitical competition collectively reshape the next decade of global economic power.

For years, the technology industry was driven primarily by consumer products:
smartphones,
apps,
social media,
streaming,
e-commerce.

Now the center of gravity is shifting toward infrastructure, industrial computing, data centers, national security and enterprise productivity — and the money flowing into the sector is reaching historic levels.

The numbers are staggering.

The world’s largest technology companies — Microsoft, Nvidia, Apple, Amazon, Alphabet and Meta Platforms — are now collectively worth well over $15 trillion. Nvidia alone added trillions in market value during the AI boom, becoming one of the most valuable companies in financial market history almost overnight as global demand for advanced chips exploded.

Projected 2026 capital spending by the largest U.S. AI hyperscalers — Amazon, Microsoft, Meta and Alphabet — has reportedly climbed from roughly $531 billion late last year to nearly $725 billion today, according to BNP Paribas estimates, underscoring how aggressively the AI infrastructure race continues accelerating.

Wall Street increasingly understands this is no longer just another Silicon Valley cycle.

Technology has become the backbone of the modern economy itself.

Banks depend on it.

Hospitals depend on it.

Manufacturing depends on it.

Governments depend on it.

Military systems depend on it.

And increasingly, nearly every business in America is becoming a technology business whether it planned to or not.

That transformation accelerated dramatically after the pandemic.

Remote work forced corporations to modernize digital systems almost overnight. Cloud infrastructure spending exploded. Cyberattacks surged. Digital payments accelerated. Data centers expanded at record pace. Corporate America realized technology was no longer simply a support function buried in the IT department — it had become operational infrastructure.

Now artificial intelligence is accelerating that shift even further.

Major corporations are spending billions integrating AI systems into logistics, software development, customer service, operations, finance, marketing and communications. At the same time, governments worldwide increasingly treat semiconductor manufacturing and computing infrastructure as matters of national security.

That geopolitical component is becoming one of the defining forces inside the modern technology market.

The United States and China are now locked in a full-scale technological arms race centered around semiconductors, artificial intelligence, cloud infrastructure and advanced manufacturing. Washington has imposed sweeping restrictions aimed at limiting China’s access to cutting-edge U.S. chip technology, while Beijing continues pouring enormous state resources into domestic chip independence.

The stakes are enormous because advanced computing power increasingly translates directly into economic and geopolitical power.

That reality is also reshaping global supply chains.

After years of relying heavily on overseas semiconductor production, the United States is aggressively rebuilding portions of its domestic chip industry through the CHIPS Act and related industrial policies. Companies including Intel, Taiwan Semiconductor Manufacturing Co., Samsung Electronics and Micron Technology are investing hundreds of billions of dollars into advanced manufacturing plants across the United States.

Meanwhile, competition around Nvidia itself is intensifying rapidly.

Amazon.com Inc. disclosed earlier this year that its custom AI chip business — including Trainium, Graviton and Nitro — has already crossed a massive annual revenue run rate as major AI developers increasingly seek alternatives to Nvidia’s dominant hardware ecosystem.

Some investors are also beginning to question whether parts of the AI spending cycle may eventually overheat.

Several institutional portfolio managers have warned that portions of the sector now depend heavily on large technology companies effectively financing each other’s AI expansion simultaneously, creating concerns about sustainability if growth slows or corporate spending weakens.

Still, demand for advanced computing infrastructure globally continues outpacing available supply.

And the ripple effects across the broader economy are becoming enormous.

The technology boom is now directly influencing energy markets, labor markets and commercial real estate simultaneously. AI data centers require enormous amounts of electricity, turning utility companies and power producers into unexpected beneficiaries of the technology rally. Analysts increasingly believe AI-driven electricity demand could reshape the U.S. energy industry over the next decade.

Cybersecurity has also evolved into one of the fastest-growing sectors in the world as ransomware attacks, digital espionage and state-sponsored cyberwarfare force corporations and governments into permanent infrastructure spending cycles.

The labor market is shifting alongside the industry itself.

Technology firms continue hiring aggressively in specialized areas like chip engineering, AI systems, cybersecurity and cloud infrastructure. But many companies are simultaneously automating administrative functions, reducing certain white-collar roles and restructuring around AI-assisted productivity.

That split is creating growing anxiety across parts of the workforce even as technology profits continue surging.

For consumers, the impact is becoming increasingly visible.

AI tools are improving productivity, accelerating software development and lowering costs in some industries. But electricity rates are rising in regions with heavy data center concentration. Automation is beginning to pressure some white-collar jobs. And the enormous infrastructure costs required to sustain the AI economy are gradually flowing through the broader economy.

Wall Street nevertheless remains overwhelmingly bullish on the sector for one simple reason:

Technology is no longer viewed as a separate part of the economy.

It is the economy.

Nearly every major growth theme now runs directly through the technology industry:

  • artificial intelligence
  • semiconductors
  • cybersecurity
  • cloud infrastructure
  • robotics
  • autonomous systems
  • digital payments
  • defense technology
  • data infrastructure
  • energy-intensive computing

And unlike earlier tech booms centered mainly around gadgets and apps, this cycle is deeply tied to national security, industrial competitiveness and long-term economic dominance.

That is why Nvidia’s earnings report matters so much tonight.

Because investors are no longer just betting on one chip company.

They are betting on whether the technological infrastructure powering the modern global economy is still accelerating — or whether the biggest market rally of the decade is beginning to slow.

By the time Nvidia executives finish speaking Wednesday evening, Wall Street may have its answer.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

NEW YORK — Ramp CEO Eric Glyman said Tuesday that the coming wave of mega-IPO listings from SpaceX, Anthropic, and OpenAI could fundamentally reshape investor expectations across public markets, bringing Silicon Valley-style hypergrowth directly onto Wall Street after years of being largely confined to private capital.

Speaking during CNBC’s “Squawk on the Street,” Glyman argued that public-market investors have spent the past decade largely investing in mature, slower-growing companies while the fastest-growing firms remained inaccessible inside venture-capital portfolios. That dynamic, he said, is now beginning to reverse in dramatic fashion.

“You’re gonna start to see companies that are growing 50%, 100%, 800%,” Glyman said, referencing the expected public-market debuts of Elon Musk’s SpaceX and leading artificial-intelligence firms Anthropic and OpenAI. “That changes what people think normal growth looks like.”

The comments come as Wall Street prepares for what bankers increasingly describe as one of the largest IPO pipelines in modern financial history. According to reports cited by The Wall Street Journal, SpaceX is targeting a potential June 12 public debut at a valuation approaching $1.75 trillion, potentially raising as much as $75 billion in what could become the largest IPO ever completed. Anthropic is reportedly preparing for a listing as early as October, while OpenAI is evaluating a fourth-quarter offering after recently completing a financing round valuing the company at approximately $852 billion.

Data from Renaissance Capital show U.S. IPO issuance has already reached roughly $28.4 billion year-to-date, though analysts say that figure would be eclipsed quickly if even one of the three AI-era giants comes public on schedule.

Glyman’s appearance coincided with Ramp being ranked No. 5 on CNBC’s annual Disruptor 50 list, which highlights the country’s fastest-growing private technology companies. Founded in 2019 by Eric Glyman, Karim Atiyeh, and Gene Lee, the New York-based fintech company has rapidly expanded into one of the largest corporate spend-management platforms in the United States.

Ramp now serves more than 50,000 businesses and crossed $1 billion in annualized recurring revenue last year. Glyman said the company currently processes roughly 3% of U.S. corporate credit-card volume and about 1% of all corporate financial transactions, including expense management and bill payments.

The company’s growth has accelerated alongside the broader AI-driven productivity boom sweeping corporate America. Ramp combines AI-powered expense controls, accounting automation, procurement management, and corporate card infrastructure aimed at reducing manual administrative work for finance departments.

“Folks are very excited about the company,” Glyman said when discussing fundraising conditions, describing Ramp’s combination of rapid revenue growth and positive cash generation as “an unusual financial profile.”

He added that the broader business environment remains highly favorable for companies deploying automation and AI to improve productivity. “It’s an amazing time to be building a company,” Glyman said, noting that the average Ramp customer is growing revenue roughly four times faster than the broader U.S. economy.

Private investors have aggressively rewarded that momentum. Ramp raised $200 million in June at a $16 billion valuation, followed by a $500 million financing round in July that lifted the company’s valuation to $22.5 billion. Another $300 million round later in the year valued the company at $32 billion. Reports now indicate a new financing could push Ramp’s valuation toward $40 billion, representing one of the fastest valuation climbs in fintech.

The broader Disruptor 50 rankings further illustrate how concentrated investor enthusiasm has become around AI and infrastructure companies. CNBC estimated the 2026 Disruptor class now carries a combined implied valuation of approximately $2.4 trillion, with nearly $2 trillion concentrated among the top five firms alone.

Anthropic, ranked No. 1, has emerged as one of Silicon Valley’s fastest-growing companies. CEO Dario Amodei recently told CNBC the AI firm increased revenue roughly 80-fold during the first quarter, one of the most explosive growth rates ever recorded among enterprise-software companies. Reports indicate Anthropic is now pursuing another financing round that could value the company near $900 billion.

OpenAI, ranked No. 2, remains at the center of the global AI race following the explosive adoption of ChatGPT and its broader AI ecosystem. Meanwhile, firms including Databricks, Stripe, and SpaceX continue building what investment banks describe as the largest IPO backlog seen since the dot-com era.

For investors, the implications could be profound. Companies that have spent years compounding revenue at extraordinary rates inside private markets may soon trade directly alongside slower-growing public benchmarks like the S&P 500, fundamentally altering how investors value growth, profitability, and future earnings potential.

Glyman’s remarks captured what many on Wall Street increasingly believe is now unfolding: the long-standing divide between private venture-backed growth companies and public-market investing is rapidly disappearing. Over the next several quarters, some of the world’s largest and fastest-growing technology firms may begin trading in real time before everyday investors — potentially reshaping market leadership, valuation standards, and risk appetite across the entire financial system.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A small Florida franchisee of Pet Supplies Plus has filed for Chapter 11 bankruptcy protection, offering a fresh glimpse into the growing financial strain facing independent retail operators even as the broader U.S. pet industry continues expanding.

According to a petition filed May 12 in the U.S. Bankruptcy Court for the Middle District of Florida, Holiday, Florida-based PSP TS LLC listed assets between $100,000 and $500,000 and liabilities ranging from $1 million to $10 million. The filing did not specify a direct cause for the bankruptcy, though court records show the company’s lone Pet Supplies Plus store remains open during the proceedings.

The parent franchisor itself was not part of the filing.

On paper, the bankruptcy is relatively modest. In practice, however, it reflects a wider challenge increasingly surfacing across America’s franchise economy: national brands continue growing while smaller operators underneath them struggle to absorb rising operating costs, labor expenses, insurance premiums, and interest rates.

The contrast is especially striking inside the pet industry, one of the most resilient sectors in consumer retail.

According to the American Pet Products Association’s 2026 State of the Industry Report, total U.S. pet-industry sales reached approximately $158 billion last year and are projected to rise to roughly $165 billion in 2026.

Consumer demand for premium pet food, veterinary care, grooming, supplements, and pet wellness services has remained relatively strong even as higher interest rates and inflation pressure spending in many other retail categories.

But beneath those strong industry-level numbers, smaller franchise operators are increasingly facing margin compression.

Industry observers say single-store and small-cluster franchisees have become particularly vulnerable because they lack the scale advantages available to larger corporate chains and multi-unit operators.

The PSP TS filing follows several similar franchisee restructurings across Florida over the past year.

In January, J.L.E.T. Enterprises, a Florida-based operator of multiple Three Dog Bakery locations, also sought bankruptcy protection in the same federal district after its franchise agreement was terminated, according to court records reviewed by restructuring consultants.

The broader Pet Supplies Plus brand itself has been navigating major changes over the past two years.

Headquartered in Livonia, Michigan, the company now operates roughly 725 stores across 44 states alongside 26 Wag N’ Wash grooming and pet-care locations. The chain carries more than 10,000 products across roughly 400 brands and has continued adding new franchise agreements despite broader retail-sector uncertainty.

Entrepreneur Magazine recently ranked Pet Supplies Plus among its top franchise systems nationally, while Forbes included the company among its leading customer-service brands.

The franchisor side of the business has remained relatively stable following a turbulent corporate restructuring at its former parent company.

Pet Supplies Plus previously operated under Franchise Group Inc., the holding company that also owned businesses including The Vitamin Shoppe, American Freight, Buddy’s Home Furnishings, Sylvan Learning, and Liberty Tax.

Franchise Group filed for Chapter 11 bankruptcy protection in late 2024 after struggling under a heavy debt load tied to aggressive acquisitions and rising interest costs.

The company eventually restructured through a deal backed by major lenders and private-equity firms, emerging from bankruptcy in mid-2025 after selling off several assets and winding down portions of its retail portfolio.

Pet Supplies Plus and Wag N’ Wash were later separated into a standalone entity known as Fusion Parent LLC.

“Even though we were already operating as an independent business, this decision allows us to formally chart our own course,” CEO Chris Rowland said at the time of the separation.

The company has since continued pursuing expansion plans and recently secured a large securitized financing facility commonly used by major franchise systems to support growth.

Analysts say the corporate-level restructuring has largely stabilized the franchisor itself.

The pressure now appears increasingly concentrated at the franchisee level.

Neil Saunders, managing director at GlobalData, said after Franchise Group’s restructuring that Pet Supplies Plus remained one of the healthier brands inside the former holding company but warned that franchise operators still face intense competition and rising operating expenses in a slowing economy.

That tension has become a defining challenge across large parts of American franchised retail.

National brands continue signing new agreements, adding locations, and posting growing revenue, while many individual operators struggle to maintain profitability at the local level.

For franchisees, costs tied to labor, rent, insurance, utilities, inventory financing, and wages have risen faster than revenue growth in many regional markets.

At the same time, consumers are increasingly shifting spending toward e-commerce, subscription delivery services, and large-scale national platforms with greater pricing power.

The result is a widening divide between franchise systems that appear healthy at the top and local operators fighting to preserve cash flow store by store.

Pet Supplies Plus still maintains a pipeline of roughly 200 pending franchise agreements across its brands, suggesting expansion plans remain firmly intact.

For smaller operators such as PSP TS LLC, however, the immediate question is far more practical: whether bankruptcy reorganization can provide enough breathing room to keep neighborhood pet stores operating in an industry where overall sales continue rising, but the economics increasingly favor scale over independence.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The U.S. Navy seized an Iran-linked oil supertanker overnight in the Indian Ocean, escalating pressure on Tehran’s oil exports and adding fresh strain to global energy markets already dealing with rising fuel prices and shipping disruptions tied to the ongoing Iran conflict.

U.S. officials confirmed that American forces intercepted the massive crude tanker Skywave after the vessel departed the Strait of Malacca carrying what analysts believe was more than one million barrels of Iranian oil.

For consumers and businesses, the move matters because it threatens to tighten global oil supply even further at a time when gasoline, diesel and shipping costs are already climbing worldwide.

Oil prices rose again Tuesday following the seizure.

Brent crude traded near $110 per barrel, while U.S. crude prices also pushed higher as traders worried that additional supply disruptions could worsen the global energy crunch.

Gasoline prices in the United States have already surged sharply since the Iran conflict began earlier this year.

According to AAA:

  • National average gasoline prices are now near $4.05 per gallon
  • Prices were below $3 before the conflict escalated
  • Diesel prices have also climbed significantly

The Skywave seizure marks the third major tanker interception since the United States launched its naval blockade targeting Iranian oil shipments last month.

Unlike earlier seizures near the Persian Gulf, this latest operation occurred much farther from the Middle East, signaling that U.S. enforcement efforts are expanding well beyond the immediate conflict zone.

Shipping analysts say the move sends a strong warning to operators participating in what is often called Iran’s “shadow fleet” — aging tankers that move sanctioned oil through complex ownership structures, false registrations and ship-to-ship transfers designed to avoid detection.

The vessel itself had previously been sanctioned by the U.S. Treasury Department under another name before reportedly changing ownership and operating under a different flag.

The broader economic effects are already spreading globally.

The Strait of Hormuz — one of the world’s most important oil shipping routes — has seen a dramatic collapse in tanker traffic since the blockade intensified.

Industry estimates suggest normal vessel traffic through the strait has fallen sharply over the past several weeks as insurers, shipowners and traders attempt to avoid military escalation and soaring war-risk insurance costs.

Insurance premiums for ships traveling through the region have surged, while thousands of seafarers and hundreds of vessels remain stranded or rerouted across global shipping lanes.

The pressure is now reaching everyday supply chains.

Higher diesel costs are increasing:

  • Trucking expenses
  • Retail shipping costs
  • Airline fuel costs
  • Manufacturing transportation costs

That creates additional inflation pressure at a moment when central banks globally are already struggling to contain rising prices.

The International Energy Agency warned this week that global oil inventories are falling rapidly, raising concerns that even if diplomatic progress eventually occurs, energy markets may remain tight for months because of damaged infrastructure, delayed shipments and disrupted tanker traffic.

Iran has continued attempting to move oil exports despite the blockade.

Satellite tracking firms reported millions of barrels of crude still moving through unofficial channels using tactics such as:

  • Disabling tracking systems
  • False location signals
  • Ship-to-ship transfers
  • Reflagged vessels

The United States has simultaneously expanded sanctions against additional tankers and shipping companies as part of what officials are calling a broader economic pressure campaign against Tehran.

Diplomatic tensions remain high.

President Donald Trump has continued warning Iran against advancing its nuclear program, while Iranian officials have publicly rejected negotiations under military and economic pressure.

For financial markets, the latest tanker seizure reinforces fears that the global oil shock may last longer than investors originally expected.

Analysts at major banks including Goldman Sachs and ING now warn that every additional month of disruption in Middle Eastern oil flows could keep prices elevated well into next year.

For consumers, that means higher fuel costs may not disappear anytime soon.

And with global shipping now increasingly entangled in military escalation, the impact is extending far beyond the Middle East — directly into supply chains, inflation and household budgets around the world.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Asian stock markets fell sharply Wednesday as rising global bond yields rattled investors and increased fears that borrowing costs could stay high much longer than markets had hoped.

For everyday investors, the message from global markets is becoming increasingly clear:
higher interest rates are starting to pressure stocks around the world.

Japan led regional losses, with the Nikkei 225 dropping nearly 1% after government bond yields surged to their highest levels since the late 1990s. Markets in South Korea, Australia, Hong Kong and other major Asian economies also moved lower as investors reacted to the ongoing global bond selloff.

The pressure is coming primarily from government bond markets, where yields have climbed rapidly over the past several days.

In the United States:

  • The 30-year Treasury yield briefly topped 5.19%
  • The 10-year Treasury yield climbed near 4.7%

Those are some of the highest levels seen in nearly two decades.

In simple terms, rising bond yields mean borrowing money becomes more expensive throughout the economy.

That affects:

  • Mortgage rates
  • Business loans
  • Credit cards
  • Corporate borrowing
  • Government financing costs

Higher yields also tend to hurt stocks because safer investments like bonds begin offering more attractive returns relative to equities.

The latest surge has been fueled largely by concerns that inflation may remain stubbornly high because of the ongoing Iran war and elevated oil prices.

Crude oil has stayed near $110 per barrel, increasing fears that energy costs could continue pushing inflation higher globally.

As a result, investors are rapidly abandoning expectations that central banks will cut interest rates anytime soon.

Some analysts are now even discussing the possibility that the Federal Reserve may eventually need to raise rates again if inflation pressures worsen.

That shift in expectations has triggered heavy selling across global bond markets.

Japan’s move is especially important because Japanese investors are among the largest holders of U.S. government debt.

As Japanese bond yields rise at home, investors may increasingly move money out of U.S. assets and back into Japan, potentially adding even more pressure to global financial markets.

Technology and AI-related stocks have also come under pressure, particularly in South Korea and Hong Kong.

South Korea’s market has been especially volatile in recent sessions as investors reassess valuations in semiconductor and AI companies after enormous rallies earlier this year.

Markets are now closely watching Nvidia earnings later Wednesday, which could heavily influence sentiment across global technology stocks.

China’s slowing economy is adding another layer of concern.

Recent Chinese economic data has disappointed investors, with weaker-than-expected retail sales and industrial output raising fears about slowing demand across Asia.

At the same time, geopolitical uncertainty remains elevated.

Russian President Vladimir Putin arrived in Beijing this week for meetings with Chinese President Xi Jinping, while markets continue monitoring developments tied to the Iran conflict and broader global tensions.

Despite the selloff, some sectors have held up better than others.

Australia’s market, for example, has been somewhat supported by mining and commodity companies benefiting from higher raw material prices.

Still, analysts say the direction of global markets now depends heavily on one central issue:
whether bond yields continue rising.

If yields stabilize, stock markets could recover relatively quickly.

But if inflation stays elevated and central banks become even more aggressive, investors may face continued pressure across both stocks and bonds — an unusually difficult environment for traditional portfolios.

For now, markets around the world are adjusting to a reality investors had hoped to avoid:
higher interest rates may not be going away anytime soon.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Gold prices struggled to recover Tuesday, hovering near $4,590 an ounce after suffering their sharpest weekly decline in months, as the unresolved U.S.-Iran conflict continued reshaping global inflation expectations and driving investors to price in a possible Federal Reserve rate hike before year-end rather than the cuts markets once expected.

The reversal marks a dramatic shift for the precious-metals market.

Earlier this year, gold surged to record highs above $5,200 an ounce as investors anticipated multiple Federal Reserve rate cuts, weakening real yields, and escalating geopolitical instability. But the prolonged energy shock tied to the Iran conflict has effectively flipped that entire macroeconomic narrative.

According to CME Group’s FedWatch Tool, traders now assign roughly a 40% probability to a 25-basis-point Fed rate hike by December, with some institutional desks placing the implied odds even higher.

The result has been unusually painful for gold despite the war backdrop that would historically boost demand for safe-haven assets.

Spot gold has fallen roughly $685 an ounce since late February, dropping from around $5,275 on the eve of Operation Epic Fury to near $4,590 this week. Over the same period, Brent crude surged from roughly $72 per barrel to near $120 at peak panic levels before stabilizing above $110.

The two assets investors traditionally pair together during geopolitical crises — oil and gold — are now moving in opposite directions.

“A geopolitical shock that simultaneously creates a severe inflation shock changes the entire rate environment,” one senior metals strategist at a major Wall Street bank said Tuesday. “That’s what gold is fighting right now.”

The core problem for gold is interest rates.

Rising oil prices tied to the Strait of Hormuz disruption are feeding directly into inflation expectations, forcing markets to assume the Federal Reserve may need to tighten policy rather than ease it.

That shift has sent Treasury yields sharply higher.

The U.S. 30-year Treasury yield climbed this week to its highest level since 2007, while the benchmark 10-year Treasury reached its highest level since early 2025. Real yields — one of the most important drivers for gold prices — are rising because nominal rates are increasing faster than inflation expectations.

That dynamic directly pressures non-yielding assets like gold.

The inflation fears intensified after recent economic data showed a much hotter-than-expected Producer Price Index reading alongside stronger industrial production numbers, effectively destroying the “soft landing” narrative that had fueled much of gold’s earlier rally.

Wall Street banks are now recalibrating their outlooks.

J.P. Morgan, which had previously projected gold could reach $6,300 an ounce by year-end, recently lowered portions of its near-term outlook as higher energy prices altered Federal Reserve expectations.

Goldman Sachs continues forecasting gold eventually reaching roughly $5,400, largely due to sustained central-bank demand, but warned clients that prolonged Hormuz disruption creates meaningful downside pressure in the near term if interest rates continue climbing.

Other bullish long-term forecasts from Bank of America, Wells Fargo, and BNP Paribas were all issued before oil prices surged above $100 and before markets began pricing in renewed monetary tightening.

The policy environment has become the exact opposite of what historically drives strong gold rallies.

Throughout most of 2025, gold benefited from expectations of lower rates, a softer dollar, slowing growth, and reserve diversification away from the U.S. currency system. The Iran conflict has reversed much of that equation.

Markets are now pricing almost no meaningful Fed cuts next year, while the U.S. dollar has strengthened as investors increasingly view the American economy — now a major oil producer itself — as more insulated from the energy shock than Europe or parts of Asia.

One major pillar supporting gold, however, remains intact: central-bank buying.

Global central banks continue accumulating gold reserves at historically elevated levels as countries seek diversification away from the dollar-dominated financial system. Surveys conducted by major investment banks show a large majority of central banks still expect gold prices to remain above $5,000 over the next 12 months.

That demand is helping establish a floor under the market even as hedge funds and institutional investors reduce positions tied to falling rate-cut expectations.

The broader strategic case for gold also remains largely unchanged.

For many long-term investors, gold increasingly functions less as a short-term inflation hedge and more as insurance against rising sovereign debt burdens, persistent fiscal deficits, and long-term currency debasement risks across developed economies.

But the near-term setup remains difficult.

Technical analysts say gold’s recent breakdown below key momentum levels leaves the market vulnerable to additional downside pressure if rates continue climbing and oil prices remain elevated. Several trading desks now view the $4,500 level as a major support zone, with further declines potentially opening a path toward the low $4,300 range.

The clearest upside catalyst would likely be a meaningful diplomatic breakthrough between Washington and Tehran.

Reports continue circulating that negotiators remain close to a framework agreement that could reopen the Strait of Hormuz in exchange for sanctions relief and restrictions on Iranian uranium enrichment. Such a deal would likely reduce oil prices, ease inflation fears, lower Treasury yields, and revive expectations for eventual Fed easing — a combination that would immediately benefit gold.

Until then, markets remain trapped in the same macro trade dominating nearly every asset class tied to the conflict.

Oil higher. Yields higher. Dollar higher. Gold lower.

The metal that traditionally protects investors during war is now being overwhelmed by the inflation and interest-rate shock the war itself created.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The British government has quietly relaxed part of its sanctions policy on Russian energy, allowing imports of diesel and jet fuel refined from Russian crude oil in third countries as the Iran war continues disrupting global fuel supplies.

For everyday consumers, the decision highlights how severe the global fuel shortage has become — and how governments are increasingly prioritizing energy stability over strict sanctions enforcement as diesel and airline fuel prices surge.

Under the new policy issued Tuesday, the UK will now allow imports of diesel and jet fuel produced from Russian oil if that oil is refined in countries such as India, Turkey or China before being sold to Britain.

The move effectively reopens a supply channel Britain had blocked last year.

Officials say the change is aimed at easing pressure on fuel markets after months of war-driven disruptions in the Middle East pushed oil, diesel and aviation fuel prices sharply higher.

The Iran conflict and ongoing instability around the Strait of Hormuz — one of the world’s most important oil shipping routes — have created major supply problems for global energy markets.

Diesel prices are especially important because diesel fuels much of the economy, including trucking, shipping, farming equipment, construction machinery and parts of public transportation.

Jet fuel shortages have also become a growing issue for airlines, where fuel can account for roughly one-third of operating costs.

As fuel prices rise, the effects often spread quickly through the broader economy in the form of higher shipping costs, more expensive airline tickets and increased prices for goods in stores.

The UK’s decision follows a similar move by the United States earlier this week extending a waiver tied to Russian oil purchases amid concerns about global energy shortages.

The European Union has also softened certain restrictions as governments try to prevent deeper fuel crises.

The situation reflects a difficult balancing act facing Western governments.

Since Russia’s invasion of Ukraine, the UK, U.S. and Europe have tried to reduce Moscow’s energy revenues through sanctions and trade restrictions. But Russia remains one of the world’s largest oil exporters, and much of its crude has continued flowing into global markets through countries that never joined Western sanctions.

India and Turkey, in particular, dramatically increased purchases of discounted Russian crude over the past several years. Refineries there then process the oil into diesel, jet fuel and other products that can legally be resold internationally.

Critics argue the policy shift weakens pressure on Russia and undermines sanctions designed to limit funding for Moscow’s war effort.

Supporters counter that restricting fuel supplies during a global energy crisis could cause major economic damage for households, businesses and airlines while doing little to actually stop Russian exports.

The UK government has framed the move as a practical response to extraordinary market conditions rather than a broader reversal of sanctions policy.

The policy currently applies only to diesel and jet fuel — not gasoline — and officials retain the authority to cancel or revise the license later if global conditions improve.

Still, the decision underscores a growing reality in global energy markets: despite years of sanctions, Russian oil remains deeply embedded in the world economy.

Analysts say many Western governments are increasingly acknowledging privately that completely removing Russian energy from global supply chains may not be realistic during periods of major geopolitical instability and tight fuel supplies.

For British consumers, the immediate impact may be modest but potentially helpful.

The move could ease some upward pressure on diesel and airline fuel prices over time, though oil prices themselves remain heavily influenced by developments in the Middle East and the ongoing Iran conflict.

As long as global crude prices stay elevated, drivers and travelers are still likely to feel pressure at gas stations and airports.

But the policy shift signals that governments are becoming more willing to compromise on sanctions enforcement when fuel shortages begin threatening broader economic stability.

— JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Florida governor intensifies attack on visa program as technology companies slash U.S. jobs while continuing to recruit foreign workers amid the AI boom.

NEW YORK — Florida Governor Ron DeSantis is escalating his attack on the H-1B visa program, accusing major technology companies of laying off American workers while continuing to import lower-cost foreign labor under the claim of a domestic talent shortage — a contradiction he says is becoming harder to defend as artificial intelligence rapidly reshapes the white-collar workforce.

In a widely circulated post on X that has since evolved into a broader policy campaign, DeSantis called the H-1B program “a scam” that has been “used to import cheap foreign labor at the expense of Americans,” adding that the practice becomes “especially galling when artificial intelligence is forecast to reduce a significant number of white collar jobs.”

The Florida governor, widely viewed as a leading Republican figure and potential 2028 presidential contender, has since moved aggressively to translate that rhetoric into policy, spearheading one of the toughest state-level crackdowns on the visa system in the country.

The criticism lands at a moment when the technology sector itself is undergoing historic upheaval.

According to layoffs tracker TrueUp, the U.S. technology industry has already logged hundreds of layoff events impacting nearly 100,000 workers so far in 2026, as corporations continue restructuring around artificial intelligence, automation and cost reduction.

Major companies across Silicon Valley and the broader tech sector have spent the past two years simultaneously cutting payrolls while dramatically increasing spending on AI infrastructure, cloud systems and data centers.

Oracle reportedly eliminated tens of thousands of positions globally this year. Amazon cut thousands of corporate roles following multiple previous rounds of layoffs. Microsoft and Meta Platforms likewise reduced headcount while continuing massive investments into AI systems and infrastructure.

At the same time, the largest hyperscale technology firms — including Alphabet, Amazon, Meta and Microsoft — are collectively projected to spend hundreds of billions of dollars this year alone on AI-related infrastructure and computing capacity.

That disconnect has become central to the political backlash now building around the H-1B program.

“These tech companies will fire Americans and hire H-1B at a discount,” DeSantis said during a University of South Florida appearance last year. “This is basically, in some respects, cheap labor that they’re bringing in to try to save money.”

DeSantis has also criticized the structure of the visa system itself, arguing that because H-1B workers are tied directly to sponsoring employers, the arrangement suppresses wages and limits labor mobility in ways that disproportionately benefit corporations.

Vice President JD Vance has echoed similar concerns publicly, arguing companies should not be allowed to lay off American workers while simultaneously claiming labor shortages to justify foreign hiring.

The debate is intensifying as artificial intelligence increasingly disrupts the technology labor market itself.

For years, the H-1B program was primarily defended as a mechanism for filling highly specialized technical positions that American companies allegedly struggled to staff domestically. But critics now argue the rapid rise of AI automation weakens that argument as technology firms simultaneously reduce hiring, automate workflows and restructure staffing models.

Supporters of the program counter that the global competition for elite engineering talent remains fierce and that restricting high-skilled immigration could ultimately weaken America’s technological leadership against competitors such as China.

The Trump administration has already moved aggressively to tighten portions of the system.

Federal policy changes imposed higher fees on new H-1B applications and shifted selection rules toward higher-paid applicants rather than purely random lottery selection. The result has been a measurable decline in filings among several major technology firms.

Meanwhile, state governments are beginning to act independently.

Under DeSantis’s direction, Florida’s university system moved to restrict new H-1B hiring across public universities through at least early 2027. Texas implemented similar restrictions at state universities earlier this year.

Labor groups and some economists say the criticism surrounding the visa system increasingly reflects broader anxiety about the future of white-collar employment itself.

Artificial intelligence is already automating portions of coding, customer service, administrative support, reporting and research functions that once required large numbers of employees. That transition is fueling fears that corporations may increasingly combine automation with lower-cost global labor strategies simultaneously.

The economic stakes are significant.

Technology remains one of the most strategically important sectors in the U.S. economy, with AI, semiconductors, cybersecurity and cloud infrastructure now tied directly to national competitiveness and national security.

But the political optics of mass layoffs alongside continued foreign hiring are becoming increasingly difficult for many companies to defend publicly.

That tension is now reshaping the national debate over immigration, labor policy and the future structure of the American workforce.

For DeSantis and other Republicans pushing H-1B reform, the argument is increasingly straightforward:
if artificial intelligence is already reducing demand for certain white-collar jobs, corporations should prioritize retraining and hiring American workers before seeking lower-cost labor abroad.

For Silicon Valley, however, the concern is different.

Technology executives warn that limiting access to global engineering talent could slow innovation at the exact moment the United States is locked in an escalating technological arms race with China.

The collision between those two realities — protecting American workers versus maintaining technological dominance — is now becoming one of the defining economic and political fights of the AI era.

And as layoffs continue spreading across the technology sector, the pressure on Washington and corporate America alike is only intensifying.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The U.S. Senate voted Tuesday to advance a war powers resolution seeking to limit American military involvement in Iran, delivering the first visible fracture in Republican support for President Donald Trump’s war posture and sending fresh shockwaves through already strained global energy markets.

The Senate voted 50-47 to discharge the resolution, marking the first time in eight attempts that supporters of limiting U.S. military operations against Iran successfully broke through procedural barriers. The vote came as the White House simultaneously prepared contingency plans for possible renewed strikes on Iranian targets if negotiations with Tehran collapse.

The political shift immediately rattled traders already navigating one of the most severe energy disruptions in decades.

Brent crude remained above $110 a barrel following the vote, while U.S. benchmark West Texas Intermediate hovered near $109 despite modest pullbacks after Trump confirmed he had paused a planned strike earlier this week following urgent requests from Gulf leaders seeking additional time for diplomacy.

The vote exposed widening fractures inside the Republican Party over the expanding conflict.

Four Republicans crossed party lines to support the resolution: Susan Collins of Maine, Lisa Murkowski of Alaska, Rand Paul of Kentucky, and Bill Cassidy of Louisiana. Cassidy’s vote drew particular attention after the Louisiana senator lost his Republican primary this past weekend following Trump’s endorsement of a challenger.

In remarks from the Senate floor, Cassidy said he continues supporting efforts to dismantle Iran’s nuclear capabilities but argued Congress has received insufficient transparency from the White House and Pentagon regarding the administration’s military campaign, known internally as Operation Epic Fury.

Sen. John Fetterman (D-Pa.) again broke with most Democrats and voted against the resolution, siding with Republicans who argued the administration needs flexibility to confront Iran.

Three Republican senators — John Cornyn, Thom Tillis, and Tommy Tuberville — missed the vote entirely, helping tip the final tally in favor of advancing the resolution.

Senate Minority Leader Chuck Schumer called the vote evidence that lawmakers are beginning to challenge what Democrats describe as an unauthorized war, while Sen. Tim Kaine (D-Va.), the lead sponsor of the measure, argued Congress must reclaim its constitutional authority over military engagement.

The resolution itself is unlikely to stop military operations. The Republican-controlled House is not expected to pass the measure in its current form, and Trump would almost certainly veto it. But markets viewed the vote less as binding legislation and more as a political signal that congressional support for prolonged escalation may be weakening.

That matters enormously for energy markets.

The International Energy Agency has warned that the conflict surrounding the Strait of Hormuz has created one of the most dangerous global energy-security disruptions in modern history. Roughly 20 million barrels of oil previously flowed daily through the strait before the crisis intensified, with as much as 14 million barrels per day now affected by disruptions, rerouting, or temporary shutdowns.

Analysts at ING have raised their baseline Brent crude forecast above $100 per barrel for the remainder of the year, arguing that even partial instability in Hormuz fundamentally alters global supply expectations.

The economic fallout has already spread far beyond oil markets.

QatarEnergy declared force majeure on exports after Strait disruptions escalated earlier this year. Combined oil production from Saudi Arabia, Kuwait, Iraq, and the United Arab Emirates reportedly fell by more than 10 million barrels per day during the height of the March supply shock.

Brent crude surged from roughly $72 per barrel in late February to nearly $120 at peak panic levels, one of the fastest wartime oil spikes on record. Dubai crude briefly hit an all-time high near $166 per barrel.

American consumers have already begun feeling the impact.

U.S. gasoline prices climbed back above $4 per gallon nationally for the first time since 2023, while parts of California briefly exceeded $5. Airlines, freight operators, and logistics companies imposed emergency fuel surcharges as jet-fuel prices nearly doubled in some North American markets.

The conflict has also destabilized global food and fertilizer supply chains.

Gulf nations heavily reliant on imports through Hormuz have scrambled to secure basic staples, with regional grocery chains airlifting food supplies to avoid shortages. Food prices across parts of the Gulf Cooperation Council region have surged sharply in recent months.

Agricultural markets are now flashing similar warnings. Analysts say fertilizer prices could rise dramatically as disruptions hit ammonia, sulfur, and urea exports flowing through the region. Asian buyers, which depend heavily on Gulf exports for agricultural inputs, are already searching for alternative suppliers.

For investors, Tuesday’s Senate vote introduced a new question into the geopolitical equation: whether growing political resistance inside Congress pressures the White House toward diplomacy — or accelerates military escalation before opposition hardens further.

Reports circulated Tuesday that U.S. and Iranian negotiators remain close to a preliminary framework agreement that could reopen the Strait of Hormuz in exchange for sanctions relief and limits on Iranian uranium enrichment.

But hawkish voices inside the Republican conference continue pushing for broader escalation.

Sen. Lindsey Graham (R-S.C.), one of Trump’s closest foreign-policy allies in Congress, said this week that future military action should directly target Iran’s energy infrastructure — comments traders viewed as deeply significant given the market’s sensitivity to any threat against regional oil production.

Secretary of State Marco Rubio has defended the administration’s legal authority under the War Powers Act, although the White House continues arguing portions of the law are unconstitutional.

The Pentagon has already acknowledged more than 2,000 U.S. strikes inside Iran since the conflict escalated and has reportedly requested an additional $200 billion in military funding beyond the estimated $18 billion already spent.

For Wall Street, airlines, refiners, defense contractors, commodity traders, and multinational corporations exposed to Gulf energy flows, Tuesday’s Senate vote may ultimately matter less for its legal effect than for what it revealed politically: the once-solid Republican consensus behind the administration’s Iran strategy is beginning to fracture.

Whether that fracture widens — or disappears after the next military escalation — could determine where oil prices go next.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Rising living costs, elevated interest rates and stagnant paycheck growth are pushing more Americans deeper into debt — while major banks report historic profits.

NEW YORK — Serious credit card delinquencies in the United States have climbed to their highest levels in more than a decade, approaching depths last seen in the aftermath of the 2008 financial crisis, according to the latest Quarterly Report on Household Debt and Credit released May 13 by the Federal Reserve Bank of New York. Total U.S. household debt now stands at $18.8 trillion — including roughly $1.25 trillion in credit card balances, nearly $1.7 trillion in auto loans, and more than $13 trillion in mortgage debt — as American families increasingly turn to high-interest borrowing simply to keep up with everyday expenses.

For millions of Americans, the financial pressure no longer feels temporary.

It feels permanent.

The paycheck arrives, but the money disappears faster than it used to. Rent is higher. Insurance is higher. Utility bills are higher. Car repairs cost more. Groceries cost more. Dining out costs more. Interest rates exploded. Nearly every part of normal life became more expensive over the past several years, and for most working families, income has not kept pace.

That strain is now showing up across the U.S. financial system. But economists say the deeper issue is not simply how much Americans owe. It is why so many households increasingly need debt just to maintain basic financial stability.

For years after the pandemic, inflation reset the cost structure of everyday American life. While inflation has slowed from its peak, prices across much of the economy never returned to previous levels. Instead, the higher costs became permanent. Families adapted the only way they could. They delayed paying down balances. They financed more purchases. They relied more heavily on credit cards to bridge the growing gap between monthly income and monthly expenses.

A report released this month by debt-management firm Achieve found that 53% of consumers now carry credit card balances to cover essential expenses — not luxuries or vacations, but groceries, gas, utilities and rent. “For many households, higher balances are less a sign of economic optimism and more a sign that wages and savings are struggling to keep pace with essential expenses like groceries, utilities and housing,” said Austin Kilgore, analyst for the Achieve Center for Consumer Insights.

The cost of carrying that debt has never been more punishing. Average credit card interest rates now sit above 22%, according to Federal Reserve data — the highest level in modern American history. Cardholders who can no longer pay off balances in full each month are paying enormous amounts in interest while making little dent in the principal.

For lower-income families, the math has stopped working.

Mark Zandi, chief economist at Moody’s Analytics, told Fortune that lower-income households are “hanging on by their fingertips financially.” Zandi warned that many families are still spending because they remain employed, but the situation is becoming increasingly fragile as hiring slows and inflation continues eating into disposable income.

The strain is showing up unevenly across the country.

Wilbert van der Klaauw, Economic Research Advisor at the New York Fed, said the deterioration is becoming increasingly concentrated in financially vulnerable communities. “Delinquency rates for mortgages are near historically normal levels, but the deterioration is concentrated in lower-income areas and in areas with declining home prices,” van der Klaauw said in the Fed’s quarterly release.

Daniel Mangrum, the New York Fed research economist overseeing the report, said the broader consumer picture remains pressured even as some debt categories stabilized temporarily. “Aggregate household debt levels rose slightly, with modest increases in most debt types offsetting a seasonal decline in credit card balances,” Mangrum said. “Delinquency transition rates were mostly steady, while student loan delinquencies are returning to pre-pandemic levels.”

Even Americans who remain employed and current on most bills increasingly describe the same feeling: they are working hard, paying their obligations, and falling behind anyway.

While American families struggle, the institutions lending them money are reporting some of the strongest profits in years.

JPMorgan Chase, Capital One Financial, Citigroup, Bank of America and American Express all posted robust quarterly earnings fueled in part by elevated lending margins and higher interest income across consumer credit businesses. The wider the gap between what banks pay for capital and what they charge American borrowers, the more profitable the credit card business becomes — and that gap has rarely been wider than it is today.

The imbalance is now fueling growing bipartisan frustration in Washington.

Senator Bernie Sanders of Vermont, who introduced legislation alongside Missouri Republican Senator Josh Hawley to cap credit card interest rates at 10%, accused major financial institutions of exploiting struggling consumers.

“When large financial institutions charge over 25 percent interest on credit cards, they are not engaged in the business of making credit available,” Sanders said. “They are engaged in extortion and loan sharking. We cannot continue to allow big banks to make huge profits ripping off the American people.”

Hawley framed the issue as a direct economic threat to working families.

“Working Americans are drowning in record credit card debt while the biggest credit card issuers get richer and richer by hiking their interest rates to the moon,” Hawley said. “It’s not just wrong, it’s exploitative. And it needs to end.”

The legislation remains stalled in the Senate Banking Committee amid fierce opposition from the banking industry, which argues rate caps could reduce access to credit and push consumers toward payday lenders and less-regulated borrowing markets.

But consumer advocates say the current system is becoming unsustainable.

Duvi Honig, founder and chief executive of the Orthodox Jewish Chamber of Commerce, Newsmax contributor and economic policy analyst, said the imbalance between banks and consumers has reached dangerous levels.

“Banks have no right to make historic profits while abusing the consumer,” Honig said. “Legislation must create a balancing scale to limit their interest rates to help the everyday American family not fall more into debt and pay such high rates on credit cards when they are forced to rely on them simply to survive rising costs.”

The squeeze on households is being amplified by broader inflation pressures still moving through the economy. AAA data shows the national average gasoline price stands above $4.50 a gallon, while food prices remain materially above pre-pandemic levels. The April Consumer Price Index rose 3.8% year over year, according to the U.S. Bureau of Labor Statistics, while wholesale food prices posted their largest annual increase in more than three years.

The Federal Reserve — the institution many Americans hoped would eventually deliver relief through lower interest rates — remains trapped between slowing the economy and containing inflation.

Mortgage rates remain elevated above 6%. Auto financing remains expensive. Credit card borrowing costs remain punishingly high. And while Americans continue hoping for meaningful rate cuts, Federal Reserve officials have repeatedly signaled caution because inflation pressures have not fully disappeared.

Former Cleveland Fed President Loretta Mester told CNBC this month that inflation still makes aggressive rate cuts difficult to justify. “I just don’t think right now he can make those arguments in a credible way, because we have an inflation problem,” Mester said, referring to new Federal Reserve Chairman Kevin Warsh.

That leaves millions of households trapped in an increasingly difficult position.

They are still working.

Still paying bills.

Still functioning.

But increasingly doing it while carrying more debt, more stress and less financial flexibility than they had just a few years ago.

The New York Fed report ultimately reveals something larger than rising delinquency numbers.

It reveals an economy where millions of Americans are no longer borrowing for luxury or excess.

They are borrowing to keep up with everyday life.

And the longer inflation stays elevated while interest rates remain historically high, the harder that cycle becomes to escape.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Imagine spending nearly 30 years building a company from a tiny yoga-wear shop in Vancouver into one of the most recognizable retail brands in America — only to have that same company publicly tell investors your ideas are “misguided,” your thinking is “outdated,” and your involvement is hurting the business.

That is exactly what just happened to Chip Wilson, the founder of Lululemon Athletica Inc.

In a sharply worded letter sent Monday ahead of the company’s June 25 shareholder meeting, Lululemon’s board accused Wilson of attacking the company for years, damaging the brand and creating distractions during one of the toughest periods in the company’s history. The board urged investors to reject the three directors Wilson wants to place on the board, warning that his return to influence could “derail” the company’s recovery efforts.

Wilson fired back hours later, saying the company’s leadership has lost touch with what made Lululemon special in the first place.

For millions of American consumers, this is more than a boardroom fight.

It is a fight over whether one of the biggest lifestyle brands of the past decade has lost the identity that made customers love it to begin with.

Why Customers Started Pulling Away

For years, Lululemon barely had competition.

If someone wanted premium yoga pants or upscale athleisure wear, they went to Lululemon. The brand became a status symbol — not just workout clothing, but part of a lifestyle.

Then the market changed.

Brands like Vuori, Alo Yoga, and On Holding exploded in popularity. Social media accelerated the shift. Suddenly consumers had options that felt newer, fresher and in some cases more fashionable.

Instead of owning the category, Lululemon became just one choice in a crowded closet.

That shift is now showing up in the numbers.

Lululemon’s U.S. store sales have been flat or declining for eight consecutive quarters. The stock has fallen more than 40% this year alone and has lost more than $50 billion in market value from its peak.

For shoppers, the feeling is simpler than the financials:

Many longtime customers no longer feel the same excitement walking into the store.

The Bigger Problem: The Product Stopped Feeling Special

Wilson’s core argument is not really about Wall Street.

It is about product.

Lululemon built its empire by creating items customers obsessed over. Products like the company’s famous Align leggings became cultural phenomena because they genuinely felt different from everything else on the market.

Recently, however, several new launches have struggled badly.

A major product line called “Breezethrough” was quietly pulled after customer complaints about fit. Another launch, “Get Low,” failed to gain traction. Online criticism about changing fabrics, inconsistent sizing and declining quality has spread across TikTok, Reddit and fashion forums.

For a company charging premium prices, perception matters enormously.

Customers will happily pay $128 for leggings if they feel exceptional.

They stop paying those prices the moment the product feels ordinary.

That is the danger Lululemon now faces.

Why Prices Are Becoming a Problem

Part of Lululemon’s success came from refusing to play the discount game.

The company rarely ran major sales because it wanted customers to believe the product justified the price.

That exclusivity became part of the brand’s identity.

But lately, shoppers have started seeing more markdowns and promotions as the company works to clear inventory and compete with newer rivals.

Wilson believes those discounts damage the brand because they train customers to wait for sales instead of paying full price.

Management argues the promotions are necessary in a slower consumer environment where shoppers are becoming more price sensitive.

Both sides may be right — and that is exactly the problem.

Because once a premium brand loses its “must-have” feeling, it becomes extremely difficult to get it back.

Consumers Are Feeling the Squeeze Too

Lululemon is also dealing with pressures consumers may not immediately see.

The company estimates tariffs and import costs will add roughly $220 million in net expenses during 2026, while labor, marketing and supply-chain costs continue rising.

Management has largely avoided aggressively raising prices further because shoppers are already pulling back across parts of the retail sector.

That means profits are getting squeezed from both directions:
higher costs on one side and weaker demand on the other.

For consumers, it reflects a broader shift happening throughout retail right now.

Even shoppers with money are becoming more selective. They still spend — but they increasingly want products that truly feel worth the premium.

That puts enormous pressure on brands like Lululemon that built their business on emotional loyalty rather than basic necessity.

Why Chip Wilson Is Fighting So Hard

Wilson still owns roughly 9% of Lululemon, making him one of the company’s largest shareholders.

He believes the board became too focused on efficiency, operations and financial targets while losing the creative energy and emotional connection that originally built the brand.

The directors he wants on the board come largely from branding, marketing and consumer-experience backgrounds rather than finance-heavy corporate résumés.

Lululemon’s current board disagrees completely.

The company says Wilson is trying to drag the business backward and argues its current leadership team — including incoming CEO Heidi O’Neill, a longtime Nike executive — is the right group to modernize the brand.

Meanwhile, activist hedge fund Elliott Investment Management has quietly built a stake reportedly worth more than $1 billion, creating even more pressure inside the boardroom.

In other words, this is no longer just a founder fighting his old company.

It is now a full-scale battle over who gets to decide what Lululemon becomes next.

What It Means for Everyday Shoppers

For most customers, tomorrow’s visit to a Lululemon store may not look much different.

The leggings will still be folded neatly on the shelves.
The stores will still smell the same.
The mirrors, lighting and branding will still feel polished and familiar.

But underneath that polished surface, one of America’s most powerful retail brands is going through an identity crisis.

The founder believes the company forgot what made customers emotionally connected to the brand.

The board believes the founder himself is stuck in the past.

Consumers — and shareholders — will ultimately decide who is right.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk
May 19, 2026

NEW YORK — U.S. stocks closed lower Tuesday for a third straight session as surging Treasury yields, renewed geopolitical uncertainty surrounding Iran, and continued weakness in semiconductor shares pressured Wall Street ahead of Nvidia’s highly anticipated earnings report Wednesday afternoon.

The S&P 500 fell 0.67% to close at 7,353.61, while the Nasdaq Composite dropped 0.84% to 25,870.71. The Dow Jones Industrial Average lost 322.24 points, or 0.65%, finishing at 49,375.46. Selling accelerated during the afternoon after the 30-year Treasury yield climbed to 5.198% — its highest level in nearly 19 years — while the benchmark 10-year yield rose to roughly 4.687%, its highest level since January 2025, intensifying concerns over borrowing costs across mortgages, auto loans, and consumer credit.

Markets also continued reacting to developments in the Middle East after President Donald Trump said he had postponed planned U.S. military action against Iran following requests from regional leaders pursuing what he described as “serious negotiations” toward a broader peace framework. While the announcement helped equities recover from steeper intraday losses, investors remained cautious after Trump later suggested the delay could be temporary. Meanwhile, Brent crude hovered above $110 per barrel for much of the session, reinforcing inflation fears already building inside bond markets.

One of the day’s biggest earnings reports came from Home Depot, which topped Wall Street expectations on both revenue and earnings before the opening bell. The home-improvement giant reported adjusted earnings of $3.43 per share on revenue of $41.77 billion, ahead of analyst estimates calling for $3.41 per share and $41.59 billion in revenue. Comparable sales rose 0.6%, while U.S. comparable sales increased 0.4%.

CEO Ted Decker said the company continued seeing steady demand despite mounting pressure on household budgets and elevated mortgage rates. “The underlying demand in our business was relatively similar to what we saw throughout fiscal 2025, despite greater consumer uncertainty and housing affordability pressure,” Decker said in the company’s earnings release.

CFO Richard McPhail told CNBC that core homeowners remain “engaged,” though larger renovation projects continue to slow as financing costs rise. Home Depot reaffirmed its full-year guidance, forecasting total sales growth between 2.5% and 4.5% and adjusted earnings-per-share growth ranging from flat to up 4%.

Housing-related stocks weakened sharply alongside rising yields. The iShares U.S. Home Construction ETF (ITB) fell more than 1%, while shares of D.R. Horton, Lennar, and Toll Brothers all closed lower, with Toll Brothers declining roughly 2%.

Semiconductor shares once again remained at the center of market attention as investors positioned ahead of Nvidia’s earnings report, widely viewed as one of the most important corporate catalysts of the quarter. The Philadelphia Semiconductor Index traded down more than 1% intraday before recovering some losses into the close. Nvidia shares ended the session down nearly 1%, while Qualcomm fell more than 4% and Broadcom lost roughly 2%.

Memory-chip stocks provided one of the few pockets of resilience inside the technology sector. Micron Technology rebounded more than 4% intraday before finishing roughly flat, snapping a three-session losing streak. Sandisk gained nearly 3%, while the Roundhill Memory ETF (DRAM) rose about 2%.

Jed Ellerbroek, portfolio manager at Argent Capital Management, told CNBC the recent weakness in semiconductors may simply reflect profit-taking after months of explosive gains. “A well-deserved breather after an epic rally,” Ellerbroek said.

On the analyst front, UBS upgraded Jazz Pharmaceuticals to buy from neutral and raised its price target to $307, implying upside of more than 33% from Monday’s close. Analyst Ashwani Verma pointed to growing optimism surrounding the company’s gallbladder-cancer treatment Ziihera ahead of its August 25 regulatory deadline, while also highlighting continued stability across Jazz’s sleep-disorder drug franchise despite pricing pressures and increased competition expected later this year.

Still, the dominant story on Wall Street remained the sharp move higher in long-term Treasury yields. Strategists said investors are increasingly grappling with a combination of rising federal borrowing needs, oil-driven inflation concerns tied to the Iran conflict, and uncertainty surrounding monetary policy under new Federal Reserve Chair Kevin Warsh.

Nathan Peterson, director of derivatives research and strategy at the Schwab Center for Financial Research, said investors should focus less on the absolute level of yields and more on how quickly rates continue moving higher. “Higher yields are not necessarily a bull market killer, because it depends on why they are going up and the velocity of the move,” Peterson said.

Attention now shifts squarely to Nvidia’s earnings release Wednesday afternoon, which many investors view as the next major test for a market attempting to stabilize after its powerful rally from March lows. Investors will also closely watch Walmart’s earnings report Thursday for additional insight into the health of the U.S. consumer as gasoline prices climb and confidence begins to soften.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

LAS VEGAS — Nvidia Corp. Chief Executive Jensen Huang said Monday that China will eventually reopen its market to American artificial-intelligence chips, signaling confidence that Beijing will ultimately ease restrictions that have frozen billions of dollars in potential sales for the world’s most important AI hardware company despite escalating geopolitical tensions between Washington and Beijing.

Speaking to Bloomberg Television’s Ed Ludlow on the sidelines of the Dell Technologies World conference in Las Vegas, Huang said Chinese leaders are still weighing how aggressively they want to shield domestic semiconductor champions from U.S. competition. “The Chinese government has to decide how much of their local market do they want to protect,” Huang said. “Over time the market will open.”

The comments landed just days after Huang accompanied President Donald Trump during a closely watched summit with Chinese President Xi Jinping in Beijing that investors hoped could unlock stalled approvals for Nvidia’s advanced AI processors. While the summit produced no immediate breakthrough, Huang’s remarks offered Wall Street its clearest sign yet that Nvidia still believes a pathway back into China remains possible.

At the center of the standoff is Nvidia’s H200 artificial-intelligence accelerator chip, one of the most advanced AI processors currently available commercially. The company already holds U.S. Commerce Department licenses allowing it to sell H200 chips to approved Chinese buyers, including major technology firms such as Alibaba Group, Tencent Holdings, ByteDance, and JD.com, along with distributors including Lenovo Group and Foxconn. But Chinese regulators have yet to fully authorize large-scale purchases as Beijing pushes domestic companies toward homegrown alternatives such as Huawei Technologies.

The delay has become one of the defining commercial and geopolitical battles of the AI era.

China once represented roughly 13% of Nvidia’s annual revenue, contributing an estimated $17.1 billion during fiscal 2025 before U.S. export controls tightened and Beijing accelerated efforts to build an independent semiconductor ecosystem. Prior to Washington’s restrictions, Nvidia controlled an estimated 95% of China’s advanced AI chip market. Today, analysts say that share has effectively collapsed to near zero.

Huang has repeatedly warned that cutting American companies off from China could backfire strategically on the United States by accelerating Beijing’s drive toward technological self-sufficiency. “If we leave the market entirely, Chinese companies will fill the gap,” Huang said in previous remarks echoed again Monday by his broader comments about eventual market reopening.

The stakes stretch far beyond Silicon Valley.

Nvidia has previously estimated the Chinese AI accelerator market could eventually exceed $50 billion annually, making it one of the largest technology opportunities in the world. The company’s ability — or inability — to participate in that market could significantly impact future revenue growth, U.S. research spending, manufacturing investment, and high-paying engineering jobs tied to the American AI ecosystem.

Trump himself acknowledged Friday that the Nvidia issue surfaced during discussions in Beijing. “The chip did come up, and I think something could happen on that,” the president told reporters after returning to Washington. Trump added that Chinese officials appear reluctant to approve purchases because they want to strengthen domestic competitors capable of challenging American firms.

Huang said Monday he did not directly negotiate H200 sales with Chinese officials during the trip, despite widespread investor speculation that his presence in the delegation was tied to efforts to secure regulatory approvals.

The broader technology landscape is rapidly shifting around the dispute. Chinese AI firms, including DeepSeek, have increasingly promoted models trained using domestic chips instead of Nvidia hardware, underscoring Beijing’s growing urgency to reduce reliance on U.S. technology. Analysts say every month Nvidia remains sidelined gives Chinese semiconductor firms more time to mature and capture permanent market share.

“This is no longer just about one company,” said Daniel Newman, chief executive of Futurum Group, in a note Monday. “The outcome will shape the future balance of power in global AI infrastructure.”

The standoff also carries implications for consumers and businesses worldwide. AI chips are becoming foundational infrastructure for everything from enterprise software and automation to healthcare systems, logistics networks, financial services, and small-business productivity tools. A prolonged fragmentation between U.S. and Chinese AI ecosystems could raise costs, slow innovation, and create competing global technology standards.

At the Dell conference Monday, Huang appeared alongside Dell Technologies Chief Executive Michael Dell, where both executives discussed surging demand for AI infrastructure, growing memory constraints, and massive global investment in next-generation data centers. Demand for advanced AI processors continues to outstrip available supply worldwide, reinforcing Nvidia’s push to maximize every possible sales channel.

Despite the China uncertainty, Nvidia shares have remained relatively resilient as investors focus on explosive demand from U.S., European, and Middle Eastern hyperscale customers racing to build AI computing capacity. Many Wall Street analysts now exclude China revenue entirely from their base forecasts for Nvidia, treating any reopening as potential upside rather than an expectation.

Still, Huang’s remarks underscored Nvidia’s long-term bet that commercial realities may eventually outweigh political tensions.

The licenses already exist. The customers are waiting. The infrastructure demand is massive. What remains unresolved is whether Beijing ultimately decides that protecting domestic semiconductor champions is worth forgoing access to the world’s most advanced commercially available AI hardware.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Rising grocery costs are colliding with slower SNAP adjustments, leaving millions of Americans struggling to stretch benefits that no longer cover what they once did.

WASHINGTON — America’s food inflation problem may have cooled from the crisis peaks of the post-pandemic economy, but for the roughly 42 million Americans relying on the Supplemental Nutrition Assistance Program, better known as SNAP or food stamps, the pressure inside supermarket aisles continues building every single week. Grocery prices across many staples remain dramatically above pre-2021 levels, while the federal system used to calculate SNAP benefits updates far more slowly than the real-world pace of inflation — creating a widening affordability gap now hitting working families, seniors, disabled Americans and lower-income households nationwide.

According to the latest U.S. Department of Agriculture Food Price Outlook, grocery prices are expected to continue rising in 2026 following several years of elevated food inflation that permanently reset prices higher across large parts of the American supermarket economy. Meat, dairy, packaged foods, fresh produce and household staples all remain materially above where they stood before inflation accelerated several years ago, even as headline inflation readings have moderated.

For SNAP recipients, the issue is not that benefits disappeared. The problem is that prices moved faster than the government system designed to keep pace with them.

SNAP benefits are recalculated annually using the federal government’s “Thrifty Food Plan,” the formula the USDA uses to estimate the cost of a basic but nutritionally adequate diet. Updated benefit levels generally take effect each October. But grocery prices fluctuate constantly throughout the year, meaning families often face months of rising supermarket costs before federal adjustments catch up.

That lag is now becoming increasingly visible at checkout counters across the country.

“The balance may look similar, but the cart keeps getting smaller,” said one Brooklyn food pantry director working with families receiving federal food assistance, describing what community organizations say has become one of the most common frustrations among SNAP recipients over the past two years.

Food banks and local charities across multiple states continue reporting elevated demand from households already receiving government assistance but increasingly running short before the end of the month. Community organizations say families are stretching meals longer, buying cheaper substitutes, reducing protein purchases and cutting discretionary spending elsewhere simply to absorb higher grocery costs.

The squeeze comes as broader household expenses remain elevated across much of the U.S. economy. Housing costs remain high in many regions. Insurance premiums have continued rising. Utility bills remain volatile. High interest rates have increased borrowing costs on everything from credit cards to automobiles. But groceries remain uniquely painful politically and emotionally because Americans experience those prices constantly — often several times a week.

The SNAP debate has also become increasingly political following changes passed under last year’s federal budget legislation signed by President Donald Trump. The law tightened future flexibility surrounding how SNAP benefit increases can be calculated and expanded work requirements for additional recipients unless exemptions apply.

Supporters of the changes argue tighter controls were necessary to slow long-term growth in federal food-assistance spending while encouraging greater labor-force participation. Critics argue the restrictions could make it harder for future administrations to rapidly adjust benefits during inflation spikes and may place additional strain on older Americans with unstable employment situations or caregiving responsibilities.

Under the updated rules, work requirements that previously focused primarily on adults ages 18 through 54 were expanded to include many adults up to age 64 unless exemptions apply. Anti-poverty advocates warn that compliance requirements could become difficult for older workers navigating inconsistent employment, physical limitations or family obligations.

The broader issue, economists say, is that food inflation behaves differently than many other categories inside the economy. Even when overall inflation slows, grocery prices often remain permanently elevated because supply-chain costs, labor expenses, transportation costs and agricultural inputs rarely move fully backward once reset higher.

That reality has created growing frustration among many lower-income households who feel official inflation numbers do not reflect what they experience at the supermarket.

Supporters of the current SNAP structure note that benefits today remain materially higher than they were before the pandemic following earlier federal recalibrations that significantly expanded payment levels. But critics argue those increases have increasingly been overtaken by the cumulative rise in grocery prices over the past several years.

The result is a growing disconnect many families now feel every time they shop: the assistance technically still exists, but the purchasing power behind it continues shrinking.

For Washington, the debate centers around budgets, labor participation and federal spending priorities.

For millions of Americans standing inside Walmart, Aldi, ShopRite, Kroger and neighborhood supermarkets across the country, the issue feels much simpler.

The SNAP card still works.

It just does not go nearly as far anymore.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

President Donald Trump’s administration on Sunday announced that China has committed to purchasing at least $17 billion in U.S. agricultural products annually in 2026, 2027 and 2028, restoring market access for American beef producers shut out for most of the past year — a major boost for U.S. ranchers at a time when the domestic cattle supply has fallen to its lowest level since 1951 and beef prices remain near record highs.

According to the official White House fact sheet released after Trump’s summit in Beijing with Chinese President Xi Jinping, China will renew expired export listings for more than 400 U.S. beef facilities and work with American regulators to lift suspensions on dozens more. The agreement restores access to one of the world’s most lucrative premium beef markets after Chinese restrictions caused U.S. beef exports to the country to collapse over the past year.

U.S. Trade Representative Jamieson Greer said Sunday the agreement is designed to reopen critical export channels for American ranchers and processors that had effectively lost access to China’s consumer market. Agriculture Secretary Brooke Rollins called the arrangement “a historic win for American cattle producers.”

The timing is significant because the U.S. beef industry is facing one of the tightest supply environments in modern history.

The U.S. cattle herd stood at 86.2 million head as of January 2026, according to USDA data — the smallest national herd since 1951. Ground beef prices climbed to roughly $6.69 per pound late last year, up nearly 20% from a year earlier and more than 70% above pre-pandemic levels. USDA forecasts wholesale beef prices will continue rising throughout 2026 as supply constraints persist.

At the same time, the United States remains cut off from millions of potential imported feeder cattle after the U.S.-Mexico border closed to live cattle shipments because of the spread of New World screwworm, a parasitic livestock threat that sharply disrupted North American cattle flows.

At first glance, exporting more beef overseas during a domestic shortage may appear contradictory.

In reality, industry economics work very differently.

Why This Is Good News for American Ranchers

China’s reopening does not suddenly create entirely new beef demand. Instead, it restores access to a market American producers already previously served before Chinese restrictions caused exports to collapse.

U.S. beef exports to China peaked at approximately $2.14 billion in 2022 before plunging below $500 million in 2025 after facility licenses expired and trade tensions escalated.

The cattle were still being raised. The beef was still being processed.

But without access to China, many high-value cuts were forced into lower-margin domestic or alternative export channels.

That matters because Chinese consumers often pay premium prices for cuts many American consumers rarely buy at scale, including short ribs, tongue, tendon and organ meats. Those products generate substantially higher margins in Asian markets than they typically do inside the United States.

For ranchers, access to those premium export channels can significantly improve profitability across the entire animal.

The Real Cause of High Beef Prices

The current beef shortage is not being caused by exports.

The core problem is simple: America does not currently have enough cattle.

Years of drought, elevated feed costs, labor shortages, rising borrowing costs and rancher liquidation dramatically reduced herd sizes nationwide. Rebuilding cattle inventories is a slow biological process that can take years because ranchers must retain breeding stock rather than immediately selling animals into the food supply.

The American Farm Bureau Federation has warned meaningful herd expansion likely will not occur until at least 2028.

Meanwhile, the closure of the Mexican cattle border eliminated a major supplemental supply source exactly when the domestic herd was already historically tight.

Restricting exports would not solve those structural supply problems.

In fact, industry economists argue it could make them worse.

Why Exports Can Actually Help Lower Prices Later

The economics are counterintuitive but important.

If ranchers cannot generate strong profits during high-price cycles, many reduce herd expansion plans or sell breeding cattle instead of investing in future production. That shrinks long-term supply even further and prolongs elevated beef prices.

Premium export markets like China help put more revenue back into the hands of cattle producers whose financial stability ultimately determines whether the U.S. herd expands again.

In other words, profitable ranchers are more likely to rebuild herds.

And larger herds eventually increase beef supply and moderate prices over time.

The Trump administration has simultaneously attempted to address domestic supply pressure through other channels, including expanding beef-import quotas from countries such as Argentina and launching antitrust investigations into the major meatpacking companies — including Tyson Foods, JBS USA, Cargill, and National Beef — which together dominate most U.S. beef processing capacity.

Federal officials argue those measures target supply bottlenecks and market concentration without sacrificing export revenue for American ranchers.

What Happens Next

The agreement with China also creates ongoing trade mechanisms intended to reduce future agricultural disputes.

Chinese Foreign Minister Wang Yi said both countries agreed to establish new U.S.-China trade and investment boards aimed at maintaining regular economic dialogue and resolving market-access issues more quickly.

Greer said Sunday the administration remains prepared to impose additional tariffs or penalties if China fails to meet its beef purchase commitments.

For now, the agreement represents the clearest sign yet that one of the most damaging parts of the recent U.S.-China trade breakdown for American cattle producers may finally be reversing.

For American consumers, however, relief at the grocery store is likely to take far longer.

The underlying cattle shortage remains severe, herd rebuilding is measured in years rather than months, and beef prices are expected to remain elevated throughout much of 2026 regardless of export policy.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

President Donald Trump and Commerce Secretary Howard Lutnick on Monday delivered the clearest public defense yet of what has quietly become the largest peacetime expansion of direct U.S. government ownership in private industry in modern history. In an interview published Monday by Fortune with Editor-in-Chief Alyson Shontell, the two men outlined a corporate-financing model that now spans at least 10 companies, more than $10 billion in committed taxpayer capital, and a deliberate shift in industrial policy away from grants and toward equity ownership. For corporate America, the message arriving on a day of tightening financial conditions and rising Treasury yields was unmistakable: federal support is no longer just a subsidy. It is increasingly a seat at the cap table.

The administration framed the strategy around Intel Corp., whose $8.9 billion federal equity stake has become the defining template for the new model. The Commerce Department acquired approximately 433.3 million Intel shares at $20.47 apiece last August, creating a roughly 9.9% ownership position funded not through a new congressional appropriation but through the conversion of unpaid grants under the 2022 CHIPS and Science Act alongside a separate secure-chip federal award. The agreement came just weeks after Trump publicly pressured Intel Chief Executive Lip-Bu Tan over his previous investments tied to China. Tan later met with Trump at the White House, remained in his role, and emerged with Washington installed as a major non-voting shareholder. Since then, Intel shares have rallied sharply, generating a significant paper gain for the government and strengthening the administration’s argument for expanding the structure into additional industries.

That expansion is already underway. The Department of Defense is now the largest shareholder in MP Materials Corp., operator of the only active rare-earth mine in the United States, through a $400 million preferred-stock investment and a separate $150 million Pentagon loan package. Once warrants are exercised, the government’s ownership position could approach roughly 15% of common equity, surpassing the stakes held by Chief Executive James Litinsky and BlackRock Fund Advisors. The arrangement also established a $110-per-kilogram price floor on MP’s neodymium-praseodymium oxide, with the Pentagon covering the difference if market prices fall below that threshold while also participating in upside gains above it. Administration officials have described the structure as a fundamental rethinking of how Washington secures strategic supply chains tied to national security.

The model has spread rapidly into other critical-minerals plays. Earlier this year, the administration committed roughly $1.6 billion to USA Rare Earth Inc., including $277 million in direct federal funding and a $1.3 billion CHIPS Act-backed loan in exchange for a government equity position potentially ranging from 8% to 16%, depending on warrant conversion. The company separately raised another $1.5 billion through a PIPE financing led by Cantor Fitzgerald & Co., the investment bank formerly chaired by Lutnick and now run by his sons Brandon Lutnick and Kyle Lutnick. The government secured its shares at an estimated 31% discount to market pricing, and the company’s stock surged following the announcement.

The portfolio now extends well beyond semiconductors and rare earths. Washington also holds a so-called “golden share” in Nippon Steel-owned U.S. Steel Corp., equity exposure tied to Lithium Americas Corp., Trilogy Metals Inc., and strategic interests connected to Westinghouse Electric Co. in the nuclear-energy sector. Research from the Center for Strategic and International Studies has identified semiconductors, nuclear infrastructure, and critical minerals as the sectors most likely to see additional federal equity activity in coming years. Of the 10 known transactions, six have already centered on critical-mineral supply chains alone.

The implications for capital markets are significant. For corporations seeking federal support, negotiations increasingly resemble strategic private-equity transactions rather than traditional subsidy applications, involving dilution terms, governance structures, warrant packages, pricing mechanisms, and eventual exit strategies. For institutional investors, the federal government’s presence on the shareholder register can imply political backing and strategic protection, but also raises concerns about future intervention, capital-allocation discipline, and the politicization of corporate decision-making.

Executives participating in the deals have emphasized that Washington is taking an economic interest rather than an operational one. Barbara Humpton, chief executive of USA Rare Earth, has publicly described the arrangement as financial rather than governance-oriented, a distinction Lutnick has repeatedly stressed as the administration attempts to reassure investors that the federal government does not intend to micromanage corporate operations.

Still, scrutiny inside Washington is intensifying. Representative Zoe Lofgren, ranking member of the House Science Committee, wrote to Lutnick earlier this year raising governance and conflict-of-interest concerns surrounding the transactions, including Cantor Fitzgerald’s involvement in several capital raises. Critics argue that federal agencies retain enormous leverage over recipient companies even when equity stakes are formally passive because Washington controls the pace and release of committed funding tied to operational milestones. Administration officials counter that existing procurement law already addresses favoritism concerns and that equity participation offers taxpayers stronger downside protection than the open-ended grant structures used previously.

For executives across strategic industries, Monday’s interview crystallized a broader shift now unfolding across corporate America. Federal support increasingly means negotiating over ownership percentages, warrants, price floors, and long-term alignment rather than simply receiving direct subsidies tied to hiring or construction targets. Trump’s willingness to merge industrial policy with capital-markets mechanics has transformed Washington from regulator and customer into shareholder.

If the strategy ultimately generates strong financial returns while rebuilding domestic supply chains, future administrations may find it difficult to reverse. If it produces losses, governance controversies, or political backlash, however, the next chapter of American industrial policy will unfold against a taxpayer-owned portfolio that markets can value in real time.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A sweeping overhaul of the federal student-loan system is poised to reshape graduate education across the United States beginning July 1, 2026, when the Federal Direct Graduate PLUS Loan program officially closes to new borrowers under legislation signed last year by President Donald Trump.

According to final regulations issued April 30 by the U.S. Department of Education, roughly 440,000 graduate and professional students annually who previously relied on Grad PLUS financing will lose access to the uncapped federal borrowing program that has underpinned American graduate education since 2006.

The policy change imposes strict federal borrowing ceilings that, for many students attending high-cost medical, law, dental, pharmacy, and graduate programs, fall dramatically below the actual cost of attendance.

Under the new rules, graduate students will be limited to borrowing $20,500 annually and $100,000 total in federal loans. Professional degree programs — including medicine, law, dentistry, veterinary medicine, optometry, podiatry, theology, clinical psychology, osteopathic medicine, chiropractic medicine, and pharmacy — will face annual caps of $50,000 and aggregate limits of $200,000.

In addition, a new lifetime federal borrowing ceiling of $257,500 across all degree levels will now apply, with prior Grad PLUS balances counted toward that cap.

The result is expected to trigger one of the largest migrations from federal student lending into private credit markets in modern U.S. higher-education history.

For nearly two decades, Grad PLUS loans allowed students to borrow up to the full cost of attendance, including tuition, housing, books, fees, and living expenses. At many elite private law and medical schools, tuition and fees alone now exceed $200,000 before accounting for housing and daily expenses.

Without Grad PLUS, the gap between actual program costs and available federal aid becomes immediate and unavoidable.

The Department of Education itself acknowledged in regulatory analysis that private student-loan originations are likely to surge as a direct result of the new caps.

Major lenders positioned to absorb the displaced volume include Sallie Mae, SoFi Technologies, Citizens Financial Group, Discover Financial Services, Earnest — a subsidiary of Navient — and College Ave Student Loans.

The financial consequences for students could be significant.

Federal Grad PLUS loans currently carry a fixed interest rate of 8.94% for the 2025–2026 academic year, with protections built directly into federal law, including income-driven repayment plans, deferment while enrolled, Public Service Loan Forgiveness eligibility, and regulated collection standards.

Private graduate loans typically provide none of those protections.

Many private loans use variable interest rates tied to broader market conditions, often require strong credit histories or cosigners, and may impose substantial late fees, refinancing penalties, or aggressive collection practices.

“There’s still no question that federal loans remain the best option available,” said Robert Farrington, founder of The College Investor, who has publicly warned that the new caps are too low to realistically finance many professional programs. “The problem is that millions of students simply won’t have enough federal funding anymore to complete these degrees.”

Existing graduate borrowers received limited protection under the legislation.

Students already enrolled in graduate or professional programs who borrowed through Direct Unsubsidized or Grad PLUS loans before July 1, 2026, may continue under the current rules for up to three additional academic years or until graduation, whichever comes first.

That carve-out, however, applies only to students who remain continuously enrolled in the same program. Anyone entering a new graduate program after July 1, 2026 — or switching degree tracks — immediately falls under the stricter borrowing caps.

The legislation also significantly tightens borrowing rules for parents.

Federal Parent PLUS Loans, previously uncapped up to full attendance costs, will now be limited to $20,000 annually per dependent student and capped at $65,000 total per child.

Banks and financial institutions are already moving aggressively to capitalize on the financing vacuum.

Major lenders including Bank of America, Wells Fargo, and U.S. Bancorp have reportedly expanded marketing around private education loans and home-equity-backed borrowing products aimed at parents financing college tuition.

Supporters of the legislation argue the reforms are necessary to curb runaway tuition inflation inside graduate education.

Republican lawmakers and incoming Education Secretary Linda McMahon have argued that unlimited federal borrowing artificially insulated universities from market pressure, allowing institutions to continuously raise tuition while students absorbed escalating debt burdens backed by taxpayers.

By limiting federal credit availability, supporters believe universities will eventually be forced to lower prices or compete more aggressively on program value and employment outcomes.

Critics argue the consequences could reshape the demographics of America’s professional workforce for decades.

Organizations including the American Medical Association, American Bar Association, American Association of University Professors, and the Association of Graduate Schools have warned the changes may disproportionately block lower-income, minority, and first-generation students from entering professions already facing labor shortages.

The American Medical Association has specifically warned that the borrowing caps could worsen a physician shortage projected to reach 86,000 doctors nationwide by 2036.

Medical schools, law schools, and graduate institutions are already scrambling to prepare.

Financial-aid offices at Harvard University, Columbia University, Stanford University, George Washington University, the University of Virginia, the University of Washington, and numerous large public university systems have begun issuing transition guidance directing prospective students toward private lending marketplaces, institutional aid programs, scholarships, and alternative financing structures.

For private lenders, meanwhile, the changes represent a potentially historic business opportunity.

The private student-loan industry has spent nearly two decades competing against a federal Grad PLUS system that effectively dominated graduate borrowing. Beginning next summer, a large portion of that market will reopen for the first time since the financial crisis era reshaped federal higher-education financing.

The broader question now facing universities, students, lenders, and policymakers is whether graduate education itself becomes structurally less accessible — or whether institutions ultimately respond by lowering tuition after years of relentless cost escalation.

The answer could redefine the economics of American professional education for an entire generation.

JBizNews Desk

Internal revolt over a controversial Nicholas Kristof column is triggering a deeper business question Wall Street increasingly cannot ignore: what happens when a media company loses trust inside its own newsroom?

NEW YORK — A widening internal backlash has erupted inside The New York Times over a controversial May 11 opinion column by longtime columnist Nicholas Kristof, exposing deep tensions between the paper’s newsroom and opinion division and raising broader concerns about the future business model of legacy media at a moment when public trust in major news institutions continues eroding.

According to reporting published by Puck News media correspondent Dylan Byers and later amplified by multiple outlets including the New York Post and Israel’s Ynet News, several Times journalists privately expressed outrage over Kristof’s column alleging systematic sexual abuse of Palestinian detainees by Israeli prison guards. At least one staff member reportedly told Puck: “I am sick of being embarrassed by the Opinion section.”

For years, President Donald Trump publicly branded The New York Times “fake news.”

Now the paper is confronting a more dangerous problem for its business: some of its own journalists are openly questioning whether parts of its opinion operation are damaging the credibility of the institution itself.

The Kristof column, titled “The Silence That Meets the Rape of Palestinians,” contained highly graphic allegations involving alleged abuse inside Israeli detention facilities, including disputed claims involving sexual violence and abuse carried out by prison guards. Critics immediately challenged the sourcing, verification standards and reliance on advocacy organizations tied to the reporting.

Inside the Times newsroom, according to multiple reports, frustration quickly spread beyond politics and into professional standards.

Newsroom reporters — who operate under stricter verification and sourcing requirements — reportedly questioned whether allegations of such magnitude would have ever cleared the paper’s traditional reporting standards if handled through the news division instead of the opinion section.

The internal criticism matters because the Times’ modern business model depends almost entirely on trust.

Unlike older newspaper economics built primarily on print advertising, the modern New York Times is fundamentally a subscription company. The paper now generates billions annually from digital subscriptions across news, cooking, games and premium content products. That business works only if readers continue believing the institution itself remains authoritative and credible.

And increasingly, credibility has become the central battlefield in American media.

The mainstream news industry has already endured years of declining public trust, falling cable ratings, newsroom layoffs and collapsing advertising economics. CNN, CBS News, ABC News, NBC News and The Washington Post have all faced varying combinations of restructuring, subscriber pressure, layoffs or advertiser weakness over the past several years as consumers increasingly fragment across alternative media, podcasts, social platforms and politically aligned outlets.

Until recently, The New York Times largely appeared insulated from the worst of that collapse.

Its digital subscription engine became the envy of the industry. Its stock price and valuation significantly outperformed most legacy competitors. Its affluent subscriber base remained unusually loyal.

But the Kristof controversy is now striking directly at the company’s most valuable asset: institutional trust.

Times leadership has publicly defended the column.

Spokesman Charlie Stadtlander said the piece relied on on-the-record testimony and documented allegations involving abuse and sexual violence. Executive Editor Joseph Kahn and Opinion Editor Kathleen Kingsbury have also defended the column’s editorial review process.

But internally, according to multiple reports, many newsroom staffers remain deeply uncomfortable with the sourcing standards surrounding some of the column’s most explosive allegations.

The controversy has already triggered growing external fallout.

Israeli Prime Minister Benjamin Netanyahu and Foreign Minister Gideon Sa’ar condemned the piece and threatened legal action against both the Times and Kristof personally. Pro-Israel organizations and advocacy groups began publicly encouraging subscription cancellations, while criticism spread rapidly across social media and competing publications.

Analysts say the financial risk is not necessarily one article itself.

It is the broader perception that the institution’s standards may be slipping.

Duvi Honig, founder and chief executive of the Orthodox Jewish Chamber of Commerce, Newsmax contributor and economic policy analyst, said the Times is now confronting the same credibility crisis that has already damaged much of legacy media.

“When a newspaper loses its own newsroom’s confidence, credibility collapses — and the business model collapses with it,” Honig said. “Subscribers cancel. Advertisers walk. The bill always comes due.”

That concern is becoming increasingly relevant across the broader media industry.

Digital advertising rates across journalism have weakened for years as Google, Meta, TikTok and streaming platforms absorbed increasing shares of advertising dollars. Subscription growth across media has also slowed as consumers hit “subscription fatigue” after years of paying for multiple streaming, news and digital services simultaneously.

That means credibility itself increasingly functions as the core product major news organizations are selling.

And once readers begin questioning whether reporting standards remain politically or ideologically consistent, the damage can spread quickly beyond a single controversy.

The Times has faced newsroom-versus-opinion tensions before.

In 2020, then-Opinion Editor James Bennet resigned following an internal revolt over publication of an opinion essay by Republican Senator Tom Cotton advocating military deployment during nationwide unrest. But media analysts note the current controversy is different because the criticism is not coming from ideological opponents outside the company.

It is coming from inside the building itself.

That distinction may matter enormously for advertisers, investors and subscribers evaluating the long-term stability of the Times brand.

The modern media economy no longer survives on prestige alone.

It survives on recurring subscription renewals, advertiser confidence and public trust that what appears under a publication’s banner meets consistent editorial standards regardless of politics.

The Times says it stands behind the column.

Some of its own journalists reportedly say they are embarrassed by it.

Now the company’s subscribers — and eventually Wall Street — may decide which judgment carries more weight.

Because for legacy media companies already battling shrinking trust across much of the country, the greatest threat may no longer be political attacks from the outside.

It may be credibility fractures emerging from within.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Carvana Co., the Tempe, Arizona-based online used-car giant, has emerged in recent weeks as perhaps the most disruptive force to hit the U.S. new-car retail market in decades, rapidly expanding into franchised dealership ownership at a pace that has alarmed automakers, dealer associations, and traditional retailers across the country.

The company has completed its seventh acquisition of a franchised Chrysler-Dodge-Jeep-Ram dealership in just 14 months, according to public dealer-acquisition disclosures and industry tracking by CBT News and CDG Circles. The buying spree has become so aggressive that Stellantis NV, parent company of Chrysler, Dodge, Jeep, and Ram, reportedly imposed an unprecedented one-store-per-year cap on Carvana’s future expansion inside its dealer network.

Carvana now operates franchised new-car dealerships in Arizona, Texas, California, Georgia, Ohio, and the Boston area. The latest acquisitions — including a Sacramento dealership purchased from Nouri/Shaver Automotive Group, an Avon Lake, Ohio location near Cleveland, and another in suburban Boston — closed in rapid succession over the past several months.

The move represents a dramatic escalation in Carvana’s ambitions. The company originally built its brand around online used-car sales, vending-machine vehicle towers, home delivery, and fully digital transactions. Now it is entering the far larger and politically protected new-car business, testing whether century-old franchise laws can withstand an online-first retail model backed by Wall Street capital.

“This is the kind of defensive measure an automaker imposes when a single capital-rich buyer is reshaping the local economics of a region’s car-retail market faster than franchised dealers can adapt,” one industry executive familiar with the Stellantis restrictions told industry analysts.

Customers increasingly appear willing to embrace the model.

Joshua Higginbotham, a 43-year-old buyer from the Kansas City area, recently purchased a new $51,000 Jeep Wrangler online through a Carvana-owned dealership located more than 1,000 miles away from his home.

“I don’t want to spend a whole day in a dealership, and they always like to make it take an entire day,” Higginbotham said after completing the transaction from his living room couch.

That frustration is becoming one of Carvana’s biggest competitive weapons.

The company’s model eliminates traditional showroom negotiations, finance-office upselling, and lengthy dealership visits. Buyers browse inventory online, receive financing digitally, sign paperwork electronically, and schedule home delivery or pickup. For younger buyers especially, the experience increasingly resembles buying electronics on Amazon rather than navigating the traditional auto-retail process.

The challenge for the dealer establishment is that Carvana is now attempting to bring that model into a regulatory system specifically designed to protect franchised local dealerships.

State franchise laws — among the most heavily defended commercial regulations in America — were largely built over the last century to prevent automakers from bypassing local dealers or consolidating excessive market power. Dealer associations argue the system protects consumers through local competition, warranty support, service infrastructure, and employment stability.

Carvana’s expansion is testing those assumptions directly.

The company began buying Stellantis franchise stores in February 2025 with the acquisition of a dealership in Casa Grande, Arizona. Since then, it has rapidly added locations in Dallas, San Diego, Union City, Georgia, Sacramento, the Boston area, and Ohio.

Industry analysts say Stellantis has been particularly vulnerable because of years of declining U.S. market share, inventory imbalances, and weak dealer profitability.

Jack Ballinghoff, chief operating officer at Ourisman Automotive Group and H Street Management, described Stellantis’ dealer network as “battered” by inconsistent product demand and operational strain.

Stellantis is now attempting an aggressive turnaround strategy aimed at reclaiming roughly 8% U.S. market share in 2026, equivalent to approximately 1.1 million annual vehicle sales. Reaching that target would require dealer volumes to rise by roughly 25%, creating significant pressure across the network.

That instability has created an opening for Carvana.

With its stock rebounding from single digits during the 2022–2023 downturn to above $300 per share, the company once again has access to capital markets and acquisition financing powerful enough to expand rapidly.

The economics are deeply unsettling for traditional dealers.

Scott Gruwell, chief executive of Courtesy Automotive Group in Phoenix, has openly acknowledged that many conventional dealerships cannot compete directly with Carvana’s pricing structure.

“One of the unique advantages they have versus normal franchise dealers is they had the ability to actually carry the paper and finance a lot of that back-end dollars,” Gruwell said. “So they could squeeze the price, compress that margin down to nothing or even below. But yet they pick it back up on the finance part.”

That financing advantage is becoming increasingly important.

According to data from One Auction View, Carvana’s listed used-car inventory surged from roughly 53,600 vehicles to 64,700 vehicles over the past three months alone. Pricing has also become increasingly aggressive, shifting from approximately 12% below market averages to nearly 15% below market pricing.

The company reported a 44% year-over-year increase in used-vehicle sales during the third quarter of 2025, reaching 155,941 units sold.

Perhaps most alarming to competitors, two formerly underperforming Stellantis dealerships acquired by Carvana now reportedly rank among the top five nationally in month-to-date sales volume.

Dealer groups and lobbying organizations are now mobilizing.

The National Automobile Dealers Association (NADA) has intensified lobbying efforts in Washington and state legislatures, arguing that the traditional franchise model protects consumers, preserves local jobs, and ensures competitive pricing through independent ownership structures.

State dealer associations from California to Georgia are also reviewing whether existing franchise statutes need tightening to prevent large-scale consolidation by online-first operators.

Carvana has already faced regulatory friction before.

Illinois suspended the company’s dealer license in 2022 after consumer complaints involving title-processing and registration delays. Similar regulatory agreements were later reached with authorities in Michigan and Pennsylvania.

But the broader industry trend may already be moving in Carvana’s direction.

Amazon.com Inc., working alongside traditional dealers, launched Amazon Autos last year, allowing consumers to browse and buy new vehicles online before completing delivery through dealership partners.

Meanwhile, Scout Motors, the new American electric SUV and pickup brand backed by Volkswagen AG, plans to sell directly to consumers under a Tesla-style model that bypasses traditional dealerships entirely. Dealer associations in Texas and South Carolina have already launched legal and political challenges against Scout’s plans.

The financial stakes are enormous.

According to Cox Automotive, Americans spent approximately $655 billion on new vehicles during 2025, compared with roughly $524 billion on used cars. While more used vehicles change hands annually, the new-car market remains the most lucrative segment of automotive retail because of higher transaction prices, warranty servicing, manufacturer incentives, and finance-and-insurance revenue.

Carvana is no longer fighting for a share of the smaller pool.

It is now moving directly into the largest and most profitable part of the automotive business — and doing so fast enough that much of the traditional dealer system is only beginning to grasp the scale of the threat.

The next 18 months may determine whether the century-old franchise model can adapt to a consumer base increasingly comfortable buying cars the same way it buys almost everything else online.

For now, Carvana is accelerating — and millions of traditional dealership customers appear increasingly willing to come along for the ride.

JBizNews Desk

Mortgage applications for newly built homes fell 2.4% in April compared with a year earlier, according to Builder Application Survey data released Monday by the Mortgage Bankers Association, marking the first year-over-year decline in new-home purchase activity since February 2025 and a sharp reversal from March’s record-high 11% annual surge.

The April reading, presented by Joel Kan, the MBA’s Vice President and Deputy Chief Economist, captures the moment the housing market began absorbing the full weight of the U.S.-Iran war, the post-conflict surge in mortgage rates, and renewed inflation pressure from elevated energy costs. Applications also declined 1% from March on an unadjusted basis, an unusual seasonal pattern given that April typically marks the heart of the spring buying season.

The pullback validates a warning Kan issued in early April, when overall purchase applications turned negative on an annual basis for the first time in more than a year. The MBA’s weekly survey through the latter half of April and early May has shown choppy, range-bound activity, with the 30-year fixed mortgage rate climbing from 6.30% in March to 6.65% as of last week, according to Mortgage News Daily. Treasury yields have remained elevated as markets price in fewer rate cuts from the Federal Reserve amid sticky inflation and energy-price pass-through from the Middle East conflict.

The MBA now estimates that new single-family home sales ran at a seasonally adjusted annual rate well below the 717,000-unit pace recorded in March, when builder activity had hit its highest level in the survey’s history dating to 2012. That earlier momentum, driven in part by builders cutting prices and offering rate buydowns to clear inventory, appears to have stalled as affordability deteriorated.

The new-home softness arrived alongside fresh confirmation of broader builder caution. The National Association of Home Builders/Wells Fargo Housing Market Index, released Monday, came in at 37 for May, up three points from April’s seven-month low of 34 but still deep in negative territory. NAHB Chairman Bill Owens, a builder and remodeler from Worthington, Ohio, said the housing market remains soft as higher mortgage rates, rising gas prices, and economic uncertainty tied to the war in Iran continue to dampen buyer demand. NAHB Chief Economist Robert Dietz pointed to climbing long-term interest rates as a continuing drag, noting that some regional markets, particularly parts of the Midwest, are showing relative strength while the broader market faces significant affordability challenges.

The NAHB index has now spent 25 consecutive months below the 50-point threshold separating builder optimism from pessimism. Roughly 32% of builders cut prices in May, down from 36% in April, but those who did reduced them by 6% on average, up from 5% the prior month. Sales incentives remained widespread, with 61% of builders offering them.

For the loan-product breakdown in April, FHA mortgages continued to account for an outsized share of new-home applications, reflecting heavy reliance on first-time and lower-down-payment buyers. The MBA’s weekly data has shown FHA contract rates running roughly 30 basis points below conventional 30-year fixed rates, a spread that has supported entry-level demand even as the overall market softens.

The Fannie Mae May Housing Forecast, released Sunday by the government-sponsored enterprise, pushed back its expectations for mortgage rate relief. The GSE now projects the 30-year fixed rate will hold near 6.3% through the first quarter of 2027 before easing to 6.2%, abandoning its earlier April projection that rates would reach 6.1% by year-end. The revision reflects the persistence of inflation pressures tied to energy prices and the labor market’s continued resilience.

The April BAS data carry implications well beyond the lending industry. Builders such as D.R. Horton, Lennar, PulteGroup, and NVR have leaned heavily on mortgage-rate buydowns and price concessions over the past two years to keep contract volume flowing. A sustained pullback in application activity would force tougher decisions on land acquisition, construction pacing, and margin protection heading into the back half of the year.

For consumers, the data underscore a market that has shifted decisively in favor of those who can still qualify and close. Unsold new-home inventory remains elevated across much of the South and parts of the West, giving qualified buyers more negotiating leverage than at any point in the post-pandemic cycle. But that leverage is being offset by the simple math of monthly payments, which have moved higher in lockstep with the recent rate climb.

The next major data point arrives Friday, when the Census Bureau releases its official April new home sales report. That figure, derived from contract signings, will either confirm the MBA’s signal of a cooling market or suggest the April slip was a temporary war-driven pause before spring demand reasserts itself.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

America’s biggest home builders are quietly setting aside hundreds of millions — and in some cases more than a billion dollars — to prepare for a growing wave of lawsuits tied to allegedly defective homes, sinking foundations, mold damage, water intrusion, and disputed lending practices, as mounting legal pressure begins reshaping the economics of the U.S. housing industry.

According to annual filings with the U.S. Securities and Exchange Commission, legal-liability reserves at several of the nation’s largest builders have climbed sharply over the past several years, reflecting growing exposure to construction-defect litigation spreading across at least 16 states.

The underlying complaints vary from case to case, but many revolve around a similar pattern: homes built rapidly during the post-pandemic housing boom that later developed moisture intrusion, structural movement, drainage failures, or ventilation issues that allegedly allowed mold and water damage to spread behind walls, beneath floors, and inside foundations.

Builders strongly dispute many of the claims and argue plaintiffs’ attorneys are aggressively encouraging litigation over isolated defects. But the rising reserve numbers, expanding court dockets, and retreat of insurance coverage are increasingly becoming impossible for investors to ignore.

Lennar Corp. increased its self-insurance reserve — funds set aside for liabilities not fully covered by insurers — roughly 21% in fiscal 2025 to $336.9 million. Meanwhile, D.R. Horton, the nation’s largest home builder by volume, raised its legal-claims reserve approximately 57% over three years, reaching roughly $1.1 billion by the end of fiscal 2025.

The issue is unfolding house by house.

For Blake and Beth Horio, the problem began shortly after purchasing a newly built PulteGroup home in Henderson, Nevada, in 2022. According to allegations in an ongoing dispute, cracks spread across ceilings, sliding doors stopped functioning properly, and portions of the home allegedly began sinking because of shifting soil beneath the property.

When an engineer later inspected the house and rolled a marble across the kitchen floor, the marble reportedly drifted toward one corner.

“Your home is sinking,” the engineer told them, according to the homeowners.

“We worked hard to get here and we can’t enjoy our home,” Beth Horio said. “I can’t even have coffee outside. I can’t get outside.”

PulteGroup acknowledged that approximately 5% of homes in the community may have experienced what it described as “compression of native soils in isolated areas,” while emphasizing the company follows strict construction standards and remains committed to repairs where necessary.

The Nevada dispute is only one example inside a much broader national litigation wave.

In Florida, Lennar is defending one of the industry’s most closely watched construction-defect lawsuits after the Seminole Tribe of Florida alleged the company built more than 450 defective homes with improperly installed roofs, mold-related damage, and significant structural failures that plaintiffs claim contributed to health concerns among residents.

Additional Lennar-related litigation involving water intrusion, alleged code violations, and structural concerns is also moving through courts in North Naples and Homestead, Florida.

Meanwhile, D.R. Horton faces lawsuits tied both to construction defects and mortgage-related allegations.

In Louisiana, thousands of homeowners have alleged moisture-related failures in Horton-built homes. Separately, a federal class-action lawsuit filed in Nevada in late 2025 accuses D.R. Horton and its mortgage arm, DHI Mortgage, of improperly calculating escrow payments using lower pre-construction tax assessments rather than final occupied-home valuations — allegedly leading to large surprise increases in homeowners’ monthly mortgage payments after closing.

The lawsuit invokes the federal Racketeer Influenced and Corrupt Organizations Act (RICO), sharply escalating the legal stakes.

D.R. Horton has denied wrongdoing and moved earlier this year to dismiss the complaint, arguing buyers received multiple disclosures before closing.

The broader industry insists the litigation surge does not necessarily reflect collapsing construction quality.

Builders argue many problems originate with subcontractors rather than the companies themselves and note they collectively deliver hundreds of thousands of homes annually across the country.

Still, the broader economics surrounding home construction have changed dramatically since the pandemic-era housing boom.

Large builders faced enormous pressure between 2020 and 2024 to rapidly deliver homes amid soaring demand, labor shortages, supply-chain disruptions, and surging material costs. Industry groups estimate the construction sector still faces a labor shortage exceeding 500,000 workers nationally, while tariffs and inflation continue driving up costs for steel, aluminum, appliances, and other inputs.

At the same time, builders have openly discussed aggressive cost-management efforts.

Lennar Executive Chairman Stuart Miller previously told investors the company had begun “value-engineering every component of the home,” while emphasizing quality was not being compromised.

D.R. Horton similarly discussed replacing certain fixtures and finishes with lower-cost alternatives while maintaining what it described as acceptable standards.

Critics argue those pressures may have contributed to weaker quality control during the housing boom, especially as builders increasingly relied on subcontractors working under compressed timelines.

The insurance market is also shifting rapidly.

Many insurers have retreated from broad post-construction defect coverage, forcing builders to self-insure larger portions of potential liabilities — one major reason reserve balances continue climbing sharply across the sector.

Meanwhile, courts in multiple states have increasingly challenged mandatory arbitration clauses in builder contracts, potentially opening broader pathways for homeowner lawsuits.

The National Association of Home Builders has pushed for stronger state-level “right-to-cure” laws requiring builders receive opportunities to repair defects before lawsuits proceed. Industry groups argue some plaintiff firms now actively target entire developments in search of settlement leverage.

Wall Street is beginning to factor the issue into the sector’s long-term outlook.

Although shares of D.R. Horton, Lennar, and PulteGroup traded modestly higher Monday, analysts increasingly view rising litigation costs, insurance exposure, and margin pressure as structural risks for the industry.

The timing is especially difficult.

Existing-home sales remain historically weak, mortgage affordability remains near multi-decade lows, and broader parts of the housing supply chain — including the appliance industry — are already showing recession-like conditions.

Now, America’s largest home builders face another challenge: growing legal scrutiny over what exactly was delivered during one of the fastest and most profitable housing booms in modern U.S. history.

The cases now unfolding across Nevada, Florida, Louisiana, and elsewhere may ultimately shape not only the future cost of construction litigation, but also how aggressively builders balance speed, affordability, labor constraints, and quality in the next phase of America’s housing market.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

For years, Americans were told artificial intelligence would make life cheaper, faster, and more efficient.

Now many are beginning to encounter AI in a very different place: their electricity bill.

Across the country this summer, households are opening utility statements that look noticeably heavier than they did just a few years ago. Air conditioning costs are climbing again. Delivery fees are rising. Utilities are requesting new rate increases almost monthly. And behind much of the pressure sits something most consumers never see directly — giant data centers quietly multiplying across America to power artificial intelligence systems that never sleep.

The buildings themselves often look anonymous from the outside. Long gray warehouse-style structures surrounded by fencing, cooling equipment, and endless rows of power lines. But inside, tens of thousands of computer chips run continuously every hour of every day, processing AI searches, generating content, training models, storing cloud data, and powering the digital systems increasingly woven into everyday life.

Each facility consumes staggering amounts of electricity.

And America is suddenly building them everywhere.

The issue moved into sharper focus Friday after reports emerged that NextEra Energy is in talks to acquire Dominion Energy, partly to gain greater access to Northern Virginia — home to the world’s largest concentration of data centers and one of the fastest-growing electricity-demand regions on earth.

To Wall Street, the potential deal is about positioning for the future of AI infrastructure.

To many consumers, however, it raises a much simpler question: who pays for all this power?

Utilities insist ordinary households are not subsidizing the AI boom. Large technology companies including Amazon, Microsoft, Google, and Meta are spending billions expanding infrastructure and signing long-term power agreements. Executives argue those investments eventually strengthen the grid and spread costs across a broader customer base.

But many Americans are struggling to see that benefit right now.

Instead, what they see are utility bills that keep rising faster than expected.

According to the U.S. Energy Information Administration, residential electricity prices have risen more than 31% since 2020, with another increase expected this year. In many regions, consumers are already cutting back elsewhere to absorb higher monthly energy costs alongside elevated insurance, grocery, and housing expenses.

The anxiety becomes more understandable once people realize how much electricity modern AI systems actually consume.

A single large AI-focused data center can use as much power as tens of thousands of homes. Entire clusters of facilities now operate around the clock in places like Northern Virginia, Texas, Arizona, Ohio, and Georgia. Unlike traditional office buildings or factories that may reduce activity overnight, AI infrastructure runs continuously — every search query, chatbot interaction, image generation request, and cloud backup drawing electricity every second.

That nonstop demand is forcing utilities into one of the largest infrastructure expansions in decades.

New transmission lines must be built. Substations upgraded. Backup systems expanded. Renewable-energy projects accelerated. Utilities are also scrambling to add natural-gas generation, battery storage, and nuclear capacity fast enough to prevent shortages as electricity demand surges for the first time in years after decades of relatively flat growth.

Consumers are increasingly caught in the middle.

Inside the utility industry itself, executives are starting to publicly acknowledge the tension. Earlier this month, Eversource Energy CEO Joe Nolan openly questioned whether attracting more data centers actually benefits ordinary households. “It’s only going to drive up the price of energy,” Nolan warned during an earnings call.

That fear is spreading beyond energy executives.

In parts of the country where data-center construction is accelerating fastest, local residents are beginning to push back against massive power usage, water consumption, land acquisition, and the growing visibility of utility infrastructure surrounding these projects.

At the same time, utilities argue they have little choice. America’s economy is rapidly becoming more digital, more electric, and more dependent on AI systems. The power demand is coming whether the grid is ready or not.

That leaves regulators trying to answer an increasingly uncomfortable question: how much of the cost should households absorb while technology companies race to build the next generation of AI infrastructure?

For now, there is no clear answer.

What is clear is that the AI boom is no longer an abstract story about Silicon Valley innovation or futuristic software demonstrations. It is becoming a real-world infrastructure story playing out across suburbs, power grids, utility commissions, and kitchen tables across the country.

For many Americans, artificial intelligence may eventually make work more productive and businesses more efficient.

But before they experience those benefits, they may first experience the cost.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

New York City Mayor Zohran Mamdani walked into JPMorgan Chase & Co.’s new $3 billion headquarters at 270 Park Avenue at noon Monday for his first in-person meeting with Chief Executive Jamie Dimon, the most closely watched private sit-down yet between the city’s new democratic socialist administration and Wall Street’s most powerful figures. The meeting came as Mamdani works to tamp down growing backlash to his “tax the rich” agenda, which has increasingly unsettled wealthy New Yorkers and major corporate employers. The JPMorgan session was held alongside a separate meeting between the mayor and Goldman Sachs Group Inc. Chief Executive David Solomon, according to Bloomberg.

According to a City Hall spokesman, the Dimon meeting focused on cutting government waste, reforming New York State’s environmental-review process to accelerate development projects, and structuring public-private partnerships aimed at addressing the city’s housing and infrastructure needs. Mamdani also discussed a large Queens-based redevelopment proposal with Dimon and other executives during the day’s meetings, including the mayor’s push for roughly 12,000 affordable housing units at Sunnyside Yards, a project he pitched directly to President Donald Trump during a surprise Oval Office visit in February. While Mamdani and Dimon sit on opposite ends of the political spectrum, both men frequently reference their Queens roots, a detail that has softened the tone of some of their recent public exchanges.

The meetings arrive amid intensifying resistance from Wall Street to the most aggressive elements of Mamdani’s economic platform. The 34-year-old mayor has placed affordability at the center of his administration, championing free city buses, a rent freeze, municipal grocery stores, and higher taxes targeting affluent New Yorkers and luxury property owners. The financial industry remains deeply sensitive to those proposals because the sector generates roughly 19% of New York State’s tax revenue and anchors a large portion of the city’s high-income tax base.

The backlash escalated sharply last month after Governor Kathy Hochul unveiled a new pied-à-terre tax targeting luxury second homes. Mamdani intensified the debate further with a social-media video highlighting Citadel founder Kenneth Griffin’s $238 million penthouse at 220 Central Park South as an example of the type of ultra-luxury property that could face additional taxation. The video quickly ignited criticism from business leaders and investor groups concerned that New York risks pushing more high earners and corporations toward lower-tax states such as Florida and Texas. City Hall has reportedly reached out to Griffin regarding a potential meeting, though none has been scheduled.

The administration’s outreach campaign to corporate America has become increasingly visible. Prior to Monday’s meetings with Dimon and Solomon, Mamdani met last week with Blackstone Inc. President and Chief Operating Officer Jonathan Gray. In the aftermath of the pied-à-terre controversy, the mayor also held a separate session at City Hall with Bank of America Corp. Chief Executive Brian Moynihan. Additional recent meetings included leadership from food company Chobani and several real-estate executives.

Dimon himself has evolved publicly in his posture toward the mayor. Last July, the JPMorgan chief described Mamdani’s progressive economic platform as “ideological mush” during an investor event before moderating his tone following the November election. JPMorgan employs more than 24,000 workers in New York City, making it one of the city’s largest private employers. At the same time, Dimon has repeatedly noted that the bank now employs more workers in Texas than in New York, a comment widely interpreted across Wall Street as a warning about the long-term risks of escalating taxes and regulation.

The fiscal backdrop surrounding the meetings remains highly consequential. Mamdani inherited an estimated $7 billion budget shortfall upon taking office, though City Hall says the gap was closed without increasing property taxes after securing several billion dollars in additional state aid and roughly $1.7 billion in agency savings. New York State Comptroller Thomas DiNapoli recently estimated that Wall Street bonus payouts alone are expected to generate approximately $91 million more in city revenue than last year, aided by a stock market that continues supporting financial-sector compensation. The S&P 500 has risen nearly 8% year-to-date, helping stabilize bonus pools that remain critical to New York’s tax base.

Still, the deeper structural conflict between progressive fiscal policy and Wall Street’s mobility remains unresolved. Many of Mamdani’s largest revenue proposals — including possible adjustments to corporate or income-tax rates — would require approval from Albany, giving Governor Hochul and state lawmakers significant leverage over how much of the mayor’s agenda ultimately becomes law. Mamdani has previously floated the possibility of property-tax increases as a negotiating tool designed to pressure state leaders into raising taxes on top earners instead.

Business organizations and financial executives continue lobbying aggressively against the proposals, warning that stacking additional city and state taxes on top-income households and luxury real estate could accelerate corporate relocations and weaken New York’s long-term competitiveness. Pershing Square Capital Management Chief Executive Bill Ackman, who supported an alternative candidate during the mayoral race, previously warned that Mamdani’s economic agenda risked destroying jobs and driving wealthy taxpayers out of the city. Ackman has since softened his rhetoric and publicly offered to assist the administration if needed. Galaxy Digital Chief Executive Mike Novogratz and several other Wall Street executives who initially threatened to relocate have similarly moderated their language in recent weeks.

For Dimon and Solomon, Monday’s meetings represent a strategic reset rather than an endorsement. Both banks maintain enormous operational footprints in New York and benefit heavily from proximity to municipal, state, and federal regulators. The symbolism surrounding JPMorgan’s new Park Avenue headquarters was difficult to miss. The 270 Park Avenue tower, completed last October, was the largest private real-estate investment in Midtown Manhattan in decades and serves as a physical statement that JPMorgan remains deeply committed to New York even as employment growth accelerates elsewhere.

Mamdani has acknowledged the importance of maintaining open communication with business leaders, telling reporters earlier this month that the meetings are part of a broader outreach effort and that he values the dialogue even amid significant disagreements.

What emerges from Monday’s discussions could shape the tone of negotiations heading into the next budget cycle. If Mamdani can convince Wall Street leaders that he is willing to engage pragmatically while still advancing his affordability agenda, he may preserve the city’s revenue engine without triggering the corporate departures critics fear. If those relationships deteriorate, however, the battle over taxes, housing, and New York’s economic direction could intensify rapidly — with implications extending far beyond Manhattan’s financial district.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The U.S. Centers for Disease Control and Prevention has invoked Title 42 to suspend entry into the United States for non-American travelers who have recently been in the Democratic Republic of Congo, Uganda or South Sudan after the World Health Organization declared an Ebola outbreak in central Africa a “public health emergency of international concern” and one American missionary doctor working in the region tested positive for the virus. The emergency order, signed Monday by Dr. Jay Bhattacharya and effective immediately, marks only the second major use of Title 42 in the modern era following its controversial deployment during the Covid-19 pandemic and has reignited a global scramble for treatments targeting a deadly Ebola strain for which there is currently no approved vaccine or FDA-authorized drug.

The 30-day travel restriction arrives alongside a State Department Level Four advisory warning Americans against all travel to affected regions. The CDC said the immediate risk to the broader U.S. public remains “low,” but officials emphasized that screening measures and restrictions could expand depending on how the outbreak evolves in coming weeks.

The outbreak, formally declared Sunday by WHO Director-General Dr. Tedros Adhanom Ghebreyesus, is being driven by the rare Bundibugyo strain of Ebola and has already killed at least 131 people with more than 500 suspected cases, according to DRC Health Minister Dr. Samuel Roger Kamba. The first known suspected infection reportedly involved a healthcare worker who developed symptoms in late April, suggesting the virus circulated undetected for weeks before authorities identified the outbreak.

An American Christian missionary physician working in northeastern Congo, Dr. Peter Stafford, tested positive for Ebola while serving at a hospital in Bunia, according to international medical charity Serge. Stafford is being transferred to Germany for treatment along with his wife, children and another physician. None of the accompanying family members are currently symptomatic.

What the Outbreak Actually Is — and How Ebola Spreads

Ebola is a viral hemorrhagic fever — a severe disease capable of causing high fever, organ damage, internal bleeding and, in many cases, death. The current outbreak involves the Bundibugyo strain, one of the rarest known Ebola variants and only the third major Bundibugyo outbreak ever recorded globally.

Unlike Covid-19, Ebola is not airborne.

A person cannot contract Ebola simply by sitting near someone on an airplane, sharing a subway ride or being in the same room with an infected person who is not showing symptoms. The virus spreads only through direct contact with bodily fluids — including blood, saliva, vomit, sweat, diarrhea or contaminated medical equipment — from someone who is already visibly ill.

That distinction dramatically limits transmission potential compared with respiratory viruses.

Dr. Dean Blumberg, an infectious-disease specialist cited by CNBC, emphasized that Ebola does not spread during its incubation period, which can last up to 21 days. In practical terms, a person who appears healthy is generally not contagious.

Symptoms initially resemble severe flu-like illness, including fever, headache, muscle aches and fatigue, before progressing in some patients into vomiting, severe diarrhea, bleeding complications and organ failure.

Historically, Bundibugyo outbreaks have carried mortality rates between roughly 25% and 50%, significantly below the far deadlier Zaire strain responsible for the catastrophic 2014-2016 West African epidemic that killed more than 11,000 people.

How This Affects Americans at Home

For the average American household, the immediate health threat remains extremely limited, according to federal health authorities.

The U.S. government’s emergency order blocks entry for most non-U.S. citizens who have recently traveled through the affected countries. American citizens and military personnel remain exempt but are subject to enhanced screening and monitoring procedures.

Travelers from affected regions are being routed through designated U.S. airports equipped with expanded public-health screening capabilities, and hospitals nationwide have reportedly been placed on alert for potential cases involving symptomatic travelers.

A key reason officials remain relatively calm is that Ebola lacks the asymptomatic airborne transmission dynamics that allowed Covid-19 to spread globally at extraordinary speed.

Past Ebola outbreaks produced isolated cases in the United States — including 11 cases during 2014 — but never triggered sustained community transmission.

Still, the outbreak creates a complicated wrinkle for international travel and major events. The Democratic Republic of Congo’s national soccer team is currently scheduled to base operations in Houston during the 2026 FIFA World Cup, raising new questions about screening, logistics and travel restrictions should the outbreak continue expanding.

Where Americans Will Feel the Impact

Most Americans are more likely to feel the effects economically and psychologically rather than medically.

Travel disruptions are already emerging across parts of central and East Africa as airlines reassess routes, governments tighten screening requirements and travelers reconsider plans. Additional quarantine requirements or flight cancellations could follow if cases spread geographically.

Financial markets are also reacting.

Pharmaceutical companies tied to Ebola countermeasures — including Regeneron Pharmaceuticals, Merck & Co., and Johnson & Johnson — are expected to see heightened investor attention as governments evaluate potential stockpiling contracts and emergency procurement activity.

At the same time, travel-sensitive stocks such as airlines, tourism operators and international hospitality firms could face pressure if outbreak fears intensify.

Public-health officials are also battling something harder to quantify: pandemic fatigue and public anxiety.

The phrase “global health emergency” now carries enormous emotional weight after Covid-19, even though experts stress the current Ebola outbreak operates under very different biological conditions.

The $32 Billion Economic Warning

The economic consequences of uncontrolled Ebola outbreaks are not theoretical.

The World Bank estimated the 2014-2016 West African Ebola epidemic caused approximately $32.6 billion in global economic damage through lost GDP, collapsed tourism, disrupted supply chains, labor-market losses and trade interruptions across affected regions.

Those losses extended far beyond healthcare systems themselves.

Past pandemic modeling by economists has repeatedly shown that infectious-disease outbreaks can trigger cascading effects throughout global commerce, transportation, consumer behavior and investment markets — even when outbreaks remain geographically concentrated.

That economic reality helps explain why governments, global-health organizations and philanthropic groups increasingly treat epidemic preparedness as a national-security and economic-stability issue rather than purely a humanitarian one.

The Pharmaceutical Gap

Despite nearly five decades since Ebola was first identified in 1976, the pharmaceutical industry still lacks approved countermeasures for several Ebola strains, including Bundibugyo.

The only FDA-approved Ebola treatment currently available is Inmazeb, developed by Regeneron Pharmaceuticals and approved in 2020. The only FDA-approved Ebola vaccine is Ervebo, manufactured by Merck & Co. A second vaccine developed by Johnson & Johnson has received authorization in Europe.

However, all existing approved therapies target the Zaire Ebola strain — not Bundibugyo.

Animal studies suggest currently approved vaccines may provide limited protection against the strain now spreading in central Africa.

Dr. Paul Offit, director of the Vaccine Education Center at Children’s Hospital of Philadelphia, said several Bundibugyo-specific vaccine candidates remain stuck in early-stage development, including experimental mRNA platforms under study internationally.

The CDC said the federal government is evaluating experimental monoclonal antibody treatments that have shown protective effects in animal testing.

The Broken Economics of Ebola Drug Development

The absence of fully developed Bundibugyo treatments highlights a longstanding market failure inside global pharmaceuticals.

Developing vaccines for rare outbreak diseases is extraordinarily expensive and often commercially unattractive because outbreaks emerge unpredictably and primarily affect lower-income regions with limited purchasing power.

Industry estimates place advanced vaccine-development costs well above $100 million per strain-specific program, while commercial revenue opportunities remain relatively modest outside emergency procurement periods.

That mismatch leaves governments, nonprofits and international coalitions such as CEPI, Gavi, and BARDA heavily responsible for funding much of the world’s epidemic-preparedness infrastructure.

What This Outbreak Changes

The current outbreak is likely to accelerate three major trends.

First, governments are expected to expand emergency stockpiles of existing Ebola vaccines and therapeutics, potentially benefiting Merck, Regeneron and Johnson & Johnson through new procurement contracts.

Second, funding for Bundibugyo-specific vaccine development is expected to increase sharply, particularly through public-private partnerships and international preparedness programs.

Third, investors are likely to revisit pandemic-preparedness companies and rapid-response biotech platforms, including firms focused on mRNA technologies, antiviral therapies and outbreak-response infrastructure.

The broader question facing policymakers and drugmakers now is whether this outbreak finally produces sustained long-term investment into Ebola preparedness — or whether funding once again fades after the headlines disappear.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The punishing global bond sell-off that has rattled markets for the past week paused Tuesday, with U.S. Treasury yields easing modestly even as a closely watched survey of global money managers warned that the 30-year U.S. government bond yield could climb to 6% — a level not seen since late 1999 — as inflation, geopolitical shock and a darkening U.S. fiscal outlook converge on the world’s most important debt market.

The yield on the 10-year U.S. Treasury note, the global benchmark for borrowing costs that influences everything from mortgages to corporate loans, slipped roughly 1 basis point to 4.6073% in early Tuesday trading after touching its highest level in 15 months during Monday’s session. The 30-year Treasury bond yield held steady at 5.1428%, just below the highest closing level since June 2007. The 2-year note yield, the maturity most sensitive to Federal Reserve policy, fell more than 2 basis points to 4.0695%. One basis point equals one one-hundredth of a percentage point, and bond yields and prices move in opposite directions.

The warning that yields could push significantly higher came from a Bank of America survey published Tuesday, which found that 62% of global fund manager respondents expect the 30-year Treasury yield to reach 6%. That level would mark the highest in more than 26 years and would represent an increase of roughly 86 basis points from current levels. Krishna Guha, vice chairman of Evercore ISI, said in a research note that the combination of rising oil prices, stalled U.S.-Iran negotiations and strong U.S. investment data is putting upward pressure on bond yields globally and creating a new headwind for equities. Subadra Rajappa, head of U.S. rates strategy at Société Générale, told Bloomberg Television that bond yields are starting to feel “unhinged.”

The U.S. story is part of a synchronized global bond rout. Japan’s 30-year government bond yield hit its highest level in history dating back to 1999. The U.K. 10-year gilt yield reached its highest since 2008, and the 30-year gilt yield touched its highest since 1998 as political turmoil swirls around Prime Minister Keir Starmer. German 10-year bund yields climbed to their highest level since May 2011.

What This Means — In Plain English

For readers not steeped in market jargon, here is what is actually happening, explained the way you would discuss it around a dinner table.

When the U.S. government wants to spend more money than it collects in taxes, it borrows. The way it borrows is by selling Treasury bonds. A person, pension fund, bank or foreign government buys the bond and gives the U.S. government cash. In return, the government promises to pay that money back later, plus interest.

The “yield” is essentially the interest rate the government has to offer in order to convince people to lend it money.

When yields rise, it means investors are demanding higher interest payments before they are willing to buy government debt. Right now, that is happening for three major reasons — and all three are hitting simultaneously.

The first is inflation.

If investors believe inflation will remain elevated, they demand more interest because the money they get repaid in the future will be worth less in real purchasing power. Recent U.S. inflation readings have remained stubbornly hot, while oil prices surged above $100 a barrel amid the escalating U.S.-Iran conflict and disruptions near the Strait of Hormuz, one of the world’s most critical energy chokepoints. National gasoline prices have climbed sharply in recent weeks, feeding concerns that inflation may reaccelerate.

The second issue is America’s growing debt load.

The U.S. government is borrowing enormous sums of money to finance deficits. Last week alone, the Treasury Department auctioned roughly $691 billion in Treasury securities. When that much debt floods the market, investors demand better returns to absorb the supply. The more bonds Washington needs to sell, the more attractive yields must become to find buyers.

The third concern is the Federal Reserve itself.

Earlier this year, investors expected multiple Fed rate cuts in 2026 as inflation cooled. But rising oil prices, stronger-than-expected economic data and persistent inflation have forced traders to dramatically rethink those assumptions. Markets are now increasingly pricing in the possibility that the Fed may keep rates elevated longer — and some traders even see a meaningful chance of another rate hike before year-end.

Why It Matters for Everyday Americans

Treasury yields are not abstract Wall Street numbers. They directly shape borrowing costs across the economy.

When Treasury yields rise, mortgage rates usually rise. Car loans become more expensive. Credit-card interest rates increase. Small-business borrowing costs climb. Corporate financing becomes more expensive. Even the federal government itself pays more interest on its debt, worsening deficit pressures further.

The average 30-year fixed mortgage rate climbed back toward 6.65% in recent sessions, according to Mortgage News Daily data, sharply increasing monthly housing costs for buyers already struggling with affordability.

For savers and retirees, higher yields can be beneficial because Treasury bonds and savings products finally offer meaningful interest income again after years of near-zero rates. But for borrowers, the effect is painful.

A higher-rate environment effectively slows economic activity because households and businesses spend more money servicing debt and less money elsewhere.

Why the 6% Level Matters

The last time the 30-year Treasury yield approached 6% was near the end of 1999, before the dot-com bubble collapsed and the U.S. economy entered recession.

Reaching that level again would represent a profound shift in America’s financial environment.

For most of the last quarter century, the U.S. economy has operated under historically cheap borrowing conditions. Low rates fueled home buying, corporate expansion, stock-market growth and massive government deficit spending with relatively manageable financing costs.

A sustained move toward 6% long-bond yields would signal the return of a much more expensive cost-of-capital environment — one many younger Americans have never experienced as adults.

What Wall Street Is Watching Next

Investors are now focused on three major catalysts.

The first is energy markets and whether oil prices continue climbing as tensions with Iran intensify.

The second is upcoming U.S. inflation data, which will heavily influence Federal Reserve policy expectations.

The third is the looming leadership transition at the Federal Reserve itself, with Kevin Warsh expected to assume the Fed chairmanship in the coming weeks. Markets are increasingly trying to determine whether Warsh will prioritize inflation control even at the expense of slower growth, or whether he may tolerate somewhat higher inflation to avoid pushing the economy toward recession.

That decision could shape the trajectory of Treasury yields, mortgage rates, equity valuations and borrowing costs across the global economy for the rest of 2026.

For now, the bond-market sell-off has paused. Whether it resumes may depend less on Wall Street itself than on forces far beyond it — wars, oil prices, inflation, deficits and the next moves from the world’s most powerful central bank.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

For years, the master’s degree functioned almost like a modern economic insurance policy.

When job markets weakened, workers stayed in school longer. When industries became more competitive, professionals added credentials. Business schools, graduate programs, and universities marketed advanced degrees as protection against uncertainty — a way to move ahead of automation, globalization, recessions, and crowded applicant pools.

Now, some of the clearest labor-market data in years suggest that bargain is beginning to break down.

A new analysis released Sunday by The Burning Glass Institute, using more than two decades of federal labor statistics, found that unemployment among workers under 35 holding master’s degrees has climbed to one of its weakest positions relative to history since records began in 2003.

The finding marks a sharp reversal in the long-standing assumption that graduate credentials reliably shield younger professionals from labor-market deterioration.

According to Burning Glass, younger master’s-degree holders now sit in roughly the 77th percentile of unemployment relative to historical norms — far above what economists typically consider a balanced labor market. In practical terms, advanced-degree holders under 35 are experiencing weaker employment outcomes than many workers with lower educational attainment, including some associate-degree holders.

That inversion would have been almost unthinkable a decade ago.

“This is fundamentally a supply-and-demand problem,” said Gad Levanon, chief economist at The Burning Glass Institute and former head of labor-market research at The Conference Board. “You have more degrees chasing fewer of the positions those degrees were originally meant to unlock.”

The divergence becomes even sharper when compared with elite professional degrees.

According to the analysis, unemployment among younger workers holding Ph.D.s, medical degrees, and law degrees remains historically low. Those credentials continue functioning as direct licensing pathways into highly specialized professions.

The master’s degree increasingly does not.

“It’s more of a signal,” Levanon said. “And signals lose value when everyone has one.”

That erosion is becoming increasingly visible across the graduate business market.

A separate survey released by Drexel University’s LeBow College of Business found that more than 40% of employers now report no plans to hire MBAs this year — a significant jump from the roughly 27% who said the same in 2025.

The Drexel report, based on responses from more than 600 employers nationwide, also found overall hiring optimism among companies at its weakest level in more than a decade.

“We found employer optimism declined to its lowest level in more than a decade,” said Murugan Anandarajan, vice dean at LeBow and co-author of the report. Companies, he said, are prioritizing operational stability and efficiency over aggressive hiring expansion.

The weakness appears especially pronounced among smaller employers, which historically absorbed large numbers of newly credentialed workers during periods when large corporations slowed hiring.

That slowdown is beginning to reshape expectations for graduate students themselves.

Kevin Vado, who enrolled in the University of Florida’s MBA program after previous banking roles at Morgan Stanley and Wells Fargo, told the Wall Street Journal he applied for roughly 200 jobs and networked extensively during school but still graduated this month without securing the kind of post-MBA role he expected.

“I haven’t gotten the amount of offers that I truly expected,” Vado said. “It’s been a bit tough getting interviews.”

His experience increasingly reflects a broader structural issue inside higher education: the supply of graduate degrees has exploded faster than the supply of elite white-collar jobs.

According to research from the Postsecondary Education and Economics Research Center, the number of master’s programs in the United States surged nearly 70% between 2005 and 2021, climbing above 33,500 programs nationally.

The expansion accelerated further during and after the pandemic as universities aggressively launched online MBAs, specialized AI and analytics programs, healthcare-management degrees, and one-year professional master’s tracks designed to appeal to working adults seeking career reinvention.

For universities, the economics were attractive. Graduate programs became one of the fastest-growing and highest-margin segments in higher education.

For students, however, the equation is becoming more complicated.

Tuition costs continue rising even as employers increasingly shift toward “skills-first” hiring models that place less emphasis on formal credentials and more weight on demonstrated capabilities.

Artificial intelligence is accelerating that shift.

Johnny C. Taylor Jr., president of the Society for Human Resource Management, said companies are increasingly questioning whether graduate credentials remain necessary for many professional roles at all.

“Hiring managers now are more receptive than ever to the idea that a person doesn’t need a graduate degree to be competitive,” Taylor said.

AI, he added, has become “the accelerant” forcing employers to focus less on diplomas and more on practical execution.

“The question increasingly is simple,” Taylor said. “Can you do the job?”

That shift is unfolding at precisely the same moment entry-level white-collar hiring has weakened broadly across the economy.

Research released earlier this year by the Federal Reserve Bank of New York found unemployment among recent college graduates reached 5.6% at the end of 2025 — well above the national average at the time.

Burning Glass separately found that more than half of the college graduates from the Class of 2023 were working in jobs that did not formally require degrees within one year of graduation.

In earlier economic cycles, higher education reliably functioned as a ladder into more stable employment.

Today, the ladder increasingly appears crowded.

None of this means graduate education has lost value entirely.

Top-tier MBA programs continue funneling students into consulting firms, investment banks, and technology leadership pipelines. Healthcare, law, and specialized technical fields still command strong demand. Overall hiring for the Class of 2026 is still projected to rise modestly, according to the National Association of Colleges and Employers.

But the automatic economic premium once attached to a generic master’s degree is becoming harder to guarantee.

That reality is beginning to alter the psychology surrounding graduate education itself.

For years, advanced degrees were sold partly as protection against uncertainty.

Now, younger professionals increasingly face a more difficult question: whether accumulating additional credentials in a rapidly changing AI-driven economy still delivers the career security universities long promised.

Levanon believes the adjustment may only be beginning.

“If I had to guess,” he said, “in the next five years, things will get worse before they get better.”

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Nvidia earnings, rising Treasury yields and fragile Iran negotiations are suddenly testing the AI-driven rally that carried Wall Street to record highs.

NEW YORK — U.S. stocks opened sharply lower Tuesday as a third straight session of selling in artificial-intelligence and semiconductor shares collided with another surge in Treasury yields and growing uncertainty surrounding the Trump administration’s negotiations with Iran, pushing Wall Street into its weakest stretch since the March market rebound began.

The Dow Jones Industrial Average fell 391 points, or 0.79%, shortly after the open to 49,295. The S&P 500 dropped 0.61% to 7,358, while the Nasdaq Composite slid 0.70% to 25,908 as investors continued pulling money out of the technology sector ahead of Wednesday evening’s closely watched Nvidia earnings report.

The broader concern inside markets is becoming increasingly clear:
Wall Street’s rally has become deeply dependent on artificial intelligence continuing to justify its enormous valuations at the exact moment inflation, oil prices and bond yields are all moving in the wrong direction simultaneously.

The Philadelphia Semiconductor Index, the broadest measure of U.S. chip stocks, fell another 0.6% Tuesday morning after already losing more than 6% over the previous two sessions. Traders across the market increasingly described the move as profit-taking and positioning reduction ahead of Nvidia’s report, which many now view as the single most important corporate earnings release of the year.

The pressure on technology stocks intensified as Treasury yields resumed climbing sharply higher.

The benchmark 10-year Treasury yield rose back above 4.6%, while the 30-year Treasury yield touched its highest level since October 2023. Rising yields typically pressure technology shares because high-growth companies depend heavily on future earnings expectations, which become less valuable when borrowing costs remain elevated.

The move also revived fears across Wall Street that the Federal Reserve may be forced to keep interest rates higher for longer — or potentially even raise rates again — if inflation pressures tied to energy and geopolitical instability continue worsening.

At the center of those inflation fears remains Iran.

President Donald Trump said Monday evening that he had postponed a planned U.S. military strike against Iran to allow negotiations with Gulf allies and Tehran to continue, calling the talks “serious negotiations” aimed at reaching a broader peace agreement.

Oil prices declined modestly Tuesday morning on hopes diplomacy could prevent a wider regional escalation.

West Texas Intermediate crude fell 1.38% to roughly $102.90 per barrel, while international benchmark Brent crude slipped 1.82% to around $110.10. Despite the decline, both remain dramatically elevated following weeks of disruption surrounding the Strait of Hormuz and continued military tensions across the Persian Gulf.

Markets are increasingly nervous because elevated oil prices continue feeding directly into inflation expectations throughout the broader economy.

Higher energy costs raise transportation expenses, industrial overhead, shipping costs and manufacturing prices across nearly every sector, making it harder for the Federal Reserve to ease monetary policy even as portions of the economy begin slowing.

The day’s corporate spotlight initially belonged to Home Depot, which reported quarterly results that modestly exceeded Wall Street expectations.

The home-improvement retailer posted adjusted earnings of $3.43 per share on revenue of $41.77 billion, both slightly ahead of analyst forecasts. Comparable sales edged higher, though executives acknowledged consumers remain cautious on large renovation and remodeling projects as elevated mortgage rates continue pressuring housing activity.

Chief Financial Officer Richard McPhail told CNBC that homeowners remain financially resilient overall but continue delaying bigger discretionary projects.

Investors, however, remained far more focused on Nvidia.

The AI chip giant reports earnings Wednesday afternoon, and the numbers are expected to heavily influence the direction of the broader market.

Analysts currently expect Nvidia to report earnings growth exceeding 100% year over year on revenue approaching $80 billion as global spending on AI infrastructure continues exploding.

Technology giants including Microsoft, Amazon, Meta Platforms and Alphabet are collectively spending hundreds of billions of dollars on AI data centers, semiconductors and cloud infrastructure, making Nvidia the central financial beneficiary of the artificial intelligence boom.

But after months of near-vertical gains across the AI trade, some investors increasingly worry expectations have become almost impossible to satisfy.

“For a stock this large, investors need reassurance that the AI story is still alive and well,” Paul Stanley, chief investment officer at Granite Bay Wealth Management, told CNBC. “Nvidia’s earnings will help set the tone for a stock market that is in need of its next catalyst after an incredible run since the March lows.”

Other strategists are becoming more cautious.

Kevin Gordon, head of macro research and strategy at the Schwab Center for Financial Research, warned this week that the recent rally may have become overly stretched as investors crowded aggressively into the same technology and AI-related trades.

That concern is now spreading across the broader market.

The Roundhill Magnificent Seven ETF, which tracks major technology leaders including Nvidia, Tesla, Meta, Amazon and Microsoft, traded lower again Tuesday as investors continued reducing exposure to high-growth technology shares.

Meanwhile, rate-sensitive sectors including homebuilders, regional banks and real estate investment trusts sold off alongside rising bond yields.

Energy shares remained one of the few relatively stable areas of the market as oil prices stayed historically elevated despite Tuesday’s pullback.

For now, Wall Street appears trapped between several competing forces all arriving simultaneously:

  • surging AI optimism,
  • rising inflation risks,
  • elevated interest rates,
  • geopolitical instability,
  • and increasingly stretched market valuations.

The next 48 hours may determine which of those forces ultimately wins.

Because by Wednesday night, investors expect Nvidia to answer the question now driving nearly the entire market:

Is the AI boom still accelerating fast enough to justify the biggest technology rally in years — or is Wall Street finally beginning to run ahead of reality?

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By Julia Parker — JBizNews Desk

Apple’s newest budget laptop was supposed to be a cleanup operation.

Instead, it has quietly become one of the company’s strongest-selling Macs in years.

When Apple Inc. introduced the $599 MacBook Neo in March, the machine initially looked like a relatively modest addition to the company’s product lineup — a lightweight 13-inch entry-level Mac aimed at students, first-time buyers, and price-sensitive consumers who historically gravitated toward Windows laptops and Chromebooks.

Behind the scenes, however, the Neo represented something more strategically important: Apple turning manufacturing imperfections into a scalable business advantage.

The laptop runs on the same A18 Pro processor family Apple introduced inside the iPhone 16 Pro in 2024, but with a subtle technical distinction. The MacBook Neo version contains a five-core graphics processor rather than the six-core configuration found in the flagship iPhone.

That difference is not accidental.

Industry analysts say the Neo is built largely around “binned” chips — processors that emerged from manufacturing at supplier Taiwan Semiconductor Manufacturing Co. with one defective graphics core that would normally prevent them from being sold as full-spec premium chips.

Instead of discarding the silicon, Apple disables the faulty GPU core and repurposes the chip inside a lower-cost device where consumers are unlikely to notice the performance difference.

The practice, known throughout the semiconductor industry as “chip binning,” has existed for decades. Intel, AMD, and Nvidia have long used variations of the technique to maximize manufacturing yields.

What distinguishes Apple’s approach is the scale and sophistication with which it has integrated binning into a vertically controlled consumer ecosystem.

According to analyst Tim Culpan, who publishes the semiconductor-focused Culpium newsletter, Apple originally expected to produce roughly five to six million MacBook Neo units using salvaged A18 Pro inventory before winding down the model.

Demand shattered those expectations.

Apple has now reportedly doubled production targets toward roughly 10 million units, forcing the company to place additional wafer orders at TSMC specifically for chips that may no longer be “salvaged” at all.

“If you can take the stuff that doesn’t meet highest-level specs and still use it, you can save money, scrap and time,” Culpan wrote recently. “Also you can reach a lot more customers you might not otherwise be able to sell to.”

That second point matters most to Apple CEO Tim Cook.

Two weeks after Neo preorders opened, Cook told analysts the Mac platform had delivered its “best launch week ever for first-time Mac customers.” For Apple, that metric is increasingly more valuable than the hardware sale itself.

The MacBook Neo is not simply a laptop. It is an ecosystem entry point.

Every new Mac customer potentially feeds revenue into Apple’s higher-margin services business — iCloud subscriptions, AppleCare, App Store purchases, Apple Music, AirPods, accessories, and recurring ecosystem spending that continues long after the original hardware purchase.

That broader strategy now stretches across much of Apple’s product lineup.

The mid-tier iPhone 17e reportedly uses a partially disabled A19 processor. The base-model MacBook Air ships with fewer active graphics cores than premium configurations. Even Apple’s earlier M1 MacBook Air quietly used a seven-core GPU variant rather than the full eight-core version available elsewhere.

Historically, Apple largely kept those distinctions buried in spec sheets.

The MacBook Neo is different because the economics are front and center.

For years, Apple effectively abandoned the low-end laptop market, allowing Windows PC makers to dominate the sub-$700 category. The Neo changes that equation by offering a full Apple laptop experience at a price point once considered impossible for the company.

Consumers receive a 2.7-pound MacBook with all-day battery life, Apple silicon, premium build quality, and access to the broader Apple ecosystem for under $600.

Apple, meanwhile, extracts value from silicon that might otherwise have been discarded.

The financial logic becomes especially important at a moment when semiconductor costs are rising sharply across the industry.

Once Apple exhausts its stockpile of defective A18 Pro chips, the economics become more complicated. The company will need to order fresh wafers from TSMC’s advanced 3-nanometer production lines, capacity that is already heavily constrained by surging artificial-intelligence demand.

Most of those new chips will arrive fully functional, meaning Apple may intentionally disable graphics cores in perfectly working processors simply to preserve consistent Neo specifications.

At the same time, component inflation is accelerating.

According to TrendForce, DRAM memory prices jumped 57% in April alone as AI-server demand consumed available supply. Cook warned investors during Apple’s latest earnings call that memory costs are becoming an increasing pressure point across the company’s hardware business.

Apple has already responded by quietly trimming lower-priced configurations across parts of its Mac lineup, eliminating several entry-level storage and memory options in recent months.

For now, however, the company’s broader financial strength gives it room to maneuver.

Apple recently reported quarterly revenue of $111.2 billion, up 17% year over year, while earnings per share climbed 22%. The company also authorized another $100 billion stock buyback and continues sitting on roughly $147 billion in cash and marketable securities.

At the same time, Apple has reportedly secured more than half of TSMC’s initial 2-nanometer production capacity for next year, positioning itself ahead of competitors for future iPhone and Mac chips.

The company is also diversifying manufacturing relationships. The Wall Street Journal recently reported Apple reached a preliminary agreement with Intel under CEO Lip-Bu Tan to potentially manufacture certain Apple chips inside U.S. fabrication plants.

For Apple, the MacBook Neo represents more than a successful budget laptop launch.

It reflects a broader philosophy that has increasingly defined the company under Cook: squeeze inefficiency out of every layer of the supply chain, turn operational discipline into margin expansion, and use lower-cost hardware not merely to generate unit sales, but to deepen long-term ecosystem dependency.

The Neo was built partly from silicon that failed inspection.

Instead of becoming scrap, it became one of Apple’s fastest-growing new products — and potentially a blueprint for how the company competes more aggressively in the lower end of the global PC market without sacrificing profitability.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Borrowing costs for home buyers across North America and Europe climbed sharply Monday as investors continued digesting the global bond-market selloff that intensified late last week, with rising oil prices, the ongoing Iran war, and a leadership transition at the Federal Reserve combining to push sovereign yields to their highest levels in more than a year. The benchmark 10-year U.S. Treasury yield touched 4.601% Monday, its highest level in roughly 15 months, while the 30-year Treasury bond yield settled near 5.13%, approaching levels last seen during the 2007 financial era. At the same time, energy markets continued climbing as the Strait of Hormuz remained disrupted. West Texas Intermediate crude closed up more than 3% at $108.66 per barrel, while Brent crude rose to $112.10. U.S. gasoline prices are now averaging above $4.50 per gallon nationwide, up roughly 51% since the Iran conflict escalated.

The pressure is now feeding directly into global mortgage markets because home-loan pricing closely tracks long-term government bond yields rather than short-term central-bank rates. Freddie Mac reported in its latest Primary Mortgage Market Survey that the average 30-year fixed-rate mortgage stood at 6.36% as of May 14, while the 15-year fixed mortgage averaged 5.71%. Sam Khater, Freddie Mac’s chief economist, said purchase demand had softened but remained modestly stronger than the same period last year. However, that survey closed before Friday’s violent bond-market repricing, meaning the next official Freddie Mac release due Thursday is widely expected to show materially higher borrowing costs. Daily lender pricing already reflects the move upward.

The macro backdrop shifted dramatically over the past 72 hours. Jerome Powell’s term as Federal Reserve chair formally ended Friday after the Senate confirmed Kevin Warsh as the next Fed chair on May 13. Powell is serving briefly as chair pro tempore until Warsh is formally sworn in, creating an additional layer of uncertainty for bond investors already navigating war-driven inflation fears and growing concerns over global fiscal deficits. Rates strategists say the market reaction has become increasingly disorderly. Subadra Rajappa, head of U.S. rates strategy at Société Générale, warned last week that Treasury yields were “getting a bit unhinged” as investors demanded higher compensation for inflation and geopolitical risk.

The mortgage market’s sensitivity to bond yields explains why borrowing costs can jump even without immediate central-bank action. In Canada, fixed mortgage rates have begun moving higher alongside Government of Canada bond yields despite expectations that the Bank of Canada, led by Governor Tiff Macklem, could still begin easing later this year if inflation stabilizes. Across Europe, sovereign yields and swap rates have also surged, putting pressure on mortgage markets that rely heavily on wholesale funding costs. European Central Bank President Christine Lagarde recently reiterated that the disinflation process remains intact, but officials continue emphasizing a data-dependent path forward. German bund yields are now hovering near their highest levels since 2011, while European natural-gas prices have surged more than 90% year-to-date.

The United Kingdom may be among the most exposed major housing markets because British homeowners typically refinance every two to five years, leaving households highly vulnerable when wholesale borrowing costs rise. Bank of England Governor Andrew Bailey has repeatedly warned that policymakers need clearer evidence that services inflation is cooling before delivering sustained rate cuts. Major U.K. lenders have already begun repricing mortgage products upward in response to recent bond-market volatility.

The broader market logic has become increasingly straightforward: if the conflict in the Persian Gulf keeps oil prices elevated, central banks may lose flexibility to aggressively cut rates, forcing bond investors to demand higher yields for longer-term debt. Mohamed El-Erian, chief economic adviser at Allianz, has argued that geopolitical shocks feed rapidly into inflation expectations and risk premia simultaneously, pressuring both sovereign debt markets and household borrowing costs. Lawrence Yun, chief economist at the National Association of Realtors, has warned that elevated mortgage rates continue freezing much of the U.S. housing market by locking existing homeowners into lower-rate mortgages while sidelining first-time buyers.

Builders, brokers, and consumer lenders are now watching inflation data and energy markets more closely than central-bank speeches. If crude prices retreat and Treasury yields stabilize, mortgage lenders could reverse part of the recent increase relatively quickly. But if oil remains above $100 per barrel and global shipping disruptions continue, housing finance markets may remain under pressure well into the summer, even as central banks continue signaling eventual easing cycles.

For investors and home buyers alike, the most important indicators are no longer simply Fed policy statements. The variables driving housing affordability now sit in global energy markets, the Treasury market, and the geopolitical trajectory of the Middle East conflict itself.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Blackstone Inc. and Alphabet Inc.’s Google unveiled a massive new artificial-intelligence infrastructure partnership Monday, launching a dedicated AI cloud company backed by as much as $25 billion in planned investment that will rent out Google’s powerful Tensor Processing Units directly to corporate customers in a move designed to challenge Nvidia’s dominance over the global AI compute market.

The venture immediately ranks among the largest standalone infrastructure bets of the AI era and signals a dramatic escalation in the race to secure the chips, data centers, electricity, and cloud capacity now powering the global artificial-intelligence economy.

“This is a generational opportunity to invest capital at scale building AI infrastructure,” Jon Gray, President and Chief Operating Officer of Blackstone, said in the companies’ announcement Monday. “The new company has enormous potential as it helps to meet the unprecedented demand for compute.”

The venture will be majority-owned by Blackstone, which is making an initial $5 billion equity commitment. Including debt financing and future expansion capital, total planned investment is expected to eventually reach approximately $25 billion, according to people familiar with the transaction.

Thomas Kurian, Chief Executive of Google Cloud, said the partnership will dramatically expand access to Google’s custom AI chips, known as TPUs, which until recently were primarily used internally by Google and select cloud customers.

“We are seeing extraordinary demand for AI compute infrastructure,” Kurian said. “This venture creates another path for organizations to access advanced TPU capacity at scale.”

The new company will be led by longtime Google infrastructure executive Benjamin Treynor Sloss, who spent more than two decades overseeing major portions of Google’s global technical infrastructure operations.

Under the arrangement, Google will contribute TPU hardware, software, networking technology, and operational services, while Blackstone will provide financing and infrastructure-development expertise spanning real estate, construction, energy systems, and digital infrastructure logistics. The venture plans to bring roughly 500 megawatts of AI data-center capacity online beginning in 2027, with expansion plans expected to grow significantly over time.

The scale is enormous.

Industry analysts estimate that a 500-megawatt AI compute footprint represents enough electricity demand to power roughly 400,000 American homes, underscoring how artificial intelligence has rapidly evolved from a software business into one of the largest industrial infrastructure booms in modern technology history.

The deal also fundamentally reshapes competition inside the so-called “neocloud” market — a rapidly growing segment where companies rent AI compute capacity to developers and enterprises outside traditional hyperscaler contracts.

Until now, much of that market has revolved around Nvidia graphics processing units, or GPUs, which dominate advanced AI training globally. Firms such as CoreWeave and Nebius Group have built multibillion-dollar businesses renting Nvidia-powered AI infrastructure to startups, model developers, and enterprise clients.

But the Google-Blackstone venture introduces something Wall Street has been waiting years to see: a scaled commercial distribution model for Google’s TPU chips outside Google Cloud itself.

For years, Google’s TPU program has quietly been viewed as one of the few credible technological alternatives to Nvidia’s accelerator dominance. Yet commercialization remained relatively limited because TPU access was largely tied directly to Google’s own cloud ecosystem.

“This is the strongest structural challenge Nvidia has faced so far in AI infrastructure,” said Dan Ives, managing director at Wedbush Securities, in a note following the announcement. “Google is effectively weaponizing its internal AI stack at industrial scale.”

The timing reflects the extraordinary surge in AI infrastructure demand globally. Major AI developers including OpenAI, Anthropic, xAI, and Meta Platforms have collectively committed tens of billions of dollars toward compute contracts, while hyperscalers including Microsoft, Amazon Web Services, Oracle, and Google continue ramping capital expenditures to historic levels.

The bottleneck increasingly is no longer software — it is physical infrastructure.

Industry executives say shortages now extend beyond chips themselves into electricity generation, transmission systems, transformers, cooling technology, construction crews, and permitting timelines. In major AI infrastructure hubs including Northern Virginia, Texas, and parts of the Pacific Northwest, utility constraints are already delaying some data-center expansion projects.

Google has steadily built momentum behind its TPU ecosystem in recent months. Earlier this year, the company signed a multibillion-dollar TPU compute agreement with AI startup Anthropic, a deal many analysts interpreted as proof that Google’s chips had reached competitive parity with Nvidia hardware for major frontier-model AI training workloads.

Monday’s announcement takes that strategy dramatically further.

By creating a separately capitalized infrastructure company backed by Blackstone’s balance sheet, Alphabet gains a scalable way to expand TPU adoption without bearing the full burden of financing massive data-center construction itself.

For Blackstone, the move represents one of its largest direct AI infrastructure investments yet and aligns with the firm’s broader strategy of targeting digital infrastructure as a defining private-capital theme of the coming decade.

Jas Khaira, Head of Blackstone N1, described Google’s TPU technology as “foundational to the AI economy” and said the platform represents exactly the type of long-duration growth investment the firm was created to support.

The venture also deepens the broader geopolitical and economic significance of AI infrastructure spending inside the United States. Massive AI buildouts increasingly require coordination with regional power grids, natural gas providers, transmission operators, and local governments as electricity demand from data centers rises sharply nationwide.

Neither company disclosed revenue projections or customer commitments for the venture. Commercial operations are expected to begin once the first wave of data-center capacity comes online in 2027.

Still, the strategic message was unmistakable: the AI infrastructure race is entering a new phase where the battle is no longer just about software models — it is about who controls the physical computing backbone of the artificial-intelligence economy.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Crude prices tumble after Trump pauses planned Iran strike, offering possible relief for inflation, gas prices and interest-rate pressure across the U.S. economy.

WASHINGTON — President Donald Trump said Monday evening that he postponed a planned U.S. military strike on Iran after Gulf leaders personally urged him to allow additional time for negotiations, triggering an immediate selloff in oil prices and injecting the first major wave of optimism into global markets since the U.S.-Iran conflict erupted earlier this year.

“There seems to be a very good chance that they can work something out. If we can do that without bombing the hell out of them, I would be very happy,” Trump told reporters during a White House event Monday night, confirming he halted a military operation that had been scheduled for Tuesday.

Earlier in the day, Trump disclosed the decision in a Truth Social post, writing that he had instructed the U.S. military that “we will NOT be doing the scheduled attack of Iran tomorrow,” while simultaneously warning the Pentagon to remain ready “to go forward with a full, large scale assault of Iran, on a moment’s notice” if negotiations collapse.

The market reaction was immediate.

U.S. West Texas Intermediate crude futures dropped more than 2% in early Asian trading Tuesday to roughly $102 a barrel after surging 3.1% during Monday’s session. International benchmark Brent crude fell toward $107 after briefly trading above $112. Despite the decline, oil prices still remain more than 50% higher than where they stood before the U.S.-Israeli conflict with Iran escalated earlier this year.

For American consumers already squeezed by elevated inflation, the move matters enormously.

AAA data shows average U.S. gasoline prices hovering around $4 per gallon nationally, up sharply since the conflict intensified. Airlines, trucking firms, retailers and manufacturers have all warned that prolonged energy disruptions are beginning to flow directly into consumer pricing. Companies including Walmart Inc. and Whirlpool Corp. previously warned investors that sustained transportation and fuel costs could force additional price increases across household goods.

Energy inflation has also become one of the Federal Reserve’s biggest concerns.

April’s Consumer Price Index accelerated to 3.8%, with energy costs responsible for a significant share of the monthly increase. Wholesale inflation has also climbed sharply, raising fears inside financial markets that prolonged conflict in the Persian Gulf could keep interest rates elevated far longer than investors previously expected.

Trump said the postponement followed direct requests from leaders in Saudi Arabia, Qatar and the United Arab Emirates, who urged the administration to allow several more days for diplomatic talks to continue.

“They think they are getting very close to making a deal,” Trump said. “Hopefully maybe forever, but possibly for a little while.”

Iran signaled publicly Monday that negotiations remain active.

Iranian Foreign Ministry spokesman Esmaeil Baghaei confirmed Tehran submitted a revised proposal to Washington through Pakistani intermediaries, though Iranian officials declined to publicly release details. Reuters reported that the latest proposal closely resembles earlier Iranian offers that Trump had previously criticized as inadequate.

At the center of the global economic concern remains the Strait of Hormuz, the narrow waterway through which roughly one-fifth of the world’s oil supply normally flows. Shipping traffic through the region remains heavily disrupted, while hundreds of oil tankers remain stranded or delayed throughout the Persian Gulf amid continued military tensions and naval restrictions.

Saudi Aramco Chief Executive Amin Nasser warned earlier this month that more than 600 tankers remain trapped inside Gulf shipping lanes, with another 240 vessels waiting outside the strait. He cautioned that even if a diplomatic breakthrough emerges soon, normalization of global oil flows could still take many months.

The military situation also remains fragile despite the diplomatic pause.

The April ceasefire between Washington and Tehran technically remains in place, but drone and missile strikes targeting regional energy infrastructure have continued intermittently. Trump himself acknowledged last week that the ceasefire was effectively on “life support.”

Retired Admiral James Stavridis, former NATO Supreme Allied Commander Europe, warned during a CNBC appearance that the administration now faces limited options if negotiations fail: expand military operations, attempt to forcibly reopen the Strait of Hormuz, or step back entirely and risk broader regional instability.

“None of them are good,” Stavridis said.

Financial markets are now laser-focused on whether negotiations can produce a breakthrough quickly enough to stabilize oil prices before deeper economic damage spreads globally.

The Federal Reserve’s next policy meeting on June 16-17 has become especially important. Newly confirmed Fed Chairman Kevin Warsh enters the meeting facing rising bond yields, elevated energy inflation and increasing investor concern that interest rates may need to remain higher for longer.

A diplomatic resolution with Iran could ease pressure on oil markets, inflation readings and borrowing costs almost immediately.

A collapse in talks could do the opposite.

For now, traders, policymakers and consumers alike are watching the Persian Gulf more closely than Washington economic reports.

Because for millions of Americans staring at higher grocery bills, rising credit-card balances and expensive gas station receipts, the next few days overseas may directly determine how much financial pressure they face at home this summer.

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The 10-year U.S. Treasury yield climbed to its highest level in a year Monday, hardening the financing math that has reshaped American commercial real estate for the past 36 months and setting the stage for what brokers, lenders, and workout specialists describe as the most consequential six months of this cycle. With Federal Reserve rate-cut expectations sliding, roughly $148 billion in office-backed debt scheduled to mature this year, and Blackstone Inc. preparing its first publicly listed data-center REIT for launch, the question hanging over the market is no longer whether higher rates broke commercial real estate. It is which parts of the market were broken, which were simply reshaped, and which emerged stronger. The data through May suggests rates did not kill the entire CRE market. They sorted it.

Office: The Distress Is Real and Concentrated

The clearest evidence of damage remains in the office sector. Office CMBS delinquency hit an all-time high of 12.34% in January before easing modestly to 11.4% in February, according to Trepp, up sharply from roughly 1.6% in mid-2022. Morningstar analysts have identified maturity defaults rather than missed monthly payments as the primary driver, meaning many buildings are still generating cash flow but can no longer refinance under current rate structures and lender requirements. Approximately $148 billion in office-backed CRE debt is scheduled to mature in 2026, with five-year loans originated during the ultra-low-rate environment of 2021 now facing the most acute pressure.

The distress is heavily concentrated in older, lower-amenity Class B and C office towers. Trophy assets continue to attract refinancing capital. Tishman Speyer closed a $2.85 billion refinancing last year on The Spiral at Hudson Yards, while the office CMBS payoff rate climbed to 70.1% in 2025, up 11.3 percentage points from 2024. But large legacy towers such as Worldwide Plaza and One New York Plaza have slipped into delinquency, individually large enough to distort national data. Michael Cohen, a CMBS workout specialist at Brighton Capital Advisors, argues the market has now moved beyond simple asset devaluation and entered a transfer-of-ownership phase where foreclosures, discounted recapitalizations, and rescue-equity transactions will define the next 18 months.

Industrial: Cooled, Not Broken

Industrial real estate spent much of the past decade as institutional capital’s favorite trade, and the hangover from that boom is now working through the system. Industrial vacancy reached 7.3% in the second quarter of 2025 as new supply outpaced demand for a third consecutive year. Cushman & Wakefield expects vacancy to peak around mid-2026 before gradually tightening again. The market’s “flight to quality” has accelerated: modern, automation-ready logistics facilities near major population centers continue leasing relatively well, while older speculative warehouse developments in secondary metros face rising vacancy and slower absorption.

Even with softer fundamentals, industrial remains one of the healthiest major property sectors. Industrial CMBS delinquency stands at just 0.62%, the lowest of any major CRE category. Long-term structural tailwinds remain firmly intact, including e-commerce penetration hovering near 16% of total retail sales, reshoring efforts tied to U.S. manufacturing policy, and continued outsourcing growth among third-party logistics operators.

Multifamily: Stable Despite the Sun Belt Hangover

Multifamily housing has weathered the rate shock better than many investors initially feared. The sector absorbed roughly 1.1 million units during the historic 2024–2025 construction wave, while national vacancy currently sits near a manageable 5.2%, according to Inland Investments research. Rent growth briefly turned negative during peak deliveries, but new construction starts have now fallen sharply, and deliveries are expected to steadily decline through 2027.

The pressure remains concentrated in Sun Belt markets including Phoenix, Austin, Dallas, and Atlanta, where developers built aggressively during the migration boom and pricing power has weakened materially. Multifamily CMBS delinquency, at 6.94%, remains elevated but relatively stable. Analysts continue to point to America’s housing affordability crisis as a powerful long-term support mechanism for rental demand, particularly as elevated mortgage rates keep homeownership increasingly out of reach for younger households.

Retail and Lodging: Quietly Recovering

Retail real estate — once viewed as structurally impaired during the e-commerce panic of the late 2010s — has quietly stabilized into one of the steadier institutional sectors. Grocery-anchored centers, discount chains, off-price retailers, and service-oriented tenants continue driving leasing demand. Retail CMBS delinquency has eased from recent highs and now sits around 7.04%.

Hotels are recovering faster than many analysts expected. Lodging CMBS delinquency fell more than 100 basis points in early 2026 to 5.56%, the lowest level since March 2024, supported by strong leisure demand and a recovering corporate-group travel market. The upcoming 2026 FIFA World Cup is expected to further strengthen hotel fundamentals, with analysts projecting roughly $900 million in incremental U.S. lodging revenue as host cities prepare for surges in international tourism.

Data Centers: The Story Changing Commercial Real Estate

The single biggest structural shift in commercial real estate is the rise of data centers from a niche infrastructure play into a core institutional asset class. Global data-center investment reached roughly $580 billion in 2025 and is projected to rise to approximately $650 billion this year, according to estimates from Colliers and Reuters. U.S. data-center vacancy now sits near 1.3%, with Northern Virginia — the country’s largest market — operating below 1%. Market rents have more than doubled over the past four years.

JLL projects roughly 100 gigawatts of additional data-center capacity will come online globally between 2026 and 2030, potentially creating more than $1.2 trillion in new real estate value. Some industry forecasts now estimate the broader sector buildout could approach $3 trillion by the end of the decade.

Institutional capital is flooding into the space. Blackstone filed in April for the IPO of Blackstone Digital Infrastructure Trust, expected to trade under the ticker BXDC and initially target roughly $2 billion in acquisitions of stabilized hyperscaler-leased facilities. Meanwhile, Amazon, Microsoft, Alphabet, Meta Platforms, and Apple collectively invested roughly $350 billion into data-center infrastructure during 2025 and are expected to deploy another $511 billion this year alone. Data centers returned approximately 11.2% over the past year, outperforming every traditional CRE category.

Wall Street’s focus now turns to Nvidia Corp., which reports earnings Wednesday in what many investors increasingly view as a quarterly referendum on the broader AI infrastructure boom driving the sector.

Not everyone is convinced the current pace is sustainable. Patrick Wilson, portfolio manager at CenterSquare Investment Management, has warned that by 2027 investors will likely demand a clearer monetization path for many of the AI workloads driving today’s unprecedented infrastructure spending. Rich Hill, global head of real estate research at Principal Asset Management, similarly cautions that while long-term demand appears durable, not every investor entering the sector will ultimately succeed.

The Opportunity Set

For investors with patience and liquidity, the current market may represent the cleanest set of dislocations since the Global Financial Crisis. Distressed office assets in major gateway cities are trading at discounts ranging from 40% to 70% below 2019 valuations, opening potential conversion opportunities into residential or mixed-use developments as cities increasingly introduce incentive programs to encourage redevelopment.

Sun Belt multifamily markets weakened by oversupply may begin presenting attractive entry points over the next 12 to 18 months as construction pipelines collapse. Industrial assets in prime infill markets remain structurally constrained despite temporary softness. And data centers — despite growing valuation concerns — continue delivering leasing economics unmatched elsewhere in commercial real estate.

What higher rates ultimately destroyed was not commercial real estate itself, but the cheap-money model that dominated the industry for more than a decade: highly leveraged acquisitions, perpetual refinancing cycles, and assumptions that cap-rate compression alone could drive returns indefinitely. The market emerging from 2026 will likely be smaller, more selective, and significantly more disciplined. But in many corners of the industry, particularly those tied to digital infrastructure and logistics, American commercial real estate has rarely looked more dynamic.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Detroit’s three largest automakers have collectively eliminated more than 20,000 U.S. salaried positions over the past four years, a roughly 19% reduction in their combined white-collar workforce that has accelerated sharply as artificial intelligence begins reshaping the way American car companies operate. The combined salaried headcount at General Motors Co., Ford Motor Co., and Stellantis NV peaked at approximately 102,000 workers in 2022 before falling to roughly 88,700 by the end of last year, according to public filings and employment data analyzed by CNBC. The pace has only quickened in recent months: GM notified between 500 and 600 information-technology workers in Austin, Texas, and Warren, Michigan, of layoffs on May 11, with the cuts tied directly to a strategic pivot toward AI-related capabilities.

The contraction marks a sharp reversal from the early-decade hiring surge that swept across the Big Three as the industry geared up for an electric-vehicle transition and a wave of software-defined platforms. GM has accounted for the largest share of the reductions, cutting roughly 11,000 salaried positions since 2022 after expanding from 48,000 white-collar workers in 2020 to 58,000 just two years later. Much of the drawdown reflects the wind-down of the company’s Cruise robotaxi unit, repeated rounds of global restructuring, and engineering and software reductions executed under Chief Executive Mary Barra. Ford has cut roughly 5,300 salaried positions from its 2020 peak, leaving the company with about 30,700 white-collar employees last year. Stellantis has fallen from 15,000 U.S. salaried workers in 2020 to roughly 11,000, with multiple rounds of voluntary buyouts targeting engineering and tech roles.

Executives at the three companies have grown increasingly direct about the role artificial intelligence is playing in the cuts. Ford Chief Executive Jim Farley told an audience at the Aspen Ideas Festival in July that AI is on track to replace roughly half of all white-collar workers in the United States and warned that the technology would leave many office workers behind. Statements from Stellantis Chief Executive Antonio Filosa, who is leading a global turnaround, have offered a more measured counterpoint: the company plans to add more than 2,000 white-collar positions in North America as part of its restructuring, though those roles are heavily weighted toward AI, software engineering, and autonomous-systems work. Combined, the three automakers currently list more than 2,000 open U.S. positions, with nearly 400 tied specifically to AI. GM alone is recruiting for more than 250 AI-related roles even as it continues trimming legacy IT, finance, and clerical staff.

The data underscores a widening divergence between the Big Three and the broader U.S. auto manufacturing sector. Bureau of Labor Statistics figures show that overall motor vehicle manufacturing employment — which includes both hourly and salaried workers — declined just 0.2% from 2022 through last year to 285,800. Toyota Motor Corp., by contrast, has expanded its U.S. white-collar headcount by roughly 31% since 2020, reaching approximately 47,500 workers. That contrast suggests Detroit’s cuts are being driven less by industry-wide demand weakness than by company-specific exposure to legacy cost structures, electric-vehicle transition losses, and mounting competition from Asian and European manufacturers building software-defined vehicles without comparable workforce overhang.

For the broader U.S. labor market, the reductions may foreshadow a wider AI-driven displacement of office workers across industries that depend heavily on repeatable cognitive labor. A recent Boston Consulting Group report projected that 10% to 15% of U.S. jobs could ultimately be eliminated as AI scales, with roughly half of all American jobs reshaped within the next two to three years. Gregory Emerson, managing director at BCG, has cautioned that companies cutting workforce faster than AI can actually replace it risk losing institutional knowledge and watching productivity deteriorate. Lenny LaRocca, who leads KPMG’s automotive practice in the Americas, argues that the focus inside the Big Three is shifting from pure headcount reduction toward using AI to make remaining workers materially more productive. Gad Levanon at the Burning Glass Institute has flagged clerical, finance, IT, and coding roles among the most exposed to AI automation, while noting that some losses could eventually be offset by growth in cybersecurity, robotics, and autonomous-systems engineering.

The economic implications for Michigan and the broader industrial Midwest are substantial. Detroit’s salaried workforce has historically anchored the region’s middle-class economy, supporting suburban housing markets, local service industries, and pension systems. The Big Three are still hiring in select areas, particularly AI and advanced manufacturing, but the broader trajectory is becoming increasingly clear. GM, Ford, and Stellantis are quietly eliminating many of the corporate and engineering roles that built modern Detroit while recruiting a smaller, more technical workforce for an industry that increasingly resembles Silicon Valley as much as the traditional assembly line.

The shift also arrives as investors intensify pressure on automakers to improve margins after years of heavy spending on electric vehicles, autonomous driving, and software initiatives that have yet to consistently deliver expected returns. AI offers Detroit executives a rare opportunity to simultaneously reduce labor costs, automate back-office operations, streamline vehicle development, and accelerate factory productivity at a moment when pricing power across the industry is weakening. Wall Street has largely rewarded those efforts. Shares of GM and Ford have both outperformed several broader industrial indexes over the past year as analysts increasingly focus on cost discipline and operational efficiency rather than aggressive EV expansion alone.

For displaced workers, however, the transition may prove far more disruptive than corporate earnings models suggest. Many of the eliminated positions involve experienced mid-career employees whose institutional knowledge took decades to build. While new AI-focused jobs continue emerging, they often require highly specialized software, data-science, or machine-learning expertise that many traditional automotive employees do not possess. The result could be a prolonged restructuring of Detroit’s professional workforce, with fewer total jobs but higher technical barriers for entry.

Industry observers increasingly believe the transformation underway inside Detroit’s automakers may ultimately serve as an early blueprint for white-collar restructuring across corporate America. As AI systems become capable of handling larger portions of coding, finance, logistics, customer service, engineering support, and administrative work, executives across multiple sectors are beginning to reassess how many office employees they truly need. The central question facing Detroit now is whether the Big Three can use AI to reduce costs and remain globally competitive without hollowing out the engineering depth, operational experience, and middle-class workforce that defined America’s auto industry for more than a century.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

America’s artificial-intelligence boom has officially reached the power grid.

NextEra Energy Inc. agreed Monday to acquire Dominion Energy Inc. in an all-stock transaction valued at roughly $67 billion, creating the largest regulated electric utility in the world by market capitalization and marking the biggest utility merger ever proposed in the United States.

The deal instantly reshapes the American energy landscape at a moment when electricity demand is accelerating faster than utilities, regulators, and Wall Street anticipated just two years ago — largely because of the explosion in AI infrastructure and hyperscale data-center construction now spreading across the country.

According to a joint statement released by the companies, the combined utility giant will serve roughly 10 million customer accounts across Florida, Virginia, North Carolina, and South Carolina, while controlling one of the largest integrated electricity portfolios in the world.

The merged company will retain the NextEra Energy name and continue trading on the New York Stock Exchange under the ticker NEE.

The strategic logic behind the merger is straightforward: artificial intelligence requires enormous amounts of electricity, and the companies positioned closest to America’s AI infrastructure buildout are rapidly becoming some of the most valuable assets in the economy.

That is what makes Dominion Energy so attractive.

Dominion controls large portions of the electricity infrastructure surrounding Northern Virginia’s “Data Center Alley,” the largest concentration of data centers in the world and the physical backbone supporting much of America’s AI cloud-computing expansion.

The region powers infrastructure used by Amazon Web Services, Microsoft Azure, Google Cloud, Meta Platforms, and dozens of other AI and cloud-computing operators now collectively spending hundreds of billions of dollars expanding server capacity.

Every new AI model requires more computing power.

Every new server farm requires more electricity.

And increasingly, the bottleneck is not chips — it is energy.

“This is a historic moment for our two companies and for the states we are privileged to serve,” said NextEra Chief Executive John Ketchum in the companies’ joint announcement. “Electricity demand is rising faster than it has in decades.”

That demand surge is now fundamentally changing the economics of the utility industry.

The combined company will control roughly 110 gigawatts of generation capacity, including one of the world’s largest renewable-energy and battery-storage portfolios, major natural-gas infrastructure, and one of the largest nuclear-power fleets in the United States.

Approximately 80% of the combined business will operate under regulated utility structures, providing the stable long-term revenue streams investors increasingly favor as utilities prepare for what many analysts believe could become a multi-decade AI-driven electricity expansion cycle.

Wall Street reacted immediately.

Dominion Energy shares surged as much as 14% Monday morning after the announcement, while NextEra shares initially fell more than 4% as investors weighed integration risk, financing exposure, and what is expected to become a lengthy and politically sensitive regulatory review process.

Under the agreement, Dominion shareholders will receive 0.8138 shares of NextEra Energy for each Dominion share they own. Following completion, NextEra investors will control roughly 74.5% of the combined company, with Dominion shareholders owning the remaining 25.5%.

The companies expect the transaction to close within roughly 12 to 18 months, pending approvals from:

  • the Federal Energy Regulatory Commission (FERC),
  • the Nuclear Regulatory Commission (NRC),
  • and utility regulators across Virginia, North Carolina, and South Carolina.

The customer politics are already being managed aggressively.

To reduce potential political opposition, the companies committed to provide approximately $2.25 billion in customer bill credits to Dominion utility customers across Virginia and the Carolinas during the first two years after closing — one of the largest consumer concessions ever offered in a U.S. utility merger.

Still, regulators and consumer advocates are expected to closely scrutinize whether consolidation at this scale could eventually lead to higher electricity costs.

The merger also highlights how dramatically the AI boom is beginning to reshape sectors far beyond Silicon Valley.

Over the past three years, AI spending has transformed semiconductor manufacturers, cloud computing, data-center real estate, and networking infrastructure.

Now it is transforming utilities.

The massive energy demands tied to AI training models, cloud storage, and high-performance computing are forcing utilities to rethink generation capacity, transmission infrastructure, and long-term capital spending plans at a pace not seen since the early internet era.

The merger also intensifies pressure on the rest of the utility sector.

Companies including Southern Company, American Electric Power, Constellation Energy, Exelon, Vistra, and Public Service Enterprise Group now face growing investor pressure to explain whether they can remain competitive as standalone operators in an industry suddenly being reorganized around scale and AI-related electricity demand.

The financial structure of the deal underscores how aggressively NextEra wanted Dominion’s footprint.

If Dominion walks away from the agreement, it would owe a $2.24 billion termination fee. If NextEra exits under certain conditions, it faces a termination fee exceeding $6.5 billion, plus additional penalties tied to regulatory failure.

The asymmetry reflects how strategically valuable Dominion’s Virginia infrastructure has become in the AI era.

The combined company will maintain dual headquarters in Juno Beach, Florida, and Richmond, Virginia.

For investors, the message from Monday’s announcement was unmistakable:

Artificial intelligence is no longer simply a technology story.

It is now an electricity story.

And the companies controlling the power behind the AI economy are rapidly becoming some of the most strategically important businesses in America.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk | May 18, 2026

Tilman Fertitta’s $18 billion pursuit of Caesars Entertainment is shaping up to be the single biggest catalyst for a new U.S. casino consolidation cycle in years, with Wall Street analysts increasingly concluding that the deal would force a sweeping reshuffling of regional gaming assets across the country. In a Friday research note obtained through CDC Gaming, JPMorgan Securities analyst Daniel Politzer estimated the transaction could require the sale of as much as $2.3 billion in casino properties to satisfy antitrust regulators and state gaming commissions — a process that could redraw the competitive map from Las Vegas to Atlantic City.

The proposed transaction centers on Fertitta Entertainment, the holding company controlled by Houston billionaire Tilman Fertitta, owner of the Houston Rockets, Golden Nugget casinos and the sprawling Landry’s restaurant empire. Caesars confirmed on April 20 that it extended Fertitta’s exclusive negotiating window after he topped a rival proposal from activist investor Carl Icahn. The current structure values Caesars at roughly $32 per share and implies an enterprise value above $18 billion once Caesars’ more than $11 billion debt load is included.

The central issue is overlap. Fertitta already controls Golden Nugget casinos in multiple markets where Caesars maintains a major presence, including Las Vegas, Laughlin and Lake Tahoe in Nevada, Atlantic City in New Jersey, Biloxi in Mississippi and Lake Charles in Louisiana. Politzer said regulators at the Federal Trade Commission, the Department of Justice, the Nevada Gaming Control Board, the New Jersey Casino Control Commission, the Louisiana Gaming Control Board and the Mississippi Gaming Commission are all likely to require property divestitures before approving the merger.

That reality is already fueling speculation about who benefits from the forced asset sales. Politzer identified Boyd Gaming, Penn Entertainment, Bally’s Corp. and Churchill Downs as the most logical strategic buyers because each has both the balance-sheet flexibility and geographic incentive to expand selectively into newly available markets. Industry executives and analysts also expect private equity and gaming real-estate investment trusts to play a major role. Apollo Global Management and Blackstone both remain active in casino real estate and hospitality transactions, while VICI Properties and Gaming and Leisure Properties Inc. hold underlying real estate tied to many Caesars operations and would almost certainly be involved in any restructuring.

The strategic logic for Fertitta extends well beyond casino floors. One of the biggest attractions is Caesars Rewards, the company’s loyalty platform with more than 60 million members. Fertitta plans to integrate his Landry’s portfolio — which includes Morton’s The Steakhouse, Mastro’s Restaurants, Rainforest Cafe, Bubba Gump Shrimp Co. and dozens of other dining brands — directly into the Caesars ecosystem. That would dramatically expand where customers can redeem loyalty points and deepen cross-selling opportunities between casinos, hotels, restaurants and entertainment venues.

The deal would also significantly expand Fertitta’s national profile in gaming. Though Golden Nugget remains a recognized brand, Caesars controls one of the broadest casino footprints in America, spanning Las Vegas Strip properties, regional casinos and online gaming operations. Fertitta has increasingly positioned himself as one of the industry’s most aggressive consolidators, particularly after selling Golden Nugget Online Gaming to DraftKings in 2022 for $1.56 billion.

A complicating factor remains Fertitta’s existing 12% ownership stake in Wynn Resorts, which makes him Wynn’s largest individual shareholder. According to FactSet filings, Fertitta has also accumulated millions of dollars in Wynn call options during 2026. Multiple gaming attorneys cited by CDC Gaming said regulators are unlikely to block the Caesars transaction because of the Wynn position, but they expect Nevada regulators to closely scrutinize the cross-ownership structure during the approval process.

The wildcard continues to be Icahn. The billionaire activist investor has maintained a competing interest in Caesars and reportedly proposed combining Caesars’ digital gaming operations with another online betting platform. Caesars Sportsbook has struggled to close the gap with market leaders FanDuel and DraftKings despite strong overall sports-betting growth nationwide. Analysts say Icahn’s continued presence could still pressure Fertitta to improve terms or alter the structure before a final agreement is reached.

Wall Street’s focus, however, has shifted toward what happens after the merger rather than whether a deal happens at all. Politzer wrote that the potential property divestitures could create the most active regional gaming acquisition market since Eldorado Resorts completed its $17.3 billion takeover of Caesars in 2020. Regional operators that missed the last major consolidation cycle may now get another opportunity to expand.

The transaction is not expected to close before 2027. But for an industry that has spent the last several years digesting pandemic disruptions, sports-betting expansion and online gaming competition, the Fertitta bid represents something larger: the return of high-stakes casino consolidation on a national scale.

JBizNews Desk
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Wall Street is beginning to recognize what business leaders and local officials in Monmouth County have been watching unfold for years: Netflix’s massive redevelopment of Fort Monmouth is evolving into one of the most significant entertainment infrastructure projects on the East Coast. The streaming giant’s planned $1 billion investment at the former Army base in Eatontown and Oceanport is moving steadily forward as analysts increasingly view the project as part of Netflix’s broader long-term growth strategy. Fresh sell-side commentary released through Friday, including reiterated bullish notes following the company’s annual upfront presentation in New York last week, has begun folding the New Jersey build into the broader bull case for Netflix shares.

The renewed investor attention intensified after Eric Sheridan, managing director at Goldman Sachs, upgraded Netflix shares to Buy on April 6 and raised the firm’s 12-month price target from $100 to $120. The analyst described a more favorable risk-reward setup following an extended decline in Netflix stock, which had fallen roughly 18% over the prior six months amid concerns tied to the company’s abandoned $82.7 billion pursuit of Warner Bros. Discovery’s streaming and studio assets. Netflix formally exited the acquisition effort on Feb. 26 after declining to match Paramount Skydance’s higher bid and later collected a $2.8 billion termination fee, shifting investor focus back toward the company’s standalone expansion strategy. Goldman’s bullish stance was reinforced last Friday when Guggenheim reiterated its Buy rating with a $120 price target, joining J.P. Morgan analyst Doug Anmuth at $118 and Jefferies at $134.

While Wall Street analysts debate valuation and advertising growth, construction activity at Fort Monmouth has already transformed large sections of the 292-acre property. Since groundbreaking last May, Netflix has demolished approximately 85 former military structures to prepare for the first phase of studio development. The company is constructing four initial soundstages in Oceanport’s McAfee Zone, with each facility measuring roughly 22,000 square feet. Structural work on the first building is already visible on-site.

The redevelopment effort extends beyond new soundstages. Historic portions of the former military installation are being preserved and repurposed as part of the broader campus design. Vail Hall, one of the site’s most recognizable historic buildings, is expected to become production office space, while several existing warehouse structures totaling more than 40,000 square feet will be renovated for storage and operational support. Netflix also plans upgrades to the Fort Monmouth Economic Revitalization Authority offices and the 92,000-square-foot McAfee Center.

Local officials have emphasized that the project represents far more than a studio complex. The master redevelopment plan includes retail components, open public spaces, support infrastructure, and a potential hotel intended to accommodate cast and production crews during long-term filming schedules. Portions of the site, including Greely Field and Cowan Park, are expected to remain publicly accessible as part of the redevelopment agreement.

The economic implications for New Jersey are substantial. The New Jersey Economic Development Authority approved approximately $387 million in Aspire tax credits to support the project, while additional incentives through the state’s Film and Digital Media Tax Credit program could allow Netflix to qualify for production-related tax credits worth up to 40% of eligible New Jersey expenses if the company maintains long-term occupancy at the site.

State officials have increasingly positioned New Jersey as a growing East Coast production hub capable of competing with traditional entertainment markets in California, Georgia, and New York. Over the past year, Netflix has filmed nearly 20 projects within the state and currently maintains active productions employing more than 500 workers across New Jersey. Once fully completed, the Fort Monmouth studio campus is projected to support as many as 1,500 permanent jobs, in addition to hundreds of ongoing construction positions.

Financially, investors continue to focus on Netflix’s advertising business as a major future growth driver. Goldman Sachs forecasts the company’s advertising revenue could expand from roughly $1.5 billion in 2025 to nearly $9.5 billion annually by 2030 as Netflix scales its ad-supported subscription model globally. At the company’s upfront presentation in New York last week, TD Cowen analyst John Blackledge highlighted that Netflix’s ad-supported tier now reaches more than 250 million global monthly active viewers, up from roughly 190 million in November. Across 32 covering analysts, the consensus rating on Netflix is now Strong Buy with an average 12-month price target near $119. Analysts also expect continued operating margin expansion and the resumption of large-scale stock buybacks following the collapse of the Warner Bros. transaction.

Netflix’s broader financial performance remains strong despite recent market volatility. The company generated approximately $45.2 billion in revenue during 2025, representing roughly 16% year-over-year growth, while net income approached $11 billion. However, shares have remained under pressure following the company’s first-quarter earnings report released in April, with the stock closing Friday at $87.02, well below Goldman’s upgraded entry target and roughly 35% off the 52-week high of $134.12. Not every voice on the Street is bullish. Raymond James analyst Andrew Marok holds a Market Perform rating, arguing the debate over user engagement is far from resolved, while Erste Group earlier downgraded the stock to Hold.

For Monmouth County, however, the investment story is increasingly visible in physical terms rather than financial models. Roads, infrastructure systems, and former military facilities continue to be reshaped into a modern production campus that local leaders believe could permanently alter the region’s economic profile. The first phase of development, known as Phase 1A, is currently scheduled to open in 2027 and will include the initial Oceanport soundstages and support buildings. A second phase planned for Eatontown, including eight additional soundstages, is targeted for completion in 2028.

Industry observers say the Fort Monmouth redevelopment could eventually reshape the geography of U.S. film and television production by creating a large-scale East Coast alternative for streaming-era content creation. As Netflix deepens its operational footprint in New Jersey, the company’s long-term wager on Monmouth County increasingly appears to be both a real estate transformation project and a strategic production expansion designed to support the next phase of global streaming competition.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By Julia Parker — JBizNews Desk

China is scaling up industrial and humanoid robots at a pace no other economy can match, but a recent court ruling, provincial reskilling mandates, and explicit central-government messaging are simultaneously pushing companies to avoid mass labor displacement. Factories pouring billions into automation are increasingly being told they cannot use new AI systems and robotics as blanket justification to cut the human workforce that powered China’s manufacturing rise.

The clearest signal emerged last month from the Hangzhou Intermediate People’s Court. In a ruling dated April 28, the court found that a technology company in eastern China unlawfully terminated a quality-assurance employee — identified in legal filings only as Zhou — after he refused a 40% pay cut and demotion tied to his role being replaced by a large-language-model system. The court rejected the company’s argument that AI deployment qualified as a “business downsizing” event and ordered compensation for the employee. Legal analysts described the case as the first major judicial indication that Chinese firms cannot cite automation alone as legal grounds for layoffs.

The ruling arrives against the backdrop of an industrial-robotics expansion of historic scale. According to the International Federation of Robotics, China accounted for 54% of all new industrial robot installations worldwide in 2024, deploying approximately 295,000 new units — more than the rest of the world combined. China’s robot density has climbed to roughly 392 to 400 robots per 10,000 manufacturing workers, nearly triple the global average of 141 and ahead of Germany, while rapidly approaching the levels seen in South Korea and Japan.

Takayuki Ito, president of the IFR, said China’s latest five-year framework is accelerating the shift away from traditional factory automation toward AI-integrated, high-end robotics systems intended to anchor the country’s next phase of industrial modernization. Beijing’s strategy increasingly treats robotics, AI, semiconductors, and advanced manufacturing as interconnected pillars of long-term economic and geopolitical competitiveness.

That policy infrastructure has expanded aggressively. China formally launched its 15th Five-Year Plan in 2026 with robotics positioned near the center of national industrial strategy, building on the earlier Made in China 2025 initiative and the newer AI+ development framework. According to Reuters, Beijing allocated more than $20 billion in subsidies, grants, tax incentives, and state-backed investment funding to the robotics sector during late 2024 and early 2025 alone. Analysts now estimate China’s industrial robotics market at roughly $47 billion, far larger than the comparable U.S. sector.

At the same time, authorities are constructing a parallel labor-protection system designed to soften the social impact of automation. Guangdong province — home to the massive manufacturing corridor surrounding Foshan and the Pearl River Delta — has launched a “Million Talents Plan” aimed at reskilling roughly 3 million industrial workers over three years, with AI operations, robotics maintenance, and advanced-manufacturing support roles prioritized heavily. Government spending on vocational and industrial AI training programs has surpassed $15 billion since 2020.

Technical institutions including Shunde Polytechnic University are now partnering directly with manufacturers such as Midea to align factory-floor certifications with real-time industrial demand. Beijing’s broader message is increasingly clear: automate aggressively, but avoid the kind of visible labor shock that could destabilize employment and domestic consumption.

The underlying tension, however, is becoming harder to disguise. According to Bloomberg, Chinese manufacturing employment has already fallen from roughly 115 million workers in 2013 to below 85 million in 2025, representing a decline of more than 30 million jobs even as Chinese exports reached record highs earlier this year.

Major manufacturers have already automated significant portions of their operations. Foxconn has removed tens of thousands of factory positions across its Shenzhen, Zhengzhou, and Kunshan facilities. Xiaomi’s Changping smartphone plant has been described as operating with virtually no human workers on portions of the production floor while producing roughly one device per second. EV and battery giants including BYD and CATL have rapidly expanded robotics integration throughout their manufacturing operations.

The humanoid robotics sector is accelerating even faster. China’s Ministry of Industry and Information Technology said more than 140 domestic humanoid robotics manufacturers were operating in 2025, with over 330 humanoid robot models already introduced. UBTECH has deployed its Walker S2 humanoid into production-line environments, while Unitree Robotics has drawn international attention with its G1 platform and its lower-cost $5,000 R1 system.

Automakers including BYD, Geely, and Xpeng have already begun integrating Unitree humanoids onto factory floors. Xpeng has reportedly explored humanoid robotics investments approaching 100 billion yuan — roughly $13.8 billion — a scale difficult to justify solely on the basis of worker augmentation rather than eventual labor replacement.

For global competitors, the numbers are increasingly difficult to ignore. U.S. robot density stands at roughly 295 robots per 10,000 manufacturing workers, still well below China’s level. None of the world’s 10 largest industrial robotics companies are headquartered in the United States, and most robots deployed in American factories continue to be imported from Japan or Germany. U.S. companies such as Boston Dynamics remain heavily focused on research, defense applications, and limited-scale commercial deployment rather than mass industrial manufacturing.

The broader challenge emerging from China is not simply technological scale, but policy coordination. Beijing is attempting to engineer a model built around maximum automation alongside minimum visible labor displacement — a balancing act with few clear historical parallels in modern industrial policy. Whether that model proves economically sustainable may help determine the competitive landscape for global manufacturing over the next decade.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

U.S. stocks closed mixed Monday as surging Treasury yields, renewed Middle East uncertainty, and mounting pressure across artificial-intelligence shares rattled investors heading into one of the most consequential earnings weeks of the year, with Nvidia Corp.’s results increasingly viewed on Wall Street as a referendum on whether the AI-driven market rally can continue carrying equities higher amid rising inflation fears and escalating geopolitical risk.

According to closing data from the New York Stock Exchange and Nasdaq, the Dow Jones Industrial Average rose 159.95 points, or 0.32%, to 49,686.12, supported by gains in industrial and financial names, while the S&P 500 slipped 0.07% to 7,403.05 and the Nasdaq Composite fell 0.51% to 26,090.73 as semiconductor and AI-linked stocks extended recent weakness. The Russell 2000 dropped 0.65% as higher borrowing costs continued pressuring smaller-cap companies, while the CBOE Volatility Index remained elevated above 18 as traders repositioned ahead of earnings from Nvidia, Walmart, and Target later this week.

Markets whipsawed throughout the session after President Donald Trump disclosed on social media that he was postponing a planned military strike against Iran following requests from the Emir of Qatar, the Crown Prince of Saudi Arabia, and the President of the United Arab Emirates. Trump said “serious negotiations” were underway and predicted a resolution “very acceptable” to both the United States and the broader region, temporarily easing fears that the conflict could escalate into a direct disruption of global oil flows through the Strait of Hormuz.

Oil prices initially surged before retreating sharply following Trump’s comments. Brent crude briefly climbed above $112 per barrel before pulling back below $110, while West Texas Intermediate crude retreated from intraday highs above $104 to roughly $102.50 by settlement. Energy traders continue viewing the Strait of Hormuz as the market’s central geopolitical flashpoint, with roughly one-fifth of global petroleum flows tied directly to the region.

While equities stabilized late in the day, the bond market painted a far more cautious picture about the inflation outlook. The benchmark 10-year Treasury yield climbed above 4.13%, its highest level in roughly a year, while the 30-year Treasury yield hovered near 5.13%, levels last seen during the pre-financial-crisis period in 2007. Long-dated sovereign debt sold off globally, with U.K. 30-year gilt yields reaching highs not seen since the late 1990s and Japanese government bond yields touching fresh multi-decade peaks as investors increasingly abandoned expectations for Federal Reserve rate cuts in 2026.

The rise in yields hit technology shares hardest, particularly across the semiconductor sector that has powered much of the market’s AI-driven gains over the past year. The S&P 500 technology sector fell more than 2% intraday before trimming losses into the close. Seagate Technology plunged nearly 7% after Chief Executive Dave Mosley warned during a JPMorgan investor conference that building enough manufacturing capacity to satisfy exploding AI-related memory demand would “take too long,” comments investors interpreted as evidence that supply-chain constraints inside the semiconductor ecosystem are worsening rather than improving. The warning dragged Micron Technology down nearly 6%, while Nvidia, Broadcom, and Intel also finished lower.

Additional pressure came from overseas after South Korean media reported that Samsung Electronics’ labor union would proceed with an 18-day strike beginning May 21 involving more than 45,000 workers, intensifying fears of further disruption across the global memory-chip supply chain tied to the artificial-intelligence infrastructure buildout.

Inside the Dow, 20 of the index’s 30 components finished higher. 3M gained 3.74% and Salesforce added 3.18%, helping offset weakness in technology-linked industrial names. Caterpillar fell 4.08% while Nvidia dropped 2.92% as some investors rotated away from high-valuation growth stocks toward defensive and cyclical sectors. Microsoft outperformed much of the broader technology complex after Bill Ackman’s Pershing Square Capital Management disclosed last week that it had accumulated a position in the software giant.

Analyst activity intensified ahead of Nvidia’s earnings release Wednesday afternoon. DA Davidson reiterated a buy rating on Nvidia and raised its price target to $300, implying roughly 37% upside from current levels, while Cantor Fitzgerald increased its price target on Applied Materials to $550 from $500 while maintaining an overweight rating tied to continued strength in AI semiconductor spending. UBS downgraded Dell Technologies to neutral from buy despite lifting its target to $243 from $167, reflecting a more cautious near-term view on valuation even as AI server demand remains strong. RBC Capital Markets also raised its target on Ford Motor to $13 from $11 while maintaining a sector-perform rating.

Cryptocurrency markets weakened alongside broader risk assets as rising yields continued reducing investor appetite for speculative trades. Bitcoin fell roughly 2% to near $76,400, its lowest level since late April, while gold and silver traded mixed as investors balanced inflation hedging against a strengthening U.S. dollar and expectations for higher-for-longer interest rates.

The broader market now enters Tuesday facing an increasingly difficult macroeconomic backdrop. Gasoline prices remain elevated, mortgage rates continue climbing alongside Treasury yields, and the prospect of near-term Federal Reserve easing has largely disappeared from futures markets. At the same time, corporate America is preparing to report earnings under the shadow of rising energy costs, tighter financial conditions, and growing geopolitical instability tied to Iran and the Strait of Hormuz.

For Wall Street, the next 72 hours may determine whether the market’s AI-fueled momentum can continue overpowering mounting macroeconomic pressure — or whether rising rates, energy inflation, and geopolitical risk finally begin forcing a broader repricing across equities.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk | May 18, 2026

The short regional flights that for decades quietly stitched together America’s smaller cities and larger economic hubs are disappearing at the fastest pace of any category in the airline industry, as surging jet fuel costs, aircraft economics, pilot shortages and mounting operational strain push carriers toward longer and more profitable routes. According to scheduling data compiled by aviation analytics firm OAG and shared with NPR, flights under 250 nautical miles have fallen 11% between 2016 and 2026 even as longer-distance routes expanded by double digits during the same period.

The trend was already underway before the Iran war sent global energy markets into turmoil earlier this year. But analysts now say the doubling of domestic jet fuel prices since February is accelerating the shift dramatically and threatening to further isolate smaller American communities from the national air network.

The disappearing routes are often the least noticed but most economically important links in the aviation system — flights such as Albany to New York, Charleston to Charlotte, Akron to Chicago or small Midwestern cities feeding traffic into larger airline hubs. For business travelers, hospitals, universities and local economies, these short-haul connections often determine whether a city remains commercially competitive.

John Grant, senior analyst at OAG, told NPR that the economics of very short flights have become increasingly difficult to justify. “A lot of the fuel is used in the takeoff and landing processes,” Grant said, noting that those phases consume disproportionate fuel relative to cruise flight, while also adding expensive wear-and-tear on aircraft engines and landing systems. Every additional landing raises maintenance costs, labor expenses and operational complexity.

The industry increasingly prefers what Grant described as the “two-hour block-time sweet spot” — generally corresponding to routes above roughly 500 miles — where larger aircraft can spread fixed costs across more passengers while maximizing fuel efficiency.

That shift is visible in the data. Flights between 501 and 750 nautical miles rose 11% to nearly 1.7 million scheduled departures this year, while routes over 750 miles and 1,000 miles also posted double-digit gains. Meanwhile, flights under 250 nautical miles fell sharply and routes between 251 and 500 nautical miles declined about 4%.

Aircraft technology is also driving the migration. Airlines have steadily replaced older 50-seat and 70-seat regional jets with newer, larger narrow-body aircraft such as the Boeing 737 MAX 8 and Airbus A320neo and A321neo families. Those planes offer dramatically better economics on medium-haul routes but make little financial sense operating 100-mile or 150-mile hops.

Ahmed Abdelghani, professor of operations management at Embry-Riddle Aeronautical University, told NPR that newer aircraft fundamentally favor longer routes because larger planes spread fixed operating costs across more seats. “Those new-generation narrow-body aircraft will have much better economics than the smaller 50-seater, 70-seater aircraft,” Abdelghani said.

The carriers most exposed are regional operators such as SkyWest, Republic Airways, Mesa Air Group, GoJet Airlines and CommutAir, which operate flights under brands including Delta Connection, United Express and American Eagle. These companies historically depended heavily on short regional flying to feed passengers into major hubs operated by the larger network airlines.

SkyWest has aggressively transitioned away from aging CRJ200 regional jets toward Embraer E175 aircraft, which are larger and more efficient but less practical on ultra-short routes. Republic Airways, which now operates entirely Embraer E170 and E175 aircraft, has emerged as one of the stronger players during the industry consolidation. Mesa Air Group, meanwhile, continues restructuring operations amid ongoing financial pressure.

Fuel costs have sharply worsened the math. According to the U.S. Energy Information Administration, Gulf Coast jet fuel prices have surged to roughly $5 per gallon from less than $2.50 before the Iran conflict intensified. Airlines including JetBlue Airways, Allegiant Travel and Spirit Airlines have all publicly trimmed routes or reduced flying schedules. Spirit ultimately ceased operations last week after prolonged financial pressure tied partly to fuel and financing costs.

The largest airlines are increasingly candid about the shift. United Airlines CFO Mike Leskinen said in late April the carrier was “actively reviewing the bottom 10% of our regional route map,” language analysts widely interpreted as preparation for additional short-haul cuts.

The communities most vulnerable are often smaller regional airports that rely heavily on federally subsidized service. The Department of Transportation’s Essential Air Service program currently supports commercial flights to roughly 175 rural communities, but federal officials are reviewing the program amid broader transportation budget pressure. Markets including Wolf Point, Montana; Watertown, South Dakota; and DuBois, Pennsylvania have already lost or face reductions in scheduled air service.

American Airlines has trimmed flights from smaller cities including Toledo, Dubuque and Salina, while niche operators such as Cape Air continue serving ultra-short routes with small nine-seat aircraft but on limited scale.

For investors, the winners increasingly appear to be airlines operating younger fleets and larger aircraft. Delta Air Lines, which Berkshire Hathaway newly disclosed a $2.65 billion stake in this quarter, remains well positioned because of its mainline-heavy network and extensive Airbus A321neo orders. United Airlines is similarly viewed as structurally advantaged.

The losers are regional pure-play carriers and the smaller cities that depend on them. OAG’s Grant also warned that short flights place disproportionate strain on already-overloaded air traffic systems because takeoffs and landings consume scarce runway slots and controller bandwidth — an increasingly important issue after the FAA’s controversial decision this week to lower its long-term air traffic controller staffing targets.

For much of America outside the largest metro areas, the result is becoming difficult to ignore. The disappearance of short regional flights is no longer cyclical or temporary. It is structural, accelerating, and increasingly reshaping how smaller American cities connect to the national economy.

JBizNews Desk
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A senior World Bank delegation is preparing to travel to Caracas in the coming days for the first formal meetings with Venezuelan officials since the institution restored relations with the country last month, marking a major milestone in Venezuela’s gradual reintegration into the global financial system.

According to people familiar with the matter cited by Bloomberg News, the mission will be led by Susana Cordeiro Guerra, the World Bank’s vice president for Latin America and the Caribbean, and will focus on rebuilding economic coordination after years of institutional isolation.

The visit represents the most concrete step yet in Venezuela’s reentry into international financial markets following the Trump administration’s January-backed political transition that removed former President Nicolás Maduro and recognized acting President Delcy Rodríguez.

World Bank and IMF Resume Venezuela Relations

The World Bank formally announced on April 16 that it would resume dealings with Venezuela for the first time since 2019, when relations were suspended amid international disputes over whether Maduro or opposition leader Juan Guaidó should be recognized as the country’s legitimate leader.

The International Monetary Fund simultaneously resumed formal recognition of the Rodríguez administration after IMF member countries representing a majority of voting power backed the transition.

Venezuela has been a member of the World Bank since 1946, but the institution has not extended new financing to the country since 2005 and has maintained no active lending programs during the years-long political and economic crisis.

The Caracas mission is expected to focus heavily on rebuilding baseline macroeconomic data — a process made difficult by years of limited transparency and institutional breakdown inside Venezuela.

Officials from the World Bank and IMF are expected to meet with representatives from Venezuela’s Finance Ministry and Central Bank to begin assembling the economic data required before any future lending programs can move forward.

Washington Pushes Venezuela Financial Reintegration

Treasury Secretary Scott Bessent said last month that the United States is working to reintegrate Venezuela into the global financial system “in a way that looks more like a normal economy.”

Washington also eased sanctions on Venezuela’s Central Bank earlier this year as part of the broader normalization process.

At roughly the same time, Maduro’s former sister-in-law stepped down as Central Bank president, with Vice President Luis Perez assuming leadership of the institution.

The financial implications are enormous.

Rodríguez has formally requested access to approximately $5 billion in IMF Special Drawing Rights — reserve assets that analysts at JPMorgan estimate Venezuela currently holds but has been unable to fully access during the years of sanctions and political isolation.

The acting government said the funds would be directed toward rebuilding electricity systems, water infrastructure, and public services that deteriorated sharply during the Maduro years.

Wall Street Bets on Venezuela Return

Global investors have already begun positioning aggressively for Venezuela’s potential return to financial markets.

Emerging-market bond traders have driven Venezuelan sovereign debt prices sharply higher over recent months as Washington and Caracas signaled greater willingness to negotiate.

Analysts estimate Venezuela’s total external debt at roughly $150 billion, including approximately $60 billion in defaulted sovereign bonds.

Major Wall Street firms including JPMorgan, Goldman Sachs, Bank of America, and Morgan Stanley are reportedly operating active Venezuela-focused trading desks as investors anticipate a possible sovereign debt restructuring process.

Any large-scale restructuring would likely require formal IMF involvement and a comprehensive debt sustainability analysis.

Still, major political risks remain.

Rodríguez’s approval ratings have reportedly weakened in recent polling, while opposition leader María Corina Machado has vowed publicly to return to Venezuela and challenge the current political arrangement.

Chevron Expands Venezuelan Oil Operations

The energy sector has emerged as the fastest-moving part of Venezuela’s reopening.

Earlier this month, Chevron Corp. reached a major agreement with the Venezuelan government to increase crude production in the country — the most significant Western oil expansion inside Venezuela since sanctions were imposed during the Maduro era.

The agreement aligns with broader U.S. strategic goals of expanding Western energy supply sources amid elevated oil prices and ongoing disruptions in the Strait of Hormuz tied to the conflict involving Iran.

Venezuela possesses the world’s largest proven crude reserves but currently produces only a fraction of its historical output following years of underinvestment, sanctions, and infrastructure deterioration.

U.S. policymakers increasingly view expanded Venezuelan production as a potential partial offset to Middle East supply risks.

Signs of Broader Economic Reopening

Additional normalization measures have accelerated in recent weeks.

Commercial flights between the United States and Venezuela have resumed, U.S. corporate delegations have begun traveling back to Caracas, and Washington has signaled openness to additional sanctions relief tied to continued political and economic reforms.

The World Bank mission is now viewed as a critical next step in determining whether Venezuela can rebuild enough institutional credibility to attract large-scale international capital again.

For global investors, oil markets, and emerging-market lenders, the stakes extend far beyond Caracas itself.

A successful reintegration into the World Bank and IMF framework could unlock billions of dollars in financing, trigger one of the world’s largest sovereign debt restructurings, and reopen one of the planet’s largest oil-producing regions to expanded Western investment.

The decisions made over the coming months — beginning with the World Bank’s visit — could shape Venezuela’s economic future for years.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

The U.S. Department of Justice’s Civil Rights Division notified the Yale School of Medicine on Thursday that a yearlong investigation concluded the school is illegally favoring Black and Hispanic applicants over White and Asian ones in violation of federal civil-rights law, citing admissions data from 2023 through 2025 that the department says shows substantial and unexplainable gaps in test scores and grade-point averages between admitted students of different racial groups, according to the Justice Department’s official press release and a copy of the letter posted by the agency. The Yale finding came one week after the Civil Rights Division announced parallel findings against the David Geffen School of Medicine at the University of California, Los Angeles. Assistant Attorney General Harmeet K. Dhillon said in the agency’s release that “Yale has continued its race-based admissions program despite the Supreme Court and the public’s clear mandate for reform.”

The findings rest primarily on Medical College Admission Test scores and grade-point averages broken down by race. At Yale, the department said admitted Black students in the 2025 cycle had a median MCAT score of 518 and admitted Hispanic students 517, compared with a median of 524 for both White and Asian admitted students against a top possible score of 528. GPA disparities followed the same pattern: a median 3.88 for Black admits and 3.91 for Hispanic admits, against 3.97 for White and 3.98 for Asian admits. For the 2023 cycle, the department said White and Asian admits had a median MCAT of 523, compared with 517 for Black and 518 for Hispanic admits. The agency calculated that at Yale, a Black applicant had as much as 29 times higher odds of being invited to interview than an Asian applicant with equivalent academic credentials, calling the gap “substantial” and stating it “cannot be explained by a coincidence.”

At UCLA, the department applied the same statistical framework, citing 2023 data showing White and Asian admits with a median MCAT score of 514 versus 507 for Black and Hispanic admits. The Civil Rights Division said internal UCLA documents reviewed during the investigation revealed leadership “intentionally selected applicants based on their race” and adhered to what the agency described as “the dubious contention that patients receive the best care when treated by a doctor of the same race, rather than by the most qualified.” The UCLA matter originated in a lawsuit filed by the anti-DEI advocacy group Do No Harm, which the Justice Department joined in January.

Both findings are framed as enforcement of the U.S. Supreme Court’s June 2023 decision in Students for Fair Admissions v. Harvard, which struck down the consideration of race in college admissions. DOJ argues that the schools have continued de facto race-conscious admissions despite the ruling, and that the consistency of demographic outcomes in admitted classes — even as the court banned the practice — points to the use of “racial proxies” to achieve the same result. The letter to Yale cites a slide from a 2024 admissions presentation as part of the documentary evidence, and references the 2023 Department of Education investigation into Yale’s collaboration with a doctoral-program diversity initiative, which resulted in a resolution agreement in February 2026.

Yale’s medical school has not yet publicly responded to the new finding. In 2020, when the first Trump administration’s DOJ brought a parallel allegation against Yale undergraduate admissions, the university “categorically” denied the conclusion and the matter was dropped by the Biden administration in early 2021. UCLA has not publicly responded to the DOJ’s May findings either, though the school is a named defendant in the ongoing Do No Harm litigation. The Justice Department said it is seeking a voluntary resolution agreement with both schools but may pursue formal enforcement, including litigation under Title VI of the Civil Rights Act of 1964, if no agreement is reached.

The financial stakes are substantial. Yale received roughly $899 million in federal research funding in fiscal 2024, with a large share flowing through the National Institutes of Health to the medical school and affiliated Yale New Haven Health system. UCLA’s David Geffen School of Medicine is among the largest NIH grant recipients in the country, with the broader UC system collecting more than $2 billion annually in federal research and training dollars. Title VI allows the federal government to suspend or terminate federal financial assistance to institutions found to be in noncompliance, an enforcement tool that the Trump administration has signaled it is prepared to use more aggressively than prior administrations.

The medical-school cases are part of a broader DOJ focus on elite university admissions after the SFFA ruling. A study published in the Journal of the American Medical Association in late 2025 found that the share of admitted medical-school applicants from groups historically underrepresented in medicine fell to about 20% in the first cycle after the ruling, from 24% in prior years. Critics of the DOJ approach, including the Association of American Medical Colleges, argue that MCAT scores are an imperfect measure of physician potential — citing 2019 data showing that students scoring between 510 and 513 still complete their first year of medical school 98% of the time — and that holistic admissions remain legal under the SFFA framework so long as race is not the determining factor.

The DOJ said it will continue similar investigations at other medical schools, signaling that Yale and UCLA are likely the opening rather than the conclusion of the federal enforcement push.

JBizNews Desk
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Walk into almost any defense industry conference this year and the mood feels conflicted.

On one side of the room, executives from America’s largest defense contractors are talking about record order backlogs, rising military budgets, and a global security environment that appears to guarantee years of elevated weapons spending. The wars in Ukraine and the Middle East have pushed governments to replenish missiles, drones, ammunition, air-defense systems, and advanced military technology at a pace not seen in decades.

But on the other side of the room, a different conversation is taking shape — one that quietly questions whether the traditional defense industry has become too expensive for the wars governments increasingly expect to fight.

The tension is beginning to reshape both military planning and investor expectations.

The headline numbers still look extraordinarily bullish for the sector.

The Trump administration’s proposed fiscal year 2027 defense budget would push total military-related spending to roughly $1.5 trillion, one of the largest defense expansions in modern American history. According to JPMorgan, the increase represents the biggest single-year jump in defense spending since the Korean War buildup in the early 1950s.

Weapons procurement alone would rise to approximately $413 billion, nearly doubling within two years. Research and development spending would climb toward $344 billion.

Global military spending overall is now projected to reach roughly $2.6 trillion in 2026, with industry forecasts approaching $2.9 trillion by the end of the decade.

The large contractors sitting at the center of that system continue reporting enormous demand.

Lockheed Martin entered 2026 with roughly $194 billion in backlog orders. RTX is carrying a record backlog near $268 billion. Northrop Grumman closed last year with nearly $96 billion in pending business.

To investors, those numbers would normally suggest years of reliable growth.

But modern battlefields are beginning to complicate the equation.

The war in Ukraine has exposed something military planners and investors can no longer easily ignore: relatively inexpensive drones and autonomous systems are increasingly capable of destroying extraordinarily expensive military hardware.

A small attack drone costing a few hundred or a few thousand dollars can now damage tanks, ships, armored vehicles, and air-defense systems worth millions. Ukrainian factories are now reportedly capable of producing millions of small drones annually at costs far below traditional Western weapons systems.

At the same time, some of America’s next-generation military programs carry staggering price tags.

The Pentagon’s planned F-47 fighter aircraft is projected to cost roughly $300 million per jet. The B-21 Raider stealth bomber may exceed $600 million per aircraft. The proposed “Golden Dome” missile-defense initiative could ultimately cost hundreds of billions of dollars if fully expanded.

That gap — between cheap mass-produced battlefield technology and increasingly expensive legacy weapons systems — is now becoming one of the defining debates inside the defense industry.

Even some military leaders openly acknowledge the shift.

Former CIA Director and retired General David Petraeus recently described the Ukraine battlefield model as “the future of warfare,” pointing to swarms of drones, AI-assisted targeting, autonomous systems, and low-cost mass production rather than smaller fleets of ultra-expensive platforms.

Inside the Pentagon, pressure is quietly building for contractors to deliver more capability at lower cost and faster speed.

That pressure intensified in January when President Donald Trump signed an executive order titled “Prioritizing the Warfighter in Defense Contracting.” The order specifically instructed major defense contractors to prioritize production capacity and accelerated procurement rather than large stock buybacks and dividend programs that have long helped support shareholder returns.

The message from Washington was unusually direct: national-security priorities may now outweigh traditional Wall Street expectations.

The market has noticed.

While traditional defense giants still benefit from massive contracts, investors are increasingly shifting attention toward newer defense-technology companies focused on drones, AI systems, autonomous vehicles, low-cost munitions, and battlefield software.

Venture-capital investment into defense-tech startups surged approximately 180% year-over-year during the first quarter of 2026, according to industry data, with money pouring into companies building autonomous systems, AI-powered surveillance tools, sensor networks, and mass-manufacturable drone platforms.

Companies such as AeroVironment, which expanded its battlefield presence through its acquisition of BlueHalo, have emerged as key beneficiaries. Private defense startup Anduril Industries has also become one of the sector’s largest magnets for capital as investors increasingly bet that future wars will rely more heavily on software, automation, and scalable drone systems than on traditional legacy platforms alone.

Even inside financial markets, the defense trade is becoming harder to interpret.

The long-term growth outlook remains strong because geopolitical tensions continue intensifying globally. The wars involving Russia, Ukraine, Iran, Israel, and broader NATO military expansion are all driving sustained procurement demand.

But investors are increasingly trying to determine where future defense dollars actually flow.

Do governments continue prioritizing ultra-expensive aircraft, missile shields, and advanced strategic systems? Or does more of the spending shift toward cheaper drones, autonomous warfare, rapid manufacturing, and AI-enabled battlefield systems that can be produced faster and in far greater numbers?

The political environment is also becoming more complicated.

The administration’s proposed budget pairs massive defense increases with tens of billions of dollars in domestic spending cuts across housing, education, agriculture, and healthcare programs, while also seeking additional emergency war funding tied to the conflict with Iran.

That tradeoff is beginning to generate political backlash as voters absorb rising deficits, inflation pressures, and economic strain at home.

For defense investors, the result is a market increasingly split between two visions of warfare.

One still revolves around the traditional giants of American military power: stealth bombers, fighter jets, aircraft carriers, missile systems, and nuclear deterrence.

The other is being shaped in real time on modern battlefields where cheaper drones, AI-assisted targeting, software systems, and mass production increasingly determine outcomes at a fraction of the cost.

Both sides of that market are growing.

The question now confronting investors is which side ultimately captures more of the money.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By Julia Parker — JBizNews Desk

A subtle but increasingly important shift is emerging inside Wall Street’s derivatives markets as institutional investors seek more sophisticated ways to protect themselves against a potential reversal in the artificial-intelligence stock boom without abandoning the rally altogether.

According to senior derivatives traders at Bank of America and UBS Investment Bank, clients are moving beyond traditional put options and increasingly deploying exotic hedging structures designed specifically for a market dominated by a handful of high-flying AI and semiconductor companies. The activity, highlighted in Bloomberg reporting Sunday, reflects a growing consensus across trading desks that investors still want exposure to the AI trade — but no longer want to remain fully exposed without downside protection.

One of the instruments drawing the strongest institutional demand is the “lookback put,” an exotic option structure whose strike price adjusts upward as the market rallies. Unlike standard put options, which lock in a fixed strike at purchase, lookback puts effectively preserve the market’s peak level as the reference point for protection. The contracts are considerably more expensive than traditional hedges, but they are specifically designed for a scenario in which stocks continue climbing before suffering a sharp reversal.

“We have seen decent client demand for lookback puts as clients hedge the scenario where markets can potentially rally before the selloff,” Neeraj Chaudhary, Bank of America’s head of exotics and flow for Europe, the Middle East and Africa, told Bloomberg. Chaudhary also co-heads the bank’s global hybrids trading desk.

A second structure gaining popularity among institutional investors is the thematic custom basket dispersion trade, which UBS says is increasingly tied to AI-heavy portfolios. Rather than betting directly on whether the broader market rises or falls, the strategy profits from widening performance gaps between winners and losers inside a selected group of stocks.

Richa Singh, managing director at UBS Investment Bank, said investors are increasingly seeking ways to hedge concentrated exposure to the dominant AI names while still preserving participation in the broader technology rally.

“In an environment where conviction is high but uncertainty remains elevated, we’re seeing growing interest in thematic custom basket dispersion,” Singh said. “The idea being that single-stock realized volatility on a basket of, for example, AI leaders can pay regardless of market direction.”

The surge in hedging activity comes as Wall Street grows increasingly divided over whether the AI rally represents a sustainable technological transformation or the early stages of another speculative bubble.

Bank of America strategists have already warned that parts of the U.S. technology sector — particularly semiconductors — are beginning to display bubble-like characteristics. The concentration statistics are striking. Roughly 30% of the S&P 500’s market capitalization and approximately 20% of the MSCI World Index are now concentrated in just five companies, the heaviest concentration in roughly 50 years.

The S&P 500 currently trades at approximately 23 times forward earnings, a valuation level not seen since the late stages of the dot-com era. AI-linked stocks accounted for an estimated 80% of total U.S. equity gains during 2025, while Nvidia briefly surpassed a market value of $5 trillion last October — larger than the annual economic output of every country in the world except the United States and China, according to World Bank data.

What has complicated bearish positioning, however, is that the underlying earnings growth has largely justified the rally so far.

Analysts expect the information technology sector to deliver roughly 44% earnings-per-share growth in the first quarter of 2026 and account for approximately 87% of all S&P 500 earnings growth this year. Goldman Sachs estimates that AI infrastructure spending alone could drive about 40% of overall S&P 500 earnings growth in 2026.

Hyperscaler capital expenditures are also continuing to accelerate. Goldman projects spending by major AI infrastructure companies will rise to roughly $527 billion this year, up from about $465 billion projected at the start of 2025.

That strength has left strategists sharply divided over where markets head next.

Morgan Stanley chief U.S. equity strategist Michael Wilson maintains one of Wall Street’s most bullish outlooks with an S&P 500 target of 7,800. By contrast, Savita Subramanian, Bank of America’s head of U.S. equity strategy, has warned of a potential “AI air pocket” if earnings fail to justify valuations and sees only modest upside from current market levels.

The divergence helps explain why many institutional investors are opting for derivatives-based protection rather than reducing exposure outright.

Few investors want to abandon the sector producing the overwhelming majority of corporate earnings growth, but many are increasingly uncomfortable with the scale of concentration risk building beneath the rally.

Global policymakers have also begun issuing more direct warnings. Officials at the Bank of England have cautioned that AI-related valuations could decline sharply if infrastructure costs prove unsustainably high. International Monetary Fund Managing Director Kristalina Georgieva has compared current conditions to the late stages of the dot-com era, warning that a severe correction in AI-related assets could ripple across the broader global economy.

Credit markets tied to the AI buildout are now attracting hedging activity as well.

The five dominant hyperscalers — Alphabet, Amazon, Meta Platforms, Microsoft, and Oracle — issued approximately $121 billion in bonds during 2025, and analysts expect another $100 billion to $300 billion in issuance this year as AI infrastructure spending intensifies.

In response, JPMorgan Chase launched a credit-default-swap basket in March tied to all five companies, allowing institutional investors to hedge or short AI-related corporate credit exposure through a single instrument. Goldman Sachs is separately marketing total-return swap structures that allow hedge funds to speculate on swings in corporate loan pricing without directly owning the underlying debt.

JPMorgan research also highlighted mounting refinancing pressure across the software sector, with roughly $51 billion in B-minus-rated or lower software debt maturing in 2028 and another $50 billion due in 2029.

Friday’s market selloff — driven largely by rising Treasury yields rather than AI-specific news — offered another reminder of how quickly sentiment can shift when macroeconomic conditions tighten.

For now, Wall Street’s message appears increasingly consistent: stay invested in the AI trade, but buy stronger insurance while the rally still lasts.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

A factory worker retiring this year in Hamburg has, on average, about €66,000 in risk-bearing financial assets to her name. A retiree the same age in Toronto has roughly €209,000. A teacher in Stockholm has nearly the same. A nurse in Lyon falls somewhere in between, with about €91,000.

Same working lives. Same decades of labor. Very different retirements.

Across Europe, policymakers are beginning to confront a problem that sat quietly beneath the continent’s economy for years: Europeans save enormous amounts of money, but too little of it actually grows.

Instead, trillions of euros remain parked in low-yield bank accounts while populations age, pension systems strain, and governments scramble to finance everything from defense spending to artificial intelligence infrastructure.

What was once viewed as a slow-moving retirement issue is now becoming one of the most important financial debates inside Europe — and increasingly one with consequences for American households as well.

On May 5, finance ministers from across the European Union gathered in Brussels at the Economic and Financial Affairs Council to debate what officials call the Savings and Investments Union, a sweeping effort aimed at pushing more European savings into long-term investments, pensions, equities, and growth capital.

European Commission President Ursula von der Leyen has described Europe’s financial system as “excessively fragmented.” German Finance Minister Lars Klingbeil warned fellow ministers against retreating behind national interests as Brussels tries to modernize how Europeans save for retirement.

Underneath the bureaucratic language sits a far more personal reality: millions of Europeans heading into retirement with savings that, adjusted for inflation, have barely grown for years.

According to research led by Patrick Augustin, associate finance professor at McGill University, alongside the Association of the Luxembourg Fund Industry, countries that built stronger pension-investment systems decades ago — including Sweden, Canada, Denmark, Australia, and the Netherlands — now leave workers entering retirement with dramatically larger pools of long-term financial assets.

Countries that relied more heavily on traditional pay-as-you-go pension systems and low-yield savings accounts did not.

The scale of Europe’s underused savings pool is staggering.

According to analysis from the World Economic Forum and consulting firm Oliver Wyman, European households held roughly €37 trillion in savings entering 2026. Yet approximately 32% remains parked in cash and bank deposits, more than double the comparable share among American households.

Roughly €10 trillion sits in low-yield accounts that European policymakers increasingly view as economically idle.

Meanwhile, the United States spent decades building one of the deepest pools of retirement and investment capital in the world through pension funds, retirement accounts, equity markets, and broad stock ownership participation. American pension systems and retirement vehicles now hold close to $40 trillion in long-term capital.

That difference helped shape the modern global economy.

American retirement savings flowed into technology companies, infrastructure, venture capital, biotech firms, defense contractors, corporate credit markets, and stock markets that compounded wealth over decades. Europe, by contrast, left far more of its household wealth sitting conservatively inside traditional banking systems generating minimal returns.

Now the cost of that approach is becoming harder to ignore.

Europe faces an estimated annual investment gap of roughly €750 billion to €800 billion, according to reports prepared for EU leaders by former European Central Bank President Mario Draghi and former Italian Prime Minister Enrico Letta. The continent simultaneously needs to finance defense expansion, semiconductor manufacturing, renewable energy infrastructure, biotech investment, digital modernization, and AI development — all while supporting rapidly aging populations.

The demographic pressures alone are severe.

According to Eurostat, people aged 65 and older now make up roughly 22% of the EU population, while the working-age population continues shrinking. Europe’s traditional pension structure — where current workers fund current retirees — was built for a younger continent with far more workers supporting each retiree.

That math no longer works as comfortably as it once did.

For ordinary Europeans, the consequences are deeply personal.

Industry research cited in the 2025 Will You Afford to Retire? report found median real returns on many European pension products hovered near just 0.3% over the past decade after inflation. Roughly 41% of Europeans contribute nothing to supplementary retirement plans beyond government systems.

The imbalance hits women especially hard. The EU’s gender pension gap averages roughly 24.5%, with significantly fewer women participating in supplementary retirement savings programs despite longer average lifespans.

Countries that moved earlier toward funded pension systems are now reaping the benefits.

Sweden, Denmark, Canada, Australia, and the Netherlands spent decades gradually shifting toward retirement systems tied more heavily to investment markets and long-term capital accumulation. Sweden’s AP7 pension fund and Britain’s NEST auto-enrollment model are now frequently cited across Europe as templates for reform.

Ireland launched a new national auto-enrollment retirement program this year. The Netherlands is continuing a major pension-system overhaul expected to transition dozens of pension funds into modernized collective investment structures through 2027.

For Americans, the story is not as distant as it may appear.

Much of Europe’s savings currently flows into U.S. assets — including Treasury bonds, American stocks, technology companies, and corporate debt. European pension funds and insurers remain major foreign buyers of U.S. financial assets.

If Europe succeeds in redirecting more of that capital internally, the effects could eventually ripple back into the American economy.

Reduced foreign demand for U.S. Treasuries could place upward pressure on borrowing costs, affecting mortgage rates, auto loans, and federal debt financing. At the same time, Europe is openly trying to build larger pools of investment capital capable of financing its own AI firms, semiconductor companies, defense contractors, and technology champions rather than relying as heavily on American markets.

Ironically, Europe is now trying to replicate many of the investment structures the United States spent decades building — broader stock ownership, retirement investing, and automatic enrollment systems — just as parts of the American system are showing growing strain themselves.

Roughly half of American private-sector workers still lack access to workplace retirement plans. Retirement wealth inside the U.S. also remains heavily concentrated among higher-income households. Social Security faces long-term demographic pressure similar to Europe’s.

The difference is timing.

Europe is confronting the problem now, aggressively and publicly, with continent-wide reforms already underway. The United States, despite facing many of the same demographic realities, has not yet reached a comparable political reckoning.

The decisions European leaders make over the next several months will not immediately change retirement checks for today’s pensioners.

But they may determine whether Europe can transform trillions in stagnant household savings into the kind of long-term investment capital capable of financing its future — and whether America continues benefiting from Europe’s money flowing across the Atlantic or begins competing against it instead.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

New York’s largest commuter rail system entered its third day of complete shutdown Monday morning as roughly 250,000 daily Long Island Rail Road riders woke up to traffic gridlock, overcrowded subway platforms, and renewed reminders of how dependent the region remains on mass transit nearly six years after the pandemic transformed office culture.

The strike — the first full Long Island Rail Road shutdown since 1994 and the largest commuter-rail stoppage in the United States in more than three decades — is now rapidly evolving beyond a transportation crisis into a broader economic stress test for New York’s fragile return-to-office recovery.

According to a joint statement issued Sunday evening by the Metropolitan Transportation Authority and confirmed by union representatives, five LIRR unions representing engineers, signalmen, and train crews officially walked off the job at 12:01 a.m. Saturday, May 16, after months of stalled negotiations over wages and healthcare costs.

Talks resumed Monday morning at MTA headquarters after a marathon overnight bargaining session ended without a breakthrough.

Meanwhile, Governor Kathy Hochul made an unusually direct public appeal to both employers and commuters.

“Effective Monday, I’m asking that regular commuters who can work from home, should. Please do so,” Hochul said Sunday, acknowledging that “it’s impossible to fully replace LIRR service.”

The message landed immediately across corporate New York.

Major employers including JPMorgan Chase, Goldman Sachs, Morgan Stanley, Citigroup, KPMG, Deloitte, EY, PwC, Northwell Health, and NewYork-Presbyterian advised many employees to work remotely wherever possible, triggering what has effectively become the city’s largest forced remote-work experiment since the COVID-era shutdowns of 2020.

Penn Station, normally one of the busiest transportation hubs in North America, appeared almost unrecognizable over the weekend, with departure boards flashing “No Passengers” while empty trains sat idle.

The LIRR carried roughly 82 million riders in 2025, according to MTA data, making it the busiest commuter railroad in North America and one of the core arteries feeding Manhattan’s office economy.

Now that artery is frozen.

And the financial burden is landing hardest on workers who cannot simply open a laptop from home.

Commuters attempting to drive into Manhattan Monday morning faced severe congestion along the Long Island Expressway, Northern State Parkway, and Belt Parkway, while ride-share prices surged sharply. Trips from western Long Island into Midtown Manhattan that normally cost between $80 and $120 were quoted as high as $250 to $400 during peak commuting hours.

Parking costs, tolls, gas prices, and additional subway transfers are rapidly compounding the burden.

A standard monthly LIRR pass from stations such as Hicksville or Ronkonkoma into Manhattan typically costs between $300 and $500. Replacing rail travel with private vehicles or ride-share services could push commuting expenses to between $80 and $200 per day, meaning a weeklong strike could cost some households nearly $1,000 in unexpected transportation expenses alone.

Hochul acknowledged Sunday that the burden falls disproportionately on workers who cannot operate remotely.

Nurses, retail employees, restaurant workers, construction crews, hospitality staff, and healthcare technicians remain among the most exposed.

“I do ultrasounds for pregnant women and gynecology, and I have to be there. I can’t do that remotely,” commuter Dana Camera told local reporters while waiting for limited shuttle service over the weekend.

The MTA has deployed temporary shuttle buses from six Long Island locations during peak hours and added capacity to portions of the subway system in Queens, but transit officials privately admit there is no realistic replacement for full LIRR service.

The political blame game is already escalating.

Governor Hochul blamed the Trump administration for failing to extend federal mediation efforts earlier this year after a previous strike threat was temporarily delayed in September 2025 through federal intervention.

President Donald Trump rejected that framing Sunday night on Truth Social.

“No, Kathy, it’s your fault, and now looking over the facts, you should not have allowed this to happen,” Trump wrote.

The National Mediation Board, which oversees rail labor disputes under the Railway Labor Act, continues facilitating negotiations but has not yet triggered the emergency-board process that could suspend the strike for an additional 60 days.

Union representative Mike Carlucci said he appreciated Hochul’s public support for commuters but argued the governor needs to become more directly engaged in the negotiations themselves.

Beyond the immediate disruption, however, the strike is reopening a much larger question hanging over New York’s economy: whether the city’s push back toward five-day office attendance remains sustainable in a region still deeply vulnerable to transportation breakdowns.

For many companies, the strike is becoming an involuntary real-time test of whether remote productivity remains viable at scale.

Commercial real-estate executives are watching closely.

Manhattan office landlords including SL Green Realty, Vornado Realty Trust, and Empire State Realty Trust have spent the last two years pushing aggressively for office normalization after pandemic-era vacancies devastated Midtown occupancy levels.

Now, many firms that had recently tightened in-office attendance policies are once again allowing broad remote flexibility almost overnight.

The ripple effects are spreading beyond offices.

Midtown restaurants, bars, and retailers reported sharp declines in weekend foot traffic. Madison Square Garden lost attendance tied to playoff games involving the New York Knicks and other events as suburban ticket holders struggled to reach Manhattan. Broadway theaters, hotel operators, and retail corridors are bracing for additional fallout if the strike continues deeper into the week.

For now, the outcome depends on whether negotiators can produce a deal before Tuesday morning’s commute.

If not, pressure will intensify on both Albany and Washington to intervene more aggressively.

In the meantime, one reality has already become unavoidable:

New York’s largest transit strike in decades has suddenly given remote work its strongest institutional endorsement since the pandemic itself.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk | May 18, 2026

The Federal Aviation Administration announced Friday that it is sharply reducing its target staffing level for certified air traffic controllers to 12,563, down 14% from the prior target of 14,633, even as AAA projects a record 45 million Americans will travel over the upcoming Memorial Day weekend, according to the agency’s statement released through Reuters. The FAA said the cut reflects a new operational framework built around what it called “modern staffing models and scheduling tools,” intended to reduce reliance on what has become a $200-million-a-year overtime regime that aviation safety researchers have increasingly described as unsustainable.

The timing immediately drew attention across the aviation industry because the staffing revision arrives just as the U.S. airline system heads into what carriers expect will be the busiest summer travel season in history. AAA forecasts 3.66 million Americans will fly over Memorial Day weekend alone, while airlines are simultaneously managing elevated fuel costs tied to the Iran war and the continuing closure of the Strait of Hormuz, which has kept crude oil above $100 a barrel and pushed jet-fuel costs sharply higher.

The numbers behind the FAA’s staffing decision are striking. The agency’s air traffic control workforce logged roughly 2.2 million hours of overtime during 2024, costing more than $200 million. Annual overtime per certified controller has surged 308% since 2013, climbing to roughly 167 hours annually from just 41 hours a decade earlier. A report published last year by the National Academies of Sciences, Engineering, and Medicine found the FAA hired only about two-thirds of the controllers called for under its own staffing models between 2013 and 2023, while the active certified controller workforce fell approximately 13% during that same period.

The same study identified what researchers described as “misallocated workforce and inefficient scheduling,” noting that controller time-on-position — the portion of a shift spent actively directing aircraft — actually declined despite a 4% increase in overall air traffic volume. FAA officials said Friday the revised staffing model is intended to improve operational efficiency by increasing average time-on-position from roughly four hours per shift to more than five hours.

The FAA currently employs about 11,000 certified controllers across more than 300 facilities nationwide, alongside roughly 4,000 additional personnel still in the training pipeline. That includes approximately 1,000 already-certified controllers retraining for assignments at new locations. Under the revised benchmark, the agency now sits at roughly 87% of its target staffing level — a materially easier threshold to achieve than the prior 14,633-controller target the FAA has struggled unsuccessfully to meet for more than a decade.

Still, the optics are difficult for regulators. The announcement comes only months after the deadly January midair collision near Reagan National Airport that killed 67 people, as well as a separate near-miss incident earlier this spring involving a Delta Air Lines aircraft and a Republic Airways regional jet near New York airspace. National Transportation Safety Board Chair Jennifer Homendy openly criticized the staffing reduction Friday, telling Reuters that “staffing decisions should be driven by safety data, not budget optimization.”

The airline industry responded cautiously. Airlines for America, the trade association representing Delta Air Lines, United Airlines, American Airlines and Southwest Airlines, said the FAA “must ensure that any restructuring of staffing targets does not compromise the operational integrity of the National Airspace System during the busiest summer travel period in U.S. history.” The National Air Traffic Controllers Association, which represents roughly 20,000 aviation workers, warned that overtime levels are “already at unsustainable burnout thresholds.”

Pilots and regional carriers are particularly sensitive to staffing shortages because smaller airports and shorter routes are often the first areas impacted by air traffic delays and scheduling restrictions. Regional operators including SkyWest, Republic Airways and Mesa Air Group — already under pressure from rising jet-fuel costs and shrinking short-haul profitability — all traded modestly lower Friday after the announcement.

The market reaction among major aerospace suppliers was muted. Shares of Boeing, GE Aerospace, Spirit AeroSystems and RTX Corp. were little changed despite each company’s exposure to long-term FAA modernization spending. L3Harris Technologies, one of the principal contractors helping build the FAA’s NextGen communications infrastructure, finished slightly lower.

The broader issue remains structural rather than temporary. The FAA’s NextGen modernization program, launched in 2003 with an expected multidecade rollout and estimated budget of roughly $20 billion, remains incomplete after years of delays, contractor disputes and evolving technology requirements. Verizon Communications and L3Harris remain central contractors on the system’s communications and surveillance upgrades, though multiple portions of the rollout continue running behind schedule.

Transportation Secretary Sean Duffy, who took office in January, has made modernization of the national airspace system a central policy priority and has pushed the FAA toward what the administration describes as “outcome-based staffing.” Supporters argue the revised targets better reflect operational realities and technological improvements rather than outdated hiring assumptions. Critics counter that lowering staffing goals risks institutionalizing shortages rather than solving them.

For travelers, the immediate concern is whether the system can handle what could become one of the busiest and most operationally strained summer travel periods in decades. Airlines are already cutting less-profitable regional flights as jet-fuel costs climb, while controller fatigue and scheduling bottlenecks continue contributing to delays throughout major hubs.

Whether the FAA’s revised staffing framework improves efficiency or simply lowers expectations will likely become clear quickly — beginning with Memorial Day weekend itself.

JBizNews Desk
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Mayor Zohran Mamdani’s proposal to open five city-owned supermarkets across New York City is rapidly escalating into one of the most closely watched economic and political fights in the city — drawing growing scrutiny from business leaders, national media, and immigrant-owned neighborhood retailers who say the plan could fundamentally reshape Main Street commerce across the five boroughs.

The effort gained immediate attention across New York’s political and media landscape because of the coalition’s unusually high-level business and civic network, with the New York Post, today’s New York Times, and Fox Business Network quickly spotlighting what many inside City Hall now view as one of the most influential emerging multicultural business coalitions and leadership teams to enter New York’s economic debate in years.

During a segment this week on Fox Business Network’s The Bottom Line with Dagen McDowell, McDowell closed the discussion by noting that her own parents made their livelihood operating a bodega and expressed concern that government-backed supermarkets could hurt immigrant-owned neighborhood stores that remain the “bread-and-butter livelihood for everyday people” across New York City.

Now, a newly formed alliance of more than 50 immigrant-led chambers of commerce says it is preparing to formally challenge the proposal before the New York City Council.

The newly launched Multicultural Business Coalition — representing Hispanic, African, Caribbean, Asian, Middle Eastern, and Jewish business organizations — has already assembled a seven-figure political and advocacy operation aimed at slowing or reshaping Mamdani’s supermarket initiative before its first major City Hall test on May 29, when the New York City Council Economic Development Committee is expected to hold its first formal hearing on the administration’s proposed $70 million municipal supermarket plan.

According to coalition chairman Frank Garcia, the organization secured a $1 million donor commitment shortly after launch and raised another approximately $100,000 from small and midsize business owners within days.

Coalition leaders say the issue is not political ideology but economic survival.

“This is not just about supermarkets,” said Duvi Honig, founder of the Orthodox Jewish Chamber of Commerce and secretary of the coalition. “This is the first time such a broad coalition of immigrant-led business organizations from across New York City has united around a single economic issue. It’s about whether government should directly compete against the same immigrant-owned neighborhood businesses that spent decades building these communities, creating jobs, paying taxes, and keeping New York’s commercial corridors alive through some of the toughest economic conditions the city has faced.

“At the same time, this is not about fighting the mayor — we are absolutely prepared to sit down together and have a serious economic discussion about how to lower costs for families while also protecting the bodegas, neighborhood grocers, and small businesses that are the economic backbone and everyday livelihood of New York City.”

That message appears to be resonating well beyond City Hall.

Unlike many previous anti-Mamdani efforts backed primarily by Wall Street donors, developers, or corporate political groups, the resistance emerging here is rooted largely inside neighborhood business corridors and immigrant-owned commercial strips throughout the city.

The coalition argues that government-owned supermarkets would receive structural advantages unavailable to independent operators, including relief from rent burdens, property taxes, financing costs, and other overhead pressures currently squeezing neighborhood grocers already operating on razor-thin margins.

Mayor Mamdani has framed the proposal differently.

The administration argues city-owned supermarkets could reduce grocery costs in underserved neighborhoods by purchasing inventory wholesale, centralizing warehousing and distribution, and operating without a traditional profit motive. The flagship location is planned for the city-owned La Marqueta site in East Harlem, with additional stores proposed across the Bronx, Brooklyn, Queens, and Staten Island.

Supporters of the initiative point to rising food insecurity across the city, with Mamdani repeatedly citing figures showing roughly one in four New York City children experiences some level of food hardship.

But critics argue the economics become more difficult once the realities of the grocery industry enter the equation.

Supermarket analyst Phil Lempert notes that grocery stores typically operate on margins between 1.5% and 2%, among the lowest in American business. Critics argue municipal stores would effectively compete against private neighborhood operators while benefiting from public support structures unavailable to existing businesses.

“A government-owned supermarket is a mission-driven business,” said Stephen Zagor of Columbia Business School. “At best, maybe they break even. More likely, they require ongoing subsidy.”

Several publicly supported grocery projects elsewhere in the country have struggled financially, including efforts in Kansas City, Atlanta, and Baltimore.

Critics also dispute whether some of the proposed New York locations qualify as true “food deserts,” noting that the planned East Harlem flagship already sits within walking distance of multiple supermarkets and dozens of grocery options.

Supermarket owner John Catsimatidis has sharply criticized the initiative, warning that government-backed stores could place additional pressure on neighborhood operators already dealing with inflation, labor costs, theft, insurance increases, and slowing consumer spending.

Meanwhile, the politics around the issue continue intensifying.

Garcia told the New York Post he rejected outreach tied to fundraising efforts connected to Mamdani allies, underscoring how quickly the supermarket debate is evolving into a wider fight over the future direction of New York’s economy.

City Council Speaker Julie Menin has already signaled caution, saying the Council intends to closely examine both the consumer benefits and the potential impact on existing neighborhood retailers before approving funding.

Without Council approval, the proposed $70 million capital package cannot move forward.

Over the coming weeks, what began as a debate over five grocery stores may evolve into something much larger — a test of whether New York City should directly enter industries traditionally built by immigrant-owned small businesses, and whether those same business communities are now becoming a coordinated political force capable of reshaping economic debates at City Hall.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

House Speaker Mike Johnson’s defense of congressional stock trading moved back into public focus this week as lawmakers, investors, and voters renewed debate over whether elected officials should be allowed to actively trade financial assets while serving in office.

Johnson’s argument, originally made last year and widely circulated again this week, centered on a reality many members of Congress quietly discuss in private: congressional salaries have remained unchanged since 2009 even as the cost of living in Washington has risen sharply.

Rank-and-file House and Senate members still earn $174,000 annually, according to the Congressional Research Service. Adjusted for inflation, congressional compensation has effectively declined by roughly 30% over the past 17 years.

Johnson argued that lawmakers today face mounting financial pressures tied to maintaining residences both in Washington and in their home districts while supporting families in an increasingly expensive economy. His broader point was that investment activity has become one of the few ways many members can preserve long-term financial stability while serving in public office.

The discussion resurfaced as new federal ethics disclosures showed President Donald Trump executed 3,642 securities transactions during the first quarter of 2026, highlighting once again how closely politics, investing, and financial markets have become intertwined at the highest levels of government.

According to filings submitted through the Office of Government Ethics, Trump’s disclosed transactions involved companies including Nvidia, Apple, Microsoft, Oracle, Goldman Sachs, Palantir, Broadcom, Dell Technologies, and Bank of America, with cumulative values reported within federal disclosure ranges totaling between approximately $220 million and $750 million.

Federal law does not prohibit a sitting president from trading securities, and disclosure forms require only broad value ranges rather than exact purchase prices or profits. A White House spokesperson said the holdings are managed through discretionary accounts while the Trump family business is overseen by Donald Trump Jr. and Eric Trump.

Members of Congress operate under a similar disclosure framework.

The STOCK Act of 2012 requires lawmakers to disclose securities trades within 45 days, though lawmakers from both parties continue debating whether disclosure alone is sufficient in an era where financial markets react instantly to government policy, regulation, and geopolitical developments.

The issue has become increasingly visible as congressional trading disclosures attract growing public attention.

Former Speaker Nancy Pelosi’s household portfolio has frequently drawn notice for outperforming broader market indexes, particularly in technology stocks, while other lawmakers including Representative Marjorie Taylor Greene have also become closely watched by retail investors who now track congressional disclosures almost in real time.

What was once a niche ethics issue has evolved into a broader conversation about wealth, public service, and how modern political life increasingly intersects with financial markets.

Behind much of the debate is the changing economics of serving in Congress itself.

Lawmakers receive no additional salary for committee assignments despite the significant time and fundraising responsibilities attached to them. Research from organizations including Issue One and the Brookings Institution has shown that members seeking seats on influential committees are often expected to raise hundreds of thousands — and in some cases millions — of dollars for party campaign organizations.

At the same time, outside earned income for lawmakers is tightly restricted under congressional ethics rules. Members may earn no more than 15% of their salary from outside employment, while honoraria have been banned for decades. Investment income, however, remains unrestricted.

That structure has gradually made investment portfolios a more significant part of long-term financial planning for many members of Congress.

Johnson’s comments reflected that broader reality.

Rather than framing stock ownership as extraordinary wealth accumulation, the Speaker described it as part of the financial balancing act lawmakers face while navigating rising housing costs, travel demands, fundraising expectations, and stagnant salaries.

Public opinion on the issue remains mixed but increasingly active.

Polling from YouGov and the University of Maryland’s Program for Public Consultation shows broad bipartisan support for restricting or banning individual stock trading by elected officials, including members of Congress, presidents, and Supreme Court justices.

Several proposals remain pending on Capitol Hill, including the Restore Trust in Congress Act, introduced by Representatives Chip Roy and Seth Magaziner, which would require lawmakers and their families to move many investments into blind trusts while prohibiting direct trading of individual stocks.

The legislation remains in committee as lawmakers continue debating where the line should be drawn between financial freedom and public trust.

The conversation unfolding around Johnson’s remarks ultimately reflects a larger shift taking place in Washington and across Wall Street: politics and financial markets are now more interconnected than at any point in modern American history.

Congress writes legislation affecting trillion-dollar industries. Presidents shape economic policy that can move entire sectors overnight. Investors increasingly monitor Washington as closely as they monitor earnings reports and Federal Reserve meetings.

Against that backdrop, the debate over congressional investing is evolving beyond ethics alone and into a broader question about how public officials should participate in the same financial system they help regulate.

Johnson’s central argument was straightforward: congressional salaries have not kept pace with inflation, and lawmakers, like many Americans, are trying to manage the economic realities that come with that shift.

Whether voters view investment activity as a reasonable extension of that reality or believe stricter limits are needed will likely shape the next phase of the debate on Capitol Hill.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

For years, India sold global investors on one of the most compelling economic stories of the century: a nation of 1.4 billion people poised to become the world’s next manufacturing powerhouse, the democratic counterweight to China, and eventually the planet’s third-largest economy. Global CEOs embraced the narrative. Wall Street poured money into Indian equities. Prime Minister Narendra Modi built much of his economic diplomacy around the promise that India’s rise was not merely coming — it had already begun.

Then the numbers changed.

On February 27, India’s Ministry of Statistics and Programme Implementation (MoSPI) quietly released a revised GDP series that effectively reduced the size of the Indian economy by hundreds of billions of dollars. Under the new methodology, nominal GDP for fiscal year 2025-26 was recalculated downward to approximately ₹345 lakh crore, compared with roughly ₹357 lakh crore under the previous series.

In dollar terms, India’s economy was effectively reduced from around $4.2 trillion to closer to $3.9 trillion.

The downgrade immediately carried symbolic and financial consequences. India, which had celebrated overtaking Japan as the world’s fourth-largest economy in 2025, slipped back behind Tokyo under the revised calculations. Estimated per-capita GDP also fell sharply, dropping from prior estimates near $2,900 to roughly $2,600.

While the government simultaneously revised headline growth rates slightly higher — lifting fiscal 2025-26 real GDP growth to 7.6% — economists quickly focused on the larger implication: India’s economy may not be as large or as structurally strong as global markets had assumed.

The timing could hardly be worse.

As investors digested the revision, nearly every major economic pressure point surrounding India began deteriorating simultaneously.

The Indian rupee fell this week to a historic low near 95.73 against the U.S. dollar, making it Asia’s weakest-performing major currency of 2026. Foreign portfolio investors have already withdrawn more than $20 billion from Indian equities during the first four months of the year, according to data from the National Securities Depository Ltd. (NSDL) — already exceeding last year’s record pace of outflows.

Meanwhile, India’s dependence on imported energy is becoming increasingly exposed amid tightening global oil markets and disruptions surrounding the Strait of Hormuz. India imports approximately 85% of its crude oil needs, leaving the economy highly vulnerable to sustained increases in global energy prices and supply disruptions tied to the ongoing U.S.-Iran conflict.

State-run oil marketing companies are reportedly losing as much as ₹1,000 crore per day as the government limits domestic fuel-price increases to contain inflation pressure on consumers.

Reserve Bank of India Governor Sanjay Malhotra warned this week that policymakers may need to intervene more aggressively if currency and inflation pressures continue intensifying.

But the growing concern among economists extends far beyond oil prices or short-term market volatility.

For years, analysts have questioned whether India’s official GDP data accurately reflects underlying economic reality.

Former Indian Chief Economic Adviser Arvind Subramanian has repeatedly argued that India’s growth figures likely overstate actual expansion because of structural distortions in measurement methodology. In March, Nicholas Lardy, senior fellow at the Peterson Institute for International Economics, published research arguing that India’s economic trajectory has been materially less stable than headline data suggested. Mumbai-based economist Dhananjay Sinha recalculated India’s post-pandemic growth under the revised methodology and concluded that true growth may be closer to 4.8%, well below earlier estimates.

The pressure intensified after the International Monetary Fund assigned India a “C” grade in late 2025 for the quality and coverage of its national accounts — the second-lowest rating possible — citing outdated methodologies and gaps in real-time economic measurement.

The deeper issue now confronting investors is whether India’s structural transformation is progressing fast enough to justify the enormous expectations embedded into global capital flows and market valuations.

Despite years of flagship initiatives including “Make in India”, production-linked incentive programs, and “Atmanirbhar Bharat” self-reliance campaigns, manufacturing still represents only about 16% to 17% of India’s GDP — far below the levels historically associated with export-driven industrial powers such as China, South Korea, or Vietnam during their rapid expansion phases.

Large segments of advanced manufacturing remain heavily dependent on imported components, machinery, semiconductors, and battery technology.

In a sharply worded note to Prime Minister Modi earlier this year, analysts at Bernstein warned that India faces a narrowing window to restructure its economy before demographic advantages begin fading. The report highlighted India’s continued dependence on imported industrial inputs, the vulnerability of the country’s massive IT outsourcing sector to generative AI disruption, and the continued concentration of labor in low-productivity informal work.

Other forecasters are already turning more cautious. BMI, part of Fitch Solutions, recently cut its fiscal 2026-27 GDP growth forecast for India to 6.7% from 7.7%, citing external pressures, energy-market disruptions, and weakening global conditions.

None of this means India’s economy is collapsing. By almost any global standard, it remains one of the fastest-growing major economies in the world. The country still possesses one of the largest consumer markets on earth, a rapidly expanding digital infrastructure, and an increasingly important role in global supply-chain diversification efforts as companies seek alternatives to China.

But investors are increasingly asking a more uncomfortable question: whether the gap between India’s global economic narrative and its underlying economic fundamentals has become too large to ignore.

The next critical moment arrives May 29, when MoSPI releases provisional annual GDP estimates under the revised methodology. Investors, economists, and policymakers will be watching closely not simply for another growth number, but for evidence of whether the economy behind the headlines is truly becoming the global economic superpower markets have spent years anticipating.

For much of the past decade, belief in India’s future helped drive investment. Increasingly, global markets are demanding harder proof.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Kevin Warsh begins his first full week as chair of the Federal Reserve with the 10-year Treasury yield at a one-year high of 4.55%, the U.S. Dollar Index at its strongest level since early March, April CPI at 3.8% — the hottest reading since May 2023 — and CME FedWatch odds of a 2026 rate hike at 45%, up from near-zero a month ago, according to data from Trading Economics, the CME Group and the Bureau of Labor Statistics. Warsh, 56, was sworn in Friday after the U.S. Senate narrowly confirmed him Wednesday, replacing Jerome Powell, whose term expired the same day. Wall Street is now waiting on Warsh’s first public communications to gauge whether the new chair will lean rules-based, hawkish, or whether he will, as some critics fear, tilt to accommodate President Donald Trump’s repeated public calls for lower rates.

Warsh’s April 21 confirmation testimony before the Senate Banking Committee offered the clearest signal of his early priorities. He told senators that “the Fed must stay in its lane” and warned that “Fed independence is placed at greatest risk when it strays into fiscal and social policies where it has neither authority nor expertise.” He committed firmly to fighting inflation but, notably, made only one mention of the labor market in his prepared remarks, a tilt that monetary historians read as a return to Paul Volcker-style single-mandate emphasis. Warsh also said publicly elected officials voicing views on rate policy does not, in his view, threaten the Fed’s “operational independence” — a comment that drew applause from the Trump administration but raised eyebrows among economists who argued the standard for political pressure should be higher.

The more consequential policy question is the balance sheet. Warsh has argued for years that the Fed must shrink its footprint in financial markets and rely primarily on the federal-funds rate as its tool, rather than the multi-trillion-dollar System Open Market Account of Treasury and mortgage-backed-securities holdings built up since the 2008 financial crisis. Any signal during his first speech that he intends to accelerate quantitative tightening could send long-end yields higher and pressure mortgage-backed securities and bank stocks. Warsh has also publicly questioned the FOMC’s 2012 decision to formally adopt a 2% inflation target, arguing the figure is “arbitrary.” A move to revise or scrap the target — even rhetorically — would be the biggest framework change since the central bank adopted its flexible average inflation targeting regime in 2020.

The optics are also unusually personal. Warsh is married to Jane Lauder, an Estée Lauder Companies Inc. board member and granddaughter of the cosmetics empire’s founder, putting the new Fed chair in the upper tier of American wealth and giving the Lauder family a direct line to monetary-policy decision-making. He served as a Fed governor from February 2006 to April 2011, dissenting on quantitative easing under chairs Ben Bernanke and Janet Yellen, and built much of his market-facing reputation on his role coordinating the 2008 Troubled Asset Relief Program with then-Treasury Secretary Hank Paulson.

Markets have given Warsh the benefit of the doubt so far. Invesco chief global market strategist Kristina Hooper wrote in a note last month that “longer-term U.S. inflation expectations remain well-contained, suggesting that markets aren’t currently pricing in concerns about political interference in monetary policy.” Five-year breakeven inflation rates have ticked up modestly but remain anchored. Standard Chartered’s Geoffrey Kendrick and Strategas Research’s Don Rissmiller have both flagged that the Warsh regime is most likely to manifest in subtle communication shifts rather than in sudden rate moves, given the FOMC does not meet again until June 16-17.

The calendar this week sharpens the focus. The FOMC minutes from the April 28-29 meeting — the last under Powell — are released Wednesday at 2 p.m. ET, and any contrast between the Powell-era tone and Warsh’s opening remarks will be scrutinized. Fed governors Christopher Waller, Michelle Bowman and Lisa Cook are also scheduled for public remarks during the week, and any divergence on policy could highlight emerging fault lines within the committee. Friday’s final University of Michigan Consumer Sentiment print for May, particularly the five-year inflation expectations component, will be the data Warsh’s team will be watching most closely.

For investors, the practical questions are three: whether Warsh signals an accelerated balance-sheet runoff, whether he hints at a higher tolerance for elevated inflation in service of growth, and whether his rhetoric on Fed independence holds up under the first wave of Trump pressure. The answers will move the U.S. Dollar Index, the 2-year Treasury yield and the S&P 500 in roughly that order of magnitude.

JBizNews Desk
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Wall Street opened the week trying to balance three different markets at once.

Stocks pushed modestly higher Monday morning. Oil climbed again after fresh geopolitical tensions in the Middle East. Bond yields stayed near multi-year highs, reminding investors that even as equities continue grinding upward, the cost of money across the economy remains elevated.

The result was a market that looked calm on the surface but increasingly tense underneath.

The Dow Jones Industrial Average rose roughly 139 points shortly after the open, while the S&P 500 hovered near fresh record territory reached last week. The Nasdaq Composite traded little changed as investors positioned themselves ahead of what is shaping up to be one of the most consequential earnings weeks of the quarter.

Hovering over nearly everything this week is Nvidia.

But before investors even reached Wednesday’s AI showdown, markets were hit Monday morning with the largest utility merger in American history.

NextEra Energy announced a $66.8 billion all-stock acquisition of Dominion Energy, creating what would become the largest regulated electric utility company in the world if approved.

The deal lands at a moment when electricity demand across the United States is beginning to surge under the weight of artificial-intelligence infrastructure expansion.

At the center of the acquisition is Dominion’s footprint in Virginia — home to the country’s largest concentration of hyperscale data centers and increasingly viewed as one of the most strategically important electricity markets in the world.

The region known as “Data Center Alley” has become ground zero for AI-era power demand.

Every new large-language model, cloud cluster, and AI server farm consumes staggering amounts of electricity, forcing utilities into what increasingly resembles an arms race to secure generation capacity before demand outruns the grid itself.

“Scale matters more than ever,” NextEra CEO John Ketchum said Monday morning as the companies unveiled the transaction.

The combined company would control roughly 110 gigawatts of generation capacity and serve approximately 10 million customers across Florida, Virginia, and the Carolinas.

Investors initially treated the deal cautiously.

Dominion shares surged roughly 13% after the announcement, while NextEra fell more than 3% as traders weighed regulatory risks, integration complexity, and the enormous capital demands tied to future AI-era infrastructure expansion.

The regulatory review could stretch well into next year, underscoring just how transformative the transaction may become for the broader utility sector.

Energy demand is now colliding directly with another force reshaping markets this year: geopolitics.

Oil prices climbed again Monday after the United Arab Emirates accused Iran of carrying out drone and missile attacks against civilian nuclear infrastructure over the weekend.

The escalation followed another round of increasingly aggressive rhetoric from President Donald Trump, who warned on Truth Social that “for Iran, the clock is ticking.”

Brent crude rose above $108 a barrel while West Texas Intermediate held near $106, levels that continue feeding inflation concerns throughout the global economy.

The bond market remains highly sensitive to those pressures.

The benchmark 10-year Treasury yield briefly climbed above 4.6% Monday morning before easing slightly, while the 30-year Treasury remained above 5.1%.

Those levels are increasingly important because they now directly shape mortgage rates, corporate borrowing costs, commercial real-estate financing, and consumer credit across the economy.

In many ways, bond markets are signaling a far less optimistic story than equities.

Investors continue betting aggressively on artificial intelligence, corporate earnings resilience, and economic durability. Bonds, meanwhile, continue reflecting concern that inflation and elevated government borrowing may keep interest rates structurally higher for longer than markets expected just a few months ago.

The biggest corporate shock Monday morning came from Berkshire Hathaway.

The conglomerate’s latest 13F filing — the first major portfolio disclosure overseen by CEO Greg Abel after Warren Buffett’s retirement transition — revealed sweeping changes across Berkshire’s investment holdings.

The company exited positions in Amazon, Visa, Mastercard, Domino’s Pizza, and UnitedHealth Group, while sharply increasing exposure to Alphabet and opening new positions in Delta Air Lines and Macy’s.

The moves are being interpreted across Wall Street as one of the clearest signs yet that Berkshire under Abel may operate differently from the traditional Buffett-era buy-and-hold strategy.

UnitedHealth shares fell nearly 5% following the disclosure.

Elsewhere in biotech, Regeneron Pharmaceuticals plunged more than 11% after a major melanoma-drug trial failed to outperform Merck’s blockbuster cancer therapy Keytruda in a closely watched Phase 3 study.

Analysts responded quickly with downgrades and price-target cuts, viewing the failed trial as a major setback for one of Regeneron’s most important future oncology programs.

Still, almost everything happening Monday feels like setup for Wednesday.

That is when Nvidia reports earnings after the close.

The AI giant now carries a market capitalization approaching $5.7 trillion and has effectively become the single most important stock in global equity markets.

Wall Street expectations remain extraordinarily high.

Analysts increasingly believe Nvidia’s Blackwell AI-chip rollout could become one of the largest product cycles in semiconductor history, fueled by hyperscale AI spending from companies including Microsoft, Amazon, Meta Platforms, and Alphabet.

KeyBanc raised its Nvidia price target again Monday morning, citing accelerating Blackwell shipments.

But expectations have become so elevated that many analysts warn the company may need a nearly flawless report simply to sustain current momentum.

“Investor positioning is already stretched,” UBS analyst Tim Arcuri warned clients.

The week also brings earnings from Home Depot, Target, and Walmart, offering one of the clearest reads yet on the condition of the American consumer after months of inflation pressure, higher gasoline prices, elevated interest rates, and slowing labor-market momentum.

The Federal Reserve will add another layer Wednesday afternoon when it releases minutes from its final meeting chaired by Jerome Powell before incoming Fed Chair Kevin Warsh formally takes over.

Markets are entering the week caught between two competing realities.

On one side sits the AI boom, record equity valuations, and massive infrastructure investment tied to the next phase of technological expansion.

On the other sits a world of $108 oil, rising Treasury yields, escalating geopolitical tensions, and an economy increasingly feeling the pressure of higher borrowing costs.

By Friday, investors may have a much clearer sense of which force is beginning to matter more.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.