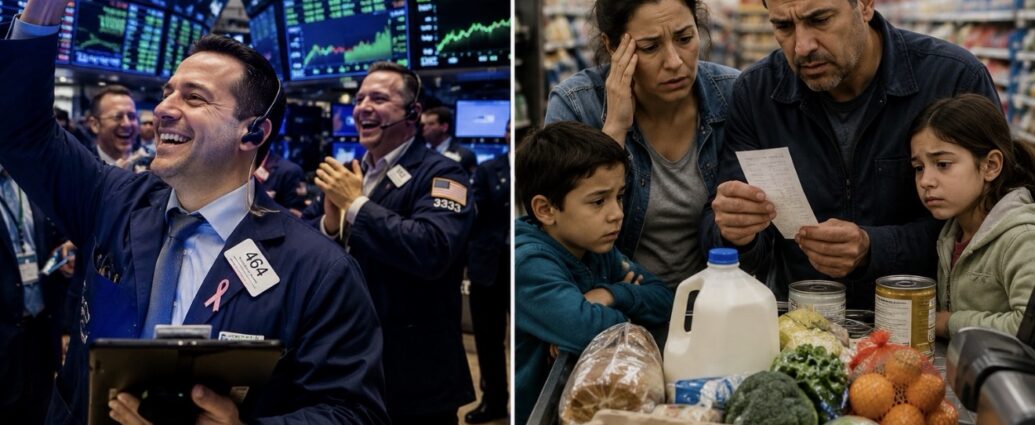
Lawmakers told the president to stop fighting Iran. The vote won’t end the war by itself — but it shows how much the war’s cost, from pricier gas to a falling stock market, is starting to bite.

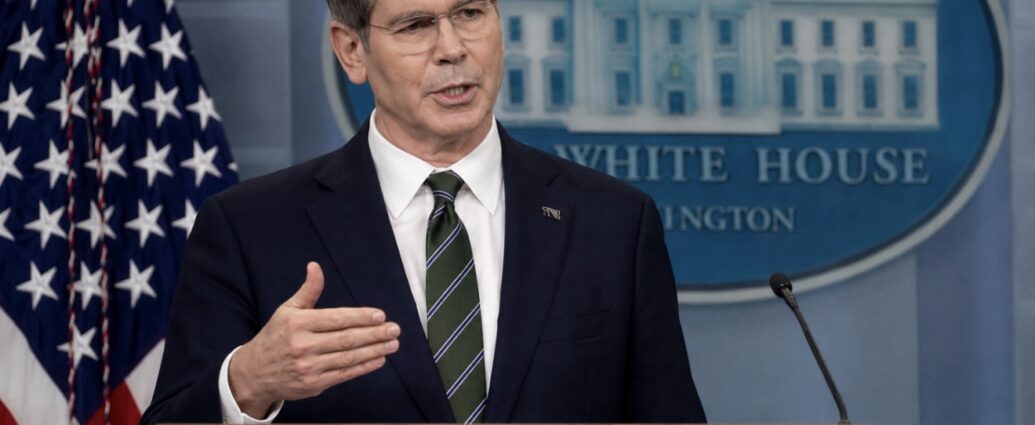
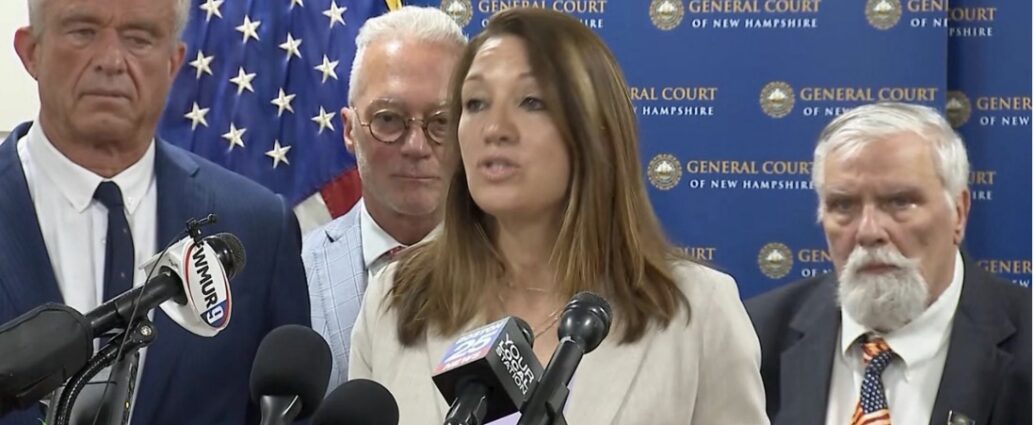
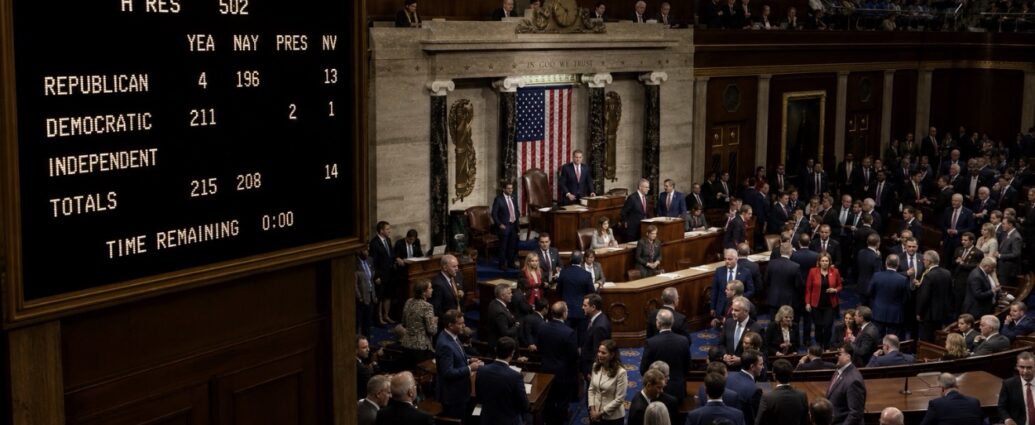
WASHINGTON, D.C.—For the first time since the Iran conflict began more than three months ago, Congress has formally voted to limit President Trump’s war powers. The House voted 215-208 on Wednesday to direct the administration to end U.S. military involvement in Iran unless Congress authorizes continued military action. The vote comes as the economic consequences of the conflict are increasingly being felt across the country, with oil prices approaching $100 a barrel, stock markets retreating from record highs, and inflation concerns resurfacing.

The House voted 215 to 208 to tell the president to stop the war with Iran. Four Republicans crossed over to join Democrats in passing the measure.

This kind of vote is called a War Powers Resolution. In plain terms, it is Congress reminding the president that, under the Constitution, only Congress is supposed to take the country to war. The resolution orders the president to pull U.S. troops out of Iran unless Congress votes to authorize continued military action.

So does this end the war?

Not by itself.

Here is why. The president can reject it — that is called a veto — and Trump is expected to do exactly that. To force him to comply anyway, Congress would need a two-thirds majority in both chambers, a much higher threshold known as a veto-proof majority. Lawmakers do not currently have those numbers, and the Senate has not yet passed its own version of the measure.

Then why does it matter?

Because it is rare.

This is the first time since the conflict began more than three months ago that either chamber of Congress has approved such a measure on a final vote. It also happened in a House controlled by Trump’s own party. When members of a president’s party break with him on a war vote, it is often viewed as a sign that concern about the conflict is spreading.

Much of that concern centers on the economy.

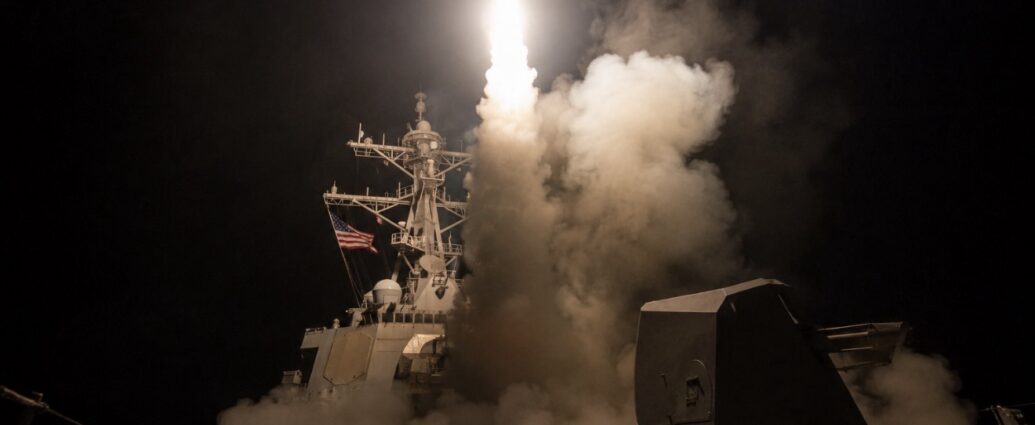
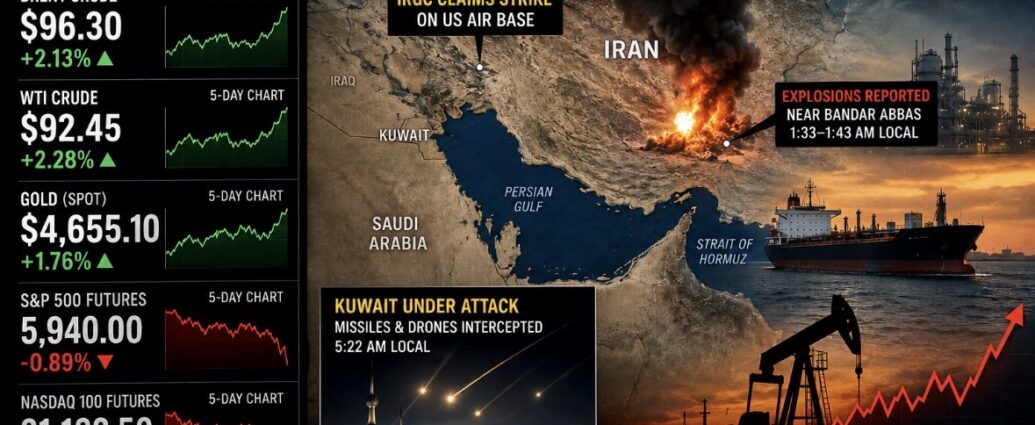
War in the Middle East has historically pushed oil prices higher, and Wednesday provided another example. Iran fired missiles at Kuwait and Bahrain, U.S. forces responded, and oil rose for a third consecutive day. Brent crude, one of the world’s key oil benchmarks, climbed toward $98 a barrel.

Why should that matter to the average family?

Because oil touches nearly everything.

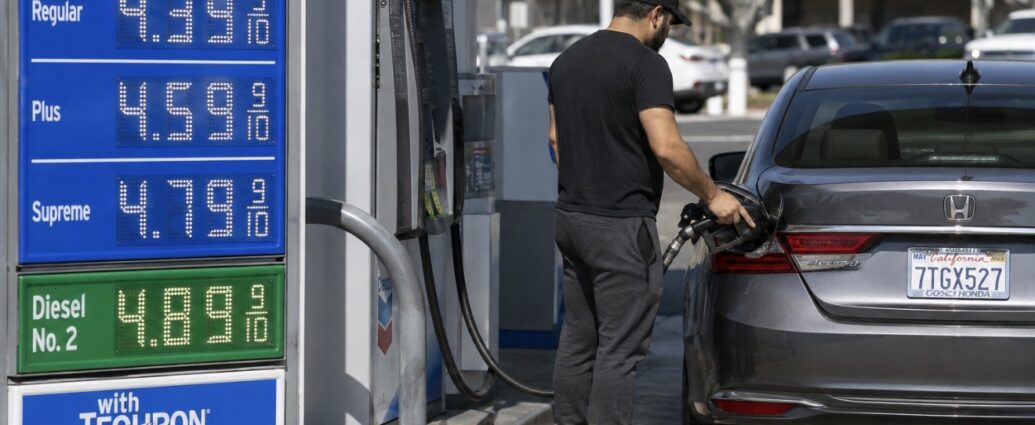
When oil becomes more expensive, gasoline becomes more expensive. The trucks, ships, and airplanes that move food and consumer goods also become more expensive to operate. Businesses often pass those higher costs along to consumers. As a result, groceries, deliveries, travel, and countless everyday products can become more expensive.

Economists call that process inflation.

The connection may seem distant, but history shows energy prices have a way of reaching nearly every household. Every major jump in oil prices eventually works its way through transportation, manufacturing, shipping, and utility costs. Even Americans who never follow foreign policy can end up feeling the effects of events unfolding thousands of miles away.

That ripple reached Wall Street on Wednesday.

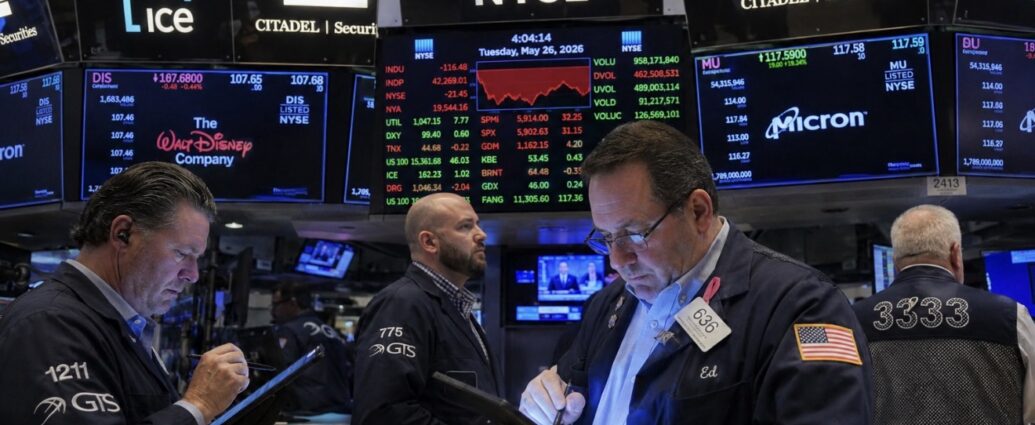
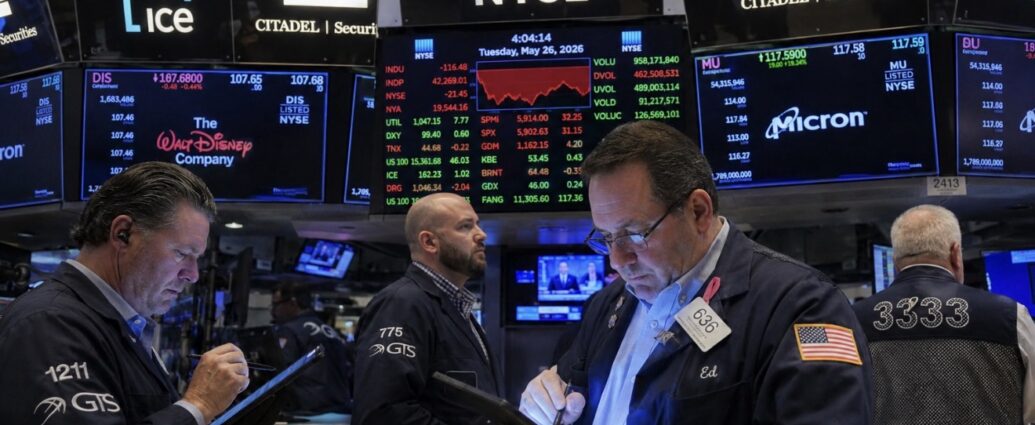
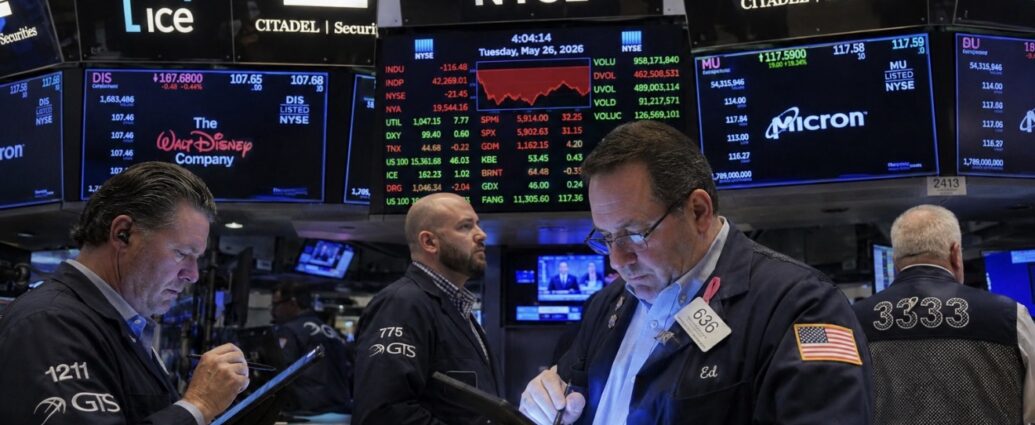
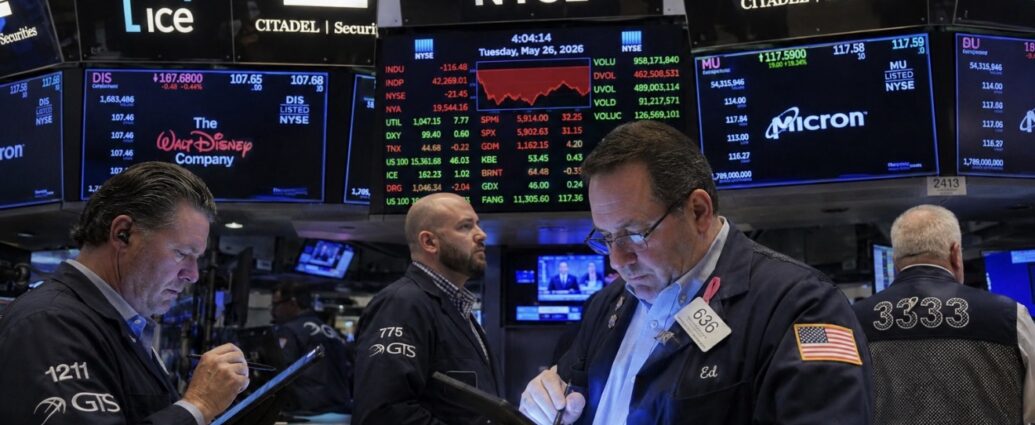
The three major U.S. stock market indexes all fell. The Dow Jones Industrial Average dropped 1.21%, the S&P 500 lost 0.73%, and the Nasdaq Composite slid 0.89%, just one day after all three reached record highs.

The war is also influencing expectations for interest rates.

The Federal Reserve, the nation’s central bank, raises or lowers interest rates to help control inflation and support economic growth. When inflation accelerates, the Fed often raises rates. Higher rates typically make mortgages, auto loans, business loans, and credit cards more expensive.

Only weeks ago, investors expected the Fed, under new Chairman Kevin Warsh, to cut rates later this year. Now, as oil prices climb and inflation concerns return, many traders believe the next move could be a rate increase instead.

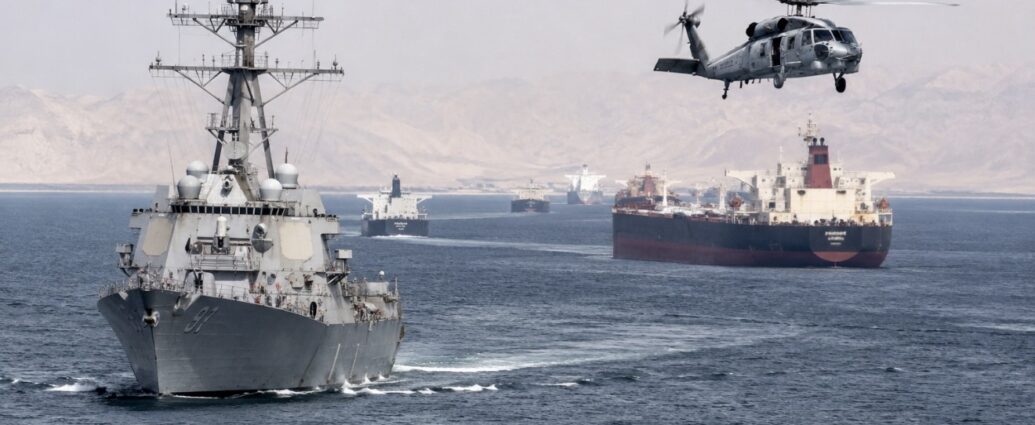
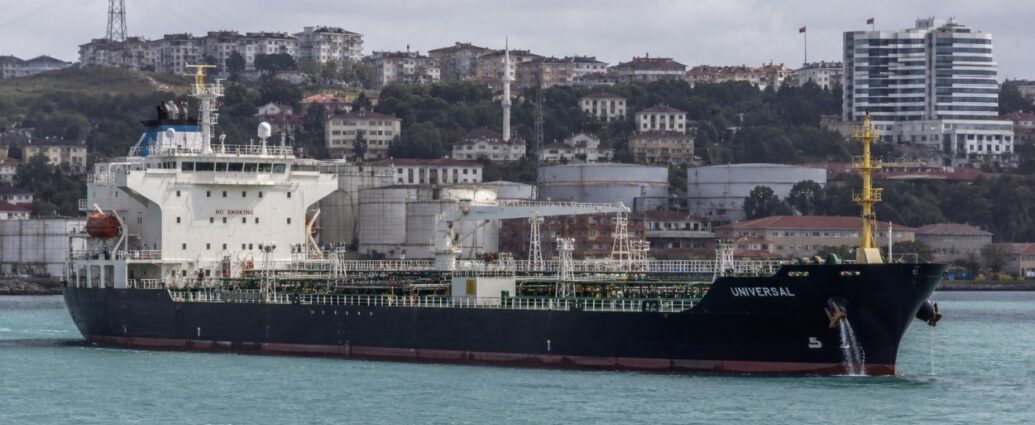
Much of that concern centers on one narrow stretch of water known as the Strait of Hormuz.

Roughly 20% of the world’s oil supply passes through the waterway each day. If shipping is disrupted—or even threatened—global oil prices can rise quickly. President Donald Trump has said a deal to keep the strait open could be reached within a week, though Iranian media outlets have expressed skepticism about the prospects for a near-term agreement.

Not everyone supported the House vote.

Most Republicans backed the president.

House Foreign Affairs Committee Chairman Brian Mast of Florida dismissed the measure as “a stupid political vote.”

Rep. Abe Hamadeh of Arizona argued that the conflict had effectively ended months ago.

“The war for all intents and purposes ended back in April,” Hamadeh said, adding that Trump should be allowed to continue negotiating a peace arrangement.

Supporters saw the issue differently. They argued that the conflict has dragged on, cost lives, increased economic uncertainty, and that Congress deserves a formal role in determining whether U.S. military involvement should continue.

Rep. Brian Fitzpatrick of Pennsylvania was among the four Republicans who joined Democrats in voting for the measure.

What happens now?

The battle shifts to the Senate, where a similar proposal led by Sen. Tim Kaine of Virginia has yet to receive a final vote. Even if both chambers ultimately approve the measure, Trump would still retain the power to veto it.

The bottom line for businesses and families is far simpler than the politics unfolding in Washington.

As long as fighting continues and oil remains elevated, gasoline prices, grocery costs, inflation expectations, and financial markets are likely to remain sensitive to every headline coming out of the Gulf.

Wednesday’s vote will not bring a single soldier home, nor is it likely to end the conflict on its own. But it delivered a clear message: as oil prices rise, markets react, and inflation fears return, the economic consequences of the war are becoming harder for lawmakers to ignore.

Whether Congress ultimately changes U.S. policy or not, the costs of the conflict are already being felt far beyond the battlefield—in gas stations, grocery stores, retirement accounts, and household budgets across America.

Washington, D.C. — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Subheadline:
David Solomon says investors are showing more greed than fear as OpenAI, Anthropic, and SpaceX prepare massive public offerings that could reshape Wall Street.

By JBizNews Desk

June 3, 2026

The head of Goldman Sachs says investors have tipped into outright greed.

Speaking Tuesday at an event hosted by the Economic Club of New York, Goldman Sachs CEO David Solomon was asked whether financial markets could absorb the enormous wave of stock offerings expected from artificial-intelligence companies. His answer was unusually direct.

“We are definitely in a moment where there’s more greed than there is fear.”

Solomon made the remarks during an interview with CNBC’s Leslie Picker, responding to questions about the growing pipeline of AI companies preparing to tap public markets.

The timing is significant. Some of the biggest names in technology — including OpenAI, Anthropic, and Elon Musk’s SpaceX — are preparing public offerings that could value individual companies at hundreds of billions, and potentially more than a trillion dollars. At the same time, dozens of AI-related businesses are seeking billions in fresh capital to build data centers, expand computing infrastructure, and purchase advanced semiconductor chips.

Wall Street Still Has Money to Spend

Solomon’s core message was simple: investors still have plenty of cash.

“There’s plenty of liquidity in the system if the world continues to remain as optimistic,” Solomon said.

In other words, the capital exists to fund these massive offerings — provided investor confidence remains intact.

As evidence, Solomon pointed to Alphabet’s recent $80 billion stock offering, one of the largest equity raises ever attempted. Despite concerns about dilution, Alphabet’s shares largely held up following the announcement.

Goldman Sachs served as an adviser on that transaction.

To Solomon, the market’s reaction suggests investors remain willing to finance enormous AI-related spending plans.

Goldman Stands to Benefit

The comments carry additional weight because Goldman is positioned at the center of the AI IPO boom.

The firm has reportedly secured the lead underwriting role for the highly anticipated SpaceX offering and is considered a leading candidate for future roles in potential OpenAI and Anthropic listings.

Following nearly $17 billion in profit last year, Goldman is poised to benefit substantially if the current IPO pipeline remains active.

Solomon himself appeared aware of how his comments might be received.

He joked during the discussion that he knew his use of the word “greed” would likely become the headline.

Why Solomon Thinks the Boom Can Continue

While acknowledging elevated enthusiasm, Solomon argued that today’s markets may still be early in the AI investment cycle.

He pointed to record levels of household and institutional wealth, suggesting that large stock offerings can be absorbed without draining investor demand elsewhere.

The proceeds from successful IPOs, he noted, tend to flow back into the economy through taxes, spending, venture investments, and new business creation.

“There’s a good chance that we’re earlier in the cycle than later,” Solomon said.

His advice to companies considering fundraising was equally straightforward:

When capital is available and a company needs it, raise it.

But the Mood Can Change Quickly

Despite the optimism, Solomon stopped short of sounding euphoric.

“Greed can turn into fear very quickly,” he warned, adding that while investor enthusiasm can last much longer than many people expect, it is never permanent.

That caution echoes remarks made recently by JPMorgan Chase CEO Jamie Dimon, who warned that market participants have become increasingly exuberant.

Neither executive predicted a crash.

Both simply observed that investor enthusiasm surrounding artificial intelligence has reached unusually elevated levels.

Why It Matters Beyond Wall Street

The stakes extend far beyond investment banks and technology companies.

The upcoming AI IPO wave could become one of the largest periods of capital formation in modern financial history.

The money raised will help fund:

  • Massive AI data centers
  • Advanced semiconductor purchases
  • New cloud-computing infrastructure
  • Artificial-intelligence research and development

These investments will directly influence the technologies consumers and businesses use every day.

If markets remain receptive, AI companies may secure the capital needed to accelerate development for years.

If investor sentiment shifts and fear replaces greed, the funding window could narrow rapidly.

The Bottom Line

David Solomon’s message was not that markets are irrational.

It was that investors remain highly willing to take risk, particularly when artificial intelligence is involved.

For now, the appetite appears strong enough to support some of the largest IPOs and stock offerings ever attempted.

Whether that optimism proves justified may become one of the defining financial stories of the AI era.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

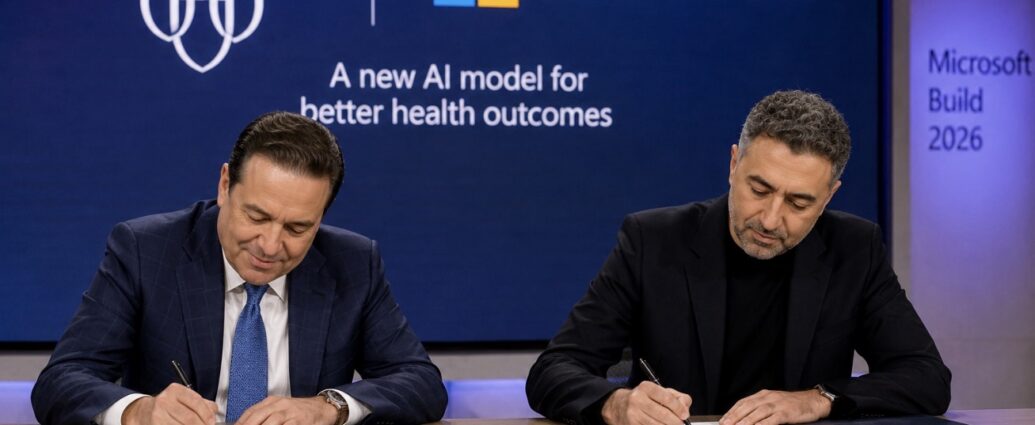
Mayo Clinic and Microsoft on Tuesday announced a partnership to build a new artificial-intelligence model trained specifically for healthcare using decades of medical records, clinical research, and physician expertise. The goal is ambitious: create a medical AI that can help patients better understand their conditions while helping doctors make more informed decisions.

The initiative was unveiled in a joint announcement timed to Microsoft’s Build 2026 developer conference and represents one of the most significant efforts yet to create an AI model built exclusively for medicine rather than the broader internet.

The project starts with a problem millions of Americans already face.

Patients once searched Google for symptoms and treatments. Today, many increasingly turn to AI chatbots for answers. The challenge is that most mainstream AI systems are trained on vast portions of the public internet, where medical information can be incomplete, outdated, contradictory, or simply wrong. Mayo Clinic itself has previously warned that health information generated by general-purpose AI systems can sometimes be inaccurate and potentially dangerous.

The solution, according to Mayo and Microsoft, is to train AI on better information.

Rather than relying on internet content, the new model will use Mayo Clinic’s de-identified patient data, medical research, and decades of clinical experience. The organizations believe that foundation can create a system capable of delivering healthcare guidance with a level of depth and accuracy not available from general-purpose consumer chatbots.

A key component of the partnership is ownership.

Mayo Clinic will own the completed AI model, a point the healthcare system emphasized as critical to ensuring responsible handling of patient information and maintaining control over how the technology is developed and deployed.

Microsoft plans to make the model available through its Azure AI Foundry platform, allowing hospitals, healthcare providers, researchers, and developers to build healthcare applications using the technology.

“Now, by combining our clinical expertise and data foundation with Microsoft’s engineering and AI capabilities, we are building something healthcare has never seen before,” said Dr. Gianrico Farrugia, President and CEO of Mayo Clinic.

Farrugia noted that Mayo launched its Mayo Clinic Platform seven years ago specifically to organize healthcare data and prepare for innovations such as this one.

For Microsoft, the project represents another major step in applying artificial intelligence to highly specialized industries.

“Frontier medical intelligence is around the corner,” said Mustafa Suleyman, Chief Executive Officer of Microsoft AI.

Suleyman described Mayo’s extensive clinical expertise and patient-care experience as the ideal foundation for creating a healthcare-focused AI model.

The project builds on earlier AI work already underway at Mayo Clinic. The healthcare system has developed tools that assist doctors in detecting heart disease and identifying pancreatic cancer. The new model aims to go much further by creating a broad medical foundation model capable of supporting multiple healthcare applications.

Potential uses include physician decision-support tools, patient-facing healthcare assistants, medical research applications, and clinical workflow systems.

Financial terms of the partnership were not disclosed.

Neither organization revealed how much they are investing in the initiative, although Suleyman described the relationship as a significant long-term commitment by both parties.

The business opportunity is substantial.

For Microsoft, every healthcare organization using the model becomes a potential Azure cloud customer, strengthening one of the company’s fastest-growing divisions.

For Mayo Clinic, ownership of the model creates the possibility of licensing its medical expertise and healthcare knowledge to organizations far beyond its own hospitals and clinics.

The partnership also places Mayo and Microsoft squarely in the middle of a rapidly expanding race among technology companies seeking to dominate healthcare AI.

Google has introduced AI-powered health coaching tools designed to help users review medical information and wellness data. OpenAI and Anthropic have also expanded healthcare-related capabilities within their AI systems.

The advantage Mayo brings is something difficult to replicate: decades of real-world clinical experience and patient care data generated through the treatment of some of the most complex medical cases in the world.

For patients, the promise is straightforward. Instead of relying on a general chatbot trained on internet content, they could eventually have access to a healthcare-specific AI capable of explaining diagnoses, medications, procedures, and treatment options using information grounded in clinical medicine.

For doctors, the technology could serve as an intelligent assistant capable of reviewing complex cases, surfacing relevant medical knowledge, and helping navigate difficult decisions.

The companies say the model will first be tested within Mayo Clinic’s own healthcare system before broader deployment.

Even so, both organizations acknowledge significant challenges remain.

Artificial-intelligence systems can still generate convincing but incorrect answers. In medicine, where decisions can directly affect patient outcomes, the stakes are far higher than in most other industries.

Questions surrounding privacy, accuracy, liability, transparency, and trust will remain central as the technology develops.

Building the system inside a controlled healthcare environment rather than releasing it immediately to the public is intended to address some of those concerns. Whether patients and physicians ultimately trust the technology enough to use it remains the larger question.

What is already clear is the direction of the industry.

As more people ask AI about symptoms, diagnoses, medications, and treatment options, healthcare providers increasingly want those answers coming from medical expertise rather than the open internet.

One of America’s most respected healthcare institutions and one of the world’s largest technology companies are now betting they can build that future together.

Rochester, Minn. — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — U.S. stocks dropped from record highs on Wednesday, June 3, 2026, after Iran fired ballistic missiles at Kuwait and Bahrain, reviving fears for Middle East energy supplies and pushing oil to a third straight day of gains. The Dow Jones Industrial Average fell 619.36 points, or 1.21%, to 50,688.43; the S&P 500 lost 0.73% to 7,554.37; and the Nasdaq Composite slid 0.89% to 26,853.98, each retreating a day after closing at all-time highs. Kuwait’s Foreign Ministry said the strike damaged infrastructure and killed at least one person, while U.S. Central Command said American forces hit Iran’s Qeshm Island and tankers bound for Iranian ports.

Oil did the damage. West Texas Intermediate crude rose about 2.7% to roughly $96 a barrel, and Brent crude climbed toward $98, extending a rally driven by the threat to Persian Gulf shipping. The U.S. Dollar Index gained 0.3% to 99.5 as investors reached for safety, the Cboe Volatility Index (VIX) rose toward 16, and gold slipped about 1.2% to roughly $4,468 an ounce as the firmer dollar weighed. The small-cap Russell 2000 was the day’s worst major gauge, down 1.25%, as higher energy costs hit economically sensitive names hardest.

The selloff reached into the bond market. The 10-year Treasury yield ticked up toward 4.45% as the oil spike kept inflation worries alive—and with them, the case for tighter policy. Under new Federal Reserve Chairman Kevin Warsh, who holds his first meeting this month, traders now price in roughly 17 basis points of rate increases by year-end, implying about a 70% chance of a quarter-point hike, with a full hike seen by March 2027. That marks a sharp reversal from the cuts markets expected before the war sent energy prices soaring, and it follows a late-May reading on the PCE Price Index that came in at its highest level in nearly three years.

The data did little to cool the inflation talk. The Labor Department reported Tuesday that job openings rose in April to 7.62 million, the highest since May 2024, a sign of still-firm labor demand. The Federal Reserve’s Beige Book, released Wednesday, said economic activity increased “a bit” in recent weeks while employment was little changed.

Software and cybersecurity stocks led the retreat into the close, several of them sliding ahead of earnings. CrowdStrike had slipped in recent sessions on worries its valuation left no room for error and on new competition after Google Cloud launched an AI threat-defense platform in late May.

After the bell, the company delivered anyway, posting adjusted earnings of $1.10 a share against the $0.88 analysts expected, a 25% beat. Wall Street had been raising the bar going in: JPMorgan analyst Brian Essex lifted his price target to $800 from $475 with an Overweight rating, Evercore ISI analyst Peter Levine raised his to $710 from $395, Benchmark analyst Yi Fu Lee went to $700 from $500 with a Buy rating, and Baird analyst Shrenik Kothari moved to $490 from $460 while maintaining a Neutral rating.

The bigger test for the market’s favorite trade came from chips. Broadcom reported revenue of about $22.19 billion, a hair under the roughly $22.27 billion Wall Street expected, with adjusted earnings of $2.44 a share topping the $2.40 estimate and AI-semiconductor revenue of $10.8 billion. The narrow top-line miss was a potential stressor for a chip sector that has been on a historic run.

Veeva Systems also reported after the close, as did a mix of names beyond tech—retailers Macy’s, PVH, and Petco, along with AI-software firm C3.ai—giving investors a read across consumer and enterprise spending.

Beneath the surface, the damage was broad. Communications, financials, and technology all finished lower, and only energy stocks drew real support as crude climbed. The session marked a pause in a remarkable stretch: the S&P 500 had set a record as recently as Tuesday, when it closed at 7,609.78, capping a month in which AI and semiconductor names carried the index to repeated highs.

The path from here runs through the Middle East. Israeli Prime Minister Benjamin Netanyahu said in a CNBC interview that Israel could strike Iran again, and U.S.-Iran ceasefire talks remained strained. President Donald Trump said a memorandum of understanding to reopen the Strait of Hormuz could be reached within a week, though Iranian media cast doubt on the progress of negotiations.

What to Watch Thursday

Wall Street opens Thursday, June 4, trying to steady itself, and futures will take their first cue from the results that just landed. Whether buyers treat Broadcom’s narrow revenue miss as a chance to add will set the tone for semiconductors, while CrowdStrike’s beat tests a stock that had run up sharply into the print.

The economic calendar centers again on jobs. Challenger, Gray & Christmas releases its monthly tally of announced layoffs in the early morning, and at 8:30 a.m. ET the Labor Department reports weekly initial jobless claims, forecast at about 211,000 against 215,000 the prior week, alongside a revised reading on nonfarm productivity. Federal Reserve Bank of San Francisco President Mary Daly speaks at 12:10 p.m. ET, and investors will parse her remarks for any signal on rate policy under Warsh. The earnings slate lightens, with names such as Ciena and a monthly sales update from Fastenal on tap.

Oil stays the swing factor, with any Strait of Hormuz headline able to move energy prices and the broader market in either direction. It all builds to Friday’s May Employment Report—the week’s marquee event, and a number that could harden the case for a Fed on hold, or tightening, if energy-driven inflation lingers. Until then, expect cautious trading: the claims data at the open, the chip reaction through the session, and the oil tape all day.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

Robinhood is letting artificial intelligence do something that until recently sounded like science fiction: shop with your credit card.

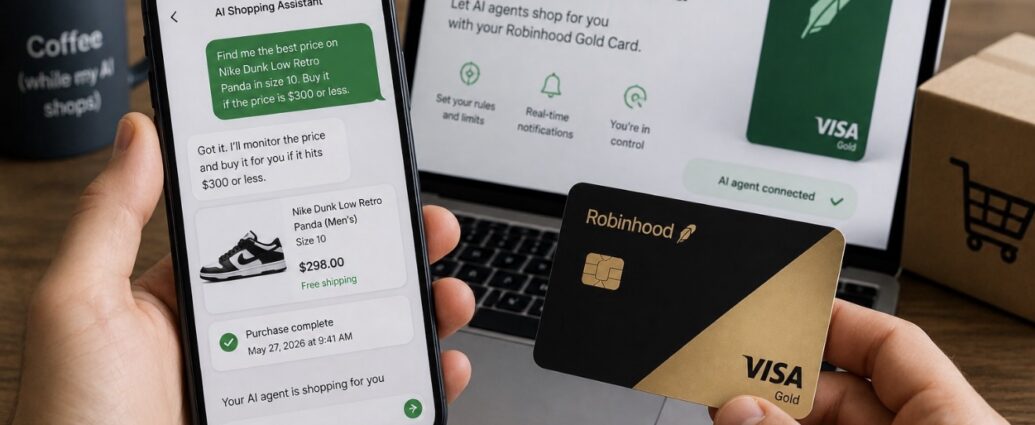
In a May 27 announcement posted to its company newsroom, Robinhood introduced its new Agentic Credit Card, a feature that allows customers to give third-party AI assistants the ability to make purchases on their behalf using a dedicated version of the company’s Robinhood Gold Card. The AI can monitor prices, track availability, and complete purchases automatically within spending rules set by the cardholder.

Vlad Tenev, Robinhood’s Chief Executive Officer, described the move as an extension of the company’s long-running mission to democratize finance, saying that mission now “extends to AI agents.”

The launch marks one of the clearest examples yet of artificial intelligence moving beyond providing recommendations and into actually spending money.

How the AI Shopping Card Works

The system is designed to work with outside AI assistants such as OpenAI’s ChatGPT and Anthropic’s Claude.

Customers connect an AI assistant to Robinhood through the Model Context Protocol, an emerging standard that allows AI systems to communicate directly with external services and applications.

Rather than giving an AI access to a customer’s actual credit card, Robinhood creates a separate virtual version of the Gold Card specifically for the AI agent.

The AI never sees the customer’s real card number and cannot access the broader account. It only receives access to the virtual card, its transaction history, and whatever spending limits and permissions the owner establishes.

The virtual card can also be revoked at any time.

Your AI Watches Prices and Buys Automatically

Once connected, the AI can act independently within the instructions provided by the user.

Robinhood’s examples include:

  • Buying a limited-edition sneaker if the price falls below $300
  • Reserving a hard-to-book restaurant table the moment one becomes available
  • Purchasing airline tickets when fares drop below a specific threshold
  • Monitoring product availability and completing purchases automatically

The goal is to eliminate the need for customers to constantly monitor prices or inventory themselves.

Purchases made through the system earn the same 3% cash back available through the Robinhood Gold Card.

The card is issued by Coastal Community Bank and operates on the Visa network.

The feature is currently available through a waitlist and requires a Robinhood Gold Card membership. Robinhood says support for its upcoming Platinum Card will follow later this year.

Built-In Controls

Robinhood says the product was designed around consumer controls and spending limits.

Users can:

  • Set monthly spending caps
  • Require approval for every purchase
  • Receive notifications before transactions are completed
  • Disable the AI card instantly

If a customer chooses not to approve each purchase individually, Robinhood requires that they establish spending limits instead.

The virtual-card structure resembles the tokenized payment systems already used by services such as Apple Pay, where merchants never receive the actual card number.

A Growing Industry Race

Robinhood is not alone.

The launch places the company near the front of a rapidly emerging market known as agentic commerce, where AI systems make purchases and transactions on behalf of users.

Stripe has introduced similar technology allowing AI agents to transact using designated payment credentials.

Both Visa and Mastercard are developing infrastructure specifically designed for AI-driven payments.

The announcement also comes just weeks after OpenAI introduced new personal-finance capabilities of its own, highlighting how quickly AI is moving deeper into everyday financial activity.

Investors have responded enthusiastically. Shares of Robinhood (NASDAQ: HOOD) have risen roughly 28% in recent sessions as Wall Street bets that AI-powered financial tools could drive greater engagement and spending on the platform.

The Biggest Question: Who Pays When AI Gets It Wrong?

That excitement is matched by growing concern among consumer advocates.

Robinhood makes clear that customers remain responsible for purchases made by their AI agents, even if those purchases ultimately prove to be mistakes.

That liability is drawing scrutiny.

Eva Velasquez, Chief Executive Officer of the Identity Theft Resource Center, warned that the technology remains too new for many consumers to fully understand the risks associated with connecting AI systems to financial accounts.

The Consumer Bankers Association echoed similar concerns in a January report, noting that agentic payments could reshape commerce but leave consumers exposed if an AI makes costly errors or unauthorized decisions.

The organization warned that regulatory protections have not yet caught up with the technology.

Americans Are Already Using AI for Money Decisions

Consumer behavior suggests growing comfort with AI-driven financial tools.

According to financial technology company Plaid, approximately 55% of Americans used AI to help manage money during the past year.

Many users already rely on AI for budgeting, financial planning, savings strategies, and spending analysis.

Robinhood’s new card pushes that trend further by moving from advice to action.

The shift raises a broader question for consumers: how much control are they willing to hand over to software?

The Bottom Line

Robinhood’s Agentic Credit Card represents one of the most ambitious attempts yet to put artificial intelligence directly between consumers and their wallets.

The technology promises convenience, automation, and the ability to act instantly when opportunities arise.

But it also introduces a new reality: when an AI assistant spends your money, you remain responsible for the outcome.

The technology may be new, but Robinhood’s position is straightforward.

If the AI buys the wrong thing, at the wrong time, for the wrong price, the bill still belongs to you.

Menlo Park, Calif. — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The investment increases Berkshire Hathaway’s exposure to artificial intelligence and signals how Warren Buffett’s successor may be willing to embrace technology more aggressively than Buffett did for much of his career.

By JBizNews Desk

June 3, 2026

Berkshire Hathaway, now led by Chief Executive Greg Abel, is investing another $10 billion into Alphabet, the parent company of Google, as part of the technology giant’s massive $80 billion capital raise to fund its artificial-intelligence expansion.

The investment, disclosed as Alphabet detailed the offering this week, lifts Berkshire’s total investment in Alphabet to approximately $26.6 billion and represents one of the largest technology bets ever made by the conglomerate.

The structure of the deal is significant. Berkshire purchased $5 billion of Alphabet’s Class A voting shares at an average price of approximately $351.81 per share, along with another $5 billion of Class C shares at roughly $348.20 per share through a private placement.

The investment forms part of Alphabet’s broader fundraising effort, which includes $40 billion through an at-the-market stock program, $30 billion in traditional public offerings, and Berkshire’s private placement.

The raise marks Alphabet’s first major straight equity offering since 2005 and is intended to help fund one of the largest AI infrastructure expansions ever attempted. Alphabet expects to spend between $180 billion and $190 billion on capital projects this year alone as it races to expand computing capacity, build data centers, and support growing demand for artificial-intelligence products.

A Growing Berkshire Position

The headline figure only tells part of the story.

Before the latest investment, Berkshire already held approximately $16.6 billion worth of Alphabet shares. The additional $10 billion brings Berkshire’s total capital invested in the company to roughly $26.6 billion.

Because Alphabet shares have appreciated significantly, Berkshire’s position is now worth more than $31 billion at current market prices, making Alphabet one of Berkshire’s largest holdings and, by some estimates, its fourth-largest equity investment.

A Different Style Under Greg Abel

The move stands out not just because of its size, but because of who is making it.

Greg Abel officially became Berkshire’s chief executive in January, with Warren Buffett remaining chairman while continuing to advise the company.

In just his first few months leading Berkshire, Abel has shown a greater willingness to deploy the company’s enormous cash reserves.

Berkshire ended the first quarter with nearly $380 billion in cash, a figure that had increasingly drawn criticism from shareholders who argued too much capital was sitting idle.

The Alphabet investment came just days after Berkshire announced its approximately $6.8 billion acquisition of Taylor Morrison Homes, meaning Abel committed nearly $17 billion in capital over a span of just two days.

What Warren Buffett Avoided

What makes the Alphabet investment particularly notable is how it contrasts with much of Warren Buffett’s investing career.

Buffett built Berkshire Hathaway through investments in businesses he viewed as predictable and easy to understand — insurance companies, railroads, utilities, banks, consumer brands, and industrial firms.

For decades, he largely avoided technology investments, arguing that rapid technological change made it difficult to forecast long-term winners.

That caution caused Berkshire to miss some of the most successful investments of the modern era.

Buffett later acknowledged that Berkshire’s decision not to invest early in Microsoft, Amazon, and Google cost shareholders substantial gains.

“That’s cost people a lot of money at Berkshire,” Buffett once admitted.

While Buffett eventually changed course with his enormously successful investment in Apple, even that position was often viewed through the lens of Apple’s consumer ecosystem rather than as a pure technology bet.

Why Abel Likes Alphabet

Abel appears willing to go further.

The Alphabet investment is not merely a bet on a technology company. It is a direct investment in one of the largest artificial-intelligence infrastructure expansions underway anywhere in the world.

From Berkshire’s perspective, however, Alphabet still possesses many of the characteristics Buffett traditionally admired.

Google continues to dominate global internet search, handling roughly 90% of worldwide search activity.

The company owns a collection of valuable businesses, including:

  • YouTube
  • Waymo
  • Google Cloud
  • Gemini AI
  • Custom AI-chip operations

Despite legal challenges surrounding its search and advertising dominance, Alphabet remains one of the world’s most profitable and cash-generating businesses.

At approximately 25.8 times forward earnings, many investors also view the stock as reasonably valued compared with other major AI beneficiaries.

The Risks Are Real

The investment is not without risk.

Abel is buying Alphabet near record highs at the same time the company is committing hundreds of billions of dollars to AI infrastructure.

Those investments could pressure profitability and free cash flow for years.

Investors also reacted cautiously to Alphabet’s capital raise itself, sending shares lower amid concerns about shareholder dilution.

The broader debate on Wall Street remains unresolved.

Supporters argue artificial intelligence will transform the global economy and justify today’s massive spending.

Skeptics question whether revenues and profits will ultimately support the extraordinary capital commitments currently being made.

The Bigger Picture

The Alphabet investment may ultimately be remembered for something larger than its dollar value.

It offers one of the clearest signs yet that the Greg Abel era could look different from the Warren Buffett era.

Buffett eventually embraced technology after initially resisting it.

Abel appears willing to embrace the technologies shaping the future much earlier.

The bet on Alphabet suggests Berkshire Hathaway is no longer merely investing in mature businesses that dominate their industries.

It is increasingly investing in the technologies that could define the next generation of industry leaders.

Whether that strategy proves successful will depend on the same question facing investors across the market today:

Will the hundreds of billions being poured into artificial intelligence ultimately generate the returns the world is expecting?

Omaha — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Millions of businesses will be automatically moved from Google’s traditional search-ad system to its new AI-powered platform, whether they choose to switch or not.

By JBizNews Desk

June 3, 2026

Google told advertisers in an April 15 post on its advertising blog that beginning in September it will automatically convert a wide swath of older Google Search ad campaigns to its new artificial-intelligence system, called AI Max — a shift that lands squarely on the small businesses and marketing agencies that have relied on those tools for years.

The change affects three advertising setups that millions of businesses still use today.

The largest is Dynamic Search Ads, a long-running Google tool that automatically builds search ads using content from a company’s website instead of relying entirely on manually selected keywords. The other two include Automatically Created Assets, where Google generates ad headlines and images, and campaign-wide Broad Match settings that allow ads to appear for a wider range of related searches.

Any eligible Search campaign still using these features in September will automatically be upgraded to AI Max.

What Is AI Max?

AI Max is Google’s next-generation AI-powered search advertising system.

Unlike Dynamic Search Ads, which primarily analyzed a company’s website to determine when ads should appear, AI Max combines website content with broader real-time search behavior and artificial intelligence models that can generate ad copy, select landing pages, and optimize campaigns with significantly less human involvement.

Google moved AI Max from testing into general availability in April and said hundreds of thousands of advertisers are already using the platform globally.

The Choice Disappears in September

Google is currently allowing advertisers to switch voluntarily.

Many businesses are already seeing prompts inside their Google Ads dashboards encouraging them to upgrade.

But beginning in September, the decision will no longer be optional.

Google says all remaining eligible campaigns will be automatically migrated, and businesses will no longer be able to create new Dynamic Search Ads through Google Ads, Google Ads Editor, or the company’s developer tools.

The company expects the migration process to be completed by the end of September.

Google Says Performance Improves

Google argues the transition should benefit advertisers.

According to company data, advertisers using the full AI Max feature set saw an average 7% increase in conversions or sales value while maintaining similar advertising costs.

The company says existing campaign settings will be copied into the new system to make the transition smoother.

However, Google noted that those performance figures primarily reflect non-retail advertisers. Businesses selling physical products are generally being directed toward separate AI-powered Shopping campaign products.

The Real Risk for Small Businesses

The biggest concern is not necessarily the technology itself.

It is businesses being caught unaware.

Marketing professionals who manage Google Ads accounts say AI Max behaves differently than the systems it replaces, even when existing settings are transferred over.

The platform gives Google greater control over:

  • Which searches trigger ads
  • How budgets are allocated
  • Which landing pages are used
  • How ad copy is written and optimized

That means campaign performance can shift unexpectedly during the system’s learning period.

For a small business spending only a few hundred or a few thousand dollars per month on advertising, unnoticed changes can quickly affect results.

Google’s Advice: Don’t Wait

Interestingly, Google’s own recommendation is for advertisers not to wait for the automatic transition.

The company urged businesses to switch on their own timetable so they can test campaigns, review performance, and make adjustments before September arrives.

That gives advertisers an opportunity to understand how AI Max behaves before Google makes the switch for them.

Part of a Much Bigger AI Strategy

The move fits into a broader transformation happening across Google’s advertising business.

Advertising remains the largest source of revenue for Alphabet, Google’s parent company.

At its recent Marketing Live event, Google outlined plans to integrate its Gemini AI technology across nearly every part of its advertising ecosystem, including placing ads directly into AI-generated search experiences.

The retirement of Dynamic Search Ads — a tool that has existed for more than a decade — is one of the clearest signals yet that Google intends to automate far more of the advertising process.

Increasingly, advertisers will set goals while Google’s AI makes many of the decisions.

What Businesses Should Do Now

For business owners, the message is straightforward.

The change is coming whether they act or not.

Businesses that review their campaigns before September will have time to understand the new system, test performance, and make adjustments.

Those that ignore the change may wake up this fall to discover that Google’s AI is managing a larger share of their advertising than they realized.

The transition marks another milestone in the broader shift from human-managed software toward AI-managed systems — a trend that is rapidly reshaping marketing, sales, customer service, and business operations across the economy.

Mountain View, Calif. — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
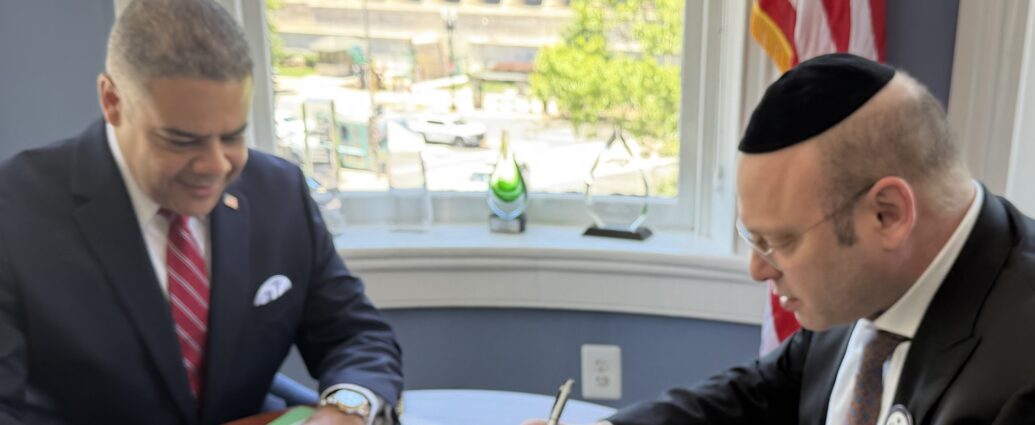
WASHINGTON, D.C. — June 3, 2026 — As businesses increasingly look beyond government contracting and toward Corporate America for growth, two organizations with roots in both the public and private sectors are joining forces to expand economic opportunity nationwide.

The National Minority Supplier Development Council (NMSDC), led by former Under Secretary of Commerce for Minority Business Development Donald Cravins Jr., and the Orthodox Jewish Chamber of Commerce signed a Memorandum of Understanding on Capitol Hill Wednesday aimed at strengthening connections between entrepreneurs, supplier networks, major corporations, chambers of commerce, and economic-development partners.

The agreement is the latest step in an effort that began at the U.S. Department of Commerce, where the Orthodox Jewish Chamber of Commerce signed a historic Memorandum of Understanding with the Minority Business Development Agency (MBDA). That agreement, which generated nationwide attention, established a framework for expanding economic opportunity, strategic partnerships, educational resources, and business growth across both the public and private sectors, while marking the first formal partnership of its kind between the U.S. Department of Commerce’s Minority Business Development Agency (MBDA) and a Jewish business organization.  

As part of the Chamber’s historic MOU with the U.S. Department of Commerce’s Minority Business Development Agency (MBDA), federal officials directed the Orthodox Jewish Chamber of Commerce to establish its own independent certification program to help advance the agreement’s broader goals of economic inclusion, business development, and expanded access to opportunities in the Public and Private sectors. The Chamber subsequently launched an inclusive Minority certification program for its Patron members backed by a rigorous vetting and due-diligence process, creating a pathway for qualified businesses to gain greater visibility and open doors that may have previously remained out of reach.  

Now, with Donald Cravins Jr.—who previously served as Under Secretary of Commerce for Minority Business Development and now leads the National Minority Supplier Development Council—heading one of the nation’s most influential supplier-development organizations, both groups see an opportunity to build upon that foundation and extend the MBDA commitment to help further its certied members reach into Corporate America.

The timing is significant. Business leaders estimate that roughly 70% of supplier-diversity and minority-business contracting opportunities originate within Corporate America, making private-sector engagement one of the most important drivers of growth for businesses seeking to scale nationally.

Founded in 1972, NMSDC is among the nation’s oldest and largest supplier-development organizations, connecting certified businesses with major corporations through a nationwide network of regional affiliates and corporate members. According to the council’s most recent economic impact report, NMSDC-certified minority business enterprises generated $599.7 billion in economic output and supported more than 2.2 million jobs in 2024.

The partnership is rooted in the belief that stronger collaboration creates stronger outcomes. NMSDC brings one of the nation’s most established supplier-development and corporate-engagement networks. The Orthodox Jewish Chamber of Commerce brings extensive experience in advocacy, public-private partnerships, economic-development initiatives, and coalition building across chambers of commerce, business organizations, government agencies, and economic-development stakeholders.

Leaders from both organizations view the relationship as highly complementary. While NMSDC focuses on supplier development, certification, and corporate engagement, the Chamber has developed a strong track record advocating for policies and initiatives that support businesses, employers, economic growth, innovation, and stronger economic participation throughout the United States.

By combining their respective strengths, networks, relationships, and expertise, both organizations believe they can help businesses identify new opportunities, strengthen supply chains, expand market access, build strategic partnerships, and contribute to stronger economic outcomes.

The collaboration is also intended to create value for Corporate America itself. By fostering stronger connections between corporations, suppliers, chambers of commerce, entrepreneurs, and community stakeholders, both organizations believe the partnership can help businesses become more competitive, strengthen procurement networks, improve access to talent and innovation, and ultimately support stronger bottom-line performance.

“This is a true partnership where both organizations bring meaningful value to the table,” said Duvi Honig, Founder and CEO of the Orthodox Jewish Chamber of Commerce. “NMSDC has built one of the most respected supplier-development and corporate-engagement networks in America. We bring advocacy, public-private partnerships, economic-development initiatives, and relationships throughout government, chambers of commerce, and the business community. Together we are stronger.”

Honig said the Chamber’s original partnership with MBDA was never intended to focus solely on government opportunities.

“The vision behind our Commerce Department partnership was always larger than government contracting alone,” Honig said. “It was about opening doors, creating opportunity, empowering businesses, and helping entrepreneurs access the relationships and resources they need to succeed across both the public and private sectors. This partnership with NMSDC strengthens that mission and expands it.”

Donald Cravins Jr., President and CEO of NMSDC, said the agreement reflects a shared commitment to expanding economic opportunity and helping businesses grow.

“Partnerships create scale and opportunity,” Cravins said. “When organizations with complementary strengths work together, businesses gain access to more relationships, more opportunities, and more resources to help them grow and succeed.”

For businesses in both networks, the partnership is expected to create greater exposure to new relationships, business-development opportunities, educational resources, supplier-engagement initiatives, conferences, advocacy efforts, workforce-development programs, and strategic partnerships. The organizations also expect to collaborate on initiatives helping businesses adapt to emerging technologies, including artificial intelligence.

The Chamber also credited Don Graves, former Deputy Secretary of the U.S. Department of Commerce, with helping foster relationships that contributed to the agreement and with supporting continued collaboration between business communities.

“We are grateful to Don Graves for his leadership and commitment to expanding economic opportunity,” Honig said. “His efforts helped lay the groundwork for partnerships that continue to create meaningful opportunities for businesses and communities across America.”

Supporters of the agreement say the Capitol Hill signing reflects a broader trend across the business community: organizations increasingly recognizing that in a more competitive economy, growth is often accelerated when networks are shared, relationships are expanded, and complementary strengths are aligned.

For both organizations, the signing represents a belief that economic growth is increasingly driven not by institutions working independently, but by partnerships that combine strengths, widen networks, strengthen Corporate America, and open doors neither side could open alone.

Washington, D.C. — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

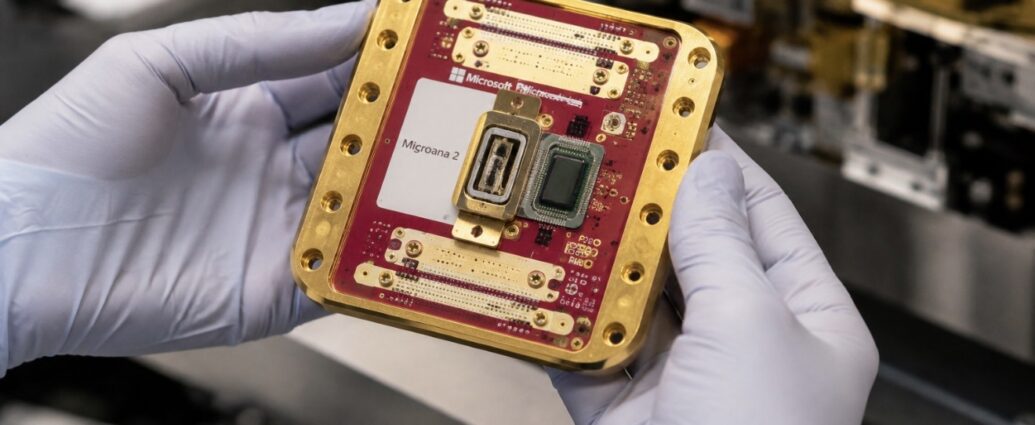
Microsoft unveiled its next-generation quantum computing chip, Majorana 2, on Tuesday at its Build developer conference in San Francisco and said the breakthrough could cut its timeline for a practical quantum computer in half — potentially bringing one to market as soon as 2029.

The company says the new chip delivers qubits that are 1,000 times more stable than those in the previous generation, a leap that Chetan Nayak, Microsoft’s Technical Fellow and Corporate Vice President of Quantum Hardware, described as a critical step toward building a commercially useful quantum computer.

If Microsoft is right, the announcement could represent one of the most important advances in computing since the birth of artificial intelligence. If critics are right, it may be another promising quantum milestone that remains years away from proving itself in the real world.

The Problem Quantum Computing Has Always Faced

Quantum computers operate using qubits, the quantum equivalent of the 1s and 0s used in traditional computers.

Unlike ordinary bits, qubits can exist in multiple states simultaneously, giving quantum systems the potential to solve certain problems dramatically faster than today’s most powerful supercomputers.

The challenge is stability.

Qubits are notoriously fragile and can lose their quantum state in fractions of a second, creating errors that must be constantly corrected.

Microsoft says Majorana 2 dramatically improves that problem.

According to the company, the new chip maintains qubit stability for an average of approximately 20 seconds, with some lasting nearly a full minute. Microsoft’s earlier generation reportedly held stability for less than 12 milliseconds.

To illustrate the difference, company researchers compared the improvement to a smartphone battery that lasts nearly three years on a single charge instead of dying after one day.

A New Material Formula

The breakthrough comes from a redesign of the chip’s physical structure.

Microsoft replaced the aluminum used in earlier versions with lead and redesigned the semiconductor layer using specialized indium arsenide compounds.

According to the company, the new materials better protect qubits from environmental interference, including cosmic radiation and microscopic disturbances that can destroy quantum states.

The new chip contains 12 qubits, up from eight in the previous generation, and performs operations in approximately one microsecond on hardware measuring roughly one-hundredth of a millimeter.

AI Helped Build the Chip

Perhaps the most notable aspect of the announcement is how Microsoft says the chip was developed.

The company revealed that its own artificial intelligence systems played a major role in designing the materials used inside Majorana 2.

Using Microsoft Discovery, an AI-driven scientific research platform, autonomous software agents helped researchers evaluate materials and accelerate development.

Agentic AI has permeated almost everything we do,” Nayak said during the presentation.

Microsoft simultaneously announced that Discovery is becoming broadly available through Azure and GitHub Copilot, signaling that the company sees AI-assisted scientific discovery as a major business opportunity beyond its internal research efforts.

The Business Opportunity Is Enormous

The convergence of AI and quantum computing represents one of the largest long-term technology bets being made anywhere in the world.

Microsoft’s vision is straightforward:

Better AI helps build better quantum computers.

Better quantum computers eventually help build better AI.

The potential applications stretch across industries:

  • Drug discovery
  • New materials development
  • Energy optimization
  • Financial modeling
  • Cybersecurity
  • Advanced manufacturing

A practical quantum computer could potentially model molecular interactions impossible for today’s computers, dramatically accelerating pharmaceutical research and materials science.

It could also eventually challenge many of today’s encryption systems, a possibility that has governments, banks, and intelligence agencies investing heavily in quantum research.

Not Everyone Is Convinced

Despite Microsoft’s confidence, the announcement was met with substantial skepticism from portions of the scientific community.

The company’s approach relies on a highly specialized quantum architecture known as topological quantum computing, built around elusive particles called Majorana modes.

The field has a complicated history.

Previous claims involving Majorana-based systems have faced criticism, and some high-profile research papers in the field were later retracted.

Several physicists say Microsoft’s latest announcement does not fully resolve long-standing questions.

Nothing in this preprint resolves the fundamental issues,” said Henry Legg, a physicist at the University of St Andrews in Scotland.

Other researchers have argued that Microsoft has yet to conclusively demonstrate that its underlying device operates exactly as claimed.

The debate highlights one of the persistent challenges in quantum computing: outside researchers often struggle to independently verify breakthrough claims.

The Race Is Intensifying

Regardless of the controversy, the broader quantum race is accelerating.

Microsoft is competing against:

  • Google
  • IBM
  • Numerous quantum startups
  • State-backed research efforts in China and Europe

All are pursuing different technical approaches toward the same goal: a practical, fault-tolerant quantum computer.

The financial stakes are immense.

Microsoft currently carries a market value of roughly $3.28 trillion, while industry analysts increasingly view quantum computing as a future market potentially worth hundreds of billions—or even trillions—of dollars.

What Happens Next

The significance of Majorana 2 ultimately depends on whether Microsoft’s approach scales beyond the laboratory.

If the company can continue improving stability and dramatically increase qubit counts, a commercially useful quantum machine by the end of the decade becomes more plausible.

If the underlying physics proves less robust than Microsoft believes, the timeline could slip years beyond the company’s current projections.

For now, one thing is clear:

The race to build the world’s first practical quantum computer has entered a new phase, and Microsoft is betting that artificial intelligence can help it get there first.

San Francisco — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3. 2026

Amazon is moving one of the biggest shopping events of the year.

The company announced Monday that Prime Day 2026 will run from June 23 through June 26, shifting the annual sales event out of its traditional July slot for the first time since 2021.

The four-day promotion will feature discounts across more than 35 product categories, including electronics, apparel, home goods, beauty products, kitchen equipment, and Amazon-branded devices.

Early deals are already live through Amazon’s website and mobile app.

Why Amazon Changed the Date

The decision comes down to timing.

Jamil Ghani, Vice President of Amazon Prime International, told Reuters that the company wanted to avoid competing with two major events dominating the summer calendar:

  • The 2026 FIFA World Cup, running from June 11 through July 19
  • The 250th anniversary of American Independence celebrations surrounding July 4

Late June offered the clearest opportunity to capture consumer attention before both events intensified.

A Test of Consumer Spending

The timing carries extra significance this year.

American consumers remain cautious as higher fuel prices and persistent inflation continue weighing on household budgets.

According to the Conference Board, consumer confidence has softened in recent months as families become more selective about discretionary purchases.

For Amazon, Prime Day represents an opportunity to pull spending forward and convince shoppers to open their wallets earlier in the summer.

Analysts Expect Another Big Year

Early forecasts suggest the strategy may work.

Sky Canaves, principal analyst at Emarketer, projects Amazon’s U.S. sales will rise approximately 7.1% during the four-day event.

That would outpace the estimated 6.0% growth expected for the broader U.S. online retail market during the same period.

Emarketer also expects Amazon’s share of all U.S. e-commerce activity during Prime Day to reach approximately 60.3%, its highest level since 2019.

The Real Goal: Prime Memberships

The discounts grab headlines.

The memberships generate profits.

Amazon’s Prime subscription currently costs $14.99 per month or $139 annually, and Prime Day remains one of the company’s most effective tools for attracting and retaining members.

Prime subscribers typically spend significantly more on Amazon throughout the year than non-members.

A discounted television, laptop, or kitchen appliance may generate a one-time sale, but a recurring membership creates ongoing revenue.

Amazon’s Full Ecosystem Is Involved

The company is deploying its entire ecosystem to drive participation.

Prime members receive additional discounts at Whole Foods Market, including an extra 10% off sale items both online and in stores.

Amazon is also offering a sweepstakes with $1 million in total prizes, including free groceries for a year for eligible members who place qualifying online grocery orders.

Meanwhile, discounts on Amazon’s own products — including Echo speakers, Kindles, and Fire TV devices — are designed to deepen customer engagement and increase reliance on Amazon services.

Retail Rivals Must Adjust

The move is likely to force competitors into action.

Retailers such as Walmart, Target, and Best Buy have increasingly launched competing sales events during Prime Day periods.

An earlier Prime Day means rivals may need to accelerate their own promotional calendars.

The shift also affects thousands of third-party sellers who rely on Prime Day as one of the most important sales windows of the year.

For many small and medium-sized businesses operating through Amazon’s marketplace, the event can generate a substantial portion of annual revenue.

A Potential Bonus for Tech Shoppers

There may be another reason consumers pay attention this year.

Several electronics retailers have warned that prices on technology products could rise later in 2026 as higher semiconductor and memory-chip costs move through supply chains.

That means shoppers considering purchases such as:

  • Laptops
  • Smartphones
  • Tablets
  • Gaming consoles
  • Smart-home devices

may find June discounts particularly attractive before potential price increases arrive.

The Bottom Line

Amazon has moved one of the biggest retail events of the year several weeks earlier, hoping to avoid competing with the World Cup and July 4 celebrations while capturing consumer spending before summer distractions take hold.

For shoppers, the message remains the same as every year:

The deals are temporary.

The membership is the real product.

Seattle — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — The summer travel season is revealing one of the clearest signs yet that America’s economy is increasingly splitting into two very different experiences.

For higher-income households, summer 2026 looks much like previous years: vacations are booked, flights are full, hotels are busy, and travel spending remains strong.

For many lower-income families, however, summer travel is simply not happening.

A new analysis from the Bank of America Institute shows that nearly four in ten households earning $66,000 or less annually expect to have no summer travel plans at all this year. At the same time, spending among middle- and higher-income households continues to increase.

The contrast highlights what economists often describe as a K-shaped economy—one in which different groups experience the same economic conditions in dramatically different ways.

For lower-income households, the explanation is straightforward.

Rising costs for necessities are crowding out discretionary spending.

According to Bank of America data, travel-related spending among lower-income consumers has declined year over year as families redirect money toward groceries, gasoline, housing, utilities, and other essential expenses.

Vacation budgets are often the first casualty.

When food, transportation, and household costs consume a larger share of income, optional purchases become increasingly difficult to justify. A flight, hotel stay, or family getaway may simply no longer fit within the budget.

The decline in savings is making matters worse.

The U.S. personal savings rate has fallen to approximately 3.6%, one of the lowest levels in recent years. Many households are using savings or credit cards to bridge the gap between income and expenses, leaving little available for travel.

For higher-income households, the picture is entirely different.

Families earning more than approximately $66,000 annually, and particularly those above $130,000, continue spending aggressively on vacations despite higher airfare, hotel rates, and travel costs.

The same economic pressures affecting lower-income families exist, but they represent a smaller share of overall household income.

A more expensive airline ticket may be frustrating.

It is not necessarily a barrier.

That difference is reshaping the travel industry itself.

Airlines, hotels, resorts, cruise operators, and travel companies are increasingly targeting premium travelers who remain willing to spend despite higher prices. Loyalty programs, premium seating options, upgraded experiences, and luxury offerings continue expanding as companies pursue higher-margin customers.

Meanwhile, many budget-conscious travelers are being priced out.

Over time, that shift could fundamentally alter how travel companies design products, set prices, and market services.

The implications extend beyond tourism.

Vacations have traditionally represented more than leisure spending. They have been one of the ways middle-class families enjoy the benefits of economic growth, spend time together, and invest in experiences beyond basic necessities.

When a growing segment of the population can no longer afford even a modest trip, it raises broader questions about how widely economic gains are being shared.

National averages often obscure the divide.

Travel surveys may show overall spending increasing, but those figures frequently reflect stronger spending among higher-income households rather than broad participation across the population.

The result is an economy where two realities coexist.

One group is booking vacations.

The other is staying home.

Both experiences are real. Both are happening simultaneously.

And together they offer one of the clearest illustrations of how uneven the economic recovery has become.

For millions of Americans, the summer of 2026 will not be defined by where they traveled.

It will be defined by the trip they could no longer afford to take.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Accusation escalates an already contentious battle over a proposed $111 billion media merger that has drawn scrutiny from Hollywood, labor groups, and antitrust regulators.

By JBizNews Desk

June 3, 2026

The battle over the proposed $111 billion merger between Paramount Skydance and Warner Bros. Discovery took a dramatic turn this week after the deal’s top attorney accused some opponents of being motivated by antisemitism.

In an interview published June 1 by the Los Angeles Times, Makan Delrahim, chief legal counsel for Paramount Skydance, said some critics of the merger are driven by “their own antisemitic views” and argued that parts of the opposition campaign have become political rather than focused on competition concerns.

The remarks immediately elevated what had largely been an antitrust and media-consolidation debate into a far more politically and culturally charged confrontation.

Notably, Delrahim did not publicly identify specific individuals or organizations he believes hold such views, nor did he provide evidence supporting the allegation. Paramount also did not immediately clarify whom he was referring to.

A Merger Facing Growing Resistance

Opposition to the transaction has been building for months.

More than 5,500 filmmakers, actors, producers, writers, and entertainment professionals have signed public letters opposing the merger.

The Writers Guild of America has vowed to challenge the deal, arguing that further consolidation in Hollywood could reduce competition, weaken worker bargaining power, and limit creative diversity.

Several Democratic lawmakers have also called for heightened scrutiny.

Senator Elizabeth Warren previously described the proposed merger as a “five-alarm antitrust fire,” while members of Congress have urged regulators to closely examine the transaction’s impact on competition across media, streaming, and news businesses.

Most opponents have focused their arguments on antitrust concerns, market concentration, employment impacts, and media ownership rather than the issues raised by Delrahim.

Why the Israel Issue Entered the Debate

The comments come against the backdrop of broader tensions within Hollywood over Israel and the Middle East.

Larry Ellison, father of Paramount CEO David Ellison and one of the transaction’s key financial backers, has long maintained close ties with Israel and has reportedly supported organizations connected to Israeli causes.

Following the October 7 attacks, Skydance publicly expressed support for Israel and contributed to Israeli humanitarian and emergency-response organizations.

Paramount also became one of the first major entertainment companies to publicly oppose efforts by certain activist groups to boycott cooperation with Israeli film institutions.

Supporters of those campaigns have argued they target institutions rather than individual Israelis, while critics have characterized some efforts as discriminatory.

Against that backdrop, Delrahim’s comments are likely to intensify an already polarized debate.

The Business Stakes Are Massive

Beyond the controversy, the financial implications are enormous.

A combined Paramount-Warner Bros. Discovery would create one of the largest media companies in the world.

The merger would unite:

  • CBS
  • Paramount Pictures
  • Warner Bros. Studios
  • CNN
  • HBO
  • Max
  • Numerous cable and streaming assets

Supporters argue the combination is necessary to compete against increasingly dominant streaming rivals such as Netflix, Amazon Prime Video, and Disney+.

Delrahim has repeatedly argued that the merger would strengthen competition rather than reduce it by creating a larger challenger capable of competing in a rapidly consolidating entertainment landscape.

Shares of Warner Bros. Discovery have risen more than 24% since reports of the merger discussions first emerged.

Regulators Hold the Final Say

The deal’s future ultimately rests with regulators.

Although Paramount has stated that the transaction has already cleared certain procedural hurdles at the Department of Justice, federal authorities retain the power to challenge the merger if they conclude it harms competition.

The DOJ’s antitrust leadership has publicly stated that the transaction will not receive special treatment despite the Ellison family’s relationships within political circles.

Delrahim has rejected suggestions that the company enjoys political advantages and insists the merger can withstand regulatory review on its merits.

Who Is Makan Delrahim?

Delrahim brings unusual credibility to the antitrust debate.

Before joining Paramount Skydance in 2025, he served as Assistant Attorney General for the Antitrust Division of the U.S. Department of Justice during President Trump’s first administration.

He later became a partner at Latham & Watkins, where he advised on major corporate transactions before joining Paramount.

Today, he serves as the chief legal architect defending one of the largest media mergers in modern history.

What Happens Next

The merger will ultimately be judged by regulators based on competition law, consumer impact, and market structure—not political rhetoric.

Still, Delrahim’s comments ensure that a transaction already attracting intense scrutiny will now face even greater public attention.

The core question remains unchanged:

Will combining two of Hollywood’s largest media companies strengthen competition against streaming giants—or further concentrate power in an industry already dominated by a handful of players?

Regulators in Washington and California will ultimately decide.

Los Angeles — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

Americans hoping for relief at the grocery store may have to keep waiting.

The U.S. Department of Agriculture’s Economic Research Service raised its food inflation forecast in its latest Food Price Outlook, warning that food costs are expected to climb faster in 2026 than officials projected just weeks ago.

The USDA now expects overall food prices to rise 3.4% in 2026, up from its previous forecast of 2.9%. Grocery prices — what the government classifies as “food at home” — are projected to increase 3.2%, placing both measures above their 20-year historical averages.

The agency noted that its grocery inflation outlook is now the highest since it began publishing forecasts for 2026 last summer.

In practical terms, shoppers who expected inflation to ease significantly this year are unlikely to see much relief.

Beef Leads the Surge

The largest contributor to rising grocery costs remains beef.

Retail beef and veal prices increased 3.1% from March to April alone and were 14.8% higher than a year earlier. The USDA now expects beef prices to rise 12.1% for the full year, one of the largest annual increases in decades.

The problem starts on the ranch.

Years of drought conditions forced many cattle producers to reduce herd sizes as feed costs surged. Rebuilding the nation’s cattle inventory takes years, leaving supplies tight even as consumer demand remains resilient.

Until herd sizes recover, beef prices are expected to remain elevated.

Vegetables Join the Inflation List

Fresh produce is also becoming more expensive.

Fresh vegetable prices rose 3.1% in April and were 11.5% higher than a year ago. Tomatoes have become one of the most visible examples, with prices nearly 40% higher than last spring.

The USDA also expects above-average price increases in:

  • Fish and seafood
  • Sugar and sweets
  • Nonalcoholic beverages
  • Coffee products

Coffee prices in particular continue to face pressure from global supply constraints and weather-related disruptions.

One Major Category Is Getting Cheaper

There is one bright spot.

Egg prices, which reached record highs during the bird-flu crisis of 2025, have fallen sharply.

According to the USDA, egg prices were already 39.2% lower in April than a year earlier, and officials expect prices to decline 29.8% for the full year — the largest annual drop recorded since the agency began tracking the data in 1974.

Dairy products and fats and oils are also expected to experience modest price declines.

Consumers Change Shopping Habits

The impact on households is increasingly visible.

Grocery prices were 2.9% higher in April than a year earlier, while the 0.7% month-over-month increase represented one of the sharpest monthly jumps since 2022.

For many families, there is little room left to cut spending.

As a result, discount retailers are benefiting.

Dollar General recently raised its full-year profit forecast and reported customer traffic growth of 1.4% during the latest quarter as shoppers sought lower-cost alternatives.

Costco has also continued posting strong sales as consumers increasingly buy in bulk to stretch grocery budgets.

Restaurants are facing pressure as well. The USDA expects restaurant prices to rise approximately 3.5% this year, leading some diners to reduce visits and prompting several chains to close underperforming locations.

Pressure Across the Supply Chain

The inflationary effects extend beyond consumers.

Limited cattle supplies are increasing costs for meat processors such as Tyson Foods, wholesalers, and grocery chains.

Retailers including Walmart and Kroger face the challenge of keeping prices competitive while protecting profit margins.

Store-brand products and private-label offerings are becoming increasingly important as shoppers search for savings.

Risks Remain

The USDA forecast assumes relatively stable conditions going forward.

Several risks could push prices even higher, including:

  • Additional drought conditions
  • New bird-flu outbreaks
  • Rising fuel costs
  • New tariffs
  • Supply-chain disruptions

For now, consumers looking to save money are likely to find the best values in eggs, dairy products, and chicken, while beef and fresh vegetables remain among the most expensive items in the cart.

The bottom line: food inflation has slowed from its pandemic-era peaks, but it has not disappeared. For many families, grocery bills are still moving in the wrong direction.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

For many small-business owners, finding grant money can feel like a full-time job. Applications are time-consuming, funding opportunities are scattered across dozens of websites, and many entrepreneurs simply don’t have the staff to track deadlines, research eligibility requirements, and prepare submissions.

Google says artificial intelligence may help change that.

The company announced a new initiative with the U.S. Small Business Administration (SBA) designed to help entrepreneurs learn how to use AI tools to identify grant opportunities, prepare stronger applications, improve marketing, and operate more efficiently. The program was unveiled during National Small Business Week as part of Google’s broader push to bring artificial intelligence into the hands of Main Street businesses.

At the center of the effort are free workshops jointly offered by Google and the SBA, along with additional training resources that remain available year-round. The goal is to help small-business owners understand how AI can reduce administrative work and uncover opportunities that many businesses may otherwise miss.

For grant seekers, the practical applications are significant. AI tools can help business owners research federal, state, local, nonprofit, and private-sector grant programs, summarize eligibility requirements, organize application materials, track deadlines, draft proposal language, and identify supporting documentation needed for submissions. What once required hours of manual searching can often be completed in minutes.

Google is also steering entrepreneurs toward its broader small-business learning programs, including a dedicated training path through Google Cloud and its AI Professional Certificate program, which includes three months of access to Google’s paid Gemini AI assistant at no cost.

The training is part of a larger effort to encourage small businesses to adopt Google’s expanding suite of AI-powered products.

Among the featured offerings is the Gemini Enterprise app, which allows businesses to build and deploy AI-powered assistants that can automate repetitive tasks, analyze information, summarize meetings, draft communications, and assist with planning. Gemini is also integrated throughout Google Workspace, including Gmail, Docs, Sheets, and Drive.

For many small businesses, that means the ability to perform tasks that previously required additional staff or outside consultants.

Google is also promoting AI-powered creative tools designed for businesses with limited marketing budgets. The company highlighted products that can generate professional-looking images, flyers, social-media content, and marketing materials in minutes, allowing smaller companies to present themselves with the polish of much larger organizations.

To encourage adoption, Google is offering limited-time incentives, including discounted Workspace subscriptions and a free 30-day trial of Gemini Enterprise.

The grant-focused training arrives at a time when many small businesses are searching for new sources of capital. Higher borrowing costs, tighter lending standards, and economic uncertainty have made grant funding increasingly attractive because, unlike loans, grants typically do not require repayment.

For business owners with limited resources, learning how AI can help locate and organize funding opportunities may prove just as valuable as the software itself.

The initiative also highlights the growing competition among major technology companies to become the primary AI provider for America’s roughly 36 million small businesses. Google is competing directly with Microsoft, OpenAI, and other technology firms that are racing to embed AI into the daily operations of businesses across the country.

Whoever becomes the platform entrepreneurs rely on for grant applications, customer communications, marketing, bookkeeping, and research could gain a long-term advantage in one of the largest business markets in the world.

Still, experts caution that technology is only a tool. Finding grants is one thing; winning them requires strong applications, clear business plans, and the ability to demonstrate impact. AI can help simplify the process, but it does not replace the judgment and preparation required to secure funding.

For now, the most immediate benefit may be the free education itself.

The workshops cost nothing, the training resources remain available, and business owners can begin learning how to use AI before committing to any paid products.

The takeaway for entrepreneurs is straightforward: grant opportunities exist, but many businesses never find them. Google and the SBA are betting that artificial intelligence can help change that — giving small-business owners another tool to compete for funding, grow their operations, and save valuable time along the way.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

South Korea’s stock market has already delivered the kind of gains most investors would expect over a decade. Goldman Sachs says the rally may still be far from over.

The investment bank raised its 12-month target for South Korea’s benchmark KOSPI Index to 12,000 in a research note published Wednesday in Seoul, implying more than 35% upside from Tuesday’s record close. The call keeps Korea as Goldman’s highest-conviction equity market anywhere in Asia and comes after a run that has already made it the best-performing major stock market in the world this year.

That Tuesday close was historic in its own right. The KOSPI finished at 8,801.49, its third consecutive all-time high, after briefly surging within roughly 66 points of the never-before-seen 9,000 level before profit-taking pulled the market lower. The index has now gained approximately 100% in 2026, a performance that leaves even the strongest U.S. benchmarks trailing far behind. Neither the S&P 500 nor the Nasdaq Composite has come close to matching Korea’s advance.

The explanation starts with one word: AI.

At the center of the rally sit two companies — Samsung Electronics and SK Hynix — which dominate the global market for high-bandwidth memory, or HBM. These advanced chips are essential components inside the artificial-intelligence servers powering data centers around the world. As companies race to build AI infrastructure, demand for HBM chips has exploded, pushing prices higher and creating a windfall for the Korean firms that supply them.

Investor enthusiasm accelerated again Tuesday after reports that Samsung Electronics became the first company in the industry to ship samples of its next-generation HBM4E memory chips. Samsung shares climbed 3.3%, while SK Hynix, after a massive rally of its own, finished little changed.

The market’s dependence on those two companies is extraordinary. According to JPMorgan, memory-chip stocks now represent roughly half of the KOSPI’s total weighting and account for approximately 70% of the market’s gains this year. When Samsung and SK Hynix rise, the entire Korean market tends to follow.

Goldman’s optimism rests on earnings growth that would be extraordinary even by historical standards. Strategists led by Timothy Moe, Goldman’s Chief Asia-Pacific Equity Strategist, project Korean corporate profits will surge approximately 300% during 2026. The firm described it as the strongest annual earnings expansion seen in any Asian market since the region recovered from the 1997-98 Asian Financial Crisis.

Earnings are driving Asian equity returns,” Moe wrote, reiterating Korea as Goldman’s top regional investment idea.

Wall Street is increasingly competing to keep pace with the rally. JPMorgan recently raised its bull-case target for the KOSPI to 10,000, while Citigroup has also upgraded its outlook. In several cases, analysts have found themselves revising targets upward almost immediately after the market surpassed their previous forecasts. Goldman itself was targeting 9,000 only weeks ago.

The surge has transformed South Korea’s standing in global finance. According to Bloomberg data, the country has overtaken India to become the world’s sixth-largest stock market, with total market capitalization climbing approximately 86% this year to about $5.04 trillion.

Government policy has helped support the advance. Seoul’s “Value-Up” initiative encourages publicly traded companies to improve shareholder returns, increase transparency, and boost corporate governance. The Korea Exchange says more than 700 companies have already submitted value-enhancement plans under the program.

Economic fundamentals have also strengthened. South Korean exports reached a record $87.8 billion in May, fueled largely by booming semiconductor shipments. Those figures provide tangible support for a market increasingly driven by expectations surrounding artificial intelligence.

The AI connection extends directly to the United States. Nvidia Chief Executive Jensen Huang recently met with SK Group Chairman Chey Tae-won to discuss deeper cooperation in advanced memory technology, highlighting the central role Korean suppliers play in powering the global AI boom.

Still, not everyone is convinced the rally can continue indefinitely.

Volatility has increased sharply. Tuesday alone saw a swing of more than 430 points, as foreign investors sold a net 6.6 trillion won worth of Korean stocks while domestic institutions stepped in to buy. Local commentators have increasingly drawn comparisons to previous speculative periods, including the 1999 dot-com boom and the years surrounding the 1997 Asian Financial Crisis.

The Korean currency has offered another note of caution. The won weakened to approximately 1,516 per U.S. dollar, suggesting the stock-market boom is not necessarily translating into strength across the broader economy.

For global investors, however, the story remains straightforward.

The Korean rally is fundamentally a bet on artificial intelligence. As long as demand for AI computing power continues to grow, and as long as Samsung Electronics and SK Hynix remain indispensable suppliers of advanced memory chips, the momentum behind the market could continue.

If that thesis proves correct, Goldman’s 12,000 target may not look so aggressive after all.

If it proves wrong, a market that has already doubled in a single year could face a difficult reckoning.

Seoul — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Research firm says Elon Musk’s space giant has extraordinary strengths, but investors may be paying too much for future AI and satellite growth before it is proven.

By JBizNews Desk

June 3, 2026

As SpaceX prepares for what could become one of the largest and most closely watched stock-market debuts in history, Morningstar is already warning investors that the excitement may be outrunning the fundamentals.

The investment research firm initiated coverage of SpaceX on Tuesday with a fair-value estimate of $780 billion, dramatically below the roughly $1.75 trillion valuation the company is reportedly targeting for its upcoming Nasdaq debut.

The call makes Morningstar one of the first major Wall Street voices openly questioning whether investors are getting carried away by the combination of Elon Musk, artificial intelligence, and one of the world’s most dominant aerospace companies.

“We think the company has been significantly overvalued,” Morningstar analyst Nicolas Owens wrote, arguing that investors may find better entry points after the stock begins trading publicly.

SpaceX is expected to begin its investor roadshow on June 4, with shares scheduled to start trading on June 12.

Where Morningstar Sees Value

Importantly, Morningstar is not bearish on SpaceX’s business.

Quite the opposite.

The firm credits SpaceX with building one of the strongest competitive positions in modern industrial history.

According to Morningstar, SpaceX accounted for approximately 83% of all payload mass launched into orbit worldwide during 2025, a remarkable level of dominance.

Its reusable rocket technology has dramatically lowered launch costs, helping establish barriers that competitors continue struggling to overcome.

The company’s Starlink satellite-internet business also continues to grow rapidly.

Morningstar estimates Starlink generated approximately $11.3 billion in revenue during 2025, up roughly 50% from the prior year, while producing more than $4.4 billion in operating income.

Taken together, Morningstar values SpaceX’s launch business and Starlink operations at approximately $611 billion.

The AI Question

The biggest disagreement centers on artificial intelligence.

Much of the valuation premium being attached to SpaceX today stems from investor expectations surrounding xAI, Musk’s artificial-intelligence company, and its integration with the broader SpaceX ecosystem.

Morningstar remains cautious.

The firm argues that while xAI’s Grok chatbot has gained visibility, it does not currently occupy the same leadership position as competitors such as OpenAI or Anthropic.

Owens also questioned some of the more ambitious AI-related projects being discussed around the company, including concepts involving orbital computing infrastructure and space-based data centers.

Morningstar modeled several possible outcomes.

Its most optimistic scenario values those initiatives at more than $1.3 trillion, but the firm assigns only a 7% probability to that outcome.

By contrast, Morningstar believes a much less successful scenario is considerably more likely.

Governance Concerns

The report also highlighted corporate-governance issues that some institutional investors may scrutinize.

Following the IPO, Elon Musk is expected to retain approximately 85% of voting power through a special share structure.

Morningstar also pointed to the recent integration of xAI and other Musk-controlled businesses into the broader SpaceX ecosystem, noting that transactions between related entities can sometimes create concerns among public shareholders.

While none of those issues are unusual for founder-led technology companies, they remain factors that investors often consider when assigning valuation premiums.

Why the IPO Could Still Surge

Even Morningstar acknowledges the stock could perform strongly after listing.

SpaceX is reportedly expected to sell only about 3% of its shares to the public, creating a scarcity dynamic that often supports newly public stocks.

The offering could raise between $50 billion and $80 billion, making it one of the largest public offerings ever attempted.

The deal is being led by a powerful syndicate of banks including:

  • Goldman Sachs
  • Morgan Stanley
  • Bank of America Securities
  • Citigroup
  • J.P. Morgan

Analysts also expect SpaceX to become eligible for major stock indexes relatively quickly, potentially creating additional demand from index funds and institutional investors.

Musk’s Counterargument

Elon Musk, unsurprisingly, sees the future differently.

Posting on X Tuesday morning, Musk pointed to Tesla’s history as evidence that investors frequently underestimate the long-term value of his companies.

“Tesla IPO market cap was 0.1% of its current value,” Musk wrote.

The message was clear: today’s valuation may look expensive only if investors underestimate tomorrow’s opportunity.

The Bigger Picture

The debate surrounding SpaceX reflects a broader question facing today’s market.

How much should investors pay today for future AI-driven growth that has not yet fully materialized?

Few dispute that SpaceX possesses extraordinary assets: dominant launch economics, a rapidly expanding satellite network, and one of the most recognized brands in technology and aerospace.

Morningstar’s argument is not that SpaceX lacks value.

It is that investors may be assigning too much value to possibilities that remain years away from becoming reality.

That debate will soon move from analyst reports to the stock market itself.

When SpaceX begins trading on June 12, investors will decide whether the company is worth closer to Morningstar’s $780 billion estimate—or something much closer to the $1.75 trillion valuation Elon Musk is seeking.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

Elon Musk’s SpaceX starts pitching investors Thursday, June 4, the opening act of a Nasdaq debut targeted for June 12 — a timeline grounded in the S-1 prospectus the company filed with the Securities and Exchange Commission on May 20. The stock will trade under the ticker SPCX, with final pricing set for June 11, and by nearly any yardstick it would be the largest market debut in history.

The scale is difficult to comprehend. SpaceX is seeking to raise as much as $75 billion at a target valuation of approximately $1.75 trillion, a figure that would make it the most valuable company ever to go public on a U.S. exchange and shatter previous IPO records. For comparison, Alibaba’s 2014 listing raised $21.8 billion, still the largest U.S. IPO on record.

The valuation itself has shifted over recent months, with some reports pointing as high as $2 trillion before expectations settled closer to the current target range.

But the number captivating Wall Street is not the size of the raise.

It is what the offering could do to the net worth of one man.

The Trillion-Dollar Question

The math remains surprisingly unsettled.

The Bloomberg Billionaires Index most recently estimated Musk’s fortune at approximately $722 billion, already making him the richest person in the world by a wide margin.

The IPO could push him into territory no individual has ever reached.

If SpaceX achieves and maintains a valuation above roughly $1.7 trillion, analysts estimate it could effectively confirm a $1 trillion personal fortune for Musk.

Some observers argue he may already be there.

Using recent private-market transactions, Barron’s estimated the value of Musk’s roughly 6.4 billion SpaceX shares at approximately $830 billion. Combined with his holdings in Tesla, that analysis placed his net worth near $1.1 trillion.

The reason those estimates vary so dramatically is simple: most of Musk’s wealth has never been assigned a public market price.

A public offering changes that.

For the first time, investors around the world will collectively determine what SpaceX is worth.

That is why June 12 matters.

Wall Street’s Biggest Names Are Behind It

The underwriting syndicate includes many of the largest banks in the world.

Goldman Sachs leads the offering alongside:

  • Morgan Stanley
  • Bank of America
  • Citigroup
  • JPMorgan Chase

and approximately 18 additional financial institutions.

The size of the syndicate reflects both the scale of the transaction and the enormous investor interest expected during the roadshow process.

The Business Behind the Hype

The excitement surrounding the IPO has overshadowed a less discussed reality.

SpaceX remains a company with substantial losses despite extraordinary revenue growth.

According to the company’s SEC filing, SpaceX generated $18.674 billion in revenue during 2025, an increase of approximately 33% from $14.1 billion in 2024.

Yet profitability moved in the opposite direction.

After reporting $791 million in net income during 2024, SpaceX posted a $4.9 billion net loss in 2025 as it accelerated spending on Starship, artificial intelligence initiatives, and the integration of xAI.

The company reported an operating loss of approximately $2.589 billion, while adjusted EBITDA reached $6.584 billion.

Starlink Is Carrying the Business

The strongest performer inside the company remains Starlink.

SpaceX’s satellite-internet division generated approximately $11.387 billion in revenue during 2025 and produced roughly $4.423 billion in operating income.

Subscriber growth also remained impressive, reaching approximately 10.3 million users by the end of March.

Those profits, however, were largely offset elsewhere.

The company’s space-launch segment recorded an operating loss of approximately $657 million, while the AI segment generated an operating loss exceeding $6.36 billion.

Debt and Valuation Concerns

The filing also highlights a growing debt burden.

SpaceX carries approximately $29.1 billion in total debt, including a $20 billion bridge loan used to retire legacy debt associated with xAI.

That loan must be repaid within six months after the IPO closes, meaning a portion of the proceeds will immediately go toward debt reduction rather than future growth projects.

For skeptics, valuation remains the central issue.

At the proposed valuation, SpaceX would trade at more than 96 times annual sales, compared with roughly 15.7 times sales for Tesla.

Critics argue that first-quarter revenue growth of approximately 15% does not justify such a premium.

Supporters counter that SpaceX occupies unique positions in satellite communications, launch services, artificial intelligence, and advanced aerospace technology.

Public Investors Won’t Control the Company

One thing will not change after the IPO.

Elon Musk will remain firmly in control.

The filing states that Musk controls approximately 85% of voting power through special Class B shares, which carry enhanced voting rights.

That structure gives him effective control over board elections and major corporate decisions.

Public shareholders will participate in the company’s financial performance, but not its governance.

A Rare Opportunity for Retail Investors

The company is also taking an unusual approach to individual investors.

According to comments by Chief Financial Officer Bret Johnsen, SpaceX intends to allocate a substantial portion of shares to retail buyers.

Johnsen reportedly told bankers that retail participation could become “a bigger part than any IPO in history.”

If that occurs, it would mark a significant departure from many high-profile technology offerings that primarily favor institutional investors.

What Happens Next

The next ten days will determine whether the most ambitious valuation in modern IPO history holds up under market scrutiny.

The roadshow begins June 4.

Pricing is scheduled for June 11.

Trading is expected to begin June 12.

At that point, speculation ends and the market takes over.

Investors will decide what a company built around rockets, satellites, artificial intelligence, and one of the world’s most famous entrepreneurs is truly worth.

And in the process, they may determine whether Elon Musk becomes the first trillionaire in history.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Bank regulators say supervision should focus on measurable financial risks—not whether a customer or industry might generate negative headlines.

By JBizNews Desk

June 3, 2026

Federal banking regulators have taken a major step toward ending one of the most controversial concepts in bank supervision, removing references to “reputation risk” from guidance used to examine the nation’s banks.

On Tuesday, the Federal Reserve, Federal Deposit Insurance Corporation (FDIC), and Office of the Comptroller of the Currency (OCC) jointly announced they had reissued 15 interagency guidance documents with all references to reputation risk removed. Regulators also said they will continue reviewing additional supervisory materials to eliminate the concept from their rulebooks.

For businesses that have struggled to obtain banking services—or feared losing them—the move could have significant implications.

What Is Reputation Risk?

For years, federal regulators defined reputation risk as the possibility that negative publicity surrounding a customer, industry, or business activity could harm a bank’s earnings, customer relationships, or legal standing.

In practice, critics argued that the concept allowed regulators to pressure banks away from serving certain lawful industries or customers, even when those relationships posed no measurable financial risk.

Industries frequently raising concerns included:

  • Cryptocurrency companies
  • Firearms businesses
  • Energy and fossil-fuel firms
  • Cannabis-related businesses
  • Certain religious organizations
  • Politically active individuals and organizations

Supporters of the change say those concerns evolved into what became widely known as “debanking”—the termination or denial of banking services based on perceived reputational concerns rather than objective financial risk.

Trump Administration Push

The effort traces directly to President Donald Trump’s Executive Order 14331, signed on August 7, 2025, titled “Guaranteeing Fair Banking for All Americans.”

The order directed federal banking agencies to prevent reputation risk from being used as a basis for limiting access to financial services.

Regulators subsequently began dismantling the practice.

The OCC stopped examining banks for reputation risk during 2025. The Federal Reserve announced similar changes later that year.

In April 2026, the OCC and FDIC finalized rules formally prohibiting regulators from criticizing or taking supervisory action against banks solely because of reputation-risk concerns. Those rules become effective on June 9, 2026.

Tuesday’s announcement represents the latest step in that process.

What Regulators Are Saying

Michelle W. Bowman, Vice Chair for Supervision at the Federal Reserve, said concerns emerged that reputation-risk standards had been used inappropriately to pressure banks into dropping customers.

She argued that supervisory decisions should not be influenced by political, religious, or other non-financial considerations.

Comptroller of the Currency Jonathan V. Gould was even more direct, stating that reputation risk is “not a sound basis for supervision.”

FDIC Chairman Travis Hill similarly argued that focusing on reputational concerns outside traditional risk-management frameworks contributes little to maintaining a safe and sound banking system.

What Is Not Changing

Regulators emphasized that this is not a rollback of core banking safeguards.

Banks must still comply with:

  • Anti-money laundering requirements
  • Sanctions screening rules
  • Consumer-protection laws
  • Safety-and-soundness regulations
  • Fraud prevention requirements
  • Credit-risk and operational-risk management standards

The agencies also included provisions designed to prevent examiners from simply relabeling reputation concerns under other supervisory categories.

In short, regulators say banks can still reject customers based on measurable risks—but not merely because a relationship could generate controversy or bad press.

What It Means for Businesses

The practical impact could be substantial.

Banks may now have greater flexibility to serve industries that have historically complained of restricted access to financial services.

For businesses operating in sectors such as cryptocurrency, energy, firearms, and other politically sensitive industries, the removal of reputation risk could make it easier to maintain banking relationships.

Compliance departments inside banks will still assess risk, but the focus is expected to shift more heavily toward objective financial metrics rather than public perception.

The Bigger Debate

Supporters view the change as restoring equal access to banking services and preventing regulators from using informal pressure to shape economic activity.

Critics argue that reputation risk gave banks a legitimate tool to avoid problematic relationships before they became financial or legal liabilities.

What both sides agree on is that a long-standing and often misunderstood supervisory tool is disappearing from federal banking oversight.

What Happens Next

The ultimate test will be whether complaints about debanking decline over the coming months and years.

If businesses that previously struggled to obtain banking services gain broader access without increasing financial-system risks, supporters will point to the reforms as a success.

For now, federal regulators are sending a clear message:

Banks should be judged on financial risk, not on whether a customer, business, or industry might create negative headlines.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

Wednesday, June 3, 2026

Wall Street opened in mixed fashion Wednesday, June 3, after two fresh reads on the economy showed steady hiring and a strengthening service sector, even as oil pushed back toward $100 a barrel following an overnight exchange of fire between the United States and Iran. The ADP National Employment Report, released Wednesday, said private employers added 122,000 jobs in May, topping the 117,000 economists expected, while the Institute for Supply Management reported its Services PMI rose to 54.5% from 53.6% a month earlier, the 23rd straight month of growth, according to committee chair Steve Miller. At the opening bell, the S&P 500 slipped 0.14% and the Dow Jones Industrial Average fell 0.56%, while the Nasdaq was virtually flat and the small-cap Russell 2000 rose 0.90%. The moves came a day after all three major indexes closed at records, with the S&P 500 posting its first finish above 7,600 at 7,609.78.

The data carried a catch for anyone hoping for lower interest rates. The same ISM report that showed services expanding also put its prices gauge at 71.3%, near a multi-year high, a sign that companies are still paying more for fuel, materials and labor and passing those costs along. The employment piece of that survey stayed below 50, meaning service businesses are still trimming staff even as orders pick up. April’s ADP gain, meanwhile, was revised down to 105,000.

Energy set the tense backdrop. Brent crude climbed toward $97 a barrel and West Texas Intermediate rose above $93, both gaining for a third straight session, after U.S. Central Command said Iran fired ballistic missiles toward neighboring states and U.S. forces carried out strikes on Iran’s Qeshm Island. Iran’s missiles hit Kuwait and Bahrain, killing one person in Kuwait, according to Kuwait’s Foreign Ministry. Adding fuel, the U.S. Energy Information Administration reported Wednesday that domestic crude inventories fell by 7.974 million barrels last week, far more than the roughly 2.9 million-barrel draw forecast and the sixth straight weekly decline. President Donald Trump said Iran had agreed not to pursue a nuclear weapon and that talks continue, though Iranian state media disputed that.

The day’s hardest hits landed on the private-equity group. Blackstone dropped about 6%, KKR fell more than 5.5% and Blue Owl Capital lost nearly 4% after Bloomberg News reported that Swiss firm Partners Group had capped withdrawals from one of its private-equity funds, a move that rattled investors holding similar managers. GitLab fell roughly 4% after the software maker guided to adjusted earnings of 17 to 18 cents a share, below the 19 cents analysts expected, and flagged $30 million to $35 million in restructuring charges. Palo Alto Networks slipped about 2% even after beating, posting adjusted earnings of 85 cents a share on $3 billion in revenue, ahead of the 80 cents and $2.94 billion expected, and lifting its full-year revenue forecast.

The chip trade still had momentum. Marvell Technology rose more than 13%, building on a 32% surge Tuesday that ranked as its best day ever after Nvidia Chief Executive Jensen Huang suggested the company could one day reach a trillion-dollar valuation. In retail, Macy’s gained about 1.5% after reporting its strongest first-quarter sales growth in four years, with revenue of $4.68 billion beating the $4.61 billion estimate and a raised full-year outlook. Cboe Global Markets rose about 1.5%, steadying after a three-day slide of nearly 20% tied to worries that newly proposed perpetual futures could eat into traditional exchanges. Ulta Beauty dipped about 1% despite a quarterly beat and a bigger $1.5 billion buyback target.

On the analyst side, Loop Capital raised Hewlett Packard Enterprise to Buy from Hold after Tuesday’s blowout quarter, in which cloud and AI revenue climbed 22.9% from a year earlier and the stock jumped about 26%. Upgrade activity this month has clustered in chip and AI infrastructure names, while several previously cautious analysts have warmed to Intel after a sharp run higher.

The day is not over. Broadcom and CrowdStrike are scheduled to report results after the closing bell, two readings that will test whether the AI-spending boom still has room to run. The bigger event comes Friday, when the Labor Department releases the May jobs report, the broadest look yet at whether hiring is holding up as oil prices climb. Beyond that, new Federal Reserve Chair Kevin Warsh holds his first rate-setting meeting on June 16–17, with markets caught between a growing economy and a war that keeps pushing energy costs higher.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

The biggest obstacle facing many recent college graduates may not be artificial intelligence after all.

According to a study published June 1 by the Federal Reserve Bank of New York on its Liberty Street Economics blog, the rise of remote work—not AI—is the primary driver behind higher unemployment among young college graduates.

The research was conducted by Natalia Emanuel of the New York Fed alongside Emma Harrington of the University of Virginia and Amanda Pallais of Harvard University.

The numbers are striking.

The unemployment rate for recent college graduates rose to 5.6% in March 2026, up from 3.6% in March 2019, before the pandemic transformed workplace norms.

The researchers estimate that approximately 64% of that increase can be attributed to work-from-home trends.

Their conclusion centers on training rather than technology.

When employees work remotely, companies become less willing to hire inexperienced workers who require mentoring and supervision. Teaching new graduates through video calls and virtual meetings is simply harder than training them in person.

As the researchers wrote, “Remote work has weakened incentives to hire young workers by impeding on-the-job training.”

The result is a growing preference for more experienced workers who can operate independently with minimal oversight.

The evidence becomes clearer when comparing different professions.

The researchers examined occupations that can be performed remotely—such as software engineering, accounting, finance, and consulting—against occupations that require physical presence, including nursing and mechanical engineering.

In fields requiring hands-on work, youth employment has largely returned to pre-pandemic norms.

Nursing, in particular, remains one of the strongest hiring sectors.

The deterioration appears concentrated almost entirely in remote-capable occupations.

That distinction is important because it weakens the argument that AI is primarily responsible. If artificial intelligence were the main cause, economists would likely expect broader effects across white-collar jobs regardless of age.

A case study involving a large technology company reinforced the findings.

After shifting to remote work, the company significantly reduced hiring of recent graduates and instead hired workers who were, on average, roughly ten years older.

When the company later implemented a stricter return-to-office policy, hiring of younger workers increased again.

The findings arrive amid a broader transformation of the American workplace.

According to Gallup, approximately 78% of jobs in remote-capable industries now operate under remote or hybrid arrangements, compared with about 40% in 2019. Fully in-office roles have fallen from roughly 60% to about 22% during the same period.

At the same time, younger workers overwhelmingly prefer flexibility. Surveys show only about 6% of Gen Z workers favor fully in-office employment, with most preferring hybrid schedules.

The Fed’s findings suggest that flexibility may carry unintended consequences.

The arrangements many experienced workers fought to secure may be making it harder for the next generation to get its foot in the door.

Other researchers are reaching similar conclusions.

A separate study from economists at the London School of Economics and the University of Oxford, examining hundreds of millions of hiring records across the United States, Canada, Australia, and the United Kingdom, likewise found remote work to be a more significant factor in early-career hiring weakness than artificial intelligence.

Some economists see a compromise.

Nicholas Bloom, a Stanford University economist known for his work on remote employment, argues that hybrid schedules may provide the best balance by preserving in-person collaboration while maintaining workplace flexibility.

For businesses, the findings raise an important strategic question.

Companies may save money and improve employee satisfaction through remote work, but they risk weakening their pipeline of future talent if fewer young workers receive the mentoring necessary to develop into future leaders.

For the broader economy, the implications are significant.

Early-career unemployment often carries lasting effects, influencing earnings, advancement opportunities, and career trajectories for years.

The researchers emphasize that artificial intelligence could eventually play a larger role.

As AI systems increasingly handle entry-level tasks, the labor market may evolve further.

For now, however, the evidence points to a different culprit.

The challenge facing many young graduates appears to be the home office—not the algorithm.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Canadian leaders push back as renewed trade tensions emerge alongside calls to revisit the USMCA trade agreement.

By JBizNews Desk

June 3, 2026

President Donald Trump reignited debate over U.S.-Canada relations this week after responding to reports that Canada had entered a technical recession with a brief but provocative post on Truth Social: “51st State!”

The comment came Monday evening after economic data showed Canada’s economy had contracted for a second consecutive quarter, meeting the common definition of a technical recession. The post quickly spread across social media and political circles on both sides of the border, drawing swift responses from Canadian officials.

The economic backdrop is real.

Fresh data released this week showed Canada’s economy shrinking for a second straight quarter, marking its first technical recession since 2020. While Bank of Canada Senior Deputy Governor Carolyn Rogers cautioned lawmakers against drawing sweeping conclusions from a single set of figures, the report nevertheless raised concerns about slowing growth, weaker consumer spending, and pressure on key industries.

For Trump, the recession provided an opportunity to revisit a theme he has raised repeatedly since returning to office.

Over the past year, the president has repeatedly joked—or suggested, depending on the audience—that Canada would be better off as America’s 51st state. He has often linked the idea to trade disputes, arguing that many economic disagreements between the two countries would disappear if Canada were part of the United States.

Canadian leaders were quick to reject the notion.

Ontario Premier Doug Ford responded publicly, stating, “Canada will never be the 51st state. Canada is not for sale.”

Prime Minister Mark Carney has previously dismissed similar remarks, saying annexation “will never happen” and emphasizing Canada’s sovereignty while continuing to pursue cooperation with Washington on trade, defense, and economic issues.

Behind the political rhetoric lies a more consequential business story.

On Tuesday, Canadian Minister for Internal Trade Dominic LeBlanc formally called for renewal discussions surrounding the United States-Mexico-Canada Agreement (USMCA), the trade pact governing commerce across North America.

The agreement affects hundreds of billions of dollars in annual trade involving automobiles, auto parts, energy, agriculture, manufacturing, and consumer goods.

Any uncertainty surrounding USMCA negotiations carries significant implications for businesses throughout the continent.

For investors and corporate executives, that may matter far more than the headline-grabbing political exchange.

Canada remains one of America’s largest trading partners, with deeply integrated supply chains stretching across automotive manufacturing, energy production, agriculture, construction materials, and technology sectors.

A slowing Canadian economy could affect demand for American exports, while renewed trade tensions could create additional uncertainty for companies already navigating elevated interest rates, geopolitical risks, and shifting global supply chains.

Markets have largely learned to treat Trump’s “51st state” comments as negotiating rhetoric rather than a serious policy proposal.

The more important questions involve tariffs, trade rules, currency movements, and the future of North America’s economic partnership.

Those issues carry real financial consequences for businesses and investors on both sides of the border.

For now, the headline may be Trump’s latest jab, but the underlying story is a Canadian economy under pressure, a critical trade agreement entering a new phase of negotiations, and a relationship that remains both politically complicated and economically indispensable.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

Long Island could soon see its first newly built hospital in more than four decades.

NYU Langone Health announced Tuesday that it intends to construct a major academic medical center in Melville, near the Nassau-Suffolk border, marking what would be Long Island’s first ground-up hospital construction since 1980.

The project ranks among the largest healthcare investments announced in the region in years.

Planned for a 45-acre site in the Huntington Quadrangle near the Long Island Expressway and Route 110, the campus will feature a hospital with more than 500 private inpatient rooms, over 70 emergency department bays, advanced surgical suites, and state-of-the-art diagnostic imaging facilities.

NYU Langone acquired the property on May 21 for approximately $135.5 million.

Local officials estimate the total investment will exceed $1 billion.

The vision extends far beyond a hospital.

Plans also include the tuition-free NYU Grossman Long Island School of Medicine, research facilities, outpatient centers, and a broader medical campus designed to integrate patient care, education, and scientific research.

“This is one of the most ambitious and exciting projects ever undertaken by NYU Langone,” said Alec Kimmelman, the health system’s dean and chief executive.

The proposal still faces extensive environmental review and multiple state and local approvals before construction can begin.

If approved, the project could deliver significant economic benefits.

A hospital of this scale would generate thousands of construction jobs during development and support a substantial permanent workforce after opening.

The surrounding area could also benefit from increased demand for housing, restaurants, retail, and professional services.

The expansion further strengthens NYU Langone’s growing presence across Long Island.

The system currently employs more than 13,000 people in the region, operates over 120 physician practices, and has expanded its regional footprint by roughly 376% since 2007, now encompassing more than 320 locations.

The Melville project follows NYU Langone’s acquisition and expansion of NYU Langone Hospital—Suffolk in Patchogue, where the health system is investing approximately $650 million in upgrades, including a new 144-bed tower.

Since joining NYU Langone, the facility has improved from two stars to four stars in federal Medicare quality ratings.

The system also emphasized that existing facilities in Mineola will continue operating and expanding even after the new campus opens.

The announcement reflects a broader national trend.

Large healthcare systems continue expanding through acquisitions, network growth, and regional consolidation as they seek greater scale, stronger negotiating leverage, and access to specialized talent.

Supporters argue consolidation improves care quality and access to advanced treatments.

Critics warn it can reduce competition and eventually contribute to higher healthcare costs.

For Long Island residents, however, the immediate significance is clear.

A region that has not seen a newly built hospital in more than 40 years could soon gain a major new healthcare destination.

Whether the project proceeds exactly as envisioned remains uncertain, but NYU Langone’s announcement signals a major long-term commitment to Long Island’s future.

Long Island — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Redfin reports down payments are shrinking for the first time in years, while separate Realtor.com data shows the national median has fallen to its lowest level since 2021.

By JBizNews Desk

June 3, 2026

The cash needed to buy a home is finally starting to come down.

A new report from Redfin, released Tuesday, found that the typical homebuyer’s down payment fell to approximately $64,000, down 1.5% from a year earlier, signaling a significant shift in housing-market dynamics after years of seller dominance.

While the decline may appear modest, it reflects a broader trend that is giving buyers more leverage than they have enjoyed since before the pandemic housing boom.

A separate Realtor.com report released earlier this year found that the national median down payment fell to $23,400 during the first quarter, the lowest level since 2021.

The difference between the two figures comes down to methodology.

Redfin’s data focuses on county records from 40 major metropolitan areas, many of them among the most expensive housing markets in America. Realtor.com’s figure reflects the national median across the broader U.S. housing market.

Together, however, the reports point to the same conclusion:

The housing market is becoming more favorable to buyers.

Bidding Wars Are Fading

The primary reason is simple.

For the first time in years, many buyers no longer have to bring oversized down payments to compete for limited inventory.

During the pandemic-era housing frenzy, buyers routinely increased down payments to strengthen offers and stand out in competitive bidding situations.

Today’s market looks very different.

Housing inventory has increased, homes are spending more time on the market, and sellers are becoming more willing to negotiate.

According to Sheharyar Bokhari, Principal Economist at Redfin, buyers now have significantly more flexibility when determining how much cash to put down.

The negotiating power has shifted.

The National Numbers Show a Bigger Change

The trend is even more visible in Realtor.com’s national data.

According to the firm’s analysis, the typical down payment has declined roughly 19% from a year ago and sits well below the approximately $32,700 peak reached in 2024.

As a percentage of the purchase price, buyers are now putting down about 12.8%, compared with 14% a year earlier.

That brings down-payment levels back near where they stood in 2021 before the market became dominated by aggressive bidding wars and rapid price appreciation.

As Hannah Jones, Senior Economic Research Analyst at Realtor.com, noted, the “down payment wall” facing prospective homeowners is beginning to come down.

Regional Differences Remain Dramatic

Despite the national decline, down-payment requirements still vary dramatically across the country.

In some of America’s most expensive housing markets, buyers continue putting down substantial amounts.

In San Jose, San Francisco, and Anaheim, typical buyers are still putting down roughly 25% of the purchase price.

Elsewhere, the numbers are far lower.

Typical down payments average approximately:

  • 2% in Virginia Beach
  • 5% in Detroit
  • 6% in Las Vegas

Those differences reflect local housing prices, lending practices, and buyer demographics.

Lower-Down-Payment Loans Are Making a Comeback

Part of the shift is being driven by increased use of government-backed mortgage programs.

More buyers are turning to FHA and VA loans, which require significantly smaller down payments than conventional mortgages.

Some FHA loans require as little as 3.5% down, while many VA loans require no down payment at all.

The tradeoff is important.

Smaller down payments reduce upfront costs but increase the amount borrowed, resulting in larger monthly payments, higher total interest costs, and often mortgage-insurance requirements.

The barrier to entry falls.

The long-term cost can rise.

Cash Buyers Are Pulling Back

Even cash buyers are becoming less dominant.

According to Redfin, approximately 28.8% of home purchases in March were completed entirely in cash, down from 29.8% a year earlier and tied for the lowest March share since 2021.

Cash purchases peaked near 35% in 2023, when mortgage rates approached 8% and buyers with available cash enjoyed a major competitive advantage.

As mortgage rates have eased closer to 6%, some of that pressure has diminished.

What It Means for Buyers

The broader housing market remains far from affordable.

Home prices remain historically high, and even after recent declines, down payments in many markets remain well above pre-pandemic levels.

Yet the trend is moving in buyers’ favor.

Inventory is growing, price appreciation has slowed, some markets are seeing outright price declines, and sellers increasingly find themselves negotiating rather than dictating terms.

For mortgage lenders, real-estate brokerages, homebuilders, and housing-related businesses, the market is entering a new phase.

For would-be homeowners, the largest obstacle to buying a home may finally be getting a little smaller.

The challenge is that lower upfront costs often come with larger monthly payments—and many Americans remain hesitant to take on those obligations amid ongoing economic uncertainty.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

A few years ago, knowing Excel could help someone stand out in the workplace.

Today, that skill is artificial intelligence.

Across Corporate America, employees who know how to use AI are increasingly becoming the people managers rely on first. They are writing reports in less time, handling more customers, analyzing data faster, creating marketing campaigns in minutes instead of days, and completing projects that once required entire teams. As a result, many companies are paying more for those workers, promoting them faster, and making AI knowledge a key factor in hiring decisions.

The shift is happening far beyond Silicon Valley.

A human resources manager using AI to screen resumes, a salesperson using AI to prepare proposals, an accountant using AI to analyze financial records, a customer service representative using AI to answer inquiries, or a small-business owner using AI to manage marketing and operations can often accomplish significantly more work than someone relying entirely on traditional methods.

That reality is beginning to reshape the labor market.

According to Stanford University’s 2026 AI Index, AI-related skills now appear in 2.5% of all U.S. job postings, a 297% increase over the past decade. Demand for AI skills is growing roughly 20 times faster than the overall job market, and employers increasingly view AI proficiency as a competitive advantage rather than a specialized technical skill.

For workers, the financial impact can be substantial.

Research from PwC found that employees with advanced AI skills earn approximately 56% more than peers performing similar work without those capabilities. Companies are increasingly rewarding workers who can use AI to improve productivity, increase sales, streamline operations, and reduce costs.

Major employers are responding quickly.

IKEA has trained more than 40,000 employees in AI literacy. Bank of America uses AI-powered simulations to improve employee performance and customer interactions. Accenture operates systems that track thousands of workforce skills and connect employees with projects and training opportunities. Manufacturers including Intel and TSMC have launched apprenticeship programs focused on AI and advanced manufacturing technologies.

The reason is simple: productivity.

Organizations across Corporate America are discovering that employees who understand AI can often complete tasks in a fraction of the time previously required. In many cases, workers are reclaiming hours every week that can be redirected toward customer service, business development, sales, strategy, and revenue-generating activities.

For business owners facing labor shortages and rising costs, that productivity boost can translate directly into stronger profitability.

Yet many employers remain unprepared.

A 2026 study by DataCamp found that while 82% of organizations offer some form of AI training, 59% still report significant AI skills shortages. Many companies have invested in AI tools but have not yet developed structured programs to help employees use them effectively.

The challenge is not simply learning how to write prompts.

Many business leaders say the most valuable employees are not those who merely know how to operate AI software, but those who can evaluate results, identify errors, challenge assumptions, and apply sound judgment. AI can generate answers quickly. Human judgment still determines whether those answers are accurate, useful, and appropriate.

The rapid adoption of AI is also fueling demand for executive education and workforce development programs. Business organizations, universities, and industry groups are expanding AI-focused courses, workshops, and conferences as employers look for practical ways to help employees integrate the technology into daily operations. Among those efforts is the JBizNews AI Leadership & Operations Summit, scheduled for July 13-14 in Eatontown, New Jersey, where business owners, executives, managers, HR professionals, and operational leaders will explore practical AI implementation, workflow automation, productivity strategies, revenue growth opportunities, and real-world business applications as organizations work to close the widening AI skills gap.

The business case remains compelling.

Research from McKinsey & Company suggests employees hired for demonstrated skills are roughly 30% more productive during their first six months than workers hired primarily on traditional credentials. As AI becomes more deeply embedded in everyday business operations, companies increasingly want employees who can produce results rather than simply hold qualifications.

For workers, the message is becoming increasingly clear.

The question is no longer whether AI will become part of the workplace.

It already has.

The employees who learn how to use it effectively may find themselves earning more, advancing faster, creating greater value for their organizations, and becoming significantly harder to replace. Those who ignore it risk watching the workplace move ahead without them.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
For more information:
Esther@ojchamber.com
212-659-5270 ext. 104

By JBizNews Desk

June 3, 2026

Israel’s defense industry delivered another record-breaking year.

The Israeli Ministry of Defense announced Tuesday that defense exports reached an all-time high of $19.2 billion in 2025, representing a nearly 30% increase from the prior year and marking the fifth consecutive annual record.

Officials said defense exports have more than doubled over the past five years and quadrupled over the past decade.

The strongest growth came from large contracts.

More than half of all export agreements signed during 2025 were valued at $100 million or more, while government-to-government agreements alone accounted for approximately $10 billion, another record.

The largest category was missiles, rockets, and air-defense systems, which represented 29% of exports.

Observation, surveillance, and optronics technologies followed at 22%, up sharply from just 6% the year before.

The customer base was global.

Europe accounted for 36% of exports, followed by the Asia-Pacific region at 32%, while the Middle East and North Africa represented 15%.

The ministry declined to identify specific buyers.

Industry officials noted that some governments publicly critical of Israeli military actions continue purchasing Israeli defense systems privately, highlighting the growing demand for combat-proven military technologies.

Israeli officials directly linked the export surge to the country’s recent military conflicts.

Amir Baram, Director General of the Ministry of Defense, said the figures reflect the strength of Israel’s defense sector, the performance of Israeli military systems in combat, and rising global security concerns.

Israeli defense manufacturers increasingly market their products as “battle-tested,” having been deployed in conflicts involving Hamas, Hezbollah, and Iran.

That distinction has become a significant competitive advantage as governments worldwide accelerate military spending.

The ministry also credited regulatory reforms that expanded access to foreign markets and streamlined export procedures.

The timing has been favorable.

Governments across Europe, Asia, and the Middle East continue increasing defense budgets amid growing geopolitical tensions and regional conflicts.

The record arrives despite persistent international criticism of Israel’s military operations.

Several advocacy groups and governments have called for restrictions on Israeli defense exports.

The latest figures suggest those efforts have done little to reduce demand.

The results carry major implications for companies such as:

  • Elbit Systems
  • Israel Aerospace Industries
  • Rafael Advanced Defense Systems

The firms manufacture many of the air-defense systems, drones, radar platforms, missiles, and precision-guided munitions driving export growth.

Record sales translate into larger production runs, expanded hiring, and growing order backlogs.

Looking ahead, officials identified counter-drone technologies as a major growth area.

Recent conflicts have highlighted the challenge of defending against low-cost drones, creating demand for new detection, tracking, and interception systems.

That market is expected to become a significant focus of future investment and export activity.

The broader takeaway is clear.

As countries around the world increase military spending, suppliers offering proven battlefield performance continue gaining market share.

Israel’s fifth consecutive record year underscores the country’s growing importance within the global defense industry—and suggests demand remains strong heading into 2026.

Jerusalem — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JOLTS report shows demand for workers jumped unexpectedly in April, though employers continue filling jobs at a sluggish pace ahead of Friday’s payrolls report.

By JBizNews Desk

June 3, 2026

The U.S. labor market delivered a surprise Tuesday morning, but not the one many economists were expecting.

According to the latest Job Openings and Labor Turnover Survey (JOLTS) released by the U.S. Bureau of Labor Statistics, job openings surged to 7.6 million in April, an increase of approximately 731,000 positions from March and the highest level since May 2024.

The figure significantly exceeded economists’ expectations of roughly 6.8 million openings and pushed available jobs back above the number of unemployed Americans seeking work.

On the surface, the report suggests employers are becoming more optimistic.

Dig deeper, however, and a different picture emerges.

The Hiring Engine Is Still Stalling

While job openings climbed sharply, actual hiring moved in the opposite direction.

Employers hired approximately 5.1 million workers in April, down from the previous month, while the national hiring rate slipped to 3.2%.

In other words, companies are posting more positions but filling fewer of them.

That disconnect has become one of the defining characteristics of today’s labor market.

Economists increasingly describe the current environment as a “low-hire, low-fire” economy, where employers are reluctant to aggressively expand payrolls but also unwilling to conduct major layoffs.

One Sector Drove Nearly All the Growth

The headline increase was also heavily concentrated.

The largest contributor was professional and business services, which added approximately 668,000 job openings, accounting for the overwhelming majority of the national increase.

The category includes consulting firms, accounting firms, legal services, administrative support providers, and other white-collar employers.

Meanwhile, health care and social assistance added roughly 89,000 openings, while financial activities actually lost approximately 134,000 positions.

Without the surge in professional services, the overall report would have looked considerably less impressive.

Big Companies Are Hiring Differently Than Small Businesses

Another notable trend emerged beneath the surface.

According to analysis from Indeed Hiring Lab, the strongest demand is coming from America’s largest employers.

Job openings among organizations with 5,000 or more employees remain roughly 81% above pre-pandemic levels.

Smaller employers tell a different story.

Businesses with fewer than 1,000 workers account for the overwhelming majority of job openings nationwide, yet demand from those firms has remained largely unchanged since mid-2024.

That matters because small and midsize businesses historically generate a substantial share of new jobs in the U.S. economy.

Workers Are Staying Put

Employees appear increasingly reluctant to switch jobs.

The national quits rate edged down to 1.9%, indicating fewer workers are voluntarily leaving positions in search of better opportunities.

At the same time, layoffs remain exceptionally low.

The layoff rate fell to 1.1%, near historic lows and further reinforcing the picture of a labor market that is slowing but not breaking.

Workers are staying put.

Employers are holding onto existing staff.

And new hiring remains cautious.

Could AI Be Playing a Role?

The concentration of openings in professional and business services is already drawing attention from economists.

Some analysts have begun exploring whether artificial intelligence is beginning to reshape demand for white-collar labor, creating new hiring needs in consulting, technology implementation, operations, compliance, and business services.

At this stage, economists caution that the data does not prove a direct AI effect.

Still, the unusual concentration of new openings in white-collar sectors is likely to attract closer scrutiny in the months ahead.

All Eyes Turn to Friday

Tuesday’s report serves as the opening act for one of the most closely watched labor-market weeks of the year.

The ADP private payroll report arrives Wednesday, followed by the government’s monthly nonfarm payrolls report on Friday.

The labor market remains one of the most important indicators guiding Federal Reserve policy.

With unemployment holding near 4.3%, policymakers are looking for signs that hiring is either accelerating or weakening enough to influence future interest-rate decisions.

For now, the message from the April JOLTS report is clear:

America has more job openings than economists expected, but employers are still moving cautiously when it comes to actually bringing workers onboard.

The labor market is not collapsing.

But it is not booming either.

It remains frozen in an uneasy middle ground—one that Friday’s payroll report may finally help clarify.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 3, 2026

America’s electricity system is being rebuilt around artificial intelligence, and the latest numbers show why.

The U.S. Energy Information Administration projects national electricity demand will reach record levels in 2026, climbing to roughly 4,250 billion kilowatt-hours, while the International Energy Agency expects global data-center power consumption to roughly double by 2030. Much of that growth is being driven by AI.

What was once a niche concern for utilities has become a national economic issue, reshaping where data centers are built, how they operate, and ultimately what households and businesses pay for electricity.

The reason is straightforward. The advanced chips used to train and operate AI systems consume far more electricity than previous generations of computing hardware. Packed into increasingly dense server farms and operating around the clock, these AI facilities are becoming some of the largest power consumers in the country.

According to the Electric Power Research Institute, data centers consumed approximately 26% of Virginia’s electricity in 2023. The organization projects that figure could rise to between 41% and 59% by 2030. Several other states, including Iowa, Nebraska, and Oregon, are expected to see data centers account for more than 20% of electricity demand.

The financial implications are staggering.

Goldman Sachs Research estimates global data-center electricity demand will increase 165% by 2030 compared with 2023 levels. Meanwhile, a study of 51 major U.S. utilities published by PowerLines found those companies now plan to spend at least $1.4 trillion through 2030 expanding and modernizing the grid, a figure more than 21% higher than utilities projected just one year ago.

Those investments ultimately find their way into electricity rates.

The growing strain is also forcing engineers to redesign how data centers are built. Operators are rethinking server density, cooling systems, backup power strategies, and electrical infrastructure as AI workloads continue expanding.

Technology companies are pursuing efficiency improvements as well. Nvidia’s latest chips deliver substantially more computing power per watt than previous generations. Yet demand continues growing faster than efficiency gains.

As Elon Musk remarked earlier this year, “Very soon, maybe even later this year, we’ll be producing more chips than we can turn on.”

Faced with grid limitations, many operators are no longer waiting for utilities to catch up.

Instead, they are building their own power supplies.

A growing number of large data centers are developing dedicated natural-gas plants, battery systems, and private energy infrastructure. Some are effectively creating what industry executives call “energy islands” that can operate independently of the public grid.

One example is a Meta campus near Columbus, Ohio, which received approval to operate using dedicated on-site natural-gas generation supplied by Williams Companies.

The shift reflects real infrastructure bottlenecks. Utilities face multi-year shortages of critical equipment such as transformers, while some grid-interconnection queues stretch so long that projects approved in 2025 had already been waiting nearly eight years.

Not everyone believes the demand surge will be as dramatic as projected.

The Information Technology and Innovation Foundation (ITIF) argues that data centers can often use existing grid capacity more efficiently by reducing consumption during peak-demand periods.

There are also signs the expansion may be occurring more slowly than some forecasts suggest. New data-center agreements reportedly fell more than 40% between the third and fourth quarters of 2025, only about one-third of announced projects are currently under construction, and reports indicate that OpenAI’s Stargate project in Texas has encountered delays.

Even so, the business effects are already visible.

Utilities are accelerating investments in generation capacity. Interest in both natural gas and nuclear power has surged. Manufacturers producing transformers, switchgear, and grid equipment face record backlogs. Chipmakers increasingly market energy efficiency as a competitive advantage.

The AI race is becoming less about access to capital and more about access to power.

For consumers, the impact is increasingly visible on monthly utility bills.

As companies and utilities invest hundreds of billions of dollars in transmission lines, substations, and power generation, regulators are wrestling with how much of those costs should be borne by households versus the technology companies driving the demand.

The bottom line is that the AI boom has quietly become an energy story.

The race to build smarter machines now runs directly through power plants, transmission lines, substations, and utility rate cases. How those challenges are resolved will shape not only the future of artificial intelligence, but also what Americans pay for electricity for years to come.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Acquisition gives Salesforce a critical content engine for Agentforce as the race to build enterprise AI platforms accelerates.

By JBizNews Desk

June 3, 2026

Salesforce Inc. has agreed to acquire Contentful, the Berlin-based content management software company, in a move designed to strengthen its fast-growing Agentforce artificial intelligence platform and deepen its position in the increasingly competitive AI software market.

The companies announced the deal Monday, though Salesforce did not disclose financial terms. The acquisition is expected to close during the third quarter of Salesforce’s fiscal 2027 year, subject to customary regulatory approvals.

While no official purchase price was announced, the transaction has already attracted attention because of the gap between Contentful’s peak valuation and what Salesforce reportedly paid.

Contentful was valued at more than $3 billion during a 2021 funding round led by Tiger Global, when software valuations across the technology sector were near historic highs. According to The Information, citing a person familiar with the matter, Salesforce paid between $1 billion and $1.5 billion for the company, representing a significant discount to its previous valuation.

What Contentful Actually Does

For many outside the technology industry, Contentful operates behind the scenes.

Founded in 2013 by Sascha Konietzke and Paolo Negri, the company provides what is known as a “headless content management system.”

Instead of storing information in traditional webpages, Contentful organizes content as reusable data that can be distributed across websites, mobile apps, e-commerce platforms, emails, digital kiosks, and other customer-facing channels.

The company says it serves more than 4,800 organizations, including approximately 30% of Fortune 500 companies, with customers including IKEA, Vodafone, Electronic Arts, and DoorDash.

Why Salesforce Wants It

The acquisition is less about content management and more about artificial intelligence.

Salesforce’s biggest growth initiative today is Agentforce, its platform for AI-powered digital agents that can interact with customers, answer questions, create content, assist employees, and automate business processes.

But AI agents require trusted information sources.

An AI system can only generate accurate responses if it has access to organized, approved, and up-to-date content.

That is where Contentful enters the picture.

By integrating Contentful into Agentforce, Salesforce gains a content infrastructure layer capable of supplying AI agents with structured information in real time.

The result could allow businesses to deliver more personalized customer experiences across multiple channels without requiring human employees to manually create every interaction.

Part of a Larger AI Acquisition Strategy

The deal continues Salesforce’s broader effort to assemble an end-to-end AI ecosystem.

Over the past two years, the company has aggressively expanded its AI capabilities through acquisitions and platform development.

Salesforce previously completed its approximately $8 billion acquisition of Informatica, strengthening its data-management capabilities, while also purchasing several smaller AI-focused firms.

The strategy reflects a growing industry belief that successful AI systems require three critical components:

  • Reliable data
  • AI reasoning capabilities
  • Structured content

Salesforce already possessed the first two.

Contentful gives it the third.

Investors Respond Positively

Wall Street welcomed the announcement.

Shares of Salesforce (NYSE: CRM) surged roughly 10% following the news, marking one of the company’s strongest single-day performances since late 2024.

Investors continue rewarding software companies that demonstrate clear AI strategies, particularly those capable of monetizing AI products through existing enterprise customer bases.

Salesforce has reported strong momentum for Agentforce, with management citing thousands of signed customer agreements and rapidly growing recurring revenue tied to AI offerings.

Questions Remain

For Contentful customers, the immediate message from Salesforce is business as usual.

The company said Contentful’s platform will continue operating normally, with future integration into Agentforce occurring over time.

Still, some customers may question whether an independent platform known for flexibility will maintain that identity inside one of the world’s largest enterprise software companies.

European observers are also watching closely.

Because Contentful is headquartered in Germany, the acquisition raises questions about data governance, digital sovereignty, and the application of U.S. laws such as the CLOUD Act, which can affect access to data held by American companies.

The Bigger Picture

The acquisition highlights how rapidly the AI arms race is reshaping enterprise software.

Companies are no longer competing simply on customer databases or cloud infrastructure.

They are competing to build complete AI ecosystems that combine customer data, business knowledge, content libraries, and autonomous digital agents into a single platform.

Salesforce believes Contentful fills a critical missing piece.

The next question is whether combining those pieces creates a stronger AI platform—or simply a larger software company.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Conference Board survey falls back below key optimism threshold as executives warn of slower growth, weaker hiring, and rising uncertainty.

By JBizNews Desk

June 3, 2026

The people who make America’s biggest hiring decisions are becoming worried again.

A closely watched survey released by The Conference Board found that confidence among chief executives of major U.S. companies fell sharply during the second quarter, signaling growing concerns about the economy and raising fresh questions about future hiring plans.

According to the Conference Board Measure of CEO Confidence, conducted in partnership with The Business Council, the index dropped to 47 in the second quarter from 59 in the first quarter. Any reading below 50 indicates that more CEOs are pessimistic about business conditions than optimistic.

The decline erased the surge of optimism that followed the start of President Donald Trump’s second term and marked one of the sharpest quarter-to-quarter swings in recent years.

“This tells us that America’s top executives have become significantly more cautious,” said Dana M. Peterson, Chief Economist of The Conference Board, noting that confidence has returned to negative territory after a brief rebound earlier this year.

The Mood Shift Is Dramatic

Just three months ago, many CEOs expected tax cuts, deregulation, and business-friendly policies to support stronger growth.

That outlook has changed.

Only 15% of executives surveyed said economic conditions were better than six months ago, down from 39% in the previous quarter.

Meanwhile, 47% said conditions had worsened, compared with only 8% in the first quarter.

The deterioration wasn’t limited to the broader economy.

About 33% of CEOs reported worsening conditions within their own industries, more than double the percentage reported earlier in the year.

What CEOs Are Worried About

The biggest concern is uncertainty.

Business leaders continue to face elevated energy prices, geopolitical tensions, supply-chain concerns, and questions about the pace of economic growth.

For executives managing large workforces and billion-dollar budgets, uncertainty often translates into caution.

And caution frequently affects hiring first.

The survey found many CEOs expect slower growth over the next six months, with roughly 40% anticipating weaker economic conditions ahead.

Historically, when executive confidence declines, hiring plans tend to soften shortly afterward.

That doesn’t necessarily mean widespread layoffs are imminent, but it often means fewer new positions, slower expansion plans, and greater scrutiny of labor costs.

A Silver Lining

Not all of the survey results were negative.

One encouraging sign was that most CEOs reported little change in planned capital expenditures.

In other words, while executives may be becoming more cautious about hiring, they are not abandoning long-term investments.

That distinction matters.

Companies that continue investing in technology, equipment, infrastructure, and growth initiatives are positioning themselves for the future rather than preparing for a severe downturn.

The behavior looks more like caution than panic.

What It Means for Workers

For employees and job seekers, CEO sentiment can provide an early glimpse into future labor market conditions.

The executives surveyed are responsible for millions of jobs and billions of dollars in investment decisions.

When they become less confident, hiring often slows before broader economic data reflects the change.

The survey’s findings suggest that while businesses are not retreating, many are becoming more selective about expansion and workforce growth.

The Bigger Picture

The survey was conducted between May 4 and May 18 and included responses from 141 CEOs of major U.S. companies.

The results align with other recent measures showing that business leaders and consumers alike are becoming more cautious about the economic outlook.

The broader message is straightforward:

America’s CEOs are not predicting a crisis.

But they are signaling that the optimism that defined the beginning of 2026 has faded considerably.

The people who decide whether companies hire, expand, invest, or wait are becoming more careful—and those decisions often shape the direction of the economy long before they appear in official economic statistics.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Higher government borrowing costs keep pushing through to mortgages, business loans and commercial property financing.

By JBizNews Desk

The yield on the 10-year U.S. Treasury note held around 4.46% on Tuesday, staying near its highest level in weeks after a fresh government report showed the job market is still running hot. New figures from the Bureau of Labor Statistics showed U.S. job openings climbed in April to their highest level in nearly two years, a sign of strength that gives the Federal Reserve little reason to start cutting interest rates soon.

Yields and rate cuts move together in investors’ minds. When traders expect the Fed to lower rates, they tend to push bond yields down ahead of time. Lately, they have been doing the opposite. Strong hiring, better-than-expected manufacturing activity in May, and inflation that remains above the Fed’s 2% target have convinced markets that cuts are further off than once hoped.

The numbers tell the story. The 2-year Treasury yield sat near 4.04% Tuesday, while the 30-year yield hovered near 4.98%. The Fed’s benchmark rate has stayed in a range of 3.50% to 3.75% since a cut last December, and futures markets now put the odds of no change at the central bank’s June 16-17 meeting at roughly 97%, according to CME FedWatch.

That meeting will be the first led by new Federal Reserve Chairman Kevin Warsh, who was sworn in May 22 after a narrow Senate confirmation. President Donald Trump picked Warsh in part because he has argued there is room to cut rates. But persistent inflation, driven higher by energy prices tied to the conflict between the U.S. and Iran, is making that case harder to act on right away.

A major reason inflation has stayed sticky is oil. April’s consumer price index rose 0.6% in a single month and ran 3.8% higher than a year earlier, well above where the Fed wants it. Investors will get more clues this week, with private payroll data due Wednesday, the May jobs report Friday, and the May inflation reading on June 10 — the last major figures before the Fed decides.

Here is why this reaches far beyond Wall Street. The 10-year Treasury yield is the reference point for the 30-year mortgage, so when it stays high, home loans stay expensive. The same is true for business loans, auto financing and the debt companies use to expand. Every month yields hold near these levels, borrowing stays costly for households and businesses alike.

The squeeze is sharpest in commercial real estate, where owners of office towers, apartment complexes and shopping centers borrow heavily and refinance often. Loans taken out years ago at low rates are now coming due, and the only financing available carries today’s much higher costs.

For now, the bond market is sending a clear message: it does not expect relief soon. Until inflation cools or hiring slows in a convincing way, the high cost of money looks set to stay — and so does the pressure on anyone who needs to borrow.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. officials say Nobitex helped facilitate billions of dollars in transactions tied to sanctioned entities, terrorist organizations, and Iran’s financial system.

By JBizNews Desk

June 3, 2026

The U.S. Department of the Treasury on Tuesday took one of its most significant actions yet against Iran’s digital-finance infrastructure, sanctioning Nobitex, the country’s largest cryptocurrency exchange, over allegations that it facilitated transactions for sanctioned entities, terrorist organizations, and key components of the Iranian regime.

The action, announced by Treasury’s Office of Foreign Assets Control (OFAC), places Nobitex directly in Washington’s crosshairs and dramatically raises the stakes for cryptocurrency firms, financial institutions, and trading platforms worldwide that may have interacted with the exchange.

For many Americans, the move may sound like another sanctions announcement.

For the global cryptocurrency industry, it represents something much larger.

It signals that Washington increasingly views major crypto exchanges as part of the modern financial system and expects them to comply with sanctions rules much like traditional banks.

The Center of Iran’s Crypto Economy

Nobitex is not a niche platform.

The exchange has emerged as the dominant cryptocurrency marketplace inside Iran, with reports indicating it serves approximately 11 million users and handles a majority of the country’s digital-asset trading activity.

As Iran’s currency has weakened under years of sanctions and inflation, many citizens have turned to cryptocurrencies and dollar-pegged stablecoins as a way to preserve savings and conduct transactions outside the traditional banking system.

Blockchain analytics firms have estimated that billions of dollars in digital assets have flowed through Nobitex in recent years, making it one of the most important gateways between Iran’s domestic economy and the broader cryptocurrency market.

According to U.S. officials, that role also made it an attractive platform for sanctioned actors.

Treasury’s Allegations

Treasury alleges that Nobitex facilitated transactions connected to entities already under U.S. sanctions, including organizations tied to the Islamic Revolutionary Guard Corps (IRGC) and other components of Iran’s financial apparatus.

Investigations by blockchain intelligence firms and international reporting organizations have previously linked wallets associated with the exchange to networks connected to Hamas, Ansar Allah (the Houthis), and other sanctioned organizations.

Nobitex has repeatedly denied those allegations and has maintained that it operates as an independent private company rather than an arm of the Iranian government.

Still, the U.S. government concluded that the exchange had become sufficiently intertwined with sanctioned activity to warrant direct designation.

What the Sanctions Actually Do

The immediate effect is straightforward.

Any property or interests in property of Nobitex that fall under U.S. jurisdiction are blocked, and U.S. persons are generally prohibited from conducting transactions involving the exchange.

The broader impact may be far more significant.

Foreign cryptocurrency exchanges, brokers, over-the-counter trading desks, payment processors, and financial institutions that continue doing business with Nobitex could expose themselves to secondary sanctions or increased regulatory scrutiny.

In practice, many global firms choose to cut ties immediately rather than risk losing access to the U.S. financial system.

That is often where sanctions derive much of their power.

Why Crypto Firms Are Paying Attention

The designation also places pressure on stablecoin issuers, blockchain analytics firms, and major cryptocurrency exchanges to identify and isolate wallets linked to the sanctioned platform.

Companies operating in the digital-asset sector increasingly face the same compliance expectations that banks have confronted for decades.

That means screening transactions, monitoring counterparties, identifying sanctioned wallets, and preventing indirect exposure to prohibited entities.

The message from Treasury is becoming increasingly clear:

Cryptocurrency may be a new technology, but sanctions compliance remains an old rule.

The Human Side of the Story

The sanctions also create challenges for ordinary Iranians.

Millions of users reportedly relied on Nobitex as a mechanism to convert savings into digital assets, hedge against inflation, and gain access to global financial markets that are otherwise difficult to reach under existing sanctions.

As compliance measures tighten, some users could find themselves facing greater restrictions or reduced access to financial services, even though they are not the intended targets of the designation.

That tension has long been one of the most difficult aspects of sanctions policy.

Measures designed to isolate governments often affect ordinary citizens as well.

Part of a Larger Campaign

Tuesday’s action fits into a broader effort by the Trump administration to increase financial pressure on Tehran through what officials have described as the Economic Fury campaign.

Recent actions have targeted Iranian-linked shipping networks, energy infrastructure, financial facilitators, and digital-asset operations.

The administration has increasingly focused on cryptocurrency as Iran and other sanctioned regimes seek alternative pathways around traditional banking restrictions.

As digital assets become more integrated into global finance, regulators are devoting greater resources to monitoring how those networks are used by governments, criminal organizations, and sanctioned actors.

What Happens Next

The next major developments will likely come from the private sector.

Market participants will be watching to see whether major exchanges, stablecoin issuers, and trading platforms move quickly to sever ties with Nobitex-linked wallets and accounts.

The response could determine how isolated the exchange becomes in the weeks ahead.

For Washington, however, the objective is already clear.

The Treasury Department is signaling that cryptocurrency exchanges operating at the center of sanctioned financial networks will no longer be treated as peripheral players in the global economy.

They will be treated as financial institutions—and held to the same standards.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

DUBAI — The United States military carried out fresh strikes on Iranian territory and disabled an oil tanker attempting to reach an Iranian port on Tuesday, prompting Iran to launch missiles and drones toward U.S.-linked targets in Kuwait and Bahrain in one of the most serious tests of the fragile ceasefire since April.

U.S. Central Command confirmed it fired a Hellfire missile into the engine room of a Botswana-flagged tanker after the vessel ignored repeated warnings over 24 hours while heading toward Iran’s Kharg Island. The action is part of Washington’s ongoing naval blockade of Iranian ports along the Strait of Hormuz. No injuries were reported on the empty tanker.

CENTCOM also conducted self-defense strikes on Iran’s Qeshm Island, targeting what it described as military sites including drone and radar positions. The moves followed Iranian claims of attacks on U.S. assets and came amid stalled nuclear and sanctions talks.

Iran’s Islamic Revolutionary Guard Corps said it responded by firing missiles and drones at U.S. positions in the region. Kuwait and Bahrain reported incoming projectiles; most were intercepted or fell short, according to U.S. and local officials. Air-raid sirens sounded in both countries.

The exchange underscores the precarious state of U.S.-Iran diplomacy. A ceasefire brokered earlier this year has been repeatedly tested by Iranian proxy actions, Israeli operations in Lebanon, and Washington’s determination to prevent Tehran from evading sanctions through maritime routes.

President Trump has repeatedly stated that any final agreement must be “good for us” and has warned of further action if talks collapse. Iranian state media has accused Washington of violating the ceasefire and threatened to suspend negotiations entirely if Israeli strikes in Lebanon continue.

The latest incidents come as Israel and Hezbollah maintain a tense partial ceasefire in Lebanon, with violations reported on both sides. Israeli operations in southern Lebanon have been cited by Iranian officials as a key obstacle to broader de-escalation with the United States.

Regional analysts note that sustained enforcement of the Hormuz blockade and targeted strikes on Iranian military infrastructure signal a shift toward maximum pressure tactics, even as back-channel talks mediated by Pakistan continue. Tehran’s ability to project force against Gulf Arab states allied with Washington remains limited by U.S. and partner air defenses.

The situation remains fluid. U.S. officials have emphasized that strikes were defensive and proportionate, aimed at deterring further Iranian aggression and protecting freedom of navigation and sanctions enforcement in the vital waterway.

JBizNews will continue monitoring developments for their implications on regional security, energy flows, and U.S. policy toward Iran.

jBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Evercore lowered its price target, but the new forecast still sits well above where the stock trades today. Investors focused on execution risks instead.

By JBizNews Desk

June 3, 2026

Shares of Carvana Co. (NYSE: CVNA) tumbled more than 9% on Tuesday, falling toward their lowest level of the past year after an analyst at Evercore ISI lowered his price target on the online used-car retailer, triggering fresh concerns about valuation and future growth.

The decline stood out because it came on a day when the broader market was largely moving higher. While major indexes remained near record levels and investors continued pouring money into artificial intelligence-related stocks, Carvana found itself moving sharply in the opposite direction.

The catalyst was a research note from Evercore ISI analyst Michael Montani, who reduced his price target on Carvana shares to $86 while maintaining an “In-Line” rating. In Wall Street terms, “In-Line” essentially means a hold recommendation, signaling expectations that the stock will perform roughly in line with the broader market.

What caught investors’ attention was not the rating itself but the timing.

Carvana shares were trading near $64.50 following the decline, meaning Montani’s new target still implied meaningful upside from current levels. Yet investors reacted as if the news was significantly more negative.

That disconnect highlights a broader reality facing the stock.

A Stock Trading on Expectations

For much of the past two years, Carvana has been one of Wall Street’s most dramatic comeback stories.

The company, which allows consumers to buy and sell vehicles entirely online, was once viewed by many investors as a potential casualty of rising interest rates and mounting debt concerns. Instead, management executed a remarkable turnaround, improving profitability, cutting costs, and restoring investor confidence.

In 2025, Carvana generated approximately $20.3 billion in revenue and $1.4 billion in net income, marking a significant improvement from earlier periods when losses dominated the narrative.

That recovery helped propel shares sharply higher.

Now investors are asking a different question:

How much future growth is already reflected in the stock price?

Execution Matters More Than Ever

Analysts say the market’s focus has shifted from survival to execution.

Investors are closely monitoring retail vehicle sales, financing activity, customer demand, and the company’s ability to maintain profitability as interest rates remain elevated.

Particular attention remains on so-called “attach rates” — the percentage of customers who purchase financing, warranties, insurance products, and other high-margin services alongside vehicle purchases.

Those products often generate significantly higher profits than the vehicle sale itself.

When Wall Street becomes uncertain about growth in those areas, even a modest analyst downgrade can have an outsized effect on sentiment.

Why the Drop Was So Sharp

Technical factors likely amplified Tuesday’s move.

Carvana shares have been trading below several key moving averages that many traders use to gauge momentum. When stocks remain under those levels, investors often become more sensitive to negative headlines, even when the underlying news is relatively modest.

The result can be a self-reinforcing cycle where selling pressure accelerates simply because traders perceive momentum as weakening.

Tuesday’s decline pushed shares closer to their 52-week low near $54.46, a level now being closely watched by market participants.

A Divided Wall Street

The debate surrounding Carvana increasingly comes down to valuation.

Many analysts continue to see substantial upside potential. Even after Evercore’s reduction, the average Wall Street price target remains well above the current share price.

Others are far less optimistic.

Some valuation models suggest the stock could be worth considerably less than where it currently trades, arguing that investors remain overly optimistic about long-term growth assumptions.

The company’s balance sheet also remains under scrutiny. While profitability has improved dramatically, Carvana still carries billions of dollars in long-term debt, making execution critical as borrowing costs remain elevated.

Why Consumers Should Pay Attention

Even for people who never own a share of Carvana stock, the company’s performance offers insight into the broader economy.

Carvana sits at the intersection of several important consumer trends: vehicle affordability, used-car pricing, online retail adoption, and auto financing availability.

When consumers are confident, financing is available, and vehicle demand remains strong, companies like Carvana tend to benefit.

When borrowing becomes more expensive or consumer spending weakens, those same businesses can feel pressure quickly.

What Comes Next

The immediate question is whether Carvana can stabilize above current levels or whether sellers will push the stock toward a new annual low.

Longer term, investors appear less concerned about whether Carvana can survive and more focused on whether it can justify the premium valuation many analysts still assign to the company.

Tuesday’s selloff suggests that for now, Wall Street is demanding proof rather than promises.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

BRUSSELS — Europe’s manufacturing recovery is running into a new obstacle: rising costs.

Fresh survey data released Monday by S&P Global showed factories across the eurozone, Germany, France, and the United Kingdom faced their sharpest increase in input costs since 2022 during May, as higher energy prices, transportation expenses, and raw-material costs linked to the Middle East conflict rippled through supply chains.

The data suggest that while European manufacturing remains in expansion territory, the recovery is becoming increasingly dependent on inventory building and defensive purchasing rather than strong underlying demand.

That distinction matters.

A factory boom driven by customers placing more orders is typically a sign of economic strength. A factory boom driven by businesses stockpiling supplies before costs rise further can signal growing concern about what lies ahead.

The latest S&P Global Manufacturing Purchasing Managers’ Index (PMI) surveys point toward the latter.

Manufacturers across Europe reported paying significantly more for fuel, electricity, transportation services, industrial metals, and imported components. Those rising costs are now being passed on to customers at the fastest pace seen since the inflation surge that followed the energy crisis of 2022.

The immediate culprit is the continuing conflict in the Middle East.

Higher oil prices have increased transportation and logistics costs, while disruptions to shipping routes have added further pressure to already fragile supply chains. For Europe, which remains heavily dependent on imported energy and international trade flows, those disruptions carry outsized consequences.

Factories are feeling the impact directly.

Energy-intensive industries—including chemicals, metals, industrial manufacturing, and transportation equipment—have been particularly exposed to higher electricity and fuel costs.

The squeeze arrives at an uncomfortable moment for the European economy.

After nearly two years of stagnation, manufacturing activity had begun showing signs of recovery earlier this year. The eurozone manufacturing PMI climbed to its highest level in almost four years during the spring before easing slightly in May.

A reading above 50 still indicates expansion, but the slowdown suggests momentum is becoming increasingly fragile.

The concern among economists is not simply that costs are rising.

It is that costs are rising while growth slows.

That combination creates a difficult environment for businesses, consumers, and policymakers alike.

Higher costs eventually work their way through the economy.

Manufacturers paying more for energy, transportation, and raw materials often respond by increasing prices on finished products. Those increases eventually reach wholesalers, retailers, and consumers.

The result can be higher prices for everything from automobiles and household appliances to packaged food and consumer goods.

For European households already facing elevated living costs, the timing is unwelcome.

Many consumers have only recently begun recovering from the inflation shock that followed the Russia-Ukraine conflict and the energy crisis that swept across Europe in 2022 and 2023.

Now a new geopolitical conflict threatens to reignite some of those same pressures.

Employment trends add another layer of concern.

European manufacturers have spent much of the past several years reducing headcounts amid weak demand and economic uncertainty.

The latest surveys suggest hiring remains subdued as companies struggle to balance rising costs against an uncertain economic outlook.

Businesses appear reluctant to commit to major workforce expansions until they gain greater confidence that demand will remain sustainable.

Dr. Cyrus de la Rubia, Chief Economist at Hamburg Commercial Bank, which helps compile the PMI surveys, has repeatedly warned that European manufacturing remains vulnerable despite recent improvements.

While conditions have stabilized compared with the depths of the downturn, many industries continue operating in an environment characterized by weak demand, elevated costs, and geopolitical uncertainty.

Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, has expressed similar concerns.

He noted that recent manufacturing gains have been heavily influenced by inventory accumulation as companies rush to secure supplies before prices rise further.

That behavior can temporarily boost production numbers, but it does not necessarily reflect durable economic strength.

Once inventories are replenished, demand can weaken quickly unless genuine customer orders take their place.

That possibility is becoming one of the central risks facing Europe’s economy during the second half of 2026.

The implications extend beyond factories.

The European Central Bank has been weighing whether additional interest-rate cuts may be needed to support economic growth.

However, persistent inflationary pressures complicate that calculation.

Central banks generally hesitate to lower borrowing costs aggressively when businesses continue reporting significant price increases.

If rising manufacturing costs translate into broader inflation, policymakers could face pressure to keep rates elevated for longer than many investors currently expect.

That would affect mortgages, business loans, commercial real estate financing, and consumer borrowing throughout the region.

Geography also remains a challenge.

Germany, Europe’s largest economy and manufacturing powerhouse, continues to struggle with slower growth than many smaller neighboring countries.

A recovery led by scattered pockets of strength rather than broad industrial momentum tends to be less durable and more vulnerable to external shocks.

For now, Europe’s factories remain operational and growing.

But Monday’s data reveal an increasingly uncomfortable reality.

The continent’s manufacturing sector is being squeezed between slowing demand and rising costs, while geopolitical tensions continue pushing energy and transportation expenses higher.

The immediate recovery remains intact.

Whether it can survive another sustained wave of inflationary pressure is the question hanging over Europe’s economy as summer begins.

Europe — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

America’s financial cushion is disappearing.

New data from the Bureau of Economic Analysis show that Americans are saving less of their income than at almost any point in the past two decades, raising concerns that households are increasingly relying on savings, credit cards, and even retirement accounts to keep up with rising costs.

The nation’s personal saving rate fell to 2.6% in April, the lowest level since June 2022 and down sharply from 5.5% a year earlier. The decline comes as inflation once again begins to outpace wage growth, squeezing consumers who have already spent much of the excess savings accumulated during and after the pandemic.

This was not a one-month anomaly.

The saving rate has steadily deteriorated throughout 2026, falling from 4.3% in January to 3.6% in February, 3.2% in March, and now 2.6% in April. The pattern suggests households are not making temporary adjustments or splurging on discretionary purchases. Instead, they appear to be systematically drawing down savings simply to maintain their standard of living.

The pressure is coming from both sides of the household balance sheet.

Inflation ran at approximately 3.8% in April, while wage growth slowed to 3.6%, marking the first sustained period since 2023 in which prices have been rising faster than paychecks. For millions of Americans, that means every month requires a little more spending power than the month before.

A major contributor has been energy.

Gasoline prices climbed above $4.20 per gallon in many regions as the conflict involving Iran and continued disruptions around the Strait of Hormuz pushed oil prices higher. Those increases quickly filtered through the economy, affecting transportation, food distribution, manufacturing, and household utility bills.

The result is that consumers are spending more money without necessarily getting more in return.

Consumers Are Spending More but Getting Less

At first glance, consumer spending appears healthy.

The Bureau of Economic Analysis reported that consumer spending rose 0.5% in April, a figure that would normally suggest a resilient economy.

But after adjusting for inflation, spending increased just 0.1%.

In plain English, Americans are paying more but receiving roughly the same amount of goods and services.

That distinction matters because consumer spending accounts for roughly two-thirds of U.S. economic output. If consumers begin running out of savings and borrowing capacity, the broader economy can slow quickly.

The latest figures have caught economists’ attention.

Heather Long, Chief Economist at Navy Federal Credit Union, said she initially thought the 2.6% saving rate figure was a mistake when she first saw it.

Outside the post-pandemic spending surge of 2022, the savings rate has rarely been this low over the past six decades.

Meanwhile, Federal Reserve Governor Lisa Cook recently acknowledged that inflation appears to be moving in the wrong direction, even while arguing that some of the current pressures could prove temporary.

For policymakers, the concern is not simply inflation itself. It is what happens when inflation combines with shrinking household savings and rising consumer debt.

The combination leaves families increasingly vulnerable to economic shocks.

A job loss, medical expense, car repair, or unexpected household emergency becomes much harder to absorb when savings accounts are already depleted.

Retirement Accounts Are Becoming Emergency Funds

The strain is increasingly visible in how Americans are managing cash flow.

Recent surveys show that approximately 37% of households now rely on some form of credit to cover basic monthly expenses, while roughly 65% report that rising prices have outpaced income growth.

Many are turning to their retirement savings.

According to Fidelity Investments, the percentage of workers with outstanding 401(k) loans climbed to 19.2% during the first quarter of 2026, up from 18.8% a year earlier.

Hardship withdrawals have also continued rising.

That trend worries financial advisers because borrowing from retirement accounts creates a double hit: households solve a short-term cash problem while reducing long-term wealth accumulation.

When families begin tapping retirement accounts to pay for groceries, rent, utilities, and gasoline, it is often a sign that traditional savings have already been exhausted.

Why Businesses Are Watching Closely

The implications stretch far beyond individual households.

Retailers, banks, credit-card companies, mortgage lenders, and consumer-products manufacturers all depend on a financially healthy American consumer.

A shrinking savings rate often signals that future spending growth may become harder to sustain.

Consumers can draw down savings for only so long before spending eventually slows.

That risk is especially important heading into the second half of 2026 as many households finish spending tax refunds and other temporary sources of cash.

Heather Long has warned that financial pressures could intensify later this year if wage growth remains below inflation and energy prices stay elevated.

For investors and business leaders, the savings rate may be becoming one of the most important economic indicators to monitor.

The American consumer remains resilient, but resilience becomes harder to maintain when the financial cushion keeps shrinking.

If inflation continues to outpace wages through the remainder of 2026, economists warn that the spending engine powering roughly two-thirds of the U.S. economy could begin showing more visible signs of strain.

For now, the message from the data is simple: Americans are still spending, but increasingly they are doing so by drawing down the reserves that once protected them from economic shocks.

Economy — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

SPRINGFIELD, Ill. — Illinois lawmakers have delayed the nation’s first attempt to ban certain credit- and debit-card swipe fees for a second consecutive year, pushing implementation of the controversial law to July 1, 2027 as a growing legal battle between merchants, banks, card networks, and federal regulators continues to unfold.

The measure, approved by the Illinois General Assembly during late-session budget negotiations and now awaiting the signature of Governor JB Pritzker, marks another chapter in what has become one of the most closely watched payment-industry disputes in the country.

For consumers, businesses, banks, and credit-card companies, the stakes extend far beyond Illinois.

The outcome could ultimately influence how card payments are processed nationwide and determine whether states can limit the fees collected by banks and payment networks on portions of transactions that include sales taxes and tips.

At the center of the dispute is Illinois’ Interchange Fee Prohibition Act (IFPA).

The law would prohibit banks and card networks from charging interchange fees—commonly known as swipe fees—on the sales-tax and gratuity portions of card transactions.

Today, merchants pay processing fees on the entire purchase amount, including taxes collected for government agencies and tips that are ultimately passed on to restaurant workers and service employees.

Retailers and restaurants argue that those portions of transactions should not generate fees because merchants never actually keep that money.

Instead, they merely collect it temporarily before passing it along to governments or employees.

The payments industry strongly disagrees.

Banks, credit unions, and payment networks argue that carving out portions of transactions would require costly changes to payment-processing systems and could create operational complications across the broader financial ecosystem.

The legal battle has become increasingly complex.

The law was originally scheduled to take effect on July 1, 2025 before lawmakers delayed implementation until 2026. The latest vote pushes enforcement back another year to July 2027.

Much of the uncertainty stems from actions taken in Washington.

The Office of the Comptroller of the Currency (OCC) recently determined that federal banking law preempts Illinois’ restrictions for national banks and federal savings associations. Those federal protections are scheduled to take effect on June 30, 2026, just one day before Illinois’ law would otherwise have become effective.

Federal regulators have argued that national banking laws supersede certain state-level restrictions, potentially limiting Illinois’ ability to enforce the law against large portions of the financial industry.

The National Credit Union Administration has moved toward similar protections for federally chartered credit unions.

The courts are still weighing the matter.

On May 8, the U.S. Court of Appeals for the Seventh Circuit vacated a lower-court ruling and sent the case back for additional review, effectively reopening major legal questions surrounding the law.

That decision erased an earlier ruling that had largely favored Illinois and returned the dispute to federal court in Chicago.

The lawsuit, Illinois Bankers Association v. Raoul, remains active.

The banking industry views the latest delay as a significant victory.

The Illinois Bankers Association, American Bankers Association, America’s Credit Unions, and the Illinois Credit Union League issued statements supporting the postponement, arguing that immediate implementation would create confusion while major legal questions remain unresolved.

Payment-industry groups were even more direct.

Scott Talbott, a senior executive at the Electronic Transactions Association, said the latest delay reflects what he described as a fundamentally flawed law.

Meanwhile, the Electronic Payments Coalition renewed calls for complete repeal, warning that Illinois risks creating operational chaos within the card-payment system.

Merchants and consumer advocates see the issue differently.

Several consumer organizations, including the National Association of Consumer Advocates and Americans for Financial Reform, have criticized federal regulators for siding with banks and card companies.

The Merchant Payments Coalition argues that swipe fees ultimately raise costs for businesses and consumers alike and has urged regulators to allow the Illinois law to move forward.

The broader concern for the financial industry is precedent.

More than a dozen states have explored similar legislation, and policymakers across the country are closely watching the Illinois case.

If courts ultimately allow states to prohibit fees on taxes and tips, industry observers believe lawmakers could eventually target other categories such as fuel purchases, groceries, or government-related payments.

For now, however, Illinois consumers will see no immediate changes.

Merchants will continue paying swipe fees on the full value of card transactions, including taxes and gratuities, while courts, regulators, lawmakers, and industry groups continue their battle over who should bear the costs of America’s electronic payment system.

The next major developments are likely to come from federal court and Washington regulators rather than the Illinois legislature.

Until then, one of the most significant payment-industry fights in America remains unresolved—and delayed once again.

Banking & Payments — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

The neighborhood Walgreens that many Americans have relied on for prescriptions, over-the-counter medicines, and everyday essentials is undergoing one of the biggest transformations in its history.

Under its new private-equity owner, Walgreens Boots Alliance is accelerating store closures, eliminating hundreds of jobs, and restructuring major parts of its business as it pursues a dramatic turnaround plan aimed at restoring profitability.

According to state labor filings in Illinois and Texas, Walgreens is cutting at least 628 jobs, including 469 positions at corporate offices in Deerfield and Chicago and another 159 jobs tied to the closure of a Houston-area distribution center. The reductions took effect June 1 and represent the latest stage of a broader restructuring effort that has been unfolding for more than a year.

The cuts come after private-equity firm Sycamore Partners completed its roughly $10 billion acquisition of Walgreens in 2025, ending nearly a century as a publicly traded company.

The new owners have made their objective clear.

According to reports, Sycamore aims to double Walgreens’ earnings over the next several years, increasing profitability from roughly $2 billion annually to approximately $4 billion. Achieving that goal requires aggressive cost-cutting, operational changes, and a significant reduction in underperforming locations.

For customers, the most visible impact will be store closures.

Walgreens had already begun shutting down locations before the acquisition. Former CEO Tim Wentworth announced plans in 2024 to close approximately 1,200 underperforming stores over three years after acknowledging that the company’s existing footprint had become unsustainable.

More than 500 stores had already closed by early 2026.

Since taking control, Sycamore has accelerated that strategy, focusing resources on locations that generate stronger financial returns while eliminating stores that consistently lose money.

The result is a leaner Walgreens—but also a smaller one.

For many communities, particularly urban neighborhoods and lower-income areas, the closures raise concerns about growing “pharmacy deserts” where residents must travel farther to access medications and healthcare services.

Healthcare advocates warn that millions of Americans already live in areas with limited pharmacy access, and additional closures could worsen the problem.

The issue is particularly significant for seniors, patients with chronic conditions, and individuals without reliable transportation.

For those customers, the closure of a nearby pharmacy can mean more than inconvenience—it can affect healthcare outcomes.

Behind the scenes, Walgreens is also dismantling parts of the broader healthcare empire it spent years assembling.

The company has reorganized itself into several separate operating units, including its U.S. retail business, the Boots pharmacy chain in the United Kingdom, Shields Health Solutions, CareCentrix, and VillageMD.

Industry analysts expect some of those businesses could eventually be sold or spun off entirely.

The company is increasingly focusing on what management sees as its core strength: pharmacy operations.

One key component of that strategy is automation.

Walgreens has expanded the use of centralized fulfillment centers that can process prescriptions more efficiently than individual stores. Company officials say these facilities now handle a significant percentage of prescription volume, allowing pharmacists to spend more time with patients while reducing labor costs.

The broader challenges facing Walgreens are not unique.

Drugstore chains across the country have struggled with shrinking profit margins, reimbursement pressures from pharmacy benefit managers, rising theft, changing consumer behavior, and growing competition from online retailers.

The traditional drugstore model has come under increasing strain.

Rite Aid entered liquidation proceedings in 2025, while CVS Health has increasingly focused on healthcare services and insurance operations rather than relying solely on retail pharmacy sales.

The era when neighborhood drugstores generated substantial profits from front-of-store purchases such as cosmetics, snacks, seasonal merchandise, and convenience items has largely faded.

Inflation and changing shopping habits have pushed consumers to spend more cautiously.

For Walgreens employees, the restructuring creates uncertainty.

Workers at surviving stores often face increased responsibilities as staffing levels are reduced and operations become more centralized. Corporate employees face ongoing concerns about future rounds of restructuring.

For investors and management, however, the strategy is designed to create a company that is smaller but financially stronger.

Whether that goal can be achieved without further weakening customer loyalty remains one of the biggest questions facing the company.

For consumers, the practical reality is already becoming visible.

Fewer stores. Fewer employees. More automation.

The Walgreens of the future will likely look very different from the one that dominated American street corners for decades.

The challenge for the company is ensuring that efficiency gains do not come at the expense of the community presence that helped make Walgreens one of the most recognizable names in retail healthcare.

Retail & Healthcare — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Voluntary review window cut from 90 days to 30 after industry pushback, as White House seeks balance between innovation and national security.

By JBizNews Desk

June 2, 2026

For business owners trying to understand Washington’s latest move on artificial intelligence, the simplest way to think about it is this:

The federal government wants an opportunity to look at the most powerful AI systems before they are released to the public—but it does not want to slow down America’s race against China.

That balancing act sits at the center of a new executive order signed Tuesday by President Donald Trump, creating the first formal framework for federal agencies to review cutting-edge artificial intelligence models before launch while stopping well short of requiring government approval.

The order establishes a voluntary process allowing leading AI developers such as OpenAI, Google, and Anthropic to provide their most advanced models to federal officials up to 30 days before public release.

Importantly, participation remains voluntary.

The executive order explicitly states that no company is required to submit models for review and that nothing in the order authorizes a government licensing regime, permit requirement, or mandatory preclearance process before an AI product can reach the market.

For businesses, investors, and technology executives, that distinction may be the most important part of the entire announcement.

What Does This Mean in Plain English?

Imagine if automobile manufacturers voluntarily allowed federal safety experts to inspect a new vehicle before it hit dealership lots.

The government would gain insight into potential risks, vulnerabilities, and safety concerns, but manufacturers would still control whether and when to release the product.

That is essentially what Washington is attempting to do with advanced AI.

The administration is seeking early visibility into the capabilities of powerful AI systems, particularly those that could affect national security, cyber defense, financial systems, utilities, healthcare networks, and other critical infrastructure.

At the same time, the White House is trying to avoid creating regulations that could slow American innovation or hand an advantage to Chinese competitors.

Why the Review Period Was Cut

The most contentious issue was timing.

An earlier version of the executive order would have created a voluntary review period of up to 90 days before launch.

Leading AI companies pushed back aggressively.

In the AI industry, where product cycles move at extraordinary speed, a three-month delay can mean losing a competitive advantage worth billions of dollars.

Industry leaders argued that lengthy review periods could weaken America’s position in the global AI race.

The final compromise reduced the review period to 30 days, a significant concession to developers while still giving federal agencies time to evaluate potential concerns.

Why Washington Is Suddenly Interested

The answer is cybersecurity.

As AI systems become more powerful, federal officials are increasingly concerned that the same technology capable of defending networks could also identify vulnerabilities in banking systems, hospitals, utilities, transportation networks, and government infrastructure.

The executive order directs agencies including the Department of Defense, Treasury Department, and the Cybersecurity and Infrastructure Security Agency (CISA) to strengthen protections for critical infrastructure.

The order also instructs the Office of the National Cyber Director to establish processes for identifying and sharing information about vulnerabilities discovered by advanced AI systems before those weaknesses can be exploited.

In practical terms, if a powerful AI model identifies a weakness in a major financial network or utility system, officials want a mechanism to alert operators before bad actors discover the same flaw.

A Shift in Trump’s AI Strategy

The order also highlights how rapidly Washington’s AI policy has evolved.

Shortly after taking office, President Trump moved aggressively to roll back portions of the Biden administration’s AI regulatory framework, arguing that excessive regulation could hamper innovation and weaken America’s competitive position.

His administration also promoted a national AI policy designed to reduce a patchwork of state-level regulations.

Tuesday’s executive order reflects a more nuanced position.

Rather than imposing direct regulation, the administration is creating a collaborative framework intended to increase visibility into frontier AI systems while preserving flexibility for developers.

In other words, Washington wants more information without taking control of product launches.

What Businesses Should Watch

For most business owners, the order will not change day-to-day operations tomorrow.

However, it signals that artificial intelligence is increasingly being viewed not merely as a technology issue but as a matter of national security and economic competitiveness.

The companies building advanced AI systems will now need to consider how voluntary federal reviews fit into product development timelines.

Meanwhile, organizations operating in finance, healthcare, energy, transportation, communications, and critical infrastructure may benefit from new federal efforts to identify cybersecurity vulnerabilities before they become public threats.

The broader message is clear: Washington is no longer standing on the sidelines of the AI revolution.

But unlike other heavily regulated industries, the federal government is attempting—for now—to influence the market through cooperation rather than mandates.

Whether that balance holds as AI capabilities continue to accelerate may become one of the most important policy questions facing American business in the years ahead.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

America is producing more oil than any nation in history, and that record output is helping shield drivers and businesses from what could have been a far more painful energy shock.

According to the latest U.S. Energy Information Administration (EIA) Short-Term Energy Outlook, the United States remains the world’s largest oil producer, pumping crude at levels never before seen. At a time when conflict in the Middle East continues to threaten global supply chains and energy markets, domestic production has become one of the most important forces keeping fuel prices from climbing even higher.

The numbers are staggering. U.S. crude oil production reached a record 13.6 million barrels per day in 2025 and is expected to remain near 13.5 million barrels per day throughout 2026. The bulk of that output continues to come from the Permian Basin in Texas and New Mexico, supported by production from offshore fields in the Gulf and growing activity in Alaska.

That production has been tested repeatedly this year.

The conflict in the Middle East and ongoing threats involving the Strait of Hormuz have rattled global energy markets. The narrow waterway serves as one of the world’s most critical oil shipping routes, handling roughly one-fifth of global petroleum trade. Any threat to traffic through Hormuz immediately raises concerns about supply shortages and higher prices.

Those concerns quickly reached energy markets.

Brent crude oil, the international benchmark, surged from roughly $61 per barrel at the start of the year to as high as $138 per barrel during periods of heightened tension. The impact was felt across the economy. The national average gasoline price approached $4 per gallon, while diesel prices climbed above $5 per gallon in many regions, increasing transportation and shipping costs throughout the supply chain.

Consumers noticed.

Businesses noticed.

And inflation pressures intensified.

Yet the story is not how much prices rose. The bigger story is how much higher they might have gone without record American production.

Every additional barrel produced domestically reduces the need for imported supply and helps offset disruptions elsewhere. As tensions squeezed global markets, U.S. shale producers effectively filled part of the gap, helping prevent a far larger spike in prices.

Think of it as a shock absorber.

The road may still be rough, but the impact is less severe because there is a cushion underneath.

Without America’s current production levels, fuel prices could have climbed substantially higher, placing additional strain on household budgets already coping with elevated housing, food, and borrowing costs.

The benefits extend well beyond drivers.

Fuel costs affect nearly every sector of the economy. Airlines, trucking companies, manufacturers, retailers, farmers, and delivery services all depend on affordable energy. When fuel prices rise, those costs eventually flow through to consumers in the form of higher prices on goods and services.

Record U.S. production has helped limit that ripple effect.

There are also signs of relief ahead.

The EIA expects global oil inventories to gradually rebuild as additional production comes online and some geopolitical pressures ease. The agency forecasts Brent crude will average approximately $89 per barrel by late 2026 and move closer to $79 per barrel during 2027.

If those projections hold, gasoline prices should gradually decline, providing welcome relief for households and businesses alike.

The story is similar in natural gas.

The United States continues to produce record volumes of natural gas, averaging more than 120 billion cubic feet per day during the first quarter of 2026. While global disruptions have pushed international gas prices higher, abundant domestic production has helped keep American energy costs lower than many other developed economies.

That advantage has strengthened America’s position as a leading exporter of liquefied natural gas while providing an additional layer of energy security.

None of this means the United States is immune from global events.

Oil remains a global commodity. A major escalation in the Middle East, prolonged disruptions in shipping routes, or unexpected supply outages could still push prices sharply higher regardless of domestic production levels.

But the reality today is very different from previous decades.

For much of modern history, America was heavily dependent on foreign oil and largely at the mercy of overseas producers. Today, record domestic production provides a significant buffer against global shocks.

For drivers filling up their tanks this summer, that may be the most important takeaway.

America’s oil boom has not eliminated higher fuel prices. It has not insulated consumers from every global disruption. What it has done is prevent an already difficult energy environment from becoming substantially worse.

As long as U.S. production remains near record highs, that cushion will continue helping protect American consumers from the full force of global energy turmoil.

Energy & Commodities — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

June 2, 2026

A growing battle over autism-therapy billing is no longer just a concern for insurers and government healthcare programs. It is increasingly becoming a financial issue for the union health funds that cover millions of American workers and their families.

The warning comes as The Wall Street Journal reports that insurers are raising concerns about alleged fraud, excessive charges, and rapidly escalating costs within parts of the autism-treatment industry. In one case highlighted by the newspaper, a family received a surprise bill totaling $911,400 for autism-related services.

At the center of the controversy is Applied Behavior Analysis (ABA) therapy, one of the most widely used treatments for children diagnosed with autism spectrum disorder. The therapy is designed to help children develop communication, social, and everyday living skills. Demand has grown significantly across the United States over the past decade as autism diagnoses have increased.

While the need for treatment is broadly recognized, the cost of providing that care has become a growing concern among employers, insurers, government agencies, and benefit administrators.

The issue is particularly important for Taft-Hartley health funds, the jointly administered labor-management health plans established under the Labor Management Relations Act of 1947. These self-funded plans cover millions of union workers, retirees, and dependents in industries ranging from construction and transportation to manufacturing and public services.

Unlike traditional insurance companies, many Taft-Hartley plans directly pay healthcare claims using funds contributed by employers under collective bargaining agreements. When healthcare costs rise sharply, the financial burden ultimately falls on the fund and its participating members.

Under the federal Mental Health Parity and Addiction Equity Act, many self-funded plans are required to provide coverage for autism treatment in a manner comparable to other medical benefits. That means trustees often have limited flexibility when faced with large claims, particularly when services are delivered by out-of-network providers charging substantially higher rates.

Recent data suggest those pressures are accelerating.

According to benefits consultant Mercer, members generating annual autism-related claims exceeding $200,000 accounted for approximately 16% of total autism spending in 2024, up from 9% the previous year. Mercer found that many of the largest claims were associated with out-of-network providers.

In practical terms, a relatively small number of cases are consuming a growing share of healthcare dollars.

Large insurers have begun publicly acknowledging the challenge. Centene Corp., one of the nation’s largest healthcare companies, cited elevated autism-treatment costs as a contributor to higher-than-expected reimbursement expenses. Company executives described some of those costs as both “unanticipated” and “unacceptable.”

For union health plans operating with smaller reserves than national insurers, a handful of unusually large claims can have a disproportionate impact on finances.

Regulators have also intensified scrutiny of the industry.

Indiana has emerged as one of the most closely watched states after years of rapid growth in autism-treatment billing. According to public records reviewed by regulators, some providers billed rates as high as $640 per hour for services delivered by relatively junior staff members. One provider reportedly collected approximately $340,000 per patient in a single year.

State officials later revised reimbursement rules and moved to terminate certain provider billing privileges as part of a broader effort to curb excessive spending.

Meanwhile, federal investigators are examining billing practices nationwide. The Department of Health and Human Services Office of Inspector General found improper or potentially improper payments in every sampled Medicaid ABA claim reviewed across Colorado, Indiana, Maine, and Wisconsin, representing nearly $200 million in questioned spending.

The findings have intensified concerns that aggressive billing practices may not be confined to government healthcare programs.

Adding another layer to the issue is the growing role of private investment in the autism-treatment sector. Industry analysts estimate that private-equity firms have acquired more than 500 autism-treatment centers over the past decade, creating larger networks capable of rapidly expanding services and billing volume.

Supporters argue that investment has increased access to treatment for families seeking care. Critics counter that financial incentives can encourage excessive utilization and higher reimbursement demands.

For trustees overseeing union health funds, the challenge is becoming increasingly difficult.

Unlike publicly traded insurers, Taft-Hartley funds answer directly to workers and employers. Significant cost increases can translate into higher contributions, reduced reserves, increased participant costs, or difficult benefit decisions.

Healthcare experts say the growing debate over autism-treatment billing may ultimately extend far beyond Medicaid budgets and insurance-company earnings reports.

Federal investigators, state regulators, insurers, and benefits consultants are all examining the issue. The next question is whether the same cost pressures that have already affected government programs and large healthcare companies will increasingly land on self-funded union health plans.

If they do, the impact will be felt not on corporate balance sheets alone, but on the healthcare benefits that millions of working families rely upon every day.

Healthcare — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
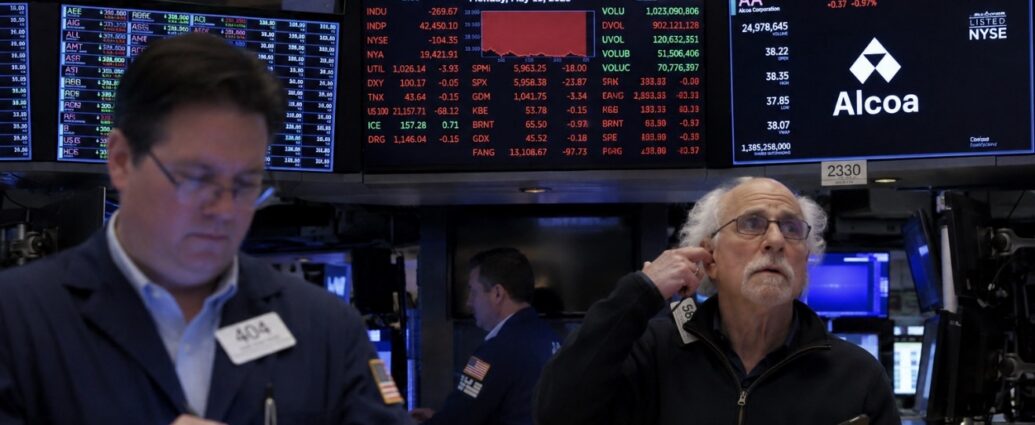
TALLAHASSEE, FL— The Independent Media Council (IMC) today applauded the Florida Legislature for once again taking a strong stand against media blacklists by including a key free speech protection in the 2026-2027 state budget. The budget now heads to Gov. Ron DeSantis, who is expected to sign it into law.

The provision prevents state agencies from contracting with advertising agencies or marketing firms that use politically biased media-monitoring and “brand safety” systems such as NewsGuard, Ad Fontes, and the Global Disinformation Index (GDI).

“Florida lawmakers deserve credit for continuing to stand up against politically driven media blacklist systems that distort advertising markets and suppress viewpoints,” said Christine Czernejewski, spokesperson for the IMC.

“Taxpayer-funded advertising should maximize public reach — not be filtered through ideological gatekeepers masquerading as neutral watchdogs. The IMC especially wants to thank Speaker Daniel Perez and State Sen. Ed Hooper for their leadership on this issue.”

Florida first enacted the provision in last year’s state budget, becoming one of the first states in the nation to directly confront the growing use of media blacklists in the advertising industry. Since then, momentum against these censorship systems has continued to grow nationwide.

West Virginia recently passed similar protections through its First Amendment Preservation Act, while Congress adopted comparable language in the National Defense Authorization Act (NDAA), restricting the Pentagon from using advertising agencies that use misinformation-monitoring systems when placing military recruitment ads.

The Federal Trade Commission has also scrutinized coordinated “brand safety” practices among major advertising firms that use media monitors like NewsGuard and GDI.

“These media blacklist operations are not neutral watchdogs — they are political pressure campaigns designed to starve disfavored outlets of advertising revenue,” Czernejewski added.

“When governments and major corporations rely on ideological scoring systems to determine which voices deserve economic support, censorship inevitably follows.”

Florida’s continued leadership on the issue is especially important given the state’s growing creator economy and its significant tourism industry. Media blacklist systems distort advertising markets, limiting the reach of taxpayer-funded tourism and public awareness campaigns.

The IMC urged Gov. Ron DeSantis to sign the budget with the provision intact, noting that Florida has already established itself as a national leader on this issue.

The organization said it expects additional states to follow suit as concerns continue to grow over the use of ideological media-monitoring systems to influence advertising markets and suppress disfavored viewpoints.

***

The Independent Media Council (IMC) is a non-profit group of conservative and independent media outlets and aligned organizations that stand for free speech and a free press. Members regularly reach over 75 million Americans. The IMC believes the antidote to misinformation and disinformation is more speech, not censorship and works to protect the speech of all media outlets and content creators.

Florida — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

DALLASSouthwest Airlines has backed away from a controversial policy that required many larger passengers to purchase a second seat in advance, restoring an option that allows travelers to receive an additional seat free of charge at the airport when space is available.

The change, confirmed by the airline Friday and widely reported Monday, marks a notable reversal for a carrier that has spent the past year eliminating several customer-friendly policies in an effort to improve profitability and satisfy investor demands.

Under the revised rules, Southwest gate agents can once again provide an adjoining seat at no additional cost to passengers who need extra space, provided two adjacent seats remain available on the flight.

The move partially restores a policy that had long distinguished Southwest from other major U.S. airlines.

The controversy began earlier this year when Southwest modified its long-standing accommodation policy for what the airline refers to as “Customers of Size.”

Beginning January 27, passengers unable to fit comfortably within a single seat’s armrests were generally required to purchase a second seat before travel. While Southwest had historically offered refunds in many cases, the new policy significantly reduced certainty around reimbursement and shifted more of the burden onto travelers.

The timing coincided with another major change.

Southwest abandoned its decades-old open-seating system and moved to assigned seating, fundamentally altering the boarding process that had become synonymous with the airline’s brand.

The two changes were closely connected.

Under open seating, gate agents could easily block or assign an adjacent seat without disrupting pre-arranged seating charts. Assigned seating made that flexibility more difficult, prompting the airline to move toward advance seat purchases.

The reaction was immediate.

Passenger advocates and social-media users criticized the policy, with some labeling it a “fat tax” that unfairly targeted larger travelers.

Organizations including the National Association to Advance Fat Acceptance (NAAFA) argued that Southwest had previously been one of the most accommodating airlines for plus-size passengers and warned the changes could make air travel more difficult and expensive for many customers.

Facing mounting criticism, Southwest adjusted course.

The revised policy allows airport personnel to provide a complimentary extra seat when available, although limitations remain.

Passengers who require additional space are not guaranteed a second seat if flights are full. In those situations, travelers may be rebooked onto a later flight where adjacent seating can be arranged.

Southwest continues to recommend that passengers who know they will require extra space reserve a second seat in advance to avoid travel disruptions.

Advocates welcomed the policy adjustment but stopped short of calling it a complete solution.

Critics note that travelers who cannot afford to purchase a second seat upfront may still face uncertainty, delays, and potential rebooking if flights operate near capacity.

Supporters of the original policy argue that requiring larger passengers to secure adequate seating in advance helps improve comfort for all travelers and reduces conflicts onboard.

The debate highlights the increasingly difficult balancing act facing airlines as they attempt to maximize revenue while maintaining customer goodwill.

For Southwest, the issue extends beyond seating arrangements.

The airline has spent the past year undergoing one of the most significant transformations in its history.

Under pressure from activist investor Elliott Investment Management, Southwest has implemented a series of changes aimed at boosting profitability and closing performance gaps with competitors.

The carrier ended its famous “Bags Fly Free” policy, introduced premium seating options, expanded overnight flights, moved to assigned seating, and pursued additional revenue-generating initiatives that would have been almost unthinkable just a few years ago.

Each move has been designed to improve financial performance.

Each has also sparked concern among longtime customers who viewed Southwest as different from traditional airlines.

That identity challenge may be becoming more important.

For decades, Southwest built customer loyalty through simplicity, transparency, and policies that travelers often viewed as more generous than those offered by competitors.

As the airline adopts practices increasingly common throughout the industry, some customers have questioned what continues to set the company apart.

Travel analysts say the plus-size seating reversal suggests management recognizes that customer goodwill remains a valuable asset.

The decision may have limited direct financial impact, but it sends a broader message about the importance of maintaining trust while pursuing operational changes.

For travelers, the practical implications are straightforward.

Passengers needing additional space can once again request a complimentary adjacent seat at the airport when available. However, availability is not guaranteed, making advance planning more important than ever.

The larger takeaway may be that customer feedback still matters.

In an era when airlines are aggressively seeking new revenue streams, Southwest’s reversal demonstrates that public pressure can still influence corporate decision-making—particularly when a company’s brand has long been built on customer loyalty.

Whether that lesson shapes future changes at Southwest remains one of the biggest questions facing the airline as it continues its transformation.

Travel & Aviation — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Strong AI demand, blockbuster earnings, and continued technology spending pushed major indexes to fresh highs despite concerns about valuations, Middle East tensions, and a massive Alphabet stock offering.

By JBizNews Desk

June 2, 2026

U.S. stocks climbed to fresh record highs Tuesday as another wave of artificial-intelligence enthusiasm swept through Wall Street, led by explosive earnings from Hewlett Packard Enterprise and a sharp rally in Marvell Technology, while investors digested Alphabet’s plans to raise $80 billion to fund its growing AI ambitions.

The S&P 500 rose 0.13% to close at 7,609.78, marking its first finish above the 7,600 level. The Dow Jones Industrial Average gained 228.91 points, or 0.45%, ending at 51,307.79 after reaching a fresh intraday record. The Nasdaq Composite edged up 0.03% to 27,093.90, while the Russell 2000 outperformed as investors rotated into smaller companies benefiting from the AI investment boom.

The biggest winner of the day was Hewlett Packard Enterprise (NYSE: HPE).

Shares surged approximately 27% after the company delivered quarterly results that significantly exceeded Wall Street expectations. Adjusted earnings came in at 79 cents per share, compared with analyst forecasts of roughly 53 cents, while revenue reached $10.68 billion, easily topping estimates near $9.8 billion and rising approximately 40% from a year earlier.

The company’s networking business soared 148%, while its cloud and AI segment grew 23%, highlighting the continued strength of enterprise demand for AI-related infrastructure.

Management also sharply increased its full-year outlook, raising adjusted earnings guidance to $3.35 to $3.45 per share, well above its prior forecast of $2.30 to $2.50. HPE additionally boosted its free-cash-flow target to $3.5 billion and announced that a representative from activist investor Elliott Investment Management would join its board.

The results reinforced Wall Street’s belief that AI spending remains one of the strongest growth stories in corporate America.

Marvell Rockets Higher on Jensen Huang Endorsement

Marvell Technology nearly matched HPE’s performance, soaring approximately 27% after Nvidia CEO Jensen Huang described the company as a future “trillion-dollar company” during remarks at the Computex conference in Taipei.

The endorsement added tens of billions of dollars to Marvell’s market value, pushing the company above $240 billion.

Investors also pointed to Nvidia’s previously disclosed $2 billion investment in Marvell, announced earlier this year, as evidence of the strategic importance of AI-related semiconductor infrastructure.

Meanwhile, Microchip Technology gained roughly 4% after forecasting its data-center business would expand 65% this year to approximately $500 million.

Alphabet Falls Despite Massive AI Bet

Not every technology giant participated in the rally.

Shares of Alphabet (NASDAQ: GOOGL) fell approximately 2.5% after the company announced plans to raise $80 billion in new capital to accelerate AI development and infrastructure investments.

The offering represents one of the largest equity raises ever undertaken by a technology company.

According to the announcement, the package includes:

  • $40 billion through an at-the-market stock program
  • $30 billion through underwritten public offerings
  • $10 billion private placement led by Berkshire Hathaway

Berkshire Hathaway is expected to purchase $5 billion of Class A shares and $5 billion of Class C shares.

The stock declined primarily on dilution concerns, though many analysts viewed the announcement as another sign that demand for AI services continues to exceed available infrastructure.

Alphabet indicated that customer demand for AI products remains stronger than the company’s ability to currently supply capacity.

Salesforce Gives Back Recent Gains

Elsewhere in technology, Salesforce fell approximately 5%, giving back some of Monday’s gains following its acquisition announcement involving Contentful.

Other software names, including ServiceNow and Intuit, also traded lower, while Super Micro Computer moved higher.

Among analyst calls, Piper Sandler initiated coverage of Take-Two Interactive with an Overweight rating and a $280 price target, citing optimism surrounding the upcoming launch of Grand Theft Auto VI.

Oil Pulls Back as Iran Tensions Continue

Outside technology, investors continued monitoring developments in the Middle East.

Crude oil prices retreated roughly $1 per barrel to around $91, giving back part of Monday’s advance.

The market remains focused on tensions involving Iran and ongoing concerns surrounding the Strait of Hormuz, one of the world’s most important energy shipping routes.

Iran suspended indirect negotiations with the United States in response to Israeli military actions in Lebanon, while President Donald Trump stated that talks were continuing at a “rapid pace.”

Those conflicting signals left traders uncertain about the next move in energy markets.

Labor Market Sends Mixed Signals

Economic data released Tuesday added another layer of complexity.

The latest Job Openings and Labor Turnover Survey (JOLTS) showed job openings unexpectedly jumping to 7.6 million in April, the highest level in nearly two years.

However, actual hiring declined to 5.1 million, reinforcing concerns that employers remain cautious despite posting more available positions.

Investors will receive additional labor-market data Wednesday through the ADP payroll report, followed by Friday’s closely watched nonfarm payrolls report.

Warnings Beneath the Rally

Despite the record highs, some Wall Street leaders remain cautious.

JPMorgan Chase CEO Jamie Dimon, speaking at the Reagan National Economic Forum on May 29, warned that markets appear increasingly “exuberant” and that investors may be underestimating risks.

Valuation measures across the market remain near historically elevated levels, even as earnings growth continues to support the rally.

Meanwhile, Bitcoin slipped to around $69,000, reflecting a recent cooling in cryptocurrency markets despite continued strength in equities.

For now, the market’s message remains clear: artificial intelligence continues to drive capital spending, earnings growth, and investor enthusiasm.

But with record valuations, geopolitical uncertainty, and Friday’s jobs report looming, Wall Street’s next test may arrive sooner than investors expect.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 4, 2026

NEW YORKSpaceX revealed Monday that it plans to reserve up to 5% of shares in its upcoming initial public offering for selected employees and a hand-picked group of friends and family connected to senior executives, giving a small circle of insiders access to one of the most anticipated stock offerings in market history.

The disclosure came in an amended securities filing as Space Exploration Technologies Corp. moves closer to an IPO that could value the company at roughly $1.75 trillion, placing it among the largest public offerings ever attempted.

The reserved shares will be distributed through what Wall Street calls a directed share program, a mechanism that allows companies to allocate a portion of IPO stock directly to individuals they choose rather than routing all shares through institutional investors and large investment funds.

SpaceX said participants will be selected at the discretion of the company’s executive officers. Any reserved shares not purchased by those participants would become available to the broader investing public.

While directed share programs are not uncommon, one feature of SpaceX’s plan stands out.

The company disclosed that recipients of these shares will not be subject to the same lock-up restrictions imposed on most other insiders.

That distinction could prove valuable.

Typically, insiders receiving IPO shares must wait several months before selling stock. SpaceX’s selected participants will have substantially greater flexibility, allowing them to potentially sell shares much earlier than many major shareholders.

By contrast, the company said more than 60% of pre-IPO outstanding shares will remain subject to a 366-day lock-up period.

That restriction includes holdings controlled by Elon Musk, who owns approximately 12.3% of SpaceX’s Class A shares and controls roughly 85% of the company’s voting power. Under the filing, Musk has agreed not to sell his shares during the lock-up period.

The result creates an unusual dynamic.

While Musk and many long-term investors remain restricted, certain employees and insiders participating in the directed share program may gain access to liquidity much sooner.

The structure has already drawn attention from market observers who note that IPO lock-ups are designed in part to prevent large waves of selling immediately after a company goes public.

Directed share programs themselves are hardly new.

Companies including Airbnb, Uber, and Rivian used similar approaches during their public offerings. When Tesla went public in 2010, it reserved more than one million shares for employees, customers, business associates, friends, and family members.

What makes SpaceX’s approach different is the exemption from traditional lock-up restrictions.

The company is simultaneously pursuing a broader goal that could make the IPO unusually accessible to retail investors.

Earlier discussions between SpaceX and underwriting banks indicated that the company may allocate as much as 30% of the offering to individual investors, dramatically above the typical 5% to 10% retail allocation seen in most major IPOs.

The strategy reflects a desire by Musk and senior leadership to cultivate a large base of long-term retail shareholders rather than concentrating ownership among hedge funds and institutional investors.

Under plans outlined to banks, Morgan Stanley’s E*Trade platform would help distribute shares to smaller investors, while Bank of America, UBS, and Citigroup would assist with broader domestic and international demand.

Monday’s filing also contained new details about SpaceX’s rapidly expanding artificial-intelligence infrastructure business.

The company disclosed an agreement to lease substantial computing capacity to Anthropic, one of the world’s leading AI developers.

According to the filing, the arrangement involves computing power equivalent to approximately 325,000 NVIDIA chips operating at the company’s Colossus and Colossus II facilities near Memphis.

If fully utilized, the contract could generate approximately $1.25 billion per month through May 2029, creating a potentially significant recurring revenue stream beyond SpaceX’s traditional launch, satellite, and space-services businesses.

However, the filing also noted that either party may terminate the arrangement after an initial three-month period with 90 days’ notice.

The company additionally identified water availability as a growing operational risk.

As demand for AI computing accelerates, data-center cooling requirements continue to rise, and SpaceX acknowledged that drought conditions or increased competition for water resources could affect future operations.

For investors, the filing highlights both the opportunities and complexities surrounding what is expected to become one of the most closely watched IPOs of the decade.

Retail investors may receive an unusually large allocation.

Employees and selected insiders gain privileged access through the directed share program.

At the same time, questions remain regarding final pricing, valuation, share allocation, and long-term profitability across SpaceX’s expanding portfolio of businesses.

The company’s final prospectus is expected to provide additional details in the coming weeks.

Until then, one fact is becoming increasingly clear: SpaceX’s public debut is shaping up to be unlike almost any IPO Wall Street has seen before.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
More than $1 billion in liquidations, persistent ETF outflows, and fading momentum hit digital assets even as stocks continue riding the AI boom.

By JBizNews Desk

June 2, 2026

Bitcoin fell below $68,000 on Tuesday, extending a sharp cryptocurrency selloff that wiped out more than $1 billion in leveraged positions and underscored the growing divergence between digital assets and a stock market that continues to march toward record highs.

The world’s largest cryptocurrency traded as low as approximately $67,200 during the session, its weakest level in roughly a month, according to market data. The decline came as investors pulled hundreds of millions of dollars from crypto exchange-traded funds and traders rushed to unwind bullish bets that had accumulated during this year’s rally.

The weakness was broad-based across digital assets.

Ethereum fell nearly 5% to around $1,900, while Solana dropped approximately 6% to the mid-$70s. XRP declined about 5%, adding to losses across the sector. The total cryptocurrency market capitalization fell roughly 3.5%, erasing tens of billions of dollars in value in a single trading session.

For many investors, the bigger question is not why crypto is falling.

It is why crypto is falling while stocks keep rising.

The S&P 500 remains near record highs, fueled by continued enthusiasm surrounding artificial intelligence, strong corporate earnings, and steady capital spending by technology giants. The Nasdaq Composite has continued benefiting from AI-driven optimism, while investors have increasingly favored large-cap equities over more speculative assets.

In effect, money that might have flowed into cryptocurrencies earlier in the cycle is finding a home elsewhere.

The first major factor weighing on crypto is the continued exodus from exchange-traded funds.

Bitcoin ETFs recorded approximately $483 million in net outflows on Monday, extending an outflow streak that has now lasted nearly two weeks. Ethereum funds have experienced a similar pattern, with investors steadily reducing exposure despite hopes that ETF adoption would provide a durable institutional bid.

The significance is straightforward.

During much of the previous rally, ETFs served as a powerful source of new demand, helping absorb available supply and support rising prices. When those flows reverse, markets lose an important source of support.

“The institutional buyer has stepped away,” one digital-asset strategist said Tuesday. “The question becomes who replaces that demand.”

At the same time, leverage amplified the decline.

According to CoinGlass, more than $1 billion in crypto positions were liquidated over a 24-hour period, with nearly all of the losses concentrated among traders betting on higher prices.

When leveraged positions are forced to close, exchanges automatically sell assets to cover losses. That selling can trigger additional liquidations, creating a cascade effect that accelerates downward moves.

The result is often a decline that appears sudden but is actually fueled by automated selling mechanisms embedded throughout the market.

Adding to investor concerns was news involving Strategy (NASDAQ: MSTR), the company led by Michael Saylor and widely regarded as the largest corporate holder of Bitcoin.

The company disclosed the sale of 32 Bitcoin for approximately $2.5 million, representing an average sale price of roughly $77,000 per coin.

While the transaction was tiny relative to Strategy’s overall holdings, traders viewed it as another negative headline in an already fragile market.

Analysts largely dismissed the sale as immaterial, noting that it does not appear to signal any broader shift in Strategy’s long-term commitment to Bitcoin.

Still, markets often react more to sentiment than size.

The contrast between crypto and equities has become increasingly difficult to ignore.

Just a few months ago, many investors expected cryptocurrencies and technology stocks to move higher together as enthusiasm surrounding artificial intelligence, digital infrastructure, and innovation accelerated.

Instead, stocks have continued attracting capital while crypto has struggled to maintain momentum.

For companies operating within the digital-asset ecosystem, including ETF issuers, exchanges, custodians, and publicly traded firms holding Bitcoin on their balance sheets, price volatility remains central to the business model.

Higher prices attract inflows, trading activity, and investor attention. Lower prices can quickly reverse those trends.

The next test for crypto markets may arrive sooner than many investors expected.

Technical analysts are closely watching the $66,000 to $65,000 range as the next major support area for Bitcoin. Should that level fail to hold, some traders believe the market could revisit levels closer to $60,000, an area that previously attracted strong buying interest earlier this year.

For now, the message from markets is clear.

Wall Street remains focused on earnings growth, artificial intelligence, and corporate investment. Crypto investors, meanwhile, are confronting a different reality—one defined by weakening fund flows, fading momentum, and a market searching for its next catalyst.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

WASHINGTON — For decades, the 529 plan had a simple purpose: help families save for college. Today, it has become something much bigger.

Under changes enacted through President Donald Trump’s One Big Beautiful Bill Act, signed into law in July 2025, 529 accounts can now be used for a much broader range of educational expenses, transforming what was once primarily a college-savings vehicle into what many financial planners are calling a lifelong learning account.

The shift could have significant implications for workers navigating career changes, professionals maintaining licenses, parents paying for K-12 education, and families looking for new ways to reduce education costs while benefiting from tax-advantaged savings.

“You can now use them really as lifelong education savings accounts,” Vivian Tsai, Managing Director of TIAA Education Savings, said in comments reported Monday. “This is hugely transformational for adult learners.”

The expansion reflects a changing reality in the American workforce.

Increasingly, workers are expected to update skills throughout their careers, obtain additional certifications, complete continuing education requirements, and adapt to rapidly evolving industries. The traditional model of completing education in early adulthood and never returning to formal learning is becoming less common.

The revised 529 rules aim to address that shift.

The accounts still operate much as they always have.

Contributions are made using after-tax dollars. Investments grow tax-free. Withdrawals remain exempt from federal taxes when used for qualified educational expenses. More than 30 states also offer additional tax incentives through deductions or credits on contributions.

What changed is the definition of education.

Previously, most qualified expenses centered around college tuition and related higher-education costs. Under the new law, the list now extends significantly further.

Qualified expenses now include professional certification programs, credentialing courses, occupational training, testing fees required to obtain or maintain professional licenses, and continuing education courses necessary for license renewals.

That means a nurse renewing certifications, a real-estate agent maintaining a license, an electrician obtaining advanced credentials, or a mid-career professional learning new technical skills may all be able to use 529 funds without triggering taxes or penalties.

The expansion effectively turns the account into a tool that can support educational expenses throughout a person’s working life.

Families with younger children also received expanded benefits.

Beginning in 2026, annual tax-free withdrawals for K-12 education increased from $10,000 to $20,000 per student.

The definition of qualifying K-12 expenses was also broadened.

In addition to private-school tuition, eligible expenses now include tutoring, online educational programs, Advanced Placement testing fees, standardized testing costs, certain educational therapies, textbooks, and other approved educational materials.

Financial advisers say the changes build on previous reforms that had already expanded the flexibility of 529 plans.

Recent legislation allowed certain student-loan repayments using 529 assets and created pathways for transferring unused balances into retirement accounts under specific conditions.

As a result, the risk of “overfunding” a 529 account has diminished considerably.

One of the most practical implications involves leftover balances.

Parents who worried about unused funds after a child graduated from college now have more options. Those assets may potentially be redirected toward future professional education, credentialing expenses, or retirement savings rather than remaining trapped inside a narrowly defined college fund.

The law also opens the door for adults to establish 529 accounts for themselves.

Someone planning a career change, professional certification, or advanced training program may be able to contribute funds, benefit from tax-free growth, potentially receive state tax benefits, and later withdraw the money tax-free for qualifying educational expenses.

For many households, that combination could make a 529 more attractive than traditional taxable savings accounts.

The contribution rules remain generous.

In 2026, individuals can generally contribute up to $19,000 annually per recipient without triggering federal gift-tax reporting requirements.

Special provisions allow contributors to front-load five years of contributions at once, enabling a single person to contribute up to $95,000 immediately or a married couple up to $190,000 per beneficiary under certain circumstances.

Financial professionals caution that the tax advantages only apply when funds are used for qualified educational expenses.

Withdrawals for non-qualified purposes remain subject to ordinary income taxes on investment earnings plus a 10% federal penalty.

The expansion arrives as families evaluate other recently introduced savings vehicles, including the new Trump Accounts, scheduled to begin accepting contributions on July 4, 2026.

While Trump Accounts offer separate advantages, including a federal seed contribution for qualifying newborns, education-focused advisers generally continue to view 529 plans as the more efficient option for funding educational expenses because qualified withdrawals remain tax-free.

The broader question is whether Americans will take advantage of the opportunity.

Industry estimates suggest only about 23% of U.S. families currently utilize a 529 plan.

That participation rate developed when many consumers viewed the accounts solely as college-savings vehicles.

Now, however, the accounts can potentially support a child’s tutoring, a teenager’s private-school education, a college student’s degree, a professional’s license renewal, and even a mid-career worker’s retraining program.

In other words, the 529 has quietly evolved from a college fund into something far more flexible.

The tax benefits have not changed.

The range of people who can benefit from them has.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

WASHINGTON — Alphabet Inc. is asking federal regulators for permission to release up to 32 million laboratory-bred mosquitoes across California and Florida over the next two years, a proposal that sounds alarming at first glance but is designed to do the opposite: reduce mosquito populations and limit the spread of disease.

The request, currently under review by the U.S. Environmental Protection Agency (EPA), was submitted by Verily, Alphabet’s life-sciences subsidiary, as part of its long-running Debug Project. The filing was published in the Federal Register on Monday, opening a public-comment period before regulators decide whether to approve the plan.

If approved, Verily would release approximately 16 million mosquitoes annually in each of the next two years at locations that have not yet been publicly identified.

The proposal may seem counterintuitive.

Why would a company fight mosquitoes by releasing millions more of them?

The answer lies in the type of mosquito being released.

Verily breeds male Aedes aegypti mosquitoes carrying a naturally occurring bacterium known as Wolbachia. When these males mate with wild female mosquitoes, the resulting eggs fail to hatch, reducing mosquito populations over time.

The males themselves do not bite humans and cannot transmit disease.

The approach is based on the Sterile Insect Technique, a method used for decades to combat agricultural pests including fruit flies and screwworms. What makes Verily’s effort different is the scale.

The company has spent years developing automated systems capable of breeding, sorting, and distributing mosquitoes in volumes large enough for widespread deployment.

According to Verily, automation and data-driven production techniques could dramatically reduce costs compared with traditional mosquito-control methods.

The public-health implications are significant.

The targeted mosquito species, Aedes aegypti, is responsible for spreading diseases including dengue fever, Zika virus, yellow fever, and chikungunya.

The Centers for Disease Control and Prevention has repeatedly identified mosquitoes as one of the world’s most dangerous disease vectors. Globally, mosquito-borne illnesses affect hundreds of millions of people annually and contribute to hundreds of thousands of deaths each year.

While the United States does not experience the same levels of mosquito-borne disease seen in tropical regions, outbreaks have increased in recent years.

Florida has periodically reported locally transmitted cases of dengue and Zika, while California has seen expanding populations of invasive mosquito species as temperatures rise and climate conditions change.

For state and local governments, mosquito control is big business.

Counties and municipalities spend millions of taxpayer dollars each year on spraying programs, public education campaigns, larvicide treatments, and monitoring operations designed to limit mosquito populations.

Verily argues that biological control methods could eventually reduce dependence on chemical pesticides.

That claim has attracted attention throughout the pest-control industry.

Traditional mosquito-management programs rely heavily on insecticides and field crews tasked with identifying breeding sites. If Verily’s approach proves effective and economically competitive, it could reshape portions of the mosquito-control market and create new competition for existing providers.

For Alphabet, the proposal represents something larger than a public-health initiative.

The project is part of the company’s broader effort to expand beyond its core advertising and search businesses.

Over the years, Alphabet has invested billions of dollars into “Other Bets” ventures ranging from autonomous vehicles and healthcare technologies to life sciences and environmental solutions.

Many of those projects have struggled to become profitable commercial businesses.

Verily’s mosquito program is viewed internally as one of the more promising opportunities to build a scalable service with measurable public-health outcomes.

A successful EPA approval could serve as an important validation of both the technology and the underlying business model.

The potential market is substantial.

Mosquito-control programs operate worldwide, particularly in regions where mosquito-borne diseases place significant burdens on healthcare systems and local economies.

Tourism-dependent destinations are especially vulnerable.

A disease outbreak can quickly discourage travel, reduce hotel occupancy, and impact local businesses. For states such as Florida, where tourism represents a major economic engine, mosquito management carries direct economic importance.

Environmental groups and community organizations are expected to closely examine the proposal during the EPA review process.

Questions remain regarding release locations, long-term monitoring requirements, ecological impacts, and overall program costs.

Verily maintains that the released mosquitoes pose minimal environmental risk because only male insects are used and the Wolbachia-based approach does not involve genetic modification.

Still, any proposal involving the release of millions of insects is likely to generate public scrutiny.

For now, the decision rests with federal regulators.

What appears on the surface to be an unusual science experiment is, in reality, a test of whether a major technology company can transform a public-health intervention into a scalable commercial business.

If the EPA grants approval, California and Florida could become the first major proving grounds for a strategy that Alphabet hopes can be deployed around the world.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

Frontier Airlines is moving aggressively to capture the customers and routes left behind by Spirit Airlines. The carrier is expanding into former Spirit markets, adding flights, and benefiting from a competitive landscape that suddenly looks far less crowded.

On paper, it looks like a smart move.

But beneath the opportunity sits a larger question. By chasing Spirit’s customers, is Frontier also inheriting the same challenges that pushed its biggest ultra-low-cost rival into bankruptcy?

For years, Frontier Airlines and Spirit Airlines were built around nearly identical business models. Offer some of the cheapest fares in the industry, then generate additional revenue through fees for checked bags, carry-ons, seat assignments, snacks, priority boarding, and other add-ons.

The approach worked for a long time.

Low fares attracted travelers. Ancillary fees boosted revenue. Investors embraced the ultra-low-cost carrier model as a way to stimulate demand and compete against larger airlines.

Then the economics changed.

Labor costs rose. Aircraft expenses increased. Airport fees climbed. Fuel prices became more volatile. Suddenly, the margin for error that budget airlines depended on became much smaller.

That pressure eventually overwhelmed Spirit.

The airline, whose bright yellow planes became synonymous with low-cost travel, spent years battling losses before entering bankruptcy proceedings. Several attempts to reshape its future failed, including a proposed merger with Frontier Airlines first announced in 2022.

The collapse delivered a harsh lesson for the industry.

The biggest threat to ultra-low-cost carriers is not necessarily rising costs. It is competition from the largest airlines in America.

Carriers such as Delta Air Lines, United Airlines, and American Airlines no longer ignore budget travelers. Instead, they compete directly through Basic Economy fares that often approach the prices offered by budget airlines.

The difference is what happens elsewhere on the plane.

Large airlines can make substantial profits from premium cabins, loyalty programs, corporate contracts, airport lounges, and international routes. A discounted seat in the back of the aircraft can be offset by thousands of dollars generated elsewhere.

Budget airlines do not have that luxury.

For them, the cheap seat is not part of the business model.

The cheap seat is the business model.

That distinction matters.

When major airlines cut prices, they have multiple ways to protect profitability. Ultra-low-cost carriers have far fewer options.

That is the trap that caught Spirit.

And now Frontier finds itself navigating many of the same conditions.

The airline appears determined to learn from what happened.

Under its “New Frontier” strategy, the company has begun adding features traditionally associated with larger carriers, including enhanced loyalty benefits, upgraded seating options, and onboard WiFi. Management is also focusing growth on routes where competition has weakened following Spirit’s retreat.

The goal is straightforward: keep costs low while improving the customer experience enough to attract a broader range of travelers.

It is a sensible strategy.

But it carries its own risk.

The more perks an ultra-low-cost airline adds, the more it drifts toward the middle of the market. At some point, the distinction that made it attractive in the first place begins to fade.

That creates a difficult balancing act.

Remain aggressively low-cost, and rising expenses threaten profitability.

Move too far upscale, and the airline risks competing directly against carriers with larger networks, stronger loyalty programs, and deeper financial resources.

Investors are watching closely because the outcome extends beyond Frontier itself.

Ultra-low-cost carriers play an important role in the airline industry. Their presence often forces larger competitors to keep fares lower than they otherwise would. When budget airlines disappear, consumers frequently end up paying more.

That makes Frontier’s future important not only to shareholders but also to millions of travelers looking for affordable flights.

For now, the airline is benefiting from Spirit’s retreat. Fewer competitors mean more customers, more routes, and greater pricing power.

The long-term challenge is much harder.

Spirit proved that attracting passengers is not enough. The real test is building a business that can survive rising costs, aggressive competition, and changing consumer expectations.

Frontier is betting it can do what Spirit could not.

Whether it succeeds may determine the future of the ultra-low-cost airline model in America.

Transportation — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

NEW YORK — The buildings powering the artificial-intelligence revolution have reached a milestone few economists or industry executives expected to see this quickly.

New data released Monday by the U.S. Census Bureau shows that spending on data-center construction surpassed $50 billion on an annualized basis for the first time in American history, underscoring the extraordinary scale of investment flowing into artificial intelligence infrastructure.

According to the Commerce Department’s April construction spending report, data-center construction now represents approximately 2.3% of all U.S. construction spending, a share that has expanded dramatically over the past year as technology companies race to build the computing capacity needed to support increasingly powerful AI systems.

The numbers illustrate how artificial intelligence is rapidly transforming from a software story into a physical infrastructure boom measured in steel, concrete, electricity, and land.

Year-to-date spending on data-center construction reached $49.5 billion through April, compared with just $13.6 billion during the same period a year earlier. The nearly fourfold increase represents one of the fastest-growing segments of the U.S. economy.

Importantly, those figures do not include many of the most expensive components housed inside the facilities, including advanced processors, servers, networking equipment, and AI accelerators. The construction numbers reflect the buildings themselves, along with built-in electrical systems, cooling infrastructure, and physical support facilities.

The true cost of the AI buildout is therefore substantially higher.

The broader construction report also showed surprising resilience across the economy.

Overall U.S. construction spending increased 0.4% in April, exceeding economist expectations and following a revised gain in March. Residential construction remained mixed, but single-family homebuilding rose 1.4%, marking a second consecutive monthly increase despite ongoing affordability pressures in the housing market.

Still, the headline story was unquestionably data centers.

The growth reflects unprecedented capital spending by major technology companies seeking to secure leadership positions in artificial intelligence.

Companies including Alphabet, Microsoft, Amazon, Meta Platforms, and other cloud-computing providers have announced aggressive expansion plans as demand for AI processing power continues to surge.

Building advanced AI models requires enormous amounts of computing capacity. Training next-generation systems involves vast server farms operating around the clock, consuming massive quantities of electricity while generating significant heat that must be continuously managed through sophisticated cooling systems.

As a result, data centers have become some of the most expensive and technically complex construction projects in the country.

The average data-center project now approaches $475 million, according to industry estimates, with some facilities costing substantially more depending on size, location, and computing capacity.

Geographically, the boom remains concentrated in a handful of states.

Texas continues to lead the nation in large-scale data-center development, while major projects are also underway across Virginia, North Carolina, Arkansas, and other regions with favorable land availability, energy infrastructure, and regulatory environments.

For local economies, these projects bring immediate benefits.

Construction activity generates demand for electricians, engineers, concrete contractors, steelworkers, HVAC specialists, and a broad range of skilled trades. Municipalities often benefit from increased tax revenues and infrastructure investment tied to large-scale developments.

However, the long-term economic impact differs from more traditional industrial projects.

Unlike manufacturing plants, which may employ thousands of workers after opening, data centers typically require relatively small permanent staffs once construction is completed.

A facility spanning hundreds of thousands of square feet may ultimately employ only dozens of full-time workers while relying heavily on automation and remote monitoring systems.

That reality has sparked debate among policymakers weighing the benefits of offering incentives to attract data-center investment.

Another challenge is energy.

The rapid growth of AI infrastructure is increasingly reshaping electricity markets across the United States.

Data centers consume enormous quantities of power, and utilities are already expanding generation capacity to meet projected demand.

According to industry data, construction starts for power-generation projects rose sharply during the first quarter, driven largely by anticipated data-center growth.

Utilities, grid operators, and regulators are now grappling with questions about how to accommodate future demand while maintaining reliable service for households and businesses.

Some energy analysts warn that sustained data-center expansion could place upward pressure on electricity prices as utilities invest billions in transmission systems, substations, and new generation facilities.

Those costs eventually flow through to consumers.

The trend also highlights a broader shift occurring within the U.S. economy.

While spending on data centers is surging, some categories of factory construction have slowed, particularly projects tied to semiconductor fabrication and certain manufacturing sectors.

The contrast reflects changing investment priorities.

America is increasingly directing capital toward digital infrastructure rather than traditional industrial capacity, betting that artificial intelligence, cloud computing, and data processing will drive economic growth for years to come.

Supporters argue that the investment wave is necessary to maintain U.S. technological leadership amid intensifying competition from China and other global rivals.

Critics question whether the industry may be overbuilding capacity in anticipation of future demand that has yet to fully materialize.

For now, investors appear willing to support the spending.

Technology companies continue to allocate hundreds of billions of dollars toward AI initiatives, and Wall Street has largely rewarded firms perceived as leaders in the emerging sector.

The April construction report provides tangible evidence of that investment.

What began as a race to develop better AI software has evolved into one of the largest infrastructure expansions in modern technology history.

The coming years will determine whether those billions generate the returns executives expect. But one thing is already clear: America is building the physical backbone of the AI economy at a pace rarely seen in any sector.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

NEW YORK — FedEx Freight’s first day as a standalone public company brought with it a notable declaration about the future of transportation. The company’s chief executive said autonomous trucking technology has advanced to the point where it is ready for broad commercial use, arguing that the primary barrier to expansion is no longer engineering, but regulation.

Speaking about the company’s extensive testing efforts, CEO John Smith said self-driving truck systems are now capable of handling nearly every aspect of a long-haul route without driver intervention.

“These tractors are able to leave the yard, navigate from the yard to the interstate, run the interstate, go to the next facility,” Smith said. “99.9% of the time the driver never touches one thing.

The comments offer one of the clearest endorsements yet from the leader of a major U.S. freight carrier that autonomous trucking technology has moved beyond the experimental phase and into operational reality.

The statement comes as FedEx Freight begins life as an independent company following its separation from FedEx Corp., placing increased attention on how management plans to improve efficiency, expand capacity, and enhance shareholder value in a highly competitive freight market.

For years, autonomous trucking has been promoted as a transformational technology capable of reshaping logistics. While early demonstrations generated excitement, many industry leaders remained cautious about whether the systems could perform consistently under real-world commercial conditions. According to Smith, those questions have largely been answered.

Over the past two years, FedEx Freight has participated in extensive testing programs designed to evaluate autonomous operations across actual freight routes. The company’s efforts have focused on major transportation corridors where long highway stretches create ideal environments for autonomous systems to operate efficiently while carrying commercial loads.

The tests have demonstrated that modern autonomous platforms can manage not only highway driving but also many of the more complex tasks that occur before and after a truck reaches the interstate. That capability is viewed as a significant milestone because it reduces the need for constant human oversight and moves the technology closer to large-scale deployment.

For the trucking industry, the implications could be substantial.

Freight carriers across North America continue to face persistent challenges recruiting and retaining drivers. Labor shortages, rising compensation costs, and increasing demand for faster delivery have pressured operators to find new ways to improve productivity without sacrificing safety.

Autonomous technology has increasingly emerged as one potential solution.

Supporters argue that self-driving systems could allow trucks to operate more efficiently, improve equipment utilization, reduce delays, and help address capacity constraints that periodically disrupt supply chains. The technology may also help reduce costs associated with driver turnover and enable carriers to better manage growing freight volumes.

Investors are watching closely because transportation companies operate on relatively thin margins, making even modest efficiency improvements potentially meaningful to earnings. Increased asset utilization and lower operating costs could provide significant financial benefits if autonomous systems achieve widespread deployment.

Still, despite the technological progress, Smith emphasized that the industry’s biggest challenge is no longer proving the systems work.

“The regulatory piece is going to be the biggest hurdle,” he said.

That hurdle remains significant.

Federal and state regulators continue to evaluate how autonomous commercial vehicles should be governed. Questions surrounding safety certification, operating standards, liability, insurance requirements, cybersecurity protections, and oversight mechanisms remain under discussion.

While regulators have approved various forms of advanced driver-assistance technology, comprehensive frameworks governing fully autonomous commercial trucking operations are still evolving. Until those rules are finalized, widespread deployment is expected to proceed gradually through pilot programs and limited operational environments.

Safety remains central to the conversation.

Proponents of autonomous trucking argue that advanced systems can reduce accidents caused by human fatigue, distraction, or impairment. Critics counter that complex road conditions, severe weather, construction zones, and unexpected traffic situations still require extensive testing and safeguards before full deployment can occur at scale.

Cybersecurity is another area receiving increased scrutiny. As trucks become more software-driven and connected, ensuring the security and integrity of vehicle systems will be essential for public confidence and operational reliability.

FedEx Freight’s testing efforts have been supported through partnerships with autonomous technology developers seeking to commercialize self-driving freight operations. Those collaborations have allowed the company to evaluate performance under real-world conditions while gathering operational data that could support future expansion.

For customers, autonomous trucking could eventually translate into more predictable transit times, improved service consistency, and enhanced network capacity. For carriers, it could create opportunities to improve efficiency while addressing longstanding workforce challenges.

The timeline for widespread adoption, however, will likely depend less on technology than on policymaking.

With one of the nation’s largest freight operators now publicly stating that autonomous trucking is operationally viable, attention is shifting toward regulators tasked with determining how quickly the technology can move from pilot programs into mainstream logistics networks.

As FedEx Freight begins its next chapter as an independent company, management is making clear that automation will play a central role in its long-term strategy. The technology appears increasingly capable. The next phase will be defined by how quickly regulators, industry leaders, and policymakers can establish the framework needed to bring autonomous trucking fully into the American transportation system.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

WASHINGTON — June 2, 2026

The top 1% of American households now control 31.7% of the nation’s wealth, according to the latest data from the Federal Reserve, the highest concentration recorded since the central bank began tracking the figure in 1989.

That top sliver of Americans now holds roughly $55 trillion in wealth — about as much as the entire bottom 90% of households combined. Meanwhile, the bottom half of Americans owns just 2.5% of the nation’s wealth, highlighting a divide that economists say has been widening for decades and accelerated after the pandemic.

The numbers help explain a question many Americans continue asking: if the economy is supposedly strong, why do so many people feel like they are falling behind?

The answer begins with ownership.

In today’s economy, wealth is increasingly built not from wages but from assets. Stocks, homes, businesses, and investment portfolios generate gains that compound over time. Those assets are heavily concentrated among higher-income households.

According to Federal Reserve data, the top 10% of Americans own roughly 93% of all stocks, while the bottom half owns only about 1%. Every time the stock market pushes higher, the overwhelming majority of those gains flow to people who already own significant investments.

For investors, wealth compounds.

For non-investors, rising markets often remain little more than headlines.

Housing tells a similar story.

For generations, homeownership served as the primary wealth-building tool for middle-class families. But rising home prices, limited inventory, and elevated mortgage rates have made ownership increasingly difficult for younger Americans and lower-income households.

Lawrence Yun, chief economist at the National Association of Realtors, has repeatedly pointed to affordability as the housing market’s biggest challenge. When families cannot access the assets that traditionally build wealth, the wealth gap naturally widens.

The divide compounds over time.

A household that owns stocks and real estate benefits from appreciation, dividends, rental income, and reinvestment. Those gains generate additional gains. Wealth creates more wealth.

Families living paycheck to paycheck face a different reality. After paying for housing, food, transportation, healthcare, insurance, and utilities, there is often little left to invest.

One balance sheet compounds.

The other struggles to keep pace with monthly expenses.

Inflation has only widened the divide.

Research released by the Federal Reserve Bank of New York found that economic outcomes diverged sharply after pandemic-era assistance programs expired. Since 2023, the real net worth of the top 1% has increased by more than 25%, while the middle 40% of households have gained less than 10%.

The reason is simple.

Inflation affects households differently.

A wealthy family may notice higher grocery, fuel, or utility bills, but those costs represent a relatively small share of overall wealth. For a family living paycheck to paycheck, those same increases directly reduce spending power.

Heather Long, chief economist at Navy Federal Credit Union, recently warned that many households are increasingly relying on savings and credit to maintain spending as inflation continues to outpace income growth for large segments of the population.

The spending data reveal another side of the story.

According to Mark Zandi, chief economist at Moody’s Analytics, the top 10% of earners accounted for nearly half of all U.S. consumer spending during the second quarter of 2025.

In other words, much of the economy’s recent resilience has been powered by households that already possess significant wealth.

That creates challenges for businesses.

Retailers, banks, homebuilders, and consumer-facing companies increasingly depend on a smaller group of affluent households to drive growth. If those consumers slow spending, the effects can ripple quickly through the broader economy.

At the same time, workers are receiving a smaller share of economic output.

The portion of national income flowing to wages recently fell to 53.8%, the lowest level since federal records began in 1947. By comparison, workers received roughly 70% of national income in the decades following World War II.

A growing share of economic gains now flows to investors, asset owners, and corporate profits rather than wages.

That trend sits at the heart of today’s wealth divide.

This is not primarily a story about effort or ambition. It is increasingly a story about ownership.

The households that own appreciating assets continue benefiting from rising stock markets, rising property values, and the power of compounding returns. Those who rely mainly on wages face a constant race against inflation and rising living costs.

There are important caveats.

Economic conditions can change. Strong job growth can narrow gaps temporarily. Market downturns can reduce wealth at the top. Consumer spending has remained more resilient than many economists expected.

The New York Fed recently noted that inflation-adjusted spending has softened across virtually all income groups, a reminder that no one is entirely insulated from economic pressures.

But the broader direction remains clear.

Unless homeownership becomes more affordable, stock ownership broadens, and wage growth consistently outpaces inflation, economists say the forces driving today’s wealth divide are likely to remain in place.

For millions of Americans, that means the economy may continue feeling far weaker than the headline numbers suggest.

Economy — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

WASHINGTON — The biggest change to Medicaid eligibility in years officially arrived Monday as the Centers for Medicare & Medicaid Services (CMS) released long-awaited rules requiring certain Medicaid recipients to work, attend school, participate in job training, or perform community service to maintain coverage.

The new policy, mandated under the Working Families Tax Cut Act (Public Law 119-21) signed by President Donald Trump on July 4, 2025, establishes an 80-hour monthly work requirement for many adults enrolled through Medicaid expansion programs and could reshape enrollment, insurance-company revenue, hospital finances, and state healthcare systems across the country.

CMS Administrator Dr. Mehmet Oz said the policy is designed to encourage workforce participation while preserving access to healthcare for vulnerable Americans.

“This rule helps Americans build skills, strengthen communities, and move toward greater independence through work, education, training, or service,” Oz said in announcing the regulation.

The deadline was set by Congress, leaving CMS little flexibility. The agency was required to issue the rule by June 1, and Monday’s release starts the countdown toward implementation across much of the country.

Under the new requirements, most non-pregnant adults ages 19 to 64 enrolled through Medicaid expansion programs must either complete 80 hours per month of qualifying activities or earn income equal to at least 80 times the federal minimum wage, roughly $580 per month under current standards.

Qualifying activities include employment, education, job-training programs, apprenticeships, and approved community-service work.

The rule applies primarily to adults enrolled through the Medicaid expansion population created under the Affordable Care Act. Currently, 43 states and the District of Columbia cover this group and will be required to implement the new standards.

Most states are expected to begin enforcement by January 1, 2027.

CMS attempted to soften some concerns by providing broad exemptions.

Individuals classified as medically frail, pregnant women, and certain other vulnerable populations will not be subject to the requirements. States will also be permitted to accept initial self-attestation for some exemptions before requiring additional documentation.

Medicaid Director Dan Brillman said the agency worked extensively with state officials to reduce administrative burdens and minimize disruptions for eligible beneficiaries.

The healthcare industry is already preparing for significant financial consequences.

Medicaid is not simply a government benefit program—it is a major business line for some of America’s largest health insurers.

Companies including UnitedHealth Group, Elevance Health, CVS Health’s Aetna, Centene Corp., and Molina Healthcare receive fixed monthly payments from states for each Medicaid member they cover.

If enrollment declines, so does revenue.

That is why investors and analysts have spent months focusing on the potential impact of work requirements.

The Congressional Budget Office estimates the new law could reduce Medicaid expansion enrollment by approximately 7 million adults over the next decade. Additional coverage losses among children and other adult populations could push the total significantly higher.

Among publicly traded insurers, Molina Healthcare and Centene appear particularly exposed because Medicaid represents a larger share of their business compared with diversified competitors.

Molina executives have already told investors they expect enrollment declines among expansion members once the requirements take effect.

The financial implications extend beyond insurance companies.

Hospitals, particularly rural hospitals and safety-net systems, are closely monitoring implementation plans because reductions in insurance coverage often translate into increases in uncompensated care.

When uninsured patients seek treatment, hospitals frequently absorb part of the cost.

That burden tends to fall most heavily on facilities already operating with thin margins.

The rule also creates a new business opportunity.

Millions of beneficiaries will need to document work hours, training participation, educational enrollment, or exemption status.

States must build systems capable of tracking and verifying that information.

Technology firms, Medicaid contractors, data-management providers, and eligibility-verification companies are already positioning themselves to help states manage the administrative workload.

For many vendors, implementation of work requirements could generate years of new contracts and recurring revenue.

Several states are moving ahead quickly.

Nebraska began enforcement efforts earlier this year, while Arkansas plans to begin a soft-launch process in July that will monitor compliance before formal penalties take effect.

States are expected to begin extensive beneficiary outreach programs during the summer and fall to educate recipients about the new requirements.

The political debate remains intense.

Supporters argue the rules encourage workforce participation, reduce dependency, and help preserve Medicaid resources for the most vulnerable populations.

Critics contend that paperwork and reporting requirements—not a lack of work—are the primary risk.

Previous state-level experiments with Medicaid work requirements found that many individuals who lost coverage were already working or otherwise eligible but failed to complete required documentation.

Healthcare advocates warn that administrative barriers could cause coverage losses even among people who satisfy the rules.

Regardless of where the debate ultimately lands, the operational reality is now clear.

The regulation has been issued.

States have begun preparing.

Insurers are modeling enrollment losses.

Hospitals are assessing financial exposure.

And millions of Medicaid beneficiaries now face a new set of requirements that could determine whether they remain covered after January 2027.

The next seven months will determine how smoothly one of the largest healthcare policy shifts in recent years unfolds—and how many Americans ultimately remain in the Medicaid system when the transition is complete.

Healthcare & Policy — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

NEW YORK — A Swedish automaker with Chinese ownership has secured a major victory in Washington, clearing one of the most significant regulatory hurdles facing the global automotive industry.

Volvo Cars announced that the U.S. Department of Commerce has granted the company authorization to continue importing and selling its connected vehicles in the United States despite new restrictions targeting Chinese-linked automotive technology.

The decision allows Volvo to move forward with its U.S. expansion plans and preserves access to one of the world’s most important automobile markets at a time when regulators are increasingly scrutinizing foreign technology embedded in vehicles.

The ruling comes amid growing national-security concerns surrounding connected cars, which now function as rolling computers capable of collecting and transmitting vast amounts of data through cellular, Wi-Fi, Bluetooth, satellite, and cloud-based systems.

For Volvo, the stakes were enormous.

The company is majority-owned by Geely Holding Group, the Chinese automotive giant that acquired Volvo from Ford Motor Co. in 2010. While Volvo designs much of its technology in Europe and maintains Swedish headquarters, its Chinese ownership structure placed it squarely within the scope of new U.S. restrictions targeting foreign-connected vehicle technologies.

The Commerce Department’s rules were designed to address concerns that vehicles containing Chinese software or hardware could potentially collect sensitive information on American drivers or critical infrastructure.

Under the regulations, restrictions began taking effect for certain model years and vehicle systems, creating uncertainty for manufacturers with Chinese ownership, suppliers, or technology partnerships.

Volvo’s approval effectively removes a cloud that had been hanging over its American operations.

The company said the authorization followed extensive discussions with federal officials regarding its corporate governance, cybersecurity protections, technology architecture, and data-management practices.

According to Volvo, regulators were satisfied that the company had demonstrated appropriate safeguards to protect U.S. consumers and national-security interests.

The outcome represents a significant win not only for Volvo but also for thousands of American workers tied to its domestic operations.

Volvo’s manufacturing facility in Charleston, South Carolina, employs more than 2,000 workers and has attracted more than $1.3 billion in investment since opening.

The plant currently produces the EX90 electric SUV and the Polestar 3, and Volvo has announced plans to begin manufacturing its popular XC60 SUV in South Carolina later this year.

Had the company been denied authorization, those expansion plans could have faced substantial disruption.

Investors quickly recognized the importance of the decision.

Volvo shares surged nearly 10% following the announcement, reflecting relief that the automaker would retain uninterrupted access to the U.S. market.

While the company continues to face broader challenges affecting the global automotive industry, the regulatory clearance removes a major source of uncertainty that had weighed on investor sentiment.

The decision also highlights the increasingly complex nature of the modern automobile business.

Today’s vehicles rely on software as much as mechanical engineering. Navigation systems, driver-assistance features, wireless updates, mobile applications, remote diagnostics, and vehicle-to-cloud communication have transformed automobiles into connected digital platforms.

That transformation has elevated cybersecurity and data protection from secondary concerns to central policy issues.

For Washington, the challenge is balancing national-security priorities with economic realities.

Modern automotive supply chains span continents. Components may be designed in Europe, manufactured in Asia, assembled in North America, and sold globally.

Attempting to separate those interconnected systems without disrupting production presents enormous difficulties for policymakers.

Volvo’s approval suggests regulators are willing to evaluate companies individually rather than apply blanket restrictions solely based on ownership structures.

That distinction could prove important for other manufacturers seeking similar treatment.

Several global automakers maintain relationships with Chinese suppliers, investors, or technology partners. Many will be closely watching Volvo’s experience to determine whether they may qualify for comparable exemptions or approvals.

The ruling may also provide a framework for future regulatory reviews.

Companies capable of demonstrating strong governance controls, independent operational structures, robust cybersecurity measures, and transparent data-handling practices may find pathways to continued participation in the U.S. market despite broader geopolitical tensions.

For consumers, the immediate impact is straightforward.

Volvo vehicles will remain available in American dealerships, preserving consumer choice in a highly competitive market. Dealers can continue selling the brand’s growing lineup of electric and hybrid vehicles, while customers retain access to one of the industry’s strongest reputations for safety and engineering.

More broadly, the case underscores how deeply interconnected the global economy has become.

A vehicle marketed as Swedish can be owned by a Chinese parent company, assembled by American workers, sold through U.S. dealerships, financed by American banks, and purchased by families across the country.

Those relationships create economic benefits but also introduce regulatory challenges that governments are increasingly attempting to address.

The broader debate over connected vehicles is far from over.

Congress, federal regulators, and national-security agencies continue to examine how foreign technology should be governed as automobiles become more connected and autonomous.

Additional rules, oversight requirements, and security standards are likely in the years ahead.

For now, however, Volvo has achieved something many competitors are still seeking: regulatory certainty.

The approval allows the company to continue investing in American manufacturing, expanding its product lineup, and competing in one of the world’s most lucrative automotive markets.

In an era of rising geopolitical tensions and growing scrutiny of foreign technology, that certainty may prove almost as valuable as the vehicles themselves.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 2, 2026

NEW YORK — California is rewriting two of its most influential environmental rulebooks at the same time, a move that could affect fuel prices, packaging costs, manufacturers, and consumers far beyond the state’s borders.

The California Air Resources Board (CARB) has approved significant updates to the state’s flagship carbon-emissions program while simultaneously advancing new regulations aimed at reducing plastic waste. Together, the actions highlight California’s ongoing effort to balance aggressive climate goals with growing concerns about affordability and economic competitiveness.

Because California remains the largest state economy in the nation, changes adopted in Sacramento often ripple across industries nationwide.

At the center of the debate is California’s cap-and-trade system, now rebranded as Cap-and-Invest following legislation signed by Governor Gavin Newsom.

The program places limits on carbon emissions and requires companies to purchase allowances that permit them to emit greenhouse gases. Revenue generated from those auctions is then directed toward state initiatives ranging from clean-energy projects to transportation infrastructure.

The latest revisions stem from legislation passed by California lawmakers last year that extended and reshaped the program.

Supporters argue the changes will help California continue reducing emissions while limiting some of the cost burdens that have increasingly drawn criticism from businesses and consumers.

The revisions include measures designed to reduce pressure on refiners and energy producers that warned earlier proposals could accelerate fuel-price increases or encourage companies to move operations outside the state.

That balancing act has become increasingly difficult.

California has some of the nation’s most ambitious climate targets. State law requires emissions to fall 40% below 1990 levels by 2030 and approximately 85% below 1990 levels by 2045.

Achieving those goals requires continued reductions in emissions from transportation, energy production, manufacturing, and other sectors.

At the same time, policymakers face pressure from voters concerned about rising living costs.

Fuel prices remain among the highest in the country, housing affordability continues to challenge households, and businesses have repeatedly warned that additional regulatory burdens could make operating in California more expensive.

CARB Chair Lauren Sanchez defended the updated approach, arguing that California can continue pursuing climate leadership while recognizing affordability concerns.

The agency says the revised rules maintain the state’s long-term emissions goals while providing greater flexibility for affected industries during the transition.

Not everyone agrees.

Environmental groups have criticized portions of the revisions, arguing that the state is providing too many concessions to oil refiners and large emitters.

Some advocates contend that easing compliance requirements could slow emissions reductions and reduce funding available for climate-related programs.

That funding matters.

Revenue generated through California’s carbon auctions has helped finance a wide range of state initiatives in recent years, including public transit projects, clean-energy investments, wildfire resilience efforts, and other environmental programs.

Analysts expect the revised structure could generate less auction revenue than previous proposals, creating potential funding challenges in future years.

At the same time California is revising carbon regulations, it is also moving forward with sweeping changes to packaging rules.

Under Senate Bill 54, California established one of the most ambitious plastic-reduction laws in the country.

The legislation requires that plastic packaging sold in California become recyclable or compostable by 2032, placing substantial pressure on manufacturers, consumer-goods companies, retailers, and packaging suppliers.

Implementation, however, has proven contentious.

The latest version of the regulations includes exemptions covering portions of the food and agricultural supply chain, including certain packaging used for produce and related products.

Supporters argue the exemptions are necessary to avoid disruptions to food distribution and supply chains.

Critics argue they weaken the law.

Several environmental organizations, including the Natural Resources Defense Council (NRDC) and Californians Against Waste, have indicated they intend to challenge portions of the regulations in court.

The groups argue that some approved recycling methods may create additional environmental concerns and that the exemptions could allow significant amounts of plastic waste to remain outside the program’s intended scope.

The legal battle could reshape the regulations once again before full implementation occurs.

For businesses outside California, the developments remain highly relevant.

Many national manufacturers choose to design products and packaging to meet California standards rather than maintain separate production lines for different states.

As a result, regulations adopted in Sacramento often become de facto national standards.

The same dynamic exists in energy markets.

Fuel producers operating throughout the western United States frequently adjust pricing and supply decisions based on California’s regulatory framework, meaning changes to emissions policies can influence costs beyond state boundaries.

Together, the carbon and plastic initiatives reveal a broader tension facing policymakers.

California continues to position itself as a leader in environmental regulation and climate policy, yet it must increasingly account for concerns about economic competitiveness, consumer affordability, and business investment.

The state is attempting to reduce emissions, limit plastic waste, support clean-energy development, and maintain industrial activity simultaneously.

Whether that balance proves sustainable remains an open question.

Environmental groups argue California is moving too slowly.

Industry groups argue it is moving too aggressively.

The coming months are likely to bring additional legal challenges, political debate, and regulatory revisions as both sides continue pushing for changes.

For now, California has signaled that it intends to continue pursuing ambitious environmental goals while attempting to soften some of the economic consequences.

Given the state’s economic influence, businesses and consumers across the country will be watching closely.

The costs and benefits of California’s decisions rarely remain confined to California.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

JERUSALEM — More than $121 million has been wagered on Benjamin Netanyahu’s political future, and despite a reported confrontation with President Donald Trump this week, traders overwhelmingly believe Israel’s prime minister will remain in office through 2026.

That is the message emerging from Polymarket, the crypto-based prediction platform that has become one of the world’s most closely watched gauges of political sentiment. As of June 1, bettors were assigning just a 4% chance that Netanyahu would leave office by the end of June and only a 9% chance that he would abandon a reelection bid before the end of July.

The odds become more competitive later in the year. By the end of December, traders place the probability of Netanyahu leaving office at approximately 44%.

In other words, the market is not betting on an immediate collapse.

It is betting on an election.

That distinction is critical because Israel’s political calendar already points toward a major test later this year. The Knesset recently advanced legislation that could dissolve parliament after an ultra-Orthodox coalition partner withdrew support over military draft exemptions. Under Israeli law, national elections would need to be held no later than October.

For prediction-market traders, that election appears far more important than the latest diplomatic dispute between Washington and Jerusalem.

The dispute itself was significant.

According to Axios, Trump delivered a blunt and reportedly expletive-filled message to Netanyahu during a phone call Monday after learning of Israeli plans to strike Hezbollah targets in Beirut. U.S. officials cited by the publication said Trump warned that further escalation could isolate Israel internationally and potentially derail ongoing diplomatic efforts involving Iran.

The timing was especially sensitive.

The Trump administration continues pursuing negotiations with Tehran, and earlier Monday Iranian officials signaled they could reconsider participation in talks following Israel’s military actions in Lebanon. Within hours of the reported call, Israel shelved plans for the Beirut operation, a move widely interpreted as an effort to avoid further tension with Washington.

Yet despite the dramatic headlines, betting markets barely moved.

Political-risk analysts note that prediction markets often focus less on daily news cycles and more on structural political realities. Netanyahu has survived wars, protests, coalition crises, corruption charges, and repeated election battles during his record tenure as Israel’s longest-serving prime minister.

From a trader’s perspective, one heated conversation with Trump does not fundamentally alter the political landscape.

Netanyahu himself appeared determined to project stability afterward, stating publicly that Israel’s position remained unchanged and that military operations in southern Lebanon would continue.

The story reaches beyond politics and into financial markets.

Prediction platforms such as Polymarket have evolved into major information hubs where participants risk real money on political, economic, and geopolitical outcomes. The size of the Netanyahu market—more than $121 million in trading volume—reflects growing interest among investors, analysts, and institutions seeking real-time measures of political risk.

The broader financial implications are even larger.

At the center of the Trump-Netanyahu dispute sits Iran and the future of negotiations that could affect energy markets worldwide. Any breakdown in diplomacy raises concerns about the Strait of Hormuz, the narrow shipping corridor through which a substantial portion of global oil supplies passes.

That matters directly to consumers.

Oil prices influence gasoline costs, transportation expenses, airline fares, and inflation across the global economy. While U.S. gasoline prices recently touched some of their lowest levels in weeks, energy analysts continue warning that renewed Middle East tensions could quickly reverse that trend.

Cryptocurrency markets also reacted, albeit modestly.

Bitcoin slipped to roughly $70,871 during Monday’s trading as investors digested headlines involving Lebanon, Iran, and the Trump-Netanyahu dispute. The decline was relatively small, but it underscored how quickly geopolitical developments now ripple through digital assets held by millions of investors worldwide.

So why are traders remaining so calm about Netanyahu’s immediate future?

Part of the answer lies in timing. With elections potentially approaching within months, markets increasingly view Netanyahu’s political fate as a question voters will answer rather than coalition partners.

Part of it lies in incentives. Leaving office before an election would do little to improve Netanyahu’s legal or political position. Remaining prime minister preserves leverage, influence, and options heading into a campaign.

And part of it lies in experience. Traders have seen Netanyahu survive seemingly impossible political moments before.

For now, the market’s verdict is clear.

The real test for Netanyahu appears more likely to arrive at the ballot box than in a phone call. Until Israel’s election campaign moves into full gear, prediction markets seem far more focused on October than on the headlines of June.

Middle East & Markets — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

WASHINGTON — A federal judge has temporarily halted a Trump administration effort to transfer control of one of America’s most important weather and climate supercomputing facilities, delivering the first significant legal setback to a broader plan targeting the nation’s premier atmospheric research center.

In a ruling issued Monday, Senior U.S. District Judge R. Brooke Jackson granted a preliminary injunction preventing federal agencies from removing control of the NCAR-Wyoming Supercomputing Center from the nonprofit organization that currently operates it.

The judge sharply criticized the government’s actions, writing that the decision appeared “arbitrary, capricious, and an abuse of discretion” under federal administrative law.

The dispute centers on the National Center for Atmospheric Research (NCAR), a Boulder, Colorado-based institution widely regarded as one of the world’s leading weather, climate, and atmospheric science organizations.

Founded in 1960, NCAR is operated by the University Corporation for Atmospheric Research (UCAR), a nonprofit consortium representing approximately 130 universities and research institutions across the United States.

The conflict began late last year when the administration announced plans to restructure and significantly reduce NCAR’s role. Supporters of the move argued that federal research programs needed reform, while critics warned the changes could disrupt weather forecasting, climate research, and critical scientific infrastructure relied upon by both government agencies and private industry.

Monday’s ruling does not end the case.

Instead, it freezes one of the administration’s most immediate actions—the planned transfer of the supercomputing center in Cheyenne, Wyoming—while litigation continues.

Judge Jackson found that the National Science Foundation (NSF) failed to adequately explain its decision and did not follow procedures typically required before implementing such a significant change.

“NSF’s failure to provide any explanation for its decision renders the challenged action arbitrary and capricious,” the judge wrote.

The case may appear technical, but its implications extend well beyond the scientific community.

NCAR’s supercomputing systems perform some of the most sophisticated weather and climate calculations in the country.

Its flagship systems, including the Derecho supercomputer and the Casper artificial-intelligence computing platform, process enormous amounts of atmospheric data used in hurricane forecasting, wildfire prediction, severe-weather modeling, climate analysis, aviation planning, and disaster preparedness.

The organization employs more than 800 scientists, engineers, and support staff and supports thousands of researchers annually.

According to court filings, approximately 3,700 researchers used NCAR resources during the past year, including scientists from more than 500 universities and institutions.

The reach of that research extends into virtually every major sector of the economy.

Insurance companies rely on severe-weather models to price risk.

Agricultural businesses use seasonal forecasting data to guide planting and harvesting decisions.

Airlines depend on atmospheric modeling to improve flight planning and safety.

Electric utilities use weather projections to prepare for extreme heat, storms, and power-demand fluctuations.

Federal agencies—including NOAA, NASA, the Department of Defense, the Federal Aviation Administration, and the Department of Energy—also depend on NCAR-generated research and forecasting tools.

The economic stakes are substantial.

According to federal disaster data, extreme-weather events caused more than $100 billion in damages during the first half of 2025 alone.

Accurate forecasting is widely viewed as one of the most cost-effective tools available for reducing those losses by giving businesses, governments, and households additional time to prepare.

Judge Jackson’s ruling also highlighted concerns about damage already occurring within the organization.

Court records indicate that dozens of employees have departed NCAR and related programs in recent months, with many citing uncertainty about the institution’s future.

The judge found that the loss of specialized scientific expertise, potential damage to UCAR’s credit profile, and risks to active maintenance and service contracts constituted irreparable harm warranting judicial intervention.

The ruling contained another notable element.

Jackson suggested that political considerations may have influenced aspects of the government’s actions, pointing to ongoing tensions between the administration and Colorado officials over unrelated policy disputes.

The judge also referenced internal documents indicating concerns about diversity-related programs within the organization and raised questions about restrictions placed on UCAR’s public communications.

Federal officials had argued that the transfer remained under consideration and therefore was not subject to court review.

Jackson rejected that argument, concluding that agency communications demonstrated a final decision had effectively already been made.

For now, the injunction preserves the status quo.

UCAR retains control of the supercomputing center, ongoing contracts remain in place, and researchers can continue accessing critical computing resources while the broader lawsuit proceeds.

The larger battle over NCAR’s future, however, remains unresolved.

The case could ultimately determine the future structure of one of America’s most important scientific institutions and influence how federal agencies manage research infrastructure that supports weather forecasting, climate analysis, national security, and economic planning.

For businesses that depend on accurate weather predictions—from insurers and utilities to farmers and airlines—the outcome could carry consequences far beyond the courtroom.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

NEW YORK — For much of the past decade, workers looking for a meaningful raise often followed a simple rule: leave your current employer.

That strategy is becoming far less effective.

New data from the Bank of America Institute shows the wage advantage enjoyed by workers who switch jobs has fallen to its lowest level in seven years, reflecting a labor market that is cooling from the hiring frenzy that defined the post-pandemic economy.

According to the report, employees who changed jobs during the first quarter of 2026 experienced average after-tax wage growth of approximately 8% year over year, compared with roughly 5% for workers who remained with their current employer.

While job changers still earned larger increases, the gap has narrowed to just three percentage points, the smallest advantage recorded since 2019.

The shift marks a dramatic reversal from the peak of the labor shortage era.

During the height of the Great Resignation in 2022, employers were competing aggressively for talent, often offering substantial salary increases to attract workers away from rival firms.

At the time, employees who switched jobs frequently secured raises approaching 18%, while workers who stayed put generally received increases closer to 7%.

The result was an unprecedented wage premium for mobility.

Today, that premium has largely evaporated.

The findings suggest the labor market has entered a new phase—one that economists increasingly describe as a “low-hire, low-fire” environment.

Companies are no longer aggressively recruiting at the same pace, but they are also not conducting widespread layoffs. Instead, employers appear focused on maintaining existing workforces while hiring selectively when needed.

That balance is reshaping compensation dynamics.

A separate report from ADP Research reinforces the trend.

ADP’s data shows the wage-growth advantage for job switchers fell to approximately 2 percentage points earlier this year, the smallest differential since the payroll processor began tracking the metric.

By April, wage growth for employees who remained with their current company averaged 4.4%, while workers changing jobs earned roughly 6.6%.

The difference remains meaningful, but it is far smaller than workers became accustomed to during recent years.

Nela Richardson, Chief Economist at ADP, summarized the labor market’s changing character succinctly.

“Small and large employers are hiring, but we’re seeing softness in the middle,” Richardson said.

That softness is affecting employee leverage.

When businesses are competing aggressively for workers, salaries tend to rise quickly as employers bid against one another. When hiring slows, the pressure to offer outsized compensation packages diminishes.

Employers simply have less reason to pay a premium to lure workers away from existing jobs.

For many Americans, the data reveals an even more sobering reality.

According to Bank of America Institute researchers, approximately half of workers who stayed with their employers received little or no pay increase during the quarter. A significant portion of workers who changed jobs also saw minimal gains, and some even experienced lower compensation.

In other words, the question increasingly is not whether changing jobs guarantees a larger raise.

For many workers, the challenge is securing a raise at all.

The trend carries important implications for younger employees who entered the workforce during one of the hottest labor markets in modern history.

For years, career advisers, recruiters, and social-media influencers frequently promoted job-hopping as the fastest path to higher earnings.

The advice was largely supported by data.

In a labor market characterized by worker shortages, changing employers often produced larger salary gains than remaining loyal to a single company.

That formula may no longer apply as broadly.

Today’s environment rewards a more nuanced approach.

Career advancement, internal promotions, skills development, and long-term opportunities increasingly matter alongside immediate salary gains.

In some sectors, remaining with an employer may now offer compensation growth comparable to changing jobs.

The shift is not uniform across the economy.

Industries facing persistent worker shortages—including portions of construction, engineering, healthcare, and specialized technical fields—continue to offer substantial incentives to attract talent.

In those sectors, switching employers can still produce significant pay increases.

Other industries tell a different story.

Technology, professional services, media, and certain white-collar occupations have experienced slower hiring activity, reducing the bargaining power of employees seeking new opportunities.

For employers, the trend brings welcome relief.

Labor costs remain one of the largest expenses for most businesses. During the peak hiring years, companies frequently found themselves matching competing offers simply to retain experienced workers.

As the wage gap narrows, businesses face less pressure to continually increase compensation to prevent turnover.

That dynamic may also help ease inflationary pressures across the broader economy.

The Federal Reserve closely monitors wage growth because rapid increases in labor costs can eventually contribute to higher prices throughout the economy.

A more balanced labor market could support the Fed’s efforts to keep inflation under control without triggering a significant rise in unemployment.

Still, economists caution against viewing the trend as entirely positive.

Worker mobility has historically played an important role in economic growth by helping employees move into positions where they can be more productive and earn higher wages.

If fewer workers pursue better opportunities, overall economic dynamism may weaken over time.

For now, however, the numbers tell a clear story.

The era when workers could reliably secure double-digit raises simply by updating their résumé and changing employers appears to be fading.

Job-hopping still pays.

It just doesn’t pay nearly as much as it used to.

As new labor-market data arrives throughout the summer, economists will be watching closely to see whether the gap continues narrowing—or whether employers once again find themselves competing aggressively for talent.

For workers navigating career decisions in 2026, the lesson may be simple: the quickest path to higher pay is no longer as obvious as it once was.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
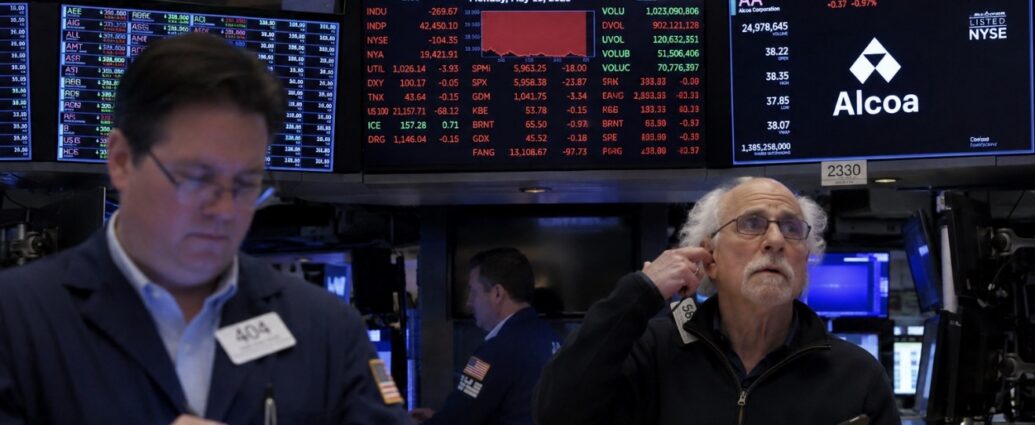
By JBizNews Desk

Tuesday, June 2, 2026

President Donald Trump named Bill Pulte, the director of the Federal Housing Finance Agency (FHFA), as acting director of national intelligence on Tuesday, adding one of Washington’s most sensitive national-security jobs to an official who already oversees America’s housing-finance system.

The development carries implications far beyond politics. In announcing the appointment on Truth Social, Trump said Pulte will continue serving as FHFA director while remaining chairman of Fannie Mae and Freddie Mac, the two government-controlled mortgage giants that collectively support more than $10 trillion in U.S. home loans.

Trump praised Pulte’s management experience and highlighted his stewardship of the housing-finance system, signaling confidence that he can simultaneously oversee both responsibilities.

That unusual arrangement means one official will now oversee the nation’s mortgage-finance infrastructure while also coordinating the work of the U.S. intelligence community.

For homebuyers, lenders, builders, and investors, that is the part of the announcement that matters most.

Many Americans have never heard of the FHFA, but its influence is felt every day throughout the housing market. The agency regulates Fannie Mae and Freddie Mac, which guarantee a significant share of U.S. residential mortgages. Their policies affect mortgage availability, underwriting standards, lender requirements, and ultimately the cost of homeownership.

When Americans obtain a conventional 30-year mortgage, there is a strong likelihood that either Fannie Mae or Freddie Mac will ultimately stand behind the loan.

Since taking office, Pulte, the grandson of the founder of homebuilder PulteGroup, has become one of the most active housing regulators in recent memory.

After being confirmed by the Senate in March 2025, Pulte moved quickly to install new leadership at both Fannie Mae and Freddie Mac while reshaping agency priorities. His tenure has included the termination of several Special Purpose Credit Programs, reductions in diversity, equity and inclusion spending, and the rescission of certain fair-lending and climate-risk guidance issued under previous administrations.

He has also become a central figure in one of the most closely watched debates in housing finance: whether Fannie Mae and Freddie Mac should eventually be released from government conservatorship.

That question has lingered since the 2008 financial crisis and carries enormous implications for lenders, mortgage investors, taxpayers, and the broader housing market. Any move toward privatization would represent one of the largest financial restructurings in modern American history.

Now, the official overseeing that process is taking on a second full-time role.

The position of director of national intelligence is among the most demanding jobs in the federal government. The office coordinates intelligence gathering and analysis across 18 agencies, including the Central Intelligence Agency (CIA) and the National Security Agency (NSA). The role serves as a central hub for national-security assessments involving terrorism, cyber threats, foreign adversaries, and military conflicts around the globe.

Unlike many previous intelligence leaders, Pulte does not come from a military, intelligence, or national-security background, a fact critics immediately highlighted following the announcement.

He succeeds Tulsi Gabbard, who served as Trump’s first director of national intelligence. Gabbard announced plans to depart the role in May amid reports of growing disagreements with the administration.

Pulte has also generated headlines through a series of criminal referrals involving prominent political figures. Those referrals included allegations involving New York Attorney General Letitia James, Sen. Adam Schiff, Federal Reserve Governor Lisa Cook, and former Congressman Eric Swalwell. All denied wrongdoing, and legal outcomes have varied across the cases.

The appointment comes at a particularly sensitive moment.

The United States remains engaged in a broader confrontation involving Iran, while energy markets continue monitoring tensions surrounding the Strait of Hormuz, one of the world’s most critical oil shipping routes. Investors have been closely watching geopolitical developments amid concerns about energy prices, inflation, and global economic stability.

Against that backdrop, a new acting intelligence chief with limited national-security experience adds another variable for markets already navigating uncertainty.

There are also limits on how long the arrangement can continue without Senate action. Under federal vacancy rules, acting officials generally may serve for a limited period while the White House determines whether to nominate a permanent replacement. Any permanent appointment would require Senate confirmation.

For now, there is no immediate indication that Pulte intends to step back from his housing responsibilities.

What This Means for Mortgage Rates

The appointment is not expected to have any immediate effect on mortgage rates or lending standards.

However, investors, lenders, and housing-industry participants will be watching closely to see whether Pulte maintains the same level of focus on FHFA policy while serving in his new role. Markets will also continue monitoring any potential efforts involving the future structure of Fannie Mae and Freddie Mac, an issue that could have significant long-term implications for the U.S. housing-finance system.

For everyday Americans, the takeaway is straightforward: the official with enormous influence over the nation’s mortgage market has just taken on one of the most demanding jobs in Washington. Whether both responsibilities can receive equal attention may become an important question in the months ahead.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
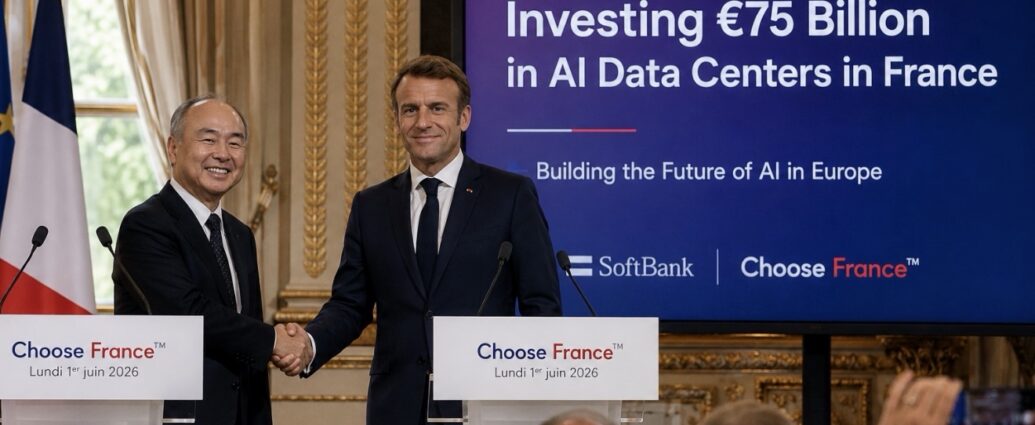
By JBizNews Desk

June 2, 2026

NEW YORK — Savers willing to lock up their cash can still earn yields that would have seemed attractive only a few years ago. The catch is that many Americans are leaving money on the table because the highest rates are often found far from the bank branch they use every day.

As of June 1, several of the nation’s largest banks were advertising certificate-of-deposit yields approaching 4%, while the national average for a one-year CD remained below 2%, according to industry data. The gap highlights a growing divide between headline rates available to shoppers willing to compare offers and the much lower returns many depositors continue to receive.

For consumers looking to protect savings without taking stock-market risk, the difference can be meaningful.

A saver placing $100,000 into a one-year CD earning 4% would collect roughly $4,000 in interest over twelve months. The same deposit earning the national average near 2% would generate only about $2,000. Over time, that gap compounds into a significant difference in returns.

The disparity has emerged as the Federal Reserve’s interest-rate outlook continues to evolve.

After cutting benchmark rates multiple times during 2025, policymakers have adopted a more cautious stance in 2026 as inflation remains stubbornly above target. That uncertainty has created an environment where banks are competing aggressively for deposits in some areas while allowing rates to drift lower in others.

The result is a marketplace where informed shoppers can often earn double what less-active savers receive.

Among major banks, promotional CD rates have remained relatively attractive, particularly for shorter-term deposits ranging from four months to fourteen months. Several institutions continue offering yields around 4%, reflecting their desire to attract stable funding without significantly increasing borrowing costs elsewhere.

Online banks remain among the industry’s most aggressive competitors.

Without the expense of maintaining extensive branch networks, many digital-first institutions have been able to offer yields exceeding those available at traditional banks. Some one-year CDs continue to pay above 4.2%, while select longer-term products remain competitive despite expectations that rates may gradually decline in the coming years.

The trend is prompting many financial advisers to encourage clients to review cash-management strategies.

For much of the past decade, low interest rates made the decision relatively simple. Savings accounts, money-market funds, and CDs often paid similarly modest returns, leaving little incentive to move money.

That environment has changed.

Today’s rate differences can significantly affect household income, particularly for retirees and conservative investors who rely on interest earnings.

The renewed popularity of CDs also reflects uncertainty about the direction of future rates.

A certificate of deposit guarantees a fixed return for a specified period. If rates decline after the CD is opened, the saver continues receiving the higher locked-in yield until maturity.

That feature has become increasingly attractive as markets debate whether the Federal Reserve will eventually resume cutting rates.

Many consumers appear to be acting accordingly.

Banks report growing interest in CDs as households seek ways to preserve purchasing power while avoiding the volatility that can accompany stocks and other investments.

Still, financial professionals caution that CDs are not appropriate for every dollar a family saves.

Unlike traditional savings accounts, certificates of deposit generally impose penalties for early withdrawals. Money committed to a CD may be difficult or costly to access before maturity.

As a result, many advisers recommend maintaining emergency funds in more liquid accounts while using CDs for cash that is unlikely to be needed immediately.

Safety remains another key selling point.

Deposits held at FDIC-insured banks are protected up to $250,000 per depositor, per ownership category, per institution. Credit-union deposits receive similar protection through the National Credit Union Administration (NCUA).

That federal backing makes CDs one of the lowest-risk financial products available to consumers.

Historical perspective also helps explain why current rates are drawing attention.

During the early 1980s, CD yields climbed into double digits as the Federal Reserve battled runaway inflation. By contrast, rates spent much of the 2010s hovering near historic lows, with many savers earning less than 1%.

The inflation surge of the early 2020s pushed yields sharply higher before recent rate cuts caused them to moderate.

Today’s rates near 4% sit somewhere between those extremes.

They are below the peaks reached during the inflation-fighting period but remain substantially higher than what savers became accustomed to during much of the previous decade.

For banks, the competition reflects a broader battle for deposits.

Higher funding costs can pressure profitability, but attracting deposits remains essential for supporting lending activity and maintaining liquidity. Institutions must balance the desire to gather deposits with the cost of paying higher rates.

Consumers ultimately benefit from that competition.

The challenge is knowing where to look.

Many depositors continue keeping large cash balances in low-yield accounts simply because of convenience or familiarity. Others actively compare rates and move money to institutions offering stronger returns.

The difference between those approaches can be substantial.

With some CDs paying around 4% while average rates remain below 2%, the simple act of comparing offers may be one of the easiest financial decisions available to savers in 2026.

For households focused on preserving capital while earning a predictable return, certificates of deposit remain one of the few places where patience is still being rewarded.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

Tuesday, June 2, 2026

U.S. stocks opened lower Tuesday, pulling back from Monday’s record close after renewed tensions involving Iran pushed oil prices higher and gave investors a reason to pause following Wall Street’s strongest run in more than a year.

Futures tied to the S&P 500 fell about 0.2% before the opening bell after the index closed Monday at a record 7,599.96, while the Nasdaq Composite also finished at a fresh all-time high. The market’s advance has been fueled largely by relentless investor demand for companies tied to artificial intelligence, data centers, networking infrastructure, and cloud computing.

The overnight catalyst came from the Middle East.

Iranian state-linked media reported that Tehran had suspended communications with Washington unless Israel halted its expanding military operations in southern Lebanon. Additional reports indicated Iran and regional allies were discussing responses that could affect key global shipping routes, including the Strait of Hormuz and the Bab el-Mandeb Strait, two of the most important energy chokepoints in the world.

The developments immediately rattled energy markets.

West Texas Intermediate crude jumped sharply Monday and remained near $92 per barrel Tuesday morning after briefly surging more than 8% during the previous session. Brent crude traded around $95, keeping oil prices roughly 30% above levels seen before the conflict escalated earlier this year.

President Donald Trump sought to calm markets, telling reporters that discussions remained on track despite what he described as a temporary setback. Trump referred to the issue as a “small glitch” that had already been addressed and also pointed to signs of reduced hostilities between Israel and Hezbollah, helping oil retreat from its overnight highs.

For investors, however, oil remains the most important variable to watch. Sustained prices near $100 per barrel could reignite inflation concerns and complicate the Federal Reserve’s policy outlook.

While geopolitical tensions dominated headlines, corporate earnings continued to reinforce Wall Street’s bullish AI narrative.

The biggest winner of the morning was Hewlett Packard Enterprise, whose shares surged more than 25% after reporting results that significantly exceeded expectations and raising its outlook for the year.

The company increased its fiscal 2026 adjusted earnings forecast to $3.35 to $3.45 per share, up sharply from its prior guidance range of $2.30 to $2.50 and well above analyst expectations. HPE also raised free cash flow guidance to approximately $3.5 billion, compared with a prior forecast of roughly $2 billion.

The strength was driven largely by AI-related demand. HPE reported that networking revenue surged 148%, while revenue from its Cloud and AI segment increased 23%, underscoring the continued spending wave flowing into enterprise AI infrastructure.

The company also announced that a representative from Elliott Investment Management will join its board, a move welcomed by investors.

Another major beneficiary of the AI boom was Marvell Technology, whose shares jumped roughly 19% in premarket trading.

Marvell unveiled its new Teralynx T100, which the company described as the industry’s first 102.4 terabits-per-second AI-optimized switch silicon platform. The chip is specifically designed for hyperscale AI data centers and uses up to 25% less power than competing products, addressing one of the industry’s biggest challenges as power demand surges alongside AI workloads.

The announcement reinforced a trend that continues to drive markets higher: demand for AI infrastructure is growing faster than supply.

The momentum extended across the sector.

Broadcom climbed nearly 6% before the open after receiving a bullish analyst call from HSBC, while investors continued piling into companies viewed as essential suppliers to the AI buildout.

Lumentum Holdings gained nearly 7% after announcing a new $2 billion investment from Nvidia, further highlighting how capital continues to flow toward the infrastructure powering artificial intelligence.

The optimism surrounding AI remains so strong that many technology executives now describe demand as exceeding available capacity, creating substantial investment opportunities across semiconductors, networking equipment, cloud services, and supporting energy infrastructure.

Still, some of Wall Street’s most influential voices are urging caution.

The benchmark 10-year U.S. Treasury yield traded around 4.43% Tuesday morning, while the CBOE Volatility Index (VIX) climbed toward 16, suggesting investors are beginning to price in higher uncertainty.

Speaking recently at the Reagan National Economic Forum, JPMorgan Chase Chief Executive Jamie Dimon warned that financial markets may be underestimating economic and geopolitical risks. Dimon cautioned that investor enthusiasm remains high despite a growing list of potential disruptions ranging from inflation and interest rates to international conflicts.

For now, however, earnings continue to overpower those concerns.

The market remains caught between two powerful forces: a historic wave of AI-driven investment and a volatile geopolitical backdrop centered on the Middle East and global energy supplies.

Tuesday’s session will test which narrative carries more weight. So far in 2026, investors have consistently chosen artificial intelligence. But with oil approaching $100 a barrel and tensions surrounding the Strait of Hormuz remaining unresolved, that confidence could face a much tougher test in the days ahead.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

PARIS — Europe landed one of the largest artificial-intelligence infrastructure commitments in its history Monday as SoftBank Group founder and CEO Masayoshi Son joined French President Emmanuel Macron in Paris to announce plans to invest up to €75 billion ($87 billion) in AI data centers across France.

The commitment, one of the largest technology infrastructure investments ever announced on the continent, is designed to establish France as a leading European hub for artificial intelligence computing power at a time when governments and corporations worldwide are racing to secure the infrastructure needed to support next-generation AI systems.

According to details released Monday, the project will ultimately create approximately 5 gigawatts of AI-focused data-center capacity, a scale that rivals some of the largest computing developments currently underway in the United States.

The first phase alone will involve roughly €45 billion in investment and deliver approximately 3.1 gigawatts of capacity by 2031.

The initial buildout will focus on the Hauts-de-France region in northern France, with major facilities planned in Dunkirk, Bosquel, and Bouchain.

The announcement marks SoftBank’s largest AI infrastructure investment in Europe and further expands the Japanese technology giant’s increasingly aggressive commitment to artificial intelligence.

Speaking alongside Macron, Son described the project as part of a broader transformation that he believes will fundamentally reshape the global economy.

The SoftBank founder has repeatedly argued that artificial intelligence represents a technological revolution far larger than previous computing cycles, including the internet boom that transformed global markets during the late 1990s and early 2000s.

The French project reflects that conviction.

Beyond constructing data centers, the investment will include manufacturing facilities, industrial infrastructure, and partnerships designed to create an integrated AI ecosystem capable of supporting cloud providers, AI developers, businesses, researchers, and public institutions.

One of the centerpiece components involves a strategic partnership with Schneider Electric, the French industrial technology company.

The two firms plan to establish a major industrial hub in Dunkirk where equipment essential to AI data centers—including power systems and infrastructure components—will be manufactured and assembled.

The project is expected to create thousands of construction jobs during the development phase and support long-term employment in engineering, operations, maintenance, manufacturing, and related industries.

For France, the announcement represents a major validation of President Macron’s effort to position the country as Europe’s leading destination for advanced technology investment.

The commitment was unveiled during the government’s annual “Choose France” investment summit, where Macron said the country expects approximately €93 billion in foreign investment commitments spanning technology, healthcare, transportation, semiconductors, critical minerals, and industrial manufacturing.

The timing is significant.

While the United States and China have dominated much of the global AI infrastructure race, European policymakers have increasingly expressed concern that the continent risks falling behind in the competition for computing capacity, talent, and investment.

Artificial intelligence requires enormous amounts of computing power, and that computing power depends on access to land, electricity, networking infrastructure, and capital.

France believes it possesses several advantages.

The country maintains one of Europe’s largest nuclear-power fleets, providing relatively stable and low-carbon electricity supplies. That matters because AI data centers have become some of the largest consumers of power in the modern economy.

Electricity costs have emerged as a major constraint on AI expansion across Europe.

Large AI facilities consume vast amounts of energy around the clock, making access to reliable power one of the industry’s most valuable strategic assets.

By locating major facilities in northern France, SoftBank is effectively betting that the country’s energy infrastructure can support long-term growth in AI computing demand.

Investors appeared encouraged by the announcement.

SoftBank shares rose approximately 14% Monday and have gained more than 70% during 2026, reflecting growing enthusiasm around the company’s AI-related investments.

The company has become deeply intertwined with the AI ecosystem through its ownership of Arm Holdings, its substantial investment in OpenAI, and a growing portfolio of AI-related infrastructure and technology assets.

Industry analysts view the French investment as part of a larger trend.

Around the world, countries are increasingly competing to attract AI infrastructure projects in much the same way they once competed for factories, ports, and industrial facilities.

Computing power is becoming a strategic resource.

Data centers, electrical capacity, semiconductor access, and AI talent are increasingly viewed as critical national assets capable of influencing future economic growth.

For France, the project offers the possibility of becoming Europe’s answer to the massive AI infrastructure expansion currently underway in the United States.

For SoftBank, it represents another major wager that demand for artificial intelligence will continue growing for years to come.

And for Europe as a whole, it sends a powerful signal that the continent intends to play a far larger role in the next phase of the global AI economy.

The competition for AI leadership is no longer taking place only between companies.

It is increasingly a competition between nations.

With €75 billion now committed to French AI infrastructure, Europe has made one of its biggest moves yet.

JBizNews Desk — Europe

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

WASHINGTON — A Trump administration effort to reshape how certain immigrants obtain permanent residency has created uncertainty for employers, foreign workers, immigration attorneys, and families navigating the U.S. immigration system.

The confusion began after U.S. Citizenship and Immigration Services (USCIS) issued a policy memorandum on May 21, 2026, addressing green-card applications filed from within the United States. Days later, agency statements suggested that some foreign nationals seeking permanent residency could be required to leave the country and complete the process through U.S. consulates abroad rather than finishing it inside the United States.

The announcement immediately sparked concern because it appeared to challenge a process that has been a central feature of U.S. immigration law for decades.

For more than fifty years, many immigrants legally present in the United States have been permitted to obtain permanent residency through a process known as adjustment of status, which allows applicants to complete their green-card process without leaving the country. The pathway is commonly used by spouses of U.S. citizens, employment-based visa holders, students transitioning to permanent residency, refugees, and asylum recipients.

The administration argues the policy represents a return to what officials describe as the original intent of immigration law.

USCIS has characterized the move as closing what it views as a loophole that expanded beyond its intended scope over time. The Department of Homeland Security subsequently stated that individuals who properly qualify for permanent residency would still be able to receive green cards, although some applicants could be directed toward overseas consular processing rather than domestic adjustment procedures.

What remains unclear is exactly who will be affected.

After initially suggesting the policy could apply broadly, USCIS later indicated implementation would occur on a case-by-case basis. The agency has not fully detailed which applicants may be required to leave the country, how pending applications will be handled, or whether specific visa categories will face greater scrutiny.

That uncertainty has become the central issue.

Immigration attorneys report being flooded with calls and emails from concerned clients seeking clarification. Many legal professionals say employers and applicants are struggling to understand how the changes could affect long-term immigration plans already years in the making.

Shev Dalal-Dheini, Senior Director of Government Relations for the American Immigration Lawyers Association, warned that the policy could fundamentally alter a process that Congress has repeatedly reaffirmed through legislation over many decades.

Other immigration attorneys argue that adjustment of status is not an administrative loophole but a statutory process explicitly created and maintained by Congress.

The business implications extend far beyond immigration law.

Many U.S. companies rely heavily on foreign-born talent in sectors including technology, healthcare, engineering, finance, research, manufacturing, and higher education.

For employers sponsoring workers for permanent residency, uncertainty surrounding green-card processing creates operational challenges.

A company may spend years recruiting specialized talent, investing in visa sponsorship, and planning long-term staffing needs. If key employees are suddenly required to leave the country for consular processing, businesses could face disruptions ranging from delayed projects to staffing shortages.

Technology companies are viewed as particularly vulnerable.

Many engineers, software developers, data scientists, and artificial-intelligence specialists working in the United States initially arrive on temporary visas before pursuing permanent residency. Any process that increases uncertainty surrounding that transition may affect both recruitment and retention.

Healthcare providers face similar concerns.

Hospitals and medical systems already experiencing physician and nursing shortages often rely on foreign-born professionals who eventually pursue green cards through employment-based immigration pathways.

Business leaders also worry about America’s broader competitiveness.

The United States has historically attracted highly skilled workers from around the world in part because it offered a predictable path to permanent residency and eventual citizenship. Critics of the policy argue that increased uncertainty may encourage talented workers to consider alternative destinations including Canada, the United Kingdom, Australia, and parts of Europe.

Complicating matters further are applicants from countries where U.S. consular operations are limited or unavailable.

In certain cases, requiring overseas processing could create logistical obstacles for individuals who may have difficulty accessing functioning U.S. embassies or consulates.

Attorneys also report increased scrutiny in immigration cases more broadly.

Requests for additional evidence appear to be rising, and lawyers say applications that previously moved through the system with relative predictability are increasingly encountering delays and requests for further documentation.

For families and employers alike, the most immediate challenge is not necessarily the policy itself but the lack of clarity surrounding its implementation.

Immigration law often depends on predictability. Businesses make hiring decisions, families make life plans, and foreign workers make career choices based on expectations about how government procedures will operate.

When those expectations suddenly become uncertain, the economic consequences can spread quickly.

The Trump administration maintains it is enforcing immigration law as intended and restoring integrity to the green-card process.

Immigration attorneys argue the rollout has created confusion around one of the most important pathways to permanent residency in the United States.

Until federal officials provide clearer guidance regarding who is affected, how applications will be evaluated, and when new procedures will take effect, employers and applicants will remain caught between competing interpretations of a policy that could affect millions of future green-card seekers.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

SAN FRANCISCO — The artificial-intelligence boom moved one step closer to Wall Street on Monday as Anthropic, the developer behind the rapidly growing Claude family of AI models, announced that it has confidentially filed paperwork with the U.S. Securities and Exchange Commission to pursue an initial public offering.

The company disclosed in a blog post that it submitted a draft registration statement under the SEC’s confidential filing process, allowing it to begin the regulatory review process without immediately disclosing detailed financial information to the public.

While the filing does not guarantee an IPO will occur, it marks the first formal step toward a public listing and positions Anthropic to become one of the most closely watched technology offerings in recent years.

The announcement arrives at a remarkable moment for the company.

Just days before the filing, Anthropic disclosed a massive Series H funding round that valued the company at approximately $965 billion post-money, placing it among the most highly valued private technology companies in the world and bringing it within striking distance of the trillion-dollar threshold.

The financing round was reportedly led by a group of major institutional investors including Altimeter Capital, Dragoneer, Greenoaks, Sequoia Capital, Capital Group, Coatue Management, and D1 Capital Partners.

The valuation increase has been staggering.

Earlier this year, Anthropic was valued at roughly $380 billion. Within months, investor demand and rapid growth pushed that figure toward nearly one trillion dollars.

The filing highlights how dramatically the economics of artificial intelligence have evolved.

Founded by former OpenAI executives, Anthropic built its reputation around AI safety, governance, and its “constitutional AI” approach to model training. Initially viewed as a smaller competitor in the race to build advanced AI systems, the company has emerged as one of the industry’s most influential players.

Its flagship Claude models have gained traction across both enterprise and consumer markets, helping fuel explosive growth.

According to company disclosures, Anthropic’s annualized revenue run rate surpassed $47 billion earlier this year, driven largely by enterprise adoption and increasing use of its AI tools for software development, research, customer service, content generation, and workflow automation.

One of the strongest growth drivers has been Claude Code, the company’s software-development platform, which has rapidly gained popularity among engineers and enterprise customers looking to automate programming tasks.

Chief Financial Officer Krishna Rao said the recent funding would help Anthropic meet what he described as historic levels of customer demand.

The challenge facing Anthropic is one confronting nearly every major AI developer: infrastructure.

Building and operating advanced AI systems requires enormous amounts of computing power, and the costs continue to rise as models become larger and more capable.

Anthropic has committed substantial resources toward securing access to those systems.

The company announced earlier this year that it plans to invest more than $100 billion through Amazon Web Services to support training and inference operations. Additional agreements with Google Cloud and Broadcom have further expanded its access to advanced computing resources.

Those partnerships underscore one of the defining characteristics of the AI industry.

Revenue is growing rapidly, but so are expenses.

The next generation of AI models requires unprecedented investments in data centers, processors, networking equipment, electricity, and specialized talent. Even highly profitable AI companies face enormous capital requirements simply to remain competitive.

A public listing could provide Anthropic with another major source of funding while offering liquidity to employees and early investors.

The company would also gain broader access to capital markets at a time when AI spending continues to accelerate globally.

Anthropic is not alone.

The broader AI sector appears increasingly poised for a wave of public offerings.

Reports indicate that rival OpenAI has also taken steps toward a potential public-market debut, while several high-profile technology companies continue exploring IPO opportunities as investor demand for AI exposure remains strong.

For Wall Street, Anthropic’s eventual filing could provide something investors have been waiting for: transparency.

Despite the extraordinary valuations attached to many AI startups, limited public financial information has made it difficult for investors to evaluate profitability, operating costs, customer concentration, and long-term economics.

A public filing would offer the first detailed look inside one of the industry’s most influential companies.

Supporters argue that Anthropic’s growth validates the enormous investments flowing into artificial intelligence.

Critics continue to question whether valuations have outpaced reality and whether AI demand can ultimately justify the hundreds of billions of dollars now being deployed across the industry.

That debate is likely to intensify once financial disclosures become public.

For now, however, the facts remain straightforward.

Anthropic has confidentially filed for an IPO, investors have assigned it a valuation approaching $1 trillion, and one of the most important companies in artificial intelligence is preparing for the possibility of entering public markets.

Whether the company ultimately proceeds will depend on regulatory review, market conditions, and investor appetite.

But the filing itself serves as another powerful reminder that artificial intelligence is no longer a niche technology story.

It has become one of the largest capital markets stories in the world.

JBizNews Desk — San Francisco

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

WASHINGTON — The Trump administration is abandoning plans for a proposed $1.8 billion Anti-Weaponization Fund after lawmakers from both parties criticized the initiative as an unnecessary political vehicle that could have directed taxpayer money toward organizations aligned with the administration.

The proposal, which had been under consideration as part of broader efforts to address what President Donald Trump and his allies describe as the political weaponization of government agencies against conservatives, quickly ran into resistance on Capitol Hill. Critics argued the fund lacked sufficient oversight, clear operational guidelines, and protections against political favoritism.

According to congressional officials familiar with the discussions, opposition emerged not only from Democrats but also from a number of Republicans concerned about creating a large federal fund with broad discretionary powers.

Several lawmakers reportedly described the proposal as a potential “slush fund,” arguing that future administrations could use similar mechanisms to reward political allies or favored organizations.

The retreat represents a rare instance in which bipartisan criticism forced the administration to reconsider a high-profile initiative tied directly to one of Trump’s central political themes.

Since returning to office, Trump has repeatedly argued that federal institutions, including law-enforcement and intelligence agencies, were used improperly against political opponents. The administration has pursued multiple reforms aimed at increasing accountability and limiting what it views as politically motivated government actions.

Supporters of the fund argued it would provide resources for investigations, legal challenges, and oversight efforts related to alleged government misconduct and abuses of power.

Opponents countered that existing agencies, inspectors general, congressional committees, and the judicial system already possess authority to investigate misconduct, making the proposed fund unnecessary.

The controversy quickly drew attention because of the fund’s size.

At $1.8 billion, the proposal would have represented a substantial federal commitment at a time when both parties continue debating government spending levels, budget deficits, and the national debt.

Fiscal conservatives questioned whether the money would produce measurable results, while Democrats argued it risked politicizing oversight activities that traditionally operate independently from the White House.

The decision to abandon the proposal may also reflect broader political calculations.

With Congress focused on budget negotiations and several major legislative priorities, administration officials appear eager to avoid a prolonged battle over a program that lacked strong support even among portions of the Republican caucus.

Political analysts noted that bipartisan opposition can be particularly difficult for any White House to overcome because it removes the possibility of framing criticism as purely partisan.

For the administration, dropping the proposal allows officials to continue pursuing anti-weaponization reforms through existing agencies and executive actions without becoming bogged down in a contentious funding fight.

The episode also highlights the continuing debate over how government accountability should be enforced.

Trump supporters argue that stronger mechanisms are needed to investigate alleged abuses by federal institutions, particularly following years of disputes involving law enforcement, intelligence agencies, and politically sensitive investigations.

Critics maintain that creating new politically directed funding structures risks undermining public confidence in independent oversight.

The White House has not indicated whether portions of the proposal may be restructured and reintroduced in a different form.

For now, however, the $1.8 billion fund appears effectively shelved.

The outcome serves as a reminder that even in Washington’s deeply polarized environment, certain proposals can still generate opposition from both sides of the aisle when concerns about transparency, accountability, and political influence converge.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

TAIPEI — After dominating the artificial-intelligence boom from inside the world’s largest data centers, Nvidia is making its boldest move yet into personal computing.

At the opening keynote of Computex 2026 in Taipei on Monday, Nvidia CEO Jensen Huang unveiled the company’s new RTX Spark Superchip, also known as the N1X, marking Nvidia’s first serious attempt to power mainstream Windows laptops and desktop systems with the same AI-focused architecture that helped transform it into one of the world’s most valuable companies.

The launch represents far more than a new processor.

It is Nvidia’s direct challenge to the companies that have controlled personal computing for decades, including Intel, AMD, Qualcomm, and even Apple, while extending Nvidia’s influence from cloud data centers into the devices consumers and businesses use every day.

Huang framed the announcement as a major platform transition rather than a routine hardware upgrade.

Speaking before thousands of developers, manufacturers, and technology executives, he argued that artificial intelligence is fundamentally changing what computers can do and that the next generation of personal devices will be defined by AI assistants capable of operating directly on the machine rather than relying entirely on cloud services.

According to Nvidia, the new processor combines a high-performance CPU architecture with an integrated RTX 5070-class graphics engine, bringing the company’s AI acceleration capabilities directly into Windows laptops.

The chip was developed in partnership with Microsoft and leverages Nvidia’s extensive CUDA software ecosystem, which remains one of the company’s most powerful competitive advantages.

For years, CUDA has served as the foundation for AI development across research labs, universities, startups, and enterprise customers.

Now Nvidia is bringing that ecosystem to consumer hardware.

The company says systems powered by the new chip will begin arriving this fall from major manufacturers including Dell, HP, Lenovo, ASUS, MSI, and Microsoft’s own Surface lineup.

The devices will run Windows on Arm, Microsoft’s increasingly important operating system architecture designed to compete with Apple’s highly successful silicon strategy.

Industry analysts view the launch as one of the most significant shifts in personal computing in years.

For decades, the laptop market has largely been dominated by processors from Intel and AMD. More recently, Apple disrupted the industry through its internally developed M-series chips.

Now Nvidia is entering the battle with a unique advantage: unmatched leadership in artificial intelligence.

The company’s goal is clear.

Rather than forcing AI applications to run through remote cloud servers, Nvidia wants users to execute increasingly sophisticated AI tasks directly on their devices.

That approach offers several benefits.

Applications can respond faster because requests do not need to travel across the internet. Sensitive information can remain on the device rather than being transmitted to external servers. Battery efficiency may improve for certain workloads, and businesses can maintain greater control over proprietary data.

Those advantages could become increasingly important as AI adoption expands.

The timing is notable.

Technology companies across the industry are racing to position themselves for what many believe will be the next major computing cycle.

Apple recently introduced new M5-powered MacBooks. Arm Holdings has unveiled its own processor initiatives. Reports indicate AMD is developing Arm-based alternatives. Meanwhile, Qualcomm continues pushing aggressively into AI-enabled PCs.

Nvidia’s entry intensifies what is becoming one of the most competitive technology battles in years.

Huang used the event to highlight Nvidia’s broader ambitions beyond personal computing.

He announced that Nvidia’s Vera CPU platform for data centers has entered full production and identified major customers including Anthropic, OpenAI, xAI, Oracle, Dell Technologies, and CoreWeave.

The company also showcased a new humanoid robotics reference platform known as Isaac GR00T, designed to accelerate development of AI-powered robots capable of operating in industrial and commercial environments.

Taken together, the announcements illustrate Nvidia’s broader strategy.

The company is no longer positioning itself simply as a chipmaker.

Instead, it is building an ecosystem that stretches from cloud infrastructure to enterprise systems, personal computers, robotics, autonomous systems, and AI software platforms.

For investors, the significance extends beyond hardware sales.

Historically, major platform shifts create waves of spending throughout the technology industry.

Businesses upgrade equipment. Consumers replace aging devices. Software developers build applications tailored to new capabilities. Service providers expand infrastructure to support emerging workloads.

If AI-powered personal computing gains widespread adoption, Nvidia could benefit not only from chip sales but from increased demand across its broader software and ecosystem offerings.

The company is effectively betting that the next generation of computing will be built around artificial intelligence at every level.

The hardware unveiled in Taipei is merely the first step.

The larger opportunity lies in the software, services, and AI applications that follow.

For now, Nvidia has taken a decisive step beyond the data center and into the devices millions of people use every day.

Whether consumers embrace AI-first computing on the scale Huang predicts remains to be seen.

But one thing is already clear: the battle for the future of personal computing has entered a new phase, and Nvidia intends to be at the center of it.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

WASHINGTON — When Canadian officials arrived in Washington this week for trade talks with the Trump administration, they led with a message that sounded almost backwards: the United States needs Canada just as much as Canada needs the United States.

At first glance, that seems like a difficult argument for Ottawa to make. Canada depends heavily on access to the U.S. market, and Washington holds far more economic leverage in any trade negotiation. Yet Canada’s negotiators arrived carrying one asset that remains critically important to the American economy: oil.

Ahead of Monday’s meeting with U.S. Trade Representative Jamieson Greer, Canada-U.S. Trade Minister Dominic LeBlanc emphasized the importance of protecting the deeply integrated North American energy market. The message, delivered through spokesperson Gabriel Brunet, came just hours before LeBlanc and Canada’s chief negotiator, Janice Charette, sat down with U.S. officials.

The focus on energy was no coincidence.

It reflects a reality that often gets lost amid political debates over tariffs, trade deficits, and manufacturing jobs. While Canada depends heavily on American consumers, the United States also depends heavily on Canadian energy.

According to data from the U.S. Energy Information Administration, the United States purchases approximately $124 billion worth of Canadian energy annually. More importantly, Canada supplies roughly 4.1 million barrels of crude oil per day to the United States, accounting for more than half of all U.S. crude imports.

No other foreign supplier comes close.

Mexico, America’s second-largest source of imported crude, shipped less than 460,000 barrels per day during portions of early 2025. The gap highlights just how dominant Canada has become in the North American energy system.

The relationship goes beyond simple trade volumes.

Many American refineries, particularly in the Midwest and Gulf Coast regions, were specifically designed to process the heavy crude oil produced in Alberta’s oil sands. Replacing that supply would not be as simple as purchasing oil from another country.

The infrastructure, refining systems, transportation networks, and investment decisions built over decades have created a deeply interconnected market that neither country can easily unwind.

That reality gives Canada leverage.

It may not be enough to dictate terms in a broader trade negotiation, but it provides Ottawa with a powerful reminder that economic dependence runs both ways.

The timing is significant.

The Canada-United States-Mexico Agreement (CUSMA) — known in the United States as the USMCA — faces a mandatory review process beginning this summer. The review will determine whether the agreement continues unchanged, is renegotiated, or becomes the subject of more extensive discussions.

For Canada, the stakes are enormous.

The agreement protects most Canadian exports from tariffs and provides the framework governing one of the largest trading relationships in the world. Any disruption could affect industries ranging from manufacturing and agriculture to energy and technology.

There is also growing pressure on Canadian Prime Minister Mark Carney to demonstrate progress.

Mexico has already moved more aggressively in its discussions with Washington, while Canada’s formal negotiating track has advanced more slowly. That has fueled criticism from business groups and political opponents concerned about the country’s position heading into the review process.

LeBlanc’s trip to Washington was designed in part to address those concerns.

The one-day visit signaled urgency and an effort to demonstrate active engagement with the administration.

By emphasizing energy before discussions even began, Canadian officials effectively highlighted the area where Ottawa holds its strongest negotiating hand.

The message was straightforward: North America’s energy system functions because both countries benefit from it.

Disrupting that relationship would impose costs on consumers, refiners, producers, and businesses on both sides of the border.

Whether that argument gains traction remains uncertain.

Greer has publicly suggested that Canada has been slower than other trading partners in engaging with the administration’s trade agenda. He has also indicated that Washington intends to conduct a serious review of the agreement rather than automatically extending existing arrangements.

At the same time, industry participants describe a more nuanced picture behind closed doors.

Executives who attended recent meetings with administration officials have said the White House appears interested in preserving the core energy relationship even as it pushes for broader trade changes.

That distinction matters.

While trade negotiations often focus on political disagreements, the North American energy market operates according to economic realities that cannot easily be altered by policy alone.

Canada needs American buyers because most of its oil infrastructure is built to serve the U.S. market. The United States needs Canadian crude because much of its refining system was designed around those supplies.

Both sides understand that reality.

The result is a negotiation in which oil serves not only as a commodity but also as a strategic reminder of how deeply intertwined the two economies have become.

The immediate story is about one meeting and one round of trade discussions.

The larger story is about a North American energy partnership worth more than $124 billion annually that neither side can afford to ignore.

As the CUSMA review approaches, Canada is making a simple argument: trade relationships may be negotiable, but energy interdependence is much harder to replace.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

NEW YORK — Alphabet Inc., the parent company of Google, announced plans Monday to raise as much as $80 billion in fresh capital to fund an aggressive expansion of its artificial intelligence infrastructure, with Berkshire Hathaway committing $10 billion through a private placement in a move that signals significant institutional confidence in the company’s long-term AI strategy.

The planned financing package would rank among the largest capital raises ever undertaken by a major technology company and reflects the extraordinary scale of investment now required to compete in the rapidly evolving artificial intelligence race.

According to the company, the capital plan includes a $40 billion at-the-market equity program beginning in the third quarter, $30 billion in underwritten offerings of common stock and mandatory convertible preferred securities, and a $10 billion private placement investment from Berkshire Hathaway.

The announcement underscores how dramatically the economics of artificial intelligence have shifted. As technology companies race to develop larger models, faster computing capabilities, and global cloud infrastructure, access to capital has become a strategic advantage alongside technological innovation.

Alphabet CEO Sundar Pichai has repeatedly described artificial intelligence as one of the most significant technological transitions in the company’s history, comparable to the emergence of the internet, mobile computing, and cloud services.

The new funding is expected to support the construction of additional data centers, the acquisition of advanced computing hardware, expanded networking infrastructure, and the continued development of next-generation AI systems that power products across Google’s ecosystem.

The commitment from Berkshire Hathaway is likely to attract particular attention from investors.

The conglomerate built by legendary investor Warren Buffett has historically maintained a disciplined approach toward technology investments, favoring businesses with durable competitive advantages and predictable long-term cash flows. Berkshire’s participation is therefore being viewed by many market observers as a strong endorsement of Alphabet’s ability to convert AI investments into future earnings growth.

The investment also reflects the growing belief among institutional investors that artificial intelligence is not simply a temporary technology trend but a foundational shift likely to reshape industries ranging from healthcare and finance to manufacturing, education, and logistics.

The funding arrives as demand for AI services continues to surge.

Google Cloud, one of Alphabet’s fastest-growing businesses, has benefited from increasing enterprise adoption of AI-powered tools, machine-learning services, and advanced data analytics platforms. Businesses across industries are investing heavily in AI capabilities to improve productivity, automate operations, and create new products and services.

That demand has placed enormous pressure on cloud providers to expand capacity.

Industry analysts estimate that major technology companies collectively could spend hundreds of billions of dollars annually on data centers, advanced processors, energy infrastructure, and networking equipment over the coming years as AI workloads become increasingly computationally intensive.

Alphabet has already significantly increased its capital spending in recent quarters as it works to maintain competitiveness against rivals including Microsoft, Amazon, and Meta Platforms, all of which are investing aggressively in artificial intelligence.

Executives have argued that maintaining leadership in AI requires unprecedented infrastructure investment. The company’s Gemini family of AI models, along with AI-powered enhancements to Search, YouTube, Workspace, and Google Cloud, depend on large-scale computing resources that continue to expand as usage grows.

Investors appeared encouraged by the announcement, viewing the capital raise as a proactive effort to secure resources before infrastructure constraints become a bottleneck to growth.

While issuing new equity can dilute existing shareholders, many analysts noted that the move strengthens Alphabet’s balance sheet and provides flexibility without materially increasing debt obligations. The company is expected to use portions of the proceeds for global infrastructure projects, strategic investments, and obligations related to employee stock compensation programs.

The broader technology industry is increasingly being defined by a race to build the physical backbone of artificial intelligence.

Data centers, high-performance chips, power generation resources, and networking systems have emerged as critical assets in determining which companies will lead the next phase of technological development. As a result, AI infrastructure spending has become one of the most closely watched metrics among investors.

At the same time, regulatory challenges remain. Governments in the United States, Europe, and elsewhere continue to evaluate issues ranging from AI safety and transparency to antitrust concerns and data privacy requirements. Alphabet’s enhanced capital position could provide additional flexibility as it navigates evolving regulatory frameworks while continuing to invest in responsible AI development.

For Berkshire Hathaway, the investment represents a notable expansion into one of the defining growth themes of the decade. For Alphabet, it provides substantial resources to continue scaling its AI ambitions.

The success of the strategy will ultimately depend on whether the company can generate sufficient returns from its massive infrastructure investments. Investors will be watching upcoming earnings reports closely for evidence that growing AI adoption translates into stronger revenue, expanding margins, and sustainable long-term growth.

For now, the announcement reinforces Alphabet’s position as one of the leading builders of the AI era—and suggests that some of the world’s most respected investors believe the company’s biggest opportunities may still lie ahead.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

BOGOTÁ — Colombian financial markets surged Monday after businessman and political outsider Abelardo de la Espriella delivered a stronger-than-expected performance in the first round of the country’s presidential election, reshaping expectations for the June 21 runoff and fueling hopes of a more market-friendly economic agenda.

Official election results showed de la Espriella capturing 43.74% of the vote, narrowly ahead of left-wing Senator Iván Cepeda, who received 40.90%. Neither candidate secured the majority required for an outright victory, sending Colombia to a runoff election that will determine who succeeds President Gustavo Petro.

The result surprised many political observers and investors alike.

For months, Cepeda had been viewed as the favorite to finish first in the opening round. Instead, de la Espriella emerged with a narrow lead, immediately triggering a rally across Colombian assets as investors reassessed the country’s political and economic outlook.

The Colombian peso strengthened sharply following the vote, while shares of Ecopetrol, the country’s state-controlled energy giant and largest publicly traded company, climbed as traders bet that a potential de la Espriella presidency could usher in a more supportive environment for oil and gas investment.

Government bonds also attracted renewed interest as markets priced in the possibility of a significant policy shift after years of uncertainty under Petro’s administration.

The reaction highlights how closely Colombia’s economic future has become tied to the election.

De la Espriella, a 47-year-old attorney often known by supporters as “El Tigre,” has never held elected office. His campaign has centered on promises to reduce government spending, lower taxes, strengthen security, attract foreign investment, and restore confidence among businesses that have grown cautious during recent years.

Perhaps most important to investors, he has advocated expanding energy development and has expressed support for new oil exploration projects.

That position marks a sharp contrast with Petro’s administration, which pursued aggressive environmental goals and restricted new oil and gas exploration initiatives in an effort to accelerate Colombia’s transition away from fossil fuels.

Those policies generated concern among investors because oil remains one of Colombia’s most important sources of export revenue, foreign exchange, and government income.

As a result, few companies are more politically sensitive than Ecopetrol.

Any shift toward increased drilling activity, expanded exploration, or a more favorable regulatory environment could significantly affect the company’s long-term outlook and Colombia’s broader fiscal position.

Market participants largely interpreted Monday’s rally as a relief trade rather than a declaration of victory.

Analysts noted that investors are responding to increased odds of a government viewed as more supportive of private-sector growth, but they cautioned that the runoff remains highly competitive and policy implementation could prove far more challenging than campaign promises.

The election arrives at a difficult moment for Colombia’s economy.

The country’s benchmark COLCAP stock index has lagged many regional peers during much of 2026, weighed down by political uncertainty, concerns over public finances, and questions about future economic policy.

Meanwhile, Colombia’s central bank has maintained relatively high interest rates as it works to contain inflation and stabilize financial conditions.

While elevated rates help support the peso and attract foreign investment, they also increase borrowing costs for consumers and businesses, creating additional pressure on economic growth.

The country’s next president will inherit those challenges.

Investors will be watching closely for proposals related to fiscal discipline, tax policy, energy development, infrastructure investment, and security.

Security remains a major theme in the campaign.

De la Espriella has pointed to the policies of El Salvador President Nayib Bukele as a model for combating organized crime and strengthening public order. Supporters argue tougher security measures could improve economic confidence and attract investment, while critics have raised concerns about civil liberties and human rights implications.

The political dynamics heading into the runoff remain fluid.

Former President Álvaro Uribe, one of the most influential figures on Colombia’s political right, has encouraged supporters of eliminated center-right candidates to unite behind de la Espriella. That consolidation could prove important as both campaigns seek to expand beyond their first-round bases.

For ordinary Colombians, the outcome carries tangible consequences.

A stronger peso can lower the cost of imported goods and reduce inflationary pressures. Expanded energy investment could generate jobs and increase government revenue. At the same time, voters will weigh competing visions for public spending, social programs, environmental policy, and economic development.

The runoff on June 21 is now shaping up as one of the most consequential elections Colombia has faced in years.

Monday’s market rally revealed where investors currently see opportunity.

Whether that optimism survives the final campaign, the runoff vote, and the realities of governing remains the question that will dominate Colombia’s financial markets throughout the summer.

Latin America — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

NEW YORK — American factories are running hotter than they have in three years — and so are the costs of keeping them running.

The Institute for Supply Management (ISM) reported Monday that its Manufacturing Purchasing Managers Index (PMI) rose to 54.0% in May, up 1.3 percentage points from April and the strongest reading since May 2022. According to Susan Spence, Chair of the ISM Manufacturing Business Survey Committee, the report points to a manufacturing sector that continues to gain momentum even as inflationary pressures remain stubbornly elevated.

A PMI reading above 50 signals expansion. At 54%, U.S. manufacturing is not merely growing — it is accelerating. ISM estimates that the May reading is broadly consistent with the U.S. economy expanding at roughly 2.2% annualized GDP growth, providing another indication that the industrial side of the economy remains resilient despite higher borrowing costs and geopolitical uncertainty.

The strongest signal came from demand.

The New Orders Index climbed to 56.8%, rising 2.7 points from April and marking its fifth consecutive month of expansion. The Production Index increased to 54.3%, extending a seven-month growth streak as manufacturers responded to stronger order activity.

Export demand also showed signs of life after months of weakness. The New Export Orders Index returned to expansion territory at 50.6%, while the Imports Index rose to 53.0%, suggesting companies are increasing purchases of foreign materials and components to support growing production schedules.

The breadth of the expansion was particularly notable.

All six of the largest manufacturing industries reported growth during May, led by Computer & Electronic Products, Machinery, and Transportation Equipment. Of the 18 manufacturing industries tracked by ISM, 16 expanded, while only Wood Products reported contraction.

That kind of broad participation is typically viewed as a sign of underlying economic strength because growth is not concentrated in a single sector or product category.

Yet the report also contained a clear warning.

The Prices Index registered 82.1%, easing slightly from April but remaining at levels historically associated with significant cost pressures across supply chains.

A reading above 80 indicates that a large majority of manufacturers are paying more for raw materials and production inputs. According to ISM survey respondents, higher costs are being driven by several factors, including elevated steel, aluminum, copper, and petroleum-based product prices.

The ongoing conflict involving Iran continues to ripple through global energy markets, while tariffs and trade-related costs remain a concern for many manufacturers.

Notably, ISM reported that the Iran conflict was referenced in approximately 42% of survey comments submitted by purchasing managers, while tariffs were mentioned in roughly 18% of responses. More than half of respondents cited price volatility as an operational challenge.

One executive in the transportation-equipment sector reported rising logistics and fuel expenses tied to higher oil prices, while a food-and-beverage manufacturer said diesel costs were putting pressure on margins even as uncertainty remained regarding tariff-related refunds and trade policies.

Perhaps most striking was what did not appear in the report.

Not a single commodity was listed as declining in price during May.

That suggests inflationary pressures remain deeply embedded within industrial supply chains even as policymakers continue to look for signs that price growth is moderating.

Employment remained one of the few softer areas.

The Employment Index improved to 48.6% but remained below the 50-point threshold that separates growth from contraction. The index has now spent 32 consecutive months below expansion territory.

Spence noted that hiring activity remains mixed, with the ratio of companies adding workers roughly equal to the number reducing or managing headcount.

In practical terms, factories are producing more goods without significantly expanding payrolls.

Many manufacturers appear to be relying on existing employees, productivity improvements, automation, and operational efficiencies rather than aggressively hiring new workers.

Buried deeper within the report was another potentially important signal.

The Customers’ Inventories Index remained at a low 42.7%, indicating that inventories held by customers are still considered too lean. Historically, low customer inventories often support future production growth because businesses eventually need to replenish depleted stock levels.

At the same time, supply-chain vulnerabilities remain.

The Supplier Deliveries Index showed continued slowing, extending a six-month trend. Respondents highlighted ongoing concerns surrounding semiconductor availability, memory-chip supplies, and access to critical minerals used in advanced manufacturing.

For consumers, the report presents both encouraging and challenging implications.

Strong factory activity generally supports economic growth, investment, and employment across industrial regions. Growing production and healthy order books suggest manufacturers expect demand to remain solid through the summer months.

However, elevated costs inside factories often find their way into consumer prices over time.

When manufacturers pay more for steel, energy, transportation, and imported components, those expenses can eventually affect the cost of automobiles, appliances, electronics, packaged foods, and other everyday products.

The report also places the Federal Reserve in a difficult position.

Strong manufacturing growth argues against aggressive monetary easing, while persistent cost pressures suggest inflation risks remain alive. At the same time, weak factory hiring indicates parts of the labor market are still cooling.

The next ISM Manufacturing Report, covering June activity, will be released on July 1 and will provide further insight into whether the current combination of strong production and elevated prices continues.

For now, May’s data delivers a clear message: America’s factories are experiencing their strongest momentum in years, but the cost of sustaining that growth remains stubbornly high.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June , 2026

Costco’s gas stations have become some of the busiest in America as drivers hunt for savings amid elevated fuel prices. Yet the retailer’s biggest advantage has little to do with oil markets and everything to do with a business model that turns cheap gasoline into customer loyalty.

That may sound strange.

After all, the gas station across the street exists primarily to sell fuel. Costco does not. Yet Costco almost always manages to offer lower prices at the pump than many traditional gas stations.

The reason lies in how the company makes money.

Most gas stations operate on extremely thin fuel margins. The gasoline itself often generates only a small profit. The real money is made inside the convenience store through higher-margin items such as drinks, snacks, coffee, cigarettes, lottery tickets, and prepared foods. Fuel is designed to get customers onto the property, where they hopefully spend more money.

Costco plays an entirely different game.

The warehouse giant’s business model is built around membership fees rather than product markups. Members pay annual fees for the privilege of shopping in Costco warehouses, and those fees have become one of the company’s most important profit drivers.

According to company filings, membership income contributes a substantial share of Costco’s overall profitability each year.

That creates an advantage few retailers can match.

Because Costco earns significant revenue from memberships, it does not need large profits on individual products. The company can afford to keep prices extremely low across many categories while still generating strong overall earnings.

The famous $1.50 hot dog and soda combo is perhaps the best-known example.

For decades, Costco has maintained the same price despite inflation, rising labor costs, and supply-chain disruptions. The purpose is not maximizing profits on hot dogs. The purpose is reinforcing the value of membership.

Gasoline follows the same logic.

Every discounted fill-up reminds customers that their membership is saving them money.

That reinforcement matters because Costco’s most valuable transaction is not a fuel purchase. It is a membership renewal.

The company understands that a member who repeatedly saves money on gasoline is more likely to renew their card year after year.

In that sense, gasoline functions less as a profit center and more as a loyalty program.

Costco also benefits from a scale advantage that smaller competitors simply cannot replicate.

The retailer purchases fuel in enormous volumes and operates high-throughput stations designed to move cars quickly. Most Costco gas stations offer a streamlined setup with limited fuel grades, efficient pump layouts, and minimal staffing requirements.

Unlike traditional gas stations, Costco generally does not maintain large convenience stores attached to its fuel operations.

That means lower overhead costs and faster customer turnover.

The result is a business capable of selling significantly more gallons per location than many independent competitors while maintaining lower operating expenses.

Volume becomes the strategy.

A traditional gas station may need a larger margin on every gallon to cover rent, staffing, maintenance, and convenience-store operations.

Costco can rely on volume and memberships.

The dynamic becomes even more interesting when fuel prices rise.

Most gas stations struggle when prices spike because consumers become more price-sensitive and often reduce discretionary spending. Station owners typically cannot increase margins much without risking customer traffic.

Costco experiences something different.

When gasoline prices climb, members often flock to Costco stations specifically because the savings become more visible. Long lines at Costco pumps frequently grow even longer during periods of elevated fuel costs.

That surge in demand reinforces membership value.

Ironically, however, gasoline remains one of Costco’s lowest-margin businesses.

Selling more fuel does not necessarily produce significantly higher profits. In some cases, a larger share of gasoline sales can actually reduce the company’s overall profit margin because fuel earns less than many other products sold inside the warehouse.

But Costco is comfortable with that tradeoff.

The company does not need gasoline to be highly profitable if gasoline strengthens customer retention.

That is why the low prices persist.

Drivers often think they are simply buying cheaper fuel.

Costco sees something larger happening.

Each visit to the pump creates another reason to keep the membership active. Each gallon sold becomes part of a broader relationship between the retailer and the customer.

The fuel purchase is not the final transaction.

It is the beginning of another shopping trip, another warehouse visit, another opportunity to fill a cart, and ultimately another reason to renew a membership.

That perspective explains why Costco continues investing in fuel even though it generates relatively modest margins compared with other parts of the business.

The company is not trying to maximize profit on every gallon.

It is trying to maximize customer loyalty over time.

Cheap gas is not Costco being generous.

It is Costco being patient.

Consumer & Retail — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 2, 2026

NEW YORK — Hewlett Packard Enterprise delivered the kind of earnings report that forces Wall Street to rethink its assumptions. After markets closed Monday, the company reported fiscal second-quarter results that significantly exceeded analyst expectations and raised its full-year outlook, citing accelerating demand for artificial-intelligence infrastructure across enterprise customers.

Revenue surged 40% year-over-year to approximately $10.7 billion, easily surpassing Wall Street expectations of $9.79 billion. Non-GAAP earnings reached $0.79 per share, more than double the $0.38 reported during the same period last year.

Investors reacted swiftly. HPE shares jumped as much as 32% in after-hours trading, reflecting one of the strongest earnings reactions in the technology sector this year.

The biggest surprise came from management’s guidance.

HPE raised its full-year fiscal 2026 earnings outlook by roughly a full dollar, projecting $3.35 to $3.45 per share, compared with its prior forecast of $2.30 to $2.50. The company also increased its revenue growth target to 29% to 33%, up from the previous range of 17% to 22%.

For the third quarter alone, HPE expects revenue between $11.5 billion and $12.1 billion, comfortably ahead of analyst projections.

Chief Executive Officer Antonio Neri said the results reflected continued investment by customers seeking to modernize infrastructure and scale AI deployments.

The company entered the quarter with a record $5 billion AI systems backlog, and both AI orders and backlog nearly doubled from a year earlier. Traditional server demand also surged as organizations upgraded computing environments to support AI inference workloads and advanced analytics.

The results provide further evidence that the AI spending boom has expanded beyond hyperscale cloud providers and is now reaching mainstream enterprise customers.

For much of the past two years, investors focused primarily on spending by technology giants such as Microsoft, Amazon, Alphabet, and Meta Platforms. HPE’s results suggest banks, manufacturers, governments, telecommunications providers, and large enterprises are increasingly joining the spending wave.

The company’s profitability improved alongside growth.

Gross margin climbed to 36.5%, representing an increase of more than 800 basis points from a year earlier. Free cash flow reached approximately $900 million, demonstrating that HPE is not simply generating revenue growth but doing so while improving operational efficiency.

The quarter also highlights the growing importance of networking infrastructure.

Last year HPE completed its roughly $14 billion acquisition of Juniper Networks, and management indicated that business is becoming increasingly important as AI deployments expand.

The company now expects networking revenue growth of 72% to 75%, reflecting strong demand for switching, routing, and connectivity solutions required to support large-scale AI systems.

As AI models grow more sophisticated, the networking equipment connecting servers often becomes just as critical as the servers themselves.

The company also tied its strategy closely to developments announced at Computex in Taiwan.

The New York Stock Exchange plans to deploy new Nvidia-powered HPE systems capable of processing more than a trillion messages daily, illustrating how AI infrastructure is increasingly moving into mission-critical financial and industrial applications.

The next stage of AI adoption is no longer limited to training large models.

Increasingly, organizations are investing in AI inference systems that allow models to operate in real time inside businesses, financial institutions, government agencies, and operational networks.

There are challenges ahead.

Neri has warned that elevated memory costs are likely to persist through at least 2027. Memory components now represent more than half of a server’s bill of materials, creating potential margin pressure if costs continue rising.

For now, however, demand appears strong enough to offset those concerns.

For investors, HPE’s report sends a broader signal about the state of the AI economy.

The spending surge that initially benefited a small group of chipmakers and cloud providers is increasingly spreading across the broader technology ecosystem. Hardware manufacturers, networking providers, software companies, and enterprise service firms are beginning to participate in the buildout.

That expansion could create opportunities across a much wider segment of the economy than many analysts originally expected.

Whether the pace of spending remains sustainable remains one of the central questions facing the technology sector.

But based on HPE’s latest results, customers are still spending aggressively, backlogs continue growing, and management believes its long-term targets are arriving years earlier than anticipated.

For now, the AI infrastructure boom shows few signs of slowing.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 1, 2026

MINNEAPOLIS — General Mills (NYSE: GIS) is handing control of one of its most recognizable consumer brands in China to a local operator, announcing Monday that it has agreed to sell its Häagen-Dazs scoop-shop business in mainland China to an investor group led by rapidly expanding tea-chain operator Ningji.

The transaction, announced by General Mills through a BusinessWire release, marks a significant shift in the company’s China strategy and reflects a broader trend of multinational consumer brands increasingly relying on local operators to navigate a fiercely competitive Chinese retail market.

Under the agreement, the investor group will acquire the mainland China Häagen-Dazs retail store business and receive an exclusive license to operate Häagen-Dazs ice-cream shops and gift sales throughout mainland China. Financial terms were not disclosed. The deal is expected to close during 2026, subject to regulatory approvals.

The sale does not represent a complete withdrawal from China.

General Mills said it will retain ownership of its Häagen-Dazs retail-packaged products and foodservice operations in mainland China, meaning the brand’s products will continue to be sold through grocery stores, hotels, restaurants, and other distribution channels. The company will also continue operating Häagen-Dazs businesses in markets outside mainland China.

Still, the move represents a notable retreat from a business that once symbolized the rise of premium Western consumer brands in China.

For years, Häagen-Dazs occupied a unique position in Chinese consumer culture. Its upscale stores became popular destinations for dates, celebrations, and premium gifting. At a time when foreign brands carried significant prestige among Chinese consumers, a Häagen-Dazs dessert was often viewed as an affordable luxury.

That market has changed dramatically.

China’s consumer economy has become more competitive, more localized, and increasingly driven by domestic brands that can move faster and operate more efficiently than international rivals. Consumer spending has also slowed as economic growth moderated, making premium-priced imported products harder to sell.

At the same time, local beverage and dessert chains have exploded across the country.

Ningji, one of China’s fastest-growing tea brands, operates more than 3,000 locations and has built a powerful presence among younger consumers. The company has expanded rapidly by offering premium tea products at accessible prices while maintaining a deep understanding of local tastes and shopping habits.

That local expertise is likely one of the biggest attractions for General Mills.

Running hundreds of retail stores from corporate headquarters thousands of miles away presents challenges that local operators often avoid. Real estate decisions, staffing, product innovation, marketing campaigns, and consumer trends move quickly in China, particularly in food and beverage categories.

A local operator with an existing retail network can often respond faster and more efficiently.

The transaction also aligns with General Mills’ Accelerate strategy, which focuses on directing resources toward higher-return businesses and simplifying operations.

While Häagen-Dazs remains a globally recognized premium brand, operating a network of physical retail stores requires significant labor, real estate, and management resources. Packaged-food businesses generally offer higher margins and greater scalability.

For a company whose portfolio includes brands such as Cheerios, Pillsbury, Betty Crocker, Nature Valley, Old El Paso, and Blue Buffalo, the economics are straightforward.

General Mills generated approximately $19 billion in annual revenue during fiscal 2025. Against that backdrop, a chain of ice-cream parlors represents a relatively small business that requires disproportionate operational attention.

Industry analysts say the move reflects a broader shift occurring throughout China’s consumer sector.

Rather than exiting China entirely, many multinational companies are increasingly choosing partnership models that allow them to maintain brand presence while reducing direct operational responsibilities. Local operators gain access to internationally recognized brands, while global companies preserve market exposure without managing day-to-day retail operations.

The arrangement often proves attractive for both sides.

For Chinese consumers, the transition may ultimately be invisible.

The Häagen-Dazs name remains. The stores remain. The products remain.

What may change is how the brand evolves.

With Ningji controlling operations, observers expect new menu concepts, expanded digital integration, localized product offerings, and potentially broader expansion into smaller Chinese cities where domestic operators often have stronger market knowledge.

For General Mills, the transaction simplifies its China footprint while preserving exposure to one of the world’s largest consumer markets.

For Ningji, it offers an opportunity to combine one of China’s fastest-growing beverage networks with one of the world’s most recognizable premium dessert brands.

As multinational consumer companies continue rethinking how they compete in China, the Häagen-Dazs transaction may prove less an exception than a preview of the industry’s next chapter.

Consumer & Retail — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Just three weeks ago, Verra Mobility executives were reassuring Wall Street that negotiations with one of the company’s most important customers were progressing smoothly.

“We have a contract extension with Avis that enables us to continue to serve the customer without interruption while we continue to negotiate a long-term renewal,” management told investors during the company’s May 6 earnings call, describing discussions with Avis Budget Group as “ongoing and constructive.”

Then the floor disappeared.

On May 26, Verra Mobility disclosed that Avis had formally terminated the relationship, with the contract set to expire in September. Verra said it was “surprised and disappointed” by the decision after what it described as extensive renewal discussions tied to the long-running partnership.

The market reaction was brutal.

Shares of Verra Mobility collapsed more than 30% in regular trading and plunged further afterward, wiping out billions in market value in less than 24 hours. The company warned that annualized Commercial Services revenue would fall by roughly $135 million to $145 million, while segment profit would decline by as much as $125 million before cost reductions.

For many investors, the scale of the damage raised an uncomfortable question: how could a company go from publicly signaling constructive negotiations to losing a major customer almost immediately afterward?

But beneath the stock collapse sits a much larger story — one increasingly haunting both credit markets and enterprise software investors.

The Verra-Avis breakup is reviving one of modern finance’s biggest structural fears: software dependency risk.

The Illusion of “Sticky” Revenue

For years, enterprise software has traded on one core assumption: once large customers deeply integrate software into daily operations, they rarely leave.

The industry even built an entire vocabulary around the concept — “stickiness,” “embedded workflows,” “mission-critical systems,” “high switching costs,” and “recurring revenue visibility.”

Those assumptions support some of the richest valuations in global equity and credit markets.

Verra’s collapse is a reminder that those assumptions can fail very quickly.

Avis represented more than 10% of Verra Mobility’s revenue during both the first quarter of 2026 and full-year 2025. In isolation, that level of concentration is not unusual in enterprise software or infrastructure services. Many successful software firms derive significant revenue from a handful of large corporate clients.

The market typically tolerates that concentration because investors assume the relationship itself is durable.

The danger is that durability often gets confused with permanence.

Verra’s situation exposed how quickly “sticky” can become “replaceable.”

Why This Frightens Credit Markets

The software industry increasingly behaves less like traditional technology and more like infrastructure financing.

Companies borrow heavily against the predictability of recurring subscription revenue. Credit investors underwrite debt based on assumptions about renewal rates, customer retention, and the stability of long-term enterprise contracts.

When a major customer exits suddenly, the damage spreads far beyond earnings.

Cash-flow assumptions weaken. Debt metrics deteriorate. Refinancing risk rises. Valuation multiples compress. Legal exposure expands. Vendor concentration suddenly becomes existential rather than manageable.

That chain reaction is exactly what credit investors fear most.

The problem becomes even more acute when management appears caught off guard.

As recently as May 6, Verra was publicly reaffirming guidance and characterizing negotiations positively. Twenty days later, the company was slashing forecasts and disclosing the loss of its largest customer relationship.

For markets, the speed of that reversal matters almost as much as the termination itself.

It raises uncomfortable questions about visibility, disclosure discipline, internal forecasting reliability, and whether software vendors themselves fully understand the stability of their largest customer relationships.

Why Customers Are Reassessing Software Dependence

The broader backdrop here is changing corporate behavior around software ownership.

For more than a decade, companies aggressively outsourced operational systems to specialized software vendors. That trend accelerated because cloud computing reduced implementation costs while enterprise software became increasingly sophisticated.

But large corporations are now reevaluating parts of that dependency model.

Artificial intelligence, internal automation tools, lower development costs, and expanding in-house engineering capabilities are making some companies more willing to internalize critical software functions rather than remain dependent on third-party vendors indefinitely.

Avis may represent exactly that shift.

The company has not publicly detailed the reasons behind the termination. But the logic is increasingly familiar across corporate America: if software becomes operationally essential enough, eventually the customer begins asking whether it should own more of the capability directly.

That creates a paradox for software vendors.

The more mission-critical the software becomes, the more strategically valuable it may become for the customer to control internally.

In other words, success itself can create exit risk.

The AI Effect

Artificial intelligence may accelerate this pressure dramatically.

Historically, replacing enterprise software required massive migration costs, long development timelines, and substantial engineering teams. AI-assisted coding tools are beginning to reduce some of those barriers.

Large corporations now have more tools to replicate, customize, or partially rebuild software systems internally than they did even two years ago.

That does not mean enterprise software disappears. But it does mean switching costs may no longer be as permanent as markets previously assumed.

The Verra situation is now being viewed through exactly that lens.

Legal and Disclosure Risks Are Growing

The fallout is no longer limited to equity losses.

Several securities-law firms have already opened investigations into Verra Mobility following the Avis termination and guidance reduction, focusing on whether investors were adequately informed about risks surrounding the relationship before the abrupt disclosure.

Even if no wrongdoing is ultimately found, the investigations themselves add another layer of pressure: legal costs, regulatory scrutiny, and reputational damage.

That combination is especially dangerous for companies already experiencing deteriorating fundamentals.

Analysts moved quickly after the announcement. JPMorgan cut its price target on Verra Mobility from $19 to $17, while Morgan Stanley lowered its target from $20 to $15, both maintaining relatively cautious ratings as uncertainty surrounding the company’s long-term revenue base intensified.

The Bigger Message

The Verra-Avis split may ultimately become more important as a warning than as an isolated corporate event.

For years, investors treated recurring software revenue almost like utility income — predictable, stable, and highly visible.

What this episode revealed is that software dependency cuts both ways.

The customer becomes dependent on the software.

But the vendor may become equally dependent on the customer.

And once that balance shifts, even very large, deeply integrated relationships can unravel far faster than markets expect.

In credit markets increasingly built around recurring revenue assumptions, that realization matters enormously.

Because in enterprise software, “sticky” only matters until someone decides to leave.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 1, 2026

The world’s leading economists are delivering one of their starkest warnings since the pandemic.

In its latest Chief Economists Outlook, released on May 28, the World Economic Forum reported that global business leaders and chief economists have sharply downgraded their outlook for the world economy, citing the ongoing closure of the Strait of Hormuz, rising energy costs, supply-chain disruptions, and mounting inflation pressures.

The numbers tell the story.

According to the survey, conducted between April 6 and April 17, 89% of chief economists now expect global growth to weaken over the next twelve months. More notably, 21% believe the slowdown will be significant rather than mild.

Just a few months ago, many economists entered 2026 expecting inflation pressures to ease and growth to stabilize. That optimism has largely disappeared.

The biggest concern is inflation.

An overwhelming 94% of economists surveyed now expect inflation to rise over the coming year as elevated energy prices and supply disruptions work their way through the global economy.

The source of those concerns lies thousands of miles away in one of the world’s most strategically important waterways.

The Strait of Hormuz, through which roughly 20% of global oil supplies normally pass, has remained severely disrupted since the outbreak of conflict involving Iran earlier this year. The closure has transformed what began as a regional geopolitical crisis into a global economic threat affecting consumers, businesses, investors, and governments worldwide.

The Forum’s economists ranked the current disruption as more economically damaging than many of the trade disputes and tariff battles that dominated headlines last year.

Several warned that if significant disruptions continue into the second half of 2026, the resulting economic effects could approach the scale of some of the supply-chain shocks experienced during the COVID-19 era.

Energy remains the most immediate transmission mechanism.

Higher oil prices increase transportation costs, manufacturing expenses, shipping rates, airline fuel bills, and food-production costs. Those increases eventually make their way into consumer prices.

For households, it means more expensive gasoline, groceries, utilities, and travel.

For businesses, it means higher operating costs, tighter margins, and greater uncertainty when planning future investments.

Despite the deteriorating outlook, economists are not yet forecasting a global recession.

Only 13% of respondents said a worldwide recession is likely.

That distinction matters.

The prevailing view among economists is not that the global economy is collapsing but that growth is slowing while inflation remains stubbornly elevated—a combination policymakers traditionally find difficult to manage.

The risks are also unevenly distributed.

Europe emerged as one of the regions most vulnerable to a potential period of stagflation, where weak economic growth coincides with persistent inflation.

That combination can leave central banks trapped between raising rates to fight inflation and lowering rates to stimulate growth.

The survey also highlighted growing concern across the Middle East and North Africa, where 88% of economists now expect weak or very weak growth conditions.

Sub-Saharan Africa was identified as the region facing the greatest inflation pressures due to its sensitivity to imported energy and food costs.

Amid the gloom, two major economies continue to stand out.

The United States and India were viewed as the most resilient large economies in the survey.

Economists cited strong domestic demand, relatively healthy labor markets, ongoing investment, and greater economic flexibility compared with many other regions.

India received particularly strong marks, with 52% of economists expecting strong or very strong growth over the next year.

Large-scale infrastructure projects, manufacturing investment, and population growth continue to support India’s economic expansion.

For multinational corporations deciding where to invest, the shifting outlook is already influencing strategy.

The Forum found that businesses are increasingly redirecting capital and supply chains toward regions viewed as more resilient, including the United States, India, and parts of Southeast Asia.

That trend reflects a broader reality emerging across global commerce: companies are no longer assuming economic risks are evenly distributed.

Instead, firms are building supply chains and investment plans around a more fragmented world.

There was one bright spot in the report.

A remarkable 92% of economists expect artificial intelligence adoption to accelerate during the next year.

However, expectations for immediate productivity gains have become more cautious.

While economists remain optimistic about AI’s long-term economic impact, many now believe the benefits will emerge gradually rather than through a rapid transformation.

For now, though, the dominant concern remains energy.

As long as the Strait of Hormuz remains constrained, oil markets will remain vulnerable, inflation pressures will stay elevated, and businesses will face higher costs.

The World Economic Forum’s message is clear: the biggest economic story of 2026 is no longer tariffs, interest rates, or even artificial intelligence.

It is a narrow stretch of water through which much of the world’s energy supply normally flows.

And until that bottleneck eases, economists expect the global economy to face a more difficult and more expensive road ahead.

Global Economy — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

June 1, 2026

WASHINGTON — President Donald Trump delivered one of his most striking comments yet on Iran Monday, brushing aside concerns that negotiations could collapse and declaring in a CNBC phone interview that he simply does not care if the talks end.

“I don’t care if they’re over, honestly,” Trump said, adding that the negotiations had dragged on for too long and had become “boring.”

On the surface, the remark sounded like a president losing patience and walking away from diplomacy. But a closer look suggests something very different. Rather than signaling surrender, Trump appears to be attempting a classic negotiating tactic: convincing Iran that the United States is prepared to walk away from the table.

The timing was no coincidence.

Earlier Monday, Iranian state media reported that Tehran was considering severing communications with Washington and moving to completely block the Strait of Hormuz in response to Israeli military operations in Lebanon. The threat immediately captured the attention of global markets because the Strait of Hormuz remains one of the world’s most important energy chokepoints, carrying roughly one-fifth of global oil shipments.

Any disruption there could send oil prices sharply higher, raising fuel costs, transportation expenses, and inflation pressures worldwide.

Markets reacted accordingly, pushing crude prices higher as traders weighed the risks.

Trump’s response, however, was the opposite of what Tehran may have expected.

Instead of expressing concern, he projected indifference.

And that may be the point.

Negotiations are often driven by leverage. A threat only works if the other side appears vulnerable to it. By publicly signaling that the United States is not afraid of talks collapsing, Trump is effectively trying to reduce the value of Iran’s threat.

The message is simple: if Washington is willing to walk away, Tehran loses some of its negotiating power.

It is a tactic Trump has used repeatedly throughout both business and politics. The side perceived as needing the deal less often gains leverage over the side perceived as needing it more.

The president reinforced that strategy by downplaying concerns about rising oil prices.

Trump told CNBC that he was not worried about recent energy-market volatility and predicted gasoline prices would eventually move lower.

Whether that forecast proves correct is another question.

Oil traders respond to supply risks, not political messaging. If Iran were to follow through on threats involving Hormuz, energy markets would likely react aggressively regardless of White House statements.

That highlights the central tension behind the administration’s approach.

Trump may be strengthening his negotiating position, but he cannot eliminate the economic consequences of a genuine disruption to global oil flows.

The most revealing moment of the interview may have been what Trump did not say.

When asked whether it was time to formally abandon the existing U.S.-Iran ceasefire framework, the president declined to answer directly.

Instead, he said he understood the question but would not reveal his thinking.

That response suggested strategic ambiguity rather than disengagement.

A president truly abandoning diplomacy has little reason to conceal his next move. By refusing to answer, Trump preserved uncertainty while keeping pressure on Tehran.

Diplomacy also continued behind the scenes.

Trump said he planned to speak with Israeli Prime Minister Benjamin Netanyahu about developments in Lebanon, and the two leaders later held discussions as regional tensions continued to evolve.

That is hardly the behavior of a White House walking away from the issue.

The contrast between Trump’s public rhetoric and private actions is significant.

Publicly, he projects confidence and indifference.

Privately, diplomacy and coordination with allies continue.

For businesses and investors, the immediate concern remains energy.

Oil prices influence everything from airline profitability and shipping costs to inflation, consumer spending, and central-bank policy decisions. Even if negotiations continue, uncertainty surrounding Hormuz is enough to keep markets on edge.

That is why traders are watching events in the Middle East so closely.

The administration’s strategy may ultimately succeed in forcing Iran back toward a more favorable negotiating position. It may also increase the risk of miscalculation if Tehran interprets the remarks as a challenge rather than a signal.

For now, however, Trump’s message appears less about ending diplomacy than reshaping the terms under which diplomacy continues.

The president is attempting to convince Iran that America is willing to walk away.

Whether Tehran believes him may determine what happens next.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

WASHINGTON — June 1, 2026

The U.S. Department of Commerce has moved to close a loophole that officials say may have allowed some of America’s most advanced artificial-intelligence chips to reach Chinese companies through overseas subsidiaries, escalating Washington’s ongoing battle to limit China’s access to cutting-edge AI technology.

In guidance issued Sunday, the department’s Bureau of Industry and Security (BIS) said advanced AI processors sold to companies headquartered in China will now require export licenses regardless of where those companies are physically located.

The move effectively extends U.S. export controls beyond China’s borders, targeting subsidiaries and affiliated entities operating in countries such as Malaysia, Singapore, and other international hubs that have become increasingly important in global semiconductor supply chains.

The policy focuses on some of the most powerful AI processors currently available, including Nvidia’s Blackwell and Rubin platforms and AMD’s MI350-series chips, which are used to train and operate large-scale artificial-intelligence systems.

These processors have become among the most strategically important technologies in the world, powering everything from advanced AI models and cloud computing platforms to military and national-security applications.

According to the Commerce Department, the new guidance is intended to ensure that existing export restrictions cannot be bypassed through foreign subsidiaries of Chinese firms.

The action addresses a gap that emerged after the U.S. government stopped enforcing the Biden-era AI Diffusion Rule in 2025. Once enforcement was paused, industry observers warned that Chinese companies could potentially acquire restricted chips through operations located outside mainland China.

In practice, a company prohibited from purchasing advanced processors directly in China could potentially seek access through an overseas subsidiary operating in another jurisdiction.

The Commerce Department’s latest guidance is designed to prevent that scenario.

Technology-policy experts have been warning about the issue for months.

Chris McGuire, a former U.S. State Department official and technology specialist, described the loophole as a major concern, arguing that overseas subsidiaries of Chinese firms may have been able to acquire advanced AI hardware without the same scrutiny applied to entities based within China itself.

Industry analysts say the exact number of chips that may have reached Chinese-linked entities through overseas channels remains unknown. However, given the intense global demand for AI processors, even relatively small volumes could represent significant computing capacity.

The new restrictions do not appear to require companies to surrender or deactivate chips already purchased under previous rules. Instead, the focus is on future transactions and licensing requirements.

For semiconductor manufacturers, the stakes are substantial.

Nvidia and AMD remain at the center of the global AI boom, with demand for advanced processors reaching unprecedented levels as corporations, governments, and cloud-computing providers race to build artificial-intelligence infrastructure.

China has historically represented one of the world’s largest markets for high-performance computing technology, making every new export restriction a significant commercial issue for chipmakers.

Nvidia Chief Executive Jensen Huang has repeatedly emphasized the importance of the Chinese market, even as Washington has steadily tightened restrictions on advanced semiconductor exports.

Investors are expected to closely monitor market reaction when trading resumes, as export-control announcements have frequently triggered volatility in semiconductor stocks. Previous rounds of restrictions have weighed on both Nvidia and AMD shares as investors assessed potential impacts on future revenue growth.

The broader conflict reflects a growing reality in global technology competition.

Artificial intelligence is increasingly viewed not merely as a commercial opportunity but as a strategic national asset. As a result, semiconductor policy has become one of the most important battlegrounds in the economic relationship between the United States and China.

Washington’s objective remains clear: limit China’s access to the most advanced AI hardware while preserving America’s technological advantage.

The challenge, however, is enforcement.

Closing a loophole may stop future shipments, but policymakers still face difficult questions about how much advanced computing power may have already reached Chinese-linked entities—and what that means for the next phase of the global AI race.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
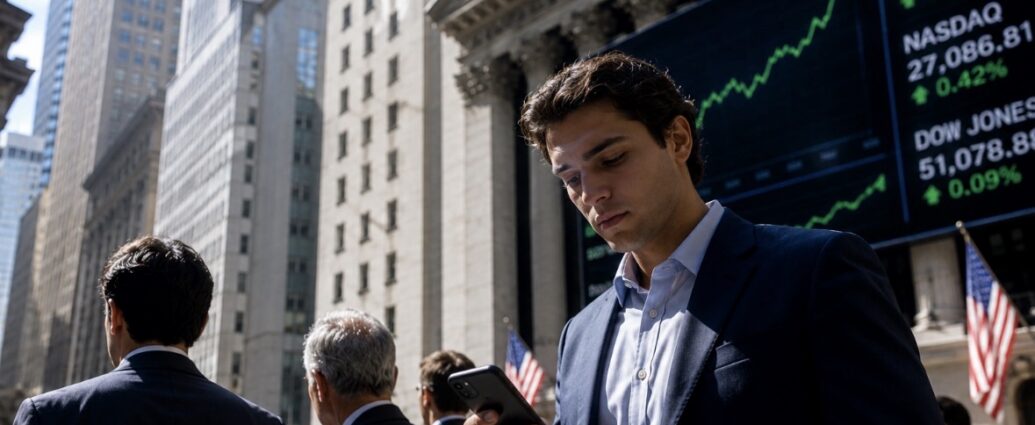
Wall Street investors and corporate landlords are pulling back from the U.S. housing market, marking a significant shift that could reshape competition for homes across the country.

According to a Redfin report released May 28, investor purchases of U.S. homes fell 6% year-over-year during the first quarter of 2026, reaching their lowest level since 2020 and among the weakest levels recorded since before the pandemic housing boom.

The report, based on county-level purchase records across 39 major U.S. metropolitan areas, found that both large institutional investors and smaller landlords have become increasingly cautious as high borrowing costs and elevated home prices squeeze returns.

The reason is simple: housing has become a much tougher investment.

Mortgage rates remain significantly higher than the ultra-low levels that fueled investor buying during the pandemic. Although rates eased into the low-6% range during the first quarter, they remain roughly double the levels many investors enjoyed just a few years ago.

At the same time, home prices continue to hover near record highs in many markets.

That combination is making it increasingly difficult for investors to generate attractive returns through rental income or property appreciation.

As a result, many investors are choosing to sit on the sidelines rather than pursue acquisitions that may not produce sufficient profits.

The cooling investment climate is particularly evident in traditionally affordable housing segments.

Investor purchases of condominiums fell 8%, reaching their weakest first-quarter level since 2015. Townhouse purchases dropped 13%, while purchases of single-family homes declined 6%.

Despite the slowdown, single-family homes still accounted for roughly 70% of all investor purchases, underscoring their continued importance within the rental housing market.

The retreat is especially visible in Florida.

Orlando recorded one of the steepest declines among major metropolitan areas, with investor purchases falling 25% from a year earlier. Investors have increasingly backed away from several Florida markets as rising insurance costs, growing housing inventory, softening home prices, and escalating homeowner-association fees weigh on profitability.

Cleveland also saw investor purchases decline sharply, falling 21% year-over-year.

Not every market is experiencing a pullback.

Investor purchases increased most sharply in San Francisco, rising 19%, followed by Virginia Beach at 15% and San Jose at 12%.

The gains highlight the continued appeal of technology-driven housing markets benefiting from strong job growth and the ongoing artificial-intelligence investment boom.

Where economic growth remains strong and housing demand is accelerating, investors continue to see opportunity.

Where ownership costs are rising faster than rents, many are heading for the exits.

The broader housing market remains sluggish overall.

Investor-owned purchases represented approximately 19% of all home purchases during the first quarter, roughly unchanged from a year earlier. Meanwhile, the share of investor-owned properties listed for sale fell to 7.8% of total U.S. listings, the lowest level in five years.

For ordinary homebuyers, the trend may offer some relief.

For years, first-time buyers have complained about competing against investors capable of making all-cash offers and quickly acquiring starter homes.

With investors purchasing fewer properties, some buyers may encounter less competition, particularly in lower-priced housing segments.

However, the development also serves as a warning sign.

The same conditions discouraging investors—high home prices, elevated mortgage rates, and uncertain returns—continue to challenge families seeking to purchase homes for themselves.

In many markets, affordability remains one of the biggest obstacles facing prospective homeowners.

The housing market now finds itself in a holding pattern.

Investors are waiting for borrowing costs to fall and profitability to improve. Homebuyers are waiting for greater affordability. Sellers are waiting for stronger demand.

Until interest rates move decisively lower or home prices adjust, much of the market appears likely to remain frozen between those competing forces.

JBizNews Desk — Real Estate

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
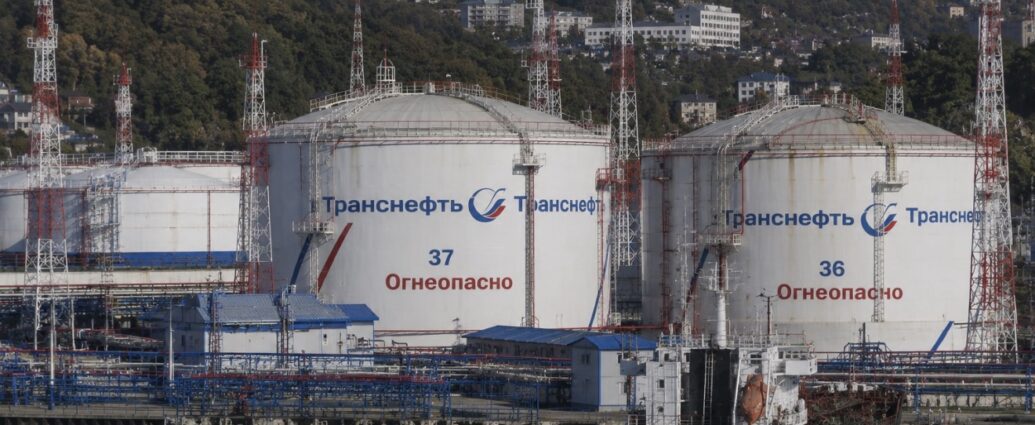
By JBizNews Desk

NEW YORK — June 1, 2026

One of Wall Street’s most closely followed economists is issuing a stark warning: the U.S. economy is no longer merely slowing—it is beginning to struggle.

On May 28, Mark Zandi, Chief Economist at Moody’s Analytics, said the combination of weakening economic growth, persistent inflation, and elevated oil prices tied to the conflict involving Iran is pushing the United States closer to recession.

“The economy isn’t just soft, it’s struggling,” Zandi wrote on X, adding that unless the conflict eases and shipping through the Strait of Hormuz returns to normal, the odds of a recession could soon become greater than 50%.

The warning comes as a growing number of economic indicators point in the wrong direction simultaneously, creating a difficult environment for consumers, businesses, and policymakers.

Growth Is Slowing

The first warning sign is economic growth itself.

Recent revisions showed U.S. gross domestic product expanded at an annualized rate of 1.6% during the first quarter, weaker than earlier estimates and well below the pace seen during much of the post-pandemic expansion.

Housing activity has softened under the weight of elevated mortgage rates. Business investment has slowed. Corporate executives have become increasingly cautious about hiring and expansion plans as uncertainty rises.

While the economy continues to grow, the pace has clearly weakened.

For many economists, the concern is not a collapse in activity but a gradual erosion occurring across multiple sectors at the same time.

Consumers Are Feeling the Pressure

The second challenge is the American consumer.

According to recent economic data, real disposable income—the money households have available after taxes and inflation—is under pressure. Savings rates have also fallen as families spend more of their income to cover higher everyday expenses.

Consumer spending has been one of the biggest reasons the U.S. economy avoided recession over the past several years. If that spending begins to slow meaningfully, the broader economy could lose one of its most important sources of support.

The pressure is becoming increasingly visible at gas stations, grocery stores, and household budgets.

Inflation Is Heating Up Again

At the same time growth is slowing, inflation has moved higher.

Consumer prices increased 3.8% over the past year, according to recent data, marking one of the strongest inflation readings since 2023 and remaining well above the Federal Reserve’s 2% target.

For households, inflation remains more than a statistic.

Higher prices for food, transportation, utilities, and consumer goods continue to reduce purchasing power, forcing families to stretch paychecks further each month.

That reality is especially concerning because inflation was expected to continue cooling in 2026. Instead, recent energy and commodity shocks have complicated that outlook.

The Oil Problem

Much of the renewed inflation pressure traces back to energy markets.

The conflict involving Iran and the disruption of shipping through the Strait of Hormuz have helped push oil prices sharply higher in recent months. The strategic waterway handles roughly one-quarter of the world’s seaborne oil trade, making it one of the most important energy chokepoints on the planet.

U.S. crude prices have recently traded near $94 per barrel, levels that ripple throughout the economy.

Higher oil prices affect far more than gasoline.

Transportation costs rise. Manufacturing costs increase. Airlines pay more for fuel. Farmers face higher operating expenses. Retailers absorb higher shipping bills.

Eventually those costs find their way into the prices consumers pay.

According to Moody’s Analytics, the average American household has incurred roughly $447 in additional fuel-related costs since the conflict began.

That figure represents a meaningful hit to household budgets at a time when many consumers already feel financially stretched.

The Fed’s Dilemma

The situation creates a difficult challenge for the Federal Reserve.

Normally, slowing economic growth would encourage policymakers to lower interest rates to stimulate borrowing and investment.

But inflation moving higher points in the opposite direction.

Fed officials have repeatedly stressed that defeating inflation remains their top priority. Speaking recently, Minneapolis Federal Reserve President Neel Kashkari warned that allowing inflation expectations to become entrenched could make the problem significantly harder to solve later.

That suggests the central bank may be reluctant to cut rates aggressively even if economic growth continues weakening.

Economists have a name for this uncomfortable combination of slowing growth and persistent inflation: stagflation.

It is one of the most challenging economic environments for policymakers because the tools used to fight one problem often make the other worse.

A Growing Recession Debate

Not every economist agrees a recession is imminent.

Goldman Sachs continues to project lower recession odds than Moody’s, while other forecasters remain cautiously optimistic that the economy can achieve a soft landing.

Still, the debate is shifting.

Just months ago, most economists were discussing recession risk as a possibility. Increasingly, the discussion has turned toward probabilities, timing, and severity.

For Zandi, the key variable remains energy.

The longer oil prices remain elevated and the longer disruptions continue in the Strait of Hormuz, the more pressure households, businesses, and financial markets will face.

The U.S. economy has proven remarkably resilient over the past several years.

The question now is whether that resilience can withstand another prolonged energy shock at a moment when growth is already slowing and inflation is once again moving in the wrong direction.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
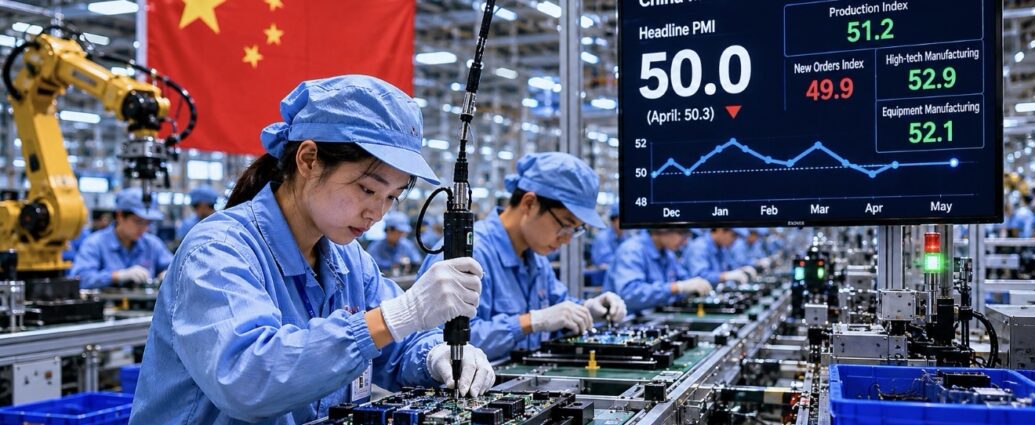
U.S. stocks opened June with another round of record highs Monday as investors poured into technology shares following Nvidia’s surprise expansion into the consumer PC processor market, reinforcing expectations that artificial intelligence demand is moving beyond data centers and deeper into mainstream computing.

The S&P 500 closed at 7,599.96, up 0.26%, while the Nasdaq Composite advanced 0.42% to 27,086.81. The Dow Jones Industrial Average added 0.09% to finish at 51,078.88. The rally came as markets responded to announcements made at Computex 2026 in Taipei, where Jensen Huang CEO Nvidia unveiled the company’s new RTX Spark Superchip platform.

The launch marked Nvidia’s first major entry into consumer CPUs in nearly a decade and immediately reshaped investor expectations around the future of AI-enabled personal computing. The new chip combines Nvidia’s Grace CPU architecture with Blackwell-based RTX graphics processing capabilities and up to 128GB of unified memory, designed specifically for AI workloads running directly on laptops and desktop systems.

“This reinvention of the computer is as big of a deal as the reinvention of the phone into the smartphone,” Jensen Huang CEO Nvidia said during his Computex keynote presentation.

Nvidia shares surged more than 6% following the announcement, extending the company’s dominant run in AI-related markets. The gains spread quickly across the broader technology sector. Shares of Dell Technologies climbed more than 10% after the company confirmed plans to launch RTX Spark-powered systems later this year. HP Inc. gained roughly 8%, while Microsoft rose approximately 2% as investors viewed its Windows-on-Arm ecosystem as a major beneficiary of Nvidia’s move.

The enthusiasm also spilled into enterprise software companies tied to artificial intelligence infrastructure. ServiceNow jumped roughly 10%, while Salesforce advanced nearly the same amount as investors bet that wider adoption of local AI computing could significantly increase demand for workflow automation and AI-enabled productivity software. IBM also posted strong gains as the broader software sector rallied.

The rally underscored how investors are increasingly treating AI not simply as a cloud infrastructure story but as a full-stack computing transition that could reshape consumer hardware, enterprise software, and semiconductor markets simultaneously.

Not every chipmaker benefited from the shift. Qualcomm shares dropped nearly 9% as investors worried Nvidia’s entry into Windows-on-Arm computing could threaten Qualcomm’s Snapdragon X franchise, which had been positioned as one of the leading Arm-based PC alternatives. Intel shares also moved lower amid concerns that competition in the PC processor market is intensifying at a time when the company is already fighting to regain market share in data center and AI applications.

The divergence highlighted what many analysts increasingly describe as a zero-sum environment developing across the semiconductor industry, where leadership in AI computing is rapidly determining valuation premiums and investor flows.

Outside technology, investors continued monitoring geopolitical developments in the Middle East. Oil prices edged higher after reports suggested diplomatic communications between Iran and the United States had deteriorated again, reducing optimism surrounding a potential ceasefire framework tied to shipping routes near the Strait of Hormuz. West Texas Intermediate crude traded near $92 per barrel intraday, while Brent crude approached $95.

The energy market reaction remained relatively contained compared with earlier geopolitical flareups this year, reflecting investor expectations that global supply disruptions have so far remained manageable despite persistent regional tensions.

Treasury markets were comparatively stable. The benchmark 10-year Treasury yield held near 4.50%, while the 2-year Treasury yield moved toward its highest level since early 2025, signaling continued concerns that inflation pressures and elevated government borrowing could keep interest rates higher for longer. Analysts at Charles Schwab noted that even meaningful de-escalation in the Middle East may not substantially lower long-term yields because fiscal deficits and sticky inflation continue to dominate bond market sentiment.

The market rally also arrived despite increasing caution from several major Wall Street executives. Last week, Jamie Dimon Chief Executive Officer JPMorgan Chase warned that investors may be underestimating geopolitical and macroeconomic risks as equities continue climbing to record levels.

“Exuberant” was how Jamie Dimon Chief Executive Officer JPMorgan Chase described portions of the current market environment during remarks at the Reagan National Economic Forum, adding to a series of warnings he has issued throughout 2026 regarding valuations and economic complacency.

Still, bullish calls continued to dominate Monday’s trading session. D.A. Davidson added Nvidia to its “best-of-breed” investment list and assigned a $300 price target to the stock. Gil Luria Analyst D.A. Davidson cited Nvidia’s margin profile and expanding competitive position as key reasons for the upgrade.

Analysts increasingly view Nvidia’s expansion into AI-enabled PCs as strategically important because it extends the company’s Blackwell architecture from hyperscale data centers directly into consumer devices. By integrating unified memory systems and AI processing locally on laptops, Nvidia is attempting to reduce reliance on cloud computing for certain AI tasks while opening a broader market for AI-assisted applications.

The transition could have major implications across software, semiconductor manufacturing, and enterprise productivity markets over the next several years. Companies capable of building AI applications optimized for local computing environments may gain a significant advantage as AI-capable hardware becomes more widely distributed across businesses and consumers.

At the same time, analysts cautioned that Nvidia’s consumer PC ambitions remain in the early stages. RTX Spark systems are not expected to launch until later this year and will likely target premium devices first. Ongoing DRAM and NAND supply constraints could also limit near-term production volumes across the broader PC industry.

Even with those constraints, Monday’s rally reflected a broader market belief that the AI trade is entering a new phase — one where artificial intelligence is no longer confined to cloud infrastructure providers but increasingly embedded directly into the devices consumers and enterprises use every day.

JBizNews Desk

By JBizNews Desk

BRUSSELS — June 1, 2026

The European Union is considering freezing its price cap on Russian oil rather than allowing it to rise automatically as higher global energy prices increase Russia’s potential oil revenues, according to officials familiar with ongoing discussions.

The proposal comes as oil markets continue to react to conflict in the Middle East, which has pushed crude prices sharply higher and complicated Western efforts to limit the Kremlin’s energy income while maintaining stable global supplies.

At the center of the debate is the EU’s existing cap on Russian crude exports. The mechanism was designed to limit the price at which Russian oil can be sold using Western shipping, insurance, and financial services. Because much of the world’s tanker insurance market remains tied to Europe and other G7 countries, the policy has become one of the West’s most important economic tools against Moscow.

The challenge facing European policymakers is that the cap was designed to adjust over time.

Under the current framework, the ceiling is periodically recalculated based on market prices for Russian Urals crude, with the goal of maintaining a discount relative to prevailing oil prices. The current cap stands at approximately $44.10 per barrel.

However, as oil prices have risen amid tensions in the Middle East, officials fear that allowing the formula to operate automatically could significantly raise the cap during its next review, potentially increasing the amount Russia earns from each barrel it exports.

Instead of tightening pressure on Moscow, policymakers worry the mechanism could unintentionally weaken sanctions at a time when European governments are seeking additional leverage.

Officials are reportedly evaluating several options.

One proposal would simply freeze the cap at its current level. Another would suspend automatic increases through the end of the year. A third approach would limit any increase to a level closer to previous G7 thresholds rather than allowing the formula to fully reflect higher market prices.

The discussion forms part of a broader sanctions package currently under consideration in Brussels.

European officials are preparing what would become the 21st round of sanctions imposed on Russia since the full-scale invasion of Ukraine in 2022. The package is expected to include additional restrictions targeting financial institutions, energy traders, intermediaries, and other entities accused of helping Russia bypass existing sanctions.

Increasing attention is also being directed toward cryptocurrency-based transactions.

Western officials have expressed concern that some Russian-linked energy transactions are increasingly being settled using digital assets such as Bitcoin, Ether, and USDT, allowing buyers and sellers to avoid traditional banking channels that are easier for regulators to monitor and restrict.

The issue highlights how sanctions enforcement continues evolving as global financial systems become more decentralized.

Meanwhile, energy markets remain highly sensitive to developments in the Middle East.

After spiking earlier during the regional conflict, Brent crude has eased from peak levels but remains elevated compared with prices seen before the crisis. Higher oil prices benefit major producers worldwide, including Russia, which remains one of the world’s largest energy exporters despite Western sanctions.

Russia has repeatedly criticized the price-cap system, calling it an illegitimate interference in global energy markets. Moscow has redirected much of its oil trade toward buyers in Asia, particularly China and India, helping maintain export volumes despite Western restrictions.

For Europe, the stakes extend beyond foreign policy.

Higher energy prices continue to pressure households and businesses across the continent, while governments attempt to balance support for Ukraine with concerns about inflation, energy security, and economic growth.

Analysts say the decision on the oil cap will ultimately come down to a simple calculation: whether maintaining a stricter ceiling on Russian revenues outweighs the risks of further disrupting already volatile global energy markets.

European officials are expected to continue negotiations in the coming days as the broader sanctions package moves toward formal consideration.

Brussels — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
China’s manufacturing sector lost momentum in May, with factory activity flattening as weaker demand offset continued growth in production, according to data released Sunday by the National Bureau of Statistics (NBS) and the China Federation of Logistics and Purchasing.

The official manufacturing Purchasing Managers’ Index (PMI) registered 50.0 in May, down from 50.3 in April. The reading places the world’s second-largest economy directly on the dividing line between expansion and contraction, signaling that factory activity effectively stalled during the month.

While the headline number suggests stability, the details underneath tell a more complicated story.

Chinese factories continued producing goods at a healthy pace. The production sub-index remained in expansion territory at 51.2, indicating manufacturers are still operating and output remains relatively resilient.

Demand, however, is beginning to weaken.

The closely watched new orders sub-index slipped to 49.9, falling just below the 50-point threshold that separates growth from contraction. The reading suggests customers, both domestic and international, are becoming more cautious even as factories continue manufacturing products.

In practical terms, Chinese factories are still making goods, but incoming orders are no longer keeping pace.

Officials highlighted stronger performance in higher-value sectors that Beijing has prioritized as part of its long-term economic strategy.

According to Huo Lihui, chief statistician at the National Bureau of Statistics, China’s newer growth industries continued outperforming traditional manufacturing segments. The PMI for high-tech manufacturing rose to 52.9, while equipment manufacturing reached 52.1, both comfortably above the expansion threshold.

Those numbers reinforce Beijing’s push to move China up the global value chain and reduce dependence on lower-margin manufacturing industries.

The divergence illustrates the increasingly two-speed nature of China’s economy.

Advanced manufacturing sectors tied to electronics, automation, industrial equipment, and technology continue showing growth. More traditional industries tied to consumer goods, construction materials, and lower-cost exports remain under pressure.

Several factors are contributing to the softer demand environment.

China continues to wrestle with a prolonged property-sector slowdown that has weakened consumer confidence and business investment. Domestic spending has improved only gradually, leaving manufacturers more dependent on exports to maintain growth.

At the same time, global economic uncertainty remains elevated.

Higher energy costs linked to ongoing tensions in the Middle East have increased expenses for manufacturers worldwide. Rising costs for oil, petrochemicals, transportation, and raw materials continue squeezing margins, particularly among lower-value industrial producers.

China’s massive industrial base gives it advantages in absorbing some of these pressures, but it cannot fully escape rising global input costs.

There are also signs of cautious optimism on the trade front.

Recent discussions between President Donald Trump and Chinese President Xi Jinping have fueled hopes that U.S.-China economic relations could stabilize after years of trade tensions. While no major breakthroughs have been announced, markets are closely watching for signs that trade conditions could become more predictable for exporters.

For global consumers and businesses, China’s manufacturing data matters far beyond its borders.

China remains one of the world’s largest producers of consumer goods, industrial products, electronics, machinery, and components. Changes in Chinese factory activity often ripple through global supply chains, affecting everything from shipping volumes to retail prices.

Economists say the May PMI reading may also increase pressure on Chinese policymakers to provide additional support for the economy.

A reading of 50.0 does not indicate a recession or severe slowdown, but it does suggest growth remains fragile. If demand continues weakening in coming months, Beijing could face growing calls to introduce targeted stimulus measures aimed at supporting manufacturing, consumer spending, and business investment.

For now, the message from China’s factories is relatively simple: production remains steady, but demand is beginning to soften.

Whether that proves to be a temporary pause or the start of a broader slowdown will likely become clearer in the months ahead.

Beijing — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The U.S. airline industry is entering a new phase of competition, and travelers are already feeling the effects.

For years, airlines fought largely on ticket prices, offering increasingly cheaper fares to fill seats. Today, the battle is shifting. Major carriers are pouring money into premium cabins, airport lounges, and luxury travel experiences while simultaneously stripping more perks from their lowest-priced tickets.

The result is an industry increasingly divided between travelers willing to pay more and those trying to fly on a budget.

The clearest evidence comes from the nation’s largest airlines.

Delta Air Lines reported that premium-ticket revenue increased 14% year-over-year during the first quarter of 2026, according to results released on April 8. While main-cabin demand remained stable, premium products continued to drive much of the carrier’s growth.

United Airlines is seeing a similar trend. The company has reported strong demand for premium seating as travelers continue spending on upgraded experiences despite broader economic uncertainty. Revenue from premium cabins has become an increasingly important profit driver for the Chicago-based carrier.

The message from airline executives is clear: travelers willing to pay for comfort, flexibility, and convenience are becoming the industry’s most valuable customers.

At the same time, airlines are making their lowest-priced fares increasingly restrictive.

American Airlines announced new changes this spring affecting basic economy travelers. Tickets purchased under the airline’s lowest fare category are no longer eligible for complimentary seat assignments, even for many frequent flyers. The move follows earlier changes that eliminated mileage and loyalty-point earning on certain basic economy tickets.

The carrier has also increased baggage fees. A first checked bag now costs up to $50 at the airport, while a second checked bag can reach $60, with higher charges for additional luggage.

American is far from alone.

Delta, United, and JetBlue Airways have all implemented baggage-fee increases in recent months as airlines seek additional revenue streams beyond the base airfare.

Industry analysts describe the strategy as “unbundling.”

Rather than including services in the ticket price, airlines increasingly separate each feature into an individual purchase. Seat assignments, checked bags, priority boarding, ticket flexibility, and even some carry-on privileges have become separate products that travelers purchase individually.

The trend is now expanding into premium travel as well.

Delta has announced plans to introduce lower-cost versions of business and first-class fares with fewer included benefits. United has implemented similar tiered offerings within its international Polaris business-class product.

Even luxury travel is becoming segmented.

Several factors are driving the shift.

One major challenge is fuel costs.

The conflict involving Iran and disruptions across the Middle East have pushed energy prices higher, increasing one of the largest expenses airlines face. Higher jet fuel prices directly impact airline profitability and often translate into higher ticket prices.

At the same time, airlines have reduced flight schedules in several markets, limiting seat supply. Fewer available seats generally support stronger pricing power.

Government data reflects the trend.

According to the Bureau of Labor Statistics, airline fares increased 20.7% over the 12 months through April 2026, making air travel one of the fastest-rising categories in the inflation report.

Competition itself is also changing.

In one of the industry’s most surprising developments this year, United Airlines CEO Scott Kirby publicly disclosed that he had approached American Airlines about a potential merger between the nation’s two largest carriers.

American CEO Robert Isom rejected the idea, calling such a combination anti-competitive and harmful to consumers. President Donald Trump also voiced opposition to the proposal.

The merger discussion ended quickly, but the fact that it was considered at all highlights how aggressively major airlines are looking for ways to strengthen their positions.

Meanwhile, pressure is mounting on the discount end of the market.

Low-cost carriers that once disrupted the industry by offering rock-bottom fares are facing growing financial challenges as operating costs rise and larger airlines compete more aggressively for price-sensitive customers.

For travelers, the implications are straightforward.

Passengers willing to pay for premium cabins, extra legroom, airport lounge access, and flexible tickets will likely see more options and improved products in the years ahead.

Budget-conscious travelers should expect the opposite.

The lowest advertised fares increasingly come with restrictions, additional fees, and fewer included services. The headline price often represents only a portion of the total cost of the trip.

That means comparison shopping has become more important than ever.

The cheapest ticket on the screen may not be the cheapest ticket once baggage fees, seat assignments, boarding privileges, and other add-ons are included.

As airlines continue reshaping their business models, travelers are discovering a new reality: the airfare you see is no longer necessarily the airfare you pay.

JBizNews Desk — Aviation

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

WASHINGTON — June 1, 2026

Millions of students and parents are facing a major change in how federal student loans work, and the deadline is fast approaching.

Beginning July 1, 2026, anyone taking out a new federal student loan will enter a significantly different repayment system than borrowers who took out loans before that date. Financial advisers say the changes could affect monthly payments, loan forgiveness opportunities, and how much families can borrow for college.

The new rules stem from the One Big Beautiful Bill Act, signed into law in 2025, and represent one of the most substantial overhauls of federal student lending in years.

“This is really high-stakes stuff,” said Kathleen Boyd, a certified financial planner and founder of Student Loan Savvy. She warns that many borrowers may not realize how dramatically the system is changing.

For years, federal student loan borrowers could choose from a variety of repayment plans based on income, career path, and financial circumstances. Beginning July 1, most new borrowers will have only two choices: the Repayment Assistance Plan (RAP) and a new Tiered Standard Repayment Plan.

The distinction between old and new borrowers could have long-term consequences.

According to student-loan attorney Stanley Tate, borrowers who already have federal loans should be especially careful before taking out additional loans after July 1. Even a relatively small new federal loan could affect which repayment programs are available in the future.

One of the most significant changes is the loss of access to Income-Based Repayment (IBR) for new borrowers. IBR has been popular because payments adjust to income levels, some borrowers can qualify for payments as low as zero dollars per month, and loan forgiveness can occur after as little as 20 years.

Under the new Repayment Assistance Plan, borrowers generally pay between 1% and 10% of their income, depending on earnings. However, forgiveness generally comes only after 30 years, meaning many borrowers could remain in repayment for an additional decade compared with some current programs.

For families already struggling with college costs, that difference could be substantial.

Graduate students are also facing major changes.

The legislation eliminates Grad PLUS loans, which have historically allowed students pursuing advanced degrees to borrow up to the full cost of attendance. Medical students, law students, dental students, and other professional-degree candidates have relied heavily on the program for decades.

Without Grad PLUS loans, students may need to cover more of their education costs through savings, scholarships, employer assistance, or private financing.

Parents will face tighter borrowing limits as well.

Higher-education expert Mark Kantrowitz notes that new Parent PLUS loans will be capped at $20,000 per year per dependent student, with a lifetime maximum of $65,000 per student. Graduate students will generally be limited to $20,500 annually and $100,000 total borrowing, while most borrowers will face an overall lifetime federal borrowing limit of $257,500.

Supporters of the changes argue that stricter limits are necessary to curb excessive student debt and encourage colleges to control costs.

Nicholas Kent, Under Secretary of Education, said the reforms are intended to help students access higher education without accumulating unsustainable debt while encouraging institutions to address rising tuition prices.

Critics argue the opposite may occur.

Higher-education advocates warn that limiting access to federal financing could make professional degrees harder to obtain, particularly for students from lower-income households. Some also fear the changes could worsen workforce shortages in fields such as healthcare, where advanced education is often required.

The economic impact extends beyond students and families.

Graduate and Parent PLUS loans account for approximately $125 billion of America’s roughly $1.7 trillion federal student loan portfolio. As federal borrowing becomes more restricted, private lenders could see increased demand, while colleges may face greater pressure to justify tuition costs and keep programs affordable.

Financial advisers recommend that students and parents review their borrowing plans before July 1.

Experts suggest checking current federal loan balances through StudentAid.gov, reviewing how future borrowing may affect repayment eligibility, and consulting financial-aid offices about how the changes could impact the upcoming academic year.

For many Americans, July 1 will simply be another day on the calendar. For students and parents planning to borrow for college, however, it marks the beginning of a very different student-loan system—one with fewer options and potentially longer repayment obligations.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Oil prices are elevated. The conflict involving Iran and disruptions around the Strait of Hormuz have injected fresh uncertainty into global energy markets, threatening a critical shipping route that normally carries roughly one-fifth of the world’s oil supply.

By the traditional rules of the oil business, that should be enough to trigger a wave of new drilling across the United States.

It hasn’t.

Instead, many of America’s largest oil producers are taking a wait-and-see approach, choosing caution over expansion despite a market environment that would once have sparked an aggressive drilling boom.

The reason is straightforward: oil companies do not believe today’s prices are guaranteed to last.

A new well is not an overnight project. It can take several months between the start of drilling and the point at which oil begins flowing to market. Producers making investment decisions today are effectively wagering that oil prices will remain attractive months from now.

Many executives are unwilling to make that bet.

Paul Mueller, an economist who follows the energy sector, noted that producers remain hesitant to commit large amounts of capital based on what could ultimately prove to be a temporary geopolitical shock.

That caution is reflected in data from the Federal Reserve Bank of Dallas, which surveyed 135 energy companies in its latest Energy Survey.

The industry’s outlook improved sharply during the first quarter. The survey’s business activity index climbed 27 points to 21, while the outlook index surged from negative territory to 32.2, signaling growing confidence in current conditions.

Yet optimism has not translated into major new drilling commitments.

Nearly 70% of large exploration and production companies reported no meaningful change to their drilling plans, while roughly half of all surveyed firms said they had not altered the number of wells they expect to drill this year.

Michael Plante, Assistant Vice President at the Dallas Fed, said uncertainty surrounding the Middle East conflict remains a significant factor affecting investment decisions.

Executives appear to be focused less on today’s oil price and more on where prices will be once geopolitical tensions eventually ease.

One producer surveyed by the Dallas Fed said the industry still lacks visibility into how quickly production and exports from the Persian Gulf region could normalize after the conflict. While some infrastructure damage could limit immediate supply recovery, the company estimated a long-term planning range of approximately $70 to $80 per barrel for U.S. crude.

Beyond the war itself, there is a deeper structural shift reshaping the industry.

For much of the shale boom, energy companies aggressively pursued growth, borrowing heavily and drilling aggressively whenever prices rose. Investors ultimately punished that strategy after repeated boom-and-bust cycles destroyed shareholder value.

Today, Wall Street rewards a different model.

Instead of prioritizing production growth at any cost, investors increasingly demand profitability, free cash flow, dividends, and stock buybacks. Industry executives refer to this approach as capital discipline, and it has become one of the defining characteristics of the modern U.S. energy sector.

The numbers illustrate the trend.

According to Baker Hughes, the U.S. drilling rig count has generally declined over the past year despite periods of elevated crude prices. Oil-focused drilling activity has softened while companies concentrate on maximizing returns from existing assets rather than pursuing aggressive expansion.

At the same time, drilling economics remain challenging.

The Dallas Fed reports that the average breakeven oil price required to profitably drill a new U.S. well now stands at approximately $66 per barrel. In the Permian Basin, America’s most productive oil region, the average breakeven price is approximately $67 per barrel.

With development costs elevated and future oil prices uncertain, many producers see little reason to rush into expensive new projects.

Instead, companies are increasingly turning to a faster and less risky option: completing wells that have already been drilled.

Diamondback Energy, one of the largest independent producers in the Permian Basin, has been working through its inventory of previously drilled wells, allowing it to increase production without committing to large-scale new drilling programs.

Because those wells already exist, companies can bring additional oil to market much faster and at lower risk than starting entirely new projects.

The willingness to expand is more visible among smaller producers.

According to the Dallas Fed survey, nearly 60% of smaller firms reported increasing the number of wells they expect to drill this year, suggesting that independent operators remain more responsive to higher prices than larger publicly traded companies.

Even so, industry expectations remain relatively modest.

Most executives surveyed by the Dallas Fed projected that current geopolitical disruptions would increase U.S. oil production by no more than 250,000 barrels per day during 2026—a meaningful figure but far short of the kind of explosive growth that characterized earlier shale booms.

For consumers, the implication is significant.

Even during a period of elevated prices and global supply uncertainty, the United States is unlikely to respond with the rapid drilling surge that once helped stabilize energy markets. That means higher fuel costs could persist longer than many motorists hope, while the inflationary effects of elevated energy prices continue to ripple throughout the economy.

The shale industry that once chased every price spike has evolved.

Today’s oil executives are less interested in betting on geopolitical turmoil and more focused on protecting shareholder returns. Until producers gain confidence that higher oil prices are sustainable, America’s drilling boom is likely to remain on hold.

JBizNews Desk — Energy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

WASHINGTON — June 1, 2026

The U.S. Department of Commerce moved Sunday to close a loophole that had allowed some of America’s most advanced artificial-intelligence processors to reach Chinese-owned companies operating outside mainland China, marking the latest escalation in Washington’s effort to restrict Beijing’s access to cutting-edge AI technology.

In guidance issued over the weekend, the department said it will require export licenses for advanced AI chips shipped to entities headquartered in China, even when those entities are located in third countries. The move targets a pathway that industry experts say may have enabled Chinese firms to acquire high-performance processors through overseas subsidiaries despite broader U.S. restrictions.

The guidance specifically applies to some of the most powerful AI chips currently on the market, including Nvidia’s Blackwell and Rubin platforms and Advanced Micro Devices’ MI350-series processors, which are used to train and operate large-scale artificial-intelligence models.

The action closes a gap that emerged after the U.S. government stopped enforcing the Biden-era AI Diffusion Rule in 2025. That regulation had established a framework governing exports of advanced AI hardware worldwide. When enforcement ended, foreign subsidiaries of Chinese companies operating in countries outside China gained a potential avenue to purchase U.S.-made chips that would otherwise face restrictions.

Industry observers say the issue has become increasingly important as demand for AI computing power has exploded worldwide. Advanced processors have become a strategic asset, often compared to oil or rare earth minerals because they serve as the foundation for modern artificial intelligence systems.

The Commerce Department’s guidance suggests Washington is increasingly concerned that Chinese firms may have used overseas operations in locations such as Southeast Asia and the Middle East to gain access to restricted technology. While no official figures have been released, supply-chain analysts have suggested that substantial numbers of advanced processors may have been sold through these channels during the past year.

Chris McGuire, a former U.S. State Department official and technology policy expert, described the issue as a significant national-security concern, arguing that foreign subsidiaries of Chinese firms were able to purchase advanced AI hardware without the same licensing scrutiny applied to entities located inside China.

The move comes amid an intensifying global competition over artificial intelligence leadership. U.S. policymakers increasingly view advanced semiconductors as a strategic technology with military, economic, and geopolitical implications. Restricting access to the most powerful chips has become a central pillar of Washington’s broader effort to maintain a technological advantage over China.

For chipmakers such as Nvidia and AMD, the policy creates additional uncertainty in one of the industry’s most important markets. China and Chinese-linked customers have historically represented a significant source of demand for high-performance computing products, though export controls have steadily tightened over the past several years.

The latest restrictions add to a growing web of licensing requirements, reviews, and compliance procedures governing AI-related exports. Companies seeking to sell advanced processors to Chinese-linked entities abroad will now face greater regulatory scrutiny and potentially longer approval timelines.

Neither Nvidia nor AMD immediately commented on the new guidance. The Commerce Department also did not provide additional details regarding enforcement or the number of transactions that may be affected.

While the immediate market impact remains uncertain, the policy underscores a broader reality: the battle for artificial-intelligence leadership is increasingly being fought through export controls, supply chains, and semiconductor manufacturing capacity rather than traditional trade measures.

For Washington, the objective is clear. By closing what officials viewed as a significant loophole, the United States is attempting to ensure that restrictions on advanced AI technology apply not only within China itself but also to Chinese-controlled entities operating anywhere in the world.

As governments increasingly view artificial intelligence as a strategic national asset, the rules governing who can access the world’s most powerful chips are likely to become even more restrictive in the years ahead.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

CHICAGO — June 1, 2026

The American Society of Clinical Oncology said its 2026 Annual Meeting, running May 29 through June 2 at McCormick Place in Chicago, drew a record number of studies led by Chinese researchers. A total of 95 studies led by researchers from China, Hong Kong, Macao, and Taiwan were selected for oral and featured presentations, marking a new record and the third consecutive year of significant growth.

That figure is more than a conference statistic. It is one of the clearest signs yet that China has evolved from a low-cost manufacturing center into a major force in global drug innovation—and the world’s largest pharmaceutical companies are taking notice.

The headline moment in Chicago belongs to Akeso, the Chinese biotechnology company whose late-stage lung cancer study earned a coveted place in ASCO’s prestigious Plenary Session. It is only the second time in the conference’s six-decade history that a clinical study involving an original Chinese-developed drug has received that distinction.

The study focused on ivonescimab, a lung-cancer treatment that has already attracted significant international attention. Summit Therapeutics, the U.S.-based company that licensed rights to the drug outside China, is currently awaiting an FDA decision after the agency accepted its filing earlier this year. A regulatory decision is expected on November 14, 2026.

Another company drawing attention is Ascentage Pharma, which operates in both Maryland and Suzhou, China. The company presented six studies at the meeting, including three selected for rapid oral presentations and three poster presentations, highlighting experimental cancer therapies developed largely through clinical trials conducted in China.

The scientific achievements on display in Chicago are being matched by an extraordinary surge in dealmaking.

For decades, pharmaceutical innovation largely flowed from Western laboratories to the rest of the world. Today, that flow is increasingly moving in both directions.

According to Vision Lifesciences, Chinese biotechnology firms now account for nearly 30% of global drug development activity, with more than 1,200 novel drug candidates currently in clinical trials. Global pharmaceutical companies that once viewed China primarily as a manufacturing hub are increasingly looking there for the next generation of blockbuster medicines.

The financial figures illustrate the scale of the shift.

Data from PharmCube show that cross-border licensing agreements between companies in Greater China and multinational pharmaceutical firms reached a record $137.7 billion in 2025, nearly ten times the $13.9 billion recorded in 2021. The number of completed out-licensing transactions rose to 186 deals, compared with 65 deals just a few years earlier.

The momentum has continued into 2026.

Chinese regulatory officials reported that cross-border licensing agreements involving Chinese biotechnology companies reached approximately $60 billion during the first quarter alone, representing a substantial increase from the same period a year earlier.

The driving forces behind the trend are straightforward.

Major pharmaceutical companies face an approaching wave of patent expirations that threatens hundreds of billions of dollars in revenue. Industry analysts estimate that patent losses could erase as much as $200 billion in annual pharmaceutical sales between 2026 and 2030, forcing drugmakers to search aggressively for new products capable of replacing those revenues.

At the same time, many Chinese biotechnology firms have demonstrated an ability to develop promising therapies more quickly and at lower cost than many Western competitors.

As demand has increased, so have prices.

Industry data cited by analysts show average upfront payments in Western-Chinese licensing agreements have climbed dramatically in recent years. What was once viewed as a lower-cost source of pharmaceutical innovation is increasingly commanding premium valuations as competition for promising assets intensifies.

The list of global buyers underscores how seriously the industry is taking the trend.

Gilead Sciences, Eli Lilly, AstraZeneca, AbbVie, GSK, Sanofi, and UCB have all entered major licensing agreements involving Chinese biotechnology firms. One of the most significant transactions came earlier this year when AstraZeneca announced a deal with CSPC Pharmaceutical covering obesity treatments, a transaction that could ultimately be worth up to $18.5 billion if development and commercial milestones are achieved.

For patients, the implications could be positive. Increased competition and larger drug pipelines may accelerate the arrival of new cancer therapies, obesity treatments, and other medicines.

For the United States biotechnology sector, however, the implications are more complicated.

While American companies continue to dominate many areas of fundamental scientific research, executives increasingly acknowledge concerns that some of the most commercially valuable early-stage discoveries are emerging elsewhere. The result could be growing pressure on U.S. biotechnology hubs that have long served as centers for high-paying research and development jobs.

Washington has attempted to address some of these concerns through various policy proposals and heightened scrutiny of certain China-related biotechnology activities. Yet despite geopolitical tensions, licensing activity continues to accelerate.

The reason is simple: pharmaceutical companies facing looming patent cliffs cannot afford to ignore promising science, regardless of where it originates.

That reality was impossible to miss at McCormick Place this week.

The immediate story is a record-setting conference, breakthrough cancer research, and billions of dollars in pharmaceutical dealmaking. The larger story is a fundamental shift in the geography of drug innovation—and a growing debate over whether the United States can maintain its long-standing leadership position as China rapidly expands its role in developing the medicines of the future.

Chicago — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

When Americans think about panic buying at Costco, they often think of toilet paper, bottled water, or pandemic-era shortages.

Today, it’s something far more ordinary — and far more important to household budgets.

According to comments from Costco CEO Ron Vachris during the company’s latest quarterly earnings call, the warehouse giant experienced some of the strongest sales weeks in its history as consumers increasingly flocked to Costco gas stations seeking relief from elevated fuel prices.

The surge became so significant that some Costco locations required additional fuel deliveries to keep up with demand.

For millions of Americans, the warehouse club’s biggest attraction right now isn’t inside the store.

It’s at the pump.

Why Costco Gas Is Drawing Crowds

The reason is simple: savings.

Costco gasoline often sells for 10 to 30 cents less per gallon than nearby stations, depending on location and market conditions.

When fuel prices rise, those savings become much more meaningful.

For a family filling multiple vehicles each month, the difference can add up quickly, making a Costco membership worthwhile based on gasoline savings alone.

Vachris said the company saw many members use Costco gas stations for the first time during the quarter as consumers became increasingly focused on reducing everyday expenses.

The trend reflects a broader reality facing American households: even small savings matter when inflation continues to pressure family budgets.

The Real Business Strategy

The most interesting part of the story is that Costco isn’t making huge profits from gasoline itself.

In fact, fuel margins are relatively thin.

Costco intentionally prices gasoline aggressively because the company’s goal isn’t maximizing profits at the pump. The goal is bringing customers onto the property.

Once members arrive for cheaper gas, many head inside the warehouse to purchase groceries, household goods, pharmacy items, electronics, and other products.

In retail, this strategy is known as a “loss leader” — offering highly competitive pricing on one product to generate sales elsewhere.

Costco has been executing that strategy successfully for years.

Record Sales Follow

The approach appears to be working.

Costco reported 11.6% growth in net sales compared with the same period last year.

Paid membership increased 4.1%, while digital sales surged 21%.

Website and app traffic climbed approximately 37%, highlighting the company’s continued ability to attract both physical and online shoppers.

The results suggest consumers remain willing to spend, but they are becoming increasingly strategic about where they spend.

Another Surprise: Gold Sales

Gasoline wasn’t the only category generating strong demand.

Costco also reported robust growth in several areas, including pharmacy, jewelry, home furnishings, tires, and one category that has received increasing attention over the past year: gold bars.

The retailer has quietly become one of the country’s more unusual precious-metals sellers, regularly offering gold products that often sell out quickly.

The combination of rising gold purchases and increased demand for discounted gasoline paints an interesting picture of the American consumer.

On one hand, shoppers are searching aggressively for ways to save money. On the other, many are purchasing tangible assets viewed as protection against uncertainty and inflation.

Both trends point to households that remain cautious about the economic outlook.

Why Investors Were Less Excited

Despite strong earnings results, Costco’s stock declined following the report.

The reason wasn’t sales growth.

Instead, investors focused on rising operating costs and concerns about profit margins.

Company executives noted that transportation expenses remained elevated and warned that some product categories could face additional cost pressures tied to higher prices for materials such as plastics and packaging.

The reaction highlights a challenge facing many retailers: strong sales do not automatically translate into higher profits if operating costs rise at the same time.

What It Means for Consumers

The rush to Costco’s gas pumps says a lot about the current economy.

Consumers continue spending, but they are working harder to stretch every dollar.

They are comparison shopping, hunting for discounts, joining membership programs, and looking for any opportunity to reduce recurring expenses.

Fuel remains one of the largest unavoidable costs for many households, particularly commuters and families with multiple vehicles.

As long as gasoline prices remain elevated, Costco’s fuel stations are likely to remain crowded.

And that’s exactly how the company likes it.

The cheap gas may bring customers in, but Costco is betting they’ll leave with a full shopping cart as well.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — JBizNews Desk — May 31. 2026

Treasury Secretary Scott Bessent confirmed Thursday that the Treasury Department has already designed a proposed $250 bill featuring President Donald Trump’s portrait, while acknowledging the currency cannot legally enter circulation unless Congress changes a federal law that has blocked living Americans from appearing on U.S. money for more than 160 years.

Speaking from the White House briefing room, Bessent said Treasury prepared prototype designs in advance but stressed that the department “will stick to the law” unless lawmakers act.

“It’s all in the hands of Capitol Hill,” Bessent told reporters.

The confirmation followed a report earlier Thursday from The Washington Post revealing that Trump-appointed Treasury officials, including U.S. Treasurer Brandon Beach, had pushed the Bureau of Engraving and Printing to produce mock-ups of the proposed bill.

The reported designs place Trump’s portrait prominently in the center alongside signatures from both Trump and Bessent.

During the briefing, Bessent held up a printed copy of the Post article and downplayed suggestions that the administration was attempting to bypass existing restrictions, describing the prototypes as preparation rather than implementation.

The obstacle standing in the way is a federal statute dating back to 1866.

U.S. law currently prohibits living individuals from appearing on American currency or government securities. Congress enacted the rule after then-Treasury official Spencer Clark controversially placed his own image on a five-cent note, triggering public backlash and forcing lawmakers to establish a permanent ban.

Because Trump remains a sitting president, the proposed $250 note cannot legally move beyond the prototype stage unless Congress formally rewrites the law.

A legislative effort already exists but has stalled.

Last year, Republican Congressman Joe Wilson of South Carolina introduced legislation directing Treasury to issue $250 bills featuring Trump’s portrait. The proposal has not advanced through Congress.

Treasury attempted to frame the effort partly around the upcoming America250 celebration marking the nation’s 250th anniversary, saying the department is preparing commemorative designs tied to the historic milestone rather than asserting any immediate authority to print the notes now.

Beyond the politics, the proposal carries substantial operational and financial implications.

The United States has not introduced a new circulating paper-currency denomination in decades. Adding a $250 note would require banks, ATM manufacturers, retailers, armored-car companies, vending-machine operators, cash processors, and counterfeit-detection systems to recalibrate equipment and software to recognize, validate, and handle the new bill.

Cash-handling infrastructure across the country would face significant upgrade and retraining costs.

There are also broader monetary-policy concerns.

The U.S. government stopped issuing circulating bills larger than $100 in 1969, retiring denominations including the $500, $1,000, $5,000, and $10,000 notes partly because officials believed high-value paper currency facilitated money laundering, tax evasion, and organized crime.

A modern $250 bill would represent a major reversal of that decades-long policy direction unless treated strictly as a limited commemorative issue rather than a widely circulating denomination.

Treasury has not clarified which path it ultimately envisions.

The proposal also fits into a broader pattern of Trump-linked federal branding surrounding the nation’s 250th anniversary.

Earlier this year, Treasury confirmed that Trump’s signature would appear on commemorative America250 currency, itself highly unusual for a sitting president. The department has also announced commemorative coin programs tied to Trump under authority granted by the Circulating Collectible Coin Redesign Act of 2020.

Supporters argue the proposals appropriately honor the president serving during a historic national milestone.

Critics counter that placing a sitting president’s image on currency risks blurring longstanding boundaries between patriotic commemoration and political branding.

For now, however, the practical reality remains unchanged.

The designs exist. The prototypes have reportedly been prepared. But unless Congress changes federal law, the proposed Trump $250 bill remains a symbolic concept rather than legal tender — a printed mock-up waiting on votes that have not yet arrived.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

CHICAGO — June 1, 2026

Wheat prices have climbed to their highest levels in nearly two years as severe drought conditions across key U.S. growing regions threaten what could become the nation’s smallest wheat harvest in more than five decades.

The rally follows a closely watched report from the U.S. Department of Agriculture (USDA) that delivered a stark warning about the state of America’s wheat crop.

In its May World Agricultural Supply and Demand Estimates (WASDE) report, the USDA projected total U.S. wheat production at just 1.561 billion bushels, approximately 186 million bushels below analysts’ expectations. If realized, the harvest would be the smallest since 1972, underscoring the growing impact of drought across major wheat-producing states.

The report immediately grabbed the attention of commodity traders.

Chicago Board of Trade wheat futures surged to nearly $6.90 per bushel in mid-May, their highest level in almost two years. While prices have since retreated modestly, wheat remains significantly above levels seen just months ago.

Since hitting a low of approximately $4.92 per bushel in October 2025, wheat prices have rallied nearly 40%, making the grain one of the strongest-performing agricultural commodities of the past year.

The primary driver is simple: there is growing concern that farmers will harvest far fewer bushels than expected.

The drought has been particularly severe across parts of the Great Plains, the heart of America’s wheat belt.

Crop scouts surveying fields in Kansas, the nation’s leading wheat-producing state, reported average yields of just 39.3 bushels per acre, compared with 53.3 bushels per acre a year earlier. The sharp decline highlights how damaging prolonged dry conditions have become.

Conditions have also deteriorated in portions of Nebraska and Oklahoma, where winter wheat crops have struggled to receive sufficient moisture during critical stages of development.

For farmers, once yield potential is lost during key growth periods, it often cannot be fully recovered—even if rains arrive later.

But weather is only part of the story.

Farmers are also confronting a renewed surge in fertilizer costs linked to geopolitical tensions in the Middle East.

Global fertilizer markets have been disrupted by concerns surrounding shipping routes and energy supplies, helping push fertilizer prices sharply higher. Nitrogen-based fertilizers such as urea and ammonia, which are heavily used in wheat production, have experienced significant price increases in recent months.

Industry estimates show some international urea prices climbing to roughly $700 per metric ton, compared with approximately $400 to $490 per metric ton before the latest geopolitical disruptions began.

For growers already operating on thin margins, higher fertilizer costs create difficult choices.

Some farmers may reduce fertilizer applications, while others may shift acreage toward crops requiring fewer expensive inputs. Both outcomes can ultimately reduce wheat production.

The financial strain is becoming increasingly visible throughout rural America.

According to a recent survey conducted by the American Farm Bureau Foundation, nearly 60% of farmers reported worsening financial conditions due to rising fuel and input costs, while roughly 70% said fertilizer prices were limiting their ability to apply all the nutrients their crops require.

Adding another layer of uncertainty is the global weather outlook.

Forecasters at the National Oceanic and Atmospheric Administration (NOAA) have warned that conditions could shift toward an El Niño pattern later this year. Such climate shifts often alter rainfall patterns across major agricultural regions worldwide and can create additional volatility in crop markets.

Meanwhile, global demand remains another wildcard.

Traders continue monitoring developments in U.S.-China agricultural trade discussions. China remains one of the world’s largest agricultural importers, and any significant increase in Chinese purchases of U.S. grain could further tighten supplies and support higher prices.

For consumers, the impact may eventually reach grocery-store shelves.

Wheat is a key ingredient in bread, pasta, cereals, baked goods, and countless other food products. While commodity prices do not immediately translate into retail prices, sustained increases often work their way through the food supply chain over time.

Whether wheat prices continue rising will depend largely on weather conditions over the coming months.

But for now, traders, farmers, and food manufacturers are all focused on the same reality: fewer bushels in the field, higher costs on the farm, and increasing uncertainty about what the next harvest will bring.

Chicago — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

A meeting that would have been unthinkable just months ago is now being viewed as a potential turning point for one of the world’s most troubled economies.

In a post on X on May 30, International Monetary Fund Managing Director Kristalina Georgieva confirmed that she met in Washington with Calixto Ortega, Vice President of Venezuela’s Economy Ministry, marking the first in-person meeting between the IMF’s top official and Venezuelan representatives since the fund resumed formal engagement with the country earlier this year.

“We discussed how the IMF can support efforts to strengthen macroeconomic stability, including through capacity development,” Georgieva wrote.

While brief, the meeting represents a significant step toward rebuilding relations between Venezuela and the global financial institutions that have largely been absent from the country for years.

A Break From Years of Isolation

The IMF and World Bank largely suspended dealings with Venezuela in 2019 amid disputes over the country’s political leadership and questions surrounding international recognition of its government.

That changed on April 16 when the IMF announced it would resume formal engagement with Venezuela under the administration of Interim President Delcy Rodríguez, reopening communication channels that had been frozen for years.

The renewed relationship follows major political changes inside Venezuela and has created an opportunity for international institutions to begin assessing the country’s economic condition after years of limited transparency and unreliable economic reporting.

According to IMF officials, current discussions are focused primarily on rebuilding economic data collection and reporting systems, a necessary first step before the fund can evaluate the country’s financial health or consider broader assistance programs.

Why the IMF Matters

For countries facing severe economic challenges, the IMF often serves as the gateway to broader international financial support.

Before debt restructuring, economic reform programs, or large-scale international financing can occur, governments typically must work with the IMF to establish credible economic data, policy frameworks, and stabilization plans.

That process is especially important in Venezuela.

The country remains burdened by one of the most severe economic collapses in modern history. Years of hyperinflation, declining oil production, economic mismanagement, sanctions, and political instability have dramatically weakened public finances and living standards.

According to IMF estimates, Venezuela’s public debt stands at approximately 180% of gross domestic product, one of the highest debt burdens in the world.

Inflation remains elevated, the currency continues to face pressure, and economic conditions remain fragile despite recent improvements.

Oil Markets Are Watching Closely

The implications extend beyond Venezuela.

The country possesses some of the largest proven oil reserves in the world, making its economic recovery a matter of interest for global energy markets.

A more stable Venezuelan economy could eventually support increased oil production, additional exports, and greater participation in international energy markets.

For global consumers, increased supply from a major producer could help ease long-term pressure on energy prices.

Several international energy companies have already begun exploring opportunities in Venezuela as conditions improve. Among them is Chevron, which has expanded engagement with the country following changes in U.S. policy and sanctions.

While a full recovery remains years away, investors are closely monitoring whether improved relations with international institutions could accelerate the process.

The Human Dimension

Behind the financial statistics lies a humanitarian crisis that has reshaped the region.

Since 2014, approximately 8 million Venezuelans have left the country, according to international organizations, making it one of the largest migration and displacement events in the world.

Many fled because of economic hardship, shortages of essential goods, collapsing public services, and limited employment opportunities.

Economic stabilization would not immediately reverse that trend, but it could create conditions that encourage investment, job creation, and eventually the return of some who left.

The outcome also matters for neighboring countries that have absorbed millions of Venezuelan migrants and for the broader Western Hemisphere, where migration pressures remain a major political and economic issue.

What Happens Next

The meeting between Georgieva and Ortega does not signal immediate financial assistance or an IMF lending program.

Instead, it marks the beginning of what could be a lengthy process involving economic assessments, data collection, policy reviews, and negotiations.

If progress continues, Venezuela could eventually receive a formal IMF economic evaluation for the first time in roughly two decades.

Such a review could open the door to future financial support, debt restructuring discussions, and access to resources currently beyond the country’s reach.

For now, the significance lies less in what was announced and more in the fact that the meeting happened at all.

After years of isolation, Venezuela is once again sitting at the table with one of the world’s most influential financial institutions.

Whether that conversation ultimately leads to economic recovery remains uncertain, but the reopening of the dialogue marks a notable shift in a relationship that many believed would remain frozen indefinitely.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
LAS VEGAS — Barry Diller’s People Incorporated has launched an $18 billion bid to take MGM Resorts International private, wagering that one of the world’s largest casino operators is worth significantly more than public markets currently recognize.

In a letter disclosed Monday to MGM Chairman Paul Salem and Chief Executive Officer William Hornbuckle, People proposed acquiring every MGM share it does not already own for $48.30 per share in cash, valuing the company at more than $18 billion and marking one of the largest gaming-industry transactions proposed this year.

Investors immediately embraced the offer. MGM shares jumped roughly 11% in early trading Monday, while People shares rose about 2%, reflecting confidence that the proposal could unlock value that shareholders have struggled to realize through the public markets.

People already holds a 26.1% stake in MGM, making it the casino operator’s largest shareholder. The proposal seeks to acquire the remaining 73.9% of outstanding shares, effectively removing MGM from public markets and placing control in Diller’s hands.

The company behind the bid may be familiar to consumers even if its new name is not. Formerly known as IAC, the business rebranded as People Incorporated earlier this year and owns more than 40 media brands, including People, Food & Wine, Travel + Leisure, Better Homes & Gardens, and Southern Living.

A significant governance issue accompanies the proposal. Diller currently sits on MGM’s board of directors and stated in the letter that he will recuse himself from any board deliberations or votes concerning the transaction, leaving independent directors to evaluate the offer.

Diller’s investment thesis has remained remarkably consistent since People first began accumulating MGM shares during the depths of the COVID-19 pandemic.

In the proposal, Diller argued that MGM represents a durable business built around physical experiences that remain difficult to replicate through technology. While artificial intelligence is reshaping media, information, and digital services, Diller believes destination resorts, gaming, entertainment, hospitality, and live experiences possess enduring value that technology cannot easily replace.

People’s original investment, he wrote, was based on the belief that MGM’s assets and businesses would continue growing over time while remaining resilient to technological disruption.

The central argument behind the buyout is straightforward: Diller believes the public market is materially undervaluing MGM.

In his letter, he said MGM’s assets and businesses are not realizing their full potential in public markets and suggested that meaningful value creation may be difficult under the pressures and expectations of quarterly reporting.

For shareholders, the attraction is clear.

The $48.30-per-share offer represents a 10.6% premium to MGM’s closing price on May 29, a 24.1% premium to the company’s average share price during the previous 30 trading days, and more than 30% above its average price over the preceding 90 trading days.

The offer allows investors to lock in a meaningful gain immediately rather than wait for the company’s valuation to improve organically.

Wall Street analysts had already become increasingly constructive on MGM before Monday’s announcement.

Stifel recently raised its target price on the company to $48 per share from $44, while Morgan Stanley analyst Stephen Grambling lifted his target to $38 from $37, maintaining an Equal Weight rating.

Diller’s proposal sits above most published analyst targets, suggesting the premium is meaningful while still remaining within a valuation range that many industry observers consider defensible.

The proposal also carries important implications for MGM’s workforce and business partners.

People indicated that it expects MGM’s current management team to remain in place following completion of the transaction, signaling continuity for day-to-day operations. Nevertheless, private ownership often brings a different operating environment.

Unlike public companies, private owners face fewer quarterly market pressures and can move more aggressively on capital allocation, operational efficiency initiatives, staffing decisions, and long-term strategic investments.

For now, the message to employees is continuity. However, MGM remains one of the largest private employers in Nevada, and any change in control is likely to be closely watched by workers, vendors, and local economic leaders throughout Las Vegas.

The financing structure is another notable feature of the proposal.

People stated that the transaction is not subject to any financing conditions, a provision designed to strengthen the credibility of the bid. The company expects to fund the acquisition through a combination of cash on hand at both People and MGM, together with additional debt financing and equity commitments.

Following completion, People expects to own approximately 50.1% of the post-closing equity, maintaining operational control while allowing co-investors and potentially existing MGM shareholders to retain minority interests.

The timing of the proposal comes as MGM navigates a mixed operating environment.

Las Vegas visitation and foot traffic have softened in recent quarters, creating challenges for operators across the Strip. At the same time, MGM has increasingly leaned on growth from its international operations, particularly in Macau, as well as its rapidly expanding digital gaming businesses.

One of the company’s brightest growth engines remains BetMGM, its online sportsbook and gaming venture, which has emerged as one of the leading players in the U.S. sports betting market. As more states embrace legalized wagering, analysts have viewed BetMGM as a potentially significant long-term growth driver.

The proposal also arrives amid a broader resurgence in gaming-sector deal activity.

Just days after reports of major consolidation activity involving Caesars Entertainment, Diller’s move places another iconic casino operator squarely in the center of takeover speculation. Together, the developments suggest investors are increasingly targeting gaming assets they believe remain undervalued despite years of industry recovery and growth.

Still, the path to completion remains lengthy.

The proposal is non-binding and subject to numerous conditions, including completion of confirmatory due diligence, negotiation of definitive agreements, financing arrangements, antitrust reviews, gaming regulatory approvals, and customary closing requirements.

Gaming-industry transactions often face particularly complex regulatory reviews because operators hold licenses across multiple states and international jurisdictions. Regulatory approval processes can take months and, in some cases, longer than a year.

For now, MGM’s board faces a consequential decision.

Diller controls the company’s largest shareholder position and has made clear that he sees substantial untapped value in MGM’s portfolio. Whether directors agree that $48.30 per share adequately reflects the worth of some of the most recognizable assets in global gaming and hospitality will determine whether one of Las Vegas’ most iconic operators remains public—or becomes the latest major company to disappear from Wall Street.

Las Vegas — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk — May 29, 2026

Canadian privacy regulators concluded that OpenAI violated federal and provincial privacy laws when building and launching ChatGPT, according to a sweeping joint investigation report that could become one of the most consequential legal threats yet facing the artificial-intelligence industry.

The ruling, released earlier this month by Philippe Dufresne, Canada’s Privacy Commissioner, alongside privacy regulators in Quebec, British Columbia, and Alberta, argues that OpenAI unlawfully collected massive amounts of personal data from the public internet to train ChatGPT without obtaining proper user consent.

The report — formally cited as 2026 BCIPC 41 — spans 128 pages and examines seven separate areas including data collection, consent, transparency, retention policies, and accuracy standards surrounding the GPT-3.5 and GPT-4 versions of ChatGPT as they operated during 2023.

At the center of the findings is how AI systems are trained.

Regulators concluded that OpenAI scraped and processed personal information from publicly accessible internet sources — including health details, political opinions, and information involving minors — without establishing a valid legal basis or obtaining meaningful consent from individuals whose data was absorbed into the training systems.

The commissioners specifically argued that collecting personal data first and adding disclosure notices later does not cure the original violation.

That legal logic could have consequences far beyond OpenAI itself.

Virtually every major artificial-intelligence company — from Silicon Valley giants to venture-backed startups — built large language models using similar methods: sweeping public internet data into massive training systems designed to teach AI models how humans communicate, write, reason, and answer questions.

Canadian regulators are now effectively arguing that much of that foundational data collection may have violated privacy law from the beginning.

The commissioners took an especially aggressive position on retroactive consent.

Privacy authorities in British Columbia and Alberta argued that if companies lacked permission when they originally gathered the data, later disclosures or consent mechanisms cannot legally repair the problem after the fact. In practical terms, regulators are suggesting that personal information already embedded inside AI training models may remain permanently tainted under privacy law.

That creates a major challenge for the AI industry because models cannot easily “unlearn” information once training is complete.

If similar interpretations spread internationally, AI developers could face long-term legal exposure over the core datasets powering their systems — including some of the industry’s most valuable assets.

OpenAI chose cooperation over confrontation.

The company agreed to implement multiple corrective measures rather than formally challenge the findings. Within three months, OpenAI will place clearer warnings on signed-out versions of ChatGPT explaining that user interactions may be used for model training and advising users not to submit sensitive personal information.

Within six months, the company also agreed to simplify user data-export tools and improve systems allowing individuals to challenge inaccurate personal information generated by the chatbot.

OpenAI additionally confirmed it retired the GPT-3.5 and GPT-4 models examined during the probe and committed to ongoing quarterly compliance reporting with Canadian regulators.

The investigation intensified following a separate controversy tied to public safety.

Canadian authorities disclosed that OpenAI had flagged warning signs tied to an alleged shooter involved in the February 2026 mass shooting in Tumbler Ridge, British Columbia, but failed to escalate concerns to Canadian law enforcement. OpenAI later apologized publicly to the community for not notifying the Royal Canadian Mounted Police.

The incident has since fueled broader discussions inside Canada about whether AI chatbots and social-media systems should face age restrictions or stricter oversight surrounding minors.

Not everyone supports the regulators’ interpretation.

The Information Technology and Innovation Foundation, a U.S.-based technology policy group, criticized the ruling as a dangerous precedent, noting that regulators themselves acknowledged that building generative AI systems serves legitimate and socially valuable purposes.

The broader dispute now reflects one of the defining legal questions surrounding artificial intelligence globally: whether privacy laws originally written for an earlier internet era can realistically be applied to AI systems built by ingesting enormous portions of publicly available online information.

For investors, executives, and AI companies, the concern is straightforward.

If the legal foundation underlying how modern AI models were trained is ultimately judged unlawful — and cannot be retroactively corrected — then the industry’s most valuable technology assets may carry permanent regulatory and legal risk attached to them.

For now, the ruling applies only in Canada.

But its underlying logic is portable — and that is exactly what may concern boardrooms financing the global AI boom.

Toronto — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

NEW YORK — June 1, 2026

Artificial intelligence has created the hottest trade on Wall Street, and it is centered on a product most consumers never see: semiconductor chips.

Chip stocks have surged to extraordinary heights in recent months as technology companies race to build the infrastructure powering the AI revolution. The gains have been so dramatic that investors, analysts, and fund managers are now openly debating whether the sector is experiencing the beginning of a long-term transformation—or the formation of another dangerous market bubble.

The numbers are difficult to ignore.

The Philadelphia Semiconductor Index (SOX), widely considered the benchmark for the chip industry, is on pace for one of the strongest rallies in its history. Semiconductor companies have become the best-performing segment of the stock market this year, significantly outpacing the broader S&P 500.

At the center of the rally is a surprising winner: memory chips.

For years, memory-chip makers were considered one of the most cyclical and volatile corners of the technology industry. Today, they have become critical suppliers to the artificial-intelligence boom. Demand for high-bandwidth memory, a key component used in AI servers and data centers, has exploded as companies rush to expand computing capacity.

Few companies illustrate the trend better than Micron Technology.

Shares of Micron have more than tripled this year as investors bet that AI demand will continue driving unprecedented growth. Analysts expect the company’s earnings to rise dramatically as hyperscale data-center operators continue purchasing massive quantities of memory products.

The spending behind the surge is coming from some of the world’s largest corporations.

Amazon, Microsoft, Alphabet, and Meta Platforms are collectively expected to invest hundreds of billions of dollars in AI infrastructure over the next two years. New data centers, advanced processors, networking equipment, and memory systems are all required to support increasingly powerful artificial-intelligence models.

Those investments have become the fuel powering the semiconductor rally.

As long as the spending continues, chip manufacturers stand to benefit.

Yet Wall Street remains deeply divided about how long the trend can last.

Kai Wu, Chief Investment Officer of Sparkline Capital, says the key question is whether AI infrastructure spending remains elevated for years or begins slowing once current projects are completed.

“If the AI buildout continues, chips will likely continue doing well,” Wu said. “But there’s also the possibility that investors are getting ahead of themselves.”

That concern has become increasingly common among market strategists.

One reason is valuation.

Chip-company profits are growing rapidly, but stock prices have risen even faster. Several analysts note that semiconductor shares now trade at levels that historically have preceded periods of significant volatility.

Jonathan Krinsky, chief market technician at BTIG, recently noted similarities between current semiconductor-market conditions and the technology boom that preceded the dot-com collapse in 2000.

By several technical measures, chip stocks are trading at some of their most extended levels in decades.

That does not necessarily mean a crash is imminent.

It does mean expectations have become extraordinarily high.

Another concern is the growing role of debt financing throughout the AI ecosystem. Many technology companies continue generating substantial cash flow, but some are increasingly relying on borrowing to help fund aggressive infrastructure expansion.

Investors generally welcome debt when it finances productive growth. However, when borrowing accelerates during periods of market euphoria, concerns about sustainability often follow.

Meanwhile, retail investors have poured into semiconductor stocks at record levels.

Historically, large inflows from individual investors often occur late in major market rallies. While that does not guarantee a downturn, it frequently increases volatility as momentum-driven trading intensifies.

The impact of the AI boom is also beginning to reach consumers.

As technology giants compete for advanced chips and memory components, prices throughout the supply chain are rising. Industry analysts warn that increased competition for memory products could eventually contribute to higher costs for smartphones, laptops, servers, and other electronic devices.

In other words, the battle to build artificial intelligence could ultimately affect the price of the technology consumers use every day.

Supporters of the rally argue that comparisons to the dot-com era miss an important distinction.

Unlike many internet companies during the late 1990s, today’s leading AI-related firms are generating substantial revenue and profits. Demand for AI computing resources is real, measurable, and growing rapidly.

Skeptics counter that strong earnings do not eliminate the possibility of a bubble. History shows that even great businesses can become poor investments if expectations become unrealistic.

For now, the AI spending wave remains intact, corporate profits continue rising, and semiconductor companies remain among the biggest beneficiaries.

That leaves investors confronting a difficult question.

Are today’s chip stocks pricing in a technological revolution that will transform the global economy for decades—or are they reflecting expectations so optimistic that reality will eventually struggle to keep pace?

Wall Street does not yet have an answer.

And that uncertainty may be the clearest sign of all that the AI boom is still in its early chapters.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
This article discusses investment-related topics and is intended for informational and journalistic purposes only. It does not constitute investment advice. Readers should consult a licensed financial professional before making investment decisions.

JBizNews Desk

The first major economic report of June arrives Monday morning, and it could offer an early indication of whether America’s manufacturing sector is truly regaining momentum or simply benefiting from temporary factors.

The Institute for Supply Management (ISM) will release its closely watched Manufacturing Purchasing Managers’ Index (PMI) at 10:00 a.m. ET on Monday, providing investors, businesses, policymakers, and workers with one of the earliest readings on economic activity for the month.

The report comes at a time when Wall Street sits near record highs and investors are looking for confirmation that economic growth remains durable despite ongoing geopolitical tensions, elevated borrowing costs, and lingering supply-chain concerns.

Recent data has offered reasons for optimism.

A preliminary May reading from S&P Global showed its U.S. Manufacturing PMI rising to 55.3, up from 54.5 in April and above economist expectations. The figure represented the strongest pace of manufacturing expansion since May 2022 and suggested that factory activity accelerated significantly during the month.

Factory output increased at the fastest rate in more than four years, while manufacturing employment posted its strongest growth since June 2025. New orders remained healthy, signaling continued demand across large parts of the industrial economy.

At first glance, those numbers suggest that manufacturing may finally be emerging from a prolonged period of weakness.

Yet economists caution that the headline figures may not tell the entire story.

According to S&P Global, part of the increase in manufacturing activity may have been driven by businesses building inventory as a precaution against disruptions linked to ongoing instability in the Middle East. Companies increased purchases of raw materials and components while supplier delivery times lengthened, reflecting concerns about potential supply interruptions.

In other words, some of the activity may have been defensive rather than demand-driven.

For investors and economists, Monday’s ISM report will help determine whether manufacturers are expanding because customers are placing more orders or because companies are temporarily stockpiling goods in anticipation of future uncertainty.

The distinction matters.

If the report shows strong new orders alongside higher production levels, it would suggest that demand remains healthy and that the manufacturing recovery has a stronger foundation. If new orders weaken while inventories continue to rise, concerns could emerge that recent gains may prove temporary.

The implications extend far beyond factory floors.

Manufacturing activity affects employment throughout the economy, including transportation, logistics, warehousing, raw materials, construction, and energy. Strong factory demand often translates into additional hiring, increased business investment, and greater economic activity across multiple sectors.

Manufacturing also plays a direct role in consumer prices.

When factories operate efficiently and supply chains remain stable, goods tend to move more smoothly through the economy, helping keep prices under control. Supply disruptions, production bottlenecks, and transportation delays can have the opposite effect, contributing to inflationary pressures on everything from automobiles and appliances to building materials and consumer products.

The timing of Monday’s report is particularly notable because it arrives amid growing attention on global energy markets. Manufacturers have spent months coping with higher fuel, transportation, and logistics costs stemming from geopolitical uncertainty and disruptions to global trade routes.

A reduction in those pressures could provide meaningful relief to industrial producers during the second half of the year.

Longer term, manufacturing leaders remain cautiously optimistic. The ISM has projected manufacturing employment growth in 2026 while forecasting revenue expansion across much of the sector. Whether those expectations are being realized will become clearer once Monday’s report is released.

For investors, business owners, and workers alike, one component may matter more than any other: new orders.

Production can be influenced by inventory building, supply concerns, and short-term events. New orders, however, provide one of the clearest signals about future demand.

If customers continue buying, factories keep producing.

That makes Monday’s report one of the most important economic indicators to watch as June begins.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

Wall Street may begin June focused on manufacturing data, oil prices, and geopolitical developments, but the economic report with the greatest impact on American households arrives Friday morning.

On June 5 at 8:30 a.m. ET, the Bureau of Labor Statistics (BLS) will release its monthly Employment Situation Report, providing the latest snapshot of hiring, unemployment, wages, and labor-market strength across the United States.

For investors, businesses, policymakers, and consumers, it is often the single most important economic report of the month.

The reason is simple: jobs drive spending, confidence, and economic growth.

A strong labor market supports household income, consumer spending, and business investment. A weakening labor market can quickly raise concerns about economic growth, corporate earnings, and the broader outlook for the economy.

The report also plays a critical role in shaping Federal Reserve policy. Hiring trends and wage growth influence inflation expectations, which in turn affect interest rates, mortgage costs, credit card rates, auto loans, and other borrowing expenses faced by consumers.

The labor market has remained remarkably resilient.

The most recent employment report showed the U.S. economy adding approximately 115,000 jobs in April, exceeding many economist forecasts. Earlier revisions also showed stronger hiring than initially reported, reinforcing the view that employers continue to add workers despite economic uncertainty.

The unemployment rate remained at 4.3%, continuing a stretch of historically low joblessness.

Several sectors led job creation.

Healthcare added roughly 37,000 jobs, while transportation and warehousing contributed approximately 30,000 positions. Retail trade also recorded notable gains. Manufacturing employment was relatively flat, while federal government employment continued to decline.

Looking ahead to Friday’s report, many economists expect another month of moderate job growth.

Forecasts generally call for payroll gains near 150,000 jobs, with unemployment remaining near current levels and wage growth continuing at a steady pace.

While the headline payroll number attracts the most attention, economists say three measures deserve particularly close scrutiny.

The first is the unemployment rate.

A stable unemployment rate would reinforce the view that the labor market remains healthy. A meaningful increase could raise concerns that economic growth is slowing more rapidly than expected.

The second is labor-force participation.

This measure tracks the share of Americans who are either working or actively seeking employment. Participation has softened in recent years, and further declines could complicate interpretations of the unemployment rate. A low unemployment rate becomes less encouraging if fewer people are participating in the labor market.

The third key figure is wage growth.

Average hourly earnings provide insight into how quickly worker paychecks are growing. Rising wages generally benefit households, but excessively rapid wage growth can also contribute to inflation pressures and potentially delay future interest-rate reductions.

For many families, these numbers matter more than stock-market records.

The jobs report serves as a real-time measure of the economy’s ability to generate income, create opportunities, and support household financial stability.

Strong hiring often translates into greater job security and confidence. Weak hiring can signal rising risks ahead.

The report arrives at a time when many Americans continue to face elevated housing costs, higher borrowing expenses, and persistent concerns about affordability. Whether the labor market remains strong enough to offset those pressures will be a central question heading into the summer months.

The broader economic outlook may depend on two developments in the days ahead: energy prices and employment.

Oil markets remain sensitive to geopolitical developments, while Friday’s jobs report will provide the clearest picture yet of whether the labor market remains a source of strength for the U.S. economy.

For households, businesses, and investors alike, that makes Friday’s report the number to watch.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The share of private loans going bad in the United States stayed at a record high in May, according to an update from Fitch Ratings released Monday, a warning sign from one of the fastest-growing and least understood corners of finance.

Fitch’s private credit default rate held near 6.0% over the trailing twelve months, matching the record it set in April.

It is the highest reading since the firm began tracking the measure in August 2024, and it caps a steady climb that has run through much of the past year.

To understand why that matters, it helps to know what private credit is.

These are loans made not by banks but by investment firms, lent directly to companies, often mid-sized businesses that might struggle to borrow elsewhere.

The market has exploded in size, growing to roughly $3 trillion from about $2 trillion in 2020, as investors chased the higher returns these loans offer.

That money increasingly includes ordinary people’s savings, with retirement funds and even retail investors now putting cash into the sector.

The reason defaults keep rising comes down largely to interest rates.

Most private-credit loans carry floating rates, meaning the interest a borrower owes rises and falls with broader rates.

With borrowing costs high, pushed up further this year by the war with Iran and stubborn inflation, companies that took on these loans are paying more to service them, and refinancing has become painful.

Many of the recent defaults involved borrowers switching to so-called payment-in-kind terms, paying their interest with more debt instead of cash, a maneuver that often signals a company is running short of money.

The pain is not evenly spread.

Healthcare-services companies have produced the most defaults over the past year, followed by consumer-products firms.

High-profile collapses, including the bankruptcies of First Brands and Tricolor, drew fresh scrutiny to the sector and raised questions about how much hidden stress is building beneath the surface.

“Higher Treasury rates make it harder for companies to refinance,” said Dan Alpert, managing partner at Westwood Capital, who said he had grown increasingly worried about weakness in private credit on top of the broader pressure from rates.

Here is why it reaches beyond Wall Street.

Private credit was once a niche played by specialized firms and wealthy investors.

Today it is woven into the wider financial system.

Banks have lent close to $300 billion to private-credit providers, according to Moody’s, linking the health of the two.

Analysts at Bank of America have called private credit the lowest-quality slice of the corporate-loan market, even as some industry leaders, including Blackstone chief executive Stephen Schwarzman, have played down the concerns.

The worry is that if stress deepens, it could ripple outward to the banks and retirement funds now tied to it.

There had been hope for relief.

Late last year, Bank of America strategists predicted defaults would ease to about 4.5% in 2026 if the Federal Reserve cut interest rates.

But the Fed has held rates steady, and with its new chair weighing whether to cut at all amid hot inflation, that easing looks far less certain.

As long as borrowing stays expensive, the companies behind these loans will keep feeling the squeeze.

For now, the record default rate is a flashing yellow light.

It does not mean a crisis is at hand, but it does show that a sector built and sold during an era of cheap money is straining under the weight of expensive money, and that more investors than ever are along for the ride.

Wall Street — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBizNews Desk

As traditional television continues to lose viewers and streaming becomes the dominant way Americans consume entertainment, The Walt Disney Company is making a major bet that advertising—not subscription fees alone—will drive the next phase of growth.

At the center of that effort is Rita Ferro, Disney’s President of Global Advertising, who is leading an aggressive expansion of the company’s advertising business across Disney+, Hulu, ESPN, ABC, and its broader media portfolio.

According to a profile published May 31 by CNBC, Ferro has become one of Disney’s most important executives as advertisers increasingly seek targeted, measurable campaigns across streaming, sports, and digital platforms.

The timing is critical. Media companies spent years chasing streaming subscribers, often sacrificing profits in the process. Now the industry is shifting focus toward profitability, and advertising is becoming one of the most important revenue drivers.

Disney’s Advertising Strategy

Ferro’s approach centers on combining Disney’s content portfolio with technology that allows advertisers to better target audiences and measure results.

That means leveraging some of the world’s most recognizable brands and franchises, including ESPN, Marvel, Star Wars, Pixar, and Disney’s entertainment networks, while expanding the company’s in-house advertising technology platform.

Advertisers increasingly want more than broad television exposure. They want precise audience targeting, performance data, and measurable returns on investment.

Disney believes its proprietary advertising technology can help deliver those capabilities while keeping more of the advertising infrastructure under its own control.

According to executives who work closely with Ferro, Disney has spent years investing in its advertising technology stack to compete more effectively against digital giants and streaming rivals.

Streaming Is Becoming an Advertising Business

The financial results explain why Disney is doubling down.

In Disney’s most recent quarter, streaming operating income surged 88% to $582 million, a dramatic improvement from earlier years when streaming operations generated substantial losses.

A key driver has been the growth of ad-supported streaming.

Disney has reported that roughly half of new Disney+ subscribers are selecting lower-cost plans that include advertising. While those plans generate less subscription revenue per user, they create additional opportunities for advertising sales.

Every new subscriber on an ad-supported plan becomes another viewer that advertisers can reach.

For Disney, that creates a dual revenue stream: subscription fees and advertising dollars.

A New Audience of Advertisers

Disney is also targeting a broader range of advertisers than it historically pursued.
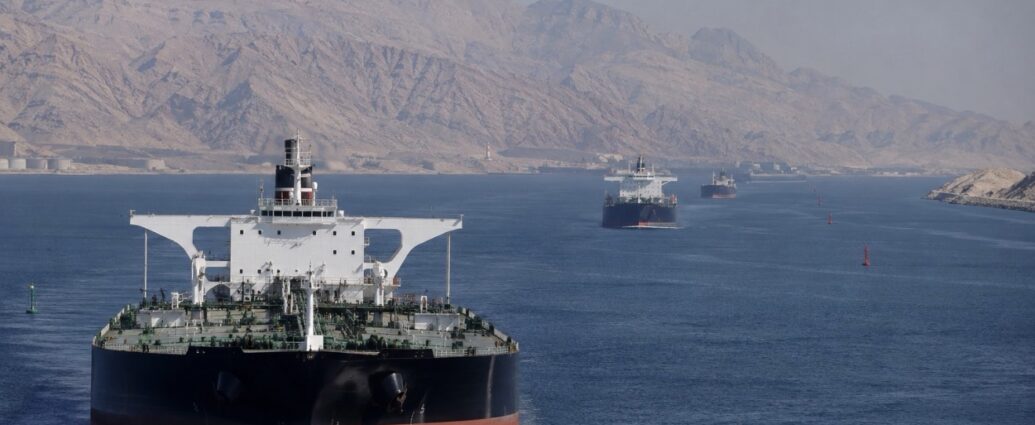
The company has expanded efforts to attract emerging brands and midsize advertisers that previously viewed national television advertising as too expensive or inaccessible.

Executives say automation and self-service advertising tools are helping make Disney’s platforms more accessible to a wider range of businesses.

The strategy mirrors trends across the broader digital advertising industry, where companies increasingly seek scalable systems that allow advertisers of all sizes to buy inventory efficiently.

Challenges Remain

The transition is not without obstacles.

While streaming advertising continues to grow, parts of Disney’s traditional advertising business remain under pressure.

Entertainment advertising revenue outside Disney+ and Hulu has softened, while certain sports advertising categories have faced challenges due to programming changes and shifting viewing habits.

The company is betting that growth in streaming advertising can offset those declines over time.

Investors will be closely watching whether that strategy succeeds as Disney negotiates advertising commitments for the coming year.

What It Means for Consumers

For viewers, the shift is already visible.

Many streaming services now offer lower-priced plans supported by advertising, and Disney continues to expand ad formats across its platforms.

Consumers receive cheaper subscription options, while Disney gains additional revenue from advertisers.

The arrangement reflects a broader transformation occurring throughout the media industry.

After years of prioritizing subscriber growth, media companies are increasingly focused on turning streaming audiences into profitable advertising businesses.

The Bottom Line

Disney’s future growth strategy increasingly depends on advertising, and Rita Ferro is leading that effort.

The company is combining its content portfolio, sports rights, streaming platforms, and advertising technology in an attempt to capture a larger share of marketing budgets moving into digital media.

As advertisers shift spending away from traditional television and toward streaming platforms, Disney is positioning itself to be one of the industry’s biggest beneficiaries.

Whether that strategy delivers sustained growth will become clearer in the months ahead, but one thing is already evident: advertising has become central to Disney’s next chapter.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — JBizNews Desk — May 29, 2026

Walt Disney’s ABC network filed early broadcast-license renewal applications Thursday for its eight owned-and-operated television stations, telling the Federal Communications Commission it was complying “under protest” while accusing the agency of carrying out an “unlawful, arbitrary and unconstitutional” attack on protected speech.

The filing marks the first time in more than 50 years that the federal government has forced a major broadcaster into accelerated license renewals before the normal schedule.

The dispute centers on an April order issued by the FCC’s Media Bureau under Trump-appointed FCC Chairman Brendan Carr, requiring ABC stations to seek early renewals years before their existing licenses expire. Some of the affected licenses were not scheduled for renewal until 2028, while others extended as far as 2031.

The order arrived shortly after President Donald Trump publicly criticized ABC and late-night host Jimmy Kimmel following a joke involving First Lady Melania Trump, though Disney’s filing stopped short of directly naming the specific incident.

Instead, ABC argued broadly that the FCC’s action was designed to pressure broadcasters into self-censorship by forcing them to consider potential regulatory retaliation before airing politically sensitive material.

“The true purpose and effect of the order is to suppress speech,” the filing argued, claiming the accelerated review process creates pressure for networks to avoid programming the government may dislike out of fear that broadcast licenses could ultimately be threatened.

Disney framed the issue not simply as a corporate dispute but as a constitutional concern affecting viewers and journalism itself.

The company argued that when broadcasters must weigh possible government retaliation before making editorial decisions, the public’s access to independent reporting and commentary is undermined.

ABC also sharply criticized the legal mechanism used by the FCC.

The filing argued the agency revived an obscure “call-up” procedure that had largely sat dormant for decades and originated during an earlier regulatory era when broadcasters faced far more direct content-based scrutiny during renewal proceedings.

Disney contended the procedure serves no legitimate operational purpose because the FCC already possesses broad investigatory authority through ongoing enforcement tools and existing regulatory processes.

The FCC has separately been investigating Disney’s diversity, equity, and inclusion practices since mid-2025, examining whether any company policies violate federal anti-discrimination rules.

ABC argued in Thursday’s filing that the DEI investigation already provides the Commission with all necessary authority and information, noting that Disney has already produced more than 11,000 pages of documents under an agreed schedule with regulators.

The dispute carries substantial financial implications for Disney.

Broadcast licenses form the legal foundation supporting station operations, advertising revenue, affiliate agreements, and retransmission deals across some of America’s largest television markets, including New York, Los Angeles, Chicago, Philadelphia, Houston, San Francisco, Raleigh-Durham, and Fresno.

Legal experts note that actually denying renewal licenses to major broadcasters remains extremely rare and legally difficult, with any challenge likely triggering years of hearings and federal court litigation while stations continue operating normally.

Still, Disney appears focused on building a constitutional challenge that could eventually move into federal court.

The ABC dispute is also not the company’s only conflict with the FCC.

Earlier this year, the agency opened a separate proceeding involving alleged equal-time rule concerns tied to ABC’s daytime program “The View,” questioning whether the show properly qualifies as a bona fide news program exempt from certain political-balance requirements.

ABC pushed back strongly against that proceeding as well, warning regulators that reopening settled broadcast standards could create a chilling effect on protected speech across the television industry.

For Disney, the immediate strategy appears carefully calibrated: comply procedurally with the FCC’s deadline while simultaneously constructing a constitutional record arguing the government is improperly using broadcast regulation to pressure editorial decision-making.

The company concluded Thursday’s filing by reserving all legal rights and formally urging the Commission to withdraw the order entirely.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

The U.S. government has delivered a blunt message to shipping companies navigating one of the world’s most important energy chokepoints: do not make deals with Iran to cross the Strait of Hormuz.

In updated guidance issued May 29, the U.S. Treasury Department warned that American companies are prohibited from accepting any arrangement with the Iranian government related to safe passage through the strategic waterway — even if no money changes hands.

Regardless of whether a payment is made, U.S. persons are prohibited from receiving services from the Government of Iran, including services related to a guarantee of safe passage,” Treasury said in its updated statement.

The guidance arrives at a sensitive moment as markets closely watch efforts to restore normal shipping through the Strait of Hormuz following months of conflict that disrupted one of the world’s most critical trade routes.

What Treasury Is Prohibiting

The updated guidance expands previous warnings that focused primarily on payments, tolls, fees, or other financial transactions involving Iranian authorities.

Under the new interpretation, simply accepting an Iranian guarantee of safe passage could constitute a prohibited service under U.S. sanctions rules.

The warning centers on the Persian Gulf Strait Authority (PGSA), a recently established Iranian entity that Tehran says is responsible for managing vessel traffic through the strait.

According to Treasury, the PGSA works alongside elements of Iran’s Islamic Revolutionary Guard Corps (IRGC) and has sought to direct shipping traffic through routes designated by Iranian authorities.

The Office of Foreign Assets Control (OFAC) has sanctioned the PGSA under U.S. counterterrorism authorities, meaning American individuals and companies face significant sanctions exposure if they engage with the organization.

Iran maintains that the system is designed to manage navigation and maritime safety. U.S. officials argue that it functions as a mechanism for coercion and control over international shipping.

Why Hormuz Matters

The Strait of Hormuz is among the most strategically important waterways on earth.

Roughly one-fifth of global oil consumption typically passes through the narrow channel connecting the Persian Gulf to international markets. Major energy exporters including Saudi Arabia, the United Arab Emirates, Kuwait, Iraq, and Qatar rely heavily on the route.

Disruptions to shipping through Hormuz can quickly affect oil prices, shipping costs, insurance rates, and ultimately consumer prices worldwide.

Since conflict escalated earlier this year, vessel traffic through the region has slowed significantly, contributing to heightened volatility across global energy markets.

The Treasury guidance underscores the difficult position many shipping companies now face.

A vessel attempting to leave the Persian Gulf cannot negotiate directly with Iranian authorities without risking sanctions exposure. At the same time, uncertainty surrounding transit security continues to complicate shipping operations and increase costs.

The Business Impact

For shipping companies, energy traders, insurers, and commodity markets, the new guidance adds another layer of complexity.

War-risk insurance premiums have risen sharply for vessels operating in the region, while shipping firms continue to evaluate route risks and security considerations.

Some tankers have successfully transited the waterway under heightened security measures and military protection, but industry executives remain cautious.

The situation is particularly important for energy markets because every disruption in Hormuz affects global oil supply calculations.

Even modest reductions in tanker traffic can tighten markets and contribute to higher fuel prices around the world.

A Complication for Broader Diplomatic Efforts

The Treasury announcement also highlights a broader policy challenge.

While discussions continue regarding a potential diplomatic framework aimed at restoring stability and reopening maritime traffic, the U.S. government is simultaneously reinforcing sanctions restrictions that limit direct engagement with Iranian authorities.

That creates a difficult environment for businesses seeking clarity on future operations.

Shipping companies, insurers, commodity traders, and multinational corporations are left navigating a rapidly changing landscape in which security, sanctions compliance, and geopolitical developments are all closely intertwined.

Adding to the uncertainty, Iranian lawmakers have reportedly advanced legislation intended to formalize the authority of the PGSA, potentially giving the organization a more permanent role in Tehran’s maritime strategy.

Such a move would not change international maritime law or remove U.S. sanctions, but it could further complicate future negotiations over shipping access and transit rights.

Why Consumers Should Care

For most Americans, the impact of the Strait of Hormuz is felt far from the Persian Gulf.

The route plays a critical role in global energy flows, and disruptions can influence the cost of gasoline, diesel fuel, airline tickets, shipping expenses, and countless products that depend on transportation.

Higher insurance costs, longer transit times, and supply uncertainty all contribute to broader inflation pressures.

A fully secure reopening of Hormuz would likely help stabilize energy markets and ease some of those costs.

Treasury’s latest guidance, however, makes clear that Washington is not willing to allow private companies to negotiate their own arrangements with Tehran to achieve that outcome.

For now, the message from the U.S. government is straightforward: American companies must stay clear of any agreements with Iranian authorities related to passage through the Strait of Hormuz.

Until broader diplomatic and security issues are resolved, one of the world’s most important shipping lanes will remain a source of uncertainty for global commerce.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

As Wall Street enters June near record highs, Bank of America is telling investors not to abandon the rally just yet.

In research highlighted May 30, Bank of America identified several of its favorite stock ideas for June, led by familiar technology giants Nvidia and Apple, while also pointing to opportunities in housing, banking, discount retail, and consumer services.

The list offers more than a collection of stock recommendations. It provides insight into how one of Wall Street’s largest banks views the U.S. economy as investors navigate questions about interest rates, consumer spending, artificial intelligence, and economic growth.

Nvidia and Apple Remain Core Favorites

The most recognizable names on Bank of America’s list are Nvidia and Apple.

Nvidia remains one of Wall Street’s strongest artificial intelligence plays, benefiting from surging demand for the advanced chips that power AI data centers, cloud computing infrastructure, and machine-learning applications.

The company has become one of the largest and most valuable businesses in the world as technology companies race to build AI capabilities.

Apple also remains a favored name, with Bank of America analysts maintaining confidence in the company’s ability to generate growth through its ecosystem of devices, services, and software.

Together, the two companies continue to serve as pillars of the broader technology rally that has helped push major indexes to record levels.

Housing Makes the List

One of the more notable selections was luxury homebuilder Toll Brothers.

Bank of America analyst Rafe Jadrosich described the company’s recent earnings performance as a rare “beat and raise” quarter, highlighting strong demand, healthy profit margins, and continued resilience in the higher-end housing market.

The call is significant because many economists expected elevated mortgage rates to weigh more heavily on housing activity.

Instead, luxury buyers appear to remain active despite higher borrowing costs.

For investors and economists alike, that suggests parts of the housing market continue to show surprising strength.

What Dollar General Says About Consumers

The bank also highlighted Dollar General, one of the nation’s largest discount retailers.

Analyst Robert Ohmes cited store modernization efforts, delivery partnerships, and improving operational performance as reasons for optimism.

The selection offers insight into how Wall Street views consumer spending.

Dollar General primarily serves value-conscious shoppers, making the company’s performance an important indicator of financial conditions facing lower- and middle-income households.

While the stock has struggled in recent months, Bank of America believes improving execution and consumer demand could support a recovery.

A Contrarian Bet on National Vision

Another name on the list is National Vision Holdings, the eyewear retailer behind brands including America’s Best.

Shares fell sharply during May, but Bank of America sees potential opportunity following the decline.

Analysts pointed to rising customer spending per visit and possible future demand drivers tied to wearable technology and vision-related products.

The recommendation reflects a broader Wall Street strategy of identifying companies whose share prices may have fallen further than their underlying business fundamentals justify.

Banking Confidence Shows Up in Citigroup

Bank of America also maintained a positive outlook on Citigroup.

The banking giant has enjoyed a strong run over the past year as investors responded favorably to restructuring efforts under CEO Jane Fraser.

The firm’s recent investor presentations included plans for approximately $30 billion in capital returns, reinforcing confidence in earnings strength and shareholder returns.

The selection suggests Bank of America remains constructive on the financial sector despite ongoing uncertainty surrounding interest rates and economic growth.

What the List Says About the Economy

Perhaps the most interesting aspect of Bank of America’s recommendations is how diverse they are.

The bank’s top ideas span artificial intelligence, consumer electronics, luxury housing, discount retail, vision care, and banking.

That breadth suggests analysts see strength extending beyond a handful of technology companies.

Critics of the current market rally have argued that gains have been concentrated in a small group of mega-cap technology stocks. Bank of America’s list reflects a different view — that economic activity remains healthy enough to support multiple sectors simultaneously.

Luxury homebuyers continue purchasing homes. Budget-conscious consumers continue shopping. Banks continue generating profits. Businesses continue investing in artificial intelligence.

Taken together, the recommendations paint a picture of an economy that remains more resilient than many expected.

A Reminder for Investors

Bank of America’s selections represent analyst opinions rather than guarantees.

Even highly rated stocks can decline, and investors should evaluate their own financial goals, risk tolerance, and investment objectives before making decisions.

Analyst ratings are best viewed as one input among many rather than a standalone investment strategy.

Still, the broader message from one of Wall Street’s largest institutions is clear: Bank of America believes the market rally has room to continue and sees opportunities well beyond the technology sector that has dominated headlines.

Whether that view proves correct will be one of the key stories investors watch throughout June.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For much of the past two years, Wall Street’s message to investors has been remarkably simple: stay long equities, ride the AI boom, and trust the economy to keep delivering.

Bob Doll thinks the situation is more complicated than that.

Doll — the longtime market strategist and current CEO and chief investment officer of Crossmark Global Investments, with more than four decades of investment experience across multiple market cycles — entered 2026 describing the current environment with a phrase that has increasingly resonated across institutional finance: a “high-risk bull market.”

At first glance, the phrase sounds contradictory. Bull markets imply confidence, momentum, and expanding risk appetite. High-risk environments usually imply caution and instability.

But what Doll is describing is a market where gains remain possible — even likely — while the underlying foundation supporting those gains grows increasingly fragile.

Five months into 2026, that framing may be proving unusually accurate.

Stocks remain elevated, artificial intelligence spending continues driving earnings growth across major technology companies, and the broader economy has avoided recession despite higher interest rates and geopolitical instability.

At the same time, inflation remains stubbornly elevated, oil prices are rising again amid Middle East tensions, Treasury yields remain volatile, valuations are historically stretched, and markets are increasingly dependent on a narrow concentration of mega-cap technology firms.

That combination is exactly what Doll means by a “high-risk bull market.”

The Bull Case Is Still Real

Doll’s broader thesis is not bearish.

In fact, he continues to argue that several major structural forces remain supportive for equities.

The U.S. economy has proven significantly more resilient than many economists expected entering 2025. Consumer spending has slowed but not collapsed. Corporate earnings, particularly in technology and AI-linked sectors, continue expanding. Fiscal stimulus and industrial spending remain historically elevated. And the Federal Reserve appears increasingly cautious about tightening policy further unless inflation reaccelerates materially.

Artificial intelligence remains central to that optimism.

The AI investment cycle is producing one of the largest capital spending booms seen in decades, with hyperscalers, semiconductor firms, data infrastructure companies, software providers, and cloud operators all experiencing surging demand tied to enterprise AI adoption.

For equity investors, that matters enormously because it creates real earnings growth rather than purely speculative enthusiasm.

That distinction helps explain why markets continue climbing despite persistent macroeconomic concerns.

Doll has also pointed toward continued government spending, regulatory easing, and a labor market that remains relatively healthy as additional support pillars for equities heading into the second half of the year.

Under normal circumstances, those conditions would form a relatively strong backdrop for stocks.

The problem is that markets are no longer priced for merely “good.”

They are priced for near perfection.

Why The Risk Side Matters More Now

This is where Doll’s warning becomes more important.

The market’s vulnerability comes less from current economic weakness and more from how little room investors now have for disappointment.

Inflation remains the clearest example.

While price pressures cooled significantly from their 2022–2023 peaks, inflation has stopped falling consistently toward the Federal Reserve’s 2% target. Recent data has shown renewed firmness in core prices, while higher oil prices tied to geopolitical tensions risk feeding additional inflation into transportation, manufacturing, food, and consumer expectations.

That leaves the Federal Reserve trapped in a difficult position.

If inflation remains sticky, aggressive rate cuts become difficult. But if rates remain elevated too long, economic growth eventually slows and financial conditions tighten further.

Markets are effectively betting policymakers can engineer a narrow “soft landing” where growth slows just enough to control inflation without damaging earnings or employment significantly.

Historically, that balancing act has been extremely difficult.

Doll has repeatedly warned about that “tightrope” dynamic.

The stock market has already delivered multiple consecutive years of double-digit gains, while corporate earnings expectations remain elevated. Historically, periods of sustained double-digit earnings growth rarely continue uninterrupted for extended stretches without eventually encountering economic or valuation pressure.

That does not mean a crash is inevitable.

But it does mean expectations leave very little room for mistakes.

The Concentration Problem

Another issue increasingly worrying strategists is market concentration.

A growing percentage of market gains continues coming from a relatively small group of mega-cap technology and AI-related companies. That concentration creates a situation where headline indexes can appear healthy even while large portions of the broader market remain weaker underneath.

In practical terms, markets are becoming more dependent on a handful of companies continuing to deliver exceptional earnings growth.

If even one or two major AI leaders stumble, the impact on broader sentiment could be disproportionate.

That concentration risk is one reason Doll continues emphasizing diversification rather than blind momentum chasing.

Why Investors Still Stay In

Despite the warnings, Doll has not advocated abandoning equities.

That is what makes the “high-risk bull market” concept more nuanced than a standard bearish forecast.

His argument is essentially that investors probably still need exposure to equities because earnings growth and economic resilience continue supporting higher prices over time. Sitting entirely in cash risks missing further upside if AI-driven growth persists longer than expected.

But participating in the market now requires accepting greater volatility, tighter margins for error, and a much wider range of possible outcomes than many investors became accustomed to during the long post-2009 bull market.

In other words: the bull market may continue, but it is becoming less forgiving.

What Wall Street Is Really Debating

Underneath the headlines, Wall Street is increasingly arguing over one central question:

Is artificial intelligence productivity growth strong enough to offset the macroeconomic pressures building elsewhere in the economy?

If AI-driven earnings expansion continues accelerating, markets may justify current valuations longer than skeptics expect.

But if inflation, interest rates, or geopolitical instability begin undermining broader growth, the market’s current optimism could face a much more difficult stress test.

That tension explains why markets in 2026 often appear strangely divided — with investors simultaneously optimistic and anxious.

Doll’s phrase captures that contradiction better than most.

This is not a euphoric bull market built on easy money and broad confidence.

It is a bull market still climbing higher while carrying an increasingly visible list of risks underneath it.

And that may ultimately make it more dangerous than it first appears.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

May 31, 2026

When a reporter asked U.S. Treasury Secretary Scott Bessent whether he had urged newly installed Federal Reserve Chairman Kevin Warsh to cut interest rates during a breakfast meeting Thursday morning, Bessent did not answer directly.

Instead, he offered a carefully crafted response that may have revealed more than a simple yes or no ever could.

Bessent confirmed he had breakfast with Warsh earlier in the day, continuing a long-standing Washington tradition in which Treasury secretaries and Federal Reserve chairs meet privately to discuss economic conditions. Such meetings are common, but details rarely become public.

Asked whether he had pushed Warsh to lower interest rates, Bessent reached back to his relationship with former Federal Reserve Chairman Jerome Powell.

“I had breakfast with Chair Powell 41 times, and I never did that,” Bessent said.

The answer immediately caught Wall Street’s attention.

Rather than directly addressing his conversations with Warsh, Bessent chose to discuss his interactions with Powell. For investors trying to assess whether the White House might pressure the new Fed chairman to lower rates, the distinction mattered.

The context helps explain why.

President Donald Trump frequently criticized Powell during his tenure, arguing that interest rates should be lower and that the Federal Reserve was unnecessarily restraining economic growth. With Powell now gone and Warsh occupying the chairmanship, investors are closely watching for signs that the relationship between the White House and the central bank may change.

At stake is one of the most important questions facing financial markets.

The Federal Reserve’s benchmark interest rate currently sits between 3.5% and 3.75%, following a series of policy adjustments designed to balance economic growth against inflation risks.

Some economists believe Warsh could pursue a more aggressive easing cycle than markets currently expect. Others argue persistent inflation pressures make substantial cuts unlikely in the near term.

The disagreement is reflected in forecasts.

Several economists project that the Federal Reserve could reduce rates significantly before year-end if economic growth slows and inflation eases. Financial markets, however, continue to price in a more cautious path, suggesting investors remain unconvinced that aggressive cuts are imminent.

That gap between expectations and reality matters.

For businesses, lower interest rates reduce borrowing costs and encourage investment. For consumers, they can eventually lead to lower mortgage rates, cheaper car loans, and reduced financing costs across the economy.

At the same time, lower rates can also stimulate demand and potentially add inflationary pressure if price increases remain elevated.

That concern has become increasingly relevant as energy markets remain unsettled.

The ongoing disruption in the Strait of Hormuz has pushed fuel prices higher, raising transportation and logistics costs across multiple sectors. Those increases have begun filtering through the broader economy, complicating the Federal Reserve’s inflation outlook.

A central bank that cuts rates while inflation remains elevated risks fueling further price increases.

That reality may explain why neither Bessent nor Warsh appears eager to signal major policy shifts.

Historically, new Federal Reserve chairs receive a period of adjustment before facing intense political scrutiny. Warsh, still early in his tenure, is likely focused on establishing his credibility with markets, policymakers, and investors before making significant changes to monetary policy.

Bessent’s response may have reflected an effort to preserve that independence.

By emphasizing that he never pressured Powell, the Treasury secretary reinforced the longstanding principle that the Federal Reserve should make decisions based on economic conditions rather than political considerations.

Whether markets accept that interpretation remains another question.

Investors will continue scrutinizing every public statement from both men for clues about the direction of interest rates, particularly as inflation, employment, and economic growth data evolve over the coming months.

For households, however, the practical takeaway is straightforward.

Expectations for sharply lower borrowing costs may be premature.

The Federal Reserve faces an economy still grappling with inflation risks, volatile energy prices, and geopolitical uncertainty. Those factors make aggressive rate cuts difficult to justify in the near term.

For now, mortgage rates, business loans, and credit card costs are unlikely to fall simply because a new Fed chairman has arrived.

The most important message from Bessent’s breakfast meeting may be that Washington is not yet ready to force the issue.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Wall Street begins June the way it ended May — at record highs, but holding its breath. In a live update Sunday afternoon, CBS News reported that President Trump had still not decided whether to sign a potential peace agreement with Iran, leaving the single biggest question of the year hanging over Monday’s open.

Trump announced Friday he would make a “final determination” on the deal after a meeting in the White House Situation Room. As of Sunday, no decision had come. In a Truth Social post, Trump laid out his terms: any agreement must reopen the Strait of Hormuz, and Iran must work with the U.S. to have its highly enriched uranium destroyed. A source familiar with the talks said Trump had made significant late edits to the draft memorandum of understanding, with his changes focused on the Strait and the removal of that uranium.

The tension didn’t stay on paper over the weekend. The U.S. military disabled a merchant vessel in the Gulf of Oman that was allegedly trying to break through the American blockade of Iranian ports — a reminder that the shooting hasn’t fully stopped even as the diplomacy advances.

A market riding high into a risky week

The averages enter June on a tear. Friday’s close put the Nasdaq Composite at 26,972.62, the S&P 500 at 7,580.06, and the Dow Jones Industrial Average at 51,032.46. All three notched fresh all-time intraday highs and capped a winning May, powered by technology and by growing hope that the Iran war is winding down.

That hope did real work last week. According to Charles Schwab, oil prices fell nearly 10% and the 10-year Treasury yield dropped 11 basis points, both driven by expectations of a peace deal. Lower oil and lower yields are exactly the combination that lifts stocks — cheaper energy eases inflation, and lower yields make shares more attractive.

But Schwab also flagged a warning sign. Both the S&P 500 and the Nasdaq now carry relative strength readings above 70, a level that signals the market may be overbought in the near term. The firm noted that if the expected U.S.-Iran agreement breaks down and oil and yields climb back up, that could be the excuse for stocks to pull back 1% to 2%.

Why the next few days matter so much

The whole setup hinges on Iran. As Wayve Capital‘s strategist put it, the real bet investors are making is that a resolution arrives in the next two to three weeks. He added that it’s hard to imagine the Strait of Hormuz still being closed in October without a serious market reaction.

Not everyone is convinced a signature ends the story. London-based defense analyst Alex Alfirraz Scheers said Trump’s declaration on a possible deal should be taken with a degree of healthy skepticism, noting that Iran has its own demands that remain unfulfilled. Analysts broadly expect markets to stay sensitive to every headline out of the negotiations, with any confirmed reopening of the Strait likely to push global stocks higher — and any breakdown likely to bring volatility back fast.

The week’s economic calendar

Beyond Iran, there’s a full slate of data. Monday kicks off at 9:45 a.m. ET with S&P Global’s final May manufacturing reading, followed at 10:00 a.m. by the Institute for Supply Management‘s Manufacturing PMI for May — the first hard economic data of the new month. The week then builds toward Friday’s main event: the May jobs report from the Bureau of Labor Statistics, due June 5 at 8:30 a.m. ET.

There’s also a seasonal headwind worth knowing. June has historically been the weakest month for stocks in a midterm election year, and many investors expect a stretch of sideways trading after the spring run to records.

What it means for everyday Americans

Strip away the Wall Street jargon and it comes down to the price at the pump and the cost of borrowing. A signed deal that reopens Hormuz would pull oil — and gasoline — lower and ease the inflation pressure that has squeezed household budgets since the war began in late February. That would also give the Federal Reserve more room to cut interest rates, which feeds straight into mortgages, car loans, and credit cards.

A breakdown would do the reverse: energy prices climbing again, inflation worries returning, and the Fed staying on hold. One detail from last week underlines how thin the cushion is. The April personal consumption expenditures data showed Americans’ savings rate dropping — meaning households have less of a buffer to absorb another shock.

So as the new month opens, the records on the board matter less than the decision sitting on the President’s desk. Watch for word on the Iran signature, watch oil, and watch Friday’s jobs number. Those three will decide whether June’s strong start holds — or whether the spring rally finally takes a breather.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

SEATTLE — May 31, 2026

For more than two decades, Bill Gates carefully transformed himself from one of the most feared executives in corporate America into one of the most trusted figures in global philanthropy.

The transition was remarkable. The hard-charging co-founder of Microsoft, whose company spent years battling antitrust regulators, evolved into the soft-spoken billionaire associated with vaccines, disease prevention, education reform, and global development. The image became so successful that many younger Americans know Gates primarily as a philanthropist rather than the businessman who built one of the world’s largest technology companies.

But a recent Wall Street Journal report is raising new questions about just how carefully that image was constructed—and whether the institution built around it can withstand mounting scrutiny.

According to current and former employees cited by the Journal, Gates’ public appearances have long been managed with extraordinary precision. Staff reportedly maintain a custom-sized mannequin used to test clothing selections in advance of appearances, while multiple pre-approved outfit combinations are prepared for events. The goal, according to individuals familiar with the process, was consistency: projecting a calm, approachable, thoughtful public persona.

The detail has generated headlines and social media commentary. But the larger issue extends far beyond sweaters, glasses, or wardrobe planning.

For the Bill & Melinda Gates Foundation and related philanthropic organizations, reputation is not merely a public-relations concern. It is a core asset.

Unlike traditional businesses that generate revenue by selling products or services, major philanthropic organizations depend heavily on trust, credibility, and relationships. Donors, governments, universities, pharmaceutical companies, nonprofit organizations, and international agencies often choose partners based as much on reputation as on financial resources.

That dynamic becomes especially important for institutions operating on the scale of the Gates Foundation.

The foundation supports programs across global health, agriculture, education, economic development, and disease prevention in more than 130 countries. Through initiatives such as Gates Philanthropy Partners and the Giving Pledge, the organization also helps attract additional capital from wealthy individuals, foundations, and institutional donors.

In many cases, the Gates name itself functions as a form of currency.

Potential donors gain confidence when they believe their contributions are associated with a respected and trusted institution. Companies become more willing to participate in public-private partnerships. Governments become more receptive to collaboration. Researchers become more eager to pursue joint projects.

That is why reputational damage can have consequences far beyond headlines.

The foundation’s investment activities provide one example.

Through strategic investments, guarantees, and partnerships, Gates-backed organizations frequently work alongside private companies to accelerate the development and distribution of vaccines, medicines, agricultural technologies, and public-health initiatives. Such arrangements often depend on mutual confidence and long-term trust between participants.

When a prominent public figure becomes the focus of controversy, that trust can become more difficult to maintain.

The timing of the renewed attention is particularly significant.

The Journal’s report arrives as Gates faces increasing scrutiny regarding past interactions with the late financier Jeffrey Epstein. Gates is expected to face questions about those relationships as congressional inquiries continue examining connections between prominent individuals and Epstein.

Regardless of the outcome of those proceedings, the publicity creates challenges for organizations that rely heavily on public confidence.

The situation also highlights a broader issue facing founder-led institutions.

Whether in business, politics, media, or philanthropy, organizations built around a single personality often benefit enormously during periods of success. A recognizable leader can attract donors, investors, employees, partners, and media attention more easily than a faceless institution.

The same concentration of influence, however, creates vulnerability.

When reputation becomes closely tied to one individual, personal controversies can quickly become organizational challenges. What begins as a public-relations problem can evolve into fundraising difficulties, partnership concerns, recruiting challenges, and broader institutional questions.

For the Gates Foundation, the stakes are particularly high because the consequences extend beyond executives and donors.

The foundation’s work supports researchers, healthcare providers, farmers, educators, and community organizations around the world. If reputational concerns eventually affect funding or partnerships, the impact would ultimately be felt far from Seattle—in clinics, laboratories, schools, and development projects that depend on philanthropic support.

None of that means the institution is in immediate danger. The Gates Foundation remains one of the largest and most influential charitable organizations in the world, with substantial resources and a global footprint developed over decades.

But the episode serves as a reminder that even the most carefully managed public image has limits.

For years, the sweaters, the measured tone, and the carefully cultivated persona helped create one of the most successful reputation transformations in modern public life.

The question now is whether the institution behind that image has become strong enough to stand independent of the man who created it.

Seattle — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

SCOTTSDALE, Ariz. — May 31, 2026

Berkshire Hathaway Inc. has agreed to acquire Taylor Morrison Home Corporation in an all-cash transaction valued at approximately $8.5 billion, marking one of the largest homebuilding deals in recent years and signaling a major new commitment by Warren Buffett’s conglomerate to the long-term strength of the U.S. housing market.

Under the definitive agreement announced Friday, Berkshire will pay $72.50 per share in cash, representing a 24% premium to Taylor Morrison’s closing stock price of $58.50 on May 29. The transaction values the company’s equity at roughly $6.8 billion and its enterprise value at approximately $8.5 billion.

The acquisition brings one of America’s largest homebuilders into Berkshire’s growing housing portfolio. Taylor Morrison, headquartered in Scottsdale, Arizona, operates more than 350 communities across 21 markets in 12 states, serving a broad range of buyers from first-time homeowners to move-up and active-adult consumers. The company also develops rental communities through its Yardly brand and operates mortgage, title, escrow, and homeowners insurance businesses.

Sheryl Palmer, Chairman and Chief Executive Officer of Taylor Morrison, will remain in her current role following the closing, and the company’s existing management team is expected to continue leading day-to-day operations. Upon completion of the transaction, Taylor Morrison will become a privately held company within Berkshire Hathaway and will be delisted from the New York Stock Exchange.

The deal expands Berkshire’s already significant footprint in residential housing. The conglomerate owns Clayton Homes, one of the nation’s largest manufactured-home builders, along with a broad collection of building-products, construction-materials, and housing-related businesses.

Greg Abel, Berkshire Hathaway’s Chief Executive Officer, said the acquisition reflects the company’s confidence in the long-term fundamentals of the U.S. housing market and complements Berkshire’s existing investments across the housing ecosystem.

According to the companies, Berkshire ultimately expects to combine its site-built homebuilding operations into a larger integrated platform, creating potential efficiencies across construction, financing, insurance, and related services.

The transaction arrives as the U.S. housing market continues to face a structural shortage of homes despite elevated mortgage rates. Industry analysts have repeatedly pointed to years of underbuilding following the 2008 financial crisis as a key factor supporting long-term demand for new housing construction.

For investors and industry executives, Berkshire’s move represents a powerful endorsement of that outlook. The company is known for making large acquisitions only when it believes the underlying business possesses durable competitive advantages and favorable long-term economics.

The acquisition also highlights an accelerating trend of consolidation within the homebuilding industry, where scale increasingly matters in land acquisition, construction costs, financing, and customer services. Taylor Morrison’s vertically integrated platform—including mortgage, insurance, and title services—offers Berkshire additional exposure to revenue streams beyond home sales alone.

The deal is expected to close during the second half of 2026, subject to approval by Taylor Morrison shareholders and customary regulatory reviews.

If completed as planned, the acquisition will rank among Berkshire Hathaway’s most significant housing investments in years and could reshape the competitive landscape of the U.S. homebuilding sector as the company deepens its presence in one of the nation’s most important industries.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

WASHINGTON — May 28, 2026 — The gap between what American companies earn and what American workers take home widened further in the first quarter, reaching levels that help explain why many households remain frustrated despite an economy that continues to grow.

New data released Thursday by the Bureau of Economic Analysis (BEA) showed the U.S. economy expanded at a 1.6% annualized rate during the first three months of 2026, down from the agency’s earlier estimate of 2.0%. The revision reflected weaker business investment and softer consumer spending than previously reported.

At the same time, after-tax corporate profits climbed to approximately $3.92 trillion at an annual rate, up 17.4% from a year earlier, according to the BEA’s accompanying corporate profits report.

The contrast between slowing economic growth and surging profits highlights a trend that economists say has been building for decades but is becoming increasingly visible across the economy.

According to data released earlier this month by the Bureau of Labor Statistics, labor’s share of economic output — the percentage of national income paid to workers through wages and benefits — fell to 54.1% in the first quarter, the lowest level since government records began in 1947.

The decline means a smaller portion of every dollar generated by the economy is flowing to workers, while a larger share is going to corporate profits and investment income.

In practical terms, the economy is producing more wealth, but workers are receiving a smaller slice of it.

The trend helps explain why consumer sentiment remains weak despite historically low unemployment rates and continued economic expansion. While corporate earnings have surged, many households continue to struggle with elevated costs for housing, groceries, insurance, healthcare, and utilities.

The disconnect is particularly visible in productivity data.

American workers produced 2.9% more output per hour over the past year, according to government figures. Yet after adjusting for inflation, real hourly compensation declined 0.5% during the first quarter.

That means workers became more productive while seeing their purchasing power shrink.

Economists have long viewed labor’s share and profit share as opposite sides of the same equation. When labor’s share falls, corporate profits typically rise.

Today, both measures are approaching historic extremes.

While workers are receiving the smallest share of economic output in modern records, corporate profits are hovering near the highest levels ever recorded.

The trend carries broader economic implications because consumer spending accounts for roughly two-thirds of U.S. economic activity. The same BEA report that showed stronger profits also showed slower consumer spending growth, raising concerns about whether household demand can continue supporting the expansion if wage growth fails to keep pace with costs.

Several structural factors have contributed to the shift.

Economists point to increased automation, advances in software and artificial intelligence, declining union membership, greater industry consolidation, and the pricing power many companies gained during the inflation surge of the early 2020s.

Those forces have allowed businesses to increase output and protect profit margins without sharing an equivalent portion of gains with employees.

For investors and shareholders, the latest figures reflect impressive corporate performance. Companies have successfully navigated inflation, higher interest rates, supply-chain disruptions, and geopolitical uncertainty while maintaining profitability.

For households, however, the experience has often looked very different.

When grocery bills rise faster than paychecks and housing costs consume a larger share of income, record corporate earnings can feel disconnected from daily reality.

The result is an economy that appears strong in aggregate statistics but feels much weaker at the household level.

Looking ahead, economists say the direction of the labor-profit divide will depend largely on the job market.

A tight labor market typically forces employers to compete for workers through higher wages and better benefits, helping labor reclaim a larger share of economic output. If economic growth slows further and hiring weakens, however, employers may retain the upper hand, allowing profit margins to remain elevated.

For now, Thursday’s government data delivered a clear message: corporate America is capturing a growing share of the nation’s economic gains while workers are receiving the smallest share on record.

That imbalance may be one of the clearest explanations for why many Americans continue to feel financially squeezed even as the broader economy remains in expansion mode.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

A treatment that once required a doctor’s prescription is about to become much easier—and potentially less expensive—for millions of Americans to obtain.

In a May 22 announcement, Galderma, the Switzerland-based dermatology company, said the U.S. Food and Drug Administration (FDA) approved Differin Epiduo Acne Gel for over-the-counter sale, making it the first prescription-strength combination of adapalene 0.1% and benzoyl peroxide 2.5% available without a prescription for individuals age 12 and older.

The product is expected to arrive at major retailers, including Walmart, Target, Ulta Beauty, and Amazon, beginning this summer.

For consumers, the approval represents a significant shift in acne treatment accessibility. For Galderma, it opens a major new growth opportunity in one of the largest segments of the skincare market.

A Dermatologist Favorite Moves to the Drugstore

For more than 15 years, dermatologists have prescribed the Epiduo formulation to patients struggling with acne. The treatment combines two well-established ingredients that attack acne from different directions.

Adapalene, a retinoid, helps prevent clogged pores and promotes skin-cell turnover, while benzoyl peroxide targets acne-causing bacteria and reduces inflammation.

Used together, the combination addresses multiple causes of acne simultaneously rather than focusing on a single trigger.

According to clinical studies cited by Galderma, the dual-action treatment consistently outperformed either ingredient used alone. Research showed reductions in inflammatory acne lesions of up to 70.3% after 12 weeks of treatment, with improvements maintained through long-term use.

For patients, the key distinction is that the over-the-counter version is not a weaker adaptation of the prescription product. It contains the same active ingredients and strengths previously available only through a healthcare provider.

Why the FDA Decision Matters

Acne is among the most common skin conditions in the United States, affecting an estimated 50 million Americans annually, according to the American Academy of Dermatology.

While many consumers rely on cleansers, spot treatments, and over-the-counter products containing a single active ingredient, more persistent cases often require prescription medications that involve physician visits, insurance approvals, and pharmacy costs.

The FDA approval removes several of those barriers.

Instead of scheduling a dermatologist appointment and obtaining a prescription, consumers will be able to purchase the treatment directly from retail shelves.

That change could save both time and money, particularly for teenagers, young adults, and families managing recurring acne treatment costs.

The Business Behind the Approval

The decision also represents an important commercial opportunity for Galderma.

The company reported strong growth in early 2026, driven by demand for dermatology products and aesthetic treatments. Expanding a long-established prescription brand into the retail market significantly increases its potential customer base.

Industry analysts often describe these transitions as “Rx-to-OTC switches,” referring to products that move from prescription-only status to over-the-counter availability after demonstrating strong safety and effectiveness records.

Such switches can transform a specialized medical product into a mainstream consumer brand.

For Galderma, the strategy allows the company to leverage years of physician trust and patient familiarity while expanding distribution into mass retail channels.

The move could also intensify competition throughout the acne-care market, where consumers spend billions of dollars annually on treatments, cleansers, creams, and skincare products.

What Consumers Should Know

Medical experts note that while the approval increases access, it does not eliminate the need for professional care in every situation.

Individuals experiencing severe, cystic, or scarring acne may still require prescription therapies or specialized dermatological treatment. Pregnant women and patients with complex skin conditions should also consult healthcare providers before beginning new treatment regimens.

Like many retinoid-based products, adapalene can initially cause dryness, redness, or irritation as the skin adjusts. Dermatologists generally recommend gradual use and consistent sunscreen application when starting treatment.

The FDA approval currently applies only to the United States market. In many other countries, the product remains available by prescription only.

A Growing Trend in Consumer Healthcare

The approval reflects a broader trend toward expanding consumer access to established treatments that have demonstrated long-term safety and effectiveness.

In recent years, regulators have approved over-the-counter access for a growing number of products that were once available only through healthcare providers, giving consumers greater control over routine health and wellness decisions.

For millions of Americans dealing with acne, the change means a treatment that once required a doctor’s signature can soon be purchased during a routine trip to the store.

And for Galderma, it means bringing one of dermatology’s most recognized prescription brands directly into the highly competitive retail skincare aisle.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 31, 2026

American consumers are sending a message that food companies and restaurant chains can no longer ignore: prices have gone too far, and shoppers are pushing back.

After several years of aggressive price increases, major food manufacturers and restaurant operators are increasingly rolling out smaller package sizes, value-focused products, and discounted meal deals in an effort to win back customers who have reduced spending or shifted to cheaper alternatives.

The financial pressure is becoming visible across the industry.

PepsiCo reported that North American snack-food volumes declined 4%, while beverage volumes fell 3%, reflecting a growing reluctance among consumers to absorb repeated price hikes. Similar volume declines have also been reported by major food companies including Conagra Brands, Kraft Heinz, and J.M. Smucker, signaling that higher prices are no longer offsetting weaker demand.

When consumers buy fewer products, even strong pricing power eventually hits a limit.

That reality is forcing many companies to rethink their strategy.

General Mills reduced prices on nearly two-thirds of its North American grocery products last year and subsequently reported improving sales volumes. PepsiCo has gone even further, announcing plans to cut prices by as much as 15% across portions of its snack portfolio.

PepsiCo Chairman and CEO Ramon Laguarta recently described the effort as a major “reset of affordability,” acknowledging that consumers across the United States and other developed markets are increasingly struggling with everyday expenses.

Some companies are pursuing a different approach.

Rather than directly cutting prices, they are introducing smaller package sizes designed to lower the amount shoppers pay at checkout. PepsiCo and J.M. Smucker have both streamlined product offerings, eliminating slower-selling items while focusing on products that consumers continue buying regularly.

The strategy allows shoppers to spend less upfront, even if they receive slightly less product.

However, that approach comes with risks.

Consumer advocates and economists continue warning about shrinkflation — the practice of reducing package sizes while keeping prices unchanged. Research released earlier this year found that shrinking package sizes have quietly contributed to food inflation, often without consumers immediately noticing.

For shoppers, experts increasingly recommend comparing unit prices rather than package prices alone to determine whether products actually represent better value.

Food manufacturers also recognize that lower prices alone may not be enough.

Conagra executives have argued that consumers, particularly younger shoppers, increasingly want innovation alongside affordability. The company has responded by introducing higher-protein offerings and expanding newer product lines aimed at health-conscious consumers.

General Mills CEO Jeff Harmening recently acknowledged that housing costs, inflation, and broader cost-of-living pressures have fundamentally changed consumer behavior.

“Value,” Harmening said, “is a core expectation that is here to stay.”

Early results suggest the affordability push may be working.

PepsiCo reported first-quarter 2026 revenue growth of 8.5% and a 9% increase in core earnings per share, attributing part of the improvement to affordability initiatives and stronger food volumes.

Restaurants are fighting the same battle.

Many national chains have continued extending value-meal promotions that were originally introduced as temporary inflation-era offerings. Executives increasingly view low-cost bundled meals as one of the most effective ways to bring budget-conscious customers back through the door.

Across grocery stores, convenience outlets, and fast-food chains, the lesson appears increasingly clear.

Consumers spent years absorbing higher prices. Now many are refusing to do so.

As shoppers become more selective about where and how they spend, companies are discovering that customers ultimately retain the strongest negotiating tool of all: the ability to simply walk away.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

May 31, 2026

UnitedHealthcare announced a significant reduction in prior authorization requirements for pediatric health services, marking one of the largest recent efforts by a major U.S. insurer to streamline access to care for children and reduce administrative burdens on physicians and families.

The company said it will eliminate prior authorization requirements for several pediatric services, allowing doctors to move forward with treatment plans more quickly without waiting for insurer approval. The changes are expected to affect thousands of pediatric patients and providers across the country.

Prior authorization has long been one of the most controversial practices in American healthcare. Under the system, physicians must obtain approval from an insurer before certain treatments, tests, medications, or procedures can be provided. Insurers argue the process helps control costs and prevent unnecessary care, while doctors and patient advocates contend it can delay treatment and create significant administrative burdens.

The latest move by UnitedHealthcare, the nation’s largest health insurer, comes amid growing pressure from lawmakers, regulators, hospitals, and physician groups to simplify the process.

Healthcare organizations have increasingly argued that prior authorization requirements consume valuable clinical time that could otherwise be spent treating patients. Pediatric providers, in particular, have raised concerns that delays can be especially disruptive when children require timely therapies, specialty care, diagnostic testing, or behavioral health services.

Industry groups welcomed the announcement as a step toward reducing bureaucracy in healthcare delivery.

The insurer said the changes are intended to improve patient access, reduce paperwork for providers, and allow clinicians to focus more directly on patient care. The company also noted that advances in data analytics and clinical review processes have allowed it to identify areas where prior authorization may no longer be necessary.

The decision reflects a broader shift occurring across the healthcare industry.

Several major insurers have recently announced efforts to simplify authorization requirements as scrutiny intensifies from both federal and state policymakers. Legislators from both parties have introduced proposals aimed at reforming prior authorization practices, citing concerns about treatment delays and growing administrative costs throughout the healthcare system.

For families, the practical impact could be significant.

Parents whose children require specialty care often face uncertainty while waiting for insurance approvals. Eliminating authorization requirements for certain services may shorten wait times, reduce administrative hurdles, and allow treatment plans to begin more quickly.

The announcement could also have broader implications for healthcare costs and insurer-provider relations. Hospitals and physician groups have frequently cited prior authorization as one of the leading sources of friction between healthcare providers and insurers.

Whether other major insurers follow UnitedHealthcare’s lead remains to be seen, but the move signals growing recognition throughout the industry that simplifying access to care may benefit patients, providers, and insurers alike.

As healthcare costs continue to rise and policymakers focus on improving patient access, prior authorization reform is likely to remain a major issue across the healthcare sector.

JBizNews Desk — Healthcare

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

There is a contradiction running through the American economy right now that touches every household in the country, and on Wednesday morning, the chief executive of the largest U.S. airline put it in plain English. The same Americans who are telling pollsters they are nervous about the economy, worried about inflation, and unsettled by the war in the Middle East are also booking summer vacations, business trips, and weekend getaways at a pace that has the country’s airlines reporting some of their strongest demand of the year.

“People still want to travel and travel is still a bargain,” Robert Isom, the chief executive of American Airlines, told Bloomberg TV. Isom said American is now seeing strong demand across international and domestic travel, as well as for its premium offerings — the higher-margin first-class and business seats that airlines have spent the past several years trying to sell more aggressively. The numbers behind that statement are striking. American is already roughly 80% booked for the second quarter. Corporate travel is up 13% year-over-year. Leisure demand, in Isom’s word, is “incredibly” strong. The airline expects second-quarter revenue to rise 15% from a year ago on about 5% capacity growth — meaning each flight is generating about 10% more revenue than it did a year ago, even as gas prices for the jet fuel that powers the planes have surged.

United Airlines Holdings Inc. said the same thing on the same morning. Demand at United, the country’s other major full-service carrier, also continues to be robust. The picture coming out of the two biggest U.S. airlines is consistent: Americans are still flying, still spending, and still booking.

For ordinary readers trying to understand why this matters, the story is much bigger than the airline industry. The reason economists and journalists watch consumer travel spending so closely is that flying somewhere is one of the most purely discretionary things a household can do. Nobody has to take a trip. When families are genuinely worried about money, the summer vacation is usually one of the first things to go. When companies are cutting costs, business travel is one of the first line items the finance department slashes. So when the airlines say bookings are strong, it is one of the cleanest real-world signals available that the American economy — at the household level — is still in better shape than the headlines suggest.

That signal sits in direct tension with what the consumer survey numbers are showing. The Conference Board reported on Tuesday that its closely watched consumer confidence index dipped to 93.1 in May, down 0.7 points from April. It was the first decline in four months. The Present Situation Index, which measures how Americans feel about the economy right now, fell more sharply — down 3.2 points to 121.2. The Expectations Index, which measures the six-month outlook, has now been below the recession-warning threshold of 80 for more than a year, sitting at 74.4 in May. Dana M. Peterson, the Conference Board’s chief economist, said in the release that “consumer confidence edged downward in May as the inflationary impacts of the war in the Middle East intensified,”  and that survey respondents are increasingly mentioning prices, oil and gas, war, and geopolitical conflict in their written-in concerns about the economy.

Two things can be true at the same time, and right now in America, they are. Households are nervous about the economy in surveys. The same households are still spending money on plane tickets, hotel rooms, restaurant meals, and summer vacations. The gap between what people say in a survey and what they actually do with their wallets is one of the most important economic stories of 2026, and air travel is the cleanest place to see it.

The reason ordinary Americans should care about this disconnect is that it changes what the rest of the year is likely to look like. If consumer confidence surveys turned out to be the right signal — meaning Americans were about to pull back hard on discretionary spending — the country would likely be heading into a meaningful slowdown by the end of the summer, with airlines, hotels, restaurants, and retail all feeling the pinch. If the actual booking and spending data turn out to be the right signal — meaning Americans are still spending despite their nervousness — the second half of 2026 could deliver another quarter of resilient growth, holding off the slowdown the surveys have been predicting since early last year. The airlines just placed their bets. They believe the real-world spending data is the truer signal.

The history of the past eighteen months gives Isom and his peers some reason for that confidence. American Airlines, along with most of the rest of the U.S. airline industry, had a very difficult spring of 2025. After President Trump’s “Liberation Day” tariffs in April 2025 sent global markets into chaos and rattled household confidence, leisure travel demand fell off sharply. American, Delta, Southwest, and United all pulled their full-year financial forecasts within weeks of each other, citing what Isom called the “reluctance of domestic passengers to get in the game.” Domestic main-cabin travel — the economy-class seats that ordinary American families fill — went soft. The airlines spent the rest of 2025 trying to figure out where the bottom was.

The picture in 2026 has been very different. Despite the war with Iran, despite oil prices that are pushing higher gasoline costs through the entire economy, despite a consumer confidence reading that has now spent more than a year flashing warning signs, Americans are still booking. The reason that matters is that the 2025 episode showed exactly how quickly travel demand can disappear when consumers genuinely panic. The fact that the same kind of collapse is not happening now, in conditions arguably more difficult than 2025, suggests that whatever is going on inside American households is not the kind of fear that ends with people canceling their summer trips.

The cost side of the airline business, however, is a real problem and worth understanding plainly. American Airlines said last month that it expects its 2026 jet fuel bill to rise by more than $4 billion compared to last year, a number that single-handedly explains why the airline cut its full-year profit forecast from a range of $1.70 to $2.70 per share down to a range of a 40-cent loss to a $1.10 profit. The Iran war’s effect on oil prices is hitting American directly. The reason the airline still expects to “repeat the profitability we had last year,” as Isom said Wednesday, is that the demand strength on the revenue side is large enough to absorb the cost hit on the fuel side. Travelers paying more for tickets, more corporate travel, and more premium-cabin bookings are covering the higher fuel bill. That math only works if demand stays where it is. If consumers genuinely pull back in the second half of the year, American’s 2026 profitability could disappear quickly.

The competitive backdrop is also worth noting because it explains some of what is happening to prices in the U.S. airline industry this summer. Spirit Airlines — the ultra-low-cost carrier that has been the price floor for budget-conscious American travelers for nearly two decades — filed for bankruptcy protection during 2025 and has materially reduced its capacity. The result is that the entire low-end of the U.S. domestic travel market is operating with fewer seats than a year ago. Less ultra-low-cost competition means slightly higher prices across the board, including at the larger carriers like American, Delta, United, and Southwest, which can sustain higher base fares because the cheapest competitor has gotten smaller. Isom was careful Wednesday not to declare the ultra-low-cost carrier model dead, but he was clear that American’s network, scale, and product mix gave it an advantage as consumers continued to spend on travel experiences.

There is also a labor and operational layer underneath the demand story that ordinary travelers should know about. American Airlines has been in an ongoing dispute with its flight attendants’ union, which passed a no-confidence vote in Isom’s leadership in February citing operational issues during winter storm disruptions. The company’s pilots have also issued no-confidence messaging. None of those internal labor problems have shown up yet in the demand picture, which is part of what makes Isom’s Wednesday comments striking. Even with a workforce in open conflict with management, with a fuel bill rising by billions of dollars, with a war in the Middle East dragging on, and with consumer confidence surveys flashing warning signs, the planes are filling up.

The biggest practical takeaway for ordinary American households reading this is that the summer travel market is not going to soften the way some of the survey data might suggest. Flights are already 80% booked for the second quarter at the country’s largest airline. Hotels, especially in cities preparing for the FIFA World Cup, are filling up. Rental car availability is tightening. Anyone who has been waiting to book a summer trip in hopes that prices will come down is unlikely to find them coming down. The combination of strong demand, reduced low-cost-carrier capacity from Spirit’s bankruptcy, and higher fuel costs being passed through to ticket prices means that the cost of summer travel in 2026 is now structurally higher than it was a year ago.

The bigger lesson for the country is the one Isom delivered in a single sentence on Bloomberg TV. People still want to travel. Travel is still a bargain — meaning that even at higher prices, Americans are looking at what they get for the money and concluding it is worth it. That is not the behavior of a country sliding into recession. It is the behavior of a country that is worried in surveys but still confident in its day-to-day spending decisions. Which of those two signals turns out to be the more accurate description of where the economy is actually heading is the question that will determine the rest of 2026 — and the airlines have just told the country, in dollars and bookings rather than words, where they think the answer lies.

For the moment, the planes are full. The summer is sold out. And the gap between what Americans say about the economy and what Americans do with their money is the most important economic story of the year.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

Sunday, May 31, 2026

Drivers are finally getting a bit of relief at the gas pump.

According to the American Automobile Association (AAA), the national average price for a gallon of regular gasoline fell for the eighth consecutive day on May 29, declining another 3.5 cents to $4.391 per gallon. While the drop is modest, it marks a welcome change after months of rising fuel costs driven by conflict in the Middle East and disruptions to global energy supplies.

The decline comes as oil markets increasingly bet that diplomacy may succeed where military escalation failed.

For months, the conflict involving Iran disrupted traffic through the Strait of Hormuz, one of the world’s most important energy chokepoints. Before the conflict, roughly one-fifth of global oil shipments passed through the narrow waterway. Concerns about supply disruptions pushed crude prices sharply higher and sent gasoline prices soaring across the United States.

Now traders are beginning to price in the possibility that more oil could soon return to global markets.

The shift has been visible in crude oil prices.

West Texas Intermediate (WTI) crude settled at approximately $87.36 per barrel on May 29, while international benchmark Brent crude closed near $92.05 per barrel. Both benchmarks have retreated significantly from wartime highs as investors increasingly focus on ceasefire negotiations and diplomatic efforts aimed at reducing tensions.

Market sentiment improved further after reports that U.S. and international negotiators had drafted a framework for extending a ceasefire and beginning broader discussions regarding Iran’s nuclear program and regional security issues.

The logic behind the market reaction is straightforward.

Oil prices reflect not only current supply and demand but also expectations about future disruptions. As fears of prolonged supply shortages ease, traders reduce the risk premium embedded in crude prices. Lower oil prices eventually translate into lower gasoline prices for consumers.

Even so, drivers should keep the recent decline in perspective.

At more than $4.39 per gallon nationally, gasoline remains expensive by historical standards and continues to place pressure on household budgets. Summer travel demand is beginning to accelerate, and millions of Americans are expected to hit the roads in the coming weeks.

Regional differences remain substantial.

Some of the lowest gasoline prices in the country are currently found in states such as Indiana, Texas, Georgia, and Mississippi, where average prices remain well below the national average. Meanwhile, drivers in several coastal and high-tax states continue paying significantly more.

The durability of the recent decline remains uncertain.

Energy markets have repeatedly swung between optimism and anxiety throughout the year as ceasefire discussions advanced and then stalled. Previous periods of falling oil prices were often followed by renewed spikes after military incidents or setbacks in negotiations.

AAA has cautioned that fuel prices remain highly sensitive to developments in the Middle East and that any disruption to ongoing diplomatic efforts could quickly reverse recent gains.

Analysts also note that even if shipping routes fully reopen, global energy infrastructure has suffered damage during months of conflict. Refineries, export facilities, pipelines, and port operations may take time to return to normal capacity.

That means oil markets could remain vulnerable to supply disruptions even under a successful peace agreement.

For consumers, however, the recent trend is encouraging.

Every decline in gasoline prices helps reduce transportation costs for households and businesses while easing inflationary pressure across the broader economy. Lower fuel costs can influence everything from airline tickets and shipping expenses to grocery prices and consumer spending.

The challenge is that the current relief remains tied to expectations rather than certainty.

The ceasefire process is still developing, key agreements remain unfinished, and energy markets continue reacting to every headline. Until a durable agreement is reached and oil flows normalize, the recent decline at the pump remains dependent on a peace process that is still unfolding.

For now, motorists are enjoying the first meaningful break in months—and hoping it lasts.

JBizNews Desk — Energy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

President Donald Trump is once again raising questions about America’s gold reserves after a former CIA official was arrested in a case involving millions of dollars in gold bars.

In a May 31 post on Truth Social, Trump shared a message calling for a physical audit of the gold stored at Fort Knox, writing that it was “Time to Physically Audit Fort Knox.” The post linked to reports about the arrest of a former senior CIA official accused of stealing government assets and allegedly storing approximately $40 million worth of gold bars at his residence.

The arrest has reignited a long-running debate over transparency surrounding one of America’s most closely guarded assets: the gold held inside the U.S. Bullion Depository at Fort Knox, Kentucky.

The Arrest That Sparked the Debate

According to federal court filings reported by multiple news organizations, former CIA official David Rush was arrested after investigators allegedly discovered approximately 300 gold bars valued at more than $40 million, roughly $2 million in cash, and dozens of luxury watches during a search of his home.

Federal prosecutors allege Rush improperly obtained government assets intended for official purposes and diverted some of them for personal use. The allegations remain pending in court.

The case drew national attention because of the sheer amount of gold involved and because Rush reportedly held a senior position with access to sensitive government programs.

For Trump and others calling for greater oversight, the case raised a broader question: if one government official could allegedly accumulate that much gold, should Americans receive additional assurance regarding the nation’s largest gold stockpile?

What Is Fort Knox?

Officially known as the United States Bullion Depository, Fort Knox is one of the most secure facilities in the world.

Located in Kentucky next to the Army installation that shares its name, the depository was completed in 1936 and began receiving gold shipments in 1937.

Today, Fort Knox reportedly holds approximately 147.3 million ounces of gold, representing roughly half of the gold owned by the U.S. Treasury.

The facility’s security measures are legendary. Its massive vault door weighs more than 20 tons, and no single individual is said to possess the complete combination needed to access the vault.

During World War II, Fort Knox also safeguarded some of America’s most important national treasures, including the original Declaration of Independence and the Constitution.

Why the Gold Matters

While many Americans rarely think about Fort Knox, the value of its holdings is enormous.

On the federal government’s books, the gold is still valued at the official statutory price of $42.22 per ounce, a figure dating back decades.

Using that accounting method, the government’s gold reserves are valued at roughly $6 billion.

At today’s market prices, however, the gold would be worth closer to $590 billion.

That difference creates one of the largest valuation gaps anywhere on the federal balance sheet.

With the national debt exceeding $39 trillion, some economists and lawmakers have argued that the government’s gold holdings deserve greater transparency and more accurate accounting.

The Audit Question

The Treasury Department maintains that its gold reserves are regularly accounted for and monitored.

However, critics argue there has not been a truly independent physical verification of all U.S. gold reserves in decades.

While government officials and members of Congress have toured portions of the facility over the years, advocates of a full audit say public confidence would be strengthened through a comprehensive independent review.

The issue has gained attention from lawmakers supporting the Gold Reserve Transparency Act, proposed legislation that would require periodic independent audits and verification of U.S. gold holdings.

Supporters argue that regular audits would improve transparency and public trust.

Critics counter that existing controls are sufficient and that there is no evidence suggesting any significant discrepancy in the nation’s gold reserves.

Why Americans Are Paying Attention

For most households, Fort Knox may seem far removed from daily life.

Yet the broader issue resonates because it touches on government accountability, public trust, and the nation’s financial position.

Questions about federal assets, debt levels, transparency, and oversight have become increasingly important as Americans pay closer attention to government finances.

Trump’s latest comments have brought those questions back into the spotlight.

As of May 31, no new independent audit of Fort Knox has been announced. Whether the president’s call leads to formal action remains unclear.

But one thing is certain: a vault that many Americans rarely think about is once again at the center of a national conversation.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

YouTube announced Wednesday that it will begin automatically detecting and labeling videos containing significant photorealistic AI-generated content, marking a major shift away from the platform’s previous reliance on creators voluntarily disclosing synthetic media themselves.

The change reflects growing pressure on major technology platforms to address the explosion of realistic AI-generated video flooding social media and online content feeds.

Under the updated system, YouTube said its detection tools will automatically apply disclosure labels when its systems identify substantial AI-generated or manipulated visual content — even if creators fail to disclose it themselves.

The rollout begins gradually this month.

The company originally introduced voluntary AI-content disclosures in 2024, but acknowledged Wednesday that users increasingly want clearer transparency surrounding synthetic media as generative video tools become more advanced and difficult to distinguish from real footage.

The labels are also becoming significantly more visible.

For standard long-form videos, the disclosure will now appear directly beneath the video player and above the description section. For YouTube Shorts, labels will appear as overlays directly on the video itself.

Less realistic or clearly fictional content will continue receiving more limited disclosures inside expanded descriptions.

The company said creators who believe their content was incorrectly flagged can appeal through YouTube Studio. However, labels may remain permanently attached in cases where videos were created using Google-owned AI systems such as Veo or Dream Screen, or when videos include embedded C2PA metadata or SynthID watermarks indicating AI generation.

YouTube said its systems rely partly on metadata analysis and watermark detection to identify synthetic content, though the company declined to fully disclose the technical methods behind the detection tools.

Importantly for creators, the labels will not directly reduce monetization eligibility or suppress videos inside recommendation algorithms.

The company framed the disclosures as informational rather than punitive, arguing that transparency offers a more scalable solution than broad removals as AI-generated content rapidly expands online.

The announcement arrives alongside a broader tightening of YouTube’s policies surrounding deepfakes and synthetic media.

Earlier this month, the platform expanded its deepfake removal protections to cover all adults over age 18, allowing individuals to request removal of AI-generated content depicting their likeness. Voice-cloning protections are also expected later this year.

For YouTube, whose business depends heavily on viewer trust and advertiser confidence, the new labeling system represents a balancing act: allowing creators to continue using AI tools while giving viewers clearer signals about what is real and what is synthetic.

As increasingly realistic AI-generated content floods the internet, YouTube is effectively betting that disclosure — rather than outright bans — will become the most practical way to manage the next era of online media.

San Bruno, California — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

For generations, homeowners bought insurance for one reason: protection when disaster strikes.

Today, there is a growing chance they may get nothing at all.

In a recent report, Weiss Ratings, the nation’s only independent rating agency covering the insurance industry, identified 15 major U.S. insurers that closed at least half of their homeowner claims in 2025 without making any payment to policyholders. The findings come amid increasing scrutiny of claim denials, rising premiums, and growing frustration among homeowners who believed they were paying for financial protection.

Martin D. Weiss, founder of Weiss Ratings, said denial levels of 50% or higher raise serious concerns about whether consumers are receiving the coverage they expect when purchasing insurance.

“High claim denial rates raise serious questions about reliability, especially as many of these same insurers show increasing profitability,” Weiss said in the report.

The release followed a recent call by President Donald Trump for greater transparency surrounding homeowner insurance claim denials, shining a spotlight on an issue that affects millions of American families.

For consumers, the consequences can be severe.

When a claim is closed without payment, the homeowner is left responsible for the entire repair bill. Whether the damage involves a leaking roof, flood damage, storm destruction, or a fire, the costs often fall directly on the family that spent years paying premiums expecting protection when they needed it most.

The Trend Is Moving in the Wrong Direction

A separate analysis published by The Wall Street Journal found similar results across the country’s largest insurance companies.

According to the Journal’s review, the five largest home insurers in the United States — State Farm, Allstate, Liberty Mutual, USAA, and Farmers Insurance — failed to make payments on more than 44% of homeowner claims they closed last year. A decade earlier, that figure stood at approximately 36%.

The increase means homeowners filing claims today face significantly greater odds of receiving no payment than they did just ten years ago.

In practical terms, many Americans now face nearly a coin-flip chance that a filed claim could result in no insurance payment at all.

Why Are More Claims Closing With No Payment?

Insurance companies argue that the issue is more complicated than outright denials.

One major factor is the rapid increase in deductibles. Many homeowners now carry substantially higher deductibles than they did in previous years. In addition, separate deductibles for wind, hail, hurricane, and other weather-related events have become increasingly common.

If the cost of repairs falls below the deductible threshold, the insurer records the claim as closed without payment even though the claim itself may have been reviewed.

Insurance companies also note that some customers withdraw claims, decide not to pursue repairs, or later reopen claims after additional damage is discovered.

A spokesman for USAA told The Wall Street Journal that many no-payment claims involve losses below deductible levels and argued that raw denial statistics fail to capture the full context behind claim outcomes.

Representatives for the major insurers similarly told the Journal that they investigate claims thoroughly and pay all covered losses according to policy terms.

Still, the industry’s explanation does not fully explain the differences between insurers.

The Journal found that some insurance companies continue to pay substantially higher percentages of claims than others. According to Weiss Ratings, MS Farm Bureau Casualty closed only 8% of claims without payment, while Homesite Insurance reported a no-payment rate of just 9%.

The contrast suggests that high denial rates are not necessarily unavoidable.

Rising Profits Add to Consumer Concerns

The issue becomes more controversial when viewed alongside insurer profitability.

Despite growing complaints from policyholders and rising denial rates, many insurance companies have remained profitable. In addition to underwriting income, insurers generate substantial earnings by investing premium dollars collected from customers before claims are paid.

Consumer advocates argue that rising premiums combined with rising no-payment claim rates create the perception that policyholders are paying more while receiving less protection.

That concern is increasingly attracting the attention of policymakers and regulators.

Legal and Regulatory Scrutiny Is Growing

Several legal challenges and regulatory investigations are already underway.

According to reporting by The Wall Street Journal, a national law firm is investigating whether some insurers altered deductible structures and payout calculations in ways that may have reduced customer recoveries.

Separately, California regulators continue to examine aspects of State Farm’s handling of wildfire-related claims.

Consumer attorneys argue that homeowners often do not fully understand changes made to policies until after a loss occurs, when the financial consequences become immediate.

What Homeowners Should Do

Industry experts say consumers should no longer evaluate insurance policies based solely on premium price.

Claim-payment history, customer service records, deductible structures, exclusions, and insurer financial strength are becoming increasingly important factors when selecting coverage.

A policy that appears inexpensive on paper may provide less protection than expected if large deductibles or restrictive claim practices limit payouts after a loss.

For homeowners facing renewal decisions this year, reviewing an insurer’s claim-payment track record may be as important as comparing rates.

The underlying purpose of insurance has always been simple: provide financial protection when something goes wrong.

The growing number of claims that end with no payment is raising a difficult question for millions of Americans: when disaster strikes, will the coverage they purchased actually be there when they need it?

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The first time the New York Knicks reach the NBA Finals in 27 years should be a fan’s dream. For many, it has become one of the most expensive tickets in sports history.

According to data released May 29 by resale platform Vivid Seats, tickets to the Knicks’ three potential home games at Madison Square Garden are now carrying the highest average sold prices ever recorded for NBA Finals games. Game 3 is averaging $4,926, Game 4 is averaging $5,265, and a potential Game 6 is averaging $5,593. Those figures represent actual average transaction prices, not asking prices.

The Knicks earned the moment. New York advanced to its first NBA Finals since 1999 after sweeping the Cleveland Cavaliers in the Eastern Conference Finals. The franchise is now making its ninth NBA Finals appearance and will face the San Antonio Spurs in a rematch of the 1999 championship series.

For New York fans, the significance goes far beyond basketball. The city has not hosted an NBA Finals game since June 1999. An entire generation of Knicks fans has never experienced a Finals game at Madison Square Garden. The result is a surge in demand unlike anything the league has seen before.

The record-setting averages only tell part of the story. According to TickPick, the cheapest available seat for Game 3 at Madison Square Garden climbed to approximately $3,745 on the resale market. Premium courtside locations have been listed for tens of thousands of dollars, with some approaching six figures.

To understand how extraordinary the jump has been, consider where prices stood only weeks earlier. During the Knicks’ playoff series against Boston, average resale prices reached approximately $1,956, already considered among the highest in franchise history. The Finals have more than doubled that benchmark.

Several factors are driving the surge.

The first is simple supply and demand. Madison Square Garden seats roughly 19,000 fans, and the Knicks are guaranteed only a limited number of home games. Every additional fan competing for those seats pushes prices higher.

The second factor is the length of the drought. Knicks fans have waited 27 years for this opportunity. For many lifelong supporters, attending a Finals game is viewed as a once-in-a-generation experience.

The third factor is New York itself. Even during regular seasons, Knicks tickets consistently rank among the most expensive in professional sports. The size of the New York market, combined with the franchise’s global brand recognition, creates a pricing environment unlike almost any other arena in North America.

Industry analysts note that Knicks fans have shown unusual willingness to absorb the increases. Previous resale-market data suggested that an overwhelming majority of buyers at Madison Square Garden were local Knicks supporters rather than neutral-event purchasers or corporate ticket brokers. That level of emotional demand helps keep prices elevated even as costs reach record territory.

The financial impact extends beyond ticket holders.

Madison Square Garden Sports Corp., the publicly traded company that owns the Knicks, has been one of the biggest beneficiaries of the team’s success. The company’s stock has climbed sharply over the past year as investors anticipate increased revenue from playoff games, premium seating, sponsorships, merchandise sales, concessions, and expanded national media exposure.

The Finals run also creates a broader economic boost for New York City. Hotels, restaurants, bars, transportation providers, and nearby businesses stand to benefit from thousands of fans traveling into Manhattan for games and related events.

Recognizing that many loyal fans have been priced out of the market, the Knicks have also distributed hundreds of tickets through the Garden of Dreams Foundation, providing opportunities for underserved New York families to attend games that would otherwise be financially out of reach.

The giveaways represent only a small fraction of available seats, but they offer a reminder that behind the record-setting prices are fans who have waited decades for this moment.

For now, the market is delivering a clear verdict. After 27 years without an NBA Finals appearance, demand for Knicks basketball has reached unprecedented levels.

And with average ticket prices now exceeding $5,500, Madison Square Garden has officially become home to the most expensive NBA Finals tickets ever sold.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

WASHINGTON — Americans are consuming more honey than ever, but U.S. beekeepers are nowhere close to producing enough of it — a widening supply gap now being filled by record imports from countries that, in some cases, American producers say do not even have enough bees to justify the export volumes they report.

The imbalance is becoming one of the clearest examples of how the modern “clean eating” movement is colliding with fragile agricultural supply chains, rising production costs and growing concerns about imported food fraud.

The numbers are stark.

According to the U.S. Department of Agriculture, the United States produced roughly 134 million pounds of honey in 2024, down 4% from the prior year. American consumers, meanwhile, used an estimated 550 million pounds over the same period.

That means nearly three out of every four jars or squeeze bottles of honey consumed in the United States came from overseas.

In 2023, the U.S. imported approximately 429 million pounds of honey, with India, Argentina, Brazil and Vietnam supplying nearly 80% of total imports.

The demand boom itself is easy to explain.

Honey has become one of the signature ingredients of the broader “clean eating” and wellness movement, where consumers increasingly avoid refined sugar, high-fructose corn syrup and artificial sweeteners in favor of products marketed as natural, minimally processed and traceable.

Honey checks nearly every modern food-marketing box: single ingredient, minimally processed, recognizable and associated — fairly or not — with health and wellness.

Restaurants, protein-bar companies, beverage brands and premium grocery chains have steadily increased honey usage over the past decade as consumers became willing to pay more for products positioned as “natural.”

That demand is now running directly into the realities of the American bee industry.

Janel Inouye, co-owner of Magpie Cafe in Sacramento, California, said her restaurant goes through a five-gallon bucket of honey roughly every three weeks for dishes including crispy pork belly and house-made honey lemonade.

She told reporters she is paying roughly 30% more for honey than she was five or six years ago.

“I don’t know that I’ve seen anything that has been a sticker shock the way that we’ve seen honey jump,” Inouye said, adding she would sooner remove dishes from the menu than substitute another sweetener.

The problem for U.S. beekeepers is that even rising retail prices have not translated into industry stability.

The biggest threat remains the varroa mite, a parasitic insect that attaches to honey bees and spreads viruses capable of wiping out entire colonies.

Researchers at Washington State University projected earlier this year that commercial U.S. honey bee colony losses could reach between 60% and 70% in 2025, dramatically above the already devastating 40% to 50% annual losses that have become common in recent years.

Pesticide-resistant mite strains are now widespread across parts of the industry.

At the same time, operating costs for commercial beekeepers have surged.

Large U.S. operators routinely truck hives across multiple states throughout the year, following crop bloom cycles — almonds in California, apples in Washington, blueberries in Maine and dozens of other pollination markets.

That makes fuel prices critically important.

The current Middle East conflict and elevated oil prices — with crude trading roughly between $100 and $106 per barrel — are feeding directly into diesel, shipping and feed costs for commercial bee operations.

“For most markets, the price is still below the actual cost of production,” said Ryan Burris, president of the California State Beekeepers Association.

Tim Hiatt, legislative liaison for the Washington State Beekeepers Association and vice president of the North Dakota Beekeepers Association, was even more blunt.

“For now, we’re just going to bite the bullet and hope the Iran War doesn’t last long so fuel and fertilizer prices go down,” Hiatt said.

Then there is the import controversy — part trade dispute, part quality scandal.

The United States remains the world’s second-largest honey market, and many of its biggest foreign suppliers are already subject to U.S. anti-dumping duties.

Current country-wide rates imposed by the U.S. Department of Commerce include 4.7% on Argentina, 2.31% on Brazil, 2.31% on India and a massive 121.97% duty on Vietnam.

Those tariffs come on top of the broader 10% blanket import tariff imposed during President Donald Trump’s second term.

The duties are intended to protect American producers from artificially cheap foreign honey.

But imports continue flooding in, and American beekeepers increasingly argue the trade data itself does not make sense.

Richard Adee, one of the largest commercial beekeepers in the United States and a former president of the American Honey Producers Association, has publicly questioned how countries like India could physically produce the export volumes they report.

“India doesn’t have anywhere near the capacity — enough bees — to produce 45 million pounds of honey,” Adee said publicly. “It has to come from China.”

That accusation matters because Chinese honey has long faced some of the steepest U.S. trade restrictions in the food sector due to prior allegations involving dumping, illegal antibiotics and pesticide contamination.

American producers argue Chinese honey is frequently rerouted through third countries and relabeled to bypass tariffs and inspections.

The authenticity problem has become so severe that organizers of the 2025 World Beekeeping Awards in Copenhagen canceled the honey competition entirely, citing widespread adulteration concerns.

In many cases, investigators say imported “honey” is diluted with cheaper sweeteners such as rice syrup or corn syrup while still marketed as pure honey.

For consumers, the implications are practical.

A premium jar of traceable, single-origin American honey sold at a specialty grocer may bear little resemblance to inexpensive imported honey sold in bulk squeeze bottles at discount retailers — even though both carry the same label.

The long-term market opportunity, however, remains substantial.

Industry researchers estimate the U.S. honey market was worth roughly $2.21 billion in 2025 and could grow to approximately $3.21 billion by 2035.

And honey itself is only part of the economic story.

When pollination services are included, American beekeepers contribute an estimated $15 billion annually to U.S. agriculture by supporting crops including almonds, apples, blueberries and dozens of other fruits and vegetables.

In practical terms, bees are not merely part of the sweetener business.

They are critical agricultural infrastructure.

Yet at the very moment demand is accelerating, federal support for bee research is shrinking.

The U.S. Department of Agriculture recently announced plans to close the Beltsville Agricultural Research Center in Maryland, home to the Beltsville Bee Research Lab, one of the nation’s most important bee disease and colony-testing facilities.

Commercial beekeepers have long relied on the lab to diagnose unexplained colony collapses and disease outbreaks.

Its closure would remove one of the few major federal support systems the industry still has during a period of historically severe losses.

For investors, food manufacturers and specialty grocery chains, the broader trend is becoming increasingly clear:

American demand for honey is rising rapidly. Domestic production is stagnating or falling. Imports remain politically contentious and increasingly suspect on quality grounds.

That combination should, in theory, benefit premium American honey producers and traceable domestic brands.

But whether U.S. beekeepers can capitalize on the opportunity depends on whether the industry can survive long enough to meet it.

Right now, consumers want more honey than America can produce.

The bees are struggling.

And the gap is increasingly being filled by foreign suppliers the U.S. government itself has already accused of unfair trade practices.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

MOSCOW — Four years after the United States, Europe and Britain moved to cripple Russia’s commercial aviation sector following the invasion of Ukraine, the country’s airlines are still flying — and in many cases carrying passenger volumes approaching prewar levels — thanks to a sprawling shadow supply network moving Boeing and Airbus parts through intermediaries across China, India, Turkey, the United Arab Emirates and Central Asia.

What Western sanctions were supposed to do was straightforward: starve Russian carriers of spare parts, maintenance support and aircraft servicing until large portions of the fleet became unusable.

That has not happened.

Instead, a sophisticated gray-market ecosystem involving brokers, shell companies, repair shops and transit hubs has emerged to keep airlines such as Aeroflot, S7 Airlines and Ural Airlines operating despite formal bans on supplying Western aircraft parts to Russia.

The scale is enormous.

According to customs records compiled by Trade Data Monitor, China alone shipped at least $961 million worth of aircraft parts into Russia between March 2022 and February 2026, more than four times the level recorded before the war. Trade records also show recurring transit activity through India, Turkey, the UAE, Kazakhstan and Kyrgyzstan, with many shipments routed through multiple jurisdictions before reaching Russian operators.

Aviation experts say the most remarkable part of the trade is not small components — it is the movement of entire jet engines.

Oleksandr Laneckij, chief executive of Lithuania-based aviation consultancy Friendly Avia Support, said the underground flow of engines into Russia “remains widespread,” estimating that as many as 50 complete engines per year are reaching Russian carriers despite sanctions.

That figure is striking because modern commercial aircraft engines are among the most expensive and tightly tracked components in global aviation.

One transaction trail illustrates how the system works.

In December 2025, a Florida-based aviation supplier called LogAir LLC sold an older CFM56-5A engine — commonly used on Airbus A320 aircraft — to an Indian firm named Chandsara for approximately $3.6 million.

Roughly two weeks later, another Indian company, Shreegee Pvt. Ltd., shipped the same engine onward to Russian airline S7 for about $5.75 million.

The transaction drew attention because the U.S. Treasury Department had already sanctioned a related company, Shreegee Impex Pvt. Ltd., in 2024 for allegedly supplying Russia with hundreds of dual-use items, including aviation components. The companies reportedly shared addresses, logos and directors.

The broader pattern appears deliberate and highly structured.

Aircraft parts often leave legitimate American or European distributors with paperwork showing apparently lawful destinations in third countries. Brokers and intermediaries then reroute the parts into Russia through shell entities created specifically for single transactions.

When Russian repair facilities cannot service components domestically, the parts are sometimes exported again under foreign ownership, repaired abroad, then quietly reintroduced into Russia through what aviation specialists describe as “one-day companies” established solely to obscure the chain of custody.

Both Boeing and Airbus publicly insist they are not participating in the trade.

Boeing says it halted parts, maintenance and technical support to Russian customers in early 2022 and continues complying with U.S. sanctions. Airbus has similarly told European investigators there is “no legal method” for aircraft, parts or technical documentation to be exported into Russia.

But both companies also acknowledge a major limitation: once parts enter the global aftermarket — the enormous web of brokers, repair stations, leasing firms and resellers operating worldwide — manufacturers have limited visibility into where components ultimately end up.

The sanctions themselves were expected to force Russian airlines to begin grounding Western-made aircraft.

Instead, the number of operational Airbus and Boeing aircraft inside Russia has barely declined since 2023, while domestic seat capacity has recovered close to 2021 levels, supported by strong internal travel demand and the lack of alternative transportation across Russia’s vast geography.

The growing concern now is safety.

Russian state agencies recorded 11 engine failures on civil aircraft between December 1, 2024 and January 20, 2025, more than double the figure reported during the same period a year earlier. Independent aviation monitors estimate Russian aviation incidents are rising at roughly 25% annually.

One widely discussed case involved a Ural Airlines Airbus A321 returning from Egypt in early 2025 after suffering a left-engine failure shortly after takeoff. The aircraft landed safely, but reports indicated the plane remained grounded because sanctions prevented access to a fully certified replacement engine.

The Kremlin has increasingly tried to frame the sanctions issue as a passenger-safety matter rather than simply an economic dispute.

At the International Civil Aviation Organization (ICAO) assembly in Montreal in 2025, Russian officials argued Western restrictions on spare parts were “discriminatory and coercive” and endangered civilian aviation safety.

Western governments rejected that argument, pointing out Russia itself seized roughly 500 Western-leased aircraft valued at approximately €10 billion after foreign leasing firms terminated contracts in 2022 following the invasion.

Russia is simultaneously trying to reduce dependence on Western aviation entirely.

The government has committed roughly $14.5 billion toward expanding domestic aircraft production through the end of the decade, aiming to raise the share of Russian-built aircraft to 81% of the national fleet by 2030.

Progress, however, has been uneven.

The Russian-built version of the MC-21 narrowbody jet only recently completed key flight testing, while production timelines for the Sukhoi Superjet and other domestic programs have repeatedly slipped because of missing Western components and ongoing supply-chain bottlenecks.

For now, the shadow supply chain remains the backbone of Russian commercial aviation.

But aviation experts warn the workaround becomes riskier with time.

Aircraft engines eventually wear out. Avionics drift outside certification standards. Maintenance histories become increasingly unreliable when parts pass through opaque gray-market channels.

Each additional year of cannibalized fleets, uncertified repairs and undocumented components raises the probability of a serious aviation accident.

And if a major crash were linked to sanctions evasion or uncertified parts, it could trigger an even harsher new round of restrictions from Western governments already struggling to contain the network.

The broader lesson for global sanctions policy is increasingly uncomfortable for Western policymakers.

Russia’s aviation industry was once viewed as one of the easiest sectors to isolate — highly dependent on Western manufacturers, globally integrated and impossible to replace quickly.

Yet four years later, the planes are still flying, the parts are still moving, and the underground network supplying them appears more sophisticated than ever.

Europe — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

More job seekers are now finding themselves interviewed not by a recruiter, but by artificial intelligence itself, as employers overwhelmed by AI-generated job applications increasingly deploy chatbots and automated systems to screen candidates.

The trend, highlighted Thursday in a new Associated Press report, reflects a rapidly escalating cycle where artificial intelligence is now reshaping both sides of the hiring process at once.

As generative AI tools make it easy for applicants to instantly produce polished résumés and mass-apply to hundreds of positions online, recruiters say the volume of applications has grown beyond what human hiring teams can realistically process.

The response has been automation.

Companies are increasingly using AI-driven interview systems during early hiring rounds, often through automated phone screenings, text-based conversations, or video interviews conducted by digital avatars and chatbot systems.

According to hiring platform Greenhouse, approximately 63% of U.S. job seekers have now experienced some form of AI-led interview process — a figure that has jumped sharply in recent months.

Sharawn Tipton, Greenhouse’s chief people officer, said companies are increasingly using AI interviewers to “filter the flood” of applicants entering the hiring system.

For candidates, the experience changes the rules of interviewing entirely.

Rather than speaking conversationally with a recruiter, applicants are effectively feeding information into a software system designed to score answers based on clarity, keywords, metrics, and structure.

Career advisers now increasingly tell job seekers to focus on highly specific, measurable responses during interviews because AI systems often struggle to interpret tone, nuance, humor, or body language the way human interviewers can.

Practicing answers out loud has also become more important, since many systems rely heavily on speech recognition and transcription analysis.

Not all candidates are embracing the shift.

Surveys cited in the report found that nearly four in ten applicants have withdrawn from hiring processes that required AI-led interviews, with some candidates expressing discomfort speaking to software rather than a human being.

Employers, however, argue the technology dramatically speeds hiring and allows companies to review every application rather than only a small subset.

Some firms report reducing hiring timelines by as much as 60% through AI-assisted screening systems.

The rapid adoption also raises broader concerns surrounding fairness, transparency, and accountability.

Many AI hiring systems operate as opaque “black boxes,” making it difficult for applicants — or even employers themselves — to fully understand how candidates are being scored or filtered.

The result is a labor market increasingly shaped by artificial intelligence at every stage: AI helps write the résumé, AI screens the application, and AI conducts the first interview before a human recruiter ever joins the process.

The human conversation, once the entry point to getting hired, is increasingly moving deeper into the hiring funnel.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The numbers tell the story of one of the fastest consumer-product shifts in the American market.

The United States imported roughly $1.7 billion worth of South Korean cosmetics in 2024, a 54% increase from the year before, according to U.S. trade data. In the process, South Korea overtook France to become America’s largest foreign supplier of skincare and beauty products — an extraordinary development for an industry that, less than a decade ago, many U.S. retailers still viewed as niche.

Korean beauty, once associated primarily with K-pop fans and internet skincare forums, has moved firmly into the mainstream American consumer economy. Products once sold only through specialty Asian beauty retailers are now stocked at Sephora, Ulta, Costco, CVS, Target, and Amazon, while brands built around snail mucin, rice extracts, fermented ingredients, and Centella asiatica have become billion-dollar global businesses.

But the rise of K-beauty is not simply a social-media phenomenon.

The deeper story is manufacturing discipline, product consistency, and a fundamentally different philosophy about skincare itself.

The Real Competitive Advantage: Consistency

The core reason Korean beauty products have gained such traction with consumers is not celebrity marketing. It is trust.

South Korean cosmetic manufacturers operate under some of the world’s most stringent production and safety standards, built around tightly enforced Good Manufacturing Practices, or GMP protocols. These rules govern every stage of production — ingredient sourcing, contamination controls, equipment sanitation, packaging integrity, formulation consistency, employee training, and product testing.

For consumers, the practical result is simple: products behave predictably.

If a Korean serum says it contains a certain active ingredient concentration, consumers increasingly believe it actually does. Shelf-life labeling tends to be accurate. Formulas remain stable batch after batch. Products that worked six months ago generally work the same way today.

That consistency matters enormously in skincare because consumers are applying these products directly onto sensitive skin barriers every day.

South Korea also maintains an unusually expansive list of prohibited cosmetic ingredients — reportedly banning roughly 1,000 substances including steroids, antibiotics, radioactive compounds, and other potentially harmful additives. Regulators are now implementing additional nationwide cosmetic safety systems tied to digital labeling and traceability requirements through QR-code disclosure standards.

The structure resembles what made South Korea globally dominant in semiconductors, displays, batteries, and advanced manufacturing more broadly: high-volume industrial precision combined with rapid product iteration.

In skincare, that manufacturing culture became a competitive advantage.

Why Korean Beauty Feels Different

The philosophy behind Korean skincare also differs sharply from much of the traditional Western cosmetics industry.

American and European skincare has historically leaned toward what dermatologists sometimes describe as a “correction” model: identify a problem — acne, wrinkles, pigmentation, dryness — then attack it aggressively with concentrated active ingredients.

Korean skincare tends to follow a “maintenance and barrier support” model instead.

Rather than relying heavily on a single strong active ingredient, Korean routines often use multiple gentler products layered sequentially to hydrate, calm inflammation, support the skin barrier, and maintain long-term skin health.

That layering approach became one of the defining signatures of K-beauty.

Products are generally applied from thinnest consistency to thickest — toner, essence, serum, ampoule, moisturizer — allowing lower concentrations of active ingredients to work together while minimizing irritation.

The strategy appeals especially to younger consumers increasingly focused on prevention rather than correction, and to customers with sensitive skin who find stronger Western formulations difficult to tolerate.

The Ingredient Strategy: Science Plus Traditional Medicine

Korean beauty’s biggest commercial breakthrough may have been turning ingredients once viewed as unconventional into mainstream global skincare categories.

Snail mucin is the clearest example.

The ingredient, derived from snail secretion filtrate, became one of the defining viral skincare trends of the past several years. What made it commercially powerful was not novelty alone, but the scientific framing around hydration, barrier repair, peptides, hyaluronic acid content, and anti-inflammatory properties.

Clinical studies cited by major medical institutions including the Mayo Clinic have shown measurable improvements in skin hydration, luminosity, and fine lines following extended use.

Korea did not invent snail mucin itself. Chilean farmers reportedly first noticed skin-softening effects while handling snails commercially.

What Korean companies did was industrialize and standardize it.

They developed large-scale filtration systems, purification methods, cruelty-conscious collection processes, clinical testing structures, and global product branding around the ingredient — effectively transforming a niche biological byproduct into a mainstream skincare category.

The same process happened with Centella asiatica, also known as cica, a medicinal plant long used in traditional Asian medicine.

Korean brands refined it into scientifically marketed skincare centered around anti-inflammatory properties, redness reduction, barrier repair, and calming effects for sensitive skin. Today, cica-based creams, serums, masks, and moisturizers occupy entire retail sections across the U.S.

This pattern repeats throughout Korean beauty: identify a promising ingredient, clinically test it, improve formulation stability, standardize manufacturing, then scale globally.

Why the Industry Is Still Growing

The K-beauty boom is occurring at the same time many traditional Western beauty conglomerates are struggling with slower growth and increasingly fragmented consumer loyalty.

Part of Korean beauty’s success comes from speed.

Korean companies release products dramatically faster than many Western competitors, adapting quickly to new skincare concerns, viral consumer trends, environmental stressors, or ingredient innovations. Whether the issue is pollution-related aging, “maskne,” microbiome care, glass-skin aesthetics, or minimalist skincare, Korean brands tend to commercialize trends faster than much larger rivals.

Social media accelerated the process.

TikTok, YouTube, Reddit, and Amazon reviews effectively replaced traditional beauty advertising for many younger consumers. Korean products built enormous momentum through user testimonials, before-and-after videos, ingredient explainers, and influencer routines emphasizing skin health rather than glamour marketing.

The products also often entered the market at lower price points than prestige Western skincare, creating unusually strong perceived value.

The Tariff Risk

The biggest near-term threat to the industry may now come from trade policy rather than consumer demand.

The United States recently ended South Korea’s tariff-free cosmetics treatment and imposed a 15% import tariff on many beauty products entering the country. Early export data already suggests the industry may be feeling pressure, with Korean beauty shipments to the U.S. slowing sharply in recent months.

The tariff creates a particular problem for smaller independent Korean brands that rely heavily on direct-to-consumer online sales and thin margins. Large multinational players may absorb some cost increases or eventually localize portions of production, but smaller companies face a much harder adjustment.

Still, industry forecasts remain bullish.

The U.S. K-beauty market is projected to roughly double from approximately $27.5 billion in 2024 to more than $55 billion by 2032.

That projection ultimately rests on one thing: consumer trust.

American consumers increasingly view Korean skincare not as a trend, but as a system — one built around standardized manufacturing, ingredient transparency, gentler formulations, and visible long-term results.

And in the beauty industry, trust is often the hardest thing to manufacture.

Asia — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Waymo is trying to turn autonomous driving from an expensive technology experiment into a scalable transportation business.

On May 28, 2026, the Alphabet-owned company announced it has begun offering rides to select customers in a new all-electric robotaxi developed with Chinese automaker Zeekr, a vehicle designed specifically to lower operating costs, increase durability, and accelerate the expansion of driverless ride-hailing across major cities.

The new vehicle, called the Ojai, is initially rolling out in Los Angeles, Phoenix, and San Francisco, where invited users are receiving free rides while Waymo gathers data and customer feedback ahead of broader commercial deployment.

The launch marks an important shift in Waymo’s strategy.

For years, Waymo focused primarily on proving that fully autonomous driving could work safely at scale. The company now faces a different challenge: proving the economics can work too.

The Ojai is built around that goal.

A Robotaxi Designed for Scale, Not Luxury

The vehicle itself is based on the Zeekr RT, a purpose-built autonomous platform developed through a partnership between Waymo and Zeekr parent company Geely, first announced in 2021.

But Waymo has intentionally removed nearly all visible Zeekr branding from the final consumer experience.

The vehicle now carries Waymo-specific badging throughout, including customized wheel center caps, while the car itself has been renamed “Ojai” — pronounced “oh-hi” — after the California mountain town known for wellness retreats and arts culture.

The naming strategy is not accidental.

When passengers enter the vehicle, the car greets them with an “Oh hi,” turning the town’s name into both a branding mechanism and user interaction cue.

The deeper branding decision, however, reflects larger geopolitical and consumer realities.

Waymo appears to have concluded that many American passengers may feel more comfortable riding in a vehicle associated directly with Waymo rather than a lesser-known Chinese automaker — particularly as political tensions surrounding Chinese technology and manufacturing continue influencing consumer perceptions in the United States.

The partnership remains central technologically.

But consumer-facing identity now belongs almost entirely to Waymo.

Why This Vehicle Matters Financially

The Ojai is less important as a product than as a cost structure.

Waymo’s biggest challenge has never been demonstrating autonomous capability. The company is widely viewed as the clear leader in fully driverless commercial deployment in the United States.

The real challenge is economics.

Waymo’s vehicles rely on expensive hardware stacks that include lidar systems, radar arrays, high-definition mapping infrastructure, redundant computing systems, and advanced sensor cleaning technology. Each Ojai includes 13 cameras, six radars, and four lidar units, alongside heaters, sprayers, and wipers specifically designed to maintain sensor performance in varying weather conditions.

That approach has produced some of the industry’s strongest autonomous-driving performance.

It has also made Waymo’s vehicles extremely expensive.

The Ojai is designed to reduce that burden.

Unlike retrofitting consumer cars for autonomous use, the Zeekr platform was engineered specifically around robotaxi operations from the beginning. The vehicle is larger, more durable, optimized for high-mileage ride-hailing use, and intended to lower maintenance and operational costs over time.

In other words, Waymo is finally moving from research-grade hardware toward fleet-grade infrastructure.

That transition is essential if the company hopes to achieve profitability.

The Race to Scale

Waymo’s ambitions are rapidly expanding.

Co-CEO Tekedra Mawakana recently said the company expects to reach approximately 1 million rides per week by the end of 2026.

That would represent an enormous increase from current operations.

As of April, Waymo was completing more than 250,000 paid rides weekly, while total paid rides last year exceeded 14 million. The company is now preparing aggressive geographic expansion into cities including Dallas, Denver, Detroit, Houston, Las Vegas, Miami, Nashville, San Diego, Seattle, Washington, D.C., and London.

Scaling to that level requires far more than software.

It requires manufacturing.

Waymo and production partner Magna are expanding vehicle production capacity at an Arizona facility expected to more than double output, with plans to produce more than 2,000 autonomous vehicles there by the end of 2026 and eventually tens of thousands annually.

That is the point where autonomous driving begins transitioning from a technology showcase into an actual transportation network business.

The Tesla Problem

The rollout also intensifies the industry’s most important competitive debate: expensive sensor-heavy autonomy versus lower-cost camera-based systems.

Waymo’s approach prioritizes redundancy and precision through lidar and radar.

Tesla, by contrast, continues pursuing a largely camera-only strategy built around neural-network vision systems. Tesla executives argue that eliminating expensive lidar dramatically lowers costs and makes scaling faster and economically simpler.

Waymo still maintains a major lead in actual fully driverless deployment.

Tesla’s current ride-hailing operations still include human safety oversight in many situations, while Waymo already operates commercial fully autonomous rides without human drivers in multiple cities.

But the economics question remains unresolved.

If Tesla eventually achieves comparable autonomy performance at materially lower hardware costs, it could pressure Waymo’s long-term margins heavily.

If Tesla’s lower-cost approach proves less reliable, Waymo’s more expensive infrastructure may ultimately look justified.

Right now, the market still does not know which model wins economically at global scale.

Why Cities Matter More Than Technology Now

The next major challenge may no longer be technical.

It may be political and urban.

Waymo’s expansion has already triggered pushback in several cities, particularly San Francisco, where residents and regulators have raised concerns about traffic disruptions, emergency-response interference, operational glitches, and the broader social impact of replacing human drivers.

As autonomous fleets grow, cities will increasingly confront questions surrounding labor displacement, curb access, congestion management, data privacy, insurance liability, and municipal regulation.

The technology race is gradually becoming a governance race.

What Waymo Is Really Betting On

At its core, the Ojai represents a simple but critical thesis:

Autonomous driving will only become transformative if it becomes affordable enough to operate at massive scale.

Waymo has already proven many consumers are willing to ride in driverless vehicles.

Now it needs to prove the business itself can sustain itself financially without indefinitely relying on Alphabet’s balance sheet.

The Ojai is designed to close that gap — a cheaper, roomier, purpose-built autonomous vehicle intended not merely to demonstrate technology, but to make robotaxis economically viable as a mainstream transportation network.

If it works, the economics of urban transportation may begin changing much faster.

If it fails, autonomous driving risks remaining a technologically impressive business that never fully scales commercially.

Silicon Valley — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

New York City Mayor Zohran Mamdani on Thursday unveiled a new Commission on Government Efficiency — or “COGE” — in a move that immediately drew comparisons to President Donald Trump’s federally backed DOGE initiative championed alongside Elon Musk, highlighting how the politics of government “efficiency” are rapidly crossing ideological lines.

The commission, announced May 28 by City Hall, will formally operate as a Charter Revision Commission empowered to review New York City’s governing structure, propose reforms to city operations, and potentially place changes directly before voters on the November ballot.

Mamdani framed the initiative as an effort to rebuild confidence in local government by improving delivery of public services and reducing bureaucratic inefficiency.

“Restoring faith in government starts with proving government can actually deliver,” the mayor said in Thursday’s announcement, describing the effort as a push to make city government operate “faster, smarter and more effectively for working people.”

The branding is politically striking.

The acronym “COGE” is an unmistakable nod to the federal Department of Government Efficiency, or DOGE, which Trump and Musk popularized nationally as part of a broader anti-bureaucracy and cost-cutting campaign aimed at shrinking federal administrative structures.

That a progressive mayor closely associated with democratic socialist politics is now embracing similar “government efficiency” language underscores how fiscal pressure and public frustration with bureaucracy are reshaping political messaging well beyond conservative circles.

But despite the branding overlap, the structure and goals differ significantly from the federal model.

A Charter Fight Disguised as an Efficiency Push

Unlike DOGE at the federal level, COGE is not primarily a cost-cutting office.

It is a formal charter review mechanism with the authority to recommend structural changes to how New York City government operates. The commission will conduct hearings across all five boroughs, gather public testimony, and draft ballot proposals that could reshape procurement systems, permitting processes, agency authority, budgeting procedures, and administrative operations.

The commission will be chaired by Patrick Gaspard, a longtime Democratic strategist and former executive director of the Democratic National Committee who also served as U.S. ambassador to South Africa under President Obama.

Mamdani additionally proposed veteran city official Ann Cheng as executive director.

The first public hearing is scheduled for June 9.

According to City Hall, the commission’s review will focus heavily on reducing bureaucratic bottlenecks that delay housing, infrastructure, and service delivery projects while modernizing city operations and improving budget efficiency.

That language matters particularly to New York’s business and real-estate sectors, where developers, contractors, landlords, and small-business owners have long complained about permitting delays, fragmented agency oversight, procurement complexity, and slow approval timelines that raise costs across nearly every part of the local economy.

If COGE meaningfully streamlines approvals or procurement, it could materially affect the cost and speed of doing business in the city.

The Fiscal Pressure Behind The Politics

The deeper reason behind the commission may be financial rather than ideological.

Mamdani’s announcement arrives only weeks after City Hall finalized a contentious $124.7 billion budget that relied heavily on agency savings and internal cost reductions to avoid broader tax increases or major reserve withdrawals.

The administration had already directed agencies to identify spending cuts through “chief savings officer” initiatives aimed at trimming operational costs over multiple fiscal years. Those savings reportedly came through reduced overtime, renegotiated outside contracts, software modernization, office consolidation, and reductions in underutilized city property holdings.

But New York’s long-term fiscal pressure remains severe.

The city comptroller’s office recently warned that projected spending growth is continuing to outpace expected revenue growth over the coming years. Current forecasts show billions of dollars in additional spending pressure annually through the end of the decade, driven by labor costs, social services, housing demands, infrastructure obligations, migrant-related expenditures, and broader inflationary pressures affecting municipal operations.

That backdrop is what makes the “efficiency” framing politically important.

For Mamdani, COGE allows the administration to present reform and modernization as proactive governance rather than austerity. For critics, however, the concern is whether “efficiency” eventually becomes a softer political label for service reductions, staffing constraints, or budget tightening.

Why The DOGE Comparison Matters

The symbolism surrounding the name may ultimately carry almost as much political significance as the commission itself.

For years, efficiency rhetoric was largely associated with center-right politics emphasizing deregulation, privatization, and shrinking government structures. Progressive administrations generally focused more heavily on expanding services, increasing investment, and enlarging public-sector capacity.

That dynamic is beginning to shift nationally.

Persistent inflation, rising deficits, high borrowing costs, and voter frustration over government responsiveness are forcing even progressive administrations to adopt more business-oriented operational language focused on speed, accountability, and measurable outcomes.

Mamdani’s use of a DOGE-style branding framework reflects that shift directly.

Rather than rejecting efficiency rhetoric as inherently conservative, the mayor is attempting to redefine it around service delivery, permitting reform, affordability, and operational modernization.

In effect, both sides of the political spectrum are now competing to claim ownership over the idea that government should function more effectively.

The disagreement increasingly centers not on whether efficiency matters — but on what efficiency should actually mean.

What Businesses Are Watching

For New York’s private sector, the outcome matters less politically than operationally.

Developers are watching whether permitting timelines shorten.

Small businesses are watching procurement and licensing reforms.

Contractors are watching agency modernization.

Technology firms are watching software and systems upgrades.

Labor groups are watching whether workforce restructuring becomes part of the conversation.

And taxpayers are watching whether the city can slow spending growth without visibly reducing services.

Those questions will shape how COGE is ultimately judged far more than its branding.

For now, Mamdani has positioned himself around one of the most politically potent words in modern governance — efficiency — while simultaneously attempting to redefine what that word means inside a progressive administration.

Whether voters view the effort as modernization, political theater, or quiet austerity may ultimately determine how much power the commission gains after November.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The 2026 FIFA World Cup was supposed to deliver a historic tourism boom across North America — a monthlong economic surge projected by FIFA and host committees to generate roughly $40.9 billion in economic activity while flooding U.S. host cities with international visitors, packed hotels, sold-out flights, and overflowing restaurants.

Instead, less than three weeks before kickoff, parts of the economic story are beginning to fracture.

What is emerging is not one problem but two separate demand shocks hitting simultaneously: weakening international tourism demand tied to inflation, visa restrictions, and political uncertainty, alongside a growing wave of airline disruptions and travel anxiety connected to the Ebola outbreak in Central Africa.

Individually, each issue might have been manageable. Together, they are beginning to threaten one of the core assumptions behind the tournament’s financial projections: that foreign visitors would arrive at massive scale and spend aggressively enough to offset softening U.S. consumer demand.

The first warning signs are already visible in hospitality data.

The American Hotel & Lodging Association reported May 28 that roughly 80% of hoteliers across the 11 U.S. host markets say bookings are tracking materially below initial expectations. That is a remarkable figure given that the World Cup has long been marketed as one of the largest tourism events on earth.

The weakness is not uniform. Premium inventory around major matches — especially the July 19 final near MetLife Stadium in New Jersey — is still commanding extremely elevated pricing, in some cases roughly triple normal summer rates. But pricing power alone does not equal demand strength.

The deeper issue is occupancy.

Group-stage cities that expected weeklong tourism surges are instead seeing meaningful hotel availability remain open deep into late May at rates far closer to a normal summer travel season than the massive compression expected for a global mega-event. Industry analysts say many hotels built pricing models around a demand spike that has not fully materialized.

The causes are broader than sports.

International tourism into the United States has been weakening for months amid higher airfare costs, global economic uncertainty, stronger border restrictions, currency pressures, and growing political friction surrounding travel policies under the Trump administration. Some hospitality analysts have begun referring to the slowdown as a “Trump slump” in inbound travel — particularly from parts of Europe, Latin America, and Africa where visa approvals and travel uncertainty have become increasingly politicized.

That weakening demand was already creating vulnerability.

Then came the airline problem.

The World Health Organization’s emergency declarations tied to the Ebola outbreak in the Democratic Republic of Congo and Uganda triggered a chain reaction across global aviation networks. Uganda Airlines suspended flights to and from Kinshasa effective May 23, while Ethiopian Airlines and other regional carriers began adjusting schedules and implementing additional health-related restrictions.

At the same time, the United States imposed strict travel bans barring entry to foreign nationals who had recently been present in Congo, Uganda, or South Sudan.

From a public-health standpoint, the measures are understandable. Ebola remains a highly dangerous disease.

But from an airline economics standpoint, the consequences extend far beyond the directly affected countries.

The global airline industry operates on network psychology as much as epidemiology. Once travel restrictions begin spreading across headlines, demand often weakens far outside the outbreak zone itself. Airlines then respond by trimming routes, consolidating schedules, reducing frequencies, or shifting aircraft to stronger-performing markets.

That secondary reaction matters enormously for the World Cup because the tournament’s economic model depends heavily on long-haul international arrivals.

FIFA projections estimate roughly 1.2 million foreign visitors will attend matches across North America, with average stays approaching 12 days and spending exceeding $400 daily. Much of that money was expected to flow into hotels, restaurants, local transportation, nightlife, retail, and short-term rental platforms.

But those assumptions rely on stable international flight capacity and consumer confidence.

The airline industry is already operating under pressure from elevated fuel prices tied to Middle East instability and rising insurance costs connected to global geopolitical risk. Additional route disruptions tied to outbreak fears or regulatory restrictions increase operational complexity at precisely the wrong moment.

The vulnerability is especially acute in gateway markets like New York, Los Angeles, Miami, Dallas, and Atlanta, where foreign tourism was expected to provide the bulk of incremental economic activity during the tournament.

Around $4.3 billion in direct tourism expenditure is forecast for the World Cup, with more than 80% concentrated in hospitality-related sectors — exactly the industries now facing both weaker-than-expected bookings and growing uncertainty around international air traffic.

The timing could hardly be worse.

Host cities and governments have collectively invested billions into stadium modernization, transportation upgrades, security infrastructure, and tourism preparation. Airbnb hosts across the 16 North American host cities are projected to generate more than $2.6 billion in rental revenue during the tournament.

Much of that projected income now depends on whether international travel confidence stabilizes quickly.

Public-health experts continue emphasizing that Ebola risk to World Cup attendees remains extremely low. The virus spreads through direct contact with bodily fluids and is not airborne. There is no evidence of widespread transmission risk tied to ordinary tourism activity.

But economic damage rarely waits for scientific nuance.

In travel markets, perception often moves faster than facts. Once flight cancellations begin, travelers reconsider plans. Reduced bookings then pressure airlines further, which can produce additional schedule cuts and weaker demand in a self-reinforcing cycle.

That feedback loop is now becoming visible just as the world’s largest sporting event approaches.

The World Cup’s economic promise always depended on converting a global audience into real-world tourism spending. What host cities are discovering now is that mega-events remain deeply exposed to forces far beyond sports itself: geopolitics, public-health fears, visa policy, airline economics, and consumer psychology.

And in a fragile global economy already showing signs of softer discretionary spending, even modest disruptions can quickly reshape the financial outcome of an event expected to redefine North American tourism.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

Walmart has begun removing self-checkout lanes from select stores and restoring traditional cashier-operated registers, a shift the company says is aimed at improving customer experience while also reducing theft losses that have increasingly pressured retailers across the industry.

The rollback reflects a growing reassessment of a technology once promoted as the future of shopping.

At a Walmart Supercenter on South Christopher Columbus Boulevard in Philadelphia, the company removed self-checkout lanes earlier this year and replaced them with staffed checkout stations, according to company officials cited by The Philadelphia Inquirer. Limited kiosks remain available for Spark delivery drivers handling online orders, but the broader return to cashier-led checkout marks one of the clearest reversals yet by a major national retailer.

Walmart said the decision was influenced heavily by customer feedback and store-level performance reviews.

The financial motivation is straightforward.

Retailers across the industry have struggled with higher shrink rates — the industry term for inventory losses caused by theft, fraud, and scanning mistakes — tied to self-checkout systems. Multiple retail studies have found stores using self-checkout experience loss rates significantly above traditional cashier-operated lanes.

Some industry surveys have also found that a meaningful percentage of shoppers admit to intentionally failing to scan items during self-checkout transactions.

For retailers, the labor savings generated by automation can quickly disappear if merchandise consistently leaves stores unpaid.

But the backlash was never purely financial.

Customers have increasingly complained that self-checkout systems transferred work traditionally handled by paid employees onto shoppers themselves, often while still forcing customers to navigate confusing interfaces, scanning errors, machine malfunctions, and employee monitoring systems.

The frustration became especially visible during inflationary periods, when consumers already feeling financially stretched questioned why they were effectively performing part of the retailer’s labor process without any price reduction in return.

Retail analysts say many shoppers now associate self-checkout with inconvenience rather than speed.

Academic research appears to support the trend.

A study published in the Journal of Business Research by researchers at Drexel University found that shoppers interacting with human cashiers reported stronger loyalty and a greater likelihood of returning to stores compared with customers using self-checkout systems.

Researchers concluded that customers often perceive cashier-assisted checkout as involving less effort and delivering a more valued shopping experience.

Walmart is not alone in reconsidering the technology.

Dollar General removed self-checkout systems from approximately 12,000 stores in 2024, while British grocery chain Booths rolled back self-checkout across nearly all locations after executives described the machines as slow, impersonal, and unpopular with customers.

Even within Walmart’s own ecosystem, the company’s Sam’s Club division has been shifting toward AI-powered “scan-and-go” systems rather than relying heavily on traditional self-checkout kiosks.

Lawmakers have also started paying attention.

Several states including California, Connecticut, Massachusetts, New York, Ohio, Rhode Island, and Washington are now considering regulations governing self-checkout usage, including potential minimum staffing requirements tied to automated checkout lanes.

The rollback comes as consumers continue navigating elevated food and household prices.

The U.S. Department of Agriculture said grocery prices in March remained roughly 2.7% higher than a year earlier, with further increases projected through the remainder of 2026. Analysts say financial strain may have increased both customer frustration and theft pressure surrounding unattended checkout systems.

What makes the shift notable is that, at least temporarily, retailer and customer incentives appear aligned.

Stores reduce inventory losses and operational headaches while many shoppers regain the human service experience they increasingly say they prefer.

For a technology once marketed as pure efficiency, the industry’s reassessment now suggests that the cheapest-looking checkout option may not have been the most effective — or the most popular — after all.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Russia is returning to the yuan bond market days after President Vladimir Putin concluded high-level talks in Beijing, deepening Moscow’s financial pivot toward China as Western sanctions continue cutting the Kremlin off from dollar and euro funding markets.

Russia’s Finance Ministry said on May 28 it will issue 10-year yuan-denominated sovereign bonds worth 10 billion yuan, or roughly $1.5 billion, carrying a coupon of 7.65%. The deal marks Moscow’s second major sovereign yuan issuance and comes immediately after Putin’s May 19–20 state visit to China, where the Russian president and Chinese leader Xi Jinping signed more than 40 bilateral agreements tied to trade, energy, finance, logistics, and industrial cooperation.

The sequencing is not accidental.

The bond sale is part of a broader geopolitical and financial restructuring underway between Moscow and Beijing — one designed to reduce dependence on the U.S. dollar system while binding Russia’s economy more tightly to China’s financial infrastructure.

For Moscow, the attraction is increasingly practical rather than ideological.

Russia’s domestic borrowing costs have surged as war spending, sanctions pressure, and inflation strain the country’s fiscal position. Comparable ruble-denominated government debt currently yields between 13.5% and 15%, while the yuan bonds issued in December 2025 priced closer to 6%–7%.

That gap matters enormously.

By borrowing in yuan instead of rubles, the Russian government effectively cuts its financing costs nearly in half at a moment when budget pressure is intensifying. Russia’s fiscal deficit widened sharply during the first quarter of 2026, reaching roughly 2.5% of GDP versus a full-year target near 1.6%, according to government data.

The deeper story, however, is about what Russia is doing with the yuan already accumulating inside its financial system.

Russian exporters — especially energy giants like Rosneft, Gazprom, and Lukoil — increasingly sell oil, gas, coal, and raw materials to China in yuan rather than dollars. Those payments then accumulate across Russian banks and corporate accounts because sanctions and capital restrictions make redeploying the currency internationally far more difficult.

That has created a structural pool of idle yuan liquidity inside Russia.

The government’s yuan bond market effectively absorbs those balances and redirects them into domestic state financing. Instead of exporters holding yuan deposits earning minimal returns, Moscow converts that money into sovereign debt issuance and channels it back into government spending.

Finance Minister Anton Siluanov acknowledged after the first yuan bond issuance in December that demand exceeded official expectations, underscoring how much Chinese currency is now circulating inside the Russian economy.

The arrangement reveals how sanctions are reshaping global finance in practice.

Russia has largely lost access to Western institutional capital markets, global dollar-clearing systems, and much of the international investor base that previously financed its sovereign debt. The yuan market offers one of the few remaining large-scale alternatives available to the Kremlin.

But the shift also exposes a growing asymmetry inside the Russia-China relationship.

China controls the currency, the clearing system, and much of the underlying financial infrastructure. Russia supplies discounted energy, commodities, and geopolitical alignment in return for financing access and trade continuity.

That imbalance became increasingly visible during Putin’s Beijing visit.

Although the two governments publicly emphasized strategic friendship and economic cooperation, Moscow reportedly failed to secure final agreement on several major long-term energy priorities, including the long-delayed Power of Siberia 2 gas pipeline project that Russia views as critical for replacing lost European gas demand.

The result is a relationship that increasingly benefits Beijing more than Moscow financially.

For China, Russia’s dependence serves multiple strategic objectives simultaneously.

It expands international yuan usage, increases Beijing’s leverage over Russian trade flows, strengthens China’s role as an alternative financial center outside Western control, and advances long-term efforts to internationalize the Chinese currency in sanctioned or politically isolated markets.

Russia’s growing use of precious metals in bilateral trade further highlights the evolving structure of this parallel financial system. Russian exports of gold and silver to China reportedly quadrupled year-over-year during the first quarter of 2026 as sanctions complicated conventional yuan-ruble settlement channels.

The trend is part barter system, part reserve diversification, and part workaround to sanctions friction.

Yet despite the political symbolism surrounding de-dollarization, the scale still remains relatively limited in global terms.

The yuan accounts for only a small fraction of global reserve holdings and international payments compared with the U.S. dollar. Western capital markets remain vastly larger, deeper, and more liquid than China’s tightly controlled financial system.

Still, what matters is not whether the yuan replaces the dollar globally tomorrow. It is whether parallel systems continue emerging in parts of the world where sanctions make dollar access politically or financially risky.

That process is already happening.

Russia’s yuan bond issuance is another sign that geopolitical fragmentation is increasingly reshaping capital markets themselves. Countries cut off from Western finance are beginning to build alternative settlement, borrowing, and reserve structures centered around China instead of New York or London.

For global markets, the immediate financial impact is modest.

But strategically, the message is significant: when access to dollars becomes restricted, countries do not stop trading or borrowing. They look for another system.

And increasingly, that system is being built around Beijing.

Asia — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Wall Street’s expectations for lower interest rates may be colliding with a new reality.

Deutsche Bank AG has raised its year-end forecast for the benchmark 10-year U.S. Treasury yield, arguing that the Federal Reserve, now led by Chairman Kevin Warsh, has likely finished cutting interest rates for the current cycle and that borrowing costs across the economy could remain higher than many investors had anticipated.

In a research note released Friday, Deutsche Bank strategists Matthew Raskin and Steven Zeng increased their forecast for the 10-year Treasury yield to 4.70% by year-end, up from their previous projection of approximately 4.45%.

While a quarter-point forecast revision may sound insignificant, the implications extend far beyond bond traders and investment managers.

The 10-year Treasury yield is one of the most influential interest rates in the global financial system. It serves as a benchmark for mortgage rates, business loans, corporate borrowing, commercial real estate financing, and countless other forms of credit throughout the economy.

When Treasury yields rise, borrowing becomes more expensive.

When they fall, financing generally becomes cheaper.

That is why Wall Street pays such close attention to every shift in expectations surrounding Federal Reserve policy.

The central argument behind Deutsche Bank’s revised forecast is straightforward: the era of rate cuts may be over.

For much of the past year, investors had positioned themselves for continued monetary easing, expecting the Fed to gradually lower rates as inflation cooled and economic growth moderated. Those expectations helped keep longer-term yields from moving significantly higher.

Deutsche Bank now believes that assumption is increasingly outdated.

The firm’s analysts argue that a Federal Reserve led by Kevin Warsh, a former Fed governor appointed by President Donald Trump, is likely to maintain a more cautious stance toward inflation and may be less willing to aggressively lower rates than markets previously expected.

Warsh has long been viewed by investors as a policy hawk—someone more focused on preventing inflation from reigniting than on providing additional monetary stimulus.

If the Fed remains on hold rather than delivering additional cuts, bond investors could begin demanding higher yields to compensate for the prospect of sustained higher interest rates.

That would push Treasury yields upward even without any formal action from the central bank.

For households, the most visible impact would likely be in housing.

Mortgage rates tend to track movements in the 10-year Treasury yield. If Deutsche Bank’s forecast proves accurate, borrowing costs for homebuyers could remain elevated through the remainder of the year, adding further pressure to affordability at a time when many Americans are already struggling with high home prices.

The effect would not stop there.

Small businesses seeking financing for expansion projects could face higher borrowing costs. Companies issuing bonds to fund investments may encounter steeper interest expenses. Consumers purchasing vehicles or financing major purchases could also find themselves paying more.

In short, a higher Treasury yield affects nearly every corner of the economy.

The picture is not entirely negative.

Higher yields benefit savers.

Money market funds, certificates of deposit, savings accounts, and newly issued Treasury securities generally become more attractive when rates remain elevated. Retirees and income-focused investors often welcome a higher-rate environment because it allows them to earn stronger returns on conservative investments.

As with many financial developments, the benefits and burdens are distributed unevenly.

Borrowers typically prefer lower rates.

Savers generally prefer higher ones.

Investors should also remember that forecasts are not guarantees.

Treasury yield predictions are notoriously difficult, and even the largest financial institutions frequently revise their outlooks as economic conditions evolve. Unexpected changes in inflation, employment data, economic growth, geopolitical events, or future Federal Reserve communications could dramatically alter the trajectory of yields over the coming months.

The official daily Treasury yield data published through the Federal Reserve’s H.15 statistical release will ultimately determine whether Deutsche Bank’s forecast proves correct.

Still, the significance of the call lies less in the precise number and more in the broader message.

For years, businesses, consumers, and investors became accustomed to declining interest rates and relatively cheap access to capital. That environment shaped everything from housing markets to corporate investment decisions.

Deutsche Bank is signaling that the next phase may look different.

The firm’s revised outlook suggests that the market may be entering a period where the cost of money remains elevated for longer than many had expected—a development that would reshape borrowing decisions throughout the economy and challenge assumptions that financing costs will steadily decline from here.

Whether the 10-year yield ultimately reaches 4.70% or not, the larger debate now unfolding on Wall Street centers on a simple question:

Has the era of falling interest rates come to an end?

The answer could influence everything from mortgage payments to stock valuations in the months ahead.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

HHS Secretary Robert F. Kennedy, Jr. announces new federal actions to combat Lyme disease in Concord, New Hampshire, on Friday, May 29, 2026, as part of his “Take Back Your Health” tour. CSPAN

Health and Human Services Secretary Robert F. Kennedy, Jr. announced one of the most ambitious federal efforts ever to combat Lyme disease on Friday, May 29, 2026, at a 2:00 p.m. press conference in Room 100 of the New Hampshire State House in Concord. The measures follow the department’s first national Lyme roundtable, held in Washington, D.C., in December 2025, at which HHS formally recognized Lyme — in both its acute and chronic forms — as a serious public-health condition for the first time.

The recognition marks a shift after years in which the federal government had no unified strategy for a disease the CDC says is diagnosed in 476,000 Americans annually, with 5 to 7 million infections over the past decade. Kennedy has acknowledged that the agency once held what he called a deliberate policy of refusing to engage with the Lyme community. Researchers estimate that 10 to 20 percent of patients treated early remain symptomatic, and emergency room visits for tick bites recently reached their highest springtime level in nearly a decade.

“Americans deserve an answer,” Kennedy said from the podium. “They deserve gold-standard science, and a healthcare system that treats suffering seriously.” He recalled that one of his sons suffered facial paralysis for a year after a Lyme diagnosis and noted that President Donald Trump first made Lyme a national priority by signing the Kay Hagan Tick Act in 2019.

In the HHS release issued the same day, Kennedy said millions of Americans with Lyme and other tick-borne illnesses “have spent years searching for answers, treatment, and support,” and described the package as “one of the most ambitious federal efforts ever to combat Lyme disease.” The department reaffirmed a goal of cutting Lyme cases 25 percent by 2035 compared with 2022 levels.

The most consequential change for patients concerns coverage. At the December roundtable, CMS Administrator Dr. Mehmet Oz confirmed that Medicare is being updated to explicitly require coverage for extended Lyme treatment, including treatment for associated co-infections — addressing a longstanding gap that has strained patients financially. CMS also issued guidance clarifying support for beneficiaries with Lyme and related conditions through its Chronic Care Management Program.

Dr. Stephanie Haridopolos, Director of National Health Communications for the Office of the U.S. Surgeon General, told the audience that roughly 31 million people are bitten by ticks each year in the United States.

“We’re going to make the invisible diseases visible now,” she said. “We know prevention is key. We can prevent not only Lyme disease, but all the co-infections that go with it.”

Dr. Kristen Honey, the HHS Chief Data Officer now managing public-private partnerships, said the effort originated outside government.

“Let me be clear that this movement did not start in government,” Honey said. “It started with all of you. It started with the patients, it started with the caregivers, it started with the frontline providers and those affected families saying there’s a problem here, and rose up, came together, formed unusual allies.”

She credited participants in the December roundtable — among them Senator Susan Collins, Representative Chris Smith, and Duvi Honig of the Orthodox Jewish Chamber of Commerce, along with Olivia Goodreau of LivLyme, Dr. Steve Phillips, and Sam Sofia — saying that without them “none of this would be happening.”

At that session, Collins, author of the Kay Hagan TICK Act, pressed for better diagnostics and cited a Maine clinical trial for a Lyme vaccine; Smith, a 30-year advocate, said Lyme patients “deserve answers”; and Honig called for CDC Updates, Nationwide awareness campaigns, expanded insurance coverage, and increased provider education.

Honey also framed the challenges in market terms.

“For the first time in four years, open innovation at HHS and LymeX is available to all the public,” she said. “All Americans and U.S. businesses can participate, not just those already in the LymeX pipeline.”

The department detailed three new LymeX challenges totaling up to $2.5 million.

The largest is the TOPx HHS Tech Sprint for AI and Invisible Illness, offering up to $2 million, including a $1 million grand prize, for tools that use artificial intelligence and open data to help patients with Lyme and other “invisible illnesses,” including Long COVID and ME/CFS, get answers and care faster.

“If it’s invisible, you are welcome here,” Honey said.

The LymeX Visible Voices Prize offers up to $250,000 for educational tools and awareness campaigns, while the LymeX Healthathon Innovation Sprint offers another $250,000 for frontline solutions, including new uses of existing medicines.

The broader Friday package, according to the HHS release, also includes a multi-million-dollar tick-control pilot program, new NIH funding to combat Alpha-gal syndrome, and a public-private collaboration to connect patients with experienced providers, all under Kennedy’s Make America Healthy Again agenda.

Separately, through the LymeX partnership, HHS is updating its Living Evidence Guidelines for clinicians treating infection-associated chronic conditions, with Version 2.0 launched in May 2026 and scheduled to refresh every six months as new science emerges.

The challenges build on the LymeX Innovation Accelerator, a public-private partnership between HHS and the Steven & Alexandra Cohen Foundation launched during President Trump’s first term. Through LymeX, HHS recently launched a $10 million Diagnostics Prize, and two improved FDA-cleared Lyme tests have reached the market over the past two years.

The National Institutes of Health invests nearly $50 million annually in Lyme research and approximately $122 million annually in broader tick-borne disease research.

The new tick-control pilot, led by the Centers for Disease Control and Prevention and HHS, will begin with researchers at the New England Center of Excellence in Vector-Borne Diseases and build on community work with the Indian Health Service and the Wampanoag Tribe in Massachusetts.

HHS also announced action on Alpha-gal syndrome, a tick-linked condition that can trigger serious allergic reactions to red meat. The CDC estimates nearly 500,000 Americans live with the condition.

NIH has identified candidate products that may protect people after a tick bite; private companies would supply the products while NIH funds research to evaluate them.

The department is also partnering with the International Lyme and Associated Diseases Society to offer a clinician locator tool through hhs.gov/lyme.

Kennedy reiterated support for reauthorizing the bipartisan Kay Hagan TICK Act, signed by President Trump in 2019, which recently advanced unanimously through the House Energy and Commerce Committee.

Officials expect another heavy tick season in 2026. The new programs mark the federal government’s most comprehensive response to Lyme disease to date and represent the first time HHS has formally aligned federal policy, reimbursement, research, innovation incentives, and public-private partnerships around both acute and chronic Lyme disease.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — Building a home in America is getting more expensive again as prices for copper, lumber, diesel fuel, and aluminum all climb at the same time, squeezing builders, contractors, developers, and eventually homebuyers already struggling with high mortgage rates.

The pressure is now spreading across nearly every stage of construction.

The Associated General Contractors of America said in an April 2026 report that construction material costs have climbed to their highest levels in almost four years, with contractors increasingly unable to absorb the increases.

Ken Simonson, chief economist for the organization, said the combination of the Iran war, supply-chain disruptions, energy volatility, and new tariffs imposed under President Donald Trump’s administration are pushing prices higher throughout the construction sector.

“Contractors who locked in prices months ago can seldom pass along cost increases after committing to a project,” said Jeffrey D. Shoaf, CEO of the AGC. “That is creating real financial pressure across the industry.”

The impact begins with lumber.

Lumber futures are now trading near $593 per thousand board feet, climbing again after the extreme volatility seen during the pandemic-era housing boom.

Canada remains one of the largest lumber suppliers to the United States, but tariffs on Canadian softwood lumber remain near an effective 35% rate, contributing to mill closures and tighter supply.

Industry analysts say additional increases are likely later this year as supply constraints continue.

Copper prices have also surged sharply.

Construction-grade copper products used in electrical systems, plumbing, and infrastructure projects have risen more than 15% year-over-year.

The increases accelerated after the administration imposed tariffs on imported copper-related products while demand simultaneously surged from:

  • AI data center construction
  • Electric vehicle manufacturing
  • Grid expansion projects
  • Industrial infrastructure upgrades

Builders are increasingly attempting substitutions such as copper-clad aluminum wiring, though building-code restrictions often limit alternatives.

Aluminum costs have climbed even faster.

Aluminum products used in:

  • Window systems
  • Gutters
  • Structural framing
  • Doors
  • Exterior materials

have experienced some of the sharpest increases inside the broader construction supply chain.

Tariffs on imported aluminum products now sit at roughly 50%, while rising energy costs continue pushing manufacturing expenses higher globally.

Because aluminum production requires enormous electricity consumption, higher natural gas prices tied to Middle East energy disruptions are feeding directly into material pricing.

Then comes diesel fuel.

Diesel prices have surged above $5.40 per gallon, reaching their highest levels since 2022.

That matters enormously because diesel powers nearly every major component of the construction industry:

  • Bulldozers
  • Excavators
  • Cranes
  • Delivery trucks
  • Concrete transport
  • Generators
  • Heavy equipment fleets

As fuel costs rise, transportation expenses and subcontractor pricing rise alongside them.

The cumulative effect is now flowing directly into housing affordability.

Construction groups estimate tariffs and rising material costs could add thousands — and in some cases tens of thousands — of dollars to the cost of building a new home.

Large national homebuilders including D.R. Horton, Lennar, and PulteGroup have greater flexibility because they negotiate bulk supply contracts and hedge certain material purchases in advance.

Smaller regional builders are facing much tighter pressure.

Some are delaying projects altogether until costs stabilize.

Others are simply passing increases directly to buyers.

The timing is especially difficult for the housing market because mortgage rates remain elevated near 6.5%, while inventory shortages continue limiting affordability nationwide.

New home prices have continued climbing despite slower overall transaction volume.

Economists increasingly warn that the combination of:

  • High rates
  • High material costs
  • Tight inventory
  • Elevated labor expenses

is keeping much of the housing market effectively frozen.

The situation also complicates policy decisions at the Federal Reserve.

Higher construction costs feed directly into inflation data the Fed continues monitoring closely.

At the same time, elevated interest rates make housing affordability worse.

That leaves policymakers balancing inflation pressure against weakening affordability and slowing construction activity.

Where prices move next may depend heavily on geopolitics.

If tensions involving Iran ease and energy markets stabilize, diesel and industrial-metal prices could cool relatively quickly.

If the conflict drags on or worsens, construction costs may continue climbing through the second half of the year.

For buyers, the reality is increasingly simple:
homes being built today cost significantly more to construct than they did only months ago.

Builders can absorb some of those increases.

Eventually, the rest appears on the final price tag.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

NEW YORK — Americans are carrying more debt than ever before, and a growing share of that borrowing is coming from households already under financial strain, according to a new Equifax Market Pulse Report released Thursday.

Total U.S. consumer debt reached a record $18.9 trillion through March 2026, up from a year earlier and marking another milestone in the steady expansion of household borrowing. While rising debt balances have become a familiar feature of the post-pandemic economy, Equifax’s latest data points to a deeper trend: lower-income consumers are increasingly relying on credit cards to pay for necessities rather than discretionary spending.

Credit-card balances, which Equifax classifies as bankcard debt, climbed to $1.085 trillion, up 3.9% from a year earlier and outpacing inflation. More striking was where the growth occurred. New credit-card accounts increased 8.1% overall, but applications approved for subprime borrowers — consumers with the lowest credit scores — surged 18.6%. At the same time, lenders expanded available credit to those borrowers, increasing credit limits by 37.6% year over year.

Maria Urtubey, an advisor at Equifax, said the numbers suggest a growing divide within the U.S. economy.

For many households, borrowing is no longer funding vacations, electronics, or discretionary purchases. Instead, credit cards are increasingly being used to cover recurring expenses such as groceries, rent, utilities, and transportation costs. Economists often refer to this phenomenon as “survival debt” — borrowing used to bridge the gap between wages and everyday living expenses.

The report reinforces what many economists describe as a K-shaped economy, where higher-income households continue to benefit from asset appreciation, strong employment, and investment gains, while lower-income consumers struggle to keep pace with rising costs.

The same dynamic appears in higher education financing. Although the number of new student loans declined by more than 10% over the year through January, the total dollar amount borrowed increased 4.7%, indicating that the cost of obtaining a degree continues to rise even as fewer students take on educational debt.

Student loans are also showing some of the most visible signs of financial stress. Equifax reported that 17.01% of student loans were at least 90 days delinquent in March, marking the fourth consecutive monthly increase. While still below the peak reached in 2025, the trend has raised concerns as federal student-loan collection efforts resume.

Historically, borrowers have prioritized mortgage and auto-loan payments ahead of student debt. However, as collection activity intensifies and household budgets remain stretched, financial analysts warn that pressure from student-loan repayments could spill into other areas of consumer credit performance.

Despite those concerns, the report also contained signs of resilience.

Delinquency rates across several major lending categories remained stable or improved compared with a year ago. The percentage of credit-card accounts more than 60 days past due fell to 2.97%, down from 3.09% a year earlier. Unsecured personal-loan delinquencies improved to 3.18% from 3.49%, while auto-loan delinquencies edged down to 1.49%.

However, lenders continue to absorb losses from loans that became troubled months earlier. Equifax noted that write-offs increased for both credit cards and auto loans as banks moved aging delinquent accounts off their balance sheets. The trend suggests that while newer borrowers are largely keeping up with payments, lenders are still dealing with the fallout from earlier financial stress.

For consumers carrying revolving credit-card balances, the cost remains significant. Average credit-card interest rates continue to hover above 21%, making credit-card debt among the most expensive forms of consumer borrowing. Financial advisers warn that carrying balances month after month can rapidly increase the total amount owed, particularly for households already operating on tight budgets.

The report also highlighted growing reliance on home equity as a financing tool. Outstanding balances on home-equity lines of credit (HELOCs) jumped 13% year over year to $431 billion, as homeowners tapped rising property values to access lower-cost borrowing compared with credit cards.

Meanwhile, mortgage balances increased to $12.86 trillion, while auto-loan balances rose to approximately $1.6 trillion.

Taken together, the figures paint a picture of an economy increasingly supported by borrowing, even as many consumers remain current on their obligations. The headline delinquency numbers suggest stability, but the rapid growth in subprime credit-card borrowing indicates that financial pressure remains concentrated among households with the least margin for error.

For millions of Americans, the credit card is no longer just a payment method. It has become a financial lifeline used to bridge the gap between paychecks and the rising cost of everyday life.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

May 30, 2026

The U.S. Treasury Department said Friday that any arrangement with Iran to purchase safe passage through the Strait of Hormuz is illegal for Americans, a warning that came as commercial shipping traffic showed tentative signs of returning to the world’s most important energy chokepoint.

For three months the strait has been effectively shut. Roughly one-fifth of the world’s pre-war oil supply normally passes through the narrow waterway, and thousands of vessels remain delayed or trapped inside the Persian Gulf. The disruption has become one of the biggest drivers behind elevated fuel prices and rising transportation costs across the global economy.

Now some ships have stopped waiting.

Traffic through the strait has picked up over the past week, helped along by quiet guidance from the U.S. military. U.S. Central Command continues to insist it is not escorting commercial vessels. Instead, military officials have reportedly provided navigational advice, threat assessments, and guidance on the safest transit windows.

The route many vessels are using hugs the coast of Oman, placing maximum distance between ships and Iranian-controlled waters. To reduce the risk of detection, some vessels have switched off their Automatic Identification Systems, or AIS beacons, which normally broadcast a ship’s location to nearby traffic.

Going dark carries risks. It increases the possibility of collisions and complicates maritime monitoring. But for captains attempting to transit one of the world’s most dangerous waterways, invisibility may offer a measure of protection.

The fragile nature of the situation was demonstrated this week when Iranian fast-attack boats reportedly approached a group of commercial vessels crossing the strait. Shortly afterward, U.S. military helicopters appeared overhead. The Iranian boats reversed course and withdrew.

That encounter illustrates the balance of power currently shaping the region.

Iran cannot directly challenge the overwhelming naval and air superiority of the United States. What the Islamic Revolutionary Guard Corps (IRGC) still possesses, however, are asymmetric tools capable of creating disruption. Fast boats, naval mines, drones, and coastal missile batteries remain inexpensive yet effective methods of threatening commercial traffic and raising costs for global shipping operators.

The U.S. response has centered on surveillance and air power. Helicopters, drones, and patrol aircraft provide persistent visibility across the shipping lanes, allowing military commanders to identify and respond to potential threats before they escalate.

The ships now making it through include vessels that have been stranded since the conflict began in late February as well as newly arriving tankers. Among them are cargoes belonging to the United Arab Emirates’ state oil company and liquefied natural gas carriers departing Qatar, precisely the energy supplies global markets have been waiting for.

Still, progress remains limited.

Industry observers estimate that only a fraction of the non-Iranian vessels trapped inside the Gulf have successfully exited. Energy traders warn that unless traffic normalizes quickly, global oil and natural gas markets could face renewed supply pressures in the weeks ahead.

A Greek-owned supertanker carrying approximately two million barrels of crude recently completed the transit using the Oman route. A Chinese-owned fertilizer vessel reportedly made a similar journey. While encouraging, those examples represent only a small percentage of the backlog still waiting to move.

The Treasury Department’s announcement adds a new layer to the confrontation.

Washington sanctioned what Tehran calls the Persian Gulf Strait Authority, an organization Iran has promoted as a mechanism for regulating transit through the waterway. U.S. officials view it differently, describing it as an attempt to charge commercial vessels for passage through an international shipping route.

“Regardless of whether a payment is made, U.S. persons are prohibited from receiving services from the Government of Iran, including services related to a guarantee of safe passage,” the Treasury Department said in a statement.

The message was clear: the United States will not permit Iran to transform one of the world’s most important trade routes into a toll road.

For American companies, the warning effectively prohibits any arrangement that involves paying Iranian authorities in exchange for transit guarantees. Even indirect participation could expose firms to sanctions risk and regulatory penalties.

The economic stakes extend far beyond oil producers and shipping companies.

The Strait of Hormuz handles roughly one-fifth of global oil shipments and a substantial share of global liquefied natural gas exports. Every week the route remains disrupted adds pressure to energy markets, transportation networks, manufacturing supply chains, and consumer prices.

The recent increase in vessel traffic represents the first meaningful sign of progress in months. Yet it falls far short of a full reopening.

The broader standoff between Washington and Tehran remains unresolved, and until a more durable ceasefire emerges, the world’s most important energy corridor will remain vulnerable to disruption.

For now, commercial captains continue making the same calculation each day: whether the risk of moving is greater than the cost of standing still.

Middle East — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Just a few years ago, San Francisco was widely portrayed as the symbol of America’s urban decline.

Downtown office towers sat nearly empty after the pandemic. Major employers were cutting space. Residents were leaving. Headlines warned of a “doom loop” fueled by crime concerns, collapsing foot traffic, falling tax revenue, and a city that appeared to be losing its grip on both workers and businesses.

Now the picture has completely reversed.

San Francisco rents have surged roughly 22% year-over-year, making the city the fastest-rising major rental market in the United States. Median home prices have climbed back above previous peaks. Luxury bidding wars have returned. One-bedroom apartment rents are averaging roughly $3,415 per month, while two-bedroom apartments are approaching $4,800 per month.

The city everyone said was dying has suddenly become one of the hottest housing markets in America again.

The reason can largely be summarized in two letters: AI.

The artificial intelligence boom has transformed San Francisco from a struggling post-pandemic downtown into the operational center of one of the fastest wealth-creation cycles the technology industry has ever seen.

OpenAI, Anthropic, Scale AI, and dozens of rapidly growing artificial-intelligence startups are headquartered inside San Francisco neighborhoods that only recently were struggling with vacancies and declining office activity.

According to PitchBook data, the San Francisco Bay Area has attracted roughly 70% of all U.S. venture-capital funding tied to AI companies since 2019.

That money is now reshaping the city in real time.

The AI sector’s hiring surge has flooded San Francisco with highly paid engineers, researchers, executives, and startup founders competing for a housing supply that was already severely constrained long before the current boom began.

Compensation packages for senior AI talent routinely range from $500,000 to well over $1 million annually, especially when stock awards are included. Employees at companies such as OpenAI and Anthropic are increasingly viewed inside Silicon Valley as potential future IPO millionaires.

The result is an extraordinary wave of housing demand concentrated inside a city that historically builds far less housing than its workforce growth requires.

According to CBRE, roughly one out of every four square feet of newly leased office space in San Francisco over the past two years has gone to AI-related companies.

Unlike previous tech booms centered around suburban Silicon Valley campuses, the AI industry has concentrated itself directly inside San Francisco neighborhoods such as SoMa, Mission Bay, and Hayes Valley, where younger founders and employees increasingly prefer dense urban living close to offices.

That concentration is rapidly changing rental economics.

Real-estate brokerage data shows luxury home sales climbing sharply, while inventory remains limited. Bidding wars have returned across desirable neighborhoods. One recent Pacific Heights apartment reportedly received 14 offers and sold roughly $400,000 above asking price.

The market is also changing in another important way: AI companies themselves are now directly subsidizing housing for employees.

Several startup founders have publicly described leasing apartments near company offices specifically to recruit and retain workers. Some firms are offering monthly housing stipends for employees who live within walking distance of the office.

That creates an entirely different pricing dynamic than a traditional housing market.

Instead of individual renters competing solely against each other, venture-capital-funded AI companies are effectively bidding for nearby housing on behalf of employees using investor money. That raises the ceiling for what neighborhoods near AI offices can command in rent.

The political backdrop also shifted.

In late 2024, San Francisco elected Mayor Daniel Lurie, who campaigned heavily on restoring downtown activity, improving public safety, and rebuilding business confidence in the city. His first year coincided with the explosive acceleration of AI investment and a broader corporate push back toward office activity.

The combined effect has produced one of the sharpest urban economic reversals in the country.

But the rebound also carries major consequences for ordinary residents.

San Francisco’s widening economic divide is becoming increasingly visible as teachers, service workers, healthcare staff, retail employees, and middle-income families struggle to compete with the purchasing power of AI-sector salaries and stock wealth.

A worker earning a typical middle-class income cannot realistically compete for housing against AI employees earning several hundred thousand dollars annually while receiving additional housing assistance from employers.

As a result, many workers who keep the city functioning are increasingly being pushed farther away from San Francisco itself.

The irony is that the same AI boom reviving the city economically is simultaneously intensifying affordability pressures that were already among the worst in the nation.

Analysts say the broader significance goes beyond California.

San Francisco is becoming the first major real-world test of what happens when artificial-intelligence wealth concentrates rapidly inside a geographically constrained urban economy.

The answer so far is clear: office markets recover quickly, luxury housing explodes higher, venture capital floods in, and affordability pressures intensify across nearly every other layer of the city.

The “doom loop” narrative that dominated San Francisco headlines from 2021 through 2023 has now largely been replaced by something very different — an AI-driven boom cycle powerful enough to overwhelm broader economic pressures such as higher interest rates, geopolitical uncertainty, and slower national housing activity.

For now, the city that Americans were fleeing only a few years ago has become one of the places the technology industry most aggressively wants to be.

The question no longer seems to be whether San Francisco survives.

It is who will still be able to afford living there if the AI boom continues at its current pace.

San Francisco — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk
Friday, May 29, 2026

Universal Music Group has rejected a $64 billion takeover proposal from billionaire investor Bill Ackman and his Pershing Square Capital Management, setting up one of the most closely watched corporate battles of the year and underscoring growing tensions over how global media companies are valued on different sides of the Atlantic.

In a statement released Friday, Universal Music Group’s Board of Directors said it had unanimously rejected the unsolicited proposal after determining that it “fundamentally and materially undervalues UMG” and would not deliver superior value for shareholders, artists, employees, songwriters, and other stakeholders.

The decision came just one day after Vincent Bolloré, the French billionaire whose holding company remains Universal’s largest shareholder, publicly urged the company to reject the offer.

The board’s rejection effectively ends Ackman’s current pursuit of the world’s largest music company, although the issues he raised about valuation and shareholder returns are likely to remain central to Universal’s future strategy.

At the heart of Ackman’s argument was not dissatisfaction with Universal’s business performance, but frustration with its stock market valuation.

Under Sir Lucian Grainge, Universal’s Chairman and Chief Executive Officer, the company has continued to dominate the global music industry. Universal reported revenue and adjusted earnings growth of nearly 9% in 2025, while maintaining a roster that includes many of the world’s most commercially successful artists, including Taylor Swift, Drake, Bad Bunny, and numerous legendary catalog assets.

Ackman openly praised Universal’s management team, describing the company as exceptionally well-run.

His concern was that investors were not rewarding that success.

Since Universal began trading independently on Euronext Amsterdam in 2021, its shares have significantly underperformed expectations despite continued growth in the global music market. Ackman argued that the valuation discount reflected factors unrelated to the company’s operating performance, including uncertainty surrounding Bolloré’s ownership position, delays in pursuing a U.S. stock-market listing, and what he characterized as insufficient communication with investors.

His solution was ambitious.

Pershing Square proposed combining Universal with its acquisition vehicle, SPARC Holdings, and relocating the company to the New York Stock Exchange, where Ackman believes investors would assign a substantially higher valuation to the same underlying business.

The proposal valued Universal at approximately €30.40 per share, representing a premium of roughly 78% to the company’s unaffected share price before the offer became public.

Investors initially reacted positively.

Universal shares surged after details of the proposal emerged, reflecting Wall Street’s long-standing view that American markets often award higher earnings multiples to media, entertainment, and intellectual-property businesses than European exchanges.

Ackman also attempted to ease concerns among artists and management.

His proposal envisioned retaining Sir Lucian Grainge as Chief Executive Officer under a new employment agreement and appointing former Disney President Michael Ovitz as Chairman. The plan additionally included dedicating approximately €750 million from any future sale of Universal’s stake in Spotify toward artist-focused initiatives, a move designed to reassure performers and songwriters that a change in ownership would not come at their expense.

For Ackman, the transaction fit into a much broader strategic vision.

The hedge fund manager has repeatedly discussed his desire to transform Pershing Square into a diversified holding company modeled after Warren Buffett’s Berkshire Hathaway, owning durable, cash-generating businesses with powerful brands and long-term growth potential.

Universal’s extensive music catalog, recurring royalty streams, and global market leadership made it an attractive candidate for that strategy.

Ultimately, however, the deal depended on one critical factor: support from Vincent Bolloré.

Ackman himself acknowledged that reality when unveiling the proposal, noting that a transaction would be virtually impossible without Bolloré’s backing.

With Bolloré publicly opposing the bid, Universal’s board faced little pressure to engage further. The unanimous rejection that followed effectively closed the door on negotiations before they could meaningfully begin.

Yet the broader questions raised by the proposal remain unresolved.

Universal continues to operate one of the strongest businesses in global entertainment, controlling a vast library of music rights that generate recurring revenue across streaming platforms, radio, social media, licensing agreements, and live-performance ecosystems.

At the same time, investors continue debating whether the company’s current market valuation accurately reflects the strength of those assets.

That debate is unlikely to disappear simply because the board rejected Ackman’s offer.

In fact, some analysts believe the proposal may ultimately accelerate discussions around a future U.S. listing—one of the very changes Ackman argued could unlock substantial shareholder value.

For now, Universal Music Group remains independent, Sir Lucian Grainge remains in control, and Bolloré remains the company’s most influential shareholder.

But the confrontation has highlighted a growing divide between what some investors believe Universal is worth and what the market currently says it is worth—a gap that could continue attracting attention from activists, strategic buyers, and shareholders alike.

Whether Universal eventually pursues a U.S. listing on its own terms may ultimately become the lasting legacy of Ackman’s failed bid.

London — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk
Friday, May 29, 2026

Major League Baseball owners have formally proposed a hard salary cap for the first time since 1994, setting up what could become the sport’s most consequential labor battle in more than three decades and raising the prospect of another work stoppage when the current collective bargaining agreement expires later this year.

According to statements released following bargaining sessions held at the Commissioner’s Office in New York on May 28, MLB owners presented a proposal that would establish a payroll floor and ceiling beginning in 2027, fundamentally reshaping the economics of professional baseball. The proposal immediately drew fierce opposition from the Major League Baseball Players Association, which has long treated any salary cap as a non-negotiable issue.

The proposal would require teams to maintain payrolls between a floor of $171.2 million and a ceiling of $245.3 million, while also introducing a 50-50 revenue-sharing structure between players and owners. Under the framework, both the payroll floor and cap would increase as league revenues rise.

The union’s response was swift.

Bruce Meyer, the MLBPA’s chief negotiator, accused owners of attempting to suppress player compensation while protecting their own financial interests.

Billionaire owners are not seeking to cap their profits or asset values, only player salaries,” Meyer said in a statement released following the meeting.

The dispute goes far beyond baseball’s labor negotiations. At stake is the economic structure of one of America’s most valuable sports businesses, an industry generating billions of dollars annually through media rights, sponsorships, ticket sales, and licensing agreements.

Unlike the NFL, NBA, and NHL, Major League Baseball remains the only major American professional sports league without a formal salary cap. Owners argue that the absence of spending limits has widened the gap between wealthy franchises and smaller-market clubs, creating competitive imbalances that ultimately hurt the sport.

Commissioner Rob Manfred recently described the current payroll landscape as “not a fair fight,” pointing to the enormous disparity between baseball’s highest- and lowest-spending teams.

The numbers support that argument.

The defending champion Los Angeles Dodgers entered the season with an estimated payroll of approximately $415 million, far above the proposed cap. The New York Mets, led by owner Steve Cohen, carried a payroll approaching $379 million, while the New York Yankees stood near $340 million.

Other clubs that would exceed the proposed ceiling include the Toronto Blue Jays, Philadelphia Phillies, Boston Red Sox, San Diego Padres, and Atlanta Braves.

Supporters of the proposal point to the opposite end of the spectrum.

Under the proposed payroll floor, lower-spending franchises would be required to invest substantially more in player salaries. Teams such as the Miami Marlins, Tampa Bay Rays, Pittsburgh Pirates, Chicago White Sox, Cleveland Guardians, and Minnesota Twins would collectively need to increase payroll spending by hundreds of millions of dollars.

For fans in smaller markets, that provision may prove attractive. Many have spent years watching homegrown stars leave for wealthier franchises that can simply outbid competitors in free agency.

MLB officials have emphasized that a cap-and-floor structure could create greater competitive balance while encouraging additional investment by lower-spending clubs.

But the players’ association sees a much different picture.

Union leadership argues that salary caps inevitably limit earning potential, particularly for elite players whose contracts often drive salary growth across the league. The MLBPA also fears that tying compensation more directly to league revenues could introduce greater uncertainty into future earnings and weaken the negotiating leverage players have maintained for decades.

Beyond competitive balance, financial considerations are driving the debate.

Professional sports franchises have become increasingly attractive investment assets, with private equity firms and institutional investors showing growing interest in ownership stakes. Limiting labor costs could significantly improve operating margins while boosting franchise valuations, a prospect that appeals to ownership groups across the league.

The timing is equally important.

Baseball’s current labor agreement, signed in March 2022 following a 99-day lockout, expires on December 2, 2026. Industry observers increasingly expect another lockout once that deadline passes if significant progress is not made.

Historically, labor negotiations intensify only when the possibility of lost regular-season games becomes real. Until then, both sides are expected to maintain firm public positions while continuing negotiations behind closed doors.

For now, the proposal represents an opening bid rather than a final framework. Both MLB and the players’ association understand that any eventual agreement will likely look very different from what was presented this week.

Still, the significance of the moment is difficult to overstate.

More than thirty years after the labor conflict that canceled the 1994 World Series, baseball is once again confronting the question that has shaped every major labor dispute in the sport’s modern history: whether Major League Baseball should finally adopt the salary-cap model used by every other major American professional sports league.

The answer could determine not only the future economics of baseball, but whether fans find themselves watching games—or another labor standoff—when the 2027 season arrives.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

TORONTO — May 28, 2026TD Bank Group raised its quarterly dividend and reported sharply higher profit Thursday as Canada’s second-largest lender by assets pointed to strong growth across its businesses and accelerating progress on cost reductions and operational improvements.

The bank increased its quarterly dividend by 4 cents to $1.12 per share, while continuing an aggressive share repurchase program. Raymond Chun, TD’s Group President and Chief Executive Officer, said the dividend increase and ongoing buybacks reflect management’s confidence in the bank’s earnings outlook and capital strength. TD repurchased approximately 19 million shares during the quarter as part of its previously announced $7 billion buyback program.

The results marked a significant improvement from a year earlier. Adjusted earnings per share rose 21% to $2.38, while adjusted net income increased 15% to $4.2 billion. The bank’s return on equity climbed to 14.4%, up more than two percentage points from the prior year.

Canadian Personal and Commercial Banking, TD’s largest division, delivered record second-quarter revenue and earnings. Net income reached $1.925 billion, up 15% year-over-year, driven by stronger lending activity, deposit growth, and improved lending margins. Average deposits increased 3%, while loan volumes rose 6%. TD also reported record penetration levels for consumer and small-business credit cards as existing customers expanded their use of the bank’s products.

The bank’s wealth management and insurance division also achieved record earnings and assets under management. New client accounts increased 15% from a year ago as investors continued shifting toward digital investing platforms and exchange-traded funds. TD said its Canadian banking operations generated approximately $9 billion in client referrals to the wealth division during the quarter.

South of the border, TD’s U.S. business continued showing signs of stabilization following regulatory setbacks that have weighed on the franchise. Adjusted net income in the U.S. segment increased 8% year-over-year, or 12% when measured in U.S. dollars. However, expenses in the division rose 10%, primarily due to ongoing investments in compliance, governance, and anti-money-laundering controls.

Those investments stem from TD’s efforts to address deficiencies identified by U.S. regulators. In 2024, the bank agreed to pay more than $3 billion in penalties following findings that it failed to adequately detect and prevent money-laundering activity through its U.S. operations. The settlement also imposed restrictions on certain growth activities within the bank’s American retail business.

Since taking over as CEO in February 2025, Chun has made remediation of those issues a central priority. Management said compliance-related expenses are expected to begin declining later this year, with major remediation milestones anticipated through 2027.

Credit quality remained stable during the quarter. TD’s provision for credit losses remained within management’s guidance range, while the allowance for credit losses declined by $147 million from the previous quarter. The bank’s Common Equity Tier 1 (CET1) ratio, a key measure of financial strength, stood at 14.3%, well above regulatory requirements.

Cost discipline also emerged as a bright spot. TD reported its slowest expense growth since 2022 and recorded a fourth consecutive quarter of positive operating leverage, meaning revenue growth outpaced expense growth. Excluding variable compensation and foreign-exchange impacts, expenses increased just 3%.

Management said the bank remains ahead of schedule on structural cost-reduction initiatives and is beginning to see benefits from investments in artificial intelligence and operational automation, while continuing to invest in technology infrastructure, branch operations, and customer service improvements.

Looking ahead, TD reaffirmed its expectation to exceed its full-year targets of 6% to 8% adjusted earnings-per-share growth and a 13% return on equity, assuming economic conditions remain stable. Executives cautioned that competition for deposits and loans in Canada remains intense and that geopolitical tensions in the Middle East could create broader economic risks if conditions deteriorate.

For investors, however, the dividend increase provided the clearest signal of management’s confidence. After a period marked by regulatory penalties, leadership changes, and heightened scrutiny, TD’s latest results suggest the bank’s recovery strategy is beginning to gain momentum.

Canada — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. stock market closed Friday, May 29, 2026, at fresh record highs across all three major indexes, capping a holiday-shortened week, after Dell Technologies reported quarterly results that stunned Wall Street and reignited enthusiasm for the artificial-intelligence trade. According to market data published at Friday’s close, the Dow Jones Industrial Average rose 363.49 points, or 0.72%, to finish at 51,032.46 — its first close ever above 51,000.

The S&P 500 added 0.22% to end at 7,580.06, while the tech-heavy Nasdaq Composite gained 0.20% to close at 26,972.62. All three benchmarks touched intraday all-time highs earlier in the session, and the S&P 500 logged its ninth consecutive week of gains, extending one of the strongest rallies of the decade.

The day belonged to Dell Technologies. Shares of the Round Rock, Texas-based company surged roughly 33%, marking the strongest single-day gain in its history, after founder and Chief Executive Officer Michael Dell delivered results that far exceeded Wall Street expectations.

For the fiscal first quarter ended May 1, Dell reported $43.84 billion in revenue, up nearly 88% from a year earlier and dramatically above analyst forecasts of approximately $35.43 billion. Adjusted earnings reached $4.86 per share, easily surpassing consensus estimates near $2.94 per share.

The driver behind the blowout performance was artificial intelligence infrastructure. Dell disclosed that revenue from its AI-optimized server business climbed to $16.13 billion, reflecting the extraordinary demand from corporations, cloud providers, and government agencies racing to build the computing capacity required for next-generation AI systems.

The results reinforced Dell’s position as one of the largest beneficiaries of the global AI investment boom. Over the past several months, the company has announced expanded partnerships with Nvidia, Google, and OpenAI, helping transform Dell from a traditional computer manufacturer into a critical supplier of AI infrastructure.

Wall Street analysts responded swiftly.

Citi analyst Asiya Merchant raised her price target on Dell to $475 from $290 while maintaining a Buy rating. JPMorgan lifted its target to $500 from $280 and reiterated its Overweight recommendation. Even UBS analyst David Vogt, who downgraded the stock earlier this month on concerns that AI optimism had already been reflected in the share price, more than doubled his target to $440 from $243.

The enthusiasm quickly spread across the broader technology sector.

Micron Technology climbed approximately 5% Friday and ended May nearly 88% higher than where it began the month. Qualcomm rose roughly 3% during the session and finished May with gains approaching 40%. Investors continued rotating into semiconductor and infrastructure companies viewed as direct beneficiaries of the AI spending cycle.

Beyond corporate earnings, markets also found support from a calmer geopolitical backdrop.

Reports circulated during the week indicating that U.S. and Iranian negotiators had reached a framework agreement to extend a ceasefire for an additional 60 days, easing fears of renewed disruptions to global energy supplies and shipping traffic through the Strait of Hormuz, one of the world’s most important oil transit routes.

That relief was reflected in energy markets.

West Texas Intermediate crude oil fell 1.73% Friday to settle at approximately $87.36 per barrel, while international benchmark Brent crude declined 1.77% to $92.05 per barrel. WTI recorded its largest monthly decline since April 2025, falling nearly 17% during May.

Lower oil prices create both winners and losers. Energy producers typically face pressure when crude declines, but consumers and businesses benefit from lower fuel and transportation costs. Heading into the summer travel season, the decline offers welcome relief after months of elevated energy prices.

The week was not entirely free of concerns.

Investors digested a hotter-than-expected reading from the government’s preferred inflation measure, the Personal Consumption Expenditures (PCE) Price Index, released Thursday. The report showed inflation running at its strongest pace in nearly three years, underscoring that price pressures remain more persistent than policymakers had hoped.

Yet traders largely looked past the data.

Strong corporate earnings, accelerating AI-related investment, and easing geopolitical tensions outweighed inflation concerns. The CBOE Volatility Index (VIX) — commonly referred to as Wall Street’s fear gauge — remained in the mid-teens, signaling relatively low levels of investor anxiety.

For investors, the broader message from this week’s rally is increasingly clear. The companies supplying the physical backbone of artificial intelligence — servers, semiconductors, networking equipment, and data-center infrastructure — are generating real revenue growth rather than merely benefiting from market hype.

At the same time, risks remain.

Dell’s gross margin declined to 17.8% from 21.1% a year earlier, illustrating that rapid revenue growth does not always translate into equally strong profitability. As competition intensifies and companies prioritize market share, investors will increasingly focus on margins and long-term earnings quality.

The holiday-shortened week also produced record closes earlier in the period. The Dow reached new highs Wednesday, while the S&P 500 and Nasdaq closed at records Thursday following strong guidance from cloud-software company Snowflake.

As June begins, Wall Street enters the new month with momentum firmly intact. Markets continue to be supported by strong earnings growth, aggressive AI infrastructure spending, and a calmer Middle East. Whether that combination can overcome persistent inflation pressures may determine whether the rally extends through the summer.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk
Friday, May 29, 2026

Ford Motor Co. is having its best month on Wall Street in nearly two decades, and the reason has little to do with pickup trucks, electric vehicles, or traditional auto sales.

Instead, investors are betting that the 122-year-old automaker may have found an unexpected way to profit from the artificial intelligence boom: supplying batteries to help power the data centers driving it.

According to market data cited by Bloomberg on May 29, Ford shares surged more than 40% during May, putting the stock on track for its strongest monthly performance since April 2009, when the company emerged from the financial crisis while rivals General Motors and Chrysler struggled through government-backed restructurings.

The catalyst behind the rally is Ford Energy, a new business unit launched on May 11 that aims to transform the company’s battery investments into a standalone energy-storage business serving utilities, data centers, and large industrial customers.

For years, Ford’s battery investments were viewed by investors as a financial burden.

The company spent billions building electric vehicle production capacity and battery manufacturing operations only to encounter slower-than-expected EV adoption, persistent losses in its electric vehicle division, and growing investor skepticism about the pace of the industry’s transition away from gasoline-powered vehicles.

Now Ford is attempting to turn that challenge into an opportunity.

The company’s strategy centers on repurposing battery production capacity originally built for electric vehicles and using it to manufacture large-scale energy storage systems. These systems store electricity when supply is abundant and release it when demand spikes, helping utilities and commercial customers stabilize power usage.

That market is expanding rapidly because of artificial intelligence.

The explosive growth of AI has created an unprecedented surge in electricity demand as technology companies race to build data centers capable of training and operating increasingly powerful AI models. Utilities across the United States are struggling to meet projected power requirements, creating strong demand for battery storage systems that can help balance energy loads and improve grid reliability.

Ford believes it is positioned to benefit from that trend.

Investors appear to agree.

The stock climbed as high as $16.50 during Thursday trading, reaching levels not seen since 2022 and extending a rally that carried shares from the low $11 range just weeks earlier.

The enthusiasm intensified after Ford Energy secured its first major commercial agreement.

On May 20, the company announced a five-year framework agreement with EDF Power Solutions North America to provide up to 20 gigawatt-hours of battery storage capacity over the life of the contract.

The deal gave investors something they had been waiting for: proof that customers are willing to buy Ford’s new energy products.

Wall Street analysts quickly took notice.

Andrew Percoco of Morgan Stanley estimated that Ford Energy could ultimately be worth as much as $10 billion as a standalone business. He expects Ford to pursue additional agreements with utilities, industrial operators, and large-scale cloud-computing companies, often referred to as hyperscalers, that are aggressively expanding data center infrastructure.

If those contracts materialize, Ford could find itself participating in one of the fastest-growing sectors of the global economy without abandoning its core automotive business.

The prospect is particularly attractive because it allows the company to monetize investments that investors had largely written off as underperforming EV infrastructure.

Still, significant questions remain.

Ford Energy does not expect meaningful commercial deployment until 2027, meaning much of the current excitement is based on future growth rather than present earnings.

The company’s traditional automotive business also continues to face the challenges that have long defined the industry: intense competition, cyclical demand, thin margins, and slowing growth.

Between 2015 and 2025, Ford’s automotive revenue grew at an average annual rate of approximately 2.2%, reflecting the realities of operating in a mature global market.

Critics argue that investors may be moving too quickly in assigning technology-style valuations to a company that remains primarily an automaker.

Yet Ford’s broader business is showing signs of resilience.

During the company’s first-quarter earnings call, Chief Financial Officer Sherry House reported that paid software subscriptions across Ford Pro, the company’s commercial vehicle platform, rose to approximately 879,000, an increase of 30% year-over-year.

Meanwhile, Ford’s highly profitable F-Series pickup franchise continues to generate substantial cash flow, providing financial flexibility as the company expands into new markets.

Under Chief Executive Officer Jim Farley, Ford has also adopted a diversified strategy that includes gasoline-powered vehicles, hybrids, and electric models, allowing the company to adjust more easily to changing consumer preferences.

Whether Ford Energy becomes a transformational second business or simply a promising side venture remains uncertain.

What is clear is that investors are beginning to view Ford differently.

For much of the past two years, the company’s battery investments were seen as evidence of an expensive and difficult transition to electric vehicles.

Today, those same assets are being viewed as a potential gateway into one of the most important infrastructure markets of the AI era.

The immediate question is whether Ford can convert investor enthusiasm into additional contracts and recurring revenue.

The longer-term question is even larger: whether one of America’s most iconic automakers can successfully reinvent part of itself as an energy company at a time when electricity has become one of the most valuable commodities in the artificial intelligence economy.

Detroit — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

A federal auction of oil and gas drilling rights across public lands in New Mexico and Texas generated more than $4 billion in winning bids and rental payments, according to the U.S. Department of the Interior, shattering the previous record for an onshore federal lease sale as the Iran war drives energy companies into a scramble for American oil acreage.

The scale of the sale was historic.

The Bureau of Land Management leased 74 parcels covering roughly 33,530 acres during its quarterly auction, producing approximately $4.008 billion in bonus bids and rental commitments. The figure demolished the prior record of roughly $972 million set during a 2018 lease sale and instantly became the largest onshore federal oil and gas lease auction in U.S. history.

Most of the acreage sits inside the Permian Basin, the country’s most productive oil field and one of the most valuable drilling regions globally.

The single highest winning bid reached approximately $357,129 per acre for a 640-acre parcel — an extraordinary number for undeveloped federal land and one that reflects how aggressively producers now expect future oil prices and production economics to remain elevated.

A federal lease sale is the first step before drilling begins.

Companies bid for the rights to explore and produce oil and gas on public land, paying upfront “bonus bids” per acre, ongoing rent, and eventually royalties on whatever energy they extract. The leases generally run for 10 years and remain active as long as production continues.

When producers are willing to spend hundreds of thousands of dollars per acre before a single well is drilled, it signals deep confidence that long-term oil prices, production demand, and drilling profitability will stay strong.

Two major forces fueled the bidding frenzy.

The first is geopolitics.

The ongoing conflict involving the United States and Iran has disrupted portions of global oil supply chains and intensified fears surrounding the Strait of Hormuz, one of the world’s most critical energy shipping chokepoints. Those disruptions have pushed crude prices sharply higher and increased the strategic value of domestic U.S. production.

The second driver is policy.

The auction was conducted under the newly enacted Working Families Tax Cuts Act, which reduced the federal royalty rate on new onshore oil production to 12.5%, rolling back the higher 16.67% royalty rate imposed under the Inflation Reduction Act. Lower royalties significantly improve drilling economics for producers and reduce long-term production costs across federal acreage.

One company emerged as a dominant force during the sale.

Devon Energy reportedly committed roughly $2.6 billion during the auction, underscoring how aggressively large operators continue competing for premium Permian Basin inventory even after years of industry consolidation. Federal officials did not publicly disclose the full list of winning bidders.

The financial impact extends far beyond Washington.

Under federal law, states receive approximately 50% of bonus payments generated from federal lease sales inside their borders. That means New Mexico alone is expected to receive roughly $2 billion immediately from the sale — a staggering windfall equivalent to nearly one-fifth of the state’s annual general fund budget.

Those funds are expected to flow heavily into education, healthcare, and other state-level public programs, while New Mexico will also continue receiving half of future royalty revenues generated from production on the leased acreage.

For the Trump administration, the result immediately became a political showcase for its energy agenda.

Interior Secretary Doug Burgum called the sale proof that President Trump’s “American Energy Dominance Agenda” is delivering results, while Texas regulators described the auction as the largest federal onshore oil and gas lease sale ever recorded.

The deeper market message may matter even more than the politics.

Oil producers do not spend record-breaking sums on undeveloped acreage unless they believe strong prices, reliable demand, and profitable drilling conditions will persist for years. The bids effectively represent a multi-billion-dollar private-sector bet that global energy markets are entering a prolonged period of tighter supply and structurally higher prices.

For the U.S. oil industry, the sale was more than a government auction.

It was a signal that energy companies increasingly believe America’s domestic fields may become one of the world’s most important strategic oil supplies in an era shaped by war, geopolitical instability, and tightening global energy markets.

Houston — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Kevin Warsh got the job he wanted.

Now he has to make the kind of decision new Federal Reserve chairmen almost never face immediately: whether to raise interest rates, cut them, or do nothing — at a moment when every option risks making the economy worse.

Warsh was sworn in May 22 as the 17th chairman of the Federal Reserve, replacing Jerome Powell after a closely watched Senate confirmation vote.

President Donald Trump picked him for a simple reason: Trump wants lower interest rates, and Warsh spent much of the past year arguing they could eventually come down.

As recently as December, Warsh publicly argued that advances in artificial intelligence would improve productivity, cool inflation pressures and open the door for future rate cuts.

Then the Iran war happened.

And suddenly the economy stopped cooperating.

To understand the problem Warsh faces, you only need three numbers.

The first is the federal funds rate itself — currently sitting between 3.50% and 3.75%.

That rate influences mortgages, auto loans, business borrowing and credit-card costs across the economy. The Fed cut rates three times in late 2025 before pausing earlier this year.

The second number is inflation.

Consumer prices in April rose 3.8% from a year earlier — the highest inflation reading in nearly three years and far above the Fed’s official 2% target.

Energy prices drove much of the increase after the Iran conflict sent oil prices sharply higher. Gasoline prices alone rose more than 28% year over year.

The third number is what makes the situation genuinely difficult:

The labor market is weakening.

Job growth has slowed for months. Hiring is softer. Economic momentum is cooling.

So at the exact moment inflation is rising again, the economy itself is no longer clearly overheating.

That creates the trap.

Normally, the Fed’s dual responsibilities point in the same direction. A strong economy with rising inflation usually calls for higher interest rates. A weak economy with slowing inflation usually calls for cuts.

Right now, those signals are pointing opposite ways.

Inflation argues for a rate hike.

The labor market argues for a cut.

And doing nothing risks satisfying nobody.

Cut rates too early, and the Fed could fuel inflation that is already approaching 4%.

Raise rates to fight inflation, and the Fed risks crushing an already fragile labor market while directly frustrating the president who appointed Warsh in the first place.

That leaves the third option: pause and wait.

At the moment, that appears to be Warsh’s instinct.

Traditional central-bank thinking often treats oil shocks differently from broader inflation. Energy spikes can temporarily push inflation numbers higher without necessarily meaning prices across the wider economy are spiraling out of control.

Warsh has long favored looking at “trimmed average” inflation measures that remove the most extreme price swings to identify underlying trends.

Under those measures, inflation appears calmer than the alarming 3.8% headline number suggests.

But even that argument is becoming harder to make.

Core inflation — which strips out food and energy entirely — still climbed to 2.8% in April. Shelter costs continued rising as well.

The oil shock may be the loudest part of the inflation story.

It is no longer the only part.

Warsh also inherits a Federal Reserve that is already deeply divided internally.

At Powell’s final meeting in April, Fed officials split 8-4 — the largest level of dissent inside the central bank since 1992.

And the divide was not simple.

Some officials objected to language hinting future cuts might come later this year, arguing the Fed should keep the possibility of rate hikes on the table instead.

At the same meeting, Governor Stephen Miran, whose seat Warsh now fills, dissented in the opposite direction and argued aggressively for immediate cuts.

That means Warsh is not stepping into a committee unified around caution.

He is stepping into one split between policymakers who think the next move could be a hike and others who think it should already be a cut.

Building consensus out of that may be harder than setting rates themselves.

There is another issue that could matter even more to Wall Street.

Warsh wants to change how the Federal Reserve communicates.

For years, the Fed has publicly telegraphed its thinking through press conferences, forecasts and the famous “dot plot” — a quarterly chart showing where officials expect interest rates to go.

Markets have built entire trading systems around interpreting those signals.

Warsh believes the Fed became too dependent on its own forecasts and trapped itself into policies it should have abandoned earlier during the inflation surge of 2021 and 2022.

He has floated scaling back press conferences and potentially eliminating the dot plot entirely.

“If one has a press conference,” Warsh previously said, “one wants to deliver some important news.”

Critics argue that approach could inject even more uncertainty into already fragile markets.

Former Fed economist Claudia Sahm said she was stunned by how far Warsh appears willing to reduce communication.

The concern is straightforward: markets can tolerate bad news more easily than uncertainty.

And uncertainty is exactly what a less communicative Fed could create.

Investors themselves are already shifting expectations sharply.

Markets now see little chance of rate cuts this year.

According to CME Group’s FedWatch tool, traders increasingly expect the Fed to hold rates steady through the summer, while expectations for a possible rate hike later this year have risen sharply.

Bank of America has projected no rate cuts until the second half of 2027.

That leaves Warsh in an uncomfortable position.

He was selected largely because the White House wanted lower rates.

But the economic data may force him to do the opposite.

As Jim Bianco, president of Bianco Research, summarized it: “He’s got a tough job there now.”

Warsh’s first major test comes June 17, when he chairs his first Federal Open Market Committee meeting.

The most likely outcome, according to nearly every major forecast, is that he does nothing at all.

He pauses.

For a chairman brought in to lower rates, the safest first move may simply be proving he can wait.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

America’s economic dashboard is flashing green.

The S&P 500 trades near 7,400, a record. The Nasdaq has pushed past 26,000, also a record. The Dow sits near all-time highs. On paper, the message could not be clearer: the economy is booming.

Now ask the average American how the economy feels. You will hear a completely different story.

Families are rationing groceries. Total household debt has climbed to a record $18.8 trillion, with credit-card balances alone near $1.25 trillion and a rising share of borrowers falling behind. Homeownership is slipping out of reach for millions. More Americans are working second jobs just to hold their ground.

Both of these realities cannot be equally true. And yet we are told they are.

The uncomfortable fact is that America’s most-watched economic indicators have stopped telling the full story.

For generations, the stock market served as a rough proxy for the nation’s economic health. Manufacturing, transportation, retail, energy, banking, healthcare, and consumer spending all fed into it. When the market rose, it usually meant the broad economy was rising too.

That link is now breaking.

A handful of companies tied to artificial intelligence are increasingly responsible for driving the major indexes. The “Magnificent Seven”, Apple, Microsoft, Alphabet, Amazon, Nvidia, Meta, and Tesla, now make up roughly 35% to 40% of the entire S&P 500 by market value. Forty cents of every dollar flowing into a passive S&P 500 index fund now pours into just seven companies.

Think about what that means. The benchmark most Americans treat as a measure of the whole economy has quietly become a concentrated bet on a single industry. When those seven names rise, the index rises, and the country is told it is prospering, even if the other 493 companies and the families who depend on them are struggling.

There is nothing wrong with innovation. AI may prove to be one of the most important breakthroughs in modern history. But when one industry grows powerful enough to pull the entire market higher while much of the country feels left behind, the market stops working as an honest barometer.

The market is supposed to reflect the economy. Instead, the economy is being overshadowed by the market.

It gets harder still. Some of Wall Street’s strongest performers are thriving precisely because of conditions that hurt ordinary Americans.

Oil companies post record profits when energy prices spike. Banks post record profits when interest rates stay high. Shareholders cheer those earnings. But many of those profits are built on the very pressures crushing families trying to cover a mortgage, a car payment, the grocery bill, and the credit-card minimum.

In plain terms: some of the most celebrated corporate earnings in America today are being fueled by the financial pain of the middle class.

That should stop policymakers cold.

Consider one striking, and openly debated, statistic. Moody’s Analytics chief economist Mark Zandi estimates that the top 10% of American households, those earning roughly $250,000 or more, now account for nearly half of all consumer spending, around 49%, the highest share since the data began in 1989. Three decades ago it was about 36%. Zandi estimates this single sliver of households drives close to a third of the entire economy.

Some economists dispute Zandi’s exact figures, and that debate is healthy. But even the more conservative estimates from the Federal Reserve Bank of Minneapolis and the New York Fed confirm the underlying truth: spending by the wealthy has pulled far ahead of everyone else since 2020, while the bottom 80% have merely kept pace with inflation. As Zandi himself put it, it is no mystery why most Americans feel the economy isn’t working for them.

When economic growth leans this heavily on the spending of the richest Americans, it manufactures the appearance of broad prosperity while millions quietly fall behind. And it builds that prosperity on a dangerously narrow foundation. Consumer spending drives about 70% of the economy. If the fortunes of the wealthy turn, say, a sharp market drop that dents their confidence, the spending that props up the whole system could pull back overnight.

Meanwhile, a growing number of Americans are taking on second jobs, side gigs, and extra shifts, not for ambition, but for survival. Housing, groceries, insurance, healthcare, transportation, and interest payments have all outrun household incomes. For millions, one paycheck is no longer enough.

That is a warning sign, not a footnote.

An economy where record market gains sit alongside record consumer debt, rising financial anxiety, and a growing need for multiple jobs is not a balanced economy. It is an economy sending two contradictory signals at once.

Now look at the moment we are living through. The Middle East remains unstable. The Strait of Hormuz, one of the world’s most vital energy corridors, faces ongoing risk. Oil prices are volatile. Consumer debt is at historic highs. Affordability is strained across much of the country.

And still, the stock market sets records.

If that does not raise hard questions about how we measure economic health, what will?

Here is the heart of it: America does not have a market problem. It has a measurement problem.

We need a new economic scorecard, one that tracks not just stock prices and corporate profits, but the things families actually live:

Wage growth versus inflation
Consumer debt burdens
Housing affordability
Small-business health
Household savings
Middle-class purchasing power
Workforce participation
Economic mobility
Sector balance across the broader economy

And we must ask, seriously, whether any single industry should be allowed to dominate the indexes Americans treat as a proxy for national health. Perhaps AI deserves its own dedicated benchmark. Perhaps the broad indexes should be reweighted to reflect real economic diversity. Perhaps we need entirely new measures built for a new economy.

The specific solution is open for debate. What is no longer debatable is that the current system is losing credibility.

I write this because someone needs to say plainly what millions of Americans already know in their gut: the economy being celebrated on Wall Street is not the economy being lived on Main Street.

The market is strong. AI is creating staggering value. Corporate profits are climbing. But beneath those headlines, millions of Americans are working longer hours, carrying record debt, and watching the American Dream drift further away.

If one industry can drive the indexes higher while much of the country struggles, if oil profits rise while families pay more at the pump, if banks book record earnings while Americans pay record interest, and if growth increasingly depends on a thin slice of high earners, then our dashboard is no longer measuring the health of the nation.

It is measuring the success of a select few while ignoring the reality facing everyone else.

Treasury Secretary Scott Bessent, Commerce Secretary Howard Lutnick, members of Congress, state legislators, economists, regulators, and business leaders should come together to modernize how America measures its economy, building a scorecard that captures affordability, debt, wages, household stability, and middle-class prosperity alongside stock prices and earnings.

This is not about politics. It is about credibility.

Because if Americans keep being told the economy is thriving while their own lives say otherwise, trust in our institutions, our markets, and our data will keep eroding. And once people stop believing the scoreboard, they stop believing in the system itself.

America deserves an economic dashboard that reflects reality, not just market performance.

America needs a new economic scorecard for a new economy.

The time for lawmakers, regulators, and business leaders to act is now.

JBizNews Desk – Duvi Honig is The Founder & CEO, of The Wall Street Based Orthodox Jewish Chamber of Commerce

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 29, 2026

Lawyers for Jonathan Andic, the son and heir of late Mango founder Isak Andic, filed an appeal Thursday seeking to overturn the provisional detention order against him, arguing that the evidence surrounding his father’s death points to an accidental fall rather than homicide, according to court filings accessed by Spanish news agency Europa Press.

The case has rapidly evolved from a family tragedy into a corporate-governance crisis surrounding one of Europe’s largest privately held fashion retailers.

Mango, founded by Isak Andic in Barcelona in 1984, grew into one of the world’s largest fast-fashion brands and a direct rival to Inditex-owned Zara, operating in more than 100 countries and generating approximately €3.8 billion ($4.4 billion) in annual sales last year. The company remains overwhelmingly controlled by the Andic family through their holding company Punta Na Holding, making the legal fight deeply tied to the future leadership and stability of the business itself.

The appeal, led by prominent defense attorney Cristóbal Martell, directly challenges the forensic foundation underlying prosecutors’ allegations.

Investigators from the Mossos d’Esquadra Mountain Intervention Unit had previously conducted a series of simulations at the scene of Isak Andic’s fatal fall, concluding that marks discovered near the location appeared inconsistent with a simple accidental slip. According to the investigative report cited by the judge, recreating the marks required repeated deliberate pressure against the ground rather than a single uncontrolled fall.

The defense argues the opposite.

Martell’s filing contends the police analysis itself admitted investigators could not determine whether a slip occurred before the fall and further argues the scene had not been properly secured, potentially contaminating evidence and undermining the reliability of later forensic testing.

The legal fight has also turned heavily toward medical evidence.

The judge’s original detention order reportedly cited the absence of palm injuries and the positioning of the body to argue against a forward accidental fall. The defense counters that forensic experts found no evidence pointing toward homicide or third-party involvement.

Defense lawyers additionally submitted an independent multidisciplinary expert report concluding the injuries remained fully consistent with an accidental fall.

A central argument now emerging from the defense is physical health.

According to the filing, Jonathan Andic’s legal team argues that his father suffered from knee weakness and mobility issues that could have contributed to an accidental stumble and fatal tumble.

The case carries unusually high stakes because of Jonathan Andic’s position inside the company.

Together with sisters Sarah and Judith Andic, he controls roughly 95% of Mango through the family conglomerate. Earlier this week, Jonathan announced he would temporarily step aside as Mango’s vice chairman while focusing on his legal defense.

The appeal also attempts to dismantle prosecutors’ claims that father and son maintained a deeply deteriorated relationship.

Defense filings reportedly include statements from Jonathan’s sisters, Isak’s brother, close family associates, household staff, Mango executives, and company leadership, all describing the relationship between father and son as positive rather than hostile.

The filing also references private therapy emails beginning in early 2024 that, according to the defense, contain no expressions of hatred or resentment toward his father.

That sharply contrasts with the narrative presented by investigators.

The judge’s earlier arrest warrant stated there was sufficient evidence suggesting Jonathan Andic may have played an “active and premeditated role” in his father’s death, citing alleged tensions surrounding money, inheritance issues, and WhatsApp messages prosecutors described as reflecting anger and resentment.

Jonathan Andic became an official suspect late last year after investigators identified what they described as inconsistencies in his testimony and seized his mobile phone during the investigation.

The defense closed its appeal by condemning what it called a premature public judgment campaign, arguing that Jonathan’s highly publicized arrest and media exposure amounted to “social condemnation as anticipated punishment” before a trial has even begun.

For Mango, the implications stretch well beyond the courtroom.

The company itself remains financially healthy and globally competitive, but the future control of one of Europe’s most important privately held fashion businesses is now tied directly to the outcome of a criminal case unfolding in Spain’s courts rather than its boardrooms.

Barcelona — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

NEW YORK — May 29, 2026 — Investors have pulled approximately $2.8 billion from U.S. spot Bitcoin exchange-traded funds over nine consecutive trading days, marking the longest withdrawal streak since the products launched and signaling a major shift in institutional sentiment as capital increasingly flows toward artificial intelligence investments.

According to data compiled by Bloomberg and analytics firm SoSoValue, the selling streak began on May 15 and continued through May 28, surpassing every previous run of ETF outflows since spot Bitcoin ETFs debuted in January 2024.

During the same period, Bitcoin fell from roughly $80,000 to around $73,000, reflecting growing pressure from sustained institutional selling.

The pace of redemptions accelerated significantly this week.

The largest single-day withdrawal occurred Wednesday when investors removed approximately $733 million from the funds. More than $528 million came from BlackRock’s iShares Bitcoin Trust (IBIT) alone, representing the largest single-day outflow in the fund’s history.

Market analysts linked part of the move to a large institutional transaction executed through private trading venues known as dark pools, where sizable trades can occur outside public exchanges.

The withdrawal streak matters because spot Bitcoin ETFs have become the primary gateway through which pension funds, wealth managers, institutions, and traditional investors gain exposure to cryptocurrency.

Unlike direct cryptocurrency ownership, the ETFs allow investors to buy and sell Bitcoin through conventional brokerage accounts. When investors add money, ETF managers purchase Bitcoin. When investors redeem shares, the funds must sell Bitcoin holdings.

As a result, ETF flows provide one of the clearest indicators of institutional demand.

Right now, that demand appears to be weakening.

Many analysts believe the outflows are less about Bitcoin itself and more about competition for investment capital.

Artificial intelligence and semiconductor stocks have dramatically outperformed cryptocurrency investments throughout much of 2026, drawing significant amounts of institutional money.

Companies tied to AI infrastructure, cloud computing, advanced chips, and data-center expansion continue to attract investors seeking exposure to one of the fastest-growing segments of the global economy.

Recent gains in major technology names have reinforced that trend.

As AI-related stocks have surged, Bitcoin has struggled to generate comparable momentum, leading many portfolio managers to shift capital toward sectors producing stronger returns.

The concentration of withdrawals suggests the selling is being driven primarily by institutions rather than retail investors.

BlackRock’s IBIT and Fidelity’s FBTC accounted for the overwhelming majority of recent outflows, a pattern that analysts say is consistent with large asset allocators reducing exposure rather than individual investors making small portfolio adjustments.

Researchers at Galaxy Research described Wednesday’s redemptions as among the largest seen this year and noted that cumulative ETF flows for 2026 have now turned negative.

Some analysts characterize the move as a broader reassessment of portfolio allocations rather than simple profit-taking.

Geopolitical uncertainty may also be contributing to the trend.

The conflict involving Iran, Israel, and the United States has increased volatility across global markets, pushing investors toward sectors perceived as offering stronger earnings visibility.

While Bitcoin is sometimes promoted as a hedge against uncertainty, periods of heightened market stress have often seen the cryptocurrency trade more like a high-risk technology asset than a traditional safe haven.

That dynamic can make digital assets vulnerable when investors become more defensive.

Not everyone sees the outflows as bearish.

Some market strategists point out that previous periods of heavy ETF selling have occasionally coincided with important market bottoms.

Historical flow data analyzed by crypto research firms has shown that extreme pessimism often emerges near turning points rather than at the beginning of prolonged declines.

Whether that pattern repeats remains uncertain.

The next major test for the market comes with the May 30 monthly options expiration, an event that could increase volatility as billions of dollars in cryptocurrency derivatives contracts settle.

If ETF outflows continue beyond that date, Bitcoin could face additional downside pressure. If redemptions slow or reverse, investors may interpret the recent withdrawals as a temporary rotation rather than the beginning of a longer-term exodus.

For now, however, the message from institutional investors appears clear.

The biggest pools of capital on Wall Street are increasingly directing money toward the companies building the AI revolution, while reducing exposure to cryptocurrency assets that have struggled to match the sector’s recent performance.

Until Bitcoin regains momentum or presents a stronger growth narrative, AI appears to be winning the battle for institutional investment dollars.

Markets — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

The United States fired more than a thousand Tomahawk cruise missiles at Iran.

Replacing them could take until late 2030.

That one number, from a new analysis released Wednesday, tells you most of what you need to know about the state of America’s weapons stockpile — and why Pentagon planners are increasingly focused on a country the U.S. has not fought yet: China.

The report came from the Center for Strategic and International Studies, a prominent Washington think tank. It was written by retired Marine Colonel Mark Cancian and researcher Chris H. Park.

Their conclusion was straightforward: U.S. defense contractors will need at least three years to fully rebuild the stockpiles of several key weapons systems used heavily during the Iran war.

The weapons matter.

Tomahawk cruise missiles are long-range precision weapons used to strike targets deep inside enemy territory. Patriot and THAAD interceptors are defensive systems designed to shoot down incoming missiles and drones.

The U.S. used all three extensively during the conflict with Iran.

Now comes the part that matters most — and the part many headlines miss.

The report does not say the United States is running out of weapons.

In fact, it explicitly says the opposite: the U.S. still has “enough munitions for any plausible scenario in the Iran war.”

What America lost was the cushion.

And the cushion matters because the Pentagon does not plan for one war at a time.

The military’s central long-term concern remains a possible conflict with China over Taiwan. The Iran war did not leave the U.S. defenseless against Iran. What it did was expose how quickly a modern high-intensity conflict can drain missile inventories that were originally built for shorter and more limited wars.

The concern inside Washington is not that Iran depleted the U.S. arsenal.

It is that fighting a medium-sized regional war was enough to reveal how thin the reserves could become before a larger confrontation with China.

The reason rebuilding takes years is surprisingly simple.

America never built these weapons in large enough numbers.

For decades after the collapse of the Soviet Union, the Pentagon assumed future wars would likely be smaller, shorter and regional. Expensive high-end missiles were produced steadily, but not at the massive industrial scale associated with Cold War stockpiles.

The Iran war tested that assumption.

In a normal year, the United States produces fewer than 200 Tomahawk missiles. During the Iran conflict, the military fired more than five years’ worth in a matter of weeks.

Raytheon, now part of RTX, is expanding facilities in Alabama and Arizona and aiming to eventually produce more than 1,000 Tomahawks annually. But those expanded production lines are still being built.

The defensive interceptors face the same issue.

The report estimates the U.S. fired as many as 290 THAAD interceptors during the war. Replacing them may take until the end of 2029. Rebuilding inventories of more than 1,000 Patriot interceptors could stretch into mid-2029.

Lockheed Martin, which manufactures both systems, says it plans to invest roughly $9 billion through 2030 to accelerate output.

The report also noted that the U.S. has started retaining THAAD interceptors for domestic use that might previously have been sold to allies overseas — a sign of how seriously officials are treating the stockpile issue.

Cancian argued the problem developed over decades, not under a single administration.

“A lot of people in the Trump administration are inclined to say that everything was terrible until they arrived, and that’s not true,” he said. “Now, it is true that the Trump administration really increased funding.”

In other words, the stockpile gap was created gradually through years of procurement decisions made under both Republican and Democratic administrations.

The politics surrounding the issue are already intensifying.

Democrats in Congress have pointed to the strain on missile inventories as evidence that President Donald Trump entered the Iran conflict without fully considering the long-term military consequences. Some Republicans, meanwhile, argue that years of military aid sent to Ukraine after Russia’s 2022 invasion also contributed to the pressure on inventories.

The Pentagon insists the situation remains under control.

Chief Pentagon spokesman Sean Parnell said the military “has everything it needs to execute at the time and place of the President’s choosing.”

Defense Secretary Pete Hegseth told lawmakers last month that rising defense spending will allow manufacturers to double or even triple output over time.

But not everyone inside the defense community is reassured.

Virginia Burger, a former Marine officer now with the watchdog organization Project On Government Oversight, said Pentagon officials almost certainly understood before the war that missile inventories would be pushed “to a critical level.”

That may ultimately be the most important takeaway from the report.

America did not run out of weapons fighting Iran.

What it discovered was how quickly a modern war can burn through advanced missiles — and how long rebuilding them actually takes.

For a country whose defense strategy is increasingly centered on deterring China, “three years to rearm” is not an especially comforting timeline.

The factories will eventually refill the shelves.

The uncomfortable question hanging over Washington now is what happens if the next major conflict arrives before they do.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The federal government is preparing to write the biggest checks American drone manufacturers have ever seen — and, in a sharp break from how Washington has historically done business with defense contractors, it intends to take ownership in return.

The Pentagon and the Commerce Department are in active discussions with U.S. drone companies about a mix of grants, loans and direct equity investments tied to building out a domestic supply chain for military unmanned systems, according to filings, public statements and reporting from multiple outlets. The talks follow President Donald Trump’s December 2025 ban on imported Chinese drones and components on national-security grounds — a decision that effectively erased the lowest-cost option from the U.S. market overnight and turned the Pentagon into the buyer of last resort for an industry that did not yet have the capacity to fill the gap.

The scale of what is coming has snapped into focus over the past several weeks. The Pentagon has already earmarked $1.1 billion to stand up a domestic manufacturing base for armed drones. Needham analyst Austin Bohlig estimates that $63 billion of the administration’s fiscal 2027 defense request is directed at unmanned or drone-related technology — more than six times current spending — with roughly $55 billion of that flowing into a new program the Pentagon is calling the Defense Autonomous Weapons Group, aimed at producing low-cost expendable drones at speed.

Defense Secretary Pete Hegseth has issued directives requiring every U.S. Army squad to be equipped with small one-way attack drones — first-person-view, or FPV, drones costing under $2,000 each — by the end of fiscal 2026. The initial Army purchase is small at roughly 10,000 units, but procurement officials have signaled it is the front end of a far larger order book.

The companies in line to build them are no longer guessing about demand. AeroVironment, maker of the Switchblade loitering munition, posted record fiscal 2025 revenue of $820.6 million, up 14.45% on the year, and has announced plans to invest $1.5 billion to expand production. Kratos Defense, whose XQ-58A Valkyrie jet-powered drone has entered Marine Corps production status, reported 2025 revenue of $1.347 billion and guided to between $1.595 billion and $1.675 billion for 2026. Chief Executive Eric DeMarco has set a revenue target of $2.5 billion to $3 billion by 2028.

Palantir, whose software is increasingly used to coordinate drone fleets, reported first-quarter 2026 revenue of $1.63 billion. Smaller names — Red Cat Holdings, Ondas Holdings, Draganfly and Unusual Machines — have all reported new federal contracts in the past year.

What is genuinely new is how the government is paying.

In December, the Defense Department announced a $1.4 billion financing package for Vulcan Elements, a roughly 30-person rare-earth magnet startup whose magnets feed drone motors, radar systems and other military electronics. The deal includes a $620 million Pentagon loan, $50 million in equity for the Commerce Department, warrants giving the Defense Department the option to acquire a future stake, and $550 million from private investors. ReElement Technologies received a parallel award. The Vulcan structure mirrors the equity model the administration has now used repeatedly: a 10% stake in Intel, becoming the largest shareholder in rare-earth miner MP Materials, a 10% stake plus warrants in Trilogy Metals, a 5% stake in Lithium Americas, and a “golden share” governance role in the Nippon Steel–U.S. Steel combination.

Commerce Secretary Howard Lutnick has publicly said the administration is studying similar arrangements with traditional prime contractors.

“Lockheed Martin makes 97% of their revenue from the U.S. government. They are basically an arm of the U.S. government,” Lutnick told CNBC, when asked whether stakes in Lockheed, Boeing or Palantir were under consideration. “There’s a monstrous discussion about defense.”

For drone makers, the implications are concrete. A Pentagon willing to take equity is a Pentagon willing to write much larger checks — and to underwrite manufacturing capacity that no commercial customer would finance on its own. It also locks the federal balance sheet directly into the upside, or downside, of the companies it picks.

That last point has drawn scrutiny. President Trump’s sons Eric Trump and Donald Trump Jr. have taken equity stakes in multiple drone and defense-adjacent ventures, including Powerus, Unusual Machines, Anduril Industries and the Israeli drone maker Xtend — companies operating in sectors where their father’s administration is now also a potential equity partner. Eric Trump told the Associated Press he is “incredibly proud to invest in companies I believe in,” adding that “drones are clearly the wave of the future.”

For an industry that has spent two decades watching China dominate the consumer and component sides of the drone business, the new posture from Washington — buy American, fund American, and own a piece of American — is the most direct industrial-policy intervention the U.S. defense base has seen in a generation. Whether it produces the drones the Pentagon actually needs, at the prices it has set, is the next question.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

OTTAWA — May 29, 2026 — Canada has officially fallen into recession for the first time since the COVID-19 pandemic after Statistics Canada reported Friday that the economy contracted for a second consecutive quarter, weighed down by U.S. tariffs, elevated oil prices, and a sharp slowdown in population growth.

According to Statistics Canada, real gross domestic product declined 0.1% in the first quarter of 2026, following a 0.6% contraction in the fourth quarter of 2025. The back-to-back declines meet the commonly accepted definition of a technical recession and mark Canada’s first recession since 2020.

The figures came as a surprise to economists and policymakers. The Bank of Canada had projected growth of approximately 1.8%, while Statistics Canada’s preliminary estimate issued last month pointed to growth closer to 1.7%.

The weaker-than-expected result underscores how quickly economic conditions have deteriorated amid growing trade tensions and global uncertainty.

Trade Pressures Mount

A major factor behind the downturn has been the impact of U.S. trade measures imposed by President Donald Trump, which have affected several key Canadian industries including steel, aluminum, copper, lumber, and automobiles.

Export demand has softened as tariffs increase costs and create uncertainty for manufacturers and investors. Businesses have responded by delaying expansion plans and reducing capital expenditures while awaiting greater clarity on the future of North American trade relations.

Although Canada’s manufacturing sector showed signs of life earlier in the quarter, helped by a rebound in auto production, output remains below year-earlier levels.

Oil Shock Creates Mixed Impact

The conflict involving Iran, the United States, and Israel has added another layer of economic pressure.

Crude oil prices have climbed sharply since the outbreak of hostilities, boosting revenues for energy-producing provinces such as Alberta while simultaneously increasing fuel, transportation, and operating costs across the broader economy.

Higher energy prices are helping some sectors but squeezing consumers already dealing with elevated living costs and persistent inflation pressures.

Seasonal maintenance activity in Canada’s oil and gas industry further weighed on economic activity during March, contributing to the quarter’s negative result.

Population Growth Reverses

Another major shift has emerged in Canada’s demographic outlook.

After years of rapid population expansion fueled largely by immigration and temporary resident programs, growth has stalled as the federal government moves to reduce immigration levels and temporary resident numbers.

A slower-growing population means fewer workers entering the labor force and fewer consumers driving demand, reducing one of the key engines that supported Canada’s economy during recent years.

Labor Market Weakening

For many Canadians, the recession may feel like a continuation of trends already visible in the labor market.

Employment growth has slowed significantly, and job losses earlier this year ranked among the steepest outside previous recessionary periods. The national unemployment rate has remained near 6.7%, considerably above recent lows.

Consumer confidence has also softened as households contend with higher borrowing costs, housing affordability challenges, and concerns about economic stability.

Bank of Canada Faces Difficult Choice

The recession now places additional pressure on Bank of Canada Governor Tiff Macklem and policymakers.

The central bank’s benchmark interest rate currently stands at 2.25%, and officials face competing concerns.

On one hand, a contracting economy traditionally argues for lower interest rates to stimulate growth. On the other hand, rising oil prices threaten to push inflation higher, making aggressive rate cuts potentially risky.

The latest GDP figures strengthen the case for monetary easing, but policymakers remain cautious about reigniting inflationary pressures.

Business Investment at Risk

The recession designation could further dampen business sentiment.

Companies often respond to economic contractions by slowing hiring, reducing expansion plans, and preserving cash. Economists warn that weaker confidence could become self-reinforcing if businesses and consumers pull back simultaneously.

Residential construction also remains under pressure as housing demand softens and affordability challenges persist.

Can Canada Recover Quickly?

Despite the disappointing headline, economists note that the downturn remains relatively shallow compared with previous recessions.

Canada still posted 1.7% growth for full-year 2025, one of the stronger performances among G7 economies, and many forecasters believe growth could resume if trade tensions ease and energy markets stabilize.

Whether that happens depends largely on factors beyond Ottawa’s control.

For now, Canada has crossed an economic threshold it had avoided for nearly six years, and attention is turning toward how long the contraction lasts and whether policymakers can prevent a deeper downturn.

The immediate challenge facing Canada is clear: navigating a trade dispute with its largest customer while absorbing the economic fallout from a volatile global energy market.

Canada — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 27, 2026

The U.S. Supreme Court on Tuesday declined to hear an appeal from Meta Platforms, allowing the state of Vermont to continue pursuing a lawsuit accusing the company of designing Instagram to addict young users — a decision that significantly increases the likelihood Meta could face similar legal exposure across all 50 states.

The justices rejected Meta’s attempt to overturn a lower-court ruling that allowed Vermont’s case to proceed, leaving intact a decision by the Vermont Supreme Court that found the state has jurisdiction to sue the social-media giant over harms allegedly caused to teenagers using Instagram. As is customary in denied appeals, the Supreme Court did not provide an explanation for its decision.

The ruling does not determine whether Meta violated any law. Instead, it clears the way for Vermont’s claims to move forward through discovery and trial proceedings — and sends a broader signal that states may continue pursuing consumer-protection and youth-harm lawsuits against major technology companies in their own courts.

The implications for Meta stretch far beyond Vermont.

The company had argued that allowing states to individually sue over platform design and user harms would expose Meta to litigation nationwide, creating what it described as an unconstitutional burden under the 14th Amendment’s due-process protections. By declining to intervene, the Supreme Court effectively left that exposure in place.

The Vermont lawsuit is part of a wider coordinated legal effort involving attorneys general from 42 states pursuing actions tied to youth mental health, platform addiction, and alleged deceptive practices involving minors.

At the center of the dispute is how Instagram was allegedly engineered.

Vermont Attorney General Charity Clark argues in court filings that Instagram was intentionally designed to exploit the psychology and neurological development of teenagers in order to maximize engagement, increase screen time, and ultimately generate greater advertising revenue.

The Vermont Supreme Court ruled in 2025 that companies operating nationwide and actively profiting from users inside a state can reasonably expect to be sued there. That interpretation now stands after the Supreme Court’s refusal to hear the case.

For Meta, the decision adds to mounting legal pressure surrounding allegations that its platforms harm children and teenagers.

Earlier this year, a Los Angeles jury found both Meta and Google negligent in a case tied to the mental-health impact of social media on a young user, awarding approximately $6 million in damages. Separately, a New Mexico jury concluded that Meta violated that state’s consumer-protection laws by misrepresenting the safety of Facebook, Instagram, and WhatsApp for younger users, resulting in a damages award of roughly $375 million.

Additional lawsuits remain active in states including Massachusetts and New Mexico.

The financial risk compounds quickly.

Each individual state case carries separate discovery costs, potential damages, legal fees, and the possibility of court-ordered operational changes to platform design and safety features. A single adverse verdict can reach into the hundreds of millions of dollars. Multiple losses across jurisdictions could transform what might otherwise be manageable litigation into a long-term structural risk for the company.

Meta has repeatedly denied claims that its platforms are intentionally harmful to children and says it continues investing in parental controls, teen-safety features, and content protections designed to improve the online experience for younger users.

For the broader technology industry, Tuesday’s Supreme Court order sends a clear message: courts remain increasingly willing to scrutinize not only what users post online, but how platforms themselves are intentionally designed to maximize engagement and profit.

The decision also weakens one of Silicon Valley’s longstanding legal defenses — the idea that nationwide technology companies can avoid being dragged into dozens of separate state-level courts simultaneously.

For Meta, the legal battle now continues one state at a time.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

The world’s legacy automakers are no longer fighting to win in China. Increasingly, they are fighting to preserve their position in the global auto industry itself.

Ford Chief Executive Jim Farley has emerged as one of the most outspoken Western executives warning about the scale of the threat coming from China’s electric-vehicle industry. Speaking in Paris while announcing a small-EV partnership with Renault, Farley said the global auto sector is now in “a fight for our lives,” describing China’s rise as even more disruptive than Japan’s automotive expansion in the 1980s.

What began as a competitive problem inside China has evolved into something much larger. Chinese automakers including BYD, Geely, Chery, Nio, and Xiaomi are no longer simply dominating their home market. They are exporting aggressively, building factories across multiple continents, reshaping global pricing, and forcing established Western manufacturers into defensive mode.

The numbers are becoming difficult to ignore.

BYD delivered approximately 4.6 million new-energy vehicles in 2025, overtaking Tesla in global battery-electric vehicle sales for the first time. More than one million of those vehicles were sold outside China, more than doubling the company’s overseas sales from the previous year. Executives at BYD have signaled ambitions to expand even further in 2026, with overseas sales targets reportedly reaching as high as 1.5 million vehicles.

This is no longer simply about cheap labor or lower-cost exports. It is increasingly viewed by Western policymakers and executives as the result of a coordinated industrial strategy.

Research firm Rhodium Group estimates that Beijing has poured tens of billions of dollars into electric-vehicle and battery manufacturing through subsidies, financing programs, infrastructure investment, and supply-chain support. European and American officials argue the support has distorted global competition. But the strategy has also succeeded in producing scale, advanced manufacturing capacity, and lower-priced EVs that consumers worldwide are increasingly willing to buy.

The impact is now appearing directly inside Western automakers’ earnings reports.

BMW reported a significant decline in pre-tax profit last year, while warning investors that growth in China remains weak and profitability is under pressure from both tariffs and falling demand. Mercedes-Benz and Volkswagen have also struggled with declining Chinese market share and slower-than-expected EV transitions.

Even luxury segments once considered untouchable are beginning to shift.

In China’s premium vehicle market, imported luxury sedans from Porsche and BMW are now facing direct competition from technology-driven domestic brands backed by companies such as Huawei. The emergence of Huawei-backed luxury models reflects how China’s technology ecosystem is increasingly converging with its automotive sector, blending software, AI systems, entertainment platforms, and advanced battery capabilities directly into vehicles.

Western manufacturers are attempting to respond.

At recent auto shows in Beijing and Shanghai, European and American automakers unveiled a wave of new China-focused models aimed specifically at local consumer tastes and software preferences. Consulting firms including McKinsey have warned global manufacturers that the coming decade will determine which companies remain globally competitive in electric vehicles and which fall behind permanently.

But Chinese companies continue expanding rapidly.

BYD is already building or operating facilities in countries including Hungary, Brazil, Thailand, Turkey, and Indonesia, while evaluating additional European manufacturing expansion. The company has also announced plans for ultra-fast charging networks and next-generation battery systems capable of dramatically reducing charging times — one of the key areas where consumers still hesitate to adopt EVs.

The competitive challenge is no longer only about price.

Chinese automakers are increasingly competing on software integration, battery efficiency, charging speed, user interface design, and consumer technology ecosystems — areas traditionally dominated by Western and Japanese brands.

Farley has repeatedly warned that the United States cannot assume tariffs alone will permanently shield domestic manufacturers.

“The Chinese auto industry has enough capacity to serve the entire North American market,” Farley warned during a televised interview last year. “If we lose this, we do not have a future Ford.”

For now, steep U.S. and European tariffs continue limiting the direct flow of Chinese-built EVs into some Western markets. But much of the developing world — including parts of Latin America, Africa, Southeast Asia, and the Middle East — remains far more open, allowing Chinese brands to rapidly gain global market share.

The larger concern for Western executives is that once Chinese companies achieve global manufacturing scale, software dominance, and brand recognition, competing against them could become significantly harder even inside historically protected markets.

For more than a century, American, European, and Japanese automakers largely dictated the rules of the global car industry. Increasingly, that balance of power appears to be shifting eastward.

And for the first time in generations, legacy automakers are confronting the possibility that they may no longer be setting the pace of the industry they once controlled.

Global Markets — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

Lululemon Athletica has reached a settlement with founder Chip Wilson, ending a bitter proxy battle that had escalated publicly over recent months and handing the company’s largest individual shareholder renewed influence inside the boardroom just weeks before its annual shareholder meeting.

Under the agreement announced Wednesday, Lululemon will appoint two of Wilson’s nominees to its board — former On Holding co-chief executive Marc Maurer and former ESPN chief marketing officer Laura Gentile — while also agreeing to add a third independent director with apparel and brand-development expertise by October.

In return, Wilson agreed not to publicly criticize the company for approximately 18 months, according to the settlement terms. The agreement also caps Wilson’s ownership stake at roughly 10%, close to his current 8.6% holding, while granting him regular access to incoming chief executive Heidi O’Neill.

The settlement ends a confrontation that had increasingly turned hostile.

Wilson, who founded Lululemon in 1998 and stepped down as chief executive in 2005, remained chairman until 2013 before leaving amid controversy following comments tied to a product recall involving the company’s signature black yoga pants. While he continued criticizing the company periodically over the years, tensions escalated sharply in late 2025 as the retailer’s stock price and competitive position deteriorated.

Negotiations between the two sides nearly produced an agreement earlier this month before talks collapsed after Wilson reportedly expanded his demands. Lululemon responded by publicly attacking its founder, accusing him in shareholder communications of promoting “outdated perspectives” and presenting “troubling conflicts of interest.”

The backdrop to the fight has been a severe decline in shareholder value.

Lululemon shares have fallen nearly 59% over the past year and are down roughly 42% so far in 2026. Investor concerns intensified after the company issued weak guidance during its March earnings report and warned that tariffs, slowing momentum, and the proxy battle itself would pressure profits throughout the year.

The settlement removes at least one major distraction as management attempts to stabilize the business.

Wilson’s criticism has centered largely on product strategy.

He has repeatedly argued that Lululemon drifted away from the “product-first” culture that originally made the brand dominant in premium athletic apparel. The addition of new board members with product and branding backgrounds suggests the company may be acknowledging at least some of those concerns.

The competitive environment has also shifted dramatically.

Newer athletic and lifestyle brands including Vuori and Alo Yoga have steadily gained market share among younger and fashion-conscious consumers, eroding the cultural dominance Lululemon once held in the athleisure market it effectively helped create.

From a governance perspective, the settlement offers advantages to both sides.

A prolonged proxy fight heading into Lululemon’s June 25 annual meeting would likely have become expensive, distracting, and unpredictable for shareholders and management alike. By granting Wilson partial influence now, the company avoids a public shareholder referendum on its turnaround strategy while securing a temporary ceasefire from its loudest internal critic.

Wilson, meanwhile, regains influence over the company without needing to win a contested shareholder vote.

Whether the peace lasts will likely depend on product innovation, sales momentum, and whether incoming leadership can restore the brand relevance and customer enthusiasm that once made Lululemon one of retail’s strongest growth stories.

For now, the company has bought itself time — but at the price of bringing its founder back into the room he never entirely left.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Something has quietly changed in the American car business, and the people who run it have stopped pretending it’s temporary.

For five straight years before 2020, Americans bought more than 17 million new cars a year. Last year they bought 16.3 million. That gap — roughly one million buyers — has not closed in six years.

The industry now believes those buyers are not coming back any time soon.

“The new norm because of reduced affordability is closer to 16 million,” Jonathan Smoke, the chief economist at Cox Automotive, has told reporters. “We’ve lost about 10% of the buying pool.” His blunt explanation: those buyers were “literally priced out of the market.”

Patrick Manzi, the chief economist at the National Automobile Dealers Association, told dealers at the NADA Show in February that 17 million is not coming back for years. His April report said sales were running at a 15.9 million pace — the eighth straight month of declines.

So where did the missing buyers go?

The simple answer is: they looked at the sticker, looked at the monthly payment, and walked away.

The average new car in America today costs about $49,000. The average sticker price has been above $50,000 for ten months in a row. Average monthly payments hit a record $772 in the last three months of 2025. One out of every five people who financed a new car last quarter signed up for a payment of $1,000 a month or more.

That is the kind of monthly bill that used to belong to a mortgage.

A natural question is whether leasing — long the industry’s tool for getting people into cars they cannot quite afford to buy — is helping.

The answer is: only for one slice of the market.

Electric vehicles are leasing for as little as $239 a month right now, less than half the national average payment. But the federal EV tax credit that made those deals work expired on September 30 of last year, new EV sales fell 28% in the first quarter of 2026, and Cox Automotive expects EV leasing to shrink this year.

For the gas-powered cars most Americans actually shop for — the Toyota RAV4, Honda CR-V and Ford F-150 — there is no cheap lease waiting on the lot.

There is another change worth understanding, because it explains why the industry is not panicking.

The people still buying new cars are richer than they used to be.

Cox Automotive found that households earning $150,000 or more now account for 43% of new-car sales. Households earning under $75,000 account for about 25%. Six years ago, those two groups were roughly equal.

Smoke put it more sharply: new cars today “almost exclusively go to the top 20%” of American households.

Automakers are not trying to reverse this. They are leaning into it.

Small, affordable cars — the kind that used to bring first-time buyers in the door — have been quietly killed off across the industry, replaced by bigger pickups and SUVs that carry bigger profits.

It is working, on their terms.

Americans spent $620 billion on new cars in 2025, up nearly 6% from the year before — even though they bought roughly the same number of cars. Fewer customers, more dollars per customer.

The showroom in 2026 reflects all of this.

S&P Global Mobility projects March sales of about 1.37 million cars, well below last year. J.D. Power says incentives are climbing — Toyota is offering up to $5,000 off some Tundras, GMC is discounting Sierras by up to 20%, Hyundai and Kia are offering zero-percent financing with deferred payments.

None of it is bringing the missing million back.

What it is doing, in Cox Automotive’s words, is pushing more shoppers to the used market — where 76% of car purchases this year have landed.

The industry is now budgeting around a 16-million-car America instead of a 17-million one. Factory capacity, dealer staffing, advertising budgets and lender underwriting are all being reset to the smaller, richer market.

The missing million have not disappeared. They are still driving.

They are just driving cars somebody else used to own.

Whether they ever come back to the new-car lot depends on whether wages catch up to a $50,000 sticker — or whether automakers eventually decide they would rather sell to them than around them.

For now, neither side is moving.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

May 28, 2026 — Newcleo Ltd., the advanced nuclear developer building reactors that run on recycled atomic waste, said in a company statement Wednesday that it has agreed to merge with NewHold Investment Corp III, a publicly traded shell company, in a deal that values the startup at roughly $2.4 billion before new money comes in. The combined business plans to trade on the Nasdaq under the ticker NWCL, with the deal expected to close in the second half of 2026.

The agreement gives Newcleo a fast route onto the U.S. stock market. Rather than running a traditional initial public offering, the company is merging into a blank-check firm that already trades publicly. The shell company, NewHold Investment Corp III, exists only to find a private business to take public. Once the two combine, Newcleo’s shares start trading without the long road of a standard listing.

The transaction is set to raise as much as $429 million in cash for the company. About $220 million comes from a private placement of stock sold to large investors and several current shareholders at $10 a share, with 22 million shares to be issued. Another $209 million sits in NewHold’s trust account, though that figure could shrink if some of the shell company’s investors ask for their money back before the deal closes, a common feature of these mergers.

Newcleo was started in 2021 by physicist Stefano Buono, who runs the company as chief executive. Before Newcleo, Buono founded Advanced Accelerator Applications, a medical isotope firm that listed on the Nasdaq and was bought by drugmaker Novartis in 2018 for $3.9 billion. The Paris-based company now operates in seven countries and employs more than 900 people. It has raised about $780 million in private funding since it began.

The business is still years away from selling power. Newcleo designs small, lead-cooled reactors that burn mixed-oxide fuel, known as MOX, which is made from reprocessed nuclear waste rather than freshly mined uranium. The pitch is that the technology can generate carbon-free electricity while shrinking the stockpile of radioactive material left over from older plants. The company holds patents across 31 families covering both the reactor design and the fuel process. It reported about $80 million in revenue and other income in 2024, almost all of it from supplying equipment to the nuclear industry rather than from running reactors.

The listing lands in the middle of a rush of nuclear companies onto public markets, driven by the enormous electricity demand from artificial-intelligence data centers. Oklo, a U.S. reactor developer Newcleo partnered with in October 2025, went public through its own blank-check merger in 2024. NuScale Power took the same path in 2022. Investors have warmed to the sector on the bet that AI’s appetite for round-the-clock power will need new sources of generation that wind and solar alone cannot supply.

Still, the structure carries real risk for buyers. Companies that go public this way have a spotty record, with many sliding sharply after their debuts. Newcleo’s $80 million in 2024 income is small against a $2.4 billion price tag, and no lead-cooled fast reactor has yet run at commercial scale anywhere. The company must clear regulators in both Europe and the United States, and any holdup could drain its cash before its first reactor produces a watt.

The deal points to how quickly money is moving into next-generation nuclear. A company that did not exist five years ago, and that has yet to power a single home, is now preparing to ask public investors for hundreds of millions of dollars on the promise of what its reactors might one day do.

JBizNews Desk

© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

By JBizNews Desk

Mark Zuckerberg said something Wednesday that could quietly reshape the cloud computing business.

Asked at Meta’s annual shareholder meeting whether the company would ever compete with Amazon and Microsoft in cloud computing, Meta chief executive Mark Zuckerberg answered plainly: “It’s definitely on the table.”

The condition he attached was just as interesting as the answer.

Meta would consider getting into the cloud business, Zuckerberg said, if the company ends up building more data-center capacity than it needs for itself.

To understand why that matters, it helps to know one thing about how Big Tech is structured today.

There are four companies in America that build computing power at a truly massive scale — what the industry calls hyperscalers.

Three of them — Amazon, Microsoft and Google — rent that computing power out to other businesses. That rental business has names everyone in tech knows: AWS, Azure and Google Cloud. Together they generate hundreds of billions of dollars a year selling computing power to companies that do not want to build their own infrastructure.

Meta is the fourth hyperscaler.

And Meta is the only one of the four that does not sell its computing power to anyone else.

Until now, Meta has built data centers strictly to power its own businesses — Instagram, WhatsApp, Facebook and, increasingly, its artificial intelligence models.

What changed is the scale of what Meta is building.

The company told investors in April that it now plans to spend between $125 billion and $145 billion on capital expenditures in 2026 — most of it on AI data centers and the chips that go inside them.

That is nearly double what Meta spent in 2025, and more than the company spent in 2025 and 2024 combined.

Meta is building so much infrastructure that one data-center campus alone, in rural Louisiana, will use roughly the same amount of electricity as 4.2 million homes.

That is the backdrop to Zuckerberg’s comment.

When a company is spending money on that scale, the question of what to do with leftover computing capacity stops being theoretical.

“Almost every week,” Zuckerberg said, “there are different companies that come to us from outside asking us to both stand up an API service or asking if we have compute that they could buy from us.”

In other words, the customers are already there.

They are knocking.

Meta has, so far, said no.

If that changes, the implications are large.

The cloud infrastructure market is worth roughly $600 billion a year and is currently dominated by three players. A fourth hyperscaler stepping in — one that already owns the chips, the buildings and the power contracts — would be the most credible new entrant the industry has seen in years.

Wall Street has been nervous about Meta’s spending for a different reason.

When the company raised its capex range in April, the stock fell sharply the next day. Investors saw a company pouring massive amounts of cash into infrastructure with no obvious way to directly earn it back.

Alphabet and Amazon reported earnings during the same period, and their stocks moved higher. The difference was straightforward: both companies already have cloud businesses that turn AI infrastructure into recurring revenue streams. Meta does not.

Zuckerberg’s comments Wednesday were the first public acknowledgment from him that this could eventually change.

He did not commit to launching a cloud business. He said it was “on the table.”

But the framing he chose — that Meta would enter the market if it ends up with excess capacity — matters. It signals that the company is no longer ruling out a path Wall Street has been pushing for over a year.

And it quietly puts Amazon, Microsoft and Google on notice that the fourth hyperscaler might someday show up as a direct competitor instead of just another customer.

For now, Meta is still buying cloud capacity, not selling it.

The company signed a cloud agreement reportedly worth more than $10 billion with Google Cloud last August, a $14.2 billion deal with CoreWeave in September, a $3 billion deal with Nebius in November, and has reportedly been in talks with Oracle for another major contract.

Meta is, at this moment, one of the largest cloud customers in the world.

The interesting question is what happens when the company finishes building enough infrastructure that it no longer needs anyone else’s.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

SEOUL — May 29, 2026 — Shares of LG Electronics surged as much as 24% Friday after the South Korean technology giant unveiled a new generation of in-car software developed with Google, a move investors viewed as a major step in LG’s transformation from a consumer electronics manufacturer into a key supplier for the next generation of connected vehicles.

The rally followed an announcement by LG Electronics on May 28 showcasing a suite of advanced in-vehicle infotainment and software-defined vehicle technologies built on Google’s Android Automotive operating system. The company said the products received recognition from both Google and global automakers, while a Google executive praised the systems for their performance, stability, voice-control capabilities, and flexibility.

The centerpiece of LG’s new platform is technology that allows multiple vehicle displays to operate from a single processor.

Modern vehicles increasingly feature multiple screens, including digital instrument clusters, central infotainment displays, passenger entertainment systems, and head-up displays. Traditionally, each screen requires separate computing hardware, increasing complexity and manufacturing costs.

LG said its new architecture enables multiple displays of varying sizes and configurations to run simultaneously from a single chip, reducing hardware requirements and lowering costs for automakers. The platform is powered by Qualcomm’s next-generation Snapdragon Cockpit Platform, one of the industry’s most advanced automotive processors.

For consumers, Android Automotive provides direct access to familiar applications including navigation, music streaming, voice assistants, and other services without requiring a smartphone connection. The platform has gained traction across the automotive industry as manufacturers seek to create more seamless digital experiences inside vehicles.

The market opportunity is substantial.

Industry estimates from Future Market Insights place the global Android Automotive software market at approximately $895.6 million in 2025, with projections showing expansion to roughly $2.14 billion by 2035 as software becomes an increasingly important component of vehicle design and functionality.

Investors appear to be betting that LG is well positioned to capture a meaningful share of that growth.

The company’s Vehicle Component Solutions division has emerged as one of its fastest-growing businesses in recent years, helping offset slower growth and margin pressure in traditional appliance and television segments. As automakers increasingly prioritize software, connectivity, and digital services, suppliers capable of delivering integrated software-hardware platforms have become strategically important.

A public endorsement from Google provides additional credibility for LG’s automotive ambitions.

The announcement comes at a particularly important time for the company. LG recently reported weaker-than-expected profitability in several of its core consumer electronics divisions, including home appliances and home entertainment products. Against that backdrop, the emergence of a potentially high-growth automotive software business offers investors a new narrative centered on future expansion rather than mature consumer markets.

The partnership also builds on a broader strategy that LG has been pursuing with major U.S. technology firms.

At the Consumer Electronics Show (CES) earlier this year, LG and Qualcomm introduced an AI Cabin Platform designed to bring generative artificial intelligence into vehicle interiors. The newly announced Android Automotive systems extend that initiative and position LG as a supplier of both the hardware and software infrastructure automakers increasingly need but may not want to develop internally.

For the broader automotive industry, the implications could extend beyond infotainment.

Vehicle interiors are rapidly evolving into sophisticated digital environments where software often plays as important a role as mechanical engineering. Automakers are under pressure to add more displays, more computing power, and more connected services while simultaneously controlling manufacturing costs.

LG’s single-chip approach addresses that challenge directly by simplifying system architecture and reducing hardware requirements.

If widely adopted, the technology could help lower production costs for vehicles while bringing premium digital features to a broader range of models.

The stock’s sharp rise reflects investor confidence that LG’s automotive technology strategy is beginning to gain meaningful traction. Whether those gains are sustained will depend on the company’s ability to convert industry recognition into long-term contracts with global automakers and successfully scale its software-defined vehicle business.

For now, however, investors appear convinced that LG’s future may increasingly be found not in living rooms and kitchens, but behind the dashboard.

Asia — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 29, 2026

Three major U.S. retailers delivered stronger-than-expected earnings Thursday morning, sending shares higher across the sector and offering fresh evidence that American consumers are still spending even as inflation climbs to its highest level in nearly three years.

The earnings from Best Buy, Kohl’s, and Dollar Tree covered three very different segments of retail — electronics, department stores, and discount chains — yet all managed to outperform Wall Street expectations at the same time, reinforcing the view that household spending has remained resilient heading into the summer.

The strongest report came from Best Buy.

The electronics retailer said comparable sales rose 2% during its fiscal first quarter ended May 2, exceeding both company guidance and analyst expectations of roughly 0.9%. Revenue reached approximately $8.9 billion, above forecasts near $8.8 billion, while adjusted earnings came in at $1.28 per share, topping estimates of $1.22.

Chief Executive Corie Barry credited broad-based demand across most major product categories, helped in part by larger tax refunds and new product launches including Apple’s MacBook Neo lineup.

Comparable sales — a closely watched retail metric measuring revenue growth at stores open at least one year — are considered one of the clearest indicators of underlying consumer demand because they exclude the effect of opening new locations. Best Buy’s return to positive comparable growth marked a notable turnaround from the prior holiday quarter, when sales had declined.

Kohl’s told a more complicated story, but still cleared lowered investor expectations.

The department-store chain posted a quarterly net loss of $14 million, or 13 cents per share, narrower than analysts had expected. Revenue totaled roughly $3 billion, slightly ahead of forecasts.

Sales trends, however, remained negative. Net sales fell approximately 1.7%, while comparable sales declined 1.1%. Still, that represented an improvement from the steeper 2.8% comparable-sales decline reported during the prior quarter.

Management reaffirmed its full-year outlook, forecasting sales ranging from down 2% to flat for fiscal 2026.

Investors appeared focused less on the decline itself and more on signs that conditions may be stabilizing. Kohl’s shares had already fallen more than 35% this year entering Thursday’s report, leaving expectations extremely low.

The company also disclosed that it has applied for approximately $190 million in tariff refunds, though no payments have yet been received. The figure highlights how directly trade policy and tariff disputes continue affecting corporate balance sheets across retail.

Dollar Tree completed the trio of positive surprises.

Shares in the discount retailer climbed after the company also posted results above expectations, benefiting from the continued shift toward value-oriented shopping behavior as consumers remain pressured by higher prices.

Discount chains historically perform well during inflationary periods as shoppers look for cheaper alternatives on household goods and everyday essentials. But what stood out Thursday was that strength appeared simultaneously across discount retail, department stores, and consumer electronics — a broader pattern suggesting consumer spending remains more durable than many economists expected.

The timing of the reports amplified the message.

The earnings arrived just hours after the Commerce Department reported that the Personal Consumption Expenditures Price Index, the Federal Reserve’s preferred inflation gauge, rose 3.8% in April, the highest reading in nearly three years.

Ordinarily, hotter inflation would be expected to pressure discretionary spending. Yet Thursday’s retail results showed households continuing to purchase electronics, apparel, and household items despite rising prices and elevated borrowing costs.

That resilience now becomes one of the central questions facing Wall Street heading into the second half of 2026.

Consumers have so far continued spending through inflation, tariffs, higher interest rates, and geopolitical uncertainty. Whether that durability can continue through the summer — especially if prices remain elevated — may determine the direction not only of the retail sector, but of the broader U.S. economy itself.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

CAPE CANAVERAL, Fla. — May 28, 2026Blue Origin’s flagship New Glenn rocket exploded during a ground test Thursday night at Cape Canaveral, dealing a major setback to Jeff Bezos’ space company at a pivotal moment in its competition with Elon Musk’s SpaceX.

The explosion occurred during a hot-fire test at Launch Complex 36 at approximately 9 p.m. Eastern, producing a massive fireball visible across parts of Florida’s Space Coast and prompting an immediate response from emergency personnel.

In a statement, Blue Origin confirmed it experienced an “anomaly” during testing and said all personnel were accounted for with no reported injuries.

“We experienced an anomaly during a hot-fire test of New Glenn,” the company said. “All personnel are safe and accounted for. We will provide additional information as it becomes available.”

Officials from Brevard County Emergency Management said there was no threat to nearby residents and that emergency crews were monitoring the situation while allowing the controlled fire to burn out.

The rocket involved was a New Glenn heavy-lift launcher, the centerpiece of Blue Origin’s orbital launch ambitions and a vehicle the company is counting on to compete directly with SpaceX in the commercial launch market.

The booster was being prepared for what could have been its fourth flight as early as June 4, carrying dozens of satellites for Amazon’s Project Kuiper, the broadband internet network designed to challenge SpaceX’s dominant Starlink constellation.

Amazon confirmed no satellites were aboard the rocket during the test.

Industry analysts said the scale of the explosion suggests the vehicle was likely fully fueled in preparation for the engine firing sequence.

The timing could hardly be worse for Blue Origin.

The explosion comes just days after SpaceX filed paperwork for what is expected to become the largest initial public offering in history. Investors are closely watching the company’s planned debut, which could value the firm at up to $2 trillion and raise tens of billions of dollars from public markets.

While SpaceX is preparing a global investor roadshow and highlighting its dominance in launch services and satellite communications, its closest American rival is now facing a potentially lengthy investigation and launchpad repairs.

For Blue Origin, the setback follows an already difficult year.

During an earlier New Glenn mission, the rocket’s upper stage reportedly suffered technical issues that prevented a payload from reaching its intended orbit. Although portions of the mission succeeded, the incident raised questions about the vehicle’s operational reliability.

Thursday night’s explosion now threatens to delay future launches and complicate Blue Origin’s effort to establish a regular launch cadence.

That schedule is particularly important because of the contracts tied to New Glenn.

Amazon has reserved numerous launches to deploy its growing Project Kuiper satellite network. The company is racing to place thousands of satellites into orbit as it attempts to build a viable competitor to Starlink, which currently serves millions of users worldwide.

Any prolonged grounding of New Glenn could force Amazon to rely more heavily on other launch providers while potentially slowing portions of its deployment timeline.

The implications extend beyond Amazon.

NASA, the U.S. Space Force, and commercial customers have all looked to New Glenn as a future source of launch capacity at a time when demand for space transportation continues to expand rapidly.

For Florida’s Space Coast economy, where launch activity supports thousands of jobs and generates substantial tourism and business spending, an extended interruption could also carry economic consequences.

Meanwhile, the incident reinforces SpaceX’s dominant position in the launch industry.

The company conducted dozens of successful launches over the past year while continuing to expand Starlink and advance development of its next-generation Starship system.

Investors evaluating the SpaceX IPO are likely to view the latest Blue Origin setback as further evidence of the significant lead Musk’s company has built in both launch frequency and operational scale.

The cause of the explosion remains under investigation.

Neither Blue Origin nor federal authorities have provided an estimate for when testing might resume or when New Glenn could return to flight status.

Despite the setback, Blue Origin has overcome technical failures before and remains one of the best-funded private space companies in the world, backed by Bezos’ substantial personal resources and long-term commitment to the industry.

Still, the image of a New Glenn rocket erupting into flames on a Florida launchpad is likely to become one of the defining space-industry moments of 2026 — and one that arrives just as Wall Street prepares to place a historic valuation on its chief competitor.

Florida — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

Apple is preparing the biggest overhaul of Siri since the voice assistant debuted nearly 15 years ago, betting that a completely rebuilt AI-powered version can help the company regain ground in the rapidly escalating artificial-intelligence race.

According to a report published Thursday by Bloomberg News, Apple plans to unveil the redesigned Siri at its annual Worldwide Developers Conference (WWDC) on June 8 as part of iOS 27, the next major software release for the iPhone, iPad, and Mac.

The stakes could hardly be higher.

While rivals including OpenAI, Google, Microsoft, and Samsung have spent the past two years aggressively integrating advanced AI assistants into their products, Apple has struggled with delays, missed deadlines, and growing criticism that Siri has fallen far behind competing platforms.

Now the company is attempting a reset.

Rather than functioning primarily as a voice-command tool, the new Siri is reportedly being rebuilt into a fully conversational AI assistant capable of maintaining context, understanding complex requests, and interacting with users much more like ChatGPT, Gemini, or Claude.

According to Bloomberg, Siri will become deeply integrated into Apple’s operating system and will live inside the iPhone’s Dynamic Island, allowing users to interact with it more naturally across applications.

Users will still be able to activate Siri by voice or by holding the power button, but Apple is also developing a new interface called Search or Ask, which opens with a swipe gesture and allows users to launch apps, create reminders, send messages, schedule appointments, search files, or ask broader AI-powered questions from a single location.

Results will reportedly appear as interactive cards directly on the screen, while a dedicated Siri application will maintain conversation history and provide summarized interactions.

One of the most significant revelations is the technology powering the assistant.

Earlier this year Apple confirmed that portions of its next-generation AI strategy would rely on a customized version of Google’s Gemini models, an unusually public acknowledgment for a company known for developing most core technologies internally.

Bloomberg also reported that Apple is exploring future support for third-party AI services, potentially allowing users to choose among providers such as ChatGPT, Gemini, and Anthropic’s Claude for specific tasks.

The broader iOS 27 update is expected to extend AI throughout the operating system.

Apple is reportedly testing photo-editing tools that respond to plain-language instructions, allowing users to request image modifications simply by describing what they want. The company is also rebuilding its Shortcuts automation platform so users can create workflows using natural language rather than manual programming.

Additional features under development reportedly include AI-generated wallpapers, systemwide writing assistance, improved grammar correction, enhanced image generation, and upgraded custom emoji tools.

For Apple, the effort goes well beyond software.

The iPhone remains the company’s largest source of revenue, and many analysts believe a compelling AI experience could become the most important driver of smartphone upgrades over the next several years.

A successful Siri relaunch would not only strengthen hardware sales but also support Apple’s broader ecosystem of services, subscriptions, and App Store revenue.

There are still uncertainties.

Bloomberg’s report notes that the published renderings are based on information from sources familiar with the project rather than official Apple materials, and the company frequently tests multiple versions of products before finalizing designs.

Some features currently under development may not be included in the first public release of iOS 27.

Apple is expected to formally unveil the new Siri at WWDC on June 8, followed by a developer beta, a public testing period later this summer, and a full release alongside the next generation of iPhones this fall.

For Apple, the launch represents more than a software update.

It is an opportunity to prove that the company that defined the smartphone era can still compete at the forefront of the AI era.

Cupertino — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — Thursday, May 28, 2026

Artificial intelligence is no longer a perk, pilot program, or side project inside Corporate America. It is increasingly becoming part of employee compensation.

According to a Bloomberg News report published May 28, Starbucks has begun tying a portion of technology employees’ bonuses directly to AI adoption, making it one of the latest major employers to put real money behind workforce AI usage.

Under the policy, approximately one-quarter of bonuses paid to many Starbucks technology employees will be linked to department-wide goals that include AI utilization. Software developers are expected to use company-approved AI coding assistants multiple times per week in order to satisfy adoption targets.

The move reflects a broader shift unfolding across Corporate America.

What began as isolated experiments has evolved into a growing trend where companies are rewarding employees for incorporating AI into daily work.

Meta Platforms has made “AI-driven impact” a formal performance expectation across its workforce beginning in 2026. Employees who demonstrate strong AI-related contributions can qualify for bonus multipliers reaching 200%, while a newly created internal recognition program can boost awards even further.

Other major employers are following similar paths.

Walmart and Pfizer have reportedly linked portions of incentive compensation to AI-related performance measures. Amazon has established internal adoption targets for engineering teams, while JPMorgan Chase and other financial institutions increasingly factor AI proficiency into promotion decisions.

At Microsoft, managers evaluate whether teams are generating measurable efficiency improvements through AI-enabled workflows, and those outcomes influence performance reviews and compensation.

The reason is simple: companies have spent billions of dollars on AI infrastructure, software licenses, and enterprise subscriptions and now need employees to actually use them.

For Starbucks, the push is closely tied to CEO Brian Niccol’s turnaround strategy.

The company invested roughly $500 million in additional store staffing and higher wages while simultaneously looking for ways to increase efficiency throughout its technology operations. Faster software development, accelerated project completion, and reduced operational costs help fund customer-facing investments across the business.

Starbucks is reportedly tracking how many strategic “Back to Starbucks” initiatives are being developed using AI tools, making adoption a business priority rather than merely a technology objective.

Other companies are pursuing the same outcome through different measurements.

Meta evaluates AI-driven impact based on business results. Amazon tracks usage levels of internal coding assistants. Accenture measures engagement with internal AI platforms and incorporates those metrics into promotion reviews. Walmart, Pfizer, and Microsoft focus more heavily on output and efficiency gains.

The common thread is accountability.

Executives increasingly want proof that AI investments are producing measurable returns.

The potential value explains the urgency.

Employees who effectively use platforms such as ChatGPT, Claude, Gemini, Grok, Microsoft Copilot, Meta AI, Mistral, and Perplexity often complete tasks dramatically faster than before.

Developers can write and debug software more quickly. Marketers can create campaigns in hours instead of days. Analysts can summarize large datasets almost instantly.

Industry estimates suggest skilled AI users save between 5 and 15 hours per week.

At labor costs ranging from $25 to $75 per hour, that translates into roughly $12,000 to $54,000 in annual operational value per employee.

Across a ten-person team, the potential productivity gain can exceed half a million dollars annually.

Those economics help explain why companies are willing to pay bonuses to encourage adoption.

A modest incentive becomes relatively inexpensive when compared with the productivity gains executives believe AI can generate.

The push is also becoming more forceful.

Recent surveys indicate that nearly 58% of U.S. companies now require employees to use AI tools, and roughly one in ten of those employers report terminating workers who refused to adopt them.

Several corporate leaders have publicly stated that AI proficiency is no longer optional.

The broader trend marks a significant shift in how artificial intelligence enters the workplace.

Just as email, spreadsheets, and cloud computing became essential business infrastructure, AI platforms are increasingly moving in the same direction.

Companies are no longer asking whether employees should use AI.

They are determining how much additional value employees can create when they do—and increasingly rewarding them accordingly.

Like Bloomberg, CNBC, and other leading business media organizations that convene industry leaders through conferences, summits, and economic forums, JBiz is bringing together business owners, executives, and teams through its AI Summit to help organizations translate AI adoption into productivity gains, new revenue opportunities, cost savings, and competitive advantage.

The two-day JBiz AI Summit will be held July 13–14 at the Sheraton Eatontown Hotel in New Jersey, bringing together business owners, executives, managers, employees, and entrepreneurs to learn how to strategically leverage multiple AI platforms to generate revenue, improve operations, reduce costs, and stay competitive in an increasingly AI-driven economy.

With studies showing employees saving between 5 and 20 hours per week through AI, the upcoming JBiz AI Leadership & Operations Summit will provide hands-on training across leading platforms including ChatGPT, Claude, Gemini, Grok, Microsoft Copilot, Meta AI, Mistral, and Perplexity. Attendees will learn practical frameworks, templates, and workflows to increase revenue, reduce costs, improve productivity, and deploy AI across their organizations immediately.

The two-day summit will be held July 13–14, 2026, from 9:00 a.m. to 5:00 p.m. at the Sheraton Eatontown Hotel, 6 Industrial Way East, Eatontown, NJ. For registration, HR Dept inquires, or team enrollment, click here, For More Information email esther@ojchamber.com, or call 212-659-5270 x104.

—JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

Dell Technologies shares surged as much as 31% in after-hours trading Thursday after the company reported a record-breaking quarter fueled by explosive demand for artificial-intelligence infrastructure, delivering results that dramatically exceeded Wall Street expectations and reinforcing Dell’s position as one of the biggest beneficiaries of the global AI spending boom.

The Round Rock, Texas-based company reported first-quarter revenue of $43.8 billion, up 88% from a year earlier and the fastest sales growth Dell has recorded since returning to the public markets more than seven years ago.

Adjusted earnings reached $4.86 per share, crushing analyst expectations of roughly $2.94 per share. Net income jumped 194% to $3.2 billion, while operating cash flow reached a record $4.1 billion.

Investors immediately focused on the reason behind the blowout numbers: artificial intelligence.

Dell disclosed that it booked an extraordinary $24.4 billion in new AI server orders during the quarter, while generating $16.1 billion in AI-server revenue. Even more importantly, the company’s AI order backlog swelled to $51.3 billion, giving investors visibility into future revenue growth that few technology companies can currently match.

Vice Chairman and Chief Operating Officer Jeff Clarke said demand exceeded internal forecasts across every major product category and geographic region.

“We saw stronger-than-expected demand across the board,” Clarke said, describing a market where customers are racing to secure AI computing infrastructure before supply constraints worsen.

The biggest driver was Dell’s Infrastructure Solutions Group, which includes servers, storage systems, networking equipment, and data-center hardware.

Revenue in that division surged 181% to $29 billion, dramatically surpassing analyst estimates of approximately $22.4 billion.

While AI servers generated most of the headlines, traditional infrastructure demand remained surprisingly strong. Non-AI server and networking revenue climbed 92% to $8.5 billion, while storage revenue increased 8% to $4.3 billion.

The results suggest businesses are not simply buying AI hardware — they are upgrading entire technology stacks simultaneously.

Dell’s personal-computer business also contributed to the growth.

Revenue in the Client Solutions Group rose 17% to $14.6 billion, driven by an 18% increase in commercial PC sales and a 9% increase in consumer PC sales. The gains indicate corporations are refreshing aging computer fleets even as they aggressively invest in artificial-intelligence infrastructure.

Despite the strong results, margins revealed one challenge facing Dell.

Chief Financial Officer David Kennedy said gross profit dollars increased 57% to $7.9 billion, but the company’s gross-margin percentage declined to 18.1%.

The reason is straightforward: AI servers generate enormous revenue but generally carry lower profit margins than many of Dell’s traditional products.

In effect, Dell is selling significantly more equipment, but a growing percentage of those sales come from lower-margin AI hardware.

Investors largely ignored that concern because management dramatically raised its outlook.

Dell now expects full-year revenue between $165 billion and $169 billion, alongside adjusted earnings of approximately $17.90 per share. The forecast significantly exceeds both previous company guidance and Wall Street expectations.

For the current quarter alone, Dell expects revenue between $44 billion and $45 billion, signaling that the AI spending wave remains far from over.

The primary risk identified by management is no longer customer demand — it is supply.

Clarke warned that shortages involving memory chips, processors, storage devices, and other critical components continue affecting production. Inflationary pressures throughout the supply chain are also forcing the company to adjust pricing frequently.

Some customers are delaying purchases due to rising costs, while others are accelerating orders to lock in supply before prices climb further.

Dell is also preparing for a corporate governance change. Shareholders are scheduled to vote June 25 on a proposal to reincorporate the company in Texas, a move that will not affect daily operations but reflects management’s broader long-term strategic planning.

For investors, however, Thursday’s story was much simpler.

Dell’s stock soared because the company demonstrated that the AI infrastructure boom remains real, demand remains enormous, and customers are still spending tens of billions of dollars to build the computing power required for the next generation of artificial intelligence.

Texas — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

Shares of Unusual Machines, the drone-components company tied to Donald Trump Jr., surged roughly 57% Thursday after reports emerged that the Trump administration is considering direct federal funding for several U.S. drone manufacturers as Washington accelerates efforts to build a domestic drone industry independent of China.

The rally followed a Wall Street Journal report published Wednesday night citing people familiar with ongoing discussions between the administration, the Pentagon, and private drone firms.

According to the report, the government is exploring financing arrangements involving multiple U.S.-based drone companies, including Unusual Machines, Neros Technologies, and Performance Drone Works, a defense contractor already tied to U.S. Army reconnaissance-drone programs.

The funding discussions reportedly involve the Pentagon’s Office of Strategic Capital, a federal financing unit originally established to support companies considered critical to national-security supply chains.

What makes the talks especially notable is the proposed structure.

Rather than relying solely on traditional defense contracts, officials are reportedly considering a mix of debt and equity financing that could give the federal government direct ownership stakes in selected drone companies.

The funding would reportedly be used to expand manufacturing capacity, increase supply-chain resilience, and reduce production costs — not simply purchase drones outright.

If finalized, the approach would mark a significant shift in how Washington supports strategic defense industries, effectively turning taxpayers into partial investors in private drone manufacturers tied to national-security priorities.

The Trump family connection runs through multiple companies involved in the sector.

Donald Trump Jr. joined Unusual Machines’ advisory board in late 2024, publicly framing the move around rebuilding American drone manufacturing and reducing U.S. dependence on Chinese-made drone parts and systems.

The stock nearly doubled when his involvement was first announced.

Separately, another drone-related transaction involving Aureus Greenway and drone-technology firm Powerus has also drawn attention due to Trump-family backing. Shares tied to that deal surged sharply in premarket trading Thursday as investors interpreted the administration’s reported funding discussions as a broad signal of incoming federal support across the domestic drone industry.

The buying spread rapidly through the sector.

Drone and defense-related companies including Red Cat Holdings, Kratos Defense, AeroVironment, and other autonomous-systems firms posted large gains during Thursday’s session as traders bet Washington may soon direct significant funding toward domestic drone production.

The broader policy backdrop has become increasingly aggressive.

President Trump signed a “Drone Dominance” executive order last year that made mass autonomous-drone deployment a formal administration priority, while the proposed fiscal 2027 defense budget includes tens of billions of dollars tied to drone expansion and low-cost autonomous warfare systems.

The Pentagon’s broader goal reportedly includes deploying up to 300,000 lower-cost autonomous drones by 2027.

A separate $1 billion Drone Dominance Program is already underway, with dozens of drone firms recently invited to participate in the program’s next qualification phase scheduled for June.

Unusual Machines also announced this week that its partner Powerus had been selected to compete in the next phase using its MatrixFold drone platform.

The strategic motivation behind the government push is increasingly explicit.

U.S. defense officials have repeatedly warned about America’s dependence on Chinese drone technology and components, particularly as geopolitical tensions with Beijing continue escalating. Washington now appears determined to build a domestic drone ecosystem capable of scaling rapidly during future military conflicts or supply-chain disruptions.

The story also carries an obvious political sensitivity.

Companies tied to the president’s family stand to potentially benefit from funding decisions made by the president’s own administration — a dynamic likely to draw scrutiny if negotiations advance further.

For now, no formal agreements have been finalized, and neither the White House nor the Pentagon publicly commented on the reported talks.

But for investors, Thursday’s rally delivered a clear message.

Inside the fast-growing drone sector, the strongest catalyst right now may no longer be earnings, contracts, or technology breakthroughs alone — but signals from Washington about where federal money could flow next.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Florida Governor Ron DeSantis on Wednesday unveiled one of the most aggressive tax-cut proposals currently under discussion anywhere in the United States: a long-term plan to eliminate property taxes on primary residences entirely for most Florida homeowners.

The proposal, which DeSantis plans to advance through a summer special legislative session, would dramatically expand Florida’s homestead exemption and eventually phase out property taxes on owner-occupied homes altogether if approved by both the legislature and Florida voters.

If enacted, Florida would become the first major state in the country with both no state income tax and effectively no property tax on primary homes.

For ordinary Floridians, the immediate impact would be straightforward: many homeowners would stop receiving large annual property-tax bills entirely.

Under the first phase of the proposal, Florida’s homestead exemption would rise from the current $50,000 level to $250,000. According to DeSantis, that single change would eliminate property taxes entirely for roughly 60% of Florida homeowners whose homes qualify as homesteaded primary residences.

The second phase would increase the exemption to $500,000, which the administration says would fully eliminate property taxes for approximately 92% of Florida homesteaded properties.

“The primary purpose of that is to make your homestead property tax free,” DeSantis said during Wednesday’s announcement.

For many households, the savings could be substantial.

Depending on the county and home value, Florida homeowners currently pay anywhere from roughly $2,000 to more than $7,000 annually in property taxes. A middle-class family owning a $400,000 home could potentially save approximately $5,000 to $6,000 per year if the proposal fully eliminates their homestead tax bill.

Retirees on fixed incomes could also see major relief after years of rapidly rising home valuations across much of the state.

But the proposal also raises enormous questions about how Florida would replace tens of billions of dollars currently funding local government operations.

Property taxes generate an estimated $55 billion to $60 billion annually across Florida and fund a significant share of public-school systems, sheriff’s departments, fire and rescue services, road maintenance, libraries, parks, and county government operations.

According to state budget figures, property taxes account for roughly 18% of county-government revenue statewide.

DeSantis said the state would create a trust fund mechanism to help backfill essential local services and restrict remaining property-tax collections primarily toward core functions such as schools, police, and emergency services.

The governor also proposed reducing the annual cap on assessment increases for small businesses from 10% to 5%, easing pressure on commercial property owners as well.

One of the most politically significant parts of the proposal is a five-year residency waiting period for newcomers moving into Florida after the amendment takes effect.

Under the governor’s framework, new residents would continue paying property taxes under the existing structure for several years before becoming eligible for the expanded homestead exemption.

That provision is designed to address concerns that eliminating property taxes could accelerate migration into Florida, further drive up housing prices, and intensify affordability pressures for existing residents.

The proposal’s effect on renters remains less certain.

Rental properties, second homes, vacation homes, and commercial real estate would continue paying property taxes because they would not qualify as homesteaded primary residences. Landlords would likely continue passing those costs into rents, meaning renters may not experience direct tax relief.

The broader housing-market impact could also prove complicated. Eliminating property taxes for homeowners could encourage more renters to purchase homes, potentially tightening rental supply. At the same time, Florida’s continued population growth could encourage additional housing development and investment activity.

The political path forward is difficult even in Republican-controlled Florida.

Because the proposal requires a constitutional amendment, it must first pass both chambers of the Florida legislature with at least 60% support before reaching the statewide ballot. It would then require approval from at least 60% of Florida voters during the November election.

Earlier property-tax reform proposals have struggled to advance through the Florida Senate despite support from DeSantis and many House Republicans.

Opposition is already emerging from county governments, school districts, municipal officials, and public-sector unions concerned about how local services would remain funded if residential property-tax revenue declines sharply.

There are also broader financial implications.

Local governments routinely borrow money for infrastructure projects using future property-tax revenue as collateral. A major reduction in homestead property taxes could force rating agencies to reevaluate municipal credit quality across Florida, potentially increasing borrowing costs for roads, schools, water systems, and public infrastructure projects.

At the same time, supporters argue the proposal would strengthen Florida’s long-term competitive position by making it the most tax-advantaged large state in the country for homeowners.

Florida has already benefited heavily from migration trends over the past five years as residents and businesses relocate from higher-tax states such as New York, California, Illinois, and New Jersey.

Supporters believe eliminating property taxes on primary residences would accelerate that trend further while helping long-term residents remain in their homes despite rising valuations.

The proposal also carries national political significance.

If Florida successfully phases out homestead property taxes, pressure could quickly build in other no-income-tax states such as Texas, Tennessee, Nevada, South Dakota, and Wyoming to explore similar measures.

The broader debate ultimately centers on one of the oldest questions in American tax policy: how governments balance homeowner relief, economic growth, and public-service funding.

For now, DeSantis has formally pushed the issue to the center of Florida politics heading into the second half of 2026.

The legislature will decide whether the amendment reaches the ballot.

Florida voters would then decide whether one of the most dramatic state tax overhauls in modern American history actually becomes law.

Tallahassee — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk

The U.S. Department of the Treasury on Thursday officially launched the new “Trump Accounts” mobile app, opening the primary gateway to a federal savings initiative that will provide tax-advantaged investment accounts — and in many cases a $1,000 government-funded deposit — for millions of American children.

Treasury Secretary Scott Bessent announced the launch Thursday morning, describing the app as a secure and simple tool designed to help families begin building long-term financial savings for children from birth.

The app is now available through major app stores nationwide ahead of the program’s formal July 4 launch.

The accounts function similarly to investment retirement-style accounts for minors, with funds placed into market-tracking investment vehicles intended to grow over time. The program’s most prominent feature is the federal contribution itself: children who are U.S. citizens born between 2025 and 2028 qualify for a one-time $1,000 Treasury-funded deposit beginning July 4.

Children born before 2025 may still open accounts but are not eligible for the government contribution.

Treasury officials said nearly 6 million children have already been enrolled ahead of the launch, although deposits and contributions cannot officially begin until July.

Parents and guardians can begin the setup process immediately through TrumpAccounts.gov using IRS Form 4547 before completing account activation through email verification.

The funds are designed as long-term investment accounts and cannot be freely withdrawn during childhood. Once the child reaches adulthood, the money may be used for major expenses such as education, housing, or other approved life costs.

The program also directly ties Wall Street and private employers into the federal savings initiative.

Treasury confirmed that Bank of New York Mellon and Robinhood partnered on the infrastructure supporting the app and account system. BNY Mellon was also among the first major institutions to pledge matching contributions for children of its U.S.-based employees, with BlackRock later joining the effort.

Employers participating in the program may contribute up to $2,500 annually per employee on a tax-advantaged basis without those contributions counting as taxable income for workers.

Several philanthropists and private organizations have also pledged additional matching contributions for qualifying families in certain states.

For financial firms involved, the program represents more than a government initiative — it potentially creates a generation of first-time investors whose earliest financial relationship begins through federally backed investment accounts connected to private financial institutions.

Supporters describe the program as an attempt to encourage long-term wealth creation and financial literacy from childhood.

Critics, however, have raised broader questions surrounding program costs, investment oversight, and whether lower-income households will continue contributing after the initial government deposit.

For now, the launch marks the moment the initiative moves from legislation and policy discussions into parents’ phones and household finances.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

Bitcoin fell below $73,000 Thursday, sliding sharply even as President Donald Trump renewed his pledge to make the United States “the crypto capital of the world,” underscoring how geopolitical fears and institutional selling are now overpowering Washington’s increasingly pro-crypto rhetoric.

According to CoinDesk market data, Bitcoin dropped as low as approximately $72,912 before stabilizing near $72,978 during Asian trading hours, down roughly 3.4% over 24 hours and more than 6% for the week.

The selloff triggered one of the largest leveraged liquidations of the year.

Nearly $1 billion in crypto positions were wiped out within a single day, with long bullish bets accounting for roughly 93% of the losses. Bitcoin and Ethereum led the liquidation wave as traders who had positioned for continued gains were forced out rapidly when prices broke below key support levels.

The catalyst was not crypto itself.

It was the Middle East.

Fresh U.S. airstrikes near the Strait of Hormuz, new sanctions targeting Iran, and rising fears surrounding broader regional escalation abruptly reversed the optimism that had built around a potential ceasefire framework earlier in the week.

Oil prices surged while global equity markets weakened — and crypto followed.

The connection between war and Bitcoin is increasingly direct.

The Strait of Hormuz handles roughly one-fifth of global oil shipments. Any threat to that corridor pushes energy prices higher, which raises inflation concerns globally and increases the likelihood that central banks keep interest rates elevated longer than expected.

Higher interest rates typically drain capital away from speculative and high-risk assets, including cryptocurrencies.

Bitcoin had managed to remain above the $74,000 level through weeks of escalating Iran headlines, but Thursday’s renewed military tensions finally broke that floor. The speed of the decline suggested many traders had been heavily positioned for further upside before the reversal hit.

Institutional investors accelerated the pressure.

BlackRock’s IBIT Bitcoin exchange-traded fund recorded approximately $527.8 million in net outflows, marking its second-largest single-day withdrawal on record. More than $2.5 billion has reportedly exited crypto ETFs over the past two weeks after strong inflows earlier this spring had fueled Bitcoin’s climb toward new highs.

When large institutional funds pull that level of capital from the market, the spot price reacts quickly.

The decline also arrived against a politically significant backdrop.

Late Wednesday, Trump posted on Truth Social that the United States would become “the crypto capital of the world” while renewing support for the Digital Asset Market Clarity Act, known as the CLARITY Act, legislation designed to establish clearer regulatory rules for cryptocurrencies and digital assets.

Bitcoin briefly steadied following Trump’s comments before resuming its decline.

Trump later doubled down publicly during the selloff, declaring he would “never let crypto down” while criticizing former SEC Chair Gary Gensler and what he called the government’s former “anti-crypto army” for pushing innovation overseas.

The legislation Trump supports is advancing.

The CLARITY Act cleared the Senate Banking Committee earlier this month with bipartisan support, representing the most significant crypto legislation to move through Congress in years. The bill would define whether digital assets fall under SEC or Commodity Futures Trading Commission oversight while establishing clearer rules for stablecoins and digital-token classifications.

Markets had previously rallied on expectations that regulatory clarity could unlock another wave of institutional adoption.

Instead, geopolitical instability and ETF outflows overwhelmed the bullish policy narrative.

The broader takeaway is increasingly clear.

For much of the past year, pro-crypto statements from Washington were often enough to drive Bitcoin sharply higher. Thursday’s selloff suggested that dynamic may be weakening as cryptocurrencies become more tied to the same macroeconomic forces driving oil, stocks, bonds, and broader global markets.

When inflation rises, war fears intensify, and institutional money begins heading for the exits, political support alone may no longer be enough to stop the slide.

The same global forces now rattling traditional financial markets are increasingly controlling digital assets too.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

LONDON — The head of Britain’s electronic intelligence agency will warn Wednesday that China is rapidly closing the technological gap with the West and that the United Kingdom and its allies are running out of time to maintain their advantage in artificial intelligence and cyber capabilities, a message landing as cybersecurity and AI stocks continue driving global equity markets to record highs.

Anne Keast-Butler, director of GCHQ — Britain’s signals intelligence and cybersecurity agency, roughly equivalent to America’s National Security Agency (NSA) — is delivering the warning during the organization’s first-ever annual lecture at Bletchley Park, the historic World War II codebreaking center associated with mathematician Alan Turing.

According to excerpts released ahead of the speech, Keast-Butler plans to describe the current environment as “a new era of radical uncertainty, contested geopolitics and rapidly changing technology,” warning that “the risk of miscalculation is as high as I’ve ever seen it.”

Her central message is direct: China has become “a science and tech superpower” with sophisticated cyber, intelligence and military capabilities, while the rise of artificial intelligence is accelerating the pace of strategic competition.

In practical terms, Western intelligence officials are increasingly warning that the technological gap separating Chinese and Western cyber capabilities is narrowing much faster than governments anticipated only a few years ago.

That matters because GCHQ rarely speaks publicly in this way.

Historically, the agency operates with minimal public visibility. When senior British intelligence officials deliver unusually direct warnings to business leaders, it is often interpreted inside government and financial circles as a sign the threat assessment inside the broader Five Eyes intelligence alliance — the United States, United Kingdom, Canada, Australia and New Zealand — has materially shifted.

The speech also underscores how closely national security, artificial intelligence and financial markets have now become intertwined.

Over the past year, investors have poured money into cybersecurity firms including Palo Alto Networks, CrowdStrike Holdings, Zscaler, Fortinet and SentinelOne, while semiconductor companies tied to AI infrastructure — including Nvidia and Advanced Micro Devices — have surged on expectations of massive government and private-sector spending tied to AI competition and cyber defense.

Much of that demand stems directly from the environment Keast-Butler is describing.

She is also expected to warn that Russia is “scaling up its daily hybrid activity” against Britain and Europe by targeting “critical infrastructure, democratic processes, supply chains and public trust.”

GCHQ officials say they are increasingly focused not only on traditional espionage but also on cyberattacks aimed at transportation systems, utilities, communications infrastructure and corporate networks.

Earlier this year, Dr. Richard Horne, head of Britain’s National Cyber Security Centre, the defensive cybersecurity arm of GCHQ, said hostile-state cyber activity against the UK now averages roughly four nationally significant incidents per week, with China, Russia and Iran identified as the primary sources.

The warnings are not theoretical.

Over the past 18 months, major British companies including Marks & Spencer, the Co-op Group and Jaguar Land Rover have suffered significant cyberattacks disrupting operations, exposing customer data and generating substantial financial losses.

British officials increasingly frame those incidents not simply as IT problems but as national economic-security threats.

“Cyber security is now a matter of business survival,” British officials have repeatedly warned in recent months.

For American investors, the implications are increasingly visible across multiple industries.

Cybersecurity spending is accelerating because corporations and governments alike now assume they face persistent attacks from sophisticated state-backed actors using increasingly advanced AI tools for phishing, intrusion and supply-chain compromise operations.

The same geopolitical pressures are also driving enormous investment in AI computing infrastructure.

Companies such as Nvidia, AMD and other semiconductor suppliers are not simply selling hardware to commercial data centers. They are increasingly selling into government, intelligence and defense ecosystems across the United States and allied countries racing to expand AI computing capacity ahead of China.

That demand helps explain why semiconductor stocks have become one of the market’s dominant themes.

The timing of the speech is also notable.

Only weeks ago, Beijing confirmed an order for 200 Boeing aircraft, publicly describing aviation as “a key area for U.S. cooperation” — part of broader efforts by both Washington and Beijing to stabilize portions of the economic relationship.

Yet on the intelligence and technology side, rhetoric from Western capitals is moving sharply in the opposite direction.

The tone coming from intelligence chiefs has grown increasingly blunt. Governments are engaging more directly with private-sector executives. And Western corporations are facing growing pressure to treat cyber defense as a strategic operating priority rather than merely a regulatory or compliance function.

The venue itself carries symbolic weight.

Bletchley Park was where British and American codebreakers worked together during World War II, laying the foundation for the intelligence-sharing alliance that eventually became Five Eyes. The speech also coincides with the 80th anniversary of the UKUSA Agreement, the original intelligence treaty linking the two countries.

At the same location in 2023, Western governments and Chinese officials signed the Bletchley Declaration on AI Safety, highlighting the increasingly complicated balance between technological cooperation and strategic rivalry.

The message from Wednesday’s speech ultimately points toward the same conclusion increasingly reflected in financial markets:

The global battles over artificial intelligence, semiconductors, cyber defense and critical infrastructure are no longer separate stories. Governments, intelligence agencies and investors are increasingly treating them as part of the same strategic competition.

And according to Britain’s top cyber official, that competition is accelerating faster than many Western governments expected.

Europe — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

U.S. stocks closed mixed Thursday but remained near record highs after new inflation data showed consumer prices accelerating to their highest level in nearly three years, while reports of a ceasefire framework between the United States and Iran helped stabilize investor sentiment and keep broader markets from retreating.

The final numbers reflected a market struggling to balance economic strength, persistent inflation, and geopolitical relief all at once.

The S&P 500 finished nearly unchanged at 7,520.36, up just 0.02%, while the Dow Jones Industrial Average slipped 0.05% to close at 50,620.36. The Nasdaq Composite outperformed, gaining 0.39% to finish at 26,777.95, remaining close to the record highs set earlier this week.

The session’s central focus was inflation.

The Commerce Department reported Thursday morning that the Personal Consumption Expenditures Price Index (PCE) — the Federal Reserve’s preferred inflation gauge — rose 3.8% year-over-year in April, climbing from 3.5% in March and 2.8% in February. On a monthly basis, prices increased 0.4%.

The PCE index carries unusual weight inside financial markets because it measures what Americans are actually paying across goods and services, making it one of the clearest indicators of persistent pricing pressure throughout the economy. A reading approaching a three-year high signals that inflation remains stubbornly elevated despite aggressive interest-rate policies over the past two years.

The report arrives at a particularly sensitive moment for new Federal Reserve Chairman Kevin Warsh, who was sworn in last week. Hotter inflation data narrows the central bank’s flexibility on rate cuts and raises the possibility that borrowing costs could remain elevated longer than markets had previously hoped.

Yet despite the inflation surprise, investors largely held their ground.

Markets found support from signs that the broader economy remains resilient. Consumer spending stayed firm, weekly jobless claims remained relatively stable, and Treasury yields eased slightly during the afternoon as energy prices retreated from earlier highs.

Geopolitics delivered the day’s sharpest swings.

Stocks fluctuated throughout the session after reports emerged that Washington and Tehran had reached a temporary framework agreement aimed at extending a ceasefire and gradually restoring energy exports from the Persian Gulf region. The proposed arrangement reportedly includes a 60-day memorandum intended to prevent further escalation following months of military confrontation near the Strait of Hormuz.

Earlier in the session, oil prices had risen sharply amid renewed reports of clashes near key shipping lanes before reversing lower after ceasefire discussions surfaced.

Underneath the broader indexes, market leadership remained concentrated in artificial-intelligence infrastructure and enterprise software stocks.

Microsoft, Oracle, and Palantir each climbed between 3% and 4% as investors continued rotating toward companies viewed as long-term AI infrastructure winners. By contrast, semiconductor stocks weakened, with Nvidia slipping roughly 1% after a powerful recent rally.

Software company Snowflake surged approximately 30% following stronger-than-expected guidance, although the rally failed to broadly lift the rest of the cloud-software sector.

Within the Dow, Microsoft, Nike, and IBM led gains, while 3M and Caterpillar weighed on the index. Retailers also saw divergent results. Best Buy advanced after beating earnings expectations, and Kohl’s jumped following stronger comparable-sales figures, while Salesforce fell roughly 2% after its quarterly report disappointed investors.

Dell Technologies moved higher ahead of its earnings release after reports that the company secured a $9.7 billion software contract tied to the U.S. military.

Looking ahead, Friday’s economic calendar remains lighter but still carries several reports closely watched by traders.

The Commerce Department is scheduled to release advanced trade-in-goods data alongside wholesale and retail inventory figures, while the Chicago Purchasing Managers’ Index (PMI) will offer another early snapshot of manufacturing and business activity across the industrial Midwest.

Markets will also continue watching whether record-high equity valuations can hold together while inflation remains elevated and the Federal Reserve faces growing pressure to maintain higher interest rates for longer.

For one more session at least, investors chose stability over panic — leaning on hopes for a calmer Middle East and continued enthusiasm surrounding AI-linked companies to offset inflation data that, under different conditions, might have triggered a much sharper selloff.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JBizNews Desk — May 28, 2026

Anthropic said Thursday it has closed a $65 billion Series H funding round at a $965 billion post-money valuation, according to a company announcement and comments from Chief Financial Officer Krishna Rao, vaulting the Claude developer past OpenAI to become the world’s most valuable private artificial-intelligence startup.

The round was co-led by Altimeter Capital, Dragoneer, Greenoaks, and Sequoia Capital, with additional backing from Capital Group, Coatue, D1 Capital Partners, Baillie Gifford, Blackstone, Brookfield, D.E. Shaw Ventures, DST Global, and Fidelity Management & Research. Anthropic indicated the financing could be among its final private raises before pursuing a public listing.

The valuation marks one of the fastest wealth surges ever recorded in the technology sector. Anthropic was valued at roughly $380 billion during its Series G financing in February and approximately $183 billion during a prior funding round last September. The latest valuation nearly triples the February figure in just a few months, reflecting the speed at which institutional capital continues flooding into the AI sector.

Driving the surge is revenue growth.

Anthropic disclosed that its annualized revenue run rate has climbed to approximately $47 billion, up sharply from around $30 billion earlier this year and roughly $10 billion in revenue generated during 2025. A major contributor has been Claude Code, the company’s AI-powered software-development platform, which has rapidly gained adoption among enterprises, engineering teams, and independent developers seeking productivity gains and automation tools.

The financing reshuffles the balance of power across Silicon Valley’s AI race.

OpenAI, maker of ChatGPT, was valued at approximately $852 billion following its March financing round, which itself had been viewed as unprecedented in scale. Anthropic’s new valuation now moves decisively ahead of that figure, signaling that investors increasingly see enterprise-focused AI infrastructure and coding systems as one of the sector’s most commercially scalable businesses.

For businesses watching the AI market from the sidelines, the funding wave sends a broader message: Wall Street believes companies are still in the early innings of adopting artificial intelligence into everyday operations.

The firms writing checks into Anthropic are effectively betting that businesses will continue paying for AI systems capable of writing software, generating documents, analyzing data, automating workflows, reducing staffing burdens, and accelerating operational decision-making. The scale of the raise suggests major investors expect AI spending to expand significantly rather than cool off.

Anthropic also used Thursday’s announcement to unveil new products aimed at enterprise customers.

The company introduced Claude Opus 4.8, its latest flagship model, alongside a new cybersecurity-focused platform called Claude Mythos Preview, which will initially be offered to a limited number of approved corporate and government users. Rao said the new capital would help Anthropic scale infrastructure, expand enterprise deployment, and maintain what he described as a research lead against rivals.

The timing also reflects how quickly the AI industry is converging with public capital markets.

Several of the largest artificial-intelligence developers are already preparing for eventual IPOs. Elon Musk’s AI venture, folded earlier this year into the broader SpaceX ecosystem, recently filed offering paperwork tied to a combined business reportedly valued near $1.25 trillion. Investors increasingly expect Anthropic and OpenAI to follow similar paths as demand for AI infrastructure, chips, cloud services, and enterprise automation tools continues accelerating.

Analysts say the newest valuation milestones underscore a deeper transformation underway across the global economy.

Unlike earlier technology cycles centered primarily on consumer apps or advertising, today’s AI investment boom is increasingly tied to operational infrastructure — tools businesses directly use to save time, automate labor, improve productivity, and increase margins. That distinction is helping justify valuations once considered impossible even in Silicon Valley.

Whether Anthropic moves quickly toward an IPO now becomes one of the biggest open questions in the technology market. Company filings and industry reports have pointed to growing internal preparations, including expanded legal and financial advisory work associated with public-market readiness.

For now, Anthropic has crossed a threshold almost no startup ever reaches — and in doing so, it has redrawn the hierarchy at the center of the global AI economy.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

For the first time in more than a decade, the assets Wall Street spent years avoiding are suddenly outperforming the markets investors once viewed as untouchable.

That is the conclusion of a new report published May 15 by UBS Asset Management, where Shamaila Khan, Head of Emerging Markets and Asia Pacific Fixed Income, argues that emerging-market debt and equities may have entered a fundamentally different investment era — one in which developing economies act less like financial weak points and more like stabilizers during periods of global stress.

The report, co-authored by Massimiliano Castelli, Philipp Salman, and Sangram Jadhav, points to a major shift in investor behavior during the recent Iran-related market shock. Instead of fleeing emerging markets as geopolitical tensions escalated across the Middle East, investors largely stayed put. In several cases, emerging-market debt outperformed developed-market credit.

That reversal matters because for years the rule across global finance was simple: when geopolitical risk rises, emerging markets get hit first and hardest. UBS argues that dynamic is now changing.

The data behind the call is notable. According to the report, emerging-market assets outperformed advanced economies in 2025 for the first time in years. During the spring 2026 Middle East conflict, hard-currency sovereign and corporate bonds from emerging economies traded relatively smoothly, avoiding the panic-driven selloffs that historically accompanied regional wars or oil shocks.

UBS says many emerging-market governments and companies entered the turmoil in unusually strong financial condition. Countries had built foreign-exchange reserves, reduced refinancing pressure, and pre-funded large portions of their borrowing needs before volatility accelerated. In practical terms, they did not need to dump bonds into distressed markets to raise cash.

Investor flows reinforced the picture. The report cites JPMorgan data showing $17.4 billion in year-to-date inflows into emerging-market debt. While March 2026 saw roughly $1.7 billion in outflows during the peak of market anxiety, UBS noted that much of the selling came from passive exchange-traded funds, while actively managed funds with stronger performance records continued attracting capital.

Emerging-market equities showed similar resilience. Through the March-April Iran shock, developing-market stocks avoided the sweeping selloff patterns investors typically associate with Middle East instability, preserving gains and containing volatility despite rising oil prices and fears of wider regional escalation.

The next phase of the UBS thesis centers on the U.S. dollar.

After years of strength, UBS argues the dollar now appears historically stretched at the same time Washington faces worsening fiscal pressures and narrowing interest-rate differentials with overseas economies. A weaker or even stabilizing dollar would materially improve returns for emerging-market investors because local currencies and bonds become more valuable when converted back into dollars.

Historically, broad periods of dollar weakness have been among the strongest drivers of emerging-market performance across both equities and debt.

The longer-term performance gap helps explain why UBS believes the shift could still be in its early stages. From January 2010 through December 2025, the S&P 500 generated average annual returns of 14.5%, while MSCI Emerging Markets equities returned just 3.9% annually. That disparity fueled one of the largest sustained allocations into U.S. equities in modern investing history.

UBS now believes that imbalance may begin reversing.

The firm argues the risk-adjusted numbers already support the case. Using data from 2003 through 2025, emerging-market corporate hard-currency debt produced a Sharpe ratio of 1.16, outperforming both global corporate bonds and the broader Global Aggregate index on a return-per-unit-of-risk basis.

Despite that, institutional exposure remains limited. Public pension systems maintain average emerging-market allocations near 5%, well below the roughly 11% weighting emerging markets represent in the MSCI ACWI benchmark. Allocations to emerging-market debt are often even smaller, typically between 1% and 3% of portfolios.

That under-allocation is central to UBS’ argument. Emerging markets now account for more than 60% of global GDP on a purchasing-power basis, yet remain structurally underrepresented in many institutional portfolios.

UBS projects emerging-market sovereign dollar debt could generate returns above 5.5% annually over the next seven years, while corporate debt could return roughly 6.1%, with materially lower volatility than the S&P 500’s projected long-term return profile.

For Khan and her co-authors, the shift is no longer simply about chasing higher yields. It is about a growing realization across global finance that the world’s fastest-growing economies may finally begin receiving portfolio allocations that better reflect their actual role in the global economy.

Middle East — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The same forces making ordinary investors nervous are about to produce one of the strongest trading quarters in years for America’s largest banks.

Speaking Wednesday at the Bernstein Strategic Decisions Conference in New York, Bank of America CEO Brian Moynihan said the bank expects second-quarter trading revenue to rise roughly 15% year-over-year, while JPMorgan Chase CEO Jamie Dimon projected approximately 11% growth in markets revenue — potentially making it one of the strongest trading quarters in JPMorgan’s history.

The drivers behind those gains are the same headlines dominating global markets every day: the war involving Iran, violent swings in oil prices, uncertainty surrounding artificial intelligence stocks, and growing concern over risks inside the rapidly expanding private credit industry.

For ordinary Americans, the dynamic may appear backward at first.

When markets become unstable, investors often become anxious. But for large Wall Street trading desks, volatility creates opportunity. Every sharp move in oil, stocks, currencies, or bonds forces institutional investors to reposition portfolios, hedge exposures, buy protection, or unwind trades. The banks facilitating those transactions collect fees and trading spreads on enormous volumes of activity across global markets.

That is precisely what is happening now.

Oil prices have repeatedly swung between roughly $80 and $110 per barrel in recent months as markets react to every development tied to Iran and the broader Middle East conflict. Semiconductor and AI-related stocks have experienced massive volatility as investors debate whether the artificial intelligence boom represents sustainable growth or speculative excess.

At the same time, Wall Street has grown increasingly cautious about the $2 trillion private credit market, where private investment firms increasingly lend directly to companies outside traditional banking channels. Even Dimon recently warned investors to revisit assumptions surrounding liquidity risks in private credit markets.

All of those concerns create exactly the kind of trading environment large banks thrive in.

The first quarter already demonstrated the pattern.

JPMorgan reported approximately $16.5 billion in net income during the first quarter, up 13% year-over-year, while markets revenue approached $12 billion, driven heavily by commodities, credit, and currency trading.

Bank of America similarly reported equity-trading revenue of approximately $2.8 billion, up roughly 30% from the prior year.

Now both institutions are signaling another unusually strong quarter ahead.

There is also a major investment-banking catalyst looming later this year: the expected SpaceX initial public offering.

JPMorgan, Bank of America, Citigroup, and numerous other banks are expected to participate in underwriting what could become the largest IPO in history if Elon Musk’s space company proceeds with its anticipated listing schedule. Underwriting fees tied to a transaction of that size could generate hundreds of millions of dollars for Wall Street banks during the second half of 2026.

Despite the market turbulence, both Moynihan and Dimon also delivered a notably optimistic view of the underlying U.S. economy.

Moynihan said Bank of America’s internal consumer data showed credit and debit card spending per household rising 4.8% year-over-year in April, up from 4.3% growth in March — a sign that consumer spending remains resilient despite geopolitical uncertainty and elevated energy prices.

Bank of America also raised its forecast for full-year net interest income growth to between 6% and 8%, reflecting continued strength in lending activity and consumer finances.

Dimon echoed similar themes regarding the resilience of the American consumer and the broader economy even as markets remain volatile.

That combination — strong consumer spending alongside elevated financial-market anxiety — is creating an unusually profitable environment for large banks.

The broader message from Wednesday’s conference was that Wall Street’s largest institutions are positioned to benefit from both sides of the current environment. If the economy remains healthy, lending and consumer spending stay strong. If markets remain unstable, trading desks continue generating elevated revenue.

For ordinary Americans, the takeaway is more nuanced.

The same uncertainty affecting gasoline prices, retirement portfolios, AI investments, and global trade is simultaneously driving large profits inside the banking system. That does not necessarily signal an economic crisis. In many cases, it simply reflects how modern financial markets operate: volatility increases demand for trading, hedging, and capital-market activity.

At the same time, unusually strong trading profits can also serve as a warning sign that the broader financial system remains unsettled beneath the surface.

Periods of extreme volatility rarely last forever. Eventually markets stabilize — or the uncertainty evolves into a more serious economic slowdown.

For now, however, America’s largest banks are making clear that they expect turbulence to continue, and they are positioning themselves to profit from it.

Between the Iran conflict, AI speculation, private credit concerns, and the approaching SpaceX IPO, Wall Street’s biggest firms are entering the summer with one message to investors:

The volatility is not hurting business.

It is the business.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Houston billionaire Tilman Fertitta is finally getting the casino empire he has spent nearly a decade chasing.

On May 28, 2026, Fertitta Entertainment announced a definitive agreement to acquire Caesars Entertainment in an all-cash transaction valued at approximately $17.6 billion, including assumed debt, marking one of the largest gaming industry buyouts in years and dramatically reshaping ownership across the Las Vegas Strip.

The transaction ends Fertitta’s years-long pursuit of Caesars, a campaign that began in 2018 when he first proposed combining the company with his Golden Nugget casino business. Multiple attempts, competing bidders, and shifting market conditions delayed the effort over the years. Now, after nearly a decade of maneuvering, Fertitta has secured control of one of the most recognizable casino brands in the world.

Importantly, this is not a sale by a single owner.

Caesars is a publicly traded Nasdaq company, meaning Fertitta is effectively buying out thousands of public shareholders and taking the company private. Shareholders will receive $31 in cash per share, representing roughly a 49% premium to the company’s share price before takeover speculation accelerated earlier this year.

The equity portion of the deal values Caesars at roughly $5.7 billion.

The much larger headline figure — $17.6 billion — comes because Fertitta is also assuming approximately $11.9 billion in existing Caesars debt, underscoring just how leveraged the modern casino business has become after years of acquisitions, expansions, and pandemic-era financial restructuring.

Fertitta’s Biggest Bet Yet

For Fertitta, the acquisition represents the largest and most ambitious deal of his career.

The 68-year-old billionaire already controls a sprawling hospitality empire through Landry’s, which owns or operates hundreds of restaurants, hotels, entertainment venues, and casinos across the United States and internationally. His holdings include the Golden Nugget casino chain and the Houston Rockets, which he purchased in 2017 for $2.2 billion.

Adding Caesars dramatically expands that footprint.

The company operates roughly 52 casino properties across the United States, including some of the most iconic names on the Las Vegas Strip: Caesars Palace, Flamingo, Planet Hollywood, and Horseshoe among them.

The deal effectively gives Fertitta direct control over a major portion of America’s gaming and hospitality infrastructure.

Why The Financing Structure Matters

One of the most closely watched aspects of the transaction is how it is being financed.

Fertitta Entertainment emphasized that the acquisition is not subject to a financing contingency — a crucial point for investors after several high-profile leveraged buyouts in recent years encountered financing instability or collapsed under deteriorating credit conditions.

Instead, the acquisition will be funded through a combination of Fertitta equity contributions, newly arranged financing from a consortium of 10 banks, and the assumption of Caesars’ existing debt obligations.

That structure reduces execution risk and signals strong lender confidence despite elevated interest rates and tighter credit conditions across much of corporate America.

Still, the debt load remains substantial.

Fertitta has long embraced highly leveraged dealmaking, often betting that strong cash-flow-generating assets can comfortably support large borrowing levels over time. Caesars now becomes the largest version of that strategy he has attempted.

The Political Angle

The acquisition also carries a political dimension analysts believe could matter during regulatory review.

Fertitta has been a prominent supporter of President Donald Trump, contributed actively during the 2024 campaign cycle, and currently serves as U.S. ambassador to Italy under the Trump administration.

Gaming deals of this scale require extensive approval processes across multiple states where Caesars operates casinos and holds gaming licenses. Regulatory scrutiny often focuses heavily on ownership structure, financing stability, competitive concentration, and operational suitability.

Analysts including Lance Vitanza of TD Cowen suggested Fertitta’s political positioning and longstanding industry relationships may improve confidence that the deal ultimately secures the approvals it needs.

That does not mean approval is automatic.

The transaction still faces shareholder approval requirements, state-level gaming reviews, and antitrust examination tied to concentration of major Strip properties under one ownership umbrella.

The agreement also includes a “go-shop” period running through approximately July 11, allowing Caesars and its advisers to solicit or evaluate competing bids before the transaction becomes final.

Why The Timing Is Interesting

The deal arrives during a softer moment for Las Vegas itself.

Visitor spending growth has moderated, discretionary travel has become more uneven, and gaming revenue trends have softened compared with the explosive rebound period immediately following the pandemic reopening years.

Yet investors still responded positively.

Caesars shares rose following the announcement and have climbed roughly 16% since initial reports of Fertitta’s interest surfaced earlier this year, suggesting markets largely view the agreed price as credible and achievable despite broader industry caution.

The acquisition also continues a longer-term consolidation trend reshaping the casino industry.

Ownership of major Strip properties has increasingly concentrated into fewer hands over the past decade as rising development costs, digital gaming competition, sports betting expansion, and capital-intensive resort operations pushed operators toward larger scale.

Fertitta’s purchase accelerates that process further.

What Fertitta Is Really Buying

At one level, this is a casino deal.

At another, it is a bet on physical experience assets themselves.

Fertitta has spent much of his career accumulating businesses tied to entertainment, hospitality, tourism, food, nightlife, sports, and experiential spending — industries that increasingly command premium pricing in an economy where consumers continue prioritizing experiences over goods.

Caesars gives him one of the most globally recognized hospitality brands in America alongside enormous real-estate positioning across Las Vegas and regional gaming markets.

The risks are obvious: debt, regulatory scrutiny, softer consumer spending, and the cyclical nature of gaming.

But Fertitta’s approach has rarely centered on avoiding leverage.

It has centered on owning trophy assets large enough to generate cash flow through economic cycles.

And after nearly ten years of trying, Caesars has now become the biggest trophy of them all.

Las Vegas — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Massachusetts believes California may have just handed Boston its best recruiting tool in years.

Business leaders, venture investors, and political officials across Boston are increasingly positioning a proposed California billionaire tax as a rare opportunity to reverse one of the city’s most frustrating economic patterns: training elite artificial intelligence founders at MIT and Harvard only to watch them leave for San Francisco.

The issue gained fresh urgency on May 28 after renewed attention around a proposed California ballot measure that would impose a one-time 5% tax on personal assets above $1 billion, aimed largely at funding healthcare programs.

For many startup founders, the danger is not theoretical.

A fast-growing AI company can achieve multibillion-dollar paper valuations long before founders actually receive liquid cash through an IPO or acquisition. That means entrepreneurs could theoretically face enormous tax obligations tied to unrealized wealth while still holding relatively limited personal liquidity.

That scenario is exactly what Boston now sees as an opening.

The Core Problem Boston Has Failed to Solve

Massachusetts has long produced some of America’s strongest technical talent.

The problem has never been education.

It has been retention.

Half of the 20 most valuable venture-backed AI companies in the United States reportedly have co-founders connected to MIT or Harvard. Yet virtually none are headquartered in Massachusetts. Instead, the companies overwhelmingly migrate westward into Silicon Valley’s financing, engineering, and startup ecosystem.

For decades, the gravitational pull of San Francisco proved nearly impossible to overcome.

Founders wanted proximity to venture capital, elite engineers, experienced startup operators, hyperscaler relationships, and other founders who had already built successful technology businesses.

That network effect became self-reinforcing.

Boston produced talent.

California captured the companies.

Now Massachusetts believes California’s own politics may finally weaken that cycle.

Why The Billionaire Tax Matters So Much To Founders

The proposed California measure is especially sensitive for technology entrepreneurs because startup wealth often exists primarily on paper.

Founders may control shares worth billions theoretically while lacking liquid cash to pay large tax bills before a company goes public or gets acquired.

That distinction is central to Boston’s argument.

Ankit Gupta, recently named Y Combinator’s first Boston-area general partner in more than a decade, warned that taxing unrealized startup wealth could create severe pressure on founders whose companies remain privately held.

He contrasted the proposal with Massachusetts’ own 4% surtax on income above $1 million, approved by voters in 2022.

That Massachusetts tax applies to realized income rather than unrealized asset appreciation — a difference many founders view as financially manageable compared with taxes tied to illiquid startup equity.

In effect, Massachusetts is trying to reposition itself politically.

For years, Boston carried a reputation as a relatively high-tax region compared with lower-tax states like Texas or Florida.

But compared directly against California and New York, the gap now looks narrower — especially if California expands taxation into unrealized wealth territory.

That shift changes the competitive narrative.

Boston’s Recruiting Push Is Already Underway

The effort is no longer abstract.

Governor Maura Healey traveled to San Francisco last month alongside Massachusetts Economic Development Secretary Eric Paley, a former venture capitalist tied to early investments in Uber and SeatGeek.

Meetings reportedly included AI giant Anthropic, accelerator powerhouse Y Combinator, and biotech leaders including Genentech.

Y Combinator CEO Garry Tan has publicly discussed exploring a Cambridge office, specifically citing the engineering concentration surrounding MIT and Harvard.

Boston Mayor Michelle Wu is also increasingly framing the city as a future center for “applied AI” — not necessarily competing directly with Silicon Valley on foundational model development, but specializing in practical AI deployment across healthcare, biotechnology, life sciences, drug discovery, hospitals, diagnostics, and enterprise systems.

That distinction matters strategically.

Boston already possesses one of the world’s densest concentrations of hospitals, research institutions, biotech firms, medical schools, and pharmaceutical infrastructure. The city’s argument is that AI’s next major commercial wave may involve integrating models into real-world healthcare and scientific systems rather than purely building the models themselves.

In that scenario, Boston may hold structural advantages Silicon Valley lacks.

Why Timing Suddenly Matters

The push also reflects economic necessity.

Boston’s biotech economy — long one of the city’s strongest growth engines — has cooled materially after years of aggressive expansion. Venture funding has slowed across life sciences, while federal research funding uncertainty tied to broader budget pressures has created additional strain for universities and medical institutions heavily dependent on federal grants.

Massachusetts leaders increasingly view AI as both an opportunity and a hedge against biotech deceleration.

Several major corporate and startup initiatives are already underway.

Genentech, owned by Roche, is expanding research operations on Harvard-linked property. Anthropic maintains a smaller Cambridge footprint. A coalition including Whoop, DraftKings, and AI music startup Suno launched the Massachusetts AI Coalition earlier this year aiming to double the number of billion-dollar tech and biotech companies headquartered in the state within five years.

The coalition has even proposed “founder starter parks” offering subsidized computing resources, office space, mentorship access, and operational support for startups willing to remain in Massachusetts during early-stage growth.

The logic is simple: once companies scale beyond roughly 10 employees, relocation becomes far harder operationally.

Boston is trying to intervene before founders leave in the first place.

The Bigger National Shift

Underneath the tax debate sits a broader structural question about the future geography of American technology.

For decades, Silicon Valley’s dominance appeared nearly unbreakable because capital, talent, and company formation all concentrated in one ecosystem simultaneously.

But remote work, distributed engineering teams, AI infrastructure, rising living costs in California, and shifting political dynamics are beginning to fragment that concentration model.

Boston is betting that taxation could accelerate the process further.

Not necessarily by driving a mass exodus from California overnight — but by making founders more willing to consider alternative ecosystems earlier in their company-building process.

The question is whether policy alone can overcome Silicon Valley’s still-enormous network advantages.

History suggests ecosystems rarely shift quickly.

But Massachusetts increasingly believes the economics surrounding startup formation are beginning to change.

And for the first time in years, Boston thinks the pull westward may no longer feel inevitable.

Boston — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

BEIJING — China’s factories posted their strongest monthly profit growth in more than two years in April, with earnings at the country’s largest industrial companies jumping 24.7% year-over-year, according to data released Wednesday, May 27, 2026 by China’s National Bureau of Statistics, underscoring how deeply the global artificial-intelligence boom is now reshaping manufacturing profits on both sides of the Pacific.

The gain marks the fastest pace of Chinese industrial profit growth since November 2023, accelerating sharply from a 15.8% increase in March and lifting year-to-date profit growth for the first four months of 2026 to 18.2%, up from 15.5% in the first quarter.

The numbers arrive as global equity markets — especially U.S. semiconductor stocks — continue surging on expectations of massive AI-driven spending on data centers, memory chips, networking equipment and computing infrastructure.

And increasingly, the same forces driving record valuations on Wall Street are also driving profits inside Chinese factories.

The strongest gains in China’s report came from the computing, communications and electronics manufacturing sector, now the country’s single largest industrial profit category. Earnings in that segment more than doubled from a year earlier as demand for AI-related hardware accelerated globally.

That matters directly to American investors.

On Tuesday, the S&P 500 closed at a fresh record high of 7,519.12, while the Nasdaq Composite finished at 26,656.18, also an all-time high, led overwhelmingly by semiconductor and AI infrastructure stocks.

Micron Technology surged roughly 19%, briefly crossing a $1 trillion market capitalization after UBS sharply raised its price target on the company. The VanEck Semiconductor ETF climbed more than 3% to a new 52-week high, while Advanced Micro Devices, On Semiconductor and Western Digital all posted major gains.

The link between the two markets is becoming increasingly obvious.

The global AI infrastructure buildout — from hyperscale data centers to inference clusters and advanced memory systems — is generating extraordinary demand across the entire semiconductor supply chain.

American chip designers are pricing that demand into equity valuations.

Chinese factories assembling servers, networking systems, electronics and hardware components are pricing it into margins and profit growth.

Both sets of numbers are effectively telling the same story at the same time.

The second major contributor to China’s April profit surge was energy.

Oil prices have climbed sharply amid the expanding Middle East conflict, with crude trading in roughly the $100 to $106 per barrel range during April. China’s oil and gas extraction industry swung from a 1.4% profit decline in the first quarter to an 8.1% gain through April as higher crude prices boosted margins for state-owned energy producers.

Government policy is also playing a role.

Chinese officials have spent years subsidizing strategic industrial sectors including semiconductors, advanced manufacturing and high-tech equipment through tax incentives, low-cost financing and direct state investment.

Earlier this year, Yu Weining, chief statistician at the National Bureau of Statistics, said profits in China’s equipment-manufacturing sector rose 21%, while high-tech manufacturing profits surged 47.4% during the first quarter alone.

But beneath the headline profit numbers, China’s broader economy remains uneven.

Industrial output growth slowed to 4.1% in April, while retail sales barely moved, rising just 0.2%. Fixed-asset investment — spending on factories, housing and infrastructure — contracted over the first four months of the year as China’s property slump continued weighing on domestic demand.

In other words, the factory-profit boom is real, but highly concentrated.

The strongest industries are tied directly to AI hardware, advanced electronics and energy — not to broad-based consumer recovery inside China.

There is also a pricing dynamic emerging underneath the data.

China’s Producer Price Index (PPI) rose 2.8% in April, the largest increase since July 2022, suggesting factories are finally regaining pricing power after more than two years of deflationary pressure and price wars across parts of Chinese industry.

Beijing has spent months trying to reduce aggressive domestic price competition that had crushed margins in sectors ranging from solar equipment to industrial machinery. April’s numbers suggest some of those efforts may now be feeding through into corporate profitability.

For Washington policymakers, however, the data also highlights a strategic complication.

The single strongest category inside China’s profit report — electronics and computing equipment — is the very sector the United States has spent years trying to constrain through semiconductor export controls and technology restrictions.

Since 2022, Washington has imposed multiple rounds of restrictions targeting advanced AI chips, semiconductor manufacturing equipment and high-end computing exports to China.

Yet Chinese manufacturers tied to AI infrastructure are still seeing profits surge.

That does not necessarily mean the export controls failed strategically, but it does suggest the global AI spending boom has become so large that Chinese firms continue benefiting even under significant restrictions.

Trade flows also remain surprisingly resilient.

China’s exports rose 14.1% year-over-year in April, while imports surged 25.3%, according to customs data released earlier this month.

Meanwhile, the fragile U.S.-China trade détente reached late last year continues holding for now. Earlier this month, Beijing confirmed an order for 200 Boeing aircraft, describing aviation as a “key area” for bilateral cooperation — a signal both governments appear eager to preserve at least limited economic stability despite broader geopolitical rivalry.

For Wall Street, the takeaway from Wednesday’s Beijing data is straightforward.

The AI capital-expenditure cycle is now large enough to push industrial profits, stock prices and corporate investment higher simultaneously across both the American and Chinese economies.

Chip designers, memory producers, foundries, server manufacturers and contract electronics firms are all feeding from the same underlying demand wave.

The Chinese numbers, in many ways, simply confirm what U.S. markets have already been pricing in for months.

The risks, however, remain equally clear.

China’s recovery remains narrow. American equity markets remain heavily concentrated in a small group of AI-linked technology companies. And the same Middle East conflict helping lift energy-sector profits also threatens broader economic stability if oil prices spike further or supply disruptions worsen.

This week, strategists at Goldman Sachs warned that today’s bull market still faces structural vulnerabilities tied to tech concentration, geopolitical tensions and volatility in bond markets.

For now, however, the message coming simultaneously from Beijing’s factory floors and the New York Stock Exchange is unmistakable:

AI hardware is generating real profits — and nearly everyone connected to the supply chain is benefiting at once.

Asia — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

American consumers are still spending — just far more selectively than they were a year ago.

That is the clearest message emerging from the first-quarter retail earnings season, where a surprisingly large number of U.S. chains are beating Wall Street expectations despite persistent inflation, elevated borrowing costs, and growing concerns about slower economic growth later this year.

According to the latest May 27 scorecard from the London Stock Exchange Group, 161 of the 188 companies tracked in its U.S. Retail and Restaurant Index have now reported quarterly results. Roughly 71% beat analyst profit expectations, while 70% exceeded revenue forecasts — unusually strong numbers for a sector many investors expected would show clear signs of consumer fatigue by now.

Across the index, profits are on pace to rise 26.4% from the same quarter last year, while total sales are tracking roughly 7.4% higher.

The results suggest something important about the current American economy: households have not stopped spending, but they are becoming dramatically more disciplined about where their money goes.

That distinction is shaping the entire retail landscape in 2026.

The Consumer Is Still Alive — But More Defensive

For much of the past year, economists and retailers feared that higher interest rates and lingering inflation would finally crack consumer spending.

Instead, shoppers continue showing resilience, supported by a still-solid labor market, rising wages in some sectors, accumulated household savings among higher-income consumers, and a growing tendency to prioritize experiences, essentials, and perceived value over discretionary splurges.

But the spending behavior itself has changed.

Consumers are comparison shopping more aggressively, trading down selectively, delaying larger purchases, and increasingly concentrating spending in categories where they believe they are getting measurable value for money.

That is why discount chains, off-price retailers, warehouse clubs, and selective specialty categories continue outperforming.

The quarter’s strongest retail results largely came from companies positioned around value, convenience, or highly targeted demand niches rather than broad discretionary consumption.

Dick’s Sporting Goods Shows Experience Spending Is Still Strong

One of the biggest surprises of the earnings season came from Dick’s Sporting Goods, which reported a massive 62.7% increase in quarterly revenue.

Comparable sales at stores open at least a year rose 6%, roughly double analyst expectations and one of the strongest major retail performances of the quarter.

The numbers align with broader federal retail data showing sporting goods remaining one of the strongest consumer spending categories recently — a sign that Americans are still allocating money toward fitness, outdoor activity, youth sports, and lifestyle-oriented purchases despite broader economic caution.

At the same time, Dick’s management maintained a relatively cautious tone about the rest of the year, acknowledging ongoing uncertainty surrounding consumer confidence and broader macroeconomic conditions.

That caution is becoming common across retail.

Even companies posting strong current results remain hesitant to declare the consumer fully healthy.

Foot Locker’s Small Improvement Carries Outsized Meaning

Buried inside the Dick’s results was another potentially important signal.

Foot Locker, which Dick’s now owns, posted a 0.6% increase in comparable sales — its first positive same-store sales reading in roughly two years.

On the surface, the number appears modest.

But for retail analysts, the significance is psychological as much as financial. Sneaker and youth apparel demand had become one of the clearest weak spots in discretionary spending over the past two years, particularly among younger consumers squeezed by inflation and rising living costs.

Even a small return to positive growth may suggest parts of discretionary retail spending are beginning to stabilize rather than deteriorate further.

Abercrombie’s Reinvention Continues

Perhaps no retailer better captures the broader transformation of American retail than Abercrombie & Fitch.

Once viewed as a declining mall-era brand, Abercrombie has now delivered 14 consecutive quarters of sales growth — one of the most remarkable turnarounds in modern apparel retail.

The company beat profit expectations again this quarter, though revenue came in slightly below forecasts.

Its strongest growth came from Asia and the Americas, particularly the core Abercrombie label, while weakness emerged in Europe and parts of the Middle East amid geopolitical instability and softer tourism demand.

Management specifically cited unrest in the Middle East as pressuring Hollister sales in the region, highlighting how global geopolitical conditions are increasingly affecting consumer-facing businesses even outside traditional industrial sectors.

Still, the broader takeaway remained positive: brands successfully repositioned around lifestyle identity, quality perception, and targeted demographics continue outperforming many traditional apparel peers.

Off-Price Retail Keeps Winning

The clearest winners of the quarter, however, were once again discount and off-price retailers.

Ross Stores and TJX Companies — parent of T.J. Maxx, Marshalls, and HomeGoods — both exceeded expectations and reinforced one of the strongest themes in retail right now: value-oriented shopping behavior is accelerating.

TJX raised full-year guidance after HomeGoods posted a 9% comparable-sales increase, while management said the current quarter has also started strongly.

The strength of off-price retail matters because it reveals how consumers are adapting to inflation psychologically.

Households are not necessarily spending less overall.

They are becoming far more strategic about where they spend.

Rather than abandoning consumption entirely, many shoppers are reallocating toward retailers that maximize perceived value, bargain discovery, or necessity-based spending.

That behavioral shift may prove more durable than investors initially expected.

Target’s Results Reveal The New Consumer Math

One of the most closely watched earnings reports came from Target, long viewed as a bellwether for middle-class consumer behavior.

The company exceeded both revenue and profit expectations, with comparable sales rising 5.6% — its first positive same-store sales growth in five quarters.

Digital sales climbed nearly 9%, helped by strong adoption of same-day fulfillment services tied to Target Circle 360.

Yet despite the strong report, Target shares still fell after earnings.

Why?

Because investors increasingly care less about what retailers just reported and more about whether the pace is sustainable.

Target itself maintained a cautious tone about the second half of the year, reflecting broader uncertainty around inflation, interest rates, consumer credit quality, and potential economic slowing.

That caution may ultimately define the retail story more than the headline beats themselves.

What Wall Street Is Really Watching

Underneath the earnings numbers, Wall Street is trying to answer one central question:

Is the U.S. consumer genuinely strong — or simply surviving longer than expected?

So far, the answer appears to be somewhere in between.

Consumers continue spending, but the quality of that spending is evolving rapidly. Value, convenience, and selective lifestyle categories are winning. Big-ticket discretionary purchases remain softer. Discount retail continues outperforming premium positioning in many categories.

The result is not a collapsing consumer economy.

It is a highly fragmented one.

That fragmentation explains why some retailers are producing exceptional numbers while others continue struggling despite operating in the same broader economy.

And it suggests the second half of 2026 may depend less on whether Americans keep spending — and more on where they decide the money is still worth it.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Wall Street may be making a major geopolitical miscalculation.

That is the view emerging from Citadel Securities, where strategist Frank Flight warned on May 28 that financial markets appear to be underpricing the probability of a meaningful U.S.-Iran breakthrough that could reopen the Strait of Hormuz more fully and trigger a broad relief rally across oil, equities, bonds, and currencies.

The argument is not that Washington and Tehran are suddenly on the verge of a grand nuclear agreement.

It is narrower — and potentially far more important for markets in the short term.

Citadel’s core thesis is that investors may be conflating two separate issues: a comprehensive nuclear accord, which remains politically difficult and likely distant, and a more limited operational agreement focused on restoring commercial shipping stability through the Strait of Hormuz.

The second outcome, Citadel believes, may be significantly closer than markets currently assume.

That distinction matters enormously because the Strait of Hormuz is not simply another geopolitical flashpoint. It is the single most important chokepoint in the global energy system, responsible for transporting roughly one-fifth of the world’s oil supply.

Markets spent much of 2026 pricing in the risk that disruption there could become semi-permanent.

Now Citadel believes traders may be positioned too heavily for escalation while underestimating the probability of stabilization.

The Market’s Current Assumption: Permanent Instability

Since the acute military escalation between the United States and Iran earlier this year, oil markets have behaved as though geopolitical instability is now structurally embedded into global energy pricing.

Even after the April ceasefire framework temporarily reduced immediate military risks, crude prices remained elevated. Brent oil largely traded between roughly $90 and $120 per barrel depending on daily headline risk, while volatility across shipping, insurance, and energy derivatives stayed unusually high.

The market’s skepticism is understandable.

Investors have seen decades of failed Iran diplomacy, repeated sanctions cycles, proxy conflicts, and fragile temporary truces that eventually unraveled. Many traders now reflexively assume any de-escalation will prove temporary.

Prediction markets reflect that caution.

Polymarket pricing and broader market positioning still imply significant skepticism toward any comprehensive breakthrough before the current negotiation deadlines expire. Traders remain highly doubtful that Washington and Tehran can rapidly bridge major disputes surrounding sanctions relief, enrichment restrictions, verification mechanisms, and long-term nuclear oversight.

But Citadel argues that markets may be asking the wrong question.

The relevant issue for near-term asset pricing may not be whether a full nuclear deal gets signed.

It may simply be whether both sides reach enough operational understanding to stabilize shipping through Hormuz.

Why Citadel Thinks Markets Are Mispricing The Situation

Several developments appear to be shaping Citadel’s view.

First, the diplomatic structure itself has evolved.

Unlike earlier periods dominated by public ultimatums and military signaling, current negotiations have increasingly shifted toward framework-based diplomacy involving multiple intermediaries including Oman, Qatar, and Pakistan. Discussions in Doha and Islamabad have reportedly focused not only on nuclear issues, but specifically on shipping access, deconfliction mechanisms, sanctions sequencing, and phased implementation structures.

That matters because shipping stabilization is economically valuable to both sides even without a final nuclear resolution.

Iran benefits from restored energy flows and reduced economic pressure.

The United States benefits from lower global oil prices, reduced inflation pressure, calmer shipping markets, and improved energy stability ahead of an already politically sensitive economic environment.

Second, Citadel appears focused on market asymmetry.

Financial markets remain heavily positioned around continued geopolitical risk premiums. Energy traders, volatility desks, inflation-sensitive assets, and defensive equity sectors all still reflect elevated assumptions about instability.

If those assumptions begin unwinding even partially, the move across markets could be sharp.

That is especially true because geopolitical risk premiums tend to collapse much faster than they build.

What A Strait Breakthrough Could Mean

The most immediate impact would likely hit oil.

Earlier this year, when the initial two-week ceasefire agreement temporarily reduced fears surrounding Hormuz disruptions, oil prices fell dramatically. Brent crude briefly dropped nearly 16%, while equities rallied sharply as traders suddenly repriced lower energy risk and softer inflation expectations.

A more durable shipping framework could produce another major repricing event.

Lower oil prices would immediately ease pressure on inflation, transportation costs, manufacturing input prices, airline expenses, freight markets, and consumer energy costs. That, in turn, would affect Federal Reserve expectations.

Markets throughout 2026 have struggled with one core problem: inflation has remained too sticky for investors to confidently price aggressive rate cuts.

A sustained decline in oil could materially change that calculus.

The knock-on effects could spread quickly into equities, particularly growth sectors sensitive to interest rates.

Technology stocks, small caps, cyclicals, airlines, industrials, and consumer discretionary names could all benefit from a combination of lower energy costs and softer inflation expectations.

Bond yields could also decline if investors begin believing energy-driven inflation pressures are easing more sustainably.

Why Timing Matters Now

The diplomatic clock is tightening.

The current ceasefire structure has already been extended multiple times and remains conditional on continued negotiations. Reports surrounding a possible memorandum-of-understanding framework suggest negotiators may now be prioritizing interim operational agreements rather than attempting to finalize every nuclear issue simultaneously.

That sequencing approach may be exactly what markets are underestimating.

A partial shipping stabilization agreement is politically easier than a full nuclear normalization deal. It requires fewer immediate concessions while still delivering meaningful economic relief to both sides.

For traders heavily positioned around worst-case escalation scenarios, that creates asymmetric risk.

If talks collapse entirely, markets may not move dramatically because substantial geopolitical fear is already embedded into pricing.

But if negotiators announce even a limited shipping framework tied to Hormuz access, energy markets could reprice rapidly lower while equities rally sharply.

That imbalance appears central to Citadel’s warning.

What Wall Street Is Really Debating

Underneath the headlines, Wall Street is increasingly debating whether markets have become too anchored to permanent geopolitical pessimism.

After years of war shocks, sanctions, inflation spikes, and supply disruptions, investors now instinctively price instability first and resolution second.

Citadel’s view is essentially that the pendulum may have swung too far.

Not because Iran suddenly becomes a stable partner.

But because even narrow operational agreements around shipping can have outsized effects on global asset prices when markets are positioned overwhelmingly for continued conflict.

And in 2026, few geopolitical variables matter more to inflation, interest rates, and global growth than the Strait of Hormuz.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — U.S. Senator Rick Scott, the Florida Republican, reintroduced legislation earlier this week that would bar American payment companies, currency dealers and even the U.S. Postal Service from handling transactions involving China’s government-issued digital currency, escalating a broader Republican push to block the digital yuan from entering the American financial system.

The legislation, formally titled the Chinese CBDC Prohibition Act of 2026, was introduced on Thursday, May 21, 2026.

CBDC stands for central bank digital currency, essentially a digital form of money issued directly by a country’s central bank rather than by commercial banks or private cryptocurrency networks.

In a Senate release announcing the bill, Scott framed the issue as both an economic and national-security threat.

“The dollar is the reserve currency of the world and the CCP wants to undermine our leadership with a digital currency they can track and manipulate,” Scott said, referring to the Chinese Communist Party.

He added: “The digital Yuan is just another tool used by the Chinese Communist Party to spy on its people and all those who use it. Xi and his thugs have no business playing big brother to American citizens and how they spend their money.”

The bill would make it illegal for American money-services businesses to process, transfer or accept transactions involving a Chinese government-issued digital currency, including the digital yuan, also known as e-CNY.

The practical reach would be broad.

Companies and institutions potentially affected include PayPal, Venmo, Zelle, Western Union, MoneyGram, airport currency exchanges, and even the U.S. Postal Service when handling money orders or certain international payment services. Under the proposal, those entities would be prohibited from facilitating transactions tied to China’s state-backed digital currency infrastructure.

The legislation reflects mounting concern in Washington over China’s rapid progress in digital finance.

Over the past five years, the People’s Bank of China has built what is widely viewed as the world’s most advanced large-scale central bank digital currency system. The digital yuan has already been tested extensively in major Chinese cities including Beijing, Shanghai, Shenzhen and Hangzhou, with Chinese consumers using it for retail payments, transportation, tourism and salary distributions.

Beijing has also openly discussed using the digital yuan for cross-border trade settlement and international commerce, a move American lawmakers increasingly see as a challenge to the dominance of the U.S. dollar.

That dominance remains one of America’s biggest economic advantages. The dollar functions as the world’s primary reserve currency, meaning central banks, commodity markets and international businesses rely heavily on dollars for trade and savings. Oil is largely priced in dollars, global debt markets revolve around dollar financing, and the U.S. government benefits from lower borrowing costs because of persistent global demand for dollar-based assets.

Republican lawmakers argue a widely adopted Chinese digital currency could eventually weaken that position, particularly if countries hostile to Washington begin settling trade outside the dollar system.

The second concern — and the one Scott emphasized most heavily — is surveillance.

Unlike physical cash, transactions conducted through a central bank digital currency can potentially be monitored directly by the issuing government. In China’s case, critics argue that gives the Chinese Communist Party extraordinary visibility into how money moves through the economy.

Scott’s Senate release argued Beijing already uses the digital yuan “as a mechanism to control the lives of its population” and warned authorities could theoretically freeze accounts or restrict access to funds instantly.

The implication for American lawmakers is that U.S. businesses or individuals using the digital yuan for trade with Chinese suppliers could expose financial activity to Chinese state monitoring.

This is not the first congressional effort targeting Chinese digital currencies.

In 2022, Senators Tom Cotton, Mike Braun and Marco Rubio introduced legislation called the Defending Americans from Authoritarian Digital Currencies Act, which sought to block app stores such as Apple’s App Store and Google Play from hosting applications supporting the digital yuan.

That proposal never became law.

Scott himself has introduced earlier versions of similar legislation in prior Congresses. Previous attempts gained Republican backing but stalled before reaching a full Senate vote.

This time, however, the political environment is different.

Republicans now control both chambers of Congress while the Trump administration continues to frame competition with China as a central economic and national-security priority. That combination may give the proposal a stronger chance than previous versions.

The timing is notable.

Just days before the legislation was introduced, President Donald Trump and Chinese President Xi Jinping held high-level discussions aimed at stabilizing U.S.-China tensions surrounding trade and technology. Trump has also publicly encouraged expanded American business engagement with China in select sectors even as Congress simultaneously moves to harden barriers around Chinese financial and technological influence.

For American businesses, the immediate practical impact of the bill would likely be limited because very few U.S. companies currently conduct routine transactions using the digital yuan. Most trade between the United States and China still settles in either U.S. dollars or traditional Chinese yuan through conventional banking systems.

But the legislation is designed less to disrupt existing behavior than to prevent future adoption before the digital yuan gains broader international traction.

The bill also reflects a growing divide in Washington between privately issued cryptocurrencies and government-backed digital currencies.

Many Republicans who support decentralized assets like Bitcoin have simultaneously opposed central bank digital currencies, arguing they could expand government financial surveillance. Scott and several other Republican lawmakers have separately criticized the idea of a potential Federal Reserve digital dollar for similar reasons.

More broadly, the legislation fits into a wider congressional effort to reduce Chinese influence across strategic sectors of the American economy, including technology, pharmaceuticals, real estate, rare earth minerals and electric-vehicle supply chains.

Taken together, the measures point toward a Washington increasingly willing to wall off sensitive parts of the U.S. economy from Chinese financial and technological penetration.

The Chinese CBDC Prohibition Act of 2026 has now been referred to committee for review. If approved by the Senate, it would still need to pass the House before reaching President Trump’s desk.

For now, the digital yuan remains legal in the United States.

Very few Americans use it.

Scott’s bill is designed to ensure that stays true.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — The Federal Aviation Administration (FAA) said Tuesday, May 26, 2026, that it is proposing a $165,000 civil fine against Alaska Airlines for allegedly allowing visibly intoxicated passengers to board 11 separate flights between February 2024 and February 2025, part of a broader federal crackdown on impairment and airline safety compliance.

In a statement released Tuesday, the FAA said federal aviation regulations prohibit airlines from allowing passengers who appear intoxicated to board commercial aircraft. The rule applies both to gate agents and flight attendants, who are expected to stop impaired travelers before they enter the aircraft cabin.

The agency did not identify the specific routes involved or disclose the conduct of the passengers at issue, but regulators said the violations occurred across multiple flights over a one-year period.

Alaska Airlines spokesperson Tim Thompson confirmed the carrier cooperated with the FAA’s review.

“We take seriously our responsibility to provide a safe and secure environment for our guests and employees,” Thompson said. “We participated fully with the FAA’s audit of our policies and practices as it relates to intoxicated guests on board our aircraft.”

He added that the airline has already implemented operational changes in response to concerns raised by regulators.

“Since the FAA shared these concerns with us over a year ago, we made meaningful changes to ensure compliance with the FAA’s expectations, including enhanced training for all flight attendants and customer service agents,” Thompson said. “We respect the results of the FAA’s audit and are confident in the changes that have been in place for the last year to ensure our shared standards are being met.”

The enforcement action highlights growing federal concern about intoxicated and disruptive passenger behavior aboard commercial aircraft, an issue that intensified nationwide after the pandemic and has remained a persistent challenge for airlines and flight crews.

Federal regulations under 14 CFR 121.575 prohibit airlines from both serving alcohol to visibly intoxicated passengers and allowing them to board aircraft in the first place. Once onboard, intoxicated travelers can create serious operational and safety risks ranging from medical emergencies and crew interference to violent confrontations and attempted breaches of aircraft systems.

One incident involving Alaska Airlines drew national attention last year. In December 2025, a passenger reportedly intoxicated after several days of drinking opened a cabin door midair during a flight between Deadhorse and Anchorage, Alaska. That event is not among the 11 flights cited in the FAA’s proposed penalty, but it underscored the dangers regulators associate with impaired passengers onboard aircraft.

The FAA’s action against Alaska Airlines is civil rather than criminal. The airline now has 30 days after receiving the enforcement notice to either pay the fine, negotiate a settlement with regulators or formally challenge the penalty before an administrative law judge.

The proposed fine is relatively small financially for the airline. Alaska Air Group, which trades on the New York Stock Exchange under the ticker symbol ALK, generates roughly $11 billion in annual revenue, meaning the penalty itself is unlikely to materially affect earnings.

The reputational impact, however, may matter more.

Alaska Airlines has spent much of the past two years rebuilding public confidence following the highly publicized January 2024 Boeing 737 MAX 9 door-plug blowout, when a fuselage panel detached during an Alaska Airlines flight shortly after takeoff, forcing an emergency landing and triggering a temporary nationwide grounding of that aircraft type.

The carrier also completed its $1.9 billion acquisition of Hawaiian Airlines in September 2024, creating a significantly larger combined airline operation spanning more than 1,200 daily flights and approximately 120 destinations across North America.

The FAA’s move against Alaska Airlines is not happening in isolation.

In April 2026, regulators proposed a separate $255,000 civil penalty against American Airlines after alleging the carrier allowed 12 flight attendants to return to safety-sensitive duties after testing positive for drugs or alcohol without completing required follow-up testing procedures.

According to the FAA, substances identified in that investigation included alcohol, cocaine, marijuana, methamphetamine and amphetamines.

Taken together, the two enforcement actions suggest the FAA is intensifying scrutiny not only of passenger behavior but also of how airlines manage impairment risks among employees and customers alike.

For travelers, the rules remain straightforward. Airlines can legally deny boarding to anyone appearing visibly impaired in the terminal or at the gate, and passengers who become disruptive onboard can face FAA fines of up to $37,000 per violation, in addition to possible federal criminal charges.

So far, investors have shown little reaction to Tuesday’s announcement. Shares of Alaska Air Group were relatively unchanged following the FAA statement.

For Alaska Airlines, however, the issue extends beyond the dollar amount. After years spent working to restore operational credibility following high-profile safety incidents, another FAA enforcement action tied to passenger management is precisely the kind of headline the carrier has been trying to avoid.

For now, the penalty remains only a proposal. The next step belongs to Alaska Airlines.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For weeks, global oil markets, grocery suppliers, and American consumers had been operating on the assumption that President Donald Trump would eventually feel political pressure from a prolonged conflict with Iran and move quickly toward a deal before the November midterm elections. On Wednesday, during a Cabinet meeting at the White House, Trump publicly pushed back against that idea.

“They want very much to make a deal. So far, they haven’t gotten there,” Trump said. “We’re not satisfied with it, but we will be. We will be either that, or we’ll have to just finish the job.”

When asked directly whether the upcoming election was influencing his decision-making, the president rejected the premise and suggested Iran believed political pressure in the United States would force him into concessions. That statement immediately carried implications for energy markets, inflation expectations, and Wall Street positioning.

The market reaction had already begun earlier in the day. U.S. crude oil fell 5.55% Wednesday to settle at $88.68 per barrel after Iranian state media claimed Tehran intended to restore commercial traffic through the Strait of Hormuz to pre-war levels within one month. The White House quickly disputed the report, calling it inaccurate, but traders still moved aggressively into a lower-oil scenario.

The Strait of Hormuz remains one of the world’s most important shipping chokepoints, carrying roughly 20% of globally traded seaborne crude oil. Any sign of stabilization immediately affects fuel prices, transportation costs, airline expenses, manufacturing forecasts, and food distribution costs across the United States.

Trump’s comments complicated that market assumption. By signaling publicly that he is prepared to continue negotiations without rushing toward a fast resolution, the administration effectively told markets that lower energy prices may not arrive as quickly as many traders had expected.

For consumers, the most immediate impact is gasoline. National fuel prices remain elevated compared with the same period last year, and the summer driving season traditionally increases demand further between Memorial Day and Labor Day. If tensions remain unresolved longer than anticipated, pressure on fuel prices could persist through the summer.

The second impact is groceries and consumer goods. Transportation costs influence pricing across nearly every part of the economy because food, retail inventory, refrigerated products, and imported goods depend heavily on diesel trucking, cargo shipping, and fuel-intensive logistics networks. Sustained oil prices near current levels can continue filtering into supermarket prices and household expenses.

Markets, however, continued to show resilience Wednesday despite the geopolitical uncertainty. The Dow Jones Industrial Average closed at a record 50,644.28, while the S&P 500 finished at 7,520.36 and the Nasdaq Composite closed at 26,674.73, also record highs.

The market’s willingness to continue buying equities despite prolonged Middle East uncertainty reflects broader investor confidence that the U.S. economy, corporate earnings, and the ongoing artificial intelligence investment cycle remain strong enough to offset geopolitical risks.

There is also a significant political layer underneath the administration’s posture. Trump entered Wednesday’s Cabinet meeting following a major Republican primary victory in Texas, where Attorney General Ken Paxton defeated four-term Senator John Cornyn after receiving Trump’s endorsement. The result reinforced Trump’s standing inside the Republican Party and may have reduced concerns within the White House that a prolonged conflict automatically weakens his political position heading into November.

At the same time, Republican strategists remain aware of the risks associated with prolonged inflation, elevated gasoline prices, and broader voter frustration tied to economic pressure. Competitive House districts across states such as Pennsylvania, Wisconsin, and Colorado remain highly sensitive to shifts in fuel costs and consumer sentiment.

For Tehran, Wednesday’s message was direct: the White House is signaling publicly that it does not view Election Day as a negotiating deadline.

For American households, the consequences are more practical. The timeline for lower gasoline prices, reduced grocery inflation, and broader economic relief may depend heavily on how long tensions in the Middle East continue — and whether negotiations ultimately produce a meaningful agreement.

The administration made clear Wednesday that it is prepared to continue the standoff longer than markets may have anticipated. Investors, consumers, and global energy markets are now adjusting to that possibility in real time.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Wall Street opened lower Thursday morning, but the market’s real message was not panic. It was confusion.

Investors on May 28 were forced to process three different forces hitting the market at the same time: inflation that is heating back up, oil prices surging again because of the Iran conflict, and a fresh reminder from Snowflake that the artificial intelligence boom is still producing real corporate growth. The result was a fractured market where indexes fell broadly while select AI-linked technology stocks exploded higher — a sign that traders are becoming far more selective rather than simply abandoning risk altogether.

The Dow Jones Industrial Average fell 0.63% shortly after the opening bell, while the S&P 500 slipped modestly and the Nasdaq Composite edged lower despite Snowflake’s massive rally. Treasury yields moved higher after the Commerce Department reported that the personal consumption expenditures price index — the Federal Reserve’s preferred inflation gauge — rose 0.4% in April and 3.8% from a year earlier.

That annual figure matters more than the headline reaction.

Just two months ago, annual PCE inflation was running at 2.8%. In March it accelerated to 3.5%. Now it sits at 3.8%, marking three straight months of upward movement and reinforcing fears that the inflation slowdown many investors expected earlier this year may have stalled entirely.

The market had spent much of early 2026 betting the Federal Reserve would begin cutting rates aggressively by summer. Thursday’s report further damaged that narrative.

“This is the type of number that keeps the Fed trapped,” one portfolio manager at a major New York asset manager said Thursday morning. “Growth is slowing, consumers are getting squeezed, but inflation is not cooling fast enough to justify cuts.”

That is what traders increasingly fear: not a recession, but something potentially more difficult — a stagflation-style environment where economic growth weakens while prices remain elevated.

Oil is making that fear worse.

Brent crude jumped more than 2.5% Thursday and briefly approached the psychologically critical $100-a-barrel level after Iran claimed responsibility for striking a U.S. air base in retaliation for fresh American military action. Traders immediately began repricing the risk of broader supply disruptions through the Strait of Hormuz, the narrow maritime corridor responsible for transporting roughly 20% of the world’s oil supply.

The move in crude matters beyond gasoline prices.

Higher oil feeds directly into transportation, manufacturing, food distribution, airline costs, chemicals, shipping, and consumer inflation expectations. It is one of the few commodities capable of rapidly spreading price pressure across nearly every part of the economy.

Federal Reserve officials Neel Kashkari and Austan Goolsbee both warned this week that renewed energy inflation could complicate any path toward lower rates. Markets are now beginning to understand that geopolitical risk may effectively be doing part of the Fed’s tightening work for it.

Yet even as the broader market weakened, investors poured aggressively into one area: artificial intelligence.

Snowflake surged roughly 37% after reporting quarterly revenue growth of 33%, one of the strongest large-cap software reports of the earnings season. Product revenue rose 34% to $1.33 billion, while the company raised its full-year forecast and announced an expanded multibillion-dollar relationship with Amazon Web Services.

What mattered most was not just the numbers themselves. It was what the rally revealed about investor psychology.

The AI trade is no longer based purely on speculation. Investors are now rewarding companies showing measurable enterprise spending tied to artificial intelligence infrastructure, cloud computing, and data management. In a market increasingly worried about slowing growth, Snowflake demonstrated that corporations are still willing to spend heavily on AI-related productivity tools even while cutting costs elsewhere.

That distinction is critical.

Wall Street is no longer rewarding “technology” broadly. It is rewarding companies perceived as direct beneficiaries of the AI spending cycle while punishing businesses exposed to consumer weakness, higher rates, or rising commodity costs.

The divergence showed up clearly Thursday morning.

Defensive retailers held relatively stable while economically sensitive sectors weakened. Small-cap stocks, represented by the Russell 2000, traded roughly flat early in the session — a subtle but important signal because smaller companies are typically among the most vulnerable to prolonged high interest rates due to heavier borrowing costs and weaker pricing power.

Investors are also increasingly focused on consumer behavior.

That is why Costco’s earnings report after Thursday’s closing bell carries outsized importance. Analysts are less interested in headline revenue than in what Costco says about discretionary spending patterns. If consumers are increasingly shifting toward essentials while pulling back elsewhere, it would reinforce fears that elevated inflation and energy prices are beginning to erode household resilience.

The market’s deeper problem is that all three dominant narratives now conflict with each other.

If inflation stays high, the Federal Reserve cannot cut aggressively.

If oil keeps rising, inflation may worsen further.

But if rates stay elevated while energy prices climb, economic growth eventually slows.

At the same time, AI-related companies continue producing some of the strongest growth numbers in corporate America, preventing investors from turning outright bearish.

That is why Thursday’s session felt so unstable beneath the surface.

Wall Street is no longer trading a single macro story. It is trading a collision between inflation persistence, geopolitical instability, and a once-in-a-generation technology spending boom. The result is a market becoming increasingly fragmented — one where indexes may struggle even as select winners continue soaring.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

EASTERN OUTER PORT LIMITS, off Malaysia — As of May 28, 2026, a stretch of open water roughly 45 miles off Malaysia’s southern coast has become one of the most important loopholes in America’s campaign to choke off Iran’s oil money. The Malaysian Maritime Enforcement Agency confirmed this month that aging tankers carrying sanctioned Iranian crude are gathering there to quietly hand off their cargo to other ships bound for China, exploiting what agency director-general Mohamad Rosli Abdullah described as gaps in maritime law that place many of the transfers beyond the reach of local enforcers.

The handoffs are the entire business model. One vessel unloads sanctioned crude onto another ship to blur the oil’s origin before it continues toward China, Iran’s biggest customer. Reporters who reached the area by boat on May 8 observed the Catalina 7, an aging tanker sanctioned by the United States for transporting Iranian crude, pumping oil through a thick transfer hose into another vessel whose name had been painted over in black. The scene underscored one of Tehran’s core economic advantages in its confrontation with Washington: despite sanctions, naval pressure, and diplomatic isolation, Iran can still sell oil and generate hard currency.

The location was chosen carefully. The Eastern Outer Port Limits lies roughly 70 kilometers off Malaysia’s Johor state, near one of the world’s busiest maritime corridors connecting the Middle East and East Asia. Many of the ship-to-ship transfers occur beyond Malaysia’s territorial waters and outside effective radar monitoring. Abdullah told reporters the area was deliberately selected to exploit jurisdictional gaps and complicate direct enforcement efforts.

The mechanics form a sprawling maritime deception network stretching thousands of miles. One group of tankers loads crude at Iran’s export facilities on Kharg Island, crosses the Indian Ocean, navigates through the Malacca and Singapore straits, and anchors offshore near Malaysia. A second group of ships then receives the oil through ship-to-ship transfers and carries it onward to China, primarily to the independent “teapot” refineries in Shandong province, which have become major buyers of sanctioned crude.

To disguise the trade, vessels frequently disable tracking transponders, obscure hull markings, repaint identification numbers, and alter registry details. Ying Cong Loh, a crude analyst at Kpler, said China often relabels Iranian oil as Malaysian-origin crude, allowing shipments to move through supply chains with limited scrutiny despite Beijing officially reporting no Iranian oil imports since 2022.

The scale is massive — and directly undermines the effectiveness of the U.S. pressure campaign. An Associated Press investigation tracked dozens of Iranian-linked oil transfers off Johor since the U.S.-Iran conflict intensified on February 28, even as Iran faced heightened naval scrutiny around the Strait of Hormuz. Advocacy group United Against Nuclear Iran said satellite imagery documented at least 42 transfers in the area during that period.

Despite the sanctions regime, the money continues flowing. The U.S.-China Economic and Security Review Commission estimates Iran has generated roughly $31 billion in oil revenue from China even without officially recorded imports. That revenue is precisely what Washington is attempting to cut off.

John Hurley, the Treasury undersecretary for terrorism and financial intelligence, said the United States remains committed to depriving Tehran of petroleum revenue used to finance military operations and weapons programs. Since returning to office, President Donald Trump has sanctioned more than 180 vessels connected to Iranian petroleum shipping, including 19 additional ships designated in May under what the administration calls its “Economic Fury” campaign.

But the fleet continues adapting faster than enforcement systems can respond.

Maritime intelligence firm Windward estimates roughly 430 tankers are currently involved in Iran-linked oil trade activity. Of those vessels, approximately 62% operate under false flags while 87% have already been sanctioned by Western authorities. Operators repeatedly restructure ownership chains, switch registries, rename ships, and acquire replacement vessels through intermediary companies faster than regulators can blacklist them.

China plays a central role in sustaining the network. Many tanker ownership entities are registered in Chinese cities, while crews are frequently Chinese nationals recruited specifically for higher-risk sanctioned trade routes. Shipping management firms openly advertise the elevated compensation tied to the work.

For global oil markets, the shadow network has become an essential pressure valve. Tanker-tracking firms estimate Chinese imports of Iranian crude averaged roughly 1.38 million barrels per day during 2025 before slipping to between 1.13 million and 1.2 million barrels daily in early 2026 as sanctions enforcement intensified. Roughly one-third of Iranian-linked tankers are now idling offshore, operating without active tracking systems, or conducting evasive maritime maneuvers.

Yet the oil continues moving.

That reality is shaping the broader negotiations surrounding Iran sanctions policy. Washington has so far resisted lifting oil restrictions during talks, viewing Tehran’s petroleum exports as the regime’s primary economic lifeline. But as long as Chinese refiners continue purchasing discounted crude and the offshore transfer system near Malaysia remains operational, Iran retains access to billions in hard currency despite escalating U.S. enforcement.

The result is a floating black market sitting in plain sight along one of the busiest trade arteries on Earth — a parallel oil economy that has so far proven resilient enough to survive sanctions, naval pressure, and one of the most aggressive financial enforcement campaigns ever mounted against an energy exporter.

Middle East — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — The U.S. Interior Department, led by Secretary Doug Burgum, announced that it is combining two major federal offshore drilling regulators into a single new agency called the Marine Minerals Administration, a restructuring that will oversee the largest expansion of American offshore energy development in decades and open new waters across the Gulf of Mexico, Alaska, California and Florida to oil, gas and seabed mining.

The move represents one of the most consequential energy-policy shifts of President Donald Trump’s second term and signals the administration’s determination to dramatically increase domestic energy production while reducing dependence on foreign mineral supplies, particularly from China.

At its core, the change merges two agencies created after the 2010 Deepwater Horizon disaster.

The first is the Bureau of Ocean Energy Management (BOEM), which has handled offshore lease sales and managed the commercial side of offshore energy development.

The second is the Bureau of Safety and Environmental Enforcement (BSEE), which has been responsible for inspecting offshore rigs, enforcing safety standards and responding to oil spills.

Both agencies were established in 2011 after investigators concluded that the previous regulator, the Minerals Management Service, had become too closely aligned with the oil industry it was supposed to oversee.

That conclusion followed the catastrophic Deepwater Horizon explosion in April 2010, when a BP-operated drilling rig exploded in the Gulf of Mexico, killing 11 workers and releasing nearly 5 million barrels of crude oil into the ocean over three months in what became the worst offshore oil spill in U.S. history.

Before that disaster, one agency handled both lease sales and safety enforcement. Critics argued the structure created an inherent conflict of interest because the same officials approving drilling projects were also responsible for policing the companies operating them.

The Obama administration broke the agency apart. The Trump administration is now putting those functions back together.

In announcing the merger, Burgum said the new structure would create a “streamlined approach” with “clearer coordination, better service to the public and stronger, more integrated oversight of offshore energy development.”

Critics, however, say the reorganization recreates many of the same structural risks exposed after Deepwater Horizon. Representative Jared Huffman, the top Democrat on the House Natural Resources Committee, has publicly opposed the merger, arguing that combining leasing and enforcement responsibilities under one roof weakens independent oversight.

The new agency will oversee three major initiatives.

The first is a dramatic expansion of offshore drilling.

In November 2025, the Interior Department proposed the 11th National Outer Continental Shelf Oil and Gas Leasing Program covering 2026 through 2031. The plan includes 34 offshore lease sales — including 21 in Alaskan waters, 7 in the Gulf of Mexico and 6 in Pacific waters off California — while also reopening areas near Florida that have not seen offshore lease activity in decades.

The scale marks a major reversal from the prior administration. President Joe Biden’s offshore leasing program proposed just three lease sales over five years, the smallest schedule ever offered by a U.S. administration.

The second major mission of the new agency is even more ambitious: building America’s first large-scale offshore mining industry.

The Marine Minerals Administration will oversee seabed mineral leasing in waters near Virginia, Alaska, Guam and the Northern Mariana Islands, targeting deep-sea deposits rich in nickel, cobalt, copper and rare earth elements — critical minerals used in batteries, electric vehicles, defense systems, semiconductors and advanced electronics.

The strategic significance is enormous because the United States currently depends heavily on Chinese-controlled supply chains for many of those materials.

Administration officials increasingly frame seabed mining not simply as an energy issue but as a national-security priority tied to competition with China in electric vehicles, artificial intelligence, military technology and semiconductor manufacturing.

The third mission of the agency is continuing the safety and spill-response role previously handled by BSEE, including rig inspections, environmental enforcement and emergency response operations.

There is one major complication: staffing and budget pressure.

Both BOEM and BSEE have lost personnel in recent years, and the Trump administration’s latest budget proposal reduces funding for the newly combined agency even as its responsibilities expand dramatically. Industry groups argue the merger will reduce duplication and improve efficiency, while critics warn the agency could become overstretched overseeing both aggressive leasing expansion and safety enforcement simultaneously.

The economic implications are substantial.

Offshore drilling already accounts for roughly 15% of total U.S. oil production, and federal estimates suggest the Outer Continental Shelf still contains approximately 68.8 billion barrels of recoverable oil and 229 trillion cubic feet of natural gas.

For major Gulf operators including Chevron, ExxonMobil, Shell and BP, the restructuring is expected to accelerate permitting and expand access to offshore acreage. Additional domestic production could eventually help moderate gasoline and natural gas prices, although most offshore projects require years of development before significant production begins.

The political response varies sharply by region.

Energy-producing states along the Gulf Coast, including Texas, Louisiana, Mississippi and Alabama, are expected to benefit economically from increased drilling activity, port traffic and infrastructure investment.

Meanwhile, officials in California, Florida and parts of Alaska are raising concerns about environmental risks, particularly the potential impact of spills on tourism, fisheries and coastal ecosystems.

The broader message from Washington is becoming increasingly clear. The Trump administration is pursuing the most aggressive expansion of offshore energy production and seabed mineral development the United States has seen in a generation — while simultaneously rolling back a regulatory structure created after the worst offshore environmental disaster in American history.

Supporters call the merger efficiency. Critics call it a return to the conditions that failed before Deepwater Horizon.

The administration is expected to finalize the new offshore leasing program by October 2026.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

BEIJING — China Customs data released Tuesday, May 26, 2026, showed that the country’s electric vehicle exports jumped 40% year-on-year in April to 278,081 units, with Brazil emerging as the single largest destination after shipments to the South American economy soared 221% from a year earlier, underscoring how Chinese automakers are pivoting aggressively away from saturated Western markets toward Latin America, the Middle East, and emerging Asia to absorb mounting overcapacity at home.

The General Administration of Customs of the People’s Republic of China reported that Brazil alone took 38,144 EVs in April, the highest volume of any single nation or territory and a dramatic acceleration from a market that ranked outside the top ten as recently as 2024. The shift reflects both Brazil’s rapid embrace of affordable Chinese-built electric vehicles and a coordinated push by mainland automakers to plant manufacturing roots in the country before tariff increases scheduled for later this year fully take hold.

The April figures from China Customs confirm a structural rebalancing of Chinese EV exports that has accelerated throughout the first four months of 2026. Total EV shipments from China over the January–April period have approached 1.4 million units, more than double the same stretch of 2025, according to industry data tracked by the China Passenger Car Association and corroborated by analysts at Benchmark Mineral Intelligence.

The export boom is unfolding against a sharply weakening domestic Chinese EV market. Wholesale data published earlier this month by the China Association of Automobile Manufacturers showed domestic new energy vehicle sales in April fell 10.8% year-on-year to 914,000 units, the fourth consecutive month of double-digit declines tied largely to the expiry of consumer subsidies at the end of 2025. Manufacturers are increasingly redirecting unsold inventory and incremental production toward overseas buyers, transforming exports into the single most important growth lever for the sector.

BYD, now the world’s largest electric vehicle manufacturer by volume, has publicly committed to exporting 1.3 million vehicles in 2026, a 25% increase over last year. The Shenzhen-based automaker has become the dominant force behind the Brazil expansion, building a manufacturing complex in Bahia state and steadily expanding local capacity to absorb anticipated tariff pressure.

Rivals including Geely Holding Group, Chery Automobile, Great Wall Motor, and SAIC Motor are pursuing parallel strategies across Mexico, Thailand, Indonesia, the United Arab Emirates, and increasingly across Europe through local assembly arrangements designed to avoid direct tariff exposure.

Europe remains one of the largest targets for Chinese EV manufacturers, but the strategy there is rapidly evolving. According to Benchmark Mineral Intelligence, roughly 22% of all EVs sold in Europe so far in 2026 were built in China, up from 19% in 2025. But rather than exporting finished vehicles directly into the European Union, automakers are increasingly shifting toward European assembly operations to bypass anti-subsidy tariffs imposed by Brussels.

Stellantis and Leapmotor announced in April plans to produce the B10 electric SUV at Stellantis’s Zaragoza facility in Spain, while XPeng has begun local production of its P7+ model through Magna Steyr’s plant in Graz, Austria. BYD continues to ramp manufacturing operations at its new facility in Szeged, Hungary, positioning itself to deepen European penetration while reducing tariff exposure.

The picture in North America is far more restrictive. United States imports of Chinese EVs remain effectively blocked by tariffs and proposed federal legislation targeting connected Chinese automotive technology. Senator Bernie Moreno, an Ohio Republican, and Senator Elissa Slotkin, a Michigan Democrat, introduced the bipartisan Connected Vehicle Security Act of 2026, legislation that would prohibit Chinese-connected vehicles and software systems from operating on American roads over national security concerns.

The measure has drawn broad support from U.S. automakers and industry trade associations worried about both cybersecurity vulnerabilities and the competitive pressure posed by heavily subsidized Chinese manufacturers.

Analysts at AlixPartners project Chinese passenger-car exports overall will rise another 20% in 2026, with electric vehicles accounting for the overwhelming majority of that growth. The consultancy argues that China’s scale advantage in batteries, lower manufacturing costs, and increasingly sophisticated supply-chain control are creating structural advantages that Western competitors may struggle to reverse this decade.

Geopolitics is adding further momentum. The ongoing disruption tied to the Iran conflict and elevated global oil prices has intensified concerns about long-term fuel costs across emerging economies including Brazil, India, Mexico, and Southeast Asia. Analysts at the Atlantic Council recently argued that sustained volatility in global crude markets could provide a major structural tailwind for Chinese EV exports through the second half of 2026 and beyond.

For Beijing, the export surge serves multiple strategic goals simultaneously. It absorbs excess industrial capacity, supports manufacturing employment during a period of weak domestic demand, and entrenches Chinese technology standards across global EV infrastructure — from charging systems and battery chemistry to connected-vehicle software ecosystems.

For policymakers and legacy automakers in Detroit, Wolfsburg, Tokyo, and Seoul, the April China Customs figures reinforce a competitive challenge that appears to be widening rather than narrowing.

The 278,081-unit April figure is unlikely to mark a peak. With BYD, Geely, Chery, and a growing list of Chinese EV startups all ramping export programs simultaneously, analysts expect monthly shipment volumes to climb above 400,000 vehicles before the end of the summer.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

The World Cup has not even kicked off yet, and FIFA is already under investigation by two state governments over how it sold tickets.

New York Attorney General Letitia James and New Jersey Attorney General Jennifer Davenport announced Wednesday that they have subpoenaed FIFA, demanding internal documents related to ticket pricing and seat assignments for the 2026 FIFA World Cup.

The investigation focuses on the eight matches scheduled for MetLife Stadium in East Rutherford, New Jersey — including the World Cup final on July 19.

A subpoena is not a lawsuit or a finding of wrongdoing. It is a legal demand for records and documents. But it signals that two major state consumer-protection offices believe there are enough complaints to warrant a formal investigation.

The case centers on two separate issues.

The first is ticket pricing.

The second is whether fans were moved out of the seats they originally believed they purchased.

Start with pricing.

For the first time in World Cup history, FIFA used “dynamic pricing” — a system where ticket prices rise and fall depending on demand. Airlines and concert promoters have used similar systems for years.

According to the attorneys general, FIFA raised ticket prices on more than 90 of the tournament’s 104 matches between October 2025 and April 2026, with average increases of roughly 34% across major seating categories.

At MetLife Stadium, some tickets are now averaging around $2,800, according to the states.

The attorneys general argue those prices are dramatically higher than previous World Cups.

But the issue is not simply that prices went up.

The larger complaint is that the pricing system may not actually have worked both ways.

In a May 7 letter sent to FIFA President Gianni Infantino, New Jersey Democratic lawmakers Frank Pallone and Nellie Pou alleged that prices remained elevated even when resale-market demand weakened.

“FIFA is continuing to sell these tickets at high prices, despite resale prices being lower,” the lawmakers wrote. “This suggests that prices are being held artificially high, even when the market signals otherwise.”

That allegation matters because FIFA promoted dynamic pricing as a market-based system that would reflect real-time demand.

Critics now argue the prices appeared to move mostly in one direction: upward.

Then there is the seating controversy.

According to the states, FIFA originally divided MetLife Stadium into four basic seating categories when tickets first went on sale.

Later, after fans had already purchased seats, FIFA reportedly created new “Front Category” premium sections inside those original seating zones.

The states allege some fans who believed they had purchased premium seats were subsequently reassigned to less desirable locations after the seating map changed.

According to the complaints, some buyers were moved farther from the field or behind the goal areas despite paying for what they believed were superior seats.

That accusation prompted unusually direct criticism from Davenport.

“Being honest about ticket sales is not complicated,” she said. “But FIFA has turned buying a ticket to the World Cup into a gauntlet of confusion, fake scarcity and impossibly high prices.”

James framed the issue more broadly as a consumer-protection matter affecting local fans.

“New Yorkers have been waiting years for the World Cup to come to their backyard, and they deserve a fair shot at affordable tickets,” she said. “No one should be manipulated into paying sky-high prices for seats, and fans should be able to trust that the tickets they purchased will be the ones they receive.”

The subpoenas seek internal FIFA records involving ticket allocation, pricing decisions, seat inventory, category changes and public communications about the sales process.

FIFA has defended its approach.

Infantino and FIFA officials have argued that World Cup demand is genuinely extraordinary and that high prices simply reflect limited inventory for one of the largest sporting events on earth.

That argument is not insignificant.

The World Cup final is among the most sought-after sports tickets globally, and resale listings for top seats have reportedly reached astronomical levels.

The investigation will likely focus on whether FIFA’s claims of scarcity accurately reflected the actual ticket inventory and pricing practices behind the scenes.

For fans in the New York and New Jersey area, the attorneys general are also encouraging consumers who believe they were affected to file complaints directly with their offices.

That detail suggests investigators are actively gathering firsthand accounts from ticket buyers in addition to reviewing FIFA’s internal records.

The tournament itself is not affected.

The first World Cup match at MetLife Stadium is scheduled for June 13, with the final set for July 19.

The games will go on.

The question now is whether FIFA will eventually need to explain its ticket strategy not just to soccer fans, but to regulators and possibly a courtroom as well.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A Russian oil tanker carrying more than 240,000 barrels of diesel fuel just changed course in the Atlantic Ocean — and that decision could deepen Cuba’s energy collapse, intensify migration pressure on Florida, and become one of the clearest signs yet that the Trump administration’s new sanctions strategy is beginning to bite.

The Russian-flagged tanker Universal, which had spent weeks drifting in the Atlantic with Cuba listed as its destination, abruptly changed its status to “for order,” a shipping-industry term meaning the vessel is awaiting new instructions. By Wednesday, maritime tracking data showed the ship turning south toward the South Atlantic rather than continuing toward Havana.

For Cuba, the consequences are immediate.

The island is now experiencing its worst energy crisis in decades. Power outages lasting 20 to 24 hours have become increasingly common across parts of Havana and other cities as Cuba’s aging electrical infrastructure struggles without sufficient imported fuel. The country’s largest power plant, Antonio Guiteras, has repeatedly gone offline, while floating power-generation units and backup facilities have faced severe fuel shortages.

Cuba consumes roughly 112,000 barrels of oil per day but produces less than half that amount domestically. Without imported diesel and fuel oil, the country’s grid becomes increasingly unstable.

Residents have already begun publicly protesting the blackouts, with reports of street demonstrations, fires, and nightly pot-banging protests spreading across neighborhoods dealing with repeated outages.

The reason the tanker turned away appears closely tied to a major policy escalation from the Trump administration earlier this month.

On May 1, President Donald Trump signed an executive order authorizing secondary sanctions against any company, vessel, insurer, or financial institution involved in supplying fuel to Cuba. The measure dramatically raised the financial risk for shipping companies and banks involved in moving oil cargoes to the island because access to the U.S. financial system could potentially be restricted for violators.

The Universal itself is already sanctioned by the United States, the European Union, and the United Kingdom, making delivery logistics even more complicated.

For weeks, the vessel appeared unable to secure a workable path into Cuba without exposing insurers, intermediaries, or financial counterparties to potential U.S. penalties. The apparent decision to reroute the cargo elsewhere reflects how aggressively global shipping companies are recalculating the risks of doing business with Havana under the new sanctions environment.

The political pressure intensified further on May 20, when the Trump administration announced legal action against former Cuban leader Raúl Castro tied to the 1996 shootdown of aircraft belonging to the humanitarian organization Brothers to the Rescue, which killed four people, including three Americans.

Together, the sanctions escalation and the legal action signaled a much harder-line U.S. approach toward Havana than markets or diplomats had anticipated earlier this year.

For Americans, especially in Florida, the effects of Cuba’s economic deterioration rarely stay isolated to the island itself.

South Florida maintains deep economic and family ties to Cuba through remittances, travel, small-business trade, humanitarian shipments, and migration flows. Historically, worsening economic conditions on the island have led to increased migration pressure toward the United States, higher remittance transfers from Cuban-American families, and growing stress across the financial and logistical networks connecting Florida to Cuba.

Banks, money-transfer businesses, travel operators, freight services, and family-run import-export companies across Miami and South Florida often feel the impact quickly when conditions deteriorate on the island.

The crisis also highlights broader geopolitical questions surrounding Russia’s willingness and ability to continue supporting Cuba while simultaneously managing its war effort in Ukraine and its own oil-export restrictions under Western sanctions.

Only one major Russian-linked delivery has successfully reached Cuba this year — the tanker Anatoly Kolodkin, which delivered roughly 730,000 barrels of crude oil earlier this spring during what analysts viewed as a brief softening in enforcement pressure.

Since then, multiple attempted deliveries appear to have stalled, failed, or been rerouted.

Energy analysts following the region say the result is no longer a temporary shortage but an increasingly structural collapse of Cuba’s fuel-import system.

For ordinary Cubans, that means fewer hours of electricity, worsening shortages of refrigerated food and medicine, unreliable water systems, and a deteriorating business environment during the peak summer heat season.

For the United States, especially Florida, the concern is whether Cuba’s energy collapse remains contained — or evolves into another broader humanitarian and migration crisis only ninety miles from the American coastline.

The broader significance of the Universal’s course change is that it demonstrates how sanctions enforcement, shipping finance, energy markets, and geopolitics now intersect in real time. A single tanker changing direction in the middle of the Atlantic may appear minor on the surface, but for Cuba’s electrical grid, Florida’s migration pressures, and U.S.-Russia geopolitical signaling, the implications are substantial.

At least for now, the message from global shipping markets appears clear: the financial and political risks of supplying fuel to Cuba have risen sharply — and even Russia may no longer be fully willing to absorb them.

Miami — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

When Ford Motor Co. shares surged roughly 21% in two trading sessions earlier this month, the catalyst was not a new truck launch, not quarterly earnings, and not anything happening inside a dealership showroom.

It was a battery announcement.

The 122-year-old Dearborn automaker quietly launched a wholly owned subsidiary called Ford Energy, a business designed to build large-scale battery storage systems for utilities, industrial operators and the exploding artificial-intelligence data-center market — instantly giving Wall Street a new way to value Ford beyond cars.

The market reaction was immediate because investors increasingly believe the next phase of the AI boom will not be driven only by chips and software, but by the physical infrastructure required to power it.

Training and operating large language models such as ChatGPT, Gemini and enterprise AI systems consumes electricity at levels the U.S. power grid was never built to handle. New hyperscale data centers are being announced faster than utilities can bring new generation capacity online. The gap is increasingly being filled by one critical piece of infrastructure: large-scale stationary battery storage.

And Ford suddenly owns one of the country’s largest planned manufacturing footprints for it.

Ford Energy launched in mid-May as a wholly owned subsidiary focused on battery energy storage systems for utilities, data centers and industrial customers. Jim Farley, Ford’s chief executive, described the business as a “high-growth, high-margin, anti-cyclical” opportunity capable of diversifying Ford’s revenue away from the volatility of vehicle sales.

Within days of launching the subsidiary, Ford announced its first major deal.

Ford Energy and EDF Power Solutions North America, the U.S. arm of France’s EDF Group, signed a five-year framework agreement allowing EDF to procure up to 4 gigawatt-hours annually of Ford’s DC Block battery storage systems — representing as much as 20 GWh over the life of the agreement.

Deliveries are expected to begin in 2028.

“We are not simply delivering hardware,” said Lisa Drake, president of Ford Energy. “We are delivering the kind of predictable quality and long-term operational confidence that grid operators and large-scale developers require.”

Tristan Grimbert, CEO of EDF Power Solutions North America, said Ford’s domestic manufacturing strategy and supply-chain traceability standards aligned with EDF’s long-term infrastructure goals.

That was the moment Wall Street stopped viewing Ford purely as an automaker.

Shares jumped 13% the day of the announcement and added another 6.7% the following session as trading volume exploded to nearly 187 million shares, pushing Ford to its highest valuation since mid-2023 and lifting its market capitalization toward $58 billion.

The analyst note that intensified the rally came from Morgan Stanley.

Clean-tech and power analyst Andrew Percoco argued that Ford Energy alone could eventually be worth roughly $10 billion as a standalone infrastructure business — a valuation framework rarely applied to traditional auto manufacturers. Percoco projected roughly $588 million in EBIT at scale and suggested Ford Energy could soon sign contracts with hyperscalers — the cloud-computing giants operating the AI economy’s largest data centers.

The physical hardware behind the strategy is already being built in Kentucky.

Ford is converting part of its BlueOval Battery Park facility in Glendale — originally designed for electric-vehicle battery production — into a manufacturing hub for stationary energy-storage systems. Its flagship product, the DC Block, is a standardized 20-foot containerized battery unit capable of storing approximately 5.45 megawatt-hours of electricity using lithium iron phosphate chemistry favored by utilities for safety and long-duration cycling.

Ford Energy is targeting roughly 20 gigawatt-hours of annual production capacity by 2027.

The move also solves a growing business problem inside Ford.

Electric-vehicle demand has softened materially across much of the U.S. market, leaving several automakers with battery-production capacity planned for growth levels that never fully materialized. Redirecting those factories toward AI-linked grid storage potentially gives Ford a higher-margin and more stable industrial business than mass-market EV manufacturing alone.

Ford has already said its money-losing Model E electric-vehicle division is now targeted to reach profitability by 2029, with Ford Energy expected to contribute directly to that turnaround strategy.

There is, however, one geopolitical complication hanging over the story.

The battery-cell technology underlying Ford’s DC Block systems is licensed from Chinese battery giant CATL, formally known as Contemporary Amperex Technology Co. The same licensing arrangement previously drew scrutiny from U.S. lawmakers when Ford announced its multibillion-dollar Michigan battery project several years ago.

For now, political pressure appears temporarily reduced following recent diplomatic engagement between President Donald Trump and Chinese President Xi Jinping, which eased immediate tensions surrounding U.S.-China industrial cooperation. But analysts continue to identify the CATL relationship as one of the primary execution risks behind Ford Energy’s long-term outlook.

The broader significance of the move extends far beyond one automaker.

The AI investment cycle is rapidly spreading into traditional industrial sectors that manufacture the physical systems required to power and cool data centers. Caterpillar has benefited from demand tied to backup power infrastructure. Vertiv Holdings has surged on AI-driven cooling systems. Utilities, nuclear operators and grid-equipment suppliers have all been revalued by investors searching for secondary beneficiaries of AI expansion.

Ford has now joined that list through batteries.

For a company that has spent years battling electric-vehicle losses, supply-chain disruptions and shrinking margins in its core vehicle business, the question “What is Ford worth?” suddenly depends less on how many F-150s leave the factory and more on how many gigawatt-hours leave Glendale, Kentucky.

The company is still selling cars.

But the stock is no longer being priced like a car company.

Detroit — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Jamie Dimon, the chairman and chief executive of JPMorgan Chase & Co., sat before investors in Manhattan on Wednesday and publicly signaled something Wall Street has not heard from the nation’s largest bank in years: JPMorgan is actively looking for a major acquisition.

“I do think there might be opportunities, and so we are on the lookout,” Dimon said at the Bernstein Strategic Decisions Conference in New York. “There might be, in the next couple years, a chance to put $10 billion or $20 billion to work buying something.”

A deal of that size would likely become the largest acquisition of Dimon’s two-decade tenure leading JPMorgan. For comparison, the bank’s government-backed takeover of failed First Republic Bank in 2023 cost roughly $10.6 billion. What Dimon described Wednesday would potentially be twice that size — and fully strategic rather than emergency-driven.

For ordinary Americans, the significance goes far beyond Wall Street headlines. JPMorgan Chase is the largest bank in the United States by assets and deposits, with relationships touching roughly half of American households through checking accounts, mortgages, credit cards, retirement accounts, auto loans, small-business lending, and brokerage services. Whatever JPMorgan eventually buys could influence consumer banking fees, digital payment systems, mortgage products, business lending, wealth management services, and the broader competitive landscape across the financial industry.

The reason Dimon’s comments drew immediate attention is because the largest U.S. banks have spent much of the post-2008 era effectively blocked from acquiring other major domestic banks due to federal concentration rules. The 10% national deposit cap, implemented after the financial crisis, prevents banks from controlling more than 10% of U.S. customer deposits through acquisitions.

That restriction historically limited the largest banks — including JPMorgan, Bank of America, and Wells Fargo — from pursuing transformational domestic mergers. Dimon’s remarks now suggest either that regulators may be becoming more flexible or that JPMorgan is exploring targets outside the traditional deposit-heavy banking model.

On Wall Street, speculation immediately centered around three broad categories of potential targets.

The first is wealth management, where firms such as Northern Trust have long been viewed as possible candidates. Northern Trust oversees more than $1.2 trillion in client assets and maintains deep relationships with wealthy families, institutional investors, and private clients.

The second category is international banking expansion, where names such as Standard Chartered have occasionally surfaced because foreign acquisitions would not significantly impact U.S. deposit concentration rules while dramatically expanding JPMorgan’s presence across Asia, the Middle East, and emerging markets.

The third — and potentially most important — category is technology. That includes fintech infrastructure, digital payments, cybersecurity platforms, or artificial intelligence systems that could strengthen JPMorgan’s position as banking rapidly shifts toward AI-driven automation and digital customer experiences.

That technology angle became even more significant after Dimon disclosed during the same conference that JPMorgan currently has approximately 1,000 artificial intelligence use cases under development, with roughly 50 to 60 considered highly significant initiatives.

For a bank of JPMorgan’s scale, those numbers underscore how aggressively large financial institutions are investing in AI infrastructure, automation, fraud prevention, trading systems, customer service tools, and internal operational efficiencies.

There was another major revelation embedded in the same appearance. Dimon disclosed that JPMorgan’s 2026 expenses are now expected to reach approximately $106 billion, about $1 billion higher than prior guidance. He also reaffirmed expectations for roughly $95 billion in net interest income while projecting 11% growth in trading revenue and 10% growth in investment banking revenue during the second quarter.

Despite those strong operational numbers, JPMorgan shares fell roughly 2% Wednesday, making the stock one of the weakest performers in the KBW Bank Index as investors weighed the implications of higher costs and the possibility of a massive acquisition consuming capital.

What made the conference appearance particularly striking was the contrast between Dimon’s acquisition comments and his simultaneous criticism of corporate executives who rely too heavily on mergers instead of organic growth.

“You sit around a lot of management meetings, the first thing they do when they’re not doing well in organic growth is they start to talk about M&A,” Dimon said. “I don’t want to hear about M&A. What are you doing to grow your business — sales, branches, tech, profits, products, services?”

Dimon emphasized that any acquisition would need to fit directly into JPMorgan’s core operations and produce tangible strategic value rather than exist as a disconnected standalone asset.

That balance may ultimately define the final phase of Dimon’s leadership. Now 70 years old, Dimon has publicly indicated he intends to remain at the bank for several more years, potentially transitioning later into an executive chairman role. Whatever JPMorgan buys next could shape not only the bank’s future but also the direction of consumer banking, payments, AI integration, and financial services for the next decade.

For everyday Americans, the practical implications are straightforward. A major fintech acquisition could reshape how consumers move money digitally. A wealth-management acquisition could consolidate financial advisory services under the Chase brand. An international expansion could strengthen global business banking services for U.S. companies operating overseas.

The broader message from Wednesday was unmistakable: the largest bank in the United States believes the regulatory climate, the technology race, and its own balance sheet now justify preparing for another transformational move.

The only remaining questions are what JPMorgan buys, when it moves, and how much further the country’s banking system consolidates as a result.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The future of American streaming television, cable news, and blockbuster movies took a major step forward Wednesday — not in Hollywood, but on Wall Street.

Warner Bros. Discovery Inc., the parent company of HBO, CNN, Warner Bros. Pictures, DC Comics, Max, and the Looney Tunes library, successfully raised $15 billion in one of the largest corporate loan deals of the year as investors rushed to finance the company’s next phase of restructuring and consolidation.

The transaction immediately became one of the clearest signs yet that credit markets remain wide open for major corporations despite years of warnings about rising interest rates and tightening debt conditions.

For ordinary Americans, however, the implications stretch far beyond Wall Street financing.

This is the financial infrastructure underneath the future of the streaming wars — the battle over what families watch, what they pay for subscriptions, which media brands survive, and how companies like Netflix, Disney, Amazon Prime Video, and Warner Bros. Discovery compete for attention inside millions of households.

Warner Bros. sold investors approximately $13 billion in dollar-denominated term loans along with roughly €1.72 billion in euro loans, bringing total financing to about $15 billion. Investor demand proved so strong that the company expanded the deal multiple times from its original target near $10 billion.

The financing was led by a syndicate of major global banks including JPMorgan Chase, Barclays, BNP Paribas, Deutsche Bank, UBS, Goldman Sachs, Wells Fargo, and others.

The loans were priced at roughly 2.5 percentage points above benchmark rates, with investors purchasing the debt at approximately 99.75 cents on the dollar.

The broader significance is that investors are still aggressively willing to lend massive sums to heavily indebted corporations — even companies operating inside industries undergoing major structural disruption.

That matters because Warner Bros. Discovery currently carries approximately $32.7 billion in total debt while simultaneously trying to navigate one of the most difficult transitions in modern media history: the collapse of traditional cable television and the rise of streaming.

The company’s financing efforts are also tied directly to the broader wave of media consolidation reshaping Hollywood.

The latest debt package helps refinance earlier bridge financing connected to the broader restructuring and acquisition activity surrounding the entertainment industry, including the massive Paramount-Skydance transaction and the ongoing battle among legacy media giants to compete with technology-driven streaming companies.

For years, traditional media companies depended on highly profitable cable bundles, movie theaters, and advertising revenue. That business model has weakened dramatically as consumers increasingly shift toward streaming platforms and on-demand viewing.

As a result, major entertainment companies are now racing to achieve enough scale to survive against streaming giants such as Netflix, Amazon, Apple, and Disney.

The outcome affects virtually every American household.

The combined media assets involved across the current consolidation wave include brands such as HBO, CNN, CBS, Paramount Pictures, Showtime, Nickelodeon, MTV, Max, Paramount+, and the broader Warner Bros. film and television catalog.

The likely result is further bundling of services, fewer standalone platforms, and continued pressure on subscription prices.

Industry analysts increasingly expect media companies to merge streaming offerings together into larger bundled ecosystems similar to how Disney integrated Hulu and Disney+. That could eventually place major entertainment franchises, sports rights, prestige television, and news programming under fewer subscription umbrellas — often at higher monthly costs for consumers.

At the same time, Wednesday’s financing success sends another important message about the broader U.S. economy.

For nearly two years, Wall Street analysts warned that corporations which borrowed heavily during the low-interest-rate era of 2020 and 2021 would eventually face painful refinancing conditions as debt matured at higher rates.

Instead, deals like Warner Bros.’ financing suggest large portions of the corporate credit market remain remarkably healthy. Pension funds, insurance companies, mutual funds, and institutional investors continue pouring money into corporate debt offerings, signaling strong liquidity across financial markets.

Ratings agencies still view Warner Bros. Discovery as highly leveraged, with debt ratings around BB+/Ba1, but agencies such as Moody’s continue projecting roughly $3 billion in annual free cash flow for the company, helping reassure investors that the business can continue servicing its obligations.

There is also a strategic reason investors were eager to participate.

Because portions of the debt were issued slightly below par value at 99.75 cents on the dollar, investors could potentially receive quick gains if future refinancing or ownership changes repay the debt at full value. That dynamic made the transaction particularly attractive for large institutional buyers searching for yield.

The political dimension remains unresolved.

Large-scale media consolidation involving companies such as Warner Bros., Paramount, and Skydance is expected to face scrutiny from federal regulators including the Federal Communications Commission and the Justice Department’s antitrust division. Questions surrounding media concentration, streaming competition, and news operations — particularly involving CNN — could become politically sensitive as regulatory reviews advance.

For now, however, financial markets delivered a clear verdict Wednesday: investors believe the entertainment industry’s restructuring wave is continuing, the financing remains available, and the largest media companies still have access to enormous pools of capital despite the challenges facing traditional television and streaming businesses.

The practical result for consumers is likely straightforward.

The entertainment companies Americans grew up with are becoming fewer, larger, more indebted, and more aggressively focused on scale.

And the future cost — and structure — of what families watch every night is increasingly being decided not in Hollywood studios, but inside Wall Street debt markets.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For the past eighteen months, the biggest question hanging over corporate America has been whether artificial intelligence is actually replacing human work yet — or whether the technology is still mostly demonstrations, hype, and investor presentations. On Wednesday afternoon, Salesforce Inc. delivered the clearest answer yet.

The software giant reported first-quarter fiscal 2027 revenue of $11.1 billion, up 13% year-over-year, while GAAP earnings per share surged 52% to $2.42. Non-GAAP earnings came in at $3.88 per share, up 50%. But the number drawing the most attention on Wall Street was tied to the company’s rapidly expanding Agentforce platform — Salesforce’s artificial intelligence system designed to deploy autonomous AI agents that can perform customer service, sales, operations, and workflow tasks traditionally handled by humans.

Salesforce disclosed that Agentforce annual recurring revenue has now reached $1.2 billion, up an extraordinary 205% year-over-year. Combined with its Data 360 business, the segment now generates nearly $3.4 billion in annual recurring revenue.

“This was an outstanding quarter for Salesforce — record revenue, record deals, and cash flow,” Marc Benioff, Salesforce chairman and chief executive, said in the company’s earnings release. “Agentic AI is the biggest growth opportunity for our customers, and for Salesforce.”

For ordinary workers and business owners, the meaning behind those numbers is straightforward: artificial intelligence is rapidly moving beyond chatbots and into systems that actually perform work inside real companies.

“Agentic AI” refers to software agents capable of independently carrying out multi-step tasks such as answering customer inquiries, qualifying sales leads, processing refunds, updating databases, scheduling appointments, handling internal communications, and completing operational workflows — functions that previously required human employees.

Salesforce revealed that during the quarter, customers consumed approximately 3.8 billion Agentic Work Units, the company’s internal metric measuring completed AI-driven tasks. That figure may represent one of the clearest real-world measurements yet of how much routine business labor is beginning to shift from human workers to autonomous software systems.

The shift also changes how enterprise software companies make money.

For decades, software firms like Salesforce primarily charged businesses “per seat” — meaning companies paid licensing fees for each employee using the platform. With Agentforce, Salesforce increasingly charges customers based on how much work the AI agents actually perform.

That change dramatically alters the economics of enterprise software because AI systems can operate continuously without breaks, vacations, benefits, or turnover costs. A single AI deployment can potentially replace dozens of repetitive customer-service or administrative functions while generating recurring usage-based revenue for Salesforce around the clock.

That transition has also created tension on Wall Street.

Despite Salesforce’s aggressive AI expansion, the stock had entered Wednesday’s earnings report down roughly 32% year-to-date, making it one of the weakest performers in the Dow Jones Industrial Average during 2026. Investors have been debating whether the growth of Agentforce can outpace potential declines in Salesforce’s older seat-based software licensing business as customers reduce reliance on large human workforces.

Wednesday’s report offered the strongest defense yet for the bullish side of that argument.

Salesforce reported $6.7 billion in operating cash flow, up 3%, while free cash flow reached $6.6 billion, also rising year-over-year. Remaining performance obligations — essentially contracted future revenue already locked in — climbed to $33.6 billion, up 14%.

The company also announced a major shareholder-return program that included approximately $27.1 billion in share repurchases and a newly authorized $25 billion accelerated stock buyback initiative.

Those numbers suggest Salesforce is successfully transitioning toward AI-driven revenue without collapsing the profitability of its broader business model.

The broader labor implications, however, may prove even more important than the quarterly financial results.

Customer service remains one of the largest entry-level employment categories in the United States, employing roughly 3 million Americans. Salesforce data earlier this year showed AI-agent adoption inside customer-service operations climbing to approximately 66% of surveyed businesses.

That means two-thirds of companies in Salesforce’s ecosystem are already integrating AI agents into at least part of their operational workflows.

Industries including healthcare, banking, pharmaceuticals, retail, logistics, and professional services are increasingly deploying AI systems to handle customer communication, scheduling, administrative processing, and internal operational tasks.

Salesforce highlighted one example this quarter involving Pierre Fabre, the French pharmaceutical company, which selected Agentforce Life Sciences as part of its customer-engagement infrastructure. In practice, deployments like that mean functions previously handled by teams of sales representatives, support staff, or administrative employees are increasingly being automated through AI-driven systems.

Salesforce itself has already undergone multiple rounds of workforce reductions over the past two years while simultaneously accelerating AI investment — a pattern many analysts now expect to spread broadly across corporate America.

At the same time, Salesforce’s earnings also revealed that the transition may not be entirely smooth for investors.

The company issued full-year fiscal 2027 revenue guidance of $45.8 billion to $46.2 billion, representing expected annual growth of roughly 10% to 11% — solid growth, but slightly below some of Wall Street’s more aggressive expectations. Salesforce shares initially fell in after-hours trading following the release as investors weighed the rapid growth of Agentforce against slower expansion in legacy software segments.

For Benioff, however, the earnings report represented major validation of a strategy he has aggressively promoted for over a year. Salesforce has committed heavily to AI infrastructure spending, including substantial partnerships and AI-computing investments tied to large language model providers.

The results Wednesday suggest that enterprise AI agents are no longer theoretical technology experiments. They are already being integrated into the operational core of major corporations — generating revenue, reshaping workflows, and beginning to alter how businesses think about staffing, productivity, and cost structures.

For workers, executives, and investors alike, the message from Salesforce’s earnings report was difficult to miss: the AI transition inside the workplace has moved from experimentation into execution.

And increasingly, the software is no longer just assisting employees.

It is beginning to replace parts of the work itself.

San Francisco — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBIZ News Desk | May 28, 2026 — Early Morning Edition
Updated with IRGC confirmation, official Kuwait Army statement, and market data

The fragile Iran war ceasefire appeared to be unraveling overnight, sending fresh shockwaves through global energy and financial markets after Iran’s Islamic Revolutionary Guard Corps publicly claimed responsibility for striking a US air base, explosions rocked Bandar Abbas, and Kuwait confirmed active missile and drone interceptions over its territory.

The developments sharply raised the risk of renewed disruption across the Strait of Hormuz — one of the world’s most critical oil shipping corridors — reversing a recent wave of market optimism that had pushed crude prices lower on expectations of a lasting diplomatic settlement between Washington and Tehran.

Iranian state-linked Tasnim News Agency reported that the IRGC launched retaliatory strikes against a US air base following what Tehran described as an American attack outside Bandar Abbas airport. The statement marks the first explicit public acknowledgment by Tehran of a direct strike on a US installation since the April 8 ceasefire brokered by Pakistan.

The escalation unfolded within hours of renewed diplomatic talks in Doha, where US and Iranian negotiators were attempting to formalize a permanent end to nearly three months of conflict. Instead, investors were confronted with a rapid sequence of military incidents stretching from southern Iran to Kuwait, reigniting fears of broader regional instability and renewed threats to Gulf energy infrastructure.

Explosions were reported east of Bandar Abbas between approximately 1:33 AM and 1:43 AM local time, according to Iran’s semi-official Fars News Agency, which said air defense systems were activated during the incident. Bandar Abbas hosts Iran’s principal naval facilities along the Strait of Hormuz and has become a central flashpoint in the conflict after US Central Command conducted strikes there earlier this week targeting IRGC mine-laying vessels and missile infrastructure.

Capt. Tim Hawkins spokesperson US Central Command said Monday that American forces had carried out “self-defense strikes” to protect US personnel from Iranian threats in southern Iran. Tehran has since accused Washington of violating ceasefire terms.

Military aviation tracking data cited by regional monitoring channels indicated heightened US surveillance and aerial refueling activity over the Persian Gulf during the overnight incidents, including AWACS surveillance aircraft, tanker operations, and maritime patrol flights.

The most immediate market concern centered on Kuwait after the country’s General Staff confirmed that air defense systems were actively intercepting incoming missiles and drones following air raid sirens heard across the country at approximately 5:22 AM local time.

In a statement posted to X, the Kuwaiti Army urged residents to follow security instructions and said explosion sounds heard across the capital area were linked to defensive interceptions. Kuwait hosts major US military facilities, including Camp Arifjan, which was previously targeted earlier in the conflict.

The renewed instability hit markets at a particularly sensitive moment. Brent crude had fallen more than 4.5% on Wednesday amid expectations that a diplomatic breakthrough could restore normalized shipping flows through the Strait of Hormuz. Prices briefly dipped below $95 per barrel before rebounding to roughly $96.30 ahead of Thursday trading.

Energy analysts now expect renewed upward pressure on oil prices as Asian and European markets absorb the implications of the overnight escalation.

Analysts Goldman Sachs Group and Analysts ING Group have previously warned that any renewed disruption to Hormuz shipping lanes could quickly drive Brent crude back above the $100 threshold. Roughly one-fifth of global oil consumption moves through the narrow waterway.

Safe-haven assets also appeared poised for reversal. Spot gold had weakened earlier in the week on easing geopolitical fears, but renewed military activity involving US assets and Gulf states is expected to increase demand for defensive assets when markets reopen.

Equity investors are also facing heightened volatility risks after US stock indexes recently reached record highs driven largely by artificial intelligence enthusiasm and resilient corporate earnings. Analysts at UBS warned earlier this week that elevated bond yields combined with Middle East instability could challenge the broader global equity rally.

The April ceasefire had already shown signs of strain in recent days. Iranian officials accused Washington of repeated violations following earlier US strikes near Bandar Abbas, while US officials maintained the operations were defensive and limited in scope.

Marco Rubio Secretary of State United States Department of State acknowledged this week that negotiations remained deadlocked over unresolved language in the proposed framework agreement. Meanwhile, Iran’s Supreme Leader Mojtaba Khamenei Supreme Leader Islamic Republic of Iran warned regional governments against serving as “shields for US bases,” while the IRGC issued statements saying its forces were “lying in wait” for further American military action.

Against that backdrop, Tehran’s decision to publicly claim responsibility for a strike on a US installation represents a major escalation signal to both Washington and global markets. Investors are now likely to focus less on ceasefire diplomacy and more on whether the conflict is entering another cycle of retaliation capable of threatening Gulf oil exports, shipping insurance markets, and broader global risk sentiment.

Whether negotiations in Doha can survive the latest overnight escalation remains uncertain. Market participants will now closely monitor any formal response from US Central Command, further statements from Tehran, and early commodity trading reactions as global exchanges reopen.

This is a developing story. JBIZ will update as CENTCOM issues a formal statement and market opens are confirmed.

JBizNews Desk

By JBizNews Desk

Iran’s government voted Tuesday to reconnect the country to the global internet — just days after a senior official publicly acknowledged that Tehran had already purchased Chinese technology designed to permanently control and restrict online access.

According to the Iranian state-affiliated Fars News Agency, Iran’s cyberspace steering body voted 9-3 to restore broader internet access after nearly three months of nationwide restrictions. The body is chaired by First Vice President Mohammad Reza Aref, and the decision now reportedly awaits final approval from the country’s leadership. The outlet Iran Focus separately reported the same account, citing an informed source familiar with the meeting.

If approved, the decision would end what monitoring organization NetBlocks has described as the longest ongoing nationwide internet blackout in the world.

Iran’s 90 million citizens have been largely cut off from the global internet since February 28, when the country’s war with the United States and Israel began. The shutdown crippled access to international websites, messaging platforms, cloud services and financial systems, effectively isolating much of the country from the digital global economy.

But the vote comes as a major internal dispute inside Iran’s leadership has spilled into public view.

On Saturday, Mohammad Sarafraz, a member of Iran’s Supreme Council of Cyberspace and former head of state broadcaster IRIB, told the Iranian online newspaper Faraz that the government had already imported Chinese equipment intended for the “permanent shutdown of the internet.”

According to Sarafraz, the system would allow the government to maintain a heavily controlled internet indefinitely — permitting access only to state-approved users and select paying customers while keeping ordinary citizens confined to a restricted domestic-only network.

In other words, one part of Iran’s government voted this week to reopen the internet.

Another part already bought the hardware to close it permanently.

The technology Sarafraz described is widely associated with China’s “Great Firewall” system. It relies on deep packet inspection, or DPI — software and network infrastructure capable of monitoring and filtering internet traffic in real time. Unlike a complete shutdown, the system allows governments to selectively block platforms, throttle traffic, monitor communications and decide which users receive unrestricted access.

Sarafraz’s comments were notable not only because he acknowledged the technology exists inside Iran, but because he openly questioned the policy itself.

Iran’s leadership has defended the blackout as necessary to prevent cyberattacks, stop foreign intelligence operations and maintain wartime stability. Sarafraz publicly challenged all three arguments, saying some of Iran’s most serious cyber breaches occurred during periods of heavy restrictions and noting that the shutdown failed to stop attacks and assassinations targeting Iranian officials during the conflict.

He also argued the blackout has inflicted major psychological and economic damage on the population.

The economic pressure is becoming increasingly difficult for Tehran to ignore.

Afshin Kolahi, an official at Iran’s Chamber of Commerce, said in April that the shutdown was costing the country as much as $40 million a day in direct economic losses, with indirect losses reaching up to $80 million daily. Iranian reporting later estimated cumulative losses approaching $1.8 billion by mid-April.

Inside Iran, the blackout has also deepened class divisions.

Government-linked individuals have reportedly been granted “white internet” access — unrestricted connections exempt from the broader shutdown. Wealthier Iranians can reportedly purchase premium services known as “Internet Pro,” allowing limited access to the global web. Most ordinary citizens remain confined to heavily restricted domestic networks.

Sarafraz criticized what he described as a system riddled with conflicts of interest.

“The same people who one day sell VPNs,” he said during the Faraz interview, “are the next day providers of special internet access.”

His comments, widely circulated by Iranian opposition and independent outlets, fueled growing accusations that some officials and connected businesses are financially benefiting from the restrictions they publicly defend.

Other Iranian technology experts have also warned that Tehran may be trying to imitate China’s tightly controlled internet model without possessing the economic strength that allows Beijing to absorb the consequences.

Aryan Eqbal, a network researcher speaking to Iranian technology outlet Zoomit, argued that China’s economic rise did not happen because of internet restrictions, but despite them.

“Iran wants to copy the control side of China’s model,” Eqbal said, “without having the economic foundation that supports it.”

At the same time, Iran appears to be expanding the institutional structure needed for a more permanent system of control.

The newspaper Shargh reported on May 19 that Tehran is forming a new centralized authority called the “Headquarters for Organizing and Guiding Cyberspace,” consolidating internet oversight under a single command structure.

That is not the type of bureaucracy governments typically build for temporary wartime measures.

For businesses, the implications are substantial.

A country of 90 million people cut off from the global internet becomes increasingly disconnected from international banking systems, foreign suppliers, software platforms, cloud infrastructure and digital commerce. Even a partial restoration of connectivity would not erase the broader shift Sarafraz described: the infrastructure for permanent control is already inside the country.

The next few days may determine which direction Iran ultimately chooses.

One Iran appears focused on reopening access because the economic cost has become unsustainable.

Another appears determined to permanently redesign the internet into something the state can tightly control long after the war ends.

At the moment, both versions of Iran are operating inside the same government.

Middle East — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Robinhood Markets shares climbed Wednesday after the retail brokerage announced plans to allow artificial intelligence agents to trade stocks and make credit-card purchases on behalf of customers, marking one of the clearest signs yet that AI is beginning to move from a productivity tool into an autonomous financial decision-maker for ordinary consumers.

The company’s stock rose roughly 3% during trading and continued gaining after hours following the announcement by Robinhood Chief Executive Vlad Tenev, who described the move as the next step in the company’s effort to “democratize finance for all.”

“Our mission has always been to democratize finance for all, and now that mission extends to AI agents,” Tenev said.

Robinhood’s new products — called Agentic Trading and the Agentic Credit Card — are designed to let AI software systems carry out financial actions automatically once users set goals and rules. The technology connects through Model Context Protocol servers, an open standard allowing outside AI systems to interact with financial platforms securely and in a structured way.

Under the setup, customers can create a dedicated AI-managed account separate from their main brokerage portfolio. Users decide how much money the AI can access and receive notifications when trades are executed. Robinhood said the beta version initially supports stock trading but is expected to expand into options, cryptocurrencies, futures, and event contracts over time.

The company also unveiled an AI-enabled virtual credit card tied to its existing Robinhood Gold Card. Users can set spending limits, require manual approval for purchases, and earn 3% cash back on transactions.

For many Americans, the announcement raises a bigger question: what exactly is an AI agent?

Unlike a traditional app that waits for a user to tap a button or enter a command, an AI agent can operate independently after receiving instructions. A customer might tell the software to buy a stock if it falls below a certain price, rebalance a retirement portfolio automatically, find the cheapest airfare for a trip, or make purchases under specific conditions. The AI then continuously monitors the situation and acts when the criteria are met — without requiring constant human involvement.

In simple terms, it functions less like a search engine and more like a digital personal assistant capable of making decisions and taking actions on a user’s behalf.

Robinhood’s move reflects a broader shift now spreading across the economy. Artificial intelligence is increasingly evolving from software that merely provides information into systems that actively perform work.

Technology firms are already using AI agents to write code and manage cybersecurity tasks. Law firms are deploying them to review contracts and draft documents. Sales organizations use them to respond to customer inquiries and qualify leads. Financial services and commerce now appear poised to become the next major battleground.

The implications could be enormous for how consumers shop, invest, and manage money.

If AI agents consistently search for the lowest prices, retailers may face increasing pressure on pricing power. If AI systems handle purchases automatically, traditional advertising strategies aimed at influencing human behavior could weaken. Brand loyalty may also erode if machines prioritize price, efficiency, and product specifications over emotional attachment to companies.

Financial markets could also become faster and more volatile as millions of autonomous systems react instantly to changing conditions without human hesitation.

Robinhood attempted to address some of the risks by emphasizing safeguards. AI trading accounts are segregated from users’ primary portfolios, spending limits can be capped, and customers can require manual approval before purchases or trades occur.

Still, concerns remain.

The same automation capable of generating profits around the clock could also amplify losses just as quickly if systems malfunction, misinterpret data, or encounter unexpected market conditions. Critics have long warned that widespread algorithmic trading can intensify market swings, and the addition of consumer-level AI agents may accelerate that trend further.

Robinhood has spent years positioning itself as the platform bringing Wall Street tools to ordinary Americans. With more than 27 million funded accounts, the company now appears to be betting that the next major transformation in finance will not simply involve giving people easier access to markets — but giving them AI systems capable of acting inside those markets on their behalf.

For consumers, investors, and businesses alike, that signals the beginning of a very different kind of economic era — one where software increasingly handles not just information, but decision-making itself.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

American investors face one of the most consequential trading days of the spring on Thursday, with the Bureau of Economic Analysis set to release the Federal Reserve’s preferred inflation gauge alongside a revised reading on first-quarter economic growth, while Costco Wholesale, Dell Technologies, and MongoDB headline a major slate of earnings reports later in the day. The releases arrive as the S&P 500 and Nasdaq Composite hover near record highs, the Dow Jones Industrial Average trades above 50,000, and the Iran conflict continues to inject volatility into energy markets and inflation expectations.

The key economic data lands at 8:30 a.m. Eastern time, when the government publishes the April Personal Consumption Expenditures price index, the inflation measure watched most closely by the Federal Reserve. The report will be released alongside personal income and personal spending figures, as well as the government’s second estimate of first-quarter GDP growth.

March PCE inflation came in at 3.5% headline and 3.2% core, both still well above the Fed’s 2% target. Economists expect inflation pressures to remain elevated as rising oil, shipping, and fertilizer costs tied to the Iran conflict continue flowing through the economy. Wall Street will focus especially on the month-over-month core reading, with anything above 0.3% likely reinforcing expectations that interest rates will remain higher for longer.

The data will also shape expectations heading into the Federal Reserve’s June 16–17 policy meeting, the first major meeting chaired by new Fed Chair Kevin Warsh, who recently took office. Markets are increasingly questioning whether the central bank will be able to cut rates at all this year if inflation continues reaccelerating.

At the same time, the government will publish its revised estimate for first-quarter Gross Domestic Product. The Atlanta Fed’s closely watched GDPNow tracker currently projects second-quarter growth above 4%, suggesting the economy remains surprisingly resilient despite higher borrowing costs and elevated energy prices.

Weekly jobless claims will also be released Thursday morning. Last week’s initial claims came in near 209,000, reflecting a labor market that continues to remain historically strong even as the Federal Reserve keeps monetary policy restrictive. Minneapolis Fed President Neel Kashkari said this week that the labor market remains “in decent shape,” giving policymakers room to continue prioritizing inflation.

Markets will also receive April durable goods orders data, offering another read on manufacturing and business spending trends.

Energy traders will turn their attention to the Energy Information Administration’s weekly crude oil and natural gas inventory reports at 10:30 a.m. Eastern. Oil prices have become increasingly unstable as markets swing between hopes for diplomacy with Iran and fears of wider military escalation near the Strait of Hormuz.

On Wednesday, West Texas Intermediate crude plunged more than 5% during the trading session after reports suggested a possible Iran agreement was near, only to rebound sharply after news emerged that U.S. forces had carried out fresh strikes on an Iranian military target. Crude later climbed back toward $90 a barrel.

After markets close Thursday, attention shifts to corporate earnings.

Costco Wholesale is expected to report quarterly earnings of roughly $4.92 per share, with investors closely watching consumer spending trends, membership growth, and pricing commentary as households continue facing elevated grocery and fuel costs. Costco has increasingly become one of Wall Street’s most important gauges of middle-class consumer behavior.

Dell Technologies will also report after the bell, with analysts expecting adjusted earnings near $2.95 per share. Dell has emerged as one of the largest beneficiaries of the artificial intelligence infrastructure boom, as corporations and cloud providers continue spending heavily on AI servers and computing equipment. Investors will closely monitor management commentary on AI demand and enterprise technology spending.

Database software company MongoDB rounds out the evening’s major reports, with consensus estimates calling for adjusted earnings of approximately $1.18 per share. The results will provide another snapshot of enterprise software demand as businesses balance technology investment against higher financing costs.

Before markets open, discount retailer Burlington Stores is expected to report earnings near $1.79 per share, with analysts watching same-store sales trends for signs of whether budget-conscious consumers continue shifting toward discount retail chains.

The setup heading into Thursday reflects one of the defining tensions of today’s market: U.S. stocks remain near record highs even as inflation stays elevated, interest rates remain restrictive, and geopolitical instability continues threatening global energy supplies.

Investors have largely continued betting on economic resilience, artificial intelligence growth, and the possibility that inflation will eventually cool without triggering a recession. Thursday’s combination of inflation data, GDP revisions, labor-market readings, energy inventories, and major earnings reports could determine whether that optimism remains intact heading into June.

By the end of the trading day, Wall Street may have a far clearer answer on the three questions now driving global markets: whether inflation is easing, whether the U.S. economy is slowing, and whether the AI-fueled rally powering technology stocks still has room to continue climbing.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Around 7 p.m. Eastern time Wednesday, a senior U.S. official confirmed the development that abruptly reversed global oil markets: American forces had struck a new Iranian military site earlier in the day after officials said the location posed a threat to U.S. troops and commercial shipping near the Strait of Hormuz. U.S. forces also reportedly intercepted several Iranian drones operating in the area, marking the third American strike on Iran in three days.

Oil prices, which had spent most of the trading session plunging on hopes of a breakthrough peace agreement, immediately rebounded. West Texas Intermediate crude rose roughly $1.42 in late trading to about $90.10 a barrel after settling down more than 5% earlier in the session near $88.39, its lowest level since April. Brent crude, the international benchmark, climbed back toward $94 after briefly falling below $93 earlier in the day.

The sharp reversal underscored how unstable the conflict has become, with markets swinging violently between expectations of diplomacy and fears of wider war.

Earlier in the day, Iranian state media reported that a potential agreement with the United States was close, claiming discussions included a partial U.S. naval pullback from the Gulf and the gradual reopening of commercial shipping through the Strait of Hormuz under joint coordination involving Oman. The report even suggested Iran could impose transit fees on vessels passing through the strategic waterway.

Traders reacted immediately, driving oil sharply lower on expectations that supply disruptions could ease. WTI crude dropped more than 5% intraday, while Brent fell to its lowest level in more than a month.

But the White House quickly rejected the Iranian reports.

“This report from Iranian-controlled media is not true and the MOU they released is a complete fabrication,” the administration said in a statement Wednesday afternoon.

Speaking during a Cabinet meeting, President Donald Trump said he was “not satisfied” with Iran’s position and warned the United States remained prepared to “finish the job” if negotiations collapsed. Trump said Iran would not receive sanctions relief and insisted Tehran would have to surrender its stockpile of highly enriched uranium as part of any final agreement.

Secretary of State Marco Rubio attempted to calm tensions, saying negotiations were still ongoing and that a framework agreement could take several more days. Iran’s Revolutionary Guard responded by warning that renewed fighting would turn parts of the Gulf region into a “graveyard for aggressors.”

Then came confirmation of the new U.S. military strike, instantly shifting market sentiment back toward fears of escalation.

The economic consequences are increasingly visible for consumers and businesses alike. AAA reported strong gasoline demand over the Memorial Day travel period even as fuel prices reached some of their highest seasonal levels in years. Analysts warn prices could remain elevated throughout the summer if shipping through Hormuz does not normalize.

The Strait of Hormuz normally handles roughly 20% of global oil and liquefied natural gas flows. Since the conflict intensified earlier this year, commercial traffic has slowed dramatically. While two non-Iranian supertankers reportedly crossed the strait Tuesday, shipping volumes remain far below normal levels.

Inside Iran, economic pressure is also intensifying. Iranian officials acknowledged Wednesday that inflation, shortages, and falling oil-export revenues are worsening internal instability as the country struggles under mounting military and economic strain.

For oil markets, the pattern has become increasingly familiar: headlines suggesting diplomacy trigger sharp selloffs, followed by renewed military action that rapidly pushes prices higher again.

Until either a formal agreement is signed or the fighting decisively ends, traders, businesses, and consumers are likely to remain trapped in a cycle of extreme volatility — with the costs ultimately flowing through to fuel stations, supply chains, transportation networks, and household budgets worldwide.

Middle East — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

St. Paul — Local municipal assemblies across Minnesota began enacting comprehensive emergency bans on non-tobacco vapor products on May 26, 2026, directly challenging the U.S. Food and Drug Administration’s recent regulatory pivot that authorized sweet flavors. Association of Minnesota Cities Executive Director Luke Fischer confirmed that local city councils are executing a coordinated regional intervention following a highly controversial federal policy overhaul. The escalating bureaucratic standoff signals a severe constitutional clash over commercial preemption, as state-level health authorities aggressively move to block physical retail distribution channels after the White House systematically relaxed restrictions to clear multi-national alternative nicotine lines.
The localized regulatory counter-offensive is a direct reaction to an unprecedented federal policy shift finalized earlier this month. The FDA granted historic marketing orders to Los Angeles-based manufacturer Glas Inc., officially authorizing the sale of its Gold (mango) and Sapphire (blueberry) liquid pods at a high-potency 50mg/ml concentration. In subsequent directives drafted days before the sudden resignation of former FDA Commissioner Marty Makary, the agency published broad “enforcement discretion” guidelines. These measures effectively shield non-vetted electronic cigarettes and nicotine pouches from federal asset seizures provided the products remain under active “scientific review.” Senior agency officials confirmed to the press that executive leadership largely bypassed traditional internal vetting protocols, a maneuver that public health agencies argue has directly flooded regional retail markets with unregulated, child-appealing fruit profiles.
For consumer goods distributors and institutional tobacco investors, the localized legislative resistance introduces a significant layer of operational volatility. Shares of major domestic alternative nicotine manufacturers, including Juul Labs and Vuse parent company Reynolds American, retreated from their mid-week highs as equity analysts at Cowen & Co. downgraded near-term retail growth projections for the Upper Midwest. Financial models indicate that if municipal blockades successfully isolate major metropolitan markets like Minneapolis and Duluth, the projected revenue gains from tech-enabled age-gating infrastructure could be entirely neutralized by localized enforcement fines. While the FDA defended its national authorization by citing Glas Inc.’s Bluetooth-enabled smartphone authentication protocols as a sufficient barrier to underage acquisition, state lawmakers are rejecting the digital safeguards as an unproven corporate defense mechanism.
Public health tracking metrics compiled by the Truth Initiative and the Campaign for Tobacco-Free Kids have added significant momentum to the local banning movement. Regional enforcement data shows that sweet and fruit profiles comprise roughly 63% of all youth nicotine initiation vectors, with adolescent consumer demand heavily indexing toward unauthorized disposable brands like Geekbar. Municipal leaders in Minnesota argue that the federal government’s newly established enforcement loopholes make it impossible for local police departments to effectively monitor retail store compliance, leaving city-level zoning laws as the only viable mechanism to suppress adolescent consumption patterns.
The legal architecture governing the tobacco trade is subsequently bracing for a high-stakes corporate challenge. Attorneys representing regional convenience store coalitions and specialized vape distributors have already signaled intentions to file for immediate injunctions against the municipal bans, arguing that state-level prohibitions directly violate the Supremacy Clause of the U.S. Constitution given the FDA’s explicit federal marketing orders. However, localized legal teams intend to rely on historical judicial precedents that preserve the statutory right of individual municipalities to enforce stricter public safety ordinances than those mandated by Washington.
As the administrative gridlock deepens, the broader commercial landscape for alternative consumer products is facing systemic fragmentation. Multi-national tobacco conglomerates are watching the midwestern test cases closely to determine whether to invest capital into compliance engineering for state-by-state supply chains or completely suspend localized shipments until federal courts rule on the limits of city-level preemption. With the FDA currently operating under an interim, unconfirmed leadership structure following Makary’s departure, the lack of a centralized federal regulatory enforcement strategy ensures that the legal and commercial warfare between state assemblies and the alternative nicotine sector will intensify throughout the upcoming fiscal quarter.

JBizNews Desk | Midwest
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.

Anthropic has acquired developer-tools startup Stainless for more than $300 million in a deal that quietly removes a critical software tool used by rivals including OpenAI and Google, escalating the infrastructure war inside the artificial intelligence industry.

The acquisition, announced by Anthropic on May 18, 2026, gives the AI company control over one of the most widely used developer connection platforms in the industry.

The significance goes far beyond the purchase price.

Anthropic is not simply buying a software company.

It is taking ownership of a tool relied upon by competing AI firms — and plans to phase out access for outsiders.

Stainless builds software libraries and API connectors that allow developers to easily integrate AI models into applications across multiple programming languages including Python, Java, Go, TypeScript, and Kotlin.

Those tools became deeply embedded throughout the AI ecosystem.

Companies using Stainless included:

  • OpenAI
  • Google
  • Cloudflare
  • Meta
  • Runway
  • Replicate

Millions of developers globally have used software generated through the platform.

Under Anthropic’s ownership, the hosted Stainless platform will eventually shut down for outside customers.

Existing integrations are expected to continue functioning, but competitors will no longer receive ongoing updates or infrastructure support through the service.

That forces companies like OpenAI and Google either to rebuild similar internal systems or seek alternative providers.

The move reflects how aggressively the AI industry is now competing beyond just model quality.

Developer infrastructure has become one of the most important battlegrounds in artificial intelligence.

The easier an AI platform is for outside developers to integrate into products, the more usage and revenue that platform ultimately generates.

That is exactly why Stainless mattered.

The company was founded by former Stripe engineer Alex Rattray, who built Stainless specifically to automate the process of generating developer libraries and SDKs used to connect applications with APIs.

Rattray confirmed the entire Stainless team would join Anthropic as part of the acquisition.

The deal continues a broader acquisition push by Anthropic over the past year as the company rapidly expands beyond being purely an AI research lab.

Anthropic previously acquired:

  • Bun
  • Vercept
  • Coefficient Bio

Each purchase added another layer of infrastructure, tooling, or operational capability around the company’s AI platform.

The company now appears focused on building a fully integrated AI ecosystem spanning:

  • Models
  • Developer tools
  • Infrastructure
  • Automation systems
  • Enterprise deployment

The strategy increasingly resembles how major cloud companies built vertically integrated software ecosystems during earlier technology cycles.

The acquisition is especially problematic for OpenAI because the company reportedly relied heavily on Stainless-generated tooling for portions of its API ecosystem.

Replacing those systems internally could require meaningful engineering resources and development time.

Google maintains larger internal developer infrastructure operations but still used portions of Stainless technology within certain AI initiatives.

Anthropic, meanwhile, has the financial resources to continue expanding aggressively.

The company’s valuation recently climbed above $180 billion following major investment commitments from firms including Microsoft and Nvidia.

Anthropic has also signed enormous computing agreements tied to AI infrastructure expansion, including multibillion-dollar arrangements involving SpaceX compute capacity.

The broader AI market is increasingly shifting into what resembles an arms race over infrastructure dependencies.

Rather than competing solely through consumer-facing products, companies are now buying suppliers, developer tools, infrastructure providers, and compute networks their rivals depend on.

The goal is not simply growth.

It is strategic leverage.

For developers currently using Stainless-generated tools tied to OpenAI or Google systems, little changes immediately.

Existing integrations should continue functioning.

But over time, companies relying on those tools may need to migrate infrastructure or adopt replacement SDK systems as support winds down.

The acquisition also highlights how quickly AI competition is evolving.

Only a year ago, most public discussion around artificial intelligence centered on chatbot quality and model performance.

Today the competition increasingly revolves around deeper infrastructure:
developer ecosystems, compute access, APIs, integrations, deployment systems, and software tooling.

Anthropic’s purchase of Stainless may ultimately matter less because of the revenue Stainless generated and more because of the operational pressure it now places on competitors.

In the AI industry of 2026, companies are no longer just building products.

They are buying the roads their rivals drive on.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

If you run a company that imports anything from China, this story is about you.

On May 26, 2026, court filings revealed that the federal government has filed a formal $285.5 million claim against bankrupt auto parts maker First Brands Group, accusing the company of cheating on the tariffs it owed for parts brought in from China. The number includes the unpaid duties plus penalties. First Brands filed for Chapter 11 bankruptcy on September 28, 2025, and it already owes more than $11.8 billion it cannot pay back. Now the U.S. Treasury wants its cut.

Here is why this matters far beyond one bankrupt auto parts company.

First Brands is not an isolated case. It is the latest name on a fast-growing list, and the people fighting this trend say what we are seeing in the data is staggering.

The Number That Should Worry Every Importer

According to a recent New York Times investigation, the average value of goods packed into a 20-foot shipping container coming from China dropped nearly 40% between January 2025 and February 2026. Over that same stretch, container values from the rest of the world barely budged.

That is not a market story. That is a paperwork story. Companies have been writing down the declared value of their Chinese shipments to lower the tariffs they pay.

Ryan Petersen, chief executive of supply chain firm Flexport, told the New York Times: “We’re seeing just total, rampant fraud.”

When the CEO of one of the largest logistics companies in America says fraud is rampant, regulators listen. And they are.

Meet The Agency Hunting Your Shipping Paperwork

On August 29, 2025, the U.S. Department of Justice and the Department of Homeland Security launched a brand-new joint operation called the Trade Fraud Task Force. It brings together civil prosecutors, criminal prosecutors, Customs and Border Protection investigators, and Homeland Security Investigations agents under one roof. Its stated mission is to go after anyone who tries to “evade tariffs and other duties.”

In May 2025, the DOJ had already put trade fraud on its list of ten “high-impact” enforcement priorities. In fiscal 2025, the DOJ recovered a record $6.8 billion through False Claims Act settlements. Seventy-eight percent of that money came from whistleblower-driven cases.

That last number is the one you need to circle. Most of these cases are not coming from government audits. They are coming from inside the building.

The Roster Of Recent Settlements Keeps Growing

This is where the First Brands case stops looking lonely.

In December 2025, the DOJ announced a $54.4 million settlement with Ceratizit USA LLC over allegations the company misrepresented tungsten carbide products from China as Taiwanese to avoid tariffs. At the time, it was called the largest False Claims Act customs fraud settlement on record.

That record did not last long.

Two weeks ago, the DOJ settled with Perfectus Aluminum for $549.5 million — more than ten times larger than the previous record — also tied to Chinese imports.

In July 2025, Grosfillex Inc. settled for $4.9 million over evading anti-dumping duties on aluminum products from China. The whistleblower in that case, a former employee, walked away with nearly $1 million.

There were smaller ones too:

  • King Kong Tools — $1.9 million
  • Dallco Marketing — $2.5 million
  • Homestar North America — $798,334

The whistleblowers collected hundreds of thousands of dollars in rewards.

That is the pattern. Same scheme. Same country of origin. Different companies. Growing penalties.

How The First Brands Case Started

The First Brands tariff case did not start with the government. It started with a whistleblower.

In March 2022, a company called Alder Wood LLC filed a sealed complaint in federal court in New York under the False Claims Act. Alder Wood alleged that First Brands imported brake parts from its own subsidiary in China without paying the right amount of tariffs.

The False Claims Act allows private parties to sue on behalf of the government when they believe a company is cheating taxpayers. If the government recovers money, the whistleblower gets a percentage.

The case stayed under seal for years while the DOJ investigated. It became public earlier this year. This week, the U.S. government formally joined it.

Mark Strauss, the attorney for Alder Wood, said this week that “the wrongdoing we alleged turns out to be the tip of the fraud iceberg.”

The Bigger Mess At First Brands

The tariff allegations were only part of the collapse.

About $2.3 billion of First Brands debt came from selling invoices to outside lenders through factoring arrangements.

Here is how factoring works in plain English. A company sells unpaid customer invoices to a lender at a discount in exchange for immediate cash. The lender then collects the payment later from the customer.

The lenders believed they were buying real invoices owed by real customers.

When First Brands filed for bankruptcy, only about $400 million of those invoices were considered legitimate, according to court filings from Leucadia Asset Management, a Jefferies-owned lender that bought roughly $885 million in invoices.

In April 2026, a court-appointed examiner found what the report called “widespread fraud” involving lenders including:

  • Raistone
  • Leucadia
  • Evolution Credit Partners
  • Katsumi Global

Some receivables were later resold to ING Belgium and Bank ABC.

First Brands founder Patrick James stepped down as CEO in October 2025.

Why This Is Happening Now

Tariff rates exploded higher in 2025.

Some imported goods were hit with rates as high as 73%, according to court filings. First Brands itself told the bankruptcy court tariffs added roughly $220 million in costs to the company.

When tariff rates triple, the incentive to manipulate customs paperwork rises with them.

A company facing a 10% or 25% tariff might decide the legal risk is not worth it. A company facing 73% tariffs starts making survival calculations.

That is what regulators believe is now happening across large parts of the importing system.

Who Could Be Next

Customs and Border Protection says the most commonly targeted categories include:

  • Steel
  • Aluminum
  • Furniture
  • Clothing
  • Honey
  • Shrimp
  • Catfish
  • Tools

The most common schemes are:

  • Undervaluation — declaring imports as worth less than they really are
  • Transshipment — routing Chinese goods through countries like Mexico, Vietnam, Malaysia, or the Philippines and relabeling them

The risks are massive.

The DOJ can seek:

  • Triple damages
  • Civil penalties
  • Criminal charges
  • Additional tariff penalties

And Customs inspects less than 1% of containers entering the United States, meaning whistleblowers are now doing much of the government’s discovery work.

The 120-Day Clock Companies May Not Know Exists

In May 2025, the DOJ Criminal Division introduced guaranteed declinations for companies that voluntarily disclose violations.

In March 2026, the department expanded that framework government-wide.

But there is a catch.

Once an internal whistleblower reports concerns inside a company, management has 120 days to self-disclose the issue to federal authorities or lose eligibility for a presumptive declination.

In plain English: the legal clock starts the moment an employee raises concerns internally.

The Bottom Line

The First Brands case is not an isolated bankruptcy story.

It is part of a growing federal crackdown that has now produced:

  • An $11.8 billion bankruptcy
  • A $549.5 million settlement
  • A $54.4 million settlement
  • A record $6.8 billion DOJ enforcement year
  • A nearly 40% collapse in declared Chinese container values that regulators increasingly believe reflects fraud

If your company imports from China — directly or indirectly — regulators are no longer assuming paperwork errors are accidental.

They are increasingly assuming intent.

And they now have whistleblowers, data analytics, Customs investigators, Homeland Security agents, and the full DOJ Trade Fraud Task Force looking for it.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. stock market closed Wednesday with the Dow Jones Industrial Average powering to another all-time high, while the broader S&P 500 and Nasdaq Composite barely moved as weakness in banks and semiconductor stocks offset a sharp drop in oil prices triggered by developments tied to the Strait of Hormuz.

The Dow gained 182.60 points, or 0.36%, to close at a record 50,644.28 after also reaching a new intraday high. The S&P 500 edged up 0.02% to finish at 7,520.36, while the Nasdaq Composite added 0.07% to close at 26,674.73. All three major U.S. indexes are now sitting at record highs, though Wednesday’s session reflected a market increasingly sensitive to geopolitical headlines, bank commentary, and the sustainability of the AI-driven rally.

The biggest driver of the session came from Iran. Iranian state media reported that Tehran intends to restore commercial shipping traffic through the Strait of Hormuz to pre-war levels within one month, sending crude prices sharply lower as traders rushed to remove part of the geopolitical risk premium that has fueled energy markets for months. U.S. crude oil fell 5.55% to settle at $88.68 per barrel.

The Strait of Hormuz remains one of the world’s most critical energy chokepoints, carrying roughly 20% of globally traded seaborne crude oil. Any indication of normalization immediately impacts pricing expectations across energy markets, transportation costs, inflation forecasts, and broader global trade sentiment.

The White House quickly disputed the Iranian report, calling it inaccurate, but markets largely traded on the expectation that supply disruptions may ease. Energy stocks remained under pressure while investors rotated back into technology and industrial names. Six of the eleven major S&P sectors finished positive, led by technology, industrials, and materials, while energy, healthcare, and consumer staples lagged.

Another major story weighing on sentiment came from JPMorgan Chase CEO Jamie Dimon, who spoke Wednesday at the Bernstein Strategic Decisions Conference in Manhattan. Dimon said the bank could deploy between $10 billion and $20 billion toward a major acquisition over the next several years, potentially marking the largest deal of his tenure.

“I do think there might be opportunities,” Dimon said. “There might be, in the next couple years, a chance to put $10 or $20 billion to work buying something.”

While the acquisition comments initially drew attention, investors focused more heavily on Dimon’s disclosure that JPMorgan now expects 2026 spending to rise to approximately $106 billion, above prior guidance. JPMorgan shares fell roughly 2%, weighing on the broader financial sector and making the stock one of the weakest performers in the KBW Bank Index.

Dimon also disclosed that JPMorgan currently has approximately 1,000 artificial intelligence use cases in development, with 50 to 60 considered significant, underscoring how aggressively major financial institutions are moving into AI deployment.

Semiconductor stocks also cooled after an extraordinary rally that has dominated markets throughout 2026. Micron Technology, which had surged 19% in the prior session and briefly crossed a $1 trillion market capitalization, traded more cautiously Wednesday as investors debated whether portions of the AI trade have become overheated.

Software stocks also remained in focus after the closing bell. Salesforce shares fell roughly 2.8% in after-hours trading after issuing softer-than-expected guidance, while Snowflake continued to benefit from enthusiasm surrounding its recent earnings report and a major Amazon Web Services commitment tied to AI infrastructure expansion.

Industrial companies helped support the Dow throughout the session. Caterpillar rose 3.26%, Honeywell gained 1.61%, and 3M advanced 1.08%, reflecting continued investor confidence in broader economic activity beyond the technology sector.

The broader picture heading into Thursday remains a market sitting at all-time highs across every major benchmark while becoming increasingly dependent on a narrow group of AI-driven technology names and rapidly shifting geopolitical headlines. Bond yields remained relatively stable, the U.S. dollar strengthened, and gold prices fell roughly 1.6% as safe-haven demand eased following the Hormuz developments.

For now, the Dow, the S&P 500, and the Nasdaq all remain at record levels. Whether the rally continues may depend less on economic data and more on geopolitical developments in the Middle East, corporate AI spending, and whether investors continue rewarding a market increasingly concentrated around a handful of dominant technology and semiconductor companies.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

WASHINGTON — U.S. Trade Representative Jamieson Greer said Tuesday, May 26, 2026, that tariffs on Mexico are not going away, even as American and Mexican negotiators begin formal talks this week on the future of the United States-Mexico-Canada Agreement (USMCA), underscoring how dramatically Washington’s approach to North American trade has shifted under President Donald Trump.

Speaking at the Council on Foreign Relations in Washington, Greer dismissed the idea that the upcoming USMCA review would restore the largely tariff-free trade environment that defined North America for decades under NAFTA and the original 2020 USMCA framework.

“The U.S. is going to have tariffs,” Greer said. “Even with somebody like Mexico, or other countries that are in our own hemisphere, we’re going to have tariffs as long as we have a giant trade deficit.”

The remarks landed as U.S. and Mexican officials opened the first formal negotiating round in Mexico City ahead of the July 1, 2026 review deadline built into the agreement’s sunset clause. Canada was notably absent from this week’s talks, highlighting growing strains between Washington and Ottawa that U.S. officials now openly describe as more difficult than the relationship with Mexico.

At the center of the negotiations is a fundamental question about what USMCA is supposed to be. When Trump negotiated the agreement during his first term to replace NAFTA, the White House pitched it as a modernized trade pact designed to keep manufacturing inside North America. Six years later, the administration is signaling the deal is evolving into something much more aggressive: a regional industrial alliance built around tariffs, supply-chain controls and coordinated pressure on China.

The current tariff structure already reflects that shift. A 50% tariff now applies to imported steel, aluminum and copper entering the United States. Mexican-made medium- and heavy-duty trucks face a 25% duty, while Mexican tomatoes carry a 17% tariff. None of those measures fall under the original USMCA framework, and Greer made clear they are not temporary.

The administration is also pushing for tougher rules of origin, one of the most important and contentious parts of the agreement. Rules of origin determine how much of a product must actually be made inside North America in order to qualify for tariff-free treatment.

Under the current USMCA structure, 75% of a vehicle’s content must come from the United States, Mexico or Canada to move across borders duty-free, and a portion of the labor must come from workers earning at least $16 an hour. The rules were designed to discourage automakers from importing low-cost parts from Asia, assembling products in Mexico and then shipping them into the U.S. market without tariffs.

Now Washington wants those requirements tightened further, with a greater percentage of manufacturing specifically tied to U.S.-made content.

The second major issue is what Greer described as “external tariff coordination.” In practical terms, the United States wants Mexico and Canada to align their own tariffs more closely with Washington’s trade barriers against countries outside the region, particularly China.

U.S. officials increasingly argue Chinese manufacturers have been routing products through Mexico and Canada to gain indirect access to the American market under USMCA rules. Earlier this month, Greer told the House Ways and Means Committee that Mexico has already raised tariffs on roughly 1,400 products from China, Vietnam and other countries. Mexican Economy Minister Marcelo Ebrard has acknowledged his government is currently working through 52 separate U.S. trade demands.

“If Mexico and Canada coordinate externally with us, there can be preferential treatment internally,” Greer said Tuesday. “Ultimately, at the end of the day, frankly, for national security reasons, I want to have our supply chain sourced from this hemisphere, right from North America.”

Mexico and Canada, however, are being treated very differently by Washington.

Mexican President Claudia Sheinbaum has worked to maintain a cooperative relationship with Trump while tying trade negotiations to White House priorities including cartel enforcement and illegal migration. Mexico has also avoided retaliating directly against U.S. tariffs and has instead moved to raise duties on Chinese imports, steps that appear to have preserved goodwill inside the administration.

Canada took the opposite approach after the Trump administration imposed tariffs last year, responding with retaliatory duties on American products. Greer said Tuesday the U.S. now has “significant” disputes with Ottawa extending well beyond trade policy alone, and he openly questioned whether a deal could be finalized before the July 1 review date.

The auto sector remains the largest pressure point in the negotiations. More than half of all vehicles and auto parts produced in Mexico are exported to the United States, alongside a major share of Mexican steel production. American manufacturers support tougher origin rules in theory but worry that escalating tariffs and shifting requirements could raise costs and disrupt deeply integrated supply chains built over three decades.

Farm products, aluminum, lumber and dairy are also emerging as flashpoints. U.S. farmers continue pushing for better access to Canadian dairy markets, while Canadian aluminum producers remain exposed to the administration’s tariff strategy.

The stakes stretch far beyond trade lawyers and diplomats. USMCA governs nearly $1.8 trillion in annual North American trade, making it one of the largest economic relationships in the world. Any major changes will ripple through car prices, appliance costs, manufacturing investment decisions and supply chains that touch millions of jobs across all three countries.

The review itself stems from a “sunset clause” built into the agreement. Every six years, the United States, Mexico and Canada must decide whether to extend USMCA for another 16 years or move into a rolling cycle of annual reviews that could eventually allow the deal to expire in 2036 if no agreement is reached.

Greer acknowledged Tuesday that negotiations are unlikely to conclude by July 1 and will continue through the summer and likely into the fall.

For businesses and consumers, however, the broader direction from Washington now appears unmistakable. The era of largely tariff-free North American trade that began with NAFTA in 1994 is ending. In its place, the United States is building a more protectionist economic bloc centered on tariffs, domestic manufacturing and strategic competition with China.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Buda Juice, Inc. became the latest company to dual-list on NYSE Texas this week as competition intensifies between multiple exchanges trying to turn Texas into a new center of American finance.

The Dallas-based juice company officially added its shares to NYSE Texas on May 26, 2026, while keeping its primary listing on NYSE American.

The move itself is relatively small financially.

The broader trend behind it is not.

Texas is rapidly becoming one of the biggest battlegrounds in the future of U.S. capital markets.

Just a few years ago, the state had no major stock exchanges.

Now it has:

  • NYSE Texas
  • The upcoming Texas Stock Exchange (TXSE)
  • Expanding operations from Nasdaq in Dallas

Together, they are reshaping the geography of Wall Street.

Buda Juice CEO Horatio Lonsdale-Hands said the listing reflects the company’s Texas roots as the brand continues national expansion.

The company produces cold-pressed juices and wellness beverages distributed through supermarkets and retailers across the country.

The listing itself is considered a “dual listing,” meaning shares trade simultaneously on more than one exchange.

For companies, dual listings are attractive because they create regional visibility without forcing businesses to move their primary exchange relationship.

That strategy has become central to the Texas exchange push.

NYSE Texas, launched by the New York Stock Exchange in 2025, has already signed more than 100 companies with combined market values exceeding $2 trillion.

The exchange is targeting companies seeking stronger ties to Texas’s rapidly growing business ecosystem while still maintaining connections to traditional financial centers.

Texas officials have spent years aggressively recruiting financial firms, investment companies, technology businesses, and corporate headquarters away from states like New York and California.

Lower taxes, lighter regulation, and faster development approvals have helped fuel the migration.

Texas now hosts more NYSE-listed companies than any other state, with combined market values approaching $4 trillion.

The next phase of the competition arrives later this year with the launch of the Texas Stock Exchange, commonly known as TXSE.

Unlike NYSE Texas, which operates under the NYSE umbrella, TXSE is an entirely separate exchange backed by major Wall Street institutions including:

  • BlackRock
  • Citadel Securities
  • Goldman Sachs
  • Bank of America
  • JPMorgan Chase
  • Charles Schwab

The exchange has already raised hundreds of millions of dollars ahead of launch.

TXSE CEO James Lee has openly criticized the quality of many companies currently trading on traditional exchanges and says his platform intends to operate with stricter standards while offering lower listing fees.

That fee competition could become important for mid-sized public companies looking to reduce costs.

Both Texas exchanges are initially focused more on attracting secondary listings than convincing companies to abandon the NYSE or Nasdaq entirely.

Switching primary exchanges can be expensive and operationally difficult.

Adding a Texas listing is far simpler.

The state’s broader business growth is helping fuel the momentum.

Texas continues attracting:

  • Technology firms
  • Financial companies
  • Energy businesses
  • Data-center developers
  • Artificial intelligence infrastructure projects

Large-scale data center developments across West Texas have accelerated as companies seek access to cheaper land and large energy supplies.

That growth has strengthened arguments that the state increasingly deserves its own major capital-markets ecosystem.

The biggest missed opportunity for Texas exchanges so far may be SpaceX.

Although Elon Musk’s SpaceX plans one of the largest IPOs in history, the company is expected to list on Nasdaq rather than NYSE Texas or TXSE.

Even so, the company’s massive Texas footprint continues reinforcing the broader narrative of financial and corporate migration toward the state.

The rise of multiple exchanges inside Texas reflects a larger shift happening across American business geography.

For decades, New York dominated capital markets almost entirely.

Now major portions of corporate America are increasingly operating from Texas, Florida, Arizona, Tennessee, and other lower-tax states.

Financial infrastructure is beginning to follow.

Companies like Buda Juice may represent relatively small listings today.

But they are early signs of a much larger battle over where the next generation of American capital markets will operate.

Wall Street is no longer competing only inside Manhattan.

It is now competing with Texas itself.

JBizNews Desk — Dallas

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

New Jersey Governor Mikie Sherrill has forced down World Cup train fares from an originally proposed $150 round-trip ticket to $98 through a high-profile public standoff with FIFA and a newly assembled group of corporate sponsors.

The fight is becoming one of the clearest examples yet of how American cities and states may handle the growing financial burden of hosting global mega-events.

At the center of the battle was a simple question:
Who should pay to move hundreds of thousands of fans during the 2026 FIFA World Cup?

NJ Transit originally announced plans to charge $150 round-trip fares between New York Penn Station and MetLife Stadium during tournament matches.

The normal cost for the same route is roughly $13.

Transit officials argued the steep pricing reflected enormous operational costs tied to hosting the tournament, including:

  • Additional train service
  • Security operations
  • Staffing
  • Equipment upgrades
  • Crowd-control logistics

NJ Transit estimated total World Cup transportation costs near $48 million.

Governor Sherrill publicly pushed back almost immediately.

She argued New Jersey taxpayers and commuters should not absorb the burden while FIFA itself is expected to generate approximately $11 billion from the tournament globally.

The disagreement quickly became political.

Compared with other host cities, New Jersey’s pricing looked dramatically higher.

Public transportation costs for World Cup fans in cities like Houston, Atlanta, Philadelphia, and Los Angeles were only a fraction of the proposed New Jersey fare.

That comparison intensified pressure on state officials to find another solution.

The breakthrough came through corporate sponsorships.

On May 12, Sherrill announced the final fare would be reduced to $98 after outside companies agreed to help offset the cost difference.

Sponsors included:

  • DoorDash
  • Audible
  • FanDuel
  • DraftKings
  • PSE&G
  • South Jersey Industries
  • American Water

The arrangement effectively created a new public-private financing model for mega-event transportation infrastructure.

Rather than fully subsidizing fares through taxpayers or forcing fans to absorb the full operational cost, the state shifted part of the burden onto corporations seeking visibility and association with the tournament.

The strategy may now influence future host-city negotiations well beyond New Jersey.

Governments hosting major sporting events increasingly face backlash over public spending tied to stadiums, transportation systems, security operations, and tourism infrastructure.

Sherrill’s approach demonstrated that sponsorship-driven cost sharing may provide a politically safer alternative.

The economics behind the move are substantial.

MetLife Stadium will host eight World Cup matches, including the final.

Each match could draw roughly 78,000 spectators.

Reducing transportation costs by more than $50 per fan potentially shifts tens of millions of dollars back into restaurants, hotels, retail shops, and local entertainment businesses instead of transit expenses.

That consumer-spending effect became part of the state’s broader economic strategy.

New Jersey and New York officials have spent months promoting programs designed to push tournament spending toward local businesses rather than concentrating revenue entirely within stadium operations.

The state has also invested heavily in transportation preparation.

NJ Transit approved millions of dollars in additional bus contracts and infrastructure upgrades tied specifically to tournament logistics.

Officials say moving large crowds efficiently will be critical to avoiding major disruptions during the event.

FIFA itself reportedly pushed back privately against the fare controversy, arguing that high transportation costs could discourage attendance and hurt the overall fan experience.

Still, the organization has largely avoided directly funding local transportation operations in host cities.

That tension is likely to continue globally as the costs of hosting major sporting events rise.

For Sherrill politically, the confrontation also delivered valuable visibility.

The governor positioned herself publicly as defending commuters, taxpayers, and small businesses against both FIFA and steep transportation pricing.

The move generated significant national media attention while reinforcing broader economic messaging around affordability and local economic benefit.

Questions remain about whether the final pricing structure will fully cover NJ Transit’s operating costs.

The model depends heavily on high ridership volumes and sponsor participation.

If too many fans rely instead on driving, ride-share services, or private transportation, financial pressure on transit agencies could persist.

Even so, the larger precedent may already be set.

Future Olympic bids, World Cup host agreements, and other mega-event negotiations are likely to study closely what happened in New Jersey during 2026.

The emerging lesson is increasingly clear:
host governments may no longer quietly absorb massive event-related costs without demanding either corporate participation or greater financial contribution from event organizers themselves.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Wix.com Ltd. is cutting roughly 1,000 jobs, about 20% of its global workforce, in the largest layoff round in company history as the company increasingly replaces engineering and design work with artificial intelligence systems.

The layoffs mark one of the clearest examples yet of a profitable software company openly acknowledging AI-driven workforce replacement as a core business strategy rather than simply a productivity tool.

The Israeli-based web development company informed employees this week that advances in AI have significantly reduced the need for human staffing across several operational and product-development functions.

Reports first surfaced through Israeli financial publications Calcalist and Globes, citing internal company sources. Wix declined public comment.

The cuts come during a difficult year for the company.

Wix reported a quarterly net loss of $57.5 million despite generating approximately $541 million in revenue during the first quarter. Shares of the company have fallen nearly 50% since the beginning of the year, pushing the stock to near 52-week lows.

The company’s market value now sits near $2 billion.

At the same time, Wix recently completed a massive $1.6 billion stock buyback effort aimed at supporting investor confidence, though the share-price decline continued.

The workforce reductions will affect nearly every division of the company and are expected to unfold gradually over the coming months.

Wix employed roughly 5,300 workers globally at the end of the first quarter, with a majority based in Israel.

What separates the Wix layoffs from many recent technology-sector job cuts is management’s unusually direct connection between AI deployment and reduced staffing needs.

Many companies have framed layoffs around “restructuring,” “economic uncertainty,” or “post-pandemic normalization.”

Wix executives reportedly tied the cuts specifically to artificial intelligence systems increasingly handling tasks previously performed by human developers and designers.

The company has spent the past year aggressively expanding its AI capabilities through acquisitions and internal development.

Among the most important moves was the acquisition of Base44, an Israeli startup focused on “vibe coding,” a fast-growing category of software tools allowing users to build applications through natural-language prompts instead of traditional coding.

Wix also acquired Hour One, another Israeli AI company focused on generative media and digital content creation.

The strategic shift reflects a much broader transformation occurring across the software industry.

AI coding assistants and automated design platforms are rapidly changing how software products are built, maintained, and updated.

Executives across Silicon Valley increasingly view leaner engineering organizations as a long-term structural advantage rather than a temporary cost-cutting measure.

Wix is effectively becoming a public case study for that transition.

The company’s revenue continues growing while headcount shrinks sharply — a dynamic many investors increasingly reward if profitability improves.

But the strategy also carries significant risks.

Wix competes directly against companies including Shopify, Squarespace, and multiple AI-native website-building startups that are accelerating their own product rollouts aggressively.

Reducing too much engineering talent too quickly could slow innovation precisely when competition is intensifying.

There are also broader labor and regulatory concerns.

Several European jurisdictions and Israeli labor regulators may scrutinize the company’s framing of the layoffs if AI replacement becomes the formal justification for workforce reductions.

Technology companies worldwide are increasingly navigating difficult legal and ethical questions surrounding AI-related displacement.

Wix also joins a much larger wave of AI-driven restructuring across corporate America.

Major companies including Amazon, PayPal, Citi, Coinbase, and others have all announced significant staffing reductions tied partly to automation, AI integration, or operational streamlining over the past year.

The Wix announcement stands out because management reportedly acknowledged the connection more directly than most public companies have so far.

For investors and executives throughout the software industry, the implications are significant.

AI is no longer being discussed solely as a tool to help engineers work faster.

At companies like Wix, it is increasingly being treated as infrastructure capable of reducing the number of engineers required altogether.

That shift changes the economics of software businesses fundamentally.

The key question now facing Wall Street is whether companies can successfully shrink workforces while maintaining product quality, innovation speed, and customer growth.

Wix is betting the answer is yes.

Other software executives are likely watching very closely.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

WASHINGTON — Fresh data published Monday, May 25, 2026, by the U.S. Energy Information Administration, alongside polling from the Kaiser Family Foundation and Climate Power, confirms that surging household electricity bills have moved to the center of the 2026 midterm election landscape, with affordability now eclipsing immigration, foreign policy, and even gasoline prices as the defining kitchen-table concern for voters across battleground states.

According to the EIA, average U.S. residential electricity rates rose nearly 13% nationwide between April 2020 and April 2025, and another 6% since President Donald Trump returned to office in January 2025. The agency projects rates could climb another 6% in 2026 and as much as 40% by 2030 if current trends in demand growth, infrastructure spending, and capacity constraints continue.

The increases are landing hardest in regions where voters had gone years without major utility hikes, transforming electric bills from a background expense into a central political issue heading into November.

The political consequences are already emerging. Climate Power, a Democratic-aligned advocacy organization, surveyed 2,710 voters nationwide in January and found that 84% cited rising electricity bills as a major economic concern. A separate Kaiser Family Foundation survey of 1,426 voters found 80% identified affordability as the most important issue heading into the election cycle, with electricity costs ranking just behind groceries and gasoline among the sharpest household pressures.

The epicenter of the crisis sits within PJM Interconnection, the regional grid operator serving 65 million Americans across 13 states and Washington, D.C. Capacity prices in PJM’s latest base residual auction reached $329.17 per megawatt-day, compared with just $28.92 two years earlier — a more than tenfold increase now flowing directly into residential utility bills.

Independent market monitor Monitoring Analytics attributed roughly 63% of the 2025–2026 auction price surge to soaring electricity demand from AI-focused data centers, translating into approximately $9.3 billion in additional annual costs for ratepayers.

The Natural Resources Defense Council estimates that without major regulatory intervention, cumulative costs tied to data-center-driven infrastructure expansion could reach between $100 billion and $163 billion for PJM customers through 2033. Tom Rutigliano, a senior advocate at NRDC, said the imbalance between exploding AI electricity demand and declining reliability from aging power generation is now driving capacity markets into crisis territory.

Pennsylvania Governor Josh Shapiro has emerged as one of the most aggressive political figures confronting the issue. Shapiro sued PJM over its pricing methodology in 2024 and later secured a settlement his office says saved consumers roughly $18 billion. At the same time, the governor has continued supporting selective data center investment projects, including public appearances with executives from PPL Corporation and Blackstone Inc. tied to new gas-fired generation projects intended to support AI infrastructure.

That balancing act increasingly reflects the broader national political dilemma: state leaders want the jobs and investment associated with hyperscale AI infrastructure while simultaneously trying to shield voters from rapidly rising utility bills.

The electoral warning signs are already visible. In Georgia’s 2025 off-year elections, Democratic challengers defeated two Republican incumbents on the Georgia Public Service Commission after campaigning heavily against repeated utility-rate increases approved for Georgia Power customers. Typical residential bills there have climbed to roughly $175 per month after multiple hikes over the past two years.

Georgia Power has since proposed another $15 billion in new generation investment, much of it designed to serve growing data center demand around Atlanta and rural Georgia counties aggressively courting AI infrastructure projects.

The pressure extends well beyond PJM territory. In Virginia, Dominion Energy customers are expected to absorb roughly $11 per month in additional charges this year and another increase in 2027. The Virginia State Corporation Commission approved a dedicated rate structure in late 2025 requiring large-scale customers, including AI data centers, to absorb a greater portion of transmission and generation costs beginning in 2027 — an effort regulators explicitly framed as protecting ordinary households from subsidizing hyperscale computing facilities.

A February report from Morgan Stanley Wealth Management, led by strategist Monica Guerra, described the situation as “the American energy paradox,” noting that the United States is simultaneously producing record oil and exporting record natural gas while household electricity affordability deteriorates across multiple swing states.

Republicans, who currently control the White House, Senate, and House of Representatives, enter the election cycle particularly exposed. Democrats are increasingly attempting to tie electricity costs to federal permitting policy, grid reliability concerns, and energy investment decisions made under the Trump administration, while Republicans argue that aggressive electrification policies and grid-transition mandates imposed over recent years accelerated the imbalance between supply and demand.

Several congressional battlegrounds in Pennsylvania, Michigan, Georgia, Virginia, Texas, Ohio, and California now overlap directly with regions experiencing both aggressive AI data center expansion and rising residential utility rates.

Consumer advocates warn the political pressure may intensify further because many approved utility increases have not yet fully appeared on household statements. Charles Hua, executive director of advocacy group PowerLines, said rate increases approved during the past 18 months are only beginning to flow through into customer bills and are likely to become more visible during the peak summer cooling season.

For millions of Americans opening utility bills while watching AI campuses rise across suburban and rural communities, the political question heading into November is becoming increasingly straightforward: who is paying for the infrastructure boom, and who is benefiting from it.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Delta Air Lines is using a homegrown artificial intelligence system to move more than 100,000 bags every day through Hartsfield-Jackson Atlanta International Airport, the busiest airport in the world by passenger traffic.

The system is part of a broader operational overhaul as airlines head into the busiest travel stretch of the year and increasingly turn to artificial intelligence to manage complex physical logistics in real time.

Paul Buckley, Delta’s director of operations in Atlanta, described the scale of the operation bluntly:
“Atlanta is an enormous operation, Delta’s biggest by a long way.”

The company says the AI-driven system has improved baggage transfer success rates by as much as 20%, a major operational gain in an industry where lost or delayed luggage remains one of the biggest customer frustrations.

The scale of the challenge is enormous.

On busy days, Delta handles well over 100,000 bags in Atlanta alone. Roughly three-quarters of those bags are connecting between flights rather than starting or ending their journeys there.

Each suitcase moves through a fast-moving network involving:

  • Aircraft unloading
  • Conveyor systems
  • Scanning stations
  • Ramp crews
  • Tug drivers
  • Gate transfers
  • Connecting departures

Even minor delays can result in bags missing flights.

The new AI platform is designed to reduce exactly that problem.

Previously, baggage tug drivers received lists of assignments and largely determined routing themselves.

The new system functions more like a real-time logistics engine.

Using live operational data, the AI constantly analyzes:

  • Aircraft arrival times
  • Gate changes
  • Weather conditions
  • Connection windows
  • Available drivers
  • Tug locations
  • Aircraft departure schedules

The software then dynamically routes baggage teams toward the most urgent transfers at any given moment.

Delta employees still physically move the bags, but the AI increasingly determines the fastest and most efficient way to do it.

The technology has already produced measurable improvements.

According to Delta, transfer success rates for connecting bags have improved significantly since implementation, reducing both delayed luggage claims and operational costs tied to baggage recovery.

The system is especially valuable during heavy travel periods when storms, delays, and gate changes create cascading operational pressure across airport systems.

The airline plans to expand the technology beyond Atlanta later this year, including deployments in Detroit and Minneapolis-St. Paul.

For Delta, Atlanta serves as the testing ground because few airports in the world present greater operational complexity.

The AI rollout also highlights a broader trend unfolding across corporate America:
artificial intelligence is increasingly moving beyond chatbots and software into large-scale physical operations.

Companies across logistics, retail, manufacturing, and transportation are now using AI systems to optimize movement, staffing, inventory, routing, and predictive maintenance.

In Delta’s case, the technology is being applied to one of aviation’s most difficult logistical challenges.

Importantly, the company says the system is not designed to replace workers.

Delta executives have emphasized that the AI functions as a decision-support tool rather than an automation replacement program.

The company says the software has proven especially helpful for newer baggage crews who may not yet have years of operational experience navigating Atlanta’s massive airfield efficiently.

The timing of the rollout is critical.

The Transportation Security Administration expects record summer passenger volumes this year as travel demand remains strong despite higher airfare and fuel costs.

Atlanta alone processes tens of millions of travelers annually, with Delta operating hundreds of departures daily from the airport.

For passengers, baggage systems typically go unnoticed when everything works correctly.

But delayed or lost bags remain among the most visible operational failures airlines face.

That makes improvements even at the margins financially meaningful for carriers.

The move also comes as airlines face increasing pressure to modernize aging infrastructure and improve reliability after several years of operational disruptions tied to weather events, staffing shortages, software failures, and record passenger demand.

For Delta, the technology represents a quieter but highly practical form of artificial intelligence deployment.

It is not flashy consumer AI generating images or writing essays.

Instead, it is software deciding which baggage tug should move which suitcase across one of the busiest airports in the world — and exactly when it needs to happen.

As summer travel volumes ramp up, the coming months will provide the largest real-world test yet for Delta’s expanding AI logistics system.

JBizNews Desk — Atlanta

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

More than 330,000 American companies paid tariffs that the U.S. Supreme Court later ruled unlawful, and now a massive refund battle is unfolding between importers and the Trump administration.

The dispute centers on billions of dollars in tariff payments collected under emergency trade powers that the Supreme Court ruled earlier this year exceeded presidential authority.

According to recent reporting and federal court filings, U.S. Customs and Border Protection has already begun processing refund claims through a newly created online portal, with more than $35 billion in repayments reportedly cleared so far.

But many companies are staying unusually quiet about the money.

The reason is increasingly political.

President Donald Trump has sharply criticized companies that publicly complained about tariffs or signaled plans to recover large refund amounts.

Corporate executives now fear becoming political targets while the legal fight continues.

The underlying case stems from a major February 2026 Supreme Court decision involving tariffs imposed under the International Emergency Economic Powers Act, commonly known as IEEPA.

In a 6–3 ruling, the Court found that the law did not authorize broad across-the-board tariff programs tied to imports from major trading partners.

The ruling invalidated portions of the administration’s earlier “Liberation Day” tariff structure along with several emergency tariffs tied to China, Mexico, and Canada.

The Court concluded that emergency economic powers did not give the executive branch unlimited authority to impose sweeping trade duties without congressional approval.

Within hours of the decision, however, the administration moved to rebuild parts of the tariff structure using different trade authorities already embedded in federal law.

That legal maneuvering triggered a second wave of lawsuits.

Earlier this month, the U.S. Court of International Trade ruled against portions of the administration’s replacement tariffs imposed under Section 122 of the Trade Act of 1974.

The court found that Section 122 authority was narrower and more temporary than the administration argued.

Still, the judges stopped short of issuing nationwide relief, meaning many tariffs remain in place while appeals continue.

Behind the scenes, companies across the country are now filing refund claims quietly through attorneys and customs specialists.

The affected firms span nearly every major industry:

  • Retailers
  • Manufacturers
  • Electronics companies
  • Auto suppliers
  • Food importers
  • Small businesses dependent on foreign components

Retail giants including Walmart, Costco, Home Depot, and Target are among the largest importers affected by the ruling, though most companies have avoided publicly discussing potential refund amounts.

Trade attorneys say many corporate executives fear public backlash or retaliation if they appear too aggressive in recovering tariff money while inflation and economic concerns remain politically sensitive.

The administration is also trying to limit the broader implications of the ruling.

Officials worry that large-scale refunds could weaken future presidential trade authority and discourage aggressive tariff use by future administrations.

The money involved is enormous.

Federal filings suggest roughly $166 billion in tariffs may ultimately be affected by ongoing litigation and refund processing tied to the Supreme Court ruling.

Customs officials say repayments may continue flowing for months because claims involve millions of individual import entries spread across multiple years.

Importers are also receiving interest payments attached to some refunds.

At the same time, many tariffs remain active under separate legal authorities.

The administration continues using Section 232 national-security powers and Section 301 trade authorities to maintain tariffs on categories including:

  • Steel
  • Aluminum
  • Autos
  • Auto parts
  • Copper
  • Select Chinese imports

The result is an increasingly fragmented tariff landscape where some duties have been overturned, others remain active, and several more continue moving through the courts.

For businesses, the uncertainty has become almost as disruptive as the tariffs themselves.

Companies must now decide:
whether to pursue refunds aggressively, stay politically quiet, or continue planning around tariffs that could disappear — or return — depending on future court rulings and elections.

The issue is likely to become even more politically charged heading toward the 2026 midterm elections.

With consumers already facing elevated prices for gasoline, groceries, and household goods, the administration is balancing competing pressures:
supporting domestic manufacturing rhetoric while avoiding additional inflation concerns tied to import costs.

For now, the refund money is moving slowly and mostly quietly into corporate accounts.

But the broader legal and political fight surrounding presidential tariff powers is far from over.

JBizNews Desk — New York

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

TEL AVIV — Avraham Novogrotzky, president of the Manufacturers Association of Israel, warned Monday, May 25, 2026, that the shekel’s powerful surge against the dollar is accelerating a structural shift of Israeli industrial production overseas, pointing to fresh filings from water-meter technology firm Arad as evidence that export-driven manufacturers are quietly relocating capacity to Spain, Italy, and Mexico to defend margins.

Novogrotzky said the appreciation of the shekel — which has strengthened roughly 20% against the U.S. dollar over the past year and surged a further 8.3% since the Bank of Israel’s previous rate decision — is squeezing exporters whose revenue is denominated in dollars while costs, especially wages, remain in shekels. He cited Central Bureau of Statistics data showing that Israeli production overseas climbed from $2.5 billion to $4.5 billion in a single quarter at the end of 2025, when the shekel’s rally began, and said the trend almost certainly intensified in the first quarter of 2026.

The dynamic was laid bare last week in financial disclosures from Arad, the Tel Aviv Stock Exchange-listed water-meter manufacturer controlled by Kibbutz Dalia and Kibbutz Ramot Menashe. The company, which carries a market capitalization of roughly 1.2 billion shekels, told investors it had taken deliberate steps to insulate itself from the currency’s appreciation, including shifting production for the European market from Israel to facilities in Spain and Italy, while moving production for the U.S. market to its group site in Mexico.

The moves are already paying off financially. Despite the dollar’s roughly 20% decline against the shekel over the past year, Arad reported first-quarter revenue rose 8% to $112.4 million while net profit climbed 26% to $9.2 million, driven by the offshore production strategy and continued strength in its domestic Israeli business.

Novogrotzky framed Arad’s disclosures as a warning shot, arguing that existing projects may remain in Israel but new industrial investment is increasingly being directed abroad. He said the Manufacturers Association is hearing similar concerns from member companies across Israel’s export sector, where competitiveness has steadily eroded as the shekel rallied to a 33-year high against the dollar.

The Arad case is not isolated. Polyram Plastic Industries, traded on the Tel Aviv Stock Exchange under ticker POLP, disclosed in its 2025 annual report that it had opened a new factory in Thailand and transferred select production lines out of Israel. The company told shareholders the move reflected a strategic repositioning of where its core manufacturing activity would be centered in the future.

Industry executives say Israeli manufacturers have long outsourced portions of production overseas to reduce labor costs and gain proximity to customers, particularly in Asia and North America. What has changed in 2026, according to Novogrotzky, is the pace and urgency of the shift, driven less by long-term planning and more by an immediate currency-driven profitability squeeze.

The pressure is colliding directly with the Bank of Israel’s broader policy challenge. Earlier Monday, the central bank cut its benchmark interest rate by 0.25 percentage points to 3.75%, explicitly citing the shekel’s strength as a key factor helping cool inflation. Yet the same currency appreciation celebrated by Governor Prof. Amir Yaron as a disinflationary force is simultaneously hollowing out the economics of Israel’s export manufacturing base.

Economists warn the trend could carry lasting consequences for Israel’s industrial footprint. Once factories, supplier networks, engineering operations, and management teams migrate overseas, they rarely return quickly. Production lines established in Spain, Italy, Mexico, or Thailand often become permanent components of a company’s global manufacturing chain.

That creates a growing disconnect inside the Israeli economy: macroeconomic indicators remain resilient, inflation is cooling, and the currency is strong, yet portions of the country’s traditional industrial base are steadily relocating abroad in search of lower costs and more stable margins.

For now, the Manufacturers Association of Israel is pressing policymakers to weigh the industrial consequences of the shekel’s rally alongside its inflation benefits, warning that without offsetting support measures or intervention, more Israeli production capacity will quietly leave the country in the coming quarters.

The Arad disclosures, Novogrotzky suggested, are not an isolated corporate adjustment. They may instead mark the early stages of a much broader manufacturing migration already underway.

© 2026 JBizNews. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By Duvi Honig

Australia’s climate minister, Chris Bowen, just gave the world a remarkably clear window into what large parts of the modern climate movement have actually become. Not simply a campaign to reduce emissions or protect the environment, but an international ecosystem capable of moving staggering amounts of taxpayer money under the protection of a cause few politicians feel safe questioning.

Bowen is defending more than 150 million Australian dollars — roughly 107 million U.S. dollars — tied to Australia’s role chairing the upcoming COP31 United Nations climate summit.

There is one important detail: Australia is not even hosting the conference. Turkey is.

Bowen’s government is spending that money largely to run the diplomatic process surrounding the summit, including staffing, travel, negotiations and administrative coordination. Documents obtained by The Australian newspaper showed government employees spent 485,602 Australian dollars on travel tied to the negotiations during just January and February 2026 alone, including trips to Turkey, Fiji, Germany and South Korea.

All of this is happening while Australian households face rising electricity bills, expensive mortgages, higher grocery prices and a cost-of-living crisis severe enough to dominate national politics.

And the most politically damaging part for Bowen is this: many of those same families struggling to pay their utility bills are living under the exact renewable-energy policies his ministry has aggressively promoted.

When opposition lawmakers called the spending a “vanity project,” Bowen responded by calling his counterpart “the biggest hypocrite in the federal parliament.”

That reaction misses the larger point entirely.

This is not really about one minister in Australia. It is about the operating structure that has grown around the global climate industry itself.

Every year, massive United Nations climate conferences draw anywhere from tens of thousands of delegates, activists, consultants, diplomats, corporate sponsors, nonprofit organizations and government officials from around the world. Entire hotel districts are reserved. International flights multiply. Temporary bureaucracies expand. Multi-million-dollar security operations are assembled.

Then the conference ends — usually with broad declarations, vague targets and promises that another conference will be needed the following year to revisit unresolved issues.

The summit itself increasingly becomes the product.

And the people paying for it are almost never the people attending it.

Bowen flies internationally to climate meetings while ordinary Australian families absorb higher power prices and taxes. Former U.S. climate envoy John Kerry faced criticism during the Biden administration for using private jets tied to climate-related travel while simultaneously warning Americans to reduce carbon emissions in daily life.

The contradiction is obvious to voters.

The pattern extends well beyond Australia.

The European Union has committed hundreds of billions of euros toward climate-transition policies even as parts of Europe struggle with energy affordability and industrial competitiveness. Germany, long viewed as the flagship of Europe’s green transition, has watched portions of its manufacturing base come under pressure from high energy costs.

In the United States, the Inflation Reduction Act authorized hundreds of billions of dollars in climate and clean-energy subsidies, much of it flowing into politically connected industries dependent on long-term government support.

Supporters argue these investments are necessary to accelerate technological transition and reduce future environmental risk.

Critics increasingly ask a different question: how much of the climate economy now exists primarily to sustain itself?

Meanwhile, the countries most responsible for future emissions growth continue expanding conventional energy production. China remains heavily dependent on coal and continues approving new coal-fired generation capacity. India is expanding fossil-fuel use to support industrial growth. Russia remains one of the world’s largest hydrocarbon exporters.

That geopolitical imbalance has become harder for Western voters to ignore.

They are being asked to absorb rising energy costs, taxes and lifestyle restrictions while many of the world’s largest emitters continue prioritizing industrial expansion and energy security.

Which brings the debate back to Bowen.

What exactly does 150 million Australian dollars buy here?

It does not directly lower electricity bills for Australian households. It does not immediately reduce global emissions. It does not suddenly solve the climate problem after three decades of increasingly large international conferences.

What it undeniably does buy is international visibility, diplomatic influence, conference infrastructure and participation inside a global climate system that has grown larger, more expensive and more bureaucratic every year.

Supporters call that leadership.

Critics increasingly call it a self-perpetuating ecosystem where the process itself has become the justification for more spending.

That perception matters politically because working families notice the contrast. They notice politicians and officials flying internationally to climate events while lecturing citizens about consumption, energy use and carbon footprints. They notice governments spending millions on conferences while households struggle with bills at home.

And once credibility begins eroding, rebuilding it becomes extremely difficult.

The danger for climate policymakers is not merely opposition from skeptics. It is broader public exhaustion with systems that appear expensive, permanent and disconnected from everyday economic reality.

The climate debate itself will continue. Serious people can disagree about policy, energy transition timelines and the balance between environmental goals and economic costs.

But the backlash now building around figures like Bowen reflects something deeper than emissions targets.

It reflects growing public suspicion that an international movement originally framed as an environmental necessity has, in some cases, evolved into a sprawling global spending structure whose most consistent outcome is the expansion of its own conferences, institutions and budgets.

And increasingly, voters are asking whether they can still afford it.

Duvi Honig is Founder & CEO of the Orthodox Jewish Chamber of Commerce and Co-founder and Secretary of the Multicultural Business Coalition.

Opinion — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.