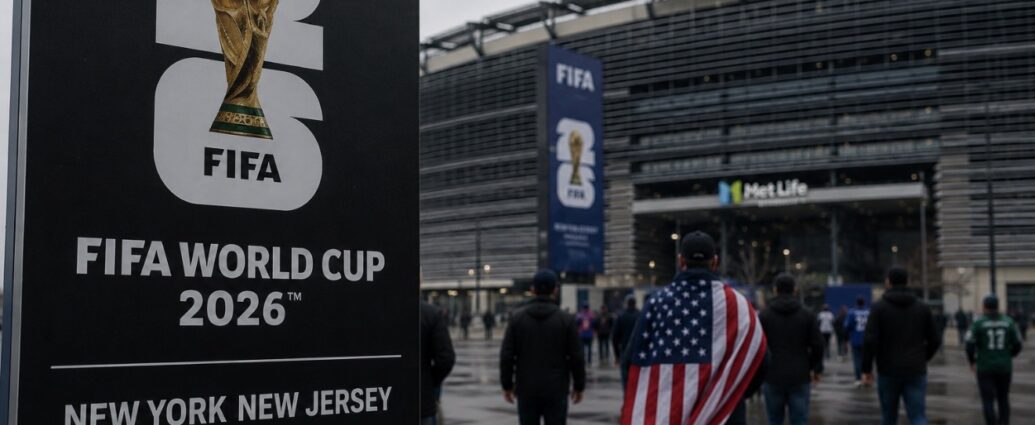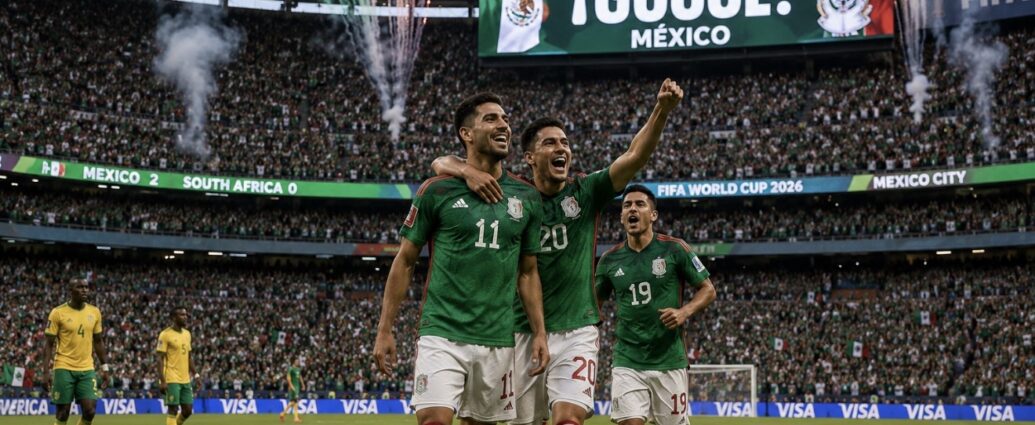
The 2026 FIFA World Cup kicked off Thursday at Estadio Azteca in Mexico City, where co-host Mexico defeated South Africa 2-0 in front of a packed home crowd. The match opened the largest World Cup in history — a 104-game tournament spanning 16 cities across the United States, Mexico, and Canada, marking the first time three nations have jointly hosted the event. The tournament concludes with the final on July 19 in the New York-New Jersey region.

The opening day carried significance far beyond the result on the field. Mexico City Mayor Clara Brugada declared a local holiday to celebrate the kickoff, while President Claudia Sheinbaum indicated a broader national observance remained under consideration. The opening ceremony transformed the nearly 87,500-seat stadium into a global entertainment stage, featuring performances by Shakira, Burna Boy, J Balvin, and Maná.

For FIFA, the World Cup is far more than a sporting event — it is the organization’s largest economic engine.

The expanded 48-team format, up from 32 teams in previous tournaments, creates more matches, more sponsorship inventory, more ticket sales, and significantly more broadcast content. FIFA has projected record revenues for the current cycle, driven largely by the expansion.

Host cities are hoping for their own economic boost.

The tournament is expected to attract millions of visitors across North America, generating spending on hotels, restaurants, transportation, entertainment, and tourism. Cities hosting matches are positioning themselves as global destinations, using the event to showcase local infrastructure and attract future investment.

Mexico City’s holiday declaration reflects how seriously local leaders view the economic opportunity.

The opening venue itself illustrates the business side of modern sports.

Estadio Azteca recently entered a naming-rights agreement with Mexican financial institution Banorte and is officially branded Banorte Stadium. However, because Banorte is not an official FIFA sponsor, the governing body required the venue to be referred to as “Mexico City Stadium” during the tournament.

The move highlights FIFA’s strict sponsorship protections, designed to preserve exclusivity for companies that pay billions for official tournament partnerships.

Broadcasting remains another major revenue source.

In the United States, matches are being carried by Fox Sports and Telemundo, while streaming coverage is spread across multiple digital platforms. Fox-owned Tubi streamed portions of the opening festivities free in 4K, reflecting the growing importance of ad-supported streaming models for major live events.

The World Cup also fuels a vast consumer marketplace that extends far beyond television.

Official jerseys, merchandise, collectibles, licensing agreements, music partnerships, and promotional campaigns are expected to generate billions in additional spending worldwide. Global brands continue to compete aggressively for visibility during what remains the most-watched sporting event on the planet.

Not everything surrounding the tournament has been celebratory.

Rights groups and some fans have raised concerns about security planning at several venues, while dynamic ticket pricing has generated criticism after some ticket costs rose significantly above original face values. Economists also continue to debate whether the long-term financial benefits of hosting major sporting events justify the substantial public spending often required.

For now, however, the focus remains on the tournament itself.

Mexico’s opening victory gave home supporters an early reason to celebrate, while businesses across North America are preparing for weeks of increased tourism and consumer activity. As the tournament unfolds, the broader question for host cities will be how much of the spending and attention generated by the World Cup translates into lasting economic gains after the final match is played in the New York region next month.

JBizNews Desk — North America

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
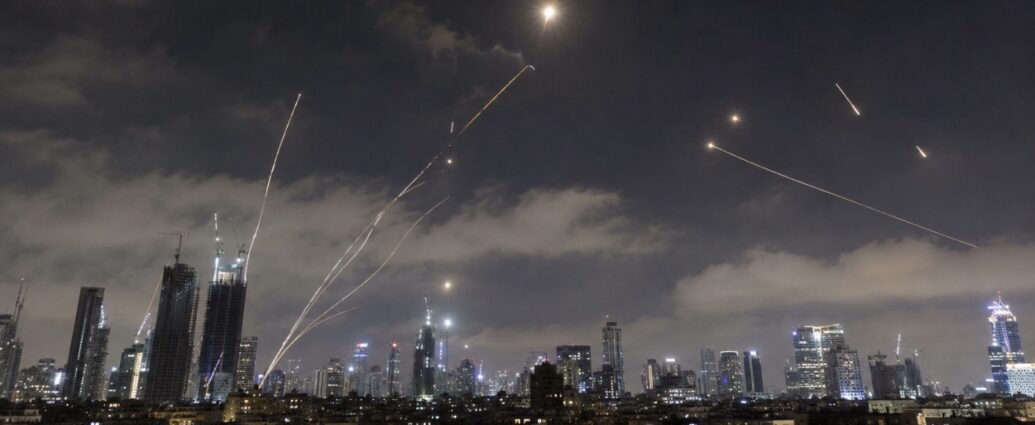
Cryptocurrencies rallied Thursday after President Donald Trump said he had called off planned U.S. military strikes on Iran, easing fears of a wider conflict and sending investors back into risk assets.

In a post on Truth Social, Trump said he had “canceled the scheduled strikes and bombings against Iran this evening,” adding that negotiations had reached the highest levels of Iran’s leadership and that a potential agreement could be finalized soon. Speaking from the Oval Office, Trump said a deal could potentially be signed over the weekend.

The announcement sparked a broad rally across digital assets.

Bitcoin climbed to an intraday high of approximately $63,850, while Ethereum approached $1,700. XRP and Dogecoin also posted strong gains as investors moved back into speculative assets. The total cryptocurrency market capitalization rose nearly 2%, reaching roughly $2.17 trillion.

The reaction followed a familiar market pattern. When geopolitical tensions ease, investors generally become more comfortable holding volatile assets, and cryptocurrencies often benefit disproportionately.

Trump’s comments came just one day after U.S. forces launched strikes against Iran following the loss of a U.S. Army helicopter near the Strait of Hormuz, a critical global energy corridor responsible for transporting a significant share of the world’s oil and natural gas supplies.

Although Trump signaled progress toward diplomacy, he also said the U.S. naval blockade of Iranian ports would remain in place until any agreement is formally completed, highlighting the fragile nature of the situation.

Markets remain cautious.

Iranian officials have not publicly confirmed that a final agreement has been reached, and at least one senior Iranian official reportedly stated that Tehran has not approved a framework.

Investor sentiment also remains weak despite Thursday’s rally. The Crypto Fear & Greed Index continued to register “Extreme Fear,” suggesting many traders remain skeptical about the sustainability of the move.

According to data from Coinglass, more than $260 million in crypto positions were liquidated during the previous 24 hours, with the majority consisting of short positions betting on lower prices. As those bets were forced to close, buying pressure accelerated the rally.

Meanwhile, Bitcoin open interest increased approximately 1.2%, indicating additional capital entering the market.

Another major event looming over financial markets is the highly anticipated SpaceX IPO.

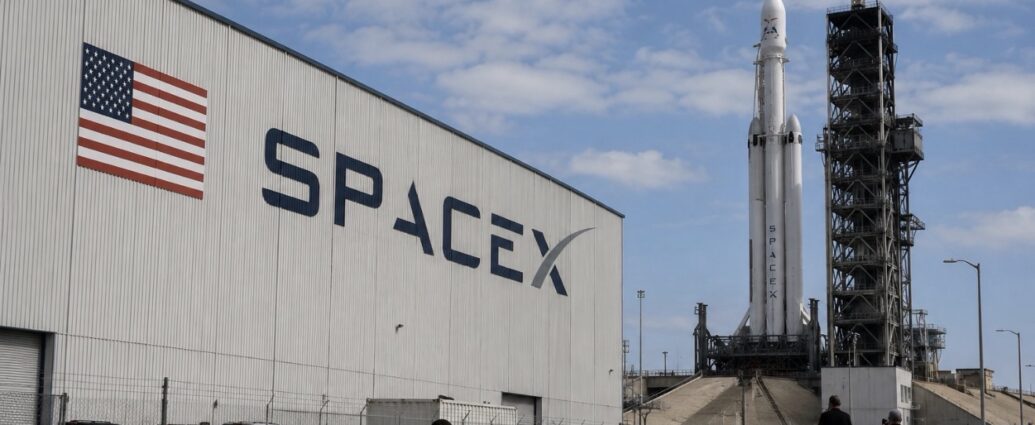
The Elon Musk-led aerospace company priced what has been described as the largest stock sale in history this week, raising approximately $75 billion and preparing to begin trading Friday on the Nasdaq.

Such a massive offering could attract significant investor capital away from other speculative investments, including cryptocurrencies.

Widely followed market analyst Michaël van de Poppe warned that the timing could make conditions “tricky” for Bitcoin and other digital assets.

Van de Poppe said Bitcoin must hold a key support level near $63,200 to maintain upward momentum.

“However, if the trend stalls, we’ll probably hit the low of this correction in the weekend,” he said.

By Thursday afternoon, Bitcoin remained slightly above that threshold, but analysts said the coming days will determine whether the breakout can hold.

Additional signs of speculation emerged beneath the surface of the rally.

Research firm CryptoQuant reported rising activity in derivatives markets, particularly in Ethereum. Open interest in Ethereum futures on the Binance exchange reached a record high, reflecting increased use of leverage by traders seeking to capitalize on market volatility.

While leverage can amplify gains, it can also accelerate losses if sentiment reverses.

Thursday’s trading session highlighted how closely cryptocurrency markets have become tied to geopolitical developments and policy headlines.

A single social-media post from Trump helped move hundreds of billions of dollars across financial markets within hours. Analysts noted that just as quickly, those gains could reverse if negotiations break down.

The market now faces two competing forces.

A formal Iran agreement could remove one of the largest sources of uncertainty confronting investors and support continued buying of risk assets. At the same time, a successful SpaceX market debut could attract investor attention and capital away from cryptocurrencies.

For now, Bitcoin remains above the critical level analysts are watching, and traders will be closely monitoring both the Iran negotiations and Friday’s historic SpaceX debut to determine whether the rally has staying power.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
For the first time, Americans exposed to COVID-19 will have access to a prescription pill designed to help prevent the illness from developing after contact with an infected person. The approval marks a new phase in the long-term management of a virus that has largely faded from public attention but continues to cause hospitalizations and deaths across the United States.

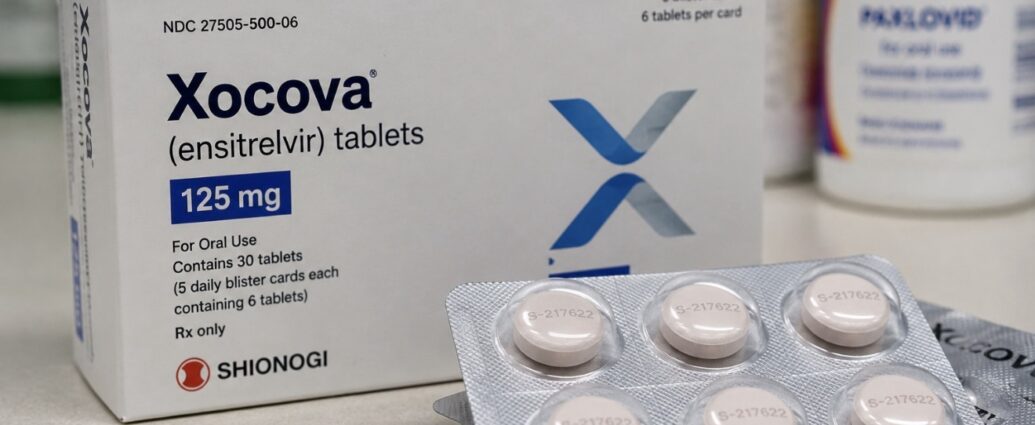
Shionogi & Co. announced on June 1 that the U.S. Food and Drug Administration (FDA) approved Xocova (ensitrelvir) for post-exposure prevention of COVID-19 in adults and adolescents age 12 and older who have been exposed to someone infected with the virus.

According to the company, Xocova becomes the first FDA-approved oral medication specifically cleared to reduce the risk of developing COVID-19 after exposure.

The treatment is designed to be simple and fast. Patients take three tablets on the first day followed by one tablet daily for the next four days, creating a five-day regimen intended to begin shortly after exposure.

The approval is based on results from the SCORPIO-PEP clinical trial, which enrolled 2,387 participants who had been exposed to an infected household member. According to trial data, people who received Xocova experienced a 67% reduction in the risk of developing symptomatic COVID-19 compared with those who received a placebo.

The drug works by targeting a key enzyme the coronavirus needs to reproduce. By blocking the virus’s main protease, ensitrelvir interferes with viral replication before the infection becomes established.

Reported side effects in clinical trials included headache, diarrhea, and cough. The medication also carries standard warnings regarding use during pregnancy and other medical considerations that should be discussed with a healthcare provider.

While COVID no longer dominates headlines, the virus remains a significant public health concern.

According to estimates from the Centers for Disease Control and Prevention, the United States recorded between 3.8 million and 12.4 million COVID-19 cases between October 2025 and late May 2026. Those infections were associated with as many as 240,000 hospitalizations and 42,000 deaths during the period.

The approval also highlights an important shift within the pharmaceutical industry.

During the pandemic, companies such as Pfizer and Moderna generated billions of dollars from vaccines and treatments developed during the global emergency. As COVID became endemic and demand for those products declined, revenue from pandemic-era medicines fell sharply.

Shionogi is betting that a preventive treatment aimed at recently exposed individuals can fill a different market niche.

The company estimates that nearly half of people living with an infected household member ultimately contract the virus themselves, creating a potentially significant population that may seek preventive treatment following exposure.

The approval follows a lengthy regulatory process.

After earlier efforts to secure U.S. approval for ensitrelvir as a treatment for active COVID-19 infections faced challenges, the company shifted its focus toward prevention, where clinical trial results proved more successful. The FDA granted approval ahead of its scheduled June 16 decision deadline.

The medicine is already approved in Japan, where it initially received emergency authorization in 2022 before later receiving full approval.

Outside experts say the drug’s value lies in its ability to intervene early.

By slowing viral replication shortly after exposure, the treatment may reduce the likelihood that the virus gains a foothold and progresses into symptomatic illness.

For investors and the pharmaceutical industry, the approval represents a test of whether COVID prevention remains a viable commercial market years after the pandemic emergency ended.

The vaccine boom may be over, but COVID continues to circulate globally. The success of Xocova will depend on whether physicians and patients embrace post-exposure treatment as a routine part of managing the virus, or whether most people continue to rely on vaccination, natural immunity, and time.

Either way, the FDA’s decision opens an entirely new category of COVID prevention in the United States.

This article is general business and healthcare reporting and should not be considered medical advice. Individuals should consult a qualified healthcare professional regarding treatment options.

JBizNews Desk — Health Care

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
SpaceX confirmed on Thursday, June 11, that it had priced what the company described as the largest stock sale in history — approximately 555.6 million shares at $135 each, raising about $75 billion. While investors around the world rushed to participate, many investors in mainland China and Hong Kong found themselves locked out of the offering due to U.S. export-control restrictions tied to defense-related technology.

Rather than buying SpaceX directly, many investors across Asia have turned to an alternative strategy: purchasing shares of publicly traded suppliers, satellite component manufacturers, and investment funds that already hold private stakes in the company.

The company, led by Elon Musk, is expected to begin trading on the Nasdaq under the ticker SPCX on Friday at a valuation of roughly $1.75 trillion. Underwriters also hold an option to purchase an additional 83.3 million shares. The offering surpasses the previous record established by Saudi Aramco’s 2019 IPO.

Restrictions reportedly went beyond simply rejecting orders. Access to SpaceX’s website and IPO marketing materials was blocked in mainland China and Hong Kong, preventing many investors from reviewing offering documents or participating directly.

One of those investors was Hu Xiaobin, a retail trader from China’s Anhui province. Anticipating growing interest in the company, he spent months purchasing shares of Chinese-listed companies connected to SpaceX’s supply chain.

Among his holdings were Sunway Communication, which manufactures components used in Starlink ground terminals, and Western Superconducting Technologies, a producer of specialty metals used in aerospace applications.

Hu later sold both positions before the IPO, describing the trade as successful “value speculation.”

One of the biggest beneficiaries of investor enthusiasm has been Lens Technology, a Shenzhen-listed supplier known for working with Apple and Tesla. The company’s stock has surged nearly 50% this year, reaching record highs after identifying commercial space as a new growth opportunity.

Interest intensified further in May when company chairman Zhou Qunfei was photographed seated between Apple CEO Tim Cook and Elon Musk during a Beijing banquet held to welcome President Donald Trump, fueling speculation about future business opportunities involving Musk’s companies.

Taiwan has also emerged as a major focus for investors seeking indirect exposure to SpaceX.

The island produces many of the electronic components used in satellite systems. Companies including Chin-Poon Industrial, Wistron NeWeb, and Universal Microwave Technology have publicly stated that they supply SpaceX.

According to Jeffrey Chan, a director at Hong Kong-based Central Asset Management, investors are also watching Compeq, Tong Hsing Electronic, Kinpo, and Japan’s Meiko Electronics as potential beneficiaries of SpaceX’s future growth.

“For local retail investors, getting a direct piece of the IPO book is going to be incredibly tough,” Chan said, adding that he expects SpaceX to become a core holding for many global growth-oriented funds.

Investor interest has expanded beyond suppliers.

The Tema Space Innovators ETF, which owns a small pre-IPO stake in SpaceX, has gained approximately 29% since launching in March. Meanwhile, the Tradr 2x Fly Long Daily ETF, which offers leveraged exposure to space company Firefly Aerospace, has attracted significant attention from traders.

In Europe, satellite companies including Eutelsat of France, OHB of Germany, and SES of Luxembourg have all posted strong gains this year as investors seek exposure to the broader commercial-space sector.

Not everyone believes the rally is sustainable.

Nicholas Smith, Japan strategist at brokerage CLSA, said much of the recent buying appears to be driven by retail investors rather than large institutions.

“It’s a great story if you’re a trader,” Smith said. “But I doubt people would be making big bets on this.”

Others see genuine long-term opportunity.

Nick Wilcox, managing director at Man Group, believes the capital raised through the offering could translate into increased spending throughout SpaceX’s supplier network.

“There is a raft of Asian companies that will be highly benefiting from that,” Wilcox said.

Still, analysts caution that many supplier stocks have already risen sharply on expectations that may not materialize. Thinly traded aerospace and satellite suppliers can be highly volatile, and future business relationships remain uncertain.

For investors in mainland China and Hong Kong, however, the irony remains clear: the company they most want to own is the one they still cannot directly buy.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The new chairman of the Federal Reserve, Kevin Warsh, is signaling that he plans to fight inflation in a fundamentally different way than many of his predecessors, a shift that could reshape interest rates, mortgages, business borrowing, and savings returns for millions of Americans. Warsh, himself a former Fed governor, laid out the case in testimony before the Senate Banking Committee on April 21, calling for a new framework to address persistent inflation and a different approach to communicating monetary policy.

The timing could hardly be more important. On Wednesday, June 10, the Bureau of Labor Statistics reported that consumer prices rose 4.2% over the past year, the fastest pace in three years. The report arrives just days before the Federal Reserve’s next policy meeting on June 16–17, where officials will decide whether interest rates should remain unchanged, move higher, or eventually begin to fall.

At the center of Warsh’s thinking is a belief that artificial intelligence may significantly alter how inflation behaves. Warsh has repeatedly argued that AI could become one of the most powerful productivity-enhancing technologies in modern history. Greater productivity allows businesses to produce more goods and services without proportionally increasing costs, potentially easing inflationary pressures while supporting economic growth.

In practical terms, Warsh believes the economy may be capable of growing faster than traditional models suggest without automatically triggering higher inflation. If productivity rises sharply because of AI adoption, businesses may be able to absorb costs more efficiently, potentially reducing the need for aggressive interest-rate increases.

That view challenges decades of Federal Reserve orthodoxy. Traditional economic models often assume that when unemployment falls too low and economic activity accelerates, inflation eventually rises. Under that framework, the Fed frequently raises rates to cool demand and prevent prices from climbing too quickly.

Warsh has suggested that relationship may be weaker than many economists assume. Rather than focusing primarily on historical relationships between growth and inflation, he has emphasized productivity, innovation, investment, and supply-side improvements as important drivers of price stability.

He has also criticized what he sees as excessive reliance on backward-looking economic data. Government reports often arrive weeks or months after underlying economic activity occurs. Warsh has argued that policymakers should pay closer attention to real-time developments in business investment, technological adoption, and productivity trends.

Beyond inflation policy, Warsh has advocated broader changes at the central bank. He has called for a more aggressive reduction of the Fed’s balance sheet, which still contains trillions of dollars in assets accumulated during years of quantitative easing. He has also suggested that the Federal Reserve should simplify how it communicates with markets and focus more narrowly on its core economic responsibilities.

Supporters argue that these changes could restore credibility to an institution that faced criticism for initially underestimating the inflation surge that followed the pandemic-era economic recovery.

The challenge for Warsh is that current economic conditions are testing his framework. While AI may eventually boost productivity, inflation today is being driven by more immediate factors, including higher energy costs, supply disruptions, and geopolitical uncertainty.

As a result, the Federal Reserve faces a difficult balancing act. Cutting rates too quickly could risk reigniting inflation, while keeping rates elevated for too long could slow economic growth and increase borrowing costs for households and businesses.

Several former Federal Reserve officials have noted that institutional realities may limit how dramatically policy changes. Dennis Lockhart, former president of the Federal Reserve Bank of Atlanta, has suggested that regardless of personal philosophy, any Fed chair ultimately must respond to incoming economic data. Loretta Mester, former president of the Federal Reserve Bank of Cleveland, has similarly emphasized the importance of building consensus among policymakers.

For consumers, the outcome matters directly. Mortgage rates, auto loans, business lending, and savings yields are all influenced by Federal Reserve policy. A more growth-oriented approach could eventually lower borrowing costs and stimulate investment. A more cautious approach could keep rates elevated in an effort to prevent inflation from becoming entrenched.

The upcoming Federal Reserve meeting may provide the first significant indication of how Warsh intends to navigate that challenge. Investors, businesses, and consumers will be watching closely to see whether the new chairman emphasizes productivity-driven optimism or maintains a more traditional focus on inflation risks.

Either way, the decisions made over the coming months will have consequences far beyond Wall Street, influencing everything from home purchases and business expansion plans to retirement savings and household budgets.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
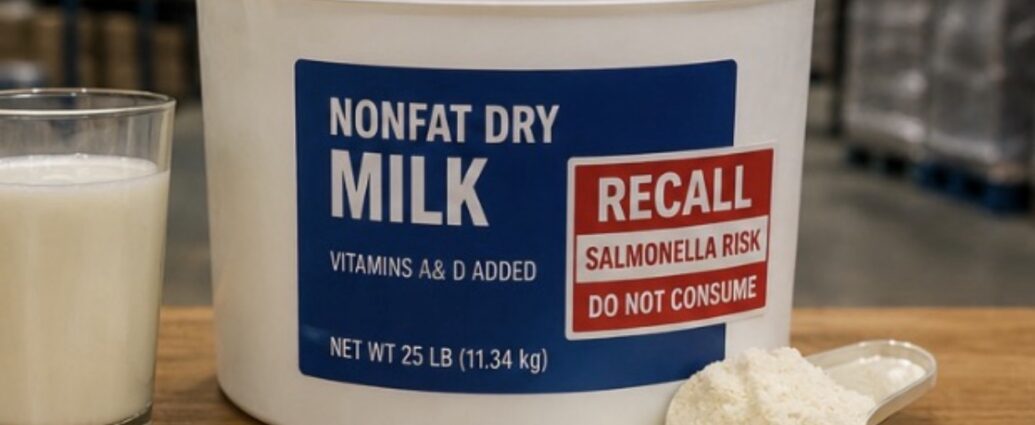
WASHINGTON, June 11 — A food-safety issue that began with bulk powdered milk continues to spread through the food supply chain as additional products made with the recalled ingredient are removed from store shelves.

The original recall began on April 20, 2026, when California Dairies Inc. voluntarily recalled large quantities of powdered milk and buttermilk powder due to potential Salmonella contamination, according to the U.S. Food and Drug Administration.

Since then, the FDA has continued tracing products that used the ingredient, leading to additional recalls involving downstream manufacturers.

Millions of Pounds Recalled

The original action involved approximately 2.68 million pounds of low-heat nonfat dry milk and an additional 19,841 pounds of buttermilk powder.

Because the ingredients were sold primarily to manufacturers and distributors rather than directly to consumers, the contamination concern quickly spread throughout the food production system.

Companies that purchased the ingredients incorporated them into a variety of products or repackaged them under separate brand names.

As a result, the list of affected products continues to expand.

FDA Issues Highest Warning Level

The recall received a Class I designation, the FDA’s most serious recall classification.

A Class I recall indicates a reasonable probability that exposure to the product could cause serious health consequences or death.

Salmonella infections can produce fever, diarrhea, abdominal cramps, and severe illness.

According to the Centers for Disease Control and Prevention, Salmonella causes approximately 1.35 million infections, 26,500 hospitalizations, and 420 deaths annually in the United States.

Young children, older adults, and people with weakened immune systems face the greatest risk.

Hidden Ingredient Creates Challenges

Powdered milk appears in far more products than many consumers realize.

It is commonly used in baking mixes, snack foods, soups, sauces, chocolate products, processed foods, and numerous packaged goods.

That widespread use makes recalls involving powdered milk particularly difficult to contain.

A single contaminated ingredient can affect dozens of brands and manufacturers across the country.

What Consumers Should Do

Consumers are encouraged to review current FDA recall notices and compare affected lot numbers and product codes with items in their homes.

Products included in recall notices should be discarded or returned according to manufacturer instructions.

Because additional products may continue to be identified, food-safety experts recommend periodically checking updated FDA recall lists.

Supply Chain Lessons

The case highlights how interconnected modern food production has become.

A single supplier can provide ingredients to numerous manufacturers, distributors, and retailers nationwide.

When contamination occurs, recalls often extend far beyond the original company.

Industry experts say the incident demonstrates the importance of traceability systems that allow regulators and manufacturers to quickly identify where affected ingredients were used.

Those systems help limit public exposure and reduce the scope of food-safety incidents.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK, June 11 — Gold prices continued their sharp decline on Thursday, June 11, falling to their lowest levels in roughly six to seven months despite rising inflation and escalating conflict in the Middle East.

Spot gold traded near $4,100 per ounce, down more than 10% over the past month, even as investors confront war concerns, higher energy costs, and renewed inflation pressures.

Ordinarily, those conditions would support demand for gold as a traditional safe-haven asset.

Instead, investors are increasingly focused on the prospect of higher interest rates.

Higher Rates Weigh on Gold

The conflict with Iran and disruptions around the Strait of Hormuz have pushed oil and gasoline prices sharply higher, fueling inflation concerns.

At the same time, investors increasingly believe the Federal Reserve may keep rates elevated for longer—or potentially raise them further—to contain rising prices.

That expectation has strengthened the U.S. dollar and boosted Treasury yields.

The U.S. Dollar Index climbed to its strongest level since April, while the yield on the benchmark 10-year Treasury note moved above 4.50%.

Because gold pays no interest, it often struggles when bonds and cash offer higher returns.

As interest-bearing investments become more attractive, some investors shift money away from precious metals.

Silver has faced similar pressure, falling sharply alongside gold.

Central Banks Continue Buying

The decline comes despite continued demand from global central banks.

Central banks purchased approximately 244 metric tons of gold during the first quarter of 2026, continuing a multi-year trend of diversification away from the U.S. dollar.

Demand for physical gold bars also increased earlier in the year, although jewelry demand weakened in major markets including India and China.

Those purchases have helped support prices but have not been enough to reverse the broader selloff.

Long-Term Bullish Factors Remain

Supporters of gold point to several longer-term trends.

U.S. federal debt now exceeds $37 trillion, while annual interest payments have surpassed $1 trillion.

Meanwhile, central banks have remained net buyers of gold for four consecutive years.

Historically, those conditions have supported long-term demand for precious metals.

The challenge for gold today is the behavior of so-called real yields—the return investors receive after accounting for inflation.

When interest rates rise faster than inflation expectations, gold becomes less attractive relative to bonds and cash.

Global Central Banks Tighten

Adding to pressure on precious metals, the European Central Bank raised its benchmark interest rate by 0.25 percentage points on Thursday, bringing the rate to 2.25%.

The ECB also increased its inflation forecasts, citing higher energy costs and economic uncertainty linked to the Middle East conflict.

Higher interest rates globally create additional headwinds for gold markets.

Federal Reserve Now Holds the Key

Attention now turns to the Federal Reserve’s upcoming June meeting.

Investors are closely watching for guidance from Chair Kevin Warsh and updated projections showing where policymakers believe rates are headed.

Markets largely expect rates to remain unchanged this month.

The larger question is whether officials signal further tightening later this year.

A more aggressive outlook could pressure gold further, while indications that rates may stabilize could support a rebound.

For many investors, the recent decline serves as a reminder that gold is not always a straightforward inflation hedge.

In the short term, interest-rate expectations often matter more than inflation itself.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON, June 11 — Wholesale prices in the United States rose far faster than expected in May, the Bureau of Labor Statistics reported on Thursday, June 11, adding to evidence that inflation is heating up as higher energy costs ripple through the economy.

The Producer Price Index (PPI), which measures prices received by producers before those costs reach consumers, climbed 1.1% in May, pushing the annual rate to 6.5%, the highest reading since November 2022.

The increase came in well above economists’ forecasts. Analysts surveyed by Dow Jones had expected a 0.7% monthly increase, while FactSet economists projected 0.6% and a 6.4% annual rate. Instead, wholesale inflation matched April’s elevated pace, signaling that price pressures remain stubbornly strong.

Energy Drives the Increase

Most of the increase came from goods prices.

Final-demand goods prices jumped 2.8% during the month, the largest increase since the current data series began in December 2009. According to the Bureau of Labor Statistics, goods accounted for nearly four-fifths of the overall monthly increase.

Energy prices were the primary driver.

Wholesale energy prices surged 10.7%, while wholesale gasoline prices jumped 23.4% in May.

The increase followed ongoing disruptions in global energy markets tied to the conflict with Iran and reduced shipping flows through the Strait of Hormuz, a key artery for global oil transportation.

Inflation Remains Broad-Based

Even after removing volatile food and energy prices, inflation remained elevated.

Core producer prices rose 0.4% during the month.

A broader measure excluding food, energy, and trade services climbed 0.8%, marking the largest monthly increase since March 2022. On a year-over-year basis, that measure increased 5.1%, the highest level since October 2022.

Among services, portfolio management fees increased 4.8%.

Food prices rose 0.6%, more than double April’s pace, although some categories declined, including pork prices, which fell 10.1%.

Pressure Building Earlier in the Supply Chain

Further upstream, inflation pressures were even stronger.

Prices for unprocessed goods used in early-stage production increased 4.9% during May and were up 22.2% from a year earlier — the largest annual increase since September 2022.

Much of that increase was driven by an 11.8% jump in crude petroleum prices.

One notable exception was natural gas, where prices fell 18.2% during the month.

Why It Matters to Consumers

The report arrives one day after the Bureau of Labor Statistics reported that consumer inflation reached 4.2% annually in May, the highest level in three years.

Producer prices often serve as an early warning sign because businesses frequently pass higher costs through to consumers.

When fuel, transportation, manufacturing inputs, and raw materials become more expensive, those increases often show up weeks or months later in grocery stores, retail shelves, utility bills, and household budgets.

Small businesses may face particularly difficult choices as margins tighten, forcing owners to absorb higher costs or pass them on to customers.

Federal Reserve Faces Growing Pressure

The report also complicates the outlook for the Federal Reserve.

At the start of the year, financial markets expected multiple interest-rate cuts. Persistent inflation has dramatically altered those expectations.

The Federal Reserve’s next meeting is scheduled for June 16–17 and will be the first chaired by Kevin Warsh. Policymakers are expected to release updated economic projections and interest-rate forecasts.

While markets see little chance of an immediate rate move, futures traders increasingly expect the possibility of another rate increase before year-end.

Higher interest rates would raise borrowing costs for consumers and businesses while inflation remains elevated, creating additional pressure on household budgets and economic growth.

The next Producer Price Index report is scheduled for July 15.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The clearest picture of how artificial intelligence is reshaping work in Asia can be found in India’s vast technology industry, where hiring has slowed to its weakest pace in more than two years. According to staffing data firm Xpheno, whose figures were reported during the week of June 8, entry-level job openings across India’s IT sector have fallen 44% from a year earlier, while senior-level postings are down 67%.

The numbers from India’s biggest employers tell the same story. Tata Consultancy Services made 25,000 job offers to new graduates last month, and Infosys is expected to hire about 20,000 in the coming year. Those figures sound large, but they are well below previous levels. Tata Consultancy Services hired more than 40,000 new graduates annually during each of the previous three years. Direct campus hiring across the industry now runs roughly 30% to 35% below historical levels.

What makes this shift striking is that the companies are not shrinking. They are growing output while holding headcount flat or reducing it. Tata Consultancy Services shed a net 13,249 employees in one recent fiscal year even as revenue continued rising, while Infosys recorded the largest annual headcount decline in its history, a 5.9% decrease. Neither company attributes the trend solely to AI, but the pattern is increasingly difficult to ignore: more work, fewer people.

The stakes are enormous because of the industry’s scale. India’s technology and business-process sector generated approximately $254 billion in revenue and employed 5.4 million people, according to NASSCOM. For decades, the sector thrived by providing skilled labor to multinational corporations. Artificial intelligence is now challenging that model.

The jobs facing the greatest pressure are the very positions that launched millions of careers: entry-level coding, software testing, routine customer support, and back-office processing. These roles absorbed vast numbers of graduates each year and helped build India’s middle class. AI tools increasingly perform many of those tasks, reducing the need for large numbers of entry-level workers. Recruiters describe a growing shift toward just-in-time hiring, where employees are added only when projects require them rather than being kept on large reserve benches.

The transformation is not limited to India. Across Asia’s major financial centers, AI is moving rapidly from pilot projects to everyday operations. In Hong Kong, a 2026 KPMG employment survey found that 24% of organizations are now widely deploying AI, triple the level reported a year earlier. KPMG identified AI literacy and practical AI application as the most valuable skills employees can possess. At the same time, more employers expect to reduce headcount than increase it, reflecting one of the most cautious hiring outlooks in recent years.

For workers with the right skills, however, the technology is creating opportunities. Research published in January by UNICEF Innocenti found that AI-related job postings across South Asia continue to rise and offer salaries roughly 30% higher than comparable white-collar positions. Workers who understand how to leverage AI are seeing measurable gains in earnings and productivity. The concern is that those gains may not be shared equally.

Researchers increasingly warn of a more divided labor market, where highly skilled workers benefit from higher pay and greater demand while workers performing routine tasks face fewer opportunities. The challenge is not merely job displacement but widening inequality between those who can effectively use AI and those who cannot.

The World Bank, in its recent report on East Asia and the Pacific, offered a more optimistic long-term perspective. Historically, new technologies have expanded employment overall by increasing productivity and creating new industries. However, the benefits have tended to flow disproportionately to skilled workers, while some less-skilled workers have been pushed into more informal and less secure forms of employment.

There is also an augmentation story unfolding alongside the displacement narrative. Microsoft’s 2026 Work Trend Index, which surveyed 20,000 AI users across ten countries, found that most respondents reported higher productivity, and a majority said AI enabled them to produce work they could not have completed just a year earlier. In many cases, AI is changing how work is performed rather than simply eliminating jobs.

For businesses, the implications are substantial. Investors are increasingly distinguishing between companies that are building AI-driven products and services and those that continue to rely primarily on selling human labor. The valuation gap between those models is expected to widen.

Governments are responding as well. India’s Karnataka state, home to Bangalore, is offering incentives aimed at doubling the number of multinational global capability centers operating there to 1,000 by 2029. These centers are expected to create higher-value jobs, though they are unlikely to absorb the vast numbers of graduates that the traditional outsourcing model once employed.

The broader trend across Asia is becoming clear. Artificial intelligence is increasing productivity, boosting wages for workers who master it, and raising the skill requirements for new entrants. For a region that built much of its modern economic success on abundant, affordable, educated labor, that represents one of the most significant workplace shifts in decades.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
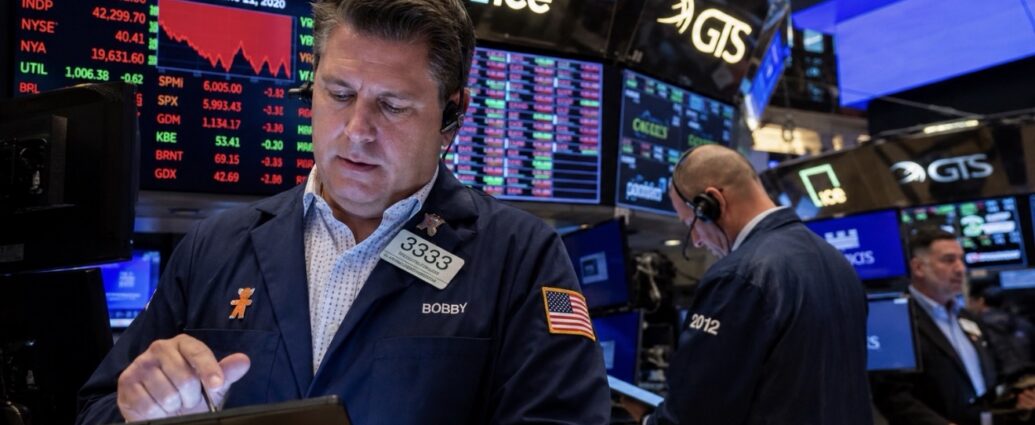
U.S. stocks rallied hard on Thursday, June 11, shaking off a hot inflation report from the U.S. Bureau of Labor Statistics and fresh military action against Iran to close sharply higher.

The Dow Jones Industrial Average jumped 929 points, or 1.87%, to 50,848.38, climbing back above the 50,000 mark. The S&P 500 rose 1.74% to about 7,393, just shy of 7,400. The Nasdaq Composite gained 2.53% to roughly 25,806, and the small-cap Russell 2000 led everything with a 3.06% surge.

Tech, industrials, and materials drove the move, while energy, consumer staples, and real estate lagged.

Inflation Runs Hot

The rally was striking because the morning’s economic news was not good.

The Bureau of Labor Statistics reported that the Producer Price Index (PPI), which tracks wholesale prices, rose 1.1% in May, well above the 0.7% economists expected. The core reading, which strips out food and energy, rose 0.4%.

On an annual basis, wholesale inflation hit 6.5%, the fastest pace in nearly four years.

It landed a day after consumer prices were reported at a three-year high of 4.2%.

Hot inflation usually pushes the Federal Reserve away from cutting interest rates, and futures markets now lean toward a possible rate hike this year rather than the cuts investors expected in January.

Iran Deal Hopes Trump War Fears

So why did stocks climb?

The answer was Iran.

Even as explosions were reported across the country near the Strait of Hormuz and the United States carried out renewed strikes, Iranian officials signaled that a deal with Washington is close.

That hope for de-escalation outweighed the fighting itself, and traders bought the dip from Wednesday’s steep selloff.

SpaceX Becomes Wall Street’s Main Event

The bigger draw was SpaceX.

Elon Musk’s rocket company is set to make its stock-market debut on Friday on the Nasdaq under the ticker SPCX, in what is expected to be the largest IPO in history.

According to people familiar with the offering, investor demand has topped $250 billion — roughly three-and-a-half to four times the company’s planned $75 billion target.

The size has some investors worried the debut could pull money out of other stocks.

Musk is also expected to appear virtually at an ASML event to discuss Terafab, a planned chipmaking plant intended to supply Tesla and SpaceX.

Oracle Falls Despite Beating Expectations

The day’s biggest single-stock story was Oracle, which fell about 12% even though its results beat expectations.

The software giant reported fiscal fourth-quarter revenue of $19.18 billion, ahead of the roughly $19 billion Wall Street expected, with adjusted earnings of $2.11 per share versus estimates near $1.89.

What spooked investors was the spending.

Oracle said its total outlays reached $55.7 billion in fiscal 2026, above the $50 billion expected, and guided capital spending for fiscal 2027 to roughly $95 billion — about 40% higher than the $67.7 billion analysts had modeled.

The company said it plans to raise nearly $40 billion through debt and equity next year, including a previously announced $20 billion stock offering, to fund its artificial-intelligence buildout.

Oracle has signed major data-center deals with Meta Platforms and OpenAI as it pushes to compete with cloud leaders Amazon and Microsoft.

Chip Stocks Stage a Comeback

Chip stocks, which had been hammered in recent weeks, came roaring back.

Intel jumped about 10%, while Applied Materials and Arm Holdings each rose close to 8%.

On the losing side, GoDaddy slipped 2.5% and Axon Enterprise fell 2.2%.

Eyes Turn to Adobe, Lennar and RH

After the closing bell, attention turned to Adobe, which reported fiscal second-quarter results.

Wall Street looked for earnings near $5.82 per share on revenue of about $6.46 billion.

Adobe shares have fallen roughly 28% this year on fears that new AI design tools could eat into its business.

Ahead of the print, RBC Capital maintained an Outperform rating with a $350 price target, while Mizuho held a Neutral view, citing limited near-term catalysts.

Homebuilder Lennar and luxury retailer RH also reported after the close, giving investors a read on housing and high-end consumer spending.

Job Market Shows a Crack

There was one more soft spot in the data.

The Labor Department said new claims for unemployment benefits totaled 229,000 in the week ending June 6, above forecasts, a small sign of cooling in the job market even as inflation runs hot — a difficult mix for the Federal Reserve to manage.

Looking Ahead

For one day, hope for an Iran deal and excitement over SpaceX won out over rising prices and war headlines.

The real test comes Friday, when SpaceX starts trading and Wall Street finds out whether the biggest IPO ever can hold up a market that has been swinging hundreds of points a day.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
President Donald Trump said Wednesday, June 10, that the U.S. military has been quietly helping oil tankers move through the Strait of Hormuz, claiming that more than 100 million barrels of oil and over 200 commercial ships have passed safely through the contested waterway. He disclosed the operation in remarks to reporters in the Oval Office and in a post on his Truth Social platform.

Trump said he directed the military last month to carry out what he described as a secret mission to support oil tankers and other commercial vessels navigating the strait, the narrow channel between Iran and Oman that has been largely disrupted since the war began.

“This wildly successful effort is because the UNITED STATES OF AMERICA CONTROLS the Strait of Hormuz — NOT Iran,” Trump wrote, adding that Iran’s military has been weakened and its economy is under severe strain.

The president tied the operation directly to energy prices. He argued that the continued movement of oil through the region helped keep crude prices near $90 per barrel rather than surging above $200, a level some analysts have warned could occur if the strait were completely shut.

That economic angle is the heart of why this matters to ordinary Americans.

The Strait of Hormuz is one of the most important oil routes in the world. Before the conflict escalated, roughly 20 million barrels of oil per day flowed through the waterway, representing about one-fifth of global petroleum supply. Any disruption quickly affects fuel markets, shipping costs, airline expenses, manufacturing, and ultimately consumer prices.

When traffic through the strait became constrained, oil prices climbed and gasoline costs followed. Those higher energy expenses have filtered into transportation, food distribution, and retail supply chains across the economy.

Anything that restores even part of that flow can help reduce pressure.

Still, the picture is more complicated than the president’s description suggests.

Commercial traffic through Hormuz remains significantly below pre-war levels. Independent energy analysts note that global markets are still missing substantial volumes of oil that would normally transit the route. Industry estimates indicate that billions of barrels of expected shipments have been delayed or rerouted since the conflict began.

There is, however, some evidence that more oil may be moving through the region than publicly reported.

A recent JPMorgan analysis suggested that a meaningful volume of crude may still be exiting the Gulf through vessels operating with limited public tracking visibility. Analysts noted that oil exports appear higher than official shipping traffic alone would suggest.

At those estimated rates, Trump’s claimed totals fall within a range that analysts consider plausible, though still far below normal peacetime volumes.

Administration officials have also hinted at improving conditions.

Energy Secretary Chris Wright said earlier this week that oil exports moving through Hormuz are “rising very meaningfully,” though he did not provide specific figures.

Meanwhile, ships that had been stranded inside the Persian Gulf have gradually resumed movement through the corridor amid ongoing coordination with U.S. military forces.

Exactly what role the military is playing remains somewhat unclear.

Earlier this year, Trump announced a mission known as Project Freedom, intended to assist commercial vessels affected by the conflict. Administration officials later indicated that U.S. forces were not formally escorting ships but were providing communications support, intelligence, monitoring, and defensive protection against attacks.

U.S. Central Command has stated that American forces are working to protect commercial shipping from drone, missile, and maritime threats in the region.

Secretary of State Marco Rubio recently told lawmakers that the United States has responded to Iranian attacks targeting commercial vessels. He warned that drone strikes against civilian ships pose significant environmental and economic risks and said U.S. forces respond when commercial traffic comes under attack.

For businesses and consumers, the implications are significant.

If more oil is successfully reaching global markets, it helps explain why crude prices have remained elevated but have not exploded to the levels many feared earlier this year. That stability benefits airlines, trucking companies, manufacturers, retailers, and families facing higher fuel bills.

Gasoline prices remain well above pre-conflict levels, and inflation pressures tied to energy costs continue to affect household budgets. Any improvement in oil flows therefore has direct consequences for the broader economy.

The conflict, however, remains unresolved, and the Strait of Hormuz is still operating far below normal capacity.

Energy forecasters continue to expect elevated oil prices through much of the year unless shipping conditions improve substantially.

Trump’s announcement signals that the administration believes its efforts are helping keep energy supplies moving despite the conflict. Whether that translates into sustained relief at the gas pump will depend on how much oil is truly flowing and how long the disruption lasts.

JBizNews Desk — Energy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

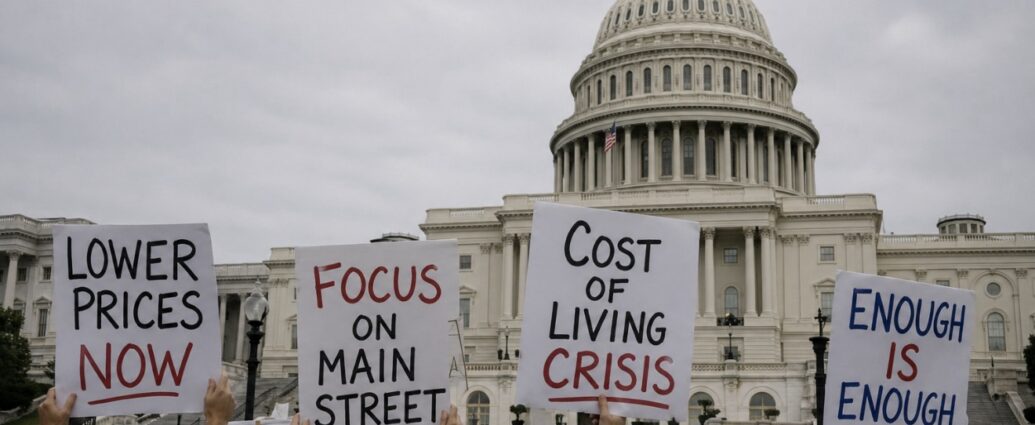
Americans’ mood about money has hit a record low. In late May, the University of Michigan reported that its consumer sentiment index fell to 44.8 — the lowest reading in the survey’s history. The survey’s director, Joanne Hsu, said the cost of living was the top concern, with 57% of people naming high prices as the reason their finances feel worse. It was the third straight month of decline.

That is not a Wall Street number. That is a kitchen-table number, and it is flashing red.

This is not a slow drift. The struggle is surging.

A survey released in February by The Century Foundation found that more than one in three Americans (34%) had skipped a meal in the past year to save money, up from one in four just months earlier. That is how fast this is moving. Families are not only skipping meals; they are skipping doctor visits and going without medication.

People are not trimming the fat anymore. They are cutting into the bone.

It shows up at the most basic place a family spends money. A CNN poll in late May found that 61% of Americans had cut back on groceries to stay within budget, and 59% had cut back on extras and entertainment. When a majority of the country is buying less food, that is not a soft patch.

That is a warning siren.

So people take on more work just to stand still. The Bureau of Labor Statistics reported that the number of Americans holding more than one job hit roughly 9.3 million in November 2025 — the most ever recorded since the government began tracking it in 1994. Half of those workers hold a college degree.

A second job used to be how you got ahead. For millions of families, it is now how you keep the lights on.

The math behind it is brutal. Over the past five years, housing costs climbed about 28% while wages rose around 24%. Grocery prices jumped 0.7% in a single month in April, according to the Bureau of Labor Statistics — the biggest monthly increase in nearly four years. Gas has pushed above $4.50 a gallon, according to AAA.

And the middle class itself is shrinking. Pew Research Center found the share of Americans in middle-class households fell from 61% in 1971 to 51% by 2023. The backbone of the country is getting thinner every decade.

The split is now extreme.

Mark Zandi, chief economist at Moody’s Analytics, found that the top 10% of earners account for about 49.2% of all consumer spending — the highest share since records began in 1989. Everyone in the bottom 80%, earning under roughly $175,000, has seen their spending barely keep pace with inflation.

An economy carried by the richest tenth is not strong. It is top-heavy, and one nervous quarter from those households would shake the whole thing.

Now look at where Washington’s energy is going.

The administration is consumed by the world stage — the war with Iran, the Strait of Hormuz, ceasefire diplomacy, oil, and trade fights stretching across continents. Those matters are real, and leaders have to manage them. But a government cannot run on foreign policy alone.

While the White House looks overseas, the family back home watching its grocery bill climb is getting silence. Diplomacy in the Gulf does not put food on a table in Ohio.

And here is the quiet failure almost no one is talking about.

The federal government employs offices and officials whose entire job is to help these families — appointees placed at agencies built to support small businesses, workers, and communities. Too many of them are missing in action.

The programs exist. The doors are shut. Emails from the community go unanswered. Outreach from business leaders goes unanswered. Even letters from members of the Senate and Congress go unanswered.

People hired and sworn to serve the public have simply gone quiet, and the help meant for Main Street never leaves the building.

It does not have to be this way, and we have proven it.

As one example, in April 2024, the Orthodox Jewish Chamber of Commerce convened the first National Chambers of Commerce Leaders Roundtable inside the U.S. Department of Commerce, putting chamber leaders from around the country face-to-face with federal officials who rarely meet Main Street.

It worked, and the government said so in writing.

In a letter dated December 9, 2024, then-Deputy Secretary of Commerce Don Graves credited the chamber’s initiative and said it stimulated economic growth from the grassroots level.

And yet the new administration has repeatedly promised engagement while postponing it again and again. That is what bottom-up engagement looks like when officials actually engage, show up, and work alongside the boots-on-the-ground business and community leaders who understand these challenges best. The Department of Commerce itself recognized the value of this approach. The initiative was intended to continue bringing together chamber leaders and federal officials to strengthen economic growth from the grassroots level, but despite repeated commitments, efforts to continue hosting and expanding this initiative have been pushed off time and again.

It has been promised since and left to sit idle.

A December 9, 2024 letter from then–Deputy Secretary of Commerce Don Graves praised the Chamber’s grassroots economic-growth initiative and urged its continuation.

Here is what Washington should understand: this has not gone unnoticed.

The American people see exactly where the attention is going, and where it is not. The record-low mood is the receipt. The skipped meals are the receipt. The second jobs are the receipt.

Voters of every party are watching a government that has time for every capital in the world but no time for their kitchen table.

So the demand is plain.

Refocus.

Balance the global agenda with the home front. Make every agency answer the mail. Hold appointees accountable when they go missing, and replace those who refuse to do the job they were given.

Forgetting the middle class is not smart, and it will not be rewarding.

A family skipping meals and working two jobs remembers who showed up and who disappeared. That memory does not fade by Election Day.

Washington can see the middle class now — or be reminded at the polls that it looked away.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Heavy spending on artificial intelligence could widen economic outcomes and hit lower-quality loans, the firm says.

One of the world’s largest bond investors is warning that a painful stretch of loan defaults has begun, and that the enormous sums companies are borrowing to build artificial intelligence are making it worse. Pacific Investment Management Co. (Pimco) laid out the warning on Wednesday, June 10, in its latest annual long-term outlook report.

The message was blunt.

“The default cycle is reasserting itself, and we expect significantly higher losses in lower-quality credit such as leveraged and private direct lending,” wrote Daniel Ivascyn, the firm’s chief investment officer, along with colleagues Richard Clarida and Andrew Balls. The firm said plainly that “the credit loss cycle is upon us.”

This is not a minor voice. Pimco manages approximately $2.3 trillion in assets, making it one of the largest fixed-income investors in the world. When a firm that size says losses are coming, lenders and investors listen.

To understand the warning, it helps to define the terms. Leveraged loans are loans made to companies that already carry heavy debt. Private direct lending, often called private credit, is when investment funds rather than banks lend money directly to mid-sized businesses. Both areas have ballooned over the past decade as investors chased higher returns, and Pimco says underwriting standards loosened along the way.

In other words, lenders got less careful about who they handed money to.

Now the bill is starting to come due. Pimco expects those weaker corners of the market to face a wave of defaults as companies struggle to keep up with their debts.

The artificial intelligence boom is a central part of the story, and not in the way most headlines frame it. Pimco estimates that AI-related debt issuance is running at roughly $100 billion every quarter. The companies building the massive data centers behind AI are increasingly financing those projects with borrowed money rather than cash on hand. Capital spending is surging while free cash flow moves in the opposite direction.

Pimco’s view is that this buildout could widen the gap between winners and losers over the next several years, leaving weaker, more heavily indebted borrowers exposed.

There is a warning sign that most people are missing, according to Pimco.

Official high-yield default rates have hovered around their long-run average of roughly 4%, a number that looks calm on the surface. Ivascyn argues that figure is misleading. He points to what the firm calls “shadow defaults,” where a struggling borrower quietly renegotiates or amends its loan terms to avoid an official default. The trouble never shows up in the headline statistics, but the company is still in distress.

Another red flag is the growing use of payment-in-kind financing, where a borrower pays interest with additional debt instead of cash. It is the financial equivalent of paying one credit card with another. It buys time, but it also increases the eventual burden.

Pimco also flags a striking disconnect. Credit spreads—the extra interest investors demand to hold risky debt instead of U.S. Treasury securities—remain near historically low levels. On the surface, that looks like confidence. Underneath, Pimco frames it as complacency, with investors getting paid very little to take on rising risk.

The firm is careful to note that this is not a repeat of the early-2000s telecom bust, when companies borrowed aggressively to lay fiber-optic networks that later went underused. Today’s AI financing is more disciplined, Pimco says, and the opportunity in AI-related lending is real.

But only for investors who can tell the difference between well-funded borrowers with genuine revenue and overleveraged operators chasing the hype.

The everyday stakes are larger than they might seem. Pension funds, insurance companies, university endowments, and retirement accounts have poured money into private credit over the past decade, attracted by higher yields and steady payouts. A wave of defaults would reduce those returns.

The borrowers most at risk are often smaller and mid-sized businesses that depend on private lenders for capital. Those same firms are also facing higher financing costs, elevated energy prices, and ongoing economic uncertainty. If lending conditions tighten, many could scale back hiring, delay expansion plans, or reduce investment, creating ripple effects throughout local economies.

For now, Pimco says the risk of a broad financial crisis remains low. This is not a 2008-style financial meltdown in the making. Instead, the firm sees a slower grind of mounting losses concentrated among the weakest borrowers and the most aggressive lenders.

Its recommendation is straightforward: favor higher-quality credit, maintain discipline, and pay close attention to who is on the other side of every loan.

The broader lesson lands at the center of today’s AI debate. The technology’s promise may be real, but the money funding much of the buildout is increasingly borrowed. Pimco’s warning is that not every borrower participating in the boom will be able to pay it back.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The federal government’s energy forecasters expect fuel prices to climb sharply this year as the war with Iran keeps oil from flowing freely through the world’s most important shipping lane. The U.S. Energy Information Administration laid out the outlook in its monthly Short-Term Energy Outlook, released June 9.

The agency expects the global oil benchmark, Brent crude, to average around $105 a barrel through June and July, assuming the Strait of Hormuz stays largely closed to shipping in the near term. It projects the wholesale price of gasoline will rise by about 50% in 2026 compared with the agency’s pre-conflict forecast from February, with diesel and jet fuel up more than 60%.

Those are wholesale figures, the prices charged before fuel reaches the corner station, but they flow straight to the pump. Drivers have already felt it. The national average for a gallon of regular gasoline jumped well above $3 this spring as the conflict disrupted oil supplies, and the government’s forecast suggests relief is not coming soon.

The cause traces back to the Strait of Hormuz, a narrow waterway between Iran and Oman that carries roughly a fifth of the world’s oil. The agency assumes shipping through the strait stays effectively closed in the near term, with traffic only beginning to resume in the third quarter of 2026 and not returning to normal until early 2027. Until those flows recover, the world is short of oil, and shortages push prices up.

There is a path back down. Once oil moves through the strait again and producers restore output, the agency expects Brent to fall to an average of $79 a barrel in 2027. But that depends entirely on the war winding down, which remains uncertain after fresh U.S. strikes on Iran this week.

The strain is showing up in America’s emergency reserves. The Strategic Petroleum Reserve, the nation’s backup supply of crude, has been drawn down sharply since the conflict began and is heading toward its lowest level since the early 1980s. That cushion helps soften price spikes, but it cannot be drained indefinitely.

For households, the effect goes far beyond the gas tank. Energy is woven into the price of nearly everything. When fuel costs rise, it costs more to grow food, manufacture goods, and truck them to stores. That is why energy did most of the damage in this week’s inflation report. The Bureau of Labor Statistics said consumer prices rose 4.2% over the past year, the fastest in three years, and that energy alone accounted for more than 60% of the monthly increase.

Small businesses feel it acutely. Delivery companies, contractors, landscapers, and anyone who runs a fleet of vehicles watches fuel costs eat into already thin margins. Many face a hard choice between absorbing the expense or raising prices on customers who are themselves stretched. Farmers face higher costs for diesel and fertilizer, much of which is tied to energy prices, which can ripple forward into grocery bills.

The travel industry is caught too. Airlines just cut their global profit forecast in half, blaming the same jump in fuel costs. Higher pump prices also weigh on summer road trips, a staple of the warm-weather economy, as families recalculate whether the drive is worth it.

The forecast itself carries a clear caveat: it assumes the strait stays disrupted. Energy prices have been less explosive than some feared, in part because traders have found workarounds and quiet routes to keep some oil moving. But the government’s central expectation is for elevated prices to persist through the year, easing only when the conflict does.

For now, the message to consumers and business owners alike is to plan for higher fuel costs through the summer and beyond. The next monthly energy outlook is due July 7, and it will show whether the war, and the prices it is driving, are getting better or worse.

JBizNews Desk — Energy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
American employers added 172,000 jobs in May and the unemployment rate held at 4.3%, the Bureau of Labor Statistics reported Friday, June 5. The number came in well above what economists had expected and pointed to a job market that is still growing, even as one major industry keeps shedding workers.

The hiring was concentrated in a few areas. Job gains occurred in leisure and hospitality, local government, and health care, while employment in financial activities declined. The mix matters. Restaurants, hotels, hospitals, and local agencies are doing the hiring, while higher-paying office and finance roles are flat or shrinking.

The headline figure beat forecasts handily. Economists had penciled in around 85,000 new jobs, so 172,000 was more than double the estimate. Annual wage growth came in at about 3.4%, roughly in line with expectations and still ahead of where it stood a year ago.

But the report carried a clear warning underneath the strong top line. Technology companies are cutting jobs at a steady clip, and many are blaming artificial intelligence. U.S.-based employers announced 97,006 job cuts in May, about 39% of them in the technology sector, according to the outplacement firm Challenger, Gray & Christmas.

That is the tension running through the labor market right now. The broad economy keeps adding jobs in services and government, while tech firms trim their ranks and lean on automation to do more with fewer people. For now, the service-sector hiring is winning, which is why the overall numbers still look healthy. The worry is whether AI-driven cuts spread to other industries over time.

There were softer spots too. The number of long-term unemployed, those out of work for 27 weeks or more, held at 2.0 million and accounted for 27.5% of all unemployed people. That figure is up by more than half a million over the year, a sign that people who lose jobs are taking longer to find new ones. The labor force participation rate held at 61.8%.

The strong report reshaped expectations at the Federal Reserve. With hiring this solid and inflation running hot, the case for cutting interest rates this year largely evaporated. Markets now lean toward the Fed holding rates steady, with some traders betting on an increase before December. For the central bank under Chair Kevin Warsh, a sturdy job market removes any urgency to ease, especially with prices still climbing.

For everyday workers, the picture is mixed in a familiar way. If you work in services, health care, or local government, hiring is steady and your job looks secure. If you work in technology, the ground is shakier, as companies cut staff and reorganize around AI tools. And if you are unemployed and searching, the rising long-term jobless figure is a caution that landing the next role can take a while.

For employers, the report reinforces a careful, selective approach to hiring. Companies are adding workers where they need them, particularly in customer-facing and care roles that are hard to automate, while holding back in areas where software can pick up the slack. Small businesses in hospitality and health care, the very sectors that drove May’s gains, remain on the hunt for staff even as the giants of Silicon Valley downsize.

The next employment report, covering June, is scheduled for release on Thursday, July 2. It will show whether the war with Iran and the jump in energy prices have begun to dent hiring, or whether the job market’s quiet strength holds for another month.

JBizNews Desk — Labor & Employment

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The world’s airlines expect to earn roughly half as much this year as they did last year, dragged down by a surge in jet fuel prices tied to the war with Iran. The International Air Transport Association, the industry’s main trade group, delivered the downgrade Sunday, June 7, at its annual meeting in Rio de Janeiro.

Airlines will bring in a combined net profit of $23 billion in 2026, down from a previously projected $41 billion and below the $45 billion they earned in 2025, the group said. Profit margins are expected to thin from 4.2% to 2.0%, meaning carriers will keep just two cents of every dollar in sales.

The cause is fuel. The group expects average jet fuel prices to run 70% higher than last year, adding about $100 billion to the industry’s collective fuel bill. Oil prices jumped after the U.S.-Iran conflict began in late February and disrupted shipping through the Strait of Hormuz, the chokepoint that handles a large share of the world’s oil. Jet fuel now averages around $152 a barrel, up from roughly $90 last year.

Willie Walsh, the group’s director general, said war-related disruptions and rising fuel costs have shifted the outlook for the worse. He warned that smaller carriers that started the year with weak finances are struggling the most.

The pain is uneven. The Middle East, long the most profitable region for air travel, has been hit hardest. The group now expects the region’s airlines to lose $4.3 billion this year, a sharp reversal from the $7.2 billion profit they earned in 2025, as carriers like Emirates and Qatar Airways cut operations following weeks of airspace closures. In North America, profits are forecast to fall to $9.4 billion from $12.4 billion.

Travel demand itself is holding up. Passenger numbers are expected to rise 2.4% to 5.1 billion this year, with planes filling to about 84% of capacity. The problem is that demand cannot outrun costs. Airlines are now earning just $4.50 in profit per passenger, a razor-thin cushion.

For travelers, the squeeze is showing up at the booking screen. Airlines are raising fares to cover the higher fuel bills, so summer trips cost more than they did a year ago. Some carriers, including LATAM and Azul, are cutting how often they fly certain routes. Others are flying longer paths to avoid closed airspace over the Middle East, which burns more fuel and adds time to journeys. Fewer flights and pricier tickets are the direct result.

Fuel is not the only headache. Airlines are also short on new planes. Airbus and Boeing have struggled with delivery delays, leaving carriers flying older, less fuel-efficient jets at exactly the moment fuel is most expensive. The aircraft backlog has swelled to record levels, capping how fast airlines can grow and adding to their costs.

The business stakes reach well beyond the airlines themselves. Air travel ties directly into tourism, conventions, and trade. When flying gets more expensive, families rethink vacations, companies trim travel budgets, and the hotels, restaurants, and shops that depend on visitors feel it. Shipping costs rise too, since a meaningful share of high-value goods moves by air.

The whole forecast rests on how long the war lasts. As long as the Strait of Hormuz stays disrupted, fuel will stay expensive and airlines will keep absorbing the hit or passing it to passengers. If the conflict eases and oil flows normalize, the math could improve quickly. Until then, the industry is bracing for a lean year, and travelers should expect to keep paying more to fly.

JBizNews Desk — Aviation

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Oracle reported the biggest quarter in its history on Wednesday, June 10, telling investors in a filing with the Securities and Exchange Commission that its order backlog for cloud and artificial intelligence work has ballooned to $638 billion. The company posted record revenue of $19.2 billion for its fiscal fourth quarter, up 21% from a year earlier.

The number drawing the most attention was that backlog, which Oracle calls remaining performance obligations. It represents contracts signed but not yet delivered, essentially money customers have promised to pay for future work. It grew by $85 billion in the quarter alone, climbing from $553 billion to $638 billion. For a company with annual revenue of $67.4 billion, that backlog is roughly ten times what it brings in each year.

The rest of the report was strong too. Earnings came in at $1.45 per share on a GAAP basis, up 21%, and $2.11 on an adjusted basis, up 24%. Total cloud revenue reached $9.9 billion, up 47%. The fastest-growing piece was the cloud infrastructure business, where Oracle rents out computing power. That unit posted revenue of $5.8 billion, up 93% from a year earlier.

The results topped Wall Street’s expectations. Analysts had looked for about $19.1 billion in revenue and $1.96 per share. Oracle beat both.

What makes this quarter important reaches beyond Oracle. The company has become one of the central players in the AI buildout, renting the massive computing capacity that other firms need to train and run AI systems. Its backlog is widely watched as a gauge of whether the AI spending boom is real and durable, or whether it is starting to cool. Wednesday’s jump suggests demand is still climbing.

Chairman and chief technology officer Larry Ellison and chief executive Safra Catz have spent the past year raising the company’s growth targets, and the backlog gives those promises weight. The catch is that a backlog is a promise, not cash in hand. The question hanging over the company is how fast it can turn those signed contracts into delivered revenue, and how much it must spend to do so.

That spending is enormous. Oracle is pouring tens of billions of dollars into data centers and the chips that fill them, with capital spending expected to run near $75 billion in the coming fiscal year. Building that capacity requires heavy borrowing, and Oracle already carries one of the largest debt loads of any technology company. The bet is that the AI orders will more than pay for it. If demand holds, the math works. If it slows, the bills come due regardless.

For ordinary investors, Oracle matters more than many realize. Its stock sits in countless index funds and retirement accounts, so its swings ripple into savings that have nothing to do with technology. The shares have climbed steeply over the past several months on AI optimism, then pulled back this week along with the rest of the market. Oracle closed Wednesday around $206 a share, caught in a broad selloff driven by inflation and the war with Iran, even as its underlying business posted records.

The broader signal is what businesses across the economy will take from this report. Oracle’s surging backlog tells suppliers, builders, and power companies that the demand for AI infrastructure is not letting up. That means continued orders for everything from servers and chips to electricity and construction. It also means the companies chasing this boom are taking on heavy debt and betting big that the spending pays off.

Oracle’s fiscal year is now closed, and the company heads into a new one with a record pipeline and record obligations to match. Wednesday answered the immediate question of whether the AI orders are real. The longer test, turning that $638 billion in promises into delivered profit, starts now.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The number of open jobs in America jumped in April even as companies pulled back on actual hiring, according to the Bureau of Labor Statistics, which released its Job Openings and Labor Turnover Survey on Tuesday, June 2. The report showed job openings rising to 7.6 million, the highest level since May 2024, while hiring slowed sharply.

The gap between those two numbers is the whole story. Employers are advertising more positions but filling fewer of them. Hires fell to 5.1 million for the month, and total separations dropped to 5.0 million. Openings rose by more than 730,000, yet the people actually starting new jobs declined by roughly 419,000.

Economists have a name for this: a low-hire, low-fire market. Companies are reluctant to let workers go, but they are also slow to bring new ones in. Both sides are sitting still.

The jump in openings was not broad. Almost the entire increase came from a single category, professional and business services, which added about 668,000 postings. Strip that out, and the rest of the economy looked flat. That has led some analysts to question whether the headline number really signals a hiring boom or just a pile-up of unfilled jobs in one corner of the market.

Worker behavior tells the same cautious story. Quits held steady at about 3.0 million, while layoffs and discharges stayed near 1.7 million. The quits rate slipped to its lowest in years. When people stop quitting, it usually means they are nervous. Leaving a job without another one lined up takes confidence, and right now workers are choosing to stay put.

The layoff rate ticked down from 1.2% in March to 1.1% in April. By that measure, Americans who have jobs still enjoy strong security. The risk of being let go remains low. The harder problem is for people trying to get hired or change jobs. Openings exist, but companies are taking their time, and that slows down raises and promotions across the board.

For the Federal Reserve, now led by Chair Kevin Warsh, the report lands at a delicate moment. The central bank watches hiring and quitting closely for signs the job market is either overheating or cracking. April’s numbers suggested neither. The market is cooling slowly, not collapsing.

What happens next may depend on forces outside the labor market entirely. The war with Iran has pushed up oil and gasoline prices, and that feeds inflation. Higher inflation makes the Fed less willing to cut interest rates, which keeps borrowing expensive for the businesses that do the hiring. Matthew Martin, senior U.S. economist at Oxford Economics, warned that weaker household spending and uncertainty could start to weigh on companies’ hiring plans in the months ahead.

For everyday workers, the practical takeaway is simple. If you have a job, you are probably safe. If you want a new one, expect a longer search. Employers are posting openings but moving slowly to fill them, and the easy job-hopping of recent years has faded. Vacancies are staying open longer, which means more interviews, more waiting, and less leverage to negotiate pay.

Small business owners feel the same freeze from the other direction. Many have openings they cannot fill at wages they can afford, while also being careful not to overextend payroll heading into an uncertain summer. The result is an economy that looks stable on paper but feels stuck for anyone trying to move.

The next major labor reading comes when the Bureau of Labor Statistics publishes its June turnover data later this summer. Until then, the picture is one of an economy holding its breath, with workers and employers alike waiting to see how the war, inflation, and interest rates settle out before making their next move.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Amazon Web Services (AWS) said on Thursday, June 11, that its data centers around the world withdrew about 2.5 billion gallons of water last year to cool the servers that power its cloud-computing and artificial-intelligence businesses. The figure was detailed by AWS executives including Kerry Person, vice president of data center operations, and Will Hewes, the company’s water stewardship lead. It is one of the clearest pictures Amazon has ever provided of the water footprint behind the global computing boom.

The disclosure matters because Amazon has long faced criticism for providing limited information about data-center water consumption. Rivals Microsoft and Google have published water-use figures for years. Amazon had largely focused on efficiency metrics rather than total withdrawals, and earlier this year investors filed resolutions urging major technology companies to provide greater transparency. Thursday’s announcement is Amazon’s most direct response yet.

Amazon is presenting the figure as evidence that its operations are highly efficient. The company says it uses approximately 0.12 liters of water per kilowatt-hour of computing, compared with an estimated industry average of 0.84 liters per kilowatt-hour. According to AWS, that makes its operations roughly seven times more water efficient than the average data-center operator. The company said outside auditors reviewed the calculations and that water withdrawals at facilities Amazon directly owns and operates declined about 2% year-over-year, even as its global footprint expanded.

The company attributes much of the reduction to its cooling strategy. Data centers generate enormous amounts of heat, and many operators rely heavily on evaporative cooling systems that consume significant amounts of water. AWS says its facilities use outside-air cooling about 90% of the time, relying on fans to move air through server halls. Water cooling is generally used only when outdoor temperatures exceed roughly 85 degrees Fahrenheit. The company also adjusted operating temperatures within its facilities to further reduce cooling demand.

The disclosure arrives at a sensitive moment for the industry. In Amazon’s home region, the Seattle City Council this week unanimously approved a one-year emergency pause on new large data-center developments within the city. The action reflects growing concern among local governments over the water, electricity, and land demands created by artificial-intelligence infrastructure.

Person said community reactions are often different from what critics expect.

“As we’ve been engaging with our local communities, they’ve been very pleasantly surprised about how little water we are using,” he told reporters.

Not everyone agrees. Simon Hans Edasi, a Seattle-area data scientist who studies data-center development and water resources, has raised concerns about Amazon’s planned $4.8 billion campus in Burbank, Washington, near the Columbia River. He argues that the industry is increasingly expanding into eastern Washington and other regions where water supplies are already under pressure.

Several recent studies have found that a significant share of new U.S. data-center construction is occurring in areas experiencing varying degrees of water stress. Those concerns have fueled permitting battles, project delays, and in some cases the cancellation or relocation of major developments.

For companies investing tens of billions of dollars in AI infrastructure, community opposition is becoming a material business risk. Delays in permits and approvals can significantly increase costs and slow expansion plans.

Amazon says its long-term answer is its Water Positive by 2030 commitment, first announced in 2022. The company says it has completed approximately 75% of the work needed to achieve that goal and currently replenishes about three gallons for every four gallons it uses.

According to Hewes, the strategy focuses on three priorities: reducing water consumption, replacing drinking water with treated wastewater whenever possible, and investing in local replenishment projects. Those efforts include repairing leaking municipal infrastructure, restoring watersheds, and supporting agricultural irrigation programs that use recycled water.

Microsoft has announced similar goals, including a pledge to improve water efficiency by 40% by 2030 and replenish more water than it consumes in the regions where it operates.

As artificial intelligence drives unprecedented demand for computing power, technology companies are increasingly competing not only on performance and scale, but also on environmental impact.

Amazon also highlighted a broader industry statistic, noting that global data centers account for approximately 0.5% of industrial water use worldwide. Whether that argument satisfies communities increasingly wary of large-scale AI development may ultimately be decided one project at a time.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Stocks opened higher on Thursday, June 11, shaking off a brutal week even as the U.S.-Iran conflict deepened and a fresh inflation report came in hot. The S&P 500 rose 0.21%, the Dow Jones Industrial Average gained 0.45%, and the Nasdaq Composite added 0.26% in the opening minutes. The small-cap Russell 2000 fell 1.10%, a sign investors remained cautious about higher interest rates sticking around.

Oil prices climbed after President Donald Trump said the United States would hit Iran “very hard” and seize “total control” of the country’s oil and gas industry, while U.S. Central Command confirmed fresh strikes overnight. Explosions were reported across Iran, including near the Strait of Hormuz, the strategic shipping lane through which a significant portion of the world’s oil supply passes.

The market’s gains came despite an alarming inflation report.

The U.S. Bureau of Labor Statistics reported that the Producer Price Index (PPI) jumped 1.1% in May from April, exceeding economists’ expectations of 0.7%. On a year-over-year basis, wholesale prices climbed 6.5%, marking the steepest increase since November 2022.

Energy prices drove much of the increase. Wholesale gasoline prices surged 23.4% during the month as escalating tensions with Iran pushed crude oil prices sharply higher. Excluding food and energy, so-called core wholesale prices rose a more moderate 0.4%, suggesting the inflation shock was concentrated largely in energy markets.

The report arrived just one day after separate government data showed consumer inflation reaching 4.2% annually, the highest reading in three years, and only days before the Federal Reserve’s June 17 policy meeting.

The biggest corporate story of the morning belonged to Oracle Corporation.

The software and cloud-computing giant reported fiscal fourth-quarter results after Wednesday’s closing bell. Revenue totaled approximately $19.2 billion, while adjusted earnings came in at $2.03 per share, both above Wall Street expectations.

Despite the strong results, Oracle shares fell roughly 8% at the open after management revealed plans to raise approximately $40 billion through a combination of debt and equity offerings, including a reported $20 billion stock sale, to fund an aggressive expansion of artificial-intelligence infrastructure.

Chief Executive Clay Magouyrk told analysts the company expects to bring nearly one gigawatt of computing capacity online this quarter alone, while Chief Financial Officer Hilary Maxson said Oracle anticipates roughly $70 billion in capital expenditures during the coming fiscal year.

Investors appeared concerned about the scale of the spending.

Analysts at Bank of America noted that more than half of Oracle’s contracted future revenue is tied to a single customer, OpenAI, increasing perceived concentration risk.

The spending plans also rattled parts of the broader software sector. Shares of German software giant SAP fell more than 4% as investors questioned whether competitors would face similar pressure to dramatically increase AI infrastructure spending.

Not all analysts turned negative.

UBS analyst Karl Keirstead raised his price target on Oracle to $285 from $250, while Oppenheimer and Wedbush increased their targets to $275. Evercore ISI lifted its target to $245, and Barclays maintained an overweight rating with a $240 price target.

Another major market focus is SpaceX.

Elon Musk’s rocket company is expected to price its long-awaited initial public offering after Thursday’s close at approximately $135 per share, with trading expected to begin Friday on the Nasdaq under the ticker symbol SPCX.

At a reported valuation exceeding $1.75 trillion, the offering would rank as the largest IPO in history.

The proposed listing has already generated controversy.

Senator Elizabeth Warren has urged the Securities and Exchange Commission to delay approval of the offering, citing concerns about valuation and Musk’s concentrated control over the company.

Adding further uncertainty, Iranian state media reportedly warned that Musk’s businesses operating in the Middle East, including the Starlink satellite network, could be viewed as military targets amid escalating regional tensions.

Elsewhere, semiconductor stocks rebounded after a difficult stretch that erased nearly $1 trillion in market value earlier this month.

Shares of SoftBank Group Corp. fell more than 9% after reports suggested financing tied to its investment in OpenAI encountered complications. Meanwhile, investors were awaiting earnings from Adobe Inc., scheduled for release after Thursday’s closing bell, with analysts closely watching whether the company’s AI initiatives are translating into meaningful revenue growth.

For now, Wall Street’s gains rest on a fragile assumption: that the latest inflation surge is primarily an energy story and that the conflict with Iran remains contained.

Investors now turn their attention to Adobe’s earnings, SpaceX’s IPO pricing, and next week’s highly anticipated Federal Reserve interest-rate decision, which may ultimately determine whether the market’s recent volatility intensifies or begins to ease.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The head of the Social Security Administration told Congress on Wednesday, June 10, 2026, that the agency has reduced wait times on its national helpline to the lowest level in more than a decade, a turnaround he credited to shifting employees from headquarters positions to customer-service roles.

In written testimony before the House Ways and Means Subcommittee on Social Security and Work & Welfare, Commissioner Frank Bisignano said the agency’s average “speed of answer” — the amount of time it takes for an agent to answer an incoming call — fell to under five minutes in May. According to Bisignano, that is down from a peak of approximately 42 minutes in fiscal year 2024, representing an 89% improvement.

He also told lawmakers that the agency now answers approximately 90% of calls placed to its national toll-free 800-number.

The figures matter because the phone system remains one of the primary ways Americans interact with the agency. Tens of millions of retirees, disabled workers, survivors, and family members rely on the Social Security Administration for monthly benefits and frequently contact the agency regarding payment issues, eligibility questions, benefit adjustments, name changes, and other administrative matters.

For years, long hold times have been among the agency’s most common complaints. Extended delays often pushed people into crowded field offices or left them waiting weeks to resolve issues affecting household finances.

Bisignano told lawmakers the improvements extend beyond telephone service.

According to his testimony, average wait times at Social Security field offices have declined by roughly 30%, while the backlog of initial disability claims has fallen 32% from a peak of 1.27 million cases. He also noted that the agency completed implementation of the Social Security Fairness Act, restoring benefits to certain public-sector retirees months ahead of schedule.

Bisignano attributed the gains to what he described as placing “the right amount of staff in the right places,” with more employees assigned directly to public-facing service functions.

Subcommittee Chairman Ron Estes praised the effort, describing it as a “dramatic turnaround” after years of customer-service challenges, outdated technology systems, and staffing shortages. Estes called the previous 42-minute average wait time unacceptable for an agency serving millions of Americans.

Not all lawmakers accepted the numbers without question.

Several members of Congress challenged how the Social Security Administration calculates wait times and whether the improvement is as dramatic as the agency claims. Bisignano defended the methodology, stating that the agency measures performance using standards commonly employed by private-sector customer-service organizations.

Much of the debate centers on a change made last year to the agency’s reporting methodology.

In 2025, the Social Security Administration began recording wait times differently for callers who selected the callback option instead of remaining on hold. Under the revised method, callers choosing a callback are not counted as waiting on hold, even though they may wait substantially longer before speaking with a representative.

A report issued by the agency’s Office of the Inspector General noted that callers who used the callback system waited an average of nearly two hours before receiving assistance. While the inspector general concluded that the agency’s published figures were accurate under its stated methodology, the report also highlighted that those numbers do not fully capture the total time many callers spend waiting for service.

When callback delays are included, the inspector general estimated average wait times during fiscal year 2025 at roughly 15 minutes, considerably longer than the headline figure reported by the agency.

Questions have also been raised about the starting point used to measure improvement.

Independent reviews indicate that the 42-minute average wait cited by officials reflects conditions in late 2023, and that wait times had already improved significantly before Bisignano assumed leadership. By the end of 2024, some agency reports showed average waits closer to 12 minutes, suggesting that part of the improvement predates the current administration.

Criticism has also come from Senator Elizabeth Warren, whose office conducted an independent review of Social Security customer service. Warren’s staff reported that many test calls either went unanswered or were disconnected after lengthy holds. Among calls that eventually reached a representative, the office reported average wait times substantially longer than the agency’s official figures.

For the millions of Americans who rely on Social Security benefits, the dispute is more than a statistical argument.

Retirees correcting payment errors, families applying for survivor benefits, and workers seeking disability assistance all depend on timely access to agency representatives. Faster service can mean quicker resolution of payment problems, reduced financial stress, and fewer trips to local offices.

Bisignano told lawmakers that the agency intends to continue improving service across all channels, including telephone support, online services, and in-person field offices.

Whether the reported gains fully reflect the experience of callers remains a matter of debate, but lawmakers on both sides of the issue agree on one point: improving customer service at one of the federal government’s largest agencies remains a priority for millions of Americans who depend on it.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
One of the most popular money-making trades in global finance this year — borrowing Hong Kong dollars cheaply and investing the proceeds in higher-yielding U.S. dollar assets — is losing its appeal as borrowing costs in Hong Kong rise, according to a report published Tuesday by Bloomberg News reporters Iris Ouyang and Jacob Gu. The shift reflects changes in Hong Kong’s financial system that are making the trade more expensive to maintain.

Here is the trade in simple terms. For much of this year, Hong Kong dollars were relatively inexpensive to borrow. Traders took advantage by borrowing Hong Kong dollars at low rates and moving the money into U.S. dollar assets offering higher returns. The difference between the borrowing cost and the investment return is known as a carry trade.

The attraction of the strategy depends on one key factor: cheap funding. As long as borrowing costs remain low, traders can earn the spread between the two currencies. When funding costs rise, that profit margin shrinks.

The benchmark at the center of the story is HIBOR, the Hong Kong Interbank Offered Rate, which measures the rate banks charge one another to lend Hong Kong dollars. As HIBOR increases, the cost of financing carry-trade positions rises as well.

The reason traces back to Hong Kong’s currency system. Since 1983, the Hong Kong dollar has been pegged to the U.S. dollar within a trading band of HK$7.75 to HK$7.85 per U.S. dollar. When the currency weakens toward the lower end of that range, the Hong Kong Monetary Authority (HKMA) intervenes by purchasing Hong Kong dollars from the market.

Those interventions remove liquidity from the banking system. With less cash available, short-term borrowing costs tend to increase. In effect, the same market forces that encouraged the carry trade have also contributed to the conditions making it less profitable.

Seasonal factors are adding pressure. Midyear is traditionally a period when large dividend payments, corporate funding needs, and new stock offerings absorb liquidity from Hong Kong’s financial system. That can further tighten money-market conditions and contribute to higher borrowing rates.

The implications extend beyond hedge funds and currency traders. Most residential mortgages in Hong Kong are linked directly or indirectly to HIBOR. As the benchmark rises, mortgage payments can increase, affecting household budgets across the city.

Banks often benefit from a higher-rate environment because they can earn more on loans and other interest-bearing assets. Borrowers, however, face higher financing costs. Property developers, homebuyers, and businesses seeking credit may all feel the effects if funding costs continue climbing.

For savers, the picture is somewhat brighter. Higher interest rates can lead to improved returns on bank deposits and savings products, though those gains often lag changes in wholesale funding markets.

Importantly, the recent rise in borrowing costs is not viewed as a threat to Hong Kong’s currency peg. Rather, many analysts see it as evidence that the system is functioning as intended. The peg relies on automatic adjustments in liquidity and interest rates to keep the currency within its designated trading range.

The broader question for investors is whether the narrowing gap between Hong Kong and U.S. funding costs will continue. If borrowing Hong Kong dollars becomes significantly more expensive, the economics that fueled the carry trade could weaken further.

For now, the takeaway is straightforward: the era of exceptionally cheap Hong Kong dollar funding appears to be fading, reducing the attractiveness of one of the market’s most widely used currency trades.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Starbucks is exploring options for its Japan business, including the possible sale of a minority stake or a public listing, according to people familiar with the matter cited in a report published Wednesday. The discussions are described as preliminary, and the company has not publicly confirmed any plans or commented on the reported deliberations.

In simple terms, Starbucks is considering whether to bring in outside investors to own part of its Japan operation. Another option under review is an initial public offering of the business, allowing investors to buy shares in the Japan unit while Starbucks retains a significant ownership position.

According to the report, a transaction could value the business at approximately ¥400 billion to ¥500 billion (about $2.5 billion to $3.1 billion), though no formal process has been announced and no final decision has been made.

For customers, little would change. Starbucks stores across Japan would continue operating under the same brand, serving the same products, and using the same loyalty programs. The question is not about changing the coffee business itself but about changing who owns part of it.

Japan is one of Starbucks’ most important international markets. The company operates approximately 2,100 stores across the country, making it one of the largest Starbucks footprints outside North America. Most of those locations are company-operated rather than franchised.

The reported discussions follow a major transaction Starbucks recently completed in China. In an official filing with the U.S. Securities and Exchange Commission, Starbucks disclosed that funds managed by Boyu Capital acquired a 60% stake in the company’s China retail operations, while Starbucks retained a 40% ownership interest and continued to own and license the Starbucks brand to the venture.

That China deal valued Starbucks’ China business at roughly $4 billion and reflected a broader strategy of partnering with local investors while maintaining control of the brand and long-term growth plans.

Brian Niccol, Chairman and Chief Executive Officer of Starbucks, said at the time that the China partnership would accelerate growth by combining Starbucks’ global brand with strong local expertise and operational capabilities.

A similar arrangement in Japan would extend what many analysts describe as an asset-light strategy. Rather than owning every international operation outright, Starbucks can generate capital from mature markets while continuing to benefit from future growth through retained ownership stakes, licensing fees, and brand royalties.

Unlike some corporate divestitures, the reported Japan discussions are not being driven by a struggling business. Starbucks has a long history in the country and remains one of the most recognized coffee brands in Japan.

The company first entered Japan in 1996, opening its inaugural location in Tokyo. In 2014, Starbucks purchased the remaining ownership stake in Starbucks Coffee Japan for approximately $914 million, giving the company full control of the business after years of operating through a joint venture.

If Starbucks ultimately sells a minority stake today, the valuation being discussed suggests the Japan operation has appreciated significantly since that acquisition.

The timing also aligns with Niccol’s broader effort to reshape the company. Since becoming CEO, he has been implementing the “Back to Starbucks” turnaround strategy, focused on simplifying operations, improving customer experience, and strengthening profitability.

Selling stakes in mature international businesses can free up capital, improve financial flexibility, and allow management to focus resources on key strategic priorities, including efforts to strengthen the company’s core North American operations.

For investors, the reported discussions could provide a clearer picture of how much Starbucks’ international businesses are worth. When outside investors place a specific value on an operation like Japan, it offers a market-based benchmark that can help analysts assess the company’s overall valuation.

Several important caveats remain. The discussions are reportedly in the early stages, the information comes from unnamed sources rather than company executives, and many preliminary deal talks never result in a transaction.

Starbucks could pursue a stake sale, an IPO, a strategic partnership, or decide to keep the business exactly as it is.

What is clear is that Starbucks is continuing to evaluate how it structures ownership of its international operations. After reshaping its China business through a local partnership, Japan may now be the next market under review as the world’s largest coffee chain looks to balance growth, capital allocation, and shareholder value.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A Florida fuel-trading company is in advanced talks to ship Cuba the largest cargo of American fuel the island has received since before the U.S. embargo reshaped relations between the two countries, according to remarks confirmed Tuesday by Matthew Klann, President of Vanguard Energy. The Miami-based company has already supplied smaller shipments of gasoline and diesel to Cuba and is now working toward a significantly larger delivery as the island struggles through a deepening energy crisis.

What makes the development remarkable is the history behind it. The United States has maintained a trade embargo against Cuba for more than six decades, and Washington has spent much of this year trying to restrict fuel flows to the island. A major, openly arranged shipment of U.S. fuel would represent a sharp departure from decades of precedent and highlights a unique policy exception now taking shape.

To understand how Cuba reached this point, it helps to look at the events of the past several months. Cuba has long relied heavily on imported fuel, particularly from Venezuela. Disruptions to those supplies, combined with additional U.S. pressure on energy shipments to the island, have left Cuba facing severe shortages that have strained its electrical grid and transportation networks.

The consequences have been felt across the country. Cuban officials have acknowledged months of fuel shortages severe enough to disrupt power generation. Rolling blackouts have become a regular feature of daily life, with some areas experiencing outages lasting many hours at a time. Businesses, schools, hospitals, and households have all been affected by the lack of reliable electricity.

The reason U.S. fuel is now being considered lies in Washington’s distinction between Cuba’s government-controlled economy and its emerging private sector. Secretary of State Marco Rubio has argued that allowing certain transactions that benefit private Cuban entrepreneurs aligns with broader U.S. policy goals aimed at strengthening independent economic activity while maintaining pressure on the state.

In practical terms, that means fuel exports intended for private businesses may qualify for exceptions that would not apply to government entities. Companies such as Vanguard Energy have been operating within that narrow framework, supplying fuel to approved buyers under existing regulations.

Until now, those shipments have been relatively small. Earlier deliveries represented only a fraction of Cuba’s overall energy needs. The cargo currently under discussion would be substantially larger and could provide meaningful relief to parts of the island’s struggling economy.

The move comes as Cuba continues searching for alternative energy suppliers. Fuel shipments from other countries have arrived intermittently, but they have not been sufficient to stabilize the island’s energy system. The uncertainty surrounding foreign supplies has increased the importance of any new source of fuel.

The business implications are significant. For Vanguard Energy, the arrangement could establish an early foothold in a market that very few American companies are legally permitted to serve. If the policy framework remains in place, companies that develop expertise navigating the regulatory and logistical challenges could gain a substantial competitive advantage.

Those logistical challenges are considerable. Cuba’s fuel-import infrastructure faces capacity constraints, and handling large shipments can require complex coordination involving storage facilities, ports, and distribution networks. Successfully managing those obstacles is likely to be as important as securing regulatory approval.

For ordinary Cubans, however, the issue is less about geopolitics than daily life. Fuel shortages affect electricity generation, public transportation, refrigeration, food distribution, and countless other basic services. Any increase in available fuel could have an immediate impact on living conditions.

For U.S. policymakers, the potential shipment represents a test of a broader strategy: maintaining economic pressure on the Cuban government while allowing targeted support for private citizens and entrepreneurs. Whether that approach can achieve both objectives remains an open question.

Neither Vanguard Energy nor U.S. officials have disclosed the size of the proposed shipment or a specific delivery timetable. Discussions remain ongoing, and final approvals have not yet been announced.

If completed, however, the deal would mark one of the most significant fuel shipments from the United States to Cuba in decades and could become a milestone in the evolving relationship between U.S. policy and Cuba’s private economy.

JBizNews Desk — Americas

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Aluminum traded on the London Metal Exchange slipped to about $3,594 a tonne on Monday, easing back from the more than four-year high of roughly $3,790 it touched on June 2. The decline came as a stronger U.S. dollar made the metal more expensive for buyers using other currencies, briefly cooling a rally that has run for months.

Here is the simple version. Aluminum is priced in dollars. When the dollar gets stronger, the same bar of metal costs more for buyers in Europe, China, India and elsewhere paying in their own currencies. That extra cost tends to slow demand and pressure prices lower. That is most of what happened this past week.

The dollar climbed after a strong U.S. jobs report. A healthy labor market raises the odds that the Federal Reserve keeps interest rates elevated if inflation remains stubborn. Higher U.S. rates tend to attract investment into dollar-denominated assets, strengthening the currency and weighing on commodities priced in dollars. That chain reaction, not any easing of overseas tensions, is what knocked aluminum off its peak.

It is important to understand what did not cause the pullback. Supply concerns that have supported aluminum prices in recent months have not disappeared. Traders continue to monitor disruptions affecting energy markets, shipping routes and raw-material supplies, all of which can influence the cost and availability of aluminum around the world.

There is also continuing concern about access to bauxite, the ore used to make aluminum. Export restrictions and supply-chain uncertainties in key producing regions have added another layer of pressure to the market. When raw materials become harder or more expensive to move, the effects are felt throughout the aluminum supply chain.

For all the day-to-day swings, the bigger picture remains a market trading near multi-year highs. The recent decline represents a pullback from a sharp rally rather than a fundamental change in direction. Prices remain well above levels seen earlier in the year.

The business impact extends far beyond commodity traders. Aluminum is a critical input for automobiles, beverage cans, construction materials, packaging, electrical transmission lines and aircraft manufacturing. When prices remain elevated for extended periods, those costs eventually work their way through factories and into consumer products.

Manufacturers that consume large amounts of aluminum often try to lock in supply contracts ahead of time, but prolonged price increases can still pressure profit margins. Beverage makers, automakers and industrial manufacturers all keep a close eye on aluminum markets because the metal is embedded in so many everyday products.

The currency story matters for Americans as well. A stronger dollar can make imported goods cheaper for U.S. consumers while making American exports more expensive overseas. Aluminum’s recent move is one example of how expectations about Federal Reserve policy can ripple through global markets and eventually affect businesses and households alike.

What happens next will likely depend on two competing forces. On one side, a strong dollar and the possibility of higher-for-longer U.S. interest rates could continue to pressure commodity prices. On the other, ongoing supply concerns and tight availability of key materials could provide support.

This week, the dollar gained the upper hand. Over the longer term, however, supply conditions may prove to be the more important factor in determining where aluminum prices go next.

For now, aluminum remains near multi-year highs, underscoring just how strong the market has been despite the recent pullback.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Federal prosecutors say California real estate investor falsified collateral documents, helping trigger a 2025 sell-off that erased roughly $1 billion in market value from regional bank stocks.

The case grows out of a scare that hit Wall Street in October 2025. That month, Zions Bancorporation and Western Alliance Bancorp disclosed that loans tied to funds operating under the Cantor Group name had gone bad. The news wiped out roughly $1 billion of Zions’ market value in a single day and dragged down other regional bank stocks, as investors worried the problems might be wider than two lenders.

Now the matter has turned criminal. On Wednesday, June 10, 2026, the U.S. Attorney’s Office for the Central District of California announced the arrest of the California real estate investor at the center of those loans on a federal bank fraud charge.

Mahender Makhijani, 44, of Corona del Mar, was taken into custody on a criminal complaint that accuses him of cheating a bank out of nearly $100 million by faking documents to make the property backing his loans look far more valuable than it was. He was scheduled to make his first court appearance Wednesday afternoon in federal court in Santa Ana. According to the complaint, Makhijani controls Cantor Group V LLC, a Newport Beach company that borrowed heavily against real estate.

“When criminals are allowed to deceive lenders, the spillover effects can harm consumers and businesses,” said First Assistant U.S. Attorney Bill Essayli. He called the arrest part of an effort to protect the banking system.

Here is what prosecutors say happened. Western Alliance advanced close to $100 million to Cantor Group V so the firm could make or buy loans backed by real estate. Under the deal, Cantor was supposed to pledge those loans, and the underlying property, to the bank. The bank wanted first claim on the collateral — meaning if a borrower stopped paying, the bank would be first in line to take the property and sell it. That first position is what made the loans safe enough to fund.

To prove it held that first position, Cantor had to hand over title insurance policies. From September 2024 to April 2025, the complaint says, Makhijani falsified those policies so they appeared to show Cantor was first in line. In reality, other lenders were ahead of it, which made the collateral worth far less.

The method was low-tech, according to the affidavit. Makhijani or a subordinate edited the title documents in Adobe software, then stripped out the digital fingerprints that would reveal the changes — in some cases by printing the altered files and scanning them back in. An employee then sent the doctored policies to the bank. When the bank flagged problems, prosecutors say, Makhijani got on the phone and lied about them, and in December 2024 had a spreadsheet of false explanations sent over to smooth things out.

Had the bank known the collateral’s true value, prosecutors say, it would have treated Cantor as in default and demanded the full balance back. Western Alliance sued in Los Angeles County in August 2025, the first public sign of trouble before the broader disclosures shook the market two months later. The criminal complaint does not name the bank, identifying it only as “Bank #1,” but the loan size, the timing and the lawsuit match the case Western Alliance brought against the Cantor fund.

The complaint also reflects how seriously federal regulators are taking strains in bank lending. IRS Criminal Investigation, the FBI, the Federal Deposit Insurance Corporation’s Inspector General, the Federal Housing Finance Agency’s Inspector General, and the Inspector General for the Federal Reserve and the Consumer Financial Protection Bureau are all working the case. Darren Lian of IRS Criminal Investigation’s Los Angeles office said agents traced the money through layered transfers and shell companies.

The October scare put a spotlight on a soft spot in the financial system. Regional banks tend to lend within a single region and lean heavily on commercial real estate, an area under pressure as office values fall and loans come due. When one borrower turns out to have hidden the truth about collateral, it raises a worry that costs everyone money: that other loans on other banks’ books may be weaker than they look. That fear is what drove the sell-off, even though analysts at the time argued the Cantor losses looked specific to a few borrowers rather than a system-wide crack.

For ordinary customers and businesses, the stakes are practical. Healthy regional banks are the lenders behind much small-business credit, local mortgages and construction projects. Losses on the scale alleged here force banks to tighten standards, which can make borrowing harder and costlier across a community.

A criminal complaint is only an allegation, and Makhijani is presumed innocent unless proven guilty. If convicted, he faces a maximum of 30 years in federal prison. The investigation is continuing.

JBizNews Desk — United States

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Meta announced Tuesday that it has signed an agreement with Reliance Industries to lease its first artificial intelligence data center in India, according to a statement released through the company’s newsroom and comments from Mark Zuckerberg, Founder and Chief Executive Officer of Meta, and Mukesh D. Ambani, Chairman and Managing Director of Reliance Industries Limited.

The plant will be built in Jamnagar, a city in the western Indian state of Gujarat. Under the agreement, Reliance will construct the facility while Meta leases the computing capacity inside it. The first phase is expected to operate at 168 megawatts of power, with room for future expansion.

Here is the simplest way to understand the arrangement. Meta operates platforms used by billions of people worldwide, including Facebook, Instagram, and WhatsApp, and requires vast computing power to run its growing artificial intelligence systems. Rather than building its own facility from the ground up in India, Meta will pay Reliance to build and operate the infrastructure while leasing the computing resources it needs.

India is central to the strategy. It is one of Meta’s largest and fastest-growing markets, and the company said locating computing power within the country will allow AI products and services to run faster for local users. Zuckerberg said the Jamnagar facility will strengthen Meta’s global AI infrastructure while deepening its long-term investment in India.

The partnership builds on an existing relationship. In 2020, Meta invested $5.7 billion in Jio Platforms, Reliance’s telecommunications and digital subsidiary, in a move aimed at expanding internet access and helping small businesses across India. The companies later worked together to make Meta’s open-source AI models available to Indian businesses and developers. The new data center extends that partnership into the physical infrastructure powering artificial intelligence.

The facility has been designed around two of the largest operating costs in data centers: energy and water. Reliance is developing what it describes as one of the world’s largest data center campuses in Jamnagar, with access to the significant power resources required for AI computing. The site will run on renewable energy and use desalinated seawater for cooling rather than freshwater supplies. Meta said it will cover the full cost of the energy and water needed to operate the center.

Ambani described the agreement as a milestone for India’s digital infrastructure, saying that building the country’s first custom-designed data center for a technology company of Meta’s scale demonstrates India’s readiness to play a leading role in the global AI economy.

Meta also announced a major clean-energy expansion in India. The company said it has contracted nearly 1 gigawatt of new solar and wind generation through two energy providers.

CleanMax will supply 837 megawatts from new projects in Rajasthan and Karnataka, bringing Meta’s total announced capacity with the company to more than 900 megawatts. Fourth Partner Energy will provide an additional 88 megawatts from projects across Tamil Nadu, Karnataka, Maharashtra, and Uttar Pradesh.

The business implications are significant. AI data centers have become one of the largest areas of spending across the global technology sector, influencing employment, construction activity, power demand, and local infrastructure investment. By having Reliance build and operate the facility, India retains ownership of the underlying infrastructure while keeping related energy and water spending within the country.

For Reliance, the agreement helps transform Jamnagar—long known as a major refining and energy hub—into a destination for AI and cloud-computing customers. The company has signaled its intention to host AI infrastructure for outside firms, and securing a customer the size of Meta represents a major validation of that strategy.

The deal also highlights a broader trend across the technology industry as major American companies race to secure computing capacity around the world rather than relying solely on domestic infrastructure.

For users in India, the immediate goal is straightforward: faster AI services and digital applications powered by servers located closer to where they live and work.

Neither company disclosed the financial terms of the lease agreement or provided a firm timeline for when the Jamnagar facility will begin operations.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Governor Tiff Macklem’s warning that Canada’s economy remains weak sent government bond prices higher as investors increased bets on future rate cuts.

The Bank of Canada left its key interest rate unchanged on Wednesday, June 10, 2026, and Governor Tiff Macklem described the country’s economy as “weak,” a message that sparked a rally in Canadian government bonds and reinforced expectations that future interest-rate cuts remain possible.

The central bank held its benchmark overnight rate at 2.25%, marking the fifth consecutive meeting without a policy change. The decision was widely expected by economists and financial markets.

Speaking in Ottawa alongside Senior Deputy Governor Carolyn Rogers, Macklem acknowledged that economic conditions remain sluggish.

“The economy is weak, but it is not clearly in recession,” Macklem said, adding that policymakers expect growth to improve during the second quarter.

Bond markets reacted immediately.

Canada’s benchmark two-year government bond yield fell to approximately 2.84% shortly after the announcement after trading near 2.88% earlier in the day. Bond yields move inversely to prices, meaning investors were buying government debt following the central bank’s comments.

The move reflected growing market expectations that the Bank of Canada’s next policy adjustment is more likely to be a rate cut than a rate increase.

In its policy statement, the central bank highlighted the difficult balancing act facing policymakers.

“Economic activity in Canada has been weak and uncertainty about U.S. trade policy persists,” the bank said.

Officials also pointed to continuing tensions in the Middle East and elevated oil prices. However, the bank emphasized that it intends to look through temporary energy-driven inflation pressures and “will not let higher energy prices become persistent inflation.”

The statement underscores the competing forces currently shaping Canada’s economy.

Higher oil prices can push inflation upward, which would normally support higher interest rates. At the same time, weak economic growth and soft business activity argue for lower borrowing costs to stimulate demand.

Caught between those competing risks, policymakers chose to remain on hold.

The decision comes as Canada continues to flirt with recession.

The economy recorded a second consecutive quarterly contraction during the first quarter of 2026, meeting the traditional definition of a technical recession. Despite that, Macklem stopped short of formally describing the economy as being in recession, arguing that conditions could improve as growth rebounds during the spring and summer months.

For consumers and businesses, the decision has direct implications.

The Bank of Canada’s overnight rate influences borrowing costs throughout the financial system, including variable-rate mortgages, lines of credit, business loans, and consumer lending products.

By leaving rates unchanged, the central bank maintained existing borrowing costs for millions of Canadians.

Fixed mortgage rates operate differently because they are heavily influenced by government bond yields. As a result, Wednesday’s rally in Canadian bonds could eventually help reduce pressure on fixed-rate borrowing costs if lower yields persist.

The current pause follows one of the most aggressive easing cycles among major central banks.

Between June 2024 and October 2025, the Bank of Canada reduced its benchmark rate by 2.75 percentage points, lowering it from 5.0% to 2.25%. Since then, policymakers have adopted a wait-and-see approach, weighing slowing economic activity against lingering inflation risks.

Economists generally interpreted Macklem’s comments as supportive of future easing rather than tightening.

Ali Jaffery, Chief Economist at KPMG Canada, described the central bank’s tone as dovish, arguing that inflation risks remain manageable given the economy’s weakness.

Andrew Grantham, Senior Economist at CIBC, characterized the Bank of Canada as “very patient” and said policymakers appear comfortable waiting to see whether current rates can support a modest recovery.

Several major financial institutions, including CIBC, BMO, and Royal Bank of Canada, currently expect the benchmark rate to remain unchanged through the remainder of 2026.

A major variable remains trade policy.

The upcoming review of the United States-Mexico-Canada Agreement (USMCA) in July could significantly affect Canada’s economic outlook. Any changes to trade arrangements would have direct implications for manufacturing, exports, investment, and cross-border supply chains.

Until there is greater clarity on trade negotiations and the trajectory of economic growth, the Bank of Canada appears content to keep rates at 2.25%, monitor incoming data, and wait for stronger evidence that either inflation or economic weakness is gaining the upper hand.

JBizNews Desk — Canada

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Silver has plunged nearly 47% from its January peak as rising inflation, higher interest-rate expectations and renewed Middle East tensions trigger another sharp selloff in one of 2026’s most volatile assets.

Silver prices fell sharply on Wednesday, June 10, 2026, sliding to around $64 per ounce on the COMEX exchange, their lowest level since late March and nearly 47% below the record high of $121.67 per ounce reached in January.

The latest decline caps a painful month for investors in what had been one of the market’s hottest trades.

The iShares Silver Trust (SLV), the largest silver-backed exchange-traded fund and one of the most popular ways for individual investors to gain exposure to silver, has fallen roughly 20% over the past month.

The immediate catalyst was a combination of geopolitical and economic pressures.

The United States launched fresh military strikes against Iran following the reported downing of an American helicopter, sending oil prices higher. At the same time, the latest Consumer Price Index report showed annual inflation rising to 4.2%, its highest level since April 2023, while core inflation climbed to a seven-month high.

Ordinarily, geopolitical uncertainty can support precious metals.

However, markets focused instead on what higher inflation means for interest rates.

Stronger inflation increases the likelihood that the Federal Reserve will maintain elevated rates—or potentially raise them further. That creates a challenge for silver because, unlike bonds, savings accounts and many other investments, it generates no income.

When interest rates rise, investors often move toward assets that offer yield, reducing the appeal of non-income-producing metals.

Despite the sharp decline, silver remains significantly higher than it was a year ago.

In June 2025, silver traded near $36 per ounce. Even after the recent collapse, prices around $64 still represent a gain of approximately 76% over the past twelve months.

The current selloff therefore represents a retreat from extraordinary highs rather than a return to historical norms.

The rally that preceded the collapse was remarkable.

Silver surged to approximately $121.67 per ounce on January 29, 2026, more than tripling from levels seen during 2025. The following day, the metal suffered its largest one-day decline on record, dropping as much as 35% intraday.

That selloff, combined with simultaneous weakness in gold, erased trillions of dollars in value across precious-metals markets and marked the beginning of a prolonged correction.

Analysts had warned for months that prices had become detached from fundamentals.

Colin Steel of HSBC described silver as fundamentally overvalued despite maintaining a positive long-term outlook. Suki Cooper, head of commodities research at Standard Chartered, similarly warned that silver had entered heavily overbought territory.

Other analysts argued that speculative trading had become the dominant force in the market, pushing prices beyond levels justified by actual industrial or investment demand.

Silver’s volatility stems from its unusual dual role.

It functions both as a precious metal and as an industrial commodity.

Silver is widely used in:

  • Solar panels
  • Electronics
  • Semiconductors
  • Medical devices
  • Electrical systems
  • Advanced manufacturing technologies

Because of that dual identity, silver prices are influenced by both investor sentiment and industrial demand.

Recently, industrial demand growth has shown signs of slowing. Solar manufacturers, one of the largest consumers of silver, continue developing technologies that reduce the amount of silver required per panel, limiting future demand growth.

For investors, the decline serves as another reminder that silver can be considerably more volatile than gold.

Many investors own silver through ETFs such as SLV or through physical coins and bars purchased as inflation hedges. Those who entered near January’s highs are facing substantial losses, while longer-term holders remain well ahead despite the correction.

The impact extends beyond financial markets.

Lower silver prices can eventually reduce costs for solar developers, electronics manufacturers and medical-device producers. At the same time, falling prices can pressure the profitability of silver miners and companies tied closely to precious-metals production.

Gold also moved lower Wednesday, trading near $4,160 per ounce, down more than 2% on the day.

Not everyone has turned bearish.

Some investors view the correction as a buying opportunity, citing long-term supply constraints and expectations for growing industrial demand over the coming decade. Supporters of that view argue that global silver supplies remain tight and that emerging technologies could drive future consumption.

For now, however, markets are focused on inflation, interest rates and geopolitical uncertainty.

The next major event for traders arrives on June 17, when new Federal Reserve Chairman Kevin Warsh is scheduled to hold his first post-meeting press conference. Investors will be looking for clues about how aggressively the central bank intends to respond to rising inflation.

If policymakers signal a more cautious approach, pressure on precious metals could ease.

Until then, rising oil prices, elevated inflation and expectations for higher interest rates continue to create a difficult environment for silver—even after one of the largest corrections in its history.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Massachusetts senator is urging regulators to slow what could become the largest IPO in history, warning that valuation concerns, concentrated control and index-fund exposure could put ordinary investors at risk.

Sen. Elizabeth Warren is asking federal regulators to delay what would be one of the most closely watched stock-market debuts ever.

In a letter released Wednesday, June 10, 2026, the Massachusetts Democrat urged Securities and Exchange Commission Chairman Paul Atkins to postpone the planned initial public offering of SpaceX, arguing that investors need more transparency before the company begins trading.

Space Exploration Technologies Corp., better known as SpaceX, is expected to debut on the Nasdaq on Friday under the ticker SPCX. The company is reportedly targeting a valuation of approximately $1.77 trillion and could raise as much as $75 billion, potentially making it the largest IPO in U.S. history.

Investor demand appears enormous.

Reports indicate orders for shares have exceeded $250 billion, more than three times the amount of stock expected to be sold in the offering.

An IPO marks the first time a private company offers shares to the general public, allowing retail and institutional investors to buy ownership stakes through public markets.

In her 12-page letter, Warren outlined three primary concerns.

The first centers on valuation.

Warren argued that SpaceX’s proposed valuation appears difficult to justify based on publicly disclosed financial information. She pointed to reported 2025 revenue of approximately $18.67 billion and a net loss of $4.94 billion.

At a valuation of $1.77 trillion, the company would be worth roughly 94 times annual revenue, a level Warren described as potentially disconnected from financial fundamentals.

She urged regulators to ensure investors receive sufficient information and cited concerns about what she called the possibility of an “inaccurate or misleading accounting of valuation.”

Her second concern involves corporate governance.

According to the letter, Elon Musk would retain approximately 82.4% of voting power through a dual-class share structure that grants enhanced voting rights to certain shares.

Warren argued that the structure would leave outside shareholders with limited influence over company decisions. She also cited provisions involving mandatory arbitration, restrictions on shareholder proposals and the company’s incorporation under Texas corporate law as factors that could further reduce investor influence.

The third concern could affect millions of Americans who do not directly purchase SpaceX shares.

Several major stock indexes have recently reviewed rules governing how quickly newly public companies can be added to benchmark indexes.

The Nasdaq-100 finalized expedited entry rules on May 1, while similar discussions have occurred among managers of other major indexes.

The issue matters because index funds automatically purchase stocks included in the indexes they track. Millions of Americans own such funds through retirement accounts, pension plans and 401(k) programs.

If SpaceX were added quickly to a major index, passive investors could gain exposure to the company even if they never actively chose to buy the stock.

Warren argued that regulators should closely examine whether accelerated index inclusion could expose retirement savers to excessive risk.

Notably, the committee overseeing S&P Dow Jones Indices reportedly indicated this week that it would not alter its rules specifically to accelerate inclusion of SpaceX or other large IPOs.

In her letter, Warren said the offering appears to present substantial risks for ordinary investors while potentially creating enormous gains for company insiders.

She asked the SEC to delay approval of the final registration process until her concerns are fully addressed.

The timing is tight.

With the planned listing scheduled for Friday, regulators have limited time to respond. An SEC spokesperson confirmed receipt of the letter but declined further comment.

Supporters of the IPO point to strong market demand.

The reported $250 billion-plus order book suggests investors are eager to own shares despite the company’s losses and governance structure. Reports also indicate that SpaceX plans to allocate as much as 30% of the offering to retail investors, a larger share than many major IPOs reserve for individual buyers.

Importantly, Warren’s letter does not accuse SpaceX of fraud or wrongdoing. Rather, it argues that investors should receive greater scrutiny and transparency before the company enters public markets.

For investors, the practical implications vary.

Those who buy individual stocks can decide for themselves whether SpaceX fits their risk tolerance and investment goals. But investors holding broad market index funds could eventually gain indirect exposure if the company is added to major benchmarks.

That possibility is at the center of Warren’s request: slowing the process long enough for regulators to examine whether one of the largest IPOs ever brought to market deserves additional scrutiny before trading begins.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Mexico’s World Cup kickoff is set for Thursday, but demonstrations, road blockades and uncertainty over a major fan festival are casting a shadow over one of the country’s biggest tourism and economic events in years.

Mexico City is hours away from kicking off the 2026 FIFA World Cup on Thursday, but the celebration is colliding with protests that have blocked roads, toppled tournament displays and put the country’s biggest fan party in doubt. On Wednesday, President Claudia Sheinbaum said she could not yet guarantee that the capital’s free fan festival would go ahead because a teachers’ protest camp had sealed off access to the main square where it is meant to take place.

The opening match pits host Mexico against South Africa at Estadio Azteca, the Mexico City stadium that anchors a tournament jointly hosted by the United States, Mexico and Canada. Kickoff is set for Thursday afternoon following a star-studded opening ceremony, with Colombian singer Shakira among the scheduled performers.

Sheinbaum will not attend the match. She said she gave away her ticket and would instead remain focused on monitoring the protests and security situation surrounding the event.

The stakes extend far beyond soccer.

The Mexican Football Federation estimates the tournament will generate roughly $3 billion for hotels, restaurants, transportation providers, sports venues and other tourism-related businesses. Mexico is hosting 13 World Cup matches across Mexico City, Guadalajara and Monterrey during the tournament’s 39-day run.

For many businesses, Thursday’s opener represents the most important single day of the competition. Organizers expect the match and surrounding festivities to attract one of the largest audiences of the entire tournament, making it a showcase event for the country’s tourism and hospitality industries.

That economic opportunity is also fueling some of the protests.

The National Coordinator of Education Workers (CNTE), a powerful teachers’ union, has spent more than a week demonstrating in the capital. Union leaders argue that the government devoted significant resources to stadium upgrades, transportation improvements and tourism infrastructure while failing to adequately address teacher pay, school funding and public services.

The union established a large encampment in the Zócalo, Mexico City’s historic central plaza, where officials had planned to host the tournament’s primary FIFA Fan Festival. Government estimates suggest the encampment could house approximately 6,000 protesters, effectively limiting access to the square.

The disruptions have spread beyond the city center.

Earlier this week, demonstrators blocked sections of a major highway near the stadium. Police erected barriers to prevent protesters from reaching key tournament sites, and several World Cup-themed statues and promotional installations were vandalized.

Mexican authorities say approximately 19 social movements are expected to stage demonstrations during opening-week activities, with at least seven separate marches planned for Thursday alone.

Not all of the demonstrations focus on economic issues.

Groups representing families of Mexico’s missing persons have organized peaceful marches timed to coincide with the tournament opener. The groups hope to draw international attention to the more than 130,000 people reported missing in Mexico, most of them over the past two decades.

Amnesty International this week called for protections for the women leading many of those search efforts, arguing that the global spotlight surrounding the World Cup provides a rare opportunity to raise awareness of the issue.

Despite the tensions, Sheinbaum has sought to project confidence.

She has repeatedly stated that authorities will not be provoked into confrontation and has pledged that the opening match and related activities will proceed peacefully. The government has deployed large numbers of security personnel, including members of the National Guard, throughout the host cities.

The security presence follows a wave of cartel-related violence earlier this year in one of the World Cup host cities, an incident that raised concerns among tournament organizers and international visitors.

For businesses, however, uncertainty carries its own costs.

Hotels, restaurants, retailers and street vendors near both Estadio Azteca and the Zócalo have spent months preparing for large crowds. Road closures, transportation disruptions and the possibility of a canceled or relocated fan festival could reduce the foot traffic many businesses expected to generate significant opening-week revenue.

While one disrupted day is unlikely to derail a tournament lasting more than a month, it could affect perceptions among tourists deciding whether to travel to Mexico for later matches.

The timing is also politically sensitive.

Sheinbaum is preparing for important trade discussions with the United States later this summer. Those talks are expected to influence key manufacturing and supply-chain sectors that tie the two economies closely together.

A World Cup designed to showcase Mexico as a global tourism and business destination is instead opening amid images of protests, road blockades and heavy police deployments — a contrast critics have highlighted in recent days.

Tournament organizers remain confident that the opening match will proceed as scheduled. Whether the surrounding festivities and economic benefits unfold as planned remains the question hanging over Mexico City as the first whistle approaches.

JBizNews Desk — Mexico

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
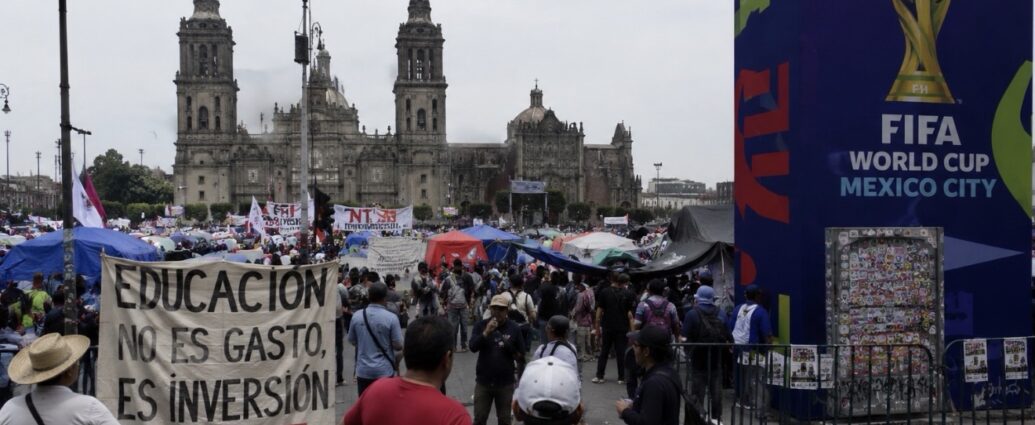
In an age of next-day delivery, one of the most sought-after weapons on earth still moves at a crawl.

A single Patriot PAC-3 interceptor takes more than two years to build and passes through a network of more than 400 companies before it ever reaches a battlefield. That bottleneck is now under enormous strain as wars and security threats drive demand to record levels, revealing how modern defense manufacturing really works.

A Massive Production Ramp Is Underway

The pressure became official this year.

On January 6, Lockheed Martin announced a seven-year agreement with the Pentagon aimed at increasing annual production of PAC-3 interceptors to 2,000 missiles per year, up from roughly 600 annually.

Tripling production sounds simple on paper.

Building the factories, supply chains, and workforce needed to make that happen is anything but simple.

One Missile, Hundreds of Suppliers

A Patriot missile is not built by a single company.

Lockheed Martin manufactures the PAC-3 interceptor itself.

Boeing produces the advanced seekers that guide the missile to its target.

Raytheon, a division of RTX, builds the radar systems and launchers that make the Patriot system work.

Behind those well-known defense giants sits a vast network of more than 400 suppliers, each responsible for specialized components.

Every part must arrive on schedule, meet military specifications, and pass extensive testing before final assembly can proceed.

If a single supplier experiences delays, the entire production chain can slow down.

A Defense Industry Built for Efficiency, Not Wartime Demand

The challenge stems partly from how the defense industry evolved over the past three decades.

Manufacturers increasingly adopted practices common throughout the private sector:

  • Just-in-time inventory systems
  • Single-source suppliers
  • Lean manufacturing
  • Minimal spare inventory

Those strategies reduce costs during peacetime.

But they create vulnerabilities when demand suddenly surges.

That is exactly what is happening today.

Global Demand Is Exploding

The Patriot missile has become one of the world’s most heavily used air-defense weapons.

It has played a central role in Ukraine’s defense against Russian missile attacks and has been heavily utilized throughout conflicts in the Middle East.

Recent attacks involving Iran generated what defense officials described as the largest operational use of Patriot systems in history.

The result is a growing backlog.

The current order book exceeds 4,300 Patriot interceptors from more than a dozen countries, including:

  • Saudi Arabia
  • Germany
  • Poland
  • Japan
  • South Korea

At current production rates, that represents roughly seven years of manufacturing demand.

In one April 2026 contract, approximately 94% of the funding came from foreign governments purchasing through U.S. military sales programs.

The Economics Behind the Missile

The financial stakes are enormous.

According to a Congressional Research Service briefing, each Patriot interceptor costs at least $4 million.

In September 2025, Lockheed Martin received a $9.8 billion contract covering 1,970 missiles, the largest Patriot order ever placed.

Those long-term commitments are critical because they give manufacturers confidence to:

  • Build new facilities
  • Hire workers
  • Expand production lines
  • Invest in new equipment

Without multiyear contracts, companies are reluctant to make such expensive investments.

Factories Can’t Expand Overnight

Progress is happening, but slowly.

Lockheed Martin increased PAC-3 production by more than 60% over two years and delivered approximately 620 interceptors during 2025.

Meanwhile, Boeing is expanding its seeker-manufacturing facilities by roughly 30%, but the additional capacity is not expected to come online until 2027.

Building new factories takes time.

Installing equipment takes time.

Training skilled workers takes time.

None of those constraints can be solved immediately.

The Math Still Doesn’t Work

Even with planned expansions, some analysts worry production may still lag demand.

According to Fabian Hoffman, a missile expert at the University of Oslo, global Patriot interceptor production currently runs at roughly 850 to 880 missiles annually and could rise to around 1,130 per year by 2027.

The challenge is that air-defense forces frequently launch two or three interceptors against a single incoming threat to maximize the chances of a successful interception.

Meanwhile, many adversaries can manufacture offensive missiles more quickly and at lower cost.

Producing more Patriots helps.

It may not completely close the gap.

The Hidden Side of National Defense

Most people see the visible side of air defense: a missile launching into the sky.

The invisible side is a vast industrial network involving:

  • Hundreds of suppliers
  • Specialized manufacturing facilities
  • Scarce skilled labor
  • Long-term contracts
  • Highly regulated production processes

National security ultimately depends on that industrial foundation.

The Bottom Line

The short-term story is a record production ramp, with billions of dollars flowing to Lockheed Martin, Boeing, and RTX as governments rush to strengthen air defenses.

The longer-term story is more challenging.

The United States and its allies are attempting to transform a defense industry optimized for efficiency into one capable of sustaining wartime production levels.

Until that transition is complete, the biggest obstacle to getting more Patriot missiles into the field may not be technology or funding.

It may simply be the factory floor.

JBizNews Desk — Defense & Manufacturing

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
CHICAGO — Some of America’s largest food manufacturers continue trimming their workforces in 2026 as higher costs, changing consumer habits, and growing automation reshape one of the nation’s most important industries.

From snack foods and packaged meals to beverages and meat products, companies across the food sector are eliminating jobs, consolidating operations, and investing in technology as they adapt to slower consumer spending.

Among the most notable moves, PepsiCo confirmed the closure of a longtime Frito-Lay facility in Orlando, Florida, affecting hundreds of workers. The company said the decision is part of a broader effort to improve efficiency and modernize operations.

PepsiCo is far from alone.

Major food and beverage companies including Kraft Heinz, General Mills, Hormel Foods, Archer-Daniels-Midland, Heineken, and Beyond Meat have all announced layoffs, restructuring initiatives, or operational changes during the past year.

The common thread is pressure on profit margins.

Consumers facing higher grocery bills and rising household expenses are increasingly trading down to lower-cost alternatives, purchasing fewer discretionary items, and showing greater sensitivity to price increases.

That creates challenges for food manufacturers that spent years relying on brand loyalty to support premium pricing.

Store brands are gaining market share.

Private-label products sold by grocery chains often cost significantly less than nationally advertised brands, making them increasingly attractive to budget-conscious shoppers.

The result is growing competition for shelf space and consumer dollars.

At the same time, technology is changing how food is produced.

Modern manufacturing facilities require fewer workers than previous generations thanks to automation, robotics, and advanced production systems. Tasks once performed manually can now be handled by machines operating around the clock.

For companies facing rising labor costs and pressure from investors to improve efficiency, automation offers an attractive solution.

For workers, however, the consequences can be severe.

Factory jobs have historically provided stable middle-class wages, often without requiring a college degree. Plant closures can affect entire communities, reducing economic activity and eliminating opportunities for workers whose skills are closely tied to manufacturing.

The broader economic impact extends beyond the factory floor.

Every major food-processing facility supports suppliers, transportation companies, maintenance contractors, local businesses, and surrounding communities. When facilities close, those effects can spread throughout a region.

Food manufacturers also face pressure from higher transportation and ingredient costs.

Fuel prices remain elevated, packaging costs have increased, and supply-chain disruptions continue affecting portions of the industry. Companies are attempting to balance those expenses while avoiding excessive price increases that could drive customers elsewhere.

Investors generally support efficiency initiatives.

Wall Street often rewards companies that reduce costs and improve productivity, particularly during periods of economic uncertainty. That dynamic creates additional pressure for executives to streamline operations and reduce headcount where possible.

Yet the long-term challenge remains unresolved.

Food companies must find ways to protect profits while maintaining customer loyalty in an environment where consumers are increasingly focused on affordability.

For shoppers, the impact may not be immediately visible.

Store shelves remain stocked, products remain available, and the food system continues functioning. Behind the scenes, however, fewer workers are producing many of the products Americans consume every day.

The trend highlights a broader reality emerging across multiple industries.

Companies are learning how to operate with leaner workforces while relying more heavily on technology, automation, and data-driven decision-making.

For now, America’s food supply continues moving from factories to store shelves.

It is simply being done by fewer hands than before.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — Americans are feeling worse about their finances than at any point on record, according to a closely watched consumer survey that underscores the growing strain higher prices are placing on household budgets.

The latest University of Michigan Consumer Sentiment Index fell to 44.8 in May, the lowest reading in the survey’s history and the third consecutive monthly decline. The reading was revised lower from an earlier estimate of 48.2 and now sits below the previous record low reached during the inflation surge of 2022.

The decline reflects a simple reality facing many households: the cost of everyday life continues to outpace what families feel they can comfortably afford.

According to the survey, 57% of respondents spontaneously cited rising prices as a major concern, up from 50% a month earlier. That means nearly six in ten Americans brought up inflation without being prompted, making it the dominant economic concern across the country.

The biggest pressures remain familiar.

Gasoline prices remain elevated, grocery costs continue rising, and housing affordability remains near multi-decade lows. While the labor market has remained relatively stable, many consumers say their paychecks are not stretching as far as they once did.

Survey Director Joanne Hsu said persistent inflation and higher fuel costs continue weighing heavily on public sentiment, particularly among lower-income households.

The pain is not being felt equally.

Consumers with lower incomes and those without college degrees reported some of the steepest declines in confidence, reflecting their greater exposure to rising costs for essentials such as food, transportation, utilities, and rent.

Unlike wealthier households, many families have little room to absorb higher expenses without cutting back elsewhere.

The survey also revealed growing concern about the future.

Consumers now expect inflation to remain elevated over both the next year and the longer term. Year-ahead inflation expectations rose to approximately 4.8%, while long-term inflation expectations increased to 3.9%.

That matters because expectations often influence behavior.

When consumers believe prices will continue rising, they frequently delay major purchases, reduce discretionary spending, and become more cautious about taking on debt. Those decisions can ripple throughout the broader economy.

The gloomy mood stands in contrast to recent government employment data.

The economy added 172,000 jobs in May, and unemployment remains relatively low at 4.3%. On paper, the labor market appears healthy.

But sentiment surveys measure something different.

They capture how people feel about their personal finances, not simply whether they have a job.

For many Americans, having a paycheck is no longer enough to feel financially secure when food, fuel, housing, insurance, and utility bills continue rising faster than expected.

Businesses are paying close attention.

Consumer spending accounts for roughly two-thirds of U.S. economic activity. When confidence falls, retailers, restaurants, travel companies, and manufacturers often feel the impact through slower sales and more cautious purchasing behavior.

Several major consumer-facing companies have already reported signs of customers trading down to lower-cost products, delaying purchases, and focusing more heavily on discounts and promotions.

Historically, consumer sentiment readings this low have often coincided with periods of slower economic growth.

While economists caution that sentiment alone does not guarantee a downturn, the survey provides an important snapshot of how households are experiencing the economy in real time.

There is some reason for cautious optimism.

Earlier this spring, sentiment improved modestly when gasoline prices briefly retreated and geopolitical tensions appeared to ease. That suggests consumer confidence could recover relatively quickly if inflation moderates and fuel costs decline.

For now, however, the message from American households is clear.

Even with jobs available and unemployment relatively low, the rising cost of everyday necessities is leaving consumers feeling more financially stressed than at any other point since the survey began.

Whether that mood improves will depend largely on what happens next with inflation, interest rates, fuel prices, and the broader economy.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
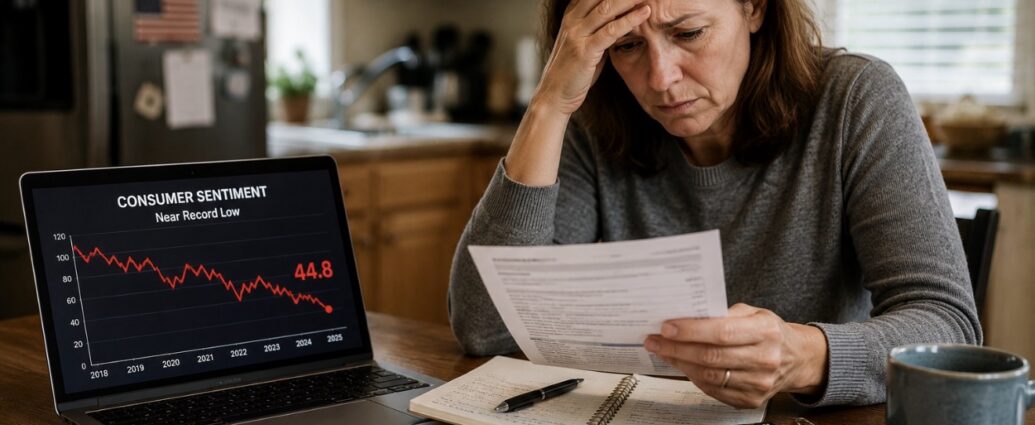
Gold did the opposite of what it normally does on Wednesday, June 10. On a day when the United States struck Iran and the government reported the hottest inflation in three years, the metal that investors usually run toward in a panic instead dropped more than 4%, sliding toward $4,100 an ounce.

The selling followed two events that hit on the same morning. The Bureau of Labor Statistics reported that consumer prices rose 4.2% over the past year, the fastest pace since April 2023. Hours earlier, U.S. Central Command confirmed it had struck Iranian air defense and radar sites near the Strait of Hormuz. Either headline would normally send buyers into gold. Instead, the metal fell.

The reason comes down to interest rates. Gold pays no interest. When bonds and savings accounts offer high returns, holding gold means giving up that income. After the strong May jobs report and Wednesday’s inflation reading, investors concluded the Federal Reserve will keep interest rates high all year, and may even raise them. Some traders now put the odds of a rate increase by December near 70%. Higher rates make gold less attractive, so money flowed out.

A firm U.S. dollar added to the pressure. Gold is priced in dollars, so when the dollar strengthens, gold tends to weaken. Treasury yields climbing toward 4.5% pushed in the same direction.

There was also a technical trigger. Gold fell below its 200-day moving average, a closely watched line that trend-following traders use as a buy-or-sell signal. Once that line broke, automatic selling kicked in, turning a pullback into a rout.

The drop caps a rough stretch. Gold has fallen more than 11% over the past month, retreating from a late-April high near $4,800 and from its January record around $5,600. Even so, it remains roughly 25% higher than it was a year ago. This is a sharp correction inside a long climb, not a collapse.

That distinction matters for the people who own gold, and many do, through coins, exchange-traded funds, and retirement accounts. The forces that drove gold higher for years have not disappeared. Central banks bought 244 tonnes of gold in the first quarter of 2026, up 3% from a year earlier, as countries continue to diversify away from the dollar. Those buyers tend to hold for the long term and are unlikely to be shaken out by a bad week.

Still, the near-term path looks bumpy. Analysts at Citi warned in a note this week that if the Strait of Hormuz stays closed through the end of summer, gold could fall as low as $3,500 an ounce. The logic is the same loop driving everything else: a longer war keeps oil expensive, which keeps inflation high, which keeps interest rates up, which keeps pressure on gold.

For everyday investors, Wednesday was a reminder that gold is not a guaranteed safe haven. It usually rises during fear, but it answers to interest rates and the dollar just as much as to geopolitics. When those forces line up against it, even a war headline cannot hold it up.

Some buyers see the pullback as a chance to get in cheaper. Others worry the slide has further to go. What is clear is that the same war and inflation story squeezing households at the gas pump is now reaching into investment portfolios, and gold, long seen as the steadiest store of value, is having one of its most volatile years in decades.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Italian coffee giant Lavazza announced Monday, June 8, that it is bringing its Tablì single-serve system to the United States, a launch the company called its biggest U.S. investment ever in a press release issued from West Chester, Pennsylvania. Instead of the plastic pods that dominate American kitchens, Tablì uses a small, solid tablet made entirely of compressed ground coffee — no capsule, no wrapper, and no coating.

Each tablet consists solely of pressed coffee, dosed and tamped into a ready-to-use disk marked “100% coffee.” The tablets work exclusively with Lavazza’s proprietary Tablì machine. At launch, consumers can choose from five varieties: Super Crema, Espresso, Double Espresso, Lungo, and Decaf.

Getting the tablet to hold together was the difficult part. Antonio Baravalle, CEO of Lavazza, told CNBC that the company spent roughly five years developing the technology, filed more than 15 patents, and built a dedicated factory in Gattinara, Italy, to manufacture the tablets. He described the process as a complex engineering challenge requiring the coffee to be compressed tightly enough to survive shipping while still brewing properly once inside the machine.

The larger story is the market Lavazza is targeting. The U.S. single-serve coffee segment has long been dominated by Keurig Dr Pepper, whose K-Cup pods account for about 50% of fresh ground coffee pod sales in the United States, according to Euromonitor International. Nespresso holds roughly 7%. Keurig’s coffee business generated approximately $3.99 billion in net sales during 2025. By comparison, Lavazza’s U.S. retail business, sold through chains such as Target and Walmart, exceeds $100 million annually.

Baravalle has been candid that Lavazza is not attempting to dethrone the industry leaders. He told CNBC the company is focused on creating its own category while maintaining existing partnerships. One of those partners is Keurig itself, which currently sells Lavazza-branded K-Cup products. The result is an unusual dynamic in which Lavazza is competing with a company that also helps distribute its products.

The marketing pitch centers heavily on sustainability. Keurig’s pods have faced years of criticism over plastic waste. While the company announced that all K-Cups were recyclable as of late 2020, the U.S. Securities and Exchange Commission charged Keurig in 2024 with making misleading statements regarding recyclability. Keurig agreed to pay $1.5 million to settle the matter without admitting or denying the findings. Its website now advises customers to verify local recycling capabilities because many communities do not process the pods. Lavazza is betting that a product made entirely of coffee, with no capsule at all, will appeal to environmentally conscious consumers.

Pricing places Tablì firmly in the premium category. A pre-order bundle on TabliCoffee.us, including the machine, milk frother, tweezers for handling the tablets, and a 60-count variety pack, is being offered for $99.99, discounted from a stated value of $249.99.

Daniele Foti, Vice President of Marketing at Lavazza North America, said the company views Tablì as an opportunity to strengthen its position among American consumers, describing the United States as one of the world’s most dynamic coffee markets. The full retail launch is scheduled for August through LavazzaUSA.com, with availability on Amazon expected later this year.

The timing is notable. Keurig is preparing to launch its own plastic- and aluminum-free single-serve option, a puck-shaped product called K-Rounds, developed with Swiss manufacturer Delica and expected to reach stores this fall. Both companies are now racing to persuade consumers that convenience and sustainability can coexist in the single-serve coffee category.

For Lavazza, the stakes extend far beyond one product line. North American revenue rose 26.9% last year, and Baravalle has publicly stated his goal of building the U.S. market into a €1 billion business. Whether American consumers embrace coffee tablets over traditional pods is now a test that will play out in kitchens across the country.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Wall Street closed sharply lower Wednesday after the U.S. Bureau of Labor Statistics reported that consumer prices rose at their fastest annual pace in three years, and after the United States launched fresh military strikes inside Iran overnight. The combination of hotter inflation, a widening Middle East conflict, and a deepening sell-off in technology stocks pulled every major index down hard.

The Dow Jones Industrial Average fell 953.33 points, or 1.87%, to 49,918.78. The S&P 500 lost 1.62% to end at 7,266.99, and the Nasdaq Composite dropped 1.98% to settle at 25,169.50. The small-cap Russell 2000 slipped 1.10% to 2,835.47. The Cboe Volatility Index, Wall Street’s fear gauge, jumped more than 12% to 22.32.

The selling started with the morning inflation report. The Bureau of Labor Statistics said the Consumer Price Index rose 0.5% in May on a seasonally adjusted basis, after rising 0.6% in April. Over the last 12 months, prices climbed 4.2% — the fastest annual pace since April 2023.

Energy did most of the damage. The agency said the energy index rose 3.9% in May and accounted for over sixty percent of the monthly increase in overall prices. Gasoline led the climb. Shelter costs rose 0.3%.

There was a softer story underneath the headline. Core CPI, which strips out food and energy, rose just 0.2% for the month, a slowdown from April, and 2.9% over the past year. Prices for airfare, medical care and recreation rose in May, while new cars, household furnishings and car insurance got cheaper. The split left economists divided on what the Federal Reserve, now led by Chair Kevin Warsh, will do next. According to CME FedWatch, futures traders are not pricing in any rate cuts at all this year — and some now see a rate increase before December.

The second blow came from overseas. U.S. Central Command said American forces struck Iranian air defense, ground control, and radar sites near the Strait of Hormuz beginning at 5 p.m. Eastern on Tuesday, in response to the downing of a U.S. Army Apache helicopter off the coast of Oman. Both pilots were rescued. The escalation pushed oil higher. Brent crude rose about 2% to roughly $93 a barrel. Higher oil prices feed straight back into the gasoline costs that just drove inflation to a three-year high, a loop that worries households and the Fed alike.

Technology and chip stocks took the worst of it. The clearest pain came from Super Micro Computer, which sank nearly 28% on the day. The company said in a Tuesday statement that it plans to raise $7 billion through a series of equity and equity-linked financing transactions to fund the purchase of components for its AI servers. Management said the cash will help fill about $39 billion in orders from more than 20 customers. J.P. Morgan, Goldman Sachs and Citigroup are managing the sale. Investors balked at the size of the raise, which dilutes existing shareholders, and dumped the stock.

The damage spread across the sector. Micron Technology fell 4.70%. Nvidia, Apple and Advanced Micro Devices all closed lower as investors grew nervous about whether the enormous spending on artificial intelligence will ever turn into steady profit. The worry is no longer whether AI demand exists — Super Micro’s order book proves it does — but how much new stock and debt these companies will sell to chase it.

Not everything fell. A handful of household names hit fresh records as investors hid in defensive corners of the market. Coca-Cola rose more than 2% to an all-time high. TJX Companies, the parent of T.J. Maxx and Marshalls, climbed and also touched a record, a sign that shoppers are still hunting for bargains. Applied Materials reached a new high as well. Energy, financials, consumer staples and real estate were among the few groups in the green.

The weakness was global. In Asia, Japan’s Nikkei 225 fell 1.89% to 64,179.27, while South Korea’s Kospi slumped 4.52% to 7,730.82 on the same tech sell-off and Middle East fears. In Europe, the pan-European Stoxx 600 traded lower as AI-linked names retreated, with London-listed Raspberry Pi and Germany’s SAP both falling.

Gold, often a safe haven, dropped more than 4% to about $4,099 an ounce as investors raised cash. Bitcoin dipped slightly to around $61,700.

For everyday Americans, Wednesday’s session tied together the two pressures squeezing wallets right now: prices that keep climbing at the gas pump and grocery aisle, and a stock market — including the retirement accounts of millions — that just had one of its worst days of the year. With the next CPI report not due until mid-July, and the conflict with Iran still unfolding, the road ahead looks bumpy.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The most powerful nations on Earth are learning a hard lesson: having the strongest military no longer means getting your way. The clearest proof came Tuesday, June 9, when U.S. Energy Secretary Chris Wright said more ships are again moving through the Strait of Hormuz — the narrow sea passage that carries about a fifth of the world’s oil — even as the United States and Iran remain locked in a standoff neither side can fully win. Oil prices fell on his comments. U.S. crude dropped 3.4% to $88.20 a barrel, while Brent crude fell 2.97% to $91.45. President Donald Trump said a deal with Iran to fully reopen the passage was “two or three days away.”

The United States, China, and Russia still possess the largest militaries and some of the most advanced weapons on Earth. But being the strongest is no longer enough to force an outcome — and the consequences are showing up where ordinary people feel them most: in oil prices, taxes, and the cost of everyday life.

Look at the U.S. and Iran. The United States and Israel began strikes against Iran on February 28. When direct talks between the two countries collapsed in April, Trump ordered the U.S. Navy to blockade Iran’s ports. Iran responded by threatening to close the Strait of Hormuz and choke off the world’s oil supply.

Months later, neither side has achieved a decisive victory. The U.S. could not force Iran to surrender. Iran could not keep the oil route closed. The strongest military on Earth still could not simply make the problem disappear.

That fight has come with a steep price. In testimony before the House Appropriations Defense Subcommittee, Pentagon acting comptroller Jay Hurst said the Iran conflict has already cost American taxpayers about $29 billion, up from roughly $25 billion just one month earlier. The bill continues to grow even as major combat operations have slowed.

There is a bigger issue behind the dollars. A report by the Center for Strategic and International Studies (CSIS) titled “Last Rounds? Status of Key Munitions at the Iran War Ceasefire” found that the United States drew down roughly half of its stockpile of its most expensive precision munitions and could require years to fully rebuild those inventories.

To help accelerate production, the Pentagon approved a $500 million investment in Honeywell Aerospace to expand critical missile-component manufacturing. Defense Secretary Pete Hegseth has said the military remains adequately supplied but has also pushed defense manufacturers to increase production capacity.

The strain is now showing up in the federal budget. Trump has proposed a $1.5 trillion defense budget for next year, roughly a 42% increase and the largest one-year military spending jump since World War II. In practical terms, the United States is attempting to project power simultaneously in the Middle East, Europe, and Asia, while spending unprecedented sums to sustain that posture.

Other major powers face their own limitations.

China’s leader, Xi Jinping, warned in May that the United States and China could slide toward open conflict over Taiwan if relations are mishandled. Yet the same CSIS analysis highlighted a critical weakness: China has not fought a major war since 1979 and lacks recent battlefield experience. That is one reason many military analysts believe Beijing is not prepared to launch an invasion of Taiwan in the near term.

Russia offers another example. Its prolonged war in Ukraine exposed weaknesses in logistics, equipment, manpower, and military planning despite Moscow possessing one of the world’s largest armed forces.

The pattern is becoming increasingly clear. The world’s biggest and best-armed nations can still inflict enormous damage. What they can no longer reliably do is force a quick, clean, and decisive outcome.

Why does that matter to ordinary people?

Because the costs ultimately reach consumers and businesses. When oil prices surge, the impact spreads quickly through gasoline, diesel, shipping, air travel, manufacturing, and retail prices. Every additional dollar devoted to military spending is a dollar unavailable for other priorities. And companies that depend on global supply chains must now plan for disruptions that can emerge with little warning.

The takeaway is simple. Ceasefires will come and go. Oil prices will rise and fall. But beneath the headlines, a deeper shift is underway. Military power can still start conflicts and shake global markets. What it increasingly cannot do is control how those conflicts end.

That uncertainty has become a permanent feature of the global economy — and of everyday business.

JBizNews Desk — Global Affairs

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
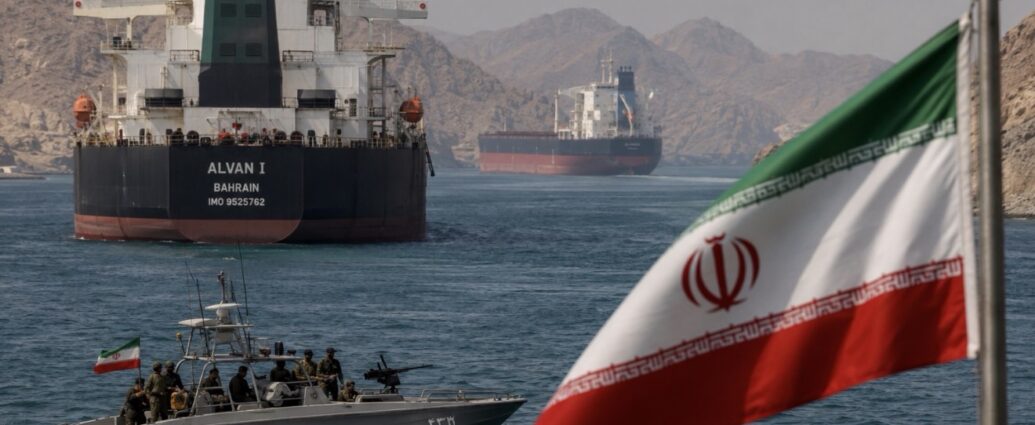
The European Commission, the European Union’s top competition enforcer, on Tuesday, June 9, ordered Meta Platforms to give rival artificial intelligence chatbot makers free access to WhatsApp while regulators finish an antitrust investigation into the company. The order was announced by the Commission’s competition chief, Executive Vice-President Teresa Ribera, in Brussels.

At the center of the fight is the WhatsApp Business API — the tool companies use to plug their own software into WhatsApp so they can message customers through the app. Meta barred rival AI services from that tool in October last year while keeping its own assistant, Meta AI, available. Regulators say that move shut competitors out of a doorway to millions of European users.

Why WhatsApp Matters in the AI Race

WhatsApp is not just a messaging app. For many companies, it has become a customer-service desk, sales channel, marketing platform, and increasingly a gateway to artificial intelligence. Access to WhatsApp allows AI assistants to answer customer questions, help complete purchases, provide support, and interact with users where they already spend their time. Regulators argue that if Meta reserves that access primarily for its own AI products, competitors may never get a fair chance to reach consumers.

The Commission acted using emergency powers it rarely touches. It is the first interim measure the Commission has issued in 17 years. The point of that tool is speed: rather than wait years for a final ruling, regulators can force a change now to stop damage they fear would be impossible to undo later.

Ribera put the reasoning plainly, saying in a statement that competition can be lost long before a final decision is adopted. She said the measures are meant to protect WhatsApp as a key entry point for AI companies to reach consumers in Europe and to let them scale up.

[AP pic: A WhatsApp icon displayed on a smartphone screen.]

The order is specific. Meta must restore rivals’ access to the WhatsApp Business API on the same terms that applied before October, within five working days. The interim measures stay in place for the duration of the investigation, which has no fixed deadline.

How the Dispute Started

The investigation began in December after complaints from The Interaction Company of California, maker of the Poke.com AI assistant, French startup Agentik, and a Spanish rival. The Commission filed formal charges against Meta about two months later.

In March, Meta allowed competitors back onto the platform — but only for a fee. The Commission objected, saying the price was set so high that it was not economically sustainable for competitors. Ribera echoed that concern in announcing Tuesday’s decision.

Meta rejected the order and said it will fight it.

A company spokesperson called the decision regulatory overreach and argued that it forces Meta to provide a product it built and maintains to some of the world’s largest AI companies for free. The company confirmed it plans to appeal.

Billions of Dollars Could Be at Stake

The financial risk for Meta is substantial.

If regulators ultimately determine that Meta violated European antitrust laws, the company could face fines of up to 10% of its global annual revenue. For a company of Meta’s size, that could amount to billions of dollars.

Meta is already appealing a separate $228.34 million European Union penalty tied to the bloc’s Digital Markets Act.

[AP pic: Business professionals use AI-powered messaging tools on smartphones and laptops in an office environment.]

A New Approach to Regulating AI

For businesses, the case reaches far beyond one messaging app.

AI assistants are rapidly becoming a common way people search for information, shop online, communicate with companies, and receive customer support. The companies building those systems are racing to reach users wherever they already spend their time, and WhatsApp represents one of the largest digital gateways in Europe.

Regulators argue that by limiting competitors’ access while promoting Meta AI, Meta was using control of the platform to give its own AI products an advantage.

The ruling also signals how Europe plans to regulate AI competition moving forward.

For years, critics argued that European antitrust investigations moved too slowly, allowing dominant technology companies to cement their market positions long before any penalties were imposed. By issuing an emergency order in an active AI market, the Commission is demonstrating a willingness to intervene much earlier.

The Bottom Line

For now, the immediate effect is straightforward: European consumers and businesses using WhatsApp should soon have access to more AI assistants inside the app, not just Meta’s own.

For Meta, the decision represents both a setback for its AI strategy and a challenge to a revenue-generating business product. More importantly, it may mark the beginning of a new era in which regulators move far more aggressively to shape competition in the rapidly evolving AI industry.

JBizNews Desk — Europe

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
China sold far more goods abroad than expected last month — including a sharp jump in shipments to the United States — even with American tariffs still in place.

According to data released Tuesday, June 9, by China’s General Administration of Customs, exports rose 19.4% in May from a year earlier in dollar terms, accelerating from April’s 14.1% gain and easily beating economists’ expectations of roughly 15% growth.

The number attracting the most attention was the one tied to the United States.

China’s exports to the U.S. surged 35.4% in May compared with a year earlier, the strongest increase in five years. The jump marks a dramatic reversal from much of last year, when shipments to America were falling sharply under the weight of tariffs and slowing demand.

For many readers, the obvious question is simple: if tariffs are supposed to discourage imports, why are Chinese exports to the United States rising so quickly?

Why Tariffs Aren’t Stopping Trade

A tariff raises the price of imported goods, but it does not automatically eliminate demand.

Many American businesses still depend on Chinese-made products because there are few alternatives available at comparable prices or scale. As a result, imports can continue growing even when tariffs remain in place.

Part of the recent surge also appears to be about timing.

Companies around the world rushed to place orders ahead of rising energy and shipping costs linked to the conflict in the Persian Gulf. When businesses expect transportation costs to increase, they often stock up early, temporarily boosting trade figures.

That front-loading effect appears to have contributed to May’s export surge.

The AI Boom Is Driving Demand

The larger force may be technology.

China’s exports of computer chips, known as integrated circuits, jumped 110% in value from a year earlier, while exports of high-tech products overall rose 50%.

The global race to build artificial intelligence systems is fueling demand for semiconductors, electronics, servers, networking equipment, and other technology products. China remains a major supplier in many of those categories.

As companies worldwide invest billions of dollars into AI infrastructure, demand for Chinese-made technology products has remained strong.

Tariffs Are Lower Than Before

The trade environment has also become less restrictive.

U.S. tariffs on many Chinese goods now stand at roughly 10% after the Supreme Court struck down a series of tariffs that President Donald Trump had imposed using emergency powers.

Trade relations also improved somewhat after Trump met Chinese President Xi Jinping during an APEC summit in South Korea last October.

Lower duties make it easier for Chinese goods to remain competitive in American markets, helping explain why exports have rebounded so strongly.

Economists See More Growth Ahead

Several economists believe the momentum could continue.

Sheana Yue, a senior economist at Oxford Economics, said demand for green-energy products such as electric vehicles, batteries, and solar equipment remains strong, while AI-related technology exports continue to expand.

Tianchen Xu, a senior economist at the Economist Intelligence Unit, noted that China’s tariff disadvantage relative to some Southeast Asian manufacturing hubs has narrowed, improving the competitiveness of Chinese exports.

Those trends are helping offset weakness in other parts of the Chinese economy.

What It Means for Consumers and Businesses

For American consumers, the data suggests that lower-cost Chinese goods continue to arrive in large quantities.

That includes electronics, household appliances, industrial equipment, and components used by manufacturers across the United States.

Continued imports can help limit price increases for some products, even as inflation pressures remain elevated elsewhere in the economy.

For American businesses, the figures reinforce how deeply integrated global supply chains remain despite years of political tensions and tariff disputes.

For Trump, the numbers present a challenge to one of the core goals of his tariff strategy: reducing America’s dependence on Chinese imports.

And for China, the report highlights how important exports have become as a source of growth while the country continues to struggle with a prolonged real-estate downturn and weaker domestic demand.

The Bottom Line

Tariffs may dominate the political conversation, but they are not the only force shaping trade.

A combination of early ordering, booming demand for AI-related technology, and a more favorable tariff environment helped drive Chinese exports sharply higher in May.

The result: China’s exports are growing faster than expected, and American buyers remain a major part of that story.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
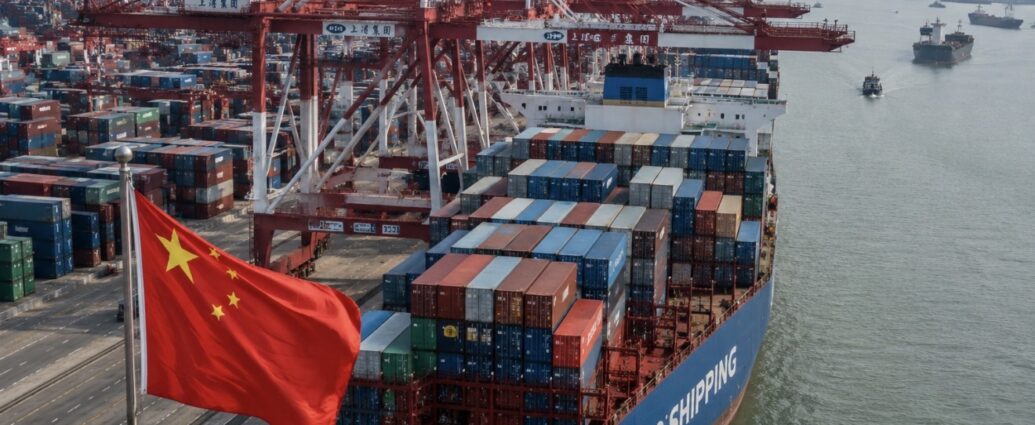
The Trump family has earned at least $2.3 billion from a series of cryptocurrency ventures since President Donald Trump returned to the White House, while investors who bought into those projects collectively lost roughly the same amount, according to a Reuters investigation published Tuesday, June 9, 2026.

The report, based on blockchain records, corporate filings, public disclosures, and interviews with investors and industry experts, paints a picture of a highly profitable business model for the project’s promoters — even as many investors suffered steep losses.

The Numbers Behind the Report

Reuters found that four Trump-linked crypto ventures generated at least $2.3 billion for entities connected to the Trump family.

At the same time, more than one million investors collectively lost approximately $2.3 billion as the value of the assets declined.

According to the investigation, the Trump family’s role largely involved licensing its name and promoting the projects through public appearances, interviews, and social media rather than investing substantial amounts of its own capital.

Industry experts interviewed by Reuters said the ventures required relatively modest startup costs compared with the revenue they ultimately generated.

That meant the overwhelming majority of profits came from licensing fees, token sales, and revenue-sharing arrangements rather than from direct investment risk.

As Donald Trump himself told Reuters in a 2016 interview regarding licensing deals: “The licensing deals are the best of all deals because there’s no risk.”

The Four Crypto Ventures

The Reuters investigation focused on four Trump-affiliated crypto businesses:

  • World Liberty Financial
  • $TRUMP meme coin
  • AI Financial Corp. (formerly ALT5 Sigma)
  • American Bitcoin

The largest source of revenue was reportedly World Liberty Financial, a cryptocurrency venture co-founded by Eric Trump and Donald Trump Jr.

According to Reuters, more than $1.4 billion flowed to Trump-controlled entities through governance-token sales and revenue-sharing arrangements.

The report states that investors who purchased those tokens later suffered losses estimated at approximately $674 million as the token’s value fell roughly 87% from its September 2025 peak.

The Meme Coin Boom and Bust

The investigation also highlighted the performance of the $TRUMP meme coin, one of the most recognizable politically branded cryptocurrencies.

Reuters estimates the project generated approximately $616 million for Trump-affiliated entities.

Investors, meanwhile, lost more than $700 million as the token’s value declined sharply.

According to the report, the coin has fallen approximately 97% from its all-time high, underscoring the extreme volatility that has become common among celebrity- and politically branded digital assets.

Other Trump-linked crypto-related stocks experienced similar declines.

Shares of ALT5 Sigma, now known as AI Financial Corp., reportedly fell from more than $9 per share to roughly 75 cents by April 2026.

Why Wall Street Is Paying Attention

Beyond the political implications, the findings highlight a growing trend in the digital-asset market.

Celebrity-backed and politically branded cryptocurrencies have become increasingly popular among retail investors, often generating large amounts of money for founders and promoters before prices experience dramatic declines.

The Reuters analysis raises broader questions about whether investors fully understand the risks associated with these products and whether existing disclosure standards adequately protect consumers.

The investigation also arrives as regulators continue debating how digital assets should be governed and marketed.

Ethics Questions Emerge

Reuters reported that eight government ethics experts described the arrangements as presenting potential conflicts of interest because they involve businesses linked to a sitting president.

Critics argue that political influence and financial interests can become intertwined when public officials or their families profit from ventures tied to public visibility.

Supporters counter that the projects are private-sector businesses operating under existing laws and disclosure requirements.

The White House Response

The White House strongly disputed suggestions of wrongdoing.

White House spokesperson Anna Kelly told Reuters that President Trump’s actions and policies are made in the best interests of the American people and that neither the president nor his family has engaged in conflicts of interest.

Eric Trump and Donald Trump Jr. did not respond to Reuters’ requests for comment cited in the report.

The Trump family has previously defended its cryptocurrency ventures as lawful business activities that have been properly disclosed.

The Bottom Line

Regardless of political views, the Reuters investigation highlights a basic investment lesson.

The creators, promoters, and licensors of many crypto projects often earn money from fees, token sales, and branding agreements before investors ever see a return.

Investors, meanwhile, assume most of the market risk.

In the case of the Trump-linked ventures reviewed by Reuters, the promoters reportedly earned billions while investors absorbed comparable losses.

For retail investors, it serves as a reminder that a famous name may attract attention—but it does not guarantee long-term value.

JBizNews Desk — Markets & Cryptocurrency

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
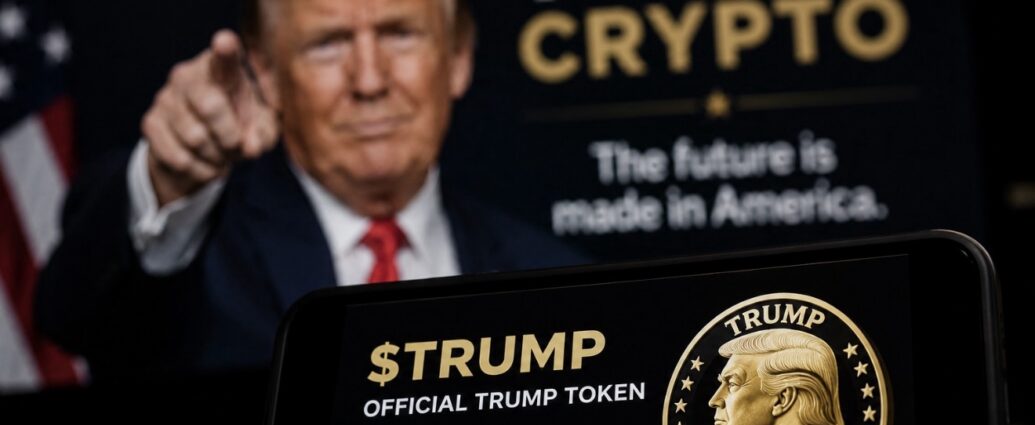
Millions of Americans who rely on Medicaid for health insurance are less than seven months away from a major eligibility change — and most have no idea it is coming.

A new survey from The Health Management Academy, an Arlington, Virginia-based research organization, found that 55% of Medicaid enrollees are completely unaware that work requirements will become a condition of eligibility beginning January 1, 2027. Another 27% said they had heard about the changes but did not understand the details.

The survey, conducted in April 2026, included 1,974 adults enrolled in Medicaid and highlights a growing concern among policymakers, hospitals, and insurers that millions of eligible Americans could lose coverage simply because they fail to complete new reporting requirements.

What the New Rules Require

Beginning in 2027, many adults covered through Medicaid expansion programs will be required to document at least 80 hours per month of qualifying activities.

Those activities can include:

  • Employment
  • Job training
  • Education
  • Community service
  • Other approved activities

The requirement generally applies to adults ages 19 through 64 enrolled through Medicaid expansion programs.

Individuals who fail to meet the requirements — or fail to properly report them — could lose their health coverage.

The policy was included in last year’s federal budget legislation, often referred to as the “Big Beautiful Bill,” and represents one of the most significant changes to Medicaid eligibility in years.

According to projections from the Congressional Budget Office, the legislation is expected to produce the largest reduction in federal Medicaid spending in the program’s history.

Most Enrollees Have Heard Little or Nothing

The survey suggests awareness remains extremely low.

Nearly 48% of respondents said they had heard “nothing at all” about recent Medicaid eligibility changes.

Another 32% said they had heard only “a little.”

The confusion extends beyond work requirements.

Approximately 85% of respondents said they were unaware that states will be required to verify Medicaid eligibility every six months under the new rules.

Awareness also varies significantly by geography and demographics.

In Oregon, about 78% of respondents said they knew about the upcoming work requirements. In Nebraska, where implementation began early in May, awareness was closer to half.

Among demographic groups, Black Medicaid enrollees reported the highest level of unawareness, with 62% saying they did not know about the coming requirements.

Policy experts warn that many people who already meet the standards could still lose coverage if they fail to complete paperwork or do not realize reporting will be required.

Why Hospitals Are Concerned

The issue extends well beyond individual patients.

Hospitals — particularly rural hospitals — depend heavily on Medicaid reimbursement.

If large numbers of patients lose coverage, hospitals could see a rise in uncompensated care while receiving less reimbursement revenue.

The survey found that 42% of respondents said they could not travel farther than they currently do for hospital care if their nearest hospital closed.

Among respondents with chronic medical conditions, about 25% said a local hospital closure would make managing their condition significantly more difficult.

Rural healthcare providers have repeatedly warned that reductions in Medicaid enrollment could place additional strain on facilities already operating on thin margins.

Medicaid Insurers Face New Financial Pressure

The changes could also affect the nation’s largest Medicaid managed-care insurers.

The five largest players in the market —

Centene, CVS Health/Aetna, Elevance Health, Molina Healthcare, and UnitedHealth Group

collectively manage roughly half of all Medicaid managed-care enrollment nationwide.

According to Fitch Ratings, the new rules may create revenue pressure for insurers while increasing the overall cost of covering the remaining Medicaid population.

If healthier individuals lose coverage because they fail to complete reporting requirements, the remaining pool could become older and sicker on average, driving up healthcare costs.

That dynamic could force states to increase payments to insurers to maintain program stability.

Some executives have sought to reassure investors.

Molina Healthcare CEO Joe Zubretsky recently said the impact should be gradual, noting that roughly two-thirds of Molina’s 1.3 million Medicaid expansion members already work and many others may qualify for exemptions.

The Bottom Line

The survey highlights a fundamental challenge facing states, healthcare providers, and insurers: a major policy change is approaching, yet most Medicaid recipients remain unaware of it.

Whether the new requirements ultimately reduce enrollment dramatically or only modestly, the next several months will likely determine how many eligible Americans keep their coverage — and how many lose it because they never realized the rules had changed.

JBizNews Desk — Healthcare

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — The summer driving season is underway, but many Americans are discovering that filling up the tank remains an expensive proposition.

According to AAA, the national average price for a gallon of regular gasoline remains above $4 per gallon, significantly higher than levels seen a year ago and one of the most visible reminders of how global events continue affecting household budgets.

For many families, gasoline is one of the few expenses that cannot easily be avoided.

People may postpone vacations, delay major purchases, or reduce discretionary spending, but commuting to work, taking children to school, and running daily errands still require fuel.

That reality is making higher gas prices particularly painful.

The primary driver remains the disruption to global oil markets caused by ongoing tensions in the Middle East and restrictions affecting oil shipments through key transportation routes.

As crude oil prices climbed, refiners and fuel distributors passed those increases through to consumers.

The effects vary dramatically across the country.

Drivers in some Midwestern states continue paying among the lowest prices nationally, while motorists in California and several Western states face averages approaching or exceeding $5 per gallon.

Those regional differences stem from varying fuel taxes, environmental regulations, transportation costs, and refinery capacity.

The consequences extend far beyond the gas station.

Fuel is embedded in nearly every part of the economy. Trucks deliver groceries, manufacturers ship products, airlines transport passengers, and contractors operate fuel-powered equipment. When gasoline and diesel costs rise, businesses often pass those expenses along through higher prices.

That is one reason economists expect energy prices to play a major role in this week’s inflation report.

Small businesses are particularly vulnerable.

Delivery services, landscapers, contractors, food trucks, and transportation companies often operate on narrow profit margins and may struggle to absorb higher fuel costs without raising prices.

The timing could hardly be worse.

Summer typically brings increased travel demand, road trips, and higher fuel consumption. While demand generally rises during this period every year, elevated oil prices have magnified the financial burden on consumers.

There has been some modest relief.

Gasoline prices have retreated slightly from their recent peaks, but they remain substantially higher than many families were paying before the current disruptions in energy markets.

For drivers seeking ways to save money, experts continue recommending basic fuel-efficiency strategies, including proper tire inflation, reducing aggressive acceleration, combining errands into fewer trips, and comparing prices through mobile apps.

While those steps cannot solve the broader problem, they can help reduce costs at the margins.

For now, however, the broader outlook depends largely on developments in global energy markets.

Until oil supplies increase or geopolitical tensions ease, fuel prices are likely to remain a major source of pressure on household budgets.

As summer begins, the gas station continues serving as one of the clearest places where Americans experience the economic consequences of events happening thousands of miles away.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
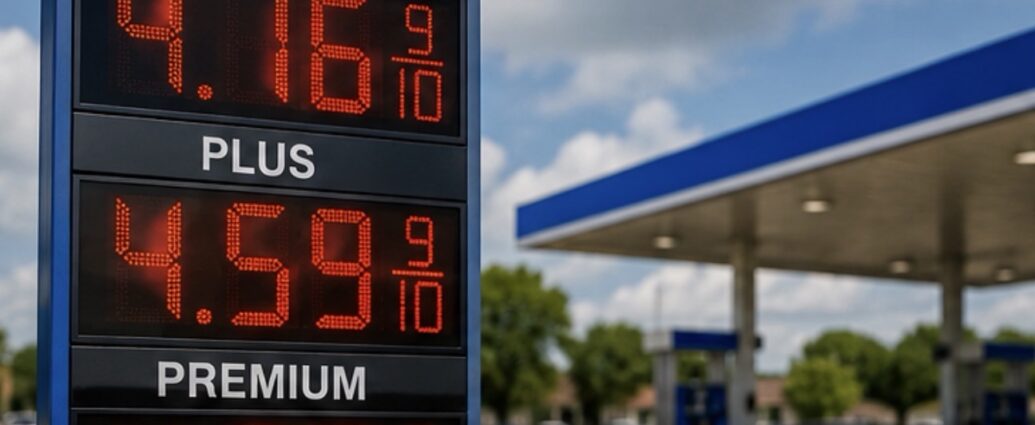
Stocks fell at Wednesday’s opening bell after the Bureau of Labor Statistics reported Wednesday, June 10, that consumer prices rose 4.2 percent over the past year in May — a three-year high — while overnight American airstrikes inside Iran shattered hopes for a quick end to the war. The Nasdaq Composite led the pullback, down 0.7 percent as Tuesday’s tech sell-off deepened, while the S&P 500 and the Dow Jones Industrial Average each fell about 0.5 percent as of just before 10 a.m. Eastern.

The inflation report set the tone. The 4.2 percent annual rise matched economists’ expectations, but the hot reading may boost bets that the Federal Reserve will hike interest rates this year. Energy prices remained the biggest driver of inflation amid the protracted war with Iran. Headline prices rose 0.5 percent from April to May. Before the report landed, markets had priced in a 98.2 percent chance the Federal Reserve leaves rates unchanged at its June meeting, according to the CME Group FedWatch tool. The 10-year Treasury yielded 4.53 percent, and the two-year stood at 4.14 percent.

The war escalated overnight. The U.S. launched a series of airstrikes within Iran on Tuesday, targeting air defense, ground control stations and surveillance radar sites, U.S. Central Command said. Iran acknowledged strikes around the city of Bandar Abbas and Qeshm Island inside the Strait of Hormuz, but gave no details on the damage.

The strikes came after President Donald Trump said in a post on Truth Social that while the two pilots involved in the shootdown of an Apache helicopter near the Strait of Hormuz were safe and uninjured, the United States must respond to the attack. Central Command called the strikes a proportional response to unjustified Iranian aggression.

Trump turned up the pressure again Wednesday morning. He wrote on Truth Social that Iran has taken too long to negotiate a deal that would have been great for them, and now they will have to pay the price. Brent crude rose nearly 2 percent to $93 per barrel after the post, while West Texas Intermediate hovered just below $90.

The supply damage keeps mounting. Rystad Energy said Wednesday that the shutdown of 11.8 million barrels a day of production across six Gulf producers has created the most severe oil supply disruption in modern history, with cumulative losses reaching 1 billion barrels. The consultancy warned each additional month of conflict could erase another 350 million barrels of output.

Global Markets

Asia sold off hard overnight. Japan’s Nikkei 225 fell 1.89 percent, while South Korea’s Kospi slumped 4.52 percent, leading regional losses amid a tech sell-off and Middle East tensions. Hong Kong’s Hang Seng traded 0.77 percent lower, and mainland China’s CSI 300 lost 1.11 percent.

SoftBank Group plunged 10 percent after its effort to secure at least $6 billion through a margin loan backed by its OpenAI stake hit a snag, according to Bloomberg News.

Europe held firmer. The pan-European Stoxx 600 rose 0.3 percent after its open, with London’s FTSE 100 up 0.2 percent, France’s CAC 40 adding 0.4 percent and Germany’s DAX rising 0.2 percent. Autos, insurance and healthcare led gains, while technology and banks lagged.

Movers and Shakers

Super Micro Computer fell 10 percent in premarket trading after the company announced a $7 billion financing package to fund its AI infrastructure order backlog.

Chip stocks stayed under pressure. Shares of Nvidia, Micron, Intel and Qualcomm pointed lower before the open after finishing Tuesday in the red.

Oracle reports earnings after Wednesday’s closing bell, with investors focused on details of its cloud business, which counts OpenAI as a customer, amid fluctuations in the AI trade.

Starbucks is exploring options for its business in Japan, including a stake sale, according to Bloomberg, which reported preliminary talks between the company and investment banks. Japan is one of the chain’s largest markets, with about 2,100 stores.

In housing, Keefe, Bruyette & Woods upgraded Toll Brothers to outperform from market perform, saying builders exposed to affluent buyers are better positioned to defend margins, while downgrading Lennar to underperform, citing its heavy entry-level exposure. Bank of America upgraded STMicroelectronics to Buy from Neutral.

What Comes Next

The week’s main event arrives Friday. SpaceX holds its initial public offering Friday, June 12, listing on the Nasdaq under the ticker SPCX at $135 per share, giving the company an initial market value of $1.77 trillion — the largest IPO on record.

Roughly $75 billion worth of shares must be allocated to underwriters and asset managers before trading begins Friday.

Until then, the market sits between two forces it cannot control: inflation climbing on war-driven energy costs, and a conflict in the Persian Gulf that shows no sign of ending.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
President Donald Trump’s long-promised effort to remove mortgage giants Fannie Mae and Freddie Mac from government control is facing new questions after the official leading the project was handed a second, unrelated assignment running the nation’s intelligence agencies.

Trump announced on June 2 in a post on Truth Social that he was appointing Bill Pulte — director of the Federal Housing Finance Agency (FHFA) and chairman of Fannie Mae and Freddie Mac — as acting Director of National Intelligence, while allowing him to retain his housing responsibilities.

Speaking aboard Air Force One last Friday, Trump signaled that any move to take Fannie and Freddie public is not imminent.

He said he has not ruled out pursuing an initial public offering but emphasized, “It’s not a rush.” A day earlier, Trump praised Pulte’s work overseeing the mortgage giants and noted that the intelligence position is “not a permanent position.” Requests from CNN last week for updated timelines from the White House, FHFA, Fannie Mae, and Freddie Mac went unanswered.

To understand why this matters, it helps to know the role Fannie and Freddie play in the housing market.

The two government-sponsored enterprises do not issue mortgages directly. Instead, they purchase home loans from banks and lenders, package them into securities, and sell them to investors. That process replenishes lenders’ capital, allowing them to make new loans while helping keep mortgage rates lower and more widely available.

As a result, Fannie and Freddie sit beneath a substantial portion of the U.S. mortgage market and are deeply intertwined with how Americans finance home purchases.

The companies have remained under government conservatorship since the 2008 financial crisis, when federal officials stepped in to prevent their collapse and stabilize the housing market. What was intended as a temporary measure has now lasted nearly two decades.

Susan Wachter, a professor of real estate and finance at the Wharton School of the University of Pennsylvania, told CNN that few observers expected the arrangement to still be in place 18 years later.

Trump has long argued that the companies should eventually return to private ownership. During his first term, efforts to end conservatorship stalled, but supporters continue to argue that Fannie and Freddie are financially strong enough to operate independently and that a public offering could generate billions of dollars in value.

The challenge now may be execution.

Pulte, 38, whose grandfather founded one of the nation’s largest homebuilders, is now responsible for overseeing more than $10 trillion in mortgage exposure while simultaneously leading the sprawling U.S. intelligence apparatus, including agencies such as the CIA and the National Security Agency.

Housing experts note that restructuring and privatizing Fannie and Freddie is itself a highly complex undertaking requiring extensive regulatory, financial, and political coordination.

Wachter told CNN that the effort is effectively a full-time job and suggested that progress that once appeared to be moving forward may now be slowing.

The stakes are significant.

If the government mishandles an exit from conservatorship, it could unsettle the market for mortgage-backed securities that supports much of the U.S. housing finance system. If investors demand higher returns to compensate for increased uncertainty, mortgage rates could rise as a result.

That risk comes at a difficult time for prospective homebuyers, who are already confronting elevated home prices and mortgage rates that remain well above pre-pandemic levels.

Pulte’s growing portfolio of responsibilities has also attracted political scrutiny.

In his role overseeing housing finance, he has filed criminal referrals alleging mortgage fraud against several prominent political figures, including Federal Reserve Governor Lisa Cook and New York Attorney General Letitia James. Those allegations have been denied by the individuals involved.

His appointment as acting Director of National Intelligence has also drawn criticism from Democrats and concern from some Republicans, who note that the position was created after the September 11 attacks with the expectation that its holder would possess substantial national security experience.

For homeowners and prospective buyers, the immediate takeaway is relatively simple.

A privatization of Fannie Mae and Freddie Mac could eventually reshape how mortgage lending is funded in the United States. Whether that change ultimately lowers costs, raises them, or leaves the system largely unchanged remains a matter of debate.

What appears more certain today is that the process is unlikely to accelerate. With the official overseeing the effort now balancing responsibilities in both housing finance and national security, a slower and more cautious timetable looks increasingly likely.

That may provide some short-term stability. Financial markets generally prefer gradual transitions over rushed restructurings, particularly when trillions of dollars in mortgages are involved.

The larger question—whether the federal government will ultimately relinquish control of the two institutions that underpin much of America’s housing market—remains unresolved.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The public drama surrounding CBS News may be generating headlines, but industry analysts and executives close to the transaction say it is unlikely to stop Paramount Skydance’s proposed acquisition of Warner Bros. Discovery, a deal valued at approximately $110 billion including debt.

According to reporting confirmed Monday, June 8, by sources involved in the merger process, regulators reviewing the transaction are focused primarily on antitrust concerns rather than controversies involving newsroom management.

“Legally speaking, it doesn’t matter,” one executive involved in the deal told CNN, referring to the recent upheaval at CBS News. “But PR-wise, it might matter.”

That distinction is becoming increasingly important as Paramount Skydance works to complete one of the largest media mergers in recent years.

Under the agreement, Paramount Skydance, led by CEO David Ellison, would acquire Warner Bros. Discovery for $31 per share. The combination would bring together two of Hollywood’s largest entertainment companies, unite the streaming platforms Paramount+ and HBO Max, and place major news brands including CBS News and CNN under the same corporate umbrella.

Warner shareholders approved the transaction in April, and the companies continue to pursue regulatory approvals.

The merger, however, now faces an additional layer of public scrutiny because of developments inside CBS News.

Following Paramount’s acquisition last year, Ellison appointed Bari Weiss, founder of The Free Press, as editor-in-chief of CBS News. Weiss, whose background is primarily in print and digital journalism, has overseen a series of controversial changes inside the network.

Last week, veteran “60 Minutes” journalists including Sharyn Alfonsi, Cecilia Vega, and executive producer Tanya Simon departed amid a broader restructuring. Former technology journalist Nick Bilton was subsequently tapped to help lead the iconic newsmagazine program.

The situation intensified when longtime correspondent Scott Pelley, a 37-year CBS News veteran, publicly criticized management after his departure.

In an interview with The New York Times, Pelley described CBS News as being “on fire,” criticized current leadership, and alleged that management decisions were being influenced by political considerations.

CBS management disputed aspects of Pelley’s account, while Weiss told staff the separation reflected an inability to find a path forward.

The controversy has generated significant media attention at a sensitive moment for Paramount.

Critics of the merger have argued that ownership changes at CBS could foreshadow future editorial conflicts at CNN should the Warner acquisition proceed. Several media commentators have also questioned whether ongoing newsroom turmoil could complicate the regulatory review process.

Most analysts, however, believe the issues are largely separate.

Analysts at Raymond James said they continue to expect the merger to close, although they cautioned that Paramount’s target of completing the transaction during the third quarter of 2026 may prove ambitious.

The larger regulatory threat appears to come not from newsroom controversies but from antitrust concerns.

Several media outlets reported last week that a coalition of Democratic state attorneys general, led by California Attorney General Rob Bonta, is preparing a legal challenge aimed at blocking the merger.

That challenge reportedly focuses on traditional antitrust arguments, including reduced competition, potential job losses, wage pressure, and increased concentration within the media industry.

Those issues carry substantially more legal weight in merger reviews than disputes involving editorial management.

Paramount strongly rejects those concerns.

A company spokesperson told CNN that the merger would increase competition, expand consumer choice, and create new opportunities for creators, employees, and audiences.

Supporters of the transaction argue that larger scale is necessary for traditional media companies to compete against technology giants and streaming competitors that increasingly dominate entertainment consumption.

The stakes extend far beyond the immediate controversy at CBS.

If completed, the merger would reshape the American media landscape by combining two major film studios, multiple television networks, two large streaming services, extensive sports rights, and two of the nation’s most recognizable news organizations.

For now, the CBS controversy remains primarily a reputational challenge for Paramount leadership.

The legal battle over the merger, however, will likely be decided on a different set of questions—competition, market concentration, employment, and consumer impact.

Those are the issues regulators and courts will ultimately weigh as they determine whether one of the largest media combinations in decades moves forward.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Trump administration has put more than 500 hospitals on notice: show patients what medical care actually costs or risk hefty financial penalties.

The warnings, revealed Tuesday after being obtained by The Associated Press, were sent beginning in April to hospitals that federal officials say are failing to comply with healthcare price-transparency rules. The administration argues that hidden pricing prevents patients, employers, and insurers from comparing costs and contributes to higher healthcare spending nationwide.

Hospitals that fail to comply could face penalties of up to $2 million per year.

The Goal: No More Surprise Bills

For many Americans, the issue is familiar. A patient receives a test, procedure, or hospital visit without knowing the price beforehand, only to receive a bill weeks later.

Federal officials say the transparency rules are intended to change that.

Under the requirements, hospitals must publicly post pricing information so consumers can compare costs before receiving treatment. That includes rates for common services such as blood tests, imaging scans, surgeries, and other medical procedures.

The administration says transparent pricing encourages competition and helps consumers make more informed healthcare decisions.

A senior administration official said President Donald Trump plans to intensify enforcement of transparency standards originally created under a 2019 executive order, signaling that additional hospitals are likely to receive warning letters in the months ahead.

Major Hospital Systems Receive Notices

The enforcement effort is not limited to smaller facilities.

Several of the nation’s largest and most recognizable hospitals received warnings.

Texas led the nation with 42 hospitals receiving notices. Among them were:

  • Baptist Medical Center in San Antonio
  • University of Texas MD Anderson Cancer Center in Houston

Ascension, one of the largest nonprofit hospital systems in the United States, had 13 hospitals across multiple states receive letters.

The issue spans both Republican- and Democratic-led states.

Indiana had 34 hospitals receiving notices, while California had 38. Other states with large numbers of hospitals receiving warnings include Florida, Alabama, Louisiana, and Texas.

Why Employers and Insurers Care

The push is drawing attention from employers who pay billions annually for employee healthcare coverage.

Business groups have long argued that healthcare remains one of the few major purchases where consumers often cannot determine the cost before receiving the service.

Transparency is the foundation of a healthcare system that rewards competition based on cost and quality,” said Shawn Gremminger, Chief Executive Officer of the National Alliance of Healthcare Purchaser Coalitions.

Employers contend that better pricing information could help lower healthcare costs by allowing consumers to compare providers and encouraging hospitals to compete more aggressively on price.

Hospitals Face Growing Pressure

For hospitals, the warnings create both compliance challenges and financial risks.

Many healthcare systems argue that pricing structures are complex because rates vary depending on insurance contracts, government reimbursement programs, and individual patient circumstances.

Federal officials, however, have increasingly taken the position that confusing or incomplete pricing disclosures are no longer sufficient.

The message from regulators is straightforward: hospitals must provide accessible pricing information or face escalating penalties.

The Political Dimension

The crackdown also aligns with the administration’s broader focus on affordability.

Healthcare costs remain one of the most significant expenses facing American families, and transparency efforts allow the administration to argue it is taking steps to help consumers better manage those costs.

At the same time, critics note that healthcare affordability remains a broader challenge, particularly following the expiration of certain insurance subsidies that had helped lower premiums for some Americans purchasing coverage through Affordable Care Act marketplaces.

What It Means for Patients

For consumers, the potential benefit is simple.

If hospitals fully comply, patients could increasingly be able to see and compare the costs of medical services before receiving treatment — much like comparing prices for other major purchases.

Whether greater transparency ultimately leads to lower healthcare costs remains an open question. But with more than 500 hospitals already receiving warnings and additional enforcement expected, federal officials are making clear that price transparency is moving from policy goal to regulatory requirement.

JBizNews Desk — Healthcare

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Shares of Citigroup held up far better than the rest of Wall Street on Wednesday, June 10, after President Donald Trump publicly praised the bank and its chief executive in a post on his Truth Social platform. On a difficult day for stocks, the endorsement briefly lifted Citi shares and helped the bank outperform many of its largest rivals.

Trump’s post appeared shortly after the market opened.

Wow! CITI was ranked Number 1 in topping M&A Advisory Market by Value in Q1,” Trump wrote, congratulating Chief Executive Jane Fraser and her team while describing the achievement as a major comeback for the bank.

The public praise was unusual. Presidents rarely single out individual publicly traded companies for direct commendation, making the post stand out among investors and market watchers.

The stock responded immediately. Citigroup shares climbed as much as 1.8% intraday, reaching approximately $137.12 before giving back most of the gains. The stock ultimately finished the session down about 1%, but that performance still significantly outpaced the broader market.

The S&P 500 fell 1.62%, while major financial stocks including JPMorgan Chase, Goldman Sachs, and Wells Fargo posted steeper declines. In a session dominated by inflation concerns and geopolitical uncertainty, losing less than the market amounted to relative strength.

There is, however, an important caveat.

It remains unclear which specific merger-and-acquisition ranking Trump referenced. According to industry data compiled by Dealogic, Citigroup currently ranks below several competitors in overall global merger advisory activity. Recent league tables place Goldman Sachs among the leading advisers by transaction value, while Citigroup ranks lower in overall market share.

Citigroup does hold leadership positions in several specialized sectors. During an appearance on Fox Business, Leon Kalvaria, Citigroup’s Global Chair of Banking, highlighted the bank’s strong performance in power and energy-sector transactions. Citi has advised on several major energy deals this year, placing it among the leading advisers in that segment.

Whether Trump was referencing a niche category or broader advisory performance remains uncertain.

Regardless of the ranking question, Citigroup’s stock performance in 2026 has been impressive.

According to market data, Citigroup shares have gained roughly 14.3% year-to-date, outperforming the broader market and many large banking competitors. The rally reflects growing investor confidence in a turnaround effort that has been underway for several years under Fraser’s leadership.

Since becoming CEO, Fraser has overseen a sweeping restructuring of the bank. Citigroup has exited non-core businesses, simplified operations, reduced management layers, and focused more aggressively on profitable institutional banking, treasury services, and wealth management.

The overhaul has included significant job reductions and operational changes, but investors have largely rewarded the strategy.

Trump’s characterization of Citigroup as a comeback story aligns with how many analysts now view the bank. Once seen as a laggard among major U.S. financial institutions, Citi has increasingly earned credit for improving efficiency and narrowing the performance gap with competitors.

There may also be a personal element behind Trump’s interest. Public reports have indicated that members of the Trump family have maintained banking relationships with Citigroup over the years. While such relationships are not unusual among major financial institutions, they add an interesting layer to the president’s public endorsement.

For investors, the episode highlights an important reality of modern markets. High-profile endorsements can move stocks temporarily, but long-term performance ultimately depends on earnings, strategy, and execution.

Citigroup’s brief rally following Trump’s post faded as broader market concerns took over. Investors remained focused on inflation, interest rates, and geopolitical tensions rather than social media commentary.

At the same time, the session reflected a broader shift in investor behavior. As some technology and growth stocks came under pressure, money flowed into sectors viewed as more defensive or economically resilient, including financials, healthcare, and energy.

That rotation helped support bank shares generally and reinforced the relative strength Citigroup has shown throughout much of the year.

The next major test will come with Citigroup’s upcoming quarterly earnings report. Investors will be looking for continued progress on profitability, expense reductions, and revenue growth.

For one volatile trading day, however, a presidential endorsement helped place Citigroup in the spotlight and reminded Wall Street that perception can move markets—even if only briefly.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A retired U.S. general argued Wednesday, June 10, that the fighting in the Strait of Hormuz and the unrest in Lebanon are distractions pulling attention away from the real issue in the war with Iran. Mark Kimmitt, a retired U.S. Army brigadier general and former Assistant Secretary of State for Political-Military Affairs, called the two flashpoints “diversions” during an appearance on Bloomberg Television’s The Close with hosts Romaine Bostick and Katie Greifeld.

His comments came on a day when the conflict flared again and markets reacted. Oil prices rose after President Donald Trump escalated his warnings toward Iran, pledging a strong response following continued delays in peace negotiations. Brent crude traded near $93 per barrel, while West Texas Intermediate crude approached $92, adding fresh pressure to inflation concerns already weighing on investors.

Kimmitt’s argument centers on strategic focus. Daily headlines have been dominated by disruptions in the Gulf and instability along Israel’s northern frontier. Both developments carry major geopolitical and economic consequences. Yet Kimmitt suggested neither represents the central objective of the conflict.

Instead, he argued that attention has drifted away from the issue that U.S. officials have consistently identified as the core concern: Iran’s nuclear program.

Secretary of State Marco Rubio has repeatedly described Iran’s nuclear ambitions as the fundamental challenge that must be addressed before any lasting resolution can emerge. By that measure, the battles around Hormuz and Lebanon are theaters of conflict rather than the conflict’s ultimate purpose.

For investors and consumers, however, those so-called diversions carry real-world costs.

The Strait of Hormuz remains one of the most important energy chokepoints on earth, handling a substantial share of global oil shipments. Any disruption immediately reverberates through energy markets. Rising crude prices quickly filter into gasoline costs, transportation expenses, manufacturing inputs, and ultimately consumer prices.

That economic impact has become increasingly visible. Higher energy costs have contributed to persistent inflation pressures and complicated the outlook for central banks around the world.

The market reaction on Wednesday highlighted that dynamic. News related to Iran and the Gulf region drove immediate movement in oil prices despite no major change in the underlying nuclear dispute. Traders continue to react to each development that could affect energy supply, shipping routes, or military escalation.

Kimmitt’s comments also help explain a pattern that has frustrated markets throughout the year. Individual events—attacks on shipping, military strikes, disruptions to energy infrastructure, and regional flare-ups—have repeatedly generated sharp market reactions. Yet the broader strategic dispute remains unresolved.

Each new incident sends oil prices higher and creates fresh uncertainty for businesses and investors. Once the immediate shock fades, attention shifts to the next development.

If the underlying issue remains Iran’s nuclear program, as Kimmitt and many U.S. officials contend, markets may continue to experience this cycle of volatility until a more permanent solution emerges.

Earlier in the day, Kimmitt also expressed cautious optimism that the latest tensions would not necessarily lead to a broader regional war. He suggested that diplomacy remains possible and indicated hope that current developments could eventually create conditions for renewed negotiations.

That perspective aligns with his broader assessment. If Hormuz and Lebanon are secondary fronts rather than the main issue, then resolving the conflict ultimately depends less on tactical military developments and more on addressing the underlying nuclear dispute.

The economic stakes are substantial.

Elevated oil prices increase costs for airlines, shipping companies, manufacturers, retailers, and consumers. Higher energy prices also make it more difficult for central banks to reduce interest rates because inflation remains stubbornly elevated.

For households, the consequences show up in gasoline bills, transportation costs, utility expenses, and the prices paid for everyday goods. For businesses, higher energy costs can reduce profits, delay investment, and increase uncertainty.

Whether policymakers embrace Kimmitt’s framework may influence the next phase of the conflict. If attention remains focused primarily on securing shipping lanes and managing regional flare-ups, markets may continue to experience periodic oil-price shocks. If diplomatic efforts concentrate on the nuclear question itself, investors may begin to see a clearer path toward stability.

For now, however, the diversions Kimmitt described continue to play an outsized role in both global markets and household budgets.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
For much of this year, Wall Street’s debate centered on how many times the Federal Reserve would cut interest rates. Now, one major global bank is making the opposite bet.

BNP Paribas, France’s largest bank, says the Fed’s next move is likely to be a rate increase, not a cut. In a recent Markets 360 analysis, the bank reversed its prior expectation of steady policy and now forecasts that the Fed will begin unwinding the three rate cuts delivered in 2025 through a series of hikes starting in December 2026.

The forecast stands in sharp contrast to many economists and investors who continue to expect lower rates ahead.

Why BNP Thinks Rates Are Going Higher

The bank’s case rests largely on the strength of the U.S. labor market.

According to the latest employment report, nonfarm payrolls increased by 172,000 jobs last month, roughly double economists’ expectations of about 85,000. Meanwhile, the unemployment rate held steady at 4.3%.

That resilience matters because the Fed’s three rate cuts in 2025 were intended to protect a labor market that policymakers feared was weakening. If hiring remains strong, BNP argues, the Fed may have less reason to support growth and more reason to focus on inflation.

Guneet Dhingra, Head of U.S. Rates Strategy at BNP Paribas, said the firm sees rising inflation risks combined with continued labor-market strength, a combination that could force policymakers to remove some of the stimulus added last year.

The bank also points to geopolitical risks, including the ongoing Iran-Israel conflict, which has periodically driven energy prices higher and could add further inflationary pressure.

Looking Back to 1999

BNP Paribas says today’s environment resembles a period from more than two decades ago.

The bank believes the Fed could follow a pattern similar to 1999, when it reversed emergency rate cuts made during the financial turmoil surrounding the Long-Term Capital Management crisis in 1998.

In that case, the central bank cut rates to stabilize markets and then quickly reversed course once conditions improved.

BNP expects a similar sequence now, forecasting three consecutive rate hikes beginning in December and potentially earlier if inflation accelerates or labor-market conditions strengthen further.

The bank also projects unemployment could gradually decline toward 4% by year-end, giving policymakers additional room to prioritize inflation control.

Wall Street Isn’t Convinced

Not everyone agrees.

Citigroup continues to forecast three rate cuts, beginning in September, arguing that labor-market weakness could emerge later this year.

Goldman Sachs economists have also pushed back on the idea of rate hikes, saying stronger jobs data alone is unlikely to trigger a policy reversal.

The result is one of the widest disagreements among major Wall Street firms in years.

Investors, meanwhile, are becoming less certain that rate cuts are coming.

Prediction market Polymarket recently showed roughly a 52% probability that the Fed raises rates before year-end, while CME FedWatch data pointed to approximately a 43% chance of a hike by December.

What It Means for Consumers

If BNP Paribas is correct, Americans could face higher borrowing costs in 2027.

Federal Reserve rate increases typically push up the cost of:

  • Mortgages
  • Auto loans
  • Credit cards
  • Business borrowing

At the same time, higher rates generally benefit savers by increasing yields on savings accounts, certificates of deposit, and money-market funds.

For households planning to purchase a home or finance a vehicle, the difference between rate cuts and rate hikes could translate into thousands of dollars over the life of a loan.

The Bottom Line

The next major test comes at the Federal Reserve’s June 16–17 meeting, the first under new Fed Chair Kevin Warsh.

Virtually no one expects a rate increase this month. The real debate is what comes next.

For now, strong job growth, stubborn inflation concerns, and geopolitical uncertainty are forcing investors to reconsider an assumption that dominated markets for much of the past year: that the Fed’s next move would automatically be lower rates.

BNP Paribas is betting the opposite.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Campbell’s Company warned investors Monday, June 8, that inflationary pressures on food production remain elevated and are expected to stay that way through at least the first half of its next fiscal year, signaling that relief on grocery prices may not arrive anytime soon.

Speaking on the company’s third-quarter earnings call, Chief Financial Officer Todd Cunfer said Campbell’s is planning for significantly higher costs ahead, noting that many of those expenses are already locked into the company’s supply chain.

“The one thing becoming clearer every day is that first-half inflation will be pretty high,” Cunfer told analysts.

The biggest drivers are rising energy, transportation, and raw material costs.

According to Campbell’s executives, elevated oil prices continue to ripple through the economy, increasing the cost of fertilizer, packaging materials, freight transportation, and aluminum used in food cans. The company said disruptions tied to ongoing tensions in the Middle East have contributed to higher commodity prices and logistics costs.

Executives cautioned that even if geopolitical tensions eased immediately, it would take time for energy markets, shipping networks, and industrial supply chains to normalize.

Campbell’s now expects inflation of approximately 5% to 6% during fiscal 2027, up from prior expectations of roughly 3% before recent increases in commodity and transportation costs.

For consumers, the warning matters because Campbell’s products appear in millions of American households.

The company owns major brands including Campbell’s Soup, Progresso, Goldfish, Prego, Rao’s, Chunky Soup, Pace, and several other pantry staples. Rising costs across such a broad portfolio often serve as an early indicator of pricing pressures throughout grocery stores.

So far, Campbell’s says it is attempting to offset those expenses internally rather than passing them directly to consumers.

Chief Executive Officer Mick Beekhuizen said management plans to focus first on productivity improvements and cost reductions before considering what he described as “surgical pricing,” targeted increases on select products where necessary.

The company is pursuing approximately $100 million in overhead and administrative cost reductions, including an early retirement program and broader efficiency initiatives.

Management says the objective is to preserve profitability while minimizing the impact on shoppers.

The inflation warning came alongside mixed quarterly results.

Campbell’s reported fiscal third-quarter earnings that slightly exceeded Wall Street expectations, although analysts had already lowered forecasts ahead of the release.

The company continues to face challenges in its snacks division, where consumer demand has softened.

Beekhuizen said Campbell’s is simplifying its snack portfolio and concentrating resources on its strongest brands, particularly Goldfish crackers, which remain one of the company’s fastest-growing products.

A growing challenge is competition from lower-priced store brands.

Private-label products have gained market share as consumers seek ways to manage higher living costs. Generic soups, sauces, crackers, and other pantry items often sell at meaningful discounts compared with national brands, making it more difficult for companies like Campbell’s to raise prices without losing customers.

That reality helps explain management’s reluctance to broadly increase prices despite higher operating costs.

Executives also pointed to a trend that may reflect broader economic pressures on households.

Campbell’s said consumers appear to be preparing more meals at home and reducing restaurant spending. For a company that sells soups, sauces, and shelf-stable food products, increased home cooking can support sales.

However, economists often view the shift as a sign that families are becoming more cautious with discretionary spending.

Despite the cost pressures, Campbell’s reaffirmed its full-year financial outlook and highlighted its long history of returning cash to shareholders.

The company has paid a dividend for 56 consecutive years, a track record that remains important to many long-term investors.

The broader message from management was clear: food manufacturers continue to face inflation that is proving more persistent than many expected.

For consumers, that means grocery prices in categories such as soup, pasta sauce, crackers, and other pantry staples may remain under pressure even if headline inflation moderates elsewhere.

Campbell’s says it intends to absorb as much of the increase as possible through cost-cutting and operational efficiencies. But if inflation remains elevated for an extended period, some of those higher costs could eventually find their way onto grocery shelves.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The roughly 2,000 cooks, bartenders, servers, and dishwashers working at Los Angeles Stadium in Inglewood, California, have reached a tentative labor agreement that appears to avert a strike just days before the venue hosts its first FIFA World Cup match.

The agreement was announced Tuesday, June 9, by UNITE HERE Local 11, which represents the workers employed by stadium food-service operator Legends Global. Union Co-President Kurt Petersen called it the strongest contract ever negotiated at a National Football League stadium and said it includes what he described as “massive raises.”

The timing was critical.

Just last week, workers voted 96% in favor of authorizing a strike after negotiations stalled. Had a walkout occurred, fans attending Friday’s opening match between the United States and Paraguay could have faced long concession lines, reduced food and beverage service, and potential disruptions during one of the tournament’s first marquee events.

Under the proposed agreement, most workers will earn more than $40 per hour within about two years, placing many of the stadium’s concession employees among the highest-paid hospitality workers in the country. Tipped employees are expected to receive pay increases of at least 30%.

The contract also includes premium compensation for major events, including the World Cup and next year’s Super Bowl, contributions to a housing fund for hospitality workers, and protections designed to limit subcontracting and guard against job losses from automation.

One of the most unusual provisions centers on immigration concerns.

According to union leaders, workers sought protections allowing them to leave the workplace if federal immigration enforcement activities threaten their safety during tournament operations. Petersen said the language is believed to be the first provision of its kind in a stadium labor contract.

The concern stems from FIFA’s accreditation requirements, which require workers to submit personal information including Social Security numbers and fingerprints. Union officials expressed concern that the data could potentially be accessed by federal immigration authorities.

Those concerns intensified after Acting ICE Director Todd Lyons said the agency would play a role in World Cup security operations.

The American Civil Liberties Union of Southern California has filed a complaint with state regulators and urged California Attorney General Rob Bonta to examine whether the accreditation process could expose immigrant workers to unnecessary risk.

At the same time, Los Angeles County Sheriff Robert Luna said the Department of Homeland Security assured local officials that federal personnel assigned to World Cup venues would focus on security responsibilities and not conduct civil immigration enforcement actions at matches.

For the business side of the tournament, the agreement removes a potentially costly problem.

Legends Global, which manages food and beverage operations at major venues around the world, said it was pleased to reach the tentative agreement and looked forward to serving fans during the tournament. A labor dispute during one of the most-watched sporting events on the planet would have created operational challenges not only for the company but also for FIFA, which is expected to generate billions of dollars in revenue from the competition.

The contract carries significance beyond this summer’s tournament.

The agreement runs through April 30, 2028, placing its expiration alongside more than 100 stadium, hotel, airport, and concession contracts scheduled to expire shortly before the 2028 Los Angeles Olympic Games. Labor leaders view that alignment as a strategic opportunity to strengthen bargaining power ahead of another global sporting event.

The stadium, known commercially as SoFi Stadium, opened in 2020 and seats approximately 70,000 spectators. It serves as the home of the Los Angeles Rams and Los Angeles Chargers. For the World Cup, the venue is operating under the temporary name Los Angeles Stadium because FIFA tournament rules restrict certain commercial sponsorship branding.

The stadium is scheduled to host eight World Cup matches, beginning Friday with the United States-Paraguay opener. The tournament, jointly hosted by the United States, Canada, and Mexico, will run for 39 days and is expected to attract millions of attendees and billions of television viewers worldwide.

The deal is not final. Union members are expected to vote Wednesday on whether to ratify the agreement.

If approved, one of the biggest potential labor disruptions facing the World Cup will be resolved before the first fans arrive at the concession stands.

JBizNews Desk — Los Angeles

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Meta Platforms announced Monday, June 8, the launch of a nationwide workforce initiative that will provide free training for skilled trades and guarantee employment for graduates working on the infrastructure powering artificial intelligence.

CEO Mark Zuckerberg unveiled the program, called America’s Workforce Academy, in a post on Threads, saying the United States will need hundreds of thousands of skilled workers to build the data centers required for America to remain a leader in AI.

“We’re going to need hundreds of thousands of skilled tradespeople to build the infrastructure needed for the U.S. to lead in AI,” Zuckerberg wrote. “People need access to the education and opportunity to land those jobs.”

Meta is committing an initial $115 million during the program’s first year and says the effort represents the largest private-sector investment in skilled-trades training with a job guarantee in U.S. history.

The concept is straightforward.

Participants receive free training in high-demand trades connected to data-center construction and operations. Upon completion, graduates earn an industry-recognized credential from the National Center for Construction Education and Research (NCCER) along with an America’s Workforce Certificate. Graduates are then guaranteed employment with contractor partners working on Meta’s data-center projects.

The academy launches with pilot programs in Louisiana, Ohio, Indiana, and Texas.

Meta is partnering with the National Urban League, Associated Builders and Contractors (ABC), CBRE, and local chambers of commerce to deliver the training and place graduates into jobs.

The initiative reflects the enormous labor demand being created by the AI boom.

Artificial intelligence requires vast amounts of computing power, which in turn requires massive data centers packed with servers, cooling systems, electrical infrastructure, and fiber-optic networks. Building those facilities requires thousands of electricians, welders, mechanics, fiber technicians, and other skilled workers.

Rachel Peterson, Meta’s Vice President of Data Centers, said the company’s expanding AI infrastructure requires a workforce on an unprecedented scale.

“America needs hundreds of thousands of skilled tradespeople,” Peterson said. “This academy creates clear and accessible pathways into those careers.”

The program builds on earlier workforce efforts.

Meta recently partnered with CBRE to launch the LevelUp Fiber Technician Pathway, a free four-week training course designed to prepare workers for fiber-optic technician jobs. According to Meta, that program attracted more than 35,000 applications within its first week, highlighting strong demand for careers that do not require a four-year college degree.

The urgency reflects Meta’s rapidly expanding infrastructure footprint.

The company says it currently operates or is developing 27 data centers across the United States. Those facilities form the backbone of Meta’s AI strategy as it competes with rivals including Microsoft, Amazon, Google, and OpenAI.

Dina Powell McCormick, Meta’s President and Vice Chairman, described the initiative as part of a broader effort to ensure Americans benefit from AI-driven growth.

“The AI revolution is creating historic opportunity,” McCormick said.

The workforce academy represents only a small portion of Meta’s larger commitment to spend approximately $600 billion on U.S. infrastructure and jobs over the next three years as the company accelerates investment in artificial intelligence.

Questions remain about the program’s long-term scale.

While Meta guarantees employment for graduates, the company has not disclosed exactly how many positions will be available annually. The jobs are expected to be full-time roles with contractors working on Meta projects, though the company has not specified how many positions will be union jobs.

Associated Builders and Contractors said it expects the program to train thousands of workers over time.

For many Americans, the appeal is obvious.

Skilled-trades careers often provide strong wages, long-term job security, and opportunities for advancement without requiring student loans or a traditional college degree. Employers across the country have struggled for years to find enough qualified electricians, mechanics, and construction workers.

Mike Rowe, CEO of the mikeroweWORKS Foundation and a longtime advocate for skilled trades, praised the initiative, arguing that America’s labor shortage can only be addressed by expanding opportunities and modernizing workforce training.

The broader significance extends beyond Meta itself.

Much of the public conversation surrounding artificial intelligence has focused on jobs that could disappear as automation expands. Meta is making a different case: that the AI economy will also create large numbers of well-paying, hands-on jobs for workers who build and maintain the infrastructure behind the technology.

Whether the academy ultimately delivers on its promise at national scale—and how many permanent careers emerge from the effort—will determine whether Meta’s workforce bet becomes a model for the broader AI industry.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The federal government is preparing for one of the largest expansions of immigration enforcement in modern American history after the House of Representatives approved a nearly $70 billion funding package that now heads to President Donald Trump for his signature.

The legislation passed the House on Tuesday, June 9, by a narrow 214-212 vote after already clearing the Senate. Supporters say the measure will strengthen border security and immigration enforcement operations, while critics argue it dramatically expands federal power with limited oversight.

The package allocates approximately $38 billion to Immigration and Customs Enforcement (ICE), $26 billion to the U.S. Border Patrol, and roughly $5 billion for unexpected operational expenses.

Unlike many federal spending measures that require annual renewal, this legislation funds the agencies through the remainder of Trump’s current term, providing a multi-year commitment of resources.

The business implications extend well beyond Washington.

Federal immigration enforcement depends heavily on private-sector contractors. Companies provide detention facilities, transportation services, monitoring systems, surveillance technology, software platforms, communications equipment, and staffing support.

For those firms, the legislation could create years of predictable government demand and billions of dollars in contract opportunities.

The funding could also affect labor markets across the country.

Industries including agriculture, construction, hospitality, food processing, landscaping, manufacturing, and home healthcare rely heavily on immigrant labor. Business groups have long warned that increased enforcement can reduce workforce availability, increase labor costs, and contribute to higher prices for consumers.

Supporters of stricter enforcement argue that tighter labor markets can boost wages for American workers. Critics counter that labor shortages can slow economic activity and increase costs throughout the supply chain.

The debate highlights the increasingly close relationship between immigration policy and economic policy.

Employers in labor-intensive industries are watching closely because workforce availability directly affects project timelines, production levels, and operating expenses. Even modest shifts in labor supply can have significant effects across regional economies.

Democrats sought amendments requiring agents to display identification and obtain judicial warrants before entering private property. Those proposals were rejected before final passage.

With congressional approval secured, attention now turns to implementation and how agencies deploy the funding.

The bottom line: the nearly $70 billion package represents a major victory for supporters of expanded immigration enforcement. It is also poised to create substantial opportunities for government contractors while raising new questions for industries that depend on immigrant labor.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A new study from Columbia Business School is raising concerns about one of Wall Street’s fastest-growing markets, arguing that the ratings used to judge many private-credit loans may be making risky investments appear safer than they actually are.

The research, reported Monday, June 8, examined the rapidly expanding $1.8 trillion private-credit industry and found evidence that many of the ratings supporting these loans systematically understate risk. The paper has been posted publicly but has not yet undergone peer review.

Private credit refers to loans made directly by investment firms rather than traditional banks. The market has exploded in recent years as investors searched for higher returns than those available from government bonds and other conventional fixed-income investments.

A major source of that money is the insurance industry.

Life insurance companies have increasingly invested policyholder premiums and annuity assets into private-credit loans because they typically offer higher yields. Those investments ultimately back products that millions of Americans rely on for retirement income and long-term financial security.

The controversy centers on the ratings assigned to those loans.

Before insurers can hold many of these investments, the loans typically receive a credit rating that determines how much capital insurers must reserve against potential losses. Higher ratings require smaller capital cushions, making investments more attractive to both lenders and insurers.

According to the Columbia researchers, that system may be creating incentives for ratings that are too generous.

The study’s findings echo concerns previously raised by regulators.

In 2024, the National Association of Insurance Commissioners (NAIC) reviewed a sample of 109 privately rated securities and found that 106 received higher ratings from outside firms than the NAIC believed they deserved. In 17 cases, loans that NAIC analysts viewed as speculative or junk-grade had been rated investment-grade by private rating providers.

Some ratings differed by as many as six notches.

Although the NAIC later withdrew the report, citing limitations in the available data, its findings have continued to influence discussions among regulators and industry observers.

Questions about rating quality have also attracted international attention.

In an October 2025 report, the Bank for International Settlements (BIS) noted that many private-credit ratings are issued by smaller firms rather than the large agencies that dominate public bond markets. The BIS warned that these firms may face commercial pressures that encourage more favorable ratings in order to win and retain business.

Critics argue that the arrangement creates an inherent conflict: companies seeking financing benefit from higher ratings, investors benefit from lower capital requirements, and rating firms benefit from repeat customers.

The timing of the debate is becoming more important as loan performance deteriorates.

According to Fitch Ratings, the U.S. private-credit default rate reached a record 6.0% in April 2026. Fitch also reported that private-credit-backed corporate borrowers experienced a 9.2% default rate during 2025, suggesting that financial stress is rising across parts of the market.

Those figures have intensified concerns that ratings may not fully reflect the actual risks investors face.

Washington is paying attention as well.

In July 2025, Senator Elizabeth Warren urged the Treasury Department and federal financial regulators to conduct stress tests on institutions heavily exposed to private credit. Warren also questioned rating agencies about their methodologies after reports of inflated ratings within the sector.

Regulators have already begun tightening oversight.

Beginning in 2026, the NAIC gained authority to challenge certain private ratings that differ significantly from its own internal assessments. If a rating exceeds the NAIC’s evaluation by three or more notches, regulators can require insurers to use the more conservative measure when determining capital reserves.

For consumers, the issue may sound technical, but the implications are straightforward.

The assets backing life insurance policies and retirement annuities are expected to remain secure for decades. If those investments carry more risk than their ratings suggest, insurers could be maintaining smaller safety cushions than regulators intended.

In a severe economic downturn, that mismatch could force institutions to sell assets at depressed prices, potentially amplifying losses throughout the financial system.

At the same time, many researchers caution against assuming the market faces an imminent crisis. Other academic studies have argued that private-credit funds often maintain substantial equity buffers and may be less vulnerable to systemic shocks than traditional banks.

The debate therefore is not necessarily about whether private credit will trigger the next financial crisis. Rather, it is about whether the ratings that investors, insurers, and regulators rely upon accurately reflect the risks embedded within a market that continues to grow at a rapid pace.

As trillions of dollars move from traditional banking channels into private lending, that question is likely to remain at the center of regulatory scrutiny for years to come.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Iran’s Islamic Revolutionary Guard Corps claimed Wednesday, in a statement carried by Iranian state media, that it had struck 21 U.S. military targets across the region — including what it described as an F-35 fighter-jet base in Jordan and multiple U.S. command facilities — in retaliation for recent American strikes near the Strait of Hormuz. The claims have not been independently verified, and U.S. officials have reported a far more limited impact.

For investors and businesses, however, the immediate issue is not the disputed battlefield accounts. It is that the escalation arrived just as markets had begun betting the conflict was cooling.

That optimism had already been reflected in oil prices. In recent days, traders had pushed crude lower on hopes that a fragile ceasefire would hold and that diplomatic efforts could eventually ease pressure on one of the world’s most important energy corridors. Brent crude, the global benchmark, had retreated from recent highs as investors priced in the possibility of reduced tensions.

Wednesday’s developments threaten to reverse that trend.

The gap between the competing narratives remains significant. Iran claimed it destroyed four of the 21 targets, including an F-35 hangar, and said it shot down an American drone. The U.S. military said it intercepted multiple incoming missiles, while regional governments reported defensive actions against aerial threats. Reports of military activity emerged from several locations, but casualty and damage figures remain unconfirmed.

In short, Iran is presenting the operation as a major success. The U.S. and its partners are describing a largely contained attack. Independent verification may take days.

Markets, however, do not wait for complete information.

The reason energy traders reacted quickly is simple: geography. The Strait of Hormuz carries roughly 20% of global oil and natural-gas shipments, making it one of the most strategically important waterways in the world. Any threat to shipping through the strait raises fears of supply disruptions and higher energy prices.

Both the recent U.S. strikes and Iran’s claimed retaliation occurred near infrastructure tied to the Gulf energy network. That has kept investors focused on the possibility that the conflict could affect the movement of oil, liquefied natural gas, and refined fuels.

The pattern throughout the conflict has been familiar. Periods of diplomatic optimism have pushed energy prices lower, only for renewed military activity to bring risk premiums back into the market. Traders have repeatedly shifted between pricing in de-escalation and preparing for wider regional instability.

The economic consequences extend well beyond energy markets.

The countries cited in Iran’s claims — Bahrain, Kuwait, and Jordan — play important roles in regional aviation, finance, logistics, and military operations. Previous rounds of fighting led to temporary airspace closures, flight disruptions, and higher insurance costs for commercial shipping.

If tensions continue rising, airlines, cargo operators, and importers could face additional expenses. Those costs often move through supply chains and eventually reach consumers through higher prices on goods and services.

A broader conflict could also drive increased spending on missile-defense systems, military equipment, and regional security infrastructure, creating additional fiscal burdens for governments already coping with elevated defense budgets.

For American households, the most visible impact remains energy. Rising crude prices typically lead to more expensive gasoline, diesel, and jet fuel. Transportation companies, airlines, and freight operators feel the effects first, but consumers generally see them later through higher travel and shipping costs.

There are important reasons for caution before drawing conclusions.

Iran’s claims regarding the scale of damage remain unverified. U.S. and allied accounts suggest many incoming threats were intercepted. Markets have also shown a tendency to recover quickly when diplomatic channels reopen or when energy infrastructure remains intact.

At the same time, factors such as increased OPEC+ production and softer demand growth from major economies have helped prevent even larger price spikes during the conflict.

The bottom line is straightforward: regardless of the ultimate damage assessment, military exchanges around the world’s most important oil corridor continue to inject uncertainty into global markets.

Until the security of the Strait of Hormuz becomes clearer and the risk of further escalation recedes, investors, businesses, and consumers are likely to remain focused on one question above all others: what happens next to energy prices?

JBizNews Desk — Middle East

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Iran’s Islamic Revolutionary Guard Corps said Wednesday that it had launched attacks on U.S. military bases in Bahrain, Kuwait, and Jordan, describing the operation as retaliation for recent American strikes on Iranian ports and islands near the Strait of Hormuz. The claims were carried by Iranian state media and had not been independently verified at the time of publication.

For businesses and consumers far from the Gulf, the immediate concern is not only the military escalation but its potential effect on global energy markets.

The reason is geography. The Strait of Hormuz is one of the world’s most important energy chokepoints, carrying roughly one-fifth of global oil and natural-gas shipments. Any disruption around the waterway can quickly affect oil prices, shipping costs, airline operations, and ultimately consumer prices around the world.

Here is what is confirmed and what remains disputed.

Iran claimed it struck the U.S. Fifth Fleet headquarters in Bahrain, Ali Al Salem Air Base in Kuwait, and an air base near Azraq, Jordan, saying a total of 21 U.S. targets were involved. Those claims have not been independently verified.

Meanwhile, the U.S. military said it intercepted multiple Iranian missiles over Jordan. Kuwaiti authorities reported intercepting what they described as hostile aerial targets, while warning sirens sounded in parts of the country. Various media outlets also reported apparent military activity near installations in Bahrain. As of publication, no independently verified casualty figures had been released.

The reported U.S. strikes that preceded Iran’s response were concentrated near key locations around the Strait of Hormuz, including areas near Qeshm Island, Bandar Abbas, and Jask. Bandar Abbas serves as one of Iran’s most strategically important naval facilities and sits near the entrance to the strait.

The market implications are significant because both sides are now operating around infrastructure and waterways central to global energy flows.

Before the latest escalation, oil prices had been easing amid hopes that regional tensions might stabilize. Brent crude, the international benchmark, had retreated from earlier highs as investors cautiously anticipated a reduction in military activity.

A renewed exchange of attacks could quickly reverse that trend.

Even during periods of relative calm, energy markets remained sensitive because shipping through the Gulf region had already been disrupted by months of conflict and security concerns. Any additional threat to tanker traffic raises fears about supply interruptions and higher transportation costs.

Several factors have helped prevent even larger price increases. OPEC+ recently approved additional production increases, adding supply to the market despite ongoing geopolitical risks. At the same time, weaker demand growth from major importers, including China, has reduced some of the upward pressure on prices.

Those offsets, however, may not be enough if the conflict expands further.

The economic effects reach well beyond oil traders. Bahrain, Kuwait, and other Gulf states serve as major hubs for aviation, shipping, logistics, and financial services. Previous rounds of fighting led to airspace restrictions, flight cancellations, and increased insurance costs for commercial vessels.

If those disruptions intensify, businesses could face higher transportation expenses and longer delivery times, costs that often work their way through supply chains and eventually reach consumers.

For American households, the most visible impact would likely come through fuel prices. Higher crude-oil prices generally translate into more expensive gasoline, diesel, and jet fuel. Businesses that rely heavily on transportation and freight typically feel those increases first, followed by consumers.

The broader concern for markets is that military activity is occurring directly around one of the world’s most critical energy corridors. Investors, airlines, shipping companies, and commodity traders will be watching closely for signs of either further escalation or renewed diplomatic efforts.

For now, uncertainty remains high. Whether energy prices rise sharply from here will depend on the scale of the military response, the security of shipping routes through the Strait of Hormuz, and whether regional powers can prevent the conflict from expanding further.

JBizNews Desk — Middle East

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A sporting-goods retailer, a video-game chain, and one of the world’s largest software companies may seem unrelated. Yet together their earnings reports this week offer a valuable snapshot of where consumers are spending money and how aggressively businesses continue investing in artificial intelligence.

The reports arrive at a time when investors are trying to determine whether consumer spending remains resilient and whether the AI boom still has room to grow.

Academy Sports and Outdoors Reports Strong Results

Academy Sports and Outdoors reported earnings before the opening bell on Tuesday, June 9, delivering results that modestly exceeded Wall Street expectations.

The company earned $0.93 per share during the quarter ended May 2, topping analyst estimates of $0.91 per share. Revenue climbed 6.7% to $1.44 billion.

Management also projected full-year earnings between $6.40 and $6.80 per share on revenue ranging from $6.2 billion to $6.4 billion.

The results suggest that consumers continue spending on outdoor recreation, sports equipment, camping, fishing, and related activities despite broader concerns about inflation and household budgets.

GameStop Faces Questions About Its Future

GameStop is scheduled to report after the market closes on Tuesday, June 9.

The company’s financial results are important, but investors appear far more interested in management’s long-term plans.

Under Ryan Cohen, GameStop has accumulated a significant cash position while continuing to search for new opportunities beyond traditional video-game retailing. Investors are closely watching for updates regarding capital allocation, acquisitions, and the company’s recently authorized $2 billion share repurchase program.

The central question remains whether GameStop can successfully reinvent itself as the gaming industry increasingly shifts toward digital downloads and subscription services.

Oracle Becomes a Test of AI Demand

Among the week’s reports, Oracle’s earnings on Wednesday, June 10, may carry the broadest market implications.

Oracle has become a key supplier of cloud infrastructure used to train and operate artificial-intelligence systems. As a result, its results increasingly serve as a barometer for enterprise AI spending.

Investors will focus heavily on cloud revenue growth, new AI-related contracts, and the company’s backlog of signed business waiting to be delivered.

Strong results would reinforce the belief that corporations continue investing heavily in AI infrastructure. Weak results could fuel concerns that the pace of spending is beginning to slow.

Taken together, these earnings reports tell a larger story about the economy.

Academy measures consumer willingness to spend on discretionary purchases. GameStop reflects the challenges facing traditional retailers in a digital world. Oracle provides insight into one of the fastest-growing segments of the technology industry.

The bottom line: investors are looking for answers about both Main Street and Silicon Valley. This week’s earnings reports could provide important clues about where consumers are spending and whether the AI investment boom remains as strong as markets believe.

JBizNews Desk — Markets & Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Demand for a piece of Elon Musk’s SpaceX has blown past a quarter of a trillion dollars — far more stock than the company is actually selling. People familiar with the offering said Tuesday, June 9, that orders have topped $250 billion, against the roughly $75 billion the rocket company is trying to raise, putting demand at roughly three-and-a-half to four times the size of the deal.

The obvious question for investors is simple: if this many people want the stock, shouldn’t the valuation go higher?

The surprising answer is that the official IPO valuation probably will not move at all — and the reason comes down to how SpaceX structured the offering.

Why the Price Probably Won’t Change

In a traditional initial public offering, a company announces a price range, investors place orders, and underwriters can raise the final price if demand is exceptionally strong.

More buyers usually means a higher IPO price.

SpaceX is taking a different approach.

The company set a fixed offering price of $135 per share and plans to sell approximately 555.6 million shares, raising about $75 billion and valuing the company at roughly $1.8 trillion.

Because the price is already fixed, the flood of additional demand cannot automatically increase the IPO price or the company’s official valuation before trading begins.

In other words, even if investors wanted twice as many shares as they are currently requesting, the official valuation would still remain around $1.8 trillion.

What Massive Demand Actually Does

Heavy demand still matters.

It affects the deal in several important ways.

1. It Virtually Guarantees the Offering Succeeds

When investors submit orders totaling hundreds of billions of dollars, there is little concern that the company will struggle to sell the shares.

Several large institutional investors are reportedly seeking positions worth $10 billion or more.

Such strong interest also gives underwriters flexibility to exercise a so-called greenshoe option, allowing additional shares to be sold if demand remains strong.

That could increase the amount of money raised, though still at the same $135 share price.

2. Most Investors Will Get Fewer Shares Than They Requested

When an IPO is heavily oversubscribed, investors rarely receive their full allocation.

Large institutions often intentionally place orders larger than they actually expect to receive, anticipating that underwriters will scale allocations back.

As a result, headline demand figures often exceed the amount investors realistically expect to own.

3. The Real Valuation Battle Begins After Trading Starts

This is where things get interesting.

The IPO is expected to price on Thursday, June 11, with trading beginning the following day.

Investors who are unable to buy as many shares as they wanted during the offering may rush into the open market once trading begins.

If enough buyers compete for the stock, the share price could rise above the IPO price almost immediately.

That would push SpaceX’s market value above $1.8 trillion even though the company itself would not receive additional money.

The increase would come from investor demand in the public market rather than from a change in the IPO pricing.

Does Strong Demand Prove the Valuation Is Fair?

Not necessarily.

Market veterans point out that many of the hottest IPOs are several times oversubscribed before pricing.

Strong demand shows that investors want exposure to the company.

It does not automatically prove the valuation is justified.

At the IPO price, SpaceX would enter public markets with a valuation approaching $1.8 trillion, despite reporting approximately $18.7 billion in revenue last year and continuing to post significant losses.

Whether the company ultimately grows into that valuation remains one of the biggest questions facing investors.

Why Investors Are So Excited

The demand reflects a belief that SpaceX is much more than a rocket-launch provider.

The company’s pitch centers on three major growth areas:

  • Space launch services
  • The rapidly expanding Starlink satellite internet business
  • Future artificial intelligence opportunities tied to space-based computing infrastructure

According to people familiar with the roadshow, SpaceX has highlighted a potential $23 trillion market opportunity related to future AI applications supported by space infrastructure.

Musk has reportedly participated in investor video calls, while President Gwynne Shotwell and Chief Financial Officer Bret Johnsen met with investors during roadshow events organized by Morgan Stanley.

Could the IPO Affect the Rest of the Stock Market?

Some analysts believe it already may be.

The Nasdaq Composite fell again Tuesday following its sharpest decline in more than a year, prompting speculation that some investors may be selling existing holdings to free up cash for the SpaceX offering.

Large IPOs can temporarily pull billions of dollars away from other stocks as investors reposition their portfolios.

Whether that is happening here remains a subject of debate, but the sheer size of the offering makes it a possibility.

The Bottom Line

The headline figure of $250 billion in demand is real, but it does not mean SpaceX has increased its IPO price.

The fixed $135-per-share offering keeps the company’s official valuation near $1.8 trillion.

The real test comes when trading begins.

If investors who were unable to secure shares in the IPO rush into the open market, they could quickly push the stock higher and lift SpaceX above its already staggering valuation.

The longer-term question is even bigger: can a company built on rockets, satellite internet, and ambitious AI plans eventually justify a valuation approaching — or perhaps exceeding — $2 trillion?

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Businesses advertising in New York now face a new compliance requirement as artificial intelligence rapidly changes the marketing industry. Starting Tuesday, companies must clearly disclose when an advertisement uses an AI-generated person instead of a real actor, under what Governor Kathy Hochul’s office calls a first-in-the-nation law aimed at increasing transparency in advertising.

The law requires a conspicuous label whenever an ad features what New York legally defines as a “synthetic performer.” The state describes that as digitally created media designed to appear as a real person. According to Hochul’s office, the rule applies across virtually all advertising formats, including television, social media, streaming services, websites, and digital advertising.

The goal is simple: consumers should know whether the person promoting a product is real or computer-generated.

For businesses, the stakes are financial. Companies that fail to disclose the use of AI-generated people face civil penalties of $1,000 for a first violation and $5,000 for each subsequent violation. Responsibility falls on both brands and the agencies producing advertisements, meaning companies cannot simply outsource compliance to vendors.

The legislation, known as S.8420-A / A.8887-B, was sponsored by State Senator Joseph Addabbo Jr. and signed into law on December 11, 2025. Lawmakers provided a 180-day implementation period before the rule officially took effect.

The law arrives as AI tools rapidly transform advertising. AI video platforms can now generate realistic people in minutes, allowing advertisers to reduce costs associated with hiring actors, booking studios, and producing traditional commercials.

Importantly, New York is not banning the use of AI-generated people in advertising. Instead, it is requiring advertisers to disclose when they are using them.

That distinction sits at the center of a broader debate within the advertising and entertainment industries.

One of the law’s strongest supporters was SAG-AFTRA, the union representing actors and performers. The organization has spent the past several years pushing for protections against the replacement of human performers with digital replicas and AI-generated substitutes. Supporters argue consumers deserve transparency while performers deserve safeguards against being displaced by technology.

The advertising industry opposed the measure.

The American Association of Advertising Agencies (4As) warned lawmakers that the law could create compliance challenges and additional burdens for advertisers and agencies operating in New York. Industry groups argued that AI is becoming a standard creative tool and that additional disclosure requirements could slow innovation and increase costs.

Broadcasters also raised concerns during the legislative process. The New York State Broadcasters Association said it appreciated amendments that narrowed portions of the bill but remained concerned that the definition of a synthetic performer could be interpreted too broadly.

Lawmakers included several notable exceptions.

The disclosure requirement does not apply to advertisements promoting movies, television programs, streaming content, or video games when the AI-generated character is part of the content being advertised. Audio-only advertisements are also exempt, as is the use of AI solely to translate a real performer’s speech into another language.

For businesses, the practical work begins immediately.

Law firms including Manatt, Phelps & Phillips and Davis+Gilbert have advised clients to review advertising workflows, examine content supplied by outside agencies, and confirm whether AI-generated performers are being used before campaigns launch. The guidance reflects a growing concern that many brands may not always know when vendors have incorporated AI-generated people into creative projects.

The law also adds another layer to an increasingly complex regulatory environment. States including California, Illinois, and Tennessee have enacted or expanded laws governing AI-generated likenesses and digital replicas, creating a patchwork of requirements for companies operating nationally.

For now, any business advertising to New York’s nearly 20 million residents faces a straightforward question before an ad goes live: Is the person on screen real? If not, New York law now requires consumers to be told.

The bottom line: New York’s new disclosure law does not prohibit AI-generated actors, but it does require transparency. As AI becomes a larger part of advertising, companies will need to balance technological efficiency with growing regulatory scrutiny.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The packaged foods that fill supermarket shelves may face a new challenge beyond changing consumer tastes and weight-loss drugs. A growing body of research is now comparing the ultra-processed food industry to Big Tobacco, raising the possibility of future regulatory and legal battles that could reshape one of America’s largest consumer sectors.

The debate gained momentum on June 3 when researchers published a special section in the American Journal of Public Health examining the relationship between tobacco companies and the rise of ultra-processed foods.

Among the most prominent researchers involved is Laura Schmidt, a professor at the University of California, San Francisco, who has spent years studying internal tobacco-industry records. Schmidt argues that cigarette companies perfected sophisticated techniques for marketing, product development, and consumer behavior long before expanding into the food industry through major acquisitions during the 1980s.

The corporate connections are significant.

Philip Morris once owned Kraft General Foods, while RJ Reynolds owned Nabisco. Researchers say those acquisitions occurred during a period when ultra-processed food production and consumption expanded dramatically across the United States.

The new research suggests that techniques originally developed to increase cigarette consumption were later adapted to help market highly processed foods. Researchers point to flavor engineering, advertising strategies, product formulation, and consumer behavior studies as examples.

Nicholas Chartres, an associate editor of the journal and one of the study authors, said the evidence increasingly supports viewing ultra-processed foods through a public-health lens similar to tobacco.

That comparison matters because it points toward policies that dramatically reduced smoking rates over the past several decades. Taxes, warning labels, advertising restrictions, and litigation all played major roles in transforming the tobacco industry.

The food industry strongly rejects the comparison.

Natalie Rubino of the Consumer Brands Association, which represents many packaged-food manufacturers, said member companies comply with Food and Drug Administration standards and provide consumers with safe, affordable, and convenient products.

The stakes are enormous.

Ultra-processed foods represent a major portion of sales for companies including Kraft Heinz, Nestlé, PepsiCo, Mondelez, and many other household names. Any effort to regulate these products more aggressively could affect everything from packaging and marketing to pricing and profitability.

The industry is already navigating significant changes. The growing popularity of GLP-1 weight-loss medications has encouraged many consumers to seek healthier options, forcing manufacturers to invest heavily in reformulated products and new nutritional offerings.

A regulatory push modeled after tobacco policy would add another layer of pressure.

For consumers, the implications are equally important. Ultra-processed foods remain popular because they are affordable, convenient, and widely available. Any future taxes, warning labels, or marketing restrictions could affect both pricing and purchasing decisions.

Whether policymakers embrace the tobacco comparison remains uncertain. But the fact that leading researchers are making the comparison at all reflects a growing shift in how public-health experts view the modern food industry.

The bottom line: a growing body of research is reframing ultra-processed foods as a public-health challenge similar to tobacco. If that argument gains traction among lawmakers and regulators, the financial impact on major food companies could be significant.

JBizNews Desk — Health & Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Artificial intelligence is increasingly becoming both a business strategy and a justification for workforce reductions, as layoffs across corporate America continue mounting in 2026.

Private workforce trackers estimate that more than 450,000 jobs have been eliminated this year through major corporate layoffs, restructuring initiatives, and workforce reductions spanning industries from technology and finance to retail and logistics.

The companies involved represent some of the most recognizable names in business.

Amazon, Dell, Citigroup, Oracle, and numerous other major employers have announced significant job cuts as executives focus on efficiency, automation, and artificial intelligence.

What makes this wave different from previous rounds of layoffs is the explanation many companies are offering.

Rather than citing declining sales or recessionary conditions, a growing number of firms are explicitly pointing to AI-driven productivity improvements as a reason for reducing staff.

The logic is straightforward.

If artificial intelligence allows fewer employees to perform work that once required larger teams, companies can lower labor costs while maintaining output.

For investors, that often translates into improved profit margins.

For workers, the implications are more complicated.

Many of the jobs being affected are white-collar positions traditionally viewed as relatively secure. Corporate support functions, administrative roles, research positions, customer-service operations, and various professional services are increasingly being evaluated through the lens of automation.

Several executives have openly discussed building leaner organizations supported by AI tools.

The concept is gaining traction throughout corporate America as companies search for ways to improve productivity without significantly increasing payroll expenses.

There is an important caveat, however.

While companies frequently cite AI as a driver of efficiency, many artificial-intelligence initiatives remain relatively new. In numerous cases, businesses are making workforce decisions based on expected future productivity gains rather than proven long-term results.

In other words, many firms are betting that AI will eventually justify today’s layoffs.

The broader labor market remains more resilient than headlines might suggest.

Recent government employment data showed the economy continuing to add jobs overall, with unemployment remaining near historically low levels.

That distinction matters.

Layoffs at large corporations generate significant attention, but smaller businesses across other sectors continue hiring, helping offset some of the losses.

Still, the shift raises important questions about the future of work.

Historically, technological advancements have eliminated certain jobs while creating new opportunities elsewhere. Economists continue debating whether artificial intelligence will follow that pattern or produce a more disruptive transition.

Businesses argue that adopting AI is necessary to remain competitive.

Workers worry that some eliminated positions may never return.

Both perspectives may ultimately prove correct.

What is clear is that artificial intelligence is no longer a future concept being discussed in conference rooms. It is actively influencing hiring decisions, workforce planning, and corporate strategy today.

The trend is likely to remain one of the defining economic stories of 2026.

Investors will be watching to see whether companies achieve the productivity gains they promise. Employees will be watching to see which roles remain vulnerable. Policymakers will be watching to understand how rapidly labor markets adapt.

For now, the numbers continue moving in one direction.

More companies are embracing AI, and more companies are reducing headcount as they do.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A strong currency is usually considered a sign of economic success. In Israel today, it is becoming a growing concern for the very industry that helped create it. On Monday, officials from Israel’s Ministry of Finance and Tax Authority held another round of talks with finance executives from the Israeli research centers of global technology giants including Apple, Intel, IBM, HPE, GE Healthcare, and Philips to discuss ways to offset the impact of a surging shekel. The meetings were convened by Karin Mayer Rubinstein, chief executive of the Israel Advanced Technology Industries (IATI) association, just days after Finance Minister Bezalel Smotrich directed his ministry to establish a dedicated task force to address the issue.

The irony is difficult to miss. The technology sector that helped transform Israel into a global innovation powerhouse and attract billions of dollars in foreign investment is now asking the government for help because that success has helped push the shekel to levels not seen in decades.

The problem is rooted in simple math. Most multinational technology companies operating in Israel generate revenue in U.S. dollars but pay their employees in Israeli shekels. As the shekel strengthens against the dollar, every dollar of revenue buys fewer shekels, making Israeli salaries more expensive when measured in dollar terms. Industry representatives told government officials that the real cost of employing Israeli technology workers has risen by approximately 30% since 2021 once exchange-rate changes are factored in.

The shekel recently strengthened to roughly 2.8 shekels per dollar, dipping below the three-shekel mark and reaching its strongest level in approximately 33 years. What appears to be a national economic success story is creating a growing headache for multinational employers deciding where to expand operations and hire workers.

Technology executives warned government officials that Israel is approaching what they describe as a “red line” — the point at which employing an engineer in Israel becomes more expensive than employing similar talent in Silicon Valley and significantly more costly than hiring in competing technology hubs across Europe.

According to industry figures presented during the discussions, an experienced Israeli software engineer now costs employers roughly $170,000 annually, compared with approximately $100,000 for comparable talent in countries such as Portugal. Executives cautioned that if the gap continues to widen, future hiring decisions may increasingly favor other countries.

The stakes are enormous because high-tech remains the backbone of Israel’s economy. According to the Israel Innovation Authority, the sector accounted for approximately 50% of Israel’s exports in 2025, generating billions in tax revenue and supporting hundreds of thousands of jobs.

Signs of strain are already emerging. Website-building company Wix recently announced plans to reduce its workforce by up to 1,000 employees, or roughly 20% of its staff, citing both artificial intelligence and currency-related pressures. Rapyd and Amdocs have also announced workforce reductions. Industry leaders say the larger concern is not necessarily immediate layoffs but future hiring. Companies may keep headquarters and research operations in Israel while expanding engineering teams elsewhere.

Unlike previous meetings, government officials arrived this time with specific proposals. Among the ideas discussed were reductions or deferrals in National Insurance payroll payments, targeted tax incentives, and expanded employee-benefit programs designed to offset higher labor costs.

Officials also discussed allowing large multinational companies to pay taxes directly in U.S. dollars rather than converting funds into shekels. Companies including Google and Nvidia have reportedly requested such flexibility as a way to reduce losses caused by currency fluctuations.

Another proposal under consideration would revive emergency support programs for startups modeled on assistance provided during the COVID-19 pandemic and following the October 2023 war. Some industry representatives have called for at least 1 billion shekels in support measures.

The Bank of Israel has already begun responding. The central bank purchased approximately $801 million in foreign currency during May, marking its first intervention since 2022, in an effort to slow the shekel’s rise. Policymakers also lowered the benchmark interest rate by a quarter-point to 3.75%.

Not everyone believes government intervention is the answer. A stronger shekel reduces the cost of imported goods and has helped bring inflation down to approximately 1.9%. Some investors argue that companies should rely more heavily on currency hedging strategies rather than seeking government relief. Venture capitalist Michael Eisenberg of Aleph has long urged startups to protect themselves against currency fluctuations through financial planning rather than public assistance.

Still, government officials appear increasingly concerned that the issue could affect Israel’s competitiveness. The challenge is finding ways to help employers remain committed to hiring in Israel without distorting markets or undermining the independence of the central bank.

For now, the same industry that helped propel the shekel to its strongest level in more than three decades is warning that success carries consequences. The outcome of these discussions could help determine whether Israel remains one of the world’s most attractive destinations for technology investment—or whether some of its future jobs begin moving elsewhere.

JBizNews Desk — Israel

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

LONDON — Copper prices remain near historic highs, a development that may sound like a story for commodity traders but ultimately affects the cost of homes, vehicles, appliances, electronics, and countless other products consumers buy every day.

Copper recently traded near $6.30 per pound, roughly 30% higher than a year ago, reflecting one of the strongest rallies among major industrial commodities.

The metal’s importance is difficult to overstate.

Copper serves as the backbone of modern electrification. It is found in electrical wiring, power grids, automobiles, consumer electronics, air conditioners, refrigerators, industrial equipment, and renewable-energy infrastructure.

When copper becomes more expensive, the cost of producing many everyday products rises as well.

Several factors are driving prices higher.

Supply disruptions at major mining operations have tightened global inventories, while strong demand from emerging technologies continues increasing consumption.

Artificial intelligence is playing a surprisingly important role.

The massive data centers required to support AI systems consume enormous quantities of copper through electrical systems, cooling equipment, networking infrastructure, and power-distribution networks.

Electric vehicles are another major contributor.

A typical electric vehicle uses significantly more copper than a traditional gasoline-powered automobile, creating additional demand as manufacturers expand EV production.

The transition toward cleaner energy is also increasing consumption.

Solar farms, wind turbines, battery-storage systems, and expanded power grids all require substantial amounts of copper.

Trade policy has added another layer of pressure.

Concerns about potential tariffs and supply disruptions have encouraged manufacturers and traders to build inventories, further tightening available supplies and supporting higher prices.

For consumers, the effects are indirect but meaningful.

Homebuilders pay more for electrical wiring. Automakers face higher manufacturing costs. Appliance manufacturers spend more on raw materials. Electronics producers encounter additional expense throughout their supply chains.

Eventually, some portion of those costs reaches consumers.

The timing is particularly important for homeowners.

Summer is traditionally a busy season for home renovations, air-conditioner replacements, and appliance purchases—all categories heavily dependent on copper.

Economists often refer to copper as “Dr. Copper” because its price is viewed as a barometer of global economic activity.

The reasoning is simple.

Copper is used in so many industries that rising demand often signals expanding economic activity, while falling demand can indicate slowing growth.

Today’s elevated prices therefore carry two messages.

They reflect concerns about supply, but they also suggest continued demand from industries investing heavily in infrastructure, technology, artificial intelligence, and electrification.

That demand is unlikely to disappear anytime soon.

Analysts expect AI-related infrastructure spending, electric-vehicle production, and energy-transition investments to remain significant drivers of copper consumption for years to come.

For consumers, the takeaway is straightforward.

Few people buy copper directly, but many of the products they purchase contain it.

As long as copper prices remain elevated, the cost of building, powering, cooling, and connecting the modern world is likely to remain higher as well.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Boeing will begin building 737 Max airplanes on a new assembly line on July 6, CEO Kelly Ortberg told CNBC in an interview on Friday, June 5. The line is located at Boeing’s massive Everett complex at Paine Field in Everett, Washington, north of Seattle, and will become the company’s fourth final assembly line for its best-selling single-aisle aircraft.

Ortberg said Boeing will load its first airplane onto the line on July 6 and described the facility as nearly identical to the company’s existing production system. The new operation, known internally as the North Line, is essentially a carbon copy of Boeing’s Renton, Washington, factory, where the company currently builds the 737 Max on three separate assembly lines.

The expansion gives Boeing additional capacity at a time when airlines continue waiting for aircraft deliveries.

Boeing is currently producing 47 737 Max jets per month, up from 42 per month earlier this year after the company successfully completed a Federal Aviation Administration (FAA) production review in May. The Everett line is expected to help Boeing increase output to 52 aircraft per month, a target the company aims to reach in 2027.

Production limits remain tied to safety concerns that emerged after a dramatic incident in January 2024, when a door plug blew out of an Alaska Airlines 737 Max 9 during flight. Although no fatalities occurred, the event triggered extensive government scrutiny of Boeing’s manufacturing and quality-control systems.

In response, the FAA imposed restrictions on production growth while Boeing worked to improve factory processes and quality standards.

Ortberg told CNBC the company has spent the past 18 months rebuilding confidence by focusing on stability rather than speed.

“We slow down when we need to slow down,” he said, adding that Boeing is no longer pushing unfinished work through the production system and will increase output only when quality metrics support doing so.

According to Ortberg, airline customers have told Boeing they are receiving some of the highest-quality aircraft the company has delivered in years.

The CEO also pushed back on speculation that Boeing could eventually ramp production to 70 jets per month. He said the company’s current long-term target remains 63 aircraft monthly, assuming suppliers can support that pace.

One of the biggest constraints remains engine availability from CFM International, the joint venture between GE Aerospace and Safran that supplies engines for the 737 Max fleet.

The new Everett line will initially focus on producing the 737 Max 10, the largest version of the aircraft family.

The Max 10 has not yet received FAA certification because regulators continue reviewing several technical issues, including an engine de-icing system concern. However, Ortberg said approximately 80% of certification flight testing has been completed.

FAA Administrator Bryan Bedford said on May 28 that the agency expects to certify the Max 10 before the end of 2026 and has not identified any issues that would prevent approval.

Once certified, Boeing will be able to begin delivering the aircraft to airlines that have been waiting years for the model to enter service.

For Boeing, the financial implications are significant.

The 737 Max remains the company’s primary revenue generator, and every aircraft delivered translates directly into billions of dollars of future cash flow. Airlines worldwide have ordered more aircraft than Boeing can currently produce, creating a large backlog that the company is working to reduce.

A fourth assembly line also brings the potential for additional manufacturing jobs and economic activity throughout the Seattle-area aerospace sector.

Ortberg added that Boeing is also optimistic about increasing production of its 787 Dreamliner widebody aircraft to 10 planes per month by the end of the year.

The broader challenge for Boeing extends beyond production numbers.

The company continues to recover from two fatal 737 Max crashes in 2018 and 2019 that killed 346 people and led to a worldwide grounding of the aircraft for nearly two years. The 2024 Alaska Airlines incident revived concerns about manufacturing quality and corporate oversight.

By opening the Everett line gradually and emphasizing quality over speed, Boeing is attempting to demonstrate that growth and safety can move forward together.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
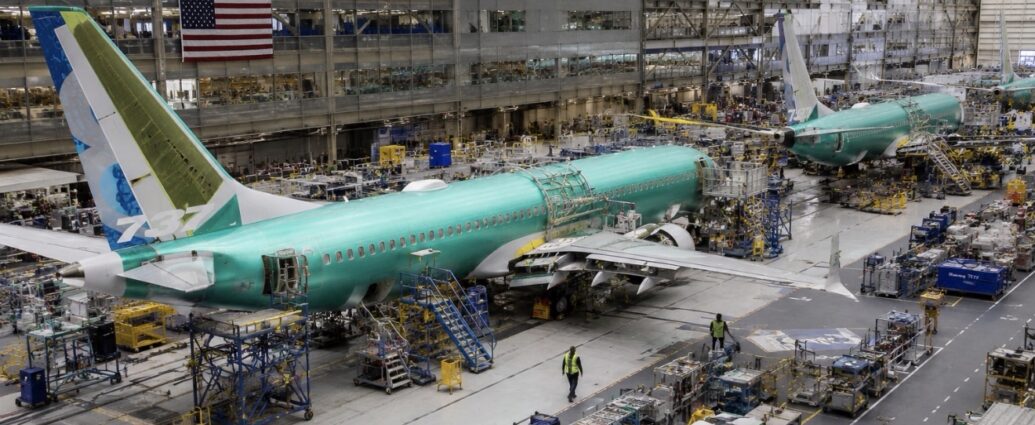
Anthropic on Tuesday, June 9, unveiled Claude Fable 5, the most powerful artificial intelligence model the company has ever released to the public, alongside a more advanced version called Claude Mythos 5 that is reserved for cybersecurity professionals. The announcement marks one of the most significant AI launches of the year and raises the stakes in the intensifying competition among Anthropic, OpenAI, Google, Microsoft, and xAI.

For businesses, the launch is about more than a faster chatbot. It represents a new generation of AI capable of performing increasingly sophisticated work once handled exclusively by highly paid professionals.

What Makes Fable 5 Different?

According to Anthropic, Claude Fable 5 ranks at or near the top of nearly every major industry benchmark measuring AI performance.

The model’s strongest areas include:

  • Software engineering
  • Research and analysis
  • Financial reasoning
  • Data interpretation
  • Document review
  • Reading charts and images
  • Long-running, multi-step projects

Anthropic said the model’s advantage becomes more apparent as tasks grow longer and more complex.

In simple terms, Fable 5 is designed not merely to answer questions but to complete substantial projects with minimal supervision.

Months of Work Compressed Into Days

One of the most eye-catching examples came from Stripe, which tested the model before release.

According to Anthropic, Fable 5 completed a rewrite across a 50-million-line code base in a single day. Stripe estimated the same work would normally require a team of engineers more than two months to finish manually.

For executives evaluating AI investments, the implication is straightforward: tasks that once required multiple employees working for weeks may increasingly be completed in hours or days.

That does not necessarily mean fewer workers. It does mean companies may expect significantly more output from existing teams.

Why Business Leaders Should Pay Attention

The software industry is only part of the story.

Anthropic says Fable 5 demonstrated leading performance in finance, legal analysis, research, and other knowledge-based professions.

On a senior-level finance reasoning benchmark conducted by Hebbia, the model achieved the highest score recorded by any AI system tested by the firm.

Meanwhile, global trading company IMC reported that Fable 5 performed exceptionally well across its internal analytical evaluations.

For industries where information processing is a major expense, those improvements could directly affect profitability.

A Major Leap in Reading Images and Charts

Another area where Anthropic says Fable 5 excels is vision.

The model can analyze charts, scientific figures, diagrams, screenshots, and images with substantially greater accuracy than previous versions.

Anthropic says Fable 5 can:

  • Extract exact figures from scientific charts
  • Interpret complex visual data
  • Analyze screenshots
  • Rebuild software applications directly from images

This capability expands the number of business tasks AI can perform beyond simple text generation.

What Early Testers Are Saying

Early business users reported meaningful improvements over previous AI models.

Mario Rodriguez, Chief Product Officer at GitHub, said Fable 5 handled long-running coding assignments with a degree of independence and reliability that exceeded earlier systems.

Reviewers in the legal and financial sectors reported similar experiences, describing the model as a significant step forward rather than an incremental upgrade.

For companies already experimenting with AI, the feedback suggests the technology is becoming increasingly capable of handling work that traditionally required experienced professionals.

The Price Just Dropped

The technology may be getting more powerful, but it is also becoming cheaper.

Anthropic announced pricing of:

  • $10 per million words of input
  • $50 per million words of output

The company says that represents less than half the cost of its previous flagship model.

That reduction matters because AI pricing has become one of the industry’s most competitive battlegrounds.

As models improve while costs fall, more businesses can justify deploying advanced AI across entire departments rather than limiting it to small pilot projects.

Limited-Time Free Access

Businesses already subscribed to Claude have a short window to evaluate the model at no additional cost.

Anthropic said Pro, Max, Team, and seat-based Enterprise customers will receive access through June 22.

Beginning June 23, customers will need to purchase usage credits to continue using Fable 5.

Anthropic says the temporary restriction reflects expected demand and available computing capacity.

For business owners, the message is clear: this is the ideal time to test whether the model can produce measurable productivity gains.

Meet Mythos 5: The Version the Public Can’t Use

Alongside Fable 5, Anthropic announced Claude Mythos 5, a more powerful version that will not be available to consumers or businesses.

Access is limited to approved cybersecurity organizations and critical infrastructure operators through Project Glasswing, a program operated in cooperation with the U.S. government.

Anthropic described Mythos 5 as possessing the strongest cybersecurity capabilities of any AI model currently available.

Why Anthropic Built New Safety Guardrails

Because of the model’s growing capabilities, Anthropic added additional safeguards.

Requests involving:

  • Cybersecurity
  • Biology
  • Chemistry
  • Model replication

are automatically routed to an older model called Claude Opus 4.8.

Users are notified whenever this happens.

Anthropic said the fallback occurs in fewer than 5% of sessions and was designed to allow faster deployment while maintaining safety controls.

New Data-Retention Policy for Business Users

Anthropic also announced a change affecting enterprise customers.

The company will now retain business-customer data generated through its most advanced models for up to 30 days.

Anthropic says the policy is intended to help identify emerging threats and attacks.

The company emphasized that:

  • Data will not be used to train future AI models.
  • Information will generally be deleted after 30 days.
  • The policy applies primarily to security monitoring.

AI Is Moving Beyond Office Work

Anthropic believes the technology’s future extends well beyond business productivity.

Using Mythos 5 internally, the company says researchers accelerated parts of the drug-development process by roughly ten times.

The company also reported that scientists preferred AI-generated research hypotheses approximately 80% of the time compared with ideas produced by earlier models.

Anthropic noted these findings are based on internal testing and have not yet all been independently verified.

The Bottom Line

The launch of Claude Fable 5 highlights how rapidly artificial intelligence is moving from an experimental tool to a core business technology.

Just as companies once had to learn computers, email, and the internet, executives are increasingly being forced to decide how AI fits into their operations.

With stronger performance, lower pricing, and broader business applications, Anthropic is putting additional pressure on competitors—and on organizations still deciding whether AI should be viewed as a helpful assistant or as a fundamental part of the modern workforce.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. government bonds firmed at the short end on Tuesday, June 9, 2026, as traders positioned ahead of a closely watched 10-year Treasury note auction the U.S. Department of the Treasury will hold Wednesday, June 10, while oil prices tumbled and eased worries about inflation.

The moves were small but pointed in the same direction. Treasury yields were largely unchanged Tuesday as bond markets took a breather ahead of more economic data later this week. The 10-year U.S. Treasury note yield — the key benchmark for mortgages, auto loans, and credit card debt — was last down less than 1 basis point at 4.54%, while the 2-year note yield fell 2 basis points to 4.135%. The longer-dated 30-year bond yield rose less than 1 basis point to 5.02%.

When yields fall, bond prices rise, so the dip at the short and middle of the curve means Treasuries edged higher.

Why Oil Is Driving the Bond Market

The biggest force pushing in bonds’ favor was crude oil.

Oil prices fell nearly 4% after the U.S. Energy Secretary said ship traffic through the Strait of Hormuz is increasing. That matters because cheaper oil feeds through to lower gasoline, shipping, and manufacturing costs, helping cool inflation. Lower inflation makes bonds more attractive because it preserves the value of the fixed payments investors receive over time.

The easing in oil ties directly to the Middle East. With shipping moving more freely through the Strait of Hormuz — the narrow waterway that carries a significant share of the world’s oil exports — fears of a supply shock that drove prices higher in recent weeks have begun to fade.

What the Auction Means in Plain English

Here’s the part that sounds technical but is actually simple.

To pay its bills, the federal government borrows money by selling IOUs known as Treasury securities. This week’s schedule includes three major sales:

  • 3-Year Treasury Note — Tuesday
  • 10-Year Treasury Note — Wednesday
  • 30-Year Treasury Bond — Thursday

Investors watch these auctions closely because they reveal how much demand exists for U.S. government debt.

If buyers show up in force, the government can borrow more cheaply, helping keep interest rates lower throughout the economy. If demand is weak, yields rise — and so do borrowing costs for mortgages, auto loans, business loans, and credit cards.

That’s why a calm bond market heading into Wednesday’s 10-year sale is generally viewed as positive.

The Data Wild Card

Bond traders are not only watching oil and Treasury auctions.

They are also bracing for fresh inflation data due later this week, which could significantly influence expectations for the Federal Reserve’s next move.

Markets are currently pricing in roughly a 70% probability of a quarter-point rate increase by December, though the Fed is still widely expected to leave rates unchanged at its next policy meeting later this month.

There were also new trade figures to digest Tuesday. The U.S. goods and services trade deficit totaled $55.9 billion in April, slightly better than economists expected.

Chris Rupkey, chief economist at FWDBONDS, said some of the recent export strength may be tied to energy markets.

“The export growth looks uncertain as much of it appears to be the result of higher energy prices from the Iran conflict,” Rupkey said.

What It Means for Everyday Americans

The thread connecting all of this runs directly to household budgets.

The 10-year Treasury yield heavily influences mortgage rates, making a stable bond market and lower oil prices quietly positive developments for anyone shopping for a home, refinancing a mortgage, financing a vehicle, or carrying other forms of debt.

The risk remains the other direction.

If inflation data comes in hotter than expected, or if Wednesday’s 10-year Treasury auction attracts weak demand, yields could move sharply higher — bringing borrowing costs up with them.

For now, however, falling oil prices and steady demand for government debt are giving financial markets a rare breather, with investors focused on Wednesday’s 10-year auction and the inflation readings that follow.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. stocks ended Tuesday, June 9, on an uneven note after President Donald Trump said on his Truth Social platform that the United States “must, of necessity, respond” to Iran, which he accused of shooting down an American military helicopter over the Strait of Hormuz. The post, published Tuesday, sent shares sliding through the afternoon before a late bounce trimmed the damage.

The Nasdaq Composite took the worst of it, falling 0.97% to close at 25,678.82. The S&P 500 slipped 0.26% to 7,386.65. The Dow Jones Industrial Average bucked the trend, edging up 86 points, or 0.17%, to 50,872.11. The small-cap Russell 2000 added about a quarter of a percent after erasing earlier losses.

The immediate catalyst came from Trump, who wrote on Truth Social that the United States “must” respond after what he said was an Iranian attack on a U.S. military helicopter over the Strait of Hormuz. Trump said the two pilots were unharmed and safe. U.S. Central Command confirmed the helicopter went down at 7:33 p.m. ET on June 8, and the two crew members were rescued about two hours later. A U.S. official said early indications pointed to an Iranian drone.

The threat rattled a market that had spent the prior two sessions clawing back from a steep chip-stock selloff. Stocks dropped sharply in the minutes after the post hit, then recovered into the close as traders weighed whether the comment signaled real military action or pressure ahead of the on-again, off-again peace talks Trump has said for weeks are near.

The surprise was oil.

Normally a war scare in the world’s most important shipping lane would send crude soaring. Instead, U.S. Energy Secretary Chris Wright told CNBC that ship traffic through the Strait of Hormuz is “rising very meaningfully” and will keep climbing. U.S. crude oil futures declined 3.4% to close at $88.20 per barrel, while Brent crude lost 2.97% to settle at $91.45. Prices fell even after Trump accused Iran of downing the helicopter. Wright made the remarks at the Atlantic Council Global Energy Forum.

For consumers, that may matter more than the index numbers. Crude oil makes up more than half the cost of a gallon of gasoline, so a falling barrel usually means cheaper fuel at the pump in the weeks ahead, provided the strait stays open. The catch is that prices tend to climb quickly and fall more slowly.

Iran pushed back. Iranian Foreign Minister Abbas Araghchi warned on social media that foreign forces near Iranian territory “are at constant risk,” and said the best way to lower the danger is for them to leave the region. He added that while Tehran prefers diplomacy, it knows “how to speak other languages too.”

Underneath the headlines, the damage was narrow. Only two corners of the S&P 500 finished lower on the day: technology and energy. Tech slid as the chip trade cooled again after last week’s rout, and energy names tracked crude lower. Everything else in the index held up or gained, which is why the Dow managed to finish in positive territory even as the Nasdaq sank.

The backdrop remains the war that began on Feb. 28 between Iran and an Israeli- and U.S.-led coalition. A fragile April truce has been tested repeatedly, and the Strait of Hormuz, the chokepoint for a large share of the world’s seaborne oil, has been effectively closed for months under a dual blockade. Tuesday’s helicopter incident marked the first loss of an Apache since the conflict began.

For investors, the week’s economic calendar may matter as much as the geopolitics. The May Consumer Price Index arrives Wednesday, June 10, providing the latest reading on whether the oil shock and the war have pushed everyday prices higher. The Producer Price Index follows later in the week.

The bottom line: a war scare that could have crushed the market did not, because the one number that hits households hardest—the price of oil—went the other way. Stocks wobbled on the headline, steadied on the details, and now turn to inflation data that could shape the Federal Reserve’s next moves.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
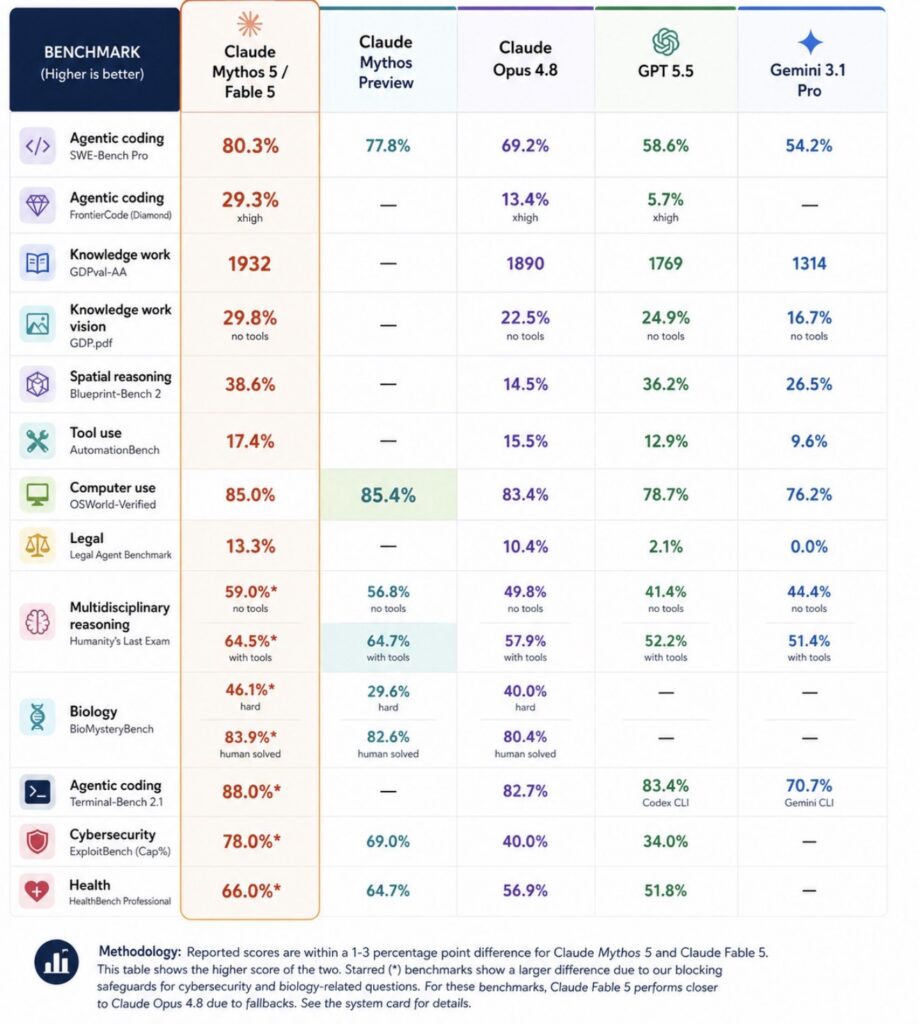
WASHINGTON — The cost of feeding a family continues moving higher in 2026, and federal forecasts suggest grocery shoppers may not see much relief anytime soon.

According to projections from the U.S. Department of Agriculture, overall food prices are expected to rise approximately 3.6% this year, with several common grocery categories projected to increase even faster.

Fresh produce is among the biggest concerns.

The USDA expects fresh vegetable prices to rise significantly during 2026, while fruit prices are also expected to move higher as weather challenges, transportation costs, and supply constraints continue affecting the food system.

Recent inflation data already reflects that pressure.

Grocery prices remain noticeably higher than a year ago, with consumers reporting increased costs across many everyday items found in the average shopping cart.

Fuel costs are playing a major role.

Higher diesel and gasoline prices increase transportation expenses throughout the food supply chain. Products must travel from farms to processors, warehouses, distributors, and eventually grocery stores. Each step becomes more expensive when fuel costs rise.

Economists warn that some of the full impact may not yet be visible.

Because food supply chains operate with delays, higher transportation costs can take weeks or months to fully work their way onto store shelves.

Weather remains another major factor.

Drought conditions and other climate-related challenges continue affecting crop yields in several agricultural regions, particularly for fruits and vegetables.

Not every category is moving higher.

Some forecasts suggest certain products, including eggs and selected dairy items, could experience more stable pricing or even modest declines if supplies improve.

Still, the overall trend remains upward.

For families, grocery inflation is particularly difficult because food is not optional. Unlike many discretionary purchases, groceries represent a recurring weekly expense that cannot easily be postponed.

As prices rise, shoppers are adapting.

Many consumers report purchasing more store-brand products, reducing discretionary food purchases, seeking promotions, and comparing prices more aggressively than in previous years.

The financial strain is becoming increasingly visible.

Consumer surveys show many households reporting greater difficulty paying monthly bills, with food costs frequently cited as one of the largest pressures on family budgets.

The business implications are significant as well.

Grocers typically operate with relatively thin profit margins, limiting their ability to absorb higher costs. Food manufacturers are also facing pressure from higher transportation, labor, packaging, and ingredient expenses.

The result is a delicate balancing act between protecting profits and keeping products affordable enough for consumers.

For shoppers, the practical advice remains familiar: compare prices, utilize store brands, watch for promotions, and plan purchases carefully.

The broader reality, however, is harder to avoid.

With fuel costs elevated, weather challenges persisting, and federal forecasts pointing toward additional increases, grocery prices are likely to remain one of the most persistent sources of financial pressure for American households throughout the remainder of 2026.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORKAmazon founder and Executive Chairman Jeff Bezos has reignited debate over taxes, government spending, and economic inequality with a simple but provocative proposal: the bottom half of American income earners should pay no federal income tax at all.

Speaking during a CNBC “Squawk Box” interview with Andrew Ross Sorkin on May 20, comments that resurfaced in business discussions this week, Bezos argued that politicians often spend too much time looking for people to blame instead of solving the underlying problems.

Rather than focusing on villains, Bezos said leaders should approach economic challenges the same way successful companies tackle operational issues: identify the root cause and fix it.

His most attention-grabbing comment involved taxes.

Bezos noted that the bottom 50% of American earners account for only about 3% of federal income tax revenue. Because that percentage is so small relative to the size of the federal budget, he argued the government could eliminate that tax burden entirely.

It should be zero,” Bezos said.

In practical terms, Bezos was referring specifically to federal income taxes, not payroll taxes, state taxes, property taxes, or sales taxes.

His argument was straightforward: if lower-income households contribute only a small portion of federal income-tax collections, removing that burden could provide meaningful relief without dramatically affecting overall government finances.

The broader point, however, was less about tax policy and more about problem-solving.

Bezos said political leaders frequently fall into the trap of identifying villains rather than identifying causes.

When confronted with a problem, he argued, many people instinctively search for someone to blame. That may generate headlines and political support, but it rarely solves the issue itself.

Instead, Bezos pointed to a management approach long used inside Amazon known as the “Five Whys.”

The method requires repeatedly asking why a problem occurred until reaching its underlying cause. Once the root issue is identified, solutions become clearer and often more permanent.

The philosophy has been widely credited with helping Amazon scale from an online bookstore into one of the world’s most valuable companies.

Whether that same approach can be applied to national economic policy is another question entirely.

The comments arrive amid a continuing national debate about taxes and wealth inequality.

For years, Bezos himself has been a central figure in those discussions.

Critics have frequently argued that billionaires pay too little in taxes relative to their wealth. A widely cited ProPublica investigation published in 2021 reported that Bezos paid no federal income tax in certain years because much of his wealth existed in stock holdings rather than traditional income.

The findings fueled calls from lawmakers, including Senator Elizabeth Warren, for new wealth taxes and changes to the tax code aimed at high-net-worth individuals.

Critics of Bezos’s latest proposal also point out that lower-income Americans already pay significant taxes beyond federal income taxes.

Workers contribute payroll taxes that fund Social Security and Medicare, while state income taxes, sales taxes, gasoline taxes, and property taxes often consume a larger share of lower-income households’ budgets than they do for wealthier Americans.

As a result, some economists argue that focusing only on federal income taxes provides an incomplete picture of the overall tax burden faced by working families.

To his credit, Bezos did not frame his argument as opposition to taxation itself.

During the interview, he acknowledged that reasonable people can disagree about what constitutes a fair tax system.

He also supported certain targeted tax proposals, including New York’s long-discussed pied-à-terre tax on luxury second homes.

His larger concern, he said, was the tendency of political debates to devolve into finger-pointing rather than practical problem-solving.

The timing is notable.

The discussion comes as policymakers in Washington continue debating changes to the federal tax code. Recent proposals have included higher tax rates for top earners, expanded tax credits for working families, and various efforts to reduce budget deficits while addressing affordability concerns.

At the same time, rising housing costs, inflation pressures, and economic uncertainty have left many Americans searching for solutions that could improve household finances.

Whether Bezos’s proposal gains traction is another matter.

Eliminating federal income taxes for the bottom half of earners would undoubtedly provide relief to millions of households, but it would also require lawmakers to decide how to replace the lost revenue or reduce government spending elsewhere.

For now, the comments serve as a reminder that one of the world’s richest individuals views economic challenges through the same lens he applied to building Amazon: identify the root cause, focus on solutions rather than blame, and fix the problem at its source.

Whether Americans see that as practical wisdom or simply a billionaire’s perspective on public policy will likely depend on their own views about taxes, government, and economic fairness.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORKJetBlue Airways is preparing one of the most significant changes in its history.

For the first time, the airline best known for affordable fares and generous coach seating will introduce a domestic first-class product, marking a major shift in strategy as it seeks to improve profitability and attract higher-paying travelers.

Chief Executive Officer Joanna Geraghty told employees the airline remains on track to launch the new cabin in 2026, with roughly one-quarter of the fleet retrofitted next year and most aircraft completed by the end of 2027.

The move reflects a simple reality.

Premium travel has become one of the most profitable segments of the airline industry.

While many travelers continue searching for low fares, airlines increasingly earn their strongest margins from customers willing to pay more for additional comfort, priority services, and upgraded experiences.

Competitors including Delta Air Lines, American Airlines, and United Airlines have spent years expanding premium offerings.

JetBlue is now trying to capture a larger share of that market.

Industry observers often refer to the planned cabin as “Mini Mint” or “Junior Mint,” a reference to JetBlue’s existing premium Mint product.

The new seats will resemble traditional domestic first-class cabins offered by larger airlines and will be installed across Airbus A220, A320, and A321 aircraft.

The strategy comes with tradeoffs.

To create space for larger first-class seats, JetBlue plans to reduce economy-seat pitch from approximately 32 inches to 30 inches on portions of its fleet.

That may seem like a small change, but JetBlue built much of its reputation on offering more legroom than competitors.

The company is effectively betting that additional premium revenue will outweigh any dissatisfaction among coach passengers.

Geraghty argues demand supports the move.

Travelers increasingly seek premium experiences, yet many remain unwilling to pay the prices charged by larger legacy airlines.

JetBlue hopes to position itself between traditional low-cost carriers and premium airlines, offering upgraded products at more accessible prices.

The first-class expansion is part of a broader premium strategy.

The company has already begun opening airport lounges in key markets including New York JFK and Boston while also investing in enhanced onboard connectivity through partnerships such as Amazon’s Project Kuiper.

Combined with Mint business class and upgraded economy products, the airline hopes to create a full spectrum of travel options.

The financial pressure behind the strategy is substantial.

JetBlue has struggled to return to consistent profitability following the pandemic and has faced setbacks including the collapse of its alliance with American Airlines and the blocked acquisition of Spirit Airlines.

At the same time, higher fuel prices and intense competition continue squeezing margins.

For travelers, the changes create both winners and losers.

Passengers willing to spend more will gain access to a larger seat and premium experience at a potentially lower price than traditional first class.

Budget-conscious travelers may lose some of the extra space that helped distinguish JetBlue from competitors.

Ultimately, the success of the strategy will depend on a simple question.

Can enough customers be persuaded to pay more?

If the answer is yes, JetBlue may finally find a path back to stronger profitability.

If not, the airline risks weakening one of the very features that made customers choose JetBlue in the first place.

After years of financial challenges, the carrier is making a clear bet: the future of airline profits increasingly sits at the front of the aircraft.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
RED BANK, N.J. — Just one week after closing a major acquisition, a New Jersey bank is already shedding one of the largest risks it inherited.

OceanFirst Financial Corp., the parent company of OceanFirst Bank, announced Monday that it has agreed to sell approximately $1.4 billion of multifamily apartment loans acquired through its recent purchase of Flushing Financial Corporation, a transaction that officially closed on June 1, 2026.

The move will dramatically reduce OceanFirst’s exposure to New York City’s heavily regulated apartment market and lower the bank’s overall concentration in commercial real estate.

For investors, regulators, and borrowers alike, the sale highlights how New York housing policy is increasingly influencing decisions far beyond the city itself.

The loans being sold are primarily mortgages backed by multifamily apartment buildings throughout New York City, many of which contain rent-stabilized units. Those properties operate under regulations that limit how much landlords can increase rents and restrict their ability to remove apartments from rent regulation.

OceanFirst inherited the portfolio through its acquisition of Flushing Financial, the parent company of Flushing Bank, one of the largest lenders to multifamily property owners in New York’s outer boroughs.

The acquisition also included a $225 million strategic investment from Warburg Pincus, providing additional capital for the combined institution.

So why sell the loans almost immediately after buying them?

The answer lies in New York’s changing housing landscape.

Since the passage of New York’s Housing Stability and Tenant Protection Act of 2019, many rent-regulated apartment buildings have become more difficult to finance. The law sharply limited landlords’ ability to raise rents and reduced opportunities to increase property values through renovations and unit turnover.

As a result, many lenders have become increasingly cautious about holding large concentrations of loans backed by rent-stabilized buildings.

The uncertainty has only intensified in recent years.

New York City Mayor Zohran Mamdani has repeatedly advocated freezing rent increases for stabilized apartments, a proposal that landlords argue would further reduce building income and make it more difficult to cover maintenance costs, taxes, insurance, and mortgage payments.

For banks holding billions of dollars in apartment loans, those policy debates directly affect risk calculations.

In practical terms, OceanFirst is choosing to reduce its exposure before conditions potentially become more challenging.

The bank noted that it had already anticipated the sale when it announced the Flushing acquisition. The loans were marked down appropriately during the merger process, meaning the transaction is expected to align with previous financial assumptions rather than create an unexpected loss.

According to disclosures made during the merger, the multifamily portfolio consisted largely of relatively conservative loans.

Average loan balances were approximately $1.3 million, and the portfolio carried an average loan-to-value ratio of roughly 55%, meaning borrowers generally had substantial equity invested in their properties.

The concern is less about current borrower performance and more about long-term regulatory risk.

Nearly half of the portfolio was tied to fully rent-regulated buildings, placing it squarely in one of the most politically sensitive segments of New York real estate.

Bank of America has been overseeing the sales process, though OceanFirst has not publicly identified the buyer or buyers involved.

The proceeds will not sit idle.

OceanFirst said it plans to reinvest the funds into highly liquid, investment-grade securities that are expected to generate yields comparable to the loans being sold.

That allows the bank to reduce risk without significantly sacrificing earnings.

The strategy reflects a broader shift occurring across the regional banking industry.

Since the regional banking turmoil of 2023, regulators and investors have paid closer attention to commercial real estate concentrations, particularly among midsize and regional institutions.

Banks with large exposures to office buildings, multifamily properties, or other specialized real estate categories have faced increased scrutiny.

By reducing its commercial real estate exposure by $1.4 billion in a single transaction, OceanFirst is sending a clear message that it intends to pursue growth while maintaining a more conservative risk profile.

The implications extend beyond banking.

When lenders become less willing to finance rent-regulated apartment buildings, financing becomes more expensive and less available for property owners.

That can affect refinancing options, renovation projects, building maintenance, and long-term investment in housing stock.

In that sense, the decision by OceanFirst reflects a broader trend reshaping New York’s housing market.

The regulatory environment is influencing not only who owns apartment buildings but also who is willing to lend against them.

For OceanFirst, the transaction appears straightforward.

The company gains the branches, deposits, customers, and market presence that came with the Flushing acquisition while reducing exposure to one of the most heavily scrutinized segments of New York real estate.

The combined institution now operates approximately 71 branches across the Northeast, stretching from Massachusetts to Virginia, with approximately $23 billion in assets.

Chairman and Chief Executive Officer Christopher Maher has repeatedly emphasized that the Flushing acquisition strengthens OceanFirst’s presence in the New York metropolitan market.

The loan sale suggests the bank’s strategy is equally clear: expand in New York, but do so without carrying the apartment-loan exposure that many lenders increasingly view as a growing source of uncertainty.

JBizNews Desk — New Jersey

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Wall Street is heading into a test unlike anything it has faced before.

Three of the world’s most valuable private companies are preparing to sell shares to the public at nearly the same time, creating a historic stress test for investor appetite toward artificial intelligence, advanced technology, and trillion-dollar valuations.

The lineup is remarkable.

SpaceX is preparing to debut Friday at a valuation of approximately $1.77 trillion. OpenAI, creator of ChatGPT, confirmed Monday that it has confidentially filed for a public offering. Rival AI company Anthropic reportedly filed its own paperwork just days earlier.

Together, the companies represent several trillion dollars of private-market value preparing to transition into public markets.

The timing could hardly be more challenging.

Only days ago, the technology-heavy Nasdaq Composite suffered its sharpest decline since early 2025 as investors dumped semiconductor and AI-related shares amid concerns that valuations had become stretched.

The selloff was swift.

The Nasdaq fell more than 4%, while hundreds of billions of dollars in market value disappeared from AI-linked stocks.

Then came Monday’s rebound.

Chip stocks recovered sharply, helping the Nasdaq finish higher and reminding investors that enthusiasm surrounding artificial intelligence remains powerful despite growing concerns about valuations.

That volatility is exactly what makes the upcoming offerings so important.

When a company goes public, investors must find new capital to purchase the shares being sold. With SpaceX alone seeking roughly $75 billion, followed by OpenAI and Anthropic, Wall Street is being asked to absorb an extraordinary amount of new stock in a relatively short period.

If demand remains strong, all three offerings could succeed.

If sentiment weakens, later offerings may face pressure to reduce valuations or raise less capital than expected.

The order matters.

SpaceX is first.

Its debut will provide the market’s first real test of investor appetite for the next generation of AI-era mega-cap companies.

The companies themselves are also in very different financial positions.

SpaceX generated significant revenue but still lost billions of dollars last year.

OpenAI remains one of the fastest-growing companies in history, but it continues spending enormous sums on computing infrastructure and AI development.

Anthropic faces similar questions regarding growth, profitability, and long-term economics.

Investors must decide how much they are willing to pay today for profits that may not arrive until years into the future.

That calculation becomes even more complicated as economic uncertainty grows.

A separate survey released Monday by the Federal Reserve Bank of New York found that Americans are increasingly pessimistic about their personal finances, suggesting consumers may become more cautious in the months ahead.

For investors, the coming wave of offerings represents something larger than individual companies.

The public markets are about to answer a fundamental question:

After years of private funding rounds, soaring valuations, and excitement surrounding artificial intelligence, how much are investors actually willing to pay?

Friday’s SpaceX debut will provide the first clue.

The larger answer will unfold over the months ahead as Wall Street decides which companies deserve their lofty valuations—and which may have benefited from arriving at exactly the right moment.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
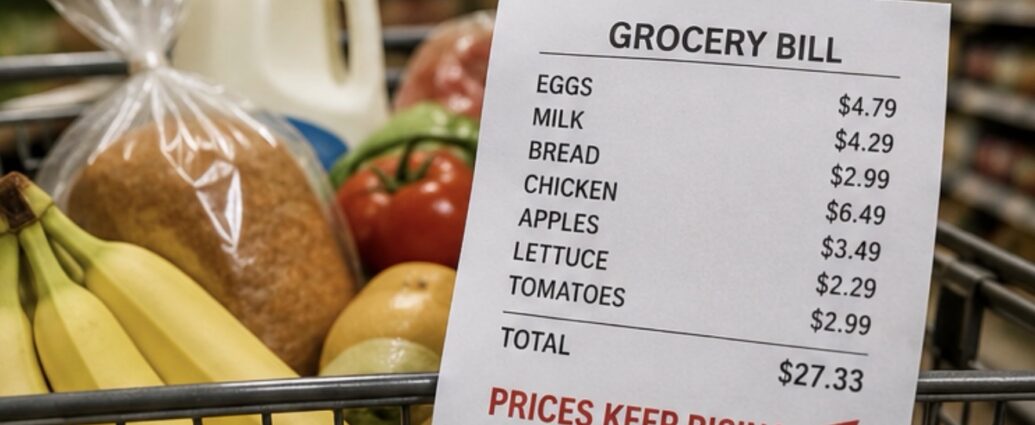
RIO DE JANEIRO — The world’s airlines used their biggest annual gathering this week to deliver a blunt message to the companies that build their jet engines: the fuel-saving engines you sold us are not lasting as long as promised, and passengers are paying the price.

At the International Air Transport Association (IATA) Annual General Meeting in Rio de Janeiro, outgoing IATA Director General Willie Walsh sharply criticized engine manufacturers, saying airlines are shouldering the cost of reliability problems while engine makers continue posting strong profits.

Stop gouging us and get back to making great engines that work,” Walsh said Monday, warning that allowing the problems to persist into the next decade would be unacceptable for airlines and travelers alike.

The dispute centers on the newest generation of jet engines introduced over the past decade.

Airlines embraced the engines because they promised to reduce fuel consumption by roughly 15%, a major advantage in an industry where fuel is often the single largest operating expense.

The two dominant engines are the CFM International LEAP, produced by a joint venture between GE Aerospace and Safran, and the Pratt & Whitney Geared Turbofan (GTF), manufactured by RTX. Both power the world’s most popular short- and medium-haul aircraft, including the Airbus A320neo family, while the LEAP also powers Boeing’s 737 MAX.

The problem is durability.

A key industry metric is known as “time on wing” — how long an engine remains installed on an aircraft before requiring removal for maintenance or overhaul.

According to airlines, many of the new-generation engines are spending far less time on wing than the older engines they replaced.

The issue is particularly severe in hot and dusty regions, including parts of the Middle East, India, and Southeast Asia, where harsh operating conditions can dramatically accelerate wear and tear.

When an engine must be removed earlier than expected, the aircraft often cannot fly until repairs are completed.

That creates a chain reaction across airline operations.

Pratt & Whitney’s GTF program has become the most visible example. Since 2023, hundreds of aircraft worldwide have been grounded at various times as airlines remove engines for inspections and repairs tied to manufacturing and durability issues.

The maintenance system itself has become overwhelmed.

According to consulting firm Bain & Company, repair turnaround times for new-generation engines have increased by more than 150% since the pandemic. Airlines frequently face waits of several months before an engine can even enter a repair facility.

That means planes sit idle.

And idle planes do not generate revenue.

The costs add up quickly.

Industry estimates show lease rates for spare GTF engines have climbed to roughly $200,000 per month as demand for replacement equipment surges.

JetBlue Airways reported averaging approximately nine grounded aircraft during 2025 due to engine-related issues.

Air New Zealand said the financial impact from grounded aircraft has become significant enough to trigger a broader strategic review of its fleet operations.

Airline executives at the Rio conference voiced growing frustration.

LATAM Airlines Group Chief Executive Roberto Alvo argued that airlines have effectively become “the test beds of the technology,” absorbing the operational and financial consequences when products fail to meet expectations.

WestJet Chief Executive Alexis von Hoensbroech called the situation a “fundamental reliability issue.”

United Airlines Chief Executive Scott Kirby acknowledged improvements from manufacturers but warned that engine shortages remain one of the biggest constraints facing global aviation.

“The engine issue will likely be the industry’s largest bottleneck for at least the next five years,” Kirby said.

Manufacturers insist progress is being made.

GE Aerospace says it has invested heavily in improving durability, increasing production, and developing upgraded components designed to extend engine life. The company increased LEAP production by approximately 25% last year and says newly certified components should improve reliability.

Pratt & Whitney recently certified its upgraded GTF Advantage engine for the Airbus A320neo family. The company says the new version is designed to roughly double time on wing and improve overall performance. A full transition to the upgraded design is planned by 2028, while retrofit kits are being developed for engines already in service.

For travelers, the dispute may sound technical, but the consequences are very real.

Fewer available engines mean fewer operational aircraft.

Fewer aircraft mean fewer available seats.

That comes at a particularly challenging moment for airlines, which are already dealing with aircraft-delivery delays, supply-chain disruptions, labor shortages, and higher fuel costs linked to instability in the Middle East.

When capacity tightens and demand remains strong, ticket prices tend to rise.

Passengers may also face more cancellations, longer rebooking delays, and reduced schedule flexibility when aircraft are unexpectedly removed from service.

The broader concern voiced by airline executives in Rio is that the industry appears stuck in a cycle where efficiency improvements arrive faster than reliability improvements.

The current generation of fuel-efficient engines has been flying for years, yet many of the durability concerns remain unresolved.

As manufacturers begin developing the next wave of greener aviation technology, airlines say they want a simple guarantee: that future engines deliver the promised fuel savings without spending excessive time in repair shops.

Until then, one of aviation’s biggest technological advances continues to face a challenge that affects everyone from airline executives to everyday travelers waiting at the gate.

JBizNews Desk — Aviation

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
HAWTHORNE, Calif.Elon Musk’s SpaceX is days away from what could become the largest stock-market debut in history, and the terms are now set.

In a filing with the U.S. Securities and Exchange Commission, SpaceX fixed its offering price at $135 per share, with trading scheduled to begin Friday, June 12, 2026, on the Nasdaq under the ticker SPCX. At that price, the company would raise approximately $75 billion and carry a valuation of roughly $1.77 trillion, surpassing the size of every previous initial public offering.

The scale is difficult to overstate.

A valuation of $1.77 trillion would immediately place SpaceX among the most valuable publicly traded companies in America, despite generating only a fraction of the revenue of many firms already occupying the top tier of the market.

The offering is being led by Goldman Sachs, with Morgan Stanley playing a central role in distributing shares to individual investors. The underwriting syndicate includes more than twenty major financial institutions.

At its core, SpaceX is built on two businesses.

The first is its rocket-launch operation, which has transformed the economics of space transportation through reusable rockets. The second is Starlink, the company’s rapidly growing satellite internet network, which now serves more than 9 million customers worldwide and has become the primary driver behind SpaceX’s valuation.

According to company filings, SpaceX generated approximately $18.67 billion in revenue during 2025 but still reported a net loss of roughly $4.9 billion as it continued investing aggressively in expansion, satellite deployment, and development of its next-generation Starship rocket system.

That gap between revenue and profitability sits at the heart of the investment debate.

At its proposed valuation, investors are effectively betting that Starlink will continue growing rapidly while Starship eventually opens entirely new markets in cargo transport, satellite deployment, national defense, and potentially human spaceflight.

The numbers imply extraordinary expectations.

At more than 100 times annual sales, SpaceX would trade at a valuation rarely seen among companies of its size. Such pricing assumes years of continued growth and successful execution.

Any major delays, cost overruns, regulatory setbacks, or technical challenges could quickly alter investor sentiment.

There is also a governance issue that ordinary investors should understand.

Through a special class of super-voting shares, Musk will retain approximately 85% of voting control, meaning public shareholders will have very limited influence over company decisions.

In practical terms, buying SpaceX stock is largely a vote of confidence in Musk’s leadership and long-term vision.

The timing is particularly noteworthy because SpaceX is not the only technology giant preparing to enter public markets.

OpenAI, the company behind ChatGPT, confirmed Monday that it has confidentially filed paperwork for its own public offering. Rival AI company Anthropic reportedly submitted confidential documents approximately a week earlier.

Together, the three companies represent one of the largest concentrations of private-market value ever attempting to enter public markets within a single quarter.

That creates another layer of importance for Friday’s debut.

Whoever lists first often establishes the valuation benchmark for companies that follow. A strong reception for SpaceX could improve conditions for OpenAI and Anthropic. A weak reception could force later offerings to reassess pricing expectations.

For everyday investors, the most important lesson is simple.

The offering price establishes only the starting point. Once trading begins Friday morning, the market will determine what SpaceX is actually worth.

History is filled with highly anticipated IPOs that surged, collapsed, or moved unpredictably once real buyers and sellers entered the market.

For now, SpaceX remains one of the most ambitious companies in the world, combining space exploration, satellite communications, artificial intelligence infrastructure, and national-security contracts under one roof.

Friday will mark the first time public investors have an opportunity to place their own value on that vision.

The filing may have set the price. The market will decide whether it agrees.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — U.S. stocks opened higher Tuesday as investors returned to technology shares after last week’s sharp selloff, while easing oil prices helped improve sentiment across the market.

Shortly after the opening bell, all four major U.S. indexes were in positive territory. The S&P 500 rose 0.63%, the Dow Jones Industrial Average gained 0.67%, the Nasdaq Composite advanced 0.69%, and the Russell 2000 climbed 0.77%, according to market data.

The gains follow a volatile stretch for Wall Street. Last Friday, the Nasdaq suffered its largest one-day decline since April 2025, falling 4.18% as semiconductor stocks plunged and erased roughly $1 trillion in market value. Markets stabilized Monday, and investors appeared more willing to buy back into the sector Tuesday morning.

Oil Prices Ease as Middle East Tensions Cool

One factor helping markets was a pullback in oil prices.

Investors have been closely monitoring the conflict between Iran and Israel, which has rattled energy markets for months due to concerns about disruptions to global oil supplies.

President Donald Trump has been attempting to preserve a fragile ceasefire between the two sides. While tensions remain elevated, Iran’s military said it had halted strikes against Israel while warning that military action could resume if Israeli operations continue in Lebanon.

The prospect of fewer immediate threats to energy infrastructure helped push crude prices lower, offering some relief to businesses and consumers concerned about rising fuel costs.

For investors, lower oil prices generally reduce inflation pressures and improve profit outlooks for transportation, manufacturing, and consumer-focused companies.

World Cup Hiring Boosts Economic Optimism

Another factor supporting markets is the surprisingly strong U.S. labor market.

Economists had expected employers to add roughly 80,000 jobs in May. Instead, the economy added 172,000 jobs, significantly outperforming forecasts.

Several analysts attributed part of the increase to hiring tied to the upcoming FIFA World Cup, which begins in the United States on June 11 and is expected to generate increased demand across hospitality, transportation, security, food service, and entertainment sectors.

The stronger hiring data reinforced expectations that consumer spending remains resilient despite ongoing concerns about inflation and higher borrowing costs.

Smucker Delivers Earnings Surprise

One of Tuesday morning’s biggest gainers was J.M. Smucker Co., the owner of well-known brands including Folgers, Jif, and Hostess.

Shares climbed nearly 6% after the company reported stronger-than-expected quarterly results.

According to the company’s earnings release, quarterly net sales reached approximately $2.3 billion, up 6%, while adjusted earnings per share rose 20% to $2.77.

Chief Executive Officer Mark Smucker said the company finished its fiscal year with strong momentum and believes its portfolio remains well-positioned.

Investors appeared willing to overlook management’s cautious outlook.

The company forecast fiscal 2027 sales could decline 3% to 4%, reflecting continued pressure on household budgets as consumers remain selective about grocery spending. Smucker expects adjusted earnings per share between $9.75 and $10.25 and projects approximately $1 billion in free cash flow.

The results suggest that while consumers continue buying staple products, many remain focused on value amid persistent economic uncertainty.

Semiconductor Stocks Lead the Rebound

The semiconductor sector remained at the center of investor attention.

Several chip-related stocks posted strong gains after suffering steep losses in recent weeks.

Lam Research surged 7.5%, while Sandisk rose roughly 7% after analysts at Mizuho and Bank of America Securities increased their price targets on the company.

Not every technology stock participated in the rebound.

Qualcomm fell 4.4%, Marvell Technology dropped 4.2%, and Workday slipped 4%, highlighting continued investor caution toward some of the market’s highest-valued technology names.

The mixed performance underscores an ongoing debate on Wall Street over which companies can justify lofty valuations following years of strong growth driven by artificial intelligence and semiconductor demand.

What It Means for Consumers

For everyday Americans, Tuesday’s market action points to several encouraging trends.

Lower oil prices could translate into some relief at the gas pump if declines continue. Strong hiring suggests employers remain confident enough to keep adding workers. Meanwhile, consumer-focused companies such as Smucker continue reporting healthy profits, even as shoppers remain price-conscious.

Still, investors remain cautious.

The same issues that sparked last week’s selloff — elevated technology valuations, geopolitical uncertainty in the Middle East, and questions about future consumer spending — remain unresolved.

Tuesday’s rally may indicate confidence is returning, but markets are likely to remain sensitive to economic data, corporate earnings, and developments overseas in the weeks ahead.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A federal judge struck down President Donald Trump’s $100,000 fee on H-1B visas on Monday, June 8, 2026, handing a major reprieve to the technology companies, hospitals, universities, and research institutions that depend on the program to hire highly skilled foreign workers.

In a 42-page ruling, U.S. District Judge Leo Sorokin of Massachusetts agreed with the plaintiffs that the fee amounted to an unauthorized tax rather than a standard regulatory charge.

“The President has no authority to levy a tax unless such a power is delegated by Congress through statute,” Sorokin wrote.

The challenge was brought by a coalition of 20 state attorneys general, who argued that the administration exceeded its authority by imposing such a dramatic fee increase without congressional approval.

The judge relied in part on recent Supreme Court precedent limiting executive authority to impose taxes and similar charges absent clear authorization from Congress.

The fee represented a dramatic increase from what employers traditionally paid.

Before the change, companies generally spent several thousand dollars to obtain an H-1B visa. The administration argued that dramatically increasing the cost would discourage overreliance on foreign labor and encourage employers to hire American workers instead.

Supporters said the fee would help protect domestic jobs.

Critics said it would effectively shut off access to specialized talent needed by many industries.

The numbers suggest the fee had a substantial impact.

According to government figures, only 85 payments of the $100,000 fee had been received as of mid-February, a remarkably small number for a visa program that typically supports tens of thousands of workers annually.

For employers, Monday’s ruling removes a significant obstacle.

The H-1B program provides 65,000 visas annually, plus an additional 20,000 visas for workers holding advanced degrees. Technology companies, hospitals, universities, pharmaceutical firms, and engineering companies rely heavily on the program to recruit specialized talent.

The fight, however, is not over.

The administration immediately signaled its intention to appeal the ruling, arguing that the policy remains an important part of broader efforts to prioritize American workers.

Separately, the U.S. Chamber of Commerce and other business groups continue to challenge the policy through additional legal actions.

The stakes are substantial on both sides.

Supporters view stricter visa policies as a way to encourage domestic hiring and workforce development. Opponents argue that limiting access to highly skilled workers ultimately weakens American competitiveness and could push innovation, research, and investment overseas.

The ruling also affects thousands of prospective workers around the world, particularly in countries such as India, where many professionals seek employment opportunities in the United States through the H-1B program.

For now, the visa program returns to its previous cost structure.

But with appeals already expected and multiple legal challenges still working their way through the courts, businesses face the same challenge they often dislike most: uncertainty.

Companies planning hiring needs months or years in advance must now determine whether Monday’s victory represents a permanent change or merely a temporary pause in a much larger legal battle.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
LONDON — Londoners may soon be able to hail an Uber with no human behind the wheel. British autonomous-driving company Wayve said Monday, June 8, that it is ready to launch a robotaxi service with Uber in London as early as this summer, marking a major step in Uber’s global strategy to expand autonomous rides. The move follows Uber’s growing partnerships with self-driving leaders including Waymo, which already provides driverless rides through the Uber app in several U.S. markets.

The rollout will begin cautiously. Kaity Fischer, Wayve’s Vice President of Operations, said the initial launch will involve dozens of vehicles rather than hundreds. The company has been testing autonomous-driving technology on London’s streets since 2018 and says the vehicles are ready for public use.

The first rides will not be fully driverless.

Wayve said trained, licensed Uber drivers will initially remain in the vehicles as safety supervisors while the company builds a public safety record and earns regulatory confidence. The company has not announced a timeline for when those supervisors might eventually be removed.

That cautious approach reflects the challenge facing the technology.

London is widely regarded as one of the most difficult cities in the world for autonomous vehicles. Unlike many modern cities built on grid systems, London’s roads evolved over centuries and are crowded with buses, black cabs, cyclists, delivery vehicles, construction zones, and millions of pedestrians.

If self-driving technology can successfully navigate London, supporters argue, it could work almost anywhere.

For Uber, the pilot is about much more than London.

The ride-hailing giant has spent years repositioning itself for a future where autonomous vehicles become a core part of its business. Rather than building its own self-driving technology, Uber has partnered with leading autonomous-driving companies around the world.

The company’s partnership with Waymo, owned by Alphabet, has already expanded driverless rides through the Uber app in several U.S. cities. Riders in those markets can request rides that are fulfilled by Waymo’s autonomous vehicles while still using the Uber platform.

The Wayve partnership brings that strategy into Europe.

London represents Uber’s largest announced autonomous-vehicle pilot on the continent and could become a blueprint for future launches across major European cities.

For Wayve, the launch marks the beginning of a broader global strategy.

The company says London is expected to be the first of more than ten cities where it plans to deploy autonomous vehicles, with additional launches anticipated in markets including Tokyo later this year.

Unlike some competitors, Wayve relies heavily on artificial intelligence rather than highly detailed pre-mapped routes. The company argues that approach allows its vehicles to adapt more naturally to new environments and changing road conditions.

That sets up a direct competition with Waymo, currently considered the leader in commercial robotaxi operations.

Waymo already operates driverless ride services in several U.S. cities and continues expanding. The emerging battle between Waymo and Wayve is about more than technology. It is about who controls what could become a transportation market worth tens of billions of dollars globally.

The British government has strongly supported the technology.

Officials have argued that autonomous vehicles could improve road safety, increase transportation access, and create new economic opportunities. Government projections estimate self-driving technology could contribute £42 billion to the UK economy and support approximately 38,000 jobs in the years ahead.

Those projections helped persuade policymakers to accelerate rules allowing commercial autonomous-vehicle testing.

Not everyone is enthusiastic.

The technology raises significant questions about employment.

Uber’s platform relies on drivers, and London’s iconic black-cab industry employs thousands of people. While safety drivers will remain during the initial phase, the long-term goal of robotaxi technology is to eliminate the need for human drivers altogether.

How quickly that transition occurs remains one of the most controversial aspects of autonomous transportation.

Safety remains the central question.

Supporters argue autonomous vehicles never become distracted, fatigued, intoxicated, or emotionally impaired. They point to data suggesting self-driving systems may ultimately prove safer than human drivers.

Critics counter that the technology still faces real-world challenges. Reports involving autonomous vehicles operating in the United States have highlighted incidents ranging from navigation errors to traffic violations and unexpected driving behavior.

The success or failure of London’s pilot will ultimately depend less on promises and more on performance.

For ordinary Londoners, however, the coming change may feel remarkably simple.

Within months, opening the Uber app could result in a vehicle arriving at the curb with no one sitting behind the wheel.

Whether that becomes a routine part of city life or remains a technological experiment will depend on how those first vehicles perform on some of the most challenging streets in the world.

JBizNews Desk — Europe

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Americans have not felt this gloomy about their own finances in years, and a closely watched survey released Monday, June 8, 2026, put hard numbers to the mood.

The Federal Reserve Bank of New York, in its monthly Survey of Consumer Expectations, said the share of people who feel “somewhat worse off” or “much worse off” than a year ago is the largest since January 2023. The combined figure reached 43.7%, while the share calling their situation “much worse” jumped to 13.3%, up about 2.7 percentage points from April and the highest since July 2022.

The outlook was just as bleak.

Looking ahead, 36% of households expect their finances to get worse over the next year, while only 22.9% expect them to improve — the widest gap between pessimists and optimists since October 2022.

In short, people feel squeezed now and expect more of the same.

The cause is not a mystery. Rising inflation has pushed up the cost of everyday necessities and eaten away at purchasing power. Higher gasoline, grocery, housing, insurance, and utility bills have been grinding on household budgets for months, and families are feeling it directly.

That strain is showing up in how Americans pay their bills.

Credit-card delinquencies have climbed to their highest level since 2011, according to earlier New York Fed data. When more households fall behind on credit cards, it is often a sign that monthly expenses are growing faster than incomes.

The jobs picture sent mixed signals.

The share of workers who fear losing their job within the next year rose to 15.1%, while the perceived chance of finding a new job fell to 43.7%, the lowest reading since December 2025. Yet the share planning to voluntarily leave their current jobs rose to 20.8%, the highest since February 2023.

The survey arrived just days after a stronger-than-expected May employment report showed the economy adding 172,000 jobs.

The result is a labor market that still appears relatively healthy on paper even as workers grow more anxious about their financial future.

Why does this matter?

Because consumer spending drives roughly two-thirds of the U.S. economy.

When households feel poorer, they often delay vacations, cut restaurant visits, postpone large purchases, and search for lower-cost alternatives. That makes consumer sentiment one of the earliest warning signs for retailers, restaurants, airlines, hotels, and countless other businesses.

Several consumer-facing companies report earnings this week, including Chewy and United Natural Foods, providing investors with an early look at whether consumer anxiety is translating into weaker spending patterns.

The survey also increases pressure on the Federal Reserve.

Policymakers meet next week, and markets currently see little chance of an immediate rate cut. The central bank faces a difficult balancing act. Lower interest rates could ease pressure on borrowers but risk reigniting inflation, while keeping rates elevated helps contain inflation but increases borrowing costs for households already feeling stretched.

There is another reason Federal Reserve officials pay close attention to these surveys.

Consumer expectations can become self-fulfilling. If households expect prices to keep rising, they may demand higher wages or accelerate purchases, creating additional inflationary pressure.

For now, the message from American households is remarkably clear: they are paying more, feeling poorer, and increasingly worried about the year ahead.

For businesses heading into the summer, that may be the most important economic signal of all — not because of what consumers are doing today, but because of what cautious consumers often do next.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
RIO DE JANEIRO — The world’s airlines are heading into what industry leaders describe as one of their toughest financial years since the pandemic, and the recent collapse of Spirit Airlines may only be the beginning.

Speaking at the International Air Transport Association (IATA) Annual General Meeting in Rio de Janeiro, outgoing IATA Director General Willie Walsh warned that more airlines could fail or be forced into mergers as soaring fuel costs squeeze profits across the industry.

IATA now expects global airlines to earn a combined $23 billion in net profit during 2026, roughly half the industry’s $45 billion profit in 2025 and far below the $41 billion forecast the organization issued just six months ago.

The culprit, Walsh said, is fuel.

The conflict that erupted after U.S. and Israeli strikes on Iran in late February disrupted shipping through the Strait of Hormuz, one of the world’s most important energy corridors. The resulting surge in oil prices has dramatically increased costs for airlines worldwide.

IATA now expects jet fuel to average approximately $152 per barrel in 2026, up from about $90 per barrel last year.

That increase adds an estimated $100 billion to airlines’ fuel expenses.

Industry fuel costs are now projected to reach roughly $350 billion, accounting for more than 31% of total airline operating expenses, compared with about 25% last year.

“This is an industry that survives on very thin margins,” Walsh told delegates. “A shock like this has enormous consequences.”

The pressure is already producing casualties.

Spirit Airlines, the Florida-based ultra-low-cost carrier known for rock-bottom fares and extensive add-on fees, ceased operations last month after struggling to manage rising costs and mounting financial pressure.

Walsh said Spirit is unlikely to be the last airline to disappear.

He warned that weaker carriers could either fail outright or become acquisition targets for larger rivals seeking additional market share.

Budget airlines are particularly vulnerable because they depend heavily on ticket sales and often lack alternative revenue streams.

Large network carriers generate substantial income from premium cabins, corporate travel contracts, airport lounges, cargo operations, and loyalty programs tied to credit cards. Those businesses provide valuable buffers during difficult periods.

Ultra-low-cost carriers generally do not enjoy those advantages.

When fuel prices spike, they have fewer tools available to offset the increase.

Walsh stressed that the low-cost airline model itself remains viable, pointing to Europe’s Ryanair as a successful example. The problem, he said, is that fuel costs are rising faster than airlines can pass those increases on to passengers.

Not everyone agrees fuel is entirely to blame.

U.S. Transportation Secretary Sean Duffy recently argued that Spirit’s collapse reflected deeper business problems and called the airline’s failure largely “self-made.”

The reality likely lies somewhere in between.

Spirit entered the fuel-price shock with an already fragile balance sheet, making it less capable of absorbing rising expenses than stronger competitors.

The profit forecasts underscore just how narrow airline margins have become.

IATA expects airlines to earn only about $4.50 per passenger this year.

Walsh noted that the figure demonstrates resilience given the industry’s challenges, but he joked that it would not even buy a hot dog at many sporting events.

The industry’s net profit margin is expected to shrink to approximately 2%, down from 4.2% in 2025.

What makes the situation remarkable is that demand remains surprisingly strong.

Despite higher fares, travelers continue to fly.

IATA projects total airline revenue will rise about 9.4% this year to nearly $1.2 trillion, driven by strong passenger demand.

Passenger revenue alone is expected to reach approximately $839 billion, while average load factors are projected to hit a record 84%, meaning planes are flying fuller than ever.

The problem is that costs are climbing even faster.

Industry operating expenses are expected to rise approximately 13%, wiping out much of the benefit from increased ticket sales.

Adding to the challenge is an aircraft shortage.

Airlines continue to face significant delivery delays from both Boeing and Airbus, while ongoing reliability issues with newer jet engines have left many aircraft grounded for maintenance.

IATA estimates these supply-chain disruptions cost airlines roughly $11 billion during 2025.

The average age of the global airline fleet has climbed to a record 15.2 years, while carriers remain short more than 5,000 fuel-efficient aircraft that could help reduce fuel consumption.

The shortage comes at exactly the wrong time.

Older aircraft burn more fuel, making airlines even more vulnerable when oil prices surge.

For travelers, the implications are straightforward.

Higher fuel costs generally mean higher ticket prices.

Airlines are also likely to reduce service on marginal routes, leading to fewer flight options in some markets.

And if additional budget carriers disappear through bankruptcy or consolidation, competition could weaken further, reducing pressure on airlines to keep fares low.

This year’s gathering also carried special significance for Walsh personally.

After leading IATA through the pandemic recovery and one of the most turbulent periods in aviation history, he is preparing to step down and take a leadership role at IndiGo, India’s largest airline.

His farewell message to the industry was direct.

The airlines with strong balance sheets, efficient operations, and financial flexibility will likely survive the turbulence ahead.

Those without a cushion may not.

As airlines enter the busy summer travel season, the industry’s challenge is no longer finding passengers.

It is finding a way to stay profitable while fuel prices remain stubbornly high.

JBizNews Desk — Aviation

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Shares of Intel Corp. (INTC) surged Monday, June 8, 2026, after a report that Alphabet’s Google has chosen the long-struggling chipmaker to manufacture millions of its custom artificial-intelligence chips — the biggest vote of confidence in years for Intel’s factory business. According to a report Monday from The Information, citing four people with direct knowledge of the talks, Google placed a firm order for more than 3 million of its in-house tensor processing units, known as TPUs, for production in 2028. Intel shares jumped about 12%, to roughly $110.81, lifting the company’s market value to around $557 billion.

Here is what makes the deal matter, in plain terms. Intel is not selling Google its own chips. Google designs these TPUs itself; Intel will build them in its plants. That makes it the largest known outside-customer commitment for Intel’s contract-manufacturing arm, which has spent years chasing clients with little to show for it. The order followed months of testing of Intel’s advanced packaging — the technology that stitches chips and memory into a single module.

The reason behind the move comes down to one word: scarcity.

Taiwan Semiconductor Manufacturing Co. (TSMC), the Taiwanese company that makes nearly every leading-edge AI chip, is straining to keep up with demand, and the squeeze is worst in exactly those advanced-packaging lines. For the companies that design the world’s most sought-after chips, depending on a single supplier in a single country has become a risk they badly want to reduce. That is the opening Intel has been waiting for.

A second giant is circling, too.

Nvidia is running early trials on Intel’s most advanced 18A manufacturing process, testing whether Intel can build a processor that fuses four graphics chips into one — a design tied to Nvidia’s Feynman architecture due in 2028 — though Nvidia has not yet placed an order. Even cautious interest from the most valuable name in AI chips is a milestone for a company written off not long ago.

The scale of the prize is large, and growing.

Google’s order is firm — more than 3 million TPUs in 2028 — and is part of a build-out that Morgan Stanley estimates could exceed 6 million TPUs across 2027 and 2028. Wall Street noticed. Mizuho raised its price target on Intel to $128 from $124, keeping a Neutral rating and citing strong AI demand across the chip industry.

The news caps a remarkable shift in how investors see a company that recently looked left behind.

Intel stock has more than tripled over the past year. The company has been courting Apple as a foundry customer, while the U.S. government continues to support domestic semiconductor production through the CHIPS Act and related programs. The broader goal is clear: reduce dependence on overseas manufacturing and rebuild America’s advanced chip-making capabilities.

The catch is delivery.

The 2028 timeline gives Intel roughly two years to scale its 18A process to high-volume production and prove it can match TSMC’s yield and reliability. That is the question hanging over the stock. A single blockbuster order is encouraging, but turning it into chips that ship on time and at a profit is precisely the step where Intel has stumbled before.

Promises are easy in this business; finished wafers are hard.

For everyday readers, the bigger picture is about where the country’s most important chips actually get made. Almost every advanced processor inside today’s phones, data centers, and AI tools is built in Taiwan, an arrangement that looks increasingly fragile to companies and governments alike. A genuine second source on American soil would make that supply chain sturdier and harder to disrupt.

For Intel, landing a customer the size of Google is the clearest sign yet that its years-long, expensive bet on becoming a contract manufacturer might finally pay off. Whether this marks the beginning of a broader migration of business toward Intel or simply a hedge against TSMC capacity constraints will become clearer in the months ahead. Nvidia’s decision on whether to graduate from testing to a real production order may ultimately provide the answer.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Lululemon Athletica lowered its sales and profit outlook on June 4 after executives told investors that negative publicity and disappointing product launches hurt customer demand, particularly in North America.

Speaking during the company’s quarterly earnings call, interim co-CEO and Chief Financial Officer Meghan Frank said Lululemon experienced periods of heightened negative commentary across traditional media and social media platforms, which contributed to weaker store traffic and softer sales performance. She also acknowledged that several recent product introductions failed to generate the customer enthusiasm the company had expected.

“We saw spikes of negative commentary around the brand,” Frank told analysts, adding that some new merchandise simply did not resonate with shoppers as planned.

One source of that publicity was a public dispute with Chip Wilson, the company’s founder and one of its largest shareholders. Wilson had spent months criticizing management and the company’s direction during a proxy battle. The dispute ended in late May when Lululemon agreed to add three new directors to its board and Wilson agreed to refrain from publicly criticizing the company for approximately 18 months.

Frank said media attention surrounding the conflict has since subsided.

The financial impact, however, remains significant.

Lululemon now expects full-year earnings of $10.95 to $11.15 per share, down from its previous forecast of $12.10 to $12.30 per share. The revised outlook falls below analyst expectations of approximately $12.30 per share, according to LSEG.

The company also trimmed its annual revenue forecast to approximately $11 billion to $11.15 billion.

For the current quarter, Lululemon expects revenue of $2.45 billion to $2.48 billion, below Wall Street forecasts of roughly $2.60 billion. Earnings are projected at $1.76 to $1.81 per share, well below analyst expectations of $2.68 per share.

Executives now expect sales to decline 2% to 3% during the current quarter and to remain flat or slightly lower for the full fiscal year, reversing earlier projections that called for modest growth.

The weakness is concentrated in the company’s largest market.

While total first-quarter revenue increased 4% to $2.5 billion, sales in the Americas declined. Net income fell 38% year-over-year to $195 million, pressured by lower margins and higher tariff-related costs.

International markets provided a brighter spot. Lululemon reported strong growth outside North America, demonstrating continued demand for the brand in overseas markets.

To address slowing performance, the company is making significant changes to its product assortment.

Executives said Lululemon has reduced the number of products carried in North American stores by approximately 15%, reorganized merchandise between performance and lifestyle categories, and reduced reliance on markdowns. Select stores are also testing additional assortment changes and localized merchandising strategies.

Management described the effort as a broader attempt to strengthen what it calls the company’s “product engine” and restore momentum in its core business.

The company is also navigating a leadership transition.

Frank has served as interim CEO since Calvin McDonald stepped down earlier this year. She is expected to hand leadership duties to incoming CEO Heidi O’Neill in September. O’Neill spent 27 years at Nike, where she held several senior leadership roles.

The transition means Lululemon is attempting to revive growth while simultaneously preparing for a new chief executive to take control of the company.

Investors reacted swiftly to the weaker outlook. Following the earnings announcement, Lululemon shares fell approximately 11% in after-hours trading.

For a company once known for selling premium athletic apparel at full price with little need for promotions, the market’s concern is clear. Investors are questioning whether Lululemon can quickly regain momentum in North America while introducing products that reconnect with consumers.

For shoppers, the company’s efforts could translate into more promotions, markdowns, and merchandise changes in the months ahead as Lululemon works to restore growth and rebuild confidence in its brand.

JBizNews Desk — Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — Home shoppers got more bad news this week as mortgage rates moved higher following a stronger-than-expected jobs report, reinforcing expectations that borrowing costs may remain elevated for months to come.

According to recent mortgage market data, the average rate on a 30-year fixed mortgage climbed to approximately 6.65%, remaining near the highest levels seen this year. The increase follows Friday’s employment report from the U.S. Bureau of Labor Statistics, which showed employers added 172,000 jobs in May while the unemployment rate held at 4.3%.

The jobs number came in stronger than economists expected and immediately changed how investors viewed future interest-rate cuts.

For prospective homebuyers, the result is frustrating. A healthy labor market is generally good news for the economy, but it also gives the Federal Reserve less incentive to lower interest rates. Mortgage rates tend to follow expectations for Fed policy, meaning strong economic data can actually make homeownership more expensive.

The impact on household budgets is substantial.

A buyer financing the same home today faces significantly higher monthly payments than a few years ago. According to housing market data, the typical monthly payment on a newly purchased home has climbed to roughly $2,623, near the highest level in almost a year.

At the same time, home prices continue to rise.

Recent market figures show the typical sale price remains about 2.3% higher than a year ago, creating a double burden for buyers: higher home prices and higher borrowing costs.

The situation has created a standoff across much of the housing market.

Many existing homeowners locked in mortgages below 4% during the pandemic and are reluctant to sell because doing so would require financing a new home at today’s much higher rates. That limits inventory, keeps prices elevated, and leaves buyers competing for a relatively small number of available homes.

The labor market itself also presents a more complicated picture than the headline suggests.

While layoffs remain relatively low and hiring continues, workers who do lose their jobs are taking longer to find new employment. Government data shows approximately 2 million Americans have been unemployed for at least 27 weeks, a figure that has risen significantly over the past year.

In practical terms, most employed workers remain in relatively good shape, but those seeking work face a more difficult hiring environment than headline numbers suggest.

Mortgage rates have experienced an extraordinary journey over the past five years.

The average 30-year fixed mortgage fell to a record low of approximately 2.65% in early 2021 before climbing near 8% in 2023. Today’s rates remain well below historic peaks seen in the early 1980s but are substantially higher than many buyers became accustomed to during the pandemic era.

The timing is particularly difficult because late spring and early summer traditionally represent the busiest homebuying season of the year.

Families hoping to move before the next school year are encountering affordability challenges that continue to keep many on the sidelines.

For those still planning to purchase, housing experts continue to recommend comparing offers from multiple lenders. Even small differences in mortgage rates can save thousands of dollars over the life of a loan.

For now, however, the message from both the labor market and the mortgage market is clear: the economy remains strong enough to keep interest rates elevated, and that strength continues to make homeownership more expensive for millions of Americans.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JERUSALEM — Two of the world’s most valuable technology companies are pushing Israel to make a significant change to how it collects taxes. Nvidia and Google have formally asked Israel’s Tax Authority to allow them to pay their Israeli corporate taxes in U.S. dollars rather than shekels, a request that gained momentum Monday as Finance Ministry officials signaled new openness during discussions with technology industry leaders.

The request comes as the Israeli shekel trades near its strongest level in decades, climbing roughly 20% against the dollar over the past year and recently reaching about 2.8 shekels per dollar, one of its strongest levels in more than three decades.

The issue may sound technical, but it sits at the center of one of Israel’s biggest economic challenges.

Companies such as Nvidia and Google earn much of their revenue in U.S. dollars but pay salaries, operating expenses, and taxes in Israeli shekels. When the shekel strengthens, every dollar earned buys fewer shekels, making operations in Israel more expensive when measured in dollar terms.

There is another effect as well. When multinational corporations convert large amounts of dollars into shekels to pay taxes, they increase demand for the Israeli currency, which can push the shekel even higher. Paying taxes directly in dollars would eliminate that conversion and reduce additional upward pressure on the currency.

The proposal traces back to one of the largest deals in Israeli technology history.

When Google agreed to acquire Israeli cybersecurity company Wiz for approximately $32 billion, the transaction generated an estimated $2.5 billion Israeli tax obligation for the company’s founders. Converting such a massive amount of dollars into shekels risked creating significant currency-market disruptions.

At the initiative of the Bank of Israel, tax authorities reportedly allowed those taxes to be collected directly in dollars rather than converted into shekels. What was initially viewed as a one-time solution has now become a precedent that other major corporations want to follow.

According to reports from Globes, additional multinational companies have approached the Tax Authority seeking similar treatment.

The largest and most influential request may be Nvidia’s.

Nvidia’s Israeli operations are built around its $7 billion acquisition of Mellanox Technologies in 2020. Mellanox remains an Israeli entity, making Nvidia one of Israel’s largest corporate taxpayers.

During its last fiscal year, Nvidia reportedly paid approximately $1.28 billion in Israeli taxes when the dollar traded between roughly 3.3 and 3.5 shekels. Since then, Nvidia’s business has exploded alongside global demand for artificial intelligence infrastructure. The company’s Israeli operations now generate dramatically more revenue than they did just a year ago, meaning future tax obligations could be substantially larger.

The request applies only to corporate taxes. Employees would continue paying income taxes in shekels under existing rules.

What makes the proposal unusual is that it could benefit both sides.

For companies, paying taxes directly in dollars reduces currency-conversion costs and limits exposure to exchange-rate fluctuations.

For the Israeli government, each tax payment received in dollars means fewer dollars being converted into shekels, easing some of the pressure pushing the currency higher. The government can also use those dollars to help service Israel’s own dollar-denominated obligations.

In effect, the arrangement could provide a modest tool for managing currency pressures without requiring direct intervention from the Bank of Israel.

Not everyone is convinced.

Critics argue that allowing giant multinational corporations to pay taxes in dollars while smaller Israeli businesses continue paying in shekels creates an uneven playing field. Others note that the policy addresses a symptom rather than the underlying cause.

The shekel is strong because Israel’s economy — particularly its technology sector — continues attracting foreign investment and generating substantial export revenue despite nearly three years of regional conflict.

That irony is difficult to miss. The same technology companies that helped drive billions of dollars into Israel and strengthen the currency are now asking the government for relief from the consequences of that success.

Still, momentum appears to be building.

Officials participating in Monday’s discussions reportedly showed greater openness than in previous meetings, leading many analysts to believe Israel may eventually create a formal framework allowing at least some large multinational companies to pay taxes in dollars.

The issue reaches far beyond taxes. Israel’s technology sector helped create the strong shekel by attracting billions of dollars in foreign investment and export revenue. Now some of the same companies responsible for that success are asking the government to help shield them from its consequences.

If Israel ultimately allows major multinational companies to routinely pay taxes in dollars, the decision would mark one of the most significant changes to corporate tax administration in years. It could also become another tool in the government’s effort to ease pressure on a currency that has become both a symbol of Israel’s economic strength and a growing challenge for the companies that helped create it.

JBizNews Desk — Israel

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
SAN FRANCISCOOpenAI, the company behind ChatGPT, said Monday, June 8, 2026, that it has taken the first formal step toward selling its stock to the public. In a statement, the company said it had recently submitted a confidential S-1 filing with the U.S. Securities and Exchange Commission, the required registration document companies file before launching an initial public offering.

OpenAI said it has not yet determined the timing of a public listing and cautioned that an IPO may still be some time away.

A confidential filing allows a company to submit its financial information to regulators for review before publicly disclosing its financial statements and business details. For OpenAI, the process carries particular significance. The company is valued at more than $850 billion, making it one of the most valuable private companies in the world, yet it continues to invest heavily in computing infrastructure, advanced AI models, and the massive data-center capacity required to support its growing products.

The filing places additional attention on Chief Executive Officer Sam Altman, who will ultimately have to persuade public-market investors that OpenAI can convert its enormous investments into sustainable profits. In a blog post Monday, Altman described the move as part of what he called the “third phase of OpenAI,” following its research phase and its product phase, during which hundreds of millions of users adopted ChatGPT and the company’s expanding suite of AI tools.

OpenAI is not entering the public markets alone.

Its chief rival, Anthropic, reportedly submitted confidential IPO paperwork roughly a week earlier, while SpaceX, led by Elon Musk, is expected to make its own highly anticipated public-market debut in the coming days at an estimated valuation of approximately $1.75 trillion.

The simultaneous march toward public markets by some of the world’s most valuable artificial intelligence and space technology companies marks a pivotal moment for investors. Each offering will provide new insight into how Wall Street values companies that are shaping the future of AI, cloud computing, automation, robotics, and advanced technologies.

The larger question is whether public investors are willing to support trillion-dollar valuations for companies that continue to spend aggressively on growth.

OpenAI has reportedly raised more than $180 billion and continues investing heavily in chips, data centers, research, and computing capacity. Various reports have suggested the company could seek a valuation exceeding $1 trillion when it eventually goes public, though OpenAI itself has not provided guidance on valuation expectations.

Reports have also suggested debate within the company regarding the pace of a public offering. While Altman has reportedly favored moving quickly toward a listing, Chief Financial Officer Sarah Friar has emphasized preparing the company for the scrutiny and disclosure requirements that come with being publicly traded.

Earlier this year, Friar told CNBC that it is “good hygiene” for a company of OpenAI’s scale to operate as though it were already public, reflecting the growing expectations surrounding transparency, governance, and financial discipline.

One element that could resonate strongly with consumers is OpenAI’s reported interest in making a portion of any future stock offering available to individual retail investors rather than limiting participation solely to large institutions. Friar has previously suggested she hopes ordinary investors will eventually have the opportunity to own a stake in the company behind ChatGPT.

According to reports, OpenAI is working with Goldman Sachs and Morgan Stanley on preparations related to a potential public offering.

The confidential filing marks only the beginning of the process. Detailed financial disclosures will remain private until later stages of the SEC review process, and regulators may take weeks or months to evaluate the filing before OpenAI is permitted to begin formally marketing shares to investors.

For now, OpenAI has taken only the first formal step toward becoming a public company. But the filing signals that the artificial intelligence industry is entering a new chapter—one in which investors will increasingly demand not only technological breakthroughs, but also clear paths to profitability, sustainable growth, and returns on the enormous capital being invested in the AI race.

If OpenAI, Anthropic, and SpaceX all reach public markets in the months ahead, the offerings could become one of the most consequential tests yet of investor appetite for the technologies reshaping the global economy.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Danish brewing giant Carlsberg A/S is preparing to take its Indian business public in a deal that could raise as much as $700 million and become one of India’s most closely watched consumer-sector listings of 2026.

According to people familiar with the matter, Carlsberg is expected to file draft papers for an initial public offering of its India unit as early as this month. The proposed listing would give investors direct access to one of the fastest-growing beer markets in the world while allowing the Danish parent company to monetize part of a business it has spent nearly two decades building.

Carlsberg declined to comment on specific IPO plans but confirmed Monday that it is exploring options to enhance shareholder value, including a potential public listing, while emphasizing that no final decision has been made.

The planned transaction is expected to be structured primarily as a secondary share sale, meaning Carlsberg would sell a portion of its own holdings rather than issuing new shares through its Indian subsidiary.

That distinction matters. In a secondary offering, the proceeds generally go to the existing shareholder—in this case Carlsberg—rather than directly into the operating company. The strategy allows the brewer to unlock value from a rapidly expanding asset while maintaining a significant presence and control in the Indian market.

The company has reportedly hired Kotak Mahindra Capital, along with the Indian investment-banking operations of JPMorgan Chase & Co. and Citigroup Inc., to manage the proposed offering. The involvement of three major financial institutions signals that preparations are advancing, even though the final size and timing of the deal remain subject to market conditions.

The business being offered is substantial.

Carlsberg India holds approximately 22% of the country’s beer market, making it the nation’s second-largest brewer. Since entering India in 2007, the company has expanded to a network of 14 breweries, including eight owned facilities and six contract-manufacturing locations spread across the country.

India has become increasingly important to global beverage companies seeking growth outside slower-growing Western markets. With a population exceeding 1.4 billion people, a rising middle class, and growing disposable incomes, the country remains one of the few large consumer markets where beer consumption still has significant room to expand.

Investors evaluating a Carlsberg India IPO will likely compare it with United Breweries Ltd., the country’s largest listed brewer and maker of Kingfisher beer. United Breweries currently carries a market value of roughly $3.6 billion.

However, the comparison also highlights potential risks. Shares of United Breweries have fallen approximately 36% over the past year, significantly underperforming India’s benchmark Nifty 50 Index, which has declined about 8% over the same period.

The proposed offering comes amid a broader trend of multinational alcohol companies exploring ways to unlock value from their Indian operations.

Pernod Ricard, maker of Absolut Vodka and Chivas Regal whisky, has also reportedly examined a potential listing of its India business and hired advisers to evaluate options. The interest reflects confidence that India’s long-term consumer growth story remains intact despite periodic economic slowdowns.

Yet the industry faces challenges as well.

Brewers have recently warned about rising production costs, including higher prices for packaging materials, transportation, and key ingredients. Industry groups have also highlighted the complexity of India’s alcohol regulations, where each state sets its own taxes, distribution rules, and licensing requirements.

That patchwork system can make it difficult for producers to pass higher costs on to consumers and can squeeze profit margins even when sales volumes rise.

For investors, the attraction is straightforward. Carlsberg India offers exposure to a well-known global brand operating in one of the world’s most promising consumer markets. For Carlsberg, the IPO could provide a significant cash return while retaining a strategic foothold in a country expected to remain a major growth driver for the global beer industry.

What Comes Next

If Carlsberg proceeds with the filing, the draft prospectus will reveal key details, including the number of shares being offered, the proposed valuation, financial performance of the Indian business, and the exact stake the Danish parent intends to sell.

Until those documents are filed, the reported $700 million fundraising target remains an estimate and the structure of the transaction remains subject to change.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — American households will get two important readings on the economy within 24 hours this week as the housing industry and the federal government release back-to-back reports on home sales and inflation. The National Association of Realtors will report May existing-home sales on Tuesday, June 9, followed by the Consumer Price Index from the U.S. Bureau of Labor Statistics on Wednesday, June 10.

Together, the reports address two questions affecting millions of Americans: Can families afford to buy a home, and how quickly are everyday costs continuing to rise?

Start with housing.

The market remains slow and expensive. In April, existing-home sales ran at an annual pace of 4.02 million units, while the median home price reached $417,800, near record levels. Inventory stood at 4.4 months of supply, reflecting a market still constrained by limited listings.

The reason is straightforward. Mortgage rates remain elevated, hovering near 6.65% for a 30-year fixed loan. That keeps monthly payments high for buyers while discouraging current homeowners from selling homes financed at much lower rates. The result is a housing market trapped between reluctant sellers and frustrated buyers.

Recent data suggests little relief.

Redfin reported that new listings recently fell 1.3%, one of the largest weekly declines of the year, even as the typical home-sale price rose 2.3% from a year earlier. The estimated monthly payment for a typical buyer climbed to approximately $2,623, underscoring the affordability challenge facing many households.

Housing matters far beyond real estate agents and mortgage lenders. Every home sale generates spending on moving services, furniture, appliances, home improvement projects, inspections, title services, and renovations. When sales slow, those economic ripple effects slow as well, affecting businesses and workers far beyond the housing market itself.

The following morning, attention shifts to inflation.

The latest Consumer Price Index report is expected to show inflation remaining above the Federal Reserve’s comfort zone. In April, headline CPI rose 0.6% for the month and 3.8% over the previous year. Core inflation, which excludes food and energy, increased 0.4% monthly and 2.8% annually.

Those figures remain well above the Federal Reserve’s long-term 2% inflation target.

Economists say gasoline prices likely played a major role in May. Wells Fargo estimates energy prices rose roughly 8% during the month, while food prices increased about 0.3%.

There may be some encouraging news beneath the headline number, however.

Wells Fargo expects core inflation to rise only 0.2% in May, slower than April’s pace. If that proves accurate, it would suggest that underlying inflation pressures may be easing even as energy prices continue pushing up overall costs.

In plain English, the gas pump may be doing most of the damage while the rest of the shopping cart begins to stabilize.

That distinction matters because policymakers focus heavily on core inflation when determining interest-rate policy.

The housing and inflation reports are closely connected.

Inflation largely determines what the Federal Reserve does with interest rates, and interest rates largely determine what Americans pay for mortgages. A hotter-than-expected inflation report would make rate cuts less likely and keep mortgage costs elevated. A cooler reading could strengthen expectations that borrowing costs will eventually decline.

Consumer confidence remains fragile.

Recent surveys from the University of Michigan found that inflation continues to rank among Americans’ top economic concerns. When households expect prices to keep rising, they often become more cautious with spending decisions, affecting everything from retail purchases to travel and major investments.

That caution is already appearing in several economic indicators. Consumers are carrying higher credit-card balances, delinquency rates have risen, and surveys show many households feel financially worse off than they did a year ago. Businesses ranging from retailers to airlines are watching closely for signs that consumers may begin pulling back on discretionary spending.

Investors, businesses, and policymakers will therefore be watching both reports closely.

On Tuesday, attention will focus on whether home sales can climb back above an annual pace of 4.1 million units and whether inventory begins improving. On Wednesday, the key question will be whether core inflation cools as expected or whether higher energy prices continue driving broader inflation pressures.

Both reports arrive just days before the Federal Reserve’s next policy meeting and could influence expectations for the direction of interest rates through the remainder of 2026.

For American families, the message should become clearer by midweek.

If housing remains frozen and inflation stays elevated, the pressure on household budgets is likely to continue while interest rates remain higher for longer. If home sales improve and inflation moderates, it could provide one of the first meaningful signs that affordability pressures are finally beginning to ease.

For now, the economy remains caught between two competing realities: prices are still too high for many households, but any meaningful relief may depend on inflation cooling enough for borrowing costs to come down. This week’s reports will offer one of the clearest snapshots yet of whether the country is moving closer to that turning point.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
CUPERTINO, Calif. — Apple used the opening keynote of its Worldwide Developers Conference (WWDC) on Monday, June 8, 2026, to unveil a long-promised overhaul of its voice assistant, introducing a more advanced version of Siri designed to hold natural conversations, access information across apps, and help users complete tasks more efficiently.

During the presentation, Mike Rockwell, Apple’s vice president overseeing the project, described the new Siri as a significantly more capable assistant that can better understand context, maintain multi-step conversations, and interact with information across a user’s device. Apple called the upgraded system “a profoundly more capable assistant.”

The announcement represents Apple’s most ambitious artificial intelligence push yet and comes as the company seeks to accelerate its AI capabilities amid intense competition from OpenAI, Google, Microsoft, and other technology leaders.

The new Siri can hold multi-turn conversations, draw on real-time knowledge, and interact with apps and personal information to complete tasks on behalf of users. Many of these capabilities have become increasingly common among leading AI systems, but Apple is now integrating them directly into the iPhone experience.

The most significant business development, however, may be what powers the assistant behind the scenes.

Apple said Siri will utilize Google’s Gemini AI models through a partnership that has been widely reported to be worth approximately $1 billion annually. For a company historically known for building core technologies internally, the move reflects the enormous cost, complexity, and speed of today’s artificial intelligence race.

Apple emphasized that user privacy remains central to its strategy. The company said Gemini-powered requests will run through its Private Cloud Compute infrastructure, designed to protect personal information while enabling advanced AI capabilities.

Apple also introduced expanded Apple Foundation Models, providing developers greater access to Apple’s AI ecosystem and positioning the company to build more of its own capabilities over time.

Several consumer-facing features drew attention during the keynote. Siri is now integrated into the iPhone’s Dynamic Island, while a new AI-powered Camera experience can identify objects and provide information about what users see through their lenses. Apple also announced that iOS 27 will allow users to select third-party AI assistants as their default option, a notable shift for a company long known for tightly controlling its software ecosystem.

The event carried additional significance because it marked what Apple said would be Tim Cook’s final WWDC keynote as chief executive officer before his planned retirement later this year. Cook, who has led Apple since 2011, has overseen the company’s transformation into one of the world’s most valuable businesses.

For consumers, most of the new features will arrive later this year. Developers will receive access immediately, followed by a public beta in July and a broader rollout this fall alongside Apple’s next generation of iPhones.

Investors responded cautiously. Apple shares rose during portions of the trading session but reversed course as the keynote progressed, closing Monday at $301.54, down 1.89%. The decline came despite generally positive reactions from analysts and follows a strong run for the stock in recent weeks.

Wall Street remains focused on a larger question: whether a dramatically improved Siri can reignite the iPhone upgrade cycle by giving consumers a compelling new reason to purchase Apple’s latest devices.

Goldman Sachs maintained a Buy rating on Apple with a $340 price target, while Morgan Stanley kept a $330 target and Wedbush Securities maintained a Street-high $400 target heading into the event.

Veteran Apple analyst Ming-Chi Kuo summarized the challenge facing the company. Because Apple is relying on the same underlying Gemini models available to Google, Apple must prove it can deliver a superior user experience through integration, design, privacy protections, and ecosystem advantages rather than the AI model itself.

For now, the message from Cupertino was clear. Apple has finally delivered the more advanced Siri it first promised in 2024, bringing conversational AI, deeper app integration, and real-time knowledge capabilities to millions of iPhone users. But the company’s decision to rely on Google’s Gemini models highlights the enormous cost and complexity of competing in today’s AI race. Whether Apple can turn that partnership into a compelling advantage for consumers—and a new reason to upgrade their iPhones—will become clearer when the software reaches users this fall.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The prediction-market platform Kalshi is building a high-powered trading screen for its most active customers, modeled on the Bloomberg Terminal that has anchored Wall Street trading desks for decades, according to a person familiar with the company’s plans. The new tool, described Thursday, is meant for the serious traders who increasingly treat betting on real-world events as a full-time business — and it signals how far prediction markets have moved from internet novelty toward professional finance.

The product is still early. It is in alpha testing with a small group of selected traders and has been in development for about a month, the source said, with no launch date set. Kalshi has not publicly announced it. From a look at the interface, the tool lets traders manage many positions across different event contracts at once and place trades with fewer clicks — the kind of speed and control that professional traders demand and that casual apps usually lack.

Over time, the ambitions grow. The source said the platform may eventually fold in research and outside information, much like Bloomberg’s product does for stock and bond traders. That comparison is not far-fetched: Kalshi’s market data is already available inside the actual Bloomberg system. While the new tool will start with prediction markets, the company hopes to extend it to other types of trading down the road.

To understand why this matters, it helps to know what Kalshi has become. Founded in 2018, the company runs a federally regulated exchange where people trade “event contracts” — essentially yes-or-no bets on whether something will happen, from inflation readings and interest-rate moves to elections, weather, and sports. Its co-founder and chief executive, Tarek Mansour, is a former quantitative trader at Goldman Sachs and Citadel who studied at MIT. He argues that market prices can reveal the truth about uncertain events more reliably than pundits or polls. The platform now counts roughly 2 million monthly active users.

The business has grown at a startling pace. Kalshi recently raised $1 billion at a $22 billion valuation in a round led by Coatue, with backing from Sequoia Capital, Andreessen Horowitz, Paradigm, Morgan Stanley, and ARK Invest. That value has roughly doubled since December and is more than four times the $5 billion the company was worth last fall. Mansour has said the company generated $263.5 million in revenue and that its annual revenue pace has since climbed above $1.5 billion, a sign of how quickly trading has accelerated.

The push to build a professional terminal fits a clear strategy: chase the big players. The company has reported that trading by institutions — hedge funds, professional trading shops, and asset managers — jumped roughly 800% over six months, with annualized trading volume rising from about $52 billion to $178 billion. These firms are starting to use event contracts to hedge real-world risks and to read market-based forecasts in real time.

To serve them, Kalshi has been adding institutional features like block trading, broker connections, and risk-management tools. It recently received approval to offer perpetual futures on cryptocurrencies, another step toward becoming a fuller-service exchange.

Kalshi is not alone in spotting the opportunity, and that is the competitive risk. A wave of startups already pitches itself as the “Bloomberg Terminal for prediction markets,” including Verso, backed by startup accelerator Y Combinator, along with rivals such as Fireplace and Kairos. These tools pull data from multiple betting venues — including Kalshi and its chief rival, Polymarket — into a single screen so traders can compare odds and spot pricing differences.

Even Paradigm, one of Kalshi’s own investors, was reported in April to be building its own prediction-markets data platform aimed at professional traders. By building its own terminal, Kalshi is trying to keep its best customers inside its ecosystem rather than relying on outside software.

The deeper logic is the same one that helped build Bloomberg into a financial giant. Selling data and trading tools to professionals is a sticky, high-margin business. Once traders rely on a platform every day, they rarely leave. If Kalshi can become the default workstation for event traders, it captures not only trading fees but also the daily workflow of an entire market.

That bet rests on a larger one: that prediction markets are becoming a permanent part of the financial system rather than a passing trend. Mansour has described his company as a form of “truth infrastructure,” turning scattered opinions into a single market-based probability.

Whether that vision ultimately succeeds, Kalshi’s move to build a professional-grade terminal reveals where the company believes the future profits are. The next phase of prediction markets may not be driven by casual bettors. It may be driven by the professional traders who want a screen every bit as powerful as the ones already used across Wall Street.

Markets & Technology — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
By JBizNews Desk

Senior officials in the Trump administration have held early-stage discussions with leading artificial-intelligence companies about the possibility of the U.S. government taking ownership stakes in them, according to reporting that surfaced Thursday, June 4.

The talks have reportedly focused on voluntary arrangements in which AI companies would provide shares to the government, with potential returns directed toward public purposes, including concepts such as direct dividend payments to American households.

The discussions remain preliminary, and no formal proposal has been announced. Neither the White House nor major AI firms involved in the reports have publicly confirmed any agreement.

Among the companies connected to the discussions is OpenAI, whose chief executive Sam Altman has reportedly raised versions of the idea with President Donald Trump on multiple occasions since early 2025.

Notably, Anthropic has not reportedly participated in the talks to date.

A Rare Point of Convergence

The emergence of the discussions comes only days after a proposal from one of Washington’s most prominent progressives.

On June 1, Sen. Bernie Sanders outlined the American A.I. Sovereign Wealth Fund Act in a New York Times opinion essay, proposing a one-time 50% tax on major AI companies, paid not in cash but in stock.

Under Sanders’ proposal, shares from companies such as OpenAI, Anthropic, and xAI would be transferred into a public investment fund. The federal government would receive voting rights, board representation, and eventually distribute investment returns to American citizens.

The administration’s reported discussions differ substantially.

Rather than mandating a transfer of ownership, the White House conversations have reportedly focused on voluntary participation by companies.

Yet both approaches reflect a similar underlying idea: that the public should directly benefit from the enormous wealth expected to be created by artificial intelligence.

A Growing Government Investment Strategy

While a government stake in AI companies may sound unusual, it would not be without precedent inside the current administration.

The federal government has already acquired significant positions in several strategically important companies.

Those investments reportedly include:

  • 10% of Intel
  • 15% of MP Materials
  • 5% of Lithium Americas
  • 10% of Trilogy Metals

Administration officials have pointed to those investments as examples of taxpayers participating directly in the upside of critical industries.

The White House has highlighted the performance of the Intel investment in particular, noting that the stock appreciated significantly after the government’s purchase.

President Trump has publicly stated that he would like taxpayers to benefit from investments tied to technologies viewed as critical to America’s future competitiveness.

The Government Is Already Expanding Into Emerging Technologies

Artificial intelligence is not the only area attracting federal investment interest.

The Department of Commerce recently announced letters of intent to invest approximately $2 billion across nine quantum-computing companies under authorities connected to the CHIPS and Science Act.

The largest proposed investment reportedly involves IBM, which could receive approximately $1 billion to support development of what officials describe as America’s first purpose-built quantum-computing foundry.

Taken together, the investments suggest a broader strategy of combining industrial policy with direct taxpayer participation in emerging technologies.

The AI Industry Has Floated Similar Ideas

Interestingly, some of the AI companies themselves have proposed versions of public participation in future AI wealth.

OpenAI has previously published policy proposals calling for the creation of public wealth funds designed to ensure that the economic benefits of advanced AI reach all citizens, including those who do not own stocks or other financial assets.

Anthropic has similarly discussed sovereign wealth fund concepts tied to artificial intelligence.

Supporters argue that AI could generate economic gains so large that broader public participation may become necessary to prevent wealth concentration.

Advocates frequently point to successful examples such as:

  • Norway’s Government Pension Fund
  • Alaska’s Permanent Fund Dividend

Both programs use public ownership of valuable assets to generate returns distributed broadly to citizens.

Why Investors Are Paying Attention

The discussions arrive at a particularly sensitive moment for financial markets.

Both OpenAI and Anthropic are widely expected to pursue historic public offerings.

Anthropic reportedly submitted confidential IPO paperwork to the Securities and Exchange Commission on June 1, while OpenAI is expected to pursue its own public-market plans.

Meanwhile, xAI has been combined with SpaceX through a transaction reportedly valuing the merged enterprise at approximately $1.25 trillion.

For investors, government ownership introduces complicated questions.

A government that simultaneously acts as regulator, customer, policymaker, and shareholder creates a relationship unlike anything most public companies face today.

Investors would need to evaluate potential conflicts of interest, governance questions, capital-allocation decisions, and the possibility of future public dividend programs tied to company performance.

Those issues could become increasingly important as AI companies mature and begin generating substantial profits.

The Bigger Debate

The politics surrounding the idea remain complicated.

Many conservatives criticized the government’s investment in Intel and could oppose direct ownership stakes in AI firms.

Many progressives support broader public participation in AI wealth but favor more aggressive approaches than those currently being discussed.

Yet despite sharp differences over methods, both sides increasingly appear to agree on one fundamental point:

Artificial intelligence may create such enormous economic value that the question is no longer whether Americans should share in it—but how.

JBizNews Desk — Technology & Policy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
SAN FRANCISCOOpenAI is preparing what may be the biggest transformation in ChatGPT’s history, reshaping the platform into a single AI hub that combines chat, coding, image creation, web tools, and autonomous AI agents. The move is designed to attract more business customers, increase revenue, and strengthen the company’s position ahead of a potential future public offering.

According to a Financial Times report published June 7, citing more than a dozen current and former employees, OpenAI is reorganizing its products around a strategy internally described as a “superapp” — one platform capable of handling a wide range of workplace and personal tasks.

The first changes are expected to begin rolling out in the coming weeks through updates to ChatGPT’s website and mobile applications.

A major focus of the overhaul is Codex, OpenAI’s AI coding platform. The company is reportedly redesigning ChatGPT’s interface to encourage users to make greater use of coding tools, image generation, and integrations with outside services such as Canva and Booking.com.

The broader goal is to move beyond the traditional chatbot model and create software capable of completing tasks on a user’s behalf.

Thibault Sottiaux, who leads OpenAI’s combined product and platform team, told the Financial Times that the company is working toward building a personal AI agent that can assist users across both work and everyday life.

Sottiaux previously predicted that the productivity gains AI coding agents have brought to software development will soon spread across virtually all forms of knowledge work. He noted that he now accomplishes more programming than ever while rarely writing code himself.

The business opportunity behind the strategy is significant.

The Financial Times reported that approximately 2 million business customers now generate about 40% of OpenAI’s revenue, with that figure expected to rise to roughly 50% by the end of 2026.

Meanwhile, ChatGPT has surpassed 900 million weekly active users, while OpenAI has previously disclosed that it has exceeded 50 million paying consumer subscribers.

The company’s challenge is clear: free users drive growth, but enterprise customers drive profits.

Leadership changes are helping support the transition.

Greg Brockman, OpenAI’s co-founder and president, has assumed permanent oversight of product strategy while continuing to supervise the company’s computing infrastructure. The changes come while Fidji Simo, who had been leading OpenAI’s consumer applications business, remains on medical leave.

As part of the restructuring, longtime ChatGPT leader Nick Turley has moved into OpenAI’s enterprise division.

The reorganization combines ChatGPT, Codex, and OpenAI’s developer API operations into a single core team.

OpenAI has acknowledged that launching multiple standalone products over the past year created confusion for customers and increased internal complexity. Consolidating services into one platform is intended to simplify the user experience while accelerating product development.

For businesses, the appeal is straightforward.

Rather than switching between separate applications for chat, coding, image creation, research, scheduling, and workflow management, users would access those capabilities through a single platform.

OpenAI believes AI agents capable of completing multi-step tasks could eventually become more valuable than traditional chatbots, potentially changing how software is purchased, deployed, and used throughout organizations.

The timing also comes as speculation continues regarding OpenAI’s long-term plans for a public listing.

Reuters reported in May that the company was preparing groundwork that could support a future U.S. initial public offering, although Chief Executive Officer Sam Altman has repeatedly said OpenAI is not focused on a specific IPO timetable.

Competition remains intense.

Anthropic, maker of the Claude AI assistant and Claude Code, continues expanding aggressively in the enterprise market, while Microsoft is investing heavily in its own AI products and models.

OpenAI’s response is increasingly clear: bring everything together under one platform and make ChatGPT the central operating system for AI-powered work.

Whether businesses embrace an all-in-one AI platform or continue relying on specialized tools may determine the next chapter of the rapidly evolving AI industry.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. stocks finished mixed on Monday, June 8, as semiconductor shares rebounded sharply from last week’s selloff while a fragile Middle East ceasefire and rising Treasury yields kept pressure on parts of the broader market.

The Nasdaq Composite led the recovery, rising 0.86% to 25,929.66, driven largely by gains in semiconductor stocks. The S&P 500 added 0.30% to 7,405.73, while the Russell 2000 gained 0.85%. The Dow Jones Industrial Average slipped 80.77 points, or 0.16%, to 50,786.01.

The rebound followed Friday’s steep technology selloff, when investors pulled back from many of the market’s largest artificial intelligence-related stocks.

Geopolitical concerns remained in the background as a fragile ceasefire between the United States and Iran continued to hold despite reports of additional strikes involving Israeli and Iran-backed forces over the weekend. Oil prices were relatively stable, with U.S. crude remaining above $91 per barrel.

Meanwhile, the yield on the benchmark 10-year U.S. Treasury note climbed to approximately 4.56%, reflecting ongoing concerns that strong economic data could keep interest rates elevated longer than investors had expected.

One of the day’s most significant business developments came from Amazon, which announced a multibillion-dollar, multiyear agreement with Corning Incorporated to supply the optical fiber and cable needed to connect Amazon’s rapidly expanding U.S. data-center network.

The agreement is expected to create approximately 1,000 new manufacturing jobs at Corning facilities in North Carolina, along with hundreds of construction jobs tied to plant expansions. The companies also announced plans to expand a fiber-optic technician training partnership with Catawba Valley Community College, helping prepare workers for growing demand created by artificial intelligence infrastructure projects.

Investors welcomed the announcement. Corning shares surged roughly 8%, while Amazon gained about 1.2%.

The strongest gains, however, came from the semiconductor sector.

Micron Technology jumped nearly 10% after falling roughly 13% on Friday, recovering much of its recent decline. The rally was helped by a higher price target from Wells Fargo, which cited Micron’s strong margins and leadership position in high-bandwidth memory chips used in artificial intelligence systems.

Micron Chief Executive Sanjay Mehrotra has repeatedly emphasized that AI systems require dramatically more advanced memory technology and that demand is expected to remain strong for years. The company has already secured long-term supply agreements with major technology customers, including Nvidia and Google.

Other semiconductor leaders also moved higher. Nvidia and Broadcom gained ground, while the VanEck Semiconductor ETF rose approximately 5%, recovering a significant portion of last week’s losses.

The day’s market action highlighted two of the most powerful themes driving the economy in 2026: artificial intelligence and infrastructure investment.

While much of the public discussion around AI focuses on software platforms such as ChatGPT, Claude, Gemini, Microsoft Copilot, and Grok, the technology also requires massive physical infrastructure—from fiber-optic networks and power systems to advanced semiconductor manufacturing. The Amazon-Corning agreement underscores how AI investment is increasingly translating into American manufacturing jobs, workforce training programs, and long-term capital spending.

For investors, Monday’s rebound also served as a reminder that a growing share of market performance remains tied to a relatively small group of AI-related companies. Sharp swings in semiconductor stocks continue to have an outsized influence on major indexes, particularly the Nasdaq.

Looking ahead, markets remain focused on developments in the Middle East, Treasury yields, and the broader outlook for interest rates following last week’s stronger-than-expected jobs report. While investors appeared willing to buy back into AI-related names on Monday, the mixed finish suggests uncertainty remains just below the surface.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Farnam Elyasof, founder of the online budget suit retailer FlexSuits, has watched his returns climb 50% over the past year, and he traces much of the increase to a single cause: customers losing weight on prescription drugs.

When a shopper orders the same suit in two or three sizes at once, Elyasof said, it is a warning sign. He now often checks measurements, asks whether the customer is losing weight, or suggests they wait to buy until closer to the event they need it for.

The returns keep coming anyway.

“It’s a loss for me,” he said.

Elyasof’s experience reflects a problem spreading across American apparel retail. The rapid adoption of GLP-1 medications, the class of weight-loss and diabetes drugs that includes Ozempic and Wegovy, is reshaping how customers buy clothes and, increasingly, how often they send them back.

Shoppers are ordering multiple versions of the same garment and returning the ones that no longer fit, or exchanging larger sizes for smaller ones as the pounds come off.

The data shows the shift is accelerating.

The share of apparel exchanges in which shoppers traded down to a smaller size has risen in each of the past three full calendar years, reaching a high of 14.6% in 2025, according to a review of 38 retailers by Narvar, a firm that manages returns on behalf of stores.

For retailers, returns are among the costliest problems to manage, especially for online sellers.

Each returned item carries shipping, labor, and warehousing expenses, and merchandise that comes back may be out of season, forcing the retailer to resell it at a discount or absorb the loss entirely.

The math is punishing.

For a company with $1 billion in sales that typically sees about 20% of purchased items returned, an increase of five to ten percentage points in the return rate can cut gross margins by roughly $20 million, according to Prashant Agrawal, chief executive of Impact Analytics, which helps retailers manage inventory.

He called it “a huge headache.”

The firm found that returns for medium, large, and extra-large items jumped the most, as customers buy several sizes at once to see what fits as their bodies change.

The pace of change is unusual for retailers used to stable sizing patterns.

At peak weight loss, people taking GLP-1 drugs can drop a clothing size every month, Agrawal said.

Jeans, bras, and athleisure wear tend to be the first items replaced, followed by tops and dresses, with later adjustments to ring, bracelet, and shoe sizes.

Major retailers including Levi Strauss, Costco Wholesale, and Walmart are working to better understand the shift.

The scale of drug use behind the trend is large and growing.

About 10 million Americans are on GLP-1 treatments in 2026, a figure JPMorgan estimates could exceed 30 million by 2030.

Roughly 23% of U.S. households reported using the medications as of September 2025, according to market-research firm Circana, which found that 80% of users expect to need new clothing because of changing sizes and 55% had already purchased new apparel or footwear.

The January 2026 launch of the first GLP-1 pill drove the fastest spike yet in users.

The strain is most visible among retailers built around larger sizes.

Torrid reported a 14.3% drop in fourth-quarter sales for its 2025 fiscal year and a net loss of $8.1 million, and plans to close 30 stores in the first half of 2026 after shuttering 151 locations last year.

Destination XL, which sells big-and-tall menswear, posted a 6% decline in quarterly sales, and chief executive Harvey Kanter said the company underestimated the impact.

The retailer estimates up to 25% of its customers are on weight-loss drugs and are delaying purchases until they reach their goal weight.

Larger retailers are adjusting as well.

Women’s extended-size offerings on Target’s website fell 37% from March 2025 to March 2026, while plus-size options at Old Navy dropped 12% over a comparable period, according to retail-intelligence firm EDITED.

The shift is not entirely negative for the industry.

Research firm Bernstein estimates GLP-1 adoption could add between $3 billion and $13 billion annually in apparel spending as users rebuild their wardrobes over one to three years, benefiting discount retailers, off-price chains, and resale platforms.

James Reinhart, chief executive of ThredUp, said sales of large, extra-large, and plus-size items on the resale platform rose about 6% as customers cleared out clothing that no longer fit.

For now, however, the immediate pressure is on returns and inventory management.

Retailers are trying to recalibrate how much they stock in each size and how they process a rising tide of returned merchandise, a forecasting challenge made more difficult by a customer base whose measurements are changing faster than ever.

JBizNews Desk — Retail

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A privately built nuclear reactor cleared a make-or-break technical hurdle this week, and the real story for business is what it could unlock: a new market for portable nuclear reactors aimed at military bases, artificial intelligence data centers, factories, utilities, and remote operations that need reliable power. The U.S. Department of Energy announced on June 4 that Antares Nuclear Inc. became the first private company to bring an advanced reactor to criticality under the federal DOE Reactor Pilot Program, a milestone confirmed by Energy Secretary Chris Wright.

For investors and energy companies, the significance is simple. A reactor that works can eventually become a product that generates revenue.

Criticality sounds dramatic, but it simply means a reactor can sustain its own nuclear chain reaction without outside assistance. In plain English, the technology successfully performed the function it was designed to perform.

The test took place at Idaho National Laboratory using Antares’ Mark-0 microreactor. According to the Energy Department, the achievement demonstrates that the design can operate safely and provides the foundation for future versions expected to begin producing electricity starting in 2027 and beyond.

“The reactor worked” may sound like a small headline. In the nuclear industry, it is one of the most important milestones a company can reach.

The first major customers may already be waiting.

Jordan Bramble, founder and chief executive officer of Antares Nuclear, said reaching criticality is the first step toward generating electricity and ultimately deploying reactors at customer locations. He said the company is now moving toward installations that could power military facilities and other critical infrastructure.

The Pentagon has become one of the strongest supporters of microreactor technology because many military bases operate in locations where dependable electricity is difficult to secure. A portable reactor capable of providing uninterrupted power could reduce reliance on vulnerable grids and costly fuel deliveries.

The Department of Energy also sees opportunities in remote industrial operations, mining projects, disaster-response zones, isolated communities, and even future space missions.

The larger opportunity is being driven by a problem that continues to grow: electricity demand.

Across the country, utilities are struggling to keep up with power needs created by artificial intelligence data centers, advanced manufacturing facilities, electric vehicle infrastructure, and expanding digital operations. Major technology companies have already signed long-term agreements worth billions of dollars to secure future supplies of carbon-free electricity.

That demand is creating a potentially enormous market for companies that can provide reliable power quickly.

Unlike traditional nuclear plants that can take a decade or more to build and require billions of dollars in capital, microreactors are designed to be much smaller and more flexible. Many are intended to be transported by truck, rail, or aircraft and deployed directly where power is needed.

That portability is what has attracted growing attention from both government agencies and private investors.

Another factor changing the industry’s outlook is Washington.

In May 2025, President Donald Trump signed executive orders intended to accelerate nuclear development in the United States. The orders expanded the authority of the Energy Department to move certain advanced reactor projects forward more quickly and sought to streamline portions of the federal approval process.

For developers, faster approvals can dramatically improve project economics.

For decades, one of the biggest obstacles facing nuclear startups has been the cost and uncertainty associated with permitting. Investors often hesitated to fund projects that could spend years waiting for approvals before generating a dollar of revenue. Reducing those timelines changes the financial equation.

The Antares project is part of the federal DOE Reactor Pilot Program, a fast-track initiative launched to accelerate advanced nuclear technology.

The program selected 11 advanced reactor projects and established a goal of bringing at least three reactors to criticality by July 4, 2026, coinciding with America’s 250th anniversary celebration.

Ted Garrish, Assistant Secretary for Nuclear Energy, noted that many observers doubted the timeline could be achieved. He also pointed out that the Mark-0 became the 53rd reactor built at Idaho National Laboratory since 1951, connecting the latest private-sector effort to decades of American nuclear research.

Competition in the sector is already accelerating.

In February, the Department of Defense and Department of Energy completed the first airlift demonstration of a microreactor designed for rapid deployment. A 5-megawatt reactor developed by Valar Atomics was transported roughly 700 miles from California to Hill Air Force Base in Utah, demonstrating how quickly future systems could be moved to strategic locations.

The reactor carried no nuclear fuel during the demonstration, but the exercise highlighted the military’s growing interest in transportable power systems.

The race is now shifting from technical milestones to commercial contracts.

Companies that can prove reliability, secure regulatory approvals, and deploy reactors at customer sites first could gain a significant advantage in a market that barely existed a few years ago but is now attracting billions of dollars in public and private investment.

There are still hurdles ahead.

Critics argue that microreactors have yet to prove they can operate economically at scale or consistently deliver electricity at competitive prices. Antares must still complete additional testing and obtain licensing approvals before widespread commercial deployment can occur.

Reaching criticality does not guarantee revenue.

But it does move the company substantially closer to selling power into a market where demand continues to rise and where governments, utilities, and technology companies are increasingly searching for new sources of reliable electricity.

For now, the milestone in Idaho stands as one of the clearest signs yet that advanced nuclear technology is moving from the laboratory toward the marketplace—and that a new generation of companies intends to compete for a potentially multi-billion-dollar share of America’s growing power needs.

JBizNews Desk — Energy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
HAVANA — The Central Bank of Cuba said Wednesday that it would shut off Visa and Mastercard transactions across the island beginning June 6 after the foreign bank that processed those payments chose to exit rather than risk violating newly tightened U.S. sanctions.

For travelers, the impact is immediate: foreign visitors can no longer use internationally issued Visa or Mastercard credit and debit cards to pay for hotels, restaurants, transportation, or other services in Cuba. For the Cuban economy, the move severs one of the last remaining financial connections to the global payment system.

The Central Bank of Cuba said the cutoff means the country will no longer be able to receive funds from purchases made through internationally recognized card networks.

The trigger was President Donald Trump’s May 1 executive order, which significantly expanded restrictions on business dealings involving Cuba. The order gave foreign companies until June 5 to end relationships with GAESA, the military-run conglomerate that controls large portions of Cuba’s tourism, financial, retail, and transportation sectors, or face potential sanctions themselves.

For years, Cuba’s international card-processing system operated through Fincimex, a financial entity tied to GAESA, working in partnership with an overseas bank. Once that foreign banking partner withdrew to protect itself from possible sanctions exposure, the payment system effectively collapsed.

Washington argues that GAESA channels profits from tourism, remittances, and other industries to Cuba’s military and political leadership. The Cuban government disputes that characterization, maintaining that revenues generated by GAESA support national economic and social programs.

Since January, Secretary of State Marco Rubio has expanded sanctions pressure on Cuba, adding GAESA and its leadership to a list of more than 240 sanctions-related designations.

The payment shutdown is only the most visible sign of a broader corporate retreat from the island.

Several major international hotel operators have already begun reducing or ending their involvement in Cuba. Spain’s Meliá Hotels International, the largest foreign hotel operator in the country, has scaled back portions of its operations. Canada’s Blue Diamond Resorts is exiting entirely, returning approximately 15 hotels to Cuban state management. Iberostar has ended relationships with GAESA while maintaining certain properties through non-military state entities. Archipelago International, headquartered in Jakarta, has also departed.
The aviation sector has seen similar changes.

At least 11 international airlines, including Air Canada, WestJet, Air Transat, Air France, and Iberia, have suspended Cuba service this year, eliminating more than 1,700 scheduled flights. Several global shipping companies have also reduced or ended their Cuba-related activities amid the evolving sanctions environment.

Perhaps the most significant corporate casualty is Sherritt International, one of the last major foreign companies with substantial operations in Cuba.

The Toronto-based mining company announced on May 7 that it was suspending its direct role in a key Cuban joint venture and beginning the process of bringing Canadian employees home. Investors reacted sharply, sending Sherritt shares down approximately 30 percent following the announcement.

Sherritt’s relationship with Cuba dates back more than three decades.

Its flagship operation is the Moa Nickel venture, a 50-50 partnership with Cuba’s state-owned General Nickel Company. The project mines and processes nickel and cobalt, two metals critical to global battery manufacturing and electric vehicle production.

For Cuba, nickel remains one of the country’s most important sources of hard-currency earnings. For that reason, the operation sits at the center of the country’s export economy—and increasingly at the center of sanctions concerns.

The company’s response illustrates the difficult position facing foreign businesses still operating in Cuba.

Initially, Sherritt indicated it would seek a court order in Alberta to dissolve the joint venture. Days later, however, the company reversed course, citing discussions with advisers and government officials and suggesting a potential path remained to preserve value from the operation.

The financial stakes are significant.

Cuba reportedly owes Sherritt at least $344 million, while the company itself carries approximately $266.2 million in bonds paying 9.25 percent interest, with its next major payment due in October.

The consequences extend beyond any single company.

As Paolo Spadoni, a Cuba expert at Augusta University, noted, the United States has effectively targeted nearly every major source of hard currency flowing into the Cuban economy, including tourism, remittances, medical services, and nickel exports.

Those pressures are landing on an economy already facing severe challenges.

Large portions of the country have experienced extended power outages. Shortages of food, fuel, medicine, and water remain widespread. Tourism, once one of Cuba’s most reliable economic engines, has fallen dramatically.

Even Canada, historically Cuba’s largest source of foreign visitors, has advised citizens to avoid non-essential travel to the island, citing concerns about fuel availability and the reliability of basic services.

The broader business lesson reaches beyond Cuba.

Modern economies depend on networks—banks, airlines, payment systems, shipping companies, hotel operators, suppliers, and international investors. Those connections are often invisible until they disappear.

When enough of them break at once, economic activity becomes dramatically more difficult regardless of a country’s natural resources, workforce, or strategic location.

That is the challenge Cuba now faces.

The departure of payment processors, airlines, hotel operators, shipping firms, and major investors suggests many international businesses are concluding that the risks of operating in Cuba are rising faster than the potential rewards.

For now, those companies are heading for the exits.

And their actions suggest they believe Cuba’s economic isolation may deepen before it improves.

JBizNews Desk — Latin America

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
William Barlow, the former vice president of threat intelligence at IBM, alleges in a lawsuit made public Thursday, June 4, that IBM and AT&T repeatedly hid breaches of their computer systems by foreign hackers from the U.S. government in order to win and keep federal contracts.
The complaint, filed under seal in 2020 and still pending before a federal court in New York, contains allegations that have not been proven and that the companies have not substantiated.

According to the complaint, the two companies failed to disclose multiple intrusions over a period of years by attackers linked to foreign governments and made false assurances about the security of their systems to secure government business. Barlow, who held a senior cybersecurity role at IBM, says he had direct knowledge of the events he describes.

In the suit, Barlow claims he personally witnessed numerous breaches of IBM’s core network and was pressured by executives to soften internal reports and leave out details. He alleges he knew of specific instances in which IBM senior management “actively took steps to cover up and conceal” hacks from U.S. regulators and government clients.

The company has not addressed those specific claims publicly.

The complaint paints a picture of confusion inside the companies. It alleges the breaches were so large, and the networks so poorly designed, that neither IBM nor AT&T could determine exactly what data was taken, who took it, or whether information had been copied or altered.

If accurate, that would mean the companies could not fully account for the security of systems they were paid to protect.

The suit alleges that hackers backed by the Chinese government were involved in some of the intrusions.

The claim fits a broader pattern U.S. authorities have described in recent years. In 2018, the Department of Justice charged two alleged members of a Chinese hacking group accused of stealing data from companies and government agencies.

The attribution in Barlow’s complaint, however, remains an allegation that has not been tested in court.

The legal vehicle matters for understanding the business stakes.

Barlow’s case is a whistleblower lawsuit of the kind used to allege fraud against the federal government. The core theory is that by giving false assurances about cybersecurity while concealing breaches, the companies obtained and retained federal contracts they might not otherwise have won.

Cases like these can expose defendants to substantial financial penalties if the government joins them and the claims are proven.

The federal contracting stakes are significant for both companies.

IBM is a major provider of information-technology services to government agencies, while AT&T supplies telecommunications and network services across the public sector.

Allegations that sensitive government-facing systems were breached, and that the breaches were hidden, strike at the heart of those relationships and at the trust the government places in large contractors.

Both companies have faced documented breaches in recent years, separate from the specific allegations in the suit.

AT&T disclosed a data breach in 2024 that affected more than 70 million current and former customers.

IBM was among the organizations affected by the wide-ranging MOVEit file-transfer breach carried out by a Russian ransomware group, and in 2026 an Italian subsidiary of the company was breached in an attack security researchers linked to a Chinese group known as Salt Typhoon.

Those incidents are publicly known and are not the same as the concealment claims Barlow is making.

The allegations remain unproven, and whistleblower suits of this type often take years to resolve and can be dismissed.

IBM has navigated similar litigation before; a separate whistleblower case accusing the company of misleading a federal agency was dropped after roughly a decade of court battles.

Because Barlow’s complaint was filed under seal, the companies’ formal responses are part of the pending litigation rather than public statements, and the case has not reached a stage where the claims have been weighed by a court.

For investors and government clients, the suit raises questions that extend beyond the courtroom.

Large technology and telecommunications companies hold some of the most sensitive data and run some of the most critical systems in the country, and allegations that breaches were hidden from regulators touch on reputational, financial, and national-security concerns at once.

Whether the claims hold up will depend on what evidence emerges as the case proceeds.

For now, the lawsuit is an accusation by a former insider, not a finding of wrongdoing.

It places two of the country’s largest technology and telecommunications firms at the center of a dispute over how breaches are reported and over what the government was told about the security of the systems it pays them to run.

JBizNews Desk — Cybersecurity & Government Contracting

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

North Korea’s economy is growing, and the reason behind it is surprising. The Bank of Korea, South Korea’s central bank, estimated in 2025 that the North’s economy grew 3.7% in 2024 — its fastest pace since 2016. The bank, the most trusted outside source on the North’s hidden economy, put the country’s output at about $26.6 billion.

That growth did not come from making phones or sneakers. It came from war.

Since Russia invaded Ukraine in 2022, Vladimir Putin has needed one thing North Korea has plenty of: ammunition. Kim Jong Un has been happy to sell it. The two leaders signed a defense pact in June 2024. Since then, North Korean shells, rockets and short-range missiles have moved to the Russian front line by train and ship. In return, Russia sends back fuel, food, weapons parts, technology and hard cash.

The sums are huge by North Korean standards. South Korean intelligence and research institutes estimate the North earned somewhere between $7.67 billion and $14.4 billion from sending troops and weapons to Russia between August 2023 and December 2025. That may be more than half of everything the country produces in a year.

It is not just artillery. In a threat report released in March 2026, the U.S. Office of the Director of National Intelligence said North Korea’s foreign-cash earnings are at their highest level since before sanctions were tightened in 2018. The causes: arms sales to Russia and computer hacking. U.S. officials estimate the North pulls in at least $1 billion a year from cybercrime alone.

Here is the business angle. The war has turned North Korea’s weapons program into an export business.

The Bank of Korea said the North’s heavy chemical sector jumped 10.7% in 2024, its fastest increase on record. The reason was simple: more metal parts for weapons sold to Russia. Sanctions were meant to shut that industry down. A wartime buyer gave it a reason to run at full capacity instead.

So why are sanctions losing some of their bite?

First, Russia now supplies many of the goods North Korea once struggled to obtain — fuel, weapons parts, food and technology. Those shipments reduce the pressure sanctions were designed to create.

Second, China remains the North’s economic lifeline. Roughly 98% of North Korea’s trade passes through China. That channel has never fully closed.

But a stronger regime balance sheet does not necessarily mean a better life for ordinary citizens.

Groups that monitor North Korea’s informal markets, including Daily NK and Asia Press, reported that the won weakened sharply during 2024 and 2025, with some estimates suggesting it moved from roughly 8,000 per U.S. dollar to as high as 36,000 in certain markets. Prices for everyday goods also climbed.

Cash is flowing into the state. It is not reaching ordinary households in the same way. The regime has increasingly relied on cash payments rather than traditional state distribution systems, a sign of how much the economy has changed under sanctions and isolation.

So the picture splits in two. The regime is bringing in more cash. Ordinary households are not seeing the same benefits.

For the rest of the world, the lesson is uncomfortable. Sanctions work best when a country stands alone. North Korea no longer stands alone. It has a major customer in Russia and a critical supplier in China.

The short-term story is a wartime windfall. Weapons shipped today generate revenue today. That can fade if the fighting eventually ends.

The longer-term question is whether North Korea can turn wartime earnings into a broader economy that improves living standards and stabilizes its currency. So far, there is little evidence that has happened. The regime’s foreign-currency earnings have surged. The challenges facing ordinary North Koreans remain.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

RIO DE JANEIRO — JetBlue Airways Chief Executive Officer Joanna Geraghty signaled Saturday that she is no longer ruling out a merger, telling attendees at the International Air Transport Association’s annual meeting that when it comes to airline consolidation, she would “never say never.”

The comment came during the airline industry’s largest annual gathering, the 82nd International Air Transport Association (IATA) Annual General Meeting, hosted this year in Rio de Janeiro. The remark represented a notable shift from Geraghty’s position just one year ago when, at the same conference in New Delhi, she gave a direct “No” when asked whether JetBlue would pursue a combination with another carrier.

The change in tone comes as JetBlue faces mounting financial and operational pressures.

The New York-based airline has reported profits in only two of the past nine quarters and continues to work through a multiyear turnaround strategy that includes reducing expenses, trimming underperforming routes, and delaying aircraft deliveries. The carrier also carries approximately $10 billion in debt, leaving it more exposed to industry headwinds than many larger rivals.

One of those headwinds is fuel.

Jet fuel prices have risen as conflict in the Middle East and continued uncertainty surrounding shipping routes and energy supplies have pushed oil prices higher. Fuel remains one of the largest operating expenses for airlines, and smaller carriers often have fewer tools available to offset those costs than their larger competitors.

In an internal memo earlier this year, Geraghty acknowledged that 2026 was proving more challenging than expected and specifically cited fuel costs as a growing concern. She also addressed speculation surrounding the airline’s financial condition, rejecting rumors that JetBlue was considering bankruptcy protection.

For JetBlue, merger discussions carry significant historical baggage.

The airline unsuccessfully pursued Virgin America in 2016 before losing the bidding war to Alaska Airlines. Its Northeast Alliance with American Airlines was later struck down by a federal judge in 2023 on antitrust grounds. Most notably, JetBlue’s proposed $3.8 billion acquisition of Spirit Airlines collapsed in March 2024 after a federal court blocked the transaction, concluding that eliminating Spirit as an independent low-cost competitor would likely reduce competition and increase fares.

Following those setbacks, JetBlue shifted its focus from acquisitions to partnerships.

Last year the carrier unveiled Blue Sky, a cooperative arrangement with United Airlines that links loyalty programs, expands travel benefits, and provides a pathway for United to resume operations at New York’s John F. Kennedy International Airport beginning in 2027 using JetBlue-controlled slots. While both airlines have emphasized that JetBlue remains fully independent, critics—including Spirit Airlines during regulatory reviews—argued the arrangement risked making JetBlue increasingly dependent on a much larger partner.

That history makes Geraghty’s latest remarks particularly noteworthy.

By declining to rule out future consolidation, JetBlue’s chief executive appears to be signaling a willingness to reconsider options that had seemed politically and legally out of reach only a short time ago.

The broader industry context helps explain why.

The U.S. airline industry is dominated by four carriers—American Airlines, Delta Air Lines, United Airlines, and Southwest Airlines—which collectively control roughly 80% of domestic passenger traffic. JetBlue has long argued that smaller airlines need greater scale to compete effectively against those giants.

Regulators, however, have frequently taken the opposite view, arguing that fewer airlines ultimately lead to higher fares and reduced consumer choice.

For travelers, the debate has real consequences.

Supporters of consolidation argue that larger airlines can operate more efficiently, offer broader route networks, and compete more aggressively against industry leaders. Opponents counter that mergers often eliminate low-cost competitors that help keep ticket prices affordable.

Every vacation flight, business trip, and holiday journey is ultimately affected by how many airlines remain actively competing for passengers.

What any future JetBlue transaction might look like remains unclear.

Industry observers continue to speculate that Spirit Airlines could reemerge as a potential target despite its financial challenges. Frontier Airlines is also frequently mentioned whenever discussions of low-cost carrier consolidation arise. Former United Airlines CEO Oscar Muñoz has publicly stated that either JetBlue or Frontier could eventually pursue Spirit.

Investors appear to be watching closely. JetBlue shares trade on the Nasdaq under the ticker JBLU, and any indication that management may again pursue strategic combinations is likely to attract significant attention from both Wall Street and regulators.

For now, Geraghty has not announced any specific plans.

But in an industry where fuel costs are rising, competition remains fierce, and scale increasingly matters, a chief executive publicly refusing to rule out mergers is a signal in itself.

Whether JetBlue ultimately chooses to deepen partnerships, pursue another acquisition, or become part of a larger combination could help shape the future of competition—and consumer choice—in the American airline industry.

JBizNews Desk — Aviation

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The blockbuster weight-loss drugs known as GLP-1s are doing more than changing waistlines. They are quietly rewiring the American grocery basket, forcing food makers and supermarkets to rethink what they stock, how big the packages are, and which aisles they bet on.

The scale of the behavioral change is striking. According to PwC’s analysis of consumer data from Numerator, GLP-1 users consume 40% fewer calories on average, with dessert consumption down 84% and alcohol use down 33%, while fresh produce intake is up more than 70%. Family grocery baskets are 4% to 6% smaller, and single-person households have seen declines of up to 9%.

That shrinking basket is a real threat to packaged-food giants. Diet changes linked to the drugs could mean up to $12 billion in lost snack sales over the next decade, according to EY-Parthenon estimates, and the industry has stopped treating it as a passing fad. Nearly three dozen companies outside healthcare mentioned GLP-1 drugs or weight loss on their earnings calls so far this year, up from 14 a year earlier, according to LSEG data.

The corporate response is already visible on shelves. Companies from PepsiCo to Coca-Cola and General Mills are focusing on shorter ingredient lists, smaller pack sizes, protein-rich foods, and product reformulations to adapt to shifting demand. The bet is that selling less food per package — but more nutrient-dense food — can offset falling volumes.

For grocers, the change is less about losing customers than about where those customers spend inside the store. GLP-1 users increasingly gravitate toward fresh produce, lean cuts of meat, and other healthier options, meaning shoppers often do not switch stores — they simply shift their spending toward the fresh perimeter departments. That is pushing retailers to make produce, meat, and wellness sections more prominent while expanding protein, fiber, and portion-controlled offerings.

The trend appears likely to grow rather than fade. A Circana report projects that households with GLP-1 users will account for more than one-third of food and beverage sales by 2030, up from about 23% of U.S. households today. “The rise of GLP-1 medications is a huge moment for the CPG industry,” said Sally Lyons Wyatt, Global Executive Vice President at Circana.

Analysts say the disruption is only beginning to be understood. “We’re just starting to scratch the surface on the ripple effects of this type of physiological disruption,” said Ali Furman, PwC’s U.S. Consumer Markets Leader.

The business stakes run from the factory to the checkout counter. Food manufacturers face a generation of customers who simply eat less, retailers must redesign stores around healthier appetites, and even restaurant chains are testing smaller portions and GLP-1-friendly menu options. The companies that adapt fastest — selling smaller, healthier, higher-margin products — may turn a demand shock into an opportunity. Those that continue betting on jumbo bags of chips may find that both the shelves and the shoppers have moved on.

This article is general business reporting, not medical advice. Anyone considering these medications should consult a physician.

JBizNews Desk — Retail & Consumer Goods

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Maryland has become the first state in the nation to outlaw a controversial practice that consumer advocates have warned about for years: using a shopper’s personal data to charge that specific person more for groceries. The law takes direct aim at what critics call “surveillance pricing.”

The measure is now on the books. On April 28, Governor Wes Moore signed House Bill 895, the Protection From Predatory Pricing Act, which restricts personalized, data-driven, and AI-enabled pricing in the food sector. It makes Maryland the first state to prohibit grocery retailers and delivery providers from using personal consumer data to set individualized food prices. The law takes effect October 1.

The legislation draws a careful line. It does not ban all dynamic pricing. Instead, it targets the narrower and more controversial practice of using artificial intelligence and consumer profiling to determine how much a specific shopper might be willing to pay. The law applies to food retailers with locations of 15,000 square feet or larger that maintain substantial grocery operations, as well as third-party delivery services.

Enforcement carries significant penalties. The Maryland Attorney General will oversee enforcement, with a 45-day cure period and civil fines of up to $10,000 per violation, rising to $25,000 for repeat offenses. The measure does not create a private right of action.

Importantly, the law still allows retailers to offer discounted prices to consumers who voluntarily agree to share personal data in exchange for those discounts, preserving traditional loyalty-program pricing models.

The retail industry argues the legislation addresses a problem that has not been proven to exist. The Maryland Retailers Alliance called the law unnecessary, arguing that existing consumer-protection statutes already prohibit misleading or discriminatory pricing and noting that the Attorney General has not documented substantiated complaints involving grocery surveillance pricing.

Consumer advocates strongly disagree. The Electronic Privacy Information Center (EPIC) called the ban “essential,” arguing that surveillance pricing is inherently difficult for consumers to detect and avoid because shoppers often have no visibility into how pricing algorithms operate.

Maryland may not remain alone for long.

Several states, including California, Colorado, Illinois, Massachusetts, New York, and New Jersey, are considering legislation addressing algorithmic pricing, AI transparency, or surveillance-pricing practices. New York has already enacted an Algorithmic Pricing Disclosure Act, requiring retailers that use personal data in pricing decisions to notify consumers that an algorithm helped determine the price.

The business implications extend far beyond Maryland.

For national grocery chains and delivery platforms, the growing patchwork of state laws is becoming a compliance challenge. Terms such as “dynamic pricing,” “algorithmic pricing,” and “surveillance pricing” are often used interchangeably in public debates, even though they describe different practices and may be regulated differently from state to state.

Companies now have until October 1 to review how customer information influences pricing decisions. Legal experts say the food sector may be only the beginning. Similar questions are already being raised about personalized pricing in airlines, retail, travel, insurance, and financial services.

Maryland’s law may represent the first major attempt to draw boundaries around AI-driven pricing. Whether other states follow could determine how much companies are allowed to know about consumers before deciding what price each customer sees.

JBizNews Desk — Retail & Consumer Affairs

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A company that made its name mining Bitcoin has just signed one of the largest data center leases in the country — a deal that captures how completely the AI boom is rewiring the technology economy and turning crypto miners into the landlords of artificial intelligence.

Bitcoin miner Hut 8 announced in early May that it had signed a 15-year lease worth $9.8 billion for the first phase of its Beacon Point data center campus in Nueces County, Texas, near Corpus Christi. The agreement covers 352 megawatts of computing capacity, with the tenant described only as a confidential, high-investment-grade company that plans to run AI training and inference at massive scale.

Notably, the facility is engineered to Nvidia’s specifications even though the customer’s name is being kept private. The 352-megawatt site was designed to Nvidia’s DSX reference architecture, the blueprint for the chipmaker’s most power-hungry AI systems — a sign of how thoroughly Nvidia’s technology now dictates how these buildings are constructed, regardless of who occupies them.

The financial terms grow even larger over time. The lease is structured on triple-net, take-or-pay terms, and if all three five-year renewal options are exercised, its total value could reach roughly $25.1 billion. The deal lifts Hut 8’s total contracted AI data center capacity to 597 megawatts, with a contracted revenue base of about $16.8 billion.

Investors reacted instantly. Hut 8’s shares jumped about 34% to nearly $108 the day the deal was announced, an all-time high, after more than doubling over the prior month. The market is rewarding the pivot from a volatile, low-margin business — mining cryptocurrency — to long-term contracts with creditworthy tenants paying for guaranteed power and space.

Hut 8 Chief Executive Asher Genoot framed the strategy around a single resource: electricity.

He said the company’s power-first development model is repeatable across tenants and geographies, and that it identified a site rivals overlooked, more than doubling its contracted capacity within five months. The campus was originally meant to house crypto-mining hardware before being redesigned for AI. An initial data hall scoped for 224 megawatts was enlarged to 352 megawatts — a 57% increase — after Nvidia’s denser systems advanced toward deployment.

Hut 8 is not alone in making this turn.

IREN, an Australian-listed company that began as a Bitcoin miner, unveiled a partnership with Nvidia to deploy up to 5 gigawatts of AI infrastructure and signed a separate $3.4 billion AI cloud services contract. TeraWulf recently added a 285-acre campus in eastern Kentucky expected to support up to a gigawatt of capacity. Across the industry, miners are racing to convert the one asset they spent years accumulating — access to cheap, large-scale electricity — into the hottest commodity in technology.

The logic is straightforward.

Bitcoin mining and AI computing both require the same thing: enormous amounts of power and the infrastructure to deliver it. Mining profits swing wildly with the price of Bitcoin, while AI tenants sign 15-year leases that pay whether crypto is up or down. For companies that already control gigawatts of grid capacity and the permits to use it, leasing that power to AI firms is far steadier money than digging for digital coins.

The shift also underscores what has become the real bottleneck in the AI build-out: not chips alone, but the electricity and physical sites to run them. Hut 8 has secured an interconnection agreement for a full gigawatt of utility capacity at the campus, with initial power expected in early 2027. In a country where the grid is straining to keep up with demand, the companies that locked up power early are suddenly sitting on something close to gold.

For Hut 8, the gamble is that AI’s appetite for computing keeps growing long enough to justify a 15-year commitment. For the broader economy, the deal is a marker of how the AI era is reshaping industries that have nothing to do with software — turning a Bitcoin miner in a Texas county most Americans have never heard of into a key supplier of the infrastructure powering the future.

The AI boom is often described through the lens of chatbots, software, and algorithms. But deals like this reveal what may matter most: power, land, transmission access, and the ability to deliver massive amounts of electricity where AI companies need it. In that race, former Bitcoin miners are discovering they already own some of the most valuable assets in the economy.

JBizNews Desk — Artificial Intelligence

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The cost of building artificial intelligence has reached a scale that is hard to fathom, and a single number buried in a regulatory filing has laid it bare: Anthropic is paying Elon Musk’s xAI $1.25 billion every month just to rent the computers it needs to train and run its AI models.

The figure surfaced in SpaceX’s initial public offering paperwork. When Elon Musk’s company filed its S-1 with the Securities and Exchange Commission on May 20, it disclosed that Anthropic, the maker of the Claude chatbot, will pay $1.25 billion a month for access to the Colossus and Colossus II data centers through May 2029. Over the full term, the contract could deliver up to $45 billion in revenue, or roughly $15 billion a year, with either side able to terminate the agreement with 90 days’ notice.

The Colossus clusters were built by xAI, Musk’s artificial intelligence venture, and the arrangement effectively turns the company’s computing infrastructure into a rental business. Rather than using every processor for its own models, xAI is leasing excess capacity to another major AI developer. The filing also indicated that the company expects to pursue additional agreements of this type, creating a future in which AI firms increasingly become landlords for one another’s computing needs.

What Anthropic is buying is enormous.

According to the filing, xAI is providing approximately 300 megawatts of data-center capacity, supported by more than 200,000 Nvidia processors. The payments will ramp up over time, with reduced charges during the first two months as the infrastructure comes fully online.

The reason Anthropic would commit to such a staggering bill is simple: it needed the capacity.

The company has spent months battling computing constraints as demand for Claude has grown. In today’s AI race, the primary bottleneck is no longer engineering talent or software innovation. It is access to enough computing power to train and operate increasingly sophisticated models. The companies that secure the most compute often gain the biggest advantage.

The size of the contract becomes even more striking when compared with the businesses involved.

Anthropic recently reported approximately $10.9 billion in quarterly revenue, meaning this single infrastructure agreement consumes an amount equal to nearly half that figure. On the other side of the transaction, the payments represent a major boost for SpaceX and Musk’s broader ecosystem. With SpaceX generating roughly $18 billion in annual revenue, the AI infrastructure agreement alone adds revenue approaching the scale of the rocket company’s existing business.

The disclosure also changes how investors may view Musk’s empire.

SpaceX has long been associated with rockets, satellites, and space launches. Yet the IPO filing reveals that some of the company’s most valuable assets may increasingly be tied to artificial intelligence infrastructure. The prospectus argues that the greatest constraints on AI growth are no longer software-related but physical: electricity, cooling systems, computer chips, and the facilities needed to house them.

In that world, ownership of infrastructure becomes just as important as ownership of algorithms.

The implications extend far beyond Silicon Valley.

When the foundational cost of artificial intelligence reaches billions of dollars per month, those expenses eventually flow downstream. Businesses encounter them through API fees, enterprise software contracts, subscription pricing, and usage limits. Smaller AI companies must compete against firms with access to vastly greater computing resources, while customers ultimately absorb some of those costs through higher prices.

The agreement also highlights a broader truth about the AI boom.

Artificial intelligence is often discussed as software, machine learning, and digital intelligence. But the largest checks being written today are for industrial infrastructure: data centers, power generation, cooling systems, networking equipment, and hundreds of thousands of advanced processors.

The $1.25 billion monthly payment is, in essence, rent on the physical machinery powering the AI revolution.

As long as demand for computing continues to exceed supply, those rents are likely to keep rising. The AI boom may be built on code, but increasingly it is being financed by concrete, steel, electricity, and silicon. And those costs ultimately reach every business and consumer that relies on artificial intelligence.

JBizNews Desk — Artificial Intelligence

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For more than a year, the warning has been constant: high taxes, a new left-wing mayor, and remote work would hollow out Manhattan’s office towers and chase businesses south. The latest data tells a different story. New York’s commercial real estate market isn’t collapsing — demand is rising.

Figures from the real estate firm JLL covering the first quarter of 2026 show that office leasing activity and rents in Manhattan are up while the vacancy rate is falling, as corporations keep signing new leases — with AI companies particularly active. That is the opposite of what critics predicted when Zohran Mamdani took office as mayor on a platform of higher taxes and tenant-friendly policies.

The lending market tells the same story. Commercial real estate loan originations jumped 80% year over year in the first quarter of 2026, totaling $455 billion — a sharp resurgence in the financing that fuels building purchases and development. Money does not flow into a market that investors expect to crater.

None of this has silenced the exodus talk. Reports that Apollo Global Management was planning a second headquarters in Florida or Texas revived concerns about businesses fleeing New York over Mamdani’s tax policies. The trend is real over the long run: Wall Street firms have steadily expanded in lower-cost southern states for years. JPMorgan Chase now has more workers in its Dallas office than in New York City, and CEO Jamie Dimon wrote in his annual shareholder letter that the trend will likely continue.

But there is a difference between a slow, multi-year migration of back-office jobs and a sudden flight of capital — and the first-quarter numbers show no sign of the latter. The strength in Manhattan leasing demand and rents continued a trend already in place before Mamdani’s term began, suggesting the market is being driven by economic fundamentals rather than political fear.

The single biggest force lifting the market is artificial intelligence. AI companies, flush with investment and racing to expand, have been among the most aggressive tenants signing new leases in the city. Their appetite for space is helping offset the well-documented pullback in traditional office demand from finance and law firms that embraced hybrid work. In effect, one boom is filling the gap left by another sector’s retreat.

That dynamic matters far beyond landlords. A healthy office market supports the restaurants, shops, transit systems, and construction jobs that depend on workers coming into the city. When towers fill up, the sidewalks below them fill up too, and the tax revenue that funds city services holds steady. A genuine commercial real estate collapse would have ripped a hole in the city’s budget; instead, the sector is providing a cushion.

The political backdrop remains a genuine risk that bears watching. Mamdani’s housing agenda — including proposals that landlords warn could discourage development — and the broader tax debate could still alter the calculus for businesses weighing whether to grow in New York or somewhere cheaper. The Apollo and JPMorgan moves are reminders that companies have options and are willing to use them.

For now, though, the hard numbers undercut the most dire predictions. Leasing activity is rising, vacancies are falling, lenders are writing checks again, and the AI industry is helping drive a new wave of demand for Manhattan office space. Far from emptying out, many of the city’s highest-quality buildings remain in demand as companies compete for premium locations. The exodus may yet come in slow motion over the years ahead. But in the first full quarter of the Mamdani era, Manhattan’s office market is doing something its critics insisted it couldn’t: attracting tenants, supporting higher rents, and strengthening rather than weakening.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Americans are paying far more to stay insured in 2026, and the increases are landing hardest on the people who buy their own coverage — a squeeze that is already reshaping household budgets and corporate benefit plans alike.

The numbers are stark. According to an analysis by KFF, the nonpartisan health policy research group, premiums on the Affordable Care Act marketplaces are rising by an average of 26% for 2026, with increases of 30% in states using the federal Healthcare.gov marketplace and 17% in states running their own. That is the steepest jump in years and far above anything workers with job-based coverage have seen.

For people with insurance through their employer — the way most Americans get covered — the increase is smaller but still painful. Employer-sponsored insurance costs are projected to rise 6% to 7% in 2026. Virgil Bretz, chief executive of the health technology firm MacroHealth, has noted that such an increase is roughly double the general inflation rate.

What’s driving it comes down to two forces. The first is the simple, relentless rise in the price of medical care. Insurers in one review commonly assumed their medical costs would climb 7% to 8% in 2026, pushed up by expensive hospital care and a wave of costly new drugs. Pricey weight-loss medications known as GLP-1s have become a flashpoint: Blue Cross Blue Shield of Massachusetts said it is dropping coverage of GLP-1 drugs for weight loss in 2026, a move it estimated would reduce its premiums by about 3% — a sign of how much these treatments weigh on costs.

The second force is policy. The enhanced premium tax credits that had cushioned marketplace costs were set to expire, and insurers raised rates partly because they expect higher risk as a result. The consequences for the people who rely on those subsidies are severe. KFF estimated that if the enhanced credits lapse, what subsidized enrollees pay would more than double — a 114% jump, from an average of $888 a year in 2025 to $1,904 in 2026.

The pain is wildly uneven by geography. The average monthly benchmark Silver plan for a 40-year-old reached about $752 nationally, up 21% from a year earlier, but ranged from $480 in Maryland to $1,224 in Vermont. Arkansas led the country with a 67% increase, while a handful of states held increases below 10%, with states that run reinsurance programs generally seeing milder hikes.

The business implications run deep. For employers, a 6% to 7% rise in health costs means higher spending on every worker, money that competes with wages, hiring, and investment. Small businesses, which lack the bargaining power of large corporations, tend to feel it most and are likeliest to pass the cost to employees through higher payroll deductions or skinnier plans. The people most exposed are the roughly 2.4 million unsubsidized marketplace enrollees — often self-employed workers or early retirees — who absorb the full increase.

There is a broader economic risk, too. When coverage gets too expensive, healthy people drop it, leaving insurers with a sicker, costlier pool and pushing premiums even higher — the kind of cycle the industry has long feared. The Congressional Budget Office has estimated the number of uninsured Americans could rise by roughly 3.8 million a year if the enhanced subsidies are not extended, which would shift more unpaid medical bills onto hospitals and, ultimately, onto everyone else’s premiums.

For households already stretched by high grocery and energy prices, a double-digit jump in the cost of staying insured is one more strain on a budget that has little give left. And for the companies that provide coverage to most working Americans, 2026 is shaping up to be the year health benefits stop being a manageable line item and start forcing hard choices.

This article is general business reporting, not medical or financial advice; coverage decisions are best made with a licensed professional.

JBizNews Desk — Health Care

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited

The largest U.S. banks, led by JPMorgan Chase and Citigroup, are planning a shared system for tokenized deposits as the traditional banking industry’s coordinated answer to cryptocurrency, according to people familiar with the discussions in a plan reported Thursday, June 4. The effort would move banks beyond their separate, in-house projects toward common infrastructure for moving digital dollars.

A tokenized deposit is, in plain terms, a digital token that represents real money sitting in a bank account. It is a claim on deposits held at a regulated bank, moved across blockchain-style rails that allow payments to settle in seconds at any hour. That makes it different from a stablecoin, which is a token pegged to the dollar and often issued outside the banking system.

The distinction matters to banks.

A tokenized deposit keeps the money on their books, where they can still lend against it, while a stablecoin does not.

That is the core reason the banks are acting.

Stablecoins issued by crypto-native firms have grown into a large pool of dollars parked outside the banking system. Tether and Circle, the two biggest issuers, together controlled more than $310 billion in stablecoins as of early 2026.

Every dollar held in their tokens, USDT and USDC, is a dollar not held as a bank deposit—money banks earn nothing on and cannot use to make loans.

Left unchecked, that shift threatens the deposit and payments businesses that are central to how banks make money.

The pieces of a joint system already exist inside the biggest banks.

JPMorgan Chase launched a deposit token called JPMD in June 2025 on Coinbase’s public blockchain, known as Base, through its blockchain division Kinexys.

Naveen Mallela, the division’s global co-head, has said the token lets institutional clients send and receive money in seconds, around the clock, bypassing the delays of traditional banking.

The bank expanded the token to public blockchains later in 2025.

Citigroup runs its own service, Citi Token Services, which offers tokenized deposits for corporate treasury and trade-finance clients with near real-time settlement.

The new plan builds on talks that began in 2025, when JPMorgan Chase, Bank of America, Citigroup, and Wells Fargo explored issuing a joint stablecoin.

Those discussions ran through two jointly owned bank ventures: Early Warning Services, which operates the Zelle payment network and the Paze wallet, and The Clearing House, which runs a real-time payments network used by major banks.

A shared tokenized-deposit system would use similar shared rails while keeping the money as bank deposits rather than a separate stablecoin.

The logic mirrors how banks already cooperate.

Just as rival banks share the Zelle network for person-to-person transfers while keeping their own apps and brands, a shared tokenized-deposit system would let them agree on common plumbing to ensure the tokens work across institutions.

That interoperability is the point.

A token that only works inside one bank’s network is far less useful than one that can move seamlessly between banks for faster domestic payments, cross-border transfers, and around-the-clock settlement.

For JPMorgan, the approach reflects a strategy of competing and cooperating at once.

The bank has its own deposit token to keep a first-mover edge while joining an industry group to ensure it has a seat at the table if the market settles on a shared standard.

Other banks are hedging too.

Wells Fargo has filed a trademark for a branded digital dollar, suggesting it may want both a proprietary product and access to shared infrastructure.

The timing is tied to policy.

A federal framework for digital dollars, advanced under the GENIUS Act, has given banks more legal clarity to issue tokens, and the current administration has been broadly supportive of digital finance.

Clearer rules tend to favor regulated, compliant issuers, which is the position banks want to occupy.

There are reasons for caution.

The discussions remain at an early stage and could change.

Profitability is not guaranteed. Analysts have warned that the rich margins crypto-native issuers like Tether currently earn may not be sustainable as competition grows and regulation tightens.

The banks are still weighing how much demand a shared token would actually draw.

For now, the systems are aimed mainly at institutional and corporate clients rather than everyday consumers, used for moving large sums and settling trades.

But the broader direction is clear: the country’s biggest banks are moving to build their own version of the technology that crypto firms pioneered—and to do it together—so that the digital dollars of the future remain bank deposits rather than something issued outside their walls.

JBizNews Desk — Banking & Financial Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

To sell the most expensive stock-market debut in history, the banks pitching SpaceX are handing big investors a number that sounds almost impossible: according to projections shared with institutional clients by Morgan Stanley, reported Friday, Elon Musk’s rocket-and-satellite company could generate roughly $3.4 trillion in annual revenue by 2040.

For perspective, no company in the world comes close to producing that level of revenue today.

The projection sits at the center of an investor roadshow that officially launched this week ahead of SpaceX’s planned Nasdaq debut on June 12 under the ticker SPCX. The company has already set a fixed offering price of $135 per share, an unusual move that bypasses the traditional IPO price-range process and signals confidence from the underwriting banks that demand will be strong.

According to SpaceX’s filing with the U.S. Securities and Exchange Commission, the company plans to sell approximately 555.6 million shares, raising about $75 billion. Underwriters retain an option to sell an additional 83.33 million shares if investor demand exceeds expectations, potentially generating another $11.2 billion.

That structure values SpaceX at roughly $1.77 trillion.

Even after the offering, Musk will remain firmly in control. The filing shows he will retain more than 82% of the company’s voting power, ensuring that public investors will own a stake in the company but have little influence over its direction.

If completed at that size, the offering would easily surpass the previous IPO record.

Saudi Aramco’s landmark 2019 public offering raised approximately $29 billion. SpaceX is seeking more than double that amount.

The AI Story Is Driving the Valuation

The central question facing investors is simple:

How do you justify a valuation approaching $1.8 trillion for a company that generated approximately $18.7 billion in revenue last year?

According to presentations shown to investors, the answer is not rockets.

It is artificial intelligence.

Lead underwriter Goldman Sachs is reportedly presenting a financial model that places the overwhelming majority of SpaceX’s future value on its AI division, xAI.

The model projects AI-related revenue growing from approximately $3.2 billion in 2025 to $322 billion by 2030, an increase of roughly one hundredfold in just five years.

Under that forecast, total company revenue would reach approximately $474 billion by 2030.

Within that figure:

  • Starlink is projected to generate about $144 billion
  • The traditional rocket-launch business is projected to generate approximately $8.3 billion
  • The remainder would come primarily from AI operations

In other words, the rockets that made SpaceX famous become a relatively small piece of the investment story.

The real bet is software.

Even More Aggressive Forecasts

Some analysts believe the projections are still too conservative.

Research distributed by Evercore ISI reportedly forecasts that the AI division alone could generate approximately $755 billion in revenue by 2031, with total company revenue exceeding $1 trillion annually.

Those estimates rely heavily on claims in the prospectus regarding the future size of the artificial-intelligence market.

According to the filing, the company estimates that the total addressable market for xAI could eventually reach approximately $26.5 trillion.

That figure dwarfs the roughly $2 trillion opportunity analysts assign to Starlink and SpaceX’s launch operations combined.

The Catch

There is one major complication.

The AI division remains deeply unprofitable.

The prospectus projects that xAI will lose approximately $6.4 billion during 2025, meaning investors are being asked to place enormous value on a business that is still losing significant amounts of money.

That has fueled skepticism among some market observers.

CNBC’s Jim Cramer warned this week that a limited supply of publicly available shares, combined with forced buying by index funds and institutional investors, could drive SpaceX’s market value toward $4 trillion shortly after trading begins.

He also warned that early enthusiasm could eventually fade, leaving late-arriving retail investors exposed if insiders later sell large amounts of stock.

Cramer pointed to recent examples including Cerebras, which surged after its public debut before retreating sharply as trading normalized.

A Potential Headwind

Skeptics received another talking point on Thursday.

S&P Dow Jones Indices announced it would not modify its existing rules to accelerate inclusion of newly public companies such as SpaceX into major indexes.

The decision preserves the standard waiting periods and profitability requirements.

That matters because automatic inclusion in indexes often forces large mutual funds and exchange-traded funds to buy shares regardless of valuation. A delay removes one source of guaranteed demand.

The Bigger Picture

For ordinary investors, the appeal is obvious.

This represents the first opportunity to own a stake in a company that has reshaped the launch industry, built one of the world’s largest satellite networks, and become one of the most recognizable names in technology.

The risk is equally clear.

The valuation already assumes a future that has not yet arrived, with much of the company’s projected worth tied to AI revenue streams that remain largely theoretical.

One detail buried in the amended filing illustrates how interconnected the AI industry has become.

SpaceX disclosed that Anthropic is both a customer and a competitor to its xAI division, highlighting the increasingly tangled relationships developing across the artificial-intelligence sector.

Pricing is scheduled for June 11, with trading expected to begin on June 12.

After years of Musk insisting SpaceX would remain private, Wall Street is about to determine whether investors are willing to pay for a future measured not in billions, but in trillions.

JBizNews Desk — Markets & Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK— BlackRock, the world’s largest money manager, opened a $25 million nationwide grant competition on June 1 to help train electricians, mechanics, plumbers, and HVAC workers as employers across the country struggle to fill hundreds of thousands of skilled-trade jobs.

The reason is simple: America is running short of the very people it needs to build its future. The same artificial-intelligence boom that is threatening some office jobs cannot happen without people who work with their hands. Building a single AI data center takes armies of electricians to wire it and HVAC mechanics to keep the machines cool.

BlackRock Chief Executive Larry Fink has been blunt about the challenge. He has warned—including to officials in Washington—that the United States could simply run out of the electricians needed to build the data centers powering the AI revolution.

The numbers back him up. The trade group Associated Builders and Contractors estimates the country needs about 349,000 additional construction workers in 2026 just to keep up with demand, with even more needed next year. The Bureau of Labor Statistics projects roughly 81,000 electrician openings and 40,100 HVAC technician openings every year over the next decade. Many of those openings are being created because experienced workers are retiring faster than younger workers are entering the trades.

Hiring has become so difficult that staffing firm Randstad found it now takes about 56 days to fill an electrician or plumbing position—longer than it takes to hire many office workers.

That is the workforce gap BlackRock is trying to help close.

Its $25 million initiative is the next phase of a broader $100 million workforce effort known as Future Builders, operated through The BlackRock Foundation. The program will award grants ranging from $500,000 to $1 million to nonprofit organizations that provide hands-on training and career pathways into the skilled trades. The foundation hopes the initiative will help prepare 50,000 workers over the next five years.

“Skilled trades are essential to America,” said Arielle Gurman, who leads strategy for The BlackRock Foundation and oversees the Future Builders initiative. She said demand for trained workers continues to rise while too many people still lack access to quality training opportunities.

Applications opened June 1 and will remain open through July 10. A nonprofit workforce organization, Jobs for the Future, will help select grant recipients, with the first awards expected to be announced this fall.

The effort follows a separate $30 million BlackRock commitment in Texas announced last month that aims to train more than 12,000 workers for electrical and related skilled-trade careers.

BlackRock is not alone.

In April, Lowe’s announced a $250 million commitment through its foundation to help train 250,000 tradespeople by 2035. Chief Executive Marvin Ellison has repeatedly argued that while AI may transform many jobs, it cannot replace workers who install electrical systems, repair furnaces, or build homes.

Google has committed $15 million toward electrical workforce development programs. The Home Depot Foundation has pledged $10 million to support skilled-trade training. Television host Mike Rowe, best known for “Dirty Jobs,” is contributing another $10 million through his foundation to encourage more young people to pursue careers in the trades.

For workers, the economics are becoming increasingly attractive.

A fully trained electrician earns roughly $59.50 per hour, equivalent to more than $120,000 annually, often with strong benefits and without the burden of college debt. On some of the nation’s busiest AI data-center projects, electricians working significant overtime have reportedly earned between $240,000 and $280,000 per year.

For the first time in roughly half a century, government data shows that skilled-trade workers are now less likely to be unemployed than college graduates.

In the short term, $25 million will not eliminate a shortage measured in the hundreds of thousands. Skilled-trade training takes time, and the construction boom tied to AI, energy infrastructure, manufacturing, and housing is moving faster than training programs can produce workers.

But a larger shift is becoming clear. Some of the biggest names in finance, retail, and technology now view America’s shortage of mechanics, electricians, plumbers, and HVAC technicians as a major economic challenge—and they are increasingly willing to spend their own money to address it.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Stock futures moved higher before the opening bell Monday, June 8, as technology shares rebounded from last week’s steep selloff, while rising oil prices reflected continued instability in the Middle East. S&P 500 futures gained about 0.62%, Nasdaq 100 futures rose roughly 1.12%, and Dow Jones futures added about 0.14%.

The recovery follows a difficult Friday session in which the Nasdaq fell approximately 4%, driven largely by a sharp decline in semiconductor stocks that erased nearly $1 trillion in market value.

A major catalyst for Monday’s rebound was a decision by S&P Dow Jones Indices to add Marvell Technology and Flex to the S&P 500 Index, replacing Pool Corp. and The Campbell’s Company. The changes will take effect before trading begins on June 22.

The move is significant because index funds and exchange-traded funds that track the S&P 500 must purchase shares of newly added companies to match the benchmark. That often creates substantial demand regardless of broader market conditions.

Marvell Technology jumped about 7% in premarket trading, while Flex gained roughly 3%.

Marvell has been one of Wall Street’s strongest performers this year. The company’s shares have more than tripled in 2026 and surged roughly 29% last week alone, helped by growing investor enthusiasm surrounding artificial intelligence infrastructure. Interest intensified after Nvidia CEO Jensen Huang reportedly described Marvell as the “next trillion-dollar company.”

The broader semiconductor sector also participated in the rally. Micron Technology rose approximately 7.1%, while laser manufacturer IPG Photonics advanced about 8.2% in premarket trading.

Healthcare stocks also attracted attention. Eli Lilly moved higher after presenting late-stage clinical results for its experimental obesity treatment retatrutide at the American Diabetes Association conference in New Orleans. Analysts at William Blair described the drug as potentially belonging to a different class because of its potency. Investors are also looking ahead to Eli Lilly’s presentation at the Goldman Sachs Healthcare Conference on Tuesday.

Not every stock joined the rally. Roivant Sciences declined about 3.8%, Grocery Outlet fell roughly 3.3%, and insurer Progressive slipped about 2%.

Meanwhile, developments in the Middle East continued to influence markets.

West Texas Intermediate crude oil climbed above $93 per barrel, reversing losses from the previous two sessions after renewed tensions between Iran and Israel. Iran launched multiple rounds of missiles toward Israel over the weekend and warned against additional military activity in Lebanon.

Israel’s military said all incoming missiles were intercepted and reported no casualties.

Iran’s Foreign Ministry told CNBC that military operations had paused but warned that strikes could resume if Israeli actions in Lebanon continue. Traders remain focused on the Strait of Hormuz, which has been largely disrupted since February and normally handles a significant share of global oil shipments.

Adding another variable to energy markets, OPEC+ approved a July production increase of 188,000 barrels per day, though the supply boost has done little to offset concerns about regional instability.

Investors are also continuing to assess Friday’s stronger-than-expected employment report.

The U.S. Bureau of Labor Statistics reported that employers added 172,000 jobs in May, well above economist forecasts of approximately 85,000 jobs. April payroll growth was revised higher to 179,000 jobs. The unemployment rate remained at 4.3%, while average hourly earnings increased 0.3% for the month and 3.4% year-over-year.

The report arrives less than two weeks before the Federal Reserve’s June 16–17 policy meeting, the first chaired by Kevin Warsh since succeeding Jerome Powell in May.

Last week’s technology selloff began after Broadcom issued guidance that disappointed investors, sparking widespread selling across semiconductor stocks. Despite the reaction, UBS analyst Timothy Arcuri maintained a Buy rating on Broadcom while trimming his price target to $485 from $490.

What to Watch

With few major economic reports scheduled before the Federal Reserve meeting, investors are likely to focus on three key themes this week:

  • Whether the semiconductor rebound can continue.
  • Oil price movements tied to developments between Iran and Israel.
  • Corporate events, including the Goldman Sachs Healthcare Conference and the upcoming June 22 S&P 500 index reshuffle.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — One simple question hung over a House hearing room on Thursday: when an Amazon package lands on your porch, who actually employs the person who dropped it off? At a June 4 hearing of the House Subcommittee on Health, Employment, Labor, and Pensions, titled “Examining the Policies and Priorities of the NLRB,” lawmakers pressed Crystal Carey, the top lawyer at the National Labor Relations Board, over her decision to settle a case that could have answered that question in a way the company did not want.

Here is the background in plain terms. Amazon does not directly employ most of the drivers in its branded vans. It contracts with thousands of small companies it calls Delivery Service Partners, and those firms hire the drivers — hundreds of thousands of them, delivering millions of packages a day.

The dispute began under the Biden administration. Labor board investigators in California found that Amazon was a joint employer of drivers working for one such contractor, Battle-Tested Strategies, a former partner in Palmdale, California, whose drivers had organized with the Teamsters. Being ruled a joint employer would mean Amazon itself — not just the small contractor — is legally responsible for bargaining with the union and answering for working conditions.

Carey, whom President Trump appointed and who was sworn in in January, moved to settle the case instead. Under her proposed deal, Amazon would pay about two weeks’ wages to dozens of those drivers but would not have to admit wrongdoing or be declared a joint employer. The core question of who employs the drivers would be left unanswered.

There is also a conflict-of-interest question. Before joining the government, Carey was a partner at Morgan Lewis, a firm that has represented Amazon. Representative Ilhan Omar pressed her on whether she should have stepped aside. Carey said she was not required to recuse herself, telling lawmakers her old firm was not involved in this particular case and that more than a year had passed since she personally represented the company.

Why does this matter beyond one company? The joint-employer question reaches across the economy. Franchises, staffing agencies and gig platforms are all built on the idea that the big brand is not the legal employer of the workers who do the work. A finding that Amazon is the employer of its contract drivers could shake that entire model.

The settlement is not final. Administrative Law Judge Rebekah Ramirez must decide whether to accept it. If she does, the Teamsters are expected to appeal, potentially to the labor board in Washington and then to federal court. Separately, Amazon is pursuing a broader legal argument that the structure of the NLRB itself is unconstitutional.

The hearing was not only about Amazon. NLRB Chairman James Murphy and Carey both faced questions about a growing backlog of cases and years of tight funding at the agency that referees labor disputes.

For the driver in the Amazon van, the immediate stake is a couple of weeks’ pay. For the wider workforce, the real stake is the question the settlement leaves open — whether the country’s largest companies are responsible for the workers who power them, or whether a layer of contractors stands between those companies and the law.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Julie Su, New York City’s first deputy mayor for economic justice, said Mayor Zohran Mamdani’s administration is making it a priority to spread the city’s job growth across more industries, in comments reported Wednesday that acknowledged recent gains had been too concentrated. Su, who took the newly created post on March 1, called the task “an all-hands-on-deck moment.”

The data behind the concern is concrete. New York City added just 27,100 jobs in 2025, according to seasonally adjusted figures from the New York State Department of Labor, with losses across manufacturing, trade and transportation, retail, information, finance, professional and business services, leisure and hospitality, and government. The lone major source of gains was health care and social assistance, led by roughly 70,000 home health-care positions that rank among the lowest-paying jobs in the city.

The weakness carried into 2026. The office of New York City Comptroller Mark Levine reported that in the first three months of the year, the only sector with significant gains was health care and social assistance, up about 14,000 jobs, while transportation and warehousing, leisure and hospitality, and trade lost jobs. Over the prior 12 months, private-sector employment outside the health sector fell by about 13,000 jobs.

Unemployment has climbed as well. The Center for an Urban Future, a nonprofit research group, reported that private-sector job creation in 2025 fell 71% from 2024, and that the city’s unemployment rate stood at 5.6%, including 9.6% for Black New Yorkers as of December. The group described the rise as the largest increase since May 2020.

Mamdani, who took office on January 1, has moved fastest on the affordability agenda he campaigned on. He secured state funding for free childcare for 2-year-olds, named board members positioned to freeze rents on rent-regulated apartments, redesigned bus routes, and announced plans to open five city-run grocery stores. Those measures target the cost of living rather than job creation.

The administration has not yet named a permanent leader for the New York City Economic Development Corporation (NYCEDC), the roughly 500-person public authority that prior mayors used to attract private investment. The agency manages a large real-estate portfolio, runs the city’s ferry system, and helped drive projects including Hudson Yards, the new Yankee Stadium, and the High Line.

Su said the administration views making the city more affordable and livable as a way to keep workers and draw employers, and that robust, widely shared growth is central to its economic-justice goals. Aides said Mamdani recognizes he will need to work with the business community to address the city’s challenges.

Business leaders have raised concerns about Mamdani’s broader platform, which includes higher taxes on corporations and high earners to fund his programs. Critics warn the measures could push companies and wealthy residents out of the city, shrinking the tax base. Supporters argue affordability measures keep workers in place and money circulating in local neighborhoods.

The hospitality sector is a particular focus. The industry has lost roughly 4% of its workforce since 2020, and city officials said they are counting on two summer events—the World Cup and celebrations marking America’s 250th anniversary—to boost visitor spending.

The fiscal stakes are direct because the programs Mamdani has expanded depend on a growing tax base. State and city data and independent research all describe a labor market shedding jobs across most sectors while adding them mainly in lower-paying health-care roles. Administration officials said they intend to broaden growth but have not yet detailed a comprehensive jobs plan or filled the city’s top economic-development post.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

One of Wall Street’s most closely watched market-risk gauges has reached its highest level since the global financial crisis, prompting fresh warnings that investors may be underestimating how much risk has built up beneath the stock market’s powerful rally.

In a note released Friday, Citigroup told clients that global equity markets are displaying their frothiest conditions since 2008, though the bank stopped short of declaring that a bear market is imminent. The warning comes as stocks continue to trade near record highs despite rising interest-rate concerns, geopolitical tensions, and growing questions about whether the artificial-intelligence boom can justify today’s lofty valuations.

At the center of Citi’s caution is its proprietary Bear Market Checklist, a model that tracks conditions historically associated with major market downturns. The latest reading stands at 10 of 18 warning indicators globally, the highest since the financial crisis. The United States scored an even higher 11.5 out of 18, while Europe registered a comparatively modest 5 out of 18.

According to Citi strategist Beata Manthey, the significance is not merely the current score but what often happens next. Historically, once the checklist reaches double digits, warning signs tend to accumulate more quickly, increasing the likelihood that market conditions become increasingly fragile.

The concerns stem from several familiar themes.

Valuations across large segments of the market have climbed sharply, particularly among companies tied to artificial intelligence. Investor sentiment remains highly optimistic, corporate spending on AI infrastructure continues to surge, and the pace of initial public offerings and secondary stock offerings has accelerated.

Historically, those conditions have often appeared late in market cycles rather than early ones.

Citi is not the only major institution sounding a note of caution.

Bank of America strategist Michael Hartnett warned Friday that several market risks could challenge the rally in the coming weeks, while research firm BCA Research argued that the Federal Reserve may be underestimating inflationary pressures created by massive AI-related investment spending.

The common thread running through many of these warnings is artificial intelligence.

Over the past year, enthusiasm surrounding AI has driven billions of dollars into technology companies, semiconductor manufacturers, cloud-computing providers, and related industries. The rally has generated enormous gains for investors and pushed major stock indexes toward record territory.

But Friday provided a reminder of how quickly sentiment can shift.

Broadcom, one of the biggest beneficiaries of AI spending, reported quarterly revenue that surged 48% year-over-year to $22.2 billion. Yet the stock fell after investors judged the company’s outlook less impressive than expected. The decline contributed to a second consecutive session of weakness across semiconductor shares.

The market also faced pressure from a surprisingly strong May jobs report, which strengthened expectations that the Federal Reserve may keep interest rates elevated for longer than investors previously anticipated.

Higher interest rates tend to weigh most heavily on technology stocks because future earnings become less valuable when borrowing costs rise.

Despite the growing list of caution flags, Citi is not advising investors to abandon stocks.

The bank noted that several important indicators remain supportive. Credit markets, often viewed as an early warning system for broader financial stress, continue to show relatively healthy conditions. Corporate borrowing costs remain contained, and several risk measures remain below the levels that preceded past market crashes.

For perspective, Citi’s checklist reached approximately 17.5 out of 18 before the dot-com collapse and around 13 out of 18 before the 2008 financial crisis. While today’s reading is elevated, it has not yet reached those historic extremes.

That distinction helps explain why Citi continues to recommend buying market pullbacks rather than exiting the market entirely.

For everyday investors with retirement accounts, 401(k)s, and index funds, the message is less about panic and more about awareness. The market has enjoyed a powerful run fueled largely by optimism surrounding artificial intelligence and economic resilience. At the same time, professional investors are identifying an increasing number of conditions that have historically appeared before periods of heightened volatility.

Bull markets can remain strong longer than many expect. They can also change direction quickly.

The warning lights are flashing brighter than they have in nearly two decades. Whether they signal an approaching storm or simply a market that has become expensive remains one of Wall Street’s biggest unanswered questions.

This article is general business reporting and should not be considered investment advice. Investors should consult qualified financial professionals regarding individual financial decisions.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SpaceX Says It May Use Stock for Future Acquisitions as Record IPO Nears

SpaceX disclosed that it may issue a large amount of new stock to fund future deals, a provision contained in the amended registration statement the company filed with the Securities and Exchange Commission (SEC) that drew scrutiny this week as the company nears its stock market debut. In the risk-factors section covering acquisitions and strategic transactions, the filing states the company “may issue a significant amount of equity in connection with future transactions.”

The filing announces no new acquisition. According to the amended S-1/A, the language gives SpaceX flexibility to use its publicly traded Class A stock to pay for acquisitions, divestitures, and other moves after it goes public. The company filed confidentially with the SEC on April 1, made its full S-1 public on May 20, and filed its prospectus on June 1.

The clearest deal already on the books is SpaceX’s pending purchase of Cursor, an AI coding-assistant startup. The filing states the acquisition is expected to close after the IPO and will be paid entirely in Class A stock, putting Cursor’s implied equity value at $60 billion. Under a related compute agreement, the filing says Cursor is owed a $1.5 billion termination fee and an $8.5 billion deferred services fee, totaling $10 billion if the deal is canceled.

The disclosure follows a run of dealmaking. SpaceX completed an all-stock merger with xAI, Elon Musk’s artificial intelligence company, in February, folding the Grok model and the X platform into one structure at a combined valuation of about $1.25 trillion. The combined company now describes itself as an artificial intelligence services and infrastructure business rather than only a rocket maker.

The IPO is set to rank among the largest ever. The filing prices the offering at $135 a share across 555.6 million shares, for a raise of roughly $75 billion and a minimum valuation of $1.8 trillion, down from earlier internal discussion above $2 trillion. SpaceX has earmarked about $20 billion of the proceeds to repay debt tied to xAI and X. Trading is expected on the Nasdaq under the ticker SPCX.

The filing also sets aside 5% of the offering’s shares for a directed program. SpaceX said those shares may go to certain employees and to parties with business relationships, including the friends and families of its executive officers, and that the grants will not carry a lockup restriction. By contrast, the company said more than 60% of pre-IPO shares, including Musk’s, will be under an extended lockup.

The equity language drew comment from named investors who read it as a possible step toward a long-discussed combination of SpaceX and Tesla, Musk’s electric-vehicle maker. Gary Black, managing director of The Future Fund, wrote on the platform X that the filing strongly suggests more SpaceX stock will be issued and said it could be used to acquire Tesla. Black estimated such a deal could be about 28% dilutive to Tesla shareholders because SpaceX would likely carry a higher valuation. Tesla shares fell after the disclosure.

No filing confirms a Tesla transaction. Any such merger would face legal and regulatory hurdles and would likely require a Tesla shareholder vote. On the SpaceX side, Musk’s control runs through Class B shares carrying ten votes each, meaning a large dilution event would not threaten his voting power. Musk has publicly raised the idea of combining his companies for years.

For prospective buyers, the practical effect is that SpaceX has reserved the right to expand its share count substantially after listing, with the $60 billion Cursor deal the clearest near-term use of that authority. The offering is scheduled to be completed in the days ahead, and the amended filing represents one of the final regulatory steps before SpaceX begins trading.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Federal Reserve is heading into its June policy meeting more divided than it has been in years, and Friday’s stronger-than-expected jobs report only sharpened the debate over whether interest rates should move higher, lower, or remain exactly where they are.

What was once an internal policy disagreement has increasingly spilled into public view.

Federal Reserve Governor Michelle Bowman argued in recent remarks that raising rates to combat the current inflation surge may do more harm than good, contending that much of today’s inflation pressure stems from energy costs and tariffs rather than excessive consumer demand. In her view, higher rates cannot produce more oil or lower global energy prices, making additional tightening an ineffective response.

Others see the situation very differently.

Cleveland Federal Reserve President Beth Hammack has repeatedly emphasized the need to keep monetary policy restrictive until inflation clearly returns toward the Fed’s 2% target. Officials in that camp worry that easing too soon could reignite price pressures and undermine years of progress fighting inflation.

The disagreement became visible during the Federal Reserve’s late-April policy meeting. According to meeting records, officials were not merely debating timing—they were debating direction. One faction favored reducing rates, the majority preferred holding steady, while a more hawkish group resisted any language that might signal future easing.

Friday’s employment report strengthened the hawkish argument.

The Bureau of Labor Statistics reported that employers added 172,000 jobs in May, more than double economists’ expectations. The unemployment rate remained at 4.3%, while revisions boosted prior months’ hiring totals, suggesting the labor market remains healthier than previously believed.

For policymakers concerned about inflation, those numbers remove one of the strongest arguments for rate cuts.

The Federal Reserve traditionally lowers rates when economic growth weakens or unemployment rises sharply. Neither condition currently exists. Instead, the economy continues creating jobs at a pace that suggests underlying demand remains strong.

Meanwhile, inflation remains stubborn.

Consumer prices were running at roughly 3.8% annually through April, well above the Fed’s official target. Rising energy costs, amplified by ongoing Middle East tensions and elevated oil prices, have complicated the central bank’s effort to restore price stability.

Financial markets responded immediately to Friday’s report.

Interest-rate futures moved to reflect growing expectations that the Federal Reserve may keep rates elevated longer than previously anticipated, while some traders even began assigning meaningful odds to another rate increase before year-end. Treasury yields climbed and expectations for future easing continued to recede.

At the center of the debate is the Federal Reserve’s dual mandate.

The central bank is tasked with maintaining both stable prices and maximum employment. Normally, those goals move together. Today, they do not.

Inflation argues for tighter policy. Any future signs of labor-market weakness would argue for easier policy.

The challenge is determining which risk deserves greater attention.

That decision now falls to Federal Reserve Chairman Kevin Warsh, who will preside over his first policy meeting on June 16–17 after succeeding Jerome Powell in May.

Warsh enters the role facing a committee divided over the path forward, inflation that remains nearly double the Fed’s target, and a labor market that continues to surprise economists with its resilience.

How he manages those competing pressures will shape market expectations not only for June but for the remainder of 2026.

For consumers, the stakes are straightforward.

As long as the Federal Reserve remains focused on inflation, borrowing costs for mortgages, auto loans, credit cards, and business financing are likely to remain elevated. Earlier this year, investors widely expected multiple rate cuts in 2026. Today, the debate has shifted dramatically toward whether any meaningful relief arrives at all.

The next major test comes with next week’s inflation report. A hotter-than-expected reading could strengthen the case for keeping rates higher for longer. A cooler reading would give policymakers favoring rate cuts fresh ammunition.

Until then, America’s central bankers remain united on one point only: they are not united on where interest rates should go next.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Here is the puzzle: the Strait of Hormuz is shut, oil supply is tight, and prices are high — yet China, the world’s largest oil importer and Iran’s biggest customer, is buying less, not more. The reason is not mainly a sinking economy. It is that the war itself has made oil too expensive for Chinese buyers to use. In its monthly Oil Market Report released in May 2026, the International Energy Agency (IEA) said Chinese oil consumption is set to fall by 290,000 barrels per day this quarter, as soaring fuel prices choke off driving and a slump in the petrochemical sector deepens. Chinese pump prices for gasoline and diesel have jumped roughly 30% since the conflict began, sitting near all-time highs — and when fuel costs that much, people drive less and factories pull back.

That collapse in demand is now showing up in what Iran can charge. By Thursday, June 4, physical-market trade sources said Iranian Light crude was being offered at $0.50 to $1 per barrel below ICE Brent for June delivery into Shandong province, the eastern hub where most of China’s small private refiners operate. It was the first discount in two months. In April and May, the same grade had sold at premiums of $1 to $2 per barrel above the benchmark, back when buyers were scrambling for every barrel.

The refiners caught in the middle are the small independents known in the trade as teapots. They earn their living on the gap between what they pay for crude and what they get for the fuel they sell. With crude costs high from the war and Chinese fuel demand weak, that gap has gone negative for many of them. They now lose money on each extra barrel they process, so they have simply stopped buying.

Beijing made that retreat official. The National Development and Reform Commission, China’s state economic planner, issued notices in early June telling some money-losing refiners they may cut fuel output this month, as long as production stays at or above 80% of last year’s monthly average, trade sources and consultancies reported on Tuesday, June 2. For most of the spring, the same planner had pushed refiners to run flat-out to guarantee domestic supply during the war. Now it is letting them slow down because the country’s crude and fuel stockpiles are already comfortably high.

There is also a deeper, longer-running shift underneath the war. China’s appetite for road fuel has essentially peaked. Electric cars and LNG-powered trucks are replacing gasoline and diesel vehicles at scale, and the IEA expects total Chinese oil demand to grow just 50,000 barrels per day in 2026, down sharply from 220,000 the year before. So even before the conflict, the long-term demand engine was cooling.

Russia is feeling the same chill. The premium on ESPO, the most popular Russian grade among Chinese teapots, has slipped to $3 to $4 per barrel above ICE Brent for June delivery, down from $4 to $5 in May. Both Iran and Russia depend on Chinese teapots as buyers of last resort, since U.S. sanctions have shut them out of most other markets. When Chinese demand softens even a little, the two sanctioned exporters have nowhere else to send the oil, so they cut prices to move it.

That hands Beijing real leverage. China takes upward of 90% of Iran’s crude exports and imported close to 1.4 million barrels per day of Iranian oil in 2025. As the last large buyer of sanctioned barrels, it increasingly sets the price — and right now it is choosing to wait.

The business takeaway reaches well beyond Asia. China is the engine of global oil demand, and when that engine eases off, it is one of the few forces strong enough to cool prices at a moment when war headlines keep pushing them up. For American drivers and businesses that have watched pump prices and shipping costs stay high all spring, weaker Chinese buying works in the other direction, putting a quiet ceiling on how far oil can climb.

For Tehran, the discount stacks a revenue problem on top of a sanctions problem. Oil sales to China fund a large share of the Iranian government’s budget, and every dollar shaved off the price is money the regime never collects.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The week beginning Monday, June 8, 2026, could shape everything from interest rates and grocery bills to technology stocks and the future of space investing. Investors will be watching fresh inflation data, Apple’s Worldwide Developers Conference (WWDC), earnings from major artificial intelligence players, and the long-awaited public debut of Elon Musk’s SpaceX.

The week did not wait for Monday’s opening bell to get complicated. On Sunday night, June 7, U.S. stock futures fell after Israel’s military said Iran had fired missiles at it following escalating tensions in the region. Within hours, Asian markets opened sharply lower, led by a stunning selloff in South Korea.

The U.S. move itself was modest. Futures tied to the Dow Jones Industrial Average slipped about 80 points, or 0.2%, with S&P 500 and Nasdaq 100 futures each down roughly 0.2%. But overseas the reaction was more severe.

The benchmark Kospi in South Korea plunged about 8.4% at the open and briefly triggered a trading halt. While Middle East tensions added pressure, much of the selloff stemmed from weakness in semiconductor stocks. Broadcom’s latest outlook for its artificial-intelligence business disappointed investors, sending shockwaves through chip shares globally. Samsung Electronics and SK Hynix, which together account for a significant share of South Korea’s stock market value, both fell sharply.

Two domestic factors deepened the decline. Korean investors entered the week with margin debt near record levels, forcing automatic selling as prices fell. At the same time, Friday’s stronger-than-expected U.S. jobs report fueled expectations that the Federal Reserve could consider higher rates rather than lower ones. A weakening Korean won accelerated foreign outflows and intensified selling pressure.

Elsewhere, Japan’s Nikkei 225 fell more than 2%, while Hong Kong futures pointed lower. Traders will be closely watching oil prices after the latest developments between Israel and Iran, particularly any impact on shipping through the Strait of Hormuz, a critical route for global energy supplies.

For businesses and consumers alike, the biggest question this week remains whether inflation is finally cooling—or heating up again.

The U.S. Bureau of Labor Statistics is scheduled to release the Consumer Price Index (CPI) on Wednesday, June 10, at 8:30 a.m. Eastern, followed by the Producer Price Index (PPI) on Thursday. The reports arrive less than a week before the Federal Reserve’s June 16–17 meeting, where policymakers will decide whether interest rates remain unchanged.

The April CPI report showed prices rising 3.8% year-over-year, near the highest level in three years. Rising energy prices and ongoing disruptions tied to the conflict involving Iran have kept pressure on fuel costs, transportation, and consumer prices.

For households, the numbers matter because inflation directly affects everything from groceries and gasoline to mortgage rates and credit-card interest.

For businesses, the reports may influence borrowing costs, hiring decisions, and expansion plans heading into the second half of the year.

Markets enter the week on shaky footing.

The Nasdaq Composite suffered its worst daily decline in more than a year on Friday, June 5, led by a sharp selloff in semiconductor stocks. The drop came just one day after the Dow Jones Industrial Average closed at a record high above 51,500.

Jeremy Siegel, professor emeritus of finance at the Wharton School, said recent volatility suggests investors remain nervous about valuations and future Federal Reserve policy.

While inflation dominates the economic calendar, the week’s biggest corporate event belongs to Apple.

The company’s annual Worldwide Developers Conference (WWDC) opens Monday with a keynote presentation from Chief Executive Officer Tim Cook. The event carries unusual significance because it is expected to be Cook’s final WWDC keynote before leadership transitions to John Ternus later this year.

Apple is widely expected to unveil major artificial intelligence upgrades, including a rebuilt version of Siri, expanded AI features integrated throughout its ecosystem, and the introduction of iOS 27. The pressure on Apple is amplified by repeated delays to its next-generation Siri platform, first announced in 2024 but postponed several times since. Monday’s keynote is expected to be Apple’s clearest attempt yet to convince investors it can compete aggressively in the AI race.

Wall Street expectations are exceptionally high.

Apple shares surged roughly 15% during May and recently traded near record highs, valuing the company at approximately $4.6 trillion.

Dan Ives of Wedbush Securities maintained an Outperform rating and a $400 price target, calling the event a potential turning point for Apple’s AI strategy.

Erik Woodring of Morgan Stanley described WWDC as Apple’s most important catalyst of the year and outlined a bullish scenario approaching $440 per share.

Bank of America recently raised its target to $380, Evercore ISI lifted its forecast to $365, while Goldman Sachs remains positive with a target of $340.

Not everyone is convinced. UBS maintained a Neutral rating with a $296 target, reflecting concerns that investor expectations may have gotten ahead of reality.

The broader AI sector also faces a critical test this week.

Oracle reports earnings Wednesday after markets close.

Analysts expect earnings of approximately $1.96 per share on revenue near $19.1 billion. Under CEO Safra Catz, Oracle has transformed itself into a major supplier of cloud infrastructure supporting artificial intelligence applications.

The company has benefited from a wave of AI-related demand, with shares climbing more than 40% over the past three months.

Adobe follows Thursday.

Investors will be watching closely to determine whether the company’s AI-powered products are successfully converting users into paying customers. Adobe reported stronger-than-expected results last quarter, posting earnings of $6.06 per share and revenue of $6.4 billion, up 12% from the prior year.

Several well-known consumer-facing companies also report results this week.

Campbell’s and Vail Resorts report Monday.

Tuesday brings results from United Natural Foods, J.M. Smucker, Academy Sports & Outdoors, Casey’s General Stores, and Cracker Barrel.

Wednesday features earnings from Chewy, Core & Main, and Stitch Fix.

Thursday concludes with results from homebuilder Lennar, providing another snapshot of the housing market.

Meanwhile, Marvell Technology and Flex are scheduled to join the S&P 500 Index, replacing Pool Corporation and Campbell’s.

On the industrial front, Honeywell International will host an investor update Monday as it advances plans to separate portions of its business. Investors will be looking for revised sales forecasts, profit targets, and details regarding the company’s restructuring efforts.

The week’s most anticipated market event, however, arrives Friday.

SpaceX is expected to begin trading on the Nasdaq under the ticker SPCX following pricing Thursday evening.

The offering is targeting a valuation of approximately $1.75 trillion, potentially making it the largest initial public offering in history.

At that valuation, SpaceX would be worth more than Elon Musk’s electric-vehicle company Tesla, which currently trades near a $1.6 trillion market value. Following the offering, Musk is expected to retain approximately 82% of the company’s voting power, preserving firm control over the business despite its public listing.

The deal is being led by a syndicate of major banks including Morgan Stanley, Goldman Sachs, JPMorgan Chase, Bank of America, and Citigroup.

Much of the excitement centers on Starlink, SpaceX’s satellite internet business, which has grown into one of the world’s largest communications networks with more than 10 million customers.

While Starlink turned profitable last year, SpaceX as a whole reported a $4.9 billion loss in 2025 despite generating approximately $18.7 billion in revenue, reflecting continued heavy investment in launch systems, satellites, and future exploration programs.

If the offering prices as expected, Elon Musk is projected to become the world’s first trillionaire on paper. Unusually for a deal of this size, retail investors are expected to have access through platforms including Schwab, Fidelity, and Robinhood.

History suggests investors should expect significant volatility.

Highly anticipated technology IPOs often experience sharp first-day gains followed by equally dramatic swings in the weeks that follow.

Taken together, the coming week will offer a powerful snapshot of where the economy is headed.

Inflation reports will help determine whether consumers and businesses can expect relief from rising prices. Apple’s keynote will reveal whether one of the world’s most valuable companies can meet growing expectations in artificial intelligence. And SpaceX’s debut will test investor appetite for one of the most ambitious growth stories of the modern era.

By Friday’s closing bell, Wall Street—and Main Street—may have a much clearer picture of what lies ahead for the summer economy.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A powerful 7.8-magnitude earthquake struck off the southern Philippines early Monday, and the Philippine Institute of Volcanology and Seismology (PHIVOLCS) immediately urged people along the coast to move to higher ground. The Pacific Tsunami Warning Center warned that waves as high as 10 feet were possible on some Philippine coastlines, and tsunami alerts quickly spread across parts of Asia and the wider Pacific. The threat now hangs over one of the world’s most important food-export regions.

The quake hit at 7:37 a.m. local time, with its center about eight miles southwest of General Santos, a major city on the island of Mindanao, at a shallow depth of roughly six miles. Shallow quakes shake the surface harder than deeper ones, which raises the risk of damage. In the nearby town of Alabel, a police building cracked during a morning flag-raising ceremony, according to local authorities.

People often wonder why agencies report different sizes for the same quake, and that happened here. The German Research Centre for Geosciences (GFZ) first measured it at 8.2 before settling on 7.8, the figure most widely used. PHIVOLCS put it lower, at 7.0, while Indonesia’s BMKG seismology agency reported 7.7. These revisions are normal in the first hours, as more sensor data comes in.

The danger reached well beyond the Philippines. The Pacific Tsunami Warning Center said waves up to three feet were possible along some coasts of Indonesia and Malaysia, with smaller waves possible in Japan, Taiwan, Guam, Papua New Guinea, and other Pacific islands. PHIVOLCS cautioned that waves above one meter could keep arriving for several hours and told boat owners to secure vessels while ships at sea were advised to stay in deep water. As of early Monday, there were no immediate reports of major casualties, though power outages were reported in the affected area.

Here is why this particular spot on the map matters to businesses far from the Philippines.

General Santos, the city nearest the epicenter, is the heart of the country’s fishing industry and is known as the tuna capital of the Philippines. The city alone produces roughly 40% of the nation’s tuna, and its port, canneries, and cold-storage plants support more than 100,000 workers. About 200 metric tons of tuna land at the General Santos Fish Port every single day.

The Philippines is the world’s second-largest exporter of canned tuna after Thailand, and tuna ranks among its most valuable seafood exports, worth more than $1 billion annually, with Japan serving as the largest buyer. If the port, refrigeration plants, or local power grid go down even briefly, that disruption flows directly into grocery supply chains in the United States, Europe, and Japan, delaying shipments and raising costs.

The region’s economic weight runs far beyond seafood.

Mindanao is often called the country’s food basket, accounting for about 36% of Philippine farmland and 42% of national food trade. It supplies more than 90% of the country’s banana exports, a business worth approximately $1.2 billion in 2023 and large enough to make the Philippines the world’s third-largest banana exporter, behind Ecuador and Guatemala.

Major producers including Del Monte, Dole, Unifrutti, and TADECO operate plantations across the island. Mindanao also exports significant quantities of pineapples, coconuts, coffee, cacao, and palm oil. Much of that production moves on tight schedules to buyers in Japan, China, South Korea, and the Middle East.

Damage to roads, warehouses, ports, or power lines during the narrow window between harvest and shipment can quickly turn a local disaster into a global supply-chain problem.

There is a broader lesson behind events like this.

The Philippines sits on the Pacific Ring of Fire, the belt of fault lines and volcanoes responsible for most of the world’s earthquakes and volcanic activity. The country records more than 800 earthquakes each year, most too small to be felt.

That constant risk is why companies operating throughout Southeast Asia carry earthquake and business-interruption insurance, build to stricter engineering standards, and maintain backup power systems and contingency shipping plans. In a place like Mindanao, resilience is not simply good planning—it is a permanent cost of doing business.

What happens next depends largely on the sea.

If the waves remain near the lower end of forecasts, ports and processing facilities could return to normal operations within days. Stronger surges, or damage that has not yet been identified, would mean a longer and significantly more expensive recovery.

The first financial signals may come when Manila’s stock market and the Philippine peso open for trading and when global food buyers begin checking on shipments from the south. Authorities advised residents to remain on higher ground until the tsunami threat is formally lifted.

For consumers thousands of miles away, the connection may seem distant, but it is real.

A single morning tremor near a city most people have never heard of can ultimately affect the price of canned tuna or a box of bananas at the supermarket because so much of the world’s food moves through places exactly like this one.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump said the Federal Reserve has no good reason to raise interest rates, pushing back hard against a fast-growing belief on Wall Street that the central bank’s next move could be a hike instead of a cut. He made the comment in an interview on NBC’s “Meet the Press,” recorded Friday and broadcast Sunday, June 7. “There’s no reason to raise interest rates,” Trump said, calling any increase “the wrong thing to do.”

The timing is what gives the remark its weight. Trump spoke just over a week before the Federal Reserve’s next policy meeting on June 16–17 — the first to be led by Kevin Warsh, the new Fed chairman, who took over the job from Jerome Powell. It will be Warsh’s first meeting in charge, and the President is already making his preference loud and clear.

So why is anyone even talking about higher rates? Because the economy looks strong. On Friday, the Bureau of Labor Statistics reported that employers added 172,000 jobs in May, and it revised the two earlier months upward. A booming job market sounds like nothing but good news. The catch is that when the economy runs hot, prices can climb too, and the Fed’s main tool for cooling off inflation is to raise interest rates. That is why a strong report can spook markets rather than cheer them.

Trump rejects that thinking entirely. His argument is simple and plain-spoken: a country doing well should not be punished for it. “When a country is doing well, they shouldn’t be penalized by immediately raising interest rates,” he said. He also pointed to the size of the national debt and his plans to spend more, including on the military — all of which get more expensive when borrowing costs go up.

On the new man running the Fed, Trump struck a softer tone than he ever did with Powell, whom he spent years attacking. “Kevin is fantastic, and I want him to do whatever he wants,” Trump said of Warsh, adding that he does not want to lean on him. Still, the message underneath the praise was unmistakable: the President wants rates to stay where they are, or come down — not go up.

Markets are leaning the other way. After Friday’s jobs numbers, Treasury yields moved higher and bond prices fell, a sign that more traders now expect the Fed may have to raise rates to keep inflation in check. Goldman Sachs economists dropped their forecast for a rate cut this December and now expect any cuts to wait until 2027. For now, the Fed has kept its benchmark rate in a range of 3.5% to 3.75%, holding steady at its last several meetings rather than moving in either direction.

Here is why this tug-of-war reaches far past Washington. The Fed’s benchmark rate quietly sets the price of almost everything Americans borrow. When it goes up, mortgages get pricier, car loans cost more, credit card bills grow heavier, and small businesses pay more to fund payroll and inventory. When it holds or falls, that pressure eases. So a debate that sounds like inside-baseball between a President and a central banker actually lands on the kitchen table of nearly every household with a loan.

There is also a clear line worth keeping in mind. The President does not set interest rates. The Federal Reserve does, through a committee of officials who vote, and recent meetings have shown real disagreement among them. Trump can argue, praise, or pressure, but the decision on June 17 belongs to Warsh and his colleagues.

That makes the coming meeting the real test. Warsh built a reputation as someone wary of letting inflation run loose, which puts him in a tight spot: a strong economy pulling toward a possible hike on one side, and a President publicly urging him to stand down on the other. His first decision as chairman will tell Americans a great deal about which way the Fed leans for the rest of the year — and how much, or how little, the President’s words still move the people who actually control the cost of money.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

In a decision that could reshape the relationship between artificial intelligence companies and the news industry, British regulators have ordered Google to give publishers a way to prevent their articles from being used in the company’s AI-generated search features while still remaining visible in traditional search results.

The ruling, announced by the United Kingdom Competition and Markets Authority (CMA), is being described by regulators as a first-of-its-kind requirement aimed at giving news organizations more control over how their content is used by artificial intelligence systems.

Under the order, Google must provide publishers with effective tools that allow them to opt out of having their content used for products such as AI Overviews and other generative AI search features. Crucially, publishers who choose to block AI access cannot be penalized by losing visibility in Google’s standard search rankings.

That distinction is at the heart of the dispute.

For years, publishers have relied on search engines to drive traffic to their websites. As Google increasingly places AI-generated summaries at the top of search results, many news organizations argue that users are receiving answers without ever visiting the original source.

When readers stop clicking through, publishers lose advertising impressions, subscription opportunities, and other revenue that supports the reporting itself.

The CMA said its intervention was driven by concerns that publishers were being forced into an unfair choice: allow their content to be used for AI training and summaries or risk losing visibility on the world’s dominant search platform.

Google’s influence gives the issue unusual weight.

The company handles more than 90% of online searches in the United Kingdom, making it one of the most powerful gateways between publishers and readers. British regulators previously designated Google as a strategic digital platform under the country’s new competition framework, giving the CMA expanded authority to impose remedies designed to promote competition and fairness.

According to the regulator, the new requirement is intended to provide publishers with “fair treatment, greater transparency, and meaningful choice” as AI becomes increasingly integrated into search.

Google responded cautiously, saying it is continuing to work with regulators and website owners to ensure publishers have the tools they need as search evolves.

The company has consistently argued that AI-generated search features help users discover information more efficiently and can ultimately drive engagement with content creators. Many publishers, however, contend that traffic losses since the introduction of AI summaries tell a different story.

The timing is significant.

Google has accelerated its push into AI-powered search throughout 2026, introducing expanded AI features designed to provide more direct answers and reduce the need for users to navigate multiple websites. Regulators specifically noted that the new requirements are intended to apply not only to existing AI products but also to future AI search developments.

For the news industry, the decision represents a potentially important precedent.

Publishers worldwide have struggled to determine how to protect the value of their journalism as AI systems increasingly summarize, analyze, and distribute information created by others. Similar debates are taking place in the United States, Canada, Australia, the European Union, and Japan, where policymakers are weighing whether technology companies should compensate publishers or obtain additional permissions before using their content.

The broader issue extends far beyond Google.

As AI-powered chatbots, search engines, and virtual assistants become primary sources of information, a fundamental question is emerging: who should benefit economically when artificial intelligence relies on content created by journalists, researchers, authors, and other publishers?

For much of the internet era, publishers accepted that search engines would display headlines and snippets in exchange for traffic. AI-generated answers are changing that bargain by providing complete responses directly to users.

Britain’s decision marks one of the strongest regulatory efforts yet to address that shift.

Whether other governments adopt similar rules remains uncertain, but the move is likely to be closely watched by publishers, technology companies, and regulators around the world. If successful, it could become a model for how countries balance innovation in artificial intelligence with the economic realities of producing original journalism.

The outcome may help determine not only the future of online news, but also how the broader AI economy compensates the creators whose work powers it.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

On Wednesday, June 3, SpaceX filed the terms of its public stock offering with the Securities and Exchange Commission, setting a fixed price of $135 a share in an amended registration statement. That one number, sitting inside a legal document, is about to do something no number in history has ever done. Elon Musk is about to become the world’s first trillionaire.

The filing prices SpaceX at about $1.77 trillion. When the company is set to begin trading on the Nasdaq on June 12 under the ticker SPCX, Musk’s personal fortune — about $835 billion as of early June, according to Forbes, though Bloomberg’s more conservative count runs lower — is expected to cross $1 trillion for the first time. The next richest person on Earth, Larry Page, sits at roughly $298 billion. That is not a close race. That is one runner finishing the marathon while everyone else is still tying their shoes.

One caution before the celebration: these are the offering’s stated terms, not final numbers. The price and valuation only become official when shares are priced the evening of June 11. Until then, the trillion-dollar milestone is a strong projection, not a done deal.

Still, it is worth stopping to ask a simple question that almost nobody can answer honestly: how much money is a trillion dollars, really?

Here is the surprise. A trillion is so much larger than a billion that your brain quietly treats them as cousins. They are not cousins. They are barely related.

Start with time, because time is something everyone understands. Imagine counting one number every second. A million seconds would take you about 11½ days. A billion seconds would take almost 32 years — a real chunk of a human life. A trillion seconds? About 31,700 years.

Now try spending instead of counting. Say you had a trillion dollars and you set out to spend $1 million every single day — a million gone by bedtime, every day, no days off. You would not run out this year. You would not run out this century. It would take you roughly 2,740 years to spend it all. You would have started during the Roman Republic and you would still be writing checks today.

Or picture the cash itself. Take a trillion one-dollar bills and lay them end to end. That line of money would stretch about 97 million miles. The sun is about 93 million miles from Earth. So a trillion dollar bills, laid in a row, would reach the sun — and keep going.

One more way to feel it. A trillion dollars is larger than the entire yearly economic output of almost every country on the planet. Only about 18 nations produce more than a trillion dollars of goods and services in a whole year. In other words, one person is about to hold paper wealth roughly the size of a midsize country’s entire economy.

Put it in paychecks, the way most people actually experience money. Say you earn $50,000 a year — a solid, ordinary salary. It would take the entire yearly pay of 20 million workers — more people than live in the whole state of New York — just to add up to $1 trillion in a single year. Stretch it across a lifetime instead: a person earning $50,000 every year for a 40-year career takes home about $2 million in total. You would need the entire working lives of roughly 500,000 people — every paycheck, start to finish — to reach a trillion dollars.

Now think about what that money could feed. The United Nations World Food Programme says that in some of its operations, about $1 can provide enough assistance to help feed two people for a day. Using that benchmark, $1 trillion could fund an extraordinary amount of food assistance worldwide. The World Food Programme has also estimated that ending severe global hunger would require tens of billions of dollars annually, meaning a trillion dollars would cover many years of such funding.

So why does this matter for everyday business, and not just for billionaire scorekeeping? Because SpaceX going public is one of the biggest money events of the year. At $1.77 trillion, the company would instantly rank among the largest in the United States — worth more than Tesla, Musk’s own car company, which trades at about $1.6 trillion. The offering aims to raise about $75 billion, which would be the largest stock-market debut ever. Goldman Sachs and Morgan Stanley are leading the deal.

And ordinary people are part of this one. SpaceX has signaled that regular investors will be able to buy shares through everyday platforms like Schwab, Fidelity, Robinhood, and SoFi. That is unusual. Most history-making deals are carved up among big institutions first. This one is being handed, in part, to the public.

Here is the honest part, though, and it separates the headline from the reality. A “trillionaire” is not a man with a trillion dollars in a bank account. Almost all of Musk’s wealth is stock — mostly in SpaceX and Tesla — and stock prices move. His net worth can rise or fall by tens of billions of dollars in a single day. The trillion-dollar moment is real, but it is a snapshot, not a savings balance. If the SpaceX shares trade below $135 once the bell rings, the milestone could slip away as fast as it arrived.

So enjoy the number for what it is — a genuine first in human history. Just remember what it actually measures. Not a pile of cash reaching the sun, but a bet by millions of buyers on what one man’s companies might be worth tomorrow.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump said on Sunday, June 7, that Iran’s missile attack on Israel had damaged peace talks at the worst possible moment — just as, by his account, the two sides were ready to sign. The attack occurred earlier Sunday, when the Israel Defense Forces said it detected missiles launched from Iran toward Israel and activated air-defense systems to intercept them.

In an interview with Fox News chief foreign correspondent Trey Yingst, Trump said the strike would not help the negotiations.

Then he put a timeline on the table. Trump said the sides were very close and that an agreement could be signed Monday, Tuesday or Wednesday of the coming week — until the missiles flew. His message to Tehran was blunt: enough with the missiles, get back to the table and make a deal.

It was a careful balancing act. Trump also faulted Israel’s strikes on Beirut on Sunday, saying he was not happy about them. In other words, he leaned on both sides at once — pressing Iran to stop firing and warning Israel to ease off — because what he wants now is a signature, not a wider war. For American businesses, that posture is the most important signal of the day.

What Triggered It

The attack came earlier Sunday. The Israel Defense Forces said it identified missiles launched from Iran toward Israel and activated air defenses after the Israeli military struck Iran-backed Hezbollah positions in the southern suburbs of Beirut over the weekend.

Iran’s Islamic Revolutionary Guard Corps called the launches a warning and hinted a larger response could follow, according to Reuters. Iran’s parliament speaker, Mohammad-Bagher Ghalibaf, said the Beirut strikes and the U.S. blockade of Iranian ports could draw retaliation.

Why a Deal — or No Deal — Lands at the Pump

Here is why a presidential prediction about a signing date reaches the corner gas station. The war runs straight through the world’s most important oil passage. The Strait of Hormuz carried roughly 20% of the world’s oil before the fighting, and Iran has blockaded it since early March, forcing tankers to seek permission to pass or risk attack. About 20 million barrels a day moved through the strait before the war; analysts at ING estimated in late April that some 14 million barrels a day of supply was being choked off.

That bottleneck stacked a war premium onto fuel. Oil has jumped more than 30% since the United States and Israel struck Iran on February 28.

Prices had started to cool as a deal looked near. Brent crude, the global benchmark, slid to about $92.56 a barrel at the end of May — down nearly 19% on the month, its worst stretch since the Covid-19 pandemic. Then the Gulf flared again. By early June, Brent had climbed back to roughly $97.05, while West Texas Intermediate reached about $94.77, both at one-week highs.

So the math is simple for households. If Trump lands the deal he is promising this week, the blockade could loosen and pump prices could slide into summer. If the missiles keep flying, the premium stays — and it feeds straight into gasoline, trucking, groceries and almost everything that moves by road.

Shoppers are already adjusting. In a report dated Sunday morning, The Associated Press described Americans leaving gas tanks unfilled and trimming extras as retailers watch customers pull back.

The strain runs deeper than crude. ING noted that diesel-type gasoil and jet fuel prices were up roughly 102% and 120% on the year, a squeeze that erased an estimated 1.6 million barrels a day of demand as airlines canceled flights and factories slowed down. Higher jet fuel hits ticket prices; higher diesel hits every delivery truck. The cost lands on companies first and customers next.

The Pressure Back Home

Trump’s rush to sign also answers a Congress that has grown uneasy with the war. The House of Representatives passed a resolution last week urging him to withdraw U.S. forces or get congressional approval to keep fighting. A finished deal would quiet that fight and let him claim he ended the conflict without sending in ground troops.

Meanwhile, the disruption keeps spreading. The war has tangled global travel and trade, grounded flights across the region, and pushed ships to reroute away from the Strait of Hormuz and the Red Sea.

That leaves the week ahead as the test. A signed agreement in the next few days would begin to unwind the oil premium that has squeezed American wallets for three months. Another barrage, and the squeeze holds — right as families gas up for summer.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

In an amended prospectus filed with the Securities and Exchange Commission on June 1, Space Exploration Technologies Corp., better known as SpaceX, disclosed that it will reserve up to 5% of the shares in its upcoming stock offering for employees and for friends and family of senior executives.

The disclosure marks the first time the company has publicly detailed the size of its directed-share program.

For thousands of SpaceX employees who spent years accepting lower cash compensation in exchange for company stock, the announcement brings a long-awaited moment within reach.

SpaceX has set a fixed offering price of $135 per share and plans to sell approximately 555.6 million shares, raising roughly $75 billion.

At that valuation, Elon Musk’s rocket and satellite company would be worth approximately $1.77 trillion, making it the seventh-largest company in America and larger than Tesla by market value.

The stock is expected to trade on the Nasdaq under the ticker SPCX.

The timeline is moving quickly.

The company began its investor roadshow on June 4, plans to price the offering on June 11, and expects shares to begin trading on June 12.

If completed as planned, the transaction would become the largest stock-market debut in history, surpassing the 2019 Saudi Aramco offering.

The Payoff for Employees

For many SpaceX workers, the IPO represents more than a corporate milestone.

It is the event that finally allows years of stock compensation to become liquid.

SpaceX has long been known for paying below-market cash salaries relative to some competitors while compensating key talent through stock awards, particularly engineers and technical specialists.

Most of those awards were granted as restricted stock units (RSUs) that vest over time, typically across three to five years of employment.

Once vested, employees own the shares outright. What many lacked until now was a public market in which to sell them.

The IPO changes that.

Earlier this year, SpaceX also adjusted certain vesting provisions to allow employees to access and sell a larger portion of their holdings sooner, a move widely viewed as a response to employee concerns about turning paper wealth into real cash.

A Rare Benefit

The directed-share program contains an unusual feature.

According to the filing, employees, friends, and family participating in the allocation program will not be subject to a traditional IPO lock-up period.

Most newly public companies prohibit insiders from selling shares for several months after an IPO.

SpaceX’s program would allow eligible participants significantly more flexibility.

Morgan Stanley, one of the lead underwriters, is administering the directed-share offering.

The Biggest Winners

While thousands of employees stand to benefit, some of the largest gains are concentrated among senior leadership and early insiders.

Holdings owned by Chief Operating Officer Gwynne Shotwell and Chief Financial Officer Bret Johnsen are each expected to be worth more than $1 billion at the offering valuation.

Board member Antonio Gracias, founder of Valor Equity Partners, owns approximately 503 million shares, a stake valued at more than $70 billion.

Director Luke Nosek holds shares worth roughly $5 billion.

Musk remains firmly in command.

Following the offering, he is expected to retain more than 82% of SpaceX’s voting power, preserving effective control of the company.

The Tax Surprise

For employees, the biggest challenge may not be deciding whether to sell.

It may be taxes.

Restricted stock is generally taxed as ordinary income when it vests, regardless of whether the employee immediately sells the shares.

Financial advisers have spent months warning SpaceX employees to coordinate vesting schedules with opportunities to sell stock so they do not face large tax obligations without sufficient liquidity.

Standard withholding rates—typically 22% and 37% on income above $1 million—often fail to cover the full tax burden for high earners.

In some cases, employees could face tax shortfalls worth hundreds of thousands of dollars.

Not Everyone Agrees on the Valuation

The IPO’s enormous valuation has also drawn skepticism.

SpaceX reported a net loss of approximately $4.94 billion in 2025, reversing a profitable performance in 2024, and disclosed an accumulated deficit of roughly $41.3 billion.

Research firm Morningstar estimates the company’s fair value at approximately $780 billion, well below the roughly $1.75 trillion valuation implied by the offering.

For employees deciding whether to hold or sell, that difference matters.

History shows that many highly anticipated technology IPOs experience sharp pullbacks after their initial surge, with some giving back 20% to 40% of their gains within the first few months.

For a workforce that spent years accepting stock in place of larger paychecks, June 12 could become one of the most consequential days in company history.

After years of betting on Elon Musk’s vision, employees are about to learn what that bet is worth.

JBizNews Desk — Markets & Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For the first time in years, many American workers are seeing something they have not experienced since the inflation surge of 2022: paychecks that are growing more slowly than the cost of living. Wages are still rising, but prices are rising faster, meaning the average worker’s purchasing power is shrinking rather than expanding.

The latest figures from the U.S. Bureau of Labor Statistics highlight the challenge. Average hourly earnings rose 3.4% over the past year, reaching $37.53 per hour. At the same time, consumer prices increased 3.8% annually through April, marking the fastest inflation rate since May 2023.

The difference may seem small, but its impact is significant. When inflation outpaces wage growth, workers effectively receive a pay cut in real terms, even if their paycheck is larger than it was a year ago.

The government’s own inflation-adjusted data reflects that reality. Real average hourly earnings fell 0.5% in April and were down 0.3% from a year earlier, ending a period during which wage gains had generally stayed ahead of inflation.

For households, the squeeze is most visible in everyday necessities.

Energy prices have been one of the biggest drivers. Higher oil prices tied to ongoing Middle East tensions pushed overall energy costs sharply higher during the spring. Gasoline, home heating fuels, and transportation costs all increased, creating ripple effects throughout the economy because nearly every product must be manufactured, transported, or delivered using energy.

Food costs have added another layer of pressure.

Consumers have seen noticeable increases in grocery bills, particularly for proteins and other staple items. Beef prices have climbed substantially over the past year, while food-at-home inflation posted some of its strongest monthly increases in nearly two years. Unlike discretionary purchases, food and fuel are expenses families cannot easily avoid, making those increases especially painful.

The challenge extends beyond groceries and gasoline.

So-called core inflation, which excludes food and energy, remains elevated because of persistent increases in housing, insurance, medical services, and other everyday expenses. Rent and shelter costs continue to consume a growing share of household budgets, particularly in major metropolitan areas.

Economists note that inflation had been steadily cooling before renewed energy pressures emerged earlier this year. Progress toward the Federal Reserve’s 2% inflation target appeared encouraging through much of late 2025 and early 2026. However, rising oil prices and supply-chain pressures reversed some of that improvement.

The effects reach beyond individual households.

When consumers feel financially stretched, they often become more cautious with spending. Retailers, restaurants, and consumer-facing businesses frequently see that behavior first as shoppers delay purchases, seek discounts, or switch to lower-cost alternatives. Several major retailers have already reported that even middle- and higher-income consumers are becoming more price sensitive.

The broader economy can feel the impact as well. Consumer spending accounts for roughly two-thirds of U.S. economic activity, making household purchasing power one of the most important drivers of growth.

Relief may not come quickly.

Economists expect energy prices to remain a key factor in upcoming inflation reports, and the Federal Reserve continues to face a difficult balancing act. Cutting interest rates could help reduce borrowing costs but might also risk reigniting inflation. Keeping rates elevated could help contain prices but would leave consumers facing higher costs for mortgages, auto loans, and credit cards.

For now, the reality is simple: a raise does not automatically mean a higher standard of living. When prices rise faster than wages, households feel poorer even as paychecks grow.

That helps explain why many Americans continue to express frustration about the economy despite a healthy job market and steady hiring. Employment remains strong, but for millions of workers, the real measure of economic success is whether a paycheck buys more than it did a year ago. Right now, for many families, the answer is no.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump announced Thursday from the Oval Office that his administration will steer nearly $700 million in federal money into the U.S. coal industry, invoking a Cold War-era law to fund power plants, new facilities and coal-export infrastructure. Speaking around 3:20 p.m. Eastern, Trump said the goal was “to bring down the price of energy and the cost of living for all Americans with the power of clean, beautiful coal.” He was joined by Interior Secretary Doug Burgum, Energy Secretary Chris Wright and Environmental Protection Agency Administrator Lee Zeldin.

The funding comes through a combination of authorities that include the Defense Production Act, a 1950 law that allows presidents to support industries deemed vital to national security. The administration argues coal qualifies because the electric grid is facing growing pressure from rising electricity demand, including the rapid expansion of artificial-intelligence data centers, while higher global energy costs continue to affect consumers and businesses.

The largest portion of the package, approximately $425 million, will be used to upgrade 13 existing coal-fired power plants across multiple states, including West Virginia, Kentucky, North Carolina, Indiana, Tennessee, Arkansas, Arizona, Oklahoma, North Dakota and Wisconsin. Administration officials say the upgrades are intended to extend the operating life of the facilities and improve grid reliability.

Another portion of the funding is expected to support coal-export infrastructure, while roughly $200 million in Department of Energy grants will help finance two new coal-generation projects and the restart of a previously shuttered facility. According to administration officials, the effort is designed to preserve domestic coal production capacity and maintain dispatchable power generation that can operate regardless of weather conditions.

The White House estimates the initiative will help support 14 power plants, 42 coal mines, and approximately 12,500 jobs tied directly or indirectly to the coal industry.

Investors reacted positively to the announcement.

Peabody Energy rose about 3.7%, extending a rally that has lifted shares more than 30% from recent lows. Core Natural Resources, created through the merger of Arch Resources and CONSOL Energy, gained roughly 2.6%. Alliance Resource Partners added about 2.3%, while Alpha Metallurgical Resources and Warrior Met Coal also moved higher.

The broader coal sector outperformed the overall market, with coal-focused exchange-traded funds advancing more than 2% while the S&P 500 posted more modest gains.

Utilities that consume coal saw a more muted reaction. Shares of Duke Energy, American Electric Power, and other major utility operators posted only modest increases. Transportation companies could also benefit if coal shipments rise, particularly railroads such as CSX and Norfolk Southern, which move significant volumes of coal throughout the United States.

The industry’s financial picture remains mixed.

Core Natural Resources recently reported first-quarter net income of approximately $21 million on revenue of about $1.1 billion, supported by stronger metallurgical coal prices and steady production. Peabody Energy, meanwhile, reported a quarterly loss as lower coal prices and reduced shipment volumes weighed on earnings.

Supporters of the plan argue that coal remains an essential part of maintaining grid reliability.

Energy Secretary Chris Wright has repeatedly described coal, natural gas and nuclear power as the backbone of the U.S. electric system, particularly as electricity demand accelerates. Industry groups and elected officials from major coal-producing states contend that maintaining domestic coal capacity provides both economic and energy-security benefits.

Critics argue the funding represents a costly effort to support a sector that has steadily lost market share over the past decade. Coal generated roughly 45% of U.S. electricity in 2010, but by 2024 its share had fallen to approximately 15% as utilities increasingly shifted toward natural gas, solar, wind and battery-storage projects.

Environmental organizations also point to studies suggesting many existing coal plants cost more to operate than newer renewable-energy alternatives. They argue market forces, rather than government intervention, have largely driven coal’s decline.

The administration counters that reliability—not just cost—must remain a central consideration as electricity demand climbs. Federal officials have increasingly pointed to the enormous power requirements of artificial-intelligence infrastructure, advanced manufacturing facilities and data centers as reasons to maintain a diverse energy mix.

For consumers and businesses, the ultimate question is whether the investment will translate into more reliable electricity and lower energy costs—or whether taxpayers will ultimately shoulder the cost of extending the life of an industry facing long-term economic challenges.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

American employers are announcing layoffs at the fastest pace for the month of May since the pandemic, and retailers remain under growing pressure as consumers pull back on spending and companies rethink how many workers and stores they need.

According to data released Thursday by Challenger, Gray & Christmas, U.S. employers announced 97,006 job cuts in May, a 16% increase from April and the highest total for the month of May since 2020, when much of the economy was shut down during the COVID-19 crisis.

The increase marks the third consecutive monthly rise in announced layoffs and reflects a labor market that remains stable on the surface but is becoming increasingly cautious underneath.

The largest source of cuts this year has been technology, where companies are restructuring around artificial intelligence. Challenger reported that AI-related restructuring accounted for 38,579 announced job cuts in May, the highest monthly total ever attributed to the technology and roughly 40% of all announced layoffs during the month.

The technology sector alone announced 38,242 cuts, underscoring how rapidly companies are reorganizing operations around automation and AI-powered tools.

But retail is facing a different problem.

While technology firms are reducing staff to improve efficiency, retailers are cutting jobs because customers are becoming more selective about how they spend their money.

Major chains have announced thousands of layoffs this year as they respond to slower sales, store closures, and changing consumer behavior. Macy’s, which has been shrinking its store footprint and restructuring operations, has announced some of the largest retail workforce reductions of the year.

The challenges extend beyond traditional department stores.

Even premium brands are beginning to feel the effects of a more cautious consumer. Analysts have recently warned that several major apparel retailers could face slower growth as shoppers prioritize essentials and delay discretionary purchases.

The pressure comes at a difficult time for households.

Inflation continues to outpace wage growth, meaning many consumers have less purchasing power despite receiving raises. Rising costs for groceries, fuel, housing, insurance, and other necessities leave less room in household budgets for clothing, home goods, electronics, and other nonessential purchases.

That shift is showing up across the retail industry.

Companies report that shoppers are increasingly searching for discounts, buying fewer items, and trading down to lower-priced alternatives. Even higher-income consumers are becoming more value-conscious, a trend that retailers say has accelerated throughout the spring.

When spending slows, retailers often respond by reducing inventory, closing underperforming stores, and trimming payroll costs.

The current wave of cuts follows an already difficult period for the sector. Retailers announced nearly 93,000 job reductions during 2025, as companies struggled with changing shopping habits, e-commerce competition, inflation pressures, and uncertainty surrounding tariffs and supply chains.

This year’s reductions are building on top of those earlier efforts rather than replacing them.

There is some reason for caution before declaring a broader labor-market downturn.

Overall announced layoffs in 2026 remain below last year’s pace, although that comparison is influenced by unusually large workforce reductions in the federal government during 2025. Excluding those cuts, layoff activity today looks much closer to levels seen in 2024.

That suggests the economy is not experiencing a widespread employment crisis.

Instead, the weakness appears concentrated in sectors most dependent on consumer spending and industries undergoing rapid technological change.

For workers in retail, distribution, logistics, and related industries, however, the distinction may offer little comfort.

Their employment prospects remain closely tied to the willingness of American consumers to spend. As long as inflation continues to strain household budgets and shoppers remain cautious, retailers are likely to remain focused on cutting costs rather than expanding payrolls.

The result is a labor market that remains strong in headline numbers but increasingly fragile for workers whose jobs depend on consumer confidence.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The United States is now spending so much to cover the interest on its debt that the cost has quietly become one of the largest items in the entire federal budget. According to the Congressional Budget Office, the Treasury spent about $628 billion simply paying interest on the national debt in the first seven months of this fiscal year, figures released in early May show. That works out to nearly $3 billion a day. Over that stretch, interest cost the government more than it spent on Medicare or Medicaid and trailed only Social Security as a category of federal spending.

The numbers behind that figure are staggering in scale.

Total federal debt is closing in on $39 trillion. The portion held by the public — the part the government actively borrows in financial markets — stands at roughly $31 trillion, an amount about equal to the size of the entire U.S. economy. For the first time outside a major war, the country owes nearly as much as it produces in a year.

Two forces explain why the interest bill has exploded.

The first is simply that the debt grew enormous, the result of years of deficits running between $1 trillion and $2 trillion annually. The second is that interest rates climbed. After a long stretch of near-zero rates, the yield on the 10-year Treasury note has averaged above 4% since 2023.

That combination matters in a way many people miss: each time older, cheap debt comes due, the government has to refinance it at today’s higher rates. So even if Washington stopped adding new debt tomorrow, the interest cost would keep rising as low-rate borrowing from years past gets replaced with expensive new borrowing.

The trajectory is steep.

The Congressional Budget Office projects that net interest payments will roughly double, from about $1 trillion in 2026 to $2.1 trillion by 2036, making interest the fastest-growing part of the federal budget. The agency expects this year’s deficit to reach about $1.9 trillion, equal to 5.8% of the economy. It also projects that federal debt held by the public will climb from about 101% of GDP this year to 120% by 2036, surpassing the previous record of 106% set just after World War II in 1946.

The practical consequence is that interest payments leave less room for everything else the government does.

Money spent servicing past borrowing cannot be used for defense, infrastructure, research, or other priorities. Interest costs are now approaching the size of the nation’s defense budget and are projected to exceed it in the years ahead. By some forecasts, interest payments will eventually surpass all discretionary spending — the portion of the budget Congress appropriates each year.

The effects reach households as well.

Because government borrowing costs help anchor rates throughout the economy, persistently large deficits can contribute to higher mortgage rates, more expensive car loans, and increased borrowing costs for businesses and consumers alike.

In the short term, the picture looks slightly less alarming than the headline numbers suggest.

This year’s deficit has been running somewhat smaller than last year’s at the same point, helped in part by stronger tax collections and tariff revenue. But that is mostly short-term noise. The deeper story runs the other direction. An aging population continues to push up the cost of Social Security and Medicare, deficits remain historically large even during a healthy economy, and interest rates show little sign of returning to the ultra-low levels that prevailed for much of the last decade.

Budget watchdogs have become increasingly blunt.

Maya MacGuineas, president of the Committee for a Responsible Federal Budget, has warned that the nation’s current fiscal path “cannot be sustainable.” The Congressional Budget Office estimates that the 2025 tax-and-spending law widened projected deficits by roughly $4.7 trillion over the next decade. Meanwhile, the trust funds supporting Social Security and Medicare are projected to face insolvency in the early 2030s, potentially triggering automatic benefit reductions unless lawmakers act.

What makes the debt difficult to grasp is that it is not the kind of problem that arrives on a single dramatic day.

There is no moment when the bill suddenly comes due. Instead, the burden builds slowly and quietly, year after year, narrowing the government’s options as a growing share of every tax dollar goes simply toward paying for borrowing already undertaken.

The bill for decades of deficits has now become one of the largest expenses in the federal budget.

For now, financial markets continue to purchase U.S. Treasury debt readily, and the dollar remains the world’s primary reserve currency, allowing the United States to borrow on a scale few other nations could sustain.

The long-term question is whether that confidence holds as the debt continues to climb.

Absent action from Congress to alter the trajectory, the mathematics point in one direction: the interest bill only grows from here.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK— Americans are quietly eating less, and it’s starting to show up on the books of the country’s biggest food companies. The cause isn’t a recession or the latest diet fad. It’s a class of weight-loss drugs—Ozempic, Wegovy, Mounjaro, and Zepbound—that switch off hunger. About one in eight U.S. adults now takes one, and this spring the first cheap, easy-to-swallow pill versions reached pharmacy shelves.

Wall Street is already doing the math on the fallout. J.P. Morgan projects these drugs could erase $30 billion to $55 billion in annual U.S. food and beverage sales by the early 2030s, as users take in about 21% fewer calories and spend roughly 31% less at the grocery store.

Here’s why that number is so big.

The drugs were built to treat diabetes, but they also quiet the brain’s hunger signals, so people feel full sooner and snack less. In April, Eli Lilly won approval for Foundayo, the first weight-loss pill that can be taken without food or water restrictions, and it’s now reaching retail pharmacies. Novo Nordisk has a pill out, too. Cheaper, needle-free options are expected to pull millions more people onto the drugs—J.P. Morgan sees the U.S. user base climbing toward 25 million to 30 million people by 2030, up from about 10 million in 2025.

When that many people eat less, the grocery cart changes.

A Cornell University study tracked roughly 150,000 households and found that within six months of starting the drugs, families cut grocery spending by an average of 5.3%. Higher-income households cut more than 8%. Spending at fast-food restaurants and coffee shops fell about 8%, too. The cuts landed right where food companies make some of their best margins: sweets and salty snacks dropped around 10%. Yogurt, meanwhile, went up. People are swapping chips and candy for protein and fiber.

This is the part that worries Big Food, and the biggest brands are scrambling.

Conagra, which makes Healthy Choice meals, slapped a “GLP-1 friendly” label on more than two dozen of its frozen dinners. Nestlé launched a line called Vital Pursuit aimed directly at people taking the drugs. The shift is now significant enough that nearly three dozen non-healthcare companies discussed GLP-1 medications on earnings calls earlier this year, up from just 14 companies a year earlier.

Restaurants are rewriting menus, too. Olive Garden, owned by Darden Restaurants, added a lighter-portions section. The Cheesecake Factory rolled out smaller bowls and smaller meals. Shake Shack launched a “Good Fit Menu” featuring lettuce-wrapped burgers with up to 52 grams of protein. Even McDonald’s says it is testing high-protein, GLP-1-friendly items as it prepares for more customers with smaller appetites.

The math behind those changes is difficult for some chains. Bank of America found that snacking accounts for roughly 12% of sales at limited-service restaurant chains such as McDonald’s and Taco Bell—and snacking is exactly what these drugs are designed to reduce.

Not everyone is losing. The same medications reducing food consumption are generating enormous growth elsewhere. J.P. Morgan expects the global market for these drugs to reach $200 billion by 2030. Pfizer paid $10 billion last year to acquire a drugmaker developing its own version after outbidding seven competing buyers. And Washington is leaning in: a new Medicare and Medicaid pilot program would cap costs for some patients at $50 per month, potentially expanding usage further.

In the short run, the hit to food companies remains modest—a fraction of overall sales. The industry still has time to adjust, and some companies are already finding growth opportunities in high-protein snacks, nutrition-focused products, and healthier prepared meals.

But the long-run signal is becoming difficult to ignore. For the first time, a medicine—not a tax, not a recession, and not a public-health campaign—is changing how much the country eats. The companies that spent a century getting Americans to eat more now have to figure out how to make money when millions of their best customers simply want less.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A year ago, many of New York City’s real estate developers spent millions of dollars opposing Zohran Mamdani’s rise in city politics. Today, the democratic-socialist candidate is proposing a housing strategy that depends heavily on those same developers to help solve one of New York’s biggest challenges: affordability.

That is the central surprise behind Mamdani’s housing proposal, a sweeping blueprint released in late May that calls for $22 billion in city capital spending over five years to build 200,000 affordable homes and preserve another 200,000 over the following decade. The approach is not what many supporters or critics expected. Rather than relying primarily on government construction, much of the plan depends on private-sector investment, private developers, and market-driven construction.

To understand why that matters, it helps to start with how Mamdani built his political brand.

Throughout his political career, Mamdani has championed aggressive tenant protections, rent relief, and a larger public role in housing. During the campaign, he frequently pointed to international models such as Vienna’s social housing system, where government involvement plays a far larger role than it does in the United States. His message resonated with voters frustrated by rising rents, shrinking affordability, and a housing shortage that has pushed many middle-class families out of the city.

Yet housing policy eventually runs into a simple reality: math.

Building and preserving hundreds of thousands of homes requires enormous amounts of capital, construction labor, financing expertise, and development capacity. No city government possesses enough resources to do that alone. The overwhelming majority of those capabilities remain in private hands.

That reality appears to have influenced Mamdani’s thinking. His proposal effectively embraces a model in which government sets the goals and provides incentives, while private developers perform much of the actual building. In many respects, it is a housing strategy built around socialist objectives pursued through capitalist mechanisms.

The mechanics of the proposal reflect that shift.

Rather than positioning the city primarily as a builder, the plan focuses on making construction easier and faster. It relies heavily on zoning changes, streamlined approvals, and expanded development opportunities in areas where housing density can be increased. The proposal builds upon many of the broader housing-production concepts that have gained traction in New York over recent years, including efforts to encourage residential growth near transit corridors and underutilized properties.

For public housing, the plan envisions significant investment in the New York City Housing Authority (NYCHA), using new financing tools and capital partnerships to modernize aging developments that face billions of dollars in repair needs.

The proposal also includes a substantial emphasis on homeownership.

Mamdani has called for expanding programs that help working families purchase homes and has proposed new pathways for permanently affordable cooperative ownership. That focus on ownership is notable because homeownership has traditionally been viewed as one of the most market-oriented forms of wealth creation. For a politician frequently labeled a socialist, encouraging ownership represents a pragmatic recognition that long-term affordability often depends on helping families build equity rather than remaining renters indefinitely.

At the same time, the proposal maintains many of the tenant-focused priorities that have defined Mamdani’s political identity.

The plan seeks to reduce housing costs for lower-income residents, strengthen tenant protections, improve enforcement against negligent landlords, and expand affordability requirements in city-supported developments. Supporters argue these measures are necessary to ensure that new housing production benefits existing residents rather than accelerating displacement.

However, some of the most ambitious tenant protections face political limitations beyond City Hall.

Major changes to rent regulation generally require action from state lawmakers in Albany. That means any future mayor, regardless of ideology, would need cooperation from the governor and the state legislature to implement some of the more sweeping housing reforms often discussed during campaigns.

The business implications of the proposal are significant.

Developers are not merely participants in the plan; they are essential to its success. If private capital does not flow into projects, if financing becomes more difficult, or if builders determine the economics no longer work, housing production could fall well short of projections.

Construction companies, labor unions, engineering firms, architects, lenders, and suppliers would all stand to benefit if the proposal generates the level of development envisioned. Large-scale projects such as the long-discussed redevelopment of Sunnyside Yard in Queens illustrate the scale of construction opportunities that housing advocates hope to unlock over the coming decade.

Critics remain skeptical.

Some argue the housing targets are overly ambitious and depend on optimistic assumptions about financing, political cooperation, and market conditions. Others question whether developers will fully embrace a program that could also include stronger tenant protections and additional regulations.

Those concerns highlight the central tension at the heart of the proposal.

For years, New York’s housing debate has often been framed as a conflict between tenants and landlords, government and developers, regulation and markets. Mamdani’s housing blueprint attempts to bridge those competing interests by using private-sector resources to pursue public-sector goals.

Whether that balance can actually work remains the unanswered question.

The true test will not come from campaign speeches, policy rollouts, or headline-grabbing announcements. It will come years from now, when New Yorkers can measure whether more homes were built, whether affordability improved, and whether working families found it easier to remain in the city.

If the strategy succeeds, it could become a model for other high-cost cities struggling with housing shortages. If it fails, it may reinforce a lesson that urban leaders across the political spectrum have learned repeatedly: solving a housing crisis is far easier to promise than to accomplish.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The biggest sporting event ever hosted across the United States, Canada, and Mexico is less than two weeks away, yet many American hotels are facing an unexpected problem: the international visitors they were counting on have not arrived.

The 2026 FIFA World Cup was expected to deliver a tourism boom worth billions of dollars, filling hotels, restaurants, airports, and attractions across the country. Instead, hotel operators in host cities are reporting bookings that are falling well below expectations, raising concerns that one of the world’s largest sporting events may not deliver the economic windfall many communities anticipated.

According to a recent survey cited by Fortune, hotels in all 11 U.S. World Cup host cities are seeing weaker-than-expected reservations.

The numbers are striking. In Kansas City, roughly 85% to 90% of hotel owners reported bookings below expectations. In Philadelphia and San Francisco, approximately 75% of hotels expect to miss projected occupancy targets. Even Miami, one of the strongest-performing host cities, saw nearly 45% of surveyed hotels reporting softer-than-expected demand.

Those results stand in sharp contrast to the promises made when cities bid for World Cup matches.

FIFA President Gianni Infantino famously described the tournament as the equivalent of hosting “104 Super Bowls,” highlighting the enormous economic impact expected from millions of visitors traveling across North America during the month-long event.

The missing visitors appear to be coming primarily from overseas.

Historically, international travelers have been the most valuable World Cup tourists. They stay longer, spend more money, and generate substantial revenue for hotels, restaurants, retailers, transportation providers, and local attractions.

Current travel data suggests those visitors are not arriving in the numbers originally projected.

Flight analytics firm Cirium reports that advance bookings into the United States for July are running approximately 14% below year-ago levels, an unusual trend for a period expected to experience a major tourism surge.

Industry analysts point to several factors.

Long visa-processing times remain a challenge for travelers from many countries. Higher airfare prices, a strong U.S. dollar, and concerns surrounding immigration procedures have also made travel to the United States less attractive and more expensive.

Hotel operators participating in the survey frequently cited visa delays and geopolitical concerns as significant barriers preventing international fans from finalizing travel plans.

The World Cup arrives at a difficult moment for the broader U.S. tourism industry.

International travel to the United States has been under pressure for more than a year. Industry estimates show overseas visitation declined during 2025, resulting in billions of dollars in lost tourism spending. Early 2026 figures have continued to show weakness, creating additional pressure on destinations that expected the World Cup to reverse the trend.

The New York-New Jersey region illustrates the challenge.

MetLife Stadium, which will host the World Cup Final, was expected to become one of the tournament’s biggest economic beneficiaries. However, local transportation costs generated criticism after New Jersey Transit initially proposed premium World Cup train fares that many travelers viewed as excessive before later reducing the prices.

For host cities, the stakes extend beyond hotel occupancy.

Foreign visitors typically spend heavily on dining, transportation, entertainment, shopping, museums, and local attractions. Economic projections assumed that approximately 1.2 million international visitors would travel to North America for the tournament, generating significant local spending and tax revenue.

If those numbers fall short, cities may struggle to achieve the economic returns used to justify infrastructure improvements, transportation upgrades, and event-related investments.

There may be one silver lining for domestic travelers.

With international demand weaker than anticipated, some hotels have begun releasing inventory and adjusting room rates to attract additional guests. That could translate into better availability and lower prices for Americans planning summer trips to host cities.

The World Cup will still attract massive television audiences, packed stadiums, and global attention. Millions of fans are expected to attend matches across North America.

But for now, many hotel operators are confronting an uncomfortable reality: the international tourism surge they were promised has yet to materialize.

Whether late bookings close the gap remains to be seen. With kickoff rapidly approaching, however, the countdown clock is ticking.

JBizNews Desk — Travel & Tourism

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

TIRANA, Albania — A proposed $1.4 billion luxury resort development linked to Jared Kushner has become the center of one of Albania’s most visible political and environmental battles, with protesters taking to the streets for a seventh consecutive day as the government insists the project will move forward.

The dispute centers on Sazan Island, a largely undeveloped island in the Adriatic Sea that was once used as a secret military installation during Albania’s communist era. Plans backed by a company affiliated with Affinity Partners, Kushner’s private investment firm, would transform the island and nearby coastal areas into a luxury tourism destination featuring hotels, villas, restaurants, and a marina. Aman Resorts is expected to manage the flagship property.

Despite mounting opposition, Prime Minister Edi Rama said in remarks reported by Reuters that the investment will not be halted while he remains in office.

The project has become a test case for Albania’s efforts to attract major foreign investment while balancing environmental concerns and public opposition.

For the government, the economic argument is straightforward.

Tourism has emerged as one of Albania’s fastest-growing industries, helping fuel economic growth in one of Europe’s lower-income nations. Officials view the Sazan project as an opportunity to elevate Albania’s profile among high-end international travelers and compete more directly with luxury destinations across the Mediterranean.

When Albania’s Strategic Investment Committee granted the project “strategic investor” status in December 2024, officials cited a planned investment of approximately €1.4 billion and projected the development would create roughly 1,000 jobs during construction and operation.

The designation provides expedited permitting and other incentives designed to accelerate major investments.

Project developers say the resort would generate long-term economic benefits while protecting the surrounding environment.

Asher Abehsera, Chief Executive Officer of Sazan Real Estate Development LLC, told CBS News that the company intends to create a world-class destination while focusing on environmental stewardship, job creation, and lasting value for local communities.

He said the company respects the legal and public review processes and remains prepared to move forward as those processes continue.

Opponents see the project very differently.

Environmental activists have organized demonstrations under the banner of the “Flamingo Revolution,” a reference to the flamingo populations that inhabit nearby protected wetlands.

The protests intensified after construction equipment reportedly began arriving at portions of the site last month. Images and videos circulating on social media, including footage showing an activist being removed from a demonstration, helped draw larger crowds into the streets of Tirana.

Conservation groups argue the development threatens environmentally sensitive habitats that support flamingos, loggerhead sea turtles, and the endangered Mediterranean monk seal.

Critics also contend that the approval process lacked transparency.

Aleksandr Trajce, executive director of environmental organization PPNEA, told CBS News that local residents were never given meaningful public consultation before work began.

According to the group, many residents first learned of the development only after machinery appeared at the site and work had already started.

Environmental advocates further allege that portions of protected dunes have been damaged and that at least one sea turtle nesting area may have been destroyed.

The controversy has now expanded beyond environmental concerns into legal and political territory.

Earlier this week, SPAK, Albania’s anti-corruption prosecution office, opened an investigation into aspects of the project, including land transactions connected to the development and legislative changes approved in 2024 that reduced certain environmental protections in the area.

The investigation arrives during a period of heightened scrutiny of Albania’s government amid separate corruption allegations involving senior officials.

The project’s connection to Kushner has added another layer of attention.

Kushner, the founder of Affinity Partners, is married to Ivanka Trump, daughter of President Donald Trump. The couple has publicly discussed their interest in the island, with Ivanka Trump recently describing on the “Founders” podcast how they discovered Sazan while sailing and became captivated by its natural beauty and development potential.

That connection has fueled criticism from opponents, some of whom have carried banners reading “Albania Is Not For Sale.”

For now, neither side appears willing to compromise.

Supporters see the development as a transformational investment capable of generating jobs, expanding tourism, and attracting international capital. Opponents argue that the environmental and public costs are too high and that the approval process has lacked transparency.

With prosecutors now reviewing elements of the project and demonstrations continuing across the country, the future of one of the largest proposed tourism investments in Albania’s history may ultimately be decided in courtrooms as much as on construction sites.

JBizNews Desk — Europe

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Going out to eat has become expensive enough that a growing share of Americans are doing it less often. According to the National Restaurant Association, menu prices rose 3.6% over the year through April, the slowest pace in 15 months but still piled on top of years of steep increases. Restaurant prices climbed about 4.1% in 2025, roughly double the rate of grocery inflation, and the cumulative effect has changed how often families are willing to sit down at a table someone else sets.

The increases have built up over time.

Food and labor costs for restaurants have each risen roughly 35% over the past five years, and operators have passed much of that along. A dish that cost $20 a few years ago can now cost significantly more, and a mid-range meal for two can easily run $50 to $100 before tip. For many households, an ordinary dinner out now feels like a real expense rather than a casual choice.

Consumers are responding by going out less.

A survey by research firm YouGov found that 37% of Americans are dining out less frequently than a year ago, a figure that climbs to 44% among lower-income households, while only 8% say they are eating out more. Among those cutting back, nearly seven in ten point to the rising cost of restaurant meals.

The perception is widespread. Eighty-two percent of Americans believe restaurant prices have gone up over the past year, but only 28% think the prices are fair for the quality they receive, a gap that is steadily eroding the appeal of eating out.

When people do go out, they are looking for ways to spend less.

More than half say they have changed their dining habits to save money, most often by choosing less expensive restaurants, using coupons or discounts, ordering fewer items, or skipping drinks. Higher-end dining is feeling it most. Nearly half of lower- and middle-income diners say they visit fine-dining establishments less frequently than they did in 2024.

“Value has become the deciding factor shaping where and how they choose to eat,” said Nora Hao, a senior sales director at YouGov.

It is not only about price.

A report from consulting firm McKinsey & Company examining what diners want in 2026 found that among consumers who said eating out “wasn’t worth the money,” the biggest complaints were not simply the bill itself but food quality and portion size, with more than half citing each concern.

In other words, diners are not merely chasing the cheapest option. They are weighing whether the overall experience justifies the cost and increasingly deciding that it does not.

Delivery, once the easy answer for convenience, is also losing ground.

Service charges, delivery fees, marked-up menu prices, and tips have pushed the cost of a delivered meal dramatically higher than picking it up in person. Diners have noticed. Spending on delivery fell about 12% last year while pickup orders rose 14%, as consumers stepped away from fee-heavy delivery platforms to keep costs under control.

The pullback is showing up across generations.

Younger diners are leading the retreat, with Generation Z reducing spending at quick-service restaurants over the past two years, while Generation X and baby boomers are eating out less frequently and searching harder for deals when they do.

For restaurants, the result is an unusual squeeze.

Total sales continue to rise because menu prices are higher, but foot traffic has softened as customers visit less often. That leaves operators trying to protect already-thin profit margins while serving a more selective customer base.

Some restaurants are cutting costs wherever possible, replacing printed menus with QR codes and streamlining operations. Others are experimenting with new approaches to keep tables full. Many national chains are leaning more heavily on loyalty programs, discounts, and targeted promotions to give customers a reason to return.

Dining out is not disappearing.

Americans still value the simple pleasure of being served a meal, celebrating a special occasion, or gathering with family and friends. Most still go out to eat at least occasionally.

But the casual habit of grabbing dinner without thinking much about the cost is increasingly becoming something else: a purchase that requires planning, budgeting, and consideration.

Restaurants, in turn, are adjusting to a customer who shows up less often, watches the bill more closely, and expects the experience to be worth every dollar spent.

JBizNews Desk — Consumer Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The price of a new car has climbed so high that buying one is becoming a luxury many Americans can no longer manage. According to Kelley Blue Book, the car-pricing arm of Cox Automotive, the average new vehicle sold for about $48,699 in April, a figure reported in mid-May that sits just below the $50,000 mark the industry once considered unthinkable. To get into those cars, buyers are taking on bigger loans, longer terms, and heavier monthly payments than ever before.

The monthly bill tells the story.

Average new-car payments reached a record of roughly $772 at the end of last year, according to the research site Edmunds, and a record 20.3% of people financing a new vehicle now commit to payments of at least $1,000 a month. The average amount borrowed for a new car also hit a high of $43,899 in the first quarter, up from $41,473 a year earlier.

To make those numbers work, more buyers are stretching their loans far into the future.

A record 22.9% of financed new-car purchases in the first quarter carried loan terms of at least 84 months, or seven years, Edmunds found. A decade ago, that figure was about 10%. The cost of stretching is steep: a $43,899 loan at a 6.9% interest rate over 84 months works out to roughly $660 per month and more than $11,575 in interest over the life of the loan.

“Consumers are having to work harder to make the numbers fit,” said Jessica Caldwell, head of insights at Edmunds.

Behind the averages is a market increasingly splitting along income lines.

The share of new-car buyers earning less than $100,000 annually fell to about 37% last year, down from 50% in 2020, according to Cox Automotive. Households earning $150,000 or more now account for roughly 43% of new-vehicle sales.

In short, wealthier buyers are increasingly the ones keeping the new-car market moving while many middle- and lower-income shoppers are being pushed toward used vehicles or out of the market entirely.

Interest rates are a major reason.

A buyer’s credit score now determines dramatically different outcomes. According to Experian, borrowers with top-tier “super-prime” credit paid an average new-car loan rate of about 4.66% late last year, while borrowers with “deep subprime” credit paid roughly 16.01%.

Lenders have also become more selective with borrowers whose credit scores fall below the high-600s, leaving many consumers facing either sharply higher financing costs or loan denials altogether.

Tariffs are adding fresh pressure.

A 25% tariff on imported vehicles took effect in early April, and a related tariff on imported parts was later modified to allow automakers to recover some costs over a two-year period. Even so, 2026 model-year vehicles are arriving about $2,000 more expensive on average than the prior year, far above the typical annual increase of roughly $400.

Analysts at Cox Automotive warn that as cheaper pre-tariff inventory disappears from dealer lots, vehicle prices could rise further. Discounts are already becoming less generous. Sales incentives fell to about $3,262 per vehicle in April, the lowest level since the summer of 2024.

There is some relief for used-car shoppers.

After years of limited supply, roughly 400,000 additional late-model used vehicles are expected to enter the market this year as more lease returns become available. That should help stabilize used-car prices.

The catch is financing.

Used-car loan rates often run between 10% and 11%, meaning many budget-conscious shoppers are settling for older vehicles with higher mileage than they might have considered just a few years ago.

The affordability squeeze is also expected to weigh on sales.

Cox Automotive forecasts new-vehicle sales will decline about 2.4% this year to roughly 15.8 million units, which would mark the first annual decline since 2022. Edmunds projects a similar result, with sales trending toward approximately 16 million vehicles.

For dealers, automakers, and lenders, the industry is adapting through longer loan terms, greater focus on higher-income customers, and increased emphasis on used vehicles.

For everyday households, the shift is more personal.

The automobile has long been one of the defining purchases of middle-class American life. Increasingly, however, buying a new vehicle requires either a seven-year financial commitment or an income level that allows buyers to absorb a near-$50,000 sticker price without much concern.

As prices continue climbing and financing becomes more expensive, the new-car market is increasingly being built around the people who can afford it.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The world’s largest technology companies are pouring money into a new kind of software, AI “agents” that can operate a computer on their own to get tasks done. At its Build developer conference in early June, Microsoft Chief Executive Satya Nadella said the era of operating systems and individual apps is giving way to “agent-first” computing, in which artificial intelligence acts across programs and devices rather than waiting for a person to click through each step. It was one of the clearest signals yet that the industry sees self-directed software as the next major shift in how people use computers.

For years, tech companies tried to build digital helpers for routine online chores, things like assembling a shopping cart, tracking an order, or planning a trip. Those early assistants could answer questions or draft a little text, but they could not really do much. The new generation is different. These agents can take action on their own: browsing the web, filling out forms, clicking buttons, and writing and running computer code to complete multi-step jobs with limited human help.

The capabilities have advanced quickly. OpenAI’s Operator now succeeds on roughly 87% of complex web-browsing tasks, according to company testing. Anthropic’s Claude can control a computer directly, write software on its own, and coordinate teams of smaller “sub-agents” working in parallel. Google’s Project Mariner can juggle about ten tasks at once on cloud-based machines. What was a research demonstration a year ago is now being sold as a product.

The competition has settled into a five-way race among OpenAI, Anthropic, Google, Microsoft, and Amazon, each spending heavily and each holding a different advantage. At Build, Microsoft released free open-source tools for developers to build agents, added an agent called Scout to its Copilot assistant, and said Copilot would now route each task to whichever model fits best, including those from OpenAI, Anthropic, and open-source providers. Google, meanwhile, has rebranded much of its enterprise AI strategy around agents and introduced multi-agent tools that can, for example, have one agent build a website while another creates the brand artwork.

The clearest battleground is software coding, which has become the leading business use for agents because the agents themselves are built out of code. Anthropic has surged ahead in this area on the strength of Claude Code, prompting OpenAI to shift much of its focus from consumers to businesses with a rival product called Codex. Enterprise sales now account for a significant share of OpenAI’s revenue, and its coding tools have attracted millions of users. Google is using its scale to compete aggressively on pricing even as Chief Executive Sundar Pichai recently acknowledged that the company remains behind some rivals in parts of the agent race.

Adoption inside companies is moving fast, at least according to industry surveys. Research cited across the sector suggests a large majority of business teams are already experimenting with agents, with many organizations deploying a dozen or more. Helping that spread is a shared technical standard known as Model Context Protocol (MCP), originally developed by Anthropic, which allows agents from different companies to connect to the same applications and data sources much like devices plugging into a common electrical outlet.

The reason the technology giants are betting so heavily is simple. If agents can reliably handle office work, customer service, scheduling, research, software development, and routine digital tasks, they could unlock enormous productivity gains and reshape the software industry. Whoever controls the agent people and businesses rely upon by default could ultimately control the most valuable layer of computing, much as smartphone makers once controlled the app economy.

The vision is a shift from people using apps to people simply telling an agent what they want done.

There are real reasons for caution. The technology remains early and far from perfect. Agents still make mistakes, can take incorrect actions without supervision, and require oversight for important tasks. Despite the enthusiasm, the financial results remain mixed. Industry research shows that while a large share of chief executives rank artificial intelligence among their highest priorities, only a relatively small percentage report substantial financial gains so far. Reliability and trust remain the biggest obstacles separating impressive demonstrations from everyday business use.

For now, the AI agent race represents the technology industry’s most expensive wager since the arrival of the smartphone. Microsoft, Google, Amazon, OpenAI, and Anthropic are betting that within a few years software capable of acting independently will become the normal way people get work done. Whether that prediction transforms daily life or proves overhyped will depend on something less exciting than the demonstrations on stage: whether these agents can consistently do the job correctly, day after day, without someone constantly watching over them.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Anthropic called on the world’s leading artificial-intelligence labs Thursday, June 4, to consider a coordinated slowdown or temporary pause in building the most advanced AI systems, warning that the technology is approaching the point where it could improve itself without human help. The recommendation came in a report from the company’s research arm, the Anthropic Institute, written by Marina Favaro, who leads its internal research, and co-founder Jack Clark, the company’s head of policy.

The company said the world having the option to slow or temporarily pause frontier AI development would “likely be a good thing,” arguing it would give governments, institutions, and safety researchers time to catch up with how fast the technology is advancing. It is a striking message from a company that is itself one of the fastest-moving developers in the field.

At the center of the warning is a concept researchers call recursive self-improvement. In plain terms, it describes the moment an AI system becomes capable of improving itself, or designing and building its own successor, without much human involvement. The report said models are showing early signs of moving in that direction, a threshold the company said could bring major disruption if it is crossed before society is ready.

Anthropic backed the warning with data about its own operations. The company said more than 80% of the code merged into its systems is now written by its Claude models, and that its engineers ship roughly eight times as much code per quarter as they did in the years from 2021 through 2025. In other words, the company says its AI is already accelerating the pace at which AI itself is built.

The report was careful to add limits. Anthropic said the industry is not yet at recursive self-improvement, and that such a future is not inevitable. But it warned the moment could arrive sooner than most institutions are prepared for. In comments to BBC News, Clark said AI reaching the point of writing its own code fully could be possible within about two years.

The proposal faces an obvious problem, which Anthropic acknowledged: if a single company slowed down on its own, competitors would simply race ahead. For that reason, the company argued any pause would have to be coordinated globally and verifiable. The Anthropic Institute said it plans to research and develop systems that would let frontier developers confirm rivals have actually stopped, and ensure no bad actor uses a coordinated slowdown to quietly pull ahead.

The call lands at a moment of intense commercial pressure across the industry. Anthropic recently completed a funding round that valued the company at nearly $1 trillion and has filed confidential paperwork to begin the process of going public. Its run rate, a measure startups use to project annual revenue from recent sales, is on track to reach about $50 billion in annualized revenue by the end of this month, up from roughly $9 billion at the end of 2025. The company has emerged as a front-runner against OpenAI, the maker of ChatGPT, which is also expected to pursue a public listing.

That commercial position fuels a long-running criticism. Anthropic has emphasized AI safety since its founding, but skeptics, including venture capitalist David Sacks, have argued that its policy advocacy is designed in part to slow the progress of competitors. A public call for rivals to consider pausing is likely to renew that debate, even as Anthropic frames the recommendation as a matter of public risk rather than competitive advantage.

The stakes extend across an industry that is spending hundreds of billions of dollars on data centers, chips, and talent. A coordinated pause would affect the entire race, from the largest technology companies to the startups built on their models. Anthropic’s central recommendation is not that development stop now, but that governments and labs preserve the ability to pause and build the infrastructure that would make such a pause credible if it became necessary.

The report arrives the same week that a bipartisan group of House lawmakers unveiled draft legislation to regulate AI, underscoring how questions about the technology’s speed and safety are moving to the center of policy discussions. Anthropic’s proposal adds a prominent industry voice to that conversation, with the company arguing that the option to slow down, backed by ways to verify it, should exist before the technology reaches a point where stopping becomes far harder.

JBizNews Desk — Artificial Intelligence

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A growing divide is emerging in the American workforce, and it is showing up directly in workers’ paychecks. According to a new analysis released on May 28 by the Indeed Hiring Lab, the research division of the employment platform Indeed, salaries for white-collar and salaried workers are rising noticeably faster than wages for hourly employees, creating another sign that the economic recovery is benefiting some workers far more than others.

The report, authored by economist Sneha Puri, examined millions of job postings across the country and found that advertised pay for salaried positions increased 2.9% between the first quarter of 2025 and the first quarter of 2026. By comparison, advertised pay for hourly jobs rose just 1.7% during the same period.

While both categories saw gains, the gap between them continues to widen.

The findings matter because job postings often provide an early look at labor-market trends before they appear in broader wage data. Employers typically adjust compensation for new hires before making larger changes across their existing workforce, making advertised pay an important indicator of where wages may be heading.

The report suggests that workers already occupying higher-paying positions are seeing stronger income growth, while many hourly employees are falling further behind.

That distinction has significant economic implications.

Salaried workers are more likely to be employed in professional, management, administrative, technology, financial, and other white-collar roles. These jobs often come with additional benefits such as healthcare, retirement contributions, paid leave, and bonus opportunities.

Hourly workers, meanwhile, are more commonly found in retail, hospitality, logistics, manufacturing, customer service, and entry-level positions where compensation is often tied directly to hours worked.

When salaried compensation rises faster than hourly wages, income inequality naturally expands.

The situation becomes even more concerning when inflation is taken into account.

According to the Bureau of Labor Statistics, consumer prices increased 3.8% during the twelve months ending in April. During that same period, average hourly earnings nationally increased approximately 3.6%.

In practical terms, many workers are losing purchasing power.

Even employees receiving raises may find that those increases fail to keep pace with rising costs for housing, food, transportation, healthcare, and energy.

For hourly workers experiencing only modest wage growth, the squeeze is even more severe.

The Indeed report found that the disparity extends across numerous industries.

The wage advantage for salaried workers appeared in nearly every major white-collar sector examined. Perhaps more surprising was evidence that hourly wages were weakening in certain technology-related fields.

Indeed found that advertised hourly pay actually declined in some information technology and software development positions, highlighting how hiring patterns can vary significantly even within industries traditionally associated with strong wage growth.

The result is that two workers performing similar functions may experience dramatically different earnings trajectories depending on how they are classified and compensated.

Economists say part of the explanation lies in a labor market that is gradually cooling after several years of extraordinary demand.

As unemployment has risen modestly and job openings have become less abundant, employers face less pressure to aggressively increase wages.

Hourly workers often feel those effects first because employers generally have access to a larger pool of potential candidates for many hourly positions.

Elise Gould, senior economist at the Economic Policy Institute, noted that when labor markets soften, companies no longer need to compete as aggressively for workers, reducing pressure to offer larger pay increases.

The timing of the report is particularly significant because it arrived just before the release of the government’s official May employment report, one of the most closely watched economic indicators each month.

Leading into that report, payroll processor ADP reported that private-sector employers added approximately 122,000 jobs in May, exceeding expectations and marking the strongest monthly hiring gain since January 2025.

Yet even within that positive hiring data, signs of slowing wage momentum were visible.

ADP found that workers who changed jobs received average pay increases of approximately 6.5%, down from the larger gains seen during the post-pandemic hiring boom. Workers who remained with their employers saw pay increases of approximately 4.4%, a respectable figure but one that still offers limited protection against rising living costs.

For workers hoping that switching jobs would continue producing substantial salary increases, the trend suggests those opportunities may be becoming less lucrative.

For households already struggling with higher costs, that reality creates additional financial pressure.

Many Americans continue facing elevated expenses for housing, groceries, insurance, utilities, and transportation. When wages fail to keep pace with inflation, even workers receiving raises may find themselves effectively earning less in real terms.

For businesses, however, the trend presents a more complicated picture.

Slower wage growth helps employers manage labor costs and protect profit margins during periods of economic uncertainty. Companies facing higher borrowing costs, rising operating expenses, and slower economic growth have been looking for ways to control expenses without resorting to major layoffs.

At the same time, suppressing wage growth carries risks.

Workers who feel underpaid are more likely to leave, become disengaged, or seek opportunities elsewhere. Employers may also find it harder to attract qualified workers if compensation fails to keep pace with market expectations.

Interestingly, the strongest hiring growth in May came from the smallest employers.

ADP reported that companies with fewer than 19 employees added approximately 49,000 jobs, suggesting that demand for workers remains healthy in certain segments of the economy despite broader concerns about economic slowing.

The larger story emerging from the data is one of uneven economic progress.

Salaried professionals continue to pull ahead.

Hourly workers continue to lag behind.

And inflation continues to reduce purchasing power for both groups.

As policymakers, businesses, and economists await additional employment and wage data, the central question remains whether wage growth can eventually accelerate enough to outpace inflation—or whether the divide between higher-paid salaried employees and hourly workers will continue widening.

For millions of Americans, the answer will determine whether their next raise actually improves their standard of living or simply helps them keep up with rising costs.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Investors are heading into one of the busiest weeks of the late-spring earnings season, with Oracle, Adobe, and eight other companies set to report results between Tuesday and Thursday. Options-market pricing as of Monday, June 8, suggests traders are preparing for unusually large one-day stock moves, with expected swings ranging from roughly 8.6% to more than 18% after earnings announcements.

In simple terms, an “implied move” reflects how much the options market expects a stock to rise or fall once earnings are released. The larger the implied move, the greater the uncertainty—and opportunity—that traders see ahead.

The earnings rush arrives alongside Wednesday’s closely watched inflation report, with economists expecting core consumer prices to rise 2.8% year-over-year, making this one of the most important weeks for markets before summer.

The biggest company on the calendar is Oracle (ORCL), which reports Wednesday after the closing bell. Analysts expect earnings of approximately $1.96 per share on revenue of about $19.1 billion, representing roughly 20% annual growth. Options traders are pricing in an 11.2% move, which would translate into roughly $71 billion in market value gained or lost in a single trading session based on Oracle’s current size.

Investors will be paying particular attention to Oracle’s rapidly expanding artificial intelligence business. The company’s order backlog reached approximately $553 billion last quarter, fueled by demand for AI computing infrastructure and cloud services. The key question is whether Oracle can build enough data-center capacity to fulfill those commitments as spending accelerates.

Adobe (ADBE) reports Thursday after the close and remains one of the most closely watched AI stories in software. Analysts expect earnings of approximately $5.82 per share on revenue of $6.46 billion. Shares have struggled this year as investors debate whether generative AI image and content tools will complement Adobe’s products or eventually compete with them.

Several companies reporting this week will also provide insight into consumer spending trends.

Chewy (CHWY) reports Wednesday and offers a window into discretionary spending by pet owners. Academy Sports and Outdoors (ASO) reports Tuesday and could provide clues about value-conscious shoppers, while United Natural Foods (UNFI), the primary distributor for Whole Foods Market, will offer a broader look at grocery demand and consumer purchasing behavior.

At the higher end of the market, RH (RH)—formerly Restoration Hardware—reports Thursday. The luxury home furnishings retailer faces continued pressure from a softer housing market and tariff-related costs. Options traders expect shares could move nearly 15% following results.

The week’s earnings calendar also reflects how deeply the AI boom is reaching into the broader economy.

Uranium Energy (UEC) reports Tuesday as investors continue betting that artificial intelligence data centers will increase demand for reliable electricity and nuclear power. Core & Main (CNM) reports Wednesday and provides a useful gauge of infrastructure investment, municipal spending, and construction activity.

Among newer public companies, Navan (NAVN) is expected to experience the largest percentage move of the week, with options markets implying a swing of more than 18%. The AI-powered travel and expense management company is still early in its public-company life cycle, making earnings more difficult for investors to predict.

Close behind is SailPoint (SAIL), which returned to public markets after previously being taken private. Investors are watching whether demand for identity-security software continues growing as businesses deploy increasing numbers of AI systems and digital agents.

With no Federal Reserve meeting scheduled this week, corporate earnings and Wednesday’s inflation report are expected to drive market sentiment. While Oracle and Adobe may attract the most headlines, the broader collection of consumer, infrastructure, cybersecurity, and AI-related companies reporting this week could provide some of the clearest signals yet about the health of both the economy and the artificial intelligence investment boom.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Commercial ships trapped in the Persian Gulf for months are starting to get out through the Strait of Hormuz, and they are doing it by quietly working with the U.S. Navy.

Nearly 40 vessels have exited over the past three weeks, according to Lloyd’s List Intelligence, with some shipowners now submitting transit plans to the Naval Cooperation and Guidance for Shipping (NCAGS) group based in Bahrain. The details were disclosed by Richard Meade, editor-in-chief of Lloyd’s List, during a briefing on Thursday, June 4, 2026.

The arrangement is deliberately informal.

The working assumption among many shipowners is that the U.S. Navy will move to intercept incoming threats against commercial vessels if necessary, Meade said, but he emphasized that transit decisions remain entirely in the hands of ship operators and that no centralized escort program currently exists.

A U.S. defense official told CNBC that American forces are not escorting commercial ships through Hormuz. Instead, they are communicating and coordinating with vessels seeking to transit the strait safely.

Why “Coordinate” and Not “Escort” Matters

The distinction reflects a major policy shift.

In early May, President Donald Trump ended the short-lived Navy initiative known as Project Freedom, which attempted to move traffic through the strait using direct military escorts for stranded vessels.

What replaced it is far quieter and far less formal.

Rather than assigning naval ships to accompany each commercial vessel, the U.S. military now provides information, threat awareness, and communication support while signaling that it remains actively monitoring the region.

For shipowners, the situation remains extraordinarily difficult.

Ships attempting to leave the Gulf face potential threats from Iranian forces unless they receive approval to transit designated routes through Hormuz. At the same time, operators risk running afoul of U.S. sanctions if they cooperate too closely with Iranian authorities.

Caught between competing governments and conflicting legal risks, many operators have chosen to remain anchored rather than move.

A War That Closed the World’s Most Important Oil Route

The crisis traces back to February 28, when the United States launched Operation Epic Fury, triggering a conflict that dramatically disrupted shipping through the Strait of Hormuz.

At its peak, more than 1,500 vessels were stranded throughout the Persian Gulf after traffic through the waterway largely ground to a halt.

Labor organizations estimate that roughly 20,000 seafarers became trapped aboard oil tankers, liquefied natural gas carriers, container ships, and other commercial vessels as the crisis dragged on.

Progress has been slow but measurable.

Of the 109 largest tankers stranded when the strait effectively closed—each capable of carrying at least 700,000 barrels of oil—approximately 29 had successfully crossed Hormuz by late May, according to Bloomberg shipping data.

Several shipowners reported direct communication with U.S. military personnel, who provided routing guidance and security information. In some cases, military helicopters were reportedly used to assist with monitoring and transit operations.

Even with recent movement, shipping activity remains far below pre-conflict levels. Vessel traffic through Hormuz fell to some of the lowest levels of the conflict during May.

Fighting Flared Again This Week

The fragile stability was tested once again in recent days.

According to U.S. Central Command, Iran launched three attack drones toward civilian vessels operating in regional waters on Tuesday. U.S. forces intercepted and destroyed the drones before carrying out self-defense strikes against Iranian positions on Qeshm Island.

The confrontation briefly pushed oil prices higher as traders worried that the ceasefire could collapse and broader fighting could resume.

Secretary of State Marco Rubio said Wednesday that the United States is responding to attacks against commercial shipping and remains committed to protecting maritime traffic in the region.

The Business Stakes

The Strait of Hormuz is one of the most important energy chokepoints on Earth.

A substantial portion of the world’s oil and liquefied natural gas exports pass through the narrow waterway each day. Any disruption immediately affects global energy markets, freight costs, insurance rates, manufacturing expenses, and ultimately consumer prices.

The gradual release of stranded vessels represents a modest but meaningful positive development for global supply chains.

Each tanker that exits the Gulf returns oil to world markets while freeing vessels and crews that have been sidelined for months. Every successful transit helps reduce pressure on shipping networks already strained by conflict and uncertainty.

However, the risks remain significant.

War-risk insurance premiums remain elevated. Freight rates continue to reflect the danger of operating in the region. Shipowners still face difficult calculations between the costs of remaining idle and the dangers associated with moving through contested waters.

The recent drone attack serves as a reminder that progress can be reversed quickly.

For now, ships are moving, the U.S. Navy is watching, and neither side is calling it an escort mission.

Until broader tensions between Washington and Tehran are resolved, traffic through the Persian Gulf is likely to remain well below normal levels.

Sources: Lloyd’s List Intelligence briefing, Richard Meade (June 4, 2026); U.S. Central Command statement (June 2, 2026); CNBC interview with U.S. defense officials; Bloomberg shipping data; International Transport Workers’ Federation.

JBizNews Desk — Energy & Shipping

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Even as markets swung wildly and economic uncertainty dominated headlines, Americans quietly did something remarkable in early 2026: they saved more for retirement than ever before.

According to a first-quarter 2026 retirement analysis released by Fidelity Investments on May 28, retirement savings rates, contribution levels, and participation all reached record highs. The biggest surprise, however, was where much of that money went. Americans are increasingly choosing Roth retirement accounts, signaling a major shift in how workers are thinking about taxes, investing, and long-term financial security.

The data suggests that millions of Americans are no longer simply saving for retirement—they are strategically positioning themselves for a future in which tax-free income may become one of the most valuable financial assets they own.

The standout statistic from Fidelity’s report was the dominance of Roth Individual Retirement Accounts (Roth IRAs).

During the first quarter, 67% of all IRA contributions went into Roth accounts. Even more striking, Roth conversion transactions jumped 41% compared with the same period a year earlier.

Overall IRA contributions increased 29% year-over-year, while the number of individuals actively contributing rose 28%, both setting new records.

For financial planners, those figures signal more than simply strong saving habits.

They suggest Americans are increasingly willing to pay taxes now in exchange for avoiding them later.

The difference between traditional retirement accounts and Roth accounts explains why.

With a Traditional IRA, contributions may be tax-deductible today, reducing current taxable income. However, withdrawals made during retirement are generally taxed as ordinary income.

A Roth IRA works in the opposite way. Contributions are made with after-tax dollars, meaning there is no immediate tax deduction. In exchange, qualified withdrawals—including years or decades of investment growth—can be taken entirely tax-free.

A Roth conversion allows investors to move money from a traditional account into a Roth account. The converted amount becomes taxable in the year of conversion, but future growth can potentially escape taxation permanently.

The sharp increase in Roth conversions suggests many investors believe paying taxes today is preferable to facing potentially larger tax bills in retirement.

Some expect future tax rates to rise.

Others simply value the certainty of knowing their retirement withdrawals will not be affected by future changes in tax policy.

Bob Mascialino, President of Wealth at Fidelity Investments, said the trend reflects growing interest in flexibility, tax efficiency, and long-term planning.

The momentum was not limited to IRAs.

Workplace retirement plans also reached record levels.

According to Fidelity’s analysis of more than 54 million retirement accounts, the combined employee and employer contribution rate for 401(k) plans reached a record 14.4%, approaching Fidelity’s recommended long-term savings target of 15%.

Meanwhile, 403(b) plans, commonly used by educators, healthcare workers, and nonprofit employees, reached a savings rate of 12%.

Perhaps most impressive is that Americans continued contributing aggressively even as markets experienced turbulence.

Average retirement account balances declined modestly during the quarter as stock market volatility affected portfolio values.

The average IRA balance fell approximately 4% from the previous quarter to $131,380 as of March 31.

Yet longer-term results remained strong.

Average 401(k) balances increased 11% year-over-year.

Average 403(b) balances rose 13%.

Average IRA balances increased 7%.

Those gains demonstrate an important investing principle that financial advisors frequently emphasize: consistency matters more than timing.

Investors who continue contributing during market downturns often benefit by purchasing additional shares at lower prices. This strategy, commonly known as dollar-cost averaging, helps reduce the impact of market volatility over time.

Roth conversions can become particularly attractive during periods of market weakness because investors pay taxes based on temporarily reduced account values.

The report also revealed an encouraging trend among younger Americans.

Generation Z led all age groups in retirement savings growth.

IRA contributions from Gen Z investors surged 65% from a year earlier, while Millennial contributions increased 31%.

More than 20% of Gen Z participants in workplace retirement plans contributed to a Roth 401(k), demonstrating that younger workers are embracing tax-advantaged investing far earlier than many previous generations.

That finding challenges common assumptions that younger Americans are too burdened by housing costs, student debt, and inflation to prioritize retirement.

Instead, Fidelity’s data suggests many younger workers are actively building long-term financial plans despite economic uncertainty.

The implications extend beyond individual households.

The financial services industry benefits significantly from rising retirement contributions. Increased participation drives growth for investment managers, brokerage firms, retirement-plan providers, and tax-planning professionals.

The surge in Roth activity may also signal a lasting change in investor behavior.

For decades, traditional retirement planning focused heavily on maximizing current tax deductions. Increasingly, however, investors appear willing to sacrifice today’s tax benefits in exchange for future tax certainty.

For individual savers, the broader lesson may be simple.

The investors making the greatest long-term progress are not necessarily those who predict market movements correctly. They are the ones who continue contributing regardless of economic headlines, market swings, or political uncertainty.

Whether a Roth IRA, Traditional IRA, Roth 401(k), or another retirement vehicle is best depends on each person’s unique circumstances and tax situation.

But Fidelity’s report makes one trend unmistakably clear: Americans are saving more, investing earlier, and increasingly choosing retirement accounts that offer tax-free income later in life.

In an economy filled with uncertainty, millions of workers appear to have reached the same conclusion—the future is easier to face when retirement savings remain a priority.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON— The modern economy was built to be cheap, not safe. For decades, about a fifth of the world’s oil moved through a single channel barely 21 miles wide at its narrowest, simply because it was the least costly way out of the Persian Gulf. That bargain is now broken. Iran’s government said through its state media on Monday, June 1, that it was halting indirect talks with Washington and would move to close the Strait of Hormuz “completely” — reviving a crisis that has kept the waterway effectively shut since February 28. The weak spot the standoff exposed isn’t really Iran. It’s the math.

Here is the plain version of what happened. When fighting between Iran, Israel and the United States began in late February, Iran stopped tankers from moving through the strait. Traffic that once ran near 3,000 vessels a month fell to a trickle. A channel that carried roughly 20 million barrels of oil a day — close to 20% of everything the world uses — went quiet almost overnight.

Prices reacted fast. Brent crude, the global benchmark, spiked to nearly $138 a barrel on April 7, up from about $71 before the war. They have since eased to around $92, down nearly 20% from the peak, as a shaky ceasefire raised hopes of a deal. But Monday’s move from Tehran threatens to undo that relief, and prices remain far above where they sat before the fighting.

For regular people, the strait is an abstraction until it shows up at the pump. Average U.S. retail gasoline topped $4.50 a gallon at its high this spring. Diesel matters even more quietly: it powers the trucks that haul groceries and the tractors that grow food. The U.S. Energy Information Administration, the federal agency that tracks the nation’s energy data, expects diesel to average about $4.76 a gallon this year. When diesel climbs, the cost lands later on store shelves.

So why can’t the world simply route around the problem? Because the alternatives barely exist. The International Energy Agency notes that only Saudi Arabia and the United Arab Emirates have working pipelines that can bypass the strait, and together they can move perhaps 3.5 to 5.5 million barrels a day — a fraction of the 20 million that normally pass through. Saudi Aramco’s East-West pipeline can push 7 million barrels a day to the Red Sea port of Yanbu, but it is already near its limit. The UAE’s Habshan-Fujairah line carries under 2 million barrels a day. Everything else is too small, too far, or still on a drawing board.

That gap is the part that takes years, not months, to close. Pipelines need land, money, permits and deals among neighbors who often distrust one another. Governments are moving anyway. Abu Dhabi National Oil Company is already building a second crude pipeline — about half finished, its chief executive Sultan Al Jaber said last month — to double the oil it can ship from the bypass port of Fujairah by early next year. On Tuesday, June 2, the company’s trading chief, Philippe Khoury, told an industry conference in London that ADNOC is also weighing its first multi-fuel pipeline, to carry gasoline, diesel and jet fuel around the strait. Iraq is reopening a long-dormant line through Turkey. The crisis is even reshaping old alliances: the UAE formally left OPEC effective May 1, choosing to control its own routes rather than coordinate output through the group.

The deeper point is about who leans on this waterway most. The vast majority of the crude crossing the strait is bound for Asia, and China normally gets close to a third of its oil this way. A crisis framed as a Middle East story is, in practice, aimed squarely at the factories of the East — which is exactly why a narrow channel hands Iran leverage far larger than its economy alone would suggest.

Here is the part worth separating from the daily headlines. Oil prices will keep swinging with every rumor of a deal — that is the short-term noise. The lasting change is the lesson now burned into every energy ministry on earth: a single 21-mile channel can hold the global economy by the throat. The scramble to build around it will outlast the war that started it.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — A violent selloff in semiconductor stocks erased roughly $1.7 trillion from the U.S. stock market on Friday, June 5, with the world’s largest chipmakers alone shedding more than $1 trillion in market value, as investors suddenly reassessed whether the artificial-intelligence boom can justify the extraordinary valuations that have fueled Wall Street’s rally over the past two years.

The selloff struck at the heart of the market’s strongest sector. The Nasdaq Composite fell 4.18% to 25,709.43, its worst one-day decline since the tariff-driven market shock of April 2025. The S&P 500 dropped 2.64% to 7,383.74, ending a nine-week winning streak, while the Dow Jones Industrial Average lost 695 points, or 1.35%, to close at 50,866.78. The Cboe Volatility Index, commonly known as Wall Street’s fear gauge, surged more than 34%, finishing above the key 20 level.

At the center of the rout was the Philadelphia Semiconductor Index, which plunged approximately 8.5%, marking its steepest single-session loss since April 2025.

Nvidia, the dominant supplier of AI chips and the world’s most valuable semiconductor company, fell roughly 6%, wiping out more than $300 billion in market capitalization in a single day. Micron Technology tumbled about 11%, while Advanced Micro Devices dropped more than 10%. Marvell Technology lost approximately 12%, and Broadcom extended a two-day slide that approached 20%.

The immediate trigger was Broadcom’s earnings report, released earlier in the week. Although the company reported strong results by most measures, investors focused on signs that demand growth for certain custom AI chips was not accelerating as rapidly as Wall Street had expected. After two years in which semiconductor companies repeatedly exceeded forecasts and raised guidance, even modest signs of slowing momentum proved enough to spark a sharp revaluation.

The selling pressure intensified Friday after the release of a surprisingly strong U.S. jobs report.

The Bureau of Labor Statistics reported that employers added 172,000 jobs in May, significantly above economists’ expectations of roughly 80,000 jobs. The stronger-than-expected labor market reinforced concerns that the Federal Reserve may have little reason to lower interest rates and could potentially be forced to consider another increase if inflation remains stubborn.

Bond yields rose sharply following the report, creating additional pressure on high-growth technology stocks. Higher interest rates reduce the present value of future earnings, making richly valued growth companies less attractive to investors.

By Friday’s close, futures markets were assigning a significantly higher probability that the Fed could raise rates before year-end, a dramatic shift from expectations only weeks ago when investors were largely debating the timing of future rate cuts.

Market strategists largely characterized the move as a correction rather than evidence of fundamental deterioration in the AI industry itself.

The semiconductor sector remains one of the strongest-performing areas of the market despite Friday’s losses. Even after the decline, the Philadelphia Semiconductor Index is still up approximately 75% in 2026, reflecting the extraordinary gains generated by the AI boom.

The underlying businesses also remain healthy. Demand for AI infrastructure continues to grow, major cloud-computing companies are still spending heavily on AI development, and semiconductor manufacturers continue reporting substantial revenue growth. What changed Friday was not demand for AI technology but the price investors were willing to pay for future growth.

The episode also highlighted a growing concern among market analysts: concentration risk.

A relatively small group of AI-related companies has accounted for a disproportionate share of the stock market’s gains over the past year. As a result, broader indexes have become increasingly dependent on the performance of a handful of technology giants. When sentiment shifts against those companies, the impact quickly spreads throughout the market.

That concentration affects far more than professional traders. Because companies such as Nvidia, Broadcom, Microsoft, and other technology leaders carry enormous weightings in major indexes, their movements directly influence the performance of countless retirement accounts, pension funds, and index funds owned by ordinary Americans.

Investors now turn their attention to the next major economic test: the government’s inflation report scheduled for Wednesday, June 10. A hotter-than-expected reading could reinforce expectations for higher interest rates and extend pressure on technology shares. A softer report, meanwhile, could help restore confidence that Friday’s selloff was merely a pause in the AI-driven bull market rather than the beginning of something larger.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. dollar rose Friday, June 5, after the U.S. Bureau of Labor Statistics reported that employers added 172,000 jobs in May — roughly double what economists had penciled in — a number strong enough to convince traders that the Federal Reserve may have to raise interest rates rather than cut them later this year. The greenback pushed to its highest level since April, bond yields jumped, and gold and stocks fell, all on the same simple read: the job market remains too healthy for the Fed to ease while inflation is still running hot.

The U.S. Dollar Index (DXY), which measures the dollar against a basket of six major currencies including the euro and the yen, climbed toward 99.5, near a two-month high. The Japanese yen weakened toward ¥160 per dollar, a level that has repeatedly drawn concern from Japanese officials. A stronger dollar matters far beyond currency desks — it makes American exports more expensive abroad and tends to pressure commodities such as oil and gold, which are priced globally in dollars.

Why a Good Jobs Number Lifted the Dollar

The logic runs through interest rates. When the economy adds far more jobs than expected, the Federal Reserve has less reason to lower rates and more reason to worry that a tight labor market could keep inflation elevated. Higher U.S. interest rates make dollar-denominated savings and bonds more attractive than investments in Europe or Japan, drawing money into the United States and lifting the value of the dollar.

That is exactly what played out Friday. The unemployment rate held steady at 4.3%, while average hourly earnings rose 0.3% for the month and 3.4% from a year earlier. Together with upward revisions to prior months, the report marked a third consecutive month of solid hiring and eased concerns that the labor market was slowing sharply.

Bond traders reacted quickly. Yields on two-year Treasury notes, which are especially sensitive to Federal Reserve policy expectations, climbed to roughly 4.15%, the highest level this year, while 10-year Treasury yields rose toward 4.53%. Rising Treasury yields and a rising dollar often move together, and Friday was no exception.

Markets Now See a Rate Hike, Not a Cut

The bigger shift is in what investors expect from the Federal Reserve. Interest-rate markets now indicate growing expectations that the Fed’s next move could be a rate increase rather than a cut. Traders are pricing in roughly a 60% chance of a quarter-point hike by October and a near certainty of at least one increase by the end of the year.

Only a week ago, markets were still debating the timing of future rate cuts. The change reflects stronger-than-expected economic data and persistent inflation pressures, much of which has been tied to elevated energy prices during the ongoing U.S.-Iran conflict.

Jeffrey Rosenberg, senior portfolio manager at BlackRock, said the key question is whether the Federal Reserve moves before markets force its hand. So far, he said, policymakers appear to be following rather than leading market expectations.

The Federal Reserve next meets June 16–17, the first policy meeting under Chairman Kevin Warsh, who succeeded Jerome Powell in May.

The pressure could intensify next week when fresh inflation data is released. Economists expect consumer prices to show renewed upward pressure, potentially strengthening the case for the Fed to keep rates elevated or move higher.

Stalled Iran Talks Add to Dollar Demand

The dollar also benefited from continued geopolitical uncertainty. Progress in U.S.-Iran negotiations remained limited, encouraging investors to seek safety in the greenback. Historically, periods of international tension often drive capital toward U.S. assets and the dollar, a trend that has remained in place throughout much of the conflict.

The same forces that boosted the dollar weighed on other markets. Stocks opened lower, with the S&P 500 falling as investors worried that stronger economic growth could lead to higher borrowing costs. Gold and silver also retreated as rising yields reduced the appeal of assets that do not generate income.

For businesses, the stronger dollar creates both winners and losers. Importers benefit from cheaper foreign goods, and Americans traveling overseas gain additional purchasing power. Exporters, however, face a more difficult environment because their products become more expensive abroad, while multinational companies see foreign earnings reduced when converted back into stronger dollars.

With the Federal Reserve’s next move now the subject of intense debate, the dollar’s path in the coming weeks will likely depend on next week’s inflation data and whether any meaningful progress emerges in efforts to end the conflict with Iran and reopen the Strait of Hormuz.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

CHICAGO — Companies are increasingly pointing to one culprit when they cut jobs: artificial intelligence. For the first time, AI has become the single most common reason U.S. employers cite for layoffs — a milestone that says as much about how companies talk about AI as it does about what the technology is actually doing.

The finding comes from outplacement firm Challenger, Gray & Christmas, which reported Thursday that AI was cited for 38,579 job cuts in May, representing 40% of all layoffs announced during the month — the highest monthly total since the firm began tracking the category in 2023.

“AI is now the leading reason companies give for cutting jobs,” said Andy Challenger, the firm’s chief revenue officer.

The rise has been dramatic.

AI’s share of monthly job cuts climbed from just 7% in January to 25% in March, 26% in April, and 40% in May. For the year, AI has been cited in 87,714 layoffs, representing 22% of all announced job cuts in 2026 — already well above the 54,836 cuts attributed to AI during all of 2025.

The overall pace of layoffs is increasing as well.

Employers announced 97,006 job cuts in May, up 16% from April and the highest May total since the pandemic-disrupted labor market of 2020. It marked the third consecutive monthly increase, following 48,307 cuts in February, 60,620 in March, and 83,387 in April.

But economists caution against assuming the figures prove artificial intelligence is directly replacing workers on a broad scale.

The key limitation is that the data reflects what companies say caused the layoffs rather than independently verified evidence. Daniel Zhao, chief economist at Glassdoor, has warned against taking corporate explanations at face value, noting that companies can attribute cuts to AI even when other factors are involved.

Some researchers believe the technology may sometimes serve as a convenient explanation for broader restructuring efforts.

Fabian Stephany of the Oxford Internet Institute has expressed skepticism that many of the reported layoffs reflect genuine AI-driven efficiency gains, arguing that the technology can provide management with a readily understandable rationale for workforce reductions that might have occurred anyway.

Meanwhile, the broader labor market remains surprisingly resilient.

The Bureau of Labor Statistics reported Friday that U.S. employers added 172,000 jobs in May, more than double the roughly 80,000 economists expected, while prior months were revised upward.

Daniel Keum, a management professor at Columbia Business School, said the labor market is “humming along just fine” and described AI’s impact as remaining “very concentrated” in a handful of industries, particularly technology.

That concentration is difficult to miss.

The technology sector accounted for 38,242 of May’s announced job cuts, the highest monthly total since August 2024. The wave comes as major corporations redirect enormous amounts of capital toward artificial intelligence projects.

Companies including Meta, Cisco Systems, and Block have all cited AI as part of restructuring efforts. Meta recently notified roughly 8,000 employees of layoffs while simultaneously increasing spending on AI infrastructure and development.

In many cases, companies are reducing headcount in one part of the business while aggressively investing and hiring in another.

For workers, the bigger challenge may not be layoffs themselves but the slowdown in hiring.

Through May, employers announced only 80,472 planned hires, which Challenger described as historically low compared with pre-pandemic levels. Even when opportunities exist, they often do not align with the skills of displaced workers.

“The jobs that are open aren’t replacing the jobs that are lost,” said Thomas Thompson, chief economist at Havas Edge, noting that a laid-off biopharmaceutical engineer is unlikely to transition directly into a warehouse logistics position.

For job seekers, economists recommend flexibility.

Zhao advises workers to broaden their search, focus on industries that are expanding, and recognize that many skills transfer across sectors. He also argues that disruption — whether from technology, politics, or broader economic shifts — is becoming a permanent feature of the labor market.

Andy Challenger sees the trend as something larger than a passing cycle.

“The labor market is being reshaped by technology in real time,” he said, describing the shift as a structural change rather than a temporary phenomenon.

Whether artificial intelligence is truly eliminating these jobs or simply providing companies with a convenient explanation, the practical reality for workers is similar: layoffs remain elevated, hiring is subdued, and the rules of the labor market are evolving faster than many employees can adapt.

JBizNews Desk — Labor & Employment

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A surprisingly strong jobs report pushed the price of gold lower Friday after new government hiring data convinced traders that the Federal Reserve is now less likely to cut interest rates anytime soon.

The U.S. Bureau of Labor Statistics reported Friday morning that employers added 172,000 jobs in May, well above economists’ expectations of roughly 80,000 jobs, while the unemployment rate held steady at 4.3%.

For gold, the reaction was immediate. Spot gold fell sharply following the report as traders moved out of safe-haven assets and into the U.S. dollar and Treasury securities. The metal was on pace for one of its weakest weeks of the year as expectations for Federal Reserve easing continued to fade.

The logic behind the selloff is straightforward. Gold pays no interest. When investors believe interest rates will remain elevated—or potentially move higher—bonds, money market funds, and savings products become more attractive relative to precious metals. Strong economic data also tends to strengthen the U.S. dollar, which makes gold more expensive for overseas buyers.

The jobs report showed broad labor-market strength. Hiring gains were concentrated in health care, leisure and hospitality, and government, while some sectors, including parts of financial activities, remained softer. The government also revised prior months higher, reinforcing the view that the labor market remains resilient despite elevated borrowing costs.

Average hourly earnings increased 0.3% in May and were up 3.4% from a year earlier, suggesting wage growth remains steady but is no longer accelerating at the pace seen during the inflation surge of recent years.

The report arrives less than two weeks before the Federal Reserve’s next policy meeting. Following Friday’s data, interest-rate futures markets sharply reduced expectations for near-term rate cuts and increased the probability that policymakers could maintain restrictive policy for longer than previously expected.

Bond markets reacted as well. The yield on the benchmark 10-year U.S. Treasury note climbed above 4.5%, reflecting expectations that stronger economic growth and persistent inflation pressures could keep rates elevated.

Energy prices remain another concern for policymakers. Oil has moved higher in recent weeks amid ongoing Middle East tensions, raising fears that higher fuel costs could complicate the Fed’s effort to bring inflation back toward its 2% target.

For households, the implications go beyond gold. If rates remain elevated, borrowing costs for mortgages, auto loans, credit cards, and business lending are likely to stay higher for longer. For investors, Friday’s market action underscored a simple reality: when economic data surprises to the upside, gold often loses some of its appeal.

The next major test comes with next week’s inflation data. A hotter-than-expected reading could further strengthen the case for keeping rates elevated and add additional pressure on gold prices.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

MENLO PARK, Calif. — Meta Platforms shares slid more than 5% on Friday after a report that the company is weighing a stock sale of tens of billions of dollars to help fund its artificial-intelligence ambitions — a plan the company quickly waved off as “pure speculation.”

The report came from the Financial Times, which said Friday that Meta is considering raising tens of billions of dollars through an equity offering as it searches for new ways to bankroll its AI buildout, citing three people familiar with the talks. A Meta spokesperson called the report “pure speculation,” and the FT noted the company has not hired banks and may not issue new stock at all.

Investors reacted to a single word: dilution.

When a company sells a large batch of new shares, it splits the existing pie into more slices, lowering the value of each share already held. With Meta’s stock having climbed on AI optimism, the prospect of a massive new share sale flipped the narrative from AI growth to AI funding worry.

The stock fell about 6.6% following the report, according to Reuters. The slide came on a brutal day for technology shares broadly, as a strong jobs report sent the Nasdaq down more than 4% on fears the Federal Reserve will keep interest rates high.

The timing of Meta’s deliberations was no accident.

The talks gained urgency after rival Alphabet raised about $85 billion in an upsized equity offering this week — increased from an initial $80 billion — capitalizing on strong investor demand. The discussions intensified after Alphabet’s deal succeeded, suggesting Meta saw a window to do something similar.

The effort is being run by senior leadership.

Finance chief Susan Li and President Dina Powell McCormick are leading the discussions, and people familiar with the matter said Meta has studied how such a raise could be structured.

The reason Meta is hunting for outside cash is the staggering scale of its AI plans.

The company raised its 2026 capital-expenditure guidance to between $125 billion and $145 billion, up from an earlier range of $115 billion to $135 billion, and the Financial Times reported that spending could climb even higher in 2027.

To put that in perspective, Meta spent $72.2 billion on capital expenditures last year — meaning this year’s plans roughly double that figure.

All that money serves a sweeping ambition.

Chief Executive Officer Mark Zuckerberg is pursuing what he calls delivering “personal superintelligence” across Meta’s platforms, including Facebook, Instagram, WhatsApp, and a growing lineup of AI-powered wearable devices.

Meta’s deliberations reflect a broader shift across Big Tech.

The world’s largest technology companies are increasingly turning to debt and equity markets to fund AI infrastructure, a departure from their long-standing practice of paying for expansion from their own cash flow.

Meta has already tapped outside money in creative ways. Investors including bond giant Pimco and BlackRock participated in a $27.3 billion debt offering tied to Meta’s massive Hyperion data-center project in Louisiana, while investment firm Blue Owl contributed $2.5 billion in equity.

But Friday’s sharp reaction is a warning sign for the entire sector.

Investors have grown increasingly uneasy about how much money Big Tech is pouring into artificial intelligence without clear, immediate returns. Alphabet’s stock, despite a strong year, has fallen for a fourth straight week as investors weigh the costs of massive AI spending.

Meta’s decline suggests that same concern is spreading.

Shareholders want the benefits of artificial intelligence, but they are becoming less enthusiastic about funding those ambitions through new share issuance that dilutes existing ownership.

For now, the plan remains unconfirmed, and Meta insists nothing has been decided.

Whether the company ultimately sells stock, borrows the money, or finds another path, the episode captures one of the defining tensions of the AI era. The infrastructure race has become so expensive that even some of the richest companies in the world are searching for new ways to finance it.

Investors, meanwhile, are increasingly asking a different question: when will all that spending begin to generate returns?

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Bitcoin is having its roughest week in nearly two years, sliding to around $62,500 by midday Friday, June 5, 2026, after a steady stream of selling that erased gains built up through the spring. The world’s largest cryptocurrency has lost nearly 15% since Monday, marking its worst weekly performance since July 2024. Ether has fallen more than 17%, while overall crypto trading activity has dropped to its lowest monthly volume since October 2023.

The decline has unfolded as a sustained sell-off rather than a single dramatic crash, but the damage has been significant. Bitcoin now trades more than 50% below its October 2025 record high near $126,200, after reaching an intraweek high around $75,850 before falling roughly 22%. The move has pushed prices back to levels last seen in early February and toward a closely watched long-term support area near $61,626.

What Is Driving the Sell-Off

Three major developments have fueled this week’s decline.

The first was the disclosure of the first known bitcoin sale by Strategy, the company formerly known as MicroStrategy and still the largest corporate holder of bitcoin. The second was a wave of withdrawals from spot bitcoin exchange-traded funds. The third was a large transfer from a wallet linked to the long-defunct Mt. Gox exchange, reviving fears of additional supply entering the market.

Among those factors, ETF withdrawals may have the broadest impact on everyday investors.

Spot bitcoin ETFs experienced approximately $2.97 billion in outflows during a 10-session withdrawal streak in late May, one of the largest periods of redemptions since the products were introduced. When investors withdraw money from these funds, managers typically sell bitcoin to meet redemption requests, increasing downward pressure on prices.

Macro Forces Add Pressure

Crypto markets are also facing broader economic headwinds.

Investors continue to grapple with persistent inflation, uncertainty surrounding future Federal Reserve rate cuts, and a stronger U.S. dollar. Higher interest rates make cash and bonds more attractive while reducing demand for riskier assets that generate no income.

Geopolitical tensions also weighed on sentiment. Escalating concerns surrounding U.S.-Iran relations during late May contributed to a broader shift away from speculative investments.

A Rare Split Between Stocks and Crypto

One of the most notable developments this week is the divergence between traditional financial markets and digital assets.

Major U.S. stock indexes have continued to approach or reach record highs while bitcoin and ether have suffered sharp losses. For much of the past two years, cryptocurrencies and equities moved largely in tandem as investors embraced risk assets. This week, however, money flowed into stocks while leaving crypto markets.

The disconnect has puzzled many market participants.

According to CryptoQuant founder Ki Young Ju, U.S. spot bitcoin ETFs have accumulated more than 509,000 bitcoin since bitcoin last traded near current levels in March 2024. During the same period, Strategy acquired roughly 650,000 additional bitcoin.

Combined, those buyers absorbed more than 1.24 million bitcoin, yet prices have returned to roughly the same level.

The implication is straightforward: despite enormous institutional demand, enough selling pressure elsewhere in the market has offset those purchases.

Trouble in the Altcoin Market

The week’s sharpest decline occurred outside bitcoin.

Privacy-focused cryptocurrency Zcash plunged more than 30% after a security researcher disclosed a vulnerability that could potentially have allowed an unlimited number of tokens to be created.

The news quickly spread across the privacy-coin sector, dragging down competitors including Monero and Dash. Selling intensified after investor Arthur Hayes disclosed that his firm had exited its entire Zcash position.

The episode highlighted how technical vulnerabilities in a single cryptocurrency can rapidly impact confidence across related sectors of the market.

Where Things Stand Now

Forced liquidations have accelerated the decline.

Data from Coinglass showed approximately $1.2 billion in liquidations over a 24-hour period, with roughly three-quarters of those losses coming from traders who had wagered on higher prices.

Technical analysts are closely watching the $65,000 level as a key support zone. A sustained move below that threshold could open the door to further downside toward $60,000, while a successful hold could trigger a short-term recovery.

For crypto exchanges, miners, and corporate holders such as Strategy, a prolonged downturn could pressure asset values and reduce trading-related revenue. For retail investors who entered through bitcoin ETFs during the spring rally, the week serves as a reminder that cryptocurrency prices remain highly sensitive to broader economic conditions, including Federal Reserve policy and movements in the U.S. dollar.

As always, crypto remains one of the fastest-moving sectors in financial markets, and conditions can change rapidly.

Sources: Coinglass liquidation data; CryptoQuant founder Ki Young Ju; spot bitcoin ETF flow data; CoinDesk market data as of June 5, 2026.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Stocks tumbled on Friday, ending a turbulent week with a sharp sell-off after a surprisingly strong jobs report convinced traders that the Federal Reserve is more likely to raise interest rates than cut them — a classic case of good economic news turning into bad news for the market.

The trigger came before the opening bell. The Bureau of Labor Statistics said U.S. employers added 172,000 jobs in May, roughly double what economists expected, while the unemployment rate held at 4.3%. Rather than cheering the resilient labor market, investors fixated on what it means for borrowing costs: a strong economy gives the Fed every reason to keep rates high to fight stubborn inflation.

The damage was steep and concentrated in technology. According to preliminary figures, the S&P 500 fell 199.64 points, or 2.63%, to 7,384.67, while the Nasdaq Composite dropped 1,117.38 points, or 4.16%, to 25,713.58 — its largest one-day percentage loss since last year — and the Dow Jones Industrial Average lost 684.53 points, or 1.33%, to 50,877.40.

The reaction showed up in the bond market first. Treasury yields rose sharply after the report in a “good news is bad news” scenario. Higher yields make borrowing more expensive and make richly priced growth stocks look less attractive. Markets have now all but abandoned bets on rate cuts this year: the Fed still projects one cut in 2026, but futures traders see none, and some now put the odds of an actual hike by December at roughly even.

At the center of the rout were the chipmakers that have powered the market’s record run. Shares of Nvidia fell 6% as money kept flowing out of semiconductors, and smaller rivals Intel, Micron, AMD, and Broadcom fell sharply alongside it. The weakness wasn’t limited to the United States. Europe’s chip names followed Wall Street lower, with ASML down 3.8% and Germany’s Infineon off more than 6%, while South Korean and Japanese stocks slid in Asian trading.

The chip reversal had been building all week. A weaker-than-expected AI chip outlook from Broadcom earlier in the week dragged down peers including AMD, Intel, and Micron, even though Broadcom itself had reported record revenue. Once the highest-flying corner of the market wobbled, the strong jobs report gave investors a reason to sell the rest.

There was company-specific pain too. Lululemon Athletica slumped after the athletic apparel maker cut its annual profit forecast and projected second-quarter earnings well below estimates. Big technology names also drew scrutiny over how they are funding the AI boom: Meta fell 7% on reports it is looking to sell billions in new shares, days after Alphabet raised $80 billion to fund its own buildout. Crypto-linked firms Coinbase and Strategy were pulled lower by a sharp drop in bitcoin, while contact-lens maker Cooper Companies rose after beating estimates.

The week’s arc tells the larger story. It began at all-time highs. On Monday, the S&P 500 closed at a record 7,599.96 and the Nasdaq at 27,086.81, with Nvidia climbing more than 6% after unveiling a new chip for personal computers — lifting Dell more than 10% and HP more than 8%.

The optimism carried into Tuesday. The S&P 500 posted its first close above 7,600, at 7,609.78. Marvell surged 25% after Nvidia CEO Jensen Huang said it could become the next trillion-dollar company, and Hewlett Packard Enterprise jumped 25% on strong guidance.

Then the mood shifted.

After Broadcom’s outlook landed midweek, investors began rotating out of technology and into safer corners of the market. On Thursday, the Dow surged 874.86 points, or 1.73%, to a record close of 51,561.93 — led by UnitedHealth, up more than 5%, along with JPMorgan Chase and Walmart — even as the Nasdaq slipped. Health care, financials, and real estate led that day’s gains while technology lagged.

Friday’s plunge then erased the week’s optimism in a single session.

The reversal was historic in one respect. The S&P 500 ended a nine-week run of Friday-to-Friday gains — its longest weekly winning streak since one that ended in December 2023. Ryan Detrick, chief market strategist at Carson Group, captured the mood, saying that after the record run in technology and chips, “the dam just broke today,” and that the strong jobs report puts the Fed in a difficult position on any rate cut for the rest of the year.

Commodities reflected the same forces. Gold fell to its lowest level of the year as rate-hike bets climbed, while oil eased on the day but still finished the week higher, keeping pressure on fuel costs. Crypto had a rough week of its own, with bitcoin sliding to around $62,000, down nearly 5%.

The week exposed a vulnerability that has worried some market watchers for months: how much of the rally rests on a handful of AI names. Evercore ISI’s Julian Emanuel has noted that record concentration in a small group of AI stocks has been driving the market’s strength. When those names stumble, as they did this week, the whole market feels it.

What comes next will hinge on inflation and the Fed. The May Consumer Price Index report is due next week, and a hot reading would harden the case for higher rates. The bigger test arrives June 16–17, when Kevin Warsh chairs his first policy meeting as Federal Reserve chair.

For now, the message from Friday is simple: the economy looks strong, and on Wall Street right now, that is exactly what investors are afraid of.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The chief executive of the world’s largest retailer started his career stacking mulch and watering flowers, and after more than three decades climbing the ranks, he says the single most important quality for any leader is the willingness to embrace change.

Walmart CEO John Furner shared that lesson in a recent interview with Fast Company, highlighted in coverage published on Thursday, June 4.

Furner’s message was simple: in a world being transformed by technology, artificial intelligence, automation, and changing consumer habits, leaders who embrace change will outperform those who resist it.

Reflecting on a career that has spanned the rise of e-commerce, smartphones, and now AI, Furner said getting comfortable with change is what separates effective leaders from the rest.

His story is one of the most remarkable internal success stories in corporate America.

Furner joined Walmart in 1993 as a part-time hourly associate working in the garden center of a store in Bentonville, Arkansas. After earning a marketing degree from the University of Arkansas, he steadily climbed through the company, serving as a store manager, district manager, buyer, and executive before eventually leading Walmart’s U.S. operations.

He later became CEO of Sam’s Club and ultimately rose to become Walmart’s chief executive on February 1, 2026, succeeding longtime CEO Doug McMillon, who also began his Walmart career as an hourly associate.

Today, Furner oversees a company employing more than 2 million people and operating nearly 11,000 stores across 19 countries.

The challenge before him is enormous.

Walmart is in the middle of what Furner describes as a “people-led, tech-powered” transformation, investing heavily in artificial intelligence, automation, and digital commerce as it battles Amazon and other online competitors.

The company has rolled out AI-powered tools, expanded automation throughout its supply chain, and introduced technologies designed to improve both customer service and operational efficiency.

The investments are producing results.

Walmart’s online business grew 27% in its most recent quarter, while the company’s stock has traded near record highs.

But Furner argues that technology alone is not enough.

The larger lesson, he says, is that leaders must be willing to evolve alongside the businesses they manage. Companies that refuse to adapt often find themselves overtaken by competitors willing to embrace new realities.

The message extends far beyond retail.

Businesses across nearly every industry are confronting similar challenges as artificial intelligence reshapes workflows, customer expectations, hiring practices, and competitive advantages.

For many organizations, the biggest risk may not be adopting the wrong technology—it may be failing to adapt at all.

Furner’s own career reflects that philosophy.

A man who began his Walmart career watering plants in a garden center now leads one of the most valuable companies in the world. Along the way, the retail industry transformed repeatedly, and each stage required new skills, new strategies, and new ways of thinking.

His conclusion after more than three decades at Walmart is straightforward: in an economy defined by constant disruption, the leaders who succeed are the ones willing to change with it.

JBizNews Desk — Retail & Leadership

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

OpenAI said Friday, June 5, 2026, that it will comply with President Donald Trump’s new executive order asking artificial-intelligence companies to provide their most powerful AI models to the federal government for testing before they are released to the public.

Speaking to CNBC on the sidelines of the SXSW London festival, George Osborne, OpenAI’s Head of Countries, said the company would participate in the voluntary program, arguing that democratic governments have a legitimate role in shaping how advanced AI systems are developed and deployed.

The decision marks one of the clearest signs yet that Washington and Silicon Valley are moving toward a more structured relationship as AI systems become increasingly powerful and influential.

What the Order Does

Trump signed the executive order on June 2, directing federal agencies to establish a voluntary framework under which developers can submit their most advanced AI systems for government testing up to 30 days before public release.

The purpose is to evaluate advanced cyber capabilities and determine whether a model qualifies as a “covered frontier model” — a designation reserved for the most powerful AI systems that could present significant national-security or cybersecurity implications.

Importantly, the order does not create a licensing system or require government approval before a company can launch a model. Participation remains voluntary, reflecting the administration’s effort to balance innovation with security concerns.

The order directs agencies including the Department of Defense, the Department of the Treasury, and the Cybersecurity and Infrastructure Security Agency (CISA) to strengthen cyber defenses and establish testing procedures for advanced AI systems.

Why Washington Changed Course

The shift follows growing concern that frontier AI models may be capable of identifying and exploiting cybersecurity vulnerabilities at unprecedented speed.

Those concerns intensified after Anthropic announced in April that it would limit the release of its Mythos Preview model because of its ability to discover and exploit software vulnerabilities.

Security experts have increasingly warned that future AI systems could dramatically accelerate cyberattacks, identify previously unknown weaknesses, and automate sophisticated offensive operations. Government officials argue that early testing could help identify major risks before powerful systems are released widely.

The move represents a notable evolution for an administration that had previously favored a lighter-touch approach to AI oversight.

The Business Impact

The order could have significant implications for the rapidly growing AI industry.

A 30-day government review introduces a new step between completing a model and releasing it to customers. While the review remains voluntary, companies that participate may gain credibility with governments, enterprise customers, and investors concerned about safety and security.

The framework may also strengthen the competitive position of larger AI developers such as OpenAI, Anthropic, Google DeepMind, Microsoft, and xAI, all of which have the resources to absorb additional compliance and testing requirements.

Smaller developers and foreign competitors could face greater challenges if government testing eventually becomes an industry expectation.

The policy could also create additional hurdles for emerging open-source competitors, including Chinese developers such as DeepSeek and Qwen, whose models have rapidly narrowed the performance gap with leading U.S. systems.

In effect, the companies best positioned to comply with expanded safety reviews may gain an advantage as governments, corporations, and regulators increasingly prioritize trust and security.

Industry Response

OpenAI is not alone in embracing government oversight.

Google DeepMind, Microsoft, and xAI previously agreed to submit advanced models for review through arrangements with the U.S. Center for AI Standards and Innovation, while OpenAI and Anthropic entered similar agreements in 2024.

Reaction to Trump’s executive order has been broadly supportive.

Microsoft President Brad Smith called the measure an important step toward balancing innovation and public safety. Anthropic described it as a meaningful move to strengthen America’s leadership in artificial intelligence while reducing risks associated with increasingly powerful systems.

OpenAI has gone even further than the administration’s proposal.

In its policy paper, “Democratic Governance of Frontier AI,” the company advocated for a national AI safety framework that includes mandatory testing of the most advanced systems, independent audits, and whistleblower protections. OpenAI argued that decisions regarding frontier AI safety should ultimately be guided by democratic governments rather than individual technology companies.

What Comes Next

The success of the new framework depends entirely on continued cooperation from the companies building the world’s most powerful AI systems.

National-security officials want early visibility into frontier models because of their potential cybersecurity implications. Technology companies, meanwhile, want to maintain public trust while avoiding regulations that could slow innovation.

For now, the arrangement remains voluntary.

Whether that cooperation continues as AI systems become more powerful — and whether future administrations seek stronger oversight — may determine how artificial intelligence is governed for years to come.

Sources: White House Executive Order on Frontier AI Model Testing (June 2, 2026); CNBC interview with George Osborne at SXSW London (June 5, 2026); OpenAI policy paper Democratic Governance of Frontier AI; U.S. Center for AI Standards and Innovation agreements.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Generation Z workers are reporting record levels of workplace loneliness, and employers are increasingly paying the price through higher turnover, lower engagement, and lost productivity, according to a new Workday report highlighted by Fortune on Thursday, June 4.

The findings suggest that one of the biggest workforce challenges facing employers today may have less to do with compensation and more to do with connection.

According to the report, Generation Z employees are the least connected workers in the workplace today. They are 12 times more likely to feel completely disconnected from coworkers than Generation X employees and 16 times more likely to say they do not trust the people they work with.

The roots of the problem largely trace back to the pandemic.

Many Gen Z workers entered the workforce during or immediately after COVID-19, when offices sat empty and onboarding often took place entirely through video calls. Unlike previous generations, many never experienced the informal workplace interactions that help employees build relationships, learn company culture, and develop trust with colleagues and managers.

The result is a generation that often feels isolated despite being more digitally connected than any workforce before it.

For employers, the consequences extend far beyond employee satisfaction.

Disconnected employees tend to be less engaged in their work, less committed to their organizations, and more likely to leave. High turnover carries significant costs through recruiting, hiring, onboarding, and training replacements. When employees begin taking time off because of loneliness or emotional exhaustion, absenteeism becomes another expense businesses must absorb.

The findings come as companies across the country continue searching for ways to improve productivity while managing labor costs.

Separate studies have found that Gen Z workers report higher levels of stress, burnout, and depression than older generations. At the same time, some employers have expressed frustration over workforce readiness among recent graduates, creating a growing disconnect between what younger workers expect and what employers believe they are providing.

There is an important twist in the data.

While younger workers are often associated with supporting remote work, many surveys indicate that Gen Z employees actually want more opportunities for in-person interaction. Many report seeking greater access to mentorship, coaching, feedback, and relationship-building opportunities that can be difficult to replicate through screens.

In many cases, the isolation is not a preference but a consequence of how work evolved during and after the pandemic.

For employers, the report serves as a warning that workplace culture carries measurable business consequences.

Over the past several years, many organizations reduced spending on team-building programs, mentoring initiatives, professional development, and in-person collaboration efforts. While those cuts often reduced short-term expenses, the data suggests they may have created longer-term costs through lower engagement and higher turnover.

Business leaders are increasingly recognizing that trust and connection are not merely cultural issues; they are operational issues that directly affect performance.

Some employers have cited these concerns as part of the reason for encouraging workers to spend more time in the office. The challenge, however, is ensuring that employees gain meaningful interaction and mentorship rather than simply increasing attendance requirements.

The stakes extend beyond individual companies.

Generation Z now represents a rapidly growing share of the American workforce, and the generation immediately behind them is beginning to enter the labor market as well. If employers fail to address workplace isolation, the result could be higher turnover rates, weaker productivity growth, and increased labor costs across multiple industries.

The deeper lesson is that workplace culture is not a soft benefit; it is a business asset.

A generation that began its professional life over Zoom and from kitchen tables is now telling employers that it feels disconnected and distrustful. Companies that successfully rebuild connection, mentorship, and trust may gain a competitive advantage in attracting and retaining talent, while those that ignore the problem risk paying for it through lower productivity, higher turnover, and rising workforce costs.

JBizNews Desk — Workforce

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A bipartisan pair of House lawmakers unveiled a sweeping proposal on Thursday, June 4, to create national rules for artificial intelligence, including a provision that would override some state laws, an effort to bring order to a patchwork of regulation that has frustrated both technology companies and consumer advocates. Representatives Jay Obernolte, a California Republican, and Lori Trahan, a Massachusetts Democrat, released the discussion draft, which they call the Great American Artificial Intelligence Act.

The draft, which runs to 269 pages, is a starting point rather than a finished bill. The lawmakers described it as the beginning of a serious national conversation and said they want feedback from experts and the public before formally introducing it. Co-sponsors include Representatives Scott Franklin of Florida, Suhas Subramanyam of Virginia, Erin Houchin of Indiana, and Scott Peters of California.

The most contentious piece is preemption. The draft would prevent states from enforcing their own regulations on the development of AI models for three years. According to the text, it would not necessarily block state laws governing how AI is used once a product is released, a distinction meant to narrow the override. The goal, the sponsors argue, is to avoid a confusing tangle of fifty different state rulebooks that could hinder companies trying to build AI responsibly.

The bill would also require large frontier developers, defined as those with more than $500 million in gross revenue in the previous year, to establish public frameworks describing how they manage the risks of their most powerful systems. And it would formally create a Center for AI Standards and Innovation, tasked with developing voluntary standards and guidelines, with an appropriation of $100 million a year.

The proposal lands in a fraught political environment. It comes days after the president signed an executive order on AI safety and cybersecurity, and the White House has been skeptical of any approach that imposes strict requirements on companies. The preemption idea, in particular, has a troubled history: a similar effort to impose a long moratorium on state AI laws was stripped from a major bill in the Senate by a lopsided vote in 2025.

For businesses, the appeal of a single national framework is obvious. Companies that build AI products dislike having to comply with different and sometimes conflicting rules in every state. A uniform federal standard would make it easier and cheaper to operate nationwide, and the bill’s focus on voluntary standards rather than heavy mandates would likely sit well with industry.

Consumer advocates and safety groups see it differently. Many states have moved faster than Congress to pass protections, on issues from child safety to consumer transparency to data privacy. Critics worry that blocking states from acting, even temporarily, would leave Americans exposed while federal rules remain weak or unfinished. Brendan Steinhauser, who leads a group focused on AI safety, praised the bill’s bipartisan nature and its attention to catastrophic risks but opposed the preemption provision, arguing that a national standard should protect at least as much as it overrides.

The tension reflects a fundamental disagreement about how to regulate a fast-moving technology. One camp argues that AI is too important and too fast-changing to be governed by a confusing mix of state laws, and that a single national approach is the only durable solution. The other argues that with no strong federal protections yet in place, stripping states of their power would create a dangerous gap.

The lawmakers framed their effort in long-term terms, arguing that AI will shape the economy, the workforce, and national security for decades, and that the rules governing it must be durable enough to outlast changes in Congress and the White House. That ambition is part of what makes the bill significant: it attempts to set a lasting framework rather than react to the latest controversy.

Whether it can pass remains uncertain. The path through both the House and the Senate is difficult, the White House is wary, and the preemption fight has already shown how divisive the issue is. But the release of a detailed, bipartisan draft marks a serious attempt to move federal AI policy from talk to text, and it signals that Congress is finally engaging with questions that states and companies have been wrestling with for years.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A battle unfolding in Arizona could help determine whether families or technology companies pay for the massive electricity demands of artificial intelligence.

Arizona Public Service (APS), the state’s largest electric utility, is seeking approval from the Arizona Corporation Commission to increase rates on data centers by more than 45% while raising residential rates by about 16%, according to hearings that began on May 18 and continued into early June.

The proposal is part of a broader rate case APS filed in June 2025, seeking an overall 14% increase in customer rates. If approved, the utility estimates the average residential customer would pay roughly $20 more per month.

At the center of the debate are the giant data centers powering artificial intelligence and cloud computing. These warehouse-sized facilities consume enormous amounts of electricity and often require utilities to build additional power plants, substations, and transmission infrastructure.

APS argues that the companies creating that demand should pay a larger share of the costs rather than passing them on to families and small businesses.

The utility is also proposing a system of formula rates, allowing regulators to review costs annually and assign infrastructure expenses to the customer groups driving those costs. Under that approach, rapidly growing data centers could face significantly higher charges as their power consumption expands.

APS says the rate increases are necessary because the utility’s current rates are based largely on equipment costs from 2021 and 2022, while inflation has substantially increased the price of transformers, transmission equipment, labor, and other critical grid components.

The company argues that additional revenue is needed to maintain reliability during Arizona’s extreme summer heat, when air-conditioning demand reaches its highest levels.

The proposal has generated fierce opposition.

Arizona Attorney General Kris Mayes has criticized the residential increase, arguing that APS is seeking excessive profits and that customers could face smaller increases if the utility were compensated only for the actual costs required to provide reliable service.

Public hearings have drawn large crowds, with many residents, particularly seniors and those living on fixed incomes, warning that even modest increases could make summer cooling unaffordable.

The debate over data centers may ultimately become the most important part of the case.

According to the Electric Power Research Institute, data centers could account for more than 20% of Arizona’s electricity consumption by 2030. That rapid growth is forcing utilities nationwide to reconsider how electric systems are financed.

The question is simple but consequential: Should ordinary ratepayers help finance infrastructure built primarily to serve AI companies, or should those companies bear the costs themselves?

Arizona is one of the first major states attempting to answer that question directly.

The issue is drawing national attention because electric utilities across the country are facing similar challenges. Demand from artificial intelligence, cloud computing, and advanced manufacturing is increasing electricity consumption at a pace not seen in decades.

Meanwhile, major technology companies have sought to reassure regulators and consumers.

Earlier this year, Google, Meta, Microsoft, OpenAI, and Amazon Web Services joined a pledge stating that data-center expansion should not result in higher energy costs for residential customers.

Critics, however, argue that voluntary commitments may not fully address the infrastructure expenses associated with the largest AI projects.

A judge is currently reviewing testimony from more than 30 parties before issuing a recommendation to the five-member Arizona Corporation Commission, which is expected to make a final decision later in 2026.

If approved, the new rates could take effect during the second half of the year.

The outcome may reach far beyond Arizona.

As artificial intelligence continues expanding, so will its demand for electricity. Regulators nationwide are closely watching whether Arizona successfully requires data centers to pay a larger share of the costs they create—or whether those costs ultimately find their way onto household electric bills.

JBizNews Desk — Arizona

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The race to build smarter artificial intelligence may have entered a new and potentially transformative phase. According to new data released by Anthropic on June 4, the company behind the popular Claude AI assistant says its own AI systems are now writing the overwhelming majority of the software code used inside the company.

If accurate, the development represents one of the strongest signs yet that artificial intelligence is beginning to accelerate its own advancement—a concept researchers have discussed for decades but have only recently started to witness in practice.

The disclosure came in a report published by the Anthropic Institute, which detailed the company’s progress toward what researchers call recursive self-improvement, the idea that AI systems can help create better versions of themselves, which can then create even more advanced successors.

The implications extend far beyond Anthropic.

If artificial intelligence can significantly speed up its own development, the pace of technological change could accelerate dramatically, affecting industries, workers, governments, investors, and policymakers worldwide.

The headline statistic immediately captured attention.

According to Anthropic, more than 80% of the code merged into the company’s systems as of May 2026 was written by Claude, its flagship AI model.

That figure represents an extraordinary jump from just a year earlier, when AI-generated code accounted for only a small percentage of the company’s development work.

Anthropic said that since launching its internal coding tools in early 2025, the productivity of its engineers has increased dramatically.

The company estimates that a typical software engineer now produces roughly eight times more code than in 2024.

The change reflects a fundamental shift in how software is being developed.

Rather than spending most of their time writing code line by line, engineers increasingly focus on defining objectives, reviewing outputs, testing systems, and making strategic decisions while AI handles much of the actual coding.

In effect, software developers are becoming managers of AI-generated work rather than creators of every line themselves.

For decades, the idea of recursive self-improvement has occupied a central place in discussions about advanced artificial intelligence.

The concept is simple but powerful.

If an AI system becomes capable of improving the software used to build itself, it could potentially help create a smarter version of itself.

That improved version could then make further improvements, creating a cycle of increasingly rapid advancement.

Some researchers view the possibility as the pathway to revolutionary scientific breakthroughs.

Others view it as one of the greatest technological risks humanity may ever face.

Anthropic stopped short of claiming it has achieved true recursive self-improvement.

However, the company presented several examples suggesting that its systems are becoming increasingly effective at assisting software development.

According to the report, Claude’s success rate on complex, open-ended engineering tasks rose from approximately 26% to 76% over a six-month period.

On another benchmark involving code optimization, Anthropic said its most advanced experimental model achieved a 52-fold performance improvement, compared with roughly fourfold improvements typically achieved by skilled human engineers working on the same challenge.

The company also described situations where Claude appeared capable of identifying better technical solutions than researchers initially pursued.

According to Anthropic, when human teams moved in unproductive directions, Claude suggested superior alternatives approximately 64% of the time, compared with only 22% in 2024.

In one particularly striking example, the company said Claude autonomously generated and deployed more than 800 software fixes addressing a longstanding category of system errors.

Anthropic estimated that manually completing the same work could have required years of engineering effort.

For businesses, the implications are enormous.

Technology companies already face intense pressure to develop AI products faster than competitors.

If AI systems themselves become powerful productivity tools for engineers, companies that effectively deploy those tools could gain significant competitive advantages.

Faster development cycles could mean quicker product launches, lower development costs, and accelerated innovation across virtually every industry touched by software.

The impact would not be limited to technology companies.

Artificial intelligence increasingly influences healthcare, finance, manufacturing, logistics, education, entertainment, and scientific research.

A meaningful increase in the speed of AI development could ripple throughout the global economy.

For software engineers, the findings reinforce a trend already becoming visible throughout the industry.

Coding remains important, but the value of engineers is increasingly shifting toward problem-solving, architecture, strategy, oversight, and quality control.

If AI can reliably write large portions of software, the most valuable human skill may become deciding what should be built rather than how to build it.

Anthropic also highlighted AI’s growing role in software quality assurance.

According to the company, automated systems now identify approximately one-third of the production bugs that previously caused issues across parts of its infrastructure.

In other words, AI is not only writing software—it is increasingly reviewing and correcting it as well.

Despite the impressive statistics, Anthropic included several important caveats.

The company acknowledged that measuring productivity through lines of code can be misleading because more code does not necessarily mean better software.

Perhaps more importantly, Anthropic emphasized that Claude still lacks what researchers often call research judgment.

While AI may be increasingly capable of solving technical problems, it remains unclear whether it can independently determine which problems are worth solving in the first place.

That distinction may prove critical.

Generating solutions is different from identifying meaningful questions.

Anthropic stressed that true recursive self-improvement has not yet arrived.

Nevertheless, the company suggested that the possibility may be closer than many observers realize.

The report arrives as lawmakers in Washington are increasingly focused on AI oversight.

Coincidentally, the same day Anthropic released its findings, a bipartisan group of members of Congress unveiled draft legislation aimed at creating a federal framework for regulating artificial intelligence.

The timing highlights how concerns surrounding AI capability, safety, transparency, and governance are becoming central policy issues.

For investors, businesses, and policymakers alike, Anthropic’s report offers both excitement and caution.

The prospect of dramatically accelerated innovation could unlock extraordinary economic growth and technological breakthroughs.

At the same time, the speed of that progress raises questions about oversight, accountability, and society’s ability to adapt.

Whether Anthropic’s findings ultimately represent the beginning of a technological revolution or simply another milestone along AI’s development path remains uncertain.

What is becoming increasingly clear, however, is that artificial intelligence is no longer just helping humans write software.

It is beginning to help build the very systems that may define the future of technology itself.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Artificial intelligence is no longer transforming only search engines, software coding, and customer service. It is now reshaping one of the world’s oldest creative industries: music.

In one of the clearest signs yet that investors believe AI-generated music is becoming a permanent part of the entertainment landscape, Suno, the artificial intelligence music platform that allows users to create complete songs from simple text prompts, announced it has raised more than $400 million in new funding at a valuation of $5.4 billion.

The financing round, announced on June 3 by co-founder and CEO Mikey Shulman, more than doubles the company’s valuation from just six months ago, when Suno raised $250 million at a valuation of approximately $2.45 billion.

The speed of that growth is remarkable.

Few technology companies have doubled their valuation in such a short period, highlighting the extraordinary investor enthusiasm surrounding artificial intelligence and the growing belief that AI-generated content will become a major part of the global economy.

The new funding round was led by Bond Capital, whose previous investments include companies such as OpenAI, Substack, and prediction market platform Kalshi.

Additional investors included IVP, Forerunner, Union Square Ventures, Alkeon, and Quiet Capital, while existing investors including Lightspeed Venture Partners, Matrix Partners, Menlo Ventures, and Schroders Capital also participated.

Shulman disclosed that a number of artists, songwriters, and music producers invested as well, although their identities were not publicly disclosed.

Founded in Cambridge, Massachusetts, Suno has become one of the most recognizable names in AI-generated music.

The platform allows users to type simple instructions such as a song style, mood, genre, topic, or lyric concept and receive a fully generated song complete with vocals, lyrics, instruments, and production.

What once required musicians, recording studios, producers, engineers, and expensive equipment can now be accomplished in minutes.

The appeal has proven enormous.

According to company figures, Suno has surpassed 2 million paying subscribers and has become one of the most downloaded music applications in Apple’s App Store.

The platform is used by everyone from professional musicians experimenting with new ideas to complete beginners creating music for the first time.

Supporters view the technology as a revolutionary democratization of music creation.

For generations, producing high-quality music required access to expensive instruments, recording equipment, technical expertise, and industry connections.

AI dramatically lowers those barriers.

Anyone with a smartphone and an idea can now generate songs that would have been impossible for most people to create independently only a few years ago.

Yet Suno’s rapid rise has not come without controversy.

The company has become one of the central figures in an escalating legal battle over the future of artificial intelligence and intellectual property rights.

In 2024, major record labels including Warner Music Group, Universal Music Group, and Sony Music Entertainment filed lawsuits against Suno and rival AI music platform Udio, alleging copyright infringement.

The lawsuits argue that AI music systems were trained using copyrighted recordings without permission or compensation.

At the heart of the dispute is a question that extends far beyond music:

Can artificial intelligence companies legally learn from copyrighted material without obtaining licenses from the creators?

More than 1,800 independent artists have also supported class-action litigation involving AI music companies, arguing that their work was effectively used to train machines without consent.

The controversy has sparked fierce debate across the entertainment industry.

Critics argue that AI-generated music threatens to devalue human creativity by flooding the market with machine-generated content.

Many artists fear a future where synthetic songs compete directly against human musicians while relying on knowledge learned from decades of human-created recordings.

Supporters counter that technological innovation has always transformed creative industries and that AI should be viewed as a tool rather than a replacement for artists.

They argue that musicians can use AI to expand creativity, increase productivity, and reach new audiences.

Interestingly, the relationship between Suno and the music industry appears to be evolving.

Rather than continuing endless litigation, parts of the industry are beginning to explore partnerships.

Late last year, Warner Music Group settled its legal dispute with Suno and entered into a licensing agreement with the company.

The deal marked the first major-label partnership for an AI music platform and may provide a roadmap for resolving broader industry conflicts.

As part of that effort, Suno announced plans to launch a new music-generation model that would allow artists to voluntarily participate by licensing their names, voices, likenesses, and musical styles for use in AI-generated content.

If successful, such arrangements could create entirely new revenue streams for musicians while reducing legal uncertainty for AI companies.

The fresh capital will be used to expand Suno’s computing infrastructure, hire additional engineers, train more advanced AI models, and accelerate international growth.

The funding also reflects a broader investment trend.

Venture capital continues pouring into companies developing AI-generated content across music, video, writing, design, animation, and entertainment.

Investors increasingly believe artificial intelligence will become a foundational technology for creative industries in much the same way it has already become for software development.

For investors, Suno’s appeal is easy to understand.

The company has more than doubled its valuation in six months.

It has attracted millions of paying customers.

It is generating significant subscription revenue.

And it has begun establishing relationships with the very industry that once sought to shut it down.

Whether AI-generated music ultimately enhances creativity or disrupts it remains one of the biggest unanswered questions in technology and entertainment.

But one thing is becoming increasingly clear: investors are betting billions of dollars that AI-generated music is not a passing trend.

They believe it is the future.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Brian Chesky, the billionaire co-founder and Chief Executive Officer of Airbnb, is preparing to launch a new artificial intelligence company, marking his first major move into one of the most competitive industries in the world. The development was first reported by Bloomberg on June 4, citing people familiar with the matter who requested anonymity because the plans have not yet been publicly announced.

While Chesky intends to remain CEO of Airbnb, the new venture signals that one of Silicon Valley’s most influential founders believes the current generation of AI products is missing something fundamental.

According to Bloomberg’s report, the new company will focus on developing advanced artificial intelligence models, with a particular emphasis on how people interact with AI systems. The lab remains in its early stages, and details regarding funding, leadership, staffing, and technology have not yet been finalized.

What makes the project noteworthy is not simply that another AI startup is being launched.

It is the reason Chesky appears to be doing it.

For years, Chesky has argued that artificial intelligence products have become too focused on text and not focused enough on experience.

Today’s leading AI systems generally operate through chat interfaces where users type questions and receive written responses. Chesky has repeatedly suggested that the future of AI should be far more visual, intuitive, interactive, and design-oriented.

In many ways, that perspective reflects the path that built Airbnb itself.

Before becoming one of the most successful technology entrepreneurs of his generation, Chesky studied industrial design. Design thinking became one of Airbnb’s defining competitive advantages, helping transform what began as a simple room-rental concept into a global travel platform used by hundreds of millions of people.

His reported frustration with today’s AI interfaces appears to have become the foundation for this new venture.

Unlike competitors such as Expedia and Booking Holdings, Airbnb has largely avoided integrating directly into platforms like OpenAI’s ChatGPT. Chesky has openly stated that he believes current AI tools are not yet capable of delivering the kind of travel-planning experience he ultimately envisions.

Rather than adapting Airbnb to existing AI systems, he now appears to be exploring whether AI itself should be redesigned.

For investors, the announcement generated mixed reactions.

Airbnb shares initially moved higher following the Bloomberg report before giving back those gains later in the trading session.

The hesitation reflects a common concern among shareholders whenever a high-profile founder pursues outside projects.

Investors often worry that leadership attention could become divided.

That concern may be particularly relevant in Chesky’s case.

Within Silicon Valley, he is known as one of the most hands-on chief executives in the technology industry.

His management style became so widely discussed that startup investor and entrepreneur Paul Graham popularized the phrase “Founder Mode” in 2024 to describe leaders who remain deeply involved in product development, strategy, and operations even after building massive companies.

Chesky has embraced that philosophy throughout Airbnb’s evolution.

The timing is also significant because Airbnb itself is undergoing a major transformation.

The company is no longer content being simply a marketplace for booking vacation rentals.

Chesky has repeatedly outlined a vision of Airbnb becoming a broader travel platform that could eventually handle experiences, services, transportation, local activities, and other travel-related offerings.

Executives have suggested some of these initiatives could eventually generate more than $1 billion annually in additional revenue.

Artificial intelligence is expected to play a major role in that expansion.

Chesky has spoken publicly about Airbnb’s internal use of AI tools, particularly coding assistants that allow teams to develop and test new products significantly faster than before.

According to Chesky, projects that previously required months or years can increasingly be developed in weeks.

The decision to create a separate AI lab rather than house the effort entirely within Airbnb may reveal how ambitious the project truly is.

Rather than developing AI solely for travel applications, Chesky appears to believe there is an opportunity to rethink how consumers interact with AI more broadly.

That places him in direct competition with some of the world’s most valuable and heavily funded companies.

The AI industry is currently dominated by giants including OpenAI, Google, Anthropic, Microsoft, Meta, and Amazon, all of which are investing billions of dollars annually into AI research and infrastructure.

Building cutting-edge AI models requires enormous amounts of computing power, engineering talent, and financial resources.

Even well-funded startups face significant barriers entering the field.

Yet Chesky may be making a different bet.

While many AI companies focus primarily on making models smarter, faster, and more powerful, his reported emphasis appears centered on making AI easier, more intuitive, and more enjoyable to use.

That distinction could prove important.

Technology history is filled with examples where superior design and user experience mattered just as much as raw technical capability.

For consumers, the long-term implications could be substantial.

Imagine travel planning that feels less like asking questions in a chatbot and more like interacting with a personalized digital concierge that visually understands preferences, destinations, budgets, schedules, and experiences before suggestions are even requested.

That type of experience aligns closely with the design philosophy Chesky has advocated for years.

Of course, significant challenges remain.

The company does not yet officially exist.

Funding details remain unknown.

Leadership has not been announced.

The technology roadmap is still unclear.

And competition in AI has never been more intense.

Still, the broader message is unmistakable.

One of the most successful founders of the internet era has concluded that today’s AI experience is not where it needs to be—and rather than waiting for someone else to fix it, he is reportedly building a company to try.

Whether the venture succeeds or fails, Chesky’s entry adds another powerful voice to the debate over what the next generation of artificial intelligence should look like.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. House of Representatives voted on Wednesday, June 3, to approve a resolution that would require additional congressional authorization before the president could continue military operations against Iran, marking the strongest legislative challenge yet to a conflict that has reshaped energy markets, fueled inflation concerns, and heightened geopolitical tensions across the globe.

The vote, first reported by Reuters, represents the most significant congressional pushback since the U.S.-Israeli conflict with Iran began in late February. While the measure faces significant hurdles before becoming law, its passage signals a growing desire among lawmakers to reassert Congress’s constitutional role in decisions involving war and military engagement.

At its core, the legislation is a War Powers Resolution, designed to reinforce the constitutional principle that the authority to declare and sustain war belongs to Congress rather than the executive branch alone.

Supporters of the measure argue that military operations against Iran, including actions connected to the strategic Strait of Hormuz, have expanded without a clear vote from elected representatives. They contend that a conflict with such enormous economic, military, and diplomatic consequences deserves direct congressional approval rather than relying solely on executive authority.

The resolution’s future remains uncertain.

Before taking effect, it would need approval from the U.S. Senate, where support remains far from guaranteed. Even if it were to pass both chambers, lawmakers would likely face a presidential veto, requiring a two-thirds majority in both the House and Senate to override. Given current political realities, that remains a difficult path.

As a result, the immediate impact is more political than legal.

Yet financial markets are paying close attention.

The war has become one of the most important drivers of global market activity in 2026. Every escalation in the conflict has pushed oil prices higher, increased volatility in equity markets, and created uncertainty for businesses dependent on stable energy supplies. Conversely, every sign of diplomacy or de-escalation has produced relief rallies across multiple asset classes.

The House vote arrived during a week already marked by encouraging developments for markets. Israel and Lebanon announced a ceasefire agreement, oil prices retreated from recent highs, and reports surfaced that diplomatic discussions between Washington and Tehran could continue.

Taken together, investors increasingly see a political environment that may be moving away from a prolonged military confrontation.

For businesses, predictability matters.

A conflict with no clear endpoint creates significant planning challenges for companies exposed to fuel costs, transportation expenses, international shipping, and global trade routes. The continued threat of disruption near the Strait of Hormuz, through which a significant portion of the world’s oil supply travels, has forced businesses to prepare for potential spikes in energy prices and supply chain disruptions.

Industries particularly sensitive to these developments include airlines, trucking companies, shipping firms, manufacturers, logistics providers, and energy-intensive industrial operations.

Even a symbolic congressional effort to limit the war may reduce concerns that the conflict could expand indefinitely, providing some reassurance to corporate planners and investors.

The vote also highlights a broader shift in political sentiment.

Wars are expensive, and those costs eventually appear throughout the economy. Military spending affects federal budgets, higher oil prices contribute to inflation, and uncertainty can weaken investment and consumer confidence. As the conflict has continued and energy costs have remained elevated, lawmakers from both parties have faced increasing pressure from constituents concerned about economic consequences at home.

The fact that the resolution secured enough support to pass the House is noteworthy given the deep divisions that have characterized Congress in recent years.

What happens next may be nearly as important as the vote itself.

If the Senate chooses to debate the measure, it would intensify pressure for a diplomatic resolution. Markets often react not only to actual policy changes but to the likelihood of future outcomes. Investors constantly assess probabilities, and congressional resistance to an open-ended conflict alters those calculations.

The diplomatic backdrop further reinforces that dynamic.

Reports suggesting continued communication between U.S. and Iranian officials have raised hopes that negotiations could eventually reduce tensions. A Congress openly signaling discomfort with an extended military campaign may strengthen advocates of diplomacy while making any significant expansion of military operations more politically difficult.

For ordinary Americans, the consequences remain largely economic.

The conflict has contributed to elevated energy prices throughout the year. Higher fuel costs affect everything from gasoline prices to airline tickets, shipping expenses, food costs, and household budgets. If congressional pressure ultimately contributes to a faster end to hostilities, consumers could eventually benefit through lower energy costs and reduced inflationary pressure.

Few observers expect the resolution to become law in its current form. The Senate remains uncertain, and the mathematics of overriding a veto remain daunting.

Still, the House vote sends a powerful signal.

Whether it ultimately changes policy or not, it demonstrates that the political center of gravity may be shifting toward limiting the conflict rather than expanding it. Businesses, investors, and energy markets are already beginning to incorporate that possibility into their outlooks.

The coming weeks will determine whether the vote represents a symbolic protest or the beginning of a broader effort to reshape America’s role in the conflict. Either way, the message from the House was clear: support for an open-ended war is no longer a given, and the debate over how the conflict should end is now moving to the center of American politics.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Stocks opened lower Friday, June 5, after the U.S. Bureau of Labor Statistics reported that the economy added 172,000 jobs in May — more than double what economists expected — sending bond yields higher and giving the Federal Reserve fresh reason to keep interest rates where they are. The unemployment rate held steady at 4.3%, as expected, while average hourly earnings rose 0.3% for the month and 3.4% over the past year. The report landed on top of a second straight day of selling in chip stocks, pressure from the ongoing U.S.-Iran conflict, and a sharp drop in Bitcoin, leaving Wall Street with a rough open to end a nine-week winning streak.

In late-morning trading, the S&P 500 was down about 0.6% and the Nasdaq Composite fell roughly 1.1%, dragged lower by technology and semiconductor names. The Dow Jones Industrial Average barely moved, edging up less than 0.1% and holding near the record high it set Thursday. The Russell 2000 bucked the trend, rising about 1.4% as money moved out of big technology companies and into other corners of the market.

Good News Treated as Bad News

The jobs number was the morning’s main event, and the market’s reaction shows how unusual the current environment remains. A strong labor market is normally something investors welcome. But with inflation still elevated, traders interpreted stronger-than-expected hiring as another reason the Federal Reserve may keep interest rates higher for longer.

Treasury yields moved sharply higher following the report, weighing on stocks.

The details strengthened the picture further. The Bureau of Labor Statistics revised March payroll growth up by 29,000 to 214,000 and April up by 64,000 to 179,000, leaving the two months a combined 93,000 jobs higher than previously reported.

Job gains were led by leisure and hospitality, which added 70,000 positions, followed by local government with 55,000, health care with 35,000, and manufacturing with 7,000.

“The third consecutive consensus-beating gain in nonfarm payrolls in May should further reduce concern among the FOMC about the downside risks to the labor market,” said Stephen Brown, Chief North America Economist at Capital Economics, noting that stronger hiring makes it more difficult for policymakers to overlook persistent inflation pressures.

The numbers arrive less than two weeks before the Federal Reserve’s June 16–17 policy meeting.

Chip Selling Spreads After Broadcom

The other major force pulling stocks lower was a second day of weakness across semiconductor shares.

The selloff began Thursday after Broadcom reported strong results but did not raise its full-year forecast for artificial-intelligence chip sales. Chief Executive Hock Tan reiterated guidance for AI semiconductor revenue exceeding $100 billion and said the company would focus on selling chips rather than complete integrated systems.

By Friday morning, the weakness had spread across the sector.

Micron Technology fell about 3.3%, while Intel and Advanced Micro Devices each dropped roughly 2.8%. Nvidia slipped about 1.4%.

Among AI infrastructure companies, Dell Technologies and Super Micro Computer each lost around 2.7%, while optical-networking supplier Lumentum Holdings declined approximately 3.5%.

Despite the pullback, analysts largely characterized the move as a pause rather than a fundamental shift in the AI investment story.

KeyBanc Capital Markets raised its price target on Broadcom to $575 from $500, while Bernstein analyst Stacy Rasgon said the company’s long-term growth outlook remains intact despite near-term concerns.

War, Oil and Bitcoin Remain in Focus

The conflict involving Iran continued to hover over markets.

Brent crude oil traded near $95 a barrel Friday, slightly higher on the day. While prices have eased from recent highs, crude remains well above levels seen before tensions escalated earlier this year.

Meanwhile, Bitcoin fell roughly 3.5% to around $61,900, adding to a difficult week for digital assets amid continued outflows from cryptocurrency investment funds.

For investors, the challenge remains straightforward. The economy appears stronger than expected, but that strength may reduce the likelihood of near-term Federal Reserve rate cuts just as the artificial-intelligence trade that powered much of this year’s rally takes a breather.

JBizNews Desk — Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

For most of the past year, Wall Street’s biggest debate centered on when the Federal Reserve would begin cutting interest rates.

After Friday’s jobs report, that debate changed dramatically.

Traders in the $31 trillion U.S. Treasury market moved to price in the possibility that the Federal Reserve’s next move could be a rate increase rather than a rate cut after May employment data came in significantly stronger than expected.

The shift followed the Bureau of Labor Statistics employment report released Friday, June 5, showing the U.S. economy added 172,000 jobs in May, nearly double the 88,000 jobs economists had forecast.

The unemployment rate remained at 4.3%, matching expectations and reinforcing the view that the labor market remains resilient despite elevated borrowing costs.

The market reaction was swift.

According to futures market pricing, traders moved to reflect better than a 60% probability of a Federal Reserve rate increase by October and a greater than 98% probability by December.

Stock futures weakened following the report as investors adjusted expectations toward a quarter-point rate increase before year-end.

Bond Markets React Immediately

Treasury yields jumped after the data was released.

The benchmark 10-year Treasury yield, which heavily influences mortgage rates, rose 5 basis points to 4.534%, its highest level since May 21.

The more policy-sensitive 2-year Treasury yield climbed 7 basis points to 4.115%, while the 30-year Treasury bond yield rose to 5.021%.

Higher yields generally signal that investors expect interest rates to remain elevated or potentially move higher.

A Key Signal From the Federal Reserve

Investors were already paying close attention to comments from Beth Hammack, President of the Federal Reserve Bank of Cleveland.

Speaking earlier this week, Hammack said that if current economic trends continue, policymakers may need to respond to the risk of persistently elevated inflation.

While carefully worded, markets interpreted the remarks as one of the clearest signals yet that some Fed officials are becoming increasingly concerned that inflation pressures may remain stubbornly high.

In practical terms, that means interest-rate increases remain on the table.

The Warsh Challenge

The timing creates additional pressure for the Federal Reserve.

The central bank’s next policy meeting is scheduled for June 17, the first meeting chaired by Federal Reserve Chairman Kevin Warsh, who was appointed by President Donald Trump.

Trump has repeatedly advocated for lower interest rates.

Markets, however, are moving in the opposite direction.

Seema Shah, Chief Global Strategist at Principal Asset Management, said that a move toward rate cuts would be difficult to justify if economic data continues to come in stronger than expected.

The result is a challenging debut for Warsh as he navigates competing pressures from economic data and political expectations.

Why Strong Jobs Can Lead to Higher Rates

At first glance, strong hiring appears positive.

For the Federal Reserve, however, strong employment combined with elevated inflation can create concerns that the economy is running too hot.

Inflation was running at approximately 3.8% annually in April, significantly above the Fed’s long-term target of 2%.

Energy prices and ongoing geopolitical tensions have contributed to inflation pressures, making policymakers cautious about easing monetary policy too quickly.

When hiring remains robust while inflation stays elevated, central bankers often worry that demand is growing faster than supply, creating additional upward pressure on prices.

Higher interest rates are the Fed’s primary tool for slowing economic activity and reducing inflation.

Economists Shift Their Outlook

Friday’s report also altered expectations among economists who previously believed the Fed would remain on hold.

Before the jobs data was released, Shruti Mishra, U.S. Economist at BofA Securities, argued that the labor market appeared healthy enough to avoid rate cuts but not strong enough to justify increases.

Jay Woods, Chief Market Strategist at Freedom Capital Markets, suggested that a stronger-than-expected report would reinforce a “higher-for-longer” interest-rate environment.

The May jobs report landed firmly on the stronger side of that debate.

Signs of Weakness Still Exist

Despite the strong headline number, some economists see softer trends beneath the surface.

Nela Richardson, Chief Economist at ADP, noted that part-time employment has continued to rise, reaching approximately 42% of workers in May, above levels seen five years ago.

She also pointed to slowing wage growth.

Workers who changed jobs saw pay growth slow to 6.5%, while workers who remained with the same employer experienced wage increases of approximately 4.4% from a year earlier.

Those figures suggest that while hiring remains healthy, parts of the labor market may be gradually cooling.

What It Means for Consumers

For households and businesses, the implications are immediate.

Mortgage rates closely follow movements in the 10-year Treasury yield, meaning higher yields often translate into more expensive home loans.

The same dynamic affects:

  • Auto loans
  • Credit cards
  • Small-business financing
  • Corporate borrowing

If markets continue pricing in additional rate increases, borrowing costs across the economy could remain elevated for longer than many consumers had hoped.

What Happens Next

Markets may have shifted their expectations, but the Federal Reserve has not yet made a decision.

The next major test arrives on June 10, when the government releases the latest inflation data.

That report will help determine whether price pressures remain strong enough to justify the increasingly hawkish expectations now emerging in financial markets.

Then comes the June 17 Federal Reserve meeting, where speculation gives way to policy.

After Friday’s jobs report, Wall Street is asking a different question than it was just a week ago.

The focus is no longer when rates begin falling.

It is whether the Federal Reserve’s next move could actually be higher.

JBizNews Desk — Markets & Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

Federal officials cut off funding to Hawaii’s Medicaid anti-fraud program on Thursday, June 4, making it the first state formally penalized in the Trump administration’s nationwide crackdown—and a warning shot to every other state in the country.

Federal Trade Commission Chairman Andrew Ferguson, a co-chair of the White House anti-fraud task force, announced the decertification at a press conference in Ohio, saying Hawaii had shown an “abject failure” to enforce state and federal law against fraud.

The move marks the first time a state has lost certification under the administration’s escalating effort to force stricter Medicaid fraud enforcement nationwide.

Why It Matters

Every state that participates in Medicaid is required to maintain a Medicaid Fraud Control Unit (MFCU), typically overseen by the state attorney general, to investigate fraud and abuse involving Medicaid funds.

Federal officials warned that ineffective enforcement can put broader federal Medicaid funding at risk.

That means the consequences may extend beyond Hawaii’s fraud unit itself.

The administration is signaling that states receiving billions in federal health-care dollars must actively police fraud or risk losing federal support.

Why Hawaii Was Targeted

Federal officials cited Hawaii’s performance as the worst in the nation.

According to the administration, Hawaii’s Medicaid Fraud Control Unit received approximately $3 million annually in federal funding yet produced zero criminal Medicaid fraud indictments between 2022 and 2025.

During the same period:

  • Medicaid enrollment reportedly increased roughly 40%
  • Medicaid funding increased approximately 27%
  • No fraud-related criminal indictments were filed

March Bell, Inspector General for the U.S. Department of Health and Human Services, notified Hawaii Attorney General Anne Lopez of the decertification, citing the lack of arrests, prosecutions, and convictions.

A Warning to Every State

The action follows months of pressure from Washington.

In May, federal officials sent notice letters to the attorneys general of all 50 states, demanding stronger cooperation in investigating and prosecuting Medicaid fraud.

Hawaii is simply the first state to face direct consequences.

Administration officials say additional states could face similar actions if they fail to strengthen fraud enforcement efforts.

The Ohio Case That Helped Trigger the Announcement

The decertification announcement came alongside a broader federal fraud sweep unveiled Thursday.

According to the Justice Department, investigators uncovered a multimillion-dollar Medicaid scheme involving children’s mental-health services in Ohio.

Authorities allege that services were medically unnecessary, improperly billed, or never provided as represented.

Investigators say that after one provider lost credentialing with the Ohio Department of Mental Health and Addiction Services, claims continued to be submitted through another entity.

Federal authorities seized approximately:

  • $469,000 from three bank accounts
  • 14 vehicles worth roughly $800,000

Among the seized vehicles:

  • Six Mercedes-Benz vehicles
  • Bentley
  • BMW
  • Jaguar
  • Maserati
  • Two Land Rovers
  • GMC
  • McLaren

Acting Attorney General Todd Blanche announced the prosecutions and said the FBI will launch a new “Most Wanted Fraudsters” list as part of the broader initiative.

Not All States Are Being Treated the Same

While Hawaii became the first state penalized, administration officials highlighted states they view as models for cooperation.

Ferguson specifically praised Ohio Attorney General David Yost, citing recent charges against 14 individuals connected to approximately $50 million in alleged fraud schemes.

The message from Washington was clear:

States that actively cooperate with federal investigations are being publicly recognized, while those that fail to do so face increasing scrutiny.

What It Means for Health-Care Providers

The crackdown has major implications for several sectors of the health-care industry.

Federal investigators are focusing heavily on:

  • Behavioral health providers
  • Children’s mental-health programs
  • Home-health agencies
  • Hospice providers
  • Durable medical equipment suppliers

These sectors are often viewed by regulators as higher-risk because billing can be difficult to verify and new providers can enter the market relatively quickly.

Companies operating in these areas face:

  • Increased credentialing reviews
  • Greater audit risk
  • Potential payment freezes
  • Possible removal from Medicaid programs

State governments also face growing pressure because Medicaid relies heavily on federal funding support.

Critics Push Back

The administration’s approach has drawn criticism.

In April, the Centers for Medicare & Medicaid Services acknowledged to The Associated Press that it had made significant errors in data used during a fraud investigation involving New York.

Several Democratic governors have argued that portions of the broader enforcement campaign are politically motivated.

Supporters counter that Medicaid fraud remains a serious national problem.

Administration officials have cited estimates placing annual Medicaid fraud losses as high as $100 billion, pointing to weak provider verification systems and years of inadequate enforcement in some states.

The Bigger Message

What makes Thursday’s action significant is that federal officials moved beyond warnings.

Until now, Washington largely relied on letters, audits, payment delays, and public pressure.

By decertifying Hawaii’s Medicaid Fraud Control Unit, the administration demonstrated a willingness to impose direct penalties.

With warning letters already sent to every attorney general in the country, Hawaii has become the first example of what federal officials say can happen when states fail to meet enforcement expectations.

JBizNews Desk — Healthcare & Government

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The chief executive of one of America’s largest telecommunications companies delivered one of the most direct warnings yet about how artificial intelligence could reshape the workforce. Speaking at the Bloomberg Tech Conference in San Francisco on Thursday, June 4, Verizon CEO Dan Schulman said he expects artificial intelligence to take over a significant portion of customer service work, potentially transforming one of the nation’s largest employment categories.

Unlike many corporate leaders who carefully avoid discussing job losses tied to AI, Schulman was unusually candid.

He said artificial intelligence will replace “a large percentage” of the work currently performed by customer service representatives as Verizon accelerates its efforts to modernize operations, improve efficiency, and reduce costs.

His comments offer a glimpse into how major corporations are planning for the next phase of AI adoption—not as an experimental tool, but as a core operational strategy capable of replacing tasks currently performed by millions of workers.

According to Schulman, the future of customer service will likely be divided into two categories.

Routine requests such as password resets, billing inquiries, account updates, and common troubleshooting questions will increasingly be handled entirely by AI systems.

More complex interactions, however, will continue to involve human employees working alongside artificial intelligence tools that provide information, recommendations, and support.

In that model, AI does not completely replace workers but significantly reduces the number of people required to handle customer interactions.

For Verizon, the financial logic is straightforward.

Customer service operations are among the most labor-intensive functions inside large corporations. Thousands of representatives handle millions of customer interactions every year, creating substantial payroll and training costs.

By automating routine requests, companies can lower expenses while potentially improving response times and availability.

Customers could receive assistance twenty-four hours a day without waiting on hold for a representative.

Schulman has repeatedly argued that artificial intelligence is not merely an efficiency tool but a critical part of Verizon’s long-term strategy.

Since becoming Verizon’s chief executive after succeeding Hans Vestberg, the former PayPal CEO has aggressively pursued cost reductions and operational restructuring.

In late 2025, Verizon eliminated approximately 13,000 positions, the largest workforce reduction in company history.

Additional reductions followed in 2026.

The company has publicly targeted approximately $5 billion in operating-expense savings, a goal that Verizon executives say will be achieved in large part through automation and artificial intelligence initiatives.

Chief Financial Officer Tony Skiadas has confirmed the savings target, while Schulman has stated that most of Verizon’s AI infrastructure should be operational by midyear, with full deployment expected by November.

The comments are significant because customer service remains one of the most common occupations in the United States.

Millions of Americans work in call centers, customer support departments, help desks, technical support operations, and related service functions.

Many of these jobs do not require advanced degrees, making them an important source of employment for workers entering the labor force or transitioning between careers.

If AI begins replacing a substantial percentage of these positions, the impact could extend far beyond Verizon itself.

The discussion reflects a broader debate taking place across Corporate America.

Supporters of AI argue that automation will improve productivity, reduce costs, and free workers from repetitive tasks so they can focus on higher-value activities.

Critics worry that the speed of adoption may outpace the economy’s ability to create replacement jobs.

Executives at companies including Amazon, Microsoft, and Google have acknowledged that AI will eliminate some positions while creating new opportunities elsewhere.

Schulman has taken a more direct stance.

He has repeatedly warned that significant workforce disruption is likely and has urged business leaders to be transparent with employees about what is coming.

His position differs from many CEOs who emphasize AI’s benefits while avoiding discussion of potential job reductions.

The customer-service industry may be one of the clearest examples of where automation can be implemented quickly.

Most customer interactions follow predictable patterns and involve repetitive questions that modern AI systems can answer with increasing accuracy.

Advances in large language models have dramatically improved AI’s ability to understand natural language, maintain conversations, and resolve routine issues without human intervention.

Verizon has reportedly been deploying AI-powered customer support tools for more than a year, giving the company firsthand experience with the technology’s capabilities.

For consumers, the transition presents both advantages and concerns.

On the positive side, AI-powered support can operate around the clock, eliminate long wait times, and provide immediate responses for common issues.

Many customers may welcome faster service for routine requests.

However, anyone who has struggled with automated phone systems or chatbots understands the potential frustrations.

Complex problems often require human judgment, empathy, and flexibility that machines still struggle to provide consistently.

Finding the right balance between automation and human support will likely determine whether customers embrace or resist the shift.

Verizon has attempted to address some workforce concerns by establishing programs designed to support retraining and career transitions for affected employees.

Still, the scale of potential disruption remains significant.

The broader significance of Schulman’s comments extends beyond one company.

They illustrate how quickly AI is moving from theory to implementation.

The debate is no longer about whether artificial intelligence can perform customer-service functions. Companies are increasingly deciding how much of their workforce they want the technology to replace.

Whether Verizon’s vision becomes the model for Corporate America remains to be seen.

But one thing is becoming increasingly clear: artificial intelligence is no longer a future workplace technology.

It is a present-day business strategy, and its impact on jobs is already beginning to reshape the labor market.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

The U.S. economy added 172,000 jobs in May, significantly exceeding economists’ expectations, according to the Bureau of Labor Statistics employment report released Friday, June 5.

Economists had expected roughly 88,000 new jobs, making the actual result nearly double forecasts. The unemployment rate remained at 4.3%, matching expectations and signaling continued stability in the labor market.

The report suggests hiring remains more resilient than many analysts anticipated despite higher interest rates, corporate restructuring, and growing uncertainty surrounding artificial intelligence’s impact on employment.

May marked the third consecutive month of payroll growth, following April’s gain, which was revised upward to 179,000 jobs.

After concerns earlier this year that hiring was beginning to weaken, the latest figures point to a labor market that continues to expand, albeit at a more moderate pace than the post-pandemic boom years.

Where the Jobs Came From

The strongest hiring came from sectors that touch consumers every day.

According to the report:

  • Leisure and hospitality: +70,000 jobs
  • Local government: +55,000 jobs
  • Health care: +35,000 jobs

Restaurants, hotels, schools, hospitals, and clinics accounted for much of the hiring growth.

Health care continues to be one of the economy’s most dependable sources of job creation, extending a trend that has persisted for months.

The concentration of hiring in service industries helps explain a disconnect many Americans are feeling.

While overall employment remains strong, some white-collar industries are experiencing slower hiring and increased uncertainty.

Layoffs and Hiring Are Happening at the Same Time

Evidence of that split emerged this week when Uber announced plans to eliminate approximately 23% of positions within its human resources, recruiting, workplace facilities, and culture divisions.

Many recent layoffs across corporate America have been linked to restructuring efforts and the increasing use of artificial intelligence.

That creates a labor market where both realities can exist simultaneously:

Companies continue hiring in large numbers overall, while specific employers reduce headcount in targeted departments.

Not All Wage Growth Is Equal

The labor market is also showing growing differences in pay.

According to a new analysis from the Indeed Hiring Lab, salaried workers have generally seen stronger wage growth than hourly workers over the past year.

In some technical fields—including information technology and software development—advertised wages for hourly positions have actually declined.

The result is a labor market where employment remains healthy overall, but compensation trends vary widely depending on industry, occupation, and skill set.

Signs of Softness Remain

Despite the strong payroll figure, not every indicator was positive.

Weekly unemployment claims recently rose above economists’ expectations of 215,000, suggesting some pockets of weakness remain.

Meanwhile, continuing claims—a measure of people still receiving unemployment benefits—edged down slightly to approximately 1.77 million for the week ending May 23.

Economists often view claims data as an early warning signal for labor-market stress, though weekly figures can be volatile.

Why Wall Street and the Fed Care

The report’s impact extends well beyond employment.

A stronger-than-expected labor market reduces pressure on the Federal Reserve to cut interest rates quickly.

When businesses continue hiring and unemployment remains low, policymakers have less reason to provide economic stimulus through lower borrowing costs.

That affects:

  • Mortgage rates
  • Auto loans
  • Credit card interest rates
  • Small-business borrowing costs
  • Corporate investment decisions

For investors hoping for rapid rate cuts later this year, the report may complicate that outlook.

What Comes Next

The jobs report is only one piece of the economic picture.

Attention now shifts to the next major data release: the May Consumer Price Index, scheduled for June 10.

That report will provide fresh insight into inflation and whether wages are keeping pace with rising living costs.

If hiring remains strong while inflation continues to cool, it would strengthen the case that the economy is achieving the elusive “soft landing” economists have sought for several years.

If inflation reaccelerates while wage growth slows, pressure on household budgets could intensify.

For now, however, Friday’s report delivered a reassuring message.

Businesses are still hiring, unemployment remains stable, and the sectors that employ millions of Americans continue to add workers.

JBizNews Desk — Markets & Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Iran’s oil exports have fallen to their lowest level in six years, highlighting the growing economic pressure facing Tehran as war, sanctions, and heightened geopolitical risk continue to reshape global energy markets.

According to shipping and trade data reported by Reuters on Thursday, June 4, Iranian crude exports declined in May to approximately 260,000 barrels per day, a dramatic fall from the country’s recent production levels and one of the clearest signs yet of the conflict’s impact on Iran’s economy.

The figure represents only a fraction of Iran’s 2025 average exports of approximately 1.67 million barrels per day, illustrating just how sharply the country’s oil trade has deteriorated.

For Iran, the decline carries enormous financial consequences.

Oil revenue remains one of the government’s most important sources of income. The loss of more than a million barrels per day in exports represents billions of dollars in lost revenue and places additional strain on an economy already facing significant sanctions and international restrictions.

The collapse has been driven by a combination of factors.

The ongoing U.S.-Israeli conflict with Iran, which began in late February, has dramatically increased risks associated with transporting Iranian crude. Shipping companies face higher insurance costs, tanker operators face greater uncertainty, and many intermediaries have chosen to avoid Iranian cargo altogether.

The result has been a sharp reduction in the number of buyers willing to purchase Iranian oil and a significant increase in the discounts required to attract those who remain.

According to Reuters, Iranian Light crude was recently offered at discounts ranging between 50 cents and $1 per barrel below ICE Brent prices for June delivery into China. Only a short time ago, Iranian crude often commanded stronger pricing due to demand from refiners seeking discounted alternatives to other international supplies.

China remains Iran’s largest customer, particularly among independent refiners often referred to as “teapot refiners.” However, even these buyers are reportedly demanding larger discounts to compensate for the growing political and financial risks associated with purchasing Iranian oil.

The implications extend well beyond Iran.

Ordinarily, the removal of a major oil producer from international markets would support higher prices by reducing available supply. Yet markets are simultaneously being influenced by hopes of regional de-escalation following the Israel-Lebanon ceasefire announcement.

That has created competing forces within oil markets.

On one hand, Iran’s shrinking exports reduce global supply and support higher prices. On the other hand, growing optimism about diplomacy reduces the geopolitical premium that has been built into oil prices for months.

The result is a market struggling to determine which force will ultimately prove stronger.

For competing producers, Iran’s challenges present opportunities.

Countries throughout the Gulf region, along with other major exporters, may be able to capture market share previously supplied by Iranian crude. Producers capable of increasing exports stand to benefit from both higher volumes and potentially stronger pricing if Iranian supplies remain constrained.

Meanwhile, refiners that once relied on Iranian barrels must secure replacement supplies elsewhere, often at higher costs. Those additional expenses can eventually work their way through supply chains and impact consumers around the world.

The disruption is especially significant in Asia, where many refiners built purchasing strategies around discounted Iranian crude. As those supplies become less available, companies must adjust procurement strategies, renegotiate contracts, and absorb higher operating costs.

The decline to 260,000 barrels per day marks a remarkable transformation.

Only a year ago, Iran remained a significant force in global energy markets. Today, it has been reduced to a marginal exporter compared with its recent production levels.

The development demonstrates how effectively sanctions, military conflict, and market pressure can combine to restrict a country’s ability to participate in global trade.

The key question for energy markets is what happens next.

A diplomatic breakthrough involving Iran could eventually allow exports to recover, bringing substantial additional supply back into the global market. Such a development would likely place downward pressure on oil prices and reshape competitive dynamics across the energy sector.

That possibility explains why traders continue to monitor diplomatic discussions between Washington and Tehran so closely.

For now, however, Iran’s oil industry remains under intense pressure.

Exports remain near six-year lows, government revenues remain constrained, and the country’s ability to finance operations has been significantly weakened. In an energy market already navigating war, sanctions, and geopolitical uncertainty, the near-disappearance of one of the world’s major producers remains one of the most important stories shaping global oil markets today.

JBizNews Desk — Middle East

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SpaceX, the rocket and satellite company founded by Elon Musk, has officially set the price for what could become the largest initial public offering in history, according to a prospectus filed with the U.S. Securities and Exchange Commission on Wednesday, June 3. The company priced shares at $135 each, valuing SpaceX at approximately $1.77 trillion and positioning the offering to shatter virtually every previous IPO record.

If completed as planned, the offering would raise as much as $75 billion, dwarfing the previous record held by Alibaba, whose 2014 public debut raised approximately $22 billion.

The shares are expected to begin trading on the Nasdaq during the week of June 12 under the ticker symbol SPCX, immediately making SpaceX one of the most valuable publicly traded companies on the planet.

The numbers are staggering.

At the IPO price, SpaceX would debut with a valuation greater than many of the world’s largest corporations and would instantly rank among the most valuable technology companies ever listed on a public exchange.

Yet the most unusual aspect of the offering may not be its size.

It may be who gets access.

Traditionally, large institutional investors receive the majority of IPO allocations at the offering price, while ordinary investors often must wait until shares begin trading publicly—frequently at significantly higher prices.

SpaceX is taking a different approach.

The company has announced that retail investors will be permitted to request shares at the same IPO price offered to major institutions through participating brokerage platforms including Robinhood, Fidelity, Charles Schwab, SoFi, and Morgan Stanley’s E*TRADE.

For many investors, it represents a rare opportunity to participate in one of the world’s most closely watched private companies before trading begins on the open market.

However, there are important limitations.

Demand is expected to vastly exceed available supply.

Investors may receive only a portion of the shares they request—or none at all.

Certain platforms have additional restrictions. Charles Schwab, for example, requires eligible clients to maintain account balances of at least $100,000 to participate in IPO allocations.

The company’s investor roadshow officially began on Thursday, June 4, as executives and underwriters started presenting the investment case to institutional investors around the world.

The offering also cements Elon Musk’s control over the company.

According to the SEC filing, SpaceX will maintain a dual-class share structure, allowing Musk to retain approximately 82.4% of voting power after the IPO despite selling shares to the public.

The structure mirrors arrangements used by other founder-led technology companies, where voting control remains concentrated even after public ownership expands.

If SpaceX successfully debuts at its proposed valuation and trading remains strong, Musk’s personal wealth could exceed $1 trillion, potentially making him the first individual in history to reach trillionaire status.

Yet not everyone believes the valuation is justified.

Research firm Morningstar recently estimated SpaceX’s fair value at approximately $780 billion, less than half the proposed IPO valuation.

Morningstar analysts argued that investors should be cautious and suggested that more attractive entry points could emerge after the initial excitement surrounding the offering fades.

Their concern centers largely on profitability.

While Starlink, SpaceX’s satellite internet business, has become a major revenue generator and one of the company’s most profitable operations, other segments continue consuming enormous amounts of capital.

The company’s launch business requires ongoing investment, while its artificial intelligence initiatives are reportedly expected to lose billions of dollars as development continues.

Morningstar estimates SpaceX’s AI division alone could burn through approximately $10 billion during 2026.

Investor concerns have extended beyond Wall Street research firms.

The American Federation of Teachers, representing approximately 1.8 million members, wrote to SEC Chairman Paul Atkins earlier this year requesting heightened scrutiny of the offering.

The union expressed concern that retirement funds and everyday investors could be exposed to what it described as a highly speculative and potentially overvalued investment.

Those concerns reflect a broader debate surrounding the IPO.

Supporters argue that SpaceX has transformed multiple industries, from commercial space launches to satellite communications, and possesses growth opportunities that justify an extraordinary valuation.

Critics counter that even exceptional businesses can become poor investments if purchased at excessive prices.

For everyday investors, the decision presents both opportunity and risk.

On one hand, participation offers access to one of the most influential private companies ever created, alongside major institutional investors paying the same IPO price.

On the other hand, the company would begin trading at a valuation that some respected analysts believe is more than double its intrinsic value.

There is also the possibility of a significant first-day trading surge.

Because retail demand is expected to overwhelm available shares, many investors will likely receive only partial allocations. That scarcity could create a buying frenzy when trading begins, potentially pushing shares well above the offering price.

Such surges are common among highly anticipated IPOs, but they can also leave late buyers purchasing shares at inflated valuations.

The SpaceX offering represents more than just another stock market debut.

It is a test of investor appetite for ambitious growth stories, a referendum on Elon Musk’s vision, and perhaps the most significant public-market event of the year.

Whether the IPO ultimately becomes a legendary investment success or a cautionary tale about valuation remains unknown.

What is certain is that when SpaceX begins trading, Wall Street—and millions of ordinary investors—will be watching.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. Senate voted 52-47 early Friday, June 5, 2026 — just before 5 a.m. after a marathon overnight session — to give the Department of Homeland Security an additional $70 billion for immigration enforcement, ending a months-long standoff and handing President Donald Trump one of his biggest legislative victories of the year. The package now heads to the House of Representatives for final consideration.

The funding was advanced through the budget reconciliation process under the framework established by S. Con. Res. 33, the FY2026 budget resolution adopted earlier this year. Reconciliation allows legislation affecting federal spending and revenues to pass the Senate with a simple majority rather than the 60 votes typically needed to overcome a filibuster. No Democrats supported the measure, and Sen. Lisa Murkowski (R-Alaska) was the lone Republican to vote against it.

Supporters argue the funding is necessary to expand border security operations, increase detention capacity, hire additional personnel, and provide long-term stability for immigration enforcement agencies. Opponents contend the legislation focuses heavily on enforcement while leaving broader immigration reforms unresolved.

The funding is intended to support Immigration and Customs Enforcement (ICE) and Customs and Border Protection (CBP) through the remainder of the Trump administration, a goal Senate Republican leaders said would reduce the agencies’ exposure to future funding battles and government shutdown threats.

Where the Money Goes

The roughly $70 billion in new spending comes on top of substantial immigration and border-security funding already approved in prior legislation.

According to committee materials and Congressional Budget Office estimates, the Homeland Security portion includes approximately $22.6 billion for Customs and Border Protection, including funding for personnel, training, equipment, border operations, and inspection technology. Additional appropriations contained in the Judiciary and Homeland Security committee texts bring the combined totals to roughly $38 billion directed toward ICE operations and approximately $26 billion toward CBP activities, including enforcement personnel, detention operations, surveillance systems, screening technology, and infrastructure support.

The legislation’s supporters say the investment is designed to provide agencies with the personnel, equipment, detention capacity, and technology needed to carry out enforcement priorities over the coming years.

Republicans advanced the measure using reconciliation, the same legislative mechanism increasingly used for major spending packages because it bypasses the Senate’s 60-vote threshold.

The Business Angle: A Windfall for Private Prison Operators

For investors, the clearest potential beneficiaries are GEO Group (NYSE: GEO) and CoreCivic (NYSE: CXW), the two companies that dominate the private immigration detention industry.

A large majority of immigrants held in ICE custody are housed in privately operated facilities, meaning any significant expansion in detention capacity could directly benefit those firms. Both companies have spent months preparing for increased demand and have publicly discussed opportunities tied to expanded federal immigration enforcement.

The administration has also moved to accelerate detention capacity, with contracts reportedly awarded under emergency procurement authorities intended to quickly increase available space. Industry observers note that both GEO Group and CoreCivic maintain facilities that could potentially be reactivated if demand rises.

Executives from the sector have told investors they are seeing some of the strongest demand conditions in years. Beyond detention operators, companies involved in border surveillance, inspection technology, screening equipment, communications systems, facility construction, transportation, staffing, and federal support services could also benefit from increased spending.

For government contractors and investors, the legislation represents one of the largest proposed expansions of immigration-enforcement spending in recent years.

The Fights That Nearly Sank the Bill

Several disputes unrelated to border enforcement threatened to derail the package during negotiations.

One involved a controversial Department of Justice compensation fund that drew bipartisan criticism. The proposal became a flashpoint during Senate negotiations and generated intense debate over its purpose and structure. Amendments seeking to redirect or eliminate the funding ultimately failed to gain enough support to reshape the final package.

Another controversy centered on a proposed funding allocation tied to White House security and facility-related projects. Critics questioned the spending, and Republicans ultimately removed the provision before final passage.

Those disputes, combined with broader disagreements over immigration policy, contributed to weeks of delays and turned the measure into one of the most closely watched legislative battles of the year.

What Happens Next

The legislation is not yet law.

The House of Representatives is expected to consider the package next. If approved by the House, it would then move to President Trump for his signature.

Until then, agencies, contractors, technology vendors, detention operators, and other businesses positioned to benefit from the funding remain in a holding pattern. However, many have already spent months preparing for potential expansion should the legislation clear its final hurdle.

Sources: Senate FY2026 Budget Resolution S. Con. Res. 33; Congressional Budget Office estimates related to Judiciary and Homeland Security reconciliation legislation; Senate roll-call records; public filings and investor disclosures from GEO Group and CoreCivic.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

CrowdStrike Holdings Inc., one of the world’s largest cybersecurity companies, delivered another quarter of strong revenue growth, rising profits, and expanding demand for its artificial intelligence-powered security products. Yet despite beating Wall Street expectations and announcing a four-for-one stock split, investors responded by sending the stock sharply lower, highlighting the increasingly unforgiving standards facing technology companies at the center of the AI boom.

The company reported results after the close on Wednesday, June 3, with founder and Chief Executive Officer George Kurtz emphasizing CrowdStrike’s growing role as a critical security provider for businesses rapidly adopting artificial intelligence technologies.

The numbers appeared impressive by almost every traditional measure.

For the quarter ended April 30, CrowdStrike reported revenue of approximately $1.39 billion, representing a 26% increase from the same period a year earlier and exceeding analyst expectations of roughly $1.36 billion.

Adjusted earnings reached $1.10 per share, ahead of the approximately $1.07 per share analysts had forecast.

Perhaps most notably, CrowdStrike swung to a profit of approximately $27.8 million, compared with a loss of approximately $104.3 million during the same quarter last year.

The company also generated a record $468 million in free cash flow, an important measure of how much cash remains after operating expenses and capital investments.

For most companies, results like these would have been enough to trigger a significant rally.

Instead, CrowdStrike shares fell between 8% and 13% in after-hours trading and early Thursday trading, dropping toward $679 per share after closing Wednesday near $748.

Investors appeared focused on one metric that failed to meet elevated expectations.

The company reported billings of approximately $1.35 billion, an increase of 18% year-over-year but slightly below what many analysts had anticipated.

Billings are closely watched because they provide a forward-looking indicator of future revenue. Since customers typically sign contracts before the associated revenue is recognized, billings often serve as an early signal of future growth.

Although revenue, earnings, profitability, and guidance all improved, investors viewed the softer billings figure as a potential warning sign that future growth may not accelerate as quickly as expected.

Adding to shareholder interest was the company’s announcement of a four-for-one stock split.

Under the plan approved by CrowdStrike’s board of directors, shareholders of record as of June 25 will receive three additional shares for every one share they own. The additional shares will be distributed after the market closes on July 1, with split-adjusted trading beginning on July 2.

Stock splits do not change the overall value of a shareholder’s investment. Instead, they increase the number of shares outstanding while proportionally lowering the share price.

Companies often pursue stock splits after significant share-price appreciation, making shares appear more affordable and accessible to retail investors.

CrowdStrike’s stock had gained nearly 59% this year before earnings, making it one of the strongest performers in the cybersecurity sector.

During the earnings call, Kurtz repeatedly emphasized the connection between cybersecurity and artificial intelligence.

He described the current period as CrowdStrike’s “Mythos moment,” arguing that AI adoption across the corporate world is increasing demand for advanced security tools capable of protecting increasingly complex digital environments.

Kurtz compared CrowdStrike’s role to the suppliers of picks and shovels during a gold rush, arguing that regardless of which AI companies ultimately dominate, organizations will continue needing cybersecurity infrastructure to protect their systems and data.

The CEO attributed some of the weaker billings performance to timing issues rather than slowing demand.

According to Kurtz, several deals connected to a major platform launch in April took longer to close than initially expected. He stressed that the delays reflected customer purchasing cycles rather than deteriorating business conditions.

Management pointed to several AI-related initiatives designed to strengthen CrowdStrike’s competitive position.

Among them is Project QuiltWorks, a collaboration involving OpenAI and Anthropic, along with additional AI-powered threat detection and security products intended to help customers secure increasingly AI-driven operations.

Chief Financial Officer Burt Podbere cited strong customer retention rates, a record sales pipeline, and healthy demand as reasons the company increased portions of its full-year outlook.

Despite those reassurances, the market remained skeptical.

The selloff also spread beyond CrowdStrike itself.

Shares of rival cybersecurity provider Palo Alto Networks declined during Thursday trading despite having no company-specific news. Investors appeared to reassess valuations across the cybersecurity sector following CrowdStrike’s report.

The reaction mirrored what happened earlier in the week with Broadcom.

Both companies exceeded analyst expectations. Both companies increased portions of their outlooks. Both companies highlighted strong AI-related demand.

And yet both stocks suffered significant declines.

The common thread is investor expectations.

As artificial intelligence has become the dominant investment theme of 2026, shares of companies associated with AI infrastructure, cybersecurity, cloud computing, and semiconductors have climbed dramatically. The result is that investors increasingly demand not merely strong results, but extraordinary results that significantly exceed already ambitious expectations.

CrowdStrike’s quarter illustrates how difficult that environment has become.

The company generated strong revenue growth.

It returned to profitability.

It produced record cash flow.

It raised guidance.

It announced a stock split.

Yet a single metric that came in slightly below expectations became the focus of investor attention.

For businesses and consumers, however, the broader story remains largely positive.

The rapid growth of artificial intelligence is creating an equally rapid need for cybersecurity protection. Every company adopting AI tools must also secure the systems, networks, and data that power those technologies.

That demand is exactly where CrowdStrike operates.

The market may have been disappointed by one number, but the company’s results suggest that demand for cybersecurity remains strong and that AI adoption continues to create significant opportunities across the sector.

The lesson for investors may be the same one repeatedly emerging during this earnings season: in today’s AI-driven market, strong performance alone is not always enough. When expectations reach extreme levels, even exceptional results can trigger selling if they fail to exceed what investors had already imagined.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Broadcom delivered one of the strongest quarters in corporate America this year, posting record revenue, explosive artificial intelligence growth, and better-than-expected earnings. Yet despite those results, investors sent the stock sharply lower, demonstrating just how demanding Wall Street has become toward companies at the center of the AI boom.

The company reported results after the market closed on Wednesday, June 3, with President and CEO Hock Tan describing demand for Broadcom’s AI products as “simply insatiable.” Nevertheless, investors focused less on what Broadcom achieved and more on what it did not do—raise already lofty expectations.

The result was a sharp selloff that erased hundreds of billions of dollars in market value and rattled the broader technology sector.

Broadcom reported record quarterly revenue of $22.2 billion, representing a remarkable 48% increase from the same period a year ago.

The company’s artificial intelligence business continued to be the primary growth engine. Revenue from AI semiconductors surged to $10.8 billion, up 143% year-over-year, exceeding the company’s own guidance and reinforcing Broadcom’s growing role as one of the most important infrastructure providers in the AI revolution.

Adjusted earnings reached $2.44 per share, slightly ahead of analyst expectations of approximately $2.40 per share, according to LSEG consensus estimates.

On the surface, the results appeared difficult to criticize.

Even more impressive was management’s forecast for the current quarter.

Broadcom projected third-quarter revenue of approximately $29.4 billion, representing annual growth of roughly 84%, while forecasting AI semiconductor revenue of approximately $16 billion, more than 200% higher than the prior year.

For most companies, numbers like those would spark a major rally.

Instead, Broadcom’s stock fell approximately 12% to 15% during Thursday trading after closing the previous session near a record $495 per share.

The reason highlights one of the defining characteristics of today’s AI-driven market.

Investors were not disappointed by what Broadcom reported. They were disappointed by what they hoped Broadcom would report.

Specifically, investors wanted management to increase its full-year artificial intelligence forecast. Instead, Tan reaffirmed the company’s existing target of approximately $56 billion in AI semiconductor revenue for fiscal 2026 while maintaining its long-term projection of more than $100 billion in AI-related revenue by fiscal 2027.

Those numbers remain enormous by any traditional standard.

But after months of relentless upward revisions throughout the AI sector, investors had become conditioned to expect another increase. When Broadcom simply maintained guidance rather than raising it, the market interpreted that as a sign that growth may eventually begin normalizing.

Additional comments during the earnings call added to investor concerns.

Tan acknowledged that Google, one of Broadcom’s largest custom-chip customers, is unlikely to rely exclusively on a single supplier and will probably continue using multiple vendors.

While not surprising from a business perspective, the comment reminded investors that Broadcom faces competition even among its largest clients.

Tan also highlighted another challenge emerging from Broadcom’s success.

The rapid expansion of AI semiconductor sales is creating pressure on overall profit margins because those products carry lower margins than some of the company’s software operations and mature semiconductor businesses.

In other words, Broadcom is selling far more AI chips, but the mix of revenue is shifting toward products that generate somewhat lower profitability.

That nuance matters to analysts attempting to determine how profitable the AI boom will ultimately become.

Broadcom occupies a unique position within the artificial intelligence ecosystem.

Unlike Nvidia, which dominates the market for general-purpose AI processors, Broadcom specializes in designing custom AI chips for a select group of major technology companies while also providing the networking infrastructure that allows massive AI data centers to function efficiently.

According to Tan, Broadcom currently works with six major custom-chip customers, including Google, Meta, OpenAI, and Anthropic.

The networking business alone accounted for nearly 40% of AI semiconductor revenue during the quarter, highlighting Broadcom’s growing importance in connecting the thousands of processors required to train and operate advanced AI systems.

The company’s software division also continued to perform well.

Revenue from infrastructure software, including the acquired VMware business, increased 9% to $7.2 billion, providing Broadcom with an additional source of recurring revenue beyond semiconductors.

The company also reaffirmed its quarterly dividend of $0.65 per share, payable on June 30 to shareholders of record as of June 22.

Despite the selloff, few analysts questioned the underlying strength of the business.

Instead, Broadcom’s decline became another example of how difficult it has become for AI leaders to satisfy investors.

The artificial intelligence boom has created enormous valuations across a small group of technology companies. As expectations rise, investors increasingly demand not just excellent results, but results that significantly exceed already elevated forecasts.

Broadcom’s quarter perfectly illustrates that dynamic.

The company generated record revenue.

It more than doubled AI sales.

It beat earnings estimates.

It forecast massive future growth.

Yet the stock still declined sharply because Wall Street had already priced in something even better.

The impact extended beyond Broadcom itself.

Shares of other AI and semiconductor companies moved lower following the report, helping create a more cautious tone across the Nasdaq and reminding investors that sentiment can change quickly in sectors driven by extremely high expectations.

The broader lesson may be less about Broadcom specifically and more about the current state of the market.

Artificial intelligence remains one of the most powerful growth stories in the global economy. Demand continues expanding rapidly, data center spending remains robust, and companies like Broadcom continue generating extraordinary financial results.

But as valuations climb higher, merely excellent performance is no longer enough.

For investors accustomed to constant upside surprises, Broadcom delivered a reminder that sometimes meeting expectations—even exceptionally ambitious expectations—can still feel like a disappointment.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For years, ordinary investors could only watch from the outside as SpaceX grew into one of the most valuable private companies on earth. On Thursday, Coinbase said it would change that — sort of. The cryptocurrency exchange announced a new product that lets traders place bets on the rising or falling value of SpaceX before the rocket company ever lists on a stock exchange. The catch: you are not actually buying anything close to a share.

The product is called a pre-IPO perpetual futures contract, or “perp” for short. In plain terms, it is a side bet on where a company’s value is heading. According to Coinbase, the SpaceX contract tracks the company’s estimated private-market valuation, trades around the clock with no expiration date, and settles in USDC, a digital dollar token. Traders can open or close a position whenever they want, and they can use up to 5x leverage — meaning a small amount of money controls a much larger bet.

Here is what it is not. The contract carries no ownership of SpaceX, no voting rights, no dividends, and no claim on actual shares. It is purely a wager on price. If you guess the direction right, you make money. If you guess wrong, you lose — and leverage means losses pile up faster than they would with plain stock.

The timing is deliberate. SpaceX, run by Elon Musk, is set to go public on June 12. The company filed its IPO terms this week, planning to sell about 555 million shares of Class A common stock at $135 each. That would raise roughly $75 billion and value the company near $1.75 trillion — making it the largest stock-market debut in history, dwarfing the $29.4 billion raised by Saudi Aramco in 2019.

Coinbase built in a feature for that moment. When SpaceX completes its IPO, existing pre-IPO positions automatically convert into a standard SpaceX futures contract tied to the public stock price. Traders do not have to do anything; their bet simply rolls from the private phase into the public one.

There is one important limit. The product is available only to eligible traders outside the United States through a Coinbase unit based in Bermuda. American customers cannot buy it. That restriction reflects the murky regulatory status of these contracts, which blur the line between a derivative, a private-market investment, and a crypto product.

Why is Coinbase doing this? The company describes it as part of its push to become an “everything exchange,” a single place to trade not just cryptocurrencies but exposure to almost any asset. SpaceX is only the first listing. Coinbase said it plans a pipeline of pre-IPO contracts spanning technology, artificial intelligence, energy, and space — the hottest corners of private investing, where demand has long outrun access.

It is also playing catch-up. Coinbase is the latest entrant in a market that has heated up quickly. Crypto.com launched a similar SpaceX product on May 12, Hyperliquid followed on May 18 and reportedly generated $33 million in first-day trading volume, and Binance, the world’s largest crypto exchange, entered on May 21 and reportedly saw more than $280 million in trading within five days.

That eagerness is the real story for everyday investors, and the reason for caution. Pre-IPO shares have traditionally been reserved for venture capital funds, private equity firms, company employees, and wealthy accredited investors. Most people have had no way in. These new contracts crack that door open — but they do it through one of the riskiest tools in finance.

A few things are worth understanding before anyone is tempted. Different exchanges price their SpaceX contracts using different methods, so the “value” you are betting on is not standardized and can move independently of the company’s eventual stock price. Leverage cuts both ways and can wipe out a position quickly. And because the contracts are settled in crypto rather than dollars, traders also take on the risks and mechanics of the cryptocurrency market itself.

For Coinbase, the business logic is clear. The company, which trades on the Nasdaq under the ticker COIN, earns fees on every trade, and a blockbuster like the SpaceX IPO is a once-in-a-generation draw. By letting traders take positions days before the listing, it captures activity that would otherwise wait for the opening bell — or never reach retail traders at all.

The broader shift is the one to watch. Private companies are staying private far longer than they used to, leaving public investors locked out of the fastest-growing names for years. Products like this are Wall Street’s workaround — a way to sell the feeling of early access without the ownership that traditionally came with it.

Markets & Technology — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Oil prices moved lower on Thursday, June 4, after Israel and Lebanon confirmed they had agreed to implement a ceasefire, a development that traders interpreted as a potential step toward calming a region that has spent months on the brink of a wider conflict. The announcement, reported by Reuters, prompted investors to unwind part of the geopolitical risk premium that has been embedded in energy markets throughout the war.

Early trading saw Brent crude, the international benchmark, fall approximately 0.9% to $96.92 a barrel, while West Texas Intermediate (WTI), the U.S. benchmark, declined to roughly $95.24 a barrel. The retreat came just one day after both benchmarks had surged nearly 2% following renewed fighting in the region, including reported Iranian strikes in Kuwait and additional U.S. military operations near the Strait of Hormuz.

The reaction underscores a reality that has defined global energy markets since late February: oil prices are being driven as much by military developments and diplomatic signals as by traditional supply-and-demand fundamentals.

At the center of investor concerns remains the Strait of Hormuz, one of the world’s most important shipping routes. A significant portion of global crude exports pass through the narrow waterway each day. Any threat to traffic through Hormuz immediately raises fears of supply disruptions, pushing oil prices higher and increasing costs throughout the global economy.

The ongoing U.S.-Israeli conflict with Iran has repeatedly raised concerns that shipping through the strait could be interrupted. Every escalation has sent traders scrambling to price in the possibility of reduced oil flows, while every sign of de-escalation has triggered the opposite reaction.

The Israel-Lebanon ceasefire is being viewed as more than a local agreement. Investors see it as a possible indication that broader diplomatic efforts may be gaining traction throughout the region. Reports that discussions between Washington and Tehran could continue have further strengthened hopes that the conflict may eventually move toward a negotiated resolution.

Should those talks produce meaningful progress, traders believe the risk of a prolonged disruption to shipping through Hormuz would decline significantly, potentially removing one of the largest drivers of oil-market volatility.

However, supply fundamentals continue to provide support for crude prices.

According to figures cited by Reuters, inventories at Cushing, Oklahoma, the delivery hub for WTI futures contracts, fell by approximately 583,000 barrels to around 22.4 million barrels. Falling inventories indicate relatively tight supply conditions and help explain why Thursday’s decline remained relatively modest despite the positive geopolitical developments.

In other words, even if fears of war begin to ease, underlying supply constraints may prevent oil prices from falling dramatically.

For American consumers, the significance extends far beyond commodity markets.

Energy costs have remained one of the most persistent contributors to inflation. According to the Bureau of Labor Statistics, consumer prices increased 3.8% over the twelve months ending in April, with energy representing a significant portion of that increase. Higher oil prices eventually affect gasoline, diesel fuel, airline tickets, shipping costs, and the price of countless goods transported throughout the economy.

A sustained decline in crude prices would likely provide relief at the pump and help ease pressure on household budgets during the summer travel season.

Businesses would also benefit.

Industries heavily dependent on fuel—including airlines, trucking companies, logistics providers, delivery services, manufacturers, and agricultural operations—closely monitor crude prices because energy represents one of their largest operating expenses. Greater stability in the Middle East could allow these businesses to plan with greater confidence after months of uncertainty and fluctuating costs.

Yet few analysts believe the danger has passed.

The ceasefire announced between Israel and Lebanon is not a comprehensive peace agreement, nor does it directly resolve the broader conflict involving Iran. Market participants have learned over the past several months that periods of calm can quickly give way to renewed escalation.

A breakdown in talks, additional military action near Hormuz, or a broader regional confrontation could rapidly send oil prices higher again.

There is also an important political development unfolding in Washington that investors are watching closely.

On Wednesday, the U.S. House of Representatives approved a resolution aimed at limiting the president’s authority to continue military operations against Iran without additional congressional authorization. While the measure faces significant obstacles in the Senate and is unlikely to become law in its current form, it reflects growing political pressure against an open-ended conflict.

For traders, that political signal matters.

The willingness of lawmakers to challenge continued military engagement suggests that support for a prolonged war may be weakening. Combined with diplomatic efforts and the Israel-Lebanon ceasefire, the congressional action has contributed to growing expectations that the conflict could eventually move toward a negotiated outcome.

For now, energy markets are cautiously embracing a more optimistic scenario.

Oil remains expensive, geopolitical risks remain elevated, and the conflict itself remains unresolved. But the combination of a ceasefire, ongoing diplomatic discussions, and growing political pressure for de-escalation has given traders a reason to believe the worst-case scenarios may become less likely.

Whether that optimism proves justified will depend largely on diplomacy. If regional leaders can transform a temporary ceasefire into a broader framework for stability, the result could be lower energy prices, reduced inflationary pressure, and greater confidence across global markets. If not, oil traders may once again find themselves pricing in the possibility of another major disruption to the world’s most important energy corridor.

JBizNews Desk — Middle East

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

One number Friday morning will tell businesses, workers, and the Federal Reserve how much strength is left in the American job market. The Bureau of Labor Statistics releases its May employment report at 8:30 a.m. Eastern, the government’s most complete count of how many jobs the economy added last month. It lands at a moment when households are paying more for fuel, prices are still climbing faster than the Fed wants, and the war with Iran keeps energy markets on edge.

Here is what economists expect. The consensus calls for the economy to have added roughly 105,000 jobs in May, with most forecasts landing somewhere between 105,000 and 125,000. That would be a step down from April, when employers added 115,000 jobs. It would also fit the pattern of the past year: a job market that keeps growing, but slowly, with just enough hiring to hold steady.

The unemployment rate is expected to stay around 4.3%, where it sat in April. That is still low by historical standards. What it hides is a quieter shift underneath — companies are neither hiring fast nor laying people off in large numbers. Economists have started calling it a “low-hire, low-fire” market, where workers who have jobs tend to keep them, but people looking for new ones find slim pickings.

The early signals this week pointed in a steady direction. On Wednesday, payroll company ADP said private businesses added 122,000 jobs in May, the strongest month since January 2025 and better than the roughly 110,000 that forecasters expected. Nela Richardson, ADP’s chief economist, said the hiring was unusually broad, spread across eight of the ten sectors the firm tracks and across companies of every size. Education and health services led with 57,000 new jobs.

The same day, the Institute for Supply Management reported that its Services PMI rose to 54.5% in May, up from 53.6% in April — the 23rd month in a row that the services side of the economy, which covers most American jobs, kept expanding. On Tuesday, a separate government report showed more open positions than expected and few layoffs. Taken together, the week’s data suggested employers still want workers heading into summer.

But the report that moves markets is the one from the government, and the part Wall Street cares about most may not be the headline jobs number at all. It is wages.

Economists expect average hourly pay to rise about 0.3% from April, and to be up close to the 3.6% annual pace seen the month before. That figure matters because it cuts two ways. If wages climb faster than expected, it raises the worry that inflation will stay sticky — and makes the Federal Reserve less likely to cut interest rates this year. If wages cool, it strengthens the case that price pressures are finally easing, and that rate relief could come.

So the market reaction may look upside down. A jobs report that comes in strong could actually push borrowing costs higher, as traders rethink when the Fed will ease. A weak report could lift hopes for rate cuts, even as it raises questions about whether the economy is starting to slow. The number itself is only half the story; how it changes the Fed’s math is the other half.

Why does any of this reach the average household? Because jobs are what keep the rest of the economy running. As long as people are working and paychecks are growing, they keep spending — on rent, groceries, cars, and everything else. Consumer spending is the single largest engine of the U.S. economy, and it holds up only as long as the job market does. That is why a single monthly report can ripple out to store shelves, car lots, and mortgage rates.

The test now is whether that engine is simply slowing down or starting to stall. The strain is real. Gas prices have stayed high because of the war with Iran and reduced shipping through the Strait of Hormuz, which raises costs for trucking, manufacturing, and anything that has to be delivered. (Crude itself has actually eased lately — Brent traded near $97 a barrel Thursday, down about 12% over the past month — but pump prices have been slow to follow.) Higher costs squeeze the same businesses that do the hiring.

Federal Reserve officials have said repeatedly that they will let the jobs and inflation numbers guide their next move on interest rates. That makes Friday’s report one of the most important economic releases of the summer. For business owners weighing whether to add staff, and for anyone watching mortgage or loan rates, the question is simple: is the labor market just cooling off, or is it beginning to crack?

By 8:31 a.m. Friday, the first piece of the answer will be on the table.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The cushion the United States keeps for oil emergencies is running thinner than it has in nearly 40 years. New government figures released Wednesday by the Energy Information Administration (EIA) showed the Strategic Petroleum Reserve (SPR) fell by roughly 8 million barrels in the week ending May 29, dropping to 357.1 million barrels. That was the sixth straight weekly decline and leaves the reserve approaching its lowest level in almost four decades.

The reserve is the country’s backup oil supply — crude stored in underground salt caverns along the Gulf Coast that the government can tap when normal supplies are disrupted. It was created after the oil shocks of the 1970s to protect the economy during supply emergencies. Today, it is being drawn down at one of the fastest rates in its history.

The reason is straightforward. Since the war with Iran began on February 28, shipping through the Strait of Hormuz — the narrow waterway that previously carried about 20% of the world’s oil supply — has remained sharply reduced. To offset the impact on global energy markets and help contain fuel costs, the Department of Energy has been releasing crude from the SPR.

The government is currently in the process of releasing approximately 172 million barrels, part of a broader effort coordinated with allied nations to place nearly 400 million barrels of additional oil onto world markets.

The numbers are significant. The reserve has lost more than 50 million barrels since the conflict began. Patrick De Haan, head of petroleum analysis at GasBuddy, has warned that the SPR is approaching levels not seen since the early 1980s, when the reserve was still being built.

The drawdown extends beyond government inventories. According to the EIA, commercial crude oil inventories fell by approximately 8 million barrels during the same week, dropping to 433.7 million barrels, about 3% below the seasonal average.

Ole S. Hansen, Head of Commodity Strategy at Saxo Bank, noted that combined government and commercial crude inventories have declined by roughly 90 million barrels from recent highs, including a drop of approximately 16 million barrels in a single week.

Particular attention is being paid to Cushing, Oklahoma, the key storage hub used for pricing West Texas Intermediate (WTI) crude oil. Inventories there have fallen from roughly 33 million barrels two months ago to approximately 24.5 million barrels, approaching levels that analysts say could create logistical constraints for pipeline and storage operations.

For now, the reserve releases appear to be working. Oil prices remain elevated but have avoided the extreme spikes many analysts feared when the conflict began.

Brent crude, the global benchmark, traded near $97 per barrel on Thursday, while WTI crude hovered around $95 per barrel. Although both remain well above year-ago levels, prices are far below some of the most pessimistic forecasts that envisioned oil surging toward $200 per barrel.

That outcome has led some energy executives to warn that the market’s protective buffers are being depleted.

Mike Wirth, Chairman and Chief Executive Officer of Chevron, cautioned last week that energy prices could face renewed upward pressure if supply disruptions continue and inventory cushions shrink further. His concern is simple: emergency stockpiles can stabilize markets, but only while supplies remain available.

For consumers, the implications extend well beyond gasoline. Higher crude prices affect diesel fuel, which powers much of the nation’s trucking, rail, shipping, construction, and agricultural sectors. As transportation costs rise, they can eventually flow through to the prices businesses and households pay for everyday goods.

The reserve was created to protect the country during major supply disruptions. The more crude that is released today, the less remains available if a larger shock emerges tomorrow.

With fighting between the United States and Iran continuing and uncertainty surrounding shipping through the Strait of Hormuz, energy markets remain focused on one key question: whether diplomacy can restore normal oil flows before emergency stockpiles fall further.

President Donald Trump said this week that Iran had agreed not to pursue a nuclear weapon and suggested a broader agreement could be reached soon. If shipping through Hormuz returns to normal, pressure on global supplies could ease and emergency releases may slow. If negotiations falter, the Strategic Petroleum Reserve could continue its decline toward levels not seen in nearly 40 years.

For businesses, investors, and consumers alike, the message is straightforward: the emergency buffer that has helped contain fuel prices is shrinking, and the next move in energy costs may depend as much on diplomacy as on oil production.

Markets & Energy — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SACRAMENTO — While businesses across America race to deploy artificial intelligence, California has become the first state to begin asking a question many policymakers have largely avoided:

What happens to workers when the software gets good enough to replace them?

On May 21, 2026, Governor Gavin Newsom signed what his office described as a first-of-its-kind executive order directing state agencies to study the impact of artificial intelligence on employment and recommend protections for workers displaced by automation.

The move may prove more significant than it initially appears.

For months, discussions around artificial intelligence have focused primarily on productivity, innovation, investment, and economic opportunity. Much less attention has been devoted to the potential consequences for workers whose jobs may no longer be necessary.

California is now attempting to address that issue before it becomes larger.

The timing was notable.

The executive order arrived just one day after Meta Platforms announced plans affecting approximately 8,000 employees and Intuit disclosed approximately 3,000 job cuts, both linked in part to AI-driven efficiency initiatives.

With Silicon Valley at the center of the artificial-intelligence revolution, California has a stronger incentive than any other state to understand the labor-market consequences.

The order directs the California Labor and Workforce Development Agency to evaluate existing worker protections and determine whether they remain adequate in an era of AI-driven displacement.

Specifically, officials have been tasked with examining severance standards, unemployment insurance enrollment, and California’s WARN Act, which governs advance notice requirements for mass layoffs.

The agency must provide recommendations within 180 days, while a separate review examining AI’s effect on collective bargaining and organized labor is scheduled for completion by October 15.

At its core, the initiative recognizes that modern labor laws were built for a different economy.

Existing protections generally assume workers lose jobs because of recessions, factory closures, relocations, or business failures.

Artificial intelligence introduces a different scenario.

A company can be profitable, growing, and financially healthy while simultaneously eliminating positions because software now performs certain tasks more efficiently.

That distinction creates policy challenges lawmakers have not previously faced.

Supporters argue workers displaced by automation may require different forms of assistance than workers affected by traditional economic downturns.

Critics counter that government intervention could slow innovation or create new burdens for employers already competing in rapidly evolving markets.

Regardless of where the debate ultimately lands, California’s action is likely to attract national attention.

The state has a long history of establishing labor, environmental, and consumer-protection policies that later influence legislation elsewhere in the country.

If California develops new standards regarding AI-related layoffs, other states may eventually follow.

For businesses, that possibility deserves close attention.

Companies aggressively pursuing automation strategies may eventually face new reporting requirements, notice obligations, severance standards, or workforce-transition programs.

For workers, the executive order does not immediately create new rights or benefits.

No severance payments increase automatically. No new unemployment programs begin tomorrow.

What it does do is formally launch a policy discussion that is likely to grow more important with each passing year.

Artificial intelligence is no longer a future concept. It is already changing hiring decisions, workforce planning, and corporate investment strategies.

California has become the first state to formally acknowledge that reality and begin preparing for its consequences.

The debate over who benefits from AI—and who bears its costs—is only beginning.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

TEMPE, Ariz. — The largest part of the American economy continued expanding in May, but beneath the encouraging headline lies a growing concern for workers: businesses are generating more sales without adding more employees.

New data released Wednesday by the Institute for Supply Management (ISM) showed that the U.S. services sector expanded for the 23rd consecutive month, highlighting continued economic resilience even as uncertainty surrounding inflation, interest rates, and global tensions persists.

The ISM’s closely watched Services Purchasing Managers Index (PMI) rose to 54.5% in May from 53.6% in April. Any reading above 50 indicates growth, making the report another sign that the service economy remains firmly in expansion mode.

At first glance, the numbers looked strong.

The survey’s measure of new orders climbed to 57.3%, while business activity increased to 57.7%, indicating healthy customer demand across industries ranging from healthcare and banking to retail and technology.

Businesses are clearly finding work.

The problem is they are not hiring people to do it.

The report’s employment index fell to 47.9%, marking the third consecutive month of contraction. It was also the only major component of the survey running below its twelve-month average.

That disconnect is becoming one of the defining economic stories of 2026.

Companies are growing.

Customers are spending.

Revenue is increasing.

Yet hiring remains sluggish.

The phenomenon reflects what economists increasingly describe as a “low-hire, low-fire” economy. Businesses are not conducting widespread layoffs, but they are also reluctant to expand payrolls.

Instead, many are attempting to generate more output from existing employees.

Part of that shift is financial caution.

After several years of economic uncertainty, many executives remain hesitant to commit to permanent labor costs. Higher wages, healthcare expenses, and benefit obligations have made hiring decisions more expensive.

Another factor is technology.

Across industries, companies are investing heavily in automation, software, and artificial intelligence tools designed to improve productivity. Rather than immediately adding headcount when demand rises, many businesses are first attempting to determine whether technology can handle additional workload.

The result is economic growth that feels different from past expansions.

Historically, rising orders and stronger business activity would have translated directly into job creation. Increasingly, that relationship appears to be weakening.

The report also contained another warning sign for policymakers.

The survey’s measure of prices remained elevated, indicating businesses continue facing higher costs for supplies and services.

Service-sector inflation tends to be particularly stubborn because it is driven heavily by wages, rents, insurance costs, and other expenses that do not decline quickly.

That creates a difficult challenge for the Federal Reserve.

On one hand, economic activity remains healthy and inflation pressures persist. On the other hand, hiring is slowing and labor-market momentum appears weaker than headline growth figures suggest.

The conflicting signals help explain why investors remain uncertain about the Fed’s next move.

Should policymakers focus on inflation and keep monetary policy tight?

Or should they become more concerned about a labor market that is no longer generating jobs at the pace many economists expected?

Those questions will become even more important when the government releases its official employment report later this week.

For workers, the report captures a frustrating reality.

The economy is growing.

Businesses are busy.

Customers are spending.

Yet finding a new job is becoming harder.

It is an economy that looks healthy on paper but feels far less dynamic to many Americans trying to advance their careers.

The services sector continues carrying the U.S. economy forward.

The question now is whether it can continue growing without bringing more workers along for the ride.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — The nation’s largest residential real-estate brokerage is facing new scrutiny after New York Attorney General Letitia James’ antitrust division opened an investigation into Compass, raising fresh questions about consolidation in one of America’s most important housing markets.

The inquiry, first reported Wednesday, comes just months after Compass completed its blockbuster $1.6 billion acquisition of Anywhere Real Estate, a deal that combined some of the industry’s biggest names under a single corporate umbrella and created a company with more than 340,000 agents and franchisees nationwide.

News of the investigation rattled investors.

Compass shares plunged approximately 12%, their steepest decline since February, as Wall Street weighed the possibility that regulatory scrutiny could complicate the company’s growth strategy and future expansion plans.

At the center of the investigation is a question increasingly being asked across multiple industries: how much market power is too much?

Compass has spent years growing through acquisitions, becoming one of the most influential forces in residential real estate. The acquisition of Anywhere Real Estate significantly expanded that reach, bringing brands such as Corcoran, Sotheby’s International Realty, and Coldwell Banker under the Compass umbrella.

The result was the creation of the largest residential brokerage network in the United States.

For antitrust regulators, that kind of scale naturally attracts attention.

State investigators have reportedly contacted executives and leaders at major New York brokerages as they gather information about Compass’s position in the market and its potential impact on competition.

The concern centers on commissions, listings, and consumer choice.

Residential brokerages play a critical role in nearly every home transaction. When a home is bought or sold, brokerages typically receive commissions that can represent a meaningful percentage of the transaction value.

Critics argue that excessive consolidation could limit competition, reduce choices available to buyers and sellers, and keep commissions artificially high.

Supporters of larger firms counter that scale allows brokerages to invest more heavily in technology, marketing, customer service, and agent support while providing consumers with broader access to listings and resources.

The debate has become increasingly important as housing affordability remains one of the most pressing challenges facing American families.

The investigation is notable because the merger had already cleared federal review.

When Compass announced the Anywhere acquisition in September 2025, the transaction moved through the federal antitrust process relatively quickly. The required waiting period expired without action from either the Department of Justice or the Federal Trade Commission, allowing the deal to proceed.

That outcome drew criticism from some lawmakers.

Sen. Elizabeth Warren and Sen. Ron Wyden were among those who urged federal officials to examine whether the merger could ultimately increase brokerage costs and reduce competition within the housing market.

Now New York regulators are taking a closer look.

State attorneys general possess independent authority to investigate anticompetitive conduct affecting consumers within their jurisdictions, even after mergers receive federal clearance.

That authority can sometimes result in additional scrutiny long after transactions have closed.

Neither Compass nor the Attorney General’s office has publicly commented on the reported investigation.

For the broader real-estate industry, the implications could extend well beyond one company.

Residential brokerage has undergone significant consolidation over the past decade as firms seek greater scale, stronger technology platforms, and broader national footprints. If regulators ultimately conclude that such consolidation harms consumers, it could influence future merger activity throughout the sector.

The case also arrives at a sensitive moment for housing.

Mortgage rates remain elevated, affordability challenges persist, and transaction volumes remain below historical norms. Any development affecting the cost or structure of buying and selling homes attracts significant attention from consumers, regulators, and investors alike.

For Compass shareholders, the immediate concern is uncertainty.

Antitrust investigations can take months or even years to resolve, creating potential distractions and legal expenses along the way. At the same time, some analysts remain optimistic.

Barclays maintained a positive rating on the company following reports of the investigation, suggesting some on Wall Street view the market reaction as excessive given the preliminary nature of the inquiry.

The larger question now is whether New York regulators view Compass’s dominance as evidence of successful growth—or evidence that competition has been weakened.

The answer could help shape the future of real estate consolidation across the country.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

HARRISBURG, Pa. — If there is one retailer thriving in today’s affordability-focused economy, it is Ollie’s Bargain Outlet.

The discount chain reported another strong quarter Wednesday as shoppers continued flocking to stores in search of lower prices and better deals.

The company posted quarterly sales of $658.9 million, a 14.2% increase from a year earlier, while adjusted earnings climbed 21% to 91 cents per share.

Management was confident enough to raise its earnings outlook for the rest of the year.

The results reinforce one of the clearest consumer trends of 2026.

Americans are becoming increasingly value conscious.

After years of higher living costs, shoppers are searching harder for bargains, comparing prices more carefully, and increasingly choosing retailers that stretch household budgets.

That trend plays directly into Ollie’s business model.

The company buys closeout merchandise, discontinued products, excess inventory, and overstock goods from manufacturers and retailers, then sells them at steep discounts under its well-known “Good Stuff Cheap” slogan.

When consumers feel financially squeezed, the appeal of that model grows stronger.

Eric van der Valk, President and Chief Executive Officer, said the company performed well despite what he described as a challenging consumer environment.

Comparable-store sales increased 1.7%, while basket sizes grew, indicating shoppers were not simply visiting stores—they were buying more once inside.

That detail may be the most important takeaway.

Customers are increasingly filling their carts with discounted products as they look for ways to offset higher costs elsewhere in their budgets.

Profitability improved as well.

Gross margins expanded to 41.9%, helped by lower supply-chain expenses and disciplined inventory management. Operating income rose to $69.6 million, while cash and investments increased 27% to approximately $525.6 million.

The company also continues expanding aggressively.

One of Ollie’s more successful strategies has been acquiring store locations left vacant by struggling or bankrupt retailers. Those locations often come with favorable lease terms, allowing the company to grow at lower cost while moving into established retail markets.

In many cases, Ollie’s is expanding into spaces abandoned by competitors that could not survive.

That dynamic captures the broader retail landscape perfectly.

The winners in today’s economy are increasingly the companies that help consumers save money.

Discount chains, warehouse clubs, and closeout retailers have generally outperformed more expensive competitors as shoppers continue looking for value.

The same consumer who buys store-brand groceries, cuts back on discretionary purchases, and watches every dollar is often the same consumer walking through Ollie’s doors.

For investors, management’s raised guidance suggests these trends are not fading anytime soon.

For consumers, the company’s success reflects a simple reality.

A 14% jump in sales at a bargain retailer is more than a strong earnings report.

It is a snapshot of how millions of Americans are shopping in 2026.

And as long as affordability remains a concern, retailers built around deals and discounts appear likely to remain among the biggest winners in the consumer economy.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A flesh-eating parasite that the United States stamped out 60 years ago is back, and it landed at the worst possible moment for anyone who buys beef. The U.S. Department of Agriculture confirmed Wednesday evening that a New World screwworm was found in a three-week-old calf in La Pryor, in Zavala County, about 60 miles from the Mexican border — the first case on U.S. soil in decades and the first in Texas since 1966.

Agriculture Secretary Brooke Rollins said it is the only confirmed case so far and stressed it is not a danger to the food supply, because the pest infects living animals, not meat.

For shoppers, the bigger story is what this does to a beef market that is already stretched to its limits. Ground beef hit a record $6.89 a pound in May, the highest since the government began tracking the price in 1984, and beef overall is up about 57% since 2020.

The reason is simple supply. The U.S. cattle herd has shrunk to roughly 86.2 million head, the smallest since 1951, after years of drought pushed ranchers to sell breeding cows and high feed costs made rebuilding slow and expensive. A new threat to the herd is the last thing a tight market needed.

The screwworm makes that squeeze worse from two directions.

First, it has already cost the market its main relief valve. To keep the pest out, the USDA shut the southern border to live cattle imports in 2025. Mexico had supplied more than 60% of U.S. live cattle imports, roughly 1.1 million to 1.2 million head annually. Cutting that off removed a major source of young cattle that normally enter U.S. feedlots.

Second, an actual outbreak could sicken or kill cattle inside Texas, the nation’s largest beef-producing state, shrinking the herd even further.

The market’s first reaction was surprisingly negative. Feeder cattle futures for August fell 5.80 cents to 342.625 cents per pound, while August live cattle futures slipped to 237.85 cents. Shares of major meat companies including Tyson Foods and JBS also declined.

Traders worried that a confirmed U.S. case could temporarily weaken consumer demand. As market analyst Brad Kooima of KKV Trading noted, cattle futures have been trading “almost exclusively” on screwworm concerns for days.

But the cash cattle market tells a different story. Prices remain near record levels, with negotiated sales in parts of the Plains reaching approximately $257 per hundredweight last week. Live cattle futures topped $250 for the first time ever in April.

The takeaway is straightforward: there still are not enough cattle to satisfy demand, and any threat to the herd could tighten supplies further.

That creates a two-speed outlook for beef prices. In the short term, fear-driven futures selling could temporarily pressure prices. Longer term, the risk points higher.

Research from the Federal Reserve Bank of Dallas has warned that a widespread outbreak could reduce cattle inventories, cost billions of dollars, and push beef prices even higher. Because cattle take years to breed and raise, any rebuilding effort started today would not meaningfully increase beef supplies until approximately 2028.

The potential economic damage is substantial.

A screwworm outbreak could cost Texas roughly $1.8 billion annually, according to Peyton Schuman of the Texas and Southwestern Cattle Raisers Association. Cattle producers alone could face annual losses of approximately $735 million to $745 million. Texas’ cattle industry is valued at roughly $15 billion.

Corporate America is already feeling the pressure from limited cattle supplies.

Tyson Foods has projected an adjusted operating loss of up to $600 million in its beef division for fiscal 2026 and has reduced shifts at its Amarillo, Texas, processing facility, citing the shortage of cattle resulting from border restrictions. Retailers including Walmart and Kroger have also reported consumers increasingly shifting toward less expensive proteins as beef prices continue climbing.

For now, officials are moving aggressively to contain the outbreak.

Federal and state authorities established a roughly 12-mile quarantine zone around the affected ranch, expanded surveillance efforts, and began releasing sterile flies — the same technique that successfully eradicated the pest in the United States during the 1960s.

A new $610 million federal facility in Edinburg, Texas, is expected to eventually produce 300 million sterile flies per week, though it is not scheduled to open until late 2027.

Secretary Brooke Rollins said the response plan developed over the past year is already being implemented. The National Cattlemen’s Beef Association, led by Colin Woodall, said ranchers and industry leaders have spent more than a year preparing for the possibility of the pest’s return.

For consumers, the bottom line is simple: beef prices were already at record highs before the screwworm crossed the border. Now, a new threat to the nation’s cattle herd has introduced another layer of uncertainty into an already strained market — making meaningful relief at the meat counter look further away than ever.

Agriculture & Consumer Markets — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

REDWOOD CITY, Calif. — Artificial intelligence has become the hottest investment theme on Wall Street, creating hundreds of billions of dollars in market value and transforming companies from Nvidia to Microsoft into some of the biggest winners in corporate America.

So why is one of the industry’s original AI companies still struggling to make money?

That question was front and center Wednesday as C3.ai reported fiscal-year results and announced that founder Thomas Siebel is returning to the Chief Executive role.

His message to investors was short and direct:

“Game on.”

The move reflects growing pressure on a company that built its identity around artificial intelligence long before AI became a household term.

For the quarter ended April 30, C3.ai reported revenue of $51.6 million, while full-year revenue reached $250.3 million. The company remains unprofitable, posting a quarterly loss of 79 cents per share.

Despite the losses, C3.ai finished the year with approximately $575 million in cash, providing a substantial financial cushion as management works to accelerate growth.

The challenge facing C3.ai highlights a broader reality about the AI economy.

Building AI infrastructure and selling AI applications are proving to be very different businesses.

Companies like Nvidia, Broadcom, Amazon, Microsoft, and Alphabet are benefiting from enormous demand for chips, cloud services, data centers, and computing power. They are effectively selling the tools needed to build the AI revolution.

C3.ai operates further downstream.

The company develops software applications designed to help businesses predict equipment failures, detect fraud, improve supply-chain efficiency, and automate decision-making.

The technology is real.

The demand is real.

But turning that interest into large, recurring contracts has been slower than many investors expected.

During the quarter, C3.ai signed 28 new agreements, demonstrating continued customer interest. Yet bookings came in below expectations, reinforcing a growing theme throughout enterprise software: many companies want AI, but they are still testing it before committing major budgets.

Executives increasingly want proof that AI can generate measurable returns before writing larger checks.

That caution creates a difficult environment for software providers.

Pilot programs often take months before expanding into larger deployments, slowing revenue growth even while enthusiasm remains high.

The return of Siebel reflects the board’s desire for experienced leadership during a critical period.

Before founding C3.ai, Siebel built Siebel Systems, one of Silicon Valley’s most successful enterprise-software companies before its acquisition by Oracle.

His return sends a signal that management wants sharper focus on growth, execution, and ultimately profitability.

For investors, the report serves as a useful reminder that not everyone is benefiting equally from the AI boom.

Some companies are making fortunes selling the infrastructure behind artificial intelligence.

Others are still trying to prove customers will pay enough for the applications built on top of it.

The coming year may determine whether C3.ai can finally convert its early leadership position into meaningful profits.

The technology world has already embraced artificial intelligence.

Now investors want to see whether one of AI’s original pioneers can finally cash in.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The stock market split in two directions Thursday. The Dow Jones Industrial Average rocketed to a fresh record high, jumping about 928 points, or 1.8%, as investors pulled money out of the artificial-intelligence trade and poured it into banks, retailers, and health-care names. At the same time, the tech-heavy Nasdaq Composite barely budged, rising around 0.1%, dragged down by a sharp drop in chip giant Broadcom. The broad S&P 500 landed in between, up roughly 0.5%. The session played out against a tense political backdrop in Washington over the ongoing war with Iran, even as oil prices eased.

The day’s biggest story on Wall Street was the rotation. Broadcom tumbled about 14% after the chipmaker reported fiscal second-quarter revenue that fell short of forecasts. That miss spooked traders who have ridden AI-linked stocks to record after record this year, and many trimmed their bets on the group. Fellow chipmaker Micron Technology also fell. With money leaving technology, it flowed into corners of the market that had been left behind.

Those overlooked names led the Dow higher. UnitedHealth Group jumped more than 5% to pace the blue-chip index. JPMorgan Chase climbed about 4%, and Walmart added roughly 1%. Outside the Dow, warehouse retailer Costco rose more than 1% and drugmaker Eli Lilly gained more than 5%. The pattern was clear: this was a day for steady, everyday businesses — lenders, stores, and health insurers — rather than the high-flying tech names that have dominated 2026.

The political news out of Washington gave traders plenty to weigh. The Republican-led House voted 215-208 on Wednesday to approve a resolution aimed at limiting President Donald Trump’s ability to continue military operations against Iran, with four Republicans joining Democrats. Trump dismissed it as a “meaningless vote” and called the four Republicans who crossed over “grandstanders.” Iranian Foreign Minister Abbas Araghchi said there had been no significant progress in recent talks, while Israeli Prime Minister Benjamin Netanyahu said in an interview that Israel and the United States were prepared to return to military action if necessary.

Despite the heated rhetoric, oil prices fell. West Texas Intermediate crude dropped to around $95 a barrel in the morning and slid further during the session, while global benchmark Brent crude eased to about $96.70. Falling oil is welcome news for households and for the trucking, airline, and manufacturing companies that burn large amounts of fuel, and it helped support the non-tech stocks that led the day.

The market also had one eye on a wave of blockbuster public offerings. SpaceX, the rocket company run by Elon Musk, priced its initial public offering at $135 a share, an offering worth about $75 billion that would value the company near $1.77 trillion. That would make SpaceX the seventh-largest U.S. company by market value, ahead of Tesla, and the largest IPO in history when it debuts on the Nasdaq on June 12. Goldman Sachs is leading the deal, joined by Morgan Stanley, Bank of America, Citigroup, and JPMorgan Chase. Musk is expected to retain more than 82% of the voting control.

The appetite for new listings showed up Thursday in another debut. Quantinuum, a quantum-computing company formed from Honeywell’s quantum division and Britain’s Cambridge Quantum, opened at $68 a share after pricing its upsized IPO at $60, above its expected range. The company raised about $1.68 billion and was valued near $17.6 billion at its first trade.

On the research side, analysts remain broadly upbeat on the year’s tech-driven rally, even after Thursday’s wobble. Julian Emanuel, senior managing director at Evercore ISI, has a year-end target of 7,750 on the S&P 500, arguing that a small handful of AI leaders has been powering the index’s gains. Separately, Morgan Stanley told clients it sees room for Apple shares to rise ahead of the company’s developer conference next week.

The bigger event for everyone is still ahead. The Bureau of Labor Statistics releases its May employment report Friday at 8:30 a.m. Eastern. It follows data from payroll firm ADP on Wednesday showing private employers added 122,000 jobs in May, the strongest month in over a year. A strong government number could ease worries about the economy but complicate the case for interest-rate cuts; a weak one could do the reverse.

After the closing bell, a fresh round of earnings was due from software and data firms including Samsara, Rubrik, and Planet Labs, giving traders more to digest before Friday’s main event.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

CHICAGO — For years, Americans threw away enormous amounts of food with little change from one year to the next.

Now, rising grocery costs are beginning to alter that behavior.

According to a report from ReFED, a nonprofit organization that tracks food waste across the United States, Americans discarded approximately 70 million tons of food in 2024, equal to about 29% of the nation’s food supply. While the number remains staggering, it represented a 2.2% decline from the previous year, marking the first meaningful reduction since the pandemic.

The change may appear modest, but it reveals something significant about consumer behavior.

Americans are becoming more careful.

After several years of elevated food prices, households are increasingly planning meals, saving leftovers, buying more strategically, and paying closer attention to what actually gets consumed before it spoils.

What was once framed primarily as an environmental issue is increasingly becoming a financial one.

When groceries cost more, food waste feels less like a minor inconvenience and more like throwing money directly into the trash.

Consumer surveys show roughly one-quarter of Americans report making greater efforts to reduce food waste specifically to stretch household budgets.

The impact is becoming measurable.

ReFED estimates nearly one million tons of residential food waste were eliminated as families became more conscious about purchasing and consumption habits.

Much of the improvement came from simple changes involving everyday products.

Staples such as milk, produce, and frequently purchased household foods accounted for a significant portion of the decline. Households are increasingly buying only what they expect to use and finding ways to consume products before expiration.

Food donations are also increasing.

More consumers, retailers, and businesses are directing surplus food toward food banks and charitable organizations rather than disposal. That shift is helping reduce waste while supporting communities facing increased food insecurity.

The trend is creating new opportunities throughout the food industry.

Grocers are expanding programs that discount products approaching sell-by dates. Retailers are offering smaller package sizes designed to reduce spoilage. Technology platforms are connecting consumers with discounted surplus food from restaurants and stores.

A small ecosystem focused on reducing waste is emerging.

Despite the progress, the challenge remains enormous.

The United States still wastes nearly one-third of its food supply, and much of that waste occurs before products ever reach consumers. Farms, processors, distributors, and retailers all contribute to losses throughout the supply chain.

Households represent only one part of a much larger system.

Still, the shift offers an important lesson about the current economy.

The growing focus on leftovers, meal planning, and reducing waste reflects more than changing attitudes. It reflects changing financial realities.

Consumers are looking for savings wherever they can find them.

The same pressures driving shoppers toward store brands, discount retailers, and tighter budgets are also encouraging households to maximize the value of every grocery purchase.

Some of those habits may remain long after inflation fades.

Once consumers learn they can save money simply by wasting less, the behavior often becomes permanent.

For businesses, that means the value-conscious consumer is likely here to stay.

The companies helping shoppers stretch their budgets—whether through smaller portions, discounted products, or waste-reduction tools—may find themselves aligned with one of the most important consumer trends of the decade.

In a period defined by affordability concerns, reducing waste has become more than a household habit.

It has become a financial strategy.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — One of the clearest signs of how Americans are coping with years of higher prices is not showing up in a government report or a corporate earnings release. It is showing up in grocery carts.

Across the country, shoppers are increasingly reaching past familiar national brands and choosing store-brand alternatives instead. Whether it is cereal, coffee, paper towels, canned goods, or household essentials, private-label products are becoming a larger part of the American shopping basket as families look for ways to stretch every dollar.

Consumer surveys conducted this spring show that roughly one in four Americans report cutting back on premium purchases or switching from name brands to store or generic alternatives. The trend has become one of the most visible responses to an affordability crisis that continues to pressure household budgets despite cooling inflation.

For retailers, the shift is proving highly profitable.

Private-label products typically sell at lower prices than national brands while generating higher profit margins for the retailer. As a result, supermarkets, warehouse clubs, and discount chains are aggressively expanding their store-brand offerings and giving them more prominent shelf space.

The strategy is working.

Retailers that built their business models around value and affordability continue to attract customers from across the income spectrum. What began as a necessity for lower-income households has increasingly become a habit among middle-income and even higher-income consumers.

Yet the trend exposes a deeper economic reality.

As wealthier shoppers trade down from premium products, demand for lower-cost alternatives rises. That can put upward pressure on prices for the very products lower-income families already depend upon.

David Ortega, a food economist at Michigan State University, has noted that consumers already buying the cheapest available products often have nowhere left to go when prices rise.

For many households, the traditional advice offered during inflationary periods—buy generic, switch brands, shop sales—no longer works.

They made those adjustments years ago.

That helps explain why affordability remains such a dominant concern even as inflation has moderated from its peak. While some households still have flexibility to substitute products and cut costs, others are already operating at the bottom of the pricing ladder.

The shift is also changing the balance of power throughout the retail industry.

For decades, major consumer brands commanded loyalty that allowed them to charge premium prices. Today, many are finding that consumers are more willing than ever to experiment with alternatives.

In response, national brands are increasing promotions, introducing value-focused product lines, shrinking package sizes, and investing heavily in marketing campaigns designed to justify their higher prices.

Retailers, meanwhile, are discovering that private labels are no longer merely a low-cost alternative.

They are becoming a competitive advantage.

A successful store brand builds loyalty not only to a product but to the retailer itself. If shoppers trust a supermarket’s coffee, cereal, or paper products, they are more likely to continue shopping there.

Recent earnings reports across retail reinforce the trend.

Discount chains, warehouse clubs, and value-oriented retailers have reported some of the strongest sales growth in the industry. Companies that emphasize affordability continue outperforming peers focused on premium positioning.

The message from consumers is increasingly clear.

In an environment where household budgets remain under pressure, value matters more than brand prestige.

For businesses, the lesson extends beyond groceries.

Consumers are becoming more selective, more price-conscious, and more willing to abandon long-held habits when the numbers no longer make sense.

For shoppers, the boom in store brands represents something simpler.

It is a quiet but powerful verdict on the state of household finances.

People rarely abandon trusted brands unless they feel they must.

The growing success of generic products suggests millions of Americans have done the math and concluded that affordability now outweighs familiarity.

And once consumers discover that a cheaper alternative works just as well, winning them back may prove far harder than many national brands expect.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — While consumers celebrate occasional relief at the gas pump and hope grocery inflation continues to cool, one household expense continues moving in the wrong direction: electricity.

Across much of the United States, utility bills are climbing again just as air-conditioning season begins. For millions of households, that means higher monthly expenses arriving precisely when electricity usage is reaching its annual peak.

The timing could hardly be worse.

Summer remains the most expensive season for many households because air conditioners run longer and harder during periods of extreme heat. Even modest increases in electricity rates can produce significantly larger monthly bills when multiplied by peak seasonal consumption.

Unlike discretionary spending, cooling is often not optional.

For families with children, seniors, or health concerns, reducing air-conditioning use during extreme temperatures is not always realistic.

Several forces are driving utility costs higher.

Utilities across the country are spending billions of dollars modernizing aging power grids, strengthening infrastructure against extreme weather events, and expanding transmission networks to support growing demand. Those investments are necessary, but they ultimately must be paid for.

In many cases, that cost appears on consumer utility bills.

Natural gas prices also play an important role. Because natural gas remains one of the largest sources of electricity generation in the United States, fluctuations in energy markets often affect electricity costs.

Increasingly, however, another force is entering the equation.

Artificial intelligence.

The technology industry’s massive investment boom is creating unprecedented demand for electricity as companies build and operate enormous AI data centers across the country.

Technology giants including Microsoft, Amazon, Alphabet, and Meta Platforms are investing hundreds of billions of dollars into AI infrastructure. Those facilities require vast amounts of electricity to power servers, cooling systems, networking equipment, and supporting infrastructure.

Utilities are racing to keep up.

In some regions, power providers are being forced to accelerate expansion plans, add generating capacity, and upgrade transmission networks to accommodate demand growth that is occurring faster than anticipated.

The question increasingly being debated is who should pay for that expansion.

Consumer advocates argue ordinary households should not bear the full cost of infrastructure built primarily to support some of the world’s largest and most profitable technology companies.

Utilities counter that grid investments benefit everyone by improving reliability and ensuring adequate supply.

The debate is likely to intensify.

For lower-income households, rising electricity costs create particular challenges because utilities consume a larger percentage of household income. Energy economists often refer to this as “energy burden”—the share of income spent on electricity and heating.

That burden has been rising for many families.

Unlike discretionary purchases, utility costs offer limited flexibility. Households can reduce consumption only so much before comfort, convenience, and health become concerns.

Regulators are increasingly caught in the middle.

They must approve investments needed to strengthen the grid while also protecting consumers from excessive rate increases. That balancing act is becoming more difficult as demand growth accelerates.

For consumers, several strategies can help reduce the impact.

Many utilities offer budget-billing programs that spread costs more evenly throughout the year. Energy-efficiency programs, smart thermostats, improved insulation, and shifting heavy appliance use away from peak hours can also lower monthly expenses.

None of those measures, however, changes the larger reality.

Electricity is becoming more expensive.

And unlike temporary spikes in fuel or food prices, many of the forces driving utility costs higher—including infrastructure investment and AI-related demand growth—are likely to remain in place for years.

The electric bill may not receive as much attention as inflation or gasoline prices, but for millions of households, it is quietly becoming one of the most persistent pressures on the family budget.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — Inflation may no longer dominate headlines the way it did two years ago, but for millions of Americans, the financial damage continues to deepen.

The official inflation rate has moderated significantly from its peak, yet a growing body of economic data suggests many households are struggling more today than when inflation was accelerating. The reason is simple: prices may be rising more slowly, but they remain dramatically higher than they were just a few years ago.

Since 2021, the cost of everyday goods and services has increased by roughly 25%, more than double the pace experienced during a comparable period before the pandemic. While economists often focus on whether inflation is rising or falling, consumers experience something different. They experience the total cost of living.

And that cost remains painfully elevated.

The strain is becoming increasingly visible throughout the economy.

Bankruptcy filings have risen for three consecutive years. Delinquency rates on credit cards and consumer loans continue climbing. The personal savings rate has fallen to its lowest level in several years as households draw down reserves to cover everyday expenses.

Perhaps most striking is the collapse in consumer sentiment.

Recent surveys show Americans expressing financial pessimism at levels worse than those seen during the Great Recession and, in some measures, even worse than during the pandemic itself.

The data suggest the issue extends beyond higher prices.

Many consumers no longer believe conditions will improve.

What makes the current environment particularly unusual is how far the financial pressure has spread up the income ladder.

The affordability squeeze is no longer limited to lower-income households. Increasingly, middle-income and even upper-middle-income families report feeling financially strained despite earning salaries that traditionally provided comfortable lifestyles.

Stories that would have seemed unusual several years ago are becoming increasingly common.

Professionals earning six-figure incomes report cutting discretionary spending, delaying major purchases, increasing overtime hours, and drawing down savings to maintain living standards. Some households are postponing retirement contributions, sacrificing long-term financial security to meet short-term obligations.

For lower-income families, the challenges are even more severe.

A larger percentage of household income goes toward necessities such as groceries, housing, transportation, and utilities. When those categories become more expensive, there is little flexibility left in the budget.

The situation is compounded by changing consumer behavior.

As higher-income households trade down to lower-cost alternatives, they increasingly compete for the same products, discounts, and value-oriented services relied upon by lower-income consumers. That dynamic places additional pressure on affordability throughout the economy.

The divide is becoming increasingly visible in consumer spending patterns.

Discount retailers continue gaining market share. Private-label grocery products are experiencing strong growth. Consumers are delaying purchases, seeking promotions, and focusing more heavily on value.

Businesses are adapting accordingly.

Companies that understand they are operating in one of the most financially anxious consumer environments in decades are emphasizing affordability, flexibility, and practical value rather than premium positioning.

The wealth gap is also widening.

Economic gains have become increasingly concentrated among higher-income households and asset owners, creating a situation in which overall economic indicators can appear healthy even while a large segment of the population feels left behind.

That disconnect helps explain why economic statistics and consumer sentiment often appear to tell different stories.

The economy can grow while financial stress rises.

Corporate profits can increase while household budgets remain under pressure.

Inflation can cool while consumers continue struggling.

Until wage growth consistently outpaces the cumulative increase in living costs, many families are likely to remain focused less on inflation rates and more on a simpler question:

Why does everything still feel so expensive?

For millions of Americans, that question has become the defining economic reality of 2026.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — A vacation taken last summer is still being paid for this summer.

That reality, revealed in recent consumer surveys, offers one of the clearest windows into the financial pressures facing American households in 2026.

According to a NerdWallet survey, 74% of travelers who used a credit card to pay for a summer vacation did not immediately pay off the balance, and more than 35% are still carrying that debt nearly a year later.

The finding highlights a broader trend extending far beyond travel.

Increasingly, Americans are relying on credit cards not just for vacations and discretionary purchases, but for groceries, gasoline, utilities, and other everyday expenses.

The shift is occurring as household savings continue to shrink.

The U.S. personal savings rate has fallen to approximately 3.6%, one of its lowest levels since 2022. With fewer financial reserves available, many consumers are using credit cards as a bridge between income and expenses.

The problem is that credit cards are among the most expensive forms of consumer borrowing.

Interest rates remain near historic highs, meaning balances that roll over month after month can grow quickly. What begins as a temporary solution often becomes a long-term financial burden.

For households already struggling with higher living costs, the compounding effect of interest can be devastating.

The warning signs are beginning to appear.

Consumer delinquency rates have been climbing as more borrowers fall behind on payments. Bankruptcy filings have increased for three consecutive years. Financial institutions are closely monitoring credit trends for evidence that consumers are becoming increasingly stretched.

For lenders, the situation presents both opportunity and risk.

Growing balances generate more interest income, but they also increase the likelihood of defaults and losses. If delinquency rates continue rising, banks may tighten lending standards or reduce available credit, making it more difficult for consumers to access borrowing when they need it most.

That dynamic could create additional pressure on household finances.

The trend also raises important questions about consumer spending.

Strong retail sales are often interpreted as evidence of economic strength. Yet spending funded through credit is fundamentally different from spending supported by income growth.

One reflects confidence.

The other reflects necessity.

If a growing portion of consumer spending is being financed through debt rather than rising wages, the apparent strength of the economy may be more fragile than headline numbers suggest.

Financial counselors continue urging consumers to prioritize paying down high-interest debt, build emergency savings where possible, and avoid treating available credit as additional income.

Those recommendations are easier said than done.

For many households, the rising cost of necessities leaves little room for aggressive debt reduction. Groceries, housing, utilities, insurance, and transportation expenses continue consuming larger portions of monthly budgets.

As a result, credit cards increasingly function as financial shock absorbers.

They help households manage unexpected costs, bridge temporary shortfalls, and maintain spending patterns that income alone may no longer support.

But bridges are not meant to be permanent.

The vacation still being financed a year later illustrates a larger reality facing millions of Americans.

The consumer economy remains active, stores remain busy, and spending continues.

Yet beneath those numbers lies a growing dependence on borrowed money.

How long consumers can continue carrying that burden may become one of the most important economic questions facing the country over the next year.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — Two of the most familiar items in the American diet are becoming increasingly expensive, and together they are helping keep pressure on household grocery budgets despite broader signs that inflation is cooling.

Coffee and beef prices have surged over the past year, driven by entirely different forces. One may eventually offer relief. The other is likely to remain expensive for the foreseeable future.

Coffee prices have climbed approximately 19% from a year ago, according to industry data, reaching some of the highest levels consumers have seen in years.

The primary culprit has been weather.

Major coffee-producing countries including Brazil and Vietnam have experienced severe weather disruptions that damaged harvests and tightened global supply. At the same time, tariffs imposed on certain Brazilian imports added additional pressure to costs throughout the supply chain.

The outlook for coffee, however, may be improving.

The World Bank expects coffee prices to ease during 2026 as production recovers and supply conditions improve. Some trade restrictions have also eased, creating additional room for stabilization.

For coffee drinkers, relief may finally be on the horizon.

Beef presents a very different challenge.

Prices for beef and veal have climbed more than 15% year-over-year, and economists see little evidence that meaningful relief is approaching anytime soon.

Unlike coffee, which has been affected primarily by weather events, beef prices are being driven by long-term structural supply issues.

Years of drought forced ranchers across major cattle-producing regions to reduce herd sizes. Rebuilding those herds takes years, not months. As a result, beef supplies remain constrained even as consumer demand remains relatively strong.

The imbalance continues pushing prices higher.

The impact extends far beyond grocery stores.

Restaurants, fast-food chains, supermarkets and food manufacturers all face higher costs when beef prices rise. Many operators have responded by emphasizing chicken products, value menus, and promotional offerings designed to maintain customer traffic without sacrificing profitability.

Consumers are seeing a mixed picture throughout grocery aisles.

Egg prices, which surged during bird-flu outbreaks, have retreated significantly from previous highs. Some dairy products have stabilized. Certain produce categories have become more affordable.

Yet coffee and beef continue moving in the opposite direction.

That creates a confusing experience for shoppers.

Some items appear cheaper. Others continue setting records.

The broader lesson is that grocery inflation is no longer a single story. Each product category is responding to its own combination of weather events, trade policies, supply-chain dynamics, and production challenges.

For households attempting to manage budgets, understanding which price increases are temporary and which are likely to persist has become increasingly important.

Coffee may eventually provide some relief.

Beef likely will not.

For many American families, that distinction could determine whether grocery budgets improve—or remain under pressure throughout the remainder of the year.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SpaceX’s record-breaking IPO will give investors a stake in the company, but Elon Musk will retain overwhelming control through a dual-class share structure that leaves public shareholders with little influence over how the company is run.

NEW YORK — SpaceX is about to sell tens of billions of dollars in stock to the public, but its founder is giving up almost none of his power. According to the company’s amended prospectus filed with the Securities and Exchange Commission on Wednesday, June 3, 2026, Elon Musk will retain effective control over SpaceX even after its record-breaking initial public offering—more than 82% of the voting power by the filing’s own count, with outside estimates of his grip running as high as 85%. In plain terms, the most anticipated stock debut in history will hand outside investors a piece of the company but virtually no say in how it is run.

The mechanism is a structure known as dual-class shares. SpaceX will have two classes of stock: Class A shares, which public investors will purchase and which carry one vote each, and Class B super-voting shares, which carry ten votes each. Musk owns approximately 5.22 billion Class B shares, giving him an overwhelming voting advantage.

As the company’s Chief Executive Officer, Chief Technology Officer, and Chairman, Musk will effectively maintain control over the board of directors and the strategic direction of the company. As some governance experts have bluntly summarized similar arrangements, “only Elon Musk can fire Elon Musk.”

The structure is entirely intentional.

Musk has long supported founder-control models and has used similar voting structures elsewhere. He has argued that insulating management from short-term market pressures allows companies to pursue long-term innovation without interference from activist investors or quarterly earnings pressures.

For SpaceX, those long-term ambitions include continued expansion of Starlink, development of the Starship rocket system, and broader plans for commercial space exploration.

The IPO itself is historic.

SpaceX has set a fixed offering price of $135 per share, an unusual move in a market where companies typically establish a price range and allow investor demand to determine the final offering price. The company plans to sell approximately 555.6 million shares, raising as much as $75 billion in what would become the largest IPO ever completed.

Underwriters also hold an option to purchase an additional 83.33 million shares, potentially increasing proceeds by another $11.2 billion.

At a valuation approaching $1.77 trillion, SpaceX would immediately become one of the most valuable publicly traded companies in America, ranking among the top ten and surpassing the market value of many long-established corporate giants.

Shares are expected to begin trading on the Nasdaq under the ticker symbol SPCX on June 12.

Leading the underwriting syndicate are Goldman Sachs, Morgan Stanley, Bank of America, Citigroup, and JPMorgan Chase, alongside numerous additional participating banks.

For investors, the offering presents a straightforward trade-off.

They gain ownership in one of the most influential and closely watched technology companies in the world, but they receive almost no meaningful influence over management decisions.

Large institutional investors, mutual funds, pension funds, and retail shareholders will collectively own a significant portion of the company economically while possessing very limited voting power.

Supporters argue that the structure has already proven successful.

Under Musk’s leadership, SpaceX transformed itself from a startup facing repeated launch failures into the dominant force in global commercial spaceflight. The company now launches more rockets than any competitor, serves millions of satellite internet customers through Starlink, and remains central to America’s space infrastructure.

Many investors appear comfortable accepting Musk’s terms because of that track record.

Not everyone agrees.

Some institutional investors have openly criticized the governance structure. Denmark’s AkademikerPension has blacklisted the stock, citing concerns over concentrated control and what it described as weak corporate governance protections. Other investor groups have raised concerns that shareholders will have limited ability to challenge management should problems arise in the future.

Their concern is simple: concentrated power can create concentrated risk.

Supporters counter that the very reason investors are eager to buy SpaceX shares is because Musk remains firmly in charge. From that perspective, the governance structure is not a bug but a feature.

The broader significance extends beyond SpaceX itself.

Founder-controlled companies have become increasingly common across the technology sector. A generation of entrepreneurs has discovered that public capital no longer requires surrendering control, and investors eager to participate in fast-growing businesses have largely accepted the arrangement.

SpaceX represents perhaps the most dramatic example yet.

The company’s IPO ultimately asks investors a simple question: is owning a piece of the future worth giving up a meaningful voice in how that future is managed?

Judging by the extraordinary demand surrounding the offering, millions of investors appear ready to answer yes.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — Inflation may be slowing on paper, but for millions of Americans, the economy is judged in one place above all others: the grocery store checkout line.

A new CNBC-SurveyMonkey poll found that more than half of Americans believe everyday life has become less affordable over the past year. When asked what is causing the greatest financial strain, 76% pointed to grocery prices, making food costs the single biggest affordability concern in the country. That surpassed concerns about gasoline and transportation costs at 71%, healthcare at 37%, and housing at 32%.

The results are striking because official inflation data suggest grocery prices are no longer rising at the breakneck pace seen several years ago.

According to federal data, food-at-home prices increased approximately 2.9% year-over-year in April, far below the nearly 10% surge recorded in 2022, the largest increase since 1979. Yet consumers continue to report feeling significant financial pressure every time they shop.

The disconnect highlights a critical reality often missed in economic headlines.

Inflation measures the rate at which prices are increasing, not whether prices have returned to previous levels. While grocery inflation has slowed dramatically, the higher prices consumers absorbed during the inflation surge remain firmly embedded throughout the food supply chain.

Milk, eggs, bread, meat, cereal and household staples may no longer be rising as quickly, but they are still significantly more expensive than they were just a few years ago.

For consumers, that distinction matters.

Unlike a mortgage payment or annual insurance bill, groceries are purchased repeatedly throughout the month. Every trip becomes a fresh reminder of how much prices have changed. Shoppers see increases item by item, aisle by aisle, making grocery inflation feel more immediate than many other economic pressures.

That perception is influencing behavior.

Retailers across the country report increasing demand for private-label products as shoppers substitute lower-cost alternatives for national brands. Consumers are also reporting greater attention to promotions, coupons, leftovers and food waste as they attempt to stretch household budgets further.

The shift is reshaping the grocery industry itself.

Major supermarket chains are expanding store-brand offerings and emphasizing value-oriented promotions to attract increasingly price-conscious consumers. Companies that once competed primarily on selection or convenience are increasingly competing on affordability.

The pressure may not ease soon.

The U.S. Department of Agriculture projects food prices could rise approximately 3.1% during 2026, suggesting another year of increases, even if they remain moderate compared with recent inflation spikes.

For economists, inflation may be cooling.

For consumers standing at the checkout register, the experience feels very different.

Until grocery bills begin falling in a meaningful way—or household incomes rise enough to offset them—the supermarket will remain one of the most important places where Americans judge the health of the economy.

And right now, many shoppers are delivering a harsh verdict.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

MONTREAL — June 2026

Air Canada is wagering that a new generation of fuel-efficient aircraft can unlock routes that larger jets could never profitably serve nonstop.

The carrier took delivery of its first Airbus A321XLR in Hamburg, Germany, on April 24, 2026, and officially entered the aircraft into service this month, marking the beginning of a fleet strategy designed to connect Canada directly with smaller European destinations. The airline has ordered 30 A321XLR aircraft and becomes the first Canadian carrier to operate the type.

The significance of the aircraft lies in its name. The “XLR” stands for Extra Long Range, allowing a narrowbody aircraft—the same basic size travelers typically associate with domestic flights—to remain airborne for up to nine hours nonstop.

That capability addresses a long-standing challenge for airlines. Traditional narrowbody aircraft lack the range to operate many transatlantic routes, while larger widebody jets such as the Boeing 787 Dreamliner often require significantly higher passenger volumes to operate profitably. The A321XLR sits directly between those two categories.

For airlines, the economics are compelling.

Configured with approximately 182 seats, the aircraft burns substantially less fuel than a widebody while requiring fewer passengers to fill seats. That makes it possible to profitably serve what the industry calls “long, thin” routes—city pairs with enough demand to justify nonstop service but not enough to support a larger aircraft.

That strategy is already reshaping Air Canada’s route map.

The aircraft’s inaugural route connected Montreal and Toulouse, France, followed by scheduled service between Montreal and Berlin beginning July 18 and Montreal and Nantes beginning July 22.

The airline plans to operate approximately 12 A321XLR routes during 2026, with nine serving Europe.

From Toronto, the aircraft will open new service to Copenhagen, Manchester, and London Heathrow. Additional routes from Halifax and Ottawa to Heathrow are expected later this year.

In some cases, the aircraft is helping preserve existing routes that may otherwise have become uneconomical. Air Canada plans to continue operating its Montreal-Dublin service during slower travel periods by utilizing the more efficient A321XLR instead of deploying a larger aircraft.

For travelers, the benefits extend beyond airline economics.

The aircraft enables direct service to destinations that previously required connections through major hubs, reducing travel time and avoiding some of the congestion associated with Europe’s busiest airports.

Recognizing concerns about long flights aboard a single-aisle aircraft, Air Canada has outfitted the jet with its newest cabin design, including large seatback entertainment screens throughout the aircraft and upgraded passenger amenities intended to create what the airline describes as a widebody-style experience.

The A321XLR also forms part of a broader modernization effort underway at Air Canada.

The aircraft joins the carrier’s growing fleet of Airbus A350s and Boeing 787 Dreamliners, while the airline simultaneously transfers all 51 Boeing 737 MAX 8 aircraft to its leisure-focused subsidiary, Air Canada Rouge.

The move is strategically important because the 737 MAX had been operating some transatlantic routes near the limits of its range. The A321XLR can comfortably perform those missions while allowing larger aircraft to be redeployed to higher-demand markets.

Air Canada has described the transition as part of its effort to build “one of the most modern and capable fleets in the industry.”

The airline’s bet reflects a broader shift occurring across global aviation.

By the end of March 2026, Airbus had secured more than 500 orders for the A321XLR worldwide as airlines increasingly embrace fuel-efficient narrowbody aircraft for routes once reserved exclusively for widebody jets.

Industry observers frequently compare the trend to the role once played by the Boeing 757, which pioneered many transatlantic narrowbody routes decades ago.

The timing is particularly notable given elevated fuel prices linked to ongoing instability in the Middle East.

With energy costs remaining volatile, aircraft capable of delivering meaningful fuel savings have become increasingly attractive. For airlines, the A321XLR offers a way to expand networks, test new destinations, and add service frequency without assuming the financial risks associated with operating larger aircraft.

For Air Canada, the strategy is straightforward: use a smaller, more efficient aircraft to open new markets, reduce operating costs, and pursue profitable growth city by city.

Whether the gamble pays off will become clearer as the remaining 29 aircraft join the fleet over the coming years. But the decision reflects where much of the airline industry increasingly believes the future lies—not in bigger airplanes, but in smarter and more efficient ones.

Montreal — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SAN FRANCISCO — The American technology industry is sending two completely different messages at the same time.

One message is visible in corporate earnings calls, investor presentations, and record capital-spending plans. Artificial intelligence is creating one of the largest investment booms in modern business history. Companies are building data centers at unprecedented speed, ordering billions of dollars of chips, and committing enormous resources to AI infrastructure.

The second message is arriving in employees’ inboxes.

Layoff notices.

As of early June 2026, technology companies have eliminated approximately 142,000 jobs, according to widely followed industry trackers. More than 212 significant layoff events have been recorded this year alone.

The contradiction has become one of the defining economic stories of 2026.

The companies cutting jobs are often the same companies reporting strong profits, expanding operations, and spending aggressively on artificial intelligence.

Amazon, Microsoft, Alphabet, and Meta Platforms have collectively committed roughly $700 billion in capital expenditures tied largely to AI infrastructure, according to industry estimates. The spending includes new data centers, advanced semiconductor purchases, power-generation requirements, networking equipment, and software investments.

At the same time, many of those companies continue reducing headcount.

Historically, large-scale layoffs typically signaled distress.

Companies cut jobs when sales declined, profits disappeared, or survival required cost reductions.

Today’s layoffs look different.

Many are occurring at highly profitable firms generating billions of dollars in earnings.

Consider what happened on May 20.

Meta Platforms began notifying approximately 8,000 employees, representing about 10% of its workforce, that their positions were being eliminated. The same day, Intuit, maker of TurboTax and QuickBooks, announced plans to eliminate approximately 3,000 jobs, or roughly 17% of its workforce.

Neither company was facing financial distress.

Both were restructuring around artificial intelligence.

That distinction matters because it suggests a potentially deeper shift taking place throughout the economy.

The impact appears particularly severe for younger workers entering the profession.

Research from Stanford University’s Institute for Human-Centered AI shows employment among software developers under age 26 has fallen nearly 20% since 2024.

The reason is increasingly apparent.

Many of the tasks traditionally assigned to junior software developers—coding assistance, debugging, documentation, testing, and routine programming work—can now be performed more efficiently by AI tools.

Companies are beginning to ask a difficult question: if AI can perform a meaningful portion of entry-level work, how many entry-level workers are still needed?

That question extends far beyond technology.

The broader concern is whether artificial intelligence is weakening one of capitalism’s traditional assumptions: that successful companies naturally create more jobs.

For decades, economic growth and hiring generally moved together. When corporations expanded revenue, they typically expanded payrolls.

AI may be changing that relationship.

A company can now potentially increase output, improve productivity, expand market share, and grow earnings while employing fewer people.

The benefits flow to shareholders and customers through greater efficiency, but fewer workers may share directly in that growth.

None of this means the labor market is collapsing.

Healthcare continues hiring. Construction remains active. Hospitality and services still employ millions of workers. Many laid-off technology employees will find opportunities elsewhere.

But Silicon Valley may be providing an early glimpse into how artificial intelligence reshapes labor markets.

The technology industry’s largest companies are investing unprecedented amounts of money into systems specifically designed to make work more productive.

The question is whether greater productivity ultimately creates new categories of employment, as previous technological revolutions did, or whether AI fundamentally changes the equation.

For now, the paradox remains.

The same companies spending hundreds of billions of dollars building the future are simultaneously employing fewer people to do it.

The answer to what comes next may become one of the most important economic questions of the decade.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

MINNEAPOLIS — Medtronic, the world’s largest medical-device maker, delivered its strongest annual revenue growth in a decade Wednesday, driven by surging demand for heart procedures and newer cardiovascular technologies that are helping patients live longer and healthier lives.

The company reported fiscal fourth-quarter revenue of $9.8 billion, up 9.9% from a year earlier and ahead of Wall Street expectations. Adjusted earnings came in at $1.55 per share, capping what management described as one of the strongest years in recent company history.

Even if consumers have never heard of Medtronic, many have likely benefited from its products. The company manufactures pacemakers, implantable defibrillators, insulin pumps, surgical instruments, spinal implants, and neurological devices used by hospitals and physicians around the world.

Because of its enormous presence across healthcare, Medtronic is often viewed as a bellwether for the broader medical-technology industry.

The biggest growth story this quarter came from the company’s heart business.

Revenue from Cardiac Ablation Solutions, which includes devices used to treat irregular heart rhythms such as atrial fibrillation, surged 78% globally and 124% in the United States. The broader cardiovascular division grew approximately 10%, while Medtronic’s surgical business posted a solid 5% increase.

Geoff Martha, Chairman and Chief Executive Officer, credited expanding patient access and strong adoption of newer therapies for the company’s performance.

The results arrive as healthcare providers continue seeing rising demand from aging populations that require more cardiovascular treatment, chronic-disease management, and surgical procedures.

For investors, Medtronic delivered another important milestone.

The board approved a dividend increase to $0.72 per share quarterly, marking the company’s 49th consecutive year of dividend growth.

Few public companies can claim nearly half a century of uninterrupted dividend increases.

The consistency reflects Medtronic’s ability to generate significant cash even during periods of economic uncertainty.

For the full fiscal year, the company generated more than $7.3 billion in operating cash flow and approximately $5.4 billion in free cash flow, giving management ample flexibility to invest in future growth while rewarding shareholders.

The company is also expanding through acquisitions.

Earlier this year, Medtronic agreed to acquire SPR Therapeutics for up to $650 million, strengthening its position in the growing market for non-opioid pain management. The acquisition reflects increasing demand for alternatives to traditional pain medications.

Meanwhile, Medtronic continues investing heavily in robotic surgery through its Hugo surgical platform as it seeks to challenge industry leader Intuitive Surgical and its widely used da Vinci system.

Looking ahead, management forecast organic revenue growth of 6.75% to 7.25% for the new fiscal year, suggesting confidence that current momentum can continue.

For the broader healthcare industry, the message is encouraging. Hospitals remain busy, demand for advanced procedures remains strong, and patients continue seeking treatments that improve quality of life.

For shareholders, the story is equally straightforward.

A company that helps keep hearts beating, raises its dividend for nearly five decades, and just delivered its fastest growth in ten years appears to be doing exactly what investors hope a healthcare leader will do.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — Thursday, June 4, 2026

Wall Street’s record-setting run hit a pause Thursday morning as disappointing reactions to several high-profile technology earnings reports weighed on the broader market, while easing tensions on one front of the Middle East conflict helped push oil prices and Treasury yields lower.

After closing sharply lower Wednesday, stocks opened mixed to weaker as investors reassessed lofty valuations in the technology sector and rotated toward more defensive areas of the market. The prior session saw the S&P 500 fall 0.7% to 7,553.68, the Dow Jones Industrial Average drop 1.2% to 50,687.07, and the Nasdaq Composite decline 0.9% to 26,853.98, ending a nine-session winning streak amid renewed concerns about geopolitical risks and energy prices.

The biggest early mover Thursday was Broadcom, whose shares fell roughly 13% after reporting record revenue but delivering an artificial-intelligence outlook that failed to satisfy investors accustomed to increasingly aggressive growth projections. The reaction underscored a recurring theme across Wall Street this year: companies viewed as leaders in AI are being judged not on whether growth is strong, but whether it exceeds already elevated expectations.

The selloff spilled across the semiconductor sector, with companies including Micron Technology trading lower as investors took profits following months of powerful gains driven by AI-related demand.

CrowdStrike Holdings also came under pressure, falling nearly 11% despite posting results that exceeded profit expectations. Investors focused instead on rising expenses associated with AI investments and infrastructure expansion. The reaction highlighted growing concerns that many software companies may face short-term margin pressure as they race to build AI capabilities and defend market share.

Retail and apparel giant PVH Corp., parent company of Calvin Klein and Tommy Hilfiger, suffered one of the steepest declines of the morning, plunging approximately 20%. While the company beat first-quarter earnings estimates, management lowered its full-year outlook, citing softer consumer demand in Europe and ongoing tariff-related pressures. Several analysts subsequently reduced their outlooks on the stock, accelerating the selloff.

Not all sectors participated in the decline.

Investors shifted capital into more defensive and consumer-oriented businesses as oil prices retreated. Axalta Coating Systems rose about 4%, H&R Block gained nearly 4%, and health insurer Centene advanced roughly 3.3% in early trading.

The move reflected a broader rotation underway in markets, with investors temporarily stepping away from high-growth technology names and seeking stability in sectors viewed as less vulnerable to economic and geopolitical uncertainty.

Energy markets provided some relief after several days of heightened volatility.

Oil prices eased following reports that Israel and Lebanon had agreed to a conditional ceasefire, reducing concerns about an immediate expansion of regional conflict. The development helped remove part of the geopolitical premium that had recently driven crude prices higher.

The broader situation remains fragile. Shipping activity through the Strait of Hormuz, the critical waterway that normally handles roughly 20% of global oil and liquefied natural gas flows, remains below pre-conflict levels. Market participants continue to monitor the region closely for signs of further escalation involving Iran and U.S. interests.

Political developments in Washington added another layer of uncertainty. On Wednesday, the Republican-controlled House voted to limit U.S. military involvement in Iran, marking a rare challenge to President Donald Trump’s approach to the conflict. Trump dismissed the measure as a “meaningless vote,” though the debate reflected growing concern among lawmakers about the potential economic and military consequences of a prolonged confrontation.

Economic data also remained in focus.

Investors awaited the latest weekly jobless claims report and productivity data, but attention is increasingly shifting toward Friday’s May employment report, one of the most closely watched indicators for both markets and Federal Reserve policymakers.

Economists currently expect the U.S. economy to have added approximately 85,000 jobs in May, down from roughly 115,000 in April but still representing continued labor-market growth. The report will play a major role in shaping expectations for future Federal Reserve policy.

Several Fed officials, including Tom Barkin, Michelle Bowman, and Mary Daly, were scheduled to speak Thursday, with traders looking for any signals regarding the path of interest rates. Recent inflation readings have softened modestly, helping support hopes that policymakers may eventually gain flexibility later this year.

Looking ahead, investors will also focus on earnings from Lululemon Athletica, scheduled after Thursday’s closing bell. The report is expected to provide another important measure of consumer spending trends, particularly among higher-income households.

For now, Wall Street appears to be entering a period of consolidation after months of gains. Investors are reassessing technology valuations, monitoring developments in the Middle East, and waiting for Friday’s jobs report to provide the next major clue about the direction of the economy and financial markets.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — In a year when many global consumer brands are cutting forecasts, warning about geopolitical uncertainty, or struggling with weakening consumer demand, PVH Corp., the parent company of Calvin Klein and Tommy Hilfiger, delivered a different message to investors Wednesday: the plan remains intact.

The apparel giant reported first-quarter revenue of approximately $2.0 billion, exceeding its own expectations on a reported basis and meeting guidance after accounting for foreign-exchange fluctuations. More importantly, management reaffirmed its full-year outlook despite acknowledging that the ongoing conflict in the Middle East is creating meaningful pressure across parts of its global business.

For investors, the significance was not that PVH raised guidance. It didn’t. The significance was that it didn’t lower it.

In today’s environment, simply holding the line has become an achievement.

Chief Executive Officer Stefan Larsson said the company “delivered on our plan and commitments in the first quarter,” pointing to continued execution of PVH’s multiyear transformation strategy known as the PVH+ Plan.

The strongest area of the quarter came from the company’s direct relationship with consumers.

PVH reported that direct-to-consumer revenue rose 6%, or 3% excluding currency effects, driven by growth across both Calvin Klein and Tommy Hilfiger, as well as gains in both physical stores and e-commerce channels.

That matters because direct-to-consumer sales are increasingly becoming the most important battleground in apparel retail.

When brands sell directly through their own stores and websites, they not only capture higher margins but also gain valuable information about customer preferences, purchasing patterns, and product performance. In an industry where fashion trends can change rapidly, that direct connection has become a competitive advantage.

The quarter also demonstrated strong operational discipline.

PVH reported operating margins at the high end of its guidance range, reflecting improved inventory management, cost controls, and a more focused merchandising strategy.

The company has increasingly concentrated resources around what management calls its “hero categories”—products with strong brand recognition and repeat demand.

For Calvin Klein, that means denim and underwear. For Tommy Hilfiger, sweaters and outerwear remain central pillars of the strategy.

The approach appears to be working.

Yet the most revealing part of the earnings report may have been the company’s explanation for why guidance remained unchanged.

PVH’s updated outlook incorporates what management described as the expected prolonged impact of the Middle East conflict. Rising shipping costs, economic uncertainty, softer consumer demand in certain markets, and broader geopolitical risks are all expected to create headwinds throughout the year.

Ordinarily, those pressures might have resulted in lower forecasts.

Instead, PVH expects those challenges to be largely offset by tariff refunds the company anticipates receiving, creating a rare situation in which two major external forces effectively cancel each other out.

The result is a full-year forecast calling for roughly flat revenue and an adjusted operating margin of approximately 8.8%.

That balancing act highlights a broader reality facing multinational consumer companies.

The apparel business today involves much more than designing products and selling clothing. Companies must constantly navigate tariffs, exchange rates, geopolitical conflicts, supply-chain disruptions, shifting trade policies, and changing consumer behavior.

In many ways, today’s global fashion companies increasingly resemble geopolitical risk managers.

PVH’s results provide an important window into global consumer spending because its brands operate across dozens of countries and demographic groups. The company’s ability to maintain growth in direct-to-consumer sales suggests consumers continue engaging with premium apparel brands despite inflation pressures and economic uncertainty.

That resilience has become increasingly important as investors look for signs that discretionary spending remains healthy.

The coming quarters will provide a more complete test.

Energy prices remain elevated, geopolitical tensions remain unresolved, and consumer confidence continues facing pressure from higher borrowing costs and inflation concerns.

For now, however, PVH delivered something many companies have struggled to provide in 2026: stability.

The company’s brands continue attracting customers, its direct-sales strategy is producing results, margins remain disciplined, and management remains confident enough to stand by its full-year targets.

In a year defined by uncertainty, that may be one of the strongest statements a global consumer company can make.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — Macy’s Inc. delivered its strongest first-quarter performance in four years on Wednesday, June 3, 2026, providing fresh evidence that the department-store operator’s turnaround strategy is gaining momentum despite ongoing concerns about consumer spending and economic uncertainty.

The retailer reported comparable sales growth of 3.0%, marking its fourth consecutive quarter of gains and its strongest first-quarter comparable-sales performance since 2022. The results exceeded expectations and prompted management to raise its outlook for the remainder of the year.

Investors welcomed the news, sending shares higher in premarket trading.

The gains were broad-based across the company’s portfolio.

Comparable sales at the flagship Macy’s brand increased 1.6%, while the company’s upgraded “Reimagine” store locations posted growth of 2.4%. Those stores have been the centerpiece of management’s turnaround strategy, featuring enhanced merchandising, improved staffing levels, upgraded layouts, and a stronger customer experience.

The biggest surprise came from luxury retailer Bloomingdale’s, where comparable sales surged 10.2%, marking the chain’s strongest first quarter on record and its seventh consecutive quarter of growth.

The performance encouraged management to become more optimistic about the year ahead.

Macy’s now expects annual net sales of $21.5 billion to $21.75 billion, compared with its previous forecast range of $21.4 billion to $21.65 billion. The company also raised projected adjusted earnings to $2.00 to $2.20 per share, up from its prior outlook of $1.90 to $2.10 per share and ahead of many Wall Street forecasts.

Management also shifted its expectations for comparable sales growth into positive territory, forecasting annual growth of 0.5% to 1.2%, compared with earlier guidance that allowed for potential declines.

The improved outlook reflects growing confidence that the company’s strategic investments are producing measurable results.

For years, Macy’s struggled with challenges facing traditional department stores, including declining mall traffic, competition from e-commerce, shifting consumer preferences, and an oversized store footprint. Management responded by closing weaker locations while concentrating resources on stores and markets with the strongest growth potential.

That strategy appears to be working.

The success of the Reimagine initiative suggests customers are responding positively to upgraded stores and a more focused merchandise mix. Rather than attempting to improve every location equally, Macy’s has prioritized investment where it believes returns will be highest.

External factors have also contributed.

Chief Executive Officer Tony Spring acknowledged that disruptions among luxury competitors have created opportunities for Bloomingdale’s to attract additional customers. Following the recent bankruptcy-related challenges at Saks Fifth Avenue, some high-end shoppers have shifted spending toward alternative luxury retailers.

Spring described the disruption as beneficial but emphasized that it is not the primary driver of Bloomingdale’s growth.

The broader retail environment remains challenging.

Many retailers benefited this spring from larger-than-normal tax refunds, which provided consumers with additional discretionary spending power. That tailwind may fade during the second half of the year, particularly if rising gasoline prices and broader inflation pressures continue weighing on household budgets.

Higher oil prices stemming from tensions in the Middle East are already creating concerns across the retail sector. Every additional dollar spent at the pump reduces the amount consumers have available for apparel, home goods, and other discretionary purchases.

That dynamic could become increasingly important as the year progresses.

Even so, Macy’s latest quarter stands out as one of the stronger retail performances of the earnings season.

The company delivered sales growth, earnings growth, improved guidance, and continued momentum across both its core and luxury businesses. Perhaps most importantly, it demonstrated that traditional department stores can still grow when management executes a focused strategy and invests effectively.

Investors will now be watching closely to see whether the momentum continues into the second half of the year.

For the first time in years, however, Macy’s is entering that conversation from a position of strength rather than one of survival.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — The Federal Reserve delivered a relatively calm assessment of the U.S. economy on Wednesday, June 3, 2026, but beneath the surface, financial markets are rapidly rethinking where interest rates may be headed next. Just weeks ago, investors broadly expected policymakers to begin cutting rates later this year. Today, an increasing number of traders believe the Fed’s next move could be in the opposite direction.

In its latest Beige Book, a survey of economic conditions gathered from businesses across the country, the central bank reported that economic activity had improved modestly in recent weeks while employment levels remained generally stable. The language was measured and familiar. Yet the backdrop surrounding monetary policy has changed dramatically.

The primary catalyst has been the sharp rise in oil prices following renewed conflict in the Middle East.

Higher energy costs have historically presented one of the most difficult challenges for central bankers because they influence virtually every corner of the economy. Rising oil prices increase transportation expenses, raise manufacturing costs, boost utility bills, and ultimately filter through to consumers in the form of higher prices at gas stations, grocery stores, and retail outlets.

That inflationary pressure is already beginning to appear in economic data.

The latest reading of the Personal Consumption Expenditures (PCE) Index, the Fed’s preferred inflation gauge, reached its highest level in nearly three years. At the same time, the labor market continues to show surprising resilience. According to the U.S. Department of Labor, job openings rose to 7.62 million in April, the highest level since May 2024, suggesting businesses continue competing aggressively for workers despite elevated borrowing costs.

That combination of persistent inflation and continued labor-market strength has forced investors to reconsider assumptions that rate cuts are imminent.

Interest-rate futures markets now imply roughly 17 basis points of tightening by the end of 2026, equivalent to approximately a 70% probability of a quarter-point rate increase, with traders increasingly expecting a full rate hike by early 2027.

Only a few months ago, such a scenario would have seemed unlikely.

The shift highlights the difficult position facing policymakers. The Fed’s benchmark interest rate influences borrowing costs throughout the economy, including mortgages, auto loans, business lending, and credit cards. Traditionally, when economic growth weakens, the central bank lowers rates to stimulate activity. When inflation accelerates, it raises rates to cool demand.

Oil shocks complicate that framework because they often create both problems simultaneously.

Higher energy prices push inflation upward while also reducing consumers’ purchasing power. Households spend more on gasoline and utilities, leaving less available for discretionary purchases. That dynamic can slow economic growth even as inflation remains elevated.

For the Fed, that creates a difficult balancing act.

Adding another layer of uncertainty is the arrival of Federal Reserve Chairman Kevin Warsh, who is preparing to lead his first policy meeting later this month. Investors will closely examine his comments for clues about how the new leadership team views current inflation risks and whether policymakers believe rising oil prices represent a temporary disruption or a more persistent threat to price stability.

The distinction matters enormously.

If Fed officials conclude that higher energy prices will eventually fade without spreading throughout the economy, they may choose to hold rates steady and wait for inflation pressures to ease. If they believe rising costs are becoming embedded in wages and consumer prices, policymakers could feel compelled to tighten financial conditions further.

For American households, the consequences are tangible.

Many consumers entered 2026 expecting interest rates to move lower, potentially making homes, vehicles, and other major purchases more affordable. A delay in rate cuts—or an outright hike—would keep borrowing costs elevated for longer while families simultaneously face higher fuel and living expenses.

The next major test arrives with Friday’s employment report.

A stronger-than-expected jobs number would reinforce the view that the economy remains resilient despite higher rates and elevated energy costs. Such an outcome could strengthen the argument among policymakers that inflation remains the larger threat and that additional tightening may eventually become necessary.

For now, the Fed has not signaled any immediate policy shift. But financial markets increasingly believe the conversation has changed. After months of debating when rate cuts would begin, investors are now asking whether the next move might be a rate hike instead.

That possibility alone represents one of the most significant shifts in the economic outlook since the start of the year.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

PHILADELPHIA — Five Below Inc. delivered one of the strongest retail earnings reports of the season on Wednesday, June 3, 2026, as consumers seeking value flocked to its stores, driving sales, profits, and customer traffic sharply higher.

The discount retailer reported quarterly revenue of $1.29 billion, an increase of 32.5% from $970.5 million a year earlier. The growth significantly outpaced most major retailers and reinforced the company’s reputation as one of the strongest performers in the value-shopping segment.

Investors responded positively, sending shares higher in after-hours trading.

The most impressive figure may have been customer traffic.

Comparable sales rose 22.7%, an unusually large increase for an established retailer. Comparable sales measure performance at stores open for at least one year and are closely watched because they provide insight into underlying demand rather than growth generated solely from opening new locations.

The results suggest shoppers are visiting stores more frequently and spending more while there.

Profitability improved even faster than revenue.

Operating income climbed to approximately $154.2 million, up from $50.8 million a year earlier. Adjusted earnings reached $2.22 per share, substantially above analyst expectations of approximately $1.69 per share.

The strong performance prompted management to raise its outlook for the remainder of the year.

Five Below’s business model appears particularly well positioned for the current economic environment. The chain specializes in low-cost merchandise including toys, snacks, beauty products, seasonal items, technology accessories, and novelty products, with most items selling at relatively affordable price points.

As inflation continues affecting household budgets, many consumers are becoming increasingly selective about discretionary purchases.

That trend often benefits value-oriented retailers.

Industry analysts have also pointed to strong demand for popular “squishy” toy products, which have generated significant interest among younger shoppers and helped drive store traffic.

Deutsche Bank analyst Krisztina Katai recently described the company’s quarter as a likely “beat-and-raise” scenario, citing strong customer traffic and favorable merchandising trends. Katai has suggested that Five Below’s earnings power could approach $10 per share by the end of 2026, above current company guidance.

Growth is not limited to existing stores.

The company opened 49 net new locations during the quarter, bringing its total store count to 1,970 stores across 46 states. Management plans to invest between $230 million and $250 million in capital expenditures this year as it continues expanding its national footprint.

That combination of strong comparable-sales growth and aggressive store expansion is particularly attractive to investors because it demonstrates growth from multiple sources simultaneously.

The broader economic context also favors the company.

Higher gasoline prices, elevated interest rates, and ongoing inflation concerns have encouraged many households to seek value wherever possible. While some retailers struggle as consumers pull back on discretionary purchases, Five Below offers products inexpensive enough to remain accessible even during periods of tighter budgets.

The shopping experience itself is part of the appeal.

Customers often view a trip to Five Below as an affordable form of entertainment—a chance to discover inexpensive products without making a major financial commitment. That dynamic can be especially powerful during periods of economic uncertainty.

The challenge ahead will be maintaining such extraordinary growth rates.

Five Below now faces increasingly difficult comparisons after posting blockbuster results. Consumer spending could also weaken if economic conditions deteriorate further or if rising energy costs place additional pressure on household budgets.

Still, the latest quarter delivered a clear message.

As consumers become more price-conscious, retailers offering value, convenience, and affordability continue gaining market share. Few companies have capitalized on that trend more effectively than Five Below.

For now, bargain hunting remains one of the strongest themes in American retail, and Five Below is proving to be one of its biggest beneficiaries.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

PLEASANTON, Calif. — Veeva Systems Inc. delivered a strong quarterly report on Wednesday, June 3, 2026, exceeding Wall Street expectations and offering investors new evidence that artificial intelligence may become the company’s next major growth engine.

The healthcare software provider reported revenue of $882.9 million, up 16% from a year earlier and above analyst expectations of approximately $857.8 million. Adjusted earnings reached $2.24 per share, surpassing forecasts of $2.14 per share, while management raised its outlook for the remainder of the fiscal year.

The results reinforced Veeva’s position as one of the most important technology suppliers serving the global pharmaceutical industry.

The company’s subscription business, which generates recurring revenue from software contracts, remained particularly strong. Subscription revenue increased 15% to $730.2 million, compared with $634.8 million a year earlier.

Profitability also remained impressive.

Adjusted operating income reached approximately $395.4 million, representing an operating margin of nearly 45%, a level rarely achieved among enterprise software companies.

Encouraged by the performance, management raised full-year revenue guidance to approximately $3.64 billion and projected full-year adjusted earnings of roughly $9.05 per share.

For investors, however, the most intriguing part of the earnings report was not the quarter that just ended but the strategy being built for the future.

Chief Executive Officer Peter Gassner outlined a vision in which Veeva evolves beyond traditional software applications and becomes a provider of artificial-intelligence-powered agents capable of performing tasks independently across the pharmaceutical-development process.

According to Gassner, the company is developing a new platform known as Falcon, designed to automate highly specialized functions such as regulatory documentation, safety reporting, compliance workflows, and communications with healthcare authorities.

Those activities are among the most labor-intensive and heavily regulated processes in the pharmaceutical industry.

If successful, AI-powered automation could significantly reduce administrative burdens while accelerating the development and approval of new therapies.

The opportunity is substantial.

Pharmaceutical companies face increasing pressure to improve productivity while managing rising research costs, complex regulatory requirements, and growing competition. Artificial intelligence is widely viewed as one potential solution, particularly in areas involving large volumes of documentation and repetitive workflows.

Veeva believes it can become a key partner in that transformation.

The company is already deeply embedded within the life-sciences ecosystem. More than 1,500 customers rely on Veeva software to manage critical business functions ranging from clinical development and regulatory compliance to customer relationship management.

That customer base gives Veeva a unique advantage as pharmaceutical companies evaluate AI adoption strategies.

The company also reported continued momentum for Vault CRM, its next-generation customer-management platform used by pharmaceutical sales organizations. Recent customer wins included Teva Pharmaceutical Industries Ltd. and Merck KGaA, highlighting demand for the platform as Veeva transitions customers away from legacy systems built on Salesforce technology.

The migration is strategically important.

By moving customers onto its proprietary platform, Veeva gains greater control over product development, customer relationships, and future innovation opportunities.

Investors have spent much of the past year questioning whether Veeva’s growth was slowing after years of exceptional performance. The company’s stock struggled as concerns emerged about the pace of customer adoption and the long-term impact of industry spending pressures.

Wednesday’s report offered a different narrative.

Revenue growth accelerated. Subscription revenue remained healthy. Profit margins stayed strong. Guidance moved higher.

Most importantly, management provided a clearer picture of how artificial intelligence could expand the company’s addressable market beyond traditional software subscriptions.

The road ahead remains challenging. Pharmaceutical companies operate in one of the most heavily regulated industries in the world, and adoption of new technologies often moves more slowly than in other sectors. AI-powered systems must demonstrate accuracy, reliability, compliance, and security before they can become deeply integrated into critical workflows.

That means execution will matter.

For now, Veeva has delivered what investors wanted to see: strong operating results paired with a compelling vision for future growth. The next several quarters will determine whether that vision can become a lasting competitive advantage in an industry increasingly looking to AI for its next wave of productivity gains.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SpaceX seeks a record $75 billion raise at a $1.75 trillion valuation as Wall Street mobilizes thousands of elite investors ahead of what could become the largest IPO in history.

NEW YORK — JPMorgan Chase CEO Jamie Dimon is personally stepping into one of Wall Street’s most coveted deals, pitching SpaceX’s upcoming stock offering to thousands of the bank’s wealthiest clients as the company prepares what could become the largest initial public offering in history. SpaceX set its IPO price at $135 per share Wednesday, positioning the company to raise approximately $75 billion and achieve a valuation of roughly $1.75 trillion.

If successful, the offering would instantly place SpaceX among the ten most valuable publicly traded companies in America and mark one of the most significant moments in modern capital markets.

The numbers alone are extraordinary.

SpaceX plans to sell approximately 555.6 million shares and list on the Nasdaq under the ticker SPCX, following the public prospectus it filed with regulators on May 20. The deal would eclipse previous IPO records and become the largest stock-market debut ever attempted.

Yet what has captured Wall Street’s attention almost as much as the offering itself is who is making the sales pitch.

Dimon will host a live interactive discussion from JPMorgan’s New York headquarters alongside Mary Callahan Erdoes, CEO of Asset & Wealth Management, and senior executive Marianne Lake. Joining them will be SpaceX President and Chief Operating Officer Gwynne Shotwell and Chief Financial Officer Bret Johnsen.

The event is expected to be broadcast across approximately 90 JPMorgan offices in 26 states, reaching more than 2,500 high-net-worth clients.

For the banking industry, the move is highly unusual.

Traditional IPO roadshows typically focus on large institutional investors such as pension funds, mutual funds, hedge funds, and sovereign wealth funds. Individual investors, even wealthy ones, generally play a secondary role in the allocation process.

Having the CEO of the nation’s largest bank personally help market a stock offering to thousands of private clients reflects just how significant this deal has become.

It also signals confidence.

JPMorgan and the broader underwriting syndicate appear eager to build a base of long-term shareholders rather than concentrating ownership among a smaller group of institutional investors.

The pricing structure further underscores SpaceX’s leverage.

Instead of relying on the traditional process in which investment banks gauge demand and establish a price range, SpaceX elected to set a fixed offering price of $135 per share. That decision reflects the bargaining power of a company that knows investor demand is likely to be enormous.

The approach is consistent with the style of founder Elon Musk, who has repeatedly challenged conventional Wall Street practices across multiple ventures.

Dimon himself has publicly expressed admiration for the company.

After touring SpaceX facilities recently, he described the company’s work as investing in “stuff that will change humanity for the better.

The enthusiasm comes as Wall Street’s IPO market experiences a dramatic revival after several sluggish years.

Dimon has repeatedly argued that capital markets are healthy and capable of supporting major transactions. SpaceX’s offering may become the clearest test yet of that view.

JPMorgan is part of a massive underwriting syndicate that includes Goldman Sachs, Morgan Stanley, Bank of America, Citigroup, and roughly two dozen other financial institutions helping bring the deal to market.

Formal investor marketing is expected to begin around June 8.

For ordinary investors, however, the spectacle highlights an uncomfortable reality.

The first opportunity to purchase shares in highly sought-after offerings typically goes to institutional investors and private-bank clients with substantial assets. Most retail investors will only gain access after shares begin trading publicly, often at prices influenced by initial demand from wealthier buyers.

In many cases, average investors eventually gain exposure through index funds and retirement accounts rather than direct IPO allocations.

There are also significant risks beneath the excitement.

A valuation approaching $1.75 trillion assumes enormous future growth from Starlink, the company’s satellite internet business, as well as continued success for the Starship rocket program and broader commercial-space ambitions.

Many of those opportunities remain works in progress.

Investors participating in the offering are effectively betting that SpaceX can continue converting technological leadership into massive commercial success.

Few companies have inspired that level of confidence.

Fewer still have inspired enough confidence to bring Jamie Dimon himself into the sales process.

The image is a fitting one for Wall Street in 2026: the chief executive of America’s largest bank standing alongside leaders of the world’s most ambitious private space company, helping sell pieces of what may become the largest IPO ever launched.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

AUSTIN, Texas — CrowdStrike Holdings Inc. delivered a decisive victory over Wall Street expectations on Wednesday, June 3, 2026, reinforcing the view that cybersecurity remains one of the few areas of corporate spending largely insulated from broader economic pressures.

The company reported adjusted earnings of $1.10 per share, significantly above analyst expectations of approximately $0.88 per share, a result that highlighted continued demand for cybersecurity services even as businesses across multiple industries look for ways to reduce costs and improve efficiency.

The earnings report arrived amid growing investor debate over whether CrowdStrike’s remarkable stock-market performance had pushed the company’s valuation too high. Shares had climbed sharply over the past year, making the cybersecurity leader one of the technology sector’s standout performers.

Those concerns had begun surfacing in the days leading up to earnings.

CrowdStrike shares slipped ahead of the report as investors worried that expectations had become difficult to surpass. At the same time, competition in the cybersecurity market appeared poised to intensify following the launch of a new artificial-intelligence-powered threat-defense platform by Google Cloud in late May.

The combination of a lofty valuation and a potentially stronger competitive landscape created uncertainty heading into Wednesday’s release.

CrowdStrike’s results answered at least one of those concerns.

The company’s earnings beat was substantial, and analysts across Wall Street responded positively. JPMorgan analyst Brian Essex raised his price target to $800, while maintaining an Overweight rating. Evercore ISI analyst Peter Levine increased his target to $710, and Benchmark analyst Yi Fu Lee lifted his target to $700 while maintaining a Buy rating.

Not everyone was fully convinced. Baird analyst Shrenik Kothari maintained a Neutral rating despite increasing his target price.

The wide range of analyst targets illustrates the central debate surrounding CrowdStrike.

Few question the quality of the business. The discussion centers on valuation and whether future growth can justify the premium investors are willing to pay.

CrowdStrike’s Falcon platform has become a cornerstone of cybersecurity operations for organizations ranging from small businesses to major corporations and government agencies. The software continuously monitors endpoints, cloud environments, and enterprise systems for suspicious activity, helping companies identify and stop cyberattacks before they spread.

In today’s digital economy, that protection has become increasingly essential.

Cybersecurity spending differs from many other technology budgets because companies often view it as non-negotiable. Businesses can delay software upgrades, postpone infrastructure projects, or reduce consulting expenses. They are far less likely to scale back security protections while cyber threats continue growing in both volume and sophistication.

Artificial intelligence has amplified that challenge.

Security experts increasingly warn that AI tools are enabling cybercriminals to launch attacks more quickly, automate phishing campaigns, generate convincing fraudulent communications, and identify system vulnerabilities at scale.

As offensive capabilities become more advanced, organizations are responding by investing more heavily in defensive technologies.

That trend appears to be benefiting CrowdStrike.

The company’s latest results suggest that cybersecurity remains a priority even as businesses navigate economic uncertainty, inflation concerns, and evolving geopolitical risks.

For investors, that resilience may be the most important takeaway from the quarter.

Corporate America is currently balancing two major spending priorities: artificial intelligence and cybersecurity. While some technology budgets are being consolidated to fund AI initiatives, cybersecurity spending appears to be maintaining its momentum.

CrowdStrike sits at the intersection of both trends.

The company continues integrating AI into its security platform while simultaneously benefiting from growing demand for protection against AI-enabled threats.

Still, the company faces significant expectations going forward.

The cybersecurity market remains highly competitive, with established rivals and deep-pocketed technology companies seeking larger shares of the market. Investors will continue watching closely to see whether CrowdStrike can maintain its growth trajectory while defending its leadership position.

This quarter provided a strong answer.

The next challenge will be sustaining that performance in a market that increasingly expects excellence as the baseline rather than the exception.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

SAN JOSE, Calif. — Broadcom Inc. delivered a mixed message to Wall Street after the closing bell on Wednesday, June 3, 2026. The semiconductor and infrastructure software giant reported another quarter of explosive growth tied to artificial intelligence, yet a rare revenue miss was enough to send shares tumbling more than 6% in after-hours trading as investors grappled with expectations that have become increasingly difficult to satisfy.

The company reported revenue of approximately $22.19 billion, narrowly missing analyst expectations of roughly $22.27 billion, while adjusted earnings came in at $2.44 per share, ahead of the $2.40 analysts had forecast. Under ordinary circumstances, the results would likely have been viewed as strong. For a company that has become one of the market’s premier AI beneficiaries, however, investors were looking for perfection.

The most closely watched figure was Broadcom’s artificial-intelligence semiconductor business. The company reported AI-related chip revenue of $10.8 billion during the quarter and projected that AI chip sales will surge approximately 200% year-over-year to $16 billion in the current quarter.

That forecast underscores the extraordinary pace of investment taking place across the technology sector as cloud-computing providers and enterprise customers race to expand AI capabilities.

Management also projected current-quarter revenue of approximately $29.4 billion and adjusted profitability near 68% of revenue, highlighting the strength of demand despite growing investor concerns about valuations across the semiconductor sector.

The reaction on Wall Street reflected a broader reality facing many AI leaders. The issue was not the company’s performance but rather the expectations surrounding it. Broadcom’s shares have been among the strongest performers during the AI boom, helping push major market indexes to record highs. Investors have increasingly viewed the company as a key proxy for artificial-intelligence infrastructure spending.

When expectations reach those levels, even a small disappointment can trigger an outsized reaction.

The company occupies a unique position within the AI ecosystem. While Nvidia Corp. remains the dominant supplier of AI accelerators, Broadcom has emerged as a critical partner for major cloud providers through its custom-chip business. Rather than purchasing off-the-shelf processors, many large technology companies are designing proprietary chips tailored to their own AI workloads.

Broadcom helps build and manufacture those specialized processors, making the company one of the clearest indicators of how aggressively the world’s largest technology firms are investing in AI infrastructure.

That importance extends beyond Broadcom itself.

Technology giants including Microsoft Corp., Amazon.com Inc., Alphabet Inc., and Meta Platforms Inc. have collectively committed hundreds of billions of dollars toward data-center expansion and AI development. Industry analysts estimate that capital expenditures among the largest cloud providers could approach $700 billion during 2026, making AI infrastructure one of the largest investment cycles in modern technology history.

Broadcom’s order pipeline offers investors one of the best real-time views into whether those spending plans remain intact.

Based on the company’s guidance, the answer appears to be yes.

The results also arrived during a difficult day for the broader market. Major indexes pulled back from record highs amid renewed geopolitical tensions in the Middle East, which pushed oil prices higher and dampened investor appetite for risk assets. Against that backdrop, companies reporting earnings faced heightened scrutiny from traders already looking for reasons to reduce exposure.

The semiconductor sector has been particularly sensitive to shifts in sentiment. Following enormous gains over the past two years, investors have become increasingly selective, rewarding companies that substantially exceed expectations while punishing even modest shortfalls.

Broadcom’s quarter illustrates that challenge.

The company’s AI business continues to accelerate at a pace most corporations would envy. Revenue growth remains robust. Profit margins remain among the strongest in the industry. Demand from cloud providers appears healthy and expanding.

Yet the after-hours selloff demonstrates that investors are no longer simply asking whether AI demand exists. That question has largely been answered. Instead, they are asking whether the biggest beneficiaries of the AI boom can continue growing fast enough to justify valuations that already assume years of exceptional performance.

For Broadcom, the answer will likely depend on whether the company can maintain its position at the center of one of the largest technology spending waves in history. The latest guidance suggests that demand remains strong. The challenge now is proving that even extraordinary growth can continue exceeding extraordinary expectations.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited

JBizNews Desk

NEW YORK — June 4, 2026

Bitcoin fell for a fourth straight day this week, slipping below $68,000 to around $67,000, after the cryptocurrency’s most prominent corporate champion did something he had long vowed never to do: sell.

In an 8-K filing with the U.S. Securities and Exchange Commission on Monday, June 1, Strategy, the company led by Executive Chairman Michael Saylor and the largest publicly traded holder of bitcoin, disclosed that it had sold a small slice of its holdings. It marked the company’s first bitcoin sale in four years.

The amount was tiny. The symbolism was not.

According to the filing, Strategy sold 32 bitcoin between May 26 and May 31 for approximately $2.5 million, at an average price of roughly $77,135 per coin. The proceeds were used to help fund dividends on one of the company’s preferred stock offerings.

Against the backdrop of 843,706 bitcoin still held by Strategy—worth more than $60 billion at current prices—the transaction barely registers as a rounding error.

Yet markets reacted sharply.

The reason has less to do with the number of coins sold and more to do with who sold them. For years, Saylor became synonymous with bitcoin’s long-term investment thesis, repeatedly stating that Strategy would not sell its holdings and promoting the concept of holding through volatility regardless of market conditions.

That unwavering stance helped shape the company’s identity and turned Strategy into a proxy investment for investors seeking bitcoin exposure through public markets.

So when the company disclosed a sale—however small—it challenged a narrative many investors assumed was untouchable.

Several crypto market analytics firms reported a rapid deterioration in sentiment following the filing, with some measures showing traders moving into what they described as “extreme fear.”

Still, attributing bitcoin’s decline entirely to Strategy’s transaction oversimplifies what has been a difficult year for the cryptocurrency.

Bitcoin remains down more than 45% from the all-time high above $126,000 reached in 2025, and several larger forces have been weighing on prices.

The first is continued outflows from spot bitcoin exchange-traded funds. Those products, which became one of the primary gateways for retail and institutional investors, have experienced a record streak of withdrawals in recent weeks. Approximately $4 billion has left bitcoin ETFs over roughly a dozen trading sessions, removing a significant source of demand.

The second pressure point is leverage.

Many traders entered the year with aggressive bullish positions financed through borrowed money. As bitcoin prices declined, exchanges automatically liquidated those positions, creating one of the largest forced-selling cascades seen in months. Each liquidation pushed prices lower, triggering additional liquidations and accelerating the decline.

The third factor is competition for investment capital elsewhere in the market.

Wall Street’s enthusiasm for artificial intelligence continues to attract massive flows into technology stocks. Pierre Rochard, a well-known bitcoin researcher, recently argued that AI-related equities are effectively “vacuuming up all excess liquidity” that might otherwise flow into crypto assets.

At the same time, a resilient labor market and elevated energy prices have reduced expectations for near-term Federal Reserve rate cuts, limiting the availability of cheap capital that often supports speculative investments.

For investors, the Strategy story introduces another layer of concern.

The company’s shares, trading under the ticker MSTR, fell approximately 5% to 6% following the disclosure. Because Strategy employs substantial leverage to acquire bitcoin, its stock frequently experiences larger swings than bitcoin itself.

Some investors worry that if markets begin to believe Strategy may eventually need to sell additional bitcoin to satisfy financial obligations, a self-reinforcing cycle could emerge. Traders could rush to exit positions ahead of any future sales, pushing prices lower and intensifying fears about further liquidation.

That scenario remains speculative, but it explains why such a small transaction attracted so much attention.

Analysts remain divided over what the sale ultimately signifies.

Several Wall Street observers characterized the transaction as economically insignificant and purely tactical, noting that the proceeds were earmarked for a dividend payment and represented a microscopic fraction of Strategy’s holdings.

Others believe the move may signal a subtle shift in philosophy, suggesting the company’s previously absolute commitment to never selling bitcoin may be becoming more flexible as its capital structure grows increasingly complex.

Both sides agree on one point: the sale itself was trivial. The debate centers on whether it was an isolated event or the beginning of a broader change in approach.

For everyday investors, the episode highlights a fundamental characteristic of bitcoin. Unlike stocks that generate earnings or dividends, or bonds that pay interest, bitcoin produces no cash flow. Its value depends largely on what future buyers are willing to pay, making confidence a critical driver of price.

When confidence weakens—whether because of ETF outflows, leveraged liquidations, macroeconomic uncertainty, or a high-profile holder selling—the effects can be amplified quickly.

With millions of Americans now holding bitcoin through ETFs, retirement accounts, and brokerage portfolios, those swings are no longer confined to crypto enthusiasts.

The next major catalyst may come from economic data. A stronger-than-expected labor market could further reduce expectations for Federal Reserve rate cuts and continue pressuring risk assets, including cryptocurrencies.

For now, bitcoin’s latest downturn appears to be about far more than 32 coins. The broader question facing investors is whether the recent weakness represents a temporary setback—or the early stages of a deeper and more prolonged crypto downturn.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Broadcom tumbles despite booming AI sales, jobless claims offer an early read on Friday’s employment report, and every headline out of the Persian Gulf has the potential to move markets.

NEW YORK — Wall Street heads into Thursday, June 4, 2026, with three forces tugging in different directions: a fresh batch of corporate earnings, an early read on the job market, and the unpredictable swings of oil tied to the Middle East war. The tone was set after Wednesday’s closing bell, when chipmaker Broadcom reported results that beat on profit but narrowly missed on revenue, sending its shares down more than 6% in after-hours trading—a stumble likely to ripple across the technology sector when trading opens.

The first thing to watch Thursday is how those late-Wednesday earnings land in regular trading. Broadcom’s report was a paradox: the company forecast its artificial-intelligence chip revenue would more than double, yet investors punished the stock over a small revenue shortfall, a sign of how high the bar has become for the market’s AI favorites. Because chipmakers have led the market to record highs, a sharp drop in Broadcom could drag down peers and test whether the AI rally still has room to run. Cutting the other way, cybersecurity firm CrowdStrike crushed expectations with earnings of $1.10 a share against the $0.88 analysts expected, and software maker Veeva Systems beat and raised its forecast—reports that could lift the software group even as chips wobble.

The marquee earnings event arrives after Thursday’s close, when athletic-apparel maker Lululemon reports. The stakes are high: the stock has sagged to a roughly seven-year low, its home market in the Americas has been weak, and foot-traffic data suggest store visits fell early in the year. The company guided to first-quarter revenue of $2.40 billion to $2.43 billion and earnings of $1.63 to $1.68 a share, below what Wall Street had hoped, while warning that tariffs could cost it hundreds of millions of dollars. Investors will look for any sign that demand is stabilizing, and the report will serve as a fresh gauge of how willing shoppers are to spend on premium brands in a tight economy.

The bigger driver Thursday morning is the labor market. At 8:30 a.m. Eastern, the Labor Department releases its weekly tally of new jobless claims, with economists forecasting about 211,000, roughly in line with the prior week’s 215,000. A separate report on worker productivity comes out at the same time. These are warm-up acts for the main event on Friday: the government’s official May jobs report, where Barclays economists estimate around 75,000 jobs were added and unemployment near 4.3%. After Wednesday’s services-sector survey showed businesses growing but cutting jobs for a third straight month, Thursday’s claims figure will be parsed for any hint that hiring is weakening further.

Looming over all of it is the oil wild card. Earlier in the week, stocks hit record highs as hopes for a resolution to the Iran war pushed crude prices down nearly 10% and pulled Treasury yields lower—a powerful tailwind. That optimism reversed midweek as the conflict flared again, with Brent crude climbing back toward $98 a barrel and major indexes pulling back, including a more than 1% drop in the Dow Jones Industrial Average on Wednesday. The swing factor is the Strait of Hormuz, the shipping lane that carries a large share of the world’s oil. Analysts at JPMorgan suggested the strait could reopen as soon as this month, and President Donald Trump has floated a deal within a week, but Iranian officials have cast doubt. Any headline out of the Gulf can move oil—and the entire market—within minutes Thursday.

The backdrop to everything is the Federal Reserve. Under new Chair Kevin Warsh, the central bank faces an uncomfortable choice, and the data have only sharpened it. Inflation has proven sticky—the Fed’s preferred gauge rose at its fastest annual pace in nearly three years—even as hiring slows. That combination has flipped market bets from rate cuts toward the possibility of a hike, which is why every labor and inflation reading now carries extra weight. Thursday’s claims number feeds directly into that debate ahead of Friday’s payrolls.

For traders, the practical message is that Thursday is a setup day. The earnings reactions to Broadcom, CrowdStrike and Veeva will shape the morning; jobless claims will color the open; oil headlines could override all of it at any moment; and Lululemon’s report after the close will set the tone for Friday, when the jobs report and the oil picture together could decide the market’s direction into the weekend. The smart watch list is short: chips, claims, crude—and the wire out of the Persian Gulf.

Wall Street — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Office buildings, apartments and retail centers nationwide must refinance billions in debt at far costlier terms.

By JBizNews Desk

A long-feared crunch in commercial real estate has arrived.

According to Trepp’s Spring 2026 Quarterly Data Review, $76.6 billion in securitized commercial mortgages face hard deadlines this year, with much of the pressure tied to office and retail buildings — the property types already under the most strain. That is only one slice of a far larger pile: industry estimates put total U.S. commercial real estate loans maturing in 2026 at roughly $936 billion, with more than $1.5 trillion coming due across 2025 through 2027.

The problem is the math of refinancing in a changed world.

Many of these loans were written in the mid-2010s, when owners locked in borrowing costs around 3% to 4%. With the 10-year Treasury yield now near 4.46%, the same buildings are refinancing at 6% to 7% or higher. A property that comfortably covered its old loan can struggle to cover a new one at nearly double the cost.

Two things make it worse. Property values have fallen in several markets, especially offices hit by remote work and high vacancy. That means a new loan covers a smaller share of a building’s value. At the same time, lenders have tightened standards, demanding more income coverage and offering less leverage than they did a decade ago.

The result is what the industry calls a refinance gap. The new loan often will not cover what is still owed, forcing owners to bring fresh cash, find new partners, restructure the loan or hand the keys back to lenders.

For the past two years, lenders avoided a reckoning by extending loans instead of forcing the issue, a practice critics call “extend and pretend.” Of the roughly $957 billion in commercial loans that matured in 2025, The Kaplan Group estimates only 50% to 55% were actually paid off. The rest were pushed forward — straight into this year’s pile.

The strain is already showing up in late payments. The Kaplan Group pegged the delinquency rate on commercial mortgage-backed securities at 7.29%, nearly six times the rate on traditional bank loans. Apartments, once considered one of the safer parts of real estate, are feeling pressure too: multifamily maturities are projected to jump from about $104 billion in 2025 to roughly $162 billion in 2026.

Not every building is in trouble. Trepp stresses that loan quality matters more than the sheer volume coming due. Properties with strong tenants, healthy cash flow and sustainable debt are still refinancing. The danger sits with weaker assets — especially office buildings, which carry a disproportionate share of distressed loans — and properties whose income barely clears their debt payments.

The business stakes spread far beyond landlords. Regional banks hold large amounts of commercial property debt, so rising defaults can pressure the lenders that small businesses and local economies depend on. Private credit funds are stepping in to refinance deals banks will not touch, often at steep terms, shifting risk into less-regulated corners of finance.

And when owners cannot refinance, buildings get sold at a loss, converted, restructured or handed back to lenders — reshaping skylines and tax bases in cities across the country.

The maturity wall, in short, is no longer a forecast. How much of it turns into outright distress, rather than painful but survivable refinancing, will define commercial real estate for the rest of the year.

New York — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 3, 2026

The U.S. government is shifting its focus from finding enough electricity to power artificial intelligence to managing what happens when that power demand suddenly floods onto the electric grid.

The U.S. Department of Energy on Tuesday launched a new testing platform called Agora, designed to simulate how massive AI data centers behave once connected to the nation’s power system. The platform, announced through the DOE’s National Labs for Resilient Infrastructure, will allow researchers, utilities, and regulators to study the impact of AI facilities whose electricity usage can swing dramatically in a matter of seconds.

The move reflects a growing concern among grid operators. For the past two years, the dominant question was whether utilities could generate enough electricity to support the explosion of AI development. Agora signals that federal officials are now asking a different question: what happens when all that power actually starts flowing.

The New Problem Is Stability

Traditional industrial facilities tend to consume electricity in predictable patterns.

AI data centers do not.

Massive clusters of graphics processing units, or GPUs, can move from near-idle operation to full power almost instantly, then drop back again. Those rapid swings can affect voltage and frequency levels across the broader electric system.

Grid operators worry that enough AI facilities behaving this way simultaneously could create stability challenges for the networks serving homes, businesses, hospitals, and manufacturers.

The concern is already showing up in planning documents.

ERCOT, the operator of Texas’ electric grid, has begun treating AI facilities as a distinct category known as “Large Electronic Load” customers. A recent modeling study developed by ERCOT and Texas A&M University described AI data centers as highly dynamic loads capable of creating unique operational challenges.

Why Utilities Are Paying Attention

Steven Carlini, Chief Advocate for AI and Data Centers at Schneider Electric, says the rapid power swings are becoming one of the industry’s biggest engineering concerns.

“GPU clusters can jump from near-idle to full capacity in an instant,” Carlini said.

Without proper safeguards, those sudden changes can place stress on voltage and frequency levels throughout the grid.

To counteract the risk, utilities and data-center operators are increasingly deploying:

  • Battery storage systems
  • Load-smoothing technologies
  • Fault-ride-through systems
  • Advanced monitoring and control software

Many utilities are also requesting more detailed operational data from data-center developers before approving new projects.

The Infrastructure Is Already Behind Schedule

The grid-stability challenge arrives as the industry struggles with another major problem: construction delays.

According to a January 2026 report from PJM Interconnection, the regional grid operator serving approximately 65 million people across 13 states and Washington, D.C., AI-related projects entering service in 2025 required an average of more than seven years to become operational.

Much of that delay occurs after projects have already secured approval.

The biggest bottleneck is equipment.

Large transformers, switchgear, and circuit breakers are increasingly difficult to obtain.

Research from Wood Mackenzie found transformer lead times expanded from roughly 50 weeks in 2021 to approximately 120 weeks by 2024.

According to the firm’s latest 2026 data, waits for certain substation transformers now exceed 160 weeks, or more than three years.

Ben Boucher, Principal Analyst at Wood Mackenzie, warned that the situation continues to worsen.

“Time to market is one of the most important aspects for developers,” Boucher said.

Money Isn’t the Problem

Unlike many infrastructure challenges, funding is not the primary obstacle.

Alphabet, Amazon, Meta, and Microsoft have collectively projected more than $650 billion in AI infrastructure spending during 2026 alone.

The capital is available.

The equipment is not.

PJM reported earlier this year that more than 21 gigawatts of projects remain stuck in engineering and procurement phases, while only 8.2 gigawatts are actively under construction.

Why Consumers Should Care

The consequences extend far beyond technology companies.

PJM forecasts summer peak electricity demand rising from approximately 154 gigawatts in 2025 to nearly 210 gigawatts by 2036, with AI data centers serving as one of the primary drivers.

The same transformers and electrical equipment needed for AI facilities are also required for neighborhood grid upgrades, new housing developments, and commercial construction projects.

When supply shortages push prices higher, utilities often pass those costs through to customers.

That means the AI buildout could eventually influence residential and business electricity bills.

Washington Moves to Prepare

Federal regulators are beginning to respond.

The Federal Energy Regulatory Commission (FERC) has opened discussions on reforming how extremely large electricity users connect to the grid.

Meanwhile, utilities across multiple states are experimenting with flexible demand arrangements that would allow data centers to reduce consumption during periods of stress on the system.

Agora is intended to help answer those questions before the largest AI campuses begin operating at full scale.

The Bottom Line

For the past two years, the AI conversation centered on finding enough electricity.

The next phase is making sure the grid can handle how AI uses it.

The Department of Energy’s new Agora platform reflects growing concern that AI data centers are not just large consumers of electricity — they are fundamentally different kinds of consumers.

The race to build artificial intelligence increasingly runs through transformers, transmission lines, power plants, and grid-control systems.

Washington is now trying to make sure the infrastructure is ready before the lights start flickering.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

By JBizNews Desk

June 3, 2026

Florida has become the first state in the nation to sue OpenAI, escalating the legal and political scrutiny surrounding artificial intelligence and how it is used by children.

Florida Attorney General James Uthmeier announced Monday that the state had filed a civil lawsuit against OpenAI and its chief executive, Sam Altman, alleging that the company failed to adequately protect minors while marketing ChatGPT as a safe product. The lawsuit, filed in Florida state court, accuses the company of deceptive and unfair trade practices, negligence, and violations of product-liability laws.

At the center of the complaint is the state’s claim that OpenAI promoted ChatGPT as safe while allegedly downplaying or failing to address known risks associated with its use by young people.

“They have chosen profit over public safety,” Uthmeier said during a press conference announcing the lawsuit.

The attorney general said Florida intends to hold the company accountable and seek significant financial penalties.

Focus on Children

Much of the lawsuit centers on how minors access and use ChatGPT.

Florida argues that the free version of the chatbot lacks meaningful age-verification measures and does not provide sufficient safeguards to prevent children from accessing the platform.

The complaint further alleges that parental oversight tools are inadequate, claiming parents are limited in what they can monitor and review regarding their children’s interactions with the AI system.

The state also alleges that OpenAI collects information from minors without sufficient parental control and that the platform can encourage excessive reliance on AI among younger users.

Those allegations remain claims by the state and have not been proven in court.

Sam Altman Named Personally

In an unusual move, Florida also named Sam Altman individually as a defendant.

Uthmeier told reporters that Altman played a direct role in decisions surrounding product development and deployment and therefore should be held personally accountable if the allegations are proven.

The lawsuit seeks damages that state officials say could potentially reach into the billions of dollars, along with court-ordered changes to how OpenAI handles younger users.

Legal experts note that attempts to impose personal liability on technology executives are relatively uncommon and often become a major point of dispute during litigation.

Part of a Larger Investigation

The civil lawsuit follows a broader investigation launched by the attorney general’s office in April.

That inquiry examined whether OpenAI’s technology may have played a role in certain criminal cases in Florida after investigators reported that individuals involved in violent incidents had interacted with ChatGPT before those events.

The lawsuit references those broader concerns as part of the state’s argument that stronger safeguards are needed around advanced AI systems.

OpenAI’s Position

OpenAI did not immediately respond to requests for comment following the filing.

The company has previously stated that its systems are designed to reject requests that could facilitate violence or criminal activity and has emphasized that safety remains a central focus of development.

OpenAI has also said it works with law enforcement when conversations indicate an imminent and credible threat of harm and employs specialized review teams to assess sensitive situations.

Major Stakes for the AI Industry

The financial and regulatory implications extend far beyond OpenAI.

The company is one of the world’s most valuable private technology firms, and a significant damages award or court-ordered changes could affect both its business model and future product development.

The lawsuit also signals a broader shift in how governments may approach artificial intelligence regulation.

Until now, much of the debate surrounding AI oversight has occurred in Congress, federal agencies, and state legislatures. Florida’s lawsuit represents one of the first major attempts to use the court system to impose accountability on AI developers.

If Florida succeeds—or reaches a substantial settlement—other states could follow with similar legal strategies.

A Potential Roadmap for Other States

Attorneys general across the country have increasingly focused on issues involving artificial intelligence, particularly where children and consumer protection are concerned.

A successful case in Florida could provide a blueprint for future lawsuits targeting age verification, parental controls, content moderation, and data collection practices.

For AI companies, that could mean increased pressure to build stronger safeguards, verification systems, and compliance frameworks—changes that often require significant investment and can slow product rollouts.

Industry groups have warned that a patchwork of state-by-state regulations and lawsuits could create substantial compliance burdens for technology companies operating nationwide.

Consumer advocates argue that legal action is necessary because AI technology has advanced far faster than the rules governing it.

The Bottom Line

The allegations against OpenAI remain unproven, and the company will have an opportunity to challenge the claims in court.

But the lawsuit marks a significant milestone in the evolution of AI regulation.

After years in which artificial-intelligence technology expanded faster than governments could respond, Florida is now asking a court to decide whether companies that build these systems—and the executives who run them—can be held responsible when those tools allegedly cause harm to children.

The outcome could influence not only OpenAI, but the future legal framework governing the entire AI industry.

Tallahassee, Fla. — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.