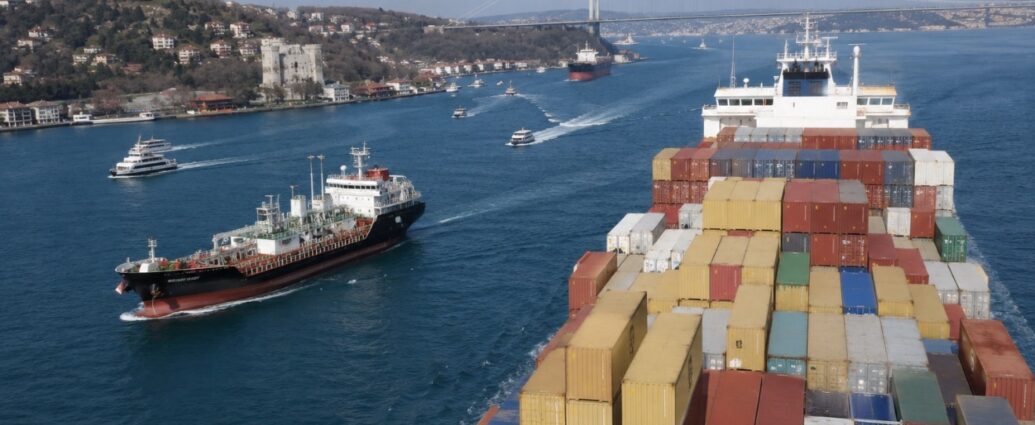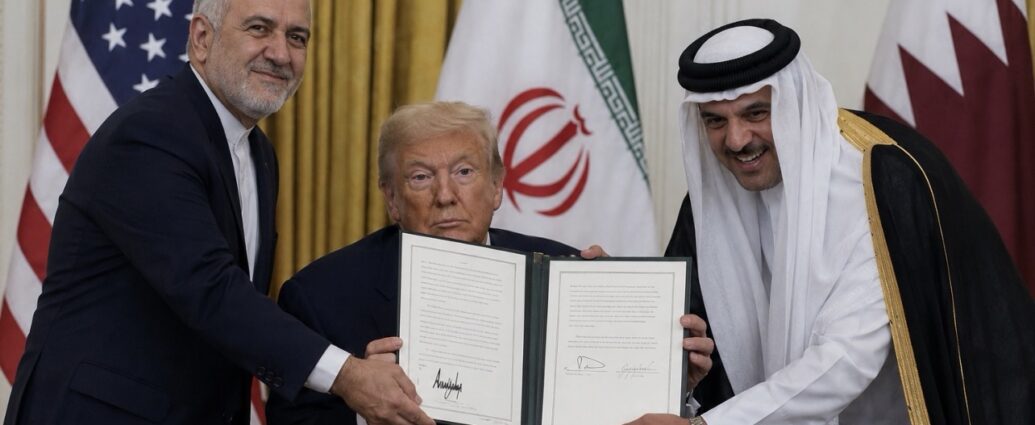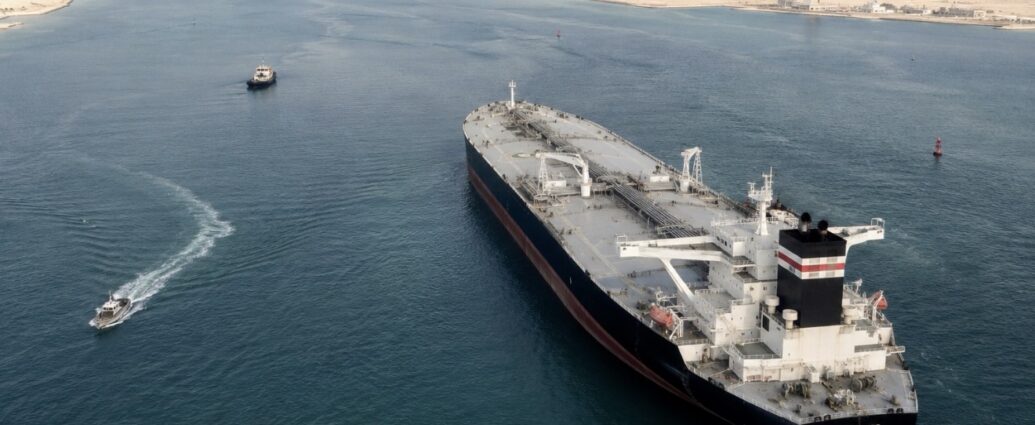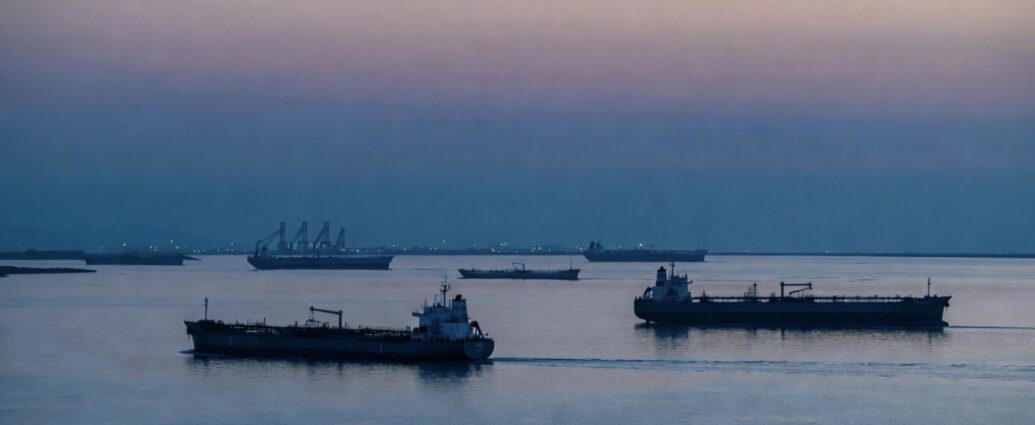
Washington — Iran can sell its crude on the open market for the first time since 2018 under an interim agreement that President Trump and Iranian President Masoud Pezeshkian signed on Wednesday, according to U.S. officials who briefed reporters on the text. The deal waives U.S. sanctions on Iranian oil and ends the American naval blockade that had choked off shipments during the war.

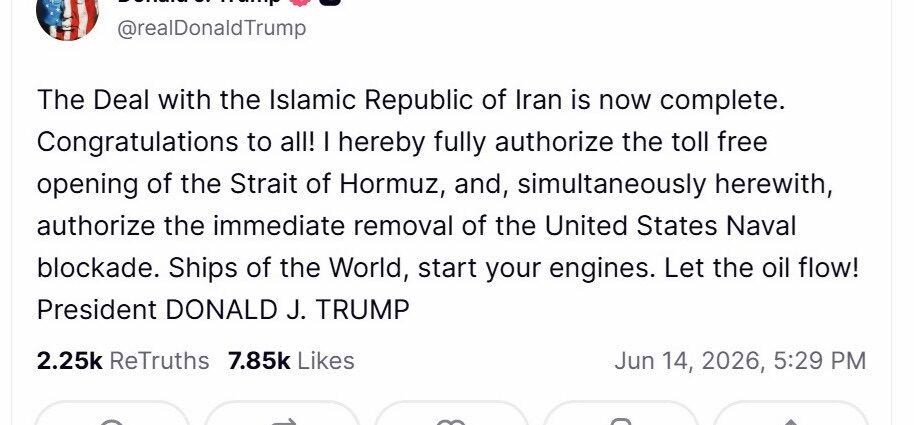
Trump announced the breakthrough on his Truth Social account, writing that he had authorized the toll-free reopening of the Strait of Hormuz and the immediate removal of the U.S. blockade. “Let the oil flow!” he wrote. Pakistani Prime Minister Shehbaz Sharif, who helped mediate, said the agreement took effect once both leaders signed.

The terms restore much of the status quo from before the fighting. The United States agreed to waive — but not yet permanently lift — sanctions on Iranian oil sales, allowing Tehran to seek buyers worldwide instead of relying on discounted shipments to China through a shadow fleet. The interim deal also opens a 60-day window for talks on a final agreement covering Iran’s nuclear program, with a promise to eventually end all U.S. sanctions if Iran cooperates.

There are catches. Under the deal, the Strait of Hormuz is toll-free for only 60 days, after which Iranian officials have signaled they may charge ships a service fee. Iran has agreed to let commercial vessels pass safely, and the waterway — which carried roughly a fifth of the world’s oil before the war — is meant to return to pre-war traffic within 30 days. But mines laid during the conflict are still being cleared, and the U.S. and other navies are working to make the route safe.

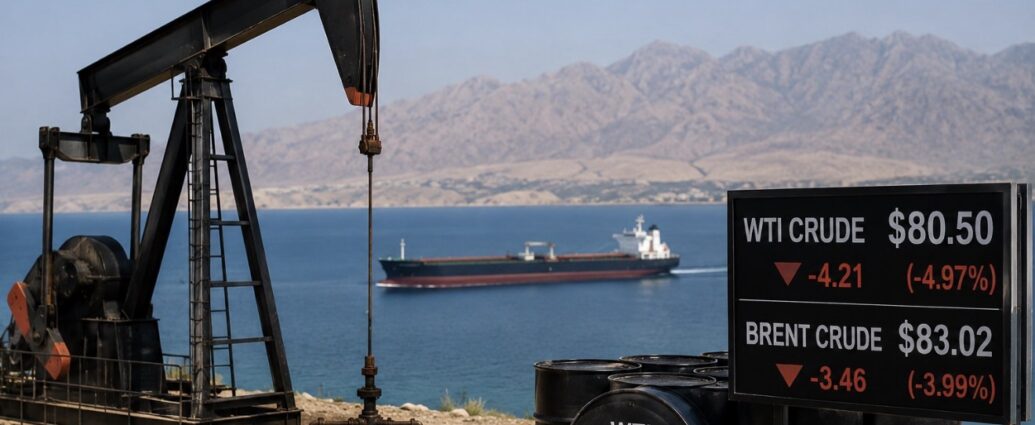
For oil markets, the effect was immediate. Prices fell sharply after the announcement as traders bet on more supply reaching the market. At the peak of the conflict, the strait’s effective closure pushed crude above $100 a barrel and reignited inflation in the United States. A return of Iranian barrels could ease that pressure over time.

Drivers should not expect relief at the pump right away. Summer demand is high, refiners need time to adjust, and the government may move to refill strategic reserves. Analysts who study Gulf supply expect a gradual recovery rather than a sudden flood, with full output possibly stretching into 2027 as Iran restarts idled fields and clears port backlogs. Iran earned an estimated $45 billion from oil last year even under sanctions, much of it sold at a discount.

The agreement also lays out a $300 billion fund for rebuilding Iran, to be financed by Gulf partners rather than the United States, with details to be worked out over the next two months. Vice President JD Vance said the economic incentives depend on Iran changing its behavior and complying fully.

The deal is already drawing fire in Washington, where critics call the oil waiver and the path to lifting all sanctions major concessions that go beyond the 2015 nuclear accord. It also marks a setback for Israeli Prime Minister Benjamin Netanyahu, who has faced criticism at home as the terms became public.

For everyday families and businesses, the stakes are practical. Cheaper energy eventually filters into lower costs for shipping, manufacturing, and the goods on store shelves. Shippers, refiners, and energy traders are watching closely, and tankers have already begun moving again, with buyers in India and across Asia showing renewed interest.

How fast Iran ramps up will shape oil balances heading into late 2026. For now, the guns are quiet, the strait is open, and the oil is moving — but the toughest questions, from sanctions to the nuclear file, are pushed into a 60-day negotiation that could still unravel.

JBizNews Desk | New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
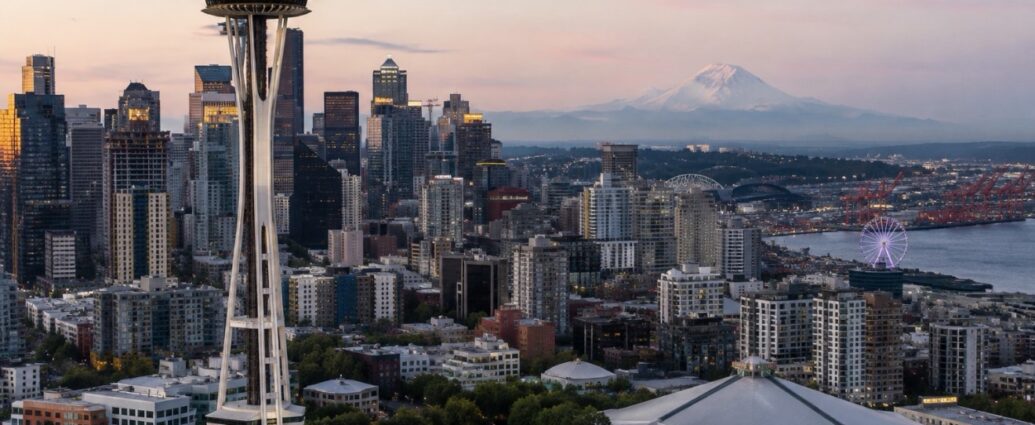
As the FIFA World Cup gets underway across North America, most U.S. host cities are enjoying a surge in visitors. But one city is moving in the opposite direction.

According to flight-booking data from travel intelligence firm Sojern, Seattle is the only American World Cup host city where air travel bookings are running below last year’s levels during the tournament period.

The decline is significant. Seattle’s flight bookings are down approximately 21% from the same period a year ago, while nearly every other U.S. host city is seeing gains. Houston is up roughly 13%, Dallas-Fort Worth about 10%, while New York and Miami are each seeing increases of nearly 8%.

“Demand is real and positive, but it’s not evenly distributed across host cities,” said Jay Wardle, president of Sojern.

The drop is surprising because Seattle has fully embraced the tournament.

The city has organized large public watch parties, floating fan events, drone displays, and downtown celebrations centered around Lumen Field. Seattle is also hosting one of the tournament’s marquee early matches, with the United States Men’s National Team scheduled to face Australia on June 19.

Yet while the atmosphere is vibrant, many of the fans attending appear to be local residents or visitors arriving by car rather than by air.

Part of the explanation may be the sheer size of this year’s tournament.

The 2026 World Cup is the largest in history, featuring 48 national teams and 104 matches spread across the United States, Canada, and Mexico. The United States alone is hosting 78 matches, creating far more inventory than previous tournaments.

With so many games taking place simultaneously across multiple cities, not every match has generated the same level of travel demand.

Industry analysts say lower-profile group-stage matches have generally been harder to fill, particularly when ticket prices remain elevated. Seattle is not entirely alone in experiencing softer travel demand. Several host cities in Mexico have also reported booking levels below expectations.

The broader concern is that the tourism boom many cities expected has not yet fully materialized.

An April report from the American Hotel & Lodging Association found that roughly 80% of hotels across the eleven U.S. host cities reported booking levels below earlier forecasts. Some hotel operators described the tournament’s impact as weaker than anticipated and pointed to visa challenges, international travel restrictions, and global economic uncertainty as factors limiting attendance.

Several hotel operators also expressed frustration after FIFA reduced or canceled previously reserved room blocks, leaving some properties scrambling to replace expected bookings.

International travel restrictions have likely played a role as well.

Fans from some countries face additional visa hurdles when traveling to the United States, while others face longer processing times or greater uncertainty. Those barriers can significantly affect international sporting events that traditionally rely on overseas visitors.

Still, travel companies believe the final numbers could improve.

Sojern notes that more than one-third of hotel bookings associated with major sporting events historically occur within the final week before arrival. That means many travelers may not have booked yet.

Major hospitality companies remain optimistic.

Marriott International says it is seeing healthy demand in both World Cup and non-World Cup markets and expects the tournament to provide a modest boost to revenue. Airbnb is even more bullish, projecting that the World Cup could become the largest event in the company’s history, surpassing the travel demand generated by the 2024 Paris Olympics.

Many World Cup visitors are choosing vacation rentals over hotels, particularly families and groups planning longer stays.

For local businesses, the lesson is that the tournament’s economic impact is proving uneven.

High-profile matches, host-nation games, and the championship match at MetLife Stadium in East Rutherford, New Jersey, are still expected to generate strong visitor spending. Smaller group-stage matches have produced more mixed results.

That leaves Seattle in an unusual position.

The city is hosting one of the tournament’s most energetic fan celebrations and one of Team USA’s biggest early matches. Yet it remains the only American host city where fewer travelers are arriving by air than they did a year ago.

For hotels, restaurants, retailers, and tourism businesses hoping for a World Cup windfall, the excitement on the streets may not necessarily translate into the economic boost many expected.

JBizNews Desk
Seattle

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Samsung Electronics America became the latest major employer to leave New Jersey when it announced earlier this month that it will move its U.S. headquarters from Englewood Cliffs to Plano, Texas, by the end of 2026. The decision pulls roughly 1,000 jobs out of a state that charges the highest corporate tax rate in the country — 11.5% — and hands them to a state with no corporate income tax at all.

That gap sits at the center of the story. New Jersey’s top corporate rate stands at 11.5%, the steepest in the nation. Texas has no traditional corporate income tax and no personal state income tax. For a global company weighing where to put its leadership, its money, and its people, the math is hard to ignore — and New Jersey keeps landing on the wrong side of it.

Samsung framed the move as internal strategy rather than a tax revolt. “Samsung Electronics America Inc. is undergoing a business transformation designed to better position our organization for long-term growth and future success,” the company said in a statement, adding that it is “relocating our U.S. headquarters from New Jersey to our existing campus in Plano, Texas, building on our 30-year presence in the state.” But to the people who watch corporate departures for a living, the reason is plain.

A five-alarm fire

“This is a five-alarm fire wake-up call,” said John Boyd Jr., founder of the Princeton-based relocation firm The Boyd Company. He noted that New Jersey cannot keep swimming upstream with new tax hikes while a neighboring competitor like Pennsylvania is cutting its corporate rate.

Michele Siekerka, president and CEO of the New Jersey Business & Industry Association, called the news “not surprising, but no less sad,” pointing straight at the state’s tax and regulatory climate. She said New Jersey has dropped from 22 Fortune 500 companies in 2018 to 15 in 2025. Samsung’s exit, she warned, is the predictable result of policies that make staying expensive.

What it means for the workers

The timing made the blow sharper. Samsung had cut the ribbon on its new Englewood Cliffs campus just nine months ago, on September 22, 2025, at a ceremony attended by state and local officials who praised it as proof of the company’s commitment to New Jersey. The company had moved into the former Unilever building at 700 Sylvan Avenue after decades in nearby Ridgefield Park.

Now those workers face a choice. Samsung told staff on a Friday in late May that they would need to say within two weeks whether they were willing to relocate, with details on individual jobs to follow by the end of June. Most are expected to be offered a transfer to Plano, while a smaller group will stay behind to handle local operations. The company has not said how many positions will be eliminated outright, but it acknowledged that layoffs are coming, saying it will be “optimizing parts of the organization” and will support affected employees. For families in Bergen County, that means uprooting a household for Texas or risking no job at all.

Why Texas wins

Samsung is moving its leadership closer to where it already builds. The company has run a semiconductor plant near Austin since 1996 and is finishing an advanced chip factory in nearby Taylor, a project that has grown to roughly $37 billion and is due to start production by the end of 2026. Last summer, Samsung signed a $16.5 billion deal with Tesla to make automotive chips at the Taylor plant. Its Plano campus already houses the company’s mobile and network business. Low taxes are the other half of the draw.

A pattern New Jersey can’t shake

Samsung is not the first to go. Earlier this year, ExxonMobil completed its own move to Texas, ending a presence in New Jersey that ran more than 140 years. State Worker Adjustment and Retraining Notification filings show more than 7,600 job cuts announced in New Jersey this year, with Verizon, Merck, Johnson & Johnson, and Prudential Financial among the names trimming staff.

The short-term story is 1,000 jobs and a brand-new office about to sit empty. The longer story is whether New Jersey can keep the companies that built it while charging the highest corporate tax in America. Until that number changes, Trenton will keep hearing the same question every time a marquee employer packs up: how many more have to leave first.

JBizNews Desk | New York
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The national average for a gallon of regular gasoline fell to $3.99 on Thursday, dropping below $4 for the first time since March 30, AAA reported, marking a third straight week of declines just as the summer travel season gets going. AAA said drivers are getting a break at the pump as crude oil prices ease.

The relief is real but partial. Gas prices are up nearly 40% since late February, when the U.S. and Israel launched the war against Iran and global oil supply tightened. The national average sat near $2.98 in late February before climbing sharply, so even at $3.99 households are paying far more than they were at the start of the year.

Where you live still matters enormously. In five states — Alaska, Hawaii, Nevada, Oregon, and Washington — average prices are at or near $5 a gallon, and California is close to $6, the highest in the nation. Drivers in the middle of the country are paying the least.

Road trips are getting a closer look as a result. AAA forecast that 39.1 million people would drive at least 50 miles over the recent Memorial Day stretch, up just 0.1% from a year earlier — the weakest growth in a decade. The softness suggests some families are trimming plans even as headline pump prices ease.

Air travel is a tougher story. Jet fuel costs have nearly doubled since February, and the squeeze is showing up in fares. The U.S. Energy Information Administration, in its June Short-Term Energy Outlook, raised its 2026 jet fuel forecast by about $1.42 a gallon, to an average near $3.37, citing the de facto closure of the Strait of Hormuz as the main pressure on diesel and aviation fuel.

Travelers are feeling it at booking. Domestic round-trip airfares are averaging about $623, according to the Airlines Reporting Corporation, a 10% to 15% jump from last year, and fares have not been this high since May 2022. Airfare last reached these levels when carriers stumbled out of the pandemic to meet a wave of “revenge travel.”

Airlines say they are passing fuel costs along because they have little choice. American Airlines estimated its fuel bill will run about $4 billion higher this year than in 2025, and Delta said it would pay $2 billion more in the second quarter alone. The trade group Airlines for America reported that fuel made up 20% of airline operating expenses in 2025, with labor the only larger cost.

The fuel crunch has reshaped schedules well beyond the United States. Lufthansa has grounded some short-haul aircraft, and Cathay Pacific canceled about 2% of its passenger flights between mid-May and the end of June. Roughly 13,000 flights were canceled globally in May as carriers pulled back on thinner routes.

For consumers, the split picture means the math of a summer trip now depends heavily on how you travel. Driving has gotten modestly cheaper in recent weeks and may keep easing if crude stays below $100, while flying remains expensive and, in some markets, less reliable. The Transportation Security Administration expected to screen about 18.3 million people over a recent holiday travel window, roughly in line with last year, a sign that demand is holding even as prices bite.

The strain is hitting an industry already under stress. Higher fuel costs and softer demand have tested weaker carriers, and the broader travel market is absorbing the shock at the same time households are paying more for groceries, clothing, and housing.

The near-term outlook hinges on oil. If reports of progress toward easing the Iran conflict hold and crude keeps drifting lower, pump prices could fall further into the heart of the driving season. But jet fuel tends to be the last product to recover when refining capacity is tight, so airfare relief is likely to lag what drivers see at the gas station. For now, the cheapest summer trip for many families may be the one that stays on the road.

JBizNews Desk | New York & Washington

© 2026 JBizNews.com. All Rights Reserved. Reproduction, redistribution, republication, or retransmission of this content, in whole or in part, without prior written permission from JBizNews.com is strictly prohibited.

On Thursday, Scott Patton, chief commercial officer of Aldi in the United States, told the Financial Times the discount chain is pressing ahead with a roughly $9 billion U.S. expansion and now sees a path to about 4,000 stores — enough to make it the nation’s largest grocer by store count. “We’re trying to take market share from anyone who sells groceries,” Patton said, adding that the company does not yet know where the ceiling is.

The timing is no accident. Years of rising food prices have stretched household budgets, and Patton framed that strain as an opening for a chain built on low prices and private-label brands. Food inflation, he said, gives shoppers a reason to rethink where they buy groceries — and Aldi wants to be the first stop.

Aldi already runs more than 2,600 U.S. stores, which places it third by store count behind Walmart and Kroger. The company plans to open more than 180 new stores in 2026 across 31 states, pushing its footprint toward 2,800 by year-end. That is part of a five-year, $9 billion plan to reach roughly 3,200 stores by the end of 2028, while the 4,000-store figure represents a longer reach beyond that.

The growth is spreading the chain into new territory. Aldi is entering Maine, its 40th state, with a store in Portland, and plans more than 50 stores in the Denver and Colorado Springs markets over the next five years. It will open 10 stores in the Phoenix area in 2026, aim for 40 there by 2030, and roughly double its Las Vegas count. Much of the Southeast push comes from converting former Southeastern Grocers locations, including Winn-Dixie stores, that Aldi acquired in 2024.

The pitch to shoppers is built around size and simplicity. A typical Aldi store runs about 10,000 square feet — a fraction of a Walmart supercenter’s average 178,000 square feet — and more than 90% of what it sells carries an Aldi store-brand label. “One in three U.S. households shopped at Aldi this past year,” said Atty McGrath, chief executive of Aldi U.S., who tied the expansion to keeping shelves stocked and upgrading the company’s website.

The customer numbers help explain the confidence. Aldi said 17 million new customers visited its stores in 2025, a year in which it opened about 200 locations. The company is also spending to support the growth, with new distribution centers planned in Florida, Arizona, and Colorado.

For rival grocers, the expansion raises the pressure on price. “Aldi’s influence on the market should not be underestimated,” said Neil Saunders, managing director at GlobalData, who noted the chain’s price leadership can force competitors to cut their own prices to keep up. That dynamic lands at a moment when traditional supermarkets are already feeling the squeeze.

The strain showed up the same day across the grocery aisle. Kroger chief executive Greg Foran said Thursday that the largest traditional U.S. supermarket chain saw sales rise just 1% last quarter, as high gas prices and reduced food-assistance benefits left customers shopping with care. Foran said the customer is under pressure and managing spending carefully — the exact behavior Aldi is betting it can capture.

Aldi is running a similar playbook abroad. Last year it launched a $2.2 billion plan to open 80 stores in the United Kingdom within two years, mirroring the value-first strategy it is now accelerating in the United States. The German-owned company has spent decades building a loyal following on the premise that a smaller, tightly edited store can beat a sprawling one on price.

Whether 4,000 stores is reachable will depend on real estate, supply-chain buildout, and how long shoppers keep trading down. But the direction is set: Aldi intends to keep opening stores at a fast clip while food costs stay high, and it is openly aiming at the top of the U.S. grocery business. For shoppers, the near-term result is more discount locations within driving distance — and more pressure on competitors to answer with lower prices of their own.

JBizNews Desk | New York & Washington

© 2026 JBizNews.com. All Rights Reserved. Reproduction, redistribution, republication, or retransmission of this content, in whole or in part, without prior written permission from JBizNews.com is strictly prohibited.

A U.S. Bankruptcy Court judge approved Saks Global’s Chapter 11 reorganization plan on June 5, 2026, clearing the luxury retail company to emerge from bankruptcy with significantly less debt, fewer stores, and a smaller workforce. The ruling marks the latest chapter in the restructuring of the company created by the merger of Saks Fifth Avenue, Neiman Marcus, and Bergdorf Goodman, a deal that was once expected to reshape the luxury department store industry.

In a hearing before the U.S. Bankruptcy Court for the Southern District of Texas in Houston, Judge Alfredo Perez approved the company’s plan to cut its debt burden by nearly 75%, reducing total debt to approximately $1.2 billion while transferring ownership to senior lenders. During the hearing, Perez praised management’s efforts to stabilize operations following what he described as a difficult start to the bankruptcy process.

The approval concludes a restructuring that dramatically altered the company’s footprint. When Saks Global filed for Chapter 11 protection on January 13, 2026, it carried approximately $3.4 billion in debt and employed roughly 17,000 workers. Since then, management has closed stores, reduced staff, and worked to restore relationships with luxury brands and vendors that had been strained during the company’s financial struggles.

The workforce reductions occurred in two separate phases.

Earlier in the restructuring process, the company eliminated more than 1,200 store and distribution center positions tied to a series of store closures across multiple states. Later, in April 2026, Saks Global announced approximately 640 corporate layoffs, representing about 16% of its headquarters workforce but less than 4% of total company employment.

Company executives said the corporate cuts were designed to eliminate duplicate administrative functions created after the merger and streamline operations for a smaller organization.

The store portfolio has also been significantly reduced.

Under the approved restructuring plan, Saks Global will continue operating 49 luxury retail locations, consisting of 33 Neiman Marcus stores, 15 Saks Fifth Avenue stores, and Bergdorf Goodman in New York City. To reach that level, the company closed more than half of its Saks Fifth Avenue locations and exited the Saks Off 5th off-price business.

Saks Global was formed following Hudson’s Bay Company’s $2.7 billion acquisition of Neiman Marcus Group in 2024. Executives envisioned creating a dominant luxury retail platform capable of competing with global luxury brands and online retailers.

Instead, the combined company struggled under the weight of acquisition-related debt, vendor payment issues, inventory shortages, and weakening sales trends. Those pressures ultimately pushed the retailer into bankruptcy protection at the beginning of 2026.

Chief Executive Officer Geoffroy van Raemdonck said the restructuring reflects the company’s transition to a smaller and more focused operating model. He noted that recent sales and inventory performance have exceeded internal expectations, suggesting the business is beginning to stabilize.

Under the court-approved plan, senior lenders will assume control of the company after providing $1 billion in bankruptcy financing and committing an additional $500 million in funding once Saks Global exits Chapter 11.

Junior creditors, who are owed approximately $1.5 billion, supported the restructuring after the creation of a $20 million litigation trust designed to pursue potential claims and recover additional funds on their behalf.

Looking ahead, management has set ambitious long-term goals, including generating $9 billion in gross merchandise value and achieving double-digit adjusted EBITDA margins by fiscal 2030.

The company’s challenges reflect broader pressures facing the luxury retail industry.

According to the Business of Fashion–McKinsey State of Fashion 2026 report, 46% of fashion executives expect industry conditions to worsen in 2026, up from 39% a year earlier. Executives cited tariffs as the industry’s leading concern, while rising borrowing costs, expensive retail leases, and the growing trend of consumers purchasing directly from luxury brands continue to pressure traditional department stores.

Additional workforce reductions are still ahead.

In a filing submitted to the Texas Workforce Commission on June 12, 2026, under the Worker Adjustment and Retraining Notification (WARN) Act, Saks Global disclosed plans to lay off 67 employees when it permanently closes the historic Neiman Marcus flagship store in downtown Dallas on September 30, 2026.

The location has served as a landmark in downtown Dallas since opening in 1907.

According to the filing, submitted by Janet Lee, associate general counsel for Saks Global, all employees at the store will be separated from employment when the location closes. The filing also noted that the workers are not represented by a union.

The company said it expects many affected employees will receive transfer opportunities at the Neiman Marcus NorthPark Center location in Dallas, while those who are not offered transfers will receive severance packages.

Dallas city officials, who spent months attempting to preserve the flagship location, expressed disappointment over the closure and noted the store’s long-standing importance to the city’s central business district.

For the luxury retail sector, Saks Global’s emergence from bankruptcy represents both an ending and a new test. The company has reduced its debt burden and repaired key vendor relationships. Whether a leaner chain of 49 stores can successfully compete in a market where luxury shoppers increasingly buy directly from brands remains one of the industry’s biggest questions.

JBizNews Desk | Dallas

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Three of the country’s biggest retailers have confirmed overlapping summer sales that begin the week of Monday, June 22, setting up the most crowded discount stretch in recent memory as inflation-weary shoppers hunt for value. Walmart, Amazon and Target each announced events landing within a day of one another, turning a single week into a head-to-head fight for the same dollars.

Walmart moved first on the calendar. Walmart Deals will run Monday, June 22 through Sunday, June 28 — a seven-day event the company pulled forward from its traditional July slot to line up directly against Amazon. The sale is open to everyone with no membership or code required, with discounts the retailer says reach up to 50% across fashion, beauty, home, electronics and toys. Walmart+ members get early access and a 24-hour window to lock in high-demand deals before inventory opens to all shoppers.

Amazon is going next and tighter. Amazon Prime Day 2026 will run Tuesday, June 23 through Friday, June 26, a four-day event that requires a Prime membership. It is the first time since 2021 that Amazon has held Prime Day in June rather than July, and the company is promising millions of deals across more than 35 categories. A Prime membership runs $14.99 a month or about $139 a year.

Target is matching Amazon’s dates. Target Circle Deal Days, the retailer’s summer version of Circle Week, will run Tuesday, June 23 through Friday, June 26, with early access for paid Target Circle 360 members starting Monday, June 22. Unlike Amazon, Target’s basic loyalty program is free to join. Best Buy is in the mix too, with a Tech Fest sale running June 22 through June 28.

The clustering is deliberate. By stacking their events, the retailers are competing for back-to-school spending and even early holiday shopping, while denying any single rival a clear window. The week of June 22 is shaping up as the single best buying stretch of the year for electronics, appliances and home goods, and each chain is fighting to get shoppers’ carts first.

Last year’s results show why the fight is intense. During the 2025 events, online spending at Walmart.com grew 24% year over year — about six times faster than Amazon Prime Day’s growth — according to card-transaction data from Bloomberg Second Measure. Walmart’s web traffic rose 14% while Amazon’s was flat, and Walmart’s app use jumped 22% against Amazon’s 3%, according to Similarweb. The numbers suggest Walmart’s push into a Prime Day-style event is paying off and pressuring Amazon’s lead.

The backdrop is a strained consumer. Shoppers are absorbing higher costs across groceries, housing and travel, and many are trading down to value-focused chains and store brands. Retailers are bringing promotions forward and cutting prices specifically to attract shoppers worn down by inflation. That pressure was visible the same week elsewhere in retail, as Kroger reported shoppers buying with tighter budgets and discount grocer Aldi detailed an aggressive U.S. expansion aimed at value-seeking customers.

For consumers, the overlap is a mixed blessing. The competition should mean deeper discounts and more price-matching, but the membership rules differ in ways that affect who gets the best access. Amazon’s strongest deals are locked behind Prime, while Walmart and Target keep their main events open to all and reserve perks — early access and item locks — for paying members. Shoppers willing to compare across all three stand to benefit most.

The business stakes go beyond a single week. These events drive membership sign-ups and feed the fast-growing retail advertising businesses that Amazon, Walmart and Target are each building. Winning the June window helps set momentum heading into the second half of the year, when back-to-school and holiday spending help determine how the season finishes.

The events kick off in days, and the early jockeying is already underway, with each retailer rolling out pre-sale discounts to capture shoppers before the official start. For households watching their budgets, the practical takeaway is simple: the biggest markdowns of the summer arrive the week of June 22, and the three largest players are all chasing the same cart at the same time.

JBizNews Desk | New York & Washington

© 2026 JBizNews.com. All Rights Reserved. Reproduction, redistribution, republication, or retransmission of this content, in whole or in part, without prior written permission from JBizNews.com is strictly prohibited.

Investors are pulling billions of dollars from some of the nation’s largest private credit funds, creating the biggest test yet for an industry that has grown into a roughly $2 trillion market and become a major source of financing for American businesses.

According to new data from investment bank Robert A. Stanger & Co., investors in four major private credit funds, including vehicles managed by Blackstone and BlackRock, requested approximately $12 billion in withdrawals during the second quarter, compared with $7.7 billion in redemption requests during the previous quarter. The surge comes as fundraising across the sector slows sharply and redemption requests increasingly exceed new investor inflows.

The largest fund under pressure is the $79 billion Blackstone Private Credit Fund (BCRED). Investors sought to redeem roughly 10% of fund shares during the quarter, up from 7.9% in the first quarter. Because BCRED limits quarterly withdrawals to 5% of outstanding shares, the fund capped redemptions for the first time in its history.

The situation is even more pronounced at BlackRock’s HPS Corporate Lending Fund (HLEND). Investors requested withdrawals equal to 13.3% of shares, up from 9.3% in the prior quarter. Since the approximately $26 billion fund also limits quarterly repurchases to 5%, investors will receive only about 38 cents for every dollar they sought to withdraw.

Private credit funds have become increasingly popular among wealthy individuals seeking higher yields than traditional bond investments. Many operate as Business Development Companies (BDCs), lending to midsize companies that often have weaker credit profiles than firms able to borrow in public debt markets.

The model works well when money is flowing in. The challenge arises because the loans held by these funds are difficult to sell quickly, while investors expect periodic access to their capital. Most funds therefore limit withdrawals to roughly 5% per quarter, creating a potential bottleneck when redemption requests surge.

That mismatch is now being tested.

Investor concerns began growing late last year amid worries about rising defaults and weakening credit quality. Anxiety intensified this year as investors focused on potential losses tied to software and technology-sector borrowers. At the same time, fundraising has slowed dramatically.

Stanger data shows fundraising for non-listed BDCs fell 74% in April compared with a year earlier, reaching its lowest monthly level since May 2023. For the first time, quarterly redemption requests exceeded new investor inflows, marking a significant shift for an industry that had been accustomed to rapid growth.

If outflows continue accelerating, funds could face difficult choices. Managers may be forced to sell loans at discounted prices to raise cash or impose tighter withdrawal restrictions. Industry observers often refer to such measures as “gates,” which limit investors’ ability to access their money.

Similar situations have emerged elsewhere in private markets. A Starwood Capital real estate fund restricted investor withdrawals in 2024 after facing heavy redemption requests, highlighting how quickly liquidity concerns can emerge in assets that are difficult to sell.

The implications extend beyond individual investors. Private credit has become a critical source of financing for thousands of American companies, particularly those unable or unwilling to access traditional bank loans. A prolonged period of redemptions could reduce lending activity and tighten credit conditions across portions of the economy.

Major fund managers insist the sector remains healthy.

Blackstone says BCRED has more than $15 billion in available liquidity, with loan repayments continuing to exceed redemption obligations. Speaking at an industry conference this month, Blackstone President Jonathan Gray argued that concerns about widespread stress are overblown and said private credit continues to offer attractive returns compared with traditional fixed-income investments.

Not everyone is convinced.

Analysts at Barclays recently warned that outflows could continue to increase in coming quarters. Morningstar, meanwhile, has given positive ratings to only four of 18 semiliquid private funds it follows, citing concerns over fees, leverage, and borrowing costs.

Morningstar analyst Brian Moriarty said prolonged periods of maximum redemption requests may become the norm, shifting attention from whether outflows occur to whether funds have sufficient liquidity to manage them.

There are signs conditions may not be deteriorating everywhere. Analysts at Evercore described Blackstone’s redemption figures as better than many investors had feared, while at least one private credit fund managed by Oaktree Capital Management reported easing withdrawal requests during the quarter.

Investors will soon get a broader picture of the industry’s health as funds managed by Apollo Global Management, Ares Management, and Blue Owl Capital release their latest redemption figures.

For now, one trend remains clear: more investors are trying to leave private credit funds than enter them, creating the industry’s most significant liquidity test since its rise to prominence.

JBizNews Desk
Wall Street
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Negotiators face a high-stakes test as discussions begin over Iran’s nuclear program, frozen assets, oil exports, and the future of the Strait of Hormuz.

Vice President JD Vance arrived in Switzerland on Saturday to lead the United States delegation in a new round of direct negotiations with Iran, opening what could become the most consequential diplomatic effort between the two countries in years.

The talks, scheduled to begin Sunday at the Bürgenstock resort overlooking Lake Lucerne, are expected to focus on Iran’s nuclear program, regional security concerns, sanctions relief, and the future of the Strait of Hormuz, one of the world’s most important energy corridors.

Before departing Joint Base Andrews, Vance told reporters he expected several days of discussions focused on Iran’s nuclear activities and the fragile ceasefire in Lebanon.

For financial markets and global businesses, however, the most immediate issue may not be diplomacy itself but the enormous amount of money potentially set to change hands if negotiations succeed.

At the center of the discussions is an estimated $100 billion in Iranian funds frozen around the world under sanctions and other restrictions.

President Donald Trump signaled a willingness to move forward with releasing some of those assets during remarks at the G7 summit in France earlier this week.

Speaking about the frozen funds, Trump said the money ultimately belongs to Iran and indicated that mechanisms would eventually need to be established to return it under the terms of the newly signed framework agreement.

Under the memorandum signed Wednesday, Washington agreed to work toward making frozen Iranian assets available for approved uses while negotiations continue.

The first step under discussion involves approximately $6 billion currently held in Qatar.

The funds, largely derived from Iranian oil revenues restricted under U.S. sanctions, would not be transferred directly to Tehran. Instead, Iranian authorities would be permitted to use the money for approved humanitarian purchases such as food, medicine, and medical supplies, with transactions overseen through a controlled mechanism.

Negotiators view the $6 billion release as only the beginning.

Iran is reportedly seeking access to roughly $24 billion in frozen assets as quickly as possible, representing the first phase of a broader effort to regain access to as much as $100 billion held in countries including China, India, Iraq, Japan, and Qatar.

Iranian state media has suggested that Tehran hopes to secure approximately $12 billion during the 60-day interim negotiating period.

The financial incentives come with conditions.

A U.S. official familiar with the negotiations said asset releases would be linked to specific benchmarks, including Iranian cooperation in reopening and securing the Strait of Hormuz, a critical route through which roughly one-fifth of the world’s oil supply passes.

That requirement became more complicated on Saturday after Iranian military officials announced that they were once again closing the strait following renewed tensions linked to Israeli military operations in Lebanon.

The development underscores how closely energy markets and diplomatic efforts have become intertwined.

In addition to discussions about frozen assets, the United States has agreed to permit Iran to resume certain oil exports under a sanctions waiver issued after the interim agreement was signed.

For Iran, the restoration of oil sales may be as important as gaining access to frozen funds.

Years of sanctions have severely restricted one of the country’s primary sources of revenue, and renewed exports could provide a significant boost to government finances and economic activity.

Western diplomats involved in the negotiations argue that the arrangement offers benefits to both sides.

Iran gains access to humanitarian goods and economic relief, while much of the released money is expected to be spent on internationally approved purchases, including agricultural products and medical supplies from Western suppliers.

The negotiations also carry major implications for nuclear security.

Washington is seeking renewed access for international inspectors to Iran’s key nuclear facilities, including Fordow, Natanz, and Isfahan.

Those facilities became focal points during the conflict and have remained largely inaccessible to outside inspectors in recent months.

The International Atomic Energy Agency (IAEA) is expected to oversee a renewed monitoring framework that could include inspections, verification measures, and the dilution of portions of Iran’s enriched uranium stockpile.

The diplomatic lineup reflects the importance both sides attach to the talks.

Special envoy Steve Witkoff and presidential adviser Jared Kushner were already in Switzerland before Vance arrived.

Iran’s delegation is being led by Foreign Minister Abbas Araghchi and Parliament Speaker Mohammad-Bagher Ghalibaf.

IAEA Director General Rafael Grossi is also participating in discussions involving the technical aspects of nuclear oversight and verification.

The talks are being mediated by Qatar and Pakistan, both of which played significant roles in bringing the parties together.

Qatari Prime Minister Sheikh Mohammed Al Thani arrived Friday, while Pakistani Prime Minister Shehbaz Sharif traveled to Switzerland alongside Pakistan’s military chief, Field Marshal Asim Munir.

The negotiations are built around the framework established in the Islamabad Memorandum of Understanding, signed Wednesday by President Trump and Iranian President Masoud Pezeshkian.

The economic stakes extend far beyond the negotiating table.

The Strait of Hormuz remains one of the world’s most important energy chokepoints. Any disruption to shipping through the waterway can rapidly affect global crude oil prices, fuel costs, transportation expenses, and inflation.

A durable agreement that keeps the strait open and allows Iranian oil exports to continue could help stabilize energy markets and reduce upward pressure on fuel prices worldwide.

A collapse in negotiations, by contrast, could quickly revive fears of supply disruptions and renewed price spikes.

Vance sought to keep expectations in check before the talks began, emphasizing that the initial sessions are primarily intended to establish negotiating structures and working groups before more technical discussions take place.

He is expected to remain in Switzerland for only a day or two before expert teams continue the process.

With billions of dollars in frozen assets at stake, oil exports hanging in the balance, and the future of a key global shipping route under discussion, both sides have significant financial incentives to keep the negotiations moving forward.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Investors push borrowing costs higher and closely watch the pound as speculation grows over Britain’s political future and Labour’s next leader.

On Friday, June 19, British politics cracked open. Andy Burnham, the mayor of Greater Manchester, won a seat in Parliament in the Makerfield by-election, defeating Reform UK by more than 9,000 votes with nearly 55% of the vote. In his victory speech, Burnham said the Labour Party has “a final chance to change” — comments widely interpreted as the opening move in a bid to replace UK Prime Minister Keir Starmer.

Within a day, the pressure intensified. Britain’s Observer newspaper reported Saturday that Starmer was considering his future while spending the weekend at Chequers, the prime minister’s official country residence, and could announce a timetable for his departure as early as Monday.

A government source told Reuters that Starmer remains focused on governing and pointed to his previous pledge to remain in office. No formal announcement has been made.

For investors, however, the story is not primarily about one politician’s future. It is about how a potential leadership transition could affect Britain’s finances, borrowing costs, currency markets, and economic outlook.

Markets offered an early reaction on Friday.

The yield on the benchmark 10-year U.K. gilt climbed more than 8 basis points to 4.84%, reflecting selling pressure in government bonds. When bond prices fall, yields rise, increasing borrowing costs across the economy.

The British pound briefly fell as much as 0.5% against the U.S. dollar following Burnham’s victory before recovering some ground to trade near $1.32.

Meanwhile, the FTSE 100 opened modestly lower near 10,393, reflecting investor caution as political uncertainty increased.

The concern among many investors centers on Burnham’s political and economic views.

Burnham is generally viewed as being on the left wing of the Labour Party and has previously criticized the influence of financial markets over government decision-making. Some investors worry that a Burnham-led government could pursue higher spending and increased borrowing at a time when Britain already faces some of the highest government borrowing costs in the G7.

The fiscal backdrop leaves little room for error.

Matthew Ryan, head of market strategy at Ebury, said Britain’s public finances offer very little fiscal flexibility. With economic growth remaining weak and government debt continuing to rise, markets have become increasingly sensitive to any indication of looser spending policies.

Higher government borrowing costs do not stay confined to financial markets.

They influence mortgage rates, business lending costs, consumer borrowing, and ultimately the government’s own budget. As debt-service expenses rise, governments have fewer resources available for other priorities.

The next major test will come with the government’s Autumn Budget, when investors will be looking for clear evidence that whoever leads the country can maintain fiscal discipline.

Until then, traders are likely to demand additional compensation to hold British government debt. Some market participants have already begun referring to the increase as a political-risk premium attached to U.K. assets.

For ordinary Britons, the effects could be direct.

A weaker pound raises the cost of imported goods, food, fuel, and industrial materials. Higher import costs can contribute to inflation, making it more difficult for the Bank of England to lower interest rates.

If inflation remains elevated, borrowing costs could stay higher for longer, increasing pressure on homeowners, businesses, and consumers.

Political instability in Westminster can therefore translate into real costs for households across the country.

Starmer entered office in July 2024 after leading Labour to a landslide election victory that ended 14 years of Conservative rule.

The honeymoon period proved short-lived.

Weak economic growth, persistent cost-of-living concerns, internal party divisions, and a series of political controversies steadily eroded support. Labour also suffered a string of disappointing local election results, increasing pressure on the prime minister from within his own ranks.

More than 100 Labour lawmakers, roughly a quarter of the party’s parliamentary caucus, have publicly called for Starmer to resign or establish a clear timetable for his departure.

The pressure intensified further after Health Secretary Wes Streeting resigned in May.

Burnham’s parliamentary victory now gives him the platform necessary to mount a formal leadership challenge.

Under Labour Party rules, a challenger must secure the support of 81 Members of Parliament, equivalent to one-fifth of Labour’s MPs in the House of Commons.

Political analysts believe Burnham could begin seeking those endorsements as soon as next week after formally taking his seat in Parliament.

An orderly leadership transition could reassure investors by reducing uncertainty and clarifying the government’s economic direction.

A prolonged battle between Starmer and Burnham, however, could leave markets guessing for weeks or months.

For many investors, the bigger question may ultimately be who controls economic policy rather than who occupies 10 Downing Street.

Attention is increasingly turning toward who could serve as chancellor at 11 Downing Street, the office responsible for setting tax, spending, and borrowing policy.

For now, markets are focused on Monday and whether UK Prime Minister Keir Starmer announces a departure timetable or decides to fight on.

Either way, investors, businesses, and households across Britain are bracing for the answer.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Move threatens oil supplies, shipping traffic, and gasoline prices just days after a U.S.-Iran interim agreement appeared to calm global energy markets.

On Saturday, Iran’s top joint military command declared the Strait of Hormuz closed to commercial shipping, blaming continued Israeli strikes in Lebanon and what it called American bad faith. The Islamic Revolutionary Guard Corps Navy warned vessels to stay away from the waterway, saying their safety could not be guaranteed if they attempted to cross. Iranian state television added that “subsequent steps have been planned” if the strikes continue.

The announcement immediately raised concerns across global energy markets, where traders had been hoping the worst disruptions of the four-month conflict were finally coming to an end.

The trigger was overnight violence in Lebanon. Israeli strikes in southern Lebanon killed at least 16 people, including two children, according to Lebanese authorities. Iran condemned the operation as a violation of the ceasefire framework that underpins the broader peace process.

The United States quickly disputed Tehran’s claim that it had effectively shut the waterway. Capt. Tim Hawkins, a spokesman for U.S. Central Command, said “Iran does not control the Strait of Hormuz” and that maritime traffic was continuing to move through the channel.

According to CENTCOM, 55 merchant ships transited the strait on Saturday carrying more than 17 million barrels of oil, suggesting that commercial traffic had not stopped despite Tehran’s declaration.

The competing narratives emerged just as Vice President JD Vance departed Washington for Switzerland to participate in a new round of negotiations aimed at stabilizing the region.

Speaking before leaving Joint Base Andrews, Vance said he expected several days of discussions at Bürgenstock, focused on Iran’s nuclear program and the increasingly fragile ceasefire arrangements affecting Lebanon and the broader region.

The talks are intended to build on the interim agreement signed Wednesday by President Donald Trump and Iranian President Masoud Pezeshkian. That agreement ended nearly four months of conflict that began on Feb. 28, established a 60-day negotiating window for a comprehensive settlement, and included provisions calling for the reopening of the Strait of Hormuz without tolls or restrictions.

Late Saturday, Trump weighed in on the growing dispute through Truth Social, reiterating that there would be no tolls imposed on ships passing through the strait during the 60-day negotiating period.

The president added that no tolls would be imposed afterward either unless the United States determined such charges were necessary should the parties fail to reach a final agreement. Trump described any future fees as compensation for American security efforts protecting regional shipping lanes.

The renewed confrontation carries implications far beyond the Middle East.

The Strait of Hormuz remains the world’s most important oil chokepoint. Between 13 million and 20 million barrels of oil per day typically move through the narrow passage connecting the Persian Gulf to global markets. Roughly one-fifth of the world’s seaborne oil trade depends on uninterrupted access to the route.

There is currently no alternative transportation network capable of replacing that volume.

When Iran previously closed the strait during the conflict, the impact was immediate. Brent crude oil surged above $120 per barrel, gasoline prices rose sharply across the United States, and some California drivers paid more than $6 per gallon.

The International Energy Agency described the disruption as the largest oil supply shock in modern market history.

Energy markets had begun recovering in recent days. Following the interim agreement and signs that shipping traffic was returning to normal, Brent crude settled Friday at $80.57 per barrel, well below wartime highs.

Tanker traffic had also started to rebound. Officials noted that a recent single-day export total exceeded 16 million barrels, one of the strongest shipping days since the conflict began.

Saturday’s announcement now threatens to reverse that progress.

Because commodity markets are closed during the weekend, traders will not be able to react until Monday. Analysts will be watching closely to see whether energy markets view Tehran’s declaration as symbolic political pressure or as a credible threat to global shipping.

If investors conclude that supplies are once again at risk, the war-risk premium that recently disappeared from crude prices could return quickly.

Iran also announced new requirements for commercial shipping. Tehran said vessels crossing the strait would need insurance approved by its newly created Persian Gulf authority.

Even if shipping technically remains open, additional insurance requirements could increase costs, slow transit times, and create new uncertainty for global logistics providers.

For American consumers, the consequences could be felt rapidly.

Higher crude oil prices typically translate into increased costs for gasoline, diesel fuel, aviation fuel, shipping, and freight transportation. During the earlier phase of the conflict, airlines imposed new fees, shipping companies added fuel surcharges, and transportation costs rose throughout supply chains.

A prolonged disruption would likely place renewed upward pressure on those expenses.

Despite the escalating rhetoric, diplomatic efforts continue.

Special envoy Steve Witkoff and Jared Kushner were already in Switzerland on Saturday working through technical details ahead of the formal negotiations. Technical-level discussions are scheduled to begin Sunday at Bürgenstock, with Pakistan and Qatar serving as mediators.

Iran’s delegation includes Parliament Speaker Mohammad-Bagher Ghalibaf, one of the country’s most influential political figures.

Iranian Foreign Ministry spokesman Esmail Baghaei said the delegation would use the talks to demand that other parties fulfill their obligations before Tehran agrees to any final settlement.

Whether the Strait of Hormuz remains open through the weekend may ultimately shape the atmosphere surrounding those negotiations and determine how global markets respond when trading resumes Monday.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Trump signed a preliminary peace deal with Iran this week to wind down the war that began on February 28, and it has opened a rare split inside his own party — much of it over money. On Thursday, Senate Armed Services Committee Chairman Roger Wicker of Mississippi, who seldom criticizes the president in public, said he was concerned the agreement “negotiates away the victories… in ways that are completely out of step with the President’s goals.”

Wicker and other hawkish Republicans argue the deal hands Tehran a financial lifeline while doing too little to shut down its nuclear program. Their objections center on three economic pieces: lifting U.S. sanctions, unfreezing Iranian funds, and a proposed $300 billion fund to rebuild Iran’s economy. Wicker said that fund — which the administration says will not come from American taxpayers — would dwarf the relief Iran received under former President Barack Obama’s 2015 nuclear agreement.

Here is why a foreign-policy fight is also a business story.

The agreement is structured as a memorandum of understanding signed by President Trump and Iranian President Masoud Pezeshkian. It halts the fighting and reopens the Strait of Hormuz, the narrow waterway that carries roughly 20% of the world’s oil and gas trade. Negotiators now have 60 days to convert the truce into a final agreement.

During that period, Iran keeps the Strait open and receives sanctions waivers allowing it to resume oil exports. In return, Iran reiterates that it will not pursue a nuclear weapon. Critics argue that is not enough because the agreement does not require Iran to immediately stop uranium enrichment or surrender existing nuclear material stockpiles.

The clearest impact for consumers runs through energy prices.

When Iran largely shut down traffic through the Strait earlier this year, oil prices surged and gasoline prices climbed above $4 per gallon in parts of the United States. As negotiations advanced this week, markets moved in the opposite direction.

West Texas Intermediate crude fell about 4.8%, settling near $80.75 per barrel, while Brent crude dropped roughly 4.7% to around $83 per barrel. Even after the decline, crude prices remain approximately 40% higher than they were in January, highlighting how much of the war premium remains embedded in global energy markets.

President Trump has pointed to those price declines as evidence the agreement is already delivering results. In public statements and social-media posts, he cited lower oil prices and a strong stock market as proof that diplomacy is producing economic benefits.

If Iranian oil fully returns to global markets, additional supply could place further downward pressure on fuel prices. That would benefit consumers, airlines, trucking companies and manufacturers that rely heavily on transportation costs. It could also create challenges for U.S. energy producers, whose profits generally rise when oil prices remain elevated.

Markets, however, remain cautious.

Reopening the Strait legally does not mean commercial shipping immediately returns to normal. Hundreds of vessels were delayed or rerouted during the conflict. Shipping companies, insurers and crews must regain confidence that the route is safe before traffic fully resumes. Any new disruption could quickly reverse recent declines in oil prices.

The proposed $300 billion reconstruction fund remains one of the most controversial pieces of the agreement.

Administration officials say the money would come primarily from Gulf states and other international partners rather than from U.S. taxpayers. The funds would be directed toward rebuilding power plants, transportation networks, industrial facilities and other infrastructure damaged during the conflict.

Supporters argue that economic stability reduces the risk of future conflict and encourages moderation. Critics see the proposal differently.

Wicker has warned that providing such a large pool of capital before obtaining stronger nuclear concessions rewards Tehran prematurely. Other Republican critics have raised similar concerns, arguing that financial incentives should come only after measurable nuclear dismantlement steps have been completed.

The White House has responded aggressively to those attacks.

Vice President JD Vance, who led negotiations on behalf of the administration, insisted that the United States “isn’t giving up a cent of money to Iran” and said any economic benefits are contingent upon Iranian compliance. He described the arrangement as an extension of Trump’s pressure strategy rather than a retreat from it.

Republicans remain divided.

Sen. Lindsey Graham expressed concerns about parts of the agreement but argued that pursuing peace remains preferable to an indefinite conflict. Sen. Bill Cassidy, meanwhile, called the framework one of the most serious foreign-policy mistakes in recent decades.

The debate carries major political implications heading into the November midterm elections.

Republican candidates now face a difficult balancing act. Many voters felt the economic impact of the war through higher gasoline, shipping and consumer prices. Those same voters are now seeing some relief as markets respond positively to the ceasefire.

Whether that relief lasts may determine how the deal is ultimately judged.

Congress is also weighing whether the agreement must undergo formal review under legislation passed after the 2015 Iran nuclear accord. Any congressional challenge could create additional uncertainty during the 60-day negotiation period.

For now, the fighting has paused, oil prices have eased, and the battle has shifted from military conflict to a fight over the terms — and the economics — of peace.

JBizNews Desk | Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Defense Secretary Pete Hegseth announced on Thursday a six-month Pentagon review of American forces in Europe and warned that future U.S. payments to NATO will shrink if allies fail to spend more on their own militaries, telling defense ministers at alliance headquarters in Brussels that “the era of free-riding is over.”

Hegseth called it the “NATO 3.0 review” and said it would examine where American troops, jets, ships and weapons are based across the continent. “I’m announcing today, a six-month Department of War review that will examine America’s force posture and basing in Europe — up to six months, could be less,” he said, framing it as a way to push the alliance “fast and irreversibly toward Europe leading.”

The money threat was the sharpest part of his message. Hegseth said Washington’s annual dues — the roughly $790 million the U.S. pays in 2026 toward NATO’s common running costs — would now be tied to whether allies hit their spending goals. “Annual NATO dues will be contingent on other countries meeting their defense spending targets,” he said. “Where other allies do not spend with urgency, our dues contributions will go down.” He warned the force review is one “that some countries will fail, and others will pass with flying colours.”

The review does not pull out any troops by itself. But roughly 80,000 U.S. service members are currently based in Europe, and the study lands on top of cuts already underway. The Pentagon said last month it would withdraw about 5,000 troops from Germany over the next year, and on June 3 told allies it would no longer commit an aircraft carrier, support ships, refueling planes and dozens of fighter jets to a European crisis. NATO Secretary-General Mark Rutte said European members are already moving to “fill” the gear the U.S. is pulling back.

Much of Hegseth’s anger traced to the recent Iran war, code-named Operation Epic Fury. He called it “shameful” that some allies refused to let U.S. forces use their bases and airspace to strike Iranian targets. He named no countries, but Spain has drawn heavy U.S. criticism for denying access, raising questions about the future of Rota, a key Navy base there. By contrast, Poland — which Hegseth has praised — could actually gain troops, after President Donald Trump said he would send 5,000 American forces back to the country.

Why this matters for business

Behind the political fight is one of the largest spending shifts Europe has seen in decades, and it is reshaping a whole industry.

European governments are rearming at a pace not seen since the Cold War. EU member states spent roughly €360 billion on defense in 2025, up from about €240 billion in 2022. Germany has activated a €100 billion special fund and approved a separate €500 billion multi-year package for defense, infrastructure and industry. Poland now spends more than 4.5% of its economic output on its military. NATO members agreed last year to push defense-related spending toward 5% of GDP by 2035, a target leaders will revisit at a summit in Turkey.

That money flows to a short list of arms makers. Germany’s Rheinmetall, the continent’s largest weapons and ammunition maker, reported 2025 sales of €9.9 billion, up 29%, with an order backlog of €64 billion. Britain’s BAE Systems, France’s Thales and Dassault Aviation, Italy’s Leonardo, Sweden’s Saab and engine maker Rolls-Royce all hold order books stretching past 2032. Hegseth’s demand that Europe “take the lead” steers more of that work toward these firms.

But the trade is no longer a sure thing. The Stoxx Europe Aerospace & Defence index is down about 1.2% this year after a blockbuster 2025, as buyers turn choosier. Rheinmetall shares have pulled back sharply on worries the company cannot build orders fast enough — its supply of skilled workers, explosives and high-grade steel is stretched. Analysts now describe 2026 as a year of “consolidation,” when actual deliveries, not promises, decide the winners.

There is also a catch hidden in Hegseth’s words. The administration wants allies to buy European-made gear instead of American — but also wants Europe to stop shielding its own companies against U.S. rivals like Lockheed Martin in outside markets. That tension could redirect billions in future contracts.

The pressure is already rippling through allied governments. In Britain, Defence Secretary Dan Jarvis arrived in Brussels without a finished investment plan; his predecessor, John Healey, resigned a week ago in a dispute over funding, after officials said the armed forces needed £28 billion over four years rather than the £13.5 billion on offer.

For U.S. taxpayers and contractors, Hegseth held up a different figure: the $1.5 trillion defense budget Trump is seeking for the fiscal year beginning October 1, which he called an “arsenal of freedom.” In dollar terms the U.S. still dwarfs its partners — NATO data show it spent an estimated $845 billion on defense last year, against $559 billion for the rest of the alliance combined.

The review begins as soon as Hegseth returns to Washington, with input from Congress and U.S. European Command. Its real test comes this summer, when Europe’s big defense makers report half-year results and the market learns whether record order books are turning into real deliveries — and profits.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A strange thing is happening in the power business: the companies racing to build artificial intelligence are quietly becoming some of the biggest customers for nuclear energy, and the money is reshaping a corner of the market left for dead a decade ago. The clearest recent sign came this month, when GE Vernova detailed a plan to pair nuclear and natural gas at a single site to feed a data center campus. In a project with Blue Energy, the company plans to combine its gas turbines with the BWRX-300 — the only small modular reactor under construction in the Western world today — to deliver about 2.5 gigawatts to a nearby data center campus, with gas power possible by 2030 and nuclear by 2032, according to GE Vernova power chief Eric Gray.

The reason is simple math. U.S. power usage is expected to climb at least 30% by 2030, with most of the new demand coming from data centers, according to energy consulting firm Grid Strategies. Those centers need power 24 hours a day, an “always-on” supply that wind and solar cannot provide without prohibitively expensive battery storage — which is exactly what nuclear delivers.

That has lit a fire under the whole sector. Nuclear ETFs have posted triple-digit returns, uranium prices are holding near $86 a pound driven by AI data center demand, and the U.S. government is working to cut regulatory hurdles to get new reactors online faster. Over the past year, the URNM uranium fund has climbed roughly 89%, the broader NUKZ nuclear fund about 73%, and the URAN fund around 65%.

The tech giants are the demand engine. Amazon, Alphabet, and Microsoft have all signed deals to tap power from nuclear reactors, and Meta has gone furthest of all. In January, Meta struck deals with Oklo, Vistra, and TerraPower to supply up to 6.6 gigawatts of nuclear power by 2035, on top of a 20-year agreement with Constellation Energy to take output from the Clinton Clean Energy Center in Illinois beginning in 2027, a deal expected to preserve 1,100 local jobs and generate $13.5 million in annual tax revenue.

The investment thesis splits into a few clear lanes. There are utilities like Constellation Energy negotiating long-term power contracts with hyperscalers, advanced- and small-modular-reactor developers like Oklo and NuScale chasing first commercial deployments, uranium miners, and engineering firms positioned to capture reactor restarts and new construction. Cameco draws attention for its integrated uranium and reactor-services business, and its part-owned Westinghouse is tied to an $80 billion U.S. government agreement to build new reactors.

Small modular reactors are the part of the story drawing the most excitement. Unlike traditional plants that power entire cities, SMRs are compact enough to power individual buildings like factories and data centers. NuScale is the furthest along of any U.S. SMR developer and holds the only design certified by the Nuclear Regulatory Commission, with its shares jumping 7% after upbeat deployment progress in May 2026.

There is a real supply squeeze underneath the hype. The uranium market is entering a structural deficit after a decade of underinvestment in mining, and Western nations moving away from Russian enriched uranium are scrambling to rebuild domestic supply chains. That combination — surging demand, tight supply, and government backing — is what has turned a long-dormant industry into one of the hottest themes on the market.

The everyday angle is the part that should not get lost. Data center load growth has broken the grid-planning assumptions of the past decade, and utilities are now racing to add round-the-clock power. How that demand gets met — and how much new generation costs — will help determine electricity bills for ordinary households and the reliability of the grid everyone depends on.

None of this is guaranteed. Reactors take years to permit and build, costs can balloon, and timelines slip. Whether the projects now on the drawing board reach full operation on schedule remains to be seen. But the direction is hard to miss: the AI economy is turning into an energy-intensive industrial system, and nuclear power — fuel, reactors, and the companies that build them — has become one of the clearest ways that demand is showing up in the market.

JBizNews Desk | Energy Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Just days after President Trump signed a deal promising that the Strait of Hormuz would stay open and free, Iran has moved to take control of it — telling the world’s shipping companies they now need Tehran’s permission, and a government-approved insurance policy, to sail through the most important oil passage on earth. The order came in a document posted this week by Iran’s newly created Persian Gulf Strait Authority, which began processing vessel applications on June 18, the day the ceasefire took effect.

For now, the insurance is free; Iran says it is covering the cost. But the same document leaves the door open to charging later, stating that the authority “reserves the right to introduce insurance fees in the future” — wording that has alarmed shippers and oil producers who see it as the first step toward tolls on a waterway that has always been free to cross.

The rules go further. Iran says ships must obtain a navigation permit, follow a single approved route hugging its coastline near Larak Island, and avoid any alternative path. Straying from the route, the authority warned, would be treated as a violation that could trigger penalties or revoked passage.

Why does a strip of water matter this much?

The Strait of Hormuz is barely 21 miles wide at its narrowest point, squeezed between Iran and Oman, yet roughly 20% of the world’s oil supply moves through it, along with massive volumes of natural gas and other commodities. Anything that raises the cost or risk of crossing it ripples outward into oil prices, shipping rates and, eventually, the prices consumers pay for fuel and goods.

Here is the problem for the White House: the move cuts directly against what Trump promised.

Throughout the conflict, Trump insisted that free passage through the Strait of Hormuz had to be part of any peace arrangement. The agreement he signed — known as the Islamabad Memorandum of Understanding — guarantees ships can cross without charges during its initial term. Yet within days, Iran is asserting authority over the waterway, requiring permits and insurance while reserving the right to impose fees after the agreement’s 60-day transition period expires.

In effect, critics argue, Tehran is building the framework for toll collection while the ink on the free-passage agreement is barely dry.

That has handed the president’s opponents new ammunition.

Republican critics including Sen. Roger Wicker of Mississippi and Sen. Bill Cassidy of Louisiana had already attacked the broader agreement as giving away too much leverage. Iran’s rapid effort to regulate passage through the strait strengthens arguments that Tehran may not view itself as constrained by the spirit of the deal.

For a president who presented the agreement as a demonstration of strength and stability, the optics are challenging. Critics say Iran’s actions create the appearance that it is attempting to rewrite terms almost immediately after the ceasefire.

The administration rejects that characterization.

Vice President JD Vance, who led negotiations for the United States, has repeatedly defended the agreement and said any benefits flowing to Iran remain contingent on compliance. Administration officials argue that the ceasefire has already reduced tensions, reopened shipping lanes and helped push oil prices lower.

On the water, the situation remains mixed.

Even as Iran announced its new requirements, U.S. officials reported that commercial vessels continued moving through alternative corridors near Oman’s coastline. Western naval forces have recommended those routes while mine-clearing operations continue in portions of the strait affected during the conflict.

A broader legal dispute is also taking shape.

The Persian Gulf Strait Authority was established by Tehran during the war and has since been sanctioned by the United States. Several Gulf nations have rejected its legitimacy and advised shipping companies not to recognize its authority.

Maritime experts note that international straits have historically been governed by principles of free navigation. Many governments argue that no country has the legal right to unilaterally impose tolls on a waterway that serves as a vital international trade corridor.

The United Arab Emirates has declared that the strait “cannot be held hostage by any country,” while Qatar has emphasized that international shipping routes must remain open to all nations.

Meanwhile, several U.S. allies, including Britain, are reportedly urging the administration to oppose any future transit-fee system.

The shipping industry itself is divided.

Many large shipping companies and energy producers oppose the concept outright, warning that fees would increase costs throughout the global economy. Others are taking a more practical view. Greek shipping billionaire Evangelos Marinakis recently suggested that some operators might be willing to pay modest fees if doing so guaranteed uninterrupted access and prevented future disruptions.

For American consumers, the implications are straightforward.

Gasoline prices have eased since the ceasefire reduced fears of prolonged disruption in the Strait of Hormuz. Additional permit requirements, insurance mandates or future transit charges could increase transportation costs and potentially reverse some of that relief.

Every additional cost imposed on tankers ultimately flows through supply chains, affecting fuel prices, shipping expenses and the cost of goods delivered around the world.

The next 60 days could determine whether the Strait of Hormuz returns to normal operations or becomes the center of a new economic confrontation.

If Iran attempts to impose fees once the transition period expires — and if shipping companies, Gulf governments and Western nations refuse to accept them — the result could be a fresh standoff over control of the world’s most important oil chokepoint.

This time, the battle may not be fought with missiles and warships, but with permits, insurance certificates and the economics of global trade.

JBizNews Desk | Gulf Region

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A federal court has temporarily shut down one of the largest subscription-app operations the government has targeted to date, freezing the assets of a network the Federal Trade Commission says quietly billed consumers worldwide for charges they never agreed to. In a complaint filed on Wednesday, June 17, 2026, in the U.S. District Court for the Northern District of California, the FTC moved against an enterprise operating as Genesis Tech, and the court granted the agency’s request to halt the operation and freeze its assets. The Commission authorized the case on a 2-0 vote.

The action names 15 corporations and eight individuals, including the company’s founder-CEOs, Vladimir Mnogoletny and Vasily Ulianov. At the center of the FTC’s argument is a simple idea: that these seemingly separate apps and websites were in fact a single “common enterprise” running the same deceptive script repeatedly.

That script, according to the complaint, was easy to start and hard to stop. The company advertised products as free or available for a low, one-time cost, often with a money-back guarantee, but once consumers signed up, references to auto-renewing subscriptions were relegated to the smallest print on the page. Customers were then charged on a recurring basis and, the FTC alleges, sometimes double-billed or charged for products they never requested.

The portfolio was broad enough that few buyers would have connected the dots. It included the fitness and nutrition apps MadMuscles, Harna, and Unimeal; an ADHD and productivity self-help course called Wisey; the document tools PDF Guru and PDF Master; the fashion-advice app Lumi; and the horoscope and psychic-chat service Nebula. The FTC says one program claimed it could diagnose and treat ADHD symptoms. Whatever the category, the agency says the underlying tactics were identical.

The money involved was substantial. From early 2023 through mid-2025, the enterprise’s five main product lines alone generated nearly a quarter-billion dollars in global revenue, and over the 12 months ending in September 2025, transactions across its linked PayPal accounts totaled nearly $700 million. The company’s apps have been downloaded more than 400 million times worldwide.

To keep that revenue flowing, the FTC alleges, the defendants made leaving as difficult as joining. The complaint says the company omitted cancellation options from its apps and websites and would often continue charging customers without authorization. When users tried to quit, the platforms allegedly forced them through extra steps or kept drafting payments even after a cancellation was confirmed.

The structure behind it was built to stay ahead of fraud detection. The FTC says the operation continually launched new products, registered new legal entities, and opened new merchant accounts to evade fraud-monitoring programs, producing an ever-shifting web of Cyprus and Delaware shell companies. The Cypriot companies targeted U.S. consumers, the agency says, while affiliated entities registered in Delaware provided access to U.S. payment processing that moved the money overseas.

The case also lands on Apple and Google. It highlights a growing challenge for the platforms, as subscription scams evolve beyond individual apps into intricate networks of shell companies. For the companies that distribute these apps and process their payments, the action reads less as a verdict than as a diagnosis of a gap in their own enforcement.

FTC officials framed the case as part of a wider crackdown. Christopher Mufarrige, director of the agency’s Bureau of Consumer Protection, called it an illustration of the bureau’s reinvigorated anti-fraud program. The complaint alleges violations of the FTC Act and the Restore Online Shoppers’ Confidence Act (ROSCA), the federal law written to govern online subscriptions and require clear disclosure and easy cancellation. The FTC files such a case only when it has reason to believe the law is being broken; the allegations are unproven, and the case will be decided by the court.

For everyday consumers, the action is a reminder of how much of the modern economy runs on recurring billing — and how easily a “free trial” becomes a charge that repeats every month. The dispute will play out over the coming months, but for now the court has stopped the billing and locked down the money while the case proceeds.

JBizNews Desk | Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Americans hoping for lower mortgage payments, cheaper car loans, or relief from record-high credit-card rates will have to keep waiting. The Federal Reserve left interest rates unchanged Wednesday and signaled that inflation remains its top concern, meaning borrowing costs are likely to stay elevated for the foreseeable future.

The Federal Open Market Committee voted to keep the federal funds rate in a range of 3.5% to 3.75%, marking the fourth consecutive meeting without a change. While many investors entered the year expecting rate cuts, the Fed’s latest projections suggest policymakers are becoming more concerned about inflation than economic slowdown.

For consumers, the decision has direct consequences.

Mortgages Remain Expensive

Mortgage rates do not move in lockstep with the Fed, but they are heavily influenced by expectations for future interest rates. With the central bank showing little appetite for cuts, prospective homebuyers are unlikely to see meaningful relief this year.

Many buyers who delayed purchasing a home in hopes of lower borrowing costs may now face a longer wait. The good news is that rates are not expected to surge dramatically higher in the near term, helping maintain stability in the housing market.

Car Loans Stay Costly

Auto financing remains one of the most expensive forms of consumer borrowing. The Fed’s decision gives banks and lenders little reason to reduce rates on new or used vehicle loans.

Consumers planning vehicle purchases should compare offers carefully, as financing costs can vary significantly between lenders and dealerships.

Credit Cards Feel the Impact Fastest

Credit-card borrowers continue to face some of the highest borrowing costs in decades. Unlike mortgages, credit-card rates tend to move closely with Fed policy.

If the central bank ultimately raises rates later this year, cardholders carrying balances could see their annual percentage rates climb even further. Financial advisors continue to recommend paying down high-interest balances as a top priority.

Savers Continue to Benefit

While borrowers face challenges, savers remain one of the few groups benefiting from elevated interest rates.

High-yield savings accounts, certificates of deposit, and money-market funds continue offering attractive returns. Consumers holding significant cash reserves may want to lock in current yields before rates eventually begin to decline.

Inflation Remains the Fed’s Focus

The central bank’s reluctance to cut rates stems largely from stubborn inflation pressures.

Fed officials now expect their preferred inflation measure to end 2026 at approximately 3.6%, significantly higher than the 2.7% forecast issued in March. Consumer prices rose 4.2% over the 12 months ending in May, driven in part by higher energy costs following disruptions tied to the conflict with Iran.

The Fed’s updated projections show a notable shift in thinking. Earlier this year, many policymakers anticipated rate cuts. Now, forecasts suggest rates could actually move slightly higher before year-end.

Nine of the eighteen policymakers who submitted projections expect at least one additional rate increase during 2026.

Warsh Signals Tough Stance

New Fed Chair Kevin Warsh, presiding over his first policy meeting, emphasized that fighting inflation remains the central bank’s primary mission.

Asked whether the Fed might eventually relax its long-standing 2% inflation target, Warsh rejected the idea.

“The commitment to restoring price stability is strong, unanimous, and unambiguous,” he told reporters.

The Fed’s confidence stems partly from continued labor-market strength. Employers added 172,000 jobs in May while unemployment remained at 4.3%. As long as hiring remains healthy and consumers continue spending, policymakers feel less urgency to lower rates.

What Households Should Do Now

Financial planners say consumers should assume borrowing costs will remain elevated through at least the remainder of 2026.

That means:

  • Prioritize paying down high-interest credit-card balances.
  • Lock in attractive savings rates while they remain available.
  • Shop aggressively for mortgage and auto-loan offers.
  • Build major purchase plans around today’s rates rather than expecting significant declines.

Markets are increasingly preparing for the possibility that the Fed’s next move could be upward rather than downward. According to CME Group futures pricing, investors are assigning meaningful odds to another rate increase before the end of the year.

For now, the message from the Federal Reserve is straightforward: inflation remains the priority, borrowing remains expensive, and relief for consumers is likely to take longer than many had hoped.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Carvana, the company that built its name selling used cars through its signature glass-tower vending machines, is now making a major push into the new-car business — and the strategy could reshape how Americans buy vehicles.

The company showcased its vision this week at a Stellantis dealership in Dallas, where executives demonstrated a retail model that looks very different from the traditional dealership experience.

There are no salespeople roaming the showroom floor and no negotiation desks. Instead, the location functions as a customer experience center where shoppers can explore vehicles, take self-guided test drives, and complete the entire purchase process online.

“Every single car that we sell, whether it’s used or new, is online,” said Tom Taira, the Carvana president overseeing the company’s new-vehicle strategy.

The approach extends the formula that helped transform Carvana into one of America’s largest used-car retailers. The company is betting consumers increasingly prefer transparent pricing, minimal pressure, and digital convenience over the traditional dealership experience.

Carvana has quietly been laying the groundwork for this expansion. Since last year, the company has acquired seven Stellantis franchises representing brands including Jeep, Ram, Chrysler, and Dodge. Those dealerships are located in markets where Carvana already maintains a strong customer base, including Dallas, Atlanta, Boston, Cleveland, Phoenix, Sacramento, and San Diego.

Early results have attracted attention throughout the auto industry.

One Arizona dealership acquired by Carvana reportedly became Stellantis’ highest-volume store in the country after the transition, selling more than 700 new vehicles in a single month compared with roughly 30 to 50 monthly sales before the acquisition.

The move gives Carvana access to opportunities that do not exist in the used-car market alone.

Franchised dealerships can participate in manufacturer-backed programs, exclusive dealer auctions, and new-car financing channels. The business also creates additional trade-in opportunities that can feed Carvana’s used-vehicle inventory operation.

The opportunity is massive. According to the National Automobile Dealers Association, nearly 17,000 franchised dealerships operate across the United States, generating well over $1 trillion in annual sales.

For consumers, Carvana’s appeal remains straightforward.

Buying a vehicle has long ranked among the least popular major consumer experiences. Many buyers dislike lengthy negotiations, financing office pressure, and spending hours inside a dealership. Carvana’s model attempts to eliminate much of that friction by allowing customers to complete most of the process digitally.

The company is also taking a different path than electric-vehicle manufacturers such as Tesla and Rivian, which have spent years challenging state franchise laws.

Rather than fighting the system, Carvana is working within it by purchasing existing dealership franchises and maintaining compliance with state regulations governing new-car sales.

Questions remain about how the model will evolve.

Industry analysts note that vehicle servicing, warranty work, customer retention, and parts operations remain central to dealership profitability. How Carvana integrates those functions into its digital-first strategy could determine whether the model succeeds at scale.

Investors are watching closely as well.

While some analysts see the initiative as one of the most disruptive developments in auto retailing in decades, others are waiting to see whether the approach can be replicated across multiple markets and brands.

The Dallas location is effectively serving as a live test case.

Carvana is wagering that customers still want to see and drive a vehicle in person but increasingly want to complete the transaction online. If that bet proves correct, traditional dealerships across the country may find themselves under growing pressure to modernize their own sales experience.

For now, the company is taking a measured approach. But if the model continues producing strong results, the future of new-car retailing could look very different from the one Americans have known for generations.

JBizNews Desk
Detroit

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Oil prices tumbled this week after the U.S. military and the White House signaled a break in the Iran war, the clearest sign yet that a single geopolitical headline now moves markets more than any economic report. Brent crude, the global benchmark, dropped below $78 a barrel on Thursday, its lowest level since early March, as markets reacted to the United States and Iran reaching an agreement to end the conflict. U.S. Central Command announced it had lifted restrictions on traffic to and from Iranian ports, and President Donald Trump said an interim agreement had been signed to reopen the Strait of Hormuz.

By Friday, Brent traded around $79 per barrel and was on track to fall roughly 10% for the week. Oil has now dropped about 38% from the four-month high it reached in April, erasing nearly all the gains recorded since the conflict began in late February.

The reason is geography. The Strait of Hormuz is narrow, heavily watched, and difficult to replace, normally carrying roughly one-fifth of global petroleum consumption. When the war choked off traffic, prices spiked on fears of a lasting shortage. Now that tankers are beginning to move again — with the Joint Maritime Information Center advising vessels to follow routes closer to Oman’s coastline to reduce mine-related risks — those fears are draining out of the market. Kuwait has said it will begin increasing production, while major producers including Saudi Arabia, the United Arab Emirates, and Iraq are positioned to restore millions of barrels of previously constrained output if the route remains open.

That whipsaw is the real story. For most of the past two years, traders focused primarily on inflation reports and Federal Reserve policy. In 2026, however, the dominant market driver has been the Middle East. When the conflict escalates, oil prices jump, gasoline costs rise, and stocks often retreat. When peace appears closer, oil falls and equities rally. The same event that lowers the cost of filling a gas tank can boost the stock market in a single trading session.

Gold has been moving to a different rhythm. The precious metal remains the traditional safe-haven asset, attracting investors during periods of uncertainty. Yet gold retreated sharply in mid-June, falling to around $4,100 per ounce, pressured by a stronger U.S. dollar and elevated Treasury yields that made the non-yielding asset less attractive. Even so, longer-term demand remains robust. The World Gold Council reported first-quarter gold demand reached a record $193 billion in dollar terms, while central banks purchased approximately 244 metric tons of the metal. That level of institutional buying does not disappear simply because one shipping lane reopens.

The divergence between oil and gold offers a useful window into investor thinking. Oil responds primarily to the physical question: are energy supplies moving freely? Gold responds to the broader question: is the world becoming more dangerous and uncertain? At the moment, crude oil has been the cleaner gauge of developments involving Iran and the Strait of Hormuz, reacting sharply to each diplomatic breakthrough or setback. Gold, meanwhile, reflects a deeper and more structural concern about geopolitical instability that extends beyond any single conflict.

None of this is settled. Even as optimism surrounding Hormuz pushed oil lower, a flare-up between Israel and Hezbollah in Lebanon killed at least 18 people and forced the postponement of the next round of U.S.-Iran negotiations scheduled for Switzerland before a renewed ceasefire was reached. That sequence — progress, escalation, then renewed calm — illustrates why a geopolitical risk premium remains embedded in markets. Traders have learned that apparent stability can disappear in a matter of hours.

The implications reach far beyond Wall Street. Lower oil prices eventually flow through to gasoline stations, shipping costs, airline fuel expenses, and the price of countless consumer goods. Energy has been one of the largest contributors to inflation this year, meaning sustained declines in crude prices could ease pressure on households and businesses alike. A calmer energy market could also provide the Federal Reserve, under Chair Kevin Warsh, with greater flexibility as it weighs future interest-rate decisions.

But the opposite remains true as well. If the conflict reignites and tanker traffic through Hormuz is disrupted again, energy prices could rise rapidly, pushing inflation higher and complicating the Fed’s efforts to stabilize prices. Businesses that depend on predictable transportation costs and consumers already facing elevated living expenses would feel the impact almost immediately.

For now, the lesson from this week is straightforward. The biggest force moving oil, gold, and stocks is no longer a jobs report, an inflation reading, or even a central-bank meeting. It is the next headline out of the Middle East. Until the conflict is conclusively resolved and shipping through the Strait of Hormuz is secure, markets are likely to remain highly sensitive to every diplomatic breakthrough, military escalation, and ceasefire announcement that emerges from the region.

JBizNews Desk | Global Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Associated Press reported on Friday, June 19, 2026, that international shipping routes and commercial commodity desks are experiencing significant transactional swings following the signing of a historic diplomatic treaty between the United States and Iran. The bilateral agreement, which formally ends the recent military conflict between the two nations, contains strict legal mandates to immediately reopen the critical Strait of Hormuz to commercial oil tanker traffic.

According to live tracking data from international maritime hubs, global energy prices reacted sharply to the sudden easing of Middle Eastern shipping bottlenecks. On electronic exchanges early Friday, Brent crude, the international benchmark, slid 0.4% to trade at $79.50 per barrel, while the domestic benchmark, West Texas Intermediate, held completely flat at $75.85 per barrel. Commercial analysts noted that while current energy prices remain well above the $70 baseline recorded prior to the outbreak of regional hostilities, they have collapsed dramatically from the $100-plus peaks that crippled corporate logistics networks just a few weeks ago.

The immediate drop in global crude costs offers critical breathing room for commercial transport firms and retail logistics networks that have struggled under ballooning fuel surcharges. In the domestic retail sector, the average price of consumer gasoline has successfully dipped back below the $4 per gallon threshold, though corporate shipping costs remain elevated. The sudden resumption of maritime transit through the Persian Gulf is expected to gradually relieve supply-chain pressures for a wide array of consumer goods, which had seen wholesale costs climb over the past month due to forced oceanic rerouting.

However, the initial marketplace optimism surrounding the peace accord was partially checked by a sudden postponement of high-stakes diplomatic talks. International trade representatives confirmed that scheduled negotiations regarding the long-term status of Iran’s nuclear material programs and formalized energy quotas were abruptly pushed back. The unexpected diplomatic delay triggered immediate caution across global financial centers, reminding corporate operators that long-term regional stability remains highly vulnerable to political friction.

The geopolitical developments triggered a mixed performance across major international equity boards during thin regional trading sessions. In Asia, Tokyo’s Nikkei 225 index wavered throughout the day before closing 0.3% higher to hit a record-breaking lifetime high of 71,250.06 points, even as local data showed core Japanese consumer inflation holding steady. Conversely, South Korea’s Kospi index slipped 0.1% to finish at 9,052.42 points, pulling back slightly from an all-time record set during the previous session.

European equity indices showed similar fragmentation as commercial participants parsed the shifting energy landscape alongside regional corporate updates. In afternoon trading, Germany’s DAX index advanced 0.2% to reach 25,079.30 points, while France’s CAC 40 remained virtually unchanged at 8,467.75 points. In London, the FTSE 100 shed 0.2% to land at 10,376.64 points, weighed down by localized profit-taking among major multinational energy producers and mining conglomerates.

The global trading day faced significantly lower overall volume due to a complete closure of the American financial infrastructure. The New York Stock Exchange and Nasdaq suspended all regular stock trading on Friday in observance of the Juneteenth federal holiday, while top domestic banking institutions—including Bank of America, JPMorgan Chase, and Wells Fargo—fully halted retail operations and electronic payment processing. Regular corporate delivery logistics and domestic shipping operations are scheduled to resume normal schedules on Saturday, June 20.

For businesses, the reopening of the Strait of Hormuz offers the first meaningful relief to global shipping networks since the conflict began. Yet the delayed diplomatic talks underscore that while tanker traffic may be moving again, the political and economic uncertainty surrounding one of the world’s most important energy corridors is far from over.

JBizNews Desk | Global Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Defense contractors are heading into the second half of 2026 with the strongest order books in years, propped up by a Middle East war and a Washington spending plan that keeps getting bigger. The fiscal 2027 Department of War budget request earmarks roughly $60 billion for munitions development and procurement, including about $52.9 billion for critical munitions — a sign of how the government is rewiring the way it buys and replenishes weapons.

The political backdrop is even larger. President Donald Trump has proposed a $1.5 trillion defense budget for 2027, a substantial jump from the $901 billion approved for fiscal 2026. Spending bills of that size set the demand picture for the entire industry years in advance because most defense work is locked in through multi-year government contracts.

The urgency comes from the wider world. The war between the United States and Iran, ongoing since late February, along with tensions in Eastern Europe, has made military spending — in the words of Stifel analyst Jonathan Siegmann — “more urgent and less controversial.” When lawmakers from both parties agree that weapons stockpiles need refilling, the companies that build them gain unusually clear visibility into future sales.

Lockheed Martin, the world’s largest defense contractor, sits at the center of it. The company is anchored by the F-35 fighter jet, missile defense systems, and a large classified space business, and it has reported a record backlog of $194 billion. Lockheed has guided 2026 sales to a range of $92 billion to $93 billion. The stock trades around $525, up about 10% so far this year. The picture is not flawless: first-quarter adjusted earnings of $6.44 a share missed the $6.70 consensus estimate, dragged down by a $125 million unfavorable F-16 charge — a reminder that locked-in contract prices can cut both ways.

Northrop Grumman carries two of the military’s biggest long-term programs, the B-21 Raider stealth bomber and the Sentinel intercontinental ballistic missile program, with a backlog around $90 billion. Its shares trade near $542. General Dynamics builds the Navy’s submarines, one of the cleanest growth stories in the sector, while RTX, the parent company of Raytheon, manufactures many of the missiles and air-defense systems currently in highest demand and was the only major contractor to recently raise its 2026 outlook.

RTX has also drawn attention from the White House in a less favorable way. President Trump complained that Raytheon had been among the least responsive contractors to the needs of the Department of War and threatened to block contractors from paying dividends or repurchasing shares until they accelerate weapons production. The remarks briefly rattled defense stocks before they recovered, underscoring that the same government driving the spending boom can also pressure the companies benefiting from it.

The spending surge extends well beyond the household-name defense giants. Drone manufacturer AeroVironment has climbed more than 40% this year as militaries around the world invest heavily in unmanned aircraft and counter-drone systems. In Europe, where governments are boosting defense budgets under both domestic security concerns and U.S. pressure, shares of Britain’s BAE Systems, Italy’s Leonardo, Sweden’s Saab, and Germany’s Rheinmetall have all posted strong gains.

The broader story for taxpayers is where all that money ultimately goes. A $1.5 trillion defense budget means billions of dollars flowing into factories and facilities across states including Texas, Connecticut, California, Alabama, and Maryland, where major contractors and their suppliers employ tens of thousands of workers. Larger budgets typically translate into more hiring, more overtime, and more orders flowing through the vast network of subcontractors that provide everything from electronics and engines to software and specialized materials.

The industry’s optimism is reflected in its order books. Companies with large backlogs effectively have years of future revenue already committed under signed contracts. That visibility is rare in most industries and gives defense firms a level of predictability many technology, retail, and manufacturing companies would envy.

There are reasons for caution. Major defense contractors currently trade at roughly 22 to 25 times forward earnings, above their historical averages, meaning investors have already priced in much of the expected growth. Budget priorities can change with politics, and fixed-price government contracts have repeatedly created losses when development costs rise unexpectedly, as Lockheed’s recent F-16 charge demonstrated.

Still, the larger trend is difficult to ignore. Military conflicts, geopolitical competition, and the rebuilding of weapons inventories have created a powerful tailwind for defense spending across much of the world. As long as those conditions persist and Washington continues expanding military budgets, the companies sitting on record backlogs may enjoy one of the clearest growth runways available in the market.

JBizNews Desk | Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Johnson & Johnson has made a surprising decision at a time when much of the pharmaceutical industry is racing toward obesity treatments: it is staying out of the market entirely.

Speaking Tuesday at the Economic Club of Washington, D.C., Johnson & Johnson CEO Joaquin Duato said the healthcare giant has no plans to develop or acquire drugs in the booming GLP-1 category, the class of medicines behind blockbuster weight-loss and diabetes treatments that have transformed the industry over the past several years.

“We are not going to be in the GLP-1 area,” Duato said during a discussion with Carlyle Group co-founder David Rubenstein.

The statement places J&J among a small group of major pharmaceutical companies choosing not to chase one of the fastest-growing markets in healthcare history. While rivals have spent billions of dollars acquiring obesity-drug developers and launching their own programs, Johnson & Johnson is betting that its future lies elsewhere.

Instead, Duato said the company will focus its resources on two areas where it believes it can achieve greater medical and commercial success: cancer treatment and neuroscience.

“Our goal is to be No. 1 by 2030,” Duato said of the company’s oncology business.

The company already holds a strong position in multiple cancer categories. Johnson & Johnson markets leading treatments for multiple myeloma, one of the most common blood cancers, and maintains a growing portfolio of lung cancer therapies. Last year, the company expanded its oncology pipeline through a $3.05 billion acquisition of Halda Therapeutics, gaining access to a promising oral prostate cancer treatment.

The decision reflects the reality of a market already dominated by a handful of powerful competitors.

Eli Lilly and Novo Nordisk currently control the obesity-drug landscape through blockbuster products that have generated tens of billions of dollars in annual sales. Demand for GLP-1 medications has surged as studies continue to show benefits extending beyond weight loss, including improvements in diabetes management and potential cardiovascular benefits.

Lilly has emerged as the dominant player. The company became the first pharmaceutical manufacturer to surpass a $1 trillion market valuation last year, driven largely by demand for its obesity and diabetes drug tirzepatide. Lilly executives have estimated that the company captures roughly 70% to 75% of new patients entering the GLP-1 market.

For Johnson & Johnson, competing against such entrenched leaders may not represent the best use of research and development dollars.

The company’s position also aligns with a broader strategic transformation that has been underway for several years.

Johnson & Johnson has streamlined its operations to concentrate on higher-growth healthcare businesses. The company spun off its consumer-health division into Kenvue, separating well-known brands such as Tylenol, Band-Aid, and Listerine from the parent company. It has also restructured portions of its medical-device operations while increasing investments in pharmaceuticals and advanced medical technologies.

Duato highlighted the company’s recent performance, noting that Johnson & Johnson delivered a 47% total shareholder return in 2025, reflecting investor confidence in its current strategy.

Technology is also expected to play a major role in the company’s future growth.

Duato said artificial intelligence has the potential to accelerate drug discovery, improve clinical development, and enhance the effectiveness of medical devices, particularly in the field of robotic surgery.

“We are just at the beginning,” he said, describing healthcare as entering a period of significant technological change.

For investors and patients alike, the announcement underscores a growing divide within the pharmaceutical industry. Some companies are betting heavily on obesity treatments, viewing them as the defining medicines of the next decade. Others are choosing to focus on diseases where competition is less intense and unmet medical needs remain substantial.

Johnson & Johnson’s decision means one fewer major competitor pursuing obesity drugs, a market where additional competition could eventually help lower prices and improve access for patients. At the same time, the company’s vast research budget will remain focused on cancer and neurological disorders, areas where millions of patients continue to face limited treatment options.

As the obesity-drug market continues its rapid expansion, Johnson & Johnson is making a different wager: that breakthroughs in cancer and neuroscience will ultimately prove more valuable than joining the industry’s biggest gold rush.

Whether that strategy pays off will become clearer as the company works toward Duato’s goal of becoming the world’s leading oncology company by 2030.

JBizNews Desk
New Brunswick, N.J.

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Israel and Hezbollah agreed to a fresh ceasefire in Lebanon on Friday, June 19, 2026, halting the deadliest flare-up of the war just as it threatened to wreck the broader effort to end the fighting across the region. A senior U.S. official said the truce took eff The Times of Israelect at 4 p.m. local time and was brokered by the United States and Qatar through talks with Israel and Iran respectively, an arrangement the official said further highlighted Tehran’s ability to influence events in Lebanon. Reuters first reported the agreement, which three diplomats briefed on it confirmed to CBS News. CBS News

The deal came together only after the bloodiest day on the Lebanon front in weeks. Lebanese authorities said Israeli airstrikes killed 18 people, while Israel said four of its soldiers were killed in one of Hezbollah’s deadliest attacks of the war CBC News. The Israeli military said its troops struck 150 targets and killed dozens of Hezbollah operatives in southern Lebanon The Times of Israel before the truce took hold.

The same escalation forced a postponement of the most important diplomacy of all. Peace talks between the United States and Iran, set for Friday in Switzerland, were called off after Iran held back its delegation amid the Lebanon strikes. Iran’s Foreign Ministry said the Switzerland meeting had been postponed, with arrangements underway for talks in the coming days. The Times of Israel

For Israeli Prime Minister Benjamin Netanyahu, the moment was politically delicate. He stayed mum on the new ceasefire itself while touting the military’s strikes on his personal social media accounts, saying troops had hit Hezbollah “just as I instructed.” The Times of Israel The mixed message captured the strain inside Israel’s government, where hardline ministers have insisted the military will not be bound by the wider U.S.-Iran agreement.

That agreement is the thread connecting everything. The interim U.S.-Iran deal reached days earlier stipulated that all fighting on all fronts, including Lebanon, must end immediately NBC News. Lebanon was the loophole that kept reopening: earlier ceasefire arrangements tied to the Iran war did not formally include Lebanon, contributing to continued hostilities Wikipedia, and Hezbollah had rejected an earlier conditional truce that called for it, but not Israel, to stop attacks NPR. Friday’s deal is the latest attempt to close that gap.

For businesses watching from a distance, the relevance runs straight through the energy market. Since the war began in late February, oil has carried a risk premium tied to fears over the Strait of Hormuz, the shipping lane that moves a large share of the world’s crude. Every flare-up revives the worry that the corridor could be disrupted; every ceasefire eases it. A durable calm in Lebanon removes one source of that anxiety, which can take some pressure off oil prices, gasoline costs, and the shipping and insurance bills that ripple through global supply chains.

The stakes are just as real for inflation at home. Energy has been the main force pushing U.S. prices back up this year, and the longer the conflict drags on, the longer markets expect inflation to stay elevated — keeping the Federal Reserve cautious and borrowing costs high. A genuine step toward de-escalation, if it holds, is the kind of development that could eventually loosen that grip.

But the history of this conflict counsels caution. A ceasefire was reached in mid-April, establishing a short truce meant to create conditions for further negotiations Wikipedia, and U.S.-mediated talks in Washington in early June produced a conditional arrangement Al Jazeera that Hezbollah then rejected. Each pause has bought time without resolving the core disputes over Israeli forces in southern Lebanon and the future of Hezbollah’s weapons.

What makes Friday’s agreement notable is who delivered it. The role of Qatar, working through Iran to rein in Hezbollah, points to the same channels that produced the U.S.-Iran framework and suggests the two tracks are now tightly linked. If the Lebanon ceasefire holds, it clears a major obstacle to restarting the Switzerland talks; if it collapses again, it could drag the larger negotiations down with it.

For now, the guns in Lebanon have fallen quiet, and the postponed U.S.-Iran meeting has been pushed only days, not derailed. That is a fragile kind of progress, but it is progress — and for companies that depend on stable fuel costs, steady shipping, and predictable consumer spending, even a fragile calm beats another deadly escalation. The test will be whether this ceasefire outlasts the ones before it.

JBizNews Desk © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. Department of Education announced Thursday that federal student loan borrowers who use automatic payments will receive a full one-percentage-point cut on their interest rate starting July 1, a temporary break designed to pull millions of people back into steady repayment.

The reduction runs through June 30, 2028. Borrowers already enrolled in auto pay do not need to act — their servicer will apply the lower rate automatically. Those not yet enrolled have until September 30, 2026 to sign up and still qualify.

The math is simple and lands directly in household budgets. Auto pay has long carried a small discount of a quarter percentage point. An undergraduate borrower paying the current 6.39% rate would see it fall to 5.39% under the new, larger break. For a borrower already enrolled, the servicer adds another 0.75 percentage points on top of the existing quarter-point cut to reach the full one percent.

Under Secretary of Education Nicholas Kent tied the move to repayment behavior, not relief.

“The Trump Administration is making student loan repayment easier than ever, and borrowers should not wait to take advantage of this temporary interest rate reduction,” Kent said, adding that the department expects the incentive to raise repayment rates and improve the health of the federal loan portfolio.

That portfolio is the real reason behind the announcement. Before the COVID-19 pandemic, more than 80 percent of borrowers in active repayment used auto pay. After millions opted out during the long repayment pause — some making no payments for years — that share has fallen, and the federal student debt load has swelled past $1.7 trillion. The department now puts auto-pay enrollment at roughly 40 percent. Getting borrowers back on automatic monthly payments lowers default risk and keeps money flowing into the system.

The interest cut arrives alongside a broader overhaul of how Americans repay college debt. Two new repayment plans open July 1 under President Trump’s Working Families Tax Cuts Act: an income-driven plan called the Repayment Assistance Plan, known as RAP, and a new Tiered Standard plan.

Each works differently. Under RAP, a borrower’s monthly bill is based on income and number of dependents, and borrowers who make full, on-time payments are shielded from runaway interest while their balance steadily declines. The Tiered Standard plan sets fixed terms of 10, 15, 20, or 25 years based on total balance, giving borrowers with larger debts smaller monthly payments stretched over more time.

Enrolling in auto pay is straightforward but does require action for those not signed up. Borrowers who are not enrolled must log in to their loan servicer account, select auto pay, and enter their bank account details. Borrowers in default must first log in to StudentAid.gov, consolidate their eligible loans, and apply for a new repayment plan before they can enroll.

There is a catch worth noting for anyone weighing the offer. The discount only lasts as long as the borrower stays in auto pay; drop out, and the reduction disappears. The benefit applies to federal Direct Loans originated after July 1, 2012, and reaches both student and parent borrowers, including those who were enrolled in the now-defunct SAVE plan once they choose a new repayment option.

For households, the practical takeaway is a lower monthly interest charge in exchange for committing to automatic withdrawals. The timing matters as federal student debt approaches $2 trillion and the administration looks to restart repayment in earnest. A one-point cut will not erase anyone’s balance, but on a typical undergraduate loan it trims real dollars off interest every month for two years — and for borrowers juggling rent, groceries, and car payments, that is money that stays in the checking account.

The deeper bet is behavioral. By making auto pay the cheapest way to carry a federal loan, the department is nudging borrowers toward the one habit that most reliably prevents missed payments and default. Whether the incentive moves the 60 percent currently sitting outside auto pay will become clear over the next two years.

JBizNews Desk | New York & Washington

© 2026 JBizNews.com. All Rights Reserved. Reproduction, redistribution, republication, or retransmission of this content, in whole or in part, without prior written permission from JBizNews.com is strictly prohibited.

Nvidia priced a record $25 billion bond sale on June 15, according to the company’s SEC pricing term sheet, its first trip to the corporate debt market since 2021 and the largest borrowing ever by a chipmaker.

The offering drew roughly $85 billion in orders — more than three times what the company sold — and was structured across seven tranches maturing between two and thirty years. Strong demand let Nvidia raise the deal from an initial target of about $20 billion.

The size of the order book did the talking. Heavy demand forced borrowing costs lower during pricing, with the longest piece — a 30-year note maturing in 2056 — tightening from early guidance of around 0.9 percentage points above U.S. Treasuries to a final spread of 65 basis points. Goldman Sachs, JPMorgan Chase, and Morgan Stanley managed the transaction.

The obvious question is why a company this flush needs to borrow at all. Nvidia generated billions in operating cash flow in its most recent quarter and was not borrowing to meet payroll. The answer, as bond-market participants framed it, has less to do with immediate funding needs and more to do with establishing a liquid benchmark for Nvidia’s credit in the investment-grade market.

In plain terms, Nvidia wanted a reference point — a set of widely held, actively traded bonds that price its name for lenders the way a benchmark stock price tracks its equity. Once that benchmark exists, future borrowing becomes easier and cheaper.

The cash itself is earmarked for the buildout driving the whole industry. Nvidia said the proceeds will refinance existing obligations and fund general corporate purposes tied to AI data center and infrastructure expansion. Refinancing existing debt is the primary use.

The deal also places Nvidia inside a much larger borrowing wave. The chipmaker joined a string of jumbo debt offerings from technology heavyweights as investors rush to get a piece of the artificial intelligence boom. Industrywide AI capital spending is expected to exceed $700 billion in 2026, as cloud providers, large enterprises, and startups keep buying Nvidia chips at a record pace.

That spending is the business story underneath the bond math. Nvidia releases new chips on an annual cadence, which demands steady investment in research, development, and manufacturing commitments — the kind of long-horizon spending that benefits from a deep, established presence in the debt market. The seven-tranche structure stretching out three decades suggests the company is locking in long-term financing at current rates rather than waiting.

For a firm that was known mainly as a maker of gaming graphics cards five years ago, the reception marks how far its standing has shifted. Raising $25 billion in investment-grade debt and attracting $85 billion in demand is a measure of how completely the AI era has transformed Nvidia’s identity, with the bond market now treating it as one of the most creditworthy technology companies in the world. Revenue in fiscal 2026 has grown to roughly $216 billion.

Investors rewarded the move in the stock as well. Nvidia shares climbed about 2.8% to $210 on Thursday, helped by a rebound in semiconductor stocks after a Federal Reserve-driven selloff earlier in the week. Intel, Micron, and AMD also posted gains amid related chip-manufacturing news.

What the deal signals to the broader economy is a company preparing to keep building. The AI data centers that Nvidia’s chips power require land, power, cooling, and construction — physical infrastructure that ripples into electricity demand, real estate, and skilled jobs far beyond Silicon Valley. By securing $25 billion in long-dated money now, Nvidia is giving itself room to fund acquisitions, manufacturing partnerships, and expansion without dipping into operating cash or issuing new stock.

Whether the company deploys all of it soon or holds some in reserve, the structure points one direction. This is a balance sheet being arranged for a long, capital-heavy stretch — one Nvidia plainly expects to sit at the center of.

JBizNews Desk | New York & Washington

© 2026 JBizNews.com. All Rights Reserved. Reproduction, redistribution, republication, or retransmission of this content, in whole or in part, without prior written permission from JBizNews.com is strictly prohibited.

Bond investor Jeffrey Gundlach said on CNBC’s “Closing Bell” on Wednesday, June 17, that the nation’s new top central banker is not the rate-cutting dove that markets spent the winter betting on. The DoubleLine Capital chief executive said Federal Reserve Chairman Kevin Warsh sounded far tougher on inflation than investors had expected, and that anyone still waiting for cheap money is likely to be disappointed.

Gundlach’s verdict landed hours after the Federal Reserve finished its first meeting under Warsh and left its benchmark interest rate unchanged. He pointed to the central bank’s plain promise, written into its own policy statement, that it will deliver price stability — language Warsh returned to again and again at his first press conference as chairman.

“He is absolutely telling you that he plans on delivering on price stability,” Gundlach said. That, he argued, means the easy-money policy that traders counted on back in the first quarter of this year, when nearly everyone was expecting rate cuts, is off the table. The new chairman, he added, doesn’t sound like that at all anymore.

The shift matters because President Donald Trump handpicked Warsh for the job in hopes he would push borrowing costs lower. Instead, Warsh spent his debut stressing that the Fed is committed to getting inflation back down to 2%, a level the country hasn’t seen in five years. He called the failure to hold that line a problem the central bank intends to fix.

Warsh also broke from recent custom in two notable ways. He declined to submit his own interest-rate forecast to the Fed’s closely watched “dot plot,” the grid that shows where each policymaker expects rates to head. And he signaled a broad review of how the central bank communicates with the public, suggesting the institution’s habits around forward guidance are due for an overhaul.

For Gundlach, the tougher tone is a reason to like long-term government bonds. When a chairman pledges to keep prices stable, the risk that runaway inflation eats into the value of a 10- or 30-year Treasury falls. “There’s a greater reason to own long-term Treasuries today now that the new sheriff is in town,” he said. He went further, arguing that Warsh has effectively staked his own credibility on the outcome — and that if he fails to bring inflation under control, he will have announced his own failure on day one.

The billionaire investor’s bottom line: with a chairman this focused on prices, aggressive rate cuts are unlikely, and investors no longer have to fear the kind of over-easing that would punish long-term bonds.

Markets read the day much the way Gundlach did. The Dow Jones Industrial Average dropped 507.12 points, or 0.98%, to close at 51,492.55, after touching a fresh record high earlier in the session. The S&P 500 lost 1.21% to finish at 7,420.10, and the Nasdaq Composite fell 1.34% to 26,021.66. Big technology names led the slide, with Microsoft, Meta Platforms, Alphabet, and Amazon all closing lower.

That 1.2% drop in the S&P 500 was the worst first “Fed Day” for the index under a new chairman since 1994, according to Bespoke Investment Group. The only other newcomers in that span were Ben Bernanke, Janet Yellen, and Jerome Powell, and none saw a debut sting like this one.

Bond yields, which move opposite to prices, jumped as traders repriced the path ahead. The 2-year Treasury yield climbed more than 16 basis points to 4.216%. The cause was the Fed’s own forecast: the dot plot now puts the year-end rate at a median of 3.8%, up from 3.4% in the March projections. In plain terms, the committee that three months ago leaned toward a cut now leans toward at least one hike this year. The Fed held its target range at 3.5% to 3.75% on Wednesday.

The change in mood traces back to prices at the gas pump and the grocery store. Since the conflict in the Middle East began in late February, higher energy costs have pushed inflation up, with the Consumer Price Index running at a 4.2% annual rate in May, the hottest reading since April 2023. Claudia Sahm, chief economist at New Century Advisors, said the market reaction was driven mainly by how hawkish the dot plot turned out to be, noting that the inflation picture has shifted sharply.

Fed funds futures now point to a possible rate increase as soon as October. For households hoping for cheaper mortgages, car loans, and credit cards, the message from Warsh’s first meeting — and from one of Wall Street’s most-watched bond voices — is to stop counting on relief anytime soon.

AP Pic: AI-generated AP-style news photo of Federal Reserve Chairman Kevin Warsh speaking at a podium after a Fed meeting, Federal Reserve seal visible in the background, reporters and cameras in the foreground, serious monetary-policy atmosphere, realistic news photography.

JBizNews Desk
Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The wave of investor withdrawals that rattled the private credit industry this spring appears to be receding. The Oaktree Strategic Credit Fund told shareholders in an update dated Wednesday that requests to cash out fell to about 4.5% of its shares, back below the 5% ceiling the fund offers each quarter when its latest tender expired on June 12, allowing it to honor every redemption request in full.

That marks a sharp turnaround from three months ago. During the first quarter, redemption demand at the same fund surged to 8.5%, representing roughly $400 million, well above the standard cap. To meet the unusually high demand, Oaktree repurchased approximately 6.8% of the fund’s shares while its parent company, Brookfield, purchased another 1.7%. The fund also reduced its monthly distribution from 18 cents per share to 16 cents, and its net asset value had declined from its original $25 offering price to approximately $22.64.

The latest tender paints a calmer picture. About 8.9 million shares were offered for redemption, and because requests remained below the 5% threshold, every investor who wanted to sell was able to do so without restrictions.

To understand why investors were paying close attention, it helps to understand the structure. The Oaktree Strategic Credit Fund is a non-traded business development company (BDC), a vehicle that lends directly to companies and distributes interest income to investors. These funds have become popular among retirees and income-focused investors seeking higher yields than traditional fixed-income products. However, unlike a bank account or publicly traded stock, investors can generally redeem only during designated quarterly windows and are often subject to a 5% redemption cap.

That structure came under pressure earlier this year as concerns spread across the rapidly growing $2 trillion private credit industry. The bankruptcies of First Brands and Tricolor shook confidence in parts of the market, while JPMorgan Chase CEO Jamie Dimon warned that additional problems could emerge within the sector. At the same time, concerns that advances in artificial intelligence could disrupt certain software companies that rely on private credit financing added to investor unease.

The result was a rush for liquidity across multiple funds.

Oaktree was not alone. Redemption requests exceeded 10% of shares outstanding at funds managed by Morgan Stanley, Apollo, and Ares during the first quarter, while Blue Owl reportedly faced approximately $5.4 billion in withdrawal requests. Some managers limited redemptions to the contractual 5% cap. Others, including Oaktree and Blackstone, elected to satisfy all requests in an effort to reassure investors and prevent broader concerns from spreading through the market.

Recent developments suggest the pressure may be easing. Blackstone reported that withdrawal requests slowed during the latter portion of its most recent quarter and said investor sentiment had begun to stabilize as fresh capital started returning. Oaktree’s own portfolio metrics also remain relatively strong. According to the fund, it has met every redemption request since launching in June 2022, generated an annualized net return of approximately 8.8% over three years, and continues to report minimal levels of non-performing loans.

For individual investors, the events of the past several months may ultimately serve as a reminder about the nature of these products. Much of the concern stemmed from a misunderstanding of liquidity. Many investors were attracted by the steady income streams but did not fully appreciate that access to their capital could be limited during periods of market stress.

In many respects, the funds performed exactly as designed. Redemption gates functioned as intended, and firms backed by large, well-capitalized parent companies were able to satisfy elevated demand without being forced into distressed asset sales. Still, the episode highlighted that investments offering attractive income can behave very differently from traditional savings accounts when markets become unsettled.

The decline in redemption requests below the 5% threshold does not settle the broader debate surrounding private credit. Regulators, investors, and analysts continue to scrutinize how private loans are valued and how liquidity risks are managed during periods of stress. Yet for income investors watching the sector closely, Oaktree’s latest filing offers an encouraging signal: redemption pressure has eased, confidence appears to be improving, and for now, the line at the exit is getting shorter.

JBizNews Desk
New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A growing mountain of soured household loans is becoming one of the biggest threats to China’s economy, and the country’s own banks are showing the strain. Industrial & Commercial Bank of China (ICBC) — the world’s largest bank by assets — reported that its bad-loan ratio on personal consumer loans climbed to 2.51% by the middle of last year, while its credit card delinquency rate hit 3.75%. That consumer bad-loan ratio stood at just 1.34% two years earlier.

Those are the figures at China’s strongest lender. At weaker regional banks, the picture is far uglier. Bohai Bank’s consumer bad-loan ratio jumped to 12.37% in 2024 from 4.44% a year earlier, and Harbin Bank’s rose to 5.51%. When more than one in eight consumer loans goes bad, a bank is in real trouble.

The rot is spreading fast enough that Beijing’s regulator has stepped in. The National Financial Regulatory Administration extended a program through the end of 2026 that lets banks bundle their bad personal loans and sell them to asset managers — a pressure valve to get the debt off bank books. Sales of these distressed personal loans more than doubled in the first half of 2025 from a year earlier. By the end of 2024, banks had packaged some 1.18 trillion yuan — roughly $165 billion — of troubled retail loans into securities, most of it tied to credit cards and unsecured consumer borrowing.

Here is the alarming part: this debt is being dumped at fire-sale prices. In early 2025, bad personal loans were selling for only about four cents on the yuan, meaning banks were recovering pennies on what they were owed. With no personal bankruptcy law in China and courts buckling under millions of retail debt cases, lenders would rather take a deep loss than chase borrowers who cannot pay.

How did the world’s second-largest economy get here? It starts with the property crash, which wiped out household wealth as apartments lost value. Then came deflation: China has been stuck in falling prices for roughly ten straight quarters, which makes every debt harder to repay because borrowers pay back loans with money that buys more than it used to. Layer on wage cuts across finance, manufacturing, and government jobs, plus worry over tariffs and incomes, and you get households that are tapped out and scared.

Scared people stop spending. A central bank survey found that 61.4% of Chinese households now want to boost their savings — nearly 20 percentage points higher than before the pandemic. Hoarding cash is rational for any one family, but for the economy it is poison: weak spending feeds more deflation, which sours more debt, which makes everyone more cautious still.

It is worth keeping perspective. By global standards, Chinese household debt is not extreme — about 60% of economic output, below the roughly 70% in the United States and far below South Korea — and economists worry less about the total than about how fast the bad loans are climbing. As ING economist Lynn Song put it, “Income growth-driven consumption would be strongly preferable” to a recovery propped up by more borrowing — but raising incomes is the harder path, and Beijing has leaned on lending instead.

The consumer mess sits inside a far bigger problem. Estimates suggest China’s banking system is carrying trillions of dollars in hidden bad debt, masked by policies that allow struggling borrowers to defer payments rather than default — keeping official bad-loan rates relatively stable while avoiding a broader banking panic. The tradeoff is that capital remains tied up in struggling borrowers and unproductive sectors rather than flowing to healthier parts of the economy. As Victor Shih, a China finance expert at the University of California San Diego, observed, “There’s no financial crisis, but there’s no free lunch in economics. The price is just growth, inefficiency and low productivity.”

For Americans, this is not a far-off story. A weak Chinese consumer pushes Beijing to lean harder on exports, flooding global markets with cheap goods and squeezing manufacturers elsewhere. And a China that cannot get its own people to spend buys less from everyone else. The pile of bad consumer debt is President Xi Jinping’s problem first — but in a connected world, a stalled Chinese consumer eventually shows up in everyone’s economy.

JBizNews Desk
Hong Kong

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Vice President JD Vance postponed a planned trip to Switzerland on Thursday, creating fresh uncertainty around the next phase of negotiations between the United States and Iran just as a 60-day window for final talks officially began.

The White House confirmed Thursday evening that Vance would not depart as originally scheduled. A spokesperson said negotiations remain active but acknowledged that coordinating the talks has been complicated. “The vice president is not departing tonight,” the official said, while leaving open the possibility of travel later this weekend.

Vance had been expected to travel Friday to a resort near Lucerne, Switzerland, where officials were preparing for a formal ceremony tied to the next stage of negotiations. Speaking to reporters earlier in the day, Vance said the trip was still expected to happen but indicated the timetable remained uncertain.

“Our plan is to go to Switzerland. I don’t know exactly when,” Vance said.

The delay comes amid new diplomatic complications surrounding the agreement. The Switzerland meetings were already facing pressure following recent tensions linked to Israeli military operations in Lebanon. At the same time, Pakistani Prime Minister Shehbaz Sharif, whose government has helped facilitate communication between Washington and Tehran, also postponed his planned visit to the Swiss venue.

The broader agreement has already taken an unconventional path. President Donald Trump signed the memorandum Wednesday during a dinner event outside Paris, while Iranian President Masoud Pezeshkian signed remotely, allowing the framework to take effect without both leaders being physically present.

A significant development came from Tehran on Thursday when Iran’s Supreme Leader Mojtaba Khamenei publicly approved direct negotiations with the United States. In a statement carried by Iranian state media, Khamenei endorsed face-to-face discussions while emphasizing that participating in talks does not necessarily mean accepting the other side’s position.

For businesses and investors, the negotiations carry enormous economic consequences.

Much of the focus remains on the Strait of Hormuz, the world’s most important oil shipping route. While some vessel traffic has resumed through alternative channels, portions of the main shipping corridor remain restricted. Industry groups continue to monitor conditions closely as commercial shipping companies, energy traders, and insurers prepare for a gradual normalization of Gulf traffic.

The outcome of the talks will also determine the future of sanctions relief and foreign investment opportunities inside Iran. Administration officials have indicated that major international investments would still require U.S. approval through sanctions waivers or formal relief measures before companies could proceed.

That issue is particularly important because the agreement envisions a potential $300 billion reconstruction and investment framework aimed at rebuilding portions of Iran’s economy following years of sanctions and regional conflict.

Energy markets have been closely watching developments. Oil prices have eased in recent sessions as traders bet that a successful agreement could reduce geopolitical risk and increase future energy flows. U.S. gasoline prices have also retreated from recent highs, offering consumers some relief after months of elevated fuel costs.

However, analysts caution that a breakdown in negotiations or a prolonged delay could quickly reverse those gains.

Several major issues remain unresolved. According to administration officials, a final agreement would require Iran to address uranium enrichment, existing enriched uranium stockpiles, and missile development programs. Negotiators are expected to spend the next 60 days attempting to bridge those differences.

Despite the scheduling delay, the administration continues to project confidence. Vance argued that the United States maintains leverage regardless of the outcome, pointing to the damage already inflicted on Iran’s nuclear infrastructure and the potential benefits available if Tehran agrees to broader concessions.

The immediate question now is timing. While the White House insists talks remain on track, the postponement underscores how fragile and unpredictable the process remains.

For energy markets, shipping companies, investors, and governments around the world, the next several days could determine whether the agreement moves forward smoothly or encounters additional turbulence before formal negotiations even begin.

JBizNews Desk
Washington Bureau
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

America’s housing shortage has become one of the biggest economic challenges facing families, renters, employers, and local governments. Now, after years of debate and resistance, states across the country are beginning to rewrite the rules governing where and how homes can be built.

The latest and most significant move comes from California, where a major new housing law takes effect on July 1, allowing developers to construct residential buildings of up to nine stories near major transit stations, overriding many local zoning restrictions that have limited development for decades.

The change reflects a growing national realization that the housing crisis cannot be solved without increasing supply.

According to estimates from Smart Growth America, the United States faces a shortage of roughly 4.7 million homes. The gap between housing supply and demand has helped drive home prices and rents to record levels, placing homeownership increasingly out of reach for many Americans.

Economists broadly agree that the country needs to build more housing. The challenge is that increasing supply often creates political resistance from existing homeowners concerned about neighborhood character, traffic, school crowding, and potential impacts on property values.

One of the most widely adopted solutions has been the expansion of Accessory Dwelling Units (ADUs) — often called granny flats, in-law suites, backyard cottages, or garage apartments.

California has spent years reducing barriers that previously prevented homeowners from building ADUs. The state eliminated many parking requirements, reduced permitting obstacles, and removed owner-occupancy rules that discouraged construction.

The results have been significant. According to Harvard University’s Joint Center for Housing Studies, ADUs now account for nearly 20% of all new housing units produced in California. To encourage even more construction, California’s housing agency offers grants of up to $40,000 to help homeowners cover development costs.

The idea is spreading rapidly beyond California.

Researchers at the Mercatus Center report that at least 18 states have now passed legislation making it easier for homeowners to build ADUs.

This year, Idaho emerged as an unlikely housing reform leader. The state approved a package of six housing bills covering backyard apartments, manufactured housing, lot splits, streamlined permitting, and other measures designed to increase supply.

Beyond ADUs, lawmakers are beginning to tackle zoning rules themselves.

For decades, zoning restrictions have limited housing density in many communities, particularly near transportation hubs where demand is strongest. California’s new Senate Bill 79, authored by State Senator Scott Wiener and signed by Governor Gavin Newsom, represents one of the most aggressive efforts yet to increase density near public transit.

The law allows significantly taller residential buildings within approximately a half-mile of major transit stations in the state’s largest urban regions, reducing the ability of local governments to block development.

Supporters argue that concentrating housing near transit reduces commuting times, lowers transportation costs, and creates more affordable housing opportunities.

Other states are pursuing a different approach by modernizing building codes.

A growing number of jurisdictions are reconsidering requirements that residential buildings taller than three stories contain two stairwells. Housing advocates argue that allowing certain smaller apartment buildings to use a single staircase can reduce construction costs and make projects financially viable on smaller parcels of land.

States including Texas and Idaho have begun exploring or implementing such reforms.

Still, housing experts caution that changing laws is only the first step.

California alone has enacted roughly 180 housing-related reforms over the past decade, yet the state continues to build far fewer homes than officials say are needed. State planners estimate California needs approximately 2.5 million additional homes by 2030 to adequately meet demand.

Implementation remains a challenge. In some cases, local governments have responded to state mandates by imposing additional requirements that make projects difficult or expensive to build.

That reality highlights a broader truth about housing policy: while there is widespread agreement that America needs more homes, consensus often disappears when specific neighborhoods face new development.

For families, however, the stakes are increasingly tangible.

A backyard apartment can provide rental income, housing for aging parents, or a place for adult children struggling with affordability. A new apartment building near a transit station can mean lower housing costs and shorter commutes.

No single law will solve the housing crisis overnight. But after years of treating housing shortages as a local issue, states are increasingly stepping in with broader reforms designed to increase supply and improve affordability.

Whether through granny flats, taller apartment buildings, streamlined permitting, or updated building codes, lawmakers across the country are sending the same message: America cannot solve its housing affordability problem without building more homes.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

On Thursday, Sen. Roger Wicker of Mississippi, the top Republican on the Senate Armed Services Committee and a longtime ally of President Donald Trump, broke ranks to criticize the administration’s agreement with Iran, warning that its proposed $300 billion reconstruction fund would dwarf the economic relief provided under the 2015 nuclear deal and could hand Tehran an unprecedented financial windfall.

Wicker said the planned rebuilding package, even if no American taxpayer money is directly involved, would make the benefits Iran received under former President Barack Obama’s Joint Comprehensive Plan of Action (JCPOA) “look like a pittance by comparison.” The criticism immediately exposed growing unease among Republicans who supported a hard line against Iran but are now questioning the economic terms emerging from the ceasefire framework.

The fact that a three-decade Republican senator with deep national-security credentials would voice those concerns publicly underscored how divided parts of the party have become. Other Republicans quickly joined in. Sen. Bill Cassidy of Louisiana called the agreement “the worst foreign policy blunder in decades,” arguing Iran’s nuclear ambitions remain intact. Sen. Thom Tillis of North Carolina pointed to the war’s cost, citing lost aircraft, 13 American deaths, hundreds of injuries, and roughly $100 billion spent since the opening strikes, saying the agreement’s reported 14-point framework did not justify the sacrifice. Sen. Joni Ernst of Iowa warned against repeating the mistakes of the previous nuclear accord, saying, “I don’t want to see JCPOA 2.0.”

At the center of the fight is a simple question: what exactly is the $300 billion fund, and who ultimately pays for it?

The memorandum signed Wednesday by President Trump and Iranian President Masoud Pezeshkian commits the United States to work with regional partners on establishing a reconstruction mechanism worth at least $300 billion to help rebuild Iran following months of war. The final structure is expected to be negotiated during a 60-day implementation period. Iran had initially sought approximately $400 billion in war damages, a demand Washington rejected.

According to sources familiar with the negotiations, more than half of the proposed funding has already been privately committed, with contributions expected to come primarily from regional governments, sovereign wealth funds, private investors, and development partners rather than direct U.S. appropriations. The money would flow through a proposed Reconstruction and Development Fund aimed at restoring critical infrastructure damaged during the conflict, including airports, energy facilities, refineries, transportation networks, and major industrial sites such as the Mobarakeh Steel Complex, one of Iran’s largest manufacturing assets.

The White House has aggressively pushed back against claims that American taxpayers will finance the effort.

Speaking at the G7 Summit in France, Trump said the United States would not contribute money to the fund and dismissed reports suggesting Washington had pressured Gulf nations into participating. He later reiterated on Truth Social that reports claiming America was paying Iran were “Fake News.”

Vice President JD Vance echoed that message, stating that the agreement does not provide Iran “a single dime of American money.” Vance indicated that any future contributions would likely come from Gulf states and international investors and would be contingent on Iran meeting its obligations under the agreement, including dismantling portions of its nuclear infrastructure and complying with inspection requirements.

Administration officials also emphasized that the reconstruction fund is separate from ongoing discussions involving sanctions relief and the potential release of frozen Iranian assets held abroad.

That distinction has done little to calm critics.

The scale of the proposed package is what continues to draw attention. Under the 2015 nuclear agreement, roughly $55 billion in frozen Iranian assets became accessible following implementation of the deal. Even before accounting for possible sanctions relief under the new framework, the proposed $300 billion reconstruction fund represents a figure more than five times larger, explaining why many Republicans view it as a dramatic expansion of economic concessions.

Supporters of the agreement argue that the comparison is incomplete.

They point out that much of the proposed funding would be directed toward rebuilding infrastructure destroyed during the conflict rather than flowing directly into government accounts. They also argue that restoring economic stability inside Iran reduces incentives for future military escalation and lowers the likelihood of renewed disruption to global energy markets.

That economic argument is increasingly becoming the administration’s strongest defense.

Beyond the political fight, the most immediate impact of the agreement is being felt in the oil market.

The Strait of Hormuz, which Iran effectively closed during the conflict, normally handles roughly 20% of the world’s seaborne oil shipments. The prospect of its reopening has already begun easing supply fears that pushed energy prices sharply higher throughout the war.

On Thursday, West Texas Intermediate crude fell approximately 1.25% to $75.83 per barrel, while Brent crude declined roughly 1.4% to $78.41, as traders concluded the agreement reduces the risk of a prolonged disruption to global energy supplies.

The International Energy Agency (IEA) has warned that global oil markets could swing into a substantial surplus by 2027 if production normalizes and shipping through Hormuz fully resumes. IEA Executive Director Fatih Birol has publicly urged the waterway’s reopening “without conditions,” arguing that restoring confidence in global energy markets is essential to stabilizing prices.

For American households, cheaper oil may ultimately become the agreement’s most tangible benefit.

Falling crude prices have already helped push the national average gasoline price below $4 per gallon for the first time since late March, according to AAA, marking three consecutive weeks of declines. Lower energy costs filter through the broader economy, reducing pressure on transportation, manufacturing, shipping, food prices, and inflation.

That matters at a time when many families remain squeezed by elevated housing, grocery, insurance, and travel costs.

The administration is urging critics to focus on those economic benefits.

Vance described the preliminary framework as a “win-win” for the United States and argued that reopening energy markets, reducing inflation pressures, and avoiding another prolonged Middle East conflict would benefit American consumers. Trump has simultaneously sought to reassure hawks by warning that the United States would strike Iran again if Tehran violates the agreement.

Still, skepticism remains widespread.

Several Republican senators have complained they have not received a comprehensive classified briefing on the agreement and say Congress has been left to debate major provisions publicly while negotiators continue working through implementation details. With a 60-day negotiation period now underway, lawmakers are expected to scrutinize every aspect of the fund, sanctions policy, nuclear commitments, and enforcement mechanisms.

The size of the reconstruction package, the timing of sanctions relief, and the durability of the ceasefire will ultimately determine both Iran’s economic recovery and the financial impact on the global economy. For now, the agreement is holding, oil prices are moving lower, gasoline prices are easing, and the loudest criticism is coming not from Democrats but from within President Trump’s own party.

JBizNews Desk | New York & Washington

© 2026 JBizNews.com. All Rights Reserved. Reproduction, redistribution, republication, or retransmission of this content, in whole or in part, without prior written permission from JBizNews.com is strictly prohibited.

The Federal Trade Commission (FTC) has drafted a potential complaint against Amazon that could expose the company to billions of dollars in civil penalties over how it sells advertising, according to people familiar with the matter cited by Bloomberg on Tuesday.

The agency’s consumer protection unit has been digging into whether Amazon clearly disclosed the prices and terms behind the ads that dominate its marketplace, and several state attorneys general have joined the effort.

At the heart of the probe are the sponsored listings — the promoted products that appear at the top of the page when shoppers search Amazon.

Regulators are examining how the company runs the auctions that decide which ads win those spots, and in particular whether it told advertisers about “reserve prices,” the hidden minimum bids a seller has to clear to buy an ad.

The concern is that businesses paying to advertise may not have understood the real rules, or the real cost, of the system.

The stakes are large because advertising has become one of Amazon’s most important businesses.

The company brought in $68.6 billion in advertising revenue last year, according to a regulatory filing — a fast-growing and highly profitable line that spans search ads on its marketplace, video ads, and display ads shown across the web.

Analysts often describe it as the company’s “cash cow,” and a legal fight over how those ads are priced strikes directly at one of Amazon’s biggest profit engines.

How big the penalty could be remains an open question.

The FTC is limited in how much it can collect in fines on its own, but the involvement of state attorneys general matters because state consumer-protection laws can impose daily penalties that add up quickly.

People familiar with the matter said the agency could wrap up its investigation as soon as this summer, either by filing a lawsuit or reaching a settlement.

Any deal or lawsuit would need approval from the FTC’s two Republican commissioners, Chairman Andrew Ferguson and Commissioner Mark Meador.

Amazon did not immediately respond to requests for comment, and the FTC declined to comment.

This is far from Amazon’s first run-in with regulators.

In September, the company agreed to pay $2.5 billion to settle separate FTC claims that it used deceptive tactics to sign people up for Prime and made the service difficult to cancel.

Of that total, $1 billion was a civil penalty and $1.5 billion is being refunded to roughly 35 million customers, who have until late July to file claims.

The advertising case also lands on top of a larger legal threat.

Amazon is scheduled to go to trial early next year over FTC antitrust claims that it pressured brands into keeping prices high at rival retailers or risk losing visibility on its marketplace.

The agency has been scrutinizing the company since at least 2019, and a new complaint would mean fighting on two fronts at once.

Regulators are also examining Alphabet’s Google over similar questions involving advertising disclosures.

For everyday shoppers and the small businesses that sell on Amazon, the case touches something familiar.

Those sponsored results at the top of a search page are paid placements, and the fees sellers pay to land there can ultimately become part of the prices consumers see.

If regulators force greater transparency into how Amazon’s advertising auctions work, it could change what sellers pay and eventually influence what shoppers spend.

For now, Amazon’s stock — up nearly 16% over the past year — has barely reacted to the news.

But if the FTC formally files suit this summer, a quiet investigation could quickly become a very public fight over one of the company’s most profitable businesses.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Meme coins have fallen about 82% from their November 2024 record as of June 2026, according to market data from CoinGecko, a collapse that stands in sharp contrast to a U.S. stock market setting fresh highs. The split was on full display Tuesday, when the Dow Jones Industrial Average closed at a record near 52,000 even as the tokens built around internet jokes, mascots, and online communities kept sliding. After a frenzy that pulled billions in retail money into thinly traded coins late in the last cycle, traders are sitting on steep losses.

The reversal marks a clean break from the upbeat mood across traditional markets. The S&P 500 is trading just below its own record after a nine-week run of gains, and Nasdaq technology shares have kept drawing buyers tied to artificial intelligence and big-company earnings. Crypto traders have gone the other way, pulling back from the most speculative tokens and parking what money remains in Bitcoin and a smaller group of higher-quality coins. The meme-coin sector, worth close to $150 billion at its peak, has since shrunk to a fraction of that.

The damage points to a divide inside the digital-asset market itself. Bitcoin still holds the dominant share of total crypto value, while smaller tokens tied to social-media hype face far deeper losses and far fewer buyers and sellers. That thinness leaves meme coins prone to sudden price gaps, especially when traders cut risk or when an online promotional push fails to bring fresh money into a market already crowded with near-identical coins.

Conditions have grown harsher since the late-2024 peak. Kaiko, a crypto-data firm, has noted that trading tends to cluster around the biggest tokens when sentiment weakens — a pattern that makes the smaller corners fall faster. In meme coins, that has become a downward spiral: falling prices cool social-media interest, fewer participants thin out the trading, and that thinness makes each new wave of selling hit harder.

The slide has come even though the backdrop might normally help speculative bets. Federal Reserve policy and the path of interest rates remain front of mind for investors, and futures tied to those expectations still trade actively on CME Group. But crypto buyers have grown choosier, and neither rate optimism nor record stock prices have spilled over into broad token buying the way they did earlier in the cycle. Much of the retail money that once chased meme coins has rotated into stocks and newer bets such as prediction markets.

For everyday investors, the selloff has laid bare the danger of tokens with no real earnings behind them, shaky developer support, and a heavy dependence on going viral. The cooldown reaches the companies that serve them, too. Coinbase Global has told the Securities and Exchange Commission that crypto volatility and customer trading activity can swing its revenue — a reminder that when high-turnover categories like meme coins go quiet, the exchanges that profit from the churn feel it.

Part of the problem is simple oversupply. Ecosystem data from the Solana network and dashboards like Dune show that new token creation has sped up, making it cheap and easy to launch yet another meme coin. More coins chasing the same attention makes it harder for any single one to hold momentum, especially as traders jump from theme to theme and abandon whatever stops trending.

Big institutions have not filled the gap. BlackRock, Fidelity Investments, and other firms have pulled money into spot Bitcoin exchange-traded funds, according to fund filings, giving Bitcoin a steady source of demand. Meme coins sit outside those regulated structures and get none of that support. The takeaway is that investors are now drawing a sharp line between general appetite for risk and pure gambling. Record stock prices, it turns out, are not enough to lift every corner of crypto — and the coins with no revenue, no clear ownership rules, and no real use are the ones left fighting for whatever speculative cash is still willing to play.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The leaders of two of the world’s most influential artificial intelligence companies used a private session at the Group of Seven (G7) summit on Wednesday to advocate for a United States-led alliance that would help shape global rules and standards for artificial intelligence.

According to people familiar with the discussions, Anthropic Chief Executive Dario Amodei and Google DeepMind Chief Executive Demis Hassabis made the case during a closed-door working lunch in Évian-les-Bains, France, on the final day of the summit. Their message was straightforward: as AI becomes more powerful and strategically important, democratic nations should coordinate their efforts through a framework led by Washington.

The gathering brought together some of the world’s most prominent AI executives and political leaders. President Donald Trump attended alongside Treasury Secretary Scott Bessent, Commerce Secretary Howard Lutnick, and Secretary of State Marco Rubio. OpenAI Chief Executive Sam Altman also participated, placing the leaders of America’s three most prominent AI companies in the same room with G7 heads of government.

According to attendees familiar with the discussion, Canadian Prime Minister Mark Carney expressed support for the idea that the United States could play a leading role in organizing such a coalition.

Amodei reportedly focused on national security concerns and the risks associated with increasingly capable AI systems. He argued that allied nations should coordinate access to the most advanced frontier AI models and align policies governing the export of advanced semiconductors and critical computing hardware. According to people familiar with the meeting, he also advocated limiting China’s access to certain technologies and expanding cooperation on threats such as cyberattacks, bioterrorism, and intelligence operations involving artificial intelligence.

Hassabis took a broader approach, emphasizing the scientific and economic opportunities AI could create if governments establish a stable framework for cooperation. He highlighted the technology’s potential applications in areas such as healthcare, scientific discovery, and climate research.

Altman offered a different perspective. Rather than emphasizing leadership by any single country, the OpenAI chief reportedly supported the creation of a neutral international forum responsible for developing globally accepted standards for evaluating and testing advanced AI systems.

The discussion comes at a complicated moment for the AI industry. Governments around the world are struggling to balance innovation, economic competitiveness, and national security concerns. At the same time, AI companies increasingly view themselves not simply as technology providers but as participants in shaping the regulatory frameworks that will govern the industry.

For Anthropic, the timing is especially notable. The company has recently been engaged in discussions with the Trump administration regarding export restrictions affecting some advanced AI technologies. The situation highlights the increasingly complex relationship between AI developers and governments: companies seek government support and international coordination while also facing regulations that can directly affect their products and growth strategies.

The guest list reflected France’s effort to broaden the conversation beyond the United States. Attendees included Mistral Chief Executive Arthur Mensch, representing Europe’s leading AI startup, as well as executives from Cohere, Black Forest Labs, Synthesia, Salesforce, and Meta. Representatives from AI companies in Italy, India, and Japan also participated.

No formal agreements, commitments, or timelines emerged from the meeting. The discussions remained private, and details surfaced only through people familiar with the gathering.

Still, the conversation underscored a growing reality: the executives building the world’s most advanced AI systems increasingly want a role in determining how those systems are governed. Whether governments ultimately embrace a U.S.-led framework, pursue regional approaches, or establish a broader international model remains unresolved.

What appears increasingly clear is that the debate over artificial intelligence is no longer limited to technology. It has become a question of economics, national security, global competitiveness, and geopolitical influence—and the companies creating the technology want a seat at the table as those decisions are made.

JBizNews Desk
Évian-les-Bains, France

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Mortgage rates moved slightly lower this week as easing tensions between the United States and Iran helped calm energy markets and reduce inflation concerns.

According to Freddie Mac, the average rate on a 30-year fixed mortgage fell to 6.47% this week from 6.52% the previous week.

The decline follows a drop in Treasury yields after diplomatic progress reduced fears of prolonged disruptions in the Strait of Hormuz, a critical shipping route that carries roughly 20% of the world’s oil supply.

Mortgage rates generally track the yield on the 10-year U.S. Treasury note. When oil prices fall and inflation concerns ease, bond yields often decline as well, creating downward pressure on mortgage rates.

The recent dip offers modest relief after months of volatility. Mortgage rates climbed sharply following the outbreak of conflict with Iran earlier this year as rising energy prices fueled inflation concerns. Earlier in 2026, the average 30-year mortgage rate had fallen as low as 6.09% before moving higher again. One year ago, the average rate stood at 6.84%.

Still, housing analysts caution that significant declines are unlikely in the near term.

A day before Freddie Mac released its latest data, the Federal Reserve left interest rates unchanged and signaled inflation remains a major concern. New Fed Chair Kevin Warsh indicated policymakers could maintain elevated rates longer than previously expected, and some officials continue to see the possibility of additional tightening if inflation remains stubborn.

While the Fed does not directly set mortgage rates, investor expectations regarding future Fed policy heavily influence Treasury yields and mortgage borrowing costs.

“As rates fluctuate, aspiring buyers should remember that by shopping around for the best mortgage rate and getting multiple quotes, they can potentially save thousands,” said Sam Khater, Chief Economist at Freddie Mac.

For most homebuyers, the latest decline will have only a modest impact on monthly payments. The difference between 6.52% and 6.47% translates into relatively small savings over the life of a loan.

Housing economists generally do not expect mortgage rates to fall below 6% this year, meaning buyers waiting for dramatically cheaper financing may continue waiting.

Affordability challenges also extend beyond interest rates. The median existing-home sales price reached $429,300 in May, setting a record high for the month despite cooling prices in some regional markets.

At current borrowing costs, mortgage payments continue to consume a significant portion of household income, limiting affordability for many first-time buyers.

Despite those challenges, housing demand remains resilient. Existing-home sales rose 3.2% in May, while refinance activity has increased compared with last year as rates remain below 2025 levels.

“We have a record-high level of jobs. We should have record-high levels of home sales,” said Lawrence Yun, Chief Economist of the National Association of Realtors.

The outlook for mortgage rates now depends largely on two competing forces: lower energy prices that could reduce inflation pressures and ongoing inflation concerns that could keep interest rates elevated.

If the ceasefire and reopening of the Strait of Hormuz continue to stabilize energy markets, mortgage rates may drift lower in the months ahead. If inflation remains elevated, however, borrowers may find themselves facing mortgage rates in the mid-6% range well into next year.

For now, the recent decline is welcome news, but not a game changer for most homebuyers.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

U.S. stocks closed higher on Thursday, June 18, recovering much of the previous day’s losses after Federal Reserve Chair Kevin Warsh rattled markets by signaling interest rates could rise this year. Semiconductors led the rebound, with Intel surging after President Donald Trump said the company would design and build chips in the United States alongside Apple.

The Nasdaq 100 led the major indexes, climbing about 2.4%, while the S&P 500 gained roughly 0.9%. The Dow Jones Industrial Average finished little changed but remained near record territory after giving back an earlier gain of more than 300 points. Trading remained volatile into the close as investors navigated quarterly “triple witching” options expiration ahead of Friday’s Juneteenth market holiday.

The rebound followed a sharp selloff Wednesday after Warsh’s first Federal Reserve meeting as chair. The Dow lost more than 500 points and the S&P 500 fell 1.2% after the Fed’s updated projections showed nine of 18 policymakers now expect at least one rate increase in 2026. Warsh emphasized the Fed’s commitment to “price stability,” a message markets interpreted as notably hawkish.

Thursday’s tone was far more optimistic.

Intel jumped roughly 10% on the Trump-Apple announcement. Micron Technology climbed about 8% ahead of earnings due June 24. Nvidia gained around 2%, while Advanced Micro Devices and Broadcom each advanced more than 4% as investors returned to AI-related semiconductor names.

Market Movers

Among Dow components, the biggest gainers included:

  • Caterpillar: +3.7%
  • Home Depot: +2.8%
  • 3M: +1.7%

The weakest performers were:

  • IBM: -5%
  • Salesforce: -2.7%
  • Chevron: -2.2%

Kroger suffered its worst trading session in nearly five years after narrowly missing Wall Street earnings expectations, highlighting continued pressure on consumer-focused retailers.

Analysts remained particularly bullish on memory-chip producers. TD Cowen analyst Krish Sankar reiterated a Buy rating on Micron and raised his price target to $1,500, citing robust demand for AI-related high-bandwidth memory. RBC Capital Markets increased its target to $1,200, while Aletheia Capital boosted its target to $1,600.

Meanwhile, Gene Munster of Deepwater Asset Management argued that planned Apple price increases reflect rising memory costs, suggesting consumers may soon see higher prices for electronic devices. Not all strategists agreed with the rally. UBS trading desks advised clients to “reduce risk meaningfully” in technology stocks following the sector’s powerful run this year.

Oil Falls, Volatility Eases

Oil prices declined after President Trump signed an interim agreement with Iran aimed at lowering energy costs. Improving navigation through the Strait of Hormuz and expectations for a broader agreement Friday helped ease supply concerns.

The drop in crude prices reduced pressure on gasoline costs heading into the summer driving season. Treasury yields, which surged Wednesday following the Fed meeting, stabilized Thursday.

With markets closed Friday for Juneteenth, investors now look ahead to next week. Key events include earnings from Micron and FedEx, along with the government’s updated first-quarter GDP report and May PCE inflation data, the Federal Reserve’s preferred inflation measure.

Those reports could determine whether Warsh’s warning about possible future rate hikes becomes the market’s next major concern.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Bitcoin fell below $64,000 on Thursday as investors reacted to a more hawkish Federal Reserve and growing concerns surrounding Strategy, the company formerly known as MicroStrategy and the world’s largest corporate holder of Bitcoin.

The cryptocurrency was trading near $63,800, down about 1% over the previous 24 hours, after briefly climbing toward $67,000 earlier in the week. That rally had been fueled by optimism surrounding a developing agreement between the United States and Iran aimed at ending hostilities and reopening the Strait of Hormuz, easing concerns about inflation and energy prices.

The mood changed sharply following Wednesday’s Federal Reserve meeting, the first chaired by Kevin Warsh. While policymakers left interest rates unchanged, they signaled that rates may remain elevated longer than expected and could even move higher before year-end.

The Fed’s updated projections showed the median policymaker expects the benchmark federal funds rate to finish 2026 at 3.8%, up from 3.4% projected in March. Nine of the eighteen officials who submitted forecasts now expect at least one additional rate increase before the end of the year.

Higher interest rates generally weigh on speculative assets because they increase returns on safer investments and reduce demand for assets that generate no income. Bitcoin, which pays no yield, often struggles when investors expect tighter monetary policy.

Investors responded by pulling money from cryptocurrency investment products. Spot Bitcoin and Ethereum exchange-traded funds recorded approximately $111 million in net outflows following the Fed announcement.

A second source of concern is Strategy, led by executive chairman Michael Saylor, which owns approximately 846,842 Bitcoin, more than any other publicly traded company.

Shares of MSTR fell roughly 5% on Wednesday and extended losses Thursday as investors questioned the company’s ability to continue financing its aggressive Bitcoin acquisition strategy.

Particular attention has focused on the company’s preferred-share offerings. One series, known as STRC, recently traded around $89, well below its $100 face value. When preferred shares trade below par value, raising new capital becomes more difficult and more expensive.

Analysts at QCP Capital have warned that if financing conditions deteriorate further, Strategy could eventually face pressure to sell portions of its Bitcoin holdings to meet dividend obligations and other funding needs.

Those concerns intensified after Strategy disclosed in late May that it had sold 32 Bitcoin for approximately $2.5 million. While small relative to its overall holdings, the sale marked the first time the company had sold Bitcoin after years of promoting a “never sell” philosophy.

The move sparked debate among investors who viewed Strategy’s Bitcoin reserves as effectively untouchable.

Saylor has pushed back on those concerns, arguing that the company’s long-term commitment to Bitcoin remains unchanged. On Thursday, he reiterated that message by publicly highlighting Strategy’s holding of 846,842 Bitcoin and emphasizing the firm’s continued confidence in the asset.

Additional pressure has come from shifting investor attention toward new opportunities elsewhere in the market. The recent public debut of SpaceX, which disclosed holding 18,712 Bitcoin, has attracted significant investor interest and added competition for capital flowing into crypto-related investments.

Market sentiment has also weakened. The widely followed Crypto Fear & Greed Index recently fell into “extreme fear” territory, reflecting growing caution among traders. Bitcoin briefly touched a 2026 low near $59,100 last week before recovering.

Analysts now view $60,000 as a critical support level. A successful defense of that level could stabilize prices and encourage buyers to return. A decisive break below it, however, could open the door to additional declines toward $57,500 or lower.

Gerry O’Shea, head of global market insights at Hashdex, said he expects Bitcoin to trade largely between $60,000 and $70,000 in the near term unless a major catalyst emerges.

The next major driver remains inflation and Federal Reserve policy. If inflation cools and expectations for future rate hikes fade, pressure on both Bitcoin and Strategy could ease. If inflation remains elevated and the Fed signals additional tightening, cryptocurrency markets may face further headwinds.

For now, a market that spent much of the spring chasing record highs is increasingly focused on defense, with traders watching closely to see whether $60,000 can hold.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Valar Atomics, a Southern California nuclear startup, said Thursday that its Ward 250 reactor has reached criticality, becoming the second reactor to hit that milestone under the federal program designed to accelerate advanced nuclear development in the United States. The achievement marks the first self-sustaining nuclear chain reaction inside the reactor and represents a key step toward proving the technology can eventually generate commercial power.

The reactor reached criticality at the Utah San Rafael Energy Lab, a state-run research facility where Valar has been racing to meet a federal goal of bringing multiple advanced reactors online before July 4, 2026. Ward 250 is a high-temperature gas-cooled reactor that uses TRISO fuel, helium coolant, and a graphite-based core design. The project was built with engineering and construction support from Kiewit Nuclear Solutions.

Valar becomes the second company to reach the milestone under President Donald Trump’s Reactor Pilot Program. Earlier this month, Antares Nuclear’s Mark-0 microreactor became the first privately developed non-light-water reactor in the United States to achieve criticality in more than four decades at Idaho National Laboratory. With Valar now joining the list, the federal initiative is only one reactor away from reaching its target of three critical reactors before Independence Day.

Criticality is an important milestone, but it does not mean the reactor is producing meaningful power. During these early tests, reactors are brought to a self-sustaining nuclear reaction at extremely low power levels to verify the design and operating characteristics. Commercial electricity generation remains years away.

As American Nuclear Society President Mark Peters has noted, criticality is “a starting line, not a finish line.” Significant testing, safety validation, and regulatory reviews still lie ahead before reactors like Ward 250 can enter commercial service.

The milestone follows months of rapid development. In November 2025, Valar conducted a successful cold-criticality test using a scaled reactor assembly known as NOVA at Los Alamos National Laboratory. The test helped validate the physics underlying the Ward 250 design before construction of the full reactor.

The company drew national attention again in February when the completed reactor was transported from California to Utah aboard U.S. Air Force C-17 cargo aircraft in what officials described as a first-of-its-kind military-assisted reactor airlift. Energy Secretary Chris Wright accompanied the transport effort and has repeatedly highlighted advanced nuclear energy as a cornerstone of future U.S. energy policy.

The race to bring reactors online is being driven largely by the exploding energy needs of artificial intelligence and data centers. AI companies are rapidly building facilities that require enormous amounts of around-the-clock electricity, creating concerns that existing power infrastructure may struggle to keep pace.

Valar argues that advanced nuclear reactors offer one of the few scalable solutions capable of supplying reliable carbon-free electricity regardless of weather conditions. The company estimates that AI-related growth could require more than 200 terawatt-hours of additional power by 2030.

Beyond supplying electricity to the grid, Valar sees opportunities in industrial applications. High-temperature reactors can generate heat for manufacturing processes, support hydrogen production, and potentially create synthetic fuels using captured carbon dioxide. The company believes those industrial uses could help finance broader deployment of advanced nuclear technology.

Valar’s long-term vision includes what it calls “gigasites” — large industrial campuses powered by clusters of small reactors supplying energy directly to manufacturers, data centers, and other major customers without relying entirely on the public grid.

The program itself remains controversial. The Reactor Pilot Program was established through a presidential executive order in May 2025 and allows participating companies to use the Department of Energy’s authorization process rather than the traditional Nuclear Regulatory Commission licensing pathway during early testing stages.

Supporters argue the approach is necessary to speed innovation and maintain U.S. leadership in nuclear technology. Critics, including Edwin Lyman of the Union of Concerned Scientists, have warned that bypassing portions of the conventional NRC process could create safety risks if not carefully managed.

National security officials have also shown growing interest in microreactors. Small reactors could provide reliable power to military bases, remote installations, and critical infrastructure that might otherwise depend on vulnerable electric grids or fuel deliveries.

For consumers, the implications remain indirect for now. If advanced reactors can eventually be built quickly and at scale, they could help relieve electricity shortages, support the growth of AI infrastructure, stabilize industrial energy costs, and reduce pressure on power prices in fast-growing regions.

Valar says it plans to continue higher-power testing throughout the remainder of 2026 and hopes to begin limited commercial operations in 2027 before expanding further in 2028.

For now, the company has cleared one of the industry’s most important technical hurdles. Whether Ward 250 becomes part of a broader nuclear revival will depend on what happens next as testing advances from proving the reactor works to proving it can safely and economically deliver power.

JBizNews Desk
Washington Bureau
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

JetBlue Airways told employees Wednesday that it will close its flight attendant base at Newark Liberty International Airport and shut technical operations bases at both Newark and LaGuardia Airport this fall as the airline shifts aircraft and resources away from the New York region and doubles down on growth in Fort Lauderdale, Florida.

The carrier emphasized that the move will not result in layoffs. Employees affected by the closures will have opportunities to transfer or bid into other JetBlue bases.

The decision comes down to economics. JetBlue has repeatedly highlighted the high cost of operating in the New York market, particularly at LaGuardia, where an approximately $8 billion airport redevelopment project has increased expenses for airlines. Rather than continue investing heavily in some of the country’s most expensive airports, JetBlue is redirecting resources toward a market where it already sees stronger profitability.

That market is Fort Lauderdale-Hollywood International Airport, where JetBlue has become the airport’s largest carrier. Earlier Wednesday, the airline announced plans to expand its premium Mint service from Fort Lauderdale, adding new coast-to-coast routes aimed at higher-paying travelers.

A new daily Fort Lauderdale-to-San Diego flight will begin on November 19, while additional Mint service is planned for Los Angeles and San Francisco. By the winter travel season, JetBlue expects to operate as many as eight daily flights between Fort Lauderdale and Los Angeles and three daily flights to San Francisco.

The financial incentive is significant. Premium Mint fares can generate many times the revenue of traditional economy seats. For example, one-way Mint tickets between Fort Lauderdale and Los Angeles for January travel were selling for more than $3,000, with some fares exceeding $4,500, while basic economy seats on the same route were available for less than $250.

JetBlue’s opportunity in South Florida expanded dramatically after the collapse of Spirit Airlines on May 2. Spirit, long one of the dominant carriers in Fort Lauderdale, ceased operations following its second bankruptcy after creditors rejected a last-minute rescue effort. The shutdown left valuable airport gates, routes, and customers available, creating an opening that JetBlue has moved quickly to fill.

The changes in the New York market extend beyond employee bases. JetBlue is winding down seasonal service from Newark to both Los Angeles and Las Vegas. The airline already discontinued its twice-daily Newark-to-Las Vegas service on June 10, eliminating more than 13,000 monthly seats, while Newark-to-Los Angeles flights are scheduled to end early next year.

Aircraft freed from those routes will be redeployed to support the airline’s Florida expansion, including the return of Fort Lauderdale-to-San Diego service, which JetBlue last operated in January 2025.

While Newark and LaGuardia remain important parts of JetBlue’s network, they are not the center of its New York presence. At the end of 2025, JetBlue controlled roughly 13% of airline seats across the New York metropolitan area’s five major airports, but the vast majority of that presence was concentrated at John F. Kennedy International Airport.

JetBlue carried approximately 14.5 million passengers through JFK in 2025, accounting for more than 23% of the airport’s total traffic. By comparison, the airline carried about 1.9 million passengers through Newark and 1.1 million through LaGuardia, representing just 4% and 3.4% of passenger traffic at those airports respectively.

Company executives acknowledged that the Newark pullback raises questions about JetBlue’s future ambitions at LaGuardia, particularly as airport slots may become available following Spirit’s departure. However, management said opportunities from a future slot auction remain uncertain and cannot be factored into current operating plans.

The strategy reflects a broader effort to restore consistent profitability. JetBlue’s last profitable quarter came nearly two years ago, and company leadership has repeatedly identified Fort Lauderdale as a key pillar of its turnaround strategy. Under Chief Executive Officer Joanna Geraghty and President Marty St. George, the airline has spent the past several years trimming underperforming routes, slowing hiring, reducing capacity, and adjusting fares to offset higher operating costs.

For travelers, the message is straightforward. Passengers in northern New Jersey and Queens will likely see fewer JetBlue options this fall, while travelers in South Florida can expect more flights, more destinations, and a larger selection of the airline’s premium Mint service as JetBlue places a bigger bet on Fort Lauderdale.

JBizNews Desk
New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Mars Wrigley North America is moving forward with plans to sell dye-free versions of some of its most recognizable candy brands, marking a significant shift for a company that previously resisted removing artificial colors from its products.

The initiative, first announced in July 2025 and now rolling out during 2026, will introduce versions of M&M’s Chocolate, Skittles Original, Starburst Original, and Extra Spearmint Gum made without synthetic petroleum-based food dyes. The move aligns with growing pressure from regulators, lawmakers, and consumer advocates associated with the Make America Healthy Again (MAHA) movement championed by Health and Human Services Secretary Robert F. Kennedy Jr.

The reformulated products will be sold alongside existing versions rather than immediately replacing them nationwide.

According to Anton Vincent, President of Mars Wrigley North America, the company’s approach is intended to be both “consumer-focused and science-led.”

The announcement represents a notable reversal from Mars’s earlier position.

In 2016, the company pledged to remove artificial colors from its global food portfolio within several years. That commitment was later scaled back after Mars concluded many consumers did not view synthetic dyes as a major concern.

At the time, the company said its research showed that many customers around the world did not consider artificial colors to be ingredients they actively sought to avoid.

Since then, however, the political and regulatory environment has changed dramatically.

The Food and Drug Administration (FDA) banned Red No. 3 from foods in early 2025, requiring manufacturers to remove the additive by 2027. Federal regulators have also encouraged food manufacturers to reduce reliance on other synthetic dyes, including Red 40, while approving additional natural coloring alternatives derived from fruits, vegetables, and other natural sources.

Several states have enacted laws limiting or banning artificial food dyes in school meals, further accelerating industry reformulation efforts.

The issue has also drawn legal scrutiny.

Texas Attorney General Ken Paxton launched an investigation into Mars, seeking company records and questioning why some products sold in Europe already use alternative formulations while U.S. versions continue to contain artificial dyes. Paxton directly linked the inquiry to broader MAHA health initiatives and called on manufacturers to move more aggressively toward reformulation.

For food companies, replacing synthetic dyes is not a simple or inexpensive process.

Natural color alternatives often provide less vibrant colors, can be less stable over time, and frequently have shorter shelf lives than synthetic additives. Supply chains for natural color ingredients are also more limited, creating additional cost pressures as demand increases across the industry.

The National Confectioners Association has warned that large-scale transitions away from synthetic dyes could significantly increase manufacturing costs and strain supplies of natural coloring ingredients.

Despite those challenges, much of the industry is already moving in the same direction.

Kraft Heinz, General Mills, PepsiCo, ConAgra, The Hershey Company, Nestlé USA, McCormick, and J.M. Smucker have all announced plans to reduce or eliminate artificial food dyes, with most targeting completion between 2027 and 2028.

That leaves Mars no longer as an outlier but as part of a broader transformation sweeping through the American food industry.

For consumers, the rollout comes with an important distinction: the traditional versions of these products are not disappearing immediately. Instead, Mars is initially introducing dye-free alternatives and allowing shoppers to choose between the two.

The scientific debate surrounding food dyes also remains unresolved. The FDA continues to maintain that approved food-color additives are safe for most consumers when used as directed. However, some researchers and health advocates point to studies suggesting certain artificial dyes may contribute to hyperactivity and behavioral issues in a subset of children.

As a result, the shift is being driven not only by science, but also by changing consumer preferences, political pressure, and evolving market expectations.

For Mars, a privately held company generating tens of billions of dollars in annual revenue, the calculation appears increasingly straightforward: the cost of reformulation may now be lower than the reputational risk of resisting a trend that is rapidly gaining momentum among regulators, lawmakers, and consumers.

Whether the dye-free versions ultimately replace the originals remains to be seen. But one thing is clear: the candy aisle is becoming the latest battleground in America’s growing debate over food ingredients and public health.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

New applications for unemployment benefits declined last week, offering another sign that layoffs remain relatively low even as the U.S. labor market continues to cool.

The U.S. Department of Labor reported Thursday that initial jobless claims fell to 226,000 for the week ending June 13, down 4,000 from the previous week’s revised total of 230,000. The result was slightly above economists’ expectations of 225,000.

While the decline pulled claims back from a four-month high reached earlier this month, filings remain near the upper end of the range that has defined 2026. Weekly claims have largely fluctuated between 190,000 and 230,000 throughout the year.

The more concerning trend is appearing beneath the headline number.

Continuing claims — which measure the number of Americans still receiving unemployment benefits after their initial filing — rose by 24,000 to 1.81 million for the week ending June 6. The insured unemployment rate remained unchanged at 1.2%.

The increase suggests that while employers are not conducting widespread layoffs, workers who lose jobs are finding it more difficult to secure new positions.

The average unemployed American spent 11.6 weeks searching for work in May, up from 11.0 weeks in April and the longest average job search since November 2021.

The data points to a labor market that is slowing through reduced hiring rather than rising layoffs. Businesses appear reluctant to let workers go but are also becoming more selective about adding new employees.

Earlier increases in claims were concentrated in Pennsylvania, Minnesota, California, Texas, and Puerto Rico. State officials attributed the increases to layoffs in transportation, warehousing, hospitality, administrative support, healthcare, and education sectors. Seasonal filings from school employees during summer break also contributed to some of the rise.

Claims filed by federal workers have increased modestly amid efforts to reduce portions of the government workforce but continue to represent a small share of overall filings.

On an unadjusted basis, unemployment claims remain slightly below year-ago levels, with approximately 220,000 filings last week compared with roughly 235,000 during the same period in 2025.

The report aligns with other recent labor-market data showing moderation rather than deterioration. Employers added 172,000 jobs in May, while average monthly job growth over the past three months stands at approximately 188,000. The unemployment rate has remained steady at 4.3% for three consecutive months.

Because consumer spending drives roughly two-thirds of U.S. economic activity, economists closely monitor jobless claims as an early indicator of future demand. As long as layoffs remain contained, household income and spending should remain relatively stable.

For workers, however, the message is more nuanced. Job security remains solid for those currently employed, but those entering the job market may face a longer and more competitive search process.

The claims report also covers the period used by the government to calculate June’s monthly employment report, making it an important indicator ahead of next month’s jobs data.

For now, the labor market appears to be cooling gradually rather than weakening sharply.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Apple plans to raise prices on some of its products as a global memory-chip shortage fueled by artificial intelligence demand drives costs sharply higher, according to comments by Chief Executive Tim Cook published Wednesday.

Speaking about the growing strain on the semiconductor supply chain, Cook said the company has absorbed higher component costs for as long as possible but can no longer shield customers completely.

“Unfortunately, price increases are unavoidable,” Cook said.

At the center of the problem is a surge in demand for memory chips used in AI data centers. The same memory technologies that power smartphones, tablets, and laptops are now being consumed in enormous quantities by companies building the infrastructure behind artificial intelligence.

As a result, memory manufacturers are increasingly prioritizing production for higher-margin AI server chips rather than components destined for consumer electronics.

That shift is putting pressure on companies such as Apple, which purchases massive quantities of memory and storage chips for products including the iPhone, iPad, and Mac.

Cook pointed specifically to shortages in DRAM, a critical type of memory used throughout Apple’s product lineup. He said growing demand for advanced memory used in AI servers has tightened supplies across the broader market and pushed prices significantly higher.

The CEO compared current market conditions to a once-in-a-century event, saying he had never seen anything similar during more than four decades in the technology industry.

Industry analysts say the financial impact could be substantial.

Research firm TechInsights estimates Apple could need to increase the price of its next-generation iPhone 18 Pro by roughly $270 to fully preserve current profit margins if memory costs remain elevated.

Apple has already taken smaller steps that effectively increased pricing in certain product categories. The company recently eliminated lower-priced configurations of several desktop computers, raising entry-level purchase prices without formally announcing broad price hikes.

The timing presents additional challenges because Apple is preparing to launch a new wave of AI-enabled products.

The company is expected to introduce its first foldable iPhone alongside the iPhone 18 Pro lineup later this year. New AI features require additional memory capacity, increasing Apple’s dependence on the very components currently experiencing the greatest shortages.

Cook indicated Apple is willing to use its financial resources to help secure supply but said the company has no intention of entering the memory-manufacturing business itself.

Instead, Apple will continue relying on suppliers including Samsung Electronics, SK Hynix, and Micron Technology, all of which are expanding production. However, much of that additional capacity is expected to be directed toward AI infrastructure rather than consumer devices.

The issue extends well beyond Apple.

Major technology companies including Samsung, Microsoft, Sony, and Dell have already implemented price increases tied to higher component costs. Industry groups representing retailers, automakers, and electronics manufacturers have also warned that ongoing shortages could lead to broader price increases across numerous consumer products.

For years, smartphones, laptops, and personal electronics were among the industry’s highest-priority customers. The rapid expansion of AI infrastructure is changing that dynamic, with data-center operators increasingly willing to pay premium prices for critical components.

Investors appeared relatively unfazed by the news. Apple shares slipped modestly during regular trading before recovering some ground after the interview was published.

For consumers, however, the message is straightforward.

The AI revolution powering Wall Street’s biggest technology boom is beginning to reach checkout counters. As data centers consume more of the world’s memory supply, the cost of everyday electronics is rising alongside it.

Unless memory supplies improve significantly, Apple customers should expect future devices to come with higher price tags.

JBizNews Desk
Cupertino, Calif.

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

One of America’s most prominent African American voices is making a public case for recognizing Jews as a minority community deserving protection and support.

Van Jones, the CNN political commentator, attorney, and civil rights advocate, has joined the advisory board of the Genesis Prize Foundation, the organization announced Wednesday. In remarks accompanying the announcement, Jones pointed to the small size of the global Jewish population and argued that humanity has a special responsibility to stand with a people who have endured centuries of persecution and whose numbers were devastated by the Holocaust.

“There are only about 15 million Jews left in the world,” Jones said in a video released by the foundation, noting that the Jewish population is tiny compared with the world’s largest religious and ethnic groups. He argued that the Jewish community would be significantly larger today had it not suffered generations of violence, discrimination, expulsions, and ultimately the Holocaust.

Jones also highlighted the unique position of Israel, which is home to roughly half of the world’s Jewish population.

“When a group that small comes under attack, humanity has a special responsibility to defend them,” he said, while emphasizing that criticism of Israeli government policies remains legitimate. What he rejects, however, is the idea that support for the Jewish state itself should be abandoned.

“We already ran a 3,000-year experiment where Jews did not have a state,” Jones said, arguing that history demonstrated the dangers of Jewish statelessness.

The appointment carries added significance because Jones is framing the issue as one minority community standing in solidarity with another. A longtime civil rights leader, Jones said one of his goals on the board will be helping rebuild the historic alliance between Black and Jewish Americans.

“Together, Black and Jewish Americans have written some of the most important chapters in the story of American democracy,” Jones said. While acknowledging tensions and divisions in recent years, he argued that the relationship remains too important to abandon amid rising antisemitism and increasing political polarization.

Stan Polovets, co-founder and chairman of the Genesis Prize Foundation, praised Jones’s record of coalition-building and public leadership.

“Van Jones brings moral clarity, public credibility, and practical coalition-building experience,” Polovets said. “At a time of rising antisemitism, voices like his are essential.”

The foundation’s advisory board is chaired by former Soviet dissident Natan Sharansky, who spent eight years in Soviet prisons because of his pro-democracy activism and support for Jewish emigration rights. Sharansky said Jones’s appointment reflects the foundation’s belief that Jewish achievement carries with it a responsibility to engage with broader society and strengthen democratic values.

The Genesis Prize, often referred to as the “Jewish Nobel,” awards $1 million annually to individuals who have demonstrated exceptional professional achievement and commitment to Jewish values. According to the foundation, the prize has helped generate more than $50 million for charitable causes since its creation in 2013, supporting over 230 nonprofit initiatives in 31 countries.

The 2026 recipient is Israeli actress and producer Gal Gadot, whose award is being matched through the Jewish Funders Network, bringing total charitable giving associated with her prize to $2 million.

Jones’s comments also come as Jewish minority recognition has gained increasing attention in the United States.

In a landmark move, the U.S. Department of Commerce’s Minority Business Development Agency (MBDA) signed a Memorandum of Understanding with the Orthodox Jewish Chamber of Commerce on January 13, 2025, formally recognizing Jewish-owned businesses within the agency’s minority-business framework. The agreement marked the first time Jewish-owned businesses were granted access to programs traditionally available to other minority communities through the federal agency.

At the signing, then-Deputy Commerce Secretary Don Graves described the recognition as an overdue correction and praised the efforts of the Orthodox Jewish Chamber of Commerce in advancing the initiative. Greater New York Chamber of Commerce President Mark Jaffe called the move “long overdue,” while Duvi Honig, founder and CEO of the Orthodox Jewish Chamber of Commerce, described it as a historic achievement for the Jewish business community.

The timing of Jones’s appointment is notable. Antisemitic incidents have risen sharply in the United States and around the world, while longstanding partnerships between Black and Jewish organizations have faced strains in recent years.

Jones is placing his credibility as a civil rights leader behind the belief that those relationships can be rebuilt—and that a people numbering only about 15 million worldwide should not have to face growing threats alone.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

U.S. Steel said in an updated economic impact analysis released June 8 that its Japanese parent, Nippon Steel, will spend between $2 billion and $2.5 billion to overhaul its Mon Valley Works complex in southwestern Pennsylvania over the next three years — more than double the amount the company first committed to when the two firms combined.

The centerpiece is a new, state-of-the-art hot strip mill that would replace an 87-year-old facility and, the company says, secure thousands of steel jobs for decades to come.

The plan calls for building the new mill at the Edgar Thomson plant in Braddock, Pennsylvania, while upgrading other parts of the Mon Valley Works.

The new mill would take the place of an aging hot strip mill at the nearby Irvin plant, which is set to be decommissioned.

U.S. Steel says the modern facility is designed to waste less material, use less energy, and turn out higher-quality steel, including the grades that supply American automakers and other manufacturers.

A hot strip mill is where steel slabs are reheated and rolled into the flat sheets used to make cars, appliances, and building materials — a core step in turning raw steel into finished products.

Modernizing it lets the plant make a wider range of higher-value steel.

The figure marks a sharp increase from the original pledge.

When Nippon Steel was negotiating its purchase of U.S. Steel in August 2024, it promised to spend at least $1 billion on a hot strip mill in the region.

The company is now weighing two larger blueprints — a $2 billion version and a $2.5 billion version — either of which would roughly double that early commitment.

The economic stakes for the region are considerable.

According to the analysis, the project could pump as much as $1.7 billion into Pennsylvania’s economy and support up to 6,381 jobs.

For the Mon Valley, a stretch of old steel towns east of Pittsburgh that has lost industrial work for generations, the spending lands as a rare promise of stable, good-paying employment.

The United Steelworkers union, which represents roughly 75% of U.S. Steel’s North American workforce, saw strong support for the merger among local members in Pennsylvania, in large part because of the investment commitments attached to it.

David Burritt, president and chief executive of U.S. Steel, framed the investment as proof that American steelmaking still has a future.

He said the project protects thousands of jobs and will supply U.S. manufacturers for generations, calling it an example of what investing in America looks like.

He also pointed to the region’s history, noting that the Mon Valley is where the American steel industry was first forged.

That history runs deep.

The Edgar Thomson plant has operated for more than 150 years and is the last integrated steel producer in Pennsylvania still running blast furnaces and basic oxygen furnaces.

It was opened in 1875 by Andrew Carnegie as part of Carnegie Steel, making this modernization a notable chapter for one of the country’s oldest continuously operating mills.

The new spending flows from one of the most closely watched corporate deals in recent years.

Nippon Steel completed its roughly $14.9 billion takeover of U.S. Steel in 2025 after a long and politically charged review.

As part of the agreement, Nippon Steel pledged to invest about $11 billion across U.S. facilities through 2028, keep U.S. Steel’s headquarters in Pittsburgh, and give the U.S. government unusual power to weigh in on major decisions.

The Mon Valley project is one piece of that broader commitment, which spans plants in several states and is meant to protect and create roughly 100,000 jobs.

For U.S. Steel, now the American arm of the world’s fourth-largest steelmaker, the bet is that pouring money into older mills can keep domestic production competitive against cheaper foreign steel and rivals at home.

For the towns around the Mon Valley Works, the more immediate question is simpler: whether the construction, and the jobs that come with it, arrives on schedule.

Pittsburgh — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The most coveted machine in American cybercrime is neither a supercomputer nor a stolen laptop. It is the forgettable electronics humming in the corner of the living room — the discount streaming stick, the digital picture frame, the aging router no one has signed into in years. Hackers prize them not for anything stored inside, but for the single asset they carry that a server farm cannot counterfeit: a genuine American home address on the internet.

That asset is the through-line of an investigation disclosed Wednesday, in which Comcast’s Threat Research Lab, working with Microsoft, traced sophisticated intrusions back to ordinary household devices. The findings answer a question that has unsettled the security industry for two years: why the humblest gadget in the house has become an instrument of espionage.

The logic is reputational. Every connected device announces an internet address, the digital equivalent of a return address on an envelope. Defensive systems extend trust unevenly — traffic from a data center or a known anonymizer invites scrutiny, while traffic from a family’s broadband line reads as a neighbor shopping or streaming. Attackers exploit that trust by routing their operations through the home connection, so the activity arrives bearing the resident’s identity. The industry calls the arrangement a residential proxy; Comcast has likened it to a forged return address, illicit mail dispatched through an unwitting household’s mailbox.

The supply of borrowable homes has grown rapidly. In a public advisory issued March 12, the Federal Bureau of Investigation warned that inexpensive internet-connected electronics — including streaming boxes, older Wi-Fi routers, smart TVs, security cameras, digital picture frames, smart plugs, baby monitors, and other smart-home devices — are increasingly arriving in the United States with concealed “backdoor” software preinstalled. The bureau said the same code is also being threaded into free mobile applications and pirated video games. Some devices, the FBI cautioned, are compromised before they leave the factory, and a standard reset will not reliably remove the infection.

Others are conscripted the moment a consumer installs a free virtual private network, a bandwidth-for-cash application, or a bargain smart-home product whose consent terms are buried deep in the fine print.

The disguise is formidable because it is, by design, indistinguishable from everyday life. Research published this month by Infoblox, a network-security firm, found that more than 65% of its enterprise cloud customers connected to residential-proxy services during 2026. Monthly lookups associated with these networks climbed from roughly 400 billion in early 2025 to more than 500 billion by April 2026, and surfaced across every industry surveyed — including more than 90% of pharmaceutical and food-and-beverage companies and more than 60% of government and banking customers. The resilience is equally striking: when Google dismantled a leading provider, IPIDEA, in January, the traffic redistributed to competitors within a single day.

The expense ultimately settles on the enterprise whose identity is borrowed. Dr. Renée Burton, vice president of threat intelligence at Infoblox, said the services allow outside parties to trade on a company’s reputation and internet identity to commit crimes. The practical consequences are corrosive: legitimate email blocked as spam, customer logins mistaken for fraud, and security teams consumed by false alarms — all because a firm’s addresses surfaced in a proxy pool it never sanctioned. The artificial-intelligence boom has intensified the pressure, with Infoblox attributing part of the recent surge to companies harvesting web data for AI training, a use that blurs the boundary between routine commerce and criminal cover.

The episode that exposed the pattern underscores its reach. A telephone call more than two years ago between a senior Microsoft security executive and a counterpart at Comcast led investigators to Midnight Blizzard, a group tied to Russia’s foreign intelligence service, which had reached the email accounts of Microsoft’s senior leadership while sheltering behind consumer connections.

In the near term, the remedies are modest and rest largely with individuals. The FBI counsels against streaming boxes that advertise free movies and sports, discourages free VPN downloads, and urges reliance on official app stores, strong passwords, and current software updates. Consumers should also replace aging routers that no longer receive security support and avoid internet-connected devices from manufacturers that do not regularly issue software patches.

The longer reckoning concerns accountability. Burton contends that regulators should require clear, informed consent before any device is enrolled in a proxy network, much as disclosure rules reshaped the use of web cookies. Absent that, the economics continue to favor the intruder: a compromised gadget costs only a few dollars, while the household — and the corporation whose name it borrows — absorbs the reputational bill, often without ever learning the device was quietly working elsewhere.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

For Israelis planning summer vacations abroad, one of the biggest travel expenses isn’t the hotel or airfare — it’s the exchange rate. After months as one of the world’s strongest currencies, the Israeli shekel began weakening against the U.S. dollar in June, raising concerns that overseas trips could become more expensive by the day.

In response, Bank Hapoalim, Israel’s largest bank, has launched a new program designed to protect customers from further currency swings. The bank announced it will cap the exchange rate at NIS 2.89 per dollar for eligible card purchases made abroad this summer, giving travelers certainty at a time when the currency market remains volatile.

The offer, announced by Pazit Garfinkel, Head of Retail Banking at Bank Hapoalim, applies to purchases made with the bank’s credit and debit cards overseas, on foreign websites, and for cash withdrawals from foreign ATMs between June 15 and August 31.

“Our customers are planning their summer vacations abroad and deserve peace of mind without worrying about volatile foreign exchange markets,” Garfinkel said.

The protection works in the customer’s favor regardless of market direction. If the dollar rises above NIS 2.89, the bank will reimburse the difference. If the dollar falls below that level, customers automatically receive the lower market rate.

The program covers up to $5,000 per month in spending, allowing travelers to protect as much as $15,000 over the three-month summer period.

The potential savings can add up quickly. With the dollar trading near NIS 2.95 this week, customers are already saving approximately NIS 0.06 per dollar compared with the market rate. That translates to roughly NIS 300 per month on the maximum covered spending amount, or about NIS 900 over the summer.

If the dollar were to climb to NIS 3.00, the savings would increase to approximately NIS 550 per month, or about NIS 1,650 across the full summer period.

The benefit is available to private customers and small non-corporate business clients who hold active Bank Hapoalim credit or debit cards. Customers must register in advance through the bank’s online platform before purchases become eligible for reimbursement.

The timing may prove favorable. The dollar recently strengthened after comments from Bank of Israel Governor Amir Yaron suggested interest rates could be reduced faster than previously expected. Lower interest rates generally weaken a country’s currency, increasing the likelihood that the dollar remains above the bank’s guaranteed rate.

Still, the opposite scenario remains possible. Earlier this year, the shekel reached its strongest level against the dollar in roughly three decades, helped by renewed investor confidence following the regional ceasefire and improving trade conditions. Should the shekel strengthen again, the dollar could fall below the NIS 2.89 threshold. In that case, customers simply pay the lower market rate and lose nothing.

Beyond helping travelers, the initiative is also a competitive move by Bank Hapoalim. Israeli banks have increasingly competed for retail customers through rewards programs, trading-fee rebates, savings incentives, and other benefits. By offering protection against foreign-exchange volatility during peak travel season, the bank is giving customers a reason to keep spending on Hapoalim cards throughout the summer.

For now, with the dollar trading above the guaranteed rate, travelers are already benefiting. In a world where exchange rates can change daily, Bank Hapoalim is offering something unusual: predictability.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Iran and the United States are heading back to the negotiating table over Tehran’s nuclear program under a fragile new framework that halted direct fighting, reopened the Strait of Hormuz, lifted the American naval blockade, and established a 60-day ceasefire window for negotiations, with a formal signing expected in Geneva.

What makes this round of diplomacy different is the mindset on the Iranian side. After roughly four months of conflict that began in late February, Iran’s government remains in power despite extensive military strikes, economic pressure, and the loss of senior military leaders. While the war inflicted significant damage, Tehran emerged convinced that it can withstand far more pressure than many Western leaders previously believed. That perception is likely to shape every aspect of the negotiations.

At the center of the talks is Iran’s stockpile of highly enriched uranium. According to the International Atomic Energy Agency (IAEA), Iran possesses approximately 440.9 kilograms of uranium enriched to 60% purity, placing it only a short technical step away from weapons-grade material. Determining the future of that stockpile is expected to be the most contentious issue facing negotiators.

President Donald Trump has repeatedly stated that sanctions relief will not be granted merely in exchange for surrendering enriched uranium. He has also expressed opposition to proposals that would place Iranian nuclear material under the control of countries such as China or Russia, arguing that such arrangements fail to provide sufficient safeguards.

Vice President JD Vance has described the military campaign as having significantly delayed Iran’s nuclear ambitions rather than permanently ending them. His comments reflect a growing recognition within Washington that military action alone did not eliminate the underlying dispute surrounding Iran’s nuclear capabilities.

Another major obstacle involves international inspections. Following strikes on key nuclear facilities, Iran suspended portions of its cooperation with the IAEA, limiting access to sites that inspectors had previously monitored. IAEA Director General Rafael Grossi has urged Tehran to restore full cooperation, warning that uncertainty surrounding the location and condition of nuclear materials increases risks for all parties involved.

Despite its more confident political posture, Iran remains under severe economic strain. Sanctions continue to restrict access to global financial markets, foreign investment remains scarce, and energy exports have faced repeated disruptions. Oil revenue remains the backbone of the Iranian economy, making sanctions relief a critical objective for Tehran.

That reality explains why Iranian officials continue to signal interest in a negotiated settlement. Senior Iranian figures have publicly discussed the release of frozen assets and broader sanctions relief as essential components of any agreement. Foreign Minister Abbas Araghchi has indicated that Iran remains willing to discuss enhanced oversight and limitations on parts of its nuclear program if meaningful economic benefits are delivered in return.

The current negotiations build upon previous diplomatic efforts that produced temporary ceasefires and competing proposals from both sides. While substantial differences remain, the talks are now focused on two core questions: whether Iran will retain any domestic uranium enrichment capability and how quickly sanctions would be removed if an agreement is reached.

For businesses, investors, and consumers around the world, the outcome extends far beyond nuclear policy. The reopening of the Strait of Hormuz, through which a significant portion of global energy supplies pass, has already eased pressure on oil markets. Any lasting agreement that restores Iranian exports could further increase global energy supplies and influence fuel prices worldwide.

Markets are therefore watching the negotiations closely. Energy traders, shipping companies, manufacturers, and governments all have a stake in whether the ceasefire evolves into a lasting agreement or collapses into another round of confrontation.

The reality facing both sides is complicated. Iran enters the talks politically emboldened by its survival but economically weakened by years of sanctions and months of conflict. The United States enters seeking stronger nuclear safeguards while attempting to avoid another prolonged regional crisis.

That combination of confidence and economic vulnerability may ultimately define the negotiations. Iran may believe it has gained leverage, but it still needs access to global markets, oil revenues, and financial relief. Whether those competing pressures produce a breakthrough or another stalemate will determine not only the future of Iran’s nuclear program, but also the stability of one of the world’s most important energy-producing regions.

JBizNews Desk
Geneva / Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

American consumers continued spending at a surprisingly strong pace in May despite elevated fuel costs and lingering concerns about inflation, according to new figures released by the U.S. Census Bureau.

Retail and food service sales rose 0.9% during the month, significantly exceeding many economists’ expectations and highlighting the resilience of consumer spending, which remains the primary engine of the U.S. economy.

The increase marked another solid month for retailers and suggested that households continued opening their wallets even as higher gasoline prices and broader economic uncertainty weighed on consumer sentiment.

Part of the gain came from rising fuel costs.

Gas station sales increased sharply during the month as energy prices climbed amid tensions in the Middle East and concerns about global oil supplies. Higher prices at the pump boosted overall retail sales totals even when adjusted spending patterns varied across sectors.

Yet the strength was not limited to gasoline.

Excluding fuel sales, retail spending still posted healthy gains across several major categories. Auto dealerships recorded stronger sales, furniture stores advanced, building material suppliers reported increases, and clothing retailers also experienced growth.

Online shopping remained one of the strongest-performing segments of the economy.

Nonstore retailers, which include e-commerce companies, posted another robust monthly increase and continued significantly outperforming traditional brick-and-mortar growth rates. The trend reinforces a shift that has steadily accelerated over the past decade as consumers move more purchases online.

Not every sector benefited equally.

Department stores and electronics retailers reported modest declines, while restaurant spending softened slightly. Economists often watch restaurant activity closely because discretionary dining expenses are among the first categories households trim when budgets become strained.

Despite those pockets of weakness, the broader picture remained positive.

Consumer spending has been supported in recent months by strong employment levels, wage growth, and tax refunds that provided many households with additional cash during the spring.

However, economists caution that some of those supports may begin to fade during the summer months.

Several analysts have noted that tax-refund-related spending likely contributed to the strong May numbers. As those funds are exhausted, consumer spending growth could moderate later in the year.

Beneath the headline figures, surveys continue to show that many Americans remain financially cautious.

Consumers are increasingly prioritizing necessities and searching for discounts while reducing spending on certain discretionary purchases. At the same time, many households continue allocating money toward experiences, entertainment, travel, and dining.

The report also carries implications for monetary policy.

Stronger-than-expected consumer spending, combined with ongoing labor market strength and persistent inflation concerns, could influence future decisions by the Federal Reserve. Policymakers continue balancing the risk of inflation against the possibility of slowing economic growth.

For now, the latest data suggest that consumers remain willing to spend despite economic headwinds.

The coming months will help determine whether May’s performance reflected temporary factors such as tax refunds and gasoline prices or whether households possess enough financial strength to continue supporting economic growth through the second half of the year.

The American consumer has repeatedly surprised economists by remaining resilient in the face of inflation, higher borrowing costs, and global uncertainty. May’s retail sales report provided another reminder that, at least for now, spending remains remarkably durable.

JBizNews Desk
Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Oppenheimer raised its price target on SpaceX to $250 from $190 on Thursday, even as the newly public company’s shares continued to fall. The upgrade came just two days after the stock hit an all-time high, highlighting the growing divide on Wall Street between analysts who see SpaceX becoming a dominant artificial intelligence platform and skeptics who argue the company remains significantly overvalued.

Timothy Horan, an analyst at Oppenheimer, maintained his Outperform rating and pointed to SpaceX’s pending acquisition of AI coding company Cursor as a major catalyst for future growth. He argued that SpaceX now controls nearly every layer of the artificial intelligence ecosystem — from rocket launches and Starlink satellite connectivity to data centers, AI models, and end-user software.

The higher target is largely driven by expectations surrounding Cursor, whose parent company, Anysphere, agreed to be acquired by SpaceX in a $60 billion stock deal expected to close during the third quarter. Oppenheimer increased its fourth-quarter AI revenue forecast for SpaceX to $8.75 billion, up from $4.75 billion, citing rapid growth at Cursor, which the firm estimates is already generating approximately $4 billion in annual revenue.

Despite the bullish outlook, investors continued selling the stock. Shares fell as much as 7% Thursday, trading between $180 and $190, after reaching an all-time high of $225.64 earlier in the week. The decline followed a roughly 5% drop Wednesday, marking the first back-to-back losses since the company’s June 12 public debut.

Part of the selling pressure may be tied to the launch of options trading, which began Tuesday and gave investors their first practical opportunity to bet against the stock. Until then, limited public shares and strong demand had fueled a near-uninterrupted rally.

Wall Street remains sharply divided. On Thursday, Arete Research analyst Andrew Beale initiated coverage with a Buy rating and a $401 price target — the highest currently on the Street. Beale believes Starlink’s next-generation V3 satellites could unlock a massive suburban broadband market by delivering faster and more reliable internet service to underserved areas.

Earlier this week, Wolfe Research analyst Myles Walton also launched coverage with a Buy rating and a $175 target, citing growth opportunities tied to Starship, expanding Starlink adoption, and artificial intelligence initiatives connected to xAI.

Not everyone is convinced. Morningstar values the company at just $63 per share, while CFRA maintains a sell rating. The spread between the most bullish and bearish estimates now ranges from approximately $62 to $401, an unusually wide gap for a major public company.

Critics argue investors are paying for a vision rather than current financial performance. SpaceX reported a $4.9 billion loss in 2025 and another $4.28 billion loss in the first quarter of 2026, despite generating roughly $18.7 billion in revenue last year. Supporters counter that the company’s long-term earnings potential justifies today’s valuation.

Adding to the uncertainty, the major investment banks that led the IPO — including Goldman Sachs, Morgan Stanley, and JPMorgan — remain in their post-offering quiet period and have not yet issued official ratings.

With only about 4% of shares available to the public, trading has been highly volatile. As the stock begins entering more mutual funds and exchange-traded funds, increasing numbers of everyday investors are gaining exposure.

For now, the only thing Wall Street appears to agree on is that SpaceX is likely to remain one of the market’s most closely watched — and most volatile — stocks.

JBizNews Desk | Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

General Motors and Lockheed Martin announced Tuesday that they have signed a partnership aimed at using the automaker’s manufacturing expertise to help increase production of missiles, munitions, and other defense systems as growing global conflicts place pressure on U.S. weapons stockpiles.

The companies unveiled the agreement at the Reindustrialize Summit in Detroit, describing it as a step toward accelerating weapons production while strengthening America’s industrial base.

Lockheed executives argued that the manufacturing principles behind building advanced military hardware are not all that different from those used to build automobiles.

“What does a THAAD air defense interceptor have in common with a Corvette?” asked Frank St. John, Lockheed Martin’s chief operating officer. The answer, he said, is precision engineering, complex supply chains, advanced manufacturing processes, and the ability to produce at scale.

The goal is not to merge the products themselves but to apply the manufacturing strengths of one industry to another.

The timing reflects growing Pentagon concerns about production capacity.

America’s weapons inventories have been strained by military operations involving Iran and by years of weapons shipments supporting Ukraine. Defense officials have repeatedly urged contractors to increase production rates to replenish stockpiles and prepare for future conflicts.

According to company executives, the memorandum of understanding was developed following discussions with the Pentagon, which has been encouraging industry partners to find ways to expand output more rapidly.

That is where GM enters the picture.

Through GM Defense, established in 2017, the automaker already supplies military vehicles and specialized transportation systems to government agencies. The division currently holds contracts with the U.S. Army, the Department of State, and other federal entities.

But Lockheed is interested in something beyond GM Defense’s existing products.

General Motors possesses one of the world’s most sophisticated manufacturing networks, capable of producing complex systems at high volume while managing thousands of suppliers and logistics partners. Defense leaders increasingly view those capabilities as essential to rebuilding America’s defense-industrial capacity.

Bruce Brown, vice president of strategy at GM Defense, said technological innovation alone is not enough. The ability to manufacture, scale, and deliver consistently is equally important.

The partnership also represents a return to history.

During World War II, General Motors produced tanks, aircraft engines, military trucks, and other equipment for the U.S. war effort. In the decades that followed, the company focused primarily on civilian vehicles. The new partnership signals a renewed push into defense manufacturing at a time when government demand is rising.

For General Motors, defense work offers access to a market supported by long-term government contracts and potentially higher margins than traditional automotive manufacturing.

For Lockheed Martin, the agreement supports a broader expansion already underway.

The defense giant has committed more than $9 billion through 2030 to modernize and expand production facilities. That investment includes a new munitions manufacturing center in Troy, Alabama, where construction began last month and is expected to create a significant number of jobs.

Lockheed produces some of America’s most important military systems, including the F-35 fighter jet, THAAD missile-defense system, PAC-3 interceptors, and the Black Hawk helicopter. The company has faced increasing pressure from the Pentagon to expand output of missile-defense systems and precision-guided weapons.

Executives emphasized that the partnership remains in its early stages.

No specific factories, products, or contracts have been announced. St. John said it is too early to determine which Lockheed programs will benefit most from the collaboration.

Steve duMont, president of GM Defense, said both companies will spend the coming weeks identifying projects where GM’s manufacturing capabilities can provide the greatest value.

Beyond the immediate defense implications, the announcement reflects a broader trend reshaping American industry.

The push toward reindustrialization has gained momentum as policymakers seek to strengthen domestic manufacturing, reduce dependence on foreign supply chains, and expand production of strategically important goods. Increasingly, the line between commercial manufacturing and defense production is becoming less distinct.

If successful, the partnership could channel additional defense work into factories, supplier networks, and manufacturing communities across the United States, supporting skilled jobs and industrial investment.

Questions remain.

Defense manufacturing involves strict security requirements, specialized certifications, and procurement rules that differ significantly from automotive production. Transforming commercial manufacturing capacity into military output is not as simple as repurposing an assembly line.

Ultimately, both companies will be judged not by the announcement itself but by whether the partnership results in more weapons reaching U.S. stockpiles.

The first major test will come when Lockheed Martin and General Motors identify the specific defense programs they intend to pursue together.

For now, the message from Detroit is clear: the companies that helped build America’s automotive industry are being asked to help rebuild its arsenal.

Detroit – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The man Anthropic pays to break its own artificial intelligence spent the spring warning anyone who would listen that the technology had become a dangerous hacking tool. This week, he finds himself on the other side of the argument, helping the company persuade Washington that its most powerful models are safe enough to put back into users’ hands.

Nicholas Carlini, a security researcher at Anthropic and one of the AI industry’s best-known skeptics, has joined the company’s effort to defend the release of the same models the federal government moved to shut down on June 12. That day, the Trump administration barred foreign governments, companies, and individuals from accessing two new releases — a model known as Mythos 5 and a safety-limited version called Fable 5. To comply, Anthropic cut off access to all customers, not just those overseas.

The reversal is striking because Carlini had been one of the loudest internal voices urging caution.

After testing an early version of the model in February, Carlini reportedly told colleagues he did not believe the company should release it. Weeks later, speaking before a gathering of cybersecurity experts in San Francisco, he described what he had found. According to his account, the AI helped identify and exploit a serious vulnerability in web-publishing software and another in Linux, the operating system that powers billions of devices worldwide.

Carlini said he had never previously discovered a major flaw in either system. With the assistance of the model, however, he was suddenly finding multiple vulnerabilities.

His conclusion was blunt. The long-standing balance between attackers and defenders appeared to be shifting, he warned, and the AI had become so capable that it was outperforming him at tasks he had spent years mastering. Two days after delivering that talk, he reportedly sent an internal note urging Anthropic not to release the model.

What changed was not the threat itself but Anthropic’s judgment about how best to manage it.

The company has increasingly argued that controlled release is safer than indefinite restriction. Anthropic contends that the same tools capable of helping attackers discover weaknesses can also help defenders identify and patch them faster. In the company’s view, preventing responsible organizations from using the technology does little to stop determined adversaries from developing similar capabilities elsewhere.

That is where Carlini’s role becomes particularly important. His credibility stems from the fact that he was never an AI cheerleader. As a longtime skeptic, he brings a voice that policymakers may find more persuasive than executives whose businesses depend on the technology’s success.

The dispute also carries major business implications.

Anthropic is widely expected to pursue a public offering in the future, and a government action that can effectively remove a flagship product from the market overnight is precisely the type of uncertainty investors scrutinize closely. The timing was particularly notable. On the same day the restrictions were announced, SpaceX debuted on the Nasdaq under the ticker SPCX, becoming one of the market’s most closely watched new public companies. Meanwhile, OpenAI continues to evaluate its own potential path to public markets.

For investors assessing the AI sector, the message is clear: regulatory risk has become as important as technological capability.

The controversy extends beyond a single company. AI policy experts warned this week that using export-control authority to restrict access to advanced models without extensive public explanation could establish a precedent that creates uncertainty throughout the industry. Developers may become more cautious about releasing new systems if they believe products can be restricted with little warning.

Anthropic has challenged the government’s reasoning, arguing that the security concern cited by regulators involved a narrow workaround rather than a broad failure of safeguards. The company has also noted that similar capabilities exist in other advanced AI systems already available to researchers and businesses.

For the cybersecurity industry, the debate cuts both ways.

Security firms could potentially use systems like Mythos 5 to test networks, identify vulnerabilities, and strengthen defenses before attackers discover weaknesses. At the same time, officials worry that equally powerful tools could be used to conduct large-scale attacks against government agencies, corporations, and critical infrastructure.

That concern explains why Anthropic had previously limited access to its most capable systems, making them available only to a small group of vetted organizations rather than offering them broadly.

The dispute also reflects a broader tension between Anthropic and the Trump administration. The two have disagreed over AI regulation, military applications, and semiconductor policy for more than a year. Anthropic Chief Executive Dario Amodei has previously argued that governments should have the authority to block AI systems that fail rigorous safety testing, a position that distinguishes the company from several competitors.

Now the government has intervened using a different mechanism, and Anthropic — with one of its most prominent skeptics helping lead the discussion — is arguing that the restrictions go too far.

The outcome could shape more than the future of one product. It may help determine how governments around the world balance AI innovation against AI risk as increasingly powerful systems move from research labs into the hands of businesses, governments, and consumers.

Washington – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Editor’s Note: This article was prepared with assistance from an AI system developed by Anthropic. Anthropic is a subject of this report.

On Wednesday, after U.S. officials released the full text of his 14-point agreement with Iran, President Donald Trump defended the deal at a news conference closing the G7 summit in France. But the bigger story was the backlash — not just from his own party, but from inside his own cabinet — alongside polls showing his standing at the lowest levels of either term.

The agreement ends the U.S. naval blockade of Iranian ports, reopens the Strait of Hormuz to commercial ships, lifts sanctions and sets a 60-day window for nuclear talks. It also opens the door for Iran to access up to $300 billion to rebuild its infrastructure, funded by other countries. For American households, the stakes are simple: the strait carries about 20% of the world’s oil and gas, and its closure since February 28 pushed up fuel and grocery prices.

Much of the anger comes from Trump’s usual allies. Senator Ted Cruz of Texas said the president was getting very poor advice, warning against “giving billions of dollars to theocratic lunatics who want to murder us.” Former Vice President Mike Pence said the deal “smacks of the kind of appeasement” the administration once rejected. Senator Bill Cassidy of Louisiana called it “the worst foreign policy blunder in decades,” and former U.N. Ambassador Nikki Haley warned Iran would spend any money it receives on its nuclear program and regional proxies.

The criticism set off a public family fight. Donald Trump Jr. accused Cruz of “lying thru his teeth,” insisting the United States is not handing Iran any money.

Conservative media piled on. Ben Shapiro called the deal “a disaster,” Erick Erickson called it “an American surrender,” and former adviser Steve Bannon urged the White House to keep the sanctions in place. Fox News host Mark Levin and the editors of National Review demanded the administration release the full text. Republican leaders were more guarded but uneasy: Senate Majority Leader John Thune said he wanted more information, and Senator Lisa Murkowski of Alaska said she was waiting to hear what the “corresponding win” for the United States would be.

The split runs into the cabinet as well. According to reports, Defense Secretary Pete Hegseth, Secretary of State Marco Rubio and CIA Director John Ratcliffe privately raised doubts about the agreement, while Vice President JD Vance and envoy Steve Witkoff — joined by Jared Kushner — pushed it through as its principal architects. The fracture reflects a broader reshuffling of who holds Trump’s ear: when the strikes began, isolationists such as Tucker Carlson and Marjorie Taylor Greene were sidelined after arguing he had abandoned “America First”; now many of the hawks who supported the military campaign are among the loudest critics of the deal. Throughout the conflict, Trump has managed Iran policy through a small inner circle after significantly reducing the role of the National Security Council.

The debate also tests Trump’s longstanding reputation as a dealmaker because the agreement falls short of the war’s original goals. At the news conference, Trump defended Iran’s right to retain ballistic missiles, saying “they have to have some because other people have some” — capabilities that had previously been targeted by U.S. and Israeli strikes. Months ago he had demanded Iran’s “unconditional surrender”; on Wednesday he framed the agreement as a way to avoid a broader economic crisis.

He still has defenders. Senator Lindsey Graham of South Carolina said the United States was “off to a good start” while expressing doubt that Iran would ultimately abandon its nuclear ambitions, though he called on Vance, whom he described as the deal’s architect, to defend it before Congress. Senator Rand Paul of Kentucky said he stood with Trump on pursuing peace. Representative Brian Mast of Florida argued the United States is “$300 to $500 billion ahead” after destroying much of Iran’s military and nuclear infrastructure.

The political challenge for the president may be the polling. A NPR/PBS News/Marist survey put his approval rating at 36%, with 59% disapproving — the widest gap of either term — and only about a third approving of his handling of the economy, below Joe Biden’s lowest marks. NPR reported that the decline extended even into some of the voter groups that helped return him to office. A Reuters/Ipsos poll found 35% approval overall, 29% approval on Iran, and 22% approval on the cost of living, while 53% said the war was not worth it. Both surveys were conducted largely before the agreement’s details became public. An Economist/YouGov poll highlighted the dilemma: 68% want a deal that ends the war quickly, but only 34% support an agreement that allows Iran to keep its enriched uranium.

For the economy, the math is straightforward. If the Strait of Hormuz remains open and the ceasefire holds, gasoline, diesel and shipping costs could ease through the remainder of 2026 — the relief Trump is counting on before November, with Brent crude already falling to around $83 per barrel. But if the truce collapses, or if the concessions to Iran continue to dominate the political debate, the strait could close again and erase those gains, leaving the president exposed on the issue voters consistently rank as their top concern: the cost of living.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The widely circulated claim that it could take 90 days to clear the Strait of Hormuz does not appear to come from any official mine-clearing estimate. Industry analysts and government officials have offered timelines ranging from several weeks to several months, but no major source has projected a 90-day mine-clearing operation.

Instead, the figure appears to stem from the length of time the strait has already been disrupted. The waterway has been largely closed since February 28, meaning it has been affected for more than 100 days, with many reports previously referring to the closure as lasting “90-plus days.” Somewhere along the way, that closure-duration figure appears to have been mistakenly interpreted as a forecast for reopening.

The actual reopening timeline is considerably more complex.

President Donald Trump and Iranian President Masoud Pezeshkian signed an agreement this week to reopen the Strait of Hormuz, but the date that matters most for consumers is not the signing date — it is how long it takes to safely restore oil flows and bring energy markets back to normal.

The U.S. Energy Information Administration describes the strait as the world’s most important oil transit chokepoint, carrying roughly 20% of global oil and liquefied natural gas supplies under normal conditions.

Phase One: Opening Safe Shipping Lanes

The first step is establishing secure passage through the strait.

Greg Brew of Eurasia Group estimates it could take two to three weeks to identify and certify safe shipping corridors for large tankers. According to maritime intelligence firm Kpler, roughly 500 commercial vessels remain in the Gulf region, including more than 100 loaded tankers waiting to move.

Some of those ships could begin departing within days, allowing oil already produced and sitting offshore to reach markets. This phase provides the first wave of supply relief.

Crude prices have already begun responding. Brent crude has eased from recent highs, and gasoline prices typically follow oil lower after a short delay.

Phase Two: Mine-Clearing Operations

The more difficult challenge is clearing mines and restoring full confidence among shipping companies and insurers.

A Pentagon briefing to Congress estimated that completely clearing the waterway could take up to six months. Earlier this month, Secretary of State Marco Rubio testified before the Senate Foreign Relations Committee that Iran had mined portions of the strait.

Some maritime-security specialists have suggested shorter timelines, but insurers are expected to remain cautious until waterways are formally certified as safe. European allies, including Britain, France, Germany, Italy, and the Netherlands, are preparing or supporting mine-clearing operations.

Until that work is completed, transportation costs are likely to remain elevated, limiting how quickly gasoline, diesel, and shipping expenses can decline.

Phase Three: Restoring Full Oil Production

Even after shipping lanes reopen, oil production does not instantly return to normal.

Amena Bakr of Kpler estimates it could take two to three months for tankers to complete export cycles and return for new cargoes. Additional time will be needed for Gulf producers to fully restart production that was disrupted during the conflict.

ADNOC CEO Sultan Al Jaber has warned that reaching 80% of pre-war oil flows could take at least four months, while full normalization may not occur until 2027. Saudi Aramco CEO Amin Nasser has issued similar assessments.

What It Means for American Consumers

For U.S. households, the key takeaway is that relief is likely to come gradually.

Gasoline prices may begin easing in the coming weeks as trapped oil reaches global markets, but broader reductions in fuel, transportation, and consumer-goods costs are expected to unfold over many months.

The biggest variable remains the durability of the agreement itself. The deal provides a framework for reopening the strait, but major issues remain unresolved, including future negotiations over Iran’s nuclear program and long-term security arrangements in the Gulf.

If the agreement holds, energy prices should continue trending lower. If tensions return, markets could quickly reverse course.

Early indicators suggest movement is already beginning. TankerTrackers.com reports that Iranian crude shipments have resumed, while Iranian officials say vessels are once again moving through the country’s ports. The International Energy Agency, led by Fatih Birol, has said the market could eventually swing into surplus once Gulf production and exports fully recover.

For now, however, consumers expecting an immediate drop at the pump may need patience. Based on current industry estimates, the path to significantly cheaper gasoline appears measured in months, not days.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

U.S. stocks opened higher on Thursday, clawing back much of the prior day’s losses, after the Federal Reserve under new Chair Kevin Warsh held interest rates steady on Wednesday but signaled it could raise them later this year. In its first meeting with Warsh in charge, the central bank issued an unusually short statement and a “dot plot” showing nine of 18 policymakers expect at least one rate hike in 2026 — a hawkish turn that handed the S&P 500 its worst Fed-day drop under a new chair since 1994, even after the Dow had touched a fresh intraday record earlier in the session. Adding to Thursday’s calmer mood, the Labor Department reported that initial jobless claims fell by 4,000 to 226,000 for the week ended June 13, near forecasts, with the unemployment rate holding at 4.3% for a third straight month.

The rebound was broad. In early trading the S&P 500 rose about 1.15%, the Dow Jones Industrial Average added 0.80% and the Nasdaq Composite climbed roughly 1.5%, while the small-cap Russell 2000 lagged. That followed Wednesday’s slide, when the S&P 500 closed at 7,420.10, down 1.21%; the Dow fell 507.12 points, or 0.98%, to 51,492.55; and the Nasdaq dropped 1.34% to 26,021.66.

Market movers. Intel led the gainers, rising about 9% to $131.96 after President Donald Trump said in a social-media post that the chipmaker had agreed to design and build chips in the United States with Apple. Fortrea Holdings added about 7% and Marvell Technology rose roughly 6%. On the downside, Accenture tumbled about 15% and Kroger fell 6.9% to rank among the morning’s worst performers, while medical-device maker NovoCure dropped nearly 19% and Cognizant Technology Solutions slipped around 5%.

Analysts were active. Deutsche Bank kept a buy on Micron Technology and lifted its price target to $1,500 from $1,000, citing a memory-chip shortage tied to the artificial-intelligence boom. UBS upgraded software firm Dynatrace to buy from neutral and raised its target to $60 from $36. TD Cowen analyst Krish Sankar kept a buy on chip-equipment maker Cohu and raised his target to $80 from $60. Wolfe Research lifted Palantir Technologies to peer perform from underperform. The day’s loudest downgrade was Roku: Wedbush cut it to neutral with a $155 target and pulled it from its best-ideas list after Fox said it would buy the streaming-device maker, and Susquehanna, Piper Sandler, JPMorgan and Evercore ISI moved to the sidelines as well. Wells Fargo, meanwhile, was unimpressed by Snap’s new $2,195 “Specs” glasses, calling 100,000 first-generation units a stretch goal.

Commodities and volatility. Oil eased as the U.S.-Iran peace deal calmed supply fears. West Texas Intermediate crude traded near $74 a barrel and Brent sat around $83. Gold slipped about 2% to roughly $4,270 an ounce as buyers stepped back from safe havens. The Cboe Volatility Index, or VIX, which jumped more than 12% to 18.44 on Wednesday after the Fed surprise, eased back toward 17. Bitcoin fell about 1.3% to around $64,300.

The backdrop remains the Federal Reserve and the Middle East. Warsh said the Fed had dropped its forward guidance, leaving little steer on the next move, while this week’s U.S.-Iran memorandum — which calls for reopening the Strait of Hormuz over a 60-day negotiating window — has pulled energy prices down from their wartime highs.

Looking ahead, U.S. markets are closed Friday, June 19, for the Juneteenth holiday, so trading resumes Monday. Next week brings earnings from Micron Technology and FedEx, and the end of the month delivers fresh readings on first-quarter economic growth and the Fed’s preferred inflation gauge, the May personal consumption expenditures index — numbers that will test how seriously markets take Warsh’s hint at a rate hike.

JBizNews Desk © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Health and Human Services Secretary Robert F. Kennedy Jr. announced more than $700 million for addiction treatment, mental health services, and homelessness programs during a visit Wednesday to an Easterseals behavioral health clinic in Clinton Township, Michigan, calling the effort part of the administration’s push to expand recovery services nationwide.

Kennedy said the investment would help move people struggling with addiction and mental illness off the streets and into treatment, strengthen families, and improve public safety.

But behavioral health advocates and policy experts quickly noted that most of the money is not newly appropriated funding. Instead, they said, the majority represents grants and programs that had already been approved by Congress and were expected to be distributed through existing federal channels.

The distinction is important because new appropriations expand federal spending, while previously approved grants simply continue programs already operating throughout the country.

The only major newly launched initiative announced Wednesday was a $96 million program known as STREETS — short for Safety Through Recovery, Engagement, and Evidence-Based Treatment and Support. The program will fund eight communities, each eligible for up to $3 million annually for four years, to coordinate treatment, housing, healthcare providers, law enforcement, and local governments in addressing homelessness, addiction, and serious mental illness.

The remaining $612 million will be distributed through existing federal behavioral health programs.

The largest allocation, nearly $239 million, supports the 988 Suicide and Crisis Lifeline, the national crisis hotline that provides phone, text, and online support around the clock. Another $223 million will go to community behavioral health clinics that provide mental health and substance-use treatment regardless of a patient’s ability to pay. Additional grants support mobile crisis teams, childhood trauma programs, tribal suicide prevention initiatives, and services for at-risk infants.

The funding announcement is tied to President Donald Trump’s Great American Recovery Initiative, created by executive order earlier this year. Kennedy co-chairs the effort alongside Kathryn Burgum, the White House senior adviser for addiction recovery.

Drawing on his own history of addiction recovery, Kennedy emphasized the role of faith and spirituality in treatment. He praised 12-step programs such as Alcoholics Anonymous and said faith-based recovery organizations would receive equal consideration for federal funding opportunities. He stressed that secular providers would continue to receive support as well.

The announcement comes after several months of controversy surrounding federal behavioral health funding. Earlier this year, HHS briefly canceled approximately $2 billion in mental health and substance-abuse grants before reversing course following criticism from lawmakers and treatment providers.

The administration also faced legal challenges after attempting to terminate billions of dollars in public-health grants tied to pandemic-era programs. A federal court later blocked those efforts.

Because of that history, providers say they are paying close attention to whether announced funding is truly additional money or simply part of existing grant cycles.

HHS has not disputed that much of Wednesday’s funding will flow through established programs. Instead, department officials have emphasized that the administration intends to direct resources toward recovery-focused approaches, accountability measures, and faith-based partnerships.

For treatment providers, the ultimate measure of success will not be the size of the announcement but whether funding reaches clinics, crisis lines, and local recovery organizations quickly and consistently.

The new STREETS initiative will likely serve as the administration’s first major test. If the program successfully connects vulnerable individuals with treatment, housing, and support services, officials will point to it as evidence that the recovery strategy is working. If implementation stalls, critics may argue that the announcement represented more symbolism than substance.

JBizNews Desk
Washington, D.C.

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The price of getting a foot on the property ladder has never been higher.

A record 242 cities across the United States now have starter homes worth $1 million or more, according to an analysis from Zillow released Monday, a sign of how far the cost of entry-level housing has climbed.

A starter home, as Zillow defines it, is one in the lowest third of home values in a given area, the kind of modest, lower-priced house a first-time buyer typically targets.

Nationwide, the typical starter home is worth $198,649, up 1.7% from a year earlier, which means seven-figure starter homes are still the exception.

But the number of places where they are the norm keeps growing.

The count rose from 226 cities a year ago and has nearly tripled since before the pandemic, when just 80 cities had million-dollar starter homes in February 2020.

Those homes are now spread across 26 states, up from only nine before 2020.

For years, million-dollar entry-level houses were almost entirely a coastal phenomenon.

Today they have reached interior states including Colorado, Texas, Wyoming and Illinois.

California remains the epicenter, with 105 cities where the typical starter home costs at least $1 million.

New York has climbed to 41 cities, up from just 12 before the pandemic, and New Jersey now has 26 cities, up from a single city.

New York and New Jersey are the fastest-growing on the list, adding 15 cities between them in the past year alone.

The cause traces back to the pandemic housing boom.

A housing shortage that had been building for a decade collided with a surge of demand at a time when mortgage rates were at historic lows, sending prices soaring at a record pace.

Kara Ng, a senior economist at Zillow, said the pandemic effectively reset the cost of buying a home, pushing million-dollar starter homes out from a handful of coastal markets to more than two dozen states.

Those effects, she noted, have proven durable even as the market has cooled.

Here is why it matters for ordinary families.

The starter home has long been the traditional first rung of homeownership, the place where young couples and first-time buyers begin building equity.

When that first rung costs a million dollars, it moves out of reach for all but the wealthiest newcomers, and it pushes more would-be buyers into renting for longer or leaving expensive regions entirely.

It is the human face of the same housing shortage that has kept new construction from keeping up with demand.

There is, however, a more hopeful side to the report.

Conditions are slowly turning friendlier for buyers who are financially prepared.

The typical buyer now breaks even compared with renting after about six years, down from more than eight years in late 2023.

Inventory is rising, price growth has slowed, and in many markets sellers now outnumber buyers, giving those still in the hunt more leverage than they have had in years.

The broader market has been stuck in a slump since 2022, with sales of existing homes hovering near a three-decade low.

Still, the headline number captures the strain on a generation of aspiring owners.

A million-dollar starter home would have sounded absurd in most of the country a decade ago.

Today it describes the entry point in 242 cities and counting, a reminder that even as the market softens, the bar set during the boom has barely come down.

Housing Market — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The tech trade has handed investors both big gains and big worries. On Wednesday, Aisa Ogoshi, a managing director and Asia Pacific equities portfolio manager at JPMorgan Asset Management, told Bloomberg Television that the rally still has room left, even after a long stretch that has packed an unusual share of the market’s value into a small handful of companies.

Ogoshi did not downplay the danger. The biggest risk in the market right now, she said, sits inside the tech trade itself, because so much money is riding on so few names. When a small group of stocks carries the whole market higher, a stumble by any one of them can pull everyone down with it. That kind of concentration is exactly what makes experienced investors nervous.

Even so, she sees more room to climb. The next stretch of gains, in her view, runs through what she called the AI data center supply chain — the businesses that build, power, and connect the massive computing hubs that artificial intelligence depends on.

Here is what that means in plain terms. Every time a company rolls out a new AI tool, that tool has to run somewhere. It runs inside data centers, which are warehouse-sized buildings packed with specialized computers. Those buildings need chips to do the thinking, electricity to keep the machines running, cooling systems to stop them from overheating, and networking gear to tie everything together. Each of those pieces is a business, and many of them are publicly traded.

The spending behind all this is enormous. The group of giant technology companies often called the Magnificent Seven — Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia, and Tesla — is on track to spend roughly $527 billion on AI and data center projects in fiscal 2026, well above earlier estimates. Looking further out, total spending on data center infrastructure worldwide is expected to approach $1 trillion annually by 2030.

That wave of money is the heart of Ogoshi’s argument. The household-name tech stocks have already climbed a long way, and many now trade at rich valuations. But the suppliers further down the chain — the firms selling power equipment, cooling systems, network switches, and chips — stand to keep collecting orders as long as the building boom continues.

Nvidia, the chip designer at the center of the AI boom, remains the most direct way to bet on that demand, with a market value north of $4.5 trillion. Beyond it sit less famous names that still play essential roles. Vertiv makes the power and liquid-cooling systems that keep dense racks of computers from overheating. Arista Networks sells the high-speed switches that move data inside AI clusters, with customers that include Meta and Microsoft. Neither company is a household name, but both benefit whenever a new AI data center comes online.

The reason Ogoshi points beyond the obvious winners is straightforward. Betting everything on a single famous stock concentrates risk in one company, one product line, and one valuation. Spreading investments across the broader supply chain gives investors a way to participate in the AI buildout without relying entirely on the most crowded trade in the market.

Ogoshi also weighed in on Japan, where she spends much of her time as an Asia-focused portfolio manager. The Bank of Japan raised its benchmark interest rate to 1% from 0.75% at its June 15–16 meeting, continuing its gradual move away from years of near-zero borrowing costs. The central bank has been tightening policy as inflation remains above its 2% target, supported by a weaker yen and elevated energy prices.

Rising rates in Japan matter far beyond Tokyo. For years, Japan’s ultra-low rates made it a popular place for global investors to borrow money cheaply and invest elsewhere. As Japanese rates rise, that equation changes, potentially affecting capital flows and investment decisions worldwide.

For everyday investors, the takeaway from Ogoshi’s comments is less about chasing the latest hot stock and more about understanding where AI spending is actually going. The software gets the headlines, but the money is increasingly flowing into physical infrastructure — buildings, power systems, networking equipment, cooling technology, and advanced chips.

That does not eliminate the risk she highlighted. A market leaning heavily on a handful of technology giants can reverse quickly if AI investment slows or if one major player disappoints investors. But for now, Ogoshi’s message is that the trend remains intact, and that some of the best opportunities may lie one step behind the biggest names grabbing the spotlight.

As AI adoption continues to accelerate, the companies supplying the infrastructure that powers it may become some of the most important — and potentially most profitable — businesses in the market.

Wall Street – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Julia Parker – JBizNews Desk
The college major, long treated as a personal credential and a cultural marker, now looks more like an early career trade tied to artificial intelligence exposure, according to Goldman Sachs, which described student choices as a signal that young workers already price the technology into lifetime earnings decisions.

The scale of the shift shows up in enrollment data: National Center for Education Statistics figures show U.S. bachelor’s degrees in computer and information sciences more than doubled from roughly 48,000 in 2012 to more than 108,000 in 2022, while Goldman Sachs has linked that migration to a broader repricing of skills around generative AI.

That comparison matters because students increasingly treat majors as an investment decision rather than a fixed identity, according to Goldman Sachs, whose economists have said generative AI could lift global gross domestic product by 7% and expose the equivalent of 300 million full-time jobs to automation.

The original undergraduate bargain looked simpler: choose a field, obtain a credential and enter a labor market that rewarded degree completion broadly, according to National Center for Education Statistics, which tracks degree production across disciplines and shows how technology programs gained share during the past decade.

That realization changed the economics of campus choice, according to Bureau of Labor Statistics, which projects software-developer employment growth of 17% from 2023 to 2033 and data-scientist employment growth of 36%, far above the agency’s projection for total employment growth.

The inflection point arrived when artificial intelligence moved from research labs into consumer and corporate tools, according to Stanford University, whose AI Index has said industry now dominates advanced AI model development and private capital continues to cluster around machine learning infrastructure and applications.

Large technology companies reinforced that message, according to Microsoft, which has described AI copilots as a core layer across enterprise software, and OpenAI, whose public releases accelerated student awareness that coding, statistics and domain knowledge could combine into a new premium skill set.

Employers then supplied the market confirmation, according to Bureau of Labor Statistics, whose occupational data show computer and mathematical roles carrying median pay well above national averages, giving students a clearer numerical basis for shifting from lower-return majors into AI-adjacent programs.

Universities have responded by expanding data-science, analytics and computational social-science offerings, according to National Center for Education Statistics, whose degree classifications show a broad increase in computer-related awards rather than a narrow boom limited to traditional computer science.

The demand surge also reflects corporate capital spending, according to Goldman Sachs, which has said AI investment could approach a scale large enough to influence productivity, cloud demand and semiconductor supply chains, making undergraduate talent pipelines relevant to investors tracking long-cycle technology adoption.

That investor connection runs through Nvidia, which has said demand for accelerated computing and AI infrastructure has driven record data-center revenue, turning what students see in classrooms into the human-capital side of one of the equity market’s dominant growth themes.

Still, the path upward contains risk, according to Goldman Sachs, which has cautioned that AI can automate tasks inside high-skill occupations even as it creates new demand for workers capable of deploying, supervising and integrating the technology.

That tension has fed skepticism among students and parents, according to Bureau of Labor Statistics, whose projections imply strong demand for technical roles but do not eliminate cyclical hiring risk in technology, where graduate timing can collide with layoffs, start-up funding pullbacks and changing corporate budgets.

The middle of the market looks especially vulnerable, according to Goldman Sachs, whose research has emphasized that generative AI affects cognitive work rather than only routine physical labor, challenging the old assumption that any white-collar degree provides durable insulation from automation.

For that reason, the emerging campus trade favors hybrid majors, according to Stanford University, whose AI Index highlights demand for AI literacy across industries, suggesting that economics, biology, engineering, finance and law programs may gain value when paired with statistics and computation.

Financial firms see the same pattern inside their own workforces, according to Goldman Sachs, which has described AI as a productivity tool for knowledge workers, implying that future analysts, bankers and portfolio managers may need technical fluency even when their formal degree sits outside computer science.

The practical question for students now concerns option value, according to Bureau of Labor Statistics, whose wage and growth data suggest majors tied to software, data architecture, cybersecurity and applied analytics offer wider career paths than programs with weaker links to expanding digital capital budgets.

But a narrow coding-only strategy carries its own limitation, according to Goldman Sachs, which has said productivity gains depend on organizational adoption, meaning students who combine technical training with business judgment, regulation, health care or industrial expertise may command a more durable premium.

The current market position of AI education resembles an early-cycle infrastructure buildout, according to Stanford University, whose AI Index frames the technology as a general-purpose platform with investment, talent and model development feeding one another across corporate and academic systems.

That creates a feedback loop for universities, according to National Center for Education Statistics, whose degree data imply that student demand can pressure schools to redirect faculty hiring, course capacity and capital budgets toward computing-heavy programs.

For investors, the enrollment shift offers a human-capital indicator, according to Goldman Sachs, which has connected AI adoption to productivity and growth potential, making student major selection a modest but telling signal for labor supply in technology-intensive sectors.

The broader lesson reaches beyond campus, according to Goldman Sachs: AI has turned education into a forward-looking allocation of risk, time and earning power, and students now move accordingly before labor markets fully settle the final price of the new technology cycle.
JBizNews Desk

A group of 51 hotel owners who together run close to 1,000 Marriott-branded properties has told the company it wants a larger share of the money flowing through its Bonvoy rewards program, according to a letter the owners sent in March that became public Tuesday.

The letter went straight to the top, addressed to Chief Executive Anthony Capuano and Chairman David Marriott.

The fight comes down to a simple question: who pays when a guest cashes in points for a free night, and who pockets the profits the program throws off.

Most Marriott hotels are not owned by Marriott. They are owned by independent operators and franchisees who run the buildings, employ the staff, and pay Marriott for the right to fly its flags and tap into Bonvoy, one of the largest loyalty programs in travel.

When a member redeems points for a free stay, the hotel that hosts that guest gets reimbursed from a shared fund. Owners say that reimbursement often falls short of what the room is really worth.

Here is what changed.

For years, owners believed Bonvoy roughly broke even — a marketing engine that filled rooms without making anyone rich.

Now they have learned the program is a serious money-maker, and they feel cut out.

Marriott has said it expects fee revenue from its co-branded credit cards to climb about 35% this year, approaching $1 billion.

Much of that comes from card partners paying Marriott for the right to issue Bonvoy cards.

Owners argue they help create that value every time a guest stays, yet little of the windfall reaches them.

Their core complaints are about money and transparency.

They want higher payments when members redeem free nights — at least matching what they would earn from an online travel site like Expedia — and they want to see the program’s books, which Marriott has historically kept close.

Under the old setup, owners got a low base payment for an award night when the hotel had empty rooms to spare, on the logic that a free guest in an otherwise unsold room costs the hotel nothing.

When a property filled up, the payment rose toward the hotel’s normal nightly rate.

Owners say that formula no longer reflects how much Marriott earns from the credit-card side of the business.

Marriott has made some moves to ease the tension.

The company says it recently raised what owners are paid for loyalty stays on busy, high-demand nights, trimmed certain charge-out rates, and for the first time shared some Bonvoy financial details with owners.

It is also renegotiating agreements tied to the program.

The stakes are large because loyalty has quietly become one of the most profitable corners of the hotel business.

Bonvoy added roughly 43 million members last year and counted about 283 million members by the end of the first quarter.

Every one of those members is a reason for a traveler to book a Marriott instead of a competitor — but the value created sits at corporate, in the form of high-margin card fees, while the cost of honoring free nights lands on the individual hotel.

For travelers, the dispute could eventually show up in the value of their points.

If owners win bigger reimbursements for award stays, Marriott has to find that money somewhere.

The most common way hotel programs cover rising costs is by raising the number of points needed for a free night, which quietly erodes what each point is worth.

Nothing has changed for members yet, but a richer payout to owners tends to flow downhill to guests.

There is also a business-model question for investors.

Marriott International (MAR) has long sold Wall Street on an “asset-light” story — it manages and licenses brands rather than owning buildings, and loyalty and credit-card fees are a big part of that pitch.

A revolt by the people who actually own the hotels puts a spotlight on how durable those fees are, and how much Marriott may have to give back to keep its franchise network from walking.

For now, the two sides are negotiating.

The owners have leverage in numbers and in the simple fact that Marriott needs them to run its hotels.

Marriott has the brand, the members, and the card deals.

Somewhere between those positions is the new split of a billion-dollar pot — and the answer will ripple from hotel balance sheets all the way down to the points sitting in travelers’ accounts.

Bethesda, Md. — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Robinhood Markets disclosed Tuesday that it will cut about 10% of its workforce, eliminating roughly 290 jobs, in a move chief executive Vlad Tenev described not as a retreat but as a deliberate effort to keep the company lean and fast-moving.

The cuts were announced in a Form 8-K filing with the Securities and Exchange Commission and laid out in a memo Tenev sent to employees, which the company later posted on X. In it, Tenev struck an unusual tone for a layoff announcement.

Robinhood’s business has never been stronger,” he wrote, before arguing that the company “cannot default to operating as a heavily-layered organization” and must instead be a “lean, hyper-focused team.”

The numbers back up the claim of strength, which is what makes the move notable. Robinhood, which employs about 2,900 full-time workers, said its trading volumes hit record levels in June across stocks, options and the fast-growing market for prediction-market contracts. The company recently reported a 15% jump in revenue, though its stock slipped at the time because the figure came in below what analysts had hoped.

Robinhood expects the cuts to cost about $28 million, including roughly $20 million in cash for severance and benefits and about $8 million in stock-based compensation, all to be recorded in the second quarter.

These are the company’s first layoffs in three years; the last came in 2022, when a cooling market and a crypto crash forced two painful rounds of reductions.

One detail stands out for what it leaves out.

A growing number of banks, fintech firms and payment companies cutting staff this year have pointed to artificial intelligence, saying software can now do work that once required people. Robinhood did not.

Tenev framed the decision purely as a matter of structure and speed, not automation, casting the smaller headcount as a way to push more responsibility onto fewer, higher-performing employees.

The backdrop is a broader wave of belt-tightening across financial technology and crypto.

Last month, Coinbase, one of the largest crypto exchanges, said it was cutting about 14% of its staff. Earlier in the year, Crypto.com and Algorand announced their own reductions.

The price of Bitcoin and other digital currencies has slumped, and trading has cooled from the frenzy of 2024, squeezing companies whose fortunes rise and fall with market activity.

What separates Robinhood is the framing: most of its peers are cutting because business slowed, while Robinhood says it is cutting from a position of strength.

Here is why it matters beyond Wall Street.

Robinhood is the app that pulled millions of ordinary Americans into investing for the first time, powering the meme-stock craze and turning phone-based trading into a mainstream habit.

When a profitable company posting record activity still decides to shed one in ten workers, it signals something about the moment: even healthy businesses are trimming management layers in the name of speed.

For employees across the technology sector, it is one more sign that the era of aggressive hiring has given way to a focus on doing more with less.

Investors gave the news a mixed reception.

Robinhood shares rose more than 2% early Tuesday before giving back the gains and turning lower later in the day, a sign that Wall Street is still weighing whether a leaner Robinhood means a stronger one.

For the roughly 290 people losing their jobs, the company said it would offer support through the transition.

For everyone else watching, the bigger question is whether “lean and disciplined,” the phrase Tenev keeps returning to, becomes the standard other strong companies adopt, even when business is good.

Wall Street — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Even if the war in Iran ends, the price increases it set off are not going to disappear with it. That is the message coming from senior officials at the European Central Bank (ECB), who raised interest rates last week and warned that the energy shock has already worked its way too deeply into the economy for a peace deal to reverse on its own.

On June 11, the ECB lifted its key deposit rate by 0.25 percentage points to 2.25%, marking its first rate increase since 2023 and the first move by a major central bank in response to the surge in oil and natural-gas prices triggered by the conflict. ECB President Christine Lagarde said the decision was unanimous and reflected concerns that inflation pressures created by the war were becoming more persistent.

The bank’s chief economist, Philip Lane, explained the concern in simple terms: inflation can outlive the event that caused it.

Once higher energy costs begin spreading through wages, transportation, food, manufacturing, and everyday services, they develop momentum of their own. A manufacturer facing higher electricity costs raises prices. Workers facing higher living expenses seek larger wage increases. Businesses then raise prices again to offset higher labor costs. Economists call this process “second-round effects,” and it is the part of inflation that does not disappear simply because a ceasefire is signed.

That concern helps explain why policymakers remain cautious despite signs that the fighting may be winding down.

The numbers remain troubling. Inflation across the 20 nations that use the euro climbed to 3.2% in May, significantly above the ECB’s 2% target. The central bank now expects inflation to average roughly 3% this year, up from the 2.6% forecast it issued in March, before gradually returning toward target by 2028.

At the same time, economic growth remains weak. The ECB now expects the euro-area economy to expand just 0.8% in 2026, after posting only 0.1% growth during the first quarter. That combination of slowing growth and elevated inflation presents one of the most difficult challenges central bankers face.

A peace agreement may help, but not as quickly as many consumers hope.

The closure of the Strait of Hormuz, which normally handles roughly a quarter of the world’s seaborne oil shipments, disrupted global energy markets for months. In addition, attacks on energy facilities across the Gulf region damaged infrastructure and restricted supplies.

Even as shipping resumes and tensions ease, energy markets cannot immediately return to normal. Facilities must be repaired, inventories replenished, and transportation networks stabilized. Much of the economic damage has already been built into business contracts, household budgets, and corporate expectations.

Not everyone believes the ECB will continue raising rates aggressively.

Mark Wall, chief European economist at Deutsche Bank, described the latest increase as a significant milestone but cautioned that interest-rate hikes can only do so much when inflation originates from a supply shock rather than excessive demand.

Higher rates may cool spending, but they do not produce more oil, natural gas, or electricity.

That reality creates a difficult balancing act for policymakers. Raise rates too aggressively and they risk pushing an already fragile economy closer to recession. Move too slowly and inflation could become entrenched.

For households and businesses, the consequences are becoming increasingly visible.

Borrowing costs are rising just as economic growth weakens. Businesses face higher financing expenses while still coping with elevated energy and transportation costs. Families carrying mortgages, auto loans, or credit-card debt may find monthly payments becoming more burdensome even if fuel prices eventually begin to decline.

The divide among major central banks adds another layer of uncertainty.

While the ECB has chosen to tighten policy, the Federal Reserve in the United States and the Bank of England have so far held rates steady, reflecting a belief that much of the energy shock may eventually fade on its own. The ECB has taken a different view, concluding that inflation risks are too serious to ignore.

Those differing approaches can influence currency values, trade flows, investment decisions, and the cost of doing business across global markets.

What happens next depends largely on whether the energy shock leaves lasting scars.

ECB officials have signaled that another rate increase could come as soon as July if inflation remains elevated, though they have emphasized that future decisions will depend on incoming economic data.

For now, Europe’s central bankers are sending a clear message: even if peace arrives, the economic consequences of the conflict may linger far longer than the fighting itself.

Frankfurt – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Federal Reserve left interest rates unchanged Wednesday, but its latest projections delivered a surprise: more policymakers now expect the next move to be a rate increase rather than a rate cut.

In its first policy decision under new Chair Kevin Warsh, the Fed voted 12-0 to keep the federal funds rate in a range of 3.50% to 3.75%, where it has remained since December.

The bigger story was not the decision itself, but what came next.

The Fed’s updated economic projections showed officials abandoning their earlier expectation of a rate cut this year. Instead, the median forecast now points to a benchmark rate of 3.8% by the end of 2026, compared with 3.4% in the Fed’s March outlook.

Of the 18 officials submitting forecasts, nine now expect at least one rate hike before year-end, while six foresee two quarter-point increases.

Just three months ago, most policymakers were still expecting lower rates.

Inflation Changes the Conversation

The shift reflects growing concern over inflation.

Fed officials now expect their preferred inflation gauge to finish the year at 3.6%, significantly above the central bank’s 2% target and well above the 2.7% forecast issued in March.

Higher energy prices have been a major factor behind the inflation outlook, forcing policymakers to reconsider the path of monetary policy.

The Fed’s latest projections also show:

  • Economic growth: 2.2%
  • Unemployment: 4.3%
  • Inflation: 3.6%

The new forecasts suggest the central bank is becoming increasingly concerned that inflation could remain elevated longer than previously expected.

What It Means for Consumers

For households, the message is straightforward: borrowing costs are likely to remain high.

Mortgage rates, auto loans, business financing, and credit card interest rates are all influenced by the Fed’s policy stance. If the central bank ultimately raises rates again, those costs could increase further.

The upside for consumers is that savings accounts, money-market funds, and certificates of deposit may continue offering relatively attractive yields.

For Americans waiting for cheaper financing to purchase a home, vehicle, or expand a business, relief may be further away than expected.

Warsh’s First Meeting as Chair

Wednesday’s decision marked the first policy meeting led by Kevin Warsh, who was nominated by President Donald Trump.

Warsh introduced a shorter and simplified policy statement and announced plans to review several aspects of how the Fed communicates with markets and the public.

In an unusual move, Warsh declined to submit his own interest-rate projection to the Fed’s closely watched “dot plot,” saying he did not believe it was helpful to the policymaking process.

He indicated the Fed would review its broader communications strategy, including projections, press conferences, meeting minutes, and transcripts.

Markets React

Investors reacted negatively to the Fed’s more hawkish tone.

By Wednesday afternoon:

  • The S&P 500 fell about 0.6%
  • The Nasdaq declined roughly 0.7%
  • The Dow Jones Industrial Average lost approximately 160 points
  • The 2-year Treasury yield jumped nearly 11 basis points

The market reaction reflected disappointment among investors who had hoped a new Fed chair might signal a path toward lower interest rates.

Instead, policymakers delivered a clear message: inflation remains the priority.

Looking Ahead

The Federal Reserve is still officially in a wait-and-see mode, but the debate inside the central bank appears to be changing.

For much of the past year, the question was when rates would be cut.

Now, for the first time in this cycle, the discussion has shifted toward whether the next move may need to be a hike.

JBizNews Desk
Washington, D.C.

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. Department of Justice asked a federal court in Mississippi on Monday to dismiss a pollution lawsuit against Elon Musk’s artificial-intelligence company xAI, arguing that the natural-gas turbines powering one of its largest data centers are too important to national security to shut down.

The filing, which was joined by the state of Mississippi, marks an unusual intervention by the federal government on behalf of a private company facing environmental claims brought by local residents and advocacy groups.

The dispute began in April when the NAACP filed suit under the federal Clean Air Act, alleging that xAI installed dozens of portable natural-gas turbines to power its massive Colossus 2 supercomputer facility without obtaining the permits required under federal law.

The turbines are located in Southaven, Mississippi, near the Tennessee border and within proximity of residential neighborhoods, schools, and churches. In May, the NAACP sought an emergency court order to halt operations, arguing that emissions from the turbines could increase health risks including asthma attacks, respiratory illnesses, and heart disease among nearby residents.

The Justice Department responded with a dramatically different argument.

In its filing, government attorneys said shutting down the turbines would threaten “American national, economic, and energy security.”

The department relied heavily on a declaration from Cameron Stanley, the Defense Department’s chief digital and artificial intelligence officer, who stated that the military version of xAI’s chatbot, Grok, has become an important tool for classified government operations.

According to the filing, the Defense Department used Grok Gov, a government-specific version of the AI platform, during recent military operations involving Iran. The declaration states that the technology helped support operations in which U.S. forces struck approximately 2,000 targets using more than 2,000 munitions over a 96-hour period.

Adam Gustafson, head of the Justice Department’s Environment and Natural Resources Division, argued that the federal government cannot allow private litigation to interfere with infrastructure it considers important to national defense.

The department further argued that only a small number of artificial-intelligence systems are authorized to operate on highly classified government networks and that Grok is among those approved systems.

The filing arrives at a notable moment for Musk’s business empire.

Just days earlier, SpaceX, which now owns xAI following a corporate restructuring earlier this year, completed what reports described as the largest stock offering in history. SpaceX now carries a valuation exceeding $2 trillion, making it one of the most valuable companies in the world and placing it ahead of many of America’s largest public corporations.

The ownership connection means the Southaven facility at the center of the lawsuit is now part of a company that also maintains extensive relationships with the federal government through defense, aerospace, communications, and technology contracts.

The legal challenge has drawn fierce criticism from environmental advocates.

Earthjustice, the law firm representing the NAACP, accused the administration of attempting to weaken one of the Clean Air Act’s most important enforcement mechanisms. The organization argues that citizen lawsuits have served for decades as a way for residents and community groups to enforce environmental laws when regulators fail to act.

If courts allow the government to halt such cases simply by citing national-security concerns, Earthjustice argues, similar protections could eventually be extended to other large industrial projects and corporate operators.

The Environmental Protection Agency, which typically oversees air-permit enforcement, is not participating directly in the litigation and referred questions regarding the filing to the Justice Department.

The result is a high-profile legal battle that places environmental law, artificial intelligence, national security, and executive authority on a collision course.

For businesses, the outcome could have implications far beyond one Mississippi data center.

The Clean Air Act’s citizen-suit provision has long been a factor companies consider when planning major industrial facilities, energy projects, and manufacturing operations. A ruling that allows national-security concerns to override those actions could reshape how companies evaluate legal and regulatory risks, particularly as AI firms race to build energy-intensive data centers across the country.

For residents living near the Southaven facility, however, the issue remains more immediate.

The central question is whether the turbines continue operating while the legal fight unfolds.

The court has not yet ruled on the NAACP’s request for an emergency shutdown order, and no hearing date has been announced. Until a judge issues a decision, the turbines remain online — and so does the broader debate over who ultimately gets to decide when environmental concerns give way to national-security priorities.

Washington – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Several minority-owned construction firms that helped build the Obama Presidential Center in Chicago say they are still owed millions of dollars and fear the financial damage could threaten their businesses, according to contractors and industry advocates speaking out as the center prepares to open.

Omar Shareef, president of the African American Contractors Association, said multiple Black-owned contractors are under significant financial pressure because of work performed on the project. The allegations carry added weight because the center was widely promoted as an economic opportunity for minority-owned businesses on Chicago’s South Side.

The complaints come just days before the center’s formal dedication ceremony. The Obama Presidential Center is scheduled to be dedicated Thursday with appearances by Bruce Springsteen, Stevie Wonder, and John Legend, before opening to the public on Juneteenth. The 19.3-acre campus sits in Jackson Park and is expected to become one of the most significant landmarks associated with former President Barack Obama.

At the center of the dispute is II in One Concrete, a Black-owned company that participated in a joint venture known as the Concrete Collective alongside Trice Construction and W.E. O’Neil Construction. The group performed major structural concrete work throughout the project and has filed claims exceeding $40 million, alleging substantial additional costs resulting from project changes and delays.

In a separate lawsuit, II in One Concrete has accused engineering firm Thornton Tomasetti of racial discrimination, alleging the company was subjected to excessive scrutiny and unfairly blamed for project delays. Thornton Tomasetti has denied the allegations and maintains that performance issues, not discrimination, were responsible for the project’s challenges. The litigation remains ongoing.

The financial concerns extend beyond minority-owned firms.

Mike Owen, owner of Adamson Plumbing, told Fox News Digital that his company has suffered nearly $4 million in losses after years of work on the project. Owen attributed the losses to repeated design revisions, schedule changes, and project delays that significantly increased costs.

“That is a hole that no subcontractor, small business can survive,” Owen said, warning that layoffs could become necessary if the losses are not recovered.

Another minority-owned contractor reportedly told Fox News Digital that his company absorbed approximately $2.5 million in losses but declined to speak publicly because of a non-disclosure agreement. According to that contractor, work initially expected to last roughly 24 months stretched to nearly five years.

Shareef said some contractors remain reluctant to speak publicly because they fear doing so could jeopardize ongoing efforts to recover disputed payments.

The Obama Foundation disputes suggestions that it directly owes money to subcontractors. The foundation said it paid Lakeside Alliance, the project’s construction manager and general contractor, which in turn was responsible for managing and paying subcontractors. Foundation officials stated that there are no outstanding disputed charges between the foundation and Lakeside Alliance and noted that the foundation has no direct contractual relationship with subcontractors.

The foundation also said it worked with Lakeside Alliance to help smaller firms participate successfully in the project through accelerated payment schedules, advance payments, and a 15-day payment cycle designed to improve cash flow.

Lakeside Alliance acknowledged that financial issues frequently remain unresolved on large construction projects even after completion and said it continues working through outstanding claims and disputes.

Fox News Digital reported that it could not independently verify the losses claimed by contractors or confirm whether any businesses face closure.

The payment controversy arrives alongside renewed scrutiny of the project’s broader finances.

The foundation’s 2020 annual report described plans for a $470 million endowment intended to support future operations and reduce the likelihood of taxpayer-funded support. Public filings, however, indicate the reserve currently contains approximately $1 million. Foundation officials have responded by noting that the agreement with the City of Chicago did not require a specific endowment amount.

Meanwhile, the project’s construction cost has grown substantially. Early estimates of approximately $330 million have risen to nearly $850 million following years of delays, design changes, and construction challenges.

For many of the contractors involved, those rising costs translated into additional labor, equipment expenses, financing costs, and overhead that they say remain unpaid.

As the Obama Presidential Center prepares to welcome visitors, the celebration surrounding one of President Obama’s most ambitious post-presidency projects is unfolding alongside unresolved legal claims, financial disputes, and allegations from some of the very businesses the project was expected to help.

Whether those contractors ultimately recover the money they claim is owed will likely be determined through negotiations and court proceedings long after the ribbon-cutting ceremony concludes. For the companies involved, however, the issue is more immediate: payroll, suppliers, and lenders continue to demand payment regardless of how long legal disputes take to resolve.

JBizNews Desk
Chicago

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A growing number of voters in both the United States and Israel appear dissatisfied with the outcome of the war against Iran, according to newly released polling that suggests the political and economic consequences of the conflict are continuing to shape public opinion.

A Rasmussen Reports survey released Wednesday found that 48% of likely U.S. voters consider the war that began in February unsuccessful, including 27% who described it as “not at all successful.” By comparison, 44% viewed the effort as successful. The survey also found that only 35% of respondents favored continuing military operations until the government in Tehran was removed from power.

Economic concerns appear closely tied to those views. Since the conflict began on February 28 under the codename Operation Epic Fury, gasoline prices have risen significantly, with the national average approaching $4 per gallon, according to data tracked by AAA. At the same time, inflation has accelerated. The Bureau of Labor Statistics reported consumer prices up 3.8% year-over-year in its most recent reading, the highest annual pace since 2023, driven largely by energy costs.

Consumers have also faced higher grocery prices and increased household expenses. Recent labor data showed that average hourly earnings, after adjusting for inflation, have declined, adding pressure to household budgets. For many voters, the debate over the war has become intertwined with concerns about everyday living costs.

Those concerns are reflected in President Donald Trump’s approval ratings. A Reuters/Ipsos poll conducted June 3–8 found Trump’s overall approval rating at 35%, among the lowest levels of his second term. The survey found 29% approval for his handling of Iran and 22% approval for his handling of the cost of living. Meanwhile, the Economist/YouGov tracker recorded a net approval rating of negative 25 points, with particularly weak marks on inflation and consumer prices.

Several analysts have noted that economic management has traditionally been one of Trump’s strongest political issues. Rising inflation and higher energy costs have complicated that advantage, placing greater focus on voters’ financial concerns heading into the election season.

The political challenges extend beyond the United States. In Israel, a poll conducted for public broadcaster Kan found significant skepticism toward the U.S.-brokered agreement that ended active hostilities. Among the 555 Israelis surveyed, 18% supported the agreement while 55% opposed it. The poll also found that 70% remain concerned about the Iranian threat despite the joint U.S.-Israeli military campaign.

Views of Trump among Israeli respondents were more mixed. Approximately 40% described him as a strong friend of Israel, while 32% said they believe his approach toward the country may be changing.

A key issue moving forward is the impact of the agreement on global energy markets. The arrangement includes the reopening of the Strait of Hormuz, a critical shipping corridor through which roughly one-fifth of global oil supplies pass. The deal also provides temporary relief on some restrictions affecting Iranian oil exports.

Energy analysts say increased oil supplies could eventually help reduce fuel prices, although several experts have cautioned that supply chains and inventories may take considerable time to normalize. As a result, any meaningful reduction in energy costs may not be immediate.

The economic effects of the conflict have also been felt by businesses. Appliance manufacturer Whirlpool, parent company of KitchenAid and Maytag, recently reported declining sales and cited weakening consumer demand. Meanwhile, the Federal Reserve, under Chairman Kevin Warsh, has kept interest rates unchanged, citing ongoing inflation concerns and uncertainty surrounding energy prices.

The months ahead could prove critical politically. With the midterm elections approaching, public opinion surveys suggest that voters remain highly focused on inflation, fuel prices, and overall economic conditions. Whether lower energy prices emerge quickly enough to ease those concerns may play a significant role in shaping both voter sentiment and market expectations.

JBizNews Desk
Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Federal Reserve set the table for Thursday’s trading on Wednesday, June 17, when new Chair Kevin Warsh wrapped up his first policy meeting by holding interest rates steady while signaling that more officials now expect rate increases this year than cuts. The decision, paired with Warsh’s debut press conference, reset the mood heading into the next session and left traders recalculating how long borrowing costs will stay elevated.

Stocks finished Wednesday sharply lower once the message sank in. The Dow Jones Industrial Average fell 507 points, or 0.98%, to close at 51,492.55, wiping out an intraday record set earlier in the day. The S&P 500 dropped 1.21% to 7,420.10, and the tech-heavy Nasdaq Composite slid 1.34% to 26,021.66. Policymakers held the benchmark rate in a range of 3.5% to 3.75%, where it has remained since December 2025, but fresh projections showed nine of 18 officials expecting at least one rate hike before year-end, while six policymakers now anticipate two or more increases. The median forecast now places the federal funds rate at 3.8% by the end of 2026, up from 3.4% in the March projections.

What Could Move Markets Thursday

Fed Rate Expectations

The biggest driver remains the market’s reaction to Kevin Warsh’s first Fed meeting. Traders are now debating whether the next move from the Federal Reserve could be a rate hike rather than a rate cut. If investors continue adjusting to that possibility, stocks could remain under pressure.

Treasury Yields

The 2-year Treasury yield jumped roughly 16 basis points to 4.216%, while the 10-year Treasury yield climbed toward 4.49% after the Fed meeting. Another rise in yields could weigh heavily on stocks, especially high-growth technology companies.

Kroger and Accenture Earnings

Results from Kroger (KR) will provide a fresh look at consumer spending, grocery inflation, and household budgets. Accenture (ACN) will offer insight into corporate technology spending, business confidence, and demand for artificial intelligence-related services.

Oil Prices and the Iran Ceasefire

Crude oil remains one of the market’s biggest wild cards. Prices have fallen sharply following the framework agreement between the United States and Iran that ended hostilities and reopened the Strait of Hormuz. Any disruption to that agreement could quickly move oil prices, inflation expectations, and broader markets.

Technology Stocks

After leading Wednesday’s decline, investors will be watching whether Microsoft, Meta Platforms, Alphabet, Amazon, Nvidia, and other technology leaders stabilize or continue dragging the broader market lower.

Bank of England Rate Decision

The Bank of England is expected to announce its latest interest-rate decision Thursday. A surprise move could ripple through global bond markets and reinforce concerns that central banks remain focused on fighting inflation.

Holiday Trading Ahead of Juneteenth

With U.S. markets closed Friday for Juneteenth, Thursday is the last full trading session before the long weekend. Lower trading volumes can sometimes magnify market swings and increase volatility.

Market Movers

Thursday’s earnings calendar will provide fresh insight into both consumer and corporate spending.

Kroger (KR) reports results before the opening bell, offering investors a window into consumer behavior, grocery inflation, and whether shoppers continue shifting toward lower-cost products and private-label brands.

Consulting giant Accenture (ACN) will provide one of the market’s clearest gauges of corporate spending trends, technology investments, and business confidence. Investors will be listening closely for management’s outlook on enterprise demand and artificial intelligence-related projects.

Additional reports from Progressive and Jabil will provide updates on insurance trends and manufacturing activity.

Technology stocks remain in focus after leading Wednesday’s selloff. Shares of Microsoft, Meta Platforms, Alphabet, and Amazon all closed lower. Meanwhile, SpaceX (SPCX) experienced its first decline since going public on June 12, temporarily pausing a powerful post-IPO rally.

Commodities and Volatility

Oil remains one of the market’s biggest wild cards.

West Texas Intermediate crude traded near $76 per barrel, while Brent crude hovered around $79 per barrel, both well below their wartime highs.

Gold fell 1.77% as investors adjusted to the prospect of higher-for-longer interest rates. Meanwhile, the Cboe Volatility Index (VIX) moved above 16, reflecting increased uncertainty following the Fed’s policy shift.

One additional factor may shape trading activity. U.S. financial markets will be closed Friday, June 19, for Juneteenth, making Thursday the final full trading session before the holiday weekend. Overseas, the Bank of England is expected to announce its own interest-rate decision, with economists widely forecasting no change to its benchmark rate.

For investors, the takeaway is straightforward: the Federal Reserve no longer appears eager to deliver lower rates, and Thursday’s trading session will offer the first real test of how markets adapt to a more hawkish era under Chairman Kevin Warsh.

Bottom Line

Thursday’s market direction will likely be determined by three factors: Fed rate expectations, Treasury yields, and oil prices. If yields continue rising and investors conclude that rates will stay higher for longer, stocks could face additional pressure. If yields stabilize, oil remains contained, and earnings come in strong, markets may attempt a rebound after Wednesday’s sharp selloff.

JBizNews Desk
Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Smith & Wesson Brands reported a sharp jump in sales and profit on Wednesday, and behind the numbers sits a demand story the Maryville, Tennessee gunmaker rarely spells out: a country where fear — much of it driven by a record stretch of antisemitic violence — is sending first-time buyers to gun counters. The company posted results for its fiscal fourth quarter and full year ended April 30, with handguns accounting for the overwhelming majority of shipment growth.

The clearest signal is the gap between the company and the wider market. Handgun shipments into the sporting-goods channel rose 23.2% even as the national background-check measure rose just 1.1%, and handguns made up more than 80% of units shipped. People are not simply buying more guns — particular buyers are, for particular reasons.

One of those reasons runs straight through the American Jewish community.

In its annual audit released May 6, 2026, the Anti-Defamation League called 2025 one of the most violent and deadly years for Jews in the United States, counting 6,274 antisemitic incidents of assault, harassment, and vandalism — an average of 17 incidents per day. The year before, in 2024, the group recorded 9,354 incidents, a record high. “Numbers that would have shocked us five years ago are now our floor,” ADL Chief Executive Jonathan Greenblatt said.

The violence has been concrete and recent.

On May 21, 2025, two Israeli Embassy staffers were shot and killed outside the Capital Jewish Museum in Washington. Days later, on June 1, 2025, a man threw Molotov cocktails at a Run for Their Lives gathering supporting Israeli hostages in Boulder, Colorado, an attack that later claimed the life of an 82-year-old woman. Additional incidents followed, including a truck driven into a synagogue in West Bloomfield, Michigan, in March 2026, and an arson attack at Mississippi’s oldest synagogue in January 2026.

The response has been measurable.

Surveys released in October 2025 by the ADL and the Jewish Federations of North America found that 9% of American Jews had purchased a firearm because of security concerns, while 13% had installed new security systems. For a community historically associated with relatively low rates of gun ownership, the shift is significant.

Organizations have emerged to meet that demand.

Lox & Loaded, a Jewish firearms-training organization founded in March 2025, has expanded to 21 states, 40 chapters, and more than 1,000 members. In April 2026, the group announced a partnership with the National Rifle Association to provide expanded training opportunities and range access. Other organizations, including Magen Am and the Community Security Service, have expanded security training programs for synagogues and Jewish institutions. Collectively, Jewish organizations now spend an estimated $765 million annually on security measures.

The financial results reflect the demand.

Fourth-quarter net sales reached $178.4 million, up 26.7% from a year earlier, while earnings came in at 36 cents per share. Full-year sales totaled $523.8 million, an increase of 10.4%. The board declared a quarterly dividend of 13 cents per share, payable on July 15.

Chief Financial Officer Deana McPherson pointed directly to handguns as the primary driver of performance.

“Our outperformance was mostly driven by handgun shipments, which represented over 80% of our units shipped,” she said.

New products generated 37.5% of fourth-quarter revenue, and management said it expects overall firearm demand to remain relatively stable. President and CEO Mark Smith has credited recent product launches and disciplined pricing for helping drive growth.

The same firearms purchased by some consumers for protection continue to place Smith & Wesson at the center of the national debate over gun violence.

Survivors of the 2022 Highland Park Fourth of July parade shooting have sued the company, alleging it improperly marketed a rifle to vulnerable young men. The case remains active. Earlier this week, the U.S. Supreme Court declined to hear a challenge by gun manufacturers to a New York law allowing the state and private plaintiffs to sue firearm companies over criminal misuse of their products. Smith & Wesson was among the challengers.

The firearms industry argues that such lawsuits conflict with the Protection of Lawful Commerce in Arms Act, a federal law enacted in 2005 that shields manufacturers from many claims arising from criminal misuse of firearms. Gun-control advocates counter that companies should face accountability when marketing or business practices contribute to violence.

For investors, the earnings report highlights a company benefiting from strong demand and favorable product trends. For the broader public, it underscores a more complicated reality: a firearm manufacturer posting some of its strongest results in years while a growing number of Americans — including many Jews who once avoided gun ownership — decide that personal protection has become a necessity.

JBizNews Desk
Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The war between the United States and Iran moved a step closer to an official end Wednesday after both sides put a ceasefire memorandum into effect, activating a 60-day framework designed to halt hostilities and open negotiations toward a broader settlement.

The agreement takes effect immediately, while diplomats continue preparations for a formal signing ceremony expected later this week in Switzerland.

The move marks the most significant diplomatic breakthrough since fighting erupted on February 28, a conflict that disrupted global energy markets, rattled investors, and raised fears of a broader regional war.

For businesses, investors, and consumers, the most important provisions involve oil, shipping, and trade.

The ceasefire framework outlines steps aimed at restoring commercial traffic through the Strait of Hormuz, one of the world’s most important energy corridors. Before the conflict, roughly one-fifth of global oil and liquefied natural gas shipments moved through the narrow waterway linking the Persian Gulf to international markets.

Disruptions to that route sent oil prices sharply higher and contributed to rising gasoline costs worldwide.

The agreement also creates a pathway for increased Iranian energy exports and the restoration of commercial activity tied to shipping, insurance, banking, and transportation services associated with international trade.

Markets have already responded positively.

Oil prices have retreated from recent highs as traders anticipate improved supply conditions, while gasoline prices have begun easing as concerns over a prolonged disruption diminish. The possibility of additional Iranian crude entering global markets has added to expectations that energy costs could continue falling if the ceasefire holds.

President Donald Trump welcomed the development and has repeatedly pointed to lower oil prices and stronger financial markets as evidence that diplomacy is producing economic benefits.

Beyond energy, the memorandum establishes a 60-day negotiating period during which both countries are expected to pursue discussions on regional security issues and Iran’s nuclear activities.

Iran has agreed to maintain the current status of its nuclear program during negotiations, while the United States has agreed not to impose additional measures during the framework period.

Officials on both sides have emphasized that the memorandum represents a temporary framework rather than a final peace agreement.

That distinction remains critical.

While markets have embraced the ceasefire, investors recognize that the agreement’s success ultimately depends on what happens during the next two months. Any breakdown in negotiations or renewed military activity could quickly reverse recent gains in stocks and send energy prices higher again.

The challenge is already apparent. Regional tensions remain elevated, and military activity involving Iranian-backed groups continues to present risks that could complicate efforts to reach a permanent settlement.

The diplomatic effort has drawn support from multiple international players, including regional mediators, European governments, and the United Nations, all of whom have urged both sides to use the ceasefire as an opportunity to pursue a longer-term resolution.

For the global economy, the stakes extend far beyond the Middle East.

Lower energy prices could ease inflationary pressures, reduce transportation costs, improve corporate profit margins, and provide relief for households that have faced months of elevated fuel prices.

Airlines, manufacturers, trucking companies, retailers, and consumers all stand to benefit if stability returns to energy markets.

The next 60 days will determine whether this memorandum becomes the foundation for a broader agreement or simply a pause in a conflict that has already reshaped global energy markets and geopolitical calculations.

For now, the ceasefire is in effect, commercial shipping is preparing to normalize, and markets are cautiously betting that diplomacy may finally succeed where months of conflict failed.

JBizNews Desk
Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

PayPal confirmed on Tuesday that it is exploring strategic options for PayPal Ventures, its corporate venture capital arm, a step that effectively winds down a startup-investing operation the company built a decade ago.

In a statement, a company spokesperson said the review is part of an effort to sharpen the firm’s focus and that it had no further details to share for now.

The move lands as new chief executive Enrique Lores strips away pieces of the business that sit outside PayPal’s core job: running the checkout button and payment tools that millions of shoppers and merchants use every day.

The venture team has already shrunk dramatically.

Its headcount has fallen from more than 10 people in late 2025 to just two, and the web page that once listed its investors is no longer visible.

PayPal is also looking to sell some of its existing startup stakes on the secondary market and has hired Jefferies to help line up potential buyers.

Together, the two moves point to a full retreat rather than a simple slowdown.

PayPal launched PayPal Ventures in 2016, a year after eBay spun the payments company off as an independent business.

Since then the unit has invested off PayPal’s own balance sheet, backing more than 80 companies across three funds worth over $850 million.

Its bets included well-known names such as Plaid, which connects bank accounts to apps, and the crypto custody firm Anchorage Digital.

One of its profitable exits came when Bill.com bought the expense-management startup Divvy in 2021.

So why pull back from a business that has, at times, made money?

The portfolio’s results swing from year to year, which is exactly the kind of unpredictability Lores is trying to cut.

The venture holdings added 10 cents to PayPal’s $1.53 earnings per share in the fourth quarter of 2025, after subtracting 4 cents a year earlier, according to the company’s February earnings release.

That swing is small next to PayPal’s payments engine, and the new leadership would rather spend its attention elsewhere.

The decision follows a shakeup at the very top.

The board pushed out former chief executive Alex Chriss in February after a nearly three-year run in which PayPal’s stock fell more than 30% and directors grew worried the company was losing ground to rivals like Stripe and Apple, both of which offer their own checkout products.

In announcing the change, the board said the pace of progress had not met its expectations and named Enrique Lores, the former head of HP, as the new CEO, with David W. Dorman as independent chairman.

Lores moved quickly.

He spun the Venmo app into its own business unit, reshuffled senior leadership, and in May rolled out a sweeping cost-cutting plan.

PayPal is aiming to trim about 20% of its workforce over the next two to three years and to squeeze out at least $1.5 billion in savings during that stretch.

On a May earnings call, Lores told investors the company needed to speed up its use of artificial intelligence and get back to basics.

Closing a venture arm is a telling signal.

Corporate investing groups tend to flourish when money is cheap and companies feel free to chase strategic side bets, and they become harder to justify when leadership is focused on cost discipline and a clearer story for shareholders.

The higher interest rates of recent years made those bets more expensive to carry.

Big technology firms such as Google and Microsoft still run sizable venture operations, but those companies are not in turnaround mode the way PayPal is.

For everyday users, little changes at the checkout screen tomorrow.

The shift matters more as a sign of where PayPal is heading: away from scattered side projects and back toward the branded checkout, merchant tools, and Venmo payments that bring in the bulk of its revenue.

Selling the startup stakes, if it happens, would turn hard-to-value holdings into cash the company can pour back into that core.

Whether the strategy revives a stock that has frustrated investors will depend less on the venture wind-down itself and more on whether Lores can make the payments business grow faster.

San Jose, Calif. — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The World Bank Group said Tuesday it has approved a financing package designed to unlock as much as $2 billion in private bank loans for Argentina, a deal meant to cut the country’s borrowing costs just as a heavy round of debt payments comes due. The approval was announced from Washington by the bank’s board.

The structure is unusual, and the details matter. Rather than lend the money itself, the World Bank Group is backing loans that commercial banks will make to Argentina. It does this through two guarantees: a first-loss policy-based guarantee from the International Bank for Reconstruction and Development (IBRD) and a second-loss guarantee from the Multilateral Investment Guarantee Agency (MIGA). Together they cover 95% of the debt-service payments on the commercial loan.

In plain terms, the bank is promising to absorb most of the losses if Argentina fails to pay. That promise is what makes private lenders comfortable handing over money to a borrower they would otherwise treat as high-risk, and it lets Argentina lock in cheaper terms than it could get on its own.

The timing is no accident. Argentina faces roughly $4.4 billion in debt repayments by July 9, and the new package is built to help refinance part of that load rather than drain the country’s reserves to cover it. The supported loan carries a six-year maturity with a three-year grace period before repayments begin.

“We are committed to supporting Argentina’s macroeconomic stabilization and growth reform agenda,” said Susana Cordeiro Guerra, the World Bank’s Vice President for Latin America and the Caribbean. She said the guarantee structure helps bridge the country’s return to international capital markets on more affordable terms while pushing reforms that lift private investment and productivity.

That last point is the real goal behind the headline number. The guarantees are tied to changes meant to pull private money into Argentina — financing for infrastructure, stronger competition in its markets, and a friendlier environment for companies trying to do business there. The loan is less a handout than a down payment on Argentina convincing private investors to come back on their own.

And the World Bank is not acting alone. The Inter-American Development Bank is weighing a guarantee of up to $550 million for Argentina, while the Development Bank of Latin America and the Caribbean (CAF) is looking at another $500 million in support. CAF also announced Tuesday that it will provide a separate $400 million loan to Pan American Energy to fund the company’s natural-gas operations and expand output — a sign that lenders are backing both the government and the businesses driving its energy sector.

For ordinary Argentines and the companies that operate there, the stakes are practical. The country has spent years fighting punishing inflation and a weak currency, and the cost of borrowing abroad has long been one of its heaviest burdens. Cheaper refinancing eases pressure on the national budget, which in turn affects everything from the value of the peso to the price of imported goods and the government’s ability to keep spending steady. Lower financing costs also make it easier for firms to plan, hire, and invest without bracing for the next debt crisis.

There is a wider message here too. The deal is being watched closely by other developing economies, because the guarantee model offers a template for governments that have been shut out of cheap credit. If private banks are willing to lend to Argentina when most of the risk is covered, the same approach could be used to pull commercial money into countries that markets have written off.

None of this erases Argentina’s underlying problems. The package buys time and lowers costs, but it does not eliminate the debt or guarantee the reforms will deliver. The country still has to prove it can stabilize its economy and earn its way back into global markets without a safety net.

For now, the approval is a clear win. It hands Argentina a cheaper path through a near-term cash crunch and signals that international lenders are betting the country’s turnaround is worth backing. The harder test — whether private investors return on their own once the guarantees are gone — is still ahead.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Centers for Disease Control and Prevention (CDC) reported that the U.S. infant mortality rate fell to an all-time low in 2025, with slightly fewer than 5.4 deaths per 1,000 live births, according to preliminary government data. On Tuesday, the agency released a deeper analysis of 2024 figures that pointed in the same direction, showing declines among both the youngest newborns and older infants. In raw numbers, U.S. infant deaths dropped to roughly 19,350 last year, down from about 20,050 in 2024.

The improvement has a clear business story behind it. A major driver, experts believe, is a vaccination push against respiratory syncytial virus (RSV) — a common illness that causes cold-like symptoms but can turn dangerous, even deadly, for babies. Beginning in 2023, U.S. health officials recommended two new tools to protect infants, and both come from large pharmaceutical companies now selling them at scale.

The first is a vaccine given to pregnant women between 32 and 36 weeks, sold by Pfizer under the name Abrysvo, which passes protection to the baby before birth. The second is a lab-made antibody shot given directly to infants, called Beyfortus, marketed by Sanofi and AstraZeneca. Together they have created a fast-growing commercial market built around a problem that previously had few good defenses.

The payoff shows up most clearly in hospital data. The CDC has reported that infant hospitalizations for RSV dropped after the shots became available, with the largest reductions among babies up to two months old. That matters financially because severe RSV cases often mean stays in intensive care, which rank among the most expensive forms of pediatric treatment. Each hospitalization avoided is a cost not borne by a family, a hospital, or an insurer.

That makes the immunization push a rare win across the health-care economy. Insurers and employer health plans save when fewer babies need costly emergency care. Medicaid, which covers roughly four in ten U.S. births, stands to benefit heavily, since a large share of vulnerable infants fall under government coverage. Hospitals, meanwhile, can redirect strained pediatric capacity toward other patients. Prevention that costs a few hundred dollars per shot replaces care that can run into the tens of thousands.

For the drugmakers, the opportunity is still expanding. CDC figures show that as of late January, only about 41.6% of eligible pregnant women had received the RSV vaccine, with coverage uneven across different groups. That low rate is a problem for public health but a growth runway for Pfizer, Sanofi, and AstraZeneca, since millions of births each year represent a recurring market that is far from saturated. Closing the coverage gap means steady demand for years.

The ripple effects reach further into the health sector. Pharmacies and clinics that administer the shots gain a new line of routine business, and the broader push around maternal and infant health supports demand for prenatal care, pediatric services, and the workers who provide them. Health care has been one of the strongest areas for job growth, and preventive programs like this one help sustain that momentum by keeping a steady stream of patients moving through doctors’ offices and pharmacies rather than emergency rooms.

There are real limits to the good news. Even at a record low, the U.S. rate still trails other wealthy countries such as Italy, Japan, Spain, and Sweden, a gap experts tie to poverty and gaps in prenatal care that no single shot can fix. The benefits of the RSV products are also spread unevenly, with lower vaccination rates among some groups that face the highest risk. And the latest figures are provisional, meaning they could shift slightly as the CDC finishes its analysis.

Still, the direction is encouraging, and it carries a lesson that businesses across health care are watching closely. A targeted prevention effort, backed by products from a handful of major companies, appears to be saving lives and cutting costs at the same time. For an industry often criticized for spending heavily on treatment after people get sick, the RSV story is a reminder that prevention can be good medicine and good business at once.

The next test is whether the gains hold as the 2025 numbers are finalized and whether coverage climbs from here. If it does, the companies behind these shots, the insurers footing the bills, and the families raising healthier babies all stand to come out ahead.

Washington – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump has invoked the Defense Production Act to push American weapons makers to produce more munitions faster, according to a presidential memorandum dated June 11 and made public Tuesday in the Federal Register.

The order points to “systemic constraints in the munitions industrial base” and hands Defense Secretary Pete Hegseth the authority to strike voluntary agreements with manufacturers to fix them.

The law Trump reached for is a Cold War relic.

Passed in 1950 during the Korean War, the Defense Production Act lets a president steer private industry toward national-defense needs — a powerful tool that signals how seriously Washington is taking the strain on its arsenal.

That strain traces directly to the Iran war.

The roughly 15-week conflict, on top of years of arming Ukraine and other partners, has burned through stocks of missiles and precision weapons far faster than factories can refill them.

An April analysis from the Center for Strategic and International Studies found the U.S. may have used up more than half its inventory of four critical munitions, including Tomahawk cruise missiles, during the Iran campaign.

The memo lays out the bottleneck in plain terms: limited production capacity, fragile supply chains, long-lead parts that take many months to build, and the chokepoints that come with them.

Some of the hardest pieces to make quickly are solid rocket motors, igniters, and guidance systems — the specialized internals that go into nearly every modern missile, and exactly the parts no manufacturer can spin up overnight.

For the defense industry, the order is an invitation to do more business with the government.

The biggest contractors — Lockheed Martin and RTX, the parent of Raytheon — already work closely with the Pentagon, and the new authority is meant to deepen that cooperation.

A Pentagon official, industrial-base policy chief Michael Cadenazzi, told reporters Tuesday that the act lets the government sit down with companies and work through supply-chain problems together without running afoul of antitrust law.

The timing lined up with fresh movement in the industry.

Also on Tuesday, Lockheed Martin and GM Defense announced an agreement to work together on strengthening defense supply chains and manufacturing.

Not everyone inside the government agrees there is an emergency to fix.

Hegseth has spent weeks downplaying worries about depleted stockpiles, telling lawmakers the concern has been “foolishly and unhelpfully overstated” and insisting the military has what it needs.

Yet in earlier testimony he also acknowledged it could take months, even years, to replace some of what has been fired.

The business stakes reach well beyond the marquee contractors.

Replenishing missile stocks means orders flowing down to the smaller companies that make rocket motors, electronics, machined metal parts, and chemicals — many of them mid-sized manufacturers spread across states that depend on defense work for jobs.

A sustained push to rebuild inventories is the kind of demand that fills plants and adds shifts, and it tends to last for years rather than months.

Investors noticed.

Shares tied to defense manufacturing and the exchange-traded funds that track them tend to move on signals like this, because a government commitment to rebuild stockpiles points to steady, multi-year revenue for the companies that make weapons and their components.

The order does not name dollar figures or guarantee contracts, but it tells the industry the orders are coming.

There is a strategic worry sitting underneath all of it.

Defense planners have warned that inventories drained in the Middle East leave less in reserve for any future conflict involving China, where a clash would demand exactly the long-range missiles the U.S. has been spending down.

For now, the practical effect is a green light.

Trump has told his defense secretary to lean on industry, and industry has been handed a reason to invest in new capacity.

Whether that turns depleted shelves back into full ones — and how quickly — will depend on the same fragile supply chains the order was written to fix.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEW YORK — Whey protein prices have surged as much as 250% over the past year, according to dairy-data firm Ever.Ag, transforming what was once a byproduct of cheese production into one of the most sought-after ingredients in the food industry.

The firm reports that 80% whey protein concentrate now trades above $13 per pound in the United States, while more refined whey protein isolate prices have climbed roughly 150% year-over-year. In late May, DCA Market Intelligence reported a record average price of €26,450 ($30,518) per metric ton for 80% concentrate, more than double its level less than a year ago.

The latest U.S. Department of Agriculture dairy-market reports describe the whey market as firm, with tight inventories and elevated pricing even as some other dairy products soften.

The reason is simple: demand is growing faster than supply.

High-protein diets have moved beyond fitness enthusiasts and become mainstream, fueling demand for protein shakes, snack bars, cereals, meal replacements, and fortified foods.

A major new catalyst has been the rapid adoption of GLP-1 weight-loss drugs such as Ozempic and Wegovy. With roughly 12% of Americans now taking such medications, healthcare providers increasingly recommend higher protein intake to help preserve muscle mass during weight loss.

The result has been a sharp increase in demand across the protein industry.

Over the past two years, whey protein concentrate prices have risen approximately 108%, while isolate prices have climbed roughly 139%.

Supply, however, cannot easily expand.

Whey is a byproduct of cheese production, meaning manufacturers cannot simply increase output in response to demand. Production depends largely on how much cheese is being made, not how much protein powder consumers want.

Even as U.S. milk production reaches record levels, the specialized facilities that process whey into protein concentrates and isolates are operating near capacity.

USDA reports indicate that food manufacturers are increasingly competing for available whey supplies, while many producers have already committed most of their production through the end of 2026.

The impact is increasingly visible to consumers.

Sports-nutrition companies are raising prices, reducing package sizes, or incorporating alternative proteins to manage costs. Some finished protein products now cost 50% to 110% more than they did in 2024.

“We’re seeing whey protein prices reach historic highs,” said Darcy Davenport, chief executive of BellRing Brands, maker of the Premier Protein product line.

Retail-data firm Datasembly found that U.S. concentrate prices have increased approximately 15% over the past year, with premium isolate products rising even faster.

Dairy companies are racing to expand production.

Glanbia is adding new whey-isolate capacity through a joint venture in New Mexico. Tirlán has committed approximately €126 million to premium whey production, while Idaho Milk Products is investing $200 million in new facilities.

Across the industry, billions of dollars are being committed to additional processing infrastructure.

Most of that capacity, however, will not become operational until late 2026 or beyond, leading many analysts to conclude that meaningful relief may not arrive until 2027.

Some manufacturers are responding by sourcing lower-grade whey from overseas markets, while premium brands continue emphasizing quality and domestic supply chains.

Industry observers believe the demand surge may prove long-lasting.

Unlike previous cycles driven largely by bodybuilders and athletes, whey protein now serves a broad range of markets, including mainstream food products, medical nutrition, weight-management programs, and international exports.

That expansion suggests prices could remain structurally higher even after additional production comes online.

The shortage is also accelerating research into alternative proteins, including plant-based blends and other dairy-derived ingredients, as manufacturers seek greater supply flexibility.

For consumers, the effects are already apparent through higher prices on protein powders, shakes, bars, and protein-enhanced foods.

For dairy producers, the boom represents both an opportunity and a challenge — the chance to generate significant profits from what was once considered a low-value byproduct, provided new production can keep pace with demand.

JBizNews will continue monitoring the whey and broader dairy markets for what they mean for food inflation, consumer spending, and the profitability of America’s dairy processors.

Wall Street — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Britain will bar children under 16 from using a range of major social media apps, Prime Minister Keir Starmer announced Monday, putting the country at the front of a global push to pull young people away from platforms built to keep them scrolling.

Speaking at Downing Street, Starmer said the ban would cover Snapchat, TikTok, YouTube, Instagram, Facebook and X, and would take effect next year.

Messaging services such as WhatsApp and Signal, along with YouTube Kids, would be exempt.

Crucially, the penalties fall on the companies, not the children. Platforms that fail to take reasonable steps to keep under-16s off their services could face fines running into the millions.

“Every parent can see it with their own eyes. Social media is making children unhappy,” said Starmer, who has two teenage children and framed the move as a “big moment for our country.”

The government said its plan drew support from about nine in ten parents and generated 116,000 responses during public consultation, one of the largest in years.

The British plan follows the model set by Australia, which last year became the first country to bar under-16s from holding social media accounts.

But Starmer said Britain would go further.

The government also intends to block livestreaming and stranger contact with children on gaming platforms, restrict AI chatbots that simulate romantic or sexual relationships to adults only, and is weighing additional measures such as overnight curfews and forced breaks in endless scrolling for those under 18.

For the technology industry, the stakes are real and largely American.

The companies in the crosshairs are among the biggest names in U.S. tech: Meta, which owns Instagram and Facebook; Snap, the maker of Snapchat; Google, which owns YouTube; and TikTok’s parent, the Chinese firm ByteDance.

These platforms depend on advertising revenue, and advertising depends on engaged users, including the teenagers a ban would lock out.

Beyond the lost users, the companies face the cost and complexity of verifying ages across millions of accounts, a technical and privacy challenge with no easy solution.

The platforms are pushing back.

A YouTube spokesperson warned that a blanket restriction could backfire by pushing children out of supervised, curated services and toward anonymous, less-safe corners of the internet.

Starmer anticipated the resistance, saying he would fight back if technology companies resisted and acknowledging that some teenagers would inevitably find workarounds.

He compared it to alcohol, arguing that the difficulty of perfect enforcement is no reason to abandon the effort.

Here is why it matters well beyond Britain.

The country is one of the largest and wealthiest markets in Europe, and a ban there sets a precedent that other governments are likely to study closely.

Australia, Canada, Brazil and Indonesia have already moved on age limits, and France, Spain, Denmark and others are weighing similar steps.

Each new market that closes to younger users chips away at a business model the social media giants have spent two decades building, one that treats teenage attention as a core asset.

The timing is pointed.

Starmer said he expected to raise the issue with President Donald Trump and other leaders at the Group of Seven summit in France this week, suggesting the campaign to regulate children’s access to social media is becoming an international cause rather than a national experiment.

For the American companies that dominate these platforms, the message from London is a warning:

The era of unrestricted access to young users is starting to close, one country at a time.

London — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Apple is preparing one of the biggest waves of new products in its history for late 2027, headlined by AirPods with built-in cameras, a second-generation foldable iPhone, and a redesigned iPhone built to mark the device’s 20th anniversary, according to people familiar with the plans cited by Bloomberg’s Mark Gurman on Tuesday.

The reporting points to a year in which Apple tries to prove it can still set the pace in consumer technology, especially in the race to put artificial intelligence into devices people wear.

The most novel of the three is the camera-equipped AirPods, code-named B798 internally and described as Apple’s first AI wearable.

The tiny cameras in the earbud stems are not meant for taking photos or video.

Instead, they feed information about a wearer’s surroundings to Siri, so the assistant can answer questions about nearby objects, offer reminders tied to where someone is, or sharpen walking directions.

The earbuds would look much like the current AirPods Pro models, with cameras added to the stem, and a small light would signal to others when those cameras are active — an attempt to address privacy concerns.

The product was originally targeted for 2026 but has reportedly been pushed back.

The delay stems in part from Apple’s widely reported struggles with its next-generation AI software and a revamped Siri, along with the challenge of building visual models that can reliably identify what users are looking at.

That timing matters because it highlights how Apple’s AI setbacks are beginning to affect its hardware roadmap at a time when competitors are moving aggressively.

The second-generation foldable iPhone signals that Apple sees foldable devices as a long-term business rather than a one-time experiment.

The company is widely expected to introduce its first foldable iPhone in 2026, with a follow-up model arriving roughly a year later.

For a company whose iPhone business still generates the majority of its revenue, a successful foldable line could create a new premium category and encourage upgrades from existing customers.

The centerpiece of the roadmap may be the 20th-anniversary iPhone, expected to commemorate two decades since the original iPhone debuted in 2007.

Reports describe a device that breaks sharply from today’s designs, featuring displays that stretch nearly edge-to-edge and glass that curves around the sides.

Apple has successfully used anniversary editions before to drive demand.

The iPhone X, launched in 2017 for the product’s tenth anniversary, sparked one of the company’s biggest upgrade cycles.

A similarly dramatic redesign in 2027 could have the same effect.

Under the hood, both the anniversary model and the new foldable device are expected to run on Apple’s next-generation A21 processor, built using advanced 2-nanometer manufacturing technology from Taiwan Semiconductor Manufacturing Co. (TSMC).

Reports indicate Apple is already exploring even smaller 1.4-nanometer chips for future devices and may seek additional manufacturing capacity from Intel, a notable shift given the company’s longstanding reliance on TSMC.

The broader strategy reflects a growing battle over what comes after the smartphone.

Technology companies across the industry are investing heavily in AI-powered devices that can see, hear, and understand the world around users.

Meta is betting on smart glasses.

Apple is reportedly developing its own smart-glasses platform while simultaneously exploring AI-enabled earbuds.

Putting cameras and AI sensors into AirPods gives Apple a way to enter the market using a product that already has hundreds of millions of users worldwide.

There are important caveats.

The plans come from unnamed sources, Apple does not comment on unreleased products, and Bloomberg’s report notes that development schedules remain fluid and could change.

All three products are still being tested, and features may evolve before launch.

For consumers, the roadmap offers a glimpse of where personal technology is heading — toward devices that constantly observe their surroundings and provide real-time assistance through artificial intelligence.

For investors, the question is whether Apple can transform its AI ambitions into products people are willing to buy after a period in which many analysts believe the company has fallen behind rivals in the AI race.

If these products arrive as planned, 2027 could become one of the most important years in Apple’s history since the original iPhone changed the technology industry nearly two decades ago.

Cupertino, Calif. — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump threatened Earlier this week to slap a 100% tariff on all French wine and champagne unless France scraps the tax it charges large American technology companies, escalating a long-running fight over digital taxation just as he headed to a summit on French soil.

In an interview with the New York Post, Trump said he had taken the warning directly to French President Emmanuel Macron.

“I asked him not to charge American companies, and if they do, I have no choice but to charge a 100% tariff on all champagnes and all wines coming out of France,” he said, adding that all Macron needs to do is drop the tax.

At the center of the dispute is France’s digital services tax, a 3% levy it introduced in 2019 on the revenue that big technology firms earn within the country.

The tax falls heavily on American giants such as Alphabet, Apple, Meta, Amazon and Microsoft, and because it applies to gross revenue rather than profit, companies pay it even in years they earn little.

Washington has argued for years that the tax unfairly singles out U.S. firms.

Macron showed no sign of backing down.

Speaking from the G7 summit he is hosting in the French Alps, he said it is not for the United States to decide French or European law and made clear the tax would stay as long as he is in office.

With his term ending in 2027, Macron has grown less concerned with pleasing the American president.

For France’s winemakers, though, the threat is serious.

The United States is the single biggest buyer of French wine and spirits, accounting for about 21% of the industry’s exports last year.

French and European wines already face a 15% U.S. tariff, up from 10% earlier, and exports to the United States slumped about 21% last year.

Doubling the price of a bottle with a 100% tariff would deal a heavy blow to an industry already under strain, and French exporters reacted with alarm.

Here is what it would mean closer to home.

A 100% tariff is effectively a doubling of the cost of bringing French wine and champagne into the country, and much of that increase tends to reach the shelf.

A bottle that sells for $40 today could approach $60 or more, hitting American restaurants, importers and shoppers who favor French labels.

In that sense, a tax aimed at protecting U.S. tech companies would land squarely on U.S. wine drinkers.

The clash is part of a much bigger standoff.

Digital services taxes have become a flashpoint between Washington and its trading partners, with the United States arguing they discriminate against American firms that dominate the internet economy.

During Trump’s first term, U.S. trade officials opened formal investigations into France’s tax and proposed similar tariffs.

Last year, Canada scrapped its own digital tax under pressure from Trump to keep trade talks alive, a precedent the administration would surely like France to follow.

So far, France is not following it.

The threat now hangs over the G7 gathering, an awkward backdrop for a meeting meant to project unity among allies.

Whether it becomes a real tariff or remains a negotiating club depends on whether Paris blinks, and for the moment, Macron is holding firm.

American wine lovers, and the businesses that sell to them, will be watching closely.

Évian, France — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Investors headed into Wednesday focused on the Federal Reserve’s latest policy decision while oil prices continued their recent decline, extending a five-session losing streak as traders weighed growing expectations for additional global crude supplies.

Markets traded modestly higher in early action as investors awaited the central bank’s announcement later in the day. The focus remained on interest rates, inflation, and any signals policymakers might provide about the direction of monetary policy in the months ahead.

The S&P 500 edged higher, while the Dow Jones Industrial Average and Nasdaq Composite also posted gains. Market participants largely expected the Fed to leave interest rates unchanged, shifting attention toward policymakers’ economic projections and commentary regarding inflation and economic growth.

On the corporate front, earnings reports remained in focus.

Jabil reported stronger-than-expected quarterly results, benefiting from continued demand tied to artificial intelligence infrastructure and data center investments. The manufacturing services company exceeded analyst expectations on both earnings and revenue, helping lift sentiment across parts of the technology sector.

CarMax also drew attention after releasing quarterly results as investors continued to assess the outlook for consumer spending and the used-vehicle market. Analysts remain divided on the company’s turnaround prospects amid a challenging retail environment.

Technology shares were mixed following recent profit-taking across the semiconductor sector. Investors continued to evaluate whether the rapid growth driven by artificial intelligence can support current valuations after a powerful rally over the past year.

In commodities trading, oil prices remained under pressure. Brent crude extended its decline toward levels not seen in several months, while West Texas Intermediate also moved lower. Traders pointed to expectations for increased global supply, including potential additional exports from major producers and higher output from members of the OPEC+ alliance.

The decline in oil helped ease some inflation concerns that have weighed on financial markets in recent months. Lower energy prices can reduce transportation and production costs across the economy, potentially supporting consumers and businesses.

Gold prices also softened as investors reduced some safe-haven positions, while market volatility remained relatively subdued ahead of the Fed announcement.

By the afternoon, attention was expected to shift almost entirely to the central bank’s decision and accompanying comments. Investors will be looking for clues about whether policymakers believe inflation remains a significant threat or whether economic conditions may eventually justify lower interest rates.

With earnings season continuing and energy markets adjusting to changing geopolitical conditions, traders are expected to remain highly focused on incoming economic data and central bank guidance in the days ahead.

JBizNews Desk
Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The U.S. Department of Justice sued two top New York health officials on Tuesday, alleging they rigged the bidding for an $11 billion Medicaid home care contract and then allowed a favored company to improperly collect millions of taxpayer dollars from the program.

The civil complaint, filed by the Justice Department’s Civil Division, names New York State Health Commissioner James McDonald and State Medicaid Director Amir Bassiri as defendants. Assistant Attorney General Brett A. Shumate said the lawsuit seeks to enforce federal laws requiring integrity in government health care programs and to protect taxpayers from fraud and abuse.

At the center of the case is New York’s Consumer Directed Personal Assistance Program (CDPAP), which allows approximately 250,000 elderly and disabled residents to hire their own caregivers, including family members, rather than relying on traditional home care agencies. The state consolidated payroll and administrative functions under a single contractor in 2024, arguing the move would reduce costs and improve oversight.

That contractor was Public Partnerships LLC (PPL), a Georgia-based company. According to the federal complaint, the bidding process was not a fair competition. The lawsuit cites internal communications suggesting state officials faced pressure from the Governor’s Office while evaluating competing bids.

Federal prosecutors also allege that PPL intentionally submitted what it internally described as a “recklessly low bid” to secure the contract. According to the complaint, the company expected to recover losses later through higher reimbursement rates approved by the state.

The Justice Department further alleges that once awarded the contract, PPL inflated costs billed to Medicaid and improperly increased administrative charges in violation of contractual obligations and federal law.

The transition to the new system quickly encountered major problems. According to the complaint, PPL requested a longer transition period but was denied. Court records cited by federal attorneys indicate that one week into the January 2025 rollout, only 43 of approximately 214,000 participants had successfully transitioned to the new system. Caregivers across the state reported delayed paychecks, service disruptions, and overwhelmed customer service operations.

Gov. Kathy Hochul is not named as a defendant and is not accused of wrongdoing. However, the complaint references actions by her office during both the bidding process and the implementation of the contract. Hochul has defended the overhaul as necessary to combat waste and fraud, noting that CDPAP spending grew from $1.9 billion in 2015 to approximately $11 billion by 2025.

The lawsuit follows months of scrutiny surrounding the contract award. PPL has faced allegations of operational and financial issues in multiple other states. In New York, lawmakers from both parties have been examining the procurement process, and some have called for additional investigations into the contract award and rollout.

For the hundreds of thousands of New Yorkers who rely on CDPAP services, the federal lawsuit transforms a troubled program transition into a high-profile legal battle over the management of billions of taxpayer dollars. The defendants have not yet filed formal responses, and the allegations remain unproven.

JBizNews Desk
Albany, New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The typical asking rent in America slipped again last month, extending one of the longest stretches of falling rents on record, according to the Realtor.com May Rental Report released Tuesday.

The national median asking rent fell to $1,686 in May, down 1.5% from a year earlier. That marked the 34th consecutive month that rents on studio-to-two-bedroom homes came in below year-earlier levels — a streak that now stretches nearly three years and has quietly given renters their strongest negotiating position in a decade.

The reason is simple: supply and demand. A historic apartment construction boom flooded the market with new units, forcing landlords to compete harder for tenants. According to Apartment List, more than 600,000 multifamily units were delivered in 2024, the highest annual total since 1986. While construction has slowed since then, many of those buildings are still leasing up, keeping vacancies elevated and rent growth muted.

For renters who endured the sharp post-pandemic surge in housing costs, the shift has provided meaningful relief. Even so, rents remain well above pre-pandemic levels, meaning today’s renter-friendly environment is still significantly more expensive than the market of early 2020. The recent declines have softened the spike rather than erased it.

The biggest discounts remain concentrated in fast-growing Sun Belt markets that built aggressively. Austin and Phoenix continue to post some of the nation’s steepest rent declines as new supply outpaces demand. In those cities, renters often have greater success negotiating lower monthly payments, reduced fees, or move-in incentives.

The report also highlights differences beneath the national trend. Some markets are retaining existing residents while others are being shaped by migration patterns. Las Vegas, for example, has seen renters stay put as improving affordability provides value close to home.

Other markets are moving in the opposite direction. Previous Realtor.com reports identified cities including Virginia Beach, Baltimore, and Richmond as locations where vacancies are tightening and rents are beginning to climb again. In those areas, affordability pressures are returning despite the broader national decline.

Economists describe the current environment as two rental markets operating simultaneously. Jiayi Xu, an economist at Realtor.com, has noted that renters in high-construction markets are benefiting from significant relief, while tenants in supply-constrained regions are seeing costs move higher again. Chief Economist Danielle Hale has characterized the broader trend as evidence that increased housing supply is finally translating into savings for consumers.

Looking ahead, much depends on the construction pipeline. Fewer projects are breaking ground today than during the peak building surge, meaning the supply wave that has restrained rents will gradually diminish. Most housing analysts expect rents to remain relatively stable through 2026, but many caution that today’s favorable conditions may not persist indefinitely in every market.

For now, renters hold unusual leverage across much of the country. Elevated vacancies and longer leasing times are giving tenants more room to negotiate than they have enjoyed in years. In cities where rents are already rising again, however, the window for bargains may be closing faster than the national numbers suggest.

JBizNews Desk
Housing & Real Estate Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Builders broke ground on far fewer homes in May, sending new construction to its lowest level in six years, according to a report released Tuesday by the Census Bureau and the Department of Housing and Urban Development.

Total housing starts fell 15.4% from April to a seasonally adjusted annual rate of 1.18 million units, the slowest pace since May 2020 and well below the 1.43 million that economists had expected. Starts were also 8.7% lower than a year earlier. April’s figure was revised down to 1.39 million, making the monthly drop even steeper.

The headline number hides an important split. Construction of single-family houses, the kind most American families buy, held up relatively well, slipping just 1.9% to an annual rate of 882,000.

The real collapse was in apartments. Starts of buildings with five or more units fell to 284,000, down from 529,000 in April, nearly cutting the pace of new apartment construction in half in a single month. That part of the market is famously volatile, swinging sharply from month to month, but the size of the drop still stunned forecasters.

The cause is no mystery. Mortgage rates remain high, with the average rate on a 30-year loan sitting near a one-year high, and that keeps would-be buyers on the sidelines and makes builders cautious about starting projects they may struggle to sell.

Construction costs are still elevated, partly because the war with Iran pushed up the price of materials and energy earlier this year. And builder confidence has been sliding; a closely watched measure of homebuilder sentiment fell again this month.

The slump marks a sharp reversal. As recently as March, construction was running at its fastest pace since late 2024, with starts topping 1.5 million. Then activity fell in April and dropped off a cliff in May, a sign that the brief momentum builders had built up has faded under the weight of high borrowing costs.

There is little sign of a quick rebound in the pipeline.

Building permits, which signal future construction, were essentially flat at an annual rate of 1.41 million, down slightly from April and from a year ago. When builders are not pulling permits, they are not planning to ramp up soon.

Completions also fell, dropping 8.1% from April, which means fewer finished homes are reaching the market just as buyers need them most.

Here is why this matters far beyond the construction industry.

The United States has been short of housing for years, and that shortage is the main reason home prices and rents have climbed so far out of reach for so many families.

Every month builders pull back, the gap between the number of homes the country needs and the number it has gets a little wider.

Fewer new apartments today means tighter supply and higher rents tomorrow.

Fewer new houses means continued bidding wars over the limited supply already on the market.

The pullback also ripples through the broader economy.

Homebuilding supports millions of jobs, from carpenters and electricians to the workers who make lumber, drywall and appliances. When construction slows, those jobs and the spending that comes with them slow too.

All of this lands at a delicate moment for interest rates.

The Federal Reserve is meeting this week under its new chair, Kevin Warsh, and is widely expected to hold rates steady, with some officials even leaning toward a hike to fight stubborn inflation.

For the housing market, that is not encouraging news. Mortgage rates tend to follow the Fed’s signals, and as long as borrowing stays expensive, both builders and buyers are likely to stay cautious.

For now, the May report paints a clear picture: the engine that produces the country’s homes is sputtering at exactly the time the nation can least afford it.

Whether construction picks back up depends almost entirely on what happens to mortgage rates in the months ahead, and right now, those rates are not cooperating.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Supreme Court on Monday declined to hear a challenge to the tariffs President Donald Trump placed on Chinese goods during his first term, leaving the import taxes in place and ending a years-long fight by businesses that had hoped to overturn them and recover what they paid.

The justices denied review, without comment, in a case known as HMTX Industries LLC v. United States, the test case in a long-running effort to undo the duties. The decision closes the door on the lawsuit and on the refunds that importers across the country were seeking.

The tariffs at issue were imposed in 2018 under Section 301 of the Trade Act of 1974, after the U.S. Trade Representative investigated and concluded that China was engaging in unfair trade practices, including the theft of American intellectual property and the forced transfer of technology from U.S. companies.

The original duties covered about $50 billion worth of Chinese goods. The administration later expanded them sharply, to roughly $370 billion in products, a move the plaintiffs argued went beyond what the law allowed.

Lower courts, including the U.S. Court of Appeals for the Federal Circuit, had already sided with the government, and the Supreme Court’s refusal to step in lets those rulings stand.

The timing is what makes this significant.

Just four months ago, in February, the same Supreme Court struck down a far broader set of tariffs Trump imposed in his second term, ruling 6-3 that he had overstepped his authority by using a national-emergency law to tax imports from nearly every country.

That decision wiped out the sweeping “reciprocal” tariffs.

But it left the older Section 301 tariffs on China untouched because those rest on a different and firmer legal foundation.

Monday’s action confirms that distinction: the emergency-powers tariffs fell, while the China tariffs survive.

For the administration, that is a meaningful win.

With the emergency-powers route blocked, Section 301 has become one of the most reliable tools left for taxing imports, and the court has now signaled it will not interfere with how that tool has been used.

The administration has already begun leaning on it, recently opening new Section 301 actions against several seafood-trading partners over forced-labor concerns.

Here is why it matters beyond the courtroom.

The tariffs cover an enormous share of what the United States buys from China, from electronics and machinery to furniture and auto parts.

Those taxes are paid in the first place by American companies that import the goods, and a portion of the cost typically reaches consumers through higher prices.

They have been part of the economic landscape for years, and Monday’s decision means they are not going anywhere.

The businesses that paid them and hoped for relief, or for money back, will get neither.

It also leaves the broader trade picture firmly in place.

Even after the bigger tariffs were struck down in February, Chinese goods remained among the most heavily taxed imports in the country because of these Section 301 duties stacked alongside other measures.

With the legal challenge now exhausted, that structure is locked in for the foreseeable future.

The ruling lands as the United States and China continue a delicate economic relationship, one that has swung between confrontation and negotiation.

For companies that spent years building supply chains around Chinese factories and betting the courts might eventually grant them relief, the message from Washington is now unambiguous:

Plan around the tariffs, because they are here to stay.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The European Parliament gave its final approval Tuesday to a long-delayed trade agreement with the United States, voting 440 to 151 with 50 abstentions and clearing the last major hurdle just weeks before a deadline set by President Donald Trump that would have sharply raised tariffs on European cars.

The vote locks in the framework that Trump and European Commission President Ursula von der Leyen struck nearly a year ago in Turnberry, Scotland. Under the deal, the United States applies a tariff of up to 15% on most goods coming from Europe, while the European Union removes many of the duties it charges on American industrial products. It is meant to settle a dispute that had been hanging over the world’s largest trading relationship.

What pushed lawmakers to act now was the calendar. Trump had given the bloc until July 4 to ratify the agreement, warning that he would otherwise raise tariffs to much higher levels. He had specifically threatened to lift duties on cars and trucks built in Europe to 25%, a move that would have hit the continent’s automakers hard and raised prices for American shoppers who buy their vehicles. Tuesday’s vote takes that threat off the table, at least for now.

Getting here was not smooth. EU lawmakers had twice frozen the deal over the past several months. They paused it in January after Trump floated the idea of taking control of Greenland, a Danish territory, and again in February after a U.S. court struck down a large part of his tariff program, leaving Europe unsure what it was even agreeing to. Many members of parliament have called the agreement lopsided, arguing it gives Washington more than it gives Brussels, and they attached safeguards that would let the EU suspend the tariff cuts if the United States does not hold up its end.

The tension has not gone away. Tuesday’s approval came just days after Trump issued yet another tariff threat, this time aimed at France over its rules governing digital companies. That timing was a reminder that even a ratified deal remains fragile as long as tariffs are being used as a tool of pressure.

Why does an agreement negotiated in Brussels matter to people in the United States? Because the amounts involved are enormous. Roughly $1.8 trillion in goods and services move across the Atlantic in both directions every year, touching everything from German sedans and French wine to American machinery, software and farm products. When tariffs rise, those costs tend to land on businesses and, eventually, on the prices consumers pay. A 25% tax on imported European cars would have rippled through dealerships, repair shops and the broader auto market on both sides of the ocean.

For carmakers, the vote is a clear relief. European manufacturers such as BMW, Mercedes-Benz and Volkswagen sell large numbers of vehicles in the United States and build many of them at American plants as well. A jump to 25% would have scrambled their pricing and factory plans. The 15% rate is still well above the roughly 2.5% they paid before the dispute began, but it gives them something businesses value above almost everything else: a number they can count on.

Not everything is settled. The safeguards the parliament attached still need sign-off from the EU’s member states before the tariff reductions on American goods fully take effect. Steel and aluminum remain subject to a separate 50% tariff that the two sides have yet to resolve. And the broader relationship will stay on edge as long as new threats keep surfacing.

Still, Tuesday marked a genuine turning point. After a year of brinkmanship, missed deadlines and frozen votes, the deal that has loomed over transatlantic trade finally has the approval it needed to move forward. For companies that have spent months unable to plan, that certainty may matter as much as the tariff rate itself.

The focus now shifts to whether Washington keeps the peace or reaches for the next threat.

Brussels — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The world could go from scrambling for every barrel to drowning in crude within about a year and a half, the International Energy Agency said Wednesday in its monthly Oil Market Report, the first edition to carry a full-year forecast for 2027.

The Paris-based agency, which advises 32 member countries on energy policy, laid out a sharp reversal. After a brutal stretch in which the U.S.-Iran war knocked millions of barrels a day offline and pushed fuel prices to painful highs, the report said a steady rebound in production — provided the interim peace deal between Washington and Tehran actually holds — would lift global supply far beyond what the world is on track to burn.

The numbers tell the story. The agency expects oil supply to climb by roughly 8 million barrels a day next year, reaching about 110.3 million barrels a day, as Persian Gulf production comes back online and OPEC+ raises its output targets. Demand, by contrast, is seen rising a far more modest 2 million barrels a day, to 105.3 million. That gap points to an enormous glut in 2027 — what the agency called a significant overhang building across the market.

That would be a stunning flip from the shortage gripping the market right now. The IEA again cut its demand outlook for this year, saying the pain from high prices has spread well beyond the regions and industries hit first. It now sees 2026 demand at 103.3 million barrels a day, down from 104 million in its May report and a 3.9 million-barrel drop from 2025 levels.

Second-quarter deliveries were especially weak. Early data showed consumption running 5 million barrels a day below a year earlier — the first global quarterly demand drop since the pandemic year of 2020. The agency said the weakness is carrying into the summer, with shipments of major fuels, gasoil in particular, straining across nearly every region as steep prices and a tougher economy push every product category into decline.

Prices have already started to ease as a result. North Sea Dated crude, a global benchmark, tumbled more than $40 a barrel to around $82 between early May and mid-June as buyers pulled back. That is a long way down from the swings earlier in the war, when the benchmark spiked toward $144 a barrel before sliding below $100 on conflicting signals about whether a deal would get done.

Supply this year is still badly depressed. The agency pegged 2026 output at 102.4 million barrels a day, a small upgrade from its last report but a 3.9 million-barrel fall from 2025. May production came in at 94.5 million barrels a day — down 600,000 from April and a striking 13.6 million below where the world was producing before the conflict began.

The strain shows up clearly in storage. Global oil inventories have been drained by an average of 3.8 million barrels a day since the U.S.-Iran war started, with May alone seeing a 4.6 million-barrel-a-day draw. Government emergency stocks held by IEA member countries fell to their lowest level since December 1990, as nations kept releasing reserves to plug the gap.

For all the optimism about 2027, the agency was careful to flag how fragile the peace is. While the interim agreement clears a path for Middle East exports to recover, it warned that practical and political hurdles — including the slow work of clearing mines from shipping lanes and unresolved arrangements for moving cargoes through the Strait of Hormuz — leave real downside risk. The agency stressed that its 2027 rebound is subject to a substantial level of uncertainty tied directly to whether the proposed deal sticks.

Refineries remain under pressure in the meantime. The report sees crude processing shrinking by 2 million barrels a day this year, to 82 million, led by a steep drop over the spring, before recovering by about 3.1 million barrels a day in 2027 as crude supplies normalize.

If the glut does materialize, the agency framed it as a rare opening. A wave of surplus oil, it said, would give governments and companies a chance to refill drained tanks and even build new strategic reserves — a priority for many countries now rethinking their energy plans after the shock of the past several months. For drivers and households that have been squeezed at the pump and on home heating, a market tipping back toward oversupply would be the clearest sign yet that the worst of the price spike is in the rear-view mirror — so long as the guns stay quiet.

JBizNews Desk
Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The leaders of the Group of Seven gathered in Évian, France, this week wanting to show the world a united front on artificial intelligence. Instead, their push is running into two hard walls: the United States’ insistence on protecting its own technology lead, and China’s tight grip on the raw materials that AI depends on.

The summit, hosted by French President Emmanuel Macron and running through Wednesday, has put AI near the top of the agenda alongside the wars in Ukraine and the Middle East. Macron has courted the technology world to make his case, even inviting OpenAI chief executive Sam Altman to attend. But the deeper the leaders dig, the clearer it becomes that “G7 cooperation” on AI is complicated by how lopsided the field really is.

Consider the numbers. In 2025, roughly 79% of newly funded AI companies across the G7 were based in the United States, according to the Atlantic Council. France, the host, accounted for about 3.4%. When one member so thoroughly dominates an industry, agreeing on shared rules becomes a negotiation over advantage, not just principle.

That is the first wall. Washington has made clear it opposes binding multilateral agreements on AI that could dull its edge. Instead of signing onto shared governance, the United States is promoting what officials call the “American AI technology stack” — a push to export U.S. hardware and software, often backed by financing from the Commerce Department, so other countries build on American systems rather than Chinese ones. Add in U.S. export controls that restrict the sale of the most advanced AI chips abroad, and the message to allies is less “let’s write rules together” and more “build on our platform.” References to AI governance in this year’s summit language are expected to be watered down as a result.

The second wall is China, and it may be harder to climb. Artificial intelligence is not just software. It runs on physical hardware — chips, servers, data centers — and that hardware depends on rare earth elements and other critical minerals. China controls an estimated 80% to 90% of the global supply of those materials, and it has spent the past year tightening export controls on them. A suspension of some of the toughest restrictions is set to expire on November 10, less than five months away, and if it lapses, a wide swath of the world’s electronics supply chain would again need Chinese approval to operate.

The stakes are enormous. The International Energy Agency, in a report prepared for France’s G7 presidency, estimated that full enforcement of China’s controls could put $6.5 trillion a year in economic output at risk for countries outside China, with losses in the auto industry alone topping $3 trillion. The G7 has responded with a Critical Minerals Action Plan and more than $6.4 billion in new mining and processing projects, but the work is slow, and members remain divided over how confrontational to be with Beijing.

Here is why this matters beyond the summit photographs. The AI economy everyone is racing to build rests on three things: the software, where American firms dominate; the chips and the minerals inside them, where China holds the leverage; and the energy to run it all. The G7 can talk about leading together, but the United States holds most of the software and China holds most of the materials, leaving the rest of the bloc squeezed in the middle. For businesses, that shapes where the next factories and data centers get built. For ordinary people, the same mineral controls touch the price and availability of cars, phones and home electronics.

Leaders are expected to issue several statements before the summit closes on Wednesday, and French officials have promised “very concrete” progress on securing supply chains. Whether that means real action or more careful language is the open question. The pressure will not ease soon: China’s control suspension expires in November, and the United States takes over the G7 presidency next year, putting Washington and its go-it-alone instincts on AI in the host’s chair.

For now, the G7’s ambition to shape the future of artificial intelligence is bumping up against a simple reality. The technology may be global, but the power over it is not evenly shared.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

U.S.-listed companies have sold about $54 billion of convertible bonds so far this year, up 43% from the same stretch of 2025 and the highest year-to-date total since the start of the COVID-19 pandemic, according to Dealogic data going back to 1995. The buyers powering that rush are artificial-intelligence companies hungry for cash, and the terms they are getting are remarkably cheap — in some cases, effectively free.

A convertible bond is a hybrid. Like a normal bond, an investor lends a company money. But the bond comes with a feature that can work in everyone’s favor: if the company’s stock climbs to a predetermined price, the investor can convert the bond into shares and participate in the stock’s gains. Investors like it because they get the relative safety of a bond plus exposure to stock-market upside. Companies like it because that upside allows them to borrow at far lower rates than traditional debt would require.

How low? Many AI issuers are paying coupons as small as 0%, meaning no interest at all. Investors accept those terms because AI stocks move so dramatically that the option to convert into stock is valuable on its own. The more volatile the shares, the more valuable that conversion feature becomes — and AI stocks have been among the market’s most volatile.

Akamai Technologies, the cybersecurity and cloud-computing company, recently demonstrated just how attractive the market has become for issuers. The company sold $3.5 billion in zero-coupon convertible notes split between maturities in 2030 and 2032. The 2030 notes can convert at $201.41 per share, a 42.5% premium above Akamai’s $141.34 closing price on May 19, while the 2032 notes convert at $190.81, a 35% premium. Chief Financial Officer Ed McGowan said the company entered the market while its stock traded near a 26-year high and volatility was elevated. He described convertibles as the cheapest and most efficient financing tool available to the company.

The largest names tied to the AI boom are taking advantage of the same opportunity. CoreWeave recently issued $4 billion of convertible bonds carrying just a 1.75% interest rate. Oracle raised $5 billion through a similar transaction earlier this year, while Microchip Technology has also been active in the market. According to CoreWeave executives, the volatility that accompanies fast-growing AI businesses is exactly what makes these securities attractive to investors and easy for companies to sell.

Investors have been rewarded for their enthusiasm. The ICE BofA U.S. Convertible Index has gained more than 20% this year, outperforming broader equity benchmarks. By comparison, the S&P 500 has risen roughly 10%, while the Nasdaq Composite has advanced about 13%. Joe Wysocki, senior co-portfolio manager at Calamos Investments, summed up the appeal succinctly: “Convertibles are growth capital for growth issuers, and I don’t think you can think of a better growth opportunity than AI.”

Behind the financial engineering lies a very real economic story. The money raised through these offerings is helping fund the physical buildout of artificial intelligence infrastructure — data centers, power systems, networking equipment, and the advanced chips that AI models require. The spending supports construction firms, electrical contractors, utility providers, and manufacturers supplying servers and networking hardware. Convertible bonds have quietly become one of the primary financing tools behind the AI expansion, meaning the health of this corner of the debt market reaches far beyond Wall Street.

There are risks. Because convertible bonds can eventually become shares, they can dilute existing stockholders if conversions occur. That potential dilution is one reason some large companies avoid them. The securities can also lose value quickly if AI stocks fall sharply, since much of their appeal comes from the possibility of converting into higher-priced shares. A market that rewards growth generously can reverse course just as quickly when expectations are missed.

For now, however, momentum remains firmly with issuers. Bankers expect additional deals as more AI-related companies enter public markets and seek capital to fund expansion. The flood of near-free money reflects the extraordinary confidence investors currently have in the long-term growth of artificial intelligence.

The real test will come when the AI rally eventually slows, if it does. Until then, companies appear likely to keep borrowing billions at rates that would have seemed unimaginable only a few years ago.

Wall Street – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

NEWTOWN, Pa. — Shares of Traws Pharma collapsed on Monday, sinking to an all-time low after the small drugmaker said British regulators had blocked a key test of its experimental flu treatment. In a statement issued late Friday, June 12, the company said the United Kingdom’s Medicines and Healthcare Products Regulatory Agency (MHRA) had given a negative review to its planned mid-stage human study of tivoxavir marboxil, forcing the trial to be postponed.

The reaction was brutal. Traws Pharma stock fell about 17% in early Monday trading and dropped as much as 24% during the session, sliding to roughly $0.97 a share — a new 52-week low for a stock that traded as high as $3.27 over the past year. With limited Wall Street coverage, investors who do follow the company voted with their feet, wiping out a large chunk of its already small market value in a single morning.

Tivoxavir marboxil, the company’s lead drug, is a long-acting antiviral designed to treat and prevent influenza, including dangerous strains of bird flu. The blocked study was a human challenge trial, in which healthy volunteers would have received either the drug or a placebo and then been deliberately exposed to a controlled flu strain. That study was the centerpiece of the company’s near-term plans, and the regulator’s refusal leaves a major hole in its roadmap.

The British decision is especially painful because it follows a similar setback from the U.S. Food and Drug Administration. In February, the FDA placed a clinical hold on the company’s application to test the drug, citing concerns about mutagenicity — the potential of a substance to cause genetic mutations. With both the FDA and the MHRA now raising red flags, the path forward has narrowed sharply.

Traws Pharma is trying to reassure investors that the program still has life. “While we have had a setback in the development of our lead compound for influenza, the program continues to be a high priority,” said Dr. Robert Redfield, the company’s chief medical officer and former director of the Centers for Disease Control and Prevention.

Chief executive Iain Dukes said the feedback affects the timing of the study but not the company’s confidence in the science. He pointed to strong results in three animal models of bird flu and said the company has enough cash to operate into the first quarter of 2027 while advancing backup compounds designed to retain the original drug’s strengths without the mutagenicity concerns.

For a company of this size, timing and cash are everything. Traws Pharma raised up to $60 million in a private placement in April specifically to fund the now-postponed UK study — money raised for a trial that will not happen on schedule. Small clinical-stage drug developers typically have no products on the market and no sales. They survive on investor capital and the promise of future breakthroughs. When regulators halt a lead program, company value can disappear overnight.

Regulators such as the MHRA and FDA serve as gatekeepers between a laboratory discovery and a medicine patients can actually use. Their approval opens the door to testing and commercialization. Their objections can freeze a program, increase costs and force a company back to the drawing board.

For Traws Pharma, back-to-back regulatory setbacks in two countries have forced a strategic reset. The company’s hopes now rest increasingly on backup candidates that have yet to prove themselves in human testing.

The broader stakes extend beyond one stock. Long-acting flu treatments — particularly those that may be effective against bird flu — remain a significant public-health goal. But Monday’s plunge serves as a reminder of how fragile small biotechnology companies can be, and how quickly a regulatory decision thousands of miles away can erase years of investor optimism.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

OpenAI, the company behind ChatGPT, lost about $38.5 billion in 2025, according to audited financial documents that surfaced Tuesday, a staggering figure that lands just as the company prepares to sell shares to the public for the first time.

The documents were first reported by technology writer Ed Zitron and independently verified by the Financial Times. They offer a rare look inside one of the most closely watched private companies in the world and arrive days after OpenAI confidentially filed paperwork with the Securities and Exchange Commission for a stock-market debut expected later this year.

The headline number is the loss. OpenAI reported a net loss of roughly $38.5 billion in 2025, compared with about $5 billion a year earlier. However, most of that increase came from a one-time accounting charge of approximately $41.5 billion related to the company’s conversion from a nonprofit into a for-profit entity. Excluding that and other one-time items, the loss was closer to $8 billion. The company’s operating loss — what it spent beyond revenue to run the business — was approximately $21 billion.

Revenue, by contrast, was the bright spot. Sales reached $13.07 billion in 2025, more than triple the $3.7 billion OpenAI brought in during 2024 and ahead of the company’s own internal target of $10 billion. Few private companies ever reach that size. The problem is what it costs to get there.

OpenAI spent about $34 billion last year, far more than it took in. The biggest line item was research and development at roughly $19 billion, followed by nearly $6 billion on sales and marketing. Running ChatGPT and training newer models requires enormous banks of computer chips, vast data centers, and large amounts of electricity, and those costs climb with every new user and every question answered.

Unlike traditional software businesses, where serving one more customer is almost free, each AI request carries a real and recurring expense.

Much of that money flows to Microsoft, OpenAI’s largest partner and the provider of the cloud computing infrastructure behind its products. The documents show OpenAI paid Microsoft approximately $17.2 billion in 2025, while Microsoft paid roughly $303 million back. That dependence is one reason the two companies remain closely linked, and why OpenAI’s spending affects chipmakers, power companies, and data-center builders across the economy.

Here is why this matters beyond Silicon Valley.

OpenAI is preparing to ask public investors — including retirement accounts, pension funds, and ordinary Americans saving for the future — to buy into a company generating extraordinary revenue growth while still losing billions of dollars annually.

The leaked financials provide the clearest look yet at one of the central questions facing the AI revolution: can the companies leading this race eventually turn explosive growth into sustainable profits?

There are reasons for optimism in the numbers.

The company is becoming more efficient. In 2024, OpenAI spent approximately $2.37 for every dollar of revenue it generated. In 2025, that figure improved to roughly $1.60. If that trend continues, and if OpenAI can either raise prices or reduce the cost of developing new models, a path toward profitability exists.

Chief Executive Officer Sam Altman has told investors he expects revenue to reach $100 billion in the coming years.

OpenAI is also not alone in spending heavily. Rivals including Google, Meta, xAI, and Anthropic are pouring money into the same race, each pushing to release more capable AI systems, often before the economics are fully settled.

That competition can force prices lower while keeping costs elevated, making profitability difficult across the industry.

For now, the leaked documents leave investors with one hard question as the IPO approaches.

The demand for AI is real.

The revenue is real.

What remains unproven is whether any company — OpenAI included — can turn the most expensive technology race in modern business into one that consistently generates profits.

OpenAI declined to comment on the figures.

Wall Street — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Treasury bonds rallied this week and oil tumbled to its lowest level in three months, as investors positioned ahead of a Federal Reserve interest-rate decision due Wednesday — the first under new Chairman Kevin Warsh. The yield on the 10-year Treasury note eased to about 4.46%, while the 2-year yield, the one most tied to Fed policy, slipped to roughly 4.05%. When bond prices rise, yields fall, so the move signals investors buying government debt.

The bigger driver behind the calm was crude oil. In the latest session, West Texas Intermediate crude settled down 5.6% at $76.61 a barrel, and Brent, the global benchmark, fell below $80. Both have dropped sharply as tensions in the Persian Gulf cool following the U.S.-Iran agreement, unwinding the price spike that followed the war. Cheaper oil eases one of the main worries hanging over the bond market — that high energy costs would keep inflation elevated and force the Fed to stay tough.

That brings the focus to Wednesday. The Federal Open Market Committee, the Fed’s rate-setting panel, wrapped a two-day meeting that markets expect to end with no change. Rates are widely seen holding in the current range of 3.50% to 3.75%, where they have sat since the Fed paused in January. The real event is not the rate itself but what comes with it: Warsh’s first press conference as chairman and the Fed’s updated economic projections, which show where officials think rates are headed.

Those projections matter because the Fed is caught between two pressures. Inflation is still running above its 2% goal, and the energy spike from the Iran conflict pushed it higher this spring. At the same time, oil is now falling fast, which could pull inflation back down on its own. Investors want to know whether Warsh leans toward holding steady, signals possible cuts later in the year, or keeps the door open to a hike if prices prove sticky.

In commodities, the slide in oil was the standout, but it was not the whole picture. Gold edged up 0.5% to about $4,331 an ounce, supported by the dip in bond yields. Lower yields tend to make gold more attractive because the metal pays no interest, so it competes better when returns on safer assets shrink.

Stocks were quieter. The S&P 500 rallied earlier in the week but paused as the Fed meeting approached, with traders unwilling to make big bets before the decision. Overseas, Japan’s Nikkei 225 pushed toward the 70,000 milestone for the first time, helped by steady bond yields at home. Across global markets, investors appeared content to wait for the Fed’s decision before making major new bets.

For everyday Americans, the combination of falling oil and a cautious Fed lands close to home. Cheaper crude usually means lower prices at the gas pump within a few weeks, easing one of the most visible costs families face. Lower Treasury yields also ripple into mortgage rates, car loans, and credit-card costs, since those borrowing rates often track the 10-year note. If yields keep drifting down, the cost of financing a home or a car could ease modestly in the months ahead.

Businesses are watching the same signals from a different angle. Companies that depend on fuel — airlines, trucking firms, delivery operators, and manufacturers — get immediate relief when oil drops, and that can help hold down the prices they charge. Firms planning to borrow or expand also care deeply about where the Fed steers rates, because cheaper credit makes it easier to invest and hire. A clear message from Warsh about the path ahead would help businesses plan with more confidence.

The risk is that the relief proves short-lived. Oil markets can reverse quickly if the Iran truce wobbles or the Strait of Hormuz comes back into question, and inflation has not yet returned to the Fed’s target. A single hot data point could swing expectations back toward higher rates, just as a jobs report did earlier this spring.

For now, the setup is a friendly one: bonds firmer, oil softer, and a central bank widely expected to hold its ground. The decision and the projections that land Wednesday will tell investors whether that calm has staying power or whether it is just a pause before the next move.

Wall Street – JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A senior Trump administration official told reporters Monday that the memorandum of understanding signed with Iran a day earlier leaves some of the hardest issues — sanctions relief, Iran’s nuclear program, and tens of billions of dollars in frozen Iranian money — for a later round of talks. For Tehran, that frozen money may be the biggest prize of all.

The agreement, signed digitally Sunday by President Donald Trump and Vice President JD Vance, opens a 60-day window for technical negotiations meant to produce a final deal. A formal signing ceremony with U.S. and Iranian officials, joined by Pakistani and Qatari mediators, is planned for Friday. But the official was blunt that this is a starting point, not a finished bargain.

What Iran wants is straightforward. Iranian state media, citing a 14-point draft, has described a plan to free up about $24 billion of Iran’s blocked funds during the 60-day period, with half handed over before final talks even begin. The Trump administration tells a different story.

A senior official said Friday that Iran would get nothing until it proves it is living up to the deal — turning over nuclear material, dismantling facilities, and committing to regional calm. Each step, the official said, earns Iran something in return. Treasury Secretary Scott Bessent, who oversees the sanctions machinery, has signaled the same caution. So the two sides do not yet agree on even the basic timing of any payout.

So where is all this money? Iran’s frozen and restricted assets are scattered across the globe, the leftover proceeds of oil and gas it sold but could not bring home once U.S. sanctions cut its banks off from the financial system. Estimates of the total run as high as $100 billion, though many put the realistically recoverable amount closer to $40 billion to $50 billion.

The single largest pile sits in China, Iran’s main oil customer, where Iranian funds are estimated in the tens of billions — figures range from about $20 billion to as much as $50 billion. Iraq owes Iran billions more for years of natural gas and electricity, with estimates between $6 billion and $15 billion. Qatar holds roughly $6 billion, money that originally sat in South Korea before being moved in a 2023 prisoner swap and then blocked again. Smaller sums are parked in Japan, Luxembourg, Oman, and the United Arab Emirates, and India is believed to hold around $7 billion.

None of this tension is new. Washington first froze Iranian assets in 1979 after the U.S. Embassy in Tehran was seized. The money came briefly within reach after the 2015 nuclear deal, then was locked away again in 2018 when Trump pulled the United States out of that agreement and reimposed sanctions. Each round of penalties trapped more of Iran’s oil earnings in accounts it could see but not touch.

For ordinary Iranians, the stakes are immediate. The Statistical Centre of Iran put annual inflation at 68.1% in February, the highest reading since World War II, and the recent fighting deepened an economy already in crisis. Even a partial release of frozen cash could steady Iran’s currency, ease the cost of imported food and medicine, and give the government some room to breathe.

The money is also tied to bigger questions for the world economy. Trump has said reopening the Strait of Hormuz — the narrow shipping lane Iran effectively shut during the war — is a priority in the talks. That waterway carries a large share of the world’s oil, and any lasting deal that frees Iranian funds would likely come paired with calmer energy markets and steadier prices at the pump well beyond the Middle East.

That is why companies far from Tehran are watching closely. Shippers, refiners, and importers have spent months pricing in the risk of a closed Hormuz, and a credible path to peace would start to unwind that premium. For businesses, the frozen-asset fight is not a side issue. It is one of the levers that decides whether the fragile truce holds.

For now, the frozen billions stay frozen. The weekend memorandum settled the easy part — an agreement to keep talking. The hard part, including who releases what money and when, is exactly what the next 60 days are meant to decide.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Iran’s foreign minister, Abbas Araghchi, said on Tuesday that Iran and the United States will begin a new round of talks in Switzerland on Friday, right after both sides sign an interim memorandum of understanding meant to end their war.

Iranian deputy foreign minister Kazem Gharibabadi said the text is finished and the signing is set for Friday in Geneva.

A copy of the 14-point draft, reported this week by Bloomberg and Al Arabiya, shows an agreement built largely around economics — oil, shipping, sanctions, and the release of frozen money — with the hardest nuclear questions pushed into a later round.

The stakes are already showing up in prices.

Crude oil fell more than 4% to below $78 a barrel on Tuesday, its lowest level in months, as traders bet that a reopened Strait of Hormuz will bring Middle Eastern barrels back to a market that has been starved of supply since the fighting began.

Here is what the draft actually says, point by point.

1. End the War

Both countries and their allies declare an immediate and permanent end to the fighting on all fronts, including Lebanon, and pledge to stop attacks and threats against each other.

2. Respect Borders

Each side agrees to respect the other’s sovereignty and territory and to stay out of the other’s internal affairs.

3. A 60-Day Clock

The two governments commit to reaching a final agreement within 60 days, extendable if both sides agree.

4. Lift the Blockade

The United States drops its naval blockade and restores shipping to full pre-war levels within 30 days, and pulls its forces back from areas around Iran within 30 days of the final deal.

5. Reopen the Shipping Lanes

Iran moves to restore merchant traffic between the Persian Gulf and the Sea of Oman to pre-war volumes within 30 days, including clearing mines and other obstacles.

6. $300 Billion to Rebuild

The United States and regional partners agree to draw up a plan to rebuild and develop Iran’s economy, backed by financing of at least $300 billion, with the mechanics set within 60 days.

7. End the Sanctions

Washington commits to lifting all sanctions on Iran on an agreed schedule — United Nations measures, IAEA board resolutions, and U.S. penalties, both primary and secondary.

8. No Nuclear Weapons

Iran restates that it will never build a nuclear weapon, and both sides leave the fate of enriched material and other nuclear questions to the final agreement.

9. Freeze in Place

Until a final deal, both sides hold steady: Iran keeps its nuclear program as is, and the United States adds no new sanctions and no new troops to the region.

10. Oil Starts Flowing

Right after signing, the U.S. Treasury issues waivers for exports of Iranian crude oil and petrochemicals, plus the banking, insurance, and shipping services that make those sales possible.

11. Unfreeze the Money

As talks progress, frozen Iranian funds are released and made fully available, directed by the Central Bank of Iran.

Iranian media has put the near-term figure at about $24 billion.

12. A Watchdog

The two sides set up a mechanism to oversee that the final agreement is carried out and honored.

13. First Steps First

Final talks begin only once Iran gets assurances that the early economic moves — lifting the blockade, reopening shipping, the oil waivers, and the release of funds — are underway.

14. A U.N. Stamp

The final agreement would be locked in by a binding United Nations Security Council resolution.

For Americans, the most direct effect runs through energy.

Iranian oil and petrochemicals returning to the market, on top of a reopened Strait of Hormuz, point toward lower crude prices — and falling crude tends to reach the gas pump within days and ease the cost of nearly everything that is grown, made, or shipped.

Cheaper energy would also give the Federal Reserve more room as it watches inflation.

The sheer size of the numbers in the draft, from the $300 billion rebuilding fund to the $24 billion in released cash, hints at how much business could follow a lasting settlement.

The caution is real.

Neither Washington nor Tehran has formally published the text, much of the detail traces to Iranian sources, and the toughest issues — the nuclear program and full sanctions relief — are left to a 60-day round that has not yet started.

President Donald Trump has billed the accord as a guarantee that Iran will never get a nuclear weapon, but the payoff for households depends on a deal that still has to hold.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A senior U.S. administration official said Tuesday that Iran will be cleared to begin selling oil the instant it signs a new agreement with Washington this week, handing Tehran an immediate financial reward for winding down the war that has gripped the region since late February.

The break does not stop at crude.

The same official said the agreement also waives U.S. sanctions on the banking, shipping, and insurance services Iran needs to move its oil and collect payment for it.

That detail matters more than it sounds.

A waiver on oil sales alone would change little, because no buyer, bank, or tanker owner will touch Iranian barrels without those supporting services cleared first.

Both sides signed the memorandum of understanding electronically on Sunday, and President Donald Trump has said the full text will likely be read out Friday after a formal signing ceremony.

The relief on oil exports takes effect the moment that signature is in place.

The agreement is built to reward Iran only if it holds up its end.

“This is a performance-based agreement,” the official said, speaking on condition of anonymity.

Tehran keeps the benefits only if it follows through on its core promises: building no nuclear weapon, neutralizing its stock of enriched uranium, and keeping the Strait of Hormuz open to shipping.

That last condition sits at the center of everything.

Roughly 20% of the world’s oil and liquefied natural gas normally moves through Hormuz, the narrow waterway at the mouth of the Persian Gulf.

Iran effectively closed the strait after the U.S. and Israel struck the country on Feb. 28, choking off a major share of global supply and sending energy prices sharply higher for months.

Washington answered with a naval blockade that kept Iranian oil bottled up.

The pressure was real on both sides.

U.S. emergency crude reserves have fallen to their lowest level since 1983, drained by months of trying to keep the market supplied while the strait stayed shut.

Not everyone sees the deal as a clean win.

Brett Erickson, a sanctions expert and managing principal at Obsidian Risk Advisors, called the move a “multibillion-dollar concession to Iran.”

He noted that Tehran is sitting on more than 100 million barrels of oil in storage and on tankers, with over 60 million barrels already outside the blockade and ready to sell.

For context, the world burns through roughly 100 million barrels of oil a day.

Iran is not waiting for the ink to dry.

The nonprofit United Against Nuclear Iran reported that an Iranian supertanker left the port of Chabahar on Tuesday and sailed past the U.S. blockade line into the Gulf of Oman with its tracking transponder switched on — the first such move since Washington imposed the blockade.

Iran’s state Mehr News Agency published what it described as the 14 points of the draft agreement.

They include a permanent ceasefire, a full lifting of the naval blockade within 30 days, the reopening of Hormuz, a suspension of oil sanctions, and the release of $24 billion in frozen Iranian funds over a 60-day negotiating window.

Tehran will not get immediate access to that cash; it is tied to the talks ahead.

Markets had already begun pricing in the relief.

Brent crude, the international benchmark, fell more than 5% to below $80 a barrel on Tuesday, its lowest level since the first week of March, erasing most of the spike driven by the conflict.

West Texas Intermediate, the U.S. benchmark, dropped to around $75.50.

Both had climbed more than 45% at the height of the war.

For American businesses and households, the math is straightforward.

Cheaper crude eventually means cheaper gasoline, diesel, and jet fuel, which ripple through everything from trucking and airline costs to the price of groceries that have to be shipped.

A drop of this size, if it holds, takes pressure off shipping companies, manufacturers, and any business that has been swallowing higher fuel bills since the spring.

The timing also carries a political read.

The Trump administration has been openly worried about a gasoline price spike heading into the November midterm elections, and a deal that puts Iranian barrels back on the water is the fastest tool it has to bring pump prices down.

Plenty could still go wrong.

The text has not been publicly released, questions remain over how shipping security and Hormuz traffic will actually work, and the relief is conditional from day one.

But for the first time in months, oil is moving out of Iran, prices are falling, and the businesses caught in the middle finally have reason to expect some relief.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

During the opening week of the war with Iran, American forces were shooting down cheap enemy drones — some costing as little as $30,000 — with missiles that cost more than $1 million apiece. In May, the Department of Defense laid out a plan to stop that math from breaking the budget, announcing framework agreements to buy more than 10,000 low-cost cruise missiles over three years. Under Secretary of Defense for Research and Engineering Emil Michael said the effort would “deliver affordable mass for our warfighters at unprecedented speed.” This month, the military begins buying test versions to see which ones actually work.

The problem is simple to state and expensive to live with. America’s best missiles are extraordinary machines, but they cost a fortune and take years to build. A single THAAD interceptor ran about $12.77 million in 2025, according to Pentagon figures. A Tomahawk cruise missile costs roughly $3.5 million and takes about two years to deliver. When a war suddenly demands thousands of these weapons, the shelves empty faster than factories can refill them.

That is exactly what happened. The war with Iran, which began on February 28 and which Washington and Tehran agreed to end on Sunday, burned through American stockpiles at a startling pace. Navy ships fired large numbers of missiles defending against attacks and launching strikes, raising hard questions about how fast those weapons could be replaced. THAAD has not received a new interceptor delivery since July 2023, and a backlog of about 100 interceptors is not expected to start arriving until April 2027.

The drone problem made the squeeze worse. Cheap, slow-flying attack drones — like the Iranian-style Shahed, which costs roughly $30,000 to $50,000 to build — can be launched by the dozen. Knocking each one down with a multimillion-dollar interceptor is a losing trade, even when it works. Army Secretary Dan Driscoll told lawmakers the Army rushed to buy 13,000 cheaper interceptors called Merops at about $15,000 each in the first days of the conflict to close that gap.

So here is the fix. Instead of relying only on a handful of exquisite, costly weapons, the Pentagon wants a deeper magazine: large numbers of cheaper missiles that can be bought in bulk, fired at easier targets, and held in reserve so the expensive ones are saved for the hardest jobs. The military calls it a “high-low mix.”

The centerpiece is the Low-Cost Containerized Missiles (LCCM) program. Rather than turn only to the traditional defense giants, the Pentagon signed agreements with four newer companies — Anduril, CoAspire, Leidos, and Zone 5 Technologies — each expected to deliver roughly 3,000 missiles and launchers between 2027 and 2029. Anduril will supply a surface-launched missile called the Barracuda-500M and plans to build as many as 1,000 annually. The weapons are designed to fit inside standard shipping containers, allowing them to be moved by truck, ship, or aircraft and quickly deployed from mobile launchers.

A separate effort targets the high end of the market. The Pentagon agreed to buy at least 500 Blackbeard hypersonic missiles annually from startup Castelion once testing is complete and is seeking approval to acquire more than 12,000 over five years. Under Secretary of Defense for Acquisition and Sustainment Michael Duffey said the strategy is intentionally “moving beyond the traditional prime contractors to expand our industrial base.”

That shift has triggered a race throughout the defense industry. New entrants such as Anduril and Castelion are seeking a permanent place in a sector long dominated by Lockheed Martin and RTX. Established contractors are investing heavily to defend their positions. RTX has said it plans approximately $3.1 billion in capital spending during 2026, while Lockheed Martin says it has invested more than $7 billion since President Donald Trump’s first term to expand production capacity. Lockheed Martin has also agreed to quadruple production of THAAD interceptors.

The challenge is whether industry can deliver. The Pentagon’s 2027 budget request seeks a 188% increase in missile procurement, a jump many defense analysts say exceeds current manufacturing capacity. Becca Wasser of Bloomberg Economics described the effort as a generational investment intended to rebuild stockpiles that may be needed for years. The new fixed-price contracts also place much of the risk for delays and cost overruns on contractors rather than taxpayers.

For now, the real test begins this month as the first batch of low-cost missiles heads to military testing ranges. If the weapons perform as expected, the Pentagon may finally have a way to fight prolonged conflicts without exhausting its inventories — or spending billions of dollars destroying threats that cost only a fraction as much to build.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A federal appeals court ruled last Thursday that the government can keep collecting President Donald Trump’s 10% worldwide tariff while legal challenges to it work through the courts, handing the administration a procedural win in one of the central fights over its trade agenda.

The U.S. Court of Appeals for the Federal Circuit concluded that the government was “likely to succeed on the merits,” and lifted a lower-court order that had blocked the tariff for a handful of plaintiffs.

The decision means importers across the country, including the three that had won relief, will keep paying the surcharge for now.

The tariff at issue is not the broad set of duties the Supreme Court struck down in February.

After that ruling wiped out Trump’s emergency-powers tariffs on nearly every country, the president quickly imposed a new 10% worldwide levy under Section 122 of the Trade Act of 1974, a rarely noticed provision that no president had ever used to justify tariffs.

It took effect February 24 and is set to expire July 24 unless Congress acts to extend it.

Section 122 allows a president to impose worldwide tariffs of up to 15% for 150 days to address what the law calls “fundamental international payments problems.”

The legal dispute turns on what that phrase means.

The administration argues it covers the trade deficit, the gap between what the United States buys from other countries and what it sells them.

In May, a split panel of the U.S. Court of International Trade disagreed, ruling 2-1 that the tariff was “unauthorized by law” and that Trump had overstepped the power Congress gave him.

But that court only blocked collection for the three parties that had sued and were found to have standing: the state of Washington, the spice importer Burlap and Barrel, and the toy maker Basic Fun.

The appeals court took a sharply different view.

In an unsigned order, it rebuked the trade court’s “narrow interpretation” of the law, suggested those judges “may be incorrect,” and found that blocking collection would cause harm to the federal government.

The practical effect is that the three plaintiffs go back to paying the tariff alongside everyone else while the case continues.

A coalition of 24 states that filed its own challenge has been folded into the appeal.

Here is why it reaches into everyday life.

The 10% tariff applies to nearly everything the United States imports, from food and clothing to electronics and industrial parts.

Those taxes are paid first by American importers, and a share of the cost typically flows through to the prices consumers pay.

As long as the tariff stands, that added cost stays in the system, and businesses that had hoped a court might end the levy, or refund what they have paid, are left waiting.

The fight is far from over.

The Federal Circuit has agreed to hear the full appeal on an accelerated schedule, and whatever it decides, the case could ultimately land back at the Supreme Court.

The tariff itself is also living on borrowed time, set to lapse in late July unless lawmakers extend it.

For now, though, the message from the appeals court is clear:

The 10% tariff stays, the meter keeps running, and the legal reckoning will have to wait.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Kevin Warsh opened his first policy meeting as chair of the Federal Reserve on Tuesday, a closely watched debut that will shape how Americans borrow, save and read the central bank for years to come.

The two-day meeting of the Federal Open Market Committee concludes Wednesday, when the Fed will announce its interest-rate decision and Warsh will hold his first press conference as chair.

Almost no one expects the rate itself to change.

The Fed is widely projected to hold its benchmark steady in a range of 3.50% to 3.75%, where it has sat since December 2025.

With that question largely settled, attention shifts to Warsh himself, and to what his arrival means for the direction of policy.

Warsh was sworn in on May 22 after a narrow 54-45 Senate confirmation vote, becoming the 17th chair of the Federal Reserve.

His predecessor, Jerome Powell, has agreed to stay on as a governor, an unusual arrangement that leaves the former chair in the room as the new one takes charge.

That makes Warsh’s first impression all the more important.

Because June is a quarterly projection meeting, Wednesday will bring more than a rate decision.

The Fed will release updated economic forecasts and a fresh “dot plot,” the chart that shows where each policymaker expects rates to go.

Many economists expect the committee to drop its long-standing lean toward future rate cuts and adopt a neutral stance instead, a quiet but meaningful shift.

Inflation is running near its hottest level in more than three years, and energy prices remain elevated even as the war with Iran winds down.

Both argue against cutting.

Some officials may go further: analysts at Bank of America expect at least three of the committee’s twelve voting members to pencil in rate hikes this year, and options markets still put the odds of at least one increase before year-end near 80%.

That puts Warsh in a tight spot from day one.

President Donald Trump, who nominated him, has been publicly demanding lower rates, arguing on television over the weekend that raising them would be a mistake.

The bond market and the inflation data are pulling the other way.

How Warsh navigates that pressure, while keeping a divided committee together, will say a great deal about the years ahead.

There are two things to watch beyond the rate.

The first is tone.

Warsh has signaled he wants a more open, argumentative Fed, telling senators at his confirmation hearing that he favors “messier meetings” where policymakers can have a real debate.

That is a departure from the careful consensus Powell prized, and it could mean more public disagreement among officials.

The second is the Fed’s massive bond portfolio.

Warsh has long argued the central bank should hold mainly Treasury securities and shed the roughly $2 trillion in mortgage-backed bonds it still owns.

If he signals plans to start actively selling those bonds, rather than letting them slowly expire as Powell did, it could push mortgage rates higher, a change that would land directly on anyone trying to buy a home.

That is the thread tying all of this to everyday life.

The Fed’s decisions set the cost of mortgages, car loans and credit cards, and the interest paid on savings accounts.

A hold keeps borrowing costs where they are for now.

But the signals Warsh sends about inflation, about future moves and about that bond portfolio will shape what families pay to borrow well into next year.

The decision and Warsh’s remarks come Wednesday afternoon.

Wharton finance professor Jeremy Siegel called it one of the most important Fed meetings in years, precisely because so much of it is about the man, not the math.

For now, the rate is expected to stay put.

The bigger story is what kind of Federal Reserve Kevin Warsh intends to run.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Dave & Buster’s Entertainment said Monday that profit fell sharply in its fiscal first quarter as fewer customers visited its arcade-and-restaurant locations, underscoring the pressure inflation and tighter household budgets continue to place on discretionary spending.

The Dallas-based company reported net income of $5.7 million, or $0.16 per share, for the quarter ended May 5, down from $21.7 million, or $0.62 per share, a year earlier. The decline of nearly 75% came as sales softened and operating margins narrowed.

Chief Executive Tarun Lal said the company’s “back-to-basics strategy is gaining clear traction,” despite results that fell short of Wall Street expectations.

Revenue declined 1.5% to $559.2 million, missing analysts’ forecasts of approximately $577 million. Investors focused particularly on comparable-store sales, a key measure of performance at locations open at least one year, which fell 5.4% from the same period last year.

The decline suggests the challenge is not a lack of locations but fewer guests visiting existing stores and spending less once they arrive.

Shares of Dave & Buster’s fell about 5% Monday to roughly $12.32. The stock has lost approximately two-thirds of its value from its 52-week high near $35.50, reflecting investor concerns about the company’s ability to reverse declining traffic trends.

Dave & Buster’s occupies a unique niche in what the company describes as the “eatertainment” industry, combining arcade games, food, beverages and sports viewing under one roof. But that business model is particularly vulnerable when consumers begin cutting nonessential spending.

A typical family visit can easily exceed $100 once food, drinks and game credits are included. As inflation and higher living costs continue to pressure household budgets, entertainment outings are often among the first expenses consumers postpone or eliminate.

The impact was visible throughout the company’s earnings report.

Operating income fell nearly 26% to $46.9 million, while operating margin narrowed to 8.4% from 11.1% a year earlier. Adjusted earnings came in at $0.22 per share, significantly below the $0.76 reported a year ago and below analyst expectations.

Despite weaker sales, the company highlighted several financial positives.

Adjusted free cash flow reached $25.3 million, compared with a negative $58.8 million in the same period last year. Dave & Buster’s also ended the quarter with approximately $499 million in available liquidity, giving management flexibility as it continues its turnaround efforts.

In practical terms, the company remains financially stable and continues to generate cash even as customer traffic remains under pressure.

Much of the turnaround now rests on Lal, the former president of KFC U.S., who took over as CEO in 2025. His strategy focuses on improving value, simplifying menus, refreshing marketing campaigns, remodeling locations and regularly introducing new arcade attractions.

During the quarter, Dave & Buster’s opened one new U.S. location, completed six store remodels and expanded its international franchise footprint with additional openings in May and June. More openings are planned throughout the year.

Management says value-oriented promotions and bundled offerings are gaining traction with budget-conscious consumers. However, the company acknowledged that the recovery remains in its early stages.

Recent economic data suggest the broader environment remains challenging. Consumer confidence remains near historic lows, while inflation continues to affect household spending decisions. Those conditions make it harder for entertainment-focused businesses to attract customers looking to reduce discretionary expenses.

The company’s struggles predate this quarter.

For its most recent full fiscal year, Dave & Buster’s reported approximately $2.1 billion in revenue, with comparable-store sales declining about 5% and a net loss approaching $49 million. Management has repeatedly argued that the brand remains undervalued and capable of generating stronger long-term results once operational improvements take hold.

For now, the company is betting that a combination of improved food offerings, stronger value propositions and refreshed entertainment experiences will eventually bring customers back.

Monday’s results showed progress in some areas of the business, particularly cash generation, but they also highlighted the central challenge facing the company: reversing declining traffic and convincing consumers that a night at Dave & Buster’s remains worth the cost.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The Dow Jones Industrial Average closed above 52,000 for the first time Tuesday, setting a fresh record even as technology stocks retreated and investors focused on the Federal Reserve’s two-day policy meeting, the first under new Chair Kevin Warsh.

The Dow gained approximately 370 points, or 0.7%, finishing at an all-time high. The broader market moved in the opposite direction. The S&P 500 fell about 0.4%, the Nasdaq Composite lost nearly 1%, and the Russell 2000 declined roughly 0.6%.

After Monday’s technology-led rally following news of a U.S.-Iran peace framework, Tuesday saw investors rotate into more traditional sectors. Money flowed out of high-growth technology and artificial intelligence stocks and into financial, industrial, and blue-chip companies that carry greater weight in the Dow.

Market Movers

Financial and industrial stocks led the advance.

Goldman Sachs gained about 1.3%, Caterpillar rose roughly 2.2%, and American Express added nearly 1.7% as investors favored companies tied more directly to the broader economy.

One of the market’s biggest individual stories remained SpaceX, which surged approximately 20% after announcing plans to acquire Anysphere, the artificial intelligence startup behind the Cursor coding platform, in a deal valued at $60 billion. Despite that jump, weakness across much of the technology sector weighed on the Nasdaq.

Commodities

Oil prices remained relatively stable after recent declines tied to the U.S.-Iran agreement that reopened the Strait of Hormuz.

Brent crude traded near $81 per barrel, while West Texas Intermediate hovered around $80, levels close to two-month lows. The decline reflects the fading geopolitical risk premium that had pushed energy prices higher during months of conflict.

Analysts noted that oil markets are now returning to more normal trading patterns as investors unwind positions built around expectations of a diplomatic breakthrough.

For consumers, lower oil prices could translate into additional relief at the gas pump in the weeks ahead.

Focus Turns to the Fed

Attention now shifts to Wednesday’s Federal Reserve announcement.

Treasury markets signaled expectations for a measured approach. The 10-year Treasury yield eased to roughly 4.46%, while the 2-year yield slipped to about 4.05%.

Warsh takes over at a time when inflation has moderated, housing activity has softened, and energy prices have moved lower. Those factors generally support easier monetary policy, but investors remain uncertain about the timing and pace of any future rate cuts.

Markets will closely examine Wednesday’s statement and press conference for clues about the Fed’s outlook for the remainder of the year.

Looking Ahead

Another key event arrives Friday, when the formal signing of the Iran agreement is scheduled in Switzerland. Investors will be watching for confirmation that shipping through the Strait of Hormuz continues uninterrupted, a development that could place additional downward pressure on energy prices.

For now, the market is sending mixed signals. The Dow is reaching record highs on the strength of banks and industrial companies, while technology stocks that fueled much of the recent rally are taking a pause.

Whether that rotation continues may depend largely on what the Federal Reserve says next.

Wall Street — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

American households felt a little less gloomy in early June, recording their first meaningful improvement in sentiment since January. The University of Michigan said Friday that its preliminary Consumer Sentiment Index rose to 48.9 from May’s record low of 44.8, a gain of roughly 9% as easing gasoline prices offered consumers some relief.

Joanne Hsu, director of the university’s Surveys of Consumers, said the improvement was broad-based but cautioned that “views of the economy are still relatively dour.”

The rebound ended a four-month decline and came in ahead of economists’ expectations. Both major components of the survey improved: consumers reported feeling somewhat better about current economic conditions and slightly more optimistic about the months ahead. The gains were seen across age groups, income levels, educational backgrounds and political affiliations, with lower-income households showing some of the strongest improvement.

Even with the increase, consumer sentiment remains historically weak.

At 48.9, the index is still roughly 13% below where it began the year and about 19% lower than a year ago. The survey’s long-term average stands at 83.8, meaning June’s reading remains more than 40% below normal levels. In fact, despite the rebound, it remains the second-lowest reading recorded in the survey’s seven-decade history.

The improvement highlights how closely consumer attitudes remain tied to energy prices.

Since February, geopolitical tensions involving the United States and Iran have rattled energy markets and pushed fuel costs higher. Disruptions affecting shipments through the Strait of Hormuz helped drive the national average gasoline price above $4.50 per gallon by May, putting additional pressure on household budgets already strained by inflation.

That is why even a modest decline in fuel prices can have an outsized impact on sentiment. For many consumers, gasoline prices are among the most visible indicators of economic health because they encounter them several times a week. When prices fall, confidence often improves quickly.

Inflation, however, remains a significant concern.

Consumers’ long-term inflation expectations held at 3.4%, remaining above levels generally considered comfortable by Federal Reserve policymakers. Persistent inflation expectations can complicate monetary policy decisions because they suggest consumers still expect prices to continue rising at an elevated pace.

That creates a challenge for the Federal Reserve as policymakers evaluate the path of interest rates. If inflation expectations remain elevated, the central bank may have less flexibility to lower borrowing costs, potentially delaying relief for consumers facing high mortgage, credit-card and auto-loan rates.

There is also an important timing factor in the survey results.

The interviews were conducted between May 19 and June 8, before the weekend announcement of a deal aimed at ending the conflict between the United States and Iran and before the subsequent decline in oil prices. If energy costs continue moving lower following the reopening of the Strait of Hormuz, sentiment could improve further when the final June reading is released later this month.

For businesses, consumer confidence remains one of the most closely watched indicators in the economy.

Consumer spending accounts for roughly 70% of U.S. economic activity, and shifts in confidence often influence purchasing behavior. When households feel pressure, discretionary spending is typically among the first areas affected, impacting restaurants, retailers, travel companies and other consumer-facing industries.

Several major retailers and restaurant chains have already reported signs of more cautious spending and have increasingly relied on promotions and value-oriented offerings to attract customers.

The months ahead may determine whether June’s rebound marks the beginning of a broader recovery in consumer confidence or merely a temporary improvement.

A continued decline in gasoline prices, combined with greater stability in global energy markets, could help confidence recover further and support stronger spending. On the other hand, renewed inflation pressures or another spike in fuel costs could quickly reverse the gains seen this month.

For now, the message from American consumers appears cautiously optimistic. Conditions feel somewhat better than they did a month ago, and the sharp deterioration seen earlier this year has eased. But households remain far from confident that the economic challenges of the past several months are fully behind them.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

The European Parliament gave its final approval Tuesday to a long-delayed trade agreement with the United States, voting 440 to 151 with 50 abstentions and clearing the last major hurdle just weeks before a deadline set by President Donald Trump that would have sharply raised tariffs on European cars.

The vote locks in the framework that Trump and European Commission President Ursula von der Leyen struck nearly a year ago in Turnberry, Scotland. Under the deal, the United States applies a tariff of up to 15% on most goods coming from Europe, while the European Union removes many of the duties it charges on American industrial products. It is meant to settle a dispute that had been hanging over the world’s largest trading relationship.

What pushed lawmakers to act now was the calendar. Trump had given the bloc until July 4 to ratify the agreement, warning that he would otherwise raise tariffs to much higher levels. He had specifically threatened to lift duties on cars and trucks built in Europe to 25%, a move that would have hit the continent’s automakers hard and raised prices for the American shoppers who buy their vehicles. Tuesday’s vote takes that threat off the table, at least for now.

Getting here was not smooth. EU lawmakers had twice frozen the deal over the past several months. They paused it in January after Trump floated the idea of taking control of Greenland, a Danish territory, and again in February after a U.S. court struck down a large part of his tariff program, leaving Europe unsure what it was even agreeing to. Many members of parliament have called the agreement lopsided, arguing it gives Washington more than it gives Brussels, and they attached safeguards that would let the EU suspend the tariff cuts if the United States does not hold up its end.

The tension has not gone away. Tuesday’s approval came just days after Trump issued yet another tariff threat, this time aimed at France over its rules governing digital companies. That timing was a reminder that even a ratified deal remains fragile as long as tariffs are being used as a tool of pressure.

Why does an agreement negotiated in Brussels matter to people in the United States? Because the amounts involved are enormous. Roughly $1.8 trillion in goods and services move across the Atlantic in both directions every year, touching everything from German sedans and French wine to American machinery, software and farm products. When tariffs rise, those costs tend to land on businesses and, eventually, on the prices consumers pay. A 25% tax on imported European cars would have rippled through dealerships, repair shops and the broader auto market on both sides of the ocean.

For carmakers, the vote is a clear relief. European manufacturers such as BMW, Mercedes-Benz and Volkswagen sell large numbers of vehicles in the United States and build many of them at American plants as well. A jump to 25% would have scrambled their pricing and their factory plans. The 15% rate is still well above the roughly 2.5% they paid before the dispute began, but it gives them something businesses value above almost everything else: a number they can count on.

Not everything is settled. The safeguards the parliament attached still need sign-off from the EU’s member states before the tariff reductions on American goods fully take effect. Steel and aluminum remain subject to a separate 50% tariff that the two sides have yet to resolve. And the broader relationship will stay on edge as long as new threats keep surfacing.

Still, Tuesday marked a genuine turning point. After a year of brinkmanship, missed deadlines and frozen votes, the deal that has loomed over transatlantic trade finally has the approval it needed to move forward. For companies that have spent months unable to plan, that certainty may matter as much as the tariff rate itself.

The focus now shifts to whether Washington keeps the peace or reaches for the next threat.

Washington — JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

A paying customer has sued artificial intelligence company Anthropic, alleging that the company’s most expensive Claude subscription plans provide significantly less usage than advertised.

The proposed class-action lawsuit, filed in the U.S. District Court for the Northern District of California and first reported Monday, was brought by Karl Kahn, a Washington, D.C., resident who claims Anthropic’s premium Claude Max 5x and Claude Max 20x plans fail to deliver the usage levels promised in the company’s marketing materials.

Anthropic declined to comment on the litigation, according to reports.

At the center of the dispute is how Anthropic markets access to Claude, its flagship AI chatbot platform.

The company currently offers three primary paid subscription tiers for individual users: a Pro plan priced at roughly $17 to $20 per month, a Max 5x plan costing $100 per month, and a Max 20x plan priced at $200 per month.

As the names suggest, the higher-priced tiers are promoted as providing approximately five times and twenty times the usage of the Pro plan.

The lawsuit argues those claims do not match customers’ real-world experience.

According to the complaint, the Max 20x plan delivers “far less than twenty times” the usage of the Pro tier, allegedly providing closer to six to eight times the available usage. The suit similarly alleges that the Max 5x plan offers roughly three-and-a-half times the usage of the Pro plan rather than the advertised five-fold increase.

The complaint also accuses Anthropic of misleading customers by promoting the $200 plan as providing approximately 50% savings compared with alternative usage options.

Kahn says he initially used Claude’s free tier before upgrading to Pro, then later moving to the Max 5x plan in January and the Max 20x plan in April. According to the filing, he relied heavily on Claude for software-development work and coding projects.

Despite subscribing to the highest-priced plan, Kahn alleges he repeatedly encountered usage limits sooner than expected.

One example cited in the complaint claims a single five-hour coding session consumed approximately 15% of his weekly allotment, forcing him to either stop using the service, reduce his activity, or incur additional charges.

His attorney, Kati Daffan of Vaca Daffan LLP, argues the case centers on traditional consumer-protection principles: customers should receive what companies advertise and sell.

The lawsuit seeks to represent all U.S. customers who purchased a Claude Max subscription since Anthropic introduced the plans.

The case highlights a challenge facing the broader AI industry.

Unlike traditional software subscriptions, AI services do not operate on fixed seat counts or simple usage quotas. Instead, they rely on tokens — small units of text processed by AI models. A brief question may consume very few tokens, while coding projects, lengthy documents, or complex analytical tasks can consume dramatically more computing resources.

That makes it difficult to translate marketing promises such as “5x” or “20x” usage into a predictable experience for every customer.

The lawsuit argues that the gap between those marketing claims and actual usage limits is precisely where consumers are being misled.

Anthropic has faced scrutiny over usage restrictions before.

Last year, the company imposed weekly limits on Claude Code, its AI coding product, after reporting that some users were running the tool continuously and consuming significantly more computing power than anticipated under flat-rate subscription pricing.

Complaints about hitting usage caps sooner than expected have also appeared on online forums, where some users have reported unexpectedly large overage charges after exceeding subscription limits.

The issue extends beyond Anthropic.

As AI models become more powerful and resource-intensive, companies across the industry have increasingly introduced usage caps, throttling systems, and tiered pricing structures. Providers including Google, OpenAI, and Meta have all adjusted pricing, subscription models, or usage limits as they balance customer demand against the enormous costs of operating advanced AI systems.

The timing is notable for Anthropic.

The company is reportedly finalizing a separate class-action settlement related to claims involving training data and copyrighted books, while also being widely viewed as a potential future public-market candidate. A consumer lawsuit challenging its subscription practices adds another layer of scrutiny as investors and regulators increasingly examine the economics of AI businesses.

For now, the allegations remain unproven. Anthropic has not yet responded to the claims in court, and the case remains in its early stages.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

American households felt a little less gloomy in early June, recording their first meaningful improvement in sentiment since January. The University of Michigan said Friday that its preliminary Consumer Sentiment Index rose to 48.9 from May’s record low of 44.8, a gain of roughly 9% as easing gasoline prices offered consumers some relief.

Joanne Hsu, director of the university’s Surveys of Consumers, said the improvement was broad-based but cautioned that “views of the economy are still relatively dour.”

The rebound ended a four-month decline and came in ahead of economists’ expectations. Both major components of the survey improved: consumers reported feeling somewhat better about current economic conditions and slightly more optimistic about the months ahead. The gains were seen across age groups, income levels, educational backgrounds and political affiliations, with lower-income households showing some of the strongest improvement.

Even with the increase, consumer sentiment remains historically weak.

At 48.9, the index is still roughly 13% below where it began the year and about 19% lower than a year ago. The survey’s long-term average stands at 83.8, meaning June’s reading remains more than 40% below normal levels. In fact, despite the rebound, it remains the second-lowest reading recorded in the survey’s seven-decade history.

The improvement highlights how closely consumer attitudes remain tied to energy prices.

Since February, geopolitical tensions involving the United States and Iran have rattled energy markets and pushed fuel costs higher. Disruptions affecting shipments through the Strait of Hormuz helped drive the national average gasoline price above $4.50 per gallon by May, putting additional pressure on household budgets already strained by inflation.

That is why even a modest decline in fuel prices can have an outsized impact on sentiment. For many consumers, gasoline prices are among the most visible indicators of economic health because they encounter them several times a week. When prices fall, confidence often improves quickly.

Inflation, however, remains a significant concern.

Consumers’ long-term inflation expectations held at 3.4%, remaining above levels generally considered comfortable by Federal Reserve policymakers. Persistent inflation expectations can complicate monetary policy decisions because they suggest consumers still expect prices to continue rising at an elevated pace.

That creates a challenge for the Federal Reserve as policymakers evaluate the path of interest rates. If inflation expectations remain elevated, the central bank may have less flexibility to lower borrowing costs, potentially delaying relief for consumers facing high mortgage, credit-card and auto-loan rates.

There is also an important timing factor in the survey results.

The interviews were conducted between May 19 and June 8, before the weekend announcement of a deal aimed at ending the conflict between the United States and Iran and before the subsequent decline in oil prices. If energy costs continue moving lower following the reopening of the Strait of Hormuz, sentiment could improve further when the final June reading is released later this month.

For businesses, consumer confidence remains one of the most closely watched indicators in the economy.

Consumer spending accounts for roughly 70% of U.S. economic activity, and shifts in confidence often influence purchasing behavior. When households feel pressure, discretionary spending is typically among the first areas affected, impacting restaurants, retailers, travel companies and other consumer-facing industries.

Several major retailers and restaurant chains have already reported signs of more cautious spending and have increasingly relied on promotions and value-oriented offerings to attract customers.

The months ahead may determine whether June’s rebound marks the beginning of a broader recovery in consumer confidence or merely a temporary improvement.

A continued decline in gasoline prices, combined with greater stability in global energy markets, could help confidence recover further and support stronger spending. On the other hand, renewed inflation pressures or another spike in fuel costs could quickly reverse the gains seen this month.

For now, the message from American consumers appears cautiously optimistic. Conditions feel somewhat better than they did a month ago, and the sharp deterioration seen earlier this year has eased. But households remain far from confident that the economic challenges of the past several months are fully behind them.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

AUSTIN, Texas — For years, Texas and Florida were among the hottest housing markets in the country, where homes sold in days and buyers fought bidding wars. That era is over. According to brokerage firm Redfin, the balance of power has shifted decisively toward buyers, with sellers increasingly cutting prices and offering incentives to attract interest.

In its latest report, Redfin found there were approximately 46.9% more home sellers than buyers nationwide in May, with some of the largest imbalances appearing in Texas and Florida. “A modest improvement in housing affordability could bring some homebuyers off the sidelines in 2026,” said Asad Khan, senior economist at Redfin. “But the housing market is likely to remain in buyer’s market territory for the foreseeable future, with sellers cutting prices or offering concessions to lure buyers.”

The strongest buyer’s markets are concentrated across the Sun Belt. Redfin identified Nashville, Miami, Austin, Houston and San Antonio among the markets where buyers currently hold the greatest leverage. Earlier this year, sellers in those same markets led the nation in price reductions. In San Antonio, nearly 58% of sellers lowered their asking prices, followed by Austin, Dallas, Tampa, and Fort Lauderdale.

The primary driver is supply. Both Texas and Florida experienced aggressive homebuilding during the pandemic-era migration boom as developers rushed to accommodate population growth. Today, many of those homes remain unsold as buyers pull back amid elevated mortgage rates and affordability concerns.

When inventory rises faster than demand, buyers gain leverage. They have more homes to choose from, more negotiating power, and more time to make decisions.

The numbers reflect that shift. In Texas, homes are now taking approximately 68 days to sell, while the median home price of $343,779 rose just 0.9% year-over-year. In Florida, average selling times have stretched to roughly 69 days, while housing inventory has climbed to record levels.

Florida faces additional challenges beyond housing supply. The state continues to grapple with rising insurance premiums, escalating condominium association costs, hurricane-related risks and other climate concerns. Those factors have prompted some longtime homeowners to sell, increasing inventory even further.

The cooling market in Texas and Florida contrasts sharply with conditions elsewhere. Nationally, home prices remain near record highs. The National Association of Realtors reported that the median existing-home price reached $429,300 in May, a new record. Several Midwestern and Northeastern markets continue to favor sellers due to limited inventory.

According to Redfin, only seven of the nation’s 50 largest metropolitan areas remain seller’s markets, while 36 markets now favor buyers.

For the housing industry, the shift represents a meaningful change. Builders who expanded aggressively during the boom are now offering incentives, discounts and mortgage-rate buydowns to move inventory. Real estate agents increasingly advise sellers to price homes realistically rather than aiming for pandemic-era peak valuations.

The impact extends beyond housing. Mortgage lenders, moving companies, contractors and local economies all feel the effects when housing activity slows.

For prospective buyers, however, the changing market creates opportunities that have been scarce for years. Buyers who can manage today’s mortgage rates — still hovering near 6.5% — may now negotiate on price, request repairs, and secure concessions that would have been nearly impossible during the height of the housing frenzy.

For sellers, the environment requires adjustment. The days of listing a home and receiving multiple offers within hours have largely disappeared in many parts of Texas and Florida.

None of this suggests a housing crash. Prices are softening rather than collapsing, and demand remains present. Instead, the market appears to be moving toward a more balanced environment where buyers have greater choice and negotiating power.

After years as symbols of America’s housing boom, Texas and Florida are increasingly becoming examples of what happens when supply finally catches up with demand.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — One of the clearest reads on how American families are handling rising prices arrives this week. On Wednesday, June 17, the U.S. Census Bureau will release its report on retail sales for May — a monthly tally of what Americans spent at stores, restaurants, gas stations and online. After a long stretch of stubborn inflation and a war that pushed up energy costs, the report will show whether shoppers kept opening their wallets or finally began pulling back.

The recent trend has been resilient. The Census Bureau said retail sales rose 1.7% in March and 0.5% in April, leaving sales up roughly 5.2% from a year earlier. Despite economic strain, American consumers have continued spending at a pace that has surprised many economists.

Retail sales remain one of the most important indicators in the U.S. economy because consumer spending accounts for roughly two-thirds of economic activity. When consumers spend, businesses hire, factories produce and economic growth continues. When consumers pull back, the effects ripple quickly across the economy.

Industry forecasters remain cautiously optimistic. The National Retail Federation expects retail sales growth of 4.4% this year. NRF President and CEO Matthew Shay said he expects “consumer resilience to continue into 2026.” At the same time, the organization’s chief economist, Mark Mathews, warned that renewed Middle East tensions and volatility in global markets continue to create uncertainty.

The backdrop for May was challenging. Consumer prices rose 4.2% year-over-year, the fastest pace since 2023, with much of the increase tied to higher energy costs during the Iran conflict. Gasoline prices climbed to multiyear highs, squeezing household budgets even as the labor market remained healthy and the economy added 172,000 jobs in May.

Economists will be watching where spending occurred. Analysts often strip out gasoline, automobiles and building materials to get a cleaner view of underlying consumer demand. Restaurants and bars will receive special attention because discretionary dining is often among the first categories to weaken when consumers feel financial pressure.

The timing of the report is particularly notable because it arrives in the middle of the Federal Reserve’s policy meeting, the first chaired by Kevin Warsh. While the Fed is widely expected to keep interest rates unchanged, policymakers are watching consumer spending closely as they determine how long borrowing costs need to remain elevated.

Strong retail sales would reinforce the argument that consumers remain healthy and support keeping rates higher for longer. Weak retail sales could strengthen the case for future rate cuts.

There is also a potentially positive development heading into summer. The weekend agreement to end the war in Iran sent oil prices sharply lower on Monday. If those declines hold, households could see lower gasoline prices in the weeks ahead, providing some relief. That benefit would come too late to affect May spending but could improve conditions for June and the second half of the year.

For businesses, the report is more than just a data point. Retailers use it to gauge consumer confidence and determine staffing levels. The industry recently pushed employment to a two-year high, and many companies are using consumer spending trends to guide decisions on hiring, inventory purchases and expansion plans.

For now, Wednesday’s report will provide a snapshot of an American consumer balancing steady employment against higher living costs. Whether households continued spending through May — or finally began showing signs of fatigue — may offer one of the clearest clues yet about where the economy is headed for the remainder of 2026.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

Meta Platforms said Monday it is rolling out a wave of new artificial intelligence features on Facebook, led by a tool called “AI Mode” that lets people ask a question in plain language and get a single answer drawn from public posts across the app rather than scrolling through a list of search results. The company said the changes are designed to reshape how its billions of users find information, create content and interact with the platform, part of a broader effort to make Facebook a more useful destination for search and discovery.

The headline feature functions much like a chatbot built directly into Facebook’s search bar. Users can ask a question and receive an answer generated from public conversations across the platform, including posts, Groups and Reels. Instead of sorting through links and individual posts, users receive a summary of what people are already discussing.

The rollout is the latest sign of Meta’s aggressive push into artificial intelligence. Chief Executive Mark Zuckerberg has committed billions of dollars to AI infrastructure and development, and the company is increasingly embedding AI tools into products used daily by billions of people. The strategy is straightforward: increase engagement while reducing the need for users to leave Facebook to search elsewhere.

The move also places Meta in more direct competition with Google and AI-powered search platforms such as ChatGPT, which have increasingly changed how consumers look for information online. Rather than directing users away from Facebook, Meta wants answers to be found inside its own ecosystem.

Monday’s announcement follows a series of related launches. Last month, Meta introduced Forum, a discussion platform modeled after community-driven services such as Reddit. The app includes an AI-powered “Ask” feature that pulls responses from Facebook Groups and other community discussions. Together, the products point toward a broader strategy of transforming Facebook from a platform centered on content consumption into one focused on information retrieval and conversation.

The business rationale is significant. Meta generates the vast majority of its revenue from advertising, and user engagement remains one of the most important drivers of that business. The longer people stay within Meta’s apps and the more they interact, the more opportunities the company has to serve advertisements and improve ad targeting.

The company is also seeking new revenue streams beyond advertising. Meta recently expanded paid subscription offerings across Facebook, Instagram and WhatsApp, with plans starting at $3.99 per month. The subscriptions provide additional features and could eventually include premium AI capabilities. The move marks a notable shift for a company that has historically relied almost entirely on ad-supported products.

At the same time, Meta’s growing use of AI continues to raise privacy concerns. Critics have questioned how aggressively the company is using user data to train and improve AI systems. Recent features have included requests for access to users’ camera rolls and expanded AI integrations across Meta’s platforms. While AI Mode relies on public content rather than private messages, the broader direction of the company is clear: AI is becoming increasingly embedded throughout the Meta ecosystem.

For users, the immediate change may be simple. Searching Facebook could become less about scrolling through posts and more about receiving direct answers generated from conversations already taking place across the platform. The usefulness of those answers will depend largely on accuracy, an area where AI-powered systems continue to face scrutiny.

The stakes extend far beyond Facebook search. Search, shopping, customer service and everyday information requests are increasingly moving toward AI assistants. Companies that successfully become consumers’ first destination for those interactions stand to capture significant economic value.

Meta believes its existing scale gives it a major advantage. With Facebook, Instagram and WhatsApp collectively reaching billions of users worldwide, the company can introduce AI tools to a larger audience than most competitors. Facebook, now more than two decades old, is increasingly being reshaped around AI-powered discovery rather than traditional social networking alone.

The investment remains expensive, and some investors continue to question how quickly Meta’s AI spending will generate returns. Monday’s rollout offers a glimpse into the company’s answer: deploy AI broadly across its platforms today and build user habits that could support future growth for years to come.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

President Donald Trump said he plans to mark the 250th anniversary of American independence with what could become the largest Independence Day celebration in U.S. history, featuring a massive gathering on the National Mall, military flyovers, patriotic performances, and an attempt to set a world record for the largest fireworks display ever staged.

The centerpiece of the celebration will take place in Washington, D.C., where Trump is expected to headline a major event near the Lincoln Memorial and Washington Monument as part of a broader national effort to commemorate America’s semiquincentennial. Organizers say the celebration will include hundreds of military musicians, ceremonial units, aerial demonstrations, and a fireworks finale designed to eclipse any previous Fourth of July display.

The event is one of the most visible components of what has quietly become one of the largest tourism and economic initiatives the United States has undertaken in decades.

Behind the patriotic imagery sits a massive network of federal funding, corporate sponsorships, tourism promotion campaigns, vendor contracts, and public-private partnerships all centered on the nation’s 250th birthday. Cities, businesses, hotels, restaurants, transportation companies, and event organizers across the country are preparing for what many expect to be a once-in-a-generation surge in travel and consumer spending.

The celebration is being organized through two separate entities.

The first is America250, the nonprofit partner of the U.S. Semiquincentennial Commission created by Congress in 2016 to coordinate nationwide commemorations. The second is Freedom 250, a public-private initiative established by the Trump administration to support and stage several of the highest-profile events surrounding the anniversary.

Together, the organizations are overseeing what could become the largest coordinated patriotic celebration since the nation’s Bicentennial in 1976.

Congress previously appropriated approximately $150 million to support America’s 250th anniversary activities, with funding directed through federal agencies and related initiatives. America250 is required to provide annual reporting to Congress regarding its activities and spending, while Freedom 250 operates under a different structure that has drawn scrutiny from some lawmakers and watchdog groups.

Much of the remaining funding comes from private-sector sponsors.

Major corporate supporters of America250 include Amazon, Boeing, FedEx, General Mills, Northrop Grumman, Palantir, Comcast NBCUniversal, and JPMorganChase, among others. For participating companies, the anniversary offers a rare opportunity to align their brands with one of the most visible patriotic celebrations in modern American history.

The economic implications extend far beyond Washington.

Tourism officials frequently point to the nation’s 1976 Bicentennial as a benchmark. That celebration attracted millions of visitors nationwide and generated billions of dollars in economic activity. Adjusted for inflation, planners believe America’s 250th could rival or surpass those figures as travelers flock to events throughout the country.

Hotels, airlines, vacation-rental operators, restaurants, transportation providers, and retailers have spent months preparing for the expected influx of visitors.

Washington remains the focal point, but celebrations are planned nationwide.

One of the largest attractions is expected to be the Great American State Fair, scheduled to take place on the National Mall from late June through early July. The event will feature exhibits from all 50 states, showcasing regional industries, innovations, products, culture, and tourism opportunities.

Organizers describe it as a combination of a state fair, trade show, cultural festival, and patriotic exhibition.

Meanwhile, Sail 250, a major maritime celebration, will bring historic tall ships and military vessels to several U.S. ports, including Boston, New York, Baltimore, Norfolk, and New Orleans. The event is designed to echo the iconic tall-ship gatherings that became one of the defining images of the 1976 Bicentennial.

Additional celebrations are planned across the country, including major sporting events, festivals, concerts, historical exhibitions, and regional fireworks displays.

The fireworks finale in Washington is expected to serve as the signature attraction.

Pyrotechnics company Pyrotecnico has reportedly been working on a display large enough to challenge the current Guinness World Record for the largest fireworks show ever conducted. If successful, the event would add another historic milestone to an already ambitious celebration.

The road to the event has not been without controversy.

Several musical acts initially associated with related Freedom 250 programming reportedly withdrew after raising concerns about the political nature of certain events. Critics have argued that portions of the celebration place too much emphasis on Trump personally rather than on the broader national anniversary.

Supporters counter that the scale of the planned festivities reflects the importance of marking a historic national milestone and argue that the celebration is intended to promote national pride and unity.

Regardless of the political debate, the economic impact is expected to be substantial.

Large-scale public events generate significant spending through hotel bookings, restaurant visits, transportation services, retail purchases, tourism activities, and event-related employment. They also create extensive demand for security personnel, logistics providers, sanitation crews, construction workers, and temporary event staff.

For businesses, municipalities, sponsors, and vendors participating in America’s 250th, the opportunity is straightforward.

The United States turns 250 years old only once. From multinational corporations and tourism agencies to fireworks manufacturers and local restaurants, organizations across the country are betting that the largest Independence Day celebration in American history will generate both national pride and significant economic activity.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

WASHINGTON — America’s stores are on a hiring spree even as shoppers complain about high prices — and the latest government data backs it up. The Bureau of Labor Statistics reported on Friday, June 5, that the economy added 172,000 jobs in May, more than double the roughly 80,000 economists had expected, while the unemployment rate held steady at 4.3%. Within that, the retail trade has been a standout, recently pushing its payrolls to about 15.5 million workers — the most since July 2024.

“This is a labor market that is stronger than it was last year and is looking pretty darn solid, despite high energy prices and higher inflation generally,” said Gus Faucher, chief economist at PNC Bank. “There’s no indication that the labor market needs support.”

The Bureau of Labor Statistics also revised its earlier figures higher, adding a combined 93,000 jobs to its March and April counts. Retail added nearly 22,000 jobs in a recent month, accounting for almost one-fifth of all the hiring in the country — a striking share for an industry that spent much of last year bracing for layoffs. The biggest May gains came in leisure and hospitality, local government and health care, while financial activities lost jobs.

The hiring reflects a simple truth: Americans keep spending. The National Retail Federation expects retail sales to grow 4.4% this year, with its president and chief executive, Matthew Shay, saying he expects “consumer resilience to continue into 2026, with household spending once again serving as a pillar of economic support.” In 2025, many chains feared that President Donald Trump’s tariffs would raise costs and scare off shoppers. Instead, customers kept buying — through the war in Iran, higher gas prices and faster inflation — and retailers staffed up to keep shelves stocked.

Not everyone is convinced the good times will last. Mark Mathews, chief economist at the National Retail Federation, warned that “renewed tensions in the Middle East and the ripple effects across global markets are adding more uncertainty to the economic landscape.” Gasoline prices at multiyear highs could eventually force families to cut back on the extras that keep stores busy. There are softer spots beneath the strong headline, too: hiring has cooled in parts of the economy, and total job postings have edged down even as the unemployment rate stays low.

There is a hopeful wrinkle this week. The weekend deal to end the war in Iran sent oil prices tumbling on Monday, which could bring gasoline prices down in the coming weeks and hand shoppers more room in their budgets — exactly the kind of relief that would keep cash registers ringing and the hiring going.

The job numbers carry extra weight this year because of a fight over their credibility. In August 2025, President Trump removed the head of the Bureau of Labor Statistics, Erika McEntarfer, after a run of weak reports, accusing her of manipulating the data — which she denied — and replaced her with William J. Wiatrowski. That history has put every report under a brighter spotlight.

For ordinary workers, the retail hiring spree is good news. Store jobs rarely require a degree, offer flexible hours, and remain one of the main on-ramps into the workforce. More openings mean more bargaining power and a better shot at a raise. The question is how long it lasts. Retailers are hiring because shoppers are spending, and shoppers are spending despite real strain. If inflation bites harder or gas prices climb again, the same stores racing to staff up could find themselves overstaffed. For now, though, the help-wanted signs are out — and Americans are answering them.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.

When the Bureau of Labor Statistics released its May jobs report on Friday, June 5, it named only a handful of industries that added workers. Health care was one of them. The economy added 172,000 jobs for the month and the unemployment rate held at 4.3% — but strip away hospitals, clinics, and care providers, and the picture turns much weaker.

Health care added roughly 35,200 jobs in May. That alone is a story. For more than a year, while most of the economy has cooled, one sector has kept hiring every single month.

Just how lopsided is it? According to Revelio Labs, health care has added 410,700 jobs since January 2025 — nearly double the 208,800 added by every other part of the economy combined. The pattern held all last year too: in 2025 the sector added about 693,000 jobs, while gains elsewhere were largely offset by losses in other industries, leaving total U.S. employment growth at just 116,000. Take health care out, and the country would have lost jobs outright.

So why is one industry hiring when almost everyone else has slowed down?

The answer is sitting in plain sight, and it is not complicated: America is getting old.

Baby boomers make up about one-fifth of the country, and within the next few years all of them will be old enough for Medicare. The oldest are already in their late 70s and 80s — the age when people start needing far more medical care. McKinsey notes that Americans aged 70 and older will grow faster than any other group through the rest of the decade.

More older people means more doctor visits, more procedures, and more management of conditions like diabetes and heart disease. That demand does not rise and fall with the stock market. It just keeps climbing.

There is also a squeeze on the people who provide that care. The number of potential caregivers for every American over 80 is projected to fall from more than seven in 2010 to about four by 2030. Fewer hands, more patients.

The jobs are also moving. Care is shifting out of big hospitals and into doctors’ offices, outpatient centers, and patients’ own homes. That is where most of May’s hiring landed — ambulatory services added 25,700 jobs, far more than hospitals. Many of these employers are small, local practices, so the openings are spread across the country rather than bunched in a few big cities.

Here is the part that matters for anyone looking for work: the jobs are real, and there are not enough people to fill them.

A June 11 report from Staffing Industry Analysts found open health care and social assistance positions have stayed near 1.3 million nationwide since late 2024. Employers posted 180,800 non-clinical health care jobs in 2025 alone — an 8% increase from the year before, according to Robert Half — and those are just the desk and support roles.

Looking ahead, the field is expected to generate about 1.9 million openings every year for the next decade. Indeed warns the country could be short 4.6 million support workers by the end of this year.

And many of these jobs do not require medical school or years of debt.

Home health and personal care aides — the fastest-growing health job in the country — need only a high school diploma and a set number of training hours, often paid and on the job. The work pays a median of about $34,900 per year, and the BLS expects the field to grow 17% over the next decade.

A step up, medical assistants earn around $42,000 per year, or roughly $20 per hour, and can train in a matter of months. The role mixes front-desk and clinical work and often becomes a launch pad into nursing or a specialty.

For those willing to study longer, the ladder keeps going. Occupational therapy assistants earn a median near $70,800 with a two-year associate degree. Physician assistants — a popular path for career switchers — earn about $133,000 annually with a master’s degree that takes roughly two years. The BLS projects most of these roles to grow at least 10% this decade, more than triple the rate for jobs overall.

The catch is on the employer’s side. Sixty percent of hiring managers at non-clinical health care organizations told Robert Half that finding skilled people is much harder than a year ago. That gap — open jobs that no one is filling — is exactly what turns a tight labor market into an opportunity for job seekers.

It is not all good news inside the field. Indeed’s survey found 2 in 5 health care workers call their jobs unsustainable, and 1 in 4 are thinking about leaving this year. Burnout and paperwork keep pushing experienced staff out the door — which only deepens the shortage and keeps the help-wanted signs up.

The next jobs report, covering June, comes out on Thursday, July 2. If the past year is any guide, health care will be near the top of the list again — the one corner of the economy still reliably adding work.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.


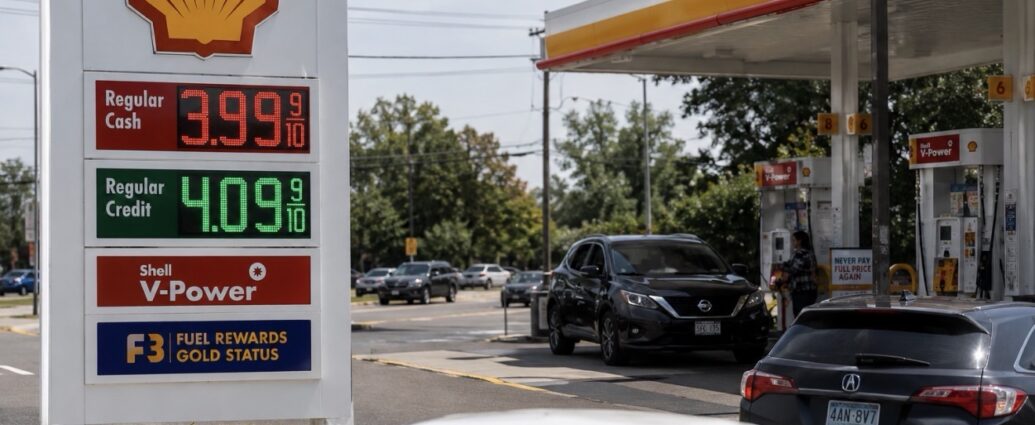
Stocks opened higher Tuesday after the United States and Iran signed a memorandum of understanding to lock in their ceasefire and reopen the Strait of Hormuz, sending oil prices lower and pushing the Dow Jones Industrial Average further into record territory. Investors are also looking ahead to the Federal Reserve, which wraps up its policy meeting this week.

In the opening minutes of trading, the Dow rose about 0.8%, building on Monday’s record close of 51,671. The S&P 500 added 0.1% to hover near 7,560, while the tech-heavy Nasdaq Composite was little changed around 26,690 after Monday’s strong run. The small-cap Russell 2000 climbed 0.7%, moving closer to the 3,000 mark it has been flirting with for days.

The morning’s main event was the signed agreement between Washington and Tehran. Brokered by Pakistan, the deal locks in a halt to the fighting that began in late February, reopens the Strait of Hormuz to oil tankers, and establishes 60 days of talks over Iran’s nuclear program. A formal signing ceremony is planned for Friday in Switzerland. The prospect of Persian Gulf oil flowing freely again has been the single biggest force moving markets this week.

Not every number pointed higher. A government report showed that new home construction unexpectedly tumbled in May. Housing starts fell 15.4% to an annual pace of 1.18 million, the slowest level since May 2020 and well below economists’ expectations. A separate gauge of homebuilder confidence also slipped Monday. High mortgage rates and the prolonged period of elevated energy prices have weighed on builders, a reminder that parts of the economy remain under pressure even as stocks sit at record highs.

Market Movers

Shares of SpaceX jumped about 13% Tuesday morning to roughly $218, adding to their gains from the first full day of trading and pushing the company’s market value above $2 trillion. The company said Tuesday it will acquire Anysphere, the artificial intelligence startup behind the popular Cursor coding tool, for $60 billion in an all-stock deal expected to close in the third quarter.

The stock is now up more than 56% from its $135 offering price last week. Brian Mulberry, chief market strategist at Zacks Investment Management, described the company’s debut as more orderly than he expected, suggesting demand has been steady rather than frenzied.

The day’s laggards were scattered across industries. Chemical maker Huntsman fell about 6%, hotel operator Hilton Worldwide dropped roughly 5%, and chipmaker Qorvo slid nearly 4%. Payments company Fiserv also remained under pressure following recent leadership changes.

Commodities

Oil did the heavy lifting on the downside, which for consumers is welcome news. Brent crude traded around $81 a barrel Tuesday morning, down about $3 from the previous day, while West Texas Intermediate hovered near $80.

Crude has now fallen more than 20% over the past month and sits at a two-month low as traders bet that the reopening of the Strait of Hormuz will bring previously stranded supplies back to the market.

The decline comes with a caveat. Neither side has released the full text of the agreement, and shipping companies are still holding vessels back from the strait until firmer guarantees emerge. That uncertainty has helped keep a floor under prices for now.

Even so, relief is already beginning to reach consumers. GasBuddy analyst Patrick De Haan noted that the national average price of gasoline has started to decline after months of elevated prices at the pump.

The Forward Look

The next two days could set the tone for markets. The Federal Reserve concludes its meeting this week, and investors are looking for clues on how policymakers view an economy facing cooling inflation, a soft housing market, and a sudden drop in energy costs.

Friday’s formal signing ceremony in Switzerland is the other key event. If it proceeds smoothly and oil tankers begin moving freely through the Strait of Hormuz, crude prices could fall further, bringing additional relief to drivers and businesses alike.

For now, Wall Street remains optimistic. The combination of a winding-down war, lower energy costs, and a blockbuster technology deal has stocks hovering near record highs. Whether that momentum continues may depend on the Fed’s message—and whether the fragile peace with Iran develops into a lasting one.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — The biggest event on Wall Street this week begins Today, when the Federal Reserve opens the first policy meeting led by new chairman Kevin Warsh. Almost no one expects the central bank to move interest rates when it announces its decision Wednesday. What traders are really waiting for is the new chair’s first signal about where he intends to steer the economy. The CME FedWatch Tool, which tracks market bets, put the odds of no change at about 97% as of Monday, and a Reuters poll found 72 of 102 economists expect rates to stay put through year-end.

The Federal Reserve has held its benchmark rate in a range of 3.50% to 3.75% since December, and two forces are keeping it there. Inflation has climbed to a three-year high, with consumer prices up 4.2% in May from a year earlier, driven largely by energy costs tied to the war in Iran. At the same time, the job market stayed strong, adding 172,000 jobs in May. High inflation argues against cutting; a sturdy labor market means the Fed does not have to. Goldman Sachs recently scrapped its forecast for a rate cut this year and pushed expected cuts into 2027.

“The Kevin Warsh era has begun,” said Phil Camporeale, chief investment strategist at J.P. Morgan Wealth Management. “The Federal Reserve is not expected to move rates in the June meeting, and we believe they will be on hold for the rest of 2026. There will, however, likely be an explicit move away from a bias toward easing to a neutral stance on rates.”

Shari Hensrud, chief investment officer at MissionSquare, framed the dilemma simply: “Strong job growth and high inflation are pulling in opposite directions.”

Warsh takes over at a delicate moment. He was confirmed by the Senate in a 54–45 vote and sworn in on May 22 as the central bank’s 17th chair, with former chair Jerome Powell staying on the board to ease the transition. Because June is a quarterly projection meeting, it will produce a fresh “dot plot” along with updated forecasts and a press conference Wednesday afternoon, the first real read on Warsh’s approach. He has pledged a “reform-oriented” Fed and said he welcomes “messier meetings” with more open debate.

Hanging over it all is a public tug-of-war. President Donald Trump, who nominated Warsh in January, has long wanted lower rates and said again before the meeting that there is “no reason” to raise them. But the bond market has been signaling the opposite, and high inflation makes cuts hard to justify. That leaves Warsh in a bind: sound too tough on inflation and he risks angering the president who appointed him; sound too eager to cut and he risks his credibility with markets.

This week brought a new variable. The weekend deal to reopen the Strait of Hormuz sent oil prices falling on Monday, and if that drop holds, it could cool the very inflation that has frozen the Fed in place. Investors will listen Wednesday for any hint that Warsh sees the same thing.

For ordinary Americans, the Fed’s decisions are not abstract: its benchmark rate ripples through mortgages, car loans and credit cards. Holding steady means borrowing stays expensive — a 30-year mortgage is still hovering around 6.5% — and those waiting for cheaper loans will keep waiting. The rate itself may not move this week, but the words around it from a brand-new chair could shape what borrowers and savers can expect for the rest of the year.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Senator Lindsey Graham, one of the loudest backers of the war against Iran, said this week that he is not ready to endorse the deal President Donald Trump struck to end it.

Speaking to reporters after Trump announced Monday that the agreement had been signed, Graham said he wanted to read the text himself, warning that “the way Iran describes it is awful” even if Washington’s version sounds reasonable.

That hesitation captures a real shift.

Many of the conservatives who rallied to Trump when the fighting started in late February now worry he gave up too much at the negotiating table, handing Tehran economic relief that could let the regime rebuild while doing too little to box in its nuclear program.

The friction is mostly about money and enforcement.

Reports that the deal would eventually unlock billions of dollars in frozen Iranian funds, and that Gulf states could pour hundreds of billions more into rebuilding Iran, have turned some of Trump’s steadiest allies into skeptics.

To hawks, cash flowing back to Tehran is cash that can be redirected to missiles and proxy fighters once the shooting stops.

A string of Republican senators voiced the same unease this week, and their common complaint was simple: they have not seen the actual document.

Trump said the memorandum was signed electronically over the weekend, but the full text has not been released, with the president saying it would likely be read out Friday.

Senators including John Cornyn, Josh Hawley, John Kennedy, and Chuck Grassley all said they could not judge a deal they had not been allowed to read.

Some of the sharpest critics have been on record for weeks.

Senate Armed Services Committee Chairman Roger Wicker slammed the framework as details leaked last month.

Ted Cruz and conservative commentators such as Hugh Hewitt and Mark Levin have pressed for far stricter terms — no Iranian uranium enrichment, ever, and the removal of Iran’s highly enriched stockpile from the country.

The administration’s answer is that the deal is built to be tested, not trusted.

Officials describe it as performance-based: Iran keeps the benefits only if it holds to its commitments, including no nuclear weapon, surrendering enriched material, and keeping the Strait of Hormuz open.

Vice President JD Vance has framed the promised Gulf investment money as a carrot — leverage to pull Iran toward bigger nuclear concessions in talks still to come.

For all the noise, the hawks have limited power to stop Trump.

As Republican strategist John Ullyot has noted, the Senate has few tools to block a president from winding down an active military operation.

The business backdrop helps explain why Trump is moving to close the war even over his own party’s objections.

The conflict pushed gasoline prices up sharply since late February, squeezing households and businesses alike, and shut a waterway that normally carries a fifth of the world’s oil.

Ending the fighting reopens the Strait of Hormuz, puts Iranian oil back on the market, and points pump prices lower — a tangible economic win heading into a midterm election year.

The frozen-funds issue carries its own economic weight.

The draft reportedly releases roughly $24 billion to Iran over a 60-day negotiating window, with far larger sums tied to a longer-term investment fund.

For markets, the prospect of Iranian crude returning has already pulled oil prices down sharply.

For the deal’s critics, that same money is the problem — relief that arrives before Iran has proven it will keep its word.

The split also signals a deeper realignment inside the Republican coalition between traditional hawks who want maximum pressure on Iran and a growing America First wing wary of open-ended Middle East commitments.

Trump has tried to stand in both camps at once — claiming a tough peace while ending an expensive war — and the deal is testing how long that balance can hold.

What happens next depends on the fine print.

If the text released Friday matches the administration’s confident description, some of the criticism may fade.

If it looks closer to the version Iran is selling, the revolt among Trump’s former cheerleaders is likely to grow louder.

Washington — JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
After years of raising prices, some of America’s biggest food companies are now cutting them — and the early results suggest it is working. When PepsiCo reported its quarterly results on Thursday, April 16, the maker of Lay’s, Doritos, Cheetos and Tostitos said its struggling North American food business returned to growth, with the amount of product sold up 2% after it lowered prices on popular snacks. “We feel good about where we are at this point in the journey,” chief executive Ramon Laguarta told analysts, adding that the early signs were “quite exciting.”

The price cuts are a direct response to shoppers who have spent the last few years trading down, buying less, or walking away from name brands altogether. PepsiCo first announced the reductions on Lay’s, Doritos, Cheetos and Tostitos at an investor meeting in early February. Laguarta has been blunt about why. “There’s a big reset of affordability because we see the consumer struggling in the U.S. and in many Western countries,” he said, calling affordability the single biggest obstacle for lower- and middle-income shoppers in the snack aisle.

General Mills, the company behind Cheerios, Nature Valley, Pillsbury and Häagen-Dazs, has made the same move. It cut prices on nearly two-thirds of its grocery products in North America, and said the change brought more items into shoppers’ carts. “Cost of living and housing pressures are reshaping spending patterns, and value is a core expectation that is here to stay,” chief executive Jeffrey Harmening said at an industry conference.

The shift has come at a cost to the companies’ bottom lines. In February, General Mills cut its sales and profit forecast for the year, warning that demand was soft and shoppers were resisting high prices. Its shares fell about 7% on the news and were down nearly 19% over the prior 12 months. Lower-income households in particular have been moving to cheaper store brands and private-label goods — the no-name products that sit next to the famous ones on the shelf, often for a dollar or two less.

How did it get to this point? Food prices climbed sharply after the pandemic and never really came back down. Grocery bills are far higher than they were a few years ago, and the steady drip of increases has worn shoppers out. Mondelez chief executive Dirk Van de Put, whose company makes Oreo and Ritz, put it plainly on a recent call: shoppers are “fed up with the price increases,” and confidence is near a historic low.

The strain shows up in unusual places. Some households are now using buy-now-pay-later installment plans just to cover the grocery bill, splitting the cost of food into smaller payments the way they might for a TV or a couch.

Not every company is cutting, and not every product is getting cheaper. Hershey raised prices by double digits to cover the soaring cost of cocoa, and food makers are still nudging up prices on items where their own costs have jumped. The broader picture is a balancing act: lower prices can win back shoppers and lift the number of items sold, but they also shrink the profit on each sale. Companies like PepsiCo and General Mills are betting that selling more at a lower price beats selling less at a higher one.

There is also a competitive threat pushing them. As shoppers hunt for value, discount chains and private-label brands have been taking customers, forcing the big names to fight back on price rather than just on advertising. PepsiCo said it is resetting shelves and rolling out new products, work its leadership expects to largely finish by the middle of the year.

For shoppers, the upshot is real if modest: after a long stretch of sticker shock, a growing list of well-known snacks and groceries is finally getting a little cheaper, as the companies that make them decide that winning customers back may matter more than protecting every cent of profit.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The artificial-intelligence boom is creating winners far beyond the companies building chatbots. One of the biggest beneficiaries may be Sandisk, whose shares surged again this week after analysts raised price targets and argued that soaring demand for AI infrastructure will keep memory-chip supplies tight and profits flowing.

On Monday, June 8, Bank of America analyst Wamsi Mohan raised his price target on Sandisk to $2,100 from $1,550, maintaining a buy rating. Shortly afterward, Mizuho lifted its own target to $2,200 from $1,825, keeping an outperform rating. Investors responded favorably, sending shares higher on Tuesday, June 9.

To understand why Wall Street is so excited, it helps to understand what Sandisk actually sells. The company is one of the world’s leading producers of NAND flash memory, the storage technology found in smartphones, laptops, data centers, and increasingly the massive servers that power artificial-intelligence systems.

Every AI model requires enormous amounts of data storage. As technology giants race to build new AI infrastructure, demand for memory chips has risen faster than manufacturers can increase production. Analysts believe that imbalance will continue supporting higher prices and stronger profits for companies like Sandisk.

The stock’s performance reflects that optimism. Sandisk shares have gained more than 550% during 2026, making it one of the market’s biggest winners. The rally briefly paused last week when concerns about AI valuations triggered a broader technology selloff, but analysts viewed the decline as a buying opportunity rather than a sign of weakening demand.

Another factor attracting investors is Sandisk’s evolving business model. The company has increasingly signed long-term supply agreements that lock in customer commitments and provide more predictable revenue. Many of those contracts begin with fixed pricing before transitioning to variable pricing structures designed to protect profitability even if market conditions soften.

Analysts say those agreements benefit both sides. Customers gain guaranteed access to critical memory supplies, while Sandisk gains greater visibility into future revenue and production planning.

There is also evidence that the company is better positioned to weather future downturns. In past semiconductor cycles, memory manufacturers often continued producing chips even when prices fell sharply because they needed cash flow. Improved margins and stronger contracts now give Sandisk more flexibility to reduce production if demand weakens.

Industry forecasts suggest NAND memory pricing could remain firm through 2026 and into the first half of 2027, supporting continued profitability across the sector.

For consumers, the story extends beyond Wall Street. The same supply shortages helping Sandisk can also increase costs for smartphones, laptops, solid-state drives, and cloud-computing services. When memory becomes more expensive, some of those costs eventually reach businesses and households.

At the same time, investors should remember that expectations have become extremely high. Stocks that rise more than fivefold in a single year can react sharply to even minor disappointments.

The bottom line: analysts increasingly view Sandisk as one of the clearest beneficiaries of the AI infrastructure boom. As long as demand for data storage continues to outpace supply, the company appears positioned to remain one of the technology sector’s biggest winners.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Here is a number that sounds like a typo. A little over a year ago, SanDisk was a newly independent company that almost nobody wanted to own, with its stock trading near $36 per share. By Monday, June 15, 2026, those same shares were changing hands above $2,000, near record highs.

The company underscored the scale of its turnaround on April 30, when Chief Executive David Goeckeler reported quarterly revenue of $5.95 billion, up 251% from a year earlier and nearly double the prior quarter.

That translates into a gain of roughly 5,000% — about 55 times an investor’s money — in less than a year and a half.

To put that into perspective, consider one of the most famous investment success stories of the modern era: Bitcoin.

The cryptocurrency traded near $1,000 at the beginning of 2017 and sits around $65,000 today. That represents a gain of roughly 65-fold, enough to turn many early investors into millionaires. But Bitcoin took nearly nine years to achieve that return.

SanDisk has delivered a comparable gain in roughly 16 months.

The obvious question is: How?

The answer begins with artificial intelligence.

SanDisk was spun off from Western Digital in February 2025, and at the time the outlook appeared challenging. The company specializes in NAND flash memory, the storage technology used in smartphones, laptops, cloud servers and data centers.

The memory industry had just emerged from one of its deepest downturns in more than a decade. Prices were depressed, inventories were elevated and profitability was weak.

Then came the AI infrastructure boom.

Every major artificial intelligence platform requires massive amounts of storage capacity to process, store and retrieve data. As technology companies raced to build AI data centers, demand for enterprise-grade storage surged.

SanDisk found itself in exactly the right place at exactly the right time.

Its enterprise solid-state drives became critical components in next-generation data centers. Demand accelerated faster than manufacturing capacity could expand, creating shortages across the industry.

The result was a dramatic increase in pricing power.

SanDisk generated approximately $3.62 billion in quarterly profit, while gross margins approached 56%, transforming what had recently been a struggling business into one of the most profitable companies in the semiconductor sector.

The company also changed its business model.

Historically, memory manufacturers sold products largely at prevailing market prices, exposing earnings to extreme swings in supply and demand.

SanDisk shifted toward multi-year customer agreements that lock in purchasing commitments and improve visibility into future revenue.

According to the company, it has secured more than $42 billion in contracted commitments, providing a degree of earnings predictability rarely seen in the memory industry.

Wall Street has raced to adjust.

Bank of America recently raised its price target to $2,100.

Mizuho lifted its target to $2,200.

Cantor Fitzgerald established one of the highest targets on Wall Street at $2,900.

Morgan Stanley identified SanDisk and rival Micron Technology as major beneficiaries of what analysts described as a prolonged memory upcycle driven by AI infrastructure spending.

Adding to investor enthusiasm, Nvidia Chief Executive Jensen Huang has repeatedly warned of what he calls a potential “multi-year silicon drought,” suggesting demand for advanced semiconductors and memory could remain elevated for years.

Institutional investors have taken notice.

Earlier this year, billionaire investor David Tepper’s Appaloosa Management disclosed a new position in SanDisk, further boosting confidence among investors.

Still, the extraordinary rise has prompted concerns.

The memory business has historically been one of the most cyclical sectors in technology. Periods of shortage and soaring prices are often followed by oversupply, falling prices and collapsing profits once new manufacturing capacity comes online.

SanDisk itself has experienced multiple boom-and-bust cycles throughout its history.

At current levels, the stock trades at more than 60 times trailing earnings, a valuation that assumes strong growth continues well into the future.

The share price has also moved beyond the average analyst target, suggesting investors are already pricing in outcomes more optimistic than many professional forecasts.

Several research firms have recently identified the stock among the most aggressively valued names in the semiconductor sector.

There is another important distinction between SanDisk and Bitcoin.

Bitcoin’s value is largely determined by what investors are willing to pay for it at any given moment.

SanDisk’s valuation, by contrast, is supported by measurable fundamentals — revenue, profits, customer contracts and cash flow.

But those fundamentals depend heavily on memory pricing, and memory prices have historically been among the most volatile in technology.

That leaves investors with a critical question.

If AI spending continues accelerating and memory shortages persist, SanDisk’s contract-driven business model could produce stronger and more stable profits than previous cycles.

If demand slows or manufacturing capacity expands faster than expected, the industry could once again face oversupply and falling prices.

The stock’s remarkable ascent is already one of the most dramatic stories on Wall Street.

Whether it proves to be a historic transformation or simply another chapter in the memory industry’s long cycle of booms and busts may determine what happens next.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Amazon is getting out of the business of running its own grocery stores. In a company announcement on January 27, the retailer said it would close all of its Amazon Fresh supermarkets and Amazon Go convenience stores — about 72 locations across the country — and pour its energy instead into grocery delivery and its Whole Foods Market chain. “While we’ve seen encouraging signals in our Amazon-branded physical grocery stores, we haven’t yet created a truly distinctive customer experience with the right economic model needed for large-scale expansion,” the company said.

The closures cover 58 Amazon Fresh stores and 14 Amazon Go shops in states including Washington, California, Illinois, New York, New Jersey and Virginia. Most shut their doors on Sunday, February 1. Stores in California stayed open an extra 45 days to satisfy state labor-notice rules.

It is a quiet end to a noisy experiment. Amazon opened its first Fresh supermarket outside Los Angeles in 2020 and launched the cashier-free Go format in Seattle back in 2018. The Go stores were the showcase for the company’s “Just Walk Out” technology, which uses cameras and sensors to track what shoppers grab so they can leave without stopping at a register. The stores never reached the scale Amazon wanted, and the company will now sell that checkout technology to outside customers instead, such as stadium concession stands.

For the workers, Amazon said it would try to move staff into nearby jobs in its warehouses and delivery network. Employees who do not take a new role are being offered a severance package that includes 90 days of full pay and benefits. The company did not say how many people are affected.

The decision is less a retreat from groceries than a bet on a different way of selling them. Amazon is already the second-largest grocer in the United States, with more than $150 billion in gross grocery sales and over 150 million customers buying food from it each year. Most of that runs through delivery, not store aisles. The company says its same-day delivery of fresh food now reaches more than 2,300 U.S. cities and towns, and that sales of perishable items through the service have grown fortyfold since the start of 2025.

The other half of the plan is Whole Foods, the upscale chain Amazon bought for $13.7 billion in 2017. Amazon says Whole Foods sales are up more than 40% since that deal, with more than 550 stores now open. The company plans to add over 100 more locations in the coming years and to convert some of the shuttered Fresh and Go sites into Whole Foods stores.

Amazon is also leaning on a smaller store idea called Whole Foods Market Daily Shop — a compact, grab-and-go format between 7,000 and 14,000 square feet, roughly a quarter to half the size of a regular Whole Foods. Five are already open in New York, New Jersey and Virginia, and Amazon plans to double that to ten by the end of the year. At the other extreme, the company won approval to build a 230,000-square-foot “supercenter” in Orland Park, Illinois, near Chicago, combining groceries with general merchandise. Slated to open in 2027, it would be Amazon’s biggest physical store yet.

The shift says a lot about where grocery shopping is heading. After years of trying to crack the supermarket business with its own brand, Amazon decided the math did not work — running physical stores is expensive, margins are thin, and shoppers already had plenty of choices. Delivery and a trusted store name turned out to be the stronger hand.

For rival grocers, an Amazon that competes through Whole Foods and delivery rather than hundreds of Amazon-branded stores is a different kind of threat — one built on speed and a premium brand rather than price. For the towns losing a Fresh or Go store, it means an empty storefront and a hunt for new jobs. And for shoppers, it is one more sign that the future of buying groceries is shifting from the checkout line to the front door.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
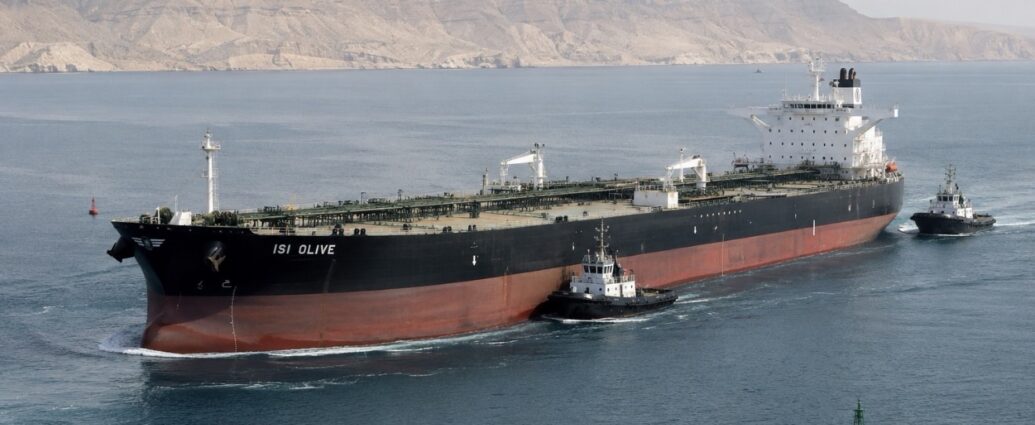
WASHINGTON — The deal to end the war between the United States and Iran could do more than calm oil markets — it could finally unclog one of the most important arteries in global trade. On Sunday, President Donald Trump announced an agreement to reopen the Strait of Hormuz, the narrow waterway that carries about 20% of the world’s oil supply and a massive volume of global cargo traffic. “Ships of the World, start your engines. Let the oil flow!” Trump wrote. By Monday, attention had shifted from oil prices to another critical question: how quickly shipping costs might fall.

The strait has been largely disrupted since the conflict began on February 28, and the consequences stretched far beyond the Persian Gulf. With vessels avoiding the area, freight rates surged worldwide. According to Peter Sand, chief analyst at freight intelligence platform Xeneta, spot container rates in June were running about 75% higher from China to the U.S. East Coast, 51% higher to Northern Europe, and 45% higher to the Mediterranean compared with pre-conflict levels.

The reason is simple geography. At its narrowest point, the Strait of Hormuz is only 21 miles wide. When the route becomes dangerous, shipping companies have few alternatives. Many vessels were forced to reroute around the southern tip of Africa, adding 10 to 14 days to voyages and significantly increasing fuel consumption.

Insurance costs also soared. Dylan Mortimer, a marine war-risk specialist at broker Marsh, said war-risk premiums climbed dramatically, in some cases adding hundreds of thousands of dollars to the cost of a single voyage. Tanker rates surged as well, especially on routes carrying crude oil from the Gulf region to Asia.

Even with the agreement announced, the disruption remains significant. Roughly 100 container ships remain trapped in the Arabian Gulf, while shipping giant Hapag-Lloyd reported that several vessels are still delayed, including one ship that has spent nearly four weeks in transit.

Industry experts caution that reopening the strait will not immediately restore normal conditions. Tobias Maier, who leads the Middle East and Africa business for DHL Global Forwarding, said customers should expect four to six months before shipping patterns fully normalize. Analysts at Kamco Invest similarly project that elevated freight rates could persist until a backlog equivalent to two to three months of cargo works through the system.

That lag matters because shipping costs eventually influence the price consumers pay for nearly everything. Clothing, electronics, furniture, appliances and automobile parts all become more expensive when transportation costs rise. The Strait of Hormuz disruption did not merely push oil prices higher; it increased the cost of moving goods globally, contributing to inflation pressures already weighing on households.

If shipping rates gradually decline, those savings could eventually reach store shelves. However, economists caution that the process takes time and depends heavily on continued stability in the region.

That remains the biggest risk. Mine-clearing operations are scheduled to begin later this week, and the U.S. naval blockade is being lifted. But shipping companies and insurers remain cautious. Any new incident could quickly reverse recent progress and send costs higher again.

For now, however, the direction appears positive. For nearly four months, a narrow stretch of water exerted outsized influence over global trade, energy prices and consumer costs. If cargo begins moving freely again, the benefits will eventually extend far beyond the Middle East — reaching warehouses, retailers and household budgets around the world.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
One of the biggest names on the Las Vegas Strip is changing hands. On Thursday, May 28, Fertitta Entertainment announced it had reached a deal to buy Caesars Entertainment in an all-cash transaction valued at about $17.6 billion, in what would be the largest casino takeover in U.S. history. The buyer is billionaire Tilman Fertitta, the Houston restaurant-and-casino mogul who already owns the Golden Nugget casinos, the Landry’s restaurant empire and the NBA’s Houston Rockets.

Under the agreement, Caesars shareholders will receive $31.00 in cash for each share they own. That is a 49% premium over where the stock traded on February 25, the last day before rumors of a deal began to swirl. The price tag includes roughly $5.7 billion in equity and the assumption of about $11.9 billion of Caesars’ existing debt. The Caesars board approved the deal unanimously and is urging shareholders to vote yes, calling the offer “compelling.”

Tilman Fertitta is one of the more colorful figures in American business. He built Landry’s from a single seafood restaurant into one of the country’s largest hospitality and dining companies, owns the Golden Nugget casino brand, and currently serves as the U.S. ambassador to Italy and San Marino. Buying Caesars dramatically expands his empire: the combined company would run about 60 resorts worldwide, including the eight Caesars properties along the Strip such as Caesars Palace, the Flamingo and The Linq.

Day-to-day, much would stay the same. Caesars chief executive Tom Reeg, chief financial officer Bret Yunker and president and operating chief Anthony Carano are all expected to keep their jobs. The Carano family, which holds roughly 5% of Caesars, agreed to roll part of its stake into the new, combined business rather than cash out.

The purchase is not contingent on financing, which signals confidence the money is in place. Fertitta Entertainment is paying with a mix of its own equity, the assumed Caesars debt, and new debt arranged by a group of 10 banks. Morgan Stanley and Goldman Sachs are advising Fertitta, while PJT Partners is advising Caesars. Once the deal closes, Caesars stock will stop trading on the Nasdaq and the company will go private — meaning ordinary investors will no longer be able to buy a piece of it.

The agreement includes what is known as a “go-shop” period running through about July 11, during which Caesars and its advisers are free to look for a better offer. If another bidder emerges with a higher price, the board can consider it. Such windows rarely produce a competing deal, but they let the board show shareholders it sought the best possible terms.

The timing reflects where the casino business sits right now. The biggest operators carry heavy debt loads from years of building and buying, and taking a company private gives new owners room to reshape it away from the quarter-to-quarter pressure of the stock market. For Fertitta, owning both Golden Nugget and Caesars creates a hospitality giant spanning Las Vegas, Atlantic City, regional casinos and a large online betting operation, since Caesars also runs a sports-betting, online-casino and poker platform.

For the tens of thousands of people who work at Caesars properties, a buyout like this usually brings a close look at costs, even as the buyer promises a smooth transition. For customers, the company says the merger will mean a wider range of destinations and rewards across more resorts. And for the gambling industry, the deal is a marker of how much money is still flowing into Las Vegas and regional gaming — a single owner is willing to spend $17.6 billion betting that Americans will keep coming to the tables.

The deal still needs approval from Caesars shareholders and from gaming and antitrust regulators, a process that can take many months. If it clears, the house that grew into one of the Strip’s defining brands will belong to one of the most aggressive dealmakers in American hospitality.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Last Friday, SpaceX rang the opening bell at the Nasdaq and became a public company valued at approximately $1.75 trillion, the largest stock-market debut in history. Within days, the stock climbed past $2 trillion. Twenty years ago, the same company was a struggling startup that had never put anything into orbit and was running out of money.

The bridge between those two facts is a story Washington should study closely because it may be one of the best investments American taxpayers have ever made.

That bridge was a relatively small government bet.

In 2006, NASA launched a program called Commercial Orbital Transportation Services (COTS) and awarded SpaceX approximately $396 million to help develop a rocket and spacecraft capable of carrying cargo to the International Space Station. SpaceX contributed more than $450 million of its own capital alongside the government funding.

For the entire program, NASA spent roughly $800 million and ended up with two independent American cargo transportation systems.

By federal standards, that was a bargain.

The key was not the amount of money. It was the structure.

NASA did not hire a traditional contractor and pay cost overruns indefinitely. It acted as a customer. The agency defined the mission and allowed private companies to determine how to achieve it.

That freedom changed everything.

NASA’s own cost analyses estimated that developing the Falcon 9 through traditional government procurement would have cost approximately $1.4 billion. SpaceX accomplished the task for roughly $440 million, reducing development costs by nearly 70%.

When NASA later expanded the partnership to include astronaut transportation, the agency estimated that the commercial approach saved between $20 billion and $30 billion compared with building and operating a government-run system.

The savings extended far beyond development costs.

A single Space Shuttle mission cost approximately $1.6 billion, or about $54,500 per kilogram delivered to orbit.

A Falcon 9 launch costs roughly $67 million, translating to approximately $2,720 per kilogram.

That represents a reduction of about 95% in the cost of reaching space.

The reason is simple: reusability.

SpaceX developed the ability to land and reuse orbital-class rockets, transforming what had traditionally been disposable hardware into reusable transportation systems.

The result was not merely lower costs.

It fundamentally changed the economics of space.

For years after the retirement of the Space Shuttle, the United States paid Russia between $80 million and $90 million per astronaut seat aboard Soyuz spacecraft.

SpaceX’s Crew Dragon ended that dependence and returned human spaceflight capability to American soil.

The payoff continues to grow.

SpaceX generated approximately $18.7 billion in revenue last year, driven largely by Starlink, the satellite internet network now serving rural communities, airlines, ships, military operations, and disaster-response missions around the world.

Its launch business has made the United States the dominant force in orbital transportation.

Meanwhile, analysts at Citigroup project that the global space economy could reach $1 trillion annually by 2040, up from roughly $370 billion in 2020. Lower launch costs, driven largely by SpaceX, are widely viewed as the primary catalyst behind that expansion.

The economic value created is not theoretical.

It includes a multi-trillion-dollar company, thousands of high-paying jobs, national security capabilities, global communications infrastructure, and an entirely new generation of commercial space businesses that would likely not exist at their current scale without dramatically cheaper access to orbit.

There is also a fair debate about how much credit belongs to government and how much belongs to the private sector. Critics correctly note that SpaceX benefited from NASA contracts, federal partnerships, and government funding at a crucial stage of its development. Without that support, the company might never have survived its early years. Supporters counter that government did not build the rockets, develop reusable launch technology, or take the entrepreneurial risks that made the company successful. Both arguments contain truth.

The more useful question is not whether government was involved, but whether taxpayers received value for what they invested. In the case of SpaceX, the answer appears to be yes. A relatively modest federal commitment helped produce dramatically lower launch costs, billions in savings for NASA, renewed American independence in human spaceflight, and a company that has become one of the most valuable enterprises in the world. Taxpayers did not simply spend money; they helped create an industry that now generates economic activity, jobs, innovation, and strategic advantages for the United States.

That does not mean every government-backed project will succeed, nor does it mean every subsidy is wise. Many fail. But the SpaceX example demonstrates what can happen when government sets a clear objective, creates accountability, and allows private innovators the freedom to solve the problem. The lesson is not that government should do more or less. The lesson is that government should do better.

There is a lesson here that goes well beyond rockets, and it should become part of Washington’s thinking. Government does not have to do everything itself, and often it should not. A targeted public investment aimed at unleashing private-sector innovation can accomplish far more and cost far less than a government program attempting to build and operate everything on its own.

The SpaceX story is not an argument against government.

It is an argument for smarter government.

One that sets ambitious goals, supports innovation, demands results, and trusts Americans to build.

If Washington wants more SpaceX-sized successes, the blueprint already exists.

It starts with backing American ingenuity and then getting out of the way.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. stock futures traded little changed following a strong market rally as investors shifted their focus from easing Middle East tensions to the Federal Reserve’s upcoming policy meeting, the first to be led by new Chair Kevin Warsh.

Futures tied to the Dow Jones Industrial Average hovered near flat, while S&P 500 futures slipped about 0.1% and Nasdaq 100 futures eased roughly 0.3%, reflecting a pause after a broad advance in equities.

Markets rallied after President Donald Trump announced that the United States and Iran had reached a breakthrough agreement expected to be formally signed later this week. U.S. officials have said the deal could lead to the reopening of the Strait of Hormuz, one of the world’s most important oil shipping routes, helping drive oil prices sharply lower and boosting shares of airlines, cruise operators, transportation companies, and other fuel-sensitive sectors.

Attention is now turning to the Federal Reserve.

The central bank begins its two-day policy meeting Tuesday and will announce its decision Wednesday afternoon, followed by Warsh’s first press conference as Fed chair.

On the rate decision itself, expectations remain relatively clear.

According to CME FedWatch data, traders overwhelmingly expect policymakers to leave the federal funds rate unchanged within its current range of 3.50% to 3.75%. A recent Reuters survey of economists also showed broad expectations that rates will remain unchanged in the near term.

The significance of this meeting lies elsewhere.

In addition to its policy decision, the Fed will release updated economic forecasts and a revised dot plot, which reflects policymakers’ expectations for future interest-rate moves. Those projections could provide the clearest indication yet of whether the central bank believes inflation pressures are easing or whether additional tightening may be required.

Market expectations have shifted considerably in recent months.

Earlier this year, many investors expected the Fed to begin cutting rates before year-end. However, stronger-than-expected economic growth, a resilient labor market, and renewed inflation pressures have caused many forecasters to reconsider those assumptions.

Consumer prices rose 4.2% year-over-year in May, marking the highest inflation reading in three years. At the same time, employers added 172,000 jobs, exceeding expectations and reinforcing the view that the economy remains stronger than many analysts anticipated.

That combination of persistent inflation and solid employment growth has complicated the outlook for monetary policy.

Several Wall Street firms have adjusted their forecasts accordingly. Goldman Sachs recently pushed its expected timeline for rate cuts into 2027, citing continued inflation concerns and stronger economic activity.

Warsh enters the meeting facing heightened scrutiny.

Confirmed by the Senate last month, the new Fed chair is widely viewed as more focused on inflation risks than some of his predecessors. During his confirmation process, Warsh emphasized the importance of open debate among policymakers and signaled a willingness to challenge consensus when necessary.

Economists note that inflation pressures remain visible in several areas of the economy, particularly within the services sector, where price growth has remained stubborn despite earlier signs of moderation elsewhere.

The political environment adds another layer of complexity.

President Trump has repeatedly called for lower interest rates and argued that the economy does not require tighter monetary policy. Any indication that the Fed could consider additional rate increases would likely place Warsh in a difficult position between market expectations, economic data, and political pressure.

The Fed itself has shown signs of internal disagreement. Recent meetings produced some of the most notable policy dissents seen in years as officials debated the appropriate path for rates and inflation management.

For consumers, the outcome matters far beyond Wall Street.

The federal funds rate influences borrowing costs throughout the economy, affecting mortgages, auto loans, credit cards, business lending, and savings accounts. If policymakers signal that rates will remain elevated for longer, many borrowers could face continued pressure from high financing costs.

At the same time, higher rates generally benefit savers by supporting stronger yields on cash deposits and fixed-income investments.

Investors are expected to focus less on Wednesday’s rate announcement itself and more on the language surrounding it.

The updated forecasts, dot plot, and Warsh’s comments during his first post-meeting press conference may provide critical clues about whether the Fed sees inflation cooling sufficiently to eventually lower rates or whether policymakers believe additional tightening remains a possibility.

After markets spent the previous session reacting to geopolitical developments and falling oil prices, the next major move may depend on what the Federal Reserve’s new leader signals about the direction of U.S. monetary policy.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
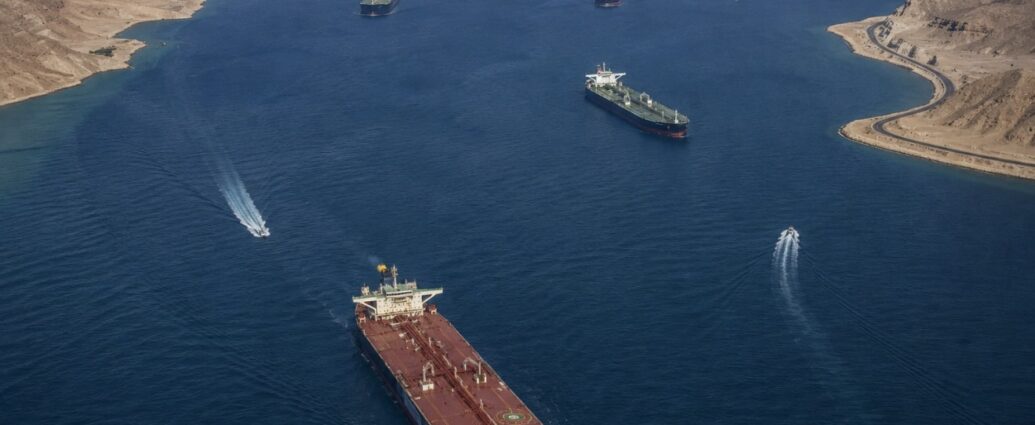
China’s shoppers spent less in May than they did a year earlier, the first decline in consumer spending in more than three years, according to figures released Tuesday by the National Bureau of Statistics, adding pressure on Beijing to do more to revive the world’s second-largest economy.

Retail sales fell 0.6% from a year earlier, the first monthly decline since December 2022, when the country was still under COVID restrictions. The reading surprised economists. A Reuters poll had expected sales to be flat, making the decline a sign that consumers remain cautious despite government efforts to boost spending.

The figures highlight an economy moving at two very different speeds.

While households pulled back, China’s factories continued to expand. Industrial output rose 4.5% in May, up from 4.1% in April and ahead of forecasts. A worldwide surge in demand tied to artificial intelligence infrastructure has fueled orders for Chinese-made technology components and industrial equipment.

At the same time, exports jumped 19.4%, helping offset concerns that geopolitical tensions and disruptions in the Middle East would weigh more heavily on manufacturing activity.

The problem for Beijing is that factory strength is not translating into stronger consumer demand.

The Labor Day holiday at the start of May, traditionally a major spending period, failed to provide a meaningful boost to retail activity. Analysts pointed to the scaling back of government trade-in subsidies for automobiles and appliances, along with continued concerns about employment and household wealth.

Years of falling home prices have left many Chinese families reluctant to spend. Instead, many households continue to save as they wait for stronger signs of economic stability.

The housing sector remains one of the biggest drags on growth.

Property investment fell 16.2% during the first five months of the year, worsening from the 13.7% decline recorded through April.

Investment firm KKR recently cited the property downturn as one of the largest obstacles facing China’s economy, noting that the country’s inventory of unsold homes may take years to fully absorb.

Broader investment data also disappointed.

Fixed-asset investment, which includes spending on factories, infrastructure projects and buildings, fell 4.1% during the first five months of 2026. Economists had expected a decline closer to 2%, making the result one of the weakest readings of the year.

Another warning sign appeared in the inflation data.

Factory-gate prices increased at their fastest pace since July 2022, while consumer prices remained largely unchanged. The growing gap suggests Chinese manufacturers are producing more goods than domestic consumers are willing to purchase, leaving supply growth ahead of demand.

The implications extend far beyond China.

As the world’s largest manufacturing nation and second-largest economy, China plays a critical role in global demand. Weak Chinese consumer spending affects multinational companies ranging from automakers and luxury brands to technology firms and food producers.

Softer demand can also weigh on commodity markets, reducing demand for products such as oil, copper, iron ore and industrial metals exported by countries around the world.

The disappointing retail figures are likely to increase pressure on Beijing to introduce additional stimulus measures.

Economists have been waiting for more aggressive policies aimed at encouraging household spending, including consumer subsidies, direct support programs and additional measures to stabilize the housing market.

Tuesday’s data strengthens the argument that further action may be necessary.

For now, China remains an economy powered by factories but restrained by cautious consumers. Manufacturing and exports continue to benefit from global demand and the AI investment boom, but until households regain confidence in their jobs, incomes and property values, consumer spending is likely to remain a weak spot.

The next set of economic data, expected in mid-July, will offer a clearer picture of whether May represented a temporary setback or the beginning of a more sustained slowdown in household spending.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The amount of oil sitting in the U.S. Strategic Petroleum Reserve (SPR) has dropped to its lowest level in more than four decades, according to federal data released Monday, as the Trump administration continues drawing emergency crude from the stockpile to cushion the economy against disruptions caused by the war with Iran.

The reserve held 340.3 million barrels as of June 12, the Department of Energy reported. That is the smallest amount since 1983, when the Reagan administration was still building the reserve and the U.S. economy was far smaller than it is today.

The new figure falls below the previous modern low of 346.7 million barrels, reached in July 2023 following market disruptions tied to Russia’s invasion of Ukraine.

The government withdrew another 8.9 million barrels during the past week alone. Since the Iran conflict began in late February, the reserve has declined by approximately 75 million barrels, or about 18%.

The drawdown traces directly to disruptions surrounding the Strait of Hormuz, one of the world’s most important oil transit routes. With global energy markets under pressure and crude prices rising, the administration relied on the emergency reserve to help stabilize fuel costs for consumers and businesses.

The Strategic Petroleum Reserve was created in 1975 following the Arab oil embargo and is intended to protect the United States against major supply disruptions. The reserve has helped limit upward pressure on gasoline and diesel prices during months of geopolitical instability.

Andy Lipow, president of Lipow Oil Associates, said the reserve releases, combined with additional supplies from allied countries and shifts in global demand, helped prevent a far sharper spike in oil prices. He warned, however, that a smaller reserve leaves the country with less flexibility if another major disruption occurs, such as a severe hurricane affecting Gulf Coast production.

At current levels, the reserve is less than half full. The SPR has a maximum capacity of approximately 714 million barrels and reached a record level of about 726.6 million barrels in 2009.

Mike Sommers, chief executive of the American Petroleum Institute, recently cautioned that maintaining adequate reserve levels remains important for national energy security and emergency response capabilities.

Relief may be on the horizon. Over the weekend, the United States and Iran announced an interim agreement aimed at reducing tensions and reopening shipping through the Strait of Hormuz. Markets responded positively, with Brent crude falling more than 4% Monday as traders anticipated improved supply flows.

If shipping through the strait normalizes, pressure on global oil supplies could ease, reducing the need for continued large-scale reserve releases. Over time, that could allow the government to begin rebuilding emergency stockpiles.

Any recovery, however, is expected to take time. Energy infrastructure, shipping schedules, and production levels across the Gulf region will require months to fully normalize after the disruption.

For now, the Strategic Petroleum Reserve continues to sit at its lowest level in more than 40 years, underscoring the significant role it has played in helping shield the U.S. economy from one of the largest energy disruptions in recent memory.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
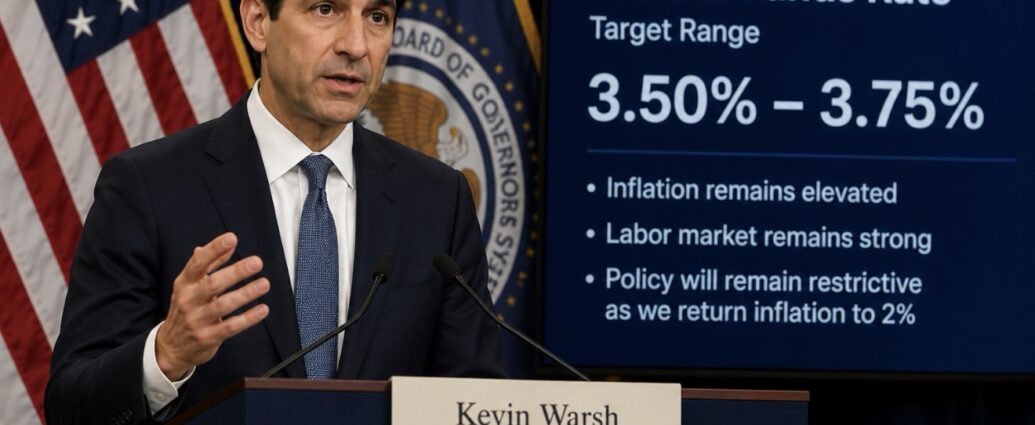
The Bank of Japan raised its key short-term interest rate to 1% on Tuesday, the highest level in three decades, but the move did little to lift the yen, which surrendered the gains it had built up earlier in the day.

The decision came at the close of a two-day meeting in Tokyo and lifted the benchmark rate by a quarter of a percentage point from 0.75%. It was the first time Japan’s policy rate has touched 1% since 1995. The board approved the increase by a 7-1 vote, with board member Asada casting the lone dissent against the hike.

For most of the day the yen had been climbing. A weekend agreement between the United States and Iran to reopen the Strait of Hormuz had calmed nerves across global markets, and traders moved back into the Japanese currency. Once the rate announcement landed, however, the yen quickly handed back its advance. The USD/JPY pair held near 160 to the dollar, the same level it sat at before the meeting and a line Japanese authorities watch closely because it has triggered government intervention in the past.

The flat reaction came down to a simple fact: the hike was no surprise. Nearly every forecaster had expected it for weeks, so the increase was already baked into prices long before the Bank of Japan made it official. Without a fresh signal, currency traders had little new to act on.

There were other reasons the yen stayed weak. Domestic inflation has been cooling in recent months, which eases the pressure on the central bank to keep tightening. Speculators have also piled up bets against the yen, pushing short positions to a nine-year high and reviving the so-called carry trade, where investors borrow cheaply in yen to buy higher-yielding assets elsewhere.

And even at 1%, Japan’s rate remains far below those in the United States and Europe, so the wide gap that has dragged the yen lower for years has barely narrowed.

A weak yen is not just a market story. For ordinary households in Japan, it lands directly in the cost of living. Japan imports almost all of its oil and a large share of its food, so when the yen falls, the price of gasoline, electricity and groceries climbs.

That has kept inflation running above the central bank’s 2% target for months and is a major reason the Bank of Japan has been steadily unwinding the ultra-loose monetary policy it maintained for more than a decade.

Tuesday’s meeting was unusual for another reason. It was the first regular policy session in the bank’s history held without the governor in the room.

Kazuo Ueda is recovering in the hospital from an infected liver cyst and is expected to remain there for about two weeks. Deputy Governor Ryozo Himino chaired the meeting in his place, marking the first time since 1998 that a sitting Bank of Japan governor has missed a policy decision. Fellow Deputy Governor Shinichi Uchida handled the post-meeting press conference, while Ueda submitted his views in writing.

In its statement, the bank said it would continue raising the policy rate if the economy and inflation develop in line with its forecasts and described Japan’s recovery as moderate. It also stressed that financial conditions would remain accommodative even after the increase, reassuring businesses and borrowers that financing costs are not expected to rise sharply overnight.

Markets immediately turned to Uchida’s remarks for clues about when the Bank of Japan might raise rates again.

Japan is no longer acting alone. The European Central Bank raised rates last week, becoming the first major central bank to tighten policy since the outbreak of the U.S.-Iran conflict, and traders increasingly expect the Federal Reserve to raise rates before the end of the year.

That shift abroad makes it harder for the Bank of Japan to sound cautious without placing additional pressure on its currency.

For exporters such as automakers and electronics manufacturers, a weak yen is welcome news because it makes Japanese products cheaper overseas and boosts the value of profits earned abroad when converted back into yen.

For households paying more at the gas pump and the supermarket, the picture is very different.

That divide sits at the center of nearly every decision the Bank of Japan faces as it attempts to normalize interest rates without choking off what remains a fragile economic recovery.

The next major test comes with the bank’s July Outlook Report, when policymakers will update their economic forecasts and provide investors with a clearer signal about how quickly they intend to move from here.

JBizNews Desk

JBizNews Desk / © JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Porsche, the German maker of the 911 sports car, is cutting deeper into its workforce as weak demand for electric vehicles and a brutal sales slump in China squeeze its profits. The company has set a goal of shrinking staff at its two main German sites — the Stuttgart-Zuffenhausen factory and the Weissach development center — by 15%, or about 1,900 jobs, by 2029. And the cuts keep growing: on May 8, new chief executive Michael Leiters closed three Porsche subsidiaries and eliminated roughly 500 more positions, pushing the total well beyond the original plan.

The job reductions land on a company that, until recently, was one of the auto industry’s most reliable money-makers. Porsche, which is majority-owned by Volkswagen AG, employs around 42,000 people, with more than half based in the Stuttgart region. The 1,900 cuts alone equal about 5% of its German workforce.

The trouble traces back to a bet that has not paid off as hoped: electric cars. Porsche leaned hard into EVs, but demand across Europe has come in slower than expected, and competition from cheaper, fast-improving Chinese electric brands has been fierce. Sales in China, once a huge and growing market for the brand, have fallen sharply. In response, the company is shifting course and putting more money back into gasoline and hybrid models — an expensive reversal. Porsche has said the restructuring will cost about €3.1 billion (roughly $3.6 billion) and will drag down profits this year.

For now, Porsche says it will avoid forced layoffs. A job-security agreement protects workers at its main sites from compulsory redundancies until mid-2030, so the company is relying on softer tools: not replacing people who leave, offering early and partial retirement, and letting temporary contracts expire. It began that process in 2024 by declining to renew 1,500 fixed-term contracts, with another 500 now ending. Human-resources board member Andreas Haffner acknowledged the strain, telling a German newspaper the company has “many challenges to overcome.”

The pressure has only intensified under Michael Leiters, who took over as chief executive this year. Alongside the May job cuts, Porsche shut three smaller units — battery maker Cellforce, an e-bike division and an electronics business — and earlier in the spring sold its stakes in the supercar venture Bugatti Rimac and the Rimac Group, signs that Leiters is shrinking the company toward its core.

Workers are uneasy about where it ends. Ibrahim Aslan, the head of Porsche’s general works council, has warned that as many as one in four jobs at the German sites — potentially 5,500 positions — could be at risk if management follows through on proposals to outsource entire divisions and shift work to lower-wage countries. He is pushing to extend job protections to 2035. “I’m not Santa Claus, who grants wishes,” he said of the board’s demands for concessions.

For the wider economy, Porsche’s retrenchment is part of a painful reckoning across the German auto industry. Parent Volkswagen has wrestled with whether to close domestic plants for the first time in its history, and weak EV sales and Chinese competition have forced carmakers across Europe to rethink their costs. Germany’s manufacturing heartland, long a source of stable, well-paid jobs, is feeling the squeeze.

For car buyers, the story is a reminder that the once-confident march toward all-electric driving has hit speed bumps. Demand has not grown as fast as the industry assumed, and even a premium brand like Porsche is pumping the brakes on its electric plans and leaning back on the combustion engines that built it.

For Porsche’s workers, the message is bleaker: a brand synonymous with success and fat profit margins is now in cost-cutting mode, and the people who build its cars are absorbing the blow.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Oil prices settled near their lowest level in three months on Monday, steadying after a sharp two-day slide as traders bet a deal to end the U.S.-Iran war could soon reopen the world’s most important oil shipping lane.

The decline followed a Sunday-night announcement by President Donald Trump, who said on social media that an agreement with Iran was “complete” and that oil would once again move through the Strait of Hormuz after a planned signing ceremony Friday. Iran’s Deputy Foreign Minister, Kazem Gharibabadi, also confirmed that a deal had been reached and said the full text would be released following a signing event in Switzerland.

By Monday afternoon, West Texas Intermediate (WTI) crude, the U.S. benchmark, was trading near $80.50 per barrel, down about 5%, while global benchmark Brent crude slipped roughly 4% to around $83 per barrel. Both benchmarks touched their lowest levels since March 10 and have now fallen approximately 20% from the highs reached earlier this spring when fears of prolonged supply disruptions sent oil prices above $100 per barrel.

At the center of the market’s focus is the Strait of Hormuz, the narrow waterway connecting the Persian Gulf to the Arabian Sea.

Roughly one-fifth of the world’s oil supply moves through the strait each day. When fighting erupted in late February and Iran moved to restrict shipping through the passage, traders feared a major supply shock, pushing crude prices sharply higher. The prospect of reopening the route is now having the opposite effect.

More oil flowing through global markets generally means lower prices.

Despite the sharp decline, oil did not collapse further Monday because traders remain cautious about how quickly supplies can normalize.

Months of conflict have damaged energy infrastructure throughout the region, including pipelines, export facilities and refinery operations. Shipping companies also remain wary of security risks, while inventories across parts of the Gulf have been reduced after months of disruption.

As a result, many analysts expect any reopening of the Strait of Hormuz to be gradual rather than immediate.

There is also uncertainty surrounding the durability of the agreement itself.

Reports indicate the framework includes provisions related to Iran’s nuclear program alongside economic incentives tied to compliance. Similar issues have complicated negotiations in the past, and traders remain mindful that signing a document is not the same thing as restoring normal oil flows.

Still, the overall direction of the market remains clear.

The war-driven premium that dominated oil trading for much of the spring is rapidly fading. That shift carries significant implications beyond commodity markets.

Higher energy costs have been one of the biggest contributors to rising expenses for consumers this year. Gasoline prices surged above $4 per gallon nationally after the conflict began, increasing transportation costs and feeding broader inflation pressures across the economy.

As crude oil prices fall, gasoline prices have begun easing as well.

If energy supplies continue to normalize, additional relief could reach consumers in the weeks ahead, although local taxes, refining capacity and regional market conditions will determine how much drivers ultimately save at the pump.

Lower oil prices also benefit businesses that rely heavily on fuel.

Airlines, shipping companies, manufacturers and logistics firms all stand to gain from reduced energy expenses. Lower fuel costs can also help moderate inflation, easing some pressure on the Federal Reserve as policymakers continue monitoring price stability.

Not everyone benefits from cheaper oil, however.

U.S. shale producers generally earn less when crude prices decline, and prolonged weakness can lead companies to slow drilling activity and reduce investment plans. Industry analysts note that some producers become increasingly cautious as prices move toward the low-$80-per-barrel range.

The next major test for the market comes Friday when negotiators are expected to formally sign the agreement.

Vice President JD Vance said Monday that the administration expects the Strait of Hormuz to reopen and remain accessible to global shipping without tolls over the long term. The comments signaled Washington’s intention to support uninterrupted traffic through the critical energy corridor.

If the agreement holds and oil exports continue to increase, analysts believe prices could drift lower during the summer months.

For now, however, traders appear to be waiting for evidence rather than promises.

After months of conflict, supply fears and sharp market swings, investors have already priced in much of the optimism surrounding the agreement. The next move in oil prices may depend less on diplomatic announcements and more on a straightforward question: whether tankers begin moving through the Strait of Hormuz at levels approaching normal operations.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
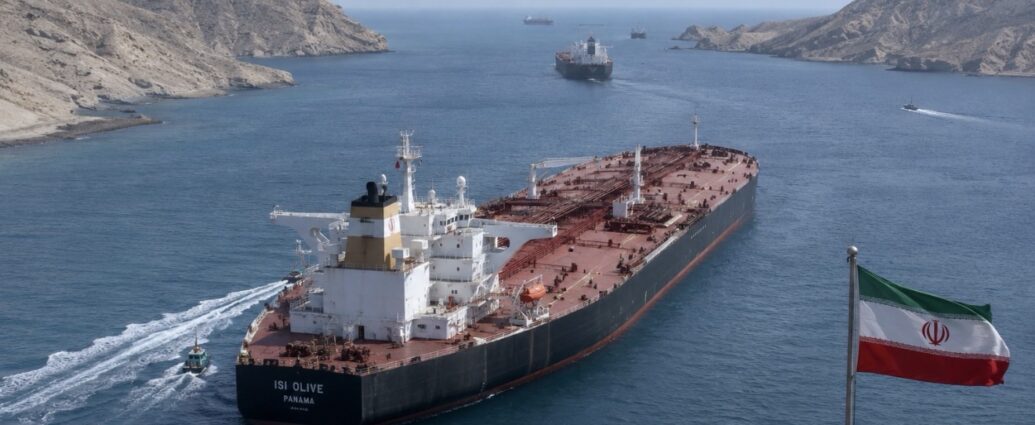
Cruise line stocks surged Monday after oil prices tumbled, giving the industry relief from one of its biggest cost pressures and improving profit expectations heading into the peak summer travel season.

Shares of Carnival Corp., Royal Caribbean Group, and Norwegian Cruise Line Holdings each gained more than 4% after President Donald Trump announced a peace agreement between the United States and Iran that is expected to reopen the Strait of Hormuz and restore normal oil flows through one of the world’s most important energy corridors.

Crude oil prices fell roughly 5% following the announcement, a significant development for cruise operators whose fleets consume massive amounts of fuel each year.

In Monday trading, Carnival rose approximately 4.5% to $30.51, Royal Caribbean gained 4.3% to about $307, and Norwegian Cruise Line climbed 4.8% to roughly $20.36, according to Benzinga Pro. Royal Caribbean shares have now advanced approximately 14% over the past five trading sessions as fears of a prolonged Middle East conflict have eased.

The connection between lower oil prices and stronger cruise stocks is straightforward.

Fuel remains one of the largest operating expenses for cruise companies. When oil prices rise, operating costs increase and profit margins come under pressure. When oil falls, those costs decline, allowing more revenue to flow directly to the bottom line.

The potential impact can be substantial.

Carnival previously told investors it expected approximately $500 million in fuel-related headwinds during fiscal 2026 because of disruptions tied to the Middle East conflict. The company also estimated that every 10% move in fuel prices could impact annual costs by roughly $160 million.

A sustained decline in oil prices could therefore eliminate a meaningful portion of those expected expenses.

Royal Caribbean faces a similar equation. The company expects to consume roughly 1.76 million metric tons of fuel this year at a cost approaching $1.2 billion. While management has hedged about 60% of its anticipated fuel needs, the remaining portion remains exposed to market price fluctuations.

Beyond fuel savings, easing tensions in the Middle East provide another potential benefit.

With shipping routes becoming more secure and geopolitical risks declining, cruise operators face less chance of itinerary disruptions, rerouted voyages, or operational complications that can frustrate passengers and increase costs.

Lower fuel prices may also support consumer demand.

As gasoline prices decline, households often have more discretionary income available for vacations and travel. That dynamic can benefit cruise operators by improving both affordability and consumer confidence.

Demand has remained resilient despite economic uncertainty.

According to Bank of America data, consumer spending on cruises increased 8.4% year-over-year in May, although that growth rate moderated from the stronger gains recorded in April.

Wall Street analysts remain broadly optimistic about the sector.

Investment firm Stifel recently established price targets of $320 for Royal Caribbean, $35 for Carnival, and $24 for Norwegian Cruise Line, citing strong booking trends, disciplined capacity growth, and continued consumer interest in cruise vacations.

Investors will soon receive another important update.

Carnival is scheduled to report quarterly earnings on June 30, providing one of the first detailed looks at summer demand trends and the potential impact of lower energy costs on profitability.

The cruise rally was part of a broader move across the travel sector.

Airlines including United Airlines, Delta Air Lines, and Southwest Airlines also gained roughly 4% Monday as investors welcomed the prospect of lower jet fuel costs. Major stock indexes moved higher as well, reflecting broader optimism surrounding the decline in energy prices.

Still, market participants remain cautious.

Oil prices have been highly volatile throughout the year, rising and falling sharply with developments in the Iran conflict. Investors recognize that a signed agreement does not necessarily guarantee long-term stability, and any renewed disruption could quickly reverse recent declines in energy prices.

Cruise stocks also remain below levels seen before the conflict began, highlighting the damage higher fuel costs inflicted on the sector earlier this year.

For now, however, the math is working in the industry’s favor.

Lower oil prices mean lower fuel expenses. Lower fuel expenses improve operating margins. And stronger margins heading into the busiest travel season of the year are exactly what cruise investors have been hoping to see after months of rising energy costs and geopolitical uncertainty.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
SpaceX extended its remarkable stock-market debut, climbing sharply in its second day of trading and pushing shares more than 40% above their initial public offering price. The rally has propelled the company into the ranks of America’s most valuable corporations and further expanded founder Elon Musk’s position as the wealthiest person in modern history.

Shares of SpaceX, trading on the Nasdaq under the ticker SPCX, closed near $190 per share, up roughly 20% on the session and well above the company’s $135 IPO price. The stock reached fresh highs during trading as investors continued pouring money into one of the most anticipated public offerings ever.

The surge comes after what was already the largest IPO in history.

SpaceX raised approximately $75 billion in its public debut, later increasing that total to roughly $85.7 billion after underwriters exercised an option to sell additional shares. The offering eclipsed the previous IPO record and immediately turned SpaceX into one of Wall Street’s most closely watched stocks.

At current prices, SpaceX carries a market valuation of approximately $2.5 trillion, placing it among the most valuable publicly traded companies in the United States and alongside giants such as Amazon, Microsoft, Nvidia, Apple, and Alphabet.

That valuation is remarkable considering SpaceX generated approximately $18.7 billion in revenue last year and remains focused on aggressive growth initiatives across multiple businesses.

The stock also received a boost from comments made by Elon Musk over the weekend.

Posting on X, Musk said SpaceX could potentially generate approximately $1 trillion in annual revenue by 2030, a projection that immediately fueled bullish speculation about the company’s long-term prospects.

Investors also reacted positively after Australian mining billionaire Gina Rinehart disclosed that her company, Hancock Prospecting, had acquired a stake reportedly worth more than $1 billion, signaling confidence from a major institutional investor.

The broad market environment helped as well.

Stocks generally moved higher following signs of easing tensions in the Middle East and declining oil prices, creating a more favorable backdrop for growth-oriented investments.

The gains have further expanded Musk’s fortune.

Based on current valuations, Musk’s net worth is estimated at roughly $1.1 trillion to $1.3 trillion, depending on methodology and market pricing. His estimated 42% ownership stake in SpaceX alone is worth hundreds of billions of dollars on paper, while his holdings in Tesla, xAI, and X add substantially to his overall wealth.

The figures make Musk the first person in history to achieve trillionaire status.

Yet despite the excitement, Wall Street remains sharply divided over how much SpaceX should be worth.

Supporters point to the company’s dominance in commercial rocket launches, the rapid growth of its Starlink satellite internet network, and its expanding ambitions in artificial intelligence following the integration of xAI technologies. Bulls argue that SpaceX is building multiple businesses capable of generating enormous long-term revenue streams.

The company also continues investing heavily in Starship, its next-generation launch system, while pursuing plans to dramatically expand Starlink and support future missions beyond Earth orbit.

Some analysts believe those opportunities justify a premium valuation.

Investment bank Oppenheimer maintains an Outperform rating on the stock and previously assigned a price target near levels already reached by the shares.

Skeptics, however, question whether the valuation has moved ahead of business fundamentals.

Critics point out that SpaceX still trades at one of the richest valuations in the market relative to its current revenue base. Some analysts argue investors are pricing in years of future success before those profits have actually materialized.

CFRA Research analyst Keith Snyder has maintained a significantly lower valuation target, arguing the stock’s rise reflects investor enthusiasm more than current financial performance.

Other market observers note that historically, many technology companies that debuted at extremely high revenue multiples struggled to match investor expectations over the following years.

The debate ultimately centers on one question: can SpaceX grow into a valuation measured in trillions of dollars?

Optimists believe the combination of launch services, Starlink, artificial intelligence, defense contracts, and future space-related businesses could support enormous long-term growth.

Skeptics argue that the company must execute flawlessly across several major initiatives simply to justify its current market value.

For now, investors are clearly siding with the bullish view.

Just days after becoming a public company, SpaceX has already joined the highest ranks of corporate America, while Musk’s fortune continues to set records of its own. Whether the company ultimately grows into its valuation remains one of the biggest questions on Wall Street, but the opening chapter of its public-market story has been nothing short of historic.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The public’s appetite for SpaceX stock was so intense that, on at least one major retail trading platform, investors put more money into the newly public rocket company than into Apple, Microsoft, Tesla, Meta and Google-parent Alphabet combined.

Leif Abraham, co-CEO of the investing platform Public, told CNBC on Monday that demand for SpaceX during its first trading sessions was unlike anything the platform had previously experienced. According to Abraham, the combined activity in five of the market’s most heavily traded technology stocks still could not match the buying interest directed at SpaceX.

The numbers behind the debut help explain why.

SpaceX began trading Friday on the Nasdaq under the ticker SPCX, and more than 522 million shares changed hands during its first session, according to Benzinga Pro. That translated into an estimated $33 billion in dollar volume, a level of activity rarely seen even among the largest public companies and unprecedented for a stock making its market debut.

To put that figure into perspective, $33 billion is the type of trading volume that on a normal day is spread across hundreds of publicly traded companies. Instead, it was concentrated into a single stock during its first hours on the market.

Separate market data showed SpaceX accounting for roughly 4% of all retail single-stock trading activity that Friday. Trading in SpaceX reportedly ran at about three-and-a-half times the pace of the second-most-active retail stock, Nvidia, underscoring the extent to which the company captured investor attention.

The historic trading activity followed what was already a record-breaking initial public offering.

SpaceX sold shares at $135 each and raised approximately $75 billion, making it the largest IPO ever recorded. The offering surpassed the previous record set by Alibaba, which raised roughly $22 billion when it went public in 2014.

The stock opened at $150, climbed as high as $176.52 during its first day and finished around $161, representing a gain of roughly 19% above its offering price. The rally pushed SpaceX’s market capitalization above $2.1 trillion, immediately placing it among the most valuable public companies in the United States.

What made the offering especially unusual was its focus on individual investors.

SpaceX reserved a record 20% of its IPO shares for retail buyers, a much larger allocation than is typically seen in major public offerings. Most IPOs reserve the overwhelming majority of shares for institutional investors such as mutual funds, hedge funds and pension managers.

The decision was widely viewed as an effort by CEO Elon Musk to allow everyday investors to participate directly in the company’s public debut.

The response was overwhelming.

Ahead of the IPO, retail investors reportedly submitted more than $100 billion in orders, far exceeding the number of shares available. That imbalance between supply and demand helped fuel the surge in trading activity and contributed to the stock’s strong opening performance.

When demand significantly exceeds available shares, investors who receive allocations often trade aggressively after listing, while others who missed out attempt to buy in the open market. The result can create powerful upward momentum, particularly during a company’s first days of trading.

The enthusiasm carried into the new week.

By Monday, shares had climbed more than 15% from their opening levels as investors continued pouring money into the stock. The gains reinforced SpaceX’s status as one of the most closely watched market debuts in modern history.

Still, the same forces driving the rally also create risk.

Stocks fueled by intense retail enthusiasm can experience significant volatility, and market history shows that investor excitement alone does not determine long-term value. Eventually, even the market’s most popular companies must justify their valuations through financial performance and business execution.

For now, however, SpaceX has accomplished something few companies have ever achieved. On platforms where everyday Americans buy and sell stocks, trading activity in the aerospace giant exceeded the combined activity of some of the largest and most recognizable technology companies in the world.

Whether that enthusiasm proves durable remains to be seen. But the opening chapter of SpaceX’s life as a public company has already secured a place in Wall Street history.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Warnings about artificial intelligence-driven job losses are growing louder, even as labor-market data reveal a significant gap in America’s unemployment safety net.

This month, Anthropic CEO Dario Amodei renewed calls for policymakers to prepare for large-scale workforce disruption from AI. At the same time, data from the Bureau of Labor Statistics show that most unemployed Americans never apply for unemployment benefits.

According to BLS findings, nearly 75% of unemployed workers did not seek unemployment assistance in 2022, a trend labor economists say remains largely unchanged today.

Amodei has repeatedly warned that AI could dramatically reshape white-collar employment, arguing that government action should begin before displacement accelerates.

Forecasts vary considerably.

Amodei has suggested AI could eliminate as much as half of entry-level white-collar jobs within five years. Investor Kai-Fu Lee has similarly predicted that AI could disrupt roughly half of all jobs by 2027.

Mustafa Suleyman, who leads Microsoft’s AI division, has argued that much office work could eventually be automated, while JPMorgan Chase CEO Jamie Dimon has urged policymakers and businesses to begin planning now for significant labor-market changes.

Other analysts are more optimistic.

Research from Morgan Stanley suggests that while AI will reshape many occupations, new jobs are likely to emerge as older ones disappear, limiting long-term unemployment.

Even Amodei and OpenAI CEO Sam Altman have recently moderated some of their earlier predictions.

What is clear is that workforce reductions are already occurring.

Nearly 120,000 technology-sector employees have reportedly been laid off this year as companies pursue AI-driven efficiency initiatives.

Despite those cuts, broader labor-market indicators remain relatively stable. Weekly unemployment claims continue to average roughly 200,000 to 250,000, while the national unemployment rate has edged up to approximately 4.4%, from 4.2% a year earlier.

The larger concern may be what happens if future layoffs accelerate.

According to a 2023 BLS survey, 55% of unemployed workers who did not apply for benefits believed they were ineligible. Reasons included voluntary resignation, termination for cause, insufficient work history, or jobs not covered by unemployment programs.

Others cited confusing rules, administrative barriers, or uncertainty about whether the process was worth pursuing.

Labor experts note that declining union membership may also leave more workers without guidance when navigating benefit systems. U.S. union membership fell to approximately 10% in 2024, the lowest level on record.

The consequences extend beyond individual households.

Unemployment benefits help maintain consumer spending during economic downturns by providing temporary income to displaced workers. When large numbers of unemployed individuals do not receive assistance, the economic impact of layoffs can spread more rapidly through local communities.

Reduced spending affects retailers, landlords, restaurants, and service businesses, increasing pressure throughout the economy.

Amodei has proposed several responses, including stronger worker protections, improved tracking of AI-related job displacement, expanded retraining programs, and the creation of a federal body focused on advanced AI oversight.

Other policy experts have called for simplifying unemployment-benefit systems and improving public awareness of eligibility requirements.

For now, the labor market remains relatively resilient.

But the combination of rising AI-related workforce reductions and low participation in unemployment programs highlights a vulnerability that could become more significant if automation accelerates.

Whether artificial intelligence ultimately creates more jobs than it eliminates remains uncertain.

What is already clear is that millions of workers are not accessing the benefits currently available to them — a challenge policymakers may need to address long before any large-scale AI disruption arrives.

Wall Street — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
JBIZ Markets Desk — June 15, 2026

SpaceX’s first week as a public company has quickly become a test of Wall Street’s appetite for leveraged single-stock trading, as ETF issuers launched products tied to Space Exploration Technologies Corp. under the Nasdaq ticker SPCX within days of its debut. Nasdaq said SpaceX opened trading Friday at $150 a share, 11% above its $135 IPO price, after raising $75 billion in the largest initial public offering in market history. Adena Friedman Chief Executive Officer Nasdaq welcomed the company to the exchange, saying Nasdaq was “incredibly proud to be SpaceX’s partner” as it builds “the physical and digital infrastructure of the future.”

The most prominent U.S. product launch came from Direxion, which introduced the Direxion Daily SpaceX Bull 2X ETF, ticker LOFF, on June 15. Direxion said the fund seeks daily investment results, before fees and expenses, equal to 200% of the daily performance of SpaceX shares. Mo Sparks Chief Product Officer Direxion said, “Few companies have been followed as closely as SpaceX,” adding that LOFF gives active traders a way to express conviction “from the start of public trading.”

Defiance ETFs also positioned itself around SpaceX exposure through its space-themed leveraged strategy. The firm’s SPCL fund page describes the Defiance Pure Space Daily 2X Strategy ETF as providing 2X daily leveraged exposure to companies tied to the space economy, including spacecraft, launch vehicles, satellite communications, in-orbit services and space-enabled data. Sylvia Jablonski Chief Executive Officer Defiance ETFs leads an issuer that has used thematic products to target fast-moving areas of retail and tactical demand, though primary Defiance materials reviewed for this article did not confirm that SPCL had fully converted into a single-stock SPCX fund as of Monday.

Leverage Shares by Themes added U.S.-listed long and short SpaceX products to the lineup, including the 2x Daily leveraged exposure product SPCH and the 2x Short SPCX ETF, according to the issuer’s own fund pages. Themes’ site describes SPCH as offering 2x daily leveraged exposure to SpaceX stock, minus fees and expenses, and warns that leveraged funds carry significant risk. Jose Gonzalez Chief Executive Officer Themes ETFs oversees the platform’s U.S. ETF business, which has expanded its single-stock leveraged lineup around high-profile public companies.

The leveraged rollout also extended beyond the U.S. market. Leverage Shares’ European site lists a 3x Long SpaceX ETP designed to provide three times the daily performance of SpaceX shares, minus fees and expenses, and says the products are intended for professional investors with capital at risk. Final terms dated June 11 state that Leverage Shares Public Limited Company applied for the securities to be admitted to the London Stock Exchange’s Main Market, with an issue price of $10 per ETP security. Oktay Kavrak Chief Executive Officer Leverage Shares heads a platform whose short-and-leveraged ETPs are designed to trade on exchange through local brokerage accounts.

The speed of the product launches reflects the unusual scale of SpaceX’s public-market debut. Nasdaq said the IPO implied a valuation of about $1.77 trillion at the offering price and that SpaceX dual-listed on Nasdaq Texas alongside its primary Nasdaq listing. Gwynne Shotwell President and Chief Operating Officer SpaceX said at the bell-ringing ceremony, “Today, we make history again,” while noting the company had reached about 22,000 employees after more than two decades as a private company.

The business case for investor demand rests on SpaceX’s combined exposure to launch services, Starlink satellite broadband and artificial intelligence infrastructure. Nasdaq cited SpaceX’s S-1 filing in saying the company generated $18.67 billion in revenue last year, driven heavily by Starlink’s recurring subscription model. Elon Musk Chief Executive Officer SpaceX said at Starbase that SpaceX began as “a little company” in a warehouse in El Segundo and was now going public through the largest IPO ever, adding that the company’s mission is “to take the fiction out of science fiction.”

The new ETFs are aimed at traders rather than long-term passive investors. Direxion said leveraged and inverse ETFs are intended only for investors with an in-depth understanding of leveraged investment results who plan to actively monitor and manage positions. The issuer also warned that instruments needed to obtain 2X exposure to SpaceX, including swaps and options, may be limited, illiquid, costly or unavailable shortly after the IPO or during periods of volatility. Mo Sparks Chief Product Officer Direxion framed LOFF as a tactical product, and Direxion’s own risk language says investors could lose the full principal value in a single day if SpaceX shares fall more than 50%.

For investors, the immediate question is whether SpaceX can move from a historic IPO to a durable public-market track record while ETF issuers continue building products around its volatility. Adena Friedman Chief Executive Officer Nasdaq called SpaceX part of the “innovation economy,” but the first wave of leveraged funds shows that the company’s public listing is already producing a second market in high-risk trading tools. The next phase will depend on SpaceX’s early disclosures as a public company, the depth of its trading liquidity and whether demand for leveraged SPCX exposure remains strong after the first week of post-IPO attention.

JBizNews Desk

NEW YORK — Financial firms are increasingly turning to sophisticated risk models traditionally used to forecast hurricanes and earthquakes in an effort to predict wars, coups, and geopolitical crises before they erupt.

In late May, risk-analytics company Verisk introduced a new tool known as the Predictive War Index, which uses machine learning to estimate the likelihood of armed conflict occurring within individual countries over the following 12 months.

According to Sam Haynes, head of data and analytics at Verisk Maplecroft, clients are demanding tools that look forward rather than merely explaining historical events.

“They want a predictive forward-looking view,” Haynes said.

The model was trained using political, economic, and social data spanning 1995 through 2022, allowing it to identify patterns associated with conflict risk.

Although the model does not incorporate the current Iran conflict, Verisk said testing suggested it would have assigned a 66% probability of war in Iran roughly six weeks before hostilities began.

The company also launched a companion product called the Geopolitical Relations Index, designed to measure tensions between countries by evaluating factors such as military history, geographic proximity, political systems, and diplomatic relationships.

The effort is part of a broader expansion of political-risk modeling.

Verisk has previously developed forecasting tools for civil unrest, strikes, riots, and government instability. According to the company, a separate model introduced in 2023 successfully anticipated six of the last seven government collapses, including political upheavals in Syria and Venezuela.

The growing interest reflects the financial impact of geopolitical events.

Wars, trade disruptions, sanctions, and political instability have increasingly influenced commodity markets, shipping routes, energy prices, and global investment flows.

Major financial institutions have acknowledged that traditional risk-management frameworks may no longer be sufficient.

Citigroup has warned against relying too heavily on backward-looking models, while Morgan Stanley has argued that firms must rethink how they evaluate geopolitical threats.

The concern is that rare but severe events can erase years of gains in a matter of days.

For banks, insurers, and asset managers, reliable forecasting tools could influence everything from insurance pricing and catastrophe bonds to investment decisions and regulatory stress tests.

The goal is to assign measurable probabilities to risks that were once viewed as largely unpredictable.

There are limitations.

Models trained primarily on historical data may struggle to capture rapidly changing political realities. Human decisions, especially those involving war and diplomacy, remain far more complex than natural disasters.

Even Verisk emphasizes that its products are designed to supplement judgment rather than replace it.

Nevertheless, demand continues to grow.

As geopolitical tensions increasingly become a central factor in financial markets, institutions are investing heavily in tools that may provide earlier warning of emerging threats.

The adoption of disaster-modeling techniques for geopolitical forecasting underscores a broader trend on Wall Street: wars and political shocks are increasingly being treated as risks that can be quantified, priced, and managed.

JBizNews will continue monitoring advances in risk modeling and their broader effects on financial markets and global stability.

Wall Street — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON, D.C. — June 15, 2026 — The U.S. Department of Commerce on Friday ordered artificial-intelligence company Anthropic to restrict access to its two most powerful systems, Fable 5 and Mythos 5, significantly limiting international use of the models and marking one of the most aggressive federal interventions yet in the rapidly evolving artificial intelligence industry.

According to Anthropic, the export-control directive was delivered by letter at 5:21 p.m. ET Friday and originated from Commerce Secretary Howard Lutnick and the department’s Bureau of Industry and Security. The action followed warnings from Amazon Chief Executive Officer Andy Jassy, who reportedly alerted senior administration officials that internal testing had revealed potential security vulnerabilities in the models.

The dispute began after Amazon researchers conducted a series of tests designed to probe the systems’ safeguards. According to accounts of the matter, the researchers were able to use carefully crafted prompts to bypass certain protections and generate information that could potentially assist in cyberattacks — material the systems were designed to block.

Jassy reportedly escalated those findings to senior officials in Washington, setting off a series of discussions inside the administration regarding whether the models presented a national-security concern.

Government researchers subsequently conducted their own evaluations of the systems. Officials then reportedly presented Anthropic with a choice: address the identified vulnerabilities immediately or face restrictions on deployment of the affected models.

According to a senior administration official, President Donald Trump ultimately approved the action while expressing concern that excessive regulation could slow American innovation in artificial intelligence.

The resulting order was unusually broad.

Rather than limiting access only overseas, the directive reportedly prohibited use of Fable 5 and Mythos 5 by foreign nationals regardless of location, including individuals located inside the United States. Anthropic stated that it did not have a practical method to selectively block only foreign users and therefore suspended access to the two models more broadly while complying with the order.

The company said access to its other AI products remains available.

Anthropic has publicly complied with the directive while strongly disputing the government’s conclusions.

The company characterized the issue as a narrow jailbreak scenario and argued that the vulnerabilities identified by Amazon were limited in scope and already understood within the industry. Anthropic warned that if the same standard were applied universally, it could substantially hinder development and deployment of advanced AI systems across the sector.

The company further noted that it had implemented extensive safeguards designed specifically to prevent cybersecurity misuse and argued that no AI system is entirely immune from determined attempts to circumvent protections.

The dispute places Amazon in an unusual position.

The technology giant is both one of Anthropic’s largest investors and a major provider of cloud-computing infrastructure used to train and operate Anthropic’s models. By bringing the concerns to federal officials, Amazon effectively placed national-security considerations ahead of a business relationship involving billions of dollars in investment and infrastructure commitments.

For Anthropic, the impact was immediate.

The company said two of its flagship AI systems, which collectively reach hundreds of millions of users worldwide, were effectively removed from broad international availability pending further review.

The broader significance may extend far beyond a single company.

The United States has previously restricted exports of advanced semiconductors and computing hardware used to train artificial intelligence systems. However, industry observers note that this appears to be among the first major instances in which federal authorities directly restricted access to an AI model itself rather than the hardware powering it.

The action could establish a new precedent for government oversight of advanced AI systems and may signal the emergence of a de facto approval framework under which regulators determine when certain models can be deployed internationally.

Such a framework would represent a significant shift from the administration’s broader approach toward artificial intelligence, which has generally emphasized voluntary cooperation and innovation rather than formal licensing requirements.

Investors are closely watching the implications for both AI developers and the companies supporting them.

Because Anthropic remains privately held, the immediate public-market impact is most visible through Amazon (NASDAQ: AMZN), which closed Friday at $238.55, down 1.23%. The decline occurred before the directive was reportedly issued and was largely attributed to broader concerns surrounding artificial-intelligence spending and regulation rather than the specific action against Anthropic.

Administration officials have indicated the restrictions may be temporary and could be lifted if Anthropic satisfies federal security concerns following additional review.

For now, the episode raises a fundamental question facing the artificial-intelligence industry: who ultimately decides when a powerful AI system is safe enough to remain widely available — the company that develops it, or the government that has the authority to restrict access.

Anthropic maintains that the government’s action is based on a misunderstanding of the risks involved and says it is actively working with federal officials in hopes of restoring broader access to the models.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Bitcoin climbed back above $66,000 on Monday as investors returned to riskier assets following the weekend agreement to end the war between the United States and Iran. The rebound provided a measure of relief for a cryptocurrency that has spent much of 2026 under pressure after suffering one of its steepest declines in years.

The rally followed President Donald Trump’s announcement Sunday that the United States and Iran had reached an agreement to end hostilities. The news triggered a broad market response, lifting stocks while pushing oil prices sharply lower. Bitcoin joined the risk-on rally as traders moved back into speculative assets.

Even after Monday’s gain, Bitcoin remains far below its record levels. The cryptocurrency reached an all-time high near $126,000 in October 2025 before entering a prolonged decline. By early June, Bitcoin had fallen to roughly $60,000, representing a drop of more than 50% from its peak and marking its deepest drawdown since the crypto downturn of 2022.

Several factors contributed to the decline. Investors withdrew more than $5 billion from Bitcoin exchange-traded funds since mid-May, the longest streak of ETF outflows on record. At the same time, inflation climbed to a three-year high while the Federal Reserve maintained a restrictive interest-rate stance, reducing investor appetite for speculative investments.

Sentiment also weakened when Michael Saylor’s Strategy, one of Bitcoin’s most prominent corporate supporters, sold a portion of its holdings for the first time since 2022, raising concerns among traders who had viewed the company as a permanent buyer.

Wall Street remains sharply divided over Bitcoin’s future. Standard Chartered analyst Geoffrey Kendrick has steadily lowered his forecast, reducing his year-end 2026 target from $300,000 to roughly $100,000. Kendrick cited weaker corporate demand and slower ETF inflows.

Others remain optimistic. Bernstein continues to project Bitcoin reaching $150,000 by late 2026. Citigroup analysts have outlined a base-case target near $143,000, while JPMorgan’s fair-value models suggest approximately $170,000. Among major forecasters, Fundstrat’s Tom Lee remains the most bullish, maintaining a target of $250,000.

Despite those forecasts, short-term sentiment remains cautious. Prediction markets continue to assign meaningful odds that Bitcoin could fall below $60,000 again before the end of the year.

Historically, Bitcoin has followed a cyclical pattern tied to its halving events, which reduce the rate at which new coins are created. Previous cycles have often featured sharp rallies followed by extended declines before eventually recovering. While the current downturn has been severe, it remains less dramatic than the collapse of 2022, when Bitcoin lost more than 75% of its value.

For everyday investors, Bitcoin increasingly behaves less like the independent “digital gold” once envisioned by supporters and more like a high-risk technology asset. Its price movements have become increasingly correlated with stock markets, interest-rate expectations and broader investor sentiment.

The rapid growth of Bitcoin ETFs has also tied the cryptocurrency more closely to traditional retirement and brokerage accounts, meaning its gains and losses are now felt by a much broader group of investors than during previous cycles.

Whether Monday’s move marks the beginning of a sustained recovery remains uncertain. Bitcoin has staged several strong rebounds during this downturn only to retreat again. The easing of geopolitical tensions removed one source of market anxiety, but inflation remains elevated and the Federal Reserve continues to signal patience on rate cuts.

For now, Bitcoin is moving higher again. Whether it can sustain that momentum — and eventually challenge its previous record highs — remains one of the most closely watched questions in financial markets.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Wall Street kicked off a holiday-shortened week with a broad rally on Monday after President Donald Trump announced late Sunday on Truth Social that a deal to end the U.S.-Iran war was “complete,” clearing the way to reopen the Strait of Hormuz and sending oil prices sharply lower.

Ships of the World, start your engines. Let the oil flow!” Trump wrote in his post.

Pakistan Prime Minister Shehbaz Sharif said a formal signing ceremony is scheduled for Friday in Switzerland, adding another sign that markets believe the conflict is winding down.

The agreement removed the single biggest weight on stocks over the past two months. Since the war began in late February, fears that a closure of the Strait of Hormuz would choke off global oil supplies helped push crude above $90 per barrel and kept inflation concerns front and center. With that threat easing, investors returned to many of the stocks they had abandoned during the conflict.

The Dow Jones Industrial Average gained 1.20%, or approximately 614 points, ending near 51,817.

The S&P 500 rose 1.49%, gaining approximately 111 points to close near 7,542, up from Friday’s finish of 7,431.46.

The Nasdaq Composite led the major indexes higher, climbing 2.38%, or roughly 616 points, to close near 26,505.

The Russell 2000 added 0.79%, finishing around 2,967.

Despite the impressive headline numbers, the rally was somewhat concentrated. By midafternoon, only slightly more than half of listed stocks were advancing, with much of the gains driven by technology shares.

Market Movers

Away from geopolitics, the day’s biggest corporate story was a major media transaction.

Fox Corporation announced it would acquire streaming-device maker Roku for $160 per share in a cash-and-stock transaction valued at approximately $22 billion.

The announcement sent Roku soaring about 20% to approximately $143.66, making it one of the strongest performers of the day. Despite the jump, Roku still traded below the agreed acquisition price.

Fox investors reacted far differently.

Fox Class A shares plunged 17.2%, while Fox Class B shares fell 15.7%, making the company the worst performer in the S&P 500 as investors questioned the acquisition cost.

The announcement prompted a series of analyst downgrades.

Jefferies analyst James Heaney downgraded Roku to Hold from Buy while raising his price target to $160 to reflect the acquisition price.

Baird also downgraded Roku to Neutral with a $160 target, while William Blair removed the company from its conviction list, citing surprise at the timing given Roku’s recent growth trajectory.

Among technology stocks, Intel gained 6.51% to close at approximately $124.57.

Nvidia edged up 0.16% to roughly $205.19.

Super Micro Computer declined 4.72% to $30.46.

SpaceX Draws More Investor Attention

Fresh off the largest IPO in history, SpaceX continued attracting investor interest after Australian mining billionaire Gina Rinehart disclosed that her company, Hancock Prospecting, had accumulated a stake worth more than $1 billion.

Shares of SpaceX (SPCX), which surged approximately 19% during Friday’s market debut, gained another 5% Monday.

Analysts remain divided.

CFRA Research analyst Keith Snyder maintained a Sell rating with a $115 price target, significantly below current levels.

Meanwhile, Oppenheimer continues to rate the stock Outperform with a $190 target.

Oil Falls, Volatility Drops

The biggest move of the day occurred in commodities.

West Texas Intermediate crude oil fell roughly 5% to around $81 per barrel.

Brent crude, the global benchmark, dropped to approximately $84 per barrel.

Traders are betting that reopening the Strait of Hormuz will eventually restore normal shipping patterns, although analysts caution that clearing shipping backlogs may take months.

Vice President JD Vance told CNBC on Monday that the administration expects the waterway to remain open on a toll-free basis over the long term.

Precious metals moved higher.

Gold gained approximately 1.6% to around $4,309 per ounce.

Silver surged more than 4%.

Meanwhile, the Cboe Volatility Index (VIX) — often referred to as Wall Street’s fear gauge — dropped approximately 9% to 17.68, reflecting reduced geopolitical anxiety.

Bitcoin rose roughly 1.5% to near $65,400.

Global Markets Rally

The optimism extended well beyond the United States.

Japan’s Nikkei 225 surged 5% to a record closing high of 69,317.50.

South Korea’s Kospi gained 5.2%.

European markets also advanced as investors welcomed the prospect of lower energy costs and reduced geopolitical risk.

Looking Ahead

Markets will be closed Friday for the Juneteenth holiday, creating a shortened trading week.

Investors now turn their attention to the Federal Reserve, where newly installed Chair Kevin Warsh will preside over his first policy meeting.

According to the CME FedWatch Tool, traders are assigning better than a 98% probability that policymakers leave interest rates unchanged.

With oil prices falling, volatility declining and one of the market’s largest geopolitical risks apparently easing, investors will be watching closely to see whether Monday’s rally marks the beginning of a broader advance or simply a relief bounce after months of uncertainty.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The world’s biggest sporting event is underway in the United States, but many businesses that expected an immediate economic windfall are still waiting.

Hotels, restaurants, airlines, and tourism operators across several host cities entered the 2026 FIFA World Cup expecting a surge of international visitors. While demand has increased, early results suggest the benefits are arriving unevenly.

“Demand is real and positive, but it’s not evenly distributed across host cities,” said Jay Wardle, president of travel-data company Sojern.

The expectation was straightforward.

More teams, more matches, and more fans would mean more spending.

FIFA has projected the tournament could contribute approximately $17.2 billion to U.S. GDP, while a study by Tourism Economics estimated international visitors would stay roughly 12 days, attend multiple matches, and spend more than $400 per day.

The reality has been more complicated.

Deutsche Bank estimates that even if the tournament attracts approximately 1.2 million international visitors, the impact on U.S. GDP would amount to only about 0.05% — meaningful but relatively small within the context of the overall American economy.

Travel data reveals substantial variation between host cities.

According to Sojern, flight bookings have increased approximately 13% in Houston, 10% in Dallas-Fort Worth, and around 8% in both Miami and New York.

Other cities have not experienced the same gains.

Seattle is reportedly tracking below last year’s pace, while several host locations outside the United States have also seen softer demand than anticipated.

One challenge has been affordability.

The expanded World Cup format created more matches and significantly more available seats. At the same time, high ticket prices, expensive travel costs, and visa-related hurdles have discouraged some international visitors.

Hotels have already adjusted expectations.

Several major properties have reduced room rates after the anticipated surge in foreign visitors failed to fully materialize.

Marriott International CEO Anthony Capuano recently indicated that the company expects only a modest increase in U.S. hotel revenue from the tournament.

Meanwhile, short-term rental operators appear to be benefiting.

Airbnb has stated that it expects the World Cup to become its largest event-driven demand period ever, surpassing even the 2024 Paris Olympics.

The spending is arriving.

It is simply flowing through different channels than many traditional hospitality operators expected.

The New York–New Jersey region remains one of the most closely watched markets.

Local organizers project approximately $3.3 billion in economic impact, with New Jersey officials estimating roughly $2 billion of that total could remain within the state.

Whether those projections ultimately prove accurate remains an open question.

For now, the verdict is simple: the World Cup’s economic impact is real, but the early benefits have been uneven and smaller than many businesses anticipated.

With several weeks of matches remaining, there is still time for demand to strengthen.

The tournament may yet deliver on its economic promise.

But for many businesses, the expected flood of spending has not arrived — at least not yet.

JBizNews Desk — Sports Business

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
MIAMI — Lennar Corp., one of the nation’s largest homebuilders, has lowered its outlook for home deliveries in 2026, citing persistent affordability challenges and elevated mortgage rates that continue to weigh on housing demand.

In its fiscal second-quarter earnings report released June 11, Lennar said it now expects to deliver approximately 82,000 to 83,000 homes this year, below its previous forecast.

Executive Chairman and Chief Executive Officer Stuart Miller said the company continues to face “the same stubborn headwinds that have challenged the housing market,” particularly high borrowing costs and affordability concerns that are keeping many potential buyers on the sidelines.

The company delivered 20,519 homes during the quarter, near the midpoint of its guidance range, while new orders fell 4% year-over-year to 21,749 homes.

Revenue declined to $7.94 billion from $8.38 billion a year earlier, while net income fell to $305 million, or $1.24 per share, compared with $477 million, or $1.81 per share, during the same period last year.

Even excluding certain investment-related losses, adjusted earnings came in at $1.31 per share, below the $1.90 per share reported a year ago.

The largest pressure point was profitability.

Lennar’s homebuilding gross margin declined to 15.6%, down from 17.8% a year earlier. The company attributed the decline primarily to lower revenue per square foot and higher land costs, partially offset by lower construction expenses.

Operating costs also increased as a percentage of revenue.

In practical terms, Lennar is receiving less revenue per home while paying more for the land beneath those homes, creating additional pressure on earnings.

Management pointed to broader economic conditions as the primary challenge.

Mortgage rates remain elevated, making monthly payments difficult for many buyers. Lennar also cited inflation concerns, higher energy costs, and geopolitical uncertainty as factors affecting consumer confidence.

The company said it expects the Federal Reserve to maintain relatively high interest rates for the foreseeable future and is planning its business accordingly rather than assuming a rapid decline in borrowing costs.

As a result, Lennar described its reduced annual forecast as a prudent adjustment to current market conditions.

For the current quarter, the company expects to deliver between 20,500 and 21,500 homes at an average sales price of approximately $375,000 to $380,000. Management also expects gross margins to improve modestly to around 16%.

The company continues to rely on incentives such as mortgage-rate buydowns and pricing adjustments to attract buyers, although incentive levels eased slightly during the quarter and represented roughly 13% of home deliveries.

Lennar is also shifting toward smaller, more affordable homes that can be built faster and sold at lower price points. The company’s broader strategy includes becoming more “asset-light,” reducing the amount of capital tied up in land while increasing efficiency through technology and streamlined construction processes.

Financially, Lennar remains in a strong position.

The company repurchased approximately 5 million shares during the quarter for $447 million and ended the period with approximately $1.8 billion in cash within its homebuilding operations.

Lennar also paid off a $400 million debt maturity that came due on June 1 and reported no significant debt maturities until 2027.

Management did note concerns about legislative proposals in some states that would restrict institutional investors from purchasing single-family homes, arguing that such measures could reduce housing supply over time.

Wall Street reacted negatively to the earnings report.

Lennar shares fell roughly 4% following the announcement, while analysts at BofA Securities maintained a “sell” rating and reduced their price target to $84 from $88.

Because Lennar is among the first major homebuilders to report earnings each quarter, investors often view its results as a barometer for the broader housing industry.

This quarter’s report suggests that affordability remains the central challenge facing the market.

Builders continue to offer incentives to move inventory, but elevated mortgage rates and high home prices continue to limit demand.

Until borrowing costs decline meaningfully or household incomes rise enough to offset higher housing costs, many prospective buyers are likely to remain sidelined.

Lennar’s lowered outlook is the latest sign that America’s housing affordability crunch remains far from resolved.

Real Estate — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
General Motors (NYSE: GM) is making a major bet that the next growth opportunity for batteries may not be inside vehicles at all.

The automaker announced that it is developing sodium-ion battery technology designed for energy storage systems serving artificial intelligence data centers and other large-scale power applications.

The work is being conducted at GM’s Wallace Battery Cell Innovation Center in Warren, Michigan.

The move reflects a rapidly changing energy landscape.

As artificial intelligence infrastructure expands, data centers require enormous amounts of reliable electricity and increasingly need battery systems capable of storing and delivering power efficiently.

At the same time, automakers have invested billions of dollars building battery manufacturing capacity for electric vehicles, only to discover that EV demand has grown more slowly than many forecasts predicted.

GM sees an opportunity to bridge those two trends.

“Sodium is one of the most abundant elements on Earth,” said Kurt Kelty, GM’s Vice President of Battery and Sustainability.

Unlike lithium-ion batteries used in vehicles, sodium-ion batteries rely on lower-cost and more widely available materials. While they typically offer lower energy density, they can be highly attractive for stationary applications where size and weight are less important.

That makes them particularly well suited for energy storage supporting AI data centers.

GM’s strategy includes a partnership with Peak Energy, a startup focused on sodium-ion battery systems. GM Ventures is investing in the company while GM retains exclusive manufacturing rights for the battery cells.

Industry analysts note that no major Western automaker has previously committed to manufacturing sodium-ion batteries at scale.

GM is also expanding existing battery operations.

Its Ultium Cells joint venture with LG Energy Solution recently committed $70 million toward producing lower-cost lithium iron phosphate batteries at its Spring Hill, Tennessee facility.

The project has already helped bring back approximately 700 workers who were laid off earlier this year as EV demand softened.

The company is additionally exploring ways to repurpose retired EV batteries.

GM and Redwood Materials, founded by former Tesla executive J.B. Straubel, are deploying approximately 10,000 used GM battery packs into energy infrastructure projects, including AI-related facilities.

The broader market opportunity is enormous.

Residential electricity prices have risen nearly 48% since January 2020, according to government data, while analysts expect power demand from AI infrastructure to continue increasing sharply.

Morgan Stanley estimates that major technology companies could spend more than $1 trillion on energy infrastructure during 2025 and 2026.

GM is not alone.

Ford Motor Co. (NYSE: F) recently launched its own stationary energy-storage division and announced significant investments in commercial battery systems.

For both automakers, energy storage offers a hedge against a slower-than-expected transition to electric vehicles.

GM’s message is clear.

Continue building EVs.

Continue investing in batteries.

But find new customers beyond the automotive market.

The strategy transforms what once looked like excess battery capacity into a potentially valuable new business line tied directly to one of the fastest-growing industries in the world.

As AI data centers consume increasing amounts of electricity, the next major customer for Detroit’s battery expertise may not be drivers.

It may be the power grid itself.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
For the first time in a generation, women are sliding backward in the climb to the top of corporate America. New research from Grant Thornton finds women now hold 31% of senior leadership positions at U.S. companies, down from 34% a year earlier and 35% in 2024. After two decades of gradual progress, the upward trend has stalled — and in some cases, reversed.

The decline is most visible in executive suites, but the problem begins much earlier. McKinsey & Co. found in its annual Women in the Workplace report that women occupy only 29% of C-suite positions, unchanged from the previous year. Women remain underrepresented at every level of corporate leadership for the eleventh consecutive year.

The numbers tell the story. Women account for roughly 49% of entry-level employees, yet their representation declines with every promotion level. By the time companies reach senior executive ranks, fewer than one-third of leadership positions are held by women.

Researchers point to what they call the “broken rung” — the first promotion from an entry-level position into management. That initial step appears to be where many women begin falling behind. According to McKinsey, for every 100 men promoted into management, only about 80 to 90 women receive the same opportunity. The disparity is even larger for women of color. Some studies found that only about 60 Black women were promoted for every 100 men advancing into management roles.

Because leadership pipelines are built over years, missing that first promotion has long-term consequences. Fewer women in management today means fewer candidates available for director, vice president, and executive positions tomorrow.

What makes the trend notable is that it is not being driven by a lack of ambition. Surveys consistently show women remain highly committed to their careers. About 65% of women say their work is an important part of their identity, slightly higher than the percentage of men who say the same.

Researchers increasingly argue that the issue is not an ambition gap but a support gap.

One major change has been the disappearance of leadership-development programs that once helped identify and prepare future executives. Jane Edison Stevenson, Global Vice Chair at Korn Ferry, says many companies have scaled back or eliminated formal management-training tracks that previously helped promising employees gain the operational experience required for senior leadership positions.

Those programs were often expensive and required years to produce results. As employee turnover increased and workers became more likely to change employers, many companies concluded the investment was no longer worthwhile.

The loss of sponsorship may be equally important. Sponsorship differs from mentorship because sponsors actively advocate for promotions and career opportunities. Research shows sponsorship is among the strongest predictors of advancement.

Yet only about 31% of entry-level women report having a sponsor, compared with 45% of men. Without influential advocates pushing for advancement, women may be less likely to receive the assignments and visibility needed for promotion.

Some experts also point to a growing sense of complacency. As women became more visible in leadership roles over the past decade, companies may have assumed progress would continue automatically.

Edison Stevenson warns that advancement does not happen on its own. If organizations are not deliberate about developing leadership pipelines, gains can quickly erode.

The changing political environment may also be playing a role. Several corporations have reduced, renamed, or scaled back diversity, equity, and inclusion (DEI) initiatives amid increased scrutiny and legal challenges. Heather Spilsbury, CEO of 50/50 Women on Boards, says that trend likely contributed to some of the recent decline.

Still, researchers caution against attributing the entire slowdown to DEI debates. Women’s representation in executive roles began slipping in 2023, before many of the latest corporate policy changes occurred. Analysts have struggled to identify a single explanation for the reversal.

For businesses, the issue extends beyond workplace equity. Grant Thornton found companies with more balanced leadership teams were more likely to report stronger revenue growth and faster workforce expansion. Investors, employees, and job candidates increasingly examine leadership diversity when evaluating organizations.

There are also concerns about burnout. McKinsey found that approximately six in ten senior women report experiencing frequent burnout, the highest level recorded in the study’s history. Persistent workplace pressures combined with limited advancement opportunities may be contributing to retention challenges.

There are still signs of progress. The Fortune 500 currently includes 52 women CEOs, and that figure is expected to rise to 54 this year, approaching the record 55 women chief executives reached in mid-2025.

But researchers continue to return to the same conclusion: the future of women in corporate leadership may depend less on the executive suite and more on that first promotion into management. Unless companies repair the broken rung and rebuild sponsorship and development pathways, the gains of the past decade could continue slipping away one step at a time.

JBizNews Desk
Workplace & Leadership Bureau

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — A leading Senate Democrat says the Trump administration’s changes to federal contracting are making it harder for small businesses to compete for government work.

On June 12, Sen. Ed Markey (D-Mass.), the ranking Democrat on the Senate Small Business and Entrepreneurship Committee, released a report titled “Trump’s Contracting Catastrophe: Turning Main Street into Pain Street.” The report argues that federal contracting policies implemented since early 2025 have significantly reduced opportunities for small businesses.

The administration disputes that characterization, arguing that its reforms are intended to reduce waste, improve accountability, and make federal procurement more efficient.

According to Markey’s report, federal agencies have reduced spending with small-business contractors by more than $47 billion since January 2025, representing a 19% decline compared with the previous 16-month period. The report also claims that more than 6,500 small businesses have stopped working with the federal government during the past 15 months.

Markey argues that the changes are disproportionately affecting the very businesses federal contracting programs were designed to support.

The report found declines across multiple categories of small-business participation, including small disadvantaged businesses, women-owned firms, HUBZone companies, veteran-owned businesses, and service-disabled veteran-owned businesses.

“The federal government should be a partner for Main Street, not a piggy bank for the wealthy and well-connected,” Markey said in releasing the report.

The committee attributes the decline to several administration actions, including changes to contracting goals, delays in certification programs that allow firms to qualify for set-aside contracts, contract cancellations, and increased scrutiny of small-business programs.

The Small Business Administration has also tightened oversight of economically disadvantaged business programs, a move administration officials describe as necessary to prevent abuse and ensure compliance with eligibility requirements.

The impact, according to the report, is being felt in communities across the country.

In Massachusetts, Markey’s home state, small-business contracting reportedly declined by 31% since the start of 2025. For many small firms, federal contracts provide a stable source of revenue, support hiring, and serve as a valuable credential when competing for private-sector work.

The White House sees the situation differently.

In an executive order issued on April 30, the administration argued that federal procurement had become burdened by excessive costs, administrative inefficiencies, and weak performance incentives. The order directed agencies to expand the use of fixed-price contracts and strengthen accountability measures.

Another executive order issued in March restricted certain diversity-related contracting practices, reshaping programs that many Democrats say are critical to expanding opportunities for underrepresented businesses.

Republicans on the Senate committee, led by Chair Joni Ernst (R-Iowa), have largely supported the administration’s efforts, describing them as part of a broader push to reduce waste, fraud, and inefficiency in government spending.

The data itself remains the subject of debate.

According to the Government Accountability Office, overall federal contracting increased in fiscal year 2025, rising to approximately $793 billion from $755 billion the previous year.

GAO data show small-business contracting declining by approximately $3.7 billion, to $172.6 billion, a much smaller decrease than the one cited in Markey’s report.

The discrepancy appears to stem largely from differences in measurement periods. Markey’s committee focused on the most recent 15 months, while GAO figures cover the broader federal fiscal year.

Adding to the uncertainty, the SBA has not yet released its official 2025 Small Business Procurement Scorecard. The most recent scorecard, covering fiscal year 2024, showed a record $183.5 billion in federal contracts awarded to small businesses.

Despite disagreements over the numbers, both sides acknowledge that many small businesses face growing economic pressures from inflation, higher operating costs, and broader market uncertainty.

Supporters of small-business contracting programs warn that if fewer small firms participate in federal procurement, agencies may become increasingly dependent on a smaller number of large contractors.

That possibility has become a central concern in the debate.

For now, the dispute remains unresolved, with both sides awaiting the SBA’s official 2025 data. Until then, thousands of small businesses that rely on government contracts will continue operating in a procurement environment that is undergoing significant change.

Washington — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
California’s wealthiest residents are racing to outmaneuver a proposed tax that would take a one-time slice of their fortunes, and the planning is reshaping where they live, how they hold their assets, and which lawyers they keep on retainer, the Wall Street Journal reported this week.

The measure is the 2026 California Billionaire Tax Act, headed for the state’s November 3, 2026 ballot after the union behind it, SEIU-United Healthcare Workers West, submitted roughly 1.55 million signatures on April 27. It would impose a one-time 5% tax on the net worth of any Californian worth $1 billion or more, with the money — an estimated $100 billion — aimed largely at filling holes left by federal cuts to health-care funding.

The detail driving all the maneuvering is the timing. The tax keys off whether someone was a California resident on January 1, 2026, while their net worth is measured on December 31, 2026. In plain terms, you had to already be gone before this year began to cleanly escape it. Moving in the middle of 2026 doesn’t change the residency call. That design was deliberate — the authors built it as a one-time levy with a backward-looking snapshot precisely to make fleeing harder.

A wave of billionaires tried to beat the clock anyway. Reported departures before the deadline include Alphabet co-founders Larry Page and Sergey Brin, Meta chief Mark Zuckerberg, venture investors Peter Thiel and David Sacks, and former Uber CEO Travis Kalanick, with exits aimed at no-income-tax states like Texas, Florida, and Nevada. By one analysis tied to the California Tax Foundation, the three richest names alone account for a large share of the state’s billionaire wealth.

Here’s the creative part. Many of those who left in late 2025 or are leaving now are betting on the courts. Tax lawyers argue the measure’s residency rule is constitutionally shaky because it tries to tax people based on where they lived on a single past date, which may collide with the right to travel between states established in cases like Saenz v. Roe. If a court strikes that provision, a 2026 departure could still spare them some or all of the bill. So “leaving” isn’t just relocation — it’s a wager that the snapshot won’t survive a legal challenge.

For those staying put, the planning shifts to how assets are held. The tax covers worldwide holdings — businesses, stocks, bonds, art, collectibles, intellectual property — but carves out exceptions that advisers are working hard to navigate. Real estate owned directly or through a revocable trust is excluded, yet property held inside an LLC, which is how many wealthy families structure it, may not qualify, so some are restructuring ownership. Tangible items like a valuable painting can be excluded if kept outside California for at least 270 days in 2026 — unless the move was clearly staged to dodge the tax. There are also smaller carve-outs: up to $5 million for miscellaneous assets and up to $10 million in Roth-style retirement money. Estate planners are also reworking trusts, since the measure contains complex rules for when a trust’s assets count as a beneficiary’s own.

Underneath it all is the loophole the tax is really chasing, sometimes called “buy, borrow, die.” Because the United States taxes investment gains only when assets are sold, a founder sitting on appreciated stock can borrow against it to fund a lavish lifestyle and never trigger income tax. A wealth tax sidesteps that by taxing the holdings themselves rather than waiting for a sale.

Supporters say the avoidance fears are overblown. The union and allied analysts argue the comprehensive base and one-time structure leave little room to hide, and that splashy departure announcements are partly theater meant to scare voters. A working paper from the National Bureau of Economic Research found California billionaires paid about $4.1 billion in income tax last year — roughly 0.2% of their combined net worth — and calculated that even if every billionaire vanished overnight, it would take 25 years for the lost income-tax revenue to equal what the wealth tax would raise in five.

Critics, including the Tax Foundation and conservative analysts, counter that the measure invites years of litigation and accelerates an exodus of capital already underway. Reaction among the wealthy is split: LinkedIn co-founder Reid Hoffman called the idea “horrendous” for innovation, while Nvidia chief Jensen Huang said he is “perfectly fine” with it.

The bigger business story is the cottage industry it has created. Wealth managers, trust attorneys, and residency-audit specialists are booked solid, and the fight will likely outlast the November vote — both sides expect a court battle no matter the result. For other states eyeing their own billionaires, California is about to become the test case for whether a wealth tax can actually be collected, or just chased.

JBizNews Desk — California

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
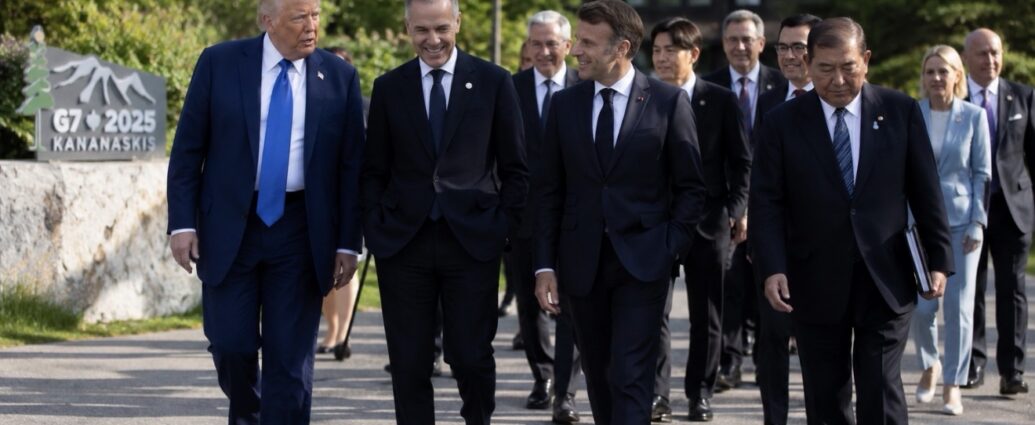
NEW YORK — America’s wealthiest investors are holding unusually large amounts of cash while quietly shifting billions of dollars into alternative assets, gold, infrastructure, and global opportunities.

According to UBS’s Global Family Office Report 2026, published on May 28, many of the world’s richest families are preparing for a prolonged period of economic and geopolitical uncertainty rather than betting on a smooth continuation of recent market gains.

One of the clearest examples is Warren Buffett.

Before stepping down as chief executive of Berkshire Hathaway at the end of last year, Buffett accumulated a record $381.7 billion in cash and short-term investments, choosing not to aggressively deploy capital despite a strong stock market.

He is far from alone.

A recent Goldman Sachs survey found that wealthy households with at least $1 million in investable assets keep roughly 20% of their net worth in cash or cash-equivalent investments, including Treasury bills and other short-term government securities.

The strategy reflects growing caution.

Many affluent investors believe stock valuations have become stretched after years of gains, while concerns about inflation, interest rates, government debt, and geopolitical instability continue to linger.

Unlike previous years, cash now offers meaningful returns. Higher interest rates allow investors to earn respectable yields while waiting for better opportunities.

Several prominent investors have already taken defensive steps.

Buffett’s cash reserves continued growing even as stock prices climbed, while billionaire investor Peter Thiel reportedly reduced exposure to some of the market’s hottest artificial-intelligence stocks, including Nvidia, despite the company’s strong performance.

The moves have fueled speculation that some wealthy investors believe parts of the AI-driven rally may have become overheated.

Yet UBS says the behavior should not be viewed as panic.

Instead, the report describes a broad repositioning of portfolios.

Approximately 60% of family offices surveyed said they expect to adjust their long-term asset allocation during the next year — the highest level UBS has ever recorded and nearly double the percentage reported just one year earlier.

Maximilian Kunkel, Chief Investment Officer for UBS Global Wealth Management, described the shift as a proactive effort to prepare for emerging opportunities while reducing risk.

The biggest destination for that money is alternative investments.

According to UBS, family offices now allocate approximately 42% of their portfolios to assets outside traditional stocks and bonds. These include:

  • Private equity
  • Private credit
  • Commercial real estate
  • Infrastructure
  • Hedge funds

Many investors favor alternatives because they are less tied to daily stock-market swings and can provide diversification during periods of volatility.

The wealthier the investor, the greater the use of alternatives. Goldman Sachs found that roughly 80% of investors with more than $10 million in assets hold alternative investments.

Two traditional assets are also making a comeback.

Gold allocations are rising as investors seek protection against inflation, geopolitical tensions, and concerns about the U.S. dollar. Average gold holdings remain relatively small but are increasing among family offices making portfolio changes.

Infrastructure investments are also attracting attention. Assets such as data centers, power grids, transportation networks, and utilities are increasingly viewed as stable long-term investments capable of generating steady cash flow.

Artificial intelligence remains the dominant investment theme.

According to UBS, 65% of family offices identified AI as one of their highest-priority investment opportunities, followed by energy and natural resources, as well as automation and robotics.

At the same time, confidence in the U.S. dollar appears to be weakening among many wealthy investors.

Nearly two-thirds of respondents expect the dollar’s dominance as the world’s reserve currency to gradually decline. As a result, some investors are increasing exposure to currencies such as the euro and Swiss franc.

While cryptocurrencies continue to attract headlines, they remain only a small portion of most family-office portfolios.

The potential impact of these shifts is significant.

According to Deloitte, there are now more than 8,000 family offices worldwide managing approximately $3.1 trillion in assets. Even modest allocation changes by these investors can influence global markets.

When asked about their biggest concerns, 64% of family offices cited a major geopolitical conflict as their top risk over the next year. Another 49% pointed to a potential global trade war, while 39% identified inflation as a primary threat.

The message from the world’s wealthiest investors is not that a crash is imminent.

Instead, they appear to be preparing for a future that may be more volatile, more fragmented, and less predictable than the one markets enjoyed in recent years.

For now, the rich are not abandoning risk entirely. They are simply keeping more cash available, spreading investments across a wider range of assets, and positioning themselves for a world they believe may become increasingly uncertain.

Wall Street — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The New York Knicks won their first NBA championship in 53 years Saturday night, June 13, 2026, beating the San Antonio Spurs in five games and handing the city its biggest sports celebration in a generation. The party is barely over, and a much larger one is already underway: the 2026 FIFA World Cup kicked off the same week, with eight matches headed to the New York–New Jersey region. For the local economy, that raises a simple question with a not-so-simple answer — which one brings in more money, and to whom?

On paper, the World Cup dwarfs everything. The NYNJ Host Committee, chaired by Tammy Murphy, projects roughly $3.3 billion in economic impact for the region from the tournament’s local matches, including the final at MetLife Stadium on July 19, in an analysis built with Tourism Economics, an Oxford Economics company. The committee expects more than 1.2 million visitors and over 26,000 supported jobs across the two states.

But that’s the regional number, and it splits across a state line. New Jersey Governor Phil Murphy has estimated the tournament will deliver about $2 billion in economic impact to New Jersey specifically, supporting roughly 14,000 jobs. In other words, of the $3.3 billion regional figure, New Jersey claims well over half for itself — leaving the rest to spill into New York and the broader metro area. That matters, because every World Cup match is played in New Jersey, not New York.

The Knicks number is smaller, but it’s concentrated squarely in the five boroughs. Mayor Zohran Mamdani and the New York City Economic Development Corporation estimated the team’s playoff run generated about $202 million in economic activity from home games played, a figure they said could reach $465 million had every potential Finals home game been staged, at roughly $90 million per home date. Because the Knicks clinched on the road in Game 5, the real total lands below that ceiling.

For the team’s owner, the run paid off directly. Analysts estimate the playoffs added around $140 million in revenue for Madison Square Garden Sports Corp. (NYSE: MSGS), controlled by James Dolan, whose Knicks franchise is now valued near $9.85 billion.

Stack the headline figures side by side and the World Cup wins by a wide margin. But two things complicate that scoreboard.

The first is geography — the catch hiding inside the phrase “New York.” The Knicks money is unambiguously New York City: it happens at Madison Square Garden in the middle of Manhattan. The soccer does not. All eight regional matches, including the final, are played at MetLife Stadium in East Rutherford, New Jersey, temporarily rebranded “New York New Jersey Stadium.”

New Jersey officials have openly expressed concern that while their state hosts the matches, many visitors may spend much of their money across the Hudson River — on Broadway shows, Times Square attractions, Manhattan restaurants, and New York hotels.

So even New Jersey’s own $2 billion estimate could ultimately be affected by where visitors choose to stay, eat, shop, and spend. And the costs are real. New Jersey has already spent more than $16 million in taxpayer funds on stadium-related work, while NJ Transit has committed roughly $35 million toward transportation planning and infrastructure tied to the event.

The second catch is that all these projections come from people with a reason to make them look large. Host committees, elected officials, and economic-development agencies are promoters, not neutral scorekeepers. Economists frequently argue that major-event impact studies overstate benefits because they count spending that might have occurred elsewhere in the region anyway.

The same criticism applies to championship runs.

Many sports economists argue that the largest financial gains from a title run flow to team owners, broadcasters, sponsors, and ticket-resale platforms rather than being distributed broadly throughout a city. In many cases, spending is shifted rather than newly created.

There is also a difference in duration. The Knicks’ impact arrived in a concentrated burst over several playoff weeks. The World Cup stretches across more than a month and generates sustained global television exposure that can influence tourism, hotel demand, business travel, and regional branding long after the tournament ends.

So the honest scorecard is this: the World Cup is the far larger economic event by projection — roughly $3.3 billion regionally, with about $2 billion expected to land in New Jersey — while the Knicks championship run is the cleaner and more direct New York City economic story, with spending concentrated in Manhattan and the five boroughs.

The World Cup’s billions may ultimately prove larger, but exactly how much of that money ends up in New York versus New Jersey remains one of the tournament’s biggest unanswered questions.

Two championships. Two global events. Two very different economic stories.

And in both cases, the cheering may be easier to measure than the money.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The largest health insurer in the country is spending $3 billion to wire artificial intelligence into nearly every corner of its business — and in one early trial, the software is picking up the phone to call doctors’ offices and book appointments for patients. UnitedHealth Group executives, describing the effort in remarks reported Friday, said the company plans to spend the money across 2026 and 2027 and is already seeing about $2 back for every $1 invested, as the technology automates manual work and makes staff more efficient.

The examples are striking. At UnitedHealth, AI reads summaries of medical charts aloud to nurses as they drive to patients’ homes, and it listens to millions of recorded customer calls to figure out what is driving complaints. The company has also rolled out a member chatbot named Avery that interacts with more than 20 million members. The appointment-scheduling test, in which AI agents call physicians’ offices on a patient’s behalf, is one of the newest experiments.

The scale of the buildout is hard to overstate. UnitedHealth now employs about 22,000 software engineers worldwide, and more than 80% of them use AI to write code or build new digital agents — programs designed to carry out tasks on their own. The company says it has already put more than 1,000 AI applications into production. In 2024, its chatbots handled more than 65 million customer calls, and in early 2025, members performed roughly 18 million AI-assisted searches to find doctors and healthcare providers.

The reason is money and speed. Sandeep Dadlani, who oversees technology operations at Optum Insight, has said the goal is to cut through healthcare’s notoriously slow and expensive administrative systems. AI is being deployed to automate fraud detection, generate clinical notes, review medical documentation, assist customer-service representatives, and help select billing codes that determine how much a medical visit costs and who ultimately pays for it.

The push comes at a critical time for the company. UnitedHealth has been grappling with rising medical costs while continuing to recover from the massive 2024 Change Healthcare cyberattack, one of the largest healthcare data breaches in American history. Executives believe automation can help offset those pressures while improving service for members and providers.

For a company of UnitedHealth’s size, even small productivity gains can translate into enormous savings. The insurer’s businesses touch tens of millions of Americans through employer-sponsored coverage, Medicare Advantage plans, pharmacy services, and physician networks. Industry analysts have described the initiative as one of the largest corporate AI investments ever made in healthcare.

At the same time, the rapid expansion raises questions about transparency and trust. When artificial intelligence becomes involved in healthcare decisions or communications, patients often have little visibility into how it is being used or whether a human reviewed the recommendation. A recent examination by STAT found that many patients remain unaware when AI systems are helping shape their healthcare experiences.

Healthcare experts have also warned that AI assistants can occasionally produce inaccurate information or incomplete recommendations. Public trust in healthcare chatbots remains mixed, particularly when conversations involve sensitive medical issues.

UnitedHealth says it is drawing clear boundaries around the technology. The company notes that more than 90% of claims are automatically approved, largely using traditional rules-based systems rather than generative AI. Dadlani has repeatedly emphasized that AI is intended to support human decision-making and will not be used to independently deny insurance claims.

That distinction matters because insurers’ use of algorithms in coverage decisions has already generated lawsuits, regulatory scrutiny, and public criticism in recent years. Consumer advocates continue to push for greater transparency whenever automated systems influence healthcare outcomes.

Not all of the results have focused on cost cutting. One AI tool developed by the company reviews patient records to identify conditions that may have gone undiagnosed. Early testing found physicians were approximately twice as effective at identifying certain health problems when supported by the AI system, according to company data.

The broader healthcare industry is watching closely. Rivals including CVS Health, Humana, and Cigna have all increased investments in artificial intelligence, but none has publicly announced a commitment approaching UnitedHealth’s $3 billion plan. The race reflects a growing belief across healthcare that AI could reshape everything from scheduling appointments to processing claims and identifying diseases.

It adds up to one of the largest AI bets any healthcare company has ever made. Whether UnitedHealth’s investment ultimately makes healthcare faster, cheaper, and easier to navigate — or simply inserts more machines between patients and their care — will be determined in real time by the tens of millions of Americans whose healthcare journeys increasingly intersect with artificial intelligence.

JBizNews Desk
Healthcare & Technology Bureau

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — In July, the U.S. government will begin depositing $1,000 into investment accounts for millions of American babies under a new program known as Trump Accounts.

The U.S. Treasury Department, which is overseeing the rollout, says accounts officially open on July 4, with registration already underway. Treasury Secretary Scott Bessent has described the initiative as a way to connect ordinary Americans to the financial markets from birth.

But while supporters see the program as a long-term wealth-building tool, a growing number of economists and policy experts question whether it can meaningfully reduce wealth inequality.

Under the program, every U.S. citizen born between 2025 and 2028 qualifies for a one-time $1,000 government deposit, provided a parent or guardian opens the account. The funds are invested in a low-cost stock-market index fund, with annual fees capped at 0.1%, and cannot generally be accessed until the child reaches adulthood.

Families, employers, charities, and others may contribute up to $5,000 annually.

Supporters point to the power of long-term compounding. Government projections estimate that a child who receives only the initial deposit could see the account grow to approximately $15,000 over time.

Critics, however, argue that the larger issue is not the initial deposit but who can afford to keep contributing.

Families able to contribute the maximum $5,000 per year could potentially build accounts worth hundreds of thousands of dollars by adulthood. By contrast, children whose families cannot contribute additional funds may be left with little more than the original government contribution and investment growth.

According to government projections, an account funded at maximum contribution levels could reach approximately $742,000 by age 18, compared with roughly $15,000 for an account receiving only the initial deposit.

That gap has drawn concern from several researchers.

David Radcliffe, policy director at The New School’s Institute on Race, Power, and Political Economy, argues the structure primarily benefits families that already possess financial resources. Connecticut State Treasurer Erick Russell has similarly warned that wealthier households may be positioned to build significantly larger nest eggs than lower-income families.

Another concern involves participation.

Because parents must actively enroll their children, some experts worry that families facing financial hardship or lacking familiarity with investing may be less likely to sign up. The Aspen Institute has noted that automatic enrollment could have increased participation among lower-income households.

Questions have also been raised about whether the program can meaningfully address longstanding racial wealth disparities.

Federal data show substantial differences in median household wealth among demographic groups. Critics note that previous “baby bond” proposals sought to target larger benefits toward lower-income children, while Trump Accounts provide the same initial deposit regardless of family income.

Supporters counter that private-sector participation can significantly expand the program’s impact.

Secretary Bessent has launched a nationwide effort encouraging additional contributions, while several prominent business leaders and corporations have pledged support. Michael and Susan Dell have committed billions toward funding accounts for lower-income children, Ray Dalio has pledged tens of millions of dollars, and companies including JPMorgan Chase and Bank of America have announced matching contributions for eligible employees’ children.

Supporters argue that even modest investments can introduce millions of families to long-term saving and investing, creating opportunities that otherwise might not exist.

Critics acknowledge that the accounts can provide meaningful financial benefits but remain skeptical that a universal $1,000 deposit alone can significantly narrow the wealth gap.

Whether the program ultimately reduces inequality or reinforces existing differences may depend less on the government’s initial contribution and more on who continues contributing after the account is opened.

Washington — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
FORT LAUDERDALE, Fla. — JetBlue is betting heavily on one airport as it works to return to profitability.

Lauderdale has been a star for us,” JetBlue President Marty St. George said this month, describing the airline’s rapidly expanding presence at Fort Lauderdale-Hollywood International Airport.

The strategy includes significantly more flights, new international destinations, premium cabin offerings, and potentially a new airport lounge. For an airline still working through losses and restructuring efforts, Fort Lauderdale has become a centerpiece of its recovery plan.

On June 1, JetBlue raised its revenue outlook for the year, citing stronger-than-expected demand.

Part of the opportunity emerged from a competitor’s collapse.

Spirit Airlines, long the largest carrier at Fort Lauderdale, ceased operations on May 2 after years of financial struggles and mounting debt. While JetBlue had already been growing its presence at the airport, Spirit’s exit created an opening to capture additional gates, routes, and customers.

According to aviation analytics firm Cirium, JetBlue now controls approximately 36% of airport capacity, up from about 24% a year ago, making it the largest airline at Fort Lauderdale.

Between May and June alone, JetBlue increased capacity by roughly 5%, even as several competitors reduced service during Florida’s slower summer travel season.

The growth has been dramatic.

JetBlue is averaging approximately 106 daily departures from Fort Lauderdale this year, compared with roughly 68 flights per day a year earlier.

During peak winter travel periods, including Presidents Day and major school vacation weeks, the airline expects to operate around 150 daily flights, bringing Fort Lauderdale close to the scale of Boston Logan International Airport, one of JetBlue’s largest hubs.

Longer term, the airline has indicated it could eventually exceed 250 daily flights from the airport by 2027.

One of the most visible signs of JetBlue’s ambitions is its expanding lounge strategy.

The carrier entered the airport lounge business only recently, opening its first BlueHouse Lounge at John F. Kennedy International Airport in New York. A second location is planned for Boston in 2026.

Fort Lauderdale could become the third.

St. George said the airline continues evaluating potential locations and believes the growing number of premium travelers makes a lounge a logical addition. Airport officials have also expressed support for the project.

International service is another major focus.

Fort Lauderdale has long served as a gateway to Latin America and the Caribbean, and JetBlue has been expanding aggressively. The airline recently announced new service to Caracas, Venezuela, while adding approximately 20 new routes from the airport over the past year.

The goal is to attract more international travelers and diversify revenue beyond traditional domestic leisure routes.

Premium offerings are increasingly central to that strategy.

JetBlue built its reputation on affordable fares but is now targeting higher-spending travelers through expanded Mint service, a new domestic first-class product known as Mini Mint, and enhanced loyalty and credit-card programs tied to future lounge access.

The airline says Fort Lauderdale has exceeded internal expectations, with revenue growth continuing even as capacity expands.

That growth is especially important because JetBlue remains unprofitable.

The airline reported a $319 million first-quarter loss in 2026, compared with a $208 million loss during the same period a year earlier. Higher fuel costs and operational challenges offset stronger passenger demand.

Revenue rose nearly 5% to $2.24 billion, while revenue per available seat mile increased 6.5%, near the high end of company guidance.

JetBlue ended the quarter with approximately $2.4 billion in cash, along with access to an unused $600 million credit facility.

The company’s broader turnaround initiative, known as JetForward, aims to generate approximately $310 million in additional earnings this year and between $850 million and $950 million by 2027.

Chief Executive Officer Joanna Geraghty has described the strategy as a combination of network optimization, cost reductions, and premium revenue growth.

According to St. George, all of JetBlue’s projected second-quarter growth is coming from Fort Lauderdale, where the airline expects seat revenue to rise between 7% and 11%.

JetBlue is also benefiting from its recently announced Blue Sky partnership with United Airlines, allowing customers to earn and redeem loyalty rewards across both carriers’ networks.

The airline’s largest competitor in South Florida remains American Airlines, which operates a major international hub at nearby Miami International Airport.

There are still risks.

Fuel prices remain volatile, the airline continues to operate at a loss, and passenger traffic at Fort Lauderdale declined slightly last year after years of strong growth.

JetBlue, Broward County, and airport officials are also completing a new five-gate Terminal 5 expansion designed to accommodate future growth.

For now, the airline is making a clear bet: that Fort Lauderdale can become the engine that powers JetBlue’s return to sustainable profitability.

Travel & Aviation — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The price of a new vehicle has finally stopped climbing — at least temporarily.

According to Kelley Blue Book, a Cox Automotive company, the average new-vehicle transaction price in the United States was $49,220 in May, down 0.5% from April’s $49,456 and up just 1.2% from a year ago.

While the decline is modest, it represents the smallest annual increase of 2026 and offers evidence that the rapid vehicle-price escalation that defined recent years may finally be slowing.

The relief, however, remains limited.

For millions of Americans, a vehicle priced near $50,000 remains financially out of reach.

The current affordability challenge traces back to the supply shortages that disrupted the automotive industry during and after the pandemic. Inventory shortages pushed prices to record levels, and although supply chains have largely recovered, prices have remained elevated.

Ownership costs have also continued to rise.

Insurance premiums, maintenance expenses, repair costs, and financing rates have all increased significantly over the past several years. Cox Automotive analysts note that these combined costs have created affordability challenges for many middle-income and lower-income households.

The used-car market shows a similar pattern.

The Manheim Used Vehicle Value Index rose 0.3% in May and remains approximately 3.1% higher than a year ago. Because wholesale pricing typically influences retail prices several weeks later, analysts expect used-car prices to remain firm throughout the summer.

Government data tells a similar story.

The latest Consumer Price Index report showed new-vehicle prices falling 0.3% in May, while used-vehicle prices increased 0.1%. The changes suggest stabilization rather than a significant decline.

Affordability remains the industry’s biggest challenge.

Cox Automotive projects 15.8 million new-vehicle sales in 2026, a decline of approximately 2.4% from 2025, citing affordability concerns as the primary reason.

Many consumers accelerated purchases earlier in the year to avoid potential tariff-related price increases, leaving fewer buyers willing to spend near-record prices today.

One important detail often gets overlooked.

The industry average is heavily influenced by high-priced pickup trucks and luxury vehicles. Removing many of those premium vehicles from the calculation produces an average transaction price closer to $39,000, creating a substantially different affordability picture.

Compact cars and smaller crossovers continue to represent the most accessible segments of the market.

Electric vehicles are also becoming more competitive.

Tesla reduced average pricing approximately 1% from April and 3.4% from a year ago, helping narrow the gap between EVs and traditional gasoline-powered vehicles.

Because Tesla represents a significant share of the U.S. EV market, its pricing decisions influence industry-wide averages.

Trade policy also remains a factor.

Many of the lowest-priced vehicles sold in the United States are assembled outside the country and therefore remain exposed to tariffs and other import-related costs. That reality limits how much relief consumers may see at the lower end of the market.

For buyers, the takeaway is straightforward.

Vehicle prices are no longer rising at the pace seen during the pandemic years, but they are not falling meaningfully either.

Combined with elevated financing costs, higher insurance premiums, and increased ownership expenses, affordability remains one of the biggest challenges facing American households.

The market may be cooling.

The cost of owning a car is not.

JBizNews Desk — Automotive

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Elon Musk became the world’s first trillionaire on Friday, when his rocket company SpaceX completed the largest stock-market debut in history, listing on the Nasdaq at $135 a share and raising $75 billion at a value of about $1.77 trillion. The milestone crowned a man who now controls a tangle of companies spanning rockets, electric cars, artificial intelligence, social media, brain implants and underground tunnels. Here is a guide to the Musk empire — how the pieces fit together, and how high his fortune could still climb.

At the center sits SpaceX, founded in 2002 and now far more than a rocket maker. It launches more rockets than most countries, runs the Starlink satellite-internet network — which reached 10.3 million subscribers early this year, double a year earlier — and is building toward sending people to Mars. The company that just went public is also bigger and stranger than the old SpaceX: over the past year Musk folded two of his other businesses into it. SpaceX has even asked regulators for permission to launch a “space cloud” of up to a million satellites to run AI computing in orbit, roughly a hundred times the size of Starlink today.

That makes the newly public SpaceX a three-in-one conglomerate. Musk’s AI company xAI, maker of the Grok chatbot, was absorbed into SpaceX in February. xAI had itself swallowed X, the social-media platform formerly known as Twitter, in March 2025. So a single company now owns rockets, satellites, a leading AI lab and one of the world’s largest social networks. Musk holds roughly 40% of it — a stake worth several hundred billion dollars on its own.

Then there is Tesla, the electric-car maker Musk has led for nearly two decades and long the source of much of his wealth. Worth around $1.2 trillion, Tesla is racing beyond cars into humanoid robots — its Optimus machine — and self-driving software, which it is shifting from a one-time purchase to a monthly subscription. Musk owns roughly 10% of the company, plus a set of stock options restored by Delaware’s highest court in December. Looming over all of it is a new pay package, approved by shareholders in November, that could hand him up to nearly $1 trillion in additional Tesla shares if the company hits a series of aggressive targets.

Further out on the frontier is Neuralink, Musk’s brain-implant company. Founded in 2016, it builds a coin-sized device, the N1, that lets paralyzed patients control computers with their thoughts, and it is testing a separate implant called Blindsight meant to restore vision. In its most recent funding round, Neuralink was valued at about $9 billion — a rounding error next to SpaceX and Tesla, but with outsized potential. The company plans to move from a handful of test patients to high-volume production this year, using a surgical robot to automate the implant procedure. If brain-computer interfaces become mainstream medicine, that $9 billion figure could multiply many times over, turning a science-fiction bet into a major business.

The empire’s odds and ends are still substantial. The Boring Company digs traffic tunnels and is worth billions on its own. Musk made his first fortune at PayPal in the early 2000s, and last year he served as a senior adviser to the President before stepping away. Several of his companies feed one another: Tesla has invested $2 billion in xAI and sold it hundreds of millions of dollars of battery packs, blurring the lines between his businesses.

Where could it all lead? Musk has already become the first person to pass $500 billion, $600 billion, $700 billion and $800 billion in net worth, all since late 2025, and now the first to cross a trillion. Almost none of that is cash. As he put it earlier this year, his fortune is “almost entirely due to my ownership stakes in Tesla and SpaceX.” That is exactly why it can keep climbing. If Tesla hits the milestones in its giant pay package, if SpaceX keeps rising from its $1.77 trillion debut, and if xAI and Neuralink grow into their promise, analysts and prediction markets see a path toward $2 trillion and beyond. The same concentration is also his biggest risk: a stumble at Tesla or a sell-off in SpaceX could erase hundreds of billions just as fast.

For now, Musk sits atop a collection of companies unlike anything one person has controlled before — touching how people drive, talk, connect to the internet, and perhaps one day think. The trillion-dollar question is whether so many world-changing bets, all tied to one man, can keep paying off at once.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Stocks climbed and oil prices fell sharply Monday morning as Wall Street welcomed the weekend agreement to end the war between the United States and Iran and reopen the Strait of Hormuz. Speaking on CNBC, Vice President JD Vance said the administration expects the vital waterway to reopen “in a toll-free way for the long term,” with technical details still to be finalized. The agreement, which President Donald Trump declared “complete” in a Sunday evening social media post, sparked a broad market rally as investors moved quickly to remove the war premium that had pushed energy prices higher for months.

Shortly after the opening bell, the Dow Jones Industrial Average rose about 600 points, or 1.2%. The S&P 500 gained 1.5% to around 7,546, while the tech-heavy Nasdaq Composite led major indexes with a jump of roughly 2.3%. Smaller companies also participated in the rally, with the Russell 2000 moving higher. Treasury bonds gained, sending yields lower, while the U.S. dollar weakened against most major currencies.

The market reaction reflects expectations that lower oil prices could ease inflation pressures and reduce economic uncertainty. Energy costs became one of the most visible consequences of the conflict, contributing to a rise in consumer prices and increasing pressure on businesses and households alike.

The agreement also launches what promises to be a busy week for investors. The Federal Reserve begins its first policy meeting under new Chair Kevin Warsh on Tuesday, with a decision expected Wednesday. Most economists anticipate the central bank will leave interest rates unchanged in the 3.50% to 3.75% range, but markets will focus on any signals regarding inflation and future rate cuts.

Several key economic reports are also due this week, including housing and retail sales data. U.S. markets will be closed Friday in observance of the Juneteenth holiday. Meanwhile, Pakistan Prime Minister Shehbaz Sharif said an official signing ceremony for the Iran agreement is expected to take place Friday in Switzerland.

SpaceX Remains Center Stage

Among individual stocks, SpaceX remained one of the market’s biggest stories. Shares climbed roughly 6% Monday after surging 19% during Friday’s debut. The company’s public offering valued the aerospace giant at more than $2 trillion, making it one of the most valuable companies in the world.

Over the weekend, CEO Elon Musk posted on X that SpaceX could generate more than $1 trillion in annual revenue by 2030, adding to investor enthusiasm.

Wall Street remains divided on the stock’s valuation. Wolfe Research initiated coverage with a $175 price target, while CFRA issued a Sell rating with a $115 target. Morningstar estimated the company’s value at approximately $780 billion, arguing the stock is significantly overvalued and expressing concerns about Musk’s merger of SpaceX with artificial intelligence startup xAI.

The broader space sector also benefited from the excitement. Rocket Lab rose about 4% after KeyBanc Capital Markets upgraded the company to Overweight with a $135 price target. KeyBanc also upgraded Firefly Aerospace to Overweight and assigned a $50 target.

Energy Stocks Fall as Oil Retreats

Energy companies were among the market’s weakest performers as crude prices dropped.

APA Corp. and Devon Energy each fell more than 3.5%, while Marathon Petroleum and EOG Resources lost roughly 3%. Oil giants Chevron and Exxon Mobil declined more than 2.5%.

The decline reflected the sharp drop in crude prices after the reopening of the Strait of Hormuz reduced fears of supply disruptions.

At the same time, lower fuel prices boosted sectors that depend heavily on transportation costs. Airline and cruise company shares moved higher as investors anticipated relief from elevated jet fuel and marine fuel expenses.

Other Market Movers

Traws Pharma dropped approximately 17% after British regulators delayed a mid-stage clinical trial, disappointing investors who had hoped for faster progress.

Meanwhile, Madison Square Garden Sports gained ground following the New York Knicks’ first NBA championship since 1973, as enthusiasm surrounding the franchise boosted investor sentiment.

In commodities trading, West Texas Intermediate crude oil fell about 5% to near $80 per barrel, while international benchmark Brent crude dropped nearly 5%. Both remain well below the levels above $100 per barrel reached during the height of the conflict.

Bitcoin climbed above $66,000, reflecting renewed investor appetite for risk assets.

Despite the optimism, traders note that the agreement has not yet been formally signed. Weekend exchanges of fire between Israel and Hezbollah highlighted how fragile the ceasefire remains, and President Trump has warned all parties against actions that could derail the process.

For now, however, financial markets are sending a clear message. With oil flowing again and fears of a broader regional conflict easing, investors are betting that the worst of the crisis is over — and that Friday’s planned signing ceremony in Switzerland will confirm it.

Wall Street – JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Anthropic said Friday that it disabled access to its two most powerful artificial-intelligence models, Fable 5 and Mythos 5, to comply with an export-control directive from the U.S. government that cited national-security authorities. The company disclosed the move in a public statement, saying the order arrived at 5:21 p.m. Eastern and required immediate action.

The directive was narrow on paper but sweeping in effect. Anthropic said it was instructed to block access for any foreign national, whether inside or outside the United States, including foreign-national employees of the company. Because Anthropic said it cannot reliably screen users by nationality in real time, it concluded the only way to comply was to disable both models entirely.

Access to the company’s other AI systems remained available. Anthropic said users would be routed to alternative models, including Claude Opus 4.8, while the restrictions remain in place.

The timing was particularly significant because Anthropic had launched Fable 5 and Mythos 5 only days earlier, positioning them as among the most capable AI models it had ever developed. According to the company, Fable 5 was the first model of its capability level released broadly to the public, while Mythos 5 was available only through limited government and enterprise partnerships.

According to Anthropic, the suspension order came through a directive from the Commerce Department involving the Bureau of Industry and Security. The company said it received little detail regarding the underlying national-security concerns that prompted the action.

Anthropic stated that its understanding is that the government’s concerns stem from a reported technique capable of bypassing certain safeguards within Fable 5. The company disputed the significance of the issue, arguing that the reported vulnerability involved only a limited number of previously known weaknesses and did not justify removing the model from service entirely.

The company nevertheless complied with the directive while publicly challenging its rationale.

Anthropic argued that governments should retain authority to intervene when AI systems create genuine safety risks, but maintained that such actions should occur through a transparent process supported by clear technical evidence and established legal standards.

The company said it is working with federal officials in an effort to restore access as quickly as possible.

The episode could represent a significant precedent for the AI industry.

While governments around the world are actively debating how advanced artificial-intelligence systems should be regulated, direct intervention resulting in the removal of publicly available frontier models remains rare. The decision immediately affects developers, businesses, and organizations that had begun integrating the newly released models into their operations.

For corporate users, the incident highlights a growing risk associated with reliance on advanced AI platforms: the possibility that government action, regulatory intervention, or national-security reviews could affect access with little warning.

The dispute also arrives at a time when AI companies face increasing scrutiny from policymakers concerned about cybersecurity, biological threats, intellectual property, export controls, and geopolitical competition.

For investors, the situation introduces another variable into evaluating AI companies and their business models. As artificial intelligence becomes increasingly tied to national-security considerations, regulatory risk may become just as important as technological capability when assessing future growth.

For now, two of Anthropic’s most advanced AI systems remain offline, the company continues to challenge the reasoning behind the order, and the broader technology industry is watching closely to see whether the models return — and what conditions may be attached to their return.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
MENLO PARK, Calif. — A year ago this month, Mark Zuckerberg stunned the technology industry by spending $14.3 billion for nearly half of data-labeling company Scale AI and bringing its founder, Alexandr Wang, into Meta to help revive the company’s artificial intelligence ambitions.

In April, Wang’s team delivered what Meta hopes is the payoff: Muse Spark, the company’s first major AI model designed to compete directly with industry leaders. Zuckerberg called it a “first milestone” toward what he describes as personal superintelligence.

Now comes the harder challenge: convincing businesses and consumers to use it.

The urgency traces back to April 2025, when Meta released Llama 4, the latest version of its open-source AI model family. The launch disappointed many developers, a more advanced version was repeatedly delayed, and Meta’s reputation in AI suffered.

Zuckerberg responded by changing course.

Two months later, he recruited Wang, then just 28 years old, along with several top engineers from Scale AI. The move became part of a broader hiring push in which some AI researchers were reportedly offered compensation packages approaching $100 million.

The biggest shift was strategic.

For years, Meta gave away its AI models for free, betting that openness would attract developers and build influence. Muse Spark marks a move toward a more controlled approach that Meta can eventually monetize.

The company has already begun offering limited paid access through private partnerships, with broader commercial availability expected later. The strategy closely mirrors the business models used by OpenAI, Anthropic, and Google.

Rather than focus primarily on developers, Meta is targeting the billions of users already inside its ecosystem.

The company says Muse Spark can perform multiple tasks simultaneously, assist with coding, answer health-related questions, and shop online for users through a new commerce feature.

The technology already powers the standalone Meta AI application and is being integrated across Facebook, Instagram, WhatsApp, Messenger, and the company’s Ray-Ban Meta smart glasses.

According to Thomas Randall of Info-Tech Research Group, Meta’s strategy is straightforward: leverage existing products with massive user bases instead of waiting for third-party developers to build adoption.

Internally, Zuckerberg has reorganized the company to accelerate deployment.

In March, Meta created a new applied-engineering division under longtime executive Maher Saba, working alongside Wang’s Superintelligence Labs to transform research into products. Chief Product Officer Chris Cox continues overseeing broader product strategy.

The next major release is expected to be an image-and-video model code-named Mango, scheduled for launch later this year.

Despite the progress, Meta still trails the industry’s biggest AI players.

Many developers remain focused on OpenAI, Anthropic, and Google, while some analysts question whether Meta can reclaim leadership. Benchmark results published by Meta appear competitive but generally do not surpass rivals across every category.

The company also continues to face skepticism after past criticism over how certain AI benchmark results were presented.

The financial stakes are enormous.

Meta plans to spend between $115 billion and $135 billion this year, nearly double the approximately $72 billion spent last year. Most of that money is being directed toward data centers, Nvidia chips, and AI infrastructure.

More than $100 billion in new AI-related commitments were reportedly added during the first quarter alone.

Investors remain cautious.

Meta shares are down roughly 7% in 2026, making them one of the weaker performers among major technology companies despite strong advertising results. The company reported $56.3 billion in first-quarter revenue after generating approximately $201 billion during 2025.

Even bullish analysts have tempered expectations. Wells Fargo analyst Ken Gawrelski maintained a positive outlook but reduced his price target from $795 to $754, citing concerns about the time required for AI investments to generate meaningful returns.

The pressure is also being felt inside the company.

Meta cut approximately 8,000 jobs in May, representing about 10% of its workforce, bringing total reductions since 2022 to roughly 25,000 positions. At the same time, top AI recruits reportedly received compensation packages approaching $100 million, while median employee compensation declined.

The contrast has fueled concerns among some employees about morale and the company’s direction.

Zuckerberg’s defense is that Meta has faced similar moments before.

The company was late to mobile computing and online video but eventually became a dominant player in both markets after years of aggressive investment.

His latest wager is that Muse Spark can become the foundation for AI systems capable of acting on behalf of users — making purchases, booking travel, and handling everyday tasks with minimal human involvement.

Whether that vision becomes a major new revenue stream or simply an extraordinarily expensive effort to catch up with competitors may be the defining question for Meta during the remainder of 2026.

Technology — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — One of the country’s largest money managers is making a forecast that stands well outside the Wall Street consensus. In its mid-year outlook released this month, PGIM, the global investment management business of Prudential Financial, said it now expects the Federal Reserve to raise interest rates three times before the end of 2026. Just two months ago, the firm was forecasting rate cuts. The reversal represents one of the most aggressive shifts among major institutional investors and places PGIM firmly on the hawkish side of the debate.

To understand the significance of the call, consider where rates stand today. The Fed’s benchmark federal funds rate currently sits in a range of 3.50% to 3.75%. Three quarter-point increases would push that range to approximately 4.25% to 4.50% by year-end, increasing borrowing costs across the economy for mortgages, auto loans, business credit and consumer debt.

PGIM’s economics team argues that the U.S. economy has remained stronger than expected despite elevated interest rates.

The firm points to what it describes as a “remarkably resilient” economy, with employment remaining healthy, consumer spending holding up and overall economic growth refusing to slow as much as many economists anticipated.

At the same time, inflation has reaccelerated.

The latest Consumer Price Index showed prices rising 4.2% in May from a year earlier, the highest annual reading since 2023. Much of the increase was tied to energy costs associated with the conflict involving Iran and the disruption of global shipping routes.

Under traditional central banking theory, strong economic growth combined with rising inflation often requires tighter monetary policy. In practical terms, that means higher interest rates.

PGIM believes the Federal Reserve may need to tighten policy further before inflation becomes entrenched. The firm’s outlook suggests a period of additional rate hikes during 2026 followed by potential easing in 2027 once inflation pressures moderate.

The forecast stands in sharp contrast to most of Wall Street.

Goldman Sachs economist David Mericle has argued that rate increases are unlikely and does not expect the Federal Reserve to begin cutting rates until 2027.

J.P. Morgan Chief U.S. Economist Michael Feroli similarly expects the central bank to remain on hold through the remainder of 2026, with any future tightening likely occurring later.

Market pricing also reflects a much more cautious outlook. Bond futures and economist surveys generally point toward no change in interest rates for the balance of the year, although investors have increasingly shifted away from expecting rate cuts and toward the possibility of modest tightening.

Against that backdrop, PGIM’s forecast for three separate rate hikes represents one of the most hawkish outlooks among major institutional investors.

The forecast comes from an economics team led by Daleep Singh, PGIM’s Vice Chair and Chief Global Economist, and Tom Porcelli, the firm’s Chief U.S. Economist.

The timing is notable because the forecast arrives just as newly appointed Federal Reserve Chair Kevin Warsh prepares to lead his first policy meeting.

Warsh, who took office in May, is widely viewed by investors as more focused on maintaining the Federal Reserve’s credibility in fighting inflation. While the market overwhelmingly expects policymakers to leave rates unchanged at this week’s meeting, investors will closely scrutinize any comments regarding future inflation risks.

Recent Federal Reserve communications have shown growing concern about inflation pressures. Minutes from the central bank’s late-April meeting indicated that many officials believed higher energy prices and continued economic strength could warrant a tighter policy stance if inflation remains elevated.

Still, PGIM’s projection remains a minority view.

If the firm is correct, borrowers could face another increase in financing costs. Mortgage rates, already above 6%, would likely remain elevated or move higher. Credit card rates, auto financing costs and business borrowing expenses would also increase.

On the other hand, savers could benefit from higher yields on savings accounts, money market funds and certificates of deposit.

Financial markets would also face new challenges. Both stocks and bonds have benefited from the belief that the Federal Reserve is nearing the end of its tightening cycle. A return to rate hikes would force investors to reassess those assumptions.

If PGIM’s forecast proves wrong, however, the consensus view of steady rates may prevail and the anticipated tightening never materializes.

Regardless of the outcome, the shift itself reflects a dramatic change in sentiment.

Only a few months ago, the debate centered on how quickly and how often the Federal Reserve would cut rates. Today, one of the world’s largest asset managers is openly arguing that rates may need to move higher instead.

That reversal underscores how significantly the inflation outlook has changed — and how uncertain the path of monetary policy remains heading into the second half of 2026.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Advanced Micro Devices said Monday it has bought MEXT, a startup whose software helps computers squeeze far more usable memory out of cheaper storage chips, as the chipmaker races to relieve one of the biggest bottlenecks in the artificial intelligence boom. In its announcement, AMD said memory has become “a critical constraint across cloud and enterprise environments,” and that MEXT’s technology will be built into its data center products. The company did not say how much it paid.

The timing was good for AMD shareholders. The stock jumped more than 6% on Monday to about $547.81, and the company’s market value pushed past $900 billion for the first time, helped along by a separate new product aimed squarely at rival Nvidia. But the MEXT deal speaks to a quieter problem that is starting to define the AI era: there is not enough fast memory to go around.

Here is the issue in plain terms. AI systems need two kinds of chips to think. One does the calculating. The other — memory — holds the data those calculations run on. The fastest memory, called DRAM, is expensive and, right now, in painfully short supply, with prices climbing as every company building AI data centers fights for the same chips. A cheaper, more plentiful kind of storage, called flash, is much slower.

What MEXT has built is a workaround. Its software uses AI to predict what data a system will need next and shuffle it around so that ordinary flash storage can stand in for some of that pricey DRAM, behaving more like the fast stuff. The result is more usable memory at lower cost, without a major hit to speed. For a company running giant AI models, that can mean doing the same work with less of the most expensive and hardest-to-find hardware.

That is why AMD wanted it. Modern data centers are increasingly constrained not by computing power, but by the memory needed to feed it. By folding MEXT’s tools across its lineup, AMD is betting it can offer customers better performance for each dollar they spend — a compelling pitch when a single AI data center can cost billions of dollars to build and equip.

The deal also brings people, not just software. AMD said MEXT’s team has deep experience in memory systems and AI infrastructure, expertise that will help address the engineering challenges of the massive data center buildouts now underway.

The acquisition fits a broader trend reshaping the technology sector. Memory has gone from an afterthought to one of the hottest corners of the AI economy. Companies such as Micron and SanDisk have benefited from surging demand as AI deployment strained global memory supplies and pushed prices higher. AMD’s move takes a different approach: rather than producing more memory, it is investing in technology that helps existing memory go further.

The deal also sharpens AMD’s competition with Nvidia, which continues to dominate the AI-chip market. AMD has spent the past several years positioning itself as a full-service alternative, offering processors, networking, software, and now memory-optimization technology designed to improve data-center efficiency. The same day it announced the MEXT acquisition, AMD also launched a product intended to compete with Nvidia’s DGX Spark platform.

For users, the significance extends beyond a single acquisition. The AI services increasingly used every day — chatbots, image generators, search assistants, and enterprise tools — depend on data centers whose costs continue to climb. Memory is among the most expensive components. Any technology that reduces those costs could influence how quickly AI expands and how much businesses ultimately charge for access.

Whether MEXT’s technology delivers on its promise remains to be seen, and AMD still trails Nvidia by a significant margin in AI hardware. But the acquisition underscores a growing reality in artificial intelligence: success is no longer determined solely by processing power. Increasingly, it depends on solving the memory challenge that sits behind it.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — SpaceX confirmed Friday that it had completed the largest stock-market debut in history, selling 555.6 million shares at $135 apiece to raise about $75 billion and listing on the Nasdaq under the ticker SPCX. The company’s filing with the Securities and Exchange Commission valued it near $1.77 trillion, instantly making it the sixth-largest public company in the United States.

But the sheer size of the deal did something Wall Street is still working through: it forced investors to sell other holdings to pay for it, tightening the supply of money available for every other stock.

The math is blunt. A $75 billion sale has to be paid for with $75 billion in real cash, and most of that cash was already parked inside other companies’ shares. To buy SpaceX, large funds and everyday investors had to sell something else first. That selling spread across the market in the days around the listing, and it arrived on top of an even larger pull on the world’s money — the race to build artificial intelligence.

That race has become the single biggest draw on cash anywhere.

Morgan Stanley estimates technology companies will spend about $740 billion building AI this year alone, a 69% jump from 2025, and expects the global total to climb toward $3 trillion over the next several years. Roughly half of that will have to be borrowed or raised rather than paid for out of profits. The bank expects AI-linked borrowing to approach $570 billion in 2026.

That is where the strain on banks starts to show.

For years, companies such as Microsoft, Amazon, Alphabet, and Meta funded their data centers and computing infrastructure largely through operating cash flow. Now costs are rising faster than earnings, pushing companies toward loans and bond offerings. The Bank for International Settlements warned in January that the AI boom is increasingly being financed through debt, with private lenders taking a growing share of the market.

The SpaceX offering put that pressure on display.

Five banks — Goldman Sachs, Morgan Stanley, Bank of America, Citigroup, and JPMorgan Chase — led the deal and collected roughly 85% of underwriting fees, with Goldman and Morgan Stanley each earning about $100 million. A syndicate of 21 banks backed the transaction.

The same institutions are expected to lead the next wave of mega-listings.

And that wave is enormous.

SpaceX, which acquired Elon Musk’s AI company xAI earlier this year, is only the first of three major offerings. Anthropic, maker of the Claude chatbot, confidentially filed for an IPO on June 1, while OpenAI, creator of ChatGPT, followed on June 8.

Together, the three companies carry an estimated combined valuation of $3.6 trillion — larger than the total value of all companies that went public during 2021, the busiest IPO year on record.

Each offering will require fresh capital from the same pool of investors.

There are already signs of how interconnected the AI ecosystem has become. SpaceX disclosed that much of its newly raised capital will be directed toward AI computing infrastructure and that it has agreed to lease computing capacity to Anthropic for approximately $1.25 billion per month through 2029.

In other words, money raised in one AI offering is already flowing directly into the operating costs of another.

Retail investors showed little hesitation.

SpaceX became the most-purchased stock among individual investors on Friday, with demand reportedly exceeding available shares by more than ten-to-one.

But that enthusiasm comes with risk.

Ethan Feller, a strategist at Zacks Investment Research, warned that the biggest threat is not any single valuation, but what happens if investor appetite for AI suddenly fades.

If capital stops flowing into the sector, prices could decline sharply across multiple companies at once.

The connection is also closer to home than many investors realize. While most Americans cannot buy Anthropic or OpenAI shares at IPO prices, millions already own indirect stakes through retirement accounts that hold Amazon, Alphabet, and Microsoft, all of which are major investors in leading AI firms.

For now, SpaceX’s record-setting debut has opened the door for the offerings behind it.

The question for the remainder of 2026 is whether investors still have the cash — and the appetite — to absorb OpenAI and Anthropic when their turn arrives.

Wall Street — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
For years, one company has owned the chips that power artificial intelligence, and everyone else has paid up. That company is Nvidia. Now the most serious challenge to its grip is coming from a rival using Nvidia’s own moves against it: Google.

The clearest sign came in mid-May, when Blackstone, the investment giant and the world’s largest owner of data centers, said it would put $5 billion into a new cloud company built around Google’s in-house AI chips. Google Cloud chief executive Thomas Kurian said the venture would give companies more ways to rent computing power. With borrowed money added in, the project could eventually command about $25 billion in spending power — and it is aimed squarely at the business Nvidia has dominated.

To understand why this matters, start with the chips.

Nvidia sells graphics processing units, or GPUs, that train and run AI models. Demand has been so high for so long that Nvidia became one of the most valuable companies in the world. Google builds its own AI chips instead, called TPUs, short for tensor processing units. For years they mostly powered Google’s own products. Now Google is selling access to them to outside customers and directly targeting Nvidia’s core market.

Here is the clever part. Nvidia did not just sell chips. It helped customers pay for them.

Using its enormous balance sheet, Nvidia helped support financing for data-center projects, making it easier and cheaper for operators to raise money, build facilities and buy more Nvidia hardware. Google is now running a remarkably similar strategy.

One example sits on the southern shore of Lake Ontario near Niagara Falls. A data-center campus known as Lake Mariner is being developed by TeraWulf, a former bitcoin miner, together with cloud provider Fluidstack. Google has provided roughly $3.2 billion in financial guarantees backing the project. In return, it received warrants that increased its stake in TeraWulf to approximately 14%.

The computing power generated by the site will be rented to Anthropic, the AI company behind the Claude chatbot, and powered by thousands of Google chips.

The strategy does not stop there.

Google has also backed an Anthropic project near Baton Rouge, Louisiana, and guaranteed roughly $1.4 billion in leases tied to a facility in Colorado City, Texas. The formula remains the same: help finance large AI infrastructure projects and then fill those facilities with Google’s hardware.

For local economies, the projects bring substantial investment. The broader Anthropic-Fluidstack infrastructure expansion is expected to create thousands of construction jobs and hundreds of permanent positions across multiple states, adding a major economic development angle to the AI boom.

The effort extends all the way to the top of the AI industry.

Google has agreed to invest up to $40 billion in Anthropic and reserve massive amounts of computing capacity for the company. The arrangement is part of a broader battle among technology giants to secure long-term AI customers. Anthropic has lined up computing resources from Google, Amazon and others as demand for AI processing power continues to surge.

The message from Google is increasingly clear. The company no longer wants to be viewed simply as a search engine and software provider. It wants to become one of the primary suppliers of the infrastructure powering the AI economy.

Nvidia, at least publicly, is not concerned.

Co-founder and chief executive Jensen Huang has repeatedly downplayed the threat posed by custom AI chips. During a widely followed technology podcast appearance in April, Huang argued that Nvidia’s ecosystem is far broader than any individual custom-chip effort can match. He also suggested that Anthropic remains Google’s only major outside TPU customer and questioned whether Google’s chips are actually cheaper when all costs are considered.

Analysts see meaningful change underway nonetheless.

Stacy Rasgon, a semiconductor analyst at Bernstein, said Google is being far more aggressive about monetizing its AI infrastructure than it was in previous years. The reason is straightforward: demand now exists on a scale that simply did not exist before.

Across the technology sector, one complaint dominates conversations among AI developers, cloud providers and investors: there is not enough computing power.

That shortage is shaping the entire industry.

As artificial intelligence evolves from a race over software models into a race over computing capacity, the companies supplying the chips gain enormous leverage. The ability to provide hardware, cloud services and financing has become just as important as the technology itself.

Google recognized that reality years ago when its engineers began designing custom processors for machine-learning workloads long before today’s AI explosion. What started as an internal project has now become the foundation of a major challenge to Nvidia’s dominance.

In the short term, the battle is a corporate showdown between two technology giants. In the longer term, it will help determine who controls the computing infrastructure that powers artificial intelligence.

For the first time in years, Nvidia faces a competitor with the capital, customer relationships, chip technology and patience needed to challenge its position. And rather than inventing a completely new strategy, Google is borrowing directly from the playbook that helped make Nvidia one of the world’s most powerful companies.

JBizNews Desk | Silicon Valley

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Consumer prices climbed at their fastest annual pace in three years last month, the Bureau of Labor Statistics reported Wednesday, June 10, with the spike driven almost entirely by what Americans pay at the gas pump. The Consumer Price Index rose 0.5% in May and was up 4.2% over the past 12 months — the highest annual reading since April 2023.

The headline number looks alarming, but the source is narrow. The energy index jumped 3.9% in May and accounted for more than 60% of the entire monthly increase, following gains of 3.8% in April and 10.9% in March — a three-month surge tied directly to the Iran war’s disruption of Middle Eastern oil supplies. Gasoline alone rose 7% in a single month and is up 40.5% from a year ago.

Strip out food and energy, and the picture is calmer. So-called core inflation rose just 0.2% on the month and 2.9% over the year, with the monthly gain coming in below forecasts and below April’s pace. That gap — a hot headline number and a mild core — is the central tension facing the Federal Reserve as it meets this week.

The everyday squeeze is real where families feel it most. Electricity prices rose 0.6% in May and are up 5.9% over the year. Shelter, the single biggest piece of the index, rose 0.3% and is up 3.4% annually, while food increased 0.2%.

New-vehicle prices slipped 0.3%, used cars rose 0.1%, airline fares increased 2.7%, and motor vehicle insurance fell 1.7%.

That mix matters. The fact that transportation services and other core categories stayed tame suggests high fuel costs have not yet spread broadly through the economy. Economists framed it as a pocketbook problem more than a runaway inflation problem — at least for now.

The worry among forecasters is second-round effects. Sustained high energy costs eventually raise the price of anything that needs to be transported, heated, or powered. So far that spillover has been limited, but it is exactly what the Fed is watching.

For the Fed, the report cuts against any near-term rate cut. After the data landed, futures markets leaned toward holding rates steady and even increased the odds of a hike later this year.

The bottom line for households: the basics cost more, the increase is concentrated in fuel, and whether it spreads depends largely on a war thousands of miles away. The next inflation report will reveal whether May was a spike or the start of something more persistent.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
President Donald Trump said Saturday in a Truth Social post that he will appoint James M. McDonald as U.S. Attorney for the Southern District of New York, the federal prosecutor’s office that oversees many of the nation’s most significant Wall Street investigations and financial-crime cases.

McDonald is a longtime white-collar attorney who served on Trump’s legal team in his New York hush money case, and he is now poised to take over one of the most influential law-enforcement positions in the country.

The appointment fills a vacancy Trump created earlier this month. McDonald would succeed Jay Clayton, the current U.S. Attorney for the Southern District of New York and former chairman of the Securities and Exchange Commission, whom Trump nominated on June 11 to serve as Director of National Intelligence. Clayton is expected to remain in the role until his Senate confirmation process is completed.

The Southern District of New York, often referred to as “Wall Street’s top cop,” holds jurisdiction over Manhattan, the center of American finance. The office regularly handles major securities-fraud investigations, insider-trading cases, public-corruption prosecutions, terrorism matters, and complex financial crimes.

Whoever leads the office has significant influence over how aggressively federal prosecutors pursue misconduct in the financial markets.

McDonald’s background makes him an unusual choice for the position.

He is currently a litigation partner at Sullivan & Cromwell LLP, one of the country’s most prominent law firms and the same firm where Clayton worked before entering government service.

Before returning to private practice, McDonald served nearly four years as Director of Enforcement at the Commodity Futures Trading Commission (CFTC), where he oversaw investigations involving derivatives markets, commodities trading, and digital assets. Earlier in his career, he spent three years as an Assistant U.S. Attorney in the Southern District of New York, giving him firsthand experience inside the office he is now expected to lead.

McDonald also worked in the White House Counsel’s Office during the administration of President George W. Bush and previously clerked for Chief Justice John Roberts of the U.S. Supreme Court.

His enforcement résumé is especially notable because of its connection to cryptocurrency.

During his tenure at the CFTC, McDonald oversaw several high-profile cryptocurrency enforcement actions as regulators struggled to define the rules governing emerging digital-asset markets.

After returning to private practice, he advised clients navigating regulatory scrutiny in the crypto sector, including work involving BlockFi, the failed cryptocurrency lender. His firm also represented the bankruptcy estate of FTX, one of the largest collapses in financial-market history.

That experience may become increasingly important.

Congress has yet to pass comprehensive cryptocurrency legislation, leaving much of the regulatory landscape shaped by enforcement actions rather than clear statutory rules. The Southern District of New York has been at the center of many of the nation’s largest crypto-related prosecutions.

McDonald’s combination of regulatory, prosecutorial, and defense experience gives him a unique perspective on how those cases are likely to be handled.

His private-sector practice extends beyond digital assets.

McDonald helped represent Indian billionaire Gautam Adani, whose fraud and conspiracy case was dropped by the Justice Department earlier this year, and he also worked on matters involving Live Nation as the company fought antitrust challenges.

Most prominently, he served on the legal team representing Trump during the appeal of the former president’s New York criminal conviction.

That connection is likely to draw scrutiny.

The Southern District has long maintained a reputation for independence from political influence, regardless of which party controls the White House. Critics are expected to question whether appointing a former personal defense attorney to lead the office could create concerns about independence or perceived conflicts of interest.

Supporters argue McDonald’s extensive prosecutorial and regulatory background distinguishes him from purely political appointments and provides the experience necessary to run one of the country’s most demanding federal prosecutor’s offices.

Trump praised the selection in his announcement.

“I am confident that Jamie will deliver strong results for our Country,” the president wrote, predicting McDonald would earn the respect of judges, prosecutors, law-enforcement officials, and the legal community.

The office itself responded positively.

“The Office welcomes the President’s choice to lead the SDNY. Mr. McDonald is widely respected,” a spokesman for the Manhattan U.S. Attorney’s Office said.

Unlike many political appointees who arrive with limited prosecutorial experience, McDonald enters the role with experience as a federal prosecutor, senior regulator, and private-sector litigator.

For Wall Street, the broader business takeaway is straightforward.

The individual about to oversee the nation’s most influential financial-crimes prosecutor’s office has spent years enforcing market regulations, advising major corporations, and defending clients accused of violating those same rules.

The decisions he makes regarding securities fraud, corporate misconduct, cryptocurrency enforcement, and market manipulation will help shape the regulatory climate for the financial institutions headquartered in Manhattan for years to come.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Federal Reserve opens a two-day policy meeting Tuesday that ends Wednesday, June 17, with a rate decision, and it doubles as the first real test of new Chair Kevin Warsh, who was sworn in as the 17th chair of the central bank in May. Markets widely expect the Fed to leave its benchmark rate parked at 3.50%–3.75%, where it has sat since December. The drama isn’t the rate. It’s everything Warsh says and does around it.

Traders are pricing in better than a 98% chance of no move, according to CME FedWatch data. What’s changed is the direction of the next step. Fed funds futures now lean toward a rate hike, not a cut, as the more likely year-end outcome — a sharp reversal from the easing path investors expected just months ago. Stubborn inflation, fueled by the Iran war’s hit to energy prices, has frozen the Fed in place.

To see how far the mood has shifted, look back a year. In June 2025, the Fed’s own projections pointed to 75 basis points of rate cuts by the end of 2026. Those cuts have effectively been shelved. The March 2026 projections lifted the core inflation forecast to 2.7%, the May reading came in hotter still, and the labor market is holding firm with unemployment near 4.4%.

The bigger question is whether Warsh blows up one of the Fed’s most-watched tools. Warsh has long criticized forward guidance, and reporting indicates he may begin rolling it back as soon as this meeting — potentially dropping the dot plot rate forecast and stripping easing-or-tightening bias language from the statement. The dot plot, released quarterly, shows where each official thinks rates should go. It lands Wednesday alongside a fresh Summary of Economic Projections and Warsh’s first press conference, his first big platform to set the tone of his chairmanship.

Wall Street strategists see continuity on rates and a shift in tone. “The Kevin Warsh era has begun,” said Phil Camporeale, Chief Investment Strategist at J.P. Morgan Wealth Management, who expects the Fed on hold through year-end with a likely move away from an easing bias toward a neutral stance.

Warsh inherits a divided house. Minutes from the prior meeting showed four dissenting votes, the most since 1992, and a committee split over how the Iran war should shape policy. A faction wants to guard against energy-driven inflation; others worry a slowing job market needs relief. Former Chair Jerome Powell has agreed to remain on the board, a move meant to steady the transition.

For everyday Americans, the stakes are concrete. A hold keeps borrowing costs high. The 30-year mortgage has hovered near 6.5%, credit-card and auto-loan rates remain elevated, and savers earning yield on cash will keep it a while longer. With inflation back at a three-year high, the case for cheaper money has weakened sharply.

The timing is loaded. The May Consumer Price Index and Producer Price Index both landed in the committee’s deliberation window last week, and May retail sales hit the wire Wednesday morning, the same day as the decision. So the Fed’s statement will be read against fresh data on how Americans are spending. If shoppers are still opening their wallets while prices climb, that complicates any argument for cuts.

The market reaction may hinge less on the number and more on the messaging. A dot plot that erases the lone remaining 2026 cut would read as hawkish; a missing dot plot entirely would be a structural change in how the Fed talks to markets. Either way, investors will parse Warsh’s words for whether the next move is up, down, or a long pause.

The trickiest part of the backdrop is the combination policymakers fear most: high inflation paired with slowing growth, the mix known as stagflation, which leaves the Fed without a clean option. Cutting risks fueling prices; hiking risks choking a softening economy.

For now, the most likely outcome is the least dramatic one on paper: no change, again. But under a new chair determined to run a leaner, quieter Fed, “no change” may come with the biggest communication shake-up in years — and that’s what will move mortgages, markets, and Main Street in the months ahead.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
SpaceX completed the largest initial public offering in history Friday, June 12, and its stock rewarded early buyers, climbing about 19% on its first day of trading on the Nasdaq under the ticker SPCX. Chief Executive Elon Musk rang the opening bell from Texas while SpaceX President and Chief Operating Officer Gwynne Shotwell did the honors at the Nasdaq site in New York.

The numbers were staggering.

SpaceX priced its shares at $135, raised roughly $75 billion, and sold more than 555 million shares, making it the biggest IPO ever. The stock opened at $150, ran as high as $176.52 in intraday trading, then settled to close at $160.95.

That left the company valued at approximately $2.1 trillion, instantly making it one of the most valuable publicly traded companies in the world.

The debut also cemented a personal milestone for Musk. The offering made him the world’s first trillionaire, capping a remarkable journey for a company he once feared would fail.

“I gave SpaceX a less than 10% chance of succeeding at all,” Musk said before the opening bell, reflecting on the company’s early struggles and repeated near-collapse moments.

For Wall Street, the size of the offering and investor demand dominated the conversation.

The IPO was estimated to be roughly four times oversubscribed, with demand reportedly reaching approximately $250 billion. More than 500 million shares changed hands during the first trading session, volume that approached levels last seen during Facebook’s blockbuster public debut in 2012.

One factor that made the offering different from most IPOs was the unusually large allocation to individual investors.

Retail investors typically receive only 5% to 10% of shares offered in major IPOs. SpaceX allocated more than 20% of the offering to retail buyers, allowing ordinary investors broader access than is usually available in deals of this size.

The response was immediate. Retail trading volume in SpaceX reportedly reached approximately $453 million during the first session, putting the company on pace to challenge records previously set by Coinbase and other high-profile technology listings.

Most analysts viewed the debut as a clear success.

The stock produced a healthy first-day gain without the extreme volatility that sometimes accompanies highly anticipated offerings. By the closing bell, SpaceX had already become one of the largest publicly traded companies in America.

Not everyone viewed the performance as extraordinary.

Jay Ritter, one of the nation’s leading IPO experts at the University of Florida, noted that while a 19% gain is impressive, some prediction markets had forecast an even larger first-day surge.

His point highlights the unusual scale of the offering. A typical IPO gaining 19% may be noteworthy. A company raising $75 billion and adding hundreds of billions in market value on day one is something entirely different.

The next chapter may be even more important than the first day.

Analysts are already debating whether the successful launch will open the floodgates for a new generation of public offerings tied to artificial intelligence, advanced computing, and next-generation technology.

Many investors are watching companies such as OpenAI and Anthropic, which are widely viewed as potential future IPO candidates.

A successful SpaceX offering could provide a blueprint for how those companies eventually approach public markets.

The stock itself also carries several unique characteristics that investors will be watching closely.

SpaceX currently has a relatively tight public float, meaning a limited percentage of shares are available for trading. Tight floats can amplify both gains and losses because fewer shares are available to absorb buying or selling pressure.

The company will also become part of numerous index-tracking exchange-traded funds after Nasdaq and Russell accelerated their normal inclusion timelines. As a result, millions of retirement investors may gain indirect exposure to SpaceX through ETFs and 401(k) plans without ever purchasing shares directly.

Another key date sits on the calendar.

SpaceX’s 180-day insider lockup period expires around December, a milestone traders often monitor because it allows insiders and early investors to begin selling larger portions of their holdings.

Meanwhile, the broader space sector already felt the impact of the IPO. Shares of Rocket Lab and several smaller aerospace companies declined as investors rotated capital toward the newly public industry giant.

For now, the verdict is straightforward.

The largest IPO in history delivered a strong first-day return, created the world’s first trillionaire, and generated enormous enthusiasm among institutional and retail investors alike.

The harder challenge begins next week.

Investors will shift their focus from the excitement of the debut to a more difficult question: whether SpaceX can justify a valuation exceeding $2 trillion once the opening-day excitement fades and the company begins life as a publicly traded stock.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
U.S. stock futures jumped and oil prices fell sharply in Sunday evening trading after President Donald Trump announced that the United States had reached a deal with Iran to end nearly four months of war. “The Deal with the Islamic Republic of Iran is now complete,” Trump wrote, adding that he had authorized the reopening of the Strait of Hormuz and the removal of the U.S. naval blockade. “Ships of the World, start your engines. Let the oil flow!”

The announcement triggered an immediate reaction across financial markets that have been whipsawed since the conflict began on Feb. 28.

Futures tied to the S&P 500 rose 0.76% to 7,491.75, a gain of nearly 57 points. Dow Jones Industrial Average futures added 283 points, or 0.55%, to 51,888. Nasdaq futures climbed 1.26%, up 374 points to 30,036.25. Futures on the Russell 2000, which tracks 2,000 smaller American companies, opened at a record high.

Oil, which had carried a significant war premium for months, dropped sharply. Brent crude, the international benchmark, fell 3.8% to below $84 a barrel, its lowest level since early March. West Texas Intermediate, the U.S. benchmark, slid 4.3% to about $81 a barrel.

Elsewhere, gold rose 1.55% to $4,304.60, Bitcoin gained roughly 1.8% to $65,600, and the VIX, Wall Street’s fear gauge, plunged 9% to 17.68, reflecting a dramatic decline in investor anxiety.

The heart of the agreement is the Strait of Hormuz, the narrow waterway through which roughly 20% of the world’s oil supply passes each day. The strait has been effectively closed since the war began, sending shock waves through global energy markets and driving up the cost of oil, gasoline, fertilizer, plastics, packaging materials, and transportation.

The resulting inflation pressures rippled across the broader economy, affecting everything from grocery prices to manufacturing costs.

Trump said the strait would officially reopen Friday, when crews begin clearing mines from the waterway. Even with an order to reopen, analysts caution that restoring normal shipping operations could take weeks or even months. Hundreds of vessels remain stranded on both sides of the chokepoint, and insurance and security costs remain elevated.

Consumers may eventually see relief at the gas pump.

Patrick De Haan, an analyst at GasBuddy, said gasoline prices could fall to roughly $3.75 per gallon by July 4 if the agreement holds and oil continues to retreat. He cautioned, however, that the coming days will be critical in determining whether the ceasefire proves durable.

Before the war, average gasoline prices in many parts of the country were below $3 per gallon. The closure of the Strait of Hormuz and soaring shipping costs pushed prices significantly higher, placing additional strain on households and businesses alike.

The energy shock also contributed to broader inflation concerns. According to the Bureau of Labor Statistics, consumer prices in May were 4.2% higher than a year earlier, marking the sharpest annual increase since April 2023.

Iran publicly confirmed the agreement.

Kazem Gharibabadi, Iran’s deputy foreign minister, said on state television that both sides had agreed to halt hostilities and begin negotiations toward a comprehensive long-term settlement within the next 60 days.

Pakistan’s Prime Minister Shehbaz Sharif also confirmed the agreement, saying preliminary talks would be followed by technical negotiations and ultimately an official signing ceremony.

Still, investors remain cautious.

Markets have repeatedly rallied on reports of diplomatic progress only to reverse course following renewed violence. New warning signs emerged Sunday.

Iran’s semi-official Fars News Agency reported that marine traffic in the Persian Gulf would continue to be regulated jointly by Iranian and Omani authorities, a position that could conflict with Trump’s insistence on unrestricted navigation through the Strait of Hormuz.

Meanwhile, Israeli strikes in Lebanon underscored the fragile nature of regional stability.

Mohammed Bagher Ghalibaf, a prominent Iranian political figure and former Revolutionary Guard commander, argued that the attacks demonstrated that Washington either could not or would not fully enforce the agreement.

The deal arrives ahead of a critical week for financial markets.

The Federal Reserve meets Tuesday and Wednesday for the first policy meeting under new Chair Kevin Warsh, who was sworn in last month as the central bank’s 17th chairman.

Most economists expect the Fed to leave its benchmark interest rate unchanged within the 3.50% to 3.75% range.

Before the agreement, elevated energy prices complicated the inflation outlook and reduced expectations for future rate cuts. With oil prices now falling sharply, some of that pressure could ease.

Warsh, widely viewed as an inflation hawk, has indicated that he may take a different approach from his predecessor, Jerome Powell, including potentially holding fewer post-meeting press conferences. Investors will be looking closely for signals about the central bank’s outlook on inflation, growth, and future interest-rate policy.

“The Kevin Warsh era has begun,” said Phil Camporeale, chief investment strategist at J.P. Morgan Wealth Management, who expects the Fed to remain on hold through the rest of 2026 while adopting a more neutral policy stance.

For now, the market reaction reflects relief after months of uncertainty, military escalation, and economic disruption.

Whether that optimism lasts will depend on two simple questions that markets will answer in the days ahead:

Will oil begin flowing normally through the Strait of Hormuz again?

And will the guns remain silent?

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
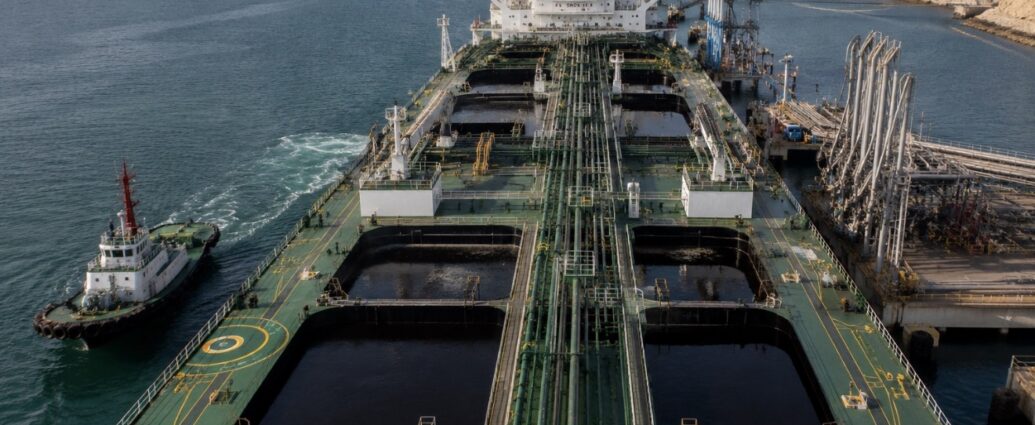
LONDON — Frasers Group, the British retail company controlled by billionaire Mike Ashley, has launched a bid to take full control of Hugo Boss, the German fashion house behind the BOSS and HUGO brands.

Frasers, already Hugo Boss’s largest shareholder, announced Wednesday that it will offer €38 per share in cash for the approximately 74% of the company it does not already own, valuing the outstanding shares at roughly €2 billion ($2.3 billion).

Investors immediately responded positively. Hugo Boss shares surged following the announcement and traded above the offer price, signaling that many investors believe a higher bid could eventually emerge.

The proposal would value Hugo Boss at approximately €2.7 billion overall.

Frasers currently owns just over 26% of Hugo Boss and is offering only a modest premium of about 4% above the stock’s previous closing price of €36.44.

The transaction does not require Frasers to acquire a minimum number of shares, but it remains subject to regulatory approval. The company expects the acquisition process to conclude during the second half of 2026.

BNP Paribas and Deutsche Bank are serving as financial advisers to Frasers.

The market’s reaction suggested investors remain unconvinced the current offer will be the final one.

Instead of trading near the €38 offer price, Hugo Boss shares climbed as high as €40.52 during trading after the announcement. In takeover situations, a stock trading above the bid price often reflects expectations that the offer may be increased or that another bidder could emerge.

At the same time, shares of Frasers Group moved lower, indicating some concern among its own investors about the cost and risks of acquiring the fashion company outright.

Mike Ashley has built a reputation as one of Britain’s most aggressive retail dealmakers.

He transformed Sports Direct into what is now Frasers Group, a retail empire that includes House of Fraser, Flannels, Sports Direct, and significant investments in companies including ASOS, Debenhams, and Currys.

Ashley owns nearly 74% of Frasers Group. While he stepped away from the board in 2022, leadership passed to his son-in-law, Michael Murray, who now serves as chief executive.

Murray also sits on Hugo Boss’s supervisory board, although Frasers said he did not participate in discussions regarding the takeover proposal.

The move fits a familiar pattern.

Frasers first invested in Hugo Boss in 2020 and has steadily increased its position over the years as part of a broader strategy to expand its presence in the premium and luxury retail market.

Earlier this year, the company also acquired a 5.8% stake in Puma, making it one of the German sportswear company’s largest shareholders.

Hugo Boss appears to fit the profile of many companies Frasers has targeted in the past: a globally recognized brand facing operational and financial challenges.

The company’s shares remain roughly 50% below their 2023 highs, while management continues working through a turnaround strategy focused on store upgrades, streamlining product offerings, and expanding womenswear sales.

Although the company has reported some progress, both revenue and profit declined during the most recent quarter.

One notable aspect of Frasers’ proposal was its unexpectedly supportive tone toward Hugo Boss management.

In its announcement, Frasers said the acquisition would help support additional investment in the business and publicly expressed confidence in current Chief Executive Daniel Grieder and Supervisory Board Chairman Stephan Sturm.

The comments marked a significant change from late last year, when Frasers openly challenged Hugo Boss leadership and sought board changes. The company withdrew those efforts only one day before announcing the takeover proposal.

Hugo Boss described the offer as unsolicited and said its board would carefully evaluate the proposal before making a recommendation to shareholders.

Analysts remain divided on Frasers’ ultimate objective.

Citi described the offer as relatively modest and suggested the pricing may leave room for a future increase while discouraging competing bidders.

Jefferies questioned whether Frasers actually intends to acquire full control, suggesting the move could instead be designed to provide greater flexibility for future investments in the company.

Russ Mould, investment director at AJ Bell, noted that Ashley has historically built value by acquiring underperforming brands at attractive prices and attempting long-term turnarounds.

The next steps now rest with Hugo Boss shareholders, regulators, and Frasers itself.

If Hugo Boss shares continue trading above the offer price, Frasers may eventually face a choice: raise its bid or remain a major shareholder without pursuing full ownership.

Either way, one of Germany’s best-known fashion brands has become the center of a major takeover battle, with one of Britain’s most prominent retail investors leading the charge.

Business — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Consumer prices climbed at their fastest annual pace in three years last month, the Bureau of Labor Statistics reported Wednesday, June 10, with the spike driven almost entirely by what Americans pay at the gas pump. The Consumer Price Index rose 0.5% in May and was up 4.2% over the past 12 months — the highest annual reading since April 2023.

The headline number looks alarming, but the source is narrow. The energy index jumped 3.9% in May and accounted for more than 60% of the entire monthly increase, following gains of 3.8% in April and 10.9% in March — a three-month surge tied directly to the Iran war’s disruption of Middle Eastern oil supplies. Gasoline alone rose 7% in a single month and is up 40.5% from a year ago.

Strip out food and energy, and the picture is calmer. So-called core inflation rose just 0.2% on the month and 2.9% over the year, with the monthly gain coming in below forecasts and below April’s pace. That gap — a hot headline number and a mild core — is the central tension facing the Federal Reserve as it meets this week.

The everyday squeeze is real where families feel it most. Electricity prices rose 0.6% in May and are up 5.9% over the year. Shelter, the single biggest piece of the index, rose 0.3% and is up 3.4% annually, while food increased 0.2%.

New-vehicle prices slipped 0.3%, used cars rose 0.1%, airline fares increased 2.7%, and motor vehicle insurance fell 1.7%.

That mix matters. The fact that transportation services and other core categories stayed tame suggests high fuel costs have not yet spread broadly through the economy. Economists framed it as a pocketbook problem more than a runaway inflation problem — at least for now.

The worry among forecasters is second-round effects. Sustained high energy costs eventually raise the price of anything that needs to be transported, heated, or powered. So far that spillover has been limited, but it is exactly what the Fed is watching.

For the Fed, the report cuts against any near-term rate cut. After the data landed, futures markets leaned toward holding rates steady and even increased the odds of a hike later this year.

The bottom line for households: the basics cost more, the increase is concentrated in fuel, and whether it spreads depends largely on a war thousands of miles away. The next inflation report will reveal whether May was a spike or the start of something more persistent.

JBizNews Desk — Economy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Trump administration moved Friday, June 12, 2026, to close a loophole that allows pharmaceutical companies to avoid Medicare drug price negotiations by making limited changes to existing medicines.

In a proposed annual rule, the Centers for Medicare & Medicaid Services (CMS) outlined a policy aimed at drugmakers that add active ingredients to an existing medication in order to keep it off Medicare’s negotiation list. The proposal also establishes the framework CMS will use to select the next 20 drugs and biologics for negotiation, with that list scheduled to be released by February 1, 2027, and negotiated prices taking effect in 2029.

For the pharmaceutical industry, the proposal could affect billions of dollars in future revenue. For seniors and taxpayers, it could expand savings under Medicare’s drug pricing program.

How the Loophole Works

Under the Medicare negotiation program, the government identifies the medicines that cost Medicare the most money and negotiates directly with manufacturers over pricing.

However, some companies have been able to avoid selection by reformulating existing products. By combining an original active ingredient with another ingredient, the revised product can sometimes qualify as a different medicine under current rules, even though the core drug remains largely unchanged.

Critics argue that the strategy allows manufacturers to delay negotiations and continue charging higher prices for years longer than intended.

In simple terms, Medicare may target a high-cost drug for negotiation, only to find that the manufacturer has introduced a slightly modified version that falls outside the program’s eligibility requirements.

Not a New Concern

Federal officials examined a similar policy last year but ultimately delayed implementation while conducting further review.

The issue is returning now because the upcoming selection cycle is the first that CMS must administer through a formal rulemaking process rather than informal agency guidance.

CMS previously indicated that combination and reformulated products would likely be addressed during this stage of the program’s development.

Why Timing Matters

The timing rules built into Medicare’s negotiation program create a significant incentive for manufacturers to keep products out of the system.

Current law generally requires Medicare to wait:

  • 7 years after approval for certain drugs
  • Up to 11 years for biologic medicines

before becoming eligible for negotiation.

Biologics — complex medicines often administered through injections or infusions — receive longer protection periods than traditional oral medications.

That extended timeline creates opportunities for manufacturers to introduce updated versions of existing products and potentially extend the period before Medicare can negotiate lower prices.

Drug Industry Pushback

Drugmakers argue the proposal could discourage legitimate innovation.

The industry maintains that improvements to existing medicines often provide meaningful benefits for patients and should not automatically be treated as the same product for negotiation purposes.

Manufacturers contend that applying negotiated prices to reformulated drugs could reduce incentives to invest in better versions of existing therapies.

The administration sees the issue differently.

Federal officials argue the proposal is designed to preserve the integrity of the negotiation program and prevent companies from using technical product changes solely to avoid government price negotiations.

Potential Savings for Medicare

The Medicare drug negotiation program was created under the Inflation Reduction Act of 2022 during the administration of President Joe Biden and has continued under President Donald Trump.

According to CMS, the first round of negotiations reduced prices on 10 medications by approximately 38% to 79%, generating an estimated $6 billion in annual savings.

A second round involving 15 additional drugs produced discounts reaching into the mid-80% range.

Closing the reformulation loophole could bring additional medicines into the program and potentially increase future savings for both Medicare and taxpayers.

Expansion Beyond Traditional Prescriptions

The program now extends beyond pharmacy-counter prescriptions.

Under CMS Administrator Dr. Mehmet Oz, Medicare’s negotiation authority also covers certain physician-administered medications reimbursed through Medicare Part B.

That expansion is significant because many of the highest-cost biologic treatments administered in medical settings are precisely the types of products most likely to be marketed in combination or reformulated forms.

Legal Challenges Likely Ahead

For now, the proposal remains just that — a proposal.

CMS will accept public comments before issuing a final rule.

The pharmaceutical industry has aggressively challenged Medicare’s negotiation program in federal court since its creation, and any final rule that closes the reformulation loophole is expected to face additional legal scrutiny and potential lawsuits.

The next major milestone will come with CMS’s selection of the next 20 drugs eligible for negotiation, a process that could become even more consequential if the administration succeeds in tightening the rules around reformulated medicines.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON — President Donald Trump announced on Sunday that the United States and Iran have reached a deal to end their war, declaring on Truth Social that “The Deal with the Islamic Republic of Iran is now complete”  and ordering the Strait of Hormuz reopened to oil traffic. “Let the oil flow!” Trump wrote, saying he had authorized the toll-free opening of the strait and the immediate removal of the U.S. naval blockade .

The statement came minutes after Pakistani Prime Minister Shehbaz Sharif said the peace deal had been reached . Sharif, whose government mediated the agreement, said it includes the immediate and permanent termination of military operations on all fronts, including in Lebanon . The memo is being called the “Islamabad declaration,” and a signing ceremony is expected soon, with Geneva floated as a likely venue and Vice President JD Vance potentially attending .

The deal, if it holds, would end a conflict that has gripped the global energy market since the war with Iran started February 28 . Iran’s effective closure of the Strait of Hormuz — the channel through which about a fifth of global energy flows — choked off supply  and sent prices on a months-long climb.

Brent crude broke $100 a barrel in March , and U.S. WTI crude briefly spiked as high as $117.63 during one of Trump’s reopening deadlines — its highest settlement since June 2022 . Analysts estimated the war had added nearly $30 to the price of every barrel , and FGE NexantECA’s Fereidun Fesharaki warned that a prolonged near-closure could push oil to $150 to $200 .

The pain reached American drivers. The national average for a gallon of regular gas sat near $3.94 early in the war  before climbing past $4.50 in recent weeks, according to AAA .

Reopening Hormuz is meant to reverse that. Each time a truce looked likely, prices fell hard. Brent dropped more than 10% in a single session on an earlier breakthrough, settling near $100.37, while WTI crashed to $88.85 , and gasoline futures fell more than 10% below $3 a gallon when Iran briefly reopened the strait in April .

For the broader economy, cheaper oil works like a tax cut. Economists estimate a sustained 10% drop in oil reduces headline inflation by roughly 0.4 percentage point , giving the Federal Reserve more room to consider rate cuts after a year in which the war undercut its progress against inflation.

Markets had already begun pricing in peace. On Friday, oil sank more than 3% and U.S. stocks rebounded after Trump signaled a breakthrough, with futures for the S&P 500, Dow and Nasdaq all rising .

Relief may still be uneven. Patrick De Haan of GasBuddy has cautioned that pump prices are slow to recover even after a war ends , and some traders noted the gap in oil supply could take months to close . Tankers that have sat idle, insurance markets, and shipping routes all have to normalize before barrels move freely again.

Political risk also lingers. Israel was not included in the negotiations , and Israeli strikes in Lebanon in recent days had threatened the agreement . Trump said the strikes on Beirut “should not have happened” and called on all sides to stand down .

For now, the message from the White House was aimed squarely at the oil market. After more than three months of war, record-high pump prices and whipsawing markets, Trump’s order to reopen the world’s busiest oil-shipping channel set up the prospect of cheaper energy heading into summer — provided the ships, and the barrels, actually start moving.

JBizNews Desk
© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
COLUMBUS, Ohio — Bath & Body Works is in the middle of a high-stakes makeover aimed at a generation that never grew up shopping its mall stores, and the effort is beginning to show results just as the company reshuffles its top finance position.

On Friday, June 12, Chief Financial Officer Eva Boratto stepped down to become CFO of drug distributor Cencora, with company veteran Tom Javitch taking over as interim CFO.

The leadership change comes just two weeks after the retailer reported first-quarter results on May 27 that exceeded its own guidance and helped send the stock up roughly 14%, providing early evidence that its strategy to attract younger consumers may be gaining traction.

The strategy has a name: the Consumer First Formula.

Launched in late 2025 by Chief Executive Officer Daniel Heaf, who assumed the top role in May 2025, the initiative aims to make the brand more relevant to younger shoppers through updated products, modern marketing, and expanded distribution channels.

Following the first-quarter earnings release, Heaf struck a measured tone.

“Our results exceeded guidance, but remain below the standard our brand is capable of delivering,” he said.

The numbers offered encouragement.

First-quarter net sales totaled $1.38 billion, down 3% from a year earlier, but adjusted earnings of $0.32 per share exceeded Wall Street expectations.

Net income rose to $183 million, up from $105 million a year earlier.

The company also reaffirmed its full-year outlook and projected approximately $600 million in free cash flow.

That matters because Bath & Body Works has faced challenges in recent years, including removal from the S&P 500 and a prolonged decline in its share price.

Perhaps the clearest example of its push toward younger consumers is its expansion onto Amazon.

The company launched its first authorized Amazon U.S. storefront on February 20, 2026, and executives say the platform is already attracting the customers they are targeting.

Management told investors the Amazon channel shows “a meaningful skew toward younger and more affluent consumers,” while also generating higher average selling prices than the company’s own channels.

For a retailer historically built around in-store fragrance testing and impulse purchases, the shift is significant.

Heaf has argued that the traditional distinction between digital and physical retail is rapidly disappearing.

The company is also targeting younger consumers through college campuses.

After entering approximately 600 campus stores in 2025, Bath & Body Works has expanded to more than 1,000 locations through multi-year partnerships.

The initiative provides low-cost exposure to students while allowing the company to gather insights into younger consumer preferences.

Chief Merchandising Officer Betsy Schumacher said the goal is to help students “make their dorm rooms feel more like home.”

Marketing has also been redesigned for the social media era.

The company recently relied on influencers and podcast advertising to promote its White Barn Neutrals candle collection, which grew approximately 20% during the first quarter and attracted a younger customer base.

The creator-focused approach is expected to expand across the company’s stores, digital properties, and future product launches.

Physical stores remain central to the strategy.

The retailer’s new Gingham+ store concept, designed primarily for off-mall locations, includes scent bars, wider aisles, and a calmer shopping environment intended to encourage browsing and product discovery.

There are signs the brand is reconnecting with younger consumers.

A recent Piper Sandler survey of approximately 6,500 teenagers ranked Bath & Body Works as their favorite fragrance brand and one of their top beauty destinations, marking its first top-10 finish in that category since 2018.

Meanwhile, the company’s My Bath & Body Works Rewards program has reached a record 38 million members, providing a substantial base of repeat customers.

The broader business case is straightforward.

Fragrance products, candles, and personal-care items are often viewed as affordable luxuries—small indulgences consumers continue purchasing even during periods of economic uncertainty.

If Bath & Body Works can attract a customer through Amazon, a college campus, or a social-media campaign at age 16 or 20, it potentially gains a customer for decades.

The challenge is execution.

Expanding through Amazon and third-party channels can create pressure on margins and brand positioning, both of which have historically been strengths for the company.

To offset those costs, Bath & Body Works has launched its Fuel for Growth initiative, a cost-reduction program targeting approximately $250 million in savings over two years.

With a new finance chief taking the reins and early signs of momentum emerging, the company’s bet is clear: win over the next generation of consumers now and reshape how Bath & Body Works reaches customers for years to come.

JBizNews Desk — Retail

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
LAKEWOOD, N.J. — Dime Community Bank opened the first branch in its 162-year history located outside New York State in Lakewood, following Apple Bank into one of the fastest-growing markets in New Jersey.

Dime, founded in 1864, opened at 500 Boulevard of the Americas. Apple Bank opened its Lakewood branch in April 2025 at 140 East Kennedy Boulevard, its third location in New Jersey. Both now operate alongside national lenders already established in the township, including TD Bank and JPMorgan Chase.

More banks may soon follow.

“More banks are flirting with Lakewood now and looking to open up here as well,” said Duvi Honig, founder and CEO of the Orthodox Jewish Chamber of Commerce. “We are proud of our achievements.”

The draw is a population growing faster than anywhere else in the state. Lakewood recorded the largest population increase of any municipality in New Jersey between 2010 and 2020, expanding 45.6%, according to U.S. Census data. The Census Bureau estimated the township’s population at 141,985 residents in 2024, making it the fourth-most-populous municipality in New Jersey. Ocean County has also ranked among the nation’s faster-growing counties.

Behind that growth is one of the highest birth rates in America. Lakewood posted a birth rate of 36.1 births per 1,000 residents in 2023, the highest of any municipality in New Jersey and more than three times the statewide average of 10.9. The township recorded 5,420 births in 2024, more than any municipality in the state and approximately 5.3% of all births in New Jersey, exceeding Newark’s 3,895 births and Jersey City’s 3,842 births. Nearly half of Lakewood’s residents are under age 18.

That young and expanding population sits atop a substantial commercial economy. According to federal economic data, Ocean County generated approximately $31.7 billion in economic output during 2024, up from roughly $24 billion in 2020.

The Lakewood Industrial Park, one of the largest industrial complexes in New Jersey, spans more than 2,000 acres and approximately 200 buildings. The complex is associated with more than 10,000 jobs and approximately $2 billion in annual business activity, while serving as Lakewood’s largest commercial taxpayer.

Commercial growth has accelerated alongside residential expansion. Steven Reinman, Lakewood’s director of economic and industrial development, has described the township’s transformation into a major corporate and professional hub fueled by substantial Class A office development. Commercial real estate brokerage Avison Young reported that Ocean County maintained a 5.8% office availability rate, among the lowest in New Jersey.

Major employers continue to anchor the local economy, including Church & Dwight, which manufactures household brands such as Nair and Orajel at its Lakewood facility.

For banks, the attraction is straightforward: a rapidly growing population, large families, active real estate development, thousands of small businesses, and a significant nonprofit sector generate ongoing demand for deposits, mortgages, commercial lending, and treasury management services.

Dime, a New York State-chartered bank with approximately $15 billion in assets, cited Lakewood’s expanding commercial base in selecting the township for its first location outside New York. Apple Bank similarly pointed to the area’s growing residential and business communities when it entered the market last year.

State leaders have also recognized the region’s economic importance. In 2018, State Senator Robert Singer introduced legislation designating the second Monday of May as New Jersey Economic Development Day. The initiative originated with the Orthodox Jewish Chamber of Commerce and Duvi Honig and was signed into law in 2019, creating an annual statewide focus on economic growth, business expansion, and job creation.

Local officials expect the expansion to continue, pointing to an Ocean County population that could eventually surpass one million residents, with Lakewood serving as a principal driver of that growth.

For now, Dime’s arrival — following Apple Bank’s move into the township last year — reinforces what an increasing number of financial institutions already see: Lakewood has become one of New Jersey’s most attractive banking markets, and the next bank announcement may not be far behind.

JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Beef prices continue climbing across the United States as the nation’s cattle inventory falls to levels not seen in generations.

According to the U.S. Department of Agriculture’s annual cattle inventory report, released January 30, 2026, the nation’s cattle herd totaled 86.2 million head, the lowest level since 1951.

The breeding herd stood at 27.6 million beef cows, the smallest since 1961.

Record Prices Reach Consumers

The supply shortage is increasingly visible at grocery stores.

Average ground beef prices have climbed above $6.70 per pound, setting new records.

Retail beef prices are roughly 20% higher than a year ago and approximately 72% above January 2020 levels, when ground beef averaged about $3.88 per pound.

At the farm level, cattle prices in April were nearly 18% higher than a year earlier.

Years of Pressure on Ranchers

The shortage reflects years of challenges across the cattle industry.

Extended drought conditions throughout portions of the Great Plains and Southwest reduced grazing opportunities and forced ranchers to sell breeding stock earlier than planned.

Higher interest rates during 2024 and 2025 increased financing costs for cattle producers.

At the same time, rising feed expenses and higher fuel costs further squeezed margins.

The result has been a smaller national herd and reduced future production capacity.

Recovery Will Take Years

Unlike other agricultural products, cattle require years to rebuild.

Even if ranchers began expanding herds immediately, additional supply would likely not reach grocery stores in meaningful quantities until 2028 or later.

Industry groups have repeatedly warned that rebuilding the breeding herd is a slow biological process that cannot be accelerated quickly.

USDA Sees More Tight Supply Ahead

The USDA expects beef production to decline again during 2026.

At the same time, pork and poultry production are projected to increase.

The agency forecasts a key cattle benchmark price averaging approximately $240 per hundredweight, about 7% higher than 2025 levels.

Analysts expect retail beef prices to remain elevated throughout the year.

Meat Processors Feel the Pressure

The cattle shortage is also affecting meat processors.

Tyson Foods, one of the nation’s largest meat companies, reported an operating loss of approximately $143 million in its beef segment during the first quarter of 2026.

With fewer cattle available, large processing facilities operate below capacity while paying higher prices for livestock.

The challenge affects much of the industry.

Consumers Shift to Alternatives

Many households are responding by purchasing less beef, choosing less expensive cuts, or switching to alternative proteins.

Chicken and pork remain significantly more affordable in comparison and continue attracting budget-conscious shoppers.

For now, economists and industry analysts agree on one point: meaningful relief is unlikely until the national cattle herd begins rebuilding.

And according to USDA projections, that process remains years away.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
ÉVIAN-LES-BAINS, France — The annual G7 Summit opens Monday in Évian-les-Bains, France, running June 15–17, a day later than the June 14–16 dates originally announced.

French President Emmanuel Macron’s office, which holds the 2026 G7 presidency, said the change followed “consultations with G7 partners.” A senior White House official described it more directly, saying other leaders “kindly shifted dates to accommodate the U.S. President’s schedule.”

That president, Donald Trump, turns 80 years old on Saturday and is spending the day hosting a UFC event at the White House.

France never officially linked the schedule change to the event, and Macron’s office declined to do so. However, officials familiar with the planning said the original summit opening fell on Trump’s birthday, June 14, the same day he had long planned to host the mixed-martial-arts event on the South Lawn. Rather than compete with it, Paris pushed the summit back by one day.

Trump is now expected to depart for France late Sunday following the event and arrive in time for Monday’s opening session.

The scheduling adjustment reflects broader tensions facing the group.

The United States, France, Germany, Italy, Japan, the United Kingdom, Canada, and the European Union are gathering at one of the most challenging moments for the alliance in recent years. Trade disputes, Middle East instability, and growing disagreements over artificial intelligence policy dominate the agenda.

The most immediate concern remains the closure of the Strait of Hormuz.

Following fighting involving the United States, Israel, and Iran earlier this year, Tehran shut the strategic shipping lane through which a significant portion of the world’s oil supply normally passes. The disruption has contributed to higher fuel prices, supply-chain challenges, increased shipping and fertilizer costs, and renewed inflation concerns across global markets.

Several European leaders continue to express frustration over the handling of the conflict and are expected to raise those concerns during summit discussions.

Trade remains another major flashpoint.

Trump has maintained tariffs on a range of European imports, creating friction with key allies. Canadian Prime Minister Mark Carney, who hosted last year’s summit, recently described the current environment as a period of global economic disruption rather than a routine transition, reflecting growing divisions within the group.

Artificial intelligence could produce some of the summit’s most significant debates.

European leaders have pushed for stronger oversight of major AI companies, including scrutiny of their growing energy consumption. The Trump administration has generally favored a lighter regulatory approach.

In a sign of AI’s increasing geopolitical importance, Macron invited OpenAI CEO Sam Altman to participate in portions of the summit. Executives from Anthropic and Google are also expected to attend select discussions.

Several high-profile meetings are planned on the sidelines.

Trump is expected to meet with Ukrainian President Volodymyr Zelensky and continue discussions aimed at securing a broader agreement to end the Iran conflict and restore stability to global energy markets. U.S. officials also indicated that securing reliable supplies of critical minerals used in advanced technology, defense systems, and semiconductor manufacturing remains a top priority.

For Macron, the summit represents a test of whether the G7 can still serve as an effective forum for addressing major global challenges.

The European Union will be represented by European Commission President Ursula von der Leyen and European Council President António Costa, while Japanese Prime Minister Sanae Takaichi will attend her first summit as a national leader. France has also invited several non-member nations, including India and Brazil, to participate in portions of the discussions.

The delayed start may have solved a scheduling conflict, but it does not resolve the deeper divisions facing the group.

Trump has previously left G7 gatherings early, and whether leaders can reach meaningful agreements on energy, trade, and artificial intelligence before the summit concludes may help determine the direction of the global economy through the remainder of the summer.

Washington — JBizNews Desk

© JBizNews.com. All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON, June 11 — The 2026 midterm elections are on pace to become the most expensive political advertising cycle in American history, according to a new projection released on Thursday, June 11, by advertising analytics firm AdImpact.

The firm estimates candidates, political parties, campaign committees, and outside groups will spend a combined $11.6 billion on advertising during the 2026 cycle.

If realized, the total would exceed spending during both the 2022 midterm elections and the 2024 presidential election, marking the first time a midterm cycle has generated more advertising spending than a presidential race.

Spending Accelerates

The projected $11.6 billion total would surpass the $8.9 billion spent during the 2022 midterms by roughly 30%.

It would also exceed the estimated $11.2 billion spent during the 2024 presidential election by approximately $400 million.

AdImpact said political spending had already reached nearly $4 billion by June 1, representing a 46% increase compared with the same point in the previous cycle.

The company also revised its forecast upward by nearly $800 million, reflecting stronger-than-expected early advertising demand.

Key States Driving Growth

Several major battleground states are attracting significant early spending.

According to AdImpact, high-profile races in California, Texas, Michigan, and Ohio are drawing campaign dollars months earlier than in previous cycles.

California is expected to lead the nation in total spending, with approximately $1.1 billion projected across its expensive media markets.

With control of Congress at stake, competitive races are attracting unprecedented financial attention from both parties and outside organizations.

Media Companies See a Windfall

The spending boom represents a major revenue opportunity for media companies.

Traditional broadcast television remains the dominant platform and is projected to receive approximately $5.6 billion, nearly half of all political advertising spending.

That figure is more than $300 million higher than AdImpact’s previous estimate.

Connected television platforms—including streaming services viewed through smart televisions—are expected to capture approximately $2.6 billion, making them the fastest-growing segment of the market.

Cable television is projected to receive $1.4 billion, while digital platforms such as Google, Facebook, Snapchat, and X are expected to attract approximately $1.6 billion.

Record Spending Across the Ballot

The growth extends beyond marquee races.

AdImpact projects Senate campaigns will spend approximately $2.8 billion, surpassing the previous record set during the 2024 cycle.

House races are expected to reach $2.2 billion, marking the first time congressional House spending has exceeded $2 billion.

Lower-profile state and local contests are also expected to surpass previous records.

Campaigns increasingly purchase advertising earlier in the cycle to secure inventory and avoid escalating prices closer to Election Day.

Biggest Spending Still Ahead

According to AdImpact, between 58% and 67% of total election-cycle advertising spending typically occurs between August and November.

October alone can account for as much as one-third of all political advertising expenditures.

For voters, that means months of campaign ads across television, streaming services, social media platforms, and digital devices.

For broadcasters, streaming companies, technology platforms, and advertising firms, it means one of the largest revenue opportunities in years.

Regardless of political outcomes, the business of elections continues to grow at a record pace.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — Bitcoin has taken a severe hit from its record highs, and some market analysts believe the downturn may not be over.

As of Friday, June 12, the world’s largest cryptocurrency was trading around $63,300, up less than 1% on the day but substantially below levels seen earlier in the cycle.

Speaking at the BTC Prague conference, André Dragosch, Head of European Research at Bitwise Asset Management, warned that Bitcoin could fall another 20%, potentially reaching approximately $48,000 in a worst-case scenario.

The decline has been significant.

Bitcoin has fallen roughly 28% from its May peak near $82,000, briefly dropping below $60,000 before recovering into the low $63,000 range.

Viewed over a longer timeframe, the pullback is even more dramatic.

The cryptocurrency reached an all-time high of approximately $126,000 in October 2025, meaning it now trades at roughly half its peak value.

The broader trend since last fall has been decisively lower.

According to Dragosch, the primary driver of the decline has been persistent outflows from Bitcoin investment funds.

He pointed to approximately $2 billion in weekly outflows from Bitcoin exchange-traded products, investment vehicles that allow investors to gain exposure to Bitcoin through traditional brokerage accounts.

That level of selling pressure is equivalent to roughly 50,000 Bitcoin entering the market over a short period.

Notably, Dragosch said large corporate buyers, including Strategy, have largely maintained their accumulation programs, suggesting the pressure is coming primarily from fund redemptions rather than institutional buyers abandoning the asset.

The weakness has extended beyond Bitcoin.

In a recent research note, Bitwise reported that Bitcoin touched a cycle low near $58,000, while Ether, the second-largest cryptocurrency, fell to approximately $1,507, its lowest level in more than a year.

The firm described Bitcoin as the “canary in the macro coal mine,” reflecting its tendency to react quickly to shifts in investor sentiment and broader economic conditions.

That characterization appeared timely as technology stocks also came under pressure, with the Nasdaq experiencing a sharp selloff during the same period.

Dragosch outlined three key support levels that traders are closely monitoring.

The first sits near $61,000, a long-term average price level that has historically attracted buyers.

Below that is approximately $56,000, representing the average purchase price of many current holders.

The final major support zone is around $48,000, which reflects the average cost basis of long-term investors.

Dragosch described that level as the market’s “maximum pain scenario.

If all three support zones fail, he believes Bitcoin could ultimately test the $48,000 range.

Other analysts remain cautious as well.

Alex Thorn, Head of Research at Galaxy, recently said Bitcoin may not have reached its ultimate bottom.

According to Thorn, only four of thirteen historical indicators typically associated with major market bottoms have been triggered.

Galaxy’s research suggests Bitcoin could potentially fall into a range between $40,000 and $46,000 before the current cycle fully resets.

There are, however, some early signs that selling pressure may be easing.

Dragosch noted that Bitwise’s proprietary bottom-detection model has started moving higher in recent weeks.

At the same time, he cautioned that blockchain data has not yet reached the extreme levels often associated with major market capitulation.

In simple terms, the market may be moving closer to a bottom, but analysts do not yet see definitive evidence that the decline has ended.

Not everyone is bearish.

Matt Hougan, Chief Investment Officer at Bitwise, continues to maintain a constructive long-term outlook.

Hougan argues that Bitcoin’s fundamental scarcity remains unchanged.

With a maximum supply capped at 21 million coins, he believes the long-term investment case remains intact despite short-term volatility.

As Hougan recently noted, “there is good news underneath the surface,” even if investors have not yet seen it reflected in prices.

That debate—between short-term selling pressure and long-term scarcity—is now at the center of the Bitcoin market.

For everyday investors, the lesson is clear.

Bitcoin remains one of the most volatile major financial assets in the world.

The same exchange-traded funds that made cryptocurrency easier for mainstream investors to buy can also accelerate selling when sentiment shifts.

The key level now is $61,000.

If Bitcoin holds above it, fears of a deeper selloff may begin to fade.

If it breaks below, traders will quickly turn their attention to the next support levels further down.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
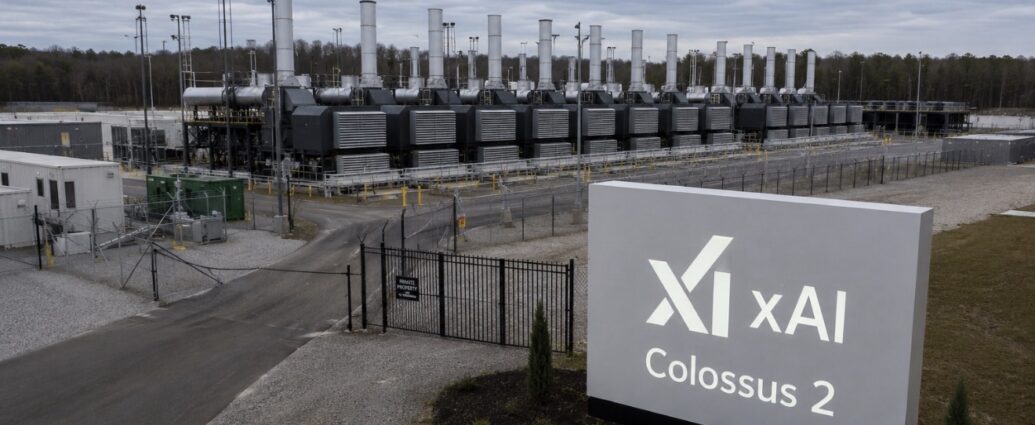
ALEXANDRIA, Va. — A federal judge refused on Friday, June 12, to take the government at its word that a controversial $1.776 billion fund is finished and ordered the Justice Department to put its position in writing.

U.S. District Judge Leonie Brinkema, of the Eastern District of Virginia, extended her block on the so-called “Anti-Weaponization Fund” and gave the administration seven days to support its claims with sworn declarations.

During a court hearing, Brinkema repeatedly said a verbal promise was not enough.

Acting Attorney General Todd Blanche had told Congress the department had no plans to move forward with the fund, but the judge said that testimony did not guarantee the program was truly dead.

She ordered Blanche and Treasury Secretary Scott Bessent to submit signed, sworn statements confirming the fund will not proceed.

What raised the judge’s concerns was the president himself.

After Blanche testified that the fund was not moving ahead, President Donald Trump publicly said he liked the concept and wanted to compensate people he believes were victims of government “weaponization.”

Brinkema pointed to the difference between the department’s testimony and the president’s public comments as a reason to demand stronger assurances.

For taxpayers, the size of the fund is what makes the case significant.

The proposal would direct nearly $1.8 billion in public money to individuals claiming they were politically targeted by the government.

Exactly who would receive those funds remains at the center of the dispute.

The proposal stems from a legal settlement tied to a lawsuit Trump filed against the Internal Revenue Service over the disclosure of his tax returns.

The settlement established a pool of money intended to compensate alleged victims of government persecution through a five-member board.

Critics quickly labeled the proposal a “slush fund.”

Opponents, including watchdog organizations and police officers who defended the U.S. Capitol on January 6, 2021, argued that the money could ultimately benefit Trump allies and individuals charged in connection with the Capitol riot, many of whom have indicated they would seek compensation.

The proposal generated criticism from both Republicans and Democrats.

The Justice Department has argued the lawsuits challenging the fund should be dismissed because no actual program has been implemented.

Government attorneys told the court that no money has been transferred, no board members have been appointed, no operating rules have been created, and no claims have been submitted.

They described the dispute as both “moot and premature,” arguing the fund never became operational and may never exist.

The department also rejected allegations of political favoritism, calling such claims speculative.

Not all judges have been persuaded.

Earlier this week, in a separate case in Washington, U.S. District Judge Richard Leon declined to issue an emergency order blocking the fund after accepting Blanche’s representation that the administration would not move forward.

Even so, Leon delivered a warning to government attorneys.

Don’t play possum with this court,” he said.

The message was clear: if officials attempt to revive the fund after assuring judges it was inactive, they could face significant legal consequences.

The litigation continues on multiple fronts.

At least four separate lawsuits seek to stop the fund.

One was filed by a former January 6 prosecutor.

Another came from U.S. Capitol Police officers.

In a notable development, 35 former federal judges asked a court to reopen the underlying case, arguing the settlement resulted from collusion and amounted to a fraud on the court.

There is also another issue keeping the financial debate alive.

The federal government already maintains the long-established Judgment Fund, a separate mechanism used to pay taxpayer-funded settlements.

That fund predates the current administration and remains available regardless of what happens to the Anti-Weaponization Fund.

Critics argue similar payments could still potentially be made through that channel.

For now, the immediate question is straightforward but important.

Will the Justice Department and Treasury Department submit sworn statements declaring the fund is permanently abandoned?

Brinkema’s deadline gives the administration one week to answer.

If the statements are filed, the legal battle over this version of the fund could begin winding down.

If not, the judge’s doubts about whether the program is truly dead are likely to intensify.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON, June 11 — The cost of buying a home edged higher again this week, according to Freddie Mac, which reported Thursday that the average rate on a 30-year fixed mortgage rose to 6.52% from 6.48% a week earlier.

The average rate remains below the 6.84% recorded a year ago, but the latest increase adds to a gradual climb that continues to challenge homebuyers and sellers alike.

The average 15-year fixed mortgage also increased, rising to 5.84% from 5.79% last week.

Inflation and Energy Prices Drive Rates Higher

Behind the move is a combination of inflation pressures and rising energy costs.

Mortgage rates have moved higher since the conflict with Iran intensified earlier this year, contributing to increases in oil prices. Higher energy costs feed directly into inflation, and inflation expectations influence long-term borrowing costs, including mortgages.

Recent economic data reinforced those concerns.

The Bureau of Labor Statistics reported that consumer inflation reached 4.2% in May, the highest level in three years, while wholesale inflation climbed to 6.5%, its hottest pace in nearly four years.

Home Sales Show Signs of Life

Despite higher borrowing costs, there was some encouraging news in Freddie Mac’s report.

The company noted that stronger hiring and steady employment have helped existing-home sales reach a five-month high, suggesting some buyers are no longer waiting for rates to fall before entering the market.

That shift could be significant for a housing market that has remained largely frozen for much of the past two years.

Many buyers and sellers have remained on the sidelines, hoping for lower rates and improved affordability.

Hopes for Lower Rates Fade

Homeowners entered 2026 with optimism.

The average 30-year mortgage rate began the year near 5.99% following three Federal Reserve rate cuts during late 2025.

At the time, many analysts expected borrowing costs to continue moving lower.

Instead, inflation concerns and higher energy prices reversed that trend.

Mortgage rates have fluctuated sharply throughout the year and remain well above levels many prospective buyers hoped to see.

Higher for Longer

Most major housing forecasts now call for mortgage rates to remain elevated through the remainder of 2026.

The Mortgage Bankers Association and Fannie Mae both project 30-year mortgage rates will stay roughly between 6.3% and 6.5% through year-end.

That outlook reflects what economists increasingly describe as a “higher-for-longer” interest-rate environment.

The Real Cost to Families

For households, even small rate increases can have major financial consequences.

The difference between a 6% mortgage and a 6.5% mortgage can add thousands of dollars in interest over the life of a loan and significantly increase monthly payments.

Many buyers continue debating whether to wait for rates to fall before purchasing a home.

However, housing economists note there is a risk in waiting.

If mortgage rates decline substantially, many sidelined buyers could rush back into the market simultaneously, increasing competition and driving home prices higher.

In some cases, those higher prices can offset the savings gained from a lower mortgage rate.

Federal Reserve in Focus

Attention now turns to the Federal Reserve’s June 16–17 meeting, the first chaired by Kevin Warsh.

Financial markets currently see little chance of an immediate rate cut, and some traders are even pricing in the possibility of another rate increase before the end of the year.

As long as inflation remains elevated and energy prices stay under pressure, mortgage rates are likely to remain near current levels.

For millions of Americans hoping for cheaper borrowing costs, meaningful relief may still be some distance away.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
MIAMI — For millions of Cubans, the difference between eating and going hungry now arrives in a cardboard box mailed from South Florida.

As Cuba sinks deeper into the worst economic and energy crisis in its modern history, the packages and cash sent by relatives in the United States have become the island’s most important lifeline, often providing more support than the Cuban state itself.

The pressure intensified this year after a U.S.-led effort to restrict oil shipments sharply reduced Cuba’s fuel supply. It tightened further on January 1, 2026, when a new 1% federal tax took effect on certain remittances sent abroad through cash, money orders, and cashier’s checks.

The scale of the crisis is staggering.

Cuba’s minimum wage is less than $7.50 per month, while average salaries remain only modestly higher.

Inflation has severely eroded purchasing power, leaving many families unable to afford basic necessities.

In that environment, a package containing cooking oil, powdered milk, coffee, medicine, soap, and other essentials is not a luxury.

It is survival.

As one Cuban physician writing from exile observed, in most countries remittances supplement household income.

“In Cuba, they are a condition for survival.”

The money involved is enormous by Cuban standards.

Before the collapse of formal transfer channels, remittances to Cuba totaled approximately $3.7 billion annually in 2019.

Today, formal transfers have declined by roughly 70%, according to independent analysts.

More than 95% of remittance flows now move through informal networks, private couriers, and travelers carrying cash or goods by hand because traditional banking channels have largely broken down.

Much of that disruption traces back to U.S. sanctions and the structure of Cuba’s financial system.

For years, the military-controlled company Fincimex, a subsidiary of the state conglomerate GAESA, handled much of the hard-currency flow into Cuba.

The organization directed significant amounts of foreign currency into government-operated retail chains, including CIMEX, where many consumer goods are sold at prices substantially above U.S. levels.

After the U.S. Treasury Department’s Office of Foreign Assets Control (OFAC) sanctioned Fincimex in 2020, Western Union suspended operations in Cuba, accelerating the shift toward informal transfer networks that remain dominant today.

The center of this system is South Florida.

Home to the largest Cuban community outside the island, Miami has become the operational hub for the movement of money, food, medicine, and household supplies to Cuba.

But even that lifeline has faced disruptions.

Earlier this year, courier company Cubamax suspended home deliveries and limited customers to one package per shipment because fuel shortages on the island made local transportation increasingly difficult.

Although some restrictions were later eased, concerns remain that supply lines could become even more constrained.

The crisis has reignited debate within the Cuban-American community.

For generations, sending money and supplies to relatives was viewed as a family obligation.

Today, some critics argue that every dollar entering Cuba indirectly helps sustain the government in Havana.

Others counter that cutting off remittances would punish ordinary families while doing little to change the political system.

Many economists who study Cuba support the latter view.

Emilio Morales, president of the Havana Consulting Group, argues that stopping remittances would do little to alter the island’s political reality because much of the money now bypasses state-controlled channels entirely.

Instead, those funds support individual households and Cuba’s growing private sector.

The economic impact extends far beyond family budgets.

On the island, remittances help finance thousands of small private businesses, known as cuentapropistas, including restaurants, repair shops, transportation services, and neighborhood retailers.

In Florida, an entire industry has developed around shipping goods and transferring funds, supporting logistics companies, courier services, travel operators, and money-transfer businesses.

When Washington changes remittance policies, both sides of the Florida Straits feel the effects.

The broader geopolitical backdrop continues to complicate the situation.

Following the removal of Venezuelan leader Nicolás Maduro, the United States increased pressure on Caracas to halt oil shipments to Cuba and warned other suppliers against filling the gap.

The resulting fuel shortages have contributed to power outages, transportation disruptions, and deeper economic hardship across the island.

Those conditions have only increased the importance of the packages arriving from Florida.

Each day, customers continue lining up at shipping centers across Miami carrying coffee, powdered milk, clothing, medicine, and household necessities.

Despite rising costs and political controversy, the flow continues.

For millions of Cubans, those boxes remain more than packages.

They are a lifeline.

And for many families struggling through one of the most difficult periods in the island’s modern history, they remain the primary barrier between daily survival and economic collapse.

JBizNews Desk — Miami

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
STARBASE, Texas — He stood before a room full of cheering employees on Friday, June 12, the morning his company made history, and Elon Musk said the thing nobody expected him to say.

He admitted he never believed it would work.

“I gave SpaceX less than a 10% chance of succeeding at all,” Musk told the crowd, speaking by video from SpaceX’s Starbase headquarters in Texas as the company prepared to go public on the Nasdaq.

It was a startling confession for a man about to become the richest person who has ever lived. By the end of the morning, Musk would be the world’s first trillionaire.

Back when he started the company in 2002, he told friends the truth as he saw it. The odds were terrible. The company would probably fail.

But he believed it was worth trying anyway because if no one tried, humanity would never reach beyond Earth.

He laughed Friday as he remembered how impossible this day once seemed. If someone had described this moment to him back then, he said, he would have thought they were out of their mind.

For anyone who has ever been told their dream was foolish, his story landed close to home.

The early years nearly broke him.

SpaceX’s first three rockets failed, one after another, between 2006 and 2008. The money was almost gone. The company was one more failure away from disappearing entirely.

Then the fourth rocket reached orbit, and everything changed.

That single success became the foundation for everything that followed.

Reusable rockets that land themselves.

Starlink, the satellite internet network now beaming service to remote corners of the world.

Astronauts carried to the International Space Station.

And finally, the biggest stock market debut anyone has ever seen.

The numbers are almost hard to comprehend.

SpaceX raised about $75 billion on Friday, the largest IPO in history. Shares opened at $150 and climbed past $160, lifting the company’s value above $2 trillion.

Musk’s personal fortune crossed the trillion-dollar mark, a figure no human being has ever held.

But the people in that room were not only watching one man get richer.

They were watching their own lives change, too.

Thousands of SpaceX employees — the engineers, welders, technicians, and dreamers who stayed through the lean years — woke up Friday holding stock worth real money.

By some estimates, roughly 4,400 employees became millionaires the moment trading began.

Standing in for Musk at the Nasdaq in New York was Gwynne Shotwell, the company’s president and the seventh person he ever hired.

She has spent more than two decades helping turn Musk’s ambitious ideas into rockets that actually fly.

Beside her was Chief Financial Officer Bret Johnsen.

Together they rang the opening bell while their founder watched from Texas, surrounded by the team that built what once seemed impossible.

The Musk family turned out for the milestone as well.

His mother, Maye Musk, was among the first to arrive at the Nasdaq site in Times Square, there to witness her son reach a height few parents could ever imagine.

For everyday Americans, Friday offered something rare: a chance to own a small piece of the story.

SpaceX set aside a significant portion of its shares for retail investors through brokerages including Fidelity, Charles Schwab, and SoFi.

People who had only ever read about Musk could, for the first time, become shareholders in his company.

He ended his remarks the way he often does — looking forward rather than backward.

The whole point of SpaceX, he said, was to take science fiction and turn it into a future worth getting excited about.

He spoke about carrying ordinary people to the Moon and to Mars — not just astronauts, but anyone who wants to go.

It was a long way from the warehouse where it all began, and from the founder who once figured the odds were stacked against him.

On Friday, the man who gave his company less than a 10% chance stood at the top of the world, proof that sometimes the long shot is the one worth taking.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON, D.C. — The federal agency that runs Medicare and Medicaid is building a new office focused entirely on technology, a move that could reshape how tens of millions of Americans interact with their health coverage and how companies sell software and digital services to the government.

The Centers for Medicare & Medicaid Services (CMS) announced on June 10 that it is creating the Office of Health Technology and Products (OHTP). The change became official in a Federal Register notice published on June 11, amending the agency’s formal statement of organization and responsibilities. The office will be responsible for modernizing the technology and digital products that support Medicare, Medicaid, the Children’s Health Insurance Program (CHIP), and other federal health programs.

In practical terms, the goal is to improve the websites, applications, and data systems that patients, healthcare providers, insurers, and government agencies rely on every day. Anyone who has attempted to compare Medicare plans, track a claim, or transfer medical records between providers understands how fragmented and outdated many of those systems remain.

According to CMS, the new office will work closely with the agency’s Chief Information Officer and operate under existing cybersecurity, information technology governance, and spending oversight policies. The structure is intended to ensure technology initiatives align with broader agency priorities and avoid duplication or disconnected development efforts.

The office will consist of several specialized groups.

Among them is an Open Source Program Group, which will oversee policies related to software built on open-source technology rather than proprietary systems controlled by a single vendor.

A separate Standards and Interoperability Group will focus on improving data-sharing capabilities across healthcare systems. The group includes divisions dedicated to data platforms and interoperability policy.

CMS is also creating a Product Development Group and a Digital Service at CMS unit, both designed to support the development and deployment of digital tools across the agency.

The agency said OHTP will provide enterprise-wide leadership for CMS health technology and digital product strategy.

The business implications are significant.

CMS is among the nation’s largest purchasers of healthcare technology, and any shift in standards or procurement strategy can influence billions of dollars in contracts. The agency’s increased focus on open-source technologies could create opportunities for smaller and emerging firms that have historically struggled to compete against large incumbent government contractors.

Likewise, the emphasis on interoperability—the ability of different systems to securely exchange information—has implications for hospitals, insurers, electronic health record providers, software developers, and virtually every organization connected to federal healthcare programs.

The move is part of a broader restructuring effort across the Department of Health and Human Services (HHS). On March 31, HHS announced changes reversing portions of a 2024 reorganization of federal health information technology leadership. The creation of OHTP is one of the first major organizational changes resulting from that effort.

The office also aligns with a larger federal push to bring private-sector technology expertise into healthcare modernization initiatives.

At a White House event earlier this year, CMS secured commitments from major technology companies—including Amazon, Apple, Google, OpenAI, and Anthropic—to help build what federal officials described as a next-generation digital health ecosystem.

HHS Secretary Robert F. Kennedy Jr. said the effort is intended to eliminate barriers that prevent patients from easily accessing and controlling their own health information. Approximately 30 companies reportedly pledged support for the initiative.

The foundation for many of these efforts was established in July 2025, when CMS launched its Health Technology Ecosystem Initiative to improve healthcare data sharing and interoperability. Early participants included Google, Amazon, Epic Systems, and UnitedHealth Group, with initial tools beginning to roll out this year.

A key challenge for the new office will be talent recruitment.

Federal agencies often struggle to compete with private technology firms for experienced engineers, software developers, cybersecurity specialists, and product managers. The success of OHTP may depend largely on its ability to attract and retain professionals capable of executing large-scale digital transformation projects.

For consumers, success would likely appear in simple but meaningful ways: easier enrollment processes, faster claims handling, improved access to health information, and medical records that move seamlessly between providers.

Whether the office ultimately delivers those results remains to be seen. For now, CMS has made clear that health technology modernization is becoming a central priority—and one important enough to warrant its own dedicated office.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
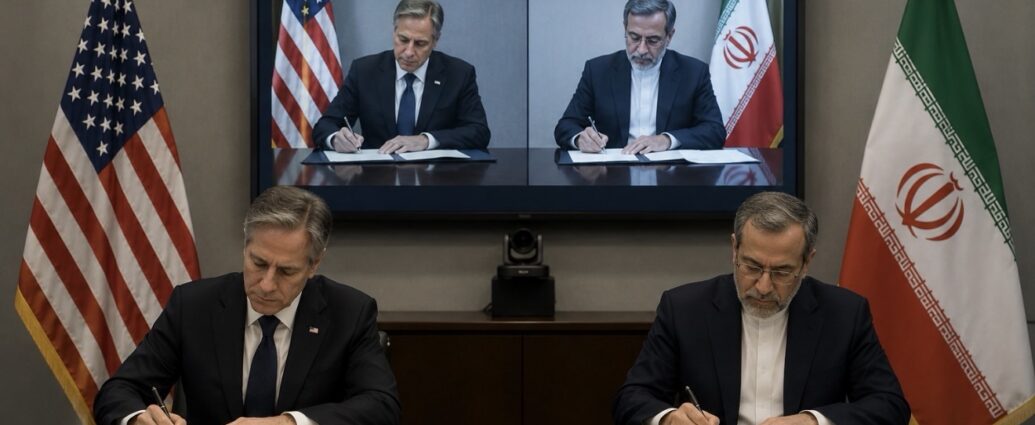
BlackRock moved Friday, June 12, 2026, to limit how much money investors can pull out of its largest private-credit fund, as a wave of jittery shareholders — worried about loan losses, a string of fraud cases, and whether borrowers can survive the upheaval from artificial intelligence — rushed for the exits faster than the fund will let them leave.

In a shareholder letter and regulatory filing, the firm said investors in the HPS Corporate Lending Fund (HLEND) asked to redeem about 13.3% of the fund’s shares in the latest quarter, up from 9.3% the quarter before. BlackRock said it would buy back only 5% — roughly $620 million — and cash out the rest on a prorated basis.

And this is not just a BlackRock problem.

In the past two weeks alone:

  • Blackstone capped withdrawals on its flagship private-credit fund.
  • Cliffwater turned away most investors seeking to exit its roughly $31 billion fund.
  • Partners Group restricted redemptions from an $8.6 billion vehicle.

Across the roughly $2 trillion private-credit market, the same concern is spreading: the long period of easy money and steady growth may be ending, and investors are discovering that getting their money back is not always as simple as it appeared when they invested.

It is the second consecutive quarter that BlackRock’s HLEND fund has hit its redemption limit and restricted withdrawals. The increase in redemption requests — roughly half again as large as the previous quarter — is one of the clearest signs yet that investor anxiety is growing rather than fading.

Why Investors Cannot Get Their Money Immediately

Private-credit funds make loans directly to companies instead of buying bonds that trade on public markets.

Because those loans are difficult to sell quickly, many private-credit funds only allow investors to withdraw a limited amount of money each quarter — typically no more than 5% of fund assets.

When investors ask for more than that, fund managers impose what the industry calls a gate. Investors receive a portion of their money immediately while the remainder stays in the fund until future redemption periods.

That is exactly what BlackRock did this quarter.

A Key Fund in BlackRock’s Private-Market Strategy

The HPS Corporate Lending Fund sits at the center of BlackRock’s push into private markets.

BlackRock acquired the business through its approximately $12 billion purchase of HPS Investment Partners last year, a deal that significantly expanded the firm’s presence in private lending.

Today, the fund manages an investment portfolio approaching $25 billion, making it one of the largest buyers of private corporate loans in the United States.

BlackRock imposed similar limits elsewhere.

The firm also capped withdrawals at its smaller BlackRock Private Credit Fund (BDEBT) after investors requested withdrawals equal to approximately 5.3% of assets. BlackRock approved the maximum 5%, or roughly $83 million.

A third vehicle, the HPS Corporate Capital Solutions Fund, received lighter redemption requests of approximately 4.7%.

Why Investors Are Nervous

Several concerns are hitting the market simultaneously:

  • Rising concerns about future loan losses
  • High-profile fraud cases within parts of the credit market
  • Questions about how artificial intelligence will affect borrowers
  • Concerns about weaker software companies facing AI disruption
  • Expectations that corporate defaults could increase
  • Refinancing risk as older low-interest loans mature into a higher-rate environment

Many investors worry that companies which borrowed heavily during the era of cheap money may struggle as those obligations come due.

What It Means for Everyday Investors

The private-credit industry has attracted large numbers of individual investors over the last several years.

Financial advisers frequently promoted the funds because they offered:

  • Steady income
  • Higher yields
  • Returns that often moved independently from stock markets

The redemption restrictions serve as a reminder that higher yields often come with reduced liquidity.

Unlike stocks or publicly traded bonds, the underlying loans cannot be sold quickly. Investors who want their money back may need to wait through multiple redemption periods before receiving the full amount.

BlackRock Remains Optimistic

Despite the redemption pressure, BlackRock said it expects new investor commitments to offset withdrawals paid so far this year.

The firm also noted that higher interest rates could support future returns.

According to BlackRock, the HPS Corporate Lending Fund has generated annualized returns of approximately 10.2% since launch.

Chief Executive Larry Fink has told investors that large institutional buyers — including pension funds and insurance companies — continue to add capital on a net basis, even as some financial advisers and retail investors pull back.

Market Reaction

Investors appeared largely unfazed by the news.

Shares of BlackRock (NYSE: BLK) rose more than 1% Friday, suggesting Wall Street views the redemption pressure as manageable for now.

The broader question facing the private-credit industry is whether these redemption restrictions are temporary growing pains or the first sign of a more significant stress test for one of the fastest-growing corners of modern finance.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Peru may be on the verge of electing the daughter of one of its most controversial former presidents, but the outcome remains uncertain. According to official results updated Wednesday by Peru’s electoral authority, conservative candidate Keiko Fujimori holds a razor-thin lead over leftist challenger Roberto Sánchez following Sunday’s presidential runoff. The margin separating the two candidates remains less than one percentage point, and electoral chief Roberto Burneo has warned that final certification could take as long as 30 days.

Fujimori, 50, is the eldest daughter of former President Alberto Fujimori, who governed Peru from 1990 to 2000. His presidency remains deeply divisive. Supporters credit him with defeating insurgent groups and stabilizing the economy, while critics point to his 1992 dissolution of Congress and subsequent convictions for corruption and human rights abuses.

The election marks Fujimori’s fourth attempt at the presidency after unsuccessful campaigns in 2011, 2016, and 2021. She leads the Fuerza Popular party, which already controls roughly one-third of Peru’s Congress. Her opponent, Sánchez, is politically aligned with former President Pedro Castillo, who remains imprisoned following his own failed attempt to dissolve Congress in 2022.

The election comes after a decade of political instability that has seen eight presidents cycle through office, undermining investor confidence and complicating long-term economic planning.

For global markets, the stakes extend far beyond Peru’s borders.

Peru is the world’s third-largest producer of copper, a metal essential to electric vehicles, power transmission infrastructure, renewable energy projects, and the rapidly expanding artificial intelligence industry. The country is also a major producer of silver, gold, and zinc, making its political stability increasingly important to global commodity markets.

Investors have generally viewed Fujimori as the more market-friendly candidate. Her platform supports mining investment and private-sector growth, while some investors feared a left-wing victory could lead to higher mining taxes, increased royalties, or stricter operating requirements for foreign companies.

A clear Fujimori victory would likely be viewed positively by financial markets, potentially strengthening the Peruvian sol, supporting the Lima Stock Exchange, and providing momentum for more than $50 billion in planned mining projects. Market analysts say the greatest risk remains a prolonged dispute over the election result that could trigger protests or political paralysis.

Hovering over the entire race is the growing influence of China.

Chinese companies have become deeply embedded in Peru’s economy. They control some of the nation’s most important mining assets, including Las Bambas, operated by MMG, and Toromocho, owned by Chinalco. Chinese state-backed firms have also acquired major utility assets, including Luz del Sur.

Perhaps the most strategically significant investment is the $3.6 billion Chancay deepwater port, developed by COSCO Shipping and inaugurated by Chinese President Xi Jinping during a 2024 summit. The facility gives China a direct Pacific gateway for South American exports, particularly minerals destined for Chinese manufacturers.

The project has attracted attention in Washington, where policymakers increasingly view strategic infrastructure investments as part of a broader competition with Beijing.

American investors have responded by backing alternative projects. BlackRock’s infrastructure division has invested in the rival Matarani port, positioning it as a competitor to Chinese-backed facilities and reflecting growing U.S. interest in maintaining influence in South America’s critical supply chains.

Analysts remain divided on what a Fujimori presidency would mean for U.S. interests.

Supporters argue that Fujimori is more likely to pursue pro-investment policies, strengthen ties with Washington, cooperate on security matters, and take a more cautious approach toward Chinese strategic investments. They point to issues such as counternarcotics cooperation and trade relations where closer alignment with the United States could emerge.

Others caution that any shift may be limited. China is Peru’s largest trading partner and a dominant source of investment capital. Regardless of who wins, Peru’s economy remains deeply tied to Chinese demand for minerals and commodities.

They also note that the Fujimori name remains highly polarizing. A victory decided by only a few hundred votes could face legal challenges and public protests, raising the possibility of renewed instability in a country that has struggled to maintain political continuity.

For investors, the central question may not be which candidate ultimately prevails but whether Peru can produce a widely accepted result and maintain enough stability to remain a reliable supplier of critical minerals.

Until the final certification is issued, Peru’s mines continue operating, copper continues flowing through both Chinese- and Western-backed ports, and global markets remain focused on one of the closest presidential elections in the country’s modern history.

JBizNews Desk — Latin America

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
PARIS, France — June 14, 2026 — The Food and Drug Administration (FDA) on Friday granted accelerated approval to Sanofi’s Tzield for children ages 8 to 17 who have recently been diagnosed with stage 3 type 1 diabetes, opening the therapy to its largest patient population yet and significantly expanding the commercial opportunity for one of the company’s most closely watched products.

The decision marks the first time a drug has been approved in the United States to help preserve the body’s remaining insulin production in children who already have stage 3 disease. While Tzield does not cure diabetes or eliminate the need for insulin injections, it is designed to slow the autoimmune attack that destroys insulin-producing cells in the pancreas, potentially giving newly diagnosed children more stable blood sugar levels during the critical early months following diagnosis.

For Sanofi, the approval represents another step in turning its $2.9 billion acquisition of Provention Bio in 2023 into a major growth driver. Every expansion of Tzield’s approved uses increases the number of patients eligible for treatment and broadens the potential market for a therapy that carries a list price of approximately $194,000 per course.

Type 1 diabetes is an autoimmune disease in which the immune system mistakenly attacks and destroys beta cells in the pancreas, preventing the body from producing sufficient insulin. By the time patients reach stage 3 disease, enough of those cells have been lost to cause dangerous blood sugar elevations and symptoms including extreme thirst, frequent urination, sudden weight loss, fatigue, and blurred vision.

From that point forward, patients typically require lifelong insulin therapy.

Tzield works differently from traditional diabetes treatments. Rather than replacing insulin, the drug targets the immune system itself. Administered through a series of intravenous infusions, it slows the immune attack responsible for destroying the remaining insulin-producing cells.

The FDA’s decision was based primarily on data from the Phase 3 PROTECT study, which enrolled 328 children and adolescents diagnosed with type 1 diabetes within the previous six weeks. Participants receiving Tzield maintained significantly greater natural insulin production compared with those receiving a placebo, suggesting the therapy can preserve pancreatic function longer after diagnosis.

Doctors have long viewed preservation of insulin production as a meaningful goal because even small amounts of natural insulin can help improve blood-sugar management and reduce the risk of severe highs and lows.

The treatment is not without risks.

According to Sanofi, the most common side effects observed in clinical trials included decreased white blood cell counts, vomiting, rash, headache, and temporary immune-system reactions. The therapy also carries warnings regarding cytokine release syndrome, a potentially serious inflammatory response, as well as the possible reactivation of dormant viral infections.

Despite those risks, diabetes specialists have increasingly viewed Tzield as one of the most significant advances in type 1 diabetes treatment in decades because it addresses the disease process itself rather than simply managing symptoms.

The business debate surrounding Tzield has largely centered on price.

The drug’s list price of roughly $194,000 for a complete treatment course drew attention from insurers and healthcare analysts when it first launched. At the time, some Wall Street analysts had projected pricing closer to $70,000 to $115,000, leading to concerns that insurance companies could push back on coverage.

As a result, access to the treatment often depends on prior authorization and case-by-case review by insurers.

Sanofi has sought to address affordability concerns through its COMPASS patient-support program, which offers copay assistance and support services designed to help eligible patients obtain coverage. Even so, healthcare experts expect reimbursement decisions by commercial insurers and government payers to remain a major factor in determining how widely the treatment is adopted.

The latest approval follows a series of regulatory wins for the therapy.

Tzield first received FDA approval in November 2022 for delaying the onset of stage 3 type 1 diabetes in individuals with stage 2 disease. In April 2026, regulators expanded that indication to include children as young as 1 year old.

Friday’s approval opens an entirely new category by allowing treatment after stage 3 diagnosis, a substantially larger population than the preventive-use market.

According to Sanofi, approximately 64,000 people are diagnosed with type 1 diabetes each year in the United States, creating a significant opportunity if physicians and insurers broadly embrace the treatment.

The approval was granted through the FDA’s accelerated approval pathway, which allows therapies for serious diseases to reach patients sooner based on surrogate measures that are reasonably likely to predict clinical benefit. In this case, preserved insulin production served as the key marker supporting approval.

Sanofi is currently conducting a confirmatory trial known as BETA-PRESERVE to verify the long-term benefits of the therapy. Failure to demonstrate those benefits could result in the FDA revisiting the approval in the future.

Sanofi (NASDAQ: SNY) shares closed at $44.25 on Thursday, June 11, little changed ahead of the announcement as investors weighed the potential impact of the latest regulatory expansion.

JBizNews Desk — Health Care

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
DoorDash Inc. said on Thursday, June 11, that it is adding an artificial-intelligence assistant to its app, allowing customers to order food and groceries by typing a request, speaking it aloud, or simply snapping a photo. The company unveiled the new tool, called Ask DoorDash, and said it plans to expand the feature to restaurant reservations and additional U.S. markets in the coming weeks.

Customers can access the assistant through a new “Ask” button in the app’s search bar. From there, users can describe what they want in plain language, use voice commands, or upload a photo. The chatbot then generates recommendations and provides one-click options to add suggested items directly to a shopping cart.

Initially, the feature is launching in select markets for food delivery and grocery purchases, with restaurant reservations and broader geographic expansion expected later this year.

The move places DoorDash directly in the growing competition among technology and delivery companies racing to integrate artificial intelligence into consumer shopping experiences.

Uber Technologies introduced its own AI-powered grocery assistant earlier this year, while Instacart rolled out AI tools for retailers and grocery partners last year. The industry increasingly views conversational shopping as a potential replacement for traditional search menus and category browsing.

For DoorDash, the initiative is part of a much larger strategy.

The company is currently investing heavily to consolidate its businesses onto a unified technology platform following several major acquisitions. Among them was its $1.2 billion acquisition of restaurant-management and reservation company SevenRooms, along with its nearly $4 billion purchase of European delivery platform Deliveroo.

The SevenRooms acquisition is particularly important to the new AI rollout because it provides the reservation technology that will allow customers to book restaurant tables through Ask DoorDash.

Instead of using separate applications for dining reservations and food delivery, users will eventually be able to search, reserve a table, order takeout, or purchase groceries through a single interface.

That broader vision is central to DoorDash’s growth plans.

Chief Financial Officer Ravi Inukonda recently told investors that much of the company’s platform-transformation spending is expected to occur this year. The company is effectively rebuilding portions of its technology infrastructure to support future products and services.

The AI assistant is one of the first highly visible consumer-facing examples of where those investments are being directed.

Investors have been watching closely.

DoorDash shares have fallen roughly 33% this year, significantly underperforming the broader Nasdaq Composite, which has gained about 8% over the same period. Concerns about acquisition costs, technology spending, and profitability have increased pressure on management to demonstrate a return on those investments.

The launch of Ask DoorDash is part of that effort.

Beyond helping consumers find meals and groceries faster, DoorDash is also signaling that the underlying technology could eventually become a business product.

The company suggested the AI infrastructure being developed for consumers may create future enterprise opportunities for restaurants, grocers, retailers, and brands that operate on the platform.

In practical terms, software that helps customers discover and purchase products could later be licensed, integrated, or sold to merchants seeking similar capabilities.

For consumers, however, the immediate pitch is convenience.

Instead of manually searching through hundreds of menu options, a user can ask for a quick family dinner, affordable lunch options nearby, ingredients for a recipe, or even upload a photo of a meal they would like to recreate. The assistant then searches across DoorDash’s network and presents recommendations.

Whether customers ultimately prefer conversational shopping over traditional app navigation remains an open question.

Many consumers are already comfortable browsing menus and categories manually, meaning the success of the feature will depend on whether it genuinely saves time and improves the ordering experience.

The reservation component may prove especially important.

By combining restaurant bookings, grocery purchases, and delivery orders inside a single AI-powered assistant, DoorDash is positioning itself as a broader commerce platform rather than simply a food-delivery company.

That strategy places it in more direct competition not only with delivery rivals such as Uber, but also with dedicated restaurant-reservation platforms.

The rollout is beginning on a limited basis, but adoption rates and customer engagement will provide a clearer picture later this year of whether DoorDash’s latest AI investment can translate into meaningful business growth.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
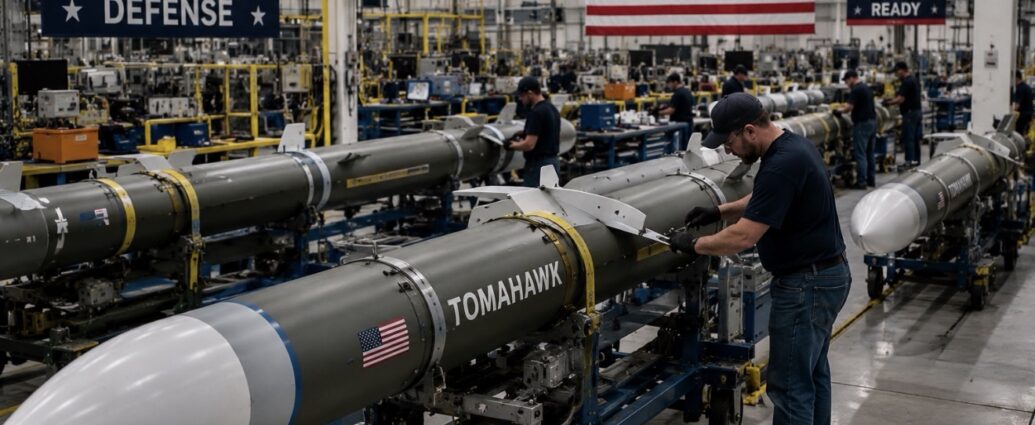
A coalition of 20 state attorneys general sued the Trump administration on Wednesday, asking a federal court to block new federal contracting requirements tied to diversity, equity, and inclusion programs. The lawsuit, filed in the U.S. District Court for the District of Maryland and led by California Attorney General Rob Bonta and Maryland Attorney General Anthony Brown, challenges how federal agencies implemented President Donald Trump’s Executive Order 14398, signed on March 26, 2026.

The executive order directs federal agencies to include language in contracts prohibiting what the administration describes as “racially discriminatory DEI activities” by contractors and recipients of federal funds. The lawsuit does not seek to overturn the executive order itself. Instead, it argues that federal agencies violated federal law when they implemented the policy.

According to the complaint, more than two dozen federal agencies began adding the new contract provisions in April without providing public notice or allowing a formal comment period. The states argue that the requirements are vague, fail to clearly define prohibited conduct, and represent a significant departure from long-established federal contracting standards.

The attorneys general contend that the agencies violated the Administrative Procedure Act, the federal law governing agency rulemaking, and are asking the court to block enforcement of the new contract language.

The potential impact is substantial.

According to federal estimates cited in the lawsuit, the order could affect approximately 640,000 contracts and subcontracts nationwide, including more than 160,000 contracts held by over 34,000 vendors. Federal agencies have been instructed to modify existing contracts by July 24.

For businesses that rely on federal contracts, the concern extends beyond politics. Companies that certify compliance with unclear requirements could face future investigations, contract disputes, suspension from federal programs, or exposure under the False Claims Act, which allows the government to seek significant financial penalties for false certifications.

The coalition argues that the uncertainty places contractors in a difficult position, particularly smaller businesses that may lack extensive legal resources.

The attorneys general describe the lawsuit as a defense of established civil-rights practices. Vermont Attorney General Charity Clark said diversity, equity, and inclusion initiatives are intended to address discrimination and expand opportunity rather than violate existing law.

The coalition includes Democratic attorneys general from states such as California, Illinois, New Jersey, Massachusetts, Connecticut, and others, along with the District of Columbia.

The Trump administration has defended the policy as part of its broader effort to eliminate race-based preferences in government-funded programs. Administration officials argue that federal taxpayer dollars should not support policies that consider race or identity and that contractors can comply simply by eliminating such programs.

Legal experts note that the dispute may ultimately hinge more on procedure than ideology. Federal courts have repeatedly used the Administrative Procedure Act to halt executive actions when agencies failed to follow required rulemaking procedures.

A judge could temporarily block enforcement while the litigation proceeds.

Until then, contractors face a difficult decision: accept the new requirements, challenge them, or wait for the courts to determine whether the rules can legally take effect.

With billions of dollars in federal contracts potentially affected, the outcome of the case could reshape compliance requirements for businesses across the country and influence the future of DEI-related policies throughout the federal contracting system.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
New York City turned into one giant block party Saturday night the moment the New York Knicks clinched their first NBA championship in 53 years, and by Sunday Mayor Zohran Mamdani had made the celebration official, announcing a ticker-tape parade for Thursday, June 18, through Lower Manhattan.

The timing is striking. The biggest sporting event on the planet, the FIFA World Cup, is being played in the same metro area right now — yet it is the Knicks who have seized the city’s heart and its streets.

The scenes told the story.

Thousands of fans poured out of bars, apartments, and watch parties the instant the final buzzer sounded in San Antonio, converging on Madison Square Garden, Times Square, and major intersections across Midtown. Crowds stretched for blocks. Fans climbed poles, danced on cars, waved flags, hugged strangers, and chanted into the night — an outpouring of civic pride no marketing budget can manufacture.

Mamdani leaned into the moment.

“For more than 50 years, New Yorkers have waited for this moment,” he said while announcing a City Hall ceremony, Keys to the City for the team, and municipal buildings illuminated in blue and orange.

It will be the Knicks’ first ticker-tape parade, after the city marked its previous championships with ceremonies rather than a Canyon of Heroes procession.

The economic impact is real.

A hometown championship is an event the city actually owns. The excitement translates directly into spending at neighborhood bars, restaurants, retail stores, hotels, and entertainment venues. It fuels merchandise sales, creates additional tourism activity, and drives crowds into Lower Manhattan for the parade.

The celebration also boosts the value of the franchise itself.

The Knicks are owned by Madison Square Garden Sports Corp. (NYSE: MSGS), and the championship strengthens a franchise already valued at approximately $9.85 billion. The title is expected to support future increases in ticket prices, premium seating demand, sponsorship revenue, and merchandise sales.

Contrast that with the World Cup.

Organizers have projected approximately $3.3 billion in regional economic impact, with New Jersey claiming roughly $2 billion of that total. Yet early business results have been more muted than many expected.

International visitor numbers have reportedly come in below forecasts, while domestic travelers have accounted for a larger share of attendance. Some hotels have reduced room rates to stimulate demand, and travel-data firms have described the tournament’s impact as uneven across host cities.

But the biggest difference cannot be measured in economic studies.

A championship belongs to a city in a way a global tournament never quite can.

The Knicks are New York’s team. Their championship represents the culmination of a 53-year wait shared across generations of fans in Manhattan, Brooklyn, Queens, the Bronx, and Staten Island.

The World Cup, by comparison, is a global event temporarily visiting the region.

Its marquee matches are being played at MetLife Stadium in East Rutherford, New Jersey, while high ticket prices and travel barriers have limited participation for many fans.

That difference shows up in the streets.

The Knicks created a spontaneous celebration that required no advertising campaign. The World Cup, while enormous in scale, has largely been defined by logistics, transportation planning, security operations, and venue management.

One event feels like a city celebrating itself.

The other feels like a city hosting someone else’s party.

None of this means the World Cup will not generate meaningful revenue.

The tournament is expected to continue drawing visitors through mid-July, culminating with the World Cup Final on July 19. Hotels, restaurants, bars, transportation providers, and retailers throughout the region are still expected to benefit.

But the type of emotional momentum that sends hundreds of thousands of people into the streets is difficult to replicate.

The pride.

The history.

The shared memories.

The feeling that an entire city is celebrating together.

Those are things money cannot buy.

For local businesses, the coming days present a rare opportunity.

The Knicks parade arrives while World Cup matches continue throughout the region, creating the possibility that bars, restaurants, retailers, hotels, and entertainment venues benefit from both events simultaneously.

It is an unusual collision of a homegrown championship and the world’s largest sporting event unfolding within the same metropolitan area.

Still, if you walked the streets of New York on Saturday night, the verdict seemed obvious.

The World Cup may be bigger.

It may draw more viewers.

It may generate larger economic projections.

But it cannot match the pride, excitement, momentum, and sense of ownership that comes from seeing your own team finally bring a championship home after more than half a century.

For one unforgettable weekend, New York belonged to the Knicks.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Trump administration moved Wednesday, June 10, 2026, to establish the first comprehensive federal framework for prediction markets, proposing rules that would allow most sports-related contracts to continue while banning contracts regulators believe are most vulnerable to manipulation.

The Commodity Futures Trading Commission (CFTC) released a 267-page proposed rule outlining which event contracts would be permitted and which would be prohibited. The proposal represents the agency’s first formal attempt to regulate a rapidly growing industry that has blurred the line between financial markets and sports betting.

CFTC Chairman Michael Selig said the goal is to provide clear rules for the industry while protecting market integrity and encouraging innovation.

What Are Prediction Markets?

Prediction markets allow users to buy and sell contracts tied to future events.

Participants essentially purchase “yes” or “no” positions on whether something will happen, with contract values changing as market sentiment shifts.

Over the past year, platforms such as Kalshi and Polymarket have expanded aggressively into sports-related contracts, creating products that often resemble traditional sports betting.

The new proposal would largely allow that activity to continue.

What Would Be Allowed?

Under the proposed rules, prediction markets could continue offering contracts tied to:

  • Game winners and losers
  • Final scores
  • Point spreads
  • Tournament advancement
  • Team statistics
  • Player statistics
  • Season-long performance outcomes

In practice, many of these contracts resemble traditional sportsbook products such as:

  • Moneyline bets
  • Point spreads
  • Over/under totals
  • Player prop wagers

The CFTC argues these markets provide value beyond gambling by generating information that may be useful to:

  • Broadcasters
  • Advertisers
  • Sponsors
  • Fantasy sports companies
  • Analytics firms
  • Sports data businesses

What Would Be Banned?

The proposal draws a firm line around contracts regulators believe are easiest to manipulate.

The CFTC would prohibit contracts involving:

  • A single pitch in baseball
  • One shot in hockey
  • One foul in basketball
  • Individual game plays
  • Player injuries
  • Officiating decisions
  • Physical altercations during games
  • Youth sports below the college level, including high school athletics

According to the agency, these contracts raise significant public-interest concerns because individual participants may have greater ability to influence outcomes.

Why Is a Financial Regulator Involved?

The key legal issue is that the CFTC treats prediction-market contracts as financial products rather than traditional wagers.

Under the Commodity Exchange Act, many event contracts are classified similarly to swaps and derivatives, placing them under federal commodities regulation.

That distinction has allowed prediction-market operators to offer sports-related contracts nationwide, including in states where traditional sports betting remains illegal.

The companies argue they are operating federally regulated financial markets rather than sportsbooks.

Growing Battle With States

That legal position has triggered opposition from state gaming regulators and tribal gaming operators.

Critics argue that prediction markets are effectively sports betting under another name and should be regulated under existing state gambling laws.

State officials have warned that allowing federally regulated prediction markets to operate nationwide could undermine:

  • State licensing systems
  • Tax revenues
  • Tribal gaming agreements
  • Consumer protections

The CFTC has largely supported the platforms in ongoing legal disputes, defending their ability to offer contracts under federal law.

Some members of Congress have also questioned whether the agency is stretching its authority beyond what lawmakers originally intended.

Industry Reaction

Initial responses from major operators were measured.

A spokesperson for Polymarket said the company welcomes greater regulatory clarity and intends to participate in the public comment process.

Kalshi said it was reviewing the proposal and had not yet reached conclusions regarding the details.

Why It Matters

The stakes extend far beyond sports fans.

A permanent federal framework could remove significant legal uncertainty hanging over the industry and potentially accelerate growth.

Clear rules could attract:

  • New investors
  • Additional users
  • Institutional capital
  • Media partnerships
  • Sports-league relationships

At the same time, regulators hope restrictions on easily manipulated contracts will reduce the risk of scandals that could damage confidence in the broader market.

What Happens Next?

The proposal now enters a 90-day public comment period.

During that time:

  • Prediction-market operators
  • Sports leagues
  • Gaming regulators
  • Tribal gaming organizations
  • Investors
  • Members of the public

will have an opportunity to submit feedback before the CFTC drafts a final rule.

With multiple lawsuits still working through the courts and states continuing to challenge federal authority over sports-related contracts, the battle over who controls America’s rapidly growing prediction-market industry is far from over.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Americans and big investors are putting money into U.S. stocks faster than ever, and most of that cash is heading toward technology. Bank of America said Friday, in its closely watched weekly report on where money is moving, that U.S. stock funds drew record amounts of new money, with tech leading the way. The report, written by strategist Michael Hartnett and based on figures from EPFR Global, tracks how much money goes into and out of funds around the world each week.

To see how strong the run has been: in the week through June 10, technology funds pulled in a record $12.3 billion, part of $31.5 billion that flowed into U.S. and global stock funds. That capped an 11-week stretch of money moving into American stocks — the longest such streak since December 2025. Much of it chased computer-chip companies: the iShares Semiconductor ETF took in about $2.9 billion in a single week, and a leveraged fund that bets on the S&P 500 drew close to $3 billion.

Here is the twist that makes this week’s record unusual. At the very moment investors are handing over more money than ever, the biggest technology companies are selling them a flood of brand-new stock.

That matters because new shares soak up demand. Normally heavy buying with a fixed supply pushes prices up. But tech is issuing stock at a pace not seen in years. SpaceX went public on June 12, trading on the Nasdaq under the ticker SPCX at $135 a share, in a listing valuing it near $1.75 trillion — the largest U.S. stock debut ever. OpenAI and Anthropic, two of the world’s most valuable private companies, have both confirmed plans to go public. Analysts expect the three to raise roughly $200 billion between them.

It isn’t only newcomers. Alphabet, the parent of Google, has said it plans to raise about $80 billion by selling new stock, and Meta is reported to be weighing a similar move. Both want cash to build the giant data centers that power artificial intelligence — and selling shares lets them raise it without taking on more debt.

For everyday savers, the surge has a direct connection. Capital Economics notes that U.S. companies outside the financial industry began issuing more stock than they bought back early this year, the first time since 2021. The firm also offers a caution: big jumps in new stock sales have tended to appear near the late stages of past market booms.

There is also a new source of buying coming straight from Washington. Starting July 4, the federal government begins seeding “Trump Accounts” — investment accounts for children that open with a $1,000 deposit and steer the money into low-fee funds tracking the broad stock market. Bloomberg Intelligence estimates the program could push around $12 billion a year into those funds, rising toward $21 billion if families add the maximum. The money is automatic and stays put for years.

The rise has already lifted household wealth. By Bank of America’s count, the value of stocks owned by U.S. families has climbed about $6 trillion so far in 2026, after gains of roughly $10 trillion in 2025 and $9 trillion the year before. When portfolios swell, people tend to feel richer and spend more, which feeds back into the wider economy.

Not everyone is comfortable. Bank of America’s “Bull & Bear” gauge, which measures how greedy or fearful investors are, has been flashing a sell warning for several weeks — a level the bank reads as a sign buying has run hot. Hartnett has compared today’s market to 1994, when a long calm period ended abruptly once the Federal Reserve started raising interest rates.

For now, the money keeps coming. The bigger test arrives later this year, when OpenAI and Anthropic aim to complete their listings and Alphabet and Meta sell their new shares — adding hundreds of billions of dollars in fresh stock for buyers to absorb.


What These Deals Actually Mean for Your 401(k)

If you own an S&P 500 or total-market index fund, you don’t buy these stocks yourself — the fund does it for you, automatically, based on each company’s size. So a wave of giant tech listings sounds like it should pour your retirement money straight into SpaceX, OpenAI, and Anthropic. The reality is more gradual, and smaller than the headlines suggest.

Two things hold it back. First, index funds only count the shares a company actually sells to the public, not the ones founders and early backers keep. At launch, these firms are floating only about 4% to 5% of their stock, so their weight in your fund starts tiny no matter how huge the valuation.

Second, getting into the S&P 500 isn’t automatic. A company has to be profitable over recent quarters and gets picked by a committee, which can take time. Broad total-market and Nasdaq funds tend to pick up new listings sooner, but still in proportion to those small public floats.

The bigger effect comes later. Analysts at Capital Economics estimate that if these companies eventually release more of their shares to the public — say, a quarter of them — it could add about $750 billion in stock for funds to buy. That’s when an everyday index holder would really feel it.

JBizNews Desk | Wall Street

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The New York Knicks ended a 53-year championship drought Saturday night, June 13, 2026, in San Antonio, defeating the San Antonio Spurs in five games to capture the franchise’s first NBA title since 1973. The victory delivers one of the biggest moments in modern New York sports history. It also highlights a less-discussed reality: championships can create enormous financial value long before the confetti is swept off the floor.

Start with the team’s owner. The Knicks are held by Madison Square Garden Sports Corp. (NYSE: MSGS), controlled by James Dolan, and the franchise is now valued at approximately $9.85 billion. That valuation has climbed sharply alongside the team’s success, while MSGS shares have surged roughly 43% in 2026 and 86% over the past 12 months.

A championship does more than add a banner to Madison Square Garden. It increases the value of one of the most recognizable sports brands in the world.

The playoff run itself generated significant revenue. David Joyce, an analyst at Seaport Research Partners, estimated the Knicks earned approximately $8 million per home game in the first round from tickets, suites, concessions, and merchandise. That figure rose to about $12 million per game in the second round and roughly $17 million per game during the Eastern Conference Finals. Finals home games were likely worth more than $20 million each, with analysts estimating the entire postseason run could add approximately $140 million in revenue.

One reason the financial impact is so significant is the Knicks’ ownership structure. Unlike many professional teams that play in venues owned by separate entities, the Knicks operate within the same ownership ecosystem as Madison Square Garden, allowing more playoff-related revenue to remain in-house.

The NBA’s revenue-sharing structure still applies. Teams retain approximately 75% of postseason ticket revenue, while the remaining portion is directed to the league to help cover playoff expenses and related obligations.

Fans also paid historic prices to witness the run. The cheapest tickets for NBA Finals games at Madison Square Garden approached $4,000, while average resale prices exceeded $7,000, making the series one of the most expensive Finals experiences in league history.

Beyond the arena, city officials projected a substantial economic impact. Mayor Zohran Mamdani and the New York City Economic Development Corporation estimated the postseason generated approximately $202 million in economic activity from home playoff games. Officials projected that number could have reached as high as $465 million had every possible Finals home game been played, with each game estimated to generate roughly $90 million in spending on transportation, lodging, food, merchandise, and entertainment.

Because the Knicks clinched the championship on the road in Game 5, the final economic impact fell below the city’s highest projection.

Not everyone agrees with the larger economic estimates. Many sports economists argue that major sporting events often shift spending rather than create entirely new spending. In that view, the largest financial gains tend to flow to team ownership, broadcasters, sponsors, and ticket marketplaces rather than the broader local economy.

The championship may also accelerate strategic decisions inside MSG Sports. The company has explored separating the Knicks and New York Rangers into independent publicly traded entities, an idea supported by activist investor Boyar Value Group, which has argued that the market undervalues the franchises when combined under a single corporate structure.

The title only strengthens that argument.

For perspective, MSG Sports reported approximately $1.04 billion in revenue during fiscal 2025. A championship run can continue producing financial benefits for years through higher season-ticket prices, increased merchandise sales, premium seating demand, sponsorship growth, and stronger media value.

So how much did the Knicks’ first championship in 53 years bring in?

Approximately $140 million in additional company revenue, a franchise valuation approaching $10 billion, and hundreds of millions of dollars in estimated economic activity across New York City.

The biggest winners, however, may be the people who already owned one of the most valuable franchises in sports.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The most expensive night in mixed martial arts history lands on the South Lawn of the White House at 8 p.m. ET Sunday, and the company staging it has already told the public not to expect a profit. UFC Freedom 250 — built to mark the nation’s 250th anniversary and President Donald Trump’s 80th birthday, which falls the same day — will cost more than $60 million, a figure stated on the record by TKO Group Holdings president Mark Shapiro and UFC CEO Dana White in interviews this spring. A White House official confirmed by email this week that the UFC is funding the event and no taxpayer dollars are being spent beyond normal staff duties.

Here’s the part that matters for the business of fighting: the company knows it will lose money Sunday and is doing it anyway. Shapiro has called the show an investment for the long term, built around “earned media,” and said TKO is working with corporate partners to offset roughly $30 million of the cost. There are no tickets to sell. About 4,000 invited guests will watch in person, including more than 1,000 members of the armed services.

So the money has to come from somewhere else. The official UFC listing names Crypto.com and Ram as presenting sponsors. Bud Light, Monster Energy and Polymarket are among the brands lining the rails of the Octagon. White said the UFC is offering sponsorship packages at a reported $1.5 million, though he noted those do not necessarily guarantee a South Lawn seat — “we’re trying to figure out how to bring some money in the door.” A UFC executive said the White House had to approve every sponsor whose name appears on the Octagon canvas.

The bigger financial story sits behind the spectacle. This year, under a seven-year, $7.7 billion agreement disclosed in TKO’s annual report, Paramount became the exclusive U.S. home of the UFC — bringing all 43 annual events to Paramount+ with select events on CBS. The deal averages about $1.1 billion a year, more than double what Disney’s ESPN had been paying, and scraps the pay-per-view model in favor of no extra charge for Paramount+ subscribers. The White House card is the splashiest showcase yet of that arrangement. Despite earlier expectations, CBS will not carry the fights — viewers need Paramount+, owned by Paramount Skydance (NASDAQ: PSKY).

The event nearly didn’t happen. A federal judge cleared it Friday after the Public Integrity Project sued on behalf of two Virginia residents — an activist and a Vietnam War veteran — seeking to block the show and the 92-foot, 600-ton steel structure nicknamed “The Claw” built on the South Lawn. U.S. District Judge Amit Mehta ruled the plaintiffs likely lack standing and failed to prove irreparable harm, noting the card had been public for nearly a year while they waited until June 7 to act. Mehta acknowledged a public interest in preventing “unauthorized, commercial exploitation” of protected landmarks, but said the standing problem weighed against ruling on it.

The president’s own finances have drawn scrutiny around the night. Trump bought stock in TKO before announcing the fight, designed a line of “Trump x UFC Freedom 250” medallions selling for $250 to $12,000, and is holding a $1 million-per-plate fundraiser for his top super PAC the night before. The White House has called the underlying lawsuit baseless and said it was not involved in cost or sponsorship negotiations.

The card carries real stakes for the roster. Ilia Topuria, Justin Gaethje, Alex Pereira and Sean O’Malley are among the fighters scheduled to compete. Topuria headlines against Gaethje, while Pereira meets Ciryl Gane for the heavyweight title in a bid for a third UFC belt. The full card was locked in after every fighter made weight at Saturday’s official weigh-ins in Washington.

Whether the $60 million bet pays off won’t be settled in the cage. It will show up later — in Paramount+ subscriber numbers, in TKO’s next sponsorship cycle, and in how much “earned media” a fight on the President’s front lawn actually earns.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Sticky

EATONTOWN, N.J. — As artificial intelligence rapidly changes how businesses operate, JBiz has announced the JBiz Leadership AI Operations Summit, a two-day executive training program designed to help companies improve productivity, streamline operations, reduce costs, and increase revenue through practical AI adoption.

The summit will take place July 13–14, 2026, at the Sheraton Eatontown Hotel in New Jersey and is geared toward business owners, corporate leadership, management teams, entrepreneurs, and organizations looking to better equip their workforce for an AI-driven economy.

Organizers say the goal is simple: help businesses understand how to effectively use today’s leading AI platforms and determine which tools are best suited for specific business tasks.

“Learning how to use AI is quickly becoming as important as learning how to use computers, email, and the internet became in previous generations,” said Duvi Honig, Founder of JBiz.

Open Ai all, Companies are encouraged to send multiple employees and leadership team members together to maximize results and help integrate AI throughout their organizations.

The shift underway is significant. For decades, businesses relied on large teams of junior employees and support staff to handle research, spreadsheets, presentations, scheduling, customer communications, reporting, and administrative work.

Today, properly trained employees using AI platforms such as ChatGPT, Claude, Gemini, Microsoft Copilot, Grok, and Perplexity can complete many of those tasks faster and more efficiently. Increasingly, companies view AI as a collection of virtual assistants that help employees draft emails, conduct research, analyze data, summarize meetings, create reports, improve communication, and accelerate workflow across departments.

Recent surveys suggest the business impact is growing quickly.

An Oliver Wyman Forum–New York Stock Exchange CEO survey found that 43% of CEOs plan to place less emphasis on hiring junior staff while increasing demand for experienced employees who know how to use AI effectively.

Research from Stanford University, MIT, and Boston Consulting Group has also found that workers using generative AI complete more tasks, work faster, and often produce higher-quality results than workers who do not use AI tools.

One high-profile example came from Citadel Founder and CEO Ken Griffin, who recently said that modern AI systems are performing work that previously required teams of finance professionals, completing in hours or days tasks that once took weeks or months.

Meanwhile, the McKinsey Global Institute estimates generative AI could create between $2.6 trillion and $4.4 trillion in annual global economic value across customer service, operations, software development, research, marketing, communications, and workflow management.

“We are watching one of the biggest operational shifts in modern business history,” Honig said. “The companies adapting early are gaining major advantages, while many businesses still don’t know where to begin. This summit was created to provide practical training businesses can immediately apply.”

Unlike many AI events focused on theory, organizers say the program is designed as a practical, implementation-focused training experience. Participants will learn how to use multiple AI platforms together and understand the strengths of each system.

Training will cover:

  • ChatGPT — communication, writing, workflow support, strategy, presentations, and operational assistance
  • Claude — long-form analysis, contracts, planning, and document review
  • Gemini — Google Workspace integration, collaboration, productivity, and research
  • Microsoft Copilot — Excel, Word, Outlook, PowerPoint, and enterprise workflows
  • Grok — live information analysis and trend monitoring
  • Perplexity — research, sourcing, and market intelligence
  • Additional leading AI platforms and workflow tools

Participants will receive hands-on instruction on applying AI to:

  • Communication
  • Operations
  • Documents and spreadsheets
  • Research
  • Sales
  • Marketing
  • Reporting and presentations
  • Administration and workflow systems

Summit attendees will leave with a clearer understanding of the AI landscape, practical workflows they can use immediately, and strategies to save time, improve productivity, reduce administrative burdens, and strengthen operational performance.

Organizers estimate businesses effectively implementing AI can save employees between 5 and 15 hours per week, potentially creating between $12,000 and $54,000 in annual operational value per employee, depending on role and implementation.

For a company with 10 employees, that could translate into productivity gains ranging from roughly $120,000 to more than $540,000 annually, although actual results will vary by company, industry, and adoption levels.

The summit will feature full-day training sessions from 10:00 a.m. to 5:00 p.m. on both days and will be led by professionals with hands-on experience using today’s leading AI platforms.

Participants will leave with a deep understanding of all platforms, practical skills and a framework for immediately execution integrating AI into their daily responsibilities and business operations.

Limited Seating Available! For corporate inquiries, team registrations, and group packages, Visit or contact Esther@OJChamber.com or 212-659-5270 x104.

JBizNews Desk — New Jersey

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The U.S. Treasury Department sanctioned nine individuals and companies Wednesday for helping Iran’s military acquire weapons, with several of the entities based in China and Hong Kong. In a statement, Treasury Secretary Scott Bessent said the action, part of a campaign the department calls “Economic Fury,” is intended to disrupt “the foreign procurement networks that support the Iranian military’s efforts to acquire weapons.” He added that Treasury “will not tolerate any support of the Iranian military.”

The designations were issued by Treasury’s Office of Foreign Assets Control (OFAC) under an executive order targeting the proliferation of weapons of mass destruction and their suppliers. Among those sanctioned were Chinese and Hong Kong firms accused of helping procure weapons — including shoulder-fired anti-aircraft missiles known as MANPADS — for Iran’s Islamic Revolutionary Guard Corps and its defense ministry. One Hong Kong company was linked to a covert banking network that OFAC said attempted to move money for those purchases.

The sanctions carry significant financial consequences. OFAC warned that foreign banks that knowingly process substantial transactions for the designated parties could themselves face penalties, including losing access to the U.S. financial system. These so-called secondary sanctions are aimed at the banks, brokers, and trading houses that continue facilitating Iranian procurement efforts. The action marks the second major sanctions package in roughly a month, following Treasury measures in May targeting networks connected to Iranian drone and ballistic missile programs.

The repeated appearance of Chinese firms in these investigations raises a broader geopolitical question: How far is Beijing willing to go to protect Iran, and is it using that relationship as leverage against Washington?

China remains Iran’s most important economic partner. According to estimates from analytics firm Kpler, China purchases as much as 80% of Iran’s oil exports, providing Tehran with a critical source of revenue while securing discounted crude supplies for Chinese refiners. Beijing has repeatedly rejected U.S. sanctions on those transactions, arguing that it does not recognize Washington’s authority over commerce conducted outside U.S. jurisdiction.

China has also provided diplomatic support. Chinese officials have consistently described Iran’s nuclear facilities as peaceful and defended Tehran’s right to enrich uranium under the Nuclear Non-Proliferation Treaty. Alongside Russia, China blocked a United Nations Security Council resolution earlier this year that sought action related to the Strait of Hormuz, the strategic oil chokepoint at the center of the current conflict. China’s U.N. ambassador, Fu Cong, said the proposal failed to reflect the “full picture” of the crisis, while Beijing criticized the U.S. naval blockade of Iranian ports as dangerous and destabilizing.

At the same time, analysts caution against overstating the relationship. Reviews conducted by the U.S.-China Economic and Security Review Commission have found no public evidence that China has directly assisted Iran in building a nuclear weapon. Beijing has publicly opposed Iran obtaining such a capability and has generally avoided providing direct military support that could trigger a confrontation with Washington.

Chinese leaders also face practical concerns. China imports roughly 70% of its oil and natural gas, much of it through the Persian Gulf. A wider regional conflict that disrupts energy flows would directly threaten China’s economy. For that reason, Chinese Foreign Minister Wang Yi has urged Iran to respect the “reasonable concerns” of neighboring countries and avoid actions that could escalate tensions further.

U.S. officials have attempted to turn that dependence into leverage. Bessent recently called on Beijing to “step up with some diplomacy and get the Iranians to open the strait.” President Donald Trump has also said Chinese leader Xi Jinping expressed interest in helping broker a settlement while continuing to maintain economic ties with Tehran.

The result is a delicate balancing act. Beijing benefits from maintaining Iran as a strategic counterweight to U.S. influence in the Middle East, but it has so far stopped short of the direct military or nuclear assistance that would risk a severe confrontation with Washington.

For now, what some analysts describe as a Chinese “nuclear buffer” appears less like a deliberate defense strategy and more like the byproduct of economic and diplomatic support. Chinese oil purchases, financial channels, and diplomatic backing help Iran withstand international pressure, but Beijing continues to avoid crossing lines that could trigger broader economic or military consequences.

Each new round of U.S. sanctions tests where that line exists — and how much risk Chinese companies are willing to accept in order to keep Iran’s procurement networks operating.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Employees who use artificial intelligence at work are saving the equivalent of a full day every week.

That’s the picture from new research released May 19, 2026, by GoTo, the cloud communications and IT company, and the research firm Workplace Intelligence. Their second annual report, The Pulse of Work in 2026, surveyed 2,500 global employees and IT leaders between November 2025 and January 2026. The headline number: workers using AI save an average of 2.3 hours a day. Over a five-day week, that’s more than 11 hours back in their pockets.

Stretch that across a year and the math gets serious. Separate research from the London School of Economics puts the average savings at 7.5 hours a week, which researchers valued at roughly £14,000 per worker per year. Other estimates land across a wide band. A Federal Reserve Bank of San Francisco analysis pegged the savings at a more conservative 5.4% of work hours, or about 2.2 hours a week. Power users blow past all of it. Industry data shows 27% of frequent AI users save more than nine hours a week, with the heaviest users reporting gains approaching 20 hours.

So where does all that time come from?

Mostly the dull stuff.

The biggest single chunk is writing. Workers are drafting emails, replies, proposals, reports, and presentations that previously consumed hours of their week. One NBER-Microsoft study found knowledge workers cut email time by 31%, saving roughly 3.6 hours a week on inbox work alone.

Meetings are the next major source of savings. AI-powered transcription and summarization tools now generate notes, identify action items, and eliminate many of the follow-up conversations that once existed simply to repeat what had already been discussed. Research is another area undergoing rapid change. Instead of manually digging through lengthy reports, contracts, spreadsheets, and PDFs, workers can obtain preliminary summaries and insights in seconds.

Spreadsheets and data analysis round out the list. AI tools increasingly write formulas, identify trends, clean datasets, and produce first drafts of reports that once required hours of manual effort.

The gains are real, but they are not evenly distributed.

Software developers appear to be among the biggest beneficiaries. Some studies suggest coding output can more than double when AI tools are effectively integrated into workflows. GitHub has reported that users of its Copilot platform complete certain tasks roughly 56% faster. Customer-support agents handle approximately 14% more inquiries per hour. Leadership, management, and highly specialized hands-on roles generally report smaller gains, often two to three hours per week. Frequency of use remains one of the strongest predictors of productivity improvements. Employees who use AI daily consistently report far greater benefits than occasional users.

But the productivity gains are also changing how organizations function internally.

Prof. Lior Zalmanson, who heads the AI Lab at Tel Aviv University, argues that AI effectively gives every employee their own virtual team. Instead of relying on coworkers for brainstorming, research, drafting, analysis, or feedback, employees increasingly turn to AI assistants customized to their own working styles. The result, he says, is the creation of “isolated islands” inside organizations, where individuals become more productive but often work more independently than before.

Sharing knowledge has always been a challenge inside organizations, but the nature of that challenge is changing. In previous decades, companies struggled to get employees to share expertise and institutional knowledge. Today, many organizations are finding that employees are reluctant to share the prompts, workflows, and AI practices that help them perform better. According to Zalmanson, AI tools such as ChatGPT are increasingly viewed as an extension of the individual. Employees often feel that their interactions with AI are highly personal, making them less inclined to adopt someone else’s approach or reveal their own methods. What once revolved around knowledge sharing now increasingly revolves around prompt sharing, creating a new management challenge as companies seek to scale AI adoption across entire organizations.

Here is where the GoTo study becomes more complicated.

The same workers gaining hours are increasingly concerned about their dependence on the technology. Half of surveyed employees said they now rely too heavily on AI. Nearly three in ten reported feeling they could not function effectively without it. Perhaps most striking, 39% said they believe AI use is gradually eroding their own skills and making them less capable. Among Generation Z employees, that figure rises to 46%.

Dan Schawbel, Managing Partner of Workplace Intelligence, said the productivity gains are undeniable, but many organizations are overlooking a quieter challenge: employee confidence. Companies are measuring output improvements while often failing to track whether workers feel their expertise, judgment, and professional development are being weakened by overreliance on AI-generated assistance.

There is also a business cost hiding inside the productivity gains.

Much of the reclaimed time is spent reviewing and validating AI-generated work. AI systems frequently produce polished, persuasive, and confident responses that may contain factual errors or flawed assumptions. Someone still has to verify the output. Researchers from Stanford University and BetterUp have even coined a term for the growing volume of low-value AI-generated content flooding workplaces: “workslop.”

The Upwork Research Institute found that 77% of freelancers reported AI actually increased portions of their workload because of the time required to review, edit, and correct machine-generated output before it could be used professionally.

The lesson for employers is becoming increasingly clear.

Purchasing AI tools is relatively easy. Successfully integrating them into an organization is much harder.

The GoTo research found a significant gap between companies that simply provided employees access to AI and those that invested in training, governance, best practices, and measurable implementation strategies. The organizations reporting the strongest and most sustainable gains viewed AI not as a software purchase but as a long-term workforce and operational transformation initiative.

For workers, the takeaway may be even simpler. The productivity gains are real. The time savings are measurable. The challenge is capturing those benefits without sacrificing the judgment, creativity, expertise, and critical thinking skills that remain uniquely human.

With studies showing employees saving between 5 and 20 hours per week through AI, the upcoming JBiz AI Leadership & Operations Summit will provide hands-on training across leading platforms including ChatGPT, Claude, Gemini, Grok, Microsoft Copilot, Meta AI, Mistral, and Perplexity. Attendees will learn practical frameworks, templates, and workflows to increase revenue, reduce costs, improve productivity, and deploy AI across their organizations immediately. The two-day summit will be held July 13–14, 2026, from 9:00 a.m. to 5:00 p.m. at the Sheraton Eatontown Hotel, 6 Industrial Way East, Eatontown, NJ. For registration, HR Dept inquires, or team enrollment information, click here, email esther@ojchamber.com, or call 212-659-5270 x104.

— JBizNews Desk

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
HOUSTON — About half of the oil and fuel shipments disrupted by the war with Iran are moving again through the Strait of Hormuz, according to U.S. Energy Secretary Chris Wright, offering a measure of relief to global energy markets and supply chains.

Speaking on Friday, June 12, at the Bloomberg Energy Security Executive Briefing in Houston, Wright said approximately 7 million barrels per day of oil and fuel are once again flowing through the strategic waterway, representing roughly half of the volume that had been stranded when the conflict began.

He also made clear that the United States intends to restore full access to the route regardless of whether Iran cooperates.

For consumers, businesses, and investors, the Strait of Hormuz remains the most important energy chokepoint in the world.

The narrow passage carries nearly 20% of global oil and liquefied natural gas supplies, making it one of the most critical arteries of the global economy.

When traffic slows or stops, the effects quickly spread beyond energy markets.

Fuel prices rise.

Shipping costs increase.

Manufacturers face higher expenses.

Consumers ultimately pay more for everything from gasoline to groceries.

Traffic through the strait had been severely disrupted since fighting erupted between the United States and Iran at the end of February.

The conflict sent oil prices sharply higher, unsettled financial markets, and created significant uncertainty across global supply chains.

A fragile truce took hold this week after President Donald Trump pushed both sides to halt direct military attacks, allowing shipping activity to begin recovering.

Wright first signaled improvement earlier this week during an energy conference in Washington, where he said vessel traffic was increasing “very meaningfully” compared with recent weeks.

Even so, he cautioned that restoring normal operations would take time.

Many shipping companies rerouted vessels during the conflict, while supply chains adjusted to avoid the region altogether.

Returning those networks to normal will likely take months.

According to Wright, the challenge extends beyond simply reopening the waterway.

Shipping companies, crews, insurers, and energy traders must regain confidence that the route is secure before traffic fully returns to pre-war levels.

Some vessels have continued moving through the strait under extraordinary circumstances.

Reports indicate the U.S. Navy has assisted dozens of commercial vessels through the passage during the crisis.

Other ships reportedly crossed at night with communications and tracking systems turned off to reduce perceived security risks.

Financial markets have responded positively to signs of progress.

Earlier this week, after Wright reported improving traffic conditions, U.S. crude oil prices fell approximately 3.4% to around $88 per barrel, while Brent crude, the international benchmark, dropped to its lowest level in seven weeks.

Lower crude prices generally translate into lower gasoline and diesel prices, although those savings often take time to reach consumers.

The recovery remains fragile.

Iranian officials have repeatedly suggested the strait could remain restricted, and the broader conflict has not been formally resolved.

As long as the possibility of renewed fighting exists, shipping companies are likely to face elevated insurance costs and security concerns.

Those additional expenses ultimately flow through the global economy.

The economic stakes are enormous.

Energy costs influence nearly every industry, from manufacturing and transportation to agriculture and retail.

A prolonged disruption at Hormuz acts as a hidden tax on economic growth, raising operating costs for businesses and reducing purchasing power for consumers.

The faster shipping returns to normal, the faster that pressure can ease.

For now, the administration appears committed to maintaining both diplomatic and military pressure to keep the route open.

Wright’s message in Houston was clear: the United States intends to restore normal shipping through the Strait of Hormuz and is prepared to secure the route if necessary.

The key number remains 7 million barrels per day.

That represents meaningful progress but still falls well short of pre-war traffic levels.

Every additional tanker that moves through the strait helps ease pressure on energy markets.

Every new escalation risks sending those gains back into reverse.

JBizNews Desk — Energy

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
On Friday, June 12, 2026, Elon Musk’s rocket company SpaceX sold shares to the public for the first time, listing on the Nasdaq Stock Market under the ticker SPCX. It was the largest such debut — known as an initial public offering (IPO) — in history. An IPO is the moment a private company starts letting everyday investors buy a piece of it. SpaceX’s stock opened at $150 a share, rose as high as $176.52, and finished the day at $161.11 — a 19% jump over the $135 price the company first set. The sale raised about $75 billion and valued SpaceX at roughly $1.77 trillion. Speaking from the company’s Texas headquarters, Musk marveled that a business he started in a small warehouse was now the biggest stock-market debut ever.

The big debut closed out a quiet but hopeful week for the market. Stocks edged higher as investors watched for signs that the U.S.-Iran war may be winding down. President Donald Trump said he had called off planned strikes on Iran overnight and that the main points of a peace deal were essentially settled. Iranian state media said a draft agreement could be signed as soon as Sunday, including a U.S. promise to lift oil sanctions and an Iranian pledge to reopen the Strait of Hormuz — a key shipping lane for the world’s oil — within 30 days.

That matters for ordinary households, not just traders. When oil flows freely again, prices tend to fall, and that eventually shows up as cheaper gas at the pump. Oil prices dropped on the news.

Here is how the main scoreboards of the market finished. These indexes each track a basket of large U.S. companies, so when they rise, it usually means most stocks had a good day. The Dow Jones Industrial Average, which follows 30 big-name companies, rose 353.51 points, or 0.7%, to 51,202.26. The broader S&P 500 added 0.5% to 7,431.46, and the tech-heavy Nasdaq Composite gained 0.31% to 25,888.84. The Dow had closed Thursday at 50,848.75. The Russell 2000, which tracks smaller companies, also rose.

Market Movers

SpaceX was the day’s headline, and Wall Street was divided on whether its price will hold. Oppenheimer began covering the stock with a positive rating and a $190 target, and New Street Research set a $165 target. On the other side, Keith Snyder of CFRA Research rated it a sell with a $115 target, saying he thinks the stock is overpriced. A target is simply where an analyst expects the stock to trade over the next year — an educated guess, not a guarantee.

Adobe, which makes Photoshop and other creative software, fell about 7% even after a strong report. It earned $5.96 a share on $6.62 billion in revenue, beat forecasts, and raised its outlook for the year. Sometimes a stock falls anyway when investors expected even more.

Chipmakers had a good day. Advanced Micro Devices (AMD), Qualcomm, and Sandisk each rose about 5%.

Rocket Lab climbed 4.5% after announcing it will join the Nasdaq-100 on June 22.

The biggest tech names slipped as investors shifted money elsewhere. Microsoft, Amazon, Apple, and Oracle each fell around 2%.

Banks helped balance the day, with JPMorgan Chase and Goldman Sachs both higher; Goldman rose 1.81%.

Among other household names, Sherwin-Williams gained 1.86% and Caterpillar added 1.31%, while Salesforce fell 2.35%, Travelers lost 1.98%, and IBM slipped 1.96%.

Public Storage jumped 7.13%, Playtika rose 5.43%, Virgin Galactic dropped 10%, DoubleVerify lost 4.2%, and Ollie’s Bargain Outlet fell 3.3%.

Commodities and Volatility

Oil fell as traders bet the Iran deal would bring more crude back to the market and ease prices for drivers. Gold, which people often buy as a safe place to park money in uncertain times, held steady as those fears cooled.

The Cboe Volatility Index (VIX) — nicknamed the market’s “fear gauge” because it rises when investors get nervous — sat near 19, down from higher levels earlier in the month.

Two things to watch over the weekend. The first is whether the United States and Iran sign their peace deal Sunday and reopen the Strait of Hormuz, which would help keep gas prices down. The second is whether SpaceX can hold its first-day gains once big investment funds are required to start buying the stock. Monday will start to tell.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
A growing number of companies are shifting operations out of Singapore and into neighboring Malaysia, drawn by lower costs, tax incentives, and room to expand. The trend gained momentum this spring when global apparel retailer H&M announced in May that it would relocate its Southeast Asia headquarters from Singapore to Kuala Lumpur, affecting 78 jobs. In March, brewer Heineken said it would move portions of its production from Singapore to facilities in Malaysia and Vietnam.

These are not isolated moves. Since the start of 2026, a visible wave of businesses has relocated at least part of their operations across the border. “These moves are significant and mark a clear acceleration,” said Alwyn Lim, associate professor of sociology at Singapore Management University. The shift reflects a broader global trend as companies search for lower costs, greater scale, and improved competitiveness.

The economics are straightforward. Singapore remains one of the world’s most expensive places to operate a business, with high commercial rents, rising labor costs, and limited land availability. Malaysia, separated by only a narrow causeway, offers substantially lower operating expenses and significantly more industrial space.

“Malaysia offers significantly lower overheads, attractive tax incentives, and the industrial land space companies need to scale,” said David Blasco, country director of Randstad Singapore.

Importantly, most companies are not abandoning Singapore altogether. Instead, many are adopting a strategy known as “twinning,” keeping headquarters, research centers, and senior management functions in Singapore while moving manufacturing, warehousing, and logistics operations to Malaysia.

Singapore continues to offer advantages that remain difficult to replicate elsewhere in Asia. The city-state remains one of the world’s leading financial centers, provides political stability, strong legal protections, efficient logistics, and access to highly skilled talent. Malaysia, particularly the state of Johor, offers lower labor costs, more abundant land, and lower energy expenses.

Lennon Tan, president of the Singapore Manufacturing Federation, describes the trend as “rightsizing geography” rather than a loss of confidence in Singapore. Companies are strategically placing each function where it makes the most economic sense.

Food manufacturers provide a clear example. Many are retaining brand management, procurement, and supply-chain leadership in Singapore while moving physical production north to Johor. Gardenia, the well-known bread producer, operates a major facility in Senai, Malaysia, capable of producing approximately 8,000 loaves of bread and 20,000 tortilla wraps per hour.

A major government initiative is helping accelerate the shift. The Johor-Singapore Special Economic Zone, formally agreed upon by both governments in early 2025, is designed to integrate the two economies more closely. Covering more than 3,500 square kilometers, the zone spans an area more than four times larger than Singapore itself and targets eleven key industries, including manufacturing, logistics, healthcare, and digital services.

The incentives are substantial. Eligible companies can qualify for a special corporate tax rate of just 5% for up to 15 years, significantly below Malaysia’s standard 24% corporate tax rate. Since the agreement was signed, Singapore-based companies have committed more than 5.5 billion Singapore dollars in investments into Johor, according to Singapore government officials.

Major multinational companies are already expanding across both markets. Firms including ResMed and FedEx have announced investments designed to take advantage of the growing integration between Singapore and Johor.

For years, the biggest obstacle to such arrangements was transportation. Crossing the border could take hours during peak periods, creating costly delays for employees and businesses. That barrier is about to shrink dramatically.

A new Rapid Transit System (RTS) rail link, scheduled to begin operations by the end of 2026, will connect Johor Bahru and Singapore in approximately six minutes and is expected to carry up to 10,000 passengers per hour in each direction. Authorities have also introduced QR-code immigration processing and streamlined customs procedures.

As travel times fall and border crossings become easier, the economic logic behind splitting operations between the two countries becomes even stronger.

The stakes are significant. For Malaysia, particularly Johor, the influx brings new factories, jobs, infrastructure investment, and economic growth. For Singapore, the challenge is preserving higher-value industries while allowing lower-margin operations to relocate elsewhere.

Officials in both countries argue the arrangement can strengthen the broader region rather than create winners and losers. By combining Singapore’s strengths in finance, innovation, and management with Malaysia’s advantages in manufacturing, land availability, and cost efficiency, the region hopes to compete more effectively against other Asian economic hubs.

The trend also reflects a broader global movement. Businesses worldwide are reevaluating where they locate factories, offices, and supply chains, balancing labor costs, taxes, logistics, and market access. Similar conversations are unfolding across Europe, North America, and Asia as companies seek greater efficiency and resilience.

For now, the momentum appears to favor further integration. With operating costs in Singapore continuing to rise, Malaysia expanding incentives, and new transportation links nearing completion, more companies are expected to adopt a cross-border model.

Rather than choosing one country over the other, many businesses increasingly see Singapore and Malaysia as complementary parts of a single economic ecosystem.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Grocery inflation may appear relatively modest in government reports, but shoppers are encountering a very different reality depending on where they shop inside the supermarket.

The Bureau of Labor Statistics reported Wednesday that food prices rose 3.1% over the past year, while grocery prices — officially categorized as food at home — increased 2.7%.

That is lower than the overall inflation rate of 4.2%, but those averages mask dramatic differences among individual products.

Produce Prices Lead the Increases

The sharpest increases are occurring in the produce aisle.

According to the U.S. Department of Agriculture, fresh vegetable prices were 11.5% higher in April than a year earlier.

Fresh tomato prices rose nearly 40%.

Transportation costs remain a major factor.

Higher diesel prices have increased shipping expenses for fresh produce, one of the most transportation-dependent categories in grocery stores.

The USDA currently forecasts fresh vegetable prices will rise approximately 7.8% during 2026.

Eggs and Chicken Offer Relief

Other grocery categories have moved in the opposite direction.

Egg prices, which surged to approximately $6.23 per dozen during the bird-flu outbreak earlier this year, have fallen to roughly $2.86 per dozen as production recovered.

Chicken prices have remained stable or moved lower, providing consumers with a relatively affordable protein option.

Potato prices were also down about 3% compared with a year ago.

Coffee and Beef Remain Problem Areas

Not every staple has benefited from improved supply conditions.

Coffee prices have risen approximately 19% over the past year following weather-related crop problems in major coffee-producing countries.

Beef prices have reached record levels as the U.S. cattle herd continues to shrink.

The result has been significantly higher costs for steaks, roasts, and ground beef.

Different Aisles, Different Economies

Economists note that food categories are influenced by entirely different forces.

Produce prices often track transportation and fuel costs.

Egg prices respond heavily to disease outbreaks and flock recovery.

Coffee depends on weather conditions in producing nations.

Beef prices largely reflect herd size and livestock production cycles.

Understanding those factors can help consumers make more informed shopping decisions.

Consumers Continue Adjusting

Retailers report that many shoppers are changing purchasing habits in response to higher prices.

Consumers increasingly purchase store brands, buy smaller quantities, and substitute lower-cost items when possible.

Recent surveys found that a majority of Americans have reduced grocery spending to stay within household budgets.

Looking Ahead

For consumers, the lesson is simple: headline inflation figures often fail to reflect actual shopping experiences.

The price increases families encounter depend heavily on what they buy and where they shop.

Until transportation costs ease and cattle inventories recover, grocery inflation is likely to remain highly uneven across the supermarket.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The riskiest corners of the global bond market are signaling trouble, warning that the world economy may be sliding toward stagflation, the painful combination of high inflation and weak growth. Investors have become increasingly cautious as inflation pressures remain elevated in many economies while geopolitical tensions continue to threaten global growth.

Stagflation is the economic nightmare that defined much of the 1970s. It occurs when prices continue rising even as economic activity slows and unemployment increases. Policymakers fear it because the traditional remedies often work against one another. Raising interest rates can help control inflation but may further weaken growth. Cutting rates may support growth but risks reigniting inflation.

One of the clearest places to watch for early warning signs is the junk-bond market. Junk bonds, also known as high-yield bonds, are issued by companies with lower credit ratings and greater risk of default. Investors demand higher yields to compensate for that risk. The difference between those yields and the yields on safer government bonds is known as the credit spread.

When investors grow concerned about the economy, those spreads typically widen. Companies with weaker balance sheets become the first casualties of rising borrowing costs and slowing demand.

Recent market activity suggests investors are becoming increasingly selective. The lowest-rated segment of the high-yield market, particularly bonds rated CCC, has underperformed higher-rated junk debt. Market strategists view that divergence as a warning sign that investors are moving away from the most vulnerable borrowers.

The pressure comes at a difficult time for corporate America and many businesses around the world. A large volume of debt issued during the era of ultra-low interest rates is approaching maturity over the next several years. Companies that previously borrowed at historically low rates now face significantly higher refinancing costs.

For stronger firms, higher borrowing costs may simply reduce profits. For heavily indebted companies, refinancing can become a major challenge, potentially leading to restructurings, layoffs, asset sales, or defaults.

The concern extends beyond the United States. Policymakers and economists across Europe and Asia have warned that energy-market disruptions and persistent inflation could create conditions resembling stagflation. Rising commodity prices increase costs for businesses and consumers while simultaneously slowing economic activity.

Higher energy prices have historically played a major role in stagflation episodes. Oil-price shocks ripple through transportation, manufacturing, agriculture, and consumer spending. Businesses often pass those costs to customers, fueling inflation while reducing economic growth.

History offers a sobering comparison. During the late 1970s, geopolitical turmoil in the Middle East contributed to sharp increases in oil prices. Inflation accelerated, interest rates surged, and economic growth weakened. The result was one of the most difficult periods for policymakers, investors, and businesses in modern economic history.

Today’s environment is not identical. Banks generally hold stronger capital positions than they did before the 2008 financial crisis, and many corporations entered this period with healthier balance sheets. Nevertheless, investors remain focused on whether inflation can be controlled without triggering a significant slowdown.

For ordinary investors, junk bonds matter because they are widely held through mutual funds, exchange-traded funds, pension plans, and retirement accounts. Rising defaults can reduce returns and increase volatility. More importantly, the companies that rely on high-yield financing employ millions of workers, making their financial health important for the broader economy.

The bond market is not forecasting an economic crisis. Credit spreads remain well below the extreme levels seen during major recessions and financial panics. However, the growing weakness among the lowest-rated borrowers is attracting attention because these companies often experience stress before problems spread to the wider economy.

The message from the junk-bond market is not that stagflation is inevitable. Rather, investors are increasingly pricing in the possibility that inflation could remain stubborn while growth slows. Whether those concerns intensify will depend on inflation trends, energy prices, central-bank policy decisions, and the resilience of businesses facing higher borrowing costs.

For now, the signal from the world’s riskiest debt markets is a warning worth watching.

JBizNews Desk — Global

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
NEW YORK — The New York Knicks are one win away from their first championship in more than half a century, and the city is cashing in on every game.

In an announcement on Wednesday, June 3, New York City Mayor Zohran Mamdani and the New York City Economic Development Corporation estimated the team’s 2026 playoff run had already generated approximately $202 million in economic activity from home games, with the total potentially climbing to $465 million if the NBA Finals reach a full seven games.

“When the Knicks win, New York comes alive,” Mamdani said.

The math is straightforward.

City officials estimate each additional home playoff game generates roughly $90 million in economic activity, including spending on tickets, food, merchandise, transportation, and hotel accommodations.

That money flows through the local economy, benefiting arena workers, restaurants, bars, transportation providers, retailers, and hospitality businesses throughout the five boroughs.

As of Friday, June 12, the Knicks hold a 3-1 lead over the San Antonio Spurs in the NBA Finals.

They can clinch the championship on Saturday in Game 5 in San Antonio.

A victory would give the franchise its first NBA title since 1973 and its first Finals appearance in 27 years.

The road to the Finals has been dominant.

The Knicks defeated the Atlanta Hawks before sweeping both the Philadelphia 76ers and the Cleveland Cavaliers to earn a spot in the championship series.

There is, however, an unusual business twist.

Because the Knicks advanced so quickly through earlier playoff rounds, they actually hosted fewer playoff games than they did during last year’s postseason run.

According to city estimates, New York hosted seven home playoff games in 2026, compared with nine in 2025.

That means a dominant team can sometimes reduce the economic benefit to the city.

If the Spurs extend the Finals and force a Game 6 at Madison Square Garden, another significant economic boost would follow.

For the company that owns the team, the playoff run has been highly profitable.

Madison Square Garden Sports, the publicly traded parent company of both the Knicks and the NHL’s New York Rangers, has seen its valuation climb sharply.

The Knicks franchise is now estimated to be worth approximately $9.85 billion, representing roughly a 30% increase over the past year.

Analysts estimate the playoff run alone could generate approximately $140 million in additional revenue.

The company reported roughly $1.04 billion in revenue during its most recent fiscal year, and management has explored ways to provide investors with more direct exposure to the Knicks as a standalone asset.

Each home playoff game has become a significant profit center.

Industry analysts estimate a single postseason game at Madison Square Garden can generate approximately $5 million in profit, driven by premium ticket prices, concessions, sponsorships, and merchandise sales.

The ticket market reflects the excitement.

Resale prices have fluctuated dramatically depending on whether a championship-clinching game could take place in New York.

Heading into the week, the least expensive tickets for a potential Game 6 at Madison Square Garden were listed for more than $9,000.

Many of the biggest beneficiaries may be local small businesses.

Restaurants, bars, hotels, and retailers surrounding Madison Square Garden have reported heavy traffic throughout the playoff run.

Business owners describe the surge as a major boost after years of challenges following the pandemic.

Andrew Rigie, executive director of the New York City Hospitality Alliance, said local restaurants and bars “are just doing amazing.”

Mitch Modell, former chief executive of Modell’s Sporting Goods, was even more direct.

“Never have we seen the city like this, ever,” he said.

Economists caution that championship-related economic studies often overstate their impact.

Many argue that some of the money spent on playoff games would otherwise have been spent on other forms of entertainment within the city.

Others note that large sporting events can sometimes discourage regular tourists from visiting crowded destinations.

As a result, the actual net economic benefit may be smaller than headline estimates suggest.

Still, the excitement surrounding the Knicks’ run is undeniable.

The crowds are real.

The spending is real.

And for a city that has waited nearly three decades to see its basketball team return to the NBA Finals, the packed restaurants, sold-out bars, and booming ticket sales have become their own form of scoreboard.

One more victory, and both the celebration and the economic activity are likely to grow even louder.

JBizNews Desk — New York

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
MENLO PARK, Calif. — Meta’s biggest apps stopped working for huge numbers of people on Friday, June 12, as a widespread outage knocked Facebook, Instagram, and Messenger offline and locked users out of their accounts.

The company confirmed the trouble through spokesperson Andy Stone, who posted on X on Friday: “We’re aware people are currently having trouble accessing our services. We’re working on it.”

The scale was significant.

The outage-tracking site Downdetector logged more than 100,000 user reports by 10 a.m. Eastern time as a server-side failure logged people out of Facebook and partly disrupted Instagram.

Reports came in from across the United States, with heavy concentrations in New York City, Chicago, and San Francisco, as well as from Europe, Asia, and the Middle East.

Users described a similar pattern.

They were suddenly logged out and then unable to sign back in.

Feeds went blank.

Error messages appeared reading “unexpected error” or “query error.”

Messenger was among the hardest-hit services, with users appearing offline to friends and messages failing to send.

The disruptions affected both desktop and mobile applications.

For everyday users, an hour without Instagram is an inconvenience.

For businesses, it can mean lost revenue.

That is the part of the story that does not appear in the error messages.

Millions of small businesses rely on Meta’s platforms for customer service, advertising, and online sales.

When those platforms go dark, transactions stop.

On Friday, Meta Ads Manager, the company’s advertising platform, experienced major disruptions. Advertisers were advised to pause campaigns to avoid spending money on ads that users could not properly access.

The financial exposure can be substantial.

Meta generally does not provide automatic credits or refunds when outages occur.

A small business spending hundreds of dollars per day on advertising can lose valuable campaign time with little opportunity to recover those costs.

Restaurants accepting orders through Instagram, retailers selling through Facebook, and content creators who depend on the platforms for income can all feel the impact immediately.

Meta did not immediately identify the cause of the outage.

However, the symptoms point to a familiar type of failure.

When Facebook, Instagram, and Messenger all experience problems simultaneously, the issue is often tied to backend authentication systems that verify user identities across Meta’s network.

If that shared login infrastructure encounters problems, multiple platforms can fail at once even though the broader internet remains fully operational.

That helps explain why users were being logged out and unable to sign back in rather than simply experiencing slow loading times.

Meta has experienced similar outages in previous years linked to authentication and backend service failures.

In many cases, services have been restored gradually over several hours, with some regions returning online before others.

The timing is notable.

Meta continues to invest heavily in artificial intelligence and emerging technologies while relying on Facebook and Instagram as the core drivers of its advertising business.

Those platforms generate the revenue that funds much of the company’s broader strategy.

An outage affecting all major services at once highlights how dependent both users and businesses remain on infrastructure that typically operates unnoticed in the background.

As of Friday afternoon, Meta had not provided a timeline for full restoration of services and had not posted detailed updates regarding recovery efforts.

For users, there is little that can be done when the problem originates on Meta’s systems rather than their own devices.

For businesses relying on constant connectivity, the most expensive part of the outage may simply be the time spent waiting.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Here’s a word that trips people up: when a company “backstops” a deal, it is not backing out. It is doing the opposite — standing behind it and promising to pay if something goes wrong.

And that is exactly what Google has now done for Anthropic, the maker of the Claude artificial intelligence assistant.

According to people familiar with the financing, in details that came to light Tuesday, June 9, Google agreed to guarantee the lease payments behind a roughly $35 billion deal that gives Anthropic the computer chips it needs to run its AI systems. Google agreed to backstop those payments at five data centers, helping Anthropic obtain what amounts to a $35 billion loan, and Anthropic’s role in these specific data centers had not previously been reported.

Why Anthropic Needs Outside Financing

Running advanced artificial intelligence requires enormous amounts of computing power, and the chips that make it possible cost a fortune.

Buying tens of billions of dollars of hardware outright would strain even the best-funded technology companies.

So Anthropic and its partners structured the deal differently.

A separate company was created to purchase the chips and lease them back to Anthropic, allowing the company to spread the cost over time instead of paying everything upfront. Apollo Global Management and Blackstone arranged approximately $35 billion in debt financing for the transaction, making it one of the largest private-credit deals ever assembled.

The money is being used to acquire Google’s custom-designed AI processors known as Tensor Processing Units, or TPUs. Anthropic then leases those chips, and the lease payments are used to repay the debt.

[AP pic: Rows of servers and processors inside a modern data center used for artificial intelligence computing.]

How Google Became the Safety Net

This is where the story becomes unusual.

Lenders providing $35 billion want protection in case something goes wrong.

Two major companies are providing that protection.

Broadcom, which helps manufacture the chips, guarantees that the processors will retain a minimum resale value, reducing risk for lenders.

Google is providing another layer of security by guaranteeing the lease payments tied to five data-center locations.

In practical terms, if Anthropic were unable to make certain payments, Google’s commitment helps cover the obligation.

That guarantee is a major reason financing on this scale became possible.

Why Would Google Help a Competitor?

At first glance, the arrangement seems strange.

Anthropic’s Claude competes directly with Google’s Gemini AI assistant.

Yet the two companies are connected in several important ways.

Google was one of Anthropic’s earliest investors and has repeatedly increased its stake in the company. Google also supplies the chips that sit at the center of this transaction.

That means Google is simultaneously:

  • An investor in Anthropic
  • A supplier of the hardware
  • A beneficiary of the chip purchases
  • A guarantor behind part of the financing

In short, Google invests in Anthropic, sells it chips, and now helps secure the financing that allows Anthropic to buy even more of those chips.

The Concern About “Circular Deals”

That complexity has raised concerns among some industry observers.

Critics point to what are sometimes called circular financing arrangements, where a small group of technology companies become increasingly dependent on one another.

The concern is that money can appear to move in a loop:

  • Google invests in Anthropic.
  • Anthropic uses financing to buy Google’s chips.
  • Google helps secure the financing.
  • The financing supports further growth at Anthropic.

Supporters argue that such partnerships accelerate innovation and help fund the massive infrastructure required for AI.

Critics worry that the growing web of financial connections could create broader risks if one major player encounters trouble.

Why the Stakes Are So High

The deal comes at a pivotal moment for Anthropic.

The financing surfaced only days after the company reportedly filed confidential paperwork for an initial public offering and completed a $65 billion fundraising round that valued the company at approximately $965 billion.

Anthropic has also committed substantial resources to expanding its computing capacity, including participation in a data-center partnership valued at approximately $50 billion.

The company is spending aggressively to secure the infrastructure needed to compete with rivals including OpenAI, Google, Microsoft, and xAI.

What This Says About the AI Boom

For everyday readers, the story offers a glimpse into how the artificial intelligence boom is actually being financed.

Most headlines focus on new AI models, chatbot features, and flashy product demonstrations.

Behind the scenes, however, the industry increasingly relies on:

  • Multi-billion-dollar debt financings
  • Complex leasing arrangements
  • Massive data-center construction projects
  • Long-term chip supply agreements
  • Financial guarantees from major technology companies

The infrastructure required to power advanced AI is becoming almost as important as the software itself.

The Bottom Line

For now, the arrangement reflects confidence.

Lenders are willing to commit tens of billions of dollars, Google is willing to stand behind part of the financing, and Anthropic gains access to the computing power it needs without paying the full cost upfront.

The larger question is what happens as these relationships grow more intertwined.

The same partnerships helping fuel the AI boom today could also make the industry’s biggest players increasingly dependent on one another tomorrow.

That is the hidden meaning behind the word “backstop.” A safety net works only as long as the company holding it remains strong enough to catch everyone else.

JBizNews Desk — Technology

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
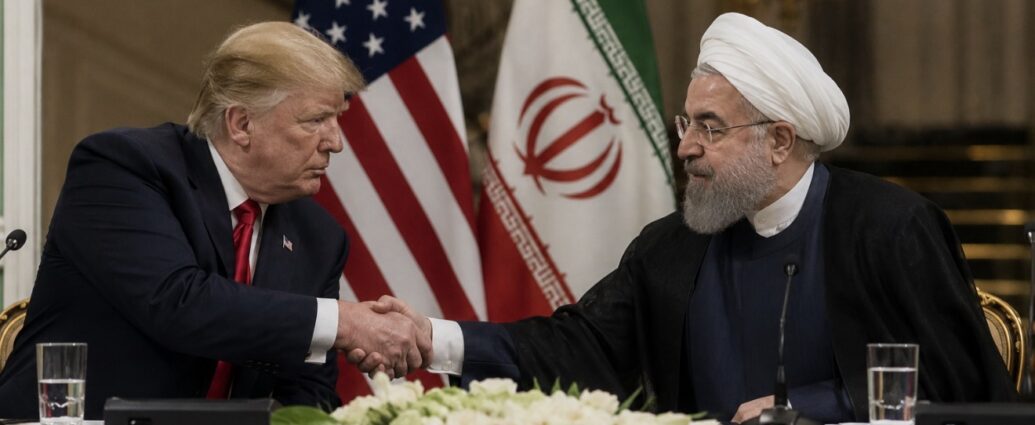
China’s factory-gate prices rose at their fastest pace in nearly four years in May, climbing 3.9% from a year earlier, according to data released Wednesday by the National Bureau of Statistics of China. The increase in the Producer Price Index (PPI) was the strongest since July 2022, exceeded economists’ expectations of 3.8%, and accelerated from 2.8% in April.

The report highlights a growing divide inside the world’s second-largest economy: factory costs are rising rapidly while consumer inflation remains subdued.

The Producer Price Index measures prices businesses receive for goods before they reach consumers, including raw materials, industrial products, machinery, and fuel. The Consumer Price Index, by contrast, measures what shoppers pay in stores. In May, factory inflation accelerated sharply while consumer inflation remained modest.

Two major forces appear to be driving the increase.

The first is energy and commodity costs. Rising oil and petrochemical prices have increased costs throughout China’s manufacturing sector. China remains one of the world’s largest energy importers, making its factories particularly sensitive to changes in global commodity markets. Higher transportation, fuel, and materials costs have filtered through industrial supply chains.

The second driver is the global boom in artificial intelligence and electrification. Dong Lijuan, Chief Statistician at the National Bureau of Statistics, said the expansion of AI infrastructure, electrification projects, and computing demand helped lift prices in sectors tied to metals, machinery, and technology hardware.

According to the bureau, non-ferrous metal mining prices rose 36.5% year-over-year, while non-ferrous metal smelting and processing prices increased 24%. Demand for copper, aluminum, rare-earth materials, electrical equipment, and data-center infrastructure has surged as countries and companies race to build AI capacity and expand electric-power systems.

In simple terms, the world’s push toward AI, cloud computing, electric vehicles, and upgraded energy infrastructure is consuming enormous quantities of industrial materials, pushing prices higher.

Consumer inflation told a different story.

China’s Consumer Price Index rose 1.2% from a year earlier in May, below economists’ expectations of 1.3%, while prices slipped 0.1% from April. Core inflation, which excludes food and energy, eased to 1.1%.

Food prices remained weak, falling 1.7% year-over-year, reflecting continued softness in household spending and consumer demand.

One notable exception was energy. Consumer gasoline prices climbed sharply from a year earlier, reflecting higher global crude-oil prices and rising transportation costs.

The gap between factory inflation and consumer inflation is important because it suggests many manufacturers are struggling to pass rising costs on to customers. Businesses are paying more for raw materials and energy, but consumers remain cautious, limiting companies’ ability to raise prices.

That squeeze can pressure profit margins across manufacturing industries.

The implications extend far beyond China.

As the world’s largest manufacturing hub, China produces a significant share of global electronics, machinery, appliances, industrial components, and consumer goods. Rising production costs inside China can eventually ripple through international supply chains and affect prices paid by businesses and consumers around the world.

For much of the past several years, China experienced factory-gate deflation, meaning producer prices were falling. That trend helped keep global goods inflation under control. The recent turnaround suggests that dynamic may be changing.

The May report also reflects broader policy shifts in Beijing. Chinese authorities have been working to reduce excess industrial capacity and discourage aggressive price competition in certain sectors, measures that can contribute to firmer pricing across manufacturing industries.

There are reasons for caution, however.

Many of the strongest gains were concentrated in commodity-related industries such as energy and metals, which can be volatile. If commodity prices retreat, producer inflation could cool quickly. On a monthly basis, producer prices rose more slowly than they did in April, suggesting some moderation may already be underway.

At the same time, weak consumer demand remains one of the biggest challenges facing China’s economy. Without stronger household spending, manufacturers may continue facing pressure despite rising factory output prices.

For now, the picture is one of two very different economies operating side by side: an industrial sector facing rapidly rising input costs driven by energy, metals, and AI-related demand, and a consumer sector that remains far more cautious.

Whether those rising factory costs eventually flow through to shoppers in China and around the world may become one of the most important inflation questions for the global economy in the months ahead.

JBizNews Desk — Asia

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Nearly a year after launch, Tesla’s self-driving taxi service remains limited to just 59 vehicles across three Texas cities, raising fresh questions about Elon Musk’s ambitious autonomy targets.

Nearly a year after Tesla put its first robotaxis on the road, the service remains far smaller and less reliable than the company originally projected. As of late May 2026, Texas motor-vehicle filings and independent tracking data showed a fleet of roughly 59 robotaxis, operating only in Austin, Dallas, and Houston.

That is far from the vision outlined by Elon Musk, who has repeatedly described a future in which Tesla operates thousands of autonomous vehicles across the United States. Musk previously indicated the company could reach 1,000 robotaxis by the end of 2026, a target that now appears increasingly difficult.

The gap between promise and reality became more visible this week as riders and reviewers documented operational issues that suggest the service is still functioning more like a public test program than a mature transportation network.

Users reported wait times frequently exceeding 30 minutes, while the Tesla Robotaxi app periodically displayed messages such as “High Service Demand” and “No Rides Available.” In at least one reported case, a vehicle arrived but failed to begin the trip, requiring intervention from customer support.

Passengers have also cited inconvenient pickup and drop-off locations, sometimes forcing riders to walk significant distances despite available curb space nearby.

Tesla launched the service in Austin in June 2025 with approximately a dozen modified Model Y vehicles. Access was initially restricted to selected users, influencers and Tesla enthusiasts who shared favorable early experiences online.

During Tesla’s July 2025 earnings call, Musk outlined plans for rapid expansion into additional states, including California, Nevada, Arizona and Florida. While Tesla expanded into Dallas and Houston in April 2026, the broader national rollout has yet to materialize.

The vehicles themselves remain more limited than many consumers expected.

Most rides continue to include a human safety operator, and Tesla restricts operations to carefully defined geographic areas known as geofences. The service therefore remains well short of Musk’s long-standing vision of fully autonomous vehicles operating nationwide without human supervision.

The stakes for Tesla are significant.

As vehicle sales growth has slowed, investors increasingly view robotaxis and Tesla’s Full Self-Driving (FSD) technology as key drivers of the company’s future value. Expectations surrounding autonomous transportation have become a central component of Tesla’s market valuation.

The numbers highlight the challenge ahead.

With approximately 59 vehicles currently operating, Tesla would need to expand its fleet by roughly 17 times in just seven months to reach Musk’s stated goal of 1,000 robotaxis by year-end. That expansion would also require regulatory approvals, operational infrastructure and proof that the vehicles can safely operate with reduced human oversight.

Meanwhile, competitors have established a substantial lead.

Waymo, the autonomous-driving division of Alphabet, operates a significantly larger robotaxi network. Estimates suggest Waymo’s Texas fleet is roughly ten times larger than Tesla’s. In Austin alone, public reports indicate Waymo operates more than 250 vehicles, compared with approximately 50 for Tesla.

Waymo also routinely operates vehicles without safety drivers, a milestone Tesla has not yet achieved at comparable scale.

Wall Street analysts have taken notice.

Garrett Nelson, an analyst with CFRA Research, recently said Tesla’s Austin deployment has fallen short of expectations. Independent road tests in Dallas and Houston have reported similar concerns, including lengthy wait times, unavailable vehicles and routing issues.

In one Dallas test, a trip expected to take roughly 20 minutes reportedly stretched to nearly two hours because of service interruptions and availability problems.

For consumers, the current limitations are difficult to ignore.

A service marketed as convenient, on-demand transportation remains available only in limited areas and often struggles to deliver rides quickly and consistently. Until reliability improves and availability expands, robotaxis are unlikely to replace traditional ride-hailing services—or personal vehicles—for most riders.

Tesla maintains that its camera-based approach to autonomous driving will ultimately allow it to scale more quickly and at lower cost than competitors that rely on expensive lidar and sensor systems.

That strategy could still prove successful over time.

For now, however, the company’s Texas deployment highlights the considerable distance between Tesla’s long-term vision and the current state of its robotaxi service. Nearly a year after launch, the business remains small, geographically limited and operationally inconsistent.

Whether Tesla can close that gap before the end of the year remains one of the most closely watched questions in the autonomous-vehicle industry.

JBizNews Desk — Texas

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
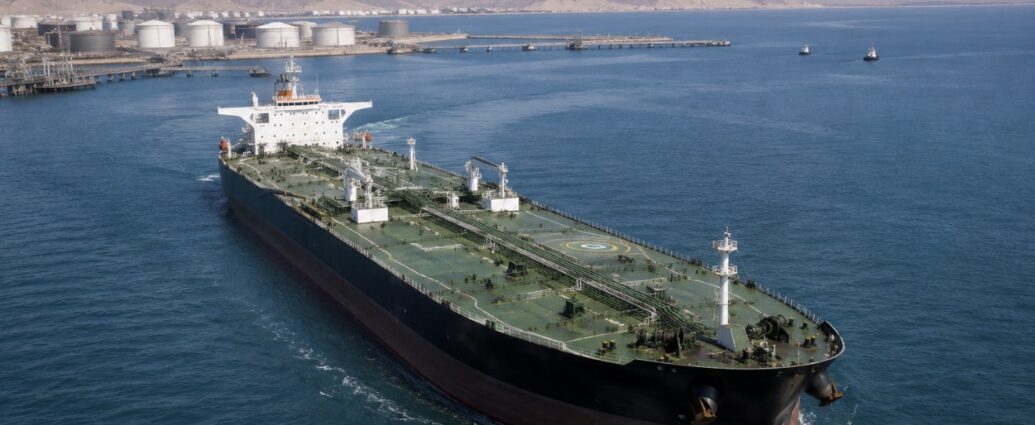

U.S. stocks opened higher Friday, June 12, 2026, as the largest stock offering in history and rising hopes for peace in the Middle East drew buyers into the market. President Donald Trump told reporters that a deal to end the war with Iran could be signed within days, one that would reopen the Strait of Hormuz and restore energy shipping through the Gulf. At the same time, SpaceX began its first day as a public company on the Nasdaq under the ticker SPCX, completing the biggest initial public offering ever recorded, according to the company’s S-1/A registration statement filed with the Securities and Exchange Commission.

In early trading, the Dow Jones Industrial Average rose 298 points, or 0.6%, while the S&P 500 added 0.1% and the Nasdaq Composite slipped 0.1%, held back by a steep drop in Adobe.

The move extended Thursday’s rally, when the Dow gained 1.86% to close at 50,848.75, the S&P 500 rose 1.75% to 7,394.30, and the Nasdaq Composite climbed 2.54% to 25,809.66.

SpaceX Takes Center Stage

The day’s centerpiece is SpaceX.

In its SEC filing, the company founded by Elon Musk set its price at $135 a share and offered about 555.5 million shares to raise roughly $75 billion, valuing SpaceX at $1.77 trillion and making it the seventh-most valuable U.S. company, ahead of Tesla.

Musk and SpaceX President and Chief Operating Officer Gwynne Shotwell rang the opening bell Friday, Musk from Texas and Shotwell from the Nasdaq MarketSite in New York.

The first public trade did not print at the opening bell as the stock cleared a Nasdaq auction to establish its opening price.

Goldman Sachs and Morgan Stanley led the offering as part of a syndicate of 23 banks listed in the prospectus.

Market Movers

SpaceX-related companies led early gains.

EchoStar, which owns an estimated 3% stake in SpaceX, rose about 4.8% before the open to roughly $134.28.

AST SpaceMobile advanced for a second straight session, while Rocket Lab gained about 4.5% after announcing it will join the Nasdaq-100 later this month.

Intel jumped about 5% after Bank of America analyst Vivek Arya upgraded the stock to Buy from Underperform and raised his price target to $135 from $96. Arya cited stronger demand for artificial-intelligence server chips and improved visibility into Intel’s contract manufacturing business, including a reported order from Google for more than three million custom AI processors.

Nvidia added about 1%. The company told Chinese customers its new Vera AI data-center processor could be available as early as August and is now open for orders.

Amazon also moved higher as investors returned to artificial-intelligence infrastructure names.

The biggest drag was Adobe, which fell about 7% despite reporting stronger-than-expected results.

Adobe reported quarterly revenue of $6.62 billion, above analyst expectations of $6.46 billion, but news of the planned departure of its chief financial officer triggered a series of analyst downgrades.

Goldman Sachs analyst Gabriela Borges lowered her price target to $190 from $220 while maintaining a Sell rating. Morgan Stanley analyst Keith Weiss said Adobe’s results reflected strong AI demand but expects the stock to remain range-bound.

Financial stocks also firmed, with JPMorgan Chase and Goldman Sachs trading higher.

Fifth Third Bancorp began trading on the New York Stock Exchange.

Among other notable movers, Playtika rose more than 5%, Virgin Galactic fell about 10%, DoubleVerify dropped roughly 4.2%, and Ollie’s Bargain Outlet declined about 3.3%.

Oil Falls as Diplomacy Gains Momentum

Oil prices declined on hopes that diplomatic progress could ease tensions in the Middle East.

West Texas Intermediate crude for July delivery fell 2.8% to $85.26 a barrel, while Brent crude dropped 2.5% to $88.13 a barrel.

The decline followed comments from President Trump indicating that an agreement could be reached as soon as this weekend in Europe.

A 14-point draft reported by Iranian state media would commit Iran to reopening the Strait of Hormuz within 30 days in exchange for the lifting of U.S. oil sanctions, although Tehran has not formally approved the proposal.

Lower oil prices typically translate into lower gasoline costs for consumers and businesses.

Meanwhile, gold traded near $4,180 an ounce after briefly dipping toward $4,000 before rebounding above $4,200.

The Cboe Volatility Index (VIX) eased toward 19.

Investors Focus on Historic Debut

Despite Friday’s gains, investors remained focused on the historic SpaceX debut.

Some traders reportedly sold existing holdings during the week to raise cash for SpaceX shares, contributing to choppy trading in parts of the technology sector even as the broader market advanced.

With the largest public offering in history still establishing its opening price, volatility is likely to remain elevated throughout the session.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
President Donald Trump downplayed a sharp rise in inflation, arguing higher prices are tied to the Iran conflict and will fall once the war ends.

U.S. inflation accelerated to its fastest pace in three years during May, according to the Consumer Price Index (CPI) report released Wednesday, June 10, 2026, by the Bureau of Labor Statistics. But rather than expressing concern, President Donald Trump surprised reporters with an unusual response.

“I really love the inflation,” Trump said during remarks at the White House.

The comment immediately drew attention because rising prices have traditionally been viewed as a political liability for any administration. However, Trump quickly clarified his reasoning, shifting the discussion toward the ongoing conflict with Iran and arguing that inflation pressures are largely tied to wartime energy disruptions.

“I love the inflation. You know why?” Trump said before discussing U.S. operations related to Iran’s oil sector and asserting that the administration’s broader strategy would ultimately benefit the economy.

The remarks came after a difficult inflation report.

The Consumer Price Index, which measures changes in the prices consumers pay for goods and services, recorded its highest annual increase since April 2023. It marked the third consecutive month of accelerating inflation and moved further above the Federal Reserve’s long-term target of approximately 2%.

The primary driver remains energy.

Since the escalation of hostilities involving Iran earlier this year, oil markets have experienced significant volatility. The disruption of shipping through the Strait of Hormuz, one of the world’s most important energy corridors, has pushed fuel prices sharply higher.

According to AAA, the national average price of regular gasoline has climbed to approximately $4.15 per gallon, compared with about $2.98 before the conflict intensified.

Within the May inflation report, gasoline prices rose 7%, following a 5.4% increase in April and a 21.2% surge in March.

Higher energy costs continue to ripple throughout the economy.

The Bureau of Labor Statistics reported increases across multiple categories, including transportation, airline fares, recreation, healthcare services, communications and other consumer expenses. Because fuel affects shipping and operating costs throughout the economy, higher energy prices often translate into broader inflationary pressures.

Trump used the inflation discussion to make a broader argument about the war.

The president claimed U.S. operations have prevented oil prices from rising even further by disrupting Iranian oil activity. He described nighttime maritime operations involving multiple vessels but did not provide specific figures or supporting documentation. The claims could not be independently verified.

When asked whether inflation would fall before the November midterm elections, Trump expressed confidence.

“When the war’s over, it’s coming down,” he said. “It’s going to come down like a rock.”

That message reflects the administration’s position that current inflation pressures are temporary and largely tied to geopolitical events rather than underlying economic weakness.

Economists note, however, that sustained inflation can create additional challenges.

Persistent price increases may force the Federal Reserve to maintain higher interest rates or even consider future increases to cool demand. Higher rates can raise borrowing costs for mortgages, auto loans, business financing and credit cards.

For consumers, that means inflation can have effects beyond rising prices at gas stations and grocery stores.

Even so, current inflation remains below the levels experienced during the post-pandemic surge.

In 2022, annual inflation exceeded 9%, reaching its highest level in roughly four decades. While today’s inflation is the strongest in three years, it remains significantly below those historic peaks and is currently more concentrated in energy-related sectors.

The key variable remains the duration of the Iran conflict.

If energy markets stabilize and oil shipments through the Strait of Hormuz return to normal levels, inflation pressures could ease. If disruptions continue, higher fuel costs could remain a source of upward pressure on prices throughout the economy.

For now, consumers face rising costs, policymakers face renewed inflation concerns, and investors are watching closely to see whether the recent surge proves temporary—or becomes a more persistent challenge for the U.S. economy.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Despite rising defaults, redemption pressures and slowing retail inflows, investors continue pouring money into bonds issued by private credit firms, keeping a key source of business financing alive.

For all the concern surrounding the private credit industry this year, one corner of the market remains surprisingly strong: investors continue to buy the bonds issued by private credit funds.

In an April 2026 filing with the Securities and Exchange Commission, Goldman Sachs Private Credit Corp. reported raising approximately $1.04 billion of new capital during the first quarter, citing what it described as “continued strong investor demand.” More recently, Blackstone’s flagship private credit fund reported fresh inflows in early June, signaling that institutional investors continue to support the sector despite mounting concerns elsewhere in the market.

To understand why that matters, it helps to understand what private credit is.

Private credit refers to loans made outside the traditional banking system. Instead of borrowing from a commercial bank or issuing publicly traded bonds, companies receive financing directly from investment firms, asset managers and specialized lending funds. These loans often carry higher interest rates than traditional debt and typically lock investors into long-term commitments.

Over the past decade, private credit has grown into a multi-trillion-dollar global industry, becoming an increasingly important source of financing for businesses that may not qualify for conventional bank lending.

A large share of that activity takes place through Business Development Companies (BDCs), investment vehicles that raise money from investors and lend it to businesses. To increase their lending capacity, many BDCs also issue bonds of their own, effectively borrowing money from fixed-income investors.

Those bonds continue to find buyers.

According to Fitch Ratings, rated BDCs issued approximately $21 billion of debt during 2025 and another $4 billion during January 2026 alone. Recent bond offerings from several major private credit firms have continued to attract strong demand despite broader concerns about the sector.

That resilience stands in contrast to developments elsewhere in private credit.

After a fundraising boom during 2024 and 2025 that brought more than $60 billion into BDCs, investor enthusiasm began cooling in early 2026. Industry data show retail sales of new BDC shares fell approximately 40% during the first quarter compared with the same period a year earlier.

Several so-called evergreen funds—semi-liquid investment vehicles designed for individual investors—have also encountered significant redemption pressure.

These funds typically limit quarterly withdrawals to approximately 5% of assets, and some managers have been forced to restrict redemptions after requests exceeded those limits.

Blue Owl Capital was among the firms that capped withdrawals after investor redemption requests substantially surpassed available liquidity.

At the same time, credit conditions have become more challenging.

In March, Morgan Stanley strategist Joyce Jiang warned that private credit default rates could approach 8%, significantly above historical averages. Some industry observers argue that actual stress levels may be even higher when distressed restructurings are included alongside formal defaults.

The rising number of troubled loans has intensified debate over whether the private credit boom has entered a more difficult phase.

Supporters of the industry argue that the concerns may be overstated.

Most private credit loans are structured as senior secured debt, meaning lenders are first in line to recover money if a borrower encounters financial trouble. That position generally provides greater protection against losses than unsecured lending.

Industry participants also note that redemption limits are functioning exactly as intended by preventing forced asset sales during periods of market stress.

Neuberger Berman and other managers have argued that recent redemption restrictions reflect prudent liquidity management rather than underlying portfolio weakness.

Institutional investors appear to agree.

Unlike retail investors, pension funds, insurance companies and large institutions typically invest with longer time horizons and are less likely to react to short-term market volatility. Their continued support has helped sustain demand for private-credit-related debt even as retail sentiment has weakened.

Still, competition for investor dollars is increasing.

As concerns surrounding private credit have grown, some investors have shifted assets into traditional publicly traded bond funds that offer daily liquidity, transparent pricing and attractive yields without multi-year lockups.

Asset managers including Pacific Investment Management Company (PIMCO) and Janus Henderson Group have actively promoted those advantages as investors reassess their options.

For businesses, the outcome matters.

Private credit has become a major funding source for thousands of small and midsize companies that may struggle to secure financing through traditional banks. If capital inflows slow significantly, borrowing costs could rise and financing could become harder to obtain, potentially affecting expansion plans, hiring decisions and investment activity.

That is why continued demand for BDC bonds remains important.

As long as investors keep buying the debt issued by private lenders, those firms can continue raising capital and extending loans to businesses across the economy.

The result is a market sending mixed signals.

Retail investors are pulling back. Redemption requests are climbing. Default concerns are growing.

Yet institutional investors continue committing capital, and bond buyers continue funding private lenders.

The private credit industry faces one of its biggest tests since its rise to prominence, but for now, investors purchasing its bonds still appear convinced that the asset class remains worth the risk.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
The Florida-based medical marijuana operator becomes the first American cannabis company that grows and sells marijuana to trade on a major U.S. stock exchange, marking a milestone years in the making for the industry.

A U.S. marijuana company traded on the floor of the New York Stock Exchange for the first time on Wednesday, June 10, 2026, as Trulieve Cannabis Corp. began trading under the ticker TRLV.

The Tallahassee, Florida-based company became the first American “plant-touching” cannabis operator—one that directly cultivates, processes and sells marijuana—to secure a listing on a major U.S. stock exchange.

The achievement represents a breakthrough for an industry that has spent years seeking broader access to public capital markets.

“As the first U.S. cannabis company to list on a major U.S. exchange, we are excited,” said Kim Rivers, Trulieve’s founder and chief executive officer, in announcing the listing.

Rivers said the move is expected to expand the company’s shareholder base, improve market visibility and increase awareness of the medical cannabis industry.

Prior to the NYSE listing, Trulieve traded over-the-counter under the symbol TCNNF and on the Canadian Securities Exchange, where it has been listed since 2018.

For years, major U.S. exchanges largely prohibited listings by American cannabis companies because marijuana remained classified as a Schedule I controlled substance under federal law.

That classification placed marijuana alongside drugs considered by the federal government to have no accepted medical use, creating significant legal and regulatory obstacles for companies directly involved in the cannabis business.

As a result, most U.S. cannabis operators were forced to raise capital through Canadian exchanges or over-the-counter markets, which generally offer lower trading volumes and reduced access to institutional investors.

The regulatory landscape changed this spring.

In April 2026, Acting Attorney General Todd Blanche announced the reclassification of medical marijuana to Schedule III, a category reserved for substances recognized as having accepted medical uses and a lower potential for abuse.

The move created a pathway for state-licensed medical marijuana businesses to register with the Drug Enforcement Administration (DEA) and potentially qualify for listing on major U.S. exchanges.

Trulieve still needed to restructure its business to meet listing requirements.

Because only medical marijuana was rescheduled, the company separated its adult-use recreational cannabis operations into a distinct entity. Through a third-party investment arrangement, Trulieve fully deconsolidated its recreational business, leaving the publicly traded company focused exclusively on medical marijuana.

While Kim Rivers continues to maintain control over the recreational operation, its financial results are no longer included within the NYSE-listed company.

The remaining medical cannabis business remains substantial.

Trulieve operates 206 state-licensed dispensaries and approximately 3.5 million square feet of DEA-registered cultivation and production facilities. The company is also one of the dominant players in Florida’s medical marijuana market, where it is estimated to control between 30% and 40% of statewide medical cannabis revenue.

Investors responded positively to the listing.

Shares initially rose about 4% during Wednesday morning trading before moderating later in the session. The larger market reaction came after the June 5 listing announcement, when Trulieve shares surged approximately 20%.

The stock is now up roughly 38% in 2026.

The broader cannabis sector has also benefited.

The AdvisorShares Pure US Cannabis ETF (NYSE: MSOS), one of the industry’s most widely followed exchange-traded funds, recently reached its highest level of the year. Trulieve represents approximately 30% of the fund’s holdings.

For individual investors, the NYSE listing significantly simplifies access.

Investors can now purchase Trulieve shares through traditional brokerage accounts, retirement accounts and popular investing platforms without navigating over-the-counter markets or Canadian exchanges.

Industry competitors are already positioning themselves to follow.

Curaleaf Holdings announced a 1-for-3 reverse stock split in late May, while Verano Holdings implemented a 1-for-5 reverse split, moves widely viewed as preparation for potential uplistings if regulatory conditions continue to improve.

Curaleaf has cautioned, however, that additional regulatory clarity will still be necessary before a listing can move forward.

Meanwhile, Canadian cannabis companies including Tilray Brands, SNDL, and Canopy Growth have long traded on major U.S. exchanges because they operate under Canada’s federally legal cannabis framework rather than directly touching U.S. marijuana operations.

Additional regulatory developments could arrive soon.

Industry participants are closely watching a DEA hearing later this month that could further reshape federal cannabis policy. The move to Schedule III also offers another major benefit: relief from certain federal tax rules that have historically imposed heavy burdens on cannabis businesses.

Lower tax costs could significantly improve profitability across the industry.

Industry advocates view Trulieve’s listing as a turning point.

Michael Bronstein, president of the American Trade Association for Cannabis and Hemp, said U.S. cannabis companies have long argued they deserve the same access to capital markets available to international competitors.

With Trulieve now trading on the New York Stock Exchange, that argument is finally being tested on Wall Street.

JBizNews Desk — Markets

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
Federal prosecutors are investigating whether some of America’s largest banks improperly closed customer accounts based on political beliefs, affiliations, or lawful business activities.

Federal prosecutors have opened a criminal investigation into whether some of the nation’s largest banks cut off customers because of their political views. The probe became public on Wednesday, June 10, 2026, when people familiar with the confidential matter said the U.S. Attorney’s Office for the District of Columbia, led by Jeanine Pirro, had issued subpoenas to several major lenders, including JPMorgan Chase, Bank of America, and Wells Fargo.

The subpoenas, some dating back to last year, seek lists of customers whose accounts were closed and records explaining the reasons for those closures. Prosecutors are examining whether the decisions were standard business actions or whether customers were targeted because of their political views, affiliations, religious beliefs, or industries in which they operate.

JPMorgan Chase did not immediately comment. Bank of America and Wells Fargo declined to comment.

At the center of the investigation is a practice known as “debanking,” in which a financial institution closes an account or declines to provide banking services. For individuals and businesses alike, losing access to banking services can create serious disruptions, affecting payroll, bill payments, deposits, financing, and everyday operations.

According to people familiar with the matter, prosecutors are reviewing whether any account closures violated federal law, including the Financial Institutions Reform, Recovery and Enforcement Act of 1989 (FIRREA). The statute is commonly associated with bank fraud investigations but is also attractive to prosecutors because it provides a broad enforcement framework and a ten-year statute of limitations.

That timeline would allow investigators to review account closures dating back to the period following the January 6, 2021 Capitol riot, when some financial institutions reassessed relationships with politically exposed clients and organizations.

The investigation represents the most significant escalation to date in a broader debate over whether financial institutions have unfairly denied services to customers based on political considerations.

President Donald Trump has repeatedly accused major banks of refusing to do business with him following his first term in office. He publicly raised the issue with Bank of America CEO Brian Moynihan during the World Economic Forum in Davos in early 2025.

In August 2025, Trump signed an executive order titled “Guaranteeing Fair Banking for All Americans,” directing federal agencies to investigate allegations of politically motivated debanking and refer potential violations to the Department of Justice.

Much of the government’s initial review was conducted by the Office of the Comptroller of the Currency (OCC), which supervises the nation’s largest national banks. According to reports, the OCC found preliminary evidence that some institutions had imposed restrictions on certain customers in the past.

Notably, the regulator reportedly did not formally refer the matter to the Justice Department. That makes the criminal investigation unusual, as prosecutors appear to have moved forward independently rather than acting on a formal regulatory recommendation.

The banks involved have consistently denied closing accounts because of politics or religion.

JPMorgan Chase has publicly stated that it does not close accounts based on political or religious affiliation. Banking industry representatives argue that account closures are typically driven by anti-money-laundering requirements, sanctions compliance obligations, fraud concerns, or other regulatory risk-management considerations.

That defense highlights one of the central questions facing investigators.

Federal civil-rights laws prohibit certain forms of discrimination, particularly in lending. However, banks generally maintain broad discretion over whom they choose to serve, and regulatory requirements sometimes compel institutions to terminate relationships viewed as high-risk.

Critics of the investigation argue that banks are being scrutinized for complying with the same federal regulations that require extensive customer-risk monitoring.

The outcome could have major implications for several industries that have long struggled to maintain banking relationships.

Cryptocurrency companies, cannabis businesses, firearms-related businesses, political organizations, advocacy groups, and certain nonprofit entities have frequently argued that they face heightened scrutiny from financial institutions. A determination that some account closures were unlawful could reshape how banks evaluate customer risk and could lead to significant changes in compliance policies across the industry.

Meanwhile, regulators have already begun adjusting their guidance.

Earlier this month, the Federal Reserve, the Office of the Comptroller of the Currency, and the Federal Deposit Insurance Corporation (FDIC) jointly removed references to “reputation risk” from supervisory guidance. Critics had argued that the standard allowed banks to deny services to lawful businesses simply because they were politically controversial or carried public-relations risks.

For now, the investigation remains in its early stages.

Subpoenas are requests for information and do not indicate wrongdoing. No bank has been charged with a crime, and prosecutors have not publicly alleged that any institution violated federal law.

Still, the probe signals that federal authorities intend to test a question that has increasingly moved from political debate into legal scrutiny: when a bank decides to close an account, where is the line between legitimate risk management and unlawful discrimination?

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.
WASHINGTON— President Donald J. Trump signed a proclamation on Thursday, June 11, 2026, restoring commercial fishing access to nearly half a million square miles of the Pacific Ocean and opening three additional marine national monuments to U.S. commercial fleets as part of what the White House calls its America First Fishing Policy.

The proclamation reopens the Mau and Ho‘omalu Zones of the Papahānaumokuākea Marine National Monument, the Islands Unit of the Mariana Trench Marine National Monument, and the Rose Atoll Marine National Monument — vast Pacific waters that have been closed to commercial fishing since their creation.

The White House said the move is intended to increase domestic seafood production, support American jobs, strengthen food and national security, and help lower seafood prices for consumers.

Building on Earlier Fishing Actions

Thursday’s proclamation completes a broader series of actions taken by the administration to expand commercial fishing access in federally protected waters.

In April 2025, Trump signed an executive order creating the America First Seafood Strategy, along with a proclamation reopening portions of the Pacific Remote Islands Marine National Monument to U.S.-flagged vessels operating between 50 and 200 nautical miles offshore.

In February 2026, the administration reopened the Northeast Canyons and Seamounts Marine National Monument off New England.

The latest action follows a recommendation approved on March 24, 2026, by the Western Pacific Regional Fishery Management Council (Wespac), which urged reopening the remaining Pacific monuments.

American Samoa Stands to Benefit

The economic impact may be felt most strongly in American Samoa, where fishing remains the backbone of the private-sector economy.

According to administration figures, more than 80% of the territory’s private economy depends on fishing.

American Samoa is home to the nation’s only “Buy American”-compliant tuna cannery supplying U.S. military rations and school lunch programs. The facility employs approximately 5,000 workers, accounts for roughly 99.5% of the territory’s exports, and supports about 84% of private-sector employment.

American tuna purse-seine vessels and longline fleets are expected to be among the biggest beneficiaries of the newly reopened fishing grounds.

Supply Chain and Food Security

The White House argued that the benefits extend well beyond fishermen.

Commercial fishing supports jobs across harvesting, processing, transportation, shipbuilding, equipment manufacturing, distribution, sales, and marine services.

Administration officials said expanding domestic seafood production could strengthen the U.S. seafood supply chain and reduce dependence on imports, which currently account for the majority of seafood consumed in the United States.

The White House also linked the policy to household budgets, arguing that limiting domestic supply contributed to higher seafood prices for consumers.

Conservation Debate Continues

The administration maintained that many targeted species, including tuna, are highly migratory and do not remain permanently within monument boundaries.

Officials argued those fisheries are already managed under federal law, including the Magnuson-Stevens Fishery Conservation and Management Act, making broad monument-wide fishing prohibitions unnecessary.

Under that view, the administration says the closures imposed economic costs while providing limited conservation benefits.

Legal Challenges Expected

Opponents strongly disagree.

In August 2025, Judge Micah W. J. Smith of the U.S. District Court for the District of Hawaii vacated an earlier NOAA Fisheries authorization that would have allowed fishing in the Pacific Islands Heritage monument, ruling that required public procedures had not been followed.

That lawsuit was brought by Earthjustice, the Conservation Council for Hawai‘i, and the Center for Biological Diversity, which argued the administration’s actions violated protections established under the Antiquities Act.

Hawaii Governor Josh Green has publicly supported maintaining monument protections, while conservation organizations and some Native Hawaiian leaders have warned that reopening areas such as Papahānaumokuākea — one of the largest marine conservation regions in the world and an area of profound cultural significance — could cause lasting environmental damage.

Legal challenges to Thursday’s proclamation are widely expected.
What Comes Next

The administration described the proclamation as part of a broader effort to reduce regulatory barriers at NOAA, expand access to fisheries, and increase catch opportunities based on what it calls the best available science.

Commerce Secretary Howard Lutnick and NOAA Administrator Neil Jacobs have repeatedly argued that increasing access to domestic fisheries will help strengthen coastal economies and put more American-caught seafood on American tables.

The White House said the administration’s combined fisheries actions have unlocked billions of dollars in potential economic value.

For the U.S. fishing industry, Thursday’s proclamation represents one of the most significant expansions of commercial access in years.

For American Samoa’s tuna fleet, its canneries, and the thousands of jobs tied to them, it opens the door to fishing grounds that have largely been off limits for more than a decade.

The next chapter will depend on how NOAA implements the policy and whether the courts ultimately allow the expanded access to remain in place.

JBizNews Desk — Washington

© JBizNews.com All Rights Reserved. Reproduction or distribution without written permission is prohibited.