How a Fed Rate Hike Would Affect Your Wallet
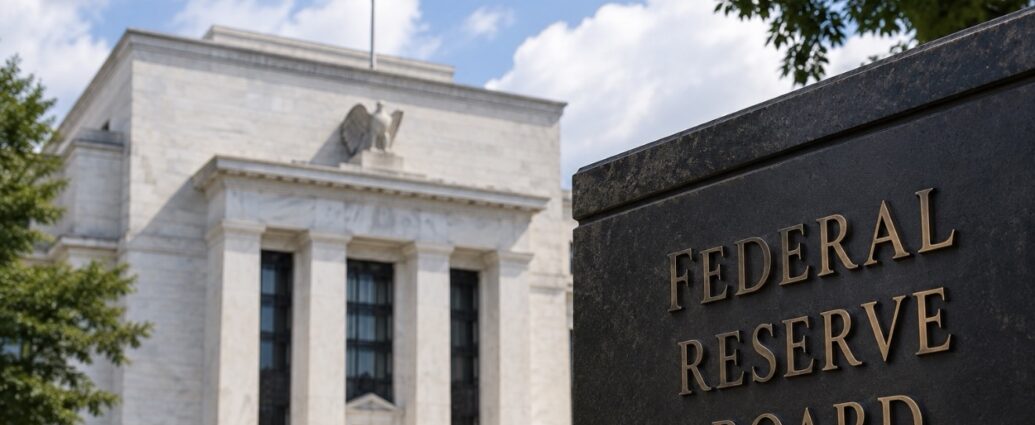
If the Federal Reserve raises interest rates by a quarter percentage point Wednesday, the effect will begin reaching American wallets almost immediately — especially anyone carrying credit-card debt, using a home-equity line or taking out a new loan.
The Fed is scheduled to announce its decision at 2 p.m. Eastern time Wednesday after its September 15–16 meeting. Financial markets are pricing in a roughly 90% chance of a quarter-point increase, which would be the first Fed rate hike in more than three years.
The expected move would take the Fed’s target rate to 3.75% to 4%.
Here is what that actually means for your money.
Credit cards are where many households will feel it first.
Most credit cards have variable interest rates tied indirectly to the Fed’s benchmark rate. When the Fed raises rates, banks can increase their prime rate quickly, and credit-card APRs generally follow.
A quarter-point increase may not look dramatic by itself.
On a $10,000 balance, an additional 0.25 percentage point equals roughly $25 more interest a year if the balance remained unchanged.
But that misses the bigger problem. A Fed hike Wednesday could be the beginning of another tightening cycle rather than a one-time move. Economists surveyed by Reuters increasingly expect additional increases if inflation remains stubborn, while some major banks are already forecasting another hike later this year.
Several quarter-point increases start adding up fast for households carrying large balances.
Your existing fixed mortgage does not suddenly become more expensive.
If you have a 30-year fixed-rate mortgage, Wednesday’s Fed decision does not change the rate or monthly principal-and-interest payment written into your loan.
Someone paying 3%, 4% or 6% keeps that rate.
The pain is for the next buyer.
Mortgage rates are not set directly by the Federal Reserve. They move heavily with longer-term bond yields and investors’ expectations for inflation and future interest rates. The 10-year Treasury yield has already pushed above 5% as markets prepared for tighter monetary policy.
That can make financing a house more expensive even before the Fed officially acts.
On a $500,000, 30-year mortgage, a one-percentage-point increase in the mortgage rate can mean roughly $300 more a month in principal and interest.
That changes what families can afford — and can force buyers toward smaller homes or larger down payments.
Home-equity lines can get more expensive much faster.
Unlike most mortgages, HELOCs commonly carry variable rates.
If your HELOC rate moves higher with the prime rate, a Fed increase can flow through to your monthly interest cost relatively quickly.
For homeowners who have been using home equity to renovate, finance a business or consolidate other debt, another cycle of rising rates matters.
Buying a car could also cost more.
Existing fixed-rate auto loans generally stay unchanged.
New borrowers may face higher financing rates as banks and other lenders adjust their cost of money.
Again, one quarter-point by itself is unlikely to transform a car payment. Multiple hikes would.
And because vehicle prices remain high, even relatively small changes in borrowing costs become more noticeable when spread across a $40,000 or $50,000 loan.
Businesses will feel the same squeeze — and consumers can eventually pay for it.
A small business carrying a $1 million variable-rate credit line would pay roughly another $2,500 a year in interest for every quarter-point increase, assuming the full balance remained outstanding and the rate moved with the Fed.
Four quarter-point increases would translate into roughly $10,000 more annually.
Businesses then have choices: absorb the expense, postpone expansion, hire fewer people or try to raise prices.
That is why the Fed rate does not remain confined to Wall Street.
It eventually reaches restaurants financing equipment, developers financing buildings, retailers carrying inventory and manufacturers borrowing to expand.
There is one group that could benefit: savers.
Higher Fed rates can push yields upward on savings accounts, money-market accounts and certificates of deposit.
But banks do not necessarily pass the increase along immediately.
The Consumer Financial Protection Bureau has previously warned that banks can be quicker to increase what they charge borrowers than what they pay depositors.
That means consumers with substantial cash should watch their bank’s yield rather than assuming it automatically becomes more competitive after a Fed increase.
The reason the Fed is considering making borrowing more expensive is inflation.
Recent inflation reports have come in hotter than expected, energy costs have climbed, and producer prices rose 5.4% from a year earlier in August. The Fed uses higher interest rates to cool borrowing and spending when it believes prices are rising too quickly.
That leaves consumers facing an uncomfortable tradeoff.
Higher rates are designed to slow inflation eventually.
But getting there means borrowing money becomes more expensive first.
For households, the most important question Wednesday will therefore not simply be whether the Fed raises rates by 0.25 percentage point.
It will be what Fed officials say about the next meeting — because one hike changes a few dollars.
A new cycle of hikes can change a household budget.
JBizNews Desk | Washington
© JBizNews.com. All rights reserved. This article is original reporting by JBizNews Desk. Unauthorized reproduction or redistribution is strictly prohibited.